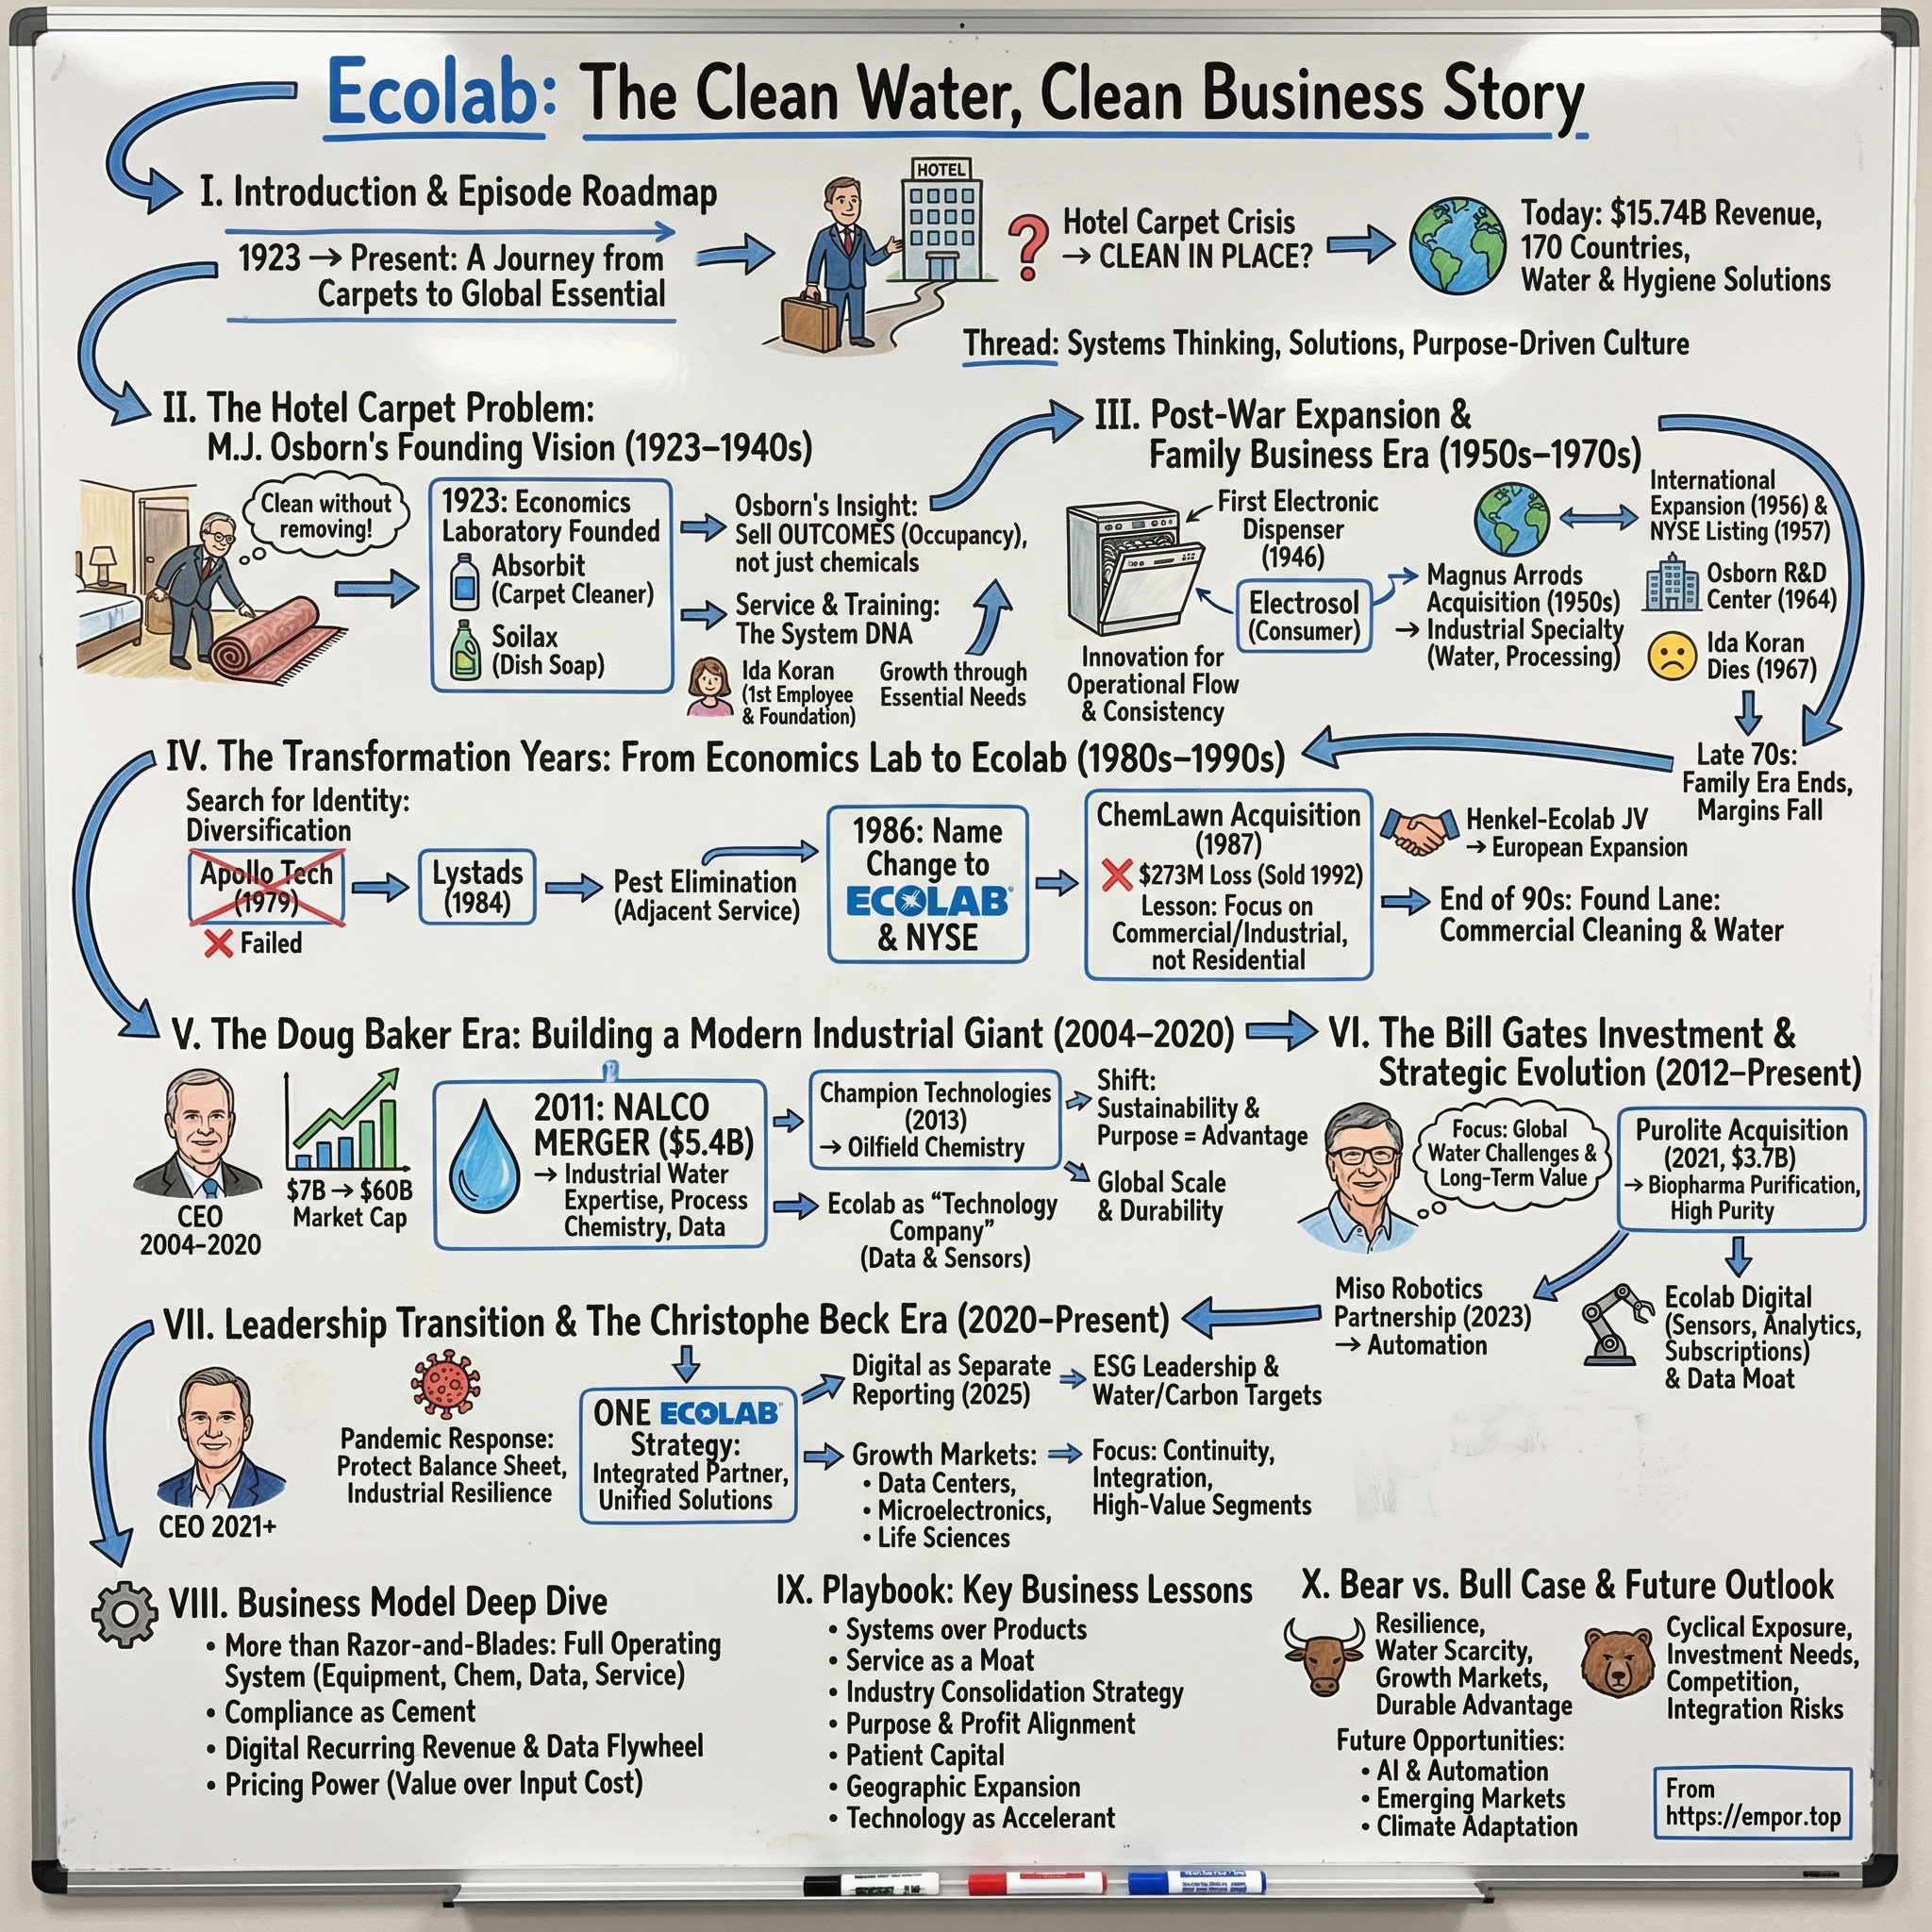
Ecolab: The Invisible Monopoly of Clean Water & Hygiene
I. Introduction & Episode Roadmap
There is a reasonable chance that within the last twenty-four hours you ate off a plate, drank a glass of milk, checked into a hotel, walked past a hospital operating theater, or sent a query to a chatbot running in a warehouse-sized building in northern Virginia — and in every one of those moments, a company you have almost certainly never bought anything from was quietly in the loop.
Ecolab Inc. does not sell directly to consumers. It sells to the businesses that serve them. It puts a dishwasher dispenser under the sink of a quick-service restaurant, a probe in the cooling tower of a paper mill, a resin bed in the purification train of a monoclonal antibody plant, and now a cold plate pressed directly against the silicon of an AI accelerator. In 2025, the company generated $16.08 billion in sales and $2.08 billion in net income, on 285 million diluted shares.1 Almost none of that revenue carries a consumer brand.
This pattern creates the central puzzle of the enterprise. The business was founded by a 44-year-old traveling salesman annoyed that hotels had to ship their carpets out for a week. A century later, the descendant of that idea claims to touch roughly half the world's milk supply, a significant share of processed food production, and, increasingly, the thermal management of capital-intensive computing infrastructure. How does a supplier of soap and water chemistry achieve an operating margin profile and customer retention record comparable to enterprise software?
The core thesis is narrower than the standard compounder narrative. Ecolab's century-long arc is a sustained experiment in escaping the commodity trap. Chemical manufacturing alone is traditionally a weak business: undifferentiated molecules, input-cost passthroughs, and customers quick to switch for minor cost savings. Ecolab's history reflects repeated efforts — some successful, several expensively flawed — to attach proprietary value to the molecule. First a dispenser. Then a service route. Then a sensor. Then a data platform. Now, with the pending purchase of a liquid-cooling hardware company, an engineered thermal system.
Three main themes define this story.
The first is the razor-and-blades structure of industrial hygiene. Ecolab's competitive moat rests not on chemistry alone — which rivals can approximate — but on the integration of installed dosing hardware, proprietary formulations tailored to that hardware, and a field force that delivers hands-on service. The company employs roughly 48,000 associates worldwide, a large share of them in customer-facing sales and service roles.2 That physical footprint creates a substantial barrier to entry at national scale, but it also represents a fixed cost that depresses margins during economic downturns, as occurred in 2020.
The second is the M&A engine, and its failures. Ecolab has executed three major acquisitions over fifteen years — Nalco, Champion, and Purolite — along with two more in the last twelve months. Evidence indicates that two of those five transactions were strategic errors or near-mistakes. An accurate assessment of Ecolab's capital allocation must evaluate the success of Nalco alongside write-downs from ChemLawn and Champion, especially as management asks investors to underwrite a $4.75 billion bet on AI data centers at 29 times forward EBITDA.3
The third is the Christophe Beck execution play. Chief Executive Officer Christophe Beck inherited a pandemic-disrupted institutional segment in January 2021 and initiated a margin-recovery strategy targeting a 20% operating income margin by 2027. Management has delivered steady margin progress, achieving an organic operating income margin of 18.5% in the fourth quarter of 2025.4 What remains unproven is volume growth. Most earnings growth under Beck has derived from price increases and product mix rather than unit expansion, creating the primary unresolved question in the investment thesis.
The narrative begins where margins did not exist at all: a hotel in Minnesota, in 1923.
 Subscribe on LinkedIn
II. The Hotel Carpet Problem: M.J. Osborn & The "Systems" Genesis (1923–1970s)
The scene that launched the company was deeply unglamorous. In 1923, a 44-year-old traveling salesman named Merritt J. Osborn was staying in a hotel and learned that the establishment's carpets had to be pulled up, rolled, and shipped out to a cleaner — a week-long process during which the rooms could not be rented. Osborn calculated what hotel operators had overlooked: the true cost was not the cleaning bill, but the empty room.5
That calculation formed the genetic code of the enterprise. Every subsequent Ecolab product shared the same core logic: rather than selling cleanliness as a standalone service, the business sold the avoidance of downtime.
Operating as Economics Laboratory in Saint Paul, Minnesota, Osborn launched Absorbit, a chemical compound that enabled hotel staff to clean guest-room carpets in place, overnight.5 The room rented the next morning. The immediate payback created a compelling pitch for a sole founder selling to cautious hotel managers.
From carpets to the dish room
The pivotal expansion occurred five years later. In 1928, Economics Laboratory introduced Soilax, a detergent formulated for the emerging category of commercial mechanical dishwashing machines.5 Commercial dishwashers represented a much larger market opportunity than carpet powder because a dishwashing machine was a fixed installation in a customer's kitchen. Carpets moved; dish machines stayed in place.
Selling detergent for a standardized machine was inherently a commodity business, as the equipment did not depend on any specific brand of powder. Economics Laboratory addressed this by designing its own dispensing equipment: devices that metered detergent precisely into the wash cycle rather than relying on kitchen staff to eyeball scoops.
This hardware integration altered the commercial pitch. Instead of competing solely on chemical price per pound, the company offered a system that promised up to 30 percent lower chemical usage, spot-free glassware, and consistent health inspection compliance. The hardware converted a commodity molecule into an integrated system, and that system established an ongoing customer relationship.
The dispensing hardware was not designed as a primary profit center, but as a mechanism for customer retention. Economics Laboratory typically installed dispensing equipment at customer sites with little or no upfront charge, recovering the investment through recurring consumable sales. The economics functioned less like appliance sales and more like a metered utility.
The family era, and its ceiling
Osborn's son, E.B. Osborn, led the company's post-war professionalization and its first major expansion outside North America — an entry into Sweden in 1956 that seeded what eventually became a substantial European business.5 The company listed publicly in 1957. Along the way, it developed cultural institutions reflecting its operational identity, including the Ida C. Koran Foundation, established in 1967 and named for the company's first employee, which anchored a corporate culture centered on the field associate rather than the laboratory chemist.5
That culture was an operational asset. In a business where customer retention depended on reliable, routine service visits, the status and execution of the field representative served as a key operating variable.
Yet the family-led model encountered limits in the 1970s. As larger industrial chemical manufacturers entered institutional sanitation to capture its attractive margins, Economics Laboratory experienced profit compression. Operating margins slipped toward the 10 percent range late in the decade, leading the Osborn family to step back from active management in 1978 in favor of professional executives.5
This margin pressure exposed a key nuance in the company's early trajectory. Switching costs alone failed to protect profitability against major competitors in the 1970s. Long-term margin defense required scale — national route density, broad R&D amortization, and a global footprint that regional chemical blenders could not match. Building that scale became the focus of the next four decades of corporate dealmaking, setting up a period that would expand the company's reach while testing its capital discipline.
III. The Corporate Crucible: ChemLawn, Rebranding, & The B2B Focus (1980s–1990s)
By the mid-1980s, executive leadership at Economics Laboratory faced a branding handicap and an ambitious growth agenda. The corporate name suggested an academic testing bureau rather than a commercial chemical partner, while management sought to expand beyond institutional dish rooms.
The identity challenge was resolved in 1986, when the company renamed itself Ecolab Inc. and moved its listing to the New York Stock Exchange under the ticker ECL.5 The expansion strategy, however, proved far more problematic.
Historical falsification case #1: ChemLawn
In 1987, Ecolab acquired the residential lawn-care provider ChemLawn for $376 million.5 On paper, the strategic rationale appeared compelling: Ecolab possessed expertise in chemical formulation and route-based service delivery, and ChemLawn applied route-based delivery to chemical applications. That logic relied heavily on assumed operational synergies.
What the acquisition thesis overlooked was the fundamental nature of the customer. Ecolab's institutional client is an enterprise whose license to operate requires strict regulatory and hygiene compliance. ChemLawn's customer was a residential homeowner deciding whether lawn aesthetics justified a recurring service expense.
Operational realities surfaced quickly. ChemLawn failed to generate sufficient cash flow to justify its purchase price. Management attempted to restore returns through price increases — a mechanism that functioned reliably in institutional hygiene but failed with retail consumers, who proved highly price-sensitive. In addition, public concern regarding residential lawn chemicals intensified in the late 1980s shortly after the acquisition closed.5 Seasonality further damaged unit economics: a service fleet sized for summer demand generated substantial fixed overhead during the remaining eight months of the year.
In 1992, Ecolab sold ChemLawn to ServiceMaster for $103 million.5 The five-year venture erased roughly $270 million in equity value, creating a durable lesson in the limits of Ecolab's operating model.
The episode illuminated a specific strategic boundary. Ecolab's competitive advantage rests not simply on combining chemical manufacturing with route distribution, but on pairing those assets with customers facing asymmetric failure risks. When the cost of product failure is catastrophic and the relative cost of the chemical is negligible, pricing power holds. Strip away the risk of catastrophic failure, and pricing leverage dissolves because the client can defer or cancel the service. A homeowner can accept a brown lawn; a hospital cannot accept contaminated surgical instruments.
This distinction provides a framework for evaluating subsequent portfolio choices. As later transactions would demonstrate, management repeated this strategic miscalculation in 2012 on a significantly larger scale.
Europe, patiently
A concurrent strategic initiative proved far more disciplined. In 1991, Ecolab established a 50:50 joint venture with Henkel to enter the European institutional market, combining Ecolab's service model with Henkel's continental distribution infrastructure and regulatory presence. The structure mitigated risk in an unfamiliar market. A decade later, in 2001, Ecolab bought out Henkel's half and fully consolidated the European operation.5
This joint-venture-then-acquisition sequence contrasted sharply with the ChemLawn transaction. Where ChemLawn represented a full-price purchase of an unfamiliar consumer market, the European venture functioned as a ten-year operational call option — allowing Ecolab to master local market dynamics alongside an established partner before committing full capital. The contrast highlights a recurring pattern in Ecolab's capital allocation history: performance has depended heavily on whether management acquired assets within customer domains it thoroughly understood.
By the early 2000s, Ecolab had established itself as a stable, high-margin institutional supplier generating several billion dollars in annual revenue. The stage was set for a major transformation when a 42-year-old marketing executive stepped into the chief executive role to initiate a sixteen-year expansion campaign.
IV. The Water Pivot: The Doug Baker Era & The Nalco Mega-Deal (2004–2020)
Doug Baker became CEO in 2004, having joined Ecolab in 1989 — a tenure that gave him a front-row seat to the ChemLawn unwind during his early years at the company. Over his sixteen-year leadership, Ecolab expanded from roughly $4 billion in annual sales to more than $15 billion, while the company's market valuation multiplied.6
Baker's central strategic contribution was redefining Ecolab's core identity: moving beyond traditional hygiene chemistry to position the enterprise as a comprehensive water management company.
Why water
The strategy stemmed from a shift in customer perspective. Hotel operators did not view their challenge strictly as dishwashing; they viewed it as managing the property's broader water infrastructure, including laundry, boilers, cooling towers, pools, and kitchen dish rooms. Industrial clients operated on a far larger scale. Food processors, paper mills, refineries, and power plants circulated millions of gallons of water through heat exchangers and cooling towers—systems constantly vulnerable to mineral scaling, metal corrosion, and biofouling, including Legionella.
A helpful analogy compares an industrial cooling tower to an arterial system, with water chemistry serving as cardiology. Left untreated, scale clogs the pipes, corrosion weakens the structure, and biological growth causes contamination. Because the chemistry required to prevent these failures costs a tiny fraction of total plant operating expenses, while an unscheduled shutdown risks millions in lost output, the value proposition mirrored Ecolab's restaurant model: asymmetric failure risk created high pricing power.
The Nalco deal
In 2011, Ecolab agreed to acquire Nalco Holding Company in a cash-and-stock transaction valued at approximately $5.4 billion, creating a combined entity with roughly $11 billion in pro forma annual sales.7 The acquisition was the largest in Ecolab's history, nearly doubling the company's size and adding substantial leverage to the balance sheet.
Nalco delivered three strategic assets. First, it provided an established global position in heavy industrial water treatment across paper, mining, power generation, and refining—customer networks Ecolab could not have built organically in a decade. Second, it brought 3D TRASAR, a proprietary system integrating chemical treatments with sensors and automated controllers to monitor and adjust water chemistry in real time. Third, it provided a massive telemetry data asset: each installed 3D TRASAR unit operated as a continuous data collection node.
That telemetry capability transformed Nalco from a standard industrial acquisition into a long-term technology platform. Rather than relying on manual water sampling and delayed lab analysis, automated controllers continuously measured system conditions, adjusted chemical dosing, and transmitted diagnostic data. Scaled across tens of thousands of customer sites over several decades, this process built a proprietary operational dataset that competitors could not easily replicate.
Ecolab paid approximately 11 times trailing EBITDA for Nalco—a full valuation for a high-quality industrial asset. The transaction proved highly value-accretive over time: Global Water expanded to become Ecolab's largest reportable segment, generating $2.0 billion in sales and $362 million in operating income in the fourth quarter of 2025 alone.4 The Nalco transaction stands as the most successful capital allocation decision of Baker's tenure.
However, the confidence gained from Nalco soon led to a far more challenging transaction.
Historical falsification case #2: Champion and the upstream energy detour
Following the Nalco acquisition, Ecolab sought further expansion in industrial water chemistry. In 2012, the company acquired Champion Technologies for approximately $2.2 billion, pushing into oilfield production chemistry for upstream oil and gas wells and gathering systems.
The underlying rationale appeared consistent: oil and gas production involves heavy water handling, an area where Ecolab possessed deep technical expertise. In practice, the purchase was heavily driven by the booming North American shale market.
The strategic thesis failed when crude oil prices crashed from roughly $110 per barrel in mid-2014 to below $30 per barrel in early 2016. Upstream operators responded by curtailing drilling activity and eliminating non-essential chemical expenditures. Ecolab's energy segment shifted from a growth catalyst into an earnings drag, introducing cyclical volatility into a corporate story built on defensive, recurring revenue.
Applying the strategic criteria established during the ChemLawn episode reveals why Champion failed to fit the core model. While chemical treatment is essential to long-term oilfield maintenance, production chemistry represents a sizeable operating line item that energy producers aggressively squeeze during downturns. More critically, when clients stop drilling entirely, switching costs offer no defense. Ecolab had purchased exposure to cyclical volume activity rather than indispensable daily hygiene operations.
Management eventually unwound the position. In June 2020, Ecolab separated its upstream energy business and combined it with Apergy to form ChampionX through a tax-efficient Reverse Morris Trust transaction.8 ChampionX was later acquired by SLB.
Two factors complicate a simplified narrative of this exit. First, the separation occurred six years after the initial 2014 energy collapse, during which Ecolab absorbed depressed segment returns and asset write-downs. Second, the transaction demonstrated a recurring risk in Ecolab's M&A execution: acquiring businesses that superficially resemble the core model but lack its structural asymmetric risk profile.
Baker stepped down as CEO on January 1, 2021, handing over leadership at a moment when institutional client facilities faced pandemic closures and healthcare customers operated under extreme stress.
V. The Christophe Beck Era: "One Ecolab", High-Tech, & Life Sciences (2021–Present)
When Christophe Beck assumed the role of chief executive officer on January 1, 2021, Ecolab's single most profitable division — institutional hygiene serving restaurants and hotels — faced an unprecedented demand collapse. His first quarter in office coincided with a severe downturn in the two end-markets that generated the company's highest-margin revenue.
Beck, a Swiss executive who spent sixteen years at Nestlé before joining Ecolab in 2007, brought a structured corporate framework to management. On earnings calls, he focuses heavily on operating metrics, basis-point margin expansion, and designated growth categories, routinely establishing explicit multi-year revenue targets and publicly tracking performance against them. Having served as president and chief operating officer starting in 2019, he became CEO in 2021 and added the chairmanship in 2023. Scott Kirkland became chief financial officer in 2023, managing the balance sheet through a period of accelerating acquisition activity.
The COVID stress test, and what it actually proved
The pandemic provided a real-world test of Ecolab's operational model, revealing both structural vulnerabilities and key portfolio strengths.
From one perspective, the crisis demonstrated that Ecolab's institutional business is not immune to broad economic disruptions. As hospitality venues closed, revenue contracted sharply, turning the company's 25,000-person field force from a competitive asset into a substantial fixed-cost burden. Management chose to draw down liquidity and preserve the route network rather than reduce frontline staffing.
From another perspective, performance over the subsequent five years validated that decision. Retaining route density allowed Ecolab to capture demand immediately when commercial activity resumed, whereas competitors that reduced field personnel struggled to restaff. Simultaneously, surging demand in food processing, healthcare disinfection, and consumer packaged goods sanitation partially offset the institutional shortfall, demonstrating internal portfolio diversification.
The analytical synthesis indicates that while Ecolab's competitive moat remains durable, its earnings fluctuate with end-market volume. Customer retention remains strong, but revenue contracts when client facilities temporarily pause operations — a critical distinction for investors evaluating the company's valuation multiple.
Purolite, and the most expensive multiple Ecolab has ever paid
In late 2021, while institutional volumes were still recovering, Beck committed $3.7 billion in cash to acquire Purolite, a family-owned producer of high-grade ion-exchange resins used in biopharmaceutical purification.9
Ion-exchange resins act as microscopic molecular sieves — polymer beads engineered to capture specific target molecules from a liquid solution. In biopharmaceutical manufacturing, these resins enable producers to isolate monoclonal antibodies or mRNA payloads from fermentation broths to strict regulatory standards. Crucially, once a specific resin is written into an approved drug's manufacturing process, replacing it requires multi-year regulatory re-validation. This requirement creates high switching costs, establishing one of the strongest retention mechanisms in Ecolab's portfolio.
However, Ecolab paid an extraordinary valuation of approximately 31 times trailing EBITDA at the peak of pandemic-era biopharmaceutical demand.
Falsification test. The acquisition thesis relied on sustained bioprocessing expansion. Contrary evidence emerged within eighteen months, as global biopharmaceutical clients spent 2023 and much of 2024 drawing down excess inventory accumulated during the pandemic. This industry-wide destocking cycle halted Purolite's growth well below management's projection and compressed Life Sciences margins. At a 31-times EBITDA entry multiple, a two-year growth stall generated weak returns on invested capital over the initial three years of ownership.
Verdict: intact but narrowed, and expensively financed. Results from 2026 indicate a structural recovery, with Life Sciences generating 15% organic growth in the second quarter of 2026 alongside operating margins in the mid-20s, leading management to characterize the business as having fully recovered.10 Yet operational recovery does not retroactively justify the initial entry multiple; it demonstrates that Ecolab absorbed a three-year lag before achieving expected asset performance. Sustainable validation requires Life Sciences to maintain double-digit organic growth through a complete biopharmaceutical capital expenditure cycle, whereas a deceleration back to mid-single digits in 2027 would indicate that recent gains reflected temporary comparisons.
The pivot to silicon and heat
The newest chapter of the Beck era — and a key driver of Ecolab's stock re-rating — is a high-tech platform that barely existed five years earlier.
Global High-Tech expanded from a roughly $150 million business in 2021 to a 29% organic growth trajectory by the second quarter of 2026, running at an annualized rate of approximately $1.5 billion, with management targeting $4 billion of sales by 2030 at a 25% operating income margin.10
The underlying operational requirement stems from semiconductor manufacturing and advanced computing. Semiconductor fabrication requires massive volumes of ultra-pure water to rinse wafers between process steps. Simultaneously, current-generation artificial intelligence accelerators generate thermal loads exceeding traditional air-cooling capacity, forcing operators toward liquid cooling systems that pump fluid through cold plates mounted directly on processors.
Ecolab positions itself as an integrated provider across that entire value chain. On the second-quarter 2026 call, Beck stated: "Water is required to produce, to power, and to cool chips. We are now the only company with integrated solutions across that value chain."10
To build this position, Ecolab expanded aggressively through M&A. In August 2025, the company agreed to acquire Ovivo's electronics ultrapure water business — a semiconductor-focused ultrapure water systems provider — for approximately CAD $2.4 billion, closing in December 2025,11 a deal management said more than doubled the size of its high-tech growth engine.12 Then, on March 20, 2026, Ecolab announced the acquisition of CoolIT Systems from KKR for approximately $4.75 billion in cash — a direct-to-chip liquid cooling specialist expected to generate around $550 million of sales over the following twelve months, expected to close in the third quarter of 2026.313
The purchase price for CoolIT represents approximately 29 times next-twelve-month adjusted EBITDA and 24 times 2027 estimated EBITDA. Funded with new debt that elevates pro forma net leverage to roughly 3 times adjusted EBITDA at closing, management targets a return to 2 times by the end of year two. The deal is not expected to be accretive to adjusted EPS until 2028.3
This transaction mirrors the Purolite structure: a high valuation multiple on a larger asset base, funded with debt within a rapidly expanding end-market. Management maintains that combining CoolIT's thermal hardware with Ecolab's water chemistry and digital service allows the company to capture three to five times more revenue per data center than water treatment alone, and it doubled its stated addressable market for high-tech from $5 billion to $10 billion on the back of the deal.310
Evaluating this expansion requires balancing two distinct realities. The strategic logic is coherent, and reported organic growth confirms immediate demand. However, the strategy reflects the pattern seen in the Champion acquisition: purchasing an adjacent business near the peak of end-market enthusiasm at a valuation requiring sustained flawless execution. Unlike upstream oilfield services, data center thermal management represents an ongoing operating necessity that cannot easily be paused. Nevertheless, hyperscaler capital expenditure remains cyclical, and Ecolab's high-tech platform has not yet been tested through a full hardware investment downturn.
That tension — genuine structural demand versus an untested cyclical exposure acquired at a full price — defines the current corporate era. Evaluating its long-term impact requires examining how the rest of the enterprise generates cash flow.
VI. Segment-Level Economics & The Service Moat Deep Dive
At 10 p.m. inside a typical chain restaurant kitchen, a field representative in an Ecolab shirt kneels in front of the commercial dish machine with a test strip and a digital tablet. The associate checks wash temperature, rinse concentration, and rack throughput, adjusts the chemical dispenser, logs whether the operator ran the equipment below sanitizing thresholds, and generates an audit record for health inspectors.
That service visit is the core product; the chemical shipment is merely the invoice line.
Ecolab operates through four principal business segments, each possessing distinct economic characteristics and operating dynamics.
Global Water — the industrial core
Global Water is Ecolab's largest segment, generating $2,017.4 million of sales and $361.6 million of operating income in the fourth quarter of 2025, with sales increasing 3% year over year.4 The division encompasses industrial process water, cooling and boiler treatment, food and beverage plant sanitation, paper and power chemistry, and the expanding high-tech platform.
The segment operates at approximately an 18% operating margin. Because products are sold to corporate procurement departments at paper mills, chemical plants, and refineries, pricing negotiations are rigorous. The competitive moat in Global Water rests on technical expertise — validated chemical performance in complex plant infrastructure supported by historical site data — rather than the high pricing leverage seen in institutional dish rooms. Consequently, this division remains Ecolab's most cyclically sensitive unit, leaving earnings exposed to macroeconomic slowdowns such as European industrial weakness.
Within Global Water, 2026 expansion has centered on semiconductor and data center thermal applications, alongside Food & Beverage, which grew 7% in the second quarter of 2026 — matching the top of management's 5% to 7% target range.10
Global Institutional & Specialty — the margin engine
Global Institutional & Specialty represents Ecolab's foundational business, serving restaurants, hotels, commercial laundries, educational facilities, and quick-service chains. In the fourth quarter of 2025, segment sales reached $1,499.0 million, up 3% year over year, while operating income rose 16% to $334.8 million.4
That divergence — 16% profit growth on 3% revenue expansion — pushed segment operating margins above 22%. The expansion reflects Ecolab's strongest pricing leverage, even as volume growth in the division remains modest.
The razor-and-blades mechanism drives these economics. Ecolab installs warewashing and chemical dosing hardware on-site, typically with minimal upfront equipment costs, and supplies the proprietary chemistry designed for those dispensers. The machinery, chemistry, and service routines function as an interdependent system. Replacing Ecolab to capture minor chemical cost savings requires an operator to remove hardware, retrain kitchen personnel, and incur operational risk in food safety, where a single compliance failure can damage a brand's reputation.
Persistent labor constraints across the foodservice industry provide an additional operational tailwind. As commercial kitchens struggle with high turnover, automated chemical metering reduces reliance on manual worker judgment during sanitation cycles.
Global Pest Elimination — the quiet compounder
Global Pest Elimination generated $307.2 million in fourth-quarter 2025 sales, a 7% increase year over year, while operating income rose 46% to $62.4 million.4 Organic sales expanded by another 7% in the second quarter of 2026.10
The 46% operating income increase on 7% sales growth illustrates the operating leverage of route density: once a service technician covers a geographic corridor, adding adjacent commercial accounts adds minimal incremental vehicle and labor expense. Ecolab focuses exclusively on zero-tolerance commercial facilities — including food processing facilities, healthcare institutions, and restaurant chains — rather than competing in residential pest control against providers like Rollins or Rentokil. That commercial specialization aligns with the strategic lessons of the ChemLawn failure by pairing route service with high customer failure risks.
Global Life Sciences — high multiple, high variance
Global Life Sciences generated $191.4 million of sales in the fourth quarter of 2025, up 7% year over year, with operating income reaching $32.6 million.4 Although it remains Ecolab's smallest reporting division, the segment has exhibited significant revenue volatility due to post-pandemic biopharmaceutical inventory destocking.
What Ecolab pruned
Alongside acquisitions, portfolio pruning has shaped Beck's tenure. In 2024, Ecolab sold its global surgical solutions business — which produced sterile drapes and fluid temperature management products generating over $400 million in 2023 sales — to Medline for approximately $950 million, closing in the third quarter of 2024.14 Management allocated a portion of the proceeds to repurchase up to $500 million in common stock during the second half of 2024.15
Unlike Ecolab's core units, surgical drapes represented a manufactured medical product sold directly through hospital purchasing organizations without associated dispensing hardware, route distribution, or recurring service visits. The divestiture demonstrated portfolio discipline by exiting an asset lacking the company's core service moat, even as management simultaneously expanded capital allocation toward complex hardware acquisitions in high-tech liquid cooling.
The field force, quantified honestly
Ecolab employs approximately 48,000 associates globally, with a substantial majority operating in customer-facing sales and service positions that conduct regular site visits throughout the year.2 Management consistently cites customer retention across core institutional and food and beverage accounts in the low-to-mid 90% range. Because this metric is disclosed by executive leadership rather than independently audited in regulatory filings, it represents a management-sourced metric.
Price realization provides a verifiable measure of customer switching costs. In the second quarter of 2026, Ecolab achieved 4% price realization, with management projecting 5% to 6% pricing in the second half of the year, while volume added 1% — or approximately 2% excluding Middle East operational disruptions.10 Securing mid-single-digit price increases without triggering customer churn indicates functional pricing power.
However, that composition also highlights the central vulnerability in Ecolab's organic trajectory. In a quarter with 5% organic sales growth, four percentage points derived from price expansion rather than new unit volume. While price-driven revenue growth confirms installed switching costs, it faces natural limits as customer operating budgets tighten, and it does not provide conclusive evidence of net account acquisition.
That dynamic underscores a key competitive question: who is actively contesting Ecolab's installed base across these markets?
VII. Competitive Dynamics, Market Structure, & The 7 Powers Framework
Ecolab does not face a single unified competitor. Instead, it encounters a distinct competitive set in every market segment, where the structural dynamics of each segment dictate the achievable returns.
The battlefield map
In industrial water treatment, the primary rivals include Solenis — which acquired Diversey in 2023 for roughly $4.6 billion to build a comparable industrial and institutional platform under Platinum Equity ownership — along with Japan's Kurita Water Industries, European provider Veolia Water Technologies, and Kemira in specialty pulp and paper chemistry. This segment presents direct competitive pressure. Solenis possesses the global scale needed to compete for multinational accounts, and its private-equity structure allows it to price aggressively for market share without the quarterly margin constraints faced by public companies.
In pest elimination, Rentokil Initial — which acquired Terminix — and Rollins both maintain larger total revenues than Ecolab's pest division. However, those competitors concentrate heavily on residential and broad commercial accounts. Ecolab focuses on highly regulated food-processing and healthcare environments, where audit documentation and regulatory compliance matter as much as extermination.
In institutional hygiene, established competitors such as SC Johnson Professional, Diversey under Solenis, and regional chemical blenders are secondary to a persistent structural threat: local chemical distributors. A local distributor can supply a restaurant group with generic detergent at a 15 percent discount, albeit without installed dispensing hardware or on-site service visits. That low-cost alternative places a permanent ceiling on Ecolab's pricing power.
In data center cooling, Ecolab enters as a challenger. Established hardware providers including Vertiv, Boyd, Motivair (now owned by Schneider Electric), and several Taiwanese original design manufacturers already supply liquid-cooling infrastructure. Furthermore, hyperscale technology clients represent highly sophisticated procurement organizations that enforce explicit multi-vendor strategies specifically to avoid supplier lock-in. This dynamic marks a critical constraint on Ecolab's high-tech strategy: the competitive moat that protects dishwashing chemistry in a 200-seat restaurant does not automatically transfer to a technology enterprise with a trillion-dollar market capitalization and an in-house thermal engineering team.
Porter, briefly
Buyer power varies considerably across the portfolio — remaining low among independent restaurants, moderate across paper mills, and substantial among technology hyperscalers. Consequently, expanding into high-tech hardware shifts Ecolab's revenue mix toward more powerful buyers. Supplier power reflects commodity chemical inputs, including ethylene, propylene derivatives, caustic soda, and solvents. This exposure was demonstrated in the second quarter of 2026, when Ecolab absorbed a roughly 9 percent increase in raw material costs and introduced an explicit energy surcharge to offset the impact.10 Rivalry remains constrained in institutional markets by route-service economics but stays intense in industrial water. Substitutes pose the primary long-term threat: clients that permanently reduce water consumption or chip architectures that lower thermal output shrink the addressable market rather than shifting accounts to competitors. New entrants encounter steep route-density barriers in core hygiene services, but face minimal structural barriers in cooling hardware manufacturing.
7 Powers, applied with a scalpel
Switching costs represent Ecolab's primary competitive advantage, driven by a pronounced cost-to-value asymmetry. Cleaning chemistry typically accounts for 1 to 2 percent of a restaurant's or food processing plant's total operating expenses, yet a sanitation failure can trigger product recalls, health outbreaks, and catastrophic brand damage. Commercial operators rarely risk business continuity to achieve minor chemical savings, as evidenced by Ecolab's ongoing price realization. However, this power remains concentrated in Institutional & Specialty and Food & Beverage; it exerts less leverage in industrial water treatment and offers little protection in high-tech cooling hardware.
Scale economies provide a substantial operational barrier. High route density allows Ecolab to add accounts along existing routes at minimal incremental cost, explaining why operating income in Pest Elimination grew six times faster than segment revenue in recent quarters. Furthermore, an annual research and development expenditure exceeding $200 million is amortized across a $16 billion revenue base — generating an absolute output that regional chemical blenders spending equivalent percentages cannot match.2
Process power derives from decades of operational data embedded in 3D TRASAR and the expanding Ecolab Digital platform. Digital sales grew 27 percent in the second quarter of 2026, which management presents as a pathway toward a $3 billion annual revenue opportunity.10 While this accumulated data asset is genuine and difficult for peers to replicate, management's $3 billion figure remains a long-term target rather than an existing backlog. Ecolab Digital generated $99 million in the fourth quarter of 2025, representing 24 percent year-over-year growth.4 Evaluating the strength of this moat requires monitoring whether digital revenues sustain that compounding rate over multiple years.
Cornered resource is the least defensible of the competitive pillars. Ecolab holds proprietary chemical formulations, patented dispensing equipment, and specialized resin production through Purolite. Yet chemical formulations can be matched, dispenser patents eventually expire, and Purolite competes directly against established bioprocessing suppliers such as Cytiva, Thermo Fisher Scientific, and Mitsubishi Chemical. No single asset provides an insurmountable barrier. The competitive moat relies on the integration of chemistry, hardware, and service — a combination that can become vulnerable when rapid acquisition activity alters the portfolio.
That structural shift turns focus to executive leadership, and whether their track record of capital allocation justifies the strategic bets currently underway.
VIII. Management Credibility, Capital Allocation, & Transcripts Guide for Investors
The test of a management team lies not in what it promises, but in how those commitments hold when operating conditions change.
For Ecolab, 2026 provided a clear test of execution when conditions shifted twice within six months: commodity costs spiked, and management committed $4.75 billion to a major acquisition while public financial targets remained under continuous scrutiny.
The margin promise, tested
Chief Executive Officer Christophe Beck's primary operational commitment has been expanding the operating income margin toward 20 percent by 2027, recovering from low-to-mid-teen troughs during the 2021–2022 inflation shock. Progress toward that goal was documented in late 2025, when organic operating income margin reached 18.5 percent in the fourth quarter — a 140-basis-point increase year over year — capping a full year of record sales, record operating margins, record earnings per share, and record free cash flow.4
Initial guidance for 2026, issued in February, targeted reported sales growth of 7 to 9 percent including the Ovivo acquisition, organic sales growth of 3 to 4 percent, an additional 100 to 150 basis points of margin expansion, and adjusted diluted earnings per share of $8.43 to $8.63 — representing a 12 to 15 percent increase over the $7.53 achieved in 2025.4 By April, with input costs rising and the CoolIT deal announced, management reiterated that earnings guidance on an ex-CoolIT basis, while noting that transaction financing and purchase accounting would dilute near-term results.16
By the second quarter of 2026, the financial picture grew more complex. Ecolab exceeded consensus expectations on revenue and earnings, generating $2.09 in adjusted earnings per share on $4.41 billion in revenue. Organic sales growth accelerated to 5 percent, while organic gross margin held at 44.4 percent despite a roughly 9 percent increase in raw material costs and volume headwinds from Middle East operational disruptions. Following those results, management adjusted its full-year guidance range to $8.05 to $8.25 per share — an outlook that formally incorporated CoolIT financing costs and purchase accounting — while reaffirming its 20 percent margin target for 2027.10
The key analytical detail lies beneath the surface of management's updated outlook: the headline earnings per share guidance range moved down over the course of 2026, rather than up. The initial February projection of $8.43 to $8.63 excluded CoolIT, whereas the August range of $8.05 to $8.25 incorporated the acquisition's immediate dilutive impact. In effect, management asked investors to absorb roughly forty cents per share in near-term earnings dilution in exchange for an artificial-intelligence liquid-cooling asset that is not projected to become accretive until 2028. While that trade-off may yield long-term strategic benefits, it represents a structural dilution rather than an operational guidance raise.
What the calls actually reveal
During the second-quarter 2026 earnings conference call, institutional analysts focused on four structural questions: whether management's second-half commodity inflation assumptions were realistic; whether operating margins could expand while top-line growth depended primarily on mid-single-digit price increases; whether CoolIT's triple-digit revenue growth rate could persist; and whether the 20 percent operating margin target for 2027 remained achievable given the amortization load from two major acquisitions.10
Beck responded quantitatively to the pricing and commodity questions, describing the company's ability to implement price adjustments and recover costs within three months — an unusually fast pace for an industrial chemical provider — as a key operating achievement of the quarter. On the question of CoolIT's growth trajectory, however, management deferred detailed projections, referring analysts to a planned November 2026 investor day.10 While deferring detailed metrics for an unclosed transaction is standard corporate practice, it postponed detailed scrutiny of the acquisition's underlying economics past two quarterly reporting cycles.
Throughout Beck's tenure, management has established explicit numerical targets, acknowledged operational headwinds such as the Purolite biopharmaceutical destocking cycle, and raised long-term goals when business units outperformed — as demonstrated by raising the Global High-Tech target to $4 billion in 2030 revenue at a 25 percent operating margin, up from a previous target of 20-plus percent annual growth at 20 percent margins.10 Yet elevating long-term targets during an end-market expansion mirrors the capital allocation pattern observed prior to the 2012 Champion acquisition. Consequently, tracking management's target revisions across changing demand environments remains a central metric for evaluating corporate discipline.
Capital allocation, scored
Management's stated capital allocation framework prioritizes organic research and development alongside capital expenditures, followed by dividend growth supported by a multi-decade record of annual increases, selective bolt-on acquisitions, and share repurchases. The 2024 sale of the surgical solutions business to Medline and the subsequent share repurchase program aligned with that disciplined strategy.
The transaction activity of 2025 and 2026 presents a sharp departure from that framework. Committing approximately $6.5 billion in capital across the Ovivo and CoolIT acquisitions — funded largely through new debt that raised pro forma net leverage to approximately 3 times adjusted EBITDA — represents a large-scale strategic transformation rather than routine bolt-on dealmaking. Furthermore, the entry valuation for CoolIT, at approximately 29 times forward EBITDA, aligns with the elevated multiple paid for Purolite rather than the 11 times trailing EBITDA paid for Nalco in 2011.39
From a skeptical investment perspective, Ecolab's high-margin legacy hygiene and sanitation businesses generate the predictable cash flow funding an expensive expansion into hardware manufacturing — a market where the company lacks long-standing operational history, faces concentrated technology buyers with substantial bargaining power, and pays valuation multiples that require uninterrupted artificial-intelligence capital spending. Conversely, management maintains that without expanding into high-tech cooling infrastructure, the broader Global Water segment would remain constrained to low-single-digit organic growth. Both perspectives reflect underlying operational realities, and evaluating the strategy will ultimately depend on multi-year return on invested capital rather than near-term growth narratives.
Where to read the primary evidence
For investors conducting independent analysis, four primary disclosures contain critical evidence. The fourth-quarter 2025 earnings release and transcript establish the baseline operating margin and initial 2026 financial framework.4 The second-quarter 2026 transcript provides the clearest detail on price realization, surcharge mechanisms, and high-tech organic growth rates.10 The CoolIT acquisition announcement contains the transaction's valuation multiples and net leverage trajectory.3 Finally, the 2024 Form 10-K provides the authoritative breakdown of segment structure, research spending, global headcount, and operational risk factors.2
IX. The Falsification Matrix, Risk Radar, & Bull vs. Bear Case
Stripping away narrative framing leaves four core investment claims, each of which has been tested by the company's historical record.
Claim one: the switching-cost moat is structural
Tested by: ChemLawn (1987–1992) and ongoing price realization.
Disconfirming evidence: The moat did not extend to residential lawn care and failed to protect margins in the 1970s when industrial competitors entered institutional sanitation. Neither exception was hypothetical; both generated material financial losses.
Verdict: intact but bounded. Ecolab's competitive advantage does not stem merely from superior chemistry. Instead, it relies on the tight integration of installed dosing hardware, dense service routes, and customers facing severe regulatory or brand consequences from sanitation failures. Where all three conditions align — in Institutional & Specialty, Food & Beverage, and commercial Pest Elimination — empirical evidence remains strong: Ecolab achieved 4% price realization in the second quarter of 2026 while maintaining positive unit volume, driving a 16% increase in Institutional operating income on 3% sales growth.410 Where those conditions are absent, the moat offers little protection. Falsifier to watch: institutional volume contracting while prices remain elevated, which would indicate Ecolab is harvesting margin rather than maintaining market position.
Claim two: capital allocation is disciplined
Tested by: ChemLawn, Champion, Purolite, Medline, Ovivo, and CoolIT.
Disconfirming evidence: Management executed two clear portfolio errors — destroying approximately $270 million in equity value with ChemLawn and absorbing years of depressed earnings and asset write-downs before exiting Champion six years after crude prices collapsed. With Purolite, Ecolab paid approximately 31 times EBITDA immediately before a two-year industry destocking cycle.9
Verdict: narrowed, not rejected. The corporate record indicates that management eventually corrects portfolio mistakes and is willing to pay full price for growth assets. However, it does not demonstrate disciplined acquirer pricing. Consequently, the CoolIT entry valuation should be underwritten as an expensive option on a secular trend rather than a value purchase. Falsifier to watch: whether CoolIT sustains annual revenue growth above 30% through 2027 and 2028, and whether management reduces net leverage back to 2 times adjusted EBITDA on schedule.
Claim three: high-tech and data centers are a decade-long growth engine
Tested by: The Champion precedent — acquiring adjacent industrial capacity during an end-market boom.
Disconfirming evidence: Ecolab has no track record navigating a hardware capital expenditure downturn in data centers. Furthermore, hyperscale technology customers represent its most powerful buyers to date, actively using multi-vendor sourcing to prevent supplier lock-in. Finally, scaling the platform from $150 million in 2021 to a $1.5 billion run rate relied heavily on acquisitions, with Ovivo alone more than doubling revenue.1011
Verdict: unproven, with genuine affirmative evidence. The 29% organic growth recorded in the second quarter of 2026 reflects real end-market demand independent of acquisitions.10 Physical requirements for ultrapure water and liquid thermal management are well established. Nevertheless, the assertion that Ecolab's institutional service moat can transfer to hyperscale hardware buyers remains unverified. Falsifier to watch: whether Ecolab retains its cold-plate business during a second-generation hardware deployment at a major hyperscaler, or is replaced once thermal architectures standardize. That single metric will reveal more than any corporate revenue disclosure.
Claim four: pricing power offsets input inflation
Tested by: The 2021–2022 inflation shock and the 2026 commodity cost increase.
Disconfirming evidence: During the 2021–2022 cycle, operating margins compressed substantially before price increases caught up, creating a multi-quarter lag that reduced earnings.
Verdict: proven, with a shortened execution lag. In 2026, Ecolab absorbed roughly 9% raw material inflation and maintained an organic gross margin of 44.4% within the same quarter by implementing an explicit energy surcharge.10 This rapid cost recovery represents a clear operational improvement over 2021 execution and provides strong evidence of current management capability. Falsifier to watch: whether the projected 5% to 6% price realization in the second half of 2026 holds without triggering volume attrition.
Risk radar
Leverage and refinancing. Pro forma net debt reaching roughly 3 times adjusted EBITDA at the closing of the CoolIT deal marks the company's highest leverage ratio since acquiring Nalco.3 While manageable for an investment-grade issuer with robust cash conversion, it eliminates balance sheet flexibility for the next two years.
Concentration in the AI capital cycle. Deceleration in hyperscale capital spending would directly impact Ecolab for the first time. This dynamic mirrors the cyclical exposure seen in Champion, though supported by stronger underlying demand trends.
European industrial stagnation. Persistent weakness in European chemical and manufacturing production suppresses industrial process water volume. This represents a structural drag rather than a temporary cyclical disruption.
Input costs and geopolitics. Petrochemical derivatives such as ethylene, propylene, and caustic soda directly dictate raw material expenses. Additionally, Middle East operational disruptions reduced second-quarter 2026 volume growth by approximately one percentage point, illustrating the geopolitical exposure inherent in a 170-country operational footprint.10
Valuation multiple. Ecolab consistently trades at a premium valuation compared to industrial and specialty chemical peers. A premium multiple reflects high execution expectations and leaves the stock vulnerable to sharp compression if volume expansion falters.
Bull case
Ecolab operates an extensive physical distribution network — tens of thousands of field representatives directly embedded in client operations — linked to essential hygiene and water chemistry services. This infrastructure generates predictable cash flows that management is redeploying into water scarcity and artificial intelligence thermal management, two durable industrial trends. The operating margin expansion program remains on track, input inflation execution in 2026 improved relative to 2021, and Life Sciences has emerged from its destocking cycle. If the Global High-Tech platform reaches its 2030 targets of $4 billion in revenue at a 25% operating margin, Ecolab will have accelerated top-line growth without sacrificing its high-margin economics.
Bear case
Recent revenue growth relies primarily on price realization rather than unit volume, as price accounted for four of the five percentage points of organic growth in the second quarter of 2026. Price-led expansion faces natural constraints. Furthermore, management allocated approximately $6.5 billion over twelve months to acquire assets in a rapidly expanding end-market at premium valuation multiples, funded with debt, with no projected earnings accretion until 2028 and no operating history through a technology sector downturn. Meanwhile, legacy institutional markets face persistent low-cost competition, European industrial clients show limited recovery, and the stock's premium valuation leaves little margin for error if demand weakens.
The KPIs that matter
Three key metrics determine the long-term investment case:
1. Organic volume growth, isolated from pricing. This represents Ecolab's most critical operational disclosure. Price realization confirms switching costs, whereas volume expansion demonstrates market share gains. Management targets combined volume and price growth of roughly 2%, but recent performance has skewed heavily toward price.
2. Global High-Tech organic sales growth. Total high-tech revenue remains distorted by the Ovivo and CoolIT acquisitions. Isolating the organic growth rate provides the only clean measure of whether Ecolab is gaining underlying data center market share or purchasing top-line expansion.
3. Organic operating income margin progress toward the 20% 2027 target. This goal represents Chief Executive Officer Christophe Beck's primary operational commitment, now being evaluated against acquisition-related amortization and ongoing commodity price shifts.
X. Playbook: Key Business & Investing Lessons
1. Sell the solution, rent the system, give away the hardware. Companies escape the commodity trap at the customer interface rather than in the chemical molecule. Ecolab's dispensing hardware, its 3D TRASAR automated controllers, and CoolIT's direct-to-chip cold plates all perform the same economic function: converting a price negotiation into a performance conversation. The hardware is not designed as the primary profit center; it serves as the physical anchor that makes recurring consumable sales defensible. Any enterprise selling undifferentiated inputs must determine what apparatus it can install at its own expense to reshape customer pricing dynamics.
2. The cost-to-value asymmetry is the strongest moat available to an unglamorous business. When a product accounts for 1 percent of a client's operating budget while preventing a total operational shutdown, price elasticity largely disappears. However, that asymmetry must be verified customer by customer rather than assumed from the product category. ChemLawn delivered similar chemical formulations to homeowners for whom product failure meant a brown lawn, causing pricing power to evaporate. Evaluating this competitive moat requires examining precisely what happens to the buyer when the product fails.
3. Discipline is measured at entry, not just at exit. Ecolab's reputation for capital allocation rests heavily on selling ChemLawn, spinning off upstream energy, and divesting surgical solutions. While those transactions demonstrated a willingness to exit mistakes, divestitures represent cleanup after the fact. The primary measure of capital discipline is what management buys and at what price. Ecolab's entry valuation multiples have ranged from 11 times trailing EBITDA for Nalco to 31 times for Purolite and roughly 29 times for CoolIT. Evaluating executive execution requires weighing entry valuations alongside exit discipline, as the company's track record on acquirer pricing is far more mixed than its divestiture record suggests.
4. A human service network can produce software-like retention — and carries costs software does not. A large field force embedded in customer operations generates switching costs comparable to enterprise software, driven by physical presence and site-specific operational knowledge. The trade-off is fixed overhead: field personnel cannot be furloughed during a downturn without damaging the underlying route asset. That structure explains why the 2020 demand collapse severely compressed operating margins and why earnings recovered rapidly when commercial activity resumed. Route-density networks create substantial operational leverage in both directions, making them less purely defensive during volume downturns than high retention statistics imply.
5. Resemblance is not strategic fit. The recurring mistake in Ecolab's acquisition history has been purchasing businesses that superficially resembled the core model. Delivering chemicals via route trucks proved insufficient in residential lawn care with ChemLawn, just as selling process chemistry to upstream producers proved vulnerable during oil price crashes with Champion. The fundamental question separating successful expansion from strategic error is not whether a management team understands how to formulate the product, but whether the target customer faces an indispensable operating necessity or a discretionary budget item.
XI. Recent News & Inflection Points
The last twelve months have marked the most active period of portfolio realignment in Ecolab's history since the Nalco transaction in 2011.
The Ovivo close. In December 2025, Ecolab completed its acquisition of Ovivo's electronics ultrapure water business following the transaction's August 2025 announcement for approximately CAD $2.4 billion.1112 Semiconductor fabrication requires water stripped of dissolved ions and organic contaminants. Operating Ovivo's ultra-purification systems positioned Ecolab at the front end of the semiconductor manufacturing process, laying the groundwork for its subsequent cooling investments at the back end.
The CoolIT acquisition. On March 20, 2026, Ecolab announced a $4.75 billion cash agreement to acquire CoolIT Systems from KKR—a direct-to-chip liquid cooling specialist supplying coolant distribution units and cold plates to hyperscale and colocation operators, scheduled to close in the third quarter of 2026.313 Management has framed the combination as a "Cooling-as-a-Service" offering that bundles thermal hardware, chemical treatment, and digital monitoring into a single contract. Executive leadership claims this integrated model can capture three to five times more revenue per data center than water treatment alone.10
Whether that commercial framing survives scrutiny from hyperscale procurement teams remains an open question. Selling bundled service contracts to cloud providers that custom-design data centers and negotiate component by component represents a fundamentally different sales motion than installing dishwashing systems for restaurant chains.
Digital, scaling from a small base. Ecolab Digital generated $99 million in revenue during the fourth quarter of 2025—up 24% year over year—and accelerated to 27% organic growth in the second quarter of 2026.410 Management has outlined a $3 billion long-term revenue opportunity by monetizing its sensor and software layers, converting telemetry from installed 3D TRASAR systems into recurring subscriptions for water audits, regulatory compliance, and predictive maintenance. While current expansion is robust, bridging the gap to management's target requires scaling revenues by thirty-fold.
The inflation episode and the surcharge. The most operationally revealing event of 2026 was not dealmaking but pricing execution. Facing roughly 9% raw material inflation in the second quarter, Ecolab instituted an energy surcharge that added four percentage points of price realization and maintained an organic gross margin of 44.4% within the same quarter.10 Compared with the multi-quarter margin compression during 2021 and 2022, this rapid pass-through demonstrates an improved pricing mechanism and provides concrete evidence of customer lock-in.
Enterprise water commitments. Corporate sustainability and water-positivity commitments among multinational clients continue to expand demand for site audits and reduction programs. This trend allows Ecolab to pitch corporate sustainability executives alongside facility managers. While this creates a viable sales channel, corporate sustainability budgets remain more susceptible to economic cycles and political shifts than mandatory sanitation and regulatory compliance.
What's next on the calendar. Management has directed analysts to an investor day in November 2026 for detailed updates on CoolIT integration, expanded high-tech financial targets, and the trajectory toward its 2027 margin target.10 Because management deferred key operational questions—including CoolIT's sustainable growth trajectory and margin targets under acquisition amortization—this meeting represents the most critical upcoming checkpoint for the investment thesis.
XII. Links & Resources
For readers seeking primary documentation behind this analysis, the essential record centers on several key corporate and regulatory sources.
Ecolab's investor relations portal hosts quarterly supplementals, earnings presentations containing segment splits, and archived webcasts.17 The financial reports and SEC filings page provides direct access to annual reports and proxy statements.18 For raw regulatory filings, SEC EDGAR under CIK 0000031462 holds every Form 10-K, 10-Q, 8-K, and proxy statement, including 8-K exhibits carrying quarterly earnings releases and segment tables.19
The FY2024 Form 10-K serves as the core reference document for segment definitions, research and development spending, headcount, geographic exposure, and corporate risk disclosures.2 The fourth-quarter 2025 earnings release establishes the operating margin baseline and initial 2026 financial framework.4 The second-quarter 2026 earnings call transcript provides the clearest disclosures on price realization, energy surcharges, high-tech organic growth, and analyst scrutiny.10
Primary documentation for the company's major portfolio transactions includes the Nalco merger announcement from 2011,7 the ChampionX separation disclosures,8 the Purolite announcement,9 the Ovivo electronics announcements,1112 and the CoolIT announcement detailing transaction multiples and net leverage trajectory.3 Additionally, Fitch's affirmation of Ecolab's 'A' credit rating following the Purolite acquisition provides a benchmark for evaluating how rating agencies assessed corporate acquisition debt prior to the more levered CoolIT transaction.20
For early corporate history—including Merritt J. Osborn's founding, Absorbit, Soilax, the ChemLawn transaction, and the Henkel joint venture—the International Directory of Company Histories provides a consolidated historical account.5 Ecolab's newsroom maintains the company's ongoing archive of press releases.21
References
-
Ecolab Inc. FY2025 Income Statement (filed 2026-02-23) — Financial Modeling Prep / SEC filing data ↩
-
Ecolab Inc. Form 10-K for Fiscal Year Ended December 31, 2024 — SEC EDGAR, 2025-02-21 ↩↩↩↩↩
-
Ecolab to Acquire CoolIT Systems, a Global Leader in Advanced Liquid Cooling for Next-Gen AI Data Centers — Ecolab Investor Relations, 2026-03-20 ↩↩↩↩↩↩↩↩↩
-
Ecolab Inc. Form 8-K Exhibit 99.1 — Fourth Quarter and Full Year 2025 Results and 2026 Outlook — SEC EDGAR, 2026-02-10 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Ecolab Inc. — Company History (International Directory of Company Histories) ↩↩↩↩↩↩↩↩↩↩↩↩
-
Ecolab and Nalco to Merge — Ecolab Press Release, 2011-07 ↩↩
-
Apergy and ChampionX Complete Combination — BusinessWire, 2020-06-03 ↩↩
-
Ecolab to Acquire Purolite to Expand Life Sciences Platform — Ecolab Newsroom, 2021-10-28 ↩↩↩↩
-
Earnings call transcript: Ecolab tops Q2 2026 estimates and lifts outlook — Investing.com, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Ecolab to Acquire Ovivo's Electronics Ultra-Pure Water Business — Ecolab Newsroom, 2025-08 ↩↩↩↩
-
Ecolab Closes Acquisition of Ovivo's Electronics Ultrapure Water Business — Ecolab Investor Relations, 2025-12 ↩↩↩
-
Ecolab to pay $4.75bn for liquid cooling specialist CoolIT — Data Center Dynamics, 2026-03 ↩↩
-
Ecolab Closes Sale of Global Surgical Solutions Business — Ecolab Investor Relations, 2024 ↩
-
Medline to buy Ecolab's surgical products for nearly $1B — MedTech Dive, 2024 ↩
-
Ecolab (ECL) Q1 2026 Earnings Call Transcript — The Motley Fool, 2026-04-28 ↩
-
SEC EDGAR Company Filings: Ecolab Inc. (CIK 0000031462) — SEC.gov ↩
-
Fitch Affirms Ecolab at 'A'; Outlook Stable — Fitch Ratings, 2021-12-01 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube