Paychex: The Friday Paycheck and the Price of Trust
I. The payroll has to clear
Picture the owner of a small plumbing business on a Thursday afternoon. Her crew has worked the week, and tomorrow is payday. Three of her people live paycheck to paycheck. One has just had a baby and changed his tax withholding. Another worked six hours of overtime across two job sites. Somewhere behind all of this sit federal withholding tables, a state unemployment insurance rate, a local tax and a filing calendar that charges penalties if anything arrives late. She will not read any of it. She will log in, approve the run, and go back to her trucks, trusting that on Friday morning eight bank balances will show exactly the right number.
Nobody notices that promise when it is kept. Everybody notices it when it is broken. A late or wrong paycheck is not a software bug to an employee. It is a missed rent payment, a bounced car loan, a reason to quit. For the employer it can bring tax penalties, angry staff and, in the worst cases, legal claims. So payroll is one of the few business tasks that is both boring and frightening, and that combination is the whole foundation of Paychex.
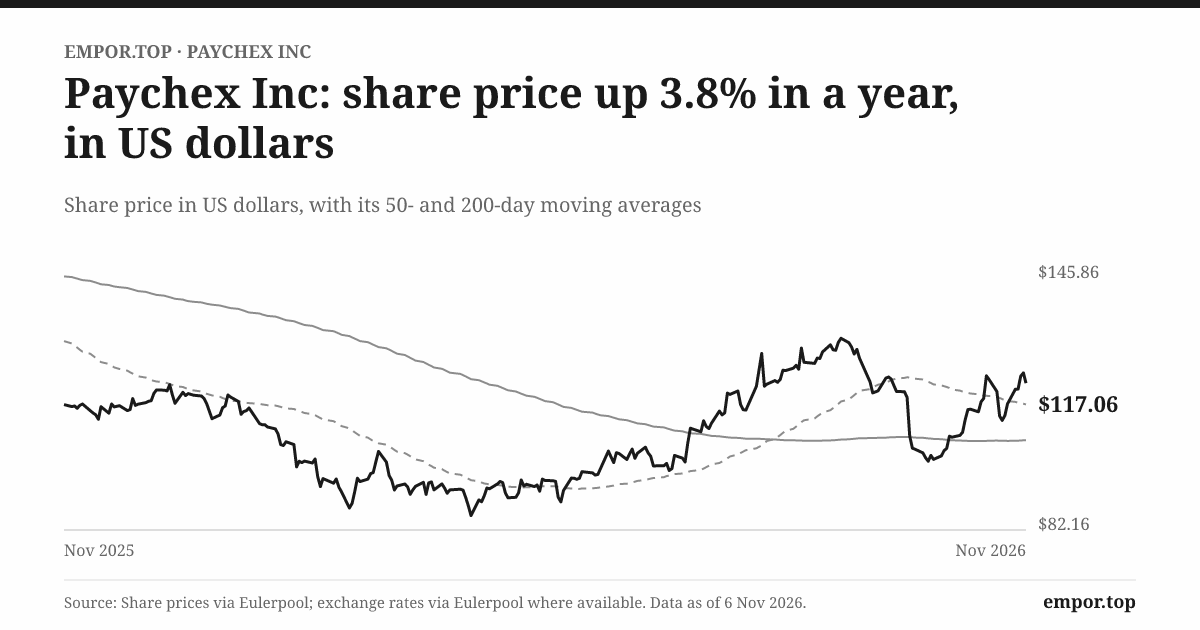
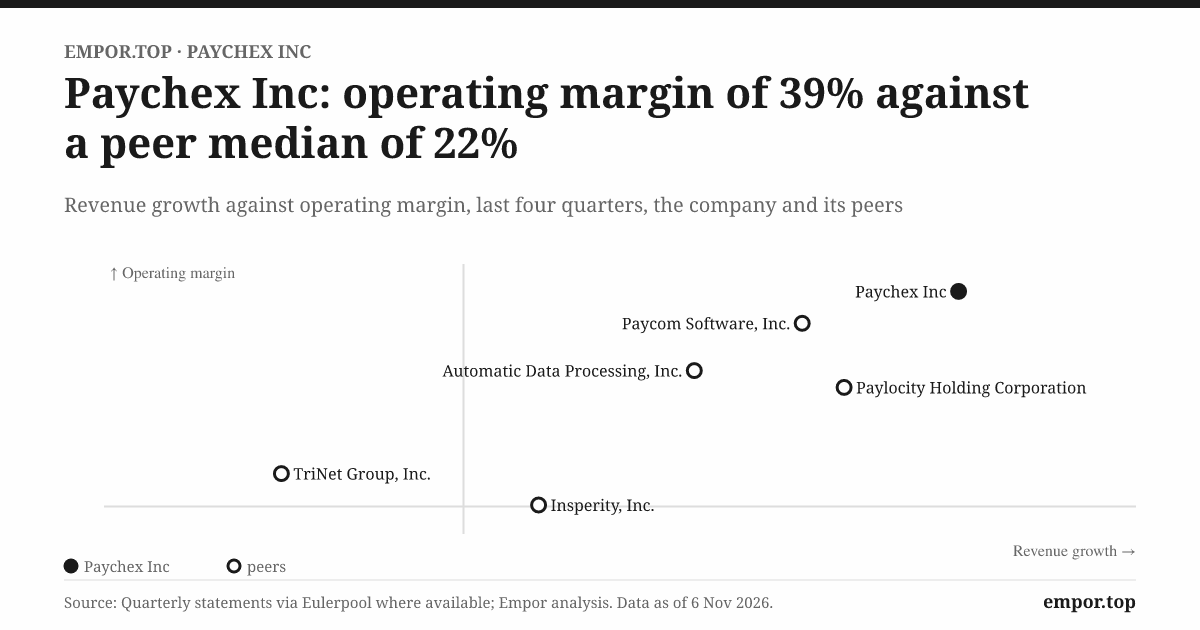
Now multiply the plumber. Paychex serves about 840,000 customers, of which about 800,000 are payroll clients.1 The company says it pays one in every 11 American private-sector workers.2 In the fiscal year that ended in May 2026 it booked about $6.5 billion of revenue, kept roughly 39 cents of every revenue dollar as operating profit, and turned about $1.8 billion of it into net profit.1 On November 3, 2026, its shares closed at $115.63, valuing the company at about $42 billion.3
Those are the numbers of a company that won. Over five decades, a business started in one Rochester office became one of the largest payroll processors in the United States. Very few providers can match its reach into the country's small and midsize employers, and fewer still have kept a client base this large for this long.
The harder question is whether the thing that made Paychex great still protects it. Payroll used to be an outsourced service, something done for a business by people who knew the rules. Increasingly it looks like a software feature: one tab inside an accounting package, an HR platform or a startup's all-in-one app. If calculating a paycheck becomes cheap enough to give away, what exactly is a customer paying Paychex for?
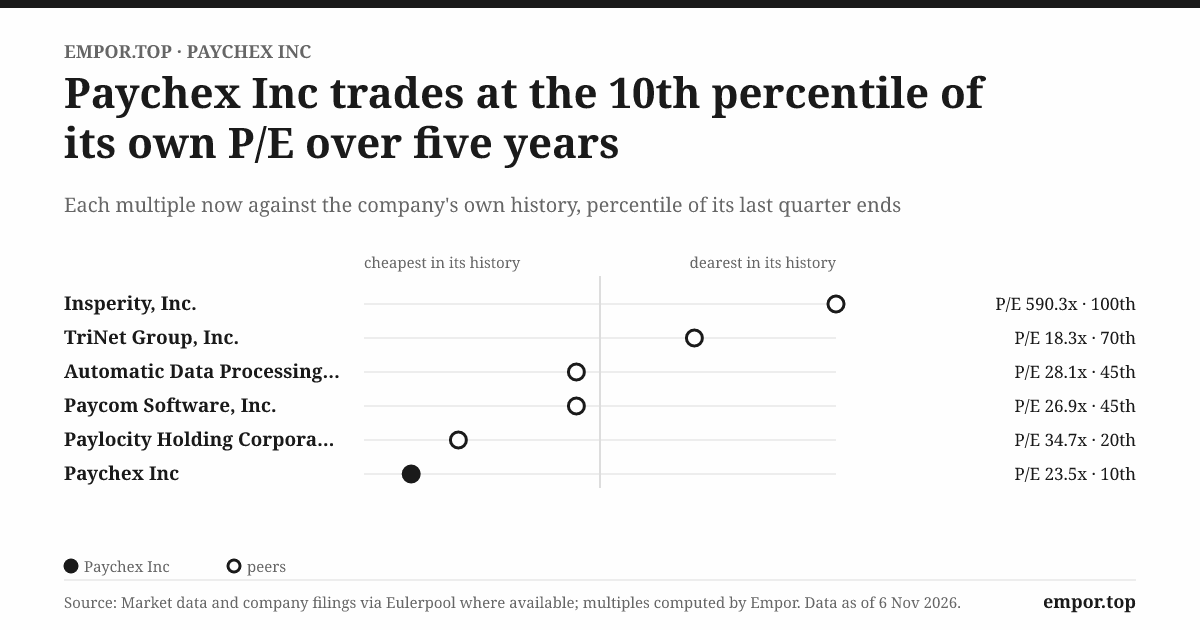
That question splits into four, and they run through this whole story. The first is whether customer trust can survive new software rivals, given that Paychex's clients can leave on 30 days' notice. The second is whether the 2025 acquisition of Paycor, the largest deal in the company's history, bought durable growth at a fair price, or simply bought revenue. The third is whether Paychex can keep paying out most of its earnings as dividends and buybacks while carrying the billions of dollars of debt it borrowed for that deal. The fourth is about price: the stock trades at about 23 times earnings, well below the roughly 28 times it has averaged over the past five years.3 Is that a market overlooking a durable franchise, or a market correctly marking down a business whose earnings have slowed?
There is a quieter tension under all four. Paychex's revenue jumped about 17% in its latest fiscal year, roughly double its ten-year pace, but its net profit grew only about 6%.1 A business that suddenly grows much faster at the top line than the bottom line is either investing for a new era or digesting something large. In Paychex's case it is mostly the second, and the story of whether the digestion goes well is the story of the next few years.
To understand why customers have trusted this company with their payday for half a century, though, it helps to start where the founder did: with a simple observation that the payroll industry of the early 1970s had decided small businesses were not worth the trouble.
 Subscribe on LinkedIn
II. The $3,000 payroll company
In 1971, B. Thomas Golisano started a payroll company in Rochester, New York, with $3,000, one employee and 40 clients.2 He called it Paymaster. The name soon changed to Paychex, but the idea did not: payroll services for small and midsize businesses, the employers the existing processors largely ignored.2
The logic behind that idea was more about selling than technology. In the early 1970s, computerized payroll was a service sold to large companies. A bank or a data-processing bureau could justify the effort of setting up a corporation with thousands of employees, because each account generated meaningful fees. A dry cleaner with eight workers did not. The setup cost was the same, the revenue was a sliver, and the owner usually wanted someone to talk to when something went wrong. To the incumbents, the small employer was an unprofitable customer.
Golisano's bet was that the incumbents had the arithmetic backwards. Any single small client was tiny, but there were vastly more small employers than large ones, and each of them faced the same legal obligations as a big company: withhold the right taxes, pay them on time, keep records, issue year-end forms. The owner of that dry cleaner either did it personally at the kitchen table, paid a local bookkeeper, or got it wrong. If a company could serve those owners cheaply and reliably, the market was not a sliver at all. It was most of the American economy.
What made this hard was that payroll is a service a customer has to trust before they can judge it. A new client cannot test-drive payday. To sign on, a business owner hands a stranger the most sensitive information in the company, including everyone's wages, bank details and tax status, and often access to the money itself. The first proof of quality arrives only after the commitment is made, when the checks either show up correctly or do not. That made the early business intensely personal. Salespeople had to knock on doors, explain what a payroll service was, and convince owners that a young company in Rochester would handle their payday better than they could.
It also made the business sticky in a particular way. A client who has been paid correctly for a year has little reason to go through the anxiety of switching. The relationship is built in increments, one clean payroll at a time, and what it builds is not a contract but a habit of relief. That pattern, earning trust slowly and then keeping it through repetition, became the defining feature of Paychex's economics decades later. It also contains the defining weakness: a habit can be broken in ways a contract cannot.
The other thing that shaped the early company was where it got its salespeople. Payroll for small businesses is a local sale. An owner wants to meet the person responsible for getting it right, and the sales cycle runs on referrals from accountants, bankers and other business owners in the same town. A single Rochester office could not reach Buffalo, let alone Florida or California. So rather than raise money to open branches everywhere, the young company expanded through franchises and partnerships, local operators who sold and serviced the Paychex model in their own markets.2
It worked. The business spread beyond Rochester quickly, carried by people who had their own capital at risk and their own reasons to sell hard. But the arrangement that made growth cheap also made the company strange. By the end of the decade, Paychex was less one company than a confederation of local businesses using the same idea, each with its own owners, economics and habits. For a service whose whole value was that payday came out right every time, everywhere, that was a problem waiting to happen.
III. The franchise network had to become one company
By 1979, the network had grown to 18 franchises and partnerships. That year, Paychex consolidated them into a single privately held company.2 It is the least dramatic event in the Paychex story, and one of the most important.
Franchising had solved the early problem of reach. Local partners brought capital the founder did not have, and they knew their markets. They could hire salespeople, find accountants who would refer clients, and build processing operations without Rochester paying for any of it. For a company with a few thousand dollars of starting capital, this was the only realistic way to grow fast.
The trouble was that a loose network of owners cannot easily behave like one service. Each partner had its own incentives. One might want to spend on sales, another on processing, another on simply taking money out. Standards could drift. New products had to be negotiated rather than launched. And the profit from each new client was split between the center and the local operator, which limited how much the company as a whole could reinvest. A brand promise of reliable payroll everywhere depends on the same systems, the same rules and the same response when something breaks. That is hard to guarantee across 18 owners who answer to themselves.
Bringing the partners into one company turned the network into something governable. Decisions about technology, pricing and service could be made once and applied everywhere, and the economics of every client flowed to one balance sheet. In a business built on scale, that matters enormously. The cost of building a payroll system that knows the tax rules in every state is large and fixed. Spreading it across one company's whole client base, rather than across many separate operators, is what turns a good idea into a low-cost machine.
Four years later, in 1983, Paychex became a publicly held company and built a new headquarters in Rochester.2 The listing supplied capital and visibility, but its real value was that it let the company scale a repeatable formula: hire salespeople, open territories, sign small employers, and process their payroll centrally. Each new client added a little revenue on top of a fixed platform, and the more clients there were, the cheaper each one became to serve.
The next decade showed what that platform could carry. Paychex did not just add clients. It added reasons for existing clients to stay. In 1987 it launched benefits services. In 1989 it introduced Taxpay, a service under which Paychex took on the job of filing and paying a client's payroll taxes. Human resource services followed in 1991, direct deposit in 1992 and 401(k) recordkeeping in 1995.2
Taxpay deserves a pause, because it quietly changed the company's economics. Once Paychex was paying clients' taxes on their behalf, it had to collect that money from them before the taxes were due. For a short time, sometimes days and sometimes weeks, Paychex held other people's money. Multiplied across hundreds of thousands of employers, those short stays add up to billions of dollars sitting in Paychex's accounts at any moment, earning interest. That float would become a meaningful income stream, and it would make the company's profits rise and fall with interest rates in a way that has nothing to do with software.
So by the mid-1990s, the shape of the modern company was visible. A national sales force sold a central service. The service started with the paycheck and expanded into taxes, benefits, retirement plans and HR. And the company was no longer just a payroll processor. It was a business that ran a growing list of chores for small employers. Which raises the question that matters most for an investor today: when a customer pays Paychex every month, what exactly are they paying for, and how much of it would they miss if they left?
IV. A Friday deadline became a year-round service relationship
Go back to the plumber. Her first conversation with Paychex was about Friday. But Friday is followed by everything else that comes with having employees. She has to hire someone, which means a job posting, a background check, new-hire paperwork and a state registration. She wants to offer health insurance to keep her best people, which means choosing a plan and collecting premiums through payroll. Her workers ask for a retirement plan. Her state requires workers' compensation insurance. A former employee files an unemployment claim, and she needs someone to tell her what to do about it. Each of these is another obligation with deadlines, penalties and forms, and each is a natural extension of the system that already knows who works for her and what they earn.
That is the Paychex business in one paragraph. The company sells payroll processing and tax administration, then layers on HR software and advice, benefits administration, retirement services, insurance, and a deeper form of outsourcing called a professional employer organization, or PEO.1 Clients can choose services one at a time or in bundles, and most of the revenue is recognized as services are performed over time.1
Here is the clause that matters most for anyone thinking about the durability of that revenue. Paychex's client agreements generally have no fixed term, and either side can end them on 30 days' notice.1 Paychex does not disclose a uniform pricing unit, a minimum commitment, or the share of revenue that is recurring.1 In other words, this is recurring usage, not a long contract. The customer comes back every pay period because the service works and because leaving is a hassle, not because a lawyer says she has to. That is both a strength and an exposure, and it shapes everything that follows.
Paychex reports one operating segment, but it breaks its revenue into lines that behave very differently, and it is worth separating them. In the quarter that ended in August 2026, the first quarter of fiscal 2027, the largest line, Management Solutions, brought in about $1.21 billion, up 4% from a year earlier.4 PEO and Insurance Solutions brought in about $368 million, up 12%.4 Interest earned on client funds added about $50 million.4
Read those three numbers as three different businesses. Management Solutions is the classic Paychex: payroll, HR software, benefits administration and retirement services, sold mostly to small and midsize businesses and now including Paycor's customers. It is roughly three-quarters of revenue and grows slowly, in line with the number of clients, the number of employees on each client's payroll, and whatever price increases and add-on products Paychex can sell. A 4% growth rate is respectable for a mature service, but it is not the profile of a fast-growing software company.
PEO and Insurance is smaller, faster and different in kind. A PEO is easiest to understand as shared employment. The small business keeps running its operations, but on paper the PEO becomes a co-employer of its staff, taking on payroll, tax filings, HR compliance, workers' compensation and access to benefits. Because the PEO pools thousands of small employers together, it can offer health plans and insurance that a 20-person company could never get on its own terms. For the employer, it is the closest thing to handing over the entire burden of having employees. For Paychex, it means revenue that scales with the number of worksite employees, deeper relationships, and a share of insurance economics. Management said on its September 2026 call that it was seeing strong conversions from its administrative-services clients into the PEO, and described the PEO as its highest-retention, highest-lifetime-value offering.5 That is a management view rather than a disclosed metric, but the faster growth rate is consistent with it.
The PEO also brings risks a software company does not carry. When Paychex co-employs a worker, it takes on exposure to that worker's injuries through workers' compensation, and to the cost of insurance claims. The company's revenue in this line depends on the number of worksite employees, which rises and falls with hiring at small businesses, and on insurance pricing and claims experience. That is an employment-cycle and insurance business wrapped inside a payroll company.
The third line, interest on client funds, is the float that began with Taxpay. Paychex collects money from clients before paying it out as wages and taxes, usually within one to 30 days and sometimes up to 90 days.1 In fiscal 2026, average client funds and corporate investments together were about $7.4 billion, and the client-fund interest included in revenue was about $211 million, a little over 3% of the total.1 The investment portfolio is conservative, with a weighted duration of about three years and a yield of about 3.7%.1 Even so, when rates rise, bond prices fall; at the end of August 2026, the portfolio showed about $94 million of gross unrealized losses, which the company attributed to rate changes and expects to recover by holding the securities to maturity.6
The point is not that float income is bad. It is high-margin, and the company has earned it by building the trust that lets it hold the money. The point is that it is a different kind of revenue. It grows when rates rise and when client payrolls grow, and it shrinks when rates fall. It is not evidence that the software is getting better or that customers are buying more. An investor who reads total revenue growth as a measure of product strength needs to strip this line out first.
So what is a customer actually paying for? Mostly, she is paying to stop worrying about a growing list of legal and administrative obligations. The deeper she goes, from payroll to HR to benefits to the PEO, the more of her business runs through Paychex and the harder it becomes to leave. But she can still leave on 30 days' notice. And the more payroll becomes something software can do well on its own, the more the question shifts from whether Paychex can do the job to whether anyone else can do it cheaply enough to make leaving worth the trouble. That is the competitive battle, and Paychex's own retention record turns out to be the best evidence of how it is going.
V. The moat is service at scale—with a visible leak
Imagine the payroll run is done. The money has moved, the taxes are filed, and the plumber's crew has been paid. If a competitor offers a slicker app, a lower fee or a bundled deal with her accounting software, she can still leave. Every pay period, in effect, the relationship is renewed by default. So the honest way to judge Paychex's competitive position is not to ask how much customers depend on payroll. They obviously do. It is to ask how often they choose to stay with Paychex when they could go.
The company answers part of that question itself. Paychex says its payroll client retention was about 82% to 83% in both fiscal 2025 and fiscal 2026.1 The striking thing is not the level. It is the persistence. A decade earlier, the fiscal 2015 annual report already described retention above 82%.7 Through a pandemic, a hiring boom, the rise of cloud-native payroll startups and a major acquisition, the share of clients Paychex keeps each year has barely moved.
There are two ways to read that number, and both are true. The bullish reading is that stability across more than a decade is itself evidence of a durable service business. If software rivals were steadily stealing Paychex's clients, retention would be sliding. It is not. The bearish reading is that 82% to 83% retention means that roughly one client in six leaves every year. On a base of about 800,000 payroll clients, that is something like 135,000 to 145,000 businesses walking out the door annually. Paychex has to win that many new clients just to stand still.
Some of those departures have nothing to do with competition. Small businesses close, get sold, or shrink to the point where the owner does payroll herself. A large share of small-business churn is simply the birth and death of small businesses. Paychex does not split its losses between businesses that failed and businesses that switched providers, and it does not disclose revenue retention, so investors cannot tell how much of the leak is competitive and how much is demographic. Management says revenue retention is high but does not quantify it.1 That is an important gap, because revenue retention is the number that would show whether the clients who stay are buying more, enough to offset the clients who leave.
Look at who is competing for those clients and the field divides into three groups. The first is ADP, the giant of the industry, with revenue roughly three times Paychex's.8 ADP competes across every size of employer and has the same advantages of scale, compliance infrastructure and brand. The second is a group of public, software-first HR platforms such as Paycom and Paylocity, each with revenue roughly a quarter to a third of Paychex's, built originally for midsize employers and selling modern all-in-one systems.910 The third is the newer generation of software-led alternatives, companies like Gusto and Rippling, along with Intuit, whose payroll products sit inside the accounting software millions of small businesses already use. None of these comparisons measure market share. They simply show that Paychex sits between a larger incumbent and a crowd of software challengers, each attacking a different part of its base.
It is worth walking through what keeps a client from leaving, because the answer is more subtle than the phrase switching costs implies. Switching payroll providers is painful in specific ways. Every employee's tax setup, bank details, deductions and year-to-date history have to be moved. A mid-year switch means reconciling tax filings across two providers. If benefits, retirement plans or workers' compensation are also with Paychex, each of those has to be moved too. For an owner with no HR department, that is weeks of work and a real chance of getting something wrong. And getting payroll wrong, as the opening scene showed, is the outcome she pays to avoid.
That burden is real, but it is not a wall. It protects best against small price differences and minor feature gaps. It protects worst at moments of change, when a business is founded, when it grows into a new tier of complexity, when it switches accounting software, or when an owner has a bad service experience. Those are exactly the moments software rivals target. A startup choosing payroll on its first day has no switching cost at all, and the products embedded in accounting and banking software can be adopted in minutes.
The economics of the buyer side push in the same direction. Paychex's customers are extremely fragmented. No single customer materially affected its receivables or revenue in fiscal 2024 through 2026.1 That means no customer has the leverage to dictate price. But fragmentation also means each customer decides independently and with little loyalty to anything except the service it gets. Bargaining power is weak at the individual level and strong in aggregate, because the aggregate is just the sum of hundreds of thousands of owners who can each leave.
Then there is pricing. If Paychex's moat were strong, the clearest evidence would be the ability to raise prices without losing clients. The company does not publish a price-realization series. What can be inferred is limited. Excluding Paycor, revenue grew at something like 5% in fiscal 2026, and the most recent quarter, with Paycor now in both years, grew about 6%.14 Analysts on recent calls have repeatedly pressed management on modest client growth and on when Paycor revenue synergies will show up.11 If client counts are growing slowly and revenue is still growing mid-single digits, then revenue per client is rising, through some mix of price increases, more employees per client, more products per client and higher float income. That is consistent with a business that has some pricing power. It is not proof of it, and the company does not let investors separate the pieces.
The exposures also differ by line, which matters when the economy turns. The small-business payroll base is sensitive to business formation and closures and to how many people each client employs, because fees scale with headcount and checks processed. The PEO is more sensitive to worksite employment and to insurance costs. A recession that hits small business hiring would hit both at once. Paychex has survived several such cycles, but the stability of its retention rate says nothing about how its revenue per client behaves when employers cut staff.
So what does the record actually support? It rejects the strong version of the moat claim, the idea that Paychex's scale locks customers in. A business that loses roughly a sixth of its clients every year and allows them to leave on a month's notice is not locked in. But the record supports a narrower and still valuable claim: that Paychex has an advantage of scale and service that has held its retention steady for more than a decade against well-funded competition, and that each client it keeps tends to buy more over time. The advantage is credible. It is not fully measured, and the number that would measure it, revenue retention, is the one the company keeps to itself.
That narrower moat also explains Paychex's strategy over the past decade. If the payroll relationship is where trust is built, the way to deepen the moat is to attach more of the employer's life to it. The cleanest example of that strategy, and the company's first large test of buying rather than building it, came with a PEO in Florida.
VI. Oasis made PEO a bigger part of the story
Paychex was not new to professional employer organizations when it went shopping in 2018. It had entered the business in 1996 by acquiring National Business Solutions.2 For two decades it built that business largely internally, alongside its payroll operation. By 2015 the company said it served more than one million worksite employees through its HR services, the most among providers focused on small and midsize businesses.2
But building a PEO internally is slow. Each worksite employee comes with an insurance relationship, a compliance profile and a client who has to be sold on co-employment. The fastest way to scale is to buy someone else's book. In December 2018, Paychex completed its acquisition of Oasis Outsourcing Group Holdings, then the largest privately owned PEO in the United States, for about $1.2 billion.12 Net of cash acquired, the price was about $1.0 billion.12 Oasis brought more than 8,400 clients, and Paychex said the combination made it the second-largest PEO in the country by worksite employees.12
The deal showed how Paychex thinks about adjacency. Oasis did not bring a new technology or a new customer type. It brought more of the same customers, small and midsize employers, at a deeper level of service. Many of them were exactly the kind of businesses Paychex already served through payroll, and the strategic case was that a co-employment relationship is stickier and more lucrative than a payroll relationship alone.
It was also the first time in its modern history that Paychex leaned on its balance sheet. The company had carried no borrowings at all through fiscal 2018; by the end of fiscal 2019 it had about $800 million of debt.3 Its return on invested capital, which had been close to 60% the year before, fell to the high 30s.3 That drop is mostly arithmetic, because buying a business adds goodwill and intangible assets to the capital base that a company built in-house never carries. But it is also a reminder that acquisitions change the kind of returns a company earns, even when the deal makes strategic sense.
Did Oasis pay off? The honest answer is that Paychex does not report the deal's lifetime return. It folded Oasis into its PEO operation, and the economics are not reported separately. What can be said is that the PEO has since grown into a meaningful revenue driver. In fiscal 2026 and again in the first quarter of fiscal 2027, PEO and Insurance Solutions grew faster than Management Solutions, by 12% in the latest quarter against 4% for the core.4 Oasis is part of the foundation for that, though eight years of organic selling, pricing and insurance changes sit on top of it.
The comparison with what came next is instructive. Oasis was large enough to matter, about a billion dollars for a company then generating about $1.1 billion of free cash flow a year.3 Paychex financed it with modest debt and kept its dividend and returns story intact. The deal deepened an existing business. The Paycor transaction, six years later, was four times as large, funded almost entirely with new debt, and aimed at a different part of the market. Oasis was a confident step. Paycor was a leap.
Before leaving the PEO, one risk needs to be named, because it is the most judgment-dependent number in Paychex's accounts. When a PEO co-employs workers, it carries their workers' compensation exposure. Claims from injuries can take years to develop, so Paychex must estimate how much it will eventually pay on claims that have already happened but are not yet settled. At the end of fiscal 2026, that reserve stood at about $237.7 million, and Paychex's auditor singled it out as the critical audit matter in its report, because it depends on actuarial assumptions about how losses will develop.1 The auditor's opinion was clean; the point is that this number is an estimate, not a count. If claims develop worse than expected, earnings take a hit later.
That is what the PEO adds to the Paychex story. It brings growth, deeper relationships and higher lifetime value. It also brings insurance risk, employment-cycle exposure and an actuarial judgment at the center of the books. PEO growth is not a software story. It is a service-and-insurance story wearing a software company's clothes. And the company later made a much larger bet on the software side.
VII. Paycor changed the scale—and the test—of the company
On January 7, 2025, Paychex announced that it had agreed to buy Paycor HCM for $22.50 a share in cash.13 The transaction valued Paycor at an enterprise value of about $4.1 billion, and the price represented a 19% premium to Paycor's unaffected 30-day volume-weighted average share price.13 Bloomberg called it a $4.1 billion deal for a rival payroll firm.14 The deal closed on April 14, 2025.1
Paycor was a Cincinnati-based provider of cloud HR and payroll software aimed at somewhat larger employers than Paychex's traditional base, the businesses with dozens to a few hundred employees that want a full HR system rather than a payroll service. Management's case for buying it rested on four claims. Paycor would strengthen Paychex's capabilities upmarket. It would bring modern cloud technology and established partnerships, including with brokers and other distribution channels. It would broaden the product range Paychex could sell. And it would produce more than $80 million of cost synergies in the near term, with revenue synergies to follow as Paychex sold its PEO, retirement and insurance products to Paycor clients and vice versa.13
The strategic logic was coherent. Paychex's biggest competitive threat in the middle of the market came from software-first platforms, and Paycor was one of them. Buying a competitor removed a rival, added a product that could compete with Paycom and Paylocity, and gave Paychex's large sales force more to sell. The question was never whether Paycor fit. It was what Paychex paid for the fit.
The price was demanding by most outside yardsticks. An industry review of human-capital-management deals published in March 2026 put the transaction at about 6.1 times revenue and 18.5 times EBITDA.15 The same review showed selected public core-HR companies trading at median multiples of about 3.2 times revenue and 9.3 times EBITDA.15 On those numbers, Paychex paid roughly twice what comparable public companies were valued at.
That comparison needs care, and its limits should be stated plainly. A transaction multiple includes a control premium, the price of buying the whole company rather than a single share, so acquisitions almost always look expensive against trading multiples. The public median and the deal were measured at different times. Paycor was growing faster than many of the companies in the median, and a significant part of its EBITDA was depressed by its own growth spending, which flattered the EBITDA multiple upward. And the price included the cost synergies Paychex expected to capture, which a public market investor in Paycor would not. Adjust for all of that, and the premium shrinks. It does not disappear. Paychex paid a full price, and the deal only makes sense if the synergies and cross-selling deliver.
It funded the purchase with cash and $4.2 billion of fixed-rate senior notes, in three pieces: $1.5 billion due in 2030 at 5.10%, $1.5 billion due in 2032 at 5.35% and $1.2 billion due in 2035 at 5.60%.16 A company that had carried no debt a decade earlier now owed more than it had ever owed.
What has been delivered so far? The first full year with Paycor was fiscal 2026, and its effect on reported growth was dramatic. Revenue rose about 17%, and roughly 12 points of that growth came from Paycor.1 Strip it out and the rest of the company grew at something like 5%, close to its pre-deal pace. Management said on its June 2026 call that it had exceeded its fiscal 2026 cost-synergy target.17 That is real evidence of execution on the cost side, though the company has not published an independently auditable breakdown.
The revenue synergies are where the promise is still a promise. Paychex has talked about selling PEO, retirement and insurance products to Paycor's clients and about Paycor's upmarket product helping Paychex win larger deals. But it does not yet disclose a durable series showing how much revenue cross-selling has produced. On the calls through fiscal 2026 and into fiscal 2027, analysts kept returning to the same two questions: why client growth has been so modest, and when revenue synergies will become visible in the numbers.181711 Management's answers have emphasized momentum, pipeline and early wins rather than a quantified figure. That is not unusual for a company 18 months into an integration. It is also not yet the evidence the deal's price requires.
The profit and loss tells the rest of the story. In the first quarter of fiscal 2027, Paychex's adjusted operating margin was 42.0%, while its reported margin was 38.0%.4 The gap of about four points is mostly the amortization of intangible assets acquired with Paycor, plus integration costs. Management prefers the adjusted figure, and there is a reasonable argument that amortizing customer lists is an accounting cost rather than a cash cost. But it is the accounting echo of a very real cash outlay. Shareholders paid for those intangibles with $4.2 billion of debt, and the interest on that debt is a cash cost that shows up below operating profit.
Here is the cleanest way to see what Paycor has done to per-share economics so far. Diluted earnings per share were about $4.67 in fiscal 2024, the year before the deal. They fell to about $4.59 in fiscal 2025, as deal costs and interest landed, and recovered to about $4.94 in fiscal 2026.1 Over two years that is growth of roughly 3% a year, well below the company's long-run record. The latest quarters are better: in the quarter to August 2026, net profit rose about 12% from a year earlier, as the comparison lapped the worst of the integration costs.4 The direction is encouraging. The level is not yet the payoff for a $4.1 billion bet.
Return on invested capital tells the same story more starkly. Paychex earned more than 50% on invested capital in the years before the deal. After it, the figure fell to the low-to-mid 20s.1 Some of that, as with Oasis, is accounting: the purchase added billions of goodwill and intangibles to the capital base. But that capital is real money that shareholders could have received or reinvested elsewhere. A 20-something percent return is still excellent by most companies' standards. It is just a different company from the one that earned 50%.
So the verdict on Paycor so far is that the deal was strategically sound and expensive, that the cost side is being delivered, and that the revenue side is not yet visible. The company is not proven to have overpaid, and it is not proven to have succeeded. What would settle it is a consistent organic-growth series, measurable cross-sell revenue and a return to high-single-digit per-share earnings growth. And the bill for the bet has arrived in a place where Paychex shareholders feel it most: the cash that once went almost entirely back to them.
VIII. The cash engine has more claims on it now
For most of its public life, Paychex had a simple deal with shareholders. The business threw off cash, the company needed relatively little of it, and most of what was left went out as dividends. Shareholders came to treat Paychex as something like a bond with growth, a stock bought for an income that rose year after year. After Paycor, that deal has more parties to it. Bondholders have a claim now, and the product needs investment to compete. The question is whether the cash engine is big enough for everyone.
Start with a distinction that confuses many readers of Paychex's accounts. The company holds two very different pools of money. One is its own corporate cash. The other is client funds, the billions it collects from employers to pay their wages and taxes. Client funds are restricted: they belong, in substance, to clients and their employees and tax authorities. Because they flow through financing activities and fluctuate with the timing of payroll and tax deadlines, they can make Paychex's reported cash flows swing in ways that have nothing to do with how the business is performing.1 An investor assessing what Paychex can return needs to look past those swings to corporate cash generation.
On that measure, the long record is excellent. From fiscal 2015 through fiscal 2026, Paychex generated about $17.8 billion of operating cash flow against about $14.5 billion of net profit.17 Cash exceeded reported profit by about a quarter, largely because large non-cash charges, including depreciation and amortization, amortization of deferred contract costs and stock compensation, reduce profit without consuming cash.1 After capital spending, free cash flow over those twelve years was about $15.9 billion.
Now follow that money. About $11.7 billion of it, nearly three-quarters, went out as dividends. The rest went to buybacks, acquisitions including Oasis and part of Paycor, and modest additions to cash. Corporate cash and short-term investments rose by only about $600 million across the period. Paychex has always paid out nearly everything it earned. That is a choice, and for a long time it was a sensible one: a company with high returns and limited reinvestment needs should return cash. But it means there has never been a large cushion.
Fiscal 2026 put the new tension in one place. Paychex generated about $2.6 billion of operating cash and about $2.3 billion of free cash flow.1 It paid about $1.6 billion of dividends and spent $611 million buying back and retiring 5.6 million shares.1 Add those together and roughly $2.2 billion of the $2.3 billion went back to shareholders, leaving very little for debt reduction. Dividends alone took about 90% of net profit, the highest payout in at least twelve years; the range over that time ran from about 72% to 90%.1 In January 2026, the board approved a new $1 billion buyback authorization with no expiration date.1
On the other side of the ledger sits the Paycor debt. At the end of fiscal 2026, borrowings were about $4.6 billion, almost all of it in fixed-rate notes that do not mature until 2030, 2032 and 2035.1 Interest expense rose to about $269.5 million in fiscal 2026, primarily because of the new notes.1 Against operating profit of about $2.5 billion, that interest is covered roughly nine times, comfortable by any standard. Net of corporate cash, debt is a little over one year's EBITDA. And at the end of August 2026, Paychex had $2.0 billion available under committed credit facilities, with nothing drawn and all covenants met.6 There is no near-term refinancing problem.
The credit agencies saw the deal in a similar light. In March 2025, S&P assigned Paychex a BBB+ rating with a stable outlook, estimating pro forma adjusted leverage of about 1.6 times EBITDA and expecting modest deleveraging.19 Its outlook assumed revenue growth of 4% to 5% and at least $1.8 billion of free operating cash flow over the following year, and it named the risks as integration, leverage reduction and disciplined financial policy.19 Moody's rated the notes Baa1, also stable.16 Those are investment-grade ratings. But they were set before Paychex's first full year with Paycor, and before the board chose to spend $611 million on buybacks in a year when debt reduction was one of the conditions the rating assumed. The next rating review will say more about the balance sheet than the last one.
That is the activist's question, and it is a fair one. Borrowings did fall during fiscal 2026, from about $5.0 billion to about $4.6 billion, but corporate cash and short-term investments fell by roughly half a billion dollars over the same year, so net debt barely moved.1 In a year when the company spent $611 million on its own shares, management chose to keep buying stock rather than reduce net debt faster. That can be defended. Fixed-rate debt at around 5%, with maturities years away, is not urgent to repay, and buying back stock at a lower multiple than its history may be a better use of cash. But it means Paychex is running with almost no free cash left after dividends and buybacks, and any slowdown in earnings would force a choice the company has never had to make: cut the buyback, slow the dividend growth, or let leverage rise.
One more number on the balance sheet looks alarming and needs explaining before it is misread. Paychex's receivables have grown enormously relative to its revenue. Measured as days of sales, they rose from about 29 days in fiscal 2015 to a peak of about 129 days in fiscal 2025, and stood at about 124 days in fiscal 2026. Taken at face value, that would mean customers now take four months to pay, which would be a serious warning sign.
The reveal is in what those receivables are. At the end of fiscal 2026, gross accounts receivable were about $1.55 billion, but only about $239 million of that was ordinary trade receivables from customers paying for services.1 The other $1.31 billion consisted of receivables that Paychex had purchased from its customers under non-recourse arrangements, a financing service in which Paychex buys clients' invoices and takes on the collection risk.1 On top of that sat about $664 million of PEO unbilled receivables, amounts for worksite-employee payrolls that had been processed but not yet invoiced at the period end.1 Add them together and they explain almost the entire 124 days. Ordinary trade receivables, the bills Paychex sends for its own services, amount to something like two weeks of revenue.
So the debtor-days figure does not show that ordinary service customers are paying late. It shows that Paychex has a sizable financing business and a PEO business whose timing creates large receivables. That is not the same as having no credit risk. The allowance for credit losses rose from about $26 million to about $40 million during fiscal 2026, and the company recorded about $38 million of credit-loss provisions.1 Those are small relative to revenue but rising, and they come mostly from a book of purchased receivables that behaves like a lending business. Paychex does not disclose the ageing of its receivables or delinquency rates, so investors cannot see how that book is performing beneath the totals. The right reading is not alarm. It is that loss provisions, allowance growth and collections deserve more attention than the headline ratio.
The cash engine, then, is still strong. It has delivered for more than a decade, and nothing in fiscal 2026 suggests it is breaking. But it now carries a dividend at the top of its historical payout range, a buyback program, interest on billions of debt and a product that has to keep pace with software rivals. Those claims fit inside the cash Paychex generates today, with very little to spare. Which makes the next question unavoidable: how much will Paychex need to invest to keep the product competitive, and what is the company's big new technology bet actually worth?
IX. AI has to earn its place in payroll
In its first quarter of fiscal 2027, Paychex introduced WISE Hire, an AI tool meant to help small employers through hiring, and said its family of WISE tools was spreading across its three main platforms: Paychex Flex, Paycor and SurePayroll.4 The WISE AI platform itself had launched earlier in 2026.2 By August 2026, the company said, more than 50,000 clients were early adopters of WISE.11 Paychex described roughly 600 AI features and agents across its products in its fiscal 2026 proxy statement.20
Those numbers are designed to signal that Paychex is not a dinosaur. A company that built its reputation on people answering the phone wants investors to know that it can also build software agents. And there is a genuine reason AI could matter more in payroll than in many industries. Payroll and HR work is full of repetitive, rule-bound tasks with serious consequences when they go wrong: checking that a new hire's paperwork is complete, catching an overtime calculation that looks off, answering the same question about a tax form for the thousandth time. An AI agent that prevents one payroll error or resolves a support call without a human is worth something, both to the client and to Paychex's cost of serving her.
That is the technical case. The commercial case is a different thing, and Paychex has not yet made it with numbers. The company does not disclose revenue from AI products, the share of early adopters who pay for anything extra, or whether AI users retain better than other clients. Fifty thousand early adopters out of roughly 800,000 payroll clients is a meaningful deployment, about one in sixteen. But an early adopter is a client who turned a feature on. It is not the same as a client who pays more, stays longer or costs less to serve. On the September 2026 call, management talked about bundling AI features with HR products and expanding its advisory services; analysts asked about adoption and monetization, and the answers emphasized usage and engagement rather than revenue or measured cost savings.11 That is a fair description of an early-stage product. It is not yet evidence of a new profit pool.
There is one place the effect might already be visible, though the company does not draw the line itself. Paychex reported about 19,000 employees in its fiscal 2025 corporate fact sheet and about 17,600 at the end of May 2026, even as revenue grew about 17%.211 That works out to roughly $370,000 of revenue per employee, a sharp improvement. Some of it is Paycor synergies, which involved cutting duplicated roles, and the two headcount figures are not prepared on a comparable basis. AI-driven efficiency may be part of the story. The company has not said how much.
On the investment side, Paychex spent about $235 million on property and equipment, including capitalized software, in fiscal 2026, up from about $161 million two years earlier, rising from about 3.1% to about 3.6% of revenue.1 It does not disclose a standalone research and development figure. So investors cannot tell whether the company is materially increasing product investment or largely harvesting an installed base with selective upgrades. The rising capital spending points mildly toward the first; the falling headcount is consistent with either.
The competitive logic of AI also cuts both ways, and Paychex acknowledges AI as both an opportunity and a potential source of disruption to its industry in its annual report.1 AI can help Paychex serve more clients with fewer people, which protects margins. But AI also lowers the cost for a startup to build payroll, tax and HR features that used to require large compliance teams. If the hardest part of payroll becomes encoding thousands of tax rules correctly, and AI makes that cheaper, then the scale advantage that took Paychex decades to build becomes less valuable. The company's defense would then rest more heavily on service, trust and distribution, which is to say on the same human relationships it is trying to make more efficient.
So WISE Hire and its siblings belong in the category of strategic options, not profit drivers. They are important to the core business, because a payroll provider that falls behind on technology will lose clients at the moments of change. But until Paychex links adoption to paid demand, retention or unit-cost savings, AI is a reason to keep watching, not a reason to believe. And whether that link gets made, and reported honestly, depends on the people now running the company.
X. John Gibson inherits the founder's trust business
For more than three decades, the face of Paychex was its founder. Tom Golisano ran the company as president and chief executive until 2004, when he retired and handed the job to Jonathan Judge, a longtime IBM executive.2 Martin Mucci later succeeded Judge.2 And in 2022, John B. Gibson became chief executive.2 Gibson took the job in October 2022.1
Gibson is not a founder figure and does not play one. He joined Paychex in 2013 and rose through its service and operations side before becoming president and chief operating officer and then chief executive.20 His background is in running large service organizations, which makes sense for a company whose product is reliability. His chief financial officer, Robert Schrader, sits beside him on the calls, and the two of them own the decisions that will define this era: the Paycor deal, its financing, the integration, the investment in AI and the balance between shareholder returns and paying down debt.
Golisano's exit from the boardroom was gradual. He left the board in July 2025.1 But he remains the largest individual shareholder, with about 10.1% of the company as of July 2026, slightly down from about 10.3% a year earlier.2022 Part of that decline came from gifts of shares to nonprofit organizations reported in 2025.23 At the November 3 share price, his stake is worth more than $4 billion. Gibson, by contrast, held about 363,000 shares.20 That is a meaningful personal investment, worth roughly $40 million at the same price, but it is a small fraction of the founder's legacy stake. The people running Paychex are professional managers with significant but not controlling ownership, which is normal for a company of this size. It does mean the founder's own alignment no longer sits at the table.
Pay is where alignment is usually tested. Gibson's reported total compensation rose to about $10.3 million in fiscal 2026 from about $8.8 million in fiscal 2025, which had itself risen from about $7.5 million in fiscal 2024.2022 Over the same latest year, net income rose about 6%.1 So the CEO's pay grew more than twice as fast as profit. Paychex explains that 91% of the CEO's target compensation is variable and that the board deliberately raised Gibson's and Schrader's equity awards to bring them closer to peers.20 A high variable share is a good design principle, but it is not proof of alignment by itself. Variable pay can rise when targets are set at levels the company expected to reach anyway, and pay in a year dominated by a large acquisition can reward size rather than per-share value. The fairer conclusion is that the structure is mostly performance-based and that the outcome, so far, has rewarded managers more generously than it has rewarded per-share earnings.
Shareholders appear broadly comfortable with that. At the October 2026 annual meeting, the advisory vote on executive pay passed with about 281 million votes for and about 9 million against.24 The more interesting signal was elsewhere. A shareholder proposal to let investors call a special meeting narrowly failed.24 That is a meaningful governance message: a large minority of owners want more power to act between annual meetings. It does not suggest an imminent fight, but it does suggest that investors are paying closer attention to governance than the pay vote alone would imply.
The board itself has ten directors, eight of them independent, with an independent lead director and committees chaired by independent directors.20 The chairman is Martin Mucci, the former chief executive, and he is classified as non-independent alongside Gibson.20 The auditor, PwC, issued unqualified opinions on both the financial statements and internal controls for fiscal 2026, with no material weakness reported; the workers' compensation reserve was its one critical audit matter.1
Related-party dealings are small. Paychex paid BlackRock, one of its largest shareholders, about $1.1 million in fiscal 2026 for investment-management services, roughly 0.02% of revenue.20 It received about $0.6 million in fees from Eastman Kodak, a company in which an entity associated with Golisano held a large stake, though the proxy says he had no direct interest in the arrangement and did not take part in it.20 There is no parent company and no controlling corporate shareholder.20 None of this rises to a governance concern.
So the test of this management team is not its governance structure, which is conventional and clean. It is its behavior over the next few years. Gibson and Schrader will be judged on whether they execute the Paycor integration and manage the balance sheet while explaining results clearly enough for investors to separate operating performance from acquisition accounting. The early record remains mixed. That brings the story to the question every investor ultimately has to answer: what is all this worth today?
XI. Analysis & Bear vs. Bull Case
On November 3, 2026, Paychex shares traded at about 23 times trailing earnings.3 Over the previous five years, the median multiple was about 28 times. The shares sat about 9.5% below their 52-week high and well above the low of about $86 reached during the year. The dividend yielded about 5% and the free cash flow yield was about 4.8%. Peers traded at higher multiples on near-date trailing earnings: ADP at about 26 times, Paycom at about 28 times and Paylocity at about 35 times.8910 Those figures use different fiscal periods and describe businesses with different growth rates and mixes, so they are signposts, not a valuation model.
What does the price seem to assume? At 23 times earnings, the market is no longer paying for the high-single-digit compounding Paychex delivered over the past decade. Net profit grew about 8.8% a year from fiscal 2016 to fiscal 2026, but only about 4.2% a year over the latest three years.1 The lower multiple looks less like a mistake than a market pricing the recent rate rather than the long-run one. Whether that is too pessimistic depends on whether the slowdown is temporary, a result of Paycor's costs and interest landing on the income statement, or a sign that the core business has matured.
The moat argument, made in full, comes down to five forces and a few powers. Rivalry is intense: ADP competes on scale, Paycom and Paylocity on modern software for midsize employers, and Gusto, Rippling and Intuit on ease of use for small businesses. Buyer power is weak per client because no client is large, but meaningful in aggregate because clients can leave on 30 days' notice. Supplier power is modest; Paychex does not disclose supplier concentration, and its key inputs are labor, technology and banking relationships. The threat of substitutes is rising, because payroll is increasingly embedded inside accounting, banking and HR software. And the threat of new entrants is moderate and growing, because AI and cloud infrastructure lower the cost of building payroll while compliance, trust and distribution still take years.
In Hamilton Helmer's framework, Paychex's strongest power is scale economies: a fixed cost base for compliance, technology and processing spread across hundreds of thousands of clients, which is visible in operating margins near 40%.1 Its second power is switching costs, real but partial, as the steady 82%-to-83% retention record shows: high enough to keep most clients, low enough that a sixth leave every year.1 A third, more debatable, is brand, the reputation for getting payday right that lets a salesperson close a client who cannot test the service in advance. Paychex has no network effect to speak of, no cornered resource and no meaningful process power that a determined competitor could not replicate over time. That adds up to a good business with two durable powers, not a fortress.
The bull case starts with the base. About 800,000 payroll clients, a service reputation built over five decades and a national sales force give Paychex a platform to attach HR, benefits, retirement and PEO services, and the retention record in fiscal 2015 and fiscal 2026 shows that the base has held.71 The bear case answers that the base is held by habit rather than contract: 30-day termination, a sixth of clients departing each year, software alternatives that grow every year, and no disclosed revenue retention to prove that the clients who stay are spending more. Weighing the two, the history supports the narrower claim. Paychex's scale and service keep its client base steady, but they do not lock it in, and the evidence of rising spend per client is inferred rather than shown.
The bull case continues with Paycor. The deal broadens the customer segment and product set, cost synergies were delivered ahead of plan, and PEO and Insurance is growing about three times as fast as the core.174 The bear case points to the price: roughly 6.1 times revenue and 18.5 times EBITDA against public core-HR medians about half as high, financed with debt, and still awaiting proof of revenue synergies.15 Per-share earnings grew only about 3% a year across the two years spanning the deal.1 On this point the record leaves the bull claim intact but unproven. The confirming evidence would be several quarters of organic revenue growth above the pre-deal pace and a quantified cross-sell figure; the falsifying evidence would be organic growth stuck near 4% to 5% while interest and amortization keep reported margins below their pre-deal level.
Finally, the bull case rests on cash. Twelve years of cash conversion above reported profit support a high dividend, and the stock offers a 5% yield and a 4.8% free cash flow yield at today's price. The bear case says that cash is now spoken for: a payout at 90% of earnings, about $4.6 billion of debt, and $611 million of buybacks that left almost nothing for deleveraging after dividends and capital spending.1 Here the history narrows the bull claim. Paychex's cash generation is real and durable. Its capacity to grow the dividend at the old pace while also cutting debt and buying stock is not, unless earnings growth accelerates.
An activist looking at Paychex would probably not demand a breakup or a sale. The portfolio is coherent and the governance clean. The challenge would be narrower: publish organic growth, revenue retention and Paycor cross-sell revenue; explain why buybacks took priority over deleveraging; and tie executive pay more directly to per-share earnings and return on invested capital rather than to totals that an acquisition inflates.
Three numbers will tell the story from here. The first is organic Management Solutions growth together with payroll client retention: the latest quarter showed Management Solutions up 4% and retention steady at 82% to 83%.41 The second is PEO worksite-employee growth alongside the workers' compensation reserve: PEO and Insurance revenue grew 12% in the latest quarter, and the reserve stood at about $238 million at the last year end.41 The third is free cash flow after dividends and buybacks, set against net debt: in fiscal 2026 that leftover was close to zero, and net debt barely moved.1 If all three improve, the lower multiple will look like an opportunity the market missed. If they stall, it will look like a fair price for a slower company.
XII. Playbook: Business & Investing Lessons
The arc of this story runs from a man in Rochester with $3,000 and 40 clients to a chief executive explaining AI agents and acquisition synergies to Wall Street analysts. Along the way, Paychex learned a handful of things about selling a service that customers cannot afford to get wrong. They are worth stating in their sharpest form.
The first lesson is to sell the relief, not the software. Paychex built its business on that promise, from payroll to Taxpay to the PEO. For founders, the lesson is that the most durable products remove a fear rather than add a feature. A product becomes essential when the customer cannot miss the deadline.
The second lesson is to build the system before the footprint. Paychex's 1979 consolidation turned a franchise network into a service it could deliver consistently. For investors evaluating any distributed service business, the question is whether the service is controlled from the center or only branded there. Local reach only scales when the service stays one promise.
The third lesson is that every attachment carries a liability. PEO's faster growth shows the strategy working, but its workers' compensation reserve shows what deeper service brings: injury risk, insurance cost and actuarial judgment. Cross-selling is usually described as free revenue. At Paychex it is a new obligation with every sale.
The fourth lesson is that an acquisition is a test of discipline that only cash can grade. Oasis deepened a business Paychex already understood. Paycor was four times as large, priced at a demanding multiple and funded almost entirely with new debt, and its revenue synergies are still a promise. Neither deal can be called a success or failure on strategic logic alone, because both made sense on paper. What will judge them is the per-share cash they eventually return. A strategic fit becomes a good deal only when the cash returns.
The fifth lesson is that AI must prove itself on payday. Paychex's early adoption is real, but its commercial value remains unproven. In a business whose entire value is reliability, a new technology earns its place by making the old promise easier to keep, not by making a better announcement. In payroll, innovation counts when payday gets easier and errors get rarer.
XIII. Epilogue
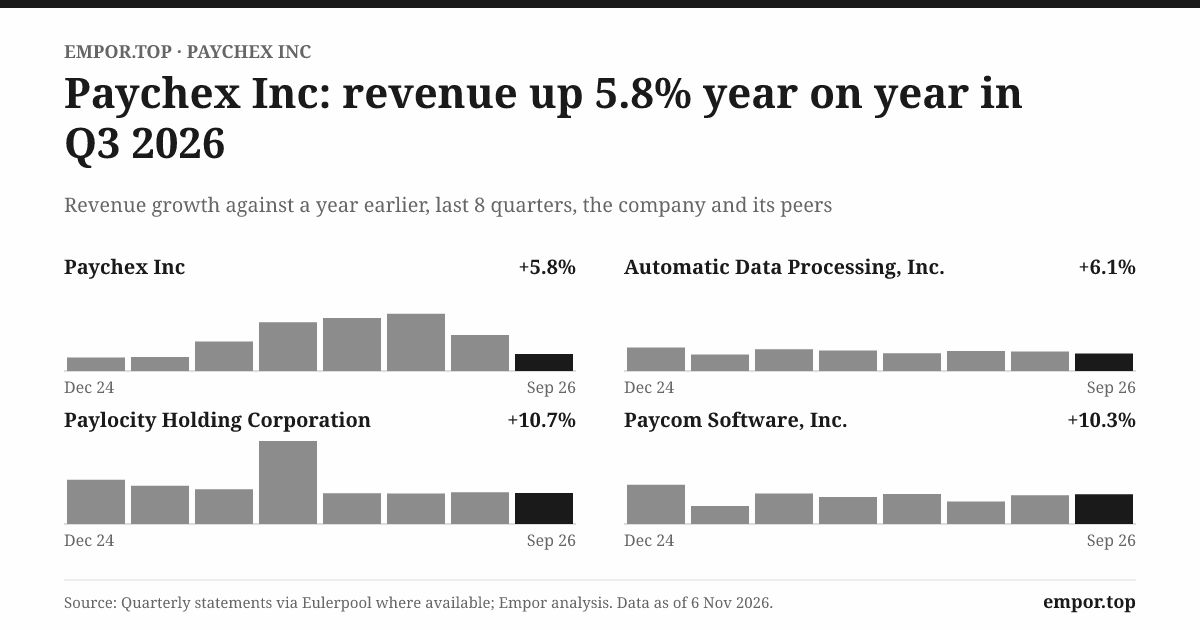
On September 23, 2026, Paychex reported the first quarter of its 2027 fiscal year.4 It was the first quarter in which Paycor sat in both the current and prior-year figures, so it was the cleanest look yet at the combined company's underlying pace. Revenue grew about 6%. PEO and Insurance grew about 12%. Adjusted operating margin was 42.0%, and reported operating margin was 38.0%.4 Management held its full-year revenue growth outlook at 5% to 6% and raised its outlook for PEO and Insurance growth to 7% to 8%, while pointing to a full-year adjusted operating margin of about 44%.4
Read against the story's four questions, that quarter answers none of them definitively, but it narrows each one. A company growing about 6% with Paycor fully in the comparison is growing roughly at its pre-deal rate, not faster. That is the core question about Paycor in one number: so far, the deal has made Paychex bigger without yet making it grow faster. The raised PEO outlook supports the bull case on attachment. The gap between adjusted and reported margins shows that the acquisition's costs are still flowing through the income statement.
The next few earnings reports will decide how the story reads. The second-quarter report, due around the end of the calendar year, will show whether the PEO momentum holds into the busiest season for benefits enrollment and whether management offers anything more concrete on Paycor cross-selling. Over the following two to four quarters, investors should look for a consistent organic-growth bridge that separates price, client growth, attachment and float income; for client and worksite-employee trends; and for a measure of Paycor revenue synergies that can be tracked from one quarter to the next. If those arrive and show growth above the pre-deal pace, the bull case strengthens considerably. If they do not arrive, the absence will itself be a signal.
The margin story runs on a parallel track. The gap between reported and adjusted margins should narrow as integration costs fade, though amortization of acquired intangibles will continue for years. Watching the two together, rather than the adjusted figure alone, will show how much of the improvement is operating progress and how much is simply costs rolling off.
The PEO needs its own watchlist. Faster growth, rising worksite employment and a stable workers' compensation reserve would confirm that the most promising part of the business is also well-underwritten. Growth accompanied by a sharply rising reserve or worse claims experience would be a reminder that the PEO's economics depend on insurance as well as service.
Then there is the cash. Free cash flow, interest expense, buybacks, dividends and net debt should be read as one record. The test is simple to state: can Paychex keep raising its dividend, keep its credit rating where it is and bring net debt down, all at once? If earnings grow at high single digits, the answer is probably yes. If they grow at 4% to 5%, something has to give, and how the board chooses will reveal its priorities.
And AI stays open. Fifty thousand early adopters is a beginning. The evidence that will matter is paid usage, better retention, fewer errors and lower cost to serve, and Paychex will need to publish at least some of it before investors can treat AI as part of the case rather than a hope attached to it. Tonight, the company stands where it has stood for much of its history: trusted, profitable, generating cash and paying most of it out. What has changed is that the next chapter has been financed in advance, and the bill is waiting for the results.
XIV. Outro
Back to Friday morning. The plumber checks her phone before the first job of the day. Eight deposits have landed. The taxes are filed. Nobody on her crew will ever think about Paychex, which is exactly what she paid for.
That is what makes this company different from another HR software business. Its product is software, but its promise is that pay arrives correctly and on time, for one in 11 American private-sector workers and about 800,000 employers who could leave next month and mostly don't.21 Fifty-five years of that promise built the company. The next chapter depends on whether Paychex can keep it while asking the same customers to trust it with far more of their business, and asking its shareholders to trust that a $4 billion bet will pay them back.
References
-
FY2026 Form 10-K — Paychex, Inc., 2026-07-17 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Q1 FY2027 Earnings Release — Paychex, Inc., 2026-09-23 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Q1 FY2027 Form 10-Q — Paychex, Inc., quarter ended 2026-08-31 ↩↩
-
Q1 FY2027 Earnings Call Transcript — Paychex, Inc., 2026-09-23 ↩↩↩↩
-
Paychex Completes Acquisition of Oasis Outsourcing — Paychex, Inc., 2018-12-21 ↩↩↩
-
Paychex Agrees to Acquire Paycor — Paychex, Inc., 2025-01-07 ↩↩↩
-
Paychex Strikes $4.1 Billion Deal for Rival Payroll Firm Paycor — Bloomberg, 2025-01-07 ↩
-
HCM Technology Year in Review 2025 — Houlihan Lokey, 2026-03 ↩↩↩
-
Underwriting Agreement for Senior Notes — Paychex, Inc., 2025-04-08 ↩↩
-
Q4 FY2026 Earnings Call Transcript — Paychex, Inc., 2026-06-24 ↩↩↩
-
Q1 FY2026 Earnings Call Transcript — Paychex, Inc., 2025-09-30 ↩
-
Research Update: Paychex Assigned BBB+ Issuer Credit Rating; Outlook Stable — S&P Global Ratings, 2025-03-31 ↩↩
-
FY2026 Proxy Statement — Paychex, Inc., 2026-09-04 ↩↩↩↩↩↩↩↩↩↩↩
-
2026 Annual Meeting Voting Results, Form 8-K — Paychex, Inc., 2026-10-15 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube