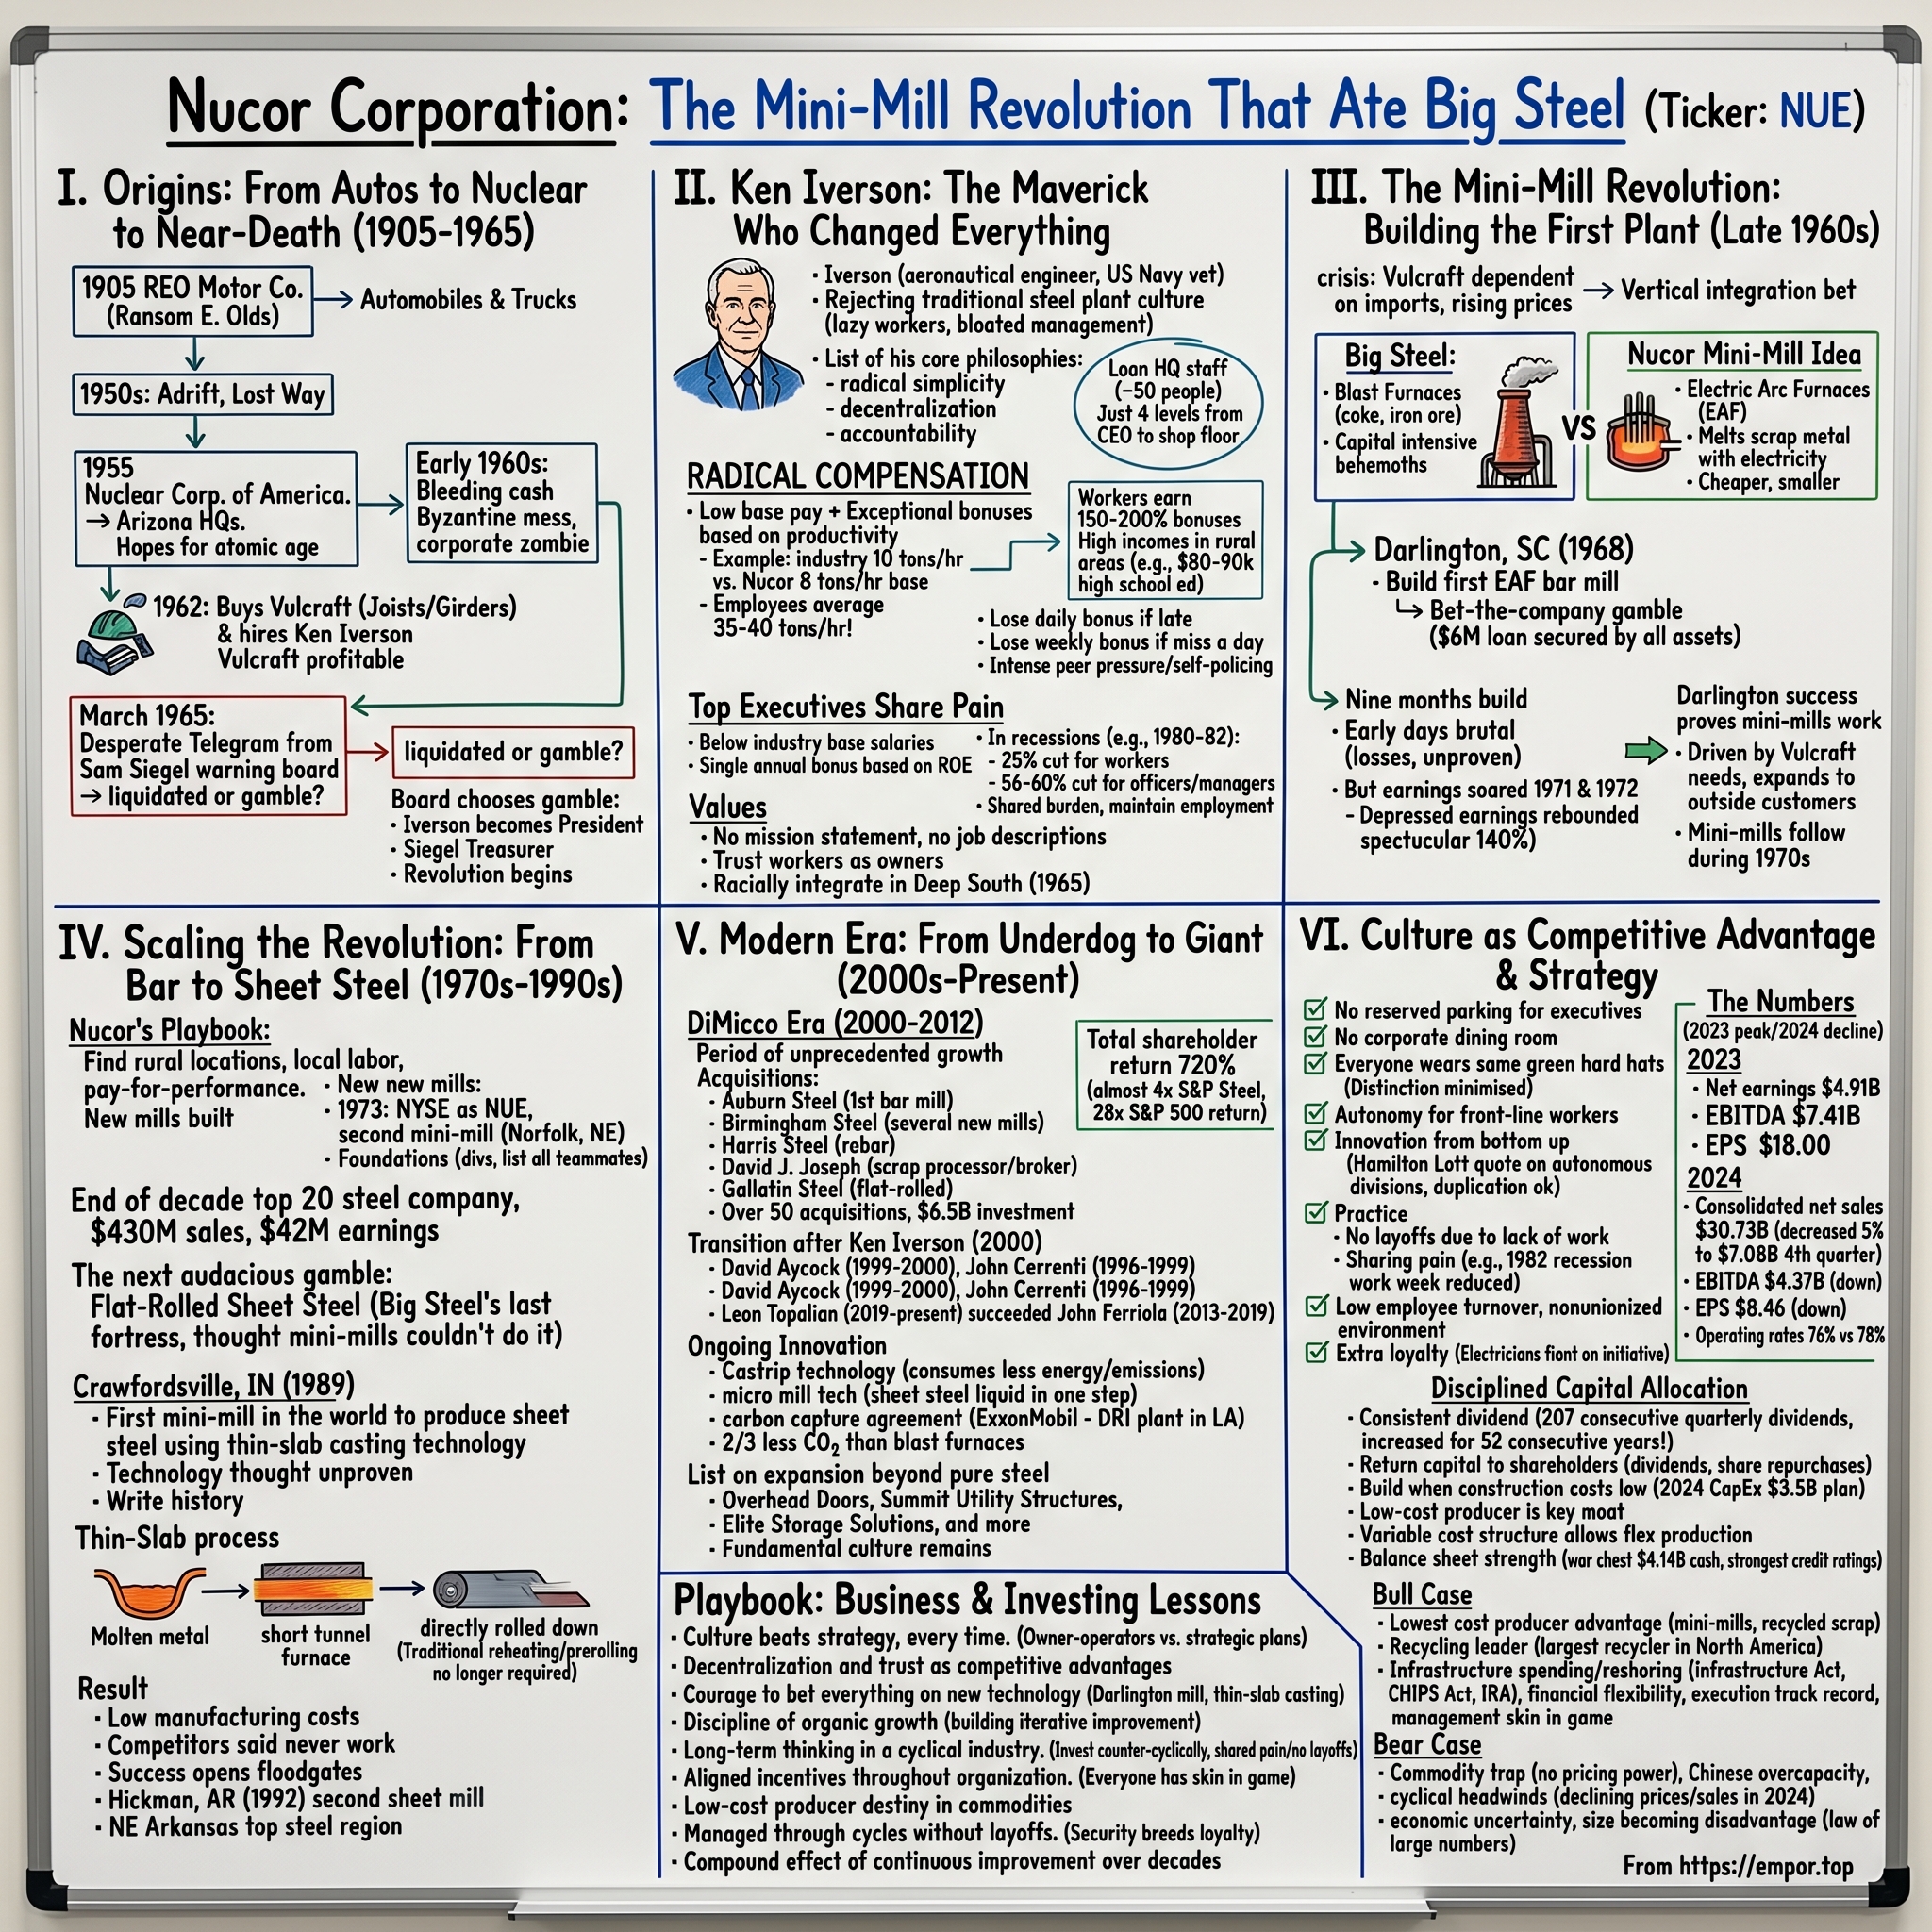
Nucor Corporation: The Mini-Mill Bet That Rebuilt American Steel
I. The Steelmaker Built for the Next Downturn
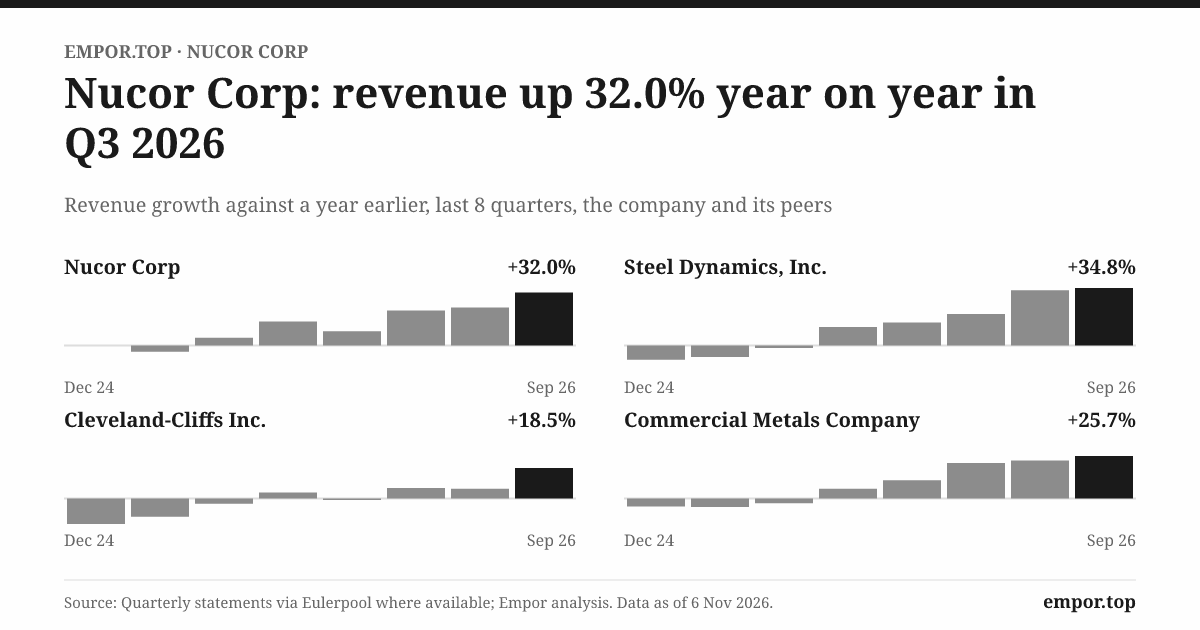
On July 27, 2026, Nucor put out the kind of quarterly report that makes a steel company look like a growth stock. Sales for the three months to July 4 came to about $10.4 billion, up almost a quarter on the same quarter a year earlier. Earnings attributable to Nucor's shareholders were about $1.16 billion, nearly double what the company had earned in the second quarter of 2025.1
Its mills shipped a record 7.1 million tons of steel and ran at 91% of capacity, the kind of utilization American steelmakers spend most of a cycle dreaming about.12 And management told investors to expect the third quarter to be better still.1
Underneath the headline sat two items that a careful reader had to set aside. The first was a $130 million reduction in the steel mills' cost of goods, made up of cash refunds tied to raw materials Nucor had bought in earlier periods. On the call, management said these mostly concerned pig iron and that it did not expect further refunds to help the third quarter or later ones in any material way.12
The second was a $61 million noncash gain, and it had nothing to do with steel. It came from a higher valuation of Nucor's stake in Helion, a fusion-energy start-up that had raised new capital during the quarter.1 Nucor stripped the Helion gain out of its adjusted earnings, which came to about $1.11 billion. It did not strip out the refund, because that was real cash.1 So the true picture is a strong quarter, flattered at the margin by one item that will not come back and another that was never steel.
That distinction matters because Nucor's whole history is a lesson in how far steel earnings can travel. In 2022 Nucor earned $7.61 billion, the most in its history.3 Three years later, in 2025, on sales that were still more than $32 billion, it earned $1.74 billion.4 More than three-quarters of the profit had vanished, and nothing had gone wrong with the company in the way investors usually mean it. No plant blew up. No fraud came to light. The market simply moved, and steel profits moved with it.
That is the paradox at the centre of this company. Nucor is one of the most financially conservative industrial companies in America. All three major rating agencies rate it in the single-A range with stable outlooks, which is rare air for a steelmaker.1 It has paid a cash dividend every quarter since the early 1970s; the payment declared in June 2026 was its 213th consecutive quarterly dividend.1
Its revolving credit line, $2.25 billion, sits undrawn.1 By every measure of financial prudence it is built for the next downturn. And yet the thing it sells, a commodity priced by the ton, can turn a $7 billion year into a $2 billion year with very little warning.
So the question that hangs over that bright July quarter is simple to ask and hard to answer: is this rebound evidence that Nucor has built a structurally stronger business, or is it the latest turn of the wheel? The story that follows tests four claims that together make up the bull case. The first is that Nucor's way of making steel still gives it an edge, half a century after it pioneered it.
The second is that the roughly $9 billion it spent on capital projects in three years will earn its keep.4 The third is that a business that now buys scrap, melts steel and fabricates finished products is more resilient than a plain steel mill. The fourth is that a management team in the middle of a generational handover can turn all that investment into lasting returns.
None of those claims can be settled by one quarter, however good. They have to be tested against the record, and the record starts with a company that was very nearly not a company at all. Nucor was born from a failing conglomerate that bet everything on a different way of making steel. Whether today's leadership can make a different kind of bet pay, on giant new mills rather than a scrappy little one, is the question this story is really about. To see why the original bet was so improbable, you have to go back to 1965, when the company was running out of money.
 Subscribe on LinkedIn
II. The Company That Was Almost Liquidated
The family tree of America's largest steelmaker begins, improbably, with a car. In 1904 Ransom Eli Olds, the man behind Oldsmobile, left the company that bore his name and founded another, which soon became the Reo Motor Car Company.5 Reo built cars and trucks for half a century, went bankrupt once, and by 1954 was barely alive. A forced takeover of a small Reo unit called Nuclear Consultants produced, in 1955, a company with a name that perfectly captured the moment: Nuclear Corporation of America.56
Nuclear Corporation was a creature of its era. It used stock offerings to buy a scattering of unrelated businesses, the kind of postwar conglomerate whose logic lived mainly in its press releases.5 One of those purchases, in 1962, was a steel joist and girder maker in Florence, South Carolina, called Vulcraft. Joists are the open-web steel beams that hold up the roofs and floors of warehouses, schools and shopping centres; they are unglamorous, essential and sold in bulk to builders. Along with Vulcraft, Nuclear acquired the man who would run it, F. Kenneth Iverson.65
Iverson did not look like a steel baron, and he did not much admire the steel barons he had met. He had earned a master's degree in mechanical engineering at Purdue, worked as a research physicist at International Harvester and then bounced through management jobs at several small metals companies.7
His first look at a big integrated steel mill, a 1947 visit to the giant works at Gary, Indiana, left him unimpressed.7 That early impression matters to this story. Iverson came to steel as an engineer who saw an industry of enormous, expensive plants run by layers of managers, and he suspected there was a better way to do it.
By 1965 the conglomerate around him was collapsing. Nuclear had about $20 million in sales and was losing money; two major loan defaults that year forced its president to resign.5 The company was on the verge of bankruptcy, and a conglomerate that cannot pay its lenders tends to end up sold for parts.5 Vulcraft was nearly the only healthy division in the portfolio.5 The board made the decision that set everything else in motion: it handed the company to the man who ran the business that worked. Iverson became president in 1965, with treasurer and controller Sam Siegel at his side.6
What Iverson did next was less a turnaround than an amputation. He sold off roughly half the divisions and cut the corporate management ranks drastically. The company booked one more loss, about $2.2 million, and then reorganized itself around joists.5
In 1966 he moved the headquarters from Phoenix to Charlotte, North Carolina, closer to the Vulcraft plants that now constituted the company, and in the same year he started a profit-sharing program.6 That small detail, buried in a list of moves made by a desperate chief executive, would become one of the defining features of the company: from the beginning of its new life, the people on the plant floor were tied to the company's results.
The joist business had a structural weakness, and Iverson saw it clearly. Vulcraft did not make steel. It bought steel, bent it and welded it. Its joist and deck businesses depended heavily on a single outside supplier whose prices kept rising.8 Every time the supplier raised its price, Vulcraft's margins shrank, and there was little Iverson could do about it. Imports were an alternative, but an unreliable one. The integrated steelmakers of the 1960s, the Bethlehems and U.S. Steels, had little reason to care about a small joist maker in South Carolina.
So in 1966 Iverson went to his board with a proposal that must have sounded mad from the president of a company that had nearly been liquidated a year earlier. He wanted Nucor to make its own steel.76 Not in a blast furnace, the towering, capital-hungry heart of an integrated mill, but in an electric arc furnace that melted scrap. Skeptics doubted that such furnaces could make steel in large volumes, or make anything beyond the most basic grades.8
Iverson's argument was practical rather than visionary. Vulcraft needed a reliable supply of steel at a price it could control. A small mill near its plants could provide that, and anything it made beyond Vulcraft's needs could be sold to others. The question was whether a little mill fed on junked cars and old appliances could ever compete with the integrated giants on cost. The board said yes to the idea. The mill itself would decide whether they had been right.
III. The Mill That Made Scrap a Strategy
In 1968 Iverson committed the company. To build its first mill, in Darlington, South Carolina, Nucor borrowed about $6 million, a sum that effectively mortgaged everything the company owned.5 For a business that had posted a loss three years earlier and whose healthy core was a handful of joist plants, it was a bet-the-company wager in the most literal sense. If the mill failed, there would be nothing left to fall back on.
To understand why the bet was even thinkable, it helps to picture two ways of making steel. The traditional, integrated route starts with iron ore and coal. Coal is baked into coke, ore and coke go into a blast furnace the height of an office building, and out comes molten iron, which a second furnace refines into steel. It is a magnificent and brutally expensive system. A blast furnace is designed to run continuously for years, so the plant has to sell enormous volumes to cover its fixed costs, and shutting one down is a major decision. The mini-mill route skips all of that.
It starts with steel that already exists, in the form of scrap, and melts it in an electric arc furnace, which works rather like a giant kettle with carbon electrodes for heating elements. Huge currents arc through the scrap, temperatures climb above 3,000 degrees Fahrenheit, and the result is liquid steel.9 The plant is smaller, cheaper to build and can be throttled up or down with demand. The trade-off, as Nucor itself puts it today, is that electric-arc producers are more exposed to scrap prices but carry lower capital and fixed operating costs than integrated rivals.4
Iverson did not invent the electric arc furnace or the mini-mill. Europeans had been running small scrap-based mills for years. What Nucor did was adapt the model for American scrap and American customers, starting with its own. Production at Darlington began in June 1969, and the early years were rough.5
The continuous-casting machine, which turns liquid steel into solid shapes, suffered regular breakouts, in which molten steel burst through the solidifying shell. The problem persisted until late 1970, and Nucor's stock fell to pennies.5 Imagine the scene for a moment: a company that had pledged its assets for a single plant, watching that plant spit liquid metal across its own floor while the share price collapsed.
Then the economics started to work. Earnings rose 140% in 1971 and another 70% in 1972, the year the company formally became Nucor Corporation and listed on the New York Stock Exchange under the ticker it still uses.56 It started paying a quarterly dividend of five cents in 1973.6 More mills followed, each a relatively small, scrap-fed operation serving a regional market; a 400,000-ton-a-year mill in Plymouth, Utah, opened in 1981.6 By the end of the 1970s Nucor had sales of about $430 million and earnings of about $42 million, and in 1980 it entered the Fortune 500.56
The leap into sheet
The first generation of mini-mills, however, had a ceiling. They made "long" products such as reinforcing bar, angles and small beams, which tolerate the impurities that come with scrap. The most valuable segment of the steel market was flat-rolled sheet, the thin, smooth steel that goes into cars, appliances and buildings' skins. Sheet required casting thick slabs and rolling them down in huge mills, a process that seemed to belong to the integrated giants alone.
Nucor's answer was Crawfordsville, Indiana. Assembly of a new kind of caster, which cast slabs a fraction of the thickness of traditional ones, began in 1988, and the first trials started in mid-1989.5 A thin slab needs far less rolling to become sheet, so the whole plant could be smaller and cheaper. It was also an unproven technology, and its start-up was a struggle. A 1991 New York Times report described the process as "fraught with problems" and said Nucor was losing as much as $1 million a week in start-up costs; larger steel producers scoffed at it.10
A fatal explosion in January 1990 drew an OSHA fine.5 Plant managers Keith Busse and Mark Millett pushed the mill through, and it eventually ran near capacity while producing flat-rolled steel at about $45 a ton less than competitors.5 Nucor now describes Crawfordsville as the world's first mini-mill to make quality flat-rolled steel with thin-slab technology, and the approach became an industry standard.610
The proof showed up in the league tables. In 1996 Nucor passed Bethlehem Steel to become the second-largest steelmaker in the United States.6 Over the next decade, as integrated producers stumbled through bankruptcies, Nucor bought mills from rivals, including Birmingham Steel and Trico Steel in 2002.6
What the edge really was
This is the moment to state the advantage plainly, once. Nucor's edge was never a secret machine. It was a cost structure: lower capital per ton, lower fixed costs, and the ability to cut output when demand fell instead of running a blast furnace at a loss. It was flexibility: dozens of mills making many products, so tons could be shifted between plants. It was recycling at scale, which turned the country's junkyards into a domestic raw-material base. And it was a local footprint, with mills placed close to customers in a business where freight costs bite.
That edge was real, but it was never permanent, and the company's own record shows where it frays. Scrap is not a perfectly renewable resource. Each time steel is recycled, it picks up copper and other residual elements that are hard to remove, so very high grades become harder to make from scrap alone.
A TIME reporter compared it to reusing a tea bag.9 Nucor's answer was to make its own purer iron. It had started producing direct reduced iron, or DRI, in Trinidad in 2006; DRI is iron ore stripped of its oxygen using natural gas rather than coal, which yields clean metallic pellets that can be mixed with scrap.6
In 2014 it brought a much larger, $750 million DRI plant online in St. James Parish, Louisiana.69 That bet did not pay off on schedule: the Louisiana plant operated at a loss during much of 2014.9 The two DRI plants supplied about 3.4 million metric tons of feedstock to Nucor's mills in 2025, and the company also took delivery of more than 2 million gross tons of imported pig iron.4 The feedstock problem has been managed, not abolished, and it costs money and capital to manage it.
The bigger erosion came from imitation. In 1993, Busse and Millett, the two managers who had dragged Crawfordsville into production, left with fellow Nucor executive Richard Teets to found Steel Dynamics. Their own thin-slab mill in Butler, Indiana, began commercial operation in January 1996.11 Steel Dynamics remains Nucor's closest listed peer and one of its fiercest competitors. The technology that had once made Nucor unique was now available to anyone with capital and the right engineers.
The scale of the competitive field today is worth a sentence. The World Steel Association ranks Nucor 16th in the world for 2025, with crude-steel output of about 22.3 million metric tons, against about 17.1 million for Cleveland-Cliffs, the largest American integrated producer.12 Global giants in China, Japan and India produce several times as much. Inside the United States, Nucor competes with Steel Dynamics and other mini-mills on cost, while integrated producers and imports often set the price.4
The verdict on the mini-mill thesis, then, is that it narrowed rather than failed. The electric arc furnace gave Nucor a lower-capital, more flexible route into steel and helped it survive downturns that crushed integrated rivals. But by the 1990s the model had spread, scrap quality had become a constraint, and the cost edge depended on scrap and energy prices that Nucor did not control. The question a skeptic would ask today is how much of Nucor's advantage is still about the furnace and how much is about how the company is run. Which is why the story now turns from machines to people.
IV. A Culture Designed Around the Mill Floor
Picture Nucor's headquarters in Charlotte in the late 1990s. Its corporate staff numbered roughly 25 people.7 There was no corporate legal department, no purchasing department, no engineering, public-relations or marketing staff at the centre. There was no mission statement and there were no job descriptions.7 Everyone, including the chief executive, flew coach. There were no company cars, no reserved parking spaces and no executive dining room.7 For an industry whose giants were famous for their towers and hierarchies, it looked almost like a prank.
It was not a prank. It was the operating system. Iverson's idea was that the people who could most improve a steel mill were the people who worked in it, and that the company's job was to pay them for doing so and otherwise stay out of the way. Base pay for most hourly and salaried employees was set at roughly 70% of the industry average.
The rest came from bonuses tied to production, so that a crew that made more good steel took home more money, often enough that bonuses exceeded base pay. In the late 1990s a typical mill worker earned close to $60,000 a year, which made Nucor's workforce among the best paid in the industry.7 The bonus plans were written down. Iverson refused discretionary bonuses because he thought they bred favouritism.7
The same logic ran up the ladder. Department heads earned bonuses tied to return on assets; officers' bonuses were tied to return on equity and fell to zero if the company earned an 8% return.7 When Nucor missed its targets in 1982, Iverson's pay dropped from $450,000 to $110,000, and a magazine named him the lowest-paid chief executive among America's 500 largest companies.
He said he wasn't ashamed of it.7 There were only four or five management layers between the chief executive and the shop floor, and decisions were pushed to the lowest practical level.78 Iverson even accepted failure as a cost of experimentation: he estimated that about half of the company's new investments yielded nothing usable.7
One of his successors captured the competitive flavour of all this in a story told years later. When John Ferriola ran the Crawfordsville mill, he wrote each crew's production rankings on a stairway where everyone could see them. Within a month, production rose by nearly 20%.9 A bonus tied to output, a public scoreboard and a crew that knew exactly where it stood: that was the Nucor model in a single image.
The culture also produced a legend that needs handling with care. Business writers in the 1990s described a company that had "never laid off an employee or shut down a facility for lack of work," because it cut shifts and workweeks in slow periods instead.7 That was a description of the company at a particular point in its history. It is not a present-day guarantee, and an investor should not treat old claims about egalitarianism and no-layoff policies as current facts. The useful question is narrower: does the incentive system still show up in the numbers at a company of today's size?
The model at 33,000 people
Nucor today employs about 33,000 people, up from about 31,600 in 2023, and the vast majority are not represented by unions.413 The pay philosophy survives in recognisable form. Nucor's compensation committee says that all of the company's incentives are team-based and that "teammates win and lose together."14
Profit sharing remains a large line: the company contributed $256 million to its profit-sharing and retirement plan in 2025, down from $298 million in 2024 because profits fell.4 The median employee earned about $134,000 in total compensation in 2025.14 That figure says something important about the model. Labour costs flex with profits, which cushions the company in downturns, but the people who carry that variability are paid well when the mills are full.
Where should the culture show up, if it is a real advantage rather than a recruiting slogan? In plant productivity, in margins through the cycle, and in whether new facilities reproduce the model. The first two are hard to isolate from the outside. What is visible is where profit is earned.
In 2025, the steel mills earned about $2.38 billion before taxes and noncontrolling interests, the steel products businesses about $1.23 billion and raw materials about $153 million.4 The mills, where the bonus system was born, remain the engine. The culture is consistent with that result. It is not proof of it, since a strong spread between steel prices and scrap costs can make any mill look well run.
The next generation takes the controls
The people now responsible for preserving all this came up inside it. Leon Topalian joined Nucor in 1996 as a project engineer and worked his way through cold-mill supervision at Nucor Steel Berkeley, melting and casting at Nucor Steel South Carolina, a stint at the company's former HIsmelt joint venture in Australia, and general manager posts at Nucor-Yamato and Kankakee.14 He became chief executive in January 2020 and chair in September 2022.14
In December 2025 the company announced the most significant reshuffle of his tenure. Steve Laxton, a Nucor veteran who had joined in 2003 and served as chief financial officer since 2022, became president and chief operating officer on January 1, 2026, taking the president title Topalian had held; long-time COO Dave Sumoski retired in June.1514 Jack Sullivan was promoted to chief financial officer on March 1, 2026.4
The proxy shows a management team whose pay still moves with results, though not as violently as Iverson's did. Topalian's reported compensation fell from about $22.5 million in 2023 to $14.9 million in 2025, as attributable earnings fell from $4.5 billion to $1.7 billion.14 His 2025 package was built mostly from stock awards, options and an annual incentive tied to return on equity and return on invested capital compared with a group of steel peers.14
In 2025 Nucor's return on equity was about 8.5%, and it ranked third among its steel comparators on return on invested capital, which produced an annual incentive of about 177% of his base salary.14 The CEO-to-median-worker pay ratio was 112 to 1.14 Shareholders approved the 2025 pay package by a wide margin, with roughly 167 million votes for and 7 million against.16
Governance has two features an activist would note. The chair and chief executive roles are combined, with Christopher Kearney serving as independent lead director; the board argues the combination serves shareholders "at this time."14 And the proxy discloses that Topalian is married to the sister of the wife of K. Rex Query, an executive vice president who is himself a named executive officer.14 Neither is a red flag by itself. Both are reasons to watch how the board holds management to account when results disappoint. Topalian's own holdings are meaningful: he beneficially owned about 475,000 shares, most of them in options, against a guideline that requires him to hold at least 100,000 shares.14
The management test, then, is not whether this team understands the culture. It plainly does. It is whether the next generation can preserve the discipline of the mill floor while managing something Iverson never attempted: a multibillion-dollar construction program and a sprawling portfolio of businesses that stretch from the scrap yard to the finished building. That portfolio was assembled through a series of deals, and the most important of them reached all the way back to the start of the supply chain.
V. The Scrap Dealer, the Fabricator and the Steel Mill
On March 3, 2008, Nucor closed a deal that turned a long-standing supplier into a subsidiary. For about $1.44 billion it bought The David J. Joseph Company, a Cincinnati scrap broker and processor founded in 1885.17 The two companies were hardly strangers. DJJ had brokered ferrous scrap to Nucor since 1969, the year Darlington opened, and then-chief executive Dan DiMicco described it as a partner of 38 years.17 In 2007 alone DJJ had brokered more than 20 million tons of ferrous scrap, and it owned more than 2,000 railcars used to move the material around the country.17
The logic was a chess move rather than a cost cut. Scrap and scrap substitutes are the single largest cost in making steel at Nucor; on average it takes about 1.1 tons of metallic feedstock to produce one ton of steel.4 A mini-mill that buys all its scrap on the open market is a bit like a restaurant that buys all its ingredients at the corner shop on the morning of service.
Owning the country's leading scrap broker gave Nucor eyes on the market, a processing network that could clean and sort material, and logistics to move it. Combined with the DRI plants, it gave Nucor more control over the feedstock that decides both the cost and the quality of its steel.
A year earlier Nucor had moved the other way, downstream, buying Harris Steel Group for about $1.07 billion to enter rebar fabrication.6 Fabricators take bars from the mill and cut, bend and bundle them to the specifications of a particular bridge or building. Over the following decade and a half, Nucor kept adding links.
It bought tubing makers in 2016, an insulated metal panels business in 2021 and, in 2024, Rytec, a maker of high-performance doors, among other steel-adjacent businesses.64 The 2022 investor day gave this branch of the strategy a name, "Expand Beyond," and an ambition: such businesses would reach about a fifth of revenue over five to six years.18
How the money actually flows
The result is a company with three segments that sell to each other as well as to the outside world, and that structure is easy to misread. In 2025 Nucor reported about $32.5 billion of consolidated sales. About $20.0 billion of that came from steel mills selling to outside customers, about $10.3 billion from steel products such as joists, decks, rebar fabrication, tubing, buildings and panels, and about $2.2 billion from raw materials.4
On top of that, the segments sold about $16.3 billion to one another, sales that disappear in consolidation.4 When a mill ships coil to a Nucor tube plant, or DJJ ships scrap to a Nucor mill, that is a transfer inside the family, not revenue from a customer. Nucor has no controlling parent and reports no parent-level royalties or fees, so these internal flows are the only "related-party" business that matters, and they are already netted out.4
How Nucor prices its steel determines how quickly cycles hit it. Most of its steel goes to spot customers who order each month, based on their needs and Nucor's prices relative to domestic and foreign rivals.4 Sheet is the exception. About 85% of Nucor's sheet sales in 2025 went to contract customers, under noncancellable agreements that typically run six to twelve months and adjust prices monthly or quarterly to market indices or input costs.4
Those contracts smooth the volume picture but do not lock in margins, because prices still follow the index. Rebar fabrication runs on yet another model, with largely fixed-price, job-based contracts.4 That last detail matters later, because a fixed price on a job bid months ago does not move when steel costs do.
Where do the profits sit? Of the roughly $3.8 billion of pretax segment earnings in 2025, about 63% came from the steel mills, about 33% from steel products and about 4% from raw materials, before corporate costs and eliminations.4 That split is the clearest single answer to the question of whether Nucor has become something other than a steel mill. It has become larger and broader, but the mills still earn most of the money.
Judging the deals
Did these acquisitions create value? Here the honest answer is partly unknowable from outside. Nucor disclosed the prices of DJJ and Harris Steel but does not publish target-level operating results that would allow anyone to compute what multiple it paid or whether the businesses have earned back their cost. The strategic case for DJJ is clear: it locked in scrap access and market intelligence for a company whose largest expense is scrap. The financial case has to be taken largely on trust.
The insulated metal panels deal is easier to scrutinise because Nucor gave its own yardstick. It paid $1 billion in cash to Cornerstone Building Brands in 2021 for a business with seven North American plants and brands such as CENTRIA and Metl-Span, which make energy-efficient wall and roof panels with a foam core sandwiched between steel or aluminium skins.19
Nucor said the price equalled about 10 times pre-pandemic EBITDA including expected synergies, and about $900 million after accounting for tax benefits.19 Ten times EBITDA is a full price for a building-products business whose demand moves with warehouse and cold-storage construction. It is the company's own benchmark, and by itself it proves nothing about value created. A synergy-inclusive multiple means the deal only looks reasonable if the synergies arrive.
The record also shows that not every capital deployment in this chain worked. In the third quarter of 2024, Nucor's raw materials segment recorded an $83 million charge to fully reserve a long-term note receivable that management concluded would no longer be collectable; in the same year it took a separate $40 million impairment on assets of a business in the steel products segment.4
Neither is large against a company of Nucor's size, and the note receivable is a different matter from the operating case for DJJ, whose brokerage operations improved in 2025.4 But they are reminders that diversification is not free and that some bets in the portfolio get written down.
The segment numbers leave a question the strategy has to answer. The point of owning fabricators and panel makers is supposed to be that they steady earnings when the mills face weak spreads. In practice, the downstream businesses had their own bad year at exactly the moment the company needed them, and the biggest promise Nucor ever made to investors was about to collide with the steel cycle.
VI. The $6.7 Billion Promise Meets a Steel Downturn
To understand the promise, start with the boom that preceded it. In 2020, as the pandemic shut factories and froze construction sites, Nucor earned about $721 million.20 Then the world reopened all at once. Supply chains snarled, builders and manufacturers scrambled for steel, and prices went vertical. Nucor's sales jumped to about $36.5 billion in 2021 and its earnings to about $6.8 billion, a record.21 In 2022 it did even better, earning about $7.6 billion on sales of about $41.5 billion and returning about $3.3 billion to shareholders.3 Topalian called it the safest and most profitable year in the company's history.3
It was in the middle of that boom, at its 2022 investor day, that Nucor told investors what it thought the company could earn on a normal basis once its new projects were built. Steve Laxton, then the chief financial officer, put a number on it: through-cycle EBITDA of about $6.7 billion.18 EBITDA is a rough measure of operating cash earnings before interest, taxes and the accounting charges for wear and tear on assets, and "through-cycle" is supposed to mean the average across good years and bad.
For comparison, the company's average EBITDA from 2017 to 2019 had been about $3.2 billion.18 Management broke the gain down: about $1.5 billion from core steel projects, about $700 million from the "Expand Beyond" businesses, and the remainder from improved margins in downstream products, long steel and flat steel.18 The project estimates were presented as midpoint-of-cycle figures that excluded the exceptional years of 2021 and 2022, and the projects were scheduled for completion by 2025.18
On paper, it was a careful framing. Management did not simply extrapolate the boom. It said it was looking at the middle of the cycle. The question is what happened when the cycle actually turned.
What the downturn revealed
It turned fast. Earnings fell from about $4.5 billion in 2023 to about $1.7 billion in 2025.4 The anatomy of the 2024 decline tells you a lot about the economics of steel. Between 2023 and 2024, Nucor's sales fell by about $4 billion, but its cost of products sold fell by only about $267 million.
Almost all of the lost revenue therefore came straight out of gross profit, which shrank by about $3.7 billion.4 In plain English, prices fell while costs stayed put. Nucor shipped steel at lower prices, but scrap, energy, labour and the depreciation of a growing asset base did not fall in step. That is what a commodity business looks like when the spread compresses.
The 2025 result was stranger and, for the bull case, more troubling. Sales recovered by about $1.8 billion. Cost of products sold rose by about $2.0 billion, so gross profit slipped further, by about $224 million.4 The segments explain why. The steel mills did better, with earnings up about $157 million on higher volumes and metal margins.
But steel products, the downstream businesses that were supposed to stabilise the company, saw earnings fall by about $367 million, even though their volumes rose, with the metal-building and rebar-fabrication businesses among those earning less.4 Corporate costs and eliminations added another $237 million of drag.4 Higher shipments did not restore profits, because the extra tons came at thinner margins.
Now set management's own words beside that outcome. In January 2025, presenting the 2024 results, Topalian said market conditions were "starting to improve and should gain momentum as we work our way into 2025."22 The mills did improve. The company as a whole earned less in 2025 than in 2024. That is not a scandal; steel forecasting is humbling. It is a data point about how much weight to put on the next optimistic outlook, and it bears directly on the $6.7 billion figure.
Testing the target
Measured on the company's own EBITDA, 2024 came in at about $4.4 billion and 2025 at about $4.2 billion.2223 Both years are below the through-cycle ambition by more than a third, and both come after most of the projects in the 2022 plan were supposed to be done. The bull will reply that 2024 and 2025 were near the bottom of the cycle, that the biggest new mill had not yet started, and that start-up costs of about $500 million to $600 million a year were depressing earnings.23
There is something to that. In the first half of 2026, Nucor's EBITDA was about $3.5 billion, which, if doubled, would run slightly above the target.124 But that half-year included the $130 million refund, the Helion gain and a market lifted by tariffs that cut finished-steel imports by about a quarter year on year,2 so it is just as hard to call it a normal year as it was to call 2022 one.
The honest verdict is that the record narrows the claim rather than rejecting it. Nucor is clearly a bigger company than it was before the plan: it ships more steel, makes more products and earns more in a weak year than it used to in an average one. That is real progress against the $3.2 billion baseline. What the record has not yet shown is that $6.7 billion is a true midpoint.
To prove it, Nucor would need to earn something like that figure in an ordinary year, with no tariff shock, no refunds and its new mills running at normal rates. Nucor's latest annual report says it believes the roughly $9.7 billion of investments made over the past three years will deliver higher returns on invested capital and make the business less volatile, but it offers no project-by-project reconciliation against the 2022 estimates.4 That reconciliation is the single most useful disclosure an investor could ask for.
Which leaves the key capital-allocation question for long-term owners. Do the new assets lift the company's returns in the middle of the cycle, or do they mostly add capacity that earns well only when spreads are favourable? The answer lies in a handful of very large construction projects that are just now leaving the building phase.
VII. The New Mills Have to Earn Their Keep
Drive along the Ohio River in Mason County, West Virginia, and you reach Apple Grove, where Nucor has been building the biggest project of its current expansion.4 When Nucor picked the site in January 2022, it described a three-million-ton, state-of-the-art sheet mill.4 Construction began in the third quarter of 2023.
In February 2025, the board approved more capital as the estimated cost rose to about $4 billion, which the company attributed to higher labour, material and equipment costs. The State of West Virginia committed $350 million, so Nucor expects its own net outlay to be about $3.65 billion.4 By the July 2026 call, commissioning had begun, and management said the mill was on time and on budget, with commercial shipments ramping in early 2027.2
West Virginia is the centrepiece of a construction wave that has reshaped Nucor's balance sheet. At the end of 2025, Nucor carried about $4.6 billion of construction in progress and equipment deposits, up from about $3.8 billion a year earlier.4 Capital spending climbed from about $2.2 billion in 2023 to $3.4 billion in 2025, or roughly 6% to 11% of sales; the company expects to spend about $2.5 billion in 2026.413
Along the way, the expense of starting things up became a fixed feature of the income statement. Pre-operating and start-up costs, mostly related to the Kentucky plate mill, the West Virginia sheet mill and the Arizona melt shop, were about $594 million in 2024 and $496 million in 2025.4 That is a lot of money spent getting plants ready before they earn anything.
Three projects, three different tests
Each of the major projects poses a different question. West Virginia is the classic greenfield test. It is a new mill in a new place, with a 76-inch tandem cold mill and two galvanizing lines, one aimed at the automotive market and one at construction, in a region historically served by blast-furnace producers.4 Its success depends on whether it can win customers from those rivals and reach high utilization quickly. Management has been explicit that the ramp will be gradual.
On the Q2 2026 call it said it was targeting about 50% utilization by the end of the mill's first year, with the emphasis through 2027 on safe, reliable and consistent production.2 When an analyst from BMO asked how demand might affect the ramp, management replied that it could shift tons among its mills to support the start-up.2 That flexibility is a genuine advantage of a multi-mill system. It also means West Virginia's early volume could partly come from other Nucor mills rather than from new customers, which is a different thing from net new market share.
Brandenburg, the plate mill in Kentucky that rolled its first plate in 2023, is further along and offers the best evidence so far of what the new assets can do.6 Plate is thick steel used in bridges, ships, wind towers and heavy equipment. In 2025 the mill shipped record tons for bridge projects funded by the 2021 federal infrastructure law, and Topalian described it as the "crown jewel" for supplying steel for new naval vessels.4
On the July 2026 call, Brad Ford, speaking for the plate business, said nearly a third of Brandenburg's second-quarter shipments were in grades and sizes the group could not previously offer.2 That is a meaningful product expansion. But when a Bank of America analyst asked whether 75% utilization was a reasonable assumption for modelling, management declined to endorse the figure and said only that utilization would continue to "creep up."2 The product range is proven. The full earning power of the mill is not.
The Arizona melt shop, at Kingman, is the smallest of the three and in some ways the most encouraging. Nucor had bought the Kingman mill from North Star Steel for only $35 million in 2003.6 Adding a melt shop turned it into a fully integrated mini-mill, and the facility came online in 2025.23 By mid-2026 Topalian said Kingman was EBITDA positive, as was the new Lexington, North Carolina rebar micro-mill, a $440 million plant with about 430,000 tons of annual capacity.24 Micro-mills are a quietly clever idea: smaller plants built close to regional customers, which win on freight costs rather than sheer scale.4
Paying for it all
Can Nucor afford all this and still pay its shareholders? On the evidence so far, yes, with less slack than the headline balance sheet suggests. In July 2026 it held about $2.7 billion of cash and short-term investments, though about $843 million of that sat inside majority-owned joint ventures, where it is less freely available to the parent.125
The $2.25 billion revolver was undrawn, and funded debt was about 23.4% of total capital, far below the 60% limit in its only financial covenant.254 Long-term debt was about $6.9 billion at the end of 2025, and the company refinanced a $1 billion maturity in 2025 with new five- and ten-year notes, a routine transaction.4
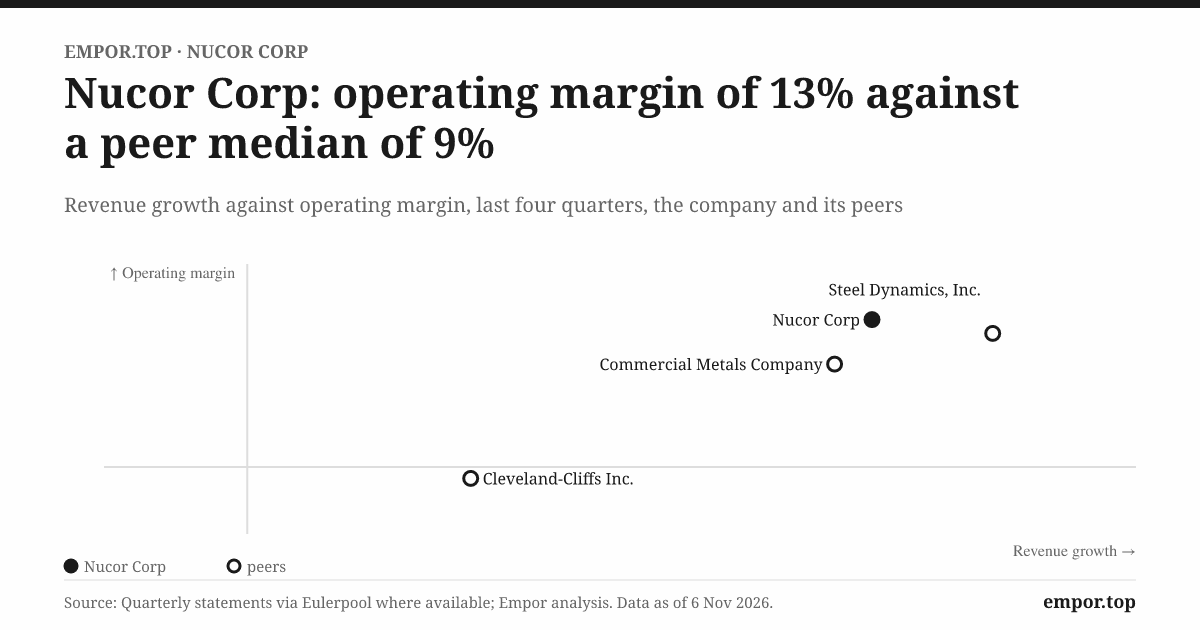
The credit picture deserves one cautionary note. When Fitch affirmed Nucor at A- in February 2025, it said a downgrade could follow if EBITDA leverage were sustained at or above 1.5 times or if the EBITDA margin fell below 14%.26 Nucor's own 2025 EBITDA of about $4.2 billion on $32.5 billion of sales works out to a margin of about 13%, and its reported debt divided by that EBITDA comes to roughly 1.7 times.234
Fitch calculates leverage its own way, and the agencies kept the ratings stable through July 2026.1 But on a simple reading of reported figures, 2025 was close to, or past, the edges Fitch had drawn. A single weak year is tolerable. Two or three, during a construction cycle, would test the rating.
Cash flow tells a similar story of strength that needs careful reading. Across 2023 to 2025, operating cash flow totalled about $14.3 billion, well above the roughly $8.3 billion of attributable earnings, thanks to depreciation and working-capital releases.4 But working capital moves against Nucor in upturns.
In the first half of 2026, receivables and inventories absorbed about $1.5 billion of cash, offset only partly by about $454 million from payables, because rising prices and volumes tie up money in steel and customer invoices.25 The second-quarter call reported free cash flow of about $829 million, which shows the business can fund itself in a good quarter; the bad quarters are when that buffer is needed.2
Then there are the buybacks. Nucor's stated framework is to return at least 40% of net earnings to shareholders each year, a commitment repeated at the 2022 investor day and again by Sullivan in July 2026.182 In the second quarter of 2026 it returned about $479 million, or about 41% of earnings, and about $733 million over the first half.21 In February 2026 the board authorised a new $4 billion repurchase program.24
An activist would look at the timing. In 2024, Nucor repurchased about 13.1 million shares at an average price of about $169, spending about $2.2 billion.224 In 2025, when earnings were lowest and the stock was cheaper, it repurchased about 5.4 million shares at an average of about $129, spending $700 million.23 In the second quarter of 2026 it bought about 1.5 million shares at an average of about $229.1
A formula tied to earnings naturally spends more when profits are high, which is usually when steel shares are expensive, and less when they are depressed. That is the opposite of buying low. It is defensible on prudence grounds, since cash is scarcer in downturns and West Virginia had to be funded. It is not, on this record, evidence of opportunistic capital allocation. The $4 billion authorisation is permission to buy, not a commitment, and how much of it is used at what price will say more than the headline.
Put the pieces together and the picture is a company that can fund its construction program, its dividend and a reasonable buyback from internal cash, without straining its balance sheet, as long as steel markets cooperate. The execution question is narrower and harder. Can West Virginia reach steady production, and can Brandenburg and the rest move from impressive first shipments to returns above their cost, while the company keeps costs, safety and margins in line? To judge that, an investor needs to understand exactly where Nucor's margin is made.
VIII. The Margin Is Made Between Steel and Scrap
Follow a single ton. It begins as a crushed car body, a demolished warehouse frame or the offcuts from a stamping plant, collected by a dealer, sorted and shredded in a DJJ yard, then loaded onto a railcar.174 At the mill it goes into the electric arc furnace with a share of DRI or imported pig iron to dilute the impurities. Roughly 1.1 tons of this metallic charge make one ton of new steel.4
The furnace consumes enormous amounts of electricity; the reheating furnaces and DRI plants burn natural gas.4 The liquid steel is cast and rolled into coil, plate, bar or beams. Some of it is sold to an outside customer. Some of it travels to a Nucor joist plant, a rebar fabricator or a tube mill, where it becomes a product with a second margin layered on top.
Almost everything about Nucor's profit is a version of one subtraction. Nucor's annual report puts it plainly: the key driver of the mills' gross margin is the difference between the selling price of steel and the cost of scrap and scrap substitutes.4 Industry people call this the metal margin or the steel-to-scrap spread.
Electricity, gas, labour, alloys and the utilization of the plant sit around that central relationship, and the mix of higher-value products, such as galvanized automotive sheet or specialised plate, can widen it. When prices rise faster than scrap, the mills print money. When scrap stays firm while steel prices fall, the spread compresses and so do profits, which is exactly what happened in 2024.
The second quarter of 2026 shows the mechanism running in Nucor's favour. The mills' average external selling price was about $1,145 a ton, up about 10% on a year earlier, while the average cost of scrap and substitutes rose only about 5%, from about $403 to about $422 a gross ton.1 The mills ran at 91% of capacity and shipped more steel than ever.1
Steel-mill pretax earnings rose to about $1.56 billion from about $1.13 billion in the first quarter, which accounted for most of the company's improvement.1 That is the recurring engine. The $130 million procurement refund and the $61 million Helion gain sit on top of it, and neither should be annualised into recurring profit. Strip the refund out of the mills' result and the quarter is still very strong; it is just less spectacular.
Now set that quarter against 2025, which tells the other half of the story. In 2025 the steel products segment shipped more, as warehouse construction stabilised and data-centre demand grew, and still earned about $367 million less than in 2024.4 Higher shipments did not guarantee better spreads. Part of the reason lies in how downstream work is priced. Much of rebar fabrication is fixed-price, job-based work, where the price is fixed when the contract is signed.4
If the cost of the steel feeding those jobs rises after the price is set, the fabricator absorbs the difference. Nucor warns that weak demand makes it harder to pass higher raw-material costs through to customers.4 On the input side, it also carries multi-year raw-material purchase contracts, some with minimum annual purchase requirements, which secure supply but limit how quickly it can adjust when markets move.4 Timing, not just price, decides the downstream margin.
What Nucor does not control is the top line. Its customers are fragmented. The largest single customer represented only about 5% of 2025 sales and consistently paid within terms, and the company repeated that figure in July 2026.425 Nucor does not disclose a top-ten customer list, a receivables ageing table or a history of customer defaults, but its credit-loss allowance has drifted down for three years, to about $81 million at the end of 2025, and its receivables turn roughly every five weeks.4
Low concentration is good for credit risk. It also means no single customer is locked in. Buyers of rebar, beams and sheet can and do compare Nucor's price with those of Steel Dynamics, Cleveland-Cliffs, other domestic mills and importers every month.4
Trade policy has become a larger part of this calculation than at any time in the company's modern history. In 2025 the United States fully reinstated the Section 232 steel tariffs without exemptions and later raised the rate to 50% for most countries; Nucor says imports fell from about 22% of the U.S. finished-steel market in the first quarter of 2025 to about 14% in the fourth.4 By the second quarter of 2026, management said finished imports were down about 25% year on year, and backlogs were "at or near record" levels.2
That support is real, and Nucor openly lobbies to keep it; on the July call management said it was pushing for changes to the USMCA trade agreement, including a requirement that steel be melted and poured in North America.2 But protection granted by policy can be withdrawn by policy. Nucor's own risk disclosures say there is no assurance about when or if tariffs will be extended, modified or terminated.4 Some of today's spread belongs to Washington, not to the mill floor.
That leaves three numbers worth tracking, because together they capture almost everything that matters. The first is steel-mill segment earnings, which at about $1.56 billion in the second quarter of 2026 were rising sharply. The second is the realized spread between the mills' selling price and their scrap cost, which widened in the second quarter as prices rose about twice as fast as scrap.1
The third is utilization at the new mills, beginning with West Virginia, where the stated target is about half of capacity by the end of its first year.2 For the third quarter, management guided to higher mill earnings on better pricing with stable volumes, and to lower raw-materials earnings as scrap prices eased and iron-ore costs rose.12
Which brings the analysis to the question that every commodity producer eventually faces. If a buyer can get comparable steel from several suppliers, and the price is set in a market Nucor does not control, what exactly makes Nucor win the next order? That is the question of the moat.
IX. The Moat Has to Survive the Cycle
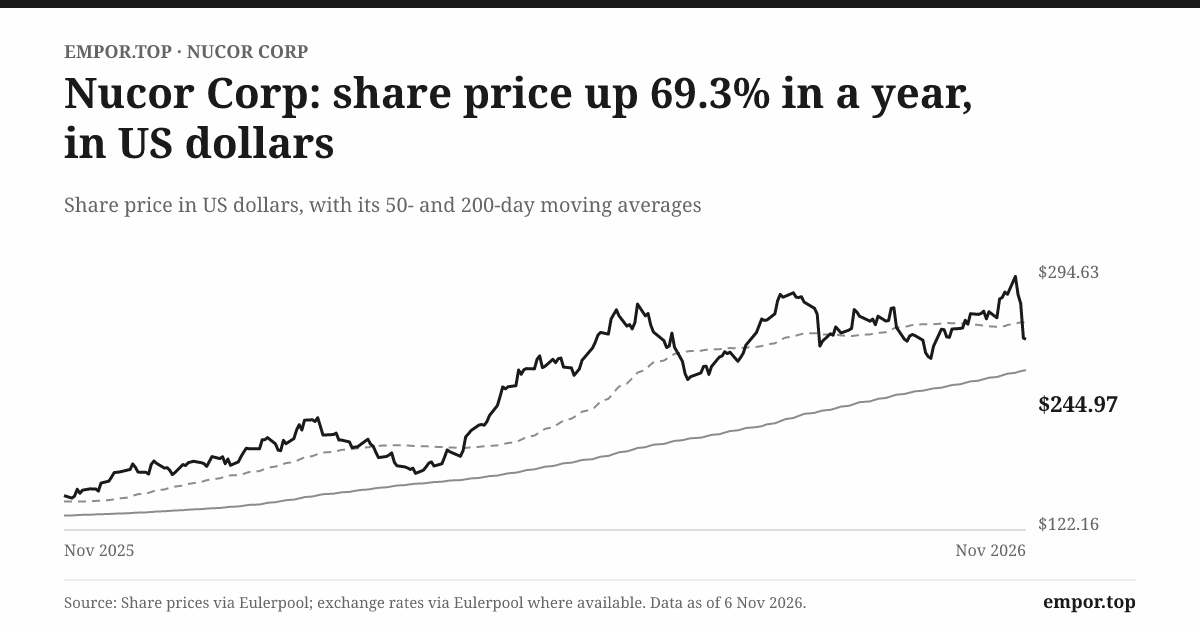
On the morning of October 26, 2026, hours before its third-quarter report, Nucor's shares traded at about 20.6 times earnings.27 Steel Dynamics, the company founded by Nucor alumni, traded at about 17.7 times.28 At first glance the market seems to be paying a premium for Nucor.
A glance at Nucor's own history shows why that first glance is unreliable. At the end of 2022, the year of record profits, the stock traded at about 4.5 times earnings. At the end of 2025, after earnings had fallen by more than three-quarters, it traded at about 21.5 times.27 The share price did not swing by a factor of five. The earnings did.
That is the trap in valuing any cyclical company on a single year's profit. At the peak, earnings are inflated and the multiple looks absurdly cheap. Near the trough, earnings are depressed and the multiple looks expensive. Between those extremes, Nucor's reported multiples ranged from about 4.6 times in 2021 to about 13.6 times in 2024.27 Today's 20.6 times sits on trailing earnings that include the weak second half of 2025 and the strong first half of 2026, so it is neither a peak nor a trough reading.
What the price appears to assume is that today's earnings are closer to the bottom of a new, higher range than to the top of an old one, which is to say that the market is already giving partial credit for the investment program. A consistent comparison with Steel Dynamics would need both companies measured on normalised, mid-cycle earnings, and on that basis the comparison is inconclusive.
Five forces, one commodity
Whether that credit is deserved depends on the moat, and the right way to test it is to run the industry through Michael Porter's five forces, then ask which of Hamilton Helmer's seven powers Nucor genuinely possesses.
Start with buyers. Nucor's customer base is fragmented, which limits the power of any single buyer.4 But collectively they hold considerable power, because steel of a given grade is substitutable. A contractor buying rebar or a fabricator buying beams can switch suppliers with a phone call, and most of Nucor's steel is sold on monthly spot terms.4 Rivalry is intense.
Nucor says its markets are highly competitive and that it competes "primarily on price and service."4 Its competitors include integrated producers such as Cleveland-Cliffs, other electric-arc producers led by Steel Dynamics, and imports. Global giants dwarf U.S. producers.12
The threat of substitutes is moderate: aluminium, concrete, composites and wood compete with steel in specific uses, and Nucor lists alternative materials among its competitive pressures.4 Supplier power is real. Scrap, pig iron, iron ore, electricity and natural gas are Nucor's largest costs, and most are priced in markets Nucor does not control, as its feedstock strategy reflects.4
The threat of new entrants is the most interesting force. A new mill costs billions, as West Virginia shows, so entry is not trivial. But electric-arc technology is not proprietary. Steel Dynamics proved that a team of experienced engineers with access to capital could build a world-class sheet mill within a few years of leaving Nucor.11 Barriers to entry in this industry are mostly financial, and capital is not a moat when markets are willing to fund steel.
Which powers survive the test?
Helmer's framework sharpens the picture. Of his seven powers, network effects, switching costs and brand are weak or absent in a business where buyers compare price per ton. Nucor has no meaningful patents on its core process; the Castrip strip-casting technology it pioneered never reached commercial viability, though it is licensed internationally.6 What remains are three candidates.
The first is scale economies, and here the claim is partly true. Nucor's size lets it run a national network of mills, shift tons between plants, as it plans to do during the West Virginia ramp, and spread purchasing and logistics costs across about 25 million tons of mill shipments a year.223 That is a real advantage over smaller mini-mills. It is not a decisive one over Steel Dynamics, which is also large and efficient.
The second is cornered resource, in the form of feedstock access. DJJ's scrap network, the two DRI plants and Nucor's closed-loop recycling programs with large customers give it more control over metallics than most rivals.4 This is probably the most durable structural edge Nucor owns. It is narrowed by the fact that competitors have pursued similar strategies, and by the costly DRI experience.9
The third is process power: the incentives, routines and know-how that grew out of Iverson's mill floor. Helmer defines process power as an advantage that is hard to copy because it lives in an organisation's routines. Nucor's culture fits that description, and the company has called it a "competitive advantage."14 The strongest counterevidence is the Steel Dynamics story: its founders carried some of that know-how with them.11 Process power that can walk away in the heads of three executives is real, but it is smaller than the legend suggests.
The verdict is that Nucor's moat is best understood as an operating system rather than pricing power. Flexible mills, feedstock access, product breadth from sheet and plate to joists and panels, and a downstream business that can sell "comprehensive, integrated solutions" are genuine sources of advantage.4 They help Nucor win orders on service and reliability and earn more than average through the cycle. They do not let Nucor set the price of steel. The KPI that would confirm a stronger moat is steel-mill margins that hold up better than peers' in the next downturn; the one that would falsify it is margins that fall in lockstep with everyone else's.
The case on both sides
The bull case is that the investment program has raised Nucor's normalised earnings. New sheet and plate capacity aimed at higher-value markets, a broader downstream offering, tariffs that have cut imports and a balance sheet strong enough to ride out a downturn all point to a company whose mid-cycle earnings are structurally higher than before.18 Data centres, infrastructure and energy projects are, by management's account, driving demand in several of its markets.4
The bear case is that the capex cycle, the start-up costs and price competition leave returns tied to the steel cycle. Steel Dynamics and others are also adding capacity. Tariff protection could fade. The downstream businesses have not yet shown that they cushion the mills. Management's 2025 forecast proved too optimistic, and the $6.7 billion target remains unproven. And 2025 returns remained modest for investors who had funded billions of new construction.14
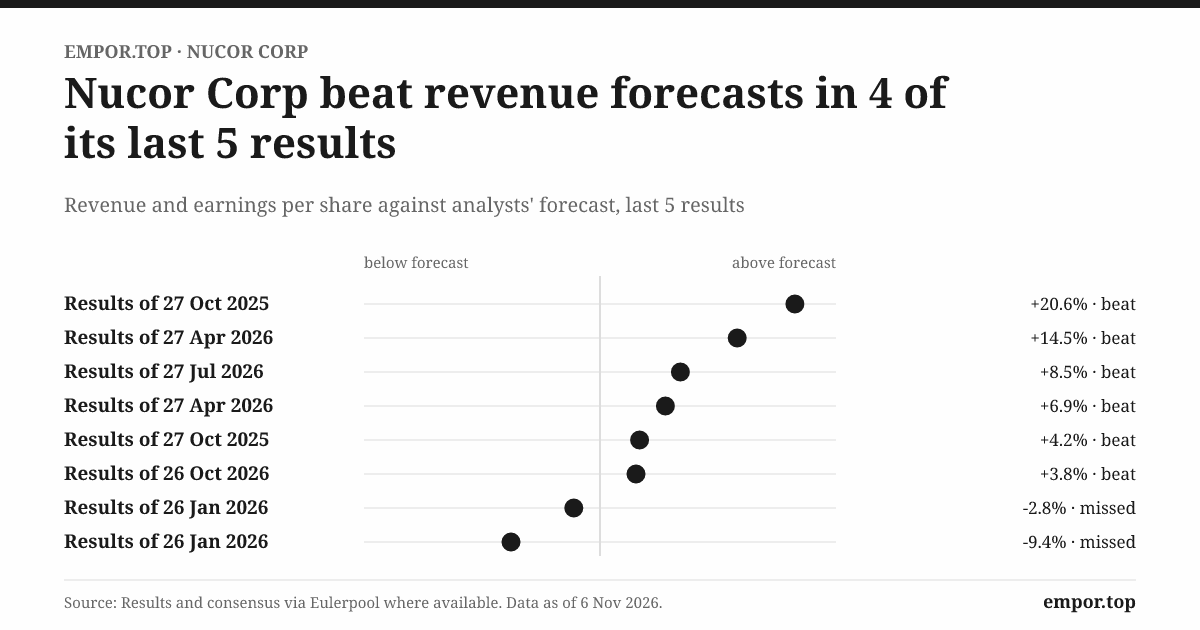
Within hours of this story's timestamp, the market will get its next data point. Nucor scheduled its third-quarter 2026 results for release after the close on October 26, with a conference call the following morning.29 Management had guided to higher consolidated earnings, higher mill pricing across all major product categories and better volumes and prices in steel products, offset by weaker raw materials.1
The result is not yet known. What the release and the call will reveal is whether that guidance held, whether the refund-free quarter still looks strong, and whether West Virginia's commissioning remains on schedule. Each of those answers will move the bull and bear cases a little. None will settle them, because the real test of a steel company is not a good quarter. It is the next bad year.
X. Business & Investing Lessons
From the $6 million Darlington bet in 1968 to about $8.9 billion in capital expenditures from 2023 through 2025, the scale changed by a factor of more than a thousand.54 The underlying wager did not: build a new way of making steel, then hope the market pays for it. Five lessons from that long arc belong to Nucor and to no other company.
The first lesson is to build the capability that solves the problem in front of you. Iverson's first mill answered Vulcraft's supplier problem.8 Because it was designed to serve a real customer, Vulcraft, it had a market before it had a reputation.
Founders tend to romanticise the grand vision. Nucor's story suggests the better bets often begin as a fix for something that is costing you money on Monday morning. The Nucor version of the lesson is short: the best moat Nucor ever dug started as a way around its supplier.
The second lesson is that a low-cost process is a starting point, not a moat by itself. Nucor's early furnace and thin-slab advantages spread; the Crawfordsville managers founded a rival, and other producers adopted the technology.1110
Nucor's edge now rests on its willingness to keep adapting around the technology. For investors, the warning is to be suspicious of any industrial company whose moat is a machine. Machines can be bought. In steel, the furnace is for sale; the habit of reinventing it is not.
The third lesson is to decentralise decisions, then measure the results. Iverson's system put decisions close to the work and linked pay to outcomes employees could see.7
Ferriola's production scoreboard at Crawfordsville captures the model.9 But the lesson has a second half that is easy to forget. Plant-level incentives earn their keep only when productivity, safety and margins show up in the numbers. At a 33,000-person company, culture has to be audited, not assumed. A bonus is only as good as the scoreboard it is paid against.
The fourth lesson is that expansion is not value creation until the new mill earns its cost. Start-up costs and West Virginia's ramp target describe effort, not reward.42 The lesson for anyone evaluating a capital-heavy growth story is to separate the moment a plant starts up from the moment it pays back, and to ask management for the second number, not the first. A new mill is a promise until it runs full.
The fifth lesson is to buy the missing link when you can explain the economics. DJJ fit the feedstock strategy, while the insulated metal panels deal relied on expected synergies.1719 The more a deal's justification relies on synergies, the more proof it owes.
Behind all five lessons sits the discipline that steel demands of anyone who tries to build a great company inside it. Nucor has spent half a century navigating the steel cycle, but no steelmaker can escape it. What it can do is choose how it meets it. The cycle gives you the test; the balance sheet gives you time to take it.
XI. Epilogue
Tonight, on the evening of October 26, 2026, Nucor sits at a hinge in its own history. For four years it has been a construction company that happened to make steel, pouring money into a sheet mill in West Virginia, a plate mill in Kentucky, a melt shop in Arizona, micro-mills, galvanizing lines and tower plants. Its chairman described the shift in his most recent letter to shareholders as moving "from building to operating."4 The cranes are leaving. The operators are taking over. The next eighteen months will show whether the expensive part is over or whether the hard part is just beginning.
The first moment that matters is the one closest at hand. The third-quarter release, due after the market closes today, and the call tomorrow morning will show whether management's guidance for higher earnings held without the help of a refund.291 A strong quarter would support the view that the second-quarter rebound was about spreads and volume rather than one-offs. A miss, especially in the steel products segment that disappointed in 2025, would revive the worry that downstream businesses still amplify rather than cushion the cycle.
The second moment is West Virginia's first year of commercial operation, which should begin with shipments ramping in early 2027.2 Management has set itself a modest, testable target: about half of capacity by the end of the first year, with steady, safe and consistent production through 2027.2 If the mill hits that target while start-up costs fall, it will be the strongest evidence yet that Nucor can still build a greenfield mill and make it work. If the ramp slips, or if the tons it produces come mostly by shifting volume from other Nucor mills rather than by winning new customers, the investment case narrows.
The third moment is the crossover in cash. Capital spending is expected to fall from about $3.4 billion in 2025 to about $2.5 billion in 2026, and management has said the next phase is about operating rather than building.4 That should free up cash for the dividend and the new $4 billion buyback authorisation.24 The test is whether operating cash flow comfortably covers capital spending and the shareholder-return commitment through a full year, including the working-capital drain that comes with rising steel prices.25 Watch, too, how much of the buyback is spent when the stock is cheap rather than dear.
The fourth moment is whether Nucor can substantiate its 2022 through-cycle EBITDA target.18 Only a full cycle, with West Virginia running, will show where the true midpoint lies. Management would earn credibility by updating that figure explicitly, project by project, rather than letting it fade.
The fifth is people. Topalian, Laxton and Sullivan now run the company in a new configuration.154 The next time a quarter disappoints, or a project runs over, or guidance has to be cut, investors will learn how this team explains bad news. That will say as much about the next decade as any capital plan.
The steel-to-scrap spread and utilization at the new mills will keep turning. Nucor has the balance sheet, the ratings and the operating history to wait out a downturn. What it has not yet shown is that its new assets will earn returns above their cost once the tariff tailwind, the refunds and the boom-year comparisons are stripped away. The story is unresolved, and the cycle, as always, will choose the moment it is tested.
XII. Outro
Go back one last time to Darlington, in the summer of 1969. A company that had nearly gone under four years earlier was watching molten steel break through its casting machine, its stock price falling toward pennies, its entire future pledged against one small mill built to stop a joist maker from being squeezed by its supplier.5 Nobody in the integrated steel industry had any reason to take it seriously.
Today that company buys the scrap, melts it, rolls it, bends it, welds it and sells it back to the people who build America's bridges, warehouses, data centres and warships. It is the largest steelmaker in the country, and still, at heart, a business that lives on a subtraction.124 Every day, trains of crushed cars and demolished buildings roll into its yards, and the furnaces turn yesterday's steel into tomorrow's product. What Nucor cannot change is the arithmetic on the other side of the furnace: what customers will pay for the ton that comes out, and what the next ton going in will cost.
That is what makes Nucor unlike any other American steelmaker. It was not born a giant that had to learn to be lean. It was born lean and had to learn to be a giant, and it has had to prove its founding bet again every time the cycle turns. The furnace in West Virginia is being commissioned. The proof starts over.
References
-
Nucor Reports Results for the Second Quarter of 2026 — Nucor, 2026-07-27 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Q2 2026 Earnings Call Transcript — Stock Analysis, 2026-07-28 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Nucor Reports Record Annual Earnings for 2022 — Nucor, 2023-01-26 ↩↩↩
-
2025 Annual Report and Form 10-K — Nucor, 2026-02-25 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Nucor Corporation Company History — Reference for Business ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Ken Iverson and Nucor Corporation — The Charlotte Museum of History ↩↩↩↩
-
Nucor Crawfordsville – and Thin Slab Casting – Turn 30 — AIST, 2019-08-13 ↩↩↩
-
Steel Dynamics Inc. Company History — Reference for Business ↩↩↩↩
-
World Steel in Figures 2026 — World Steel Association, 2026 ↩↩↩
-
Nucor Announces Promotion of Steve Laxton to President and Chief Operating Officer; Dave Sumoski to Retire — Nucor, 2025-12-04 ↩↩
-
Nucor Completes Acquisition of The David J. Joseph Company — Nucor, 2008-03-03 ↩↩↩↩↩
-
2022 Investor Day Transcript — Stock Analysis, 2022 ↩↩↩↩↩↩↩↩
-
Nucor to Acquire Insulated Metal Panels Business from Cornerstone Building Brands — Nucor, 2021-06-07 ↩↩↩
-
Nucor Reports Results for Fourth Quarter and Year Ended 2020 — Nucor, 2021-01-28 ↩
-
Nucor Reports Record Quarterly and Annual Earnings for the Fourth Quarter and Year Ended 2021 — Nucor, 2022-01-27 ↩
-
Nucor Reports Results for the Fourth Quarter and Full Year 2024, Form 8-K Exhibit 99.1 — Nucor, 2025-01-27 ↩↩↩
-
Nucor Reports Results for the Fourth Quarter of 2025 — Nucor, 2026-01-26 ↩↩↩↩↩↩
-
Nucor Reports Results for the First Quarter of 2026 — Nucor, 2026-04-27 ↩↩↩
-
Fitch Affirms Nucor's IDR at 'A-'; Outlook Stable, Rating Disclosure — Fitch Ratings, 2025-02-28 ↩
-
Nucor Financial Ratios — Stock Analysis, accessed 2026-10-26 ↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube