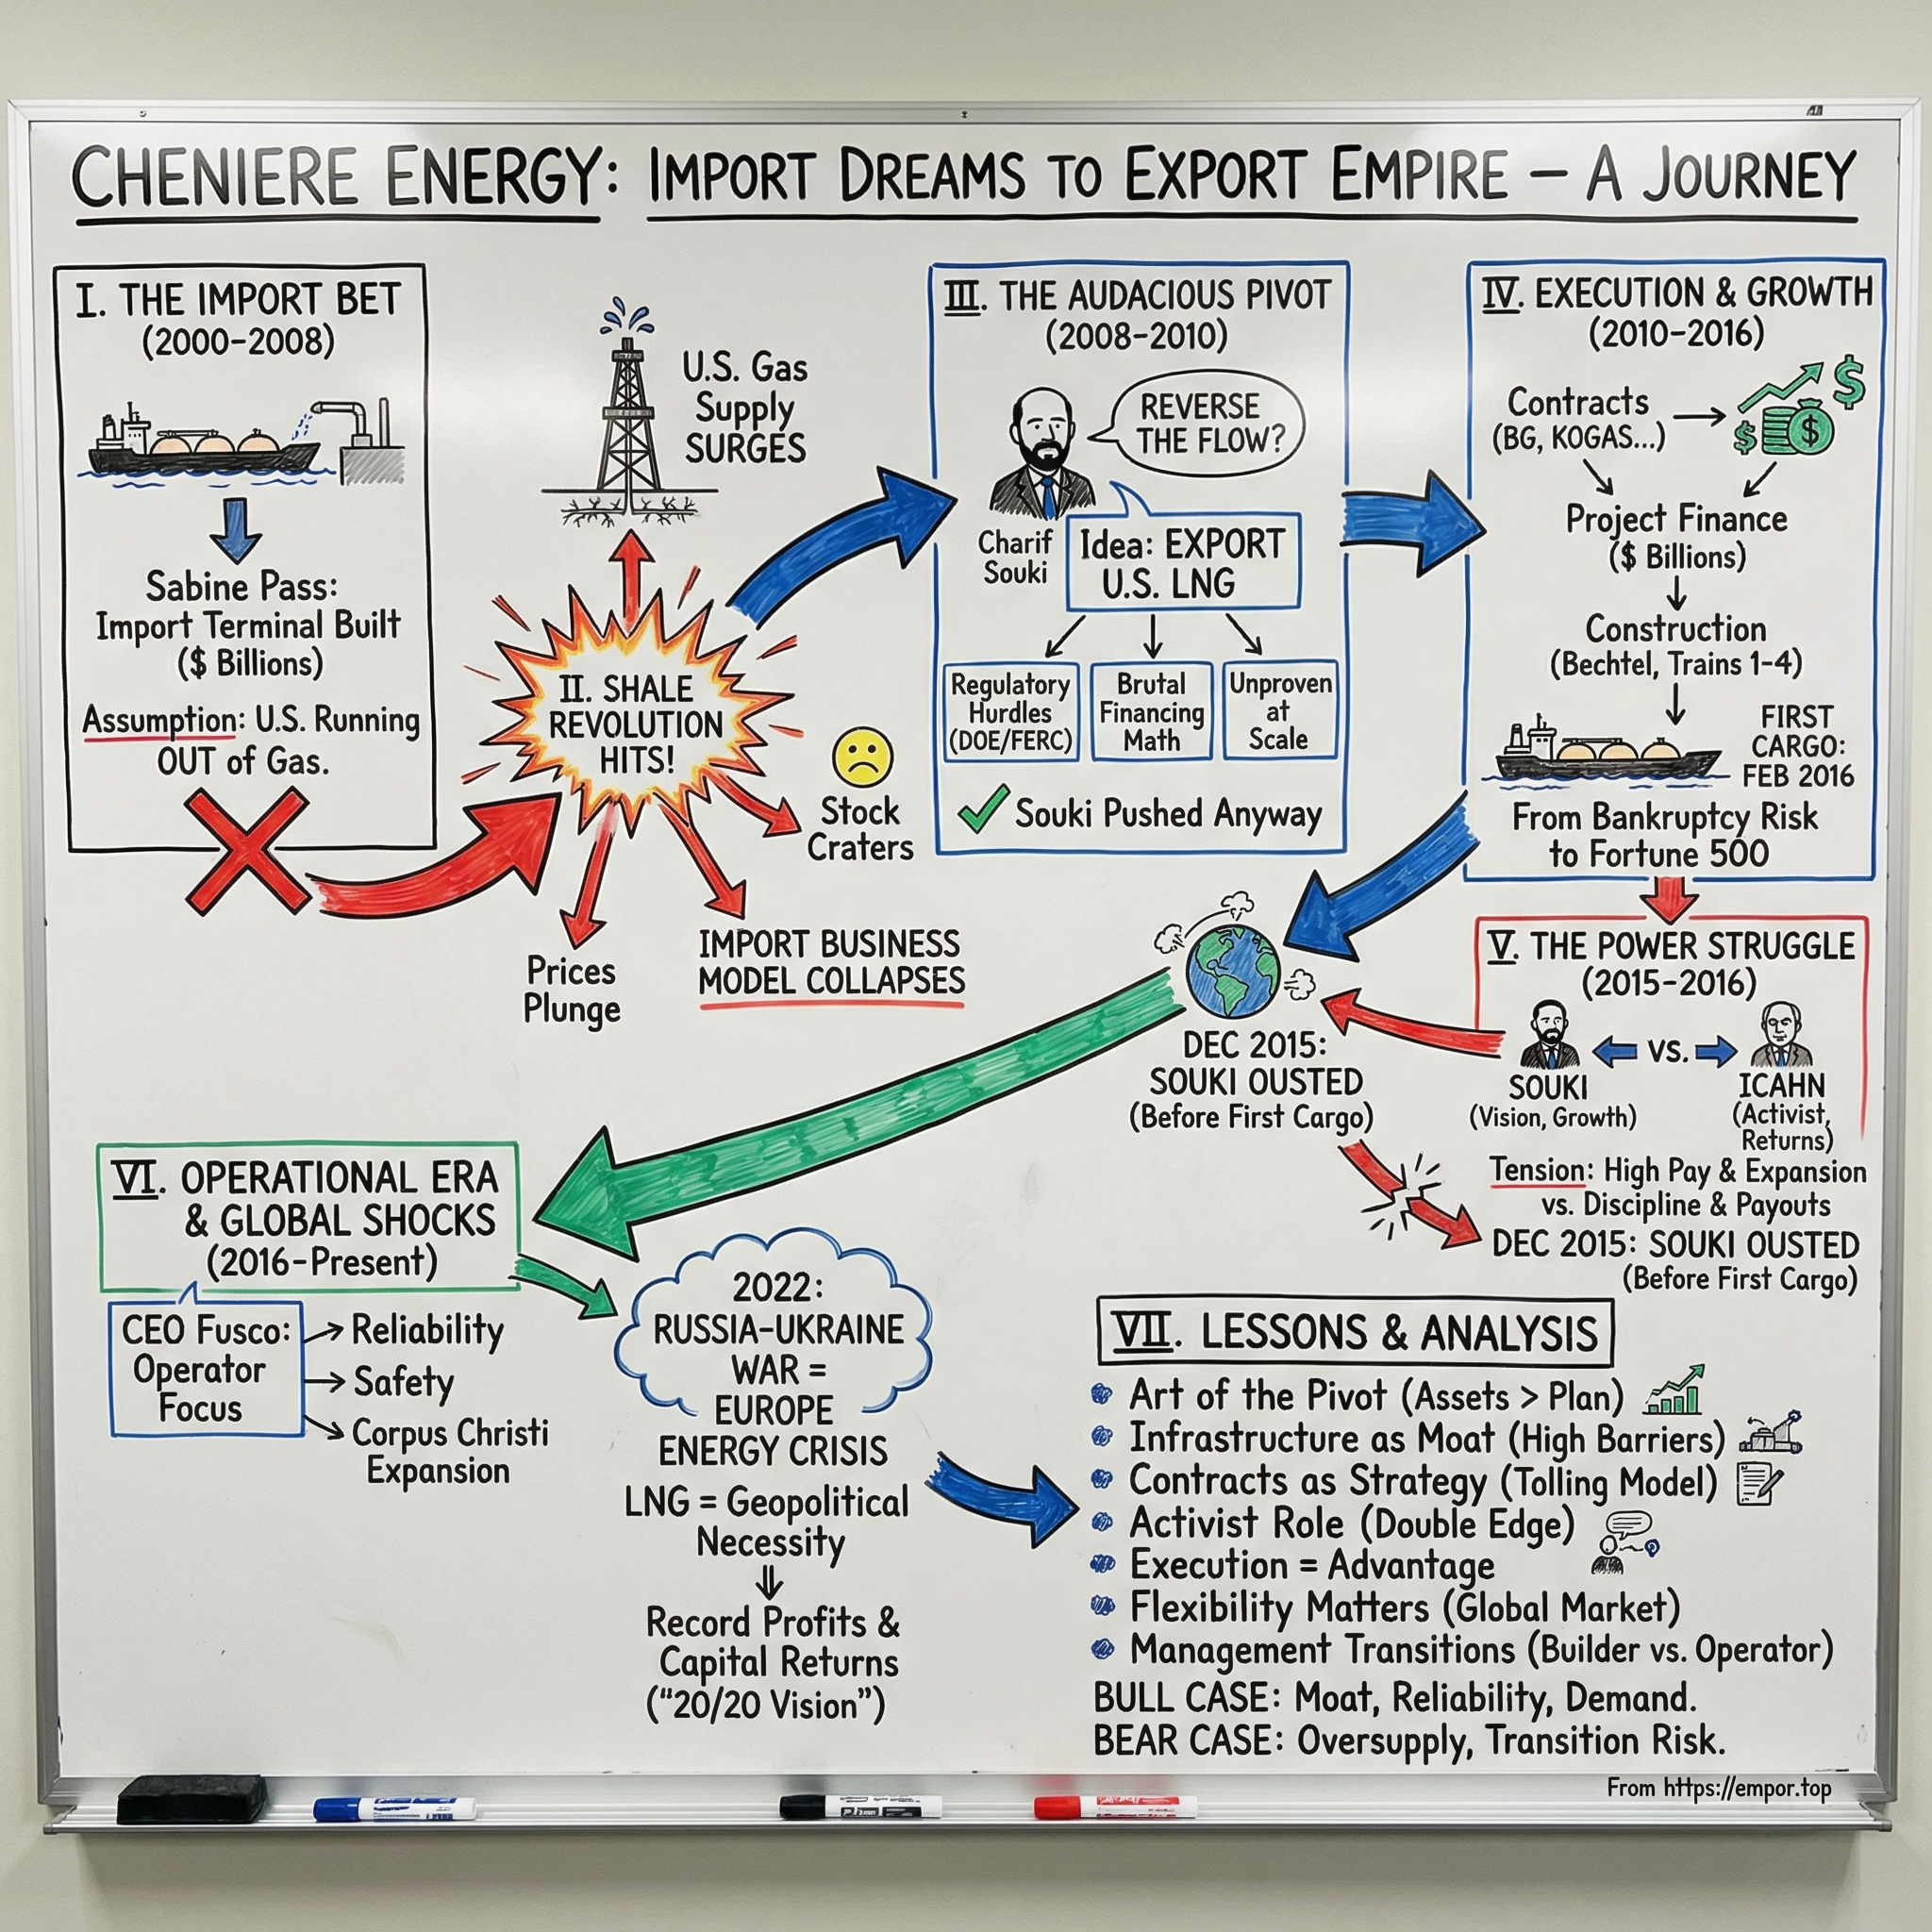
Cheniere Energy: The Tollbooth on the Gulf
I. Introduction & The Central Questions
Picture the marsh at the mouth of the Sabine River, where Louisiana meets Texas. It is flat, wet, full of mosquitoes, and in 2008 it held one of the most expensive mistakes in American energy. Cheniere Energy had just finished a giant terminal there. Its job was to take in tankers of super-chilled liquid gas from Trinidad, Qatar and Nigeria, warm the liquid back into gas, and send it into U.S. pipelines. The company had bet everything on one belief: that America was running out of natural gas.
The belief was wrong, and the timing could hardly have been worse. In the same years the cement was curing, drillers in Texas, Louisiana and Pennsylvania worked out how to crack open shale rock with horizontal wells and hydraulic fracturing. Gas went from scarce to abundant almost overnight. A terminal built to import gas into the best-supplied gas market on earth had no customers to serve, and Cheniere's shares fell to the low single digits, weighed down by debt raised to build it.1
Nearly two decades later, the same piece of coast runs the other way. Cheniere now has nine large liquefaction "trains" at Sabine Pass and Corpus Christi, plus a newer string of smaller trains at Corpus Christi. A train is a production line that cools gas until it turns to liquid. Together they make Cheniere the largest exporter of liquefied natural gas (LNG) in the United States and the second largest in the world.2 Revenue went from about $270 million in 2015 to a peak above $33 billion in 2022.2
The way Cheniere makes money explains most of the story. It is not a driller and it does not, in the main, bet on gas prices. It acts more like a refrigerated toll road. Long-term customers pay a fixed fee of roughly $2.50 to $3.50 for each million British thermal units (MMBtu) of capacity they reserve. They owe that fee whether or not they collect a cargo. On top, they pay 115% of the U.S. Henry Hub gas price, which covers the gas Cheniere buys plus the gas it burns to run the plant.2 The fixed fee is the profit. The Henry Hub part mostly passes straight through.
That model makes Cheniere look like a bond with a refinery attached. Three questions decide whether the comparison holds up.
The first is about the toll. Qatar and a crowd of new Gulf Coast projects are adding a large wave of liquefaction capacity through 2030. Can Cheniere keep signing new 20-year deals at fees like the old ones, or will a glut force fees down when today's contracts start to expire?
The second is about the plumbing between the projects and the shareholder. About $20 billion of Cheniere's roughly $23 billion of debt sits at operating subsidiaries rather than at the parent.2 Close to half of the partnership that owns Sabine Pass belongs to outside unitholders.2 Cash has to climb a ladder of loan covenants and minority claims before it reaches a Cheniere shareholder. How much of it arrives?
The third is about the gas itself. U.S. demand for gas is rising from data centers, electrification and new factories. If that raises Henry Hub prices or fills the pipelines into the Gulf Coast, the contract customers pay more, but Cheniere's merchant and supply-linked businesses could be squeezed.
The route to those questions runs through a restaurant owner who became a wildcatter, a turnaround that turned the terminal around, an activist who fired the founder, an engineer-CEO who turned construction into a routine, and a war that briefly made the company one of the most valuable sources of energy in Europe. It begins with the mistake.
 Subscribe on LinkedIn
II. All American Burger to Sabine Pass: The Wrong-Way Bet (1996–2008)
Charif Souki did not look like an energy baron. He was born in Egypt, raised in Lebanon, studied at Colgate and Columbia, and worked as an investment banker before going into restaurants. He ran the All American Burger chain in Los Angeles and part-owned Mezzaluna, the Italian restaurant chain whose Brentwood branch became famous in the O.J. Simpson case. He had a salesman's ease and a banker's appetite for leverage. In 1996 he took over a small listed company and named it Cheniere, after the Cajun word for the oak ridges that rise above the Louisiana marsh.1
For several years Cheniere was a minor exploration company working seismic data in the shallow waters of the Gulf. Souki's real idea came at the start of the 2000s. Conventional U.S. gas fields were in decline, and official forecasters expected America to import more and more. In 2003 Federal Reserve Chairman Alan Greenspan warned Congress that tight gas supplies were driving up prices and that the country would need large-scale LNG imports. Henry Hub prices spiked above $13 per MMBtu after the 2005 hurricanes. The consensus could not have been clearer: the U.S. would import gas from the Middle East and West Africa for decades.
Souki moved faster than anyone. Cheniere secured land along the Sabine-Neches Waterway, a deep ship channel with straight access to the Gulf, and won federal approval to build a regasification terminal there. The site had storage tanks, docks deep enough for the largest LNG tankers, and room to connect to the interstate pipeline grid. Cheniere also planned a second terminal at Corpus Christi and a third at Creole Trail, plus pipelines to carry the gas away.3
Building it all took borrowing on a large scale. Cheniere raised money at the parent, at the terminal, and at a new partnership, Cheniere Energy Partners, that it listed in 2007 to own Sabine Pass. Capacity at Sabine Pass was signed up by Total and Chevron for use fees, which gave the terminal some contracted income. But the rest of the empire was a bet on importing, and the parent carried the cost.
Then came the shale revolution. George Mitchell's company had spent the 1990s experimenting with ways to get gas out of the Barnett Shale in Texas. By the mid-2000s, horizontal drilling combined with multi-stage hydraulic fracturing worked at scale, and the methods spread to Louisiana's Haynesville and Pennsylvania's Marcellus. U.S. production turned up sharply. Prices that had been above $13 fell toward $4, and later lower.
Sabine Pass received its first import cargo in April 2008.3 It was a cutting-edge plant built for a world that had already ended. Few cargoes arrived, because foreign gas was worth more in Europe and Asia than in a newly over-supplied America. The financial crisis struck in the autumn. Cheniere's shares fell to around a dollar and a half.4 It cancelled or shelved the Creole Trail and Corpus Christi import plans, and the market began to treat it as a likely bankruptcy.
What saved Cheniere was not its thesis. The thesis was dead. What saved it was what the thesis had left behind: a permitted site on deep water, a dock that took the world's largest tankers, LNG storage tanks, and pipeline connections into one of the densest gas networks on earth. Those are hard to replace in the United States. They take years of approvals and great amounts of capital, and few coastal sites have the right depth, land and pipeline access.
The useful lesson is narrower than "Cheniere got lucky." The import terminal destroyed value. It never earned its cost as an import terminal. But a few of its parts—marine access, land, tanks and permits—were assets whose value did not depend on which way the gas flowed. An investor looking at the 2008 wreckage needed to tell those parts apart from the dead business. Souki was about to do exactly that.
III. The $280 Billion Turnaround: Inventing the U.S. Export Model (2009–2015)
Imagine the gap Souki saw around 2009 and 2010. In Louisiana, gas sold for less than $4 per MMBtu and drillers were swimming in it. In Tokyo and Seoul, utilities paid prices linked to oil, often well above $10 and later close to $16 after the Fukushima disaster pushed Japan onto gas. In Europe, prices were somewhere between. The same molecule of methane was worth three or four times as much on the far side of an ocean.
The obvious move was to run Sabine Pass backward: chill U.S. shale gas into liquid and ship it out. The difficulty was that no one had exported LNG from the lower 48 states at scale, there was no contract model for it, and Cheniere had no money to build the plant. A liquefaction train costs far more than a regasification terminal, because chilling gas to minus 162°C needs huge compressors, heat exchangers and refrigerant loops.
Cheniere first had to win permission. Exports to countries with a U.S. free-trade agreement are approved almost automatically, but most of the big buyers—Japan, most of Europe, India, China—have no such agreement. Exports to them require the Department of Energy to find that they are in the public interest. Sabine Pass Liquefaction won the first such long-term authorization for the lower 48 in 2011, and in April 2012 the Federal Energy Regulatory Commission approved the construction of the export plant.5 Being first mattered. The approval process later became much slower and more political, and the head start became part of what made Cheniere hard to catch.
The bigger innovation was the contract. Traditional LNG deals tied the price to oil and often limited where the buyer could send the cargo. Cheniere offered something else. The buyer would pay a fixed fee per MMBtu of reserved capacity, plus 115% of Henry Hub for the gas. The buyer would take the cargo at the Sabine Pass dock and could send it anywhere in the world. And the fixed fee was due whether the buyer lifted the cargo or not.2
This design moved almost every price risk off Cheniere. If U.S. gas got expensive, the buyer paid more. If the cargo was worth less in Asia than in America, the buyer could leave it, but still owed the fee. Cheniere kept only the risk of building and running the plant. For a utility in Korea or Spain, the attraction was a supply priced off a deep, transparent U.S. market rather than oil, with the freedom to re-sell it. For lenders, it was something they could understand: a 20-year stream of fixed payments from strong customers.
The first buyers lined up between 2011 and 2013. BG Group (later bought by Shell) signed first, followed by Gas Natural Fenosa (now Naturgy), Korea Gas Corporation (한국가스공사 KOGAS), India's GAIL, Total and Centrica, with each deal sized to support one or more trains.3 Meg Gentle, who led the commercial work and later became president of the marketing unit, became the face of the pitch to foreign utilities.
With signed contracts in hand, Cheniere could raise money. Banks lent against the contracted fees at the project level, and equity came in at the partnership. In 2012 Blackstone agreed to invest about $2 billion in Cheniere Energy Partners to help fund the first trains, one of the largest private equity bets on U.S. energy infrastructure at the time.3 Bechtel signed on as the builder.
Fast-forward to the end of 2024 and the scale of what this contract design produced is clear. Cheniere's signed contracts were worth an estimated $280 billion in future revenue. Of that, about $105 billion was fixed fees that customers cannot cancel; the remaining $175 billion or so was the Henry Hub pass-through, which depends on future gas prices and is mostly cost.2 The fixed portion is the number that matters for value. It is a little like a building owner with leases signed for 15 to 20 years: the rent is promised, while the electricity bill simply flows through.
The customer list explains why lenders were comfortable. No single customer made up 10% of consolidated revenue in 2022, 2023 or 2024, and buyers without investment-grade credit have to post letters of credit or parent guarantees.2 Revenue in 2024 was spread across buyers in the United States, Singapore, Ireland, Britain, Korea, Spain, India and others.2 Many of those country labels reflect trading arms of global energy firms rather than end users, but the spread is real.
The skeptical reading is that Cheniere's contract was less an invention than a clever use of a passing price gap. That gap did not last; by 2015 oil had collapsed and Asian LNG prices fell close to U.S. levels plus shipping. Had Cheniere waited three years, it might have found no takers. The contracts were signed in a narrow window, and the company's later success rests partly on that timing.
Still, the structure outlived the window, and that is the stronger claim. Every major U.S. export project since has copied some form of it, which says that the design solved a real problem for buyers and lenders, not just a price gap. What the structure did not solve was who would run the company once the money arrived. That question was about to be answered in a boardroom.
IV. The Boardroom Coup: Carl Icahn vs. Charif Souki (2015–2016)
On Sunday, December 13, 2015, Cheniere's board met and removed Charif Souki as chairman and chief executive.6 He had led the company for 19 years and taken it from a near-bankrupt import terminal to the edge of America's first big LNG exports. The first export cargo was weeks away. On paper, he had won. In the boardroom, he had lost.
The trouble had been building for two years. In 2013 Souki received pay valued at about $142 million, largely in stock, which made him one of the best-paid chief executives in America at a company that had not yet produced a dollar of export revenue.6 Shareholders rejected a plan to expand the stock pool that funded such awards, and the company had to rework it. The pay itself mattered less than what it signaled: a board that would let the founder set the terms.
Souki's ambitions also kept growing. He wanted Corpus Christi, which was sensible. But he also explored building a larger merchant trading business, buying ships, adding projects without signed buyers, and even investing in gas reserves upstream. Each would have made Cheniere less like a toll road and more like an integrated energy company carrying commodity risk. With the oil price crash of 2014–2015 hurting gas prices around the world, investors grew nervous that a company with about $20 billion of project debt and no export income was about to take on more risk.6
Carl Icahn saw the gap between the asset and the management. He began buying in 2015 and built a stake of about 13.8%.4 He won two board seats in August 2015. Icahn's view was that Sabine Pass and Corpus Christi, once built, would be very valuable cash streams, and that the main danger to shareholders was the cost of further empire-building. According to the Wall Street Journal's account, Souki and the board disagreed over strategy, including how to fund growth, and the board voted him out.6
Neil McCuin? No interim names are needed; the key appointment came in May 2016, when the board named Jack Fusco chief executive.3 Fusco was a power-plant man. He had run Calpine, the largest U.S. operator of gas-fired power plants, taking it out of bankruptcy and through a long period of cost control. Before that he had worked at Goldman Sachs and in power trading. He was not a deal-maker in Souki's mold. He was the operator who checked the run times.
Fusco's first moves set the tone. He cut back side projects, reduced overhead, and focused the company on finishing trains on time and on budget and on filling them with contracts before committing to more. Growth would only proceed with long-term buyers already signed. He also began to talk about debt reduction long before most investors expected a newly producing company to talk about anything except growth.
Was Icahn right? The record is mostly on his side. Under Fusco, Cheniere went from construction to nine working large trains and a growing set of midscale trains, while the debt load fell and buybacks began.2 Icahn sold his stake between 2020 and 2022, at prices far above his purchase cost; Bloomberg reported the bet as one of his most profitable.4 Governance has also become more ordinary: nine of ten directors are independent, and shareholders have backed executive pay by roughly 95% in recent years.78
The fair caveat is that Souki's gamble made the company Icahn wanted to own. Without a founder willing to sign contracts no one had seen and borrow against plants that did not yet exist, there would have been nothing for an operator to run. The 2015 coup was less a verdict on who was the better executive than on which kind of executive the company needed next. And the next phase called for a builder.
V. Bechtel, Cryogenics, and the Manufacturing Machine (2016–2021)
On February 24, 2016, the tanker Asia Vision pulled away from Sabine Pass carrying the first cargo of LNG exported from the lower 48 states.3 It was bound for Brazil. For an industry that had spent a decade expecting America to import gas, it was a strange sight: a ship riding low in the water, loaded with Louisiana gas, heading out into the Gulf.
To see why the next five years mattered, it helps to understand what an LNG train does. Natural gas from the pipeline is cleaned: water, carbon dioxide, sulfur, mercury and heavier hydrocarbons are removed, because they would freeze or corrode the equipment. Then the gas is chilled in stages through a series of refrigeration loops until it becomes a liquid at about minus 162°C. The liquid takes up roughly one six-hundredth of the space of the gas, which is what makes it worth shipping. It is, in effect, an enormous industrial freezer the size of several football fields, fed by pipelines and emptied into ships.
Cheniere used the same basic design over and over: ConocoPhillips' Optimized Cascade process, built by Bechtel. The trains at Sabine Pass and Corpus Christi are close copies. That sounds dull, but in the LNG business it was unusual. In Australia in the same decade, projects such as Chevron's Gorgon and Shell's floating Prelude ran far over budget and behind schedule, partly because each was a one-off design in a remote place with costly labor. Cheniere's projects were on a well-served coast, near a deep pool of skilled workers, using a repeated design with one builder.
The contracts with Bechtel were mostly lump-sum turnkey. Bechtel agreed to deliver a working train for a fixed price, carrying most of the risk of cost overruns. Cheniere paid more up front for that certainty, but it protected the equity from the overruns that sank others. The most recent example is the Corpus Christi Stage 3 expansion, seven smaller "midscale" trains with a contract price of about $6 billion including change orders.2
The trains came online one after another. Sabine Pass grew to six trains, about 30 million tonnes a year. Corpus Christi, built from scratch, added three trains of about 15 million tonnes a year.2 Most came in on or ahead of schedule. Revenue followed: from $2.8 billion in 2016 to about $8 billion in 2018 and $9.3 billion by 2020.2
The real test came in 2020. When COVID-19 shut down much of the world economy, demand for gas collapsed and prices in Europe and Asia fell below what it cost to ship U.S. LNG. Buyers had the right not to lift cargoes, and they used it: over the spring and summer of 2020, they cancelled well over a hundred cargoes. Analysts asked whether the contract model would crack.
It did not. Buyers who cancelled still paid the fixed fee. Cheniere did not need to buy the gas or run the trains at full rate, so its costs fell along with the volumes. The fixed fees—the profit—kept coming. Cheniere still reported a small net loss of about $85 million in 2020, but most of that was accounting for long-term contracts rather than lost cash, and its operating cash flow held up.2 The bond-like claim had been tested against a real shock and passed.
There is a fair caveat. COVID was short; buyers knew prices would recover and had every reason to stay in good standing. A long glut, in which a buyer pays fixed fees for years on cargoes it cannot sell at a profit, would be a harder test. The contracts are legally firm; the question is whether a large buyer under real financial stress would pay, renegotiate or fight. Cheniere has not faced that, and none of its buyers has defaulted.2 So the 2020 evidence supports the claim that the contracts hold in a sharp, short shock, and leaves a long glut untested.
By 2021 Cheniere had something rare: a set of projects that had performed the way the spreadsheets said they would. That brought a new problem. The money now flowed, and it flowed through a complex web of subsidiaries.
VI. The Fortress and the Plumbing: Capital Structure & Structural Subordination
Zach Davis became Cheniere's chief financial officer in February 2020, just before the pandemic.2 The finance job at Cheniere is less about raising money now and more about moving it. Cash is made at the dock and the train. It has to travel up through several layers of companies, each with its own lenders and its own rules, before it reaches the parent and its shareholders.
Here is the ladder. At the bottom, Sabine Pass Liquefaction owns the six Sabine Pass trains and has its own secured bonds. Above it is Cheniere Energy Partners, the listed partnership. Cheniere, Inc. owns the general partner and about 48.6% of the partnership's units; outside investors, including affiliates of Blackstone and Brookfield and the public, own about 49.4%.2 Corpus Christi is different: its trains sit in Cheniere Corpus Christi Holdings, which Cheniere owns outright. So does Cheniere Marketing, the trading arm.
The debt follows the ladder. At the end of 2024 Cheniere had about $23 billion of debt. Roughly $8.4 billion was secured at Sabine Pass Liquefaction, $6.8 billion at the partnership, and $4.9 billion at Corpus Christi Holdings. Only about $3 billion was owed by the parent.2 Lenders closest to the plants are paid first. The parent's bondholders and its shareholders sit behind them and depend on cash moving up through distributions.
This is what rating agencies mean by "structural subordination." Each project loan includes conditions on paying cash upward, typically a debt-service coverage test: the project must earn comfortably more than it owes in interest and principal before it can pay distributions. If a train breaks down or a hurricane closes the port, cash can be held below until the tests are met. Fitch, S&P and Moody's all point to this as a constraint, even as they rate the group investment grade: S&P at BBB+, Moody's at Baa2 and Fitch at BBB.91011
The minority leak is the second issue. Because outsiders own about half of the partnership, they get about half of what it pays out. In 2024 that came to about $846 million in distributions, after about $1 billion in 2023 and $947 million in 2022.2 In accounting terms it shows up as income attributable to non-controlling interests: in 2024, $1.24 billion of Cheniere's consolidated net income belonged to others.2 An investor who looks at consolidated cash flow without subtracting it will overstate what Cheniere shareholders own.
Is that leak a hidden flaw? Mostly it is a cost that was paid long ago. Blackstone's money funded the first Sabine Pass trains when Cheniere could not have funded them alone. The outside unitholders own their share of the economics because they put up capital when it was most needed. The useful takeaway for the Cheniere shareholder is simple: Sabine Pass is only about half theirs, while Corpus Christi—including the new Stage 3 trains—is wholly theirs. Growth at Corpus Christi is therefore worth more per tonne to the parent than growth at Sabine Pass.
Cheniere has worked to simplify the ladder. It bought out the public holders of a separate holding company, Cheniere Energy Partners LP Holdings, in 2018, removing a layer. And it has paid down a great deal of debt. Management has said it retired more than $12 billion of consolidated debt in the years following 2020, part of reaching investment grade across the structure.12 The 2024 debt total, about $23 billion, compares with about $24 billion a year earlier; maturities are spread out, with no year before 2030 carrying more than about $3 billion.2 None of the main credit lines was drawn at year-end 2024.2
Cash on hand tells the same story with one caveat. At year-end 2024 Cheniere held about $2.6 billion of unrestricted cash and about $0.55 billion of restricted cash locked under project agreements for debt service and reserves.2 The restricted part cannot be used for buybacks. The unrestricted part is real, but some of it also sits at subsidiaries.
In September 2022 management set out a plan it called "20/20 Vision": roughly $20 billion of capital to deploy through 2026 across debt paydown, buybacks, dividends and growth, alongside a goal of more than 20 million tonnes a year of brownfield expansion.13 Buybacks have since been large. Cheniere bought back about $1.4 billion of stock in 2022, $1.5 billion in 2023 and $2.25 billion in 2024, and the diluted share count fell from about 253 million to about 229 million over those three years.2 In June 2024 the board added $4 billion to the buyback authorization, leaving roughly $3.9 billion available through 2027.2 A dividend that began in 2021 at $1.32 a year reached $2.00 by late 2024.2
The structural subordination question therefore has a calibrated answer. The ladder is real and it has teeth: covenants can trap cash, and half of Sabine Pass belongs to someone else. But it has not prevented large returns to the parent's shareholders, because Corpus Christi is wholly owned and the projects have generated more cash than they need. The question would bite only in a period of serious operating trouble, which Cheniere has not had. The figure to watch is how much free cash flow comes from wholly owned Corpus Christi versus Sabine Pass as Stage 3 ramps up, since that share decides how much of the group's cash is truly the shareholder's. In 2022, an unexpected war tested the system from the opposite direction: too much money, not too little.
VII. The Geopolitical Crucible: Ukraine, Europe, and the $33 Billion Apex (2022–2024)
When Russian troops crossed into Ukraine in February 2022, Europe got roughly 40% of its gas from Russia, much of it by pipeline. Over the months that followed, Gazprom cut flows, first on some routes and then on Nord Stream, which was later damaged by explosions in September. Europe had to replace around 140 billion cubic meters a year of pipeline gas, about as much as Germany burns in a year, mostly with LNG brought in by ship. Prices at the Dutch TTF hub, the European benchmark, at one point passed the equivalent of $90 per MMBtu in August 2022. Normal levels before the crisis had been well under $10.
Cheniere did not set those prices, and most of its output was locked into contracts at the old formula. But it did have some flexible volume. A small share of production—typically around 5% to 10%—was not sold under long-term deals and was available to Cheniere Marketing to sell on short-term terms. Trains also often ran above their rated output, producing extra cargoes. In 2022 those flexible cargoes sold into Europe at prices many times what the long-term buyers paid. In addition, many long-term buyers sent their own cargoes to Europe, making the U.S. the biggest supplier of LNG to the continent.
The results were extraordinary. Revenue hit about $33.4 billion in 2022, up from under $16 billion the year before, and cash from operations reached about $10.5 billion.2 Then prices eased and revenue fell to about $20.4 billion in 2023 and $15.7 billion in 2024.2 Most of that swing came from the pass-through and marketing parts; the fixed fees moved far less. That is the point of the toll model: the windfall came on top, and its loss did not hit the core.
The accounting during these years confused many readers. Under U.S. rules for derivatives, Cheniere must mark certain long-term contracts to market every quarter—chiefly some long-term gas purchase deals whose price is linked to international gas prices. When global prices spike, those contracts look like large losses on paper, even though no cash changes hands. When prices fall, the losses reverse into gains.
Here is how it played out. In 2022, consolidated net income was about $2.6 billion, held down by about $6.5 billion of paper losses on derivatives, while cash from operations was about $10.5 billion. In 2023 the reverse happened: net income jumped to about $12.1 billion, flattered by about $7.9 billion of paper gains, while operating cash flow was about $8.4 billion. In 2024 the two converged: net income of about $4.5 billion against operating cash flow of about $5.4 billion.2 Across the three years, cash from operations of about $24.3 billion exceeded net income of about $19.2 billion.2 In plain English, the reported profits in this period were noise; the cash was the signal.
What did Cheniere do with the windfall? Some went into the balance sheet, paying down debt and helping secure the credit upgrades. Some went to buybacks and dividends. And a large part paid for Corpus Christi Stage 3: about $2.1 billion of capital spending in 2023 and $2.2 billion in 2024.2 Stage 3 used seven smaller, factory-built trains, each designed for about 1.5 million tonnes a year, adding a little over 10 million tonnes in all. Bechtel produced the first LNG from Stage 3 at the end of December 2024, ahead of schedule.14 Cheniere funded the expansion without issuing new shares, a meaningful result for a company whose founder era was built on dilution.
The tempting story is that 2022 permanently tied Europe to U.S. Gulf Coast gas. Part of that is supported: Europe has kept buying large amounts of U.S. LNG since and has largely ended its dependence on Russian pipeline gas, and many European buyers signed new long-term deals with U.S. suppliers. But "permanent" is too strong. Europe's own climate policy aims to cut gas use over time; its gas demand has already fallen from pre-war levels; and new supply from Qatar will compete for the same buyers. The firmer conclusion is that 2022 turned a policy preference for diverse supply into signed contracts, many running into the 2040s. Those contracts are the lasting effect. The extreme margins were not.
For a shareholder, 2022 left a stronger balance sheet, a smaller share count and a new set of trains, all paid for by one exceptional year. The question it leaves is whether Cheniere's position is strong enough to keep earning good returns when the next war is not there to help. That is a question about the moat.
VIII. Moat Assessment: Helmer's 7 Powers & Porter's 5 Forces
Picture a typical would-be rival on the Gulf Coast in the 2010s and early 2020s. It finds a site, spends years on environmental studies, files with FERC and the Department of Energy, faces lawsuits from local and environmental groups, and seeks long-term buyers so banks will lend. Many of these projects stalled. Several were delayed by court challenges to their environmental reviews. Some never reached a final investment decision. In early 2024 the Biden administration paused new approvals to export to countries without free-trade agreements while it reviewed the effects, a pause later lifted by the following administration. A developer that has spent hundreds of millions on paper can still end up with nothing.
That background makes the case for Cheniere's moat. But a moat must be tested against what would break it, so each claimed power below is set against its strongest challenge. This is the one place the full moat argument is made.
Scale economies: strong, but not unique. Cheniere buys a very large share of all gas used for U.S. LNG exports, from many producers through many pipelines. It can spread overhead, marketing and maintenance over nine large trains and a growing number of midscale ones, and it can shift cargoes between Sabine Pass and Corpus Christi when one has a problem. Revenue per employee in 2024 was about $9 million, with roughly 1,700 staff running the whole system.2 The challenge: Venture Global, Sempra and the QatarEnergy-ExxonMobil Golden Pass venture are also building at large scale on the same coast. Scale makes Cheniere efficient; it does not stop others from reaching scale.
Cornered resource: real, but local. Permitted waterfront sites with deep water, pipeline access and room to expand are scarce. Cheniere owns two, each with land for more trains. Adding trains at an existing site—"brownfield" growth—is cheaper and faster to approve than starting fresh. The challenge: competitors also hold permitted sites, and approvals, while slow, keep coming. The resource is scarce, not exclusive.
Process power: the strongest claim. Cheniere and Bechtel have built more than a dozen trains together with repeated designs. That shared know-how shows up in cost and timing; Stage 3 produced first LNG ahead of schedule.14 The challenge: Bechtel builds for others, too. The fairest version is that Cheniere's edge lies in its record as a buyer and operator—how it sets scope, manages change orders and starts up trains—rather than in a secret that cannot be copied.
Switching costs: high during contracts, modest afterwards. A buyer locked into a 20-year take-or-pay deal cannot leave without paying. But methane is methane. When a contract ends, a buyer can go to Qatar, Venture Global or anyone else. Cheniere's average remaining contract term was in the range of the mid-teens of years, according to rating agencies, so the test will come gradually in the 2030s.9
Counter-positioning: historic. The Henry Hub-plus-fee design once put Cheniere in a place oil-linked sellers could not easily follow. Today it is the industry standard for U.S. exports, so the advantage has been spent.
Branding: modest. A record of delivering on time does count with buyers and lenders. A buyer choosing between a working plant and a paper project will pay something for certainty. But that premium is bounded by the cost of waiting for the paper project.
Network effects: none. An LNG plant is not a platform; one more buyer does not make the plant more useful to others.
Porter's forces point the same way. Barriers to entry are very high: a new phase costs billions, approvals take years and can be paused by politics, and few contractors can build these plants. Buyer power is low during a contract and moderate when contracts renew or when new capacity is sold; the buyers are big utilities and energy majors who can compare offers. Credit risk with them looks small: Cheniere's allowance for bad debts was about $4 million at year-end 2024 against receivables of more than $700 million, because cargoes are usually paid within days under letters of credit.2 Supplier power is low to moderate: gas producers in the Permian and Haynesville often have more gas than pipelines can take, and a large buyer like Cheniere is welcome. Substitutes are a long-run question: renewables and nuclear threaten gas in Europe, while coal-to-gas switching in Asia offers growth. Rivalry is rising sharply, as Venture Global, Sempra's Port Arthur, Golden Pass, NextDecade's Rio Grande and Qatar all add capacity.
The peer comparison clarifies what the moat really is. NextDecade is still building its first trains and has no operating cash flow from them yet. Golar LNG owns floating liquefaction vessels, a different model. New Fortress Energy built a downstream gas-and-power business with much higher leverage, more than six times debt to EBITDA.12 Cheniere is the only one of these with a decade of operating history, investment-grade credit and a full order book. Venture Global, which went public in early 2025, is the closest true rival in scale, and its early approach—selling cargoes on the spot market during commissioning while long-term buyers waited—caused disputes with major customers. That episode, in turn, makes Cheniere's reputation for honoring its contracts a real selling point.
So the verdict is a narrower moat than the outline's language of "near impossible" entry. Cheniere's advantage is the combination of permitted brownfield room, repeat-build know-how, and a balance sheet and reputation that make it the low-risk choice for long-term buyers. It is a moat of cost and certainty, not of exclusion. Rivals can and do get built. What they struggle to match is Cheniere's cost per additional tonne at an existing site and its record. The KPI that will confirm or weaken this view is the fixed fee Cheniere wins on new long-term contracts compared with what rivals win. If that fee holds near past levels while supply grows, the moat is real; if it slips toward rivals' prices, it is mostly scale. Before trusting the moat, though, an investor should look at what the company's own filings flag as risks.
IX. Historical Falsification & Critical Audit Scrutiny
Every year, Cheniere's auditor, KPMG, signs off on the accounts. In the 2024 report, the auditor gave a clean opinion but named one "critical audit matter," the area it found hardest to judge: the value of certain long-term gas supply contracts.2 At year-end 2024 these contracts were carried as a liability of about $801 million, measured using Level 3 inputs—meaning values that cannot be read off any market and must be estimated by Cheniere's own models.2
These contracts come from a program Cheniere calls Integrated Production Marketing. Under them, gas producers such as EOG Resources and Canada's Tourmaline sell gas to Cheniere at prices linked partly to international LNG prices rather than to Henry Hub. Cheniere liquefies and sells the LNG. In effect, the producer takes some of the international price risk, and Cheniere secures supply. Because the contracts run for years and depend on gas price curves far into the future that no market quotes, valuing them requires choosing assumptions about prices and volatility. Small changes in those assumptions move the number by hundreds of millions of dollars.
This matters for two reasons. First, it is the main source of the large swings in reported profit described earlier, so readers should look past GAAP net income to cash. Second, it is a small but genuine exception to the claim that Cheniere carries no commodity price risk. Most of the IPM risk is offset by matching sales, and the accounting swing overstates the economic one. But it is a sign that Cheniere's earnings depend partly on judgments that outsiders cannot check.
The environment adds a different kind of risk. In April 2023 the Louisiana Department of Environmental Quality issued a compliance order and notice of potential penalty concerning formaldehyde emissions from 44 combustion turbines at Sabine Pass.15 The issue stemmed from a federal emissions standard that the EPA had put on hold for 18 years and then reinstated in 2022. Cheniere filed test results in December 2024 showing that all 44 turbines met the standard in 2024.2 The amounts involved are small for a company this size. The larger lesson is that a gas-fired plant on the Gulf Coast is subject to shifting environmental rules, and those rules can change with administrations and courts.
Customer concentration is the third item. No single customer made up 10% of revenue in recent years, but one customer accounted for about 20% of trade receivables at the end of 2024, up from 13% a year earlier.2 Cheniere does not name the customer. Given the letters of credit and fast payment terms, this is more a disclosure to note than a red flag, but it is worth tracking.
The most important test of the "disciplined operator" claim, however, is history. The current management team's record is strong. The company's earlier record is not. Under the founder regime, Cheniere drilled exploration wells that came to little, planned import terminals and pipelines that it later cancelled—Creole Trail chief among them—and lost money on early trading. The import terminal itself was a multi-billion-dollar misjudgment. Souki's pay and his expansion plans led directly to his removal.6
Weighing it fairly, those failures belong to a different leadership with a different strategy. The relevant record for today's claim is the one since 2016, and over that decade the evidence is consistent: projects delivered on time, no project abandoned after a final investment decision, debt reduced, and growth tied to signed contracts. The earlier record narrows the claim rather than refuting it. "Cheniere is disciplined" is not a permanent trait of the company; it is a description of the Fusco era, and it will need to be re-earned when leadership changes. The event that would test it most is the next big round of growth, especially if Cheniere decided to build capacity without long-term buyers signed.
X. Playbook: Business & Investing Lessons
Lesson 1: Abandon Sunk Costs to Save the Enterprise
In 2009 and 2010, Charif Souki stood in front of a terminal built to bring gas into America and accepted that it would never do that job. He did not try to wait out the shale boom. He took what was still valuable—the deep-water dock, the tanks, the permits, the pipelines—and decided to send gas the other way. The broader lesson for founders is that sunk costs should be split into two piles: the strategy that failed and the physical assets that can serve another purpose. Most companies mourn both. Cheniere kept the second and buried the first.
"A monument to the past is an anchor; an infrastructure footprint that can run in reverse is an empire."
Lesson 2: Package Operational Risk into Unbundled Tolling
The 115%-of-Henry-Hub-plus-fixed-fee contract is the single most important design choice in Cheniere's history. It made the buyer own the gas price, the shipping and the destination, and left Cheniere with the plant. That is why 2020 hurt so little and why lenders funded tens of billions. For investors, the lesson is to look past what a company sells to which risks its contracts make it bear. Two companies that both "sell LNG" can have nothing in common.
"Sell the box and the ice; never speculate on the fish."
Lesson 3: The Critical Boundary Between Developer and Operator
In December 2015, with the first export cargo weeks away, the board removed the man who had made it possible. It replaced him with a power-plant operator who cared about run times and debt ratios. The lesson is not that founders should be fired. It is that a company's needs change at the point when building turns into running, and a board's main job at that moment is to notice.
"You need a pirate to take the island, but you need a civil engineer to run the city."
Lesson 4: Structure EPC Contracts to Survive the Cycle
While Australian mega-projects ran billions over budget, Cheniere kept giving Bechtel fixed-price contracts for nearly identical trains. It paid a premium up front for certainty and got projects that arrived on time, with Stage 3's first LNG ahead of schedule. For investors evaluating any heavy-build company, the question is not how cheap the plan looks but who pays if it costs more.
"In mega-projects, fixed-price engineering isn't an expense line—it's an existential survival suit."
Lesson 5: Capital Discipline as the Ultimate Re-Rating Engine
The 2022 windfall could have funded a merchant fleet, an acquisition spree or unsigned trains. Instead it went to debt paydown, buybacks, dividends and one contracted expansion. That choice turned a speculative company into investment-grade credit. The lesson is that how a company spends a windfall reveals more than how it earned it.
"Commodity windfalls belong to the balance sheet first, the share count second, and management's imagination never."
XI. Valuation Framework & Bull vs. Bear Case
Picture the analyst calls in early 2025. Cheniere had just reported 2024 adjusted EBITDA of about $6.2 billion and guided to $6.5 billion to $7.0 billion for 2025, helped by the first Stage 3 trains.12 At roughly the same time, Qatar was building a 48 million tonne a year expansion of its North Field, and new U.S. plants were starting up. The debate was simple to state: is Cheniere a contracted toll road that deserves a steady multiple, or a company at the top of a cycle?
GAAP earnings are a poor guide, for the reasons the derivative swings made clear. The better tools are enterprise value to EBITDA and distributable cash flow—the cash left after interest, maintenance spending and payments to minority holders. On figures from early 2025, Cheniere carried an equity value of about $56 billion and an enterprise value of about $75 billion, or roughly 10 times trailing adjusted EBITDA and about 20 times trailing earnings.12 During 2022–2023 the earnings multiple had looked much lower because of the derivative gains; the EBITDA multiple is the more stable measure. Golar LNG traded at a similar range of EBITDA multiples; NextDecade, without operating trains, trades on its project prospects rather than earnings.
What does a multiple of about 10 times EBITDA assume? For an asset with roughly $105 billion of fixed fees contracted over the next 15 to 20 years, it implies that the market does not treat Cheniere as a pure bond. It is pricing in some risk that renewal fees, merchant margins, or new expansion returns will be lower than today. In other words, the market is already discounting part of the glut debate.
Two KPIs matter most for following this. The first is adjusted EBITDA, which was about $6.2 billion in 2024 and guided higher for 2025; its direction shows whether new trains are offsetting lower merchant margins.12 The second is distributable cash flow per share, which combines cash generation with the falling share count; with the diluted share count down by about 10% from 2022 to 2024, this has been rising faster than EBITDA.2 A third, longer-run measure is the fixed fee on newly signed long-term contracts, which is the clearest read on the moat.
The bull case. Europe stays off Russian gas for good and turns its crisis-era deals into lasting supply relationships. Asia—China, India, Southeast Asia—switches power and industry from coal to gas, absorbing new supply. Stage 3 finishes, capital spending eases, and free cash flow grows, funding more buybacks and dividend increases. Rivals struggle with approvals and costs, so brownfield trains at Sabine Pass and Corpus Christi remain the cheapest new supply on the coast. In this world, Cheniere's fixed fees on new contracts stay near past levels and the multiple rises toward that of regulated infrastructure.
The bear case. Qatar's expansion, Golden Pass, Plaquemines and other new plants arrive together in 2026–2030. The gap between global prices and Henry Hub narrows. Merchant margins fall, and new long-term contracts are signed at lower fees, perhaps closer to $2 than $3. Meanwhile, U.S. demand for gas rises from data centers and new industry, raising Henry Hub prices and filling pipelines, which makes U.S. LNG less competitive for buyers and squeezes Cheniere's IPM and marketing businesses. Structural subordination limits flexibility if a terminal is hit by a hurricane or outage. And European methane rules, which begin to require import emissions data and later intensity limits, add cost to U.S. gas compared with Qatar's.
Weighing them, the base case lies between. The contracted fees protect Cheniere's core cash flow for most of the next decade; that much is shown by the contracts themselves and by 2020. What the market is really pricing is the growth and renewal period after that—how much new capacity Cheniere can build at attractive fees and what old contracts are re-signed at in the 2030s. The bull case needs Asian demand to absorb new supply; the bear case needs supply to arrive faster than demand. Both are possible. The deciding evidence will be the fees on new contracts and the actual cost of new trains at Sabine Pass.
An activist reviewing Cheniere would probably not attack its operations. The questions would be about structure: Should Cheniere buy out the remaining CQP unitholders to own all of Sabine Pass and end the minority leak, perhaps paying in shares? Is it right to keep pushing brownfield expansion as global supply grows, or should more cash go to buybacks? And is the $801 million IPM liability, and the program behind it, worth the earnings noise it brings? None of these is a sign of trouble; each is a lever on the cash the shareholder actually receives.
XII. Epilogue: The Next Inflection Points
Tonight, Cheniere stands at the end of one building phase. The Corpus Christi Stage 3 trains have been coming online since first LNG at the end of 2024, adding a little over 10 million tonnes a year of capacity that Cheniere owns outright.14 The company has been moving from heavy construction toward harvesting cash, and the question is no longer whether it can build but what it should build next and at what price.
Three moments will shape the next chapter.
The first is the full ramp-up of Stage 3. All seven midscale trains need to run steadily at or above their rated output. If they do, Cheniere's wholly owned share of capacity rises meaningfully and the minority leak becomes a smaller part of the whole. If they suffer early problems, it will be the first operational stumble of the Fusco era and a direct test of the "manufacturing machine" claim.
The second is the expansion at Sabine Pass, known as Stage 5, and further growth at Corpus Christi. Cheniere has said it will reach a final investment decision only after enough long-term contracts are signed. The fee it achieves will answer the toll question more directly than any forecast. A fee near $2.50 or more, signed while Qatar and others are adding supply, would support the moat; a fee well below that would say Cheniere's advantage is mostly cost rather than pricing power.
The third is the domestic gas showdown. Texas and Louisiana are adding large power-hungry data centers, factories and gas-fired plants. If that drives up the cost of moving gas to the coast or widens price gaps between gas hubs, Cheniere's supply costs and its IPM and marketing margins will feel it, even if contract buyers absorb most of the Henry Hub price.
And then there is the man who started it all. After leaving Cheniere, Charif Souki co-founded Tellurian in 2016 to build another export project in Louisiana, Driftwood LNG. He tried to fund it with a model different from the one he had pioneered, leaning on equity partners and sales to traders rather than a full set of long-term take-or-pay buyers. The contracts never came in volume, the money ran short, and Souki left the board in late 2023 amid a dispute over personal loans. In 2024 Woodside Energy bought Tellurian for about $1.2 billion, a fraction of what had been spent.16 It is hard to find a cleaner proof of Cheniere's own lesson: the plant is only as valuable as the contracts that pay for it.
The tension that remains is this. Cheniere's past decade proved that a toll road on the Gulf can hold through a pandemic and a war. The next decade will test whether it can still set the toll when there are more roads.
XIII. Outro
Go back to Cameron Parish. A pilot boards a tanker three hundred meters long, its insulated tanks full of liquid colder than anything in nature on earth. The ship eases down the Sabine-Neches Waterway, past the tanks that were built to receive gas from the other side of the world, and turns out into the Gulf. The gas inside came out of rock in Texas and Louisiana a few days ago. In two weeks it will be warming homes in France, running factories in Germany or powering a grid in Korea.
Charif Souki built that dock for ships coming the other way. He was wrong about which way the gas would flow and right about everything else: that the dock would matter, that the contracts could be designed, that the world would pay for American molecules. The people who came after him added what he lacked, the patience to run it the same way every day. Cheniere is a reminder that the biggest fortunes in commodities rarely go to those who guess the price. They go to whoever owns the narrow gate the commodity must pass through, and runs it like a clock.
References
-
Cheniere Energy, Inc. Form 10-K for the Fiscal Year Ended December 31, 2023 — U.S. Securities and Exchange Commission, 2024-02-22 ↩↩
-
Cheniere Energy, Inc. Form 10-K for the Fiscal Year Ended December 31, 2024 — U.S. Securities and Exchange Commission, 2025-02-19 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Cheniere Energy, Inc. Form 10-K for the Fiscal Year Ended December 31, 2016 — U.S. Securities and Exchange Commission, 2017-02-24 ↩↩↩↩↩↩
-
How Carl Icahn Turned a 13.8% Bet on Cheniere Energy into a Multi-Billion Dollar Windfall — Bloomberg, 2022-06-15 ↩↩↩
-
Federal Energy Regulatory Commission Order Granting Authorization Under Section 3 of the Natural Gas Act for Sabine Pass Liquefaction — FERC, 2012-04-16 ↩
-
U.S. Natural Gas Export Leader Cheniere Ousts CEO Charif Souki Under Activist Pressure — The Wall Street Journal, 2015-12-13 ↩↩↩↩↩
-
Cheniere Energy, Inc. Definitive Proxy Statement (DEF 14A) — U.S. Securities and Exchange Commission, 2024-04-12 ↩
-
Cheniere Energy, Inc. Current Report on Form 8-K: Shareholder Meeting Voting Results — U.S. Securities and Exchange Commission, 2024-05-17 ↩
-
Fitch Rates Cheniere Energy Partners' Senior Notes 'BBB' — Fitch Ratings, 2024-02-15 ↩↩
-
Research Update: Cheniere Energy, Inc. Upgraded to 'BBB+' on Sustained Deleveraging and Operating Performance — S&P Global Ratings, 2023-03-28 ↩
-
Rating Action: Moody's Upgrades Cheniere Energy's Senior Unsecured Notes to Baa2; Outlook Stable — Moody's Investors Service, 2023-06-20 ↩
-
Cheniere Reports Fourth Quarter and Full Year 2024 Results and Introduces Full Year 2025 Financial Guidance — Cheniere Energy, Inc., 2025-02-20 ↩↩↩↩↩
-
Cheniere Energy, Inc. Investor Day Presentation & Capital Allocation Strategy — Cheniere Energy, Inc., 2022-09-12 ↩
-
Bechtel Commences First LNG Production at Corpus Christi Stage 3 Expansion Ahead of Schedule — Bechtel Corporation, 2024-12-30 ↩↩↩
-
Louisiana Department of Environmental Quality (LDEQ) Consolidated Compliance Order and Notice of Potential Penalty AE-CN-22-00833 — Louisiana DEQ Public Records, 2023-04-20 ↩
-
Woodside Energy Completes $1.2 Billion Acquisition of Troubled Tellurian and Driftwood LNG Project — Reuters, 2024-10-03 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube