L3Harris Technologies: The Prime That Wasn't Built to Be One
I. Cold Open: The Chairman's Phone Call (August 17, 2026)
The deal was struck on a Sunday. Over the weekend of August 15 and 16, 2026, the board of L3Harris Technologies finished an investigation it had run with independent counsel, concluded that its chairman and chief executive had broken the company's code of conduct, and negotiated his exit rather than firing him for cause.12 Christopher Kubasik, 65, signed a separation agreement that gave him no severance and no bonus.
He admitted nothing, and the agreement bars him from saying anything publicly that contradicts the company's account.1 On Monday morning, August 17, the company told the market that Kubasik had stepped down as chairman, chief executive and director, effective immediately, that Sam Mehta would run the company, and that Lewis Hay III, the lead independent director, would become independent chairman.3
The board chose its words with care. The conduct, it said, was "not consistent with the values of the Company" and was "unrelated to the Company's financial reporting, controls, customer relationships or operational performance."3 It gave no further detail, then and since. In the same release it reaffirmed every piece of its 2026 guidance: revenue, organic growth, segment margin, earnings per share and free cash flow.3 The message was plain. The man is gone; the machine is fine.
Investors were not quite ready to believe that. The shares fell more than 4% that day.1 They had already taken a much harder hit eighteen days earlier, on July 30, when the company said it was shelving the planned public listing of its Missile Solutions business, the missile-propulsion franchise it had built around Aerojet Rocketdyne. The stock fell 8.6% that day, which erased about $4.8 billion of market value in a single session.4 Two shocks in under three weeks, one about the price of the company's most prized asset and one about the man who had sold it to Wall Street.
Tonight, on October 27, 2026, the stock trades around $258. Its 52-week high was about $379, so the shares sit roughly a third below their peak, and not far above the year's low of about $232.5 The whole company is valued at about $48 billion in equity and about $57 billion once its debt is included.6 And here is the strange part. The order book has never been fuller.
At the end of June the company carried a record $42 billion of backlog, and in the second quarter it booked $1.20 of new orders for every dollar of revenue it recognised.7 About three-quarters of its revenue comes from a single customer, the United States government, and its chief executive told investors in July that the country was on a "wartime footing."89
So which signal is real: the order book, or the boardroom and the busted listing? That is the question this story sets out to answer, and it breaks into four parts. The first is whether the August exit was a contained governance event or a sign that a company in the middle of a restructuring had lost some grip on itself.
The second is whether that record backlog can finally lift returns on capital above the roughly 6% the 2019 merger left behind. The third is what the postponed missile listing says about what the market thinks the crown jewel is worth, and what it does to the balance sheet. The fourth is how much of the profit L3Harris reports comes from building things, and how much from a pension surplus, a tax rate and a cost programme.
To answer any of them you have to go back to the moment this company was assembled, because L3Harris was not born a defence prime. It was built from two mid-sized contractors who decided they were stronger together, and the bill for that decision is still on the balance sheet.
 Subscribe on LinkedIn
II. Two Mid-Tier Players and a Merger (Harris, L3, 2019)
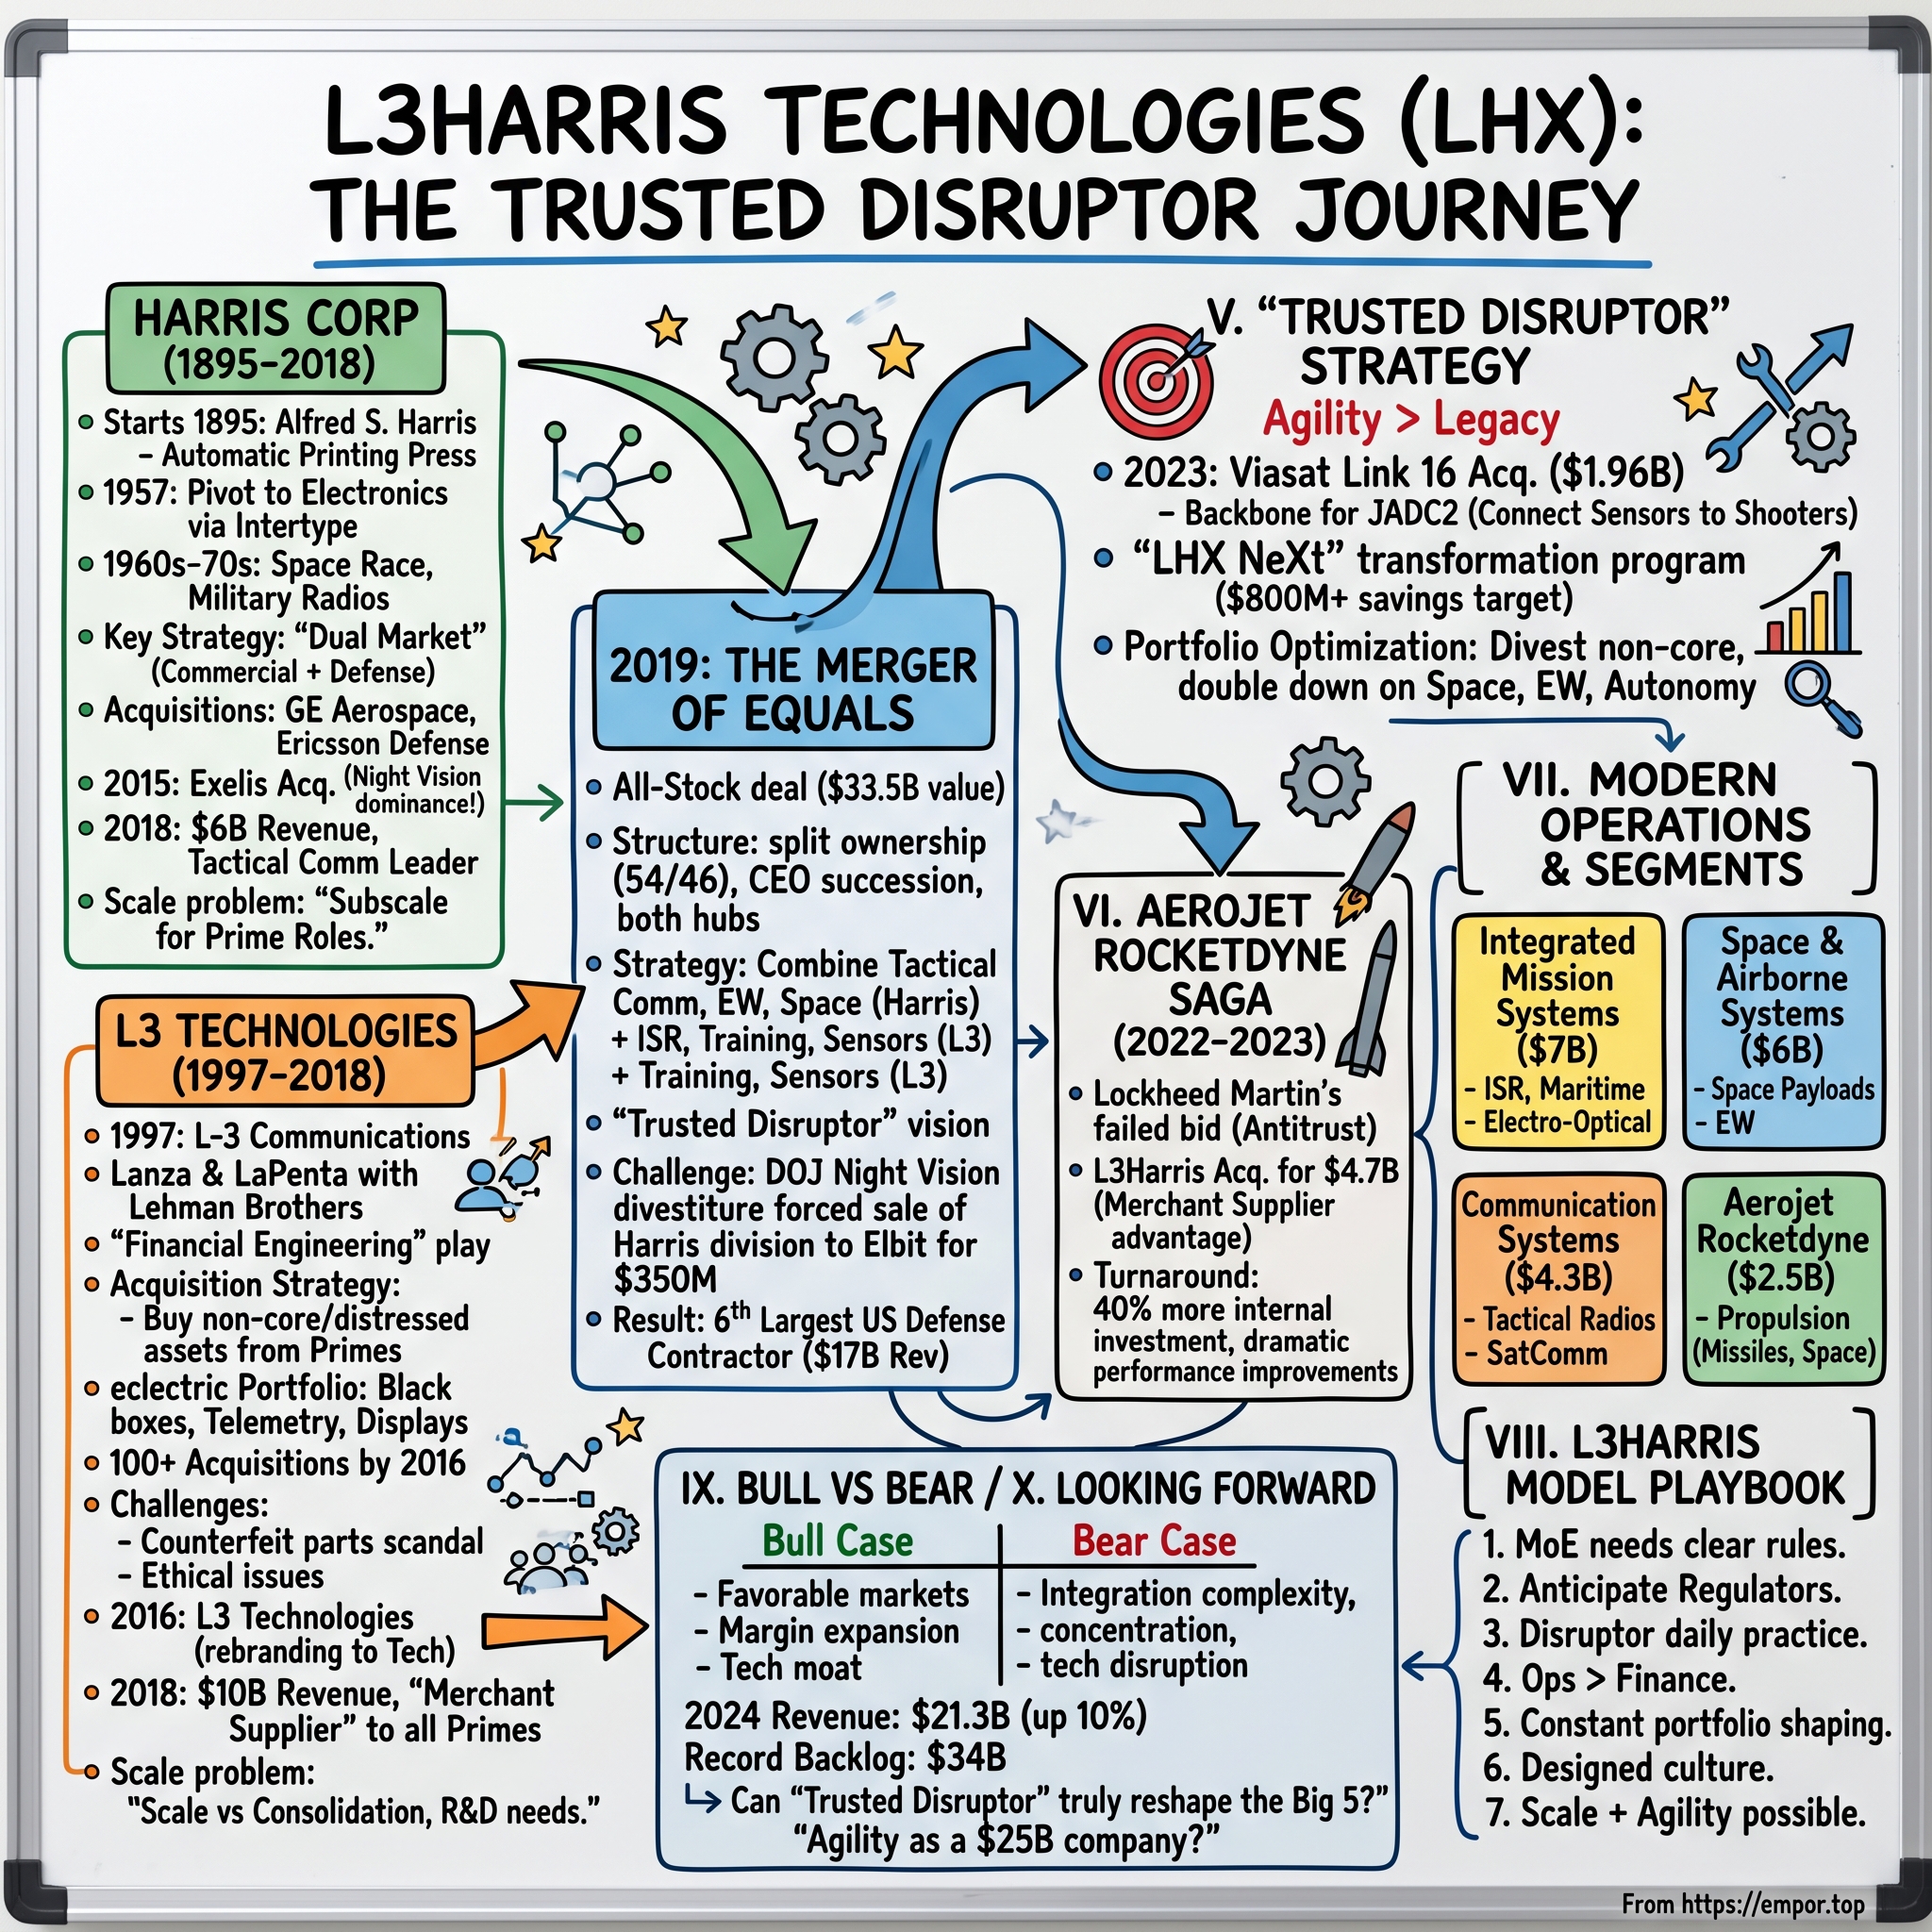
On October 14, 2018, two defence companies that most Americans had never heard of announced that they would become the sixth-largest defence contractor in the country.10 Harris Corporation, headquartered in Melbourne, Florida, and L3 Technologies, based in New York, called it a merger of equals, and they meant it almost literally. L3 shareholders would receive 1.30 Harris shares for each of theirs, leaving Harris holders with about 54% of the combined company and L3 holders with about 46%. The new board would have twelve seats, six from each side.10 Together they expected roughly $16 billion of revenue, $2.4 billion of operating profit and about 48,000 employees.10
The two companies had very different childhoods. Harris began in 1895 as the Harris Automatic Press Company in Ohio, making the large multicolour presses used to print books and newspapers.11 It found its way into electronics through a string of acquisitions, the most important of which came in 1967, when it paid $56 million for Radiation Inc., a Melbourne, Florida, company that had grown up in space rented from a naval air station and built electronics for the space race.
The combined business took the name Harris Corporation in 1974.11 By the 2010s the printing presses were long gone, and Harris was best known for the tactical radios that soldiers carry on their backs, a business with the margins of a technology company rather than a shipyard. In 2015 it bought Exelis, a defence electronics spin-off, for about $4.75 billion including debt, which brought in night-vision goggles, electronic warfare and space payloads and lifted Harris's revenue by more than half the following year.128
L3 had no such pedigree. It was created in 1997 when Frank Lanza and Robert LaPenta, two former executives of the defence electronics maker Loral, persuaded Lockheed Martin to sell them ten businesses Lockheed had inherited when it bought most of Loral the year before for $9.1 billion.13 A partnership led by Lehman Brothers owned half the new company. Lanza became chief executive and LaPenta president and chief financial officer, and the name came from Lanza, LaPenta and either Lockheed or Lehman, depending on who tells the story.13
L3 then did what its founders were good at: it bought things. It became a sprawling collection of sensors, simulators, communications gear and aircraft services, larger than Harris by revenue but less profitable: on the companies' own 2018 figures, L3 brought roughly $10 billion of the combined $16 billion of revenue but only a little over half of the $2.4 billion of operating profit.108
The logic of the merger was the logic of size. In an industry dominated by a handful of giant primes, two companies of mid-tier scale risked being stuck as subcontractors to Lockheed, Raytheon and Northrop. Together they promised about $500 million a year of gross cost savings by the third year, or $300 million after passing part of the savings back to government customers, and they set a target of $3 billion of free cash flow by year three.10
Harris's chief executive, Bill Brown, would run the combined company for its first two years, with Kubasik, then L3's chairman and chief executive, as his vice chairman, president and chief operating officer. In year three the two would swap roles.10 Regulators asked for one sacrifice: Harris had to sell its night-vision business, an estimated $150 million to $160 million revenue unit that had come with Exelis, because L3 made night-vision equipment too. Elbit Systems of America bought it for $350 million, and the sale closed in September 2019.14
The merger closed on June 29, 2019, and the handover happened exactly on schedule two years later, when Kubasik succeeded Brown as chief executive on June 29, 2021, and Brown became executive chair.15 (A quirk in the reported figures from that period, a short transition period around the change of fiscal year, shows a quarter of zero operating profit and a nonsensical five-year growth comparison. Those are bookkeeping artefacts of stitching two companies together, not events in the business.)
Now the reveal. In its last full year on its own, Harris earned about 16 to 18 cents of operating profit on every dollar of revenue and a return on invested capital of roughly 13% to 15%.8 The combined company has never come close. Its operating margin was about 12% in its first full year as one company and has hovered around 9% to 10% ever since. Its return on invested capital has sat near 6% for five straight years.8 Revenue roughly tripled from old Harris's $6.8 billion to about $18 billion. The returns roughly halved.
Why? The easy story is that L3 was a lower-margin business that dragged Harris down. That is part of it, but the bigger answer is hiding in a line of the income statement that most investors skip. Every year L3Harris charges itself for the amortisation of intangible assets it acquired in its deals, mostly the customer relationships and technology it paid for in the merger. In 2025 that charge was $769 million.16 On about $22 billion of revenue, that is three and a half points of margin.
Add it back, along with the restructuring charges, and the company's segments earned about 15.8% in 2025, close to the old Harris record.17 In other words, the operating businesses are not broken. The price of assembling them is. Goodwill and acquired intangibles now total about $26.5 billion, about 64% of total assets and more than the whole of shareholders' equity.8 Return on capital is low because the denominator includes everything L3Harris paid for, not because the radios stopped making money.
The merger's own promises offer a cleaner test. The companies said they would generate $3 billion of free cash flow by the third year.10 They produced about $2.3 billion in 2021 and $1.9 billion in 2022.8 The $3 billion figure finally appeared as guidance for 2026, seven years after closing.18 Scale arrived on time; the cash it was supposed to throw off arrived years late.
The record therefore narrows the case for the merger rather than rejecting it. It created a prime by size, a company big enough to bid as a prime and win. It did not create a better business than old Harris, and nothing in seven years of results says it has yet. The returns case is unproven, and the next decision would add to that burden. Having built a bigger company by merger, Kubasik's L3Harris went shopping again, this time for a strategically important asset in American missile-making.
III. Buying the Missile Supply Chain: Viasat TDL and Aerojet Rocketdyne (2022–2023)
On Sunday, February 13, 2022, Lockheed Martin walked away from the biggest acquisition of Jim Taiclet's tenure as chief executive. Lockheed had agreed to buy Aerojet Rocketdyne, the California-born maker of rocket motors, for about $4.4 billion. Then the Federal Trade Commission sued to block it.19 The government's argument was blunt. Aerojet was the nation's last independent supplier of key missile propulsion components. If Lockheed owned it, Lockheed could cut off its rivals' access to rocket motors, raise their prices, and let quality and innovation slide. Lockheed decided the fight was not worth it, and Taiclet said that terminating the transaction was "in the best interest of our stakeholders."19 No break fee changed hands.
That left one of the most important assets in American defence sitting on the table, and Kubasik picked it up. In December 2022 L3Harris agreed to buy Aerojet in a cash deal valued at about $4.7 billion.20 It is worth pausing on why L3Harris could buy what Lockheed could not. The problem the FTC had with Lockheed was not the asset; it was the buyer. Lockheed builds missiles, so owning their motors would have made it the supplier to its own competitors. L3Harris was not a major missile prime.
It could promise to sell motors to Lockheed, Raytheon and everyone else on equal terms, as a merchant supplier rather than a rival. The deal still drew scrutiny, and Senator Elizabeth Warren asked the FTC and the Pentagon to examine it in January 2023, but on Wednesday, July 26, 2023, the FTC told L3Harris it would not block the deal.20 Two days later, on July 28, the acquisition closed, bringing more than 5,000 employees and becoming L3Harris's fourth business segment.21
Aerojet was not the only purchase. Weeks earlier, on January 3, 2023, L3Harris had closed its $1.96 billion purchase of Viasat's tactical data links business, the maker of the Link 16 terminals that let allied jets, ships and ground units share a common picture of the battlefield, a business with about $400 million a year of sales.22
Put the two together and L3Harris spent about $6.7 billion in seven months. In 2023 its cash outflow on investments was about $7 billion, its borrowings rose from about $7.8 billion to about $13.9 billion, and its debt grew from about 42% of shareholders' equity to about 74%.8 Revenue jumped almost 14% that year, but much of that was bought rather than grown.8
Did L3Harris pay a fair price? The honest answer starts with what the buyers themselves said. On the July 2026 earnings call, Kubasik put it plainly: "3 years ago, we acquired Aerojet at full price," acknowledging that the business "needed work" and that analysts' questions about the multiple and integration risk had been fair.9 The comparisons bear him out. Lockheed's abandoned bid valued Aerojet at about $4.4 billion; L3Harris paid roughly 7% more two years later.1920 Even after three years of growth, the price looks full.
In 2025 the Aerojet segment's revenue was a little over $2.8 billion at a 12.5% margin, or roughly $350 million of segment profit, so the purchase price was about 1.7 times 2025 sales and about 13 times 2025 segment profit.18 Viasat's data-links business cost almost five times its annual sales.22 For context, the market today values all of L3Harris at about two and a half times sales.6 Neither deal was a bargain. Whether either was an overpayment depends on what Aerojet becomes, and that is the subject of the listing that stalled.
The deals also have to be judged against what came before and after them, because L3Harris has a habit of buying and then shedding. In 2023 the company wrote down $374 million of assets, including $296 million on its aviation business.8 It sold its commercial aviation business at the end of March 2025, and over the same period divested an antenna business and other product lines.16 In late 2024 it took a smaller impairment on assets tied to the Tactical Data Links acquisition, less than two years after buying it.16
And in January 2026 it agreed to sell a 60% stake in Aerojet's civil and commercial space propulsion business, the unit that makes the RL10 engine for United Launch Alliance's Vulcan rocket and nuclear power systems for lunar and Martian missions, to the private equity firm AE Industrial Partners, which plans to revive the old Rocketdyne name.23[^24]
The deal valued that business at $845 million, and L3Harris kept about 40% and the RS-25 rocket engine business, which was excluded from the sale.23 That unit had generated $571 million of revenue and $82 million of segment profit in 2025, so it went for about one and a half times sales and roughly ten times profit, a lower multiple than L3Harris had paid for Aerojet as a whole.9
A pattern emerges. L3Harris buys broadly, then prunes what does not fit, and the pruning comes with write-downs and losses on sale. That is not by itself a sign of bad capital allocation. Management argues it is the price of reshaping a portfolio toward what the Pentagon wants, and Kubasik told investors in January 2026 that the company had "acquired and divested billions of dollars of businesses" over six years to align with the fastest-growing defence priorities.18 But it does mean that the word disciplined needs qualifying. The company paid full price for its best asset, impaired parts of its other purchases, and is selling a slice of Aerojet at a lower multiple than it bought the whole.
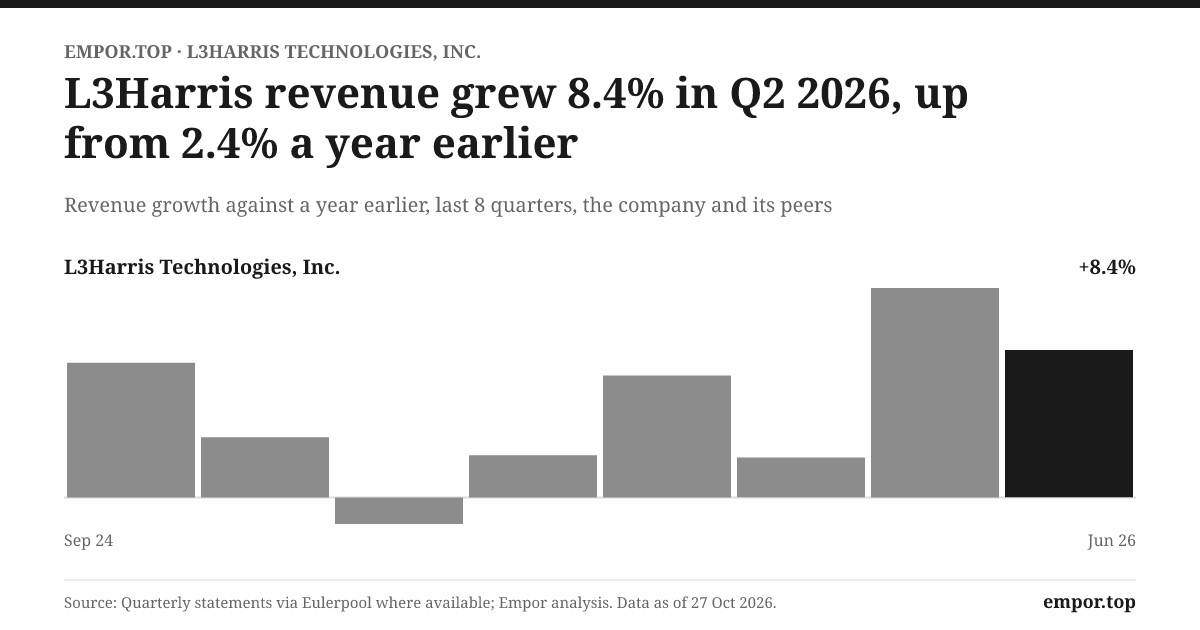
The growth record tells the same story. Revenue grew almost 14% in 2023 and almost 10% in 2024, both flattered by the acquisitions.8 In 2025 reported growth fell to about 3%, though stripping out the businesses it sold, organic growth was about 5%.17 Then came something new: growth of about 12% and 8% in the first two quarters of 2026, with every segment contributing.87 For the first time since the deals, the company appears to be growing without buying.
Strategically, Aerojet was the right asset in the right market, at a moment when rearmament was turning solid rocket motors from a sleepy industrial niche into a national bottleneck. Financially, the deals stacked more debt-funded acquisitions on top of a 6% return. The verdict on Aerojet will be written in its margin: whether a business earning about 12% can become one earning in the high teens. That depends on how the money is actually made at L3Harris today, on the factory floor and in the contract fine print.
IV. How the Money Is Actually Made: The Business Today
Picture a production line building rocket motors or satellites under a fixed-price contract. The price was agreed at the start. If the parts cost more, if a weld fails inspection, if a supplier is late and the line sits idle, the extra cost comes out of the contractor's profit, not the government's budget. Three-quarters of L3Harris's revenue comes from contracts like that.8
And because those contracts run for years, the company has to estimate, every quarter, how much it will cost to finish each one, and book revenue in proportion to how much of that total cost it has already spent. Accountants call this the cost-to-cost method. If a programme is 40% of the way through its expected costs, the company books 40% of the contract's revenue and profit.
The method works beautifully until the estimate is wrong. If engineers discover that a programme will cost more than they thought, the company does not just book less profit in the future. It has to go back and reduce the profit it already booked, all at once. That is why L3Harris's auditor singled out exactly one critical audit matter in the 2025 annual report: the estimates of costs to complete these long-term contracts.8 The auditor is saying, in effect, that this is the place in the accounts where judgement matters most and where mistakes would hurt.
The balance sheet shows the method at work. At the end of 2025 L3Harris held about $3.6 billion of contract assets, which are amounts it has earned under cost-to-cost accounting but has not yet billed, up about $340 million in a year, plus about $1.4 billion of receivables, up about $300 million.8 Contract assets grew about 10% while revenue grew about 3%.
With a normal customer that would be a warning about collections. With the United States government it is not, because the sovereign pays. The risk in these balances is not that the money will never arrive. It is that the estimates behind them turn out to be too optimistic. The government always pays; the question is what you agreed to build and for how much.
On the other side of the ledger, demand is the least uncertain part of the case. The company ended 2025 with backlog of more than $38 billion and a book-to-bill ratio of 1.3, meaning it booked $1.30 of new orders for every dollar it recognised as revenue.17 By the end of June 2026 backlog had climbed to $42 billion.7 The company expects about 45% of its year-end backlog to turn into revenue by the end of 2026 and about 70% by the end of 2027.8 That is unusually good visibility for any business. The open question is not whether the work will come. It is how much of each dollar of work will turn into profit.
Three businesses, three economic models
At the start of 2026 L3Harris reorganised itself from four segments into three, and the new shape makes the economics far easier to see.18 Space & Mission Systems is a classic prime contractor: satellites, missionised aircraft, air traffic control systems and classified programmes, built mostly to the customer's specification. It is the biggest segment, with about $3 billion of revenue in the second quarter of 2026, but it earned a margin of just 9.8%.7 Missile Solutions, built around Aerojet plus L3Harris's seekers, fuzes and weapon-release systems, brought in about $1.05 billion in the quarter at about 12%.7 Communications & Spectrum Dominance, the radios, electronic warfare and airborne sensors business, brought in about $1.9 billion at a remarkable 26.9%.7
Do the arithmetic and the picture snaps into focus. In that quarter, Communications & Spectrum Dominance produced about a third of the company's segment revenue but more than half of its segment profit: about $520 million out of about $940 million.7 Missile Solutions gets the headlines and Space & Mission Systems gets the size, but the radios are the profit engine, and the segment that moves the value of L3Harris more than any other.
Why are the margins so high? Management describes this segment as delivering "primarily commercial products at commercial margins."18 The company designs a radio with its own money, owns the intellectual property, and then sells the finished product to many customers, at home and abroad, rather than being paid to develop something bespoke for one buyer. Think of the difference between a builder who constructs a single custom house to a client's blueprint and a manufacturer who designs one model of car and sells it a million times. The second business takes the development risk but captures the upside of every additional sale.
L3Harris's radios are software-defined, which means new capabilities can be loaded onto hardware already in the field. On the July 2026 call Kubasik described a software application called RateShield that lets the company's radios detect and jam incoming drones without adding equipment to a soldier's kit, and said such software would contribute to licensing revenue.9 International customers are a growing part of this business; across the whole company, international sales rose more than 20% in the second quarter and reached about 23% of revenue.9 The segment's margin jumped 2.3 points in the quarter, which management attributed to stronger international revenue.7
That is the bull case for the profit engine. The record attaches two caveats. First, the domestic radio market depends on the US Army, and the Army is reshuffling. In January 2026 Kubasik acknowledged that the government's 2026 budget request had reduced funding for some tactical radio lines, that some of those programmes were now competitive, and that the company was willing to compete with "any and all newcomers and incumbents."18 Second, the segment's growth in the second quarter was only about 4%, slower than the company as a whole.7 The radios are a superb business. They are not, on present evidence, a fast-growing one, and the high margin depends partly on export orders that arrive in lumps.
Space & Mission Systems is where the estimate risk lives. Over 2024 and 2025 L3Harris struggled with what it called "challenging space programs," and in January 2026 the then chief financial officer, Kenneth Bedingfield, told analysts that the company had "stabilized a few programs" that had been challenged in parts of 2024 and into 2025.18 In the fourth quarter of 2025 the old Integrated Mission Systems segment's margin fell 2.7 points, partly because of the aviation divestiture and partly because of unfavourable performance in its maritime business.16 Fixed-price contracts put cost errors straight into profit, and this segment is where L3Harris has made them.
The space business is also where the company has won big. In December 2025 it won an award worth about $850 million to build 18 satellites for the Space Development Agency's Tranche 3 missile-tracking layer, and management says it is the only company awarded contracts across all four tranches of that programme.18 On the same call, a Bernstein analyst pointed out that three of L3Harris's peers were also on Tranche 3.18 Winning every round is real evidence of technical credibility; sharing the round with three rivals is real evidence that the customer is deliberately spreading its bets.
What the dip in the December quarter really was
The quarterly record has one alarming-looking moment. In the last quarter of 2025 L3Harris's reported operating margin fell to about 7%, from about 11% in the quarter before and about 13% a year earlier.178 Was that a programme blowing up? The results release answers the question. Reported operating income fell to $393 million from $569 million, but segment operating income barely moved, and the segments' adjusted margin actually rose 0.4 points to 15.7%.16
The drop came from corporate items the company does not allocate to its segments, which rose to $410 million from $253 million. The biggest single cause was $150 million of losses and impairments tied to businesses being sold, chiefly a non-cash goodwill write-down on the space technology group headed to AE Industrial. On top of that sat $68 million of restructuring costs and $191 million of amortisation.16 The dip was portfolio surgery, not a programme failure, and by the first half of 2026 reported margins were back at about 11%.7
Step back from the quarterly noise, and the longer pattern is a company that has reinvested modestly while sitting on $42 billion of orders. In 2025 it spent $536 million of its own money on research and development, about 2.5% of revenue, and $424 million on capital expenditure, about 2% of revenue. Its net property, plant and equipment shrank from about $3.6 billion to about $2.7 billion over two years, partly because of divestitures.8 It employs about 45,000 people, roughly 18,000 of them engineers and scientists.8 Its cost-cutting programme, LHX NeXt, cost $167 million to implement in 2025, down from $267 million in 2024, and management says the programme delivered more than $1 billion of savings a year ahead of plan and has now been folded into normal operations.1618
The exception is missiles. For 2026 the company guided to about $600 million of capital spending, up 35% to 40%, and on the July call the new chief financial officer, Kenneth Sharp, said total commitments for missile capacity, facilities, equipment and supply chain had reached $2 billion, some of it funded through finance leases that do not appear on the balance sheet until the buildings are in service.189
Kubasik said the company was putting up about 60 buildings and nearly a million square feet of new missile capacity, including a highly automated factory for GMLRS rocket motors, which management called the Arsenal of Freedom building and said was due to open in August 2026, and a new PAC-3 facility due in late 2027.9 He said investment in Aerojet's R&D and capital spending had risen roughly tenfold since the acquisition, deliveries were up more than 60%, and nearly all the delinquent deliveries the company inherited had been cleared.9
Those are management's numbers, and the most important of them, the tenfold rise and the 60% delivery gain, are not broken out in the audited accounts. What the accounts do show is that the Missile Solutions margin was "substantially similar" to the prior year in the second quarter of 2026, at about 12%.97 The money is going in. The margin has not moved yet.
So is the backlog turning into returns above the cost of capital? Not yet. Demand is strong, segment margins are healthy, the profit engine is a radio business with commercial economics, and the dip that frightened investors at the end of 2025 was accounting for divestitures rather than a programme failure. But returns on capital remain near 6%, and the one big reinvestment bet is still in the building phase. Whether it pays off depends partly on L3Harris and partly on the customer that sets the rules for everyone in this industry.
V. Industry Structure, Moat and the Customer That Sets the Rules
Imagine the Pentagon's acquisition office as a buyer looking down at a two-storey marketplace. On the top floor sit the prime contractors, Lockheed Martin, RTX, Northrop Grumman and General Dynamics, who assemble finished weapons systems and sign the biggest contracts. On the floor below sit the merchant suppliers, who make the motors, seekers, radios and sensors that go inside those systems and sell to every prime on the top floor.
For most of the past thirty years the Pentagon let the two floors merge, as primes bought their suppliers and the industry shrank to a few giants. Now it wants the opposite. In January 2026 Kubasik framed L3Harris's missile strategy as "reinvigorating competition following decades of consolidation," and, when asked on the same call whether the Department of War had placed any conditions on how L3Harris would run its missile business, said there were none: "They want competition. They want scale. They want speed."18
L3Harris sits on both floors. In space and airborne systems it acts as a prime. In missiles it is primarily a merchant supplier. In radios it sells finished products to everyone. That positioning is the core of its "trusted disruptor" pitch, the phrase Kubasik used to describe a strategy the company "embarked on" several years ago: big enough to be trusted with critical programmes, nimble enough to disrupt the old primes.9 It is a good slogan. The question is whether it describes an economic advantage.
The five forces, from the buyer down
Start with the force that dominates everything else: the buyer. About 75% of L3Harris's revenue comes from the US government, including sales made through other primes and foreign military sales funded through Washington, and no other customer accounts for more than 5%.8 That buyer can terminate contracts for its own convenience, depends on annual appropriations from Congress, audits costs through the Defense Contract Audit Agency, and could suspend or debar a contractor, an outcome L3Harris's own filing calls material.8 It also sets the rules on profit.
The best evidence of buyer power in the current cycle is the missile framework agreement L3Harris signed shortly after the second quarter of 2026: seven years of THAAD and PAC-3 production worth about $12 billion of future revenue and about $2 billion of future profit.9 That works out to roughly 17%, an attractive margin, but management also revealed that the framework covers about 80% of the work, and spoke of the opportunity to deliver more than 80% "to cover any potential shortfall from competitors."9 The customer is deliberately keeping a second source alive. That is what a powerful buyer does.
The threat of new entrants is real and rising. The Pentagon is courting venture-backed companies, and Kubasik himself said L3Harris has "always embraced and encouraged venture backed tech companies to join the defense ecosystem," investing about $50 million in each of two funds run by Shield Capital.9 In solid rocket motors, where Aerojet was once described by regulators as the nation's last independent supplier, the customer is now funding additional suppliers and said in public that it wants competition.1918
Supplier power is moderate: L3Harris carries about $10.2 billion of purchase obligations, mostly open orders under government contracts, and management has spoken repeatedly of bottlenecks in second- and third-tier suppliers.818 Substitutes come mostly from technology rather than from rivals: cheap drones and low-cost interceptors threaten to change what the customer buys, though L3Harris says it has positioned products in both areas.9 Rivalry among the big primes is intense but disciplined, because every major programme is competed and every competitor knows the customer's rules.
Seven powers, tested
Of Hamilton Helmer's seven powers, the sources of durable advantage, L3Harris can credibly claim two. The first is switching costs. Once a radio waveform is fielded across an army, or a Link 16 terminal is fitted to tens of thousands of jets and ships, changing suppliers means recertifying, retraining and losing interoperability with allies, and Kubasik's argument that soldiers "want to carry one radio" is a switching-cost argument.18 The second is a form of cornered resource: qualified production capacity in solid rocket motors, where Kubasik described L3Harris on the July call as "the only company producing these solid rocket motors at scale on factory today," and sole-source positions on attitude-control motors and lethality enhancers for PAC-3.9
Both powers are real but narrower than they look. The cornered resource is being uncornered by the customer itself, through the 80% framework and the investment in new suppliers. The switching costs in radios have not prevented the Army from cutting radio budget lines and putting some of them out to competition.18 Scale economies matter but do not distinguish L3Harris from Lockheed or RTX, both far larger. There is no network effect, no brand power in the consumer sense, and no counter-positioning that the giants cannot copy. And none of these powers delivers what powers are supposed to deliver: pricing power. L3Harris cannot raise prices on its main customer, which negotiates the profit rate into each contract.
The peer comparison confirms this. On a comparable basis, as measured by the same data provider on the same day, L3Harris's operating margin of about 13% sits in the middle of the pack: roughly level with Northrop and RTX at about 13%, and a little above Lockheed and General Dynamics at about 10% to 11%.624252627 If the trusted-disruptor model created an economic edge, it would show up as a margin or return premium over the old primes. It does not.
There is also a new twist in the buyer relationship: the customer is becoming a shareholder. In 2026 the Department of War agreed to invest $1 billion directly in L3Harris's Missile Solutions business, under what Kubasik called "a novel partnership structure."282918 He insisted the government's stake was "solely economic," that it wanted capacity quickly and a return on its money.18 Perhaps. But when the buyer that negotiates your profit rate also owns part of your equity, the relationship acquires a new layer of complexity, and investors will want to know whether the shareholder ever influences the customer, or the other way round.
The moat, then, is real but narrow: qualified incumbency in missile propulsion, tactical radios and space sensors, protected by certification, interoperability and capacity that takes years to build. It is not pricing power, and the customer is actively working to make it narrower. Technical capability is not revenue, and the trusted-disruptor label has not yet shown up in the margin record. The clearest test of what the market thinks these powers are worth came this summer, when L3Harris tried to sell a piece of its missile business to public investors.
VI. The Missile Solutions IPO That Stalled (2026)
In January 2026, L3Harris unveiled a partnership with the Department of War, the name the Pentagon had adopted by then, unlike anything a listed defence contractor had done before. The department would invest $1 billion in L3Harris's Missile Solutions business, and L3Harris would take that business public in the second half of 2026, creating what Kubasik described as "a $4 billion-plus revenue majority-owned public company with sustainable double-digit growth."2818 The money would help expand solid rocket motor plants in Camden, Arkansas; Huntsville, Alabama; and Orange, Virginia, among other sites.29 L3Harris would keep more than 80% and continue to consolidate the business in its accounts.29
The terms, laid out by Bedingfield on the January call, were generous to the government. The department's money took the form of a convertible preferred security in the missile business, which would convert into common shares at the IPO at a 20% discount to the IPO price, plus detachable warrants for about 3% more of the equity at a premium price. After conversion, Bedingfield said, the government would hold a single-digit ownership stake.18 The deal closed on April 23, 2026.29
Here the arithmetic gets interesting, because those terms contain an implied valuation. If $1 billion converts at a 20% discount, the department receives shares worth $1.25 billion at the IPO price. If that is a single-digit stake, under 10%, then the missile business's equity must be worth at least about $12.5 billion at the IPO price. On the January guidance, the business was expected to produce about $620 million of EBITDA in 2026.18 That implies a value of roughly 20 times EBITDA, at a time when the market valued L3Harris as a whole at about 14 times.6
This is only an approximation, since the exact stake was never disclosed, but the direction is clear. The structure assumed that public investors would pay a growth multiple for the missile business that they had never paid for L3Harris itself. That is the whole logic of a carve-out: show the market a fast-growing asset without the slower parts attached, and let it be valued like a growth company. The parent keeps control, collects the higher valuation on its remaining 80%-plus stake, and funds new factories without issuing shares at the parent level.
For a while, the market played along. By early March 2026 the stock had reached about $362, close to the 52-week high.30 Then, on the evening of July 29, alongside a strong second-quarter report, L3Harris announced it was pausing the listing and would revisit it in mid-2027.3128 "Market conditions have evolved and do not reflect the tremendous value we are building," Kubasik said on the call.32 The next day the shares fell sharply.4
Look at what happened that day. The company had just beaten expectations, raised its full-year revenue and earnings guidance, and reported a record backlog.7 And yet the market took away almost five times what the government had invested. One reading is that investors had been paying for the IPO itself, as a catalyst that would reveal the hidden value, and the delay removed it. A harsher reading is that the market had been asked, through the sponsor's terms, to value the missile business at a premium, and declined. The listing was postponed precisely because the price on offer was lower than the price management wanted. You can announce a valuation, but only the market can clear it.
What management said, and what it did not
The analysts on the July call pushed on this. Myles Walton of Wolfe Research asked for the reasoning behind the delay, why mid-2027 rather than late 2026, and noted the company had signed retention agreements with some senior managers of the missile business.9 Kubasik's answer was revealing.
The business had "land," "operating factories, backlog," "great financials," and was "actually making money," he said, while "a lot of the recent IPOs are obviously missing some or all of those key elements," and "the market is adjusting to valuation. I think we are kind of caught in that process a little bit."928 He added that most of the cash the IPO was meant to raise would not be needed until late 2027, 2028 and 2029, which made waiting "a prudent business decision."9
That last point is concrete and checkable. The rest is less so. The answer did not say what valuation had been on offer, how far it fell short, or what would have to change by mid-2027. Kubasik listed budget fights, a continuing resolution, the election and executive orders as headwinds that would "get resolved."9 Those are reasons the market might eventually pay more. They are not evidence that it will.
Other answers were more specific. Asked about growth, Sharp said the company expected the missile business to grow in the high teens for at least the next couple of years, with propulsion growing 20% or more.9 Asked by Robert Stallard of Vertical Research whether the roughly 17% margin implied by the THAAD and PAC-3 framework was a ceiling, Kubasik said "something in the 15%, 17%, 18% range is something to strive for" as volumes rise and supply contracts lengthen.9
And he said the company was negotiating more than $20 billion of new missile contracts, which would roughly triple the missile backlog.928 Note the verbs: negotiating, striving. The 12% margin is what the business earns. The 17% is what it hopes to earn under contracts that are still being turned from frameworks into firm orders.
The claim that does not wait for the IPO
Meanwhile, the government's money is already on the balance sheet, and the accounting is worth a closer look. In the second quarter L3Harris received $973 million of net proceeds from issuing Series A convertible preferred stock in its missile subsidiary.7 That is the department's $1 billion investment net of costs: the company's guidance explicitly reflects a "Department of War preferred stock investment noncash deemed dividend cost" of $55 million for 2026, and the second quarter carried $14 million of it.97 At the end of June the balance sheet carried $968 million of redeemable subsidiary preferred stock in a mezzanine category between debt and equity, plus two liabilities: $130 million for the preferred's conversion feature and $186 million for the warrants.7
Why does this matter? Because the security was designed to convert at an IPO, and the IPO has not happened. Until it does, the department holds a preferred claim on the missile business that sits ahead of L3Harris shareholders' interest in that business, and it accrues a non-cash cost that reduces the earnings available to common shareholders.
The warrants and the conversion feature are carried as liabilities, so their recorded values can be revised as views of the missile business's worth change. The government's claim on the crown jewel exists whatever the IPO date. The longer the listing waits, the longer L3Harris shareholders carry a partner whose terms were set on the assumption of a public market that has not yet appeared.
The market priced Missile Solutions in July as what its accounts say it is today: a fast-growing defence manufacturer earning about 12% margins and spending heavily on factories, not a space-and-missile growth asset deserving a premium multiple. Management may yet be proved right that the market undervalues it, if the margin rises toward the high teens and the $20 billion of contracts are signed. But the man who designed the carve-out, negotiated the government's investment and told investors the market was wrong would not be the one to prove it. Eighteen days later, he was gone.
VII. Who Is in Charge: Kubasik's Exit, Mehta's Inheritance
The number that leapt out of the August announcement was the one the board did not have to put in writing. Fortune calculated that Kubasik forfeited at least $45 million by leaving, and possibly as much as $62 million if performance awards had paid out at their maximum.1 He gave up his 2026 bonus, unvested restricted stock and performance shares, $7.6 million of options and $9.3 million of cash severance he would not have been eligible for.
He kept some options worth about $23 million and more than 200,000 shares worth nearly $57 million, about $80 million in all.1 The board also retained the right to claw back his options if a court ever established undisclosed misconduct such as fraud, harassment or a securities violation.1
It was not the first time Kubasik had left a company this way. In 2012 he was vice chairman, president and chief operating officer of Lockheed Martin and had been named to become chief executive in 2013. Weeks before he was due to take over, an ethics investigation confirmed a close personal relationship with a subordinate, and he was forced to resign; Marillyn Hewson took the job he had been promised.1 L3 then made him its chief executive, and the merger made him L3Harris's chief operating officer and then chief executive.1015
The 2012 episode belongs to the man, not the company. The 2012 episode was public long before L3Harris confirmed him as chief executive in 2021, and the only governance question it raises is whether that knowledge should have changed how closely he was overseen. The board's own record since the investigation, a quick inquiry with outside counsel, a negotiated exit with real forfeitures and a clawback provision, looks like a board doing its job.
The executive who inherits the order book
Sam Mehta, 53, is a very different figure. He spent more than 17 years at Sikorsky, the helicopter maker, then ran the advanced structures business of Collins Aerospace, part of RTX, before joining L3Harris in January 2023 as president of Communication Systems, the radio business that was then and remains the company's most profitable.3
In March 2026 he was given both Space & Mission Systems and Communications & Spectrum Dominance, which together account for more than 80% of revenue.32 He arrives as an operator who has run the profit engine and the largest segment, rather than as a dealmaker, and that matters for a company whose central question is no longer how big it can get but how much it can earn.
His inheritance also includes a remarkable amount of change in a single year. Kenneth Sharp became chief financial officer on March 16, 2026, replacing Bedingfield, who left the finance role to focus exclusively on leading Missile Solutions.33 With Mehta's promotion, Lauren Barnes, who came from Boeing in 2023, took over Space & Mission Systems, and Christopher Aebli, a company veteran since 1991, took over Communications & Spectrum Dominance.32
In the space of five months L3Harris got a new chief executive, a new chairman, a new chief financial officer and new heads of its two largest segments, and even its head of investor relations moved to run an operating sector.9 For a company mid-restructuring, with a carve-out pending, that is a lot of new hands on the wheel at once.
The Bedingfield move deserves a moment. When the missile listing was being prepared, the man who ran the company's finances was also being lined up to run the business being sold. That could be seen as a useful alignment, putting the person who knew the numbers best in charge of the asset that would be valued on them. It could also be seen as a conflict, since the chief financial officer was setting the parent's guidance while preparing to lead a subsidiary whose value depended on it. The March separation of the two roles resolved that tension before it became a problem.
Pay, votes and promises
Kubasik's pay was the shareholders' most visible complaint. In 2025 his base salary was $1.55 million, unchanged for three years; his annual cash bonus paid out at 200% of target, or $6.2 million; and his annual equity award had a target value of $14.2 million, up 5%.33 Including all components, his reported pay for 2025 was about $25.6 million, and he received $66.3 million over three years.331
More than 90% of his target pay was at risk.33 The board's case for that pay was the share price: L3Harris returned 48% to shareholders in 2025, placing it in the 94th percentile of its peer group.33 The case against it is the profit record: net profit grew about 7% in 2025, and return on capital stayed near 6%.8
Shareholders registered their unease. In 2025 only 74% voted for the company's pay plan, down from an average of about 93% over the previous five years.33 The board responded by meeting holders of about 45% of the shares, tightening the payouts on its relative share-return metric, dropping a loosely defined "strategic goals" metric from the bonus and putting more weight on operating margin and revenue.33
It worked. At the annual meeting on May 11, 2026, about 95% of the votes cast for and against approved the pay plan, and all eleven directors were re-elected.34 Independent directors make up about 91% of the board and all of every committee.33 Whatever happened in the executive suite, the formal machinery of governance responded to shareholders.
The best test of management credibility is the guidance record, and on that test the Kubasik regime did well in its final year. In January 2026 it guided to 2026 earnings per share of $11.30 to $11.50 and about $3 billion of free cash flow, and claimed that its 2026 targets exceeded the financial framework it had set out at its December 2023 investor day.18
By July it had raised the earnings range twice, to $11.80 to $12.00, while holding the cash target.7 The board reaffirmed that guidance the day Kubasik left.3 Rising guidance is not proof of good management, because a company can set low targets in order to beat them. But it is the opposite of the pattern that usually precedes a governance crisis.
The evidence therefore supports calling the August exit a contained governance event as far as financial controls and operations are concerned. The board says so explicitly, the guidance held, and the pay and voting machinery responded to shareholder pressure. It does not settle the cultural question, because the company has disclosed nothing about what Kubasik did, and the leadership churn means the new team will be tested on everything at once. Two quarters under Mehta with intact guidance, steady segment margins and a clear timetable for the missile listing would settle it. Until then, investors have to judge the company by the one thing no change of chief executive can alter overnight: the quality of the earnings it reports.
VIII. What Is Profit and What Is Accounting? (Quality of Earnings)
Somewhere in L3Harris's accounts sits a pension fund with more money than it needs. It is a legacy of decades of defined-benefit promises to employees of Harris, L3, Exelis and their predecessors, and because its assets exceed its obligations, it generates income for the company. In 2025 that surplus, along with gains on deferred-compensation assets and other items, contributed $419 million to pre-tax profit, of which $356 million was pension income.8 That is about a fifth of the company's roughly $1.9 billion of pre-tax profit.8 Measured per share, pension income alone was worth $1.63 of the $8.53 the company earned in 2025.16
None of that income comes from building radios or rocket motors. It depends on investment returns and discount rates, and it can shrink as quickly as it grew. L3Harris has been steadily de-risking the fund. In 2025 it moved $1.4 billion of pension obligations to insurers through annuity purchases, and the plans ended the year with net assets of about $1.2 billion.8 That reduces the risk of a future pension deficit, but each transfer also removes part of the asset base that produces the pension income. A defence business judged on a 9.8% margin in its largest segment is, for now, getting a meaningful lift from a fund it inherited.
The tax rate that made two years look different
The second distortion is the tax rate. In 2024 L3Harris paid an effective tax rate of about 5%, an unusually low figure for a large American company. In 2025 the rate returned to about 17%.8 That swing made 2024's earnings growth look better than the business deserved and made 2025 look worse. Pre-tax profit rose by about a fifth in 2025, from about $1.6 billion to about $1.9 billion. Net profit rose only about 7%.8
In other words, roughly two-thirds of the underlying improvement in 2025 was absorbed by the return to a normal tax rate. Investors who looked only at net profit saw a business slowing down. Those who looked at pre-tax profit saw it accelerating. The truth, once the pension income is also stripped out, is in between: the operating business improved solidly in 2025, but less dramatically than pre-tax profit suggests and more than net profit implies.
The first half of 2026 showed the same pattern in a different form. In the second quarter, reported operating income rose about 15%, but pre-tax profit rose about 35%, helped by pension income and by gains on venture investments made through the Shield Capital funds, which Sharp described as "below operating income gains" that "positively benefit the EPS."79 They are real gains. They are not the business.
The cash flow statement looks reassuring at first glance. Over the eleven years since 2014, L3Harris and Harris before it reported about $9.9 billion of net profit and generated about $17.8 billion of operating cash, roughly 1.8 times as much.8 That gap mostly reflects the amortisation of acquired intangibles, a large non-cash charge that reduces reported profit without costing any cash, along with impairments and depreciation that exceeds capital spending.8 It flatters the conversion ratio rather than revealing hidden cash. The amortisation is the accounting echo of the purchase price, and the cash that price consumed left the building years ago.
The 2025 cash figures have two specific tailwinds. L3Harris generated about $2.7 billion of free cash flow, well above its $1.6 billion of net profit.8 But taxes receivable fell from $379 million to $53 million as refunds arrived, and accounts payable rose by $456 million, meaning the company paid suppliers more slowly.8 Bedingfield acknowledged in January that the year's cash growth reflected "favorable tax planning strategies and tax reform" alongside earnings growth and working-capital management.18
Neither tailwind can repeat indefinitely. In the first half of 2026 free cash flow was $584 million against a full-year target of about $3 billion, which means the company needs to generate about $2.4 billion in the second half.7 That is typical of a contractor whose government customers pay heavily at year-end, but it means the cash promise rests on the next two quarters.
Where the money went
Over the same eleven years, L3Harris generated about $15 billion of free cash flow and paid about $5.7 billion of it, roughly 38%, in dividends.8 The dividend has risen for 24 consecutive years, and Sharp has said reaching the 25-year mark that defines a so-called dividend aristocrat is "important to us."9 The company also buys back stock: about $1.2 billion in 2025, $554 million in 2024 and $525 million in the first half of 2026.87 In 2025, dividends of about $900 million plus buybacks of about $1.2 billion added up to about $2.1 billion, against about $2.7 billion of free cash flow.8
The debt is manageable but not trivial. At the end of 2025 L3Harris owed about $11.2 billion, most of it at fixed rates, with about $520 million of cash interest due over the following year. Its commercial paper balance was zero.8 By the end of June 2026 the portion of debt due within a year had risen to about $1.8 billion, and Sharp said the company's leverage was down to about 2.3 times.79
With the propulsion sale proceeds, the company expected to finish 2026 with about $4 billion of cash before any debt repayment or additional buybacks.9 That money has competing claims: $2 billion of missile capacity commitments, $1.8 billion of maturing debt, a dividend streak and an analyst on the July call asking whether political pressure on defence contractor buybacks would change the company's appetite.9
So how much of L3Harris's reported profit is operating? Most of it, but less than the headline. Strip out pension income and venture gains, normalise the tax rate and adjust cash flow for the tax refunds and the payables stretch, and the underlying business looks like one that is growing profit at a respectable but unspectacular pace. That makes the next question unavoidable: what should investors actually learn from a company like this?
IX. Playbook: Lessons From L3Harris
The first lesson is that scale and quality are different things: the merger made L3Harris bigger, but returns on capital remain near 6% because of the price paid to assemble it. A deal priced on synergies has to earn back its premium every year after closing. A merger of equals can make a bigger company without making a better one.
The second lesson comes from Aerojet: its strategic value depended as much on who owned it as on the asset itself. The deal was a strategic chess move made possible by someone else's antitrust problem. For anyone buying in a concentrated industry, the identity of the owner can be worth as much as the asset itself. The antitrust problem was who the buyer was, not what the asset was.
The third lesson is that fixed-price contracts move risk from collection to cost estimates. Estimate risk shows up in the quarters when a space programme or a maritime contract turns out to cost more than planned. The government always pays; the question is what you agreed to build and for how much.
The fourth lesson comes from the stalled listing. The market did not accept the premium valuation management wanted, and the parent lost $4.8 billion in market value the next day. Every company that thinks the market misunderstands its best asset should remember what happened next.
The fifth lesson comes from the August exit, which the board called unrelated to the accounts, customers or operations. Investors do not price only what a company reports; they price the probability that they do not know everything yet, and an undisclosed reason for a chief executive's departure, coming weeks after a failed listing, raised that probability. Governance events are priced even when the business is untouched, because trust in the reporting is part of what the earnings multiple pays for.
X. Bull vs. Bear and KPIs
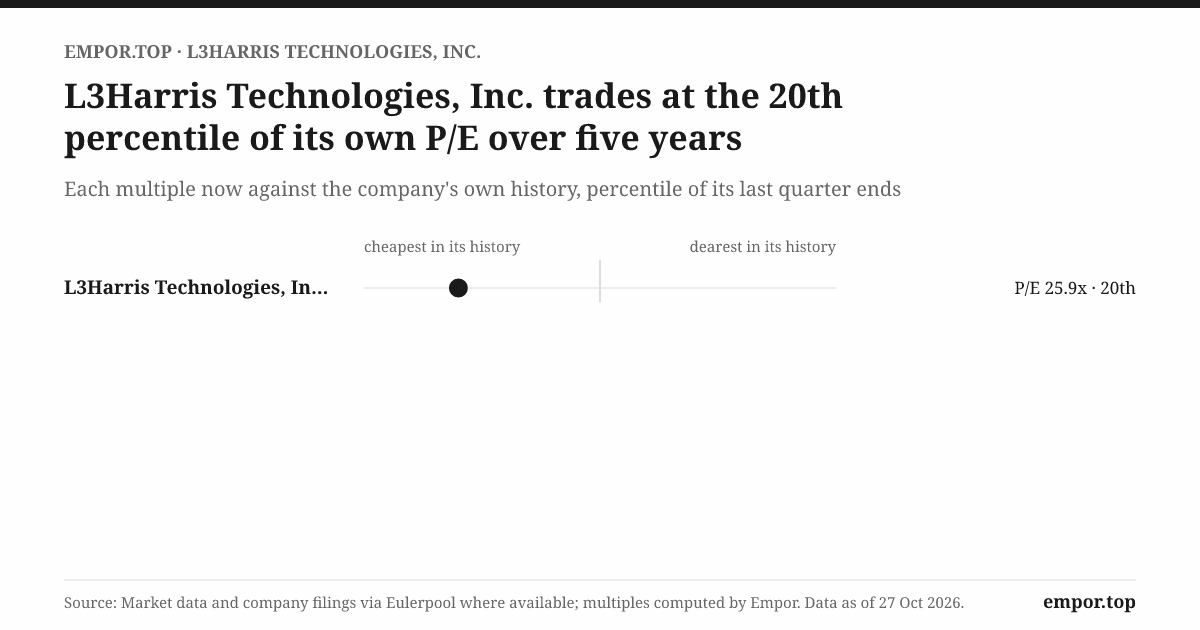
Lay out the valuation sheet. At about $258 a share, L3Harris trades at about 26 times its earnings over the past twelve months, below its own five-year median of about 32 times.68 On analysts' forward estimates it trades at about 21 times, and at about 22 times the midpoint of its own 2026 earnings guidance.67 Its enterprise value is about 14 times EBITDA, its free cash flow yield is a little under 6%, and the 2025 dividend of $4.80 a share works out to a yield of a little under 2%.68 Its shares trade at about 2.3 times book value, but that book value is largely goodwill.
Against the old primes, L3Harris sits in the middle. Lockheed trades at about 22 times trailing earnings and 20 times forward, General Dynamics at about 22 and 20, Northrop at about 18 and 19, and RTX, with its commercial aerospace business, at about 32 and 25.26272425 On EBITDA, Northrop is cheaper at about 13 times, and Lockheed, General Dynamics and RTX are all more expensive at about 15 to 17 times.24262725 The market is not paying L3Harris a premium for the missile business it tried to list, nor demanding a discount for the governance shock. It is pricing it as an ordinary large defence contractor, which is roughly what the margin record says it is.
The bull case is straightforward. A $42 billion backlog and a book-to-bill above one give visibility that few industries can match. Missile demand is strong, backed by a seven-year THAAD and PAC-3 framework and more than $20 billion of contracts under negotiation.9 The radio business earns commercial-style margins of about 27%.7
Free cash flow is guided to about $3 billion, and the stock is about a third below its high, so investors are not being asked to pay peak prices for peak expectations.75 If the missile margin climbs toward the high teens that management says it is striving for, and the listing happens in 2027 at something like the implied valuation, the parent's return on capital would finally start to move.
The bear case is equally clear. Return on capital has been stuck near 6% for five years.8 Three-quarters of revenue is fixed-price, so cost overruns flow straight into profit. Pension income that cannot grow forever accounts for about a fifth of pre-tax profit. Goodwill and intangibles of about $26.5 billion exceed shareholders' equity, so any significant write-down would hit book value hard.8 The listing is stalled, the government holds a preferred claim on the missile business, and a near-complete change of leadership is still settling in.
A skeptical investor would push on one question in particular. In the first half of 2026 L3Harris spent $525 million buying back shares and $470 million on dividends, while committing $2 billion to missile capacity and postponing an IPO that was meant to help pay for it.79 Management says most of the IPO money would not have been needed until late 2027 and beyond.9 But if the listing slips again, will the company keep buying back stock while the factories it promised the Pentagon still need funding? Is the buyback financing a story the IPO should have funded? The answer will come from how the $4 billion of year-end cash is spent.
The risks that matter are few. Budget timing is the first: continuing resolutions and shutdowns delay awards, and the government shutdown in late 2025 set the Space Force back by about 45 days, Kubasik said.18 Fixed-price execution is the second, and the cost-to-complete estimates the auditor flagged are where it would show. Munitions demand is the third; it is surging now, but defence spending moves in cycles, and the missile factories are being built for a peak that may not last. Refinancing is the fourth, with about $1.8 billion falling due within a year.7 A goodwill impairment is the fifth. Currency is not among them; the company says a 10% move would not be material.8
Three numbers will tell investors which case is winning. The first is return on invested capital, about 6.3% over the past twelve months and essentially flat near 6% for five years.8 It is the single measure that captures whether the merger, the acquisitions and the missile investment are earning their keep. The second is book-to-bill, 1.2 in the second quarter and 1.3 over the trailing twelve months, which shows whether demand keeps outrunning revenue.9
The third is free cash flow against guidance: $584 million in the first half against a $3 billion target for the year.7 If L3Harris hits its cash target without stretching suppliers or relying on tax refunds, the earnings are real. If it misses, the questions about earnings quality become questions about the dividend and the buyback.
The verdict, on today's evidence, is a well-backlogged defence contractor priced roughly in line with its peers, with an unproven returns story and a governance question that is contained on paper but not yet tested in practice. What decides it will happen in the next six months.
XI. Epilogue: The Next Six Months
Two days from now, on Thursday, October 29, 2026, L3Harris will report its third-quarter results before the market opens and hold its earnings call at 10:30 a.m. Eastern time.35 It will be Mehta's first call as chief executive, and every question that this story has asked will be in the room with him.
On returns, the call will show whether segment margins held at their low-16% guidance, whether Space & Mission Systems recorded any adverse revisions to its cost-to-complete estimates, and whether the Missile Solutions margin finally began to move as the new GMLRS factory comes online. A quarter of steady margins and confirmed guidance would suggest the operating engine is running independently of who sits in the corner office. A downward revision on a fixed-price programme, especially in space, would revive the concern that the company's biggest risk is the one its auditor flagged. The fourth-quarter report, due in late January if the company follows its usual timing, will show whether the year's cash target was met.18
On governance, the market will listen for any further detail about the investigation and any sign of change in how the board works with its new chief executive and chairman. Silence is the most likely outcome, because the separation agreement was written to keep it that way. But a new chief executive also has a window, early in his tenure, to reset expectations, and if Mehta lowers guidance or takes charges in his first quarters, investors will have to decide whether he is clearing the decks or revealing problems.
On the missile listing, the next milestone is a public filing of the registration statement that Kubasik once said the company would file in late 2026, and that now waits on the mid-2027 timetable.189 Before then, investors will watch for the conversion of the $20 billion of contract negotiations into signed orders, any change in the terms of the government's preferred security, and whether the propulsion business sale, which was scheduled to close in August, has been completed.9
If the contracts are signed and the margin begins to rise, the case for a premium valuation in 2027 becomes stronger. If not, L3Harris may have to choose between listing the business at a lower price and keeping it, with the government as a long-term partner on terms designed for a listing that never came.
On earnings quality, the full-year 2026 results will show how much of the profit came from operations rather than pension income, venture gains and the tax rate. A tax rate in the mid-teens and pension income that stops growing would leave a cleaner picture of what the business really earns.
Each outcome points somewhere different. Steady margins, signed missile contracts and met cash targets would reinforce the board's account of the August shock. Slipping margins, a quiet listing and a cash shortfall would suggest that the strength of the order book had hidden something more fragile. The tension remains the one that has followed L3Harris since 2019: whether it can earn enough on the capital it took to assemble.
XII. Outro
On a Sunday in August a board negotiated away a chief executive, and on Monday it told the world that nothing about the business had changed. In a sense that was true. The backlog was still $42 billion, the radios still earned 27 cents on the dollar, and the rocket motor factories were still going up in Arkansas and Alabama. But the board's reassurance also revealed the company's oldest problem.
L3Harris has spent seven years proving it could be big, through a merger of equals, an acquisition its rival could not complete and a carve-out the market would not yet pay for. It has not yet proved it can be good, in the plain sense of earning a return on all that capital that its customer, its size and its order book would seem to promise.
Harris began by building printing presses and invented its way into electronics. L3 began by buying other companies' leftovers. Their combination became a prime by assembly rather than invention, and the measure of Sam Mehta's tenure will be whether he can turn that assembly into something that earns what invention did.
References
-
Ousted L3Harris CEO Chris Kubasik forfeits $45 million — Fortune, 2026-08-17 ↩↩↩↩↩↩↩↩
-
L3Harris Names Sam Mehta CEO After Christopher Kubasik Steps Down Following Conduct Investigation — Pulse 2.0, 2026-08-17 ↩↩↩
-
L3Harris Technologies Appoints Sam Mehta, Proven Aerospace and Defense Executive, as President and Chief Executive Officer — L3Harris, 2026-08-17 ↩↩↩↩↩↩↩
-
L3Harris shares drop around $4.8 billion after postponed missile IPO — Ground News, 2026-08-02 ↩↩
-
L3Harris Technologies (LHX) stock page — MarketBeat, 2026-10-27 ↩↩
-
L3Harris Technologies (LHX) statistics and valuation — StockAnalysis, 2026-10-27 ↩↩↩↩↩↩↩
-
Exhibit 99.1, L3Harris second quarter 2026 earnings release — SEC, 2026-07-29 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
L3Harris 2025 Annual Report (Form 10-K) — L3Harris Technologies, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
L3Harris Technologies Q2 2026 earnings call transcript — MarketBeat, 2026-07-29 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Harris and L3 to combine in merger of equals (Form 425 press release) — SEC, 2018-10-14 ↩↩↩↩↩↩↩↩
-
Harris Corporation to acquire Exelis (Exhibit 99.1) — SEC, 2015-02-06 ↩
-
L-3 Communications Holdings, Inc. company history — Company Histories ↩↩
-
Elbit Systems' U.S. arm closes buy of Harris night vision unit — Washington Technology, 2019-09-16 ↩
-
Christopher E. Kubasik succeeds William M. Brown as CEO of L3Harris Technologies (Exhibit 99.1) — SEC, 2021-06-29 ↩↩
-
L3Harris fourth quarter 2025 earnings results — L3Harris, 2026-01-29 ↩↩↩↩↩↩↩↩
-
L3Harris Technologies reports strong full year and fourth quarter 2025 results — L3Harris, 2026-01-29 ↩↩↩↩
-
L3Harris Technologies Q4 2025 earnings call transcript — MarketBeat, 2026-01-29 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Lockheed Martin terminates deal for Aerojet Rocketdyne — Via Satellite, 2022-02-14 ↩↩↩↩
-
L3Harris closes purchase of Aerojet Rocketdyne — Defense News, 2023-07-28 ↩↩↩
-
L3Harris completes Aerojet Rocketdyne acquisition — L3Harris, 2023-07-28 ↩
-
L3Harris completes $2 billion purchase of Viasat Link 16 assets — Defense News, 2023-01-03 ↩↩
-
L3Harris to sell majority stake in Space Propulsion and Power business to AE Industrial — L3Harris, 2026-01-05 ↩↩
-
Northrop Grumman (NOC) statistics and valuation — StockAnalysis, 2026-10-27 ↩↩↩
-
RTX Corporation (RTX) statistics and valuation — StockAnalysis, 2026-10-27 ↩↩↩
-
Lockheed Martin (LMT) statistics and valuation — StockAnalysis, 2026-10-27 ↩↩↩
-
General Dynamics (GD) statistics and valuation — StockAnalysis, 2026-10-27 ↩↩↩
-
L3Harris presses pause on Missile Solutions IPO plan — Washington Technology, 2026-07-30 ↩↩↩↩↩
-
L3Harris closes $1B investment from Department of War in Missile Solutions business — L3Harris, 2026-04-23 ↩↩↩↩
-
The Pentagon Invested $1 Billion in L3Harris: Here's What Analysts Say — TIKR, 2026-03-11 ↩
-
L3Harris Pauses IPO Of Missile Solutions Business, Says Market Undervalues — Defense Daily, 2026-07-30 ↩
-
L3Harris Delays Missile Solutions Unit IPO — Aviation Week, 2026-07-30 ↩
-
L3Harris Form 8-K, results of 2026 Annual Meeting of Shareholders — SEC, 2026-05 ↩
-
L3Harris sets date for third quarter 2026 earnings release — L3Harris, 2026-10-05 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube