JPMorgan Chase: The Fortress and the Succession Problem
I. Introduction & Episode Roadmap
On 25 June 2026, JPMorgan Chase did the thing big companies usually handle with great care. It reshaped the top of the firm in public. The board named two co-presidents, Doug Petno and Troy Rohrbaugh. By the end of the same day, Marianne Lake was gone. For years outsiders had seen her as the most likely next chief executive. Jamie Dimon later explained that she chose to retire once the board had named the co-presidents.5 The most closely watched succession race in American finance lost its front-runner in one afternoon, and it still had no finish line.
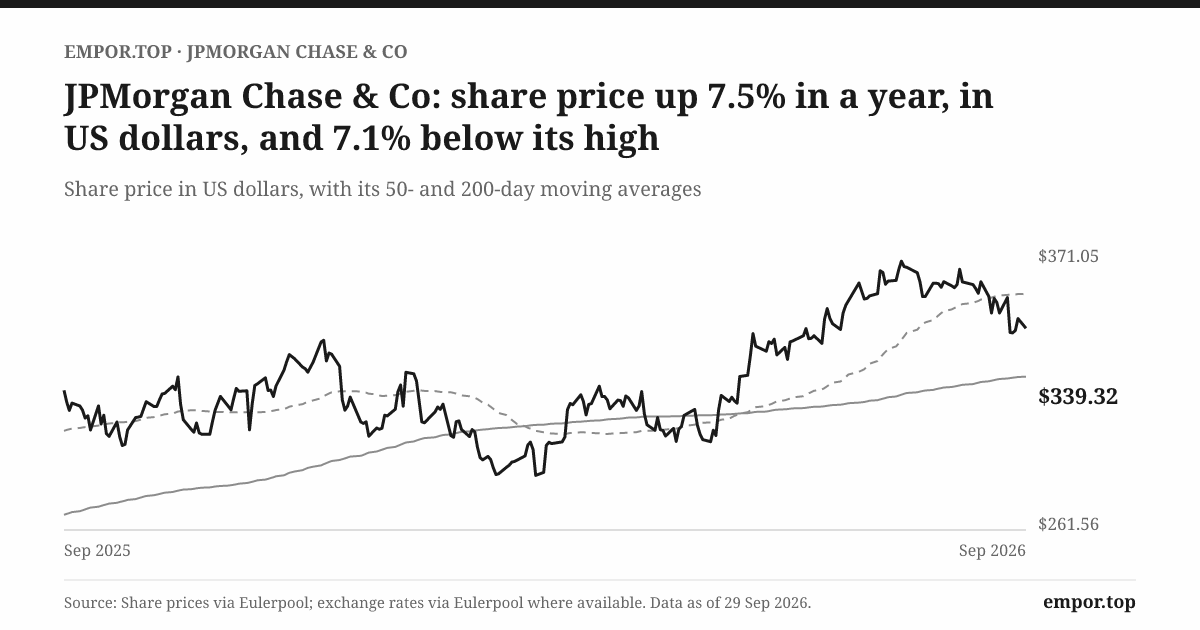
The drama mattered because of what sits underneath it. On 29 September 2026, JPMorgan was worth about $933bn in the market, at roughly $339 a share.1 No bank anywhere is worth more. In FY2025 it earned $182.4bn of net revenue, which is what a bank has left after paying interest to depositors and lenders.1 It employed 318,512 people at year-end.1 It runs three lines of business on a balance sheet of $4.42tn: Consumer and Community Banking, the Commercial and Investment Bank, and Asset & Wealth Management.1 Put simply, it is a retail bank, a Wall Street dealer and a global wealth manager in one company, and each of the three would rank as a major institution by itself.
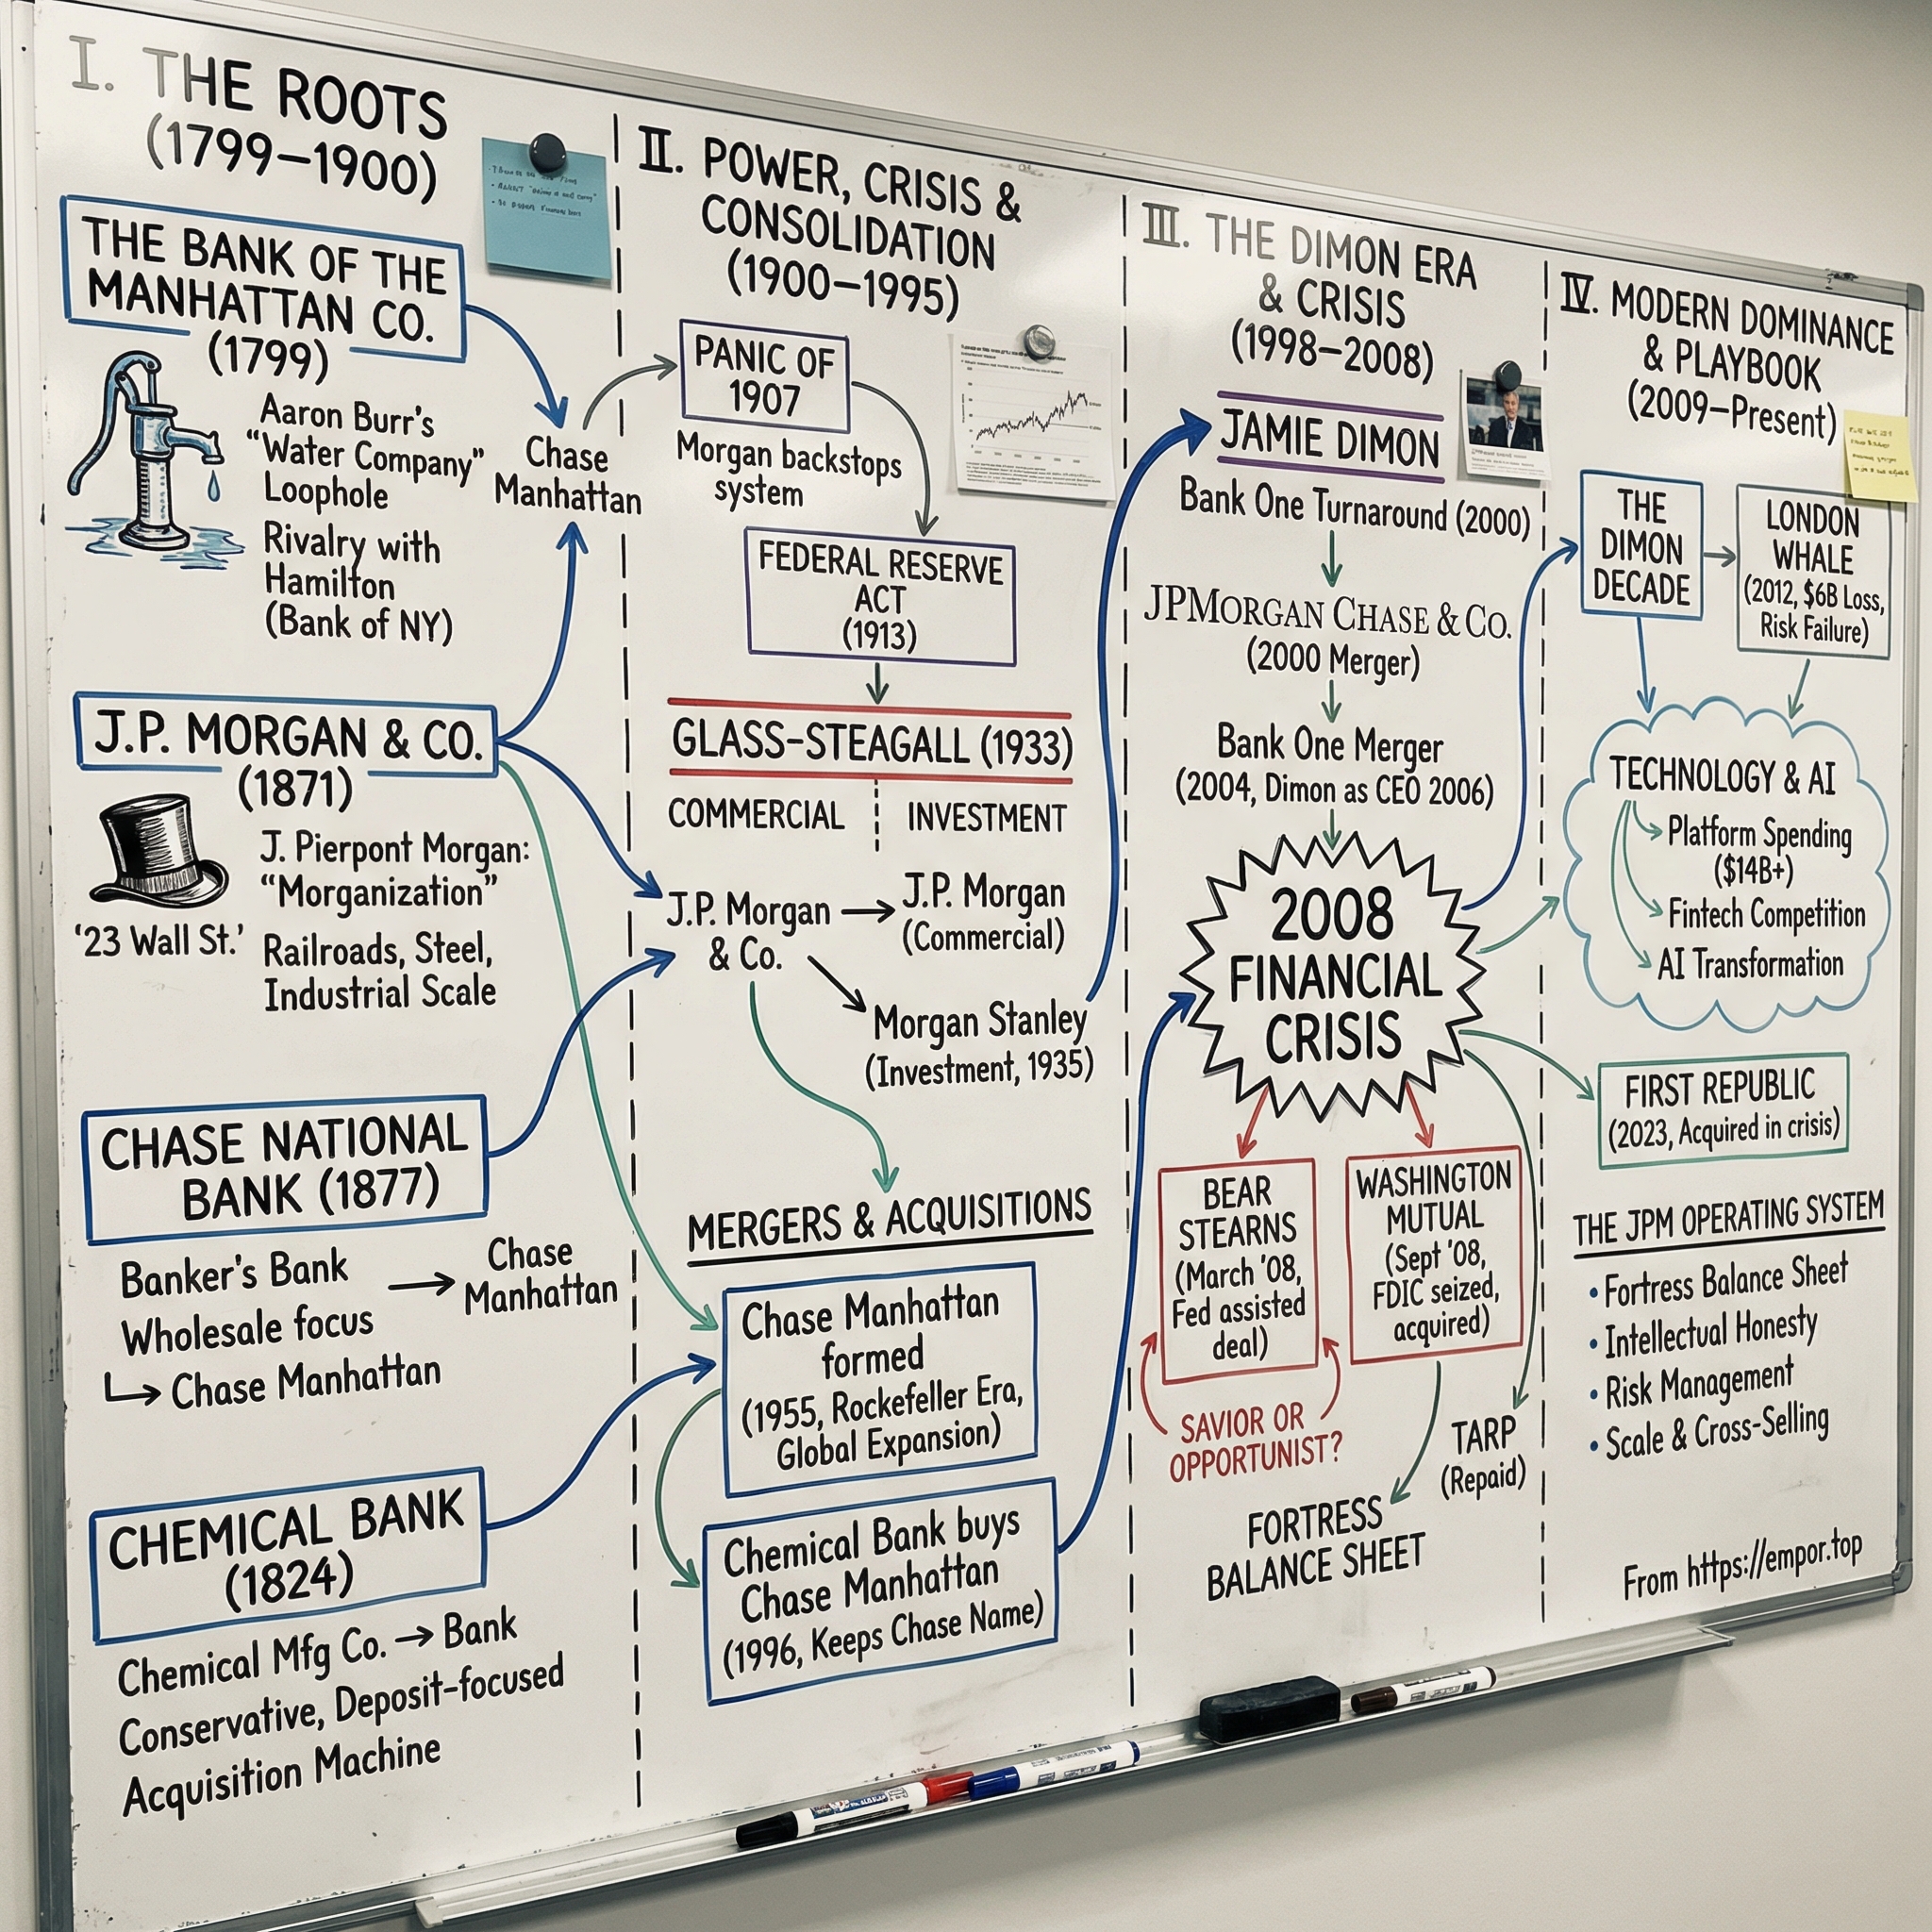
The corporate family tree starts somewhere unlikely. In 1799 New York chartered the Manhattan Company to pipe fresh water into a city struggling with yellow fever. Aaron Burr made sure the charter carried a clause that let the company use its surplus capital for any lawful business. Within months the water company had opened a bank.8 That loophole is the founding myth of Chase, and it fits the firm that grew from it. JPMorgan has always been at its best when it spots a door that others have missed or cannot afford to walk through.
This story works through four questions, and each has a figure that will eventually settle it.
First, how much of the recent profit surge will repeat? Net income in Q2 2026 was $21.2bn, but about $5.6bn of that came from a Visa share exchange and gains on equity investments.2
Second, is credit getting worse in the normal way after a boom, or is a much larger reserve build on its way?
Third, can the firm keep handing about three-quarters of its earnings back to shareholders while a growing balance sheet eats capital?
Fourth, who runs the bank after Dimon, and could the handover damage the franchise?
The story takes these in order. It begins with the mergers that produced today's company, then the crisis deals that made Dimon's name and the legal bill that followed them, then the First Republic rescue. The middle sections take apart the three businesses, the moat, the credit book and the capital return. The last sections cover succession, the lessons and what to watch.
The short verdict can go up front. The franchise has no true equal. What is still open is how much of today's earnings is recurring and who leads after Dimon. A note on figures: the data services that feed most screens show JPMorgan's "revenue" as about $280bn. That number counts interest income before interest paid. This story uses the company's net revenue instead, because that is the pool of money the bank actually earns from.
The founding clause is the right starting point, because the firm's shape comes from its family tree.
 Subscribe on LinkedIn
II. Four Banks in a Trench Coat: Only the Lineage That Matters
Imagine one company wearing the letterheads of four. At the bottom is the Manhattan Company, the water utility that became a bank in 1799. Next comes J.P. Morgan & Co. In 1907, during a panic with no central bank to stop it, Pierpont Morgan shut the leading financiers of the city in his library and kept them there until they had put up enough money to rescue the system.8 Then Chase National and Chemical, two big commercial banks of mid-century New York. Last is an outsider from the Midwest, Bank One of Chicago, whose chief executive would end up running the whole combination.
The history moves quickly and most of the dates are useful mainly as sign-posts. In the 1930s Glass-Steagall forced banks to separate commercial lending from securities underwriting. J.P. Morgan kept the lending business, and the dealmakers left to set up Morgan Stanley.8 In 1955 Chase National merged with the Bank of the Manhattan Company to create Chase Manhattan.8 Chemical bought Chase in 1996 and took the more famous name.8 By then the old wall between commercial and investment banking was already coming down. In 2000 the new Chase bought J.P. Morgan, which brought together a mass-market deposit franchise and a prestige Wall Street brand.8 In 2004 it bought Bank One, and that brought Dimon.8
For today's investor, three things carry forward from this lineage and the rest is trivia.
The first is the brand pairing. "Chase" is the name on the branch and the card. "J.P. Morgan" is the name on the trading floor and in private banking. The firm has kept the two separate on purpose, and both are worth something.
The second is the universal-bank model. Deposits pay for loans, loans lead to treasury relationships, and treasury relationships lead to underwriting and advisory mandates. The mergers of 1996 to 2004 assembled that machine before most rivals had one.
The third is Dimon himself. He did not rise through JPMorgan. He came in with the Bank One deal. He became president and chief operating officer, and he took over as chief executive at the end of 2005.8
Did the firm overpay in these deals? The honest answer is that nobody can tell from price alone. The 2000 purchase of J.P. Morgan came at the peak of the dot-com era, and deal pricing across the industry was rich. The firm soon took a series of charges for bad telecom and energy lending, Enron among them, which suggests it acquired risks as well as franchise.8 Bank One in 2004 looks better in hindsight, mostly because it came with a manager. Without a price benchmark from comparable deals it would be wrong to call either one an overpayment. Stating that plainly is better than inventing a verdict.
A cleaner test of the merger record is the compounding that came afterwards. Tangible book value per share, meaning common equity less goodwill and intangibles, divided by the shares outstanding, reached $113.35 at Q2 2026.2 It has kept rising through crises, buybacks and a very large dividend. A firm that repeatedly overpaid for acquisitions would show that as goodwill write-downs and stalled tangible book. JPMorgan's record shows neither. The lineage points to a habit of buying when others were under strain. The next section tests whether that habit paid for itself.
III. The Dimon Playbook and the Crisis Trades (2004–2013)
It is a Friday in March 2008 and Bear Stearns is running out of cash. Counterparties have stopped rolling its overnight funding. Hedge funds are moving their accounts. The Federal Reserve Bank of New York has already routed emergency funding to Bear through JPMorgan. Over the weekend, working with Treasury and the Fed, JPMorgan agreed to buy Bear, first at $2 a share and then, after an angry reaction from Bear shareholders, at about $10.10 The Fed set up financing of up to $30bn against a pool of Bear's less liquid assets, and JPMorgan absorbed the first $1bn of any losses.10 In a single weekend Wall Street's fifth-largest investment bank turned into a JPMorgan division.
The man behind the playbook
To understand the weekend you need to know the man. Dimon was raised in Queens, the son and grandson of stockbrokers. He wrote his Harvard Business School application essay about his family's firm. He then spent years as Sandy Weill's lieutenant, helping build what became Citigroup. In 1998 the two fell out in a way that became part of Wall Street lore, and Weill forced him out.8 Dimon spent the next period out of work, reading and thinking. In 2000 he took the job running Bank One, a Chicago bank in poor shape. He cut costs, merged the computer systems and rebuilt the capital.8 The Weill split left him with a lasting dislike of being dependent on anyone, a board included. Bank One gave him a method.
That method has a name: the "fortress balance sheet." In practice it meant three things. Hold more capital and liquidity than regulators require. Mark assets conservatively. Refuse to chase the most profitable products at the top of the cycle, which in 2006 meant subprime CDOs and structured investment vehicles. JPMorgan did not avoid mortgage losses completely. It did go into 2008 with fewer of the self-inflicted wounds that ruined Citigroup, Merrill Lynch and Lehman.8 The fortress did more than protect the bank. It gave the firm the means to buy when everyone else was forced to sell.
Bear and WaMu: price, financing and the benchmark
Six months after Bear, in September 2008, federal regulators seized Washington Mutual, the largest US savings and loan, and sold its banking operations to JPMorgan for about $1.9bn.8 With that one purchase Chase gained a branch network in California and Florida, where it had been thin.
Compared with what else happened that year, the prices were low. Bank of America paid about $50bn in stock for Merrill Lynch. Wells Fargo paid about $15bn for Wachovia. Both buyers took on large losses along with the franchises.8 Measured against those deals, JPMorgan paid a fraction of the price for Bear and WaMu and had official backstops behind it. On that measure the crisis trades were cheap.
The falsification pass: the legal bill
The "free lunch" version of the story, the one where Dimon collected two banks for almost nothing, does not survive the next five years. Most of the mortgages that later became the subject of lawsuits had not been written by JPMorgan. They were written by Bear's EMC unit and by WaMu before JPMorgan owned either. JPMorgan paid for them anyway.
The largest single payment was a $13bn settlement with the Justice Department and state and federal partners in November 2013, which covered mortgage-backed securities sold before the crisis.12 Dimon later told shareholders that roughly 70% of the firm's mortgage-related legal and repurchase costs, which had run beyond $19bn, came from the Bear and WaMu books rather than JPMorgan's own.8 He also said the board would not let him take a call like the Bear one again on the same terms.8
That is the real accounting of the crisis trades. JPMorgan paid a low price at the time, and then added a large legal bill years later. The deals still made the firm bigger and stronger relative to rivals. They were not a gift, and anyone who calls them one has left the 2013 settlement out of the numbers. The honest claim is narrower: the deals were good, but they were not costless.
The legal tail has also shrunk a great deal. Legal expense fell from $1,436m in 2023 to $740m in 2024 and $361m in 2025.1 At that level litigation is a rounding error against a firm that earns more than $50bn a year. It is no longer a drag on the investment case.
TARP, and the London Whale
In October 2008 the Treasury required the largest banks to accept TARP capital, JPMorgan's $25bn included, whether they wanted it or not. JPMorgan repaid it in 2009.8 Dimon says JPMorgan never needed the money. The claim is plausible, but it cannot be proven, because every large bank was also supported by the Fed's system-wide backstops.
The strongest evidence against the "best risk manager on Wall Street" label came in 2012 and was self-inflicted. A synthetic credit portfolio in the Chief Investment Office's London operation grew so large that traders nicknamed the trader behind it the "London Whale." At first Dimon called press coverage of it a "tempest in a teapot." In May 2012 the firm disclosed a loss of about $2bn, and the final figure turned out to be several times larger. Regulators in the US and UK later fined the firm about $920m, and the episode led to a restatement of quarterly results and a Senate investigation.8 The unit that was supposed to hedge the firm's risk had become its biggest single bet.
How much should an investor weigh this today? Economically the loss was modest, well under one year's profit. Organisationally it was damaging. It showed a gap between what the board was told and what the traders were doing, and the chief executive had played it down in public before he understood it. Since then the firm has rebuilt the CIO's mandate and has not repeated a loss of that kind. The conclusion is that the "best risk manager" claim survives, but in a narrower form: a management team that avoids the industry's big mistakes, not one that never makes its own. The London Whale was fourteen years ago. Its lesson is about how a very large bank can hide risks from its own leaders, and that lesson does not age.
The same reflex that bought Bear and WaMu came back fifteen years later, and this time the cost of the deal was known on day one.
IV. The First Republic Trade and the Same Reflex 15 Years On
In the early hours of 1 May 2023, the California regulator closed First Republic Bank. Its wealthy depositors had been moving their money out since Silicon Valley Bank failed seven weeks earlier. The FDIC ran a weekend auction and JPMorgan won.11 When San Francisco woke up, First Republic branches were open as JPMorgan branches. Most customers noticed nothing, and that was the aim.
The terms are worth setting out, because they show the playbook working with its caveat attached. JPMorgan took on all of First Republic's deposits and most of its assets. The FDIC agreed to share losses on single-family mortgages and commercial loans that were transferred in the deal.11 The FDIC estimated that the failure would cost its deposit insurance fund about $13bn.11 In effect the government took the tail risk, and JPMorgan got a book of wealthy clients whom it had been trying to win for years.
It was also, literally, a bigger bank getting bigger. Regulators normally bar any bank that holds more than 10% of US deposits from buying another deposit-taker. That cap does not apply to a failed-bank rescue.11 The buyer that regulators preferred was the one the rules would otherwise have stopped.
Compare it with the other failures of spring 2023. SVB's deposits went to First Citizens, a much smaller bank. Signature's went to New York Community Bancorp, which ran into trouble of its own within a year. Those other buyers were smaller banks taking on large books and mismatched funding. JPMorgan absorbed First Republic without strain. That makes it the fair benchmark for the reflex: in a crisis, the strongest balance sheet can take on a failed bank and the risk becomes manageable in a way it is not for a mid-sized buyer.
The accounting kept paying out long after the weekend. In Q1 2025 the firm booked a $588m gain related to First Republic.1 During 2025 it released $763m of accruals for the FDIC special assessment, the levy the FDIC charged large banks to refill the insurance fund after the spring 2023 failures.1 Both amounts were real. Neither is part of JPMorgan's recurring earning power. They are the first examples of a pattern that the earnings sections below return to: reported profit that includes gains an investor should not multiply by a P/E ratio.
What does First Republic tell us about the reflex overall? It confirms that the pattern works under one specific condition: when a regulator asks for help and shares the risk. Bear, WaMu and First Republic all came with official backstops. No deal in JPMorgan's history shows the playbook working at scale without that support. So the claim needs narrowing again. JPMorgan is very good at crisis deals that the government brokers. Whether it would be as disciplined in a large voluntary deal at a full price has not been tested. Dimon's own statements about large acquisitions suggest he doesn't want to find out.
Deals built the company, but the everyday earnings come from three businesses running on one balance sheet. That is the next stop.
V. The Engine Room: Three Businesses and Where Profit Comes From
Consider three customers on the same Tuesday. A nurse in Phoenix taps her Chase Sapphire card for groceries and pays off only part of the balance. A CFO in Frankfurt calls her coverage banker to hedge a euro bond before it is issued. A family office in Palm Beach meets its J.P. Morgan private banker to shift part of its cash into a money market fund. None of them sees the others, and all three are funded by, and add to, the same $4.42tn balance sheet.
The shape of the revenue
In FY2025, Consumer and Community Banking generated $76.0bn of net revenue and the Commercial and Investment Bank $78.5bn. Asset & Wealth Management added $24.1bn, and Corporate, mainly the treasury function, contributed $7.0bn.1 Measured by how the money is earned, net interest income was $95.4bn and noninterest revenue $87.0bn.1 The firm is close to an even mix of spread and fees, which is unusual for a bank this size and which cushions it against changes in interest rates.
The number that matters most is hidden inside those totals. Markets revenue, meaning trading in fixed income and equities, grew 19% to $35.8bn.1 Net interest income excluding Markets, which is the core spread earned on deposits and loans, was $92.6bn and essentially flat on the year.1 Last year's growth therefore came from trading floors and fee businesses, not from the core banking spread. Management explained the flat core NII as a set of offsets: deposit margins shrank and rates fell, while higher card revolving balances and wholesale deposits made up the difference.1 This is the distinction an investor needs to hold on to. Market revenue swings with volatility and investor appetite, and core spread income is the steadier base under it.
CIB: the trading floor and the league table
The Commercial and Investment Bank is where JPMorgan earns its Wall Street reputation. It earns money in three main ways. It trades for clients, earning the spread between buy and sell prices on bonds, currencies, derivatives and shares. It underwrites stock and bond issues and advises on mergers. And it provides payments and treasury services, meaning the pipes that move money around the world for corporations. The payments business rarely makes headlines, but it is sticky. When a multinational's treasury runs through JPMorgan's cash management systems, switching banks means rewiring its finance department.
The Markets result is the clearest example of both the business's strength and its cyclicality. A 19% gain in one year is a very large move for a franchise that size, and it reflects a market environment with plenty of volatility, heavy client hedging and financing demand as much as any gain in share. The same franchise can give back that growth in a quiet year. The firm has held the top global investment-banking fee ranking for years, but its share is a few points, not a dominant one. A CFO choosing a lead bank normally chooses among JPMorgan, Goldman Sachs and Morgan Stanley, with Bank of America and Citigroup in contention for particular mandates.
CCB: branches, deposits and cards
Consumer and Community Banking is the biggest employer, with 144,196 of the firm's staff.1 It earns money three ways. Deposits pay interest below what the bank earns on them. Cards earn interest on balances that customers carry and interchange fees on every swipe. And mortgage and auto lending add further volume. The card business is the most profitable and the riskiest part of the consumer bank, a theme the credit section develops below. In deposits, JPMorgan has the largest US share, ahead of Bank of America and Wells Fargo, and that low-cost funding base is the single most important economic asset in the building.
AWM: the quiet compounder
Asset & Wealth Management earns fees on the money it manages or advises on, which makes it the most capital-light of the three businesses. At $24.1bn it is the smallest, but it grows with the value of client assets and needs relatively little balance sheet. It also puts the J.P. Morgan brand in front of wealthy families, who often turn out to be the owners and CFOs of the companies the investment bank wants to serve.
Reinvestment as evidence
Management says it invests through the cycle. The cost lines let an investor check that claim. Technology, communications and equipment expense rose from $9.8bn to $11.0bn in 2025, about 12%.1 Marketing rose from $5.0bn to $5.5bn.1 Compensation rose from $51.4bn to $54.5bn.1 Net revenue, meanwhile, grew about 3%.
Those numbers do not describe a firm harvesting its franchise. They describe a firm spending ahead of revenue, consistent with management's stated approach. A skeptic can argue the other side: rising costs against flat core NII are how efficiency ratios erode. The case for the spending rests on whether it has kept JPMorgan ahead, and the best evidence is that its deposit and card shares have held or grown during years in which fintech companies were supposed to take them. The firm often cites a total technology budget in the teens of billions, including capitalised software. The 10-K does not break out that total, so the $11.0bn expense line is the verifiable figure.
AI gets both attention and money from the firm. It could cut costs in operations, software development and client service, and it could let competitors copy services that used to require scale. The 10-K does not quantify either effect. For now the practical evidence is simple: compensation, the line AI would be expected to reduce, is still rising.
A few smaller items round out the picture. The Apple Card portfolio will be large enough to matter and is discussed under credit. Payments competes against fintech processors and new real-time rails, which comes up again under the moat. Neither yet changes the main economics.
The engine room shows what JPMorgan earns. The harder question is why it earns more than its rivals, and whether that advantage will last.
VI. Why It Wins: Moat, Porter and Seven Powers
Picture the CFO of a large industrial company planning a $10bn acquisition. She needs a bank that can commit the bridge loan, lead the bond deal, hedge the currency and later advise on the equity. In practice she has a list of two or three names. That short list is the moat, and the question for this section is whether it is structural or mostly the product of size and a tolerant regulator.
The returns that need explaining
Return on equity was 15.7% in FY2025.1 The more useful measure for a bank is return on tangible common equity, or ROTCE, because it strips out goodwill from old acquisitions and shows what the bank earns on the capital that actually supports its business. ROTCE was 29% reported and 23% excluding significant items in Q2 2026.2 For a bank, returns in the low 20s after one-off items are exceptional. Most large peers aim for the mid to high teens.
The main source of the returns is funding. JPMorgan held $2.51tn of deposits in 2025, and their average cost fell to 1.80% from 2.08%.1 Deposits are the raw material for lending, and a lender with cheaper raw material wins over time. Consumers keep their paychecks at Chase because of the branch on the corner, the app, the card rewards and inertia, not because Chase pays the best rate.
Porter's five forces, briefly
Buyer power is split. Retail depositors individually have almost none. Large corporations have real power and spread their business across several banks, which limits pricing for loans and plain vanilla services.
Supplier power mostly means the price of labour and capital. Star traders and bankers can extract high pay, which is one reason compensation takes such a large share of revenue. Depositors, the other key supplier, are cheap for the reasons just described.
The threat of new entrants into full-service banking at JPMorgan's scale is effectively zero. The capital required, the regulatory licences and the trust needed to hold trillions of dollars take decades to build.
The threat of substitutes is real and is discussed below.
Rivalry among the large banks is intense but disciplined. The top half dozen compete fiercely in investment banking and cards and much less on deposit rates.
The Seven Powers that apply
Of Hamilton Helmer's Seven Powers, four clearly apply to JPMorgan.
Scale economies: the firm can spend more on technology than peers while keeping a similar efficiency ratio, because it spreads the cost across more revenue. A regional bank cannot match an $11bn technology line.
Switching costs: they are real in treasury services, where corporate finance departments are built around the bank's systems, and in primary operating accounts, where moving direct deposits and bill payments is a chore.
Branding: "J.P. Morgan" carries weight in boardrooms and "Chase" in households, and the firm is widely seen as the safest large bank, which pulls in deposits in every crisis.
Counter-positioning on technology is weaker. Mid-sized banks cannot copy the firm's technology spending without destroying their own margins, but that is closer to scale than to a true counter-position.
What would break it
Three substitution mechanisms deserve more attention than they usually get.
The first is private credit. Direct lenders and large asset managers have taken a growing share of leveraged and middle-market lending, which used to be a bank business. JPMorgan has responded by setting aside capital for its own direct lending, which is an admission that the threat is real. The firm does not disclose any lost mandates to private credit, so the scale of the leakage is unknown.
The second is payments. Stablecoins and real-time payment rails could eventually cut into deposit float and card interchange. JPMorgan has built its own blockchain-based deposit token and payment network, and is investing to be a player rather than a victim. So far no measurable deposit loss to these rails appears in its figures.
The third is fintech in cards and consumer banking. It has not visibly cut into Chase's share. The Apple Card deal points the other way: a technology company that tried to run a card program with a different bank chose to move it to JPMorgan.
Peers and the pricing question
Against peers, JPMorgan's excess return comes mostly from scale and funding cost, not from charging customers more. Bank of America has a comparable deposit franchise but a weaker investment bank. Citigroup has a global transaction network but has been restructuring for years and earns well below JPMorgan. Wells Fargo spent years under an asset cap. Goldman Sachs and Morgan Stanley have strong investment banks but lack a comparable cheap deposit base. The evidence for pricing power over rivals is thinner than the ROTCE implies. The returns come mainly from a lower cost base and a wider product range per client.
Regulation works both ways. It keeps entrants out and makes a trusted incumbent more valuable in a panic. It also sets a capital surcharge that grows with the firm's systemic importance, which caps how much it can return to shareholders, as the capital section shows.
The verdict: the moat is real, and it rests on scale, funding cost, breadth and brand. It is not an unbreachable pricing monopoly, and the substitutes it faces, private credit most of all, are growing. The KPI that will show whether it is holding is ROTCE excluding significant items. A reading in the low 20s through a full credit cycle would confirm the moat. A slide toward the mid-teens would show it narrowing.
A moat protects the franchise, but every bank's earnings eventually depend on whether borrowers pay back. That brings the story to credit.
VII. Is Credit Turning? Cards, Wholesale and the Apple Deal
On 30 December 2025, a day before the year closed, JPMorgan signed a forward purchase commitment to acquire the Apple Card portfolio.1 The announcement came on 7 January 2026.1 Because the firm had committed to buy loans in the future, accounting rules required it to reserve against their expected losses immediately, and a $2.2bn provision hit Q4 2025.1 The Apple Card had become one of the most prominent consumer card programs in the US. Now it was about to join the card lender that was already the largest.
The direction of credit
The trend in charge-offs is clear. The firmwide net charge-off rate, meaning loans written off net of recoveries as a share of loans, rose from 0.52% in 2023 to 0.68% in 2024 and 0.74% in 2025.1 Card net charge-offs ran at 3.31%, while wholesale charge-offs stayed at 0.16%.1 Nonaccrual loans, where the bank has stopped booking interest, rose from $8.8bn to $9.9bn.1
Those figures describe normalisation, not a credit crunch. The 2021 to 2022 years were unnaturally clean, with consumers flush with stimulus savings and few defaults. Losses are drifting back toward pre-pandemic levels. The allowance for credit losses, the reserve for future losses, stood at $31.2bn, and loan loss reserves equalled 1.83% of retained loans, slightly down from 1.87%.1 The reserve ratio did not rise even as charge-offs did. That is either a sign of confidence or the thing to watch, depending on what the economy does next.
The most recent quarter looked calm. In Q2 2026 the provision was $2.5bn, charge-offs were $2.4bn and the net reserve build was only $149m.2 The bank essentially reserved for what it was writing off and added little extra.
Where the judgement sits
The auditor points to where the uncertainty lies. PwC designated the allowance as a critical audit matter, focused on the model-based reserves for two books: $15.6bn of allowance against $247.8bn of card loans, and $7.6bn against $788.0bn of wholesale loans.1 Those reserves are driven by forecasts for US unemployment and GDP.1
Put simply, card losses are expected to run many times higher than wholesale losses, and the size of the reserve depends mostly on what the bank assumes about the labour market. If unemployment rises more than the base case, card losses rise quickly and reserves have to be rebuilt at once, all charged to current earnings. Management cited geopolitical tensions and elevated asset prices among the main risks to the outlook, but it has not signalled a turn in the credit cycle.2
The Apple Card: volume and weight
The Apple Card adds a large and well-known book, but it also adds credit and capital weight. The purchase is expected to reduce the Standardized CET1 ratio by about 25 basis points, and it is due to close about 24 months after the agreement, around the end of 2027.1 Strategically it adds card volume, a younger customer base and a partnership with the most valuable consumer brand in the world. Financially it adds more of the loan type with the highest loss rates to a firm whose charge-offs are already rising. The book's previous owner reportedly had higher losses than Chase's own portfolio, which is partly why a reserve was needed on day one.
The base rate: 2020
For anyone who thinks reserves are a technicality, 2020 is the proof otherwise. When the pandemic hit, JPMorgan built reserves on the assumption of mass unemployment, and net income fell to $29.1bn.1 In 2021 the feared losses never materialised, reserves were released and net income jumped to $48.3bn.1 That is a swing of about $19bn in profit in a single year, driven mainly by changes in assumptions rather than actual losses. It is the base rate for the credit question. Reserve cycles can move JPMorgan's annual profit by tens of billions in either direction.
The verdict for the second central question: credit is normalising, not deteriorating sharply, and the reserve cushion looks reasonable against current losses. But the outcome depends on the labour market, and the firm is adding a large card book at a time when consumer credit is getting worse at the margin. The KPI to follow is the card net charge-off rate, latest 3.31%. If it holds near that level after the Apple book arrives, credit was just normalising. A sustained rise toward the 4-plus percent range would signal the larger reserve build the bears expect.
Credit costs decide how much profit the bank makes. The capital rules decide how much of that profit it can hand back.
VIII. The Capital Question: Returning Three-Quarters of Earnings
During 2025 JPMorgan bought back 114.4m of its own shares for $31.6bn, at an average of $276.55.1 The average rose steadily through the year, from about $252 in the first quarter to about $310 in the fourth.1 On 29 September 2026 the stock traded at $339.1 The buybacks have so far worked in holders' favour. The question is whether the same program still makes sense at a much higher price with a thinner capital buffer.
How much is going back
Add up dividends and buybacks. In FY2025 the firm paid $16.6bn in dividends and repurchased $31.6bn of stock, against net income of $57.0bn.1 That is about 84% of earnings returned. On the company's own trailing-twelve-month measure the payout was 73% at Q2 2026.2 The fact sheet's dividend payout of 29% counts dividends only, so it understates the total by a wide margin. In Q2 2026 alone, net buybacks were $6.2bn and the common dividend was $4.0bn, or $1.50 a share.2 At year-end 2025 the firm had $33.4bn of repurchase authorisation left.1
The buffer is thinning
The capital ratio has been falling at the same time. CET1, the core capital ratio that measures common equity against risk-weighted assets, was 15.7% at the end of 2024 on the Standardized basis. It fell to 14.6% at the end of 2025 and to 14.1% by Q2 2026.12 During 2025 the Advanced approach, which uses the bank's own risk models, became the binding constraint.1 In Q2 2026 the ratio fell 20 basis points in the quarter, as profits were more than offset by higher risk-weighted assets and distributions.2
Why is capital being absorbed? Because the balance sheet is growing. Total assets reached $4.42tn.1 Repurchase-agreement funding, where the bank borrows against securities, rose 49% to $442.4bn.1 Long-term debt rose 8% to $435.2bn, and investment securities climbed from $681bn to $777bn.1 Much of the growth reflects the Markets business, which needs a larger balance sheet to finance client trading. The fact sheet shows "debt to equity" of 2.6. For a bank that number describes how it funds itself, not financial stress. Borrowing is a bank's raw material, much as steel is a carmaker's.
The stress test and the liquidity backstop
The buffer that matters is the gap between the actual CET1 ratio and the requirement, which includes the stress capital buffer set each year by the Federal Reserve's stress test. The Fed's 2026 stress test results set the buffer for the year ahead, and JPMorgan's result is the checkable item that determines how much capital it must hold.9 At 14.1% the firm stays well above its requirement. The margin is narrower than it was two years ago.
Liquidity is not the constraint. The firm reported about $1.5tn of liquidity sources at the end of 2025, including about $915bn of high-quality liquid assets.1 It has not issued new common equity in the recent periods reviewed.1 The contrast with 2008 is useful. During the crisis, even the fortress raised common equity to strengthen its position after taking on Bear and WaMu.8 Buybacks are a luxury of calm periods, and the firm's own history shows that.
The skeptic's case and the rebuttal
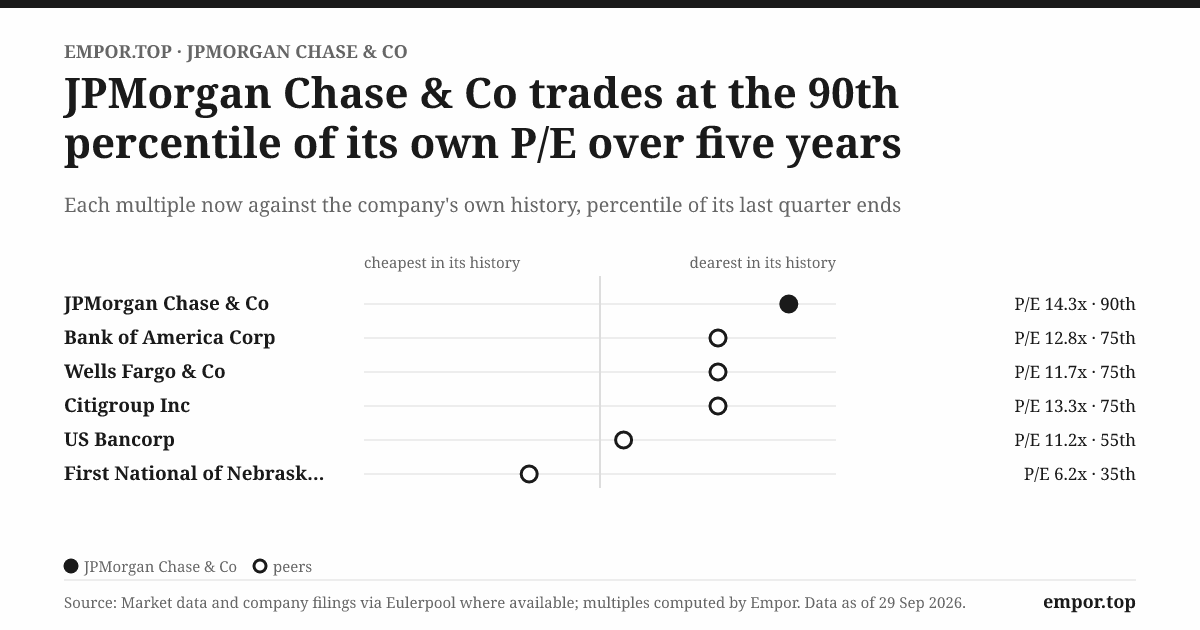
A skeptical investor would argue as follows. JPMorgan is buying stock at about 14 times earnings, far above its five-year median of about 10 times.1 The price paid per dollar of earnings has risen by almost half. It is doing so while capital ratios fall, the Apple Card is about to arrive and credit is getting worse at the margin. Buying stock at the top of a valuation range and then being forced to stop during a downturn, when shares are cheap, is the classic mistake of bank capital allocation.
The other side of the argument is also strong. Surplus capital that the firm cannot deploy in loans at a good return has no better use than going back to owners. Retaining it would drag down return on equity. Dimon himself has repeatedly told shareholders that he prefers buying back stock at lower prices and would slow buybacks when shares look expensive. The firm did slow repurchases at times in the past when it judged the price too high.8 The fair verdict is that the capital return is real, but the buffer is thinning and the price per share has gone up. Whether the program can repeat depends on two things outside management's full control: the capital rules regulators set and the pace of balance-sheet growth.
What the rating agencies say
The credit rating agencies still view the firm as among the strongest in the industry. At the end of 2025 the parent company carried ratings of A1 from Moody's, A from S&P and AA- from Fitch, all with stable outlooks. The main bank subsidiary was rated Aa2, AA- and AA.1 On 19 May 2025, Moody's moved the bank's outlook to stable from developing, following its one-notch downgrade of the US government.113 Put simply, the agencies see a bank that is about as strong as a private bank can be when the sovereign behind it has been downgraded.
The capital question and the earnings question are really the same question from two angles. How much of the profit is recurring decides how much can safely be returned.
IX. The Earnings Puzzle: What Is Repeatable?
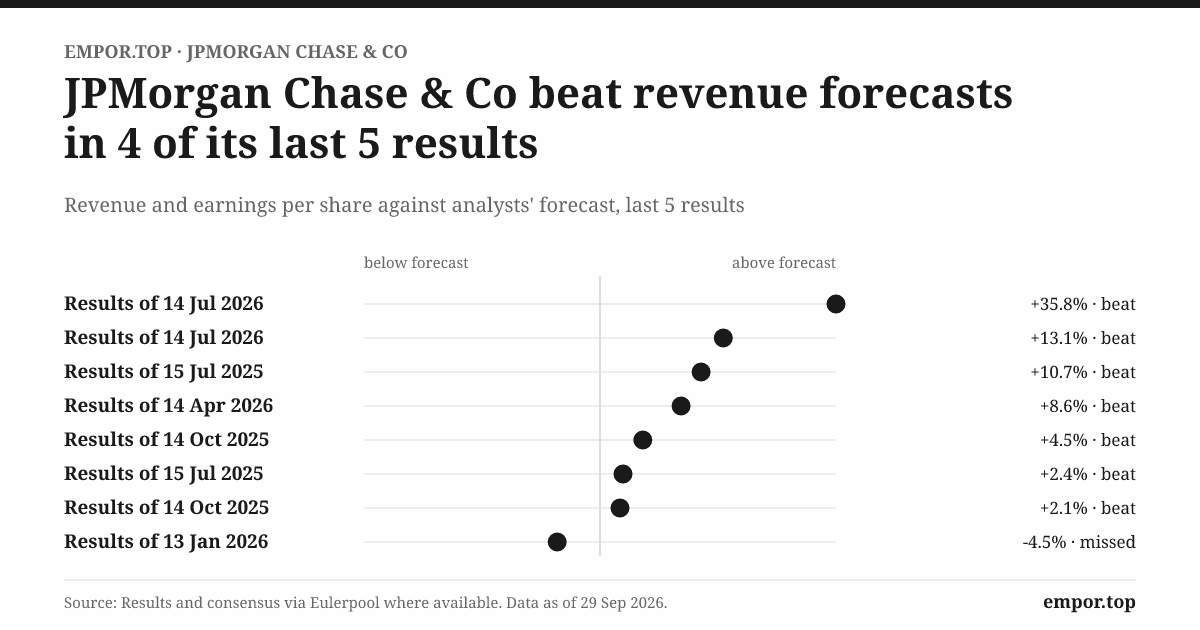
When JPMorgan reported Q2 2026, the headline was EPS of $7.70.2 Buried a few lines down was a second number: $6.14 excluding significant items.2 The gap of $1.56 a share is where this section lives.
The one-offs
Most of the gap was a $4.6bn gain from a Visa share exchange, with another $1.0bn from gains on equity investments.2 Together they made up about a quarter of reported net income. Excluding them, net income was $16.9bn and ROTCE 23% rather than 29%.2
It had happened before. In Q2 2024 the firm booked a $7.9bn net gain on Visa shares.1 That was part of why FY2024 net income reached $58.5bn and why FY2025 net income, at $57.0bn, came in 2% lower.1 The decline was not a sign of weakness. It was the missing one-off. The Visa stake dates from the old Visa card association, whose member banks received shares when Visa went public, and JPMorgan has been gradually converting and selling it.
The fact sheet reports Q2 2026 net profit growth of 41.2%. It is correct as arithmetic and wrong as a guide to momentum. Most of the growth is the Visa gain.
The long base rate
Over 10 years, net profit grew about 8.8% a year. Over five years the rate was 14.4%, and over three years 14.8%.1 The recent figures look higher because they start from a low base. FY2020 was depressed by pandemic reserves, and the three-year window includes the rate boom that inflated interest income in 2023. The 10-year rate, covering a full cycle of rates, credit and markets, is the more honest base rate.
The recent picture is easy to read once the one-offs are removed. In FY2025, net revenue grew about 3% to $182.4bn, and pre-provision profit, meaning revenue less operating expenses and before credit costs, grew about 1% to $86.8bn.1 The provision for credit losses rose 33% to $14.2bn, including the $2.2bn Apple Card reserve.1 The company's EPS was $20.02.1 Underlying earnings were therefore roughly flat in 2025 and then grew in the first half of 2026 as Markets stayed strong. A reasonable estimate of underlying growth is high single digits to low double digits, far from the 41% headline.
The rate path
Net interest income is the biggest single line in the income statement, and it depends on interest rates. When rates fall, the bank earns less on its floating-rate assets while it tries to cut the rate it pays depositors, and deposit margins shrink. That is what held core NII flat in 2025.1 A deeper cutting cycle would put more pressure on the spread. Growth in card balances and deposits is the offset management points to.
How management framed it on the calls
On the calls from Q4 2025 through Q2 2026, management consistently presented the Visa gains as significant items, separated out, and pointed investors toward the numbers excluding them.7 That is to its credit, as it does not hide the one-offs. Analysts pushed hardest on NII excluding Markets and on expenses, asking whether the core spread could grow again as rates fell. Management answered by pointing to card balances and deposit growth, while declining to promise much.7 The tone was consistent across the three calls: cautious guidance and a standard warning from Dimon about risks in the economy and asset prices.
Valuation as data
The stock trades at about 14.3 times trailing earnings, compared with a five-year median of about 10.1 times, at 2.5 times book value and with a dividend yield of about 1.8%.1 The PEG ratio is 0.84, but that is calculated on a growth rate flattered by the low 2020 base. The trailing P/E is itself flattered by Q2's Visa gain, which included about $1.27 of EPS from the Visa exchange and $0.29 from equity gains.2 On underlying earnings, the multiple is somewhat higher than 14.3 times.
What does the price assume? It assumes that the returns of the last three years are the new normal rather than a cyclical peak, that credit stays contained and that the handover goes smoothly. In five years the stock has fallen by as much as 40.6% from peak to trough, and one-year volatility was 22.5%.1 The market has shown before that it can reprice this franchise quickly. JPMorgan has long traded at a premium to other large US banks on price to book, reflecting its higher returns. Whether today's premium is wider than the gap in returns can justify is the question the valuation is really asking.
The numbers point back to the people. A premium multiple is partly a bet on management, and management means one man and whoever comes after him.
X. The Dimon Question: Pay, Power and the Post-Dimon Bench
The reshuffle of 25 June 2026 laid out the new bench. Doug Petno, long-time head of commercial banking and then co-head of the Commercial and Investment Bank, and Troy Rohrbaugh, the Markets chief who also became CEO of Consumer and Community Banking, were named co-presidents.5 Marianne Lake, who had run the consumer bank and been seen as a leading contender, retired.5 Jennifer Piepszak and Mary Erdoes each received $20m retention awards.5 Dimon, who is 70, said he expects to stay "a few more years, plus or minus," and possibly continue afterward as executive chairman.5
The bench, and what it tells us
The board has built a bench. It has not named a successor. Putting two people in co-president roles invites a contest, and handing Rohrbaugh a second job running the consumer bank looks like a deliberate test: a trader asked to run branches and cards. Retention awards for Piepszak and Erdoes are an attempt to keep the other candidates from leaving, as Lake did. The risk is not that the bank lacks talent. It has plenty. The risk is that the longer the race continues, the more talent leaves, and that a successor who has not been clearly chosen inherits a firm built around one person's judgement.
Dimon's timeline has become something of a running joke on Wall Street, because he has said "a few more years" in one form or another for most of a decade. No date has been announced. Until one is, this question stays open.
Pay and incentives
Dimon's 2025 pay was $43.0m: $1.5m salary, $5.0m cash incentive and $36.5m in performance share units.34 The PSUs pay out according to the firm's return on tangible common equity over a multi-year period, both in absolute terms and relative to peers, so they link most of his pay to the same measure this story uses to judge the moat.3 Other 2025 awards were $31.0m for Erdoes, $27.5m each for Rohrbaugh and Petno and $19.5m for CFO Jeremy Barnum.34
Shareholders now support the pay design. Say-on-pay passed with about 91% approval.3 The contrast with 2022 is striking. That year, support fell to about 31% after the board gave Dimon a special retention award worth about $52.6m.3 The board did not repeat the special award, and support returned. The lesson for the board: shareholders accept high pay tied to returns, and they object to large one-off grants.
Dimon owns a stake worth billions of dollars, built up over two decades of share awards and open-market purchases, and he has rarely sold.3 His wealth is tied to the stock.
Governance
Dimon is both chairman and CEO, and the board has a Lead Independent Director. There were 11 director nominees, all independent except Dimon.3 A shareholder proposal to separate the chair and CEO roles was on the ballot at the 19 May 2026 annual meeting.3 The final vote counts are filed in the 8-K reporting the meeting results.6 Similar proposals have failed at JPMorgan in past years, and the combination of the roles under Dimon has broad support from large holders.
Credibility over time
The best way to judge a CEO is to compare what he said with what happened. Dimon's record is strong but not spotless. In 2008 he warned about risks early and kept the balance sheet clean. In 2012 he called the London Whale a "tempest in a teapot," then had to retract the comment and apologise. His annual shareholder letters have warned about a long list of risks: inflation, geopolitics, asset prices and government deficits.8 Some of those warnings came true. Others did not happen on the timetable he suggested. A reader of the letters learns that Dimon tends to be cautious in words and aggressive in action, and that combination has served shareholders well.
Smaller governance items
Related-party dealings are routine. Directors, executives and the two named 5% holders, BlackRock and Vanguard, were customers of or had transactions with the firm in the normal course of business.3
Political and legal exposure is more visible than material. In August 2025 an executive order on "fair access to banking" targeted what the administration called debanking. In January 2026 Donald Trump and affiliated entities sued the firm in Florida state court.1 In India, the Enforcement Directorate fined J.P. Morgan India about $31.5m in 2021 over the Amrapali matter, and the firm is appealing.1 All three are small compared with the firm's estimate of reasonably possible losses beyond reserves, which ranges from zero to about $1.2bn.1 Together they show that a bank this large is also a political target.
PwC, the auditor, flagged two critical audit matters: the allowance for loan losses and the fair value of certain Level 3 instruments, which are valued with models rather than market prices.1 Its opinion contained no material weakness.1
The verdict for the fourth central question: pay is high but linked to returns and backed by shareholders. The bench is deep. The successor is not named, and the front-runner has left. The handover risk is less about competence than about continuity of judgement at a firm where a single person has made the defining calls for twenty years.
The story so far holds lessons, some unique to JPMorgan and some learned the hard way.
XI. Playbook: Lessons From the Fortress
Hold the cash before you need it. In March 2008, JPMorgan could buy Bear Stearns over a weekend because it had spent years holding capital and liquidity that rivals thought were wasteful. Today the firm keeps about $1.5tn of liquidity on hand, an amount that looks idle in calm years. The lesson for any business is that a strong balance sheet is not a cost of safety. It is a call option on everyone else's panic, and it pays only when it is already there. At JPMorgan, the fortress is the strategy, not the insurance.
The best time to buy is when the regulator is calling, and read the fine print. Bear, WaMu and First Republic each came at a low price with official backstops. Bear and WaMu also came with a legal bill that ran into the tens of billions over the following five years. First Republic came with FDIC loss sharing that made the cost known on day one. For investors the lesson is to count the tail as well as the purchase price. For founders, the cheapest assets are the ones nobody else can buy, and you still pay for them later.
Numbers are for understanding, not for proving what you think. Dimon often says that data should be used to learn, not to confirm a view. The London Whale is the case where the firm forgot that. A hedging unit reported comfortable risk numbers while its positions were growing out of control, and the CEO accepted the comfortable version for a few weeks too long. Even the best-run bank can be fooled by its own reports.
Spend through the cycle. In 2025, technology spending rose four times as fast as revenue, and compensation and marketing grew faster too. That is the opposite of the reflex most companies have when growth slows. It is also the reason Chase has held deposit and card share against a decade of fintech challengers. The discipline is not cutting costs. It is choosing which costs to protect.
Don't count the gift as the paycheque. In two of the last three years, a Visa share gain has been the single biggest swing factor in reported earnings. The firm labels those gains clearly, and investors who strip them out see a business growing at a steady rather than spectacular pace. Every company has its Visa stake. The skill lies in not paying a multiple for it.
The last lesson is about size itself. JPMorgan's scale makes it the first call in a crisis, the cheapest funder and the biggest technology spender. The same scale sets its capital surcharge, draws political fire and prevents it from buying another healthy bank. At JPMorgan, the moat and the constraint are the same thing.
XII. Analysis: Bull vs. Bear and What to Watch
Picture two analysts across a table. One started covering the stock when it reached its 52-week high of about $365.1 The other remembers when it fell more than 40% within five years.1 Both look at the same bank. They disagree about the price.
The bull case
The bull argues that JPMorgan is the best-run large bank in the world, with no weak link across its three businesses. It holds the largest US deposit base, funds itself more cheaply than peers and earns an ROTCE in the low 20s even after stripping out the Visa gains.2 It spends more on technology than any rival and has held share against fintech. It returns most of its earnings to shareholders. Most of all, it has come through every crisis since 2008 stronger than it went in. On this view a premium multiple is the price of quality, and the 10.1x five-year median reflects a period of unusual pessimism about banks rather than a fair benchmark.
The bear case
The bear argues that the stock is priced for a peak. Reported earnings are inflated by one-off gains. Core NII excluding Markets is flat, and the recent growth came from trading, which is cyclical. Credit costs are rising, and the Apple Card will add more card risk. CET1 has fallen about 1.6 points in eighteen months while buybacks continue at a higher price. The front-runner for CEO has left, the co-presidents are in a contest and the CEO is 70. Politics is also more hostile. On this view, a P/E of 14.3x leaves little room for a normal recession.
Weighing them
The evidence supports the bull's description of the franchise, and it supports the bear's concerns about the price. Moat, funding advantage and resilience are proven by the record. The recent earnings pace, the capital buffer and the handover are unproven or weakening. At today's price the market already credits the strengths. What remains open is whether underlying earnings keep growing, credit stays contained and the transition goes well.
The KPIs that matter
Three measures will decide the case.
ROTCE excluding significant items, latest 23%.2 Holding in the low 20s would confirm the moat. A slide toward the mid-teens would narrow it.
CET1 on the binding basis, latest 14.1% and falling.2 It will show whether the buyback program can continue at this pace.
The card net charge-off rate, latest 3.31% and rising.1 It will be the earliest signal of whether credit is normalising or turning.
NII excluding Markets, flat at $92.6bn, is the fourth line worth following, because it measures the core spread without the trading floor.1
Risks and their mechanisms
A rate-cutting cycle would compress deposit margins and pressure core NII. A recession would lift card and wholesale losses and force reserve builds, as happened in 2020. AI and cyber threats could raise costs or lower barriers to entry, and a successful attack on a bank this interconnected would be a systemic event. A change in capital rules, in either direction, would directly change how much can be returned. None of these risks is new, but all are sensitive to where the cycle stands.
What remains thin? A formal peer comparison of valuation multiples, direct evidence of lost lending share to private credit and any quantified effect of AI on expenses. Those gaps are why the verdict above stops short of certainty.
XIII. Epilogue
Tonight JPMorgan is the largest and most profitable bank in the world, worth about $933bn and trading 7% below its high.1 The next eighteen months will settle each of the four questions.
The first answer comes in October, with Q3 2026 results, and then January, with Q4 and full-year 2026. If net income excluding significant items keeps rising at a high-single-digit pace or better with no Visa gain to help, the first question is answered in the company's favour: the earnings are recurring. If underlying earnings stall as Markets cools, the 14x multiple starts to look like it was built on a one-off.
The credit answer comes more slowly. The card net charge-off rate through 2027 is the gauge. A plateau near today's level would mean the firm reserved correctly and the Apple Card arrives into a stable book. A steady climb, together with a rising unemployment rate, would bring back the reserve builds of 2020, on a smaller scale but with the same effect on profits.
The capital answer comes with the next stress test and the buyback pace over the next two quarters. If buybacks continue while CET1 stabilises around 14%, the payout is sustainable. If the firm slows repurchases to protect the ratio, the three-quarters payout becomes a two-thirds payout. The Apple Card closing, roughly two years out, takes another quarter point of capital with it.
The succession answer may come at any time and in any form: a dated announcement, a co-president who leaves, or another year of "a few more years."
Behind all four is the tension that runs through the whole story. A bank whose strength is its size, whose defining decisions were made by one person, now has to prove it can keep that strength once he goes, under a chief executive who is 70 and has never given a date.
XIV. Outro
In 1799 a water company slipped a banking clause into its charter, and a loophole became an institution. More than two centuries later, that institution is the one Washington calls when others fail. It took on Bear Stearns over a weekend, Washington Mutual overnight and First Republic before the branches opened on a Monday morning.
JPMorgan is the bank the system leans on in a crisis. The one question it cannot yet answer is who will be standing there after Dimon.
References
-
FY2025 Form 10-K — JPMorgan Chase & Co. ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Q2 2026 earnings release narrative (Exhibit 99.1) — SEC EDGAR, 2026-07 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
JPMorgan's Dimon: Lake chose retirement after board named co-presidents — Banking Dive, 2026-06-25 ↩↩↩↩↩
-
JPMorgan Chase 8-K filings, including May 2026 annual meeting results — SEC EDGAR ↩
-
Quarterly earnings materials and call archive — JPMorgan Chase ↩↩
-
Annual reports and shareholder letters — JPMorgan Chase ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Federal Reserve press release on the JPMorgan–Bear Stearns financing — Federal Reserve Board, 2008-03-24 ↩↩
-
FDIC announcement on First Republic Bank sale to JPMorgan Chase — FDIC, 2023-05-01 ↩↩↩↩
-
Justice Department, federal and state partners secure record $13 billion global settlement with JPMorgan — U.S. Department of Justice, 2013-11-19 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube