Jabil: The Factory Behind the AI Boom
I. The Company You Don’t See
Somewhere in a data hall tonight, a rack of servers is drawing more electricity than a small apartment building, cooling itself with liquid that flows through pipes as thin as a pencil, and answering questions for people who will never think about where it came from. The chips inside it carry famous names. The cloud company that owns it carries a famous name. The model running on it may be the most famous name of all. The metal frame, the power shelves, the cabling, the cooling loops, and the hours of testing that turned thousands of parts into one working machine may carry no name the end user would recognise. Quite often, that unseen name is Jabil.
That is the strange position at the heart of this story. Jabil Inc. reported $36.0 billion of revenue for the fiscal year that ended on August 31, 2026, making it one of the largest manufacturers in the United States by sales, and yet almost nobody outside the electronics supply chain could name a single product it makes.1 It does not sell phones, cars, insulin pens or servers under its own brand. It builds them, or builds the most complicated parts of them, for the companies whose logos go on the box. The company began in 1966 as a two-man circuit-board operation near Detroit working for one customer.3 Sixty years later, its largest single segment is making equipment for the data centres at the centre of the artificial-intelligence buildout.
The scale of that pivot shows up in one ratio. In fiscal 2024, the segment Jabil calls Intelligent Infrastructure, which covers cloud and data-centre hardware, networking, and related capital equipment, was about 32% of revenue. In fiscal 2026 it was half of the company.1 In two years, the centre of gravity of a $36 billion business moved from consumer gadgets and a wide mix of industrial programmes toward the racks that power AI. Revenue grew 20.6% in fiscal 2026, and management later guided to roughly $44.5 billion for fiscal 2027, which would be another step up of almost a quarter.2
It is worth slowing down before that headline carries the story away, because the longer record is more sober. Over the three years from fiscal 2023 to fiscal 2026, Jabil's revenue grew only about 1.2% a year.1 Revenue had reached nearly $35 billion in fiscal 2023, fell to about $29 billion in fiscal 2024 after the company sold a large mobility business, and only climbed back above its old peak in the latest year. The surge of fiscal 2026 is real, but over a three-year window it looks less like a new growth rate and more like a recovery that turned into a boom. A single strong year can be the beginning of a new chapter. It can also be the top of a cycle. The investor's job is to tell those apart before the market does.
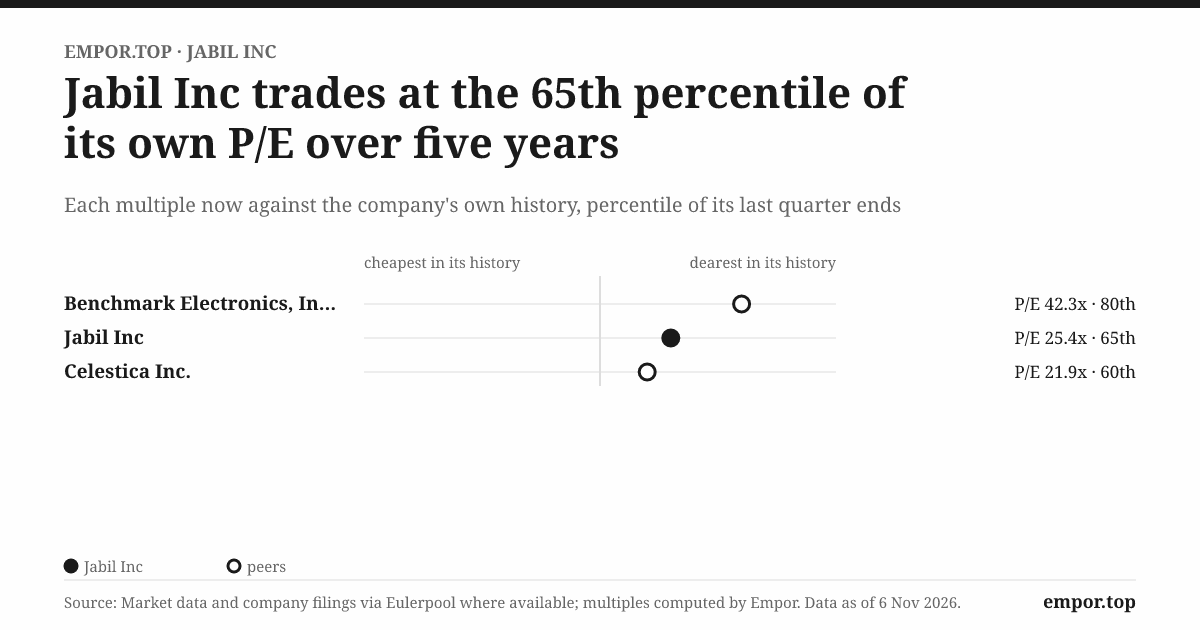
Four questions run through everything that follows. The first is whether Jabil's scale has built a real competitive edge in a business notorious for thin margins, or whether size simply makes it one of a handful of giants competing for the same purchase orders. The second is whether AI infrastructure can sustain growth beyond a single investment cycle, given that a few very large customers control the timing. The third is whether cash generation is durable as customer receivables swell along with sales. The fourth is whether the share price, which values Jabil at about 27.5 times trailing earnings against a five-year median of about 11, leaves any room for disappointment.1
Those margins frame every other question. In fiscal 2026, Jabil kept about $4.70 of GAAP operating profit from every $100 of revenue, and about $2.90 of net profit.1 That is a thin layer of profit to spread over 140,000 workers, more than a hundred factories, and billions of dollars of inventory and receivables. A software company that sees revenue jump 20% can keep most of the increase. A contract manufacturer has to buy the parts, staff the lines, and wait to be paid. The question is never only how fast Jabil grows. It is how much of each new dollar it can keep, and how much capital it has to tie up to earn it.
The person now answering those questions is Michael Dastoor, a long-serving Jabil finance executive who became chief executive in May 2024 after an abrupt leadership change at the top.4 He inherited a company in the middle of reshaping itself: the large mobility business had been sold to 比亚迪 BYD, the remaining portfolio was being reorganised around three segments, and AI-related demand was starting to arrive in volume. Since then Dastoor has bought a data-centre power company, a pharmaceutical manufacturer and a supply-chain services business, borrowed a billion dollars in the bond market, and kept shrinking the share count.1 The bet is visible. Whether it is the right bet will depend on how the AI demand wave behaves when it stops rising in a straight line.
To see why Jabil is positioned the way it is today, it helps to go back to the very beginning, to a kitchen table, a borrowed sum of capital, and a single customer that needed something fixed.
 Subscribe on LinkedIn
II. A Kitchen Table, One Customer, and the First Production Order
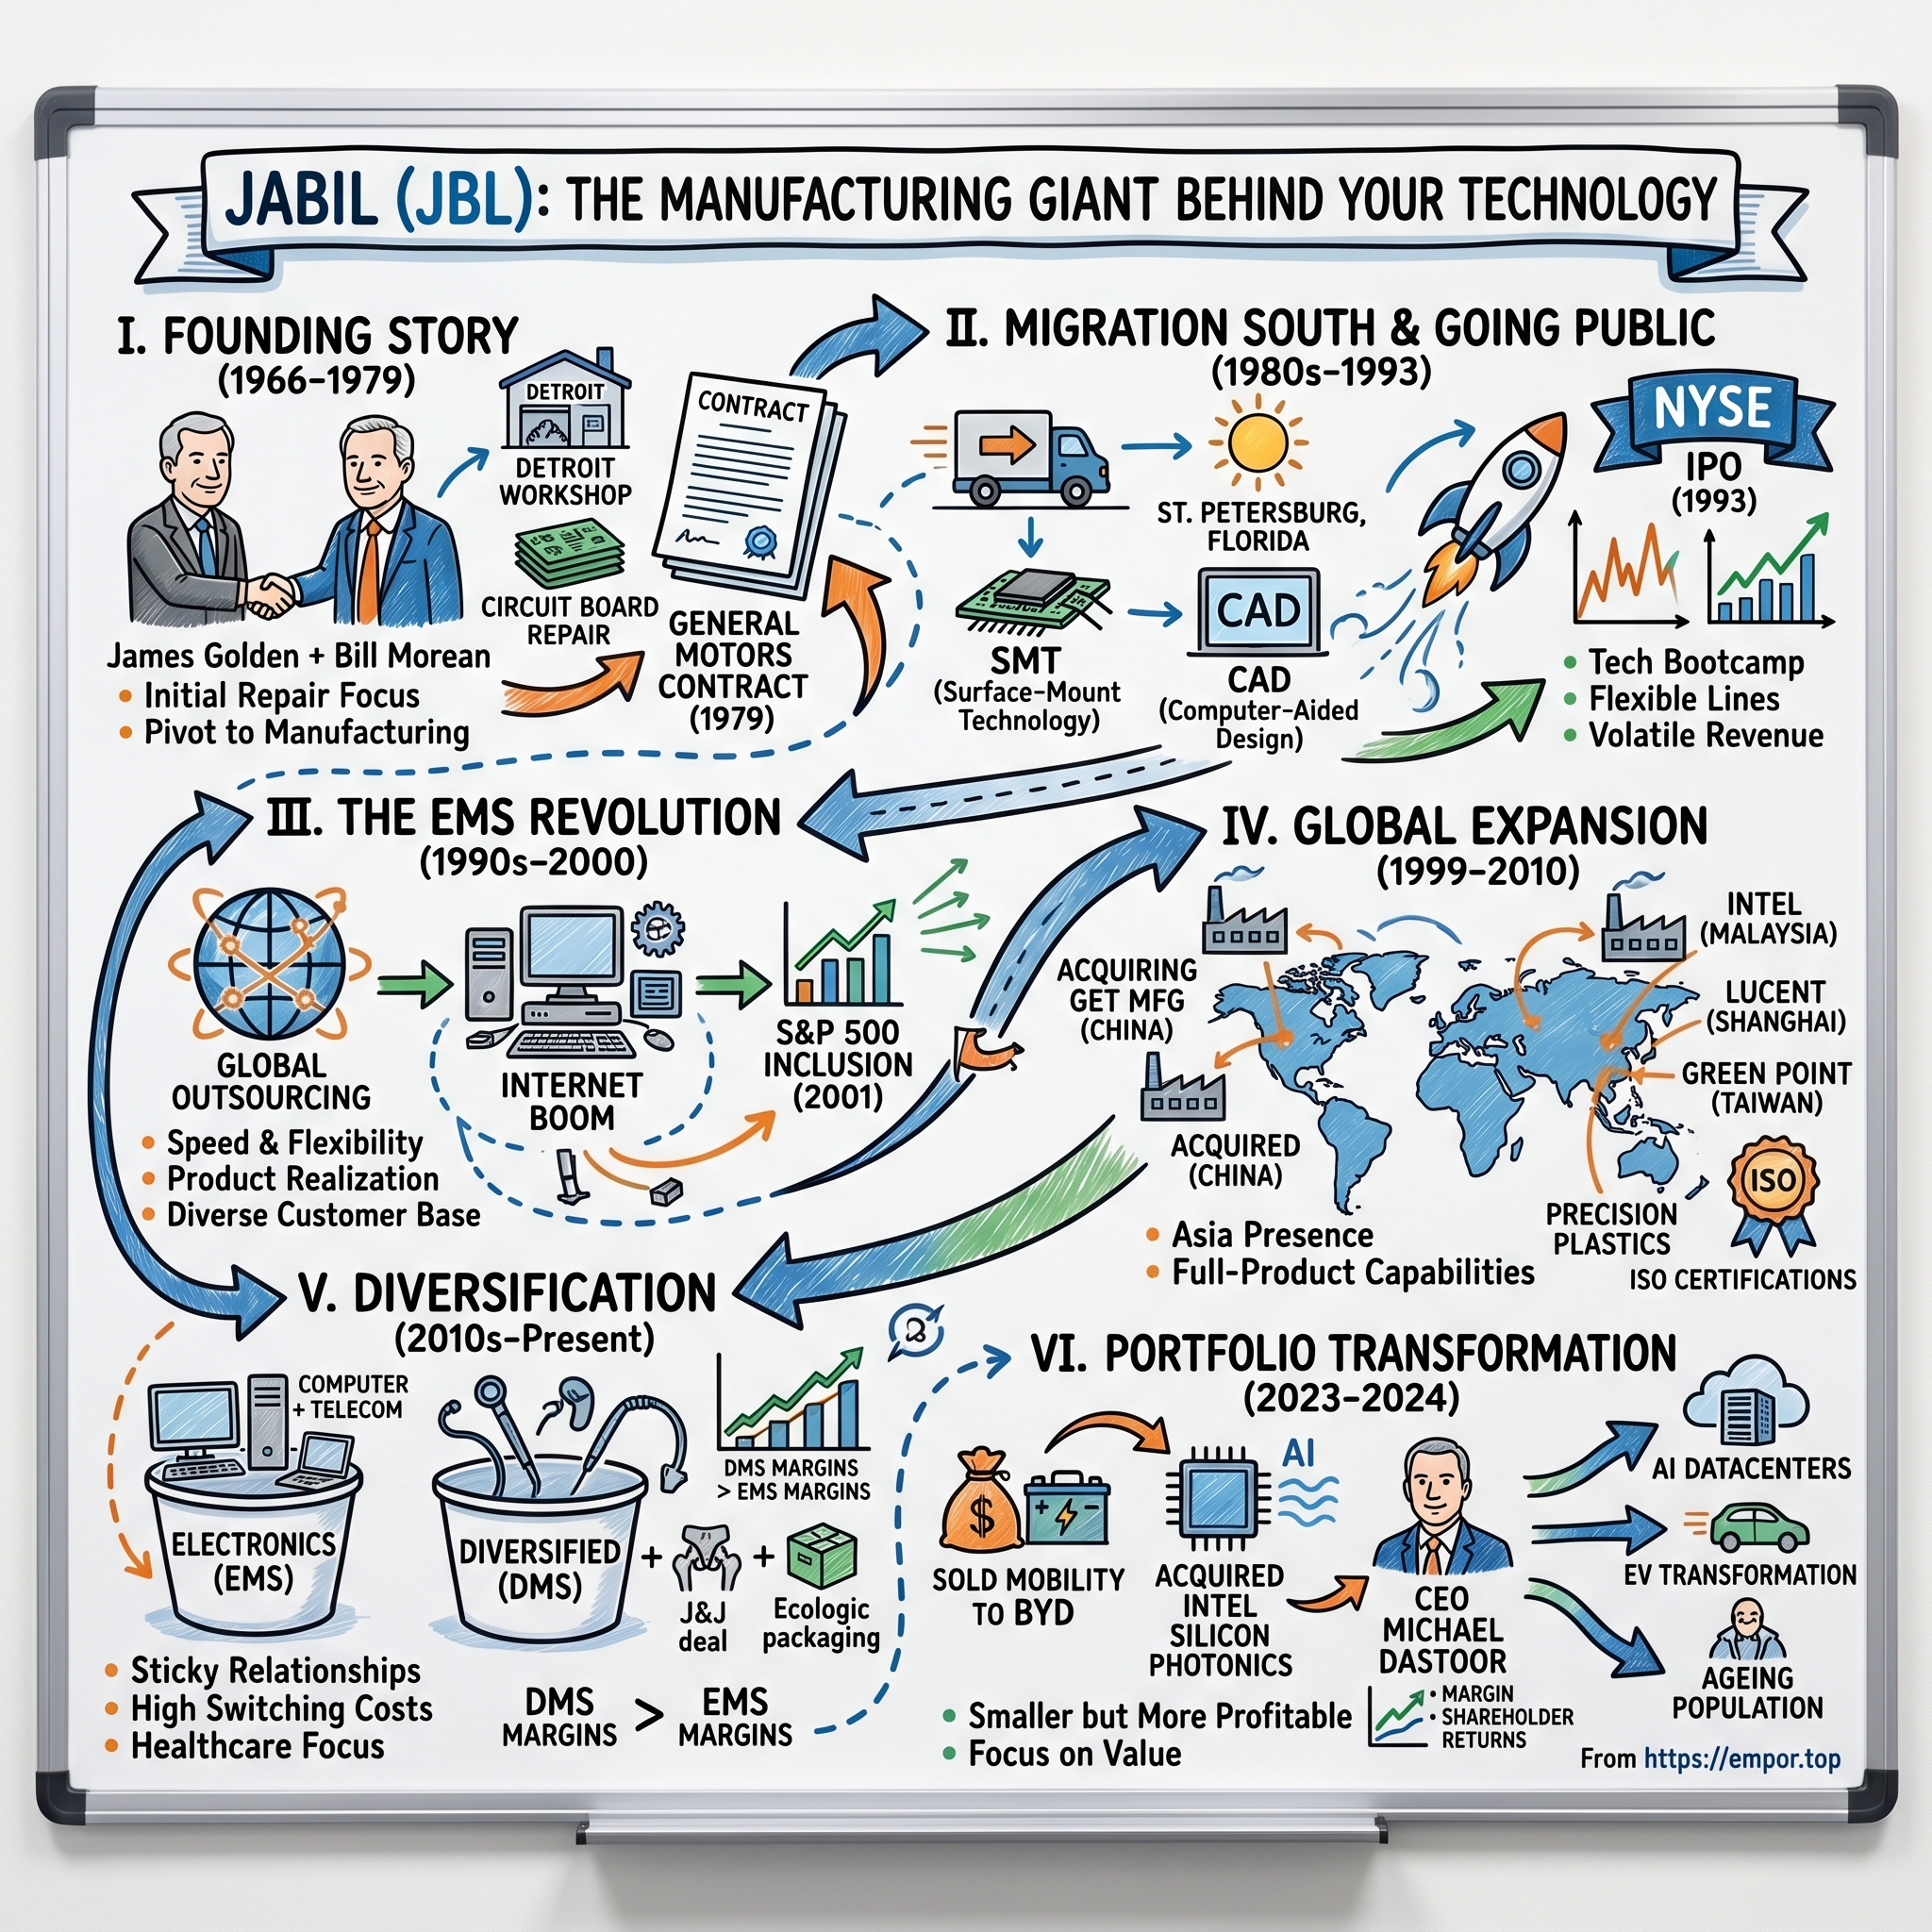
In 1966, the American automobile still ruled Detroit, but a different kind of machine was beginning to matter. Mainframe computers were spreading through corporations and government, and every one of them was stuffed with circuit boards that failed, wore out, and needed attention. Two men in the Detroit area, James Golden and William Morean, saw an opening in that unglamorous work. With about $5,000 of capital, they began assembling and repairing boards for Control Data Corporation, then one of the most ambitious computer makers in the country.3
The company's name was a piece of the founders' own identity. Jabil came from the first letters of James and Bill, a small, homemade brand for a small, homemade business.3 There was no grand theory of outsourcing in that choice, and no vision of global supply chains. There was one customer, some soldering equipment, and the kind of meticulous, repetitive work that most engineers would rather hand to somebody else.
The shift that mattered came quickly. In 1967, the young company received its first production order, which turned it from a repair shop into a builder.3 That transition sounds simple, but it changed the economics of the business. Repairing a broken board is craft work: every job is different, every fault is a puzzle, and the revenue depends on how many things happen to break. Building boards to a customer's design is process work. The same assembly is repeated hundreds or thousands of times, and every improvement in yield, speed or materials cost compounds across the whole order. A repair shop sells hours. A manufacturer sells reliability at volume.
That idea, turning one customer's problem into a repeatable process, became the template for everything Jabil would later do. Over the next decade, the company added customers and capabilities, but its most consequential early move came from the industry its home town knew best. In 1979, Jabil won a programme with General Motors, building electronics for one of the largest manufacturers in the world.3 Cars were starting to carry more electronics, and an automaker's volumes and quality standards were a very different discipline from those of a computer maker's repair department. Serving General Motors meant learning to produce at high volume, to tight specifications, on a schedule set by somebody else's assembly lines.
The second shaping move was geographic. In the early 1980s, Jabil relocated its headquarters from the Detroit area to St. Petersburg, Florida, where it remains today.3 The move took the company away from its origins in the auto belt and toward a region that would let it recruit, build and grow outside the gravity of a single industry. It was an early sign of the trait that would define Jabil for decades: a willingness to go wherever the customers, the workers and the costs pointed, rather than wherever the company happened to start.
Then came the capital. In 1993, Jabil listed its shares on the New York Stock Exchange.3 For a contract manufacturer, a public listing is not a vanity milestone. The business consumes capital in a way that its thin margins cannot easily fund on their own. Each new customer programme may require new equipment, new floor space, and, above all, inventory and receivables that must be financed before the customer pays. A regional board shop could grow only as fast as its own profits allowed. A listed company could raise capital, borrow on better terms, and promise large customers that it would still be standing when their next product launched. The listing gave Jabil the balance sheet to follow its customers abroad, which is where the next chapter begins.
There is a version of origin stories that treats every founding detail as foreshadowing. Jabil's does not need the embellishment. What matters for an investor is the business question that the young company had to answer, and that the $36 billion company still has to answer today. Why would a customer pay Jabil to make something the customer could, in principle, make itself? And once Jabil is making it, what stops the customer from moving the work to somebody cheaper? The first question is about value. The second is about power. Every chapter of Jabil's history, from the first production order to the latest AI rack, is an attempt to answer both at a larger scale.
III. The Outsourcing Machine Learns to Travel
By the late 1990s, the technology industry had discovered something that would reshape manufacturing for a generation. Brands did not need to own factories to sell hardware. Networking companies, computer makers, and telecom equipment suppliers could design products, market them and support them, while handing the physical work to specialists who would build them at scale, in the right country, at the right cost. The internet boom poured fuel on the idea. Demand for routers, switches and servers was growing so fast that original equipment manufacturers, the OEMs whose names went on the products, could not build plants quickly enough. Contract manufacturers could.
The bargain behind that boom is still the bargain behind Jabil. An OEM gives up the ownership of factories, and with it the fixed costs, the labour management and the capital tied up in inventory. In return it gets access to Jabil's manufacturing, procurement, engineering and supply-chain capabilities, spread across a global footprint that no single brand would build for itself.1 Jabil, in turn, gives up control of demand. It does not decide how many units the customer will sell. It builds against customer programmes and purchase orders, which means its volumes rise and fall with somebody else's product launches, inventory decisions and end markets.1 Think of it as a superb restaurant kitchen that cooks only for other people's restaurants: the chefs can be excellent, but the dining rooms decide how many meals are ordered tonight.
To keep up with those customers, Jabil had to travel. In 1999, it expanded into China, entering the country that would become the centre of global electronics manufacturing.3 Over the following decade, it built and bought its way into a network of sites across Asia, Europe and the Americas. Some of that growth came through acquisitions of factories and operations, including sites in Malaysia and operations bought from Philips, and some came through a practice peculiar to contract manufacturing: taking over a customer's own plant, workforce and equipment as part of an outsourcing agreement.3 For a brand, selling a factory to Jabil and then buying the output back was a way to convert fixed assets into a variable service. For Jabil, it was a way to win new customers and new capabilities in one transaction.
The most consequential of those deals was Green Point, a Taiwanese maker of precision plastic and metal components that Jabil acquired in the mid-2000s.3 Green Point gave Jabil expertise in the casings and mechanical parts of consumer devices, the shells and enclosures that hold electronics together. That capability pulled Jabil deeper into the smartphone era, where those components were made in enormous volumes for a small number of very demanding customers. It also seeded the large China mobility operation that Jabil would eventually sell. The acquisition playbook worked as growth: buy a capability, attach it to a large customer, and scale it across the network. Whether it built lasting bargaining power is a different question, and the answer would come later.
The industry Jabil grew into is not a cosy oligopoly. In the 2025 rankings of electronics manufacturing services and original design manufacturing companies, Jabil reported about $31 billion of revenue, roughly the same scale as Flex at about $28 billion.5 Above them both sits 鴻海精密 Hon Hai Precision, better known as Foxconn, at roughly $260 billion, more than eight times Jabil's size.5 Those rankings mix companies with very different profiles: some design products as well as build them, some concentrate on a few huge consumer programmes, and some report revenue that includes large pass-through component costs. They are a sense of scale, not a measure of market share. Still, the picture is clear. Jabil is a large player, but not the largest by far, and it competes directly with Flex, Celestica and Sanmina in many of the more complex, lower-volume programmes where engineering matters as much as cost.
So does global reach make Jabil hard to replace? There is a case that it does. A cloud company or a medical-device maker shifting production between suppliers faces requalification, testing, new tooling, and months of risk to quality and delivery. A supplier that can build the same product in several regions, manage component purchasing for thousands of parts, and absorb a customer's own factory has real value to an OEM managing a fragile supply chain. That value is the reason contract manufacturing exists at all.
Yet the disclosed terms of the relationship show the limits of that lock-in. Jabil says it generally does not place material orders for components until it has received a matching commitment from a customer, which is prudent risk management.1 It also says those purchase orders are usually cancellable beyond a window of several weeks.1 Customer contracts generally establish a framework, with purchase orders specifying quantities at predominantly fixed prices, and the company does not disclose minimum volumes or contract duration.1 In other words, a long relationship is a valuable thing, but it is not a guaranteed revenue stream. The customer keeps the right to change its mind, and with it, much of the leverage.
That leaves an investor with a moat claim that the filings cannot fully test. Jabil does not publish customer retention rates, win and loss data, or price realisation on renewed programmes.1 Without those, the strength of its competitive position has to be inferred from the evidence it does publish: how concentrated its customers are, how high its margins run, and how reliably profits turn into cash. Each of those clues tells a part of the story, and the clearest test of them came in 2023, when Jabil decided that one of its biggest businesses would be worth more in somebody else's hands.
IV. Selling the Mobility Business, Then Rebuilding the Portfolio
On August 28, 2023, Jabil announced that it had agreed to sell its China-based mobility business to BYD, the Chinese electric-vehicle and electronics giant, for about $2.2 billion.6 The business it was selling was the descendant of the Green Point bet: large-scale production of components for consumer mobile devices, concentrated in Chinese factories serving a small number of very large customers. It had been a major source of revenue. It had also tied Jabil's fortunes to the volume cycles of a few consumer programmes, in a country where geopolitical risk for American suppliers was rising.
It is important to be precise about what was sold. Jabil did not sell itself, and nobody bought the listed company. It sold one operating business, a large and concentrated one, and kept everything else.6 The strategic logic was a portfolio reset. Exiting mobility reduced Jabil's exposure to one demanding category and freed capital that could be redeployed into businesses where management believed engineering and complexity were better rewarded. The deal closed during fiscal 2024, and the effect showed up immediately in the revenue line. The divestiture and softer demand in parts of the remaining business both contributed to the decline.1 Either way, Jabil started its new chapter smaller.
The accounting made that year look much stronger than it was. In fiscal 2024, Jabil recorded a pre-tax gain of about $942 million on the divestiture.7 That gain pushed GAAP operating income to about $2.0 billion and GAAP operating margin to 7.0%, the highest in the company's modern history.7 It was a one-time event, not a sign that Jabil had suddenly learned to make more money on each board. Management's preferred measure, core operating margin, which excludes items such as divestiture gains, amortisation of acquired intangibles, stock-based compensation and restructuring, was about 5.5% that year.7 In fiscal 2025, GAAP operating income fell to about $1.2 billion, which included a $53 million net loss from divestitures, while core margin was about 5.4%.8
Read together, those figures tell a quieter story than the GAAP swings suggest. Strip out the sale, and Jabil's underlying profitability was roughly flat through the reset: about five and a half cents of core operating profit on every dollar of revenue, give or take a tenth of a point. The headline drop in GAAP operating income from fiscal 2024 to fiscal 2025 was mostly the absence of a gain, not a collapse in the business. Anyone comparing those two years on reported numbers alone would conclude that something went badly wrong. Anyone looking at core margins would conclude that very little changed. The more useful conclusion is in between: the divestiture did not make the remaining business more profitable on its own. Any improvement would have to come from what Jabil did with the money and the management attention it had freed up.
Much of that cash went back to shareholders through repurchases, and some went into acquisitions that show where Dastoor's team thinks the future lies. In fiscal 2025, Jabil paid about $309 million for Pharmaceutics International, known as Pii, a contract developer and manufacturer of pharmaceutical products based in Maryland.89 The deal extended Jabil's healthcare work beyond medical devices and drug-delivery hardware into the manufacture of drugs themselves, a regulated and potentially higher-value niche. In fiscal 2026, the company made two more purchases. It paid about $752 million for Hanley Energy, a provider of power-management and energy infrastructure for data centres, and about $133 million for Rebound, a supply-chain services provider focused on returns, repair and reverse logistics.1
Each of those deals fits a story. Hanley brings Jabil closer to the power systems that have become a bottleneck for AI data centres, where getting enough electricity into a building, and managing it safely, has become as important as the compute itself. Pii gives Jabil a foothold in pharmaceutical manufacturing, which carries more regulatory depth than most electronics work. Rebound adds services on the far end of the product life cycle, where customers want help handling returned or refurbished equipment. The pattern is coherent: move toward work that is harder to do and harder to switch away from.
What the filings cannot yet tell anyone is whether Jabil paid sensible prices. The purchase accounting shows how much of each price went into goodwill, the premium over identifiable assets that represents expected future benefit. Hanley carried about $339 million of goodwill, Pii about $142 million, and Rebound about $44 million.1 That means roughly 45% of the Hanley price, nearly half of the Pii price, and about a third of the Rebound price were paid for things a balance sheet cannot hold on its own: customer relationships, know-how, and growth expectations. Jabil does not disclose the revenue or earnings of the acquired businesses at the time of purchase, so there is no deal multiple to compare with peers.1 Without that, nobody outside the company can say whether Jabil overpaid or bought bargains. The test will come from what those businesses contribute in the next two years, and from whether any of that goodwill is later written down.
The first of those tests has already produced a warning. On August 27, 2026, the U.S. Food and Drug Administration issued a Warning Letter to the Pii facility in Hunt Valley, Maryland, citing concerns about manufacturing practices and quality systems.1 Manufacturing at the site was paused pending a corrective-action plan and FDA approval.1 Jabil has not quantified the financial impact, and against a $36 billion group, one pharmaceutical site is unlikely to move the consolidated numbers much. But the episode matters more than its size, because the purpose of the Pii acquisition was to show that Jabil could bring its process discipline into a more regulated business. Eighteen months after closing, the regulator found that the process needed fixing. Pharmaceutical warning letters are not rare, and many sites resolve them, but they can take a long time to close, and they consume management attention and customer goodwill while they remain open.
The mobility sale, then, was a genuine strategic reset: it changed what Jabil makes and reduced its dependence on one category. But the gain that came with it is not evidence of discipline. Discipline will be proven, or not, by the returns on the money redeployed. That judgment would fall to a chief executive who took the job in circumstances nobody had planned.
V. A Leadership Shock Becomes a New CEO’s Test
In the spring of 2024, Jabil's board did something unusual for a company of its size and steadiness. Kenneth Wilson, who had succeeded long-time chief executive Mark Mondello only the year before, was placed on paid leave while the board investigated matters related to the company's corporate policies.47 For a contract manufacturer whose customers prize predictability above almost everything else, a sudden vacancy at the top was a jolt. When the investigation concluded, the board appointed Michael Dastoor as chief executive in May 2024.4
The details of that investigation matter less to investors than its boundaries. Jabil said the matter did not affect its financial statements.7 There was no restatement, and the auditor's opinions in the years since have been unqualified.1 The episode belongs in the story as governance context: it shows a board willing to act quickly on conduct at the top, and it explains why the company had three chief executives in little more than a year. It does not, on the available evidence, say anything about the integrity of the numbers. Jabil's leadership moved from Mondello to Wilson in 2023 and then to Dastoor, a sequence recorded in the proxy.4
Dastoor was not an outsider brought in to clean house. He had spent roughly two decades at Jabil, much of it in finance, and had been chief financial officer before moving into the top job.4 That background shaped how he has run the company. A CFO-turned-CEO tends to talk in the language of cash, returns and capital allocation, and Dastoor's tenure so far has been heavy on exactly those levers: portfolio pruning, restructuring, acquisitions, repurchases and margin targets. It also means his credibility rests on a particular kind of promise. A former finance chief cannot fall back on product vision as a defence. He will be judged on whether the numbers he guides to are the numbers he delivers.
His pay offers one lens on how the board views that job. For fiscal 2025, Dastoor's reported total compensation was about $16.1 million, including about $11.3 million of stock awards.4 In the two previous years, his reported total had been about $5 million.4 The jump reflects his promotion and the equity grants that came with it, and grant-date stock values are not cash in hand; much of the award will be worth more or less depending on how the shares perform and whether performance targets are met. Still, the optics are worth stating plainly. Reported CEO pay roughly tripled in a year when net profit fell by more than half, from about $1.4 billion to about $657 million, largely because the prior year had included the mobility gain.41 Jabil ties executive incentives to operating income, free cash flow, earnings-per-share growth and relative shareholder return, which at least points the reward toward the right scorecard.4
Ownership is a weaker lens. Dastoor's beneficial ownership is modest relative to a company valued at nearly $29 billion, and like most American chief executives of widely held companies, he is a steward rather than an owner.4 The largest holders listed in the proxy are index giants, with Vanguard shown at about 14% and BlackRock at about 10%, but those percentages come from filings reporting ownership as of December 2023.4 They are a snapshot of passive ownership nearly three years old, not a guide to who holds Jabil today. There is no controlling shareholder, no founder family steering the board, and no parent company above Jabil. The governance question is the ordinary one for a large American company: whether an independent board holds a professional management team to account.
The shareholder vote at the January 2026 annual meeting suggests that, for now, investors are content. The advisory say-on-pay proposal received about 84.7 million votes in favour against about 2.5 million against, roughly 97% of votes cast.10 A shareholder proposal on the right to act by written consent was also on the ballot, a reminder that some investors want more tools to hold the board accountable between meetings.10 A 97% vote is a signal of comfort, not a verdict on strategy. Approval votes tend to be high when the share price is rising, and Jabil's had been rising sharply.
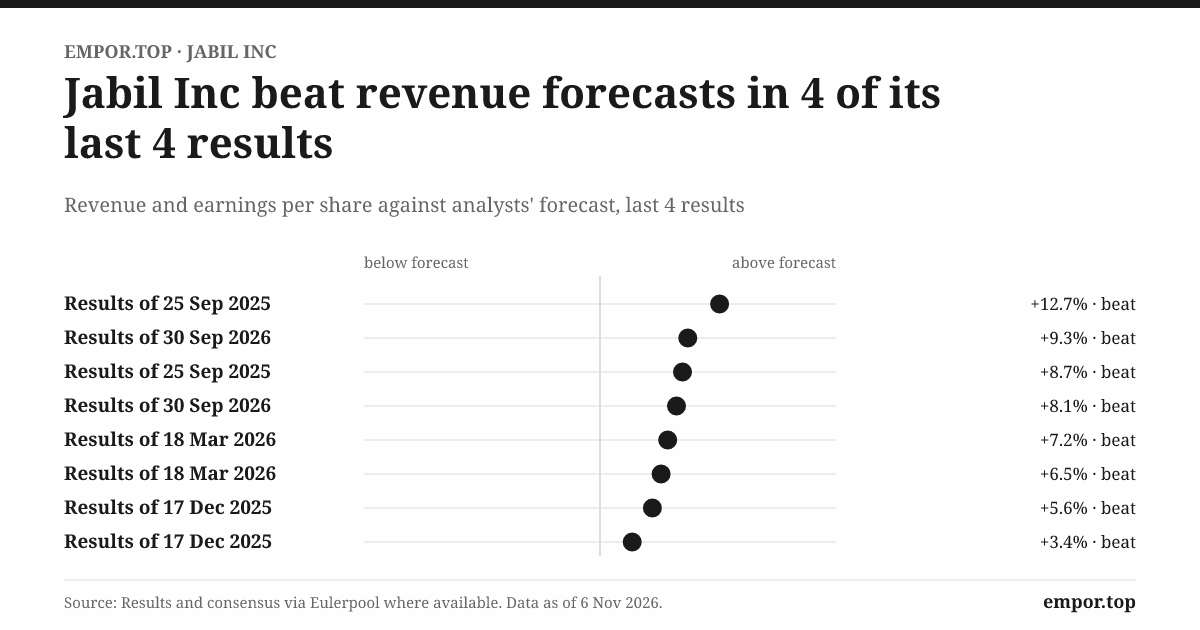
The more revealing evidence is how management's story has evolved from one earnings call to the next. Through fiscal 2024, Jabil was explaining a shrinking top line and restructuring meant to resize the cost base after the mobility sale.7 The tone through 2025 shifted. On the second-quarter call in March 2025, management raised its outlook for AI-related revenue for the year to about $7.5 billion, framing data-centre demand as the clearest source of growth in the portfolio.11 When it issued its first fiscal 2026 outlook in September 2025, the AI ramp had become the centrepiece of the plan.12 By the first-quarter fiscal 2026 call in December 2025, the AI-related revenue expectation for the year had reached about $12.1 billion.13
That sequence matters for two reasons. The first is that the forecasts kept rising, and the results kept them company: Intelligent Infrastructure ended fiscal 2026 at about $17.9 billion of revenue, a segment total that includes more than AI-specific programmes, but one that grew 45% in the year.1 Management's "AI-related revenue" is its own defined category, which cuts across segments and is not audited, so the two numbers should not be confused. Still, the direction of every estimate was upward, and that is a better pattern than the reverse. The second reason is less comfortable. The questions that matter most, such as which customers are driving the ramp, how long their programmes run, and what margins the new work carries, are exactly the ones Jabil's disclosures leave unanswered: the company does not name its customers or publish programme-level margins.1 That is normal for a contract manufacturer bound by confidentiality agreements. It also means investors are being asked to trust the trajectory more than they can verify its foundations.
Dastoor's first two and a half years, then, have a clear shape. He inherited a company recovering from a divestiture and a leadership shock, sharpened its portfolio, rode an enormous demand wave, and met or beat a rising set of forecasts. What he has not yet faced is the thing that tests a contract manufacturer's management most sharply: a downturn in the very customers who made the boom. To understand how exposed he is to that moment, the story has to move inside the data centre.
VI. The Data Center Moves from Side Bet to the Center
Picture the back of a modern AI data hall. The aisles are not lined with the neat, air-cooled server boxes of a decade ago. They are lined with tall racks, each one a dense block of accelerators, networking switches, power shelves and cooling manifolds, built as a single integrated system and shipped as a unit. A rack like that can weigh more than a car and consume enough power to need its own liquid cooling. It is not something a hyperscale cloud company wants to assemble one cable at a time in the building. It wants the rack to arrive tested, configured and ready to switch on.
That shift, from components to integrated systems, is the opportunity Jabil has spent the last three years chasing. Its Intelligent Infrastructure segment builds and integrates server racks, power systems, cooling, networking equipment and other data-centre hardware for cloud and infrastructure customers, along with capital equipment for semiconductor and related industries.1 It is worth being clear about what that is and what it is not. Jabil is not designing the chips, writing the models, or owning the cloud. It does not capture a share of AI software economics. What it sells is manufacturing and engineering complexity: the ability to take thousands of parts from hundreds of suppliers, assemble them into a working machine at very high quality, and deliver it on the timeline of a customer racing to build capacity. An analogy helps. If the AI companies are writing the music and the chipmakers are building the instruments, Jabil is the crew that assembles the stage, wires the sound system and makes sure everything works on opening night.
The numbers show how quickly that crew became the centre of the show. Intelligent Infrastructure was about 32% of Jabil's revenue in fiscal 2024, about 41% in fiscal 2025, and about 50% in fiscal 2026, when its revenue grew 45% to roughly $17.9 billion.1 The other two segments moved in different directions. Regulated Industries, which covers automotive and transportation, healthcare, packaging, renewable energy and energy infrastructure, grew about 7% to roughly $12.7 billion, or 35% of the company.1 Connected Living and Digital Commerce, the home of consumer devices, retail technology and the remaining consumer work, shrank to about $5.4 billion, or 15% of revenue, down from roughly a quarter of the company in fiscal 2024.1 In two years, Jabil went from a company where the consumer and AI businesses were broadly comparable in size to one where AI infrastructure is more than three times the consumer segment.
Where the profit sits is just as revealing as where the revenue sits, and it complicates the easy story. Intelligent Infrastructure produced about $1.07 billion of segment income in fiscal 2026, Regulated Industries about $699 million, and Connected Living and Digital Commerce about $301 million.1 Divide each by its revenue, and the margins are strikingly similar: roughly 6.0% for Intelligent Infrastructure, about 5.5% for Regulated Industries, and about 5.6% for the consumer segment. The AI business is the largest profit pool by far because it is the largest revenue pool, not because it earns spectacularly more on each dollar. That is an important clue. If AI racks were a uniquely high-margin product protected by exclusive capabilities, the segment's margin might stand far above the others. Instead, it sits only modestly higher, which is what one would expect from a complex but competitive manufacturing service.
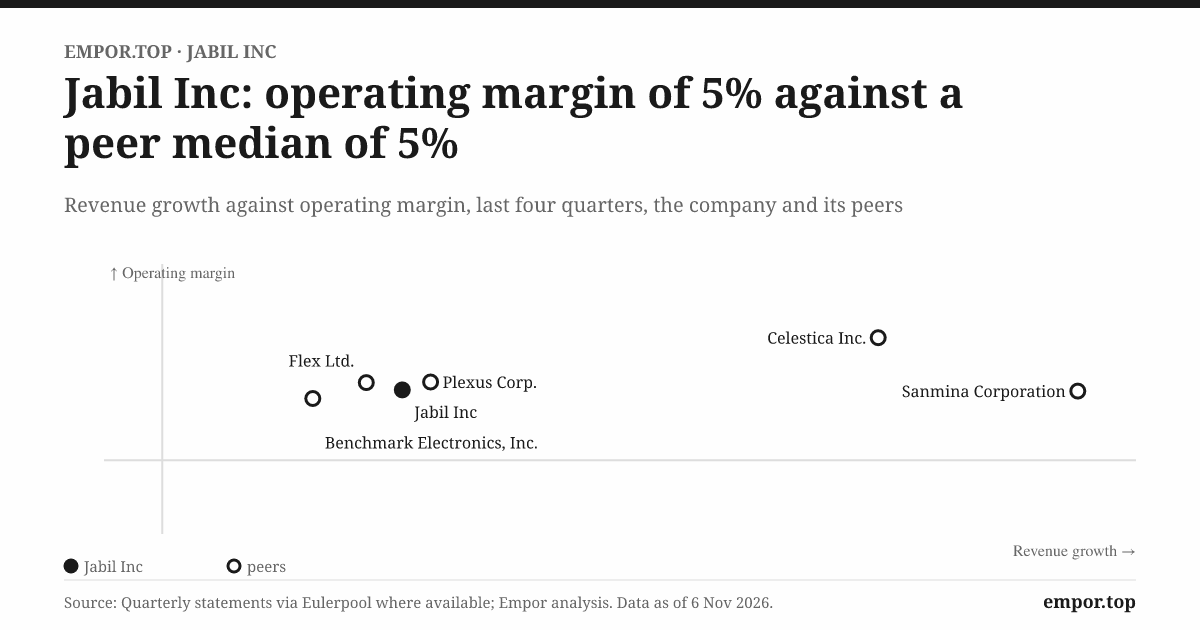
The mix shift has still helped the company's economics at the margin. Gross margin rose to about 9.2% in fiscal 2026 from about 8.9% the year before, and Jabil attributed the improvement primarily to the product mix in Intelligent Infrastructure.1 Core operating margin reached about 5.8%, up from about 5.4%.2 GAAP operating margin, which includes amortisation of acquired intangibles, restructuring costs, stock-based compensation and other items, was about 4.7%.1 Those are better numbers than Jabil has posted for most of its history. They are also still thin for a business that ties up so much capital and carries so much operational risk. A three-tenths-of-a-point improvement in gross margin on $36 billion of revenue is worth about $100 million of gross profit, which is meaningful. A single programme that ramps late, or a quarter of under-used capacity, could erase it.
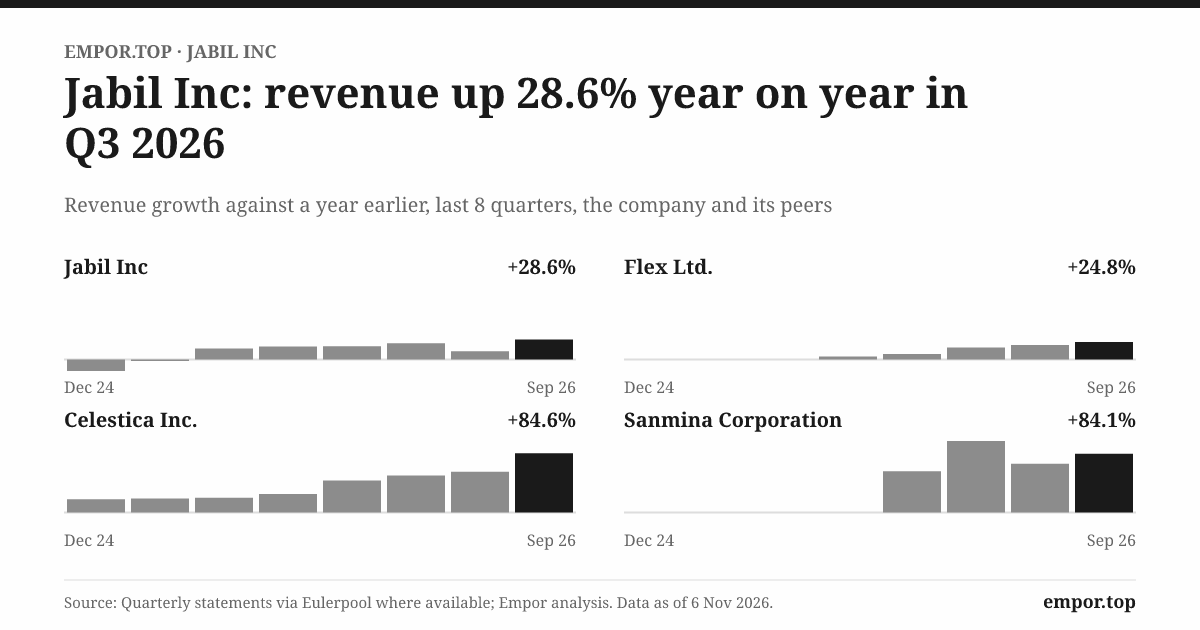
Quarterly results show how steep the climb became late in the year. In the quarter ended August 2026, revenue reached about $10.6 billion, up almost 29% from a year earlier, and operating margin was about 5.7%, the best quarterly reading outside the period inflated by the divestiture gain.1 Growth had been accelerating through the year, and so had profitability. That is the pattern of a business absorbing large new programmes efficiently, which supports the bull case. It is also the pattern one would expect at the peak of a customer investment cycle, when factories run full and every new order arrives on top of a well-utilised base.
Management's guidance assumes the climb continues. For fiscal 2027, Jabil has guided to about $44.5 billion of revenue, a core operating margin of about 6.1%, core earnings per share of about $17.55, and roughly $1.6 billion of adjusted free cash flow.2 That outlook implies revenue growth of almost a quarter on top of fiscal 2026's 20.6%, along with another three-tenths of a point of core margin. If it is delivered, Jabil will have grown its revenue by about half in two years, almost entirely from the businesses it kept after the mobility sale.
The sequence of forecasts that led here is a useful record of management's reliability. In March 2025, the company raised its AI-related revenue outlook for that fiscal year to about $7.5 billion.11 By December 2025, its expectation for fiscal 2026 AI-related revenue had reached about $12.1 billion.13 The segment's eventual $17.9 billion outcome, which includes AI and non-AI infrastructure work, came in well ahead of the pace those early forecasts implied, and the fiscal 2027 guide extends the line further.2 A management team that keeps raising its numbers and then meeting them earns some credibility. But the same pattern is common in the up-phase of any capital-spending cycle. Customers ordering aggressively make forecasts look conservative. The question is how forecasts behave when customers slow down, and Jabil's current management team has not yet been tested by an AI demand pause.
Any investor listening to those calls would want three answers: how concentrated the AI customers are, how long their programmes run, and whether the margins on rack integration will hold as more competitors build capacity. Jabil answers the first only in aggregate, through its customer-concentration disclosure, and does not publish the second or third.1 Investors can draw their own conclusion from the absence. Without customer-level detail, the durability of this business must be judged from segment results over time, not from management's description of its position.
The competitive landscape in AI hardware is crowded with much larger players. Foxconn, 緯創 Wistron and 廣達 Quanta, three Taiwanese manufacturers with deep relationships with chip designers and cloud companies, are all far larger than Jabil by reported revenue, and all have been building server and rack capacity for the same customers.5 Celestica and Flex are the closest listed peers by profile, each pushing hard into data-centre hardware and power. Similarities in end-market exposure do not make these companies identical. Some of the Taiwanese firms design servers as well as build them, earning a different kind of margin on a different kind of work. Some have heavier exposure to a single chip designer's reference platforms. Jabil's niche sits in the integration of racks, power and cooling for cloud customers, plus capital equipment, which is different from building the core server boards. But the existence of several well-funded competitors chasing the same customers is a reminder that capacity alone does not guarantee pricing.
That leads to the central test of this chapter. Is AI infrastructure a durable change in Jabil's economics, or a concentrated cycle that could reverse quickly? The evidence supports a narrower version of the bull claim than the market narrative. The business is already financially material: half of revenue, the largest profit pool, and the main reason gross margin improved. It is supported by real engineering complexity and by customers' preference to buy integrated systems rather than parts. What the evidence does not yet show is a through-cycle moat. Jabil does not disclose AI-programme retention, contract duration, win rates or customer-specific margins.1 The segment margin is only slightly above the rest of the company. And every customer in this market is also a buyer with enormous negotiating power. The clearest confirmation would be continued segment growth and stable segment margins after the current capacity build is absorbed, ideally through at least one period when cloud customers slow their spending.
There is also a cost to growing this fast that the income statement does not show. Every rack built and shipped before the customer pays ties up cash in inventory and receivables. When a $36 billion business grows by $6 billion in a year, and plans to grow by $8 billion more, that working capital has to come from somewhere. Which brings the story to the part of Jabil's model that matters most and gets discussed least: the cash cycle.
VII. The Factory’s Cash Cycle
Imagine a single AI rack moving through Jabil's system. Long before it ships, the company has ordered processors, memory, power supplies, cables, metal frames and cooling components, often thousands of distinct parts, from hundreds of suppliers. Those suppliers expect to be paid. The parts arrive and sit in inventory until the line is ready. The rack is assembled, tested and shipped to the customer, who then takes weeks or months to pay. At every moment in that journey, money is tied up somewhere: in parts waiting to be used, in finished goods waiting to ship, or in invoices waiting to be paid. For a business earning five or six cents of operating profit on each dollar, the timing of those payments can matter as much as the profit itself.
That is why the simplest test of a contract manufacturer is whether its accounting profits become cash. On that long-run test, Jabil scores well. Over the twelve fiscal years from 2015 through 2026, the company reported about $6.7 billion of cumulative net profit and about $12.2 billion of cumulative cash from operations, or about 183% of profit.1 Part of that gap is structural and healthy. Depreciation and amortisation, which reduce profit but do not consume cash, added back about $681 million in fiscal 2026 alone.1 A business with large depreciation charges will naturally generate operating cash well above net income. Even so, a decade of operating cash nearly double reported profit is a strong record, and it is the foundation of Jabil's ability to fund capacity, acquisitions and repurchases.
The record is not perfectly smooth. In fiscal 2017 and fiscal 2018, reported cash from operations was deeply negative, at roughly minus $1.5 billion and minus $1.1 billion, while cash from investing was strongly positive in the same years.1 That mirror-image pattern points to how collections on sold receivables were classified between operating and investing activities, rather than to a business burning through cash. It is a reminder that cash-flow statements for this kind of company depend heavily on how receivables are financed and categorised, and that a single year's operating cash flow can say as much about accounting presentation as about the underlying business.
The latest year shows the moving parts clearly. Fiscal 2026 cash from operations was about $2.0 billion, and free cash flow, after capital spending of about $628 million, was about $1.4 billion.1 But inside that total, very different forces were at work. Inventory, receivables and contract assets absorbed a lot of cash as the business grew. At the end of August 2026, net trade receivables had reached about $6.5 billion, up from about $4.0 billion a year earlier, and contract assets, which represent work completed but not yet billed, had reached about $1.3 billion, up from about $1.1 billion.1 Against that drain, higher payables, accrued expenses and other liabilities supplied a large inflow.1 In plain terms, Jabil's customers were taking longer to pay, while Jabil was taking longer to pay its own suppliers. The second effect more than offset the first.
The working-capital ratios capture the paradox. Measured as days of revenue, receivables rose to about 79 days in fiscal 2026, compared with about 30 days a decade earlier.1 Inventory rose to about 83 days of cost of revenue.1 On those two measures alone, the business looks like it is tying up far more capital than it used to. Yet days payable, the time Jabil takes to pay its suppliers, reached about 162 days.1 Add receivables and inventory, subtract payables, and the cash conversion cycle, the number of days between paying for parts and collecting from customers, came out at roughly one day.1 Jabil is, in effect, using its suppliers' money to finance the inventory and receivables of its customers. Year-end ratios like these can be distorted by a surge of late-year purchases, and the jump in payables partly reflects the steep growth of the final quarter. The company's own quarterly measure of days sales outstanding was about 55 days in the fourth quarter of fiscal 2026, up from about 44 days a year earlier, a rise Jabil attributed primarily to the timing of payments.1 The two measures differ in method, but they point the same way.
There is one more mechanism that makes Jabil's cash flow look smoother than its customers' payment behaviour might suggest. The company sells receivables to banks and other financial institutions under uncommitted programmes. In fiscal 2026, it sold about $18.3 billion of receivables this way and recorded about $79 million of pre-tax losses on those sales.1 Selling a receivable means taking cash today, at a small discount, rather than waiting for the customer to pay. The proceeds are included in operating cash flow.1 To put the scale in perspective, $18.3 billion is about half of Jabil's annual revenue. That does not mean half of all sales are financed at any one time, because receivables turn over several times a year, but it does mean receivable sales are a central part of how Jabil manages cash, not a side arrangement.
These programmes are legitimate and widely used across the industry. They also introduce a specific risk. Because they are uncommitted, the banks are not obliged to keep buying receivables. In normal times, that does not matter. In a credit squeeze, or if a major customer's credit quality deteriorated, banks could pull back just as Jabil most needed the cash. At that point, the company would have to finance its receivables on its own balance sheet, and its operating cash flow would fall even if nothing else changed. The roughly $79 million cost of the programmes is also not trivial: it is about 6% of fiscal 2026 pre-tax profit, a recurring price paid for speed.
Concentration adds another layer. Customer A, Jabil's largest customer, accounted for about 33% of receivables at the end of fiscal 2026, up from about 24% a year earlier.1 Jabil does not name Customer A and does not disclose an ageing schedule of receivables or an annual history of bad-debt write-offs.1 There is no evidence of collection problems; large customers in this industry are typically very creditworthy. But when a third of the money owed to a company comes from one source, the timing of that source's payments becomes a material driver of the company's cash flow.
So what does the cash record really say? Over the long run, Jabil has been a genuine cash generator, converting profit into cash at rates most manufacturers would envy. In the short run, its annual cash flow depends on three levers that can move against it: how quickly customers pay, how long suppliers will wait, and how much receivables financing banks will provide. In fiscal 2026, all three were working in Jabil's favour, or at least not against it. The test of durability is whether operating cash stays close to earnings in a year when payables shrink, receivable sales slow and customers stretch their payments. That year has not arrived yet. When it does, the question will be not only how resilient the cash is, but how much power Jabil has to protect it.
VIII. What the Network Can—and Cannot—Protect
There is a single line in Jabil's annual report that captures both the strength and the vulnerability of its business. Customer A, the company's largest, accounted for about 20% of fiscal 2026 revenue and about 33% of receivables.1 The five largest customers together accounted for about 37% of revenue, and 76 customers accounted for about 90%.1 Jabil serves hundreds of customers across more than 100 sites in roughly 30 countries.1 Yet a fifth of its business depends on one buyer, and a third of the money it is owed sits with that buyer. That is the shape of a company that is valuable to its customers and dependent on them at the same time.
Michael Porter's five forces offer a clear lens on what that shape means for Jabil's long-run profitability. Start with buyer power, which is plainly high. When one customer supplies a fifth of revenue and the top five supply more than a third, those customers have enormous leverage over pricing, terms and allocation of work. Customer A's share rose from about 16% in fiscal 2025 to about 20% in fiscal 2026, so the concentration is increasing, not diminishing.1 Another former large customer, Customer B, accounted for about 11% of revenue in fiscal 2024 and has since fallen below the 10% disclosure threshold, which shows how quickly a major relationship can shrink.1 Buyers with that much weight do not need to threaten to leave to shape the economics. They only need to allocate the next programme to a competitor.
Rivalry is intense. Jabil competes against Foxconn, Flex, Celestica, Sanmina and a range of Asian manufacturers, many of them much larger, for the same programmes.5 The industry has no strong product differentiation in the traditional sense; customers buy a capability, not a brand. Supplier power is moderate but sharp at the edges: many components, especially advanced chips, memory and certain power parts, come from a handful of sources, and Jabil's ability to secure supply depends partly on its customers' own relationships with those suppliers.1 The threat of new entrants is low at the scale Jabil operates, because building a global network of qualified factories requires large investment and years of customer qualification, especially in regulated industries such as healthcare and automotive. And substitution is a real and permanent threat: any customer can bring manufacturing in-house, split work across multiple suppliers, or move to an original design manufacturer that also designs the product.
Against those pressures, Jabil has real capabilities. Its network spans more than a hundred sites, allowing customers to build in multiple regions and shift production when tariffs, geopolitics or disasters disrupt one location.1 It offers engineering, design services and supply-chain management alongside manufacturing, so it can be involved earlier in a product's life and handle more of its complexity.1 Much of what it makes has no alternative use outside the customer's programme, which is why much revenue is recognised over time as work is done: Jabil has an enforceable right to payment for work in progress, because the half-built rack cannot be sold to anybody else.1 That accounting detail is a quiet sign of how tightly Jabil's work is tied to each customer's design. It is also a reminder that the customer, not Jabil, owns the product.
The evidence against an easy moat story is just as concrete. Purchase orders are usually cancellable beyond several weeks.1 The largest customer's share of receivables has grown. Jabil does not disclose customer retention, contract renewal rates, or price realisation.1 And the margin record is the most telling evidence of all. A business with strong switching costs and pricing power would expect to earn steadily higher margins as it grows and adds capabilities. Jabil's GAAP operating margin rose from about 3% in fiscal 2015 to about 4.7% in fiscal 2026, an improvement, but one achieved over a decade and still leaving the company with less than a nickel of operating profit on each dollar.1 That is the margin profile of a valued supplier, not a toll collector.
On Customer A specifically, discipline matters. The company does not name it in its annual report, and investors should not speculate about its identity or treat its share of receivables as evidence of default risk.1 Large concentrated receivables in contract manufacturing usually reflect the scale and payment terms of the biggest programmes, not doubts about the customer's solvency. The relevant risk is not that the customer fails to pay. It is that the customer decides to pay less, order less, or move work elsewhere.
Geography adds a second layer of exposure, though it is often overstated. About 73% of fiscal 2026 revenue was foreign-source, down from about 75% in fiscal 2025 and about 83% in fiscal 2024, as more work shifted to U.S. sites and the China mobility business left the portfolio.1 Foreign-source revenue is not the same as net currency exposure: Jabil also incurs most of its foreign costs in the same currencies, and it uses forward contracts to hedge transaction risks.1 The company says a hypothetical 10% move in exchange rates would not materially affect its financial statements.1 The more material geographic risk is political rather than monetary: tariffs, export controls and pressure on customers to build in particular countries. Jabil's multi-region network is an asset in that environment, because it lets customers move production, but it also requires constant capital spending to keep the right capacity in the right places.
The verdict on Jabil's moat, then, has to stay narrow. Network scale and execution make Jabil valuable to complex customers, especially those that need to manage risk across regions and want a supplier who can integrate design, manufacturing and supply chain. Those are real capabilities, and they explain why Jabil keeps winning large programmes. But the filings do not show that those capabilities translate into strong switching costs or durable pricing power. A small number of large buyers retain considerable leverage, and the company's margins look like those of a supplier that is needed but not irreplaceable. The strongest proof of a moat would be downturn performance: whether margins and customer relationships hold when demand falls. Jabil has been through downturns before, but never with this much of its revenue tied to a single kind of customer. Until that test arrives, the moat claim remains plausible, not proven. And because Jabil is spending heavily on the assumption that it is real, the next question is what that spending has done to the balance sheet.
IX. Buybacks, Debt, and the Price of Growth
In January 2026, as Intelligent Infrastructure orders were piling up and the share price was climbing, Jabil went to the bond market and sold $1.0 billion of senior notes.1 It was not an equity raise; the company was borrowing, not diluting shareholders. At the same time, it kept buying back its own stock, and in July 2026 its board authorised up to $1.5 billion of new repurchases.1 Borrowing to fund capacity and acquisitions while also returning cash to shareholders is a familiar move for a confident management team. It is also a choice that raises the stakes if the confidence proves misplaced.
The capital-allocation trade is visible in three numbers. Jabil had about 104.5 million shares outstanding at the end of fiscal 2026, down from about 107.5 million a year earlier, a reduction of nearly 3% in twelve months.1 Total borrowings rose to about $4.0 billion, from about $3.4 billion, while cash fell to about $1.7 billion from about $1.9 billion.1 And debt-to-equity reached about 2.5, more than three times its level a decade ago.1 That last figure looks alarming, but it needs context. Jabil's shareholders' equity is unusually small, about $1.6 billion, because the company has spent years repurchasing shares, which reduces book equity.1 A business valued at nearly $29 billion with a book value of $1.6 billion will show high debt-to-equity almost by construction. The more meaningful measures of leverage compare debt to earnings and cash flow, and on those measures the picture is more comfortable, though not free of risk.
The dividend is almost an afterthought. Jabil paid about $35 million in dividends in fiscal 2026, against about $1.4 billion of free cash flow.1 That is about 2.5% of free cash, a token payment that signals the board's real priorities lie elsewhere: repurchases, acquisitions and capacity. The fiscal 2026 acquisitions alone, Hanley and Rebound, cost about $885 million, more than half the year's free cash flow.1 For an investor, that means the value of Jabil's capital allocation depends almost entirely on two questions: whether the shares were bought back at sensible prices, and whether the acquisitions earn a return above their cost.
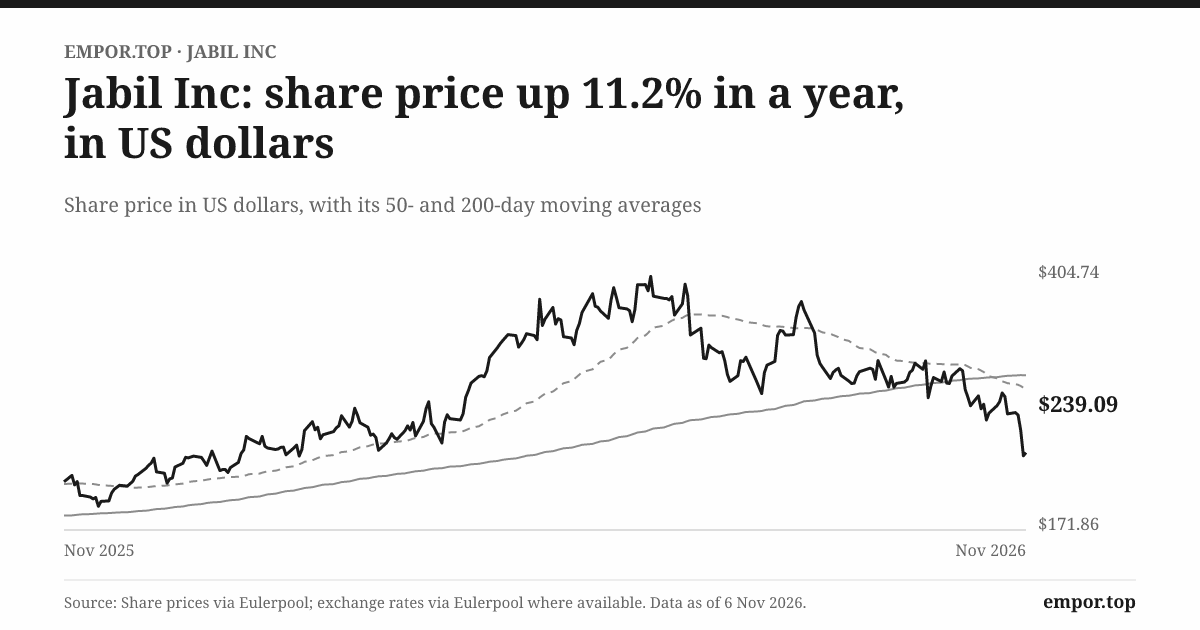
Both questions have become harder as the share price has risen. Repurchases at 11 times earnings, Jabil's five-year median, return a great deal of value per dollar spent. Repurchases at 27.5 times trailing earnings, where the stock traded in early November 2026, return less.1 The shares closed at about $259 on November 4, 2026, about 34% below their 52-week high of about $392 and well above their 52-week low of about $192.1 That range, and a one-year volatility of nearly 48%, shows how quickly the market's view of Jabil has swung.1 A company buying back shares at that valuation is making a large bet that the AI demand wave has much further to run.
The debt itself is well structured. Notes payable and long-term debt, excluding leases, were about $3.38 billion at the end of fiscal 2026, with about $499 million due in fiscal 2027, another $499 million in fiscal 2028, and about $795 million in fiscal 2029.1 The nearest major note maturity is in May 2027. Lease liabilities added about $960 million.1 Jabil had about $4.4 billion of unused borrowing capacity under its credit facilities, and was in compliance with its covenants at year-end.1 There is no sign of refinancing pressure. The company's interest expense, about $181 million in fiscal 2026, is manageable relative to operating income of about $1.7 billion.1
The credit rating agencies see Jabil as solidly but not comfortably investment grade. Fitch affirmed its BBB− long-term rating with a Stable outlook in January 2026, the lowest rung of investment grade, matched by Moody's at Baa3 and S&P at BBB−.142 What is more useful than the rating itself is Fitch's list of what would change it. A downgrade could follow if EBITDA leverage were sustained above 3.0 times, if Fitch-adjusted free-cash-flow margin fell below 1%, or if EBITDA margin dropped below 5%.14 Jabil's fiscal 2026 EBITDA was about $2.1 billion on $36 billion of revenue, a margin of roughly 6%, which leaves about one percentage point of cushion above that 5% threshold.1 On a business that has historically swung from margin peaks to troughs in a single downturn, a point of cushion is not much. The rating does not look at risk today. It could look at risk quickly if margins compressed.
Valuation is where the market's assumptions become most visible. At 27.5 times trailing earnings, Jabil is well above its five-year median.1 On the same date, Celestica traded at about 22 times trailing earnings and Sanmina at about 26 times.1516 Those peer snapshots use different business mixes and different accounting, so the comparison should not be pushed too far. But they show that the whole group has been re-rated by AI enthusiasm, and that Jabil sits at the higher end of it. On management's fiscal 2027 core earnings guide of $17.55 a share, the shares trade at about 15 times, a much less demanding figure.2 The gap between 27.5 times GAAP trailing earnings and 15 times forward core earnings is the market's bet: that the guidance will be delivered, and that the adjustments between core and GAAP earnings, including amortisation, stock compensation and restructuring, will not keep absorbing so much of the profit.
The market value of about $28.7 billion and enterprise value of about $31.0 billion translate into about 0.8 times sales and about 15 times EBITDA.1 For a company earning thin margins, the sales multiple is the more telling one: investors are paying close to a dollar for each dollar of revenue, which only makes sense if margins keep rising and growth persists. The free-cash-flow yield of about 5.3% is respectable, and it is the strongest argument that the valuation is not untethered.1 But it is a yield on a year when working capital was helping cash flow.
A skeptical investor would ask a pointed question here. If AI demand is a cycle, and Jabil's own history suggests its revenue swings sharply with customer programmes, should it slow repurchases or acquisitions to protect its debt capacity and returns? Management's answer, implicit in its actions, is no: it sees enough demand visibility to invest and return capital at the same time. That confidence may prove right. But it should be judged against results, not rhetoric. The test is whether guidance is met, whether cash flow holds as working capital normalises, and whether Hanley, Pii and Rebound produce returns that justify their premiums. On that scorecard, the next two years will matter more than the last two. Which is exactly where the bull and bear cases begin.
X. Bull vs. Bear Case
Jabil's fiscal 2027 outlook promises another sharp step up, to about $44.5 billion of revenue, a core operating margin of about 6.1%, core earnings per share of about $17.55, and roughly $1.6 billion of adjusted free cash flow.2 It arrives at a moment when the market is pricing the shares at about 27.5 times trailing earnings, far above their five-year median of about 11.1 That combination sets up the debate cleanly. If the guidance is delivered and the growth continues, today's multiple may look reasonable in hindsight. If the AI demand cycle turns, the same multiple could compress quickly, and the thin margins underneath would offer little protection.
The bull case begins with a measurable engine. Intelligent Infrastructure is already half of revenue and grew about 45% in fiscal 2026, and its growth has been accompanied by higher gross margins, not lower ones.1 That matters because the usual risk of a contract manufacturer chasing volume is that it buys growth with price concessions. So far, Jabil has grown its largest segment while improving company-wide gross margin, which suggests the new work carries at least comparable economics to the old. The bull case adds that AI infrastructure is broadening, from servers and racks into power, cooling and networking, and that the Hanley acquisition positions Jabil in the power systems that have become a bottleneck for data-centre construction. Each new layer of the rack is another layer of complexity Jabil can be paid to manage.
The second leg of the bull case is diversification. Regulated Industries, at about $12.7 billion and 35% of revenue, spans automotive, healthcare, packaging, renewable energy and energy infrastructure.1 It grew about 7% in fiscal 2026, slower than AI but steadily, and it offers a second base of growth that does not depend on cloud spending.1 Healthcare and automotive programmes tend to run for many years once qualified, because regulators and safety standards make switching suppliers expensive. The free cash flow adds weight: about $1.4 billion of reported free cash flow in fiscal 2026, rising to roughly $1.6 billion of adjusted free cash flow in the fiscal 2027 guide, gives Jabil the means to fund capacity, acquisitions and repurchases without straining its balance sheet in normal conditions.12
The bear case starts with history. Over the three years to fiscal 2026, revenue grew only about 1.2% a year.1 Jabil's revenue has swung sharply in the past, including the 17% decline of fiscal 2024, and the latest surge has come from a narrow set of customers in a single market. Five customers still account for about 37% of sales, and one accounts for about 20%.1 If even one of those large AI customers slows spending, or moves a major programme to a competitor, the effect on revenue and utilisation could be abrupt.
The second leg of the bear case is the cash cycle. Receivables, contract assets and receivable sales have all grown with revenue, and the fiscal 2026 cash flow depended on suppliers waiting longer to be paid.1 Thin margins magnify every misstep: a programme that ends early, a ramp that is delayed, or capacity built ahead of demand can wipe out a year's margin improvement. The third leg is valuation and credit. The multiple sits far above Jabil's own history, while its investment-grade rating carries downgrade thresholds that a margin squeeze could approach.14 A combination of slower growth, lower margins and a compressing multiple is not a remote scenario for a cyclical manufacturer. It is what happened to many such companies after previous technology booms.
Hamilton Helmer's seven powers framework sharpens the debate by asking which durable advantages, if any, Jabil actually holds. Scale economies are the most plausible. Jabil's purchasing volume, global footprint and ability to spread engineering and quality systems across a large base give it cost and capability advantages over smaller rivals. But scale is relative, and Foxconn, Quanta and Wistron are larger, so scale protects Jabil against small competitors more than against the giants.5 Switching costs are real but bounded: qualification, tooling and supply-chain integration make switching expensive mid-programme, but cancellable purchase orders and the absence of disclosed retention data mean those costs reset at each new programme.1 Process power, the hard-to-copy organisational know-how that comes from decades of manufacturing complexity, is plausible, especially in regulated healthcare and automotive work, though the FDA warning letter at Pii shows that process discipline does not automatically transfer to new businesses.1 Network economics, counter-positioning, a cornered resource and brand power do not meaningfully apply. Jabil's customers do not become more valuable to each other because they all use Jabil, it has no unique resource competitors cannot reach, and its brand is invisible to end users by design.
Put Porter's forces and Helmer's powers together, and the moat argument narrows. Jabil has scale and process power that let it win and execute complex programmes, and modest switching costs that hold customers within a programme. It does not have the kind of power that lets it raise prices or protect margins when customers push back. That is why its margin has never gone much above 5% on a GAAP basis outside a divestiture year.1 The competitive position is good enough to win a large share of the AI buildout. It is not strong enough to guarantee that Jabil keeps much of the value when the buildout slows.
Three measures will tell investors which case is winning. The first is Intelligent Infrastructure's growth and segment margin: in fiscal 2026, revenue grew about 45% and the segment earned roughly 6% on its sales.1 Rising growth with a stable or rising margin supports the bull case; slowing growth with a falling margin supports the bear. The second is debtor days and receivables sales: Jabil's receivables rose to about 79 days of revenue, and it sold about $18.3 billion of receivables in the year.1 Stabilising days and steady or falling reliance on receivable sales would show that growth is not being financed through looser customer terms. The third is operating cash flow against net income: over twelve years, operating cash has run at about 183% of profit, and in fiscal 2026 it was about $2.0 billion against about $1.0 billion of net profit.1 If that ratio holds as payables normalise, the cash engine is real. If it falls toward one, the business was borrowing from its suppliers.
What would change the view? Sustained segment margins and cash conversion through a broader technology slowdown would strengthen the bull case considerably, because they would show that Jabil's position in AI infrastructure survives a cyclical test. Falling segment growth, rising receivable concentration, or weak returns on the acquired businesses and new capacity would weaken it. The evidence so far supports a company riding a powerful wave with real skill. It does not yet prove a company that can protect its economics when the wave breaks. Which raises the larger question of what Jabil, over sixty years, actually teaches about building a business behind other people's brands.
XI. Playbook: Business & Investing Lessons
From Jabil’s first production order to an integrated AI rack leaving a facility in 2026 lies one of the longest-running experiments in American business: whether a company can build enormous scale entirely in service of other companies’ products.31 The answer so far is yes, to $36 billion of revenue, but still on a GAAP operating margin of about 4.7%.1 Four lessons emerge from that experiment, and each belongs to Jabil more than to any other company.
The first lesson is that the factory can be invisible, but the customer’s dependence cannot. Jabil began with one customer, Control Data, and its entire fate rested on that relationship.3 Sixty years and hundreds of customers later, Customer A remains a major source of dependence.1 The arc is circular. Scale did not free Jabil from concentration; it simply raised the stakes of it. For founders building service businesses, the lesson is that growth with a few large customers is the fastest route to scale and the most dangerous foundation for it. For investors, it is that the most important number in a contract manufacturer’s annual report is often buried in a footnote about customer concentration. Jabil’s history says the factory survives by being invisible. Its balance sheet says it survives at the pleasure of the few customers who can see it.
The second lesson is that a sale can create a reset, but the next return decides whether it was discipline. The 2023 mobility divestiture reset the portfolio, but its gain did not prove the next investments would pay off.67 The redeployed capital went into data-centre power, pharmaceuticals and returns logistics; the Pii acquisition soon faced an FDA warning letter.1 The lesson for management teams is that a divestiture is applauded on the day it is announced and judged on the returns of whatever replaces it. For investors, it is a warning against treating portfolio activity as strategy. A company that sells well and buys poorly has simply converted a business it understood into one it does not.
The third lesson is that complexity earns a seat at the table, but it does not guarantee the price. Jabil’s move into more complex work, from circuit boards to integrated AI racks, has made it more valuable to customers.31 Yet even its most complex work has not pushed operating margins much beyond a nickel on each dollar of revenue.1 That is the defining paradox of the contract manufacturer: the harder the work, the more the customer needs you, but the customer still writes the purchase order and still has other suppliers to call. Founders who sell capabilities to powerful buyers should take that seriously. Being essential is not the same as being able to set the price.
The fourth lesson is that cash is a process, not a headline. Jabil’s twelve-year record shows operating cash at nearly twice reported profit, a figure that looks like evidence of exceptional earnings quality.1 Look inside it, and cash depends on a negotiation with suppliers, customers and banks that can run in reverse.1 None of that is improper. All of it is a process that can run in reverse. A manufacturer’s cash flow is not a fact about the year; it is a negotiation with suppliers, customers and lenders that has to be won again each quarter. Investors who read the headline number without reading the working-capital notes are not reading the business. They are reading the outcome of last year’s negotiation.
Together, the lessons describe a company that has built remarkable scale through service and repeated reinvention, while never gaining much control over the demand it serves. That is not a criticism. It is the nature of the business Jabil chose on the day it took its first order. The question is what that nature means as the company heads into its next test.
XII. Epilogue
Tonight, Jabil stands at the high point of a remarkable run. Its fiscal 2026 results were among its strongest on an underlying basis, its largest segment is riding a major capital-spending cycle in the technology industry, and its management has guided to another year of rapid growth.12 And every one of those facts depends on what happens next with a handful of customers that Jabil does not control.
The fiscal 2027 guidance is now the scorecard. Management's outlook calls for another year of rapid growth and cash generation.2 The first real check on that promise will come with the first-quarter results in December 2026, followed by updates each quarter through the fiscal year ending in August 2027. What matters is not only whether Jabil hits the revenue number, but how the growth converts into margin and cash. Revenue growth with flat margins would suggest that customers are taking the benefits of scale. Revenue growth with rising margins would suggest that Jabil's engineering role is earning a premium. Revenue growth with falling cash conversion would suggest that the business is financing its customers' expansion.
Intelligent Infrastructure is the segment to watch first. Its growth and segment margin will tell investors whether the AI ramp is broadening across customers and products, or narrowing to a few large programmes. The comparison with management's guide will show whether the forecasting record that has served Jabil well in the up-phase holds as the cycle matures.
The cash cycle is the second watchpoint. If debtor days stabilise and receivable sales stop rising faster than revenue, the fiscal 2026 cash flow will look like a durable feature of the business. If customers stretch their payments further, or suppliers begin to demand faster payment, the cash engine will slow just as the company is borrowing and buying back stock.
The acquisitions are the third watchpoint. Hanley's contribution to data-centre power capabilities will show whether Jabil's move into power systems creates new revenue and margin, or simply adds goodwill to a balance sheet that already carries more debt than it did. Pii's remediation of its FDA warning letter will show whether Jabil can bring its process discipline into a regulated business it did not build. Jabil has not quantified the cost of the FDA matter, and the filings do not yet establish returns on any of the three acquisitions.1
Above all, investors will need to revisit customer concentration and valuation if the AI infrastructure cycle cools. The bull and bear cases still turn on whether Jabil can hold its margins through a slowdown. That tension, between a strong position and an unproven moat, is the question the next two years will answer.
XIII. Outro
Sixty years ago, a circuit board sat on a kitchen table near Detroit, waiting to be repaired for a computer company most people today have never heard of.3 Tonight, a finished data-centre rack rolls out of a Jabil factory, tested and ready to power a model that millions of people will use without ever knowing who built the machine underneath it. The distance between those two images measures what Jabil has achieved: a transformation into a $36 billion company at the centre of the technology buildout.1
And yet, after all that growth, Jabil still depends on other people's demand and keeps only a small share of the value it helps create. It makes the infrastructure behind the future, and must still prove it can keep enough of the value.
References
-
Jabil FY2026 Form 10-K — U.S. Securities and Exchange Commission, 2026-10-23 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Jabil Q4 FY2026 Results and Investor Briefing — Jabil, 2026-09-30 ↩↩↩↩↩↩↩↩↩↩
-
Jabil 2026 Proxy Statement — U.S. Securities and Exchange Commission, 2025-12-12 ↩↩↩↩↩↩↩↩↩↩↩
-
Jabil Announces Definitive Agreement to Divest Mobility Business for $2.2 Billion — Jabil, 2023-08-28 ↩↩↩
-
Jabil FY2024 Form 10-K — U.S. Securities and Exchange Commission, 2024 ↩↩↩↩↩↩↩
-
Jabil FY2025 Form 10-K — U.S. Securities and Exchange Commission, 2025 ↩↩
-
Jabil Acquires Pharmaceutics International, Inc. — Jabil, 2025-02-04 ↩
-
Jabil Annual Meeting Voting Results, Form 8-K — U.S. Securities and Exchange Commission, 2026-01-27 ↩↩
-
Jabil Q2 FY2025 Earnings Call Transcript — Jabil, 2025-03-20 ↩↩
-
Jabil Q4 FY2025 Earnings Call Transcript — Jabil, 2025-09-25 ↩
-
Jabil Q1 FY2026 Earnings Call Transcript — Jabil, 2025-12-17 ↩↩
-
Fitch Affirms Jabil at BBB−/F3, Stable Outlook — Fitch Ratings, 2026-01-20 ↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube