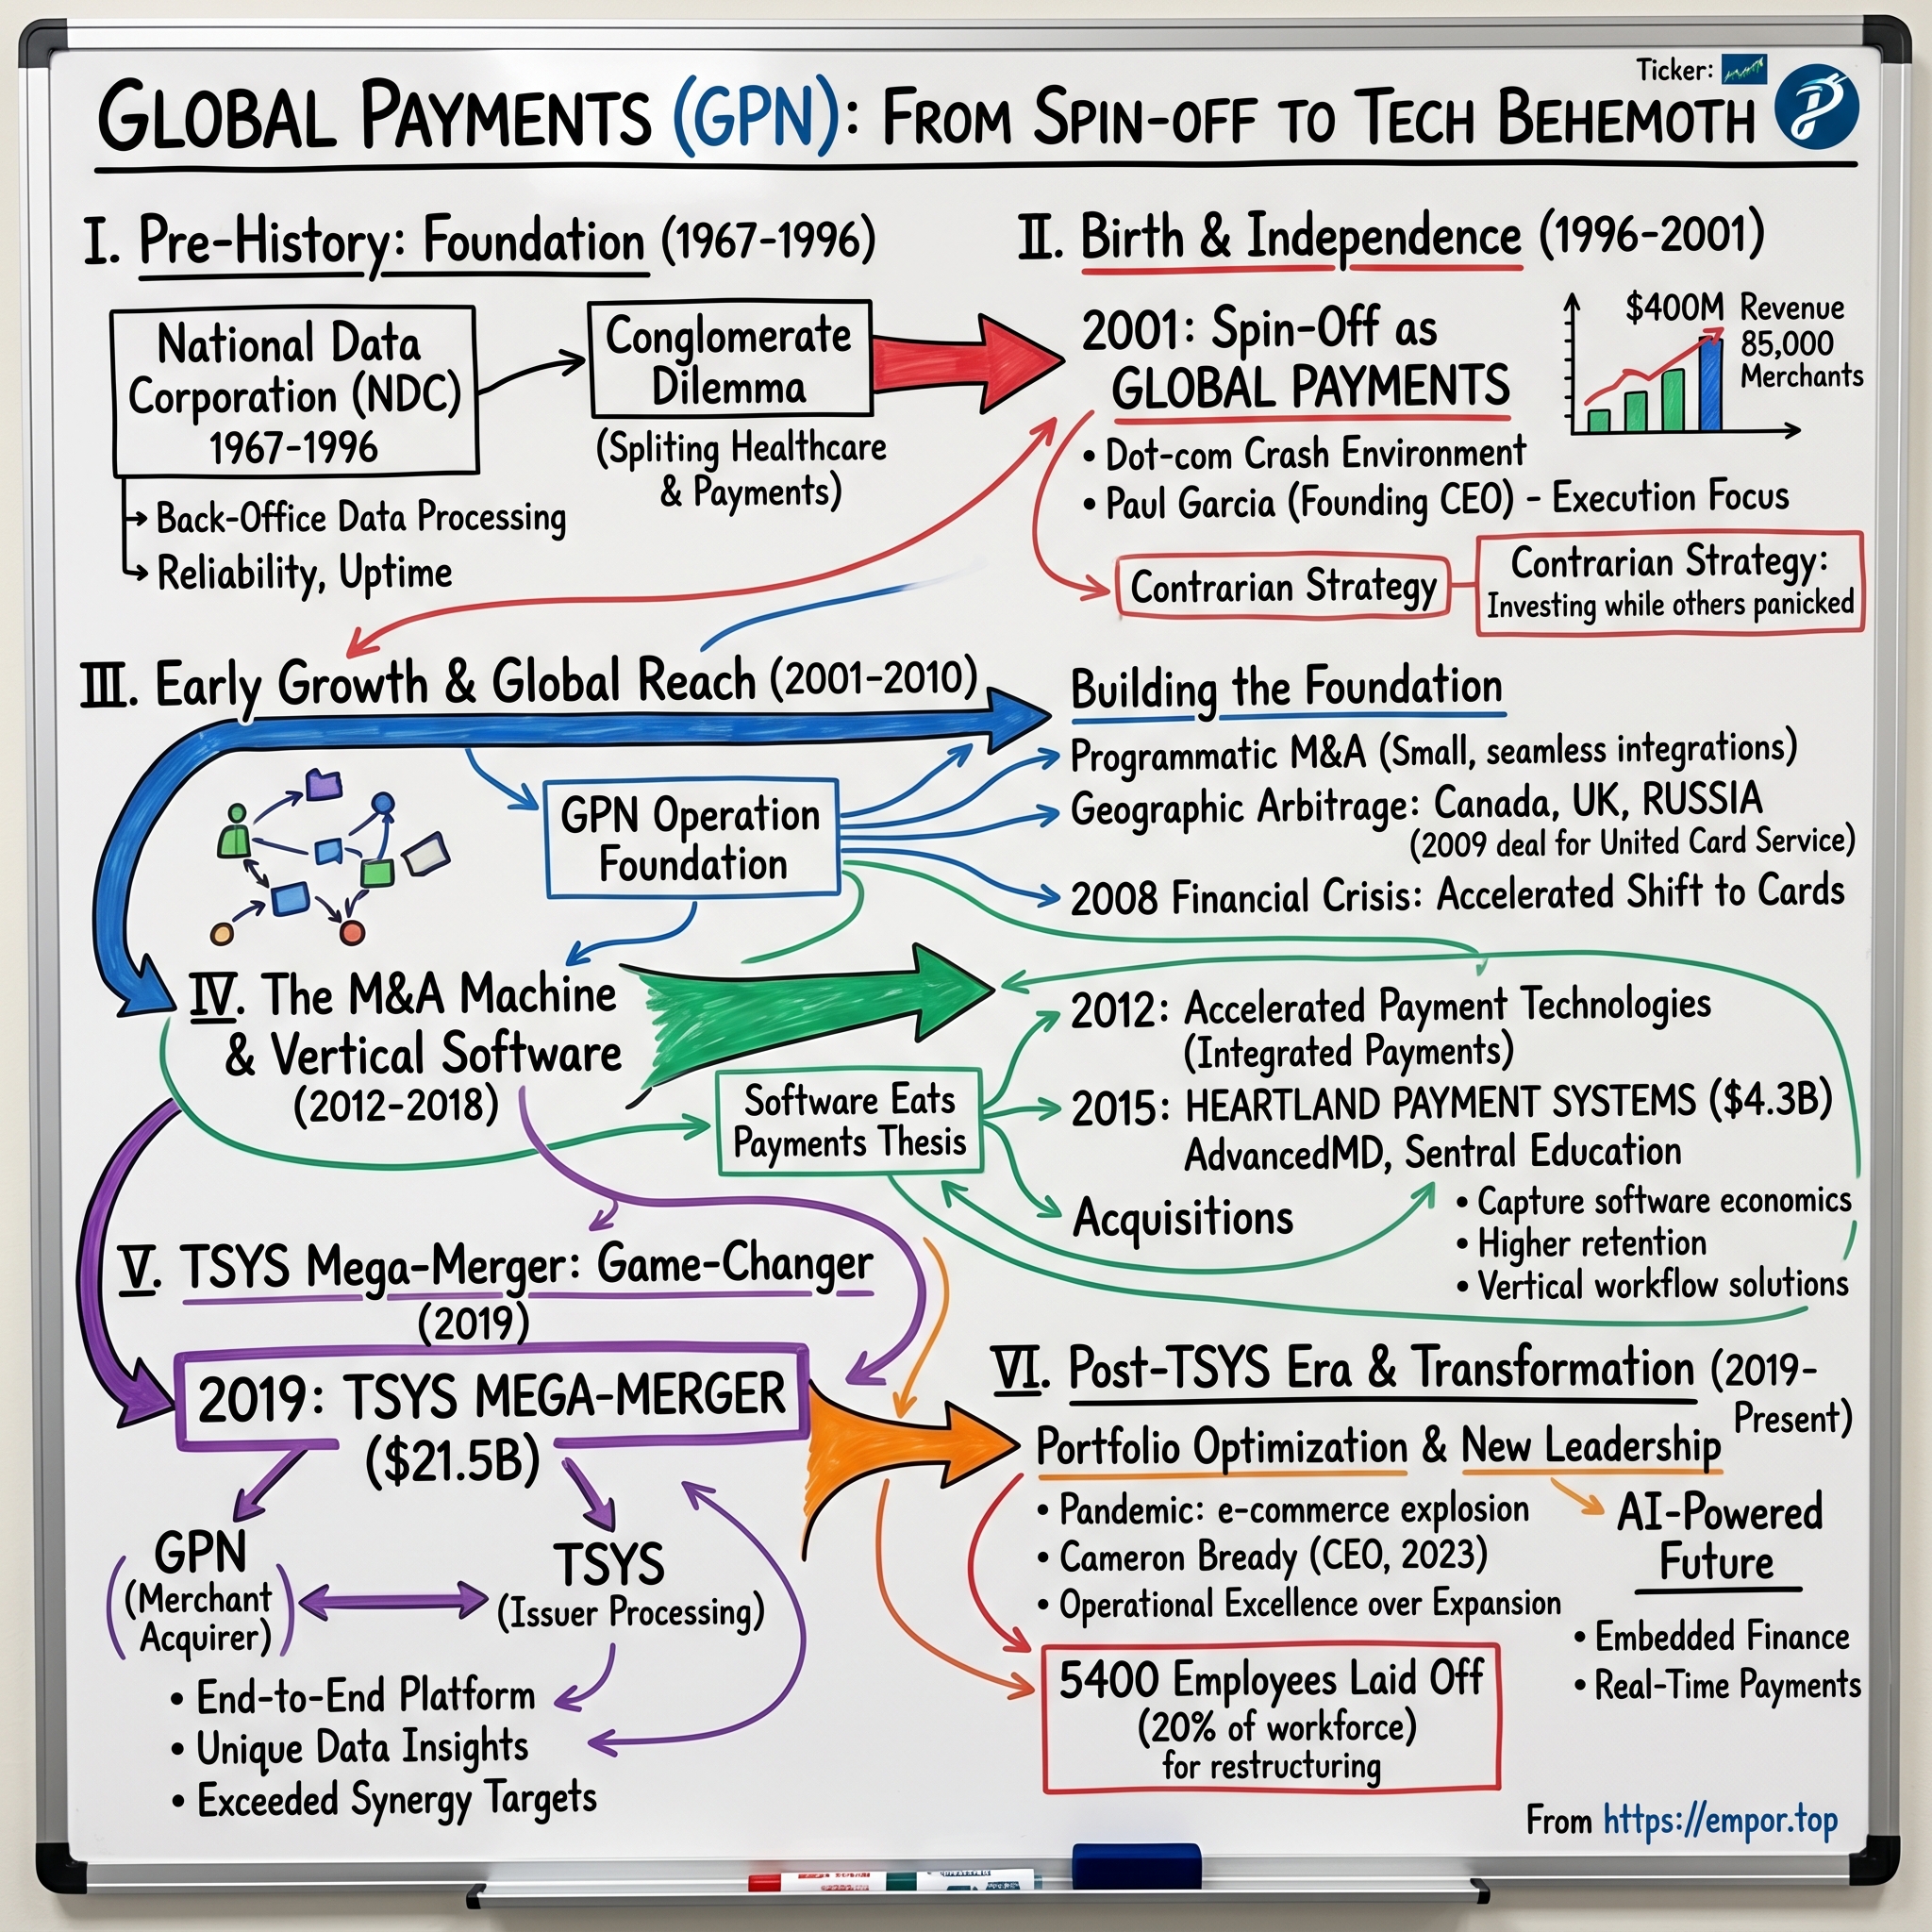
Global Payments: The Great Consolidation, The Conglomerate Mirage, and The Worldpay Gambit
I. Introduction & Episode Roadmap
A Monday in January, Seven Years in the Making
On Monday, January 12, 2026, three press releases crossed the wire on the same morning—one from Atlanta, one from Jacksonville, and one from Chicago. Read together, they described an unusual transaction in corporate America: two of the world's largest payment processors handing each other the core businesses they had spent most of a decade attempting to integrate.
Global Payments Inc. (NYSE: GPN) announced that it had completed its acquisition of Worldpay from FIS and the private equity firm GTCR. Simultaneously, it closed the sale of its Issuer Solutions division—the legacy TSYS card-issuing franchise—to FIS1. Regulatory filings dated the legal acquisition to January 9, 2026, with the companies formally announcing completion on January 1223.
The headline figures were substantial. Worldpay was valued at $24.25 billion, offset by approximately $1.55 billion in anticipated tax benefits, yielding a net purchase price of roughly $22.7 billion4. FIS paid $13.5 billion to acquire Issuer Solutions5. Following the transaction, Global Payments characterized itself as a "pure-play commerce solutions provider," reporting a footprint spanning more than 6 million merchant locations, roughly 94 billion annual transactions, and approximately $3.7 trillion in transaction volume across more than 175 countries1.
The strategic reversal is stark. In May 2019, Global Payments announced its merger with TSYS under the headline "Global Payments and TSYS Combine to Form Leading Pure Play Payments Technology Company"6. Seven years later, management adopted an entirely different definition of "pure play," divesting the very TSYS franchise it had previously promoted as essential.
The Central Question
This is the evolution of how a 1960s data-processing company transformed into a merchant-acquiring roll-up, expanded into a software-and-payments conglomerate, became a two-sided payments giant, and ultimately returned to its origins as a focused merchant processor—all while carrying tens of billions of dollars in accumulated goodwill from each successive era.
For long-term investors, the core inquiry extends beyond whether Worldpay is an attractive asset. The sharper question is whether a decade of rapid dealmaking that outpaced organic execution has finally yielded a simpler, cash-generative franchise that the market misprices, or whether the same acquisition engine has simply placed a larger wager under a new label.
The Road Map
The analysis unfolds in six parts. The narrative begins with the industry plumbing: the mechanics of how a card transaction generates revenue, and how National Data Corporation's authorization business evolved into Global Payments. The second part traces the software expansion under former chief executives Paul Garcia and Jeff Sloan, spanning the 2012 APT acquisition, Heartland, and an extensive vertical-software roll-up.
The third part examines the conglomerate era: the TSYS megamerger, the Netspend detour, EVO Payments, and the 2023 leadership transition. The fourth follows Chief Executive Cameron Bready's restructuring, from headcount reductions and the Genius rebrand to the Worldpay asset swap and the arrival of an activist investor on the share register.
The fifth part surveys the operating business today: its three operating segments, their underlying economics, and the competitive environment alongside Fiserv's Clover, Adyen, Stripe, and Toast. The final section evaluates the investment thesis through strategy frameworks, historical precedent, and a balanced bull-and-bear framework. The logical starting point is the core plumbing, tracing where the economics of a card transaction actually flow.
 Subscribe on LinkedIn
II. The Merchant Acquiring Engine & Foundations (1967–2001)
Four Parties and a Toll Road
Picture a coffee shop in Atlanta. A customer taps a card for a five-dollar latte, and in under two seconds a quiet relay race runs across several financial intermediaries. The coffee shop's payment processor—known as the acquirer—routes the authorization request across a card network such as Visa or Mastercard to the bank that issued the customer's card. The issuing bank approves the charge, and within a day or two the funds settle back to the merchant, minus a series of deductions.
The aggregate fee deducted from the merchant is called the merchant discount, and it comprises three distinct layers. The Federal Reserve Bank of Kansas City identifies the largest layer as interchange, which is collected by the card issuer but established by the card network. Next are network assessment fees paid to Visa or Mastercard for switching and routing. Last is the processing markup retained by the acquirer for providing the terminal, connecting to the network, and settling funds into the merchant's bank account7.
The structural reality that underpins this business is that the acquirer captures the thinnest slice of the fee pool. Interchange represents the overwhelming majority of the total cost; one merchant trade group cited in the Kansas City Fed's research estimated that interchange accounted for roughly 85% of supermarket card acceptance fees7. For debit cards issued by large financial institutions, federal regulations under the Durbin Amendment have capped interchange at 21 cents plus 0.05% of the transaction amount since 20117.
Merchant acquiring functions essentially as a toll road where third parties dictate the toll rates. Acquirers generate operating profit through scale, by extracting wider pricing spreads from small merchants who lack negotiating leverage, and by layering value-added software and services directly onto the payment flow.
Pricing structure plays a decisive role in profitability. Small businesses typically pay a bundled, flat-rate fee—such as 3% per transaction—that absorbs interchange, assessments, and processing into a single charge. Larger enterprise merchants negotiate "interchange-plus" pricing, where interchange and network fees pass through at cost alongside an itemized, basis-point processing markup7. Because blended flat-rate pricing yields substantially higher gross margins, the battle for small and midsize businesses has defined industry competition for more than two decades.
National Data Corporation: The Authorization Pioneer
The corporate lineage traces back to 1967, when George W. Thorpe, a retired deputy director of intelligence in the U.S. Air Force, established National Data Corporation (NDC) in Atlanta to provide specialized telecommunications and data-processing services8. NDC found immediate traction in the emerging bank card sector. By 1977, half of all banks in the United States and Canada relied on NDC to handle authorization routing for MasterCharge cards, and by 1984 the company processed more credit card transactions than any other entity globally8.
Over the subsequent decade, NDC evolved into an unwieldy conglomerate operating two disparate business lines under one corporate umbrella: health-information systems and electronic payment processing8. By the late 1990s, the strategic logic had eroded. Hospital and pharmacy software clients shared no operational overlap with merchant-acquiring accounts, and public markets heavily discounted the blended business model.
The Spin-Off
NDC addressed the conglomerate discount through a corporate separation. Global Payments was formally incorporated as a wholly owned subsidiary on September 1, 2000, and on January 31, 2001, NDC distributed 100% of its ownership to shareholders at a ratio of 0.8 Global Payments shares for every NDC share held9.
The spun-off entity was modest compared to its modern scale. In its inaugural fiscal year, ended May 31, 2001, Global Payments generated $353.2 million in revenue, almost entirely derived from merchant acquiring. The company processed over 2.7 billion transactions annually across more than 1 million merchant locations with a workforce of approximately 1,700 employees9.
The company was led by Paul R. Garcia, who had previously headed National Bancard Corporation before running NDC's eCommerce division and stepping into the chief executive role at Global Payments in September 20009. Garcia's opening transaction established the strategic playbook that would govern the company for the next decade: in March 2001, Global Payments acquired the merchant-acquiring book of Canadian Imperial Bank of Commerce (CIBC), issuing shares that left CIBC with a 26.8% equity stake in the company9.
That transaction became the repeatable model for regional expansion. Traditional commercial banks, viewing merchant processing as a low-margin back-office operation, systematically outsourced their merchant portfolios to Global Payments in exchange for minority equity stakes, upfront cash, or exclusive multi-year marketing referral agreements. Global Payments secured immediate processing volume without financing an expensive direct sales force, while financial institutions retained payment capabilities for commercial clients.
The bank-referral alliance served as an efficient growth engine for a business governed by unit volume and narrow basis points. However, it also embedded a core operational vulnerability: top-line expansion relied predominantly on buying back-book bank portfolios rather than winning merchant accounts organically. The strategic limits of that roll-up model would quickly become apparent once integrated software began transforming how merchants selected payment providers.
III. The Integrated Payments Revolution & The M&A Roll-Up (2001–2018)
The Bank-Partnership Decade
Through the 2000s, Paul Garcia expanded Global Payments primarily along regional bank relationships. In June 2008, the company paid HSBC $439 million in cash for a 51% equity stake in a joint venture holding HSBC's UK merchant-acquiring business. That operation held roughly 15% of the UK acquiring market across 135,000 merchant outlets and generated about $229 million in 2007 revenue10. Garcia noted at the time that the company was "thrilled that HSBC, one of the world's most respected financial institutions, has agreed to expand its relationship with Global Payments into the United Kingdom"10.
Global Payments also expanded into higher-risk international territories. On April 30, 2009, it completed the $75 million cash acquisition of ZAO United Card Service (UCS), a direct merchant acquirer and indirect processor in Russia11. More than a decade later, following Russia's invasion of Ukraine, Global Payments divested the business, with then-chief executive Jeff Sloan describing it as "a difficult time for our team members, customers and partners across the region and especially in Ukraine"12.
While financially modest, the Russian exit illustrated an enduring structural trade-off of the bank-partnership model: international scale assembled through localized joint ventures inevitably exposed an acquirer to political and regulatory risks that portfolio diversification could not eliminate.
Operational risk also surfaced during this era. In 2012, Global Payments disclosed a major data breach. By January 2013, the company reported that cumulative breach costs had reached $93.9 million, encompassing investigation, remediation, credit monitoring, and $35.9 million in estimated fraud losses and card-network fines13. For an electronic transaction processor, security failures translated directly into income-statement losses and challenged the institutional trust of the sponsor banks and card networks that govern market access.
The Goldman Banker Arrives
In March 2010, Garcia made a leadership appointment that would define the company's trajectory for the next thirteen years. Jeffrey S. Sloan, a partner at Goldman Sachs and global head of its financial technology banking group, was named president of Global Payments, effective June 1, 2010. Sloan had spent a decade directing payments-industry investment banking at Goldman14, prompting Garcia to characterize him as "a highly respected and knowledgeable leader in financial services"14. Sloan was subsequently elevated to chief executive officer in 201315.
Sloan's advisory background signaled a fundamental shift in capital allocation. Having monitored payments consolidation from the investment banking side, he was well versed in merger arithmetic, synergy realization, and the valuation premiums public markets awarded to recurring software revenue.
APT: The $413 Million Epiphany
The strategic turning point arrived with a relatively modest transaction. In August 2012, Global Payments agreed to acquire Accelerated Payment Technologies (APT) from private equity firm Great Hill Partners for $413 million in cash16. APT processed roughly $8 billion in annual card volume for small and midsize merchants, but its core asset was distribution: a network of 700 value-added resellers across 30 vertical markets16.
A single disclosure in the regulatory filing revealed the strategic logic. Global Payments noted that its reported revenue "will not materially change" because it was already clearing the vast majority of APT's transactions through an existing independent sales organization relationship16. Global Payments effectively deployed $413 million not to acquire incremental processing volume, but to buy direct ownership of the distribution channel.
The commercial rationale reflected changing merchant buying behavior. A dental clinic or specialty retailer does not evaluate payment processors in isolation; it selects practice-management or point-of-sale software, and that software application directs the underlying acquiring gateway. Whoever controls the application controls the payment relationship. APT had built that connectivity, integrating payment gateways directly into the day-to-day business management software that small merchants used.
Global Payments codified this insight into what became known across the industry as the integrated or independent software vendor (ISV) channel. Rather than competing against software developers for merchant accounts, the company paid developers recurring revenue shares to embed Global Payments' acquiring tools into their platforms. Software vendors gained a lucrative new income stream, while Global Payments acquired highly defensible merchant volume with low churn, since switching processors would require replacing the merchant's core operating software.
That acquisition established an executive lineage that continues today. Robert "Bob" Cortopassi joined Global Payments through the APT transaction as a senior vice president and serves as the company's president and chief operating officer, overseeing technology, product, and operations17. The integrated-payments framework he helped establish would outlast most of the corporate strategies built around it.
Heartland: "The Most Valuable Payments Company on the Planet"
If APT provided the strategic blueprint, Heartland represented the scale transformation. On December 15, 2015, Global Payments agreed to acquire Heartland Payment Systems for $4.3 billion, paying Heartland shareholders $100 per share in a consideration mix of $53.28 in cash and 0.6687 Global Payments shares18.
Heartland was founded by Robert O. Carr, an outspoken payments entrepreneur whose firm built an extensive direct sales force focused on independent restaurants and retail merchants. After Heartland survived a severe 2008 data breach, Carr had turned the crisis into an industry campaign, publicly advocating for end-to-end encryption, tokenization standards, and EMV chip technology19.
Carr framed the business combination in expansive terms: "Under Jeff's leadership, I believe the combination of our companies will become the most valuable payments company on the planet," he said18. Sloan similarly positioned the transaction as a defining milestone that would transform Global Payments "into the leading provider of integrated payments technology solutions in the world"18.
When the transaction closed on April 22, 2016, at a total enterprise value of $4.4 billion including $0.4 billion in assumed debt, it contributed over 300,000 merchant relationships, a 1,400-person direct sales force, and $130 billion in annual card processing volume20. Management targeted approximately $125 million in annual run-rate operational synergies18.
The Heartland acquisition equipped Global Payments with a dedicated, nationwide direct sales force—a capability it had never possessed in the United States. That field presence remains a strategic pillar. In 2026, management cites local, in-person installation and ongoing customer service as an operational differentiator against the digital-only onboarding models of cloud competitors21.
Buying the Software Itself
Sloan subsequently took the APT logic a step further. If embedding payments into third-party software generated high-margin, defensive volume, full vertical ownership appeared even more attractive, eliminating the risk that an ISV partner might defect to a competing processor. Global Payments embarked on an acquisition spree to purchase vertical software providers outright.
On September 1, 2017, the company acquired ACTIVE Network, a cloud software provider for community activities and health-and-fitness event management, for $1.2 billion. On September 4, 2018, it acquired AdvancedMD, a cloud-based practice-management platform for outpatient physician clinics, for approximately $707 million. On October 17, 2018, it followed with the $409 million purchase of SICOM, a provider of enterprise management software for quick-service restaurants22. Corporate filings increasingly highlighted "technology-enabled" revenue as the primary driver of top-line expansion22.
Falsification Check: Did Owning the Software Build a Moat?
The premise behind this capital deployment was that owning vertical software creates durable customer switching costs and captures combined software-and-processing profit pools.
Subsequent corporate actions directly challenged that assumption. In October 2024, Global Payments agreed to sell AdvancedMD to private equity firm Francisco Partners for up to $1.125 billion—comprising $1 billion in cash at closing and up to $125 million contingent on sponsor returns—against roughly $250 million in annual revenue23. Discussing the divestiture, Cameron Bready acknowledged that the business "was not the best strategic fit," citing healthcare's intensive regulatory compliance demands and the persistent risk of "channel conflict with partners"23.
That concession highlighted a structural flaw in the proprietary software strategy: owning an application vendor placed Global Payments in direct competition with the independent software partners whose acquiring volumes it courted across the wider vertical.
While AdvancedMD nominally sold above its acquisition price, that return masks six years of maintenance capital, management attention, and opportunity cost. The transaction reflected a broader strategic retreat. Global Payments retained vertical software assets in defensible niches where partner channel conflict was minimal, while divesting or de-emphasizing proprietary software in heavily regulated, capital-intensive markets.
By 2026, management's positioning narrowed the thesis further. Bready noted that small and midsize businesses increasingly procure payments directly "from their software provider," conceding that outside core restaurant and retail segments—where the company distributes its proprietary Genius platform—Global Payments intends to reach vertical markets through third-party software partnerships rather than owned software suites24.
Historical execution ultimately narrowed the original claim: owning vertical software created an enduring competitive moat in select captive niches, but failed as an all-encompassing operating model. The test of this adjusted strategy lies in whether growth in the partner-led Platforms segment can outpace the proprietary SMB channel. Sloan's software roll-up had transformed Global Payments into a substantial enterprise; in 2019, he chose to assemble a much larger conglomerate.
IV. The Conglomerate Mirage: The $21.5B TSYS Mega-Merger (2019–2023)
The Summer of Mega-Deals
During the first half of 2019, an unprecedented wave of consolidation swept through the payment processing sector. In January, Fiserv agreed to acquire First Data for approximately $22 billion. In March, FIS followed with an agreement to acquire Worldpay, completing the transaction on July 31, 2019. Then, on May 28, Global Payments and Total System Services (TSYS) announced an all-stock "merger of equals" valued at $21.5 billion2526.
All three transactions shared a common thesis: that massive scale was necessary to defend against emerging technology competitors, and that owning broader stretches of the transaction value chain would yield substantial cost efficiencies. FIS chief executive Gary Norcross framed the Worldpay combination as a "transformative combination" that would allow clients to "capitalize on growth opportunities at a time of rapid marketplace change"26. Five years later, both FIS and Global Payments would unwind the core of that thesis in the same transaction.
The Anatomy of the TSYS Deal
Based in Columbus, Georgia, roughly one hundred miles south of Global Payments' Atlanta headquarters, TSYS operated primarily as a processor for card-issuing financial institutions. The company ran the core back-office infrastructure that enabled banks to issue and manage credit cards. It also maintained a merchant-acquiring division alongside Netspend, a prepaid debit card business TSYS had acquired in 2013 for $1.4 billion, or $16 per share in cash27.
Under the merger terms, each TSYS share was converted into 0.8101 Global Payments shares25. Global Payments shareholders retained a 52% majority ownership of the combined entity, while TSYS shareholders held 48%. Corporate headquarters were split between Atlanta and Columbus6. Sloan remained chief executive officer, while Troy Woods, TSYS's chairman and CEO, became chairman of the board6.
On a pro forma basis, the combined enterprise generated approximately $8.6 billion in adjusted net revenue plus network fees and $3.5 billion in adjusted EBITDA, serving roughly 3.5 million merchant locations and more than 1,300 financial institutions across over 100 countries6. Management pledged to generate at least $300 million in annual run-rate cost synergies and $100 million in annual revenue synergies within three years6. The transaction officially closed on September 18, 201925.
The Promised Holy Grail
The strategic rationale promised that a single company operating across both merchant acquiring and card issuing could unlock capabilities neither side could achieve alone: routing transactions internally to reduce card-network interchange and assessment fees, identifying cross-network fraud patterns, and packaging bundled issuing and acquiring services to commercial banks. Sloan stated that the combination "accelerates our technology-enabled, software-driven payments strategy"6. Announcements also emphasized TSYS's e-commerce capabilities alongside the international merchant reach Global Payments could provide to TSYS's card-issuing partners6.
Public equity markets initially rewarded the scale narrative. Boosted by the pandemic-era acceleration in digital payment volumes and rising fintech valuation multiples, Global Payments stock reached an all-time high of $220.81 on April 26, 202128.
The Netspend Detour and the EVO Shuffle
The first structural strain appeared within Netspend. By mid-2022, a consumer-facing prepaid card operation no longer aligned with an enterprise seeking premium software-company valuation multiples. On August 1, 2022, Global Payments unveiled three interrelated capital-allocation moves.
The company agreed to sell Netspend's consumer business—representing roughly 85% of the unit—for $1 billion to Searchlight Capital Partners and Rêv Worldwide. Simultaneously, it agreed to acquire EVO Payments for $34 per share in cash, representing an enterprise value of approximately $4 billion and a 24% premium over EVO's prior closing price, supported by a $1.5 billion convertible-note investment from Silver Lake29.
EVO served approximately 550,000 merchant accounts across 50 markets, expanding Global Payments' acquiring presence in Poland, Germany, Chile, and Greece while adding specialized business-to-business payment capabilities. Management targeted $125 million in annual run-rate operating synergies29.
Wall Street responded with skepticism. Equity analysts at Mizuho highlighted the conflicting strategic priorities: "Global Payments is making a big acquisition while underlying fundamentals remain challenged. Will this help improve sentiment? We doubt it"29. The Netspend divestiture closed on May 1, 2023, returning the consumer card business to its original founders, Roy and Bertrand Sosa30. TSYS had paid $1.4 billion for all of Netspend a decade earlier; Global Payments sold the consumer division for $1 billion.
Why the Two-Sided Thesis Failed
The thesis underpinning the TSYS merger did not unravel suddenly; it eroded gradually under three persistent operational frictions.
The first was client and operational divergence. Issuer processing relies on long-term, multi-year enterprise contracts negotiated with risk-sensitive bank committees, whereas merchant acquiring depends on distributed sales to restaurants, retailers, and software partners. Operationally, the two businesses shared almost no day-to-day overlap. The cross-selling opportunities management promoted—such as pitching card-issuing processing to commercial banks that already maintained merchant-referral alliances—never materialized as a discernible growth driver in financial filings.
The second friction was financial structure and the resulting conglomerate valuation discount. Issuer processing functioned as a slow, steady utility; in 2025, Issuer Solutions generated revenue growth of 4.5%31. Investors seeking a high-margin software growth story resisted owning a capital-intensive issuing utility, while defensive investors seeking steady utility returns were unwilling to accept the churn and macroeconomic exposure of merchant acquiring.
The third was intensifying competition across both operating units. While Global Payments focused management attention on integrating TSYS, cloud-native challengers captured share. In merchant acquiring, modern platforms such as Adyen, Stripe, Toast, and Fiserv's Clover captured market growth. Concurrently, Issuer Solutions faced pressure from both legacy processors and modern cloud card issuers, with the company's annual 10-K citing direct competition from Fiserv, FIS, and Marqeta32.
The Handover
On May 1, 2023, Global Payments announced that Sloan would step down as chief executive officer and resign from the board of directors, effective June 1, 2023, concluding a 13-year executive career at the firm15. Sloan characterized the business as operating "back in an environment of normalcy," pointing to the completion of the EVO acquisition, the Netspend divestiture, and the $415 million sale of the company's gaming payments division15. First-quarter earnings released that morning reflected operational pressure, showing a quarterly net loss of $4.4 million compared with a $249.6 million net profit a year earlier15.
The board named Cameron M. Bready, then 51, as his successor. Bready had joined Global Payments as chief financial officer in 2014 and had served as president and chief operating officer since 201915. Before entering financial technology, Bready served as CFO of electric transmission utility ITC Holdings, following earlier finance positions at Northeast Utilities and Mirant17.
That executive background signaled a deliberate change in operational orientation. Bready's formative experience was in regulated utilities—a sector where capital is expensive, balance-sheet discipline is paramount, and returns are driven by execution rather than speculative dealmaking. Equity analysts at Baird endorsed the appointment, calling him "a top fin tech executive"15.
Yet Bready was also a primary architect of the previous era. As CFO and COO alongside Sloan, he had financed and executed the very conglomerate transactions he would now be called upon to dismantle. Whether his promotion represented a fundamental strategic break or merely a change in tone became the central question facing shareholders.
V. The Great Unwinding & The Worldpay Gambit (2024–2026)
Quiet Cuts, Loud Signals
Cameron Bready's tenure as chief executive began with cost reductions rather than an expansive strategic vision. In September 2024, trade publication Payments Dive reported that Global Payments was eliminating staff across the United States, following an earlier round of workforce reductions that year. While the company declined to disclose specific figures, Wolfe Research analyst Darrin Peller estimated that the earlier round affected approximately 400 positions out of roughly 27,000 global employees across 35 countries at year-end 202333. Peller anticipated that management would systematically prune non-core assets that failed to generate adequate returns on invested capital33.
Although external reports speculated on substantially larger layoff totals throughout 2024, Global Payments never confirmed aggregate workforce reductions, leaving the full extent of the early restructuring unquantified.
The Investor Day: "One GP"
On September 24, 2024, Global Payments convened an investor conference in New York to articulate a new operational direction. Bready presented a company that had "reoriented to a unified operating model globally to address its complexity"34. The stated ambition was to establish Global Payments as "the worldwide partner of choice for commerce solutions"34.
The plan rested on four pillars. First, unify the company's fragmented point-of-sale offerings worldwide under a single brand, Genius. Second, execute an operational transformation projected to deliver more than $500 million in adjusted run-rate operating income benefits by the first half of 2027. Third, return $7.5 billion of capital to shareholders across three years. Fourth, pursue disciplined "dispositions of select assets"34. Management established medium-term financial targets calling for mid-single-digit revenue growth in 2025, accelerating to mid-to-high single digits across 2026 and 2027, alongside low-teens growth in adjusted earnings per share34. Global Payments later increased that operational transformation target to more than $600 million35.
Portfolio reshaping followed swiftly. As outlined in the software evaluation, the company reached an agreement to divest AdvancedMD in late 202423. In May 2025, Global Payments agreed to sell its payroll business to Acrisure for $1.1 billion, directing after-tax proceeds toward shareholder returns while "maintaining leverage neutrality"36. On May 16, 2025, the company introduced the unified Genius point-of-sale platform at the National Restaurant Association trade show, launching Genius for Restaurants across the United States and Canada, with Retail and Enterprise editions scheduled to follow37.
The Swerve
Then, on April 17, 2025, the strategic roadmap abruptly altered course. Seven months after committing to simplification, internal focus, and heavy capital returns, Global Payments announced the largest transaction in its corporate history.
The transaction was structured as a multi-party asset swap. Global Payments agreed to acquire 100% of Worldpay from FIS and private equity firm GTCR for $24.25 billion, or $22.7 billion net of anticipated tax assets, while simultaneously divesting its Issuer Solutions business to FIS for $13.5 billion4.
Management characterized the transaction economics as an advantageous multiple arbitrage, purchasing Worldpay at 8.5 times adjusted EBITDA—inclusive of run-rate synergies—while selling Issuer Solutions at 12.3 times adjusted EBITDA4. In plain terms, Global Payments was divesting a slower-growing issuing utility at a premium valuation to acquire a much larger, lower-multiple merchant processor at a discount.
Financing the transaction required deploying the Issuer Solutions sale proceeds, existing cash balances, approximately $7.7 billion in newly issued debt, and equity consideration. GTCR agreed to accept Global Payments common stock valued at $97 per share, representing an approximate 15% pro forma equity stake4. The combined enterprise was projected to generate roughly $12.5 billion in adjusted net revenue and $6.5 billion in adjusted EBITDA on a 2025 pro forma basis4. Management targeted $600 million in annual run-rate cost synergies alongside at least $200 million in revenue synergies within three years, guiding net leverage from approximately 3.5 times at closing down to 3.0 times within 18 to 24 months, with an expectation of preserving investment-grade credit ratings of BBB-, Baa3, and BBB4.
"Today marks a defining day for Global Payments," Bready declared4.
Public equity markets reacted with immediate skepticism. Shares dropped approximately 20% to their lowest level in a decade38, touching a monthly trough of $65.93 in April 202528. Having been promised operational simplicity and disciplined capital returns just seven months earlier, equity investors were asked to endorse a complex, debt-financed $24 billion megadeal that required no shareholder vote38.
The $97-per-share fixed valuation assigned to GTCR's equity consideration carried significant implications. While that pricing shielded existing shareholders from deeper immediate dilution given where the stock previously traded, it also meant that an experienced private equity sponsor was accepting equity at a valuation level that public markets instantly rejected.
Worldpay's Long Road Here
Worldpay arrived at this juncture after years of ownership churn and volatile private-market valuations. Cincinnati-based processor Vantiv acquired London-listed Worldpay Group in January 2018 for approximately $10.4 billion, adopting the Worldpay identity. FIS subsequently acquired the combined entity in July 2019 in a transaction valued at approximately $43 billion including assumed debt26.
That conglomerate combination quickly soured. In February 2023, facing escalating pressure from activist hedge funds D.E. Shaw and Jana Partners, FIS recorded a massive $17.6 billion non-cash goodwill impairment against the merchant business and announced plans for a tax-free spin-off39. Five months later, in July 2023, FIS altered course and agreed to sell a 55% controlling stake to GTCR at an $18.5 billion valuation—including $1 billion in contingent consideration—which priced the business at 9.8 times expected 2023 adjusted EBITDA against upfront cash consideration of $17.5 billion, with FIS retaining a 45% stake40.
Against that transaction history, the $24.25 billion headline valuation delivered GTCR an attractive markup on its entry point after less than two years of ownership, while representing a steep haircut from the valuation FIS had paid during the 2019 consolidation frenzy. At closing, GTCR co-chief executive Collin Roche emphasized the sponsor's focus on operational discipline and highlighted its "expertise executing complex transactions"3.
Enter Elliott
On July 16, 2025, reports revealed that Elliott Investment Management had accumulated a substantial equity stake in Global Payments. The stock gained 5.4% in after-hours trading38, with the company's equity market capitalization hovering near $19 billion38.
The activist presence coincided with an unusual degree of public self-reflection from the executive suite. In August 2025, Bready publicly conceded: "We are assessing whether any of the decisions we made prior to our September investor conference, we would take a different view of now"41. That same month, equity analysts at William Blair observed that while they felt "encouraged" by the unified software-integrated point-of-sale rollout, they cautioned that such product "innovations will prove too little, too late in an increasingly competitive market"41.
On September 29, 2025, Global Payments and Elliott reached a formal cooperation agreement. Two new independent directors joined the board immediately: Patricia Watson, former chief information officer at NCR Atleos, TSYS, and Bank of America; and Archana Deskus, former chief technology officer at PayPal with prior CIO tenure at Intel and Hewlett Packard Enterprise42. The board expanded to 12 directors, with the parties agreeing to identify a third independent director and creating an ad hoc Integration Committee dedicated to monitoring the operational integration of Worldpay and the realization of targeted synergies42.
"Global Payments has a substantial value-creation opportunity that will require disciplined execution," remarked Elliott partner Jason Genrich42. In February 2026, Vivek Sankaran, the former chief executive of grocery retailer Albertsons, was appointed as the third mutually agreed independent director under the pact43.
Closing, and What Global Payments Now Is
The portfolio pruning continued on schedule. The payroll sale to Acrisure closed on October 1, 2025, with management allocating $500 million of the proceeds to an accelerated share repurchase that it characterized as "incremental to the $7.5 billion of capital returns" pledged for the 2025 to 2027 period44. The marquee Worldpay asset swap closed in January 2026, completing ahead of its initial first-half 2026 timeline5. For FIS, acquiring Issuer Solutions secured an enterprise card-issuing platform processing more than 40 billion transactions annually across more than 75 countries5.
For Global Payments, the transaction left an enterprise entirely stripped of its bank card-issuing operations, reorganized across three core merchant processing segments: Small and Midsize Business (SMB), Enterprise, and Platforms. To anchor product strategy across this consolidated footprint, the company appointed Cindy Turner as chief product officer, recruiting her directly from Worldpay following her earlier leadership of PayPal's Braintree enterprise business17.
By early 2026, the structural unwinding of the conglomerate era was complete. Whether that balance-sheet transformation translates into durable economic returns depends on the competitive reality inside those three merchant segments—the subject of the operating analysis that follows.
VI. Business Model, Segment Economics & Competitive Battlefield
Three Engines Under One Hood
In August 2026, Global Payments reported its first quarterly earnings under its reorganized segment structure, offering the clearest operational look yet at the consolidated post-Worldpay enterprise.
For the second quarter of 2026, adjusted net revenue reached $3.16 billion, up 4% on a normalized basis adjusting for divestitures and the Worldpay transaction. Adjusted operating margin stood at 42.0%, and adjusted earnings per share rose 12% to $3.46, compared to GAAP diluted earnings per share of $0.052.
That disparity between 5 cents and $3.46 captures the central tension for market skeptics. The delta largely reflects acquisition-related amortization, integration expenses, and separation charges that management routinely strips out of non-GAAP metrics. While adjusted figures offer a cleaner baseline for quarter-to-quarter operating trends, they also obscure the cumulative cash costs of the dealmaking that assembled the firm.
SMB (roughly half of revenue). Serving merchants generating under $50 million in annual card volume, this segment produced $1.51 billion in second-quarter revenue—up 4% normalized alongside 4% volume growth—delivering $891 million in segment operating income, representing a 59% contribution margin24.
With revenue and transaction volume expanding at an identical pace, the company demonstrated no immediate expansion in processing yield—the net revenue captured per dollar processed. Management's turnaround thesis hinges on the Genius platform reversing that dynamic. During the earnings call, executives reported that new customer yields increased 75% year over year and that Genius bookings expanded by more than 25% sequentially, while acknowledging that the platform's revenue contribution remains "relatively modest today"24.
Enterprise (about a quarter of revenue). Anchored by the heritage Worldpay corporate book, this segment caters to enterprise merchants processing more than $50 million in annual card volume. Segment revenue was $838 million, rising 7% on a normalized basis despite an estimated 400-basis-point headwind from geopolitical conflict in the Middle East dampening cross-border travel. Card-not-present revenue, representing global e-commerce volume, expanded in the low double digits. Segment operating income totaled $653 million, representing a 78% contribution margin24.
That 78% margin figure warrants scrutiny. Because Global Payments reports corporate overhead and shared technology infrastructure separately, contribution margins reflect the extreme operational leverage of clearing large-volume enterprise accounts rather than fully loaded economic profitability.
Platforms (about a fifth of revenue). Representing the direct descendant of the 2012 APT strategy, the Platforms segment distributes acquiring services through independent software vendors, payment facilitators, and online marketplaces. Revenue grew 7% normalized to $628 million on 10% volume growth, generating $284 million in operating income for a 45% contribution margin, supported by 48 new partner signings during the quarter24. Volume outpaced revenue growth because the fastest-expanding component—managed payment facilitation—commands lower yields than traditional integrated referrals24.
Other. A legacy runoff bucket composed of non-core portfolios, this segment accounted for roughly 8% of 2025 revenue and is projected to decline to approximately 6% in 2026. It comprises legacy bank referral relationships that no longer originate new merchant accounts alongside a managed-services client actively migrating off Global Payments' platform24. Bready characterized the portfolio candidly, acknowledging that these legacy assets "will be a drag until they're gone"24.
Unit Economics: Where the Margin Lives
The operational economics follow directly from the four-party payment model. In the SMB segment, merchants typically operate on bundled, flat-rate pricing structures. That leaves ample spread for acquirer margins while creating room to cross-sell software subscriptions, point-of-sale hardware, online ordering modules, customer loyalty tools, and merchant working-capital lending.
In Enterprise, large merchants pay interchange-plus and negotiate every fraction of a basis point. Acquirers must generate profit through scale, foreign exchange conversion spreads, and ancillary value-added services. Management points specifically to its "revenue boost" authorization-optimization tools, claiming the product has generated $2 billion in annual merchant approval uplift and added an incremental 50 basis points to authorization rates using machine-learning decision models, according to management24.
For a global enterprise merchant, an additional 50 basis points of approval represents substantial top-line recovery; legitimate transaction declines represent permanent lost sales. However, these uplift metrics represent management disclosures rather than independently audited benchmarks.
Ancillary services have consequently become central to management's narrative. When core transaction processing fees are compressed toward zero, acquirer economics depend on surrounding software: fraud screening, transaction retry logic, currency conversion, accelerated payouts, and embedded financing. According to management, these value-added services grew approximately 25% year over year within the Platforms segment during the second quarter, while Enterprise cross-sell bookings increased by roughly 30%24. If sustained, those expansion rates provide the clearest operational evidence that Global Payments can decouple revenue growth from raw volume throughput.
Genius: The Product Bet Under the Hood
Genius warrants close examination because it carries the weight of the company's SMB turnaround. At launch in May 2025, management described it as a single platform replacing the company's separate point-of-sale products, starting with restaurants in the U.S. and Canada and extending to retail and enterprise tiers37. Cortopassi called it "a single, scalable and feature-rich continuum"37.
Fifteen months into deployment, the platform incorporated artificial-intelligence handheld devices supporting on-device voice ordering alongside conversational natural-language business reporting. Commercial adoption expanded into multi-unit franchise brands, winning rollouts at chains such as Long John Silver's and Pollo Tropical24. In Canada, financial cooperative Desjardins began distributing Genius across its bank network24.
A balanced assessment indicates that while Genius demonstrates competitive parity in product capabilities and early commercial traction, its macro financial contribution remains difficult to verify. Management has promised more specific Genius metrics, including absolute revenue scale and organic growth rates, as it heads into 202724. Until audited segment reporting breaks out those figures, public market investors must evaluate the platform's progress based on management-selected sequential bookings disclosures.
The Competitive Map
Fiserv and Clover. Fiserv's Clover represents the established benchmark in North American SMB point of sale and the primary competitive hurdle for Genius. Global Payments counters Clover through multi-channel physical distribution: commercial bank referrals, Heartland's direct field sales force, and Worldpay's extensive financial-institution relationships. Management said the heritage Worldpay business included roughly 6,000 U.S. bank branches21 and that 30 of its largest bank partners would begin distributing Genius in the fourth quarter of 202624. In parallel, the company accelerated direct sales recruitment following its 2024 restructuring, with more than 300 of a planned 500 new sales professionals onboarded by May 202621.
Adyen. Having engineered a single, unified global processing engine from inception without legacy code or integration debt, Amsterdam-based Adyen stands as the global standard for enterprise merchant acquiring. Global Payments counters with geographic reach and localized physical presence, deploying sales and service staff in more than 40 countries and the ability to facilitate payments across 175 countries21. Bob Cortopassi added a newer argument: in a world of "resurgence of nationalism," Global Payments presents itself as "a true global company" rather than a U.S. firm with global distribution21. Whether that pitch resonates with multinational corporate treasurers evaluating unified tech stacks remains an open question.
Stripe. Stripe remains the dominant force in developer-centric digital payments, marketplace infrastructure, and subscription billing. Global Payments competes with it in the Platforms segment for software companies seeking to embed payments into their applications. The company's partner wins, including an expanded relationship with software provider Xplor, show it can still win platform mandates, especially where international reach matters24.
Vertical software (Toast, Shopify, and others). Specialized vertical platforms represent the most formidable structural challenge to traditional acquiring distribution. "More and more SMBs are procuring their payment solutions from their software provider," Bready said in August 2026. He added that SMB would therefore grow at mid-single digits, with other verticals shifting to the Platforms business over time24. In effect, management accepts that outside of core restaurant and retail environments where it deploys Genius directly, the software vendor, not the processor, controls the customer relationship.
How Global Payments Wins, and the Limits
Global Payments' competitive position rests on three interrelated assets: boots-on-the-ground distribution combining direct sales, regional bank networks, and independent equipment dealers; localized acquiring licenses and settlement connections spanning dozens of regulatory regimes; and an expansive web of software integrations cultivated since the APT acquisition.
None of these moats is impregnable in isolation. Maintaining thousands of field sales representatives requires substantial ongoing capital, and bank-referral exclusivity can be contested. Global licensing capabilities appeal primarily to multinational enterprise merchants, precisely the customer cohort where Adyen's unified architecture is most competitive. Furthermore, software integrations remain durable only so long as independent software vendors refrain from developing proprietary payment gateways or migrating to modern payment facilitators. Global Payments' operational advantage lies in the intersection of all three pillars—a sprawling hybrid model that delivers formidable scale, but also demands relentless executive coordination.
VII. Leadership, Governance & The Activist Stress Test
The Operator Team
The executive lineup on Global Payments' post-Worldpay investor calls illustrates the institutional crosscurrents shaping the consolidated firm: Cameron Bready as chief executive officer, Josh Whipple as chief financial officer, and Bob Cortopassi as president and chief operating officer21. The composition blends distinct corporate disciplines: a utility-trained finance executive in Bready, a former investment banker and corporate strategist in Whipple, and an operating veteran in Cortopassi who rose through the integrated payments channel.
Whipple spent more than a decade in financial technology investment banking at Bank of America Merrill Lynch and Bear Stearns before serving as Global Payments' chief strategy and enterprise risk officer from 2015 to 2022, when he assumed the CFO role17. That continuity underscores an important operational reality: the finance chief overseeing the present restructuring previously directed corporate strategy during the TSYS merger and the subsequent vertical-software acquisition campaign. The current executive suite is not an outside turnaround team appointed to dismantle a predecessor's portfolio; rather, it comprises the very leaders who helped assemble the conglomerate they are now tasked with streamlining.
Guidance Discipline: The 2026 Test
For public equity markets, management credibility depends fundamentally on guidance discipline, and the post-merger enterprise faced its first operational stress test during 2026.
In February 2026, management established initial full-year guidance calling for adjusted earnings per share of $13.80 to $14.00—representing 13% to 15% annual growth—alongside approximately 5% constant-currency revenue growth, excluding divestitures31. The company reaffirmed that outlook in May45. By August, however, leadership lowered its targets, guiding to an adjusted EPS range of $13.60 to $13.80—translating to 11% to 13% growth—and trimming full-year revenue growth expectations to 4% to 5%2.
Management attributed the downward revision primarily to macroeconomic pressures in its corporate travel book. Whipple explained that regional conflict in the Middle East dampening cross-border travel had "persisted longer than anticipated"24. While executives had estimated an adverse impact of roughly 70 basis points on second-quarter performance, the realized drag reached closer to 100 basis points24.
Rather than adjusting assumptions on an ad hoc quarterly basis, management opted to project the travel headwind through the end of 2026. Bready elaborated that recovering airline seat capacity was concentrated predominantly in lower-yielding short-haul regional flights rather than high-margin international routes24. While the downward revision was comparatively modest and driven by external geopolitical factors rather than execution breakdowns, it nevertheless represented a guidance cut during the opening year of an asset swap intended to re-establish investor confidence.
Integration Costs and Free Cash Flow
Achieving the targeted transaction synergies requires substantial upfront cash deployment. Whipple outlined approximately $600 million in cumulative one-time costs to deliver the integration roadmap, reporting that Global Payments had spent roughly $300 million through the first half of 2026, with approximately $100 million in additional outlays projected over the remainder of the year, including technology separation costs24.
Bready noted that the company had deliberately accelerated its technical decoupling from FIS infrastructure. Emphasizing that the expedited schedule was "not a knock on FIS," Bready stressed that the merchant business needed to eliminate operational reliance "upon coordination through FIS" as rapidly as possible24. While pulling separation costs forward elevated near-term expenses, it compressed the transitional window during which Worldpay remained dependent on its former parent.
For institutional investors, free cash flow conversion represents the critical metric of earnings quality, and the company's cash generation remains heavily weighted toward the second half of the year. In the second quarter of 2026, adjusted free cash flow reached $687 million, representing a 75% conversion rate from adjusted net income, while management reiterated its full-year expectation of conversion exceeding 90%24. When Wolfe Research analyst Darrin Peller noted on the earnings call that achieving that target would require a sharp second-half rebound, Whipple cited the company's historical seasonality, pointing to free cash flow conversion above 100% during the second half of 202524.
Across full-year 2025, the standalone pre-Worldpay enterprise generated $3 billion in free cash flow, delivering a conversion rate above 100%31. While second-half cash strength aligns with corporate precedent, the scale of non-GAAP adjustments separating reported GAAP results from adjusted free cash flow has expanded substantially during the integration period.
Capital Allocation Guardrails
Management has paired its operational restructuring with explicit capital return targets. The company committed to returning more than $2 billion to shareholders during 2026, forming part of a broader $7.5 billion capital-return target scheduled across 2025 through 202731. Backing that commitment, the board authorized a $2.5 billion share repurchase program in February 2026, executing successive accelerated share buybacks that included a $550 million agreement announced alongside fourth-quarter results and an additional $500 million authorization in May3145.
Simultaneously, management targeted reducing net leverage to 3.0 times adjusted EBITDA by year-end 2027 while pledging to maintain its investment-grade credit ratings24. At the end of the second quarter of 2026, net leverage stood just below 3.5 times, with fixed-rate debt representing more than 90% of total borrowings at an average interest cost of approximately 4%24.
This capital structure creates an exacting operational balancing act. Global Payments is seeking to reduce leverage by half a turn, return more than $2 billion annually to equity holders, fund approximately $1 billion in annual capital expenditures, and absorb roughly $600 million in cumulative one-time integration expenses simultaneously24. The underlying financial model remains viable so long as free cash flow meets guided targets; however, it leaves narrow margin for macroeconomic deceleration, customer attrition, or integration delays.
Executive Pay and Board Oversight
The cooperation agreement with Elliott Investment Management expanded technical governance by adding experienced enterprise software and infrastructure leaders to the board, while establishing a dedicated Integration Committee to oversee the Worldpay combination42. The agreement did not, however, alter the chief executive role or split the responsibilities of the board leadership.
That intervention provided an institutional check on execution without overhauling executive leadership. Whether governance reforms will translate into revised compensation structures—such as tying executive incentive awards more heavily to return on invested capital rather than non-GAAP earnings metrics—remains to be seen in future regulatory proxy disclosures.
The operational test for the board is clear. By 2027, shareholders will be able to measure realized synergies against the $600 million run-rate objective and compare cumulative one-time integration charges against the $600 million budget. If the Integration Committee functions effectively, those disclosures should provide an unambiguous accounting of whether the Worldpay transaction fulfilled its financial promises.
VIII. Strategy Frameworks: Five Forces & 7 Powers
Porter's Five Forces
Threat of new entrants: low at the core, high at the edges. Establishing a direct, licensed merchant acquirer requires years of lead time, substantial balance-sheet capital, clearing capabilities across multiple regulatory jurisdictions, and direct integrations into payment network settlement systems. That operational barrier shields Global Payments' processing core. At the customer interface, however, software providers can launch as payment facilitators virtually overnight by partnering with wholesale infrastructure providers. As a result, emerging competitors rarely seek to displace merchant acquirers directly; instead, they intermediate the customer relationship and relegate processors to backend commodity suppliers.
Buyer power: high for enterprise, moderate for SMB. Large corporate merchants negotiate aggressively and increasingly multi-home their processing volume across several payment providers to secure redundancy and lower basis points. While Enterprise segment revenue grew faster than transaction volume in 2026 due to the cross-selling of value-added software—suggesting Global Payments retained some pricing power24—that result reflects only a single year of post-merger operating history. Small and midsize merchants possess limited individual bargaining leverage, yet they can migrate away from legacy processors simply by adopting new point-of-sale software.
Supplier power: very high. Visa and Mastercard establish operating rules, security protocols, and interchange schedules, which acquirers must accept as price takers. Regulatory intervention remains an external variable. The Credit Card Competition Act, reintroduced in the U.S. Senate on January 13, 2026, would require large card-issuing financial institutions to enable at least two unaffiliated routing networks on credit cards46. Legislative sponsors argue the mandate would introduce competition and lower merchant swipe fees46. For transaction acquirers, the structural impact is nuanced: while lower card fees might support merchant economics, complex routing mandates expand technical processing workloads. As of March 2026, the legislation had not passed either chamber of Congress47.
Threat of substitutes: moderate. Account-to-account bank transfers, sovereign real-time settlement rails, and digital wallets present potential alternatives to traditional card networks. While acquirers can often process these alternative rails, customer adoption patterns evolve slowly. Management has positioned agentic commerce—automated AI software executing purchases on behalf of consumers—as an additional transaction channel the company intends to support, citing multiple commercial pilots underway with artificial intelligence platforms and enterprise retailers24. However, software pilots do not represent recurring revenue, and Global Payments' historical record of converting nascent payment concepts into material financial returns remains mixed.
Rivalry: intense. Fiserv, Adyen, Stripe, JPMorgan Chase's merchant acquiring arm, Toast, Square, and regional processors compete across every commercial tier. The company's 2024 annual report identified Fiserv, Worldpay, and Chase Paymentech as primary domestic competitors, alongside Worldline and Nexi in international markets32. Following the 2026 asset swap, one of those primary domestic competitors is now housed within Global Payments itself.
Hamilton Helmer's 7 Powers
Scale economies: real but not unique. Processing $3.7 trillion in transaction volume spreads fixed investments in software infrastructure, regulatory compliance, and network connectivity across a broad volume base1. However, scale operates as a prerequisite for industry participation rather than an exclusive moat; peers such as Fiserv and JPMorgan operate at comparable volume, while Adyen achieves substantial operational efficiency through a single, modern code base.
Switching costs: strong in proprietary software and embedded integrations, weak in plain processing. A restaurant deploying the unified Genius platform for kitchen management, online ordering, inventory tracking, and payments faces high friction when considering a transition. Conversely, a merchant utilizing Global Payments strictly as a card-settlement pipe can switch providers with minimal operational disruption. The rollout of Genius represents an effort to establish software-based switching costs across the SMB merchant base; however, that initiative remains unproven at scale, with management characterizing the platform's overall financial contribution as "relatively modest"24.
Network effects: weak. Merchant acquirers do not benefit from traditional two-sided network flywheels; adding an incremental merchant to the processing platform does not enhance the service's utility to retail cardholders. The closest structural analogue is data density: processing billions of transactions enables machine-learning models to optimize fraud detection and improve authorization approval rates, a capability highlighted by management24. Yet competing merchant acquirers operating at comparable transaction volume possess access to similar data feedback loops.
Counter-positioning: historically disadvantageous. Adyen's unified, single-stack architecture represented a modern operating model that Global Payments—burdened by dozens of acquired legacy platforms—could not emulate without stranding existing infrastructure and cannibalizing maintenance cash flows. The deployment of Genius and the target enterprise architecture announced in 2026 represent a concerted attempt to narrow that architectural gap24. Nonetheless, legacy platform consolidation is a multi-year effort that carries recurring customer attrition risks during technical migrations.
Cornered resource: moderate. Exclusive bank-referral networks—including Worldpay's distribution reach across roughly 6,000 U.S. bank branches—and localized acquiring licenses spanning international jurisdictions are difficult for new entrants to reproduce quickly21. However, bank partnerships remain subject to competitive renegotiation upon contract renewal, while regulatory licenses can be obtained by well-funded challengers over time.
Process power: moderate. Decades of operational experience managing chargeback disputes, merchant underwriting, international settlement, and cross-border regulatory compliance provide genuine operational capabilities. Nevertheless, this institutional proficiency represents the baseline standard required of any established commercial processor.
Branding: emerging. Genius represents the company's first structured effort to build a recognized, merchant-facing brand comparable to Clover or Toast. Management noted that an initial broadcast advertising campaign drove a nearly 60% increase in branded search queries24. While encouraging as an early indicator of market awareness, search traffic does not constitute an economic moat.
These analytical frameworks describe an incumbent supported by tangible but standard structural assets: transaction scale, localized licenses, bank distribution channels, and processing data. Because each of these attributes is shared with well-capitalized industry peers, operational execution—rather than an uncontested structural moat—remains the decisive variable governing financial performance.
IX. The Historical Falsification Layer & Thesis Stress Test
Test 1: The Software-Led Moat and ISV Protection Thesis
The claim. Integrated software relationships and owned vertical software protect Global Payments from price competition and merchant churn.
The strongest evidence against it. The most direct counter-evidence comes from management's own disclosures. In August 2026, Cameron Bready acknowledged a secular industry shift where small and midsize merchants increasingly procure payments directly through their primary software providers, which caps standalone SMB processing growth in the mid-single digits. Management conceded that Global Payments will compete with its proprietary software primarily in restaurants and retail, while relying on third-party software partners across other vertical markets24.
Corporate actions reinforced this retreat. Global Payments divested AdvancedMD partly because owning healthcare software generated recurring "channel conflict with partners"23. It subsequently sold its payroll division, a software-adjacent asset, for $1.1 billion36. Meanwhile, the managed-services client actively migrating off the platform within the runoff "Other" reporting bucket demonstrated that substantial partners can internalize acquiring capabilities and depart entirely24.
Weighing it. This evidence is recent, directly observed within the core merchant portfolio, and acknowledged by current leadership. Against it, the Platforms segment generated 7% normalized revenue growth in the second quarter of 2026, with embedded payment volume expanding approximately 20%. That momentum indicates that Global Payments continues to win processing share as backend infrastructure for software platforms, even if those arrangements command lower processing yields24.
Verdict: narrowed. The software moat holds where Global Payments controls the operational workflow—such as Genius across restaurants and retail—or serves as an embedded infrastructure partner to independent software developers. It does not insulate the standalone SMB acquiring book, where growth faces secular deceleration. The critical operational indicator to monitor is normalized SMB revenue growth relative to transaction volume. If Genius succeeds in driving software cross-sell, revenue growth should decouple and outpace volume; if it falters, revenue and volume will remain locked in lockstep parity.
Test 2: The Serial Acquirer Capital Allocation Thesis
The claim. Global Payments creates shareholder value through repeated large acquisitions and synergy capture.
The strongest evidence against it. A transaction-by-transaction review reveals repeated strategic reversals:
- TSYS, completed as a $21.5 billion all-stock merger of equals in 201925, culminated in the divestiture of its core card-issuing franchise in 2026 for $13.5 billion5. While Global Payments retained the TSYS merchant acquiring portfolio and captured several years of issuer cash flows, the foundational rationale for the combination—unifying both sides of the payments value chain—was entirely abandoned.
- Netspend, originally acquired by TSYS for $1.4 billion in 201327, saw its core consumer business divested for $1 billion a decade later in 20232930.
- Equity valuation suffered severe multiple compression, plunging from an all-time peak of $220.81 in April 2021 to a monthly low of $65.93 in April 2025, even as management continued debt-financed dealmaking28.
- Reported results through the first half of 2026 illustrate the cumulative drag of dealmaking overhead, with acquisition amortization and restructuring charges creating an extreme gap between second-quarter GAAP diluted earnings of $0.05 per share and adjusted earnings of $3.46 per share2.
The counter-evidence. Not every transaction proved destructive. The 2012 APT acquisition established the foundational architecture for today's high-margin Platforms segment. AdvancedMD was sold for more than its cumulative purchase price2322. Furthermore, the Worldpay asset swap executed an advantageous multiple trade, divesting a slower utility asset at 12.3 times EBITDA while acquiring a larger enterprise merchant franchise at a stated 8.5 times EBITDA inclusive of run-rate synergies4.
Verdict: the history rejects the claim of superior serial compounding. The historical record demonstrates an ongoing pattern of initial synergy promises, followed by quiet impairments or divestitures of assets once heralded as essential, leaving the share price well below its 2019 to 2021 highs. While the Worldpay acquisition may represent the most favorably priced megadeal in company history, realizing its economic value requires rigorous integration execution—a discipline the TSYS conglomerate era failed to deliver. Key benchmarks for accountability include tracking net realization against the $600 million annual run-rate cost synergy target within the $600 million one-time integration budget24, while ensuring net leverage falls to 3.0 times adjusted EBITDA by year-end 2027 alongside ongoing capital returns.
Test 3: The Worldpay Scale Champion Thesis
The claim. Worldpay's addition creates an enterprise commerce leader that can hold its own against Adyen and Stripe.
The strongest evidence against it. Worldpay has endured three corporate ownership changes in approximately eight years: acquired by Vantiv in 2018, absorbed by FIS in 201926, carved out in a majority sale to GTCR across 2023 and 202440, and now combined into Global Payments. The massive $17.6 billion goodwill impairment FIS recorded in 2023 reflected both decelerating organic expansion and market-share erosion as small merchants migrated toward embedded cloud providers39. Each transition triggered executive turnover, conflicting technical roadmaps, and protracted platform carve-outs—an operational toll reflected in elevated separation outlays through 202624.
What the early data say. Initial operating data from the first half of 2026 offer preliminary stability. Second-quarter Enterprise segment revenue rose 7% on a normalized basis, absorbing an estimated 400-basis-point drag from suppressed international air travel. Card-not-present e-commerce revenue expanded at a low double-digit rate, year-to-date bookings climbed 10%, and enterprise implementations went live with major multinational brands including Aldi, Morrisons, and Careem24. Cameron Bready indicated that management targets high-single to low-double-digit organic growth across the Enterprise division over time24. Conversely, performance across Worldpay's legacy UK small-merchant acquiring portfolio exhibited softness, highlighting lingering regional vulnerability24.
Verdict: intact but unproven. Six months of data cannot confirm or reject a multi-year integration claim. The decisive tests will emerge in 2027, when organic Enterprise growth can be evaluated without the distortion of regional travel headwinds, and in whether the projected $200 million revenue synergy target begins materializing in reported numbers. Management guided to approximately $100 million in realized revenue synergies during 2028 before exiting that year at the full annual run rate21. If organic Enterprise revenue growth decelerates into the mid-single digits once macro conditions normalize, the argument for Worldpay as an engine of differentiated enterprise growth collapses.
Myth vs. Reality
Myth: the Worldpay deal was a panic move forced on management. Corporate chronology refutes this narrative. Management announced the asset swap in April 2025, three months before news broke that Elliott Investment Management had built an equity position438. The activist arrived after the transaction was agreed upon, and its cooperation agreement centered on strengthening board-level integration oversight rather than dismantling the combination42.
Myth: Global Payments sold its "bad" business and bought a "good" one. Issuer Solutions was not an impaired franchise. In 2025, the division delivered 4.5% revenue growth and produced roughly $1.04 billion in operating income on $2.16 billion in revenue—a 48% operating margin that exceeds standard merchant acquiring spreads31. For FIS, the acquired issuing platform was projected to contribute roughly $500 million in adjusted free cash flow in 20265. Global Payments exchanged an insulated, high-margin utility cash flow for a larger merchant franchise carrying higher top-line potential alongside substantial execution risk—a calculated strategic trade-off, not the disposal of a distressed asset.
Myth: the new company is a clean slate. Legacy drag persists across several fronts. Non-core portfolios in the "Other" reporting bucket represented approximately 8% of 2025 revenue and require years of managed attrition to run off24. In the executive suite, key leaders—including the chief executive and chief financial officer—previously designed and executed the conglomerate strategy they are now tasked with reversing17. Furthermore, technical separation and integration expenditures will persist into 202824. While the corporate taxonomy is streamlined, the operational infrastructure and leadership retain direct continuity with the prior decade.
Reality: the balance sheet is stretched but orderly. Net leverage of about 3.5 times adjusted EBITDA, insulated by a debt structure that is over 90% fixed at an average interest rate near 4%, and protected by investment-grade ratings commitments, outlines an enterprise with constrained flexibility rather than impending solvency peril244. The central investment hazard is not balance-sheet failure, but capital allocation gridlock: a prolonged period in which mandatory debt paydown, capital expenditures, integration cash outlays, and promised share repurchases exhaust available free cash flow.
These three empirical tests converge on a single operational reality: while Global Payments has simplified its corporate architecture to a degree unseen since 2019, its multi-year record of synergy capture and organic compound growth remains unproven. The entire investment thesis rests on execution discipline—providing the baseline for evaluating the competing bull and bear cases that conclude the analysis.
X. The Investment Case: Bull vs. Bear
The Bull Case
A simpler story at a discounted multiple. Following its April 2025 low, Global Payments traded at a steep discount to its historical valuation. At its peak in 2021, the stock traded at multiples that priced in an extended runway for software-led growth28. The return to a pure-merchant architecture removes the card-issuing utility that public markets struggled to value alongside merchant acquiring. If the streamlined business delivers steady mid-single-digit revenue growth, modest operating margin expansion, and disciplined share repurchases, the market may come to value the company on sustainable free cash flow rather than its past conglomerate missteps.
Cash flow that funds buybacks. The standalone pre-Worldpay business generated $3 billion of free cash flow in 202531. On the second-quarter 2026 earnings call, equity analysts referenced an adjusted free cash flow target of approximately $4 billion for 2027, an expectation management did not dispute24. Share repurchases have been substantial: the company repurchased approximately 8 million shares for $550 million in the second quarter of 2026 alone24. If free cash flow conversion holds near targeted levels, a steadily shrinking share count can drive double-digit growth in adjusted earnings per share even alongside modest revenue expansion.
Synergies with a clear audit trail. The cost-synergy roadmap features a defined budget and public accountability, monitored directly by an ad hoc board committee that includes Elliott-backed independent directors42. In May 2026, management reiterated confidence that it could "achieve or exceed" its stated revenue and expense synergy targets21.
Genius and new distribution. Although Genius launched from a modest baseline, reported annual location growth exceeding 50% alongside a 75% rise in new customer yields indicate that the unified point-of-sale platform is building commercial traction. Distribution is expanding further through Worldpay's established commercial bank branch network24. If newly originated front-book sales across the U.S. SMB channel transition almost entirely to Genius over the next one to two years, as Bready projected24, SMB revenue growth could systematically decouple from—and outpace—raw transaction volume.
The Bear Case
Too many simultaneous projects. Management is simultaneously absorbing Worldpay, untangling its technology from FIS infrastructure, rationalizing legacy platforms under a target enterprise architecture, expanding Genius internationally, onboarding hundreds of direct sales professionals, and returning more than $2 billion annually to shareholders, all while working to reduce balance-sheet leverage2421. Each initiative presents distinct operational risks. Taken together, this operational congestion heightens the probability of service disruptions, sales-force turnover, or partner attrition during complex technical migrations.
Structural share loss to vertical software. Management has conceded that small and midsize merchants will increasingly procure payments directly through specialized business software vendors24. Concurrently, Adyen and Stripe continue to capture the most lucrative enterprise e-commerce and developer-led platform volume. If Genius fails to gain decisive ground against established point-of-sale platforms like Clover, Toast, and Square in core restaurant and retail verticals, the SMB division—which generates approximately half of total company revenue—risks becoming a slowly eroding legacy annuity.
Leverage and macroeconomic vulnerability. Net leverage of roughly 3.5 times adjusted EBITDA appears manageable while transaction volumes remain resilient and more than 90% of debt is locked into fixed rates near 4%24. Yet the corporate travel slowdown in 2026 illustrated how abruptly geopolitical or macroeconomic shocks can erode performance, creating an estimated 400-basis-point headwind in the Enterprise segment from a single regional conflict24. A broader pullback in consumer spending would simultaneously depress payment volume, stall balance-sheet deleveraging, and constrain guided share repurchases.
Regulatory pressure and price compression. Reintroduced in early 2026, the Credit Card Competition Act renews political scrutiny on card-network interchange and transaction routing rules46. Beyond legislative intervention, large corporate merchants will continue using multi-homing strategies to negotiate processing markups downward, while the runoff merchant portfolio in the Other reporting segment will remain an ongoing top-line drag for several years24.
Porter and Helmer in the Balance
Strategic frameworks offer neither camp a decisive edge. Card-network supplier power remains formidable, competitive rivalry is relentless, and the company's most durable competitive powers—processing scale, regulatory licenses, and bank distribution—are shared with well-capitalized peers. The investment debate ultimately hinges on execution: whether management can translate raw transaction volume into differentiated software products, and convert sprawling distribution into higher merchant yields. Relative to Fiserv, Global Payments has yet to demonstrate the software momentum that Clover established across North American SMBs. Relative to Adyen, it carries decades of accumulated legacy architecture and integration overhead. Relative to Stripe, it commands far broader physical field distribution but substantially less developer mindshare. Global Payments' principal strength is operational breadth; its principal vulnerability is organizational and technical complexity.
The KPIs That Matter
Three operational indicators will measure whether execution aligns with management's targets:
- Normalized, constant-currency adjusted net revenue growth by segment, specifically measuring SMB revenue growth relative to transaction volume growth to verify Genius pricing yields, and evaluating Enterprise momentum once international travel headwinds subside.
- Net leverage progress toward 3.0x by the end of 2027, alongside free cash flow conversion above 90%, confirming whether share repurchases and debt paydown are funded by organic operational cash rather than balance-sheet engineering.
- The Worldpay synergy scorecard, tracking realized cost synergies against the $600 million annual run-rate target, cumulative integration expenses against the $600 million budget, and commercial progress on the path toward $200 million in revenue synergies.
XI. Playbook: Business & Investing Lessons
1. The Trap of the Two-Sided Financial Conglomerate
In 2019, three of the largest payment processors in the world concluded that owning both the issuing and acquiring ends of the value chain would unlock structural advantages. By 2026, Global Payments and FIS had effectively swapped core assets to undo that premise15. The strategic lesson is not that large-scale combinations inherently fail, but that a thesis predicated on owning both sides of a transaction demands identifiable, operational synergies that flow through to the income statement rather than remaining theoretical pitch-deck concepts.
While the TSYS merger may have delivered its promised $300 million in cost synergies, the broader strategic claim—that a two-sided payment conglomerate would command a valuation premium over its standalone parts—was steadily dismantled by public equity markets over the subsequent half-decade.
2. Technical Debt Is the Hidden Cost of Roll-Ups
Every acquisition added another point-of-sale system, payment gateway, or back-office settlement platform. For nearly a decade, relentless top-line acquisition growth masked the compounding operational expense of maintaining disparate systems. When cloud-native competitors operating on unified, single-stack architectures accelerated, Global Payments was forced to embark on multi-year restructuring programs, the Genius point-of-sale consolidation, and the design of an entirely new target enterprise architecture3424.
Absorbing Worldpay introduces another sprawling technology estate. Management's decision to accelerate decoupling from FIS infrastructure indicates that leadership recognized the hazards of prolonged technical entanglement24. Whether the organization has fully internalized the cost of technical fragmentation, however, will be measured by the speed with which it retires legacy gateways and migrates merchant accounts onto a consolidated stack.
3. Regulatory and Clearing Moats Are Durable but Not Decisive
Securing localized acquiring licenses, direct settlement integrations, and commercial bank networks across dozens of international jurisdictions requires substantial capital and years of regulatory engagement. These operational moats explain why an asset like Worldpay, despite multiple ownership changes and goodwill write-downs, still commanded a $24.25 billion enterprise valuation4. Yet backend clearing capabilities cannot prevent agile competitors from capturing merchant relationships at the software layer. An institutional moat protects the processing pipes; it does not secure the customer interface.
4. Credibility Is a Form of Capital
In September 2024, Global Payments laid out a clear multi-year roadmap focused on operational simplification, internal focus, and disciplined capital returns. Just seven months later, management executed an abrupt strategic pivot by announcing the largest transaction in corporate history, prompting equity markets to send the stock down to a decade low3438. Within three months, an activist investor had built a significant equity stake38.
The Worldpay asset swap may ultimately prove financially advantageous on paper. However, executing an unheralded about-face without prior market conditioning depleted executive credibility—an intangible asset management spent the subsequent year working to rebuild. In corporate governance, the transparency with which leadership navigates a strategic realignment matters almost as much as the industrial logic of the transaction itself.
XII. Epilogue & What to Watch
The Company That Remains
In August 2026, Global Payments gathered clients and partners at its Genius World event in Las Vegas to showcase a platform that did not exist in its current form until May 20252437. The gathering captured the central paradox of the company: an established payments processor presenting a modern software face, wagering that a unified point-of-sale product and an expanded distribution network can accomplish what a decade of conglomerate acquisitions failed to deliver.
The result is the most focused version of Global Payments since its 2001 spin-off from National Data Corporation. The company serves merchants from local restaurants to global retailers through three operating channels, processing transaction volume on a scale few competitors can match1. Yet it is also more leveraged, carries deeper European exposure through Worldpay, and depends more heavily on seamless technical integration than at any prior point in its history.
Three Things to Watch
The Worldpay integration scorecard. The primary operational benchmark is whether annual run-rate cost synergies track toward management's $600 million target while cumulative one-time restructuring charges remain near their $600 million budget, and whether the board's Integration Committee translates its oversight into clear, regular disclosures4224.
Organic merchant growth. Once cross-border travel headwinds subside, management's segment targets imply blended organic revenue growth in the mid-to-high single digits. Bready stated that 2027 should be an accelerating year "without a doubt"24. If top-line expansion accelerates as projected, the multiple-expansion thesis gains credibility; if organic growth remains stalled near 4%, public markets are likely to continue discounting Global Payments as a mature, slow-growth processor.
Deleveraging. Management faces the demanding task of reducing net leverage from roughly 3.5 times adjusted EBITDA toward 3.0 times by the end of 2027 while completing its $7.5 billion capital-return commitment24. Achieving both milestones concurrently would demonstrate that reported free cash flow is durable and self-funding. Falling short on either would reveal whether leadership prioritizes balance-sheet discipline or share repurchases when capital becomes constrained.
Final Reflection
Global Payments' 25 years as a public company offer an instructive lesson for the payments sector. Scale remains essential in merchant acquiring, where thin operating margins and heavy regulatory and technological overhead penalize smaller competitors. Yet scale assembled through acquisitions faster than systems can be consolidated becomes an operational liability that compounds over time. Global Payments spent seven years and tens of billions of dollars to return essentially to where it began: a company that processes payments for merchants. The coming years will show whether it can finally combine that hard-won scale with sustained operational focus.
References
-
Global Payments Completes Acquisition of Worldpay and Divestiture of Issuer Solutions Business, Creating Leading Pure-Play Commerce Solutions Provider — Global Payments via Yahoo Finance, 2026-01-12 ↩↩↩↩↩
-
Global Payments Reports Second Quarter 2026 Results — Global Payments Inc., 2026-08-05 ↩↩↩↩
-
GTCR Completes Sale of Worldpay to Global Payments — GTCR via PR Newswire, 2026-01-12 ↩↩
-
Global Payments Announces Agreements to Acquire Worldpay and Divest Issuer Solutions — Global Payments Inc., 2025-04-17 ↩↩↩↩↩↩↩↩↩↩↩
-
FIS Completes Strategic Acquisition of Global Payments’ Issuer Solutions Business and Sale of Worldpay Stake — FIS, 2026-01-12 ↩↩↩↩↩↩
-
Global Payments and TSYS Combine to Form Leading Pure Play Payments Technology Company — Global Payments Inc., 2019-05-28 ↩↩↩↩↩↩↩
-
Debit Card Interchange Fees Charged to Small Merchants After Regulation II — Federal Reserve Bank of Kansas City ↩↩↩↩
-
Global Payments Inc. Form 10-K405 for fiscal year ended May 31, 2001 — U.S. Securities and Exchange Commission, 2001 ↩↩↩↩
-
Global Payments and HSBC form UK merchant acquiring joint venture (Exhibit 99.1) — Global Payments Inc., 2008-06-17 ↩↩
-
Global Payments Inc. Form 10-Q for quarter ended November 30, 2009 — U.S. Securities and Exchange Commission, 2010-01 ↩
-
Global Payments first quarter 2022 results (Exhibit 99.1) — U.S. Securities and Exchange Commission, 2022-05 ↩
-
Global Payments Breach Tab: $94 Million — BankInfoSecurity, 2013-01-08 ↩
-
Global Payments names Jeffrey S. Sloan President (Exhibit 99.1) — Global Payments Inc., 2010-03-30 ↩↩
-
Global Payments to replace CEO — Payments Dive, 2023-05-01 ↩↩↩↩↩↩
-
Global Payments Inc. Form 8-K: Agreement to acquire Accelerated Payment Technologies — U.S. Securities and Exchange Commission, 2012-08-14 ↩↩↩
-
Global Payments to acquire Heartland Payment Systems (Exhibit 99.1) — U.S. Securities and Exchange Commission, 2015-12-15 ↩↩↩↩
-
Heartland Payment Systems: Lessons Learned from a Data Breach — Federal Reserve Bank of Philadelphia, 2010-01 ↩
-
Global Payments Inc. Form 10-KT for transition period ended December 31, 2016 — U.S. Securities and Exchange Commission, 2017 ↩
-
Global Payments (GPN) Q1 2026 Earnings Transcript — The Motley Fool, 2026-05-06 ↩↩↩↩↩↩↩↩↩↩
-
Global Payments Inc. Form 10-K for fiscal year ended December 31, 2018 — U.S. Securities and Exchange Commission, 2019 ↩↩↩
-
Global Payments sells AdvancedMD for $1.1B — Payments Dive, 2024-10-30 ↩↩↩↩↩
-
Global Payments (GPN) Q2 2026 Earnings Call Transcript — The Motley Fool, 2026-08-05 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Global Payments, TSYS Merger Finalized in Landmark Transaction — PYMNTS, 2019-09-18 ↩↩↩↩
-
FIS completes acquisition of Worldpay (Exhibit 99.1) — U.S. Securities and Exchange Commission, 2019-07-31 ↩↩↩↩
-
TSYS Buying Netspend for $1.4 Billion — Yahoo News, 2013-02-20 ↩↩
-
Global Payments Inc (GPN) Stock Price History — StockScan ↩↩↩↩
-
Global Payments buys Evo at a premium — Payments Dive, 2022-08-01 ↩↩↩↩
-
Rêv and Searchlight Complete Acquisition of Netspend for $1 Billion — Searchlight Capital, 2023-05-01 ↩↩
-
Global Payments Reports Fourth Quarter and Full Year 2025 Results — Global Payments Inc., 2026-02-18 ↩↩↩↩↩↩↩
-
Global Payments Inc. Form 10-K for fiscal year ended December 31, 2024 — U.S. Securities and Exchange Commission, 2025-02 ↩↩
-
Global Payments CEO reshapes the business — Payments Dive, 2024-09-11 ↩↩
-
Global Payments Shares Updated Strategy and Medium-Term Outlook at Investor Conference — Global Payments Inc., 2024-09-24 ↩↩↩↩↩↩
-
Global Payments Reports Fourth Quarter and Full Year 2024 Results — Global Payments Inc., 2025-02-13 ↩
-
Global Payments Announces Agreement to Divest Payroll Business — Global Payments Inc., 2025-05-28 ↩↩
-
Global Payments Launches New Genius POS Platform — Global Payments Inc., 2025-05-16 ↩↩↩↩
-
Elliott takes Global Payments stake following $24.3bn Worldpay deal — Hedgeweek, 2025-07-16 ↩↩↩↩↩↩↩
-
FIS plans to spin off merchant unit — Payments Dive, 2023-02-13 ↩↩
-
FIS Accelerates Path to Create Two Highly Focused Independent Companies; Announces Agreement for GTCR to Acquire Majority Stake in Worldpay (Exhibit 99.1) — U.S. Securities and Exchange Commission, 2023-07-06 ↩↩
-
Global Payments mulls more divestitures — Payments Dive, 2025-08 ↩↩
-
Global Payments Announces Board Additions to Enhance Shareholder Value Creation — Global Payments Inc., 2025-09-29 ↩↩↩↩↩↩↩
-
Global Payments Announces Board Appointment — Global Payments Inc., 2026-02-18 ↩
-
Global Payments Completes Divestiture of Payroll Business — Global Payments Inc., 2025-10-01 ↩
-
Global Payments Reports First Quarter 2026 Results — Global Payments Inc., 2026-05-06 ↩↩
-
Durbin, Marshall Reintroduce the Credit Card Competition Act — Office of Senator Dick Durbin, 2026-01-13 ↩↩↩
-
CCCA seeks new path to passage — Payments Dive, 2026-03-13 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube