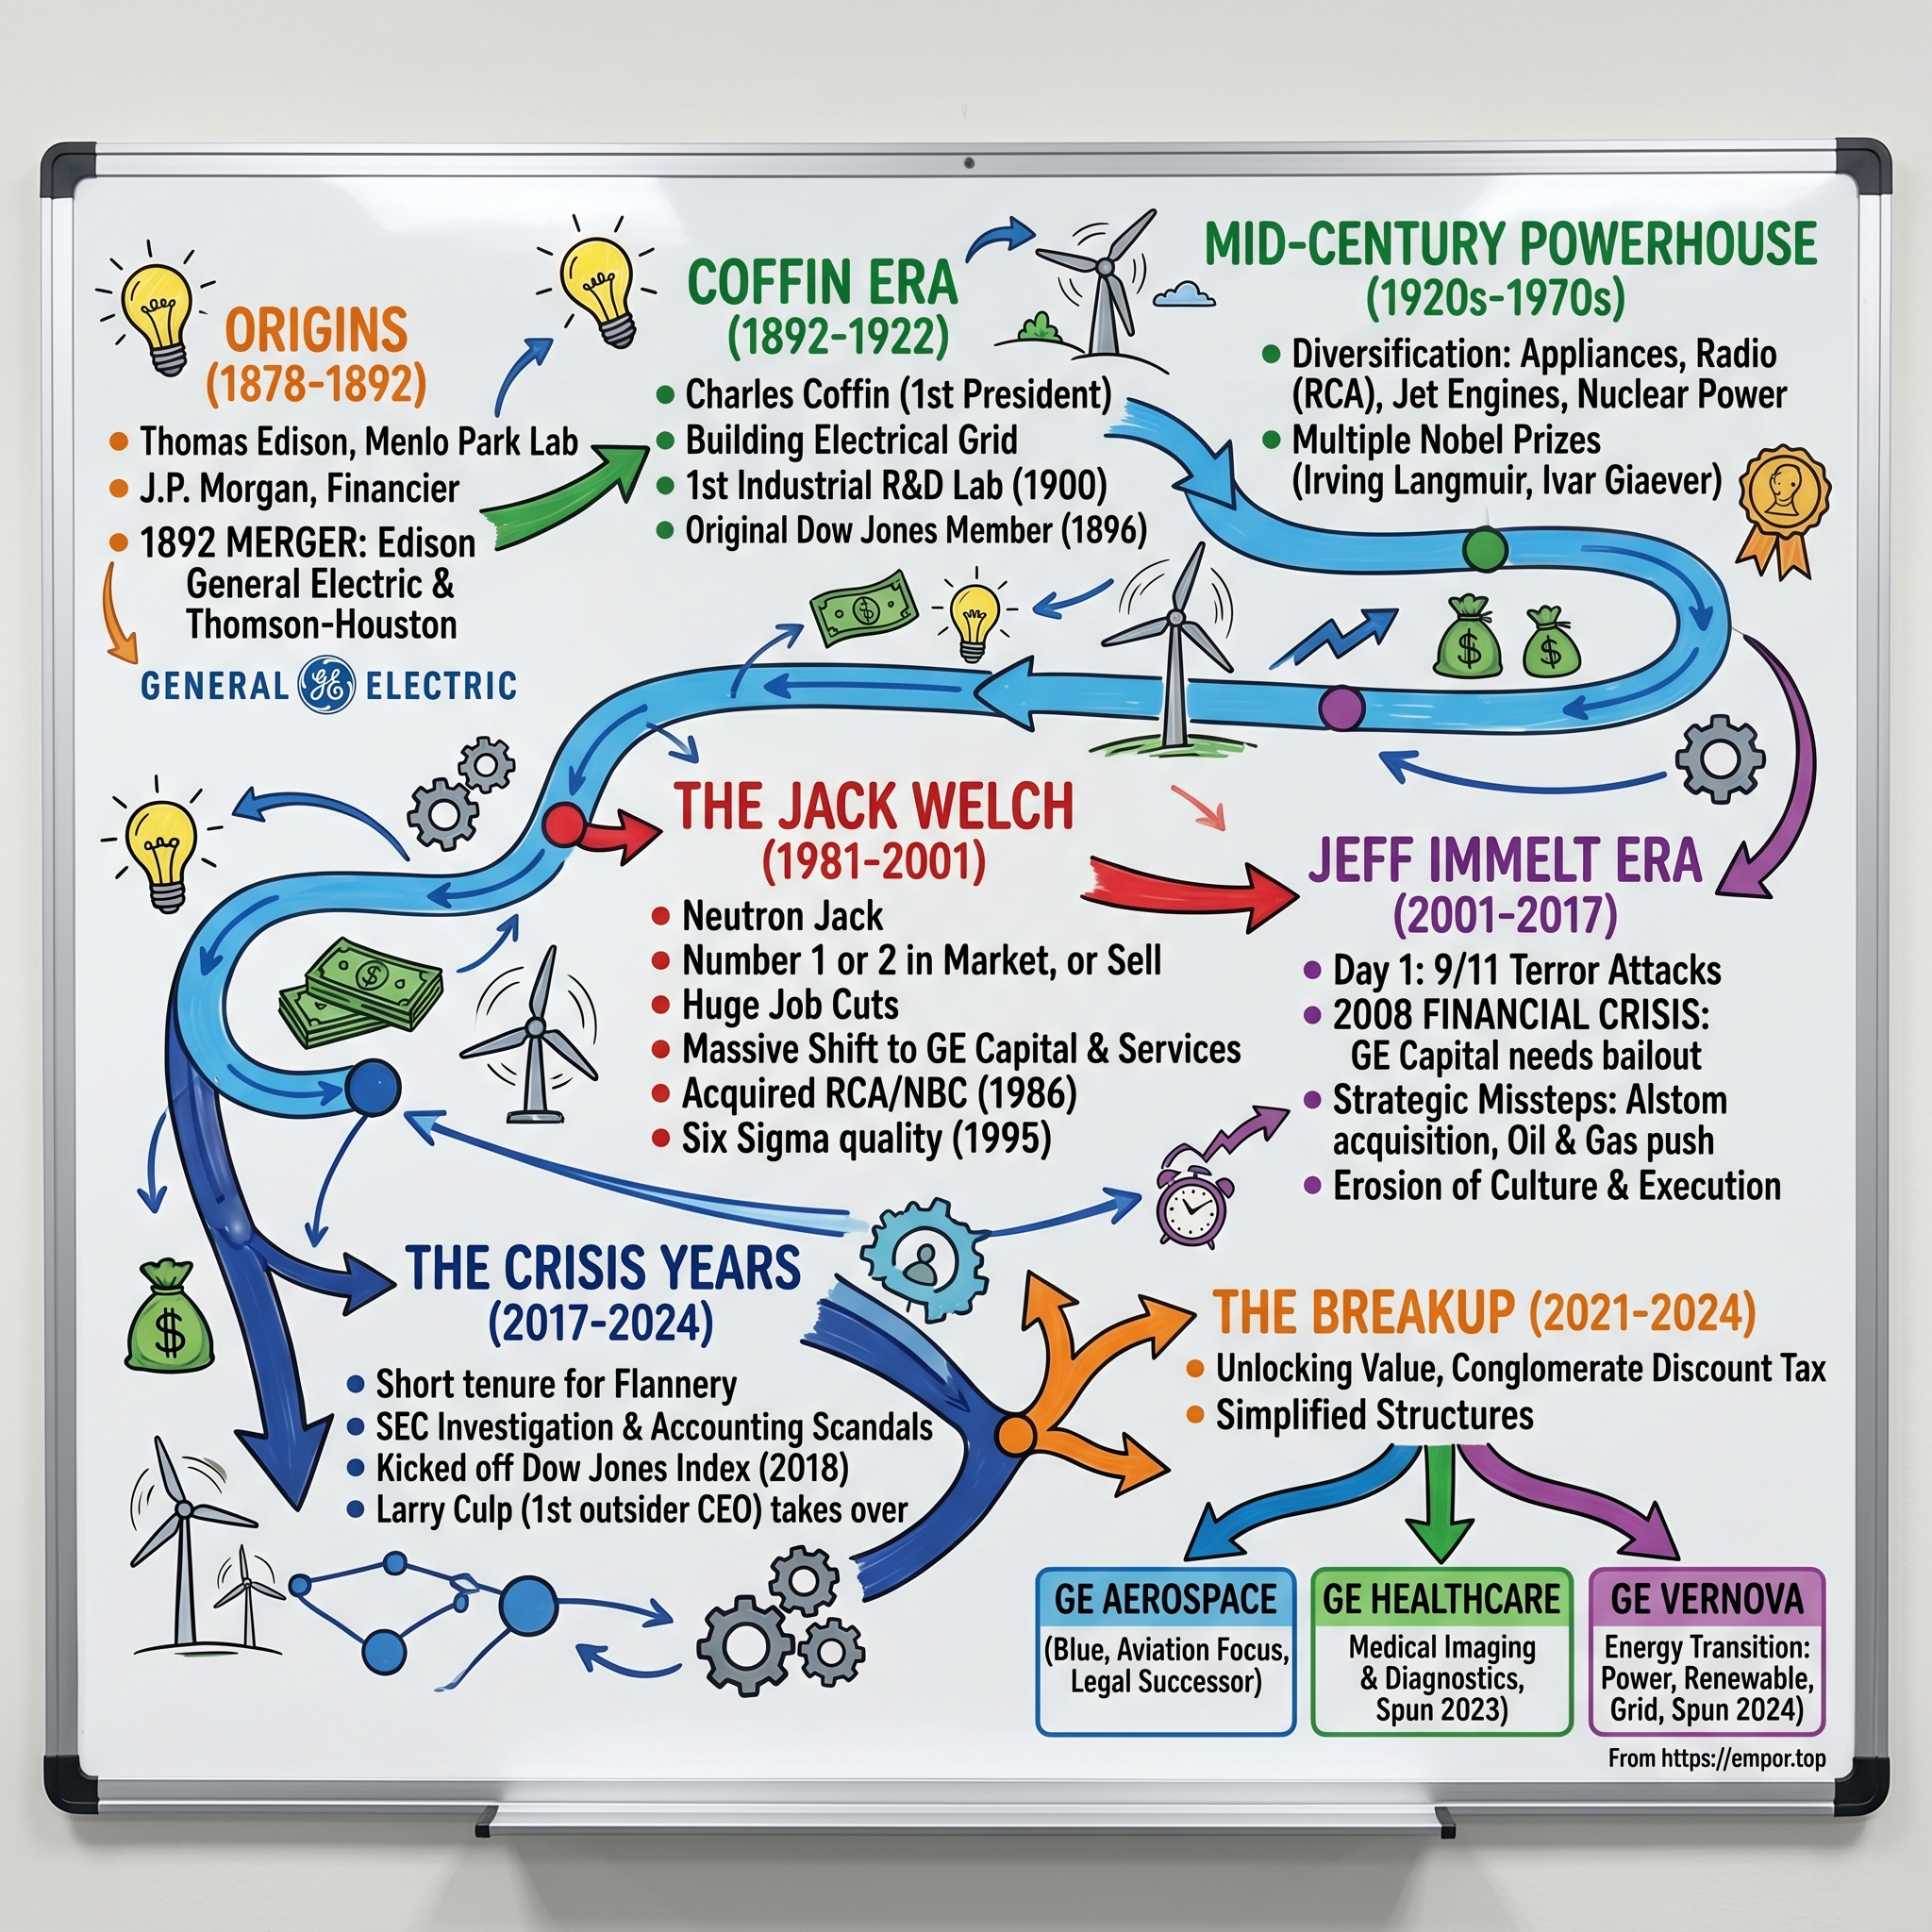
GE Aerospace (NYSE: GE): The Crucible of American Capitalism
I. Introduction & The Standalone Thesis
At 9:30 a.m. on April 2, 2024, two executive teams stood side by side on the balcony of the New York Stock Exchange to ring the opening bell together. One group represented GE Vernova, the energy and power-generation company that had just been spun off and was trading publicly for the first time. The other represented GE Aerospace, which retained a corporate identity far older than any newly minted listing: the two-letter ticker GE, a trading symbol that had represented American industrial enterprise for generations.1 Larry Culp, the chairman and chief executive officer, described the morning as "a historic final step in the multi-year transformation of GE."1 Fifteen months earlier, GE HealthCare had been separated through the same process, with the parent company distributing approximately 80.1% of its shares to stockholders.[^2]
What remained is an unusual corporate survivor in American industrial history. The legal entity that once spanned light bulbs, household appliances, NBC, rail locomotives, a subprime mortgage lender, a long-term care reinsurance portfolio, and a commercial aircraft fleet has narrowed to a dedicated jet engine manufacturer. Its disclosures outline an installed base of roughly 50,000 commercial and 30,000 military engines, with aftermarket maintenance and services generating around 70% of total revenue.2 The company employs roughly 57,000 people, with approximately 30,000 based in the United States.2
A company that finally looks like its best business
Operating performance since the spinoff reflects an accelerating business rather than a mature incumbent settling into place. In 2024, its first full year as a pure-play aerospace manufacturer, GE Aerospace reported $38.7 billion in GAAP revenue, $7.3 billion in operating profit, and an operating margin of 20.7%.3 Growth accelerated across 2025: adjusted revenue climbed 21% to $42.3 billion, operating profit expanded 25% to $9.1 billion, free cash flow reached $7.7 billion, and total orders surged 32% to $66.2 billion.4 By July 2026, management had lifted its full-year 2026 operating profit guidance to between $10.55 billion and $10.75 billion.5
That upward revision is telling. At its March 2024 Investor Day, management guided the market to expect "approximately $10 billion" of operating profit in 2028.6 The company lifted that 2028 target to about $11.5 billion in July 2025,7 and it is now pacing to exceed the original milestone two full years ahead of schedule. Surpassing a multi-year plan by that margin points either to conservative initial forecasting, to an unmodeled surge in aftermarket services, or to a combination of both. Determining which dynamic predominates is essential to evaluating how much of the company's current earnings power is durable.
The central question
How did an enterprise built on Thomas Edison's patents and J.P. Morgan's capital, celebrated under Jack Welch as the premier benchmark of American corporate management, and later driven to the brink of a liquidity crisis by its own finance unit, emerge as one of the market's most streamlined industrial franchises?
The direct answer is that the jet propulsion division was long the highest-quality asset within General Electric. For decades, its cash-generation profile was obscured by adjacent operations: a captive finance arm that borrowed against GE's triple-A credit rating, a power equipment division that acquired assets at cyclical peaks, and an accounting framework that smoothed quarterly volatility across disparate units. The comprehensive answer spans six distinct eras, each offering distinct lessons for industrial investors.
The story begins with the founding of the modern industrial research laboratory, then examines the mid-century commitment to jet propulsion that produced the CFM International joint venture with France's Snecma, now Safran Aircraft Engines. From there, the narrative traces the Welch and Immelt eras, when financial engineering initially boosted reported earnings before exposing the enterprise to systemic balance-sheet risk, followed by the turnaround led by Culp, who dismantled the conglomerate step by step. The second half of the analysis examines the operational mechanics of the engine portfolio, weighs the core investment thesis against historical execution risks, and outlines the forward metrics that will show whether that thesis remains intact.
A critical caveat overhangs the current outlook. A notable share of GE Aerospace's recent margin strength stems from a temporary market imbalance: older CFM56 engines are staying in airline fleets longer and requiring additional shop visits because delivery delays at Boeing and Airbus have slowed aircraft replacement cycles. Management has acknowledged that CFM56 fleet retirements are projected to accelerate beginning in 2027. Disentangling structural competitive moats from cyclical aftermarket tailwinds remains the central task for investors—and the foundation of that dynamic took shape in 1892.
 Subscribe on LinkedIn
II. The Genesis: Menlo Park, J.P. Morgan, and Coffin's Infrastructure Empire (1878–1922)
The inventor and the salesman
In the early 1890s, two figures defined the emerging electrical equipment industry. Thomas Edison, operating from his laboratories in New Jersey, was convinced that direct current was the only safe path to electrify America. Charles A. Coffin, a former shoe manufacturer from Lynn, Massachusetts, who ran the Thomson-Houston Electric Company, grasped a different commercial reality: in a capital-intensive young industry, the enterprise that controlled patents, distribution, and financing held decisive leverage over an enterprise relying solely on a famous inventor.
Edison's electric lighting ventures had been financed from their inception by New York capital, including J. Pierpont Morgan. By 1890, Edison's various enterprises had been consolidated into Edison General Electric.8 Thomson-Houston, established by Elihu Thomson and Edwin Houston, had built a strong position in arc lighting and alternating-current equipment while Edison waged the "War of the Currents" against George Westinghouse and the AC system associated with Nikola Tesla. Because each company held patents the other needed, escalating patent litigation threatened to paralyze both.
Morgan's response mirrored the strategy he applied to railroads and steel: consolidate. On April 15, 1892, Edison General Electric and Thomson-Houston merged to form the General Electric Company, with Coffin, rather than Edison, installed as its first president.8 Edison's name was dropped from the corporate banner, and the inventor drifted away from the business that retained his legacy. The structural lesson was set at inception: General Electric would be directed by professional managers and financiers rather than by its pioneering founder.
Inventing the industrial lab
Coffin's most enduring contribution was organizational. On December 15, 1900, GE established a dedicated research laboratory in Schenectady, New York, under its first director, Willis R. Whitney, with mathematician and engineer Charles Proteus Steinmetz serving as a primary intellectual catalyst.9 The facility is widely regarded as the first systematic effort by a major American corporation to embed scientific research directly into its commercial strategy.9 Rather than waiting for independent inventors to approach with outside patents, GE institutionalized innovation on its own payroll.
The model produced tangible technological assets. Irving Langmuir, an early recruit at the laboratory, later received the Nobel Prize in Chemistry for his work in surface chemistry.9 More consequential for GE's long-term trajectory, the Schenectady laboratory fostered an internal discipline in materials science—metallurgy, high-temperature alloys, and specialized coatings—that four decades later positioned GE to build the United States' first operational jet engine. The technological lineage connecting Schenectady in 1900 to the single-crystal turbine blades inside a modern LEAP engine is direct.
GE was also one of the original constituents of the Dow Jones Industrial Average in 1896, and it maintained continuous membership in the index from 1907 until 2018.10 Across more than a century, the company served as a primary proxy for American industrial enterprise.
The original sin: financing the customer
A second, less celebrated innovation emerged alongside the industrial laboratory. During the 1890s and 1900s, local municipal and private utilities frequently lacked the liquid capital required to purchase the costly dynamos and generators GE manufactured. To facilitate equipment sales, GE extended customer credit, accepting securities in utility operating companies as payment and eventually organizing those assets into a dedicated holding company, the Electric Bond and Share Company, early in the twentieth century.
That arrangement planted the institutional seed for GE's subsequent balance-sheet vulnerabilities. Vendor financing is a standard commercial tool in moderation: providing credit lowers purchasing friction and accelerates equipment adoption. However, it also transforms an industrial manufacturer into a lender, carrying credit and liquidity risks divorced from engineering execution. A century later, that same operational instinct—financing customer demand to accelerate reported industrial sales—expanded into GE Capital, creating a balance sheet vast enough to imperil the entire enterprise.
For investors, this founding era establishes an enduring analytical frame. GE's durable competitive advantages have consistently originated in slowly accumulated technological competencies: metallurgy, precision manufacturing, and proprietary patents. Conversely, its historical crises have repeatedly stemmed from financial leverage layered over those core industrial operations. That distinction proved foundational as the jet propulsion business emerged directly from the company's early investments in high-temperature materials science.
III. The Mid-Century Innovation Engine: Turbosuperchargers to Jet Age Hegemony (1920s–1970s)
A secret package in Lynn
In the autumn of 1941, before the United States formally entered the Second World War, a small group of GE engineers in Lynn, Massachusetts, received an extraordinary assignment. General Henry "Hap" Arnold, commander of the U.S. Army Air Forces, had observed a test flight of an experimental British jet powered by Frank Whittle's W.1 engine. At Arnold's request, the British government shipped a version of the engine across the Atlantic, and the U.S. Army selected GE's Lynn facility to replicate and refine it.11 Whittle later traveled to Lynn under wartime secrecy to assist the engineering team directly.12
GE won the contract because of institutional expertise developed by engineer Sanford Moss. Moss had spent decades perfecting the turbosupercharger, a turbine driven by high-temperature exhaust gases to compress intake air for piston engines, allowing aircraft to preserve engine power at high altitudes. The thermodynamic challenge of spinning turbine wheels in extreme exhaust heat matched the core physics of jet propulsion. Thanks to its Schenectady materials research, GE already understood how to make alloys withstand those operating environments.11
The Lynn team advanced rapidly. On April 18, 1942, engineers conducted the first successful bench test of the engine, designated the I-A. Six months later, at Muroc Dry Lake in California, twin I-A engines powered the maiden flight of the Bell XP-59A Airacomet, inaugurating American military jet aviation.11 Conducted under strict wartime secrecy, the desert trials confirmed that operational jet propulsion was viable.
From fighters to airliners
The postwar decades established GE as a primary military propulsion contractor. The J47 turbojet entered large-scale production to power frontline platforms including the North American F-86 Sabre and the Boeing B-47 Stratojet bomber, while the subsequent J79 powered supersonic fighters such as the Lockheed F-104 Starfighter and McDonnell Douglas F-4 Phantom II. GE soon attempted to adapt its military architectures for commercial transport, beginning with the CJ805 for Convair jetliners—an effort that proved commercially disappointing—before achieving lasting success with high-bypass turbofans.
The high-bypass turbofan warrants a brief structural explanation because that layout remains the standard for commercial aviation today. Conceptually, the engine pairs a compact, high-temperature core with a large forward fan. The core burns fuel to drive turbines that spin the fan, which pushes a large volume of relatively cool air around the outside of the combustion chamber. Because the majority of total thrust comes from this bypass air, moving a large mass of air at moderate velocity consumes far less fuel than expelling a smaller stream at extreme speeds. GE's TF39, developed for the Lockheed C-5 Galaxy military transport, pioneered this high-bypass layout, and its commercial derivative, the CF6, went on to power widebody airliners including the McDonnell Douglas DC-10, the Boeing 747, and the Airbus A300.11
The masterstroke: CFM International
The strategically decisive move of the era—and ultimately one of the most lucrative alliances in commercial aviation history—arose from a partnership with France. In the early 1970s, France's state-owned aero-engine manufacturer, Snecma, sought to develop an engine in the 10-ton thrust class for a planned generation of 150-seat, single-aisle airliners. Snecma possessed strong relationships with European airframe builders and state financial backing, but lacked a sufficiently modern, fuel-efficient core. GE held precisely that technology in the core of its military F101 engine, designed for the Rockwell B-1 bomber.
Gerhard Neumann, the head of GE's aviation division, recognized the strategic opportunity in Europe and negotiated an equal 50/50 joint venture.13 Transferring a sensitive military core to a foreign state-backed enterprise triggered national security concerns across Washington. The impasse was resolved in June 1973, when Presidents Richard Nixon and Georges Pompidou met in Reykjavik, Iceland, and granted political clearance for the collaboration.13 The formal joint-venture agreement was signed on January 24, 1974, and CFM International was incorporated as an equally owned operating entity later that year.14
A prolonged commercial drought followed. For its first five years, the CFM56 failed to secure a single airline customer, prompting the French government to consider canceling the program. The turning point arrived in March 1979, when United Airlines selected the CFM56 to re-engine its fleet of McDonnell Douglas DC-8 freighters.13 The engine earned certification on November 8, 1979, and entered revenue service with Delta Air Lines in April 1982.13
That initial adoption established an enduring commercial flywheel. Contracts to re-engine U.S. Air Force KC-135 tankers and commercial Boeing 737 Classic transports provided manufacturing scale. In February 1987, the CFM56-5 powered the maiden flight of the Airbus A320, securing a foundational position on Europe's new single-aisle platform.13 Boeing cemented that market presence by selecting the CFM56 as the exclusive powerplant for the 737 Next Generation family. By 1999, CFM had delivered its 10,000th engine,13 establishing the CFM56 as the most-produced commercial aircraft engine in aviation history. Reflecting the durability of the arrangement, GE and Safran extended the partnership through 2050 in 2021, expanding its mandate to cover comprehensive maintenance and aftermarket services.15
Why the partnership mattered
The structural mechanics of CFM International addressed the central economic challenge of commercial aerospace. Developing a clean-sheet jet engine requires billions of dollars in upfront capital and up to a decade of engineering work before delivering meaningful revenue. CFM distributed that financial and technological exposure between two companies and two governments, expanded engineering capacity, and secured GE an entrenched position within European aviation just as Airbus emerged as a major global competitor to Boeing. In exchange, GE surrendered half of the program's equity returns—a trade that produced exceptional cumulative earnings over the subsequent half-century.
For investors, the evolution of CFM illustrates the fundamental economic model of the commercial propulsion sector: programs absorb heavy upfront development costs and endure severe commercial vulnerability before establishing an installed base that delivers recurring, high-margin aftermarket cash flow across three or four decades. That legacy also introduces the primary fleet-transition challenge confronting GE Aerospace today. The unmatched scale that turned the CFM56 into an extraordinary cash generator created an installed base that will eventually face mass retirement. Before that transition arrived, however, GE entered an era under leadership that would temporarily relegate the propulsion business to the periphery of a sprawling financial empire.
IV. The Welch Era: Financialization, "Neutron Jack," and the Seed of Destruction (1981–2001)
The son of a railroad conductor
Jack Welch, a chemical engineer with a doctorate, joined GE's plastics division in 1960 and rose through the company's operating ranks over two decades. In 1981, at age 45, he succeeded Reginald Jones as chairman and chief executive officer. Over the next twenty years, GE's market capitalization expanded from roughly $14 billion to more than $400 billion, and Fortune eventually named Welch the "manager of the century."16
Welch quickly initiated a sweeping restructuring. He eliminated tens of thousands of jobs across the conglomerate, earning the moniker "Neutron Jack"—a reference to the weapon that eliminated people while leaving buildings intact.16 He instituted a strict portfolio mandate: every operating unit was required to rank first or second in its market, or face restructuring, sale, or closure. Under his annual performance appraisal system, known as the "vitality curve" or "rank and yank," managers ranked employees and routinely dismissed the lowest-performing tier. In the mid-1990s, Welch introduced Six Sigma quality methodology across the company, tying compliance directly to executive compensation and promotion.
Welch also pursued aggressive inorganic expansion. In 1986, GE acquired RCA for $6.4 billion, bringing the NBC television network under the corporate umbrella.17 An enterprise built on electrical and mechanical engineering was now broadcasting prime-time entertainment and network news.
The shadow bank
The most consequential transformation occurred inside GE Capital. Under Welch, the vendor financing arm expanded far beyond its original mandate of facilitating customer purchases of GE equipment. The unit broadened into commercial real estate, consumer credit cards, insurance and reinsurance underwriting, private equity investments, and aircraft operating leases through GE Capital Aviation Services. By the late 1990s, GE Capital had become one of the largest non-bank financial institutions in the world.
The unit operated on an advantageous structural spread. Backed by the industrial parent's triple-A credit rating, GE Capital borrowed at low interest rates—relying heavily on short-term commercial paper—and lent at higher yields, unencumbered by the statutory capital reserves and regulatory oversight imposed on commercial banks. In practice, the industrial conglomerate was renting out its credit rating to fund an expanding financial balance sheet.
Beyond immediate interest margins, GE Capital provided executive leadership with earnings flexibility. Financial portfolios can be adjusted, monetized, or revalued at quarter-end, giving management discretionary tools to offset cyclical volatility across industrial divisions. Under Welch, GE developed a reputation for meeting or narrowly exceeding Wall Street consensus earnings forecasts with clockwork precision, commanding a premium valuation multiple for that perceived consistency. Yet that predictability masked a fundamental operational reality: capital-intensive industrial manufacturers exposed to airline travel cycles and utility capital budgets do not naturally produce unbroken quarterly earnings trajectories.
Subsequent regulatory actions revealed the extent of that earnings management. In August 2009, the Securities and Exchange Commission charged GE with accounting fraud in connection with conduct during 2002 and 2003, resulting in a $50 million civil penalty that GE settled without admitting or denying the allegations.18 One of the four violations cited by regulators directly involved commercial aviation: an improper accounting adjustment in 2002 covering commercial aircraft engine spare parts that inflated net earnings that year by $585 million.18 A second violation involved prematurely booking year-end locomotive transactions that had not closed.18 The spare-parts aftermarket that now underpins GE Aerospace's core profitability had, two decades earlier, served as an instrument to manage corporate earnings.
Rot beneath the gloss
Two episodes at the close of Welch's tenure highlighted the emerging vulnerabilities of the conglomerate. First, in late 2000, Welch orchestrated a proposed $42 billion acquisition of Honeywell International, seeking to bundle GE's commercial engines with Honeywell's avionics, flight-control systems, and auxiliary power units. While United States antitrust authorities cleared the transaction, the European Commission unanimously blocked the merger on July 3, 2001, following an extensive investigation into market concentration across aero-engines, avionics, and related aerospace components.19 The regulatory veto signaled that GE's aerospace franchise had achieved sufficient market power to trigger international antitrust resistance.
Second, the conglomerate Welch prepared to hand over had grown structurally dependent on financial earnings. GE Capital generated roughly half of the parent company's total profits and carried substantial asset-liability mismatches, financing long-dated loans with short-term commercial paper. That funding structure performed reliably during an era of declining interest rates and expanding liquidity, but it left the enterprise vulnerable to any systemic disruption in wholesale credit markets.
Welch's tenure established a central analytical lesson for industrial investors: high-quality manufacturing operations can be obscured by aggressive financial engineering. Beneath the conglomerate's expanding financial leverage, the jet propulsion division continued to build technical barriers to entry and expand its commercial engine fleet. Yet GE's aggregate equity valuation had become tied to a shadow bank whose structural balance-sheet risks were obscured by quarterly earnings smoothing. When Welch retired in September 2001, his successor inherited those embedded liabilities.
V. The Collapse: Immelt, Capital Leaks, Alstom, and the SEC Accounting Trap (2001–2018)
Four days before the world changed
Jeffrey Immelt assumed the chief executive role on September 7, 2001, just four days before the September 11 terrorist attacks grounded commercial aviation and triggered severe underwriting losses across global insurers. Immelt, a former Dartmouth football player who had earned a Harvard MBA and risen through GE's medical systems division, brought an expansive optimism and a commitment to sustaining the double-digit earnings growth demanded by Wall Street.
For much of the 2000s, that growth model appeared to function as designed. GE Capital continued to expand its assets and earnings contributions, offsetting cyclical softness across industrial divisions. Yet the structural fragility inherited from the Welch era—financing long-term commercial loans and leases with short-term commercial paper—remained unaddressed until the global credit markets froze in September 2008.
Calling Hank Paulson
When Lehman Brothers collapsed and short-term debt markets seized, General Electric confronted the reality of operating a massive financial institution funded by short-term commercial paper. According to former Treasury Secretary Hank Paulson's memoir, Immelt privately confided to him that GE was having trouble selling commercial paper.20 For an enterprise that had funded multi-year loans and leasing assets through the wholesale commercial paper market for decades, that liquidity freeze posed an existential threat.
Emergency stabilization arrived through private and federal backstops. On October 1, 2008, GE announced that Warren Buffett's Berkshire Hathaway would invest $3 billion in perpetual preferred stock carrying a 10% dividend, plus warrants to buy $3 billion of GE common stock at $22.25 per share.21 In November 2008, the Federal Deposit Insurance Corporation approved GE Capital's participation in the Temporary Liquidity Guarantee Program, which allowed it to issue up to $139 billion of government-guaranteed debt.22 One of America's preeminent manufacturing franchises was, for a period, dependent on the sovereign credit of the United States to fund its balance sheet.
Shareholders absorbed the operational cost four months later. On February 27, 2009, GE cut its quarterly dividend from $0.31 to $0.10 per share, its first dividend cut since 1938, saving about $9 billion a year.[^24] For retail and institutional investors who had long treated GE equity as a substitute for fixed-income bonds, the reduction permanently altered the stock's profile.
The central takeaway extends beyond the credit risks assumed by GE Capital. The crisis demonstrated that GE's industrial units, including its commercial propulsion business, had become hostage to a wholesale funding model outside their control. Engineering leadership and proprietary intellectual property offered little insulation when parent-level solvency depended on credit markets that could freeze without warning.
A masterclass in buying at the top
Immelt responded over the following decade by paring back GE Capital and directing capital back into the core industrial divisions. While the strategic intent to refocus on industrial engineering addressed an undeniable vulnerability, execution was compromised by aggressive acquisitions completed near cyclical peaks.
The defining transaction of that reallocation was the French conglomerate Alstom. On November 2, 2015, GE completed its acquisition of Alstom's power and grid businesses, its largest-ever industrial acquisition, for a final price of €9.7 billion, or about $10.6 billion.23 At closing, GE told investors the deal would add $0.15 to $0.20 of earnings per share by 2018.23 Instead, global demand for large gas-fired turbines contracted sharply as utility-scale renewable energy expanded and operating efficiency eroded power generation margins. On October 1, 2018, GE said it expected to take a goodwill impairment for GE Power that would likely constitute substantially all of its $23 billion goodwill balance.24 The promised earnings accretion culminated in one of the largest corporate goodwill write-downs in industrial history.
A concurrent capital commitment targeted the energy sector. On July 3, 2017, GE combined its oil and gas business with Baker Hughes, contributing $7.4 billion to fund a special dividend to Baker Hughes shareholders in exchange for a 62.5% stake in the new company.25 Completed near the peak of an oilfield services upcycle, the transaction left GE holding a majority stake that it subsequently liquidated over several years into an energy market characterized by lower commodity prices and compressed multiples.
The insurance time bomb
While industrial acquisitions faltered, an unhedged exposure emerged from GE Capital's legacy operations. Deep within its run-off portfolio sat reinsurance obligations on long-term care insurance policies—contracts structured to cover nursing home and assisted-living expenses. These policies had been underwritten decades earlier using actuarial assumptions regarding policyholder longevity and medical inflation that proved profoundly inaccurate.
In January 2018, John Flannery—who succeeded Immelt in mid-2017—disclosed a $6.2 billion after-tax charge tied to this portfolio and said GE Capital would need to contribute about $15 billion to its insurance reserves over seven years.26 The revelation signaled to capital markets that the corporate balance sheet contained legacy financial liabilities that external analysts had not incorporated into their valuation models.
Equity markets adjusted swiftly. On June 26, 2018, GE was removed from the Dow Jones Industrial Average, replaced by Walgreens Boots Alliance — ending a continuous membership that dated to 1907.10 Its stock fell almost 75% across 2017 and 2018 as the power and insurance problems came to light.27
The SEC's reckoning
Regulatory scrutiny intensified in the wake of those balance-sheet revisions. On December 9, 2020, GE agreed to pay a $200 million penalty to settle SEC charges over disclosure failures in its power and insurance businesses.27 The SEC found that GE had described GE Power's profit growth without telling investors that about a quarter of 2016 profits, and nearly half of profits in the first three quarters of 2017, came from reductions in prior cost estimates on long-term service contracts.27 It also found that GE failed to disclose that its reported improvement in industrial cash collections came largely from internal sales of receivables from GE Power to GE Capital, at the expense of future cash.27 The settlement, formalized in an administrative order, was made without GE admitting or denying the findings.28
For aerospace investors, this enforcement action carries direct analytical relevance. Long-term service agreements—under which an engine manufacturer estimates multi-decade maintenance costs and recognizes revenue and margin as services are performed—remain the structural core of GE Aerospace's commercial aftermarket model. The SEC's findings demonstrate that accounting for long-term service agreements relies on subjective management estimates, and revisions to those assumptions can elevate reported accounting margins without generating cash flow. That divergence explains why disciplined cash flow conversion, rather than reported operating income alone, serves as the primary metric for assessing underlying earnings quality.
The Immelt era demonstrated how a capital-intensive conglomerate equipped with an internal financial division can misallocate tens of billions of dollars while presenting outwardly stable operating performance. By the autumn of 2018, the board concluded that corporate recovery required leadership from outside GE's managerial ranks.
VI. The Dismantling: Larry Culp, Danaher Lean, and the Tri-Partite Spin (2018–2024)
The outsider
On October 1, 2018, GE's board unanimously appointed H. Lawrence Culp Jr. as chairman and chief executive officer, effective immediately, replacing Flannery after barely a year.24 Culp had joined the board only six months earlier, in April 2018, making him the first outside chief executive in the company's history.
Culp built his reputation at Danaher, the Washington, D.C.-based industrial conglomerate that structured its operations around the Toyota Production System. Having joined Danaher in 1990 at an operating subsidiary, Culp rose through its business units and served as chief executive officer from 2000 to 2014, a span in which Danaher's annual revenue and market capitalization each expanded roughly fivefold, to about $20 billion and $50 billion, respectively.29 He subsequently taught at Harvard Business School. Where Welch had prioritized portfolio deals and Immelt had emphasized sweeping industrial visions, Culp operated from the factory floor, focusing on shop-floor mechanics and process discipline rather than expansive corporate rhetoric.
The Danaher framework centers on lean manufacturing, an operating philosophy focused on identifying and eliminating operational waste. The system relies on a concise set of Japanese principles: kaizen, or continuous incremental improvement, and gemba, meaning "the real place" where work is physically performed. Rather than directing operations through high-level spreadsheets, managers are expected to observe factory workflows directly, uncover root causes of delay, and reduce excess inventory. Culp introduced this disciplined operating model across GE under the internal designation FLIGHT DECK.
Selling the silverware to save the house
Before shop-floor process reforms could deliver results, corporate leadership faced an immediate liquidity challenge. GE entered late 2018 burdened by heavy debt, shrinking operating cash flows in its power division, and the multi-billion-dollar insurance reserve obligations disclosed under Flannery.
The first major divestment required parting with one of the conglomerate's most profitable assets. GE agreed to sell its BioPharma business to Culp's former employer, Danaher, in a transaction valued at $21.4 billion that closed on March 31, 2020—just as the initial wave of COVID-19 pandemic lockdowns began disrupting global markets.30 While sacrificing a high-growth life sciences franchise extracted a premium operating asset, having that capital on hand as international airline traffic collapsed insulated GE's balance sheet through the most severe contraction in commercial aviation history.
The subsequent transaction dismantled the remaining core of the shadow bank. On November 1, 2021, GE completed the sale of GE Capital Aviation Services (GECAS), its commercial aircraft leasing operation, to AerCap Holdings. In exchange for transferring roughly $34 billion of net assets, GE received approximately $23 billion in cash, 111.5 million AerCap ordinary shares representing about 46% of the combined company, and $1 billion of AerCap senior notes.31 That transaction allowed GE to announce that total debt reduction since late 2018 would reach roughly $75 billion.31
These divestments reflected practical necessity rather than financial wizardry: they represented the balance-sheet price required to resolve two decades of debt-fueled capital misallocation. Management's primary contribution lay in executing the asset sales rapidly, at viable valuations, before capital market conditions deteriorated further.
The breakup announcement
With parent-level leverage reduced to manageable proportions, leadership addressed the structural discount that had long depressed GE's equity value. On November 9, 2021, GE announced a comprehensive plan to divide the conglomerate into three independent, investment-grade public companies focused on aviation, healthcare, and energy.32 The blueprint outlined a clear sequence: spin off GE HealthCare in early 2023 while retaining a 19.9% equity stake, combine Renewable Energy, Power, and Digital into a single energy entity to be spun off in early 2024, and leave behind a dedicated aerospace enterprise.32
The economic rationale was straightforward. Decades of operational history had demonstrated that the conglomerate structure created a holding-company discount rather than cross-business synergies. Equity investors seeking pure exposure to commercial jet engines were forced to absorb cyclical downturns in utility power generation, while capital allocation and executive attention were divided across three disparate industries with non-synchronous operating cycles.
The restructuring unfolded strictly to schedule. GE HealthCare began regular-way trading on the Nasdaq on January 4, 2023.[^2] GE Vernova completed its spin-off on April 2, 2024, leaving the standalone propulsion business trading under the historic ticker symbol GE.1
FLIGHT DECK in practice
Evaluating the impact of Culp's operating discipline requires distinguishing operational improvements from a powerful commercial aerospace upcycle. Industrial manufacturers routinely credit internal management frameworks for earnings growth that broader cyclical tailwinds largely generate.
Concrete operating disclosures offer a balanced view of execution. During the second-quarter 2026 earnings call, Culp stated that FLIGHT DECK initiatives had reduced production lead times for the F110 military fighter engine by approximately 60%, while joint engineering workflows with supplier GKN had cut component inspection times by roughly 90%.33 Those represented measurable process gains rather than corporate slogans. On the same call, however, Chief Financial Officer Rahul Ghai disclosed that spare parts delinquencies—orders the company had been unable to fill on schedule—rose 20% sequentially during the second quarter.33 Lean practices improved internal throughput, but factory output had yet to match surging commercial demand.
For investors, the Culp era achieved the primary structural remedy: an unencumbered, single-industry manufacturer equipped with a repaired balance sheet and an operating framework focused on shop-floor execution. What remained was determining what that business was worth on its standalone fundamentals—a calculation that requires examining the operational mechanics of the propulsion portfolio itself.
VII. The Engine Room: GE Aerospace Business Architecture & Segment Economics
A dusty morning in Delhi
Consider an Airbus A320neo idling on the tarmac in Delhi on a midsummer morning, the ambient air thick with fine dust and temperatures exceeding 40 degrees Celsius. With each takeoff, the engine draws thousands of pounds of particulate-laden air through its compressor. Inside the hottest sections of the combustor and high-pressure turbine, airborne silica melts and vitrifies across the turbine blades, gradually eroding their protective thermal barrier coatings. The engine remains airworthy and safe, but it must be removed from the wing for maintenance considerably sooner than an identical unit operating in Northern Europe.
That operating reality captures the underlying economics of GE Aerospace. The company generates only a modest portion of its lifetime earnings when an engine is initially built and delivered. Instead, profits are harvested over three decades of subsequent operation, each time an engine requires inspection, maintenance, component repair, or a complete overhaul. Harsh environmental conditions, heavy aircraft utilization, and aging fleets all expand that maintenance workload. Understanding GE Aerospace's financial profile requires examining this industrial razor-and-blade model.
Segment one: Commercial Engines & Services
Commercial Engines & Services (CES) forms the primary engine of corporate earnings, generating 73% of total revenue in 2025, with aftermarket services accounting for approximately 75% of segment sales.2 In 2025, CES operating profit rose 26% to $8.9 billion.4 Operational momentum continued into 2026: in the second quarter, CES revenue expanded 27% to $9.7 billion, generating an operating margin of 27.3%.5
The product line spans nearly every major category of commercial transport:
Narrowbodies. Through CFM International, the LEAP family serves as the direct successor to the CFM56. The program encompasses three primary applications: the LEAP-1A is one of two engine choices on the Airbus A320neo family; the LEAP-1B serves as the exclusive powerplant on the Boeing 737 MAX; and the LEAP-1C powers the COMAC C919. As the primary high-volume single-aisle platform, the LEAP fleet will define the company's commercial aftermarket earnings through the 2030s.
Widebodies. In twin-aisle aircraft, GE's proprietary engines dominate long-haul fleets: the GE90 powers the Boeing 777, the GEnx serves the Boeing 787 Dreamliner and 747-8, and the GE9X was developed as the exclusive powerplant for the delayed Boeing 777X program. In the second quarter of 2025, GE announced the largest widebody engine agreement in its history, securing an order from Qatar Airways covering more than 400 GE9X and GEnx engines.7
The razor and the blade
The economic mechanics of commercial propulsion depend on lifetime monetization. When selling original equipment to airframers such as Boeing or Airbus, pricing is intensely competitive; on early production runs of clean-sheet programs such as the LEAP and GE9X, engines are routinely delivered at an initial loss. In effect, the manufacturer subsidizes fleet placement to establish a captive installed base that will fly for decades and require recurring shop visits—comprehensive overhauls in which an engine is disassembled, inspected, fitted with new life-limited parts, and rebuilt.
Those shop visits generate revenue through two primary contracting structures:
Under time and material arrangements, airlines pay directly for the parts and specialized labor required during each overhaul. This transactional approach produces fluctuating revenue that tracks flight cycles, but yields high margins on proprietary replacement components.
Under contractual service agreements, typically billed on a rate per engine flight hour, the carrier pays a steady fee for every hour flown, and GE assumes responsibility for maintenance logistics and shop visits. While this model provides predictable recurring cash flows, it requires management to forecast maintenance and component costs across multi-decade lifecycles—the precise area where subjective accounting estimates enter the balance sheet.
Proprietary spare parts remain the most lucrative component of the aftermarket. Because stringent aviation safety regulations require certified components, airlines and independent maintenance facilities must source critical rotating parts directly from the original manufacturer, granting GE pricing power that original equipment sales rarely provide.
The CFM56 sweet spot — and its expiration date
Currently, GE Aerospace is capitalizing on the most profitable phase in the lifecycle of its most prolific platform. The CFM56 fleet is mature and heavily utilized, placing a substantial proportion of engines in the window where they require their second and third major overhauls. Furthermore, persistent delivery delays at Boeing and Airbus have prevented airlines from replacing older aircraft on schedule, forcing carriers to keep CFM56-powered airframes in service longer.
Management has explicitly structured near-term guidance around this trend. GE and Safran entered 2026 expecting approximately 2,300 CFM56 shop visits in each of 2026 and 2027, subsequently raising the 2026 projection to a range of 2,300 to 2,400 visits.34 Ghai noted that fleet retirement assumptions had been lowered repeatedly—falling from an initial 3% to 4% range to between 2% and 3% entering 2026, and down to 1.5% to 2% by mid-year—even as the company maintained a planning baseline that retirements will rebound toward 3% to 4% in 2027.34 Indicating substantial remaining overhaul demand, management disclosed that roughly two-thirds of the active CFM56 fleet has not yet completed its second shop visit.35
This dynamic highlights a central strategic challenge. The company's largest current profit pool is a legacy aftermarket that management itself projects will level off and eventually contract as aircraft retirements accelerate. Sustaining long-term earnings growth requires the newer LEAP aftermarket to expand rapidly enough to offset the eventual decline of CFM56 cash flows.
The LEAP transition problem
The LEAP aftermarket has not yet achieved the profitability of the platform it replaces. On the second-quarter 2026 earnings call, Ghai highlighted three distinct headwinds restraining margins: volume growth in negative-margin new engine deliveries, LEAP services margins that remain below the portfolio average, and early-stage manufacturing costs on the GE9X—pressures he described as timing-related and projected to ease after 2028.33 Management has stated that it expects LEAP services margins to reach parity with the broader commercial portfolio around 2028 as early production engines begin entering their first cycle of major overhauls.35
These expectations reflect internal projections rather than demonstrated results. While management has been transparent regarding the transition timeline, investors must treat 2028 as an unproven operational target rather than an assured milestone.
Segment two: Defense & Propulsion Technologies
The company's second operating division, Defense & Propulsion Technologies (DPT), generated 23% of revenue in 2025.2 The segment provides military propulsion systems, including the F110 fighter engine powering variants of the F-16 and F-15, and the F414 powering the Boeing F/A-18 Super Hornet and Saab Gripen, as well as serving as the selected powerplant for India's Tejas Mk2.36 It also manufactures the T700 turboshaft family utilized on Black Hawk and Apache helicopters, alongside avionics, electrical power distribution systems, and the Avio Aero propulsion business. In the second quarter of 2026, DPT revenue rose 16% to $3.4 billion, delivering an operating margin of 13.8%.5 For full-year 2026, management guided DPT operating profit to between $1.6 billion and $1.7 billion.5
The stark margin contrast between the two divisions—with commercial margins roughly double those in defense—illustrates where the corporate profit engine resides. Defense provides stable, non-cyclical baseline revenue governed by government procurement cycles, but commercial aviation generates the preponderance of economic profit.
Financial anatomy
Across the consolidated enterprise, aftermarket services account for approximately 70% of total revenue.2 GE Aerospace directed roughly $3 billion toward research and development in 2025, with approximately $1.6 billion funded directly by the company and the balance financed by customers and government partners.2 Underpinned by commercial services strength, management guided full-year 2026 free cash flow to between $8.9 billion and $9.2 billion.5
The operational evidence indicates an enterprise whose valuation is anchored not in original equipment manufacturing, but in monetizing an expansive installed base across multi-decade service cycles. Over the next several years, corporate performance will hinge on executing the generational handoff from the CFM56 to the LEAP. That transition represents the primary operational vulnerability where competitors seek to gain ground, raising the question of how defensible GE's market position truly is.
VIII. The Strategic Moat: 7 Powers & Porter's 5 Forces Analysis
The war game
Dislodging CFM from its dominant position in narrowbody propulsion would require a challenger to navigate severe structural barriers. An aspiring competitor would need roughly a decade and billions of dollars in upfront capital to develop a clean-sheet engine architecture, followed by rigorous airworthiness certification from the Federal Aviation Administration and the European Union Aviation Safety Agency. An airframe builder would then have to engineer wings, pylons, and integration systems around that specific powerplant, while commercial airlines would need to commit to twenty-five years of operational reliance on an unproven architecture. Finally, the manufacturer would have to establish a global maintenance, repair, and overhaul network with distributed pools of certified spare parts before aircraft leasing companies would agree to finance fleets carrying the engine.
Pratt & Whitney undertook precisely that challenge with its geared turbofan, securing a dual-source position on the Airbus A320neo. That competitive battle provides the clearest empirical test of GE's economic moat, demonstrating both its resilience and its boundaries.
Hamilton Helmer's 7 Powers
Cornered resource. GE's deepest competitive advantage lies in accumulated metallurgy and materials science: single-crystal nickel superalloy turbine blades, ceramic matrix composites capable of withstanding temperatures exceeding the melting points of traditional metals, and proprietary thermal barrier coatings. Decades of specialized manufacturing and empirical testing make this tacit know-how difficult to duplicate through patents alone. However, this expertise serves as a barrier against outside entrants rather than a monopoly among incumbents, as Rolls-Royce and Pratt & Whitney maintain sophisticated proprietary metallurgical capabilities of their own.
Switching costs. Switching costs in commercial aviation are exceptionally high, but they function at distinct structural junctures. At the airframer level, designing a wing, pylon, and avionics interface around a specific engine locks in the architecture; Boeing cannot substitute the LEAP-1B on the 737 MAX without undertaking an extensive and costly airframe redesign. At the airline level, carriers that standardize on a single propulsion platform invest heavily in spare engines, dedicated maintenance tooling, and type-rated mechanics, creating friction against introducing a rival powerplant. However, on dual-sourced airframes like the Airbus A320neo, airlines retain the operational flexibility to evaluate both engine options and switch suppliers on subsequent aircraft orders.
Scale economies. CFM's vast installed base amortizes multi-billion-dollar development, certification, and tooling expenses across tens of thousands of delivered engines. Scale also compounds in the aftermarket, where a dense global fleet drives down unit overhaul costs and increases the operational utilization of specialized service facilities.
Network effects. While aerospace manufacturing does not exhibit software-style network effects, an analog operates through fleet liquidity. As an engine type achieves widespread adoption, independent maintenance providers, component supply pools, and aircraft lessors develop deep infrastructure around it. A liquid secondary market makes aircraft carrying that powerplant easier to finance, lease, and trade, reinforcing airline preference for the dominant engine on future procurement rounds.
Counter-positioning, process power, and branding. These remaining powers play secondary roles. Process power represents the operational objective behind Culp's FLIGHT DECK lean manufacturing system; whether continuous shop-floor improvements yield a structural advantage over competitors with mature production frameworks remains to be demonstrated over a full aerospace cycle.
Porter's 5 Forces
Threat of new entrants: low, but not zero. The most prominent long-term challenger is the Aero Engine Corporation of China (AECC), whose CJ-1000A turbofan is being developed to provide a domestic alternative to the LEAP-1C on the COMAC C919. While state financial and political backing is substantial, aviation history shows that matching Western standards of high-cycle reliability and fuel efficiency takes decades. Consequently, the realistic medium-term risk to GE is not market displacement on global routes, but the potential erosion of new deliveries within China's domestic fleet.
Bargaining power of suppliers: high. The primary operational bottleneck facing GE Aerospace is supply rather than customer demand, driven by tight industry capacity across high-temperature structural castings, forgings, and specialized raw materials supplied by a consolidated vendor base. On the second-quarter 2026 earnings call, Culp highlighted this constraint, noting, "It's much more a supply-side challenge than it is a demand."35 Persistent tier-one supplier constraints continue to inflate input costs and lengthen delivery schedules across the aerospace sector.
Bargaining power of buyers: split. Airframe manufacturers such as Boeing and Airbus exert significant pricing leverage during initial equipment competitions, compelling engine makers to deliver initial production lots at narrow margins or outright accounting losses. Once engines enter active service, however, commercial airlines possess limited bargaining power over proprietary, certified replacement parts. While parts-manufacturer-approval (PMA) alternatives and used serviceable material provide modest price discipline, the original manufacturer retains substantial pricing power over critical hot-section components.
Threat of substitutes: very low. Alternative propulsion technologies, such as battery-electric and hydrogen powerplants, face severe volumetric and gravimetric energy-density constraints that preclude their commercial adoption on mainline passenger transports within any practical investment horizon. Concurrently, the adoption of drop-in sustainable aviation fuels preserves the utility of existing engine architectures, extending rather than threatening the installed base.
Rivalry among existing competitors: concentrated duopolies. Competitive dynamics are defined by narrow, entrenched duopolies. In narrowbody aircraft, CFM International competes directly with Pratt & Whitney on the Airbus A320neo while maintaining an exclusive sole-source position on the Boeing 737 MAX. In widebody propulsion, GE contends primarily against Rolls-Royce across long-haul passenger and freight platforms.
The Pratt & Whitney test
The durability of GE Aerospace's commercial moat faced an empirical test through its competition with Pratt & Whitney's PW1100G geared turbofan on the Airbus A320neo. In 2023, parent company RTX disclosed that microscopic contaminants in powdered metal used to forge high-pressure turbine disks would require accelerated removals and inspections for 600 to 700 engines between 2023 and 2026, grounding hundreds of A320neo aircraft and resulting in a pre-tax charge of approximately $3 billion.37 Airline customers that had selected the geared turbofan faced substantial operational disruption and extended aircraft groundings.
The commercial fallout underscored how execution lapses by a direct rival can alter market share. In July 2026, IndiGo—India's largest airline and an operator that previously divided its single-aisle fleet between the LEAP-1A and the PW1100G—signed a memorandum of understanding with CFM for more than 1,000 LEAP-1A engines to power 510 A320neo-family aircraft, representing the largest engine order in the history of the LEAP program.38 That selection demonstrated the tangible value airlines assign to on-wing durability over theoretical fuel-burn advantages.
Yet the episode also highlighted the structural boundaries of the moat. Prior to that procurement decision, one of the world's most prolific single-aisle operators had deliberately split its engine orders between both manufacturers. Because Airbus actively maintains dual-source propulsion options across its high-volume platforms to prevent supplier lock-in, CFM cannot rely on captive monopoly economics on the A320neo; it must continually defend its market share customer by customer and order by order.
For investors, the strategic moat around GE Aerospace is formidable yet contested: structurally insulated against outside entrants, monopolistic on sole-source airframes, and fiercely competitive wherever airframe builders preserve supplier choice. The central question is whether this competitive architecture can sustain earnings momentum when weighed against the execution risks and cyclical vulnerabilities embedded in the company's own operating history.
IX. The Historical Falsification Layer: Stress-Testing the Thesis
Test 1: "The untouchable CFM single-aisle franchise"
The claim. The LEAP family is a secure, growing cash annuity through the 2040s.
The disconfirming evidence. Premature wear in demanding operating climates revealed an early engineering vulnerability. In hot, sandy regions—notably across the Middle East and South Asia—LEAP engines required shop visits much sooner than planned. These early removals disrupted carrier flight schedules and elevated maintenance costs under GE's long-term service agreements, where the manufacturer bears unexpected repair expenses. To improve durability, GE engineered a high-pressure turbine retrofit kit. The Federal Aviation Administration certified the LEAP-1A kit, which the company stated would roughly double on-wing operating time in harsh environments.39 The LEAP-1B upgrade received FAA approval in July 2026.40 Although more than 40% of the LEAP-1A fleet had been retrofitted by mid-2026, most of the global LEAP fleet will not complete upgrades until the early 2030s, and Culp acknowledged "unfinished business" on durability.35 In May 2026, the company argued that newly delivered LEAP engines should ultimately match the durability of the legacy CFM56.41
Second, commercial airframers deliberately preserve supplier competition. On the A320neo, Airbus offered airlines an engine choice, allowing Pratt & Whitney to capture substantial platform share with its geared turbofan. While CFM gained market share as Pratt struggled with component durability, Airbus maintains its dual-source policy, preventing CFM from operating as a monopoly supplier on the platform.
Third, sole-source exposure binds CFM to Boeing's assembly performance. Because the LEAP-1B is the exclusive powerplant for the 737 MAX, factory disruptions in Renton flow directly into engine delivery schedules. Following the January 2024 door-plug blowout on an Alaska Airlines flight, the FAA capped 737 MAX production at 38 aircraft per month.42 Regulators raised that monthly ceiling to 42 in October 2025,42 and in May 2026 Boeing stated it had met the requirements to increase to 47.43
The verdict. Operating history narrows the claim rather than invalidating it. The franchise remains structurally entrenched—737 MAX customers cannot switch powerplants, and CFM continues to win market share on the A320neo—yet describing the business as "untouchable" overstates its insulation. Durability retrofits consume capital and customer goodwill, Boeing's factory pace governs narrowbody delivery volume, and segment earnings expansion requires the LEAP aftermarket to reach CFM56-like profitability. The milestone that will confirm or falsify this progression is whether LEAP services margins achieve parity with the broader commercial portfolio around 2028, as management has guided.35
Test 2: "Military propulsion hegemony"
The claim. The defense business is an unshakable, counter-cyclical source of cash and strategic position.
The disconfirming evidence. The largest military propulsion procurement of the century went to a direct competitor. GE spent years developing the XA100 adaptive-cycle engine under the Adaptive Engine Transition Program, proposing it as a replacement powerplant for the Lockheed Martin F-35. In March 2023, the Pentagon chose instead to upgrade Pratt & Whitney's existing F135, citing overall cost and doubts that GE's engine would work across all F-35 variants.44 The Air Force stated it would continue adaptive-engine development under its Next Generation Adaptive Propulsion program.45 In the second quarter of 2026, GE completed an assembly readiness review for its XA102 engine under that program.5
Foreign military procurement also involves substantial commercial trade-offs. In June 2023, GE signed a memorandum of understanding with Hindustan Aeronautics Limited to produce F414 engines in India.36 Reporting in 2026 described a contract for up to 99 engines with around 80% technology transfer, including hot-section manufacturing.46 Sovereign customers building domestic industrial capacity extract proprietary engineering and local production as prerequisites for market access, which can dilute contract margins and foster future regional competitors.
The verdict. Historical evidence refutes the claim of defense hegemony. GE remains an established defense contractor with major franchises in fighter and helicopter propulsion, but it lost the flagship fifth-generation re-engining competition, and its defense operating margins hover at roughly half those of its commercial business. The accurate assessment is that defense provides portfolio diversification and technological cross-pollination, not market dominance. The forward indicator to monitor is whether GE secures a primary production role in sixth-generation adaptive propulsion.
Test 3: "Flawless modern management and governance"
The claim. Culp's operating discipline has eliminated governance risk and fully aligned management with shareholders.
The disconfirming evidence. In August 2020, as part of an agreement extending Culp's employment contract, the board canceled existing stock awards and granted new incentives tied to lower financial targets.47 At the May 4, 2021 annual meeting, nearly 58% of votes cast opposed the advisory executive pay program, which could have paid Culp as much as about $230 million; proxy advisers ISS and Glass Lewis had opposed the package, arguing that lowering the performance bar was unjustified.47 In response, the board reduced Culp's annual equity grant in 2022 from $15 million to $5 million, though it left the controversial retention award intact.48
The verdict. The governance record qualifies the narrative of seamless alignment. Culp's operational turnaround and portfolio restructuring have generated substantial shareholder value, yet the board's mid-crisis downward adjustment of executive targets showed a willingness to insulate executive compensation when operating conditions deteriorated. The governance response was a partial concession rather than a full structural realignment. The forward test is whether the performance share awards tied to Culp's current contract pay out strictly against their original financial and operational hurdles.
Test 4: Accounting credibility
The company's historical record makes this evaluation necessary. General Electric settled SEC accounting or disclosure investigations twice in recent decades—in 2009, partly involving commercial aircraft engine spare parts accounting, and in 2020, involving cost-estimate changes in long-term service contracts.1827 Today, GE Aerospace manages an extensive portfolio of long-term service agreements that rely on similar multi-decade estimates of overhaul frequency, parts consumption, and shop labor. While there is no public evidence of current reporting issues, this regulatory history requires analytical caution: reported operating margins on long-term contracts can decouple from underlying cash collections if cost revisions are recognized before operational validation. For that reason, sustained free cash flow conversion remains the primary benchmark of reported earnings quality.
Stress-testing these assumptions leaves a narrower, more disciplined thesis: a commercial engine franchise with durable but bounded advantages, a steady but non-dominant defense division, and an executive leadership team that has executed an effective operational turnaround while operating within legacy corporate governance frameworks. The leadership structure responsible for navigating that environment is the next focus of the analysis.
X. Current Management, Governance, & Capital Allocation
The contract
On July 1, 2024, three months after completing the GE Vernova spinoff, the board announced a new employment agreement for Culp, securing his tenure as chairman and chief executive officer through December 31, 2027, with an option to extend through December 31, 2028, by mutual agreement.49 The compensation structure established a $2 million base salary, a target annual bonus of 200% of salary, and an annual equity award valued at $15.25 million, alongside a one-time performance share grant scheduled to vest at the end of 2027, subject to operational targets and continued service.4950
In design, the package links the majority of executive pay to multi-year financial hurdles. Yet in light of the board's 2020 decision to reprice performance targets during an operating downturn, governance analysts continue to evaluate the contract less on its structural formula and more on whether directors maintain those performance bars if market conditions soften.
The CFO
Rahul Ghai assumed the role of chief financial officer on September 1, 2023.51 He had previously served as CFO of Otis Worldwide from 2019 to 2022, helping direct its spinoff from United Technologies, and as CFO of Harris Corporation from 2016 to 2019.51 In investor presentations and earnings calls, Ghai has consistently isolated margin headwinds into identifiable components—negative-margin engine delivery volumes, the mix of early-stage LEAP service contracts, and upfront development costs on the GE9X—while mapping each pressure against a defined recovery timeline. That level of operational granularity provides public checkpoints against which investors can track execution.
Management credibility over time
A standard test of managerial credibility is measuring reported performance against initial guidance. Across its first two years as an independent enterprise, GE Aerospace established a consistent record of exceeding targets. Management outlined a 2028 operating profit milestone of approximately $10 billion at its March 2024 Investor Day,6 raised that 2028 target to roughly $11.5 billion in July 2025,7 and by July 2026 guided to between $10.55 billion and $10.75 billion for 2026 alone.5 During that same July 2026 update, the company raised full-year guidance across operating profit, earnings per share, and free cash flow.5
A balanced assessment requires recognizing that this earnings acceleration coincided with an unprecedented commercial aftermarket upcycle, driven partly by delivery delays at Boeing and Airbus that kept legacy engines flying. At the same time, management has demonstrated candor when confronting exogenous shocks. In the first quarter of 2026, following the outbreak of Middle Eastern conflict in late February, GE lowered its full-year global airline departures forecast to flat to low-single-digit growth while maintaining consolidated profit guidance; Culp noted that earnings guidance likely would have risen "were it not for current events."52 On the second-quarter call, Culp stated that first-half flight departures were "roughly flat" but emphasized that the company had "not observed any changes in customer behavior."33 Disclosing headwinds with operational precision rather than ambiguous caveats reinforces executive credibility.
Capital allocation
Research and development. The company's flagship next-generation initiative is the CFM RISE program (Revolutionary Innovation for Sustainable Engines). Unveiled in 2021, the partnership targets a 20% reduction in fuel consumption compared with current powerplants, aiming for potential commercial entry in the mid-2030s using an "open fan" architecture that eliminates the conventional nacelle casing around the fan blades.5315 By mid-2025, the program had completed more than 350 test runs.7 Investors must treat RISE as a technology demonstration platform rather than a guaranteed commercial product. Aviation history provides a sober base rate: the CFM56 endured years of zero customer orders following certification before achieving commercial viability, while GE's adaptive-cycle military engine achieved technical success without winning production volume on the F-35. Technical milestones do not automatically translate into commercial revenue.
Shareholder returns. Capital return has accelerated alongside operating cash flow. After completing a $15 billion share repurchase authorization launched in March 2024, the board approved an additional authorization of up to $20 billion in December 2025.54 In July 2025, management outlined plans to return approximately $24 billion to shareholders between 2024 and 2026, while committing to return at least 70% of free cash flow through dividends and buybacks thereafter.7 The quarterly dividend currently stands at $0.47 per share.55
M&A. Strategic deployment remains disciplined around organic investment and direct capital returns rather than large-scale acquisitions. Given General Electric's history of value-destructive transactions—most notably the Alstom acquisition, the Baker Hughes combination, and the aggressive expansion of GE Capital—managerial restraint on mergers and acquisitions represents a prudent posture. Sustaining that discipline remains an essential metric for investors, as accumulated cash balances have historically tempted industrial leadership toward inorganic expansion.
An activist-style skeptic would press on three unresolved questions: whether large-scale share repurchases executed at premium valuation multiples represent the optimal use of capital relative to direct supplier investments; whether executive compensation oversight has permanently tightened since the 2020 repricing; and whether earnings recognized under long-term service agreements continue converting into cash at high rates. While none of these dynamics currently signals operational distress, they outline the core variables that define the broader investment debate.
XI. The Investment Spine: Bull vs. Bear & Key Operating KPIs
The setting
In July 2026, during the second-quarter earnings call, Culp summarized the bull case concisely: "We do not have a demand problem."33 He cited a commercial services backlog of roughly $170 billion.33 The ensuing question-and-answer session exposed the counterarguments just as clearly: spare parts delinquencies increased 20% sequentially, operating margins contracted 130 basis points year over year, and analysts questioned whether the full-year guidance raise was sufficient.535 Both realities coexisted on the same balance sheet.
The bull case
1. The aftermarket supercycle has room to run. Commercial airlines are flying older airframes longer because replacement aircraft remain scarce, and CFM56 retirement rates have tracked well below historical planning baselines.34 Management noted that approximately two-thirds of the active CFM56 fleet has not yet completed its second major shop visit.35 Commercial services revenue expanded 32% across the first half of 2026, and leadership reiterated that it saw no structural reason for 2027 to diverge from double-digit services growth.533
2. The LEAP aftermarket should mature. As the LEAP fleet transitions from early, warranty-covered repairs to standard overhauls, and as high-pressure turbine durability upgrades reduce maintenance costs, services margins are projected to expand. Management expects LEAP services profitability to reach parity with the broader commercial portfolio around 2028.35
3. The competitor stumbled. Durability challenges with Pratt & Whitney's geared turbofan prompted carriers to reevaluate fleet commitments, and IndiGo's selection of more than 1,000 LEAP-1A engines provided tangible proof of market share shifting toward CFM.38
4. The capital return machine. A franchise that converts more than 100% of net income into cash while committing to return at least 70% of free cash flow to shareholders beyond 2026 compounds per-share value even under moderate growth assumptions.47
The bear case
1. The supply chain is the ceiling. Customer demand is not the operational ceiling; component availability is. Spare parts delinquencies climbed 20% sequentially even as supplier output improved.33 If high-temperature castings and forgings remain constrained, GE cannot fully monetize the aftermarket surge, and unit operating costs will rise.
2. The CFM56 peak is visible. Management's internal planning baseline assumes that fleet retirements will accelerate to between 3% and 4% in 2027.34 If commercial airframers accelerate aircraft output—a process signaled by Boeing's push toward a production rate of 47 aircraft per month—older engines will retire, contracting the company's most profitable profit pool before the LEAP aftermarket fully replaces it.43
3. Boeing risk. Both the LEAP-1B and the GE9X depend entirely on Boeing's assembly and delivery execution. Initial delivery of the 777X slipped to 2027, accompanied by a $4.9 billion charge recorded by Boeing.56 A GE9X mid-seal crack discovered in January 2026 required an engineering redesign; GE stated the modification will not delay the 777X past 2027, subject to FAA certification of the fix.57 Concurrently, upfront manufacturing costs on early production GE9X units continue to weigh on segment margins through approximately 2028.35
4. Airline and geopolitical risk. The outbreak of Middle Eastern conflict in early 2026 demonstrated how quickly airline flight schedules can stall; departures across the Middle East account for roughly 5% of global air traffic and were projected to decline by low double digits in 2026.52 A broader slowdown in commercial aviation would directly erode flight-hour-based service revenue.
5. Expectations. Following an extended run of outperformance and consecutive guidance increases, equity valuations reflect substantial forward optimism. While valuation alone does not constitute an operational risk, it compresses the margin of safety if delivery schedules or aftermarket shop visits falter.
Weighing it
The core pillars of the bull case are structural: a massive global installed base, high switching barriers across sole-source platforms, and an executive leadership team with an established record of meeting or exceeding targets. Conversely, the primary elements of the bear case are cyclical and operational: an approaching peak in CFM56 shop visits, acute tier-one supply bottlenecks, and deep reliance on Boeing's assembly recovery. The defining window spans 2027 through 2029, when the CFM56 aftermarket is projected to plateau and the LEAP aftermarket must absorb the earnings burden. Management asserts that this fleet transition will proceed smoothly; operating results to date support that trajectory, but have not yet conclusively demonstrated it.
Myth vs. reality
Myth: GE Aerospace operates as an unregulated monopoly. Reality: The company holds exclusive sole-source positions on select airframes—most notably the Boeing 737 MAX through CFM International and the 777X via the GE9X—but competes aggressively across the rest of the market. On the Airbus A320neo family, airlines evaluate CFM against Pratt & Whitney on an order-by-order basis, while in widebody commercial aircraft Rolls-Royce remains an entrenched competitor.
Myth: The commercial aftermarket functions as a perpetual annuity. Reality: Propulsion revenue represents a sequence of overlapping multi-decade product lifecycles. The CFM56 aftermarket is approaching its cyclical plateau under management's planning baseline, while the replacement LEAP services stream is still in its maturation phase, characterized by lower current margins.3433
Myth: FLIGHT DECK lean manufacturing alone drives the company's margin expansion. Reality: While Culp's lean initiatives have delivered verified cycle-time reductions across targeted manufacturing lines, the predominant catalyst behind performance between 2024 and 2026 has been a structural shortage of newly delivered airframes that forced carriers to keep older engines in service. Both dynamics contribute, but the aftermarket tailwind originates outside executive control.
Myth: Balance-sheet and accounting risks were entirely eliminated. Reality: Although the shadow bank was dismantled and GECAS was sold, the run-off insurance liabilities disclosed in 2018 established a multi-year funding commitment, and the company's regulatory history means that accounting estimates on long-term service contracts warrant continued analytical attention.2627
The three KPIs to track
1. Commercial services organic revenue growth. This metric provides the clearest gauge of flight activity across the installed base, reflecting shop-visit volume, spare parts demand, and contractual pricing power. Tracking this growth will signal whether aftermarket momentum is decelerating as the CFM56 fleet reaches peak overhaul density.
2. CES operating margin. Operating margins in Commercial Engines & Services reveal whether pricing gains, FLIGHT DECK productivity improvements, and the maturation of LEAP service contracts are outpacing supply chain cost inflation, initial delivery losses on new engines, and upfront manufacturing investments on the GE9X. With management projecting that several margin headwinds will moderate after 2028, this benchmark will confirm or refute that operational timeline.
3. Free cash flow conversion. Measuring the proportion of net income converted into free cash flow serves as the primary safeguard for earnings quality. Given the company's historical reliance on long-term contract accounting estimates, consistent cash conversion above management's 100% target offers tangible proof that reported accounting profits represent realized cash.
Together, these three indicators address the central strategic question facing investors: whether GE Aerospace's current earnings power reflects a durable, structural advantage or the cyclical crest of an aftermarket boom.
XII. Playbook: Business & Investing Lessons
Lesson 1: Conglomerate synergy is usually a story, not a mechanism
For decades, General Electric argued that its disparate divisions reinforced one another through shared executive talent, centralized capital allocation, and cross-disciplinary research. In practice, bundling jet engines, healthcare scanners, gas turbines, and a commercial finance company obscured balance-sheet risks rather than diversifying them. An internal capital market allowed a captive finance arm to borrow cheaply against the industrial parent's credit rating until wholesale liquidity froze, while enabling capital misallocation such as the Alstom acquisition at the peak of the thermal power cycle. The market's rerating of the standalone entities confirmed what conglomerate theory resisted for generations: the whole was worth materially less than the sum of its operating parts.
Lesson 2: The financialization trap
Renting an industrial balance sheet to fund a captive shadow bank provides management with earnings-smoothing tools during economic expansions, but it introduces systemic refinancing risk when credit markets seize. In 2008, when short-term commercial paper markets seized, GE required emergency capital from Berkshire Hathaway, federal debt guarantees from the FDIC, and its first dividend reduction in seven decades to maintain solvency. The subsequent balance-sheet repair consumed a decade and forced the divestment of premier operating franchises, including BioPharma and GECAS. The recurring lesson for industrial investors is that financial engineering generates deferred liabilities: the bill inevitably arrives during an operating downturn, and paying it typically demands sacrificing the company's highest-quality assets.
Lesson 3: Razor-and-blade economics in regulated markets are extraordinary — but time-bound
In safety-critical, heavily regulated industries, original equipment sales function as call options on three decades of high-margin, proprietary aftermarket cash flows. Stringent airworthiness certifications and specialized manufacturing barriers ensure that the engine maker captures lucrative spare parts and maintenance overhauls throughout an airframe's operating life. Yet that annuity is not permanent; every propulsion architecture follows a discrete lifecycle. GE Aerospace is currently monetizing the peak overhaul window of the CFM56, while the replacement LEAP platform remains in its lower-margin maturation phase. Evaluating long-term earnings durability requires mapping where each individual platform sits along that generational curve rather than extrapolating aftermarket growth in perpetuity.
Lesson 4: Lean is about speed, not just cost
Where twentieth-century corporate turnarounds focused primarily on headcount reductions and cost-cutting, lean operating frameworks prioritize eliminating process bottlenecks and shortening manufacturing cycle times. In an aerospace upcycle where demand materially exceeds industry capacity, cycle-time reductions—such as compressing fighter engine lead times or accelerating component inspections—expand effective manufacturing capacity without requiring proportional capital expenditure. Faster throughput translates directly into realized revenue. However, internal shop-floor discipline cannot entirely decouple an enterprise from an interconnected tier-one supply chain. When specialized castings, forgings, and raw materials remain constrained across the industry, internal process gains reach a natural ceiling, as reflected in rising spare parts delinquencies.
Lesson 5: Accounting judgment is a risk factor, not a footnote
Long-term service agreements require multi-decade management assumptions regarding maintenance frequency, component durability, and overhaul expenses. Because accounting rules permit revenue and margin recognition based on estimated lifetime contract costs, adjustments to those subjective assumptions can mechanically lift reported operating income without generating cash. General Electric's regulatory settlements in 2009 and 2020 both centered on the disclosure and timing of profit estimates, spanning commercial engine spare parts and long-term service agreements. In businesses anchored by long-duration contracts, reported accounting margins are an incomplete gauge of corporate health; sustained free cash flow conversion remains the indispensable test of underlying earnings quality.
XIII. Epilogue & Horizon
Back to Lynn
At the Lynn manufacturing facility in Massachusetts, operations still occupy the same site where engineers replicated Frank Whittle's jet engine under wartime secrecy in 1941, and where Sanford Moss spent decades developing turbosuperchargers to withstand extreme exhaust heat. The enterprise that grew around those early high-temperature alloys evolved across a century into an electrical equipment monopoly, an industrial manufacturing icon, a media empire, a shadow bank, and ultimately a corporate cautionary tale. After spending more than a decade divesting non-core assets to pay down legacy liabilities, what remained was the propulsion franchise that had been compounding value beneath the surface all along.
Today, GE Aerospace presents a far more transparent operating structure than General Electric offered at any point over the preceding half-century. That structural focus functions as an analytical asset: investors can evaluate the commercial installed base, long-term service contracts, tier-one supply bottlenecks, and execution risks directly, without the distorting effects of a captive finance arm or legacy insurance obligations.
The open fan question
The next era of competitive positioning will be decided by propulsion engineering rather than balance-sheet engineering. Through the CFM RISE program, the joint venture is betting that an open-fan architecture—an un-ducted fan positioned conceptually between a turboprop and a conventional turbofan—can deliver a 20% reduction in fuel consumption without exceeding airport noise limits or complicating airframe integration.53 If successful, CFM could secure a dominant position on the next generation of single-aisle commercial aircraft entering service in the late 2030s. If the architecture encounters technical or regulatory obstacles, or if airframers favor alternative configurations, the single-aisle market could reopen to contested competition for the first time in four decades.
The long-term investment case for GE Aerospace does not turn primarily on the next quarterly earnings report or even on the exact timing of the CFM56 aftermarket peak. Instead, it hinges on whether an enterprise that once compromised its solvency through financial engineering can sustain technical execution, navigate the fleet transition to the LEAP, and maintain disciplined capital allocation across an entire multi-decade aerospace cycle.
For an institution forged by Thomas Edison's laboratory and Charles Coffin's corporate consolidation in 1892, that represents the ultimate structural test: whether the operational rigor of the engineering floor can permanently outlast the financial ambitions that once brought the enterprise to the brink.
References
-
GE Aerospace Launches as Independent, Investment-Grade Public Company Following Completion of GE Vernova Spin-Off — GE Aerospace, 2024-04-02 ↩↩↩
-
GE Aerospace Form 10-K for Fiscal Year 2025 — U.S. Securities and Exchange Commission, 2026-01-29 ↩↩↩↩↩↩
-
GE Aerospace Announces Fourth Quarter 2024 Results (Form 8-K Exhibit) — U.S. Securities and Exchange Commission, 2025-01-23 ↩
-
GE Aerospace Announces Fourth Quarter 2025 Results — GE Aerospace, 2026-01-22 ↩↩↩
-
GE Aerospace Announces Second Quarter 2026 Results (Form 8-K Exhibit) — U.S. Securities and Exchange Commission, 2026-07-16 ↩↩↩↩↩↩↩↩↩↩
-
GE Aerospace Hosts 2024 Investor Day — GE Aerospace, 2024-03-07 ↩↩
-
GE Aerospace Announces Investor Update and Second Quarter 2025 Results (Form 8-K Exhibit) — U.S. Securities and Exchange Commission, 2025-07-17 ↩↩↩↩↩↩
-
Edison General Electric Company — Thomas A. Edison Papers, Rutgers University ↩↩
-
General Electric Opens Research Laboratory — EBSCO Research Starters ↩↩↩
-
Walgreens Boots Alliance Set to Join Dow Jones Industrial Average — S&P Dow Jones Indices, 2018-06-19 ↩↩
-
The U.S. Enters the Jet Age: Mr. Whittle's Secret Stay in Lynn — GE Aerospace ↩
-
GE Aviation and Safran Launch Advanced Technology Demonstration Program for Sustainable Engines; Extend CFM Partnership to 2050 — GE Aerospace, 2021-06-14 ↩↩
-
Jack Welch, Former Chairman and CEO of GE, Dies at 84 — CNBC, 2020-03-02 ↩↩
-
Jack Welch, GE Chief Who Made Bold Acquisition of RCA, NBC, Dies at 84 — SHOOT Online (Associated Press), 2020-03-02 ↩
-
SEC Charges General Electric With Accounting Fraud (Press Release 2009-178) — U.S. Securities and Exchange Commission, 2009-08-04 ↩↩↩↩
-
The Commission Prohibits GE's Acquisition of Honeywell — European Commission, 2001-07-03 ↩
-
Paulson Book: Behind the Scenes, GE's Top Exec Confided Credit Woes — ProPublica, 2010-02 ↩
-
Warren Buffett Announces Investment in GE (Form 8-K Exhibit) — U.S. Securities and Exchange Commission, 2008-10-01 ↩
-
GE Completes Acquisition of Alstom Power and Grid Businesses — GE, 2015-11-02 ↩↩
-
H. Lawrence Culp, Jr. Named Chairman and CEO of GE — GE, 2018-10-01 ↩↩
-
GE Announces Completion of GE Oil & Gas and Baker Hughes Merger — Business Wire, 2017-07-03 ↩
-
GE Still Grappling with Legacy Insurance Business — Insurance Journal, 2018-01-16 ↩↩
-
General Electric Agrees to Pay $200 Million Penalty for Disclosure Violations (Press Release 2020-312) — U.S. Securities and Exchange Commission, 2020-12-09 ↩↩↩↩↩↩
-
SEC Administrative Order in the Matter of General Electric Company (Release No. 33-10899) — U.S. Securities and Exchange Commission, 2020-12-09 ↩
-
H. Lawrence Culp, Jr. Biography — Export-Import Bank of the United States, 2018 ↩
-
Danaher Completes Acquisition of the Biopharma Business of General Electric Life Sciences; Business Will Be Called Cytiva — Danaher, 2020-03-31 ↩
-
GE Completes GECAS Transaction with AerCap (Form 8-K) — U.S. Securities and Exchange Commission, 2021-11-01 ↩↩
-
GE Plans to Form Three Public Companies Focused on Growth Sectors of Aviation, Healthcare, and Energy — Business Wire, 2021-11-09 ↩↩
-
Earnings Call Transcript: GE Aerospace Beats Q2 2026 Estimates, Raises Outlook — Investing.com, 2026-07-16 ↩↩↩↩↩↩↩↩↩
-
CFM56 Overhaul Demand Remains Strong, GE Aerospace Says — Aviation Week, 2026 ↩↩↩↩↩
-
Q2 2026 Earnings: GE Aerospace Keeps the Beat Despite a Few Missed Notes — Leeham News and Analysis, 2026-07-16 ↩↩↩↩↩↩↩↩↩
-
GE Aerospace Signs MOU with Hindustan Aeronautics Limited to Produce Fighter Jet Engines for Indian Air Force — GE Aerospace, 2023-06-22 ↩↩
-
RTX Provides Update on Pratt & Whitney GTF Fleet — RTX, 2023-09-11 ↩
-
IndiGo and CFM Sign MoU Paving the Way to a Record Agreement for 1,000+ LEAP-1A Engines — GE Aerospace, 2026-07-20 ↩↩
-
FAA Certifies More Durable Hardware for CFM LEAP-1A Engine — GE Aerospace ↩
-
FAA Approves LEAP-1B High-Pressure Turbine Durability Kit — FlightGlobal, 2026-07 ↩
-
GE's LEAP Engines Shipped Today Should Match Durability of the Venerable CFM56, Company Says — Leeham News and Analysis, 2026-05-27 ↩
-
FAA Raises Boeing 737 Max Production Cap to 42 a Month — CNBC, 2025-10-17 ↩↩
-
Boeing CEO Says Company Met Requirements to Increase 737 Max Production to 47 Jets per Month — CNBC, 2026-05-27 ↩↩
-
Pentagon Rethinks F-35 Engine Program, Will Upgrade F135 — Defense News, 2023-03-13 ↩
-
Air Force Skips AETP Engines for F-35, Presses on with NGAP — Air & Space Forces Magazine, 2023-03 ↩
-
GE Aerospace, HAL Finalise Key Tech Transfer Terms for F414 Jet Engine Production in India — Swarajya, 2026 ↩
-
GE Shareholders Reject CEO Culp's $230 Mln Pay in Rare Rebuke — Reuters via Yahoo Finance, 2021-05-04 ↩↩
-
After Shareholders Balk, GE's Culp Is Poised for Less Pay — The Boston Globe, 2022-03-18 ↩
-
GE Aerospace Board of Directors Extends Employment Agreement for Chairman and CEO H. Lawrence Culp, Jr. — GE Aerospace, 2024-07-01 ↩↩
-
Form 8-K: Employment Agreement and Performance Award for H. Lawrence Culp, Jr. — U.S. Securities and Exchange Commission, 2024-07-01 ↩
-
GE Announces Chief Financial Officer Transition — GE, 2023-05-18 ↩↩
-
GE Aerospace Q1 2026 Earnings: Conflict in the Middle East Overshadows Strong Start to 2026 — Leeham News and Analysis, 2026-04-21 ↩↩
-
5 Things to Know About the CFM RISE Program — CFM International ↩↩
-
GE Aerospace Form 10-Q for the Quarter Ended March 31, 2026 — U.S. Securities and Exchange Commission, 2026-04 ↩
-
GE Aerospace Board of Directors Authorizes Quarterly Dividend — GE Aerospace, 2026 ↩
-
Boeing Extends Delay on Deliveries of First 777X Aircraft to 2027 — The National, 2025-10-29 ↩
-
Boeing 777X Hit by New GE9X Problem, But GE Delivers Major Update — Aviation A2Z, 2026-09-18 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube