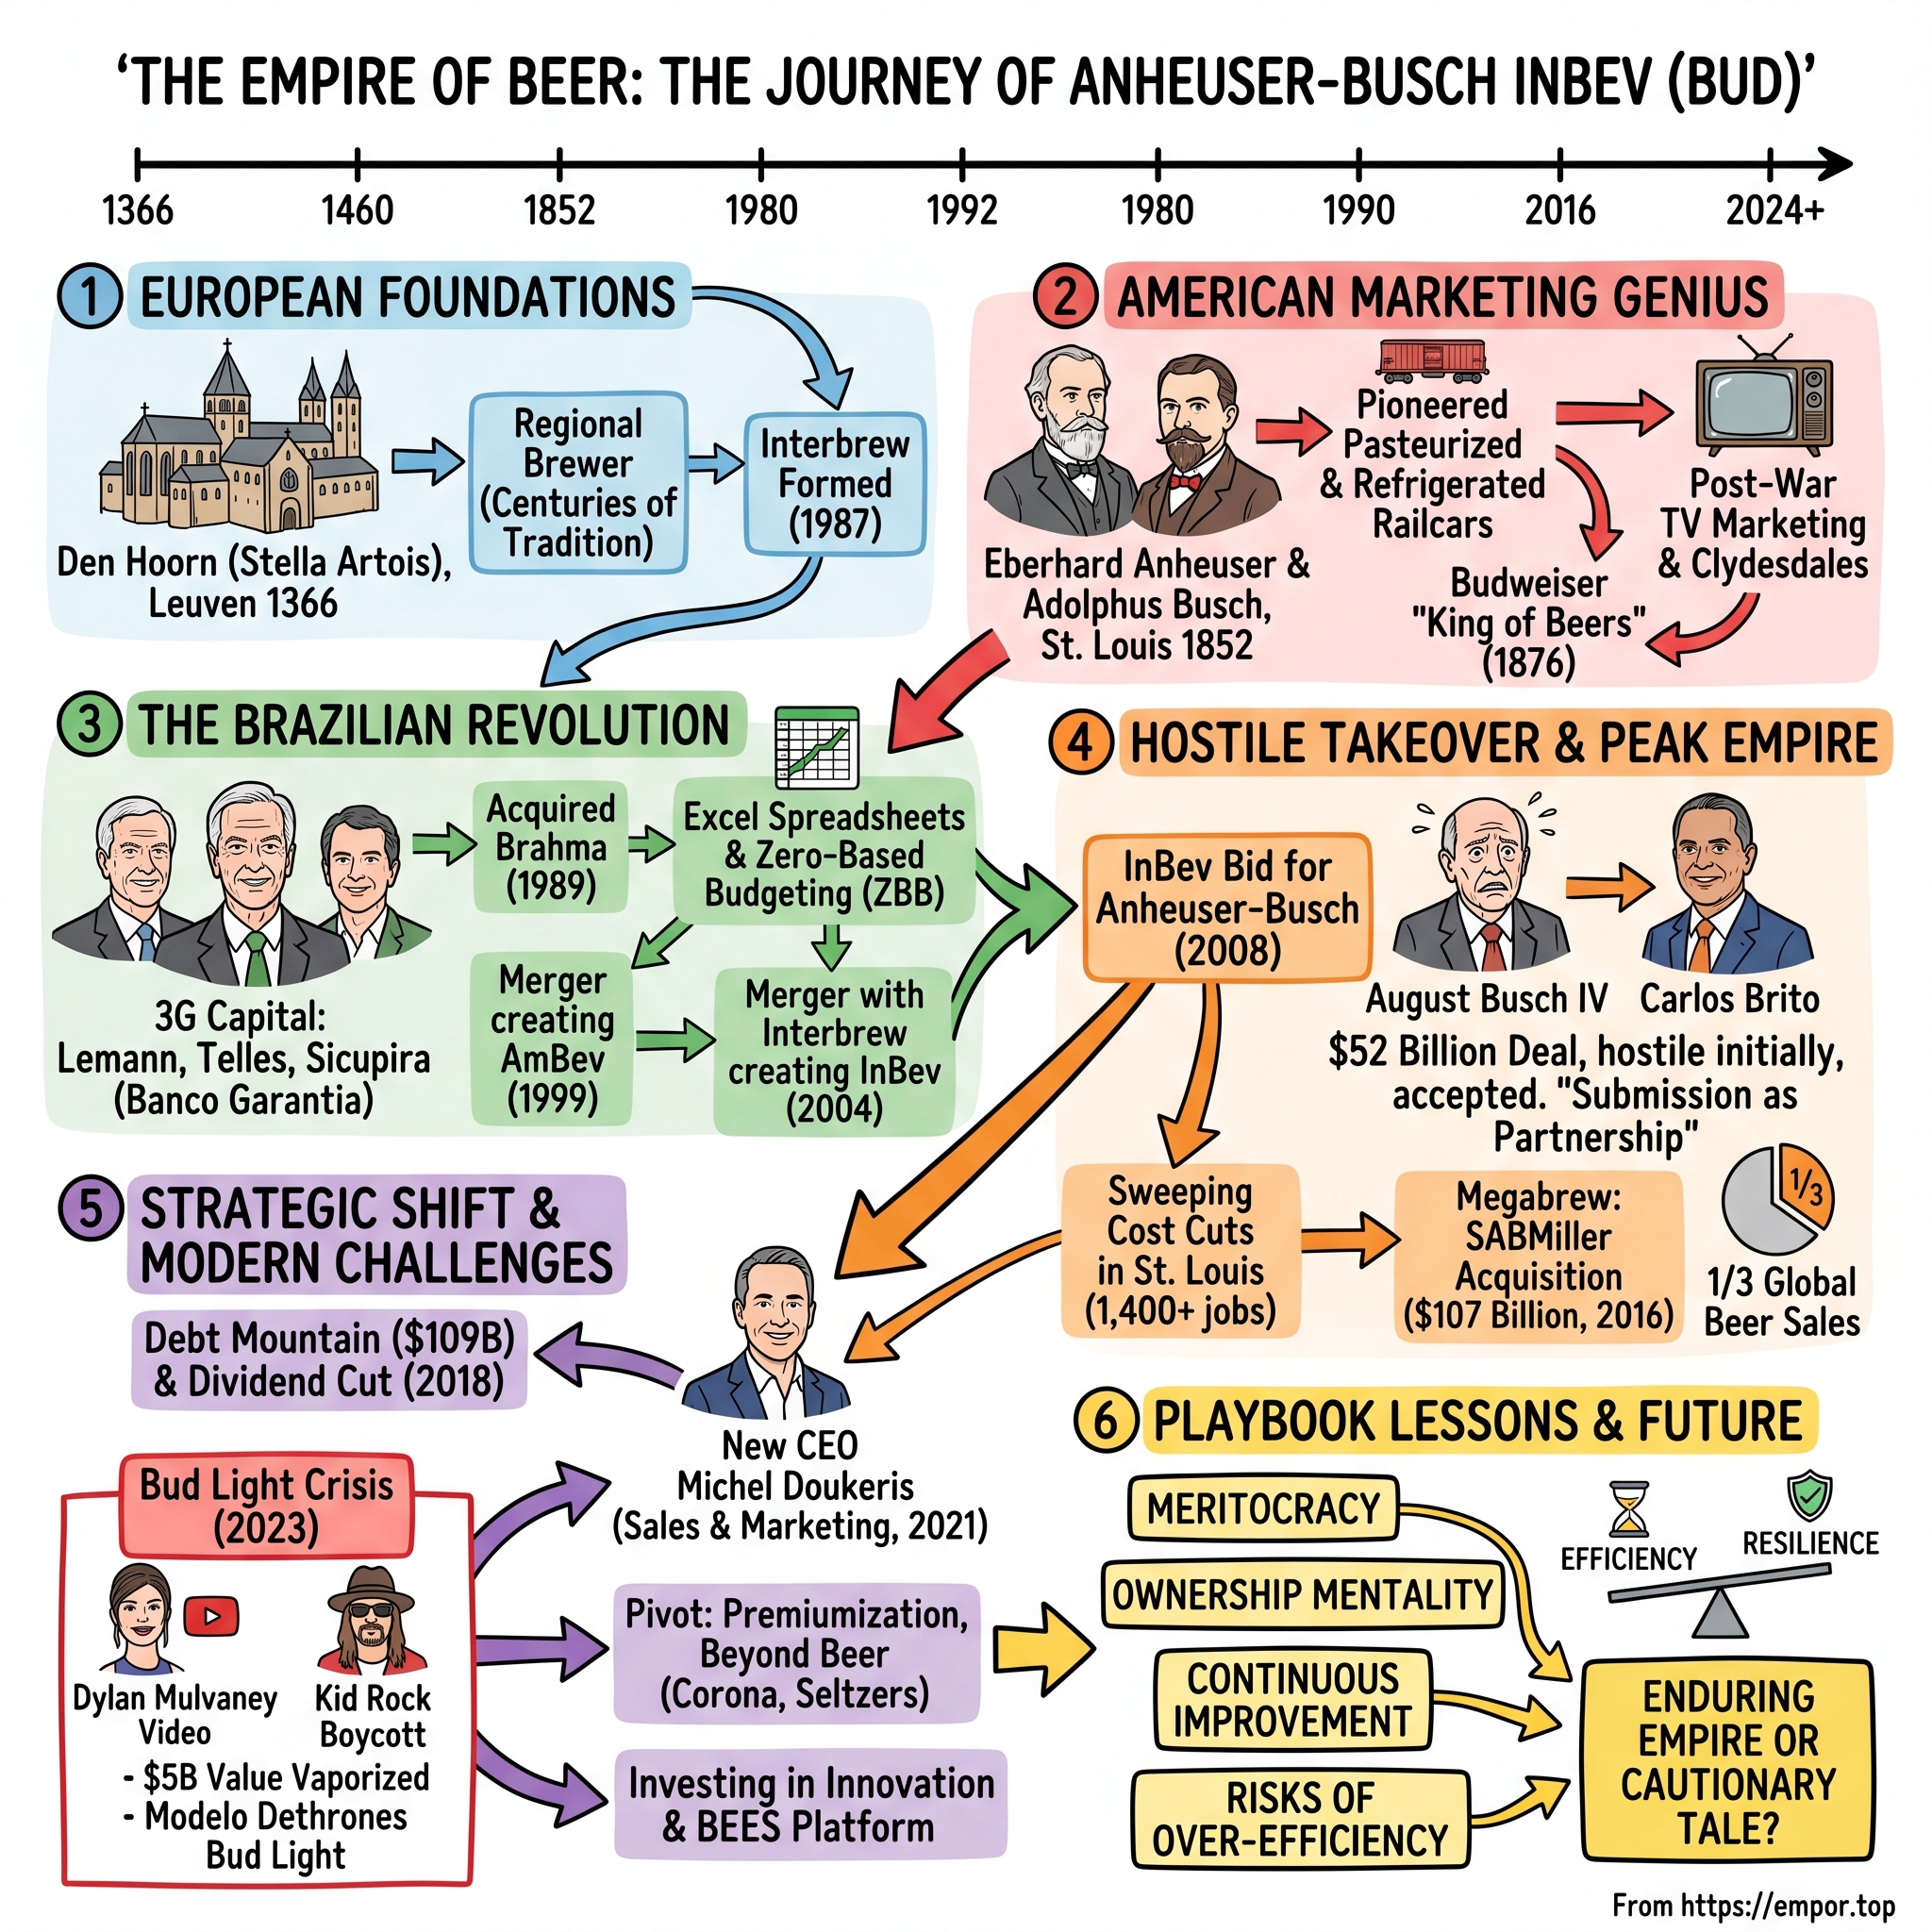
Anheuser-Busch InBev: The Empire of Beer
I. Introduction & Episode Roadmap
There is a stone cellar in Leuven, Belgium, where monks were brewing beer in 1366—before Gutenberg, before Columbus, and before Belgium existed as an independent nation. Six and a half centuries later, the corporate descendant of that cellar operates in roughly 30 markets on the BEES digital ordering platform alone, sells beer in more than 100 countries, and generates $59.3 billion in annual revenue.12 One in every four or five beers consumed globally carries one of its labels.
That origin story makes for compelling marketing, but on closer inspection, it is a misdirection. The Leuven monastery narrative is corporate mythology—a historical lineage attached to what is, in reality, a business built between 1989 and 2016 by three Brazilian investment bankers. They acquired a modest Rio de Janeiro brewery and spent twenty-seven years leveraging it into the largest consolidation campaign in consumer goods history. Anheuser-Busch InBev is not a 660-year-old brewer; it is a 37-year-old financial vehicle operating behind a 660-year-old heritage.
Understanding that distinction is central to evaluating the company.
The scale, stated plainly. In fiscal 2025, AB InBev reported 561.1 million hectoliters in beverage sales—the equivalent of roughly 75 billion bottles—generating $59.3 billion in revenue and $21.2 billion in normalized EBITDA.2 The portfolio spans more than 500 brands: Budweiser, Bud Light, Michelob Ultra, and Busch Light in the United States; Stella Artois and Leffe in Europe; Corona and Modelo in Mexico; Brahma, Skol, and Antarctica in Brazil; Harbin and Budweiser in China; Cass in South Korea; and Castle Lager across southern Africa. The physical infrastructure behind it—breweries, truck fleets, cold-chain depots, and direct sales relationships with millions of small retailers—is the core asset. The brand portfolio is the mechanism used to monetize that infrastructure.
The central argument of this story. AB InBev stands as both a primary case study in leveraged consolidation and operational austerity within consumer packaged goods, and a clear cautionary tale about the limits of that model. The aggressive discipline that expanded North American margins after 2008 also starved the core brands generating those returns. The debt-funded acquisitions that assembled a global oligopoly left a $108 billion net debt load at precisely the moment further major acquisitions became unviable. And a mass-market brand that long stood as America's top-selling beer proved vulnerable enough for a single social media campaign to erode two decades of market leadership in ninety days.
Today, in September 2026, the company is entering its third act. Net debt has dropped to 2.86 times EBITDA, down from a peak above 5.5 times.3 Volumes have returned to modest organic growth after years of decline.4 A B2B software platform little-known outside the industry five years ago now processes tens of billions of dollars in merchandise annually.2 Whether this platform represents a durable growth engine or merely smooths a structural decline in developed markets is the central question this analysis examines.
How the story unfolds: two founding traditions on two continents; the Brazilian transformation that swallowed both; the hostile acquisition of Anheuser-Busch; the cost-cutting model and its craft-beer misadventure; the $107 billion megadeal that marked the peak; the debt reckoning and dividend cut; the Bud Light repositioning fallout; the Doukeris pivot and the BEES platform; and finally, the segment economics, competitive dynamics, and current bull and bear cases.
It begins with two family-owned brewing traditions on separate continents, each unaware of the other's existence.
 Subscribe on LinkedIn
II. European & American Foundations: Two Worlds of Brewing (1366–1989)
Picture two rooms, four thousand miles apart.
The first is in Leuven, a Flemish university town, where in 1717 a master brewer named Sébastien Artois purchased the Den Hoorn brewery — "The Horn" — a business whose brewing activity in Leuven the company dates to 1366.12 Artois gave the brewery his name. Two centuries later, in 1926, his successors launched a pale lager for the Christmas season and called it Stella Artois: stella, the star of Bethlehem.12 What began as a seasonal beer became a permanent offering.
The second room is in St. Louis, Missouri, where in 1860 a German-born soap manufacturer named Eberhard Anheuser took control of the failing Bavarian Brewery he had been financing. Four years later, his daughter Lilly married a brewing-supplies salesman named Adolphus Busch, reshaping the American brewing industry.
The Belgian Line: Consolidation as Instinct
The Belgian tradition was never about a single dominant brand. Belgium was a small market with a high density of breweries — abbey ales, lambics, saisons, and pilsners — where commercial logic emphasized aggregation rather than single-brand dominance. The defining moment came in 1987, when Belgium's two major brewing dynasties, Brouwerij Artois of Leuven and Brasserie Piedbœuf of Jupille, merged to form Interbrew.12 It was a marriage of Flemish and Walloon capital that created a business with a limited home market and an mandate to expand abroad.
Interbrew's strategy for the next fifteen years was straightforward: acquire national champions in foreign markets, preserve their local brands, and layer Stella Artois on top as a premium import. It acquired Labatt in Canada in 1995, followed by Whitbread's brewing operations in the United Kingdom. Adding Rolling Rock, Bass, Beck's, Oranjeboom, and breweries across Eastern Europe and South Korea, Interbrew accumulated an international brand portfolio rather than a single corporate identity.
This strategy established a distinct corporate culture: Interbrew managed beer brands as financial assets on a spreadsheet. Unburdened by sentimental attachments to individual labels, the company prioritized disciplined capital allocation — an orientation that would shape the industry's eventual consolidation.
The American Line: Beer as Civic Religion
Adolphus Busch operated on an entirely different premise. He sought a single brand sold nationwide, building the industrial infrastructure to make that physically possible. In the 1870s, he introduced three connected innovations: pasteurization so the beer survived transport, refrigerated railcars for summer shipment, and a network of rail-side icehouses stretching across the country. In 1876, working with St. Louis restaurateur Carl Conrad, he launched a pale, light-bodied, highly carbonated pilsner modeled on the beer of the Czech town of Budweis. Budweiser was engineered to be shippable12, consistent, and broadly palatable — designed for a national distribution system that Busch was simultaneously constructing.
The result was America's first nationwide consumer brand, establishing a distribution footprint that predated Coca-Cola's national reach. During Prohibition, the family business survived by selling yeast, ice cream, truck bodies, and non-alcoholic malt. After repeal, August A. Busch Jr. — "Gussie," who purchased the St. Louis Cardinals in 1953 and drove Clydesdale hitches through American stadiums — turned Anheuser-Busch into a cultural institution. His son August Busch III later pushed the company past 50% U.S. market share by the 1990s through a combination of massive brewery scale, the 1982 launch of Bud Light, saturation sports sponsorship, and a fiercely loyal network of independent wholesalers.
The Divergence That Set Up Everything
By the late 1980s, these two traditions had produced fundamentally different corporate organisms.
Anheuser-Busch functioned as a single-market fortress: dominant domestic share, a protected marketing budget, corporate aircraft, a theme-park division, a bird sanctuary, and family leadership that viewed the brewery as a civic trust. It was highly profitable, but operationally comfortable.
Interbrew functioned as a portfolio: operations across multiple countries, mid-single-digit market shares in most, minimal emotional attachment to specific brands, and an institutional habit of buying rather than building.
While both models succeeded in their respective environments, Anheuser-Busch's high cost structure and reliance on a single market left it structurally vulnerable to an outsider focused on financial discipline. In 1989, four thousand miles south of St. Louis, three Brazilian investors acquired their first brewery.
III. The Brazilian Revolution: 3G Capital & The AmBev Machine (1989–2004)
That acquisition in Rio de Janeiro marked the beginning of an operational transformation that reshaped the global brewing industry, led by a former national tennis champion turned investment banker.
Three Men and a Bank
Jorge Paulo Lemann played at Wimbledon, studied economics at Harvard, and in 1971 acquired control of Garantia, a small Rio de Janeiro brokerage. He built it explicitly on the Goldman Sachs partnership model: recruit young talent, pay modest base salaries, grant substantial equity to top performers, and systematically phase out the bottom decile each year. He brought in Carlos Alberto Sicupira, an aggressive operator, and Marcel Telles, a trader who would later oversee the group's brewing operations. Garantia quickly grew into one of the most formidable institutions in Brazilian finance.
Their initial operating test came at Lojas Americanas, a struggling retail chain Sicupira assumed control of in 1982. He restructured the business using zero-based budgeting, a management technique borrowed from American consultants and executed with unprecedented rigor.
1989: Buying Brahma
In 1989, the trio paid roughly $60 million for Companhia Cervejaria Brahma, Brazil's second-largest brewer. At the time, Brazil was experiencing severe macroeconomic instability: inflation ran in the hundreds and eventually thousands of percent annually, the national currency was repeatedly renamed, and price controls shifted constantly. Managing a capital-intensive, high-fixed-cost, low-margin business under those conditions required extreme operational discipline.
It also served as an effective testing ground. Operating where input costs repriced weekly forced management to control cost per hectoliter with extreme precision. Telles took operational control of Brahma and imported Garantia’s corporate culture: open-plan offices, no private suites, coach travel for executives, compensation dominated by variable performance bonuses tied to ambitious targets, and mandatory exits for underperformers. He also shifted recruiting toward engineering schools rather than business schools. Among those hires was Carlos Brito, a young mechanical engineer whom Telles sent to Stanford for an MBA on the condition that he return to the firm—which he did.
The Operating System, Explained Simply
Zero-based budgeting is straightforward in concept yet radical in execution. In a conventional corporate environment, a department's annual budget begins with the prior year's baseline, with discussions focused on incremental adjustments. Under zero-based budgeting, every line item resets to zero each fiscal year, requiring managers to justify every expense from scratch as if establishing the department anew. When paired with designated "cost owners"—executives globally accountable for specific expense categories, such as aluminum procurement or IT systems—the process systematically strips out structural overhead.
Complementing this budgeting mechanism was a variable compensation model aligning manager incentives with equity owners, alongside a corporate framework Lemann summarized as "dream, people, culture": set expansive long-term targets, recruit high-performing talent, and let meritocratic accountability maintain standards.
Analytically, three characteristics define this operating model. First, it reliably reduces operating costs across corporate sectors. Second, it functions primarily as an efficiency engine rather than a growth engine, converting existing cost waste into cash flow without inherently generating new consumer demand. Third, it relies on a steady pipeline of acquisitions. Without new targets to streamline, cost reduction eventually reaches structural limits. The strategic decisions that followed in AB InBev's history stemmed directly from these operational dynamics.
1999: Creating AmBev
At the end of the 1990s, Brahma merged with its longtime competitor, Companhia Antarctica Paulista, to form AmBev12—Companhia de Bebidas das Américas. Brazil's competition authority, CADE, approved the transaction with conditions, creating an entity that controlled roughly two-thirds of the Brazilian beer market alongside a major regional Pepsi bottling franchise.
How AmBev leveraged that dominant market position defined its long-term strategy. Rather than relying solely on price increases, the company overhauled its distribution network. Brazil's retail market was fragmented across hundreds of thousands of small independent bars and corner shops purchasing limited inventory per order. AmBev bypassed third-party wholesalers, investing heavily in a direct route-to-market model using its own distribution fleets and sales teams. That capital investment built the high-density distribution network that continues to underpin the company's highest-margin operations and ultimately laid the foundation for the BEES digital platform.
2004: The Reverse Takeover Nobody Understood at the Time
In March 2004, Interbrew announced a combination with AmBev valued at roughly $11 billion12. Structurally, the transaction appeared to be an acquisition of the Brazilian brewer by the Belgian company: Interbrew took majority control of AmBev, the Belgian founding families retained the largest voting block, and the merged entity was renamed InBev, headquartered in Leuven.
In practice, AmBev's management team gained operational control. Within a year, the corporate integration was well underway, and by December 2005, Carlos Brito—the Brazilian engineer who had run AmBev's North American operations—was appointed CEO of InBev. While the Belgian families held the equity control, the Brazilian executives directed operating policy.
The transaction operated as an effective management takeover. It established a global platform: InBev combined a premium European brand portfolio, an emerging-market cash generator, an investment-grade balance sheet, and a management team built for rapid integration. The consolidated company possessed an operating machine that required a larger acquisition target to sustain its expansion strategy.
There was only one candidate of sufficient scale.
IV. The Hostile Takeover: InBev Conquers St. Louis (2008)
On June 12, 2008, Carlos Brito sent an unsolicited proposal to Anheuser-Busch's headquarters on Pestalozzi Street in St. Louis. InBev offered $65 per share in cash—totaling roughly $46 billion—for a company controlled by the Busch family for 148 years.
Why the Fortress Was Vulnerable
Despite its historic dominance, Anheuser-Busch entered 2008 with structural vulnerabilities. Domestic sales volumes were flat to declining as consumer preferences shifted toward imported beers, craft brews, wine, and spirits. The company's share price had stagnated for nearly a decade, burdened by a cost structure built over generations of market leadership, including corporate aircraft, extensive real estate holdings, a theme-park division, and a marketing budget managed without aggressive cost constraints.
Governance challenges compounded these commercial headwinds. August Busch III had passed executive leadership to his son, August Busch IV, in 2006. The younger Busch faced a divided board that included his father. When InBev made its proposal, Anheuser-Busch lacked both a convincing standalone turnaround strategy and a white-knight bidder capable of matching an all-cash offer. A proposed defensive combination with Grupo Modelo, in which Anheuser-Busch already held a 50% stake, failed to materialize.
The Backlash and the Capitulation
The bid prompted immediate local and political resistance across Missouri, featuring community rallies, state legislative resolutions, public opposition from the governor, and litigation intended to block the transaction. For St. Louis, Anheuser-Busch represented a cornerstone civic institution as much as a major regional employer.
Despite public pushback, financial realities prevailed. InBev increased its bid to $70 per share, valuing the company at approximately $52 billion, and the board accepted the offer on July 13, 2008.20 Shareholders approved the transaction on November 12, 2008, and the deal closed later that month20—coinciding with the severe tightening of credit markets following the collapse of Lehman Brothers. Syndicating roughly $45 billion in debt during a global financial crisis demonstrated exceptional execution by InBev's deal team and established an operational template for the merged firm: a willingness to operate with higher financial leverage than industry peers.
Brito assumed the role of CEO of the newly formed Anheuser-Busch InBev.
The Playbook Lands in Missouri
The post-merger integration in St. Louis rapidly applied the cost-reduction framework developed in South America. The company eliminated approximately 1,400 U.S. positions, primarily at corporate headquarters, divested the corporate jet fleet, curtailed traditional employee perks, restricted administrative spending, and reassigned executive private offices to open floor plans. Management also extended supplier payment terms from 30 days to 120 days, effectively converting supply-chain liabilities into non-interest working capital. In 2009, AB InBev sold the theme-park division to Blackstone for approximately $2.7 billion to accelerate debt repayment.
The financial impact was immediate. North American EBITDA margins expanded from the high-20% range into the 40% range within a few years, allowing the company to pay down acquisition debt ahead of schedule and drive a re-rating of its equity valuation. For several years, market analysts cited AB InBev as a benchmark for operational efficiency in consumer packaged goods.
Testing the Claim: Does ZBB Harm the Franchise?
Evaluating the long-term impact of zero-based budgeting requires examining the trade-offs behind these margin gains. While the model succeeded in extracting structural waste, evidence from 2008 through the mid-2010s highlights clear operational constraints.
First, extending supplier payment terms to 120 days functioned primarily as a working-capital transfer from vendors to AB InBev's balance sheet rather than a true efficiency gain, creating friction with packaging, agricultural, and logistics partners. Second, while market shifts toward craft beer and changing consumer demographics contributed to Budweiser's declining U.S. volumes, sustained marketing efficiency targets coincided with a fifteen-year loss of market share for the core brand. Third, because the U.S. three-tier distribution system prevented AB InBev from owning its direct routes to market, aggressive redesigns of distributor incentive programs strained relationships with independent wholesalers.
These dynamics delineate the scope of the 3G operational model. Zero-based budgeting proved highly effective as a post-merger integration tool for bloated corporate targets, establishing durable margin expansion in St. Louis. However, its focus on expense reduction offered limited capacity to drive top-line volume growth or generate organic consumer demand. With its North American integration complete, balance sheet leverage reduced, and operating cash flow restored, AB InBev began seeking its next major consolidation target.
V. The Cost-Cutting Machine & Craft Roll-Up Era (2008–2015)
Between 2008 and 2015, AB InBev operated under a recurring cycle: cut costs, generate cash, repay debt, restore balance sheet capacity, acquire, and repeat. For management, deleveraging was never the ultimate goal; it was the mechanism to reload for the next transaction.
Grupo Modelo: Buying Back the Family Silver
Anheuser-Busch had held roughly half of Mexico's Grupo Modelo since the 1990s—a passive, non-controlling stake that yielded steady dividends but offered limited operational control. In 2012, AB InBev agreed to acquire the remaining 50% for approximately $20.1 billion5, securing full ownership of Corona, Modelo Especial, Pacifico, and Mexico's dominant brewing franchise.
The Mexican market represented a key strategic asset. Operating as a structural duopoly alongside Heineken's local business, Mexico combined rising per-capita beer consumption with a route-to-market anchored by company-controlled retail outlets. Consequently, Middle Americas has consistently served as the group's highest-margin large region.2
The Consent Decree That Created a Monster
The U.S. Department of Justice moved to block the Modelo transaction on January 31, 2013, alleging that the deal would substantially lessen competition nationwide and across at least 26 metropolitan areas.5 To resolve the antitrust suit, AB InBev divested Modelo's entire U.S. business to Constellation Brands in a transaction valued at approximately $5.3 billion.5 The regulatory settlement granted Constellation perpetual U.S. rights to Corona, Modelo Especial, and Pacifico, alongside Modelo's interest in the Crown Imports joint venture and the state-of-the-art Piedras Negras brewery, which Constellation agreed to expand.
The long-term commercial consequences of that divestiture proved severe for AB InBev. In securing global rights to Modelo, the company was forced to surrender perpetual control of its fastest-growing U.S. product lines to a mid-cap competitor. Over the subsequent decade, Modelo Especial expanded at double-digit annual volume rates, driven by demographic growth among Hispanic consumers and broader mainstream adoption, turning Constellation's beer division into one of the top-performing assets in U.S. consumer goods. When Bud Light experienced a dramatic market decline in 2023, the brand that replaced it as America's top-selling beer was the exact asset AB InBev had been legally compelled to sell.
This outcome illustrates a broader dynamic in corporate consolidation: the remedy assets regulators require companies to divest are rarely incidental. They represent the precise assets antitrust authorities identify as most competitively dynamic, effectively creating a formidable direct rival.
The High End: Buying Craft
Simultaneously, the U.S. beer market was fragmenting. Independent craft breweries were capturing share at the premium end of the category as consumer preferences expanded from light lagers toward hoppy, localized, and flavor-forward styles.
AB InBev responded with a targeted acquisition strategy. The effort began in 2011 with the purchase of Chicago-based Goose Island for roughly $39 million. Over the next six years, the company acquired a portfolio of regional craft brewers—including Blue Point, Elysian, 10 Barrel, Golden Road, Breckenridge, Devils Backbone, Four Peaks, Karbach, and Wicked Weed—organizing them under a dedicated "High End" business unit managed separately from its mainstream lager operations. The commercial logic appeared straightforward: acquire authentic regional brands and scale them through AB InBev's expansive national distribution system.
Testing the Claim: Can Scale Distribution Carry Craft?
Empirical results ultimately disproved the thesis that distribution scale alone could sustain acquired craft brands.
The acquisitions generated immediate friction within the craft brewing community. The Brewers Association updated its official definition of a "craft brewer" specifically to exclude breweries owned by major beverage conglomerates, while a subset of core consumers viewed corporate ownership as disqualifying. Following Wicked Weed's acquisition in 2017, several independent craft partners publicly canceled collaborative brewing projects. At a structural level, the value proposition of an independent craft brand rested on local scarcity and authenticity—qualities fundamentally at odds with an acquirer whose core strength was national ubiquity.
The financial outcome was finalized in August 2023, when Anheuser-Busch sold eight beverage brands—including Shock Top, Breckenridge, Blue Point, 10 Barrel, Redhook, Widmer Brothers, Square Mile Cider, and HiBall—to Tilray Brands.[^13] The reported purchase price of approximately $85 million[^13] represented a steep discount relative to the cumulative capital deployed to acquire and build those assets.
Analytically, the craft roll-up demonstrated clear limits to the 3G operational playbook. While AB InBev proved remarkably effective at extracting structural costs from mature, capital-intensive brewing operations, it struggled to preserve brand equity in niche segments where consumer appeal depended on independence. That track record provides relevant context for evaluating the company's current "Beyond Beer" portfolio—such as Cutwater, NÜTRL, and BeatBox—where long-term valuation depends on sustaining organic growth years after acquisition rather than relying solely on initial distribution gains.
By 2015, however, craft beer represented a secondary strategic concern for executive leadership in Leuven. The operational machine required another major consolidation target to maintain its acquisition-driven model, and only one global competitor remained of sufficient scale.
VI. Peak Empire: The $107B SABMiller Megabrew (2015–2016)
In September 2015, a London law firm filed a brief announcement under the UK Takeover Code: SABMiller plc confirmed it had been approached regarding a potential offer. The market recognized the implications immediately: the two largest brewers on Earth were moving to combine.
The Logic and the Prize
SABMiller was the strategic counterweight to AB InBev. Founded in 1895 as South African Breweries to serve miners on the Witwatersrand, the company spent a century assembling an extensive emerging-market footprint. Its holdings included dominant positions across sub-Saharan Africa, a substantial Latin American business acquired through Colombia's Bavaria, Central European assets, operations in Australia and India, and a 49% stake in China Resources Snow Breweries, producer of the world's highest-volume beer brand.
AB InBev's primary objective was Africa. The continent offered favorable demographics—a young, rapidly urbanizing population—and per-capita beer consumption well below global averages in markets where SABMiller frequently controlled over 50% market share. Africa represented the category's last major long-term growth region, and competing organically against an incumbent with a century-long head start was impractical.
After several rejected proposals, AB InBev secured an agreement at £44 per share in cash, valuing SABMiller at approximately $107 billion—at the time one of the largest corporate acquisitions in history.7 The transaction closed in October 2016, creating a consolidated entity that produced roughly one out of every three beers consumed globally.
The Price of Permission
Regulators across major jurisdictions required substantial structural divestitures before approving the deal.
In the United States, the Department of Justice required AB InBev to divest SABMiller's entire U.S. footprint—including its 58% stake in the MillerCoors joint venture and the global Miller brand portfolio—to Molson Coors for approximately $12 billion.[^6] The consent decree extended beyond asset sales: it capped the proportion of U.S. volume AB InBev could sell through company-owned distributors and prohibited wholesaler incentive programs designed to curtail the distribution of rival craft brands—a direct regulatory intervention targeting distribution practices developed since 2008. The Justice Department modified and extended these decree obligations in 2018, signaling that antitrust authorities viewed ongoing oversight as necessary.6
In China, AB InBev sold SABMiller's 49% stake in Snow Breweries to China Resources Beer. In Europe, it divested premium brands Peroni, Grolsch, and Pilsner Urquell to Japan's Asahi Group Holdings, later selling SABMiller's remaining Central and Eastern European assets to Asahi in transactions totaling roughly $11 billion.
In total, AB InBev deployed $107 billion to acquire SABMiller and immediately divested approximately $25 billion in assets to satisfy regulatory mandates. The remaining operations provided dominant positions in Africa, Latin America, and Australia while eliminating the company's only global peer of comparable scale.
The Debt Tower
Funding the acquisition required unprecedented debt issuance. AB InBev secured a $75 billion committed credit facility and executed a record $46 billion corporate bond offering in January 2016. By the time the transaction closed, net debt exceeded $108 billion, pushing financial leverage above 5.5 times normalized EBITDA—a debt ratio typical of a private equity leveraged buyout rather than an investment-grade consumer goods enterprise.
The Analytical Reading
The strategic thesis in 2016 rested on three premises: AB InBev had secured an unparalleled emerging-market asset base, management could extract substantial cost savings from SABMiller's overhead structure, and strong cash generation would allow the company to deleverage within three to four years, repeating its post-2008 playbook.
The first two premises proved sound: the African and Latin American franchises remained high-quality, long-duration assets, and management successfully delivered targeted cost synergies. However, the critical deleveraging assumption relied on two vulnerable forecasts: that developed-market sales volumes would remain stable and that emerging-market currencies would hold their value. Neither condition materialized. The Brazilian real, South African rand, Colombian peso, Argentine peso, and Nigerian naira depreciated significantly against the U.S. dollar—the currency in which the bulk of the debt was denominated—while beer volumes in North America and Western Europe continued a steady structural decline.
This dynamic exposed a structural vulnerability in AB InBev's financial model: generating operating cash flows in volatile emerging-market currencies while servicing debt fixed in hard currencies. While transactional currency risk can be managed through financial hedges, translation risk at this scale cannot be effectively hedged over long periods. Roughly $60 billion in net debt today still rests on top of that currency mismatch.2
By early 2017, AB InBev stood as the largest brewing enterprise in history. Yet within eighteen months, the weight of its debt service obligations would force management to cut the dividend in half.
VII. The Turning Point: Debt Crises, Dividend Cuts & Kraft Heinz Parallels (2017–2021)
On October 25, 2018, AB InBev released third-quarter financial results alongside an announcement that its board had decided to reduce the dividend by 50%. The company's shares fell roughly 10% in a single trading session and stood approximately one-third below their post-SABMiller high. For an enterprise that had spent a decade assuring investors that its operational cash flows could sustain high financial leverage, the dividend reduction signaled a fundamental shift in strategy.8
The Machine Ran Out of Fuel
The strategic constraint was mathematical. The 3G operational model depended on a repeating cycle: acquire a large, cost-heavy competitor, extract structural overhead, deploy cash flows to reduce debt, and execute the next acquisition. After the SABMiller transaction, potential major targets were virtually non-existent. Peer global brewers such as Heineken and Carlsberg were insulated by foundation control structures and faced insurmountable antitrust barriers. Meanwhile, regional competitors like Molson Coors and Constellation Brands existed in their expanded forms precisely because regulatory authorities had built them out of AB InBev's required divestitures. The consolidation campaign had reached an absolute regulatory boundary.
This boundary left AB InBev carrying a debt load structured for a serial acquirer, supported by an operating framework built for cost extraction rather than organic volume generation. Concurrently, core developed-market franchises—specifically mainstream light lagers in North America and Western Europe—faced structural volume headwinds as consumer preferences shifted toward spirits, wine, flavored malt beverages, and non-alcoholic options.
The Credit Squeeze
Credit rating agencies responded quickly. Moody's and S&P downgraded AB InBev to the Baa1/BBB+ tier with negative outlooks—just two notches above high-yield status. Although the rating subsequently stabilized in the BBB+ range15, debt markets priced the paper to reflect heightened risk. With gross debt exceeding $100 billion, a further downgrade to high-yield status would have triggered mandatory selling across institutional bond holders.
The 50% dividend reduction was a mandatory defense of investment-grade credit ratings, preserving approximately $4 billion in annual cash flow for debt paydown. The move highlighted a critical structural reality: the company had levered its balance sheet against cash-flow projections vulnerable to foreign exchange fluctuations and volume declines, leaving equity holders to absorb the capital structure adjustment.
The Kraft Heinz Mirror
The limitations of the cost-cutting framework became broader market consensus four months later. In February 2019, 3G-backed Kraft Heinz announced a $15.4 billion write-down of its Kraft and Oscar Mayer brand assets, reduced its dividend, and disclosed an SEC investigation into procurement accounting practices.9 Market analysts viewed the development as evidence that aggressive cost reduction could erode brand equity and long-term asset value faster than balance-sheet write-downs reflected.
The implications for AB InBev were clear. The company carried massive goodwill and intangible asset balances from its acquisitions of Anheuser-Busch, Grupo Modelo, and SABMiller while applying similar efficiency programs across mature brand portfolios. Carrying value judgments on those intangible assets depended on long-term volume growth and discount rate assumptions—both of which faced deteriorating market conditions.
Selling the Furniture
Deleveraging became executive leadership's sole operational priority. In 2019, AB InBev agreed to sell its Australian business, Carlton & United Breweries, to Asahi Group Holdings for approximately $11.3 billion—capitalizing on a high valuation multiple for a mature market.
A companion asset sale proved more complex. In July 2019, AB InBev withdrew a planned initial public offering of its Asia-Pacific subsidiary in Hong Kong after institutional investors rejected the targeted valuation. Management restructured the transaction two months later, floating Budweiser Brewing Company APAC Limited (百威亚太) on the Hong Kong Stock Exchange under ticker 1876 for approximately $5.7 billion.13 The delayed, downsized listing underscored the capital market pressure facing the parent company.
The Succession
In April 2021, AB InBev announced that Carlos Brito would step down after fifteen years as chief executive officer, succeeded on July 1, 2021, by Michel Doukeris.10
Doukeris offered a distinct professional background compared to his predecessor. A chemical engineer by training, he joined AmBev in 1996 as a sales trainee and built his career across commercial and strategy roles: serving as sales director in Brazil, leading the China zone from 2010 to 2016—where he developed Budweiser into a leading premium brand—and subsequently running the North America zone from 2018. He was also instrumental in designing and launching the BEES digital platform.
The leadership change reflected a strategic pivot. For over a decade, AB InBev had been directed by an executive focused primarily on operational integration and cost engineering. Under Doukeris, leadership shifted to a commercial strategist. The central question for investors became whether an organization structured around expense discipline for thirty years could generate organic top-line growth—and whether commercial innovation could replace acquisition-led expansion.
Doukeris had less than two years to execute this strategy before a major brand crisis in North America tested the company's resilience.
VIII. The Bud Light Crisis: Culture Wars & Distribution Squeeze (2023–2024)
On April 1, 2023, a transgender social-media personality named Dylan Mulvaney posted a sponsored Instagram video holding a personalized can of Bud Light, promoting a March Madness contest. The activation was small — a single influencer post, commissioned cans not sold at retail, and a marketing expenditure that would not have registered on any internal executive report.
Within ten days, it had become the most expensive Instagram post in corporate history.
The Mechanics of the Collapse
The backlash moved through conservative media and social platforms with unusual velocity. High-profile musicians filmed themselves destroying cases, and boycott calls spread through channels reaching Bud Light's core demographic: working-class, male, disproportionately rural and southern American drinkers.
What made this crisis different from a typical week-long brand controversy was the underlying product. Bud Light's core proposition was never taste, provenance, or performance. It was a light American lager, competently produced and virtually indistinguishable from several alternatives sitting on the same shelf at the same price point. Its primary differentiation was identity — signaling a specific vision of ordinary American life. When the brand was recoded as signaling the opposite, the switching cost for consumers dropped to zero: a buyer could simply reach eight inches to the left for a Coors Light or a Modelo.
Sales declines surpassed 20% year-over-year within weeks and deepened through the summer. In May 2023, Modelo Especial — the brand AB InBev had been legally compelled to sell to Constellation a decade earlier — overtook Bud Light as the top-selling beer in the United States by retail dollars, ending a leadership streak dating back to 2001.11 For full-year 2023, North American organic revenue fell sharply, and zone EBITDA contracted by roughly a quarter.
The Response, and Why It Failed
Management's handling of the episode highlighted broader governance challenges beyond mere communications strategy.
The company's initial corporate statement was so heavily hedged that it committed to no clear stance, offering only an acknowledgment that the business never intended to be part of a divisive public debate. Two marketing executives were placed on leave, while executive leadership released a video highlighting American manufacturing, military veterans, and traditional sports sponsorships. At no point did the company explicitly defend the campaign or repudiate it.
Consequently, the response alienated both sides: boycotting consumers remained unappeased, while LGBTQ+ advocacy groups criticized the company for failing to support a campaign partner under pressure, leading the Human Rights Campaign to suspend AB InBev's corporate equality rating. The company effectively turned a single-constituency crisis into a two-constituency conflict. On subsequent earnings calls, management routinely framed the downturn as an isolated U.S. consumer challenge while emphasizing international share gains — a factually accurate framing that nevertheless avoided addressing internal decision-making accountability.
The Wholesaler Problem Nobody Outside the Industry Saw
The most consequential structural damage occurred within the distribution network. Under the post-Prohibition three-tier system, AB InBev cannot distribute directly to most U.S. retailers. Instead, it relies on independent wholesalers that hold exclusive territorial rights, manage their own logistics, and depend on Bud Light for a major share of their volume and profits.
Those independent distributors absorbed the financial shock directly. To stabilize a network it does not own but entirely relies upon, AB InBev deployed hundreds of millions of dollars in financial support, including expanded marketing funds, inventory buybacks of expired beer, and direct assistance payments. Many distributors were ultimately forced to reduce headcount.
This dynamic illustrates a key structural vulnerability in the company's U.S. operating model. In markets such as Brazil or Mexico, a demand shock is absorbed directly within AB InBev's consolidated balance sheet. In the United States, that shock falls on third-party partners whose relationship is commercial rather than corporate — and whose operational commitment directly determines shelf space, cold-box placement, and sales velocity for the rest of the company's brand portfolio.
Testing the Claim: Do Mega-Lager Brands Have Moats?
The assumption that mass-market beer brands possess deep consumer switching costs and durable brand equity was fundamentally challenged by this episode.
The empirical evidence was swift, substantial, and specific to the flagship brand: an asset built over forty years with tens of billions of dollars in cumulative advertising lost roughly a third of its volume in less than a year following a single low-budget influencer post, and by mid-2026 had still not recovered to its prior baseline. Rather than funding a long-term recovery for Bud Light, AB InBev reallocated capital across its portfolio: in the first seven months of 2026, Bud Light's U.S. media spending fell roughly 14% year-over-year to $44 million, while media spending for Michelob Ultra rose about 38% to $114 million.
The narrower, more durable insight for investors lies in where brand power actually resides in the beer industry. Competitive advantage exists primarily at the category level, the consumption occasion, and within distribution scale — not in permanent consumer attachment to a single mainstream label. AB InBev's core advantage is its ability to supply whichever light lager captures market demand. This structural dynamic was demonstrated during the reallocation of market share, as defecting Bud Light volume shifted heavily toward stablemates Michelob Ultra and Busch Light, driving Michelob Ultra to become the top-selling beer brand in the United States by volume by 2025.2
However, this represents a more constrained economic moat than an unassailable single-brand franchise, serving as a reminder that the portfolio mobility supporting Michelob Ultra's rise could eventually operate in reverse. The critical benchmark for evaluating this thesis is total U.S. alcohol market share rather than single-brand volume trajectories. If AB InBev maintains or expands aggregate category share while individual brands rotate, the portfolio model holds; if aggregate share declines, the underlying moat is deteriorating.
That aggregate market-share metric became the primary operational focus for the incoming management team.
IX. Modern Era & Strategic Evolution: Michel Doukeris, BEES & Premiumization (2021–Present)
In small groceries across São Paulo, Bogotá, and Johannesburg, the process of reordering beer no longer relies on sales representatives, phone calls, or paper invoices. Instead, shop owners open a mobile application, view personalized pricing and recommendations, place orders for next-day delivery, track loyalty balances, and add non-beer products—from soft drinks to cleaning supplies—manufactured by third parties.
The platform driving this shift, known as BEES, represents a major digital route-to-market transformation for an enterprise historically reliant on physical distribution fleets.
The Managers
As chief executive, Michel Doukeris has shifted AB InBev's operational focus from pure cost extraction toward volume growth, revenue per hectoliter, and overall alcohol category share. Management has organized this strategy around three core pillars: lead and grow the category, digitize and monetize the ecosystem, and optimize the business.2
Chief Financial Officer Fernando Tennenbaum, appointed in 2020, inherited the substantial debt load from the SABMiller acquisition and has executed a systematic liability-management program—repurchasing and redeeming debt ahead of maturity, extending the maturity profile, and maintaining the average gross coupon near 4%.2 In fiscal 2025, the company repurchased or redeemed $6 billion of bonds while issuing €3.2 billion.2
Executive compensation has similarly shifted away from strictly operating margin targets toward top-line growth, cash conversion, and deleveraging. While this realigns management incentives with organic performance, shifting metrics toward growth after a decade of cost reduction can also encourage a renewed appetite for acquisition-led expansion.
A Correction to the Governance Story
A common misconception in corporate governance discussions is that 3G Capital completely exited AB InBev. In reality, 3G Capital as a private equity buyout firm—the entity behind investments in Burger King and Kraft Heinz—is distinct from the founders' private equity holdings. Those personal stakes are maintained through BRC, an entity that owns half of Stichting AK, a Dutch foundation whose combined structure holds roughly a third of AB InBev's shares.19 In December 2023, co-founder Marcel Telles transferred his equity interest—valued at approximately $6.1 billion—to his son Max, who assumed joint ultimate control of BRC alongside Jorge Paulo Lemann and Carlos Alberto Sicupira.19 This transfer reflected generational estate planning rather than an institutional divestment.
The practical implications for corporate governance are significant. AB InBev remains a controlled company: the restricted shareholder group, operating alongside the Belgian founding families, elects a majority of the board and maintains effective voting control at general meetings. Consequently, public minority shareholders, including holders of New York Stock Exchange-listed American Depositary Shares, exercise limited influence over strategic decisions. While this structure insulates management from short-term market pressures, it also removes standard accountability mechanisms, preventing activist investors from forcing capital reallocation or structural breakups.
Compounding this governance dynamic is an ongoing equity supply overhang. Altria, which acquired a major stake in the combination, has systematically reduced its position. In March 2024, Altria sold 35 million American Depositary Shares at $61.50 each in a global secondary offering, while AB InBev repurchased $200 million of shares directly alongside it, completing a combined $2.4 billion transaction that left Altria at about 8% of the company.18 The presence of a persistent, known seller has created a structural overhang on the stock, contributing to the valuation discount AB InBev trades at relative to global consumer staples peers.
BEES: What It Actually Is
BEES was launched in 2019 as an internal initiative to digitize AB InBev's distribution architecture. While the company's emerging-market positions rested on direct route-to-market networks built in South America—deploying company fleets to serve millions of small independent retailers—the order-capture layer had long relied on manual sales visits, paper invoices, and phone calls.
Digitizing this order process generated immediate operational efficiencies: lower transaction costs, fewer stockouts, improved delivery routing, and real-time visibility into point-of-sale sell-through rather than lagging wholesale shipments. More strategically, establishing a digital transaction platform across millions of retail outlets transformed an internal ordering system into a broader distribution network.
By leveraging physical distribution assets built over decades—including warehouses, truck fleets, cold-chain infrastructure, and commercial credit relationships—AB InBev established BEES Marketplace to distribute third-party merchandise. The platform enables independent retailers to order spirits, soft drinks, snacks, and household goods alongside beer. Under its asset-light third-party model, AB InBev avoids inventory risk, earning transaction fees and delivery commissions on goods shipped through its established logistics channels.
The Numbers, and What They Mean
By the end of fiscal 2025, BEES was live in 29 markets with roughly 72% of group revenue captured through B2B digital platforms, processing $52.5 billion of gross merchandise value for the year, up 12%.2 The marketplace segment—encompassing third-party products—grew 61% to $3.5 billion, with the asset-light 3P model roughly tripling.2 Concurrently, the direct-to-consumer digital ecosystem, including Zé Delivery in Brazil, TaDa, and PerfectDraft, generated $1.3 billion of revenue, with over 76 million e-commerce orders.2 Expansion continued into 2026: second-quarter BEES gross merchandise value reached $15.0 billion, up 16%, and marketplace gross merchandise value grew 50% to $1.2 billion, with the platform live in 30 markets.4
Evaluating these metrics requires distinguishing between platform scale and financial reporting transparency. On the second-quarter 2026 earnings call, Doukeris stated that the platform had been profitable since inception, characterizing its EBITDA contribution as equivalent to "a top 20 country" within the group, and among the top ten drivers of EBITDA growth.17 However, these statements reflect management commentary rather than audited segment reporting, as AB InBev does not disclose BEES as a standalone operating segment with explicit revenue, cost, and margin breakdowns.
Furthermore, gross merchandise value does not equal net revenue. Framing BEES as a high-margin software platform requires qualification: a marketplace generating $3.5 billion in annual third-party gross merchandise value yields net take-rate revenue in the low hundreds of millions of dollars—a modest contribution relative to a $59 billion parent company. While BEES provides a genuine competitive advantage in route-to-market distribution that peers have struggled to replicate, its thesis as a high-margin third-party revenue engine remains unproven. Verifying its long-term valuation impact will require management to disclose explicit take rates and standalone segment economics.
Brands: Premiumization and Balanced Choices
Beyond digitization, AB InBev's commercial strategy relies on portfolio premiumization and category diversification. In fiscal 2025, mainstream beer accounted for roughly half of group revenue and remained approximately flat, while the above-core premium portfolio represented about 35% of revenue and grew at a low-single-digit rate; overall growth came from the newer categories.2 Global flagship Corona generated 8.3% revenue growth outside Mexico, supported by double-digit volume growth in 30 markets.2 Concurrently, the non-alcoholic portfolio grew revenue 34%, led by Corona Cero.2 The "Beyond Beer" segment—encompassing ready-to-drink spirits, flavored malt beverages, and hard seltzers—grew 23% and represented about 3% of revenue, with Cutwater growing triple digits in the U.S.2
This portfolio evolution represents a strategic defense against structural shifts in consumer demand, as younger demographics consume less traditional lager and favor spirits, ready-to-drink cocktails, and non-alcoholic alternatives. By expanding proprietary brands across these adjacent categories and pushing them through its distribution network, AB InBev aims to protect aggregate market share.
However, executing this strategy requires building and sustaining smaller brands—an operational capability where AB InBev's historical track record is mixed. Rapid initial growth in acquired brands often reflects immediate distribution gains rather than permanent brand equity, as demonstrated during the company's craft beer roll-up. On the second-quarter 2026 earnings call, Doukeris addressed competitive pressure from ready-to-drink spirits by asserting, "In this case, we are the competition," pointing to Cutwater's trajectory toward $1 billion in annual revenue.17 Whether Cutwater can maintain its momentum after initial distribution scaling will serve as a critical test of AB InBev's long-term brand-building capacity.
X. Segment-Level Deep Dive & Global Brewing Economics
Beer is a counterintuitive business to analyze, because almost nothing about its underlying economics is driven by the liquid itself.
The Physics of the Business
Water, barley, hops, and yeast are inexpensive. A brewery, by contrast, is a large, capital-intensive, fixed-cost facility that must run continuously to maintain efficiency. Packaging — aluminum cans, glass bottles, and cardboard casing — typically costs more than the contents inside. Furthermore, the finished product is heavy, low in value per kilogram, temperature-sensitive, and costly to transport.
The consequence is that the decisive variable in beer profitability is drop density: how many hectoliters a truck delivers per stop and how many stops it makes along a given route. A distributor delivering forty cases to each of twenty nearby storefronts operates with a fundamentally lower cost structure than one delivering four cases to twenty scattered locations. This physical reality explains why market share in brewing carries far greater value than in most consumer categories. In a territory where a brewer holds a 60% market share, every delivery truck runs full and every route remains dense; a competitor holding 10% share pays significantly more per hectoliter to serve the same street. This creates a localized, physical, compounding advantage that drives regional beer markets toward duopolies or near-monopolies.
This dynamic also explains the strategic importance of returnable glass bottles across Latin America and Africa. Returnable containers lower the retail price point for lower-income consumers while establishing a deposit relationship that anchors retailers to the brewer, as empty bottles must be returned to the original supplier.
Where the Money Actually Comes From
In fiscal 2025, the group's $59.3 billion in revenue and $21.2 billion in normalized EBITDA reflected a geographic imbalance that many investors underestimate.2
Middle Americas — comprising Mexico, Colombia, Peru, and Ecuador — generated $17.4 billion in revenue and $8.7 billion in EBITDA, achieving an industry-leading 50.0% operating margin. Organic revenue increased 4.7%, while EBITDA grew 7.0%.2 Representing roughly 29% of total company revenue, this single division produced approximately 41% of group EBITDA. Mexico operates as a structural duopoly supported by a company-controlled retail store network, while Colombia functions near monopoly levels inherited from SABMiller's Bavaria transaction. Consequently, these franchises represent the group's highest-margin and most defensible cash generators, supporting a disproportionate share of AB InBev's corporate valuation.
North America generated $14.2 billion in revenue and $4.7 billion in EBITDA at a 33.0% margin. While volumes declined 3.0% and organic revenue slipped 1.0%, EBITDA remained roughly flat as margins expanded 37 basis points.2 These figures reflect a business managing structural volume headwinds for cash generation, maintaining profitability through price increases and portfolio mix rather than expansion.
South America — dominated by Ambev's operations in Brazil and Argentina — produced $12.0 billion in revenue and $3.9 billion in EBITDA at a 32.6% margin. Despite a 3.5% volume contraction, organic revenue grew 4.9% and EBITDA rose 7.5%.2 Because Ambev trades as a separately listed entity in Brazil, a portion of these operating earnings accrues to public minority shareholders rather than fully to AB InBev.14
EMEA — encompassing Europe and ex-SABMiller African operations — generated $9.5 billion in revenue and $3.1 billion in EBITDA. The African business provides a long-term growth profile driven by favorable demographics, lower per-capita consumption, and dominant incumbent market positions, whereas the European market remains mature and stagnant.
Asia Pacific represented the primary operational headwind in fiscal 2025, with revenue falling to $5.7 billion and EBITDA declining organically by high single digits.2 Weakness in China drove the downturn, where soft demand in restaurants and bars — the key on-premise channels for premium beer — combined with subdued consumer spending weighed heavily on AB InBev's premium-focused portfolio. The slowdown persisted into 2026: second-quarter revenue in China fell 8.8%, prompting CEO Michel Doukeris to acknowledge on an earnings call that management was "not happy with our performance in China" and that "there is more work to do."17 While management has acknowledged the shortfall, stabilizing China will require sustained execution in an uncertain macroeconomic environment.
The Competitive War-Game
Heineken N.V. stands as the second-largest global brewer and AB InBev's primary international competitor. Its flagship Heineken brand enjoys broader global recognition as a premium lager than Budweiser, supported by strong market positions across Vietnam, Brazil, and Mexico. Operating with significantly lower financial leverage, Heineken is insulated by a foundation voting structure that prevents hostile acquisition and allows long-horizon strategic capital deployment. Conversely, AB InBev retains superior distribution density across key emerging markets and a more advanced B2B digital infrastructure.
Carlsberg A/S maintains a regional focus concentrated in Western, Central, and Eastern Europe, as well as Asia, operating with a smaller global scale. Its long-term valuation remains constrained by geopolitical exposure, highlighted by the expropriation and loss of its Russian Baltika business.
Constellation Brands presents an unusual competitive dynamic as the beneficiary of AB InBev's forced divestiture of Modelo's U.S. assets. For a decade, Constellation expanded its U.S. beer division on Hispanic population growth and broader market adoption of Modelo Especial and Pacifico. However, recent deceleration in demand among Hispanic consumers coincided with Michelob Ultra capturing U.S. volume leadership.2 Constellation also faces significant concentration risk, operating as a single-country enterprise dependent on a small portfolio of brands.
Molson Coors captured temporary volume gains following the 2023 Bud Light boycott as Coors Light and Miller Lite gained retail shelf space. However, lacking emerging-market exposure, its market-share momentum subsequently faded. This trajectory underscores that sustained advantage in mainstream lager depends on long-term distribution execution rather than transitory shifts in consumer sentiment.
The overarching competitive reality across all four peers is that further major M&A is off the table, as the global brewing industry has reached its regulatory consolidation limit. Future performance depends entirely on organic execution — category share, premium mix, and cost control per hectoliter — shifting competition to the operational capabilities AB InBev continues to adapt after decades of acquisition-led growth.
XI. Playbook: Business & Investing Lessons
1. Zero-based budgeting has a half-life. Zero-based budgeting serves as an effective post-merger integration tool, extracting hundreds of millions of dollars in structural waste within months, as demonstrated in St. Louis. However, it functions as an efficiency engine rather than a growth engine. Its financial yield declines with each consecutive year applied to the same asset base, and over time, spending cuts begin eroding the investments required to generate future demand. When a company's earnings growth consistently outpaces revenue growth for five or six consecutive years, operational cost-cutting is approaching its structural limit.
2. Debt-funded roll-ups have a terminal condition, and it is regulatory. Leverage-backed consolidation models can generate strong returns while acquisition targets remain abundant. The cycle terminates not necessarily from a single flawed transaction, but from the absence of a next target—a boundary enforced by antitrust regulation rather than capital markets. AB InBev reached that threshold in 2016 carrying financial leverage calibrated for perpetual acquisitions. For serial acquirers, the essential analytical question is not whether an individual deal is accretive, but how the balance sheet performs once consolidation reaches its regulatory limit.
3. Distribution density is a powerful moat in physical goods. Route-to-market advantage in beer is highly defensible because it is local, physical, and self-reinforcing. Layering digital software onto established physical infrastructure, as the BEES platform demonstrates, increases retailer switching costs. A small independent retailer managing ordering, credit, and rewards through a unified platform is difficult for a rival brewer to displace through product marketing alone. This physical and digital density explains why AB InBev's Latin American operations sustain significantly higher margins than its North American business.
4. Brands built on social signaling are fragile in a way that brands built on product are not. The Bud Light contraction serves as a modern case study in brand equity. For investors, the key diagnostic test is identifying what a consumer actually loses by switching products. If switching sacrifices taste, functional performance, compatibility, or deeply ingrained habit, the economic moat remains durable. If the primary switching barrier is social identity, the moat can erode rapidly when the brand's cultural signal changes meaning.
5. Divestiture packages create your future competitor, by design. Regulatory authorities do not require the sale of secondary assets to clear major mergers. The mandatory divestiture of Modelo's U.S. business to Constellation Brands illustrates how antitrust remedies build capable rivals, costing AB InBev long-term control over the fastest-growing beer segment in its primary profit market. Corporate acquirers must price regulatory remedy risk as a permanent strategic cost rather than a routine closing condition.
6. Watch who controls the votes. A controlled company backed by an entrenched shareholder bloc remains insulated from public market intervention. Where voting power is concentrated in foundational trusts and insider groups, activist campaigns and external shareholder pressure cannot force strategic realignments or capital reallocation.
XII. Analysis: 7 Powers, 5 Forces, & Bear vs. Bull Case
Helmer's 7 Powers, Applied Honestly
Scale economies — strong, and the most durable power here. Global procurement of aluminum, barley, and glass; brewery scale; and the ability to fund a marketing portfolio spanning the Super Bowl, the FIFA World Cup, the Olympics, and, starting in 2027, UEFA club competitions.2 Being named the world's most effective marketer for four consecutive years by industry bodies indicates that global advertising capital is professionally deployed.2 The limit: scale in brewing is substantially local, meaning global scale confers less operating leverage than overall enterprise size implies.
Cornered resource / route-to-market — strong in Latin America and Africa, structurally capped in the United States. Direct distribution to millions of independent retailers across Brazil, Mexico, and Colombia is nearly irreplicable. In the United States, the three-tier system legally prevents direct route-to-market ownership, while the 2018 consent decree explicitly limits distributor acquisition and incentive programs.6 These two regulatory operating environments produce fundamental differences in competitive advantage.
Network economies — emerging, unproven. BEES Marketplace displays genuine two-sided network characteristics: expanding retail adoption attracts more third-party sellers, which increases platform utility for shop owners. While user and transactional growth are documented, standalone unit economics remain undisclosed.
Branding — bifurcated and weaker than total portfolio size suggests. Corona functions as a genuine global premium brand with demonstrable pricing power. Michelob Ultra has established a defensible position around fitness and low-carbohydrate consumption that is functional rather than purely symbolic—explaining its relative commercial resilience. Conversely, Budweiser and Bud Light hold substantially less brand power than market consensus assumed prior to 2023.
Switching costs — near zero for the drinker, high for the retailer. This inversion represents a central structural dynamic of the business model. Commercial lock-in exists at the retail store level rather than with individual consumers.
Counter-positioning and process power — essentially absent. The 3G operating framework once functioned as a process power, but it has been widely analyzed and replicated across the industry, while its incremental cost-yield at AB InBev has naturally diminished over time.
Porter's Five Forces
New entrants: Very low threat at global scale, where capital and distribution requirements present high barriers to entry. Threat remains moderate at the fringe: craft microbreweries and ready-to-drink beverage startups require minimal initial capital, creating persistent margin drag at the premium end of the category.
Buyer power: High and expanding across developed markets. Retail giants such as Walmart, Costco, Tesco, and European discount chains have consolidated, negotiating aggressively while private-label and value options pressure mainstream beer lines. Buyer power remains low across emerging markets, where the company sells directly to millions of fragmented small storefronts—explaining why those operations generate 50% margins compared to 33% in North America.
Supplier power: Moderate. AB InBev acts as the dominant institutional purchaser of key agricultural commodities and packaging materials. However, aluminum and energy remain subject to global market volatility; management cited unhedged energy costs as a margin headwind for the second half of 2026.17 The 2026 reacquisition of a 49.9% minority stake in U.S. metal container plants for $2.9 billion represents a direct vertical-integration response to supply-chain exposure.3
Substitutes: The most intense force shaping the industry and the core of the bear case. Alternatives include spirits, ready-to-drink cocktails, wine, legal cannabis, GLP-1 medications that reduce alcohol consumption, and a broader demographic decline in drinking among younger adults. The company's strategic defense relies on acquiring proprietary substitute brands, an approach that is logically sound but unproven regarding long-term returns.
Rivalry: Moderate and disciplined. The market functions as a consolidated oligopoly with limited price wars, competing primarily through brand equity investment and distribution execution.
The Bull Case
Balance sheet deleveraging is largely complete. Net debt to EBITDA reached 2.87 times by the end of 2025 down from a peak above 5.5 times, bringing overall net debt down by $15.3 billion since 2021 after first crossing below 3.0 times in 202416, while free cash flow reached $11.3 billion annually.2 That balance sheet transition shifted the investment profile from debt reduction toward capital return, supporting a 15% dividend increase for fiscal 2025 and a $6 billion share buyback program launched in October 2025.2
Operational trajectories showed improvement in 2026. Sales volumes returned to positive organic growth in the first half of 2026, rising 0.8%,21 alongside organic revenue growth of 5.7%, EBITDA growth of 5.6%, and a 22.1% increase in underlying earnings per share to $2.18—reflecting operating leverage, reduced interest expenses, and a declining share count.3 This pattern of modest top-line volume growth converting into strong per-share earnings expansion represents the mathematical profile of a deleveraging enterprise executing share buybacks.
The long-term emerging-market thesis remains intact. Mexico, Colombia, Brazil, and sub-Saharan Africa provide favorable demographics, lower per-capita beer consumption, and dominant route-to-market density. Furthermore, Michelob Ultra's expansion demonstrates ongoing portfolio development capability, while the BEES digital platform provides unpriced structural optionality.
The Bear Case
Sales volume remains a central operational challenge. Fiscal 2025 volumes contracted by 2.3%, extending a multi-year trend where revenue expansion depended primarily on price increases and product mix rather than growing consumption.2 Revenue per hectoliter rose 4.4% in fiscal 2025 while physical volumes fell, indicating that pricing carried top-line performance.2 In a category facing structural demand headwinds, aggressive pricing risks accelerating volume erosion over time.
Secular headwinds present a persistent structural challenge rather than a temporary cyclical dip. Per-capita beer consumption across most developed markets has declined for two decades, younger consumer cohorts exhibit lower drinking frequency, and product substitutes are more varied than in prior market cycles.
Currency mismatch remains an ongoing structural risk given the geographic divide between emerging-market operating cash flows and hard-currency debt obligations. Meanwhile, performance in China has deteriorated without a clear management turnaround, while key input costs—including aluminum, energy, and logistics—remain exposed to market pressure.17
Corporate governance constraints persist for public investors: voting control rests with an insider shareholder group, preventing minority holders from influencing board composition or capital allocation, while Altria maintains a significant equity stake. Additionally, the balance sheet carries substantial goodwill and intangible asset carrying values from historical acquisitions that rely on long-term volume assumptions.
The Activist Stress Test
An institutional investor conducting a rigorous stress test would focus on four core operational areas. First, reporting transparency: management frequently highlights BEES as a primary EBITDA growth driver, yet does not break it out as a standalone reporting segment with disclosed unit economics. Second, corporate structure: separate public listings for Brazilian and Hong Kong subsidiaries introduce minority interest leakage and holding-company valuation discounts. Third, capital allocation discipline: following commitments to financial austerity, the company deployed $2.9 billion to repurchase container plant equity alongside the 2026 acquisition of BeatBox3—transactions that warrant monitoring against stated share buyback priorities. Fourth, executive accountability: no senior executive was publicly held accountable for the historic market-share contraction of Bud Light.
Because AB InBev is a controlled company, these structural criticisms do not trigger activist-driven realignments or forced asset sales.
The Three KPIs That Matter
Evaluating the company's forward performance depends primarily on three core metrics:
Organic volume growth, by zone. Operating margins and pricing power derive fundamentally from physical volume trends. Performance hinges on distinguishing between demographically supported growth regions in Middle Americas and South America versus mature markets in North America, Europe, and Asia Pacific where structural volume declines require ongoing management.
U.S. total-alcohol market share. Individual brand trajectories matter less than overall portfolio performance. The thesis following the 2023 market shift is that competitive advantage rests on distribution infrastructure and portfolio breadth rather than a single flagship label; aggregate U.S. alcohol share serves as the primary metric confirming or refuting this model.
BEES Marketplace GMV alongside disclosed monetization rates. Gross merchandise value growth alone does not demonstrate standalone software economics. Confirming BEES as a high-margin distribution platform requires management to report explicit take rates, net marketplace revenue, and operating margins. Until disclosed, platform optionality requires conservative valuation.
XIII. Epilogue & "What Would We Do?"
There is a distinct symmetry to this corporate trajectory. An enterprise assembled through relentless consolidation reached the regulatory limits of acquisition-led growth, discovering that the foundational pillars of its operating model—identifying the next target and extracting structural overhead—no longer applied. The years since have represented an effort to convert a financial vehicle into an operating enterprise, led by a chief executive trained in commercial strategy rather than cost engineering, and competing in a category facing structural volume headwinds in its highest-margin regions.
As of September 2026, the corporate scorecard remains mixed. Financial leverage has been repaired, while cash generation remains strong and consistent. Sales volumes have stabilized only recently after years of stagnation. Capital returns to shareholders have been restored, and the U.S. portfolio has reoriented around Michelob Ultra rather than Bud Light. Yet challenges persist: performance in China remains unresolved, and while the BEES digital platform demonstrates substantial growth, its segment economics remain insufficiently disclosed.
From an analytical perspective, three strategic priorities emerge for management.
First, reallocate capital away from rehabilitating Bud Light. Management has already begun shifting resources through its media budget, reflecting sound commercial logic: restoring a brand whose cultural identity has been publicly contested is far more capital-intensive than expanding an uncontested brand. Michelob Ultra's positioning rests on functional attributes—fitness and low carbohydrates—creating a more durable consumer value proposition than symbolic identity. Simultaneously, Cutwater and the non-alcoholic portfolio align directly with shifting consumer demand. Capital deployment should follow these consumption trends rather than paying a strategic tax to legacy labels.
Second, provide transparent financial reporting for the BEES digital platform. Management asks public markets to attribute substantial equity value to the software ecosystem while withholding standalone financial metrics. Disclosing marketplace net revenue, explicit take rates, and segment operating margins would either substantiate management's growth thesis or introduce market discipline. Resolving this ambiguity is essential, as the stock's persistent valuation discount relative to consumer staples peers partly reflects an opacity discount. Potential future strategic options for BEES—such as a spin-off or commercial partnership—remain secondary to establishing financial transparency.
Third, maintain strict capital discipline regarding major acquisitions. The primary risk to equity valuation is not a modest, structural decline in developed-market beer volumes—a scenario already largely priced into the stock. Instead, the risk is that a management team incentivized on growth might pursue a large, debt-funded acquisition to manufacture top-line expansion. Having repaired the balance sheet through years of financial restraint, and with the company generating roughly $11 billion in annual free cash flow, capital allocation arithmetic favors repurchasing undervalued equity over pursuing external consolidation.
Final thought. The 660-year-old monastery narrative in Leuven remains a compelling marketing origin, but it is fundamentally a story. The physical enterprise consists of breweries, truck fleets, cold-chain infrastructure, direct retailer relationships, and a B2B digital platform—assembled through the largest consolidation campaign in consumer goods history and financed with unprecedented leverage. Today, that operational machine is being challenged to achieve what it was never originally designed to do: generate sustained organic growth. Whether the platform can deliver that transition remains an open question, one that physical volume trends and category share metrics over the coming years will ultimately decide.
References
-
AB InBev Reports Full Year and Fourth Quarter 2025 Results — Anheuser-Busch InBev, 2026-02-12 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Anheuser-Busch InBev SA/NV — Form 6-K, Half Year 2026 Report — U.S. Securities and Exchange Commission, 2026-07-30 ↩↩↩↩
-
AB InBev Reports Second Quarter 2026 Results — StockTitan, 2026-07-30 ↩↩
-
Justice Department Reaches Settlement with Anheuser-Busch InBev and Grupo Modelo in Beer Case — U.S. Department of Justice, 2013-04-19 ↩↩↩
-
United States v. Anheuser-Busch InBev SA/NV and SABMiller plc — U.S. Department of Justice, 2018-10-22 ↩↩
-
AB InBev Seals $107 Billion Megabrew Takeover of SABMiller — Financial Times, 2015-11-11 ↩
-
AB InBev Halves Dividend to Pay Down SABMiller Debt Burden — Bloomberg, 2018-10-25 ↩
-
Kraft Heinz Slashes Dividend, Takes $15.4 Billion Write-Down — The Wall Street Journal, 2019-02-22 ↩
-
AB InBev Appoints Michel Doukeris as New CEO — The Wall Street Journal, 2021-05-06 ↩
-
Modelo Especial Dethrones Bud Light as Top U.S. Selling Beer — Reuters, 2023-06-14 ↩
-
Budweiser Brewing Company APAC Limited — Investor Relations (HKEX: 1876) ↩
-
Anheuser-Busch InBev SA/NV — Form 6-K, Full Year 2024 Results — U.S. Securities and Exchange Commission, 2025-02-26 ↩
-
Earnings Call Transcript: AB InBev Q2 2026 — Investing.com, 2026-07-30 ↩↩↩↩↩
-
Altria Announces Secondary Offering of ABI Shares and Share Repurchase Program Increase — U.S. Securities and Exchange Commission (Altria Form 8-K), 2024-03-14 ↩
-
Investment Billionaire Hands Son His $6.1 Billion Stake in AB InBev — Fortune, 2024-01-02 ↩↩
-
Anheuser-Busch Companies, Inc. — Form 8-K, Shareholder Approval of InBev Combination — U.S. Securities and Exchange Commission, 2008-11-12 ↩↩
-
AB InBev Q2 2026 Slides: Volume Returns to Growth — Investing.com, 2026-07-30 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube