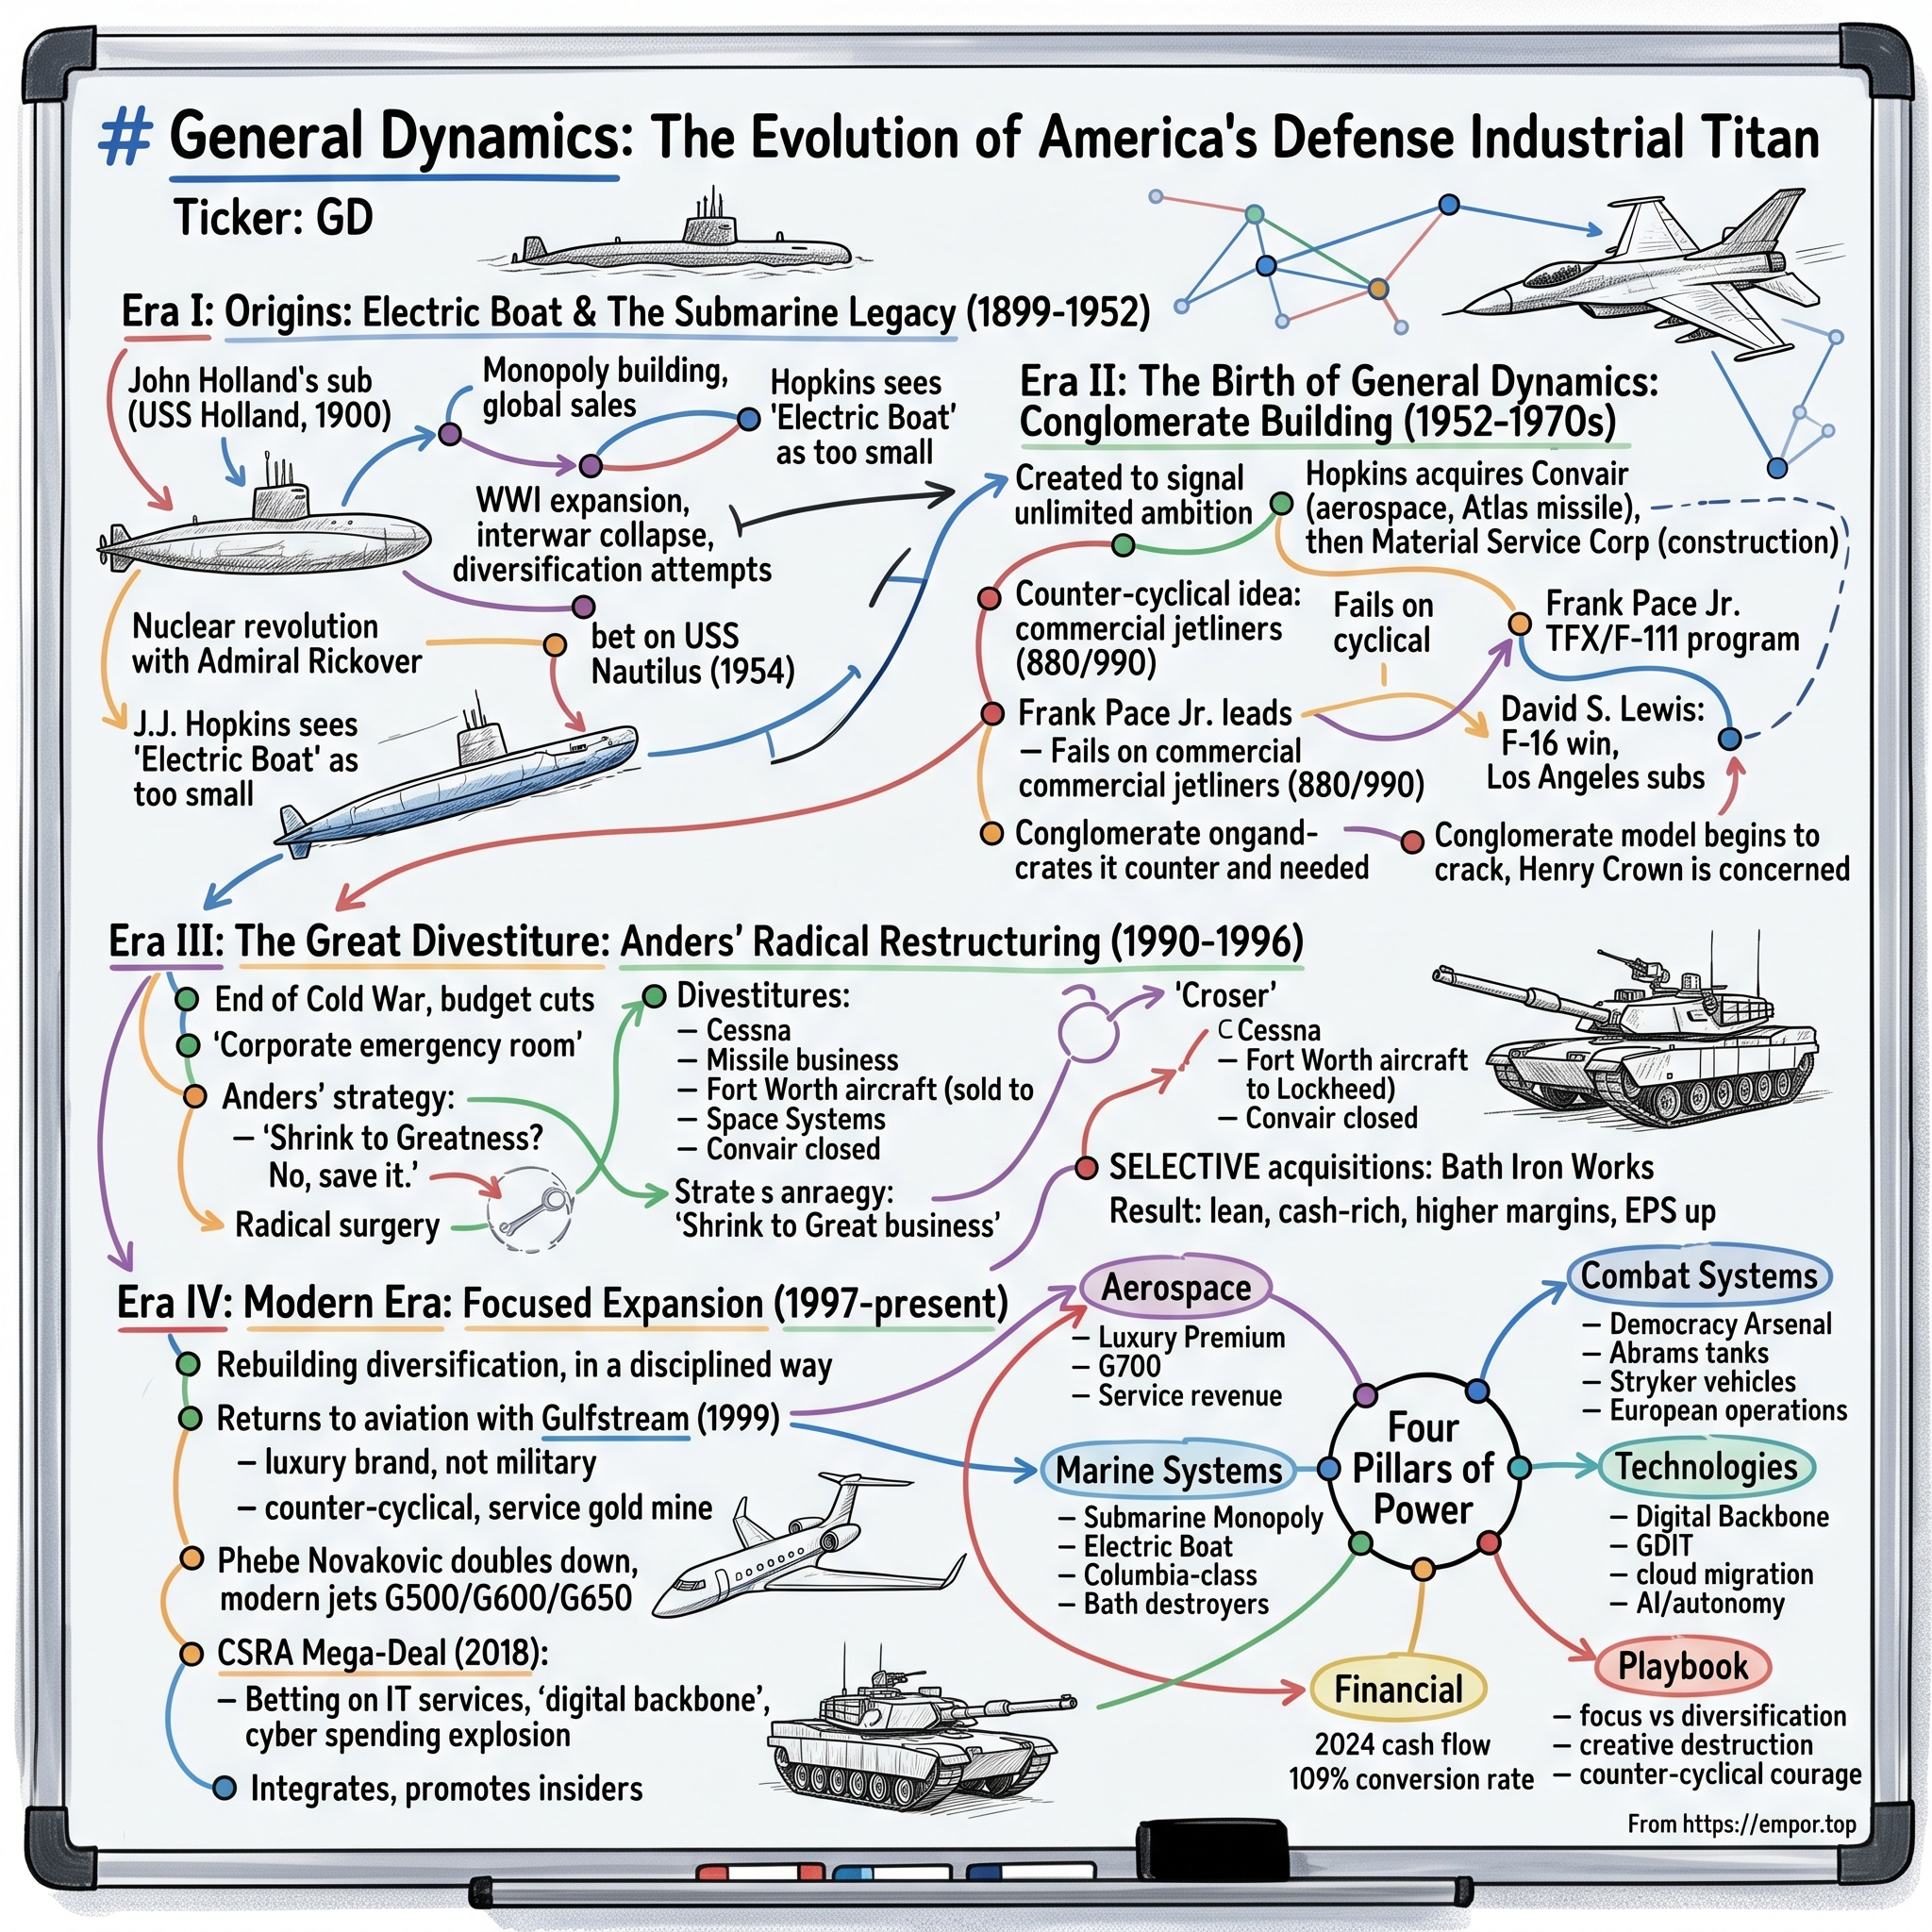
General Dynamics: The Anti-Conglomerate Defense Empire
I. Introduction & The Conglomerate Paradox
Picture two production floors roughly a thousand miles apart. In Groton, Connecticut, welders in fire-resistant jackets climb scaffolding around a steel cylinder more than forty feet across: a hull section for a submarine that will carry a major share of America's nuclear deterrent into the 2080s. In Savannah, Georgia, technicians in white gloves fit hand-stitched leather and burled wood into the cabin of a corporate jet designed to fly executives from Teterboro to Tokyo nonstop. The two facilities share almost nothing in common: not the customer, not the regulator, not the business cycle, and not the workplace culture. What they share is a parent company, a corporate treasury, and a chairman and chief executive who has led the enterprise since January 2013.
That enterprise is General Dynamics, and on paper, it defies contemporary corporate fashion. Over the past decade, Wall Street dismantled the classic American conglomerates. General Electric split into three separate companies. United Technologies spun off Carrier and Otis before merging its aerospace operations into Raytheon. The prevailing investment consensus held that managerial complexity destroys value while single-industry focus unlocks it. General Dynamics rejected that trend. It continues to combine nuclear submarines, surface combatants, battle tanks, artillery munitions, federal IT contracts, and the Gulfstream business-jet franchise, expanding its revenue base and operating profitability along the way.
The scale of the enterprise is substantial. In 2024, General Dynamics reported revenue of $47.7 billion, up 12.9%, operating earnings of $4.8 billion, and diluted earnings per share of $13.63.[^1] It closed that year with a $90.6 billion backlog and a total estimated contract value, including options and indefinite-delivery contracts, of $144 billion.1 The following year brought further expansion: 2025 revenue reached $52.6 billion, diluted EPS rose 13.4% to $15.45, and backlog jumped to $118 billion on a 1.5-times book-to-bill ratio for the year.2 By the end of June 2026, backlog had reached a record $136.5 billion, up 32% year over year, and total estimated contract value stood at $186.9 billion.3 In July 2026 management raised full-year guidance to about $55.7 billion of revenue and EPS of $16.80 to $16.90.4
The four pillars and what each actually contributes
General Dynamics reports four operating segments, and the division is instructive primarily because the distribution of revenue looks nothing like the distribution of profit. In 2024, Marine Systems was the largest by revenue at $14.3 billion, but its $935 million of operating earnings came at a thin margin of about 6.5%.1 Technologies, which combines General Dynamics Information Technology (GDIT) with Mission Systems, earned $1.26 billion on $13.1 billion of revenue.1 Aerospace, which is Gulfstream plus the services business Jet Aviation, produced $11.25 billion of revenue, up 30.5%, and roughly $1.46 billion of operating earnings, the largest profit contribution of any segment.1 Combat Systems, the smallest by revenue at $9 billion, earned $1.3 billion at a margin near 14%.1
Put simply, the largest business delivers the lowest margins, while the unit most exposed to the commercial business cycle generates the largest share of profit. That internal tension shapes the company's operating profile. By 2025 the mix had moved: Marine Systems grew to $16.7 billion of revenue with a 7.0% margin, Aerospace to $13.1 billion at 13.3%, Combat to $9.2 billion at 14.4%, and Technologies to $13.5 billion at 9.5%.2
The customer base is concentrated. In 2025, 68% of revenue came from the U.S. government. U.S. commercial customers, mostly Gulfstream buyers, accounted for 15%, and non-U.S. customers for 17%.5 About half of the U.S. government business was fixed-price work and 44% was cost-reimbursable.5 That contract split matters because fixed-price arrangements leave General Dynamics holding the risk of cost overruns and inflation, as its shipyards experienced during post-2021 supply dislocations.
The thesis to test
This analysis tests one core thesis: that General Dynamics is not an unwieldy conglomerate, but a portfolio of four high-barrier franchises anchored by cash discipline and led by Phebe Novakovic, who judges every business on return on invested capital. Key elements of that claim hold up under scrutiny. Other parts depend heavily on the U.S. Navy's patience and the Federal Aviation Administration's certification timetable. With the shares recently around $344 and the company's market value near $93 billion,6 investors are paying roughly 20 times this year's guided earnings. At that valuation, understanding where structural competitive advantages end and operational execution risks begin is critical.
Myth versus reality, up front
Three common beliefs about General Dynamics warrant testing up front. The first is that the company holds a submarine monopoly. In fact, it shares construction with Huntington Ingalls under an arrangement mandated by the U.S. Navy, which ultimately determines pricing and delivery terms. The second is that Gulfstream is purely a luxury brand insulated from industrial cycles. Management rejects that label, and the segment's 2024 delivery delays underscored that it remains an industrial manufacturing enterprise vulnerable to aerospace supply-chain bottlenecks. The third belief is that General Dynamics converts more than 100% of net income into free cash flow every year. Over multi-year stretches that pattern roughly holds, but conversion rates fluctuate sharply from one fiscal year to the next. Each belief contains an element of truth, yet each overstates the underlying reality. The rest of this analysis examines the gap between the two.
The story starts with a man who wanted to build a boat that could sink on purpose and come back up.
 Subscribe on LinkedIn
II. Genesis & The Submarine Monopoly: Holland to Nautilus (1899–1955)
John Philip Holland was an Irish-born schoolteacher who had spent decades trying to solve an engineering problem that had defeated or killed many early pioneers: how to make a vessel dive, maintain a steady depth, and surface under control. Early submarines tended either to sink directly to the seabed or to pitch unpredictably like a cork. Holland's solution combined ballast tanks for buoyancy control, diving planes for vertical steering, and an internal combustion gasoline engine on the surface paired with an electric motor underwater. While the design was mechanically sound, he lacked the capital to produce it at scale.
Financing arrived through Isaac Rice, a lawyer and storage-battery entrepreneur. In 1899, Rice founded the Electric Boat Company to commercialize Holland's patents, and on April 11, 1900, the U.S. Navy purchased and commissioned the Holland as its first submarine.[^8] That sale established a structural dynamic that still defines the business 126 years later: a single, highly demanding government customer, a complex platform virtually no competitor could build, and a contractor whose financial stability rose and fell with defense appropriations.
War, peace, and the lesson of the cliff
Two world wars converted Electric Boat from a boutique yard into an industrial heavyweight. During World War II, the company and its affiliates built submarines, surface vessels, and PT boats in high volumes for the Pacific theater.7 Peace, however, brought immediate contraction. After 1945, the yard retained only about 4,000 of its 13,000 wartime workers, and its share price dropped from $30 to $10.7 The drawdown underscored the defining vulnerability of a single-product defense supplier: when a conflict concludes, procurement dries up almost overnight.
John Jay Hopkins, who had directed the company since 1937, responded with structural diversification. In 1947, Electric Boat purchased the Canadian aircraft manufacturer Canadair from the Canadian government for $22 million, and in 1952, the combined business was reorganized under a new holding company, General Dynamics Corporation, with Electric Boat and Canadair as operating subsidiaries.7 Hopkins sought an enterprise whose identity was not tethered to a single military platform. Much of the subsequent corporate history of General Dynamics—including decades of acquisitions, divestitures, and debates over portfolio construction—traces back to that initial pivot.
Underway on nuclear power
The breakthrough that cemented Electric Boat's enduring franchise was its partnership with Admiral Hyman Rickover, the Navy's demanding head of nuclear propulsion. On June 14, 1952, President Harry Truman laid the keel of the Nautilus at the Groton, Connecticut yard, which was already operating as a division of General Dynamics.[^10] Mamie Eisenhower launched the boat on January 21, 1954, and on January 17, 1955, Commander Eugene Wilkinson transmitted the signal that inaugurated a new era of naval architecture: "Underway on nuclear power."[^10]
The enduring value of the Nautilus program lay not in a discrete patent or product line, but in an industrial organization built from scratch. Electric Boat mastered the technical disciplines of welding specialized high-strength steel to nuclear-certified standards, integrating a pressurized water reactor inside a combat submarine hull, engineering acoustic dampening to avoid detection, and operating under the rigorous oversight of Naval Reactors—an inspection culture among the most stringent in global manufacturing. Groton went on to build the first fleet ballistic missile submarine, the George Washington, and later hulls across the Ohio, Los Angeles, Seawolf, and Virginia classes.[^8]
In financial terms, this specialized capability created an exceptional economic moat, but also total dependence on a monopsony buyer. Seven decades after the Nautilus first put to sea, that industrial base remains General Dynamics' core strategic asset, yet the company remains beholden to a single customer that dictates procurement quantities, pricing models, and delivery schedules. Hopkins had already recognized that a defense contractor could not rely entirely on naval hulls. His successors would take portfolio diversification much further—and for a time, that expansion nearly derailed the enterprise.
III. The Cold War Conglomerate & The Anders Revolution (1955–1996)
By the late 1950s, General Dynamics looked like the model of a modern industrial titan. The company that built the Nautilus had also, through its 1954 acquisition of San Diego-based Consolidated Vultee Aircraft (Convair), become a major manufacturer of intercontinental ballistic missiles, supersonic interceptors, and commercial jetliners.7 In 1959, it merged with Henry Crown's Material Service Corporation, a Chicago building-materials enterprise, establishing the Crown family as one of General Dynamics' most influential shareholders for decades.7
Yet rapid expansion exposed the limits of managerial reach. Convair's commercial jet program, the 880 and 990, arrived late to market with chronic design defects and generated roughly $425 million in losses, marking one of the steepest corporate deficits in American history up to that point.7 The F-111 swing-wing fighter drew intense public criticism as an emblem of defense mismanagement.7 Meanwhile, relations with Admiral Rickover deteriorated, culminating in his public castigation of Electric Boat over severe cost overruns on Los Angeles-class submarines.7 Sheer conglomerate scale provided no insulation from poor execution.
The good bets: Fort Worth and the tank
Alongside those costly missteps were exceptionally shrewd investments. The company's Fort Worth division engineered the F-16 Fighting Falcon, an agile, lightweight, and cost-effective fighter that entered serial production in 1978 and became an export mainstay across NATO allies.7 Then, in 1982, General Dynamics paid $336.1 million to acquire Chrysler Defense, the nation's sole domestic manufacturer of main battle tanks, bringing on roughly 7,000 employees and an estimated $1.75 billion backlog that included the newly fielded M1 Abrams.8 Reorganized as General Dynamics Land Systems, that single transaction continues to anchor the corporation's Combat Systems segment more than four decades later.
The Wall falls, and a former astronaut takes charge
When the Berlin Wall fell in November 1989, the defense sector faced an abrupt demand cliff, sending industry shares down roughly 40%.9 Major contractors found themselves burdened with extensive industrial capacity engineered for an existential global standoff that had evaporated overnight. Seeking a decisive strategic break, General Dynamics' board appointed William Anders as chairman and chief executive in January 1991, succeeding Stanley Pace.10
Anders brought an unconventional pedigree to the corner office. As an Apollo 8 astronaut in 1968, he had captured Earthrise, the historic photograph of the planet cresting above the desolate lunar horizon.9 Later, as an executive under Jack Welch at General Electric, he managed nuclear and aircraft-equipment divisions.9 From GE, Anders absorbed Welch's strict portfolio doctrine: compete only in businesses where the company could secure the first or second market position. What distinguished Anders in the defense sector, however, was his cold-eyed assessment of post–Cold War structural oversupply. As he later observed when divesting the fighter franchise: "There is massive overcapacity in the industry... The industry was sized for the Cold War. The Cold War is over."11
The great fire sale
Over the next two years, Anders orchestrated one of corporate America's most aggressive restructuring campaigns. In January 1992, General Dynamics sold light-aircraft manufacturer Cessna to Textron for $600 million in cash.12 A data-systems division was divested to Computer Sciences Corporation for approximately $200 million.10 The tactical missile unit was offloaded to Hughes Aircraft for at least $450 million in General Motors Class H stock.13 Then, in December 1992, Anders enacted the centerpiece divestiture: selling the Fort Worth tactical military aircraft division—producer of the F-16, participant in the early stages of the F-22 program, and employer of roughly 20,000 people—to Lockheed for $1.53 billion in cash.11
Rather than redeploying that capital into speculative acquisitions, Anders returned the windfall directly to shareholders. In the summer of 1992, General Dynamics repurchased approximately $955 million of its common stock—nearly 30% of outstanding shares—via a Dutch auction tender offer.10 Warren Buffett initially evaluated the tender as a short-term arbitrage trade, but reversed course after examining Anders' capital allocation discipline. Buffett later recounted that "Bill had a clearly articulated and rational strategy; he had been focused and imbued with a sense of urgency."14 Berkshire Hathaway subsequently acquired a 14.9% stake in General Dynamics for roughly $325 million,10 granting management a discretionary proxy to vote the shares for the duration of Anders' tenure as chief executive.15 Few corporate turnarounds have earned such an unambiguous vote of confidence from institutional capital.
Did Anders sell the family silver too cheaply?
Wall Street lore frequently celebrates Anders as a masterclass in shareholder-value creation, a verdict reinforced by the surging share price of the early 1990s. With several decades of hindsight, however, that legacy appears considerably more nuanced. The Fort Worth assembly plant, sold for $1.53 billion, evolved into the operational hub of Lockheed Martin's tactical aircraft empire and the manufacturing home of the F-35 Joint Strike Fighter—the most lucrative defense procurement program in history. By exiting those lines, General Dynamics permanently surrendered its role as a prime contractor in both military aviation and tactical missiles, two domains that subsequently captured outsized shares of Pentagon procurement budgets. The long shadow of that decision surfaced on the company's second-quarter 2026 earnings call: asked whether General Dynamics would benefit from Pentagon initiatives to establish secondary manufacturing sources for missiles and solid rocket motors, the company's president acknowledged that General Dynamics was "a part of the supply chain, but certainly not a prime there."4
A balanced appraisal suggests the divestitures were tactically rational in the moment, yet strategically costly over the long run. In 1992, no executive could guarantee that Fort Worth would capture the next-generation fighter contract, and maintaining idle, capital-intensive manufacturing lines through an extended defense downturn carried substantial downside risk. Anders converted an uncertain option into certain cash returned to shareholders. The lasting consequence, however, is that General Dynamics' defense portfolio today has no footprint in combat aircraft or missiles, two strategically vital categories. The broader lesson of the Anders era is that disciplined sellers sometimes divest future winners—and that an enterprise built on pruning must eventually master the art of rebuilding. Within a decade, General Dynamics did precisely that, turning once again to aviation to reshape its future.
IV. The Return to Flight: Gulfstream & Assembling the Four Pillars (1999–2008)
In May 1999, General Dynamics announced an unexpected transaction. The company that had spent the early 1990s stripping itself down by divesting its fighter jets, tactical missiles, and Cessna was buying Savannah-based Gulfstream Aerospace, maker of the long-range business jets favored by corporate executives, heads of state, and ultra-wealthy individuals. The all-stock deal was valued at roughly $5.3 billion when unveiled, and General Dynamics' shares fell about 10% on the news.16 By the time the transaction closed on July 30, 1999, the one-for-one share exchange was worth about $4.8 billion, reflecting the decline in General Dynamics' own stock price.17 Gulfstream brought roughly 7,700 employees into the enterprise.17
Wall Street met the acquisition with deep skepticism, and for understandable reasons. A contractor whose principal customer was the Pentagon was wading into a cyclical commercial market where private buyers pay tens of millions of dollars for cabin comfort and transoceanic range—and readily cancel orders when a recession arrives. General Dynamics' chief executive, Nicholas Chabraja, rejected the criticism: "Gulfstream is well within our core competencies and one of the strategic areas where I said we would move."16
The logic, and the part of it that aged well
Management's rationale for the transaction rested on three arguments. First, the two business cycles were expected to counterbalance each other: corporate jet demand tracks enterprise profits and equity valuations, while defense outlays follow geopolitical threats and congressional appropriations, two forces that often move independently. Second, the engineering appeared complementary: advanced aerodynamics, systems integration, and rigorous regulatory certification carry over between military platforms and high-end civil aerospace. Third, and ultimately most consequential, Gulfstream offered a premier brand in a consolidated market with only a handful of serious global competitors.
That third element proved decisive. Gulfstream subsequently introduced the G650 and its long-range successors, entrenching the franchise in the ultra-long-range cabin category where manufacturer pricing power is strongest. Over the decade following the acquisition, General Dynamics delivered a total return of more than 120%, with Gulfstream serving as a meaningful contributor to that expansion.16 Yet the counter-cyclical offset theory proved weaker than its proponents suggested. During the 2008–2009 financial crisis, business-jet demand plummeted even as defense spending continued to rise—a dynamic that demonstrated the offset functioning mechanically as designed, but also highlighted its cost. By housing Gulfstream inside a defense enterprise, General Dynamics exposed a large share of its earnings base to precisely the commercial macroeconomic shocks that investors buy defense stocks to avoid. Segment diversification softened top-line volatility across the corporation over time, but it introduced distinct cyclical vulnerability of its own.
Building the armored and marine franchises
While Gulfstream marked General Dynamics' return to aviation, the company was also systematically rebuilding its core defense platform through a series of disciplined, bolt-on acquisitions. In 1995, it paid $300 million in cash to acquire Maine-based Bath Iron Works, the primary surface-combatant shipyard for many classes of Navy warships, adding approximately $830 million in revenue and roughly $2 billion in backlog.18 A few years later, it added NASSCO in San Diego, the primary West Coast yard building auxiliary and support ships for the fleet.
The land combat division expanded through a parallel playbook. In March 2003, General Dynamics completed its $1.1 billion purchase of General Motors' defense business in London, Ontario, which generated roughly $950 million in annual revenue and manufactured the light armored vehicles that became the basis for the U.S. Army's Stryker fleet.19 General Dynamics European Land Systems subsequently aggregated Spanish, Austrian, and Swiss armored-vehicle producers into an integrated platform that later secured substantial production contracts amid European and NATO rearmament.
Aviation services grew concurrently. In November 2008, General Dynamics acquired Zurich-based Jet Aviation for approximately $2.25 billion, absorbing roughly 5,600 employees across 25 airport facilities specializing in maintenance, cabin completions, fixed-base operations, and charter management.20 In practical terms, Jet Aviation generates aftermarket revenue from aircraft throughout their operational lifecycles, providing the Aerospace segment with a service-based revenue stream that is less exposed to lumpy new-order cycles.
The strategic pattern across these transactions was consistent. Chabraja rarely paid for a troubled business with the goal of orchestrating an operational turnaround. Instead, he targeted companies that already held dominant positions in defensible niches: the Navy's lead surface-combatant yard, the manufacturer of the light armored vehicle the Army was standardizing around, the largest independent business-aviation service network, and the benchmark brand in ultra-long-range executive aircraft. Specialized assets with entrenched competitive positions and high barriers to entry are inherently harder to impair. Tellingly, General Dynamics' most severe write-down—a multibillion-dollar goodwill impairment in 2012—would stem from a series of smaller information-technology acquisitions that failed to satisfy that disciplined test.
By 2008, all four operating pillars of modern General Dynamics were firmly in place. Chabraja had reconstructed the multi-division enterprise that Anders had dismantled, but with far tighter selectivity: nearly every major deal of this era secured a commanding position in a specialized niche protected by immense industrial and regulatory moats. The company's subsequent acquisition wave in information technology, however, would unfold far less smoothly, eventually delivering the organization its most painful financial setback in two decades.
V. The Novakovic Era: Crisis, ROIC Discipline, & The $9.7B CSRA Gambit (2012–Present)
In late January 2013, only weeks into her tenure as chief executive, Phebe Novakovic confronted that reckoning when she announced General Dynamics' first annual loss in two decades. The company reported a fourth-quarter net loss of $2.1 billion, driven primarily by a $2 billion goodwill impairment across its Information Systems and Technology group.21 For the full year 2012, General Dynamics recorded a net loss of $332 million on $31.5 billion in revenue, down sharply from a $2.55 billion profit the prior year.21 In accounting terms, a goodwill impairment represents an explicit acknowledgment that past acquisitions failed to deliver their projected economic value, formalizing earlier capital misallocations as non-cash write-downs.
While some post-mortems categorized the write-down across multiple operating units, contemporary reporting confirmed that the $2 billion IS&T goodwill impairment was the central charge.21 The broader verdict on the pre-2013 IT roll-up was unmistakable. Novakovic herself acknowledged the misstep, characterizing her predecessor Jay Johnson's acquisition strategy as "somewhat broken."22 Johnson's early retirement had been announced in June 2012.22
The spy who ran the shipyards
Novakovic brought an unconventional pedigree to the executive suite. After studying government and German at Smith College, she drew inspiration from her father, a Serbian immigrant who had served as an Air Force intelligence officer.22 She joined the Central Intelligence Agency in 1983 as an operations officer, earned an MBA from Wharton in 1986, and transitioned into the budgetary machinery of the federal government. At the White House Office of Management and Budget, she rose to oversee defense and intelligence spending, before serving as a special assistant to Defense Secretary William Cohen and Deputy Secretary John Hamre.22 She joined General Dynamics in 2001, running the Marine Systems group before ascending to the top corporate role in 2013.22
That background fundamentally shaped her managerial philosophy. Having spent years scrutinizing contractor balance sheets and budget justifications from inside the Pentagon and OMB, she applied that same fiscal rigor internally. Upon taking charge, she cut corporate headquarters headcount from roughly 190 to 140, flattened management layers by eliminating corporate vice president roles, and declared a freeze on acquisitions "until we have re-established discipline," redirecting capital toward dividends and share buybacks instead.22 She also walked away from marquee procurement programs that failed to meet her profitability or core competency criteria, including the U.S. Air Force's T-X advanced pilot training competition, an opportunity with an estimated lifecycle value of $30 billion to $40 billion.22
Her direct, uncompromising posture on quarterly earnings calls quickly became an executive hallmark. She once brushed aside market anxiety regarding business-jet demand cycles as mere "rumor intelligence, or RUMINT," and when an analyst teasingly noted her fondness for the word "axiomatic," she dryly shot back, "it helps to have been a liberal arts major. I do know the English language."22 That guarded demeanor has endured. On the second-quarter 2026 earnings call, she cut off an analyst probing future Aerospace operating margins with a flat "let me interrupt you," refusing to offer multi-year margin guidance, and later deflected an M&A inquiry by remarking, "Nice try... this is something we always look at and something we never talk about."4 Supporters view that stance as admirable operational discipline and a refusal to indulge Wall Street speculation. Critics interpret it as an unwillingness to be held accountable to transparent long-range operating benchmarks. Both assessments capture the reality of her management approach.
The counter-consolidation: CSRA
Five years after taking the write-down on General Dynamics' previous IT expansion, Novakovic executed the largest transaction of her tenure—once again in information technology. In February 2018, General Dynamics agreed to purchase CSRA, a major provider of government IT services generating roughly $5 billion in annual revenue, for $40.75 per share in cash, a transaction valued at about $9.6 billion including the assumption of $2.8 billion in debt.23 The move cut against the prevailing defense-industry tide: peer contractor Lockheed Martin had recently exited government IT services via a tax-free spin-merge with Leidos, seeking to escape the sector's compressed margins. When rival CACI International countered with an unsolicited bid of $44 per share in cash and stock, General Dynamics raised its all-cash offer to $41.25 per share. CSRA's board endorsed the revised terms, and General Dynamics closed the approximately $9.7 billion acquisition on April 3, 2018.24[^28]
Management justified the transaction on the grounds of scale and cash generation. Novakovic argued that combining CSRA with GDIT would yield "attractive free cash flow coupled with good incremental return on capital."24 General Dynamics projected annual pre-tax cost synergies of roughly 2% of combined revenue by 2020, while anticipating net debt of approximately $10.5 billion upon closing—a substantial leverage load for an executive who had spent the preceding five years preaching balance-sheet conservatism.23
Stress-testing the CSRA thesis
A financial post-mortem on the CSRA transaction reveals a mixed record. In terms of market scale, the acquisition succeeded: GDIT established itself as the primary peer and competitor to Leidos across federal IT contracting.24 Operating execution within that lane has remained solid. In 2024, the Technologies segment reported contract win rates in the low 80% range, competitive capture rates in the mid-60% range, and a record $14.7 billion in total orders.1 Its operating margins, hovering between 9.5% and 9.8%, sit at the high end for government technical services, leading management to characterize them as "industry-leading."1 While that claim reflects the inherently low-margin structure of cost-plus federal IT services, it remains management's own framing.
The weaknesses in the CSRA thesis emerge in relative revenue growth and margin contribution. Technologies revenue rose just 1.6% in 2024,1 and by the first half of 2026, management continued to cite "elongated procurement cycles" as an ongoing headwind across federal IT awards.4 Because the segment operates at structural margins well below the 13% to 14% generated by Combat Systems and Aerospace, every incremental dollar of Technologies growth effectively dilutes consolidated corporate profitability. Debt reduction, however, proceeded steadily: net debt decreased from the approximately $10.5 billion expected at closing23 to $7.1 billion by year-end 20241 and reached $3.2 billion by mid-2026.3 Yet that deleveraging was powered as much by cash generation from Gulfstream deliveries and naval shipyard billings as by GDIT itself.
Ultimately, the CSRA outcome yields a nuanced verdict. The transaction did not destroy shareholder capital like the pre-2013 roll-ups; it triggered no impairments and created a competitive, cash-generative federal contractor. What it failed to demonstrate is that government IT services possess the formidable economic moats of nuclear submarines or bespoke business aircraft. Instead, it remains a commoditized, contract-dependent business in a competitive market. For investors, the crucial operational indicator remains organic top-line growth at GDIT: if expansion lingers in the low single digits while Marine Systems and Aerospace expand at double-digit clips, structural questions regarding the portfolio's logic will only intensify. Before addressing those portfolio tensions, however, attention turns to the franchise that commands the largest share of General Dynamics' operating profits—and has endured the most turbulent operational hurdles in recent years.
VI. Marine Systems: The Submarine Industrial Crisis & Moat Stress-Test
In the fall of 2024, Novakovic told investors something unusual for a defense contractor: Electric Boat, the shipyard that built the Nautilus, was going to slow down deliberately. Parts from suppliers were not arriving on schedule, and when components did reach the yard, some suffered from quality defects. "The supply chain is not getting better at a fast enough rate as we had hoped," she explained on the October 2024 call. "Through our internal efficiency, we have now outpaced them... We're going to adjust our pace to align with what we now see is more of a predictable supply chain schedule."[^29] In effect, the Western world's premier submarine shipyard was operating below capacity because it could not secure enough basic components like valves and turbines.
What Electric Boat actually builds
Marine Systems encompasses three primary shipyards. Electric Boat in Groton, Connecticut, and Quonset Point, Rhode Island, builds nuclear submarines. Bath Iron Works in Maine constructs Arleigh Burke-class destroyers, while NASSCO in San Diego produces fleet oilers and auxiliary support vessels. Electric Boat is by far the anchor of the segment. It serves as the prime contractor for the Columbia class, a 12-boat program of ballistic-missile submarines designed to replace aging Ohio-class hulls; the company's annual report values the program at more than $125 billion, with the lead vessel scheduled for delivery in 2028.5 Electric Boat also builds the Virginia-class fast-attack submarines, the core of the Navy's undersea fleet and the centerpiece of the AUKUS security partnership, which plans to transfer three in-service Virginia boats to Australia in the 2030s.[^30]
Segment revenue has expanded rapidly. Marine revenue climbed 15.1% to $14.3 billion in 2024,1 rose to $16.7 billion in 2025,2 and management projected full-year 2026 revenue of approximately $18 billion.4 At the end of June 2026, Marine backlog stood at $65.2 billion,3 a figure that did not yet reflect the largest naval shipbuilding award in American history. On July 29, 2026, following nearly three years of negotiations, the Navy awarded Electric Boat and Huntington Ingalls' Newport News yard a $76.6 billion contract covering nine Block VI Virginia submarines—plus advanced procurement materials for a tenth—alongside five Build II Columbia boats, with production running through July 2038.[^30]
The moat, stated fairly
The industrial barriers guarding this franchise rank among the highest in global manufacturing. Replicating Electric Boat would require a nuclear-certified shipyard, formal authorization from Naval Reactors, high-level facility security clearances, and thousands of specialized tradespeople—including nuclear-qualified welders, pipefitters, and radiological test engineers—whose skills require up to a decade to develop. In Hamilton Helmer's framework, Groton represents a quintessential cornered resource: the United States cannot replace it on any realistic operational timeline. On the fourth-quarter 2024 call, Novakovic rejected the premise that physical yard capacity was constraining production: "Our infrastructure is not the issue. We have a very robust, mature and advanced infrastructure. The issue has been within the industrial supply chain."1
The strategic role of the Columbia program reinforces that economic moat. Ballistic-missile submarines form the most survivable leg of the American nuclear triad because their stealth at sea makes them virtually invulnerable to a pre-emptive strike. Because the legacy Ohio-class boats are reaching the end of their operational hull lives, the replacement timetable is governed by metallurgy and physics rather than discretionary budget cycles. That operational imperative underpins Electric Boat's bargaining position: the Navy cannot cancel or indefinitely postpone the program. Yet that same existential urgency cuts both ways. When schedules slip, naval leadership exerts intense scrutiny and direct operational intervention, directing targeted funding into tier-two and tier-three suppliers, funding regional workforce training, and tightening schedule oversight.
Falsification 1: Not a monopoly, but a mandated duopoly
Despite common characterizations of Electric Boat as a monopoly, General Dynamics does not build American submarines alone. The Navy deliberately divides construction between Electric Boat and Huntington Ingalls' Newport News Shipbuilding. Under this teaming arrangement, the two yards build dedicated structural modules and alternate final assembly so that both industrial facilities remain operational. The $76.6 billion award in July 2026 went to both shipbuilders jointly and did not specify the exact division of work.[^30] The Pentagon structured this duopoly specifically to limit sole-source pricing leverage. A true monopolist dictates prices; General Dynamics' submarine business operates within financial boundaries established by its customer.
Falsification 2: The schedule record
A cornered industrial asset is only as valuable as its output, and in recent years that output has suffered chronic delays. In April 2024, the Navy's 45-day shipbuilding review revealed that the lead Columbia boat was running 12 to 16 months late, while Virginia Block IV and Block V attack submarines were delayed by 36 months and 24 months, respectively.[^31]25 Subsequent Navy fiscal year 2026 budget documents revised the expected delay on the lead Columbia hull to roughly 17 months.26 Through mid-2025, the domestic industrial base was completing roughly one Virginia-class boat per year against a stated Navy procurement target of two.[^30] Asked about build rates in July 2026, General Dynamics' president declined to provide specific annual delivery milestones, stating only that the company was "on that path" toward delivering two Virginia boats and one Columbia submarine per year "in the early 2030s."4
Falsification 3: Out-of-sequence work and margin destruction
The primary driver of Marine Systems' margin compression carries a straightforward industrial name: out-of-sequence work. Modern submarines are assembled from massive, pre-outfitted cylindrical hull modules, each weighing thousands of tons, joined together in an exacting sequence. In residential construction, installing plumbing and electrical wiring through open wall studs is fast and economical; if the pipes arrive only after the drywall is finished, workers must tear open walls, work inside cramped spaces, and rebuild what was already completed. In submarine manufacturing, Novakovic explained, out-of-sequence work can cost "as much as eight times more" than executing tasks in their planned order.[^29]
That dynamic explains why Marine Systems' revenue expanded rapidly while operating profits contracted. In the fourth quarter of 2024, Marine revenue rose 16.2% while operating earnings fell 7.8%, with segment margin declining 130 basis points due to supplier delays and parts rework.1 Post-pandemic inflation compounded the pressure. While shipbuilding contracts incorporate economic price adjustment clauses, Novakovic pointed out that certain material costs surged 37%, far exceeding what those clauses were designed to absorb.1 Fixed-price shipbuilding contracts negotiated prior to broad macroeconomic inflation effectively functioned as unhedged options sold by the contractor to the Navy.
The recovery, and what it proves
Operating performance has since begun to stabilize. In the fourth quarter of 2025, Marine operating earnings rebounded 72.5% year over year, supported by a 13% expansion in submarine tonnage produced at Electric Boat.27 By the second quarter of 2026, Marine margins recovered to 7.3%, prompting management to raise full-year margin guidance to 7.4%.34 At Electric Boat, Columbia labor hours earned increased 37% in the first half of 2026, while deliveries of sequence-critical components rose 65% year over year during the second quarter.4
Even so, an operating margin in the 7% range represents a return to an ordinary industrial baseline rather than proof of an unassailable franchise. Capital requirements are climbing in parallel: management projected 2026 capital spending between 3.5% and 4.0% of sales, directed primarily toward shipyard modernization,4 up from 1.9% of sales in 2024.1 The disclosed evidence supports a narrower conclusion than the popular monopoly thesis suggests. Marine Systems is an irreplaceable national asset whose pricing is governed by a monopsony buyer. It offers decades of visibility on federal demand, but with financial returns bounded by government contract structures. The critical operational benchmarks remain segment operating margins—now stabilizing above 7%—and steady delivery cadences. The finalized terms of the Block VI contract will show whether the Navy has priced in more realistic inflation and supply-chain buffers. Meanwhile, the enterprise's most profitable division, Gulfstream, contends with a very different operating constraint: regulatory approvals rather than industrial parts.
VII. Aerospace: Gulfstream, The G700 Certification Saga, & Luxury Economics
In the second half of 2024, Savannah, Georgia, confronted an operational bottleneck that illustrates the dynamics of the Gulfstream franchise. The G700, the company's new flagship, received Federal Aviation Administration (FAA) certification on March 29, 2024.28 Customers were waiting and the order book was full, yet finished aircraft stalled on the factory floor instead of heading to buyers. On the fourth-quarter 2024 earnings call, Novakovic explained the breakdown: jet engines had arrived late from suppliers, but Gulfstream proceeded to paint the airframes anyway, ultimately forcing crews to repaint many of them. The company also pushed airframes into interior completion centers before installing the engines, bypassing the standard operational step of testing every electrical and cabin system under power. "It seemed like a rational decision at the time," Novakovic acknowledged, but it "turned out to be quite troublesome."1
The delivery impact was severe. Gulfstream had initially guided to 50 to 52 G700 deliveries in 2024, but handed over only 30. In the third quarter of that year, it planned for 15 to 16 deliveries and managed just four.1 A defective supplier component forced replacements across multiple airframes, bespoke handcrafted interiors required separate cabin certifications, and international buyers faced their own protracted registration reviews.1 For investors, the disclosure offered a rare window into operational self-assessment: management acknowledged an internal execution failure, quantified the cost, and outlined the procedural remedies. It also underscored a fundamental distinction in aerospace manufacturing: Gulfstream was not demand-constrained, but execution-constrained.
The business aviation machine
Gulfstream's in-service lineup now spans the G500, G600, G700, and G800, with the G400 and a new super-midsize G300 under development.5 The G700 is certified for a range of 7,750 nautical miles at Mach 0.85, with a maximum operating speed of Mach 0.935.29 The G800, optimized for ultra-long-range missions and sharing substantial parts commonality with the G700, earned dual certification from the FAA and the European Union Aviation Safety Agency (EASA) in April 2025, offering a range of 8,200 nautical miles.30 In September 2025, Gulfstream introduced the G300 to replace the legacy G280.31 Complementing the manufacturing operation, Jet Aviation provides maintenance, completions, fixed-base operations, and aircraft management—generating recurring aftermarket services revenue throughout the operational life of the fleet.
The manufacturing recovery took hold quickly. In the fourth quarter of 2024, Aerospace revenue surged 36.4%, driven by 47 deliveries in the final three months of the year.1 Total Gulfstream deliveries climbed from 136 aircraft in 2024 to 158 in 2025.2 By the second quarter of 2026, Aerospace generated $510 million in operating earnings on $3.5 billion of revenue—a 14.5% operating margin—while posting a 1.5-times book-to-bill ratio.3 For full-year 2026, management projected approximately 160 aircraft deliveries and an operating margin near 14.7%.4
The seven powers, tested
Does the business-jet unit possess an enduring economic moat? In strategic terms, three distinct mechanisms support its defensibility. The first is brand equity and pricing power. While Novakovic avoids discussing list pricing, order backlogs stretching beyond a year, coupled with expanding margins alongside higher delivery volumes, demonstrate that buyers are paying full value rather than negotiating discounts. The second is fleet commonality and switching costs. Corporate flight departments train pilots on specialized type ratings and maintain proprietary spare-parts inventories for specific aircraft families. Gulfstream deliberately engineered its fleet architecture, in Novakovic's words, "to satisfy the missions that we knew that our customers flew."4 Transitioning an entire corporate fleet to Bombardier or Dassault entails substantial switching costs in crew retraining, tooling, and maintenance infrastructure. The third is aftermarket services revenue, which expands predictably as Gulfstream's installed fleet grows.
Yet the counter-arguments are equally substantive. Bombardier's Global 7500 and Global 8000 compete directly against Gulfstream at the pinnacle of the market, while Dassault's Falcon 10X represents a formidable future entrant. Gulfstream's market leadership requires continuous capital outlays to refresh model lines and preserve performance supremacy. Furthermore, when an analyst suggested Gulfstream shares the economics of high-end luxury goods makers boasting operating margins above 20%, Novakovic firmly rejected the framing: "I'm going to quarrel with you on 1 word, luxury... These are not luxury yachts that sail around the Mediterranean."4 Beyond brand semantics, her pushback served as a cautionary note against modeling luxury-brand margins. She also declined to provide long-range margin targets, pointing out that an earlier margin peak was "really all around 1 product," whereas the current portfolio blends multiple models at differing margin profiles.4
Certification is not commercialization
The protracted development of the G700 demonstrates that regulatory approval represents a substantial operational risk. When Gulfstream unveiled the program at the National Business Aviation Association convention in October 2019, it targeted entry into service by 2022.32 Final FAA certification was delayed until March 2024,28 as regulatory agencies enacted far more exhaustive review protocols following the Boeing 737 MAX disasters. The multi-year delay tied up significant working capital: in 2024, General Dynamics converted only 85% of net income into free cash flow, a shortfall management attributed directly to working-capital absorption from completed airframes awaiting delivery.1 The experience altered executive expectations. As Novakovic bluntly told analysts, "I'm no longer in the business of estimating EIS [entry into service] given that the regulators set the pace."4
Macroeconomic cyclicality poses an even greater structural threat. During an economic downturn, corporate aviation is historically among the first capital expenses curtailed. Clients defer scheduled deliveries, offload pre-owned airframes, and freeze new orders, creating an influx of used aircraft that depresses secondary prices and undercuts new-build demand. Gulfstream's recent order momentum has been buoyed by years of elevated equity markets and robust corporate profits. While management cites healthy sales prospect counts, regional interest, and a 1.3-times trailing book-to-bill ratio,4 that backlog represents past customer commitments rather than a shield against a sudden macroeconomic shock.
Operational transitions also lie ahead. Deliveries of the final G280 aircraft are scheduled for the second quarter of 2027, with the replacement G300 not expected until "late '27, early '28," creating a planned production hiatus in the mid-size category.4 Meanwhile, G700 margins continue to ramp up as the Savannah completion center refines its learning curve.4 Broader geopolitical and macroeconomic crosscurrents also linger; in the second quarter of 2026, Novakovic acknowledged "cautious concern from customers in the Middle East," even as those buyers remained active in the sales pipeline.4
Aerospace remains General Dynamics' highest-return operating division, propelled by strong order books and a favorable multi-model product cycle. Yet it is also inherently cyclical, beholden to regulatory timetables, and vulnerable to complex manufacturing missteps, as the 2024 delays proved. For investors, the decisive metric to track is segment book-to-bill by dollar value. If that ratio drops persistently below 1.0, it will signal that the private aviation cycle is cooling. The company's defense divisions, meanwhile, confront an entirely different set of strategic dilemmas: whether their legacy platforms remain suited to the evolving realities of modern warfare.
VIII. Combat Systems & Technologies: Heavy Armor, Artillery, and Federal Cyber
In September 2023, the U.S. Army announced the cancellation of the M1A2 SEPv4, the next modernization of the Abrams main battle tank that General Dynamics had developed for years and had expected to enter production that spring.33 "The Abrams Tank can no longer grow its capabilities without adding weight," explained Major General Glenn Dean, noting that "the war in Ukraine has highlighted a critical need for integrated protections for soldiers, built from within instead of adding on."3334 In its place, the Army pivoted to developing the M1E3, a lighter and more fuel-efficient design engineered for the operating environment of the 2040s, with initial fielding projected for the early 2030s.33
The cancellation confirmed that General Dynamics' signature land-warfare platform had reached the structural limit of incremental upgrades. Battlefield footage from Ukraine of multi-million-dollar armored vehicles disabled by low-cost commercial drones rapidly shifted how military planners evaluated heavy armor. While General Dynamics Land Systems retained its franchise role as the Abrams prime contractor, the Army's decision required a clean-sheet architectural redesign rather than bolt-on electronic enhancements.
Combat Systems: strong demand, uneven execution
Despite that platform reset, Combat Systems has remained the corporation's most consistent operating unit, delivering operating margins of 14.2% in 2024 and 14.4% in 2025.12 Demand has been propelled by widespread rearmament among NATO allies. In the fourth quarter of 2025, the segment posted a book-to-bill ratio of 4.3 times, driven by more than $4 billion in orders for Eagle armored vehicles from Germany.27 That momentum carried into the second quarter of 2026, when book-to-bill reached 2.1 times—supported by contracts for Canadian armored combat support vehicles—lifting segment backlog to a record $29.4 billion.34 Management guided to double-digit revenue growth across both European Land Systems and Ordnance and Tactical Systems (OTS), projecting "high-single-digit growth for the group going forward," even as the domestic Land Systems business works through what executives termed a "transition period."4
The international expansion represents a deliberate structural hedge. Because General Dynamics European Land Systems operates through long-established subsidiaries across the continent, Novakovic pointed out in early 2025 that European governments' growing preference for purchasing from local manufacturers had not disadvantaged the business.1 That sovereign footprint provides a tangible competitive edge over purely American suppliers. Yet it does not insulate General Dynamics from intensifying regional rivalry. Continental competitors such as Rheinmetall and KNDS are expanding their own production lines using the same rearmament funding, and European procurement ministries routinely distribute manufacturing work across national industries to protect local employment. While the segment's record backlog demonstrates robust international demand, it does not guarantee that General Dynamics will capture more than its historical share of the European market.
Falsification: the artillery shell shortfall
The war in Ukraine also caused an acute global ammunition crisis, as NATO stockpiles of 155-millimeter artillery shells depleted rapidly. In 2024, the U.S. Army established an urgent target to surge domestic production from 14,000 rounds per month to 100,000 by October 2025, placing General Dynamics' OTS unit at the center of the industrial ramp.[^42] To anchor that expansion, the Army committed $469 million toward a highly automated metal parts facility in Mesquite, Texas, operated by General Dynamics OTS, which opened in 2024 with a design capacity of 30,000 projectile bodies each month.[^42]
A Department of Defense Inspector General report released in July 2026, however, revealed that the Mesquite plant had produced zero production shells.[^42] Across the wider industrial base, the Army was producing roughly 36,000 rounds monthly as of March 2026, falling well behind its target timetable.[^42] General Dynamics' Scranton plant was manufacturing approximately 15,000 shells a month against a 35,000-round target, while its Wilkes-Barre facility, producing roughly 21,000 rounds, was meeting operational goals.[^42] The production shortfall drew rare public censure in February 2026 from Brent Ingraham, the Army's principal deputy assistant secretary for acquisition, who stated: "I'm not happy with where we are at Mesquite either."[^43] General Dynamics OTS subsequently confirmed it had "reached an agreement with the Army" and would make additional capital investments of its own to complete the site, while the Army prepared to scale back the facility's planned manufacturing configuration from three lines to two.[^42]
The setback extends well beyond the struggles of an individual factory. Executive commentary regarding munitions expansion had been consistently upbeat; on the fourth-quarter 2024 earnings call, Novakovic assured investors that new artillery capacity "is coming online."1 The Inspector General's findings illustrated the significant gap between announcing production targets and delivering finished munitions. While artillery revenue will continue to rise given sustained Pentagon orders, the Mesquite bottlenecks demonstrate that General Dynamics is not immune to complex manufacturing and tooling delays when scaling new production facilities.
Falsification: the Ajax saga
The British Army's Ajax armored vehicle program highlights an even more severe operational breakdown. In 2014, General Dynamics Land Systems UK secured a £5.5 billion fixed-price contract to deliver 589 Ajax armored reconnaissance vehicles.35 Initial operating capability was originally scheduled for 2017. Troop trials were subsequently halted after soldiers sustained severe noise and vibration injuries, leading the UK Ministry of Defence to withhold progress payments starting in 2020; payments totaling £480 million resumed only in 2023 under a restructured timetable.35 Although the platform finally reached initial operating capability in November 2025, the fleet was grounded three weeks later after 31 soldiers reported acute health issues during Exercise Titan Storm on Salisbury Plain.36 British Defence Minister Luke Pollard responded that the government would refuse to accept "any platform that we did not think was safe."36
While the Ajax program represents a relatively modest share of General Dynamics' total corporate revenue, it carries substantial weight in assessing the company's execution discipline. The episode illustrates how an inflexible fixed-price development contract can impair capital, strain a premier allied customer relationship for over a decade, and leave a flagship platform's operational deployment in doubt.
Technologies: the quiet cash engine
By contrast, the Technologies segment operates without the high-profile manufacturing setbacks seen in heavy armor, though with comparatively modest top-line growth. In the second quarter of 2026, the unit generated $3.6 billion in revenue, up 4.1% year over year, with an operating margin of 9.4%, as Mission Systems outpaced GDIT.34 Mission Systems, which produces secure communications gear, cryptographic devices, and command-and-control architectures, completed a multi-year portfolio repositioning away from legacy programs; management reported that its international sales had risen more than 35% since 2024.4 Meanwhile, GDIT secured more Other Transaction Authority contracts during the first half of 2026 than in all of 2025, pointing to an active qualified pipeline exceeding $120 billion.4 Even so, GDIT competes in a crowded government-services field alongside Leidos, Booz Allen Hamilton, CACI, and SAIC, where contract pricing remains tightly contested.
A longer-term structural challenge centers on technological disruption. When asked by analysts whether generative artificial intelligence could compress GDIT's addressable procurement market, Novakovic cited the company's internal "digital accelerators" but did not quantify the financial downside.4 That strategic question is likely to intensify: because a substantial portion of federal IT services is billed through labor hours, productivity gains delivered by automation could directly diminish billable contract revenue. For now, Technologies serves as a predictable, asset-light generator of cash that helps support the capital requirements of the company's shipyards and aerospace completion lines. How those contrasting operating profiles hold up under formal scrutiny, however, requires evaluating General Dynamics across established competitive frameworks.
IX. Strategic Tear-Down: Porter's Five Forces & Hamilton Helmer's 7 Powers
Picture a war-game room with four tables—one for each General Dynamics operating segment, each with its own opponent and its own customer. At one table, the U.S. Navy and Huntington Ingalls sit across from Electric Boat. At another, Bombardier and Dassault face off against Gulfstream. At the third, Rheinmetall, BAE Systems, and the U.S. Army's M1E3 program office flank Land Systems. At the fourth, Leidos, Booz Allen Hamilton, and a steady stream of contract bid protests confront GDIT. General Dynamics is not engaged in a single unified competition; its strategic standing is really four distinct contests, requiring competitive frameworks to be applied franchise by franchise.
Hamilton Helmer's 7 Powers, applied piece by piece
Cornered resource represents General Dynamics' most formidable power, anchored primarily in Groton. Nuclear-certified submarine construction is an industrial capability the United States cannot realistically replicate or replace. Gulfstream's Savannah campus—with its engineering corps, interior completion centers, and decades of FAA certification experience—also constitutes a cornered resource, albeit a less exclusive one given that Bombardier and Dassault possess comparable facilities. The structural limit on this power remains customer monopsony: the Navy ultimately controls how much economic rent General Dynamics can extract from its yards.
Switching costs protect two corners of the portfolio. Corporate flight departments face costly pilot retraining, dedicated spare-parts inventories, and established maintenance relationships if they switch airframe manufacturers. Within Technologies, GDIT's classified network architectures are deeply embedded in agency operations, confronting federal buyers with significant transition risks they typically prefer to avoid. Yet that protection has boundaries: federal IT contracts face mandatory recompetes on set procurement schedules, and GDIT's capture rate in the mid-60% range on competitive bids1 implies that it loses roughly one out of every three competitions.
Scale economies are comparatively moderate. Combat Systems benefits from component purchasing volume and long production runs across tracked and wheeled vehicles, but continental peers—most notably Rheinmetall—are rapidly expanding manufacturing capacity on the back of the same European rearmament surge.
Counter-positioning is largely a historical artifact rather than an active defense. Bill Anders' 1990s playbook—shedding peripheral businesses to focus ruthlessly on select defense niches while rivals pursued sprawling mergers—effectively counter-positioned General Dynamics against traditional defense conglomerates. Today, having assembled its own multi-pillar enterprise, General Dynamics embodies the very conglomerate model it once defied, leaving the framework largely inapplicable to its current posture.
Network economies and process power offer minimal structural advantage across the portfolio, while brand serves as a genuine differentiator only at Gulfstream, where corporate and private buyers assign substantial equity to the marque.
Porter's Five Forces
Bargaining power of buyers: extreme. The U.S. government accounted for 68% of revenue in 2025, or $35.8 billion.5 As a monopsony buyer, the Pentagon establishes contract structures, audits accounting overhead, stretches out procurement timelines—negotiations for the Block VI submarine contract spanned nearly three years[^30]—and cancels major development efforts outright, as it did with the cancellation of the SEPv4.33 On the second-quarter 2026 earnings call, an analyst asked whether the administration's push toward fixed-price contracting would alter GDIT's operating economics.4 Another raised the Defense Department's reportedly critical posture toward defense contractor share buybacks.4 Both inquiries illustrate that the customer exercises considerable sway not merely over contract terms, but over corporate capital allocation itself.
Threat of new entrants: very low. The capital requirements, regulatory hurdles, and security clearances needed to construct nuclear-powered submarines, certify transoceanic business jets with the FAA, or establish heavy armored manufacturing lines run into billions of dollars and take decades to assemble, effectively barring de novo entrants.
Threat of substitutes: moderate and rising. The proliferation of loitering munitions and commercial drones has fundamentally challenged the tactical utility and survivability of heavy armor. In naval warfare, unmanned undersea vehicles serve primarily to augment rather than displace manned nuclear submarines, while digital conferencing tools have had only a marginal impact on executive business aviation. The acute substitution threat remains concentrated in Land Systems.
Supplier power: high. Single-source and specialized suppliers of heavy forgings, marine valves, steam turbines, and jet engines dictate operational tempo for both Electric Boat and Savannah. As General Dynamics' president noted in July 2026, "areas of concern haven't really changed where we have single sources of supply for large complex components."4
Competitive rivalry: intense within each segment. Rather than facing a single corporate adversary, General Dynamics confronts dedicated, well-capitalized specialists in every domain: Huntington Ingalls Industries in naval shipbuilding; Bombardier and Dassault in long-range business jets; Rheinmetall, BAE Systems, and KNDS in armored ground vehicles; and Leidos, Booz Allen Hamilton, CACI, and SAIC in federal IT contracting.
The overarching paradox of General Dynamics' strategic architecture is that its most impenetrable franchise—nuclear naval construction—is where its customer wields near-absolute bargaining leverage, while its most lucrative earnings driver—Gulfstream—is where it confronts its fiercest commercial rivals. That structural tension explains much of the enterprise's unique financial and cash-generation profile, which the next section examines.
X. Financial Architecture, Capital Allocation, & Governance
Every January, Novakovic opens the fourth-quarter earnings call with a measured litany of metrics: revenue, operating earnings, net income, and diluted earnings per share, each systematically benchmarked against the prior year and the prior quarter. The ritual underscores how General Dynamics seeks to be evaluated. Management makes few promises of rapid top-line expansion, framing the investment case instead around steady cash generation and return on invested capital. The question for investors is whether the underlying cash record supports that discipline.
The cash conversion claim, checked
General Dynamics' stated goal is free cash flow conversion "at or around 100%" of net income.1 In practice, the annual performance fluctuates considerably. Free cash flow conversion reached 115% in 2023 before dropping to 85% in 2024, when the company generated $3.2 billion of free cash flow on $4.1 billion of operating cash flow, resulting in a three-year average conversion rate of 100% from 2022 through 2024.1 In 2025, operating cash flow climbed to $5.1 billion, or 122% of net income, producing roughly $3.96 billion in free cash flow after deducting $1.2 billion in capital expenditures.2 Cash generation in the first half of 2026 proved exceptionally strong, delivering $3.6 billion in free cash flow and a conversion rate exceeding 150%, though the chief financial officer guided full-year conversion down to approximately 105% to account for accelerating capital spending, a $500 million voluntary pension contribution, and cash tax payments weighted heavily toward the second half.4
Market summaries often cite a 109% conversion rate for 2024. That calculation, however, reflects operating cash flow divided by net income. Free cash flow conversion—the stricter standard General Dynamics itself targets—was 85% that year.1 While the distinction may appear semantic, it illustrates why investors must scrutinize the exact cash metrics in company disclosures. Over multi-year horizons, General Dynamics' claim to approximately 100% free cash flow conversion holds up. Yet in any individual year, working-capital swings—driven by completed Gulfstream airframes awaiting final customer delivery or shipbuilding milestone billings that have yet to be finalized—can shift the conversion rate by 15 to 30 percentage points.
Where the cash goes
Capital allocation priorities have begun to shift in a visible way. Capital spending stood at 1.9% of sales, or $916 million, in 2024,1 but management projected outlays between 3.5% and 4.0% of sales in 2026.4 That expansion represents a significant strategic pivot, channeling operating cash away from discretionary shareholder distributions and directly into shipyard infrastructure and automated manufacturing capacity. Dividends have remained a steady baseline, absorbing $1.5 billion in 2024 and $1.6 billion in 2025.12 In March 2026, the board increased the quarterly payout to $1.59 per share,37 extending an uninterrupted record of annual dividend increases that now spans more than three decades.
Share repurchases, by contrast, have fluctuated alongside operating needs. In 2024, General Dynamics repurchased 5.4 million common shares for $1.5 billion at an average price of $277, returning roughly 95% of its free cash flow to shareholders.1 Buybacks subsequently slowed to $637 million in 20252 and totaled $319 million during the first half of 2026, an amount management described as primarily designed to offset executive compensation dilution.34 Cash flow was directed instead toward deleveraging: net debt fell from $7.1 billion at year-end 2024 to $5.7 billion by late 2025 and dropped to $3.2 billion by mid-2026.123 With the shares recently trading near $344,6 the repurchases executed in 2024 were completed at an advantageous valuation. The deliberate moderation in share buybacks also aligns with the political climate in Washington, where Pentagon officials and lawmakers have grown increasingly critical of major defense contractors retiring equity while flagship procurement programs face multi-year delivery delays.
The balance sheet, quietly repaired
The corporate balance sheet has undergone a more comprehensive restructuring than headline figures suggest. While General Dynamics relied on the commercial paper market to manage short-term liquidity throughout 2025, it had completely vacated that facility by mid-2026. Net interest expense declined from $177 million in the first half of 2025 to $118 million in the first half of 2026, and the chief financial officer confirmed that the company had no plans to refinance notes maturing later that year.4 In parallel, the planned $500 million voluntary pension contribution was engineered to "derisk those plans and eliminate significant volatility," moving several legacy plans toward fully funded status.4 Collectively, these balance-sheet adjustments position the enterprise to absorb heavy shipyard capital commitments while preserving dry powder for future transactions. While Novakovic routinely deflects M&A inquiries, she has acknowledged that a "particularly attractive bolt-on" acquisition remains under active consideration.4
That financial flexibility invites historical scrutiny. The last time General Dynamics accumulated comparable balance-sheet headroom, it deployed approximately $9.7 billion to purchase CSRA in 2018. Preserving dry powder is advantageous only if subsequent acquisitions satisfy a far more demanding return threshold than the information-technology roll-ups that triggered the 2012 write-down. Until management announces its next strategic transaction, that capital discipline remains an open question.
Management credibility: promises versus outcomes
A balanced evaluation of management requires weighing public commitments against ultimate operational results. In 2024, executive guidance for Gulfstream missed expectations by a wide margin; management responded with a more conservative posture for 2025, ultimately exceeding its targets by delivering 158 business jets against an initial forecast of 150.12 Similarly, initial 2025 guidance projected Marine Systems revenue near $15 billion with an operating margin of 6.8%;1 the division outperformed, generating $16.7 billion at a 7.0% margin.2 For 2026, management raised full-year EPS guidance twice, moving from an initial range of $16.10 to $16.20 in January to $16.80 to $16.90 in July.4 Over the recent period, the company has established a pattern of guiding conservatively and subsequently outperforming. That approach mirrors Novakovic's refusal in early 2025 to commit to a margin floor for Marine Systems, citing persistent "unknown unknowns" across the naval supply base.1
Taking a longer view, the record reveals notable forecasting lapses. In 2024, Savannah leadership projected with high confidence that G700 deliveries would ramp evenly across three quarters, only to miss its delivery target by roughly 40%.1 Prior to 2023, Marine Systems guidance repeatedly factored in an imminent supply-chain recovery that failed to materialize, forcing executives to explain the compounding costs of out-of-sequence assembly quarter after quarter.[^29]1 The conservative guidance of recent years is partly a reaction to those earlier miscalculations. Restoring credibility through subsequent outperformance is commendable, but investors must remember why that baseline had to be reset.
Operational hurdles have also surfaced across other divisions, including internal completion bottlenecks on the G700, protracted tooling delays at the Mesquite artillery plant, and persistent vibration issues on the British Ajax fleet. These episodes demonstrate that while management provides unusually candid, detailed forensic post-mortems when problems emerge, operational execution remains vulnerable to industrial friction.
Governance and succession
General Dynamics continues to combine the roles of chairman and chief executive, both of which Novakovic has held since January 2013. In recent quarters, however, a structured succession path has become increasingly visible. Danny Deep, an insider who spent more than two decades at General Dynamics and previously led Land Systems and the wider Combat Systems segment, was appointed president in December 2025 and elected to the board of directors in August 2026.38 Deep fielded a significant portion of operational questions from equity analysts on the second-quarter 2026 earnings call.4 While the board has made no formal leadership announcement, the market increasingly regards him as the presumptive successor. For long-term investors, the eventual transition from Novakovic's return-driven, idiosyncratic leadership style represents the central corporate governance milestone ahead.
XI. The Activist Stress-Test & The Bull vs. Bear Case
Picture a letter from an activist investor arriving at General Dynamics' Reston, Virginia headquarters. The core thesis would be straightforward. General Dynamics trades at roughly 20 times guided 2026 earnings.46 As a standalone enterprise, Gulfstream might command the premium valuation multiples awarded to civil aerospace leaders. GDIT could be merged with a pure-play government IT services provider. Meanwhile, the remaining defense hardware business—nuclear submarines, surface combatants, armored fighting vehicles, and munitions—could trade as an unencumbered rearmament pure play. The activist's conclusion would be familiar: the sum of the parts is worth materially more than the whole.
The case for the break-up
The strongest version of that breakup argument uses General Dynamics' own segment reporting. Aerospace and Combat Systems generate operating margins of 14% and higher,3 whereas Marine Systems delivers roughly 7% and Technologies sits near 9.4%.4 Consolidated corporate operating margins around 10.5%4 simply average two high-margin franchises with two lower-margin units, diluting the headline performance of the best businesses. An activist would also argue that this structure creates a reciprocal valuation penalty: Gulfstream's commercial cyclicality leads defense investors to discount the predictable government earnings, while the low single-digit growth of the defense and IT segments leads aerospace investors to discount Gulfstream.
Why management resists, and whether the reasoning holds
Management's defense, rarely articulated as a formal manifesto but evident in corporate capital allocation, centers on balance-sheet resilience and counter-cyclical funding. Marine Systems requires capital expenditures that will roughly double as a share of sales in 2026,4 and working capital absorbs substantial cash whenever Gulfstream delivery milestones slip or when major defense contract terms remain in negotiation.1 Anchoring four distinct operating divisions under a unified corporate treasury allows General Dynamics to absorb those cash-flow swings internally without issuing equity. In 2024, steady cash generation from Technologies and Combat Systems cushioned Gulfstream's working-capital drain; by 2026, robust cash flow from Gulfstream deliveries helped finance heavy shipyard modernization.4
That logic is operationally coherent, yet financially incomplete. A standalone Electric Boat, backed by direct Navy capital investments and an investment-grade credit rating, could likely fund its own requirements. The far more practical constraint is institutional: the U.S. Navy strongly prefers a well-capitalized, multi-billion-dollar corporate parent standing behind its sole nuclear ballistic-missile shipyard. A breakup proposal therefore confronts a formidable political and customer obstacle alongside any financial hurdles. So long as Novakovic remains chief executive, the multi-pillar structure is virtually unassailable. Following an eventual leadership transition, however, the sum-of-the-parts debate will inevitably re-emerge.
The long-term bull case
The submarine supercycle. The $76.6 billion award in July 2026[^30] secures shipyard volume well into the late 2030s, while Marine Systems margins are rebounding from post-inflation lows. If build cadences accelerate toward two Virginia-class attack boats and one Columbia-class submarine annually, the company's largest segment by revenue will enjoy a sustained, multi-year expansion accompanied by steady margin improvement.
Gulfstream's product renewal. A fully refreshed lineup spanning the G300 through the G800, rising G700 margins as the Savannah manufacturing learning curve matures,4 and an Aerospace backlog standing at $24 billion3 provide the corporation's most profitable earnings engine with long-term visibility.
Global rearmament. Book-to-bill ratios in Combat Systems ranging between 2.1 and 4.3 times in recent quarters327 demonstrate that European, Canadian, and allied demand for armored fighting vehicles and munitions represents a durable, structural rearmament cycle rather than a temporary surge.
Balance-sheet flexibility. Having brought net debt down to $3.2 billion,3 General Dynamics commands ample balance-sheet headroom to pursue selective bolt-on acquisitions, accelerate share buybacks, or increase dividend distributions, regardless of executive reticence regarding M&A on quarterly calls.
The long-term bear case
Fixed-price shipbuilding risk. If contractual pricing for Block VI Virginia and Build II Columbia submarines once again understates industrial inflation and supplier delays, Marine Systems margins could remain pinned near 7% across an expanding revenue base, tying up elevated capital spending while generating depressed returns on invested capital.
The business-jet cycle. A broader macroeconomic downturn, a sharp contraction in corporate earnings, or falling equity valuations could rapidly curtail new orders at Gulfstream. The planned production pause in the mid-size cabin segment during 2027,4 as the legacy G280 phases out ahead of the G300, compounds operational vulnerability during that transition.
Budgetary and political friction. Protracted congressional reliance on continuing resolutions, fiscal debates, and shifting Pentagon modernization priorities create procurement instability. As Novakovic observed in July 2026, "there are a lot more factors today influencing the budget than there have been historically."4
Tactical vulnerability of heavy armor. The proliferation of loitering munitions and commercial drones on modern battlefields continues to challenge the operational survivability of heavy armor. While the clean-sheet M1E3 program33 preserves General Dynamics' development role, it introduces architectural uncertainty and could open the door to competing design philosophies over time.
Execution credibility. Tooling and ramp-up stalls at the Mesquite artillery plant, chronic developmental and injury setbacks on the British Ajax fleet, and the 2024 delivery logjam on the G700 illustrate a recurring operational vulnerability: General Dynamics routinely excels at high-rate serial manufacturing on mature platforms, yet repeatedly encounters friction when standing up new facilities and fielding clean-sheet programs.
Succession risk. Novakovic has defined corporate strategy and operating culture since 2013. Her return-on-invested-capital discipline, deep relationships across the national security establishment, and uncompromising operational posture are difficult to institutionalize, making the eventual leadership transition a central test of organizational durability.
Weighing the two cases
Weighing the evidence reveals clear asymmetries between the two arguments. The contracted backlog is documented and legally binding, meaning the demand foundation of the bull case rests on verifiable commitments. By contrast, the margin-expansion thesis relies largely on executive forecasts and four to six quarters of operational stabilization following years of shipyard margin compression—a relatively brief track record. The bear case on industrial execution draws on specific, documented setbacks at Mesquite, on Ajax, and across the G700 delivery ramp, none of which has fully receded. Conversely, the bear case on demand—incorporating private aviation downturns and congressional budget gridlock—remains a plausible risk rather than a dynamic visible in current order books. The most balanced appraisal is that the demand case is established, the margin-recovery case is partly demonstrated, and the operational-execution case remains unproven.
Ultimately, the bull case depends on executing a backlog General Dynamics already holds, while the bear case rests on the twin hazards of manufacturing execution and fixed-price contract discipline. The decisive variable governing future returns is therefore not customer demand, but operational delivery. The final sections turn to the enduring strategic lessons investors can draw from this defense empire.
XII. The General Dynamics Playbook: Durable Business Lessons
On the second-quarter 2026 earnings call, when an analyst asked whether the Pentagon's push for secondary missile suppliers might benefit the company, management's response—that General Dynamics operates as a subcontractor and "certainly not a prime" in missiles4—reflected a consequential strategic choice made in 1992. For investors and corporate strategists, the enduring lessons of an enterprise with more than a century of operating history are valuable only when they account for both sides of that ledger.
1. Pruning has costs as well as benefits. Bill Anders proved in the early 1990s that divesting non-core or oversupplied businesses and returning the windfall directly to shareholders can unlock substantial capital in short order.1014 Yet the divestiture of the Fort Worth tactical aircraft division demonstrated the long-term cost: operations offloaded during cyclical troughs can evolve into the most valuable defense franchises of the following generation. Portfolio pruning demands analytical discipline not only about current cash returns, but about the long-term option value being surrendered.
2. Counter-cyclical balance sheets reduce volatility but do not remove it. Housing civil business aviation and nuclear shipbuilding under a single corporate treasury provides genuine cyclical diversification, as commercial demand and defense appropriations often move independently. Yet 2024 demonstrated that systemic industrial friction—most notably widespread supply-chain dislocations and parts shortages—can impair both operating units simultaneously.1 Segment diversification cushions macroeconomic earnings volatility, but it offers limited protection against shared industrial and supply-chain vulnerabilities.
3. When a company has one dominant customer, its terms define the franchise. Owning an irreplaceable, cornered industrial resource creates a formidable economic moat, but when that asset serves a monopsony government customer that dictates pricing, contract structures, and procurement pacing, high barriers to entry do not automatically translate into premium returns on invested capital. The operating history of Electric Boat demonstrates that an unassailable strategic position and an exceptional return on capital are distinct economic realities.
4. Out-of-sequence work costs rise non-linearly. Novakovic's observation that out-of-sequence manufacturing can cost as much as eight times more than planned assembly[^29] holds true across any complex industrial operation. When supplier components arrive late, forcing assembly lines forward without them often inflicts far greater financial damage than pausing production. The margin compression at Electric Boat and the costly decision to paint airframes and complete interiors before engine installation on the G700 in Savannah both demonstrated that premature progress destroys operating margins.1
5. Measure cash, not only earnings. General Dynamics' benchmark of converting roughly 100% of net income into free cash flow—and management's detailed accounting in years when conversion fell short, such as 20241—provides a rigorous framework for evaluating corporate performance. Yet investors must apply that same scrutiny to executive commentary: distinguishing between operating cash flow and true free cash flow, and assessing conversion rates over multi-year cycles rather than single-year anomalies where working-capital swings distort the headline figures.
XIII. Epilogue & The Next Horizon
John Holland’s first submarine for the U.S. Navy was a small gasoline-and-electric boat—virtually the entire output of an enterprise dependent on a single investor’s capital. In 2026, the corporation descended from that hull expects roughly $55.7 billion in revenue,4 employs more than 120,000 people,3 and holds an order backlog extending into the late 2030s.3[^30] Yet while the scale has transformed, the fundamental bargain remains unchanged: General Dynamics builds what one sovereign customer deems vital, and it accepts the financial and operational terms that customer dictates.
What to watch
Three key performance indicators capture the core of the investment case going forward.
Marine Systems operating margin, alongside submarine delivery rate. This is where the corporation’s largest revenue stream intersects with its primary operational risk. Margin expansion beyond the current 7% baseline as Block VI and Build II contracts phase in would validate that supply-chain bottlenecks are easing; a stall would confirm that government contract structures continue to cap profitability. Physical delivery cadences provide the parallel test: tracking progress toward delivering two Virginia-class attack submarines and one Columbia-class boat annually, which management targets for the early 2030s,4 will show whether shipyard throughput is keeping pace with contract awards.
Aerospace book-to-bill (dollar-based). This metric serves as the leading indicator for Gulfstream demand. The ratio stood at 1.5 times in the second quarter of 2026 and 1.3 times over the trailing twelve months.4 Several consecutive quarters below 1.0 would signal that the corporate aviation expansion has peaked and that macroeconomic headwinds are reaching executive order books.
Free cash flow conversion over multiple years. While annual conversion rates fluctuate sharply with working-capital movements, General Dynamics' ability to convert approximately 100% of net income into free cash flow across multi-year cycles underpins its dividend record and balance-sheet repair. A sustained shortfall—particularly if elevated shipyard capital expenditures fail to generate higher operating margins—would challenge management's central thesis of capital discipline.
Final reflection
General Dynamics has endured because it understands its structural identity: an asset-heavy industrial manufacturer building platforms central to national defense, paired with a premier civil aerospace franchise. Its competitive advantages are formidable, yet strictly bounded. Groton’s shipyards cannot be replicated, but the Navy ultimately dictates what they earn. Gulfstream leads its category, but its deliveries depend on broader economic health and regulatory approval timetables. Combat Systems rides a global rearmament wave, yet remains prone to production friction on new platforms. Technologies delivers predictable cash flow, but operates in a crowded, low-margin federal services market.
As a leadership transition approaches, the decisive question is whether that operational discipline has become permanently embedded across General Dynamics’ divisions, or whether it was primarily the product of Phebe Novakovic’s tenure. How the company executes on its record submarine contracts and navigates the next aerospace cycle will provide the answer.
References
-
General Dynamics (GD) Q4 2024 Earnings Call Transcript — The Motley Fool, 2025-01-29 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
General Dynamics Reports Fourth-Quarter and Full-Year 2025 Financial Results (Form 8-K Exhibit 99.1) — U.S. Securities and Exchange Commission, 2026-01-28 ↩↩↩↩↩↩↩↩↩↩↩
-
General Dynamics Reports Second-Quarter 2026 Financial Results (Form 8-K Exhibit 99.1) — U.S. Securities and Exchange Commission, 2026-07-29 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
General Dynamics (GD) Q2 2026 Earnings Call Transcript — The Motley Fool, 2026-07-29 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
General Dynamics Corp Form 10-K for Fiscal Year 2025 — U.S. Securities and Exchange Commission, 2026 ↩↩↩↩↩
-
General Dynamics Corp Profile & Market Data — New York Stock Exchange ↩↩↩
-
General Dynamics Corporation — Company History — Company-Histories.com ↩↩↩↩↩↩↩↩↩
-
Chrysler sells profitable defense arm — UPI Archives, 1982-02-19 ↩
-
A Good Unwinding: Bill Anders and General Dynamics — Commoncog Case Library ↩↩↩
-
Buffett buys 14.9 percent of General Dynamics — UPI Archives, 1992-07-23 ↩↩↩↩↩
-
Lockheed to acquire jet division; General Dynamics selling F-16 program — The Baltimore Sun, 1992-12-10 ↩↩
-
Textron to buy Cessna for $600 million — UPI Archives, 1992-01-20 ↩
-
General Dynamics to sell missile unit; Hughes deal continues consolidation — The Baltimore Sun, 1992-05-12 ↩
-
Buffett gives General Dynamics proxy on shares — UPI Archives, 1992-09-17 ↩
-
The Biggest Acquisition In Private Jet History — Simple Flying ↩↩↩
-
General Dynamics Corp Form 8-K (Completion of Gulfstream Merger) — U.S. Securities and Exchange Commission, 1999 ↩↩
-
General Dynamics buys Bath Iron Works — Tampa Bay Times, 1995-08-18 ↩
-
General Dynamics completes purchase of GM Defense — Automotive News, 2003-03-03 ↩
-
General Dynamics to Acquire Jet Aviation (Form 8-K Exhibit 99.1) — U.S. Securities and Exchange Commission, 2008-08 ↩
-
General Dynamics announces $2.1B loss — Military.com, 2013-01-23 ↩↩↩
-
Phebe Novakovic: The Spy in General Dynamics' Corner Office — Fortune, 2015-09-11 ↩↩↩↩↩↩↩↩
-
General Dynamics to Acquire CSRA (Form 8-K Exhibit 99.1) — U.S. Securities and Exchange Commission, 2018-02-12 ↩↩↩
-
General Dynamics completes CSRA acquisition — Defense News, 2018-04-03 ↩↩↩
-
Navy 45-Day Shipbuilding Review Findings & Delays — U.S. Naval Institute (USNI News), 2024-04-02 ↩
-
Navy Columbia (SSBN-826) Class Ballistic Missile Submarine Program: Background and Issues for Congress — Congressional Research Service ↩
-
General Dynamics (GD) Q4 2025 Earnings Transcript — The Motley Fool, 2026-01-28 ↩↩↩
-
Gulfstream G700 Earns FAA Certification — Gulfstream Aerospace Corporation, 2024-03-29 ↩↩
-
Globe-girdling Gulfstream G700 Gets FAA Greenlight — Aviation International News, 2024-03-29 ↩
-
Gulfstream G800 Wins FAA and EASA Certification — Aviation International News, 2025-04-16 ↩
-
Gulfstream G700 On Track For 2022 Entry-Into-Service — Aviation Week ↩
-
US Army scraps Abrams tank upgrade, unveils new modernization plan — Defense News, 2023-09-06 ↩↩↩↩↩
-
Army Announces Modernization Strategy for M1E3 Abrams Tank — U.S. Army, 2023-09-06 ↩
-
UK's Ajax vehicle program now on track after noise, vibration issues — Defense News, 2023-03-20 ↩↩
-
Ajax on hold as 31 fall ill in major safety setback for Army's beleaguered £5.5bn AFV — Forces News, 2025-11 ↩↩
-
General Dynamics Board Declares Dividend — PR Newswire, 2026-03-09 ↩
-
General Dynamics Elects President Danny Deep to Board — GovCon Wire, 2026-08-07 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube