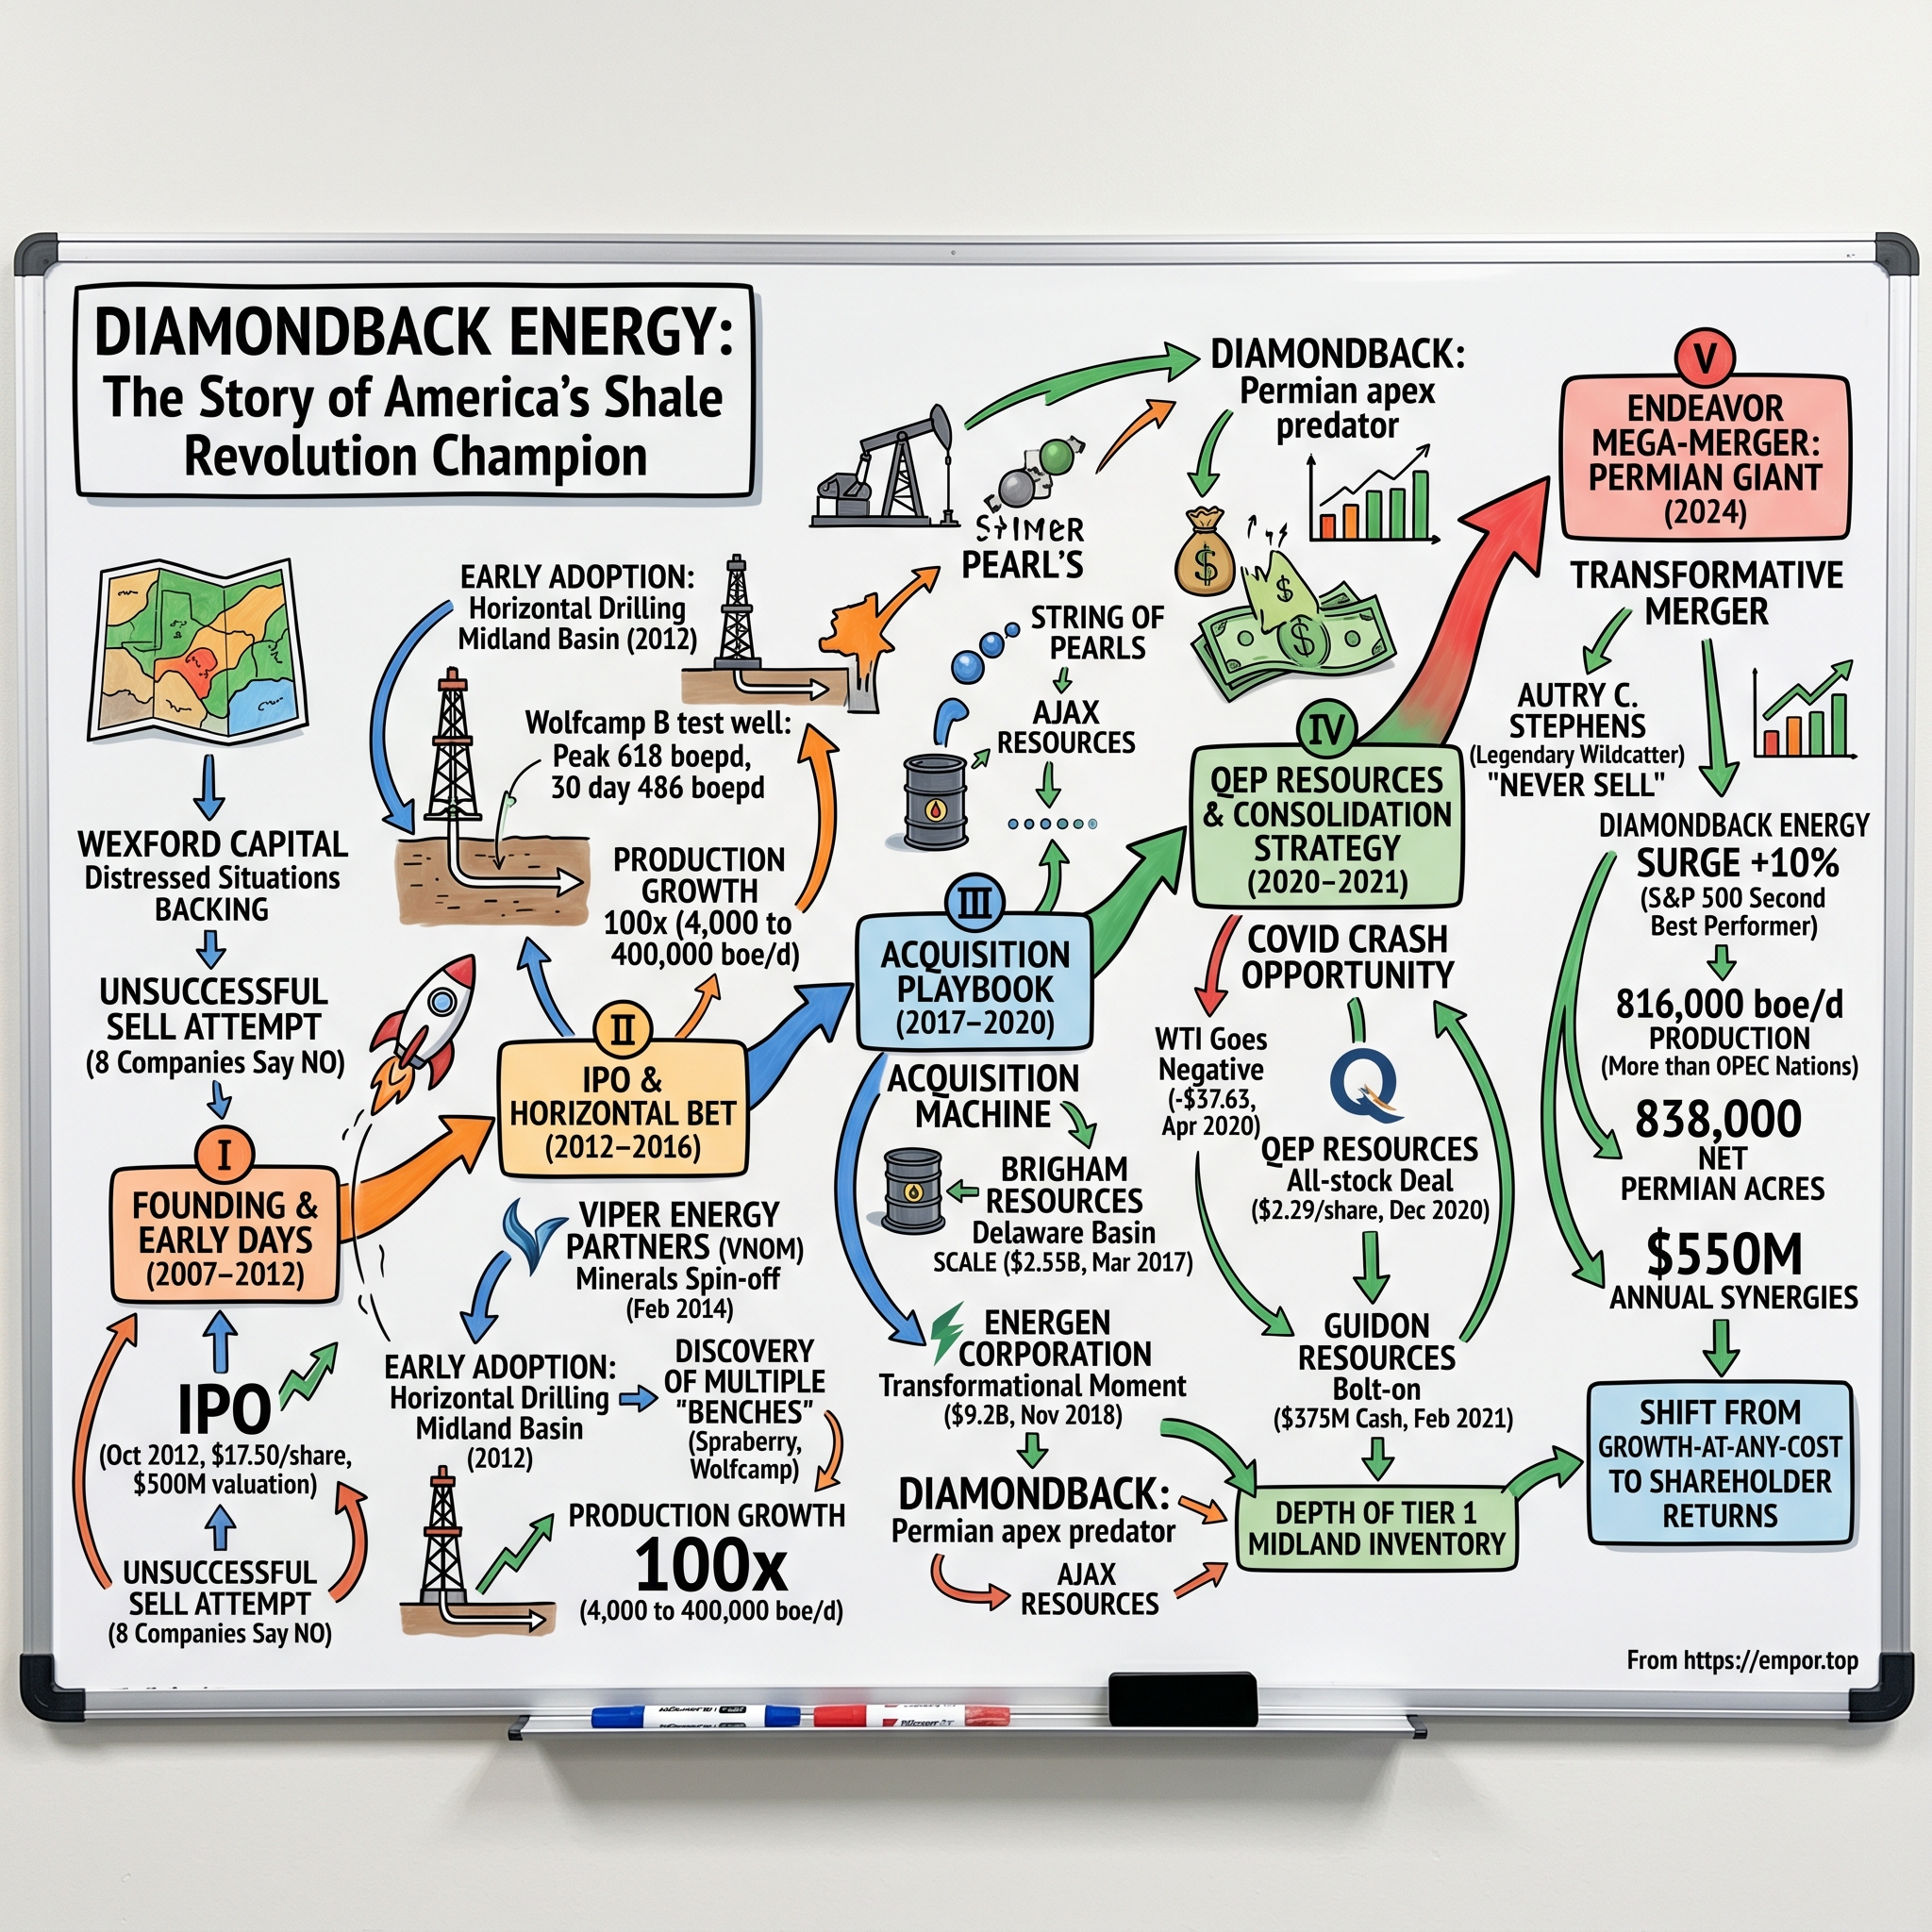
Diamondback Energy: The Story of America's Shale Revolution Champion
I. Introduction & Episode Roadmap
There is a particular kind of silence that settles over a data room when nobody bids.
In late 2011, a small West Texas oil company with a few thousand acres of Permian Basin acreage put itself up for sale. Eight separate exploration and production companies reviewed the well logs, evaluated the economics, and walked away without submitting an offer. The private equity sponsors backing the company had reached their investment limits and declined to provide additional capital. The company carried a name that sounded more like a sports mascot than an oil producer—Diamondback—and possessed no clear operational path forward.
Fifteen years later, that same enterprise produces more than a million barrels of oil equivalent per day, holds the largest pure-play acreage position in the Permian Basin, and has become one of the most aggressive consolidators in the history of American shale.
Understanding whether Diamondback's position is durable or primarily the product of favorable timing requires examining why its strategy succeeded. Diamondback did not discover unknown geology; operators across Midland knew the Wolfcamp formation existed. Instead, Diamondback was small, late to the play, and under capitalized enough that it operated without a legacy business model to defend.
The company today. Diamondback Energy, Inc. trades on the NASDAQ Global Select Market under the ticker FANG, and operates as an independent oil and natural gas producer focused entirely on the Midland and Delaware sub-basins of the Permian Basin in West Texas.[^1] As a pure-play operator, it maintains no international assets, deepwater acreage, refining operations, or liquefied natural gas initiatives. Its focus remains strictly on West Texas acreage and extracting hydrocarbons at a low cost per barrel.
The scale. Diamondback completed its initial public offering in October 2012 at $17.50 per share while producing fewer than 4,000 barrels of oil equivalent per day.1 By the second quarter of 2026, production reached 1.018 million barrels of oil equivalent per day—including 525,000 barrels per day of crude oil—generating $5.56 billion in quarterly revenue.2 This represents roughly a 250-fold volume expansion over fourteen years, a growth trajectory uncommon in a commodity industry with an unrefined end product.
The core strategic questions. How did an enterprise established in December 2007—months before crude oil prices collapsed—navigate early funding constraints to become a central consolidator in the Permian Basin? And following extensive consolidation across the basin, what growth options remain?
This question reflects statements from company leadership. In May 2025, founding Chief Executive Officer Travis Stice stated to shareholders that "we believe we are at a tipping point for U.S. oil production at current commodity prices," and that "it is likely that U.S. onshore oil production has peaked and will begin to decline this quarter."34 This assessment from the chief executive of a major independent Permian producer highlighted potential constraints on the underlying domestic resource base. Evaluating Diamondback requires examining how its business model aligns with these inventory dynamics.
Section outline. This analysis covers six key areas: 1. The company's founding and early financing challenges. 2. The strategic shift to horizontal drilling in a region then dominated by vertical wells. 3. The structural design of Viper Energy, a publicly traded royalty entity used to monetize mineral rights. 4. The M&A sequence spanning Brigham, Energen, QEP, and the $26 billion Endeavor transaction. 5. Operational efficiency metrics, analyzing structural cost factors versus broader market conditions. 6. Governance changes and leadership succession, including Stice's transition of the CEO role to Kaes Van't Hof alongside long-term inventory considerations.
Diamondback has demonstrated strong execution across operating metrics. At the same time, it remains a price-taker in global commodity markets, subject to legal, environmental, and depletion dynamics inherent to natural resource extraction. The central analytical question is how its operational model performs through changing industry cycles.
 Subscribe on LinkedIn
II. Origins & The 2007 Crisis Bet: Building Diamondback in the Permian Dust (2007–2012)
In late 2007, the Permian Basin looked vastly different from the high-volume industrial complex operating today. There were no massive fleets of service trucks stacked at pad sites, no worker housing camps outside Pecos, and no multi-million-dollar sand logistics networks. The Permian was widely viewed as a mature producing region past its prime. Having produced oil since the 1920s, its primary fields—including Spraberry, Wasson, and Yates—were heavily waterflooded and drilled almost exclusively with shallow vertical wells that yielded modest volumes over decades. Major operators like Exxon were steadily divesting assets, while industry capital flowed primarily to offshore developments in the Gulf of Mexico, West Africa, and Kazakhstan.
Into this environment, in December 2007, a group of energy investors associated with Windsor Energy and Gulfport Energy assembled a starter position of 4,174 net acres in West Texas.5 The market timing was unfavorable. Within nine months of the land assembly, West Texas Intermediate crude oil peaked near $145 per barrel before dropping to the $30s by December 2008 during the global financial crisis. Acreage acquired at the height of the market lost significant value, leaving a small operator with no production scale, no public stock currency, and minimal cash flow.
The operator: Travis Stice
Unlike many energy executives of that era, Diamondback's eventual chief executive came from operational production rather than financial engineering or exploration geology. Travis Stice began his career at Mobil Oil in 1985 as a petroleum engineer, spending the next quarter-century in production roles at Burlington Resources, ConocoPhillips following its acquisition of Burlington, Laredo Petroleum, and Apache Corporation, where he served as a production manager.[^1]
That operational background shaped his strategic perspective. Stice framed oil extraction not as high-variance exploration aimed at discovering unknown deposits, but as a repeatable manufacturing process. In a shale formation where geology is largely continuous across hundreds of square miles, the central economic question shifts from geological discovery to manufacturing efficiency: how cheaply, consistently, and quickly can an operator drill and complete identical wells?
In 2010, while many Texas independents still prioritized prospect generation and wildcat discoveries, Diamondback's leadership focused on unit economics and process standardization. Management tracked metrics such as drilling days per well, completion stages per day, lateral cost per foot, and water recycling to reduce trucking expenses. In a manufacturing framework, incremental gains in operating efficiency lower unit costs over time.
However, operational optimization offered little immediate relief without adequate capital.
The near-death experience
By 2010 and 2011, Diamondback faced severe capital constraints. Its private equity sponsors had reached their fund allocation limits and declined to commit additional capital, leaving the company without the cash required to fund development across its acreage.
In late 2011, management initiated a formal sale process. Eight exploration and production companies evaluated the asset package, but zero submitted bids.5
This lack of buyer interest exposed the limitations of the company's initial business model. The original thesis had relied on vertical wells drilled into the Spraberry formation to generate acceptable returns. The 2008–2009 price collapse demonstrated the flaws in that approach. Vertical Permian wells carried high lifting costs relative to their modest flow rates, requiring years to recover capital. At $30 crude, operating margins disappeared. Evaluated strictly on its vertical development potential, the asset base was economically unviable.
The eight potential buyers who reviewed the data room evaluated the assets based on vertical well economics. What transformed the asset's value was not a change in the underlying geology, but the application of new technology. The combination of extended horizontal laterals and multi-stage hydraulic fracturing—previously proven in the Barnett, Bakken, and Eagle Ford formations—was beginning to be deployed across the Permian's stacked shale layers. Acreage that yielded uncompetitive returns under vertical drilling presented dramatically different economics when horizontal wellbores contacted thousands of feet of reservoir rock.
Without private equity backing or an acquiring partner, Diamondback was forced to seek capital in public markets, setting the stage for its initial public offering.
III. The 2012 IPO & The Horizontal Drilling Gamble (2012–2016)
An initial public offering is typically a celebration of past success, but for Diamondback Energy, listing on public markets functioned more as a financial lifeline.
In October 2012, the company listed on the NASDAQ at $17.50 per share, raising approximately $218 million in gross proceeds.1 Its resulting market capitalization remained under $500 million—a fraction of the size of Permian Basin incumbents and too small for many institutional energy funds to build a position. Diamondback entered the public market not as an established growth story, but as an enterprise seeking fresh capital after exhausting its private funding options.
The prospectus outlined a production base of fewer than 4,000 barrels of oil equivalent per day. Fourteen years later, a single high-performing Diamondback well pad can match that total volume in its initial months of operation. At listing, the company's production represented a negligible fraction of broader U.S. output.
Counter-positioning: the horizontal bet
Management directed the $218 million in IPO proceeds toward a fundamental operational transition. In competitive strategy terms, the move illustrated counter-positioning—adopting a business model that established competitors could not copy without damaging their existing business.
In 2012 and 2013, the Midland Basin remained dominated by vertical drilling. Incumbent operators held vast vertical well inventories, surface infrastructure engineered for vertical extraction, reserve bookings based on vertical production curves, and technical teams trained in vertical completions. Transitioning entirely to horizontal drilling would have required writing down legacy assets, restructuring field operations, and accepting lower near-term returns during an operational transition. Consequently, established producers had rational economic incentives to move slowly.
Diamondback had no legacy vertical inventory to protect, as prospective buyers had passed on its acreage during the 2011 sale process. Management directed nearly all growth capital toward multi-stage horizontal wells targeting the Spraberry and Wolfcamp shales.
The structural difference between vertical and horizontal extraction is substantial. A vertical well drills straight down through geological layers, contacting only a few dozen feet of an oil-bearing formation. A horizontal well descends to the target zone before turning sideways, running a mile or more through the reservoir rock. Multi-stage hydraulic fracturing then injects water and sand under high pressure along the lateral, fracturing the tight shale rock and propping open pathways for hydrocarbons to flow.
While horizontal wells required higher initial capital expenditures than vertical wells, they yielded significantly higher production volumes and front-loaded cash flows into the first 18 to 24 months. Because discounted cash flow models heavily weight early production, this rapid capital recovery offset the steep initial decline rates typical of shale wells.
The operational pivot drove rapid growth. Production expanded from roughly 3,800 barrels of oil equivalent per day at listing to over 400,000 barrels per day by 2022—a hundredfold increase achieved through horizontal drilling and targeted acquisitions.[^1]
The 2014–2016 stress test
Commodity producers inevitably face market downturns, and Diamondback encountered a major stress test within two years of its public offering.
In November 2014, OPEC maintained its production levels rather than cutting output, choosing to protect global market share against expanding U.S. shale volumes. West Texas Intermediate crude, which traded near $100 per barrel during the summer of 2014, fell throughout 2015 and bottomed near $26 per barrel in February 2016. The sharp price decline triggered widespread financial distress across the American shale sector.
High leverage exposed many independent producers that had borrowed heavily under the assumption of sustained $90 oil. Operators including Swift Energy and Linn Energy filed for Chapter 11 bankruptcy protection. The prevalent shale business model—spending beyond operating cash flow to boost production and relying on debt markets for refinancing—proved fragile when prices collapsed.
Diamondback responded by targeting unit operating expenses. Management reduced lease operating expenses—covering electricity, field labor, water handling, chemicals, and workovers—to below $5.00 per barrel of oil equivalent.[^1] At the same time, drilling times per well decreased as crews standardized bit designs, drilling fluids, and pad operations.
This cost reduction differed from broader industry trends. While much of the sector's cost savings during 2015 and 2016 resulted from temporary price concessions by oilfield service providers, Diamondback achieved a substantial portion of its reductions through permanent process efficiencies. Fewer drilling days and streamlined pad workflows established structural cost savings that persisted after service-market rates recovered.
These structural efficiency gains helped establish Diamondback's low-cost operating profile. Evaluating whether that cost advantage reflects permanent structural efficiency or cyclical market conditions remains a central analytical consideration.
Navigating the downturn with a manageable balance sheet provided Diamondback with financial stability and a valuable public equity currency. During the collapse in 2014, management began deploying that currency toward strategic asset acquisitions.
IV. Financial Architecture: Inventing Viper Energy & Royalty Drop-Downs (2014–2017)
Understanding Diamondback's subsequent expansion requires examining a distinct aspect of American property law: the legal separation of surface rights from underground mineral rights.
In most countries, the state owns the hydrocarbons beneath private land. In the United States, landowners can hold title to the mineral estate separately from the surface property. When an oil producer intends to drill, it leases those mineral rights and pays the owner a royalty—a fixed percentage of gross revenues from every barrel extracted, collected before operating expenses are deducted.
Operating an oil well requires purchasing equipment, contracting crews, paying for sand and water, absorbing inflation, and bearing dry-hole risk. By contrast, a mineral owner assumes no capital outlay or operational cost, simply receiving royalty distributions off top-line production.
The genesis of Viper
In June 2014, Diamondback separated its Permian mineral and royalty interests into a publicly traded entity: Viper Energy Partners LP, listed on NASDAQ under the ticker VNOM.[^7] It marked the first public mineral and royalty vehicle sponsored by an exploration and production operator—a structural financial adaptation rather than an operational shift.
The move exploited a clear valuation arbitrage. Held directly by Diamondback, mineral assets were valued like typical exploration and production operations: as part of a capital-intensive, cyclical enterprise trading at modest cash-flow multiples. Isolated within a dedicated vehicle, those same assets carried a vastly different financial profile, generating royalty revenue with operating margins between 85% and 90%, minimal capital expenditure requirements, and no direct exposure to service-cost inflation.6 Public equity markets assign higher valuation multiples to this profile because its economics resemble financial yield instruments rather than industrial operations.
By transferring mineral rights from a lower-multiple corporate structure to a higher-multiple vehicle while retaining majority ownership, Diamondback unlocked equity value without producing additional physical barrels. The structure also offered financial flexibility at the parent level, allowing Viper to issue its own equity to fund mineral acquisitions without diluting Diamondback shareholders.
The strategic layer
Viper served as more than a valuation mechanism; it functioned as a consolidation vehicle in a highly fragmented market.
Permian mineral ownership has historically been divided across generations of landholders into fractional interests held by numerous scattered heirs. Aggregating these fragmented holdings requires dedicated, transaction-by-transaction negotiation—a process better suited for a specialized entity with public equity currency than a primary field operator.
The parent company also realized operational cost benefits. When Diamondback drills on acreage where Viper owns the underlying mineral rights, royalty payments flow to a majority-owned affiliate rather than a third-party landowner. On a consolidated basis, this arrangement reduces net royalty costs and lowers the effective breakeven crude price across core development blocks. Because this represents an internal transfer rather than a reduction in physical extraction costs, the realized savings depend directly on the spatial overlap between Viper's mineral holdings and Diamondback's drilling schedule.
The vehicle continued to scale its footprint. In June 2025, Viper agreed to acquire Sitio Royalties Corp. in an all-equity transaction valued at approximately $4.1 billion, which closed on August 19, 2025.7[^10] The deal added roughly 34,300 net royalty acres—including 25,300 in the Permian—expanding Viper's Permian royalty position by about 42%, from approximately 60,400 to 85,700 net acres.8 The transaction combined two of the largest publicly traded mineral rights entities in the United States.
The skeptical read
This financial arrangement introduces two primary structural criticisms.
First, governance conflicts arise because Diamondback controls Viper while remaining its primary operating counterparty. Decisions regarding drilling location, pace, and development timing directly influence how economic value is split between two distinct public shareholder bases. In American energy markets, drop-down transactions between affiliated entities have historically created tension, particularly during the master limited partnership expansion of 2010–2015 when sponsor-favorable deals harmed public unitholders. Although Diamondback's asset transfers have avoided major shareholder disputes, the underlying structural conflict of interest remains inherent to the model.
Second, the royalty entity's financial performance remains tied to operator activity. While Viper maintains a capital-light business model at the entity level, capital expenditure remains necessary at the operational level, borne by Diamondback and peer producers. If drilling activity across the Permian slows significantly, Viper's royalty revenues decline accordingly, regardless of its high operating margins. A royalty stream ultimately depends on the capital deployed by the operators drilling beneath the land.
Nevertheless, the vehicle provided Diamondback with a secondary, independently valued equity currency during cyclical downturns when parent-company shares traded at lower multiples. That acquisition currency proved essential as Diamondback turned toward larger corporate consolidations across the Permian Basin.
V. The M&A Consolidation Engine: From Brigham to Energen (2017–2019)
A specific geometric relationship explains almost every Permian Basin acquisition of the past decade.
A horizontal well's economics improve significantly with lateral length. The fixed costs of drilling down through two miles of rock overburden, running and cementing casing, and constructing surface pad locations remain roughly constant whether the horizontal lateral extends one mile or three miles. Extending the lateral spreads those upfront fixed costs across far more productive reservoir rock. A three-mile lateral typically costs roughly twice as much as a one-mile lateral while contacting three times as much producing formation.
However, drilling three-mile laterals requires owning contiguous, three-mile-long acreage blocks with compatible lease terms. Decades of leasing, trading, and land inheritance left Permian acreage fragmented into a checkerboard pattern. Single operators rarely held consecutive sections, preventing neighboring companies from drilling the longer, lower-cost horizontal wells both preferred.
Consequently, Permian M&A focused heavily on adjacency rather than geographic diversification. Combining adjacent tracts allowed operators to unlock longer lateral designs while eliminating redundant surface infrastructure—consolidating separate water networks, central tank batteries, and field offices into single operating units.
This geometry underpinned Diamondback's consolidation strategy for nearly a decade.
Brigham Resources, March 2017
In March 2017, Diamondback made its first major move outside the Midland Basin, acquiring Brigham Resources for $2.55 billion and adding approximately 76,300 net acres in the Southern Delaware Basin.[^1] Unlike subsequent acquisitions focused on immediate acreage adjacency, Brigham represented an entry into a distinct geological province. Located on the western side of the Permian Basin across Texas and New Mexico, the Delaware Basin features deeper, more highly pressurized, and gassier formations with higher initial production rates and greater well construction complexity.
Entering the Delaware Basin expanded Diamondback's inventory in a region where per-well initial productivity exceeded Midland Basin averages. However, the transaction also introduced operational complexity, higher drilling costs, and increased exposure to associated natural gas, which later became a regional price liability.
Ajax Resources, October 2018
In October 2018, Diamondback completed a $1.25 billion acquisition of Ajax Resources, adding roughly 25,000 net Midland acres as a bolt-on into the heart of the existing position.[^1] The deal served as a direct application of adjacency logic, integrating acreage directly into Diamondback's core producing footprint.
Energen, November 2018
In August 2018, Diamondback agreed to acquire Energen Corporation in an all-stock transaction valued at approximately $9.2 billion including assumed debt.9 The deal closed on November 29, 2018.10
Energen, a former utility holding company based in Birmingham, Alabama, had transformed itself into a Permian producer with acreage spanning both the Midland and Delaware sub-basins. Combining the two footprints created a pure-play Permian operator holding roughly 340,000 net acres, establishing Diamondback as one of the largest independent producers in the basin.
Management promised $2.0–$3.0 billion in net present value synergies, with cash lease operating expense savings targeted within the first twelve months.9 By using equity rather than cash for the purchase price, Diamondback avoided issuing new debt directly to sellers, though it absorbed Energen's existing balance-sheet liabilities.
The falsification: what Energen actually cost
While corporate presentations emphasized acreage scale and operational synergies, the aggressive transaction sequence expanded balance-sheet risks.
Funding the Brigham and Ajax purchases, absorbing Energen's balance sheet, and continuing an aggressive development program pushed Diamondback's total debt above $5 billion.[^1] In mid-2018, with West Texas Intermediate crude trading above $70 per barrel, that debt load appeared manageable. However, crude prices declined sharply in the fourth quarter of 2018, dropping from the mid-$70s in October to the low $40s by late December. As Diamondback's stock price fell, the effective cost of the equity issued for Energen increased in hindsight.
The leverage became more acute in 2020 during the global oil demand collapse. As cash flows contracted, leverage ratios expanded, forcing Diamondback to reduce capital expenditures by more than half. Shareholders who bought into the post-Energen growth narrative experienced a severe equity drawdown driven largely by the leverage required to execute the corporate expansion.
This sequence highlights a distinction in Diamondback's strategic track record. The company demonstrated discipline in acquiring high-quality, contiguous physical assets that offered immediate operational efficiencies. At the same time, it took on substantial balance-sheet risk by pursuing debt-financed acquisitions and assuming corporate obligations ahead of commodity price downturns. Evaluating Diamondback's model requires separating operational asset selection from financial leverage management.
The resilience of a levered consolidator is tested when commodity prices fall sharply. For Diamondback, that stress test arrived in March 2020 under market conditions that exceeded standard downside scenarios.
VI. The 2020 Bust, Distress Consolidation, & The Capital Return Pivot (2020–2023)
On April 20, 2020, the front-month West Texas Intermediate crude futures contract settled at negative $37.63 per barrel.
A negative oil price meant that sellers were paying buyers to take physical delivery of crude. This occurred because storage capacity at Cushing, Oklahoma—the primary delivery point for the contract—was effectively full. Global oil demand had fallen by roughly a fifth as pandemic lockdowns halted travel, while a price war between Saudi Arabia and Russia flooded global markets with additional supply, creating an acute physical oversupply.
For U.S. shale producers, the downturn posed an existential challenge rather than a standard cyclical dip. Shale's economic model relies on high initial well decline rates that require continuous reinvestment; when reinvestment stops, output drops rapidly. Dozens of operators filed for bankruptcy protection throughout 2020, while capital markets closed to the sector.
Diamondback survived by making deep operational cuts: stacking drilling rigs, releasing completion crews, and sharply reducing capital expenditures. The company emerged from 2020 smaller, with a reduced operating footprint and a strategic reorientation that defined its direction over the next five years.
Buying the wreckage
Surviving operators with stable balance sheets faced rare opportunities as acreage that had been out of reach in 2018 became available at steep discounts.
In December 2020, Diamondback agreed to acquire QEP Resources in an all-stock transaction, completing the deal on March 17, 2021.11 The headline enterprise value was approximately $2.2 billion, which included roughly $1.6 billion of QEP net debt, valuing QEP shares at approximately $2.29 each.[^1] QEP contributed Midland Basin acreage directly adjacent to Diamondback's core footprint, alongside non-core Williston Basin assets in North Dakota that Diamondback subsequently divested.
Simultaneously, Diamondback acquired Guidon Operating LLC from an affiliate of Blackstone in a cash-and-stock transaction valued at approximately $375 million, adding roughly 32,500 net acres in the northern Midland Basin.[^1]
These transactions presented a clear contrast to the earlier Energen acquisition. Diamondback acquired assets when sector capital costs were high, issuing its own stock at a time when equity valuations across the industry were depressed. The strategic value of the QEP acquisition relied on geographic adjacency: integrating QEP's Midland acreage into existing development blocks enabled longer horizontal laterals, increasing inventory value under Diamondback's operational model. Conversely, the non-adjacent Williston Basin assets offered few operational synergies, leading to their eventual sale.
The paradigm shift
The 2020 downturn accelerated a broader strategic shift across the shale sector.
For roughly fifteen years, the U.S. shale industry had pursued volume expansion, routinely reinvesting over 100 percent of operating cash flow and relying on debt and equity issuance to fund capital deficits. While this growth model transformed the United States into the world's top crude producer, it generated poor aggregate cash returns for investors. By 2020, institutional capital had largely pulled back from the sector due to persistent cash flow shortfalls.
In response, Diamondback and its peers inverted their operating strategy. Rather than maximizing volume growth, operators prioritized free cash flow generation by capping production near flat levels, restricting capital spending to maintenance levels, and directing the majority of cash flow to shareholders. This return structure combined a sustainable base dividend, variable dividends linked to commodity prices, and opportunistic share repurchases. Under this framework, Diamondback committed to returning at least 75% of free cash flow to shareholders.[^1]
During fourth-quarter 2020 and first-quarter 2021 earnings calls, management explicitly committed to keeping crude oil production roughly flat even as commodity prices recovered.[^15] In a cyclical commodity market, limiting production during a price recovery ran counter to traditional operator incentives, where higher prices historically triggered expanded drilling. Industry executives argued that unrestricted growth had previously eroded shareholder capital.
For investors, this capital discipline was largely market-enforced rather than internally initiated, taking hold only after external capital availability contracted. Evaluating the sustainability of this model requires monitoring capital allocation behavior when commodity prices rise and cash balances expand.
This commitment to capital discipline faced its largest operational test with the arrival of a $26 billion transaction.
VII. The Endeavor Mega-Merger: Creating a Permian Giant (2024)
For years, operators across the Permian Basin watched a single privately held company control one of the region's premier acreage positions: Endeavor Energy Resources.
Autry Stephens and the last great private position
Its founder, Autry Stephens, built the enterprise over four decades following a distinct operational model. After beginning his career as a petroleum engineer and bank evaluation engineer, Stephens started purchasing Permian land in 1979. Over the next 45 years, he assembled the largest privately held pure-play position in the Permian Basin without taking the company public.
That private structure directly influenced the quality of Endeavor's asset base. Public exploration and production companies face quarterly market pressure to replace reserves and expand production, often accelerating the depletion of their highest-quality drilling inventory. Operating outside public markets, Stephens kept undeveloped core acreage off the market for years. By the early 2020s, Endeavor owned a highly concentrated, relatively un-depleted acreage position in the heart of the Midland Basin—inventory that public peers had largely exhausted across their own footprints.
While private ownership allowed Stephens to preserve inventory, evaluating un-drilled private acreage carries analytical risks. Privately held reserve data lacks public disclosure scrutiny, and descriptions of undeveloped core rock were heavily emphasized by parties incentive-aligned with maximizing transaction valuation.
The transaction
On February 12, 2024, Diamondback announced a definitive agreement to combine with Endeavor Energy Resources LP in a cash-and-stock transaction valued at approximately $26 billion, including Endeavor's net debt.[^16]12 The consideration comprised approximately 117.3 million shares of Diamondback common stock and $8.0 billion in cash, with the cash component financed through new debt and cash on hand.[^16]13 The merger closed on September 10, 2024.[^1]
The combined enterprise held roughly 838,000 net acres across the Permian Basin and produced more than 800,000 barrels of oil equivalent per day at closing, including over 450,000 barrels per day of crude oil.[^16] Management priced the acquisition at approximately 5.8 times enterprise value to EBITDA, projecting immediate accretion to free cash flow per share. The company targeted $550 million in annual synergies, driven by corporate overhead reductions, lower capital costs, and operational gains from combining contiguous acreage blocks to drill three- and four-mile horizontal laterals.[^16]
What was actually bought
Beyond the transaction mechanics, the acquisition represented a strategic purchase of premium inventory.
By 2024, the primary operational constraint across U.S. shale was no longer capital availability, drilling technology, or service equipment, but access to high-quality, undrilled Tier-1 rock. 15 years of intensive development had depleted top-tier locations across the Bakken, Eagle Ford, and core Permian formations. While producers could still expand production, doing so increasingly required drilling secondary acreage with lower productivity. Equity markets increasingly evaluated exploration and production companies based on the longevity of their Tier-1 inventory at current extraction rates.
Endeavor's asset base extended Diamondback's premium inventory runway by several years. The deal also satisfied the geographic adjacency model: Endeavor's Midland Basin acreage interlocked with Diamondback's existing footprint, enabling extended horizontal laterals that neither operator could have drilled independently.
However, acquiring inventory at a $26 billion valuation carries structural commodity price risk. Paying upfront for long-dated reserves implicitly assumes crude prices will remain high enough over a decade or more to justify the acquisition cost. Furthermore, funding the $8.0 billion cash component required issuing substantial new debt, reintroducing balance-sheet leverage after management had spent 2020 through 2023 paying down obligations. Although Diamondback subsequently focused on debt reduction—cutting net debt by $1.6 billion in the second quarter of 2026 alone—the Endeavor transaction required a multi-year deleveraging effort.214
Regulatory scrutiny
The Federal Trade Commission issued a Second Request under the Hart-Scott-Rodino Act, initiating an in-depth review into whether the combination would concentrate the Permian crude market. The agency cleared the transaction in the third quarter of 2024 without requiring asset divestitures.[^1]
The clearance aligned with regulatory decisions on other major Permian acquisitions during that period. The FTC determined that crude oil is a globally traded commodity, meaning even a dominant Permian producer accounts for a modest fraction of global supply. While that market definition satisfied antitrust scrutiny, it did not resolve separate legal inquiries pending in federal courts regarding whether domestic shale producers had engaged in coordinated output decisions.
The follow-on
Diamondback continued its consolidation strategy into 2025. On April 1, 2025, the company completed the acquisition of Double Eagle IV's Midland Basin assets for approximately $4.1 billion in cash and stock.8 Alongside Viper's acquisition of Sitio Royalties four months later, Diamondback and its subsidiary committed roughly $8 billion toward M&A in 2025—the same year management publicly cautioned that U.S. onshore production was approaching a peak.
This dual focus highlights a core tension in Diamondback's capital strategy. If leadership expected domestic inventory to tighten, acquiring remaining core acreage represented a logical step to secure future production. At the same time, executing multi-billion-dollar, debt-funded transactions alongside a commitment to return 75% of free cash flow to shareholders required managing competing financial priorities. Balancing shareholder returns with balance-sheet funded consolidation remains a key operational test.
VIII. Operational Anatomy & Permian Pure-Play Economics
Driving west from Midland along Highway 158 reveals the operational mechanics of the modern Permian Basin. Legacy pump jacks operating over vertical wells sit beside compact pads housing six to eight horizontal wellheads. Flanked by pipe racks, sand silos, and roadside water infrastructure, the landscape resembles a distributed manufacturing network rather than a traditional oil field.
The two basins
The Permian is not a single geological entity, but a collection of sub-basins separated by the Central Basin Platform. Diamondback concentrates its acreage across the two primary sub-basins.
The Midland Basin, to the east, contains the foundation of Diamondback's asset base and the majority of its production. Its defining geological feature is vertical stacking: multiple productive shale layers—including the Lower and Upper Wolfcamp, Middle and Lower Spraberry, and Jo Mill—are layered on top of one another. A single surface pad location can host wells targeting several stacked zones at different depths. Midland wells are generally shallower, less expensive to drill, more crude-heavy, and more predictable. Decline curves track technical expectations closely, providing higher capital planning visibility.
The Delaware Basin, to the west, features deeper and more pressurized formations. Higher reservoir pressure generates elevated initial production rates, though it also produces higher gas-to-oil ratios, resulting in a larger proportion of natural gas relative to crude oil. Delaware wells require higher drilling and completion expenditures and yield substantially larger volumes of produced water. Handling produced water raises operating costs and, in certain areas, introduces induced seismicity risks that have prompted regulatory restrictions on deep disposal wells.
The two sub-basins require distinct operational approaches: the Midland Basin rewards process repetition, while the Delaware Basin requires higher engineering intensity.
The efficiency machine
Three primary operational levers drive Diamondback's low cost structure.
Simul-frac and trim-frac. A standard hydraulic fracturing operation stimulates one well at a time using a single fleet of high-pressure pumps, blenders, sand equipment, and field crews—an operational spread that incurs high hourly fixed costs regardless of active pumping time. Simul-frac operational design splits that pump horsepower to stimulate two wells simultaneously. Because equipment, crews, and sand logistics are already deployed on-site, simultaneous stimulation eliminates transition downtime between wells. Across the onshore industry, these techniques have driven completion cost reductions of 15% to 20% alongside shortened completion schedules per pad.[^1] Trim-frac techniques build on this approach, increasing completed stages per day by reducing non-productive idle time.
The economic principle mirrors standard factory throughput: maximizing the duty cycle of high-cost pumping equipment lowers per-stage costs.
Lateral length. Extended horizontal laterals represent a clear metric of operational evolution in shale. Diamondback's early horizontal wells averaged roughly 5,000 feet of lateral length. Following the integration of contiguous acreage blocks from the Endeavor transaction, the company drills laterals extending 15,000 feet and beyond, with four-mile lateral designs included in its development queue.[^16] Because drilling the vertical section of a well represents a fixed upfront expenditure, extending the horizontal lateral spreads that fixed cost over a longer productive interval, reducing cost per productive foot.
However, physical constraints limit the returns of extended laterals. Horizontal wellbores exceeding three miles encounter elevated friction, mechanical difficulties when running casing and completion tools, and uneven hydraulic fracture distribution between the heel and the toe of the well. Because hydrocarbon recovery per foot tends to diminish at extreme lateral lengths, cost efficiencies flatten as lateral distances approach physical limits.
Cost position. Diamondback has maintained lease operating expenses consistently below approximately $5.50 per barrel of oil equivalent, placing its direct extraction costs near the bottom of North American onshore producers.[^1] Including gathering, transportation, production taxes, and cash general and administrative costs, the company maintains a low-cost cash operating profile relative to U.S. peers.
What the cost position is and is not
Evaluating Diamondback's cost structure requires separating structural operational advantages from external variables.
A low cash cost per barrel provides downside protection during market contractions. When West Texas Intermediate crude prices decline toward $45 per barrel, corporate survival depends on maintaining positive operating cash margins. Diamondback's low cash operating costs allow its wells to remain economic in price environments that force higher-cost operators to curtail production.
However, three analytical qualifications contextualize this cost profile.
First, part of the operational cost advantage stems from geological endowment. The Midland Basin's shallow, stacked, oil-rich rock is inherently less costly to produce than deeper Delaware intervals or northern Bakken formations. Comparing lease operating expenses across regions reflects underlying geological characteristics as well as management performance.
Second, operational innovations in shale tend to converge across operators rather than remaining proprietary. Completion techniques diffuse rapidly as oilfield service providers offer standardized equipment across the sector and technical staff transition between firms. Simul-frac, which represented a novel approach in 2019, became standard industry practice by 2023. Process-driven cost leads in shale typically function as temporary advantages lasting two to three years rather than permanent structural moats.
Third, efficiency gains occur against a moving industry baseline. When competing producers adopt identical efficiency improvements simultaneously, aggregate regional supply increases, exerting downward pressure on realized oil prices and offsetting unit-cost gains at the sector level.
Competitive positioning
Following extensive consolidation between 2024 and 2026, the Permian operator landscape thinned significantly. Corporate transactions removed major independents from public markets, including ExxonMobil's acquisition of Pioneer Natural Resources, Chevron's acquisition of Hess, and Diamondback's combination with Endeavor. The remaining independent Permian producers—including Diamondback, Occidental Petroleum, EOG Resources, ConocoPhillips, Devon Energy, and Coterra Energy—compete directly alongside the Permian operating divisions of integrated global majors.
This consolidated landscape creates distinct strategic trade-offs for Diamondback. As a major independent pure-play operator, it offers public markets a direct equity vehicle for Permian exposure. At the same time, competing for remaining acreage puts Diamondback against integrated majors such as ExxonMobil and Chevron, which possess lower corporate capital costs and broader global portfolios that insulate them from single-region downturns.
Seven Powers, honestly applied
Evaluating Diamondback through standard competitive framework models highlights where its structural capabilities reside:
Scale Economies — Demonstrates strong structural alignment. Spreading fixed corporate overhead across more than one million barrels of oil equivalent per day provides measurable per-unit cost savings. Scale also generates procurement leverage across proppant, water handling, casing tubulars, and pressure pumping services.
Process Power — Present, though subject to industry diffusion. Having completed more than a thousand horizontal wells, Diamondback maintains operational expertise in pad configuration, completion sequencing, and fluid recycling. However, because shale operational techniques replicate across competing producers within a few years, process efficiencies require continuous refinement to preserve a lead.
Counter-Positioning — Largely historical. The original counter-positioning strategy—directing capital to horizontal drilling while established competitors defended legacy vertical assets—was decisive after 2012 but is now universal. A pure-play Permian focus relative to diversified majors represents a portfolio choice: it avoids allocating capital to higher-cost international projects, but leaves the enterprise without geographic diversification when regional commodity prices fall.
Diamondback's operational model delivers consistent execution, but its core technical methods remain replicable across the industry. Consequently, long-term performance relies heavily on capital allocation decisions and management oversight—an area shaped by leadership changes in 2025.
IX. Management Credibility, Governance, & Leadership Transition
In an industry where founder-chief executives often exit either through an outright acquisition or amid operational distress, Travis Stice executed a planned leadership transition.
The transition
Stice served as chief executive from the company's initial public offering in 2012 through the 2025 annual meeting, at which point he transitioned to Executive Chairman.[^1] His successor, Kaes Van't Hof, assumed the chief executive role after previously serving as President and Chief Financial Officer.[^20]
Van't Hof's background contrasts directly with Stice's operational engineering career. Beginning in investment banking at Citi before moving into energy investments, Van't Hof joined Diamondback on the financial side. He served as the primary architect behind the financial structuring of the Energen, QEP, and Endeavor transactions, and led Viper Energy as chief executive during a key period of its growth.[^20]
This succession marks a strategic shift in Diamondback's center of gravity—from an operational engineer to a capital markets strategist. The logic of that transition reflects changing industry demands. When an enterprise competes primarily on drilling efficiency, operational expertise is paramount. But as a basin matures and reinvestment yields flatten, the key operational challenge shifts to capital allocation: balancing dividend returns, share repurchases, debt reduction, and inventory acquisitions. Given Stice's public assessment that domestic shale production is approaching its peak, the appointment of a financial strategist indicates the board's focus on capital discipline and portfolio management over volume expansion.
Evidence on credibility
Evaluating management credibility requires examining execution across commodity cycles rather than relying on corporate communications. Diamondback's operating history reflects a consistent capital return strategy alongside periodic balance-sheet strain.
On one hand, management has maintained its 2021 capital return framework through shifting market conditions rather than abandoning commitments during price declines. The company provided specific, quantified synergy targets for the Endeavor merger and communicated openly regarding regional resource constraints, such as Stice's public comments on peak domestic onshore production. Furthermore, when crude prices dropped sharply in 2025, Diamondback reduced operational activity and lowered production guidance rather than expanding output to defend volume targets.4
On the other hand, management has repeatedly expanded balance-sheet leverage during major acquisition cycles, requiring subsequent debt-reduction efforts during market downturns. The debt accumulated following the Energen and Endeavor transactions highlights a recurring pattern: operational discipline paired with aggressive financial leverage during consolidation cycles. This tendency introduces balance-sheet risks when commodity prices soften ahead of planned deleveraging schedules.
Management's public guidance also displays shifting tactical messaging across market conditions. In May 2025, leadership stated that U.S. onshore production was peaking. By the second-quarter 2026 earnings call, Van't Hof indicated that Diamondback was considering low single-digit organic production growth for 2027 to meet expected global inventory refilling.1415 While a broader macroeconomic view of national production constraints can co-exist with company-specific volume growth, the shift in tone highlights the tension between macro production forecasts and micro operating decisions.
That tension was visible during the same second-quarter 2026 update. Diamondback raised its full-year 2026 crude oil production target to at least 522,000 barrels per day—up from 520,000—and increased total output guidance to at least 1.0 million barrels of oil equivalent per day from 972,000, while leaving capital expenditure guidance unchanged at approximately $3.90 billion.215 Generating higher volumes within an unchanged capital budget reflects operational efficiency. At the same time, the guidance increase followed an operational acceleration in March 2026, when production ran roughly 4% above original forecasts.14
Alignment and ownership
Executive compensation structure aligns management incentives with capital efficiency. Incentive metrics are tied to return on invested capital, free cash flow per share, and operational safety and environmental targets rather than unconstrained volume expansion.[^1] Aligning compensation with capital returns represents a structural departure from historical shale practices, which prioritized production growth at the expense of shareholder returns. Insider ownership remains relatively high compared to large-cap exploration and production peers, though a significant equity block post-Endeavor is held by former Endeavor owners, whose investment horizons may differ from long-term public equity holders.
Environmental record
Environmental performance is directly integrated into corporate governance, with approximately 25% of the executive bonus scorecard tied to key performance indicators, including routine flaring reduction and water recycling targets, where the company reuses over 90% of its completion water.[^1]
Water recycling provides dual environmental and financial benefits. Well completion requires extensive water volumes, and producing wells yield large quantities of highly saline wastewater over time. Historically, operators trucked produced water to deep disposal wells for underground injection—a costly process that contributed to induced seismicity risks and triggered regulatory restrictions in parts of the Permian Basin. Recycling produced water for subsequent fracturing operations lowers freshwater acquisition costs, reduces trucking logistics, decreases disposal expenses, and mitigates regulatory risk.
Managing flaring presents a more persistent operational challenge, and Diamondback's performance in flaring reduction has drawn scrutiny from external observers.
X. Historical Falsification & Skeptical Investor Stress Test
Evaluating Diamondback's strategic trajectory requires testing its core thesis against historical operational challenges and the physical limits of the Permian Basin.
The gas problem: Waha and negative pricing
A structural operational challenge facing West Texas producers is that natural gas at the regional Waha hub has frequently traded at negative prices.
The underlying mechanism is driven by geology and midstream infrastructure constraints. Because Permian operators target crude oil, natural gas emerges as associated gas—an unavoidable byproduct of reservoir pressure. The volume of associated gas is dictated by oil production rather than natural gas market demand. When regional gas output outpaces pipeline takeaway capacity to the Gulf Coast, and new pipeline construction takes years to permit and build, regional prices collapse below zero. In those periods, producers must pay midstream operators to remove natural gas to avoid shutting in oil-producing wells.
For Diamondback, negative natural gas realizations at Waha reduce overall revenue per barrel of oil equivalent, forcing periodic volume curtailments. Because takeaway limits represent an external midstream constraint, operational efficiency alone cannot solve the bottleneck. Furthermore, Diamondback's Delaware Basin footprint carries higher gas-to-oil ratios, increasing its exposure to regional gas price discounts. While expanded pipeline capacity periodically alleviates market pressure, subsequent regional production growth restores takeaway constraints.
Parent-child interference: the inventory that wasn't
A more fundamental subsurface challenge directly impacts the inventory estimates supporting Permian asset valuations.
During the early expansion of horizontal drilling, operators assumed wells could be tightly spaced to maximize total hydrocarbon recovery per section. Equity markets rewarded high well-density models, as higher location counts implied longer inventory runways.
Subsurface performance altered that assumption. When operators drill a secondary "child" well near an established "parent" well, the child's hydraulic fractures propagate toward the pressure-depleted zone created by the parent, often connecting directly to the original wellbore. Across the Permian, child wells have frequently produced 15% to 25% less oil than adjacent parent wells.
Operators, including Diamondback, responded by widening well spacing to preserve individual well productivity. While technically necessary, widening spacing reduced total well locations per section. Consequently, producers across the sector revised location counts downward and reduced disclosures regarding secondary inventory tiers.
This subsurface reassessment directly affects inventory longevity calculations, including the estimates that supported the purchase price of the Endeavor transaction. Years of inventory metrics represent model outputs dependent on spacing assumptions that remain subject to further downward revision.
Flaring and the ESG gap
Building on the environmental oversight highlighted in corporate governance audits, third-party satellite monitoring in 2023 accused Permian operators—including Diamondback—of unlit flaring and methane leakage during takeaway outages, with observed emissions exceeding self-reported metrics.16
A lit flare combusts methane into carbon dioxide, whereas an unlit flare vents raw methane directly into the atmosphere, where its warming impact is significantly higher over a twenty-year horizon.
This distinction carries growing regulatory and financial risk. Tightening environmental standards and independent satellite tracking have made emissions data publicly verifiable. Discrepancies between internal zero-routine-flaring targets and third-party emission observations present governance and reporting challenges for operators.
The antitrust overhang
The company also faces ongoing legal exposure from broader industry litigation.
Beginning in 2024, federal class-action lawsuits alleged that U.S. shale producers, including Diamondback, coordinated output reductions to inflate prices for crude oil and refined fuels through public guidance and interactions involving OPEC representatives.17 The matters were consolidated as In re Shale Oil Antitrust Litigation in the U.S. District Court for the District of New Mexico.
On August 31, 2026, U.S. District Judge Matthew Garcia largely denied the producers' motion to dismiss.18 The court rejected the defense that the claims involved nonjusticiable political questions related to foreign policy, ruling that alleged domestic coordination falls under antitrust law. The court concluded that plaintiffs plausibly alleged a conspiracy based on production patterns, public statements, and interactions among producers going beyond ordinary industry information exchange.18
While the ruling does not establish liability, it advances the litigation into discovery, opening internal communications and executive testimony to judicial review while increasing legal costs and tail risk.
The litigation also draws scrutiny to the sector's post-2020 operating model. Following the 2020 downturn, public producers explicitly committed to restricting output growth to prioritize cash returns—a practice praised by equity markets as supply discipline. The antitrust claims reframe that industry-wide capital discipline as potential market coordination, linking the sector's primary financial strategy to its most significant legal vulnerability.
The peak shale bombshell
Internal management assessments have also highlighted long-term resource constraints.
In a May 2025 letter to stockholders, Travis Stice stated that U.S. onshore oil production was reaching a tipping point at current prices and was likely peaking before entering a decline.3 The assessment cited declining activity metrics, noting that the national hydraulic fracturing crew count had dropped roughly 15% year-to-date, the Permian crew count had fallen about 20% from its January peak, and the oil-directed rig count was expected to decrease nearly 10% by the end of the second quarter.4 Diamondback simultaneously reduced its own 2025 production guidance.19
This executive assessment redefines the investment thesis for pure-play shale operators. While low-cost producers remain positioned to generate cash flow in a contracting market, the perspective challenges expectations of long-term volume expansion, confirming that Tier-1 inventory constraints are actively limiting domestic production growth at moderate commodity prices.
Consequently, the core investment proposition shifts from sustained volume expansion to low-cost cash extraction from a depleting asset base. Under this framework, performance is evaluated not by top-line production growth, but by capital efficiency per unit of maintained production—specifically whether the capital required to keep output flat increases as development moves into secondary acreage.
XI. Playbook: Business & Investing Lessons
Stepping back from the operational specifics, Diamondback's history offers five strategic lessons that extend beyond oil and gas extraction.
1. In a homogeneous commodity, cost per unit is the primary durable advantage—and even that advantage is relative. Diamondback cannot influence the market price of its product. No marketing campaign, brand equity, or customer relationship alters the realized price of a barrel of West Texas Intermediate crude. In an unrefined commodity market, the primary variable management controls is unit production cost, and the central strategic question is whether an operator sits lower on the cost curve than the marginal producer. Crucially, cost position is relative. If the entire industry improves efficiency simultaneously, low-cost extraction keeps an operator solvent without generating outsized returns. Diamondback's cost reductions during 2015 and 2016 preserved its balance sheet while competitors filed for bankruptcy—a survival payoff rather than a guarantee of wealth creation.
2. Consolidation creates value through adjacency rather than sheer scale. Diamondback's most effective acquisitions shared a clear geographic feature: the acquired acreage physically adjoined existing holdings, allowing the operator to drill longer horizontal laterals and consolidate surface infrastructure. These assets held higher operational value for Diamondback than for competing bidders, providing a rational basis for paying a control premium. Where that physical synergy was absent—such as the Williston Basin assets acquired in the QEP transaction—the holdings were promptly divested. In capital-intensive industries, corporate combinations create value when they unlock operational capabilities that neither party could achieve independently, rather than pursuing scale for its own sake.
3. Financial engineering can unlock genuine equity value, but it creates structural conflicts of interest. Creating Viper Energy transferred mineral cash flows from a lower-multiple exploration wrapper to a higher-multiple royalty vehicle, provided an acquisition currency to consolidate fragmented mineral rights, and reduced Diamondback's effective royalty burden on overlapping acreage. The underlying economics were real. However, sponsor-controlled affiliated entities introduce inherent governance conflicts between parent and subsidiary shareholders. The history of master limited partnerships in the energy sector highlights why investors must evaluate intercompany asset transfers and development timing rather than assuming automatic alignment between corporate entities.
4. Balance-sheet leverage determines survival through market downturns. Diamondback's liquidity pressures in 2011 and 2020 stemmed from capital availability rather than subsurface inventory constraints. The post-2020 industry standard targeting net debt below 1.0 times EBITDA emerged directly from the wave of restructuring that eliminated over-leveraged peers. However, Diamondback's operating history reveals a recurring pattern: management allowed debt to expand during major acquisition cycles—such as the Energen and Endeavor transactions—before prioritizing debt reduction during subsequent recoveries. For investors, stated leverage targets function as policy preferences subject to deal opportunities rather than binding constraints.
5. Market-enforced capital discipline requires ongoing behavioral scrutiny. The shale sector's pivot from volume growth to free cash flow returns restored institutional investor interest in energy equities. Yet that discipline originated primarily as a forced reaction to tightening equity and debt markets after 2020. Evaluating whether capital discipline is permanently embedded requires observing management decisions when commodity prices are strong and capital is accessible, rather than relying on statements made during downturns. Diamondback's multi-billion-dollar M&A spending in 2025, executed alongside its commitment to return 75% of free cash flow to shareholders, illustrates the ongoing tension between returning capital and expanding asset scale.
XII. Analysis, Strategic Position, & Bull vs. Bear Case
The bull case
The primary investment case for Diamondback rests on its strategic position in a consolidating and depleting basin rather than top-line volume growth.
Following its acquisitions of Endeavor and Double Eagle IV, the company holds the largest pure-play acreage position among independent Permian operators, concentrated in a region characterized by high well productivity, established midstream infrastructure, and regulatory stability. Diamondback maintains cash operating costs near the bottom of the North American onshore cost curve, allowing its wells to generate positive cash margins at prices that force higher-cost production offline. If marginal producers curtail output during market downturns, low-cost operators gain market share by default.
The company's capital return framework—returning at least 75% of free cash flow through base dividends, variable dividends, and share repurchases—converts operating efficiency into direct shareholder cash distributions rather than continuous reinvestment. In an environment where domestic supply growth slows while global demand remains steady, a low-cost operator with an extensive inventory runway provides a clear cash-generation thesis.
Second-quarter 2026 financial and operating results supported this execution thesis: production ran roughly 4% ahead of internal forecasts, management raised full-year oil and total production guidance while holding the annual capital budget flat at approximately $3.90 billion, and the company reduced net debt by $1.6 billion in a single quarter.21415 Delivering higher volumes within an unchanged capital budget while reducing debt aligned directly with the financial commitments established in 2021.
The bear case
Inventory depletion represents the central long-term risk. Founding Chief Executive Officer Travis Stice publicly stated that U.S. onshore oil production was reaching a peak. Industry-wide parent-child well interference previously forced spacing revisions and inventory write-downs. As development transitions from Tier-1 acreage to secondary rock, well productivity declines while water handling requirements and associated gas ratios rise, reducing revenue per dollar of capital invested. This trend reflects the physical dynamics of resource extraction rather than operating execution alone.
Commodity exposure is unhedged by business segment. Unlike integrated energy majors, Diamondback maintains no downstream refining capacity, international assets, or chemical operations to buffer against falling crude prices. Earnings depend almost entirely on global benchmark prices governed by OPEC+ policy, macroeconomic conditions, and geopolitics. In 2025, crude price weakness driven by trade-policy concerns prompted activity reductions and a guidance cut within a single quarter.419 Pure-play Permian exposure creates two-way leverage to commodity cycles.
Regional gas takeaway constraints recur structurally. Negative price realizations at the Waha hub occur whenever Permian oil extraction outpaces midstream pipeline capacity, repeating across successive infrastructure buildout cycles.
Legal and regulatory liabilities have expanded. The consolidated antitrust litigation survived a motion to dismiss in August 2026, advancing the proceedings into material discovery and executive depositions. Simultaneously, emissions regulations are tightening as independent satellite monitoring makes flaring and venting practices publicly verifiable.
Balance-sheet leverage has a mixed history. Financing the cash component of the Endeavor merger reintroduced debt that management has subsequently worked to pay down. Pursuing another major debt-funded acquisition ahead of a commodity price downturn represents a key financial vulnerability.
Porter's Five Forces
Rivalry among existing competitors is intense but muted by commodity fungibility. Producers do not compete for end customers, as crude oil is a globally traded fungible commodity. Instead, competition occurs across three fronts: acquiring remaining core acreage, securing oilfield services and skilled labor, and attracting institutional investor capital. While consolidation has reduced the total number of Permian operators, remaining competitors include integrated majors like ExxonMobil and Chevron, which possess lower corporate capital costs and broader global portfolios.
Supplier power is moderate and highly cyclical. Pressure pumping crews, sand logistics providers, and water management firms exercise pricing leverage during industry upturns and concede pricing during downturns. Operating at more than one million barrels of oil equivalent per day provides Diamondback with substantial procurement leverage, though localized shortages of skilled Permian labor periodically constrain field operations.
Buyer power is low at the wellhead but significant at the midstream level. Producers sell crude at benchmark pricing without individual customer negotiation. However, midstream pipeline operators function as regional chokepoints, exercising operational leverage during takeaway shortages, as demonstrated by recurring negative gas pricing at Waha.
Threat of substitutes is gradual on the demand side but immediate on the supply side. Electric vehicle adoption and efficiency gains moderate long-term growth in transportation fuel demand, though petrochemical feedstocks, aviation, and heavy shipping remain difficult to substitute. A more immediate threat comes from competing supply sources, including lower-cost international basins and OPEC+ spare capacity, which can displace U.S. shale barrels faster than long-term demand transitions.
Threat of new entrants is low for large-scale operations and moderate at the margin. Assembling a contiguous Permian footprint matching Diamondback's scale would require tens of billions of dollars in capital and access to acreage that is largely consolidated. However, smaller private operators can enter during high-price environments, deploying capital without the production discipline constraints observed by public companies and adding marginal supply that can weaken market pricing.
The structural profile favors low-cost producers while presenting persistent risks for higher-cost operators. Diamondback maintains a favorable operational position, but the durability of its advantage relies on preserving a relative cost lead as Permian reservoirs mature.
The three KPIs that matter
Evaluating Diamondback's long-term performance centers on three key operational and financial metrics.
1. Maintenance capital intensity—the capital required to maintain flat production. This metric synthesizes reservoir quality, well productivity, oilfield service costs, and operational efficiency into a single indicator. If keeping production flat requires rising capital expenditures over time, it indicates that Tier-1 inventory depletion is impairing economics regardless of published location counts. Conversely, stable or declining capital intensity signals that efficiency gains continue to offset reservoir depletion.
2. Free cash flow per share. Measuring cash generation on a per-share basis evaluates whether corporate acquisitions create net value for existing equity holders. Because major transactions like the $26 billion Endeavor acquisition were funded significantly through equity issuance, per-share free cash flow measures whether consolidation has generated per-share accretion rather than top-line volume growth.
3. Realized price per barrel of oil equivalent relative to West Texas Intermediate. The spread between realized revenues per barrel of oil equivalent and the WTI benchmark reflects regional natural gas discounts, natural gas liquids pricing, transportation differentials, and shifting hydrocarbon mix as development moves into gassier or higher-water-cut formations. A widening discount serves as an early indicator of reservoir stream degradation even when gross production volumes remain stable.
XIII. Epilogue: The Next Decade in U.S. Energy
Return, for a moment, to that West Texas data room in 2011.
Eight companies reviewed Diamondback's acreage and concluded there was nothing worth buying. They were applying the established economics of West Texas vertical drilling, and by those standards their evaluation was correct. What those potential buyers overlooked was that horizontal drilling and multi-stage fracturing—technologies already proving effective in other basins—were about to transform the Permian, demonstrating that the value of an oil asset is never determined by geology alone.
Diamondback's expansion from a zero-bid starter position to an enterprise producing over a million barrels of oil equivalent per day highlights a central shift in U.S. shale. Yet the trajectory reflects specific operational realities rather than strategic invincibility. The company was not driven by extraordinary foresight; leadership adopted horizontal drilling out of necessity after conventional options failed. Nor does the enterprise hold an unassailable moat; the pad completion efficiencies and operating practices that established its low-cost profile diffused across competing producers within a few years. Diamondback's trajectory was shaped by positioning—through a combination of timing, capital constraints, and tactical execution—to capture a technological transition, followed by the operational discipline needed to navigate three major commodity price collapses that bankrupted dozens of peers.
This trajectory mirrors the evolution of the broader American shale sector. Over two decades, shale transitioned from an unproven concept to a production engine that established the United States as the world's leading crude producer, through a phase of capital-inefficient volume expansion, into a disciplined cash-return model, and ultimately—as company leadership acknowledged in 2025—toward a mature asset base facing eventual natural decline.
The next decade presents a fundamentally different strategic challenge than the last. The central question for Diamondback is no longer how rapidly it can expand production, but how efficiently it can harvest its asset base. Its performance will depend on several critical factors: how much cash flow can be extracted from a finite, depleting resource base; what portion of that cash flow is returned to shareholders versus allocated to further consolidation; how long core Tier-1 inventory actually lasts under real-world well spacing; and whether a leadership team accustomed to expansion can maintain capital discipline during a period of asset maturity.
Simultaneously, operational and legal constraints are intensifying. Methane and flaring compliance is increasingly monitored by independent satellite data rather than self-reported metrics. Consolidated antitrust litigation has advanced into discovery, exposing executive communications to judicial scrutiny. Infrastructure bottlenecks at the Waha hub continue to trigger negative regional natural gas prices during periods of rapid crude extraction. Above all, realized revenues remain tied to volatile global commodity prices beyond any single producer's control.
In commodity markets, low-cost operations do not guarantee permanent competitive advantage. Success relies on relative cost positioning, balance-sheet discipline, and the willingness to deploy capital when competitors are constrained. Diamondback has demonstrated those capabilities across more than a decade of consolidation. Whether those attributes remain sufficient for the next decade depends on navigating a domestic resource base that company leadership has acknowledged is approaching its physical peak—marking a transition from rapid volume expansion to the more complex phase of inventory stewardship.
References
-
Diamondback Energy SEC EDGAR Filings (Form 10-K, 10-Q, 8-K) — SEC EDGAR ↩↩
-
Diamondback Energy, Inc. Form 8-K, Second Quarter 2026 Results Exhibit 99.2 — SEC, 2026-08-03 ↩↩↩↩
-
Letter to Stockholders Issued by Diamondback Energy, Inc. — GlobeNewswire, 2025-05-05 ↩↩
-
U.S. oil production has likely peaked and will start to decline due to price plunge, Diamondback CEO warns — CNBC, 2025-05-06 ↩↩↩↩
-
Diamondback Energy, Inc. Annual Report on Form 10-K — SEC EDGAR ↩↩
-
Viper Energy SEC EDGAR Filings (Form 10-K, 10-Q) — SEC EDGAR ↩
-
Diamondback Energy's Viper Energy buys Sitio Royalties for $4 billion in merger of top two minerals players — Fortune, 2025-06-03 ↩
-
Diamondback's Viper Closes $4.1B Sitio Royalties Merger Acquisition — Hart Energy, 2025-08-19 ↩↩
-
Diamondback Energy to Buy Energen for $9.2 Billion — The Wall Street Journal, 2018-08-14 ↩↩
-
Diamondback Completes Acquisition of Energen Corporation (Form 8-K) — SEC, 2018-11-27 ↩
-
Diamondback Completes Acquisition of QEP Resources (Form 8-K) — SEC, 2021-03-17 ↩
-
Diamondback Energy to buy Endeavor Energy in $26 billion deal — Reuters, 2024-02-12 ↩
-
Diamondback Agrees to Buy Endeavor in $26 Billion Permian Deal — Bloomberg, 2024-02-12 ↩
-
Diamondback Tops Output Plan by ~4% and Cuts Net Debt $1.6B, CEO Says Inventory Refill Sets Up 2027 Growth — BigGo Finance, 2026-08-04 ↩↩↩↩
-
Diamondback Energy (FANG) Q2 2026 Earnings Call Transcript — The Motley Fool, 2026-08-10 ↩↩↩
-
Permian oil producers face tightening methane and flaring scrutiny — Financial Times, 2023-10-25 ↩
-
US shale producers face class action antitrust lawsuit over oil price-fixing claims — Reuters, 2024-01-16 ↩
-
US Judge Rules Shale Oil Antitrust Case Can Proceed Against Major Producers — EnergyNow, 2026-09 ↩↩
-
"We are at a tipping point for U.S. oil production" – Diamondback CEO — BOE Report, 2025-05-08 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube