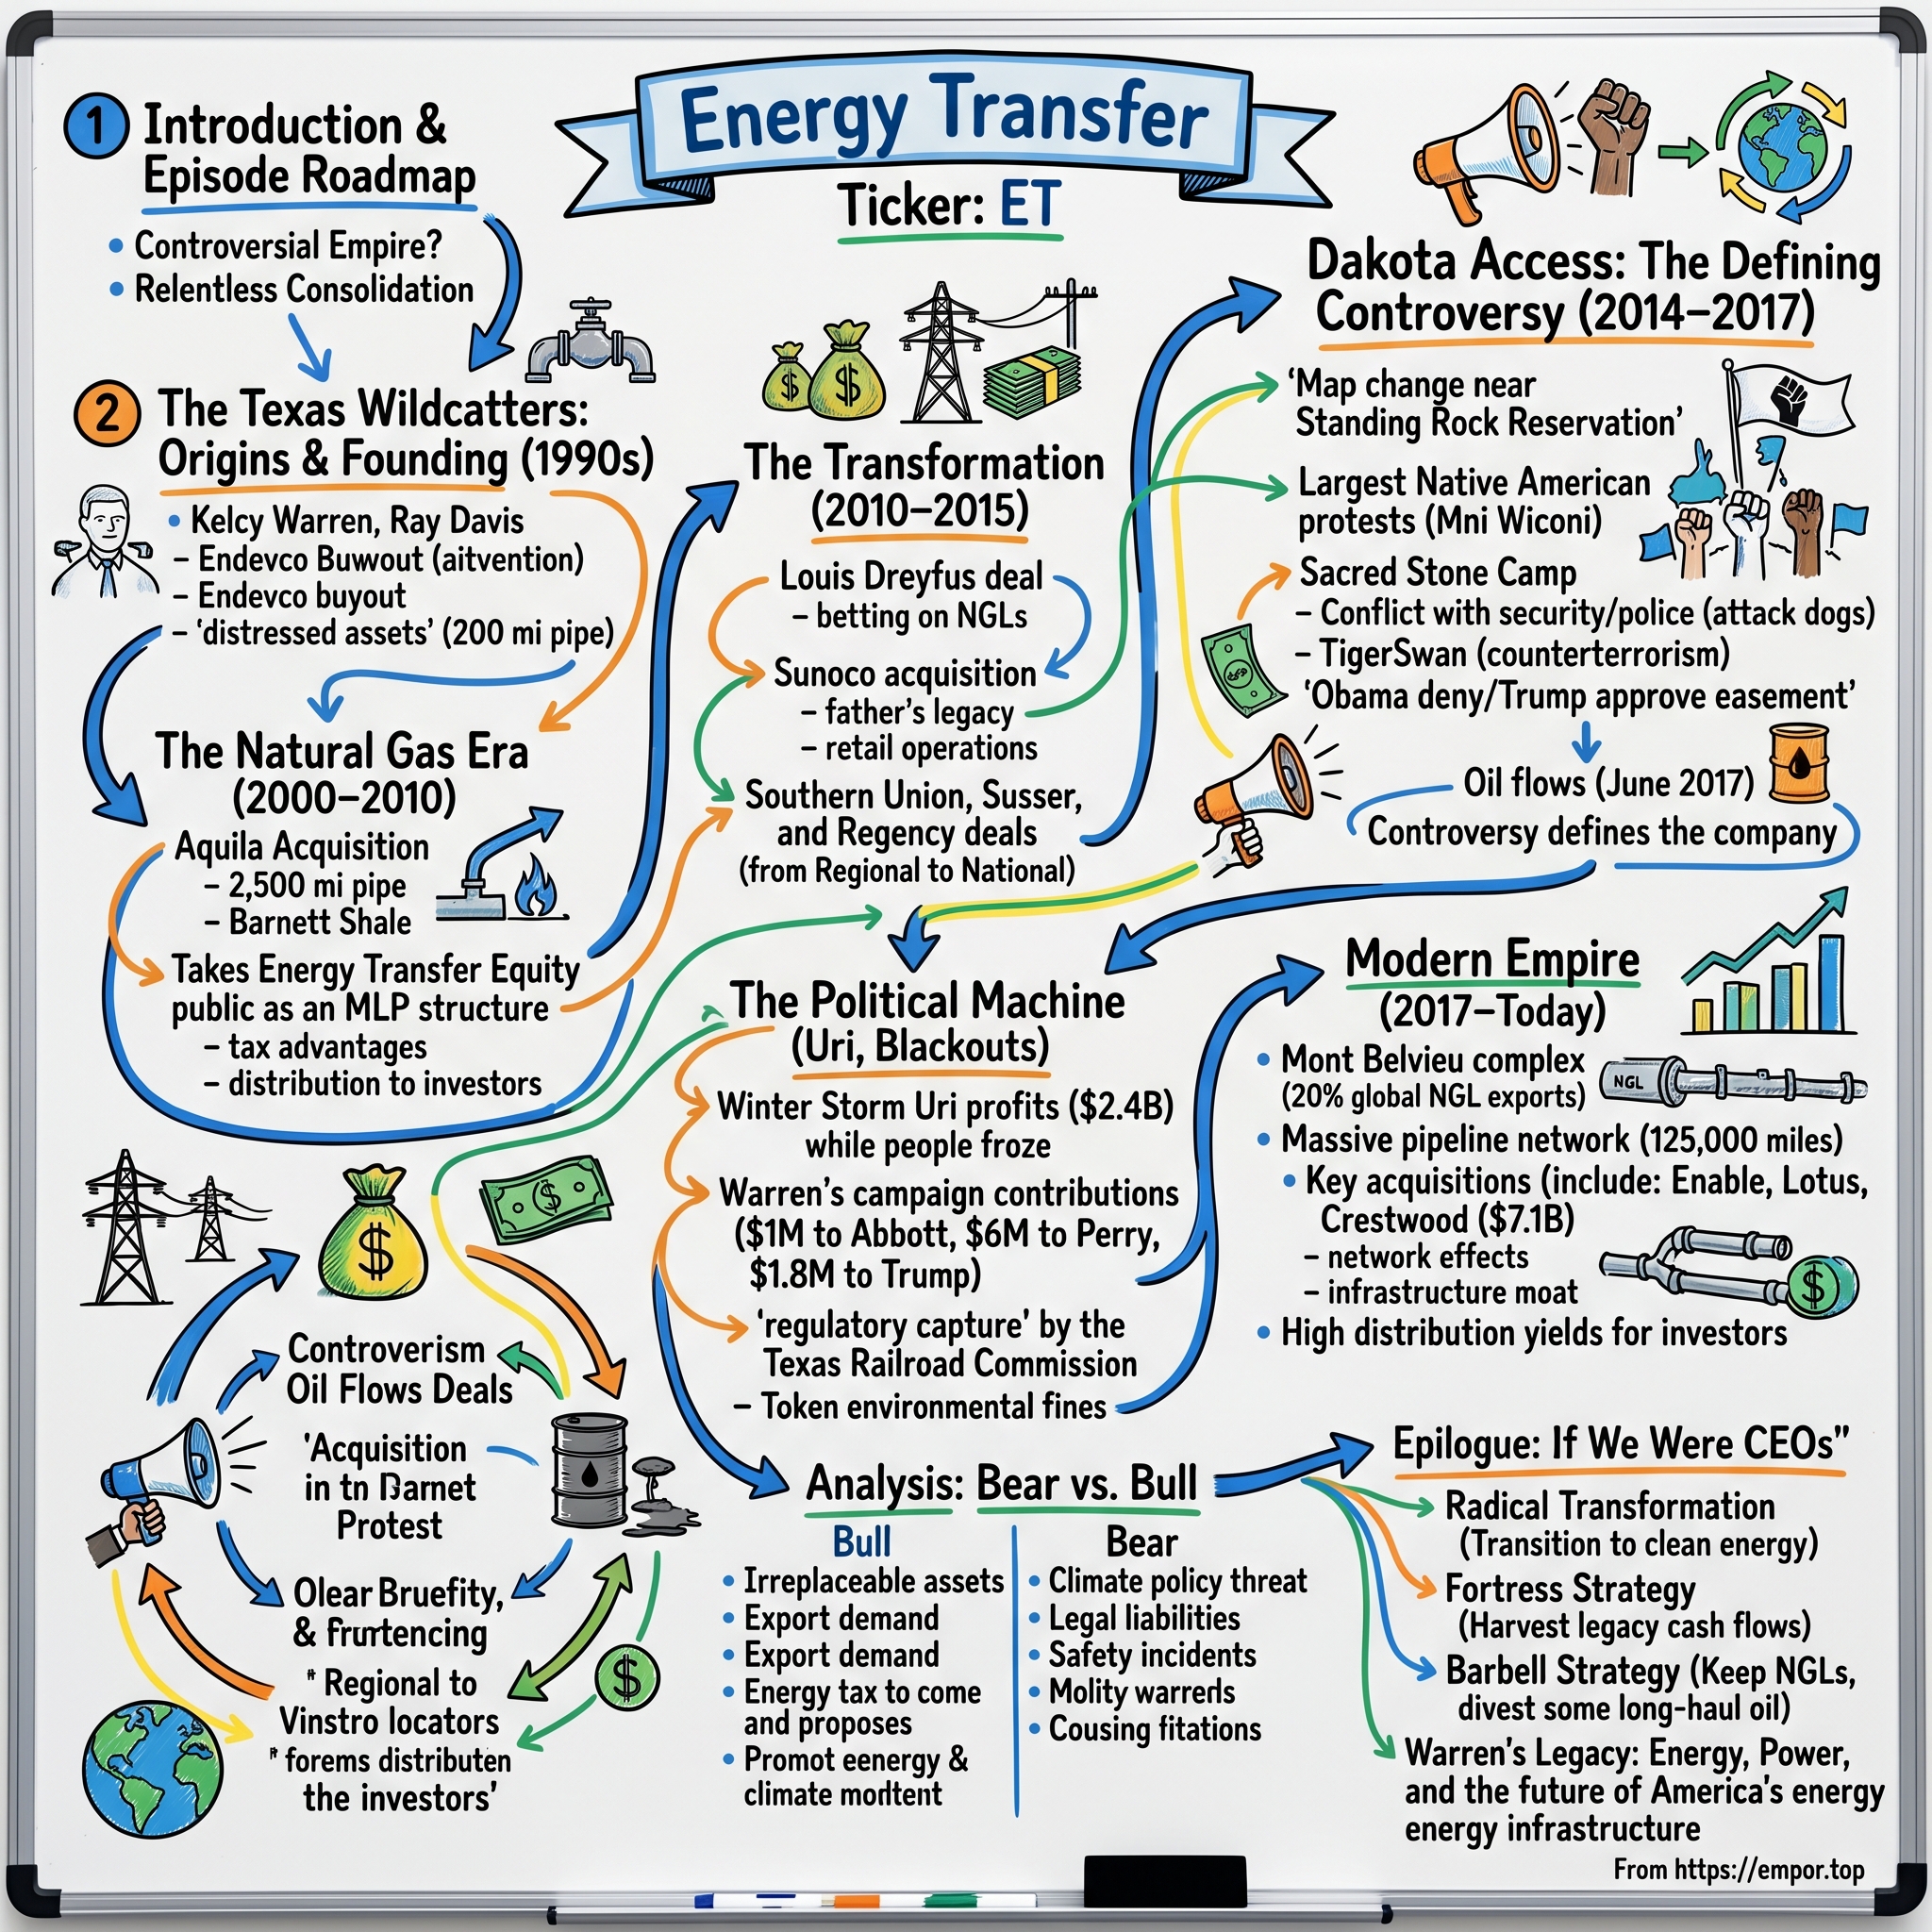
Energy Transfer LP: Building America's Midstream Empire
I. Introduction & Episode Roadmap
There is a particular kind of American fortune that is not built in a garage. It is built in a leased office above a bank in Dallas, with two founders, a map of East Texas, and a phone line to a seller needing cash before quarter-end.
Energy Transfer LP is what that fortune looks like three decades later. The partnership operates roughly 130,000 miles of pipeline across the United States—a network large enough that a meaningful fraction of the natural gas burned in American power plants and the crude oil fed into American refineries has, at some point, moved through steel that Energy Transfer owns.1 Management has told investors the company handles a double-digit share of U.S. natural gas and crude throughput alongside a large portion of global natural gas liquids exports.1 Those are company-sourced framings, and they should be read as such, but the underlying physical footprint is not in dispute. It remains visible in county easement records from North Dakota to Pennsylvania to the Louisiana Gulf Coast.
The central story is deceptively simple. Two Texas energy executives—Kelcy Warren, a civil engineer by training, and Ray Davis, a veteran operator—bought a few hundred miles of unloved gas gathering pipe in the 1990s and spent the next thirty years converting industry distress into scale. Through Enron's collapse, the 2008 financial crisis, the 2015 shale bust, and the COVID-19 pandemic, Energy Transfer stepped in when the sector broke. The result is not a technology company or a consumer brand, but a tollbooth business: an asset base whose value derives less from operational complexity than from the near-impossibility of replicating its network.
That is the bull case in one sentence. The bear case is equally direct: this is a business that has repeatedly asked its unitholders to absorb the cost of its ambition through equity dilution, heavy leverage, a distribution cut that contradicted management's prior assurances, and governance maneuvers that landed the partnership in Delaware court against its own merger counterparty.
Both statements are true. This analysis examines how much weight each deserves.
The narrative unfolds across nine sections. First, the wildcatter origins and the mechanics of midstream economics, establishing how fractionation spreads drive profitability. Second, the Master Limited Partnership structure that transformed a regional gatherer into an industry consolidator, along with the incentive alignment buried inside it. Third, the Williams merger battle of 2015–2016, which serves as a prime case study of management behavior under pressure. Fourth, key infrastructure battles—including Dakota Access, Mariner East, and the Greenpeace litigation—where legal assertiveness became a core operational strategy. Fifth, the 2020 distribution cut and the subsequent Winter Storm Uri windfall, a sequence that tested management credibility. Sixth, a segment-by-segment audit of the modern empire. Seventh, governance and capital allocation under current leadership. Eighth, two prospective growth drivers: AI data center natural gas demand and Lake Charles LNG. Finally, key analytical frameworks, including strategic takeaways, competitive moats, risk factors, and the core bull and bear investment theses.
The story begins with a partnership that barely survived its first decade.
 Subscribe on LinkedIn
II. The Texas Wildcatters & Midstream Economics: Origins (1990s–2002)
Kelcy Warren grew up in Gladewater, in the East Texas oil patch, as the son of a pipeline field hand — an upbringing that exposed him early to the economics of pipeline ownership versus field labor. After earning a civil engineering degree from the University of Texas at Arlington, he entered the natural gas industry, working at Lone Star Gas and then Endevco under Ben Cook. Cook emphasized a core industry principle: energy profits often accrue not to exploration companies, but to midstream intermediaries positioned between producers and end users.
Ray Davis served as the operational counterweight. While Warren focused on dealmaking, Davis concentrated on asset-level costs and compressor station operations. This combination — an aggressive dealmaker paired with a disciplined operator — established the founding orientation of the business, though the company's subsequent history often reflected moments when transaction volume superseded operational restraint.
In 1996, Warren and Davis purchased roughly 200 miles of struggling natural gas gathering pipeline in East Texas for under $20 million.1 The acquisition was not a grand strategic thesis, but a distressed purchase of overlooked assets by two operators seeking immediate cash flow following a difficult corporate chapter.
A short course in the middle of the value chain
The American oil and gas industry operates across three distinct segments. Upstream covers exploration and production, where operators assume geological and commodity price risks. Downstream handles refining, processing, and retail distribution. Midstream occupies the space between them, providing infrastructure designed to transport and store hydrocarbons.
A midstream operator performs four main functions on a hydrocarbon stream. It gathers raw production through small-diameter lines connected to individual wellheads. It processes natural gas by separating dry methane from heavier liquids. It transports energy products across long distances using high-pressure trunklines. Finally, it fractionates and stores natural gas liquids (NGLs), splitting mixed liquid streams into individual components — ethane, propane, butane, and natural gasoline — while maintaining storage capacity in salt caverns and tanks.
Midstream revenue falls into two distinct categories, which carry vastly different risk profiles.
The first model is fee-based transport, functioning much like a toll road. A producer signs a contract to move volumes through a pipeline at a fixed tariff, frequently backed by a minimum volume commitment that requires payment regardless of actual throughput. Because revenue depends on contracted capacity rather than underlying commodity prices, this structure generates predictable, cash-generative returns that formed the financial basis for the Master Limited Partnership (MLP) model.
The second model involves commodity spread arbitrage, which carries higher volatility. Because Energy Transfer operates pipelines connecting distinct market hubs, it can capture price differentials between regional locations. For example, natural gas at the Waha hub in West Texas often trades at a discount to gas at the Katy hub near Houston due to localized takeaway constraints. By purchasing gas at Waha and shipping it to Katy, a pipeline owner captures the basis differential. Similarly, a fractionation spread reflects the price difference between raw mixed NGL barrels and the aggregate market value of the extracted purity products. While these margins can expand significantly during supply disruptions, they can contract rapidly when competing pipeline capacity enters the market and narrows location differentials.
The distinction resembles owning both a toll highway and a freight trucking fleet: highway tolls provide stable cash flow, whereas merchant trucking margins fluctuate with market conditions.
Enron dies; Energy Transfer is born
During its initial years, Energy Transfer's East Texas gathering business operated at a modest scale, covering payroll without generating substantial excess capital. Rather than executing a long-term compounding strategy, the company was essentially waiting for asset opportunities to emerge.
That opportunity arrived with the collapse of Enron in late 2001.
Enron's bankruptcy undermined the asset-light energy trading model adopted across the sector by companies such as Dynegy, Aquila, El Paso, and Williams. As credit ratings declined and bank credit lines tightened, merchant energy companies were forced to sell physical pipeline assets rapidly to raise liquidity.
This market distress created Energy Transfer's primary growth catalyst. The company acquired core infrastructure in a market where sellers prioritized execution speed over valuation maximization.
In 2002, Energy Transfer acquired Aquila's Texas intrastate pipeline system for approximately $265 million.1 The transaction expanded the company from a regional gatherer into a major intrastate transporter with significant North Texas pipeline capacity. Crucially, it provided interconnectivity across the Texas energy grid, laying the foundation for an integrated intrastate network within the nation's largest energy-consuming state.
Testing the origin myth
The standard narrative frames Warren and Davis as opportunistic value investors who systematically built a pipeline portfolio. However, historical context reveals a more nuanced reality that informs the company's subsequent governance decisions.
The founders' predecessor entity, Endevco, experienced severe financial distress in the 1990s, forcing asset sales to settle debt. Warren and Davis were thus familiar with operating under financial pressure. Energy Transfer's early performance similarly reflected a period of operational survival rather than deliberate capital compounding.
Energy Transfer's initial competitive advantage was positional and opportunistic — operating as an unlevered buyer in Texas when over-leveraged market participants were forced to liquidate assets — rather than a structural analytical edge. Leveraging such an advantage requires maintaining sufficient balance sheet flexibility to act during market downturns. In subsequent years, however, Energy Transfer frequently expanded using heavy leverage and capital deployment that tested that balance sheet flexibility.
The partnership structure chosen to fund this expansion became the defining financial mechanism of Energy Transfer's next phase.
III. The MLP Money Machine & The Aggressive Consolidation Engine (2003–2014)
If the Aquila acquisition provided Energy Transfer with foundational assets, the Master Limited Partnership (MLP) structure provided the financial engine for rapid expansion. Understanding the partnership's trajectory during the 2000s requires examining why the MLP model served as one of the most potent capital-raising mechanisms in American energy — and how its underlying incentives eventually created systemic vulnerabilities.
The structure, explained plainly
Unlike traditional C-corporations, which pay entity-level income tax before distributing dividends to shareholders who are taxed again, an MLP functions as a pass-through entity. It pays no federal corporate income tax, passing income directly to its partners. For an asset-heavy business generating substantial depreciation charges, this tax shield allowed the partnership to distribute high levels of cash while deferring immediate tax liabilities for unitholders.
This tax efficiency directly lowered the cost of capital. Yield-seeking investors accepted lower required equity returns in exchange for tax-advantaged cash distributions. That lower hurdle rate translated into cheaper equity capital, enabling MLPs to outbid traditional corporate competitors for midstream assets while remaining accretive on a per-unit basis.
Energy Transfer Partners completed its initial public offering in 2004, followed by the parent entity, Energy Transfer Equity, in 2005. This dual-entity structure created two distinct equity currencies — operating partnership units and general partner units — both of which could be issued into a yield-hungry market to fund acquisitions.
The core driver of the parent's financial model was the Incentive Distribution Right (IDR).
An IDR gave the General Partner (GP) a contractual claim to an escalating share of incremental cash distributions. As the operating partnership increased its per-unit distribution through pre-determined tier thresholds, the GP's share rose from 15 percent to 25 percent, eventually reaching a maximum split of 50 percent. At those top-tier splits, half of every additional dollar of cash distributed by the operating entity went directly to the GP, leaving the remaining half to be divided among all public limited partners.
While advertised as an alignment mechanism — rewarding the GP only when unitholder distributions grew — the structure created an incentive to pursue distribution growth via aggressive acquisition programs. Because any acquisition that added even marginal per-unit cash flow enabled a distribution increase, the GP benefited disproportionately through high split payments, while public unitholders absorbed the long-term dilution of constant equity issuances and added debt burdens.
This structural flaw affected the entire midstream sector. Energy Transfer ultimately addressed the friction in 2018 through a corporate simplification that folded Energy Transfer Partners into Energy Transfer Equity and collapsed everything into a single class of LP equity.2 That multi-billion-dollar restructuring marked an explicit admission that the high-split GP model had become economically unsustainable.
The acquisition spree
Utilizing its low cost of capital, Energy Transfer launched an aggressive acquisition campaign across key North American energy corridors.
In 2004, the partnership acquired TXU's fuel pipeline system, using it as the core for the Texas Independence Pipeline — a 42-inch trunkline that linked disparate gathering systems into an integrated state-wide grid. This transaction demonstrated Energy Transfer's core operational strategy: combining standalone pipeline assets into interconnected networks. Transforming point-to-point lines into a multi-directional system established commercial optionality, allowing shippers to redirect natural gas to regional hubs with the highest real-time pricing.
In 2011, Energy Transfer diversified its earnings base by acquiring Louis Dreyfus Highbridge Energy for approximately $2 billion, gaining natural gas liquids infrastructure including fractionation capacity at Mont Belvieu, Texas, and Gulf Coast storage.1 Mont Belvieu serves as the primary pricing and processing hub for North American NGLs, where mixed liquid streams are fractionated into purity products. Securing major assets at Mont Belvieu positioned Energy Transfer at the center of the growing NGL export corridor.
In 2012, Energy Transfer executed two major transactions. It acquired Southern Union Company for approximately $9.4 billion following a competitive bidding war with Williams Companies — establishing a corporate rivalry that would resurface three years later. Southern Union added major interstate trunklines including Panhandle Eastern and Trunkline: FERC-regulated, long-haul, contracted pipe reaching from the Gulf into the Midwest.1 That same year, Energy Transfer purchased Sunoco for roughly $5.3 billion, adding refined products pipelines, logistics, the Marcus Hook facility on the Delaware River, and a retail fuel network later re-architected into the separately traded Sunoco LP.1
In early 2015, Energy Transfer absorbed Regency Energy Partners at an enterprise value of approximately $18 billion, consolidating Permian and Eagle Ford gathering and processing.1
Within four years, Energy Transfer had established positions across every major segment of the midstream value chain and nearly every prolific U.S. producing basin. While this rapid consolidation created an expansive logistics network, it required immense financial leverage to execute.
The price of the empire
During the peak shale expansion, midstream assets commanded elevated EBITDA valuation multiples, and Energy Transfer routinely emerged as the winning bidder over conservative peers like Enterprise Products Partners. Whereas Enterprise prioritized balance sheet discipline, lower leverage, and organic self-funding, Energy Transfer relied heavily on debt and equity issuance to finance large-scale acquisitions.
Acquisition premiums can be justified when targeted assets are irreplaceable and the buyer's cost of capital remains low. However, funding high purchase prices with equity issued at cyclical market tops and debt issued during low-interest environments left the partnership vulnerable when market conditions shifted. As Energy Transfer's consolidated debt expanded into tens of billions of dollars, its elevated leverage reduced financial flexibility ahead of an impending energy downturn.
The governance design demonstrated how incentive structures that reward payout growth while passing capital costs to unitholders can encourage over-expansion. The IDR mechanism served as the primary accelerator for Energy Transfer's initial decade of expansion, but it did so without adequate risk controls or capital discipline.
When crude oil prices collapsed in late 2014, the commodity cycle turned abruptly, exposing the financial strain of Energy Transfer's debt-heavy structure and setting the stage for its most contentious corporate battle.
IV. The Empire Strikes Back: Williams Merger War & The 2015–2016 Debt Crisis
In the summer of 2015, Kelcy Warren was attempting to build the largest energy infrastructure company in the world.
Williams Companies — the Tulsa-based owner of Transco, a key natural gas pipeline system serving the East Coast — had put itself up for sale. Energy Transfer pursued the target aggressively, having lost a bidding war to Williams for Southern Union four years earlier. In September 2015, the two companies agreed to a transaction valued at approximately $37 billion, structured with a mix of equity in a new entity and a fixed cash component of roughly $6.05 billion payable to Williams shareholders.3
That fixed cash obligation proved to be the transaction's central vulnerability, as deal terms set at the peak of a market cycle quickly collided with changing macroeconomic conditions.
The floor falls out
Between the signing and the expected closing, West Texas Intermediate crude fell from more than $100 a barrel to less than $30 a barrel, dragging natural gas prices down with it. Across the midstream sector, unit valuations plummeted, yields spiked into double digits, and the equity-issuance model that had financed a decade of consolidation effectively halted.
For Energy Transfer, the challenge shifted from growth strategy to balance-sheet survival. Funding $6.05 billion in cash required taking on substantial new debt in an unreceptive credit market, raising corporate leverage to levels that rating agencies warned could trigger a downgrade below investment grade. For a midstream operator, losing investment-grade status increases borrowing costs, triggers collateral requirements in commercial contracts, and restricts access to institutional debt capital.
Faced with these pressures, Energy Transfer sought to terminate the agreement. Williams shareholders, seeking to preserve a transaction struck at peak valuations, voted to approve the merger in June 2016.
"Even a desperate man can be an honest winner of the lottery"
The resulting legal dispute became one of the decade's most prominent corporate law battles. The merger agreement was contingent on Energy Transfer's counsel, Latham & Watkins, delivering an opinion that a key portion of the transaction qualified as a tax-free exchange under Section 721 of the Internal Revenue Code. As unit prices collapsed, the law firm concluded it could not issue the required tax opinion.
Williams filed suit in the Delaware Court of Chancery, contending that Energy Transfer had manufactured the tax issue or failed to exercise commercially reasonable efforts to secure the opinion in order to abandon the deal.
In June 2016, Vice Chancellor Sam Glasscock III ruled in Energy Transfer's favor. Although acknowledging Energy Transfer's strong desire to exit the transaction, the court held that the tax opinion failure was genuine, noting that "even a desperate man can be an honest winner of the lottery."3 The Delaware Supreme Court affirmed the decision in March 2017 over a dissent.4
The ruling was not an endorsement of Energy Transfer's overall conduct; rather, it reflected a finding that Williams had not established the specific contractual breach alleged. This distinction is often omitted in management's characterization of its litigation history.
The preferred units
Parallel to the merger litigation, Energy Transfer executed a financing transaction that caused lasting harm to its governance standing.
In March 2016, with the transaction in doubt and markets anticipating a distribution reduction, Energy Transfer Equity issued Series A Convertible Preferred Units through a private placement offered selectively to key insiders, dominated by Kelcy Warren. The preferred units were structured to insulate participating holders' distribution cash flows if common unitholder distributions were cut or suspended.
Williams filed a lawsuit challenging the issuance as self-dealing. Beyond the legal disposition, the placement signaled to the market that during a period of severe distress for common unitholders, controlling insiders secured downside protection unavailable to public investors. This structural asymmetry contributed to a persistent governance discount, resulting in Energy Transfer trading at a lower valuation multiple than conservative peers like Enterprise Products Partners for much of the subsequent decade. In corporate finance, a governance discount represents a tangible increase in the cost of equity capital that reduces long-term investment returns.
Weighing the claim
Management has contended that it exercises prudent risk management during commodity downturns. The historical record challenges that assertion in its strongest form.
The evidence includes a peak-of-the-cycle merger agreement structured with a fixed cash commitment that threatened corporate solvency; two years of costly legal conflict; credit metrics that fell to the lowest tier of investment grade, necessitating asset sales, capital expenditure cuts, and prolonged balance-sheet remediation; and ultimately, Energy Transfer paying Williams approximately $410 million in subsequent litigation related to the aborted transaction.4
What the record does demonstrate is management's capability in navigating out of self-created crises through aggressive litigation, strategic asset sales, and core operational cash generation. While operational resilience is a practical strength, it differs fundamentally from balance-sheet prudence. A key test for investors going forward is whether the partnership preserves balance-sheet capacity before market downturns or continues to pursue large-scale acquisitions at peak valuations.
While legal proceedings unfolded in Delaware, field operations continued in North Dakota, laying the groundwork for infrastructure conflicts of a different nature.
V. Dakota Access Pipeline & Mariner East: Infrastructure Battlegrounds (2014–2025)
On the night of November 20, 2016, on a closed bridge north of the Standing Rock Sioux Reservation, law enforcement officers used water cannons against protesters in sub-freezing temperatures. The resulting images circulated globally within hours. For most of the public, that night served as a stark introduction to a company few had previously tracked.
The asset that caused it
From a pure infrastructure standpoint, the Dakota Access Pipeline addressed a critical logistical bottleneck. The Bakken shale formation in North Dakota was producing vast volumes of light sweet crude in a region lacking pipeline takeaway capacity, forcing producers to rely on rail transport—a slower, costlier, and higher-risk alternative. Dakota Access was built as a 1,172-mile trunkline connecting the Bakken to an interstate shipping hub in Patoka, Illinois, initially rated at 470,000 to 570,000 barrels per day and later expanded toward 750,000 barrels per day.1 The capital cost for the Dakota Access segment was approximately $3.8 billion within a broader $4.8 billion Bakken pipeline system, structured as a joint venture in which Energy Transfer serves as operator alongside equity partners including Enbridge, Marathon Petroleum, and Phillips 66.1
The economic logic was straightforward. Transporting crude via pipeline rather than rail saved shippers several dollars per barrel, enabling Energy Transfer to secure long-term, fee-based contracts from producers—a clear execution of the toll-road business model.
Standing Rock
The pipeline’s alignment crossed beneath Lake Oahe, a Missouri River reservoir located immediately upstream of the Standing Rock Sioux Tribe’s primary water intake. The Tribe argued that the U.S. Army Corps of Engineers had conducted an inadequate consultation process and underestimated the risk of an oil spill to local water supplies and culturally significant lands. Critics noted that an earlier alternative route north of Bismarck had been rejected during development, fueling arguments that environmental risks had been shifted away from a municipal population toward a tribal community.
Throughout 2016, resistance encampments expanded from dozens of participants to thousands. The #NoDAPL movement emerged as the largest inter-tribal gathering in modern U.S. history, attracting national environmental groups, military veterans, and extensive media coverage.
Energy Transfer responded by taking a hardline stance. The partnership retained TigerSwan, a private security firm staffed by former special operations personnel whose leaked internal documents revealed the use of counterinsurgency terminology to describe protesters. That confrontational posture escalated a regulatory permitting dispute into a high-profile civil liberties controversy, creating substantial reputational fallout for the company.
In December 2016, the Obama administration withheld the Lake Oahe easement and ordered a comprehensive environmental review. On January 24, 2017, four days after taking office, President Donald Trump signed an executive memorandum directing an expedited review; the Corps granted the easement within weeks, allowing the pipeline to enter service in June 2017.1
This sequence highlighted a fundamental vulnerability in Energy Transfer’s regulatory risk profile: the operational status of a multi-billion-dollar infrastructure asset hinged directly on an executive election outcome. Investors viewing pipeline permits as permanent competitive moats must weigh that political exposure.
The court that took it back
Legal challenges persisted long after commercial operations began. In March 2020, Judge James Boasberg of the U.S. District Court for the District of Columbia ruled that the Army Corps’ environmental assessment was legally deficient. In July 2020, the court vacated the Lake Oahe easement, ordered a full Environmental Impact Statement (EIS), and initially instructed Energy Transfer to empty the pipeline.[^5] Although federal appellate courts stayed the shutdown order—permitting oil to flow—the asset operated for years without a valid federal easement while the Corps completed its EIS review.[^5]
This episode provides critical disconfirming evidence against the traditional regulatory moat narrative. While high regulatory hurdles protect incumbents from new market entrants, Dakota Access proved that legal protection for existing assets remains vulnerable to retroactive judicial intervention years after billions of dollars in capital have been deployed.
The analytical distinction is vital: rights-of-way represent a scarce physical resource, whereas administrative permits remain subject to legal and political challenge. For investors, the key metric testing asset durability is whether Energy Transfer can maintain valid, unencumbered federal authorizations across changing presidential administrations without operating under vacated easements.
Mariner East
A parallel battle unfolded in Pennsylvania over the Mariner East pipeline system, built to transport natural gas liquids from the Marcellus and Utica shales across the state to the Marcus Hook export terminal. Construction involved horizontal directional drilling through densely populated suburban neighborhoods near Philadelphia. Execution failures were frequent: sinkholes opened in residential areas, drilling fluids leaked into wetlands and private water wells during repeated inadvertent returns, and state regulators issued multiple construction stay orders.
In October 2022, the Pennsylvania Attorney General announced that Energy Transfer had pleaded no contest to criminal charges linked to construction violations, agreeing to pay environmental restitution and submit to independent monitoring after a grand jury indictment detailed dozens of counts.5 A criminal disposition stemming from construction conduct goes beyond routine operational friction, serving as an important counterweight to management's throughput and uptime metrics when evaluating operational quality.
The Greenpeace verdict
In March 2025, Energy Transfer shifted from defendant to plaintiff in the legal arena. The partnership pursued litigation against Greenpeace entities over the Standing Rock demonstrations, alleging defamation, tortious interference, and a coordinated campaign to disrupt project development. A North Dakota state jury returned a verdict awarding Energy Transfer approximately $660 million in damages.6
The verdict—which faces ongoing appeals and drew criticism from civil liberties organizations characterizing the lawsuit as a strategic action against public participation—exemplifies Energy Transfer’s aggressive legal strategy. Where industry peers typically absorb activist opposition as a cost of doing business, Energy Transfer treats opposition as a commercial tort and seeks monetary recovery through the courts.
For unitholders, this aggressive posture presents a double-edged dynamic. On one side, legal combativeness can deter future blockades and defend asset economics, yielding a notable legal award rather than ongoing defense costs. On the other side, it reinforces a confrontational corporate profile that deters certain institutional investors, invites heightened regulatory scrutiny, and remains contingent on appellate court reviews. Treating the jury award as realized capital is premature.
The external combativeness that defined Energy Transfer’s infrastructure battles was, by 2020, about to turn inward toward a self-inflicted financial crisis.
VI. Winter Storm Uri, Political Power, & The 2020 Distribution Cut (2020–2022)
In October 2020, Energy Transfer took a step management had spent fifteen years insisting it would never take.
Breaking the promise
The partnership announced a 50 percent reduction in its quarterly distribution, lowering the payout from $0.305 to $0.1525 per unit to retain roughly $1.7 billion in annual cash flow for debt reduction.1
For retail unitholders, the decision undermined the core premise of their investment. Unlike institutional total-return investors who weigh dividends against share repurchases, retail unitholders—including many retirees—purchased partnership units for predictable cash yield. Management had repeatedly cited distribution coverage in 2018 and 2019 investor communications as evidence that the payout remained secure.
From a capital allocation perspective, the reduction was necessary. The COVID-19 pandemic severely depressed fuel demand, consolidated debt exceeded $50 billion, and the partnership's cost of capital was deteriorating. Maintaining the payout to satisfy short-term yield expectations would have reflected the incentive-distribution-right era's priorities, compounding financial strain.
Yet executing the correct financial move in 2020 did not validate management's prior forward guidance. The episode demonstrated a key governance reality: Energy Transfer's leadership will ultimately make pragmatic capital allocation choices when forced by market conditions, but its forward distribution guidance carries limited predictive value. Investors must treat management's policy assurances not as firm guarantees, but as conditional statements subject to shifting balance-sheet pressures.
Four days in February
Four months later, in February 2021, Winter Storm Uri brought severe arctic temperatures to Texas. The freezing conditions disrupted wellhead production, disabled compressor stations, forced power generation offline, and triggered widespread outages across the Electric Reliability Council of Texas grid.
As supply contracted, spot natural gas prices at Texas market hubs surged from a few dollars per million British thermal units to several hundred dollars, as utilities and marketers scrambled to fulfill delivery obligations.
Energy Transfer maintained operational throughput across its Texas intrastate network. Crucially, the partnership held substantial inventory at its Bammel storage facility near Houston—one of the nation's largest natural gas storage caverns—which had been filled with lower-cost gas prior to the storm. By withdrawing stored gas and selling into hyper-inflated spot markets, the partnership reported approximately $2.4 billion in favorable Adjusted EBITDA impact from the storm.7
That single-week windfall equaled an entire year of earnings for several of Energy Transfer's operating segments combined.
What the windfall actually proves
Evaluating the financial impact requires distinguishing between operational capability and market conditions.
The first interpretation emphasizes operational preparedness: weatherized assets, ample storage reserves, and flexible grid dispatch enabled the partnership to deliver gas when competing networks froze. Executing high-volume spot sales during an emergency required fully integrated infrastructure, commercial agreements, and real-time dispatch capability.
The second interpretation views the result as a wealth transfer caused by structural market breakdown. Extreme price spikes transferred capital from utilities and ratepayers to asset owners holding unconstrained physical inventory, framing the profit as a positional windfall resulting from acute regulatory and market failure.
Both dynamics contributed to the result, but the analytical takeaway remains unchanged: this earnings surge is non-recurring and should not be capitalized into baseline valuation models. Valuation metrics that incorporate the 2021 windfall as normal earning power distort the partnership's underlying cash-generation capacity. Management itself has acknowledged the storm's earnings impact was non-recurring.
The key insight lies in how management deployed the windfall. Rather than immediately restoring the distribution, Energy Transfer prioritized debt reduction, accelerating deleveraging toward its stated target ratio of 4.0x to 4.5x debt-to-EBITDA before rebuilding the payout in increments over subsequent years.[^9] While this delayed gratification frustrated income-oriented unitholders, prioritizing balance-sheet health lowered long-term borrowing costs across the partnership's project portfolio. The capital allocation sequence provided strong evidence that current leadership weights balance-sheet durability over short-term distribution optics—a departure from the leverage-heavy practices of the IDR era.
The politics
The aftermath of Winter Storm Uri also underscored the role of political relationships in regulated infrastructure. Energy Transfer and its affiliates have long maintained a substantial presence in Texas political funding, including a widely reported $1 million contribution from Kelcy Warren to Governor Greg Abbott's campaign in the months following the storm, which prompted an unsuccessful lawsuit by a Texas resident alleging improper influence.6
Beyond individual contributions, the structural reality is that Energy Transfer's intrastate pipeline network is regulated by the Railroad Commission of Texas, an elected three-member panel whose political campaigns rely heavily on industry contributions. This environment creates a distinct regulatory risk profile: while favorable oversight provides operational flexibility under supportive administrations, it leaves the partnership exposed to policy backlash if public scrutiny drives regulatory reform.
With lower debt, improved credit metrics, and a restored distribution, Energy Transfer entered the mid-2020s on firmer financial footing. Evaluating the durability of that transformation requires a segment-by-segment examination of its modern operating portfolio.
VII. Modern Empire: Business Segments, Industry Structure & Scale Moat Today
Picture a hydrocarbon molecule's journey across the network, because the segment structure functions as a physical narrative.
A well in the Midland Basin produces natural gas mixed with heavier liquids. Energy Transfer's gathering pipeline collects the raw stream. A processing plant strips out the liquids. The dry gas enters an intrastate line toward Houston or an interstate line bound for the Midwest. The liquids travel along a natural gas liquids (NGL) pipeline to Mont Belvieu, where a fractionator separates them into ethane, propane, and butane. The propane moves to the Nederland terminal on the Texas coast to be loaded onto an export tanker bound for Asia. Meanwhile, a barrel of Bakken crude moves down the Dakota Access Pipeline toward the Gulf Coast. In Pennsylvania, a Sunoco-branded station sells gasoline delivered through a refined products pipeline.
Energy Transfer collects a fee at every stage of that handoff. That physical logistics network constitutes the entire business, with segment reporting dividing the earnings stream by operational phase.
Where the money is made
Consolidated Adjusted EBITDA has run at roughly $5 billion per quarter in recent reporting, distributed across six primary reporting lines.[^9]
NGL and refined products represents the largest segment, generating approximately one-quarter of total earnings. It includes the Mont Belvieu fractionation complex, the Marcus Hook export facility on the East Coast, and the Nederland terminal on the Gulf Coast—the infrastructure that connects American shale production to international markets. The segment benefits from structural growth drivers: as U.S. NGL output expands faster than domestic petrochemical demand, excess volume must be exported. Because Gulf Coast dock capacity remains difficult to permit and build, this asset position represents one of the most durable components of Energy Transfer's portfolio.
Midstream gathering and processing generates roughly one-sixth of total earnings. Operating across the Permian, Eagle Ford, Mid-Continent, and Haynesville basins through more than 100 processing facilities, it is the most cyclical segment. Gathering throughput tracks producer drilling activity and prevailing commodity prices, while percentage-of-proceeds contracts directly expose a portion of earnings to market spreads.
Crude oil transportation and services contributes a comparable share, anchored by the Dakota Access Pipeline, the Permian Express system, and Gulf Coast terminal facilities. As such, it carries the highest exposure to regulatory and legal permitting risks.
Interstate natural gas—comprising Panhandle Eastern, Trunkline, Rover, and Trans-Mexico pipelines—provides the most stable earnings profile. Regulated by the Federal Energy Regulatory Commission (FERC), revenues rely heavily on firm reservation charges paid regardless of throughput volumes, rendering the segment largely insulated from short-term commodity price shifts. However, it exhibits slower volume growth and remains subject to periodic FERC rate reviews.
Intrastate natural gas, while the smallest reported segment by baseline earnings, holds strategic importance across the overall network. Encompassing the Texas intrastate grid—including the Oasis Pipeline, the Katy hub, Waha interconnections, and Bammel storage—it generates modest EBITDA during normal operating conditions but expands dramatically during market dislocations, as demonstrated during Winter Storm Uri. It also positions the partnership to capture emerging demand from natural gas power generation.
Sunoco LP and USA Compression complete the reporting mix. Energy Transfer holds equity interests in both publicly traded partnerships, consolidating their financial results while owning a partial economic share. This dual structure adds corporate complexity: layered entities, minority interests, and intercompany arrangements make consolidated financial analysis less transparent than for single-entity peers, contributing to a structural valuation discount.
The fee-based question
Management states that approximately 90% of Adjusted EBITDA is fee-based, derived from tariffs, firm reservation charges, and minimum volume commitments rather than direct commodity exposure.[^9]
While fee-based contracts mitigate direct price volatility, they do not eliminate underlying volume risk. A gathering contract backed by a minimum volume commitment protects revenue only until the contract term expires; if local acreage depletes, contracts may renew on less favorable terms. Similarly, long-term transportation tariffs on interstate lines protect cash flow until contract expiration, after which re-contracting rates depend on regional pipeline capacity. The 90 percent fee-based metric reflects short-term price insulation rather than guaranteed multi-year earnings durability.
Furthermore, the remaining 10 percent commodity-sensitive exposure remains material. In volatile market environments, spread fluctuations across that unhedged portion can move consolidated annual results by more than $1 billion in either direction.
The competitive set
Four primary peers frame Energy Transfer's market positioning.
Enterprise Products Partners serves as the primary operational and financial benchmark. Featuring a similar asset footprint and export focus, Enterprise maintains significantly lower leverage, a sustained record of self-funding growth capital from retained cash flow, and a distribution growth record that continued uninterrupted through market downturns where Energy Transfer executed cuts. Enterprise consistently trades at a higher valuation multiple; narrowing that gap represents the single largest value-creation opportunity under management control.
Kinder Morgan pursued a structural conversion from an MLP to a C-corporation in 2014 and reduced its dividend in 2015, resulting in a loss of institutional investor trust that required years of balance-sheet remediation to repair. It operates the nation's largest natural gas pipeline network by throughput.
ONEOK has expanded aggressively through corporate acquisitions, including its purchase of Magellan Midstream, creating an integrated NGL system spanning the Bakken and Permian basins that competes directly with Energy Transfer.
MPLX and Targa Resources represent focused basin competitors. MPLX relies on its refining sponsorship with Marathon Petroleum and an established Appalachian gathering footprint, while Targa's Permian gathering and processing position poses a direct competitive challenge to Energy Transfer's market share in that basin.
The competitive landscape highlights a clear trade-off: Energy Transfer commands the broadest physical footprint and the most fully integrated midstream value chain, Enterprise maintains a superior balance sheet and lower cost of capital, and Targa and ONEOK hold concentrated exposure to high-growth basins. While scale provides operational flexibility, it has not translated into a valuation premium, reflecting persistent market skepticism regarding historical governance and capital allocation choices.
That governance record remains central to evaluating the partnership's investment thesis.
VIII. Current Management, Capital Allocation & Governance Audit
Kelcy Warren no longer manages Energy Transfer's daily operations. Serving as Executive Chairman, his influence on the investment thesis is structural rather than operational: he remains the largest individual unitholder, with a reported beneficial stake of approximately 11% of common units, valued at well over $1 billion.1
That substantial ownership position carries dual implications for public unitholders.
The constructive interpretation centers on economic alignment: no individual absorbs a larger absolute financial loss from a permanent impairment of unit value than Warren himself. The critical interpretation emphasizes control without public accountability. Unlike corporate shareholders, limited partnership unitholders do not elect board directors. Governance oversight relies primarily on capital markets discipline—and the market's response has manifested in the persistent valuation discount applied to the partnership's equity. Furthermore, Warren's historical participation in the 2016 Series A preferred transaction demonstrated that during periods of corporate distress, insider capital secured downside protection that was unavailable to common unitholders.
The co-CEO structure
Energy Transfer operates under a dual-chief-executive model—an unusual arrangement in corporate governance, yet one reflecting distinct operational responsibilities.
Mackie McCrea leads commercial strategy. A multi-decade veteran who advanced through the Texas intrastate system, McCrea focuses on commercial contracting, capacity marketing, and customer acquisition. On quarterly earnings calls, his commentary centers on concrete volumetric metrics—such as billion cubic feet per day—and specific counterparty engagements rather than general industry themes.
Tom Long oversees financial policy, having served as Chief Financial Officer prior to his appointment as co-CEO. Long focuses on capital structure discipline, tracking debt maturity schedules, distribution coverage ratios, and fixed-charge obligations. Given the financial strains of the 2015–2016 period, embedding a chief financial officer's perspective directly within top executive leadership provides a structural counterweight to aggressive expansion.
The analytical question for investors is how the co-CEO framework functions during strategic disagreements. Dual-executive leadership depends on consensus; when commercial expansion collides with financial conservatism, historical precedents—such as the Williams merger attempt—demonstrate that growth ambitions have frequently superseded balance-sheet restraint.
The second acquisition wave
Following its post-2020 balance-sheet remediation, Energy Transfer resumed corporate acquisitions, adopting a modified financial playbook.
Enable Midstream, acquired in 2021 for approximately $7.2 billion in an all-equity transaction, expanded the partnership's presence across the Mid-Continent and Haynesville basins.1 Issuing equity units rather than expanding debt represented a clear departure from pre-2016 transaction structures.
Lotus Midstream was acquired in 2023 for roughly $1.45 billion, adding Permian Basin crude gathering assets.1
Crestwood Equity Partners was absorbed later in 2023 for approximately $7.1 billion, acquiring Bakken and Delaware Basin gathering infrastructure at a valuation multiple that management characterized in the single digits after accounting for operational synergies.8
WTG Midstream closed in 2024 for roughly $3.25 billion, deepening Permian natural gas gathering capacity and adding processing facilities that feed directly into Energy Transfer's downstream NGL value chain.9
The strategic rationale of this second consolidation phase differs fundamentally from the 2011–2015 expansion. Rather than acquiring standalone or disconnected systems, recent transactions focused on assets that channel hydrocarbon volumes directly into Energy Transfer's existing infrastructure—delivering gathered gas and NGLs into company-owned processing plants, trunklines, fractionators, and export terminals. By capturing fees across multiple stages of the midstream logistics chain, a transaction executed at a standalone enterprise value of seven times EBITDA can generate higher effective returns for Energy Transfer than for a non-integrated bidder.
The credibility scorecard
Evaluating current leadership requires balancing recent operational discipline against historical governance actions.
On execution, management has delivered measurable progress: consolidated leverage was reduced into the target range of 4.0x to 4.5x debt-to-EBITDA and maintained; quarterly distributions were systematically rebuilt following the 2020 reduction; recent acquisitions incorporated higher equity components and lower headline valuation multiples than prior cycles; and asset integration proceeded without material operational disruptions.
Conversely, structural governance concerns remain unaddressed: distribution assurances offered in 2018 and 2019 were promptly reversed in 2020; the selective 2016 preferred unit issuance continues to weigh on governance perceptions; multi-tiered entity structures—including listed affiliates, minority holdings, and related-party arrangements—introduce corporate complexity that depresses valuation multiples; and a combative legal and public policy posture continues to generate reputational friction.
Consequently, the argument that Energy Transfer's management has permanently adopted capital discipline remains supported but unproven. Recent operational improvements occurred during a favorable commodity backdrop while the balance sheet underwent mandatory repair. The ultimate test of management's financial discipline will occur when a large, strategically attractive acquisition opportunity emerges at a time when the partnership possesses available balance-sheet capacity.
Two prospective expansion opportunities—data center power demand and Lake Charles LNG—present that precise test.
IX. Hidden Optionality & Dark Horses: AI Data Center Power & Lake Charles LNG
On an earnings call, an analyst asked co-CEO Mackie McCrea how much real demand lay behind the emerging market interest in natural gas for AI data centers. McCrea outlined active commercial discussions to supply natural gas to dozens of prospective power plants and data center facilities, with aggregate potential demand reaching billions of cubic feet per day. Crucially, he noted that a portion of those discussions had converted into signed contracts rather than remaining exploratory conversations.[^9]
Why a pipeline company is suddenly an AI story
The underlying physical logic is straightforward. Training and serving large artificial intelligence models requires data centers that consume hundreds of megawatts of continuous electricity—with major campuses requiring power equivalent to a mid-sized city. That load operates continuously and requires uninterrupted baseload power. While wind and solar generation offer low marginal costs, their intermittency limits their capability to provide constant power, and utility-scale battery storage remains constrained to short durations. Nuclear power offers continuous generation, but construction timelines extend out years. For technology developers seeking dispatchable, fast-to-deploy baseload power across Texas and the Southeast over the near-to-medium term, natural gas turbines represent the primary practical solution.
Operating a gas turbine requires a steady fuel supply, which depends on pipeline interconnections with sufficient capacity and high operational reliability. For a data center operator, fuel pressure loss represents an unacceptable service disruption.
Energy Transfer's key advantage in this sector is geographical rather than technological. The Texas intrastate pipeline grid built over previous decades passes directly through key data center expansion corridors: the Dallas–Fort Worth exurbs, the Interstate 35 corridor toward Austin and San Antonio, and the Houston industrial belt. Connecting a new facility to an existing high-pressure trunkline requires constructing only a lateral line and a meter station—a project costing tens of millions of dollars over months, compared to greenfield pipeline construction requiring billions of dollars and multi-year permitting processes. Consequently, lateral interconnections off an existing pipeline network generate high incremental returns on invested capital, making the positioning commercially significant beyond headline volumetric numbers.
How much to believe
Evaluating this growth vector requires analytical caution. Announced data center capacity does not automatically translate into completed construction, and signed gas supply agreements do not guarantee active throughput. Energy sector history demonstrates that major expansion cycles—including liquefied natural gas exports in 2013 and Permian Basin takeaway capacity in 2018—frequently generated far more proposed projects than operational facilities, with completed assets occasionally overbuilding capacity and compressing returns.
The appropriate assessment frames AI-driven gas demand as a material, partially contracted growth opportunity with attractive incremental economics, where customer execution and project timing remain the primary variables rather than pipeline construction capability.
The key metric for tracking execution is contracted firm transportation volume specifically bound for power generation and data center facilities—disclosed in quarterly filings—rather than management's total pipeline of commercial discussions.
Lake Charles LNG: the option that has not been exercised
The second long-term option carries a more extended development history.
Energy Transfer owns an LNG import terminal in Lake Charles, Louisiana—an asset constructed when the United States imported natural gas, before domestic shale production transformed global energy flows. For over a decade, the partnership has evaluated converting the facility into an export terminal capable of producing approximately 16.5 million tonnes per annum.
The conversion proposal has evolved through multiple structural iterations and partner transitions. Shell previously participated before exiting the venture. Department of Energy export authorizations have been granted, extended, and subjected to regulatory reviews across multiple presidential administrations, while preliminary offtake agreements and potential equity partners have been announced incrementally.
This trajectory illustrates the distinction between regulatory authorization and commercial execution. An export license provides regulatory permission, but does not secure committed customers or capital. Lake Charles has maintained regulatory authorizations for years without reaching a final investment decision (FID).
Management's public guidance on the project has remained cautious. Executives have repeatedly stated that Energy Transfer will not issue a final investment decision without securing substantial long-term offtake contracts and equity partners to share capital expenditures, specifically to prevent balance-sheet strain.[^9] That policy protects capital discipline, effectively signaling that investors should not include Lake Charles cash flows in baseline valuation models until commercial terms are finalized.
The decisive indicator remains a formal final investment decision backed by equity partners and binding offtake commitments. Until such an announcement occurs, Lake Charles represents an unexercised real option with an unpriced valuation impact.
Both opportunities depend on Energy Transfer's foundational physical asset base: an interconnected, non-replicable pipeline network across major U.S. demand corridors.
X. Playbook: Business & Investing Lessons
Strip away three decades of dealmaking and four core lessons emerge, each applicable beyond the energy sector.
1. The right-of-way is the asset; the pipe is a commodity
Steel and specialized labor are market commodities. What cannot be easily replicated is the legal right-of-way to cross thousands of individual private land parcels, multiple state jurisdictions, dozens of river crossings, and intervening federal property. Constructing a modern cross-country pipeline requires environmental reviews, state permits, eminent domain proceedings, tribal consultations, Federal Energy Regulatory Commission authorizations for interstate lines, and defense against federal litigation brought by persistent opponents.
Energy Transfer's core rights-of-way were assembled primarily during periods when regulatory and legal hurdles were lower. Consequently, the true barrier to entry is not physical replacement cost, but regulatory and legal feasibility; in many key corridors, building a duplicate system is effectively impossible at any price.
The broader business takeaway is that the most durable competitive advantages are frequently legal and historical rather than technological. Evaluating an incumbent's moat requires asking whether its physical footprint could be legally permitted and constructed today by any competitor at any cost. Where the answer is no, the advantage reflects structural scarcity rather than operational differentiation.
2. Be liquid when everyone else is not
Every major expansion phase in Energy Transfer's history traces to counterparty distress: Enron's collapse in 2002, the 2008–2009 financial crisis, the 2015–2016 shale downturn, and the 2020 pandemic. The underlying physical assets retained their long-term utility during those disruptions, but the sellers lost financial flexibility.
The corresponding operational lesson is the necessity of balance-sheet capacity. Counter-cyclical acquisitions require reserved financial flexibility—maintaining leverage capacity specifically for periods of market dislocation. An operator burdened by high leverage at a cyclical peak cannot exploit distressed asset prices at the trough. Energy Transfer entered 2016 financially constrained and unable to capitalize on market distress; by contrast, it entered 2021 with lower leverage, allowing its post-2020 consolidation wave to proceed on more favorable terms.
3. Vertical integration compounds the fee
Tracing a hydrocarbon molecule from a Midland Basin wellhead to an export tanker at Nederland illustrates how integrated infrastructure compounds toll collection: gathering, processing, natural gas liquids transport, fractionation, storage, terminalling, and marine loading. A standalone gatherer collects a single fee, whereas an integrated midstream operator captures sequential margins on the same physical volume stream.
This multi-stage fee capture enables an integrated operator to justify higher acquisition valuations for gathering systems like Crestwood and WTG Midstream than non-integrated competitors can offer, as the acquired volumes generate incremental cash flow across the broader downstream network. The offsetting risk is structural vulnerability: a vertically integrated logistics chain presents multiple single points of failure, where operational disruptions at any stage constrain throughput across the entire network.
4. Aggression as a capital allocation choice
The final lesson centers on management's distinct approach to legal and political conflict. Energy Transfer treats litigation and regulatory assertiveness as core operational tools evaluated on financial return. The partnership litigated to terminate the Williams merger, operated the Dakota Access Pipeline through a vacated easement during judicial appeals, contested Pennsylvania environmental enforcement until reaching a criminal disposition, and pursued activists in civil court to secure a multi-hundred-million-dollar jury award.
Evaluated strictly on asset economics, this combative posture has frequently preserved commercial operations. Evaluated on capital costs, however, it has proven expensive: persistent governance concerns and headline risks create a structural valuation discount that acts as a permanent tax on the partnership's equity currency. For investors, management's aggressive posture represents neither a simple strength nor an unmitigated liability, but a deliberate and consistent operational trait priced into the equity and unlikely to shift while the founder serves as Executive Chairman.
Those four structural characteristics define Energy Transfer's position within the North American energy hierarchy.
XI. Competitive Benchmarking, 7 Powers & Porter's 5 Forces Analysis
Hamilton Helmer's 7 Powers
Cornered Resource — the primary power, with a caveat. Energy Transfer's rights-of-way, export terminals, Mont Belvieu fractionators, and Bammel storage facilities represent a cornered resource: strategically located, legally established under historical regulatory regimes, and virtually impossible to duplicate today. The primary caveat is that a cornered resource protects against new market entrants, not against legal challenges targeting existing operational permits. The physical network remains cornered, but the administrative license to operate it requires ongoing compliance and remains subject to judicial review.
Scale Economies — high and demonstrable. Fixed operating expenses—including compressor stations, pipeline dispatch, telemetry systems, maintenance, and corporate overhead—are distributed across daily throughput measured in millions of barrels of liquids and tens of billions of cubic feet of natural gas. The most significant scale advantage is operational optionality per connection: an interconnected network can reroute volumes to higher-priced regional hubs, a capability that standalone point-to-point pipelines cannot replicate.
Process Power — moderate, and demonstrated under stress. Real-time dispatch across an interconnected intrastate grid during physical market disruptions represents a developed operational capability, as demonstrated during Winter Storm Uri. However, a single extreme weather event provides limited evidence of a durable, proprietary process power; much of the financial performance reflected physical asset location rather than unique operational methodology.
Counter-Positioning — absent. Energy Transfer's aggressive, debt-financed consolidation strategy is not a business model competitors are unable to copy due to fear of damaging their core operations. Rather, conservative peers such as Enterprise Products Partners have deliberately chosen not to adopt it, prioritizing balance-sheet stability and organic capital return instead.
Switching Costs — moderate and contractual. Connecting a producer's gathering infrastructure directly to Energy Transfer's pipeline network creates physical switching costs, as redirecting flow requires building new connection lines. However, these switching costs protect cash flows only for the duration of the contract term. In basins with overlapping competitor pipelines, contract renewals face active market pricing pressure.
Branding and Network Economies — not applicable. Neither force provides a meaningful competitive advantage. Hydrocarbon streams are fungible commodities, and counterparty selection depends on tariff rates, reliability, and interconnect availability rather than brand equity or network effects.
Porter's Five Forces
Threat of new entrants: very low. Substantial capital commitments, multi-year regulatory reviews, complex land acquisition, and organized environmental opposition create high entry barriers for long-haul infrastructure. This dynamic is evidenced by the multiple greenfield pipeline projects cancelled over the past decade after developers incurred hundreds of millions of dollars in unrecoverable planning costs.
Bargaining power of suppliers (producers): low to moderate. E&P operators in basins like the Bakken or Delaware have limited physical egress options for depleting reserves that require continuous monetization, creating an asymmetry that favors midstream operators. However, supplier bargaining power increases in mature producing areas where multiple gathering networks compete for the same wellhead acreage.
Bargaining power of buyers: low to moderate, but rising in growth segments. Refineries, petrochemical facilities, and export terminals require firm transport capacity, while regulatory oversight and long-term tariffs limit pricing extraction in tight markets. The key emerging exception is the data center and power generation customer class—well-capitalized buyers capable of constructing lateral interconnects and soliciting competitive bids across multiple pipeline networks. As power generation becomes a larger portion of new volume additions, buyer bargaining power within the expansion portfolio will exceed that of the legacy asset base.
Threat of substitutes: low near-term, uncertain long-term. Renewable power and battery storage continue to capture market share at the margin in electricity generation, while electric vehicle adoption presents a long-term headwind for refined product demand. Conversely, natural gas remains the primary dispatchable fuel for firm electrical capacity, and natural gas liquids serve as essential petrochemical feedstocks with no direct electrical substitutes. Consequently, the NGL and export logistics business exhibits greater substitution resistance than the refined products transport segment.
Rivalry: moderate, but sharpening in basin gathering. Long-haul interstate transportation operates as a stable, rational oligopoly. Conversely, basin-level gathering and processing features direct competition among Enterprise Products Partners, Targa Resources, ONEOK, and MPLX for producer acreage—the specific segment where Energy Transfer continues to direct significant growth capital.
The composite analysis reveals a structurally defensible midstream position anchored by an irreplaceable cornered resource. However, that competitive moat remains vulnerable to administrative and legal challenges, while commercial rivalry is most intense in the gathering and processing segment where growth capital is concentrated.
XII. Analysis & Bear vs. Bull Case (With Risk Radar)
Current risk radar
Permitting and litigation. Dakota Access remains the primary case in point. The federal environmental review process around the Lake Oahe crossing has created a multi-year overhang, demonstrating that courts can invalidate an operating authorization years after project construction.[^5] The mechanism of harm is specific: a shutdown order removes a major crude egress route, strands Bakken production volumes, and eliminates a meaningful earnings contribution overnight. Any future greenfield project carries a similar risk profile.
Refinancing and cost of capital. With total debt near $50 billion, Energy Transfer refinances continuously. In a higher-interest-rate environment, maturing debt rolls over at higher coupons, turning incremental interest into a direct, permanent subtraction from distributable cash flow. This persistent expense compounds quarterly without generating major headlines. Consequently, the partnership's credit rating trajectory—and management's willingness to defend it—carries greater weight than equity markets often recognize.
Permian egress overbuild. Multiple large natural gas pipelines out of the Permian Basin have recently entered service or remain under construction. Each additional line narrows the Waha-to-Gulf Coast basis differential that drives commodity spread profitability. In a classic midstream cycle, wide price differentials attract new pipeline capital, which subsequently compresses those differentials. The arbitrage component of Energy Transfer's earnings is thus vulnerable to margin compression as new capacity comes online, making recent peak spread capture an unrepresentative baseline for future performance.
Concentration and complexity. The layered corporate structure of listed affiliates, minority holdings, and related-party arrangements makes consolidated financial analysis more complex than for single-entity peers. Equity markets routinely apply a valuation discount to structures that are difficult to model cleanly.
The bull case
The bull case rests on four pillars, arranged by evidential strength.
First, the export franchise provides the strongest structural foundation. Because U.S. natural gas liquids production continues to outpace domestic petrochemical consumption, excess volumes must be exported by sea. Gulf and East Coast terminal capacity remains scarce and subject to stringent permitting barriers. Energy Transfer's integrated fractionation-to-terminal network captures multiple sequential fees on these flows, representing the asset class where its cornered-resource advantage is most defensible against substitution.
Second, the balance sheet has undergone genuine remediation. Maintaining leverage within management's target band, rebuilding distribution coverage, and funding recent acquisitions with meaningful equity components have allowed the partnership to generate positive free cash flow after distributions and maintenance capital. This transition alters the character of the equity, shifting it from a highly leveraged growth vehicle toward a cash-generation model.
Third, physical network connectivity creates a compounding advantage. Incremental Permian volumes frequently flow into Energy Transfer's downstream system, rendering basin gathering acquisitions structurally more valuable to an integrated operator than to standalone competitors.
Fourth, the data center and power demand opportunity offers attractive incremental returns. While this catalyst is supported by initial contracted volumes, it remains the least proven of the four pillars and requires measured position sizing.
The bear case
The bear case does not dispute the quality of the underlying physical footprint; rather, it questions how much value accrues to public unitholders and at what cost.
Governance remains the central vulnerability. The 2016 Series A preferred unit issuance, the 2020 distribution reduction following prior coverage assurances, limited unitholder voting rights, and a controlling insider with a history of asymmetrical downside protection collectively justify a higher required return on Energy Transfer equity relative to conservative peers like Enterprise Products Partners. This governance discount reflects a rational risk premium for documented management history, and it is likely to narrow only through a prolonged period of predictable execution.
Long-term terminal demand carries structural uncertainty. While near-term throughput remains robust, multi-decade cash flow models face demand ambiguity in 2040 and beyond. Pipeline assets are valued on long-term cash generation, and the back half of those projections depends on long-term hydrocarbon demand trajectories that remain difficult to forecast.
Capital discipline remains unproven in an unconstrained environment. Although post-2020 capital discipline has been evident, it occurred during a period of mandatory debt reduction. Current leadership has not yet been tested by a large, competitive acquisition opportunity at a time when the balance sheet possesses excess borrowing capacity.
An activist playbook highlights clear governance remedies: simplifying the corporate affiliate structure to eliminate the complexity discount; disclosing return on capital by segment rather than segment EBITDA alone to measure growth efficiency; establishing a firm leverage cap rather than an elastic target range; and introducing formal governance reforms to address founder control directly. While management has not implemented these measures, executing them could narrow the valuation gap with industry peers.
The metrics that actually matter
Three primary metrics warrant continuous evaluation:
First, consolidated leverage—net debt to Adjusted EBITDA—relative to management's 4.0x to 4.5x target band. This metric serves as the primary gauge of ongoing capital discipline, where a sustained increase to fund an acquisition would challenge the balance-sheet reform thesis.
Second, distributable cash flow coverage of the distribution and the pace of payout growth. Coverage demonstrates whether distributions are fully supported by underlying operating cash flows rather than external capital markets.
Third, contracted firm transport volumes tied specifically to power generation and data center load. Tracking quarter-over-quarter volume growth converts speculative market enthusiasm into verifiable commercial execution.
Headline EBITDA, proposed project pipelines, and gross throughput records remain secondary indicators governed by these three core metrics.
XIII. Epilogue & "If We Were CEOs"
American corporate history divides cleanly between consumer-facing brands and underlying industrial infrastructure. Energy Transfer belongs firmly to the second category—an indispensable midstream operator whose network underpins daily energy logistics.
End users rarely select their pipeline provider. A Texas homeowner does not choose which pipe delivers natural gas to a regional power plant, just as a data center developer negotiating power supply lacks a menu of competing interstate grids. Hydrocarbons follow physical infrastructure, reflecting a founding premise that long-term enterprise value in midstream energy accrues to network control rather than upstream reserve ownership.
The partnership's central analytical tension is that its primary competitive strength and its structural equity discount share the same origin. The aggressive posture that built the network—acquiring distressed assets during downturns, pursuing contentious litigation, and pushing through regulatory opposition—also generated the persistent governance discount. Investors evaluating the partnership must recognize that acquiring the asset base entails accepting the management style that constructed it.
From an operational and governance perspective, three strategic priorities would address these structural friction points:
Institutionalize balance-sheet discipline rather than treating it as an elastic target. Management could formally commit to a strict net-debt-to-EBITDA ceiling of 3.75x, subordinating distribution growth to leverage targets. The objective is not merely securing higher credit ratings, but permanently lowering the partnership's cost of capital. In an industry where acquisition success depends heavily on capital efficiency, a lower cost of capital functions as a structural moat—a competitive advantage that Enterprise Products Partners maintains over Energy Transfer.
Provide structured disclosure on AI and power generation demand. Management could report quarterly firm contracted volumes specifically tied to power plants and data centers, alongside weighted-average contract tenors and allocated growth capital. Transparent reporting would allow public unitholders to evaluate management's commercial commentary against verified execution, separating contracted cash flows from speculative market interest.
Require risk-sharing prior to a final investment decision on Lake Charles LNG. Management should condition any final investment decision on securing a substantial equity sell-down to third-party infrastructure investors and contracting a large majority of facility capacity under long-term agreements. Executing a mega-project without equity partners risks over-leveraging the balance sheet, undermining post-2020 deleveraging efforts and repeating past cycles of debt-financed expansion at market peaks.
While management aims to focus Energy Transfer's next chapter on Texas power substations and Gulf Coast export docks, the partnership's extensive regulatory and legal history indicates that judicial and administrative oversight will remain an active factor in its execution.
References
-
Energy Transfer LP — Investor Relations, Filings and Company Overview ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Energy Transfer Equity and Energy Transfer Partners Announce Simplification Transaction — Business Wire, 2018-08-01 ↩
-
Delaware Court of Chancery Opinion: The Williams Companies, Inc. v. Energy Transfer Equity, L.P. — Delaware Court of Chancery, 2016-06-24 ↩↩
-
Delaware Supreme Court Affirmance: The Williams Companies v. Energy Transfer Equity — Delaware Supreme Court, 2017-03-23 ↩↩
-
Pennsylvania Attorney General Mariner East Pipeline Criminal Case Resolution — Commonwealth of Pennsylvania Office of Attorney General, 2022-10-21 ↩
-
North Dakota Jury Verdict in Energy Transfer v. Greenpeace — Reuters, 2025-03-01 ↩↩
-
Energy Transfer Reports First Quarter 2021 Results and Winter Storm Uri Impact — Business Wire, 2021-05-06 ↩
-
Energy Transfer to Acquire Crestwood Equity Partners — Energy Transfer Press Release, 2023-08-16 ↩
-
Energy Transfer to Acquire WTG Midstream Holdings — Energy Transfer Press Release, 2024-05-28 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube