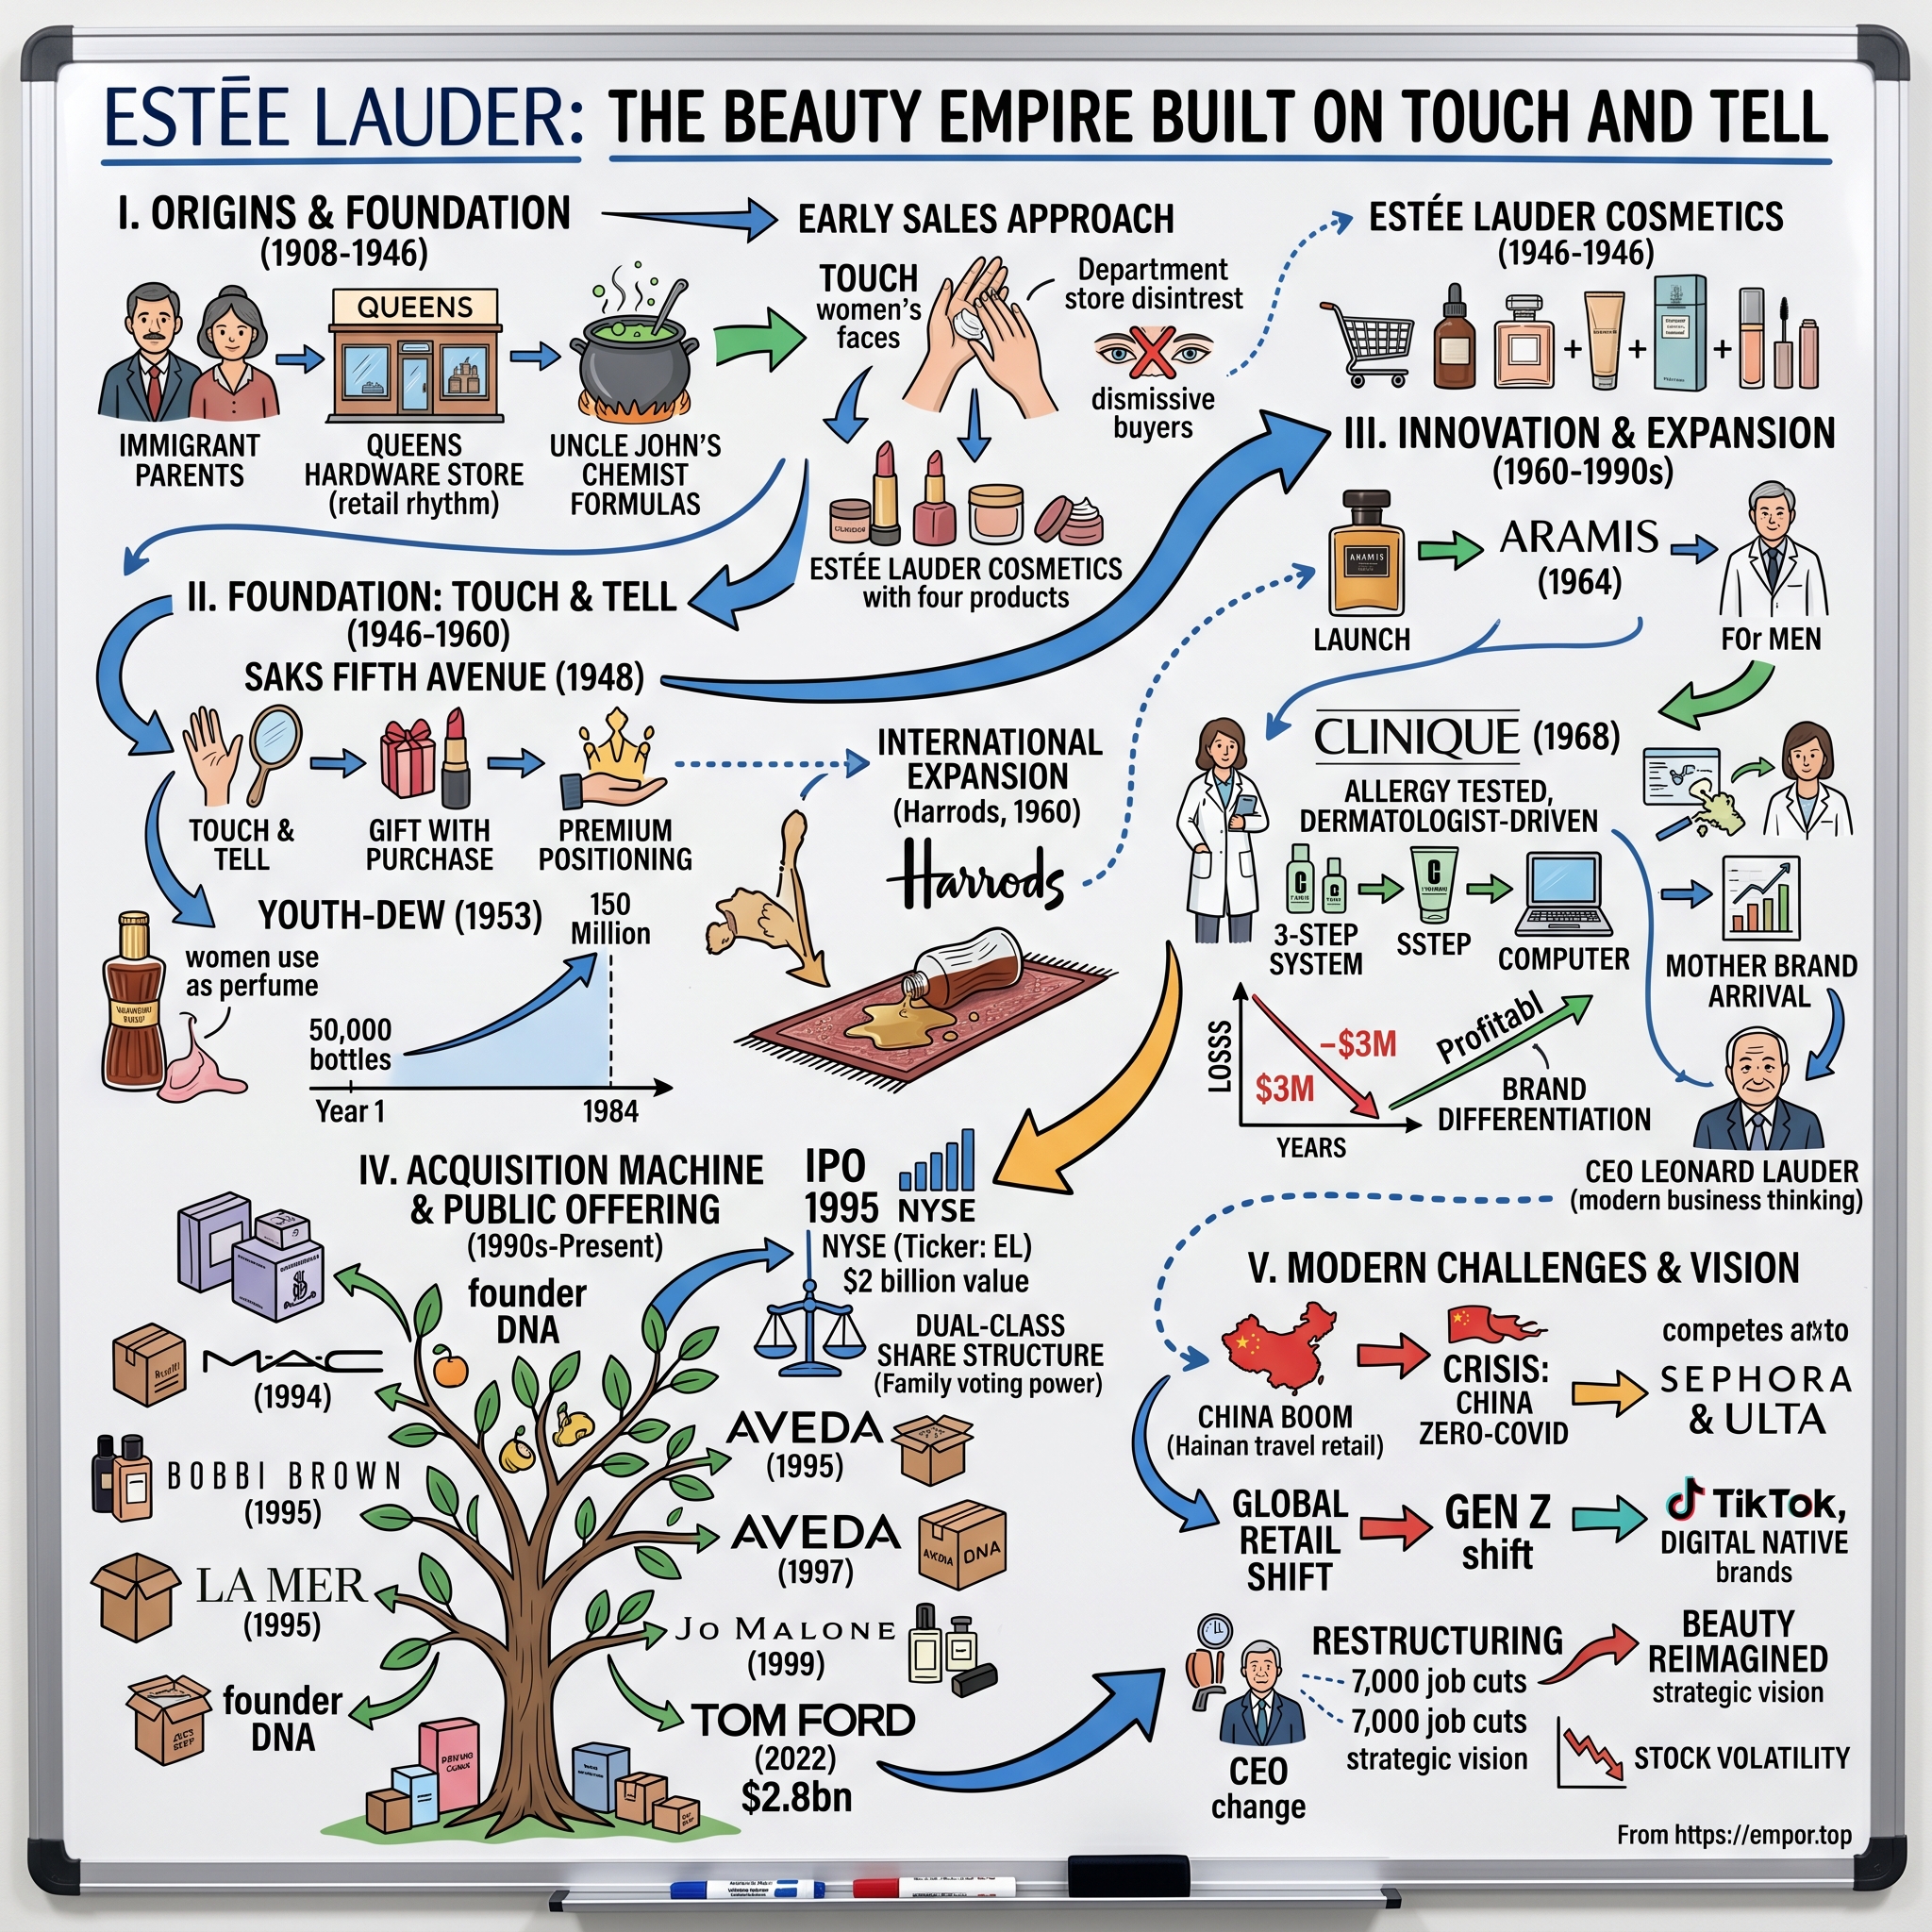
The Estée Lauder Companies: The Prestige Beauty Empire at a Crossroads
I. Introduction & Episode Roadmap
There is a photograph that circulates in beauty-industry circles: a woman in a white smock standing behind a glass counter, reaching across it, thumb loaded with cream, pressing it onto a customer's cheek without asking permission first. That direct engagement was the core business model. Not traditional advertising, nor complex distribution agreements, but a direct hand on a face.
Eighty years after Estée and Joseph Lauder founded the company in 1946 with four skin-care products sold to women sitting under salon hair dryers, the enterprise that grew out of that gesture generated $15.0 billion in net sales in the fiscal year ended June 30, 2026.12 The Estée Lauder Companies Inc. (NYSE: EL) ranks second in global prestige beauty behind L'Oréal, operating across four reported categories — Skin Care, Makeup, Fragrance, and Hair Care — through a portfolio that reflects the evolution of modern brand building.
The portfolio includes house brands created internally: Estée Lauder itself, Clinique, Aramis, and Prescriptives. It features luxury acquisitions that defined its second phase: Crème de la Mer, Jo Malone London, M·A·C, Bobbi Brown, Aveda, and TOM FORD. It also encompasses modern disruptors acquired to protect market position: Le Labo, KILIAN PARIS, Dr.Jart+, and Deciem's The Ordinary — a brand positioned around ingredient transparency over premium markups.
This highlights a central question for investors. How did a Queens-born entrepreneur blending creams in a converted stable build a dominant architecture in global luxury beauty — and how did a business with gross margins above 75%, decades of accumulated brand equity, and a strong acquisition track record manage to lose roughly three-quarters of its market capitalization from its late-2021 peak and post an operating loss of $785 million in fiscal 2025?3
That drop was not driven by a competitor introducing a superior moisturizer. It stemmed largely from the company's distribution strategy — making those channel decisions critical context for assessing its outlook.
Five key threads define this trajectory.
First, foundational marketing. Estée Lauder did not invent cosmetics; she reshaped the selling of prestige beauty. Practices like the "Touch and Tell" demonstration, Gift-with-Purchase, and department store counters operated as dedicated retail space became industry standards — transforming pioneering tactics into standard practice that no longer confers a sole competitive advantage.
Second, two growth engines. The company developed Clinique organically, nearly exhausting its capital in the process. It then spent three decades refining a different strategy: acquiring founder-led brands at modest scale and integrating them into its global distribution system. That transition from internal creation to acquisition forms the core of how the company generates revenue, yielding a mixed record that warrants close analysis.
Third, the super-cycle. Under CEO Fabrizio Freda beginning in 2009, two external drivers converged into a decade of growth: rising Chinese consumer demand for prestige skin care, and the expansion of Asia travel retail — encompassing airport duty-free and duty-free complexes in 海南 Hainan — into a high-margin profit driver.
Fourth, the hangover. Over-allocation to travel retail distributors, regulatory enforcement targeting 代购 daigou grey-market resellers, rising competition from domestic Chinese brands, and a delayed response to e-commerce shifts toward Amazon and specialty retailers culminated in a multi-year earnings decline and consecutive guidance reductions that impaired management credibility.
Fifth, the reset. Stéphane de La Faverie assumed the role of CEO on January 1, 2025, as William P. Lauder stepped back from Executive Chairman. The company launched a restructuring initiative, titled "Beauty Reimagined" and executed through its Profit Recovery and Growth Plan, which eliminated approximately 10,000 positions.[^4]1
For fiscal 2026, reported on August 19, 2026, initial operational metrics showed recovery: organic sales grew 3% for the year, adjusted operating margin expanded 320 basis points to 11.2%, and mainland China sales rose 9% organically.1 Equity markets responded positively, with shares rising sharply following the release.4 The broader analytical question is whether this turnaround signals a structural recovery of the underlying franchise, or if short-term margin expansion reflects aggressive cost reduction across a business facing altered competitive dynamics relative to 2019.
Evaluating that distinction requires starting where the business model originated: behind a retail counter, with a hand on a cheek.
 Subscribe on LinkedIn
II. The Founder's Blueprint: Touch & Tell and the Birth of High-Touch Beauty (1908–1960s)
The stable behind the house in Corona, Queens smelled of gas burners and lanolin. Josephine Esther Mentzer — born in 1908 to Hungarian-Jewish immigrant parents who ran a hardware store — spent her adolescence watching her uncle, a chemist named John Schotz, cook face creams over a stove. Schotz sold his formulations under names like Six-In-One cold cream and Viennese Cream. He had product, but no idea how to sell it.
His niece did. That asymmetry — simple chemistry paired with extraordinary distribution instincts — laid the foundation for the company's early growth.
Estée, as she renamed herself, began by approaching women in beauty salons on Long Island, hotel resorts, and beach clubs. The insight was retail-geographic: a customer sitting under a hair dryer was a captive audience for forty minutes, already focused on her appearance. The founder later summarized her marketing philosophy with the phrase "Telephone, Telegraph, Tell-a-Woman." Lacking capital for traditional advertising, word of mouth functioned as the primary promotional engine.
In 1946, she and her husband Joseph formally founded the company with four products.5 Two years later, the business secured its first department store account at Saks Fifth Avenue in Manhattan, opened in 1948 on the strength of an initial order of roughly $800 in merchandise.6 While company lore holds that the inventory sold out in days, the verifiable outcome was the structural precedent it set: Saks became the template for every prestige counter that followed, and by 1960 the company had crossed the Atlantic into Harrods in London, establishing a playbook for entering luxury department stores market by market.6
Joseph Lauder managed manufacturing and financial operations, while Estée Lauder drove sales and brand positioning. This division of labor established a structural blueprint for the company's future expansion: pairing a creative brand visionary with operational discipline. Decades later, the company's acquisition strategy mirrored this dynamic by purchasing founder-led brands and integrating them into its global corporate infrastructure.
The initial product line remained narrow — a handful of creams and a cleansing oil. Lacking an advertising budget, the company recycled gross profits directly into physical presence: expanding retail counters, training sales advisors, and distributing samples directly to consumers. Because growth was constrained by cash flow, building brand equity relied on direct, counter-level customer relationships.
Three core innovations emerged during this period, operating as structural business-model mechanisms rather than standard marketing tactics:
Touch and Tell. Rather than selling across a counter, the founder applied product directly to the customer's face. This shift converted a standard retail transaction into a consultative service interaction. The technique raised initial sales conversion while establishing long-term customer relationships, building customer lifetime value directly at the point of sale.
Gift with Purchase. The company pioneered offering a curated sample set alongside a qualifying purchase. Structurally, this strategy preserved price integrity while driving trial of complementary product lines. Paid through cost of goods sold — a low unit cost given gross margins exceeding 70% — the tactic functioned as an efficient customer-acquisition model. As competitors adopted the practice across the prestige beauty industry, Gift with Purchase transitioned from a proprietary advantage into a mandatory operating cost.
The counter as owned real estate. Prestige beauty in department stores operated primarily through brand-employed advisors working dedicated counter space. The brand maintained control over staffing, merchandising, training, and customer relationships, while the host retailer provided foot traffic. For five decades, this model allowed the brand to capture high margins and customer access while retail landlords assumed real estate risk.
The vulnerability of this structure emerged as physical retail patterns shifted. As a fixed-cost, high-touch architecture, performance depended entirely on department store foot traffic. When U.S. department store visits entered a multi-decade decline, extensive counter networks transformed from distribution moats into fixed-cost overhead. Furthermore, a model predicated on physical interaction proved difficult to replicate directly in digital channels.
This structural tension between a retail model rooted in physical interaction and the shift toward digital commerce became a central operational challenge for the business. Before those channel shifts materialized, however, the company expanded rapidly behind a strategic product launch in bath oil.
III. The Engine of Organic Line Building: Youth-Dew, Clinique, and Aramis (1953–1980s)
In 1953, French perfume houses marketed fragrance primarily as a rare luxury—a gift purchased by men for women on special occasions, leading consumers to use it sparingly. Estée Lauder identified an underlying inefficiency in this model: purchase frequency was constrained not by consumer demand, but by social convention.
Her solution was Youth-Dew: a scented bath oil, priced and packaged for daily bathing, yet concentrated enough to function as a lasting perfume.6 Women purchased it for everyday use, applied it directly to their skin, and critically, bought it for themselves rather than waiting for a gift.
Framed as a strategic move rather than a mere product release, Youth-Dew repositioned an entire fragrance category from periodic gifting to self-directed purchase. The shift expanded the addressable frequency of fragrance consumption while maintaining prestige positioning through high product formulation standards. Youth-Dew became the company's primary cash generator, funding its subsequent expansion.
Aramis (1964) applied similar line-building logic to an unaddressed market: a dedicated prestige men's grooming and fragrance line sold at department store counters, at a time when the industry offered little beyond basic aftershave. Whether Aramis created the modern men's prestige category or capitalized early on an emerging trend, it demonstrated a repeatable core strength: capturing adjacent consumer segments already walking past department store counters.
Youth-Dew also yielded a critical second-order financial effect, shaping the company's capital structure for three decades. High-frequency, high-margin, self-purchased products generated predictable cash flows that periodic gifting items could not match. That liquidity enabled the privately held, family-controlled firm to fund international expansion without external equity financing for nearly 50 years, prior to its 1995 initial public offering. The family's ultimate ability to retain voting control through a dual-class stock structure was thus underwritten by decades of self-funded operations.
That financial stability was soon tested by a major strategic gamble.
Clinique: the masterclass, and the bill
In 1967, Vogue published an article titled "Can Great Skin Be Created?", written by editor Carol Phillips based on insights from dermatologist Dr. Norman Orentreich. The article proposed that skin health could be systematically improved through clinical protocols rather than treated as a fixed aesthetic trait. Evelyn Lauder—the founder's daughter-in-law and a key executive—recognized the commercial potential and advocated developing a brand around the concept. The company recruited Phillips to head development and retained Orentreich as clinical advisor.
Clinique launched at Saks Fifth Avenue in September 1968 with a 117-product lineup built on non-traditional design choices.7 Products were allergy-tested and 100% fragrance-free, deliberately omitting the industry's traditional sensory emphasis. Beauty advisors wore white lab coats, diagnostic sliding tools evaluated skin types at the counter, and products were sold as a 3-Step System—cleanse, exfoliate, moisturize. The system encouraged customers to purchase three complementary items simultaneously and return on a predictable replenishment cycle.
Conceptually, Clinique established the standardized skincare regimen as a commercial model, generating recurring customer purchases prior to modern subscription platforms. Today, Clinique remains positioned as the first dermatologist-developed prestige cosmetic brand.8
However, the financial reality of Clinique's development challenges the narrative of effortless internal brand creation.
A common investment thesis drawn from Clinique is that the company possesses a repeatable internal brand incubation engine. Historical financial performance presents a more complex picture. Clinique generated operating losses for approximately its first seven years, accumulating roughly $3 million in losses through the mid-1970s.9 The brand survived because cash flows from the core Estée Lauder line and Youth-Dew cross-subsidized its development—a long-term capital commitment enabled by private family ownership that an independent startup or public firm might not have tolerated.
Subsequent internal brand launches yielded diminishing results. After Prescriptives launched in 1979, internal development yielded no further billion-dollar brands. Every major scale brand added to the portfolio in subsequent decades—including M·A·C, Crème de la Mer, Jo Malone London, TOM FORD Beauty, Le Labo, and The Ordinary—entered the company via external acquisition.
This trajectory suggests that the company's internal brand-creation capability was bound to a specific eleven-year window ending in 1979, supported by capital-patient family ownership in a less crowded market. Over the subsequent four decades, internal incubation did not produce major standalone brands at scale. Instead, the company's primary growth competency shifted: identifying founder-led brands with established equity and integrating them into its global distribution, marketing, and supply chain infrastructure.
Scaling that acquisition-driven model required broader access to capital markets and acquisition currency, prompting the Lauder family to take the company public in 1995.
IV. Going Public & The Grand M&A Playbook (1995–2010s)
On November 16, 1995, The Estée Lauder Companies listed on the New York Stock Exchange at $26.00 per share, selling 17.6 million Class A shares and raising over $450 million.10 The stock closed its second trading day near $34.50 — a 33% gain that signaled strong public market demand for a pure-play prestige beauty asset.
The structure of the offering proved more consequential than the initial pricing. The company established a dual-class share structure: Class A common stock sold to the public carried one vote per share, while Class B stock retained by the Lauder family carried ten votes per share.11 This enabled the founding family to raise substantial growth capital without relinquishing voting control.
This voting arrangement established the central governance dynamic of the business. Supervoting control allowed the family to invest on multi-decade horizons and absorb initial losses — such as funding Clinique through seven unprofitable years — without bowing to short-term Wall Street pressure. Conversely, the structure removed external governance checks when operational judgment faltered. Activist investors could build economic stakes but lacked the voting power to force strategic change. Consequently, course corrections depended entirely on internal family initiatives, slowing institutional response times during market downturns.
The acquire-and-scale machine
Equipped with public equity as acquisition currency, the company began assembling a broader prestige beauty portfolio through a repeatable acquisition model.
M·A·C Cosmetics. Founded in Toronto by Frank Toskan and Frank Angelo as a professional line for makeup artists and photographers, M·A·C possessed strong cultural authority but lacked global infrastructure. Estée Lauder acquired an initial stake in 1994 and assumed full ownership by the end of the decade, integrating the brand into its global supply chain, department store counters, and international retail network. M·A·C subsequently grew into a multi-billion-dollar brand and the dominant force in prestige color cosmetics for years.
Bobbi Brown (1995). Founded by makeup artist Bobbi Brown around skin-tone-matching foundations and natural lip shades, the acquisition established a multi-artist brand strategy. Rather than stretching a single house brand across every aesthetic, the company acquired distinct, authentic creative perspectives.
Crème de la Mer (1995). Developed by aerospace physicist Dr. Max Huber, who fermented sea kelp into a proprietary blend following a laboratory accident, La Mer represented a niche cult moisturizer. Estée Lauder acquired the formula and brand heritage, building it into a global ultra-luxury skincare reference with retail price points spanning hundreds to over a thousand dollars per jar.
The economic logic of these acquisitions rested on high gross margins. Because manufacturing costs for ultra-premium skincare represent a small fraction of retail pricing, product value depends heavily on brand equity, ritual, packaging, and point-of-sale positioning. Integrating an authentic niche brand into Estée Lauder's worldwide distribution allowed incremental revenue to flow through at elevated gross margins. Elevated acquisition multiples were thus rapidly amortized, provided the underlying brand equity proved durable.
Portfolio expansion continued across adjacent categories: Aveda (1997) added plant-based hair care and a professional salon network, while Jo Malone London (1999) introduced niche British lifestyle fragrance, expanding over time into one of the company's billion-dollar brands.1
Where the playbook broke: Too Faced
On November 14, 2016, the company announced the acquisition of Too Faced for approximately $1.45 billion — its largest transaction to that point, representing a valuation multiple of roughly eight times sales — with the transaction closing the following month.[^13]12 Too Faced had built a strong social media following among millennial consumers by capitalizing on a trend toward heavy-glam, full-coverage color cosmetics.
However, consumer preferences quickly shifted away from heavy cosmetics toward skincare, minimalist formulas, and clean beauty. As Too Faced's momentum slowed, portfolio-wide valuations faced pressure. Across fiscal 2024 and fiscal 2025, Estée Lauder recorded substantial goodwill and intangible asset write-downs in its makeup portfolio, culminating in $1.3 billion of impairment charges in fiscal 2025 concentrated primarily on TOM FORD and Dr.Jart+.313
Evaluating the full M&A record reveals a clear structural divergence. When the company acquired brands with durable, timeless equity — such as luxury skincare or heritage fragrance houses — global distribution expanded their margins and yielded long-term compounding returns. Conversely, when it acquired brands tied closely to ephemeral cosmetic trends, Estée Lauder paid peak valuation multiples at the height of a cycle, leading to subsequent write-downs. The strategic challenge for management lies not in identifying popular brands, but in distinguishing enduring brand equity from transient consumer trends before committing high acquisition multiples.
These impairment charges also highlight ongoing balance-sheet risks. Goodwill and indefinite-lived intangible assets accumulated during the expansion era remain sensitive to changes in discount rates and long-term brand projections. Consecutive fiscal years of major write-downs indicate that earlier internal growth forecasts proved overly optimistic, underscoring the need for analytical scrutiny regarding forward projections in company filings.
Yet in 2016, market optimism remained high. The company was entering a period of unprecedented expansion, driven by geographic and channel shifts that far exceeded the scope of its original department store footprint.
V. The Golden Decade: The Freda Era, China Boom, and Hainan Super-Cycle (2009–2021)
Fabrizio Freda arrived at Estée Lauder in 2008 and became CEO in 2009, bringing a Procter & Gamble operational background to a family-controlled enterprise weathering the global financial crisis as traditional department store foot traffic waned.
Where the company had historically relied on founder-driven creative vision and counter-level merchandising, Freda instituted a systematic operating framework. He introduced strategic portfolio management, supply chain rationalization, SKU discipline, and a deliberate reallocation of capital toward Asia and travel retail. Over the following decade, operating margins expanded from high single digits to high teens.
External demand trends soon accelerated this operational transformation.
The China skin-care super-cycle
Throughout the 2010s, expanding middle- and upper-income demographics in China drove rapid growth in prestige beauty, with consumer demand heavily weighted toward skin care over color cosmetics. Estée Lauder's heritage products capitalized directly on this shift: Advanced Night Repair, a repair serum sold since 1982, emerged as a status symbol, while Crème de la Mer became a flagship luxury gift. At the peak of the cycle, China-related demand generated a major share of total net sales and a disproportionate portion of operating profits.
The travel retail machine
This demand was further amplified by the rapid expansion of travel retail. Operating primarily through airport duty-free shops and large downtown complexes — such as those established by the Chinese government in Hainan to capture domestic luxury spending — travel retail became a primary growth vector.
The economics of travel retail were highly lucrative, making an understanding of its structure essential to analyzing the company's subsequent operational downturn.
In traditional department stores, brands incur counter fees, employ sales advisors, compete for floor position, and convert walk-in traffic. In travel retail, Estée Lauder sold directly to a concentrated group of large duty-free distributors catering to captive streams of international travelers. Exemption from import duties and value-added taxes allowed distributors to price products below domestic retail rates while maintaining strong margins. High sales density lowered operating expenses per unit, while wholesale contract terms allowed Estée Lauder to recognize revenue upon shipment to distributors rather than at final consumer sale.
By fiscal 2021, travel retail accounted for approximately 25% of net sales and a major share of operating profit. While management characterized the channel as a structural compounder, it operated as a wholesale model with a sell-through demand signal lagging reported revenue by several months — creating an inventory-visibility gap that eventually triggered a broader earnings crisis.
Buying the future, at 2021 prices
Supported by strong cash generation, management accelerated external acquisitions to capture emerging growth segments.
Dr.Jart+ (2019). The company acquired the remaining two-thirds interest in South Korea's Have & Be Co. for approximately $1.1 billion, valuing the business at roughly $1.7 billion — expanding its exposure to K-beauty product development cycles and skin-care formats.14
Deciem / The Ordinary. A strategic move into ingredient transparency. Deciem's flagship brand, The Ordinary, offers active ingredient formulations in standardized dropper bottles at value price points that contrast with traditional prestige markups. Estée Lauder initially acquired a minority stake in 2017, expanded to majority control in 2021, and purchased the remaining equity on May 31, 2024, for an estimated $860 million, bringing total investment across three tranches to approximately $1.7 billion net of cash.1516
TOM FORD (2022–2023). The company acquired the TOM FORD brand outright in a transaction valued at approximately $2.8 billion, completing the deal on April 28, 2023, and converting a licensed beauty relationship operated since 2005 into full trademark ownership.[^19]
The TOM FORD transaction highlighted the strategic tension between portfolio ownership and acquisition timing. Securing full trademark control permanently eliminated licensor risk for a proven billion-dollar beauty line. However, the purchase was executed in late 2022 near the peak of the luxury market using elevated Chinese growth assumptions. Within two years, TOM FORD was cited among the principal drivers of $1.3 billion in impairment charges.3 While the trademark offers long-term brand equity, its purchase price and timing reflected peak valuation assumptions.
Across these three transactions, a consistent strategic pattern emerged: each represented a capital allocation strategy aimed at purchasing external capabilities — agile Korean formulation cadences, clinical transparency, and an owned luxury trademark. While acquisition provided immediate capability additions, purchasing established assets at peak market valuations created balance-sheet vulnerabilities when macro growth trends shifted.
The compounding weight of these channel imbalances and peak valuation commitments soon materialized across the business.
VI. The Great Hangover: Travel Retail Collapse, M&A Missteps, and the C-Beauty Threat (2021–2024)
Picture a warehouse in a Hainan free-trade zone in 2022. It is full of Advanced Night Repair serum. It has been full for months. The boxes were shipped by The Estée Lauder Companies, invoiced to a duty-free distributor, and recognized as revenue on the company's income statement. Yet not a single unit has been sold to an end consumer.
That image captures the multi-year operational crisis in a single frame.
How a wholesale channel becomes a trap
Because travel retail recognized revenue upon shipment to distributors, the channel could — for a time — generate high top-line growth independent of end-consumer demand. During the COVID-19 pandemic, with international travel suppressed but Hainan remaining operational and corporate targets in place, shipment volumes into Asia travel retail ran far ahead of actual consumer purchases. Inventory accumulated steadily throughout the distribution pipeline.
This dynamic produced a textbook bullwhip effect: every unit over-shipped in one period became a unit that could not be shipped in a subsequent period, requiring steep promotional discounts to clear excess inventory. The eventual operational correction proved far sharper than the initial over-expansion, as distributors halted new orders entirely while working down existing stock.
The 代购 daigou crackdown
What escalated an inventory accumulation problem into structural brand-equity damage was the grey market. 代购 daigou — literally "buying on behalf of" — refers to unauthorized resellers who purchased duty-free goods in Hainan, Seoul, or Hong Kong and resold them into mainland China at substantial discounts relative to domestic retail counters via 淘宝 Taobao, 拼多多 Pinduoduo, and social commerce channels. For years, this semi-tolerated purchasing pool artificially inflated travel retail sales volumes well beyond genuine traveler consumption.
When Chinese regulatory authorities tightened enforcement against unauthorized reselling, this purchasing pool contracted rapidly. Two distinct structural damages followed. First, a substantial portion of wholesale demand evaporated immediately. Second, Chinese consumers became accustomed to purchasing flagship products well below official department store prices. This shift directly impaired the company's pricing power. Because luxury beauty relies on perceived prestige, training a broad customer base to treat retail prices as negotiable caused long-term brand equity erosion that traditional marketing could not quickly reverse.
The C-beauty problem
While the company was working through channel inventories, domestic Chinese competitors expanded rapidly. Brands such as 珀莱雅 Proya, 薇诺娜 Winona, and 花西子 Florasis built market share through a distinct operational model: product formulations tailored to local skin needs and climate, development cycles measured in months rather than the two-year timelines typical of multinational firms, and native integration into digital platforms like 抖音 Douyin and 小红书 Xiaohongshu, where beauty discovery in China occurs through livestream commerce and creator content.
Compounded by 国潮 guochao — a cultural shift favoring domestic Chinese brands — foreign prestige beauty companies suffered structural share loss rather than a temporary cyclical decline. This distinction remains critical for investors: while cyclical share loss recovers when consumer spending rebounds, structural share loss occurs because consumers have permanently adopted alternative brands they consider superior in relevance or execution.
The channel lag at home
In North America, performance suffered from a parallel delay in adapting to changing retail channels. The company remained heavily reliant on traditional U.S. department stores — such as Macy's, Nordstrom, and Dillard's — even as foot traffic across physical department stores continued a multi-decade decline. Meanwhile, competitors like L'Oréal, alongside digital-native and celebrity-backed brands, captured growth across specialty retailers like Sephora and Ulta Beauty, as well as direct-to-consumer digital channels.
The company's strategy regarding Amazon illustrated this channel lag. For years, management avoided selling core brands on Amazon Premium Beauty to protect prestige brand positioning and avoid mass-market brand dilution. However, as Amazon developed into the primary product search engine for U.S. consumers, competitors established strong channel positions. The company eventually launched flagship brand storefronts on Amazon Premium Beauty in early 2024, entering a marketplace where rivals had compounded market share for years.
The second-order damage: data blindness
The wholesale travel retail structure created a major secondary vulnerability: a loss of end-consumer data visibility. When products passed through distributors into grey-market demand pools, management tracked wholesale shipment volumes rather than consumer purchasing behavior. Key consumer metrics — including customer identity, purchase frequency, price realization, and repeat rate — remained with duty-free operators and downstream resellers. A business founded on direct counter-level customer relationships had lost real-time visibility into consumer demand across its most profitable distribution channel.
This visibility gap explains why subsequent restructuring plans emphasized direct-to-consumer and digital channels. Expanding presence on Amazon, Douyin, Sephora, and owned retail stores served a dual purpose: capturing foot traffic while re-establishing the direct consumer demand signal that wholesale distribution had severed.
The credibility collapse
The financial record through this period reflected these structural challenges. Operating margin dropped from high-teen levels in fiscal 2021 into low single digits before turning negative: fiscal 2025 net sales declined 8% to $14.3 billion with an operating loss of $785 million, versus operating income of $970 million the prior year.3 Adjusted operating income fell 28% to $1.1 billion and adjusted EPS dropped 42% to $1.51.3
However, the erosion of management credibility outpaced the decline in reported financial results. Across fiscal 2023 and fiscal 2024, management repeatedly reduced financial guidance. Each downward revision highlighted an underlying operational issue: reported revenue and end-consumer sell-through had become decoupled by the wholesale distribution structure, impairing management's ability to forecast demand. For institutional investors, missing financial targets presented a standard operational challenge, but a loss of demand visibility posed a far more fundamental risk.
This operational environment formed the backdrop when Stéphane de La Faverie assumed the chief executive role on January 1, 2025.
VII. The Turnaround Blueprint: Leadership Overhaul, "Beauty Reimagined," and Amazon Pivot (2025–Present)
When the company announced its leadership succession on October 30, 2024, the governance changes carried significant strategic implications. Chief Executive Fabrizio Freda announced his retirement, with Stéphane de La Faverie named President and CEO effective January 1, 2025. Concurrently, William P. Lauder stepped down as Executive Chairman to become non-executive Chairman of the Board.[^4]
The transition of the Lauder family from active executive management to board oversight represented a pivotal shift in governance. For most of its history as a public company, a member of the founding family held a top executive position. Transitioning family leadership to non-executive roles while entrusting operational authority to a professional manager signaled a major structural concession under a supervoting share framework, acknowledging that reversing operational declines required independent executive leadership.
Although de La Faverie is a long-standing insider, his background extends beyond traditional department store brands. Prior to his appointment as CEO, he served as Executive Group President, overseeing a portfolio that included the core Estée Lauder brand alongside newer acquisitions such as Le Labo and Deciem's The Ordinary. He framed his turnaround agenda around improving operational agility and decision-making speed across the enterprise.1718
Beauty Reimagined and the PRGP
Management announced a restructuring initiative in February 2025, initially targeting between 5,800 and 7,000 global job cuts. As operational needs evolved, the program expanded. By the release of its fiscal 2026 results, the company had eliminated approximately 10,000 positions — reaching the top of its revised target of 9,000 to 10,000 jobs — while incurring $1.4 billion in cumulative restructuring and related charges against a projected total range of $1.5 billion to $1.7 billion.191
Offsetting these upfront charges, the Profit Recovery and Growth Plan generated approximately $1.2 billion in gross annual run-rate savings, achieving the upper bound of its $1.0 billion to $1.2 billion projection.1 During the fourth-quarter conference call for fiscal 2026, Chief Financial Officer Akhil Shrivastava characterized the program as having proceeded faster and yielded greater structural efficiencies than initially anticipated.20
The strategic importance of the plan lies in how management reallocated those cost savings rather than the net headcount reduction alone. Rather than retaining all realized savings to boost short-term earnings, the company reinvested capital directly into demand generation. In fiscal 2026, consumer-facing investments — including advertising, sampling, in-store experience, and creator content — increased 7%, while non-consumer-facing corporate overhead remained flat.1 For a brand-driven business, reallocating resources from administrative overhead toward consumer touchpoints addresses core brand equity needs, though one year of initial results represents early progress rather than definitive long-term recovery.
Accompanying cost rationalization was an effort to consolidate regional business units and decentralize decision-making authority. This structural shift was most pronounced in China, where de La Faverie reported during the fourth-quarter call for fiscal 2026 that approximately 30% of global product innovation originated from the company's Shanghai research and development facility.20 Shifting formulation and product design directly into key growth markets served as a direct operational response to agile domestic Chinese competitors, whose local development cycles operate significantly faster than centralized North American facilities in Melville, New York.
Channel and digital realignment
The company also reversed its historical distribution stance toward third-party digital platforms. By the end of fiscal 2026, Estée Lauder had expanded 13 portfolio brands across 11 geographic markets on Amazon.1 E-commerce revenue rose to a record 34% of total reported net sales, up three percentage points from the prior year.20 Concurrently, M·A·C launched across select U.S. Sephora doors in March 2026, broadening its access to specialty retail channels.1 Marketing budgets were similarly reallocated toward digital channels, expanding campaigns across social commerce and livestream platforms such as Douyin, TikTok Shop, and Instagram.
The governance and incentive question
Despite operational changes, the Lauder family retains voting control through its Class B supervoting shares. Consequently, governance analysis focuses primarily on executive compensation design — specifically whether performance metrics have been re-anchored to operating margin expansion, free cash flow conversion, and return on invested capital rather than raw net sales growth. This distinction is critical: the excess inventory shipments that precipitated the travel retail crisis were structurally aligned with top-line net sales targets. If executive compensation continues to reward wholesale shipments over end-consumer sell-through, channel inventory imbalances could recur. The proxy statement, rather than executive commentary on earnings calls, remains the primary mechanism for evaluating these structural incentives.
While initial restructuring efforts have stabilized reported financial performance, evaluating whether the core franchise has achieved durable recovery requires analyzing the fundamental sources of its ongoing cash flows and category economics.
VIII. Portfolio Economics & Segment-Level Deep Dive
Evaluating The Estée Lauder Companies requires examining four distinct operating divisions with sharply contrasting economics, where consolidated performance reflects which segment dominates the trajectory.
Skin Care: the profit engine, structurally repaired but not restored
Skin care has historically operated as the company's largest category and primary profit engine, generating the portfolio's highest gross margins. It was also the division that bore the full impact of the travel retail restructuring, as flagship products like Advanced Night Repair and Crème de la Mer represented the primary inventory flowing through Hainan distribution channels and grey-market 代购 daigou networks. In fiscal 2025, skin care net sales declined 12%, with contraction concentrated in the core Estée Lauder brand and La Mer.3
The segment stabilized in fiscal 2026, delivering 4% organic sales growth supported by product innovation at La Mer, expansion at The Ordinary, and momentum in the core Estée Lauder brand.1 That product composition reflects a distinct barbell structure: demand expanded at the ultra-luxury tier and at the value-priced entry point of The Ordinary—the precise positioning intended by the Deciem acquisition, though it demonstrates that top-line recovery relies on a broader price mix rather than a simple return to legacy luxury price points.
Fragrance: the genuine bright spot
Fragrance remained the portfolio's most resilient segment throughout the operational crisis. Sales held flat in fiscal 2025 as other categories contracted, before expanding 10% organically in fiscal 2026 behind strong demand for Le Labo, TOM FORD, and KILIAN PARIS.31 During fiscal 2026, Jo Malone London and TOM FORD reached billion-dollar brand status, bringing the portfolio's total count of billion-dollar brands to six.1 To support the category's expansion, the company added 33 net new freestanding fragrance boutiques globally.1
Three structural mechanisms account for fragrance's distinct performance profile. First, fragrance exhibits high consumer habituation: customers tend to retain a signature scent for years, insulating the category from rapid trend cycles. Second, purchasing decisions depend on sensory appeal rather than clinical efficacy, protecting products from competitive disruption based on active-ingredient concentrations. Third, artisanal luxury scents yield high price realization—frequently ranging between $200 and $500 per bottle—against minimal incremental unit production costs. Le Labo exemplifies this economic model by distributing through owned boutiques and tightly controlled retail channels, standing in sharp contrast to the wholesale duty-free distribution that created inventory imbalances in skin care.
Makeup: the hardest category, finally stabilized
In fiscal 2025, makeup sales fell 5% due to declines across M·A·C, Estée Lauder, Too Faced, and Bobbi Brown.3 Performance improved by roughly 500 basis points in fiscal 2026 to finish essentially flat, as M·A·C reclaimed its number-one prestige ranking in the fourth quarter following expanded distribution in Sephora, increased social commerce activity, and what management characterized as a blockbuster lip stain launch.20
While stabilizing sales after consecutive years of decline marks operational progress, that outcome stemmed primarily from expanded retail channels rather than organic brand revival. Color cosmetics remains the most volatile category in the portfolio, characterized by short product lifecycles, low consumer switching costs, complex supply chain requirements, and continuous pressure from new market entrants. Management projected a return to sales growth for the makeup segment in fiscal 2027, making that guidance a key metric for evaluating operational execution.1
Hair Care: the strategic orphan
The hair care division, comprising Aveda and Bumble and bumble, declined 10% in fiscal 2025 and contracted an additional 1% organically in fiscal 2026.31 Representing approximately 4% of total net sales, the segment remains too small to materially drive consolidated revenue yet persistent enough in its weakness to prompt ongoing strategic questions regarding its portfolio fit. Its reliance on salon networks and traditional department store counters leaves the division tied to legacy distribution channels, creating an operational headwind in an enterprise focused on modernizing retail channels.
The geographic picture
Geographic performance in fiscal 2026 reflected a more balanced distribution of growth than the previous decade: mainland China sales rose 9% organically, supported by six consecutive quarters of market share gains; the broader Asia/Pacific region grew 4%; Europe, the Middle East, and Africa expanded 1%; and the Americas increased 1%.120
These regional figures present contrasting indicators for the business. On one hand, operations in mainland China stabilized on a normalized channel inventory base, with the company securing the top prestige beauty position across major platforms during the 618 and 双十一 Singles' Day shopping festivals.1 On the other hand, modest 1% growth across North America and Europe demonstrates that recovery remains geographically concentrated in the Asian markets that previously experienced the sharpest downturn, while core Western markets have shown limited top-line expansion. Management acknowledged this disparity by projecting that incremental growth acceleration in fiscal 2027 will originate primarily from Western markets.20
The travel retail channel—now representing approximately 15% of total net sales, down from its historical peak—delivered mixed operational results. In the fourth quarter of fiscal 2026, retail sales in Hainan posted double-digit growth and South Korea accelerated to double digits, though concession transitions across major airports in Beijing and Shanghai created localized headwinds. Throughout these disclosures, management emphasized a commitment to align wholesale shipments directly with end-consumer sell-through—characterizing its current posture as "shipping to demand."20 Verifying whether inventory shipments remain strictly aligned with true consumer sell-through represents a central test for assessing the durability of the company's operational reset.
IX. Playbook: Business & Investing Lessons
1. High-touch service builds habituation — and a fixed-cost base that ages poorly. The counter model built genuine consumer habituation and high customer lifetime value by converting a retail transaction into a personal consultation. In prestige skin care, habituation is formidable: a customer committed to a multi-step regimen for a decade does not casually switch brands. However, that high-touch model required a physical footprint and dedicated counter headcount that could not be easily scaled down when foot traffic in host department stores declined. The 10,000 positions eliminated under the company's restructuring plan represent, in large part, the deferred expense of a service model that outlived its primary distribution channel. Service-intensive operational moats provide strong customer retention, but they are expensive to unwind when retail dynamics shift.
2. Acquiring founder-led luxury compounds — acquiring founder-led trend does not. The core distinction lies between brands whose equity rests on enduring identity—such as a signature scent, heritage, or craft—and brands whose popularity depends on aesthetic timing. Assets like Crème de la Mer, Jo Malone London, and Le Labo compound value over time; trend-focused acquisitions like Too Faced do not. The critical diagnostic at acquisition is whether a brand's core customer would continue buying if prevailing makeup trends shifted entirely. Paying eight times sales can represent a reasonable valuation for enduring equity, but it becomes an impairment risk when paid for transient aesthetic cycles.
3. Wholesale channels with recognition-on-shipment can mask end-consumer demand. Any distribution model where revenue is recognized upon shipment to a distributor, rather than upon final sale to a consumer, can absorb over-shipment for multiple quarters—generating reported top-line growth that disconnects from true underlying demand. When demand softens, the correction is sharper than the initial over-expansion because it requires simultaneous inventory destocking and heavy promotional discounting to clear grey-market supply. The lasting damage is not merely several quarters of reduced revenue, but the retraining of consumers to expect discounted pricing. Consequently, management's pledge of "shipping to demand" is a critical metric to track, requiring investors to prioritize retail sell-through rates and inventory-day disclosures over reported wholesale net sales.
4. Dual-class share structures demonstrate governance tradeoffs in both directions. The supervoting share structure that enabled the Lauder family to absorb seven years of initial losses while developing Clinique also permitted a decade of delayed e-commerce adoption, slow channel diversification, and deferred executive succession without activist intervention. Dual-class control is neither inherently positive nor negative; rather, it introduces high structural variance into corporate governance. Investors must evaluate family control by monitoring the family's willingness to grant operational autonomy to independent executive leadership.
5. Owning a disruptor provides strategic defense, but at a margin cost. The acquisition of Deciem's flagship brand, The Ordinary, offers a clear example of counter-positioning defense in consumer goods. Because The Ordinary's ingredient-focused model directly challenges traditional prestige pricing, ownership allows Estée Lauder to capture shifting consumer demand across both value and ultra-luxury price tiers. However, owning a disruptor does not halt structural industry shifts; it primarily ensures the parent company captures market share during the transition. While growth at The Ordinary helps offset revenue pressure in premium skin care, it dilutes overall corporate gross margins even when the strategic defense is sound.
Those lessons all converge on a single question: what, if anything, still structurally protects this business?
X. Strategic Position: Porter's 5 Forces, 7 Powers & Management Stress Test
7 Powers, tested rather than asserted
Brand (strong, but narrower than it was). The durable version of this power now lives primarily in fragrance and ultra-luxury skin care. Le Labo, Jo Malone London, TOM FORD, and Crème de la Mer sustain price realization with minimal promotion, and a consolidated gross margin of 75.5% in fiscal 2026 provides direct evidence that pricing power holds at the portfolio level.1 Countering that strength, the Advanced Night Repair grey-market episode demonstrated how distribution decisions can erode brand equity in a matter of years, while the TOM FORD impairment showed that even an enduring brand can be acquired at a value-destructive price. Verdict: intact where the brand is identity-based, demonstrably damaged where it was channel-exposed.
Cornered resource (weakening). Prime counter locations and exclusive duty-free arrangements constituted a genuine cornered resource when department stores and airport outlets dominated prestige beauty distribution. In an omnichannel landscape defined by Sephora, Ulta, Amazon, Douyin livestreams, and direct-to-consumer platforms, physical counter space is merely one channel among many. Furthermore, the Beijing and Shanghai airport concession transitions that created headwinds in fiscal 2026 serve as a reminder that concession-based real estate access remains subject to third-party renewal.20 Verdict: substantially eroded.
Scale economies (strong and genuine). Scale economies represent one of the company's most durable remaining advantages. Global media purchasing, centralized research and development facilities, regulatory compliance infrastructure across dozens of international markets, and a shared supply chain supporting more than 20 brands create structural efficiencies that independent competitors cannot replicate. This scale also underwrites the ongoing execution of the acquire-and-scale playbook. Verdict: intact.
Counter-positioning (moderate, via Deciem). Owning Deciem provides a counter-positioning defense, though the strategy converts a market-share loss into a product-mix shift rather than eliminating competitive pressure entirely. Verdict: real but partial.
Switching costs (weak to moderate). Switching costs vary significantly across product categories: near zero in color cosmetics, moderate in skin care through daily regimen habituation, and highest in fragrance, where signature scents create personal identity lock-in. This hierarchy closely tracked fiscal 2026 organic performance across categories, where fragrance sales rose 10%, skin care grew 4%, and makeup remained flat.1 Verdict: category-dependent.
Porter's five forces
Buyer power: high and rising. The shift from fragmented department stores to concentrated retail gatekeepers—including Sephora (owned by competitor LVMH), Ulta, Amazon, and dominant Chinese e-commerce platforms—has altered channel power. Where the company once drove foot traffic and managed counter staffing directly, digital platforms and specialty retailers now control customer relationships and purchasing data.
Threat of new entrants: high. Contract manufacturing, third-party logistics networks, and social media distribution have reduced the capital required to launch a beauty brand. Domestic Chinese competitors demonstrated this dynamic at scale in Asia, while creator- and celebrity-backed brands continue to capture niche market share in Western markets.
Threat of substitutes: moderate and growing. Beyond competing skincare products, consumers increasingly consider clinical dermatological procedures, cosmetic injectables, laser treatments, and med-spa services as substitutes for premium topicals. Additionally, rising consumer spending on aesthetic treatments adjacent to GLP-1 weight-loss therapies diverts discretionary budgets away from traditional luxury skincare.
Competitive rivalry: intense. Competitors continue to challenge Estée Lauder's market position. L'Oréal consistently outpaced the company through this cycle by leveraging a broader channel mix and a strong dermatological beauty division. LVMH controls both Sephora's distribution network and a competing prestige luxury portfolio, while Shiseido, Beiersdorf, Coty, and emerging Asian brands compete across remaining market segments.
Management credibility, on the evidence
Evaluating management execution reveals three distinct elements:
The failure remains significant: management failed to anticipate the travel retail inventory buildup that company shipments helped create, resulting in consecutive guidance reductions across fiscal 2023 and fiscal 2024. Furthermore, two consecutive years of asset impairments indicated that initial growth assumptions underpinning major acquisitions were over-optimistic.
The operational correction reflects tangible execution rather than strategic intent. The Profit Recovery and Growth Plan achieved $1.2 billion in annual run-rate savings against its $1.0 billion to $1.2 billion target, backed by disclosed headcount reductions, transparent restructuring charges, and concrete distribution expansions onto Amazon and into Sephora.1
The unresolved question centers on forward guidance discipline. During the fourth-quarter earnings call for fiscal 2026, management addressed questions regarding fiscal 2027 organic growth guidance of 3% to 5% by detailing the underlying math: the midpoint represents approximately 100 basis points of acceleration over fiscal 2026, while the upper bound implies a 200 basis point expansion driven primarily by Western markets.20 While a conservative outlook contrasts with prior over-promising, a single prudent forecast does not yet establish a multi-year track record.
XI. Analysis & Bear vs. Bull Case
The bull case
The core argument is that The Estée Lauder Companies owns an irreplaceable set of luxury brand assets, that the operational breakdown from 2021 through 2025 was self-inflicted and fixable, and that fiscal 2026 offers the first tangible evidence of recovery.
The supporting metrics are notable. Adjusted operating margin expanded 320 basis points in a single year to 11.2%, gross margin reached 75.5%, adjusted diluted earnings per share rose 66% to $2.51, and management raised its fiscal 2027 adjusted operating margin target to between 12.7% and 13.5%.1 Fragrance is compounding at double-digit rates with strong pricing power and controlled distribution. Organic sales in mainland China grew 9%, supported by six consecutive quarters of market share gains and a localized Shanghai research facility now generating 30% of global product innovation.20 The digital pivot is also evident, with e-commerce reaching 34% of total sales and 13 portfolio brands operating on Amazon across 11 markets.120 Meanwhile, travel retail returned to growth across Hainan and South Korea on a normalized inventory base.
Put simply: with distribution channels cleared, an annual cost base reduced by $1.2 billion, and core brand equity intact, a business operating at 75% gross margins retains significant operational leverage as volume recovers.
The bear case
The bear case does not dispute the fiscal 2026 results; it questions what those results prove long term.
The margin expansion is primarily a cost-reduction story. Organic sales grew 3% for the full year, while adjusted operating margin expanded 320 basis points. Most of that improvement stemmed from eliminating roughly 10,000 positions and $1.2 billion in structural overhead rather than expanding end-consumer demand. Restructuring plans yield a one-time step up in efficiency. If organic sales growth remains in the low single digits, margin expansion beyond the Profit Recovery and Growth Plan will depend on revenue leverage that has yet to materialize.
Market share loss in China may be structural rather than cyclical. Six quarters of share gains are encouraging, but they are measured against a severely depressed prior-year base. They do not demonstrate that a multinational operating on a two-year product cycle can permanently outpace agile domestic competitors. The Shanghai innovation center is a step in the right direction, but local formulation capabilities remain relatively young.
Travel retail may never match its historical profitability. The channel was previously inflated by grey-market arbitrage that Chinese regulatory enforcement has curtailed. A travel retail division generating 15% of sales by serving legitimate travelers represents a fundamentally smaller, lower-margin business than a channel accounting for 28% of sales driven by daigou resellers.
Pricing power across flagship skincare lines faces persistent pressure. Years of heavily discounted grey-market availability for products like Advanced Night Repair recalibrated consumer price expectations. Restoring premium brand equity requires more than a single year of channel stabilization.
Retail partner power continues to shift against the company. Expanding distribution for M·A·C into Sephora was necessary for growth, but it grants valuable retail leverage to a subsidiary of competitor LVMH. Partnering with Amazon carries similar tradeoffs, exchanging short-term volume growth for weaker long-term channel control.
Governance structures limit external pressure. With the Lauder family retaining supervoting control, external investors cannot force strategic adjustments or asset divestitures — such as rationalizing hair care or underperforming makeup brands — if execution slows.
Where the evidence leaves the thesis
Evaluating the evidence leads to a narrowed version of the bull case rather than a complete rejection. The thesis that The Estée Lauder Companies remains an unchallenged, broadly dominant prestige beauty empire does not align with the historical record: the business lost structural share in its key growth market, mismanaged its most profitable distribution channel, and wrote down major acquisitions within years of purchase.
What remains intact is a more defined investment thesis: the company owns premier luxury fragrance and ultra-premium skincare assets supported by pricing power and disciplined distribution, alongside a lower-margin makeup and hair care portfolio, operated by a management team that has demonstrated cost discipline but has yet to prove sustained demand generation across developed markets. That represents a viable investment thesis, even if it reflects a lower valuation baseline than the market assigned in 2021.
The three KPIs that matter
Everything above reduces to three key metrics to track each quarter.
1. Adjusted operating margin trajectory. Fiscal 2026 adjusted operating margin reached 11.2%, with management projecting 12.7% to 13.5% for fiscal 2027.1 The critical test is whether operating margins continue expanding after restructuring benefits fully annualize, which will distinguish true revenue leverage from one-time cost reduction.
2. Travel retail inventory and sell-through alignment. Disclosures in Asia travel retail require close monitoring. Investors should track whether reported net sales align with retail sell-through and distributor inventory levels, as any divergence between wholesale shipments and consumer demand would signal a return to previous channel imbalances.
3. Organic growth in fragrance. Fragrance organic sales expanded 10% in fiscal 2026, serving as the clearest indicator of durable brand power in the portfolio.1 If fragrance growth decelerates toward the corporate average while makeup remains flat, the argument for differentiated luxury pricing power weakens. Sustained double-digit growth in fragrance, by contrast, provides strong support for the broader turnaround thesis.
XII. Epilogue & "If We Were CEOs"
Eighty years separate the converted stable in Queens from the fiscal 2026 earnings call, and the distance between them is fundamentally a story about where the customer is standing. In 1946, she was sitting under a salon hair dryer on Long Island. In 1968, she was at a Saks Fifth Avenue counter answering questions evaluated by a diagnostic sliding tool. In 2018, she was walking through a Hainan duty-free complex. In 2026, she is watching a livestream on Douyin late at night.
The enterprise that mastered the first three took too long to adapt to the fourth, losing roughly three-quarters of its market capitalization and eliminating 10,000 positions before executing a reset.
For executive leadership navigating the next phase, three operational priorities follow from the empirical evidence rather than legacy sentiment.
Prune the portfolio down to core pricing power. The categories that command pricing power and customer habituation—luxury fragrance and ultra-premium skin care—possess fundamentally different economics and durability from trend-dependent color cosmetics and a subscale hair care division. While management has not announced divestitures, defending underperforming makeup assets and hair care on the grounds of shared supply chain scale risks diluting capital and managerial focus across value-destructive segments.
Complete local decentralization. Sourcing 30% of global product innovation from the Shanghai research facility represents initial progress against faster domestic competitors, but it marks a starting baseline rather than an endpoint. Product formulation, marketing, and pricing authority for China must reside locally to operate on monthly iteration cycles. A similar framework applies to emerging growth markets across Southeast Asia, India, and the Middle East, where managing local preferences from centralized North American headquarters risks repeating past channel lags.
Align incentives strictly to consumer sell-through. The most critical governance reform is hard-wiring executive compensation and internal sales targets directly to end-consumer sell-through rather than wholesale net shipments. The central lesson of the travel retail drawdown was not that duty-free distribution is inherently flawed, but that evaluating performance at the wrong point in the supply chain guarantees misaligned operational incentives.
Estée Lauder founded her business on the insight that prestige beauty is sold through personal connection rather than passive advertising. That core premise remains intact, even as the primary point of engagement shifts. The company established the modern prestige playbook around a physical interaction behind a department store counter. The central strategic question—unresolved after one year of stabilization following a multi-year downturn—is whether an enterprise built around physical consultation can deliver comparable intimacy and brand equity through a digital screen, at the operating speed of competitors born online.
References
-
The Estée Lauder Companies Reports Fiscal 2026 Results — The Estée Lauder Companies Inc., 2026-08-19 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Estée Lauder Companies Investor Relations Portal — The Estée Lauder Companies Inc. ↩
-
The Estée Lauder Companies Reports Fiscal 2025 Results — The Estée Lauder Companies Inc., 2025-08-20 ↩↩↩↩↩↩↩↩↩
-
Earnings call transcript: Estée Lauder beats Q4 2026 estimates, shares jump 16% — Investing.com, 2026-08-19 ↩
-
How Clinique was Created, and How It Nearly Killed Estée Lauder — Commoncog Case Library ↩
-
Carol Phillips and the Creation of Clinique — Clinique Skin School ↩
-
Form 424B4 Prospectus — The Estée Lauder Companies Inc., SEC EDGAR, 1997 ↩
-
Estée Lauder Companies to Acquire Too Faced (Exhibit 99.1) — SEC EDGAR, 2016-11-14 ↩
-
Form 10-K Annual Report (Fiscal Year 2025) — The Estée Lauder Companies Inc., SEC EDGAR, 2025-08-20 ↩
-
The Estée Lauder Companies to Acquire Dr. Jart+ — BeautyMatter ↩
-
The Estée Lauder Companies Completes Acquisition of DECIEM — ELC Newsroom, 2024-06-03 ↩
-
Estée Lauder Completes DECIEM Acquisition in $1.7 Billion Deal — BeautyMatter ↩
-
Stéphane de La Faverie aims to restore agility at The Estée Lauder Companies — Premium Beauty News ↩
-
Inside Estée Lauder CEO Stéphane de La Faverie's Fast-paced Reset of the Prestige Beauty Giant — WWD ↩
-
Everything we know about Estée Lauder Companies' job cuts, results and profit recovery plans — Cosmetics Business ↩
-
Estée Lauder (EL) Q4 2026 Earnings Call Transcript — The Motley Fool, 2026-08-19 ↩↩↩↩↩↩↩↩↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube