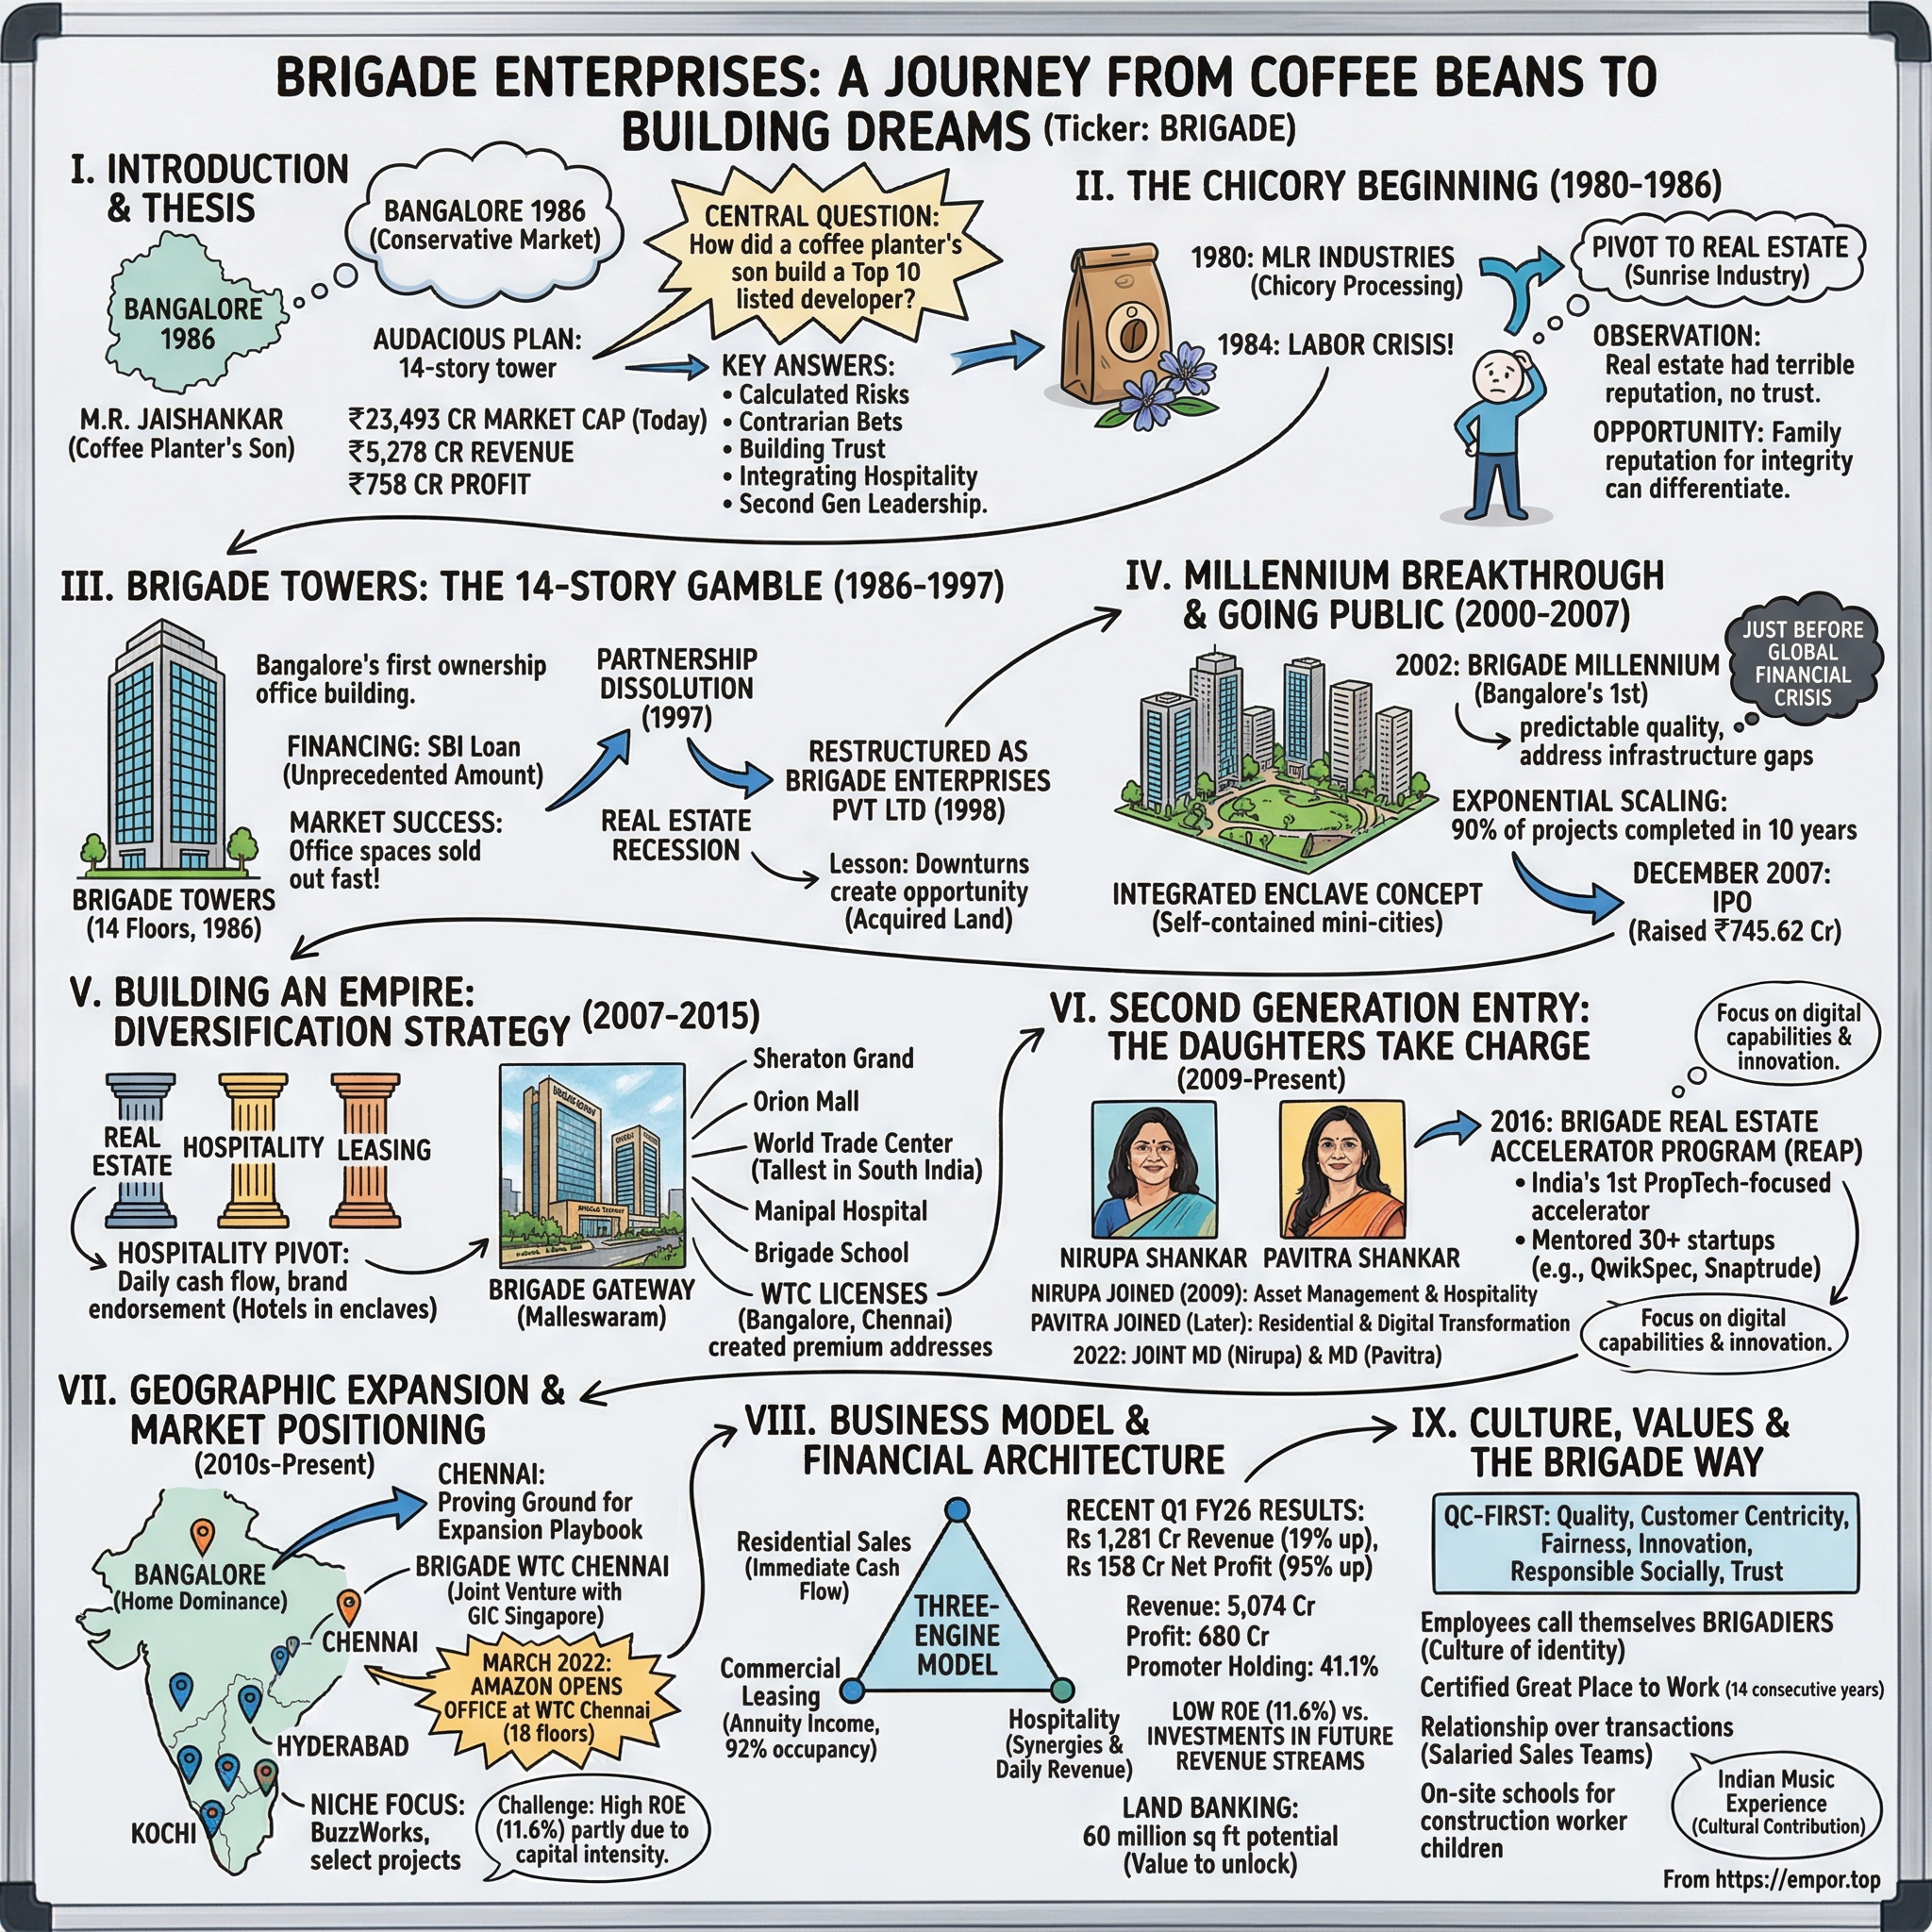
Brigade Enterprises: The Quiet Profit Engine Behind Bangalore's Skyline
I. Introduction & Episode Thesis
Stand on Rajajinagar's Dr. Rajkumar Road in west Bengaluru and look up. The Sheraton Grand rises on one side. Orion Mall hums below it. Behind them, the World Trade Center Bangalore — for years the tallest building in South India — throws a shadow across a lake that most of the city has forgotten exists. Apartments, offices, retail, a hotel, a hospital, a school: all of it on one contiguous parcel, all of it built by one company, all of it feeding the same set of tenants and buyers. This is Brigade Gateway, and it is the closest thing Indian real estate has to a physical thesis statement.
The company that built it is smaller than you would guess from the skyline. Brigade Enterprises carried a market capitalisation of roughly ₹21,400 crore in early September 2026, with the shares changing hands near ₹645 to ₹656 — well off a 52-week high of ₹802 and well above a 52-week low of ₹451.1 That places it far below Godrej Properties at roughly ₹59,600 crore and below Prestige Estates, and comfortably above Sobha Limited at roughly ₹13,300 crore.2324 Yet in the fiscal year ended March 2025, Brigade booked ₹7,847 crore of pre-sales — the value of apartments and offices customers agreed to buy — putting it within striking distance of Sobha and in a different league from its own market value relative to peers.7 Meanwhile the two giants of the listed pack, Godrej Properties and Prestige, booked ₹34,171 crore and ₹30,024 crore respectively in FY26.2 Brigade booked ₹7,424 crore in that same year, and it went down, not up.4
So this is a mid-sized regional developer in a market where scale is winning. That is the story most investors know. Here is the story they mostly do not.
Look at where Brigade's profit actually comes from. In FY26, the real estate development segment — building and selling apartments and offices — generated ₹4,002 crore of revenue, roughly two-thirds of the group total, and threw off ₹525 crore of segment EBITDA. The leasing segment — the offices and malls Brigade owns and rents out rather than sells — generated ₹1,303 crore of revenue, about a fifth of the total, and threw off ₹906 crore of EBITDA at a margin near 70%.3 Read that again slowly. The business that produced three times the revenue produced barely half the profit. The landlord inside Brigade Enterprises earns more than the builder that surrounds it.
That is not a projection or a management aspiration. It is what the segment disclosure said for the year just closed. And it raises the question this piece chases: if the majority of the profit pool is annuity rent from Grade-A office space in the tightest office market in India, why does the market keep pricing Brigade like a homebuilder?
There are honest answers on both sides. One is that annuity income buried inside a development company is worth less than the same income inside a REIT, because the developer can always spend it on the next land parcel — which, as we will see, is precisely what Brigade did in FY26. Another is that Bengaluru concentration cuts both ways: it is the source of the leasing engine's strength and the source of the single largest risk in the equity story. A third is that the rental book is financed with debt, and the debt has been growing.
The people running this are the second generation. M.R. Jaishankar, who started with a chicory factory in 1980 and got into property because a labour dispute pushed him out of manufacturing, remains Executive Chairman.5 Operating control passed in October 2022 to his two daughters — Pavitra Shankar as Managing Director and Nirupa Shankar as Joint Managing Director.17 They inherited a brand, a land bank, and a set of habits. What they are now being tested on is whether they can hit their own numbers, allocate capital without favouring the promoter family, and eventually tell the market what the leasing business is actually worth.
In the past eighteen months, all three of those tests have been graded in public. The company missed its own pre-sales guidance by a wide margin. It proposed a promoter-friendly warrant issue and withdrew it within 48 hours under institutional pressure. And a state environmental authority revoked the clearance on a ₹2,000 crore Chennai project sitting near a Ramsar-listed wetland. This is not a quiet company at the moment. It is a company whose story is being stress-tested in real time.
To understand any of it, start with the chicory.
 Subscribe on LinkedIn
II. Origins, Compressed: From Chicory to Concrete (1980-2007)
Chicory is a root. You roast it, grind it, and blend it into coffee powder to add body and a faint bitterness that South Indians have loved for generations. It is not glamorous. In 1980, a 34-year-old agricultural sciences graduate from a Chikmagalur coffee-planting family started a small-scale unit making the stuff and, within a few years, MLR Industries had become the largest chicory supplier to Brooke Bond India.5 M.R. Jaishankar had an agriculture degree from Bangalore and an MBA from Mysore University, and by the standards of 1980s small-town Karnataka industry, he was winning.
Then, in 1984, the labour trouble started. Industrial relations at the plant deteriorated badly enough that Jaishankar concluded he needed a second business. He did not shut the chicory unit — he kept running it until 1991 — but he began looking for somewhere to put his energy that did not involve a shop floor.5 The version of this story Jaishankar has told over the years carries a wry gratitude toward the union leader who made his life difficult. Without that dispute, the largest developer in Bengaluru by brand recognition might never have existed.
What he chose was property, in a city that in 1986 barely had a property industry. Bangalore then was a pensioner's town with public-sector electronics factories and a climate people wrote poems about. Jaishankar formed a partnership firm, Brigade Investments, backed by his family and two family friends, and proposed building an office tower on Brigade Road. His partners wanted a modest ground-plus-three structure. He wanted fourteen storeys.5
He got fourteen. Brigade Towers became the tallest privately built building in the city, financed with a State Bank of India loan of ₹10 million — an unusually large facility for a first-time developer with no track record.5 It is worth pausing on what that decision actually reveals, because the pattern repeats. Jaishankar's instinct at the first fork was to take the biggest available swing, in the one city he understood, financed with more leverage than convention allowed. Four decades later, Brigade is still doing versions of that trade.
He also did something almost nobody in Indian real estate was doing in the late 1980s: he marketed. Brigade ran what the company describes as the first advertisement placed by an Indian property developer in India Today.5 In an industry where product was sold through brokers, relatives and word of mouth, treating a building like a consumer brand was a genuine departure. It seeded the brand equity that Brigade still trades on today.
The next two decades were less romantic. The partnership dissolved in 1997, and the group's various entities were only fully consolidated into a single company — Brigade Enterprises — under a High Court order in 2004.5 The dissolution and restructuring landed squarely in the middle of a nasty Indian property downturn. There is a temptation to narrate this as visionary counter-cyclical positioning. The more defensible reading is simply that a partnership broke up at an awkward time and took seven years to sort out, and the company came through it because the underlying Bangalore market recovered.
The genuinely important innovation came in 2002, with Brigade Millennium on J.P. Nagar. Instead of a standalone apartment block, Brigade built what it called an "integrated enclave": residential towers plus retail plus a club plus a school, all inside one gate. The insight was that in an Indian city with unreliable public infrastructure, buyers were not really purchasing square footage — they were purchasing a functioning micro-environment. Once you own enough contiguous land to build one, an integrated enclave commands a price premium a single tower cannot, and it locks the developer into a multi-year revenue stream from the same parcel. Brigade Gateway, Brigade Cornerstone Utopia and the current Neopolis project in Hyderabad are all descendants of the Millennium template.7
By 2005 the five-person startup had passed a thousand employees.5 In December 2007, Brigade went public — roughly nine months before the global financial crisis hit Indian real estate with full force. That timing matters less as a judgment on management than as a data point about the company's relationship with capital markets, which has never been shy. Brigade has raised institutional equity repeatedly since: a ₹500 crore qualified institutional placement in 2017, another in 2021, and a ₹1,500 crore QIP in September 2024 that will feature heavily later in this story.19 Any characterisation of Brigade as a company that avoids dilution would be simply false.
What carried forward from these years into 2026 is a specific and narrow set of capabilities: how to assemble land in Bengaluru, how to get a large integrated project through civic approvals, how to sell a brand in an industry where buyers are terrified of being cheated, and a comfort with debt-funded scale. Those capabilities are real. They are also, notably, geographically bounded. To understand why that bound matters so much, you have to understand how money actually moves through Indian real estate.
III. How Indian Real Estate Actually Makes Money: Industry Structure Before the Company
Here is a thing that surprises people who come to Indian property from Western markets: for most of its history, the Indian developer's principal skill was not construction. It was land aggregation, approvals navigation, and cash management — in roughly that order. Concrete was a commodity you outsourced.
The reason is the pre-sales model, and it is the single most important structural fact in this entire industry. An Indian developer typically sells apartments before they are built, sometimes before the foundation is poured. Buyers pay in construction-linked instalments. The developer uses those instalments to fund the build. In effect, the customer is the primary lender, and the developer runs on other people's money at a cost of capital of approximately zero.
That model is spectacular when it works and catastrophic when it does not. Before 2016, developers routinely took money from Project A and spent it on land for Project B, leaving Project A's buyers waiting years — sometimes forever. The Real Estate (Regulation and Development) Act, which came into force through 2016 and 2017, attacked exactly this. RERA forced project registration, mandatory disclosure, and — critically — an escrow requirement, so a defined share of customer collections has to stay ring-fenced for the project those customers bought into.
RERA is usually described as a consumer-protection law. For listed developers it functioned as something closer to a competitive weapon. Escrow discipline and disclosure raised the working-capital cost of being a small, informal builder. The Goods and Services Tax regime added compliance overhead on top. And then, in 2018 and 2019, the collapse of IL&FS and the ensuing non-banking finance company credit freeze cut off the shadow-banking channel that had funded thousands of undercapitalised developers. Three shocks in three years, all pushing in the same direction: toward developers with brands, balance sheets and audited books.
The consolidation is visible in the numbers. India's 28 largest listed developers together booked ₹1.95 trillion of pre-sales in FY26, up 17% from ₹1.66 trillion the prior year.2 That is a growth rate well ahead of the underlying housing market, which is the definition of share gain. But the ceiling is still low. Even after a decade of consolidation, listed and organised developers remain a minority of Indian residential volume; the market is dominated by thousands of local builders operating one or two projects at a time.
For an investor, that framing does two things at once. It supports a long runway — if the organised share keeps climbing, the listed cohort can grow faster than the market for years. And it warns you that "the industry is consolidating" is not itself a competitive advantage, because it is available to every listed player simultaneously. Godrej Properties, Prestige, Lodha, DLF and Brigade all get the same tailwind. What separates them is where they operate, how they source land, what they do with the cash, and whether they deliver on time.
Which brings us to the second structural fact: the pre-sales figure everyone quotes is not revenue. Indian developers recognise revenue on project completion, so a booking made in FY26 may show up in the profit and loss account in FY29. The gap between the two makes pre-sales the leading indicator of the business and reported revenue a lagging, and often confusing, one. When Brigade reported ₹5,909 crore of total income for FY26 while booking ₹7,424 crore of sales, both numbers were correct and they were measuring different years.4
There is a third fact, and it is the one that produced Brigade's most important business almost by accident. Because pre-sales funded development, and because Indian office tenants preferred to lease rather than buy, developers who built commercial space had to decide: sell the building, or keep it and collect rent. Selling gave you cash today. Keeping it gave you an annuity — and required you to fund construction with real debt rather than customer money. Most Indian developers, cash-constrained, sold. A handful — DLF, Embassy, Prestige, Brigade — kept.
Thirty years later, that decision is why one of these businesses looks like a homebuilder on the top line and something quite different underneath.
IV. The Core Business: Real Estate Development — Bangalore's Home-Field Advantage and Its Limits
On May 7, 2026, Brigade's management team dialled into an earnings call to explain a number nobody wanted to explain. Full-year pre-sales had come in at ₹7,424 crore, down 5% from the prior year.3 Twelve months earlier the company had guided to growth of 15% to 20%.4 The gap between what was promised and what was delivered was somewhere north of ₹1,500 crore of bookings — a miss large enough that it is worth understanding precisely how it happened, because the explanation is the test of management credibility for the next two years.
The anatomy of a miss
Brigade had planned to launch about 12 million square feet of new residential product in FY26. It launched 8.3 million.4 Roughly 3.3 million square feet of planned launches, mostly in Chennai, slipped into the following fiscal year on approval delays, and many of the launches that did happen landed in the back half of the fourth quarter, leaving almost no selling window.4 Pavitra Shankar framed it on the call as timing rather than demand: the shortfall was "primarily on account of delays in obtaining approvals, with many project launches pushed to the latter half of Q4."4
Two things about that explanation deserve scrutiny. First, it is specific and falsifiable, which is more than most managements offer. She named the mechanism, named the geography, and gave a quantum. Second, "approval delay" is the most-used excuse in Indian real estate, and the base rate for it being the whole story is not high. Prestige Estates used almost exactly the same explanation for a 19% pre-sales decline in FY25 — and then nearly doubled bookings to ₹30,024 crore the following year, which is decent evidence that approval delays genuinely can be a timing problem rather than a demand problem.2 The honest read is that the explanation is plausible and partially corroborated by a peer's experience, and it will be settled by whether FY27's guided ₹9,000 crore actually lands.3
There is a wrinkle that makes the "just timing" framing harder to accept in full. The largest single stuck project, Brigade Morgan Heights in Chennai, did not merely wait in a queue. Its environmental clearance — granted in January 2025 for around 1,275 apartments on roughly 14.7 acres near Perumbakkam, a project valued at about ₹2,000 crore — was revoked outright on May 12, 2026, following a State Level Environment Impact Assessment Authority meeting that cited the absence of wetland authority permission and the site's proximity to the Pallikaranai marsh, designated a Ramsar wetland of international importance in April 2022.11 Brigade called the revocation "legally unsustainable, factually incorrect and arbitrary," argued that the land had been classified as dry punjai land since 1935, noted that a public interest litigation against the project had been dismissed by the Madras High Court in February 2026, and filed a challenge.1112 On the Q1 FY27 call in August 2026, management said it had approached the court, that status quo was being maintained, and that it remained committed to the project.10
That is not a queue. That is a live siting dispute over a protected wetland with a political dimension, and the outcome is genuinely uncertain. Investors should treat Morgan Heights as a contingent item rather than a deferred one — and should note that a company describing a revoked clearance as an "approval delay" is technically accurate but rhetorically generous to itself.
What the price line is telling you
Set the volume miss aside and look at what Brigade sold each square foot for. Average realisation moved from ₹7,968 per square foot in FY24 to ₹11,138 in FY25 — a 40% jump the chairman attributed largely to a better product mix rather than pure price increases — to ₹12,109 in FY26, up 9%.73 In the June 2026 quarter it reached ₹14,256, up 21% year on year.10
That trajectory is genuinely impressive and genuinely ambiguous. On the Q4 FY26 call, management was careful about it: asked how much was true pricing power, the answer was that "on a like-to-like basis, what we've been able to take across various projects is high single digits."3 In other words, most of the headline realisation gain is mix — Brigade is selling more expensive product in more expensive locations, not charging dramatically more for the same apartment. High-single-digit like-for-like price growth in a market with sub-8% office vacancy and strong end-user demand is respectable. It is not evidence of a pricing moat.
The combination — volume down, price per foot up sharply, most of the price gain from mix — reads as a company leaning on premiumisation to cover a launch drought. That is a reasonable short-term response. It is not a strategy that compounds unless launches normalise, because you eventually run out of premium inventory to sell.
Margins, and why the core business funds rather than compounds
Development is the thinnest-margin business Brigade operates. In FY26 the segment converted ₹4,002 crore of revenue into ₹525 crore of EBITDA — about 13%.3 The June 2026 quarter was much better, at 21% on ₹707 crore of revenue against roughly 12% a year earlier, driven by better realisation and cost control.10 The improvement is real but a single quarter of it in a business with multi-year revenue recognition should not be extrapolated.
Compare that to the roughly 70% margins in leasing, and the structural point becomes clear: Brigade's largest business by revenue is its least profitable per rupee. Development is the engine that generates volume, brand presence and land-bank turnover. It is not the engine that generates profit.
Land: the JDA machine, and a spree with awkward timing
How Brigade buys land is the most capital-efficient thing about it. The dominant model is the joint development agreement, where the landowner contributes land and receives a share of the finished project or revenue, rather than a cheque up front. The developer avoids paying full land cost in cash, and the landowner takes development risk alongside. Roughly speaking, JDAs convert a large fixed cost into a variable one — the real estate equivalent of revenue-share rather than a licence fee.
In FY26 Brigade added ₹15,000 crore of gross development value across 13 million square feet, weighted about 60% to Bengaluru and 30% to Hyderabad.3 It also did something new: a 50:50 joint venture with Bain Capital for a 10.8-acre mixed-use project in Whitefield comprising roughly 2 million square feet of office plus a 250-key hotel, on a 40-month timeline.3 Bringing in institutional private-equity capital at the asset level is a meaningful signal — it suggests a third-party underwriter validated the economics — though a single JV is not yet a funding model.
The residential land bank stood at 57 million square feet, about 75% of the total portfolio.3 Not all land is JDA, though. The Neopolis parcel in Kokapet, Hyderabad, was bought outright at public auction for more than ₹750 crore, and Jaishankar told shareholders at the 2025 AGM that construction had started, with L&T as contractor, and that of the first phase of roughly 297 apartments, about 250 had been sold generating more than ₹1,000 crore of bookings.7 That is a fast conversion on an expensive parcel, and it is the strongest single piece of evidence that Brigade's brand travels outside Bengaluru.
The awkward part is timing. Brigade bought aggressively, partly with debt, in the same year its own bookings went backwards. And this was not an unforeseeable tension. In its March 2025 rating rationale — which revised the outlook on Brigade's CRISIL AA- rating to Positive — CRISIL explicitly flagged "aggressive land acquisition through bank borrowing" as a monitorable, alongside the observation that roughly 91% of total debt was secured against lease-generating assets.9 The rating agency named the risk; the company then took it.
Whether that is discipline or overreach depends entirely on execution. There is a defensible case: land is the scarce input, prices in Bengaluru and Hyderabad have been rising, and buying into a soft patch is how land banks get built cheaply. There is also a case that a company which just missed its sales guidance should be conserving rather than deploying. On the available evidence the verdict is genuinely open, and the thing that resolves it is not the land purchases themselves but whether the FY27 launch pipeline — 11.6 million square feet with ₹11,900 crore of GDV as guided at the FY26 results, revised to 12.4 million square feet and ₹13,400 crore of GDV across the four quarters from mid-2026 — actually converts into bookings.310
The concentration problem, stated precisely
Brigade is a Bengaluru company that operates elsewhere. ICRA's July 2025 rationale put the number bluntly: about 79% of saleable area in ongoing residential projects sat in Bengaluru as of March 2025, and 51% of leasing segment revenue came from the same city.8 CRISIL's read on collections was similar, at 74% Bengaluru, with the agency crediting Brigade with a 12-13% share of the Bengaluru market and more than 90 million square feet developed over three decades.9
A 12-13% share of one of India's best property markets is a real asset. It buys relationships with landowners, familiarity with civic authorities, contractor availability and a brand that buyers recognise without being sold to. That is the home-field advantage, and it is why Brigade converts land into bookings faster in Bengaluru than a national player parachuting in.
It is also a single point of failure. Management has stated an intention to bring Bengaluru's share of the mix down over time through Chennai, Hyderabad and Mysuru, and the FY27 launch plan is more balanced than the land-buying pattern would suggest — 4.5 million square feet in Bengaluru against 3 million each in Chennai and Hyderabad.3 But in the June 2026 quarter, Bengaluru still supplied the largest share of the launch pipeline, and the FY26 land additions skewed 60% back to the home city.310 Stated diversification and revealed capital allocation are pointing in different directions. That gap is the thing to watch, and it is measurable: the share of pre-sales coming from outside Bengaluru is a number the company reports every quarter.
The development business, then, is a capable regional operator with a genuine local edge, a thin margin, an unresolved guidance miss, and a live legal problem in its second-largest market. It is not where the profit is. To find that, you have to look at the buildings Brigade decided not to sell.
V. The Quiet Profit Engine: Leasing
In the middle of 2026, Amazon walked out of 630,000 square feet at World Trade Center Bangalore.3 In most office markets on earth, a single tenant vacating that much space in one building is a small disaster — months of vacancy, a rent cut to fill it, and a hole in the year's numbers.
Here is what Brigade's management told analysts on the Q4 FY26 call: they had already re-let 100,000 square feet, and they expected to re-lease the space at rates 10% to 15% higher than Amazon had been paying, with some smaller floor plates going out at 20% above.3
That single exchange tells you more about the economics of Bengaluru office real estate than any market report. When your anchor tenant leaves and you expect to raise the rent, you are not in a normal property market. You are in a supply-constrained one.
Why the segment disclosure is the most interesting page in the annual report
Brigade's leasing business generated ₹1,303 crore of revenue in FY26, up 12%, and ₹906 crore of EBITDA, up 18%.3 That is a margin near 70%, which sounds implausible until you understand what a leasing segment's costs actually are: property management, common-area maintenance, some marketing, and not much else. The building is already built. The depreciation and the interest sit below the EBITDA line. What is left between rent collected and cash operating costs is enormous.
Set that beside the development segment's ₹525 crore of EBITDA on three times the revenue, and the shape of the company inverts.3 Roughly 55% of Brigade's FY26 segment EBITDA came from renting space out. About 32% came from building and selling it. The rest came from hotels.
This is not a story about a future business becoming material. It is a description of what already happened. And it has a direct valuation consequence: annuity rental income from Grade-A offices with long leases and institutional tenants is, in every market in the world, capitalised at a higher multiple than lumpy, cyclical, project-by-project development profit. If a sum-of-the-parts investor valued Brigade's leasing EBITDA on rental-asset multiples and its development business on developer multiples, the arithmetic would not resemble a single blended earnings multiple on a market cap of ₹21,400 crore.1
The falsification test: does the annuity actually hold?
The bull argument for the leasing segment rests on three claims — the space is full, the rents are rising, and the demand driver is structural. Each deserves testing against the record rather than the pitch.
Occupancy. The FY25 annual report reported an operational portfolio of 8.13 million square feet at 90% occupancy, against what it cited as an 88% industry average.6 By the June 2026 quarter, portfolio occupancy was 88%.10 That is a modest decline, not a collapse, and it followed a large anchor departure. But note that ICRA had already flagged market risk on 0.91 million square feet of vacant area in completed commercial projects as of its July 2025 review, and management disclosed 375,000 square feet still unleased at WTC Bangalore in mid-2026, attributing slow decision-making partly to conflict in West Asia delaying large tenant commitments.810 The annuity is strong; it is not frictionless.
Rents. The re-leasing spread on the Amazon space is the single best evidence of pricing power in this entire company — better than anything in the residential business. It is one data point, but it is the right kind of data point: a real transaction, in a real building, at a stated premium to the prior contract rent.
The demand driver. This is the piece most likely to be misunderstood. The consensus fear after 2020 was that hybrid work would gut office demand. In Bengaluru it did the opposite of what the fear predicted, because the buyer changed. Global Capability Centres — the offshore engineering, finance and analytics arms that multinationals set up in India — accounted for 42% of national office leasing in the second quarter of 2026, with flexible-workspace operators at 27%, and Bengaluru alone absorbed roughly 5.59 million square feet, about 27% of all Indian office demand in the quarter.13 Citywide average warm-shell rents pushed above ₹100 per square foot per month.13
Jaishankar himself gave the counter-argument at the 2025 AGM, and it is worth quoting because it is unusually candid for a chairman's speech. He noted that AI and a 2% workforce reduction at TCS had "sent ripples and shockwaves," making Indian IT companies cautious about leasing new space, and described GCC expansion as "the saving grace for Indian office real estate sector."7 That is the chairman of a landlord telling shareholders that one of his two demand pillars is wobbling and the business now depends on the other. It is the right framing, and it bounds the bull case properly: Brigade's office annuity is a leveraged bet on multinationals continuing to build capability centres in India. Management's own FY26 disclosure showed GCC tenants at 58% of the leased portfolio against traditional IT and ITES at 26%.3 That mix is a strength today and a concentration if global corporate cost-cutting ever turns against offshore centres.
The catalyst that does not yet exist
Here is the sharpest limitation on the leasing thesis, and it belongs right next to the thesis rather than in a footnote. Brigade has demonstrated appetite for monetising a non-core segment — it listed its hotel subsidiary in 2025. It has not announced any concrete plan to separately list, spin off or REIT the office portfolio. In the FY25 annual report, the FY26 and Q1 FY27 earnings calls, and the 2025 AGM transcript reviewed for this piece, no such commitment appears; at the AGM, the CFO's answer to a shareholder question about leasing simply described it as "about 20%-22% of the overall revenue of the organization," without reference to its share of profit or any monetisation intent.63107
That silence matters. A sum-of-the-parts argument with no corporate action behind it is an analytical observation, not an investable catalyst. The value can sit unrecognised indefinitely, and the cash it generates can be — and in FY26 was — recycled into land and commercial capex rather than returned or crystallised. The correct calibration is that the leasing profit pool is real, proven, and currently the dominant source of group earnings; and that its re-rating potential is entirely dependent on a management decision that has not been made.
Meanwhile the segment is growing capital-intensively. Brigade has a pipeline of about 10 million square feet across FY27 and FY28 requiring roughly ₹6,000 crore of capital expenditure, with an estimated ₹800 crore of additional rental income from ongoing completions.3 If those numbers land, the annuity roughly doubles. If they slip, the debt arrives before the rent does.
BuzzWorks: promising, and not yet a business
Tucked inside the leasing segment is BuzzWorks, Brigade's managed-office and co-working platform. By the end of FY25 it operated 18 centres with 6,200 desks, with another 3,500 planned and expansion targeted at Hyderabad, Chennai and Mumbai.6 It signed its largest Hyderabad lease to date in 2026, a 550-seat anchor deal.
It is a sensible adjacency — flex operators are the second-largest occupier category in India, and a landlord that operates its own flex brand captures that margin rather than leasing to a WeWork-style intermediary. But BuzzWorks is not separately disclosed as a revenue line, its contribution to the ₹906 crore of leasing EBITDA is not broken out, and the honest description is a growing initiative of undisclosed profitability rather than a proven business. Treat it as optionality, not as earnings.
The leasing business, then, is where Brigade actually makes its money, backed by a genuinely tight market and demonstrated re-leasing power — and it is simultaneously the part of the company with the least clarity about how, or whether, that value ever gets recognised by anyone other than the company itself. For a template on how Brigade handles monetisation when it does act, there is one recent, instructive case.
VI. Hospitality and the Brigade Hotel Ventures IPO: A Monetization Test Case
On July 31, 2025, Brigade Hotel Ventures listed on the NSE and BSE. The IPO had been priced at ₹90 per share. The stock opened at ₹81.10 on the NSE — a discount of just under 10% — and ₹82 on the BSE.15
This was not a failed book-build. The offer had been subscribed 4.48 times, drawing bids for 22.95 crore shares against 5.12 crore on offer, and it had raised ₹324.7 crore from anchor investors before opening.1415 Investors wanted the paper. They just did not want it at ₹90 once trading started — the grey market premium ahead of listing was zero, which is about as clear a sentiment signal as that opaque market provides.15
That gap between subscription enthusiasm and listing-day reality is the single most useful fact in this section, and it should temper any assumption that Brigade's other assets would fetch premium prices in a public monetisation. When the company actually tested the market's appetite for one of its non-core segments, the market said "yes, at a discount."
How the hospitality business got built
Brigade entered hotels in 2010 with the Grand Mercure in Bengaluru and grew into a portfolio of nine operating hotels and 1,604 keys across Bengaluru, Chennai, Kochi, Mysuru and GIFT City, operated under Marriott, Accor and IHG brands.14 The model is worth understanding: Brigade owns the real estate and the operating economics; the global chain supplies the brand, the loyalty programme, the distribution and the management. The developer takes property risk and keeps the upside on the asset; the operator takes a fee and supplies demand.
This is a sensible fit with the integrated-enclave strategy. A hotel inside Brigade Gateway is not a standalone hospitality bet — it is the amenity that makes the offices more leasable and the apartments more saleable, while generating its own cash. Vertical integration in real estate mostly means capturing more of the value your own land creates.
Segment economics in FY26 were solid but decidedly secondary: ₹604 crore of revenue, up 13%, with ₹207 crore of EBITDA — a margin around 34% — and occupancy stable at 78% with revenue per available room up 6% on a 7% improvement in average daily rate.3 In the June 2026 quarter, the segment produced ₹144 crore of revenue and ₹45 crore of EBITDA, with profit after tax of ₹17 crore against ₹7 crore a year earlier, though management noted West Asian conflict had reduced meetings-and-events business by roughly 10%.10 Hotels are around a tenth of revenue and about an eighth of segment profit. Real, growing, not the story.
The structure, and what it revealed
The listing was a straight subsidiary IPO, not a REIT. Brigade retained majority control, diluting roughly 25% of the hotel entity's equity.7 The fresh issue raised ₹759.6 crore, supplemented by ₹126 crore from a pre-IPO placement in July 2025 — the ₹885 crore Jaishankar described to shareholders at the AGM.15167
The stated uses of proceeds were disclosed clearly: ₹468.14 crore to repay or prepay borrowings at the hotel company and its material subsidiary SRP Prosperita Hotel Ventures, ₹107.52 crore to purchase an undivided share of land from the promoter — that is, from Brigade Enterprises itself — and the balance for general corporate purposes.15
That land purchase deserves a moment. It was disclosed in the offer document, it was priced, and it was an ordinary consequence of carving a hotel business out of a parent that owned the underlying land. It was also, functionally, a transfer of roughly ₹107 crore of public-market money to the parent company. Nothing about it was hidden. But a skeptical investor is entitled to ask whether the land was valued independently and whether minority shareholders in the listed hotel entity got the better half of that trade — and the answer is not something an outside investor can verify from public disclosure.
A second, smaller item emerged later and is worth a sentence because it is exactly the kind of thing that shows up in the quarterly monitoring report and gets ignored. Reviewing fund utilisation for the quarter ended March 31, 2026, the hotel company's audit committee flagged that payments for certain IPO expenses had been routed from the public issue and monitoring account into the company's overdraft account, which contained numerous other transactions — a co-mingling concern about transaction segregation. The company confirmed the funds had been deployed without deviation from stated objectives.16 This is a controls observation rather than a misuse finding. But controls observations are how larger problems announce themselves early, and it sits alongside the promoter-land purchase as a pattern worth watching rather than dismissing.
What comes next, and how much to believe
The plan is to roughly double the room count from about 1,600 keys to more than 3,000 by 2030, adding nine to twelve hotels to reach a portfolio of 18 to 21, funded partly from the listed entity's own balance sheet.7 Brands under discussion have included Grand Hyatt, Fairfield by Marriott and Ritz-Carlton.
Doubling a hotel portfolio in five years is a capital-intensive promise, and the relevant historical check is that Brigade took fifteen years to build the first 1,604 keys. The plan is not implausible — the company now has dedicated listed capital for it, which it did not before — but it requires a materially faster build rate than the company has ever demonstrated in this segment. Progress against the key count is the specific, published metric that will confirm or falsify it.
The broader lesson of the hospitality listing is about the parent, not the subsidiary. Brigade showed it is willing to separate a segment and let the market price it. It also learned that the market prices Brigade's assets conservatively even when the order book is oversubscribed. Anyone modelling a future leasing spin-off should discount accordingly. And anyone assessing this management team's governance instincts now has two data points from the same twelve months — one from the IPO, and one considerably more dramatic.
VII. Second-Generation Command: Succession, Incentives, and a Live Governance Stress Test
The board of Brigade Enterprises approved a resolution on July 15, 2026, to issue 34.23 lakh convertible warrants to Mysore Holdings Private Limited — a promoter entity — at ₹526 per warrant, raising ₹180.05 crore.18
Two days later, on July 17, the board withdrew it.18
The stated reason was that the decision came "in deference to sentiments and feedback expressed by institutional funds and public investors," following direct negative pushback from institutional investors on dilution and pricing.18 The company retained its separate plan to raise up to ₹1,500 crore through non-convertible debentures, which went to shareholders at the annual general meeting on August 13, 2026.18
Forty-eight hours from proposal to reversal is fast. It is also the single most informative governance event in Brigade's recent history, and it can be read two ways — both of which are true.
The charitable read: institutional shareholders have real leverage at this company, and this board listens. Promoters held about 41.1% as of the June 2026 quarter, with mutual funds at roughly 22.6%, foreign institutional investors at 15.6% and retail at 17.8%.21 At that ownership split, the promoter family cannot simply out-vote a determined institutional bloc on a related-party resolution, and management appears to have recognised that before the vote rather than after losing it. Boards that withdraw before defeat are, on balance, better boards than ones that ram resolutions through.
The skeptical read: somebody in that room thought issuing discounted convertible paper to a promoter entity was a good idea in the first place, and the board approved it. Warrants to promoters are a familiar structure in Indian listed companies — the promoter pays 25% up front, gets 18 months to decide, and captures the upside if the stock runs while risking only the deposit. Institutional investors dislike them for precisely that asymmetry. The instinct to route capital toward promoter vehicles exists at Brigade, and it was checked by external pressure rather than by internal restraint.
The calibrated conclusion is that this event narrows rather than confirms the "clean governance" claim. Brigade's governance is responsive, not preemptive. The specific thing that would confirm the stronger version — that the instinct itself has changed — is the absence of a similar promoter-favourable structure appearing again in the next few years. The specific thing that would falsify it is another one appearing and being pushed through.
The two people running the company
Pavitra Shankar became Managing Director in October 2022; her sister Nirupa became Joint Managing Director in the same reshuffle, with Jaishankar staying on as Executive Chairman.17 Both received five-year terms.
Pavitra came to Brigade in 2018 after a Columbia Business School MBA and a career in US real estate private equity, and by FY25 had been associated with the company for over seven years.6 Her remit is residential — the largest, thinnest-margin, most operationally demanding part of the group — plus digital transformation. Her public communication style, as visible across the FY26 and Q1 FY27 calls, is notably concrete: she quantifies, she names projects, she separates timing from demand explicitly rather than gesturing at macro conditions.410 On the August 2026 call, discussing whether the FY27 target was still live, she anchored the answer to the launch pipeline rather than to sentiment: the pipeline, she said, gives confidence the company remains on track for its guidance.10
Nirupa, a Cornell hospitality graduate with prior experience at EY, runs the two businesses that generate most of the group's profit — commercial leasing and hotels — plus human resources and innovation. She chairs Brigade Hotel Ventures. She launched Brigade REAP, described by the company as Asia's first real estate accelerator, in 2016.6
The division of labour is unusually clean for an Indian family business: one sister owns the revenue engine, the other owns the profit engine, and the father retains the chair. There is no evident overlap of mandate and no public sign of the sibling friction that has broken up other Indian promoter families. That is worth something. It is also only four years old, and the succession has not yet been tested by a genuine crisis or a strategic disagreement between the two.
Pay, and what it says about alignment
The FY25 annual report discloses the numbers precisely. Jaishankar received ₹8.49 crore, of which ₹6.78 crore was commission — that is, profit-linked — representing 68.98 times the median employee's remuneration, and a 4.46% decrease year on year. Pavitra Shankar received ₹3.88 crore, 32.55 times median, up 16.04%. Nirupa Shankar received ₹3.92 crore, 32.98 times median, up 17.54%. Executive Director Amar Mysore, also a family member, received ₹3.85 crore.6 Median employee remuneration was ₹10.40 lakh, and the company had 1,138 permanent employees on its own rolls.6
Aggregate that: roughly ₹20 crore of FY25 director remuneration went to four members of the promoter family. Against FY25 profit before tax of ₹869 crore, that is a little over 2% — not egregious by Indian promoter standards, and the heavy commission weighting means it flexes with profit.7 Jaishankar's own pay fell in a year when profits rose sharply, which cuts against the usual critique. But the trajectory over four years is worth noting: his remuneration moved from ₹5.46 crore to ₹6.78 crore to ₹7.17 crore to ₹8.49 crore across the period disclosed in the related-party note.6 Pay at the top has compounded at roughly 16% a year. Shareholders have not.
The auditors, the tax survey, and the accounting record
Two second-layer items belong here rather than in a generic risk list.
First, between December 9 and 13, 2025, the Income Tax Department conducted a survey at Brigade's registered office and other locations. The company disclosed it to the exchanges, stated it cooperated fully, said operations were unaffected, and reported that the financial impact, if any, was undetermined.22 A survey under the Income Tax Act is a fact-finding exercise, not a search or a raid, and it is not evidence of wrongdoing. It is a watch item, and it remains one until either an assessment order or nothing follows.
Second, on the accounting record: the FY25 annual report was signed with an unqualified audit opinion, which the chairman confirmed at the AGM.7 Contingent liabilities disclosed at March 31, 2025 were modest for a company of this size — ₹14.86 crore of sales tax and entry tax claims, ₹29.07 crore of service tax claims, ₹49.64 crore of letters of credit and bank guarantees, and ₹207.04 crore of corporate guarantees to subsidiaries restricted to outstanding loan amounts, down from ₹450.04 crore a year earlier.6 One joint development agreement dispute involving ₹8.60 crore of advances sat in arbitration, with management assessing the advances as recoverable.6 Loans and advances written off during the year were ₹67 lakh.6
That is a clean-looking picture, and it should be described precisely rather than generously: across the FY25 financial statements and the FY25 and FY26 disclosures reviewed for this piece, no material impairment, restatement or abandoned venture appeared. That is a bounded observation over two years of records, not a general assurance about four decades of history.
The one place a capital-allocation claim can be tested over a longer horizon is Brigade REAP. Launched in 2016, the accelerator had by FY25 supported over 82 startups, of which nearly 45% secured further investment, with portfolio companies raising over ₹65 crore in follow-on funding.6 Brigade's own cumulative investment in REAP was disclosed at ₹2 crore.6 That is the right way to run an innovation programme — tiny cheques, ecosystem access, no balance-sheet exposure. It is also a decade-old initiative with no disclosed revenue contribution, which is a useful calibration for how quickly this company converts innovation programmes into earnings: slowly, or not at all. Apply the same discount to BuzzWorks and to any future "new vertical" announcement.
The governance picture, then, is a family business with a genuinely professional structure, disclosed and profit-linked pay, a clean recent audit record, one open tax matter, and a promoter-financing instinct that had to be corrected from outside. That last item leads directly into the balance sheet, because the warrant proposal did not appear in a vacuum — it appeared during a year when Brigade needed money.
VIII. Financial Architecture: Deleveraging, Then Re-leveraging
In the space of about sixteen months, two rating agencies upgraded their view of Brigade Enterprises and the company then did something that pushed in the opposite direction. Watching that sequence is the fastest way to understand how this balance sheet actually works.
On March 28, 2025, CRISIL reaffirmed its AA- rating and revised the outlook to Positive, citing strong net sales bookings, continued inventory liquidation, a project pipeline of 10 to 12 million square feet over the following three to four quarters, cash and equivalents of ₹3,400 crore at December 2024, and ₹724 crore of undrawn facilities. It described liquidity as strong.9 On July 31, 2025, ICRA went further, upgrading the long-term rating from AA- to AA with a Stable outlook, pointing to healthy residential sales and collections, sustained commercial leasing performance, improving hospitality, and expected leverage of under 2.25 times.8
Both agencies were describing the same thing: FY25 was a genuine deleveraging year. Net debt fell to ₹962 crore and net debt to equity to 0.14 — an almost unrecognisably conservative balance sheet for an Indian developer — helped substantially by the ₹1,500 crore raised in the September 2024 QIP.
Then FY26 happened. Net debt rose to ₹2,278 crore and debt to equity to 0.27; by the June 2026 quarter net debt stood at ₹2,218 crore with the ratio at 0.26.310 Leverage did not become dangerous — 0.27 is still low by sector standards, the average cost of debt fell 110 basis points to 7.57%, and operating cash flow was ₹1,411 crore on collections of ₹7,476 crore.3 But it roughly doubled in twelve months, in a year when pre-sales went backwards.
Where the debt actually sits, and why that changes the risk
The critical detail is that this is not homebuilding debt. ICRA's analysis found roughly 86% of total external debt attributable to the leasing segment and 11% to hospitality as of March 2025, with limited debt on residential; management's FY26 commentary put approximately 92% of debt in the commercial segment.83 The residential business is largely self-funded by customer collections, with an adequacy ratio — receivables from sold area against pending cost plus outstanding debt — of a healthy 95%.8
That structure matters enormously for how an investor should think about the risk. Debt secured against leased, income-producing offices with 88% occupancy and contracted rents is a fundamentally different instrument from debt funding speculative apartment inventory. ICRA calculated leasing rentals of ₹1,197 crore in FY25 rising to an expected ₹1,250-1,300 crore in FY26, implying debt-to-rental of 3.2 to 3.3 times.8 That is a serviceable, lease-rental-discounting profile, not a stretched one.
But it also means Brigade is deliberately using its balance sheet to build more of the annuity business — roughly ₹6,000 crore of commercial capex against an expected ₹800 crore of incremental rent.3 Strip away the narrative and that is the actual capital allocation decision this management team has made: take the cash from the low-margin development business, add debt, and buy more of the high-margin rental business. Judged on returns, that is a defensible trade. Judged on risk, it front-loads the borrowing and back-loads the rent, and it does so while the development engine is running below its guided rate.
ICRA named the downgrade trigger explicitly: consolidated total debt to cash flow from operations remaining above 2.5 times on a sustained basis, or considerable debt-funded investment in new projects weakening leverage metrics.8 That is the specific, published threshold an investor can monitor.
The QIP, and how much equity goodwill remains
In early September 2024, Brigade allotted 1,30,43,478 shares at ₹1,150 each, raising ₹1,500 crore, priced at a 1.26% discount to the floor of ₹1,164.70.19 Institutional investors bought in.
Two years later, the arithmetic on that raise is unflattering, though less so than the headline suggests. In May 2026 the board recommended a 1:3 bonus issue — one new share for every three held — with a record date of June 17, 2026, alongside a final dividend of ₹2 per share.204 Adjusting the QIP price for that bonus gives an effective cost of ₹862.50 per share. Against a market price near ₹645 in early September 2026, QIP participants were carrying an unrealised loss of roughly 25%, before the ₹2.50 and ₹2.00 per share dividends declared for FY25 and FY26.174 Not the 44% a raw comparison to the unadjusted ₹1,150 would imply — but a meaningful loss over two years, in a period when the broader listed real estate cohort grew pre-sales 17%.2
This is the context in which the July 2026 warrant proposal should be read. A management team whose last institutional equity round is under water, proposing to issue convertible paper to a promoter entity at ₹526 — below where institutions had bought, adjusted or not — was always going to draw fire. The withdrawal was not just good governance instinct; it was arithmetic.
The practical consequence is that Brigade's equity currency is impaired for now. The August 2026 AGM asked shareholders to approve ₹1,500 crore of NCDs and a ₹10,000 crore borrowing limit — debt, not equity.18 That is the rational path given the share price, and it also means the commercial capex programme will be funded with borrowing rather than dilution for the foreseeable future, which mechanically pushes leverage up before the new rent arrives.
The return profile, honestly stated
Work Brigade's return on equity out from its own disclosures rather than from a screener. FY26 consolidated profit after tax was ₹725 crore; net debt of ₹2,278 crore at a net-debt-to-equity ratio of 0.27 implies shareholders' funds of roughly ₹8,400 crore.3 That is a return on equity in the region of 9% — unspectacular in absolute terms, and low enough that a casual reader might file Brigade under "capital-intensive, low-return developer" and move on.
That filing would miss the mechanism. A pure developer converting 13% of revenue into segment EBITDA cannot generate a 9% return on equity without either heavy leverage or very fast asset turns, and Brigade has neither. The blended return is being carried by the leasing segment's roughly 70% margins on a fifth of revenue.3 In other words, Brigade's returns are not developer returns diluted by a rental drag; they are rental returns supporting a thin development business. Peers built on a different model — Oberoi Realty's Mumbai-only, ultra-premium, near-debt-free approach being the clearest contrast — generate higher returns through a route Brigade has not attempted and could not easily replicate from a Bengaluru land bank. The takeaway is not that Brigade earns great returns. It is that the source of the returns it does earn is the segment most investors are not looking at.
On earnings, FY26 consolidated profit after tax was ₹725 crore, up 7%, on total income of ₹5,909 crore.34 Against a market capitalisation near ₹21,400 crore, that is roughly 29 times trailing consolidated earnings — a multiple that embeds neither disaster nor enthusiasm.1
What the financial architecture says, in one sentence: Brigade runs a conservatively levered balance sheet by sector standards, deliberately borrows against rent-producing assets to buy more rent-producing assets, and has temporarily lost the option to fund that programme with equity. That is a coherent strategy with a clear failure mode, and it depends heavily on a culture that can execute large commercial projects on time.
IX. Culture, the "Brigadiers," and the Brand
Walk into a Brigade site office and the employees will tell you they are "brigadiers." It is the kind of internal coinage that either signals genuine identity or corporate cringe, and in this case there is at least some external evidence for the former: the company has been recognised as a Great Place to Work for well over a decade, ranking in India's top 100 workplaces ten years running, and was named among the country's top 50 workplaces for millennials.7
The formal values framework goes by the acronym QC-FIRST — Quality, Customer-centricity, Fairness, Innovation, Responsible-socially, and Trust. Values statements are the easiest thing in corporate life to write and the hardest to verify. What can be verified is the substrate underneath: the Jaishankar family's Chikmagalur coffee-planting lineage carries, by the company's own account, more than a century of local business reputation predating Brigade itself.5
In most industries that would be sentimental backstory. In Indian real estate it is closer to an economic asset. This is a sector where buyers have historically handed over their life savings for an apartment that existed only as a brochure, to a builder who might or might not finish it. Trust was the binding constraint on the whole market. RERA formalised parts of that trust; brand supplied the rest. Brigade's FY25 annual report notes the company crossed 100 million square feet of completed construction across more than 300 buildings, serving more than 50,000 customers, and was ranked National Brand Leader of Indian Real Estate by the Track2Realty BrandXReport for 2024-25.7
Delivery track record is the mechanism by which that brand converts into economics — it is why a buyer will pay a premium for a Brigade apartment over an equivalent one from an unknown local builder, and why a GCC signing a ten-year office lease will accept the landlord's terms. It is genuinely a competitive advantage. It is also the least durable-sounding one in the portfolio, because brand in real estate is a stock of accumulated deliveries that a single high-profile failure can deplete quickly. A revoked environmental clearance on a project where 1,275 families expected apartments is exactly the sort of event that draws on that stock.
The soft edges of the culture are real but small. The Brigade Foundation runs schools, laid the foundation stone for a second not-for-profit hospital with St. John's at Brigade El Dorado, planted a lakh of trees, and completed the renovation of Bengaluru's 50-year-old Venkatappa Art Gallery, which the chairman singled out at the AGM.7 The family also built the Indian Music Experience museum. On sustainability, 78% of the operational office portfolio held LEED Platinum or IGBC Net Zero certification.6 For institutional tenants with their own emissions commitments, green certification has become a genuine leasing prerequisite rather than a marketing flourish — one of the few places where corporate social responsibility spending has a direct commercial payoff.
None of this is a business line. It is the accumulated goodwill that makes the rest of the machine run slightly more smoothly, and it is worth understanding because it is a large part of why a mid-sized regional developer competes successfully against national players in its home market at all.
X. Playbook: What Brigade Teaches About Regional Real Estate
Strip Brigade down to its transferable lessons and four things stand out — each of them with a limit attached.
The integrated enclave is a scale advantage disguised as a product feature. Building a township with residential, retail, office, hotel and school on one parcel creates a self-reinforcing micro-economy: the office tenants shop at the mall, the mall anchors the apartments, the hotel serves the offices. It commands a price premium and it extends the revenue life of a single land acquisition across a decade. But it only works if you already control enough contiguous land, which in a mature city is a function of having bought early and locally. The model is a moat for incumbents in their home market and nearly impossible to replicate as a new entrant. Brigade's Hyderabad Neopolis project — 2.3 million square feet of residential alongside about 2.5 million square feet of commercial including a mall, a World Trade Center and an InterContinental hotel — is the test of whether the template travels.7 Early evidence from first-phase sales is encouraging; the commercial half is unbuilt.
Joint development agreements let you build a pipeline without owning the balance sheet risk of land — until you want commercial. JDAs work beautifully for residential, where the landowner is happy to take a share of a fast-turning project. They work far less well for offices you intend to hold for thirty years, because the landowner wants an exit and you want an annuity. That is precisely why Brigade's FY26 leverage rose: the residential book stayed asset-light while the commercial buildout consumed debt. Any developer trying to run this dual model should expect the same asymmetry.
Cross-subsidising a cyclical business with an annuity business is a real playbook, not a Brigade invention. DLF, Embassy and Prestige all run versions of it. What is distinctive about Brigade's version is not the strategy but the disclosure gap: because the annuity sits inside a company whose name and revenue mix say "homebuilder," the market has less occasion to price it as a landlord. That is an information asymmetry, not a durable advantage — and it can close either through corporate action or simply through more investors reading the segment note.
Telegraphed family succession is achievable, and it does not end the governance question. The 2022 handover was announced, staged, and gave each successor a distinct mandate — a marked contrast to the abrupt, contested transitions that have damaged other Indian promoter groups. But the 2026 warrant episode demonstrated that a clean succession does not inoculate a company against promoter-favourable capital actions. Governance in a family-controlled listed company is a continuous process, not a milestone.
The one thing Brigade's history most clearly teaches is about the limits of regional dominance. A 12-13% share of Bengaluru is a formidable position that produces genuine operating advantages. It does not produce the balance sheet, land-buying firepower or approvals leverage of a Godrej Properties operating in eight cities. The regional champion's playbook is to be undisplaceable at home and opportunistic elsewhere — which is exactly what Brigade is attempting, and exactly why the Chennai and Hyderabad numbers matter more than the Bengaluru ones.
XI. Porter's Five Forces / Strategic Position Summary
Run the classic framework across Brigade's three businesses and something useful emerges: the forces point in opposite directions depending on which segment you are looking at, which is itself the strategic story.
Buyer power is high in residential and low in office. A homebuyer in Bengaluru can walk across the road and compare a Brigade apartment against Prestige, Sobha, Godrej and a dozen local builders on price, location, amenities and delivery record. Switching costs before booking are zero. That is why development margins sit near 13% and why like-for-like price increases run in high single digits rather than double.3 In Grade-A office leasing the calculus inverts. A GCC signing a multi-year lease is buying certainty, location, floor-plate efficiency, power reliability and green certification — and relocating a thousand-person engineering centre is enormously disruptive. That asymmetry is exactly what showed up when Brigade expected to re-let the vacated Amazon space at higher rates.
Supplier power concentrates in land. Construction inputs — cement, steel, contractors — are competitive and substitutable; Brigade has moved more construction in-house, which the CFO explained at the AGM raised the cost-of-materials line while improving cost-effectiveness and efficiency.7 Land is the genuinely scarce input, and landowners in prime Bengaluru micro-markets hold real bargaining power. The JDA structure is the industry's answer: instead of outbidding rivals in cash, share the upside. It converts a supplier into a partner, and it is the single most important reason Brigade can build a 57-million-square-foot residential land bank without a correspondingly enormous balance sheet.3
Threat of new entrants is bifurcated and moving in Brigade's favour. At the informal end, entry remains trivially easy — anyone with a plot and a contractor can build. At the organised end where Brigade competes, RERA compliance, escrow discipline, brand trust and access to institutional debt have raised the barrier substantially since 2016. The new entrants that matter are not startups; they are established developers from other regions entering Bengaluru with deeper pockets.
Substitutes are weak for physical office space in a supply-constrained market and meaningful for undifferentiated apartments. The remote-work substitution thesis has not played out in Bengaluru, where vacancy sits at a post-pandemic low and 4.66 million square feet of new supply in a quarter was absorbed against 5.59 million square feet of leasing.13 In residential, the substitute is simply another developer's identical two-bedroom apartment two kilometres away — which is why the integrated enclave, with its amenities and micro-environment, exists as a differentiation strategy.
Rivalry is intense and structurally differentiated. The five major listed South and pan-India peers each occupy a distinct position: Godrej Properties pursues pan-India scale through an almost entirely asset-light JDA model; Prestige is Bengaluru-headquartered but national and has re-accelerated dramatically; Sobha differentiates on in-house construction quality and carries Gulf exposure; Oberoi Realty is Mumbai-only, ultra-premium and debt-light. Brigade's position is the diversified regional incumbent with an unusually large annuity book relative to its size. That is a defensible niche. It is not a dominant one, and in a straight land auction against Godrej or Prestige, Brigade will usually be the one that walks away.
The net strategic read: Brigade's competitive position is strongest exactly where its revenue is smallest, and weakest exactly where its revenue is largest. That inversion is the company in a sentence.
XII. Current Risk Radar
Not every macro risk applies to a Bengaluru developer. These five do, and each has a specific transmission mechanism into the numbers.
Geographic concentration is the risk that contains all the others. With roughly 79% of ongoing residential saleable area and about half of leasing revenue in one city, a Bengaluru-specific shock — a regulatory change on floor-space index, a groundwater or lake-protection ruling affecting approvals, a downturn in GCC hiring, or a municipal approvals freeze — hits Brigade far harder than it hits a genuinely pan-India developer.8 Diversification is stated policy and slow practice. The FY26 land additions still ran 60% Bengaluru.3
Regulatory and political risk is no longer hypothetical. The Morgan Heights revocation demonstrated that a state authority can withdraw an already-granted environmental clearance on an under-construction project following civil-society pressure and a change in political posture.11 The mechanism is straightforward: environmental clearances in India are granted by state-level authorities whose composition and priorities shift with governments, and wetland and lake-buffer rules in fast-growing South Indian cities are being applied more aggressively than they were a decade ago. For a developer whose land bank sits in exactly the peri-urban belts where these disputes arise, this is a recurring cost of doing business, not a one-off. It should be underwritten as such.
Execution and approvals risk shows up directly in the pre-sales line. The FY26 miss traced to launches that could not open, not to apartments that would not sell — collections held roughly flat at ₹7,476 crore, which is a genuine indicator that existing buyers kept paying.3 That distinction matters: a demand problem shows up in collections and inventory, an approvals problem shows up in launches. So far the evidence supports the latter. Unsold inventory stood at 7.5 million square feet at the FY26 year end with conversion running 10-12% across cities.3
Refinancing and cost-of-capital risk is manageable but directionally worsening. The leverage doubling, the impaired equity currency, and the shift to a debt-funded capex programme combine into a single exposure: if pre-sales stay soft while ₹6,000 crore of commercial capex proceeds, the company will be carrying construction debt on unlet buildings during a period of weaker cash generation. The mitigant is that leasing debt is serviced by contracted rent from existing assets and that average borrowing cost has been falling.3 The trigger to watch is ICRA's published 2.5x debt-to-operating-cash-flow threshold.8
Tenant-mix concentration in the office book. The bull case for leasing depends on GCC demand, which at 58% of the leased portfolio is now the dominant tenant category.3 The chairman's own AGM warning about AI-driven caution among Indian IT companies is the near-term version of this risk; the longer-term version is that GCCs are a cost-arbitrage phenomenon, and cost arbitrage is exactly the sort of thing automation eventually compresses.7 There is no evidence of that happening yet — quite the opposite, given record 2026 leasing — but a landlord with 58% of its tenants in one demand category should be honest about the correlation.
Two risks that are frequently listed for Indian developers do not merit inclusion here. Data-centre and AI-driven demand disruption is not currently material to Brigade's residential, office and hospitality mix in either direction. And input-cost inflation, while real, has been offset by the shift toward in-house construction and by realisation gains that have outpaced construction cost increases.
XIII. Bear vs. Bull Case
The bull case
Start with the fact that reframes everything: a business generating more than half its segment EBITDA from annuity rent at roughly 70% margins is not the same animal as a homebuilder, and the market's blended multiple does not obviously distinguish between them.3 If Brigade's ₹6,000 crore commercial pipeline delivers the ₹800 crore of incremental rent management has indicated, the annuity book roughly doubles from here — and it does so in the tightest Grade-A office market in India, where a departing anchor tenant creates a rent increase rather than a rent cut.3
Second, the composition of the returns is better than the headline level suggests. A high-margin annuity book, not a leveraged development balance sheet, is what carries Brigade's roughly 9% return on equity — which means the return has a durable source and improves mechanically if the commercial pipeline lands.3
Third, the succession is structurally sound and the governance mechanism demonstrably works — a promoter-favourable capital action was proposed and reversed within two days under institutional pressure, which tells you the shareholder register has teeth.18
Fourth, the operating environment is favourable. Bengaluru absorbed about 27% of all Indian office demand in a single quarter of 2026 with vacancy at post-pandemic lows and rents rising, while the listed developer cohort grew pre-sales 17% as consolidation continued.132
Fifth, the balance sheet remains conservative in absolute terms — 0.26 to 0.27 net debt to equity, falling borrowing costs, and an ICRA AA rating — with the debt concentrated against income-producing assets rather than speculative inventory.1038
The bear case
The concentration is deepening, not diminishing. Management says diversification; capital allocation says Bengaluru. Until the share of pre-sales from Chennai and Hyderabad rises materially and stays there, the diversification story is an intention.
The guidance record now has a real blemish. Guided at 15-20% growth, delivered minus 5% — the first genuine test of the new leadership's target-setting, and it failed.4 The FY27 target of ₹9,000 crore requires more than 20% growth off a reduced base, which means the company has effectively promised to make up two years in one.3 It is doing so with a Chennai project of roughly ₹2,000 crore value under active legal challenge.11
Leverage doubled in a single year into a slowing sales environment, and the rating agency had explicitly named debt-funded land buying as a monitorable months earlier.9 Whether that reads as conviction or as inattention to a stated risk is a judgment call, but it is not a neutral fact.
There is no announced plan to unlock the leasing value. The sum-of-the-parts argument is analytically sound and corporately unfunded, and Brigade's one actual monetisation — the hotel listing — priced at a discount to the IPO band despite being oversubscribed 4.48 times.1514 That is direct, recent evidence that the market does not automatically pay up for Brigade's carve-outs.
And the last equity raise is under water by roughly a quarter after adjusting for the bonus issue, which constrains the funding options for a capital-intensive expansion and was the immediate backdrop to a governance episode the company would rather not have had.19201
Reading it through the 7 Powers
Hamilton Helmer's framework is useful here because it forces the question of which advantages are actually durable.
Scale economies: present but modest, and local. Brigade's 12-13% Bengaluru share buys contractor availability, approvals familiarity and land-sourcing relationships.9 It does not buy national purchasing power. Against Godrej Properties or Prestige at four times the market capitalisation, Brigade is subscale.
Switching costs: essentially absent in residential — a buyer who has not booked has zero switching cost — and genuinely present in office leasing, where relocating a large GCC is disruptive and expensive. This is the clearest single Power in the portfolio, and it maps precisely onto the segment generating most of the profit.
Branding: real, and better evidenced than most such claims. A century of family reputation, 100 million square feet delivered, more than 50,000 customers, and a national brand-leadership ranking are the ingredients.7 In an industry defined by counterparty risk, brand converts directly into price and velocity. It is also depletable by delivery failures.
Counter-positioning: none. Brigade does nothing structurally that Godrej, Prestige or Sobha could not imitate. The integrated-enclave model is copied widely; the annuity-plus-development mix is DLF's and Embassy's playbook too.
Cornered resource: partially, in the form of the specific contiguous land parcels Brigade assembled decades ago in what are now prime Bengaluru locations. Brigade Gateway could not be assembled today at any price. That is a genuine cornered resource, but it is a stock, not a flow — it does not renew itself.
Process power: unproven. In-house construction is being expanded, and the company claims cost and efficiency benefits, but there is no external evidence of a durable construction-cost advantage over Sobha, which has built its entire identity on in-house execution.7
Network economies: not applicable.
The honest synthesis: Brigade has one strong Power (switching costs in office leasing), one moderate and depletable Power (brand), one historical and non-renewing Power (legacy land), and four that are absent or unproven. The strong Power sits in the segment producing the majority of profit and the minority of revenue. That is a defensible investment argument. It is also a narrow one, and it depends on management continuing to feed the segment where the Power actually is.
The three KPIs that matter
Everything above compresses into a small number of published metrics.
First, pre-sales value against guidance. This is the leading indicator of the entire development business and the direct test of management credibility after the FY26 miss. The ₹9,000 crore FY27 target is the specific number.3
Second, leasing segment EBITDA and portfolio occupancy. This is where the profit lives. Occupancy tells you whether the annuity is holding as new supply completes; segment EBITDA tells you whether the ₹6,000 crore capex programme is converting into cash.310
Third, the share of pre-sales from outside Bengaluru. This is the single cleanest measure of whether stated diversification is real, and it directly addresses the largest structural risk in the equity story.
A reader tracking those three quarterly will know more about Brigade's trajectory than one tracking earnings per share.
XIV. Looking Forward: What Would Change the Story
Five things over the next eighteen to twenty-four months would materially revise the analysis in either direction.
Whether FY27 pre-sales actually reach ₹9,000 crore. This is the cleanest available test of whether the FY26 shortfall was timing or demand. Management has staked its explanation on approvals and launch scheduling, and it has a launch pipeline of 12.4 million square feet with ₹13,400 crore of gross development value across four quarters to prove it.10 Hitting the number would validate a specific, falsifiable claim and materially restore guidance credibility. Missing it twice would suggest something structural about either Brigade's approvals capability or its demand base, and would reset how every future target from this management team should be read.
Whether the Chennai clearance dispute resolves. Morgan Heights is roughly ₹2,000 crore of project value, and its outcome determines whether Chennai becomes a genuine second market or a cautionary tale.11 More broadly, the resolution will indicate how much regulatory risk should be priced into Brigade's peri-urban land bank generally.
Whether leverage stabilises as commercial capex proceeds. The company is deliberately borrowing to build annuity assets. If net debt to equity plateaus near current levels while rental income steps up, the strategy will have worked as designed. If it keeps climbing past the point where rent covers the increment, the ICRA downgrade trigger becomes live and the cost of the whole programme rises.8
Whether management ever articulates a plan to separately value the leasing portfolio. Nothing in the current disclosure suggests this is imminent. But it is the single largest potential re-rating event available to this company, and it would convert an analytical observation into an investable one. The hotel listing showed both the willingness and the pricing reality; an office REIT or listed vehicle would be a far larger test of both.
Whether Chennai, Hyderabad and Mysuru scale into a genuine third of the business. The FY27 launch plan is more balanced than the FY26 land buying, which sets up a natural experiment: if launches are distributed roughly evenly but bookings still cluster in Bengaluru, that tells you the brand does not travel as well as the company believes. If bookings follow launches, the diversification thesis gains real support.
There is also a question of what does not change. Brigade will remain a family-controlled company with a 41% promoter stake, a Bengaluru centre of gravity, and a capital structure that borrows against rent to build more rent.21 Investors underwriting this business are underwriting a specific set of assets in a specific city, run by a second generation four years into the job, in a sector where the largest listed players are pulling further ahead. That is a coherent proposition with identifiable ways to be wrong, which is more than can be said for many stories in Indian real estate.
XV. Recent News
Q1 FY27 results, reported August 2026. Consolidated revenue of ₹1,179 crore with EBITDA of ₹425 crore at a 36% margin — a sharp margin expansion driven by real estate development EBITDA margin reaching 21% against roughly 12% a year earlier. Pre-sales of ₹1,061 crore were 5% lower year on year, but average realisation rose 21% to ₹14,256 per square foot and cash collections rose 7% to ₹1,856 crore. Net debt stood at ₹2,218 crore with debt to equity at 0.26. Management reaffirmed the ₹9,000 crore FY27 pre-sales target, citing the launch pipeline.10
Warrant withdrawal, July 2026. The board approved and then withdrew, within two days, a ₹180.05 crore issue of 34.23 lakh convertible warrants to promoter entity Mysore Holdings Private Limited at ₹526 per warrant, following institutional and public investor feedback on dilution and pricing.18
AGM resolutions, August 2026. Shareholders considered the retained proposal to raise up to ₹1,500 crore through non-convertible debentures at the meeting held on August 13, 2026, alongside an increased borrowing limit.18
Bonus issue, June 2026. A 1:3 bonus issue — one new share for every three held — was implemented with a record date of June 17, 2026, expanding the share count by a third.20
Chennai environmental clearance revoked, May 2026. The State Level Environment Impact Assessment Authority withdrew the January 2025 clearance for Brigade Morgan Heights near Perumbakkam, citing the absence of wetland authority permission and proximity to the Pallikaranai marsh Ramsar site. Brigade contested the decision as legally unsustainable and pursued a legal challenge; the project remains under status quo.111210
FY26 results, May 2026. Full-year pre-sales of ₹7,424 crore were 5% below FY25 against guidance of 15-20% growth, with roughly 3.3 million square feet of launches deferred to FY27. Consolidated profit after tax was ₹725 crore on total income of ₹5,909 crore, and the board recommended a final dividend of ₹2 per share.34
Income Tax survey, December 2025. The Income Tax Department conducted a survey at Brigade's registered office and other locations between December 9 and 13, 2025. The company disclosed full cooperation, stated operations were unaffected, and reported that the financial impact, if any, remained undetermined.22
References
-
Brigade Enterprises Share Price Today — Live NSE: BRIGADE Stock Price & Chart — Kotak Neo, 2026-09-01 ↩↩↩↩↩
-
India's 28 big listed realty firms clock ₹1.95 trn pre-sales in FY26 — Business Standard, 2026-06-24 ↩↩↩↩↩
-
Brigade Enterprises Limited (BRIGADE) Q4 2026 Earnings Call Transcript — AlphaStreet, 2026-05-07 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Brigade Enterprises FY26 Pre-Sales Dip 5% to ₹7,424 Crore on Delays in Fresh Supply — Outlook Business, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩
-
Brigade Enterprises Integrated Annual Report 2024-25 — Brigade Group, 2025-07-27 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Brigade Enterprises Limited 30th Annual General Meeting Transcript — Brigade Group, 2025-08-21 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Brigade Enterprises Limited: Long-term rating upgraded to [ICRA]AA (Stable) — ICRA, 2025-07-31 ↩↩↩↩↩↩↩↩↩↩↩
-
Rating Rationale — Brigade Enterprises Limited — CRISIL Ratings, 2025-03-28 ↩↩↩↩↩
-
Brigade Enterprises Limited (BRIGADE) Q1 2027 Earnings Call Transcript — AlphaStreet, 2026-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Vijay govt halts Rs 2,000-crore housing project in Chennai after environment clearance revoked — ThePrint, 2026 ↩↩↩↩↩↩
-
Brigade Challenges Revocation of Chennai Project Clearance — Construction World, 2026 ↩↩
-
Bengaluru Office Market Overview Q2 2026 — Meraqi Advisors, 2026 ↩↩↩↩
-
Brigade Hotel Ventures IPO ends with 4.48x subscription — Business Standard, 2025-07-29 ↩↩↩
-
Brigade Hotel Ventures lists at Rs 81 on NSE, nearly 10% below IPO price — Business Upturn, 2025-07-31 ↩↩↩↩↩↩
-
Brigade Hotel Ventures: Funds Used As Planned, Audit Flags Co-mingling — Whalesbook, 2026 ↩↩
-
Pavitra Shankar appointed as MD for Brigade Enterprises — RealtyNXT, 2022-10-11 ↩↩
-
Brigade Enterprises withdraws proposed ₹180 crore promoter warrant issue following investor feedback — Sahi, 2026-07-17 ↩↩↩↩↩↩↩↩
-
Brigade Enterprises raises Rs 1,500 crore by selling shares via QIP — Business Standard, 2024-09-06 ↩↩↩
-
Brigade Enterprises Fixes June 17 Record Date For 1:3 Bonus Share Issuance — Sahi, 2026 ↩↩↩
-
Brigade Enterprises Shareholding Pattern 2026 — Choice India, 2026 ↩↩
-
Brigade Enterprises Faces Income Tax Survey, Operations Unaffected — TipRanks, 2025-12 ↩↩
-
Sobha Share Price Today — Live NSE: SOBHA — Kotak Neo, 2026-09-02 ↩
-
Godrej Properties Share Price Today — Live NSE: GODREJPROP — Kotak Neo, 2026-09-02 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube