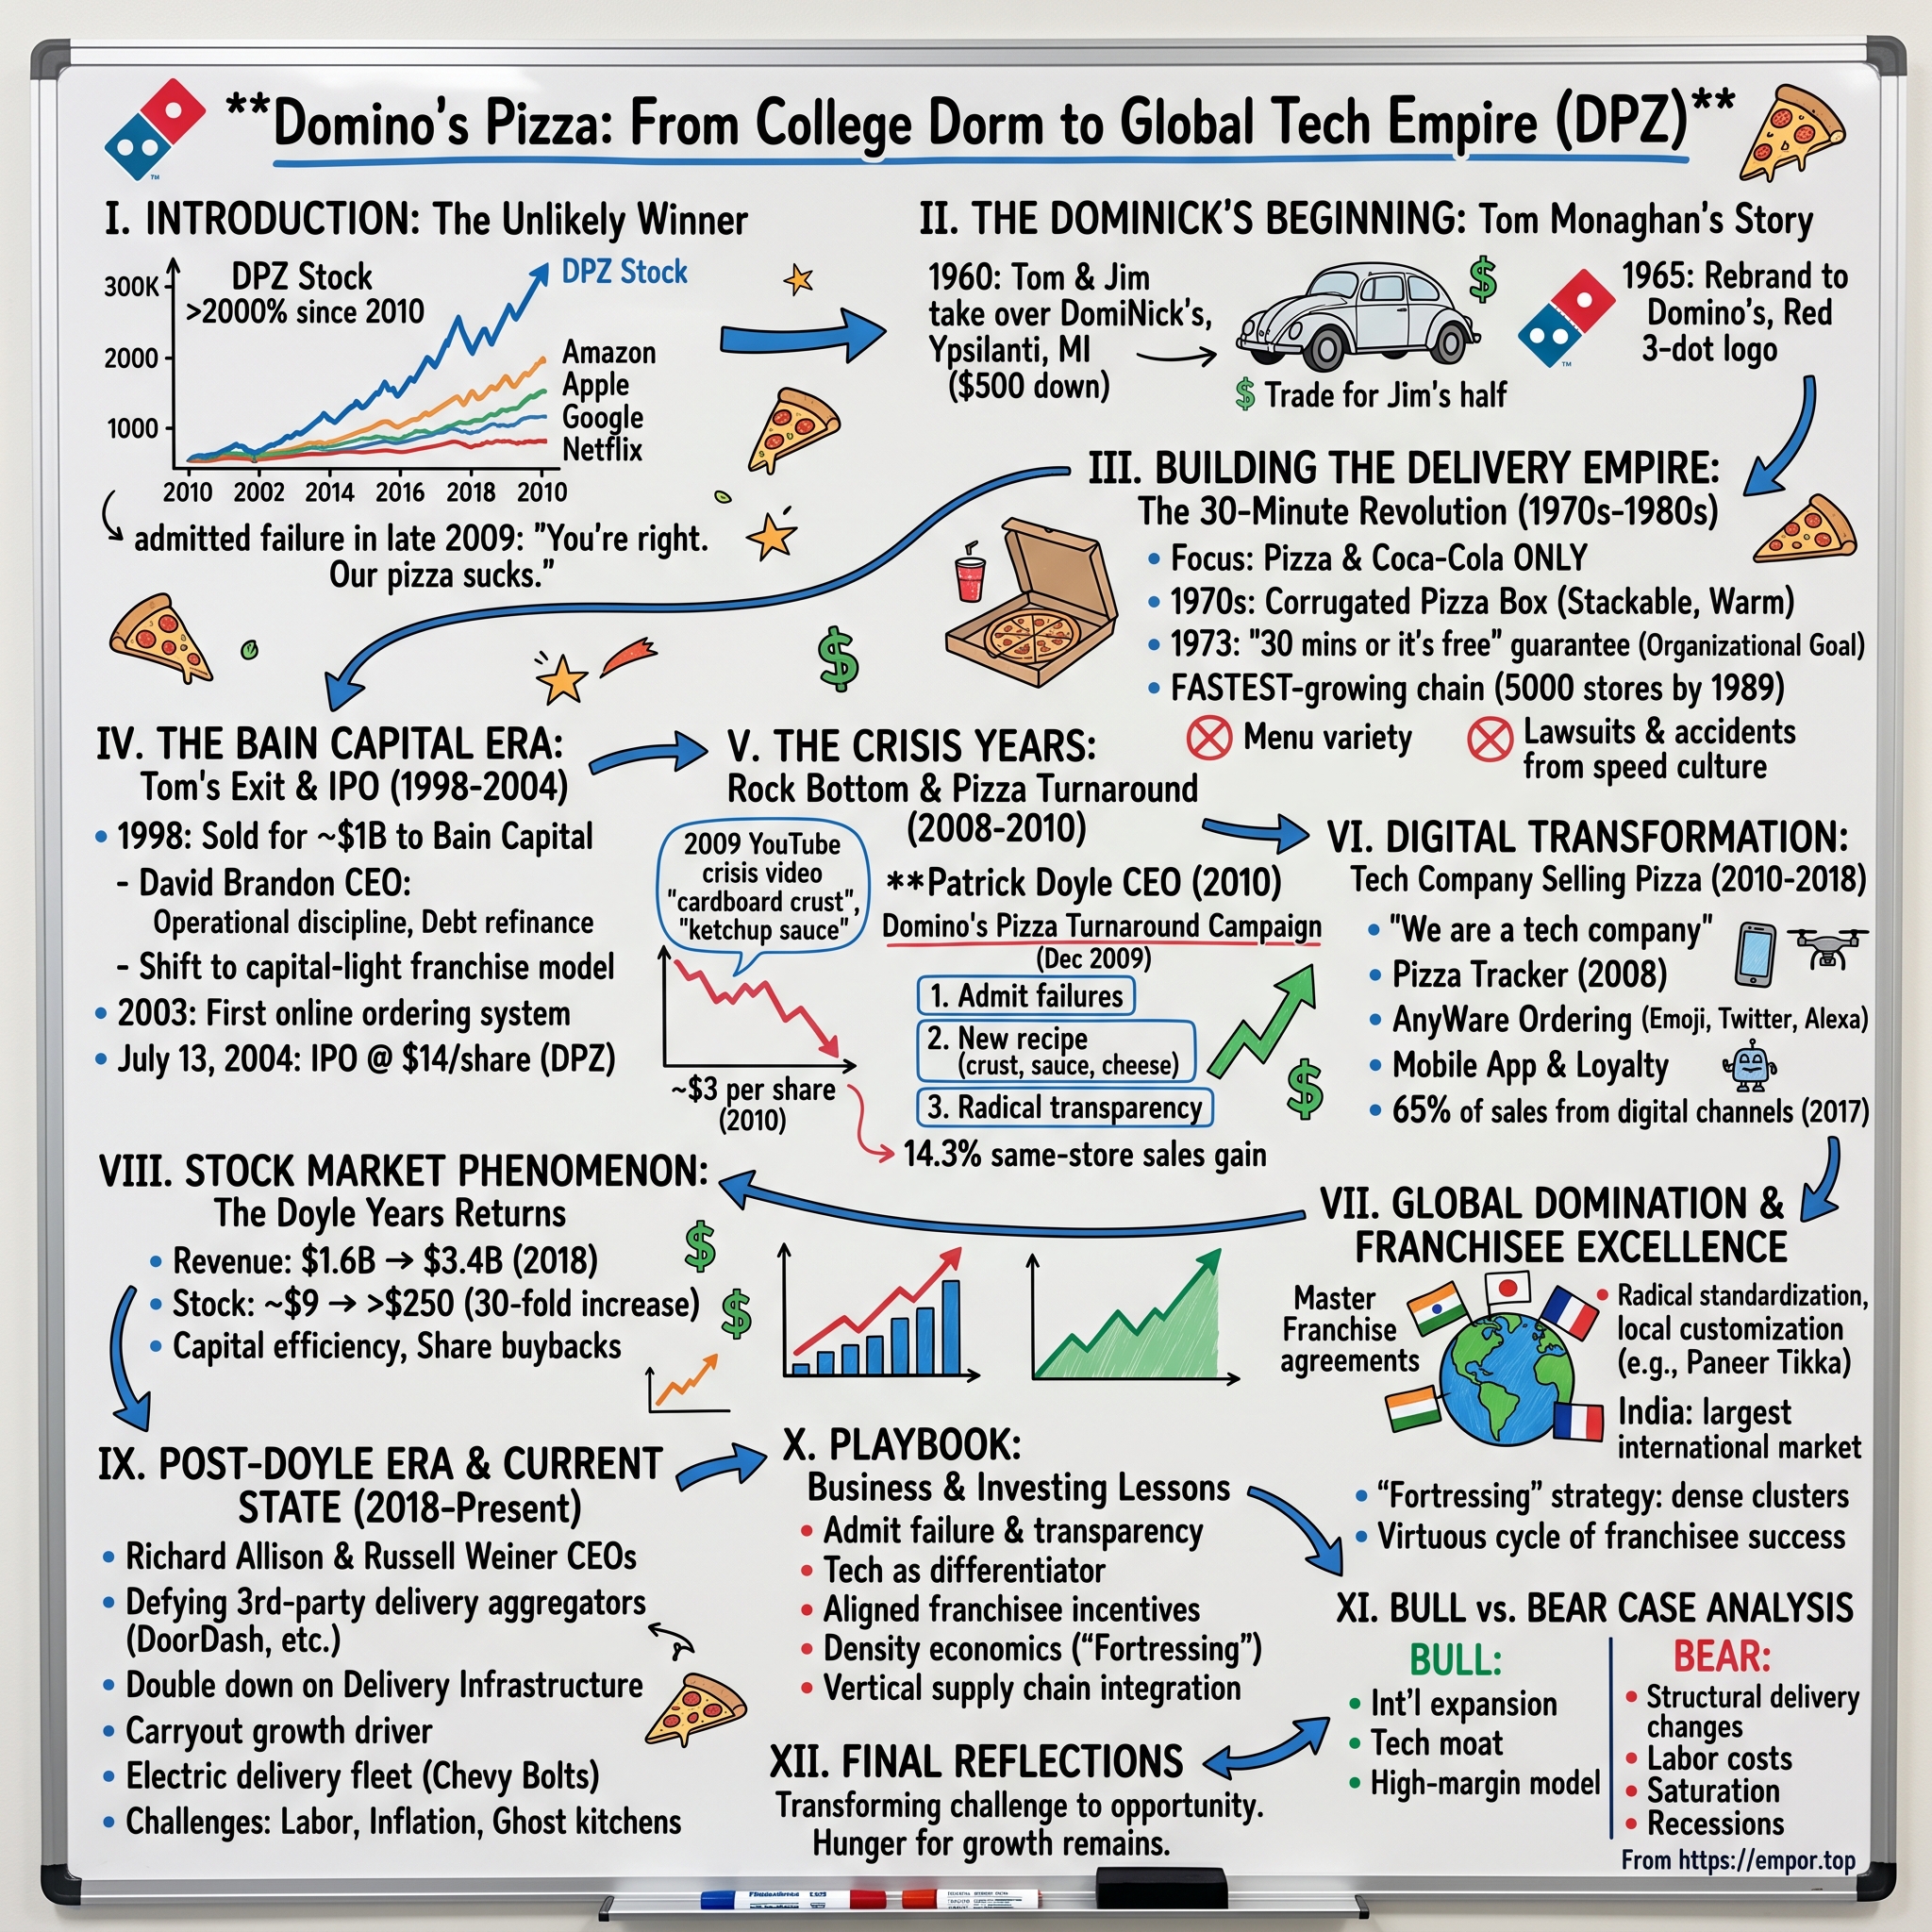
Domino's Pizza: The Dough-Driven Cash Machine and Tech-Powered QSR Empire
I. Introduction & Thesis: The $5B Pizza Supply Chain Disguised as a Fast-Food Chain
Walk into a Domino's store on a Friday night and the front-of-house operation looks like standard fast-food theater: an employee stretching dough on a flour-dusted counter, a conveyor oven running continuously, and a driver carrying an insulated bag to a delivery car. What remains hidden is the business segment that generates the majority of the company's revenue.
That dough ball arrived on a refrigerated truck from one of roughly two dozen company-owned manufacturing and distribution centers. It moved on a software-scheduled route and was sold to the franchisee at a markup alongside cheese, sauce, boxes, napkins, and equipment. The franchisee paid for the entire invoice, which Domino's Pizza, Inc. recorded as revenue. And that single line item — supply chain — has for years accounted for the clear majority of the company's consolidated revenue, a proportion visible on the face of its segment disclosures in every annual report.1
This structural distinction defines the economics of Domino's Pizza, Inc. (DPZ). While the consumer brand sells pizza, the parent corporation operates primarily by selling inputs to franchisees and collecting royalties on their sales. In practice, the business functions as a food distributor paired with a licensing model rather than a traditional restaurant operator. These economics — high returns on invested capital, franchisee-funded unit expansion, and fee streams scaling with systemwide sales rather than corporate headcount — produced notable long-term equity returns: from its July 2004 listing at $14.00 a share through its peak, Domino's compounded at a rate that beat many major technology names of the same era.2
That historical performance established a reputation for capital efficiency, but its core growth drivers require careful examination. The factors that supported growth over two decades — proprietary delivery speed, a strict anti-aggregator policy, store-fortressing strategies that added locations to existing markets, and an expanding international master-franchisee network — have each faced structural challenges. Drivers migrated to gig platforms, franchisees resisted local market cannibalization, a master franchisee liquidated an entire national market, and in 2023 Domino's abandoned the anti-aggregator position it had defended for fifteen years.
The analysis that follows examines this operational and financial trajectory: how a single college-town shop in Michigan grew into the world's largest pizza delivery network; how whole-business securitization reshaped the balance sheet and what that leverage costs as interest rates shift; how Patrick Doyle's public product overhaul became a textbook consumer brand turnaround; how the supply chain profit-sharing mechanism aligns franchisee incentives; and what Russell Weiner's "Hungry for MORE" plan promises when measured against verifiable execution. Throughout, factual claims are evaluated directly against disconfirming operational evidence.
The company's evolution begins with two brothers, a struggling store, and a used car.
 Subscribe on LinkedIn
II. The Origins & Dominick's Genesis (1960–1998)
In 1960, Tom Monaghan was a University of Michigan dropout when he and his brother Jim bought a small pizzeria called DomiNick's in Ypsilanti, Michigan. They paid $500 down and assumed $900 in debt — a modest sum even for the era. Monaghan had spent part of his childhood in orphanages and foster homes, served a stint in the U.S. Marine Corps, and dropped out of architecture school. Operating a pizzeria began as a matter of immediate circumstance rather than a grand corporate strategy.
Within months, Jim grew tired of the grueling hours. In 1965, he traded his half of the business to Tom for the store's delivery vehicle — a used Volkswagen Beetle. The trade remains a central piece of company lore, illustrating how little even its founders foresaw the enterprise's potential scale.
What Monaghan did next set the company's operational trajectory: he focused not on marketing, but on operational subtraction.
The radical menu cut. Monaghan examined early-1960s pizzeria economics — sit-down seating, sub sandwiches, lengthy menus, and unpredictable preparation times — and eliminated most of them. He removed dining rooms and side items to focus strictly on pizza delivery and carryout. While competitors viewed menu variety as essential to driving volume, Monaghan narrowed the product line so that small store crews could produce consistent output at speed. The target customer naturally followed from this operational constraint: college campuses and nearby dormitories filled with dense populations of students lacking kitchens and cars.
The box. At the time, delivered pizza traveled in thin chipboard cartons that sagged, collapsed, and trapped steam, ruining crust texture. Domino's introduced a rigid corrugated cardboard box that held its shape when stacked while providing superior insulation. The innovation was critical to delivery economics: stackable boxes enabled a single driver to deliver five orders per trip instead of one, improving route efficiency. It marked an early example of the company's operational playbook: isolate a key constraint, engineer a practical solution, and allow lower unit costs to drive competitiveness.
The name and the dots. The business rebranded as Domino's Pizza in 1965. The three red dots on its new logo represented the company's first three locations. Monaghan originally intended to add a dot for every new store opened, a practice quickly abandoned as the footprint expanded past 200 stores in 1978 and into the thousands during the 1980s.
"30 Minutes or It's Free." Introduced in 1973, the delivery guarantee became a powerful consumer marketing tool, though it introduced operational liabilities the company had not fully priced. The guarantee gave the brand a clear value proposition while establishing a strict internal operational benchmark. Order preparation, bake times, route planning, and staffing schedules were all engineered around a precise time target.
However, the financial and human costs of that incentive structure eventually caught up with the model. Delivery drivers operating under strict time limits faced heightened accident risks, leading to legal liabilities. In 1993, after a jury awarded $78 million in damages following a severe accident involving a delivery driver, Domino's ended the 30-minute guarantee in the United States. The brand's primary growth driver was dismantled because its core incentive structure compromised public safety.
That failure established a recurring theme in Domino's corporate history. The company repeatedly built competitive advantage by optimizing a single operational variable — first delivery speed, later digital platform dominance, and eventually store density — only to discover that extreme optimization shifts external costs onto drivers, franchisees, or the balance sheet. Eliminating the guarantee forced a strategic pivot toward overall system consistency. By the late 1990s, Monaghan was ready to step back from the mature empire he had built, setting the stage for institutional investors to acquire the business.
Internal franchisee recruitment. Another foundational policy from the Monaghan era shaped the company's long-term operating culture and capital structure. Monaghan franchised early and almost exclusively to internal store managers. Rather than selling franchises to passive financial investors seeking yield, Domino's built a network of operators who had proven their ability to manage stores on the ground. This internal promotion pipeline generated a resilient base of multi-unit franchisees with hands-on technical expertise and deep commitment to brand standards. Concurrently, it created a politically powerful franchisee constituency — a dynamic that would create friction in later decades when corporate leadership sought to split existing store territories to increase market density.
Monaghan's tenure also left a distinct corporate culture tied to personal ownership. Under his leadership, corporate funds often reflected personal passions, including classic car collections, professional sports franchises, custom architecture, and extensive philanthropic projects. The business operated around a founder's preferences rather than a formal capital allocation framework. When Bain Capital acquired a controlling stake in 1998, it introduced rigorous corporate financial discipline, requiring every dollar of free cash flow to be evaluated against competing investment returns — a standard practice across public companies that marked a major operational shift for Domino's.
III. Private Equity, the 2004 IPO, & Capital Structure Innovation (1998–2008)
The 1998 sale of a roughly 93 percent controlling stake to Bain Capital for approximately $1.0 billion marked a straightforward leveraged buyout of a mature franchised asset. In practice, it transformed Domino's from a founder-led enterprise into an engine of financial engineering.
Bain's contribution was institutional rather than culinary. The firm centralized supply chain operations, standardized franchise management, and reframed the core economics of the business: a franchise royalty stream is less like restaurant cash flow and more like a bond. It is contractual, senior to franchisee operating profits, directly tied to systemwide sales, and requires minimal capital to maintain.
That conceptual reframing became the foundation for the company's subsequent capital markets strategy.
The listing. Domino's Pizza, Inc. went public on July 13, 2004, on the New York Stock Exchange under the ticker DPZ, pricing at $14.00 a share and raising roughly $339 million at an initial market capitalization near $1.0 billion.2 (The listing later transferred to NASDAQ.) The public offering generated modest initial enthusiasm. In 2004, investors generally viewed pizza delivery as a low-growth, highly commoditized category driven by discounting — a description that aligned with market realities at the time.
Whole-business securitization. The capital structure Domino's subsequently pioneered in the restaurant sector represents a key structural mechanism in its financial model.
Unlike a conventional corporate bond where investors lend against a company's general corporate credit, a whole-business securitization isolates a company's most predictable cash-generating assets. Domino's placed substantially all of its franchise royalty streams, intellectual property—including trademarks and recipes—and supply chain assets into bankruptcy-remote subsidiaries. Those subsidiaries then issued debt secured directly by those cash flows. Because the collateral is contractual and diversified across thousands of stores, rating agencies evaluate the debt similarly to structured-finance instruments rather than corporate loans. This structure allowed Domino's to secure larger borrowing capacity at lower fixed interest rates and longer maturities than its corporate balance sheet alone would justify.
In essence, the model mortgages the royalty stream rather than the operating company. The critical trade-off lies in debt covenants: if systemwide sales or cash flows fall below specified performance thresholds, cash becomes trapped within the securitization entity and cannot be distributed to corporate equity holders. Lenders grant lower borrowing costs precisely because they maintain strict priority claims.
What the leverage was used for. Rather than funding acquisitions or diversifying into adjacent restaurant brands—a strategy that led competing franchisors toward write-downs—Domino's directed its debt proceeds primarily toward share repurchases. Over two decades, aggressive share buybacks sharply reduced the diluted share count. Coupled with an invested-capital base minimized by the franchise model, this strategy generated industry-leading returns on invested capital and drove earnings-per-share growth well above underlying operating income growth.
However, this financial architecture relies on interest-rate stability and steady cash-flow predictability. Total debt stood near $4.8 billion entering 2025, a figure that must be evaluated against the company's modest physical asset base rather than a traditional industrial balance sheet.1 When interest rates rose sharply between 2022 and 2024, the financial dynamics of the prior decade shifted: low-coupon debt required refinancing at materially higher rates, and each additional dollar of interest expense directly reduced funds available for share repurchases. Chief Financial Officer Sandeep Reddy's focus on refinancing efficiency during this period highlighted management's effort to navigate a genuine capital constraint.
Whole-business securitization is not a permanent competitive advantage; it functions as an amplifier. It accelerates equity returns when store-level cash flows expand predictably, but intensifies downside pressure when growth stalls, because fixed debt obligations remain constant while underlying cash flows fluctuate. Domino's confronted this reality when its operational performance faltered in the late 2000s.
The pre-crisis operational breakdown. Between the 2004 listing and the 2008 financial crisis, Domino's executed standard franchisor playbooks: expanding store counts, refinancing debt, and repurchasing shares. However, operational focus on delivery speed came at the expense of product quality. To maintain sales volumes, the company relied heavily on promotional discounting. In a consumer category with low switching costs, heavy discounting creates a sticky expectation, as customers accustomed to promotional pricing resist buying at full menu rates. By 2008, Domino's relied on discounted volume, same-store sales turned negative, and its debt-heavy balance sheet was structured around cash flows that failed to materialize as credit markets froze.
This convergence of high leverage, deteriorating product perception, and tight credit liquidity drove Domino's stock down to approximately $3 per share in early 2009. The episode serves as a critical case study for evaluating the company's capital structure: when store-level cash flows contract, fixed debt obligations amplify equity drawdowns far more than proportionally.
IV. The Patrick Doyle Transformation & Digital Blueprint (2008–2018)
As Domino's stock collapsed toward roughly $3 a share in early 2009, macroeconomic pressures during the financial crisis were compounded by severe product dissatisfaction that corporate research laid bare.
In consumer taste tests and focus groups, Domino's pizza consistently ranked at or near the bottom among national quick-service chains. Participant feedback was unusually candid: respondents described the crust as tasting like cardboard and the sauce like ketchup, with one participant remarking that the pizza tasted as if it were made from the packaging itself. After four decades of optimizing delivery speed and logistics, the company had underinvested in product quality.
Patrick Doyle assumed the role of CEO in March 2010, and his management team used that negative feedback to anchor a comprehensive operational pivot.
The apology. Most consumer brands facing similar feedback reformulate quietly and launch conventional promotional campaigns. Domino's took the opposite approach. The 2010 "Pizza Turnaround" campaign broadcast focus-group footage directly on national television, highlighting actual customers criticizing the food alongside company chefs acknowledging recipe flaws. Simultaneously, Domino's overhauled its core product, introducing a garlic-and-herb-seasoned crust, a sweeter tomato sauce, and shredded mozzarella to replace the previous cheese blend.
The financial response was immediate. Domestic same-store sales surged 14.3% in the first quarter of 2010. In a mature system of approximately 5,000 domestic locations, a quarterly gain of that magnitude indicated that lapsed customers were returning en masse rather than new buyers discovering the brand for the first time. The campaign succeeded because brand awareness was already high, and the transparent admission of past product shortcomings created an opening to regain customer trust.
However, public candor succeeded only because it was backed by a genuine product overhaul; an identical campaign attached to a minor reformulation would have likely accelerated brand erosion.
The software company that sold pizza. The second phase of Doyle's tenure focused on building proprietary technology capabilities. Domino's chose to develop its order management software internally rather than license third-party platforms — an investment that appeared costly in 2008 but created a distinct operational advantage by 2015.
The Pizza Tracker, introduced in 2008, displayed a visual progress bar tracking an order from preparation and baking to quality checks and dispatch. While often viewed as a consumer novelty, the tool addressed a key friction point in food delivery: customer uncertainty during the waiting window. Rather than speeding up prep times, the tracker made the fulfillment process visible, reducing inbound call volumes and freeing store staff to focus on order assembly.
Domino's subsequently expanded its digital access points under the "AnyWare" initiative, enabling orders through mobile applications, text messaging, smartwatches, voice assistants, connected vehicles, and a streamlined single-click application. Beneath these marketing features sat a unified order engine linking customer profiles with saved addresses, payment methods, and default orders. By 2017, digital channels generated more than 65% of U.S. systemwide sales, outpacing digital adoption rates at major competitors such as Pizza Hut and Papa John's.
This digital footprint generated a detailed customer dataset, providing Domino's with direct visibility into purchasing frequency, product preferences, and price sensitivity. Controlling the customer relationship end-to-end served as the primary rationale for refusing to partner with third-party delivery aggregators for nearly fifteen years. Yet the capital that funded this digital infrastructure was ultimately sustained by the cash flows of the underlying distribution network.
The limits of the digital claim, stated while the claim is still fresh. The strategic value of Domino's digital advantage was subject to two major structural constraints. First, proprietary ordering software represented an early-mover advantage that eventually commoditized. By the early 2020s, mobile ordering, saved user profiles, and real-time delivery tracking became standard baseline features across the industry, offered through internal IT platforms or provided directly by third-party delivery marketplaces at no upfront cost to competing chains. Domino's maintained a multi-year lead, but as competitors caught up, the software alone no longer provided a defensible moat.
Second, the strategic value of the customer dataset was contingent on maintaining exclusive control over every transaction. The decision in 2023 to partner with third-party aggregators partially compromised that exclusivity. For years, executive leadership argued that protecting customer data justified foregoing incremental aggregator order volume. When labor shortages and shifting consumer habits eventually forced a strategy shift, management demonstrated that incremental order volume was ultimately prioritized over complete data exclusivity.
Doyle stepped down as CEO in 2018 following a period of substantial market capitalization growth, leaving successor Russell Weiner — who had led the 2010 turnaround marketing strategy — to manage the operating model. Yet neither product reformulations nor digital interfaces represented the primary profit engine of the enterprise.
V. The Core Economic Engine: Supply Chain Vertical Integration & Franchisee Economics
At three in the morning in an industrial park outside a mid-sized American city, an industrial mixer turns flour, water, and yeast into dough at a commercial scale. The dough is portioned, chilled, trayed, and loaded onto refrigerated trucks scheduled to reach dozens of stores before the lunch rush. Inside Domino's headquarters, this operation is recognized for what it is: food manufacturing and cold-chain logistics, representing the company's largest business segment by revenue.
The three segments, and what each actually is.
The supply chain segment operates roughly two dozen dough manufacturing and distribution centers across the United States and Canada. Generating annual revenue of $2.9 billion to $3.0 billion, it accounts for well over half of consolidated revenue.1 Its operating margin is thin by franchisor standards — functioning as a distribution business with single-digit to low-double-digit margins — but it provides the operational backbone for the entire system.
The U.S. stores segment reflects the classic franchisor model: collecting royalties of roughly 5.5% of sales from several thousand franchised locations, alongside the operating results of a small estate of company-owned stores maintained primarily as testing laboratories and training facilities rather than profit drivers.
The international franchise segment represents the company's highest-margin cash flow: a royalty of roughly 3% of sales collected from master franchisees who operate the vast majority of the global store count, requiring virtually no corporate capital deployment by Domino's itself. Though it generates a relatively small portion of consolidated revenue, it delivers a disproportionate contribution to total operating profit.1
The 50/50 mechanism. A structural feature distinguishing Domino's from most quick-service franchise systems is its profit-sharing arrangement: Domino's returns 50% of the pre-tax profits from its domestic supply chain centers to participating U.S. franchisees.
This arrangement defuses a historic source of friction in franchise models. In many systemwide networks, franchisor-mandated supply chains create ongoing conflict, as franchisees suspect corporate headquarters of marking up ingredients to extract profit — tension that led to prolonged litigation at chains such as Papa John's and Subway. By sharing half of distribution profits, Domino's aligns franchisee incentives. Franchisees are motivated to purchase more inputs through the corporate supply chain and support distribution efficiency, knowing that operational savings increase their own rebate checks.
For investors, the secondary effect is significant: it creates highly sticky supply chain revenue without relying on coercive contracts. Franchisees buy virtually all their ingredients through Domino's because net-of-rebate pricing remains competitive, and sourcing elsewhere means forfeiting the rebate. This financial incentive provides a more durable foundation than a supply mandate enforced through legal compliance.
It also creates an accounting nuance: reported supply chain margins understate the total economic rent generated by the system while overstating standalone corporate profit extraction — a distinction that must be factored in when comparing Domino's segment margins against conventional distributors.
Store-level economics. A standard U.S. Domino's store generates average annual unit volumes of $1.3 million to $1.5 million from a compact operational footprint. Initial build-out costs range from $350,000 to $500,000 — significantly below the $2 million or more required for a traditional drive-thru quick-service restaurant with a large site footprint. Store-level cash EBITDA of $140,000 to $170,000 implies approximately a three-year payback period on invested capital.
This rapid payback period serves as the primary engine of systemwide expansion: Domino's does not fund its own store growth; its franchisees do. An attractive three-year cash return encourages existing operators to build additional units, allowing unit expansion to be financed by third-party franchisee capital while corporate Domino's collects royalty and supply chain revenue on every new store from its opening day. This capital-light dynamic drives the company's high returns on invested capital.
However, that payback calculation depends directly on store-level input costs, which faced severe headwinds in the early 2020s. Spikes in agricultural commodity prices, particularly cheese, coincided with rising delivery-driver wages driven by gig-platform labor competition. As store profitability compressed, franchisee appetite for new unit development slowed accordingly — demonstrating how store-level margin compression directly impacts systemwide expansion.
Why the supply chain is a moat and not merely a business. The competitive moat provided by the supply chain rests on specific structural dynamics rather than broad economies of scale.
While a regional sixty-unit pizza chain purchases cheese through third-party distributors, Domino's buys directly from dairy producers in volumes that allow it to operate as an institutional counterparty. This scale enables forward contracting, hedging, and pricing terms unavailable to smaller operators. Domino's then manufactures its own dough internally, capturing the manufacturing margin. Finally, it operates a dedicated fleet along delivery routes dense enough to minimize the marginal cost of adding store stops — an efficiency further enhanced by market fortressing. Stacked across the entire bill of materials for thousands of stores, these incremental savings compound into a structural cost baseline that smaller competitors cannot match through operational execution alone.
This cost position manifests directly in menu pricing. When Domino's runs national price promotions, it exercises an underlying cost advantage rather than sacrificing unit margins to acquire customer traffic. In an industry with low switching costs, this structural supply chain efficiency remains one of the brand's most durable competitive assets.
The counter-argument an analyst should put to it. Capital-intensive vertical integration introduces substantial fixed operating leverage. Operating two dozen distribution facilities, a truck fleet, and dedicated supply chain staff creates fixed overhead that operates in both directions. During periods of declining order volume or store closures, fixed facility costs do not decline alongside revenue, and the segment's narrow percentage margin offers little buffer before operating income contracts. Consequently, the same vertical integration that drives cost advantages during growth cycles amplifies profit drops when domestic order volume weakens.
Furthermore, consolidated accounting dynamics warrant careful interpretation. Because supply chain revenue reflects gross ingredient sales while rebates are distributed separately, top-line revenue growth can be inflated by commodity price inflation passed along to franchisees. In such periods, reported revenue rises because raw material costs increased, not because order volumes expanded. For this reason, global systemwide retail sales growth — rather than consolidated corporate revenue — serves as the primary metric for evaluating underlying business growth.
VI. Current Management & Strategy: Russell Weiner and "Hungry for MORE" (2022–Present)
When Russell Weiner presented a five-year growth plan to analysts in December 2023, he brought decades of brand experience to the stage. Weiner had joined Domino's in 2008 as chief marketing officer, leading the brand's transparent turnaround campaign, before serving as president of Domino's USA and chief operating officer prior to his appointment as chief executive officer in July 2022.[^3]
That career path marks a distinct profile for a quick-service restaurant executive. Rather than a finance professional managing a corporate portfolio or an operational lead inheriting another team's marketing, Weiner directed the company's brand strategy before assuming responsibility for operations and capital allocation. While that institutional background provides deep operational continuity, a long-serving executive may also face structural resistance to dismantling legacy strategies—a dynamic demonstrated when Domino's reversed its long-standing anti-aggregator policy only after severe labor constraints forced a strategy shift.
Sandeep Reddy joined as chief financial officer in April 2022, following financial leadership roles at Six Flags and Guess?. In earnings commentary, Reddy focused on supply chain procurement productivity, strict expense discipline, and managing refinancing schedules across the company's securitization debt stack. Executive incentive compensation targets global retail sales growth, operating income growth, and return on invested capital (ROIC)—three key metrics for an asset-light franchisor, as retail sales generate both royalty and supply chain revenue while ROIC limits unaccretive capital expansion. Investors should verify exact metric weightings and executive shareholdings in annual proxy disclosures rather than relying solely on executive commentary.3
"Hungry for MORE." During the December 2023 investor day, management outlined long-term annual targets for the 2024–2028 period: at least 7% global retail sales growth, 8% operating income growth, and 10% earnings-per-share growth.[^5] The spread among those figures reflects the company's financial model. Operating income is designed to outpace top-line sales through supply chain productivity gains and an expanding franchise mix, while earnings per share is intended to outpace operating income through continuous share repurchases. Approximately two percentage points of the targeted earnings-per-share growth rely not on expanding pizza sales, but on contracting corporate equity.
Evaluating the individual components of the strategy against operational evidence highlights key execution mechanics:
M — Most Delicious Food. Product initiatives include Pepperoni Stuffed Cheesy Bread, Parmesan Bites, and the "Emergency Pizza" loyalty promotion. These offerings function primarily as tools to drive ticket size and order frequency rather than create distinct product categories. Performance is reflected in same-store sales composition, carrying the risk that limited-time promotional gains recede once marketing pushes end.
O — Operational Excellence. The central operational initiative is DomOS, a cloud-native store operating system replacing legacy point-of-sale and back-of-house software while integrating predictive demand forecasting. Rather than store managers estimating prep volume intuitively, the system projects store-level hourly demand to guide dough preparation. Underestimating demand creates service bottlenecks during peak windows, while overestimating leads to product waste—both of which create continuous margin leaks across thousands of locations. Operational benefits should materialize through improved store margins and faster delivery times, though external verification remains unproven until franchisee financial metrics demonstrate sustained improvement.
R — Renowned Value. Domino's restructured its loyalty program by lowering the earning threshold to transactions starting at $5. The change aimed to capture carryout traffic and smaller orders during periods of consumer price sensitivity. However, loyalty economics involve tradeoffs: while a lower hurdle expands the active member base, it can also dilute margins by rewarding transactions that customers would have completed without an incentive.
E — Enhanced by Best-in-Class Franchisees. Management established a long-term goal of 50,000 global stores alongside an annual store-level franchisee cash profit target near $170,000.[^5] The store-count objective represents a broad directional target, whereas franchisee profitability serves as the decisive operational benchmark governing whether store operators continue reinvesting capital into unit expansion.
The aggregator capitulation. For fifteen years, Domino's maintained a strict policy against third-party delivery marketplaces. Executive leadership routinely argued that joining platforms like DoorDash or Uber Eats would compromise customer transaction data, impose margin-diluting commissions, and surrender control over final-mile delivery.
Persistent delivery-driver shortages and shifting consumer habits eventually rendered that stance unviable. In July 2023, Weiner announced a global agreement with Uber, listing Domino's menu on Uber Eats and Postmates while keeping order fulfillment strictly with Domino's delivery drivers.4 This hybrid structure allowed Domino's to capture incremental order demand from aggregator user bases while retaining control over customer interaction and fulfillment quality. Management projected the U.S. market opportunity at approximately $1 billion in incremental annual retail sales.
The partnership reflected operational pragmatism under changing market conditions, but it also highlighted the boundaries of Domino's proprietary delivery network. Had the company's internal delivery logistics provided an impenetrable competitive moat, partnering with third-party aggregators would not have been required to sustain order volume growth.
Reading the plan as a promise rather than a slide. The long-term metrics outlined in the five-year plan provide clear benchmarks for evaluating management performance over the 2024–2028 horizon.
Achieving these targets requires navigating two structural challenges. First, expanding operating income faster than systemwide retail sales demands multi-year margin expansion through supply chain productivity, favorable international growth mix, and corporate operating leverage. Sustaining cost efficiencies over extended periods grows increasingly difficult as initial productivity gains are realized. Second, reaching the targeted earnings-per-share growth relies heavily on continuous share buybacks, which remain sensitive to prevailing borrowing costs in the securitization market.
Franchisee health as the hinge. Ultimately, store-level franchisee economics determine the plan's viability. If unit cash profits approach management's target, franchisees are incentivized to deploy capital into new store development, driving retail sales, supply chain throughput, and corporate royalty fees. Conversely, if franchisee margins remain under pressure, unit expansion slows regardless of corporate strategic initiatives. As a result, store-level cash profitability serves as the primary leading indicator for evaluating Domino's broader multi-year growth trajectory.
VII. Competitive Landscape, Industry Structure, & Strategy Stress-Test
Pizza is the most structurally competitive category in quick-service dining for a fundamental reason: entry barriers require little more than an oven and a commercial lease. Every neighborhood in America features independent pizzerias producing items many local consumers prefer at prices national chains cannot always undercut. What national chains sell is not necessarily superior pizza, but reliability, speed, predictable pricing, and — historically — the standard infrastructure for hot food delivery.
The field. Domino's leads the category on scale, generating over $18 billion in global retail sales and holding the largest market share in U.S. quick-service pizza. Yum! Brands' Pizza Hut operates a global store footprint of comparable size but generates lower sales volume, burdened by a legacy dine-in footprint and a slower transition to digital ordering. Papa Johns competes on ingredient marketing with roughly a quarter of Domino's global retail sales, constrained by smaller supply chain scale and historical franchisee friction. Privately held Little Caesars attacks from the value end with a carryout-only, hot-and-ready model requiring no delivery infrastructure or fulfillment expense.
Meanwhile, third-party delivery marketplaces present a broader structural challenge. Platforms such as DoorDash and Uber Eats provided independent pizzerias with instant delivery logistics, real-time tracking, and digital storefronts in exchange for a commission fee. This shift altered industry economics by reducing the scarcity value of Domino's proprietary delivery network — built over four decades — in less than ten years.
Seven Powers, applied honestly.
Scale economies represent Domino's primary structural advantage. Roughly two dozen supply chain centers processing millions of pounds of dough weekly yield purchasing terms, freight density, and manufacturing costs that regional competitors cannot match. Returning 50% of supply chain profits to domestic franchisees ensures this benefit is shared rather than contested, creating a durable and measurable moat.
Process power applies to store workflow and systems like DomOS — the sequence moving orders from intake to oven to delivery on a standardized schedule. While process capabilities are difficult to replicate because they rely on trained store personnel rather than written manuals, they decay quietly when store-level driver staffing falters.
Counter-positioning served as a historical growth driver rather than an ongoing advantage. Operating focused delivery-and-carryout units severely disrupted Pizza Hut's capital-intensive dine-in model in the 1990s. With that structural transition complete, counter-positioning no longer generates incremental competitive advantage.
Brand provides high top-of-mind recall for delivery speed, yet consumer switching costs remain minimal. A customer accessing a delivery app can switch competitors instantly; the loyalty program represents an effort to engineer switching costs that the core product does not naturally possess.
Notably, Domino's exhibits neither network effects nor a cornered resource, making assertions of a broader economic moat unpersuasive.
Porter, briefly. Buyer bargaining power is high, as consumers face zero switching costs and have been conditioned by decades of promotional pricing to expect discounts. The threat of substitutes is significant and frequently understated: frozen pizza quality has improved, and the broader competitive set includes all quick-meal options rather than pizzerias alone. Supplier power is concentrated in dairy, where cheese prices are determined by volatile commodity markets; while scale procurement mitigates price swings, it cannot eliminate commodity risk. Industry rivalry remains intense and persistently promotional.
Falsification, part one: the delivery and tech moat.
The claim: Proprietary digital ordering paired with an owned driver fleet forms an unassailable competitive moat.
The disconfirming record: Severe driver shortages in 2021 and 2022 forced store locations to reduce operating hours, resulting in longer delivery times and declining delivery order counts. Gig platforms attracted labor by offering schedule flexibility rather than higher base compensation, proving that Domino's core delivery asset depended on external labor conditions beyond corporate control. Domino's subsequently listed its menu on Uber Eats in 2023.
The verdict: Empirical evidence narrows the scope of the original claim. Domino's maintains a cost and consistency advantage in final-mile fulfillment when stores are fully staffed, rather than an exclusive operational capability. Furthermore, digital ordering features have commoditized as aggregator applications offer comparable tracking and ordering interfaces. The defensible claim is that Domino's can deliver items at a lower marginal cost than an independent operator paying platform commissions — an advantage that matters most on value menu items. The key metric evaluating this dynamic is organic delivery order volume growth excluding third-party aggregator channels. If owned-channel delivery transactions expand independently, the narrowed moat holds; if growth relies entirely on aggregator platforms, Domino's operates primarily as a menu supplier to third-party marketplaces.
Falsification, part two: fortressing.
The claim: Splitting delivery territories by opening stores closer together reduces delivery distances, lowers driver fulfillment costs, improves service speed, and increases total market sales.
The disconfirming record: Domestic franchisees publicly opposed territory splitting between 2021 and 2023, noting that new locations cannibalized sales from existing stores during a period when elevated cheese prices and rising wages were already compressing unit margins. While corporate headquarters collects royalties and supply chain revenue on all system volume, individual franchisees absorb the sales dilution of split territories.
The verdict: Although fortressing theoretically improves service times, its execution creates direct financial friction between corporate and franchisee incentives. Consequently, fortressing offers a narrower growth runway in mature suburban markets than headline store expansion targets suggest, requiring franchisee alignment that has previously faced resistance. Net U.S. store additions evaluated alongside franchisee unit profitability serve as the primary benchmarks for progress.
A note on the aggregator arithmetic. Incremental volume generated through third-party commission channels carries different economic implications than direct orders processed through owned applications. Platform commissions apply to gross order values and directly impact franchisee store-level margins. As a result, aggregator channels are immediately accretive to corporate earnings — which collect top-line royalties and supply chain sales regardless of delivery channel — while placing additional margin pressure on store operators. While the 50/50 supply chain rebate aligns corporate and franchisee interests on ingredient procurement, platform commissions highlight a structural divergence in channel economics.
The testable thesis turns on a clear distinction: whether aggregator order volume expands franchisee unit profitability or merely inflates top-line systemwide sales. Only the former supports sustainable, long-term store network expansion.
VIII. Global Master Franchise Network: Real Scale vs. Regional Stumbles
In August 2022, a master franchisee filed for bankruptcy and closed all 29 Domino's locations in Italy, abandoning an initial plan to build 880 stores.5 The failure in the birthplace of pizza stands as the most instructive operational setback in the company's international history, and understanding why it occurred requires examining how Domino's exports its business model globally.
The model. Domino's grants exclusive master franchise rights for an entire country or region to a single corporate operator — such as Jubilant FoodWorks in India, Domino's Pizza Enterprises across Australia, Japan, France, and Germany, or DP Eurasia and DP Poland in their respective territories. The master franchisee raises its own capital, builds stores, manages labor, adapts the menu, and absorbs local operating risk. In return, corporate Domino's collects a royalty of roughly 3% of sales while deploying essentially no capital.1
For the franchisor, this arrangement operates as a senior financial claim on a third party's operational business. This dynamic explains why the international segment generates a modest share of consolidated revenue while contributing a disproportionate share of operating profit, allowing global store counts to expand for decades with minimal corporate capital investment.
However, this structure also limits corporate control over operational outcomes. A master franchisee's capital structure, real estate expansion discipline, and local consumer judgment remain outside corporate management's direct control — a reality that becomes evident when international markets underperform.
What works: India. India emerged as Domino's largest international market by store count, expanding past 1,900 locations by abandoning the assumption that the American playbook could be exported unchanged. Master franchisee Jubilant FoodWorks redesigned the menu around local preferences, introducing extensive vegetarian items, paneer offerings, and tailored spice profiles. Store footprints were scaled down to fit local commercial real estate, and fulfillment logistics were adapted for urban environments where car-based delivery and suburban street address systems do not apply.
This outcome illustrates a general operational principle: international expansion success has consistently depended on a master franchisee's willingness to adapt the product line and operational footprint to local market conditions, rather than relying on brand equity alone.
What failed: Italy. When master franchisee ePizza SpA entered Italy in 2015 targeting 880 locations, it encountered two structural obstacles. First, local consumers maintained strong preferences for traditional pizzerias; Domino's entered the market competing on logistics rather than product quality or price. Second, during the COVID-19 pandemic, third-party delivery platforms expanded rapidly across Italy, granting independent pizzerias the same fulfillment capabilities Domino's offered.5 Once local competitors gained delivery access, the brand's primary point of differentiation evaporated.
This liquidation highlights a fundamental boundary condition of the international model: when third-party aggregators neutralize delivery logistics in a market where consumers prefer local product alternatives, brand presence alone is insufficient to sustain operations.
What else broke. Geopolitical and operational disruptions elsewhere highlighted further network vulnerabilities. In August 2023, the master franchisee operating in Russia initiated bankruptcy proceedings following international sanctions and unsustainable operating losses.6 More significant for ongoing investment analysis, Domino's Pizza Enterprises — the publicly traded Australian master franchisee operating across Australia, Japan, France, and Germany — issued profit warnings and announced store closures, including approximately 80 locations in Japan alongside additional closures in France, citing post-pandemic over-expansion and elevated labor costs.7
Unlike political market exits, the restructuring at Domino's Pizza Enterprises reflected core operational friction: an established master franchisee overestimating post-pandemic demand density and contracting its store base in response to unit-level margin pressure.
The calibrated conclusion. The master franchise structure protects corporate balance sheets from direct capital losses; Domino's lost virtually no corporate capital in Italy, Russia, or Japan because third-party operators funded the physical assets. However, the international record refutes the assumption that global store expansion functions as an automatic compounding driver. International expansion depends entirely on third-party capital allocation and local operator health, both of which fluctuate based on regional economic conditions and unit-level profitability. Consequently, long-term targets such as management's 50,000 global store goal must be evaluated alongside market liquidations and store closures across key master franchise territories. Net global store additions — quarterly store openings minus closures — serves as the primary metric for tracking actual international expansion momentum.
Financial disclosure dynamics. Because master franchisees bear operating risk, market downturns manifest on corporate Domino's income statement as muted royalty growth rather than operational losses. This accounting insulation protects corporate earnings but can obscure unit-level stress within international markets. While corporate filings reflected store closures in Japan and France as minor royalty headwinds, the public financial disclosures of listed master franchisees in Australia, India, and China revealed substantial operating margin pressure. Evaluating third-party franchisee disclosures provides essential context on network health, as capital-light insulation protects the corporate franchisor from financial losses without insulating it from the slowdown in store growth that occurs when franchisees face financial pressure.
IX. Strategic Playbook & Investor Lessons
Strip away the product details, and four transferable strategic principles emerge from Domino's trajectory, each bounded by clear operational limits.
Align the supply chain with the franchisee, not against them. The 50/50 profit-sharing mechanism converts traditional franchisor-franchisee tension into a shared financial interest. It remains among the most structurally effective operational concepts in franchising, yet is rarely replicated because it requires corporate headquarters to surrender half of a profit pool it could legally retain. However, this alignment carries a clear boundary: sharing ingredient profits does not align corporate and franchisee incentives on store density, which explains why territorial fortressing triggered franchisee resistance despite supply chain alignment.
Radical transparency can beat corporate defense — when the underlying fix is real. The 2010 turnaround campaign succeeded because the public admission of product flaws was backed by a genuine culinary overhaul. The strategic takeaway is not simply to acknowledge operational failures, but to acknowledge failures that have already been resolved. A public admission without a substantive product fix merely amplifies the original criticism.
Pragmatism beats doctrine. The decision to partner with Uber Eats demonstrated management's willingness to abandon a long-defended anti-aggregator policy when market conditions shifted. Adaptability is valuable in an industry where corporate leadership often defends legacy playbooks. The qualification remains timing: the strategic pivot occurred after labor shortages had already constrained delivery volume and damaged customer frequency.
Financial engineering is an amplifier, never a moat. Whole-business securitization and sustained share repurchases amplified underlying operational growth into high equity returns. However, that same financial architecture intensifies equity drawdowns when operating performance stalls. Evaluating Domino's requires analyzing store-level cash flow stability first and capital structure efficiency second — never in reverse.
A foundational lesson sits beneath each of these principles: the company's competitive advantage has consistently derived from identifying physical constraints and engineering systemwide solutions — from corrugated boxes and conveyor ovens to central dough manufacturing, optimized routing, and predictive prep forecasting. Domino's has succeeded through logistics and operational execution. When performance faltered — whether in Italy, during domestic driver shortages, or through territorial cannibalization — the business stumbled by misjudging consumer preferences and labor dynamics that operational efficiency alone could not overcome.
A final observation for capital allocators. Domino's provides a clear demonstration that in a franchised business model, corporate management does not directly control systemwide growth rates. Expansion is driven by thousands of independent operators evaluating store-level payback periods quarter by quarter. Every corporate initiative — product innovation, marketing, supply chain productivity, and technology — ultimately serves to improve unit-level economics on franchisee balance sheets. Franchisors that overlook this dynamic risk setting aggressive store development targets that independent operators decline to build, as demonstrated by recent store contraction across key international master franchise territories.
X. Bull vs. Bear Case Analysis & Key Forward KPIs
The bull case.
The bull thesis hinges first on the premise that third-party aggregator channels provide genuinely incremental order volume. Third-party platform users skew toward higher household incomes and were not previously reached by owned ordering channels, leading management to size the U.S. aggregator market opportunity near $1 billion in annual sales.4 Crucially, this volume flows through existing store capacity without requiring incremental store build-outs, yielding high contribution margins even after paying platform commissions. If aggregator channels drive U.S. same-store sales growth without cannibalizing direct orders, the capital return on the decision is substantial.
Second, the company's supply chain scale remains its most defensible structural asset. Automated dough manufacturing facilities continue to widen unit-cost advantages over regional competitors. Unlike brand equity or store process speed, this cost position is quantifiable and independent of strategic marketing narrative.
Third, an international growth runway persists in regions where master franchisees have adapted the operating model—such as store density in India under Jubilant FoodWorks and expansion in China through DPC Dash—even after accounting for recent market liquidations and store closures.
Finally, the core unit-development flywheel remains intact: annual store-level cash profits of $140,000 to $170,000 against initial build costs below $500,000 generate a payback period attractive enough to ensure third-party franchisee capital continues funding network expansion.
The bear case.
Channel dependency and margin transfer. Every transaction shifting from the owned Domino's app to third-party marketplaces incurs platform commissions while eroding direct customer relationships—a relationship executive leadership long categorized as essential. The primary risk is long-term: as consumer ordering habits consolidate on third-party platforms, Domino's risks facing future commission renegotiations from a weakened bargaining position. Aggregator mix as a share of total orders serves as the key metric determining whether third-party marketplaces represent incremental demand or a gradual transfer of customer ownership.
Domestic saturation. Territorial fortressing faces mathematical limits in mature suburban markets, and franchisee resistance over store-splitting indicates that density strategies may be approaching local market saturation sooner than aspirational store targets suggest.
Input cost volatility. Raw material price swings present ongoing margin risk. Cheese represents the company's single largest commodity exposure, supplemented by pork and wheat. While scale procurement mitigates short-term price fluctuations, it cannot eliminate underlying commodity volatility, leaving the supply chain segment's single-digit margins vulnerable to input price inflation.
Leverage and refinancing. Carrying roughly $4.8 billion in securitized debt against a modest physical asset base means refinancing debt at higher interest rates directly reduces cash available for share repurchases.1 Because approximately two percentage points of the annual earnings-per-share growth target depend on share count reduction, elevated borrowing costs complicate management's ability to achieve its 10% earnings-per-share target even if underlying operating income goals are met. This structural reliance on low interest rates represents a central vulnerability in a higher-rate macroeconomic environment.
The activist's stress test. A rigorous investment assessment centers on three key questions. First, are share repurchases value-accretive under current borrowing costs and debt levels, or do they primarily offset rising interest expense through share count reduction? Second, how much of the "Hungry for MORE" operating income target relies on DomOS efficiency gains that external observers cannot independently audit? Third, does an executive leadership team raised within the legacy operational framework possess the incentive to proactively adapt core strategies before external market pressures force changes—a question highlighted by the reactive timing of the aggregator pivot? While not disqualifying, these questions define the core execution risks that management must address in upcoming operating cycles.
The three KPIs that matter.
-
U.S. same-store sales growth, decomposed into order count versus ticket size. This metric provides the primary indicator of underlying consumer demand. Same-store sales gains driven solely by higher average ticket sizes during inflationary periods reflect pricing power rather than transaction growth. Conversely, expanding order counts indicate true demand gains while revealing whether aggregator order volume is additive or merely substituting for direct channel orders.
-
Net global store additions. Measured as store openings minus closures with international markets separated, this figure provides a direct measure of master franchisee economic health while serving as a realistic check on long-term store expansion targets against recent contraction records in markets such as Japan, France, Italy, and Russia.
-
Average store-level cash profitability. Unit-level cash EBITDA represents the primary driver of network expansion. When store profitability expands, franchisees invest in unit growth, royalty streams compound, and supply chain volumes increase. When store-level cash flows contract, systemwide growth decelerates accordingly.
These three metrics, systematically reported in public disclosures, cut through quarterly noise to isolate the core operating trajectory of the enterprise.
Weighing the two sides. The investment thesis is asymmetrical. The bull case depends on a verifiable supply chain cost advantage and channel expansion economics that can be evaluated over short operating horizons. In contrast, the bear case involves second-order dynamics that unfold gradually—third-party platform reliance, domestic market saturation, and the compounding cost of refinanced debt. Because these structural risks develop over multi-year trends rather than single reporting periods, monitoring long-term trajectory metrics remains essential for evaluating Domino's ongoing performance.
XI. Management Signal & Earnings Call Analysis Guide
Evaluating Domino's management communications requires distinguishing between binding operational commitments and strategic narrative.
The primary sources. The December 2023 investor day serves as the anchor document for underwriting corporate strategy, establishing the 2024–2028 financial targets, the DomOS rollout plan, and the franchisee profitability benchmark against which subsequent quarterly execution must be evaluated.[^5] The Q2 and Q3 2023 earnings calls provide critical insight into executive alignment, as analysts questioned Chief Executive Officer Russell Weiner and Chief Financial Officer Sandeep Reddy directly on the strategic reversal regarding Uber Eats — specifically addressing brand dilution, commission economics, and the long-standing defense of customer data ownership. Management's willingness to detail why its prior position was wrong offers a key reference point when evaluated against transcripts from earlier quarters when the opposing case was argued.4 Meanwhile, the Q4 2024 and Q4 2025 annual earnings calls deliver empirical operating evidence: domestic order count trajectory, supply chain margins, and international store closures.1
Reading prepared remarks versus Q&A. Prepared remarks outline management's preferred narrative, whereas analyst question-and-answer sessions highlight operational pressures that cannot be side-stepped. Two specific analytical areas warrant close scrutiny.
The first is the operational mix between delivery and carryout transactions. While carryout expansion offers favorable store-level economics by eliminating driver labor, delivery generates higher average ticket sizes and represents the channel where the brand's core identity resides. When executive commentary repeatedly emphasizes carryout strength in response to questions regarding delivery performance, it signals underlying softness in owned delivery channels.
The second is the analysis of commodity pricing and franchisee supply chain rebates. Due to the 50/50 profit-sharing structure, reported supply chain operating margins do not directly reflect raw procurement efficiency, as a portion of procurement gains is returned to domestic store operators. Consequently, when management reports supply chain margin expansion, analysts must isolate whether margin growth stemmed from sustainable procurement productivity, temporary commodity price deflation, or structural mix shifts — three distinct drivers with varying levels of durability.
A third overarching evaluation centers on narrative consistency over multi-year cycles. Tracking how specific growth drivers — such as third-party aggregator contribution, loyalty program participation, or international store growth — are framed across consecutive quarters reveals management's reporting discipline. Executive teams that shift the primary growth narrative from quarter to quarter without explaining prior metrics are often managing narrative rather than business execution. Across recent operating cycles, Domino's leadership has maintained relatively consistent disclosure standards, with the 2023 aggregator reversal standing as the primary strategic shift — a decision management acknowledged directly rather than attempting to obscure.
A final word on what these metrics will not tell you. None of the primary metrics — same-store sales composition, net global store additions, or average store-level cash profitability — directly measures underlying brand health. In a quick-service dining category characterized by zero consumer switching costs, brand perception operates as a critical baseline variable that evolves gradually beneath reported financial results. Because standard quarterly filings lack direct metrics for brand equity, secondary indicators include order frequency within the active loyalty base and the balance between promotional discounts and full-price purchases. While neither figure is disclosed independently, both can be inferred over time through executive commentary. Relying exclusively on high-level operational KPIs creates an analytical blind spot, risking a failure to detect gradual brand erosion similar to the operational decay that preceded the 2008 financial crisis.
XII. Final Reflections & Epilogue
The surprising thing about Domino's, in the end, is how little of its success came from pizza.
It came from a box engineered to stack without collapsing. From a menu narrowed so a small crew could execute it at speed late at night. From dough plants and optimized truck routes. From a rebate formula that aligned thousands of independent business owners with corporate headquarters. From a progress tracker that made waiting tolerable. From a decision to borrow against a royalty stream as though it were a mortgage. And, once, from the willingness to put customers on national television saying the food tasted like cardboard.
What remains genuinely durable in 2026 is narrower than the long-term stock chart suggests. Scale economics in the supply chain: real, measurable, and un-eroded. Franchisee alignment: structurally sound, though tested by territorial splitting and cost inflation. Operational process power: real, but dependent on a labor market that has already proved it can constrain capacity. The delivery moat in its original, exclusive form: gone, dissolved by aggregator platforms, and formally surrendered in July 2023.
What comes next is another operational question rather than a culinary one. AI-driven prep forecasting, if DomOS delivers, attacks waste and speed simultaneously across thousands of stores — solving the same class of problem as the corrugated box and the delivery route with a digital tool. Autonomous delivery, if deployed at scale, would address the driver labor cost line that has constrained the business since 1960. Yet because autonomous technology would benefit all competitors, a company experienced in optimizing delivery routes is well-positioned to exploit it — even as the technology itself fails to yield an exclusive moat.
Domino's remains the operational benchmark in global quick service. The open question for the next five years is not whether the company can run stores efficiently. It is whether operating efficiency alone is sufficient when the delivery convenience it monopolized for four decades is accessible to any competitor with a mobile application and a commission agreement.
A closing thought on how to hold this story. The temptation with Domino's is to view its two-decade financial performance as proof of a permanent machine, reasoning backward from equity returns to the inevitability of strategy. The empirical record does not support that narrative. It includes a delivery guarantee abandoned under legal liability, a product baseline so weak it required a public televised apology, a securitized capital structure that amplified downside risk during the 2008 financial crisis, a labor shock that forced a fifteen-year strategic stance to be reversed, a franchise network that resisted corporate market-density plans, and a national market where operations liquidated entirely.
What survives those setbacks is narrower and more compelling than corporate myth: a demonstrably superior cost position in food manufacturing and supply chain distribution, an incentive structure that aligns independent operators with system growth, and a management culture that has repeatedly shown a willingness to break its own strategic orthodoxy when market pressures demand it. Whether those structural assets are sufficient to deliver management's 2024–2028 financial commitments is not a matter of brand reputation. It remains a question of three core metrics, reported quarterly, and open to continuous verification.
References
-
Domino's Pizza, Inc. Form 10-K Annual Report (Fiscal Year Ended December 29, 2024) — SEC EDGAR ↩↩↩↩↩↩↩
-
SEC EDGAR Entity Filings: Domino's Pizza, Inc. (CIK 0001286681) — U.S. Securities and Exchange Commission ↩↩
-
Domino's Pizza, Inc. Form DEF 14A Definitive Proxy Statement — SEC EDGAR ↩
-
Domino's Pizza Partners With Uber Eats to Boost Delivery Orders — Reuters, 2023-07-12 ↩↩↩
-
Domino's Pizza Pulls Out of Italy After Failing to Win Over Locals — Reuters, 2022-08-10 ↩↩
-
Domino's Master Franchisee DP Eurasia to File for Russian Bankruptcy — Reuters, 2023-08-21 ↩
-
Domino's Pizza Enterprises Investor Relations & Store Closure Announcements — Domino's Pizza Enterprises Ltd ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube