Dow Inc.: The Ethane Advantage, Trough Discipline, and the Net-Zero Gamble
I. Introduction & Episode Roadmap
There is a particular kind of industrial building that most people have driven past without ever registering what it does. It is a forest of steel piping, fractionation towers, and flare stacks, usually sited on a flat coastal plain near a deepwater port, glowing at night like a small city that never sleeps. Inside, a molecule of ethane — a two-carbon gas that comes out of the ground alongside shale natural gas, and which for most of the twentieth century was considered a nuisance to be stripped out and burned — enters a furnace heated to roughly 850 degrees Celsius, is torn apart in less than a second, and emerges as ethylene. From there, it is polymerized into the film that wraps a pallet of bottled water, the insulation on a high-voltage cable, the liner of a landfill, or the diaper in a nursery.
That transformation, repeated billions of times a second across a handful of sites on the U.S. Gulf Coast, in Alberta, in the Netherlands, and in Argentina, is essentially how Dow Inc. operates. The company reported net sales of $42.96 billion in 2024 across manufacturing sites in 31 countries, employing approximately 35,900 people.1 It is one of the largest materials science companies in the world, trading on the NYSE under the ticker DOW.
The central question of this story is not whether Dow makes useful products. It does. The critical question is how a 129-year-old electrochemical pioneer, born from Michigan salt brine, navigates a global chemical trough, a surge of Chinese ethylene overcapacity, and the deindustrialization of European energy-intensive manufacturing — while simultaneously committing billions of dollars to a net-zero ethylene complex in Alberta whose payback depends on a market that has not yet matured.
That tension — between the cash-generating assets Dow operates today and the decarbonized infrastructure it aims to build — forms the core of this analysis.
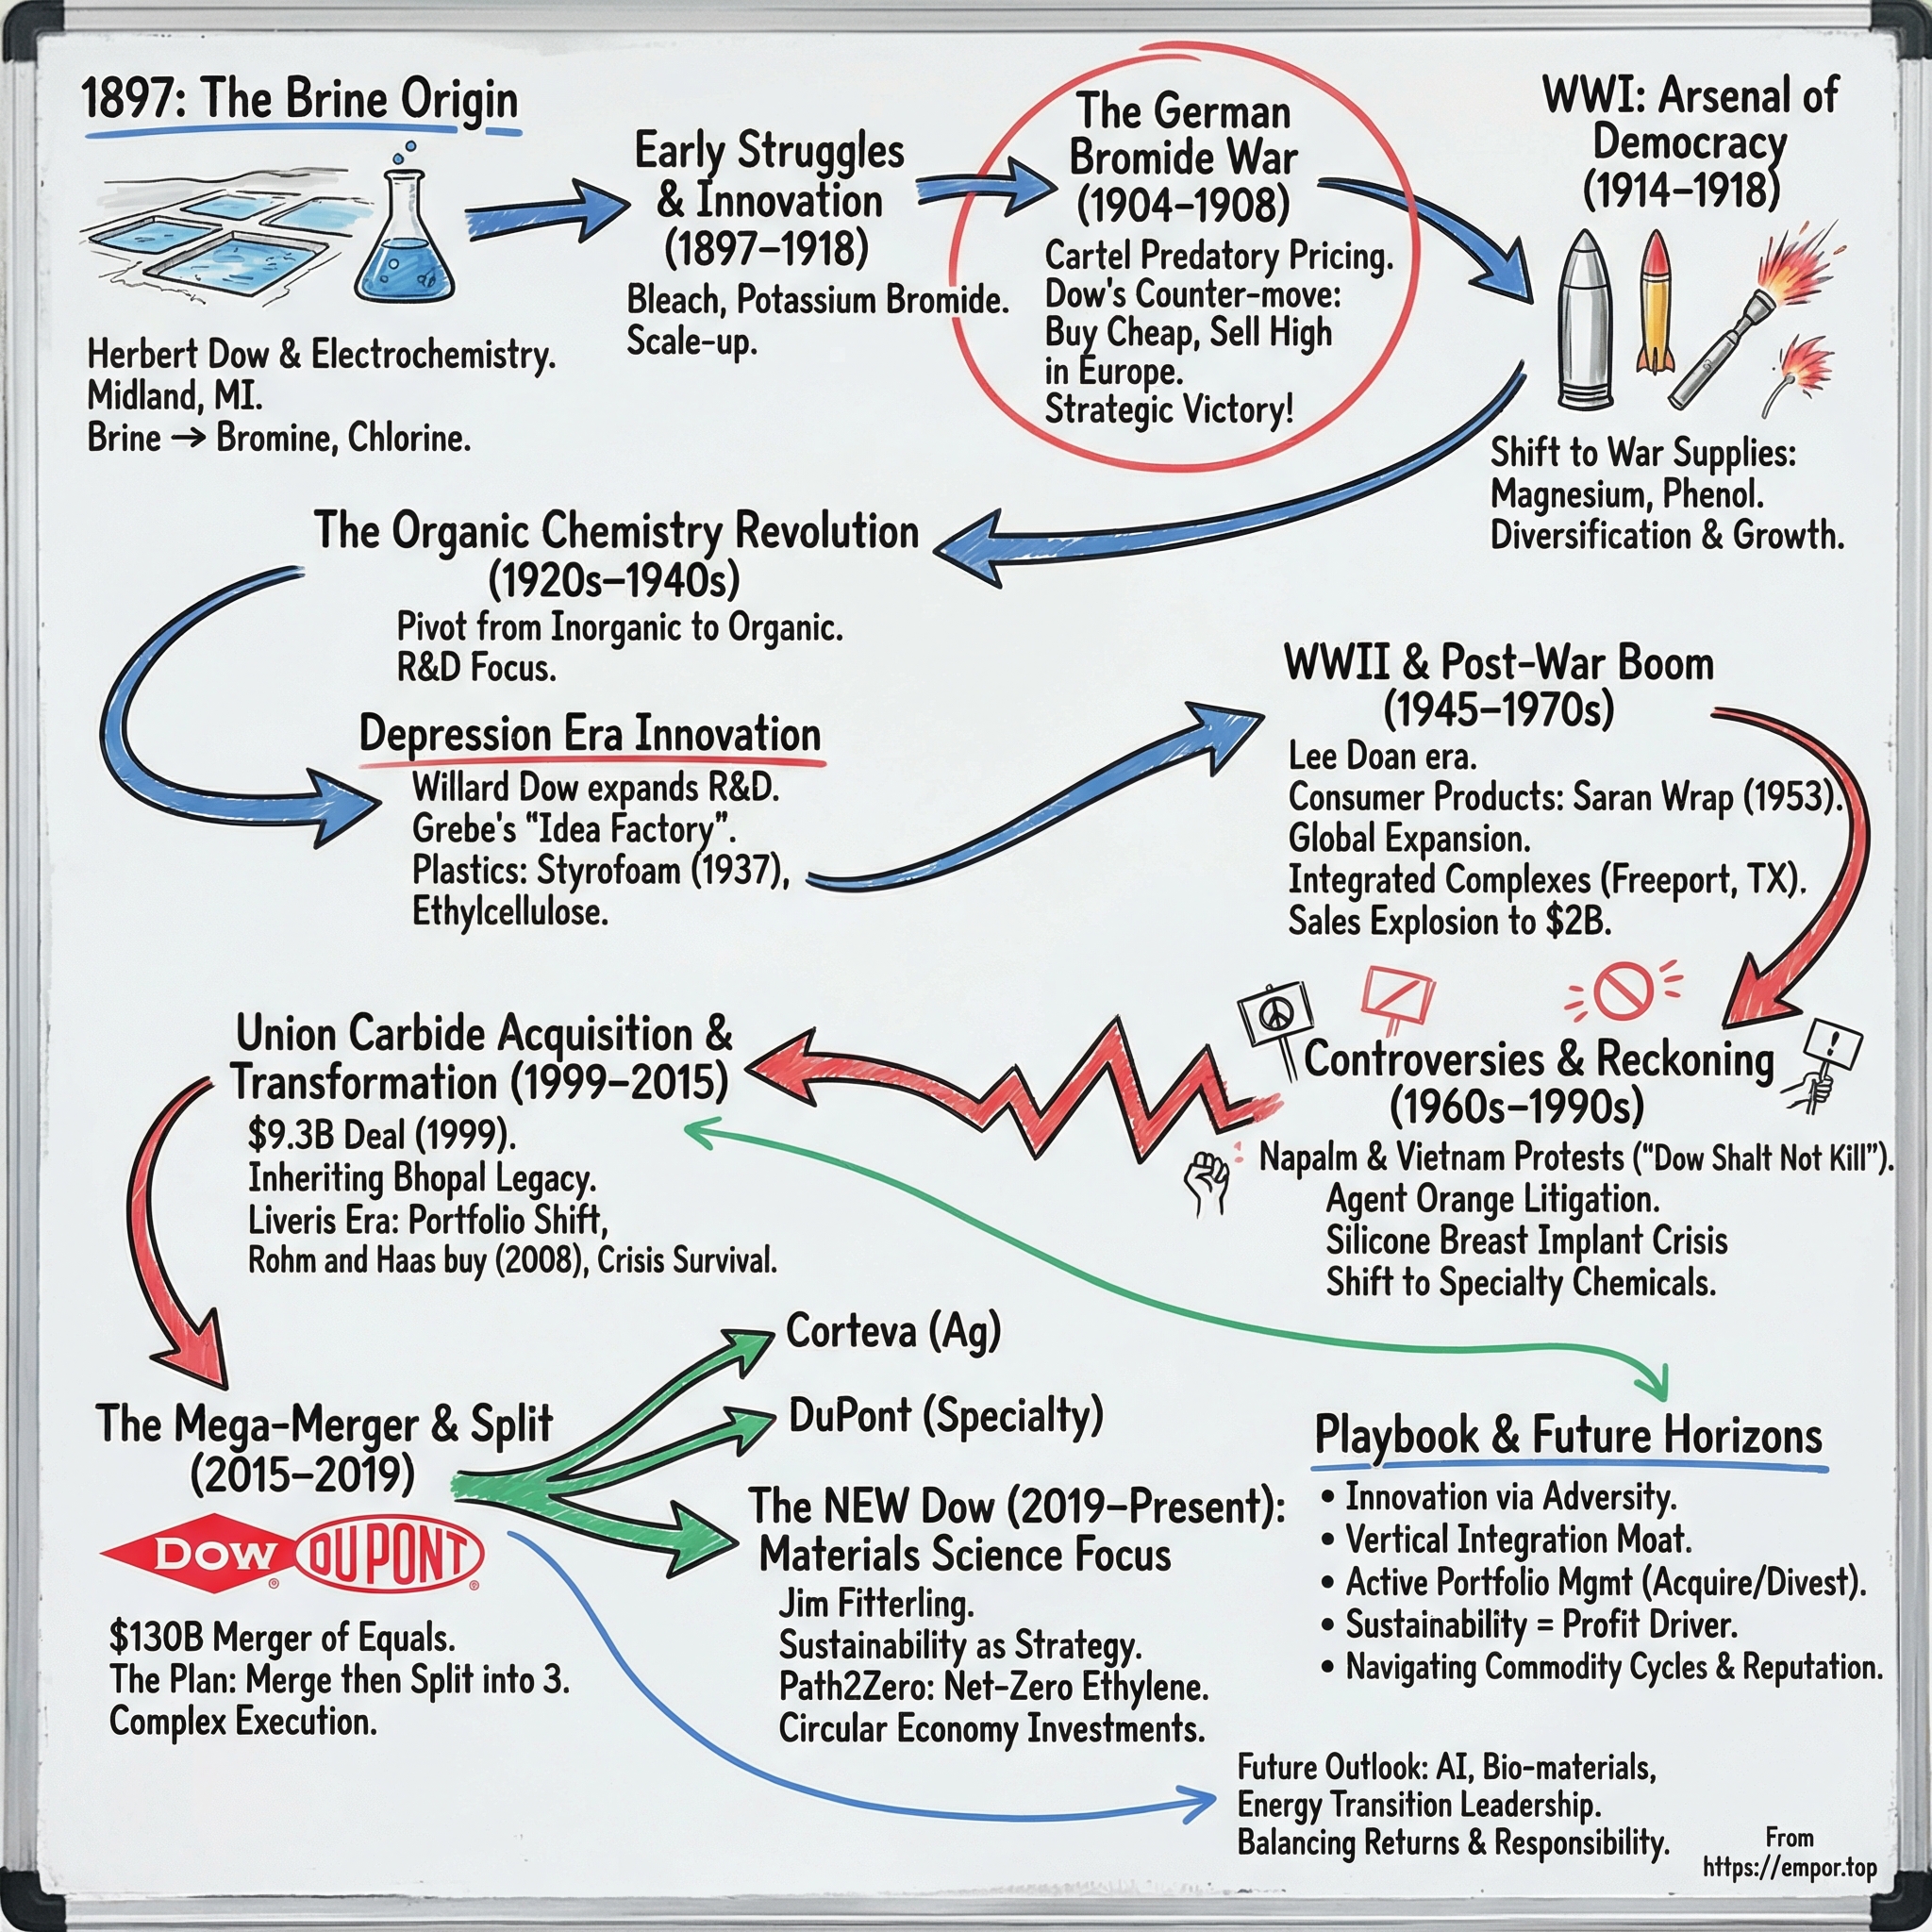
The story unfolds across seven sections. First, a tour of the foundations: Herbert Dow's brine electrolysis, the Bromide War against a German cartel, the synthetic-materials revolution, and the enduring impact of Napalm, Agent Orange, and the Dow Corning bankruptcy — legacy liabilities that remain central to the company's operational DNA. Second, the pre-merger M&A history spanning Union Carbide, the acquisition of Rohm and Haas, and the Sadara joint venture in Saudi Arabia. Third, the DowDuPont merger and subsequent three-way split, representing a major milestone in activist-driven financial restructuring within the chemical industry. Fourth, an examination of core operational economics: the mechanics of a steam cracker, the strategic importance of ethane, and the revenue drivers across Dow's three business segments. Fifth, leadership and capital allocation under former CEO Jim Fitterling and Karen S. Carter, who assumed the CEO role on July 1, 2026. Sixth, the Path2Zero project and circular-plastics initiatives, evaluated against their financial scale. Finally, an investment playbook featuring a bull-versus-bear stress test and key metrics for evaluating performance.
A fundamental dynamic underpins this business: Dow's fortunes depend heavily on external variables outside management's control — including the price spread between natural gas liquids and crude oil, the pace of Chinese capacity expansions, and European industrial energy policy. Evaluating Dow requires separating management's execution from macro-cyclical forces, a distinction maintained throughout this analysis.
 Subscribe on LinkedIn
II. The Brine & Electrochemical Origins
In 1890, a young chemistry graduate named Herbert Henry Dow began inspecting the brine wells of Midland, Michigan — a played-out lumber town whose primary remaining economic resource was the salty underground water earlier settlers had used to produce table salt. While the brine was known to contain bromine, existing extraction methods relied on fuel-intensive boiling processes that made large-scale recovery cost-prohibitive.
Dow's breakthrough was electrochemical: passing an electric current through the brine separated the bromine electrolytically without requiring coal or heat, substantially lowering production costs. Despite initial skepticism from financial backers and the failure of his first two corporate ventures, Dow founded The Dow Chemical Company in Midland in 1897.
The Bromide War
The episode that established Herbert Dow's operational strategy occurred a few years later. In the early 1900s, bromine was a globally cartelized commodity dominated by a German syndicate, the Bromkonvention. The cartel fixed global prices and allowed American producers to operate domestically on the condition that they did not export overseas. Dow rejected the restriction and began exporting bromine to England.
The German syndicate responded with predatory pricing, flooding the U.S. market with bromide at roughly 15 cents per pound — below Dow's cost of production — aiming to bankrupt the company domestically while protecting high monopoly prices in Europe.
Rather than matching the price cuts, Dow quietly hired secret agents in the U.S. to buy up the discounted German bromide, repackage it, and ship it back to Europe and Asia, undercutting the cartel's own inflated prices. Unaware of the arbitrage scheme, the syndicate continued lowering its U.S. prices, effectively subsidizing the inventory Dow used against it. The price war ultimately forced the collapse of the German cartel's pricing discipline.
The strategy established an operational blueprint that defined Dow's long-term orientation: in commodities, the low-cost producer who understands global arbitrage flows wins, while reliance on brand premium or legacy relationships fails. Dow has operated as a cost-curve-focused chemical producer ever since.
The Synthetic Age
Under Herbert's son, Willard Dow — who led the company from 1930 until his death in a 1949 plane crash — the enterprise expanded from inorganic extraction into organic chemistry. The firm developed magnesium metal extracted from seawater, as well as styrene and synthetic rubber, which became strategically vital when Japanese forces cut off Allied access to Southeast Asian natural rubber plantations during World War II. Dow also commercialized Styrofoam in 1941 for flotation and insulation, and adapted Saran Wrap from a military protective coating into a consumer household staple.
Alongside product expansion came a foundational structural innovation: the integrated complex model. Rather than operating standalone facilities, Dow clustered steam crackers, chlor-alkali cells, and downstream derivative units on single sites linked by pipelines and shared utilities — a practice known in the chemical industry as Verbund. Under this framework, byproduct streams from one unit serve as feedstocks for another, waste heat from exothermic reactions powers adjacent endothermic processes, and unified logistics infrastructure serves multiple product lines. Major complexes like Dow's sites in Freeport, Texas, and Terneuzen, Netherlands, function as integrated ecosystems where cost advantages depend heavily on physical co-location. This structural interdependence becomes a key consideration when evaluating later activist proposals to divest individual underperforming segments.
The Liability Shadow
The same chemical capabilities that enabled consumer product expansion also generated substantial reputational challenges and long-tail legal liabilities.
During the Vietnam War, Dow manufactured Napalm B for the U.S. military and was among several suppliers of the herbicide Agent Orange. The company became a prominent target of anti-war protests in the late 1960s, creating severe reputational drag that persisted for decades.
A more financially material liability arose through Dow Corning, a 50/50 silicones joint venture formed with Corning Incorporated in 1943. Beginning in the early 1990s, Dow Corning faced extensive product liability litigation alleging that its silicone breast implants caused autoimmune disorders. Although subsequent epidemiological studies largely challenged the medical claims, the sheer volume of claims forced Dow Corning into Chapter 11 bankruptcy protection in 1995. The entity emerged in 2004 under a reorganization plan that established a multibillion-dollar settlement trust for claimants.
For investors, the company's first century established three enduring themes. First, Dow's structural advantages — vertical integration, low-cost feedstock extraction, and site-level Verbund economics — were established early and remain core to its operating base. Second, cyclical volatility is an inherent feature of selling commoditized molecules priced at the margin. Third, legacy liabilities — including environmental remediation and toxic tort litigation — represent ongoing claims on cash flow that conventional earnings-multiple valuations risk overlooking.
This historical foundation set the stage for an era in which Dow sought to hedge against cyclical volatility through large-scale corporate acquisitions.
III. The Pre-Merger M&A Rollercoaster & Capital Lessons
If the first hundred years of Dow were about chemistry, the fifteen years spanning 1999 to 2015 were about deals — and about what happens when a company signs a fixed obligation against a variable source of funds.
Union Carbide: Scale and Shadow
In 1999, Dow agreed to acquire Union Carbide Corporation in a stock transaction valued at approximately $11.6 billion, completing the deal in February 2001 after a lengthy antitrust review.[^2] The industrial logic was straightforward: Carbide brought world-scale ethylene and polyethylene capacity, the UNIPOL gas-phase polymerization process technology, and a licensing franchise. It roughly doubled Dow's basic chemicals footprint.
It also brought Bhopal. Union Carbide's Indian affiliate had operated the pesticide plant where, in December 1984, a methyl isocyanate release killed thousands of people in the worst industrial accident in history. Union Carbide had settled with the Indian government in 1989 for $470 million, and Dow has consistently maintained that it never operated the plant, that the liability was resolved before its acquisition, and that Union Carbide's Indian subsidiary was sold prior to the transaction. Indian activists and elements of the Indian government have contested that position for decades. The financial exposure has not materialized into a large charge, but the reputational overhang has never fully cleared — reflecting the broader reality that acquiring a chemical producer involves acquiring its historical liabilities alongside its operational assets.
The K-Dow Collapse: A Case Study in Funding Risk
The period that followed brought Dow to the brink of corporate financial crisis.
By 2008, CEO Andrew Liveris — an Australian-born chemical engineer who had joined Dow in 1976 and advanced through its Asia-Pacific operations — outlined a strategic thesis: Dow was overly exposed to basic commodities. Management aimed to divest portions of its basic petrochemical business and reinvest the capital into specialty chemicals, which offered higher margins and lower cyclical volatility, in an effort to expand the company's valuation multiple.
The execution plan depended on two interconnected transactions.
Leg one: In December 2007, Dow agreed to form K-Dow Petrochemicals, a 50/50 joint venture with Kuwait's state-owned Petrochemical Industries Company (PIC), contributing a large slice of its commodity petrochemicals business in exchange for roughly $9 billion in cash.2
Leg two: In July 2008, Dow agreed to acquire Rohm and Haas — a Philadelphia specialty chemicals maker with a strong coatings and electronic materials portfolio — for $78 per share in cash, a transaction valued at approximately $18.8 billion including debt.3 The price represented a substantial premium, struck near the peak of the pre-crisis market.
The expected cash proceeds from K-Dow were designed to serve as the primary funding source for the Rohm and Haas acquisition.
However, the macroeconomic landscape shifted rapidly. Lehman Brothers filed for bankruptcy in September 2008, crude oil prices dropped from nearly $147 per barrel to below $40, and credit markets tightened. On December 28, 2008 — days before the scheduled closing — Kuwait's Supreme Petroleum Council cancelled the K-Dow joint venture outright amid domestic political opposition.2
Dow remained contractually obligated to complete the $18.8 billion cash purchase of Rohm and Haas without the anticipated joint-venture proceeds, amidst declining chemical end-market demand. The merger agreement contained no financing contingencies or market-material-adverse-change clauses.
When Dow sought to delay closing, the Haas family trusts — holding approximately one-third of the shares — filed suit in Delaware Chancery Court in January 2009 to compel specific performance.4 Dow contended that completing the transaction under the original terms posed existential solvency risks, while Rohm and Haas maintained that the contract remained binding.
A settlement reached in March 2009 required Dow to complete the transaction. To fund the purchase, Dow raised roughly $4 billion in equity-linked capital from investors including Berkshire Hathaway and the Kuwait Investment Authority. Berkshire's $3 billion allocation of cumulative convertible perpetual preferred stock carried an 8.5% dividend.5 Dow also secured bridge financing, divested assets such as its stake in Total Raffinaderij Nederland and its calcium chloride unit, and reduced its common dividend by 64% — the first dividend reduction in its history as a public company.
Dow subsequently pursued legal recourse. In May 2013, an arbitration panel awarded Dow approximately $2.2 billion in damages from PIC over the cancelled transaction, which Dow ultimately collected.6
While the arbitration recovery eventually mitigated part of the financial loss, the sequence highlighted significant funding and timing risks. Management's strategic pivot toward higher-margin specialties relied on a capital structure that assumed an uncommitted, politically governed funding source would arrive on schedule. The failure was not the strategy. It was the sequencing. This distinction remains central when evaluating capital allocation execution, demonstrating how external funding dependencies can constrain balance-sheet flexibility.
Sadara: The Megaproject Problem
A second major capital deployment presented distinct operational challenges.
In 2011, Dow and Saudi Aramco executed definitive agreements to establish Sadara Chemical Company, a joint venture to construct an integrated chemicals complex in Jubail Industrial City, Saudi Arabia. The development encompassed 26 manufacturing units with a total capital investment estimated at approximately $20 billion, marking one of the largest single-phase chemical construction projects ever undertaken.7 The strategic rationale centered on access to cost-advantaged Saudi feedstocks, a flexible cracker capable of processing both ethane and naphtha, and downstream derivative products designed to enter emerging regional markets.
The project experienced construction cost overruns and schedule delays, with initial operations commencing across 2015 and 2016. Certain specialty derivative markets generated lower returns than projected, while the complex carried substantial project-finance debt obligations into a softening global chemical pricing environment.
In 2021, Sadara completed a debt restructuring with its lending group to extend maturities and defer principal payments, supported by guarantees and commitments from Dow and Aramco.8 Dow recorded non-cash impairment charges related to its equity investment in Sadara during this timeframe.
Together, the Rohm and Haas acquisition and the Sadara megaproject illustrate two structural capital lessons. The Rohm and Haas transaction demonstrated that committed obligations require secured financing prior to execution. The Sadara joint venture showed that massive, single-phase greenfield developments concentrate execution and market-timing risks, proving that cost-advantaged feedstock alone does not guarantee targeted equity returns when downstream derivative markets face global supply competition.
That insight becomes directly relevant when evaluating the company's multibillion-dollar net-zero complex in Alberta.
By 2015, Dow operated with a restructured balance sheet and refined capital allocation priorities, setting the stage for subsequent activist shareholder engagement and corporate restructuring.
IV. The DowDuPont Mega-Merger & Financial Engineering Split
By late 2015, two of the oldest names in the American chemical industry — Dow and DuPont — were both under siege from activist investors. The activists reached remarkably similar conclusions: both companies operated as conglomerates whose constituent parts were worth more than the whole, burdened by high corporate overhead and valued at a discount because financial analysts struggled to model their disparate business lines coherently.
The Activists
Dan Loeb's Third Point disclosed a stake in Dow in 2014 and launched a public campaign, publishing a critical letter that questioned whether Dow's commodity petrochemical assets belonged inside a company claiming to pursue a specialty chemicals strategy. Loeb noted that Dow had underperformed its peer group over the prior decade, pushing for a separation of the petrochemical business. The dispute culminated in a November 2014 settlement that added four independent directors to Dow's board.
Nelson Peltz's Trian Fund Management ran a parallel campaign at DuPont, leading to a 2015 proxy fight that Peltz narrowly lost. However, within months, DuPont CEO Ellen Kullman retired, making way for Edward Breen — a corporate restructuring executive who had previously broken up Tyco International.
Breen and Liveris moved quickly to negotiate a transaction.
The Merger of Equals
On December 11, 2015, the two companies announced an all-stock merger of equals to create DowDuPont, a combined entity with a market capitalization of roughly $130 billion, with the explicit intention of subsequently separating into three independent publicly traded companies focused on agriculture, materials science, and specialty products.9
The strategic logic was unusual: the companies proposed to merge in order to split. Management argued that combining first allowed the combined assets to be recut along cleaner operational lines — pairing DuPont's agriculture business with Dow's, and DuPont's performance materials with Dow's plastics — producing three focused enterprises more efficient than either parent could create independently, while capturing operational synergies along the way.
Management targeted approximately $3 billion in run-rate cost synergies, to be realized largely within the first 24 months of closing, plus roughly $1 billion in growth synergies.9 The merger closed on August 31, 2017, following a prolonged antitrust review that required asset divestitures by both parties.
Testing the Synergy Claim
Did the transaction deliver on its promises? An independent assessment reveals a picture distinct from corporate press releases.
DowDuPont reported reaching its run-rate cost synergy target ahead of schedule. However, cost synergies represent one of the most manageable targets in corporate finance, measured against a management-defined baseline and realized primarily through headcount reductions, procurement consolidation, and facility rationalization — efficiency measures reachable without a mega-merger.
The more critical evaluation centers on the transaction's friction costs. Operating three separate public companies required three corporate boards, three executive teams, triplicated legal, audit, and investor relations functions, separate enterprise resource planning implementations, and three headquarters. The separation process absorbed years of management focus alongside billions of dollars in transaction, separation, and restructuring expenses. Both companies disclosed substantial integration and separation costs between 2017 and 2019.
The evidence indicates that while cost savings were realized, the dis-synergies of establishing three standalone corporate structures substantially offset them. Consequently, the transaction's enduring value rested almost entirely on the portfolio recut rather than net operational synergies. Whether that structural realignment justified roughly two years of operational disruption depended entirely on which resulting equity an investor held.
April 1, 2019: The Split
The corporate split proceeded in stages. Dow Inc. was spun off first, with the distribution of shares completed on April 1, 2019.10 Corteva Agriscience separated on June 1, 2019, taking the combined seeds and crop protection business. The remaining entity retained the DuPont name, holding electronics, water solutions, protection materials such as Kevlar and Nomex, and industrial specialties.
This division raises a central question: did Dow get the hard deal?
By revenue, Dow received the largest share by a wide margin. By business quality, the outcome was less favorable. Dow inherited the capital-intensive asset base — multi-billion-dollar steam crackers, chlor-alkali units, and world-scale polyethylene facilities — carrying heavy sustaining capital requirements, direct exposure to unhedgable commodity price spreads, and the bulk of legacy environmental remediation obligations and Union Carbide asbestos liabilities. DuPont retained asset-light, higher-margin, technology-differentiated businesses that command structurally higher valuation multiples.
This outcome was deliberate. The three-way split was structured explicitly to categorize assets by economic profile, allowing public markets to price each risk profile independently. Dow was introduced to the market as a cash-generating, dividend-paying, cyclical materials producer — and its performance has reflected that structural design.
For investors, the strategic takeaway is clear: Dow's valuation multiple will not re-rate toward specialty chemical levels through strategic repositioning alone. The multiple remains bound to capital intensity and earnings volatility. Generating equity returns depends on cash flow generation, low-cost operational positioning, and chemical cycle timing rather than multiple expansion.
Evaluating Dow's long-term investment thesis therefore requires understanding, precisely, where that cost position comes from.
V. Core Business & Market Structure: The Ethane Steam Cracker Machine
Understanding Dow's market position begins with the primary technical engine of its basic chemicals business: the steam cracker.
What a Steam Cracker Actually Does
A steam cracker is an industrial furnace that breaks complex hydrocarbon molecules into simpler chemical building blocks. The furnace mixes a hydrocarbon feedstock with steam, heats the mixture to roughly 850°C for a fraction of a second, and quenches it rapidly. The thermal shock shatters and recombines the molecular bonds, producing a stream dominated by ethylene — the world's most widely produced organic chemical and the fundamental feedstock for polyethylene.
The central operational variable is the choice of feedstock.
Cracking ethane — a light two-carbon gas extracted from natural gas — yields an output slate composed of roughly 80% or more ethylene. This high yield simplifies downstream separation and reduces capital intensity.
Cracking naphtha — a liquid distillate derived from crude oil refining containing longer carbon chains — generates a far more varied product mix. Naphtha yields less ethylene alongside substantial volumes of co-products, including propylene, butadiene, and aromatics such as benzene, requiring more complex separation trains and higher operational capital.
This technical distinction underpins the sector's competitive economics. Ethane pricing tracks natural gas, whereas naphtha pricing links directly to crude oil. When natural gas trades at a discount to crude oil — the structural reality in North America since the shale revolution — ethane-based crackers generate substantially higher margins per ton of ethylene than naphtha-based competitors. Dow has consistently framed this North American ethane advantage as a cash cost benefit of hundreds of dollars per ton of ethylene over naphtha-reliant producers in Europe and Asia.
A key dynamic governs this feedstock pricing. Because ethane is a byproduct of natural gas processing, its price behavior is bounded by natural gas markets. If ethane's chemical market value falls below its heating value, natural gas processors leave the molecule in the gas stream to sell as pipeline fuel — a mechanism known as ethane rejection. Rejection establishes a functional price floor while leaving a vast latent supply that can be recovered quickly whenever chemical demand rises. For much of the past decade, U.S. ethane has traded near its fuel value, securing low feedstock costs for major buyers such as Dow.
The underlying economic reality remains clear: Dow's primary structural advantage stems from geography and domestic energy supply rather than proprietary chemical synthesis. The advantage reflects North American shale geology. Dow's operational achievement lies in constructing and maintaining the capital-intensive asset network required to capture that yield — world-scale crackers, fractionators, distribution pipelines, salt-dome storage caverns along the U.S. Gulf Coast, and downstream units that process ethylene into commercial polymers. While this physical infrastructure is costly and difficult to replicate, it represents a location-based cost position rather than a proprietary innovation advantage. Consequently, such regional cost advantages remain vulnerable to overbuild by domestic competitors or global trade realignment as logistics networks evolve.
The European Mirror Image
The inverse economic dynamic has severely affected European manufacturing. Following the 2022 disruption of Russian pipeline natural gas, European industrial energy and electricity costs reset at a structural premium compared to North America. European crackers, already burdened by higher-cost naphtha feedstock, frequently sank into cash-negative territory during cyclical troughs.
In response, Dow moved to rationalize its European operating footprint. In 2025, the company announced it would shut down a set of upstream assets in Europe, including an ethylene cracker at Böhlen, Germany and chlor-alkali and vinyl assets at Schkopau, Germany, along with a siloxanes plant at Barry in the United Kingdom — actions the company framed as removing structurally disadvantaged capacity and targeting roughly $200 million of annual EBITDA improvement once complete.11
These closures represent permanent capacity retirements rather than temporary cyclical suspensions. Management effectively acknowledged that elevated European energy costs permanently impaired these assets' ability to earn their cost of capital. For investors, this restructuring underscores the geographic divide within Dow's portfolio: while its North American footprint retains a low-cost advantage, a significant portion of its international capacity faces structural cost headwinds.
The Three Segments
Packaging & Specialty Plastics serves as the company's main revenue and cash driver. The division encompasses Hydrocarbons & Energy — housing the steam crackers — alongside polymer production units that convert ethylene into various grades of polyethylene, including linear low-density for stretch films, high-density for rigid containers and piping, and low-density for extrusion coatings. The business also produces functional polymers for wire and cable insulation and operates the UNIPOL process licensing franchise inherited from Union Carbide. In 2024 this segment generated net sales of $21.7 billion, roughly half the company.1
The segment operates strictly on cost-curve dynamics, as polyethylene is sold against technical specifications rather than brand preference. Plastics converters prioritize melt index, density, and unit cost. Dow maintains a position in the lowest global cost quartile through backward integration into upstream ethylene, world-scale manufacturing facilities, proprietary catalyst technology, and an established distribution network. However, these cost efficiencies do not confer traditional pricing power; Dow remains a margin price taker whose earnings fluctuate sharply with the spread between polyethylene prices and ethane feedstock costs.
Industrial Intermediates & Infrastructure represents the portfolio's primary cyclical swing factor. Its product portfolio includes polyurethanes — specifically isocyanates and polyols used in mattress foams, automotive seating, refrigeration insulation, and construction panels — as well as ethylene oxide and ethylene glycol for antifreeze and polyester synthetics. The division also operates chlor-alkali and vinyl units producing chlorine and caustic soda, alongside industrial solutions for diverse chemical applications. In 2024 the segment recorded net sales of $11.9 billion.1
Because demand in this division depends heavily on global residential construction, automotive manufacturing, and durable consumer goods, high interest rates and prolonged weakness in China's real estate sector have made it the primary drag on corporate earnings during the recent industry downturn.
Performance Materials & Coatings functions as the company's higher-margin, customer-formulated segment. It comprises Consumer Solutions, centered on silicones, and Coatings & Performance Monomers, which produces acrylic binders for architectural paints. Dow assumed full ownership of the silicones business in 2016, when it restructured Dow Corning to acquire Corning's 50% equity interest in a transaction valued at approximately $4.8 billion.12 In 2024 the segment recorded net sales of $8.6 billion.1
Silicone products feature greater technical differentiation than commodity polyethylene, requiring specialized customer formulations and rigorous qualification cycles for applications in personal care, electronics, and automotive components. Nevertheless, rapid expansion of Chinese siloxane manufacturing capacity created broader market oversupply, compressing the segment's operating margins alongside Dow's commodity lines.
Competition and the Structure of the Industry
Dow competes globally against major chemical producers including LyondellBasell, ExxonMobil Chemical, Chevron Phillips Chemical, INEOS, Formosa Plastics, and state-backed Middle Eastern and Chinese entities such as SABIC. In Europe, BASF operates the world's largest integrated Verbund site in Ludwigshafen, Germany, facing similar structural energy cost disadvantages.
Evaluating the sector through Porter's Five Forces illustrates the industry's challenging structural landscape: - Rivalry among existing competitors is high and expanding as global capacity additions outpace near-term demand growth for commoditized molecules. - Buyer power is substantial, as large packaging converters and consumer product companies purchase in high volumes and maintain multi-sourcing strategies. - Supplier power remains low where Dow maintains backward integration into feedstocks, but increases significantly for non-integrated international assets. - Threat of new entrants is constrained for private commercial entities due to multi-billion-dollar capital requirements and extensive regulatory permitting timelines for world-scale complexes. However, this entry barrier is weakened by state-supported producers operating with lower capital return requirements. - Threat of substitutes is moderate, with paper, glass, aluminum, and post-consumer recycled resins competing at the margin, accelerated by environmental regulations.
Framed within Hamilton Helmer's 7 Powers, Dow maintains competitive advantages across three specific dimensions: - Scale economies: World-scale integrated production complexes reduce fixed costs per unit across massive production volumes. - Process power: Decades of proprietary catalyst development and chemical engineering expertise — partially monetized through its UNIPOL licensing business — present high technical hurdles for rivals to duplicate. - Cornered resource: Critical, hard-to-replicate physical infrastructure along the U.S. Gulf Coast, including pipeline right-of-way networks, salt-dome storage caverns, and deepwater export terminal access.
Equally defining are the powers Dow lacks. The business exhibits no network effects and minimal brand equity within its core commodity polymer divisions. Customer switching costs exist within specialized silicones and performance coatings but remain low in standard commodity resins. Ultimately, Dow operates fundamentally as a cost-advantage producer, making the durability of its investment thesis dependent on maintaining its relative feedstock and operational cost positioning.
That core cost advantage is currently facing its most severe test from a rapid expansion of production capacity in China.
VI. Management, Governance, & Capital Allocation under Fitterling & Carter
Quarterly earnings calls often reveal more than formal press releases, particularly when management answers challenging questions with shifting sentiment rather than hard numbers. Dow's executive leadership has faced many such moments since 2023.
Jim Fitterling
Jim Fitterling joined Dow in 1984 as a systems analyst and spent more than three decades inside the company — running Asia-Pacific operations out of Hong Kong, leading the hydrocarbons and energy business, serving as COO through the DowDuPont integration — before becoming CEO of Dow Inc. on April 1, 2019, at the moment of the spin.10 An engineer by training, Fitterling combined operational detail with a pragmatic stance on decarbonization, establishing the principle that Dow would pursue its "Decarbonize and Grow" strategy strictly where return hurdles were met.
His tenure as CEO encompassed extreme cyclical swings: the 2020 pandemic demand shock, an unprecedented 2021 polyethylene boom driven by supply chain disruptions and a U.S. Gulf Coast freeze, the 2022 European energy crisis, and subsequently the longest chemical downcycle in decades.
The Trough
That downturn provides the essential context for evaluating executive performance. From 2022 onward, three structural forces compounded: a massive wave of new ethylene and derivative capacity built by Chinese producers pursuing petrochemical self-sufficiency, a weak Chinese property sector that failed to absorb the supply, and severe European cost inflation that compressed operating margins across the continent.
Dow's response evolved from cyclical adjustments to structural retrenchment. Following a strategic review in April 2025, the company enacted the European facility shutdowns detailed in the preceding section, targeting roughly 1,500 role reductions globally.11 Management also reduced planned 2025 capital expenditures by approximately $1 billion, bringing annual capital spending down to around $2.5 billion, and announced delays to major growth projects.13
In July 2025, management executed the action income investors had feared: it cut the dividend in half, reducing the quarterly declared rate from $0.70 to $0.35 per share.14
Reading the Dividend Cut Honestly
The dividend reduction represents the single most critical test of management credibility in the post-split era.
For six years following the spin, Dow promoted its dividend as a foundational pillar of its equity story. Management repeatedly characterized the payout as a top capital priority and cited across-the-cycle cash generation as its support. However, as earnings deteriorated through 2023 and 2024, Dow funded the payout partially through U.S. Gulf Coast infrastructure asset monetizations and balance-sheet capacity rather than operating cash flow alone.
The 50% cut in July 2025 demonstrated that the pre-2025 dividend was not, in fact, covered across the cycle in the way the narrative implied, falsifying a core premise of the post-spin equity case. While management defended the reduction as a prudent step to preserve financial flexibility during a prolonged trough, the decision permanently altered the investment proposition for income-focused shareholders.
This gap between guidance and execution demonstrates why the current capital allocation narrative should be assessed against outcomes rather than accepted on stated intent, requiring rigorous verification of forward targets. Although industry forecasters did not anticipate a downcycle of this depth and duration, the outcome highlighted the inherent risks of maintaining fixed dividend commitments against volatile commodity cash flows.
Conversely, management demonstrated balance-sheet discipline once cash generation degraded. Rather than adding leverage to defend an unearned payout, leadership curtailed capital spending, shuttered non-competitive international assets, monetized non-core infrastructure, and reduced the dividend to safeguard the company's investment-grade credit rating. Compared to the 2008–2009 financial crisis — when Dow used heavy borrowing to sustain strategic initiatives until forced to adjust — the 2025 restructuring reflected significantly greater financial conservatism.
The Handover to Karen S. Carter
In 2026, Dow's board announced a leadership transition. Karen S. Carter became Chief Executive Officer effective July 1, 2026, with Fitterling continuing as Executive Chairman.
Carter brings a background distinct from traditional chemical industry chief executives. After holding various commercial and marketing roles, she served as Chief Human Resources Officer and Chief Inclusion Officer before assuming P&L responsibility for Packaging & Specialty Plastics — Dow's largest business — and subsequently serving as Chief Operating Officer. This progression from commercial strategy and organizational governance to core manufacturing operations points toward an emphasis on commercial execution and operational discipline rather than capital project expansion.
Carter inherits a clear mandate: complete the global cost-reduction and asset-rationalization program, restore free cash flow conversion, calibrate capital spending on the Path2Zero project, and maintain balance-sheet flexibility. Investor evaluation of her tenure will depend on cash generation rather than strategic positioning.
Jeffrey Tate serves as Chief Financial Officer, having been named to the role in 2025. Dow's executive compensation program ties performance share units to operating return on capital and cash flow metrics alongside relative shareholder return, aligning management incentives with cash generation across the cycle.
The Capital Allocation Waterfall, Restated
Following the dividend reduction, Dow's capital allocation hierarchy prioritizes: sustaining essential operations and fulfilling safety and environmental obligations; funding the reduced dividend; servicing debt maturities within investment-grade parameters; allocating growth capital strictly to high-return projects; and executing share repurchases opportunistically.
The key operational metric for investors is whether trough operating cash flow covers sustaining capital requirements and the reduced dividend without relying on asset sales. If cash flow covers these commitments, the balance sheet remains secure, positioning the equity as an option on cyclical recovery. If a shortfall persists, capital returns remain constrained by balance-sheet capacity.
This capital discipline leads directly to the largest discretionary claim on company cash flow.
VII. Path2Zero, Circularity, & Future Optionality
In November 2023, Dow announced plans for what it described as the chemical industry's first net-zero Scope 1 and Scope 2 emissions integrated ethylene cracker and derivatives complex. Located at an existing Dow site in Fort Saskatchewan, Alberta — northeast of Edmonton — the project represented a total planned investment of approximately $6.5 billion.15
How It Is Supposed to Work
The engineering behind the design targets carbon dioxide emissions at two main points: fuel combustion to heat the furnaces, and byproduct gases generated during the thermal cracking reaction.
Dow's design addresses both sources. Byproduct off-gas from cracking, rich in hydrogen and methane, is routed to an autothermal reformer that converts the stream into clean hydrogen and a concentrated stream of carbon dioxide. Burning the hydrogen fires the furnaces while producing water vapor instead of CO2. The concentrated carbon dioxide stream is captured and piped to Alberta's carbon sequestration infrastructure for permanent underground storage. On the Scope 2 side, purchased renewable electricity powers facility operations.
The project's underlying economics rest on three structural factors. Alberta provides cheap, ethane-rich natural gas and established natural gas liquids infrastructure, offering a feedstock cost position comparable to the U.S. Gulf Coast. The region also features geology suitable for carbon storage alongside an established regulatory permitting framework. Finally, public financial support — including the Alberta Petrochemicals Incentive Program and federal clean technology and carbon capture investment tax credits — materially improves projected returns.15
Management stated the complex would expand Dow's global polyethylene capacity by roughly two million metric tons per year at full buildout, while targeting approximately $1 billion in incremental annual EBITDA at full run rate.
The Delay
However, as the broader chemical industry trough deepened, capital priorities shifted.
In April 2025, Dow announced it was delaying construction on Path2Zero as part of a broader program to reduce 2025 capital spending by approximately $1 billion.13 The company subsequently extended the project timeline by roughly two years, pushing first-phase startup from 2027 to 2029, with the second phase deferred accordingly.
What the Delay Actually Tells Us
The timeline extension offers three distinct interpretations, each capturing part of the strategic reality.
The charitable reading: this represents capital discipline operating as intended. Adding two million metric tons of polyethylene capacity into a market struggling with structural global oversupply would destroy capital, regardless of the product's carbon footprint. Deferring capital outlay aligns with market conditions.
The skeptical reading: the delay suggests project returns were insufficiently robust to withstand a cyclical downcycle, and that a "net-zero premium" — willingness by customers to pay higher prices for low-carbon polyethylene — has not materialized at a scale capable of underwriting incremental capital costs. If decarbonized resins commanded a consistent price premium, project economics would show far less sensitivity to macro cycles.
The structural reading, and the perspective most relevant for investors: this pattern mirrors prior capital deployment cycles. Sadara represented a multi-billion-dollar single-phase megaproject built on cost-advantaged feedstock, expecting premium margins in downstream markets that ultimately softened during construction, leading to cost overruns and debt restructuring. While Path2Zero is smaller, phased, supported by government subsidies, and located in a lower-risk operating jurisdiction, the underlying category of risk remains similar: a capital-intensive greenfield asset whose financial return depends on market conditions years after the capital commitment.
This context does not imply Path2Zero will fail. Rather, it indicates the $1 billion incremental EBITDA target is a model projection rather than a guaranteed return, arguing for a discounted valuation until the initial phase completes commissioning and commercial sales. The falsifying event to watch for is straightforward: whether Dow, on subsequent calls, reaffirms both the total capital figure and the revised startup dates, or quietly revises either. On a project of this magnitude, capital cost inflation serves as the primary leading indicator of execution risk.
Circular Polymers: Sizing Optionality Honestly
Alongside Path2Zero, Dow has assembled a portfolio of circular economy initiatives. These include mechanical recycling partnerships, an equity position and offtake agreement with Mura Technology — which uses a hydrothermal process to convert mixed plastic waste into feedstock oil — and a stated goal to commercialize three million metric tons of circular and renewable solutions annually by 2030.
Evaluating these initiatives requires strict proportional context. Circular and bio-based polymers currently represent a minor fraction of Dow's total revenue, reaching a low single-digit percentage at most. Furthermore, advanced chemical recycling technologies have a documented history of pilot-scale facilities encountering feedstock contamination, low yields, and elevated operating costs, leading to delays and cancellations across the broader sector.
The accurate strategic framing positions circularity as a license-to-operate hedge and a customer-retention tool rather than a near-term margin driver. Major consumer packaged goods companies face public commitments for recycled content and increasingly include circularity metrics in procurement contracts. A polymer supplier unable to offer compliant resins risks losing sales on its core, high-volume conventional product lines. While this dynamic provides a valid commercial rationale for investment, it represents a defensive posture rather than a standalone growth engine. Assigning substantial valuation credit to Dow's circularity portfolio today extrapolates a business model that has not yet demonstrated commercial scale.
The overarching pattern across both initiatives remains consistent: Dow is committing capital to position for a decarbonized materials market whose timing and pricing dynamics remain unproven, while its core cash engine operates under trough conditions. This strategy represents a defensible allocation of modest capital reserves, provided capital commitments do not expand ahead of market evidence.
VIII. Playbook: Strategic & Business Lessons
Strip away the chemistry and corporate drama, and Dow's 129-year history yields several strategic lessons that extend well beyond the chemical industry.
1. In commodities, position on the cost curve beats everything else. Dow does not win by out-marketing rivals; commodity polyethylene carries no brand premium. It succeeds when input costs are structurally lower and struggles when they are not — a dynamic illustrated by the stark divergence between its North American and European operations over the past five years. The same molecule, produced by the same company using identical technology, functions as a high-margin cash generator on one continent and a cash drain on another, driven entirely by regional feedstock and energy pricing. Any enterprise selling undifferentiated molecules must be evaluated first by its position relative to the marginal producer, and only second by strategic narrative.
2. Never sign a fixed obligation against an uncommitted source of funds. The sequence linking K-Dow and Rohm and Haas stands as a classic case study in corporate finance of funding risk masquerading as strategic ambition. While the underlying strategic pivot was defensible, the transaction structure was not: committing to a binding, unconditional, multibillion-dollar cash acquisition funded by a joint venture with a state-owned entity that had not closed — and remained subject to political cancellation — created severe balance-sheet strain. The ultimate cost included an 8.5 percent preferred dividend coupon, a historic common dividend cut, and years of forced deleveraging.
3. Financial engineering reshuffles risk; it does not eliminate it. The DowDuPont merger and subsequent three-way split created entities with more focused corporate narratives. For Dow, however, the restructuring resulted in pure-play exposure to the exact commodity cyclicality that activist investors had originally criticized. Dismantling a conglomerate exposes the true economic profile of each constituent unit, occasionally demonstrating that higher-performing segments previously cushioned lower-margin commodity operations.
4. Trough discipline requires abandoning corporate commitments in the right order. Dow's 2025 restructuring sequence — curtailing growth capital, shuttering uncompetitive assets, monetizing non-core infrastructure, and ultimately halving the dividend — prioritized balance-sheet integrity over the shareholder narrative. While painful, borrowing to sustain payout levels through an extended downturn is a primary path to distress for cyclical, capital-intensive businesses. For investors, observing the order in which executive teams alter commitments under stress reveals their true operational priorities.
5. Geopolitics can permanently impair world-class assets. European chemical manufacturing was built on the assumption of cheap, reliable pipeline natural gas. When that supply model collapsed, facilities that had operated competitively for decades became structurally unviable on a permanent basis. No degree of operational efficiency can offset a primary energy input cost that has doubled relative to international competitors. Asset quality remains bound to underlying macroeconomic and geopolitical conditions beyond executive control.
6. Technical achievement is not commercialization. Constructing a net-zero steam cracker represents a major engineering milestone, but technical capability alone does not generate revenue. The distance between manufacturing low-carbon polyethylene and securing a durable customer price premium sufficient to cover incremental capital costs is where decarbonization initiatives succeed or fail. Dow's decision to delay the Fort Saskatchewan project demonstrates that green premiums are not yet large or predictable enough to insulate capital investments from cyclical downcycles.
These lessons converge on a single analytical framework for the evaluation that follows: test corporate claims against empirical performance rather than accepting management narratives at face value.
IX. Investment Thesis, Skeptical Stress-Test, & Bear vs. Bull Case
The Spine: Why Dow Wins From Here
The bull case for Dow rests on four primary pillars.
Cost position. Dow's North American assets sit in the global low-cost quartile for ethylene and polyethylene production because they run on ethane linked to cheap North American natural gas. In a commodity business where the marginal producer sets the market price, operating structurally below marginal cost enables Dow to generate cash under conditions where high-cost naphtha producers in Europe and Northeast Asia incur losses. This advantage reflects an enduring structural spread between regional energy markets.
Operating leverage into a recovery. Because Dow operates a capital-intensive fixed-cost base against variable selling prices, even a modest recovery in polyethylene spreads generates a disproportionate expansion in EBITDA. Having operated through a deep cyclical trough at depressed utilization rates and compressed margins, a normalization of market conditions — whether driven by demand recovery, rationalization of high-cost global capacity, or both — creates significant earnings upside without requiring additional growth capital.
Committed self-help. The European facility closures, workforce reductions, and capital expenditure cuts represent completed strategic decisions rather than speculative targets. Their cost-saving benefits accrue independently of broader chemical market cycles, providing the highest-confidence element of the bull thesis because realization depends on internal execution rather than external macro conditions.
Balance-sheet defense. Although painful for income investors, the 50% dividend reduction in July 2025 cut roughly $1 billion in annual cash obligations. Combined with capital spending discipline, this move preserved Dow's investment-grade credit profile and demonstrated management's willingness to protect balance-sheet stability during extended downturns.
Why Dow Loses
Structural Chinese overcapacity. The primary bear thesis hinges on the risk that Chinese supply expansion represents a structural regime shift rather than a standard inventory cycle. China has added ethylene capacity rapidly to achieve domestic self-sufficiency, with state-backed complexes coming online under mandates prioritizing industrial policy, employment, and supply security over market-driven returns on capital. Facilities built under these non-commercial incentives rarely shutter when operating margins turn negative, breaking traditional cost-curve economic assumptions. If state-supported capacity keeps global operating rates depressed for years, Dow's low-cost position will shield it from cash losses but fail to deliver the margin expansion required for a broader earnings recovery. Being the low-cost survivor is not equivalent to generating high equity returns.
Persistent European cost drag. While Dow has shuttered its most uncompetitive European assets, its remaining regional footprint stays exposed to structural energy and electricity premiums over North America, keeping long-term operating margins compressed across its European operations.
Delayed and unproven growth capital returns. The financial contributions from the Path2Zero project in Alberta have been delayed by roughly two years, pushing expected cash flows into a market facing broader capacity headwinds. Capital outlays have already begun while incremental EBITDA has been deferred. Furthermore, historical execution challenges on large-scale greenfield projects, such as the Sadara joint venture, justify investor skepticism regarding whether Path2Zero will achieve its projected $1 billion in incremental EBITDA on schedule.
Permanent cash claims from legacy liabilities. Environmental remediation duties, asbestos liabilities inherited from Union Carbide, and ongoing site cleanup commitments represent continuous annual cash drains that persist regardless of chemical cycle dynamics.
Vulnerability of the regional feedstock spread. Dow's core low-cost advantage depends on a persistent price gap between North American natural gas liquids and global crude oil. If U.S. natural gas prices rise structurally due to expanding liquid natural gas (LNG) export capacity, the ethane-to-naphtha price spread will narrow, eroding the cost cushion of Dow's North American assets.
The Activist Stress Test
A skeptical activist investor examining Dow's current position makes a compelling case:
"Dow trades at a depressed multiple on depressed earnings — a classic value-trap setup. Management has effectively acknowledged its historic dividend was uncovered across the cycle. The Industrial Intermediates & Infrastructure segment has consumed substantial capital while generating weak returns and should be divested or spun off. European operations should be exited entirely rather than rationalized at the margins. Growth capital spending should be paused until polyethylene spreads recover to mid-cycle levels, with free cash flow redirected to debt reduction and share repurchases at depressed valuations. Finally, the board must justify why management — having twice committed billions to greenfield megaprojects like Sadara and Path2Zero that encountered unfavorable market timing — should be trusted with capital allocation on large-scale builds."
That critique is formidable, but the substantive counter rests on operational physics rather than financial modeling.
Dow's manufacturing complexes are physically integrated by design. Chlorine from a chlor-alkali cell feeds vinyls and downstream derivatives; ethylene from a steam cracker supplies both polyethylene in Packaging & Specialty Plastics and ethylene oxide in Industrial Intermediates & Infrastructure. Shared utilities, docks, storage caverns, and rail terminals serve multiple business lines on a single footprint. Carving out Industrial Intermediates & Infrastructure would require either physically uncoupling co-located plants or negotiating complex intercompany supply agreements that replicate operational dependencies without unity of ownership. As established in the company's historical development, Verbund cost advantages belong to the physical site rather than the corporate structure; separating legal entities risks destroying those shared operational efficiencies. This physical interdependence explains why chemical breakups are far more complex than standard industrial splits, and why the DowDuPont separation divided assets along downstream end-market lines rather than physical plant sites.
The argument for aggressive share buybacks is logically cleaner, yet it collides with balance-sheet reality: a cyclical commodity producer funding share repurchases with debt or constrained cash flow during a trough risks severe financial strain. Prioritizing debt reduction and liquidity preservation over buybacks remains defensible, given the funding crisis Dow experienced during the 2008–2009 downturn.
However, the critique regarding megaproject governance remains valid. Having navigated execution and timing challenges on the Sadara joint venture, the board owes investors detailed oversight regarding Path2Zero — specifically concerning project phasing, contracting structures, cost contingencies, offtake agreements, and return thresholds. While the decision to delay construction reflects capital discipline under trough conditions, ultimate verification depends on final execution costs and delivered returns.
The Three KPIs That Matter
Evaluating Dow's path forward boils down to three primary operational metrics:
1. The U.S. integrated polyethylene margin — the spread between polyethylene selling prices and ethane feedstock costs per metric ton. This metric dictates Dow's baseline cash generation, capturing both global demand dynamics (polyethylene resin pricing driven by global operating rates and Chinese supply additions) and regional cost advantages (ethane pricing tied to North American natural gas markets). If this spread expands, Dow's earnings recover with substantial operating leverage; if it remains compressed, internal cost reductions alone cannot offset the shortfall.
2. Free cash flow conversion — operating cash flow expressed as a percentage of operating EBITDA. Management has targeted converting a clear majority of operating EBITDA into cash across the cycle. During a cyclical downcycle, this metric indicates how effectively working capital and capital expenditures are managed — and whether operating cash flows cover sustaining capital and dividend obligations without relying on debt or asset sales. Sustained conversion shortfalls serve as an early warning signal of balance-sheet stress.
3. Operating return on capital. Dow's long-term mid-cycle target has been in the low-to-mid teens percentage range. During the 2023–2026 downturn, return on capital fell significantly below that threshold and below the company's cost of capital. The core investment debate centers not on current trough levels, but on whether operating return on capital will recover toward historical targets as global capacity rationalizes, or if global overcapacity has permanently lowered Dow's achievable mid-cycle returns. Operating return on capital across the next full cycle will determine whether the company's structural cost advantage remains an effective engine for shareholder value.
X. Epilogue & Outlook
There is a symmetry to Dow's story that is almost too neat.
Herbert Dow built a company on the insight that a cheap, abundant, locally available raw material — Michigan brine that competitors disregarded — paired with an innovative process could outperform established producers globally. One hundred twenty-nine years later, the enterprise operates on the same core principle, applied to a different molecule: cheap, abundant American ethane that for much of the twentieth century was burned off as waste fuel.
The critical difference lies in the nature of the competition. Herbert Dow faced a German cartel that could be out-maneuvered through commercial arbitrage. Today, Dow competes against state-backed industrial strategies that do not prioritize market-driven returns on capital. A corporate producer cannot easily arbitrage a national policy.
Karen S. Carter leads an enterprise that has taken disciplined operational steps during a prolonged trough: closing uncompetitive international assets, reducing capital expenditures, defending the balance sheet, and deferring a major decarbonization project rather than adding capacity into an oversupplied market. Those decisions reflect lessons learned from the 2008 financial crisis and the Sadara megaproject — measures within management's direct control that do not rely on an immediate cyclical recovery.
What executive leadership cannot do is manufacture global demand or dismantle state-funded Chinese crackers. Dow's equity remains a leveraged claim on the eventual normalization of global chemical operating rates — anchored by an advantaged North American feedstock position, carrying persistent legacy liabilities, and tied to a multibillion-dollar growth build whose cash returns will lag capital outlays by years.
The open question for investors to track each quarter is straightforward: can Dow fund its reduced dividend and sustaining capital out of operating cash flow through the remainder of the trough, while completing Path2Zero at the stated cost, before enough of the world's high-cost capacity exits to let margins recover?
If the answer is yes, management's structural rationalization and low-cost feedstock positioning will yield substantial operating leverage upon recovery. If the answer is no — if the downcycle outlasts balance-sheet capacity or project costs escalate — the company will face difficult choices similar to those of 2009, with the key difference that it has already drawn down its dividend defense.
Herbert Dow's original thesis was that being the lowest-cost producer of an essential commodity would ultimately prevail, regardless of how long the cycle lasted. That core bet remains active today. What has changed is the capital discipline, market patience, and financial return expectations of the global competitors operating on the other side of the trade.
References
-
Dow Inc. 2024 Form 10-K Annual Report — SEC EDGAR, 2025-02-07 ↩↩↩↩
-
Dow Chemical Receives $2.2 Billion Settlement from Kuwait over Canceled K-Dow JV — Bloomberg, 2013-05-06 ↩↩
-
Rohm & Haas Sues Dow Chemical to Enforce $18.8B Merger Agreement — Wall Street Journal, 2009-01-26 ↩
-
Dow Inc. EDGAR Company Profile — U.S. Securities and Exchange Commission ↩
-
Dow Chemical Receives $2.2 Billion from Kuwait over Canceled Joint Venture — Bloomberg, 2013-05-06 ↩
-
Dow and Saudi Aramco Restructure $10 Billion Debt for Sadara Chemical JV — Bloomberg, 2021-03-25 ↩
-
Dow and Saudi Aramco Sadara Debt Restructuring — Bloomberg, 2021-03-25 ↩
-
Dow Chemical and DuPont Announce $130 Billion Merger of Equals — Wall Street Journal, 2015-12-11 ↩↩
-
Dow Inc. Form 8-K: Separation from DowDuPont & Distribution of Shares — SEC EDGAR, 2019-04-01 ↩↩
-
Dow Inc. Investor Events, Presentations, and Earnings Webcasts — Dow Investor Relations ↩
-
Dow Delays Construction on Path2Zero Project, Cuts 2025 CapEx by $1B — Reuters, 2025-04-24 ↩↩
-
Dow Inc. Company Stock Overview & Financial Ratios — Reuters Markets ↩
-
Dow to Build World's First Net-Zero Scope 1 and 2 Emissions Ethylene Complex in Alberta — Reuters, 2023-11-29 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube