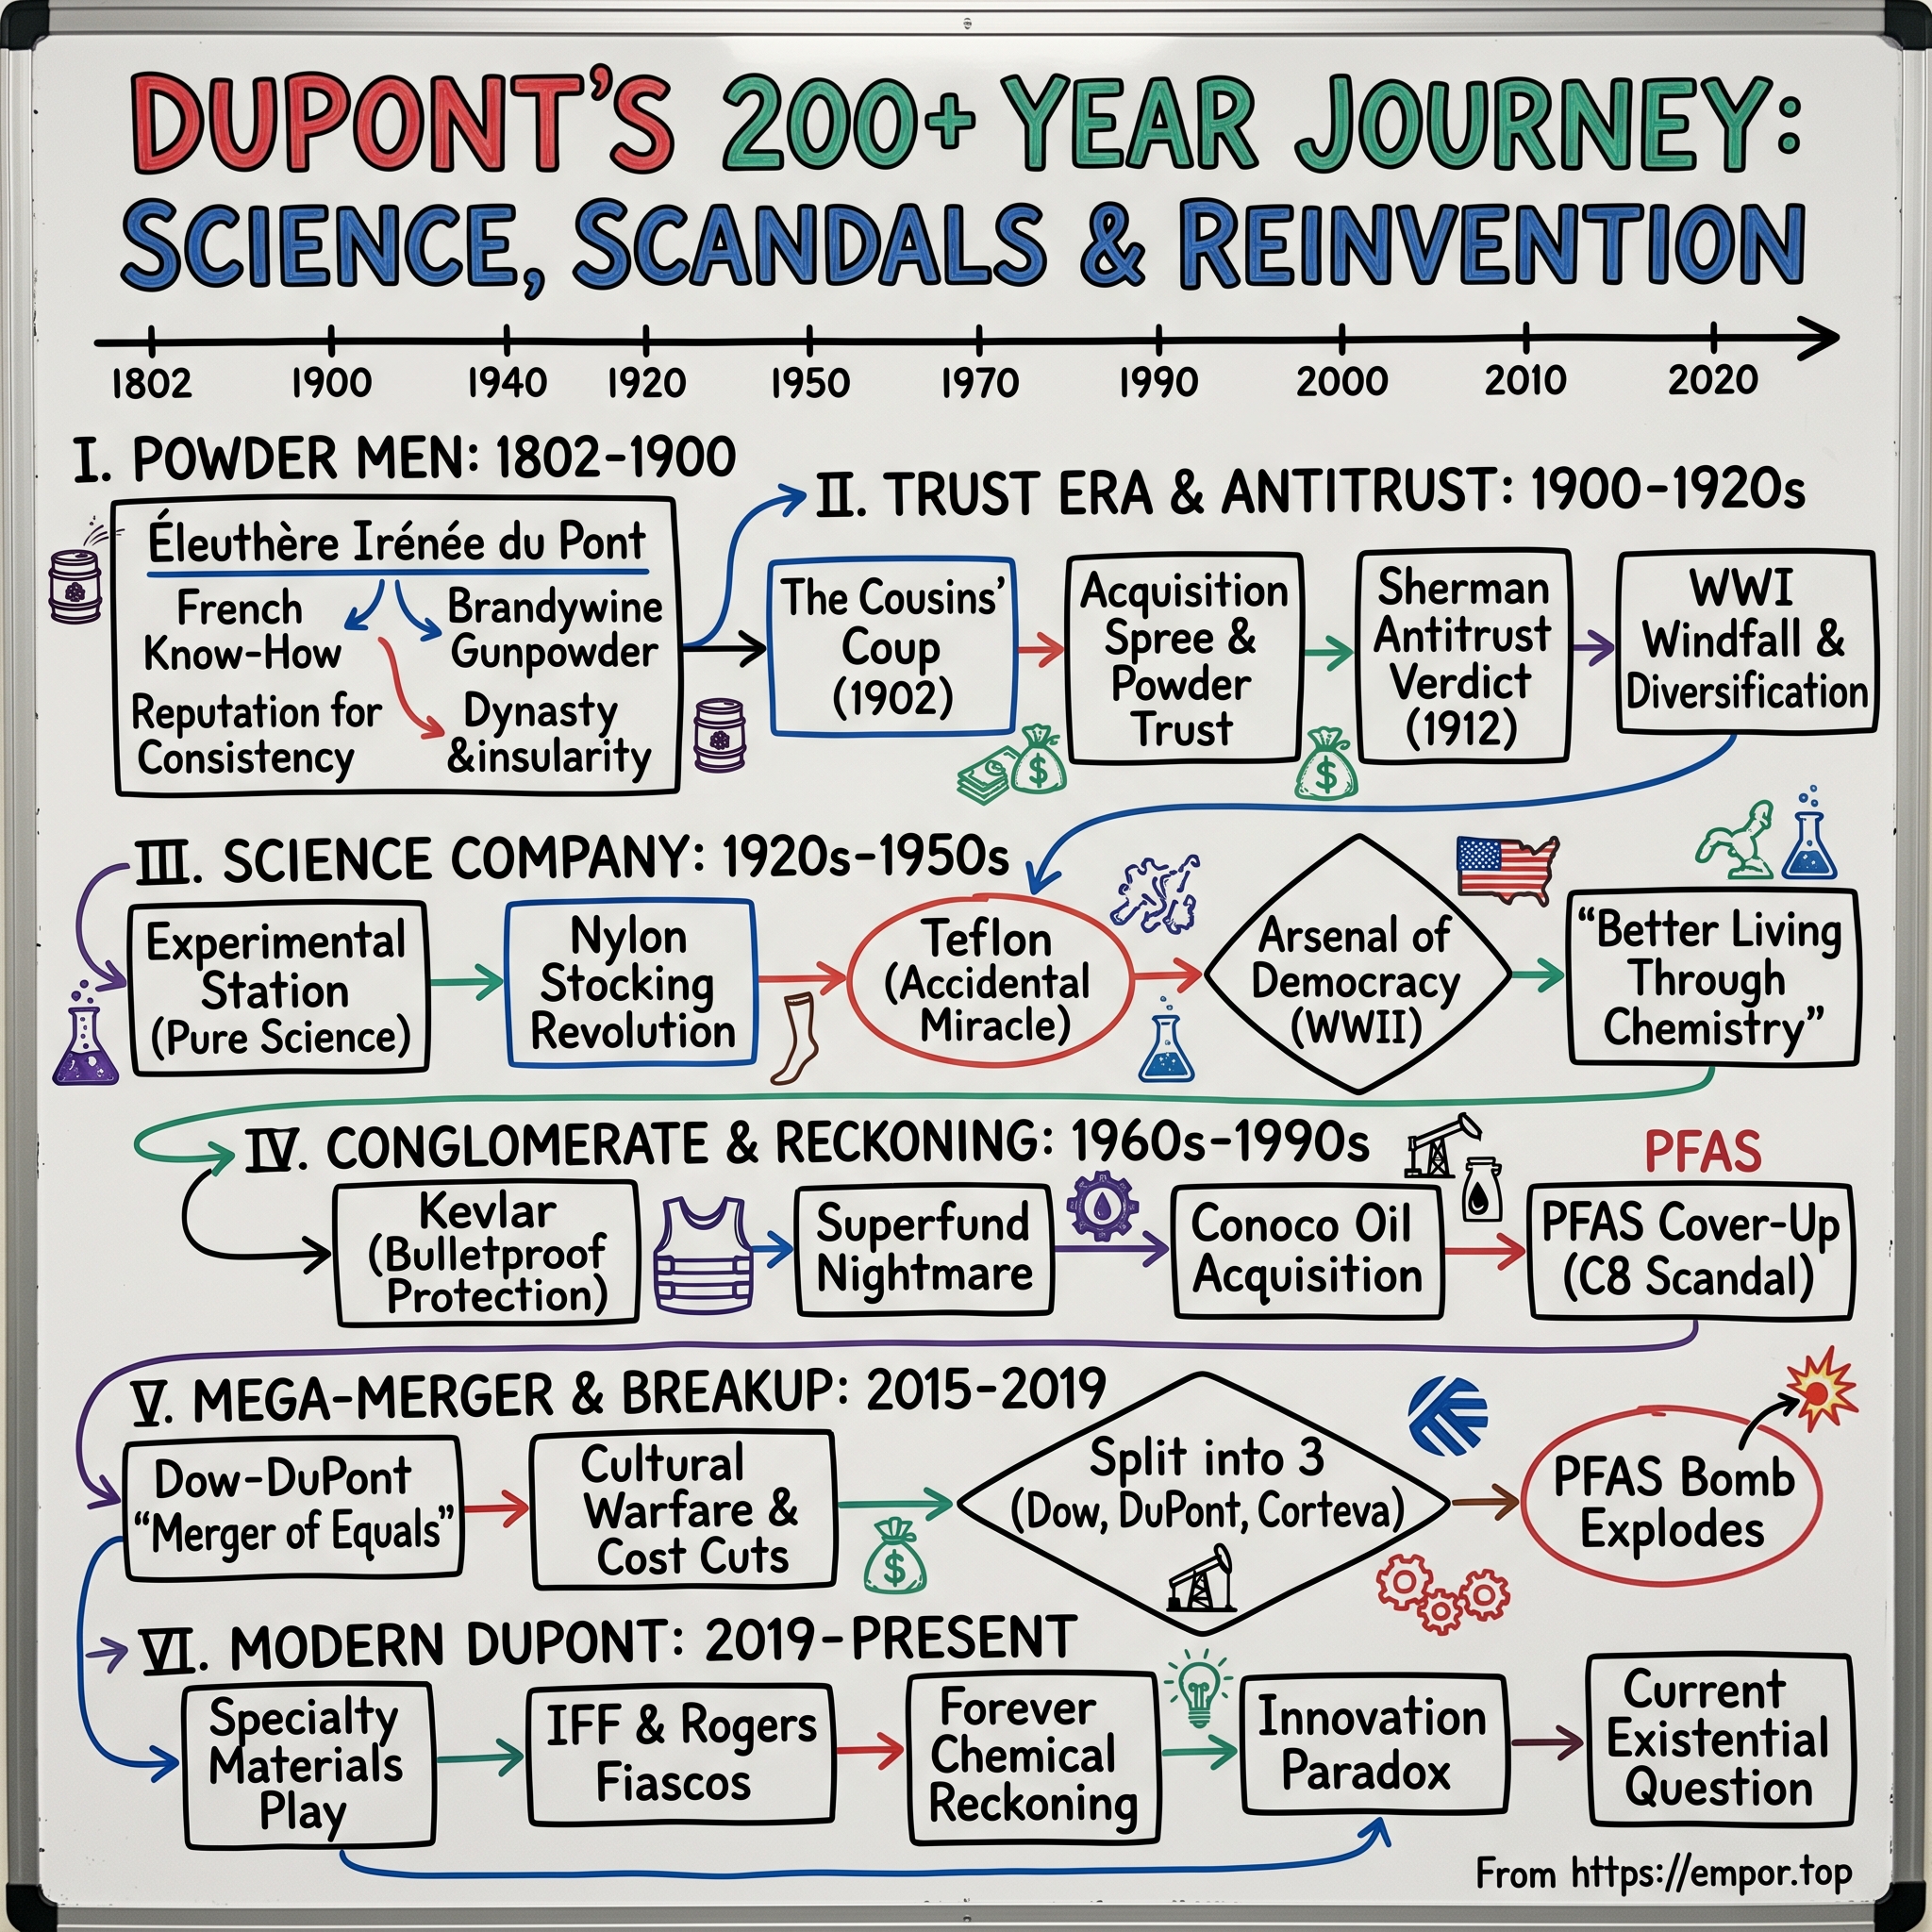
DuPont de Nemours: From Gunpowder to a $7 Billion Materials Company, Twice Rebuilt
I. Introduction & Episode Roadmap
On a Monday morning in early August 2026, DuPont's investor relations team put out a press release that would have been unintelligible to anyone who last looked at the company three years earlier. Quarterly sales of $1.8 billion. Two reporting segments, neither of which existed under those names in 2023. And, buried near the bottom, a note that as of July 31, 2026, the Global Industry Classification Standard had moved DuPont out of Basic Materials and into Industrials.1
A sector reclassification is the kind of thing that normally interests exactly two constituencies: index arbitrageurs and the investor relations department that lobbied for it. But in DuPont's case it was something closer to a death certificate for an identity. For 224 years — since Éleuthère Irénée du Pont opened a black powder mill on the banks of Delaware's Brandywine Creek in 1802 — the name DuPont meant chemistry. Nylon. Teflon. Kevlar. Lycra. The company that put "Better Living Through Chemistry" on the side of American life. In the summer of 2026, a committee at S&P Dow Jones Indices and MSCI decided that whatever DuPont now is, it isn't that.
They had a point. Consider what has left the building. In 2019 DuPont spun out agriculture as Corteva and commodity chemicals as Dow. In February 2021 it handed its Nutrition & Biosciences division to International Flavors & Fragrances. In late 2021 it agreed to buy Rogers Corporation for $5.2 billion, then walked away a year later having paid $162.5 million for the privilege of nothing.2 In 2023 it sold most of Delrin. In May 2024 it announced a three-way split; in January 2025 it cancelled one leg of that split eight months later.3 On November 1, 2025, it spun off its largest, fastest-growing and most prestigious division — the electronics materials business — as Qnity Electronics.4 On April 1, 2026, it sold Kevlar and Nomex.5
What is left is a company with roughly $7.2 billion of expected 2026 revenue, two segments, and a market capitalization of about $17.7 billion — smaller, by market value, than the electronics business it gave away ten months ago.16
That is the fact worth sitting with before anything else. Qnity Electronics, distributed to DuPont holders at one Qnity share for every two DuPont shares, currently carries a market capitalization in the mid-$25 billion range against DuPont's $17.7 billion. The parent is now the smaller half of its own child. Whether that is a triumph of value unlocking or a confession that the good business was the one they let go is the question this piece exists to examine.
So here is the central tension. Management's story is that after a decade of surgery, DuPont has finally arrived: a focused, higher-margin, secularly-growing industrial company with medical packaging and water membranes at its core, a conservative balance sheet, and a credible operating agenda. The skeptic's story is that DuPont's leadership has spent a decade being very good at corporate structuring and largely untested at organic growth — and that a company which announced a three-way split and reversed part of it within eight months has not yet demonstrated that it holds a plan long enough for the plan to be judged.
Both stories are supported by real evidence. The job here is to weigh them.
The route: two centuries of history compressed to the drivers still visible in 2026; the environmental reckoning and the first activist siege; Ed Breen's DowDuPont gambit; the portfolio surgery of 2019–2023; the second breakup and the Water U-turn; the business as it actually exists today, sized by materiality; the PFAS liability structure and where it stops protecting shareholders; a capital allocation and management credibility scorecard; and a bull/bear framework built on mechanisms rather than adjectives.
Start where DuPont started: with explosives.
 Subscribe on LinkedIn
II. Origins to Empire: Two Centuries, Condensed (1802–1980s)
Éleuthère Irénée du Pont had studied gunpowder manufacture under Antoine Lavoisier in France, and when he arrived in the United States in 1800 he found American powder so poor that he decided to make his own. The mills he built on the Brandywine were designed with three stone walls and one wooden wall facing the river — so that when a mill exploded, and mills did explode, the blast would vent across the water rather than into the next building.
That detail is the origin myth DuPont has told about itself for two hundred years, and it is worth taking seriously for exactly one reason: it is the source of a genuine operating culture. The du Pont family lived on-site, next to the powder yards. Safety was not a compliance function; it was a matter of whether your children survived the week. The modern descendant of that culture is the operational-excellence and cost-of-poor-quality metrics management now cites on earnings calls — on the second-quarter 2026 call, CEO Lori Koch noted the company was running cost of poor quality at about 4% of sales against an industry benchmark she put near 5%.7 The lineage is real. It is also, by itself, worth nothing to an investor unless it converts into margin, which is a test applied later.
The company's second formative event was a breakup. By the early 1900s DuPont controlled the great majority of American explosives production, and on July 31, 1907, the Justice Department brought an antitrust action against the powder combination. The courts ruled against DuPont in 1911, and the decree that followed carved two competitors out of the company: Hercules Powder and Atlas Powder.8
Pause on that. The first great structural event in DuPont's corporate life was a forced separation into focused entities. The most recent one, 115 years later, was a voluntary separation into focused entities. In between, the company added and shed businesses more or less continuously. Whatever else DuPont is, it is an institution with an unusually long track record of being taken apart — sometimes by regulators, sometimes by activists, most recently by its own board.
The third formative event was the invention of the industrial research laboratory. DuPont opened its Experimental Station near the Brandywine yards in 1903,8 and in the late 1920s research director Charles Stine made an argument that was genuinely radical for its time: that a corporation should fund fundamental science with no specified commercial application. To run it he recruited a Harvard instructor named Wallace Hume Carothers, a chemist of extraordinary gifts and severe depression.9
Carothers' group delivered on a scale that has almost no parallel in corporate history. In April 1930 an assistant, Arnold Collins, isolated chloroprene, which polymerized into what became neoprene — the first commercially successful synthetic rubber made in the United States. In early 1934 the team pivoted from polyesters to polyamides, and out of that pivot came nylon, which entered production in 1939 and was introduced to the public as a silk-stocking substitute at the New York World's Fair.9 Carothers did not see it. He died by suicide in April 1937, just as the magnitude of what he had made was becoming clear.9
The postwar decades were the compounding of that single research bet: Teflon, Lycra, Mylar, Tyvek, Kevlar, Nomex. "Better Living Through Chemistry" was not marketing hyperbole so much as an accurate description of a company that had invented a meaningful fraction of the materials in a mid-century American household.
Here is why this matters in 2026, and it is not nostalgia. DuPont's self-image — the thing management still reaches for when explaining why it deserves an industrial multiple rather than a chemical one — is that it is an innovation-driven materials scientist. Koch defends that framing with a specific number: a "vitality index" of roughly 30% in 2025, meaning about $2 billion of the year's revenue came from products launched in the prior five years, with those products carrying about 145 basis points of margin above the company average.10 By the second quarter of 2026 she was citing roughly 35%.7
But the historical record cuts both ways, and it cuts hard. Every one of the franchises listed above — nylon, Teflon, Lycra, Kevlar, Nomex, Delrin, and most recently the chemical-mechanical planarization slurries and photoresists that went to Qnity — has been sold, spun, or exited. DuPont has repeatedly proven it can invent a category-defining material. It has just as repeatedly proven that it will not own that material forever. The innovation engine is real; the claim that innovation produces durable DuPont franchises is the one the history rejects. Whatever moat exists today should be assessed on its own present-tense mechanics, not on the ghost of nylon.
The postwar sprawl that made DuPont a household name is also what made it, eventually, a target.
III. Diversification, Environmental Reckoning & the First Activist Siege (1980s–2015)
In July 1981, DuPont agreed to buy Conoco for roughly $7.3 billion, outbidding Seagram in what was at the time the largest corporate merger in American history.11 The logic was vertical integration: DuPont's chemical operations consumed something like 300,000 barrels of oil a day, and most of its competitors already owned captive oil supply.11 It was a defensible strategic argument in a decade when energy security dominated boardroom thinking.
It was also the beginning of an eighteen-year detour. DuPont sold 30% of Conoco in a 1998 public offering and disposed of the remainder through a tax-free split-off completed in 1999. The company that emerged had spent the better part of two decades as a hybrid oil-and-chemicals conglomerate before deciding it wanted to be neither. Then it bought Pioneer Hi-Bred and became an agriculture company instead.
The pattern is not subtle: DuPont has a long institutional habit of buying into an adjacent industry at scale, holding it for a business cycle or two, and then exiting. Any assessment of the current portfolio's permanence has to be discounted by that record.
Meanwhile, the environmental bill was coming due. DuPont's role in chlorofluorocarbons — it was the largest producer of the refrigerants implicated in stratospheric ozone depletion — put it at the center of the Montreal Protocol negotiations in 1987. The company ultimately supported the phase-out, in part because it had substitutes to sell. That episode became a template the company would not repeat with its next chemistry problem.
That problem was C8, also called PFOA, a processing aid used in making Teflon at the Washington Works plant on the Ohio River in West Virginia. The story is now widely known — the litigation, the science panel, the film Dark Waters — and its financial consequences are treated in full in Section VIII. What matters here is a structural point about how DuPont handled it: in 2015 the company spun off its performance chemicals business, including the fluoroproducts operations at the heart of the C8 story, as The Chemours Company. Chemours took the assets and, by design, a large share of the liabilities.
That spin-off was completed the same year DuPont faced the most serious governance challenge in its modern history.
Nelson Peltz's Trian Fund Management had built a position and, by early 2015, was running a full proxy contest, nominating four directors and arguing that DuPont was an underperforming conglomerate whose parts were worth more than its whole. The vote came on May 13, 2015. DuPont won — all of management's nominees were elected — but the margin was narrow, and both major proxy advisers, ISS and Glass Lewis, had recommended shareholders support Trian.12 Retail investors, who held over 30% of the register, were decisive.12
Then something instructive happened. Five months later, in October 2015, CEO Ellen Kullman retired following an earnings shortfall. The activist had lost the vote and won the argument.
This is the single most important piece of historical context for judging DuPont today, and it deserves to be stated plainly rather than left as an anecdote. Trian's 2015 thesis was that DuPont should be broken into focused pieces because the market persistently prices focus above diversification. Over the eleven years since, DuPont has executed essentially that thesis — three times over, into Dow, Corteva, IFF, and Qnity. Management has never framed it as capitulation to an activist; the deals were designed and sequenced by DuPont's own board. But the direction of travel has been Trian's direction of travel, continuously, for over a decade.
Which raises the obvious follow-on: if the 2015 activist case has now been fully implemented, is there a new one? That question is taken up in Section XI.
Kullman's successor arrived in November 2015 with a very specific reputation, and a very specific plan.
IV. Ed Breen's DowDuPont Gambit & the Three-Way Split (2015–2019)
Edward Breen was not a chemist. He was a turnaround operator whose reputation had been built at Tyco International, where he took over in 2002 after a spectacular governance scandal and spent the following decade dismantling a conglomerate into focused pieces. He had joined DuPont's board in February 2015 — in the middle of the Trian fight — and became interim CEO when Kullman left.
Breen's diagnosis was that DuPont's problem was structural, not operational. A company containing seeds, enzymes, refrigerants, electronic materials, aramid fibers and building products could not be efficiently valued by any single analyst or owned naturally by any single shareholder base. His prescription, announced in December 2015, was extraordinary in its ambition: merge with Dow Chemical in a roughly $130 billion combination, integrate for long enough to reorganize the assets, then split the combined entity into three focused public companies.
The synergy language in the announcement was real but secondary. This was never fundamentally a merger. It was a legal and tax vehicle: by combining first and separating second, DuPont and Dow could reshuffle divisions across corporate lines and distribute them to shareholders without triggering a taxable event that a straight sale would have caused. It was, in effect, a $130 billion reorganization dressed as a merger of equals.
Execution took three years and was genuinely hard. The companies had to clear global antitrust reviews — including divestiture requirements from European and American regulators — while simultaneously running an internal reorganization designed to be undone. DowDuPont closed in August 2017. The separations came in 2019: Dow, holding commodity and performance materials, in April; Corteva, holding seeds and crop protection, in June; and a "new" DuPont holding specialty products.
How should an investor grade it? Fairly, and without the benefit of hindsight the participants didn't have.
The honest verdict is that the structural logic worked and the operational cost was substantial. Three standalone companies with distinct capital allocation, distinct peer sets and distinct investor bases replaced a conglomerate that no one could model cleanly. Corteva today carries a market capitalization near $57 billion; Dow trades as a recognizable commodity chemicals name; and the specialty piece has since been broken down twice more. Against that: three years of management attention consumed by integration and de-integration, meaningful transaction and separation costs, and a merged entity that in 2018 wrote off approximately $4.6 billion of goodwill on its agriculture reporting unit — a write-down that says something about what had been paid for those assets in the first place.
The deeper point for anyone assessing DuPont in 2026 is that the DowDuPont transaction established a template. It taught this management team, and specifically Breen, that a tax-efficient structural separation is a reliable way to convert a conglomerate discount into shareholder value. The company has now run some version of that template three more times. Whether a tool that works is the same thing as a strategy that compounds is a question the last decade has not yet answered — and it is the question that governs everything after 2019.
The immediate task, though, was to figure out what "new DuPont" actually was.
V. Portfolio Surgery: Building "New" DuPont (2019–2023)
The specialty products company that began trading independently in June 2019 was a collection rather than a business. It held electronic materials, water filtration membranes, protective apparel, medical packaging, aramid fibers, engineering polymers, building products, and a nutrition and biosciences division inherited from the 2011 Danisco acquisition. Breen's task for the next four years was subtraction.
The first move was the most elegant. On February 1, 2021, DuPont completed the separation of Nutrition & Biosciences into International Flavors & Fragrances using a Reverse Morris Trust — a structure that lets a parent monetize a division tax-efficiently by spinning it out and immediately merging it with an acquirer. The mechanics matter. DuPont received a one-time cash payment of approximately $7.3 billion. It then ran a split-off exchange offer in which roughly 197.4 million DuPont shares were tendered and retired in exchange for about 141.7 million shares of the N&B entity, at a ratio of 0.7180.13
Read that again, because it is the most underappreciated capital allocation event of the period. DuPont did not just sell a division. It retired something on the order of a quarter of its own shares outstanding while receiving $7.3 billion in cash, and it did so without paying corporate-level tax on the gain. Whatever one thinks of the price achieved, the structure was excellent.
There is a temptation to go further and credit DuPont with foresight, because IFF's shares subsequently fell more than half from their peak amid integration difficulties and quality problems in the acquired business. That temptation should be resisted. The RMT structure protected DuPont shareholders from IFF's post-close performance automatically, by construction — it did not require anyone at DuPont to predict that performance. The correct conclusion is narrower and still favorable: DuPont chose a structure that eliminated stranded-equity risk. Whether N&B was sold for full value is genuinely not knowable from the outside, and the collapse in the acquirer's stock is at least as consistent with DuPont having sold well as with anything else.
Then came the deal that did not work.
On November 2, 2021, DuPont announced an all-cash agreement to acquire Rogers Corporation for $277.00 per share, an enterprise value of approximately $5.2 billion. The premium was 33% to Rogers' prior close and 46% to its one-month volume-weighted average. The strategic rationale was electrification: Rogers made elastomeric and ceramic materials used in electric-vehicle powertrains, advanced driver assistance systems and 5G infrastructure, and the plan was to fold it into DuPont's Electronics & Industrial unit. Closing was expected in the second quarter of 2022.14
It never closed. The gating item was clearance from 国家市场监督管理总局 State Administration for Market Regulation (SAMR), China's antitrust authority. The regulator did not block the deal; it simply did not act. The merger agreement's outside date passed on November 1, 2022, and the next day Rogers announced termination. DuPont paid a $162.5 million termination fee and received nothing.2
This deserves direct scrutiny rather than a footnote. DuPont spent a year of senior management attention, plus advisory and financing costs, plus $162.5 million in cash, on a transaction whose completion depended on a foreign regulator with no obligation to explain itself, in a deal with limited overlap in the Chinese market. The termination fee structure tells you the risk was priced — but paying an insurance premium is not the same as having avoided the loss.
The generous reading is that cross-border antitrust risk in 2021–2022 was genuinely hard to forecast, and that DuPont walked away rather than extending into an open-ended regulatory limbo, which several acquirers in that period did not. The uncharitable reading is that a company committing $5.2 billion at a 33% premium bears responsibility for underwriting the closing risk, and that the Rogers episode is the clearest single capital allocation error in DuPont's recent record. Both readings can be held simultaneously; what should not be conceded is any framing in which the outcome reflects discipline. DuPont did not choose to walk away from Rogers on valuation grounds. It was prevented from buying it.
Smaller surgery continued in parallel. On November 1, 2023, DuPont completed the sale of an 80.1% interest in the Delrin acetal homopolymer business to TJC, valuing the unit at $1.8 billion. DuPont took approximately $1.28 billion in pre-tax cash at close plus a $350 million note receivable, and retained a 19.9% non-controlling equity stake.15 Note that structure carefully — cash, plus paper, plus a minority stub in a private-equity-owned entity. It reappears almost exactly in 2026.
And in January 2021, alongside all of this, DuPont, Corteva and Chemours signed the memorandum of understanding that would define how legacy PFAS liabilities are shared for the following two decades.16 It committed no growth capital and appeared in no strategy deck. It is arguably the most consequential capital allocation decision of the period, because instead of deploying capital offensively it bounded a liability that had no natural ceiling. Section VIII takes it apart.
By early 2023, DuPont had a portfolio that could be described in a sentence: electronics materials, water and healthcare, and a collection of industrial businesses. The obvious next question was whether those three things belonged together at all.
VI. The Second Breakup: The Qnity Spin-Off, the Water U-Turn & the Koch Transition (2023–2025)
Lori Koch joined DuPont's predecessor in 1998 and worked her way up through finance, becoming chief financial officer in 2019 — the year new DuPont began trading — and chief executive on June 1, 2024.17 She had spent five years as the CFO who explained every one of the divestitures described above to analysts. When she took the top job, she was not inheriting a strategy she needed to learn. She was inheriting one she had helped build and sell.
Ed Breen did not leave. He moved to executive chairman, and remained in that role until November 1, 2025, when he transitioned to non-executive chairman.17 The significance of that timing is easy to miss: Breen held an executive role at DuPont through the entire design and execution of the second breakup, and stepped back to a non-executive seat on precisely the day the electronics spin completed. Koch became solely accountable for DuPont's operating performance only in November 2025. Her track record as an operator, as opposed to a portfolio manager, is ten months old.
The plan she inherited had been announced in May 2024, a few weeks before she took over: DuPont would separate into three independent public companies — an electronics business, a water business, and a remaining diversified industrial DuPont. It was the DowDuPont playbook, run a third time.
Eight months later, on January 15, 2025, DuPont announced it was not doing that. The Water separation was cancelled. Water would stay. And the Electronics separation would be accelerated, with a target date of November 1, 2025.3
The stated rationale came in two parts. Breen framed the acceleration: "Achieving an independent Electronics company as soon as possible is the right decision for our shareholders." Koch framed the retention: "The decision for Water to remain with DuPont provides the new organization with greater strategic flexibility and another high growth business alongside Healthcare."3
Take the arguments in favor seriously first, because they are not weak. Separating one business is meaningfully simpler than separating two simultaneously, and the simplification showed up in disclosed numbers: on the February 2025 call, CFO Antonella Franzen said total separation costs, previously guided around $700 million, would come in below that, and that dissynergies would fall from roughly $60 million to roughly $40 million.18 Retaining Water also left the remaining company with two high-growth franchises rather than one, which materially changes what "new DuPont" is as an investment. And there is a governance argument for a management team that changes its mind when the analysis changes, rather than executing a bad plan because it was announced.
Now the skeptical read, which is equally legitimate. A three-way split is not a tactical decision. It is the most significant structural commitment a board can make, and it should be stress-tested before announcement, not eight months after. Reversing one leg of it that quickly — weeks before a new CEO's first full quarter — invites the question of what analysis changed between May 2024 and January 2025 that could not have been done in April 2024.
Here is where the earnings-call record is genuinely informative, and where it points somewhere slightly uncomfortable. On the February 11, 2025 call — the first opportunity analysts had to press management on the reversal in a live setting — nobody did. The questions covered AI-related electronics revenue, incremental margins, Water's growth drivers, semiconductor node transitions, tariff pull-forward, separation costs, construction demand and capital deployment. Aleksey Yefremov of KeyBanc came closest, opening with "How are you thinking about Industrials' portfolio now that you decided to keep the Water business?" — treating the reversal as settled premise rather than as something to interrogate.18 John Roberts of Mizuho asked whether Water would be kept as a separate reporting segment, which Franzen confirmed, adding that Water and Healthcare would be highlighted "given their growth profile."18
That exchange is worth dwelling on, because Roberts was asking, politely, whether DuPont was preserving the optionality to spin Water later after all. Franzen's answer neither confirmed nor denied it.
So the calibrated conclusion on the Water reversal is this: the evidence does not support the strong claim that DuPont's leadership is strategically erratic — one reversal, with a coherent stated rationale and a measurable execution benefit, is not a pattern. But neither does it support management's implicit claim of rigorous strategic process. What it does establish is that the sell side did not treat the reversal as a credibility event, which means the market has priced approximately zero penalty for it. That, in turn, means a second reversal would land on a much less forgiving audience. The falsifying event to watch for is specific: any move to separate, sell or IPO the Water business, or any further restructuring of Diversified Industrials announced within a year of the medium-term targets set at the September 2025 investor day.
The Electronics spin, meanwhile, executed cleanly and on the accelerated schedule. On November 1, 2025, DuPont completed the separation of Qnity Electronics. Holders of record on October 22 received one Qnity share for every two DuPont shares, and approximately 209 million Qnity shares were distributed; the stock began trading on the NYSE under "Q" on November 3.4 Koch's statement was appropriately anodyne: "Today's announcement marks the beginning of exciting new chapters for both DuPont and Qnity as independent companies."4
The chapters have not been equally exciting. Qnity reported full-year 2025 net sales of $4.75 billion, up 10%, with adjusted pro forma operating EBITDA of $1.4 billion at a 29.5% margin, and guided 2026 revenue initially to $4.97–$5.17 billion.19 It has since raised that guidance substantially, and the market has responded: Qnity's equity value is currently in the mid-$25 billion range against DuPont's roughly $17.7 billion. Measured that way, the spin was an unambiguous success for shareholders who kept both pieces — and a fairly pointed comment on what the market thinks of the piece that stayed.
Then came the last cut. On April 1, 2026, DuPont closed the sale of its Aramids business — Kevlar and Nomex — to Arclin, a TJC portfolio company, for approximately $1.8 billion: $1.2 billion in pre-tax cash, a $300 million note receivable, and a $325 million non-controlling equity stake of roughly 16%.5 The economics of that deal are examined in the next section, because they raise a real question.
Net effect: in seventeen months, DuPont separated from the two most technologically distinguished franchises it owned. What remains is a company built around sterile medical packaging and water filtration membranes on one side, and construction and industrial materials on the other. That company is worth examining on its own terms.
VII. Inside Today's DuPont: Segments, Economics & Competitive Position
Strip away the corporate history and here is the operating reality as of mid-2026.
DuPont finished 2025 with net sales of $6.849 billion on a continuing-operations basis, up 2%, with operating EBITDA of $1.628 billion at a 23.8% margin — 100 basis points better than the prior year — and transaction-adjusted free cash flow of $689 million.20 Through two quarters of 2026, it has raised full-year guidance twice, landing at $7.155–$7.195 billion of sales, $1.75–$1.77 billion of operating EBITDA, and adjusted EPS of $7.17–$7.32 on a post-reverse-split basis.1
The composition of that revenue is the story.
Healthcare & Water Technologies: the engine, and what actually drives it
This segment generated $3.233 billion of 2025 revenue — 47% of the company — growing 9% reported and 7% organic, with operating EBITDA of $972 million at a 30.1% margin that expanded 170 basis points.20 It is the smaller segment by revenue and the larger one by profit contribution per dollar of sales.
Healthcare Technologies is best understood through one product. Tyvek is a flash-spun high-density polyethylene sheet, and its properties are unusual in a specific way: it lets water vapor and sterilizing gas through while blocking liquid water and bacteria. That combination is why a surgical instrument can be sealed in a Tyvek pouch, run through an ethylene oxide sterilization cycle, and stay sterile on a hospital shelf for years.
The economic point is not the chemistry. It is the regulatory consequence of the chemistry. A medical device manufacturer that validates a sterile barrier system with a regulator has qualified a specific material from a specific supplier made on a specific line. Changing that supplier means re-running validation — stability testing, sterilization validation, regulatory filings — across every affected product code. The cost of switching is not the price difference on the packaging; it is the time and regulatory risk of requalification. That is a genuine switching-cost moat, and it is the single most defensible position in the portfolio.
Around Tyvek, DuPont has bolted on medical device components through the Spectrum and Donatelle acquisitions, and biopharma materials under the Liveo brand, which the company expanded again in 2026.7 Management describes the device exposure as weighted toward cardiovascular and vascular applications, where procedure growth runs above the general surgical average — Koch put general surgical procedure growth near 4% and DuPont's market-weighted exposure closer to 5%.10 Personal protection garments, also Tyvek-based, sit in this segment and grew at a double-digit rate in the second quarter of 2026.7
Water is a different business with a different logic. DuPont sells the separation elements themselves: FilmTec reverse-osmosis and nanofiltration membranes, AmberLite ion exchange resins, and ultrafiltration modules. Management's claim is that DuPont is the only player with leading positions across all four principal filtration technologies.10 That claim is not independently verifiable from public data — specific market share figures are not disclosed — but the breadth is real, and it matters commercially because large water projects specify multiple technologies in sequence.
What is the actual evidence that Water is a secular growth business rather than a project-cyclical one? The strongest proof point in 2026 is not desalination. It is semiconductors. Ultra-pure water is a consumable input to chip fabrication, and on the second-quarter call Koch said that business had been growing "in the 20%-plus range" for several quarters running, driven by AI-related fab construction and utilization.7 That is a genuine, verifiable, high-growth vector with a demand driver entirely independent of municipal water budgets.
The weaker proof point is the Middle East. Desalination is concentrated there, and regional conflict pushed project timing around enough that DuPont cut its full-year Water growth expectation from mid-single digits to low-to-mid single digits. Koch was careful and, to her credit, specific: the projects were "not getting pulled," just moving; ex-Middle East organic growth was mid-single digits; and the Middle East is about 10% of Water sales.7
Take that at slightly less than face value. "Projects delayed, not cancelled" is the standard formulation of every project-exposed industrial company, and it is right most of the time and catastrophically wrong occasionally. The disconfirming test is mechanical and available: if Water's second-half organic growth comes in near the high-single-digit rate management guided, with fourth-quarter growth around 7% for the total company, the delay explanation holds.7 If the second half lands mid-single-digit and the Middle East revenue slips into 2027 with a fresh explanation, the correct interpretation shifts from timing to demand.
Competitively, DuPont occupies a narrower position here than the names it gets compared to. Xylem, which acquired Evoqua in 2023, sells integrated water treatment systems and services. Ecolab's Nalco Water sells treatment chemistry programs bundled with service. Veolia operates infrastructure. DuPont sells the separation element inside someone else's system. That is a more specialized and more defensible technical position, and also a structurally smaller share of the customer's wallet with less recurring service revenue. Koch has acknowledged the gap directly: asked in February 2026 whether the business lacked scale, she noted DuPont has "the leading technology across all the main components within water filtration" but that expanding within filtration would be "difficult from a regulatory perspective" precisely because of that position — meaning antitrust would likely block consolidation in DuPont's core — and that adjacent water assets have been trading at valuations that "would make it difficult" for DuPont to justify.10 She also confirmed DuPont has no service revenue in Water today.18
That is an unusually candid statement of a strategic box: the company cannot buy more of what it is best at, and what it could buy is expensive.
Diversified Industrials: the larger half, and the harder question
This segment produced $3.616 billion of 2025 revenue — 53% of the company — but it shrank, down 3% reported and 2% organic, with operating EBITDA of $800 million at a 22.1% margin that contracted 30 basis points.20 It contains Building Technologies, which sells into residential and non-residential construction, and Industrial Technologies, which spans aerospace, automotive adhesives, printing and packaging.
The 2026 trajectory has been better. In the second quarter, Diversified Industrials grew 3% organically with EBITDA up 7% and margin up 70 basis points, on aerospace and electric-vehicle battery strength plus multifamily residential construction.17 Koch sized the EV battery adhesives business at roughly $70 million of revenue heading into triple digits across 2026–2027, within a total automotive portfolio of about $900 million.7
Two observations, and the second is more important than the first.
First, the recovery is real but it is cyclical recovery, not structural improvement. Aerospace build rates, EV model launches and multifamily starts are end markets turning up. Management's own framing supports this: Franzen attributed the step-up in second-half organic growth almost entirely to carry-forward pricing taken to offset oil-and-gas input inflation — about $90 million of price for the year, roughly two points of growth in the second half — rather than to accelerating volume.7 Price taken to recover input cost is margin-neutral by construction; Franzen confirmed the company is managing to "price/cost dollar neutrality."7 It is not evidence of pricing power.
Second, and more consequentially: DuPont has just removed its two best brands from this segment. Kevlar and Nomex were the highest-recognition, most technically differentiated assets in Diversified Industrials. What remains is a portfolio of construction and industrial materials with meaningful buyer power on the other side of the table — distributors and OEMs who can and do multi-source in commodity-adjacent categories.
Which brings us to the price DuPont accepted.
The Aramids multiple, examined
The Aramids business generated roughly $1.3 billion of revenue in 2024. It sold for approximately $1.8 billion of headline consideration.5 That is about 1.4 times revenue for Kevlar and Nomex — two of the most recognized brand names in industrial materials, with defense, aerospace, protective apparel and electrical insulation end markets.
For context, DuPont as a whole trades at roughly 2.3 times enterprise value to trailing revenue, and around 10.8 times enterprise value to the midpoint of guided 2026 EBITDA. The Aramids transaction was struck below the parent's own revenue multiple.
There are legitimate explanations. Aramids is capital-intensive with long asset lives and periodic capacity investment requirements. Its growth profile is slower than Healthcare or Water. Buyers of carve-outs from large corporates price in standalone cost structure and transition risk. And a 1.4x revenue multiple can be a perfectly good EBITDA multiple if the margin is modest — DuPont has not disclosed standalone Aramids EBITDA, so the earnings multiple is genuinely not calculable from the outside.
But there is also the structure to consider, and the structure is the tell. DuPont did not receive $1.8 billion. It received $1.2 billion of cash, a $300 million note receivable, and a $325 million minority equity stake in Arclin.5 Roughly 35% of the consideration is paper whose value depends on the future performance and refinancing capacity of a private-equity-owned buyer. Koch confirmed on the February 2026 call that net-of-tax cash proceeds were about $1 billion.10
This is precisely the Delrin structure repeated: cash, plus a note, plus a minority stub, sold to the same sponsor.15 Running the same seller-financed structure twice with the same counterparty is efficient if you trust the buyer and want to keep upside. It is also a way to book a higher headline number than the cash justifies, and it leaves DuPont with two illiquid stakes and two notes on the balance sheet whose carrying values are management estimates rather than market prices.
The calibrated verdict: the Aramids sale is consistent with a company optimizing for portfolio simplicity and speed rather than for maximum value, and it should not be described as evidence of capital-allocation discipline without qualification. What would falsify the concern is straightforward and observable — full and timely collection of the Delrin and Arclin notes, and no impairment of either minority stake in future filings. What would confirm it is any write-down of those instruments.
Direct lithium extraction: optionality, correctly sized
On July 15, 2026, DuPont launched an end-to-end direct lithium extraction portfolio: more than twenty products spanning lithium-selective AmberSorb sorbents, FilmTec LiNE nanofiltration and reverse-osmosis elements, ion exchange resins and ultrafiltration modules, aimed at extracting lithium from brine as an alternative to hard-rock mining or evaporation ponds.21 No revenue figure was disclosed in the announcement.21 On the second-quarter call, Koch sized the addressable DLE market at roughly $200 million and confirmed the offering required no incremental capital — it is application development across existing product lines.7
That last detail is the one that matters, and it cuts in DuPont's favor on risk while cutting against it on significance. A capital-free product launch into a $200 million market cannot destroy value. It also cannot move a $7 billion company's growth rate. Treat it as a legitimate cross-sell of existing membrane and resin capability, not as a growth pillar — and note that DuPont's own history counsels patience here. The company built a world-class agricultural biotechnology capability over two decades and ultimately did not commercialize it as a DuPont franchise at all; it went out the door as Corteva. Technical capability at DuPont has a long record of becoming someone else's revenue. Wait for disclosed DLE revenue before capitalizing it.
Where the power actually sits
Run the portfolio through a competitive-strategy lens and the picture is narrower than the DuPont name suggests.
In Hamilton Helmer's framework, the clearest power DuPont holds is switching costs, concentrated in regulated medical applications where requalification is expensive and slow. There is a secondary process power claim in membrane and Tyvek manufacturing — these are hard products to make consistently at scale, and the manufacturing know-how is not trivially replicable. Beyond that, the cupboard is comparatively bare. There is no network effect. There is no cornered resource of the kind aramid fiber patents or CMP slurry formulations once represented, because those went to Arclin and Qnity. There is no meaningful scale economy relative to Ecolab, Xylem or 3M, all of which are larger.
On Porter's five forces: buyer power is the pressing issue, and it is asymmetric across the company. In Healthcare, buyer power is genuinely low — a device OEM cannot casually re-source a validated sterile barrier. In Water, buyer power is moderate; membranes are specified but engineering firms do evaluate alternatives on large projects. In Diversified Industrials, buyer power is high and rising, because distributors and OEMs multi-source building and industrial materials as a matter of routine. Supplier power showed up concretely in 2026 through oil-and-gas-linked input inflation, which DuPont could pass through on price but only to dollar-neutrality, not margin-neutrality.7 Rivalry is intense in water treatment and moderate in medical packaging. The threat of substitutes is the quiet long-term risk in Healthcare — alternative sterile barrier materials and alternative sterilization modalities both exist and both are being developed.
The investment conclusion for this section: DuPont's defensible earnings are concentrated in roughly a third of its revenue. The medical packaging and device franchise is a genuinely good business with a mechanism behind its returns. Water is a good business with a real technology position and an unresolved question about whether component supply without service is a durable place to stand. Diversified Industrials, at 53% of revenue and 22% margins in a cyclical recovery, is where the company's growth story is most exposed and its competitive position weakest.
And sitting underneath all of it is a liability older than any of these segments.
VIII. The PFAS Overhang: Who Actually Pays for Forever Chemicals
The chemistry that created the problem is easy to describe and very hard to undo. Per- and polyfluoroalkyl substances are built around carbon-fluorine bonds, among the strongest in organic chemistry. That bond strength is exactly what makes the materials useful — nothing sticks to them, nothing dissolves them, nothing degrades them — and exactly what earned them the name "forever chemicals." What does not break down in a frying pan also does not break down in groundwater, or in human blood serum.
DuPont used PFOA, known internally as C8, as a processing aid in manufacturing Teflon at the Washington Works plant in West Virginia from the 1950s onward. The litigation that followed — the class actions, the epidemiological science panel, the decades of discovery — produced one of the most extensively documented corporate environmental records in American history, and the reputational damage attached to the DuPont name rather than to any particular legal entity.
Which is the first thing an investor has to get right, because it is genuinely confusing. The company that operated Washington Works and generated most of the legacy liability is EIDP, Inc. — the old E.I. du Pont de Nemours and Company — which today sits under Corteva. The fluoroproducts operations went to Chemours in the 2015 spin-off. Today's DuPont de Nemours is a 2017-vintage holding company that inherited a share of legacy obligations by contract, not by having operated the plants. This does not reduce the cash exposure. It does mean that headlines naming "DuPont" often describe liabilities whose economics are shared three ways.
The structure that governs that sharing is the January 2021 memorandum of understanding, and it is the single most important document for sizing this risk.
Under the MOU, announced January 22, 2021, the three companies agreed to share qualified PFAS-related expenses arising from pre-July 2015 conduct on a 50/50 basis — Chemours bearing half, DuPont and Corteva bearing the other half between them — until the earlier of December 31, 2040 or $4 billion of aggregate qualified spend. DuPont and Corteva's combined $2 billion ceiling breaks down to roughly $1.36 billion for DuPont and roughly $640 million for Corteva. The parties also established an escrow of up to $1 billion, funded $500 million by Chemours and $500 million by DuPont and Corteva together over an eight-year contribution schedule. Alongside the MOU, the three settled approximately 95 pending cases in the Ohio PFOA multi-district litigation for $83 million, with DuPont and Corteva contributing $27 million each and Chemours $29 million.16
Two things follow. First, DuPont's exposure to this defined category of liability is bounded at approximately $1.36 billion over twenty years — a number that, spread across two decades against a company generating close to $700 million of annual free cash flow, is manageable rather than existential. Second, the arithmetic of the split has been visibly stable in practice. In the June 2023 settlement with U.S. public water systems, the three companies established a $1.185 billion fund, with Chemours at 50%, DuPont at approximately $400 million and Corteva at approximately $193 million.22 That is the MOU allocation working exactly as designed.
The New Jersey settlement approved in 2026 is the largest test to date. On August 4, 2025, Chemours, DuPont and Corteva reached an agreement with the State of New Jersey to resolve all environmental claims — PFAS and otherwise — across four current and former sites: Chambers Works, Parlin, Pompton Lakes and Repauno, plus statewide PFAS claims including aqueous film-forming foam and obligations under the state DEP's Statewide PFAS Directive. The consideration is $875 million paid over 25 years, which the companies valued at roughly $500 million on a pre-tax net present value basis. Chemours takes 50%, DuPont 35.5% and Corteva 14.5% — putting DuPont's present-value share near $177 million. DuPont and Corteva separately agreed to purchase Chemours' rights to certain PFAS-related insurance proceeds for $150 million.23
Note the 35.5%/14.5% split. Within their combined 50%, DuPont bears roughly 71% and Corteva roughly 29% — the ratio that governs the DuPont/Corteva side of the arrangement.
On August 7, 2026, a federal court approved the New Jersey settlements. Chief District Judge Renee Marie Bumb also approved a separate settlement with 3M valued at up to $450 million. Together the two are valued at approximately $2.5 billion, with proceeds directed to PFAS abatement, natural resource damages, remediation funding and a reserve fund.24
Now the part that management materials do not emphasize, and that any serious analysis has to place directly alongside the containment story rather than in a distant risk paragraph.
The MOU covers pre-July-2015 conduct within its defined scope. It does not automatically resolve every claim a plaintiff can construct. Two 2026 developments demonstrate the boundary.
In Hoosick Falls, New York, a class action filed in 2016 over PFOA contamination of the village water supply, originally against Saint-Gobain Performance Plastics and Honeywell, ended with EIDP as the last remaining defendant. It settled for $27 million, receiving preliminary approval in November 2025 and final approval on April 29, 2026, plus an additional $6 million to expand a medical monitoring program established in a 2021 settlement with the other defendants.25 The absolute number is small. The precedent is not: DuPont's legacy entity was pursued to the end as the residual defendant at a site it did not operate, on the theory that it supplied the chemistry.
And on July 9, 2026, New York Attorney General Letitia James sued 3M, EIDP, Chemours, Corteva and DuPont de Nemours over PFAS in consumer products — carpets, cosmetics, grease-resistant coatings — alleging the companies concealed toxicity and failed to warn. The relief sought includes cleanup funding statewide, an injunction against selling PFAS-containing products without warnings, disgorgement of profits, restitution and penalties.26
That last suit is categorically different from everything above it. Site remediation and drinking water contamination claims are geographically bounded and quantifiable: you can count the sites and price the cleanup. A consumer-products failure-to-warn theory is bounded by nothing except the volume of goods sold and the number of state attorneys general willing to file. It is closer in structure to tobacco or opioid litigation than to a Superfund allocation.
So the honest framing is a two-part one, and both parts must be held together. The known, MOU-governed legacy liability is structured, shared and capped in a way that is unusual and genuinely favorable — DuPont's shareholders are protected from the tail of the C8 story to a degree that shareholders of, say, 3M have not been. But newer claim types outside that scope are live, expanding, and not quantifiable from public disclosure. Neither "DuPont is protected" nor "PFAS could sink the company" is the right conclusion. The right conclusion is that the old problem is fenced and the shape of the new one is not yet known.
The KPI is specific and available annually: track disclosed PFAS-related cash outflows in the 10-K liquidity and legal proceedings footnotes against the $4 billion / 20-year MOU ceiling and DuPont's roughly $1.36 billion share, and watch for any new state action naming DuPont de Nemours as a primary defendant on post-2015 conduct — because that is the category the MOU does not reach.
Liability structure is one form of capital allocation. The rest of the record deserves its own accounting.
IX. Capital Allocation & Management Credibility Scorecard
Put the last five years of capital decisions on a single page and a pattern emerges that is neither as clean as management's narrative nor as damning as a short seller's.
The successes are structural. The Reverse Morris Trust into IFF monetized a division for $7.3 billion of cash while retiring roughly 197.4 million shares, tax-efficiently. The Qnity spin created an entity now worth more than its former parent. The Delrin and Aramids carve-outs removed cyclical, lower-multiple businesses from a portfolio the market was struggling to value.
The failure is transactional. Rogers cost $162.5 million and a year, and produced nothing.
And the ambiguity is strategic. A three-way split was announced and then partially reversed.
The buyback, the split, and what they signal
On November 3, 2025 — two days after the Qnity separation — DuPont announced a $2 billion share repurchase authorization. It executed a $500 million accelerated share repurchase in 2025, which Koch said would contribute about 2.5 percentage points of EPS growth in 2026, and announced a further $250 million repurchase for the third quarter of 2026.20107 Against a market capitalization near $17.7 billion, $750 million of executed and announced buyback in under a year is roughly 4% of the company — meaningful without being aggressive.
Then there is the reverse stock split, which is more interesting than it looks. Shareholders approved an amendment permitting a split at a ratio between 1-for-2 and 1-for-4 at the May 21, 2026 annual meeting; the board chose 1-for-3, effective June 24, 2026, reducing shares outstanding from roughly 405 million to roughly 135 million.2728 Koch's stated rationale on the second-quarter call was that it "aimed to align our key performance metrics with those of our industrial peer set."7
That is a candid admission of what the split was for: optics. A reverse split changes no economics whatsoever. Combined with the GICS reclassification lobbying — which management pursued openly for more than a year, telling analysts in February 2026 that changing the classification was "clearly our intent"1018 — it describes a company working deliberately on how it is perceived and categorized as well as on how it performs. That is not illegitimate; multiple expansion from peer-group repositioning is a real source of shareholder return, and Koch has been unusually transparent that she is pursuing it. But an investor should register that a portion of DuPont's 2026 return driver is re-rating rather than earnings.
The balance sheet
At the end of 2025 DuPont carried roughly $3.19 billion of total debt against $757 million of cash, for net debt near $2.44 billion — about 1.5 times operating EBITDA. By June 30, 2026, following receipt of the Aramids proceeds, cash had risen to $1.74 billion against $3.13 billion of debt, cutting net debt to roughly $1.39 billion, or under one turn of EBITDA. Koch has said DuPont typically prefers to carry about $1 billion of cash and retains "well over $1 billion" of capacity for acquisitions after the buyback.710
This is a genuinely conservative capital structure with no near-term refinancing pressure. It is also, from an activist's perspective, an underlevered one for a company generating high-visibility cash flow — and the M&A pipeline Koch describes is where that capacity is pointed.
One balance-sheet item deserves a second look. Goodwill and intangible assets stood at roughly $10.6 billion at June 30, 2026 — approximately half of total assets and about 77% of book equity. That is the accumulated purchase accounting from two decades of acquisitions, and it is a real accounting judgment risk. DuPont has taken large impairments before, including approximately $4.6 billion written off the DowDuPont agriculture reporting unit in 2018 and further goodwill charges against Nutrition & Biosciences in 2019 and 2020. Retained earnings currently sit at negative $24.3 billion, a figure that reflects spin-off distributions but also the cumulative history of writing down what was paid for. PricewaterhouseCoopers was ratified as auditor at the 2026 annual meeting with essentially no opposition.28 There is no going-concern issue or restatement here — this is a balance sheet flag, not an alarm.
Guidance discipline, tested against the record
DuPont has now raised full-year 2026 guidance twice. In February, the company guided to about 3% organic growth, $1.725–$1.755 billion of EBITDA and adjusted EPS of $2.25–$2.30 pre-split.20 In May, after a first quarter with 2% organic growth but 230 basis points of margin expansion and adjusted EPS up 53%, it raised the range.29 In August, after a quarter with 4% organic growth, 80 basis points of margin expansion, adjusted EPS of $1.88 up 21% against prior-year pro forma, and free cash flow conversion of 127%, it raised again.17
Two consecutive raises with beats underneath them is a good start and a short record. The specific thing worth testing is composition. Franzen was explicit that roughly two points of the guided second-half organic growth is carry-forward pricing taken to recover oil-and-gas input inflation, and that the pricing is designed to be dollar-neutral to cost.7 Strip that out and the underlying volume trajectory in the back half is closer to the first half than the headline suggests. Management is not hiding this — Franzen volunteered the bridge in response to an analyst question — but a reader looking only at "organic growth accelerating to 6%" would misread the business.
The second thing worth testing is whether the operating agenda is producing measurable change or vocabulary. Koch has introduced a dense internal lexicon: business system, vitality index, on-time-in-full, cost of poor quality, net productivity, 80/20. Some of it comes with numbers attached — 3% net productivity target against COGS, with about 200 basis points delivered in the second quarter contributing roughly 100 basis points of margin; roughly 30% win rate on new commercial sales plays against a historical high-teens rate; about $5–6 million of incremental Tyvek garment sales from those plays.7 Those are small, specific, checkable numbers, which is a point in their favor.
Some of it does not. The 80/20 program, piloted in four Diversified Industrials businesses, is contributing "a few million" of second-half EBITDA on a base of $1.76 billion.7 Jeff Sprague of Vertical Research opened the second-quarter call by asking, essentially, for something to anchor on — a quantified contribution from the innovation and commercial initiatives. Koch's answer was that the company is "not quite sizing what the upside is."7 That is a fair answer eighteen months into a cultural program. It is also the answer that has to change if the program is to be credited.
Management alignment and governance
Koch's fiscal 2025 total compensation was approximately $16.1 million, against a target total direct compensation of about $13.1 million — the gap reflecting performance outcomes, with roughly $12.5 million of the total in stock awards.17 DuPont's stock ownership guideline for the CEO is six times base salary, with executives required to hold company-granted shares until the requirement is met.17 That is at the stronger end of large-cap practice.
At the May 21, 2026 annual meeting, the advisory say-on-pay proposal received roughly 92% support of votes cast — solid, unremarkable, not a governance signal in either direction. All ten director nominees were elected. The highest opposition went to Alexander Cutler with about 13.3 million votes against, followed by Ed Breen with about 10.7 million; on a base of roughly 341 million shares voted, neither approaches a level indicating investor revolt.28
The credibility verdict
Weighing the record: Lori Koch inherited a strategy she helped design, executed the largest piece of it — the Qnity separation — on an accelerated timeline and without visible operational disruption, has beaten and raised guidance twice, and has been notably specific and non-evasive in analyst Q&A, including on unflattering topics like Middle East softness and the limits of the 80/20 program's early results. On the evidence available, she explains misses rather than deflecting them.
What is not yet established is organic execution over a full cycle. Ten months of sole accountability, in a period when two of her three main end markets were recovering off depressed bases and a third was benefiting from AI-driven fab construction, is not a test. The test arrives when a segment misses and there is no portfolio action available to change the subject.
That is also the question the market is implicitly asking about the stock.
X. Playbook: Durable Business & Investing Lessons
Four lessons generalize out of this history, and none of them are specific to chemistry.
The Reverse Morris Trust is an underused instrument, and DuPont has become expert at it. The mechanics are worth understanding because they recur across large-cap industrials. A parent spins a division into a new entity, that entity immediately merges with a buyer, and if the parent's shareholders end up owning more than half the combined company, the whole thing avoids corporate-level tax on the gain. Pair it with a split-off exchange offer — where shareholders tender parent stock for the new entity's stock — and the parent simultaneously monetizes an asset and shrinks its own share count. DuPont's IFF transaction did both: $7.3 billion of cash in, roughly 197.4 million shares out.13 The lesson for investors is to watch for it: when a diversified industrial announces a "merger" of a division with a competitor, the tax structure is often the entire point.
Cross-border antitrust has become a de facto veto, and termination fees are the market price of that risk. The Rogers deal was two American companies with modest Chinese revenue overlap, and it died because one regulator did not act.2 That is now a permanent feature of the deal landscape. The practical investing implication: when an acquirer announces a transaction requiring approval from a jurisdiction with limited process transparency, the announced deal value should be discounted by more than the historical base rate of deal breaks, and the termination fee tells you what the parties themselves thought the odds were.
Conglomerate-to-focus arbitrage is real, repeatable, and eventually exhausted. DuPont has now run it three times and the market has rewarded it each time — most starkly with Qnity, whose equity value exceeds its former parent's. But the arbitrage works because the market pays for legibility, and legibility is a finite resource. Once a company is down to two segments, further separation stops creating information and starts creating stranded costs. DuPont is close to that boundary, which makes the remaining question — is Diversified Industrials the next thing to go? — genuinely open rather than obviously yes.
R&D-driven advantage has a shelf life, and technical leadership does not imply ownership. This is the hardest and most important lesson. Nylon, Teflon, Kevlar, Nomex, Delrin, CMP slurries — each was, in its era, a genuine moat, and DuPont has sold or spun every one of them once a buyer or a public market valued the franchise more highly than the conglomerate discount allowed. The company's innovation engine works. Its record of retaining the franchises that engine produces is the opposite of a track record. An investor evaluating any current DuPont technology position — the Tyvek qualification moat, the four-technology water filtration stack, the DLE portfolio — should assume a meaningful probability that a successful version of it ends up owned by someone else.
Which brings the analysis to where it must end: what has to be true for this to work, and what would break it.
XI. Bear vs. Bull Case & What to Watch
The bull case, stated at its strongest
Post-spin DuPont is the cleanest version of itself in a generation. Roughly half its revenue sits in Healthcare & Water Technologies, growing high-single-digits organically in 2025 with EBITDA margins around 30% and a switching-cost mechanism in medical packaging that is mechanically defensible rather than rhetorically asserted.20 Margins are expanding at the company level — 100 basis points in 2025, another 80 in the second quarter of 2026 — against medium-term targets of 3–4% organic growth, 150–200 basis points of margin expansion, 8–10% adjusted EPS growth and free cash flow conversion above 90% set at the September 2025 investor day.12030 Cash conversion is running well ahead of that target.7
The balance sheet carries under one turn of net leverage, leaving capacity for both the $2 billion buyback authorization and a healthcare or water acquisition, with Koch stating explicit return discipline: mid-teens gross valuation multiples, low-teens net of synergies, and accretion to the growth algorithm.7 Legacy PFAS liability is capped and shared rather than open-ended. And there is a genuine, verifiable growth vector in ultra-pure water for semiconductor fabrication that ties DuPont to AI capital expenditure through a consumable rather than a cyclical equipment sale.7
At roughly 10.8 times enterprise value to guided 2026 EBITDA, DuPont trades below the multiples typically accorded to Ametek, Ecolab or Dover — the diversified industrial and water peers it has now formally joined. If the GICS reclassification, the reverse split and two years of consistent execution close even part of that gap, the re-rating is the return.
The bear case, stated at its strongest
Fifty-three percent of revenue sits in Diversified Industrials, which shrank in 2025 and carries 22% margins in construction, automotive and industrial end markets with real buyer power.20 The stated turnaround plan is an 80/20 program contributing single-digit millions on a $1.76 billion EBITDA base, and portfolio pruning that has just removed the segment's two best brands.7 Second-half organic acceleration is roughly one-third input-cost pass-through pricing that management confirms is dollar-neutral.7
The Aramids sale went at about 1.4 times revenue for Kevlar and Nomex, roughly 35% of it in a note and a minority stake in a sponsor-owned buyer, using the identical structure DuPont used for Delrin — which leaves two illiquid instruments carried at management estimates.515 The Water separation was announced and reversed inside eight months, and management confirmed Water is preserved as a distinct reporting segment, which is precisely how a business is kept spin-ready.18
A first-time CEO with a finance background has had sole operating accountability since November 2025, in a period when the portfolio actions rather than organic performance drove the equity story. PFAS containment holds for the MOU's defined scope but not for the consumer-products theory New York filed in July 2026, which has no natural boundary.26 Goodwill and intangibles equal roughly half of assets in a company with a long history of impairments. And the market's own verdict on where the value was is unambiguous: the business DuPont gave away is worth more than the business it kept.
The activist stress test
If Trian's 2015 thesis has been implemented in full, what would a new activist argue in 2026?
Probably this: DuPont is still two businesses stapled together, and the market is still applying a blended multiple to a 30%-margin growth asset and a 22%-margin cyclical one. Separate Healthcare & Water Technologies — or sell Diversified Industrials to a strategic or a sponsor — and the growth half re-rates toward water and medical technology comparables while the industrial half finds a natural owner. The counterargument is stranded cost: a $3.2 billion revenue standalone cannot carry a public company cost structure as efficiently, and DuPont has already absorbed corporate-cost dissynergies from the Qnity separation.
A second line of attack would be governance and the pace of change itself: a board that has announced and reversed a major structural plan, run three separations in seven years, and lobbied for a sector reclassification and executed a cosmetic reverse split, could be characterized as more focused on presentation than on operating results. The defense is the results themselves — two guidance raises and expanding margins — which is exactly why the back half of 2026 matters more than it looks.
A third would target the buyer paper: an activist would push for disclosure on the carrying values and terms of the Delrin and Arclin notes and equity stakes, and ask why a company with a conservative balance sheet accepted seller financing at all rather than demanding cash.
Current risk radar, restricted to what is material
Construction and industrial cyclicality is the largest near-term earnings risk, and it is concentrated in the majority segment. Management expects U.S. construction roughly flat for 2026 with non-residential and repair-and-remodel up low single digits offsetting a residential decline; the observed outperformance so far has come from multifamily, which is itself a cyclical category.107
Geopolitical and supply chain exposure is live and specific rather than generic: Middle East conflict is both delaying desalination projects and driving the oil-and-gas input inflation that DuPont is pricing through.7 Both effects reverse if the conflict resolves — the first favorably, the second by removing about a point of full-year price.
Regulatory and litigation risk is the PFAS tail described above, plus the broader possibility that PFAS restrictions eventually touch fluoropolymer-adjacent products DuPont still sells.
Execution risk in the transformation is the honest framing of the operating agenda. The business system, 80/20 and commercial excellence programs are the entire organic growth thesis. If they deliver, the medium-term targets are achievable; if they remain vocabulary, DuPont is a 2–3% grower with cyclical margins.
Technology substitution is slow-moving but real in the highest-value franchise: alternative sterile barrier materials and alternative sterilization methods both exist, and the qualification moat that protects Tyvek today also means that any successful challenger's qualification is similarly durable once achieved.
The three KPIs that matter
Everything above reduces to three things worth tracking each quarter.
Healthcare & Water Technologies organic growth rate. This is the entire quality argument for the equity. The segment grew 7% organically in 2025 and 4% in the second quarter of 2026, with management guiding mid-single digits.207 Whether it sustains mid-single-digit-or-better organic growth — and specifically whether Water re-accelerates once Middle East project timing normalizes — determines whether DuPont is a growth industrial or a GDP-plus industrial.
Diversified Industrials organic growth. The stabilization-versus-further-decline question. It went from −2% organic in 2025 to +3% in the second quarter of 2026, but roughly a third of the guided second-half rate is cost-pass-through pricing.207 The signal to watch is volume growth net of price.
Total-company operating EBITDA margin against the 25–25.5% medium-term target. Margin is where management's operating agenda either shows up or doesn't. The company exited 2025 at 23.8% and is guiding 2026 to about 24.5%.201 Sustained progress toward the 2028 target with volume growth underneath it validates the business system; margin expansion driven purely by mix and cost-cutting while volumes stagnate does not.
Alongside those, the annual check on disclosed PFAS cash outflows against the MOU ceiling remains the tail-risk monitor described in Section VIII.
XII. Epilogue & Reflections
There is a version of this story that is straightforwardly triumphant. A conglomerate that had become unanalyzable was taken apart with skill and tax efficiency across a decade, and every piece — Dow, Corteva, IFF's acquired nutrition business, Qnity — now has its own investor base, its own capital allocation, and its own accountability. Shareholders who held through all of it own a portfolio of focused companies rather than one incoherent one. Judged as a sequence of corporate finance decisions, DuPont's decade is close to a case study in doing it right.
There is another version that is more unsettling, and it is not a criticism of any individual decision. It is a question about what remains when the process ends.
DuPont today shares almost nothing operationally with the DuPont of 2015. Not the agriculture business, not the nutrition business, not the electronics business, not the aramid fibers, not the engineering polymers. The Experimental Station still stands on the Brandywine, but the categories that Station created have almost all been sold to buyers who valued them more highly than the market valued them inside DuPont. That last clause contains the whole tension. Financial engineering has been, unambiguously, the highest-return activity at DuPont for over a decade. Organic growth has not been demonstrated at all.
Which raises the uncomfortable framing: is a 224-year-old name that has been reduced, repeatedly, to whatever the market will pay a premium for, a company — or a process? The optimistic answer is that the process has finally converged, that Healthcare & Water Technologies is a genuinely good business that no acquirer will price better than the public market does, and that Lori Koch's operating agenda is the beginning of a different kind of value creation. The skeptical answer is that DuPont has two segments left, one of which is a growth asset and one of which is a cyclical, and that the same logic which produced Corteva, IFF and Qnity applies to that pair with equal force.
The company will not settle that question with a press release. It will settle it with four to eight quarters of organic growth in a segment that isn't being sold, at margins that expand because the operating system works rather than because the mix improved when something left. That is an unglamorous test, and DuPont has never before been asked to pass it.
Two hundred and twenty-four years in, the powder mills on the Brandywine were built with one wall facing the water so that when things blew up, the damage went somewhere else. It is an oddly apt metaphor for a company that has spent a decade engineering structures — Reverse Morris Trusts, spin-offs, cost-sharing memoranda — that direct value and liability precisely where they are meant to go. The remaining question is what happens when there is nothing left to direct anywhere, and the only thing left to do is run the business.
XIII. Recent News
The near-term calendar is unusually well-defined for a company that has spent a decade in structural motion.
Third quarter 2026 results, due early November 2026. Management guided to net sales of about $1.835 billion, operating EBITDA of about $448 million — flat with the second quarter — and adjusted EPS of $1.80 to $1.90, with roughly 5% organic growth after adjusting for the prior-year order timing shift, and about a 50 basis point margin headwind from oil-and-gas inflation.7 The specific things to check: whether Water re-accelerates as the Middle East projects management says are "on the books" convert, and whether Diversified Industrials volume growth holds once pricing is stripped out.
PFAS litigation after the New Jersey approval. The August 7, 2026 order resolved New Jersey.24 The open items are the New York Attorney General's July 2026 consumer-products action26 and whether other state attorneys general adopt the same theory. Any new suit naming DuPont de Nemours as a primary defendant on post-2015 conduct would sit outside the MOU's scope and is the development most likely to change the liability framing.
Capital deployment. The $250 million third-quarter repurchase was announced for execution in the current quarter,1 leaving roughly $1.25 billion of the November 2025 authorization outstanding. Koch has described an active M&A pipeline weighted toward healthcare — medical packaging and contract development and manufacturing — with more than $1 billion of capacity.7 A first meaningful acquisition under her tenure would be the first real read on Koch-era deal discipline, given that the Rogers episode belongs to the prior regime.
The Arclin and Delrin paper. DuPont holds a $300 million note and a roughly 16% stake in Arclin,5 and a $350 million note and 19.9% stake in the Delrin entity.15 Carrying values, interest accrual and any impairment disclosures in the 2026 Form 10-K are the cleanest available test of whether the seller-financed divestiture structure was value-accretive or merely headline-accretive.
Further portfolio action in Diversified Industrials. Nothing has been announced. Koch said in February 2025 that shareholders should "continue to see portfolio activity on the new DuPont side."18 Whether that means bolt-on additions to Healthcare and Water or subtraction from Industrials is the strategic question the next twelve months will answer.
XIV. Links & Resources
On the C8 and PFAS story. Nathaniel Rich's 2016 New York Times Magazine investigation "The Lawyer Who Became DuPont's Worst Nightmare" is the foundational long-form account of attorney Rob Bilott's litigation, and Bilott's own memoir Exposure (2019) covers the same ground from inside. Dark Waters (2019), directed by Todd Haynes, dramatizes it. Sharon Lerner's multi-year reporting for The Intercept documents the internal record in greater technical depth than the film does. For the primary source material, the C8 Science Panel's published findings remain the reference point on epidemiological linkage.
On DuPont's own history. The Hagley Museum and Library in Wilmington holds the DuPont corporate archive and maintains detailed public chronologies, including the records of the 1907 antitrust action and the 1912 dissolution.8 The Science History Institute's biography of Wallace Carothers and its "Nylon: From Labs to Legs" exhibition cover the invention of the modern industrial research laboratory.9 Alfred Chandler and Stephen Salsbury's Pierre S. du Pont and the Making of the Modern Corporation remains the standard account of the management systems DuPont invented and General Motors inherited.
On the activist episode. The Harvard Law School Forum on Corporate Governance published a post-mortem on the 2015 proxy contest that is unusually clear on the mechanics of how DuPont won a vote both major proxy advisers recommended against.12 Harvard Business School's case study "Proxy Contest at DuPont" covers the same events in teaching format.
On the current business. The most useful primary documents are the FY2025 Form 10-K, the September 18, 2025 investor day materials setting the 2026–2028 medium-term framework,30 and the quarterly earnings call transcripts — where the analyst Q&A consistently contains more disclosure than the prepared remarks, particularly on segment volume-versus-price composition and on the composition of guided growth.
On the peer set. Following the July 2026 GICS reclassification,1 the relevant comparables have shifted. For the Healthcare and Water franchises, Xylem, Ecolab and Veolia remain the operating comparisons; for the reclassified whole, Ametek and Dover are the multiple benchmarks investors will increasingly apply. Qnity Electronics' own filings are worth following as a live read on what the market pays for the assets DuPont chose not to keep.
References
-
DuPont Reports Second Quarter 2026 Results — PR Newswire, 2026-08-04 ↩↩↩↩↩↩↩↩↩
-
Rogers Announces Termination of Merger Agreement with DuPont — Rogers Corporation, 2022-11-02 ↩↩↩
-
DuPont Provides Update on Separation Plans, Reaffirms Financial Guidance — DuPont, 2025-01-15 ↩↩↩
-
DuPont Completes Separation of Qnity Electronics — DuPont Investors, 2025-11-03 ↩↩↩
-
DuPont Completes Divestiture of Aramids Business — DuPont Investors, 2026-04-01 ↩↩↩↩↩↩
-
DuPont (DD) Q2 2026 Earnings Call Transcript — Seeking Alpha, 2026-08-04 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
DuPont Company Chronology: 1890–1921 — Hagley Museum and Library ↩↩↩
-
DuPont (DD) Q4 2025 Earnings Call Transcript — The Motley Fool, 2026-02-10 ↩↩↩↩↩↩↩↩↩
-
Du Pont to Swallow Conoco in Record-Breaking Merger — The Christian Science Monitor, 1981-07-07 ↩↩
-
Winning a Proxy Fight — Lessons from the DuPont-Trian Vote — Harvard Law School Forum on Corporate Governance, 2015-05-18 ↩↩↩
-
DuPont Form 8-K Exhibit 99.3 — Completion of N&B Exchange Offer and IFF Merger — SEC EDGAR, 2021-02-01 ↩↩
-
DuPont Announces Acquisition of Rogers Corporation — Rogers Corporation, 2021-11-02 ↩
-
DuPont to Complete Sale of ~80% Ownership in Delrin Business to TJC — DuPont, 2023-11-01 ↩↩↩↩
-
DuPont, Corteva, and Chemours Announce Resolution of Legacy PFAS Claims — DuPont Investors, 2021-01-22 ↩↩
-
DuPont 2026 Definitive Proxy Statement (DEF 14A) — SEC EDGAR, 2026 ↩↩↩↩
-
DuPont de Nemours, Inc. (NYSE:DD) Q4 2024 Earnings Call Transcript — Insider Monkey, 2025-02-11 ↩↩↩↩↩↩↩
-
Qnity Reports Fourth Quarter and Full Year 2025 Results — Qnity Electronics, 2026 ↩
-
DuPont Reports Fourth Quarter and Full Year 2025 Results — PR Newswire, 2026-02-10 ↩↩↩↩↩↩↩↩↩↩↩
-
DuPont Launches End-to-End Portfolio to Advance Direct Lithium Extraction — DuPont, 2026-07-15 ↩↩
-
Chemours, DuPont and Corteva Reach Comprehensive PFAS Settlement with U.S. Water Systems — DuPont, 2023-06-02 ↩
-
Chemours, DuPont and Corteva Reach Agreement with the State of New Jersey to Comprehensively Resolve All Environmental Claims Including PFAS — DuPont, 2025-08-04 ↩
-
Federal Court Approves Historic PFAS Settlements Valued at Approximately $2.5 Billion — New Jersey Office of the Attorney General, 2026-08-07 ↩↩
-
$27M Class Action Settlement Ends Lawsuit Over Alleged Hoosick Falls (NY) PFOA Drinking Water Contamination — ClassAction.org ↩
-
Attorney General James Sues Some of the Nation's Largest Chemical Companies Over Toxic PFAS — New York State Office of the Attorney General, 2026-07-09 ↩↩↩
-
DuPont Announces Reverse Stock Split and Reaffirms 2026 Financial Guidance — DuPont, 2026 ↩
-
DuPont Form 8-K — 2026 Annual Meeting Voting Results — SEC EDGAR, 2026-05-21 ↩↩↩
-
DuPont Reports First Quarter 2026 Results — DuPont Investors, 2026-05-05 ↩
-
DuPont to Outline Value Creation Strategy and Financial Framework — DuPont, 2025-09-18 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube