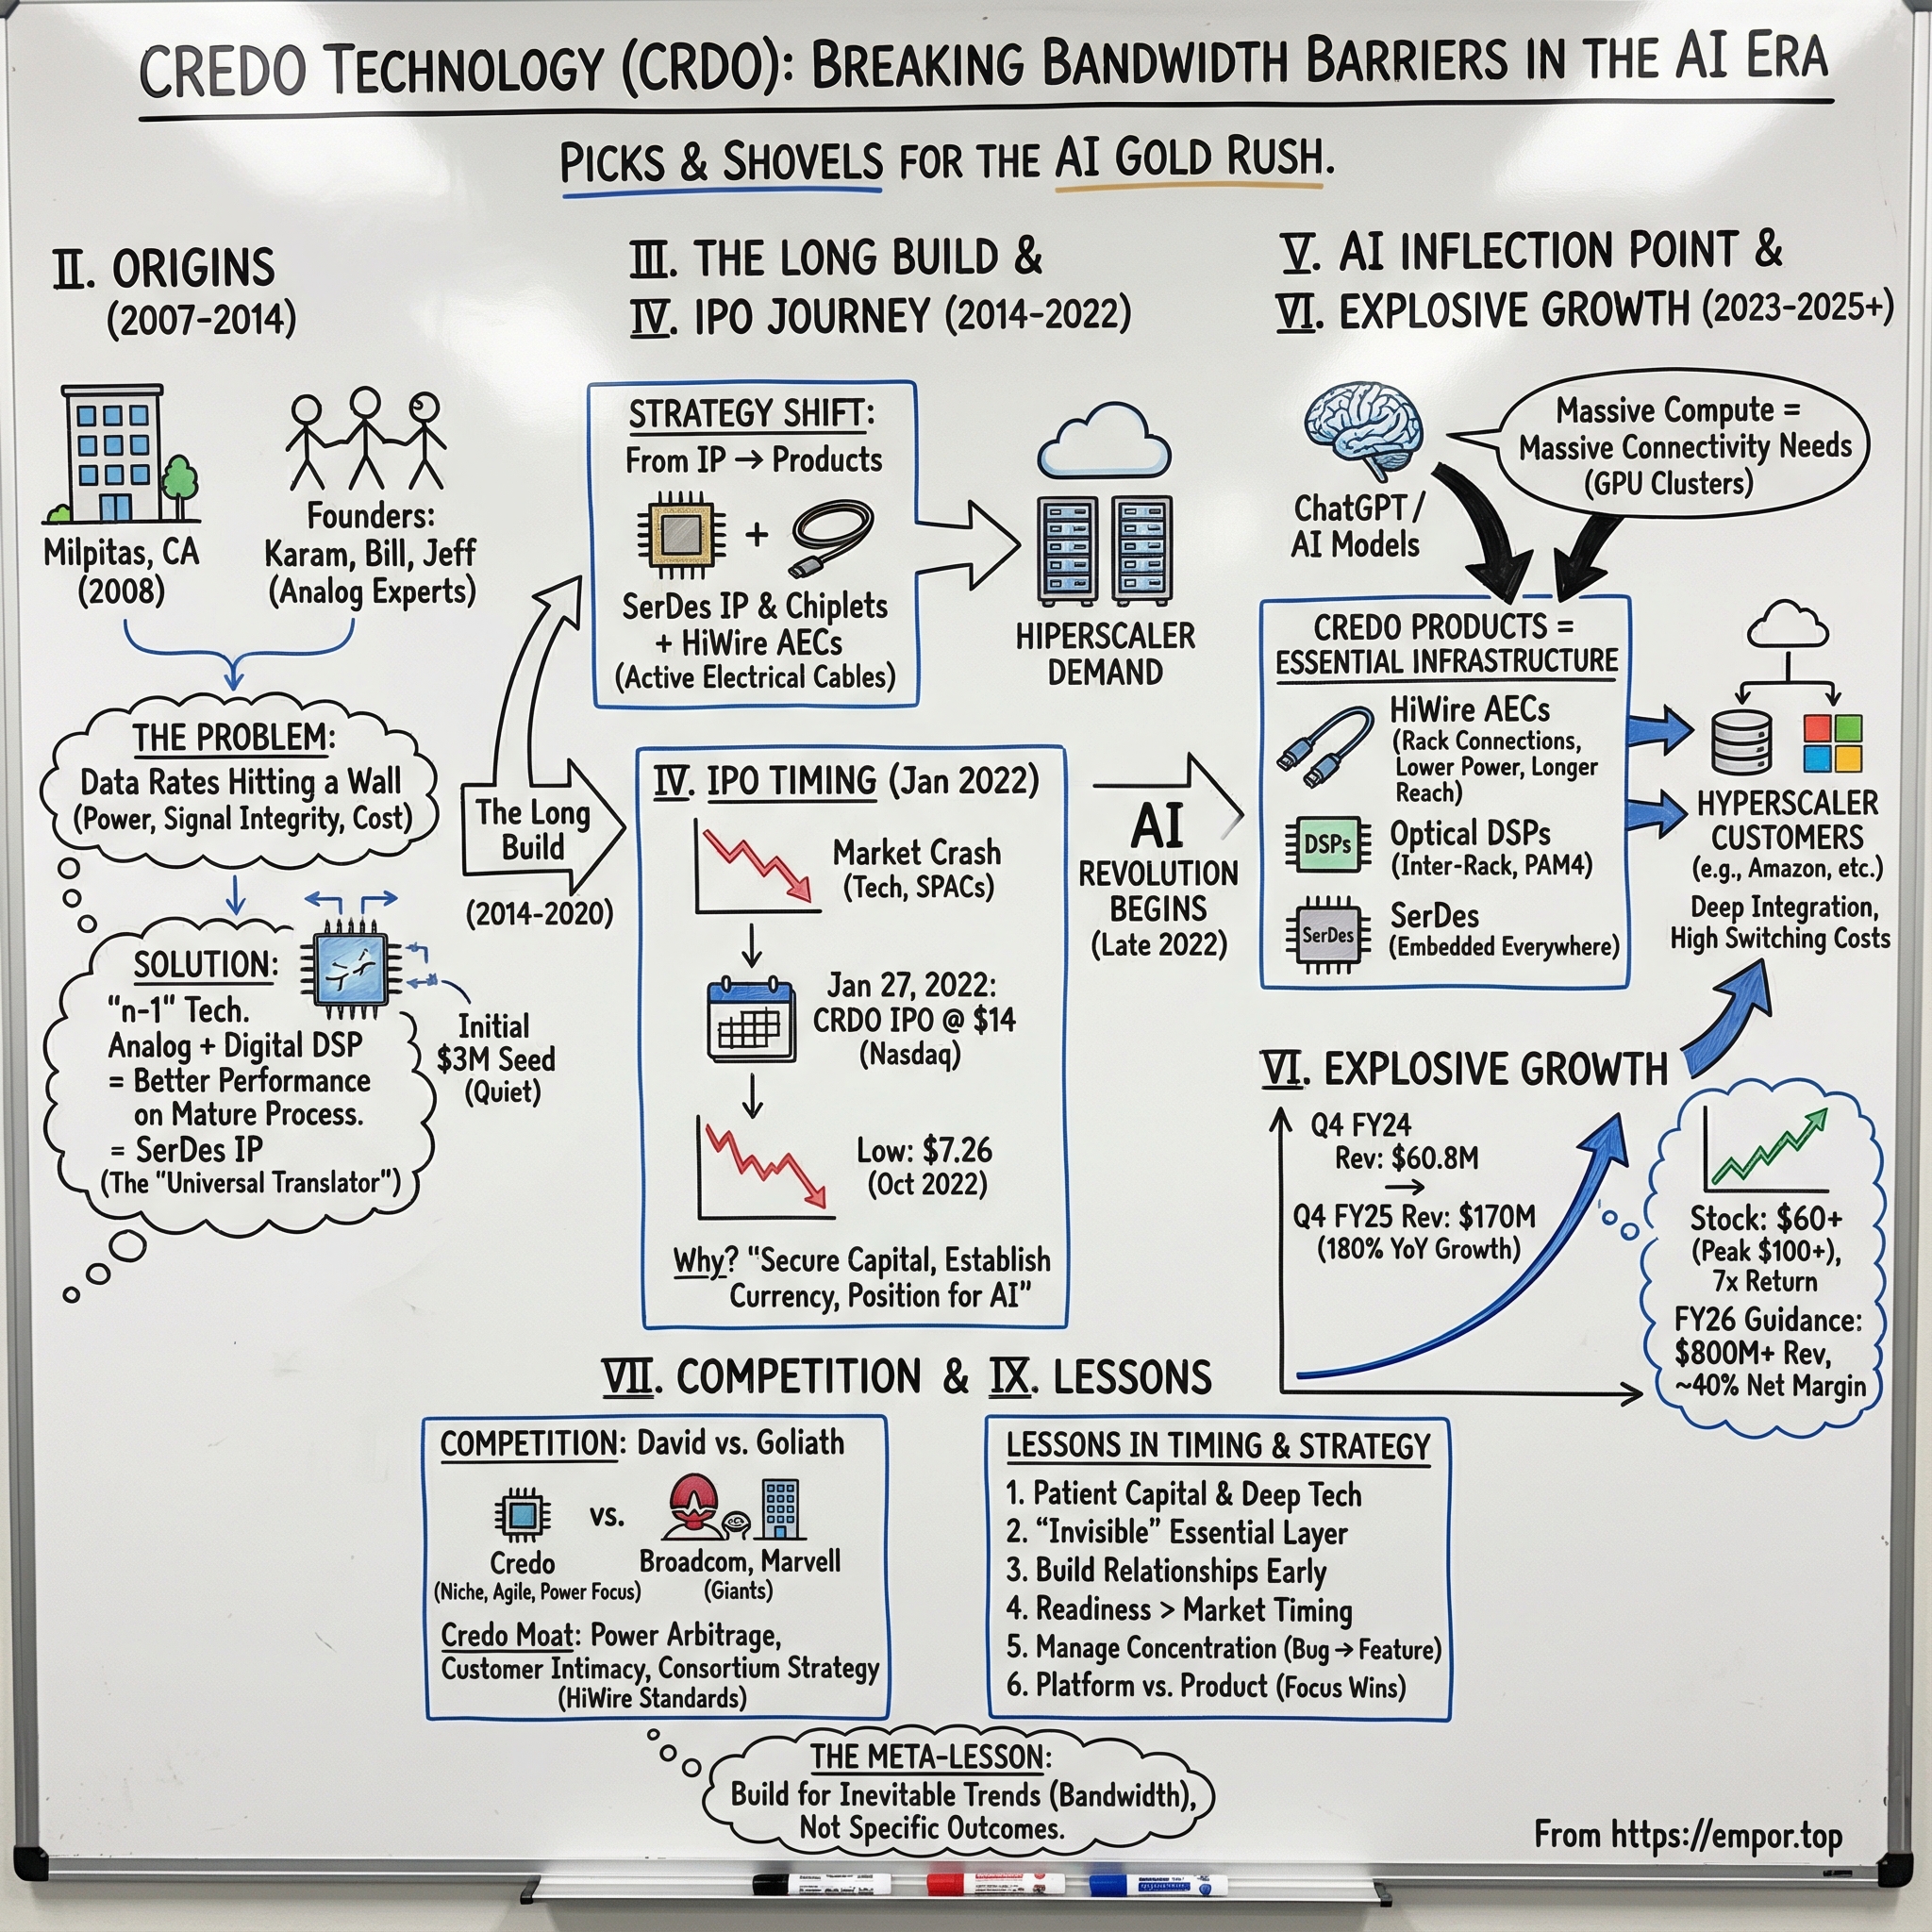
Credo Technology Group (CRDO): The Copper-to-Light Bet on AI's Connectivity Bottleneck
I. Introduction & Episode Teaser
On the afternoon of Tuesday, September 1, 2026, Credo Technology Group — incorporated in the Cayman Islands and operated out of San Jose — reported the strongest quarterly results in its history. Revenue reached $479.0 million, up 114.7% from the same quarter a year earlier, while non-GAAP net income more than doubled to $236.3 million, or $1.20 per diluted share. Management guided revenue for the following quarter to between $525 million and $535 million, comfortably exceeding Wall Street projections.1
The next morning, the stock fell 20%.3
That sharp contrast — a quarter featuring 115% revenue growth followed immediately by a one-day sell-off — highlights the complex dynamics surrounding Credo. By the close on September 4, 2026, shares traded around $171, giving the company a market capitalization of approximately $31 billion, compared to a 52-week range of roughly $86 to $309.2 Investors had watched the stock nearly quadruple before surrendering about half those gains in a matter of weeks, even as the company's financial performance continued to accelerate.
The magnitude of this expansion provides essential context. For the fiscal year ended April 2024, Credo generated $193.0 million in total annual revenue.5 Just two fiscal years later, in the fiscal year ended May 2, 2026, annual revenue reached $1.335 billion, with non-GAAP net income of $661.5 million.4 That represents a nearly sevenfold increase in top-line scale over two fiscal years, marking one of the fastest organic expansions in recent semiconductor industry history.
Credo does not manufacture GPUs or core switch chips. Instead, it supplies high-speed connectivity infrastructure: serializer-deserializer (SerDes) circuits, digital signal processors (DSPs), retimers, and active electrical cables (AECs). In the topology of an AI training cluster, where GPU suppliers build the compute engines and switch vendors build the main network interchanges, Credo provides the short-reach interconnects and high-bandwidth links that tie those components together.
This highlights the central question facing investors. Is Credo a structurally advantaged supplier controlling a physical connectivity bottleneck in AI infrastructure? Or is it a component vendor with substantial operating leverage, selling into a concentrated group of hyperscale buyers powerful enough to shift demand rapidly — as demonstrated in February 2023, when its largest customer reduced demand forecasts and Credo's stock dropped more than 40% in five trading days?6
That 2023 downturn serves as a baseline case study. Management's claims regarding revenue durability, customer diversification, and expanding optical capabilities must be evaluated against a corporate record that already contains a sharp customer-concentration shock.
The analysis ahead traces Credo's evolution: fourteen years developing mixed-signal silicon, an initial public offering executed during a closing market window, the demand shock that derailed its initial growth story, the AI inflection that reshaped its trajectory, three acquisitions within twelve months as the company expanded from copper to optical interconnects, and an assessment of the arguments shaping the current market debate.
 Subscribe on LinkedIn
II. Origins: The Long, Quiet Build (2008-2020)
Popular accounts of Credo's origins often place CEO Bill Brennan among the founders, but the company's regulatory filings tell a different story. Credo was founded in 2008 by two mixed-signal engineers, Chi Fung "Lawrence" Cheng and Yat Tung "Job" Lam, veterans of analog and SerDes design who spent their careers solving complex signal-integrity challenges in chip development.9 Brennan joined later as an experienced operating executive, acting as the commercial architect of Credo's product strategy and go-to-market execution. He is not a founder, a distinction that later becomes evident in the company's equity ownership structure and executive incentives.
At the heart of Credo's strategy was a core technical focus on serializer/deserializer (SerDes) architecture. A SerDes circuit takes wide, slower parallel data streams inside a microchip, compresses them into a narrow, high-speed serial stream for transmission across physical media, and reconstructs the parallel stream at the destination. At ultra-high speeds, signals transmitted over copper or optical channels degrade into electrical noise and distortion. The receiver's function is to accurately reconstruct the original binary data from this degraded signal.
This mixed-signal design work operates at the intersection of analog physics and digital logic. For venture investors, evaluating such deep technical execution was difficult, as design cycles spanned several years and lacked immediate software-style engagement metrics. Success depended on whether a circuit could close timing at demanding thresholds, such as 56 gigabits per lane. Cheng and Lam focused on a specialized domain where technical credibility was the primary asset, requiring patient capital willing to support long design-win cycles.
That niche also presented structural barriers to competitors. Major high-speed connectivity incumbents, such as Broadcom and Marvell, built broad, integrated product portfolios where SerDes circuits functioned as supporting blocks within larger system-on-chip architectures. By treating signal integrity as its standalone focus, Credo sought to out-engineer broader competitors that allocated resources across dozens of design priorities.
Credo's initial business model reflected these capital and channel constraints. Rather than immediately marketing finished semiconductors without brand recognition or sales infrastructure, the company licensed its SerDes intellectual property to established chipmakers. Although IP licensing generated lower margins, it required prospective customers to evaluate Credo's silicon designs in detail while providing revenue during early development phases. Licensing served as technical proof-of-work; when Credo later introduced physical-layer products to those same accounts, established relationships facilitated customer evaluation.
Consequently, Credo remained private for fourteen years. Navigating the long development timelines of data-center infrastructure meant winning sockets that would not generate volume shipments until customers launched next-generation hardware platforms, often two to three years later. While traditional venture funds with ten-year lifecycles found this timeline challenging, Credo sustained operations through private funding rounds and steady IP licensing.
A significant financing milestone occurred near the end of Credo's private period. Amid global economic uncertainty during the COVID-19 pandemic, Credo raised a Series D round of approximately $100 million, recruiting public-market institutions BlackRock and Capital Research as lead investors.9 Dan O'Neil, who joined in 2018 to lead corporate development and investor relations, later noted that these institutional backers "could give us the guidance and understanding of what public company investors might want to see, if we eventually went public."10
This strategic positioning served as a multi-year preparation for an eventual public listing. Credo began participating in sell-side institutional conferences in January 2019, establishing relationships with investment banks and buy-side analysts years before filing its registration statement.10 Rather than treating an initial public offering as a discrete event, management cultivated an institutional investor base well in advance.
During this same period, Credo developed the product line that reshaped its trajectory. In the late 2010s, the company expanded from selling standalone retimer chips to delivering fully integrated active electrical cables (AECs) containing embedded retimers. Transitioning from a discrete component vendor to a system-level cable supplier meant taking ownership of end-to-end link performance rather than competing solely on chip specifications. It also required developing capabilities in physical cable assembly, connector mechanics, and supply chain management uncharacteristic of a traditional fabless semiconductor firm. Brennan later framed this shift to investors: "We've pioneered a new high-speed connectivity category."12 While Credo did not invent retiming technology, it successfully commercialized integrated AECs at data-center scale ahead of competitors.
This disciplined, multi-year positioning yielded a testable capability: when market conditions tightened, Credo was positioned to complete an IPO when many peers could not.
III. The IPO: Into a Closing Window
By January 2022, the public market window for technology listings had rapidly deteriorated. The record flood of 2021 issuance had saturated the market, regulatory scrutiny had curtailed special purpose acquisition company (SPAC) activity, and the Federal Reserve was signaling monetary tightening. As long-duration technology valuation multiples compressed daily, companies that began public preparations in early 2021 — including Credo — faced a drastically altered pricing environment.10
Credo proceeded with its offering on January 27, 2022, pricing at $10.00 per share — the bottom of its expected $10.00 to $12.00 range. The offering comprised 20 million shares, with 18,383,800 issued by the company and 1,616,200 offered by selling shareholders, raising approximately $184 million in gross proceeds prior to the underwriters' option. Lead underwriters Goldman Sachs and BofA Securities, alongside syndicate members Cowen, Mizuho, Needham, and Stifel, brought the shares to the Nasdaq Global Select Market under the ticker CRDO.11
While pricing at the bottom of a range often signals weak demand, completing a traditional listing in early 2022 stood out as many peers postponed or canceled deals. Credo's execution reflected its prior institutional preparation: cornerstone investors secured during private rounds, established bank relationships, and an investor relations function operating with public-market discipline for two years.10
The transaction structure also reflected these tight market conditions. Existing shareholders sold fewer than two million of the 20 million total shares.11 Early venture backers and insiders retained the vast majority of their equity, entering public life with pre-IPO ownership largely intact while leaving a sizeable supply overhang subject to lockup agreements — a setup that would gain significance years later as insider liquidation accelerated at higher valuations.
Credo's initial year as a public company proved challenging. The stock traded below its issue price throughout 2022 amid a broader semiconductor downcycle. At the time of its listing, Credo remained a modest, hybrid business. Fiscal 2022 revenue totaled $106.5 million, up 81% year-over-year, but a significant portion — including $11.1 million, or roughly 30%, in the quarter ended March 2022 — derived from intellectual-property licensing rather than physical product sales.12 On its inaugural earnings call, management signaled that IP licensing would normalize to between 10% and 15% of total revenue over time.12
In mid-2022, Credo was not yet an AI-centric platform; it was a SerDes IP licensor commercializing an emerging active cable line with heavy reliance on a single lead customer. During the June 2022 earnings call, Chief Executive Officer Bill Brennan guided fiscal 2023 revenue to "at least $200 million," projecting 88% annual growth supported by a reported 52-week customer order backlog.12
That guidance appeared credible during the industry-wide supply shortages of mid-2022. Extended semiconductor lead times had prompted data-center operators to place advance orders to guarantee allocation, giving Credo's 52-week backlog the appearance of revenue visibility.12 However, orders submitted during periods of component scarcity functioned more like non-binding reservations than guaranteed commitments. When supply constraints eased and customer architectural priorities shifted, that backlog provided little structural protection against order cancellations.
This dynamic highlighted a broader risk for component suppliers: order visibility derived from customer allocation scheduling rather than binding purchasing contracts persists only as long as market supply remains constrained.
Credo ultimately generated $184.2 million in fiscal 2023 revenue — missing management's initial annual target.5 That shortfall represented the first major test of Credo's public track record, stemming from a sudden customer-concentration shock that would fundamentally challenge the company's core growth thesis.
IV. Active Electrical Cables and the Core Business: Industry Structure, Competition, and the 2023 Reckoning
The physics problem Credo sells into
Picture the inside of an AI cluster. Racks of accelerators, each needing to talk to switches and to every other accelerator at speeds that were exotic a decade ago and are now table stakes. The data moves across three possible media, and choosing between them is one of the genuinely consequential architectural decisions a hyperscaler network engineer makes.
Option one is passive copper — a direct attach cable, or DAC. It is a wire. It is cheap, it consumes essentially no power, and it is dumb. The problem is that as per-lane speeds climb from 50 to 100 to 200 gigabits, the signal degrades so fast inside the copper that the usable reach collapses. What worked at three meters at the older speed works at one meter at the newer one. Copper does not scale with Moore's Law; physics does not care about your roadmap.
Option two is optics — convert the electrical signal to light, send it down fiber, convert it back. Reach is effectively unlimited for data center purposes. But optical modules are expensive, they burn meaningful power, and — this is the part that keeps operators up at night — they fail. In a cluster with hundreds of thousands of links, an optical transceiver that flaps offline is not a nuisance; it can stall a training job that has been running for days.
Option three is what Credo commercialized: the active electrical cable. Take a copper cable and put a DSP-based retimer chip inside the connector at each end. That chip receives the smeared signal, cleans it up, and retransmits it fresh. You get several meters of usable copper reach at high speed, at a fraction of the power and cost of optics, and with the reliability profile of a wire rather than a laser. For in-rack and cross-rack runs of up to roughly seven meters — which is a very large share of the links in a modern cluster — it is the pragmatic middle path.
Credo's specific claim on that middle path is reliability, marketed as ZeroFlap, with the company asserting error rates up to a thousand times better than commodity optics. That is a marketing figure from the vendor, not an independently audited benchmark, and should be read as such. But the underlying reason customers believe some version of it is structural rather than promotional, and worth understanding.
Why Credo has won share — the mechanism, not the slogan
Two things distinguish Credo's position, and both are verifiable from how the business is built rather than from what management says about it.
The first is vertical integration. Credo designs both the DSP silicon and the cable assembly itself. Its closest analog in the retimer world, Astera Labs, sells chips and relies on partners for the physical cable. That sounds like a minor distinction until you understand that AEC performance is a joint property of the chip and the wire — the equalization the DSP applies is tuned to the specific loss characteristics of the copper it is driving. Owning both sides of that boundary means Credo can iterate the cable and the silicon together rather than negotiating across a corporate seam. In a product whose entire value proposition is reliability under marginal signal conditions, that is a real engineering advantage, not a slide.
The second is what you might call studied neutrality. Credo does not sell switch ASICs. Broadcom does, and Broadcom's dominance in merchant switch silicon gives it natural pull-through into retimers and cables and close relationships with Asian module manufacturers. Marvell leads in optical interconnect DSPs. Astera Labs owns the PCIe and CXL retimer niche. Each of those competitors carries adjacency baggage. A hyperscaler that has already accepted deep dependence on one vendor's switch silicon has a rational, self-interested reason to source its cables from someone who cannot use that position as leverage. Credo's lack of a switch business is, paradoxically, a distribution asset.
In Hamilton Helmer's 7 Powers vocabulary, this is not scale economies and it is certainly not a network effect. The closest fit is process power layered on switching costs: deep design-in with hyperscaler network architects, qualification cycles measured in quarters, and accumulated know-how in a discipline where know-how genuinely compounds. That is a real power. It is also a narrower and more revocable one than a cornered resource, because the switching cost sits at the platform-generation boundary. When a customer designs its next cluster, the decision reopens.
Which is exactly what happened.
The moat claim already broke once — same product, same customer regime
On February 15, 2023, Credo disclosed that its largest customer had reduced its demand forecast for certain Credo products. Guidance for the fiscal fourth quarter of 2023 was cut to $30 million to $32 million against a consensus above $45 million — roughly a third below the Street. The stock fell more than 40% over the following five trading days.6 Management attributed the reduction to macroeconomic headwinds rather than to any dissatisfaction with Credo's products.7
The independent research firm SemiAnalysis published a dissenting mechanism the same day, and it is the more uncomfortable one. Its argument was that Microsoft had adopted AECs at limited volume and for a specific, temporary reason: early InfiniBand deployments supporting A100-generation AI instances had reliability problems, and AECs were a patch. As InfiniBand switch reliability improved, SemiAnalysis argued, Microsoft "moved back to the cheaper options of DAC and multi-mode optics in this AI application." The firm's broader claim was that AECs offered no cost advantage against optics at hyperscale volume, making reliability-driven adoption structurally unstable once the underlying problem was fixed.8
You do not have to accept SemiAnalysis's framing to take the episode seriously, because the financial record settled the near-term question on its own. Fiscal 2024 revenue was $193.0 million, up 4.8% from fiscal 2023's $184.2 million.5 That is essentially flat, across a full year, at a company that had just told public investors to expect 88% growth. This was not a one-quarter inventory wobble. It was a twelve-month air pocket caused by a single customer's architectural choice.
Weigh it properly. The evidence involves the same product line, the same category of buyer, and the same management team that runs the company today. It was economically consequential — it cost roughly a year of growth and more than 40% of the equity value in a week. It was not remediated by a fix; it was outgrown by a different demand cycle. And crucially, it was never disproven as a mechanism. What happened instead is that a much larger wave of AI capex arrived, and newer buyers adopted AECs for their own reasons.
So what does the history do to the moat claim? It does not reject it — Credo's reliability and vertical-integration advantages are distinct from the 2023 cause, which was an architecture and timing decision rather than a quality failure. But it narrows the claim materially. The defensible version is: Credo has a genuine, evidenced engineering advantage in a product category whose attach rate is a customer design choice, revisited at every platform generation, by buyers who have already demonstrated once that they will reverse it. That is a moat around the product. It is not a moat around the demand.
Concentration has not gone away
If the 2023 lesson were purely historical, the concentration data would show it fading. It does not.
In the fourth quarter of fiscal 2026, four customers each accounted for at least 10% of revenue, ranging from 34% at the top down to 10%.15 In the first quarter of fiscal 2027, Credo's 10-Q disclosed two direct customers at 43% and 28% of revenue respectively; on the earnings call, management described the largest end customer at 33% with four customers above the 10% threshold.1416 The gap between those two framings is itself informative — the filing counts the entity Credo bills, which for hardware often means a contract manufacturer, while the call describes the end customer whose architecture decision actually drives demand. Investors should treat the filed figures as the harder constraint. On either basis, roughly three-quarters of revenue sits with a handful of buyers.3
Management's own position is that this improves. CFO Daniel Fleming told analysts on the fiscal 2026 year-end call that the company expects "increasing diversification in fiscal 27."15 That is a forecast, and it belongs in the same paragraph as the disclosure it is meant to soften.
The KPI that resolves this argument is not revenue growth. It is the count of distinct hyperscaler and neocloud customers with AEC designs in volume production, and the quarterly trend in the disclosed concentration percentages. If the top customer's share grinds down toward the twenties while the total customer count rises, the 2023 pattern is genuinely being diluted. If the top line grows while the top customer stays above 40%, the company has simply gotten bigger without getting safer.
That question — can Credo diversify faster than its concentration risk compounds — is what makes the last three years so interesting, because the growth arrived with a violence nobody, including management, forecast.
V. The AI Inflection and the Optical Pivot: FY2024-FY2027
Few corporate disclosures contrast as sharply with prior forecasts as the commentary delivered on Credo's fiscal 2026 year-end call in June 2026.
"The rapid shift to AI workloads continue to drive new and broad based customer engagement," Chief Executive Officer Bill Brennan said, "and we executed well to grow at more than twice the rate we expected at the beginning of the year."15 Chief Financial Officer Daniel Fleming added: "We were pleased to see fiscal year 26 play out better than we had expected."15
Three years after guiding to 88% annual growth and delivering flat results due to a sudden customer pullback, management had guided conservatively and ended up outperforming its initial target by more than double. Total annual revenue expanded from $193.0 million in fiscal 2024 to $436.8 million in fiscal 2025, and reached $1.335 billion in fiscal 2026, while non-GAAP net income surged from $14.6 million to $661.5 million over the same period.54
This dramatic shift offers a nuanced lesson for both bulls and bears. Credo's management has now been materially wrong on annual guidance in both directions within four years. Rather than indicating management misdirection, this volatility reflects a fundamental structural reality: in a market dominated by a handful of hyperscale capital expenditure committees, a component supplier positioned three layers away from the final purchasing decision possesses limited long-term visibility. Investors should treat near-term guidance with caution in either direction, rather than viewing recent outperformance as proof of superior forecasting ability.
The pivot: from copper to light
The central strategic question facing Credo is whether it can establish a second high-growth product engine before its core copper business reaches maturity. Management's answer centers on optics, backed by specific revenue targets.
On the June 2026 call, Brennan outlined an ambitious benchmark: "In fiscal 27, we expect our optical DSPs, SiPho PICs, and ZeroFlap optics will each contribute more than $100 million of revenue. And in total, more than $600 million of revenue."15 Fleming detailed the composition of that target, noting that roughly half of fiscal 2027's absolute dollar growth would come from optical products and half from the existing copper portfolio, with the optical ramp accelerating in the second half of the fiscal year.15
The product architecture spans three distinct hardware layers. An optical digital signal processor (DSP) is the integrated circuit inside an optical transceiver that cleans up degraded light signals, performing the same function for optical links that retimers perform for copper cables. A silicon photonics photonic integrated circuit (SiPho PIC) converts electrical signals to optical signals on a silicon wafer in a semiconductor fab, shifting optical production from labor-intensive assembly to scalable semiconductor manufacturing. Finally, ZeroFlap optics represent fully integrated optical modules sold under Credo's reliability branding. Brennan noted on the call that these complete optical modules command three-digit average selling prices compared to two-digit prices for discrete components, meaning that full modules, rather than individual chips, carry the primary revenue weight.15
This optical initiative represents a major strategic expansion, but it must be evaluated as a commercial objective rather than an established result. Three factors temper the optimistic thesis.
First, Credo is entering the optical DSP market against Marvell, an established incumbent with deep customer relationships and proven market share in that specific socket. Operating as a challenger in a component category characterized by modest average selling prices and a limited operational track record is a far more demanding competitive posture than acting as the first-mover in active electrical cables.
Second, product mix creates margin pressure. Optical hardware generates lower gross margins than Credo's high-margin copper cable business, creating an immediate margin headwind examined in detail in Section VIII.
Third, Credo's track record of converting technical milestones into sustained market revenue in optics remains unproven. While the company successfully scaled active electrical cables into a major product line, it has not yet demonstrated comparable execution in optical systems. Initial data points show early progress: on the September 2026 earnings call, management reported record optical DSP revenue alongside first revenue from silicon photonics PICs, while reaffirming the greater-than-$600 million optical target and raising full-year fiscal 2027 revenue growth guidance above 85%.16 Nevertheless, initial revenue generation does not yet constitute a fully scaled production ramp.
The optionality, sized honestly
Two secondary growth initiatives warrant measured consideration.
The first involves specialized GPU cloud operators — often termed neoclouds — which have emerged as a distinct customer segment alongside traditional hyperscalers. When asked whether neoclouds could eventually generate one-fifth of total revenue, Brennan affirmed: "I definitely think it could be on the order of 20%."15 If realized, this expansion would represent the most direct mitigation of Credo's customer concentration risk by introducing buyers with independent architectural requirements and purchasing cycles. At present, however, this target remains a management estimate without a binding timeline.
Other emerging initiatives remain further from commercialization. Credo's OmniConnect memory-interconnect architecture and its Active LED Cable portfolio are projected to enter production ramps in fiscal 2028, with initial revenue from co-packaged and near-package optics designs also targeted for fiscal 2028.15 Management explicitly treats these projects as long-term options rather than immediate revenue drivers.
The key metric for evaluating Credo's transformation is the quarterly revenue split between copper and optical products against the greater-than-$600 million fiscal 2027 target, particularly whether optical revenue accelerates in the second half of the fiscal year as guided. Any delay in that ramp would present a direct challenge to the structural-transformation thesis — posing a greater threat to investor confidence than a temporary quarterly miss by calling into question Credo's ability to build a viable second growth engine.
Furthermore, Credo did not construct its optical capabilities entirely from internal research. It acquired the bulk of its optical technology through rapid acquisitions, funded by capital generated from its recent expansion.
VI. Capital Deployment: Three Acquisitions in Twelve Months
Here is the first thing an analyst should say about Credo's capital allocation record: there isn't one.
Before fiscal 2026, Credo had made no acquisitions of consequence. There is no multi-decade record of deals to score, no history of write-downs to hold against management, no pattern of discipline or indiscipline to extrapolate. What exists instead is a burst of activity compressed into roughly twelve months, beginning almost exactly when the company's equity became extraordinarily valuable and its cash flow turned substantial. That timing is itself the analytical fact worth noting — companies tend to buy most aggressively when their own currency is strongest, which is when overpayment risk is highest.
Three deals, in order.
Hyperlume, closed September 29, 2025. An Ottawa-based startup founded in 2022, developing micro-LED-based optical interconnects — using arrays of tiny LEDs rather than lasers to move data as light over short distances. Hyperlume had raised a $12.5 million seed round roughly seven months before being acquired, co-led by BDC Capital's Deep Tech Venture Fund and ArcTern Ventures, with Intel and LG venture arms participating. Credo initially did not disclose the price. Its subsequent SEC filing did: approximately $92 million in cash, or about $82.5 million net of cash acquired.18
That number deserves a moment. Credo paid roughly $92 million for a three-year-old company with a seed round behind it and no meaningful revenue, and disclosed it only in a subsequent quarterly filing. It is not a large sum against Credo's balance sheet. It is a very large multiple of anything Hyperlume had built commercially, and it seeded the Active LED Cable roadmap that management has guided will not generate revenue until fiscal 2028.15
CoMira Solutions, announced February 24, 2026 and closed the following month. CoMira brought link-layer, error-correction, and security semiconductor IP for scale-up and scale-out AI architectures. Financial terms were not disclosed at announcement; Credo's fiscal 2026 Form 10-K records the consideration at approximately $35.1 million in cash.1913 This is the least controversial of the three — a small IP tuck-in of the kind semiconductor companies do routinely to fill gaps in a protocol stack.
DustPhotonics, announced April 14, 2026 and closed May 28, 2026. This one is different in kind.
DustPhotonics was founded in 2017, headquartered in Modiin, Israel, with an office in Cupertino, and had roughly 70 employees. It had raised approximately $150 million, with Intel Capital among its investors and the serial semiconductor entrepreneur Avigdor Willenz as chairman. It built silicon photonics technology for optical transceivers.20
Credo paid $750 million in cash plus approximately 0.92 million shares upfront, with up to an additional 3.21 million shares contingent on financial milestones — a package valued at up to roughly $1.3 billion.21 Credo's Q1 fiscal 2027 10-Q recorded total purchase consideration of approximately $1.3 billion, including roughly $770 million of cash consideration, $171.5 million of equity consideration, and $310 million of contingent consideration.14 The transaction closed and DustPhotonics remained in Israel as a local engineering base.22
The balance sheet effect was immediate and large. Goodwill rose to $986.4 million from $92.8 million, and intangible assets to $378.8 million from $29.3 million, driven principally by DustPhotonics.14 Cash fell to $466.9 million from $1.2 billion, with short-term investments roughly stable at $297.4 million.14 A company that ended fiscal 2026 with $1.4 billion in cash and no debt spent a majority of it on a single transaction within weeks.4
How to score a deal with no revenue multiple
Be honest about what can and cannot be assessed. DustPhotonics was not a scaled revenue business, so there is no meaningful revenue or earnings multiple to benchmark against public comparables. Anyone quoting one is inventing it.
What can be said is what kind of deal this is. It is a technology and roadmap acquisition — a purchase of engineering capability and a place in the co-packaged and near-package optics architectures that hyperscalers may adopt in the second half of this decade. Management's own framing supports that reading: Brennan told analysts that "based on current customer engagements, initial revenue for CPO and NPO designs is expected in our fiscal 28."15 Credo paid up to $1.3 billion for a call option whose payoff, by management's own account, does not begin for two years.
That is not automatically a bad decision. Silicon photonics talent is genuinely scarce, the capability is hard to build from zero, and the window to be designed into next-generation architectures is now. But it is unambiguously the most expensive and least evidence-backed capital allocation decision in the company's history, funded from cash generated during a demand environment that has already proven capable of reversing.
One specific bear claim on the sell side links Credo's fiscal 2027 gross-margin guidance to how the acquisitions were structured — earn-out accounting and purchase-price allocation effects flowing through cost of revenue rather than pure product mix. That is a named, testable assertion, and it should be tested against the filings rather than accepted. What the Q1 fiscal 2027 numbers actually show is a 3.5-percentage-point gap between GAAP gross margin of 64.5% and non-GAAP gross margin of 68.0%, versus a gap of essentially zero in fiscal 2026 — consistent with acquired-intangible amortization now running through cost of revenue.14 The mix explanation and the purchase-accounting explanation are not mutually exclusive; both appear to be operating.
Capital allocation posture
Fleming was explicit on the fiscal 2026 call about what Credo will not do: "We have no current plans to raise any capital at this point. Nor do we plan to do a share buyback."15 With roughly $1.4 billion of cash at the time and operating cash flow running at a substantial clip, that is a coherent stance — self-fund the acquisition program, keep maximum strategic flexibility, return nothing.
It is also worth interrogating rather than admiring. A company issuing stock-based compensation at $88.0 million in a single quarter — roughly 18% of revenue — and declining to repurchase shares is making a clear choice to let dilution run while spending cash on unproven technology assets.14 There may be good reasons. But "no buyback while diluting at 18% of revenue" is a capital allocation position that should be defended, not assumed.
The scorecard on all of this will not be available for years. The nearest checkpoint is specific: whether DustPhotonics-attributable revenue materializes and whether the 3.21 million contingent shares are earned. A trigger would validate the thesis and cost shareholders roughly 1.7% dilution — a good trade. A miss would be the first genuine data point in Credo's M&A record, and it would be a negative one.
Which brings us to the people making these calls, and what they are actually paid to optimize.
VII. Management: Incentives, Ownership, and Credibility
On May 28, 2026 — days after closing the largest acquisition in company history, and with fiscal 2026 revenue having just tripled — Credo's board granted Bill Brennan a one-time performance share award that tells you more about how this company thinks than any strategy deck.
The grant covers up to 1,437,000 ordinary shares in six equal tranches of 239,500. Each tranche requires both a revenue goal and a stock price goal. Tranche one: $2.5 billion of revenue and a $244.70 share price. Tranche six: $7.5 billion of revenue and a $489.40 share price. The performance period runs through June 30, 2031. There is one escape hatch — if trailing four-quarter revenue reaches $5 billion, the first two tranches vest regardless of the share price.24
Read the bottom rung of that ladder carefully. It requires revenue to grow roughly 87% from fiscal 2026's $1.335 billion before a single share vests. The top rung requires more than five times fiscal 2026 revenue and a share price roughly 2.9 times where the stock traded in early September 2026. This is a genuinely demanding award — dual-metric, no time-vesting floor, no participation trophy. It is also enormous, and it locks a CEO's economic outcome to a growth trajectory that would require the AI infrastructure cycle to continue for another half decade. Incentive design shapes behavior. A CEO paid only for hypergrowth is a CEO structurally disinclined to slow down.
That design choice looks deliberate when you see the ownership table. As of July 31, 2026, Brennan beneficially owned 1,858,982 shares against 187,869,136 outstanding — just under 1%.23 For a CEO of more than a decade at a company worth roughly $31 billion, that is modest, and it is the direct consequence of his not being a founder. His alignment runs almost entirely through unvested equity rather than a legacy stake. His fiscal 2026 compensation totaled $14.4 million, including a $650,000 base salary and $12.6 million of stock awards.23
The co-founders remain in operating roles and on the board. Lawrence Cheng, the CTO, held 5,861,028 shares, or 3.12%. Job Lam, the COO, held 2,922,110 shares, or 1.56%.23
Both have been selling as the stock re-rated, and at a scale worth quantifying rather than hand-waving. On July 15, 2026, Lam sold 55,998 shares at a weighted average of $225.44, for $12.6 million, under a Rule 10b5-1 plan adopted April 15, 2026; counting a same-day disposition through a separate entity, he sold roughly 106,000 shares for about $23.9 million combined, retaining more than 3.1 million shares.27 On July 21, 2026, Cheng sold 27,500 shares at a weighted average of $222.34 under a plan adopted in September 2025, retaining roughly 5.8 million shares held through a family trust.26
The correct reading is neither dismissal nor alarm. These are plan-based sales representing a small single-digit percentage of each executive's holdings, executed by founders whose stakes had appreciated more than 120% over a year. That is textbook diversification, not a signal. What it is not is evidence of conviction — founders selling into strength tells you nothing bullish either. The observation that matters is the aggregate: the three people running Credo collectively hold under 6% of a company whose CEO award requires the stock to nearly triple, and the two who hold the most are systematically reducing.
The compensation governance question
One anomaly deserves a sentence, and only a sentence. Credo's grants to its legal officers have been unusually large for the role — former Chief Legal Officer Katherine Schuelke received a $7.2 million stock award in fiscal 2024 for a partial year, and her successor James Laufman received an $11.5 million stock award in fiscal 2025. Those are figures more typical of a chief operating officer at a company this size than a general counsel.
Shareholders were nonetheless comfortable. At the annual general meeting on October 13, 2025, the say-on-pay advisory proposal passed with 116,591,772 votes for against 7,323,034 against — roughly 94% support. All three Class I directors up for election, including Brennan, Lam, and Cheng, were elected with support above 94%, and Ernst & Young was ratified as auditor with 143,658,171 votes in favor.25 There is no meaningful voting dissent on this register, and no activist presence.
The credibility ledger, both directions
Assessing this management team requires holding two contradictory facts at once, and refusing to resolve them prematurely.
In favor: the February 2023 guidance cut, however painful, proved directionally accurate. Management said demand had fallen, and fiscal 2024 came in roughly flat exactly as the reduced trajectory implied.5 Telling investors bad news early and being right about it is a genuine credibility marker, and many management teams fail that test.
Against: the initial fiscal 2023 target of "at least $200 million" set in June 2022 was missed by roughly 8%, and the last two fiscal years were beaten by margins management itself called more than double its expectations.1215 A forecast that is wrong by 8% on the downside and 100%-plus on the upside within four years is not a forecast investors should build a model around.
The most useful framing is that Credo's management appears honest and appears to have limited visibility — a combination that is common in component suppliers with concentrated customers, and that argues for weighting disclosed order patterns and customer counts over guidance ranges.
In the absence of an activist, the adversarial function has been performed by the independent research community — SemiAnalysis in 2023, and a steady stream of skeptical sell-side and buy-side pieces through 2026. That is worth noting for what it implies: the bear case on Credo has been articulated publicly and specifically, and has been available to every investor who bid the stock to $309.
The place where that argument gets settled is the income statement.
VIII. Financial Architecture and Unit Economics
For most of the semiconductor industry's history, quadrupling revenue in two years while holding gross margin flat would be considered impossible. Volume that steep usually arrives with price concessions, mix degradation, and expedited manufacturing costs.
Credo held it. Non-GAAP gross margin was 68.1% for fiscal 2026, essentially unchanged from the prior year's level and up meaningfully from the 62.5% recorded in fiscal 2024 — margin expansion during a period when the business grew nearly sevenfold.45 That combination is the single strongest piece of evidence in the bull case, and it is worth being precise about why. Holding price through a volume ramp of that magnitude means customers were not, on the whole, extracting concessions in exchange for scale. In a market with a handful of enormous, sophisticated, multi-sourcing buyers, that is a meaningful indicator of pricing power — not proof of a moat, but the observable footprint one would leave.
Operating leverage was the other half of the story. Fiscal 2026 non-GAAP operating expenses ran at $81.7 million in the fourth quarter against $437.0 million of quarterly revenue, and non-GAAP net income for the year reached $661.5 million against $1.335 billion of revenue.4 The business scales. That is not a matter of interpretation.
And then the margin cracked
Which brings us to the specific number that took 20% off the stock.
In the first quarter of fiscal 2027, GAAP gross margin came in at 64.5% against fiscal 2026's 68.0% — a contraction of roughly 3.5 percentage points. Non-GAAP gross margin held at 68.0%, at the midpoint of guidance.14 Guidance for the following quarter put GAAP gross margin at 62.9% to 64.9% and non-GAAP at 67.0% to 69.0% — meaning management expects the GAAP measure to compress further while the adjusted measure holds.1
Two forces are visible in that gap. The first is acquisition accounting: amortization of intangibles acquired with DustPhotonics now runs through cost of revenue on a GAAP basis and is excluded on a non-GAAP basis, which mechanically opens a spread that did not exist a year ago. The second is product mix: optical content carries lower margin than the copper franchise, and management has guided fiscal 2027 non-GAAP gross margin to be "broadly consistent with fiscal year 2026 levels."15
The market's fear is not about this quarter. It is that the optical ramp dilutes margin structurally rather than transiently — that the second growth engine Credo is building is a fundamentally less profitable business than the one it already has. Management's guidance is a direct claim against that fear. Whether it holds through the second-half optical ramp is the thing to watch, and it is genuinely unresolved. One quarter of stable non-GAAP margin during the earliest stage of an optical ramp does not settle a question about what margins look like when optical is a third of revenue.
The geography puzzle
Credo's disclosed revenue by geography moved violently, and it is easy to misread. In fiscal 2026, United States revenue was roughly $768 million against roughly $378 million from Hong Kong — a reversal from fiscal 2025, when Hong Kong was the larger of the two.13 The quarterly detail is starker. In Q1 fiscal 2027, the United States accounted for $255.4 million versus $82.8 million a year earlier; Hong Kong rose more modestly to $91.2 million from $74.9 million; Malaysia jumped to $74.5 million from $6.4 million; and mainland China collapsed to $1.1 million from $51.8 million.14
Resist the temptation to read this as geographic derisking or as a China exposure story with a clean narrative. Semiconductor revenue is booked to the entity that takes title, which for hardware frequently means a contract manufacturer or distribution hub rather than the operator of the data center where the product ultimately runs. A shift from Hong Kong or mainland China billing toward direct United States and Malaysian billing most plausibly reflects a change in who Credo invoices — direct hyperscaler relationships and shifting contract-manufacturing footprints — not a change in where end demand lives. It is a disclosure artifact worth caveating, not a thesis. The one substantive observation available is that the collapse in mainland China billings to near zero is consistent with the broader relocation of AI hardware supply chains out of China, which is a real trend even if this particular line item is a poor measure of it.
The dilution question
Two balance-sheet facts belong together. Credo carries no debt, which removes refinancing risk entirely and is genuinely valuable in a business with this much demand volatility. And stock-based compensation ran at $88.0 million in the first quarter of fiscal 2027, against $35.5 million a year earlier — roughly 18% of revenue, allocated $45.0 million to R&D, $37.3 million to SG&A, and $5.7 million to cost of revenue.14
Eighteen percent of revenue in stock compensation is elevated even by growth-semiconductor standards, and it is not a non-cash abstraction — it is a real transfer of ownership from existing shareholders to employees, layered on top of the equity issued for DustPhotonics. Combined with an explicit decision not to repurchase shares, the per-share economics improve considerably more slowly than the headline growth rate implies. That is a legitimate structural criticism, and it is the kind of thing an activist would lead with if one ever showed up.
Inventory is the other line to watch. It rose $62.2 million sequentially to $313.1 million in Q1 fiscal 2027, and operating cash flow fell roughly $92 million sequentially to $90.2 million on working capital changes, leaving free cash flow of $82.9 million.16 Building inventory ahead of a guided second-half ramp is exactly what a company confident in its order book does. It is also exactly what a company does immediately before a demand air pocket — which, as established, has happened here before.
The KPI that matters most in this section is singular: non-GAAP gross margin through the optical ramp. If it holds near 68% while optical revenue clears $600 million, the structural-dilution fear is disproven. If it drifts toward the low sixties, the second engine is a fundamentally worse business than the first, and the multiple should reflect that.
IX. Bear vs. Bull Case, and the Skeptical-Investor Stress Test
Set the industry structure first, because both cases are downstream of it.
Run Porter's five forces across AI interconnect and the picture is unusually lopsided. Buyer power is extreme — a handful of hyperscalers and a growing set of neoclouds, all of them sophisticated, all of them running deliberate multi-sourcing policies, all of them capable of redesigning around a component. Supplier power is moderate: Credo depends on foundries and on the optical and cable supply chain, but nothing about its inputs is uniquely constrained. Threat of substitution is the central force in this market and it is high — copper, AEC, and optics are genuinely substitutable across overlapping distance ranges, and the boundaries move with every speed generation. Rivalry is intense and asymmetric: Broadcom and Marvell are vastly larger, with adjacent franchises that generate pull-through; Astera Labs and MaxLinear compete in overlapping niches. Barriers to entry are real but not absolute — mixed-signal design talent is scarce, qualification cycles are long, but none of that stops a company with Broadcom's resources from deciding to compete harder.
That structure supports a moderate moat around a specific capability, not a wide moat around a market position. Which is roughly what the evidence shows.
The bull case.
AI cluster interconnect spend is early in its cycle, and Credo sits at a physical chokepoint that neither GPU vendors nor switch vendors solve for them — the reliability and power characteristics of a link over a few meters of copper. That problem gets harder, not easier, as per-lane speeds rise, which means the value of solving it well compounds.
The advantages are evidenced rather than asserted. Vertical integration across cable and silicon is a structural design capability competitors selling only chips do not have. Neutrality on switch ASICs is a distribution asset that Broadcom, structurally, cannot replicate. And the margin evidence — 68% gross margin sustained through a near-sevenfold revenue increase — is the observable signature of pricing power rather than a claim about it.45
If the optical portfolio delivers the guided greater-than-$600 million in fiscal 2027, Credo will have demonstrated something genuinely rare: the ability to build a second product franchise at scale, in a new physical medium, inside two years. The first evidence is on the board — record optical DSP revenue and first silicon photonics PIC revenue in Q1 fiscal 2027, with full-year growth guided above 85%.16
And neocloud adoption, if it approaches the 20% of revenue Brennan considers plausible, addresses the concentration problem structurally rather than cosmetically.15
The bear case, with the record folded in.
Customer concentration is not a theoretical risk at this company. It is a realized one. The February 2023 collapse happened under materially the same customer structure management describes today, and the recovery came from new demand rather than from any change in the underlying dependency.6 Four customers above 10% of revenue, with the largest direct customer at 43%, is not a diversified book.14
The SemiAnalysis mechanism — that AEC adoption can be a reliability patch a customer reverses once its own infrastructure matures — has never been refuted.8 It has been overtaken by a larger demand wave. Those are different things. Every new hyperscaler and neocloud that adopts AECs today is making the same class of architectural decision Microsoft made and unmade, and each of them will revisit it at their next platform generation.
Valuation re-rated enormously ahead of the evidence. A company worth a low single-digit number of billions in early 2024 was worth roughly $31 billion in September 2026, and the optical business underpinning a large share of the forward growth expectation had produced its first PIC revenue that same quarter.216
Roughly $986 million of goodwill and $379 million of intangibles now sit on the balance sheet from an M&A program twelve months old, whose largest transaction targets first revenue in fiscal 2028.1415 There is no prior deal record to give management the benefit of the doubt, in either direction.
And the September 2026 price action is itself the most honest evidence about expectations. When a 115% growth quarter with a raised outlook produces a 20% single-day decline, the market is telling you it had priced something close to perfection.3
The activist stress test.
What would a skeptical concentrated investor actually challenge? Four things, in order.
First, capital allocation: spending the majority of the cash balance on a pre-revenue-scale asset, weeks after telling investors there were no plans to return capital, with the payoff two fiscal years out and no track record to underwrite it.1514
Second, dilution: stock compensation near 18% of revenue plus acquisition equity, with an explicit refusal to repurchase shares.1415
Third, disclosure asymmetry: the gap between the concentration figures in the 10-Q and the softer end-customer framing on the call, and the initial non-disclosure of the Hyperlume price until a later filing revealed $92 million.1418
Fourth, incentive design: a CEO award that pays only on extreme growth and a high share price, at a company whose forecasting record in both directions suggests limited demand visibility.24
None of these is a scandal. Each is a legitimate question that the company has not fully answered.
How to weigh it.
The history does not reject Credo's core thesis. It narrows it. The defensible claim is that Credo has a real, evidenced engineering and distribution advantage in high-speed interconnect, serving a demand pool that is growing explosively but is controlled by a small number of buyers who have already demonstrated the ability to reverse an adoption decision. The advantage is around the product. The risk is around the customer. Those are separable, and conflating them is how both the bull and bear cases go wrong.
Three events would resolve the open questions, and investors should name them in advance:
One. Does fiscal 2027 optical revenue clear $600 million, and is the ramp genuinely second-half weighted as guided?15 This tests whether Credo can convert technology into revenue in a medium where it is the challenger.
Two. Does non-GAAP gross margin hold near 68% through that ramp, or does it compress toward the low sixties?4 This tests whether the second engine is as good a business as the first.
Three. Does the disclosed customer concentration broaden, or does any single customer cut its forecast sharply again?14 This tests whether anything structural has actually changed since 2023.
Those three questions are the entire investment case. Everything else is commentary.
X. Playbook: Durable Lessons
Stripping away company-specific details, Credo offers several transferable lessons, some of which challenge conventional investment wisdom.
Patient capital in a genuinely hard niche can compound invisibly for a decade, then re-rate almost instantly. Credo spent fourteen years building SerDes capabilities that generated $106.5 million of revenue in fiscal 2022.12 The technical foundation was largely established before the market catalyst arrived. What changed was not Credo's core engineering capability, but the broader industry's demand for it: AI cluster scale-out transformed a specialized discipline into a critical infrastructure bottleneck. The lesson is not that deep technology always triumphs, but that capability and catalyst are distinct variables — and a technical edge can sit fully formed and unpriced for years.
Picks-and-shovels is not a synonym for safety. Conventional market wisdom suggests that selling components into a boom carries lower risk than building the end applications. Credo's February 2023 experience provides a clear counterexample. Operating one step removed from headline AI applications gave Credo substantial operating leverage during expansion, but also extreme exposure when a single customer adjusted its architecture. A component supplier sitting three layers away from the final deployment decision experiences amplified rather than dampened demand sensitivity. Investors treating component providers as defensive proxies for a secular theme often take on concentrated customer risk rather than insulating against it.
Strategic non-participation can create a distribution advantage. Credo's decision to forgo selling switch ASICs might look like a product-roadmap limitation, but it functions as a strategic asset when negotiating with a concentrated group of powerful buyers. When hyperscalers actively manage vendor concentration to avoid over-reliance on dominant suppliers, a vendor's inability to leverage an adjacent switch franchise becomes a commercial advantage. It represents a rare, structurally durable form of positioning because a larger incumbent cannot easily replicate it without sacrificing a broader, high-margin business.
Evaluate guidance in both directions. Market participants routinely punish management teams for guidance cuts and reward them for beats. Credo's operational history suggests a more analytical approach: management issued an accurate downward guidance adjustment in February 2023, then vastly exceeded its own financial targets in fiscal 2025 and 2026.515 A management team that misses its original targets by wide margins in both directions is not necessarily misleading investors; rather, it operates with limited forward visibility. The appropriate analytical response is to discount formal guidance ranges and focus on underlying operational disclosures — specifically customer concentration metrics, inventory levels, and design-win commentary.
Rapid, self-funded acquisitions following a market re-rating warrant close monitoring rather than reflexive applause. A company experiencing rapid stock appreciation and surging cash flow faces an elevated risk of overpaying for target assets. Across twelve months, Credo deployed roughly $880 million in cash along with equity to acquire technologies whose revenue contributions management expects primarily in fiscal 2028.181415 Those transactions may ultimately prove strategic or excessively costly. Without a prior track record of integration, the substantial goodwill and intangibles sitting on Credo's balance sheet represent the explicit financial weight riding on those technology bets.
When a company changes identity, do not average across the seam. Blending a legacy IP licensing business with an AI-driven hardware growth story obscures both past vulnerabilities and current operating leverage. Assessing each stage of Credo's evolution on its own terms remains the fundamental requirement for evaluating where the business stands today.
XI. Epilogue & Key Takeaways
There are two Credo Technology Groups, and blending them produces nonsense.
The first was a mixed-signal IP and early-stage hardware business that spent fourteen years in private development, listed at the bottom of its range in a hostile market, generated $106.5 million in revenue during its debut public fiscal year, and then saw growth stall for a full year after its primary customer altered its architectural path.11125 Its early financial record is a study in the gradual accumulation of technical credibility.
The second began in fiscal 2025 and represents one of the fastest operational scale-ups in semiconductor history, growing annual revenue from $436.8 million to $1.335 billion in a single fiscal year, with non-GAAP net income of $661.5 million, a balance sheet reshaped by acquisitions, and a market capitalization that reached roughly $57 billion at its peak before settling near $31 billion.42 Its financial record is barely two years long.
Any analysis that averages those two eras together — computing a five-year growth rate or a through-cycle margin — is measuring a chimera. The more relevant question is narrower: which of the two offers a better guide to the next five years?
The answer depends entirely on whether the customer structure has evolved, and the empirical record shows it has not. Credo remains heavily concentrated, with four customers accounting for more than 10% of revenue each and one exceeding 40% on a direct-billing basis — in a business whose defining historical setback stemmed from a single customer's shift.14 Management expects customer diversification, and emerging neocloud operators may eventually deliver it, but neither outcome is visible in the current results.
The central open question for a long-term investor, then, is not whether AI infrastructure spending continues — Credo's fortunes will track that spending regardless. It is whether the fiscal 2027 optical expansion proves that Credo can establish a second durable revenue engine with a broader customer base and defensible margins, or whether it simply repeats the active electrical cable pattern by selling new products to the same concentrated group of buyers.
A realistic assessment avoids both market caricatures. Credo is not an absolute toll booth on AI connectivity — toll booths do not lose 40% of their equity value in a week when a single customer changes route. Nor is it a narrative-driven bubble — 68% non-GAAP gross margins sustained across a sevenfold revenue expansion reflect genuine operational leverage, not promotional storytelling.4
What the evidence in September 2026 demonstrates is a company possessing a genuine technical advantage within a physically constrained infrastructure niche, selling to a concentrated group of buyers powerful enough to have already demonstrated that they can pivot away from a product line overnight. The engineering advantage is real. The customer concentration is real. So is the historical precedent.
XII. Recent News
September 2, 2026 — A 20% single-day decline on a record quarter. Credo shares fell roughly 20% the day after reporting first-quarter fiscal 2027 results, despite 115% revenue growth and guidance exceeding consensus. Contemporaneous coverage attributed the market reaction to persistent customer concentration—with the three largest customers accounting for roughly three-quarters of revenue—and to a valuation that had priced in near-perfect execution. Even after the sell-off, the stock traded at approximately 59 times trailing earnings.3
September 1, 2026 — Q1 fiscal 2027 results. Credo reported revenue of $479.0 million, up 9.6% sequentially and 114.7% year over year. GAAP gross margin reached 64.5%, while non-GAAP gross margin stood at 68.0%. Net income reached $129.4 million on a GAAP basis and $236.3 million on a non-GAAP basis, or $1.20 per diluted share. Cash and short-term investments totaled $764.3 million following the DustPhotonics closing, while second-quarter revenue guidance was set between $525 million and $535 million.128 On the accompanying earnings call, management reported record optical DSP revenue alongside initial silicon photonics PIC revenue, reaffirmed its target of more than $600 million in fiscal 2027 optical revenue, and raised full-year top-line growth expectations to above 85%.1617
August 25, 2026 — Definitive proxy filed. Credo's annual proxy statement disclosed fiscal 2026 CEO compensation of $14.4 million, detailed beneficial ownership positions for executive officers and founders, and outlined the terms of the executive incentive program.23
July 2026 — Founder share sales. Chief Operating Officer Job Lam sold approximately 106,000 shares for roughly $23.9 million across two transactions on July 15, while Chief Technology Officer Lawrence Cheng sold 27,500 shares on July 21, with both transactions executed under pre-arranged Rule 10b5-1 trading plans.2726
June 1, 2026 — Fiscal 2026 results and CEO performance award. Credo reported full-year revenue of $1.335 billion—more than triple the prior fiscal year—alongside non-GAAP net income of $661.5 million.4 Concurrently, the board granted CEO Bill Brennan a performance share award of up to 1,437,000 shares that vest only upon meeting ambitious revenue and stock-price hurdles through June 2031.24
May 28, 2026 — DustPhotonics acquisition closed. Credo completed its acquisition of DustPhotonics for total purchase consideration of approximately $1.3 billion—comprising roughly $770 million in cash, $171.5 million in equity, and $310 million in contingent earn-outs—adding approximately $894 million in goodwill to the balance sheet.2214
XIII. Links & Resources
- Credo Technology Group Holding Ltd — Investor Relations
- Form 10-K, fiscal year 2026 (filed 2026-06-15)
- Form 10-Q, Q1 fiscal year 2027 (filed 2026-09-02)
- Form S-1 IPO registration statement (filed 2022-01-03)
- DEF 14A definitive proxy statement, 2026 annual meeting
- Q4 and full-year fiscal 2026 earnings release (8-K exhibit)
- Q1 fiscal 2027 earnings release (8-K exhibit)
- Q4 fiscal 2026 earnings call transcript
- Q1 fiscal 2027 earnings call transcript
- Q4 fiscal 2022 earnings call transcript (IPO-era baseline)
- Thick Cables, Thin Margins — SemiAnalysis, 2023
- Form 8-K, 2025 annual general meeting voting results
- Form 4 — insider sales, July 2026
References
-
Credo Technology Group Holding Ltd Reports First Quarter of Fiscal Year 2027 Financial Results (Form 8-K Exhibit 99.1) — SEC, 2026-09-01 ↩↩↩↩↩
-
Credo Technology Group Holding (CRDO) Stock Price & Overview — Stock Analysis, accessed 2026-09-05 ↩↩↩
-
Why Credo Technology Stock Plunged 20% Today — The Motley Fool, 2026-09-02 ↩↩↩↩
-
Credo Technology Group Holding Ltd Reports Fourth Quarter and Fiscal Year 2026 Financial Results (Form 8-K Exhibit 99.1) — SEC, 2026-06-01 ↩↩↩↩↩↩↩↩↩↩↩↩
-
Credo Technology Group Holding Ltd Reports Fourth Quarter and Fiscal Year 2024 Financial Results — Credo Investor Relations, 2024-05-29 ↩↩↩↩↩↩↩↩↩
-
Credo Technology collapses after significantly lowering revenue guidance — TipRanks, 2023-02-15 ↩↩↩
-
Credo Technology (CRDO) says largest customer has reduced its demand forecast for certain Credo products — StreetInsider, 2023-02-15 ↩
-
Thick Cables, Thin Margins – Microsoft, Amazon, and Google Demand Overstated By $CRDO Credo — SemiAnalysis, 2023-02-15 ↩↩
-
Form S-1 registration statement — Credo Technology Group Holding Ltd, SEC, 2022-01-03 ↩↩
-
Opening bell: The story behind Credo Semiconductor's IPO — IR Impact, 2022-11 ↩↩↩↩
-
Credo announces pricing of initial public offering — GlobeNewswire, 2022-01-27 ↩↩↩
-
Credo Technology Group Holding Ltd (CRDO) Q4 2022 Earnings Call Transcript — The Motley Fool, 2022-06-02 ↩↩↩↩↩↩↩↩
-
Form 10-K, fiscal year ended May 2, 2026 — Credo Technology Group Holding Ltd, SEC, 2026-06-15 ↩↩
-
Form 10-Q, quarter ended August 1, 2026 — Credo Technology Group Holding Ltd, SEC, 2026-09-02 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Credo (CRDO) Q4 2026 Earnings Call Transcript — The Motley Fool via The Globe and Mail, 2026-06-01 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Credo Technology Group Holding Ltd (CRDO) Q1 2027 Earnings Call Highlights — GuruFocus via Investing.com, 2026-09-02 ↩↩↩↩↩↩
-
Credo Technology Group Holding Ltd (CRDO) Q1 2027 Earnings Call Transcript — Seeking Alpha, 2026-09-01 ↩
-
Credo paid $92 million USD in cash to acquire Hyperlume, SEC filing reveals — BetaKit, 2026-03 ↩↩↩
-
Credo acquires CoMira to expand AI connectivity IP portfolio — Investing.com, 2026-02-24 ↩
-
US-based Credo Tech snaps up Israeli maker of silicon chips for up to $1.3 billion — The Times of Israel, 2026-04-14 ↩
-
Credo Technology Group acquires DustPhotonics in $1.3bn cash and stock deal — Data Center Dynamics, 2026-04 ↩
-
Credo Completes Acquisition of DustPhotonics — Business Wire, 2026-05-27 ↩↩
-
DEF 14A definitive proxy statement, 2026 annual meeting — Credo Technology Group Holding Ltd, SEC, 2026-08-25 ↩↩↩↩
-
Credo (CRDO) triples FY26 revenue and grants CEO performance PSU award (Form 8-K) — StockTitan, 2026-06 ↩↩↩
-
Form 8-K, 2025 annual general meeting voting results (Item 5.07) — SEC, 2025-10-13 ↩
-
Form 4 — insider sales, COO Yat Tung Lam and CTO Chi Fung Cheng, July 2026 — SEC ↩↩
-
Credo Technology COO sells 55,998 shares for $12.6 million — The Motley Fool, 2026-07-16 ↩↩
-
Credo Technology Group Holding Ltd Reports First Quarter of Fiscal Year 2027 Financial Results — Business Wire, 2026-09-01 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube