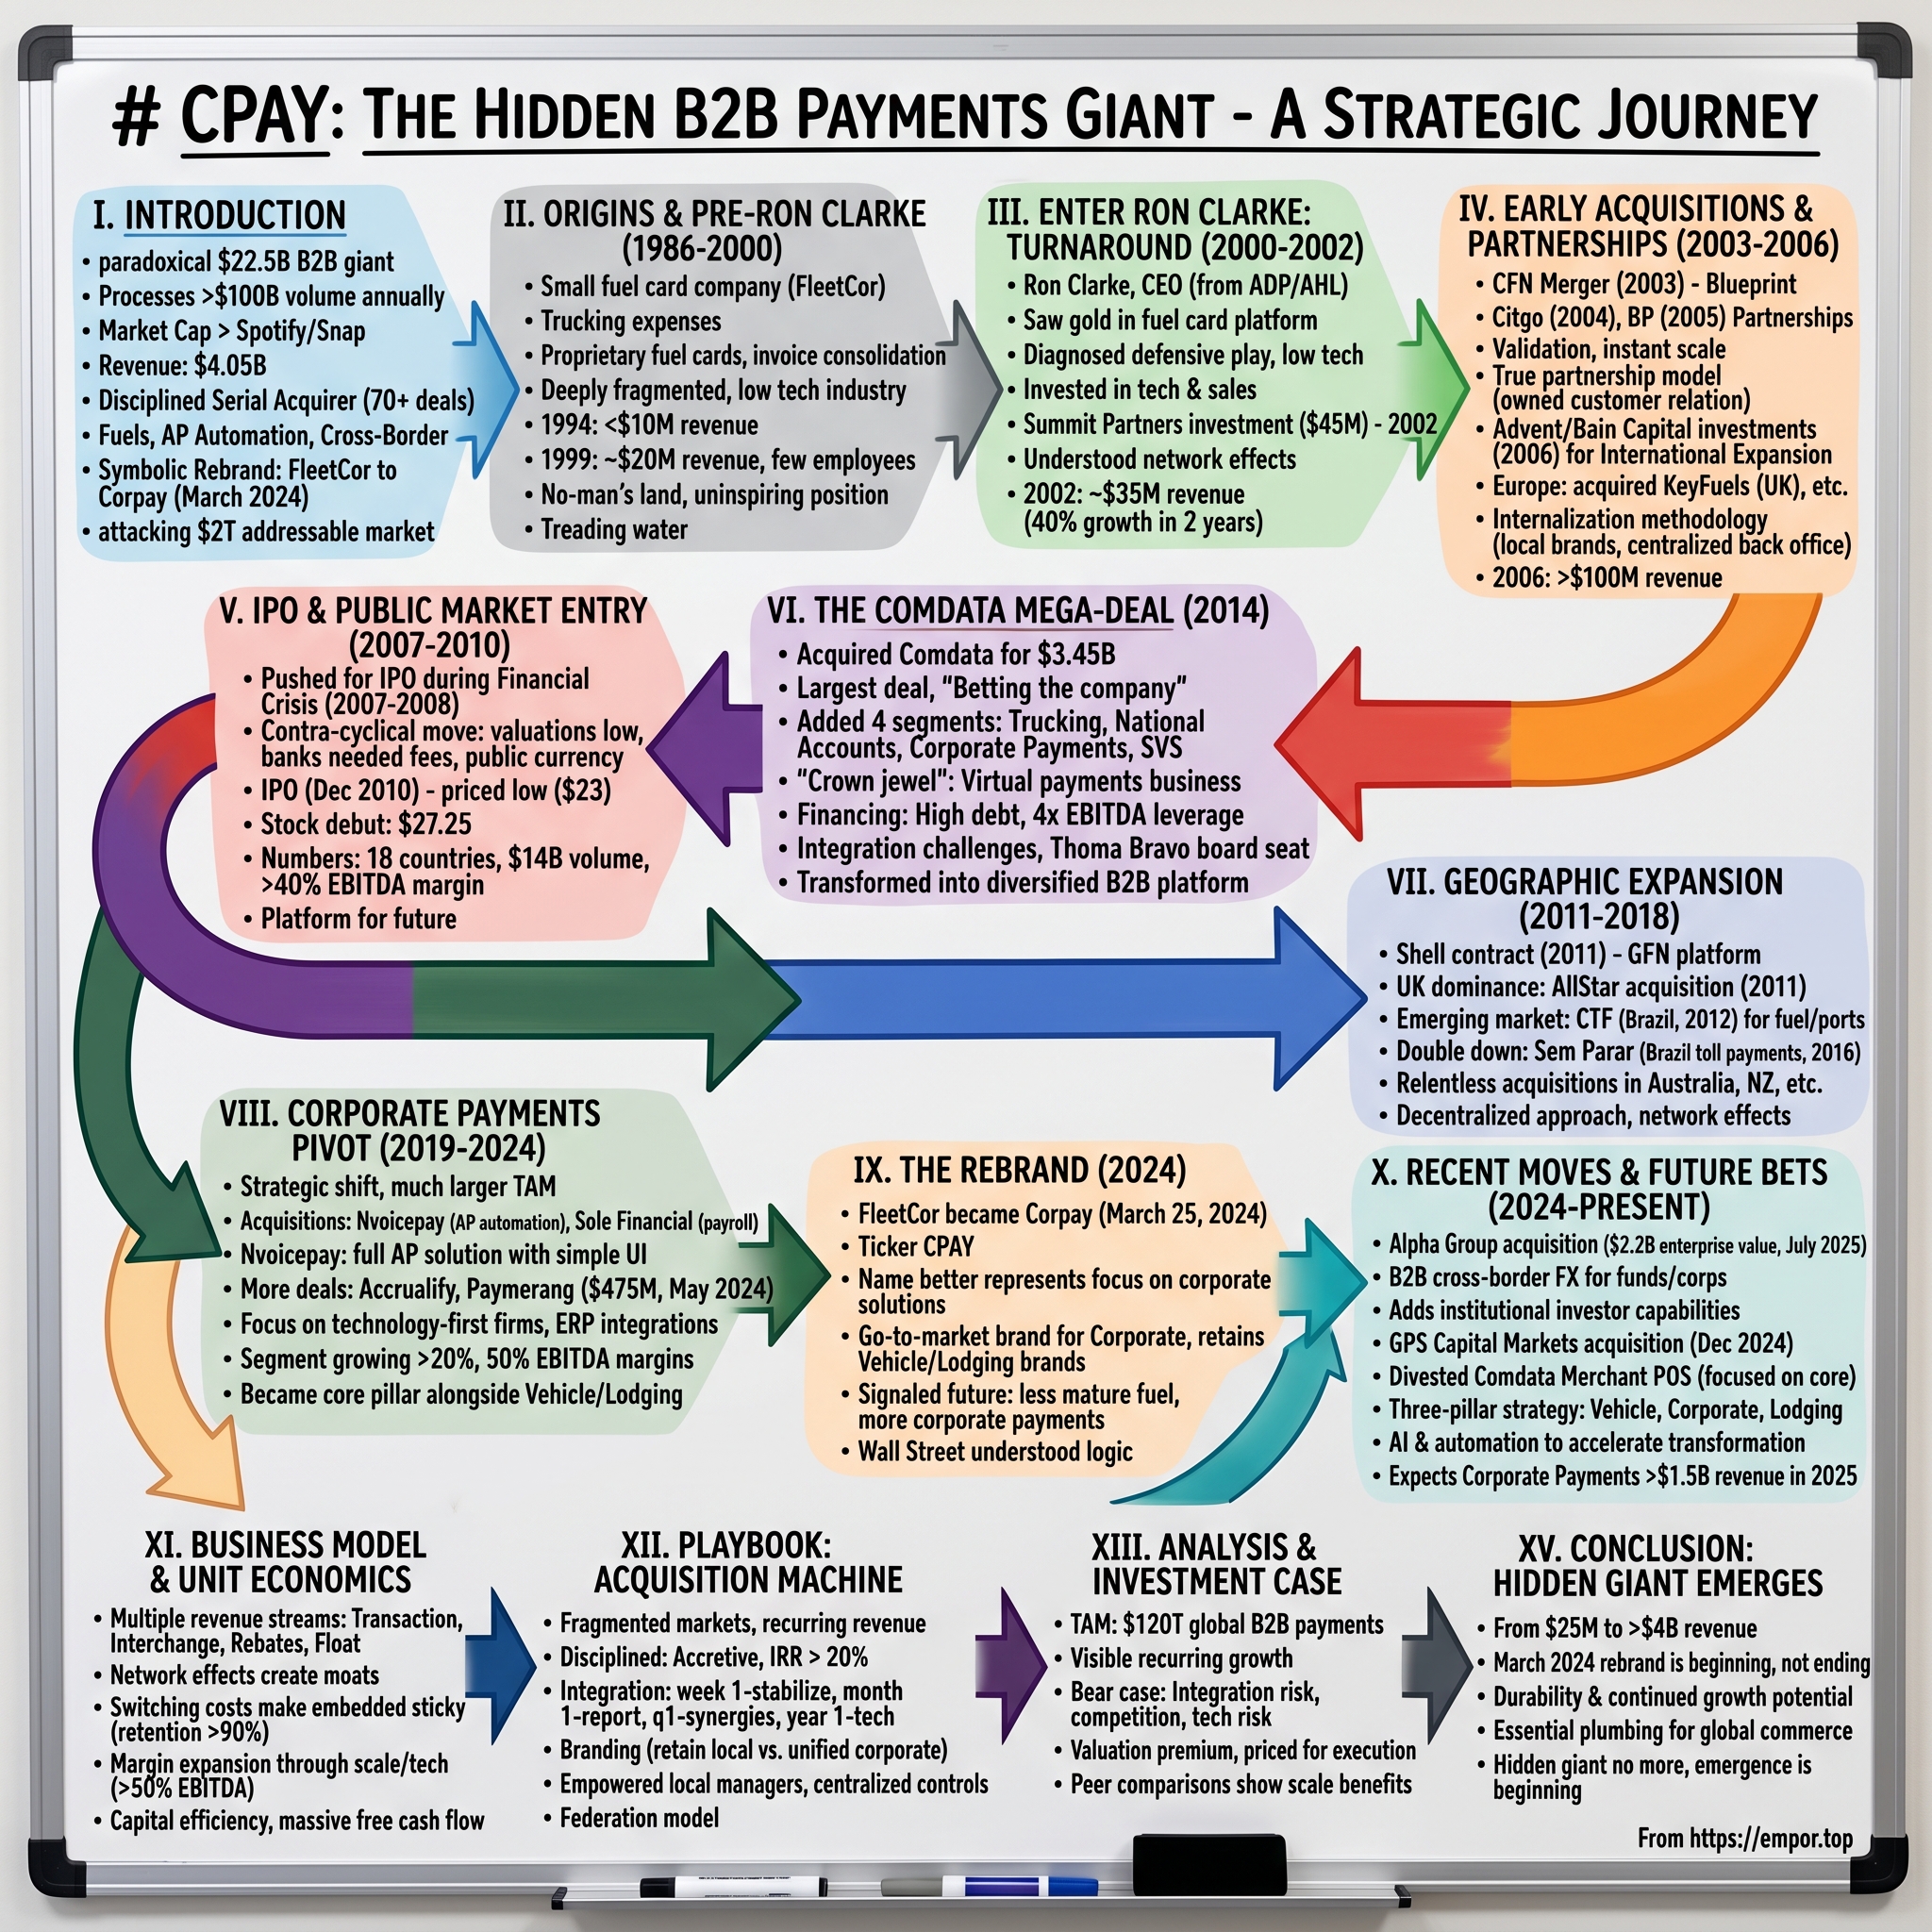
Corpay: The Hidden B2B Payments Giant
I. Introduction & Episode Roadmap (5–10 min)
Somewhere on Interstate 75 outside Macon, Georgia, a driver for a mid-sized HVAC contractor swipes a plastic card at a diesel pump. The card is not a Visa in the way most people understand a Visa. It tracks which truck he is driving, how many gallons the tank should hold, what time of day he is authorized to buy fuel, and whether the odometer reading he punches in is plausible given the last transaction. If he attempts to buy energy drinks or cigarettes on the same swipe, the authorization can be declined at the line-item level before the pump even starts.
That transaction—mundane, invisible, worth roughly eighty dollars—is one of billions that flow through Corpay, Inc. every year. A member of the S&P 500, Corpay generated $4.53 billion of revenue in 2025. With 68,050,296 shares outstanding as of February 17, 2026,1 its equity was worth roughly $27 billion at the prices prevailing through the summer of 2026.2 By its own count at the time of its 2024 rebrand, it serves more than 800,000 business customers globally,3 yet almost nobody outside the payments industry can explain what it does.
That anonymity is core to the business model. Consumer payments companies spend billions on branding because they need individual consumers to reach for their card. Corpay targets the decision-maker who signs the invoices—the fleet manager, the controller, the treasurer. Once that workflow is integrated into Corpay's systems, the driver at the pump has no say in card selection. The company built its business on administratively burdensome financial flows across the economy: fuel, highway tolls, hotel rooms for pipeline crews, and the ocean of B2B invoices that still move partly by paper check.
The central question is simple to state but complex to evaluate: in 2000, this was a regional fuel card processor generating roughly $30 million of revenue.4 Today, it is a global payments conglomerate whose fastest-growing business handles cross-border foreign exchange for European investment funds. How that transformation occurred—and whether the engine that produced it remains durable for equity underwriters—forms the core of this analysis.
That engine follows a specific architecture. Corpay did not invent a single technology and ride its adoption curve. By the company's own disclosure, it executed over forty acquisitions between 2002 and its 2010 initial public offering alone, standardizing platforms, repricing services, and channeling cash flow into the next deal.4 That roll-up strategy carried a specific vulnerability, which materialized when regulatory scrutiny intensified. In December 2019, the Federal Trade Commission sued the company and its chief executive personally, alleging that a material portion of reported pricing power was derived from hundreds of millions of dollars in fees customers never knowingly agreed to pay.5 In January 2026, the Eleventh Circuit affirmed summary judgment against the company on all five counts.6 In the second quarter of 2026, the company recorded a $100 million charge for a preliminary settlement.7
That context frames March 2024, when FleetCor Technologies became Corpay and changed its ticker symbol from FLT to CPAY.3 Management described the rebrand as an operational reality catching up with business mix—arguing that the Corporate Payments segment had become the primary growth driver while "Fleet" functioned as a restrictive legacy label. While that narrative is defensible, the rebrand also arrived while the company was appealing a federal injunction over its fuel card fee practices.
The analysis traces this trajectory chronologically. It begins with the fourteen years preceding Ron Clarke's arrival, followed by the private-equity-funded roll-up machine he built leading to the 2010 IPO. It evaluates the $3.45 billion Comdata acquisition that nearly doubled the company and opened the door to corporate payments,8 as well as the governance reckoning marked by the FTC litigation and three consecutive failed say-on-pay advisory votes. The roadmap then covers the strategic pivot through Paymerang, GPS Capital Markets, a Mastercard partnership, a minority position in AvidXchange, and the $2.4 billion purchase of Alpha Group International.9 Finally, it examines segment economics, competitive dynamics, management execution, the long-term investment case, and the specific metrics that would indicate operational breakdown.
 Subscribe on LinkedIn
II. Origins & The Pre-Ron Clarke Era (1986–2000) (15–20 min)
The business began in New Orleans in the mid-1980s, inside an industry that barely qualified as one.
A trucking fleet or plumbing contractor with fifteen vans faced a mundane but expensive operational problem: fuel theft and accounting chaos. Drivers paid cash or used corporate credit cards. Receipts arrived crumpled, weeks late, or lost entirely, making it nearly impossible to reconcile which gallon went into which vehicle. A portion of fuel spend routinely vanished—filling a driver’s personal vehicle, a friend's tank, or non-fuel store purchases. For a company where fuel represented the second-largest operating cost after labor, that leakage represented substantial cash.
The solution that emerged in the 1970s and 1980s was the fleet fuel card: a closed-loop payment instrument restricted to participating stations and approved purchases while capturing line-item transaction data at the pump. The predecessor to Corpay was organized in the United States in 1986 to do exactly this.4 It operated as a traditional paper-and-plastic business—issuing physical cards to drivers, mailing printed reports to fleet managers, and stitching together a regional gas station network by contract.
The economics were thin, but the model solved a key operational friction. The processor sat between the merchant and the commercial fleet, taking a small transaction fee while delivering functionality standard card networks could not match: control and granular data. An ordinary credit card network is built to be open, maximizing transaction volume by allowing cards to work everywhere while deliberately abstracting away purchase details. A fleet card network is intentionally closed, restricting usage to specific locations and items to capture the level 3 transaction data open networks omit: purchase amount, driver identification, vehicle identification, and itemized purchase details.4
Trading universal acceptance for granular information provided commercial buyers with what they were actually paying for: operational control over field spending.
Translating that concept into a scalable enterprise took time. For fourteen years, the company operated as a modest regional player. By 2001—the earliest year disclosed in the company's IPO prospectus—annual revenue reached $30.7 million.4 It remained a small business serving regional markets with fragmented IT infrastructure, lacking meaningful scale advantages against the proprietary card programs of major oil companies, and showing no obvious path toward national expansion.
That plateau stemmed from three structural limitations. First, the business was geographically constrained; a closed-loop network provides value only if merchant coverage matches a fleet's route structure, restricting a regional network to regional customers. Second, the technology infrastructure was a patchwork; each legacy partnership or small acquisition introduced a distinct processing platform, creating redundant operating expenses. Third, the broader processing industry remained highly fragmented, split among dozens of local players that lacked the capital to consolidate merchant networks and customer bases.
That fragmentation presented a clear financial opportunity. An industry defined by high fixed platform costs and low marginal transaction costs favors a strategy of acquisition and integration. Adding merchant transactions and customer volume to an existing infrastructure spreads fixed costs over a broader base, reducing the marginal cost to serve. Executing that strategy required an operator focused on platform standardization, disciplined capital allocation, and aggressive pricing strategies.
In August 2000, that management transition began.
III. Enter Ron Clarke & The PE Engine (2000–2009) (25–30 min)
Ronald F. Clarke arrived in 2000, and the company changed its name to FleetCor Technologies, Inc. that same year.4 The pairing of those two events in the initial public offering prospectus illustrated how completely the new chief executive represented a strategic restart rather than a standard management succession.
Clarke's background was in operations and systems rather than payments—specifically, the discipline of standardizing fragmented operations. He came out of large-company general management and consulting before running divisions at Automatic Data Processing, Inc. (ADP). ADP served as a formative model: it generates revenue by absorbing repetitive administrative burdens across thousands of enterprise clients, running those workflows at scale on a unified platform, and charging fees that remain modest compared to the customer's internal costs. Clarke's central insight at FleetCor was to recognize that fleet fuel cards shared that exact business model. Fleet customers were not simply purchasing fuel; they were buying the elimination of administrative overhead, a service whose perceived value is dictated by the severity of the operational friction rather than the underlying cost of delivery.
The resulting operating playbook relied on four core levers: consolidating acquired processing platforms onto shared infrastructure, centralizing back-office functions to prevent administrative headcount from scaling linearly with volume, executing aggressive cost reduction upon closing, and systematically optimizing yield per customer by adjusting fee structures on legacy accounts.
Growth equity backed the expansion strategy. Summit Partners and Bain Capital both acquired significant stakes in FleetCor during the 2000s and remained major shareholders through the 2010 initial public offering before gradually unwinding their positions; Summit's total return on the investment eventually exceeded ten times its invested capital.10 While those figures underscored the model's financial returns for early sponsors, they did not automatically explain the operational drivers behind that performance.
The pace of acquisitions illustrated the underlying growth engine. By its December 2010 initial public offering, the company disclosed that it had completed over forty acquisitions of companies and commercial account portfolios since 2002.4 That pace averaged roughly one transaction every ten weeks over an eight-year span. Transactions ranged from small commercial account portfolios—effectively purchasing customer rosters for platform migration—to network mergers expanding merchant acceptance and European acquisitions providing FleetCor's initial international presence. As a result, revenue grew from $30.7 million in 2001 to $381.3 million on a managed basis in 2009, representing a compound annual growth rate of 37 percent.4
Historical falsification: was the early growth organic?
A recurring claim in the company's narrative suggests that Clarke built early scale primarily through superior product design and compounding network effects.
The company's disclosures offer strong disconfirming evidence against that thesis. Completing more than forty acquisitions in eight years reflects an asset-purchasing program rather than an organic network effect.4 True network effects manifest as accelerating organic transaction volumes on a stable asset base. FleetCor's disclosures instead revealed a serial acquirer whose top-line growth was arithmetically dominated by inorganic additions. Indeed, reporting 2009 revenue on a managed basis was necessary because frequent acquisitions altered the reporting entity's structure so rapidly that unadjusted year-over-year comparisons were uninformative.
A second line of evidence bears directly on the quality of that early growth. The Federal Trade Commission's 2019 complaint alleged that FleetCor's internal analysis showed fleet customers saved only a fraction of a cent per gallon—compared to advertised savings of five to ten cents per gallon—and that certain fee structures were delayed for several billing cycles to make them harder for customers to detect.5 To the extent that revenue per account was driven by unannounced or unexpected fee adjustments, yield optimization served as the primary growth catalyst rather than product differentiation.
The historical record supports a more nuanced thesis: Clarke identified a fragmented industry with high fixed costs, secured institutional capital for consolidation, and consistently executed platform integration and expense reduction across dozens of transactions. While serial acquisition frequently destroys value through failed integrations, FleetCor demonstrated disciplined operational consolidation. However, that capability represents an execution edge on a financial roll-up strategy rather than an intrinsic product moat. The distinction is critical for evaluating long-term competitive durability: execution capabilities must be successfully repeated with every acquisition, whereas product moats compound organically.
Evaluating whether newly acquired businesses accelerate organically post-integration—rather than merely contributing baseline revenue—provides the key test for that capability. The analysis returns to that benchmark in evaluating the acquisition of Alpha Group International.
By 2009, the business operated six proprietary closed-loop networks spanning approximately 83,000 accepting merchant locations, serving over 530,000 commercial accounts across eighteen countries with roughly 2.5 million active cards.4 Having scaled beyond the limits of private equity backing, FleetCor prepared for a public listing—accessing broader capital markets while exposing its operating model to public market scrutiny.
IV. The Public Market Entry & The Fuel Card Moat (2010–2013) (30–35 min)
December 2010 was not an obvious moment to bring a leveraged, acquisition-hungry payments company public. The financial crisis was two years in the rear-view mirror, credit markets were still nervous, and "roll-up" was closer to an insult than a compliment in most investor conversations.
FleetCor went anyway. The offering priced on December 14, 2010 at $23 per share — 12,675,000 shares, of which the company itself sold only 430,961 and existing stockholders sold 12,244,039.11 Trading began the next day on the New York Stock Exchange under FLT. With the underwriters' over-allotment exercised, the deal totaled 14,576,250 shares and roughly $335 million of gross proceeds.12
Read that share split again, because it is the most informative number in the transaction. Ninety-seven percent of the primary offering was existing holders selling down. This was not a growth company raising capital to fund expansion; it was a mature private company creating liquidity for its sponsors and a public currency for future acquisitions. That is a perfectly normal outcome for a decade-old buyout, but it sets the tone for everything after: FleetCor's public equity existed at least as much to be spent on deals as to be raised against them.
What the moat actually was
The closed-loop advantage in this period was real and worth explaining plainly, because it is the foundation of everything the company later monetized.
Think of it as the difference between a toll road and a public highway. On the open highway — the Visa and Mastercard networks — anyone can drive, the operator collects a small toll, and nobody records what is in your trunk. On a private toll road, you control who gets on, you can refuse entry to certain vehicles, and because you own both the gate and the road, you know exactly what passed through.
FleetCor owned toll roads. It negotiated directly with fuel merchants — the major oil brands and, critically, thousands of independent truck stops and stations — for wholesale economics on volume it could steer. It then sold the fleet customer a product the open network structurally could not match: purchase controls that block non-fuel items, per-driver and per-vehicle limits, exception reporting that flags the driver buying 40 gallons for a 25-gallon tank, and clean line-item data that dropped into the customer's accounting system without a human retyping receipts.
The switching cost this produced was not primarily technological. It was administrative. Once a fleet manager's month-end close depends on a specific report format from a specific provider, and once that data feed is wired into an expense system, moving to a competitor means rebuilding a process that currently works. Payments businesses rarely lose customers because a rival is 3 basis points cheaper; they lose customers when the incumbent breaks something. That is why retention in this industry is high and why revenue is unusually predictable.
Armed with that, FleetCor went international fast. In December 2011 it acquired Allstar Business Solutions from the Arval Group — a BNP Paribas subsidiary — for £194 million, roughly $304 million, bringing approximately 40,000 UK customers and about one million cardholders, heavily weighted toward small and medium enterprises.13 Five months later, in May 2012, it entered Brazil by acquiring CTF Technologies for $180 million — a platform processing fuel payments for over-the-road fleets, ships, mining equipment and railroads, connected into Bradesco, Itaú, Petrobras and Ipiranga, and running more than three billion liters of fuel through its system in 2011 alone.14
Notice the difference between those two moves. Allstar was a customer-base deal in a mature market where FleetCor could apply its cost playbook to an underpriced book of SME accounts. CTF was a geographic option on a large emerging market with weak incumbents, bought for a fraction of the price and justified by growth rather than by cost-out — Clarke's own framing at the time was that CTF fit a strategy of "identifying attractive assets with performance upside."14 Two entirely different acquisition logics executed within five months. Whatever else is true about this management team, it was never running a single template.
Historical falsification: was the closed-loop data moat unassailable?
The strong version of the moat claim is that proprietary closed-loop networks and Level 3 data capture made FleetCor structurally immune to the open-loop card networks. The record does not support that version, for two reasons visible in the company's own disclosures.
First, the card networks moved. Visa and Mastercard expanded enhanced commercial data capabilities over the 2010s, and commercial banks built fleet offerings on top of them. Corpay's own FY2025 10-K lists U.S. Bank Voyager Fleet Systems among its named fuel competitors, alongside WEX, Edenred, Sodexo, Alelo and Radius — a competitive set that includes both closed-loop specialists and bank-issued open-loop programs.2 A moat that keeps a large money-center bank out of your category is a moat. A moat that lists one as a competitor in your annual report is a barrier with a gate in it.
Second, and more tellingly, FleetCor itself chose to stop being purely closed-loop. The company today describes its virtual card products as operating on Mastercard networks alongside its proprietary merchant acceptance, and in 2024 it described itself as the number one B2B commercial Mastercard issuer in North America.32 You do not become the largest issuer on somebody else's rails if your thesis is that your own rails are unbeatable. The economics of riding an open network are different — you share economics with the network and the sponsoring bank rather than keeping the full spread — and the company has not disclosed a like-for-like yield comparison between proprietary and open-loop transactions, so the magnitude of that trade-off is not public.
The calibrated conclusion: the closed-loop data advantage was real but is best understood as a time-limited head start in commercial data rather than a permanent structural barrier. What survives the test is the workflow lock-in — the administrative switching cost described above — which is genuine and has held up. What does not survive is the idea that the network itself is the moat. Watch customer retention rate, disclosed by management quarterly, as the direct KPI on that question; it stood at 93 percent in the second quarter of 2026.15
By 2013, FleetCor had proven it could buy fuel card businesses anywhere in the world and make them more profitable. The open question was whether it could be anything other than a fuel card business. In 2014, it bet the balance sheet on the answer.
V. The Comdata Mega-Deal: Betting the Company (2014–2018) (35–40 min)
Every serial acquirer eventually faces a defining moment. Tuck-in transactions generate steady compound cash flow, and then a target emerges that dwarfs prior deals—a company roughly equal in scale, operating in an adjacent vertical, priced at a level that consumes years of free cash flow while stretching leverage covenants. Declining the deal preserves the status quo; accepting it risks spending a decade repairing balance-sheet damage if integration fails.
FleetCor chose to take that risk.
On November 17, 2014, the company completed the acquisition of Comdata from Ceridian LLC—a portfolio company of Thomas H. Lee Partners and Fidelity National Financial—for $3.45 billion.8 Comdata was far more than a bolt-on transaction. Processing over $54 billion in annual payments, serving more than 20,000 customers, and employing roughly 1,300 people,8 the target represented a major operational expansion.
Comdata's core business centered on over-the-road trucking, operating the fuel and cash-advance networks long-haul carriers relied on across North American truck stops. Expanding into heavy trucking was strategically intuitive, establishing FleetCor as the dominant heavy-fleet processor overnight. Yet Clarke cited a broader rationale at closing, stating: "We believe this acquisition has great potential, particularly the corporate payments business, which will add a completely new growth leg to FleetCor."8
That 2014 rationale laid the foundation for the business structure in place by 2026. Comdata provided virtual card technology and accounts payable automation—tools designed to settle general supplier invoices rather than just fuel purchases. The transaction served as FleetCor's beachhead into broader corporate spending, establishing the strategic playbook for subsequent acquisitions including Cambridge Global Payments, Paymerang, and Alpha Group International.
The financing, and what it says about risk appetite
Funding the $3.45 billion purchase required a combination of new debt and equity. Thomas H. Lee Partners received an equity stake in FleetCor as partial consideration, and Managing Director Thomas M. Hagerty joined the board.8 Leverage rose well above historical operating norms, marking a dramatic escalation in balance-sheet risk for a management team that had previously executed far smaller roll-up transactions.
While the enterprise survived and the corporate payments unit eventually expanded, evaluating the transaction requires examining more than top-line survival. The post-acquisition record reveals specific operational oversights within the deal structure.
Historical falsification: was Comdata a clean platform acquisition?
A common claim holds that Comdata represented a flawless platform acquisition that seamlessly expanded FleetCor's addressable market. Two key pieces of evidence challenge that thesis.
First, transaction pricing. FleetCor did not disclose an enterprise value to EBITDA multiple for Comdata, making secondary market estimates unverified. However, the transaction structure, substantial debt load, and involvement of private equity sellers operating a competitive auction indicate that FleetCor paid full market value rather than securing a discounted entry.
Second, FleetCor acquired non-core assets that took a decade to divest. Comdata included a merchant point-of-sale hardware and software unit serving truck stops, managing physical terminals and back-office plaza systems. This capital-intensive, lower-growth hardware business remained inside FleetCor's operating structure for ten years. In December 2024, Corpay finally sold Comdata Merchant Solutions to PDI Technologies as part of what management described as a strategic review to simplify the company and focus on the core.16
That ten-year holding period provides essential context regarding management's responsiveness to capital allocation missteps. While moving rapidly to execute acquisitions, leadership took a decade to divest an underperforming peripheral unit. Any evaluation of capital allocation discipline must weigh swift deal execution against delayed portfolio pruning.
The calibrated conclusion: Comdata was strategically sound but operationally flawed. It established the corporate payments platform that serves as the company's primary growth engine, validating Clarke's 2014 thesis. However, it also introduced a decade-long operational drag that management addressed only after portfolio simplification became a priority. Historical performance demonstrates strong capabilities in asset acquisition paired with delayed rationalization—a pattern leadership began attempting to reverse in 2024.
Between 2014 and 2018, the company integrated Comdata, acquired Cambridge Global Payments to build cross-border capabilities, and benefited from favorable market conditions. Revenue climbed and the stock compounded. Executive compensation expanded sharply alongside that growth: in 2017, Clarke's total compensation reached $52.6 million—a 79 percent increase over the prior year—driven by $35.4 million in stock options and $15.1 million restricted shares.17
And then the bill arrived.
VI. Regulatory Reckoning & The FTC Injunction (2019–2023) (40–45 min)
The complaint the Federal Trade Commission filed on December 20, 2019 in the U.S. District Court for the Northern District of Georgia reads less like a regulatory technicality than like a prosecution.5
The FTC alleged that FleetCor marketed its fuel cards on three promises — you will save money on fuel, you will be protected from unauthorized charges, and there are no setup, transaction, or membership fees — and that all three were false in practice. Against the savings claim, the agency pointed to FleetCor's own internal analysis showing customers saved a fraction of a cent per gallon against advertised savings of five to ten cents. Against the fee claim, it catalogued an inventory of charges: late fees assessed on customers who had paid on time, "high credit risk" fees, industry-specific "high risk" fees aimed at trucking and transportation customers, and per-transaction charges presented in a way that obscured them. And it alleged the timing was deliberate — that many fees did not begin until several billing cycles had passed, precisely when a new customer had stopped scrutinizing the invoice.5
The most damaging item was not a number. It was an internal email, quoted by the FTC, in which the practice of unauthorized purchases was described as "the most egregious customer impact we do as it takes customers by surprise."5 Regulators can lose arguments about whether a disclosure was adequate. They rarely lose when the defendant's own employees have already written down the answer.
The agency named Ronald Clarke personally as a defendant. That is not routine. Individual liability under Section 5 requires showing the executive had authority over the practices and knowledge of them, and the FTC's willingness to plead it signals confidence in the evidentiary record.
The governance signal that preceded the lawsuit
Here is the part that matters most for anyone assessing management, and it happened before the FTC filed.
FleetCor's shareholders had been voting against the company's executive compensation for years, and the escalation is documented in the company's own proxies. More than 60 percent of shares voted against the compensation program in the vote preceding the 2017 award.17 The company's 2019 proxy statement acknowledged, in writing, that FleetCor had received the lowest say-on-pay support of any company in the S&P 500 for the 2018 vote.18 Support recovered only to approximately 26 percent at the 2019 annual meeting.19
That is not a disagreement about a metric. A say-on-pay result at the bottom of the entire index means index funds, active managers and both major proxy advisers had independently reached the same conclusion about the board's compensation committee. The board's response was to cap Clarke's 2018 compensation at $8 million — an approximately 85 percent reduction from 2017 — and to move from triennial to annual say-on-pay votes.17 Both changes were imposed by shareholder pressure rather than volunteered, which is itself the analytically relevant fact.
Separately, the company settled a securities class action for $50 million in cash, with final court approval on April 15, 2020. The complaint, brought in the Northern District of Georgia on behalf of purchasers between February 5, 2016 and May 3, 2017, alleged that FleetCor was reliant for a substantial percentage of its revenues on allegedly improper fees and failed to disclose it — with the practices surfacing publicly through investigative journalism in late 2016 that preceded a 22 percent decline in the share price.20
Put those three things in one frame — a compensation revolt, a securities settlement about fee disclosure, and a federal consumer protection action about fees — and the picture is not three unrelated problems. It is one problem expressing itself in three venues. The board had been told, repeatedly and by nearly every shareholder it had, that the incentive structure was wrong. The FTC case is what that structure produced downstream.
How it resolved
The district court granted the FTC summary judgment on liability against both FleetCor and Clarke on August 9, 2022, while denying the FTC's request for monetary relief. The company said publicly that it disagreed, that the liability finding had been "reached prematurely," and that it had been voluntarily cooperating with regulators and enhancing disclosures since 2017 with no material business impact; it announced it would appeal.21 A permanent injunction followed in June 2023.
On January 6, 2026, a panel of the Eleventh Circuit — Judges Rosenbaum, Lagoa and Wilson — affirmed summary judgment against the company on all five counts: deceptive per-gallon discount advertising, false "fuel only" card limitation claims, misleading "no transaction fees" representations, deceptive billing statements regarding unauthorized fees, and unfair fee and late-fee practices.6 Against Clarke personally, the court affirmed on four counts and vacated on one — Count II, the "fuel only" advertising claim — finding insufficient evidence of his knowledge on that specific count and remanding it.6
The injunction survived intact, and its terms are operationally significant. Corpay must obtain express informed consent before charging fees. Material terms cannot be placed behind a hyperlink. Disclosures must be "unavoidable." And the company must secure separate assent for each fee it charges.6 On monetary relief, the court granted Corpay's motion, following the Supreme Court's AMG Capital decision holding that Section 13(b) of the FTC Act does not authorize equitable monetary recovery.6
The story did not end there. On July 1, 2026, Corpay and the FTC staff reached agreement on the terms of a proposed consent order that would resolve the investigation, the district court claims, the administrative action, and remaining issues. The company recorded a $100 million charge in the second quarter of 2026 for the preliminary settlement, subject to approval by the FTC Commissioners and the District Court, and disclosed that it could incur additional redress or penalties if the order is not approved as proposed.7 That is a live overhang as of this writing, not a closed chapter.
Historical falsification: was there ever structural pricing power in fuel cards?
This is the single most important falsification test in the entire Corpay story, so it deserves to be stated precisely.
The claim: FleetCor's high margins in its legacy vehicle business reflected genuine pricing power derived from switching costs.
The disconfirming evidence is a federal court's finding, twice affirmed, that a portion of that revenue came from fees customers did not knowingly consent to — fees timed to evade detection, disclosed behind hyperlinks, and in at least one internal characterization, designed to take customers by surprise.56 That is not a dispute about interpretation. Summary judgment on all five counts means the court found no genuine factual dispute.
Does this reject the pricing power claim outright? Not entirely — and the distinction matters. Vehicle Payments continued to grow after the injunction took effect. In 2025 the segment generated $2.14 billion of revenue, up 6.5 percent, with organic growth of 9 percent driven by 7 percent transaction volume growth.2 In the second quarter of 2026 it grew 8 percent organically.15 A business whose margins were purely a function of hidden fees would not have compounded through a permanent injunction requiring fee-by-fee consent.
So the record narrows the claim rather than rejecting it. What survives: fleet customers do face real switching costs, and the business does have durable transaction economics. What does not survive: the idea that the pre-2019 margin structure was a clean read on pricing power. The pre-injunction margin profile included an extractive component that has been legally removed, which means historical fuel card margins are not a reliable baseline for what the segment can earn going forward. The forward test is straightforward and public: Vehicle Payments organic revenue growth, decomposed between volume and rate. If growth continues to come predominantly from transaction volume — as it did in 2025 — the narrowed claim holds. If rate has to do the work again, be skeptical.
The strategic consequence of all this is the more interesting point. A ceiling on fee yield in the legacy business, imposed by federal injunction, makes the pivot to corporate payments less a matter of ambition than of arithmetic.
VII. The Pivot to Corporate Payments & The Corpay Rebrand (2024–Present) (40–45 min)
On March 7, 2024, a company that had spent thirty-eight years with fuel in its name announced it was getting rid of it.3
The mechanics were simple: FleetCor Technologies, Inc. would become Corpay, and on March 25, 2024 the shares would begin trading on the NYSE under CPAY instead of FLT.3 The reasoning Clarke gave was equally simple: "The Corpay name better represents what we do now, which is provide corporate payment solutions."3 Notably, the company did not rebrand its operating businesses. The fuel cards kept their existing market-facing names; so did lodging. Corpay was to be the go-to-market brand for the Corporate Payments segment and the umbrella for the holding company.3
That detail is more revealing than the rebrand itself. A company genuinely convinced its legacy brands were toxic would have retired them. A company that wanted its equity story re-rated while its cash-generating businesses kept operating under names customers already recognized would do exactly what Corpay did. Both readings are consistent with the facts, and the more interesting question is whether the capital allocation that followed matched the rhetoric.
It largely did. What followed was the most concentrated burst of deal-making in the company's history, all pointed in one direction.
The buying spree
Paymerang, an accounts payable automation platform serving healthcare, education and media, was acquired in July 2024 for $179.2 million net of $309 million of cash and restricted cash acquired, against a headline announcement figure of approximately $475 million.22 The gap between those numbers is instructive and recurs throughout this story: AP automation businesses hold enormous customer float on their balance sheets, so "price paid" and "enterprise value" diverge sharply. Goodwill on the deal was $303.9 million — more than the net cash consideration, which tells you the tangible asset base was minimal and Corpay was buying a customer book and a workflow.22
GPS Capital Markets, a cross-border FX provider serving the upper middle market, closed in December 2024 for $577.1 million net of $190.7 million of cash acquired.22 Goodwill of $335.2 million on that transaction was fully tax-deductible — a structuring detail worth roughly $70 million of present-value tax shield at a 21 percent federal rate, and a sign of a deal team paying attention to the parts of a transaction that do not make the press release.
AvidXchange is the most unusual of the set. In October 2025 Corpay did not buy the mid-market AP automation software company outright. It co-invested alongside TPG in a take-private valuing AvidXchange at approximately $2.2 billion of equity value, putting in approximately $578 million for roughly 35 percent of the acquiring partnership, with TPG holding 56 percent and management the remainder.22 Corpay accounts for it as an equity investment with put and call rights, at an enterprise valuation of approximately $1.9 billion.22
Think about what that structure buys and what it costs. It gives Corpay economic exposure to one of the largest independent AP automation platforms and a commercial relationship with it, without consolidating a lower-margin software business into its own reported growth rate, and without writing a $2.2 billion check. It also gives Corpay no control. If the thesis is that Corpay's edge is operational — taking acquired businesses and running them better — a 35 percent non-controlling LP interest is a strange way to express it. The honest reading is that this was a financially-structured option on the AP automation market rather than a demonstration of the integration playbook.
Alpha Group International was the real one. Announced on July 23, 2025 and completed on October 31, 2025, Corpay acquired the UK-listed B2B cross-border FX business for £42.50 per share — approximately £1.8 billion, or $2.4 billion, for the total share capital, at an enterprise value of about $2.2 billion, and at a 55 percent premium to Alpha's undisturbed closing price on May 1, 2025.97 Net of $4.5 billion of cash acquired, the cash consideration was approximately $2.1 billion.7
Alpha was not primarily a payments company in the way Paymerang was. It served corporations and, distinctively, investment funds, and it had pioneered what it called alternative bank accounts — a simpler way for investment managers to fund investments and pay expenses across Europe than opening accounts with a traditional custodian bank in each jurisdiction. At acquisition it held approximately $3 billion of deposits across more than 7,000 client accounts.9 Clarke's stated rationale was that Alpha was "a large, highly complementary, fast-growing corporate payments asset with good prospects."9
Two things about Alpha deserve an investor's attention. The first is the premium: 55 percent is a full price, and it was paid in cash for a business in a category — FX brokerage — where competitors are numerous and the barriers are relationship-based rather than structural. Corpay did not disclose an EV/EBITDA multiple for the transaction. The second is the deposit book. Those $3 billion of client deposits generate float income, and float income is a function of interest rates that Corpay does not control. Management said as much on the fourth-quarter 2025 call: 2026 organic revenue guidance was set at 10 percent rather than the 11 percent the company had run at for three consecutive quarters, specifically because of a heavier float headwind concentrated in Corporate Payments, driven by lower rates and Alpha's deposit-heavy mix.23
That is a management team bounding its own growth claim in public, and it belongs directly alongside the growth story rather than in a distant risk section. The Corporate Payments segment delivered 16 percent organic growth in the second quarter of 2026, but management disclosed on the same call that float revenue was a 180 basis point drag on the segment — meaning the underlying rate excluding float was closer to 18 percent.15 Investors underwriting "16 percent Corporate Payments growth" as a structural rate should understand that roughly two of those points are a rate-cycle variable moving against the company, and that the same variable moved for the company during the high-rate years of 2023 and 2024.
The Mastercard arrangement
On April 29, 2025, Corpay and Mastercard announced an expanded partnership. Mastercard invested $300 million for what the announcement described as an approximately 3 percent stake in Corpay's cross-border business — a 2.8 percent interest, per the company's filings — implying an enterprise valuation of $10.7 billion, which Mastercard characterized as roughly 20 times forward EBITDA.2422 Commercially, Corpay became the exclusive provider of currency risk management and large-ticket cross-border payment solutions to Mastercard's financial institution customers, and agreed to exclusively offer Mastercard virtual card programs to its own customers.24
The commercial logic is strong: Mastercard has thousands of bank relationships and no non-carded large-ticket cross-border product; Corpay has the product and no bank distribution. Clarke's framing was that "Mastercard's sponsorship of our cross-border solutions will accelerate our financial institution revenue build."24
But read the investment terms carefully, because they are not a straightforward equity endorsement. Mastercard holds a put right allowing it to require repurchase at invested capital plus 8 percent annually, exercisable for six months beginning July 1, 2027; Corpay holds a reciprocal call beginning April 1, 2028.22 A structure where the investor is guaranteed its money back plus 8 percent is closer to a partnership fee dressed as equity than to a strategic investor taking equity risk at a $10.7 billion valuation. That does not make the partnership less valuable — it makes the $10.7 billion valuation a much weaker piece of evidence about what the cross-border business is worth than it appears at first glance.
As for whether the channel is producing: on the fourth-quarter 2025 call management reported two joint sales closed with "50 to 70 in-process opportunities"; by the second-quarter 2026 call that had become ten closed financial institutions against a pipeline of roughly 100 prospects.2315 That is real progress, from a very small base, and it is the specific number to keep watching.
Simplification: the other half of the pivot
The buying is only half the story, and the less novel half. What is genuinely new about the 2024–2026 period is that Corpay started selling things.
Comdata Merchant Solutions went to PDI Technologies in December 2024 — the point-of-sale hardware and software business inside truck stops, retained inside FleetCor for a decade.16 PayByPhone, the mobile parking payments business, was agreed for sale to Lightyear Capital in February 2026, with Clarke framing it plainly: "The transaction is another step to simplify our portfolio, and speed our rotation to more corporate payments."25 It closed in the first quarter of 2026 for approximately $421.7 million of proceeds net of cash disposed, generating a pre-tax gain of $122.9 million.7 In June 2026 the company signed a definitive agreement to sell its Maintenance business for approximately £600 million — roughly $800 million — subject to UK and Australian regulatory approval, with $194.3 million of goodwill moved to held-for-sale in the second quarter.7 On the second-quarter 2026 call Clarke committed to three to four additional divestitures over the following six to twelve months, describing the goal as "a simpler company with fewer bigger businesses."15
This is the most credible evidence in the record that the pivot is more than branding. Selling assets is harder than buying them — it requires admitting something was not working, it shrinks reported revenue, and it removes management's own empire. A company doing it repeatedly, at real prices, while its share price is near all-time highs, is behaving like one that means what it says. The unresolved question is whether the proceeds get redeployed into more expensive acquisitions or into the share count.
VIII. Segment Economics & Materiality Breakdown (35–40 min)
Strip away the narrative and Corpay is three businesses of very different character stapled to a common balance sheet, plus a residual.
For the full year 2025, Vehicle Payments generated $2,138.7 million of revenue, up 6.5 percent, with 9 percent organic growth on 7 percent transaction volume growth. Corporate Payments generated $1,635.1 million, up 33.8 percent, with 17 percent organic growth on 31 percent spend volume growth and roughly $169 million of contribution from acquisitions. Lodging Payments generated $469.5 million, down 3.9 percent, on lower workforce room-night volume driven by reduced emergency activity.2 Total revenue was $4.53 billion.2
The mix is shifting fast. Through the first nine months of 2025, Vehicle was 48 percent of revenue, Corporate 35 percent, Lodging 11 percent and Other 6 percent.22 By the first half of 2026 — post-Alpha, post-PayByPhone — Vehicle was 44 percent, Corporate 40 percent, Lodging 9 percent and Other 6 percent.7 Four points of mix shift in nine months is fast for a company this size, and roughly half of it came from a single acquisition rather than from differential organic growth.
Corporate Payments: the growth engine, and what actually drives it
This is where the equity story lives, so it is worth explaining what the segment actually sells in plain terms.
Three product families. AP automation takes the invoices a company receives, digitizes and codes them, routes them for approval, and then executes the payment — replacing a person who currently opens envelopes, types data into an accounting system, and prints checks. Virtual cards are the monetization layer on top: instead of paying a supplier by check or bank transfer, Corpay generates a single-use card number for the exact invoice amount, the supplier runs it like any card payment, and the interchange fee that the supplier's acquirer pays gets split between Corpay and its customer. The buyer often gets a rebate, which is why they participate. Cross-border FX is a different animal entirely: a company owing €400,000 to a German supplier needs someone to convert dollars to euros and deliver the funds, and Corpay earns a spread on the conversion, plus fees on hedging instruments — spot, forwards and options across roughly 200 countries and 145 currencies.2
Four revenue mechanics, then: a software or per-transaction fee, an interchange split, an FX spread, and interest on client float. Only the first is straightforwardly recurring in the SaaS sense. The interchange split depends on supplier acceptance rates and on card network economics that Corpay does not set. The FX spread depends on volume and on competitive intensity in a category where clients can and do get quotes from banks. And float income depends on central banks.
The segment's operating momentum is genuine. Second-quarter 2026 spend volume grew 43 percent to $94.6 billion, new sales rose 30 percent, and Corporate Payments revenue reached $548.7 million, up 42 percent year over year and 41 percent of consolidated revenue.15 On the second-quarter call, when pressed by KBW's Sanjay Sakhrani on whether the growth was sustainable, Clarke pointed to "40% more sales in the quarter" — framing the growth as a function of sales-force productivity and investment rather than of one-time volume effects.15 That is a concrete answer rather than a deflection, and it is testable: if new sales growth decelerates and revenue growth persists, the story is float or FX; if new sales lead revenue, the story is distribution.
Vehicle Payments: the cash cow that refuses to be a cash cow
The conventional framing is that Vehicle Payments is a declining legacy business funding the pivot. The numbers do not quite support that. The segment grew 9 percent organically in 2025, 10 percent in the first quarter of 2026, and 8 percent in the second — with management noting on the fourth-quarter 2025 call that US same-store sales had turned positive for the first time in six quarters.22315
Some of that strength is Brazil, where Corpay has quietly built something larger than a fuel card business: the Sem Parar toll network with proprietary RFID tags, parking, and — via the Zapay and Gringo acquisitions — vehicle registration, tax and fine payments.2 Gringo, acquired in February 2025 for $153.7 million net of cash, was a consumer super-app with over 20 million downloads that let Brazilian drivers pay "car debts" digitally.22 Management has said the car-debts market is roughly three times the size of tolls and far less penetrated.
That is a meaningful and underdiscussed asset. It is also a reminder that "Vehicle Payments" is a reporting convention rather than a coherent business: it contains a mature US fuel card operation constrained by a federal injunction, a European fuel and maintenance business partly being sold, and a fast-growing Brazilian consumer-adjacent mobility platform exposed to Brazilian rates, currency and regulation. Aggregate organic growth of 8 to 10 percent is the average of things moving in opposite directions.
Lodging: the honest problem
Lodging is the smallest segment and the only one shrinking. It houses workforce travel — crews for utilities, pipelines, construction — plus airline crew and disrupted-passenger accommodation, and insurance-displaced residents.2 Revenue fell 3.9 percent in 2025 on lower emergency activity, which is a polite way of saying the business is levered to hurricanes, storms and disasters.2 On the fourth-quarter 2025 call, management named Lodging and US vehicle payments together as the company's "problem child," and guided to flat-to-negative growth through the first half of 2026.23 By the second quarter, the segment had improved sequentially by two percentage points and management expected a return to organic growth in the second half.15
At under 10 percent of revenue, Lodging cannot make or break the thesis. Its analytical value is as a credibility check: management labeled it a problem publicly, set an explicit recovery timeline, and has so far tracked toward it. That is the behavior of a team willing to explain misses rather than bury them — a genuinely useful signal, and one that was not obvious from the pre-2020 record.
The segments tell you where the money is. The next question is who else wants it.
IX. Competitive Landscape, 7 Powers & Porter's 5 Forces (35–40 min)
Run the war-game properly and Corpay is not one company facing one competitive set. It is three companies facing three, and the competitive intensity is inversely correlated with where the growth is.
The direct comparison: WEX
The cleanest peer test available is WEX Inc., the other large public fleet card operator, because both companies faced the same fuel prices, the same freight cycle, and the same commercial payments opportunity over the same period.
The results diverged sharply. WEX generated $2.66 billion of revenue in 2025, up 1.2 percent. Its Mobility segment — the direct fleet comparable — declined 1 percent to $1.386 billion, with payment processing revenue down 7 percent. Its Corporate Payments segment declined 2 percent to $477.4 million. Adjusted operating margin fell from 40.3 percent to 37.5 percent, and the company flagged a net $27.0 million unfavorable impact from fuel prices and spreads.26 Corpay grew 14 percent over the same year, with Vehicle Payments up 6.5 percent and Corporate Payments up 33.8 percent.2
That is not a small gap; it is a different trajectory in the same weather. Two mechanisms explain most of it. First, geography: Corpay's Vehicle segment has Brazil and Europe growing while the US fuel market stagnates, whereas WEX's Mobility business is far more US-concentrated. Second, Corporate Payments scale: Corpay's is roughly three and a half times WEX's and has been fed by acquisitions that WEX did not make. WEX has also been fighting an activist: Impactive Capital ran a contested slate into the 2026 annual meeting, rejecting WEX's offers to seat two of its three nominees and demanding, among other things, separation of the chair and chief executive roles.27
The honest caveat: a meaningful share of Corpay's outperformance is bought, not earned. Strip out Alpha, GPS, Paymerang and Gringo and the growth differential narrows substantially. The organic comparison — roughly 10 to 11 percent for Corpay versus low-single-digit or negative for WEX — still favors Corpay, but by less than the headline.
The rest of the field
Corpay's own 10-K names the competitive set, which is a more reliable guide than industry commentary.2 In fuel: WEX, U.S. Bank Voyager Fleet Systems, Edenred, Sodexo, Alelo and Radius. In Brazilian tolls: ConectCar, Veloe and Repom. In parking: ParkMobile, ParkHub and FLASH. In Corporate Payments: banks offering similar services, plus American Express and Coupa. In Lodging: traditional travel management companies including American Express Global Business Travel.
Read that list and something jumps out. In Vehicle, the competitors are specialists Corpay can outspend and outbuy. In Corporate Payments — the growth engine — the competitors are banks and American Express, entities with lower cost of funds, deeper treasury relationships, and no need to earn a return on $7.15 billion of goodwill.7 The competitive intensity is highest exactly where the company is placing its capital. Add the venture-funded cohort the 10-K does not name — Ramp, Brex, Bill.com in the SMB and mid-market spend-management layer — and the picture is of a category with abundant capital, falling technical barriers, and no shortage of entrants.
Seven Powers, applied honestly
Hamilton Helmer's framework asks which specific, durable mechanisms let a business earn returns above its cost of capital. Applied to Corpay:
Switching costs — strong, and the most defensible power the company has. Not because the software is irreplaceable, but because it is embedded. An AP automation deployment touches the ERP, the approval hierarchy, the vendor master file and the month-end close. Ripping it out means re-onboarding thousands of suppliers. The evidence is the retention rate: 93 percent in the second quarter of 2026, held stable through a rebrand, a federal injunction and four large acquisitions.15 That is the single most persuasive number in the Corpay story.
Scale economies — real but partial. At $94.6 billion of quarterly Corporate Payments spend volume, the marginal cost of processing an incremental transaction is close to zero, and the company spent approximately $408 million on technology in 2025 — a fixed cost a smaller rival cannot match.152 But scale in processing is not scale in distribution, and a bank with 3,000 corporate treasury relationships has distribution scale Corpay does not.
Cornered resource — absent. There is no patent, no exclusive license, no irreplaceable talent pool. The Mastercard exclusivity is the closest thing, and it is a contract with a defined term and a put option attached, not a cornered resource.2422
Counter-positioning — weak and weakening. Corpay's historical advantage was that banks were slow to build custom B2B workflows. That was true for two decades. It is less true now, and the presence of both banks and American Express in the company's own competitor list is the acknowledgment.
Network economies — largely absent in the growth business. The closed-loop fuel networks had a genuine two-sided quality. Cross-border FX and AP automation do not: a new Corpay customer makes the product no better for existing customers.
Process power and branding — the honest answer on process power is that the integration playbook is real but is an execution capability that has to be re-demonstrated on every deal, and on branding, a company that changed its own name in 2024 is not claiming brand power.
Net: one strong power, one partial, four weak or absent. That is a respectable but not extraordinary structural position, and it means the return profile depends heavily on continued execution rather than on structure doing the work.
Porter, briefly
Buyer power is moderate and rising in Corporate Payments — enterprise treasurers run competitive processes on FX spreads and virtual card rebates, and rebate competition is the mechanism through which interchange economics get competed away. Supplier power runs through the card networks and sponsoring banks: Corpay's virtual cards operate on Mastercard rails, which means a portion of unit economics is set by a counterparty.2 Threat of substitutes is the sharpest force — real-time bank rails, stablecoin settlement, and bank-issued virtual cards all attack the same flows. Notably, on the fourth-quarter 2025 call management said stablecoin demand was near zero despite infrastructure investment, which is a candid answer and worth noting precisely because it cuts against a fashionable narrative.23 Rivalry is intense in AP automation and moderate in fuel. Barriers to entry are genuinely high in cross-border for regulated, multi-jurisdiction, large-ticket flows — licensing across dozens of countries is slow and expensive — and low in the software layer.
The forces analysis points at one conclusion: Corpay's defensibility is concentrated in regulatory licensing and installed-base inertia, not in technology. That is a defensible position, but it is one that erodes if execution slips — which puts management under the microscope.
X. Management Credibility, Governance & Capital Allocation Stress Test (30–35 min)
Twenty-six years is a long time to run a public company. Ron Clarke arrived in 2000 at a business doing roughly $30 million of revenue and, as of the second quarter of 2026, still chairs the board and runs a company guiding to $5.29 billion to $5.33 billion of revenue for the year.415 Very few operators in any industry get a quarter-century to compound a single strategy. The question is what the record of those years actually establishes.
What the record supports
Three capabilities are genuinely evidenced rather than asserted.
The first is deal sourcing and integration at volume. Forty-plus transactions before the IPO, and a steady cadence since, without the balance-sheet accident that usually ends serial acquirers. That is not a small thing: the base rate for roll-ups is poor, and the graveyard is full of companies that bought faster than they could integrate.
The second is cost discipline. It shows up in the willingness to name a $75 million expense savings target on the fourth-quarter 2025 call and report $50 million already executed, and in the margin structure that lets a payments company convert revenue into $1.5 billion of free cash flow in 2025.23
The third — and this is the newest — is a demonstrated willingness to shrink. The Comdata point-of-sale sale, PayByPhone, the Maintenance business, and a stated plan for three to four more divestitures inside a year is a genuine break from twenty years of one-way accumulation.1625715 Management has attached itself publicly to that plan, which makes it falsifiable: if the divestiture count comes in at zero or one by mid-2027, the simplification narrative was rhetoric.
What the record does not support
The counterweight is governance, and it is heavy.
Corpay's own 2026 proxy discloses that Clarke beneficially owned 3,194,870 shares — 2,344,870 held outright plus 850,000 acquirable through options — representing 4.64 percent of the 68,050,296 shares outstanding as of February 17, 2026.1 That is meaningful alignment, considerably larger than the typical professional-manager stake, and it is a real answer to the question of whether he is exposed to the same outcome as shareholders.
But alignment is not the same as accountability, and the compensation record is what a skeptical investor would press on. The say-on-pay history is not a single bad year; it is a multi-year pattern in which shareholders repeatedly told the board its pay design was wrong and the board repeatedly needed to be forced. Support has since recovered — the 2025 say-on-pay proposal received approximately 54 percent — but that figure deserves precision rather than celebration.1 Fifty-four percent is a passing grade in the sense that it exceeds half. It is a failing grade by the standards of the S&P 500, where support in the nineties is unremarkable and anything below 70 percent is generally treated by proxy advisers as a signal requiring board response. A company nine years past its first revolt, still unable to clear 60 percent, has not resolved the underlying disagreement.
The board composition adds to the picture. Twelve directors, eleven of them independent, with the independent directors averaging nine years of tenure and 66 years of age.1 Nine-year average tenure on a board overseeing a founder-figure chief executive who is also chairman is the classic structure that governance analysts flag: long-serving directors evaluating a long-serving CEO they largely served alongside. Shareholders noticed. The 2026 annual meeting included a shareholder proposal requiring an independent board chair, which the board recommended voting against.1
That proposal is the cleanest expression of the governance stress test. Clarke holds both the chair and CEO roles at a company that lost the lowest say-on-pay vote in the S&P 500, settled a securities class action over fee disclosure, and lost a federal consumer protection case on all counts through appeal. A skeptical investor would argue those are precisely the conditions under which independent board leadership matters most. Management's counterargument — continuity of a strategy that has compounded shareholder value for two decades — is not frivolous. But it is the argument every entrenched chair-CEO makes, and it should be weighted accordingly.
Capital allocation: the priority stack, tested
Corpay's stated capital allocation framework is straightforward: deploy free cash flow and incremental debt capacity into whichever of corporate payments M&A or share repurchases offers the better return, while managing leverage. Management has quantified the opportunity at roughly $15 billion of deployable capital over its mid-term forecast horizon, generated by free cash flow and expanding debt capacity as earnings grow.15
The recent behavior is more balanced than the historical pattern would predict. In the fourth quarter of 2025 the company repurchased 2.6 million shares for $782 million.23 In the first half of 2026 it repurchased 3.4 million shares for approximately $1.1 billion, with the board adding $1.0 billion to the authorization on April 23, 2026 and roughly $1.4 billion remaining as of June 30.7 Repurchasing roughly five percent of the share count in nine months, while simultaneously closing a $2.4 billion acquisition, is aggressive on both legs at once.
That is only prudent if the balance sheet can carry it, which brings us to leverage. Reported leverage was 2.83 times at the end of 2025, and 2.55 times at the end of the second quarter of 2026, with roughly $1.6 billion of revolver capacity available and the revolving facility increased by $1.0 billion to $3.7 billion.2315 Absolute debt sits at approximately $8.3 billion — $2,225.4 million current and $6,098.1 million long-term as of June 30, 2026.7
One accounting nuance deserves flagging because it can badly mislead a screen-based reading. Corpay's balance sheet carries very large cash balances — the Alpha transaction alone brought $4.5 billion of cash and equivalents onto the books — but a substantial portion of that is customer and client funds held for settlement, not corporate cash available to repay debt.7 A naive "net debt" calculation subtracting all cash from all debt will produce a number far below the company's own reported leverage ratio. Management's 2.55 times is the figure that reflects economic reality; the screened version does not.
The other item a forensic reader should note: goodwill and intangibles dominate the asset base. Goodwill alone stood at $7.15 billion at June 30, 2026, down from $7.56 billion at year-end 2025 as PayByPhone goodwill was derecognized and Maintenance goodwill moved to held-for-sale.7 Alpha added $1.21 billion of goodwill and $994.5 million of intangibles, of which $946.1 million was customer relationships amortized over eleven to twenty years.7 An eleven-to-twenty-year life on customer relationships in a competitive FX brokerage business is an accounting judgment, not a fact — it flatters reported earnings relative to a shorter assumption, and it is the kind of estimate an impairment test would eventually revisit if Alpha's client attrition ran faster than modeled. Nothing in the record suggests it has. But the judgment is there, it is material, and readers should know it exists.
The calibrated conclusion on management: strong and repeatedly demonstrated on operating execution and deal integration; genuinely improved on portfolio pruning since 2024 after a decade-long lapse; and persistently weak on the governance dimension, where the pattern is of a board that responds to shareholder pressure rather than anticipating it. None of those three verdicts cancels the others. All three should be priced.
XI. The Investment Story Spine: Bull vs. Bear Case (25–30 min)
Strip the story to its load-bearing beams and the debate over Corpay comes down to one question: is this a compounding platform that happens to use M&A, or an M&A machine that will stop compounding when the deals stop?
Why this company wins from here
The bull case rests on three mechanisms, each with evidence behind it.
The B2B payments transition is genuinely unfinished. Corpay estimates that businesses spend approximately $145 trillion annually in transactions with other businesses — a company estimate, not an audited figure, and one that should be read as a framing device rather than a serviceable market.2 But the underlying observation holds: a large share of business-to-business payment is still executed by check, bank transfer with manual reconciliation, or a treasury workflow built around a spreadsheet. Every invoice that moves from check to virtual card creates interchange economics that did not previously exist, and Corpay's second-quarter 2026 spend volume growth of 43 percent to $94.6 billion is evidence that the conversion is happening at its accounts rather than merely in industry forecasts.15
Distribution is compounding faster than the market. New sales rose 30 percent in the second quarter of 2026, and Clarke's answer to the sustainability question pointed at sales productivity rather than at market tailwind.15 The Mastercard channel, if it converts, adds a distribution asset Corpay could not have built — ten financial institutions closed against a pipeline of roughly 100 prospects as of the second quarter, up from two closed and 50 to 70 in process two quarters earlier.1523 The trajectory is right; the absolute numbers are still small.
Retention holds the whole thing together. Ninety-three percent customer retention through a rebrand, a permanent injunction, four large acquisitions and a leadership-continuity question is the strongest single piece of evidence that the workflow lock-in is real rather than asserted.15
What could break it
The float problem is the most underappreciated risk, and management has already told you about it. Corpay earns interest on client balances — the deposits sitting in cross-border accounts and AP settlement pools between the moment a customer funds a payment and the moment the supplier is paid. That income is high-margin and requires no incremental effort, which is exactly why it flatters segment economics during a high-rate period and drains them during a cutting cycle. Management guided 2026 organic growth down to 10 percent from an 11 percent run rate explicitly because of float compression concentrated in Corporate Payments, worsened by Alpha's deposit-heavy mix, with a 70 to 75 basis point impact concentrated in the first quarter.23 The bull case's headline growth number and the bear case's biggest structural question are the same number viewed at different points in the rate cycle.
The M&A treadmill is a real dependency, not a rhetorical one. Consolidated revenue grew 14 percent in 2025 and is guided to roughly 17 percent in 2026, against organic growth of 10 to 11 percent.21523 The gap is acquisition. That is not inherently bad — buying growth at a good price is a legitimate use of capital — but it means the reported growth rate is a policy choice that requires continuous deployment. If large, reasonably-priced cross-border and AP assets stop being available, or if a deal goes wrong, the reported number converges toward the organic number, and the multiple the market pays for a 17 percent grower is not the multiple it pays for a 10 percent grower.
Competitive encroachment is structural, not cyclical. The threat is not that Ramp or Brex takes Corpay's enterprise cross-border business tomorrow; it is that abundant venture and bank capital compresses the take rate across the whole category. Rebate competition on virtual cards is the specific mechanism: as buyers get sophisticated, more of the interchange is passed back to them, and the issuer's retained spread narrows. This does not show up as customer loss. It shows up as revenue growing slower than volume — and volume growing 43 percent against segment revenue growing 42 percent in the second quarter of 2026 is not yet evidence of it, but it is the ratio to watch.15
The regulatory overhang is not closed. The proposed FTC consent order agreed with staff on July 1, 2026 remains subject to Commissioner and District Court approval, and Corpay has disclosed that changes to the terms could produce additional redress or penalties beyond the $100 million charge already taken.7 Separately, the vacated Count II against Clarke was remanded rather than dismissed.6 And the injunction's operating requirements — unavoidable disclosure, fee-by-fee assent — are permanent constraints on how the legacy business can price, not a one-time cost.
The activist lens
What would a well-armed skeptic actually attack? Four things. Portfolio complexity: a company with fuel cards in Brazil, hotel rooms for pipeline crews, parking, vehicle tax payments, FX for European fund managers and virtual cards for US healthcare AP is difficult to value on a sum of the parts and easy to argue is worth more broken up — an argument management has partly conceded by divesting. Governance: the combined chair-CEO role, the say-on-pay history, and a board with long average tenure. Disclosure: the company reports organic growth and cash EPS as its headline metrics, and the reconciliation between GAAP net income of $1.07 billion in 2025 and management's adjusted framework is where a short seller would spend a weekend. And capital allocation: whether $578 million into a 35 percent non-controlling stake in AvidXchange was a better use of capital than buying back more of a business management says is undervalued.22
Notably, the last of those demands is precisely what an activist pressed on Corpay's closest peer during 2026, which suggests the category is on the screens.27
The two or three numbers that actually matter
Most metrics in this story are noise. Three are not.
Corporate Payments organic revenue growth, decomposed for float. This is the entire equity story in one line. The headline number blends genuine volume and new-sales expansion with an interest-rate variable, and management now discloses the float drag explicitly. The ex-float rate is the honest read on whether the growth engine is working.
Customer retention rate. Reported quarterly, currently 93 percent. It is the single cleanest test of whether workflow lock-in is real, and it is the metric that would deteriorate first if competitive take-rate pressure were turning into actual churn.
Reported leverage (net debt to EBITDA, on management's definition). Not a screen-computed version. It is the constraint that determines whether the company can keep doing both M&A and buybacks, and it is the number that would break first if an acquisition underperformed.
Everything else — quarterly EPS beats, fuel prices, individual deal announcements — is texture around those three.
XII. Playbook & Durable Business Lessons (20–25 min)
Regardless of an investor's view on the equity, Corpay remains an instructive case study in modern business strategy because it demonstrates four principles that generalize well beyond payments.
Boring flows are where the margin hides. Consumer payments is the high-profile half of the industry and a tougher environment in which to earn sustained returns: branding is expensive, regulators cap interchange rates, and consumers switch for rewards or promotions. Commercial payments shares few of those traits. The buyer is a controller or treasurer who values administrative control and automated reconciliation over unit pricing; the flows are recurring and predictable; and fleet fuel cards rarely require consumer marketing. The broader lesson applies across software and services: when evaluating a category, determine who the buyer is and what problem they are optimizing to solve. A buyer seeking administrative relief pays differently—and far more durably—than a buyer shopping strictly on transaction price.
Yield extracted through complexity is borrowed, not earned. This proved to be the most expensive lesson in Corpay's history. The fee architecture that expanded margins between 2012 and 2019 ultimately led to a federal lawsuit, a $50 million securities settlement, a $100 million regulatory charge, a permanent injunction constraining legacy pricing practices, and the lowest say-on-pay vote in the S&P 500.520718 What makes the episode analytically instructive is not merely the regulatory enforcement, but that the resulting revenue was reported as structural pricing power for years before external observers could separate yield optimization from customer value creation. For analysts, the diagnostic takeaway is clear: when a business demonstrates margin expansion without corresponding product improvements, inspect what the customer is receiving in return. If the answer is nothing, the expanded margin is an unrecognized liability with a delayed maturity date.
Rebranding works only when capital follows the narrative. Corporate name changes are frequently cosmetic and often deserve market skepticism. The transition from FleetCor to Corpay represents a case where capital allocation was large enough to make the narrative descriptive rather than aspirational: allocating roughly $3.3 billion of announced consideration across Paymerang, GPS Capital Markets, Alpha Group International, and the AvidXchange stake within eighteen months, funded in part by divesting non-core assets.229 The test of any corporate rebrand is whether the balance sheet moves to match the repositioning. Here it did—making the earlier ten-year retention of the Comdata point-of-sale hardware business a clear contrast case in portfolio management.
An execution edge carries inherent limits. Corpay's core advantage is not a patent or a network that automatically grows more valuable with every user. It is a repeatable operating playbook—identify a fragmented market, acquire assets, standardize infrastructure, cross-sell services, and reduce operating costs—executed consistently over two decades. Operating playbooks are valuable, but they depend entirely on key leadership. While structural moats can endure poor management, execution edges typically do not. That vulnerability makes executive succession—which the company's 2026 proxy does not detail in depth—a primary analytical concern rather than a routine governance detail.1
XIII. Transcript Guidance for the Downstream Article Writer (15–20 min)
The most useful discipline in following a company like Corpay is reading earnings call transcripts in sequence rather than in isolation. The primary signal is not what management asserts in any single quarter, but whether the narrative remains consistent when underlying facts shift.
Tracking executive commentary across recent quarters yields three primary conclusions.
The rebrand-era framing has held up. When the company announced its name change in March 2024, management argued that Corporate Payments had become its main business and that the corporate identity should reflect that reality.3 That rationale is verifiable and supported by reported results: the segment expanded from roughly one-third of total revenue through the first nine months of 2025 to 40 percent in the first half of 2026, with leadership deploying capital to back the repositioning.227 While skeptics can point out that the rebrand coincided with an active Federal Trade Commission appeal, the business mix shift behind the new name has materialized.
Management has shown transparency in identifying operational challenges. On the fourth-quarter 2025 earnings call, leadership explicitly categorized Lodging and U.S. vehicle payments as operational drag points, guiding toward flat-to-negative revenue growth in the first half of 2026.23 Two quarters later, Lodging revenue improved sequentially by two percentage points, with management projecting a return to organic growth in the second half of the year.15 Similarly, when asked about loosening credit terms to capture freight volume, leadership responded directly on the second-quarter 2026 call: "We are not gonna weaken our underwriting standards to gain business."15 That concrete commitment provides an explicit baseline for evaluating credit-loss trends in subsequent quarters.
Guidance discipline has remained consistent, even when reflecting operational headwinds. The clearest example occurred when management set the 2026 organic growth target at 10 percent—down from an 11 percent trailing run rate—and clearly detailed the expected float drag rather than obscuring it.23 A narrative-driven team might have maintained the 11 percent figure and blamed rate cuts later. Conversely, management raised full-year guidance twice during 2026, raising revenue expectations to between $5.29 billion and $5.33 billion and adjusted earnings per share to between $27.15 and $27.55 after the second quarter.15 This pattern indicates conservative initial goal-setting, though the key test remains whether management maintains that conservative posture when setting initial guidance in January 2027.
Executive disclosures remain less detailed on unquantified strategic questions. During the second-quarter 2026 call, management responded to analyst questions regarding margin pressure by indicating full-year margins would finish "slightly below last year" due to reinvestment.15 However, leadership did not provide a detailed breakdown separating the margin impact of acquired-business mix from organic capital expenditure. Furthermore, expected cost synergies for Alpha Group International were presented as a combined figure alongside AvidXchange—approximately $1.00 of 2026 adjusted earnings per share across both entities—making it difficult to evaluate Alpha's standalone deal economics.23 Additionally, management has yet to provide a financial bridge illustrating how consolidated growth will fare if divestitures subtract more revenue than acquisitions generate.
These analytical gaps reflect typical operational complexity during a multi-year portfolio repositioning. Nevertheless, they establish the key monitoring priorities for upcoming earnings calls: tracking the divestiture count against management's target of three to four transactions, measuring Corporate Payments growth excluding float as interest rates adjust, monitoring the conversion of Mastercard bank partnerships into active revenue streams, and verifying final regulatory approval of the FTC consent order. Tracking these four factors sequentially will clarify the unresolved questions surrounding Corpay's multi-year outlook.
References
-
Corpay, Inc. — Definitive Proxy Statement (DEF 14A) — SEC EDGAR, 2026-04-10 ↩↩↩↩↩↩
-
Corpay, Inc. — Annual Report on Form 10-K for fiscal year ended December 31, 2025 — SEC EDGAR, 2026-02-27 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
FLEETCOR Announces Rebranding to Corpay (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2024-03-07 ↩↩↩↩↩↩↩↩
-
FleetCor Technologies, Inc. — Form 424B4 IPO Prospectus — SEC EDGAR, 2010-12-15 ↩↩↩↩↩↩↩↩↩↩↩
-
FTC Alleges Fuel Card Marketer FleetCor Charged Hundreds of Millions in Hidden Fees — Federal Trade Commission, 2019-12-20 ↩↩↩↩↩↩↩
-
Federal Trade Commission v. Corpay, Inc. (11th Cir.) — FindLaw Caselaw, 2026-01-06 ↩↩↩↩↩↩↩
-
Corpay, Inc. — Quarterly Report on Form 10-Q for the quarter ended June 30, 2026 — SEC EDGAR, 2026-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
FleetCor Completes Acquisition of Comdata (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2014-11-17 ↩↩↩↩↩
-
Corpay to Acquire Alpha Group, a B2B Cross Border FX Company — Corpay, 2025-07-23 ↩↩↩↩↩
-
Summit and Bain reduce stakes in FleetCor — Private Equity International ↩
-
FleetCor Prices Initial Public Offering — Corpay, 2010-12-14 ↩
-
FleetCor Completes Initial Public Offering — Corpay, 2010-12-20 ↩
-
FleetCor Acquires UK Fuel Card Company for approximately $304 Million — Corpay, 2011-12-13 ↩
-
FleetCor Enters Brazil with Acquisition of CTF Technologies — Corpay, 2012-05-01 ↩↩
-
Corpay (CPAY) Q2 2026 Earnings Call Transcript — The Motley Fool, 2026-08-12 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
PDI Acquires Comdata Merchant Solutions — PDI Technologies, 2024-12-02 ↩↩↩
-
FleetCor Boosts CEO Ron Clarke's 2017 Pay 79% to $52.6 Million — Transport Topics ↩↩↩
-
FLEETCOR Technologies Inc — Definitive Proxy Statement (DEF 14A) for the 2019 Annual Meeting — SEC EDGAR, 2019 ↩↩
-
FLEETCOR Technologies Inc — Definitive Proxy Statement (DEF 14A) for the 2020 Annual Meeting — SEC EDGAR, 2020 ↩
-
FleetCor Technologies, Inc. — securities class action case page — Bernstein Litowitz Berger & Grossmann LLP, 2020-04-15 ↩↩
-
FLEETCOR to Appeal Ruling in FTC Case — Corpay, 2022-08-10 ↩
-
Corpay, Inc. — Quarterly Report on Form 10-Q for the quarter ended September 30, 2025 — SEC EDGAR, 2025-11 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Corpay (CPAY) Q4 2025 Earnings Call Transcript — The Motley Fool, 2026-02-04 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Mastercard and Corpay Launch Strategic Partnership in Cross-Border Payments — Mastercard Investor Relations, 2025-04-29 ↩↩↩↩
-
Corpay Agrees to Divest PayByPhone (Form 8-K, Exhibit 99.2) — SEC EDGAR, 2026-02-04 ↩↩
-
WEX Inc. Reports Fourth Quarter and Full Year 2025 Financial Results — WEX Inc. Investor Relations, 2026-02-04 ↩
-
WEX Inc. — Additional Definitive Proxy Soliciting Materials (DEFA14A) regarding the Impactive Capital proxy contest — SEC EDGAR, 2026-04-16 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube