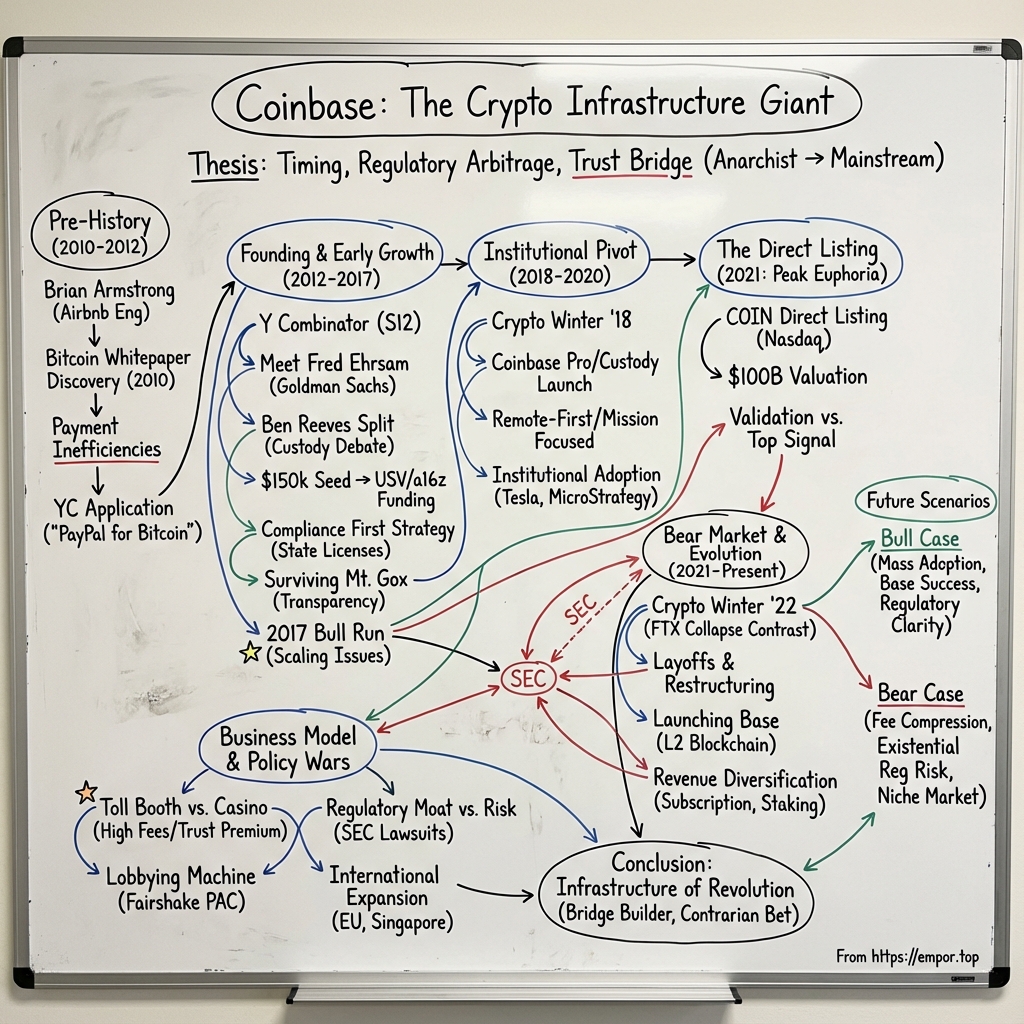
Coinbase: The Crypto Infrastructure Giant
I. Introduction & Episode Thesis (5–10 min)
On the afternoon of July 30, 2026, Coinbase did something no traditional financial institution would dream of: it held its quarterly earnings call live on X, took questions from a podcaster, a YouTube creator, and a JPMorgan analyst in the same session, and reported a net loss of $359.5 million.
The loss was not the headline management wanted. The headline they wanted was that Coinbase had just posted its fourteenth consecutive quarter of positive adjusted EBITDA — $207.8 million of it — and that subscription and services revenue had reached 48% of net revenue, the highest share in the company's history as a public company.1 Both statements were true simultaneously. That is the central puzzle of Coinbase Global, Inc. as an investment: a business that has spent four years deliberately engineering itself out of dependence on crypto price speculation, yet still reports GAAP losses when crypto prices fall.
Coinbase was founded in June 2012 by Brian Armstrong, a former Airbnb engineer, and Fred Ehrsam, a former Goldman Sachs foreign exchange trader.2 Fourteen years later, it is the largest regulated crypto exchange in the United States, the custodian behind most of the American spot bitcoin ETF complex, the largest distributor of the USDC stablecoin, and the operator of Base, the largest Ethereum layer-2 network. In full-year 2025, it generated $7.18 billion of revenue and $1.26 billion of net income.3 In the first half of 2026, it generated roughly $2.6 billion of revenue and lost roughly $754 million, almost entirely because the crypto and equity investments sitting on its own balance sheet fell in value.14
The central question of this story is not whether crypto matters. It is narrower and harder: how did a Y Combinator startup run out of a two-bedroom apartment become the toll collector on American crypto — and is that tollbooth a durable franchise or a leveraged bet on asset prices wearing the costume of an infrastructure company?
The arc runs from a Ruby-on-Rails bitcoin wallet, through a state-by-state licensing grind, to an institutional prime broker, to a layer-2 protocol operator, to an "Everything Exchange" selling equities, commodities futures, and prediction-market contracts alongside bitcoin. Along the way, its market capitalization has swung between roughly $8 billion and well over $100 billion. As of early September 2026, it sits near $52 billion, with shares having traded between $139 and $402 over the prior twelve months. That range is not a rounding error. It is the business model showing through the share price.
Three themes carry the story.
Compliance as a moat — and the limits of that claim. Coinbase spent its first decade acquiring money transmitter licenses state by state, submitting to audits, and refusing to list assets its lawyers disliked, while offshore competitors optimized for leverage and listing speed. Two of those competitors — FTX and, in a different way, Binance — are gone or diminished. That looks like vindication. But the same compliance apparatus did not travel: when Coinbase tried to plug into India's payment rails in 2022, the local system rejected it within three days. A moat built inside one legal perimeter is not a moat everywhere.
The volatility tollbooth, and the attempt to escape it. At the 2021 direct listing, more than 85% of net revenue came from transaction fees, and the vast majority of that came from retail customers paying spreads that could exceed 150 basis points.2 Management has spent five years building a second engine — interest income on USDC reserves, staking commissions, custody fees, a consumer subscription — precisely so that the company survives an 80% drawdown in crypto prices. By 2025, that second engine produced $2.8 billion of revenue.3 Whether it is genuinely non-cyclical is the most important open question in the story, and the evidence cuts both ways.
Platform transitions. Single-asset wallet, to retail exchange, to institutional custodian, to layer-2 operator, to multi-asset-class exchange. Coinbase has re-platformed itself roughly every four years. Most of those transitions worked. Some — an NFT marketplace, a social feed on Base — did not, and the record of the failures is as informative as the record of the wins.
Keep one contrast in mind throughout. In the S-1 filed in February 2021, Coinbase told investors its business was overwhelmingly about trading crypto.2 On the Q2 2026 call, Armstrong noted that bitcoin-related transactions, once more than half of company revenue, had fallen to about 12% of the business.1 Management presents that as diversification. A skeptic would note that the denominator shrank too. Both readings deserve a hearing, and the rest of this story is an attempt to adjudicate between them.
Which requires going back to a software engineer in San Mateo who could not stop thinking about a nine-page PDF.
 Subscribe on LinkedIn
II. Pre-History & The Bitcoin Discovery (25–35 min)
Brian Armstrong read Satoshi Nakamoto's bitcoin white paper in 2010. He described the effect in near-religious terms: a mathematical solution to a problem he had assumed was permanent, namely that moving money required trusting an institution to keep the ledger.2
What set him apart was not the reading—thousands of engineers read the paper in 2010—but his day job. Armstrong had joined Airbnb as a software engineer working on international payments, spending his working hours inside the plumbing of cross-border money movement across roughly 190 countries. That was a specific kind of practical education. He was not theorizing about payment friction; he watched hosts in Argentina wait days for settlement, absorb foreign exchange haircuts, and pay fee stacks extracted by intermediaries who had never met. To someone doing that work, bitcoin was not an abstract thesis; it was a competing architecture.
He wrote code on nights and weekends—Ruby on the back end, JavaScript on the front—building a wallet designed so ordinary people could buy, hold, and send bitcoin without ever seeing a private key or a command line.2 That premise sounds trivial today. In 2011, it was heretical to early bitcoin purists, creating an ideological fault line that nearly killed the company before it started.
The macro backdrop mattered more than the technology. Three currents converged between 2010 and 2012.
The first was post-crisis distrust. The 2008 financial crisis and subsequent quantitative easing produced a durable constituency convinced that monetary authority had been abused. Bitcoin's fixed supply schedule was a political statement as much as a technical parameter, famously signaled by the genesis block's embedded headline about bank bailouts. That constituency provided early demand.
The second was the smartphone. Within four years, the iOS App Store and Android trained hundreds of millions of people to trust mobile devices with their money and expect financial actions to take a single tap. Simultaneously, Stripe and Square proved that payments could be delivered as developer APIs rather than bank relationships. Coinbase was a bet that crypto would arrive through that same consumer-application door rather than a terminal window.
The third was the fragile state of existing crypto infrastructure. The dominant venue was Mt. Gox, a Tokyo-based exchange with an improvised operational structure that would eventually collapse and lose hundreds of thousands of customer bitcoin. Beyond that lay command-line wallets vulnerable to typos, and over-the-counter trades arranged on Bitcointalk forums between pseudonymous strangers mailing cash. In 2011, buying bitcoin safely with dollars from an American bank account was nearly impossible.
The timing was critical, defined by a narrow window. Entering in 2009 meant navigating a market with no quoted price, no liquidity, and no customers. Entering in 2015 meant competing against funded incumbents under a colder regulatory climate. The year 2012 offered a distinct opening: bitcoin had a quoted price and a genuine, if small, network effect; infrastructure was so unreliable that basic operational competence formed a defensible product; and neither Wall Street nor mainstream Silicon Valley venture capital had arrived. Investors like Fred Wilson and Chris Dixon would show up within eighteen months. Fidelity and BlackRock would take another decade.
That timing explains Coinbase's founding advantage: not proprietary technology or early regulatory compliance, but arriving first in a market where basic competence was scarce, then surviving as repeated market downturns tested the business.
Yet early entry is only valuable if a company survives its launch. Coinbase's entry triggered an internal co-founder dispute that turned on the single most consequential product decision in the company's history.
III. The Y Combinator Sprint & Finding Fred (30–40 min)
In early 2012, Armstrong met Ben Reeves, a British programmer, on a bitcoin forum. Reeves was already well known in the community for building Blockchain.info, a widely used block explorer and wallet. The two proposed a joint venture: a platform where users could store a wallet, convert dollars to bitcoin, and pay merchants. They applied to Y Combinator's Summer 2012 batch and received an invitation almost immediately.5
Then the partnership collapsed over a fundamental question that still divides the crypto industry.
Reeves believed users had to hold their own private keys. Anything else re-created a traditional bank—a trusted third party that could freeze, lose, or seize user funds—and defeated the purpose of the technology. Armstrong believed that mainstream adoption required the opposite: Coinbase should hold the keys, manage security, and allow users to reset forgotten passwords like any standard website. If ordinary users stood to lose their savings permanently because of a lost text file, mainstream adoption would never happen.6
Both men identified real trade-offs. Reeves correctly identified that custodial services re-introduce the exact counterparty risk crypto was designed to eliminate—a lesson the industry relearned during the collapse of major platforms in 2022. Armstrong correctly recognized that a product requiring strict key management capped its user base at a few million technical enthusiasts. The disagreement was not merely technical; it was a fundamental conflict over target customers.
Days before Y Combinator began, Armstrong locked Reeves out of the company's accounts and ended the partnership, telling him co-founding was like a marriage and that they were incompatible. Reeves subsequently built Blockchain.com into a major crypto firm in its own right.6 This episode provides an early signal of Armstrong's management style: a willingness to make swift, irreversible, and socially costly decisions when he believes a strategic direction is wrong. That pattern recurred in 2020 with his "mission-focused" workplace memo, in 2022 with sudden layoffs, and in 2026 during an AI-driven restructuring. For investors, this decisiveness under friction represents a persistent management trait rather than a series of isolated events.
Armstrong entered Y Combinator alone—a rarity in the accelerator's culture. He posted on Hacker News looking for a co-founder; the request circulated across forums, including Reddit's bitcoin community, where he was an active participant.56 Through that search, he connected with Fred Ehrsam.
Ehrsam was a 23-year-old Duke computer science graduate who had traded foreign exchange at Goldman Sachs. He brought practical experience from an adversarial, high-volume market, understanding order books, bid-ask spreads, and trade settlement.
The partnership proved complementary. Armstrong drove product design, engineering, and long-term vision; Ehrsam managed market structure, trading mechanics, and financial industry credibility. Ehrsam stepped down from day-to-day operations in 2017 to co-found the venture firm Paradigm while retaining his board seat—a smooth transition that nevertheless removed Coinbase's most market-literate executive from daily operations just before its largest operational scaling test.
The initial product was intentionally basic. It featured a simple web interface with two buttons—buy and sell—linked to a U.S. bank account via ACH transfer. There was no order book, no charting package, and no leverage. Coinbase quoted a price, collected a spread, and executed the settlement. While experienced traders dismissed the simple design, the product bypassed traditional exchange competition entirely by offering mainstream American users their first accessible entry point into bitcoin.
User growth followed the elimination of that access barrier. By early 2013, Coinbase was processing more than $1 million a month in bitcoin volume, attracting venture capital interest.5 In May 2013, Fred Wilson's Union Square Ventures led a $5 million Series A round at a valuation of roughly $22 million. That December, Chris Dixon at Andreessen Horowitz led a $25 million Series B—at the time the largest venture round raised by a bitcoin startup—with Union Square Ventures and Ribbit Capital participating. The investment brought total capital raised to about $31 million and added Wilson and Dixon to the board.7
A $31 million funding base for a company that would eventually generate $7 billion in annual revenue represents a notable return on paper. However, investors in December 2013 were underwriting a two-year-old firm in a legally ambiguous market, whose business model relied entirely on trading spreads for a $10 billion asset class, just three months before that asset class entered a prolonged downturn.
The next four years were defined by survival.
IV. Building the On-Ramp: Product Evolution & Early Growth (2012–2017) (45–55 min)
In February 2014, Mt. Gox stopped processing withdrawals, filed for bankruptcy, and admitted that hundreds of thousands of customer bitcoin had vanished. As the market price collapsed, the dominant exchange in the industry was exposed as an operationally incompetent black box, leading mainstream media to broadly conclude that crypto as a whole was fundamentally unsafe.
For Coinbase, that catastrophe became the foundational argument for its long-term strategy. If the industry's primary failure mode was reliance on un-auditable intermediaries, the winning strategy was to become the platform that regulators and institutions could audit.
The licensing grind. Coinbase pursued the least glamorous work in technology: state-by-state regulatory licensing. Money transmitter licenses in the United States required individual applications, capital reserves, examination schedules, surety bonds, and compliance staffing across every state. With no federal shortcut available, the process was slow, costly, and yielded no immediate consumer features. Coinbase built out this coverage state by state, eventually securing a BitLicense from the New York State Department of Financial Services—the country's strictest crypto regulatory framework. By the time it filed to go public, Coinbase cited this licensing network as a core operational asset, and by 2026 management routinely pointed to roughly 80 licenses and registrations worldwide.28
The strategic rationale is central to the bull case for Coinbase. Regulatory compliance is a fixed cost that scales poorly for small entrants but efficiently for established operators. A startup incurs similar legal and compliance overhead whether it serves ten thousand customers or ten million. By incurring those expenses upfront and expanding into the infrastructure, the per-customer cost drops significantly, turning compliance from an operational tax into a barrier to entry.
Surviving the winter with merchants and a real exchange. Revenue remained thin through 2014 and 2015, prompting Coinbase to pursue two distinct initiatives to bridge the gap. First, it developed merchant payment processing, onboarding prominent brands such as Overstock, Dell, and Expedia to position bitcoin as a medium of exchange. Though this effort ultimately proved a strategic dead end—as consumer spending in bitcoin remained negligible and merchants quietly departed—it kept the company visible during a prolonged market downturn. Crucially, it also established Coinbase's payment API capabilities, infrastructure that would prove relevant a decade later in stablecoin processing.
Second, and more consequentially, Coinbase launched a dedicated order-book exchange. While its initial retail buy-and-sell product operated on consumer spreads, an institutional exchange required market makers, limit orders, and deep order books. Introduced as Coinbase Exchange, then rebranded to GDAX and later Coinbase Pro, the platform provided the liquidity depth that the retail application lacked. In exchange businesses, liquidity operates as a network effect: volume concentrates where bid-ask spreads are narrowest, and spreads narrow where volume concentrates.
Then 2017 happened. The rise of Ethereum and the initial coin offering boom triggered crypto's first mass retail influx. As new users registered faster than onboarding systems could process them, the Coinbase app climbed to the top spot on the Apple App Store in December 2017, marking crypto's entry into mainstream financial awareness.
That surge also exposed severe operational vulnerabilities. The platform experienced repeated outages during peak trading volatility, support tickets faced multi-week delays, and users were locked out of transactions during major market moves. Coinbase generated record revenue while visibly failing to maintain basic service availability.
The operational lesson for Coinbase was that for financial exchanges, system availability is the core product. System uptime during volatile market windows directly determines platform trust. Management subsequently directed substantial capital toward infrastructure resilience, resolving many core scaling bottlenecks. Outages persisted occasionally: during a sharp market selloff in February 2026, some users again temporarily lost transaction access. On the company's fourth-quarter 2025 earnings call, Chief Financial Officer Alesia Haas attributed the disruption to a technical issue unrelated to trading volume or market conditions, noting that while the firm remained confident in its platform investments, "we will still have technical bumps at points in time."8 The statement acknowledged a persistent operational reality: a decade of technical investment reduced the frequency of system disruptions without eliminating them entirely.
Falsification test: was the regulatory moat really a moat?
The bull thesis holds that early compliance created an enduring, hard-to-replicate moat. The clearest counter-evidence in Coinbase's operational history emerged in India.
In April 2022, Coinbase launched retail trading in India—a market with a massive, tech-savvy population—by integrating with the Unified Payments Interface, the country's primary retail payment network. Within three days, Coinbase was forced to disable UPI integration after the National Payments Corporation of India issued a statement indicating it was not aware of any crypto exchange using UPI, and banks and payment providers withdrew.9 Chief Executive Brian Armstrong later told investors on an earnings call that the company had faced "informal pressure" from the Reserve Bank of India.10 Without a formal statutory prohibition to challenge or comply with, local payment rails simply disconnected, effectively stalling Coinbase's Indian retail exchange.
Verdict: The evidence refines the scope of the compliance moat rather than invalidating it. Regulatory compliance functioned as a powerful asset specifically within the U.S. legal framework, where licensing standards are codified, administrative procedures are binding, and legal compliance provides operational protection. It offered minimal advantage in jurisdictions where access depends on discretionary control over payment rails and central bank oversight. This distinction directly impacts Coinbase's ongoing international expansion strategy: a regulated footprint guarantees market access only where access is governed by statutory rule rather than regulatory discretion. The metric that validates an international moat is not total license count, but the proportion of revenue generated in international markets entered after 2022.
Domestically, however, the early regulatory strategy positioned Coinbase for an unexpected catalyst: the arrival of institutional capital that required strictly compliant counterparties.
V. The Institutional Pivot & Professionalization (2018–2020) (40–50 min)
By 2018, the retail wave had crested and receded, leaving Coinbase with a problem common to consumer fintech: enormous, highly cyclical revenue coupled with a thin institutional base.
The company's response was an intentional institutional build-out. Between 2018 and 2020, Coinbase executed three key acquisitions that together reveal how its management team allocates capital—including its missteps.
Earn.com (April 2018, reportedly over $100 million). The stated purpose was a product: a portal that paid users in cryptocurrency to complete tasks and answer emails. The primary objective, however, was talent acquisition. Earn.com chief executive Balaji Srinivasan, a prominent technologist and former Andreessen Horowitz general partner, joined Coinbase as its first Chief Technology Officer.[^11]
Falsification test on this acqui-hire. Srinivasan departed in 2019 after roughly a year. Earn.com was rebranded as "Coinbase Earn" and repurposed into an educational token-distribution channel rather than a major standalone revenue driver. As capital allocation, the deal was costly: a nine-figure sum, primarily in equity, for approximately twelve months of executive tenure and a product with limited standalone scale. It stands as Coinbase's clearest example of paying a premium for executive star power during a bull cycle, serving to temper uncritical appraisals of the firm's acquisition track record.
Xapo's custody business (August 2019, $55 million). The acquisition of Xapo's institutional arm was the operational counterpart to the Earn.com deal. Xapo was a digital asset custodian known for high-security infrastructure—including physical vaults housed in decommissioned military bunkers—and a client base of major financial institutions. Coinbase acquired the institutional unit and, according to contemporaneous reporting, secured the deal despite submitting a lower offer than competing bidders, as Xapo founder Wences Casares noted that higher bids came from entities his clients would not accept on security or regulatory grounds. Suitors reportedly included Fidelity. The purchase raised Coinbase Custody's assets under custody past $7 billion, establishing it at the time as the world's largest crypto custodian.11
This transaction highlights two structural dynamics. First, deploying $55 million to secure a market-leading position in an asset class that would later underwrite a spot bitcoin ETF ecosystem represented high capital efficiency. Second, Coinbase won the transaction on regulatory trust rather than purchase price—providing initial empirical evidence that its regulatory investments could generate commercial dividends.
Tagomi (May 2020, reported at roughly $75–100 million). Tagomi operated as a crypto prime brokerage, utilizing smart order routing across multiple trading venues to afford institutional funds optimal execution without distorting order books on a single exchange.12 Coinbase integrated Tagomi into what became Coinbase Prime, expanding the scope of its enterprise offerings.
The distinction between retail trading and prime brokerage is central to Coinbase's margin structure. A retail exchange generates high margins by selling convenience to price-insensitive individual users. A prime broker provides execution, financing, custody, and reporting to institutional clients operating under negotiated fee schedules, yielding lower unit margins. However, institutional prime brokerage builds high switching costs; once an institutional client integrates custody, financing, and staking through a single provider, migration to a competitor becomes operationally complex. Purchasing a lower-margin business to secure high-switching-cost relationships laid the groundwork for Coinbase's subsequent institutional asset management and ETF custody contracts.
Contrasting Tagomi and Xapo with Earn.com reveals a consistent pattern: Coinbase's core infrastructure acquisitions have compounded in value, whereas its talent acquisitions and product-trend purchases have often underperformed.
The "mission-focused company" memo (September 2020).
In September 2020, amid widespread political discussion within American tech firms, Armstrong issued a company-wide memo declaring Coinbase a "mission-focused company." The policy restricted workplace discussions on political and social topics unrelated to the firm's core product, offering a standardized severance package to employees who chose to depart.13
Approximately 60 employees—roughly 5% of the workforce—accepted the severance package. The decision drew sharp media coverage and created internal friction, particularly among employees who argued the mandate muted internal feedback on workplace culture.
Evaluated on operational terms, the policy achieved its primary management goal: it minimized internal policy debate as Coinbase prepared for rapid headcount growth and a public listing. Conversely, it created recruitment friction in specific talent pools and resulted in the loss of experienced staff. It also set a governance precedent of top-down workplace speech boundaries. In subsequent years, Armstrong became an active corporate donor in national political campaigns—a shift that raised questions regarding the alignment between corporate neutrality mandates and executive political engagement, an issue examined further in Section IX.
Remote-first (May 2020). During the same period, Coinbase closed its San Francisco headquarters and adopted a decentralized, remote-first operational structure. The immediate benefit was lower real estate costs and access to a broader geographical talent pool. However, remote operational scaling introduced long-term organizational friction. In May 2026, Armstrong informed staff that the company needed to return to startup-level execution speed, initiating an organizational restructuring aimed at eliminating redundant management layers and roles focused exclusively on administrative management.14 The 2026 adjustments reflected the long-term coordination costs associated with the remote-first model adopted in 2020.
By the end of 2020, Coinbase had established a licensed U.S. retail platform, an institutional custody business, a prime brokerage offering, and a restructured organizational framework. Net revenue for full-year 2020 reached $1.28 billion, generating $322 million in net income and marking the company's first year of sustained profitability at scale.2
This operational foundation coincided with an unprecedented public listing window for the digital asset industry.
VI. The Direct Listing: Peak Euphoria (2021) (50–60 min)
In the first quarter of 2021 alone, Coinbase generated roughly $1.8 billion in revenue—surpassing its $1.28 billion total for all of 2020—while posting net income between $730 million and $800 million as monthly transacting users more than doubled from 2.8 million to 6.1 million.28
This illustrated the volatility tollbooth operating at maximum volume. Unlike traditional software companies that expand by adding enterprise seats or recurring contracts, Coinbase captured transaction fees on a surge of speculative trading. That structural distinction defined the company's financial performance over the subsequent eighteen months.
Why a direct listing?
Coinbase chose a direct public offering on Nasdaq under the ticker COIN, with a reference price of $250, rather than a conventional underwritten IPO.2 The mechanics of that structure were central to understanding the market dynamics that followed.
In a traditional IPO, an issuing company creates new shares, investment banks allocate them at a negotiated price, early investors face lockup periods, and the firm pays underwriting fees. In a direct listing, no new shares are created and no fresh capital is raised. Instead, existing shareholders sell directly to the public on opening day. Without new share issuance or underwriter stabilization, the listing itself serves as the primary liquidity event.
For Coinbase, the choice aligned with both its financial position and its core identity. With hundreds of millions of dollars in quarterly profits, the business did not require fresh capital. A direct listing also fit the company's ethos of eliminating financial intermediaries by bypassing traditional Wall Street underwriters. However, the structural reality remained: a direct listing relies entirely on existing insiders to supply shares on day one.
April 14, 2021.
When trading opened on April 14, 2021, shares opened at $381—far above the $250 reference price—and climbed as high as $429.54, briefly pushing Coinbase's fully diluted valuation above $100 billion before closing at $328.28.15 For a single afternoon, the nine-year-old enterprise carried a higher valuation than established financial exchanges and traditional asset managers.
The listing marked the peak of the market cycle. Bitcoin reached a local high within days, peaked again that November, and entered a prolonged downturn. Coinbase's share price would not reach $429 again.
Management credibility and the insider-selling stress test.
On opening day, insiders and early backers sold roughly $5 billion of stock into the public market. Brian Armstrong personally sold 749,999 shares across three tranches at prices between $381 and $410.40, generating proceeds of approximately $291.8 million.16
Evaluating this volume requires distinguishing between structural mechanics and market perception.
From a structural perspective, insider sales in a direct listing provide the market float; without selling shareholders, no public trading can occur. Armstrong's transactions represented less than 2% of his total holdings and were executed under a pre-arranged 10b5-1 trading plan.
From a market perspective, executive and venture selling coincided with the market peak, yielding billions of dollars in liquidity shortly before the stock declined by roughly 90% over the next eighteen months. While structurally routine, the optics created a lasting reputational strain with retail investors and contributed to a shareholder base dominated by short-term traders rather than long-duration institutional holders.
The fee-compression question management dismissed.
During earnings calls in early 2021, analysts repeatedly questioned whether retail take rates ranging from 150 to 200 basis points were sustainable as traditional brokerages adopted zero-commission trading and competing crypto venues offered lower fees. Management responded that retail clients selected Coinbase for trust and platform security rather than price.8
That strategic narrative remained consistent over the following five years. On the first-quarter 2026 earnings call, when asked if Coinbase would reduce fees in response to lower pricing from entering traditional banks, Chief Financial Officer Alesia Haas maintained that position: "Our clients are not choosing us because we're the cheapest... They're choosing us today because we're the most trusted, we're the easiest to use, the most crypto stored." Haas acknowledged that fees could contract over time as trading commoditizes—underscoring the push for revenue diversification—but stated that fee compression was "not what we're seeing in the near-term business."17
This persistence carries two distinct implications. On one hand, retail take rates did not collapse to zero over the subsequent five years, demonstrating that retail crypto trading retains higher pricing power than equity brokerage.
On the other hand, the mechanism of fee pressure shifted. Instead of cutting headline fees, Coinbase steered price-sensitive traders into lower-fee tiers like Advanced Trading or the Coinbase One subscription, which provides zero-fee trading. When asked on the first-quarter 2026 call to quantify the impact of this product migration on overall take rates, Haas stated that management could not project when headline take rates would compress, noting only that more volume would transition into subscriptions.17 On the second-quarter 2026 call, asked whether a Coinbase One subscriber was accretive or dilutive per dollar traded, Haas characterized it as an "unsatisfying answer," explaining that subscribers trade higher overall volumes and generate superior unit economics across the product suite, despite variation among individual accounts.1
That response acknowledged that headline take rates alone no longer fully measure fee compression, as the business model shifts toward total revenue per customer across subscription and services lines. The peak euphoria of the 2021 direct listing gave way rapidly, leaving little time for the platform's financial resilience to be tested in a moderate environment.
VII. Bear Market Navigation & Strategic Evolution (2021–Present) (45–55 min)
The 2022 crypto downturn was not merely a price correction; it was a systemic solvency crisis that eliminated much of the industry's second tier.
Terra's algorithmic stablecoin failed, wiping out tens of billions of dollars in market value within weeks. Three Arrows Capital, a heavily leveraged crypto hedge fund, defaulted and dragged its lenders down with it. Retail yield platforms Celsius and Voyager, having promised depositors unsustainable returns, froze withdrawals and filed for bankruptcy. Then, in November 2022, FTX—whose founder had been celebrated as crypto's respectable institutional face—collapsed into fraud allegations within days.
Coinbase's share price plunged from its record high of $429.54 to a low of $31.55 in late 2022, a drop of roughly 93%.
The over-hiring test.
This downturn provided the most direct test of management's cost discipline, and Coinbase failed it on the record.
Throughout 2020 and 2021, as trading volume exploded, Coinbase expanded its workforce rapidly, growing from roughly 1,250 employees at the start of 2021 to more than 4,900. When trading volumes evaporated, the expanded cost base remained. In June 2022, Coinbase eliminated about 1,100 roles—18% of its staff—with Chief Executive Brian Armstrong writing candidly that "it is now clear to me that we over-hired."18 In January 2023, the firm cut another 950 positions, representing roughly 20% of its remaining workforce, incurring restructuring charges between $150 million and $160 million.19
Verdict: The claim that management maintains counter-cyclical cost discipline is contradicted by the 2021–2023 record. Coinbase hired into peak revenue as if extraordinary trading volume represented a permanent baseline, then executed two major involuntary workforce reductions within seven months. Armstrong's public acknowledgment of the mistake was notable for a chief executive, but acknowledgment is not a structural fix.
That pattern re-emerged in 2026. Headcount had expanded back to 4,951 full-time employees by the end of 2025, up 3% quarter-over-quarter, as management cited continued investments in product, customer support, and compliance.8 Five months later, in May 2026, Coinbase cut approximately 700 jobs—about 14% of its workforce—citing market conditions alongside a transition to what Armstrong termed an "AI-native" organization, incurring $50 million to $60 million in restructuring charges while targeting no more than five organizational layers below the chief executive or chief operating officer.1417
Chief Financial Officer Alesia Haas acknowledged that market headwinds and AI-driven efficiency gains were interconnected factors behind the 2026 cuts.17 While plausible, this marked the firm's third major workforce reduction in four years, each following a period of expansion during strong revenue cycles. For investors evaluating management's commitment to investing through market cycles, the track record shows a consistent ability to cut costs during downturns rather than maintaining steady investment across them.
The NFT miss.
In April 2022, near the peak of the digital collectibles boom, Coinbase launched an NFT marketplace to capture market share from incumbent platform OpenSea. The strategic rationale relied on user distribution: Coinbase possessed tens of millions of verified users with funded accounts, whereas OpenSea served a specialized crypto-native niche.
The initiative failed to gain traction, generating negligible trading volume relative to OpenSea and capturing virtually no global market share. Coinbase effectively wound down the standalone marketplace in July 2024, disabling functionality except for listing cancellations and redirecting web traffic to Base in August 2024.20
What this actually falsifies. The significance of the failure extends beyond the general decline of the NFT market. It exposes the limits of cross-selling through user distribution. Management assumed that retail spot-traders would naturally transition into buying illiquid, taste-driven digital assets. The transition failed because user profiles, liquidity structures, and community dynamics differed fundamentally from exchange trading. This outcome provides context for ongoing efforts to cross-sell traditional equities, prediction markets, and commodities futures to existing crypto users: broad distribution alone does not guarantee product adoption.
Building the derivatives franchise.
Alongside these operational missteps, Coinbase assembled a significant derivatives infrastructure. In January 2022, it acquired FairX, a small, CFTC-regulated futures exchange, for approximately $300 million, securing a regulated U.S. derivatives framework that enabled the launch of nano bitcoin and ether futures.21 The acquisition prioritized regulatory licensing over existing revenue, granting Coinbase access to global crypto derivatives markets where the vast majority of trading volume occurs.
The derivatives strategy culminated in 2025. In May, Coinbase agreed to acquire Deribit, the dominant global venue for crypto options, for approximately $2.9 billion in cash and stock, completing the transaction in August.2223 The deal stood as the largest acquisition in crypto industry history, providing Coinbase with immediate scale in institutional options trading, established market-maker relationships, and substantial open interest.
Early performance highlights both the strengths and cyclical vulnerabilities of the asset. Deribit posted record results in the fourth quarter of 2025, helping drive overall derivatives revenue to all-time highs across Coinbase's domestic and international platforms in the first quarter of 2026. However, in that same first quarter, institutional transaction revenue fell 27% sequentially to $136 million. President and Chief Operating Officer Emilie Choi attributed the decline to reduced market volatility, which curbed hedging demand on Deribit and lowered options activity from fourth-quarter records.17 While Deribit secured Coinbase a market-leading options franchise with stable open interest share, the acquisition diversified the firm's product suite without insulating it from broader trading volatility.
Base (February 2023).
The firm's most ambitious structural move was the launch of Base in February 2023, an Ethereum layer-2 network built on Optimism's open-source OP Stack.24
To understand the mechanics, Ethereum's main network operates as a shared global ledger where every participant verifies every transaction—a design that provides high security and decentralization but results in network congestion and high transaction fees during peak usage. A layer-2 network, or rollup, functions as an execution lane alongside the main blockchain: transactions process cheaply off-chain, then bundle into compressed batches posted back to Ethereum for settlement. The operator managing this bundling process, known as the sequencer, captures revenue equal to the difference between user fees collected and the data-posting costs paid to Ethereum.
Coinbase reasoned that if global financial activity migrates to blockchain rails, operating an exchange captures trading venues but misses underlying network activity. Base represented an attempt to build and control that network infrastructure, establishing Coinbase's wallet, fiat on-ramps, and custody services as default tools for ecosystem activity.
By mid-2026, Base had established itself as the leading Ethereum layer-2 network across major operational metrics. However, its direct revenue contribution remains modest relative to the broader business. On the fourth-quarter 2025 earnings call, Chief Financial Officer Alesia Haas clarified that sequencer fees are categorized under other transaction revenue rather than subscription and services, emphasizing that Base's primary economic value is indirect—driving USDC balances and broader ecosystem engagement that monetize across other Coinbase products.8 Total other transaction revenue, which includes sequencer fees, reached approximately $253 million for full-year 2025.3
Base functions as a strategically important ecosystem investment whose primary economic thesis relies on indirect monetization rather than standalone fee capture.
The 2026 reality check.
These strategic initiatives lead into a financial picture in 2026 that illustrates the dual nature of Coinbase's financial structure. In the first quarter of 2026, revenue dropped 21% sequentially to $1.4 billion, yielding a GAAP net loss of $394 million alongside positive adjusted EBITDA of $303 million.17 In the second quarter of 2026, revenue declined to $1.22 billion, with a GAAP net loss of $359.5 million and adjusted EBITDA of $207.8 million.1
The divergence between GAAP net results and adjusted EBITDA stems primarily from balance-sheet accounting. Coinbase holds crypto assets directly on its balance sheet and makes regular market purchases, alongside strategic equity holdings in entities such as Circle. In the fourth quarter of 2025, an unrealized portfolio loss of $718 million on crypto holdings and a $395 million loss on strategic investments resulted in a $667 million GAAP net loss, even as adjusted EBITDA reached $566 million.8
Under fair-value accounting rules, balance-sheet crypto assets must be marked to market through quarterly net income. Consequently, GAAP net income reflects quarterly price swings in underlying digital assets rather than core operational performance alone, boosting reported earnings during bull markets and depressing them during downturns. While management's adjusted EBITDA metric excludes these unrealized investment marks to isolate operational cash flow, it also removes the financial results of discretionary balance-sheet asset allocations.
Concurrently, Coinbase executed substantial capital returns. Through February 10, 2026, the company deployed $1.7 billion to repurchase 8.2 million shares, fully offsetting stock-based compensation dilution from 2025 at what Haas described as an $815 million notional discount relative to average issuance prices; the board authorized an additional $2 billion buyback in January 2026, leading to the repurchase of roughly 6 million shares for $1.1 billion in the first quarter of 2026.817 While repurchasing shares at lower valuations using cash reserves of more than $10 billion represents disciplined capital allocation, it also reinforces the firm's overall exposure to the broader crypto asset cycle.
VIII. Power & Business Model Analysis (35–45 min)
Strip away the corporate messaging and Coinbase operates four distinct business lines attached to a single balance sheet, sharing few commonalities beyond their customer base.
1. Net transaction revenue — the same product sold at two completely different prices.
Retail. An ordinary customer buying bitcoin through the flagship Coinbase app pays a blended fee and spread cost historically ranging between 150 and 200 basis points. This represents the company's highest-margin segment by a wide margin. In 2025, consumer transaction revenue generated $3.32 billion—down slightly from $3.43 billion in 2024 despite a stronger first half of the year, illustrating a shift in revenue mix.3
Institutional. The identical trade executed through Coinbase Prime costs an institutional fund a small fraction of that rate—single-digit basis points at scale, dropping below five basis points for the largest transaction volumes. Consequently, institutional transaction revenue reached $480 million in 2025 despite processing significantly higher notional volume.3
The unit economics between retail and institutional trading are sharply asymmetric. Coinbase's transaction gross profit remains overwhelmingly a retail phenomenon. The institutional franchise operates primarily as a customer-acquisition funnel for higher-margin custody, financing, and staking services rather than a standalone fee driver. Treating institutional volume expansion as directly revenue-accretive misunderstands the business model.
2. Subscription and services — the structural stabilizer, with an asterisk.
This segment represents the core of management's revenue-diversification thesis, expanding to $2.8 billion in 2025—up 23% year-over-year and more than five and a half times its prior cycle peak in 2021.8 By the second quarter of 2026, subscription and services accounted for 48% of net revenue.1 Four primary components define this business line:
Stablecoin revenue — $1.35 billion in 2025, up roughly 48% year-over-year.3 USDC is a dollar-backed stablecoin issued by Circle, with reserves held in cash and short-term U.S. Treasuries that yield interest income. Coinbase distributes USDC rather than issuing it directly. Under a revenue-sharing agreement restructured in August 2023—when the Centre Consortium dissolved and Coinbase acquired an equity stake in Circle—Coinbase earns a share of reserve interest based on platform balances and network-wide distribution.[^26]
This structure generates high-margin interest income on customer deposits with minimal incremental operational expense. Average USDC held across Coinbase products reached a record $19 billion in the first quarter of 2026. Management noted that Coinbase stores over 25% of global USDC while capturing roughly 50% of total USDC revenue economics.17 Management has also reiterated that the Circle commercial arrangement auto-renews every three years in perpetuity, cannot be unilaterally terminated, and has already satisfied its renewal conditions.171
However, stablecoin revenue remains subject to three external variables beyond management's control: short-term interest rate levels, total circulating USDC supply, and platform balance share. Furthermore, Coinbase passes a significant portion of reserve yields back to customers as promotional rewards. Chief Executive Brian Armstrong noted on an earnings call that statutory restrictions prohibiting stablecoin yield rewards would ironically increase corporate profitability by allowing Coinbase to retain interest income currently distributed to users.8 This distinction highlights that reported gross stablecoin revenue functions partly as a customer acquisition cost, with USDC reward payouts representing the single largest driver of year-over-year expense growth in 2025.8 Gross stablecoin revenue and net stablecoin profit remain distinct financial metrics, only one of which is fully itemized in public disclosures.
Blockchain rewards — $677 million in 2025, down slightly from $706 million in 2024.3 Proof-of-stake networks such as Ethereum and Solana issue network rewards to asset holders who lock up tokens to validate transactions. Coinbase operates validator nodes and collects a commission of approximately 25% on generated yields. Revenue from this line contracted in 2025 despite an increase in staked native tokens, as underlying protocol reward rates and asset prices declined. Consequently, staking income remains directly exposed to digital asset price volatility and protocol policy changes, making it the least recurring component of the subscription suite.
Custodial fees — roughly $247 million in 2025, up from $142 million in 2024.3 Coinbase charges a basis-point fee on assets under management, positioning the unit as a primary beneficiary of institutional ETF adoption. Following the SEC's approval of U.S. spot bitcoin ETFs in January 2024, eight of eleven initial issuers—including BlackRock's iShares Bitcoin Trust and Grayscale—selected Coinbase Custody, concentrating an estimated 80% or more of ETF bitcoin assets under its administration.25
Other subscription revenue — about $555 million in 2025 — includes interest and financing fees from institutional lending alongside Coinbase One, which surpassed one million paid subscribers by the first quarter of 2026 and achieved record revenue in the second quarter of 2026 despite broader trading volume declines.3171
Helmer's 7 Powers: which powers does Coinbase actually hold?
Counter-positioning — the strongest claim, and largely earned. Coinbase established a compliant business model that offshore competitors could not match without abandoning their primary volume drivers: comprehensive U.S. registration, audited financial statements, conservative asset listings, and a prohibition on proprietary house leverage against customer positions. The collapse of FTX and regulatory enforcement against Binance validated this approach inside U.S. borders. However, counter-positioning advantages diminish as regulatory frameworks normalize. If statutory legislation such as the CLARITY Act or formal SEC rulemaking establishes a clear federal registration pathway, traditional financial institutions and tech platforms—including Robinhood, Charles Schwab, Fidelity, Morgan Stanley, and Stripe—can acquire regulatory compliance rather than building it over a decade. Coinbase's active advocacy for comprehensive federal legislation creates a structural paradox: lobbying for laws that expand the addressable crypto market simultaneously risks eroding its regulatory counter-positioning advantage.
Switching costs — real, but concentrated in institutional. Re-platforming billions of dollars in institutional digital assets requires updated legal opinions, compliance procedures, audit trails, and board approvals. This operational complexity creates genuine institutional retention. Conversely, retail switching costs remain low, as users can transfer balances to competing platforms within minutes. Retail retention relies primarily on brand familiarity, user experience design, and the Coinbase One subscription bundle rather than structural switching barriers.
Scale economies — real and quantifiable. Fixed overhead—including security architecture, regulatory licensing, insurance coverage, and legal defense—scales efficiently across a large asset base. Management estimates that Coinbase holds approximately 12% of global digital assets under custody, exceeding the combined total of its four largest competitors and resulting in lower per-dollar custody costs.8 The 12% custody figure reflects internal company estimates rather than independent third-party audits.
Network economies — present in liquidity and USDC, weaker than claimed elsewhere. Deep order books attract market makers and institutional traders, which further deepens platform liquidity. Similarly, stablecoins exhibit network effects; Armstrong observed on the second-quarter 2026 earnings call that despite competing corporate stablecoin launches, USDC and Tether maintained market share because users prefer avoiding conversion friction between dollar-equivalent tokens.1 However, extending this network effect model to layer-2 blockchains represents an unproven strategic hypothesis rather than established operational evidence.
Branding — the power management invokes most and evidences least. Management frequently highlights Coinbase as the "most trusted brand in crypto." That reputation is supported by fourteen years of operating without a core wallet or platform security breach, alongside its selection as primary custodian for major ETF issuers. However, brand trust is not absolute. In May 2025, Coinbase disclosed that foreign customer-support contractors were bribed to exfiltrate personal identification data on approximately 1% of monthly transacting users—roughly 69,000 accounts—leading to a $20 million extortion attempt. Coinbase declined to pay the ransom, established a $20 million bug bounty, terminated the involved vendors, and incurred between $180 million and $400 million in remediation and customer reimbursement costs.26 While management's response was transparent and structured, the insider-access failure highlights persistent operational risks within customer-support infrastructure.
Porter's Five Forces: where the pressure actually comes from
Threat of substitutes — high, and this is the most underappreciated force. U.S. spot bitcoin and ether ETFs allow retail and institutional investors to gain direct price exposure within traditional brokerage accounts at annual expense ratios of single-digit basis points, bypassing exchange fees, spreads, and self-custody management. While Coinbase earns custodial fees on these ETF assets, basis-point administration yields significantly lower revenue than retail trading spreads of 150 to 200 basis points. A shift in volume from retail exchange trading to ETF products represents a negative revenue mix shift for the firm.
Bargaining power of buyers — bifurcated and widening. Institutional clients negotiate custom fee schedules near single basis points, whereas retail users historically exhibited lower price sensitivity. However, price-sensitive retail volume is increasingly migrating toward lower-cost tiers and subscription models. Coinbase is effectively managing a structured reduction in its headline take rates to prevent unmanaged customer churn to cheaper venues.
Rivalry — high and intensifying from an unexpected direction. Competing exchanges such as Kraken and Gemini compete on execution fees, while decentralized venues like Uniswap offer broader asset selection without custodial intermediaries—prompting Coinbase to integrate decentralized exchange routing into its primary application. The most direct competitive pressure comes from Robinhood, which pairs an established equities and options trading interface with lower crypto pricing and its own layer-2 network launched in 2026. Asked on the second-quarter 2026 earnings call about competitive dynamics with Robinhood, Armstrong discussed broader blockchain consolidation trends rather than addressing relative fee structures or retail market share.1 The factors driving retail users to accept higher transaction spreads relative to discount brokerages remain unquantified in public disclosures.
Supplier power — unusual and worth naming. Coinbase depends on key external counterparties, including Circle for stablecoin reserve revenue, proof-of-stake protocol networks for staking yield rates, and Kalshi for underlying prediction market contracts. The Circle commercial partnership represents the largest single subscription dependency, explaining management's focus on long-term contract renewal terms—even as Coinbase hedges this exposure by participating in a multi-issuer stablecoin consortium.1
Threat of new entrants — the force that changes most with legislation. High under current conditions, with the potential to increase substantially if federal legislation creates standardized licensing pathways for traditional financial institutions.
The three KPIs that matter
Core operational performance depends primarily on three fundamental metrics:
1. Crypto trading volume market share. Disclosed quarterly, market share measures competitive position independently of broader asset price movements. Coinbase's share reached a record 10.3% in the second quarter of 2026, expanding approximately fivefold from the first quarter of 2023 despite muted market conditions.117 Market share gains during market drawdowns provide empirical support for the platform trust thesis, whereas share losses during market expansions would signal competitive erosion.
2. Average USDC held in Coinbase products. This metric drives the primary subscription revenue line and is reported quarterly in dollar terms. Revenue generation depends on both aggregate platform balances and prevailing short-term interest rates.
3. Subscription and services revenue in absolute dollars. Evaluated in nominal terms rather than as a percentage of total net revenue, which inflates mechanically when transaction volumes fall. Absolute dollar growth measures whether non-transaction revenue functions as a true counter-cyclical stabilizer.
Secondary metrics—including monthly transacting users, total platform assets, and product counts exceeding $100 million in revenue—remain derivative of these primary operational drivers.
IX. The Crypto Policy Wars (25–35 min)
On June 6, 2023, the Securities and Exchange Commission sued Coinbase in federal court in the Southern District of New York. The complaint alleged that Coinbase had operated for years as an unregistered securities exchange, broker, and clearing agency, that at least a dozen tokens on its platform were unregistered securities, and that its staking-as-a-service program constituted the unregistered offer and sale of securities.2728
The timing was pointed. It came one day after the SEC sued Binance, and it targeted a company that had spent a decade insisting it was the compliant venue. Coinbase chose to fight rather than settle—a decision worth examining because settlement is standard practice across the financial industry.
Chief Legal Officer Paul Grewal, a former federal magistrate judge, built the defense around a jurisdictional argument rather than a factual one: that the tokens traded on Coinbase were not investment contracts under the Howey test, because a purchaser of a token on a secondary market acquires no ongoing contractual claim on an issuer's efforts. Coinbase also argued that it had repeatedly asked the SEC for a clear registration pathway without receiving one, contending that the agency was regulating by enforcement and punishing conduct it had declined to define.
March 27, 2024: the ruling that made the fight real.
Judge Katherine Polk Failla largely denied Coinbase's motion to dismiss. The exchange, broker, and clearing-agency claims survived, as did the staking claims, while the court dismissed only the claim relating to the self-custodial Coinbase Wallet application.29
For Coinbase, this was a serious adverse development. Retrospective analysis should not treat the eventual resolution as inevitable: in March 2024, a federal judge had found the SEC's theory plausible enough to proceed to discovery against the largest U.S. crypto exchange on claims challenging whether its core business was lawfully constituted. The overhang represented an existential threat to its operating model.
February 2025: the case disappears.
The landscape shifted not through a judicial ruling, but through political change. Following the November 2024 U.S. election and subsequent leadership changes at the SEC, the Commission established a Crypto Task Force in January 2025 to develop a regulatory framework. On February 27, 2025, the SEC agreed to dismiss its action against Coinbase with prejudice—meaning the specific claims cannot be refiled—stating that the dismissal would facilitate efforts to reform its regulatory approach to the industry.30 Commissioner Hester Peirce, an internal critic of the agency's previous enforcement stance, issued a statement welcoming the dismissal.31 A related Freedom of Information Act dispute between Coinbase and the SEC was subsequently settled in July 2026.32
Now the uncomfortable analysis.
While Coinbase secured a dismissal, investors must be precise about the mechanics of that outcome. The company's legal theory was never adjudicated on the merits; its motion to dismiss was denied, and the action ended because the plaintiff elected to withdraw it. The primary variable was the presidential election.
This distinction is central to pricing ongoing regulatory risk. Because the resolution of Coinbase's primary legal overhang was political rather than judicial, it remains vulnerable to future political shifts. A subsequent administration with different policy priorities would inherit a precedent in which a federal judge held that these enforcement claims could proceed to trial. While a dismissal with prejudice binds the SEC on those specific historical claims, it leaves the underlying legal status of digital tokens uncodified. This reality explains why Coinbase prioritizes statutory legislation over administrative forbearance, making the legislative track the true determinant of its long-term business model durability.
Political mobilization: Fairshake.
This dynamic led to an unprecedented level of political spending by a financial technology company.
During the 2024 election cycle, Coinbase became a primary financial backer of Fairshake, a crypto-focused super PAC that also received substantial funding from Andreessen Horowitz and Ripple. Fairshake and its affiliated committees deployed well over $100 million, targeting key congressional races based on candidate positions on digital assets—most notably contributing to the defeat of Senate Banking Committee Chairman Sherrod Brown of Ohio. Before the 2024 cycle concluded, Coinbase and Andreessen Horowitz committed an additional $78 million to the 2026 midterms.33
The political infrastructure expanded further in the subsequent cycle. Fairshake entered 2025 with $116 million in cash on hand, and by 2026 disclosures indicated a total war chest near $193 million, with Coinbase's cumulative contributions across the cycle exceeding $50 million.3435 By the 2026 midterm elections, the digital asset industry had established itself as one of the largest source categories of campaign capital in American politics.
Did it work? On the legislative record, yes.
The GENIUS Act—establishing the first federal regulatory framework for payment stablecoins—passed the Senate in June 2025, cleared the House on July 17, and was signed into law on July 18, 2025. The statute mandates full reserve backing in cash or short-term U.S. Treasuries along with monthly public reserve disclosures.3637 The legislation represented a major strategic win for Coinbase, legitimizing the underlying asset class of its largest subscription revenue line while establishing operational standards that favor regulated, well-capitalized incumbents. Chief Executive Brian Armstrong later cited announcements by roughly 150 companies initiating stablecoin integrations within three months of enactment as evidence of institutional adoption.8
Conversely, comprehensive market structure legislation under the CLARITY Act has proven more difficult to pass. Tracking management's public statements across four quarterly earnings calls reveals shifting timelines.
On the fourth-quarter 2025 call in February 2026, Armstrong expressed optimism about securing passage "in the next few months."8 On the first-quarter 2026 call in May, Chief Legal Officer Paul Grewal offered a specific timeline, projecting committee markup that month, a floor vote in early summer, and "a signed piece of legislation by the end of the summer."17 By the second-quarter 2026 call in late July, with the August congressional recess approaching, the bill remained awaiting a Senate floor vote while prediction markets reflected a 30% probability of passage; Armstrong reiterated optimism for a floor vote while acknowledging that legislative outcomes cannot be guaranteed.1
Assessment: Management has consistently offered optimistic legislative forecasts that have missed stated target dates. Grewal's May 2026 projection of enacted legislation by summer's end did not materialize by early September 2026. This forecasting gap on a primary regulatory variable indicates that investors should evaluate management's legislative timelines with caution.
When asked on the second-quarter 2026 call about the implications of the bill failing to pass, Armstrong noted that Coinbase already operates under standards that mirror many of the bill's proposed requirements, and that regulatory agencies would continue writing rules under existing authority.1 While logical, that position highlights an underlying tension: if the absence of federal statute does not disrupt operations, then the firm's $50-plus million in political contributions represents a substantial capital expenditure that requires rigorous scrutiny regarding long-term return on investment.
Regulatory arbitrage versus regulatory capture.
The regulatory debate surrounding Coinbase presents two distinct interpretations. Under the first, strict domestic oversight disadvantaged Coinbase for a decade by driving trading volume to offshore venues operating with high leverage and minimal listing standards; its political expenditures represent an effort to establish a level regulatory playing field for compliant domestic operators. Under the second, Coinbase constructed an expensive compliance infrastructure, recognized that regulatory complexity functions as a barrier to entry against new competitors, and committed capital to codify those compliance standards into federal law.
Both interpretations are consistent with the historical record. The core analytical takeaway is that Coinbase's competitive position has derived significant value as a political asset. Unlike technological infrastructure or contractual rights, political assets carry distinct risk profiles because their underlying value remains subject to electoral and legislative cycles.
X. Playbook: Lessons for Founders & Investors (20–30 min)
Fourteen years of Coinbase's operating history yield five transferable lessons, best understood as strategic tests rather than simple maxims.
1. Structure the balance sheet for the drawdown you cannot forecast. Coinbase's survival through the 2022 downturn was not a triumph of foresight—management demonstrably failed to predict the severity of the crash, as its aggressive over-hiring showed—but a triumph of liquidity. The company entered the crypto winter with billions of dollars in cash and no obligation to return it, buying management time to execute two rounds of cost cuts while continuing to build. By mid-2026, Coinbase held over $8.6 billion in cash and cash equivalents, with total cash including restricted cash topping $13 billion.1 The lesson for founders in cyclical industries is that cash is not idle capital; it is the option to be wrong about a market cycle without being destroyed by it. For investors, a cyclical firm's cash balance is a far more reliable predictor of survival than its peak growth rate.
2. Compliance costs behave like capital expenditure, not operating expense—within a single jurisdiction. The state-by-state licensing grind generated no direct revenue for years, but eventually yielded the custody franchise behind major bitcoin ETFs, an institutional prime brokerage, and the compliance foundation to absorb an SEC lawsuit that might have crushed a less prepared venue. However, the firm's rapid withdrawal from India defines the boundary of this advantage: regulatory investment compounds only in jurisdictions governed by statutory rules rather than discretionary policy. Founders must evaluate whether a target jurisdiction regulates by legible law or by informal discretion.
3. Owning infrastructure is a distinct business from owning a trading venue—and monetizes far slower than pitch decks suggest. Base is a genuine strategic milestone and a leading Ethereum layer-2 network. Yet it contributes modestly to reported top-line revenue, monetizes primarily through indirect ecosystem activity, and operates in a category where protocol developers actively work to drive transaction fees toward zero. Founders should build the digital roads, but investors should discount road revenue until it materializes as a distinct line item in financial filings.
4. Political spending is capital allocation and demands equal scrutiny. Coinbase converted itself into a major political donor and secured the federal stablecoin legislation it sought. Yet management has simultaneously argued that failing to pass broader market-structure legislation would leave the firm operating under "business as usual." Both statements cannot be equally true. Founders engaging in political expenditures must define the exact counterfactual: what specific commercial asset does this capital secure that the core business cannot build? Investors should demand the same rigor, recognizing that political capital does not appear on a balance sheet and can be written off in a single election cycle.
5. Distinguish infrastructure tuck-ins from trend-chasing based on outcomes rather than intentions. Coinbase's acquisition record offers a clear contrast. Transactions that acquired capability within a regulatory perimeter—Xapo's institutional custody assets, Tagomi's execution stack, FairX's CFTC futures license, and Deribit's derivatives book—have compounded in value. Conversely, expenditures intended to acquire executive star power, such as Earn.com, or to capture a peaking market trend, like the standalone NFT marketplace, failed to scale. The key differentiator was not transaction size or diligence quality, but whether an acquisition secured an asset that was structurally difficult to replicate rather than one that merely appeared attractive during a bull market.
A final caution is warranted before interpreting this record as evidence of broad M&A discipline. Management disclosed that Coinbase completed ten acquisitions and acqui-hires in 2025 alone, with deal-related integration costs driving a material portion of expense growth in the second half of that year.8 Ten transactions in twelve months does not inherently reflect selectivity. It may represent disciplined opportunism during a market drawdown, or it may prove to be the aggressive 2021 hiring pattern repeating in a different form. The evidence that resolves that question—whether those ten acquisitions generate sustained revenue lines or result in balance-sheet impairments—will take several years to emerge.
XI. Bull vs. Bear Case & Future Scenarios (20–30 min)
The bull case, stated at its strongest
Coinbase is becoming the regulated interface between traditional finance and every asset that moves onto a blockchain. The evidence is structural, and the market share gains achieved during drawdowns were captured in a falling market—the most demanding environment in which to expand share and the most indicative of durable retention. Beneath that, Coinbase reports twelve products generating over $100 million of annualized revenue, six of them above $250 million, with retail derivatives operating at a $200 million-plus annualized run rate and prediction markets reaching a $100 million-plus run rate within two months of launch.17 That performance demonstrates an ability to operationalize and scale new revenue lines.
The subscription engine has fundamentally reshaped the company's financial model. Non-transaction revenue is now worth more than double Coinbase's total 2020 revenue, generating fourteen consecutive quarters of positive adjusted EBITDA through market expansions, drawdowns, and transition periods.18 Whatever the analytical limitations of adjusted EBITDA, that operational continuity reflects a structural shift in cash-flow generation.
Institutional adoption is expanding across infrastructure built by Coinbase. Five global systemically important banks and roughly 150 government agencies are active clients; average daily institutional loan balances reached a record $1.4 billion in the first quarter of 2026; and Chief Operating Officer Emilie Choi reported that 45 major financial institutions moved tokenization projects from concept into production in a single quarter.817
Legislative clarity, if enacted, expands the total addressable market faster than it erodes regulatory counter-positioning. This premise represents management's central strategic hypothesis, supported by the passage of the GENIUS Act: statutory enactment was followed by broader corporate stablecoin integrations rather than immediate competitive displacement by new exchanges.
The bear case, stated at its strongest
The high-margin retail spread engine is being systematically compressed—partly through internal product migration. The substitution and buyer-power dynamics are active operational trends embedded within Coinbase's own offerings. Management has acknowledged an inability to project where blended take rates will stabilize, stating only that customer volume will continue migrating into subscription tiers.17 The firm's highest-margin segment is being managed downward without a disclosed floor for terminal pricing.
Stablecoin revenue functions as an interest-rate derivative marketed as recurring subscription income. Reserve earnings represent the mathematical product of USDC circulating balances and short-term interest rates. Coinbase controls neither variable, returns a substantial portion of yield to users as promotional rewards, and records those payouts as its fastest-growing expense item. A decline in benchmark interest rates compresses the primary driver of subscription revenue at the exact point in a credit cycle when trading activity slows, as rate cuts and broader risk aversion historically coincide. The thesis that subscription revenue operates independently of trading cycles overlooks this shared macroeconomic driver.
Base's unit economics face structural margin compression. Ethereum's EIP-4844 upgrade reduced layer-2 data posting costs, benefiting end users while lowering sequencer fee margins, as layer-2 transaction pricing naturally trends toward marginal data availability costs. Furthermore, Base is built on open-source code; the underlying OP Stack can be deployed by competitors, as demonstrated by Stripe and Robinhood launching proprietary networks.1 Chief Executive Brian Armstrong has argued that industry consolidation will follow infrastructure fragmentation and that Base holds a two-year operational head start.1 However, asserting that Coinbase will capture that eventual consolidation remains a prospective claim, while Base's direct financial contribution remains combined within undifferentiated transaction fee lines.3 Concurrently, Base's non-trading product initiatives have faced operational shifts: Base creator Jesse Pollak publicly acknowledged in July 2026 that socialfi and creator-token experiments failed to gain traction, leading to the discontinuation of the application's social feed and creator rewards program, with leadership transitioning to Jordan "Cobie" Fish to refocus the platform on trading infrastructure.38 Allocating $375 million to acquire Echo and subsequently redirecting its leadership to pivot the Base application away from its initial scope highlights ongoing strategic iteration rather than a finalized roadmap.2439
Custodial concentration represents a systemic liability that institutional clients are actively mitigating. The bull thesis highlights that eight of eleven initial U.S. spot bitcoin ETF issuers selected Coinbase Custody. However, market participants responded to concentration risks by establishing secondary custodial relationships—BlackRock added Anchorage Digital, competing issuers integrated BitGo, and Fidelity opted for internal custody from inception.25 By April 2026, market commentators publicly cited this custodian concentration as a potential single point of failure.40 Coinbase's dominant custodial market share is undergoing incremental dilution as major institutional clients deliberately implement multi-vendor mandates to manage operational risk.
Balance-sheet asset allocations amplify operational volatility. Coinbase regularly purchases bitcoin for its balance sheet, maintains strategic equity stakes in entities like Circle, and executes corporate share repurchases. All three asset categories correlate directly with the broader digital asset cycle. That structural alignment explains how a quarter with $566 million in positive adjusted EBITDA resulted in a $667 million GAAP net loss in late 2025.8 While transparently disclosed, this balance-sheet structure ensures that reported GAAP earnings will experience sharp cyclical swings, indicating that public equity shares carry higher underlying crypto asset beta than an infrastructure tollbooth model implies.
Weighing it
The analytical synthesis indicates that while product diversification has advanced, cyclical decoupling has not occurred. Coinbase has reduced its reliance on any single trading asset—reflected in bitcoin's declining share of total revenue—by expanding into options, perpetual futures, traditional equities, prediction markets, institutional lending, staking, custody, subscriptions, and stablecoin reserve sharing.1 However, the business model remains tied to broader digital asset market participation. Nearly every revenue segment requires sustained demand for crypto assets, with non-crypto offerings such as equities and prediction markets representing recent, unproven lines.
The central investment thesis—that Coinbase operates as an indispensable tollbooth on the digital asset economy—remains valid but bounded. Coinbase functions as a diversified toll operator on a single primary highway. While that highway has expanded and attracted institutional volume unavailable in prior cycles, operational performance remains bound to activity on that specific road.
The key indicators that would validate the expansion thesis include: maintaining crypto trading volume market share above 10% during volume recoveries; expanding absolute subscription and services revenue through monetary easing cycles; and demonstrating that non-crypto asset classes contribute a material, disclosed portion of transaction revenue. Conversely, the indicators that would signal thesis breakdown include: market share contraction during trading volume expansions; declining subscription revenue during lower-rate environments; and non-crypto revenue lines plateauing below $250 million in annual run rate.
XII. Epilogue: What Would We Do? (10–15 min)
For an executive team managing $13 billion in liquidity while navigating a share price down more than 50% from its historical peak, three strategic priorities command immediate attention.
1. Monetize the institutional franchise harder, because it is the least cyclical asset in the business. Coinbase Prime already commands an institutional client base—spanning global systemically important banks, government agencies, ETF issuers, and asset managers—alongside record loan balances.17 The natural extensions of this footprint include collateral management, automated portfolio financing, and the custody of tokenized real-world assets, all of which generate recurring fee income tied to asset balances rather than speculative trading volume. Chief Executive Brian Armstrong has cited third-party projections that tokenized real-world assets could expand from roughly $30 billion to $16 trillion by 2030.17 Even discounting consultant forecasts, securing custody and administration fees at single-digit basis points on a fraction of that volume offers long-term shareholders more durable value than temporary retail trading features. Balance-based revenue provides the operational stability required for a financial platform to remain investable across market cycles.
2. Prove the commercial viability of the international footprint before expanding it further. Coinbase holds a Markets in Crypto-Assets (MiCA) license in the European Union and operates a Bermuda-regulated international exchange, with management consistently emphasizing global expansion on quarterly earnings calls. However, the abrupt exit from India illustrates why international expansion requires verified revenue rather than regulatory milestone announcements. The necessary corporate discipline is to report non-U.S. revenue as a distinct financial line item, allowing shareholders to evaluate whether international licenses translate into active customer adoption. Without segmented disclosures, a global regulatory footprint remains a compliance achievement rather than a commercial moat.
3. Complete the consumer super-app, while clearly accounting for its structural cost. The firm's most compelling unbuilt asset is a seamless bridge between the custodial Coinbase application—where customer trust and funds reside—and self-custodial protocols on Base, enabling retail users to access decentralized exchanges and lending protocols without managing private keys or gas fees. Coinbase controls the necessary building blocks: the retail wallet, the layer-2 network, the stablecoin distribution, the developer platform, and the x402 agentic payment standard.17 The underlying strategic challenge is that successful integration accelerates the migration of user activity from high-margin retail exchange spreads to low-margin on-chain rails. Accepting a fraction of a basis point on-chain while cannibalizing a 150-basis-point retail spread may be necessary to defend against external disintermediation, but management should explicitly address this margin trade-off with shareholders rather than framing on-chain growth as purely additive.
Finally, management should complete a transition it has only partially embraced: moving away from adjusted EBITDA as the definitive metric of corporate profitability. While fourteen consecutive quarters of positive adjusted EBITDA demonstrate operational cash-flow resilience, reporting two consecutive quarterly GAAP net losses totaling roughly $754 million—driven by balance-sheet asset revaluations—remains an equal financial reality.117 An enterprise seeking valuation as core financial infrastructure must evaluate its performance against the reporting standards of infrastructure peers.
XIII. Recent News & Developments (15–20 min)
The past twelve months have been among the busiest in Coinbase's corporate history, yet its share price has declined nonetheless. Both dynamics reflect a company rapidly expanding its product footprint while remaining bound to broader market cycles.
The regulatory overhang closed, then a new one opened. The SEC's enforcement action was dismissed with prejudice in February 2025, and associated Freedom of Information Act litigation was settled in July 2026.3032 However, the CLARITY Act—the market structure bill intended to provide statutory rather than discretionary ground rules—remained unpassed as of early September 2026, missing management's guided timeline of enactment by summer's end.171 Coinbase also opened a new legal front: within twenty-four hours of launching prediction markets nationwide, it preemptively sued state regulators in Connecticut, Illinois, and Michigan in federal court, seeking rulings that prediction markets fall under exclusive CFTC jurisdiction.41 The company that spent a decade defending against federal regulatory actions now sues state officials first.
The Everything Exchange arrived, fast. At a December 2025 product event, Coinbase announced 24/5 stock and ETF trading, prediction markets in partnership with Kalshi, and a broad expansion beyond digital assets.4243 Predict launched across all fifty U.S. states on January 28, 2026, and reached a $100 million annualized revenue run rate by March—within two months of release.4117 Equities rolled out with nearly 10,000 tickers, while non-crypto futures in commodities like gold, silver, and oil grew more than fourfold quarter-over-quarter in the first quarter of 2026.817 During a sharp crypto selloff in February 2026, gold and silver futures drove record notional volume on Coinbase's exchange, helping push the platform to its highest 24-hour trading volume in over a year.8 This performance offers real-time evidence of product diversification, providing the bull case with its strongest recent support.
The Deribit integration is the year's biggest execution risk. Management expects to unify spot, perpetual futures, dated futures, and options onto a single platform during 2026, while a launch timeline for U.S. crypto options remains unannounced, as Chief Financial Officer Alesia Haas declined to provide one.17 Unifying margining and liquidity across four distinct instrument types represents a complex engineering challenge, forming the gating item for the $2.9 billion acquisition thesis.
Stablecoins consolidated and got competitive. USDC reached a record market capitalization of roughly $75 billion in the fourth quarter of 2025, supported by record balances in Coinbase products, which reached further highs in the first quarter of 2026.817 Base accounted for 62% of all stablecoin transaction volume in the first quarter by management's count, with Chief Executive Brian Armstrong stating on the second-quarter call that Base processed roughly $32 trillion in stablecoin transfer volume over the trailing twelve months.171 Coinbase also established a USDC commercial partnership with the derivatives protocol Hyperliquid—sharing revenue economics to embed USDC into a major trading venue—and joined the Onyx USD multi-issuer consortium, which a JPMorgan analyst characterized as a potential competitor to USDC.1 Haas defended the Hyperliquid terms as an investment in network effects, while Armstrong framed the consortium as a multi-stablecoin platform strategy. Both explanations are coherent, yet both confirm that Coinbase is now deploying revenue share to defend USDC's market position rather than simply harvesting reserve interest.
Agentic payments became the new narrative. Coinbase reported that over 90% of on-chain agentic transaction volume settles on Base and that artificial intelligence agents paying on-chain select USDC 99% of the time, utilizing the x402 protocol Coinbase incubated before contributing it to the Linux Foundation.17 While the strategic logic is clear, an analyst raised a fundamental question on the second-quarter 2026 call: because AI agents lack brand loyalty and optimize strictly for cost and latency, does agentic commerce force Coinbase to compete on price in ways consumer crypto never required? Armstrong responded that software agents will value reliability, compliance, and liquidity much like human traders, citing Base's sub-cent fees and sub-second settlement.1 The argument is plausible, but it remains unevidenced by reported revenue, as management offered no financial figures for agentic transactions.
The cost base was cut and the balance sheet deployed. The 14% headcount reduction in May 2026 eliminated approximately $500 million in annualized expenses relative to the fourth-quarter 2025 exit rate, bringing guided 2026 adjusted expenses to between $4.3 billion and $4.6 billion.1417 Management noted that excluding growth in USDC reward payouts, 2026 operating expenses would remain roughly flat compared to 2025—underscoring that the firm's fastest-growing cost is the yield subsidy attached to its fastest-growing subscription line.17 Meanwhile, cumulative share repurchases have offset roughly 90% of stock-based compensation dilution since the fourth quarter of 2024, and the company's $1.3 billion convertible note obligation was scheduled for retirement at its June 1, 2026 maturity absent conversion.17
And the leadership bench turned over. Coinbase experienced multiple senior executive departures during the second quarter of 2026 across human resources, legal, and institutional functions, with internal successors named to each role. Asked about the turnover on an earnings call by a JPMorgan analyst, Armstrong stated that strategic priorities remained unchanged, citing succession planning and leadership depth; Haas similarly emphasized that outgoing leaders had prepared their successors and that there was "nothing from a strategy standpoint to read into these changes."1 Simultaneous turnover across three core executive functions during a market downturn warrants close observation. While no public evidence contradicts management's explanation, key operational indicators to monitor include whether incoming legal and institutional leaders maintain the aggressive stance that secured the SEC dismissal and established dominance in spot ETF custody.
References
-
Form 8-K — Q2 2026 Earnings Presentation, Coinbase Global, Inc. — SEC, 2026-07-30 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Form S-1 Registration Statement — Coinbase Global, Inc., 2021-02-25 ↩↩↩↩↩↩↩↩↩
-
Form 10-K Annual Report — Coinbase Global, Inc., 2026-02-12 ↩↩↩↩↩↩↩↩↩↩
-
SEC EDGAR Entity Landing Page — Coinbase Global, Inc. (CIK 0001679788) ↩
-
7 Secrets From Coinbase's Early Days — Decrypt, 2021-04-13 ↩↩↩
-
Coinbase Raises $25M From Andreessen Horowitz To Build Its Bitcoin Wallet And Merchant Services — TechCrunch, 2013-12-12 ↩
-
Coinbase Q4 and Full Year 2025 Earnings Call and Shareholder Letter — Coinbase Investor Relations, 2026-02-12 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Coinbase Suspends UPI Payments in India Three Days After Launch — Forbes India, 2022-04-11 ↩
-
Coinbase CEO Cites RBI's Informal Pressure For Halting UPI Payments — Inc42, 2022-05-11 ↩
-
Crypto Exchange Coinbase Acquires Xapo's Institutional Custody Business — CoinDesk, 2019-08-16 ↩
-
Coinbase Buys Tagomi to Boost Crypto Offering for Institutions — Bloomberg, 2020-05-27 ↩
-
Coinbase is a Mission-Focused Company — Brian Armstrong / Coinbase Blog, 2020-09-27 ↩
-
Coinbase Cuts Headcount by 14%, Citing AI Acceleration — CNBC, 2026-05-05 ↩↩↩
-
Coinbase Valuation Tops $100 Billion in Nasdaq Debut — Bloomberg, 2021-04-14 ↩
-
Coinbase CEO Sold $291.8M in Shares on Opening Day — CoinDesk, 2021-04-17 ↩
-
Coinbase Q1 2026 Earnings Call — Coinbase Investor Relations, 2026-05-07 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Coinbase Lays Off 18% as Execs Prepare for Recession and 'Crypto Winter' — CNBC, 2022-06-14 ↩
-
Coinbase to Cut 20% of Staff in Latest Layoffs — The Wall Street Journal, 2023-01-10 ↩
-
Coinbase to Buy Crypto Futures Exchange FairX — Reuters, 2022-01-12 ↩
-
Coinbase Acquires Crypto Derivatives Exchange Deribit for $2.9 Billion — CNBC, 2025-05-08 ↩
-
Coinbase Completes $2.9 Billion Cash-and-Stock Acquisition of Deribit — The Block, 2025-08-14 ↩
-
Introducing Base: An Ethereum Layer 2 Network — Coinbase Blog, 2023-02-23 ↩↩
-
Coinbase's Custody of 8 Out of 11 Bitcoin ETF Vaults Sparks Concentration Fears — Crypto Briefing, 2024 ↩↩
-
Protecting Our Customers — Standing Up to Extortionists — Coinbase Blog, 2025-05-15 ↩
-
SEC Civil Enforcement Complaint against Coinbase, Inc. and Coinbase Global, Inc. — SEC.gov, 2023-06-06 ↩
-
SEC Sues Crypto Exchange Coinbase in US Court — Reuters, 2023-06-06 ↩
-
Coinbase Must Face SEC Lawsuit, Judge Rules in Major Decision — Bloomberg, 2024-03-27 ↩
-
SEC Press Release: Commission Votes to Dismiss Enforcement Action Against Coinbase — SEC.gov, 2025-02-27 ↩↩
-
Getting Back on Base: Statement of Commissioner Hester M. Peirce on the Dismissal of the Civil Enforcement Action Against Coinbase — SEC.gov, 2025-02-27 ↩
-
Coinbase and SEC Settle FOIA Lawsuit — Reuters, 2026-07-15 ↩↩
-
Coinbase, a16z Contribute $78 Million to Pro-Crypto PAC for 2026 Election — CNBC, 2024-11-04 ↩
-
Crypto Super PAC Fairshake Has $116 Million on Hand to Grow Industry's Influence in 2026 Election — CNBC, 2025-01-30 ↩
-
Fact Sheet: President Donald J. Trump Signs GENIUS Act into Law — The White House, 2025-07-18 ↩
-
Stablecoin Legislation: An Overview of the GENIUS Act of 2025 (P.L. 119-27) — Congressional Research Service / Congress.gov, 2025 ↩
-
Coinbase's Jesse Pollak Hands Base App Leadership to Cobie After Admitting Social Bets Fell Short — The Block, 2026-07-15 ↩
-
Coinbase Buys Crypto Fundraising Firm Echo for $375M — CoinDesk, 2025-10-21 ↩
-
'Choke Point' — Bitcoin's $77B Coinbase ETF Warning Shocks Markets — Forbes, 2026-04-17 ↩
-
Coinbase and Kalshi Team for Prediction Market for Crypto Exchange's U.S. Customers — CoinDesk, 2026-01-27 ↩↩
-
Coinbase Rolls Out Stock Trading, Prediction Markets and More in Bid to Become the 'Everything Exchange' — CoinDesk, 2025-12-17 ↩
-
System Update: The Future of Finance Is on Coinbase — Coinbase Blog, 2025-12-17 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube