The Carlyle Group: From Washington Boutique to a $485 Billion Capital Machine
I. Introduction & Episode Roadmap
On the morning of August 5, 2026, Harvey Schwartz sat down for his fourteenth earnings call as chief executive of The Carlyle Group and delivered a sentence he had been building toward for three and a half years: the second quarter, he said, was "one of Carlyle's strongest quarters in recent years."1 The numbers backed him. Record fee-related earnings of $358 million, up 11% from the prior year. The highest distributable earnings in nearly four years. Assets under management at an all-time high of $485 billion. Nearly $7 billion returned to fund investors in three months, $37 billion over twelve.1
And then the market did what it has done to Carlyle with unnerving consistency: it shrugged.
This is the central puzzle of the Carlyle story in 2026. Here is a firm that has grown from $147 billion of assets at its 2012 IPO to roughly $485 billion today, a firm that has posted three consecutive years of record fee-related earnings, a firm whose current CEO has hit essentially every financial target he publicly set — and it still trades at the lowest multiple of any large diversified alternative asset manager. Since Schwartz walked in the door in February 2023, Carlyle stock has badly trailed Blackstone, KKR, and Apollo. It has been a good operating story attached to a mediocre stock.
There are two ways to read that gap. One is that the market is slow, that a three-year turnaround takes five years to price, and that the discount is an opportunity. The other is that the market is looking past the fee-related earnings headline at things the headline does not capture: a flagship buyout fund that missed its target by nearly half, credit assets inside Carlyle's own house showing stress, an insurance strategy structurally thinner than Apollo's, and a governance record in which the founders removed a sitting CEO once and watched another leave early — the same founders who still sit as co-chairmen of the board today.
This article tests both readings. It is not a story about whether Carlyle is a good company. It is a story about whether a specific set of management claims — a "fundraising super cycle," a durable shift from carry to fees, a disciplined use of permanent capital, a revived defense franchise — survive contact with Carlyle's own forty-year record.
That record is unusually useful, because Carlyle has already run most of these experiments. It already built a leveraged permanent-capital vehicle; it blew up in 2008 in the most public way imaginable. It already tried to hand the firm from founders to professional managers; that failed twice in five years. It already owned a defense franchise built on Washington relationships; that franchise both made the firm and, on one September morning, embarrassed it.
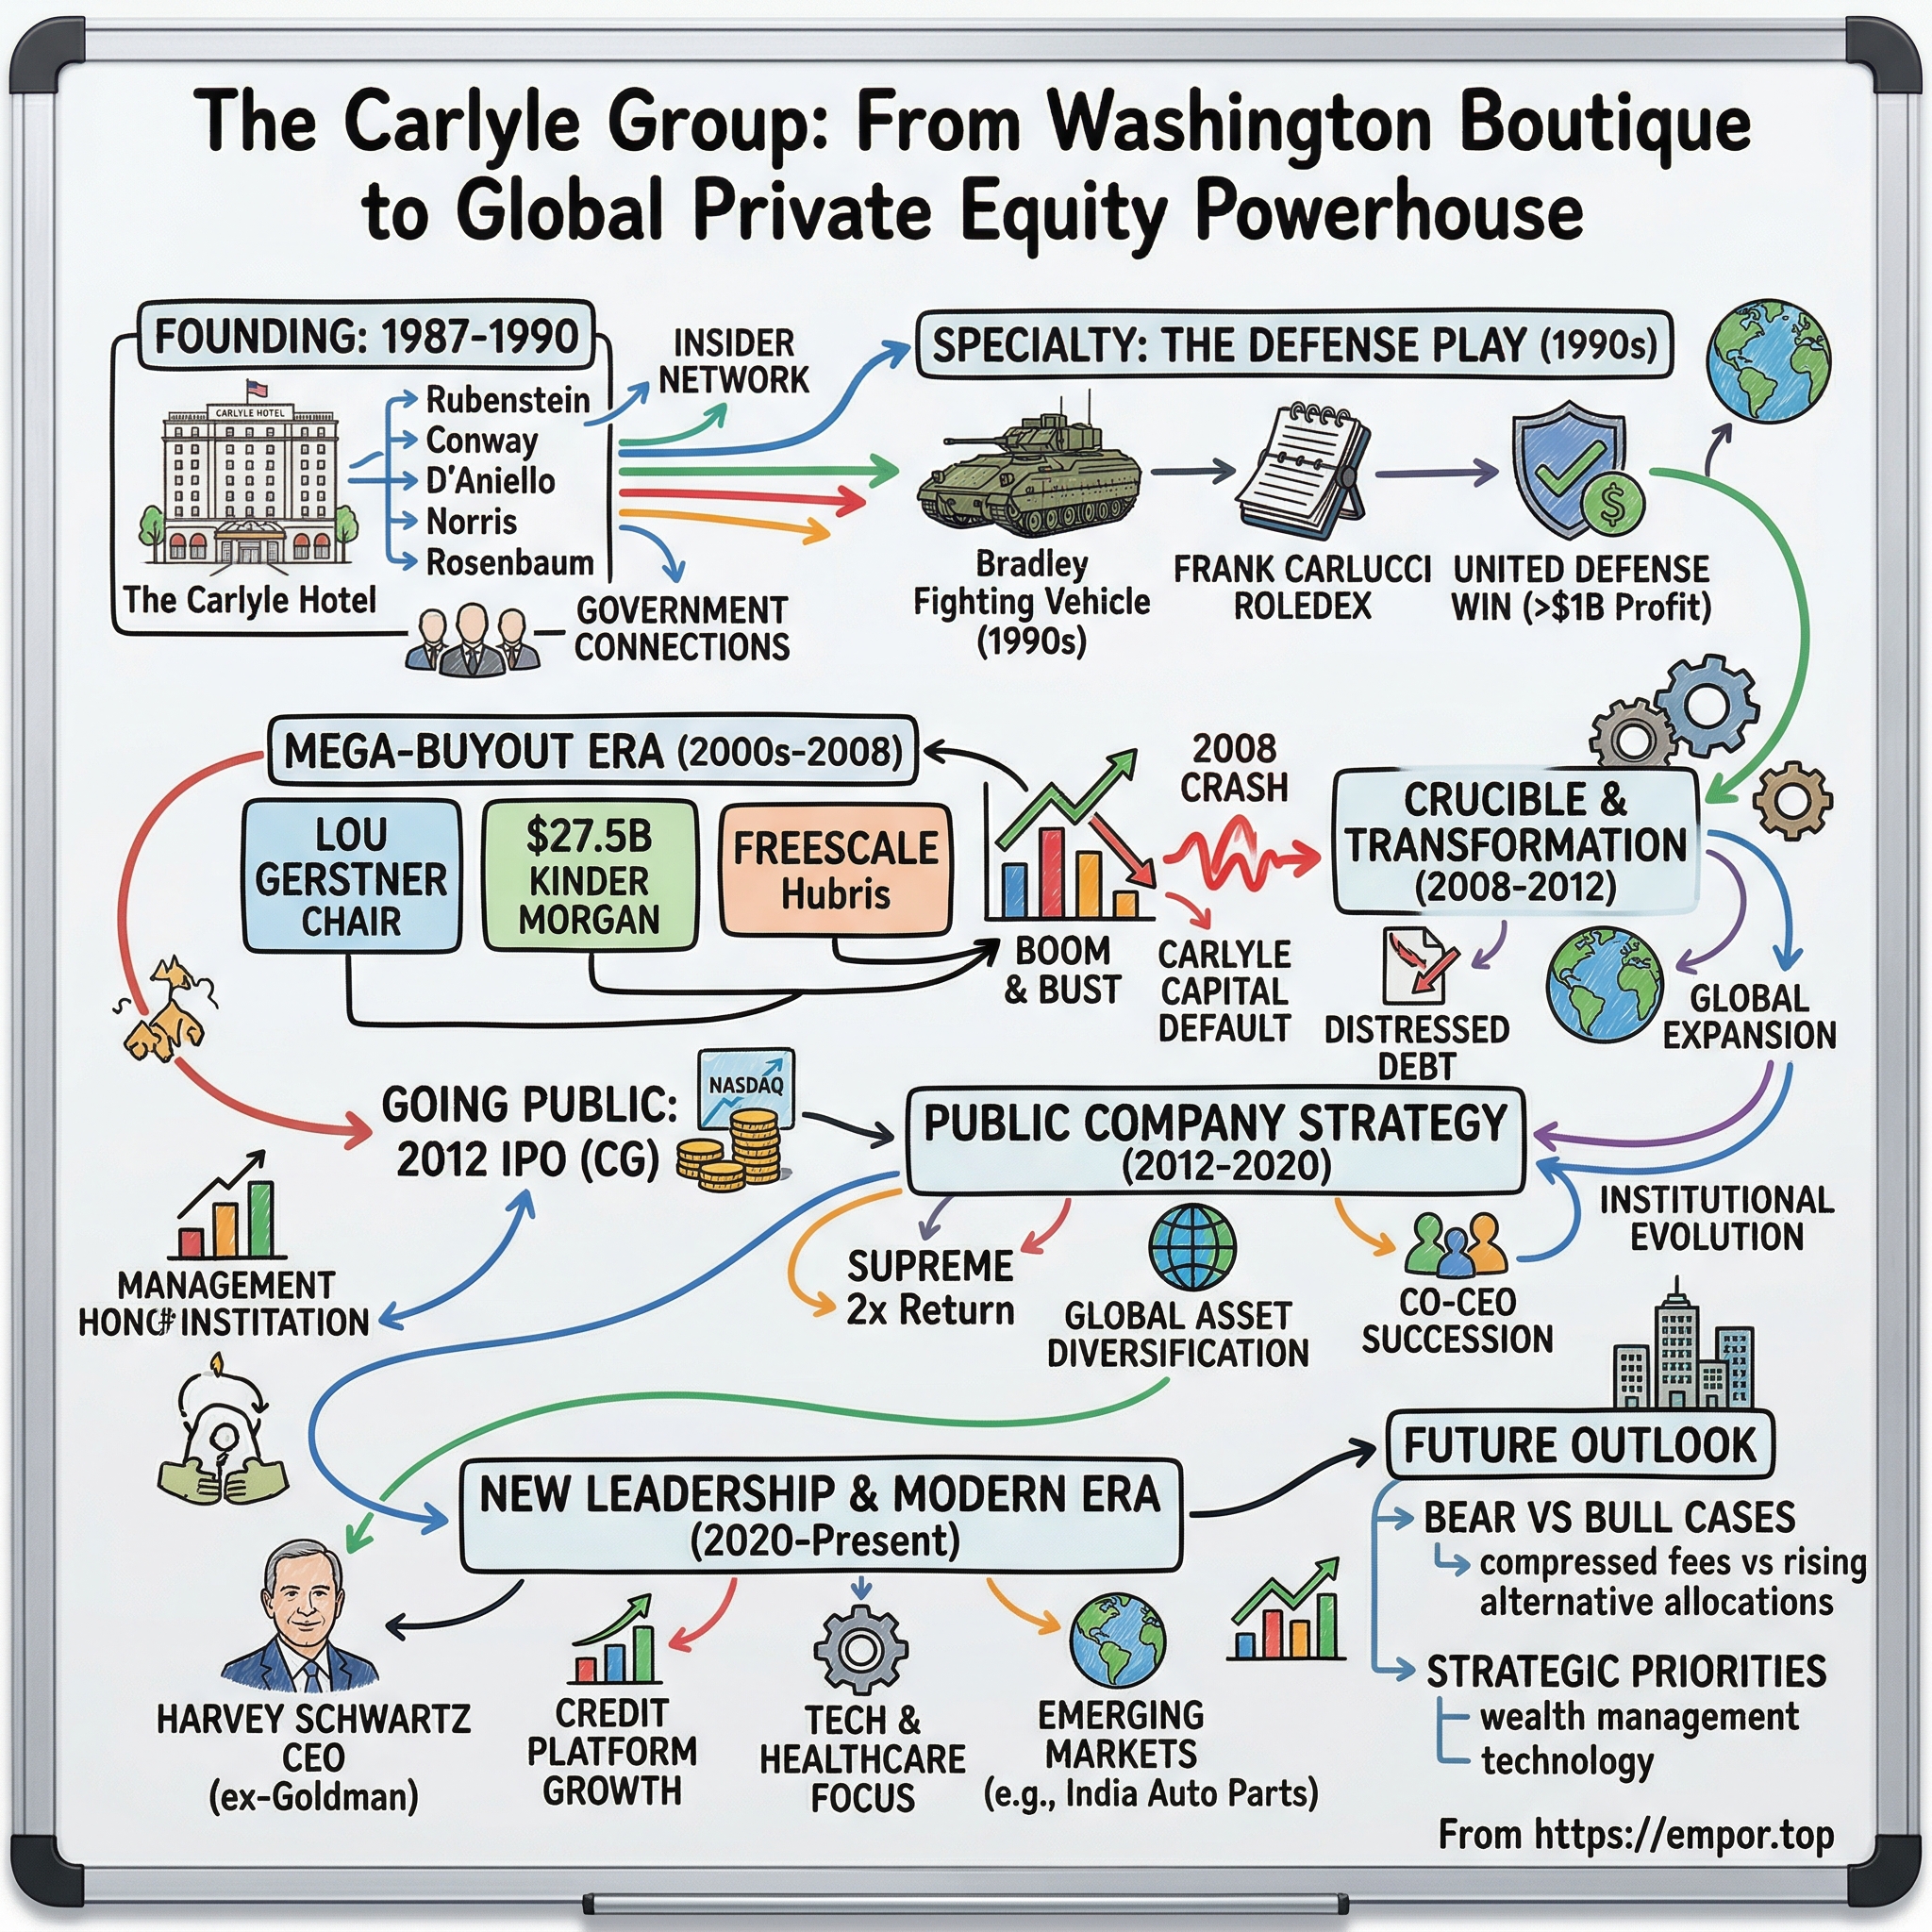
The roadmap: origins and the defense-industry playbook, compressed. The mega-buyout era and the 2008 reckoning. The IPO that changed what Carlyle had to be. The 2022 governance break that is still the most important unresolved fact in the modern story. Schwartz's rebuild — what was delivered, what was missed, and what remains unproven. Today's three segments and their very different economics. Capital deployment, where a spectacular win and a total write-off share the same vintage. The competitive landscape and the persistent discount. Risk, bull and bear, and the handful of numbers that will actually settle the argument.
Start where Carlyle started: with a phone list.
 Subscribe on LinkedIn
II. Origins, Compressed: Boutique to Buyout Shop (1987–2001)
The founding myth of most private equity firms involves a trading floor or a business school. Carlyle's involves a Rolodex.
In 1987, five men — William E. Conway Jr., Stephen Norris, David Rubenstein, Daniel A. D'Aniello, and Greg Rosenbaum — set up shop in Washington, D.C., and named the firm after the Carlyle Hotel in New York, where some of the early conversations had taken place. Rosenbaum left within the first year; Norris departed in 1995, leaving the trio of Conway, Rubenstein, and D'Aniello who would define the firm for the next three decades.
The choice of Washington was not incidental, and it was not conventional. Every serious buyout firm of that era clustered in New York, close to the banks that financed deals. Carlyle sat two hundred miles south, close to the government that awarded contracts. Rubenstein, a former domestic policy adviser in the Carter White House, was not a financier by training — he was a lawyer with an unusually well-developed instinct for who knew whom. The Washington Post would later describe his particular genius as pairing the powerful with the rich: bringing former officials onto Carlyle's payroll and advisory boards, and using their names and access to raise money from investors who wanted proximity to both.
The strategy needed an industry, and it found one in defense. The end of the Cold War produced a decade-long consolidation of American defense contractors, and consolidation is the natural habitat of a leveraged buyout firm. Carlyle bought GDE Systems, a General Dynamics electronics unit, in 1992. It bought Magnavox Electronic Systems in 1993. In 1997 it assembled United Defense Industries, a combat-vehicles and armaments maker, for roughly $850 million — the largest deal in the firm's history to that point — and took it public in 2001.
What made these deals work was not financial engineering. It was that Carlyle understood how defense procurement actually behaved: revenue tied to appropriations rather than the business cycle, contracts that ran for years, and a buyer — the U.S. government — whose purchasing decisions were legible to anyone who had worked inside the building. That is a genuine informational edge, and it produced genuine returns.
It also produced Carlyle's first reputational crisis, and the timing could not have been worse. On September 11, 2001, Carlyle was hosting its annual investor conference at the Ritz-Carlton in Washington. Among the guests was Shafiq bin Laden, a member of the Saudi construction family that had invested with the firm and whose half-brother would within hours become the most notorious name on earth. Former President George H. W. Bush, then a Carlyle adviser, had been at the event. Nothing improper occurred. But the image — a defense-focused buyout firm staffed with former officials, hosting the bin Laden family on the morning of September 11 — hardened into a decade of conspiracy literature that Carlyle spent years and considerable money trying to outrun.
The lesson is not that access is bad. It is that access is a two-sided asset: it lowers your cost of information and raises your cost of scrutiny, and you do not control which side dominates in any given news cycle. That trade has never fully gone away. Carlyle exited most of its bin Laden family relationships and steadily de-emphasized the "Washington insider" branding through the 2000s, rebuilding its identity as a global, sector-specialist investor rather than a political one.
But the underlying franchise survived. Aerospace, defense, and government services remains one of the oldest and most differentiated sector practices Carlyle owns — and in 2026, management reached for exactly that history to justify its newest growth bet, a dedicated middle-market defense and industrials platform.2 Whether forty-year-old relationships still constitute an edge in a sector that now attracts every large sponsor on earth is a question this article returns to.
For the moment, though, the defense franchise did something more immediate. It made Carlyle credible enough, and rich enough, to chase much bigger game.
III. Scaling to a Buyout Giant and the 2008 Reckoning (2002–2012)
By the middle of the 2000s, the constraint on private equity was no longer ideas. It was the sheer physical difficulty of deploying money fast enough.
Credit was nearly free, covenants had evaporated, and the largest firms had discovered they could club together to buy companies that had previously been beyond any single sponsor's reach. Carlyle was in the thick of it. In 2006, alongside Goldman Sachs and others, it participated in the $27.5 billion take-private of Kinder Morgan. That same year, it joined a consortium led by Blackstone — with Permira and Texas Pacific Group — to acquire Freescale Semiconductor, the chipmaker spun out of Motorola, for $17.6 billion at $40 a share, the largest leveraged buyout of a technology company ever done at that point.3
These were the trophy deals. The instructive one was smaller and went badly.
In 2004 Carlyle agreed to buy Verizon's Hawaii telephone operations for roughly $1.6 billion, closing in 2005 and renaming the business Hawaiian Telcom. Carlyle put in about $425 million of equity and borrowed nearly $1.2 billion. The business then had to separate itself from Verizon's systems, a migration that went so badly it damaged customer service and billing for years, in a market where competition from wireless and cable was accelerating. Hawaiian Telcom filed for Chapter 11 in December 2008, and Carlyle's equity was wiped out.4
Hawaiian Telcom is worth dwelling on because it is the pure form of a carve-out gone wrong: a stable-looking regulated asset, heavy leverage, and an operational transition that the sponsor underestimated. It is also a reminder that "asset with predictable cash flows" and "asset that can support 74% debt" are not the same statement.
But the failure that genuinely defines this era for Carlyle — and the single most relevant piece of history for judging what the firm is doing today — carried the firm's own name.
Carlyle Capital Corporation: the balance sheet as a weapon
In 2007, Carlyle launched Carlyle Capital Corporation, a listed vehicle in Amsterdam designed to hold a portfolio of residential mortgage-backed securities issued by Fannie Mae and Freddie Mac. The logic was seductive and, on paper, conservative: buy the safest mortgage paper in the world, paper with an implicit government guarantee, and manufacture an attractive return by borrowing against it in the repo market. Because the underlying assets were nearly risk-free in credit terms, you could borrow an enormous amount against them.
The vehicle raised roughly $670 million of investor equity and used it to assemble a bond portfolio of about $21.7 billion — leverage of roughly 32 times.5
Here is the mechanism, in plain terms. In a repo trade you pledge a bond as collateral for a short-term loan. The lender demands a haircut — say, they lend you 98 cents against a dollar of bonds. If the market value of your bonds falls even slightly, the lender issues a margin call and you must post more cash. At 32x leverage, a 3% decline in the value of your assets mathematically consumes your entire equity. The credit quality of the underlying bonds is almost irrelevant; what kills you is the price volatility of assets you have to mark and fund every single day.
In early 2008, as the mortgage market seized, agency paper stopped trading at prices anyone trusted. Margin calls arrived faster than the vehicle could meet them. On March 12, 2008, Carlyle Capital announced it expected its lenders to seize its remaining assets; it was in default on roughly $16.6 billion of debt.5 Days later shareholders voted for a compulsory winding-up under Guernsey law, and the vehicle was liquidated.6 The shares, which had listed at $19 in July 2007, lost more than 90% of their value.5
Carlyle the firm survived; the vehicle was legally separate and the parent's capital at risk was limited. But the reputational damage was real, and the intellectual lesson was sharper still: Carlyle had built a permanent-capital vehicle whose entire economic engine was borrowing against spread assets, and it discovered that permanence of capital on the liability side means nothing if your funding is overnight.
Keep that sentence. Section VI will describe a 2026 Carlyle that is deliberately building spread-based, insurance-linked, balance-sheet-adjacent capital — Fortitude Re, a Bermuda sidecar, evergreen credit vehicles — and management will describe this as diversification. The 2008 precedent does not prove the current strategy is dangerous. The structures are genuinely different: insurance liabilities are long-dated and sticky, not overnight repo. But it does establish that this firm has previously mistaken asset credit quality for funding safety, and that is the specific error to watch for.
Going public, and what that actually changed
On May 2, 2012, Carlyle priced its initial public offering: 30.5 million common units at $22, below the $23–$25 range it had marketed, raising $671 million.78 The units began trading the next day on the NASDAQ Global Select Market under the ticker CG.7 The firm listed with about $147 billion of assets under management. The founders, who had built the business from a Washington townhouse, became billionaires on paper.
The discounted pricing generated the day's headlines, and it was the least important thing about the transaction.
What mattered was the structural change. A private partnership dependent on carried interest can afford to be lumpy. Carry arrives when portfolio companies are sold, sales cluster in good markets, and partners simply accept that some years are enormous and others are thin. Public shareholders will not accept that. They want an earnings stream they can model. From May 2012 forward, Carlyle had to stand up every quarter and explain fee-related earnings, margins, fundraising, and capital return — and to be valued on a multiple of something.
That is the frame for the entire modern story. Every strategic decision Carlyle has made since — the push into credit, the insurance relationships, the evergreen wealth products, the emphasis on management fees over performance fees — descends from a single problem created in 2012: how do you make an inherently cyclical business look like a compounder?
The founders' first attempt to answer that question was to hand the firm to someone else. It did not go well.
IV. The Governance Break: Kewsong Lee's Ouster and What It Revealed (2017–2023)
On October 25, 2017, Carlyle announced the succession plan that was supposed to end the founder era. Kewsong Lee and Glenn A. Youngkin would become co-chief executives effective January 1, 2018. Rubenstein and Conway, who had run the firm as co-CEOs since 1987, would become co-executive chairmen. D'Aniello would become chairman emeritus.9
It was a textbook plan, and it was very deliberately a pair. Youngkin was the internal man: twenty-five years at Carlyle, an engineer by training, a Harvard MBA, the operator who had run the firm's day-to-day functions and its industrial businesses. Lee was the outsider-insider: a Harvard-trained former Warburg Pincus executive who had joined Carlyle in 2013 specifically to build out businesses beyond buyouts — credit, in particular. Together they represented continuity and change, which is exactly what succession committees like to see and exactly what tends to produce conflict.
It lasted thirty months. In July 2020, Carlyle announced Youngkin would retire, leaving Lee as sole CEO.10 Youngkin went on to run for governor of Virginia and win. Carlyle framed it as a personal decision, and it plausibly was. But the firm's carefully balanced two-person structure had collapsed into a one-person structure inside three years, and the person left standing was the one whose mandate was to change things.
Lee changed things. Under his leadership Carlyle leaned harder into credit and insurance, deepened its relationship with Fortitude Re, and pushed toward the fee-heavy, less carry-dependent model that every large alternative manager was chasing. Operationally, 2021 was the best year in Carlyle's history. And then, in August 2022, with roughly a year left on his five-year contract, Lee abruptly departed.11
What actually happened
The company's disclosure said almost nothing. Bill Conway would serve as interim CEO while the board searched for a successor; no cause was given.1112
Reporting filled in the rest, and the details matter because they are specific rather than atmospheric. Lee had been negotiating a new compensation package reportedly worth on the order of $300 million over five years. The founders — Conway, Rubenstein, and D'Aniello, who between them held roughly a quarter of the company and retained board seats — balked.13 But the money was the proximate cause, not the underlying one. According to that reporting, board members aligned with the founders had come to believe Lee was pushing Carlyle's diversification into credit and insurance too fast, was reshaping the firm's culture without adequate consultation, and had presided over a run of senior-partner departures.13 Conway — who had championed Lee's rise — took the interim job, and the search stretched into 2023, with external candidates reportedly wary of joining a firm whose founders appeared unwilling to relinquish control.13
Why this is the most important governance fact in the modern story
The standard way to test management quality is promises versus outcomes. Here the promise was explicit and dated: in October 2017, Carlyle told the world it had solved founder succession.9 Within five years, that plan had failed twice — one co-CEO gone early, the other forced out in a dispute the market learned about from journalists rather than filings.
Two failures is not a coincidence; it is a pattern. And the pattern has a specific shape: when a non-founder CEO's strategy or economics diverged from the founders' preferences, the founders won.
It is worth calibrating this against peers, because founder friction is endemic to private equity. KKR's transition was slow, telegraphed, and orderly: Henry Kravis and George Roberts named Joe Bae and Scott Nuttall co-presidents in 2017 and elevated them to co-CEOs in 2021, with the founders moving to executive co-chairmen. Apollo's transition was messier — Leon Black stepped back in 2021 following an independent review of his personal dealings with Jeffrey Epstein, and Marc Rowan took over — but it produced a single, durable leader who then executed a coherent strategy without visible board interference. Blackstone never faced the question, because Stephen Schwarzman never left and Jon Gray's elevation to president was a designation rather than a handover.
Against that base rate, Carlyle stands out. It is the only one of the four where the founders removed a professional CEO and then had to run an external search from a position of visible weakness.
That search ended on February 6, 2023, when the board unanimously appointed Harvey M. Schwartz — former president and co-chief operating officer of Goldman Sachs, and before that Goldman's chief financial officer — as CEO effective February 15.14 Schwartz was a genuine break in kind. Carlyle had always grown its own. Schwartz had never worked in private equity. He had spent his career in trading, risk, and capital allocation at a public financial institution, and his last job before retiring from Goldman in 2018 had been running a balance sheet through a regulatory regime. He is a New Jersey native who came up through commodities sales, holds a black belt in karate, and is widely described as impatient with internal politics — a fair description of the problem he was hired to solve.15
The forward-looking question is whether the founder-intervention pattern is dormant or resolved. The honest answer is that it is unproven. Conway and Rubenstein remain co-chairmen of the board; D'Aniello is chairman emeritus; the founders collectively retain a meaningful economic stake. Governance influence has never fully transferred from the founders to outside shareholders, even fourteen years after the IPO. There is a real, structural sense in which Carlyle is a public company with a private control group.
Shareholders have registered mild discomfort. At the 2026 annual meeting, the say-on-pay proposal passed with roughly 82% support — 246.9 million shares for against 55.0 million opposed.16 That is a comfortable pass. It is also a dissent tail large enough to be a message rather than noise; blue-chip say-on-pay votes typically clear 90%.
The irony sitting underneath all of this is that the strategy the founders used to justify removing Lee — aggressive diversification into credit and insurance — is, in its essentials, the strategy Schwartz has spent three years executing. What changed was not the destination. It was who was allowed to drive.
V. The Schwartz Rebuild: Delivered Numbers, One Real Miss, and an Unresolved Fundraising Test
Harvey Schwartz arrived in February 2023 to a firm that had just missed badly at the thing it was supposed to be best at.
Carlyle Partners VIII, the eighth flagship U.S. buyout fund, had launched fundraising in 2021 into the most favorable environment private equity had ever seen. It closed in August 2023 with $14.8 billion — against an original target that had been set at roughly $27 billion.1718 A shortfall of nearly half, on the firm's marquee product, in the strategy that made its name. Schwartz's own public verdict on that year was blunt: he said Carlyle had "not been pleased with fundraising in 2023."17
That candor is worth noting, because it set the tone for everything after. Schwartz's diagnosis was that Carlyle had been valued as a private equity firm with a volatile earnings stream because that is what it was, and that the fix was not to fundraise harder but to change the composition of earnings: more management fees, more permanent and semi-permanent capital, more fee streams that did not depend on selling companies into a receptive market. Less carry, more annuity.
What was actually delivered
Judge a turnaround on a multi-year arc, not a quarter. The arc here is genuinely good.
In fiscal 2024, Carlyle produced record fee-related earnings of roughly $1.1 billion, up about 32% year over year, with the FRE margin expanding roughly nine percentage points to 46% — and management stated it had met every financial target it set for the year.19 Margin expansion of that magnitude in a single year is not a market gift; it reflects fee revenue growing while the cost base stayed roughly flat, which in an asset manager means headcount and compensation discipline. That is a real managerial act.
Fiscal 2025 was better. FRE margin reached 47%. Inflows came in at $54 billion against an original target of $40 billion. Full-year assets under management set a record at roughly $477 billion. And the proxy disclosed cumulative total shareholder return of 119% for the 2023–2025 period.1916
Then, at those full-year results, Schwartz did the thing that makes management credible or destroys it: he put dated numbers on the board. By 2028, Carlyle targets $1.9 billion of fee-related earnings, $200 billion of cumulative fundraising, $2.8 billion of management fees, an FRE margin above 50%, and distributable earnings per share above $6.19
These are the numbers to hold management to. They are specific, they are dated, and they are falsifiable — which is exactly why they are useful to an outside investor and exactly why most managements avoid setting them.
The miss, and what it revealed
Four months later, Carlyle missed.
First-quarter 2026 distributable earnings came in at $0.89 per share against consensus of $0.91, down from $1.14 a year earlier. Segment revenue missed consensus by roughly 16% and fell about 28% year over year, driven by a sharp pullback in realized performance revenue. The stock fell hard on the print.20
Then the second quarter rebounded almost violently. Record quarterly FRE of $358 million at a 47% margin; distributable earnings of $472 million, the highest in nearly four years; $16.8 billion of inflows; AUM at a record $485 billion, of which $334 billion was fee-earning and $113 billion — about 34% — was perpetual capital.12122
The pattern is the point. Carlyle's own results, two quarters apart, demonstrate that the "flywheel" language management favors overstates the smoothness of the machine. Fee-related earnings really are more stable than carry — that part of the thesis holds. But distributable earnings, which is what shareholders actually get paid out of, still swings on realizations, and realizations still swing on markets. An investor who models Carlyle as a fee annuity will be surprised roughly once a year.
Carlyle's capital allocation in the quarter was the more encouraging signal. The firm repurchased $304 million of stock, a record pace, leaving $1.6 billion of a $2 billion authorization, while maintaining the $0.35 quarterly dividend.121 Buying back aggressively while the stock sat near multi-year lows is the behavior you want from a management team that believes its own numbers. It is also, in fairness, the cheapest way for any asset manager to signal conviction, and it does not by itself validate the operating thesis.
The fundraising claim, tested against the record
Here is where management's framing and Carlyle's history collide most directly.
On recent calls, Schwartz has described the industry — and Carlyle specifically — as entering a "fundraising super cycle," anchored in part by a $5 billion commitment toward the next flagship U.S. buyout fund, which the firm signaled it would launch around the end of 2025.2223
Sitting immediately next to that claim is Carlyle Partners VIII's roughly 45% shortfall.1718 That is not ancient history and it is not a different business: same product, same LP base, same brand, one CEO ago. It is the strongest available disconfirming evidence against the super-cycle framing, and it tests the claim through exactly the right mechanism — whether limited partners will actually write checks at flagship scale.
So what does the history do to the claim? It does not reject it outright. The 2025 inflow number of $54 billion against a $40 billion target is real evidence that Carlyle can raise money in aggregate, and the mix has genuinely shifted: much of that came through credit, secondaries, and evergreen wealth vehicles rather than flagship buyout.19 What the history does is narrow the claim. The defensible version is: Carlyle has demonstrated it can grow fee-earning assets across a diversified product set. It has not yet demonstrated that its flagship buyout franchise has recovered LP demand at the scale it once commanded.
The event that settles this is specific and near: the final close of the next flagship U.S. buyout fund, measured against its stated target. Close near target and the CP VIII shortfall reads as a 2023 cyclical artifact. Close 30–45% short again and it reads as a structural repricing of Carlyle's position in the LP hierarchy — which is precisely what the PEI 300 rankings discussed in Section VIII already imply.
The capital markets flywheel — a genuinely new earnings stream
One piece of the rebuild is less contested. Since 2023, Carlyle has built an internal capital markets business, which arranges and syndicates financing for its own portfolio companies and for third parties, capturing transaction and advisory fees that previously leaked to investment banks. In the second quarter of 2026 it generated more than $100 million of transaction fees.122
This matters more than the dollar amount suggests. It is fee income tied to deployment activity rather than exit activity, it requires little balance sheet, and it partially decouples Carlyle's earnings from the timing of realizations — the exact weakness the first quarter exposed. It is the clearest structural improvement in the earnings mix that Schwartz has produced, and it is one Goldman alumni are unusually well equipped to build.
Incentives, and where the rebuild is admittedly unproven
On compensation, the picture is cleaner than the 2022 fight would suggest. Schwartz's 2025 total compensation was roughly $7.15 million.16 His 2023 figure of roughly $187 million was dominated by a one-time sign-on equity award tied heavily to stock performance — enormous, but non-recurring, and structured so that he is paid if shareholders are.1516 On the founder side, Rubenstein sold roughly $35 million of stock during 2025, about 2.2% of his holding — a portfolio management decision, not a signal.
Management has also been reasonably honest about what has not arrived yet. Revenue from the wealth channel and the 401(k)/retirement opportunity is not expected to contribute meaningfully until 2027. And on the second-quarter call, Schwartz characterized insurance block deal flow — a core input to the credit growth story — as having gone through "a little quieter" period.22
Both admissions belong next to the growth narrative, not in a footnote. The two engines management points to for the next leg of growth are, by its own account, not yet running. That is not a scandal; it is a timing risk with a date attached, and 2027 is when it becomes checkable.
The disconnect
Which brings the section back to the stock. From Schwartz's start in February 2023 through January 2025, Carlyle shares rose about 48% — respectable in isolation, and badly beaten by Blackstone at roughly +78%, Apollo at +128%, and KKR at +150%. The shares then fell from a 52-week high near $69.85 in September 2025 to a low around $41–42 in mid-2026.
Three years of record operating results, and a stock that has round-tripped. The operating story and the equity story are telling different stories about the same firm. To understand why, you have to look at what Carlyle actually owns.
VI. Business Model Today: Three Segments, Very Different Economics
The phrase "alternative asset manager" hides more than it reveals. Carlyle is three businesses stapled together, and they have almost nothing in common economically. One is the brand. One is the growth. One is the future distribution channel. Take them in order of what they mean for earnings.
Global Private Equity: the brand, and the slow lane
Roughly $163 billion of assets, down about 1% year over year, generating $134 million of fee-related earnings in the second quarter of 2026.2122 This is the business the firm was built on — corporate buyouts, real estate, infrastructure, growth capital — and it is now Carlyle's slowest-growing segment.
There is a genuine, measurable edge inside it. Carlyle's U.S. buyout funds have been returning capital to investors at roughly 23% of fair value over the trailing year, against a stated industry average near 10%.22 In a market where limited partners have spent three years complaining that private equity takes their money and never gives it back, distributing at more than twice the industry pace is the single most valuable thing a general partner can do. It is the reason to believe Carlyle's LP relationships are healthier than the CP VIII headline suggests.
But hold those two facts in the same hand, because they are in tension. Carlyle returns capital faster than peers, and Carlyle raised less than half its flagship target. If distribution pace alone drove re-up decisions, that combination would be impossible. It suggests that LPs were reacting to something else — the 2022 governance rupture, the senior-partner departures that accompanied it, or simple portfolio concentration after a decade of over-allocation to buyouts. The realization edge is real but it is not, on the evidence, sufficient.
For investors, the practical read is that Global Private Equity is no longer the growth story. It is the performance-fee engine and the source of brand credibility. Its job is to stop shrinking.
Global Credit: the largest segment, and the one carrying the thesis
Roughly $211 billion of assets — now Carlyle's biggest business — growing about 10% year over year as of full-year 2025, with fiscal 2025 fee-related earnings of $402 million, up 21%, and a record $138 million of segment FRE in the second quarter of 2026.192122
The business spans direct lending to mid-sized companies, structured credit, asset-backed finance, collateralized loan obligations, and — the strategically important part — insurance capital. Carlyle manages a large portion of the general account of Fortitude Re, a Bermuda-based reinsurer holding roughly $101 billion of reserves, and in October 2025 the two established FCA Re, a Bermuda sidecar capitalized with over $700 million and aimed at Asian block reinsurance, which Carlyle has framed as adding roughly $10 billion of fee-earning assets over time.24[^25]
The mechanic here is worth explaining plainly, because it is the engine of the entire alternative-manager sector right now. An insurance company collects premiums today against claims it will pay decades from now. That float has to be invested, and traditionally it went into public bonds. If an asset manager can persuade the insurer to put some of that float into privately originated loans yielding two or three percentage points more, the insurer earns a better spread and the manager collects a fee on assets that will not leave for twenty years. It is the most reliable fee stream in the business — genuinely permanent capital, not the marketing version.
Now test it against Carlyle's own record, because this is the balance-sheet instinct that produced Carlyle Capital Corporation. Two things are different and one is not. Different: insurance liabilities are long-dated and cannot be margin-called, which removes the specific mechanism that killed the 2008 vehicle. Also different: Carlyle earns fees for managing Fortitude's assets rather than owning the risk itself. Not different: the returns still come from a spread between what assets yield and what liabilities cost, and spreads compress when credit deteriorates or rates move against you.
And there are live credit-quality signals inside Carlyle's own book, which is the most relevant possible evidence.
The first is Carlyle Secured Lending, the firm's listed business development company. In 2026, CGBD reset its base dividend to $0.35 per share from $0.40 — a 12.5% cut — explaining that the reduction would support stable net asset value and improve dividend coverage, and telling investors that earnings would trough in the second quarter before recovering as recently ramped joint ventures contributed.2526 The stock has traded at a substantial discount to net asset value.27 A BDC cutting its base dividend is not a catastrophe; it is a management team acknowledging that the yield on its existing loan book has fallen faster than expected and that spread compression in direct lending is real. It is a data point about the asset class Carlyle is growing into, delivered by Carlyle's own vehicle.
The second is ManTech, the government IT services company Carlyle took private for $3.9 billion in 2022. In November 2025, a $2.3 billion loan sale tied to the business was pulled on weak investor demand.28 A pulled syndication is the credit market's way of saying no. It does not mean the borrower is failing — it means lenders wanted better terms than the arrangers were offering, which usually reflects doubts about leverage, earnings trajectory, or both.
The third is redemption behavior in the semi-liquid channel, and it is the most immediate. In the first quarter of 2026, investors requested to withdraw roughly 15.7% of assets from the Carlyle Tactical Private Credit Fund — more than three times the 5% quarterly repurchase limit the fund normally honors.29 The context was sector-wide: Cliffwater's large non-traded BDC received 17% redemption requests in its May 2026 window against its own 5% cap, and shares of listed private credit managers, Carlyle included, fell on the news.3031
This is the structural vulnerability of "semi-permanent" capital stated as clearly as it can be stated. These vehicles promise retail investors periodic liquidity from portfolios that are fundamentally illiquid. The gates work — that is what they are for — but a gate is a promise partially broken, and gates are visible. The perpetual-capital share of fee-earning assets, at 34%, is a genuine improvement in earnings quality. It is not the same as locked-up institutional fund capital, and it should not be modeled as if it were.
The calibrated conclusion on insurance and credit: the strategy is sound in structure and is producing real fee growth, and the specific 2008 failure mode does not obviously recur. But the claim that this represents a durable, low-risk earnings base is currently unproven at the point where it matters — through a credit downturn. Three separate signals inside Carlyle's own house in the past twelve months are early-cycle stress, not late-cycle distress, and they deserve to be read as such rather than dismissed.
Carlyle AlpInvest: the fastest engine, and the distribution bet
Roughly $112 billion of assets, growing about 16% year over year, with fiscal 2025 fee-related earnings of $274 million — up roughly 60%.1921
AlpInvest does secondaries and portfolio finance: buying existing stakes in private funds from investors who want out early, and lending against portfolios of fund interests. In a market where exits have been slow and institutions are over-allocated to private assets, being the buyer of liquidity is a structurally advantaged position. The seller needs the transaction more than the buyer does, which shows up in pricing.
AlpInvest has also become Carlyle's wealth-channel workhorse. Evergreen assets — the perpetually offered vehicles sold through financial advisers rather than pension consultants — grew more than 60% year over year to over $20 billion.19 That is the distribution bet: individual investors, allocated to alternatives at a fraction of institutional rates, represent the largest untapped pool of capital in the industry.
It is also where the 2027 timing risk lives, and where the CTAC redemption episode is a warning rather than an abstraction. Growth in evergreen assets is being reported now; the revenue inflection management points to arrives later; and the channel's behavior under stress has already been demonstrated once this year.
The hierarchy, stated plainly
Global Credit is the largest segment and the largest contributor to FRE growth in dollars. AlpInvest is the fastest-growing and owns the distribution future. Global Private Equity is the brand, the performance-fee engine, and no longer the growth story. Any investor thesis on Carlyle is, in practice, a thesis on credit and secondaries wearing a private equity firm's name.
Which raises the obvious question: when Carlyle does deploy capital into companies, how good is it? The last four years give an unusually clean answer, because they contain both a triumph and a zero.
VII. Capital Deployment and M&A: A Real Win, a Real Loss, and a Live Test
In December 2025, bankers rang the bell on the largest healthcare initial public offering in history. The company was Medline, the Illinois-based medical supplies distributor, and the sellers were three private equity firms that had bought it four and a half years earlier in what was then one of the biggest leveraged buyouts ever attempted.
Medline: the best evidence for the Schwartz era
In June 2021, Blackstone, Carlyle, and Hellman & Friedman agreed to acquire a majority stake in Medline from the founding Mills family in a transaction valued at approximately $34 billion — Carlyle's largest deal ever.32 The family retained a substantial stake and continued to run the business, which is unusual and, as it turned out, important.
The thesis was mundane in the best way. Medline manufactures and distributes the unglamorous consumables that hospitals consume constantly — gloves, gowns, surgical kits, wound care. The business had been growing steadily for decades under family ownership, underinvested in distribution infrastructure relative to its opportunity, and had never had access to institutional capital at scale. The sponsors' job was to fund a large distribution build-out and let the business compound.
It worked. In the first half of 2025, Medline grew sales roughly 9.7% year over year to $13.5 billion, with profit of $655 million.33 In December 2025, the sponsors executed a $7.2 billion IPO at a valuation of roughly $65 billion — approximately double the entry enterprise value in about four years, and the largest healthcare listing ever completed.33
What does this prove, and what does it not? It proves Carlyle can source, underwrite, and hold a very large, boring, cash-generative asset through a period that included the sharpest rate-hiking cycle in forty years, and can exit it at scale in the public markets. That is the full round trip, which is more than most large 2021-vintage buyouts can claim. It does not prove much about Carlyle's operating capability specifically — Medline was a three-sponsor deal in which the founding family retained control and continued running the company, and Blackstone led. Attributing the outcome to Carlyle's value-add would be generous. What it fairly demonstrates is judgment: Carlyle picked the right asset at a moment when a great many sponsors were paying peak multiples for far worse businesses.
Dainese: the same vintage, the opposite outcome
In 2022, Carlyle bought Dainese, the Italian maker of motorcycle and ski protective gear, from Investcorp. It is a beautiful brand with real heritage — the armor that MotoGP riders wear — and the thesis was the familiar one: premium brand, direct-to-consumer expansion, international growth.
It went to zero.
Dainese posted a loss of roughly €120 million in 2024, nearly three times the prior year's loss, including an €86 million goodwill impairment. Carlyle injected about €15 million as a rescue. It was not enough.34 In January 2026, the business was handed to its creditors — private credit lenders HPS and Arcmont — in a debt-for-equity swap for a nominal €1, with the transfer subsequently cleared by European regulators.35 Carlyle's equity was extinguished.
Set Medline and Dainese side by side, because they are the same era, the same management regime's inheritance, and opposite results. A goodwill impairment of €86 million against a business of Dainese's size is an admission that the acquisition price embedded growth assumptions that did not materialize. The €15 million follow-on injection is the more revealing detail: it is a small check written into a deteriorating situation, the kind of decision that is either a bridge to recovery or good money after bad, and here it was the latter.
The honest synthesis is that Carlyle's capital allocation record over this period is mixed with a favorable weighting by size. The win was enormous and the loss was small in dollar terms — Dainese never approached Medline's scale. But the existence of a complete wipeout in a consumer brand deal, in the same window as the triumph, is the appropriate corrective to any narrative of restored underwriting discipline. One deal each way, four years apart, is not a track record. It is two observations.
Jagex and ManTech: the ordinary middle
Between the extremes sit the ordinary deals. Carlyle agreed in February 2024 to sell Jagex, the British studio behind the online game RuneScape, to CVC Capital Partners and Haveli Investments in a transaction reported at roughly $1.1 billion.36 Clean process, decent outcome, immaterial to a firm of Carlyle's size.
ManTech is the more consequential holding, and it sits awkwardly beside the firm's newest strategic bet. Carlyle took the government IT contractor private for $3.9 billion in 2022, and in November 2025 the pulled $2.3 billion loan sale signaled that lenders had reservations.28 The federal services market has faced budget pressure and contract-award turbulence; whatever the specific cause, the credit market's refusal is the operative fact.
The 2026 defense relaunch: the live test
In May 2026, Carlyle launched a dedicated middle-market platform focused on aerospace, defense, government services, and industrials, targeting up to $3 billion. Its first investment came in July 2026: Secturion Systems, a Utah-based maker of high-speed, NSA-certified hardware encryption products used to protect classified data across airborne, maritime, and ground systems, whose customers include the U.S. Navy and Boeing. Carlyle installed Sean Berg, formerly CEO of Everfox, to lead it.237 Management has framed the opportunity around roughly $8 trillion of projected global defense spending over the coming decade.37
The strategic logic is coherent: rising defense budgets across NATO and the Indo-Pacific, a fragmented supplier base ripe for consolidation, and a firm with a forty-year history in the sector. Secturion is a sensible first deal — a specialized, certification-gated niche where incumbency is genuinely defensible, because getting NSA certification for encryption hardware is slow and the switching costs for a program of record are high.
But three cautions belong right here rather than in a distant risk section. First, everyone is doing this: rising defense budgets are the most consensus trade in private markets in 2026, which means Carlyle is competing for assets against every large sponsor plus a wave of dedicated defense-tech funds, and competition shows up in entry multiples. Second, Carlyle's own defense holding is the one showing credit stress — ManTech's pulled loan sale is direct evidence that a Washington-relationship franchise does not immunize you against the credit cycle. Third, government customers have structural bargaining power that most private equity theses underweight: budgets are appropriated annually, programs get restructured, and a customer that can rewrite the specification or re-compete the contract is not a captive customer.
The claim being made is that a forty-year defense franchise is a cornered resource. The evidence supports a narrower version: Carlyle has genuine domain knowledge and relationships that help it source and diligence deals in a complicated sector. It does not support the claim that this produces superior returns in a market where capital is abundant and everyone has read the same NATO spending forecast.
Rounding out the picture: Carlyle has done a set of smaller, opportunistic deals — Surventis, a BASF carve-out; MAI Capital, a wealth-management acquisition that feeds the distribution channel; and participation in a $1 billion round for Castelion, a hypersonic missile startup. Castelion in particular should be read as venture-style optionality with a lottery-ticket payoff distribution, not as evidence of anything, and it is immaterial to Carlyle's earnings.
The realization story is the one that actually shows up in the numbers: $37 billion returned to fund investors over the trailing year, more than $20 billion of it from Global Private Equity.1 Management describes this as an industry-leading pace. Peer disclosure conventions differ enough that a clean apples-to-apples comparison is not available from public filings, so the honest framing is that the pace is high in absolute terms and consistent with the firm's stated 23%-of-fair-value distribution rate, with the "industry-leading" superlative being management's characterization rather than an independently verified fact.
Which raises the comparison Carlyle cannot escape. How does it actually stack up against the firms it is measured against?
VIII. Competitive Landscape: A Real, Persistent Discount
Every year, Private Equity International publishes the PEI 300, ranking firms by capital raised over the preceding five years. It is the industry's most-watched scoreboard. Between 2010 and 2015, Carlyle sat at number one on that list more often than any other firm.
In the 2025 edition, the top five were Blackstone, KKR, EQT, Thoma Bravo, and TPG.38 Carlyle was not among them.
That single fact does more work than any valuation multiple in explaining why the stock trades where it does.
The scale gap, and why it compounds
Start with size. Carlyle's roughly $485 billion of assets sits well behind Blackstone at around $1.3 trillion, Apollo at roughly $785 billion, and KKR at roughly $744 billion. The market capitalization gap is wider still: Carlyle has traded in a range of roughly $16–21 billion against Blackstone's $108–185 billion, KKR near $96 billion, Apollo near $76 billion, and Ares around $45 billion.
The market cap gap is proportionally larger than the AUM gap. That is the whole argument in one observation: the market pays less for each dollar Carlyle manages than for each dollar its peers manage.
Growth explains part of it. Over the two years to 2025, Carlyle's AUM grew roughly 20%. TPG grew 77%, Apollo 33%, KKR 24%. Carlyle grew, but it grew slower than a peer set that was already larger — which is the mathematical definition of falling behind.
Scale in this industry is not vanity. Large limited partners have spent a decade consolidating relationships, writing bigger checks to fewer managers to reduce administrative burden and gain fee leverage. That dynamic mechanically favors the top three or four platforms and squeezes everyone in the tier below. Carlyle is in the tier below.
The discount is specific, not vague
Carlyle has traded around 11 times forward distributable earnings — the lowest among large diversified alternative managers. The components of that discount are identifiable rather than mysterious: earnings volatility that the first quarter of 2026 demonstrated in public; visible credit-quality questions in the firm's own vehicles; the residual governance overhang from 2022 and the unresolved question of founder influence; and the CP VIII shortfall as concrete evidence about franchise strength.
An investor arguing the discount is unjustified needs to argue those four points are either wrong or fixed. Three of the four are, on current evidence, not yet fixed.
The Apollo comparison, stated plainly
The most instructive competitive contrast is with Apollo, because Apollo did the same strategic thing Carlyle is doing — pivot toward insurance-linked permanent capital — and did it differently.
Apollo owns Athene outright. Athene's balance sheet is Apollo's balance sheet; the merger completed in 2022 fused the asset manager and the insurer into a single entity. That means Apollo captures the full spread economics, controls asset allocation directly, and cannot lose the relationship.
Carlyle's arrangement with Fortitude Re is a management relationship. Carlyle manages assets and earns fees; Fortitude is a separate company with its own owners and its own board. The economics are thinner — fees rather than spread — and the relationship is, in principle, terminable.
State this plainly rather than diplomatically: Carlyle's insurance moat is structurally shallower than Apollo's. It is a very good fee-generating relationship. It is not ownership, and it should not be valued as if it were. The FCA Re sidecar, in which Carlyle has capital at risk alongside Fortitude, moves modestly in the ownership direction — and correspondingly moves Carlyle modestly back toward the balance-sheet risk profile that Section III described.
The five forces, and where the power actually sits
Run the competitive analysis properly and the picture is mixed.
Buyer power is rising, and it is the dominant force. Limited partners have never had more leverage. They demand fee-free co-investment rights, negotiate management fee breaks, and increasingly use continuation vehicles and the secondaries market — Carlyle's own AlpInvest business — to manage their own liquidity rather than waiting on general partners. CP VIII is what rising buyer power looks like in a single data point: LPs simply declined to fund the target.
Rivalry is intense and increasingly structural. The top platforms compete for the same institutional wallets, the same wealth-channel shelf space, and the same insurance mandates. Differentiation is narrowing.
Barriers to entry are high, but the barrier protects a group, not a firm. A new entrant cannot easily assemble a global platform with a twenty-year track record. But that barrier equally protects Blackstone, KKR, Apollo, Ares, EQT, and Carlyle — so it does not explain relative performance among them.
Substitution is real and growing. Direct investing by sovereign wealth funds and large pensions, index-like private markets products, and continuation vehicles all substitute for traditional fund commitments.
Supplier power — the ability to recruit and retain investment talent — is where the 2022 senior-partner departures did lasting damage. In a people business, franchise value walks out the door in pairs.
On Hamilton Helmer's 7 Powers, Carlyle's position is thinner than its size implies. It has scale economies in fund administration and fundraising, but less than the top three. It has branding — the Carlyle name still opens doors globally. It has something approaching a cornered resource in aerospace, defense, and government services, built over four decades. What it conspicuously lacks is switching costs of the Apollo/Athene variety, where the capital literally cannot leave, and it lacks network economies entirely; asset management does not have them.
The single most defensible power in the portfolio is the defense franchise. And as Section VII established, that resource is being actively contested by every sponsor with a PowerPoint about NATO spending.
That competitive position defines the risk set — which is more specific than the usual macro checklist.
IX. Risk Radar
Carlyle's risks are not the generic ones. They are structural, and most of them have already produced observable evidence in the past twelve months.
Rate and spread sensitivity in the credit and insurance base. With 34% of fee-earning assets in perpetual vehicles, much of it credit and insurance-linked, Carlyle's fastest-growing earnings stream is exposed to the shape of the yield curve and the direction of credit spreads.1 The mechanism: when base rates fall, floating-rate loan income falls with them; when spreads compress because too much capital is chasing direct lending deals, the yield on newly originated loans declines. That is not a forecast — CGBD's own dividend reset was management's explicit acknowledgment of yield pressure on the existing book.25
Credit quality inside Carlyle's own portfolio. The CGBD reduction and ManTech's pulled loan sale are actual events, not scenarios.2528 Two signals do not make a cycle. But they are the kind of signal that appears first, in the manager's own vehicles, before it appears in aggregate industry data.
Fundraising concentration and LP fatigue. CP VIII's shortfall is the evidence. If the next flagship repeats it, the 2028 targets — $200 billion of cumulative fundraising, $2.8 billion of management fees — become arithmetically difficult, because flagship funds carry the highest fee rates in the complex.
Wealth-channel execution and liquidity mismatch. The 2027 revenue inflection is a promise with a date. The 2026 redemption episode at Carlyle Tactical Private Credit — 15.7% requested against a 5% cap — is a demonstration of how the channel behaves when sentiment turns.29 Gates protect the portfolio. They do not protect the sales narrative.
Regulatory. The environment has eased: the SEC's Private Fund Adviser Rules, which would have imposed extensive disclosure and side-letter restrictions on private fund managers, were vacated by the Fifth Circuit in 2024. But examination priorities, the amended Regulation S-P data-protection obligations, and continued scrutiny of fee and expense allocation remain live. The retirement-account opening that underpins the 401(k) opportunity is itself a policy-dependent asset — it exists because of a regulatory posture that a different administration could reverse.
Geopolitical dependency in the defense bet. Defense budgets are a political variable, and a portfolio concentrated in government-facing businesses inherits appropriations risk, program-cancellation risk, and the bargaining power of a monopsony buyer.
Governance. The founder-influence question is unresolved rather than closed. The most likely moment for it to resurface is the next CEO succession — which is not imminent, but which is exactly the event that has twice revealed how this board actually behaves.
Weigh these together and a pattern emerges: nearly every Carlyle risk is a variation on the same theme. The firm is trying to convert cyclical, relationship-dependent earnings into structural, contractual ones, and the conversion is genuinely underway but not complete. Which is precisely the argument between the bulls and the bears.
X. Bull Case vs. Bear Case
Set the two cases against each other honestly, because both are built on real facts.
The bull case
Three consecutive years of record fee-related earnings is not a fluke, and the margin expansion from the mid-thirties to 47% is not a market gift — it reflects operating leverage that management engineered.19 Backing it are dated 2028 targets that management chose to make public and can be held to: $1.9 billion of FRE, $2.8 billion of management fees, a margin above 50%, DE per share above $6.19
The diversification is real, not cosmetic. Global Credit is now the largest segment and AlpInvest the fastest-growing; the historical buyout business no longer determines the firm's growth rate.21 The capital markets business has created a genuinely new fee stream tied to deployment rather than exits.22 Perpetual capital has reached 34% of fee-earning assets.1
Carlyle returns capital to LPs at more than twice the stated industry pace, which is the currency that matters most in a market starved of distributions.22 Medline demonstrated the firm can underwrite and exit at the largest scale.33 Buybacks at a record $304 million in a single quarter, executed near multi-year share price lows, show a management team allocating capital consistently with its own stated view.1
And the valuation embeds low expectations. At roughly 11 times forward distributable earnings — the lowest in the peer group — the bull does not need Carlyle to become Blackstone. The bull needs the flagship fund to close respectably and credit to hold, at which point the discount has no remaining justification.
The bear case
The discount looks earned.
CP VIII's roughly 45% shortfall is hard evidence against the "super cycle" framing, delivered by the exact constituency whose behavior the framing predicts.1718 Dainese's total wipeout sits in the same vintage window as Medline's win, which means the capital allocation record is two data points rather than a demonstrated capability.3435 CGBD's dividend reduction and ManTech's pulled loan sale are credit-quality flags inside the growth engine itself, not in some adjacent market.2528 The insurance strategy earns fees rather than spread and is structurally thinner than Apollo's owned model.
The governance record is the part that does not improve with time. The founders removed one CEO and lost another early, and the removal was over a specific compensation dispute and a specific strategic disagreement about the pace of diversification — the same diversification Schwartz now runs.13 Those founders still chair the board. And 18% of votes cast opposed the 2026 say-on-pay proposal.16
Finally, the two engines management points to for the next leg — wealth-channel revenue and insurance block flow — are, by management's own description, not contributing yet.22
The activist's angle
A skeptical activist looking at Carlyle would not attack the operating results. They would attack the structure around them.
They would ask why a firm generating record fee-related earnings trades at the group's lowest multiple, and answer their own question by pointing at the board: two founders as co-chairmen fourteen years after the IPO, a quarter of the company historically in founder hands, and a documented history of founder intervention in CEO tenure. They would push for founder retirement from the board, or at minimum a public, dated succession framework, on the theory that governance is the cheapest part of the discount to close.
They would question portfolio complexity — three segments with different economics, a BDC trading well below book, and an insurance relationship that is neither fully owned nor fully arm's-length — and argue that a simpler Carlyle would be a more valuable one. They would note that a firm buying back stock at a record pace is implicitly agreeing its shares are mispriced, and ask why the board is not doing more of it.
And they would go directly at the CP VIII shortfall as the accountability test: who was responsible, what changed, and why should the next flagship be different?
The synthesis
Weigh the evidence and the verdict is neither vindication nor rejection. It is narrowing.
The claim that Carlyle has durably shifted toward stable fee-related earnings is substantially supported: three years of results, a structurally different segment mix, a new capital markets fee stream, and 34% perpetual capital. The first-quarter miss shows the shift is incomplete at the distributable-earnings line, not that it is illusory.
The claim that Carlyle is entering a fundraising super cycle at flagship scale is not supported by evidence yet. Aggregate inflows beat targets in 2025; the flagship franchise has not been retested since a 45% miss.
The claim that management has restored capital allocation discipline is unproven. One outstanding win, one total loss, four years of data.
The claim that the aerospace and defense franchise is a durable cornered resource is narrowed: it is a real sourcing and diligence advantage in a complicated sector, and it is not evidence of superior returns in a crowded market where Carlyle's own defense holding is showing credit stress.
The claim that governance risk is behind the firm is unresolved, and it will remain so until a CEO transition happens without founder drama.
What to watch
Three things settle most of this, and an investor tracking Carlyle should watch them rather than the quarterly headline.
First: the final close of the next flagship U.S. buyout fund, against its stated target. This is the single most decision-relevant number. It directly tests LP demand, the super-cycle claim, and the achievability of the $200 billion cumulative fundraising target — and it does so in the highest-fee product Carlyle sells.
Second: fee-related earnings margin, tracked against the above-50% 2028 target. FRE margin is the cleanest single measure of whether the business model transformation is actually working, because it captures fee growth and cost discipline simultaneously, and it is not contaminated by realization timing.
Third: credit health in Carlyle's own vehicles — non-accruals and net asset value at CGBD, and redemption requests versus repurchase limits in the semi-liquid funds. These are Carlyle's early-warning instruments for the asset class carrying the growth thesis, and they are disclosed quarterly.
Secondary markers worth noting as they arrive: whether evergreen and retirement revenue actually inflects in 2027, and how the board handles the eventual succession question.
XI. Durable Lessons
Strip away the tickers and Carlyle's forty years offer four lessons that generalize well beyond one asset manager.
Access founds a firm; it does not sustain one. Carlyle's original edge was that a group of Washington insiders understood defense procurement better than New York financiers did. That edge built a franchise. But relationships are not a moat in the technical sense — they do not raise a competitor's costs or lock in a customer. They generate proprietary deal flow, which is valuable, and they attract scrutiny, which is expensive. Four decades on, the same defense franchise that founded the firm is the one that produced ManTech's credit stress, and access did not prevent it. Relationships help you find deals. They do not make the deals work.
Permanent capital is powerful, and leverage discipline is the entire game. Carlyle already learned this at maximum cost. Carlyle Capital Corporation held some of the safest bonds in existence and still went to zero, because the risk was never in the assets — it was in the funding. Any investor evaluating the current insurance and evergreen buildout should ask the 2008 question rather than the 2026 marketing question: not "how good is the credit?" but "what happens to this structure if the liability side wants its money back faster than the asset side can produce it?" The 15.7% redemption request at Carlyle Tactical Private Credit is a small, contained echo of exactly that question.
Founder-to-professional succession is hard, and the difficulty is not a soft factor. Two failed transitions in five years, at a sophisticated firm with a professional board and every governance adviser money can buy, is a data point about how power actually distributes in founder-built financial firms. Ownership concentration plus board seats plus institutional memory equals control, whatever the org chart says. Investors in founder-influenced public companies should price that as a real variable rather than a footnote — and should treat the second failure, not the first, as the one that establishes a pattern.
Fee-related earnings can genuinely be grown independent of carry — and demand at the top of the product line is a separate question. This is the most useful thing Carlyle's recent record demonstrates for the whole sector. Three years of record FRE with 900 basis points of margin expansion in a single year is real evidence that the annuity conversion is achievable. And the CP VIII shortfall is equally real evidence that growing fees in credit and secondaries does not automatically mean your flagship franchise is healthy. Both can be true simultaneously.
The market has, so far, sided with the second observation. Whether it should is what the next flagship close will decide.
XII. Recent News
August 5, 2026 — Second-quarter results. Carlyle reported record fee-related earnings of $358 million, up 11% year over year at a 47% margin, and its highest distributable earnings in nearly four years. Assets under management reached a record $485 billion, with $334 billion fee-earning and $113 billion perpetual. Inflows totaled $16.8 billion; nearly $7 billion was returned to fund investors in the quarter and $37 billion over the trailing year. Capital markets transaction fees exceeded $100 million. The board declared a $0.35 quarterly dividend, and the firm repurchased $304 million of stock, leaving $1.6 billion on its $2 billion authorization.12122 The Wall Street Journal characterized the quarter as continued capital inflows alongside climbing distributable earnings.39
July 2026 — First deal in the new defense platform. Carlyle acquired Secturion Systems, a Utah-based manufacturer of NSA-certified high-speed hardware encryption products serving customers including the U.S. Navy and Boeing, and named Sean Berg chief executive. It was the first platform investment for the dedicated middle-market aerospace, defense, government services and industrials strategy launched in May 2026, which has been targeting up to $3 billion.237
June 2026 — Private credit redemption pressure across the sector. Cliffwater's large non-traded business development company received redemption requests equal to 17% of the fund in its May window against a 5% cap, and listed alternative managers including Carlyle traded lower on the news. Separately, investors requested withdrawal of roughly 15.7% of assets from the Carlyle Tactical Private Credit Fund in the first quarter of 2026, more than three times its standard repurchase limit.303129
May 2026 — First-quarter miss. Carlyle reported distributable earnings of $0.89 per share against $0.91 consensus and down from $1.14 a year earlier, with segment revenue missing consensus by roughly 16% on a sharp decline in realized performance revenue. Shares fell on the report.20
April 2026 — Annual meeting. Shareholders approved the advisory say-on-pay proposal with roughly 82% support, 246.9 million shares in favor and 55.0 million against.16
January 2026 — Dainese handed to creditors. Carlyle transferred ownership of the Italian protective-gear maker to lenders HPS and Arcmont in a debt-for-equity swap for a nominal €1, following a 2024 loss of roughly €120 million that included an €86 million goodwill impairment. European regulators subsequently cleared the transfer.3435
December 2025 — Medline IPO. Carlyle, Blackstone, and Hellman & Friedman completed a $7.2 billion initial public offering of Medline at a valuation of approximately $65 billion, the largest healthcare listing on record, roughly doubling the enterprise value at which they acquired the business in 2021.3233
November 2025 — ManTech loan sale pulled. A $2.3 billion loan sale tied to Carlyle-backed government IT contractor ManTech was withdrawn on weak investor demand.28
October 2025 — FCA Re established. Fortitude Re and Carlyle launched FCA Re, a Bermuda-based sidecar capitalized with more than $700 million to pursue Asian block reinsurance, which Carlyle has framed as adding roughly $10 billion of fee-earning assets over time.[^25]
XIII. Links & Resources
- Carlyle Investor Relations — quarterly earnings releases, supplemental financial data, and investor presentations
- Carlyle quarterly results archive — historical earnings releases and presentations
- The Carlyle Group Inc. Form 10-Q, quarter ended June 30, 2026 — segment detail, AUM roll-forward, and risk factors
- The Carlyle Group Inc. Form 10-K filings on EDGAR — annual reports including full fund performance tables
- The Carlyle Group Inc. 2026 proxy statement (DEF 14A) — executive compensation, board composition, and voting results
- Carlyle Q2 2026 earnings call transcript — prepared remarks and analyst Q&A
- Carlyle Secured Lending investor materials on EDGAR — the listed BDC's quarterly results, useful as a credit-quality read-through
- Private Equity International — PEI 300 — annual five-year fundraising league table
References
-
Carlyle Reports Second Quarter 2026 Financial Results — The Carlyle Group, 2026-08-05 ↩↩↩↩↩↩↩↩↩↩
-
Carlyle Announces Acquisition of Secturion Systems — Carlyle, 2026-07-27 ↩↩↩
-
Freescale Semiconductor Reaches Agreement with Private Equity Consortium in $17.6 Billion Transaction — Blackstone, 2006-09-15 ↩
-
Carlyle's Hawaiian Telcom Files for Bankruptcy — The Washington Post, 2008-12-02 ↩
-
Carlyle Capital in Default, on Brink of Collapse — CNBC, 2008-03-13 ↩↩↩
-
Carlyle Capital Bankrupt, to Wind Up Fund — CNBC, 2008-03-17 ↩
-
The Carlyle Group Prices Initial Public Offering — The Carlyle Group, 2012-05-02 ↩↩
-
The Carlyle Group Raises $671 Million in Its IPO — CNBC, 2012-05-03 ↩
-
The Carlyle Group Names New Executive Leadership Team — Form 8-K Exhibit 99.1, 2017-10-25 ↩↩
-
Glenn Youngkin to Retire as Co-CEO; Kewsong Lee Named Sole CEO — Form 8-K Exhibit 99.1, 2020-07-20 ↩
-
Carlyle Group Inc. — Form 8-K Exhibit 99.1, Kewsong Lee departure, 2022-08-08 ↩↩
-
Carlyle CEO Kewsong Lee steps down in abrupt early departure — CNBC, 2022-08-08 ↩
-
Carlyle CEO's Exit Exposes Fault Lines With Founders — Bloomberg, 2022-08-17 ↩↩↩↩
-
Harvey Schwartz Named CEO of Carlyle and Member of the Board — The Carlyle Group, 2023-02-06 ↩
-
New Carlyle Group CEO Harvey Schwartz hates office politics, has a black belt in karate, and his pay package is inextricably linked to one metric — Fortune, 2023-02-10 ↩↩
-
The Carlyle Group Inc. — Form DEF 14A, 2026 Proxy Statement, 2026-04-23 ↩↩↩↩↩↩
-
The Carlyle Group's fundraising failure — Private Equity Stakeholder Project ↩↩↩↩
-
Carlyle closes flagship Fund VIII under target amid industry slump — Buyouts, 2023 ↩↩↩
-
Carlyle Reports Fourth Quarter and Full-Year 2025 Financial Results — The Carlyle Group, 2026-02 ↩↩↩↩↩↩↩↩↩
-
Carlyle Shares Plunge as Q1 Earnings Miss Estimates — Yahoo Finance, 2026-05 ↩↩
-
The Carlyle Group Inc. — Form 10-Q, quarter ended June 30, 2026, filed 2026-08-10 ↩↩↩↩↩↩↩
-
The Carlyle Group Inc. (CG) Q2 2026 Earnings Call Transcript — Seeking Alpha, 2026-08-05 ↩↩↩↩↩↩↩↩↩↩↩
-
Carlyle eyes Q4 2025 launch for next private equity flagship — Private Equity International ↩
-
Carlyle Advances Insurance Solutions Strategy; Raises $2.1 Billion for Fortitude Re — Carlyle, 2025 ↩
-
Carlyle Secured Lending, Inc. — Form 8-K Exhibit 99.1, Q1 2026 results and dividend declaration, 2026-05 ↩↩↩↩
-
Carlyle Secured Lending: 12.5% Dividend Reduction, Signs Of Stability — Seeking Alpha, 2026 ↩
-
Carlyle Secured Lending: Downside Risks Remain Due To Software Exposure — Seeking Alpha, 2026-06-12 ↩
-
Carlyle-Backed Defense Contractor Pulls $2.3 Billion Loan Sale — Bloomberg, 2025-11-22 ↩↩↩↩↩
-
Carlyle Private Credit Fund Faces Surge In Redemption Requests Totaling 15% — TIKR, 2026 ↩↩↩
-
Cliffwater Private Credit Fund Stung by 17% Redemption Requests — Bloomberg, 2026-06-02 ↩↩
-
Private credit stocks tumble on Cliffwater redemption surge — Investing.com, 2026-06 ↩↩
-
Blackstone, Carlyle and Hellman & Friedman to Invest in Medline — Carlyle, 2021-06 ↩↩
-
Blackstone, Carlyle, Hellman & Friedman Win Deal of the Year for Medline's $7.2B IPO — Private Markets Minute, 2025-12 ↩↩↩↩
-
Carlyle-backed Dainese considering debt restructure following losses — Private Equity Wire, 2025 ↩↩↩
-
Dainese Sale Approved By EU, It's Now Owned By HPS and Ontario Teachers' — RideApart, 2026 ↩↩↩
-
Carlyle Agrees to Sell Jagex to CVC Capital Partners and Haveli Investments — Carlyle, 2024-02-09 ↩
-
Carlyle strikes first deal in new defense push — Semafor, 2026-07-27 ↩↩↩
-
Carlyle Continues to Bring in Capital as Distributable Earnings Climb — The Wall Street Journal, 2026-08-05 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube