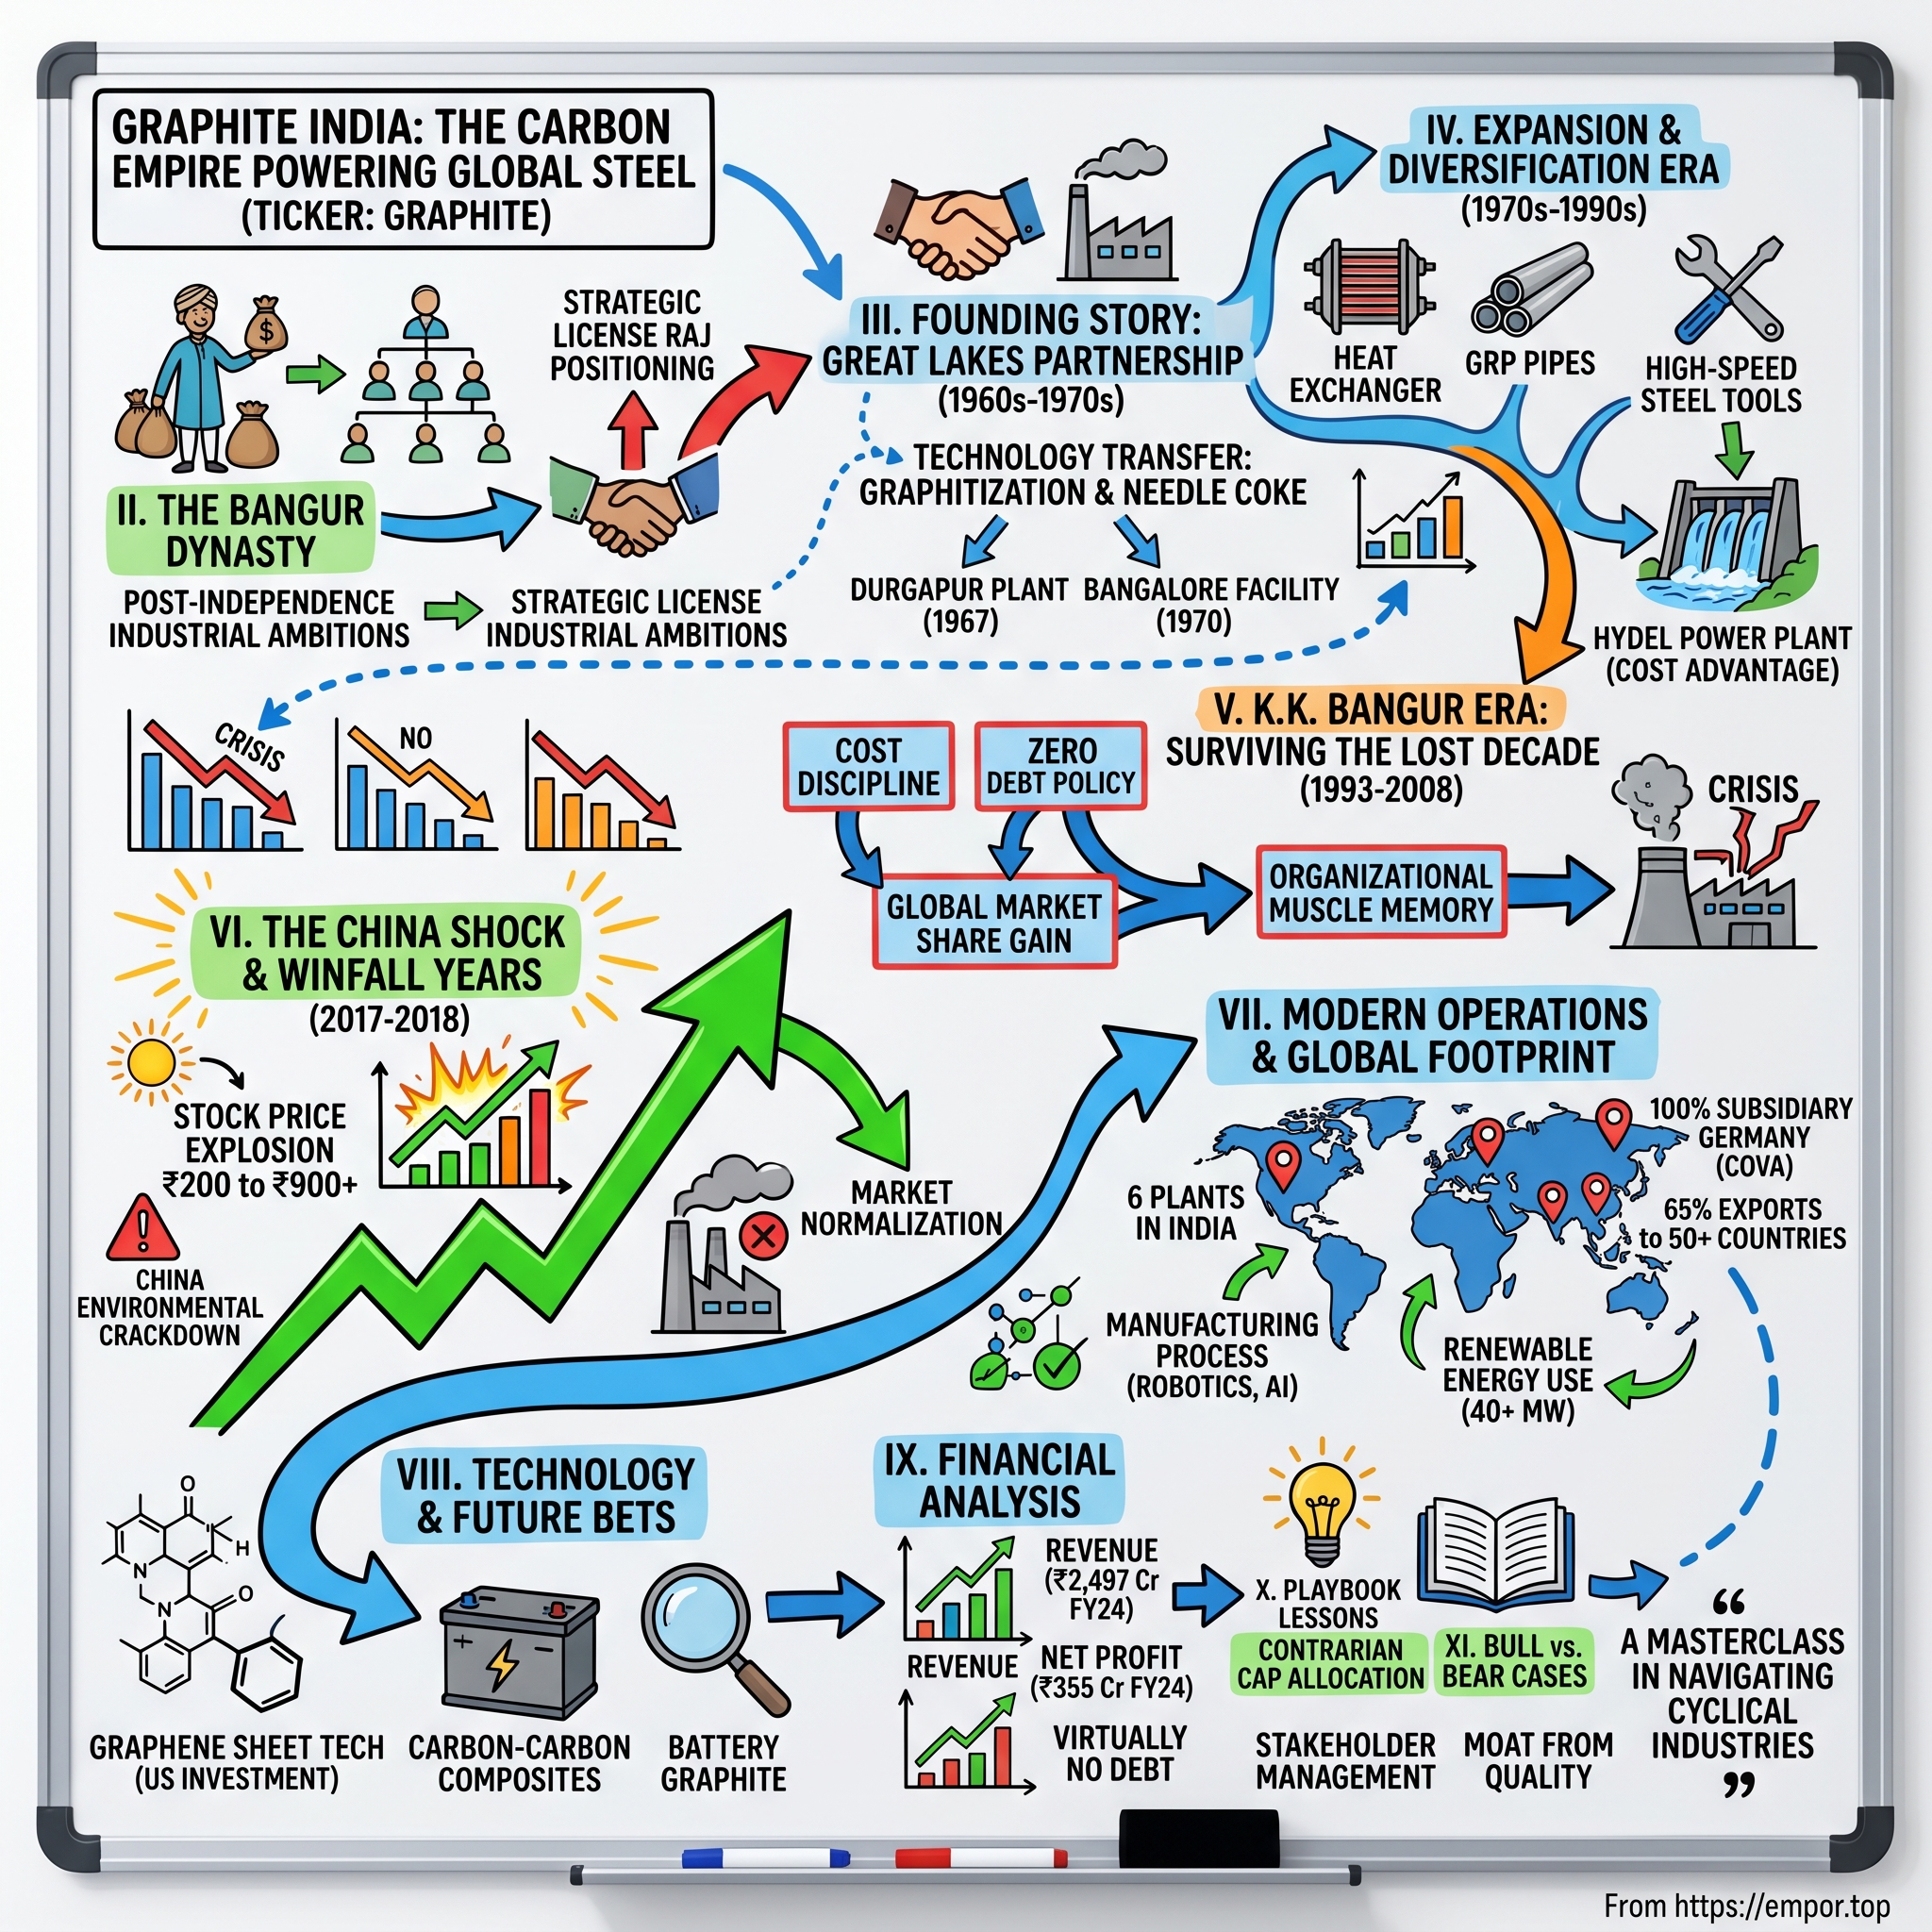
Graphite India: The Carbon Crucible, the Windfall Trap, and the Battery Pivot
I. Cold Open & Episode Roadmap
On September 9, 2026, an announcement from the United States moved a stock in Kolkata. GrafTech International, an indebted American electrode manufacturer, informed customers that it would raise graphite electrode prices by at least 30% worldwide, effective immediately, citing years of falling realization levels alongside rising raw material, energy, and logistics costs. By the close of trading, Graphite India's shares had jumped 14.44% to ₹840.50.1 In an unusual twist, a price hike declared by a foreign competitor proved to be the most potent catalyst Graphite India's shareholders had received all year. Graphite India, as it happens, holds nearly a tenth of that rival.
That single trading session captures the company in miniature. Graphite India Limited, the flagship enterprise of the K.K. Bangur group, produces one primary commercial product: large cylinders of synthetic graphite that serve as consumable electrical conductors in electric arc furnaces. Its financial fortunes rarely reflect operational fine-tuning in any single operating period. Instead, they depend on the global balance between electrode supply and demand, and on the spread between what steelmakers pay for finished electrodes and what the producer pays for needle coke, the petroleum-derived precursor baked into them. In FY2017, the company generated approximately ₹70 crore in net profit on ₹1,468 crore of revenue. Just two years later, in FY2019, net profit surged to ₹3,396 crore on ₹7,858 crore of sales, translating into operating margins of 64%.2 Few industrial manufacturers in India have navigated an earnings swing that violent. By FY2021, it was reporting a loss again.2
Today, the company presents a strategic paradox backed by a liquid balance sheet. At the end of June 2026, it held net cash and liquid investments of ₹3,939 crore,3 against a market capitalization of about ₹15,900 crore on September 24, 2026.2 Cash reserves account for roughly a quarter of its market valuation—a substantial defensive cushion, though noticeably below the 40% figure that occasionally circulates among market commentators. Around that treasury sit three capital allocation commitments that will define the coming decade: a board-approved ₹4,330 crore plan to manufacture synthetic graphite anode material for lithium-ion batteries,4 a 25,000-tonne expansion of the core electrode business,5 and a ₹230 crore portfolio stake of 9.79% in GrafTech itself.6
Why a Humble Cylinder Matters
To understand why this product matters, consider how an electric arc furnace functions. A steelmaker charges a massive refractory-lined vessel with shredded motor vehicles, decommissioned rail track, and demolition scrap. Three graphite columns, each as thick as a tree trunk and several metres in length, descend toward the metal. The furnace operator routes a massive electric current through the assembly, striking an arc from the electrode tips to the scrap like a continuous lightning strike. The metal liquefies into molten steel. Because the electrode tips continuously oxidize and erode in the extreme heat, fresh sections are screwed onto the top of each column while in service, much like extending a pencil that is being sharpened away from the tip.
Only synthetic graphite can perform this role at commercial scale. It conducts electric current efficiently, withstands furnace temperatures without melting, and counter-intuitively gains mechanical strength as temperatures climb. GrafTech's regulatory filings estimate average consumption at approximately 1.7 kilograms of electrode per tonne of electric-arc-furnace steel, with electrode expenditure accounting for roughly 2% of the total cost of producing that steel.7 That economic reality dictates the dynamics of the market: steelmakers cannot operate an electric furnace without electrodes, yet because the product represents such a modest fraction of overall input expenses, mills will pay steep premiums during a shortage. In an oversupplied market, however, buyers can rapidly defer shipments, draw down working inventories, and play suppliers against one another, since no mill purchases more electrodes than its melting schedule demands.
The production sequence is protracted and capital-intensive. Petroleum needle coke is crushed, blended with coal-tar pitch, extruded into dense "green" cylinders, baked, impregnated with additional pitch under pressure, rebaked, graphitized via electrical resistance heating up to roughly 3,000°C, and finally machined with precision threaded sockets. GrafTech describes the cycle as taking about two months on average.7 That production lag explains why supply-demand imbalances swing so violently. Supply cannot ramp up quickly during an unexpected shortfall, and once high-temperature assets are brought online, capacity cannot easily be idled without absorbing severe cash drag.
The Road Ahead
This analysis traces Graphite India across nine movements. It begins with the Bangur family and the licence-raj origins of Indian synthetic graphite, then examines the prolonged downturn when Chinese blast-furnace capacity depressed global electrode consumption and prices. It then analyzes the 2017–2019 windfall—one of the sharpest earnings spikes in modern Indian corporate history—and the ensuing correction: an expensive inventory hangover, the environmental closure of its Bengaluru facility, and the rationalization of its European operations. The second half evaluates the operating business today: global industry structure, unit economics, capital allocation across international ventures, and the capital-intensive battery anode initiative designed to decouple the company from steel industry cycles. It concludes with a strategic scorecard, balanced bull and bear scenarios, and the critical operating metrics investors need to monitor.
The central question running through the story is one the company has yet to resolve definitively: Is Graphite India a disciplined, cycle-tested manufacturer hoarding capital to exploit inevitable downturns, or a conservative holding entity that has conflated caution with strategic direction? Answering that question requires returning to Kolkata, and to an industrial house established decades before Indian independence.
 Subscribe on LinkedIn
II. The Bangur Dynasty & The License Raj Foundations
Chowringhee Road in Kolkata is the kind of address where Indian capitalism kept its offices long before the country had a modern equity market. Graphite India's registered office still sits there, at 311 Chowringhee Road.8 The address serves as a tangible reminder that the enterprise was established as a Marwari family business before it became a widely traded public entity. The Bangurs, a merchant clan with roots in Rajasthan, migrated east during the colonial era and built a diversified industrial empire that eventually spanned cement, paper, textiles, and heavy engineering.
Building Carbon in a Closed Economy
Graphite India traces its origins directly to the planned-economy era. Post-independence industrial policy positioned steel at the core of national development, and every electric steel furnace required consumable carbon conductors. In the 1960s, nearly all graphite electrodes had to be imported, requiring scarce foreign exchange reserves. Domestic manufacturing was the logical solution, but electrode synthesis required specialized thermal and chemical know-how held by a small group of Western producers. The founders pursued the established path for ambitious Indian industrialists of the era: they secured an overseas technical collaborator. The company's integrated graphite electrode plant at Durgapur in West Bengal was commissioned in 1967 in collaboration with Great Lakes Carbon Corporation of the United States, and was described at the time as the first integrated electrode plant in that part of the world.9
The Durgapur location was carefully chosen. It sat in the heart of eastern India's steel belt, close to the state-owned steel mills that served as initial anchor customers and adjacent to the coal and power infrastructure that graphitization requires. Under the Licence Raj, securing an industrial licence, capital goods import permits, and foreign exchange clearances created barriers to entry as formidable as proprietary manufacturing know-how. Those administrative permissions effectively granted domestic market dominance. Yet while regulatory barriers created a captive market, state-granted moats inevitably erode when industrial policy changes.
The Split and the Heir
The pivotal event that shaped the modern company arose from within the dynasty. In 1991, the extended Bangur family partitioned its corporate holdings. Krishna Kumar Bangur's branch received the graphite electrode business among other assets, while another branch, led by Benu Gopal Bangur, took the cement operations.10 The timing was critical. India launched comprehensive economic liberalization that same year, dismantling the import tariffs and industrial licensing regimes that had sheltered domestic electrode producers.
K.K. Bangur assumed full executive control at age 34, following his father's death in 1994. Forbes India later summarized the operational deficit he inherited: a company that "was only a domestic player until then and was not even equipped to produce high-grade electrodes."10 Furthermore, the technical alliance with Great Lakes Carbon, an operating pillar since the 1960s, unravelled after the family split.10 Stripped of its foreign technical partner just as borders opened, the heir faced the strategic challenge that would define his stewardship: whether an independent Indian electrode producer could survive against global competitors on quality and cost.
His response focused on modernizing facilities and targeting international markets. Management upgraded manufacturing processes to produce higher-specification electrodes and aggressively expanded exports across Europe, the Middle East, and Southeast Asia. Graphite India in its current corporate form emerged from a merger of two group companies in 2001.10 Decades later, after the historic pricing cycle of 2018 briefly made him a billionaire on paper, Bangur articulated what remains the company's operating philosophy: "We are in a venture—not an adventure."10
What the Origin Story Explains
That formative era established three durable legacies. The first is proprietary process knowledge: decades of trial and refinement in pitch impregnation, baking profiles, and graphitization recipes. That accumulated operating experience forms the technical barrier separating low-margin commodity producers from manufacturers capable of reliably delivering large ultra-high-power (UHP) electrodes. The second is logistics: manufacturing assets strategically located across eastern and western India, situated close to domestic electric-arc furnaces and export ports.
The third legacy is capital conservatism. Backed by a promoter group that controls roughly 65% of the equity,2 management operates free from market pressure to chase growth for its own sake, with every incentive to safeguard its balance sheet. Over the following two decades, that caution faced a severe test as the rapid expansion of blast-furnace steelmaking in China drove the global graphite electrode market into a protracted downturn.
III. The Lost Decade & The Commodity Crucible (1998–2016)
During the opening decade of the twenty-first century, China expanded blast-furnace steelmaking at an unprecedented pace. These traditional facilities convert iron ore and coking coal into molten iron, which basic oxygen furnaces subsequently refine into steel—a metallurgical sequence that consumes no graphite electrodes. By 2024, China was producing just over a billion tonnes of crude steel annually, with only about 10% originating from electric arc furnaces.11
For electrode producers worldwide, this divergence became the defining structural headwind of the era. Global steel output surged, but the scrap-based electric-arc-furnace segment that required consumable electrodes expanded at a far more subdued rate. In tandem, Chinese mills flooded international markets with inexpensive, ore-derived steel, compressing margins for scrap-reliant mills across Europe, North America, and India. Concurrently, China built an expansive domestic electrode manufacturing base of its own, primarily focused on smaller, standard-power specifications.
Overcapacity as a Way of Life
The consequence was a protracted global glut. GrafTech's 2015 annual report estimated worldwide graphite electrode capacity at roughly 1.85 million tonnes, operating at approximately 65% utilization.7 In an industry where more than a third of installed capacity stood idle, pricing power evaporated. Western producers restructured operations, mothballed plants, or pursued distress sales. Brookfield Asset Management acquired control of GrafTech on August 15, 2015, positioning itself as a patient sponsor "with experience in cyclical capital intensive industries."7 That same regulatory filing identified Graphite India and HEG alongside SGL Carbon, Showa Denko, and Tokai Carbon as GrafTech's principal competitors,7 demonstrating how substantially the Kolkata company had expanded its international stature since its domestic-only beginnings.
Graphite India's financial record during this prolonged downcycle was distinctly unglamorous. In FY2015, the business earned a modest net profit of ₹58 crore on revenue of ₹1,711 crore; by the cyclical trough in FY2017, operating margins slipped below 3%, yielding operating profit of just ₹40 crore.2 It was an enterprise enduring rather than prospering. Yet two strategic choices separated it from more leveraged Western peers: it refrained from taking on heavy debt, and it continued to invest in brownfield capacity. In 2012, it added 20,000 tonnes of capacity at its West Bengal plant for approximately $43 million.10 Adding capacity during a downturn represents a classic counter-cyclical wager, but it pays off only when the market turns—and for most of that decade, the timing of an upturn remained impossible to forecast.
The German Bet
In 2004, K.K. Bangur acquired a bankrupt German electrode manufacturer and set about rehabilitating it.10 Operating as Graphite COVA GmbH in Nuremberg, the acquisition provided the company with a wholly owned European subsidiary and roughly 18,000 tonnes of annual capacity inside the European Union.912 The strategic rationale appeared compelling at the time. A manufacturing base in the heart of Europe positioned the company closer to the continent's major electric-arc-furnace steelmakers, provided a hedge against import duties, and offered German engineering credentials that resonated with conservative European metallurgists.
The acquisition price was not publicly disclosed, precluding any reliable valuation assessment. What can be evaluated is the ultimate operational outcome: as detailed in Section V, the Nuremberg facility ceased electrode manufacturing entirely in 2022. The underlying thesis was coherent when formulated, but it rested on an assumption that proved vulnerable over the long run: that German industrial energy costs would remain globally competitive.
Two Indian Survivors
By the end of those lean years, India possessed only two graphite electrode manufacturers of scale: Graphite India and HEG Limited, an arm of the LNJ Bhilwara group. Credit rating agency ICRA continues to describe Graphite India as "among the only two graphite electrode manufacturers in the country."5 HEG pursued a different architectural strategy than its Kolkata counterpart, concentrating its manufacturing footprint at a single large site in Mandideep, near Bhopal, where it eventually built 100,000 tonnes of annual capacity.13 Graphite India, by contrast, dispersed its operating assets across multiple Indian locations and, for nearly two decades, across two continents.
Characterizing this market structure as a domestic duopoly, however, overstates the commercial insulation it provides. While both companies account for domestic production, graphite electrodes are traded internationally, realizations track global benchmark pricing, and both producers rely heavily on export markets. A domestic duopoly in an open, globally traded commodity bears little resemblance to the pricing leverage enjoyed by regional cement cartels. What the lost decade ultimately instilled in both Indian producers was structural endurance—a discipline that was about to be rewarded on an unprecedented scale.
IV. The China Shock & The Parabolic Super-Cycle (2017–2018)
In 2017, the catalyst arrived from Hebei province. For years, hundreds of unlicensed workshops had operated induction furnaces—basic electrical crucibles that melted scrap into low-grade steel known colloquially as ditiaogang, or "strip steel." The output was cheap, substandard, and heavily polluting. Beginning in 2016 and accelerating across 2017, environmental inspectors intervened as Beijing launched an aggressive campaign against industrial overcapacity and urban smog, an initiative later formalized as the "Blue Sky Defense War." Commodity consultancy CRU estimated that authorities eliminated roughly 125 to 140 million tonnes of illegal steelmaking capacity—predominantly induction furnaces, mini blast furnaces, and outdated blast furnaces—followed by a further 35 to 40 million tonnes of mandated winter curtailments announced in November 2017.14
How a Crackdown Became a Shortage
The policy intervention squeezed the graphite electrode market from both directions at once. On the demand side, induction furnaces use no graphite electrodes. When regulators dismantled those clandestine operations, steel production shifted toward compliant electric arc furnaces that relied directly on electrode columns, even as domestic mills absorbed more scrap. On the supply side, regional environmental audits shuttered smaller domestic electrode baking and carbon plants. CRU characterized the fallout plainly: needle coke and electrode availability had been "under pressure since 2017 following substantial financially- and environmentally-driven capacity closures, particularly in China."14
The international market possessed no spare inventory to cushion the shock. A decade of depressed realizations had already forced Western producers to decommission high-cost plants permanently. Because the specialized manufacturing sequence requires roughly two months,7 surviving operators could not quickly expand throughput. Steelmakers accustomed to purchasing consumable electrodes on short notice suddenly discovered that spot supply had vanished.
Beneath the finished-goods shortage lay a second, tighter supply bottleneck. Ultra-high-power (UHP) electrodes—the massive columns required by industrial-scale electric furnaces—rely on premium needle coke, an anisotropic, highly crystalline carbon derived from petroleum refinery decant oil or coal-tar pitch. CRU noted that UHP electrodes require needle coke for more than 95% of their raw material recipe, compared to only 20% to 30% for lower-grade high-power electrodes.14 Commercial needle coke manufacturing remained concentrated among a handful of global refiners, and the nascent lithium-ion battery sector had begun competing for the exact same precursor to synthesize battery anodes. CRU projected that battery-anode demand for needle coke would expand more than eightfold between 2018 and 2028.14 Electrode manufacturers were abruptly forced to bid for a constrained input against an accelerating clean-technology supply chain just as their own end market experienced unprecedented demand.
The Windfall, in Plain Numbers
For Graphite India, the financial consequences were extraordinary. In FY2018, revenue more than doubled to ₹3,266 crore, while net profit escalated from roughly ₹70 crore to ₹1,032 crore. In FY2019, revenue reached ₹7,858 crore and net profit surged to ₹3,396 crore, generating operating profit of ₹5,020 crore at a margin of 64%.2 To put that sudden windfall in context: over the three fiscal years from 2015 through 2017 combined, the company earned a total net profit of approximately ₹211 crore.2 In FY2019 alone, it delivered sixteen times that three-year aggregate.
Operating metrics illustrate where that capital originated. A heavy industrial plant network operating near capacity cannot suddenly quintuple finished tonnage in twenty-four months; the revenue surge was driven almost entirely by price realization. Graphite India had not reinvented its operating architecture between 2017 and 2019. It simply controlled scarce, installed capacity when the international market placed a historic premium on immediate availability. That distinction mattered: investors who priced the shares on the assumption that FY2019 operating margins represented a structural baseline were capitalizing an ephemeral supply dislocation rather than an enduring competitive advantage.
The wealth creation was immediate. Forbes India reported that FY2018 revenue had doubled to roughly $507 million while net profit surged fourteen-fold to around $159 million, propelling K.K. Bangur onto the publication's national wealth ranking for the first time with an estimated net worth of $1.7 billion, anchored by his family's roughly 65% promoter holding.10 In Bhopal, peer producer HEG recorded an almost identical earnings trajectory. On Dalal Street, both shares became the defining momentum instruments of the season.
What Management Did With the Money
Yet the most critical capital allocation choice of the boom was the commitment Graphite India refrained from making: it did not break ground on a debt-financed greenfield electrode plant. In light of subsequent market developments, that restraint protected the enterprise. Any multi-year expansion commissioned at peak pricing would have come online precisely as global realizations unraveled.
Instead, the board returned a portion of the windfall to shareholders and retained the remainder as liquid capital. Dividend distributions absorbed roughly one-third of net profit in both FY2018 and FY2019,2 returning more than ₹1,000 crore to investors across the two boom years—with approximately two-thirds accruing to the promoter family in line with its equity stake. The retained balance built the corporate treasury that continues to characterize the balance sheet: investment assets that stood at ₹369 crore in FY2015 had expanded to ₹4,063 crore by FY2026.2
Whether that conservatism constituted optimal stewardship remains subject to debate. Proponents emphasize solvency: a cyclical commodity producer with substantial cash reserves can comfortably endure severe downturns that destabilize leveraged peers. Critics observe that holding substantial treasury balances within an operating company creates an ongoing drag on equity returns, locking up capital that shareholders could deploy elsewhere. Financial tracking platform Screener places Graphite India's ten-year average return on capital employed at approximately 5%,2 a figure that incorporates the most profitable operating super-cycle in the industry's history. Regardless of that debate, the fleeting nature of the windfall was about to become unmistakably clear.
V. The Hangover: Environmental Crisis, European Losses & The Collapse (2019–2023)
Commodity booms invariably unwind along a familiar path: buyers stop panic-buying, working inventories refill, mothballed high-cost capacity restarts, and spot realizations decline far faster than operating costs. For Graphite India, the conclusion of the electrode super-cycle arrived through three distinct structural setbacks in rapid succession, each challenging a central pillar of the bull thesis.
The Needle Coke Trap
The first setback stemmed directly from the mechanics of the operating model. Needle coke is procured under quarterly or semi-annual contracts that lag spot market movements, while the multi-stage baking and graphitization cycle forces manufacturers to carry several months of raw materials and work-in-progress. When electrode realizations were surging, that procurement lag expanded operating spreads: mills paid peak spot prices for finished cylinders synthesized from lower-cost coke purchased months earlier. When realizations broke in 2019, that operating leverage reversed with equal force. Graphite India found itself delivering into an oversupplied market using raw materials acquired at peak cycle valuations.
The financial records illustrate the speed of the contraction. Revenue dropped from ₹7,858 crore in FY2019 to ₹3,094 crore in FY2020 and bottomed at ₹1,958 crore in FY2021. Operating performance shifted from an operating profit of ₹5,020 crore to operating losses of ₹86 crore in FY2020 and ₹215 crore in FY2021.2 Within twenty-four months, operating margin plunged from 64% into negative territory.
That inventory squeeze remains an inherent operational risk rather than an isolated cycle aberration. Rating agency ICRA highlights that the business model remains "highly working capital intensive," with net working capital requirements absorbing 35% to 40% of annual revenue, noting that holding substantial inventories "poses the risk of devaluation" whenever market pricing softens, "as witnessed in the previous fiscals."5 Disclosures confirm the ongoing nature of these balance-sheet adjustments: Graphite India recorded an inventory write-down of ₹113 crore at the close of March 2025, which moderated to ₹47 crore by March 2026, reflecting the "overall fall in electrode prices."8 An additional write-down of ₹24 crore followed in the first quarter of FY2027 ending June 2026.1 For analysts modelling the company's normalized earnings power, inventory write-downs represent a recurring feature of cyclical downturns rather than non-recurring extraordinary charges.
Falsification Case One: Whitefield
The second setback challenged the assumption that Graphite India's geographically dispersed Indian manufacturing network represented an unencumbered, low-cost operating foundation. Its Whitefield manufacturing facility in Bengaluru had been constructed decades earlier when the district was an industrial peripheral zone. Over subsequent decades, Bengaluru's information technology boom enveloped the plant in residential housing, commercial office parks, and suburban apartment developments.
Neighbourhood residents had lodged pollution complaints since the late 1990s, and local villagers in nearby Seetharampalya formally petitioned the Karnataka State Pollution Control Board during the early 2000s.15 In 2012, the regulatory board ordered the facility closed for failing to implement mandated emissions controls; in 2014, a state appellate authority overturned that directive in a 2–1 split decision, with the dissenting member urging an independent ambient air-quality inquiry.15 Sustained advocacy by the Whitefield Rising civic federation kept the issue before judicial authorities. On October 29, 2018, during wider air-pollution hearings, the Supreme Court of India held the plant accountable for emissions violations, observing that "Graphite India has taken instructions and will deposit Rs.50 lakhs with the Karnataka State Pollution Control Board."15
While a ₹50 lakh penalty had negligible financial impact on a company generating thousands of crores in operating cash flow that fiscal year, the regulatory outcome proved decisive. Following directives from the National Green Tribunal, manufacturing operations at Bengaluru ceased in February 2019, and the board of directors formally resolved to decommission the facility permanently in April 2019.16 Area residents subsequently reported noticeable reductions in particulate pollution, though the state pollution board refrained from attributing regional air-quality improvements solely to the closure.16
The Whitefield closure demonstrated that domestic operating cost advantages remain conditional. Low conversion costs depended partly on historical environmental tolerances that municipal growth and regulatory scrutiny eliminated. Synthesizing electrodes generates carbon particulate, coal-tar pitch volatiles, and intense thermal emissions, while consuming substantial regional electric power. Operating older pyrometallurgical assets within expanding urban corridors creates regulatory exposure. ICRA now explicitly identifies increasingly stringent air-quality regulations and local community protests as operating risks that "might impact the expansion/modernisation plans."5 Process expertise remained intact, and management redistributed production volume across its remaining 80,000-tonne domestic capacity footprint between Durgapur and Nashik.8 Nevertheless, the episode qualified the low-cost domestic manufacturing thesis: Indian assets maintain an advantage in direct labour costs, but they operate under environmental and community-licence constraints that earlier investment models overlooked.
Falsification Case Two: Nuremberg
The third setback undermined the company's international manufacturing footprint. Following the Russian invasion of Ukraine in 2022, European natural gas and wholesale power costs climbed to historic highs. While industrial energy inflation strained manufacturing broadly, it proved prohibitive for graphitization furnaces, which rely on continuous, intensive electric currents to attain 3,000°C temperatures. In October 2022, executive management halted electrode graphitization at Graphite COVA in Nuremberg, citing severe increases in energy and gas tariffs, and initiated restructuring around its less energy-intensive carbon specialties and coating divisions.12 The German subsidiary accounted for roughly 18,000 tonnes of annual capacity—about 18% of the group's aggregate nameplate footprint of 98,000 tonnes—and had accumulated operating losses across multiple quarters.12
The operational retreat proved final. On July 8, 2026, Graphite India announced the full closure of Graphite COVA's remaining specialty carbon and surface-coating activities, pointing to persistent war-related energy inflation and a protracted cyclical downturn in European specialty demand.17 While ICRA still references the Nuremberg site within the group's nominal 98,000-tonne capacity profile, it classifies the European facility as "currently non-operational."5
The outcome of the 2004 German acquisition was clear. For nearly two decades, the Nuremberg site had provided direct European customer integration and German industrial credentials. Ultimately, however, structurally higher European utility tariffs rendered local high-temperature processing uneconomic. Management chose a phased shutdown over prolonged operating subsidies, permanently mothballing the group's primary overseas manufacturing facility.
The Profit Crater
Between FY2022 and FY2025, consolidated revenue settled into a subdued operating range of ₹2,500 crore to ₹3,200 crore.2 The earnings composition in FY2024 revealed the structural shift in the business: Graphite India posted an operating loss of ₹143 crore, yet reported a consolidated net profit of ₹805 crore, buoyed by ₹1,258 crore in non-operating treasury income and mark-to-market portfolio adjustments.2 For that operating period, the business functioned essentially as an investment fund running an industrial electrode plant. ICRA's performance records reflect that divergence, showing consolidated operating margins sinking to minus 4.9% in FY2024 before recovering to 7.8% in FY2025 as raw material needle coke costs softened.5
That period framed the central strategic tension confronting the company today. Substantial liquid reserves cushioned reported bottom-line results through deep industry downturns. Yet non-operating treasury yield does not constitute a competitive moat in manufacturing, and portfolio income fluctuates across reporting cycles. Evaluating the company's enduring economic value requires examining the competitive discipline of its underlying industrial operations.
VI. Core Business Today: Industry Structure, Economics & The Duopoly
A walk through the Durgapur plant reveals the physical scale of the enterprise: rows of baking furnaces packed with electrodes buried in coke for weeks, graphitization bays drawing as much electric power as a small town, and finished cylinders—some wider than a person's shoulders—resting on racks before being threaded and crated for export across three continents. This is where the overwhelming majority of Graphite India's operating revenue is generated.
What the Company Actually Sells
The Graphite and Carbon segment is the core of the business. In FY2026, it generated approximately ₹2,594 crore of the group's ₹2,852 crore in consolidated revenue.8 Credit rating agency ICRA estimates that graphite electrodes and carbon products account for more than 90% of both consolidated revenue and operating profit.5 The modest remainder originates from glass-reinforced plastic pipes, high-speed and alloy tool steel, and small captive power installations.95 These represent legacy diversifications; none is large enough to alter the investment thesis, and company disclosures indicate management treats them as incidental.
Within electrodes, Graphite India manufactures a broad spectrum of specifications but focuses on large-diameter ultra-high-power (UHP) grades, which ICRA identifies as the "higher margin" segment of the market.5 Operating capacity stands at 80,000 tonnes per annum across its two active Indian facilities in Durgapur and Nashik.8 Capacity utilization, which lingered in the low 80% range during FY2025, rebounded to 104% in the quarter ending March 2026 and remained elevated at 97% in the June 2026 quarter.83 In operational terms, the company's existing plants are running at effective capacity. Near-term volume growth must come from new capacity, and Graphite India is currently adding 25,000 tonnes of electrode capacity, with the initial phase scheduled for commissioning in FY2027.58
The Demand Engine: Where Steel Gets Melted
Electrode demand does not correlate neatly with general economic growth or headline infrastructure expenditure. Instead, it tracks the operating hours of electric arc furnaces. Globally, electric arc furnaces produced approximately 29.1% of total crude steel in 2024, but regional adoption varies widely: roughly 72% in the United States, 44% in the European Union, more than 50% in India, and just over 10% in China.11
That distribution defines both the long-term bull thesis and its near-term constraints. Industrial decarbonization is encouraging steelmakers to transition toward electric arc furnaces, which melt recycled scrap or direct-reduced iron using electricity rather than burning metallurgical coking coal. Company management emphasizes this transition as a primary structural driver. In the FY2026 earnings presentation, K.K. Bangur highlighted the European Union's Carbon Border Adjustment Mechanism, which "entered its implementation phase in January 2026," as an institutional catalyst expected to "accelerate the ongoing global shift from Blast Furnace to EAF based steelmaking."8 Domestic momentum provides additional support: India expanded crude steel production by 10.2% in calendar 2025 to 164.9 million tonnes, even as Chinese steel output contracted by 4.4%.8
Yet the headwinds facing this demand narrative are equally substantive. China still manufactures roughly half the world's crude steel, and its electric-arc-furnace share remains modest;11 even an incremental percentage shift in Chinese steelmaking methods would influence global electrode consumption far more than capacity additions elsewhere. Meanwhile, international steel demand outside India has remained sluggish. The company's presentation projected steel consumption across developing economies excluding China to expand by just 2.5% in 2026, weighed down by geopolitical instability in the Middle East.8 Structural demand growth tied to electric-arc adoption operates as a gradual multi-year tide rather than a sudden surge—and that secular trend had been widely anticipated for years without shielding producers from the severe pricing slump of 2023 through 2025.
The Competitive Map
The global graphite electrode sector is highly concentrated. ICRA observes that production capacity resides predominantly with "five to six major players globally."5 Outside China, the primary manufacturers are Japan's Resonac (formerly Showa Denko) and Tokai Carbon, the United States-based GrafTech International, and India's two domestic producers.718 Inside China, large industrial producers such as Fangda Carbon dominate an expansive domestic sector whose historical expansions focused predominantly on lower-grade high-power specifications.14
For Indian equity investors, the central comparison remains between Graphite India and HEG Limited. HEG operates a single, centralized 100,000-tonne manufacturing complex at Mandideep in Madhya Pradesh, exporting to more than 30 countries.13 Graphite India's 80,000 tonnes of active capacity are divided between Durgapur in West Bengal and Nashik in Maharashtra. Operating a single consolidated mega-facility gives HEG operational scale efficiencies in power procurement, maintenance overhead, and localized logistics, leading several sell-side brokerages to identify HEG as their preferred cyclical vehicle; ICICI Securities highlighted that preference explicitly following the June 2026 quarterly results.3 Graphite India counters with superior liquidity and balance-sheet resilience.
Meanwhile, GrafTech serves as the global benchmark, but its operating position has deteriorated significantly. In the quarter ending June 2026, the American producer shipped 30,800 tonnes at an average realized price of roughly $3,900 per tonne, generating an adjusted EBITDA of just $2 million and recording a net loss of $40 million, while burdened by approximately $1,080 million in net debt.19 An incumbent operator under that degree of financial leverage cannot sustain further price concessions. That operational distress explains why GrafTech's September 2026 decision to raise global electrode prices by at least 30%1 resonated so strongly across the international market.
Unit Economics: The Spread Is Everything
The underlying unit economics of an electrode facility hinge on a single fundamental calculation: the realized selling price per tonne of finished electrode minus the cost of the calcined needle coke required to synthesize it. Conversion expenses—electricity, labour, binder pitch, freight, and depreciation—remain meaningful, but they are relatively predictable. The operating spread between the finished electrode price and raw needle coke costs dictates corporate profitability.
Credit rating agency ICRA uses this spread as an explicit benchmark, noting that it could downgrade Graphite India's credit profile if a sustained industry slump compresses "the industry spread between GE and needle coke (CNC) prices to below $1,600 per tonne on a sustained basis."5 During the first half of FY2026, average electrode realizations fell approximately 12% compared to the prior-year period; softening needle coke procurement costs provided partial relief, but net spreads contracted nonetheless.5 K.K. Bangur provided a corresponding assessment in late 2025, noting that operating margins remained constrained by a "subdued pricing environment" alongside "raw material costs not declining in line with electrode prices."20
Electrical power represents the second decisive cost variable. Because graphitization relies on resistance heating, utility tariffs determine which manufacturing facilities remain viable across cyclical troughs—a reality underscored by the idling and closure of the Nuremberg plant. In India, power-related risks manifest through regulatory and legal friction: Graphite India's FY2026 financial statements incorporated ₹15 crore in interest stemming from an adverse judicial order in an electricity duty dispute.21 Direct labour costs offer Indian manufacturers an advantage against peers in Europe, Japan, and North America, but that benefit is partially diluted by reliance on imported needle coke and maritime shipping expenses. Regional conflicts in West Asia elevated ocean freight and transit expenditures through early 2026, with the chairman noting operational adjustments caused by the "rationing of certain energy based inputs."8
Trade Walls Cut Both Ways
A recurring assumption in Indian market commentary suggests that trade barriers primarily insulate domestic manufacturers from low-cost Chinese competition. By 2026, however, international trade dynamics have increasingly turned against Indian exporters.
Early in 2026, the United States initiated anti-dumping and countervailing duty investigations into imports of large-diameter graphite electrodes from both China and India, prompted by petitions from domestic manufacturing subsidiaries of Resonac and Tokai Carbon. In July 2026, the U.S. Department of Commerce published preliminary countervailing subsidy rates: 3.68% for Graphite India and 6.99% for HEG, compared to a punitive 103.49% assigned to Chinese exporters, with final determinations scheduled for December 8, 2026.18 Direct financial exposure to the American market remains modest—India's electrode shipments to the United States totaled just $2.2 million in 202518—yet the regulatory precedent carries broader implications. In Brazil, foreign trade authorities initiated an anti-dumping investigation in March 2026 following a petition filed on July 31, 2025, by GrafTech's Brazilian subsidiary. That petition alleged an Indian dumping margin of $1,607 per tonne, or 57.3%—substantially higher in proportional terms than the 9% margin alleged against Chinese suppliers.22
These actions challenge the premise of a sheltered domestic duopoly. Graphite India operates as an export-reliant manufacturer whose international competitors are aggressively petitioning for trade protection. While its preliminary U.S. duty rate compares favourably against domestic peer HEG and Chinese competitors, that determination remains interim. The final American ruling in December 2026 and the subsequent Brazilian findings will test whether Indian electrode producers can preserve unrestricted access to key export jurisdictions.
VII. Capital Deployment & M&A Benchmark: From Nürnberg to GrafTech
Every family-controlled, cash-rich enterprise eventually confronts the same fundamental question from public minority shareholders: whose capital is this, and what is its strategic purpose? At Graphite India, that question has grown acute because management's capital allocation over the past two decades has encompassed fundamentally disparate bets: a distressed German electrode manufacturer, a speculative American graphene start-up, a minority stake in a leveraged American competitor, and a massive greenfield battery-materials complex. Each warrants scrutiny on the disclosed operational record rather than through corporate press releases.
Myth Versus Reality: The Cash Floor
The myth: Graphite India is insulated by cash, with liquid treasury reserves accounting for nearly half its market valuation, providing an impregnable downside floor for the equity.
The reality: Cash and liquid investments stood at ₹4,134 crore in March 2026 against gross debt of ₹367 crore, yielding net cash of ₹3,767 crore;8 net cash expanded to ₹3,939 crore by the end of June 2026.3 Measured against a market capitalization of roughly ₹15,900 crore,2 liquid reserves represent about a quarter of equity value. While that constitutes a substantial cushion, three structural factors qualify its defensive strength. First, the treasury is exposed to market volatility: in FY2026, management acknowledged that treasury yields were "severely impacted due to volatility in financial markets," as other income contracted from ₹438 crore to ₹174 crore.8 Second, significant portions of that liquidity are already spoken for. The board-approved ₹4,330 crore synthetic anode initiative is slated for funding through "a mix of internal accruals and debt,"5 reinforced by shareholder approval in August 2026 authorizing the board to issue up to ₹5,000 crore in non-convertible debentures and bonds.23 Third, cash balances inside a promoter-controlled enterprise establish an effective valuation floor for public minority investors only if capital is eventually returned through dividends or buybacks. Its ultimate value to shareholders depends entirely on how prudently it is deployed.
The drag of retaining that liquidity is directly visible in headline returns. Financial tracking platform Screener reports the company's three-year average return on equity at roughly 4%, with return on capital employed lingering near 3% in FY2026.2 While cyclical weakness in electrode pricing explains part of that underperformance, basic balance-sheet arithmetic accounts for the rest: when a substantial share of total assets sits in debt mutual funds and fixed-income instruments generating modest single-digit pre-tax yields, consolidated returns on capital will struggle to achieve double digits even during respectable operating periods for the core business.
The Optionality Test: General Graphene
On September 2, 2018, near the peak of the electrode windfall, Graphite India's Netherlands subsidiary agreed to invest up to $18.595 million in staged tranches in General Graphene Corporation, a US-based start-up developing roll-to-roll production of large-area graphene sheets, securing an initial equity interest of approximately 46%, with tranches tied to development and manufacturing milestones.24 Graphene—a two-dimensional lattice of carbon atoms—is among the most celebrated materials in modern materials science, but also one of the most notoriously difficult to produce economically at commercial scale.
Eight years later, Graphite India has expanded its ownership stake to 60.25%, with group disclosures maintaining that General Graphene has "developed a breakthrough proprietary technology."8 What disclosures have not demonstrated is material commercial revenue. General Graphene is not reported as an independent operating segment, and across FY2026 all non-graphite operations combined accounted for only about a tenth of revenue.8 Graphite India did enter into an arrangement in December 2025 with Kivoro to distribute a graphene-based heat-transfer additive across India's corrugated paperboard sector,25 signaling ongoing commercialization trials, but at volumes that remain immaterial to consolidated results.
The eight-year operational record indicates that General Graphene remains a speculative research-and-development option rather than a self-sustaining commercial enterprise. That outcome carries implications that extend beyond advanced carbon films. It represents the company's sole track record in translating an early-stage material science frontier into commercial revenue, and to date the tangible cash contribution remains negligible. That history provides an important operational precedent when evaluating the group's far larger pivot into battery anode manufacturing.
The Strategic Shock: Buying a Piece of GrafTech
On September 22, 2025, Graphite India disclosed that it had acquired 6.82% of NYSE-listed competitor GrafTech International for ₹168.13 crore through open-market transactions under India's Overseas Portfolio Investment regulations.26 On May 11–12, 2026, management disclosed an additional ₹62.25 crore of purchases, expanding the equity position to 9.79% and bringing its cumulative capital outlay to roughly ₹230 crore.6 Management justified the investment by pointing to GrafTech's global manufacturing footprint and its backward integration into petroleum needle coke.26
GrafTech was trading at depressed multiples for understandable reasons. Brookfield had taken the company private in 2015 near a cyclical trough,7 and the post-boom hangover had battered its financial structure. Its balance sheet carried roughly $1.2 billion in gross debt, with principal maturities deferred until December 2029, while its core operations were barely generating positive EBITDA by mid-2026.19 What GrafTech did possess, however, was Seadrift, its proprietary petroleum needle coke facility in Texas. GrafTech's regulatory disclosures noted that Seadrift provided approximately 140,000 tonnes of annual calcined coke capacity, establishing the enterprise as the industry's only vertically integrated electrode producer.7
Graphite India was not the first Indian manufacturer to pursue this equity foothold. Peer producer HEG acquired an 8.23% interest in GrafTech for ₹248.62 crore in October 2024, categorizing the allocation strictly as an investment asset.27 Together, the two Indian competitors hold roughly 18% of their foremost Western rival. HEG took the initial initiative; Graphite India's market purchases followed eleven months later.
Stress-Testing the GrafTech Thesis
There are three possible rationales for the investment, each supported by the public record to differing degrees.
A treasury bet on a cyclical recovery. This interpretation aligns most directly with regulatory filings. The shares were acquired through portfolio-investment channels rather than as a formal strategic alliance, and the holding remains below the 10% threshold. The mark-to-market swings have been severe. In the quarter ending March 2026, a sharp decline in GrafTech's share price generated a ₹212 crore fair-value loss that drove consolidated EBITDA to an operating loss of roughly ₹139 crore. In the subsequent quarter ending June 2026, a ₹73 crore mark-to-market gain helped lift reported profit.283 Absorbing a ₹212 crore valuation swing in a single quarter on a ₹230 crore cumulative cost outlay underscores how volatile the exposure is. Because GrafTech's equity trades as a thin junior tranche atop approximately $1 billion in net debt,19 minor percentage shifts in its total enterprise value trigger violent swings in its stock price.
A raw-material hedge. Upstream needle coke access is an undeniable strategic vulnerability. Brokerage ICICI Direct argued that the allocation provided a hedge "from raw material volatility and supply disruptions arising from the ongoing West Asia conflict."6 Yet an open-market portfolio holding beneath 10% conveys no legal entitlement or contractual call on Seadrift's production. Unless formalized into an off-take agreement, the position serves as a hedge only in the indirect sense that GrafTech's share price might appreciate if global needle coke markets tighten.
A seat at the consolidation table. If GrafTech is ultimately forced into a comprehensive debt restructuring, large equity blocs might theoretically seek a voice in any corporate reorganization, where broader industry capacity discipline could lift benchmark realizations. However, GrafTech's substantial debt load sits senior to its common equity. In a court-supervised or creditor-led restructuring, bondholders rather than minority equity investors dictate terms, leaving common shareholders vulnerable to substantial dilution or outright elimination.
A curious contradiction complicates all three explanations. On July 31, 2025, GrafTech's Brazilian operating subsidiary filed an anti-dumping petition alleging that Indian electrode producers were dumping material into Brazil at a 57.3% margin22—filed less than two months before Graphite India disclosed its initial share accumulation. In July 2026, GrafTech management affirmed that it was aggressively pursuing "trade cases in key jurisdictions, including the United States and Brazil" to defend pricing structures.19 Graphite India is effectively deploying treasury capital to accumulate shares in a direct competitor that is actively petitioning trade tribunals to impose punitive tariff walls against Indian exports. While a global recovery in electrode realizations engineered by GrafTech would theoretically lift benchmark prices for all surviving mills, this legal friction dispels any narrative that the stake represents a coordinated strategic alliance.
The unvarnished conclusion is that the GrafTech investment currently functions not as a strategic operating lever, but as a volatile, leveraged equity position. That assessment would change only under two specific conditions: if the companies negotiate a formal supply agreement, governance board seat, or collaborative operational pact; or if GrafTech enters a restructuring in which Graphite India leverages its voting block into genuine corporate influence. In the absence of either development, investors should treat the holding as a volatile equity portfolio position whose quarterly mark-to-market fluctuations will continue to distort reported operating results.
A governance footnote highlights the regulatory friction that such capital deployments generate. On March 30, 2026, the BSE issued a formal surveillance inquiry regarding an unusual surge in Graphite India's trading volumes. The company responded that it had "no undisclosed material information."29 While there is no suggestion of impropriety, a capital-intensive manufacturer deploying liquid treasury reserves into discretionary overseas equity trades naturally invites heightened market scrutiny.
VIII. The Next Battlefield: The ₹4,330 Crore Battery Anode Gamble
Gonde is an industrial corridor in Maharashtra's Nashik district. In August 2025, it became the designated staging ground for the largest capital commitment in Graphite India's history. Under a memorandum of understanding signed with the state government on August 29, 2025, the company proposed to build a synthetic graphite anode material facility there, announced at the time as a ₹4,761 crore project.3025 In late January 2026, the board formally approved a revised ₹4,330 crore phased investment in synthetic anode manufacturing, structured to be funded through a mix of internal accruals and debt.425
Why Anodes, and Why Graphite India
Every lithium-ion battery cell requires two electrical terminals. The anode, on the negative side, consists overwhelmingly of graphite—either mined natural flake that has been purified and spheroidized, or synthetic graphite synthesized from petroleum needle coke and related carbon precursors. Synthetic anode manufacturing shares foundational thermal and chemical processes with electrode production. Both begin with heavy hydrocarbon feedstocks, and both require intensive graphitization at extreme temperatures approaching 3,000°C. The divergence lies in physical form and chemical precision: steelmaking electrodes are massive, machined solid cylinders, whereas battery anode material is an engineered, coated powder whose particle morphology, surface area, and chemical purity must adhere to exacting cell-maker specifications.
The strategic rationale is straightforward. Global electrode demand tracks the cyclical fortunes of electric-arc steelmaking, offering modest volume growth over long cycles. Battery demand in India, by contrast, is expanding rapidly from a nascent base. Brokerage ICICI Direct estimated domestic lithium-ion cell demand at 150 to 160 gigawatt-hours by 2030, translating into roughly 140,000 tonnes of annual anode material consumption, and projected that an Indian manufacturing operation could generate "25%+ EBITDA margins and 20%+ ROCE."31 For Graphite India, the project promises a second operating pillar: leveraging decades of high-temperature graphitization expertise and deploying surplus balance-sheet liquidity to decouple corporate earnings from the steel cycle.
The operational contours are precisely defined. Credit rating agency ICRA reports a planned aggregate capacity of roughly 30,000 tonnes per annum for an estimated ₹4,330 crore, structured around an initial 10,000-tonne phase budgeted at approximately ₹1,600 crore, targeted for commissioning within three fiscal years.5 Emphasizing the operational risks inherent in such a large greenfield venture, ICRA identified "timely execution and funding tie up" alongside the project's impact on corporate leverage as "a key rating monitorable."5
The Falsification Test: Who Sets the Price of Anode Material?
Any projection of twenty-five percent operating margins must be evaluated against the market that dictates global clearing prices. That market is China, and its anode manufacturing sector has been locked in an aggressive price war.
Chinese producers—led by industry giants such as BTR New Material Group, Ningbo Shanshan, and Putailai—expanded graphitization assets well ahead of downstream battery demand. Commodity pricing agency Fastmarkets reported that China's synthetic anode graphitization capacity more than doubled in just nine months, surging from roughly 1.0 million tonnes in March 2022 to over 2.3 million tonnes by December 2022. Shanshan's Yunnan manufacturing hub alone inaugurated a 200,000-tonne initial phase in June 2023, representing a 9.7 billion yuan investment, even as market participants warned the commissioning would compound "the current market weakness amid the slow demand and excess supply."32 By mid-2023, synthetic anode grades that had commanded a pricing premium over natural graphite earlier that year were trading at steep discounts to it.32
Placed in that global context, Graphite India's entire planned 30,000-tonne footprint represents roughly one-seventh of a single phase at Shanshan's Yunnan complex. Chinese incumbents possess colossal scale advantages, captive precursor access, highly subsidized industrial power in regions such as Inner Mongolia and Yunnan, and deeply entrenched commercial qualification partnerships with global tier-one battery manufacturers. An Indian greenfield facility cannot underprice that industrial ecosystem on direct unit conversion costs. It must compete on an entirely different commercial premise.
The Policy Hedge, and Its Fragility
That alternative premise is geopolitical diversification. Automotive original equipment manufacturers and battery cell-makers across North America, Europe, and India increasingly seek supply chains independent of Chinese domestic processing. Beijing has demonstrated a willingness to use its dominant position in synthetic graphite as strategic leverage. On October 9, 2025, Chinese trade authorities announced sweeping export controls governing lithium-ion batteries, graphite anode materials, and related manufacturing equipment and technical know-how. Four weeks later, on November 7, 2025, authorities suspended the implementation of those restrictions until November 10, 2026.33 That deadline is now only weeks away. Whether Beijing allows the suspension to lapse, implements strict licensing quotas, or extends the waiver will provide an immediate test of the economic premium international buyers are willing to pay for non-Chinese anode material.
Yet policy premiums represent a precarious foundation for multi-decade capital investments. Beijing demonstrated how rapidly regulatory levers can be engaged and paused, and an export restriction that can be suspended or reinstated arbitrarily cannot guarantee sustained pricing power for high-cost alternative mills. Furthermore, Western trade defense measures against imported Chinese materials face high evidentiary thresholds and can fail during final injury determinations before trade tribunals. Graphite India's synthetic anode thesis rests substantially on a sustained geopolitical premium, and financial models should discount that margin assumption accordingly.
The Domestic Race
Within India, domestic peer HEG holds a decisive head start. Its dedicated subsidiary, TACC Limited, is constructing a synthetic graphite anode facility at Dewas, near Indore, with an initial capacity of 20,000 tonnes per annum. Budgeted at over ₹2,000 crore and backed by ₹1,250 crore in project debt from the State Bank of India, the plant is scheduled for commercial commissioning in the first quarter of 2027, supported by a demonstration and testing unit at Mandideep that is already conducting qualification trials with international battery manufacturers.34
The Dewas project also provides an instructive case study in execution timelines. When HEG originally announced its battery anode initiative in November 2022, executive management projected that the first phase would be "operational by 2025";35 that commissioning target has since migrated to early 2027.34 Graphite India is therefore positioned to enter the market as the second domestic producer, trailing a domestic rival building twice its initial nameplate capacity. Crucially, both companies will be seeking customer off-take agreements within a domestic battery cell manufacturing sector that remains largely in development.
Weighing It
Management presents the battery anode initiative as an engine of secular, counter-cyclical growth. The historical record suggests three specific reasons for analytical caution. First, the group's prior frontier material science venture, General Graphene, has generated negligible commercial revenue after eight years of equity funding. Second, its last major capital project outside India—the German electrode operation—was dismantled by industrial power tariffs that management could not control. Third, the execution experience of its direct peer demonstrates friction: HEG's anode timeline has already stretched by approximately two years relative to initial guidance.
Against those cautionary precedents stand legitimate competitive advantages: decades of operational familiarity with high-temperature graphitization chemistry, a liquid treasury capable of underwriting the ₹1,600 crore initial phase without financial distress, and an evolving international trade architecture that encourages geographic diversification away from Chinese processing. The balanced conclusion is that Graphite India's anode thesis remains structurally viable but unproven, with commercial prospects narrower than headline capital commitments imply. The venture represents a credible candidate to emerge as a policy-favoured regional supplier to Indian and Western cell-makers, albeit at operating margins well below the elevated projections of sell-side models.
The milestones that would validate the thesis are unambiguous: a binding, disclosed off-take or commercial qualification agreement with a tier-one battery manufacturer, alongside on-time commissioning of phase one within its ₹1,600 crore capital budget. Conversely, the evidence that would falsify the investment thesis would be a project delay extending past the three-year commissioning horizon highlighted by ICRA, or a protracted global pricing slump in which Chinese synthetic anode exports remain structurally below any realistic Indian production cost.
IX. Strategic Position: Porter's 5 Forces & Hamilton Helmer's 7 Powers
Consider a procurement manager at a major electric-arc-furnace steel mill in the Middle East in the spring of 2026. She has competing bids on her desk from Kolkata, Bhopal, Japan, and China, knowing full well that the global electrode market has endured three consecutive years of oversupply. She also knows that suppliers' production lines are running hot, shipping routes through West Asia face elevated freight rates, and GrafTech is recording operating losses. Applying strategic frameworks to Graphite India is effectively a formal method of evaluating who holds the upper hand in that commercial negotiation, and why that bargaining power oscillates so violently across the commodity cycle.
Porter's Five Forces
Supplier power: high. Calcined needle coke, the decisive raw material, originates from a tightly concentrated cohort of petroleum refiners and coal-tar distillers, with GrafTech's captive Seadrift facility standing as one of the few integrated sources outside China and Japan.7 Concurrently, lithium-ion battery anode manufacturers compete for the exact same precursor stream, with commodity consultancy CRU projecting that anode-related needle coke demand would expand severalfold over the decade.14 Because procurement contracts lag spot movements, suppliers capture the operating spread during an upswing, leaving electrode manufacturers exposed to inventory write-downs when the cycle turns. Electrical utility power, the second primary input, remains regulated, capital-intensive, and susceptible to regional tariffs, legal disputes, and supply disruptions.
Buyer power: moderate to high, and intensely cyclical. Steelmakers purchase consumable electrodes through periodic competitive tenders and routinely maintain multiple qualified vendors. Because electrodes represent only about 2% of overall steel conversion costs,7 mills exhibit limited price sensitivity during acute shortages, paying steep premiums for immediate delivery. In an oversupplied market, however, that dynamic reverses: buyers can switch between approved producers with negligible friction, defer contracted purchase orders, and deplete in-house safety stock. The 12% decline in average electrode realizations during the first half of FY20265 illustrates that commercial leverage in practice.
Threat of new entrants: low for ultra-high-power electrodes, higher for standard grades. Commissioning a commercial ultra-high-power manufacturing facility requires decades of proprietary thermal profiling, substantial high-voltage electrical grid infrastructure, and protracted qualification testing with conservative furnace operators. For that reason, global manufacturing capacity outside China remains concentrated among five or six primary producers.5 China represents the structural exception to this barrier. Domestic Chinese producers have repeatedly demonstrated the capacity to add capacity at scale, and their gradual technical ascent into higher-specification grades represents the foremost long-term threat of entry.
Threat of substitutes: very low in core steelmaking electrodes. No commercially viable substitute for synthetic graphite electrodes exists in electric arc furnaces; the material's unique combination of electrical conductivity, thermal stability, and mechanical strength at 3,000°C remains unmatched. The substitution risk operates at the broader technology level: steelmakers can modulate their operating balance between scrap-melting electric furnaces and traditional blast furnaces, or eventually adopt alternative direct-reduction and smelting routes with differing consumable requirements. In the battery anode arena, however, substitution risk is tangible, as cell chemistries incorporating silicon-carbon composites or alternative solid-state architectures could alter long-term graphite consumption trajectories.
Rivalry: high. A highly concentrated market structure has done little to soften competitive intensity. Protracted global overcapacity, driven primarily by expanded Chinese output, has depressed benchmark realizations for years, forcing manufacturers to compete not only on pricing and terms, but through international trade litigation, as reflected in anti-dumping and countervailing duty proceedings in the United States and Brazil.1822
Hamilton Helmer's 7 Powers
Hamilton Helmer's strategic framework poses a more exacting test than Porter's structural analysis: Does the enterprise possess a durable structural power that enables it to generate economic returns above its cost of capital, protected by a barrier that prevents competitors from replicating it?
- Scale economies: weak to moderate. Graphite India ranks among the largest non-Chinese electrode manufacturers,5 but its domestic competitor HEG operates a larger single manufacturing complex at Mandideep,13 while China's aggregate industrial capacity dwarfs all Western and Indian producers combined. Scale delivers incremental efficiencies in procurement and overhead absorption, but offers insufficient pricing power to defend operating margins during an industry glut.
- Network economies: none. Graphite electrodes are consumable industrial goods; utilization by one steel mill confers no direct or indirect utility to another.
- Counter-positioning: none. Graphite India operates an orthodox, capital-intensive manufacturing architecture identical to that of its global peers.
- Switching costs: low to moderate. Qualifying an alternative electrode supplier requires operational trials, and in-furnace electrode breakages entail expensive downtime. Nonetheless, major steel mills routinely maintain multiple pre-qualified vendors specifically to switch procurement volumes based on delivered price.
- Branding: low. Steelmakers evaluate graphite electrodes on rigorous, quantifiable technical metrics—bulk density, electrical resistivity, flexural strength, and consumption rates per tonne of crude steel melted—rather than corporate brand equity.
- Cornered resource: partial and eroding. The specialized capability to synthesize large-diameter ultra-high-power electrodes reliably is technically scarce, but it is not proprietary to Graphite India. Furthermore, needle coke access—the genuinely scarce physical resource—remains controlled by upstream refiners rather than electrode converters.
- Process power: moderate. Decades of accumulated shop-floor experience in pitch impregnation, baking profiles, and graphitization cycles represent a genuine operational asset that cannot be easily or quickly duplicated. The limitation of process power, however, is that while it optimizes yields and lowers internal defect rates, it cannot insulate realizations when industry-wide capacity exceeds market demand.
The strategic synthesis is that Graphite India possesses operational capabilities rather than a structural economic moat. It functions as a disciplined, well-capitalized participant within a concentrated global oligopoly that behaves like an uncoordinated commodity sector throughout most of the cycle. Its profitability remains tethered to cyclical timing and strict conversion cost discipline, while its long-term survival is anchored by balance-sheet solvency. Neither analytical framework identifies a structural mechanism that allows mid-cycle returns to compound comfortably above the cost of capital. A ten-year average return on capital employed of roughly 5%2 is entirely consistent with that economic reality.
X. Management Credibility, Governance & The Capital Allocation Record
K.K. Bangur has led the company for more than three decades. He has also held Singapore permanent residency since 2012, obtained, Forbes India reported, as part of a deliberate push to expand internationally.10 His public communication occurs primarily through formal chairman's statements accompanying earnings presentations, and his characterization of the business as a "venture—not an adventure"10 functions more as a corporate risk doctrine than a marketing slogan. The promoter group's equity holding has remained constant at 65.34% across recent reporting periods.2
Governance on the Record
The annual general meeting on August 4, 2026, offered a clear snapshot of shareholder voting patterns. Every proposed resolution passed comfortably: K.K. Bangur's reappointment secured 99.36% support, while an enabling mandate authorizing the board to issue up to ₹5,000 crore in debt securities garnered 99.99% approval. The lowest tally, at 94.13%, governed commission payments for non-executive directors.23 With the promoter group controlling nearly two-thirds of the voting equity, these margins reveal little about independent minority sentiment, but no resolution encountered organized public dissent.
Several pending legal and accounting matters warrant ongoing monitoring. Beyond the disputed electricity duty interest charge, the company faces unresolved income tax appeals relating to FY2018–19 and FY2019–20—the peak windfall years—which could crystallize into future cash liabilities.21 Adjustments under India's new labour codes resulted in an ₹11 crore exceptional charge in FY2026.8 Meanwhile, assessing inventory at net realizable value represents a substantial accounting judgment across volatile cycle turns: the balance-sheet write-down provision shifted from ₹113 crore in March 2025 to ₹47 crore in March 2026,8 swinging reported operating margins alongside it.
Promises Versus Outcomes
A balanced audit of management's stewardship requires distinguishing what the leadership team controls from exogenous commodity swings.
On the positive side of the ledger, management avoided the debt burdens that pushed Western peers into distress. Consolidated gearing stood at an austere 0.03 times in March 2025,5 and credit rating agency ICRA maintained its AA+ rating with a stable outlook through three years of severe industry turbulence.5 Management exercised restraint by refusing to break ground on speculative greenfield electrode capacity at the 2018 market top, and it moved decisively to shutter the uncompetitive German subsidiary rather than sustaining open-ended cash subsidies.
On the negative side, the record of deploying capital outside the domestic electrode core is distinctly troubled. The 2004 German acquisition ended in complete operational closure. The Bengaluru plant was permanently shuttered after two decades of community pollution disputes. General Graphene has failed to generate material commercial revenue after eight years of funding. And the minority investment in GrafTech has delivered sharp mark-to-market volatility without yielding disclosed strategic off-take or operational integration. None of these missteps was reckless in isolation, and none threatened corporate solvency. Taken together, however, they reveal a consistent pattern: management's discipline has proved most effective when deciding not to deploy capital, and least compelling when attempting to build or acquire new operating assets. That historical asymmetry provides the essential context for evaluating the ₹4,330 crore battery anode commitment, which dwarfs every previous corporate venture.
What the Analysts Keep Asking
Earnings conference discussions and sell-side coverage between FY2022 and FY2026 converged on four unresolved themes, eliciting management responses that have been consistent, if seldom exhaustive.
The cash question. Why maintain nearly ₹4,000 crore in liquid treasury assets rather than distributing surplus capital to shareholders? Management's official position, reiterated across investor communications, cites the necessity of maintaining balance-sheet liquidity "for future organic and inorganic growth."8 The greenfield anode project and the open-market accumulation of GrafTech shares now represent the tangible manifestation of that strategy, shifting the debate from whether surplus reserves should be spent to whether these specific commitments represent prudent capital allocation.
The inventory question. Why do operating margins collapse so violently during cyclical downswings? Management routinely attributes these margin contractions to raw material procurement costs "not declining in line with electrode prices."20 While factually accurate, disclosures have not outlined a concrete operational strategy to compress the raw material procurement lag or hedge against downstream inventory devaluation.
The GrafTech question. Does the US shareholding represent a strategic commercial alliance or a passive market wager? Statutory filings define the allocation strictly as an overseas portfolio investment and nothing more.266 In the absence of a governance seat or contractual off-take agreement, investors are fully justified in evaluating the holding as a volatile equity trade.
The anode question. Where are the qualified anchor customers? As of September 2026, the company has disclosed no binding commercial off-take commitments or formal testing partnerships with battery cell-makers. The chairman's operational update noted only that the project "continues as previously announced."8 For the largest capital expenditure program in the group's history, that degree of disclosure remains thin, leaving investors with limited visibility into actual commercial adoption.
The Activist's Memo
A constructive institutional shareholder or activist investor scrutinizing Graphite India's balance sheet would likely target three distinct governance reforms. First, the introduction of a formal capital allocation framework that explicitly demarcates what portion of the treasury is surplus to core operational requirements and the phased anode outlay, returning that excess capital through structured share buybacks or regular special dividends. Second, the establishment of transparent hurdle rates and staged capital commitments for the synthetic anode project, ensuring that phase two capital is released only after phase one satisfies verified commercial volume and return-on-capital benchmarks. Third, an explicit mandate governing the GrafTech investment: management should either articulate a concrete strategic roadmap with measurable commercial objectives, or reclassify the holding under a disciplined treasury investment mandate with defined risk boundaries. None of these proposals challenges the enterprise's underlying solvency. Instead, they address the central governance question confronting public investors: whether minority shareholders are being appropriately compensated for their long-term patience.
XI. Bull vs. Bear Case & What to Watch
By late September 2026, the graphite electrode market stands at an ambiguous inflection point. Graphite India's domestic plants are running at effective full capacity, and GrafTech has announced an across-the-board global price hike of at least 30%,1 having already secured fresh purchase commitments at premiums of 15% or higher above first-quarter pricing levels.19 Yet Graphite India's financial results for the quarter ending June 2026 showed realized electrode prices still slipping, falling 4% sequentially.3 Evaluating the company requires weighing an overdue cyclical pricing recovery against persistent structural vulnerabilities.
The Bull Case
A cyclical price recovery takes hold. After three consecutive years of global oversupply, the highest-cost Western incumbent is bleeding cash and posting operating losses at the EBITDA line,19 prompting it to push through aggressive price increases. In cyclical commodity sectors, pricing turns when the marginal supplier can no longer absorb cash burn. With Graphite India's capacity utilization running above 95%,3 any sustained price increase flows almost directly into expanded operating spreads without sacrificing sales volume. If those higher realizations hold, the depressed conversion spread between finished electrodes and raw needle coke will widen rapidly.
A structural decarbonization tailwind. Electric arc furnaces already account for close to 30% of worldwide crude steel output.11 Institutional catalysts such as the European Union's Carbon Border Adjustment Mechanism, combined with India's rapidly expanding, electric-arc-heavy domestic steel sector,8 provide durable baseline growth in consumable electrode consumption outside China. While this transition represents an incremental secular shift rather than an explosive super-cycle, it systematically raises the demand floor of each successive downturn.
Favourable relative positioning in Western trade disputes. The preliminary countervailing duty rate determined by the United States Department of Commerce assigned Graphite India a modest 3.68% subsidy tariff, lower than domestic rival HEG's 6.99% and a negligible fraction of the punitive 103.49% levied on Chinese manufacturers.18 If Western jurisdictions erect higher protectionist barriers against Chinese carbon products, a lightly penalized Indian producer stands to capture export market share.
Balance-sheet liquidity and strategic optionality. Net cash and liquid investments of approximately ₹3,900 crore3 fully underwrite the 25,000-tonne brownfield electrode expansion and the initial phase of the synthetic anode project without overextending the balance sheet. That liquid hoard also provides management with rare flexibility to acquire distressed overseas assets or intervene opportunistically should Western competitors face formal financial restructuring.
Anode optionality supported by geopolitical realignments. Beijing's willingness to deploy export controls across its battery and graphite supply chain, even when temporarily suspended,33 reinforces Western and Indian automaker demand for localized, non-Chinese procurement. Decades of proprietary graphitization know-how position Graphite India to exploit that geopolitical premium.
The Bear Case
The price increases may fail to stick. GrafTech's unilateral price increase reflects acute corporate balance-sheet distress rather than genuine market tightness, and Chinese electrode exporters have demonstrated no comparable capacity discipline. The June 2026 quarter's sequentially lower realizations and a fresh ₹24 crore inventory write-down1 demonstrate that the cyclical downturn had not concluded by mid-2026.
The battery anode venture could become a capital sink. Massive Chinese overcapacity has already driven synthetic anode processing margins into a prolonged slump,32 and Graphite India enters the domestic race as the second mover behind HEG's larger, dedicated TACC facility.34 Furthermore, the group's track record in commercializing advanced material science—epitomized by eight years of funding General Graphene without material revenue—warrants caution regarding execution timelines and cell-maker qualifications. If phase one faces cost overruns or yields sub-par spreads, it will depress consolidated returns for years while introducing external leverage to the balance sheet for the first time in decades.
Protectionist barriers turning against Indian exporters. Brazil's anti-dumping petition alleges an Indian dumping margin of 57.3%, significantly higher in relative terms than the margin alleged against Chinese mills,22 while ongoing American trade investigations could establish precedents for other regional steel hubs. For an export-dependent producer needing to place output from 80,000 tonnes of active capacity alongside 25,000 tonnes of upcoming expansion, unrestricted international market access is increasingly vulnerable.
Treasury volatility and earnings opacity. Operating results in FY2026 demonstrated that investment yields can contract abruptly during market turbulence, while the open-market GrafTech equity stake can swing quarterly consolidated profit by hundreds of crores of rupees through non-operating mark-to-market valuations.828 Reported financial results are increasingly decoupling from core shop-floor operating fundamentals, complicating earnings visibility for public shareholders.
Structural cost pressures on raw needle coke. As battery manufacturers aggressively compete for premium petroleum needle coke feedstocks without corresponding additions to Western refinery capacity, the structural operating spread for electrode producers could settle permanently below historical mid-cycle averages. ICRA's explicit credit downgrade sensitivity—triggered if the finished electrode to needle coke spread compresses below $1,600 per tonne on a sustained basis5—defines the threshold where cyclical margin compression threatens balance-sheet quality.
The Three KPIs That Matter
For investors navigating the noise of commodity swings, mark-to-market portfolio adjustments, and corporate announcements, the investment thesis distills into three critical operating indicators:
- The electrode-to-needle-coke spread. The realized price per finished tonne minus the delivered cost of calcined needle coke dictates group gross margins. ICRA's downgrade sensitivity of $1,600 per tonne5 provides an essential reference benchmark; quarterly management commentary on average realizations and procurement lags indicates whether that spread is structurally recovering or deteriorating.
- Capacity utilization during the capacity ramp. Capacity utilization hovering near 100% across the existing 80,000-tonne domestic asset base8 provides the business with its primary operating defense. The forward test is whether management can absorb the additional 25,000 tonnes of upcoming capacity without sacrificing price realization or accumulating unremunerative inventory.
- Synthetic graphite anode material execution milestones. Performance against the estimated ₹1,600 crore initial phase budget and the three-year commissioning timeline tracked by ICRA,5 paired with verified disclosures of commercial qualifications or binding off-take contracts with cell manufacturers. Until accredited commercial volumes ship, the battery anode pivot represents capital expenditure rather than earnings power.
XII. Epilogue: The Dual Nature of Industrial Carbon
In the soot-stained history of Whitefield and the humming bays of Durgapur lies the central paradox of Graphite India. Carbon was the quintessential villain of the twentieth-century industrial narrative: coal smoke, blast-furnace emissions, and the airborne particulate that Bengaluru residents spent two decades fighting to eliminate. Yet carbon has also emerged as a critical enabler of twenty-first-century clean technology. It forms the consumable columns of the electric arc furnaces that recycle scrap into steel with a fraction of the emissions of blast furnaces, and it supplies the powdered anodes of the lithium-ion batteries that store renewable energy and power electric vehicles. The same elemental material—and often the same high-temperature graphitization technology—occupies both sides of the global energy transition.
For investors, the company's six-decade corporate history offers a narrower, more pragmatic lesson. Graphite India did not endure by making prescient commercial bets; its exploratory ventures, from the Nuremberg acquisition to early-stage graphene research, produced little tangible cash return. It endured because it managed its balance sheet with defensive rigor, kept debt negligible, dismantled operations that could no longer cover their operating costs, and held liquid reserves through prolonged industrial downturns that destabilized or restructured better-known global rivals. Yet that very conservatism explains why its long-term equity returns have remained subdued. A manufacturing enterprise designed primarily to survive the cyclical trough is rarely optimized to compound capital smoothly across the cycle.
The coming chapter will test whether that defensive inheritance can support an offensive transformation. In its core electrode operations, domestic facilities are running at effective capacity just as competitor price increases hint at an overdue cyclical recovery. Meanwhile, the corporate treasury accumulated during the 2018 windfall is finally being committed to capital projects: a board-approved ₹4,330 crore synthetic anode development and an open-market portfolio stake in a leveraged American rival. For the first time in modern memory, an industrial house whose primary competitive virtue was balance-sheet restraint is deploying capital on a transformative scale. Whether the operational discipline that preserved Graphite India through half a century of commodity shocks can successfully build a competitive clean-technology business is the strategic question that will define its seventh decade.
References
-
Graphite India surges 14% as US rival GrafTech hikes global electrode prices by 30% — Trade Brains, 2026-09-09 ↩↩↩↩↩
-
Graphite India Ltd consolidated financials, shareholding and market data — Screener, 2026-09-24 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Graphite India reported mixed performance in Q1FY27 — ICICI Direct, 2026-08-05 ↩↩↩↩↩↩↩↩
-
Graphite India Board approves ₹4,330 crore investment in synthetic graphite anode materials — ScanX, 2026-01-28 ↩↩
-
Graphite India Limited: Ratings reaffirmed — ICRA, 2026-01-30 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Graphite India raises stake in US-based GrafTech to 9.79% with ₹62 crore investment — ICICI Direct, 2026-05-12 ↩↩↩↩
-
GrafTech International Ltd. Form 10-K for fiscal year 2015 — U.S. SEC, 2016 ↩↩↩↩↩↩↩↩↩↩↩
-
Q4 and FY2026 Earnings Presentation — Graphite India Limited, 2026-05-28 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Graphite India Ltd. – Carbon pioneers in India — StockEdge ↩↩↩
-
Graphite India: Historical arc — Forbes India, 2018 ↩↩↩↩↩↩↩↩↩↩
-
The share of EAF in global steel production in 2024 increased to 29.1% — GMK Center, 2025-06-12 ↩↩↩↩
-
Graphite India plans to shut down its German graphite electrode production — ICICI Direct, 2022-10-03 ↩↩↩
-
Needle coke market under pressure: is there an end in sight? — CRU Group, 2019-05-09 ↩↩↩↩↩↩
-
The long road to clean air: Behind the court ruling on GIL's Whitefield plant — Citizen Matters, 2018-11-19 ↩↩↩
-
Graphite: Pollution levels claimed to fall following closure of Graphite India's Bengaluru plant — LinkedIn (Sue Shaw), 2019 ↩↩
-
Graphite India shuts 2 German divisions citing high energy costs and low demand — Sahi, 2026-07-08 ↩
-
Commerce preliminary countervailing duty investigations of large diameter graphite electrodes from China and India — International Trade Administration, 2026-07-27 ↩↩↩↩↩
-
GrafTech Reports Second Quarter 2026 Results (Form 8-K exhibit) — U.S. SEC, 2026-07-24 ↩↩↩↩↩↩
-
Graphite India navigates headwinds with strategic diversification in Q3 FY2026 — Multibagg, 2026-02-10 ↩↩
-
Graphite India FY26 revenue up 16%, profit declines 41% on charges — Whalesbook, 2026-05 ↩↩
-
Initiation of anti-dumping investigation: graphite electrodes from China and India — Chambers and Partners, 2026-03 ↩↩↩↩
-
Graphite India shareholders approve ₹5,000 crore debt mandate — ScanX, 2026-08-04 ↩↩
-
Graphite India subsidiary to invest $18.595 million in General Graphene Corporation — Graphene-Info, 2018-09-02 ↩
-
Graphite India invests ₹4,330 Cr in synthetic graphite anode materials for lithium-ion batteries — Saur Energy, 2026-01-29 ↩↩↩
-
Graphite India buys 6.82% stake in GrafTech International for ₹168 crore — India Infoline, 2025-09-22 ↩↩↩
-
HEG picks up 8.23% stake in GrafTech International — India Infoline, 2024-10-07 ↩
-
Graphite India reported a healthy performance in Q4FY26 — ICICI Direct, 2026-05-29 ↩↩
-
Graphite India denies insider info after stock volume jump — Whalesbook, 2026-03-30 ↩
-
Nashik: Investment proposals worth thousands of crores signal industrial expansion — Free Press Journal, 2025-08 ↩
-
Graphite India signed MoU with Maharashtra to invest in synthetic graphite anode material projects — ICICI Direct, 2025-09-01 ↩
-
Yunnan Shanshan fires up new graphite anode project amid challenging market conditions — Fastmarkets, 2023-07-07 ↩↩↩
-
China temporarily suspends export controls on key raw materials, including rare earths, lithium batteries and diamonds — CIRS Group, 2025-11-07 ↩↩
-
TACC's ₹2000 crore leap into lithium-ion battery anode manufacturing — EVreporter, 2026-03-10 ↩↩↩
-
HEG Limited to invest INR 1000 crore into a new manufacturing facility for graphite anode — EVreporter, 2022-11-14 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube