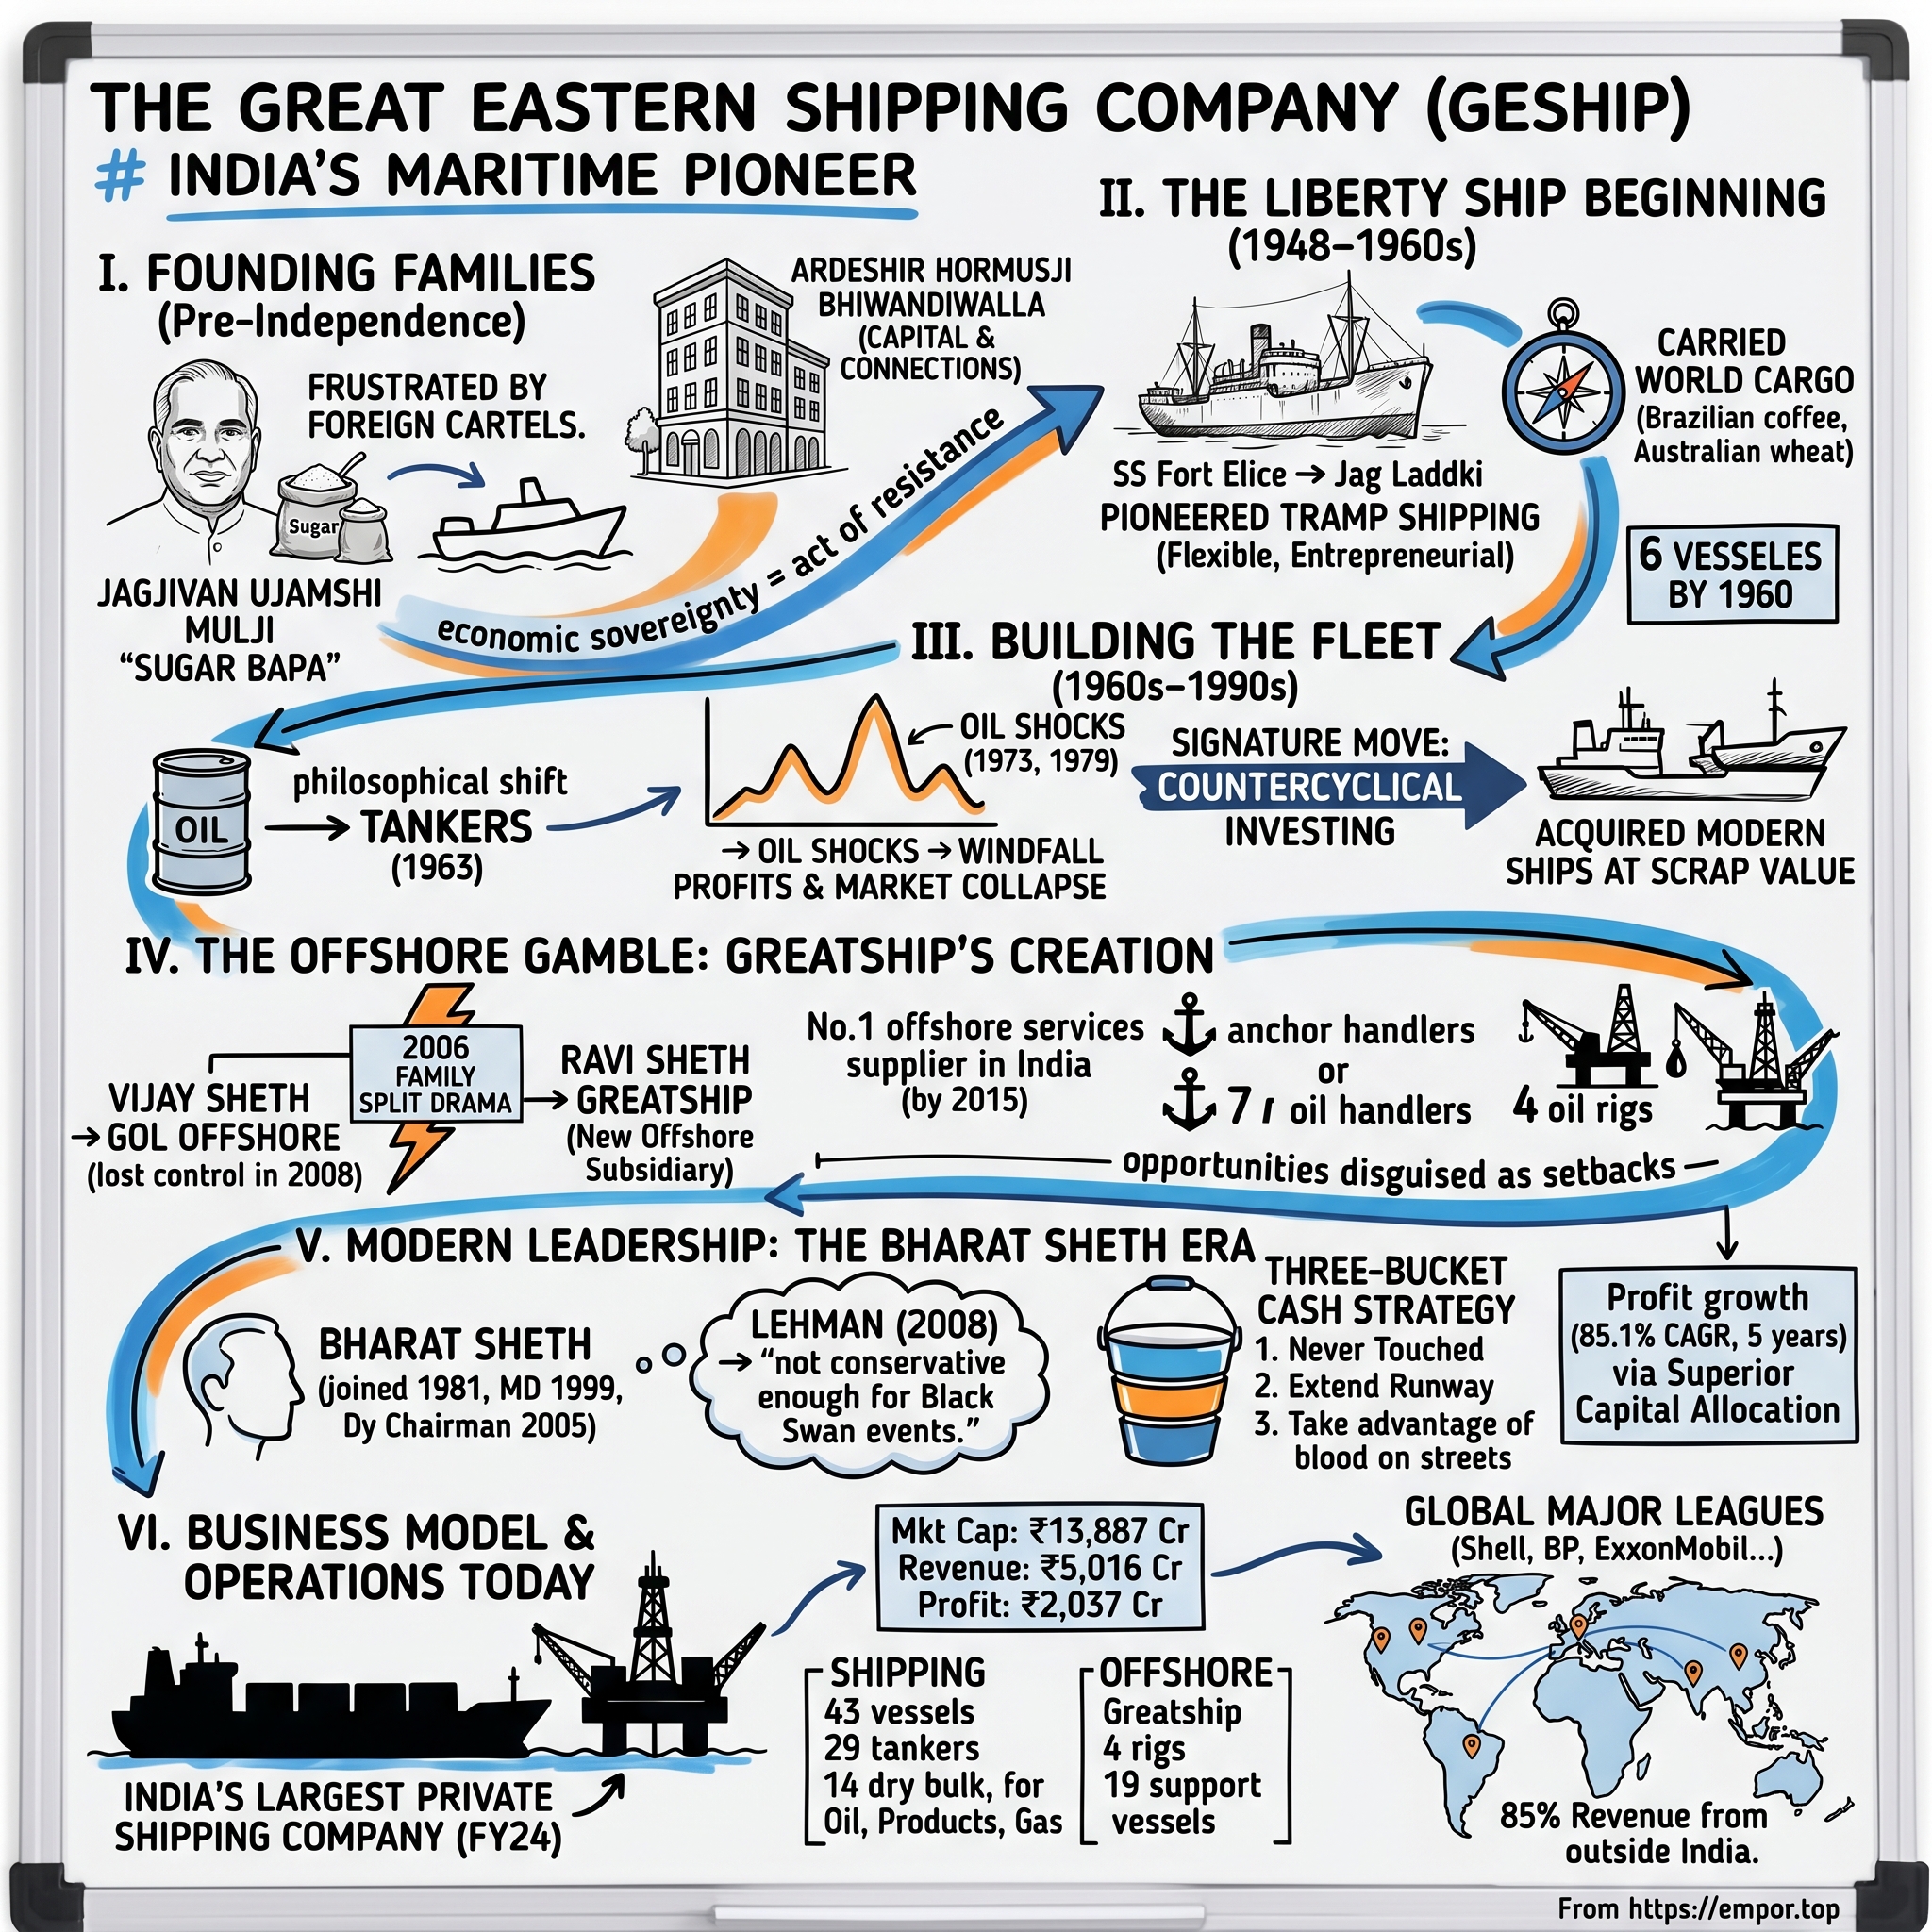
Great Eastern Shipping: India's Counter-Cyclical Maritime Fortress
I. Introduction & Episode Roadmap (10–15 min)
The ship that came back
In the first quarter of 2026, a 2015-built Very Large Gas Carrier joined the fleet of The Great Eastern Shipping Company. Management gave it a name that long-time observers of the business recognized immediately: Jag Vijay.1 Seventy-eight years earlier, the company's inaugural vessel had carried that exact name—a mothballed wartime Liberty ship purchased second-hand as the founding families set out to establish an Indian merchant fleet from scratch.2
The modern Jag Vijay arrived in a markedly different operating climate. Following the closure of the Strait of Hormuz, Middle Eastern crude exports dropped by roughly half within a single month, pushing tanker charter rates to levels that would have appeared unimaginable just a few years earlier.1 Great Eastern's shipping division posted the strongest quarter in its history, and then eclipsed that performance in the April–June quarter of 2026 with a consolidated net profit of roughly ₹1,309 crore over three months.3
This performance highlights a fundamental puzzle. Commercial shipping has historically destroyed shareholder capital: it provides a commoditized service priced on spot markets, demands vast capital commitments, and remains vulnerable to volatile geopolitical shocks, shipyard order backlogs, and fluctuating monthly iron ore purchases by Chinese steelmakers. Yet Great Eastern, a family-promoted business based in Mumbai, has weathered nearly every major shipping downturn since Indian independence, entering late 2026 with cash reserves far exceeding its debt. How the business engineered that resilience is the core question.
The modern profile
Great Eastern trades as GESHIP on the National Stock Exchange and 500620 on the BSE.1 The company operates as India's largest private-sector provider of maritime shipping and oilfield services across two operating divisions.1
The first is the standalone shipping operation. As of May 2026, it controlled 39 vessels aggregating approximately 3.19 million deadweight tonnes, comprising 5 crude oil tankers, 15 refined product tankers, 4 liquefied petroleum gas (LPG) carriers, and 15 dry bulk carriers.1 Fleet adjustments through early August 2026 brought that tally to 40 vessels and roughly 3.24 million deadweight tonnes.3
The second division is Greatship (India) Limited, a wholly owned offshore energy services subsidiary. Greatship owns and operates 4 jack-up drilling rigs alongside 19 offshore support vessels, including anchor-handling tug supply vessels, platform supply vessels, multipurpose support vessels, and remotely operated vehicle (ROV) support units.1
For the fiscal year ended March 31, 2026 (FY26), consolidated revenue including other income reached approximately ₹6,312 crore, yielding reported EBITDA of about ₹4,051 crore. Reported consolidated net profit touched a record ₹2,943 crore, aided partly by foreign exchange gains; on a normalized basis adjusting for currency movements, net profit stood at ₹2,688 crore.1 By fiscal year-end, consolidated net cash totaled roughly ₹7,402 crore against gross debt of ₹1,049 crore.1 The company's disclosed consolidated net asset value (NAV) stood at ₹1,796 per share in March 2026 before expanding to ₹1,886 per share by June 2026.13
In February 2025, CRISIL upgraded Great Eastern's long-term credit rating to AAA/Stable from AA+/Positive, pointing to financial leverage that had remained comfortably below 1.0x equity for an entire decade.4 That distinction provides crucial context: the top-tier credit rating arrived late in the cycle, earned during an extraordinary freight rate upswing.
The central enigma, and the roadmap
The central insight is not that Great Eastern discovered a way to bypass shipping cycles. It has not. The group absorbed heavy write-downs during the 2010s, endured a multi-year downturn in its offshore subsidiary, and maintains an older average fleet profile than many international peers would permit. The substantive thesis is more focused: management designed the business model to survive severe sector downturns, preserve liquidity, and acquire distressed tonnage from overleveraged competitors at cyclical bottoms.
This analysis examines that counter-cyclical framework. Section II traces the company's 1948 origins and its foundational tramp-shipping philosophy. Section III explores the family restructuring, the eventual collapse of spun-off Great Offshore, and the conservative balance-sheet discipline Bharat Sheth codified following the 2008 global financial crisis. Section IV details how each fleet segment generates operating cash flow, while Section V unpacks the core capital-allocation playbook: acquiring second-hand tonnage, maintaining a net cash balance sheet, and returning capital to shareholders. Section VI tests this strategic thesis against moments where historical execution deviated from stated policy. The concluding sections evaluate the three operating metrics that matter most, assess the bull and bear investment cases, and confront the fleet decarbonization challenges and leadership succession questions lying ahead.
The trajectory begins where modern Indian mercantile history often starts: with physical commodity traders.
 Subscribe on LinkedIn
II. Origins, Tramp Pioneering & The Pre-Liberalization Crucible (1948–1980s) (25–30 min)
Sugar, textiles and a Parsi financier
In the Bombay of 1948, newly independent India faced an immediate commercial constraint: its ports were active, yet virtually all maritime cargo moved aboard foreign vessels. British-dominated liner conferences dictated freight tariffs across primary shipping lanes, leaving domestic merchants with little negotiating leverage.
Two Gujarati brothers encountered this bottleneck directly. Maneklal Ujamshi Mulji and Jagjivan Ujamshi Mulji had established a textile trading business before expanding into sugar distribution. Maneklal's success in coordinating that distribution network earned him the moniker "Sugar King."2 Jagjivan managed the chartering operations, having learned the mechanics of maritime freight while hiring vessels to transport imported sugar. Corporate records describe him as driven by commercial ambition alongside nationalist conviction.2
Underwriting the venture required external capital, which arrived through Ardeshir Hormusji Bhiwandiwalla, a prominent Parsi financier. Bhiwandiwalla stepped in as the inaugural Chairman, steering the board from 1948 until 1973.2 Great Eastern took shape in 1948 as a structured partnership between the Sheth and Bhiwandiwalla families.2
Both families left institutional signatures that persist across the fleet today. Every Great Eastern vessel carries the prefix "Jag" in honor of Jagjivan, while the company's house flag and vessel funnels display the initials "AHB" commemorating Bhiwandiwalla.2 Few Indian enterprises of that vintage still maintain their founders' direct identifiers across every operational capital asset.
The Liberty ship and the tramp
That initial asset was the SS Fort Elice, a surplus wartime Liberty ship that had been laid up before the nascent firm acquired and rechristened it Jag Vijay.2 Purchasing a decommissioned vessel offered an economical entry into an industry with high capital barriers. More importantly, it established an acquisition playbook that would define the company's capital allocation for decades: acquiring unloved, discounted second-hand tonnage and deploying it into cash-generative trades.
The operational architect behind this strategy was Jagjivan's son, Vasant J. Sheth. Internal company histories identify Vasant as the prime architect of Great Eastern, crediting him with introducing the commercial tramp-shipping model to India's domestic maritime sector.2
Tramp shipping represents the antithesis of scheduled liner services. Where a liner operates along predetermined routes on a rigid timetable, much like a municipal bus service, a tramp vessel functions like an on-demand taxi, steaming wherever charterers need cargo moved. The shipowner books revenue on prevailing voyage or time-charter rates and immediately seeks the next fixture. While this operational flexibility exposes owners directly to volatile spot-rate swings, it rewards astute commercial judgement regarding regional cargo imbalances and voyage economics.
Great Eastern adhered to this tramp philosophy across nearly eight decades. In May 2026, the company's chief financial officer characterized the fleet as a portfolio of "highly liquid assets operating in the spot market," deliberately eschewing long-term, fixed-contract industrial shipping commitments.5 That strategic focus stands out in Indian corporate history, where few industrial firms have maintained an identical operating doctrine across multiple macroeconomic eras.
Operating inside the License Raj
For its first four decades, Great Eastern navigated the administrative strictures of the License Raj, operating in one of the most thoroughly regulated post-war market environments outside the planned socialist economies. Acquiring tonnage required bureaucratic clearances, foreign exchange allocations remained tightly rationed, and vessel debt typically ran through state-directed financial channels. While granular historical records of regulatory interactions from this era are not disclosed in recent corporate filings, the broader outcome is documented: Great Eastern endured, preserved private ownership, and emerged ahead of the 1991 economic reforms as India's primary private counterweight to the state-owned Shipping Corporation of India.
The managerial generation that steered the business through those decades continues to influence corporate governance. K. M. Sheth joined Great Eastern in 1952, took a board seat in 1970, assumed the role of Deputy Chairman and Managing Director in 1975, and rose to Chairman and Managing Director in 1992.1 He retired from the chairmanship in November 2025 following a tenure spanning more than seven decades, after which the board designated him Chairman Emeritus for life.1 At that juncture, Bharat K. Sheth, who had entered the business in 1981, succeeded him as Chairman and Managing Director.1
That managerial continuity represents a critical operational asset. Executive leadership trained directly under veterans who had navigated multiple multi-year shipping cycles—an institutional memory that proves difficult to replicate in an industry where cyclical downturns routinely wipe out unseasoned operators.
The drift toward energy
Across successive fleet renewals, Great Eastern shifted away from break-bulk general cargo toward bulk commodity transportation. Management expanded sequentially into crude oil tankers, clean product carriers, LPG gas vessels, and modern dry bulkers, before later establishing an offshore oilfield exploration and production services arm. By the mid-2000s, the conglomerate housed both shipping and offshore oilfield assets within a single corporate entity, with distinct branches of the founding family presiding over the two divisions. Managing those competing capital priorities within one balance sheet proved increasingly fraught.
The initial half-century embedded the core traits of Great Eastern's operating model: counter-cyclical acquisitions of second-hand tonnage, deliberate spot-market exposure, and a merchant's discipline regarding asset valuation. Yet that institutional framework was approaching an unprecedented test of family governance—one that would ultimately fracture the business and sever part of the founding dynasty from the corporate fold.
III. The Great Demerger & The Lehman Crucible: 2006–2009 (35–40 min)
A family divides the fleet
In corporate India, family settlements typically unfold quietly in lawyers' offices and emerge publicly as concluded transactions. Great Eastern's restructuring followed that path. Following reported board-level disagreements, the offshore business was carved out into a newly incorporated entity, Great Offshore Limited, established in April 2005. Under the agreed settlement, the core Great Eastern shipping business remained under the stewardship of K. M. Sheth.6
Vijay K. Sheth, who had directed Great Eastern's offshore division, took charge of the independent firm. Great Offshore debuted on the Bombay Stock Exchange on December 21, 2006, listing at ₹727 per share.6
Vijay Sheth was not the first family member to depart. His cousin Ghanshyam Sheth had earlier managed Gesco Corporation, a property development enterprise that originated as a Great Eastern division. In 2000, Gesco confronted a hostile takeover bid from a minority shareholder. The family successfully defended the company with backing from the Mahindra group and HDFC, and the business eventually evolved into Mahindra Lifespace Developers under the majority ownership of Mahindra & Mahindra.6 With two separate branches of the family now operating outside the parent enterprise, subsequent years demonstrated how decisively capital structure and leverage governed their respective fates.
The boom and the pledge
Initial operating results appeared vindicating. Amid an offshore drilling boom, Great Offshore's shares surged from their listing price to reach an all-time peak of ₹1,101.9 on January 7, 2008.6 By fiscal year 2009, the company reported annual net profit of roughly ₹211 crore, more than doubling the ₹91 crore generated at the time of demerger.6
The fundamental vulnerability lay not in vessel demand, but in the promoter's ownership financing. To consolidate a stake of approximately 15% in Great Offshore, Vijay Sheth borrowed heavily, pledging a substantial portion of his equity holdings to financial institutions including Motilal Oswal and IL&FS.6 Promoters pledging shares against debt essentially take on margin loans: if the underlying stock drops significantly, lenders issue margin calls demanding additional collateral or liquidate the shares on the open market.
When the global financial crisis struck in 2008, equity valuations plunged. By December 29, 2008, Great Offshore's stock had collapsed to ₹208.85, down over 80% from its January peak.6 With margin calls intensifying, Vijay Sheth sought emergency liquidity, securing a ₹240 crore loan from the promoters of Bharati Shipyard and pledging 5.53 million Great Offshore shares as collateral.6
The bidding war
When the loan obligations could not be met, Bharati invoked the pledge. In May 2009, Bharati assumed ownership of a 14.89% equity stake at ₹315 per share. The invocation reduced Vijay Sheth's holding to less than 1%, stripping him of managerial control.7 What ensued became one of corporate India's most fiercely contested hostile takeover dramas.
On June 4, 2009, Bharati launched an open offer to acquire an additional 20% stake at ₹344 per share. Nineteen days later, rival shipbuilder ABG Shipyard mounted a counter-bid, offering ₹375 per share for a 33.8% stake. Bharati countered by purchasing another 14.5% in a bulk transaction at ₹403 per share while lifting its open-offer price to ₹405. ABG raised its bid to ₹450 and subsequently to ₹520, prompting Bharati to escalate to ₹560. In December 2009, on the eve of the tendering period, Bharati raised its offer once more to ₹590 per share, at which point ABG abruptly withdrew from the contest.7
ABG's tactical retreat proved lucrative, generating a trading profit of roughly ₹50 crore as the company offloaded its accumulated position to Edelweiss and other market buyers at ₹570 to ₹580 per share.8 Bharati tendered for and secured an additional 27.5% stake in Great Offshore through its open offer, yet market analysts estimated the acquisition would require approximately ₹440 crore in incremental capital, roughly doubling Bharati's balance-sheet debt-to-equity ratio.7
Bharati won the battle for control, but did so by overleveraging itself at the peak of the market. A capital-intensive shipyard had absorbed a debt-burdened offshore services operator precisely as the offshore energy cycle was about to deteriorate. The resulting entity could not survive the subsequent downturn. Great Offshore, eventually rebranded as GOL Offshore, entered court-supervised insolvency and received a judicial winding-up order in December 2017.9 Bharati Shipyard met an identical fate, collapsing under the weight of its accumulated debt obligations.10
The view from the parent company
For Bharat Sheth at the parent enterprise, the turbulence of 2008 offered a vivid cautionary tale both from within the shipping sector and from right across the family tree. Great Eastern navigated the global liquidity freeze without imperiling its balance sheet. Even so, Bharat Sheth later identified the collapse of Lehman Brothers as a defining philosophical watershed:
"We were always conservative as a company. Lehman taught us we were not conservative enough for Black Swan events and that was a huge learning."11
He framed the managerial response in explicit capital-allocation terms: "Shipping is a very capex-intensive business, and everything hinges on capital allocation. The question is: What is the leverage within which you are willing to play the game."11 Rather than waiting for lenders or ratings agencies to demand fiscal rectitude, he noted that the decision to pare down debt was taken proactively while Great Eastern still commanded a top-tier credit rating.11
The operational philosophy distilled from that crisis crystallized into an executive maxim: "With a balance sheet in control, I can take an operational risk."11 For Great Eastern, accepting operational and market risk—deploying vessels on volatile spot freight rates—required systematically insulating the balance sheet from financial distress.
A net-cash religion? Not exactly
This historical juncture is where the popular narrative requires nuance. Great Eastern did not emerge from 2008 as a net-cash business overnight, nor did it maintain an unyielding aversion to leverage. The company's own disclosures outline a net debt "expansion phase," where net debt peaked at approximately $361 million in the mid-2010s, followed by a "reduction phase" that culminated in a substantial net cash reserve.1 In January 2024, the chief financial officer described the cycle plainly: "We had levered up to buy ships and then now we've levered down because we've had very strong cashflows."12
Bharat Sheth characterized the 2008–2016 period as navigating aboard "the Titanic and not hitting the iceberg but changing direction." Asset prices had cratered, he noted, "and we had the capacity to invest."11
The Lehman crisis did not prompt Great Eastern to renounce debt altogether. Instead, it refined how and when borrowing was utilized. Management tapped leverage counter-cyclically when asset prices were depressed, and deleveraged as freight rates and vessel values surged, keeping balance-sheet obligations conservative enough to avoid being forced into asset liquidations during a slump. The contrast with Great Offshore was stark: Vijay Sheth faced the same macroeconomic cycle and shared an identical maritime heritage, but leveraged promoter equity near the peak of the market.
For market participants, Great Eastern's conservatism is tangible, yet dynamic rather than dogmatic. Management recalibrates leverage across the shipping cycle. The operative test is whether borrowing expands when vessel valuations trough and contracts when they peak. That discipline defined corporate capital allocation over the subsequent fifteen years, providing the baseline for evaluating how management will navigate the next sector downturn.
That brings the story to the ships themselves.
IV. Anatomy of the Fleet: Tankers, Bulk, Gas & The Greatship Offshore Arm (40–45 min)
How a ship earns money
Consider a Suezmax tanker loading crude in the Atlantic Basin for an Indian refinery in March 2026. Prior to the Hormuz disruption, that refinery might have sourced Middle Eastern barrels just a few days' sail away. With those barrels cut off, replacement crude must travel thousands of nautical miles farther, tying up the same tanker for additional weeks per voyage. The physical asset has not changed, but the global energy system suddenly requires far more vessel capacity—measured in ship-days—to deliver the same quantity of oil.
This dynamic reflects the core arithmetic of maritime freight: ton-miles, defined as cargo volume multiplied by distance traveled. Charter rates correlate less with aggregate global oil consumption than with the total voyage days required to move those barrels. When transit routes lengthen, the effective supply of shipping capacity shrinks immediately, even without a single vessel being retired or scrapped. Great Eastern's management highlighted this dislocation in May 2026, observing that substituting Atlantic Basin barrels for Middle East-to-Asia routes generated "a big spike in demand for ships and therefore, a big spike in the freight rates."5
To measure earnings across these shifting voyages, the shipping industry relies on Time Charter Equivalent (TCE)—referred to in Great Eastern's accounts as TCY. Calculated as gross voyage revenue minus direct voyage expenses like bunker fuel and port tariffs, expressed on a per-day basis, the metric functions as the net daily rental yield earned by a vessel.
The consolidated mix
In FY26, standalone shipping generated approximately ₹4,420 crore of revenue including other income, out of the consolidated group's ₹6,312 crore. At the bottom line, standalone net profit contributed ₹2,356 crore toward consolidated net profit of ₹2,943 crore.1 Standalone shipping thus accounts for roughly three-quarters of group revenue and net earnings, with the offshore services arm generating the remainder. During pronounced tanker upcycles, tanker earnings serve as the predominant engine of group profitability.
Crude tankers: the swing factor
Great Eastern's crude tanker fleet consists of five vessels—a mix of Suezmax and Aframax carriers with an average age of roughly 15 years as of May 2026.1 Notably absent from the roster is a Very Large Crude Carrier (VLCC), the maritime industry's largest crude carrier class.
When an analyst questioned that absence on the May 2026 earnings call, Rahul Sheth from the Managing Director's office pointed out that between 2022 and late 2025, mid-sized Suezmax and Aframax tankers had "outperformed the VLCCs considerably," with VLCC earnings having only "come into their own" over the preceding six to nine months.5 Chief Financial Officer G. Shivakumar outlined the underlying arbitrage: because a 2-million-barrel VLCC cargo equals roughly two 1-million-barrel Suezmax liftings, any excessive rate divergence prompts charterers to split cargoes across two smaller vessels, pulling segment rates back into equilibrium.5
The recent commercial trajectory of these crude carriers illustrates how powerfully geopolitical turbulence can reshape voyage economics. Following Russia's invasion of Ukraine in 2022, European embargoes on Russian crude rerouted Russian barrels on extended long-haul voyages to Asia, while European refiners replaced regional supply with distant imports. Great Eastern's disclosures noted that the EU embargo "further boosted ton-miles growth," propelling consolidated net profit in the quarter ended March 31, 2023, nearly fourfold year on year to approximately ₹722 crore.13
Even amid those record quarterly returns, Bharat Sheth cautioned that "recessionary pressures may be building up in some advanced economies."13 Pairing exceptional quarterly numbers with warnings of cyclical vulnerability has long formed a staple of his communications with investors.
Route disruptions subsequently escalated. When Houthi missile and drone strikes redirected maritime traffic away from the Suez Canal beginning in late 2023, the U.S. Energy Information Administration estimated that a Persian Gulf-to-Rotterdam voyage circumnavigating the Cape of Good Hope required nearly 35 days, compared with approximately 19 days via Suez.14 Then the Strait of Hormuz closed in early 2026. Great Eastern's benchmark Suezmax market index for FY26 averaged roughly $74,000 per day—nearly double the FY25 figure.1 The company's own crude fleet realized approximately $61,400 per day during the January–March 2026 quarter,1 before surging to roughly $90,000 per day in the April–June quarter as the geopolitical premium fully fed through.15
Inside the Hormuz shock
The Hormuz closure also directly affected Great Eastern's operating assets. In May 2026, two vessels under company control were waiting to exit the Persian Gulf—one owned and one chartered in.5 Contractual structure determined which party absorbed the financial loss: on a time charter, the charterer remains liable for daily hire, meaning idle waiting days continued to generate revenue; on a voyage charter, as Shivakumar noted, "the time is on our account," leaving Great Eastern to absorb the idle demurrage risk on that vessel.5 By August 2026, management confirmed that once both ships exited the Gulf, the company had "not gone into that area" again, with the sole exception of a vessel fixed on a long-term time charter to ADNOC operating within the Strait.15
The macro numbers underscore why charter rates spiked disproportionately relative to lost cargo volumes. Shivakumar estimated that the bottleneck trapped roughly 5% of global crude tanker capacity and approximately 2% of product and LPG tonnage inside the Gulf, while the proportion of stranded export cargo was substantially higher.5 The tanker sector simultaneously lost trade volumes and active trading tonnage, compelling the remaining operational fleet to steam far longer routes. Entering the June 2026 quarter, Great Eastern had locked in employment for only 52% of its crude tanker days, 66% of product tanker days, 76% of dry bulk days, and 100% of its LPG capacity.1 By preserving substantial spot-market exposure across its tanker fleet, the company captured the full upswing of the disruption.
Product tankers: refinery dislocation
Great Eastern's 15 to 16 product tankers transport refined petroleum products, including diesel, gasoline, and jet fuel. The fleet is composed primarily of Medium Range (MR) tankers alongside larger Long Range 2 (LR2) vessels.13 Product tankers generate attractive returns during periods of geographic mismatch between refining hubs and consumer demand—such as the January–March 2026 quarter, when robust run rates propelled U.S. refined product exports up roughly 22% year on year.1
The segment features a unique operational flexibility: large LR2 product tankers can transition to hauling dirty crude when crude freight rates surge, provided their cargo tanks undergo thorough cleaning. Approximately 30 LR2 tankers across the global fleet switched into crude service during the March 2026 quarter, tightening available capacity in the clean product market. Great Eastern capitalized on that dynamic by switching "a couple" of its own LR2s into crude carriage.15 Across the product tanker fleet, daily earnings averaged approximately $30,500 during that quarter.1
LPG carriers: steady until they are not
The company's four gas carriers transport liquefied petroleum gas, a trade where the United States operates as the marginal swing exporter and India represents a primary import destination under subsidized domestic cooking-gas initiatives.5 Unlike the tanker divisions, Great Eastern historically insulated its LPG carriers from spot volatility by securing fixed-rate time charters.5 That defensive chartering structure yielded steady fleet earnings of approximately $45,000 per day in early 2026.1
During 2026, however, spot freight rates surged past those fixed charter levels. In May 2026, Rahul Sheth described spot LPG earnings as "close to all-time highs. No, probably the all-time highs."5 In response, management signaled an intent to "run more on spot," executing an initial transition through a hybrid floating-rate charter structure.5
Yet the gas segment also carries the steepest medium-term supply overhang. Shipyard order books for large gas carriers represented approximately 28% of the active global fleet in May 2026 and expanded to roughly 35% by August.115 That looming wave of newbuilding deliveries represents an acute competitive challenge for a company whose four LPG vessels averaged more than 17 years of age.1
Dry bulk: China, Guinea and grain
Averaging approximately 11.6 years as of May 2026, Great Eastern's 15 dry bulk vessels represent the youngest segment of its fleet.1 Spanning Capesize, Kamsarmax, Supramax, and Ultramax specifications, these bulkers transport raw commodities including iron ore, thermal and coking coal, agricultural grain, and bauxite. During the quarter ended March 31, 2026, industry-wide Capesize earnings jumped roughly 77% year on year, buoyed by Chinese iron ore replenishment, resilient grain flows, and a 14% expansion in Guinean bauxite export shipments.1 Great Eastern's bulk fleet realized an average of about $16,700 per day over that period.1 While well below tanker realizations, that rate remained comfortably above the company's operating cash breakeven.
Unlike the wet tanker trades, dry bulk fundamentals correlate primarily with Chinese industrial activity rather than Middle Eastern geopolitical chokepoints. As management observed, the Strait of Hormuz closure had "not really affected the dry bulk trade much."5 That structural decorrelation provides genuine portfolio diversification, ensuring that dry bulk cash flows do not move in tandem with tanker market cycles.
Greatship: the offshore arm
Greatship (India) Limited operates across a separate maritime dynamic. Its four jack-up drilling rigs, averaging roughly 14.6 years of age, deploy directly on the seabed in shallow waters to drill offshore wells, while 19 offshore support vessels averaging 16 to 17 years provide towing, anchor handling, platform supply, and subsea intervention services.1 Greatship's dominant customer is state-run Oil and Natural Gas Corporation (ONGC), which procures offshore assets through competitive multi-year tenders.
Technical barriers to entry partially insulate this operating niche. As Great Eastern's CFO explained, offshore drilling locations on India's continental shelf frequently demand specific rig footprint and weight specifications to match existing seabed soil conditions and platform leg slots, significantly restricting the pool of eligible international competitors.16
Offshore operations rebounded sharply in FY26, delivering what management characterized as Greatship's strongest net profit since FY2016, driven primarily by high utilization and firm rates across the offshore vessel fleet.5 By early 2024, Indian offshore contract renewals had already begun repricing "between 50% and 100% higher than their previous contracts" across both drilling rigs and support vessels.12
Nevertheless, contracting dynamics highlight the concentration risk inherent in dealing with a dominant state-owned patron. In April 2026, ONGC abruptly canceled a major jack-up drilling tender after day rates surged roughly 60% in nine months—from $35,606 to $56,195—citing official concerns over "potential collusive practices." A subsequent press investigation noted that ONGC had scrapped four separate tenders covering 15 jack-up rigs since 2014.17 Greatship countered that monopsony power by diversifying its client base: by May 2026, two of its four jack-up rigs were deployed under short-term charters with alternative operators.5 Although one rig remained idle from late April, management confirmed on its August 2026 call that it had secured a three-year ONGC charter, reducing the number of rigs requiring contract renewals in the second half of FY27 from three to two.15
This operational survey reveals a deliberate commercial structure: four diversified commercial shipping trades that rarely peak in unison, balanced by an offshore energy services subsidiary anchored to state-backed exploration budgets. That asset distribution mitigates the risk of an enterprise-wide collapse across all segments simultaneously. It does not, however, eliminate the brutal cyclicality inherent in any individual division. How management allocates capital across those divergent cycles—buying assets when markets despair and harvesting cash when rates spike—is the subject of the next section.
V. The Playbook: Counter-Cyclical Asset Play, Net Cash & 7 Powers (35–40 min)
Buying from forced sellers
Picture a shipbroker's office in 2016 or 2017. Dry bulk carrier values had plunged toward historic lows. European commercial banks that had aggressively funded the prior shipping boom were desperate to purge maritime debt from their balance sheets, forcing overleveraged owners to liquidate tonnage. Because prospective buyers faced identical liquidity constraints, the select few market participants holding dry powder could dictate purchase terms.
That dynamic forms the bedrock of Great Eastern's operating model. While day-to-day voyages generate the cash flow required to meet operating overhead, a decisive share of cumulative equity returns stems from asset trading—known in maritime parlance as sale and purchase (S&P). As Chief Financial Officer G. Shivakumar acknowledged on the May 2026 earnings call: "We've done best on the projects where we bought when current yield was close to 0." In shipping, the group achieved its highest lifetime returns on vessels acquired when prevailing charter earnings were practically nonexistent.5
Shivakumar elaborated on that counter-intuitive discipline: "Typically, current yield is a bit of a trap."5 Conventional shipowners routinely commit capital pro-cyclically, ordering or acquiring tonnage when freight rates are peaking—precisely when second-hand hulls and new shipyard slots command premium valuations.
Switching, not growing
Between 2024 and 2026, with second-hand vessel values elevated across all vessel classes, management pivoted its capital-allocation framework toward what it terms "switch transactions." Under this approach, the company offloads an aging ship at cyclically elevated asset prices and reinvests the proceeds into a younger hull within the same vessel category. This fleet-modernization strategy lowers average fleet age without expanding overall market exposure at peak asset valuations.5
Fleet transactions during the March and June quarters of 2026 illustrated this rollover mechanism in practice. Great Eastern took delivery of a 2015-built VLGC, a 2013-built MR product tanker, and two 2019-built bulk carriers, while divesting a 2002-built VLGC, two MR tankers built in 2003 and 2007, and a 2011-built Kamsarmax bulker.1 Far from being mere operational maintenance, opportunistic vessel sales generated approximately ₹441 crore of net profit in FY26, following ₹490 crore in FY25.1
In January 2024, Shivakumar spoke candidly about the trade-offs governing these exchanges. Management was "capturing the premium on the older assets and using it to subsidize in our minds the new assets that we are buying," acknowledging that "it's tough to put a number or with great confidence as to what we can earn on these projects standalone."12 Consequently, he cautioned investors that net fleet expansion would proceed slowly.12 More than two years later, executive guidance had not wavered: "Replacing we will continue to do. Increasing we will not do for current yield."5 Net fleet size did expand modestly, from 38 vessels in February 2025 to 40 by August 2026.43 Across that upcycle, corporate actions matched stated managerial policy.
Newbuilds? Rarely
Great Eastern's recent fleet additions have consisted entirely of second-hand vessels.1 Management's rationale, reiterated across multiple investor briefings, centers on delivery timing and shipyard cycle risk: with commercial shipyards booked years in advance at elevated yard prices, commissioning a newbuild contract commits upfront capital to an asset that will deliver into an unpredictable freight environment three to four years later. In May 2026, Shivakumar pointed out that contracting a newly built vessel would likely push delivery out to 2029.5
By purchasing modern second-hand tonnage instead, Great Eastern gains immediate operational cash flow during upswings, avoiding multi-year shipyard execution risk. Yet this preference for existing tonnage also carries distinct operational and environmental trade-offs, a tension examined in subsequent sections.
The balance sheet as a weapon
By June 2026, consolidated net cash had climbed to approximately ₹8,056 crore. Outstanding gross debt stood at roughly $119 million, structured for full amortization by November 2028.3 Management noted that this residual debt remains on the balance sheet solely because specific loan covenants prohibit penalty-free prepayment.5
This liquidity cushion provides strategic flexibility across cycle turns. In May 2026, Shivakumar characterized the balance sheet as an intentional double hedge: "We have a very large proportion of our fleet in the spot market... So we are in a position to take advantage if there is market strength. And as we have collected so much cash and we are waiting to invest, if the markets go the other way, we are there to invest."5
A pristine balance sheet also bolsters commercial standing with oil majors and charterers. When CRISIL upgraded Great Eastern's long-term rating to AAA in February 2025, the rating agency highlighted a net cash position of ₹5,372 crore as of December 2024 alongside the promoter family's 75-year operating record.4 CRISIL noted that sustained net debt exceeding 1.5 times EBITDA could trigger a future downgrade.4 Given its multi-thousand-crore net cash surplus, the company operated with substantial breathing room beneath that threshold.
Why spot, and why so little debt
Underpinning this cash policy is an empirical view of maritime contract economics. During cyclical freight rallies, time-charter rate curves typically slip into backwardation: the longer the charter duration, the lower the contracted daily hire rate. Rahul Sheth outlined this dynamic in May 2026 with an illustrative trade-off. If the prevailing spot freight market yields an index value of 100, a charterer seeking a one- or two-year term contract might bid only 80 or 70. The shipowner who locks in term employment essentially forfeits substantial operating upside to purchase revenue certainty. In an environment defined by extreme geopolitical disruption, Sheth observed that fixing forward rates "can maybe do more harm than good."5
When asked on an earnings call whether long-term charters backed by bank leverage generate superior equity returns over full cycles compared with unleveraged spot trading, Rahul Sheth responded that the company had "studied our history" and "always found this latter to be better." Pursuing the former model, he emphasized, would require "a lot more debt. We find that a riskier strategy."5 Shivakumar added that charterers fixing long-term contracts accept lower rates because they are paying to offload enterprise risk, whereas "the spot market operator typically tends to be taking more risk."5
That same operational arithmetic governs Great Eastern's chartering-in policy. The company chartered in only two vessels—a Suezmax and an MR tanker. Shivakumar reflected that Great Eastern "used to have a significant in-chartering operation 15-plus years ago."5 He illustrated the underlying margin mechanics: while an owned Suezmax incurs cash operating expenses of approximately $6,000 to $8,000 per day, a chartered-in vessel incorporates the third-party owner's required capital recovery into its daily hire rate. Consequently, while both vessels might generate $60,000 per day in a roaring spot market, the chartered-in hull retains far less operating margin for the charterer.5 Operating fully owned hulls purchased with equity capital locks in the lowest possible fixed-cost base, providing a distinct operating edge during prolonged cyclical downturns.
Dividends and buybacks
As shipping cash flows expanded during the 2020s upcycle, shareholder distributions surged in tandem. Consolidated dividends per share, which had lingered in single digits between FY18 and FY22, climbed to ₹36.30 in FY24 and ₹35.10 in FY26.1 The ₹14.40 per share dividend declared for the June 2026 quarter marked the company's 18th consecutive quarterly shareholder payout.3
Share repurchases, by comparison, have been deployed far more selectively. Prior to 2026, the company's most recent buyback was a ₹225 crore open-market program capped at ₹333 per share, executed during the first half of 2022.18 For several subsequent quarters, management cited uncompetitive domestic corporate tax rules as a barrier to share buybacks. However, when an analyst noted in May 2026 that regulatory adjustments had leveled the tax playing field, Shivakumar agreed that "one of the biggest impediments has been removed," reiterating that "everything is at a price."5
On the August 4, 2026 earnings call, management addressed the timing of capital returns by stating that in the absence of an immediate program, "we are waiting."15 Three weeks later, on August 27, the board approved an open-market share buyback of up to ₹900 crore at a ceiling price of ₹1,530 per share, representing approximately 4.12% of total equity, with promoter participation excluded.19 Crucially, the ₹1,530 maximum buyback price stood at roughly 81% of the company's disclosed June 2026 consolidated NAV of ₹1,886 per share.319 In financial effect, management was repurchasing its underlying maritime fleet at a 19% discount to prevailing market asset values.
The people
Behind this capital-allocation framework stands an unusually stable executive core.
Bharat K. Sheth joined Great Eastern in 1981, guiding operations as Deputy Chairman and Managing Director for more than two decades before succeeding K. M. Sheth as Chairman in November 2025.1 His investor communications reflect a disciplined conservatism: commodity cycles remain inherently unpredictable, balance-sheet liquidity is paramount, and executive management does not attempt to forecast freight rates. He concurrently serves as Chairman of Greatship.1
G. Shivakumar joined the company as a management trainee in 1990, advancing through corporate finance, treasury, human resources, and strategic planning. He was appointed Chief Financial Officer in 2008 and Executive Director in November 2014, while concurrently holding the CFO role at Greatship.1 Shivakumar opens quarterly earnings calls with his trademark operational disclaimer: "We don't forecast the market."5 In an industry where executives often market promotional freight forecasts, Great Eastern's leadership deliberately refuses to issue speculative market guidance.
Ravi K. Sheth spearheaded the creation and expansion of Greatship as its Managing Director. In April 2015, at his own request, he stepped down from his executive directorship at the parent shipping company to dedicate his focus exclusively to the offshore energy services business.1
Corporate governance is reinforced by an external board that includes veteran financial executive Keki Mistry, former banker Kalpana Morparia, former National Security Advisor Shivshankar Menon, media executive Uday Shankar, and business editor T. N. Ninan.1 As of March 2026, promoter entities held approximately 30% of outstanding equity, foreign portfolio investors held 29%, domestic financial institutions owned 15%, and public retail investors accounted for the remaining 26%.1 A 30% promoter holding affords the founding family effective strategic direction without insulating them from institutional shareholder scrutiny, while the independent directors bring heavyweight institutional credibility.
Seven Powers, audited
Evaluating Great Eastern through Hamilton Helmer's Seven Powers framework clarifies why conventional competitive moats rarely apply to ocean shipping:
Scale economies are marginal. A fleet of 40 vessels represents a negligible fraction of global maritime tonnage, leaving Great Eastern as an absolute price-taker on spot routes.
Network effects do not exist in point-to-point commodity haulage.
Switching costs are virtually zero in spot markets, where commodity charterers fix the lowest-priced vetted vessel available for any given voyage window.
Branding offers modest utility. Major oil companies subject tankers to rigorous safety and technical vetting before chartering, but clean inspection reports merely grant commercial permission to compete; they command no rate premium over equally qualified tonnage.
Cornered resource provides minimal defensibility. While India's domestic cabotage and Right of First Refusal (ROFR) policies afford Indian-flagged vessels preference in state-backed tenders, public-sector procurement mechanics ensure that domestic owners must match the lowest international commercial bid to secure contracts.
Only two competitive advantages withstand scrutiny. The first is counter-positioning. Heavily leveraged shipping peers cannot replicate Great Eastern's strategy of accumulating massive cash reserves and waiting years for distressed acquisition opportunities. Doing so would depress return on equity during market booms, alienating lenders and private equity backers whose financial structures demand maximum leverage at the top of the cycle. The second is process power: over seven decades of accumulated operational expertise in timing vessel sale-and-purchase transactions, paired with lean fleet operations. Management estimated consolidated fleet cash operating breakeven at roughly $9,000 to $9,500 per day, with total book breakeven between $11,000 and $12,000 per day.5 While an institutional investor on the May 2026 call noted that certain U.S.-listed tanker peers reported daily cash breakevens around $11,000,5 differing segment definitions make direct cross-border comparisons imprecise. Nevertheless, Great Eastern's debt-free fleet maintains an exceptionally competitive cash operating floor.
Ultimately, Great Eastern's competitive edge is behavioral rather than structural. It rests upon organizational restraint and balance-sheet conservatism—attributes that depend entirely on managerial discipline. Whether that discipline has held consistently across history, or whether management has at times succumbed to the very cyclical temptations it decries, is the focus of the falsification tests that follow.
VI. Historical Falsification Layer: Stress-Testing the GESHIP Thesis (30–35 min)
The bull case for Great Eastern rests on three central propositions: first, that domestic regulations provide the company with a protected commercial moat; second, that management possesses an exceptional ability to time asset purchases at cyclical bottoms; and third, that eschewing expensive newbuilds insulates shareholder capital from erosion. Each claim can be stress-tested against the company's historical operating and financial record.
Test 1: Is Indian cabotage and RoFR a pricing moat?
The claim. Indian-flagged vessel operators benefit from a regulatory Right of First Refusal (RoFR) on commercial cargo tendered by domestic public-sector enterprises. Under Directorate General of Shipping guidelines, Indian-flagged vessels "will have right to match the lowest bid" submitted by lower-priority categories, with Indian-built, Indian-flagged tonnage occupying the top priority tier.20
The disconfirming mechanism. The regulation grants the right to match the lowest bid, not to dictate or beat it. An Indian shipowner secures the cargo only by matching the lowest freight rate offered by a foreign competitor. When global owners slash charter rates toward marginal operating costs during a sector downturn, an Indian operator must accept those identical depressed rates to win the business. The framework secures access to cargo volume, but confers zero pricing power. Furthermore, subsequent policy revisions granting first priority to Indian-built hulls relegate Great Eastern's second-hand, foreign-built fleet to a secondary tier in the allocation queue.20
Geographic revenue distributions reinforce this reality. According to a 2024 Business Today profile, approximately 85% of Great Eastern's revenue originated outside India.11 An enterprise whose underlying cash generation depended on captive, protected domestic trades would not exhibit such extensive international exposure.
Verdict: the claim is narrowed. While the RoFR framework enhances vessel utilization and reduces idle ballast voyages for Indian-flagged vessels, it provides no structural rate premium. Disproving this finding would require evidence of a sustained, verifiable margin between Great Eastern's domestic public-sector realizations and comparable international spot fixtures—a gap that does not appear in corporate disclosures.
Test 2: Is the capital allocation flawless? The offshore winter
The claim. Management consistently buys assets at cyclical troughs, divests at peaks, and avoids capital misallocation.
The disconfirming evidence. The offshore services subsidiary presents the clearest historical counter-example. Greatship acquired the bulk of its drilling rigs and offshore support vessel fleet during the boom years preceding 2014. When crude oil prices plunged in late 2014, global offshore exploration and production activity collapsed in tandem.
Accounting disclosures reflect the magnitude of that downturn. When Great Eastern transitioned to Ind AS accounting, it marked its fleet of rigs and vessels down to fair market value as of April 1, 2015, absorbing an asset write-down of approximately ₹2,000 crore split roughly evenly between the offshore and shipping divisions.16 On the May 2017 earnings call, the chief financial officer noted that vessel valuations had "dropped significantly after that," an additional decline not yet captured by that opening balance-sheet adjustment.16
That same quarter brought a further impairment of about ₹175 crore on offshore support vessels, with management explaining that "the day rates that are getting fixed for charters have gone down to extremely low levels."16 Greatship's quarterly EBITDA dropped by roughly ₹90 crore in a single quarter as drilling rigs sat idle and support vessels rolled off expiring contracts.16 Consolidated net asset value at the time hovered between ₹375 and ₹415 per share, and management conceded that offshore asset valuations were "not very clearly ascertainable."16
In practice, the offshore arm had committed substantial capital near the crest of the cycle. Only the liquidity and debt-absorption capacity of the parent shipping business carried Greatship across the extended downturn until offshore day rates finally staged a structural recovery. FY26, which delivered Greatship's strongest net profit since FY2016, served as a sobering reminder of just how protracted that offshore slump had been.5
The standalone shipping division experienced its own capital-timing friction. Roughly half of the initial ₹2,000 crore Ind AS write-down stemmed from conventional shipping assets acquired prior to 2015.16 The company has absorbed occasional asset impairments in subsequent years as well, including a ₹69 crore charge on select vessels in the quarter ended March 31, 2025.1
Verdict: the claim is rejected in its absolute form and refined. Management does not navigate every cyclical turn cleanly. What the empirical record demonstrates is that in commercial shipping, Great Eastern accelerates acquisitions when asset prices trough and divests when valuations peak. Management levered up aggressively between 2015 and 2018 to purchase discounted hulls and subsequently used upcycle cash flows to extinguish that debt. Crucially, past capital-allocation mistakes proved survivable because the balance sheet was deliberately engineered to absorb severe shocks. The critical metric to watch is whether net debt expands during the next severe industry downturn while vessel valuations are falling. That expansion would confirm counter-cyclical execution; if the company instead hoards cash through an extended price collapse, fiscal conservatism will have drifted into capital paralysis.
Test 3: Newbuild discipline, or deferred capex?
The claim. Refusing to order expensive shipyard newbuildings protects shareholder capital from cyclical destruction.
The disconfirming evidence. A disciplined refusal to contract new tonnage inevitably drives up fleet age. By May 2026, the average age of Great Eastern's shipping fleet had climbed to roughly 14.3 years, comprising an average of 15.3 years for crude tankers, 15.4 years for product tankers, and 17.3 years for gas carriers.1 CRISIL reported an average fleet age of approximately 14 years twelve months earlier, confirming an aging profile.4
Regulatory pressures bear heavily on older tonnage. International Maritime Organization (IMO) mandates governing the Energy Efficiency Existing Ship Index (EEXI) and Carbon Intensity Indicator (CII) became compulsory on January 1, 2023. Under these rules, each vessel receives an annual carbon-intensity rating from A to E. A vessel rated D for three consecutive years, or E for a single year, must formulate an approved corrective action plan, with emissions benchmarks tightening steadily toward 2030.21
Operating much like an environmental efficiency grade, CII penalizes legacy engines and older hull designs. While shipowners can mitigate carbon intensity through specialized hull coatings, propeller modifications, or slow-steaming, operating at reduced speeds reduces the total voyages a ship can complete each year, capping revenue potential.
Commercial acceptability also tightens with vessel age. Shivakumar pointed out that while a crude tanker can legally trade up to 25 years of age, "beyond 20 it becomes a little difficult to operate, little less acceptable in the market" as primary charterers tighten technical vetting standards.12 With Great Eastern's tanker segments averaging over 15 years, a significant portion of the wet fleet is operating within five years of that commercial threshold.
The mitigating evidence. Management contends that hull age alone does not dictate investment returns. In May 2026, Rahul Sheth dismissed the assertion that younger tonnage routinely achieves superior earnings, observing "not really," and emphasizing that "the price at which you entered and the segments at which you enter" fundamentally govern asset economics.5 Meanwhile, management's opportunistic "switch transactions" have systematically exchanged aging vessels for younger second-hand tonnage without expanding overall capacity. To satisfy environmental benchmarks and optimize efficiency, the company retrofitted Mewis ducts—devices mounted ahead of the propeller to optimize water inflow—alongside high-performance hull paint and modified propeller blades, while utilizing biofuels on select voyages to comply with European emissions rules.1
Verdict: the claim is validated, but constrained by eventual replacement realities. Avoiding peak-price shipyard contracts has shielded capital from aggressive asset depreciation. The trade-off is that fleet modernization has been postponed rather than eliminated, meaning a substantial share of current net cash represents deferred capital expenditure for future vessel renewal. The essential metric to monitor is whether average fleet age stabilizes around 14 years or drifts higher, and the acquisition prices management pays for replacement tonnage.
A diligence aside: reading the reported numbers
Accounting adjustments require close inspection when interpreting Great Eastern's financial results. The company historically raised rupee-denominated debentures and entered into currency swaps to convert them into synthetic U.S. dollar debt aligned with its dollar-denominated shipping assets. Following its transition to Ind AS, Great Eastern discontinued hedge accounting treatment for those derivative swaps, requiring period-end mark-to-market fluctuations to flow directly through the profit-and-loss statement. Management warned investors in 2017 that this reporting change would inject "a lot more volatility in our quarterly results."16
Financial performance in FY26 illustrates this divergence. Reported consolidated net profit of ₹2,943 crore included approximately ₹433 crore in foreign exchange gains alongside roughly ₹153 crore in derivative valuation losses. On a normalized operating basis adjusting for these currency swings, consolidated net profit stood at ₹2,688 crore.1 The record earnings posted in the January–March 2026 quarter similarly benefited from favorable exchange movements, as management acknowledged on its earnings call.5 Investors assessing core cash generation should rely on normalized earnings to evaluate recurring fleet performance.
The capital arrangements between the parent enterprise and its offshore subsidiary also warrant tracking. As of March 2026, Greatship carried approximately ₹392 crore in outstanding loans from Great Eastern, alongside ₹272 crore in preference shares subscribed by the parent during the offshore downturn.5 While these intra-group balances eliminate upon consolidation, they demonstrate that parent shipping cash flows directly underwrote the offshore services division through its prolonged slump.
These historical stress-tests narrow the analytical thesis. Great Eastern is neither an infallible market-timing vehicle nor the beneficiary of a domestic regulatory moat. The enterprise functions as a disciplined, well-capitalized trader of second-hand tonnage that has absorbed notable cyclical missteps—particularly in offshore drilling—and survived because its balance sheet was deliberately engineered to outlast the cycle. The subsequent section examines the three primary operational metrics that indicate whether that discipline remains intact.
VII. The 3 KPIs That Rule the Waves (15–20 min)
A maritime shipping company can generate record accounting profits even as its underlying equity value stagnates, because a vessel acquired at the peak of the market may generate lucrative short-term cash flows while shedding asset value faster than it earns. Conversely, an operator can report subdued net income while quietly accumulating deeply discounted tonnage at cyclical troughs. Evaluating Great Eastern therefore requires looking past reported earnings to monitor the underlying assets, cash generation, and capital deployment through three primary operational metrics.
KPI 1: Consolidated NAV per share, and the price-to-NAV ratio
Each quarter, management discloses Net Asset Value (NAV), calculated as the third-party broker valuation of every vessel and rig plus net cash. Over a five-year period, standalone NAV expanded from ₹489 per share in March 2021 to ₹1,422 in March 2026, while consolidated NAV climbed from ₹538 to ₹1,796.1
Management highlights a subtle distinction in that trajectory: the majority of this five-year value expansion stemmed from accumulated operating cash earnings rather than speculative vessel price inflation. In May 2026, Shivakumar pointed out that NAV "keeps converting into cash because the ship earns cash."5
Shivakumar also cautioned investors on the asymmetrical speed of asset depreciation. While an annualized $200 million decline in fleet values could easily be absorbed by annual operating cash earnings exceeding $300 million, an equivalent drop concentrated within a single quarter could overwhelm earnings.5
The underlying valuation methodology also requires scrutiny. Standalone shipping NAV is reported as a single point estimate because liquid international sale-and-purchase markets allow brokers to price tankers and bulk carriers with relative precision. In contrast, consolidated NAV is presented as an indicative range—spanning ₹1,772 to ₹1,821 per share in March 2026—reflecting the illiquidity of offshore assets where transactions are infrequent.1 That distinction recalls management's concession during the offshore slump in 2017, when it acknowledged that offshore asset values were "not very clearly ascertainable."16 Consequently, analysts place greater analytical weight on standalone shipping NAV than on the offshore component.
The companion metric is the ratio of market price to NAV. In January 2024, after the share price had roughly tripled over two years, the stock traded at approximately 0.75 times consolidated NAV.12 It stood at around 0.83 times in May 2026 and 0.74 times in early August 2026.13 Tracking the trajectory of NAV alongside this valuation discount reveals market sentiment: a widening discount during an NAV expansion suggests equity markets treat peak charter rates as transient, whereas a narrowing discount reflects growing investor conviction that elevated cash flows will endure.
KPI 2: Fleet TCE versus cash breakeven
The second operational benchmark measures realized daily earnings against operating cost structures. Management estimates consolidated fleet cash operating breakeven at approximately $9,000 to $9,500 per day, with total book breakeven between $11,000 and $12,000 per day.5 Once daily revenue clears that fixed hurdle, as Shivakumar confirmed, incremental earnings drop almost entirely to operating profit.5 Across a fleet of roughly 40 operational vessels, every additional $1,000 per day in average fleet TCE translates to approximately $14 million in annualized pre-tax cash flow.
Evaluating this metric requires tracking two variables in quarterly disclosures: realized TCE across individual fleet segments, and the proportion of operating days committed to forward contracts. Management estimated forward time-charter cover at under 20% in May 2026, nudging that figure to roughly 25% to 26% by August 2026.515 Maintaining heavy spot-market exposure maximizes operating leverage during freight spikes, but accelerates earnings declines when voyage charter rates inevitably recede toward breakeven.
KPI 3: Net cash, and how it is deployed
The third core metric monitors the dry powder accumulated to exploit the next cyclical trough: consolidated net cash, which reached approximately ₹8,056 crore by June 2026.3 The critical strategic test lies in how that surplus is allocated. Capital deployment generally divides across three channels: capital-neutral "switch transactions," which modernize tonnage while keeping overall fleet capacity stable; net fleet expansion, which management deliberately avoided at elevated asset valuations; and direct shareholder returns through dividends and share repurchases. The ₹900 crore share buyback authorized in August 2026 represents the first substantial cyclical test of management's willingness to deploy capital into its own equity.19
The timing of cash deployment provides the ultimate test of counter-cyclical discipline. If net cash continues to accumulate through a severe downturn while vessel valuations crater, fiscal conservatism will have lapsed into capital paralysis. Conversely, if cash reserves diminish rapidly due to aggressive fleet additions at market tops, management will have compromised its core capital-allocation framework. The strategic objective is to harvest cash during cyclical peaks and deploy it aggressively into distressed assets at cyclical bottoms.
These three metrics establish the empirical baseline for evaluating the central tension surrounding the stock: the competing bull and bear investment theses examined next.
VIII. Bull vs. Bear Case & Skeptical Investor Stress Test (25–30 min)
The confrontation on the call
On the May 2026 earnings call, an institutional investor put forward a pointed comparison. Several U.S.-listed tanker operators trading near net asset value were announcing sizable share buybacks. Why was Great Eastern, despite trading at a persistent discount to NAV, reluctant to pursue a similar program?
Shivakumar did not dispute the premise: "Our approach is of a value buyer... we buy only at certain prices, even in ships. Different companies just -- some companies just will just keep buying irrespective of the market... This is something which has served us well over many decades, and so we stick with this."5
Another analyst pressed management on the fleet. With cash reserves mounting and average vessel age creeping upward, why not deploy capital to capture prevailing high yields? Rahul Sheth countered that "current yields can change. You have to look at the business from a more longer-term point of view."5 By August, executive guidance sharpened, with management noting that Great Eastern would be "best served by holding on to the majority of the money, rather than investing it in ships today."15
A skeptical investor would challenge this posture across four distinct dimensions. First, the promoter family exercises operating control with an equity holding of roughly 30%, while net cash reserves have expanded to represent over 40% of the company's total market capitalization.1319 Against an August 2026 market capitalization of approximately ₹19,231 crore, holding roughly ₹8,056 crore in net cash ties up an extraordinary share of enterprise value in liquid balances.319 Second, the stock has traded at a persistent discount to NAV throughout the cycle, suggesting that public markets discount cash held on the balance sheet. Third, capital-allocation discipline appears reactive: the company authorized a share repurchase program only after management had repeatedly emphasized that it preferred to wait. Fourth, questions linger over whether Greatship belongs within the consolidated group given its prolonged historical slump, even if the recent offshore recovery has blunted immediate calls for a separation.
The ₹900 crore share buyback authorized in late August 2026 addresses shareholder impatience only partially. Absorbing roughly 11% of accumulated net cash, the program represents an incremental deployment of surplus capital rather than a fundamental pivot in balance-sheet strategy.319
The bull case
Supply remains relatively tight across primary segments, though less constrained than in prior quarters. Tonnage retirements have remained negligible. Throughout calendar 2025, shipowners scrapped less than 1% of the global crude tanker, product tanker, and dry bulk fleets, as extraordinary freight rates justified trading even vintage hulls.1 In May 2026, management observed that across tankers and dry bulk, the scheduled shipyard order book was roughly balanced by the volume of aging tonnage eligible for demolition, leaving large gas carriers as the sole segment facing an unhedged supply overhang.5
Geopolitical friction continues to elevate voyage distances. Western sanctions on Russian energy exports, missile strikes rerouting vessels around the Cape of Good Hope, and the closure of the Strait of Hormuz occurred in rapid succession. Each shock lengthened trade lanes and expanded ton-mile demand. Bullish observers argue that energy-importing nations will respond to recurring logistics bottlenecks by expanding strategic inventories and diversifying sourcing hubs. Shivakumar analogized this structural realignment to the post-pandemic supply chain transition "from just in time to just in case."5 Replenishing those stockpiles creates an incremental layer of maritime demand: Rahul Sheth noted that the U.S. Strategic Petroleum Reserve had dropped from approximately 700 million barrels to around 450 million before the conflict and faced further drawdowns, while Chinese buyers had accumulated substantial onshore crude reserves.5 Rebuilding national reserves would support tanker employment independently of global consumption trends, though management characterized this dynamic as an informed conjecture rather than a firm forecast.5
The offshore energy cycle has entered an upswing. Domestic offshore drilling and support vessel contracts were renewing at rate increases between 50% and 100% by early 2024.12 Furthermore, global shipyard construction of jack-up rigs has remained largely frozen since the 2014 crude price collapse.5 By May 2026, the active jack-up order book stood at roughly 2.4% of the global fleet.1 Greatship's progressive charter diversification beyond ONGC provides incremental insulation against single-customer contract volatility.5
The balance sheet offers an explicit margin of safety. The stock trades at a notable discount to disclosed NAV backed by substantial net cash, delivers an 18-quarter sequence of regular dividends, and is repurchasing equity at a discount to underlying fleet value. Should freight markets roll over, Great Eastern is positioned to acquire distressed tonnage from overleveraged competitors rather than being forced to sell.
The bear case
The shipyard order book has expanded significantly. This shift dismantles a central premise of the earlier bull thesis: the assumption of a historically depleted shipyard pipeline. In January 2024, Shivakumar highlighted a crude tanker order book that sat below 5% of the operating fleet.12 By May 2026, crude contracting had rebounded to between 22% and 24% of existing tonnage, expanding to roughly 27% by August. Product tanker orders reached 20% to 21%, while the order book for large gas carriers approached 35%.115 Shipyard capacity previously monopolized by container vessels and LNG carriers has rotated toward tanker construction.5 These newbuildings will hit the water in increasing volumes through 2027 and 2028.5 Management acknowledged that the swelling delivery schedule "makes you maybe a little more concerned."5 While optimistic investors had assumed that shipyard delivery slippages would defer new tonnage, Rahul Sheth reported in May that the company had "not seen any significant data on the slippages" capable of altering forward fleet balances.5 By August, management cited this looming supply wave as the primary justification for withholding capital from high-priced second-hand vessel acquisitions.15
Geopolitical freight premiums can evaporate rapidly. Management acknowledged that several factors supporting elevated ton-miles remain "not quite structural."15 A full reopening of the Strait of Hormuz, normalization of Russian crude flows, or a return of commercial traffic through the Red Sea would immediately shorten average voyage lengths, expanding effective fleet capacity. While Rahul Sheth observed that an initial reopening might generate a brief rate spike as tonnage repositions into the Gulf, management declined to project rate trajectories beyond that immediate rebalancing.5
Dry bulk earnings remain hostage to Chinese economic momentum. Because bulk carriers move foundational raw materials, any deceleration in Chinese steel manufacturing, real estate investment, or industrial construction impacts Capesize and Kamsarmax hire rates directly, irrespective of geopolitical tensions across the Middle East.
Fleet modernization liabilities are drawing closer. With average fleet age exceeding 14 years and environmental compliance mandates tightening under IMO carbon intensity rules, the company faces an unavoidable capital expenditure program in the late 2020s. Contracting replacement tonnage at elevated yard prices risks locking in structurally depressed returns on capital across the subsequent cycle.
The offshore arm remains vulnerable to customer concentration. ONGC has repeatedly scrapped commercial tenders and publicly alleged price collusion among offshore service contractors in April 2026.17 Operating against a dominant state-owned monopsonist severely limits Greatship's ability to extract peak contract pricing during upcycles.
Porter's five forces, applied
Bargaining power of buyers is high. International oil companies, independent commodity traders, and state-owned refiners procure shipping capacity on purely competitive, commoditized terms. In offshore exploration, ONGC functions as an effective monopsony across India's continental shelf.
Bargaining power of suppliers is equally formidable. Commercial shipyard capacity is concentrated among a handful of dominant shipbuilders in China, South Korea, and Japan, including China State Shipbuilding Corporation (中国船舶集团), HD Hyundai (HD현대), and Samsung Heavy Industries (삼성중공업). When yard delivery slots are committed years in advance, shipbuilders hold absolute pricing leverage over vessel buyers.
Threat of new entrants mirrors the shipping cycle. While acquiring maritime tonnage requires substantial upfront capital, uncommitted financial capital and speculative ordering regularly flood the sector during prolonged freight rallies, as evidenced by the rapid expansion of the tanker order book.
Threat of substitutes is virtually nonexistent. For intercontinental bulk energy carriage and raw mineral transport, maritime shipping possesses no economically viable logistical alternative.
Competitive rivalry is fierce and structural. Thousands of independent shipowners deploy standardized, interchangeable assets across frictionless global chartering markets, competing directly on spot price.
This competitive structure clarifies why individual shipping operators cannot establish lasting commercial moats. Operational advantage derives not from structural barriers, but from capital-allocation discipline and balance-sheet survival capability. The meaningful peer group consists of other disciplined operators—including select U.S. and European tanker companies that combine spot exposure with conservative financial leverage. Management makes no claim to unique operational formulas; on the question of leverage, Rahul Sheth observed that "a lot of companies run largely spot, but the amount of debt they take varies."5 Great Eastern distinguishes itself primarily by anchoring at the conservative extreme of that spectrum across multiple decades.
Both the bull and bear arguments ultimately converge on a single assumption: that executive leadership will maintain this counter-cyclical discipline through the next sector downturn. How that discipline navigates impending executive succession and the regulatory transition toward decarbonized propulsion forms the subject of the final section.
IX. Epilogue & Future Outlook: Decarbonization & Succession (15–20 min)
The fuel question
Global commercial shipping is confronting its most profound propulsion transition since the shift from wind to steam. Competing alternative fuels—principally liquefied natural gas, methanol, ammonia, and biofuels—each require specialized engine architectures, pressurized or cryogenic fuel storage, and bespoke bunkering infrastructure, with no single technology yet establishing operational dominance.
For a counter-cyclical shipowner like Great Eastern, this technological divergence presents a classic dilemma in modern guise. Ordering dual-fuel newbuilds at cyclically elevated shipyard prices commits premium capital to propulsion systems whose underlying supply chains remain speculative. Conversely, deferring fleet replacement leaves an aging fleet exposed to tightening carbon intensity benchmarks under International Maritime Organization mandates. For now, the company has elected to wait, adopting energy-saving hardware, conducting biofuel trials, and participating in European carbon-market compliance, while avoiding substantial capital bets on any single nascent fuel technology.1 That posture aligns directly with historical precedent: allow capitalized first-movers to absorb initial technological depreciation, and acquire standard, proven tonnage once second-hand markets mature.
Management has also ruled out the most prominent alternative transition asset. When asked on the May 2026 earnings call about entering the liquefied natural gas (LNG) carrier market, Rahul Sheth stated that Great Eastern would not venture into the segment, citing prohibitive capital ticket sizes and long-term fixed charter commitments that render the trade "more like project financing."5 While that decision strictly preserves Great Eastern's opportunistic tramp-shipping identity, it also ensures the fleet will not participate in the shipping segment most directly aligned with transitional gas infrastructure.
Succession
In November 2025, K. M. Sheth retired from the chairmanship after more than seven decades with the enterprise, after which Bharat Sheth assumed leadership as Chairman and Managing Director.1 On recent earnings calls, a younger family voice has become increasingly prominent: Rahul Sheth, designated as General Manager in the Managing Director's office, who routinely addresses inquiries regarding market structure, VLCC strategy, and chartering dynamics.5 Disclosed investor materials outline neither a formalized board succession roadmap nor his precise familial lineage.
In capital-intensive maritime shipping, leadership transitions carry outsized significance because Great Eastern's competitive edge is fundamentally behavioral rather than structural. The primary risk confronting shareholders is not technical incompetence, but generational amnesia: an incoming leadership team inheriting an ₹8,000 crore cash hoard without the direct institutional memory of the severe downturns that forged that conservatism. Executive bench strength provides meaningful continuity in the near term: G. Shivakumar has served the company since 1990 and has been CFO since 2008.1 The unresolved governance question is whether that cautious discipline will endure once the executive generation shaped by the Lehman crisis and the Great Offshore demerger has departed.
The lessons
The Great Eastern story yields several durable principles for operating inside hyper-cyclical industries.
The first is that operating volatility and financial leverage cannot be combined without existential hazard. Great Offshore and Great Eastern emerged from the same founding dynasty, operated in the same maritime domain, and confronted an identical macroeconomic shock. One collapsed into judicial liquidation, while the other secured a top-tier AAA credit rating. The defining divergence lay in debt, and in particular borrowing secured against pledged promoter equity near the crest of the market.69
The second principle is that strategic restraint is frequently the most demanding operational choice during a cyclical boom. Refusing to order newbuildings at market peaks, declining to chase short-term charter yields, and refusing to issue speculative freight forecasts can appear passive to outside observers. Over multiple decades, that deliberate inaction has served as Great Eastern's primary value-preservation strategy.
The third is that counter-cyclical discipline does not equate to commercial infallibility. The ill-timed offshore rig expansion, the multi-thousand-crore Ind AS asset impairments, and an aging fleet profile demonstrate that management makes recurring capital miscalculations. Great Eastern survived those missteps because its balance sheet was never engineered around operational perfection.
The final question—and the crucial test confronting investors as the cycle matures—is whether an organization conditioned by years of defensive conservatism can pivot decisively to offensive capital deployment when industry distress arrives. The ₹900 crore share repurchase authorized in August 2026 confirms that management can act when equity trades at a steep discount to underlying net asset value. Yet the ultimate validation of Great Eastern's maritime fortress will unfold only when spot freight rates inevitably collapse, testing whether management will aggressively convert its accumulated cash into discounted tonnage while competitors struggle to survive.
References
-
Investor Presentation Q4 FY26 — The Great Eastern Shipping Company Limited, 2026-05-15 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
About Us — The Great Eastern Shipping Company Limited ↩↩↩↩↩↩↩↩
-
Great Eastern Shipping Q1 FY27 slides: record profits on tanker surge — Investing.com, 2026-08-04 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Rating Rationale: The Great Eastern Shipping Company Limited upgraded to Crisil AAA/Stable — CRISIL Ratings, 2025-02-28 ↩↩↩↩↩
-
Q4 & Full Year FY26 Results Conference Call Transcript — The Great Eastern Shipping Company Limited (NSE filing), 2026-05-20 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Vijay Sheth is second in family to lose control — Business Standard, 2009-05-09 ↩↩↩↩↩↩↩↩↩
-
Open offers for Great Offshore conclude — Business Standard, 2009-12-23 ↩↩↩
-
Takeover battle between Bharati Shipyard Limited and ABG Shipyard Limited ended — iPleaders ↩
-
High Court Orders Liquidation of GOL Offshore (Formerly Great Offshore) — Splash247 Maritime News, 2017-12-07 ↩↩
-
Great Offshore: How Bharati Shipyard Won Control and Lost Everything — Livemint, 2009-12-08 ↩
-
Bharat K. Sheth's tough decisions propelled Great Eastern Shipping into the front ranks — Business Today, 2024-04-04 ↩↩↩↩↩↩
-
Q3 FY24 Earnings Conference Call Transcript — The Great Eastern Shipping Company Limited (BSE filing), 2024-01-31 ↩↩↩↩↩↩↩↩
-
Great Eastern Shipping net profit jumps nearly four-fold to Rs 721.94 cr — Business Standard (PTI), 2023-05-12 ↩↩
-
Red Sea attacks increase shipping times and freight rates — U.S. Energy Information Administration, 2024-02-01 ↩
-
Earnings call transcript: Great Eastern Shipping posts record Q1 profit — Investing.com, 2026-08-04 ↩↩↩↩↩↩↩↩↩↩
-
Q4 FY17 Earnings Conference Call Transcript — The Great Eastern Shipping Company Limited, 2017-05-05 ↩↩↩↩↩↩↩↩↩
-
ONGC: Tender to hire jack-up rigs cancelled due to steep surge in price — Business Standard, 2026-04-22 ↩↩
-
Great Eastern Shipping shares surge nearly 4% as board approves buyback of up to ₹900 crore — Upstox, 2026-08-28 ↩↩↩↩↩↩
-
DG Shipping – Right of First Refusal guidelines — Absolute Infra Blog, 2013-12-06 ↩↩
-
EEXI and CII – ship carbon intensity and rating system — International Maritime Organization ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube