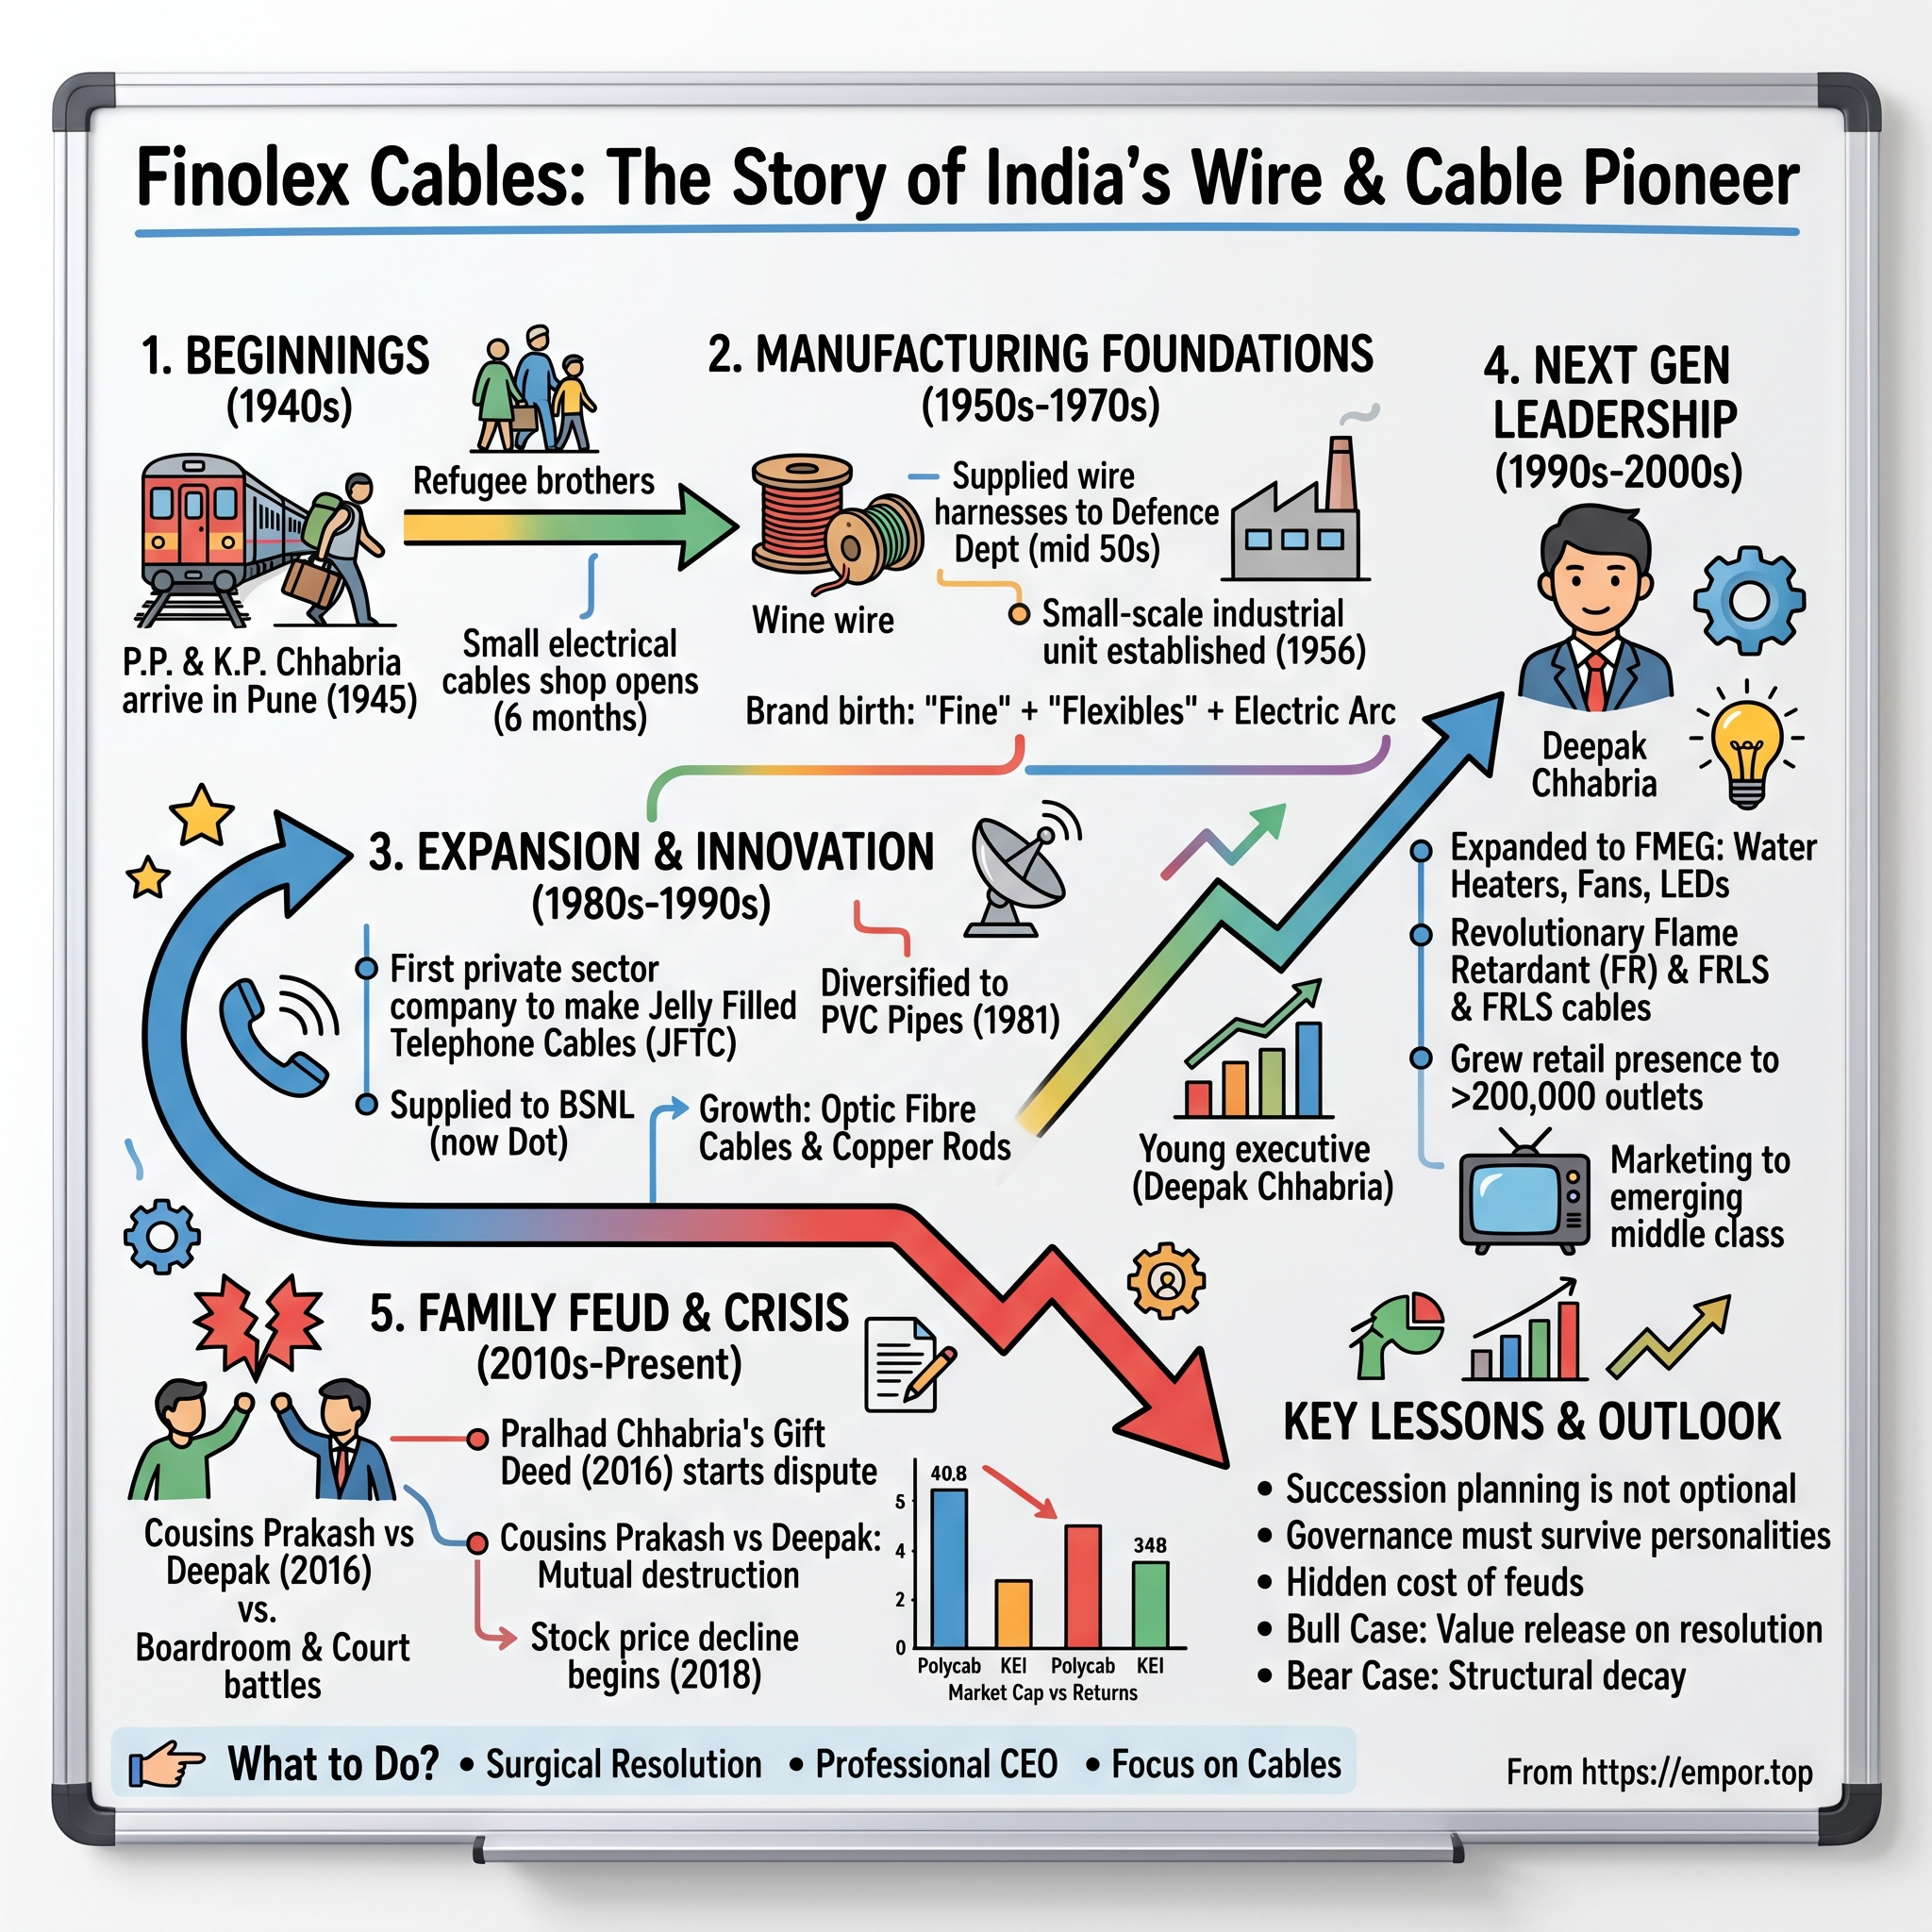
Finolex Cables: The Story of India's Wire & Cable Pioneer
I. Introduction & Episode Roadmap
In July 1945, two teenage brothers arrived in Pune from Karachi with virtually no capital, patrons, or commercial backing as the subcontinent neared partition. Within a decade, they were supplying wire harnesses to the Indian Ministry of Defence. Within four decades, they had built a household electrical wire brand in India—a trusted choice among electricians and homeowners, supported by product reels stacked behind the counters of 200,000 hardware shops.
Yet during India's electrification and construction expansion over recent decades, the company grew slower than the market it had helped establish.
That is the tension at the heart of this story. Finolex Cables Limited, listed on the NSE as FINCABLES, is a business with an established brand, a debt-free balance sheet, and an investment portfolio that at the end of FY2026 stood at roughly ₹4,195 crore against borrowings of just ₹19 crore.1 It is also a business whose founding family has spent a decade in open legal warfare with itself—cousins litigating over a gift deed, an annual general meeting, a holding company, and ultimately control of the chairman's seat. That conflict reached the Supreme Court of India, produced a ₹1 crore contempt fine against the company's executive chairman, and triggered an inquiry into a tribunal bench.[^5]
Here is where the conventional framing needs updating, and it is a key detail for investors to analyze. For most of the past decade, the Finolex narrative was framed as a value trap: cheap stock, trapped cash, a frozen board, and shrinking market share. Some of that remains true, but recent financial metrics challenge the simplest version of the bear case. Revenue, which had grown modestly from ₹5,014 crore in FY2024 to ₹5,319 crore in FY2025, climbed to ₹6,321 crore in FY2026—roughly 19% growth—delivering a net profit of ₹714 crore.1 The market has partially responded: the stock no longer trades at the mid-teens earnings multiple that aligned with the value-trap thesis, changing hands in September 2026 at a trailing price-to-earnings ratio in the high twenties.1 The valuation discount relative to Polycab India and KEI Industries has narrowed, though a gap remains.
The central question has therefore evolved. It is no longer simply whether cash is trapped, but what specifically is driving this revenue reacceleration, how much of it is durable, and whether a company operating under unresolved promoter litigation deserves to re-rate toward peers without governance disputes.
The route to an answer runs through five themes. First, immigrant entrepreneurship and import substitution in a licence-permit economy—how regulatory scarcity built an industrial base. Second, technological obsolescence: the episode in which mobile technology disrupted Finolex's lucrative landline cable business. Third, the B2B-to-B2C transition that established a retail distribution network of wide reach, but whose depth requires examination. Fourth, capital allocation and governance breakdown—the Orbit Electricals saga. And fifth, a falsification pass on core claims: brand equity, distribution moat, the fast-moving electrical goods (FMEG) optionality bet, and the balance sheet itself.
The story starts where the family started: with nothing.
 Subscribe on LinkedIn
II. Karachi to Pune: The Refugee Brothers & Early Manufacturing (1945–1972)
In the late 1940s, Pune was a garrison town and an educational hub rather than an industrial center. The local cantonment bought goods from small traders, and contractors wired bungalows with imported cable because virtually no domestic alternative existed. Into this commercial environment stepped Prahlad Parsram Chhabria—known as P.P. to colleagues—and his younger brother Kishandas, or K.P.
They opened a small electrical goods shop doing straightforward trade arbitrage: buying imported cable and electrical hardware, selling it to local contractors, and learning what those contractors required on the job. What set the Chhabria brothers apart was what they observed behind the counter. While typical traders focused on price spreads, manufacturers-in-waiting recognized supply deficits.
The brand name emerged from that counter-level insight into customer expectations. Finolex was coined from "Fine" and "Flexibles"—a brand promise for flexible PVC-insulated cable, paired with a logo featuring an electrical arc across the letter "O". In a market where wire was historically sold by weight and judged by guesswork, branding the quality attribute served as a key differentiator.
A critical operational turning point arrived in the mid-1950s via state procurement. The Ministry of Defence required wire harnesses—bundled looms of insulated cable that distribute power through military vehicles—for trucks and tanks. Awarding that contract to two Pune traders marked a pivotal moment of customer development. It required the brothers to meet stringent technical specifications, while highlighting a structural vulnerability: a country reliant on imported wire assemblies could not service its military fleet during a conflict.
In 1956, the brothers established a small manufacturing unit to produce PVC-insulated automotive cables domestically. This marked the transition from retail to manufacturing. The underlying economics are instructive, as the same mechanics persist throughout the industry. Wire and cable manufacturing functions as a metal conversion business: a producer purchases raw copper, draws it into conductor wire, extrudes polymer insulation around it, and sells the finished cable at a spread over metal costs. The underlying commodity cost is largely passed through; value creation depends on extrusion quality, conductor consistency, and brand equity that supports premium pricing. Mastering extrusion in 1956 gave the business the foundational technical capability it would monetize over subsequent decades.
The 1960s brought further expansion driven by macroeconomic policy. As India's foreign exchange reserves came under severe strain, the government imposed strict import controls. For a domestic cable producer, this created a strong regulatory shield: domestic demand was established, foreign supply was restricted, and import-dependent traders lacked manufacturing infrastructure. Finolex expanded by supplying state electricity boards and automotive manufacturers, operating within a licensing regime where production capacity was granted by regulatory permission rather than market competition.
For investors analyzing the company's trajectory, the key insight is that Finolex's initial advantage stemmed less from a technological breakthrough than from early manufacturing entry paired with a protective regulatory environment. Import substitution fostered domestic production, but it also shielded companies from open market competition. Decades later, when the Indian cable market fully liberalized and faced intense competition, this regulatory heritage proved significant.
In 1972, the partnership converted into a private limited company. This structural shift enabled the entity to raise external capital, hold industrial licenses, and establish a corporate foundation. The Pimpri plant near Pune served as its primary manufacturing hub.
Two operational characteristics from this era shaped the corporate culture that followed. First, the Chhabrias approached industry as traders who became manufacturers, rather than engineers who launched a business. A trader's priority centers on customer demand and pricing dynamics, whereas an engineer prioritizes technical specifications. Finolex developed a strong responsiveness to contractor and electrician preferences, accompanied by a conservative stance toward capital deployment in unproven technical categories.
Second, P.P. Chhabria maintained centralized authority over operations for decades. He functioned as founder, chief strategist, and primary arbiter of organizational decisions, relying on personal authority over formalized governance processes. While this centralized leadership drove decision-making during the company's growth phase, governance challenges re-emerged decades later.
By 1972, the brothers had established a viable manufacturing enterprise. The subsequent period would see Finolex transition into a publicly listed company, creating the equity ownership structure that would eventually become the subject of corporate dispute.
III. The Defense Contract, License Raj & Public Listing (1972–1989)
The 1970s and early 1980s marked a period of deliberate adjacency expansion for Finolex—moving from automotive wire harnesses into commercial power cables, residential building wires, and industrial control cables. The underlying manufacturing process applied the company's core extrusion capability to progressively larger conductors and broader technical specifications. While customer segments evolved, the core operational logic remained consistent.
In July 1983, Finolex Cables Limited listed on the Bombay Stock Exchange through a heavily oversubscribed public offering.8 Indian retail investors in 1983 had limited opportunities to participate in domestic industrial growth, making an established manufacturer with military and state electricity board credentials a compelling investment.
Rather than deploying capital solely to expand finished cable capacity, P.P. Chhabria directed funds backward into the supply chain, investing in PVC compounding and copper wire drawing. In a metal conversion business, backward integration functions as a margin-enhancement strategy alongside supply assurance. Manufacturing copper rod and insulating compound in-house allowed Finolex to capture intermediate spreads, control product quality at the source, and insulate operations from supplier delays during demand spikes.
A decisive structural move occurred in 1981. Recognizing that PVC resin served as a critical input for both cable insulation and agricultural piping, P.P. Chhabria established Finolex Industries Limited (FIL) as a separate corporate entity. FIL subsequently constructed a major PVC resin production complex at Ratnagiri in coastal Maharashtra.
While operationally effective, this dual-company architecture introduced complex long-term governance dynamics. Two separately listed operating companies shared a common brand, family leadership, and a network of cross-holdings controlled through private family vehicles—most notably Orbit Electricals. As a result, control of Finolex Cables did not reside cleanly with its public shareholders, but within an interconnected holding structure. Recent disclosures indicate Orbit Electricals holds 30.70% of Finolex Cables.10 Combined with Finolex Industries' equity stake, this block held voting control.
This corporate division also defined the boundaries of Finolex Cables' margin profile. Housing PVC resin production inside a separate listed company meant Finolex Cables captured the conversion economics of cable manufacturing, but not the upstream chemical margins of raw polymer production. Capital allocation and governance were segmented: Finolex Cables operated as a wire and cable manufacturer, while Finolex Industries functioned as a petrochemical-linked pipe producer. The arrangement functioned smoothly under unified founder leadership, but created systemic governance risk once family alignment fractured.
The 1980s also established Finolex's long-term capital allocation pattern. Supported by IPO proceeds, steady cash generation from its growing brand, and regulatory protections under the licence-permit regime, the company consistently prioritized vertical integration and balance-sheet liquidity over aggressive distribution expansion. This conservative posture persisted for decades. While competitors such as Polycab India later deployed capital to expand retail distribution depth, Finolex focused on securing raw material inputs and building financial reserves—a strategy that preserved balance-sheet strength but delivered slower long-term market share growth in retail channels.
Disconfirming evidence: was this an institutionalised structure?
A common assumption regarding founder-led Indian industrial groups of this era is that the 1980s brought formal institutionalization—governance structures, professionalized boards, and structured succession planning. Finolex's corporate history presents a clear counter-example.
The group built an organization centered entirely around a single founding patriarch. There was no publicly documented voting trust binding the second generation, no legally enforceable family constitution, and no structural separation between operating management and the entity holding voting control. Under the licence-permit regime, this informal centralized structure offered operational efficiency: decisions were executed quickly and capital moved across related entities without bureaucratic delay. However, this model left the organization vulnerable once founding authority ended.
Finolex's informal management style mirrored many 1980s Indian promoter groups, but its specific corporate architecture—two listed operating companies, a private holding vehicle, and a shared brand—concentrated governance risks into a single point of failure. Resolving that latent conflict required only the absence of unified founder control.
That transition lay three decades ahead. In the immediate term, Finolex entered a period of rapid operational growth before technological shifts disrupted its primary product lines.
IV. The Telecom Golden Age & The Mobile Phone Crash (1980s–1990s)
In the late 1980s, India embarked on a major expansion of its landline telecommunications network. Spearheaded by Sam Pitroda and the Telecom Technology Missions, the initiative sought to establish telephone access across a country where connections had previously involved multi-year waiting lists. The physical infrastructure underlying this expansion relied heavily on underground copper cabling.
Specifically, the network required jelly-filled telephone cable (JFTC). Bundling hundreds of thin insulated copper pairs inside a protective sheath, manufacturers flooded internal air gaps with a petroleum jelly compound to block moisture ingress. In a monsoon climate where cables were buried across diverse geography, water damage degraded signal quality and destroyed wire pairs. The national buildout required JFTC at industrial scale.
Finolex became the first private sector manufacturer of JFTC in India, securing long-term supply contracts with the Department of Telecommunications and its subsequent corporatized entities, Bharat Sanchar Nigam Limited (BSNL) and Mahanagar Telephone Nigam Limited (MTNL). For over a decade, JFTC represented one of the most profitable lines in Indian industrial manufacturing. Operating with a state monopsony buyer, standardized product specifications, large order volumes, and high barriers to entry for unapproved suppliers, Finolex generated substantial cash flows that funded further capital expenditure.
The company constructed a major manufacturing complex at Urse, along the Mumbai-Pune industrial corridor. The Urse facility expanded beyond JFTC into continuous cast copper rod production and optical fiber cable manufacturing. The copper rod line completed backward integration for conductor feedstock, enabling Finolex to melt and cast its own copper inputs.
This period of state purchasing also shaped the company's internal resource allocation. A manufacturer supplying standardized products to state telecommunications monopolies under long-term contracts operates with high revenue visibility, predictable specifications, and negotiated pricing. By contrast, building wire requires continuous commercial effort to win incremental sales through electrical contractors and retail channels. As management focused capital and organizational attention on state telecom tenders, the retail distribution franchise received less strategic focus during a period when India's consumer economy was expanding.
This product mix also introduced capital intensity risks. Manufacturing lines for optical fiber, JFTC, and continuous copper casting required specialized, long-lived capital equipment with limited alternative uses. High fixed-cost assets dedicated to a single primary customer segment created dual-ended operating leverage: while rising volumes generated strong profit margins, demand declines magnified revenue losses and forced asset write-downs.
That demand structure collapsed around the turn of the century. Between 1999 and 2001, the rapid rollout of GSM and CDMA wireless networks fundamentally altered Indian telecommunications economics. Wireless networks connected subscribers through cell towers and radio spectrum rather than buried copper pairs. While overall telecom capital expenditure accelerated, demand for copper-based JFTC fell precipitously. State procurement orders evaporated, resulting in a structural collapse in order volumes rather than a temporary cyclical downturn.
The transition disrupted Finolex's operations. The company faced unutilized specialized capacity, excess inventory, and a cost structure designed for higher demand volumes. Operating margins compressed, JFTC-related assets underwent write-downs, and return on capital remained depressed for several years as management sought alternative applications for its manufacturing infrastructure.
The shift also required organizational restructuring. Operating as a state-focused contractor had encouraged specialized internal teams dedicated to government tenders, regulatory compliance, and bulk production scheduling—capabilities with limited utility in competitive consumer markets. To recover, Finolex had to re-establish commercial relationships across thousands of independent retail dealers and hardware stockists.
Falsification: did technical pioneer status create a moat?
The early-mover thesis assumed that first-mover status, technical certifications, government relationships, and manufacturing scale created a durable moat in telecommunications cables.
Subsequent developments disproved that thesis. Finolex's competitive advantage was tied to a specific product technology rather than an enduring customer requirement. The underlying need—connecting telecommunications subscribers—was reassigned to wireless technology, transforming specialized copper manufacturing assets into underutilized liabilities. Furthermore, reliance on a monopsony buyer exposed the business to sudden shifts in public capital allocation. When state agencies redirected spending toward wireless infrastructure and spectrum, vendor qualification provided no protection against revenue loss.
This structural vulnerability remains relevant for evaluating Finolex's communication cable division, which continues to experience demand cycles linked to external technology shifts.
Having navigated the contraction in state telecom procurement, Finolex pivoted back toward its core retail operations: building wires for residential and commercial construction.
V. The Building Wires Moat & The 200,000 Retailer Network (2000s–2010s)
Walk into a hardware shop in a Tier-3 Indian town and observe a typical purchase. The homeowner is rarely the decision-maker; the electrician is. Hired to wire a residence, the tradesman specifies the wire brand. The homeowner—unable to evaluate conductor purity or polymer insulation grade and aware only that faulty wiring causes fires—defers to that recommendation. In turn, the retailer stocks what local electricians request. Understanding this three-way dynamic early gave Finolex a distinct strategic advantage in Indian building wire.
The post-telecom pivot was therefore more than a product shift; it was a shift in customer orientation. For over a decade, the company had sold to government procurement engineers against rigid technical specifications. Now it had to persuade hundreds of thousands of independent tradesmen whose buying habits were driven by familiarity, brand trust, and daily installation experience.
This pivot also restructured the company's working capital profile and operational risk. Selling to state agencies generated large receivables from a creditworthy but slow-paying monopsony, with revenue arriving in lumps tied to tender cycles. Selling through a retail distribution network generated thousands of smaller receivables, faster inventory turnover, and continuous cash flow—backed by stock deployed across thousands of retail counters. The retail model offered greater structural resilience, as no single buyer could imperil the business. However, it was also structurally more expensive to build, requiring a manufacturer to finance the distribution channel alongside factory production. Finolex's historical reluctance to finance the channel aggressively proved to be the precise vulnerability competitors later exploited.
Finolex addressed this retail market through a three-part strategy.
Standards as a weapon. The company introduced flame retardant (FR) and fire resistant low smoke (FRLS) multi-strand PVC copper wire into the Indian mass market. The technical distinction was crucial for installer adoption: while a solid single-core conductor consists of a single thick copper rod, multi-strand wire bundles multiple fine copper filaments together. The stranded design bends around tight wall conduits without work-hardening or cracking. Meanwhile, FR and FRLS insulation grades directly address fire safety by limiting flame propagation and reducing toxic smoke emissions during electrical fires. By educating electricians on these specifications, Finolex established higher safety standards as a baseline requirement, effectively marginalizing competitors selling unrated, lower-grade wire.
The electrician as the real customer. Finolex established direct relationship programs for electricians at scale, combining point-of-sale reward schemes, insurance coverage, and practical product training. This strategy recognized a key commercial reality: wire represents a minor fraction of overall construction costs, end consumers cannot independently judge technical quality, and installer recommendations carry decisive weight. Securing tradesman loyalty offered far greater commercial value than targeting consumer advertising alone.
Width. The company expanded its distribution footprint across a broad network of retail outlets, extending from major metros down to small Tier-3 towns. The accompanying brand tagline, "No Stress, Finolex", embedded safety and reliability into broader consumer awareness.
The economics of this consumer-facing model were exceptionally favorable. Retail building wire commands significantly higher profit margins than institutional or commodity cabling because the buyer base is fragmented, individual order sizes are modest relative to total project budgets, and the cost of product failure is catastrophic. Homeowners rarely economize on electrical wiring buried inside their walls. This willingness to pay a premium for safety—captured in the "No Stress" positioning—formed the economic foundation of the Finolex brand, enabling the company to generate solid returns on cable manufacturing capital even during periods of corporate distraction.
Falsification: is the retail network a cornered resource?
However, evidence from the subsequent decade challenges the assumption that distribution scale creates an impregnable moat.
Distribution width does not automatically translate into channel loyalty. A hardware dealer operates a profit-driven business, choosing which brand to push based on trade margins, credit terms, and inventory turnover. Throughout the 2010s, competitors such as Polycab, RR Kabel, and Havells aggressively targeted those commercial variables by offering higher dealer margins and flexible supply-chain credit—at a time when Finolex's promoter family was increasingly occupied by internal governance disputes.
The impact was evident in market share trends. Finolex's share of the organized retail building wire market declined from historic highs near 30% toward the mid-twenties by FY24, while Polycab captured the majority of market growth. Finolex did not experience an absolute contraction; it maintained a substantial volume base and grew modestly alongside broader market expansion. However, it surrendered incremental market gains. In a sector compounding at double-digit rates, ceding incremental growth allows aggressive rivals to capture leadership without the incumbent ever reporting a declining top line.
This empirical record requires narrowing the bull case thesis. Finolex retains genuine brand pull among electricians and end consumers, as evidenced by its ability to hold substantial market share while offering lower dealer margins than aggressive rivals—the classic signature of consumer pull over channel push. Yet its distribution network is not a cornered resource; the retail channel remains contestable, and competitors successfully gained ground. The corrected thesis describes a durable, non-exclusive brand franchise in a category where channel access can be contested by well-capitalized rivals willing to incentivize dealers more aggressively.
A second piece of evidence highlights input-side limitations on pricing power. Because retail building wire is sold at a premium over raw copper costs, the business is sensitive to commodity price shocks. When copper prices rise sharply, retailers and electricians defer purchases to work through existing channel inventory. Management documented this behavior during FY26 and FY27, noting that modest building wire volume growth stemmed from market resistance against persistent copper price increases and subsequent channel destocking.34 This pattern reveals clear boundaries to brand pricing power: while Finolex commands a trust premium, it cannot force the channel to absorb rapid raw material inflation without triggering demand deferral. A truly unassailable brand would demonstrate lower volume elasticity under similar cost pressures.
Going forward, the primary benchmark for evaluating the franchise is volume growth rather than headline revenue, as revenue fluctuates directly with copper prices. On recent earnings calls, management acknowledged that building wire volumes grew only modestly due to channel destocking and buyer resistance to continuous copper price hikes.34 Sustained volume growth that trails the broader organized market serves as a clear falsification signal, whereas volume growth matching or exceeding peer expansion indicates business model repair.
Having re-anchored its business around retail building wires, Finolex subsequently sought to emulate peer diversification by leveraging its electrician network to expand into adjacent electrical consumer products.
VI. The FMEG Expansion: B2B to B2C Ambition vs. Reality (2014–Present)
The strategic logic appeared compelling and possessed a clear industry precedent. Havells India had successfully transitioned from industrial switchgear into fans, lighting, and home appliances, earning consumer-company margins and a corresponding market valuation multiple. Finolex possessed an established brand, extensive distribution, and deep electrician relationships. Adding fast-moving electrical goods (FMEG)—including fans, LED lighting, miniature circuit breakers, water heaters, and small appliances—seemed like a straightforward path to generating incremental revenue across an existing dealer network.
However, this precedent proved difficult to replicate. Havells had not merely stretched its brand across store shelves; it had spent years developing specialized consumer capabilities—product design, after-sales service networks, category management, and consumer-oriented marketing—under a unified leadership team. Finolex attempted to copy the end state without building the underlying operational capabilities.
The company committed substantial capital to the initiative, launching major marketing campaigns featuring celebrity brand ambassadors to reposition Finolex from an industrial cable manufacturer into a consumer electrical brand. Management outlined ambitions to become a significant player across multiple FMEG categories within a few years.
A decade later, the operational evidence reveals a stark divergence between strategy and execution.
FMEG has consistently accounted for only a small single-digit percentage of consolidated revenue and has struggled to deliver meaningful profitability, as elevated marketing expenditures and distribution inefficiencies absorbed gross margins. On recent earnings calls, the segment remained an ongoing drag on performance: management attributed weakness in FY26 and Q1 FY27 to adverse seasonal weather affecting fan sales, regulatory shifts in energy-efficiency ratings, and fuel and PVC supply disruptions, while maintaining that a target of roughly ₹500 crore in FMEG revenue by FY28 remained achievable.34
This persistent gap between targets and outcomes highlights an important management credibility issue for investors to evaluate. Across multiple reporting periods, management routinely attributed quarterly shortfalls to temporary external factors—unfavorable weather, regulatory adjustments, or raw material bottlenecks—while keeping long-term segment targets unchanged. While each explanation appears plausible in isolation, their accumulation over ten years of underperformance indicates a structural execution problem rather than a series of temporary disruptions.
A secondary operational challenge emerged within the distribution network itself. FMEG items compete with building wires for dealer shelf space and working capital, but present less attractive unit economics for retailers when stocking unproven lines—yielding lower turnover, higher return rates, and lower absolute margins. Encouraging hardware dealers who generate steady profits on building wire to stock slow-moving appliances risks diluting channel goodwill, suggesting that the FMEG expansion may have exerted a subtle drag on the core business rather than operating as a neutral adjacent experiment.
Why it has not worked. The operational mismatch stems from fundamentally different business models. While electrical wire and ceiling fans share shelf space at retail counters, their backend requirements differ entirely. Cable manufacturing operates as a metal conversion business characterized by long product lifecycles, zero after-sales service, minimal design cycles, and spec-driven purchasing. In contrast, FMEG requires rapid SKU innovation, consumer-facing warranty service networks, complex seasonal demand forecasting, and aggressive retail shelf competition against established specialists such as Havells, Crompton Greaves, Orient Electric, and Bajaj Electricals—companies whose organizational structures were built specifically for consumer retailing. Finolex attempted to enter this fast-moving category while retaining the operating pace and structure of an industrial cable manufacturer.
Falsification verdict. The hypothesis that FMEG provides high-margin optionality capable of driving a consumer-goods valuation re-rating is disproved by the company's ten-year track record. Ten years offers a sufficient sample size to evaluate structural viability. FMEG remains economically immaterial to consolidated earnings, absorbs management attention disproportionate to its financial contribution, and functions primarily as a brand-awareness asset that completes a dealer's product display rather than an independent profit engine.
Consequently, valuation models should treat Finolex principally as a wire and cable business, evaluating FMEG as an operational expense with potential upside if profitability materializes. A meaningful revision to this thesis would require concrete evidence: the segment achieving sustained positive earnings before interest and taxes (EBIT) while approaching management's revenue targets, without requiring further operational caveats. Until then, the division's primary analytical value lies in what it reveals about corporate goal-setting and execution consistency.
The organizational bandwidth required to resolve these FMEG execution challenges was further constrained by parallel developments at the corporate level—specifically, the internal governance conflict examined in the following section.
VII. The Great Chhabria Family Feud: Orbit Electricals, Legal Warfare & Governance Paralysis (2016–Present)
P.P. Chhabria died in May 2016. Having spent seven decades building an enterprise around his personal authority, he left behind a corporate structure—two listed operating companies, a private holding vehicle, complex cross-holdings, and no enforceable succession mechanism—with only one load-bearing element: himself.
The battle that followed pitted first cousins against each other, with each leading one half of the group.
What made the conflict unusually destructive was that both sides possessed legitimate claims to authority. One cousin managed daily operations, while the other controlled the voting shares. In typical corporate disputes, incumbent management faces an external challenger. At Finolex, the challenger held voting control through shareholding, while the incumbent held operational authority inside the enterprise. Because the founder had never established a neutral governance mechanism, the corporate structure lacked an internal referee.
Deepak Chhabria, son of K.P., served as Executive Chairman of Finolex Cables—the operating entity holding the primary manufacturing assets, the brand, and the retail network. Prakash Chhabria, son of P.P., served as Executive Chairman of Finolex Industries, the PVC resin and piping business, and crucially controlled Orbit Electricals Private Limited.
Control followed the holding structure rather than operations. Orbit Electricals owns 30.70% of Finolex Cables.10 Combined with Finolex Industries' equity stake in Finolex Cables, Prakash's side commanded a voting block of roughly 45% in the enterprise his cousin managed. In a widely held public company, a 45% stake represents decisive voting control at any general meeting.
The legal battle began over share transfers within Orbit itself. Deepak challenged a gift deed through which shares in Orbit Electricals passed to Prakash, alleging questionable execution, and disputed board minutes that he contended stripped away his protective rights. Filed in 2016, that petition remained subject to active amendment eight years later.[^6]
For seven years, the dispute proceeded through tribunals without resolving operational authority. Then came the Annual General Meeting.
September 29, 2023. Finolex Cables held its AGM, where Resolution 4 proposed the reappointment of Deepak Chhabria as Executive Chairman. Orbit Electricals and Finolex Industries voted against. When scrutinizers completed the vote tally, 72.34% of votes cast opposed the resolution.[^4]9 On paper, the shareholders of Finolex Cables had voted their executive chairman out of office.
What followed had little precedent in Indian corporate law.
Deepak Chhabria contested the vote count, bringing the matter before the National Company Law Appellate Tribunal (NCLAT), where a bench issued an order favorable to him. However, the bench delivered its ruling without adhering to Supreme Court directions regarding the scrutinizer's report.[^5] The Supreme Court, under Chief Justice D.Y. Chandrachud, responded decisively: it set aside the NCLAT judgment, ordered the NCLAT chairperson to conduct an inquiry into the bench's conduct, and in October 2023 imposed a ₹1 crore fine on Deepak Chhabria and a ₹10 lakh fine on the scrutinizer for contempt.[^5] The NCLAT subsequently suspended its order pending the inquiry.
For shareholders, the implications were stark. This was not a routine governance disagreement resulting in proxy advisory criticism; the nation's highest court had fined a listed company's sitting executive chairman ₹1 crore for contempt and ordered an investigation into a judicial tribunal.
The aftermath. In 2024, the NCLAT declined to interfere with the AGM outcome on Resolution 4, confirming the shareholder vote.9 Separately, appeals filed by Deepak Chhabria and his wife against Orbit Electricals were rejected, and in July 2024 the NCLAT upheld an NCLT order permitting amendments to the nine-year-old company petition on the grounds that subsequent events could be introduced by amendment.[^6][^7]10 That ruling kept the original 2016 oppression-and-mismanagement petition active and expanded, prolonging litigation rather than resolving it.
As of September 2026, operational board control rests with Prakash Chhabria's side, while the underlying share-ownership dispute continues through the tribunal system. The operating company has moved forward under professional management, including Chief Financial Officer Sachin Naik, who joined on June 1, 2026.3
A complete assessment must also note what did not happen. Throughout the legal proceedings, the operating business continued to manufacture, pay dividends, and generate cash flow. Finolex Cables experienced no accounting irregularities, going-concern warnings, debt defaults, or auditor qualifications. The dispute centered on corporate control rather than underlying operational solvency. That distinction preserved core equity value, creating the foundation for a valuation re-rating once control clarified.
What did this cost shareholders?
The costs split into two distinct categories.
The first was capital allocation paralysis. During a major expansion cycle in Indian construction and infrastructure, Finolex accumulated an extensive treasury portfolio, reaching approximately ₹4,195 crore in investments by FY2026.1 While maintaining cash provides downside protection for a cyclical manufacturer, holding reserves of that scale while competitors built extra-high-voltage capacity and expanded market share through dealer financing reflected strategic passivity. A board embroiled in litigation rarely approves large acquisitions, major greenfield expansions, or aggressive share buybacks, defaulting instead to treasury investments that require no strategic consensus.
The second cost was lost time. Building institutional sales relationships, securing extra-high-voltage product qualifications, and establishing dealer financing infrastructure require multi-year commitments. Competitors spent the 2016–2023 period executing those initiatives while Finolex remained focused on legal proceedings.
The activist's opening question—which sets up the subsequent strategic analysis—is direct: with voting control effectively established, what is the justification for maintaining a treasury of that scale? That capital must either finance a major operational expansion or be returned to shareholders. Holding these cash reserves while generating a return on equity in the low teens remains difficult to defend under standard capital allocation principles.
This leads directly into the detailed financial analysis.
VIII. Financial Anatomy & Segment Economics (FY24–FY26)
Finolex's financial trajectory presents a more nuanced picture than standard value-trap assumptions suggest, rendering older analytical notes outdated.
Evaluating a cable manufacturer requires understanding its metal conversion economics. Raw copper represents the largest single cost component, priced on global commodity exchanges and passed through to customers with an operational lag. Consequently, headline revenue growth overstates underlying volume expansion during periods of rising metal prices and understates it during declines. Similarly, percentage gross margins function poorly as a trend metric, as rising copper prices dilute percentage margins even when unit profitability remains unchanged. Furthermore, inventory gains and losses impact quarterly profits independently of core operational efficiency. Assessing Finolex therefore requires evaluating volume growth first, segment-level operating earnings second, and reported percentage margins last.
The trajectory. Consolidated revenue grew modestly from ₹5,014 crore in FY2024 to ₹5,319 crore in FY2025—a 6% expansion that, given raw material cost dynamics, represented essentially flat volume performance. That stagnation reinforced the value-trap thesis. FY2026 interrupted that pattern, as revenue climbed 19% to ₹6,321 crore, while net profit rose modestly from ₹701 crore to ₹714 crore.1
The divergence between top-line expansion and bottom-line growth highlights underlying margin dynamics. While revenue expanded by 19%, net profit grew by less than 2%, reflecting compressed operating spreads. On the Q4 FY2026 earnings call, management attributed this margin contraction to late-quarter raw material price increases, currency depreciation, and supply chain disruptions in communication cables.4
The core engine: electrical wires and cables. The electrical segment continues to generate the vast majority of revenue and operating profit. During FY2026 and Q1 FY2027, volume expansion was driven primarily by industrial and specialty product lines: automotive and battery cables, flexible industrial cables, power cables, and solar cables all recorded double-digit volume gains, lifting segment revenue 47% year over year to ₹1,767 crore in Q1 FY2027.34 High demand kept solar cable operations near full capacity utilization, prompting management to plan further capacity additions.4
Conversely, core consumer product lines lagged. Retail building wire—historically the company's principal brand driver and margin anchor—recorded only marginal volume growth,34 while agricultural cable volumes contracted by 15% to 16% due to monsoon-related disruptions.4
This divergence represents a critical analytical insight. Finolex's recent revenue acceleration relies heavily on industrial and application-specific cables—such as solar, automotive, battery, and industrial flexible products—rather than the consumer retail building wire franchise. Winning in technical, specification-driven industrial categories validates manufacturing capabilities and aligns with broader infrastructure spending. However, industrial cabling carries lower operating margins, requires higher capital expenditure, and operates in a more competitive environment than retail building wire. Consequently, the specific franchise that justifies a consumer-goods valuation multiple remains dormant.
Communication cables: the drag that became the star. For years, the communication cable division suffered from the legacy of the telecom downturn. Global optical fiber overcapacity depressed pricing, while domestic demand remained dependent on the timing of government broadband tenders, driving operating margins down from double digits into low single digits.
Performance shifted markedly in FY2026 and early FY2027. Communication cable revenue reached ₹176 crore in Q1 FY2027, up 62% year over year, driven by strong data-center demand linked to artificial intelligence infrastructure. International sales comprised 35% to 40% of segment revenue,3 and segment operating margins approached 30%.
In contrast to its communication regarding the FMEG business, management provided conservative margin guidance. Chief Executive Officer Mahesh Viswanathan clarified that near-30% margins resulted from lower-cost inventory gains and projected normalized segment margins in the lower double digits.3 Proactively managing expectations during an operational surge provides a helpful benchmark for evaluating executive disclosures.
To support expanded demand, the company allocated ₹300 crore in FY2027 capital expenditure guidance. The investment plan doubles fiber draw tower capacity from 4 million to 8 million fiber kilometers, expands cabling capacity from 8 million to 10 million kilometers, and stabilizes an internal preform manufacturing facility.3
The discipline required here is historical. Finolex has previously expanded manufacturing capacity during telecom demand surges, only to see assets underutilized when customer buying patterns shifted. Current demand differs constructively from earlier cycles, as data-center construction offers a more diversified, export-oriented customer base than historical state procurement monopsonies. Nevertheless, expanding capacity into a globally cyclical optical fiber market requires analytical discipline. Evaluating the segment requires modeling earnings at normalized margins rather than peak inventory-assisted levels, treating capital deployment as a cyclical investment rather than a structural re-rating.
Two smaller items worth noting. The copper rod division sells modest volumes externally at thin conversion spreads, functioning primarily as internal feedstock. Meanwhile, the Sumitomo joint venture achieved profitability in FY2026, generating ₹21 crore in net profit on ₹450 crore of revenue—a 4% to 5% net margin that demonstrates operational execution in collaborative ventures.4
From a corporate governance perspective, recent disclosures reflect standard administrative reporting. Regulatory filings document routine tax correspondence, including orders from Goods and Services Tax (GST) authorities, alongside routine leadership updates in secretarial and finance functions, including the appointment of Chief Financial Officer Sachin Naik.3 These items represent ordinary-course compliance rather than structural operational risks. The primary governance factor remains the promoter litigation, which represents a known and disclosed equity discount factor rather than an unquantified operational risk.
The balance sheet. Total borrowings stand at ₹19 crore against ₹4,195 crore in investments and treasury assets, with return on equity (ROE) at 12.3% and return on capital employed (ROCE) at 16.0%.1 The balance sheet provides exceptional downside protection; the company has avoided equity dilution, distress refinancing, or solvency risks. However, holding large low-yielding cash reserves depresses overall returns. Mathematically, Finolex operates as two distinct entities: a high-performing cable manufacturing business earning solid returns on operating assets, combined with a large fixed-income portfolio generating modest investment yields. The spread between 16.0% ROCE and 12.3% ROE reflects the return drag created by excess cash reserves.
The financial performance thus presents a clear synthesis: core cable operations are expanding in industrial categories, the legacy retail building wire franchise shows modest volume growth, communication cable performance remains subject to industry cycles, and capital allocation choices continue to constrain consolidated return on equity.
That financial profile leads directly to a comparison with peers that expanded market share during Finolex's corporate dispute.
IX. Competitive Benchmarking: How Polycab & KEI Outmaneuvered Finolex
Understanding what Finolex surrendered over the past decade requires examining the growth trajectory of Polycab India.
In FY2026, Finolex generated just over ₹6,300 crore in revenue.1 By contrast, Polycab operated at a multiple of that scale, while KEI Industries generated roughly double Finolex's top line.56 Fifteen years earlier, no such performance gap existed. Finolex was the premier household brand, whereas Polycab was a regional manufacturer based in Gujarat with a strong institutional business but limited consumer presence. The industry's reordering occurred within a single decade.
The strategic issue is not merely why Polycab expanded faster, but why an incumbent holding a superior consumer brand ceded leadership in a market driven primarily by construction demand. On paper, Finolex entered the decade with the industry's most valuable asset.
Three operational mechanisms explain this reordering.
First, institutional and extra-high-voltage (EHV) scale. Extra-high-voltage power cabling—heavy-gauge conductor that transfers electricity across national grids and substations—operates under distinct business dynamics from building wire. It requires substantial capital outlay, lengthy qualification cycles with utilities and engineering, procurement, and construction (EPC) contractors, and the capability to execute multi-year infrastructure contracts. Both Polycab and KEI committed early to EHV infrastructure, positioning themselves directly in the path of major industrial tailwinds: grid modernization, renewable energy integration, industrial capital expenditure, and power distribution for data centers. Finolex remained anchored in retail building wire and specialized application cables, maintaining minimal presence in high-voltage utility lines.
EHV manufacturing is not inherently a superior business; it carries higher capital intensity, tender dependency, and extended receivable cycles. However, institutional spending represented the primary growth engine of Indian electrical demand over the past decade. An established manufacturer can execute effectively within its core niche yet still lag peers if capital remains allocated away from expanding demand segments.
Second, distribution as a financing vehicle. Polycab's channel expansion relied on financial structuring alongside brand advertising. By establishing distributor financing arrangements, Polycab enabled retail stockists to hold larger inventory volumes than their independent working capital would otherwise support. In retail hardware distribution, a dealer's primary operational constraint is working capital rather than shelf space. Consequently, a manufacturer providing channel financing can capture dealer loyalty from a stronger incumbent brand. Despite possessing a recognized consumer brand and a strong balance sheet, Finolex refrained from deploying its cash reserves to finance trade channels, allowing rivals to gain retail market share.
Third, professional management continuity. Polycab recruited experienced executives across sales, supply-chain logistics, and consumer operations, delegating operational authority to professional management. Conversely, Finolex spent the same period navigating family litigation and contested leadership. While corporate enterprises can tolerate strategic missteps, prolonged leadership uncertainty frequently destabilizes operations. Executive attrition and management distraction served as the primary conduits translating promoter governance disputes into operational underperformance.
A balanced assessment must also account for the operational risks embedded in competitor strategies. Polycab and KEI carry vulnerabilities that Finolex avoids. Project and EPC exposure introduces working capital risks, collection delays, and contract execution hazards. Furthermore, both peers operate with higher debt levels relative to Finolex's virtually debt-free balance sheet, while trading at earnings multiples that price in continued rapid expansion. For investors, evaluating the three companies involves weighing operational momentum at premium valuations against a slower-growing, debt-free enterprise operating under capital allocation uncertainties.
What does Finolex retain? Three core strengths remain evident.
First, Finolex maintains strong brand equity among electricians and end consumers in retail building wire—a reputational asset that is difficult and costly for competitors to replicate.
Second, the company retains a debt-free balance sheet. In an industry where competitors frequently fund working capital and project expansion through debt, zero leverage provides structural resilience during cyclical downturns, preserving capital optionality while leveraged peers manage receivable stress.
Third, Finolex continues to demonstrate manufacturing capability in specialized technical segments. Recent volume expansion across solar, automotive, battery, and industrial flexible cables demonstrates an ability to convert technical expertise into growing sales outside traditional building wire.
The valuation question, correctly posed. Finolex continues to trade at a discount to Polycab and KEI Industries, though the valuation gap has narrowed relative to the peak litigation period.1 The analytical question is not whether a discount exists, but whether current market pricing accurately reflects structural differences. A business generating slower multi-year growth, earning lower returns on equity, maintaining a large cash treasury, navigating unresolved promoter litigation, and registering modest volume growth in core retail building wire naturally warrants a lower valuation multiple than faster-growing, higher-return peers. The core investment question is narrower: whether the current valuation discount exceeds what those operational constraints justify, and what specific catalysts could narrow the gap.
X. Playbook: Business & Investing Lessons
1. Family business governance is a structural variable, not a soft one.
The Finolex case demonstrates that succession planning belongs on an enterprise risk register alongside financial leverage and customer concentration. What eroded value was not a single failed operational decision, but the absence of a formal governance mechanism—such as a binding voting arrangement, a clear holding structure, or an enforceable family constitution—to resolve an inevitable leadership conflict. An informal understanding functions as a governance model only while the founding patriarch who commands deference remains alive. For investors, the practical assessment is mechanical: in any promoter-controlled enterprise, identify who controls voting rights, through which entity, and what legal mechanism governs that entity upon the founder's passing. If corporate continuity depends on ongoing goodwill between relatives, market pricing must reflect that structural risk.
2. Trapped cash is not a fortress.
A large net-cash balance is conventionally viewed as downside protection—and during a severe cyclical trough, it serves that function. Yet capital creates shareholder value only through disciplined deployment or return. Finolex held substantial treasury reserves through a major Indian infrastructure and construction expansion, while competitors deployed capital into extra-high-voltage capacity, distributor financing, and market share acquisition. That opportunity cost did not register as an explicit income-statement loss; rather, it manifested in modest multi-year revenue growth of 3% to 6% while peers compounded top-line sales in the high teens. The structural lesson is that governance deadlock converts a balance-sheet asset into a return-on-equity drag—a dynamic reflected in the persistent gap between return on capital employed and return on equity. When those two metrics diverge materially in an unlevered enterprise, the balance sheet signals that capital is sitting idle.
3. Brand equity is category-bound, and channel access is not a product.
The underperformance in fast-moving electrical goods (FMEG) offers an insight more precise than a generic warning against corporate diversification. Finolex's core brand identity represented safety and reliability in building wire—a trust-based attribute attached to a product with no after-sales service requirement, design trend, or frequent repurchase cycle. Conversely, consumer appliances and fans require entirely distinct organizational capabilities: continuous product innovation, seasonal inventory management, after-sales service networks, and warranty logistics. Shared distribution channels can tempt management into assuming market entry is largely solved because retail counters already carry the primary product line. Yet channel availability does not automatically generate consumer pull; securing shelf space is fundamentally distinct from winning consumer preference.
4. Monopsony risk and technology obsolescence compound each other.
The historical collapse of the jelly-filled telephone cable business was not merely a case of technological obsolescence; it was technological disruption magnified by extreme customer concentration. Either vulnerability in isolation can prove manageable: a diversified manufacturer can absorb a product transition, while a concentrated supplier operating in a stable technology category can sustain operations for years. Occurring simultaneously, they trigger sharp, structural earnings contractions. The broader strategic principle for industrial producers is to broaden the customer base before a secular technology shift materializes, as commercial leverage dissipates once market displacement begins. This framework remains directly relevant for evaluating the communication cable segment's optical fiber demand: investors must assess the customer concentration of current data-center and export demand, alongside the speed with which global competitors can expand matching production capacity.
XI. Strategic Position, Bull vs. Bear Case & Activist Stress Test
The bull case, stated at its strongest.
The governance overhang has substantially resolved. The chairmanship question was settled by shareholder vote and confirmed by the appellate tribunal, and the company now operates under a professional management team with a chief financial officer in place.39 Whatever litigation continues in the tribunals regarding historical share transfers, the operational paralysis that defined 2016–2023 has lifted—and the FY2026 revenue reacceleration to ₹6,321 crore reflects that operational recovery.1
Underneath the headline numbers, the product growth mix shows encouraging signals. Solar cable operates at full capacity utilization, accompanied by double-digit volume growth in automotive, battery, and industrial flexible cables, an optical fiber business benefiting from data-center and AI-driven demand with a significant export share, and a Sumitomo joint venture that has turned profitable.34 Capital expenditure is finally being directed toward manufacturing capacity rather than treasury investments.3 Meanwhile, the balance sheet remains a formidable competitive asset in a cyclical, working-capital-intensive industry.
The bear case, stated at its strongest.
The core growth engine shows signs of slowing. Retail building wire—the high-margin, brand-driven business that justifies a premium valuation multiple—has recorded only marginal volume expansion, with management citing channel destocking and buyer resistance to copper price hikes.34 If the core consumer franchise fails to compound volume, Finolex increasingly resembles a lower-margin industrial cable producer in a market where key competitors possess far greater scale.
The high-performing communication segment remains inherently cyclical, as management acknowledges. Optical fiber margins near 30% benefited from lower-cost inventory gains and are expected to normalize into the lower double digits.3 Adding fiber draw capacity into an industry marked by historical overcapacity risks repeating past mistakes, deploying capital into a global demand wave the company neither created nor controls.
The fast-moving electrical goods division continues to absorb managerial focus and capital without delivering meaningful earnings. Meanwhile, input-cost pressure from rising copper prices and currency depreciation is already reflected in the widening gap between FY2026 revenue and net profit growth.4 Finally, ownership litigation remains active: the amended 2016 petition continues through the tribunal system, leaving open the risk of future promoter-level disruption.[^6][^7]
Porter's five forces, honestly applied.
Rivalry is the dominant structural force and remains intense. Major peers—including Polycab, KEI Industries, Havells, and RR Kabel—compete directly in Finolex's core categories, with the market leaders leveraging superior procurement scale and aggressive channel margin structures.
Supplier power is moderate yet structurally asymmetric. Raw copper is a globally traded commodity, giving individual suppliers little direct leverage over Finolex. However, the commodity itself exerts power: rapid copper price appreciation compresses operating spreads through pass-through lags and triggers buying resistance across retail channels.
Buyer power varies significantly across product lines. In retail building wire, buyers are fragmented and electrician brand preference dilutes buyer leverage—representing the most defensible portion of the business. In institutional and state-linked segments, buyer power remains high. In optical fiber exports, purchasing is concentrated among large, sophisticated buyers.
Threat of substitutes is low at the individual wire level—physical electrical connections cannot be replaced wirelessly—yet company history demonstrates that substitution often occurs at the system level rather than the product level. Aluminium substitution for copper in specific industrial applications represents the contemporary manifestation of that risk.
Barriers to entry are moderate for basic commodity wire but high for brand-driven retail distribution and extra-high-voltage manufacturing. Crucially, Finolex sits behind the retail distribution barrier but remains outside the extra-high-voltage category.
Seven Powers: which does Finolex actually hold?
Applying Hamilton Helmer's Seven Powers framework, Finolex maintains a partial claim to only one strategic power. Branding remains genuine: the willingness of electricians and end consumers to request Finolex despite lower trade margins than rivals offer provides empirical proof of brand equity—a franchise that survived a decade of promoter conflict. However, that brand power has been progressively contested by competitors offering superior dealer incentives.
Scale economies favor market leaders like Polycab rather than Finolex. Switching costs are low, as retail hardware stockists can easily transition inventory to competing brands. Network economies do not exist in cable manufacturing. Counter-positioning is absent, given that Finolex operates a standard business model easily duplicated by rivals. Cornered resource fails to hold, as the distribution network proved contestable under competitive pressure. Process power remains unproven, with no evidence of proprietary manufacturing processes that peers cannot replicate.
Holding a single, partially compromised power within an industry dominated by intense rivalry argues against expecting complete valuation parity with higher-growth peers based on brand strength alone.
The activist stress test.
A disciplined institutional investor holding a significant equity stake would likely present three core operational demands to the current board:
Return excess capital. With operational control clarified and treasury investments standing at approximately ₹4,195 crore against borrowings of just ₹19 crore, the burden of proof regarding capital allocation has shifted.1 Maintaining idle cash during active governance litigation was understandable; retaining reserves of that scale without an explicit allocation strategy is harder to justify. A ₹300 crore annual capital expenditure guidance does not require a multi-thousand-crore treasury portfolio.3 Management must either commit that capital to high-return capacity expansions or acquisitions, or return excess funds to shareholders to improve return on equity.
Fix or restructure FMEG. After a decade of operations, the consumer electrical segment yields immaterial revenue and persistent margin drag, while long-term financial targets are repeatedly reaffirmed without operational convergence. An activist framework would mandate strict performance deadlines, recognizing that ongoing segment losses dilute earnings generated by core cable manufacturing without delivering tangible distribution synergies.
Institutionalize management independence. The professional management team overseeing daily operations should be structurally insulated from future promoter disputes, backed by independent board oversight and compensation structures tied directly to volume expansion and market share metrics.
The activist's most critical challenge centers on optical fiber capital deployment. Shareholders have valid reasons to question funding an expansion to an 8-million-kilometer fiber draw capacity during a demand surge that management acknowledges was margin-enhanced by inventory timing—particularly given the company's historical experience of expanding telecom cable capacity ahead of a sudden market contraction. Validating that capital deployment requires management to articulate explicit return hurdles, customer concentration metrics, and order book visibility rather than relying solely on headline capacity numbers.
XII. Epilogue & Key KPIs to Watch
The central arc of Finolex's eight-decade history reveals an organization that repeatedly excelled at manufacturing while remaining vulnerable to external structural shifts—a licensing regime that granted early domestic dominance before liberalization removed protection, a state telecom buyer that generated high profits before wireless technology rendered copper cabling obsolete, and a centralized family architecture that operated effectively under a founding patriarch before internal litigation consumed a decade following his death.
The current chapter presents the most genuine strategic uncertainty in years, for reasons the conventional value-trap narrative overlooks. The primary governance impasse has largely cleared, and the business responded with its strongest top-line expansion in a decade.1 Yet that expansion originates largely outside the core consumer brand: industrial, solar, automotive, and optical fiber exports are driving growth, while the retail building wire franchise that underpins a premium consumer valuation recorded marginal volume gains.34 Meanwhile, the multi-thousand-crore treasury portfolio once justified by board deadlock now lacks a clear strategic rationale.
Falsifying the constructive thesis requires more than a single weak quarter; it requires a persistent pattern: building wire volumes continuing to trail the organized market while optical fiber margins normalize and cash reserves remain idle. Conversely, validating the bull case requires retail volume expansion matching peer growth, communication cables sustaining double-digit margins post-normalization, and active capital deployment.
Three primary operational metrics warrant continuous monitoring:
1. Building wire volume growth versus organized-market growth. Volume—rather than headline revenue—serves as the primary indicator of performance, given that revenue fluctuates directly with copper prices and reveals little about underlying market position. This metric provides the clearest measure of whether the retail brand moat remains intact or continues to cede ground to Polycab, KEI Industries, and RR Kabel.
2. Communication cable segment EBIT margin through normalization. Management guided that near-30% operating margins will normalize into the lower double digits.3 Where profitability settles as global fiber capacity expands determines whether this division functions as a durable secondary growth engine or a temporary cyclical surge.
3. Deployment of the investment portfolio. Tracking the treasury balance reveals how capital is prioritized: whether executive leadership directs reserves into major capacity expansion, extra-high-voltage capabilities, strategic acquisitions, share buybacks, or dividend distributions. Continued cash accumulation alongside a return on equity in the low teens signals that resolving leadership disputes changed who holds executive control without altering how the enterprise allocates capital.
The first two metrics evaluate whether Finolex retains an operational franchise capable of sustaining a valuation re-rating. The third indicates whether leadership will deploy the company's balance-sheet strength to regain competitive momentum.
References
-
Finolex Cables Ltd — Consolidated Financials, Ratios and Balance Sheet — Screener.in ↩↩↩↩↩↩↩↩↩↩↩
-
Finolex Cables Limited Official Investor Relations Portal — Finolex Cables ↩
-
Earnings Call Transcript: Finolex Cables Q1 FY2026-27 Results and Management Commentary — Investing.com, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Finolex Cables Ltd (BOM:500144) Q4 2026 Earnings Call Highlights — Yahoo Finance / GuruFocus, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Polycab India Limited Investor Relations Portal — Polycab India ↩
-
KEI Industries Limited Financial Results — KEI Industries Investor Relations ↩
-
Finolex Cables Limited Stock Quote and Corporate Announcements — National Stock Exchange of India ↩
-
Finolex Cables Limited Corporate Information and Filings — BSE India ↩
-
NCLAT Permits Finolex Cables CEO Deepak Chhabria to Remain Chairman — Communications Today ↩↩↩
-
NCLAT Rejects Appeal Filed by Deepak Chhabria of Finolex Cables Against Orbit Electricals — M&A Critique ↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube