Eternal Limited: From Restaurant Discovery to India's Quick Commerce Super-App
I. Introduction & Episode Roadmap
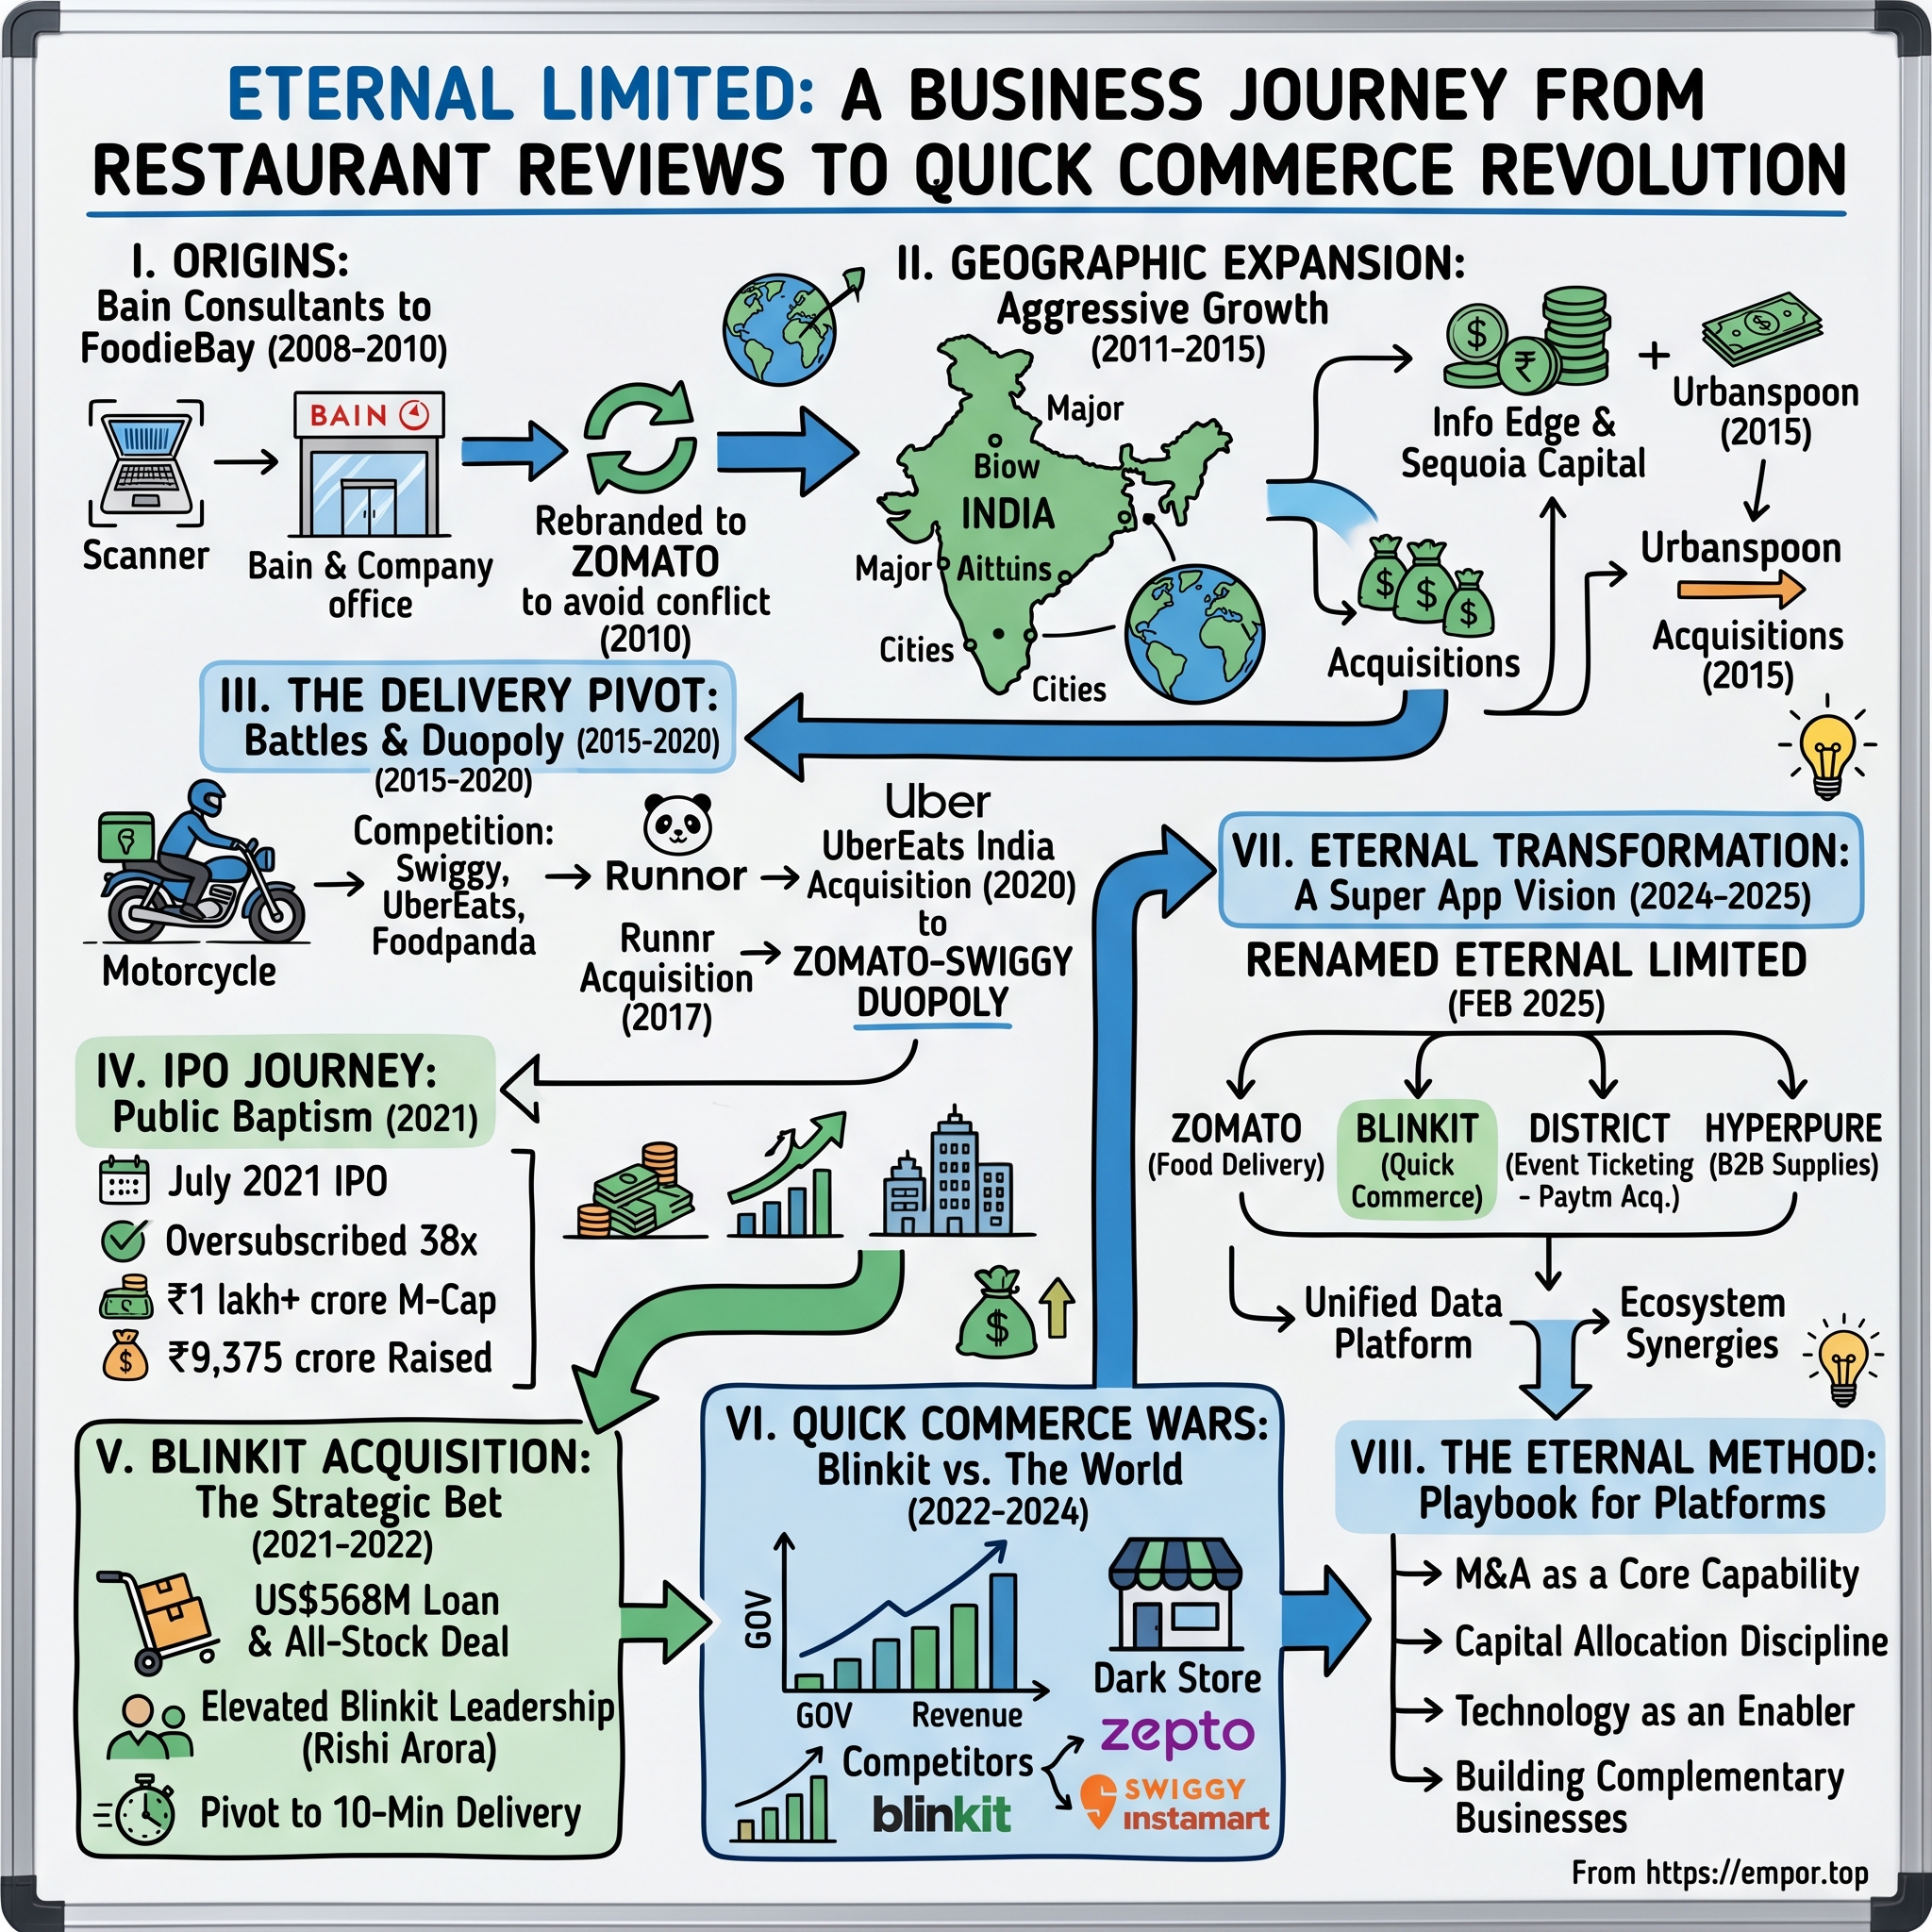
In the summer of 2008, on the fourth floor of a Bain & Company office in Gurgaon, an analyst named Deepinder Goyal grew tired of watching colleagues queue at the cafeteria notice board to read a laminated lunch menu. He scanned the menus, uploaded them to the company intranet, and tracked the traffic numbers. The intranet page quickly became the most-visited internal link in the office—the sole market research behind what is today a company valued at roughly ₹2.97 lakh crore on the National Stock Exchange.1
Eighteen years later, the company that grew out of those scanned menus does not primarily sell restaurant discovery, does not primarily sell food delivery, and no longer carries the name that made it famous. Eternal Limited—the listed parent entity of Zomato, Blinkit, Hyperpure, and District—recently traded near ₹322 per share, within a 52-week range of approximately ₹213 to ₹368.1 In the quarter ended June 2026, more than three-quarters of its reported revenue derived not from restaurant services but from selling groceries, electronics, and toys out of 2,443 dark stores—neighbourhood warehouses mostly established within the last three years.23
That core shift defines any serious analysis of the business. Eternal is no longer a food-delivery platform with a grocery side project; by revenue, it has transformed into an Indian retailer with a profitable food-delivery cash flow attached. The central investment question is therefore not how effectively Zomato operates food delivery, but whether the cash flow generated by its food-delivery segment can fund a durable position in quick commerce—a ten-minute delivery format whose long-term economics remain unproven, and where it competes simultaneously against Swiggy, Zepto, Flipkart, Amazon, and Reliance.
The central thesis this article tests is the path suggested by the company's own history: two former management consultants built a major Indian consumer internet platform, learned costly lessons about capital discipline abroad, survived intense delivery wars and a 60% post-IPO market drawdown, made a controversial $568 million acquisition of a struggling grocery startup that ultimately became the group's most valuable asset, and subsequently restructured the corporate entity—its name, ownership structure, and leadership—around that bet. Each of these claims carries a counter-narrative, which this analysis presents alongside management's track record.
Understanding the company's financial reporting is essential to interpreting its trajectory. In fiscal year 2026, Blinkit transitioned from a marketplace model—where only commissions were recorded as revenue—to an inventory-led model, where the full value of groceries sold is revenue.18 Consequently, reported group revenue grew by approximately 169% in FY26 to ₹54,364 crore.14 That surge reflects accounting mechanics rather than a sudden shift in underlying consumer order volume. Throughout this piece, the figures providing meaningful operational context are net order value, which measures actual customer expenditure, and adjusted EBITDA, which measures underlying segment profitability.
The roadmap:
- Origins and the discovery era (2008–2014): scanned menus, Info Edge's patient money, and the hard revenue ceiling on selling restaurant advertising.
- The global expansion misstep (2014–2016): the $60 million Urbanspoon acquisition and what happens when you export a playbook that was never the product.
- The food delivery wars (2015–2020): building physical logistics from a software company, buying Runnr, absorbing Uber Eats India, and the restaurant revolt that exposed how fragile merchant goodwill was.
- The public market baptism (2020–2022): COVID, the July 2021 IPO, and the crash that reset how Indian tech companies talk about profit.
- The Blinkit gambit (2021–2023): rescuing Grofers, dark-store economics, and the slow vindication of the least popular decision management ever made.
- The multi-pillar architecture (2023–2025): the first consolidated profit, the platform fee, Hyperpure, and the ₹2,048 crore purchase of Paytm's ticketing business.
- Eternal and the ownership shield (2025–2026): the rebrand, the foreign-ownership cap, the inventory-led pivot, the ₹8,500 crore QIP, and Goyal's exit from the CEO chair.
- Helmer's 7 Powers and Porter's 5 Forces, applied with the evidence available rather than the labels.
- Management credibility, capital allocation, and a historical falsification pass.
- The skeptical investor's stress test, the live risk radar, and the bull/bear spine.
The story begins where the company started: with a spreadsheet, a scanner, and no business model at all.
 Subscribe on LinkedIn
II. Origins: Two Consultants and a Scanner (2008–2012)
In 2008, Delhi-NCR offered thousands of restaurants but virtually no reliable way to confirm what any of them served, what it cost, or whether it delivered to a given block. Google returned basic phone directory listings. The authoritative source of truth was a paper menu stuffed in a kitchen drawer or the memory of a neighbour. For a management consultant accustomed to treating information asymmetry as a business opportunity, this was an unusually large and mundane inefficiency.
Goyal, an IIT Delhi graduate from a schoolteacher family in Muktsar, Punjab, teamed up with colleague Pankaj Chaddah. In July 2008, the two registered DC Foodiebay Online Services and began collecting menus across the National Capital Region—physically visiting restaurants, photographing or scanning menus, typing up the text, and uploading it.[^4] The business lacked a technical moat. Its advantage rested entirely on a willingness to execute tedious fieldwork at scale in a market where nobody else would.
Two decisions from this period mattered far more than the founding story. The first was the 2010 rename to Zomato, driven by the obvious trademark hazard of a consumer brand containing "eBay," and by the desire for a name with no semantic ceiling—something that could later encompass more than food.[^4] Fifteen years later, the same logic produced "Eternal," reflecting a consistent approach to corporate brand architecture: keep consumer brands specific, and keep the umbrella corporate brand broad enough to accommodate future shifts.
The second critical decision was accepting capital from Info Edge. Sanjeev Bikhchandani's Naukri.com parent invested $1 million in 2010 and underwrote the company through successive pivots, at one point holding a majority economic interest.[^4] The significance of that patient backing is easy to underestimate. Zomato spent roughly a decade between its founding and finding a profitable model with true product-market fit. Few capital structures tolerate that timeframe. An Indian classifieds company run by a founder who had survived the dot-com bust did—though that patience carried a cost in equity dilution that founders elsewhere might have rejected.
What the early product actually was. The company's initial version was intensely manual. Field staff walked into restaurants, requested paper menus, and brought them back to an office to be manually entered into a database. There were no APIs, no partner integrations, and no financial incentives for restaurants to cooperate beyond basic politeness. Consequently, Zomato's earliest competitive advantage was labor arbitrage on data entry: paying local graduate wages to assemble a structured dataset that Western competitors would have found uneconomic to build. While effective in an emerging market, that advantage did not travel easily, as the same cost dynamic did not exist in markets like Seattle.
The culture that came out of it. Two features of Eternal's operating style trace back to this era and persist today. The first is a preference for handling operationally complex tasks in-house rather than outsourcing—moving from menus to delivery riders, dark-store warehouses, and direct inventory management. The second is a practice of unusually candid written communication. Goyal's blog posts and subsequent quarterly shareholder letters have been notably more discursive and willing to acknowledge missteps than standard Indian corporate disclosures. For investors, that transparency provides useful diligence context, but it should not be confused with objective analysis: a management team that writes articulate post-mortems is still curating its own historical record.
Now for the uncomfortable structural reality, which belongs in any honest assessment of early strategy.
Myth vs reality: the discovery moat. The conventional narrative holds that Zomato built an unassailable restaurant-discovery moat in India, upon which all subsequent businesses were built. The company's financial results contradict that strong claim. Restaurant discovery—comprising banner ads, sponsored listings, menu photography, and review pages—generated annual revenue in the tens of crores of rupees at a time when the platform already claimed millions of monthly active users. Traffic was substantial, but monetization was not. Restaurants refused to pay meaningful rates for exposure they could not directly tie to transactions, and Zomato could not verify attribution because it processed neither payments nor orders. A high-traffic directory lacking a transaction layer functions as a media business with a structurally low take rate, competing directly against search engines that provide basic listing data for free.
The actual asset was narrower and more specific than a classic moat. In this era, Zomato established content supply—the most comprehensive structured dataset of Indian restaurant menus, pricing, and photos—and built a consumer habit around searching its platform. Those were valuable assets, but they could generate substantial profits only once the company controlled the transaction rail and order fulfillment. That reality, dictated by unit economics rather than strategic grand design, eventually forced a high-margin software directory into the low-margin logistics of delivering hot meals through congested urban traffic.
Before committing to logistics, however, the company pursued an alternative path aligned with a consulting playbook: taking its digital directory global.
III. International Expansion: The Urbanspoon Misstep (2012–2016)
Early success in its home market generated rapid confidence. By 2013, Zomato viewed its playbook as inherently portable: deploy a small team to a new city, hire field agents to collect menus, digitise restaurant supply, purchase initial search traffic, wait for organic discovery to compound, and sell restaurant advertising. Because none of those steps depended on uniquely Indian market dynamics, Zomato pursued rapid overseas expansion.
By early 2015, the company operated across 21 countries—including the UAE, Sri Lanka, Qatar, the UK, New Zealand, and the Philippines. To skip the cold start of organic user acquisition, Zomato acquired local directory platforms, including MenuMania in New Zealand, Cibando in Italy, and Gastronauci in Poland. Then came its largest deal. In January 2015, Zomato acquired the American restaurant-discovery platform Urbanspoon for a reported $60 million—its largest acquisition to that point and, by a wide margin, its most consequential misstep.[^5]
Management's internal logic was straightforward: Zomato's Indian cost structure allowed it to maintain a menu-collection and content operation at a fraction of Yelp's operating expense. If restaurant discovery was fundamentally a data-entry and advertising sales operation, leveraging lower-cost operations in Gurgaon to service high-ARPU Western markets appeared to offer significant geographic arbitrage.
The failure of that strategy highlights a fundamental misdiagnosis of the Western competitive landscape.
The cost base was the wrong variable. Low content costs were never the primary competitive barrier in Western restaurant discovery; local merchant relationships were. Yelp's cost structure was driven not by menu collection, but by an extensive, commission-based local sales force calling restaurant owners month after month. That expense could not be offshored, because small-business owners in Seattle or Portland demanded local account management. Zomato attempted to deploy a cost advantage into a market where content costs were secondary to merchant sales overhead.
Urbanspoon provided user traffic, but it lacked the two components required to convert traffic into sustainable revenue: an established local merchant sales force and a transaction fulfillment stack. In India, Zomato had spent years building field operations and brand equity among local restaurateurs. In Seattle and Melbourne, it possessed neither. Furthermore, it entered markets where Yelp and TripAdvisor had spent a decade building review volume and ad relationships, and where Yelp's public financial disclosures indicated that restaurant-discovery advertising suffered from high merchant churn and sluggish growth. Zomato effectively purchased trailing pageviews in mature markets at a price that assumed it could out-monetize entrenched incumbents.
The organizational cost. Beyond the direct financial outlay, the international strategy imposed substantial organizational overhead. For roughly three years, executive focus, key product talent, and capital were diverted to markets that ultimately generated minimal returns. During this same period, domestic rival Swiggy built delivery density in Bengaluru largely unhindered. Consequently, the true cost of the Urbanspoon transaction extended beyond the $60 million purchase price; it handed a multi-year head start to a domestic competitor in Zomato's primary growth market.
Historical falsification: a non-replicable playbook. The historical record demonstrates that Zomato's initial playbook was not globally scalable. Within two years of the transaction, Zomato heavily wrote down the value of the Urbanspoon assets. By 2019, the company had closed or sold its operations across North America, Europe, and Australia, having burned well over $100 million on its broader international expansion.[^5] Hyperlocal density proved non-transferable: market dominance in Delhi provided little leverage in Dublin, as the underlying asset was not a global software network, but a localized supply graph and sales force that required rebuilding from scratch in every new market.
The primary exception was the Middle East, where high South Asian diaspora population density, urban restaurant concentration, and existing brand recognition enabled Zomato to sustain profitable operations for years. Conversely, every attempt to capture consumer mindshare from established Western incumbents proved unsuccessful.
For capital allocators evaluating Eternal's current management, this episode presents two distinct conclusions. First, it demonstrates that early capital allocation included high-risk, discretionary M&A that destroyed substantial value within 24 months—a historical counterweight to claims of unblemished strategic discipline. Second, it highlights management's willingness to recognize failed bets and exit unviable markets rather than double down. Every major acquisition following Urbanspoon took place within India, closely tied to core operational capabilities, and aimed at consolidating market share or acquiring logistics infrastructure rather than buying unmonetized traffic.
The withdrawal from international markets coincided with an escalating competitive threat at home. As Zomato wound down overseas directory operations, Swiggy was proving across Indian metros that the primary economic opportunity lay not in cataloging restaurants, but in fulfilling their deliveries.
IV. The Food Delivery Wars: Building Logistics & Duopoly Rationalization (2015–2020)
Swiggy entered the market in 2014 with a fulfillment-first model: rather than simply listing menus, it managed the end-to-end delivery process. Zomato's original model relied on restaurants handling their own delivery while Zomato collected advertising fees for lead generation. Swiggy, by contrast, assumed responsibility for logistics, leaving restaurants to focus strictly on food preparation. Consumers responded strongly to the difference, as in-house restaurant delivery had long been an unreliable link in the ordering experience.
In March 2015, Zomato launched its own food-delivery service, fundamentally altering its economics. While a digital advertising platform incurs virtually no marginal cost per incremental order, a delivery network requires paying a rider for every journey, navigating urban congestion and weather, while keeping delivery fees low enough to preserve order volume on modest average order values. In shifting from a high-margin listing directory to a low-margin logistics operator, Zomato sacrificed software-like unit economics to capture the underlying transaction rail—a pivot that proved irreversible.
What the shift cost the income statement. The structural difference between the two models was stark. Under the advertising model, restaurants paid monthly listing fees, and Zomato’s marginal cost to process an additional order inquiry was negligible. Under the delivery model, every order incurred rider payouts, payment gateway fees, customer support overhead, and platform-funded discounts designed to drive consumer adoption. For years, the total cost of fulfilling a food-delivery order in India exceeded the combined fees collected from the restaurant and the consumer. Venture capital effectively subsidized that shortfall for both Zomato and Swiggy for nearly five years.
To construct its logistics infrastructure, Zomato pursued targeted, capability-driven acquisitions rather than broad user-acquisition deals. The 2015 purchase of MapleGraph's MaplePOS integrated Zomato into restaurant point-of-sale systems where order data originated. The 2016 acquisition of Sparse Labs added real-time tracking and dispatch algorithms to batch and route orders efficiently. Finally, in 2017, Zomato acquired logistics startup Runnr, transitioning the platform from reliance on third-party contractors to a dedicated delivery fleet.
The underlying economics of food delivery depend heavily on order density. Delivery cost is not fixed; it varies with batching efficiency and order frequency. If a rider completes only one delivery per hour, a single order must generate enough gross revenue to cover that hour of rider compensation. However, if geographic density allows a rider to batch multiple co-located orders and complete three deliveries per hour, the fulfillment cost per order drops by roughly two-thirds even as rider earnings increase. Hyperlocal order density thus serves as both a margin driver and a competitive moat. Regional market share within specific neighborhoods dictates unit profitability far more than nationwide scale—a dynamic that disadvantages third-tier players and later formed the operational logic for quick commerce dark stores.
The war as both sides fought it. Between 2016 and 2019, Zomato and Swiggy engaged in heavy price competition that effectively subsidized Indian urban consumers. Free-delivery thresholds, introductory discounts, cashback offers, and elevated peak-hour rider incentives ran concurrently across both platforms. Neither player could unilaterally withdraw subsidies without immediately losing market share to its multi-homing user base. This dynamic created a classic prisoner's dilemma, where industry profitability could be restored only through capital exhaustion, market consolidation, or regulatory intervention.
In January 2020, a major structural shift altered industry dynamics. Uber, having burned substantial capital without achieving scale in India, transferred Uber Eats India to Zomato in an all-stock transaction that gave Uber a 9.99% equity stake in Zomato.4 Executed without cash outlay, the deal eliminated a competitor that was reportedly burning approximately $20 million per month. The acquisition consolidated a fragmented three-way subsidy battle into a disciplined duopoly alongside Swiggy. Subsequent gains in segment margins stemmed primarily from this market consolidation rather than internal product innovations, as reducing the field to two rational operators enabled both companies to scale back aggressive customer acquisition discounts.
What the duopoly did and did not deliver. Market consolidation stabilized the segment, but it did not grant either player unconstrained pricing power. Swiggy remained a well-capitalized competitor, leading both platforms to adopt nearly identical monetization structures over time—including similar restaurant commission bands, comparable subscription tiers, and platform fees introduced in close sequence. While this structural convergence supported steady margin improvement, neither firm possessed the power to raise take rates unilaterally without risking order volume. Take rates across the sector continue to be governed by tacit duopoly balance rather than absolute pricing authority.
The restaurant revolt. That structural tension became evident in 2019 with Zomato Gold, a premium subscription offering buy-one-get-one offers on food and drinks. While popular among diners, the program drew strong resistance from partner restaurants responsible for absorbing the discount costs. In August 2019, the National Restaurant Association of India led the #Logout campaign, resulting in over 2,500 dining establishments delisting from the service.5 Zomato was ultimately forced to revise the program's terms. The boycott demonstrated that merchant supply could not be treated as captive: despite industry fragmentation, organized restaurant associations and high-end dining brands retained significant leverage over platform terms.
Two falsified in-house theses. Management also tested operational concepts that ultimately failed to scale. First, Zomato Infrastructure Services attempted vertical integration into supply by master-leasing commercial real estate to build cloud kitchens for restaurant partners. In practice, the initiative burdened the balance sheet with long-term lease liabilities while placing Zomato in direct competition with its own restaurant clients; the project was shut down in 2019. Second, Zomato Instant, launched in 2022 to deliver hot food within ten minutes, encountered severe operational constraints. Food quality suffered, kitchen preparation throughput bottlenecked, and public criticism mounted over potential safety risks for delivery riders. Management shelved the initiative within nine months of launch.
The pattern across Zomato Infrastructure Services, Zomato Instant, and the earlier Urbanspoon acquisition underscores a defining trait of the company's operating strategy: rapid experimentation paired with a willingness to quickly terminate unviable bets. While high-conviction winning initiatives can yield substantial returns, this track record suggests that new strategic ventures carry considerable execution risk until proven.
Throughout this era, these operational shifts occurred away from public markets. That dynamic changed when Zomato prepared to list during an unusual macroeconomic environment.
V. The Pandemic Boost, IPO Baptism & Public Market Meltdown (2020–2022)
In April 2020, India's food delivery volumes dropped precipitously. Dining establishments closed, consumers expressed anxiety over food packaging safety, and delivery riders faced severe mobility restrictions. Within Zomato, internal planning temporarily shifted to basic survival. What followed instead was a profound demand shock across the Indian consumer internet landscape. As mobility restrictions eased while offices remained closed, food delivery transitioned from an occasional consumer convenience into essential urban infrastructure. Order frequency expanded, average order values rose as multi-person household orders replaced single-seat office lunches, and the customer segment willing to pay fulfillment fees expanded permanently.
Why the pandemic mattered more than the volumes suggest. While order volume recovery generated headlines, the more durable transformation occurred on the supply side. Restaurants that had historically resisted delivery aggregators as low-margin distractions recognized during lockdowns that delivery represented their sole revenue channel. Kitchens were reconfigured for packaging efficiency, menus were optimized for transit resilience, and restaurateurs increasingly treated delivery platforms as essential infrastructure rather than existential threats. That structural supply-side integration proved far harder to reverse than consumer habits, preventing post-pandemic order volumes from regressing to 2019 baselines.
The pandemic period also demonstrated significant elasticity in delivery fleet supply. As alternative service-sector employment contracted, delivery platforms absorbed urban labor at scale. This labor surplus contained fulfillment costs precisely when order volumes expanded. However, this convergence temporarily inflated the unit economics of 2021 and 2022 in a manner that proved unrepeatable, rendering straight-line growth extrapolations from that period overly optimistic.
Capital markets responded accordingly. Prior to listing, Zomato secured over $1 billion in private funding from institutional investors including Ant Financial, Tiger Global, Kora Management, and Fidelity, at valuations far exceeding its 2019 pre-pandemic levels.
In July 2021, Zomato conducted its initial public offering. The IPO priced at ₹76 per share, was subscribed roughly 38 times, and raised ₹9,375 crore at a market capitalisation around $13 billion.6 The transaction represented a market milestone: no comparable Indian consumer technology platform had previously listed on domestic exchanges. Domestic capital markets lacked established valuation frameworks for loss-making internet platforms on the National Stock Exchange, and institutional investors faced regulatory uncertainty regarding mutual fund allocation mandates for unprofitable equities. Zomato's public listing established the template for subsequent tech IPOs in India, setting the valuation benchmarks for equity offerings by Nykaa, Paytm, PolicyBazaar, and eventually Swiggy.
Market sentiment deteriorated rapidly across 2022. Global central bank rate hikes compressed technology valuation multiples, leaving newly public Indian platforms vulnerable due to valuations heavily dependent on long-term terminal value projections. Zomato fell more than 60% from its highs to an all-time low near ₹40 in July 2022, as pre-IPO lock-ups expired and early backers sold.7 Uber liquidated its entire equity position, while Tiger Global and Ant Financial reduced their stakes. At its nadir, equity markets priced the company near the net cash value on its balance sheet plus a minimal value for the core food delivery operation—effectively assigning negative valuation to its broader growth strategy.
The market drawdown forced a fundamental shift in corporate operating priorities. Prior to listing, management prioritized gross order value expansion. Following the equity decline, public shareholders demanded audited net profitability rather than adjusted contribution metrics or indefinite paths to margin breakeven. Management subsequently responded through a combination of operating leverage and newly introduced consumer fee structures. Whether this financial discipline reflected permanent corporate restructuring or external market pressure remains a central debate among investors. Zomato achieved net profitability when public markets demanded it in 2023, yet later accepted margin compression in 2025 to fund aggressive quick-commerce expansion. Analysts view this shift either as disciplined capital deployment for long-term category leadership or as evidence that near-term profitability remains subordinate to strategic land-grab initiatives.
The capital available for that expansion originated from a pivotal acquisition executed near the trough of the market drawdown—a deal initially met with widespread market skepticism.
VI. The Blinkit Gambit: Rescuing Grofers & Winning Quick Commerce (2021–2023)
That acquisition involved Grofers, which by early 2022 was depleting its cash reserves for the second time. Founded in December 2013 by Albinder Dhindsa and Saurabh Kumar, Grofers spent years operating as an asset-light grocery marketplace, taking customer orders and dispatching runners to partner kirana stores for delivery within a few hours. The model suffered from a structural weakness: Grofers controlled neither product assortment, pricing, nor real-time availability. Competitors like BigBasket, which owned their inventory, guaranteed stock availability, whereas Grofers could not. Grofers incurred heavy operational losses, retreated from tier-two cities, and by 2020 struggled to remain competitive.
In August 2021, Dhindsa pivoted the business. Grofers closed its marketplace, rebranded as Blinkit, and restructured its operations around ten-minute delivery from company-controlled dark stores—small, windowless warehouses of roughly 2,000 to 4,000 square feet. Located within two kilometers of target customer zones, each store carried a tightly curated inventory of a few thousand stock-keeping units selected using hyper-local demand data.
Dhindsa's background influenced this operational restructuring. A Delhi College of Engineering graduate with training in transport economics and urban infrastructure consulting, he worked in the United States before co-founding Grofers. His management style prioritized logistics metrics—assortment breadth, picking speeds, and store density—over broad promotional narratives. Having closed an unviable marketplace model, he applied those operational lessons directly to the quick-commerce rebuild.
The mechanics of ten-minute delivery relied on strategic inventory placement rather than rapid transit alone. Traditional supermarkets require consumers to travel to retail locations, while standard e-commerce fulfills orders from regional distribution centers over one to two days. A dark store positions targeted inventory inside neighborhood zones, shortening the final delivery distance to roughly two kilometers. Because workers avoid retail checkout queues, browsing aisles, and parking delays, riders complete deliveries in under ten minutes. Stationed workers pick and pack orders within ninety seconds inside a compact 2,000-square-foot facility. Rapid fulfillment is thus the byproduct of predictive, localized inventory placement.
This format also aligned with existing Indian consumer habits. Urban households historically purchased groceries through frequent, small-ticket transactions—buying daily produce, milk, or flour—due to limited home storage and easy access to local kirana stores. Unlike Western grocery delivery services that attempted to transition consumers toward large weekly online orders, quick commerce intercepted pre-existing shopping patterns, lowering the barrier to consumer adoption.
Zomato, an existing investor in Grofers, extended a debt bridge of approximately $150 million in early 2022. In June 2022, Zomato’s board approved the full acquisition: an all-stock transaction valuing Blinkit at ₹4,447 crore, or roughly $568 million.[^10]
Equity markets reacted with sharp skepticism. Analysts and retail shareholders questioned the deal, viewing it as an equity-funded rescue of a struggling company at a time when Zomato’s own stock price was plunging and its core food-delivery segment remained unprofitable. Their objections cited clear operational risks: Blinkit had recently abandoned its primary business model, quick-commerce unit economics remained unproven globally, and the acquisition was funded using depressed Zomato shares. Consequently, the stock fell to new lows in the weeks following the announcement.7
Subsequent performance, however, revealed the operational value of the acquired assets. Zomato secured an established urban real-estate lease network, specialized store management software, and an experienced logistics leadership team. Dhindsa retained operational autonomy as CEO, while Rishi Arora joined as a co-founder-level partner to manage store expansion. In return, Zomato provided Blinkit with capital reserves and access to a dense, established delivery fleet operating across identical urban markets.
The operational turnaround proceeded faster than market expectations. Blinkit expanded its dark-store network from several hundred locations to over a thousand. Average order values stabilized above ₹600, compared with food delivery’s average of roughly ₹400. Because delivery costs are primarily fixed per trip rather than per rupee spent, larger basket sizes improved unit economics. Furthermore, high-margin advertising fees emerged as a lucrative revenue stream, as consumer packaged goods brands paid premium placement rates to feature products prominently in search listings. By late 2023, Blinkit achieved positive contribution margins.
In retrospect, the Blinkit acquisition created substantial enterprise value despite being executed near market lows against widespread initial opposition. However, evaluating management solely on this outcome overlooks earlier capital allocation missteps, such as the Urbanspoon acquisition. The transaction demonstrates management's willingness to execute high-conviction, high-risk deals during market downturns. While alignment with Indian shopping habits validated the core thesis, such concentrated bets carry ongoing execution risk, as earlier failed initiatives demonstrated.
With quick commerce achieving unit-level profitability, market attention turned to whether consolidated net profit would follow.
VII. Segment Economics & The Profitability Watershed (2023–2025)
On 3 August 2023, Zomato reported a consolidated quarterly net profit of ₹2 crore against a loss of ₹186 crore a year earlier—the first profitable quarter in its history, and a figure so small it was effectively a rounding error.8 Symbolically, however, the result was monumental: India's flagship loss-making internet platform had printed a positive bottom line roughly two years after listing, achieving breakeven without relying on one-off accounting gains.
Two primary drivers delivered the shift, though they differed significantly in underlying quality.
The first was genuine operating leverage in food delivery. As order density increased and promotional discounting rationalized across the duopoly, adjusted EBITDA as a percentage of gross order value climbed from negative territory to roughly 3%, with management steering toward a long-term target of 4% to 5%. This margin expansion stemmed from structural operational gains: batching more deliveries per rider hour and spreading fixed technology costs across a larger transaction base.
The precise magnitude of this shift matters, because ₹2 crore in quarterly profit was less about the absolute sum than the trajectory. The critical achievement was reversing direction: a business that had lost ₹186 crore in the same period a year earlier crossed into positive territory while continuing to expand.8 Equity markets, which had spent months questioning the viability of the food-delivery model, responded with a substantial re-rating of the stock over the subsequent eighteen months.
The second driver was the introduction of a platform fee—a direct monetization lever that warranted close scrutiny. Zomato added a small flat fee per order, independent of transaction value, starting around ₹2 and gradually increasing to between ₹6 and ₹10 in major metropolitan markets. Because existing delivery charges already covered order fulfillment costs, this fee dropped almost entirely to the bottom line. Multiplied across millions of daily orders, the platform generated incremental profit without requiring product improvements. The strategy succeeded because both duopoly players introduced similar charges concurrently, and because the fee remained small relative to the average meal cost. However, it represents a finite lever: each incremental increase tests consumer willingness to pay, a boundary the company can identify only after crossing it.
Testing management's narrative consistency. Examining shareholder letters sequentially highlights how management's strategic emphasis evolved. Across fiscal 2024 and 2025, communications focused heavily on consolidated profitability, food-delivery margin expansion, and the expectation that quick commerce would quickly become self-funding. By fiscal 2026, the corporate narrative pivoted toward infrastructure investment, larger stores, and a willingness to absorb temporary margin compression to secure market share. While each position reflected management's operational priorities at the time, investors who built long-term models around the fiscal 2024 harvest narrative saw those assumptions re-priced within eighteen months. The shift illustrates that management's operational focus adapts rapidly to competitive conditions, meaning strategy statements in any single quarter may be superseded as market dynamics change.
By fiscal 2025, the group's operations consolidated into four distinct business pillars, whose relative financial contributions subsequently diverged.
Food delivery functioned as the mature cash generator. While the segment continued to grow—with net order value rising 13% year over year in the June 2025 quarter to approximately ₹8,967 crore—disclosures from that period pointed to maturing demand.9 Growth was constrained by subdued discretionary consumer spending, prompting restaurant partners to fund elevated discounts to maintain order volumes. Monthly transacting users reached approximately 22.9 million in that quarter and expanded to roughly 27.2 million a year later, supported by a network of about 328,000 restaurant partners.92 With user acquisition expanding in low double digits while quick commerce grew at over 80%, management increasingly treated food delivery as a stable cash flow engine rather than the primary growth driver.
Quick commerce emerged as the core value driver. In the June 2025 quarter, Blinkit's net order value reached ₹9,203 crore, surpassing Zomato's core food delivery net order value of ₹8,967 crore for the first time—a milestone achieved within twelve quarters of the acquisition.10 The crossover highlighted rapid operational scaling: an acquired unit purchased for under $600 million overtook a decade-old core business in total transaction value in three years.
Hyperpure, the B2B division supplying fresh produce, ingredients, and packaging to restaurants and Blinkit dark stores, remains the group's most misunderstood unit. Operating as a low-margin wholesale distributor rather than a digital platform, its strategic value is operational: it provides quality control over raw materials while giving the company a secondary commercial touchpoint with restaurant partners beyond delivery commissions. In the March 2026 quarter, Hyperpure generated ₹978 crore in revenue and ₹5 crore in adjusted EBITDA—a 0.5% margin typical of high-volume wholesale operations.11 Reported segment revenue declined year over year as internal sourcing for Blinkit was reclassified under the inventory-led accounting structure, though like-for-like sales to independent restaurants grew by approximately 37%.11 For analysts, Hyperpure operates primarily as a supply-chain asset and procurement aggregator rather than a standalone profit center.
District, the experiential consumer pillar, was established following the August 2024 acquisition of Paytm's movie and event ticketing business for ₹2,048 crore, or roughly $244 million, creating a standalone application covering dining, live events, movies, and nightlife.12 The business leveraged Zomato's existing restaurant-discovery traffic in a high-frequency, negative-working-capital category. However, operational scaling progressed more slowly than initially projected. In the March 2026 quarter, District recorded revenue of ₹277 crore—up 21% year over year but down sequentially—alongside an adjusted EBITDA loss of ₹81 crore, narrowing from a ₹121 crore loss in the preceding quarter.1113 On a subsequent earnings call, management noted that while District customers exhibited higher spend per transaction than food-delivery users, the overall user base remained smaller, leading the company to scale back its planned city rollouts.3 The adjusted strategy marked a practical moderation of the original acquisition narrative.
Balance sheet considerations. Beyond segment metrics, two financial structural items warrant ongoing monitoring. First, the group carries substantial goodwill and intangible assets resulting from the Blinkit and Paytm ticketing acquisitions. The valuation of these assets depends on periodic impairment testing, an accounting judgment where management precedent—such as the earlier Urbanspoon write-down—demonstrates a willingness to recognize capital impairments when performance diverges from projections. Second, the transition to an inventory-led model introduces working capital management to a business model that historically operated without inventory risks. Managing store stock levels, supplier payables, and working capital cycles introduces operational complexity, where rising inventory days could weigh on cash conversion efficiency.
Consolidated group performance reflected this operational restructuring. For fiscal 2026, consolidated revenue from operations rose approximately 169% year over year to ₹54,364 crore, up from ₹20,243 crore in fiscal 2025.14 However, the expansion was primarily driven by accounting mechanics following the shift to inventory-led revenue recognition at Blinkit rather than a proportional surge in underlying transaction volumes.
VIII. Rebranding to Eternal Limited & Capital Defense (2025–2026)
In February 2025, Zomato Limited officially changed its corporate name to Eternal Limited, trading under the ticker ETERNAL.[^18] While individual consumer-facing brands remained unchanged, the corporate narrative shifted. Eternal presented itself as an operating holding company overseeing four distinct pillars—a structure designed to accommodate strategic evolution without anchoring corporate identity to a single service. The rebrand also served a practical financial purpose: repositioning the group away from being valued strictly as a food-delivery platform. Subsequent financial reporting demonstrated why that corporate distinction mattered commercially.
The more consequential corporate restructuring, however, involved equity ownership rather than corporate branding.
Under Indian foreign direct investment regulations, foreign-owned e-commerce platforms may operate as digital marketplaces connecting buyers and sellers, but are prohibited from directly owning inventory. Consequently, Blinkit operated for years through independent third-party vendor entities that held inventory on their own balance sheets. While legal and industry-standard, this structure exposed the company to regulatory scrutiny over platform control while restricting operational flexibility. For a quick-commerce model dependent on micro-curating localized inventory, operating without direct inventory ownership posed a structural constraint on operating margins.
To resolve this limitation, the board proposed, and shareholders approved in April 2025, a strict cap on fully diluted foreign ownership at 49.5%. This cap enabled Eternal to reclassify from a foreign-owned entity to an Indian-owned and controlled company (IOCC).15 As of 31 March 2025, domestic ownership reached approximately 55%—surpassing the 51% statutory threshold—while foreign ownership stood at roughly 44.9%.15 A critical prerequisite for this transition was an ₹8,500 crore ($1 billion) qualified institutional placement completed in late 2024, which bolstered capital reserves while expanding domestic institutional ownership.16
This regulatory reclassification represents a sophisticated piece of corporate capital structuring, though it involved clear strategic trade-offs. By capping foreign shareholding, Eternal voluntarily limited its access to global capital pools and established an artificial ceiling on foreign institutional equity demand, creating uncertainty regarding its inclusion in international benchmark indexes.17 Management accepted those capital market constraints to secure operational control over its retail supply chain.
The operational benefits materialized in fiscal 2026 as Blinkit transitioned to an inventory-led model, purchasing and holding stock directly.18 The model enhanced merchandise selection, enabled direct supplier negotiations, and captured full retail margins. Accounting rules also altered income statement reporting: rather than recognizing only marketplace commissions, Eternal began recording gross transaction value as revenue. This accounting transition accounted for the bulk of reported revenue expansion. In the June 2026 quarter, Blinkit generated ₹15,664 crore in revenue—representing roughly 77.5% of Eternal's total operating revenue of ₹20,211 crore.2 Consequently, evaluating headline revenue growth without adjusting for accounting mechanics distorts underlying operational performance. Net order value and adjusted EBITDA offer more reliable metrics: business-to-consumer net order value grew 54% year over year to ₹31,120 crore in the June 2026 quarter, while consolidated adjusted EBITDA reached ₹555 crore.[^23]
Direct inventory ownership also introduced operational risks absent from marketplace models, particularly stock spoilage and shrinkage. In the June 2026 quarter, Blinkit's inventory write-downs reached 1.8% of net order value—amounting to approximately ₹308 crore, primarily in perishable goods.3 Given that Blinkit recorded segment adjusted EBITDA of ₹102 crore in that same quarter, inventory shrink represents a primary determinant of operating profitability.193 Managing perishable stock loss thus replaced vendor administration as a core operational capability.
The leadership transition. In January 2026, the company announced an unexpected executive transition. The board accepted Deepinder Goyal's resignation as Managing Director and CEO effective 1 February 2026, appointing Blinkit founder Albinder Dhindsa as group Chief Executive while Goyal assumed the role of Vice Chairman.20 Goyal attributed his departure to a desire to pursue early-stage ventures outside public market constraints, having separately committed approximately $25 million to longevity research and founded LAT Aerospace to develop short-haul aircraft.20
This transition presents two distinct implications for institutional investors. On one hand, executive leadership transferred to the founder of the division generating the majority of group revenue through an internal, orderly succession. This transition mirrored prior executive delegation, such as the July 2025 appointment of four-year company veteran Aditya Mangla as food delivery CEO following Rakesh Ranjan's departure.21 On the other hand, a founder who previously framed the enterprise in multi-decade terms relinquished operational control eighteen years after founding it to pursue external ventures, precisely as quick-commerce competition intensified. As the founder premium diminishes, investment analysis must increasingly rely on observable segment execution rather than founder vision.
IX. Strategic Frameworks: Helmer's 7 Powers & Porter's 5 Forces
Analytical frameworks are useful only when applied without sentiment. Evaluated against economic evidence, Eternal possesses two distinct powers, two partial ones, and three that are frequently claimed but poorly supported by the data.
Scale economies — strong, and the primary driver. The fixed costs in this business comprise technology, brand equity, and real estate, while the primary variable expense remains delivery rider time. Because higher network density allows each courier to complete more fulfillments per hour, and because the shared courier pool serves both food and grocery orders across the same urban market, the marginal cost per order drops as volume expands. This dynamic explains why operating margins expanded primarily through fulfillment density rather than price increases. It also highlights the significance of management's updated baseline assumptions: raising projected capital expenditure per store from ₹1 crore to ₹2.5 crore to include regional warehousing, while increasing target daily net order value per store by 57%—from ₹7 lakh to ₹11 lakh—representing the single most informative disclosure of the past year.3 Operating larger dark stores at higher volume represents the scale-economies thesis expressed through capital allocation, creating a strategy whose ultimate success depends on store-level payback periods over coming quarters.
Network effects — genuine in food delivery, weaker in quick commerce. Food delivery operates as a classic two-sided market, where expanding diner demand attracts restaurant partners, and comprehensive menu supply draws additional users. Quick commerce, however, exhibits limited direct network effects. Consumers select platforms based on immediate inventory availability and speed rather than the size of the user base. The true multi-sided dynamics appear in digital advertising: consumer packaged goods brands bid for digital shelf space to reach an aggregated user base, generating high-margin revenue that can fund lower retail pricing and attract further order volume. While this creates a functional advertising flywheel atop a retail operation, it represents a monetization mechanism that scaled competitors can replicate rather than an unassailable network effect.
Process power — partial, representing a critical operational test. Sub-ninety-second warehouse picking, postal-code demand forecasting, algorithmic dispatch, and inventory loss control reflect specialized operational expertise built across thousands of dark-store operating weeks. Evidence supporting this power appears in financial execution: Blinkit achieved segment adjusted EBITDA profitability at scale—generating ₹37 crore in the March 2026 quarter compared to a ₹178 crore loss a year prior—ahead of its well-capitalized peers, while expanding adjusted EBITDA to ₹102 crore in the June 2026 quarter despite executing the sector's fastest store rollout.1119 Counter-evidence suggests this barrier remains narrow: absolute operating margins remain modest, and an inventory write-down rate of 1.8% indicates that localized demand forecasting remains an evolving capability.
Cornered resource — the weakest strategic assertion. Proponents argue that the network of 2,443 high-density urban dark-store leases represents a scarce real estate asset that late entrants cannot replicate.2 Industry data contradicts this thesis: Flipkart Minutes reportedly added approximately 100 dark stores per month during 2026, while both Flipkart Minutes and Amazon Now scaled past 500 stores.22 Unlike prime retail real estate, urban micro-warehousing in India remains relatively abundant with short lease durations. Blinkit maintains an operational head start—possessing historical localized demand data for established postcodes while operating cash-generative stores as rivals absorb setup losses. However, an operational head start reflects a temporary lead rather than a cornered resource, and such leads erode as competitors scale.
Switching costs and branding — modest structural barriers. Subscription programs such as Zomato Gold encourage consumer retention, and the group's consumer brands maintain high brand awareness across Indian metropolitan centers. However, prevalent multi-homing behavior among urban consumers demonstrates low switching costs: users routinely maintain multiple food and grocery applications to compare pricing and delivery times. Management implicitly acknowledged this dynamic on a recent earnings call, characterizing competitor volume gains as purely price-driven.3 Reliance on promotional pricing by consumers underscores the absence of structural switching costs, leaving platforms vulnerable to competitive discounting.
Counter-positioning — historically valid, but increasingly eroded. Ten-minute fulfillment from localized dark stores initially presented a classic counter-positioning advantage: incumbent e-commerce giants could not adopt quick commerce without undermining their existing two-day regional distribution model. This structural reluctance provided Blinkit several years of unhindered expansion. However, major e-commerce platforms have since absorbed that cannibalization risk and entered the market directly. Once incumbents choose to compete directly within the new format, counter-positioning transitions into conventional head-to-head competition.
An additional attribute frequently ascribed to the business is formal branding power in the strategic sense, which requires that customers pay a price premium for identical goods based on brand equity. In Indian quick commerce, consumer behavior reveals the opposite pattern. While Blinkit's brand identity drives efficient user acquisition and default platform consideration, it does not command premium pricing for commodity items. Conflating brand awareness with pricing power risks misinterpreting a high-volume retail intermediary as a branded consumer goods business.
Porter's Five Forces analysis highlights where structural pressures concentrate across the business:
Rivalry represents the most intense force, operating unevenly across segments. Quick commerce faces aggressive multi-platform competition among six major operators: Blinkit leads with approximately 48% market share as of January 2026, followed by Swiggy Instamart near 24%, Zepto near 22%, alongside BigBasket, Amazon Now, and Flipkart Minutes.22 By contrast, food delivery operates as a rationalized duopoly, generating stable cash flows that subsidize quick-commerce expansion.
Threat of new entrants remains low in food delivery due to established logistics networks, but high in quick commerce, where entry is driven by well-capitalized domestic retail and global technology conglomerates.
Buyer power is high. Low switching costs and transparent price comparison across applications enable consumers to shift order volumes rapidly.
Supplier power varies across stakeholder groups. While individual restaurants rely heavily on platforms for order volume, organized merchant associations retain collective bargaining power. Consumer packaged goods manufacturers compete for digital shelf placement, benefiting platform advertising revenue; however, as quick commerce accounts for a growing double-digit share of urban brand sales, major manufacturers command greater pricing leverage. Simultaneously, delivery riders represent an increasingly organized labor pool backed by emerging regulatory protections.
Substitutes remain significant despite digital adoption. Home meal preparation and neighborhood kirana stores remain the primary default for most Indian households. Consequently, incremental quick-commerce demand competes directly with local physical retail rather than traditional long-tail e-commerce.
In summary, Eternal's competitive positioning rests on density-driven fulfillment cost advantages, accumulated operational expertise, and a cash-generative food delivery segment funding quick-commerce capital requirements. While these assets provide clear operational leads, they do not constitute an unassailable economic moat, requiring sustained capital deployment and execution to preserve market leadership.
X. Current Risk Radar & Skeptical Investor Stress Test
Evaluating Eternal's investment thesis requires distinguishing between temporary operational headwinds and structural risks that directly threaten the business model.
Regulatory exposure to the FDI and inventory question. The Indian-owned and controlled company (IOCC) reclassification serves as the legal foundation for owning retail inventory directly, with the 49.5% foreign ownership cap functioning as the mechanism maintaining compliance. Both elements are now load-bearing for more than three-quarters of reported revenue. Any regulatory adjustment disturbing that calculation—such as a shift in how foreign ownership is computed on a fully diluted basis including employee stock options and convertibles, a legal challenge to the reclassification, or an adverse retrospective interpretation of the historic third-party vendor structure—would directly impact the core operating model rather than mere financial disclosures. While Eternal has structured its capital base carefully and faces no active regulatory dispute, the underlying regulatory risk remains concentrated and non-diversifiable.
Gig worker legislation, which has moved from theoretical debate to operational compliance. India's Social Security (Central) Rules, 2026 took effect on 8 May 2026, requiring digital aggregators to register gig and platform workers in real time.23 Aggregators were mandated to onboard all delivery partners onto the government's eShram portal by 21 June 2026.24 The statutory framework contemplates aggregator contributions of 1% to 2% of turnover, capped at 5% of total worker payouts, whichever is lower, with eligibility tied to workers completing at least 90 days of service with a single aggregator in the preceding financial year; category-wise contribution rates were still being operationalized through scheme notifications as of mid-2026.23 Across its ecosystem, Eternal engaged approximately 638,000 food delivery partners and 521,000 quick-commerce partners in the June 2026 quarter.3 Applying even a 1% turnover-linked levy to an inventory-led business booking full merchandise value as revenue would severely compress unit margins—making the 5% worker-payout cap the critical statutory safeguard for investors to track. At the conservative end of analyst estimates, a fully loaded compliance cost of ₹15 to ₹20 per delivery would entirely erase the quick-commerce segment's current adjusted EBITDA margin.
The capital arms race. Zepto continues to secure substantial private funding, Swiggy maintains post-IPO liquidity, and both Flipkart Minutes and Amazon Now draw on parent balance sheets where quick commerce serves as a broader strategic defense rather than a standalone profit center. Blinkit has countered with capital deployment into physical scale, committing roughly ₹3,000 crore toward store and warehouse expansion as an operational moat. On a recent earnings call, CEO Albinder Dhindsa informed analysts that the June 2026 quarter marked "the peak of competitive intensity," anticipating that promotional discounting across the sector would normalize.3 That projection reflects management expectation rather than guaranteed market dynamics, touching the single operational variable Eternal controls least. Well-capitalized competitors can afford to absorb sustained losses without immediate capital market discipline, prolonging margin pressure across the category.
Platform fee ceilings and demand elasticity. Flat per-order platform fees provided the initial push into net profitability, but that monetization lever faces natural consumer resistance. The June 2025 quarter illustrated the vulnerability of group earnings during period transitions: net profit declined roughly 90% year over year to ₹25 crore despite 70% revenue growth, as management directed food-delivery cash flows toward funding quick-commerce dark store expansion.9[^30] While management characterized the margin compression as a deliberate strategic reinvestment, the performance demonstrated that consolidated profitability at this stage of expansion remains discretionary rather than structurally guaranteed.
Balance sheet strength and capital allocation risk. Eternal closed the March 2026 quarter holding ₹17,972 crore in cash reserves with no material debt liabilities.11 This substantial liquidity buffer provides operational flexibility during an industry capacity war, stemming directly from the late-2024 institutional equity raise. Consequently, potential equity dilution poses less of a distress risk than an operational choice—either to fund further dark-store acceleration or to satisfy ongoing stock-based compensation obligations. While the institutional placement was secured on the rationale of reinforcing balance-sheet resilience, management has progressively deployed those funds toward dark-store and warehouse capital expenditure, actively converting cash reserves into physical infrastructure.16
Data governance and targeted advertising exposure. Processing the purchasing histories of tens of millions of urban households to power a high-margin digital advertising platform exposes Eternal to evolving compliance standards under India's Digital Personal Data Protection framework. Beyond compliance overhead, tighter regulatory restrictions on user data profiling present a strategic risk to advertising monetization. Because targeted ad revenues from brand partners generate the high-margin cash flow necessary to offset dark-store operating costs, regulatory constraints on consumer data targeting directly impact the group's most profitable revenue stream.
Evaluating the group through a skeptical institutional lens highlights four primary structural concerns:
1. Structural margin ceilings in quick commerce. Skeptics argue that quick-commerce adjusted EBITDA will cap out between 3% and 4% of gross sales due to irreducible last-mile fulfillment costs, leaving the format structurally inferior to physical supermarkets operating at 8% to 10% margins. Under this view, adding courier compensation to grocery retail economics while eliminating the consumer's unpaid travel time creates an inherent margin drag. The counter-thesis notes that dark stores avoid high-street retail rents, cashier labor, and extensive interior fit-outs while generating brand advertising yields unavailable to traditional grocers. Financial disclosures remain ambiguous: while Blinkit generated ₹102 crore in segment adjusted EBITDA on ₹17,132 crore of net order value in the June 2026 quarter, operating margins remained paper-thin at roughly 0.6%.19 Long-term margin validation will ultimately depend on inventory loss control and warehouse throughput rather than incremental price adjustments.
2. Capital allocation and operational focus. Allocating ₹2,048 crore to acquire Paytm's ticketing business diverted capital and executive attention during an intense quick-commerce land grab, while the resulting District segment remains loss-making with management scaling back planned city rollouts.113 Skeptics view this transaction as capital misallocation that broadened corporate scope without adding immediate operational synergy. While management maintains that District monetizes existing dining-out consumer traffic and generates working-capital float, those financial benefits have yet to materialize in segment results, raising questions over whether the asset should be restructured or operated strictly for cash generation.
3. Reporting transparency and metric comparability. The transition to an inventory-led accounting model distorted year-on-year revenue comparability, shifting analytical focus toward non-GAAP management metrics including net order value, adjusted revenue, and adjusted EBITDA. Although Eternal provides supplemental disclosures on order volume and like-for-like store growth, reported headline figures—such as the 169% revenue growth in fiscal 2026—reflect accounting structural changes rather than proportional underlying transaction growth.14 Furthermore, segment adjusted EBITDA metrics exclude stock-based compensation expenses, masking a material ongoing cost for a company that relies heavily on equity incentives to retain key personnel.
4. Execution history and leadership variance. Evaluating management requires balancing notable strategic failures—including the Urbanspoon write-down, the cloud-kitchen exit, the rapid closure of Zomato Instant, ongoing District losses, and Deepinder Goyal's departure from the CEO role during a pivotal competitive phase—against key successes. Those successes include acquiring Uber Eats India, executing the Blinkit turnaround, implementing platform fee structures, navigating the IOCC regulatory restructuring, and delivering consolidated profitability. The track record reflects high-variance capital allocation paired with an ability to terminate unsuccessful initiatives rapidly—an operating profile that institutional investors must factor directly into long-term valuation models.
XI. Bear vs. Bull Investment Case & Key Operating KPIs
The bull case rests on a sequence, not a single claim. Food delivery, growing at low double digits with improving margins, generates steady cash flow without requiring new capital. That cash funds dark-store expansion without equity dilution — the ₹17,972 crore cash balance as of the March 2026 quarter provides several years of runway at current burn rates.11 Blinkit, already profitable at thin margins while expanding fastest in the sector, is extending from groceries into electronics, beauty, home goods, and apparel, multiplying the addressable retail market severalfold and raising basket values on existing rider trips. Operating larger stores at ₹11 lakh of daily net order value drives the operating leverage required to lift group adjusted EBITDA margins materially above current levels.3 District eventually achieves profitability, giving Eternal a dominant position in out-of-home entertainment with no equivalent-scale competitor. Under this scenario, the company becomes the central transaction layer for urban Indian consumption — covering food, groceries, general merchandise, and live events — with a fulfillment cost structure no new entrant can replicate without years of store-level learning.
The bear case is equally coherent and relies on fewer assumptions. Quick commerce is fundamentally retail, and retail with a dedicated delivery rider is structurally less profitable than traditional retail. Competitors including Zepto, Swiggy Instamart, Flipkart Minutes, and Amazon Now have strong incentives to keep prices below sustainable levels for years — for the e-commerce conglomerates, this is a defensive necessity funded by parent cash flows — keeping segment contribution margins trapped in the low single digits. Meanwhile, gig worker statutory contributions represent a permanent per-order cost against a business earning under one rupee of EBITDA per rupee of goods sold. Non-grocery categories present distinct operational hurdles: returns, warranty logistics, and inventory obsolescence in electronics and apparel differ fundamentally from high-velocity grocery fulfillment, exposing Eternal directly to write-offs under its inventory-led model — the 1.8% shrink rate already recorded in perishables signals the learning curve of managing direct inventory risk.3 Food-delivery growth, meanwhile, decelerates to high single digits as urban discretionary spending softens, weakening the cash engine funding expansion, while the founder who led the platform's pivotal strategic pivots has stepped down to pursue aviation ventures.
Evaluating both perspectives reveals the key assumptions: the bull case requires quick-commerce margins to expand from near-breakeven to meaningful profitability while the sector continues adding capacity, and assumes regulatory compliance costs for riders land at the lower end of projections. Neither assumption is unreasonable, but neither is yet established. The bear case requires only that current competitive intensity persists longer than management anticipates. What tilts the balance slightly is that Eternal remains the only major player in this format currently generating positive adjusted EBITDA, meaning a prolonged price war proves more costly for rivals than for Eternal — provided management's store expansion budget does not consume that cash advantage.
A critical external variable could shift both cases: industry consolidation. Quick commerce currently features six active competitors in a market that likely supports only two or three profitable operators. If weaker players retrench — mirroring how food-delivery unit economics improved rapidly once the market consolidated to a duopoly — sector margins could expand without internal operational gains. Conversely, if deep-pocketed retail parents view quick commerce as an essential loss leader to defend core e-commerce market share, price competition could persist indefinitely. That divergence represents the core fork in the investment thesis, determined by competitor capital allocation rather than internal execution.
The three KPIs that matter, and nothing else comes close.
Net order value per dark store per day, alongside store-level payback. This metric captures the core quick-commerce thesis. Management has established a target threshold of ₹11 lakh per store per day against capital expenditure of ₹2.5 crore per store, including regional warehousing.3 If reported throughput per store trends toward that target as the 2,443-store footprint matures, fixed-cost operating leverage is taking effect and margin expansion should follow. If throughput stalls while store counts rise, the platform is using capital to purchase unremunerative order volume.
Blinkit's adjusted EBITDA margin on net order value, evaluated alongside inventory shrink. Analyzing margin in isolation is incomplete. Adjusted EBITDA margin indicates whether network density and platform pricing are generating leverage, while a 1.8% inventory shrink rate measures how effectively the company forecasts localized perishable demand under an inventory-led structure. Expanding margins accompanied by declining shrink indicate genuine operational progress, whereas margins supported by fee increases alongside rising shrink would suggest pricing power is masking operational inefficiency.
Monthly transacting customers and order frequency across both platforms. Monthly transacting users in quick commerce reached approximately 31.8 million in the June 2026 quarter, up from 16.9 million a year earlier, compared to roughly 27.2 million in food delivery.3 Transacting user growth indicates whether quick commerce is broadening adoption within Indian households, while the divergence in user numbers between the two services reveals where long-term transaction volume is concentrating.
Ultimately, the core hypothesis to test over the coming year is management's assertion that competitive intensity peaked in mid-2026. If Blinkit expands margins while scaling store count and reducing inventory shrink, the density-driven operational moat is validated. If margins compress across subsequent quarters of store expansion, quick commerce must be evaluated as a capital-intensive retail operation with permanently thin structural margins.
XII. Epilogue, Outro & Summary
There is a version of this story framed as pure triumph, but that narrative overlooks a messier and more instructive historical record. In the triumphant version, two consultants foresaw the market, built a super-app, and achieved ultimate vindication. The reality is less clean. The company spent roughly a decade failing to monetize a discovery product that millions of people used. It exported an unproven playbook abroad, writing off most of a $60 million acquisition in the process. It closed a cloud-kitchen venture, shelved a ten-minute food delivery experiment within nine months, and acquired a ticketing business that remains loss-making. Its market position stabilized largely because Uber's retreat created a rational duopoly, while its turn to profitability relied on a contrarian acquisition executed near its stock-price trough, flat platform fees added to consumer orders, and a corporate ownership restructuring to navigate foreign investment laws.
What emerges from that record is not a lesson about vision, but a demonstration of pragmatic operational shift. Moving from high-margin advertising into low-margin logistics, retreating from 21 international markets, issuing equity to acquire Blinkit when public markets resisted the deal, sacrificing reported profits in 2025 to accelerate dark-store expansion, capping foreign capital access to secure direct inventory control, and transferring the chief executive's chair from the founder to the operator behind the growth engine—each decision required surrendering a comfortable corporate narrative to secure an essential operational requirement.
Eternal today is a fundamentally different business from the platform that listed in 2021, or even the corporate entity that rebranded in 2025. It operates as a large-scale Indian retailer supported by a cash-generative food-delivery annuity, competing in the country's most contested consumer format. Yet its operating margins remain thin enough that execution over upcoming quarters will determine whether its aggressive expansion built a durable enterprise or an expensive land grab. With the founder's departure, the original vision-led narrative drops away. What remains is the operational arithmetic of store throughput, rider payouts, and inventory shrink—the fundamentals of retail, a sector Indian capital markets have evaluated for generations.
References
-
Eternal Ltd. (ETERNAL.NS) market quote — Financial Modeling Prep, 2026-09 ↩↩
-
Zomato, Blinkit owner Eternal records Rs 20,211 crore revenue in Q1 FY27; profit jumps 268% to Rs 92 crore — Indian Startup News, 2026-07-22 ↩↩↩↩
-
7 key takeaways from Eternal Q1 FY27 earnings call — MediaNama, 2026-07 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Zomato acquires Uber Eats India business in all-stock deal — Financial Express, 2020-01-21 ↩
-
NRAI Logout campaign: Over 2,500 restaurants delist from Zomato Gold — Moneycontrol, 2019-08-15 ↩
-
NSE India Equity Information: ETERNAL — National Stock Exchange of India ↩
-
BSE India Stock Information & Corporate Filings: ETERNAL (543320) — BSE India ↩↩
-
India's Zomato posts first-ever quarterly profit — Reuters, 2023-08-03 ↩↩
-
Eternal Q1FY26 results: Profit takes 90% hit on quick commerce push — Business Standard, 2025-07-21 ↩↩↩
-
Eternal reports 90% profit drop in Q1 FY26, Blinkit overtakes Zomato in net order value — The Tech Portal, 2025-07-21 ↩
-
A full picture of Eternal's Q4 FY26 results: From Blinkit to Zomato and beyond — Indian Startup News, 2026-04-28 ↩↩↩↩↩↩↩
-
Zomato acquires Paytm's entertainment ticketing business for Rs 2,048 crore — Moneycontrol, 2024-08-21 ↩
-
Eternal's reality check: Blinkit's thin margins and District's losses — Entrackr, 2026 ↩
-
Eternal Limited revenues skyrocket 168% to ₹54,364 crore in FY26 — Adgully, 2026-04 ↩↩↩
-
Why Eternal is seeking cap on foreign ownership — Business Today, 2025-04-21 ↩↩
-
Zomato raises Rs 8,500 crore via QIP to bolster balance sheet — Business Standard, 2024-11-28 ↩↩
-
Eternal Draws the Line on Foreign Ownership — Could MSCI Be the Next to Exit? — Outlook Business, 2025 ↩
-
Blinkit eyes margin boost as it shifts to inventory-led model — YourStory, 2025-07 ↩↩
-
Eternal Q1 profit jumps fourfold to ₹92 crore on Blinkit strength — Business Standard, 2026-07-22 ↩↩↩
-
Deepinder Goyal Steps Down as Eternal Group CEO — Entrepreneur India, 2026-01 ↩↩
-
Eternal appoints Aditya Mangla as CEO of food ordering and delivery — Business Standard, 2025-07-06 ↩
-
Quick Commerce War 2026: Blinkit Tops Brutal 6-Way Fight — StartupFeed, 2026 ↩↩
-
Gig Workers Need 90 Days of Work for Social Security Benefits — MediaNama, 2026-05 ↩↩
-
India mandates aggregator onboarding to eShram portal to expand social security coverage — DLA Piper, 2026 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube