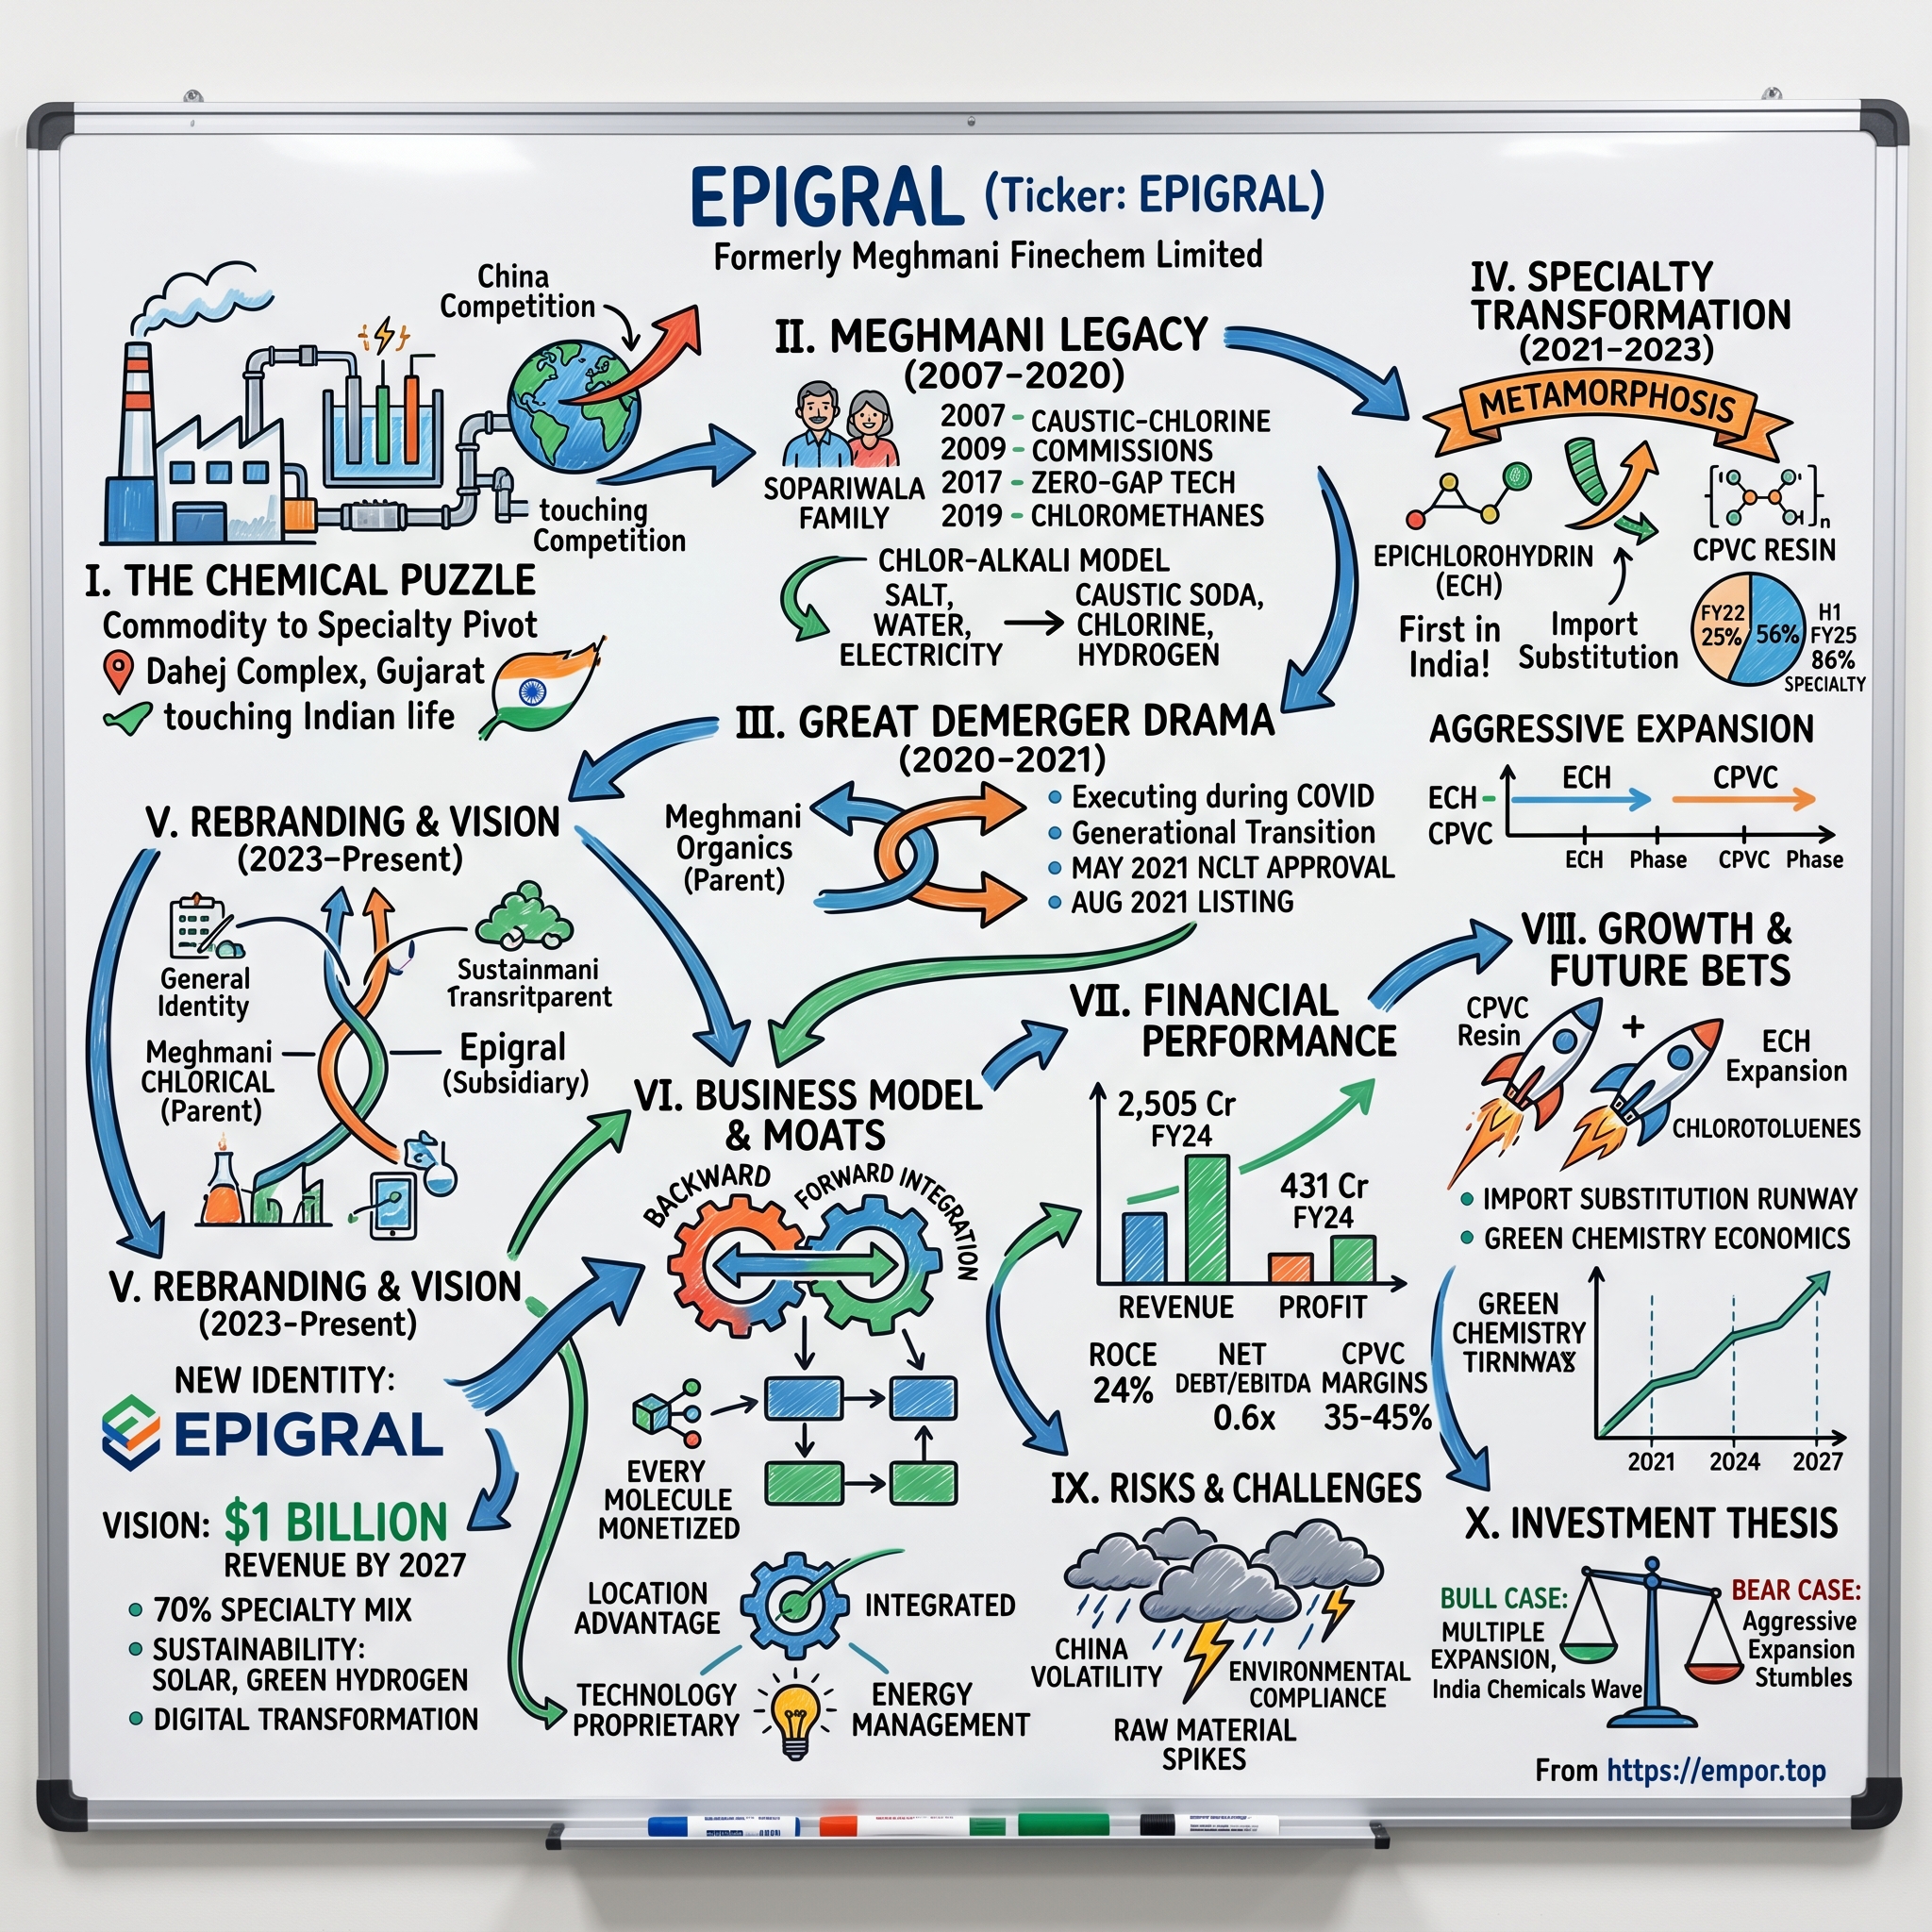
Epigral: From Chlor-Alkali Commodity to Specialty Chemical Champion
I. Introduction & The Specialty Chemical Pivot
There is a particular operational challenge that defines chlor-alkali manufacturing: the chlorine balance.
Consider the Dahej industrial belt on the Gulf of Khambhat, roughly 200 kilometres south of Ahmedabad. Salt pans, sea breeze, and a dense lattice of pipe racks connect industrial plants whose outputs supply essential everyday materials. Inside that lattice sits an electrolysis cell house—row upon row of membrane cells drawing electricity to split industrial salt water into three products simultaneously: caustic soda, which market demand readily absorbs; hydrogen, a useful byproduct; and chlorine, a corrosive gas that cannot easily be stored or transported over long distances, yet is generated in a fixed chemical proportion to caustic soda.
Every chlor-alkali producer operates under that arithmetic. For roughly every tonne of caustic soda manufactured, producers output just under nine-tenths of a tonne of chlorine, regardless of prevailing demand. In India, during weak cycles, merchant chlorine has fetched near-zero or even negative realisations, requiring producers to pay to have it offloaded. Consequently, the central question for any chlor-alkali business is not simply how cheaply it can produce caustic soda, but how effectively it handles surplus chlorine.
Epigral Limited—which trades on the National Stock Exchange under the ticker EPIGRAL and on the BSE under scrip code 543332—represents a sustained, capital-intensive effort to address that question.1112
Founded in 2007 as Meghmani Finechem Limited, a chemicals subsidiary of Ahmedabad-based agrochemicals and pigments producer Meghmani Organics, the company was carved out of its parent through a National Company Law Tribunal-sanctioned demerger in 2021, listed independently, and rebranded as Epigral in 2023.12 Over that span, the company constructed a sequence of production facilities: chloromethanes, hydrogen peroxide, India's first epichlorohydrin plant, India's largest chlorinated polyvinyl chloride (CPVC) resin plant, a CPVC compounding line, and an integrated chlorotoluenes value chain. With the partial exception of hydrogen peroxide, each unit was designed to consume captive chlorine at higher margins than merchant sales would yield.10
That operational shift frames the core investment question: does converting a commodity byproduct into specialty derivatives create durable pricing power, or does it shift commodity exposure further down the value chain?
Epigral's recent financial results illustrate this tension. Revenue expanded from roughly ₹829 crore in FY21 to ₹2,188 crore in FY23, declined to about ₹1,929 crore in FY24 during a global chemical downcycle, and recovered to ₹2,565 crore in FY25. In FY26, revenue flattened at roughly ₹2,527 crore, while net profit slipped from ₹357 crore to about ₹333 crore and return on capital employed compressed to around 15%.6 During that same window, the company more than doubled its gross block, raised ₹333.05 crore of fresh equity through a qualified institutional placement in October 2024, and increased the derivatives-and-specialty share of revenue from 25% in FY22 to roughly 52% in FY26.[^7]6
This combination—expanding capital expenditure and an increasing specialty mix alongside stagnant top-line growth and compressing returns—defines Epigral's current balance-sheet dynamics.
The following analysis begins with the company's origin within Meghmani Organics and the core chemistry governing downstream production. It examines the 2021 demerger that granted an independent balance sheet and capital expenditure mandate. It evaluates the Dahej complex to test whether pipeline integration provides a structural cost advantage or primarily freight savings. It examines the three main specialty investments—epichlorohydrin, CPVC, and chlorotoluenes—and evaluates management's import-substitution thesis against disclosed operational data. It benchmarks Epigral against industry peers including DCM Shriram, Gujarat Alkalies and Chemicals, Chemplast Sanmar, and Grasim. Finally, it tests capital allocation efficiency, corporate governance, and execution performance against past management targets.
Start where the chemistry starts.
 Subscribe on LinkedIn
II. The Meghmani Foundation & Chlor-Alkali Commodity Roots (2007–2020)
By the mid-2000s, Meghmani Organics represented a familiar pattern of Indian industrial growth—a family-founded Ahmedabad chemicals group with over three decades of operation, manufacturing pigments for printing and plastics alongside agrochemical technicals and formulations for domestic and export markets. While profitable, the business was inherently cyclical: pigment spreads fluctuated with Chinese supply, while agrochemical demand tracked monsoons and global crop prices.
In 2007, the group incorporated a subsidiary to pursue a structural shift: moving from downstream chemical formulation into basic industrial building blocks.10 The chosen anchor was chlor-alkali.
The chemistry, in plain language
Chlor-alkali manufacturing relies on a foundational electrochemical reaction. Dissolving common salt (sodium chloride) in water and applying a direct current across a membrane-separated cell splits the compound into three co-products: caustic soda (sodium hydroxide), a primary alkali used in aluminium refining, paper production, textiles, detergents, and water treatment; chlorine gas; and hydrogen.
Two core dynamics govern the economics of this process.
First, chlor-alkali is essentially an energy business operating under a chemical label. Power represents the single largest variable cost in plant operations. Producers with access to low-cost, reliable electricity hold a structural cost advantage, explaining why Indian chlor-alkali capacity clusters in Gujarat—where salt fields, coastal logistics, and power infrastructure converge—and why captive power generation remains vital.
Second, the chemical output follows an unyielding ratio: producing caustic soda automatically yields a fixed proportion of chlorine. Consequently, industry profitability is measured by the Electrochemical Unit (ECU)—the combined realization from one unit of caustic soda together with its co-produced chlorine and hydrogen. The chlorine component introduces persistent volatility; because the gas is hazardous, tightly regulated, and costly to store or transport, weak domestic market conditions have repeatedly driven merchant chlorine prices to zero or negative levels.
The scale trap
Following standard industry strategy, Meghmani Finechem expanded aggressively. Its caustic soda capacity grew from 167,000 tonnes per annum (TPA) in 2015 to 400,000 TPA after a major expansion commissioned in September 2022, bringing its total chlor-alkali footprint to 421,000 TPA by FY26.10
Yet every addition to caustic capacity created a corresponding volume of byproduct chlorine. Scaling was not merely a growth initiative; it imposed an operational mandate to build downstream captive chlorine units fast enough to match cell-house output and prevent surplus gas from depressing ECU realizations. Forward integration was not a discretionary corporate choice, but a structural necessity dictated by the primary manufacturing process.
The Dahej advantage — real, but widely shared
The company established its operations at Dahej, within Gujarat's Petroleum, Chemicals and Petrochemicals Investment Region. The location provided distinct operating efficiencies: deep-water port access for imported raw materials and exports, proximity to local salt pans, established utility infrastructure, and direct pipeline connectivity to neighboring industrial plants.
Evaluating this location requires distinguishing between regional advantages and proprietary moats. While Dahej presents high entry barriers for greenfield developments due to land scarcity, lengthy environmental permitting, and strict hazardous-material regulations, many established chemical competitors maintain operations in the same industrial zone. Consequently, Dahej offers a shared regional cost advantage against non-Gujarat producers rather than a unique competitive differentiator against primary peers.
Testing the claim: is chlor-alkali a "bulletproof cash engine"?
Management has consistently framed the core chlor-alkali business as a predictable cash-flow engine designed to fund downstream specialty expansion. However, historical performance demonstrates significant variability in that cash flow.
Chlor-alkali remains highly cyclical, as caustic demand follows global industrial production while supply is dictated by long-life, capital-intensive assets operating continuously. In both FY20 and FY24, global caustic prices dropped sharply from peak levels while domestic chlorine realizations weakened concurrently—compressing both components of the ECU simultaneously. Epigral's 12% revenue contraction in FY24, despite expanded operating capacity, illustrates this vulnerability.6
A more accurate assessment yields a narrower conclusion: chlor-alkali provides a large, low-cost, captive raw material base for downstream plants and generates strong cash flow during mid-to-peak cycles—but it does not stabilize earnings during downturns, when its own margins compress. This distinction reframes Epigral's forward-integration strategy not as a discretionary reinvestment of commodity profits, but as a deliberate attempt to reduce reliance on commodity volatility.
That operational imperative set the stage for the corporate restructuring required to execute the strategy.
III. The Demerger Masterstroke: Birth of Meghmani Finechem (2020–2021)
By 2020, the Meghmani group faced a classic corporate structure dilemma: public markets were valuing the parent entity as a composite whole at a discount to its underlying growth assets.
Investors in Meghmani Organics evaluated the company primarily as a cyclical manufacturer of agrochemicals and pigments, discounting earnings to account for monsoon dependency, crop price cycles, and low-cost Chinese competition. Embedded within its consolidated accounts, however, was a capital-intensive chemical infrastructure business with fundamentally different economics: long asset lives, high fixed operating costs, substantial operating leverage at scale, and an aggressive multi-year expansion program.
The two businesses placed conflicting demands on the balance sheet. Agrochemical formulation is working-capital intensive and short-cycle, where incremental capital generates returns within a single crop season. Chlor-alkali derivatives require multi-year capital deployment, with new plants taking years to commission and reach steady-state returns. Operating under a single corporate umbrella forced these competing capital priorities to contend for internal funding against short-term quarterly performance.
The separation
The scheme of arrangement demerging Meghmani Finechem Limited from Meghmani Organics received National Company Law Tribunal sanction, with the company filing the final order and listing documentation with stock exchanges in May 2021.1 The consideration structure was straightforward: shareholders of Meghmani Organics received one equity share of Meghmani Finechem for every share held in the parent entity.2 The transaction involved no cash payouts, external private equity placements, or fractional choices for existing investors.
Management framed the strategic rationale as unlocking shareholder value through operational focus.2 Corporate demergers warrant analytical scrutiny, as restructurings can sometimes serve to isolate debt or underperforming divisions. Subsequent execution, however, validated the strategic logic: the demerged entity inherited operational manufacturing assets at Dahej and an active capital expenditure pipeline, going on to expand revenue roughly threefold from FY21 to FY26.6 A detailed evaluation of corporate governance and capital allocation follows in later sections.
The second generation takes the wheel
Beyond financial restructuring, the demerger formalised an operational leadership transition to the promoter family's second generation.
Maulik Patel assumed the role of Chairman and Managing Director. His executive communication has focused consistently on production capacity, chemical selection, and import substitution rather than short-term price fluctuations. In public discussions, he has repeatedly emphasized a strategy of identifying chemistries heavily dependent on imports with durable long-term demand, and subsequently constructing domestic capacity at scale.9 This approach prioritises addressing structural gaps in the domestic supply chain, using scale and pipeline integration to secure operating margins.
Kaushal Soparkar took charge as Managing Director overseeing operational execution, site infrastructure, plant commissioning, and supply chain integration across the Dahej complex. In a process-industry business where asset utilization and commissioning timelines dictate annual return profiles, operational execution represents a primary driver of performance.
This leadership structure combines clear execution capability with strategic risks. On execution, management successfully commissioned multiple complex manufacturing chains within a tight timeframe—including chloromethanes, hydrogen peroxide, epichlorohydrin, CPVC resin, CPVC compounding, and chlorotoluenes. However, an aggressive expansion strategy exposes the balance sheet to cyclical risk, as gestating capital projects can coincide with downturns in global chemical pricing, a dynamic visible between FY24 and FY26.
Listing and the shape of the register
Meghmani Finechem listed independently on the National Stock Exchange and the BSE in August 2021.1 The listing presented public investors with a pure-play, single-site, chlor-alkali-to-derivatives manufacturer backed by a multi-year expansion roadmap and concentrated promoter ownership. Promoter holding has remained stable at approximately 68% to 69%, standing at 68.83% in recent disclosures.6
High promoter equity ownership aligns long-term insider incentives with public shareholders. Conversely, it concentrates voting control, meaning minority investor protections depend fundamentally on disclosure transparency, board oversight, and strict compliance governing related-party transactions.
The related-party question
Corporate separation did not end commercial interactions between the two entities. Meghmani Finechem and Meghmani Organics continue to operate adjacent facilities in the Dahej industrial zone, where shared utilities and physical chemical flows—including chlorine, caustic soda, and process steam—remain operationally practical. Consequently, asset transfers, land leases, and ongoing chemical supply agreements between the entities represent related-party transactions subject to statutory arm's-length pricing rules and audit committee approval.
Disclosed annual filings show no adverse auditor qualifications or material weaknesses in internal financial controls across the period.[^2] While clean audit opinions confirm regulatory compliance in reporting, investors monitoring long-term governance must evaluate ongoing related-party schedules to verify that pricing terms and transaction volumes between the group entities remain commercial.
With the corporate architecture established, management turned its focus to executing its capital deployment program at Dahej.
IV. Building the Integrated Dahej Complex: Caustic Soda to Chloromethanes & H2O2
At the Dahej complex, Epigral's corporate strategy is physically visible in the site layout.
The membrane cell house occupies the center of the facility. From there, two of the three electrochemical co-products leave by pipeline rather than tanker truck: chlorine gas flows directly to adjacent downstream consuming plants, while hydrogen feeds the hydrogen peroxide facility. The third output, caustic soda, is shipped offsite as lye or solid flakes to merchant buyers—the one co-product with a deep, reliable merchant market.
This single-site footprint—spanning over one million square metres designed around internal chemical transfers rather than external logistics—serves as the physical implementation of management's integration thesis.[^1] Replacing hazardous road transport with pipeline feeds eliminates handling, packaging, and freight costs.
The first wave: chloromethanes and hydrogen peroxide
Under the first phase of derivative expansion, Epigral constructed a 50,000-tonne-per-annum (TPA) chloromethanes facility that combines captive chlorine with purchased methanol to produce industrial solvents: methylene chloride, chloroform, and carbon tetrachloride.10 These chemicals serve as essential reaction solvents, extraction media, and refrigerant feedstocks for India's pharmaceutical and agrochemical industries. Within this segment, Epigral ranks as India's sixth-largest producer.6
The company's 60,000-TPA hydrogen peroxide facility, commissioned in July 2020, addressed the surplus hydrogen byproduct.10 Rather than burning electrolytic hydrogen for low-value process heat, the unit converts it into a bleaching and oxidizing agent for paper, textile, and water-treatment applications. Epigral ranks fifth among Indian hydrogen peroxide producers.6 From a unit-cost perspective, the process converts a low-value byproduct into a marketable chemical, benefiting from a captive feedstock whose primary production cost is absorbed by chlor-alkali operations.
These market positions—sixth in chloromethanes and fifth in hydrogen peroxide—indicate that first-phase derivatives provided operational chlorine and hydrogen sinks rather than market dominance. They established profitable domestic volume alongside multiple established incumbents, but did not grant Epigral significant pricing power.
Power: the input that decides everything
Power cost remains the primary determinant of chlor-alkali competitiveness. To secure low-cost electricity, Epigral expanded its captive thermal power capacity over time, reaching 96 megawatts (MW) following a 36-MW addition in June 2020, before progressively integrating renewable energy sources.10 In FY26, the company committed to a 38.14-MW wind-solar hybrid project as part of its ongoing capital expenditure program.7
For an electro-intensive business where electricity constitutes the largest operating expense, substituting renewable power for thermal generation lowers long-term energy costs while hedging against coal price spikes and grid tariff increases. Furthermore, reducing Scope 1 and Scope 2 emissions satisfies increasingly strict supply-chain sustainability audits from international epoxy resin and polymer buyers.
What pipeline integration is actually worth
Evaluating the competitive advantage of pipeline integration requires distinguishing between immediate operational savings and a true economic moat.
The direct cost advantages of captive pipeline consumption are substantial. Merchant chlorine sales require energy-intensive gas compression, liquefaction, specialized tonner filling, regulated hazardous-materials transport, and exposure to depressed local spot prices. Consuming chlorine via pipeline at the point of production eliminates compression, packaging, transport insurance, and freight costs. This generates a cost savings of several thousand rupees per tonne of chlorine compared to standalone downstream processors relying on merchant supply.
While pipeline integration provides a clear structural cost edge over non-integrated downstream processors, it offers little cost differentiation against integrated peers. Major domestic chlor-alkali producers—including DCM Shriram, Gujarat Alkalies and Chemicals, Chemplast Sanmar, and Grasim Industries—have similarly expanded captive downstream chlorine consumption. Consequently, downstream pipeline integration represents the entry ticket to the game, not a winning hand within it.
Testing the claim: does downstream integration insulate you from the cycle?
Management's central strategic claim—that expanding into downstream derivatives insulates company earnings from commodity chlor-alkali cycles—was tested during the chemical downturn in FY24.
Despite achieving aggregate sales volume growth as new production capacity ramped up, Epigral's consolidated revenue declined by roughly 12% in FY24, falling from ₹2,188 crore in FY23 to about ₹1,929 crore.6 Downstream product realizations compressed alongside primary chlor-alkali prices as global chemical overcapacity, particularly from China, depressed Asian market pricing for chloromethanes and hydrogen peroxide. Consequently, higher physical sales volumes failed to prevent a top-line contraction.
This outcome illustrates a core financial reality of basic chemical integration: integrating into a basic derivative removes handling risk and captures a logistics margin; it does not create pricing power. When downstream derivatives are themselves globally traded commodities subject to supply gluts, forward integration shifts exposure from one commodity cycle to another rather than eliminating cyclical risk.
This dynamic raises a central strategic question: if basic derivatives fail to confer pricing power during cyclical downturns, does expanding into higher-value specialty chemicals—where domestic production is limited or absent—provide a more durable hedge?
V. The Specialty Breakthroughs: ECH & CPVC Resin/Compound (2021–2024)
In June 2022, a plant started up at Dahej that had no precedent in India.3
Product 1: Epichlorohydrin, and the seduction of "India's first"
Epichlorohydrin—ECH—is an industrial chemical intermediate whose primary application is the manufacture of epoxy resin. Epoxy serves as a crucial bonding and protective material across modern manufacturing: it coats wind turbine blades, encapsulates semiconductor packages and printed circuit boards, protects marine hulls and industrial pipelines, and provides the structural matrix for aerospace and automotive composites. Wherever applications demand corrosion resistance and high structural adhesion, epoxy resin is required, and producing epoxy requires ECH.
For decades, India lacked domestic ECH production, fulfilling annual market demand exceeding 80,000 tonnes entirely through imports. Meghmani Finechem constructed a 50,000-tonne-per-annum (TPA) facility—the country's first domestic plant—and commissioned it in June 2022.310
The plant's process technology represented a key operational choice. While conventional global ECH manufacturing relies on propylene derived from petrochemical feedstocks, Epigral adopted a glycerine-based process that reacts crude glycerine—a byproduct of biodiesel manufacturing—with captive chlorine. This route replaces petroleum feedstocks with an agricultural waste stream, lowering carbon intensity while absorbing captive chlorine output. However, it also introduces a distinct margin vulnerability: Epigral's ECH profitability is governed by the spread between ECH selling prices and crude glycerine feedstock costs, an agricultural commodity subject to global biodiesel policy changes in Indonesia, Malaysia, and Brazil.
Testing the claim: is ECH a cornered domestic monopoly?
Evaluating this import-substitution thesis reveals the distinction between domestic market exclusivity and pricing power.
Operating as the sole domestic producer of an imported chemical does not confer monopoly pricing dynamics. Domestic pricing for importable commodities is governed by import parity—the landed cost of international supply, including freight, insurance, and customs duties. Because domestic buyers can readily purchase foreign alternatives, Epigral cannot price above landed import costs.
Through FY24, global ECH prices fell sharply from post-pandemic highs as substantial Chinese capacity additions entered a market where Chinese domestic demand—tied closely to construction and wind energy capital expenditures—was slowing. Exported Chinese volumes entered Asian markets, including India. Simultaneously, global glycerine costs spiked during 2022–2023, compressing operating spreads from both input and output sides. Consequently, plant utilization remained well below rated capacity during the early part of the fiscal year before recovering.
This operational outcome demonstrates a key principle: manufacturing capability does not equal pricing power. Epigral's domestic ECH plant provides clear operational advantages, including shorter delivery lead times, elimination of ocean freight, reduced import working capital requirements, local currency pricing, and rapid delivery to domestic epoxy formulators. These factors command a modest logistics-based margin over landed imports, but they do not support a structural pricing premium.
Ultimately, ECH provides Epigral with a structural share of Indian demand and a logistics-based cost advantage over imports, but operating profitability remains bound to an international commodity spread outside management's control. Going forward, the primary key performance indicator governing segment returns is the spread between ECH and its glycerine and chlorine inputs, alongside the progress of trade remedy petitions before the Directorate General of Trade Remedies, which represents the primary mechanism capable of raising domestic import parity ceilings.
Product 2: CPVC — the better business, quietly
While ECH attracted market attention as an import-substitution milestone, CPVC represents a commercially stronger franchise within Epigral's portfolio.
Chlorinated polyvinyl chloride (CPVC) is produced by chlorinating standard PVC resin, a process that significantly elevates the polymer's heat deflection temperature. While standard PVC pipe is limited to cold-water applications, CPVC handles hot-water flows, establishing it as the standard material for indoor residential plumbing in India and replacing traditional galvanized iron piping.
Historically, India imported virtually its entire CPVC resin requirement from international suppliers such as Lubrizol, Sekisui, and Kaneka. Domestic pipe manufacturers—including Astral, Finolex, Ashirvad, and Prince Pipes—purchased imported resin or compounds for pipe extrusion.
Epigral entered the market in July 2022 with a 30,000-TPA resin plant, subsequently commissioning an additional 45,000-TPA expansion in April 2024 to reach a total capacity of 75,000 TPA, making it India's largest domestic CPVC resin producer.10 In June 2024, the company commissioned a 35,000-TPA CPVC compounding facility, enabling direct sales of formulated, ready-to-extrude compound to pipe extruders.10
The forward integration into compounding represents a key strategic step. In polymer processing, technical value concentrates in compound formulation, where base resin is blended with stabilizers, impact modifiers, lubricants, and processing aids tailored to specific extrusion machinery and end-use standards. Selling compounded material rather than raw resin allows Epigral to capture formulation margins while creating customer switching friction. Because qualifying a new compound requires pipe manufacturers to conduct extended trial runs, validate pressure and thermal performance, complete regulatory certifications, and re-tune extrusion lines over a six-to-twelve-month cycle, customers rarely switch suppliers for minor price differences.
This qualification requirement provides a genuine switching-cost advantage, representing the most durable non-cost competitive moat in Epigral's specialty portfolio.
Testing the claim: is CPVC immune to construction cycles?
Financial performance during FY24 and FY25 demonstrated that CPVC remains exposed to broader macro cycles. CPVC demand tracks Indian residential construction and real estate activity, which experiences both seasonal slowdowns during monsoon periods and cyclical fluctuations in housing starts. Additionally, channel inventory dynamics influence short-term purchasing: when raw PVC prices decline, pipe manufacturers reduce inventory holdings to avoid holding high-cost stock. During FY24, Epigral expanded CPVC sales volumes, but declining realizations partially offset the margin benefits of capacity additions.
On its Q4 FY25 earnings call, management noted that it expected CPVC realizations to experience downward pressure over subsequent quarters while ECH spreads stabilized—reflecting the commodity-linked nature of domestic pricing.
Consequently, scale leadership and downstream compounding provide Epigral with a defensible domestic market position and customer stickiness, but product realizations remain tied to global import parity and domestic real estate cycles. Segment performance must therefore be tracked via volume growth alongside realized unit margins rather than volume metrics alone.
By 2023, with two specialty chemical platforms operational, management concluded that the company's legacy name no longer reflected its expanding derivative footprint.
VI. Rebranding to Epigral & The Chlorotoluenes Frontier (2023–Present)
In August 2023, Meghmani Finechem Limited rebranded as Epigral Limited. Beyond corporate marketing, the change signaled a strategic shift: dropping the family name after three decades positioned the fastest-growing entity within the group to be evaluated independently on its own chemistry, capital returns, and global customer base.
Alongside the new identity, management established an explicit operational benchmark: raising the derivatives and specialty chemicals share of revenue from 25% in FY22 to 70% by FY28.[^1] Progress toward that target has not been linear. The specialty mix reached roughly 56% in FY25 before slipping to about 52% for FY26 as a whole, concluding the fourth quarter of FY26 at 54%.67
This temporary decline illustrates the nuance of tracking revenue mix. Because the ratio depends on relative prices, a recovery in primary chlor-alkali realizations expands the commodity denominator, reducing the specialty percentage even if downstream volumes remain steady. Consequently, achieving the 70% target by FY28 depends on both specialty volume expansion and favorable relative pricing, making absolute specialty earnings an essential parallel metric for evaluating structural transformation.
Chlorotoluenes: the most genuinely specialty thing Epigral has built
In March 2024, Epigral announced its entry into the chlorotoluenes value chain.4 On 24 March 2025, the company commissioned the facility, establishing India's first integrated chlorotoluenes complex.10
This chemistry represents a distinct operational step. Reacting toluene—an aromatic solvent—with chlorine generates a branching family of downstream intermediates: benzyl chloride, benzaldehyde, benzotrichloride, and ring-chlorinated ortho- and para-chlorotoluenes. These intermediates serve as essential feedstocks for agrochemical active ingredients, pharmaceutical intermediates, fragrance and flavor molecules, dyes, and personal care products.
Unlike basic derivatives or import-parity commodities such as ECH and CPVC, chlorotoluene derivatives operate under true specialty economics. Buyers evaluate suppliers on exact impurity profiles, batch consistency, regulatory documentation, and supply security. Because qualifying a pharmaceutical intermediate for a regulated drug requires rigorous validation, customer relationships are sticky, contracts are negotiated individually, and switching friction is high. Historically, India relied on European and Chinese imports for most chlorotoluene chemistries, with limited domestic production from niche suppliers like Chemcon Speciality Chemicals.
Testing the claim: flawless capex execution?
The chlorotoluenes deployment also highlights execution realities that challenge claims of uninterrupted project timelines. Originally targeted for commissioning between late FY24 and early FY25, commercial operations commenced in March 2025, with management indicating that product ramp-ups would yield a "sizeable contribution to revenue" expected only in FY27.910 This timeline reflects a delay of roughly one year to commissioning, followed by a multi-year ramp to full revenue contribution.
While timeline adjustments are common when building complex hazardous chemical facilities subject to environmental licensing, the extended gestation period impacts financial metrics in two ways. First, capital remains tied up in non-earning assets for longer periods, placing downward pressure on returns—as seen in return on capital employed compressing to roughly 15% in FY26 from the low-20s during peak years.6 Second, it indicates that future project timelines should be evaluated with realistic buffer periods for commissioning and customer qualification.
The capital allocation shift
In October 2024, Epigral executed a qualified institutional placement, raising ₹333.05 crore at ₹2,093.13 per share.[^7]
From a risk-management perspective, raising equity during a chemical downcycle strengthened the balance sheet midway through an intensive capital expenditure program. Securing equity funding when available provides operational flexibility during periods of macro uncertainty.
However, the transaction diverged from prior management guidance emphasizing that expansion would be funded through internal cash generation. That gap between stated capital allocation strategy and execution warrants detailed examination in the governance analysis.
From a structural perspective, the issuance increased total share count by approximately 3.6%, expanding shares outstanding from roughly 4.16 crore to about 4.31 crore.[^7] While the resulting dilution was modest, issuing equity during an expansion cycle impacts per-share return compounding.
With these assets built, the central question turns to whether market structure and competition will permit Epigral to sustain long-term returns on its expanded capital base.
VII. Competitive Dynamics, Industry Structure & Helmer's 7 Powers
                       +-------------------------------------------------------+
                       |           CAPTIVE RAW MATERIAL PLATFORM               |
                       |       Industrial Salt + Water + Captive Power         |
                       +-------------------------------------------------------+
                                                   |
                                       [Electrolysis Cell House]
                                                   |
                   +-------------------------------+-------------------------------+
                   |                               |                               |
        Caustic Soda (Lye/Flakes)           Chlorine Gas                     Hydrogen Gas
             [~46-48% of Revenue]           [Captive Pipeline]              [Captive Pipeline]
                   |                               |                               |
         Merchant Sales & Regional       +---------+---------+            +--------+--------+
            Industrial Markets           |                   |            |                 |
                                    Chloromethanes      CPVC Resin     Hydrogen       Epichlorohydrin
                                       (CMS)            & Compound     Peroxide (H2O2)     (ECH)
                                         |                   |            |                 |
                                         |            Chlorotoluenes      |                 |
                                         |                   |            |                 |
                                  +--------------+----------------+---------------+-----------------+
                                  |   DERIVATIVES & SPECIALTY CHEMICALS DIVISION (~52-54% FY26)     |
                                  +-----------------------------------------------------------------+
Evaluating this operational structure through Porter's Five Forces reveals an industry environment more favorable on entry barriers than on competitive rivalry.
Threat of new entrants: low to medium. An integrated chlor-alkali-to-derivatives complex requires more than ₹1,500 crore in capital expenditure, multi-year environmental and hazardous-material permits, a large contiguous land parcel within an established industrial corridor, and deep technical expertise in handling chlorine gas at scale. Consequently, greenfield entry by a new player is formidable. However, the primary competitive threat is not a new entrant, but an existing chlor-alkali peer expanding into identical downstream derivative units without incurring site-creation delays.
Bargaining power of buyers: medium to high. Epigral's customer base consists of large, sophisticated industrial buyers—including pipe manufacturers such as Astral and Finolex, epoxy resin formulators, and pharmaceutical and agrochemical producers. These buyers typically negotiate formula-based pricing tied directly to international import parity, maintain active global supply relationships as leverage, and command substantial volume relative to Epigral's production capacity. Customer qualification requirements in CPVC compound and chlorotoluene derivatives provide meaningful pricing friction. In basic derivatives like ECH, chloromethanes, and caustic soda, however, buyer bargaining power remains high.
Bargaining power of suppliers: low. Industrial salt is abundant across Gujarat, while power requirements are anchored by captive thermal generation and expanding renewable energy contracts. Auxiliary feedstocks—such as methanol, crude glycerine, and toluene—are globally traded commodities available from multiple suppliers. Consequently, individual suppliers hold limited bargaining leverage. The primary operational exposure is input price volatility rather than supply availability—a margin risk rather than a structural supply constraint.
Threat of substitutes: low, within each application. Within their specific end uses, Epigral's core molecules face minimal threat of direct substitution. CPVC lacks an economical alternative for hot-water residential plumbing in India. ECH remains irreplaceable in conventional epoxy resin formulations, while caustic soda has no functional substitute in alumina refining or paper bleaching. While market demand for these foundational molecules is structurally secure, product pricing and margins remain vulnerable to broader commodity cycles.
Competitive rivalry: high in commodities, moderate in specialty. In primary chlor-alkali, Epigral competes directly on production cost against established peers including DCM Shriram, Gujarat Alkalies and Chemicals, Chemplast Sanmar, and Grasim Industries—all of which operate at comparable or larger scale, occupy low-cost coastal locations, and pursue identical downstream integration strategies. In ECH, CPVC resin, and chlorotoluenes, domestic rivalry is limited by Epigral's first-mover entry. However, competitive pressure from lower-cost international imports remains intense.
Helmer's 7 Powers, applied honestly
Process Power — moderate. The integrated Dahej complex—featuring direct pipeline feeds for chlorine and hydrogen gas alongside captive power generation—eliminates packaging, handling, and freight expenses compared to standalone processors. However, this advantage falls short of strong process power under Helmer's framework, which requires a proprietary operational capability that competitors cannot easily replicate. Constructing pipeline connections between adjacent manufacturing units is readily copyable by any capitalized peer with contiguous land access.
Scale Economies — moderate to strong, product-specific. Operating India's largest CPVC resin capacity, with plans to scale toward 150,000 TPA, enables Epigral to spread fixed overhead costs across a multi-product single site.79 This scale advantage is genuine in CPVC. It is far weaker in chloromethanes and hydrogen peroxide, where Epigral ranks sixth and fifth in domestic capacity, respectively—positions that deliver negligible scale benefits.6
Cornered Resource — moderate. Epigral's contiguous land parcel at Dahej, alongside its existing environmental clearances and hazardous-material handling permits, presents a significant barrier to greenfield competitors. However, these assets represent a hurdle primarily for prospective entrants rather than for established industry incumbents who already hold comparable operating permits.
Switching Costs — moderate, but the most defensible power. Extended qualification cycles—ranging from six to twelve months for CPVC compounds with pipe extruders, and even longer for pharmaceutical-grade chlorotoluene derivatives—create customer stickiness. This advantage is poised to strengthen as the chlorotoluenes portfolio matures, representing the primary structural mechanism by which Epigral can realize pricing above landed import parity.
Counter-Positioning — weak. Integrated incumbents face no structural dilemma or business-model cannibalization in adopting Epigral's forward-integration playbook. Competitors like DCM Shriram and Gujarat Alkalies and Chemicals are actively pursuing downstream chlorine integration. Consequently, Epigral holds a temporary timing lead rather than a counter-positioned structural advantage.
Network Effects — absent. Industrial chemical manufacturing functions without demand-side network dynamics.
Brand Power — weak. Epigral operates as a business-to-business supplier in industrial markets where customer purchasing decisions are dictated by landed cost and product specification compliance. There is no evidence of a sustainable pricing premium driven by brand equity.
The composite verdict: Epigral's competitive strengths are tangible, but they remain primarily cost- and timing-based rather than structural. Cost advantages narrow as peers deploy capital, while timing leads naturally diminish over time. The single advantage capable of compounding—qualification-driven switching costs in high-specification specialty derivatives—remains the newest and least proven segment of the business.
How that competitive balance translates into revenue, operating margins, and balance-sheet returns is revealed on the income statement.
VIII. Financial Engine, Unit Economics & Capital Allocation Audit
Epigral's five-year financial record demonstrates how a manufacturing business can simultaneously expand capacity and remain bound to underlying commodity cycles.
The top line
Revenue expanded from roughly ₹829 crore in FY21 to ₹2,188 crore in FY23—nearly tripling in two years as new epichlorohydrin, CPVC, and caustic soda capacity commissioned during a post-pandemic pricing surge.6 In FY24, top-line sales contracted roughly 12% to about ₹1,929 crore despite higher operating capacity, illustrating the impact of softening global chemical prices.6 Revenue recovered to ₹2,565 crore in FY25,6 before flattening at about ₹2,527 crore in FY26.67
The quarterly progression within FY26 offered clearer insight into operational momentum than the full-year figure. Following a sluggish first half impacted by monsoon-related construction slowdowns and scheduled plant maintenance, demand recovered in late 2025. The fourth quarter generated ₹736 crore in revenue—a 17% year-over-year increase and 22% sequential gain—driven by plant utilization exceeding 80% and net profit doubling sequentially to ₹82 crore.7 That operational momentum extended into the first quarter of FY27, when revenue increased 15% year-over-year to ₹709 crore and net profit rose 25% to ₹99 crore, yielding an EBITDA margin of 25%.8
Margins and returns — the number that matters most
Operating margins highlight the underlying shift in unit profitability over the expansion cycle. Epigral's operating margin stood at 32% in FY21 before moderating to 22% in FY26,6 demonstrating that top-line revenue growth coincided with lower profitability per unit of sales.
Two opposing dynamics drove this margin compression. On pricing, market realizations across caustic soda, ECH, CPVC, and chloromethanes normalized significantly from peak levels in 2021 and 2022 as global chemical supply expanded. On volume mix, the specialty and derivative share of revenue expanded from roughly 25% in FY22 to over half of sales in FY26, providing higher-margin volume to counter commodity price resets.6
To date, this mix shift has cushioned price declines rather than fully offsetting them. While maintaining an operating margin between 22% and 25% during a downcycle demonstrates stronger resilience than standalone commodity chlor-alkali producers achieve, it also indicates that expanding downstream derivatives has protected operating margins rather than expanding them through cyclical troughs.
Return metrics reflect this ongoing transition. Return on capital employed (ROCE), which exceeded 20% during peak market conditions, compressed to approximately 15% in FY26, alongside a return on equity of roughly 16%.6 This compression reflects rapid balance-sheet expansion, as Epigral deployed ₹394 crore in capital expenditure during FY26 alone into projects—including CPVC capacity additions, chlorotoluenes, and renewable power infrastructure—that had not yet reached full commercial utilization.7
Consequently, Epigral's current return on capital reflects a heavy investment phase rather than a mature steady state. The long-term investment case depends on whether capital returns recover toward 20% as newly commissioned capacity achieves higher utilization and market absorption. If expanded CPVC, ECH, and chlorotoluene lines achieve high plant utilization at stable unit margins, capital returns will expand. Conversely, if new capacity operates in oversupplied import-parity markets, expanded capital deployment will generate revenue growth without expanding return on capital.
The balance sheet
Epigral's balance sheet retains moderate leverage despite active capital expenditure. Total debt stood at approximately ₹572 crore in FY26, down modestly from ₹593 crore in the prior year.6 Relative to full-year EBITDA of roughly ₹550 crore to ₹560 crore—implied by a 22% margin on ₹2,527 crore in revenue—net debt remains below one time EBITDA, maintaining a conservative capital structure and supporting the investment-grade credit ratings maintained throughout the expansion.5
Capital deployment has relied on a combination of operating cash flows, moderate debt, and targeted equity financing. For FY26, the board proposed a final dividend of ₹5 per share, reflecting a modest payout ratio consistent with a company reinvesting nearly ₹400 crore annually in growth capital.7
Working-capital metrics show an increase in receivables intensity, as trade debtor days rose from 42 to 60 during FY26.6 This 18-day extension in credit terms occurred during a period of volume recovery alongside soft chemical pricing, indicating that industrial buyers exercised greater payment flexibility in a supply-abundant market. While manageable within current liquidity levels, persistent extensions in receivables during periods of flat revenue would signal shifting competitive leverage with downstream buyers.
Capex ahead
Looking ahead, management guided for capital expenditure of approximately ₹350 crore to ₹400 crore in FY27.9 Furthermore, during the first quarter of FY27, the board approved an additional ₹600 crore investment to construct a 125,000-TPA epoxy resin and formulations facility alongside a multi-purpose plant for downstream ECH and chlorotoluene derivatives, with both projects targeted for commissioning in the second half of FY28.8
The decision to enter epoxy resin manufacturing aligns directly with Epigral's broader integration strategy. Because Epigral produces both ECH and caustic soda captively, internal feeds will supply over half the raw materials required for epoxy production, while epoxy resin represents the primary global end-use for ECH.8 Consuming captive ECH internally to produce finished epoxy resin allows the company to reduce reliance on merchant import-parity markets for ECH, extending forward integration further downstream.
This ongoing investment cycle extends the company's asset construction phase through at least FY28, keeping returns on capital weighted by gestating gross block and project execution timelines. Ultimately, whether continuous capital deployment generates compounding economic returns or simply maintains revenue growth depends on realized product spreads, which remain tied to international supply conditions and global market dynamics.
IX. Management Quality, Governance & The Skeptical Investor Stress Test
Evaluating a management team requires looking beyond corporate strategy decks to compare historical commitments against actual operational delivery.
The people
Chairman and Managing Director Maulik Patel has established a consistent capital allocation strategy: identify imported industrial chemicals, construct domestic capacity at scale, integrate production into the Dahej chlorine platform, and repeat the process. In public commentary, he has highlighted domestic demand growth—noting to analysts that Indian CPVC demand could grow 10% to 13% annually to reach 500,000 tonnes per annum by 2030, while confirming that the company actively evaluates new import-substitution chemistries.9
This strategic focus has built an integrated chemical complex, but it also carries inherent balance-sheet risks if capital deployment outpaces market absorption. The commissioning of six chemistry platforms since 2020, alongside two additional projects approved in 2026, reflects a management team that demonstrates confidence primarily through capital expenditure. While public markets have generally rewarded this expansion, the compression of return on capital employed to roughly 15% in FY26 illustrates the immediate cost of gestating asset additions.6
Managing Director Kaushal Soparkar oversees plant execution and site operations. The operational track record is generally solid, though project commissioning timelines have periodically stretched—most notably during the chlorotoluenes rollout. Nevertheless, overall manufacturing complex utilization exceeding 80% in the fourth quarter of FY26 demonstrates strong operational performance once facilities reach full commercial readiness.7
Executive alignment remains high, anchored by promoter equity ownership of 68.83%.6 This concentrated stake aligns the promoter family's financial outcomes with minority shareholders, though minority investors remain subject to the control asymmetry inherent in promoter-led governance.
Stress test 1: the guidance-versus-outcome test
Evaluating capital allocation discipline requires examining instances where operational choices diverged from public guidance.
Management previously stated that its multi-year derivative expansion would be funded entirely through internal accruals and existing cash flows. However, in October 2024, Epigral issued fresh equity via a qualified institutional placement, raising ₹333.05 crore at ₹2,093.13 per share.[^7]
Assessing this divergence requires balancing strategic flexibility against guidance reliability.
On one hand, management set explicit expectations regarding capital structure that investors incorporated into per-share earnings models. While equity dilution was modest at approximately 3.6%, capital-structure decisions reside entirely within management control, making adherence to funding guidance a key measure of corporate predictability.
On the other hand, the capital raise occurred following a sharp cyclical downturn in global chemical earnings, allowing Epigral to strengthen its balance sheet at a favorable valuation without increasing debt leverage. The equity proceeds were deployed directly into announced capital expenditure projects rather than debt servicing or working-capital repair, preserving balance-sheet stability through a period of macro uncertainty.
The calibrated conclusion: Epigral's execution record demonstrates ongoing balance-sheet prudence, but it challenges the assumption that capital-structure guidance is absolute. Management has shown a willingness to prioritize balance-sheet safety over strict per-share dilution targets during uncertain market cycles. The forward test is specific and binary: whether the FY27–FY28 expansion program—comprising ₹350 crore to ₹400 crore in annual capex alongside the ₹600 crore epoxy resin and multi-purpose plant projects—can be fully funded through internal cash flows and existing debt headroom. If completed without additional equity issuance, management's capital discipline claim will be substantially rehabilitated. If another equity dilution occurs, it will establish a pattern rather than an exception.89
Stress test 2: did the demerger actually create value?
A common risk in corporate demergers is the potential separation of high-performing assets from legacy liabilities. Five years of financial data challenge that skeptical reading in Epigral's case. Following its 2021 demerger, the company inherited viable manufacturing assets, expanded annual revenue roughly threefold from FY21 to FY26, maintained return on equity in the mid-teens during an industry trough, and funded the majority of its capital expansion from internal cash flows.6 The restructuring successfully granted the chlor-alkali and derivatives platform an independent balance sheet and market valuation aligned with its long-cycle capital requirements.
Stress test 3: what would an activist attack?
An activist investor auditing Epigral's corporate structure would likely focus on four specific areas:
Return on capital. A compression of return on capital employed toward 15% raises structural questions regarding whether ongoing capital deployment generates compounding economic value or simply maintains top-line scale. Ultimate return trajectories will depend on realized unit margins across newly commissioned capacity as plant utilization matures.
Portfolio sprawl. Managing an expanding product portfolio—comprising caustic soda, caustic potash, chlorine, hydrogen, chloromethanes, hydrogen peroxide, epichlorohydrin, CPVC resin, CPVC compound, chlorotoluenes and derivatives, and upcoming epoxy resins and multi-purpose facilities—increases operational and regulatory complexity.6810 While operating from a single integrated site provides shared infrastructure efficiencies, running diverse downstream sales channels places increasing demands on management capacity.
Segment disclosure transparency. Epigral reports consolidated financial results broken down by chlor-alkali and derivative revenue shares, but does not disclose product-level operating margins. Consequently, external investors cannot independently verify individual return metrics for epichlorohydrin, CPVC, or chlorotoluenes, leaving a disclosure gap regarding unit-level profitability.
Promoter remuneration. Executive compensation for promoter directors remains within the statutory limit of 10% of net profits, conforming to established regulatory frameworks.[^2] While compliant, institutional investors continue to monitor executive pay structures given promoter control over board appointments.
The auditor signal
Independent audit reports for Epigral have remained unqualified, with statutory filings confirming effective internal financial controls and reporting no adverse material findings under the Companies (Auditor's Report) Order.[^2] Additionally, credit rating agencies have maintained Epigral's investment-grade credit rating with a stable outlook throughout the chemical downcycle.5 These disclosures confirm regulatory compliance and financial stability, providing a baseline of accounting integrity as the company advances its next phase of expansion.
X. Material Risk Radar & Macro Sensitivity
Unlike standard risk disclosure lists, Epigral's operating risks feature a clear hierarchy dominated by one primary vulnerability.
Risk 1: Chinese overcapacity — high impact, high probability, already happening
Chinese industrial chemical capacity expanded to supply an economy built around extensive real estate construction. As domestic residential property development slowed, excess chemical capacity turned toward export markets. India—a large, growing market with limited domestic supply in several of these surplus molecules—became a primary export destination.
The mechanism impacting Epigral is direct and immediate: all of Epigral's core products are priced at import parity. When Chinese producers export output at marginal cost to maintain plant utilization, landed import prices in India decline, driving Epigral's realized prices lower regardless of operating efficiencies at the Dahej complex. This exposure was the primary driver of the company's FY24 revenue decline and remained a persistent headwind across FY25 and FY26 pricing.6
Three potential circuit breakers could alter this dynamic. First, Chinese domestic demand could recover and absorb surplus production at home. Second, Indian trade remedies—such as anti-dumping duties recommended by the Directorate General of Trade Remedies—could raise landed import price floors. Third, Epigral can shift its product portfolio toward higher-value specialty derivatives where import parity dictates pricing less rigidly—the core rationale behind expanding into chlorotoluenes, epoxy resins, and downstream multi-purpose facilities. Because only the portfolio shift lies within management's direct control, the company continues to deploy growth capital into downstream specialty assets.
Risk 2: raw material spreads — medium impact, high probability
Three key raw material feedstocks introduce distinct margin exposures:
Glycerine governs epichlorohydrin profitability and tracks global biodiesel mandates in Indonesia, Malaysia, and Brazil. Consequently, policy changes to Indonesian biofuel blending requirements can compress operating margins at Dahej without any direct event occurring within the chemical industry.
Methanol dictates chloromethanes production economics and fluctuates with global natural gas and energy markets.
Toluene drives the chlorotoluenes value chain, tracking oil refining spreads.
None of these feedstock dependencies threatens physical raw material availability. However, all three present persistent margin risks that downstream pipeline integration cannot eliminate. Captive pipeline feeds secure only the chlorine portion of the chemical equation, leaving co-reactants fully exposed to global commodity market swings.
Risk 3: environmental and safety — high impact, low-to-medium probability
Environmental and safety hazards represent operational risks that escape financial models yet carry severe corporate consequences. Epigral processes toxic chlorine gas at industrial scale alongside hazardous compounds like benzotrichloride and chlorinated aromatics at its Dahej complex. A major chemical leak, industrial fire, or environmental breach could trigger regulatory shutdown orders from the Gujarat Pollution Control Board, potential criminal liabilities, and the revocation of environmental operating consents that form a primary barrier to entry.
Two structural factors amplify this vulnerability. First, single-site concentration leaves Epigral without geographic diversification; an operational stoppage at Dahej directly halts company-wide manufacturing. Second, increasingly strict zero-liquid-discharge standards and hazardous-waste compliance mandates require ongoing capital expenditure that adds to operating overhead without generating incremental revenue.
Risk 4: end-market cyclicality — medium impact, medium probability
Epigral's downstream product portfolio serves diverse end markets with distinct demand drivers. CPVC demand tracks domestic residential construction and plumbing installations. Epichlorohydrin tracks epoxy resin consumption across wind energy infrastructure, electronics, and industrial coatings. Primary chlor-alkali output supplies textiles, alumina refining, and paper manufacturing. Chlorotoluenes feed agrochemical active ingredients and pharmaceutical intermediates, with agrochemicals exposed to crop pricing cycles and distribution channel inventory adjustments.
While these varied end uses theoretically offer portfolio diversification, operational performance during FY24 demonstrated that these markets can compress simultaneously. Synchronized downturns occur because these sectors share a common underlying driver in global industrial activity and transmit pricing pressure through landed Chinese import parity. A similar dynamic emerged in the first half of FY26, when monsoon-related construction slowdowns coincided with scheduled plant maintenance to suppress short-term earnings.
The overlay: geopolitics and cost of capital
Management attributed the operating environment in the first quarter of FY27 to "severe macroeconomic volatility driven by geopolitical tensions in West Asia."8 For a manufacturer importing glycerine and methanol while exporting finished products through the Gulf of Khambhat, maritime disruptions in the Red Sea and West Asia directly influence ocean freight rates and raw material delivery schedules.
Regarding capital costs, net debt under one times EBITDA and a stable investment-grade credit rating indicate that the cost of capital does not pose an immediate risk, but approving ₹600 crore in new projects alongside ongoing capital expenditure leaves the balance sheet with less financial slack in FY28 than it retains today.58
XI. The Investment Thesis & Falsification Matrix: Bull vs. Bear Case
The bull case
The mix shift is structural, moving the business toward higher-value products. Specialty and derivative products expanded from 25% of revenue in FY22 to roughly 52% in FY26, supporting management's target of reaching 70% by FY28.[^1]6 Even during a severe chemical downcycle, the company maintained an operating margin of 22%—a level standalone chlor-alkali producers struggle to defend under weak market conditions.6 If the chlorotoluenes complex, the doubled capacities in epichlorohydrin (ECH) and CPVC resin, and the upcoming epoxy plant perform as projected, Epigral's earnings base will become structurally less price-elastic than the cash flows that contracted in FY24.
Scale leadership in genuine import-substitution markets. Epigral operates India's largest CPVC resin plant, scaling toward 150,000 tonnes per annum (TPA), stands as the nation's sole domestic ECH producer, expanding capacity to 100,000 TPA, and established India's first integrated chlorotoluenes chain.910 In each segment, Indian structural demand growth remains intact while domestic supply remains constrained, giving Epigral control over physical volume growth.
Forward integration into epoxy closes the value loop. The ₹600 crore epoxy resin investment relies on captive ECH and caustic soda for over half its raw material requirements, converting an import-parity intermediate into a finished resin for wind energy, electronics, infrastructure, and automotive applications.8 Extending downstream reduces direct exposure to merchant commodity pricing.
A structural cost floor anchors operational resilience. Direct pipeline integration for chlorine gas, captive thermal and expanding renewable power generation, single-site fixed-cost absorption, and the elimination of hazardous freight expenses provide an enduring cost advantage. In a sustained price war, Epigral can operate at realizations that would force non-integrated downstream processors to shut down.
The bear case
Margin trends have not yet confirmed the transformation thesis. Operating margins narrowed from 32% in FY21 to 22% in FY26, while return on capital employed compressed from over 20% to approximately 15%.6 Despite nearly doubling the specialty revenue share over that period, unit profitability fell. To date, the product mix shift has cushioned price declines rather than driving structural margin expansion, leaving the re-rating thesis as a forward forecast rather than a proven result.
Import parity establishes an unyielding price ceiling. The FY24 ECH downturn demonstrated that operating as India's sole domestic producer delivers logistics advantages, not independent pricing power. Unless trade remedies elevate price floors or the product mix shifts decisively into custom-synthesized specialty molecules, Chinese marginal production costs will continue setting Epigral's domestic realizations.
Continuous capital deployment compresses return metrics. Capital expenditure reached ₹394 crore in FY26, with ₹350 crore to ₹400 crore guided for FY27 and ₹600 crore approved for projects targeted for commissioning in the second half of FY28.789 Gross block additions continue arriving ahead of the revenue required to justify them, while the chlorotoluenes rollout shows that commercial revenue ramp-ups lag physical commissioning. Remaining in a perpetual construction cycle depresses return on capital employed, forcing investors to underwrite prospective steady-state returns that have not been observed since peak market conditions.
Capital allocation discipline has previously diverged from guidance. Management's October 2024 equity placement diverged from prior commitments to fund expansion strictly through internal accruals.[^7] A second equity dilutive event to fund the FY28 investment program would turn an exception into a pattern, materially reducing long-term per-share compounding.
Single-site operational concentration. Epigral's entire revenue base and asset infrastructure remain concentrated within a single manufacturing complex in Dahej, exposing operations to localized industrial, environmental, and regulatory risks.
The falsification matrix
+---------------------------------------------------------------------------------------------------+
|                                 THE HISTORICAL FALSIFICATION MATRIX                               |
+--------------------------+------------------------------------+-----------------------------------+
| THESIS CLAIM             | DISCONFIRMING HISTORICAL EVIDENCE  | FORWARD FALSIFICATION KPI         |
+--------------------------+------------------------------------+-----------------------------------+
| 1. ECH monopoly gives    | FY24 spreads compressed as Chinese | ECH realisation over glycerine +  |
|    structural pricing    | exports reset Asian ECH pricing    | chlorine cost; DGTR trade-remedy  |
|    power                 | and glycerine costs spiked.        | outcome; utilisation at 100 KTPA. |
+--------------------------+------------------------------------+-----------------------------------+
| 2. Capital allocation    | Oct 2024 QIP of Rs 333.05 Cr       | FY27-28 capex (Rs 350-400 Cr p.a. |
|    discipline funded by  | diluted ~3.6% after emphasis on    | plus Rs 600 Cr epoxy/MPP) funded  |
|    internal accruals     | internal-accrual funding.          | with zero further equity issue.   |
+--------------------------+------------------------------------+-----------------------------------+
| 3. Specialty mix makes   | FY24 revenue fell ~12% despite     | Derivatives share above 65% with  |
|    earnings structurally | volume growth; FY26 OPM 22% vs     | operating margin sustained above  |
|    less cyclical         | 32% in FY21; ROCE ~15% in FY26.    | 25% through a pricing downcycle.  |
+--------------------------+------------------------------------+-----------------------------------+
| 4. Flawless project      | Chlorotoluenes slipped roughly a   | Epoxy resin and MPP commissioned  |
|    execution             | year to Mar-2025 commissioning,    | in H2 FY28 as announced, with     |
|                          | with revenue contribution in FY27. | utilisation above 70% within a yr.|
+--------------------------+------------------------------------+-----------------------------------+
The KPIs that actually matter
Evaluating Epigral's operational execution requires monitoring three core metrics.
First: unit realization per tonne over aggregate volume. Performance during FY24 confirmed that volume growth alone does not guarantee top-line expansion. Evaluating performance requires dividing segment revenues by physical output where disclosed, treating physical volume growth accompanied by falling unit realizations as a margin warning rather than an operational achievement.
Second: incremental return on expanded gross block. The investment thesis depends on whether the ₹394 crore deployed in FY26, alongside ₹350 crore to ₹400 crore scheduled for FY27 and ₹600 crore committed by FY28, generates adequate economic returns. Consolidated return on capital employed trending back toward 20%—as ECH capacity reaches 100,000 TPA, CPVC capacity reaches 150,000 TPA, and chlorotoluenes reach full utilization—serves as the primary indicator. If return metrics remain in the mid-teens after these facilities reach capacity, capital deployment will have expanded revenue scale without improving baseline returns.
Third: specialty revenue share evaluated alongside absolute specialty profitability. Management's commitment to expand the derivative and specialty mix to 70% by FY28 represents its central public benchmark.[^1] Because revenue proportions fluctuate with commodity chlor-alkali prices, the metric must be evaluated alongside unit margins. A rising specialty share combined with operating margins holding above 25% during a weak pricing cycle would provide empirical evidence of a structural business transformation.
XII. Playbook: Core Business & Investing Lessons
1. The byproduct problem is the whole business. In fixed-ratio chemistry, the product a company cannot sell determines the economics of the product it can. Epigral's entire strategic evolution represents a sequence of operational answers to a single question about chlorine. When analyzing any process industry with joint outputs—refining, meat processing, or polymetallic mining—find the output nobody wants and examine how the company manages it. That is where the strategy actually lives.
2. Integration is a cost advantage, not a pricing advantage—and the distinction is everything. Piping chlorine directly to downstream plants eliminates compression, packaging, freight, and insurance expenses. It does not permit a manufacturer to charge a premium over an imported alternative. A cost advantage protects margins during a downturn; a pricing advantage captures excess returns during an upturn. They represent fundamentally different moats that support distinct valuations. Investors who conflate them systematically overpay for integrated commodity producers.
3. "India's first" is a manufacturing achievement, not an economic one. Operating as the sole domestic producer of an importable commodity caps pricing at import parity rather than a monopoly premium. Shorter lead times, reduced working capital requirements, and local currency pricing offer real logistics benefits worth a modest margin—not a structural franchise. Genuine domestic pricing power requires a trade barrier, a product deeply locked into customer specifications, or prohibitive freight costs. Investors must identify which mechanism applies before granting a specialty valuation multiple.
4. A demerger works when separated divisions operate on different capital clocks. The value unlocked by Epigral's 2021 demerger stemmed from aligning capital deployment horizons rather than generic corporate focus. A multi-year expansion program and a short-cycle working-capital business were competing for internal funding under a single board, leaving both mispriced. When conglomerates contain divisions with fundamentally different investment horizons, a clean demerger with independent management and a direct share ratio represents a high-probability value catalyst.
5. Track capital-structure commitments against execution. Demand forecasts can fall short due to external market shifts, but capital-structure guidance remains strictly within management control. When leadership commits to funding expansion through internal cash flows but subsequently issues dilutive equity, the appropriate analytical response is to adjust guidance reliability accordingly. Epigral's next capital discipline test—funding the epoxy resin and multi-purpose plant program through FY28 without further equity issuance—is already established.
6. A company permanently under construction displays permanently compressed returns. Continuous capital deployment is not inherently flawed; it forms the foundation of long-term corporate growth. However, gestating assets suppress reported return on capital employed, making historical return metrics an incomplete guide to underlying asset quality. Valuing an expanding producer requires forecasting returns on uncommissioned facilities rather than relying on historical steady-state performance—a forecast that should be priced with appropriate conservatism.
XIII. Primary Earnings Call & Q&A Roadmap for the Article Writer
For anyone wanting to test this analysis against the primary record, the useful material is concentrated in a handful of calls, and the Q&A sections consistently carry more information than the prepared remarks.
Q4 FY22 and Q1 FY23. The commissioning window for ECH and CPVC resin. Worth reading for the original margin framing on both products and the initial articulation of the import-substitution thesis — because those early statements are the benchmark against which everything since should be measured.
Q3 FY24 and Q4 FY24 — the essential downturn baseline. These are the most valuable calls in the archive precisely because they were the hardest. Analysts pressed management on ECH margin compression, glycerine cost volatility, ECU realisation collapse and utilisation shortfalls. The test to apply while reading: did management explain the miss mechanically, or attribute it to "market conditions" and move on? Did they name a recovery plan with observable milestones?
Q2 FY25 and Q3 FY25. The QIP calls. Management's own explanation of why equity was raised after emphasising internal accruals, plus updates on the chlorotoluenes timeline and progress toward the FY28 specialty target.[^7]
Q4 FY25. Notable for specificity: management guided that CPVC realisations would soften over the following quarters while ECH firmed — a falsifiable directional call that can be checked against what subsequently happened, which is the single best way to calibrate a management team's forecasting honesty.
Q4 FY26 and Q1 FY27. The recovery and re-acceleration calls, covering the record ₹736 crore quarter, FY27 volume growth guidance in the 10–12% range, the ECH and CPVC capacity doublings targeted for commissioning from Q2 FY27, and the ₹600 crore epoxy and multi-purpose plant approval.789
Across all of them, the questions worth tracking are the same four: the arithmetic of chlorine realisation within the ECU, the spread over glycerine, methanol and toluene, project timelines against the previous call's stated timelines, and working capital days during destocking. Prepared remarks at this company reliably emphasise volume, milestones and renewable energy share. The Q&A is where realisation, spread and slippage get discussed — and those are the variables that determine whether the specialty pivot is a transformation or a very expensive lateral move.
References
-
Meghmani Finechem Demerger Scheme Order & Listing Filings — BSE Corporate Announcements, 2021-05-20 ↩↩↩
-
Meghmani Organics Demerges Finechem Biz to Unlock Value — Business Standard, 2021-05-20 ↩↩↩
-
Meghmani Finechem Commissions India's First Epichlorohydrin Plant — Indian Chemical News, 2022-06-02 ↩↩
-
Epigral Enters Chlorotoluenes Value Chain to Expand Specialty Footprint — Indian Chemical News, 2024-03-18 ↩
-
CRISIL Credit Rating Rationale — Epigral Limited, 2024-08-14 ↩↩↩
-
Epigral Ltd — Financial Summary, Ratios and Shareholding, Screener.in ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Epigral Limited Q4 FY26 Financial Results and Dividend — Investywise, 2026 ↩↩↩↩↩↩↩↩↩↩
-
Epigral Q1 PAT Surges 25% to Rs 99 Cr — Indian Chemical News, 2026 ↩↩↩↩↩↩↩↩↩↩
-
CPVC and Epichlorohydrin Expansions to Double Capacity in FY27: Maulik Patel, Chairman & Managing Director, Epigral — Indian Chemical News ↩↩↩↩↩↩↩↩↩
-
Epigral Ltd — Company Summary, Capacities and Commissioning Milestones, India Infoline ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
National Stock Exchange of India — Epigral Limited (EPIGRAL) Equity Page ↩
-
BSE Limited — Epigral Limited (Scrip Code: 543332) Filings & Financials ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube