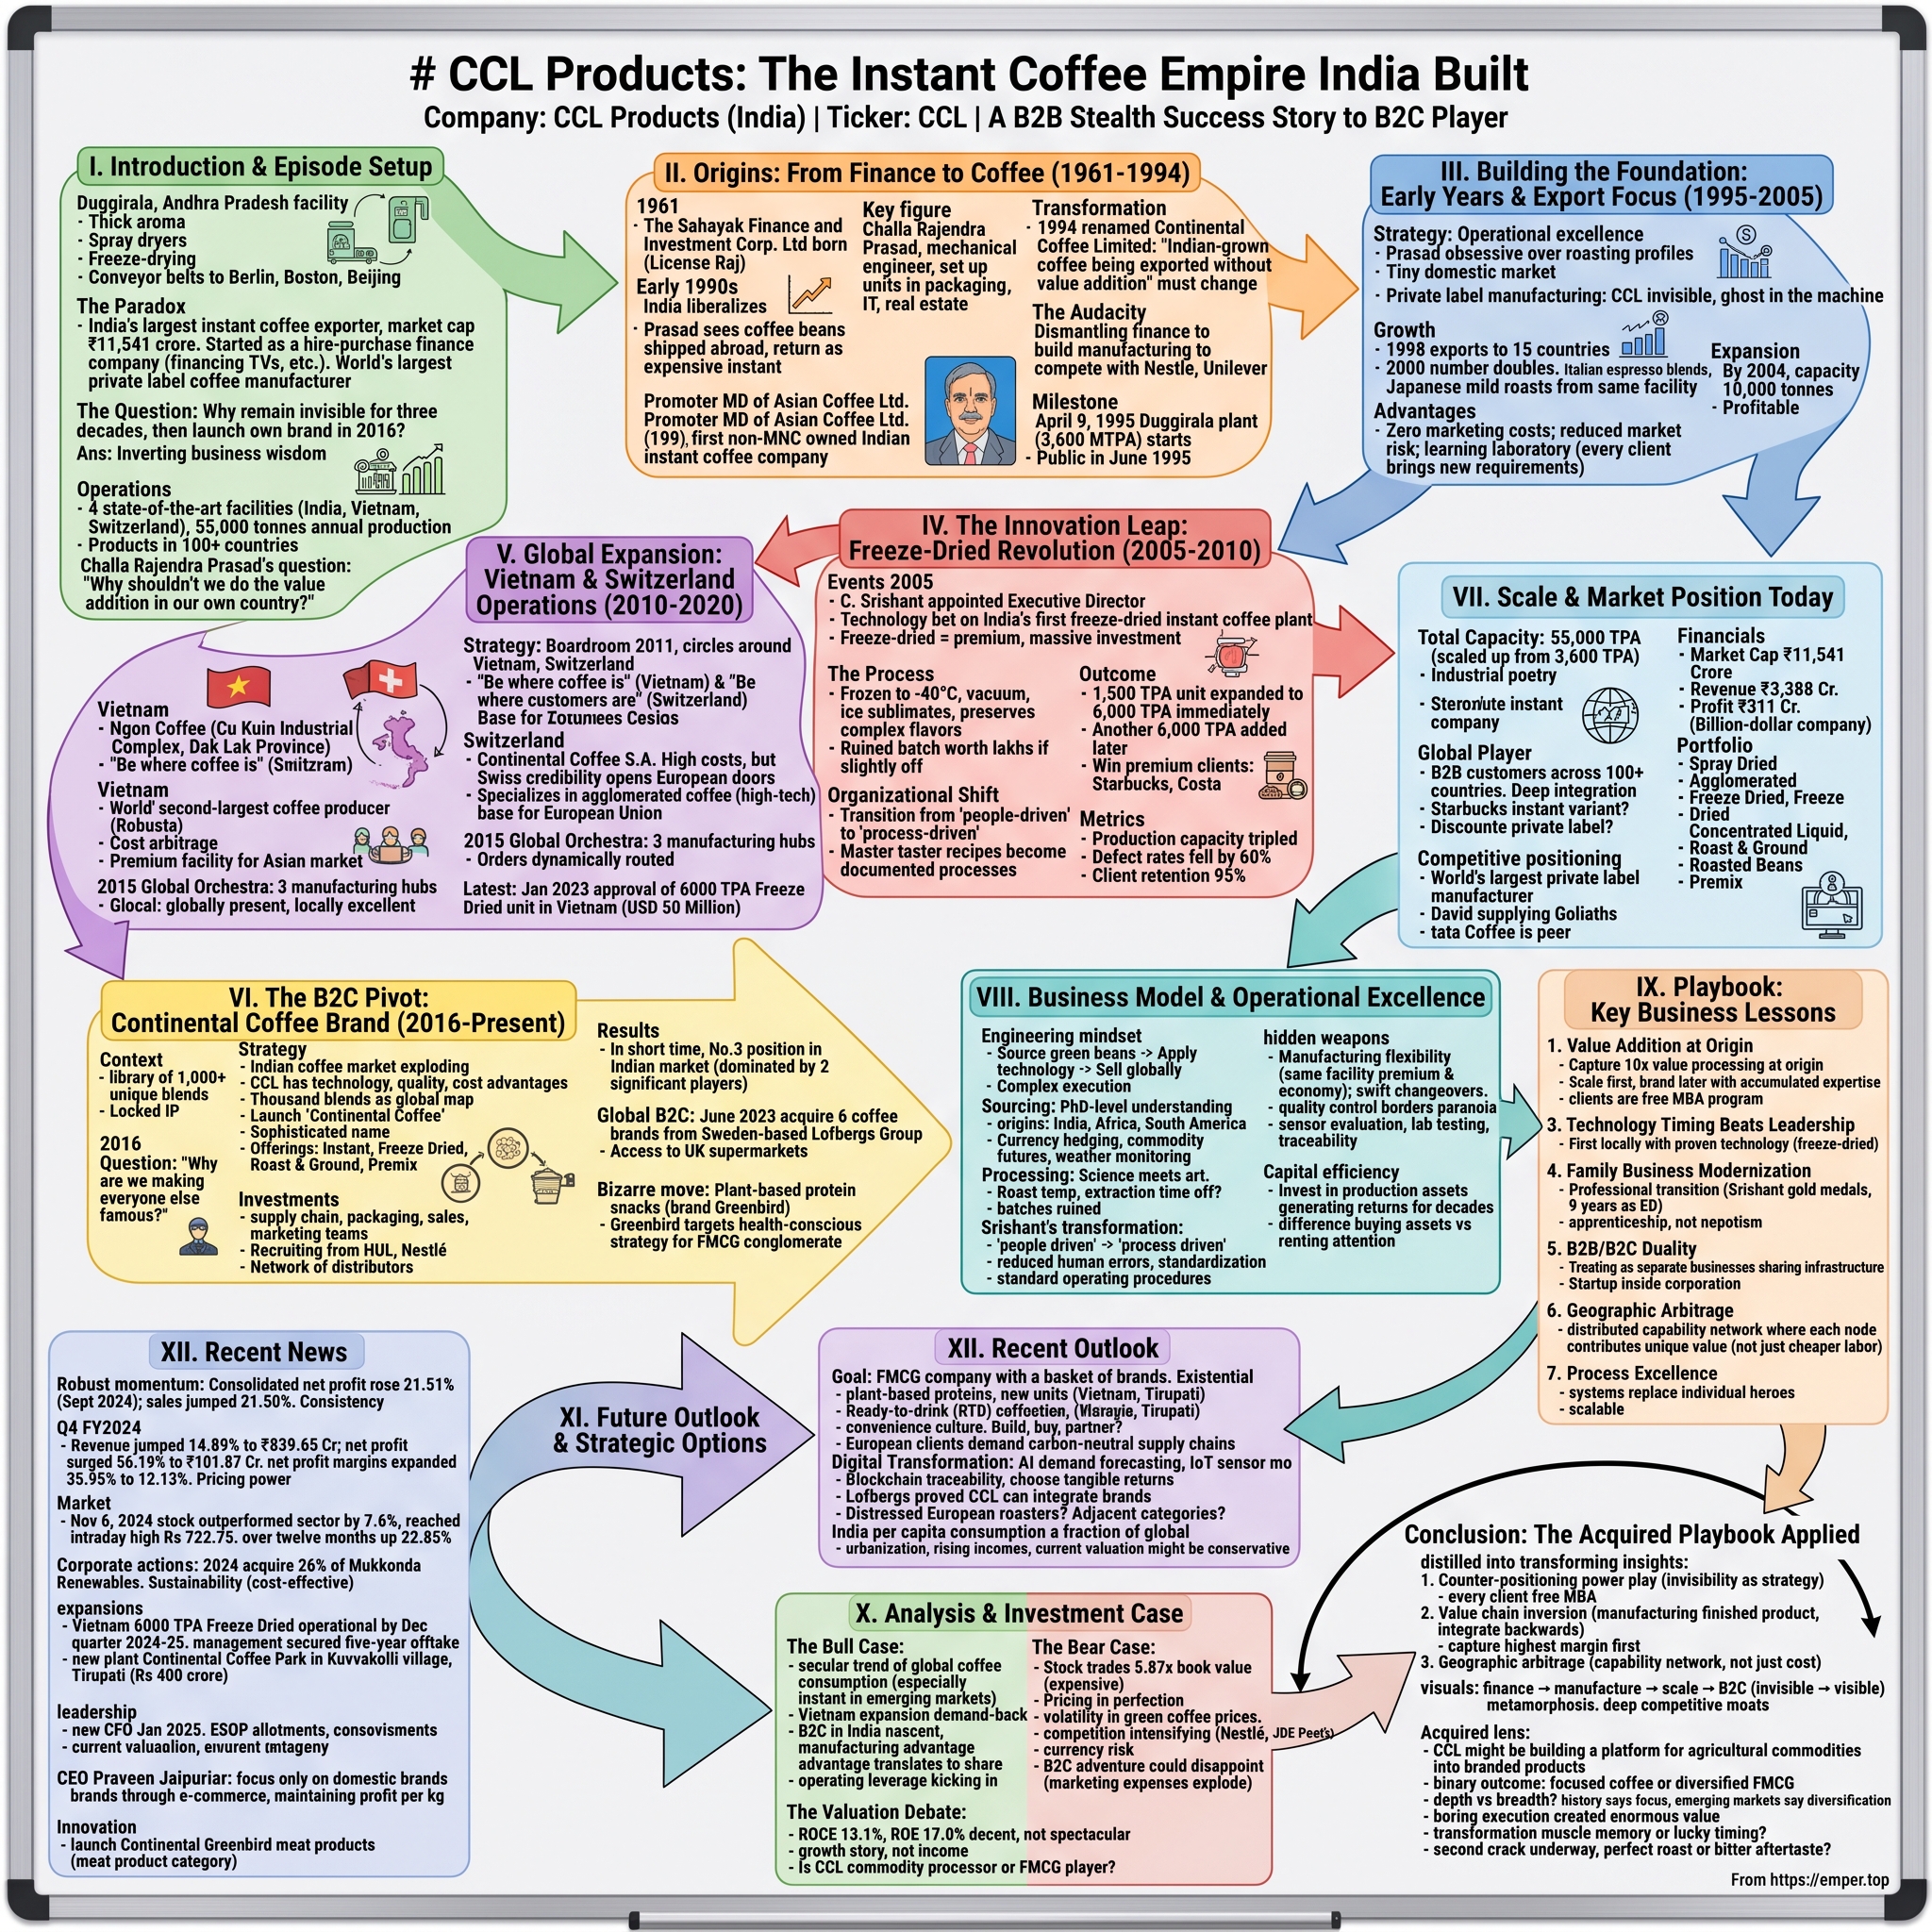
CCL Products (India): The Invisible Coffee Company
I. Introduction: The Cup You Drink Without Knowing Whose It Is
Somewhere in a supermarket in Warsaw, a shopper reaches for a jar of own-label instant coffee. The label carries the retailer's name, the retailer's colours, the retailer's promise about ethical sourcing. Nothing on that jar mentions a small town in coastal Andhra Pradesh called Duggirala, population somewhere in the tens of thousands, where the granules inside were very likely dried, blended and packed. The shopper will never know. That is precisely the point, and it is the entire business model of CCL Products (India) Limited.
CCL is one of the strangest listed consumer companies in India, because for the first twenty-five years of its life it was not a consumer company at all. It made a product that everybody consumes and nobody attributes. It has never had to fight for shelf space, never had to buy television advertising, never had to convince a household to switch brands. It simply sold soluble coffee, in bulk and in jars, to the people who do fight for shelf space — the Nestlés and the Tescos and the Carrefours and the hundreds of regional brands and private-label programmes that between them cover more than 110 countries.1 Management describes it as one of the world's largest private-label instant coffee manufacturers, and on the available evidence about the outsourced segment of the trade, that description holds up.2
The scale is now real without being enormous. In the financial year ended March 31, 2026, the group reported consolidated revenue from operations of ₹4,457.37 crore and net profit of ₹388.11 crore.1 The market has capitalised that at roughly ₹14,500 crore — a mid-cap, not a bellwether, trading well within a 52-week band that has swung from about ₹815 to about ₹1,242 a share.3 For a company that sells an addictive daily consumable into a hundred-plus countries, that valuation tells you something important: the market is not sure how much of CCL's economics belongs to CCL, and how much belongs to the coffee.
That question is the spine of this story. There are really only four things you need to resolve about this business, and they are all contested.
The first is whether the manufacturing position is a moat or a service. CCL prices on a cost-plus basis, converting green coffee into soluble coffee for a fee expressed in rupees per kilogram. Management is explicit that the commodity passes straight through and the margin is the value-add.4 That is either a beautifully hedged toll booth or a contract-manufacturing business with no pricing power at all, depending on whether the "plus" is defensible. The company's own numbers say the plus has drifted upward over five years. An analyst on the most recent call pointed out that an unnamed listed peer earns considerably more per kilogram on lower volumes — and the CEO declined to explain the gap.4
The second is geography. A large share of the group's manufacturing capacity and, on a standalone basis, a large share of the group's reported subsidiary profit now sits in Vietnam, in an entity that paid no tax in FY26.1 That is a legitimate structural advantage — proximity to robusta, a duty map that works, tax incentives — and it is also a concentration of value in a single jurisdiction that a policy change could reprice.
The third is the brand. Since 2019 CCL has been trying to become the thing it spent a quarter-century enabling: a consumer brand.5 Continental Coffee has grown fast and taken measurable share in South India. It has also cost money, and the company's record with non-coffee diversification is not encouraging — a plant-based meat brand launched with fanfare in 2022 was quietly wound down by early 2026.67
The fourth is the balance sheet. Between 2022 and 2024 a historic commodity spike drove group debt to roughly ₹1,950 crore, and the company spent the following eighteen months digging out of it.4 Management now describes the balance sheet as de-risked. The interesting question is not whether the dig-out happened — it did — but whether the hole was dug by the coffee market or by the company.
This is not a story about a genius product. Instant coffee was invented long before anyone at CCL was born. It is a story about a founder who sold his first coffee company and immediately built a second one, about arbitraging the map, and about a business that spent thirty years being deliberately invisible and has now decided it wants to be seen. Start with the man.
 Subscribe on LinkedIn
II. The Founder Who Sold His Coffee Company and Built Another (1961–2000)
There is a version of the Indian coffee story that most people know, and it is about beans. India grows arabica and robusta in the hills of Karnataka, Kerala and Tamil Nadu, and for most of the twentieth century it did what colonial-era agricultural economies do: it shipped the raw material abroad and let someone else capture the margin. Green coffee left Indian ports; roasted, branded, value-added coffee did not come back.
Challa Rajendra Prasad — an engineer by training, and an entrepreneur by temperament — looked at that arrangement and saw the obvious arbitrage. The value in coffee is not in growing it. It is in the industrial step that converts a perishable agricultural commodity into a shelf-stable powder that dissolves in hot water. India had the beans, the cheap power, the cheap labour and the engineering talent. It did not have the plants.
In 1989 he built one. Asian Coffee Ltd was, by the company's own account, the first Indian non-multinational-owned company engaged in producing instant coffee — a meaningful distinction in an era when the soluble-coffee business in India was effectively an outpost of foreign multinationals.8 Asian Coffee also became the first Indian company to secure backing from Britain's Commonwealth Development Corporation, which mattered less for the money than for the signal: a development finance institution had underwritten the proposition that an Indian promoter could run a technically demanding continuous-process plant to export standards.
And then, in the mid-1990s, he sold it to the Tata group.8
Pause on that decision, because it is the most revealing thing in the company's pre-history and it gets glossed over in most write-ups. A founder had spent five years proving that Indian instant coffee could work, had built the first indigenous plant, and then handed the asset to a much larger industrial house. There is no public record of the deliberation. What is observable is the sequel: he did not retire, did not diversify into real estate, did not take the proceeds and go quiet. He built the same business again, this time keeping the equity.
The corporate shell he used had an odd history of its own. The entity now called CCL Products (India) Limited was originally registered in 1961 under a completely unrelated name in the finance and investment business — which is why the 2026 annual general meeting, scheduled for September 8, 2026, is the company's sixty-fifth, despite the coffee operation dating only to the mid-1990s.1 The name was changed to Continental Coffee Limited when instant coffee production began, and to CCL Products in 2002.
The plant went up at Duggirala, in Guntur district, Andhra Pradesh, and it went up as a 100% export-oriented unit. That structural choice deserves emphasis because it defined the company for twenty-five years. CCL was never designed to sell to Indians. It was designed to make coffee that Indians would never see, for buyers who would never mention its name, in a currency it did not spend. Everything downstream of that — the cost-plus contracts, the invisibility, the absence of an advertising budget, the eventual awkwardness of learning to be a brand — flows from a decision made at the drawing board in the early 1990s.
The technical bet that followed was the one that actually built the franchise. In 2005, the Duggirala plant produced India's first freeze-dried instant coffee.8 It is worth explaining what that means, because it is the difference between a commodity and a premium product, and it is not obvious to anyone who has not stood in a coffee plant.
Spray drying is the workhorse process. You brew an extremely concentrated coffee extract, spray it as a fine mist into a tower of hot air, and the water flashes off, leaving a powder. It is fast, it is cheap, it runs at high throughput, and the heat destroys a meaningful share of the volatile aromatic compounds that make coffee smell like coffee. Freeze drying does the opposite. You freeze the extract into a slab at deeply sub-zero temperatures, break it into granules, and then pull a vacuum so the ice sublimates — passing straight from solid to vapour without ever becoming liquid.9 Nothing gets cooked. The aromatics survive. The granule you tip into your cup looks and smells far closer to the coffee it came from, which is why every premium instant SKU on a Western supermarket shelf is freeze-dried and why it commands a premium price.
The catch is capital. A freeze-drying line is expensive, slow, energy-hungry and — critically — needs to run continuously to be economic. CCL's CEO put the constraint plainly on the most recent call: freeze-dried expansion demands certainty of demand "because it's a high capex and the plant needs to run 24/7, so has to be very, very sure before we do it."4 In 2005, no Indian company had been willing to take that risk. Taking it first, and taking it a decade before Indian consumers themselves cared, is the single clearest evidence in the record that this management team sees product cycles early.
By the turn of the millennium the shape of the company was set: an export-only, technically capable, promoter-controlled soluble coffee manufacturer in Andhra Pradesh, with no brand and no domestic market, selling into a global trade dominated by giants. The next question was how a business like that earns anything at all.
III. The Private-Label Bargain: How CCL Actually Makes Money (2000–2015)
Here is the trade CCL offers, and it is worth stating baldly because almost every argument about the company reduces to whether you think it is a good one.
A European supermarket chain wants its own-label instant coffee. It does not want to buy green coffee, hedge it, operate a spray dryer, run a food-safety regime across certifications, develop blends for a dozen regional palates, or carry the working capital. It wants jars on a pallet, at a specification, on a date, at a price. CCL buys the green coffee, converts it, blends it, packs it, and ships it. In return it charges the cost of the coffee plus a fixed conversion margin.
That margin is the whole company. It is measured internally in rupees of EBITDA per kilogram of coffee sold, and it is the number CCL's management asks investors to track above all others. "We work on a cost-plus model," the CEO told analysts in July 2026, "and our focus always is on the volume growth."4
Understand what that structure does and does not do. What it does is neutralise the commodity. If robusta doubles, CCL's revenue balloons and its reported EBITDA margin percentage collapses — not because anything got worse, but because the denominator inflated. Management has had to explain this to analysts roughly every quarter for years, and did so again in May 2026: the apparent margin contraction, the CEO said, "is only optical in nature as we have always maintained that our business works on per kilo EBITDA where there is no contraction."10 Conversely, when prices fall, revenue can shrink while profit grows. In the June 2026 quarter, the group grew volumes by about 20% but revenue by only 13.76%, because green coffee had come down.4 Anyone modelling this company off the top line is modelling the weather.
What the structure does not do is confer pricing power in the ordinary sense. A cost-plus contract manufacturer earns what the market will pay for conversion. The margin is not set by the strength of a brand; it is set by how many qualified alternatives the customer has, how painful it would be to switch, and how much value-add sits on top of the basic drying step.
So does CCL earn a good conversion margin, and is it improving? The company's own disclosures let you answer that, and the answer is genuinely favourable — with an important qualification.
The per-kilogram margin has ratcheted up. A long-term retail shareholder on the July 2026 call noted that when he started tracking the company three or four years earlier the figure was around ₹110 to ₹115 per kilogram; it now runs at roughly ₹135 to ₹140.4 Management confirmed the trajectory, adding that as recently as eighteen months prior it hovered nearer ₹125 to ₹130, and attributed the improvement to a richer mix: more freeze-dried, more small-pack and consumer-ready formats, more direct relationships with end customers rather than traders.4 Freeze-dried, as a rule of thumb, earns 30% to 40% more EBITDA per kilogram than spray-dried.4
That is a real and measurable improvement, and it is the strongest single piece of evidence that CCL is more than a toll converter. Mix enrichment of roughly 20% to 25% per kilogram over four or five years, achieved while volumes were also growing, is not what a pure commodity processor looks like.
Now the qualification, and it belongs right here rather than in a distant risk paragraph. Management has explicitly guided that the ratchet stops. Asked in July 2026 whether an increasing freeze-dried share would push margins higher still, the CEO said no — the freeze-dried mix shift is already in the base, and if the proportion keeps rising, per-kilogram economics "may have a tendency to even come down."4 The guidance for FY27 is not improvement but maintenance at ₹135 to ₹140. On the May 2026 call he was more explicit about why: several of the efficiencies that lifted FY26 "got preponed," were now baked into the comparison, and would not repeat.10 An analyst pressed the same point from the other direction — that when coffee prices fall, lower-margin customers and traders return to the market and dilute the blend. The CEO agreed the risk was real and said the company would try to offset it.10
So the honest characterisation of CCL's unit economics is this: the conversion margin has improved for identifiable structural reasons, and management itself expects the improvement to plateau. It is not a permanent escalator. It is a step-up that has been taken.
The second half of the bargain is switching cost, and this is where the case is weaker than the bulls usually allow. Private-label buyers are professional procurement organisations whose entire function is to maintain alternatives. CCL's defence is not contractual lock-in; it is qualification friction. To become an approved supplier to a large European retailer you must pass audits, certifications and blend-approval processes that take time and money, and the buyer bears real cost in switching a working supplier for a marginal price gain. CCL supports this with breadth: spray-dried powder and granules, freeze-dried, freeze-concentrated liquid coffee, roast and ground, whole beans, and premixes, across pure, chicory-blended, decaffeinated, flavoured, cold-brew, microground and certified-sustainable variants.9 The pitch to a buyer is that one supplier can cover the whole own-label range across formats and price points.
That is a genuine advantage, but it is a service advantage, not a structural one, and the evidence that it binds customers is indirect. CCL does not disclose customer concentration or contract tenure. What it does disclose, through management commentary, is that the contract book shifts with the commodity cycle: in early 2025, with prices spiking, buyers went short-term and "wary to commit long-term"; by early 2026, with prices settling, "we are seeing a lot of long-term contracts" and some freeze-dried capacity was booked long.1110 Read plainly, that is customers optimising against CCL when the cycle favours them, and committing when it does not. It is a functioning commercial relationship. It is not a cornered resource.
Which raises the obvious question a manufacturer with no pricing power must answer: if you cannot charge more, where do you find advantage? CCL's answer, over the following decade, was to stop competing on the factory floor and start competing on the map.
IV. Geography as Strategy: Vietnam, Switzerland and the Duty Map (2011–2026)
Drive inland from the Vietnamese coast into the Central Highlands and the landscape changes into something a coffee trader would recognise instantly: red basalt soil, tin-roofed drying yards, and robusta bushes running to the horizon. This is Dak Lak province, the heart of the country that supplies more robusta than anywhere on earth. It is also, since the early 2010s, where a meaningful share of CCL Products' industrial capacity has lived.
The logic is not exotic. It is the same logic that puts steel mills next to iron ore. Green coffee is heavy, perishable in the sense that quality degrades with handling, and expensive to finance while it sits on a ship. If your factory is next to the farm, you shorten the physical supply chain, shorten the cash-conversion cycle, and cut the number of days your working capital is doing nothing but floating on the ocean. Management has described the mechanics in exactly these terms: buying from Vietnam or Indonesia into a Vietnamese plant builds in perhaps fifteen to twenty days of transit; buying from Brazil builds in far more.12
CCL's Vietnamese vehicle is Ngon Coffee Company Limited, a wholly owned subsidiary. Its expansion completed during FY2025-26, taking rated capacity to 36,000 tonnes a year.1 That is roughly half of the group's total installed base of about 77,000 tonnes, and it explains a comment that slipped out almost as an aside at the end of the July 2026 call, when a shareholder asked why standalone results looked so much flatter than consolidated ones. The answer from the management side was blunt: capacity at the parent company "has been constant for the last more than 10 years," every expansion has been housed in subsidiaries, and "majority of the growth will start coming in from the subsidiary companies only."4
Read that again, because it reframes the whole company. The listed Indian entity is, increasingly, a holding structure with an old plant attached. The growth engine is offshore.
And the engine is productive. Ngon reported revenue of ₹2,032.17 crore in FY26 against ₹1,299.41 crore the year before, and net profit of ₹314.23 crore against ₹207.56 crore — with a provision for taxation of nil in both years.1 A caveat matters here: subsidiary standalone figures do not sum to the group, because intra-group sales and unrealised inventory profits are eliminated on consolidation, so it is wrong to say Ngon "is" 81% of group profit. But the direction is unmistakable, and management has been open about the driver. Asked in May 2025 why subsidiary profitability had jumped, the CEO cited customer mix and efficiencies, and then added the plain fact: "at a net level, Vietnam is a tax-free this thing, so you get to see more profits there."12
That is a genuine, durable-looking structural advantage — and it is also a single-jurisdiction concentration of the group's economics. Tax incentives for export manufacturing are a policy choice, not a property right. Nothing in the public record suggests any change is imminent; equally, nothing in the public record locks the arrangement in. An investor should hold the Vietnam advantage as real and currently unthreatened, while recognising that a change in Vietnamese incentive policy would hit the group's post-tax economics without touching a single kilogram of volume.
The second leg of the geography strategy has performed far less well, and it is instructive precisely because CCL rarely talks about it. Continental Coffee S.A. sits at Les Verrières in Switzerland and specialises in agglomeration — the step that turns fine soluble powder into the coarser granules European consumers prefer — plus packing, and customisation of spray- and freeze-dried variants for premium European private-label clients.19 On paper it is the perfect complement: an EU-adjacent finishing plant that lets an Indian manufacturer put a "made in Switzerland" quality frame around the last stage of production.
In practice, in FY26 the Swiss unit turned over ₹487.82 crore and lost ₹3.88 crore at the net line, against a ₹4.52 crore profit the previous year.1 Roughly a tenth of group revenue passing through an operation that earned essentially nothing before interest and depreciation is the signature of a low-value-add finishing and trading step, not a premium franchise. Management has been consistent rather than evasive about this — in May 2025 the CEO volunteered that the profit improvement was at the Vietnamese unit "and not really with the granulation unit" in Switzerland.12 The honest read is that Switzerland buys market access and optical positioning, and currently costs money for the privilege. It is small enough not to matter to the thesis, and large enough that anyone modelling group margins from Indian unit economics will be wrong.
There is a third leg that is easy to miss: Jayanti Pte Limited in Singapore, a wholly owned subsidiary that exists as an investment vehicle and has no operations to report.1 It is a holding structure, not a business.
Where the multi-country footprint has demonstrably earned its keep is in trade policy. The 2025-26 tariff cycle was, for Indian exporters generally, a genuine shock — and the company's own management discussion described using Vietnam as a "fungible second manufacturing base," supported by agile sourcing and customer engagement, to keep supply uninterrupted.1 By February 2026 the United States and India had concluded an interim trade agreement applying an 18% reciprocal tariff to a wide slate of Indian goods.13
What is striking is how little CCL claims from any of it. Asked on the February 2026 call whether tariff stabilisation would release pent-up customer demand, the CEO said no on both sides of the ledger: the earlier disruption "did not affect us" because supply could be shifted, and equally "the lowering of tariff also is not going to help us," so "our position remains stable as it was before."7 That is an unusually unpromotional answer in a season when many Indian exporters were selling tariff relief as a growth story, and it is consistent with what the company had said a year earlier, when the CEO argued that coffee was structurally unlikely to be a point of trade conflict because the United States neither grows nor meaningfully produces it.12 Narrative consistency across three calls, through a period when the convenient story changed twice, is a modest but real credibility marker.
So the geography bet resolves as follows. Proximity to robusta and a favourable tax and duty position have measurably improved group economics and provided genuine optionality when trade policy turned hostile. That is the strongest structural argument in CCL's favour, and it is better evidenced than the moat arguments usually made on its behalf. The offset is that the advantage is now concentrated in one country under one policy regime, in a subsidiary the parent's own capacity has not competed with for a decade. The next test is not tariffs. It is what happens to Vietnamese supply if the weather turns — a risk management flagged in July 2026 when it noted El Niño reports threatening the November-December Vietnamese crop, while arguing that in past shocks the flow of coffee held up even as prices went wild.4
Which is a useful segue, because while CCL was building factories where nobody would ever see its name, it had begun a very different experiment eight thousand kilometres away — putting its name on a jar.
V. Becoming a Brand: Continental Coffee and the B2C Bet (2019–2026)
For twenty-five years CCL had solved a problem that most consumer companies would envy: it never had to persuade anyone of anything. Its customers were procurement managers who cared about specification, price and reliability. Then, on August 13, 2019, the company announced it was launching its own brand in India — Continental Coffee, spanning instant and filter coffee across multiple pack sizes and price points.5
This was a much harder thing than it looked, and the company knew it. India is not a coffee market in the way Europe is. It is a tea market with a coffee-drinking South, and its instant coffee shelves have been owned for decades by two multinationals with distribution armies and advertising budgets that dwarf anything CCL could contemplate. Entering that fight from a standing start, with a name nobody recognised, using cash generated by a business whose whole identity was not having a brand, was either strategic foresight or a category error. Seven years on, the evidence leans toward foresight — with real caveats.
The man hired to run it arrived in late 2021. Praveen Jaipuriar was appointed Chief Executive Officer with effect from October 29, 2021, having previously run the domestic branded subsidiary.14 His background is not coffee; it is consumer marketing. He completed an MBA at K.J. Somaiya in 1997 and spent more than two decades in sales, marketing and business management across FMCG categories — health care, foods, oral care, personal care, home care, beverages and culinary — at organisations including Balsara Home Products and Dabur India.14 Handing the CEO role of a B2B industrial exporter to a brand marketer is a statement of intent. It also means that on every earnings call since, the voice explaining a cost-plus conversion margin to commodity analysts belongs to someone whose professional instincts were formed in a world of shelf space, trade margins and share of voice — which is audible in how he answers questions, and in which questions visibly interest him.
The numbers show a brand compounding from a small base. Branded sales were around ₹200 crore in FY24, roughly ₹300 crore in FY25 on domestic gross turnover of about ₹440 crore, and approximately ₹440 crore in FY26 within a domestic gross turnover of about ₹650 crore.111210 In the June 2026 quarter branded sales ran at about ₹125 crore, up roughly 26% year on year, and management guided to ₹550-600 crore of branded revenue for FY27 with volume growth of 25% to 30%.4
Growth alone proves little — plenty of brands buy volume with discounts. The more interesting evidence is about brand strength rather than brand size, and here CCL discloses more than most.
First, share. By July 2026 the company put its urban market share in South India above 6%, double-digit share inside both Reliance and DMart, and high single digits approaching double digits across quick-commerce platforms in aggregate — against low single digits eighteen months to two years earlier.4 Management describes Continental as India's number three coffee brand overall.10 That claim should be treated as management's characterisation rather than an independently audited fact, but the channel-level share figures are specific enough to be falsifiable.
Second, trade economics. The company now pays a retailer margin of about 10% and a distributor margin of 5% to 6% — broadly in line with what the largest FMCG houses pay, where distributor margins run nearer 4% to 5%.4 A new brand normally has to bribe the trade with fatter margins to win space; not needing to is a real signal.
Third, and most telling, about 70% of the branded business is done on cash-and-carry terms — the distributor pays before or on delivery rather than taking credit.4 In Indian FMCG, cash-and-carry is a privilege reserved for brands the trade is confident it can sell. Getting there in roughly six years is the single most persuasive piece of evidence that Continental has crossed from "cheap alternative" to "brand."
The economics are deliberately suppressed. The branded business runs at 5% to 6% EBITDA margins, up from the 4% to 5% band management guided to a few quarters earlier, and management has said explicitly that it will not "start milking it" while share is available.4 That is a defensible choice, but investors should be clear that it means the branded business is currently a use of cash, not a source of it, and that the reported group margin flatters the coffee business by burying a low-margin consumer operation inside it.
The international brand extension has been small and, so far, modestly encouraging. In June 2023 the company entered an asset-purchase agreement with the Löfbergs Group to acquire six UK-registered brands — Percol, Plantation Wharf, Rocket Fuel, Percol Fusion, The London Blend and Perk Up — for £550,000, a price that says a great deal about what was being bought: shelf access and heritage, not a business.15 Percol had been launched in 1987 and carried a sustainability positioning, and CCL had already supplied some of its blends.15 By FY26 the UK operation was doing roughly ₹25-30 crore of revenue, and management described it in July 2026 as having "turned around," with discussions under way with distributors in the United States and the Middle East to carry both Percol and an Indian brand aimed at the diaspora.104 A brand acquired for the cost of a small Mumbai apartment, restored to a ₹26-27 crore run rate and used as a beachhead, is competent small-scale capital allocation. It is not yet material to the group.
Now the part of this story that gets left out of the bull case, and that belongs here rather than in a risk appendix.
In July 2022 CCL announced its entry into frozen foods with a plant-based meat brand, Continental Greenbird, offering chicken-like nuggets, seekh kebab and sausage plus a mutton-like keema, built on pea, chickpea and soya protein.6 It was rolled out through modern trade and grocery in Hyderabad and then extended to other cities. It no longer exists. On the February 2026 call the CEO explained that the plant-based category "has not done well," was "almost on a shutdown basis," and that "we quickly cut down on the losses and we stopped that category."7
Two readings are available and both are true. The generous one is that management killed a losing venture fast rather than defending it for pride — a discipline many Indian promoters lack. The less generous one is that the venture should never have been launched by a coffee manufacturer with no frozen-supply-chain capability, that the category's structural problems were visible to anyone reading Western plant-based results in 2022, and that shareholders funded a three-year lesson.
Nor is it the only sub-scale consumer experiment. Continental Coffee Private Limited, the Indian subsidiary running food and beverage kiosks including a "Coffee on Wheels" format, reported FY26 revenue of ₹1.29 crore against ₹2.36 crore the prior year, and a net loss of ₹5.41 crore against ₹4.37 crore.1 Revenue halved; losses grew. That is a business shrinking and getting more expensive at the same time.
Which is exactly the lens to apply to the newest adjacency. The company has begun selling traditional South Indian snacks — chegodi, murukku, and more recently banana chips — under the brand Malgudi, first as a 100-to-150-store pilot and, from roughly late July 2026, as a broader rollout.104 Management is refreshingly modest about it, expecting "maybe a couple of crores" in FY27 and saying it will press harder only if the expanded launch works.4 Given a record of one abandoned category and one shrinking loss-making format, the appropriate treatment of Malgudi in any valuation is close to zero until it demonstrates repeat purchase at scale — not because the idea is bad, but because this management has not yet proven it can build a non-coffee consumer business, and it has twice shown it can lose money trying.
The calibrated conclusion on the B2C bet is therefore narrower than the enthusiasm around it. Within coffee, where CCL owns the manufacturing, understands the palate and can undercut incumbents on cost, the brand is genuinely working and the trade-behaviour evidence supports it. Outside coffee, the record is 0 for 2. The claim that CCL is "becoming an FMCG company" is not supported; the claim that it is becoming a credible branded coffee company is.
And all of this — the brand, the plants, the geography — was tested far harder than any strategy document anticipated when the commodity underneath the entire business went vertical.
VI. The Price Shock: When Cost-Plus Met a Commodity Melt-Up (2022–2025)
By December 2024, the finance team at CCL was looking at a number nobody at the company had seen before. Group debt had climbed to roughly ₹1,950 crore.4 For a business whose defenders had spent years describing it as structurally insulated from commodity prices, that number was awkward, and it demanded an explanation.
The context was a coffee market losing its mind. Adverse weather in Brazil and supply anxiety across origins drove arabica to a record of about $9 per kilogram in February and March 2025, with robusta approaching $6 — after arabica had nearly doubled year on year in the first quarter of that year and robusta had risen by roughly two-thirds over 2024 levels.16 Management's own framing was starker and more useful: green coffee that traded around $1,000 a tonne in the 2015-to-2020 window was, by mid-2025, near $5,000.12
Here is the mechanism that the "commodity pass-through" story misses, and it is the single most important thing to understand about CCL's balance sheet. Cost-plus protects the income statement. It does nothing for the balance sheet. CCL still has to buy the beans, pay for them, hold two and a half to three months of green coffee inventory, convert it, ship it, and wait to be paid.4 When the price of that inventory quintuples, the rupees tied up in it quintuple too — and those rupees have to come from somewhere. They came from the banks.
By December 2024 the shape of it was visible: about ₹1,200 crore of working capital borrowing, long-term debt of roughly ₹790-800 crore taken on for capacity expansion, and total debt around ₹2,000 crore.11 Worse, the seller's market changed payment behaviour against CCL. As the CEO explained, with shortages cited everywhere, suppliers stopped extending credit — you had to secure the coffee then and there — while in a falling market the same counterparties would happily sell forward on terms.12 The working capital squeeze was not only about price levels; it was about the direction of prices flipping the negotiating table.
The second casualty was volume, and this is where the model's limits showed most clearly. In the December 2024 quarter, volume growth came in at just 3% to 4%, against about 13-14% in the first quarter of that year and 9-10% in the second, leaving nine-month growth near 10%.11 The full year finished around 10%.12 The company had entered FY25 guiding to a 10% to 20% band, having previously anchored investors on a long-term aim of about 15%.11 It landed at the bottom of the range.
The explanation management gave was candid and analytically damning of the strong form of the cost-plus thesis. "While we are able to pass on something," the CEO said, "the market is probably not ready to take on everything that we want to pass on," and he named this directly as "one of the reasons we have not been so aggressive on the volumes."11 In other words: at extreme prices, CCL can hold its margin per kilogram or hold its volumes, but not always both. The model is margin-protective, not demand-protective. Any investor who believed CCL was indifferent to the coffee price learned in FY25 that indifference has limits.
The most valuable exchange of the entire cycle came on the May 2025 call, when an investor who had followed the company a decade earlier laid out the contrast plainly: working capital had once run at 30-35% of sales against a persistent 45% for four years, and a company that had carried perhaps ₹200-300 crore of debt now carried close to ₹1,800-1,900 crore. Was this just the coffee cycle, he asked, or had CCL grown so large in outsourced instant coffee that the economics themselves were deteriorating?12
The answer was specific rather than defensive, which counts for something. The CEO rejected the market-share-saturation thesis outright, argued that a fivefold move in the input price alone accounted for most of it — noting pointedly that debt had not risen fivefold — and separated the long-term borrowing, which he attributed to a capacity cycle that recurs "every 6-7 years," from the working capital borrowing, which he said was against confirmed contracts rather than speculative inventory. He then made a forecast: over the following three to four years, debt would slide back as term loans amortised and, if coffee softened, inventory holding costs fell too.12
That forecast is now testable, and it is the most important credibility check available on this management team. Three months earlier, on the February 2025 call, the CEO had told an analyst that even with 15% volume growth, peak debt could reach around ₹2,200 crore and would not go beyond that in the following year or two.11 So the stated plan in early 2025 was: peak near ₹2,200 crore, then decline over three to four years.
There is one accounting judgment worth flagging alongside this, because it flattered how the strain looked at the time. While the Vietnamese facility was under construction, interest was being capitalised rather than expensed — the CFO later put the FY25 figure at roughly ₹25-30 crore.10 Reported finance costs in the stressed year therefore understated the true cost of carrying the balance sheet, which is standard accounting but matters when comparing years. It also explains why, when debt fell sharply in FY26, reported interest did not fall proportionately: the FY25 comparison had been artificially light.
The strain showed up somewhere else, too. On a standalone basis the Indian parent earned net profit of just ₹92.30 crore in FY25, against consolidated profit of ₹310.34 crore.1 The listed entity's own plant — the one whose capacity had not grown in a decade — was carrying interest and depreciation while the growth and the profit sat offshore.
So the calibrated verdict on the price shock is this. The claim that CCL is insulated from coffee prices survives in a narrowed form: it is insulated at the gross margin per kilogram, and it is not insulated in volumes, working capital, leverage or the cost of debt. That narrowing is not a hypothesis; it is what the FY25 record shows. What the record could not yet show, in May 2025, was whether management's recovery plan was a real plan or a hopeful one. That answer arrived twelve months later.
VII. The FY26 Snapback: What Actually Changed on the Balance Sheet
The May 2026 earnings call had a different texture from the one a year earlier. The tone was not relief; it was the slightly clipped confidence of a finance team that had been given a target and hit it early.
The headline operating numbers were strong. For the year ended March 31, 2026, consolidated EBITDA rose about 32% to ₹741.38 crore, profit before tax rose about 31% to ₹460.74 crore, and net profit rose about 25%.10 The fourth quarter alone delivered revenue of ₹1,226.39 crore, up 46%, though EBITDA and profit grew far more slowly, at about 16% and 12% respectively — a reminder that quarterly optics in this business are dominated by where the coffee price sat in the comparison period.10 Management decomposed the full-year top line honestly: roughly 18% to 20% of it was volume, and another 20% to 25% was simply the coffee price flowing through.10
That decomposition is the analytical heart of the year, and it generalises. Over the four years to FY26 the group compounded revenue at about 32% a year, but profit after tax at only about 17% and net worth at about the same rate.1 Anyone who looked at CCL's revenue chart and concluded that the business had roughly tripled in economic terms was reading an inflation gauge, not a growth gauge.
The balance sheet is where the year was actually won. Net debt at March 31, 2026 stood at about ₹1,073 crore, a reduction of more than ₹750 crore in twelve months. The debt-to-equity ratio fell to 0.5 from 0.92, and net debt to EBITDA to 1.45 from 3.1.10 By June 30, 2026 net debt had gone below ₹1,000 crore, to ₹963 crore, against gross debt of ₹1,268 crore split between a ₹517 crore term loan and ₹751 crore of working capital facilities.4
Two operating metrics explain the move, and they are more informative than the debt figure itself. Operating cash flow surged to ₹858 crore in FY26 from ₹290 crore the prior year and just ₹55 crore the year before that. Working capital days fell by 80 days, to 166.4 An eighty-day reduction in the cash-conversion cycle of a commodity converter is a large operational change, not a rounding adjustment.
The CFO's framing of how it was done deserves scrutiny because it makes a strong claim: the deleveraging happened "without dilution of equity, without sale of any non-core assets or without pausing the growth."4 On the first limb, the annual report confirms there was no change in paid-up share capital during FY26, which stood at ₹2,670.56 lakh across 13,35,27,920 shares of ₹2 each.1 The employee stock option pool is 5,00,000 options — under 0.4% of the share count — of which 4,74,310 had been granted by the date of the FY26 report.1 For that year, and on those records, the no-dilution claim holds. It is worth noting separately that CCL has used equity-market mechanics before: in 2013 the board approved a subdivision of the ₹10 share into five ₹2 shares together with a 1:1 bonus issue.18 Those are capital restructurings, not capital raises, and they do not contradict the FY26 statement — but "the company has never gone to shareholders for money" is a broader characterisation than the available record supports, and it is not one worth asserting.
More important is that management immediately bounded its own achievement, which is the behaviour you want to see. Asked how the cash would be deployed, the CFO said flatly that repeating ₹858 crore of operating cash flow "looks highly unlikely," because the correction had been a multi-year catch-up of accumulated working capital inefficiencies, and because the business does not run a negative working capital cycle — it must buy inventory, convert it, and then sell.4 Converting a portion of profit into cash, he said, would itself be a significant achievement given the trade. That is management deflating its own best number in public. It is also the correct read: FY26's cash flow was a stock adjustment, not a run rate.
The remaining plan is specific enough to be graded later. Term loan repayments of about ₹140 crore were scheduled across the last three quarters of FY27, taking the year's total to roughly ₹200 crore, followed by another ₹200 crore in FY28 and the balance thereafter, heading toward roughly ₹1,000 crore of gross debt and ₹800 crore of net debt.4 Borrowing costs run at 7% to 7.5%, and against roughly ₹130 crore of interest in FY26 the CFO guided to about ₹100 crore in FY27.10
Capital intensity has, for now, gone away. Standalone capital expenditure in FY26 was ₹34.75 crore, and the FY27 plan is ₹25 crore to ₹50 crore of upgrades and small additions, with no major capacity programme contemplated for two to three years.14 Aggregate utilisation runs at 65% to 70%, higher within freeze-dried.4 A company earning a return on capital employed of 22.15%, up from 18.21%, while spending almost nothing on capex is a company in the harvesting phase of its cycle.1
What it does with the harvest is the open question. Dividends went up modestly rather than dramatically: FY26 totalled ₹5.75 per share — an interim ₹2.75 plus a recommended final ₹3 — against ₹5 the prior year, a 15% increase, costing roughly ₹76.78 crore.1 Against ₹388 crore of profit that is a payout ratio near 20%, which is a choice, not an accident. Management's stated priority order is debt reduction first, then acquisitions "where we can leverage some of our omnichannel distribution network," with an explicit preference for tuck-ins over expansive deals.4 Notably, management said it was not actively pursuing overseas brand acquisitions, preferring to build on Percol and the other brands already owned.4
The honest summary of FY26 is that two things happened at once and they are hard to separate. The company genuinely improved its operating discipline — eighty days of working capital does not come out of a business by accident. And the coffee price came down, which mechanically released cash from inventory and receivables. Management would argue the first caused the second to be captured rather than squandered, and the ₹55 crore of operating cash flow two years earlier suggests something did change. But the test is not FY26. The test is the next spike: whether working capital days stay anywhere near 166 when green coffee next runs, or whether the company reverts to type and the debt goes back on.
Which brings the story to the claims the market currently makes about this business, and whether the company's own history supports them.
VIII. Myth vs Reality: Testing the Load-Bearing Claims
Every widely-held company accumulates a set of comfortable beliefs that get repeated until they stop being examined. CCL has four, and each one is partly true — which is what makes them dangerous. The useful exercise is not to knock them down but to find the smaller, more accurate version of each that the company's own eleven-year public record will actually support.
Myth one: coffee demand is inelastic, so CCL's volumes are safe. Management states this directly. Even at record prices, the CEO said in July 2026, "we did not see any drop in consumption," and "coffee consumption has been pretty inelastic to the price changes," with the caveat that consumers might shift from freeze-dried to spray-dried.4
The end-consumer claim is plausible and broadly consistent with how caffeinated staples behave. But it does not transfer to CCL's order book, and the company's own results falsify the transfer. In the worst quarter of the price spike, CCL's volumes grew 3% to 4%, and the year finished near 10% against a long-term aspiration of 15%.1112 Global coffee drinkers did not stop drinking coffee; CCL's customers stopped ordering at the pace CCL wanted, because CCL could not pass on the full increase without becoming uncompetitive. The reality is that end demand is sticky and contract volumes are not. The revised claim — that CCL's volumes are resilient across ordinary price movement but compress at cyclical extremes — is what the record supports, and it should be priced accordingly.
Myth two: the margin ratchet is structural and will keep climbing. The per-kilogram improvement is real and was described earlier. What is not supported is extrapolation, and the most direct disconfirming evidence comes from management's own mouth rather than from any outside analysis: the freeze-dried mix shift is in the base, further increases in freeze-dried share could push per-kilogram economics down, and FY27 guidance is maintenance rather than expansion.4
There is a second, sharper test available, and it did not go well. On the July 2026 call an analyst from Veer Growth Fund put the uncomfortable comparison directly: an unnamed listed peer reports roughly ₹160 to ₹170 of EBITDA per kilogram on lower volumes and a smaller freeze-dried share, while CCL sits nearer ₹137. What explains the structural gap? The CEO declined, twice, to engage: "You will have to ask that company about their EBITDA profile," and when pressed, "I just told you, you'll have to ask that company about the structural factor."4
It is fair to note that management genuinely cannot speak to a competitor's cost structure, and that a blended margin across a very broad customer base will differ from a narrower book. But CCL asks investors to track EBITDA per kilogram as the metric of the business. Being asked why the headline number trails a smaller peer's is the most predictable question that metric invites, and the absence of any explanation — not a rebuttal, not a mix argument, not a customer-quality argument — leaves the single most important competitive benchmark unaddressed in the public record. The honest conclusion is that CCL's scale leadership in outsourced instant coffee has not translated into best-in-class unit economics, at least against one listed comparator. The claim survives as "margin per kilogram has improved and is being defended," and does not survive as "scale confers superior unit economics."
Myth three: capacity will never constrain growth. This is stated as an assurance rather than a plan. "We will never let capacity hinder our growth," the CEO told an analyst who had modelled utilisation hitting 95% by FY28 on a 15% growth path.4 The supporting evidence is genuine: both the Indian and Vietnamese sites are brownfield, with land and civil works already in place, which management says compresses the build cycle.
The record partly backs this. In 2021, unable to construct during the pandemic, the company bought capacity from outside rather than let growth stall — and management has cited that episode twice, in May 2026 and again in July 2026, as proof of intent.104 That is a real precedent.
Two things temper it. First, the record shows mistiming as well as resourcefulness. The capacity that came on stream through FY25 ran at only 10% to 15% utilisation for that year, arriving precisely as volume growth stalled and the balance sheet was under maximum strain — the company was paying interest on new plant it could not fill.12 Adding capacity into an air pocket is not a governance failure, but it is the opposite of the timing precision the assurance implies. Second, the gestation estimate itself moved between consecutive calls: in May 2026 the CEO said capex takes "1.5 to 2 years to materialise"; in July 2026 he put a brownfield addition at "9 months to a year."104 Those are both defensible depending on scope, and no one should hang an investment case on a discrepancy of that sort — but an investor modelling FY29 volumes should use the longer number, and should note that management has said it will start working on additions when utilisation crosses 75% and will need them at 85% to 90%.4 With utilisation at 65% to 70% and 15% growth guided, that decision point is not far away, and it will land in the same year the balance sheet finally reaches its target leverage.
Myth four: management guides conservatively and delivers. This one holds up better than the others, with an important asterisk about how the guidance is constructed.
The pattern across three years is consistent: wide bands, no upgrades mid-year, and a refusal to extrapolate good quarters. Entering FY25 the company guided to 10% to 20% volume growth and finished around 10% — the bottom of the range, but inside it.1112 In FY26 it guided to 15% to 20% EBITDA growth and delivered about 32%, and when asked why it was not raising the bar for FY27, the CEO explained specifically which FY26 tailwinds — freeze-dried mix, preponed efficiencies, small-pack proportion — were now in the base and would not repeat.10 In July 2026, having just posted 20% volume growth, management explicitly declined to upgrade its 15% full-year guide, citing residual coffee-price volatility and buyer hesitancy.4
The most concrete promise-versus-outcome test is the debt one. In February 2025, at the depth of the strain, the CEO told investors peak debt could reach roughly ₹2,200 crore and would not exceed that in the following year or two; in May 2025 he predicted debt would slide back over three to four years.1112 What actually happened is that debt peaked below the warned level, at roughly ₹1,950 crore, and the decline came faster than the three-to-four-year framing.4 Under-promising and over-delivering on the most stressed metric, during the most stressed period, is the strongest single piece of evidence on management credibility in this file.
The asterisk is that a 10-to-20% band is wide enough that almost any outcome counts as a hit, and that "we do not upgrade guidance" is a low-cost posture when the guidance floor is comfortably below trend. The defensible version of the claim is that this management does not talk its book, explains its misses in specific rather than atmospheric terms, and has honoured its balance-sheet commitments. What it has not done is set a target precise enough to be meaningfully missed.
Underneath all four myths sits the same structural question, which no amount of guidance discipline can settle: how contestable is CCL's position? For that, look at who else is building.
IX. The War Game: Competition, Porter, and Seven Powers
In May 2025 — the same month CCL's management was fielding hostile questions about a ₹1,800 crore debt load — ofi opened a soluble coffee facility at Linhares in Espírito Santo, Brazil. The site runs two complete lines covering both freeze-dried and spray-dried production, employs 300 people permanently, and the company positioned it explicitly as reinforcing its standing as a top-three independent producer in soluble coffee.17
Look at what that plant is. It is CCL's own strategy, executed by a larger competitor, on the other side of the world: put the converter next to the beans, cover both drying technologies, sell to the same private-label and brand-owner customers. Espírito Santo sits in the middle of Brazil's coffee belt the way Dak Lak sits in Vietnam's. If CCL's advantage were a moat, this would not be replicable in three years by a well-capitalised trader. It was.
That is the frame for the competitive analysis, and it needs one clarification first, because CCL's addressable market is much narrower than "instant coffee." The global soluble market splits three ways: coffee that branded giants manufacture themselves, coffee that is sold under strong brands, and the outsourced pool — private label and third-party manufacturing — which is the only part CCL plays in. Management is candid that it "can't compete in the branded and the captive consumption market."7 Within that outsourced pool, at roughly 77,000 tonnes of capacity, management estimates CCL at 10% to 11%, rising to perhaps 12% to 13% at full utilisation, with a theoretical path toward 100,000 to 120,000 tonnes.47
So the company is the largest player in a fragmented, capital-intensive, contestable segment of a market whose most profitable portion it cannot enter. Now run the forces.
Buyer power is high, and it is the defining feature. CCL's customers are professional procurement organisations at retailers and brand owners whose institutional purpose is to maintain alternatives and grind down conversion costs. The company does not disclose customer concentration, contract tenure, or renewal rates. What can be observed is that contract behaviour flexes with the cycle in the buyer's favour: short-termism when prices spike, longer commitments when prices settle.1110 Qualification friction gives CCL a real but bounded defence — enough to prevent casual switching, not enough to set price.
Supplier power rises exactly when it hurts most. Two-thirds of the company's purchases run through trading houses — 67% in FY26, down from 76% — spread across 738 counterparties.1 That breadth looks reassuring until you read the next line: purchases from the top ten trading houses jumped to 69% of trading-house purchases in FY26, from 49% the year before.1 Sourcing became substantially more concentrated in a single year. That may reflect deliberate consolidation for reliability during a shortage, and it is not disclosed which. Either way, a converter whose input supply is increasingly channelled through ten counterparties has less negotiating room than one dealing with 738, and the FY25 experience — suppliers withdrawing credit terms in a seller's market — showed what that costs.12
Rivalry is high and getting more capitalised. Beyond ofi's new Brazilian capacity, the CEO himself observed in February 2025 that "the world has a lot of excess capacity" in the trade.11 Excess capacity plus commoditised conversion plus sophisticated buyers is not a structure that supports margin expansion; it is a structure that supports a competent low-cost operator earning a fair, stable spread. Which is roughly what CCL earns.
Substitution is a slow leak the company has chosen not to plug. The fastest-growing formats in coffee are out-of-home and whole-bean, and management said so plainly in May 2026: consumption of beans is growing "at a much faster pace" driven by out-of-home demand, but "we largely are not into beans because that is something that we very localized. There is not much of value addition. So we don't see that market as a very big market for us."10 That is a rational decision about where value-add exists, and it is simultaneously an acknowledgment that CCL has ceded the category's fastest-growing format outside India. Premiumisation within soluble — the freeze-dried upgrade — is the company's answer, and it is a good one for as long as the migration runs from spray-dried to freeze-dried rather than from soluble to beans.
Barriers to new entry are real in freeze-dried, thin in spray-dried. The economics that make freeze-drying attractive — high capital cost, continuous running requirement — are the same economics that deter casual entrants, which is why management is careful about adding it. Spray-dried capacity is a far lower hurdle, and origin countries have every incentive to move up the chain.
Against Hamilton Helmer's seven powers, the picture is a hybrid rather than a fortress. Scale economies are present and genuine: the largest outsourced position, purchasing scale across origins, and brownfield expandability. Process power is arguably the strongest claim — two decades of freeze-drying experience since being first in India, a blend library built customer by customer, and the ability to serve powder, granules, freeze-dried, liquid concentrate, roast-and-ground, beans and premixes across pure, chicory, decaffeinated, flavoured, cold-brew, microground and certified variants from one relationship.9 That breadth is not trivially copied. Counter-positioning exists in a limited sense: branded incumbents cannot enthusiastically supply the private label that cannibalises them, which structurally reserves part of the market for independents. Branding is emerging but confined to India. Switching costs are weak-to-moderate. Cornered resource is absent — the closest analogue is the Vietnamese location and tax position, which is an advantage available to anyone willing to build there, as ofi demonstrated in Brazil. Network economies do not apply.
The synthesis matters more than the labels. CCL's durable advantage is a cost-and-capability position, not a moat: it converts coffee cheaply, in more formats than most, from locations close to the beans, for customers who have qualified it. That is worth a stable mid-teens-to-low-twenties return on capital, and the FY26 figure of 22.15% is consistent with exactly that.1 It is not worth the pricing power investors sometimes attribute to it. And it is defended by relative cost and switching friction rather than by anything a determined, well-funded rival cannot build in two to three years — because one just did.
X. The Bull Case, the Bear Case, and the Activist's Notepad
Set out plainly, the two cases are unusually clean, which is a virtue in a company this cyclical.
The bull case rests on four legs. First, there is volume runway without capital: aggregate utilisation of 65% to 70% means the company can grow for roughly two years on plant it has already paid for, at maintenance capex of ₹25 crore to ₹50 crore a year, which converts operating profit into free cash at an unusually high rate.4 Second, the mix continues to improve at the edges — freeze-dried, small packs, direct end-customer relationships rather than traders — even if the step-change is done. Third, the balance sheet has been repaired on a stated glide path toward roughly ₹1,000 crore of gross debt, with interest costs falling and return on capital employed already up nearly four percentage points in a year.41 Fourth, the Indian branded business is compounding at 25%-plus with genuine equity markers, and is being deliberately run at suppressed margins, which means reported group profitability understates the underlying franchise if and when the investment phase ends.
The bear case rests on the same facts read differently. A cost-plus converter with high buyer power, no disclosed customer concentration, a per-kilogram margin its own management has guided flat, and a peer earning materially more per kilogram, is a well-run industrial business rather than a compounder. Its growth engine sits offshore in one country under one tax regime while the listed parent's capacity has not expanded in over a decade. Its balance sheet risk is not leverage in the ordinary sense but inventory: the next commodity spike will re-lever it, and the FY25 experience showed that the same spike also suppresses volumes. Its diversification record outside coffee is nought for two. And the segment it leads is fragmented, over-supplied by management's own description, and has just absorbed a large new competitive plant.
Neither case is exotic. The disagreement is entirely about how much of FY26 was skill and how much was the coffee price falling — and that is a question only the next cycle answers.
Now the skeptic's notepad, which is where the more interesting details live.
Disclosure asymmetry. CCL asks investors to evaluate it on volume growth and EBITDA per kilogram, then declines to publish volumes. Asked directly for tonnage in July 2026, the CEO said "we will not detail out the volume numbers," and on utilisation splits by geography he was explicit about the reason: "we don't kind of get into too much of details on capacity utilisation. It works against us sometimes."410 That is an understandable commercial instinct in a business where customers read transcripts. It is also a company asking to be judged on a metric it will not disclose the denominator for, and it leaves outside analysts triangulating tonnage from margin arithmetic. Customer concentration is likewise absent from the disclosure set.
Related-party intensity. The FY26 business responsibility report shows related-party transactions at 14% of purchases and 15% of sales, loans and advances to related parties at 84% of total loans and advances, and investments in related parties at 99% of total investments.1 Almost all of this is intra-group traffic between the parent and wholly owned subsidiaries — coffee moving from India to Vietnam or Switzerland, capital moving to fund plant — and is not, on its face, a governance concern. But in a group where profit, growth and lending are increasingly concentrated in offshore wholly owned entities, and where segment-level disclosure is thin, an investor is relying heavily on the consolidation rather than on visibility into the parts.
Remuneration. In FY26 the Managing Director's remuneration rose 42.93% and the Executive Director's 38.69%, against a 13.39% increase in median employee pay; non-executive directors' remuneration rose 73.61% from a low base. The Managing Director's package stood at 135.83 times the median employee remuneration of ₹4,16,688, and the Executive Chairman took no increase at all, at 100.80 times the median.1 In a year of 25% profit growth and a large deleveraging, a step-up is defensible; the founder declining one is a notable counterpoint. What would deserve challenge is a repeat in a flat year.
Governance and ownership. The promoter and promoter group held 6,15,69,812 shares, or 46.11%, at the end of FY26.1 Succession is already largely executed: the founder remains Executive Chairman, Challa Srishant is Managing Director, and day-to-day operating leadership sits with a professional CEO and a CFO appointed in February 2025.1 The founder's continued engagement is visible rather than ceremonial — analysts on the February 2026 call remarked on his presence.7 The statutory auditors' reports contain no qualifications, reservations, adverse remarks, matters of emphasis or disclaimers, and the secretarial auditor's report is likewise clean.1
Legal and tax overhang. Disputed income tax claims stood at ₹38.85 crore at March 31, 2026, down from ₹48.75 crore a year earlier, with ₹28.83 crore already deposited under protest; bank guarantees were ₹19.25 crore.1 Against net worth of ₹2,344 crore these are immaterial in scale, but they are the only disclosed litigation of consequence, and the group's use of multiple tax regimes — a Vietnamese entity paying no tax, a domestic entity under India's concessional corporate regime, and others at full rates, blending to a consolidated effective rate the CFO guided to around 17% — is inherently more exposed to future transfer-pricing and residence scrutiny than a single-jurisdiction manufacturer would be.10
Small-ticket capital allocation. One minor deployment illustrates the house style better than any strategy slide. To secure captive renewable power, the group took 26% of Mukkonda Renewables Private Limited — 20.54% through the parent and 5.46% through CCL Food and Beverages — investing ₹2.87 crore to access up to 7.9 MW under group captive mode, as Indian electricity rules require an equity stake to qualify.1 It is a regulation-shaped, cost-driven, small-cheque investment. That instinct is a real asset in a cyclical business. It is also the same instinct that produced a £550,000 brand acquisition that worked and a plant-based meat launch that did not, so it should be read as a preference for low-stakes optionality rather than as proof of allocation skill.
Key-person and capability risk. The brand strategy, the quick-commerce push, the category extensions and the investor narrative all run through one professional CEO hired from consumer marketing. The manufacturing franchise would survive his departure. The consumer ambition, on current evidence, might not.
What none of this resolves is the central tension, so it is worth stating without hedging. CCL is a genuinely good industrial business — low cost, technically capable, well located, run by people who have kept their commitments through a violent cycle and who kill their mistakes reasonably fast. It is not a business with pricing power, and the market's willingness to value it as a consumer compounder rests on a branded operation that is still under 10% of group revenue and deliberately unprofitable. The gap between those two descriptions is where the risk and the opportunity both live.
XI. Three Numbers That Matter From Here
Most investors track CCL's revenue. Most investors are therefore tracking the price of robusta with extra steps.
The first number that matters is volume growth in tonnes, against management's standing guidance of about 15% a year. Revenue is a commodity gauge; volume is the business. The company will not publish tonnage, so the practical proxy is absolute EBITDA growth, which management has repeatedly said should track volume growth closely. The specific thing to watch is whether the 20% posted in the June 2026 quarter persists or fades back to the guided 15% — and, if it persists, whether the capacity decision gets pulled forward from the "two to three years away" framing, because that is when capital returns and leverage stops falling.
The second is EBITDA per kilogram, currently guided to hold at ₹135 to ₹140. This is the cleanest single read on whether the business is a converter or something better. Three forces pull on it in opposite directions: a rising freeze-dried and small-pack share pushes it up, management's own warning that a further freeze-dried shift could pull it down, and the return of low-margin traders and opportunistic buyers in a softer coffee market. If the number drifts toward ₹150 without a mix explanation, the pricing-power case strengthens materially. If it slips below ₹130 while volumes grow, the commodity-converter case is confirmed and the peer gap becomes the whole story.
The third is working capital days, and net debt behind them. FY26 took 80 days out of the cycle, to 166, and net debt to ₹963 crore by June 2026. The company's own CFO has said the cash flow that achieved this will not repeat. The test is not whether debt keeps falling in a benign year — it should — but what happens at the next spike. If green coffee runs again and working capital days hold anywhere near current levels, the operational improvement was structural and the FY25 episode was a one-off failure of discipline. If days blow back out toward the levels that produced a ₹1,950 crore debt peak, then FY26 was the commodity cycle wearing a management-competence costume, and the company remains what it has always been underneath: a very good factory, financing somebody else's coffee.
References
-
CCL Products (India) Limited — Annual Report 2025-26 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
CCL Products, the world's largest private label coffee manufacturer, turns into a billion dollar company now — Business Standard, 2023-06-27 ↩
-
CCL Products (India) Ltd (NSE: CCL) Stock Price & Overview — StockAnalysis, accessed 2026-09-02 ↩
-
CCL Products (India) Limited — Q1 FY27 Earnings Conference Call Transcript, 2026-07-28 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
CCL Products launches Continental Coffee brand in domestic market — Business Standard, 2019-08-13 ↩↩
-
CCL Products ventures into the frozen foods category with plant-based meat products — Business Standard, 2022-07-11 ↩↩
-
CCL Products (India) Limited — Q3 FY26 Earnings Conference Call Transcript, 2026-02-05 ↩↩↩↩↩↩
-
CCL Products Corporate Presentation 2024 — CCL Products (India) Limited ↩↩↩↩
-
CCL Products (India) Limited — Q4 and FY26 Earnings Conference Call Transcript, 2026-05-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
CCL Products (India) Limited — Q3 FY25 Earnings Conference Call Transcript, 2025-02-06 ↩↩↩↩↩↩↩↩↩↩↩↩
-
CCL Products (India) Limited — Q4 and FY25 Earnings Conference Call Transcript, 2025-05-06 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
United States-India Joint Statement — The White House, 2026-02 ↩
-
Outcome of Board Meeting: Appointment of Mr. Praveen Jaipuriar as Chief Executive Officer — CCL Products (India) Limited, 2021-10-28 ↩↩
-
Intimation and press release: CCL Products (India) Ltd acquires several coffee brands from Löfbergs Group — CCL Products (India) Limited, 2023-06-08 ↩↩
-
Beverage prices soften but risks are brewing — World Bank Data Blog, 2025-05-20 ↩
-
ofi opens soluble coffee facility in Brazil, expanding its manufacturing capacity with focus on sustainable innovation — ofi, 2025-05 ↩
-
CCL Products rallies as board approves stock split, bonus issue — Business Standard, 2013-07-04 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube