Emami: The Ayurvedic FMCG House Running Low on Category-Creation Magic
I. Cold Open
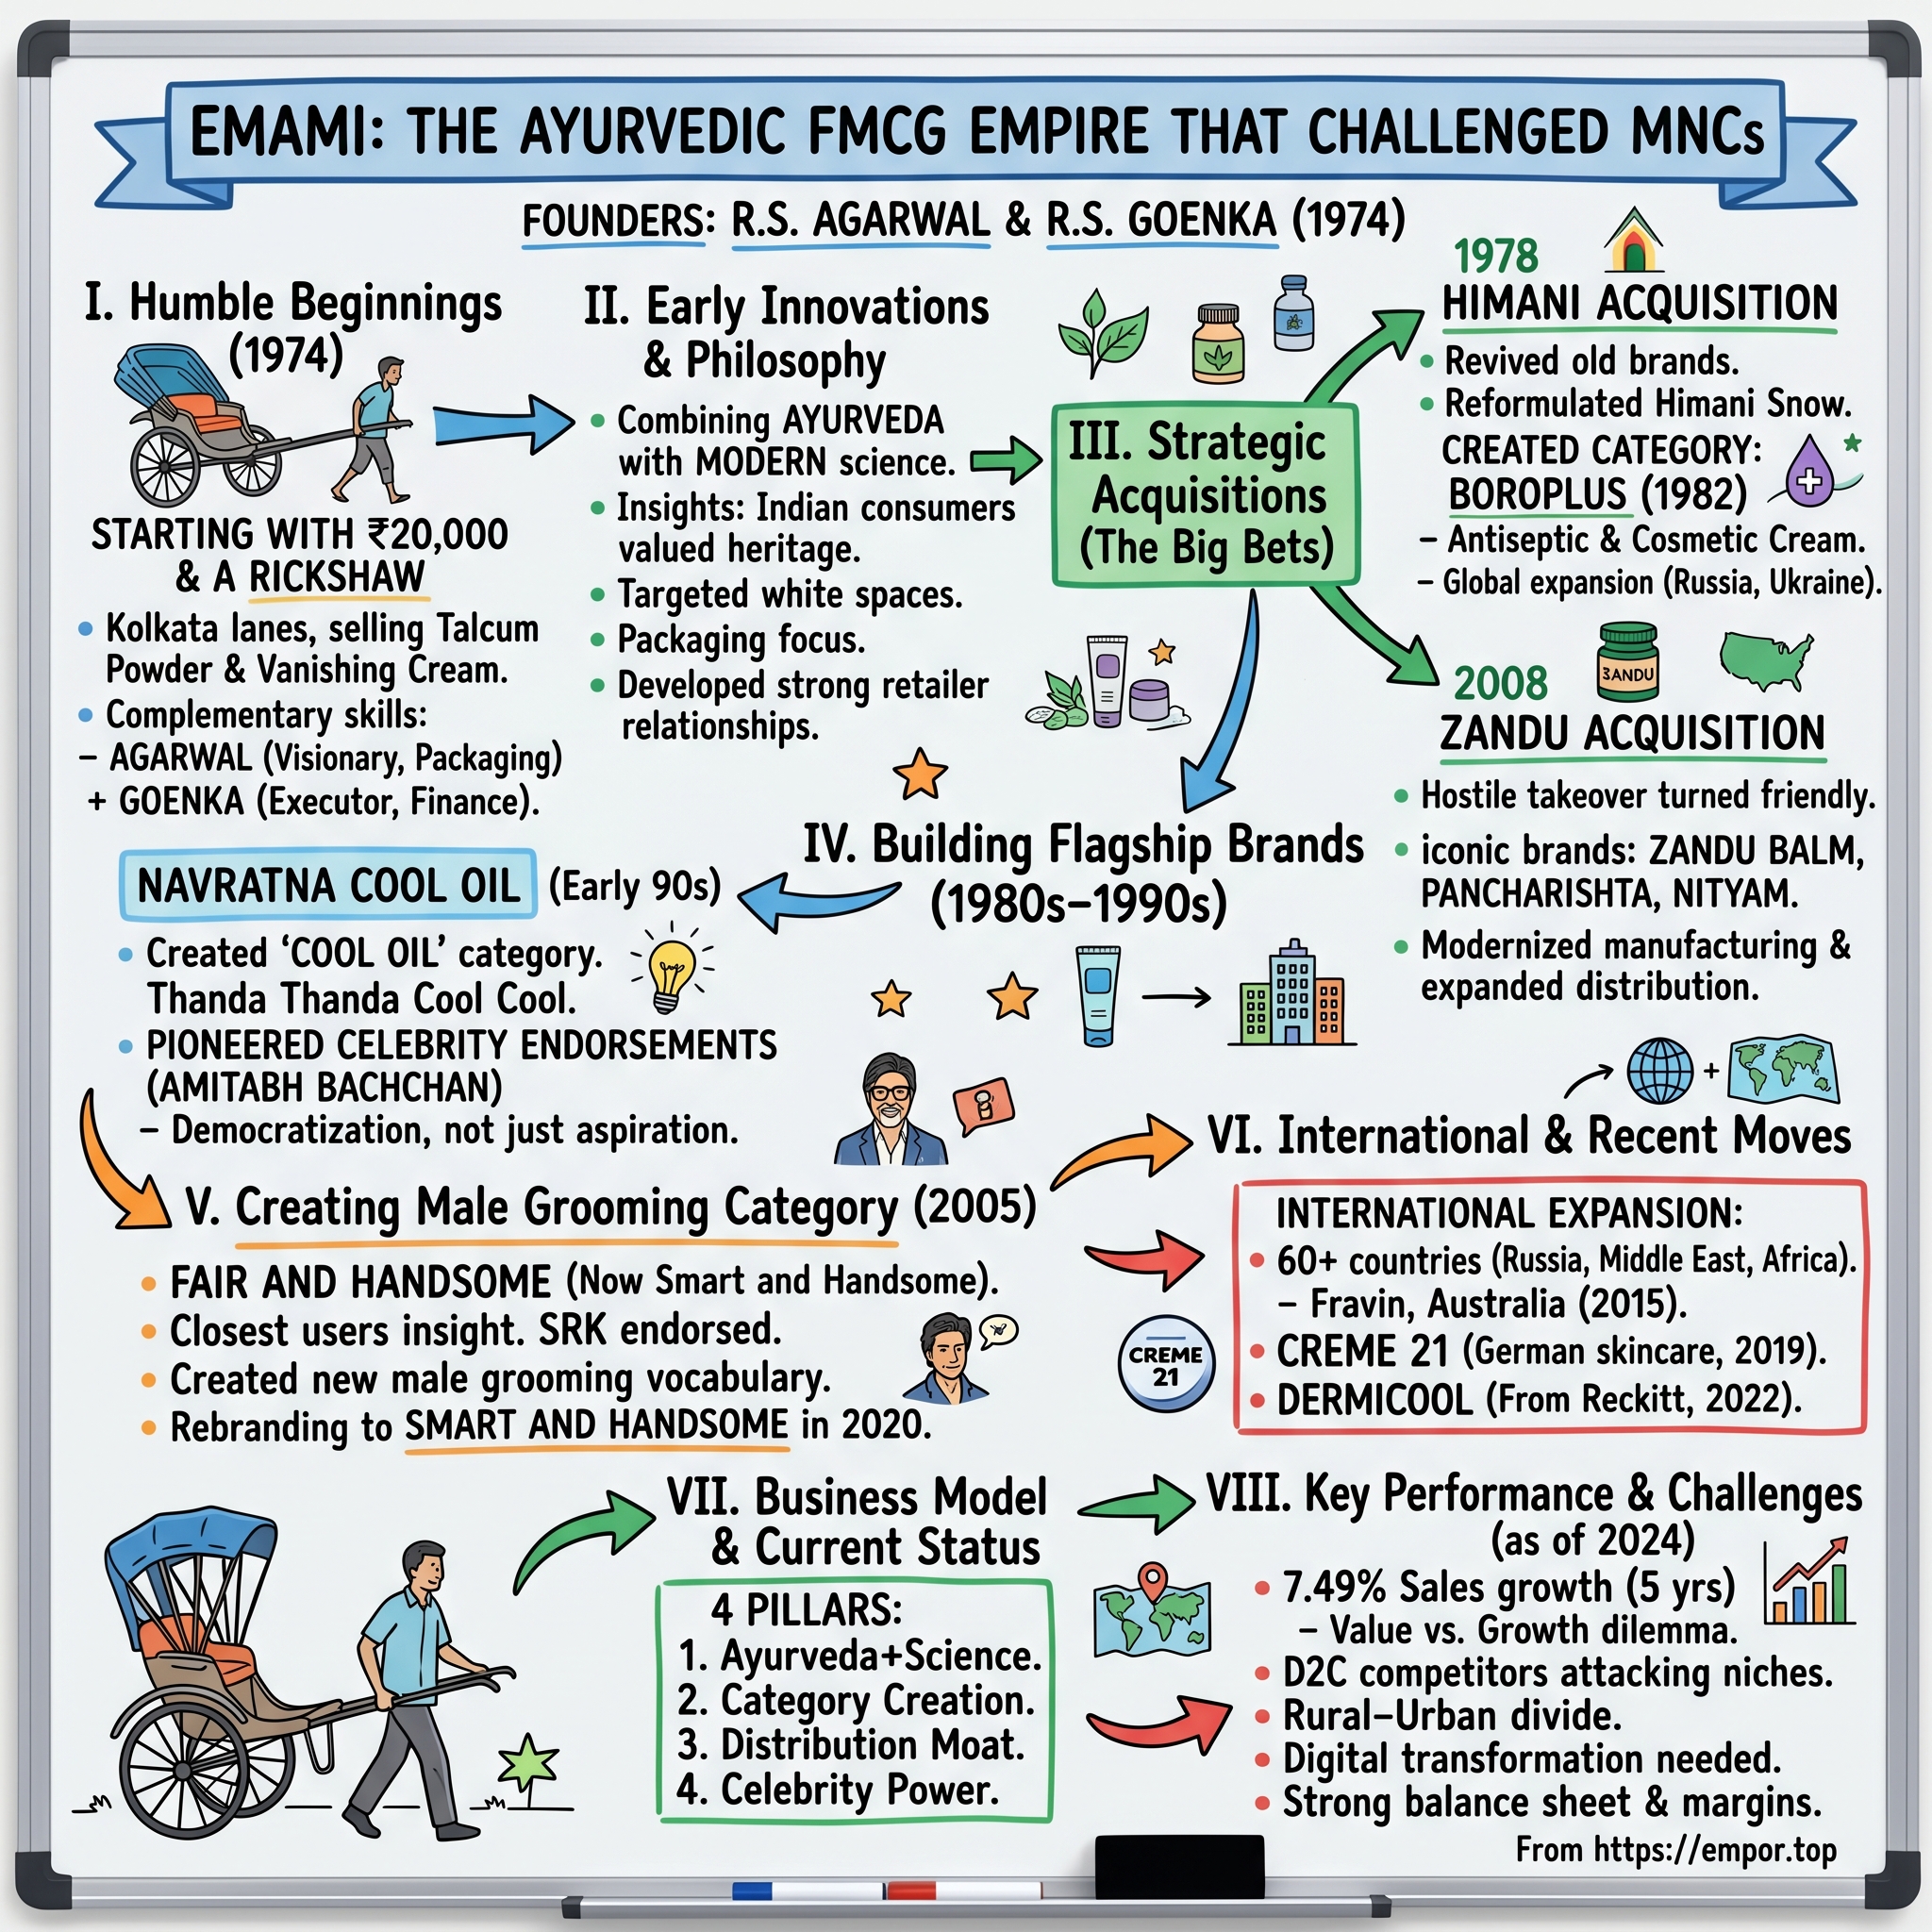
In 1974, two chartered accountants walked out of comfortable jobs at the Birla Group — then among the most prestigious employers in India — and pooled ₹20,000 to start a cosmetics manufacturing unit in a rented corner of Kolkata's Burrabazar.1 They had no distribution, no brand, and no obvious reason to believe anyone would buy talcum powder and vanishing cream from two men whose previous job description involved audit files. So they loaded the product onto a hand-pulled rickshaw and pushed it through Kolkata's markets themselves.
Five decades later, that partnership owns BoroPlus, Navratna, Zandu Balm and Kesh King. It sells more than 500 products through roughly 5.4 million retail outlets in India and into over 70 countries.2 It carries essentially no debt — overall gearing of 0.03x at the end of FY25 — and it returns more than half its earnings to shareholders every year.23 By any conventional measure of Indian entrepreneurship, Emami Limited is a success story that ended well.
Which makes the last eighteen months uncomfortable to explain.
Emami's stock closed at ₹368 in early September 2026, against a 52-week high of ₹618 — a decline of roughly 39% over one year, leaving a market capitalisation of about ₹16,000 crore.3 Fiscal 2026, which ended in March, was the first year in recent memory when revenue actually went backwards: consolidated operating income of ₹3,779.5 crore against ₹3,809.2 crore the year before, with profit after tax slipping to ₹775.3 crore from ₹802.7 crore.45 Management had entered that year guiding to double-digit growth. It delivered minus one percent. Five-year compounded sales growth now sits at roughly 6%, and ten-year compounded profit growth at about the same.3 For a company whose entire self-image is built on inventing categories that did not previously exist, that is a slow, grinding kind of failure.
The most recent quarter complicates the picture rather than resolving it. In the June 2026 quarter — Q1 FY27 — consolidated revenue jumped 15% to ₹1,039 crore, and management pointed to 20% domestic growth as evidence the engine had restarted.6 But strip out the businesses Emami has bought in the last eighteen months and the like-for-like domestic number was 12%, with volumes up 8%.6 Profit after tax still fell 16%, to about ₹137 crore, as input costs blew out by 360 basis points and the tax rate normalised.67 The headline growth was, in meaningful part, purchased.
That is the tension this story is about. Emami built its reputation on a specific and genuinely rare skill: finding a product category that nobody had bothered to define, defining it, putting a celebrity on it, and owning it for twenty years. Cool oil. Ayurvedic antiseptic cream. Men's fairness cream. Each was, at the time, an act of invention. The question a long-term investor has to answer in 2026 is whether that engine still runs — or whether Emami has quietly become something else: a collector of royalties on brands built thirty years ago, now buying its growth in the open market, run by a promoter family that has a documented history of pledging the listed company's own shares to fund bets that had nothing to do with shampoo or balm.
This is the story of how that happened, told through the origin, the acquisitions, the handover, the economics of the core, the new-age bet, and — with no attempt to soften it — the evidence on both sides.
 Subscribe on LinkedIn
II. Origins, Compressed: From a Rickshaw to a Public Company (1974-1995)
Radhe Shyam Agarwal and Radhe Shyam Goenka were childhood friends from Kolkata who followed nearly identical paths: same schooling, same profession, same employer.1 Working inside the Birla Group in the early 1970s meant proximity to one of the most sophisticated industrial machines in India — and also to its ceiling. Salaried professionals in a family conglomerate could rise, but they could not own. The decision to leave was less a leap into the unknown than a calculated bet that the fastest-growing consumer market on earth had room for a brand built from nothing.
The name came from the Italian Amami — "love me."1 It was an odd choice for a Kolkata cosmetics unit, and a revealing one: from day one, these were people who thought about a product as a story before they thought about it as a formulation.
The early years were pure hustle. Emami Talcum Powder, Emami Vanishing Cream, then cold cream and glycerine soap. The rickshaw distribution was not a colourful anecdote invented later; it was the actual go-to-market. What made it work was an obsession with presentation that far exceeded the company's means — packaging borrowed from French cosmetics conventions, labelling techniques studied from Japanese practice, all applied to a product being sold to shopkeepers who had never heard of the brand. By 1978, Emami's vanishing cream had taken roughly 22% of its category.8 For a four-year-old company with no advertising budget worth naming, that is a striking number, and it tells you something important: the founders had already worked out that in Indian personal care, perceived premiumness could be manufactured far more cheaply than actual product differentiation.
Then came the move that defined everything afterwards.
The Himani Template
In 1978, the partners acquired Himani Ltd, a roughly hundred-year-old Kolkata cosmetics company that had run into trouble.1 Himani had something Emami could not buy at any price with ₹20,000 of capital: a name that Bengali households already trusted, built over three generations. What it lacked was money, energy, and distribution — all of which Kemco could supply.
That transaction established the pattern that Emami has run for the next forty-eight years, at steadily increasing scale and steadily increasing price: find an asset with real brand equity but weak operations, buy it at a distressed or at least defensible valuation, and push it through Emami's marketing and distribution machine. Zandu in 2008, Kesh King in 2015, Creme 21 in 2019, Dermicool in 2022, The Man Company across 2017-2024, Axiom Ayurveda and IncNut Digital in 2026 — all of them are Himani, repeated.12 The critical variable across those deals is not the strategy, which has been consistent. It is the price. Himani was cheap because it was broken. Kesh King, as we will see, was neither.
BoroPlus Antiseptic Cream launched under the Himani umbrella in 1982, and Navratna Cool Oil in 1989.1 Both remain, in 2026, among the largest revenue lines in the company. That is worth sitting with: a business generating close to ₹3,800 crore in annual revenue still leans heavily on two products conceived during Indira Gandhi's and Rajiv Gandhi's terms in office. It is simultaneously the strongest evidence for the durability of Emami's brand-building and the most damning evidence about the recency of it.
In 1995, Kemco Chemicals converted from a partnership into a public limited company and listed on the Bombay Stock Exchange; Himani was formally merged in three years later.1 The founders were now answerable to outside capital — a constraint that would matter enormously two decades later, when the family's non-FMCG ambitions collided with the listed company's shareholder register.
What the origin story tells an investor is narrower than the mythology suggests. It does not prove that Emami can create categories forever. It proves that a specific pair of operators, working in a market with almost no organised competition in herbal personal care, were exceptionally good at brand packaging and distribution arbitrage. Whether that skill transfers to a 2026 market of venture-funded direct-to-consumer challengers and quick-commerce shelves is the entire open question — and the next section is where the strongest version of the "yes" case gets built, and then tested.
III. Building the Brand Vault: Category Creation as the Core Skill (1990s-2005)
Picture a hair oil aisle in an Indian general store in 1988. Coconut oil. Amla oil. Mustard oil in some regions. All of it commodity, all of it sold on price, most of it unbranded. Nobody was asking for a hair oil that made your scalp feel cold, because "cooling" was not a product attribute anyone had thought to sell.
Navratna Cool Oil, launched in 1989, invented that attribute.1 The insight was disarmingly simple and very Indian: in a country where a large share of the population works outdoors in punishing heat, physical relief from heat is not a luxury feature — it is the product. Emami did not improve hair oil. It reframed what hair oil was for. Nearly four decades later, Navratna still leads the category it created, and in the June 2026 quarter it was still delivering double-digit growth inside Emami's hair and scalp care segment.7
That is the purest form of what Hamilton Helmer would call branding power combined with a first-mover cornered resource: Emami owns the mental category, and a competitor entering "cool oil" is implicitly advertising for Navratna. It is a real moat. It is also, importantly, a narrow one — cool oil is a small pond, and Emami is the biggest fish in it precisely because the pond is not worth a global multinational's full attention.
Celebrity as Manufacturing Equipment
The second pillar of the playbook was celebrity endorsement deployed with unusual aggression. Emami has put Amitabh Bachchan, Shah Rukh Khan and a long line of film stars behind products that, chemically, were not radically different from what a local manufacturer could produce. In a market where consumers cannot easily verify efficacy claims about an antiseptic cream or an Ayurvedic balm, a trusted face is a substitute for a trusted lab result.
This is not costless. Emami spent 18.28% of sales on advertising and promotion in FY25, essentially flat against 18.4% in FY24.2 That is a heavy, permanent tax on the P&L — and it is the honest price of the branding moat. Emami's brands are strong because Emami pays continuously to keep them strong. Stop paying and the moat erodes, which is a materially different proposition from a moat built on switching costs or scale economics that persist without annual reinvestment.
Fair and Handsome: The Category Creation That Aged Badly
In 2005, Emami launched Fair and Handsome.1 The commercial insight behind it was genuinely sharp and came from sales data rather than a boardroom: a large share of purchases of "women's" fairness creams were being made by men, quietly, for themselves. Emami built a product and a brand that let those men buy openly. It worked. Fair and Handsome dominated the men's fairness category for roughly two decades and became the template every competitor copied.
Now apply the falsification test, because this is exactly where a flattering narrative would stop.
The category Emami created was built on a socially corrosive premise, and India's relationship with that premise changed underneath the brand. The "Dark is Beautiful" campaign built sustained pressure through the 2010s. In 2020, Hindustan Unilever — the largest player in the space — renamed Fair & Lovely and Fair and Handsome to Glow and Lovely and Glow and Handsome, absorbing the reputational cost of the rebrand rather than defending the positioning. Emami did not follow for nearly five more years. Then, in December 2024, an Indian consumer court fined Emami ₹15 lakh in an eleven-year-old case over misleading claims made for Fair and Handsome.9 Weeks later, in January 2025, Emami announced a ₹15 crore rebrand of Fair and Handsome to "Smart and Handsome," with Kartik Aaryan as ambassador and a stated ambition of reaching ₹1,000 crore in revenue over three to four years by expanding from face cream and face wash into a full men's grooming range addressing a market it sized at ₹17,850 crore.1011
The fine is small — ₹15 lakh is a rounding error against ₹3,800 crore of revenue. The signal is not. The sequence matters: competitor rebrands, five years pass, court fine lands, rebrand follows within a month. Management has framed the change around evolving consumer vocabulary and a shift toward individuality and confidence.10 That framing may well be sincere. But the timing does not support reading the rebrand as a confident, offensive category expansion executed from strength. The more defensible reading is a delayed repositioning under accumulated reputational and legal pressure — and the credit ratings agency CARE noted that revenue from Fair and Handsome actually declined in FY25, alongside Kesh King, The Man Company and Brillare.2
So where does that leave the category-creation claim?
The claim survives, but narrowed. Emami demonstrably created at least three durable categories — cool oil, Ayurvedic antiseptic cream, men's grooming — and two of them still generate cash forty and twenty years on. That is a genuinely rare record, and it should not be dismissed because the third one soured. But the flagship instance of the skill is now a brand in decline, carrying a live social-licence problem, that required a ₹15 crore relaunch and a new name to keep selling. The revised claim an investor can actually underwrite is: Emami can create categories, and the ones grounded in physical function (cooling, antiseptic, pain relief) have proved far more durable than the one grounded in social insecurity. The KPI that would confirm or falsify the narrower version is whether Smart and Handsome grows toward that ₹1,000 crore ambition or simply stops shrinking — and Emami discloses brand-level revenue only sporadically, which is itself a disclosure limitation worth noting.
Category creation, in any case, stopped being Emami's primary growth mechanism a long time ago. From 2008 onward, growth came from the chequebook.
IV. M&A as the Growth Engine — and Whether Emami Overpaid
In late 2008, with global credit markets seizing up, Emami did something that looked close to reckless: it bought a 150-year-old Mumbai pharmaceutical house in a deal that had begun as a hostile raid.
Zandu (2008): The Deal That Set the Standard
Zandu Pharmaceutical Works was controlled by the Vaidya and Parikh families and sat on two things Emami wanted badly — a portfolio of trusted Ayurvedic formulations, and Zandu Balm, a pain-relief product with the kind of household recognition that cannot be manufactured. Emami accumulated a stake, the target resisted, and the situation eventually converted into a negotiated transaction valuing Zandu at roughly ₹730 crore.12 The financing structure was the interesting part: acquisition debt plus a ₹310 crore qualified institutional placement, with the company working the balance sheet back to debt-free within about two years of closing.12
Read that sequence carefully, because it is the single best piece of evidence in Emami's favour on capital allocation. The company took real financial risk at a moment of maximum market fear, bought an asset with irreplaceable brand equity, used equity to cap the leverage, and then deleveraged fast. Zandu today anchors an entire healthcare segment — the balm, the Pancharishta digestive range, and a pain-management line that has since extended into roll-ons, gels and sprays.
Zandu is the standard. Every subsequent deal deserves to be measured against it, and management deserves credit for it. It is also, notably, eighteen years old — executed by the founding generation, not the current one.
Kesh King (2015): The Standard Not Met
Seven years later, Emami paid roughly ₹1,654 crore for Kesh King, an Ayurvedic hair oil and shampoo brand, funding around 60% of it with debt.13 The price implied a multiple of sales well above what Indian FMCG brand deals of that era typically cleared, and the strategic logic — an Ayurvedic hair-fall brand slotting neatly beside Navratna and Zandu — was sound enough that the stock initially rose on the announcement.13
Then the ramp did not happen on schedule. Through the first twelve to eighteen months post-close, revenue growth badly lagged what the price had implied, and analysts pointed to distributor overstocking in the pre-acquisition channel and a slower migration of the brand onto Emami's own system than modelled.14 The brand did eventually earn a place in the portfolio and contributed for years. But "eventually" is doing real work in that sentence.
And here is the piece that makes Kesh King more than an old story: eleven years after the acquisition, Emami engaged Boston Consulting Group to run deep consumer research on the brand and relaunched it in the September 2025 quarter as Kesh King Gold, repositioned on an "Ayurveda Science" platform.2 Companies do not commission BCG and relaunch a brand from scratch when that brand is compounding nicely. CARE Ratings recorded plainly that Kesh King revenue declined in FY25.2 So the honest scoreboard on the single largest acquisition in company history is: paid a rich price in 2015, waited years for the growth, and by 2025 needed an expensive strategic reset to arrest a decline.
That does not make Emami a bad acquirer. It makes the "disciplined capital allocator" framing something narrower than it is often presented as — and it matters that Harsha Agarwal and Mohan Goenka, who run the company today, were senior executives inside it when the Kesh King price was agreed.
Dermicool (2022): The Market Voted
In March 2022, Emami bought the Dermicool prickly-heat brand from Reckitt for ₹432 crore, roughly £43 million.15 Emami's stock fell to a 52-week low on the day of the announcement.15 It is worth being precise about what a market reaction does and does not tell you: it is not a verdict on the deal's eventual economics, and markets misprice acquisitions in both directions constantly. But it does establish that at the moment of announcement, the marginal investor's read on the price paid for a single seasonal brand was negative, not positive. That is a data point against the idea that Emami's acquisitions are self-evidently well-priced.
Dermicool has since been folded into Emami's summer portfolio — which, as Section VI shows, is precisely the part of the business that has been hit hardest by weather over the last two years. CARE specifically named Dermicool and Navratna as the products behind the summer-demand shortfall in the first half of FY26.2 Emami bought more exposure to its most weather-dependent category at the top of that category's cycle.
The Man Company: A Deal Done in Instalments
Emami's approach to Helios Lifestyle, which owns the male-grooming brand The Man Company, was structurally different and arguably smarter: a strategic minority stake in 2017, majority control and subsidiary status in 2022, then a buyout of the remaining approximately 49.6% for ₹177 crore in 2024, by which point the brand had done roughly ₹183 crore of turnover in FY24, up 59% year on year.16 Buying in tranches let Emami observe the business for seven years before paying up for full control. That is a defensible way to handle brand risk in a category where most startups do not survive.
It is also worth pairing with an inconvenient fact from the same period: The Man Company was one of the brands CARE listed as having declined in FY25 — the year after Emami paid for full control.2 The tranche structure limited the risk; it did not eliminate the possibility of buying at the top of a brand's growth curve.
The One That Got Away
Around 2019, Emami was reported to be in discussions for Splash Corporation, a Philippines personal-care company. Wipro Consumer Care closed that transaction instead. There are two readings. One: Emami exercised discipline and walked away from a price it did not like, which is exactly what you want from an acquirer. Two: Emami lacked the balance-sheet conviction to pursue meaningful international scale at the precise moment its promoters were consumed by a pledge crisis at home — a timing coincidence that the next section will make hard to ignore. The public record supports both readings, and there is no disclosure that resolves which is true. What can be said is that Emami's international business remains modest and geographically awkward, which the Splash deal might have changed.
Where the M&A Record Actually Lands
Emami's acquisition engine is real, repeatable, and produces assets that mostly justify their existence in the portfolio. It is not a flawless capital-allocation machine, and the pattern in the record is specific: the deals executed at distress or dislocation (Himani 1978, Zandu 2008) have worked far better than the deals executed at full price during good times (Kesh King 2015, arguably Dermicool 2022). That is not a subtle distinction; it is the difference between an acquirer with an edge and an acquirer with a strategy.
Which brings the question forward. Emami has just made its two largest new commitments in years — the remaining 73.5% of Axiom Ayurveda in April 2026 and 60% of IncNut Digital in May 2026. The forward test is straightforward: do these price and integrate like Zandu, or like Kesh King? The people who will answer that question took over the company in 2022.
V. The Handover: Second-Generation Management Since 2022
Founder successions in Indian family businesses tend to happen one of two ways: too late, in a crisis, or too suddenly, in a boardroom fight. Emami's went the third way, which is rarer and mostly to its credit.
In February 2022, R.S. Agarwal and R.S. Goenka announced they would step down from executive roles effective April 1, 2022, while remaining on the board.17 Harsha Vardhan Agarwal became Vice Chairman and Managing Director; Mohan Goenka became Vice Chairman and Whole-time Director.2 Neither was a surprise appointment. Both had spent roughly two decades running major functions inside the company — they had been in the room for the Zandu financing, the Kesh King price, and the fairness-cream strategy. The handover was the formalisation of an arrangement that had already been operating for years, which is the least risky way to transfer control of an operating business.
The governance architecture around them is conventional for a promoter-controlled Indian company: a sixteen-member board with equal representation between promoter-side and independent directors.2 The promoter family holds roughly 54.84% of the equity, principally through two investment vehicles, Diwakar Finvest and Suraj Finvest; domestic institutions hold about 27% and foreign institutions about 7.9%.3
The Pay Question, and What It Actually Signals
Harsha Agarwal's FY26 remuneration came to about ₹8.5 crore — ₹3.36 crore of salary, ₹4.55 crore of commission, and roughly ₹64.7 lakh of perquisites — up 22.4% year on year.18 Set against peers, that is strikingly modest: Marico's Saugata Gupta drew ₹39 crore, ITC's Sanjiv Puri ₹25.66 crore, Nestlé India's Suresh Narayanan ₹23.47 crore, HUL's Rohit Jawa ₹23.23 crore, and Dabur's Mohit Malhotra ₹14.6 crore in the same year.18
The obvious conclusion — restraint — is only half right. A promoter-manager who controls 54.84% of a company paying out more than half its earnings as dividends already captures the economics through ownership. Emami's dividend yield of about 2.7% on a ₹16,000 crore market cap, applied to a majority stake, dwarfs an ₹8.5 crore salary.3 So the pay figure is better read as structurally low because it does not need to be high rather than as evidence of unusual personal frugality. It does, however, produce a genuine alignment benefit: the controlling manager gets paid the same way minority shareholders do, through dividends on shares, which is a cleaner incentive than a large cash package indexed to short-term targets. The one discordant note in the FY26 disclosure is that median employee remuneration rose 9.88% while managerial remuneration rose 27.13% — a widening internal gap that a governance-focused investor would at least want explained.18
The Credibility Test: Promoter Pledging
Here is where the assessment of this management team gets harder, and it belongs here rather than in a distant risk section, because it goes directly to the question of whether promoter control at Emami is an alignment asset or a liability.
Through the late 2010s, the promoter families were building capital-intensive businesses outside the listed FMCG company — cement, power, real estate, edible oil. Those businesses needed money. The collateral they used was Emami Limited stock. By the peak of the episode, the ratio of pledged promoter shares had reached 89.24%.19 Put plainly: nearly nine-tenths of the family's stake in a listed consumer company was encumbered to lenders financing ventures that listed shareholders had no exposure to and no vote on.
The unwind was painful and public. In February 2019, the families sold a 10% stake in Emami for ₹1,600 crore to institutional buyers including SBI Mutual Fund, Premji Invest, Amundi, IDFC and L&T Mutual Fund, explicitly to pare group debt.19 The stock rose sharply on the news — a market telling you, unambiguously, that removing the pledge overhang was worth more than the dilution of promoter control. In 2020, the group sold Emami Cement to the Nirma group's Nuvoco Vistas at a ₹5,500 crore valuation, and the pledge ratio came down from the crisis level toward roughly 45%.2019
That was six and seven years ago, and by any fair reading the crisis-level risk has been resolved. But the behaviour has not gone to zero, and this is the part that matters for a forward-looking view.
CARE Ratings, in its December 2025 rationale, recorded that outstanding loans against pledged shares had declined only modestly, from ₹776 crore in August 2024 to ₹723 crore in July 2025 — roughly a 7% reduction over eleven months.2 That is not a runoff; it is a plateau. More tellingly, CARE listed as an explicit positive rating factor "reducing pledge of the promoters' share in EL to negligible levels and maintaining such position on a sustained basis," and as an explicit negative factor a "material increase in the percentage of pledge."2 When a rating agency puts promoter pledging on both sides of the sensitivity table for an essentially debt-free company, it is telling you the encumbrance is a live credit consideration, not a historical footnote.
And the pledging continues in real time. Through 2026, exchange disclosures show Diwakar Finvest and Suraj Finvest repeatedly creating and releasing encumbrances against lenders including Bajaj Finance and HSBC InvestDirect, with Diwakar's encumbered position moving in a range around 6-6.5% of total share capital and Suraj's around 2-3% during the year.2122 Aggregate encumbrance in the high single digits of total capital translates to somewhere in the low-to-mid teens as a percentage of the promoter holding — an order of magnitude below 2019, but persistent and actively managed rather than being retired.
The calibrated conclusion: the claim that Emami's promoter family provides stable, aligned, long-horizon ownership survives, but only in a narrowed form. The family has demonstrated it will use the listed company's shares as collateral for capital needs elsewhere in its empire, and has not stopped doing so — it has simply reduced the scale to a level that no longer threatens control. The forward KPI is not complicated: whether the loan balance against pledged shares continues drifting down from ₹723 crore toward zero, or resumes climbing. CARE has told the market exactly what it will do in each case.
Third Generation, and What the AGM Vote Showed
Aditya Vardhan Agarwal sits on the board as a non-executive director; Prashant Goenka serves as a whole-time director. At the 43rd annual general meeting on August 25, 2026, held by video conference with 134 members participating, the reappointment of Harsha Vardhan Agarwal as Vice Chairman and Managing Director for a further five years from April 1, 2027 passed with 99.67% support, and the increase in his fixed remuneration component from ₹30 lakh to ₹34 lakh per annum passed with 99.91%.23 Adoption of the financial statements cleared with over 99.99%.23
The interesting numbers are the lower ones. Aditya Vardhan Agarwal's reappointment as a director drew 93.47% support, and Prashant Goenka's 95.67%.23 Against a promoter block of nearly 55%, that implies meaningfully more institutional dissent on the family-director resolutions than on the executive ones — small in absolute terms, but a consistent signal that some institutional holders are more comfortable with the operating managers than with the breadth of family representation on the board. It is not a revolt. It is a mild, measurable preference worth tracking at future AGMs. On the auditor's report for FY26, the AGM record indicates an unqualified opinion; no auditor qualification appears in what is publicly available for that year, though that observation is bounded to the FY26 annual filings and AGM disclosures reviewed here rather than being a general assurance.23
Governance, in the end, is a question about what management does with the money. So the next thing to examine is where the money actually comes from.
VI. The Core Business: Personal Care and Healthcare Economics
Strip away the acquisitions, the D2C ambitions and the family history, and Emami is a fairly simple machine. It sells inexpensive, high-margin, habit-driven personal care and Ayurvedic health products to Indian households, mostly through small independent shops, with brand names that Indian consumers have known for decades.
The scale of that machine: about 5.4 million retail outlets in India served through more than 3,400 distributors and 26 depots, plus organised retail, e-commerce, quick-commerce platforms including Blinkit, Zepto and Swiggy Instamart, eB2B platforms like Udaan and JioMart, and institutional sales through the government's Canteen Stores Department.2 Roughly 83% of revenue is domestic; international was ₹648 crore in FY25, or about 17.1%, up from ₹617 crore in FY24.2
Gross margins run in the high sixties to low seventies. Operating margin at the PBILDT level was 26.69% in FY25 — comfortably above the FMCG industry average.2 Return on capital employed is around 28% and return on equity around 26%.3 The working capital cycle was 47 days in FY25, improved from 52 days, with debtor days falling to 33.2 from 42.3.23 These are the financial fingerprints of a business with genuine pricing power in narrow categories and very little capital intensity.
What Actually Sells
The June 2026 quarter gives the cleanest current snapshot of segment shape. Hair and scalp care contributed ₹271 crore of domestic net sales, about 30%, growing 11%. Skin care contributed ₹246 crore, about 27%, growing 3%. Health care contributed ₹232 crore, about 26%, growing 2%. Strategic investments — the acquired new-age brands — contributed ₹160 crore, or 18%, growing 61% on a like-for-like basis.6
Read those four lines together and the situation becomes uncomfortably clear. The two segments that constitute the historic identity of the company — skin care, which is BoroPlus and Smart and Handsome and the talc portfolio, and health care, which is Zandu — grew 3% and 2% respectively in a quarter management characterised as strong. Hair care did better at 11%. And the fastest-growing 18% of the domestic business is the part Emami bought rather than built. Nominal growth of 2-3% in a market with roughly that much inflation is, in real terms, flat to negative volume. The legacy core is not collapsing; it is standing still.
The Competitive Reality
Emami's brands are leaders in categories that are, by design, too small to attract a full-scale multinational assault. But "too small to attack" is not the same as "unattacked."
In antiseptic cream, BoroPlus competes with Reckitt's Dettol and ITC's Savlon — both brands with vastly larger parent balance sheets and, in Dettol's case, one of the most trusted hygiene names in India. In pain-relief balms, Zandu Balm shares shelf space with Reckitt's Moov and Sun Pharma's Volini. The history of that category contains a warning Emami should take personally: Iodex, once dominant, lost enormous ground to newer entrants that simply out-executed it on format, fragrance, packaging and celebrity marketing while Iodex stood still. Category leadership in Indian personal care is not defended by having been the leader. It is defended by continuous reinvestment — which is exactly why that 18%-of-sales advertising line is permanent rather than discretionary.
On distribution, the honest comparison is unflattering. Emami's 5.4 million outlets sit against Hindustan Unilever's claimed 9 million-plus direct outlets and Marico's roughly 5 million.224 Emami is competitive with Marico and structurally behind HUL. Distribution reach is therefore not a durable edge against the largest listed peers; it is table stakes that Emami has paid. Where Emami does have an edge is category-specific: HUL does not want to build a cool-oil business, and Reckitt did not want to keep a prickly-heat brand — which is why Emami was able to buy Dermicool at all.
The Seasonality Problem Nobody Prices Correctly
Here is the structural risk that gets least attention and deserves the most.
BoroPlus is a winter product — its usage is driven by dry, cold skin. Navratna, Dermicool and the talc and prickly-heat portfolio are summer products, driven by heat. A meaningful share of Emami's revenue is therefore a leveraged bet on the Indian weather calendar behaving normally, and the last two years have demonstrated exactly how that bet breaks.
In the June 2025 quarter, an unusually soft summer and an early monsoon drove the talcum and prickly-heat category down 17% year on year. Excluding that category, the core domestic business grew 6% in value.25 Consolidated revenue for the quarter was essentially flat at ₹904.1 crore, and only cost control — gross margins expanded 170 basis points to 69.4% — allowed profit after tax to rise 9.1% to ₹164.3 crore.25 One weather pattern, one quarter, and an entire product line down nearly a fifth.
Then the same mechanism ran in reverse three months later. Extended monsoons hit summer categories for a second consecutive quarter, and this time they coincided with the GST transition, producing a quarter in which consolidated revenue fell 10.3% to ₹798.5 crore and profit fell 29.7% to ₹148.3 crore.26 CARE, in its December 2025 assessment, named the cause precisely: unfavourable weather hitting summer demand for Dermicool and Navratna, plus deferred winter-portfolio loading for BoroPlus around the GST change.2
This is not a risk that management can hedge away, and it is not adequately reflected in the way Emami's business is usually described. It is the operational reason that any single-quarter comparison for this company is close to meaningless, and the reason a long-horizon investor should evaluate Emami on rolling twelve-month or two-year stacked growth rather than on quarterly prints.
Rural, Urban, and a Widely Misread Narrative
Management has repeatedly pointed to resilient rural demand offsetting soft urban demand. That is accurate as far as it goes. It is also, crucially, an industry-wide pattern — Dabur, Marico and HUL all flagged versions of the same mixed picture through FY25 and FY26. It should not be read as evidence of Emami-specific outperformance in rural India, and any framing that presents it as a competitive advantage is describing the weather, not the boat.
The International Business: A Real Global Niche, in Difficult Geography
BoroPlus is the largest-selling antiseptic cream not just in India but in Russia, Nepal and Ukraine — a genuine, verifiable number-one position for an Indian FMCG brand in overseas markets, and a rare one. Emami sells more than ten brands internationally across over 70 countries.2
The geography is the problem. Two of those three flagship overseas markets sit inside an active war zone, with all the currency, payment, logistics and sanctions complexity that implies. And exposure to the Middle East has now bitten directly: in the June 2026 quarter, international net sales fell 12% to ₹122 crore, dropping to about 12% of consolidated revenue, with management attributing the decline to geopolitical disruption in West Asia.6 Emami's export head told the Q1 FY27 call that OTC pain-management products remained blocked from export out of India, with personal-care recovery underway ahead of the healthcare lines.7 Roughly 200 of the 360 basis points of input-cost inflation in that quarter were also attributed to the West Asia conflict — crude-linked packaging and freight.67
The international business is therefore best understood as a genuine but fragile asset: real brand leadership, negligible ability to control the environment it operates in, and enough size to swing consolidated results by several percentage points in either direction.
That is the machine that generates the cash. What management is doing with that cash is the next chapter of the story — and the one it is asking investors to underwrite.
VII. The New-Age Bet: Strategic Investments Portfolio
Every legacy consumer company in India spent the last five years watching the same thing happen: a brand nobody had heard of raised venture money, bought Instagram ads, put its product on Blinkit, and built a hundred crores of revenue without ever meeting a distributor. Mamaearth's parent, Honasa Consumer, went public on the back of that model. In 2025, Hindustan Unilever bought the actives-based skincare brand Minimalist — putting the country's deepest distribution network behind a digital-native challenger and, in doing so, defining the counter-attack.
Emami's answer is a portfolio it calls strategic investments, and it started earlier than most: minority stakes in The Man Company and Brillare Science from 2017, both since taken to 100%.227 A 30% stake in Cannis Lupus Services, the pet-care brand Fur Ball Story, in July 2022, raised to 47% in FY25.2 A 26% stake in Axiom Ayurveda — maker of the AloFrut herbal juice range — for ₹109.56 crore in October 2023, with the remaining 73.5% acquired in April 2026 to take full control and open a beverages front.228 And in May 2026, a 60% stake in IncNut Digital, parent of the personalised-Ayurveda brand Vedix and the dermatology-led SkinKraft, for ₹321 crore, with performance-linked adjustments over 24 months and the remaining 40% to be acquired in two further tranches over about four and a half years subject to performance.28
That last structure deserves attention on its own. Emami did not write one cheque for a D2C brand at a peak multiple; it wrote 60% of a cheque, tied part of the consideration to performance, and staged the rest over years. Given the Kesh King experience, that is a visible, structural response to a prior mistake — the kind of behavioural evidence that is more informative about management than any statement on a call.
The Numbers, and the Target
Strategic investments contributed roughly 6% of consolidated turnover in FY26.27 Management's stated ambition is approximately 16% in FY27 and about 25% by FY30 — a roughly fourfold increase in three years.2927 In the June 2026 quarter, the portfolio delivered ₹160 crore, 18% of domestic sales, growing 61% like-for-like, and Chief Growth Officer Dhruv Aggarwal told analysts the growth was "sustainable and driven by all four subsidiaries," with the portfolio targeted at ₹750-800 crore for the full FY27.7
Three things should be held in mind at once.
First, a large part of the jump from 6% to 16% is arithmetic, not organic performance. Consolidating Axiom and IncNut for most of a year mechanically moves the ratio. The 61% like-for-like number is the one that carries information about execution; the 20% headline domestic growth in the same quarter, against 12% like-for-like, is the same effect showing up at the top line.6 An investor tracking whether the FY30 target is credible should watch the like-for-like line, not the contribution percentage.
Second, on profitability, management was refreshingly direct rather than promotional. Asked about the portfolio's economics, Aggarwal said the four brands are collectively "about EBITDA neutral, breakeven," with gross margins above 55% across the group and some above 70%.7 That is an honest answer, and it establishes the correct frame: this portfolio currently contributes revenue and optionality, not profit. Emami is funding growth in these brands out of the cash generated by BoroPlus and Zandu. If the legacy core stays flat and the new-age portfolio stays at breakeven, consolidated earnings do not grow regardless of how good the revenue optics look.
Third, the strategy is coherent — buying scale-stage digital brands and pushing them through 5.4 million outlets is genuinely something a D2C founder cannot replicate — but it is unproven at Emami specifically. The evidence from the company's own record is mixed: The Man Company and Brillare, the two oldest members of this portfolio and the ones Emami has had longest to improve, both saw revenue decline in FY25 after Emami took full ownership.2 That is the most relevant available disconfirming evidence for the claim that Emami's distribution turns acquired digital brands into growth machines, and it involves the exact same capability, management regime and portfolio as the claim it tests.
The calibrated conclusion: the strategic-investments thesis is not rejected — the FY26 and Q1 FY27 like-for-like growth rates are real, and the deal structuring has improved. But the claim that Emami has demonstrated it can scale acquired D2C brands is not yet supported; the two longest-held examples went backwards in the most recent full year for which brand-level commentary is available. What would confirm it is specific and observable: the portfolio hitting the ₹750-800 crore FY27 figure while moving from EBITDA breakeven to positive contribution. What would falsify it is the portfolio reaching the revenue target only through further acquisitions while like-for-like growth decelerates and the segment stays at breakeven. Management has helpfully given the market both numbers to check against.
The channel context is at least favourable. Quick-commerce sales tripled during FY26 and e-commerce reached about 14% of domestic revenue, up from roughly 12% in FY25.272 By the June 2026 quarter, organised channels were 32% of the domestic business and growing 19%, with quick commerce alone accounting for 35% of e-commerce sales.6 Digital media absorbed more than half the total media budget.27 Emami is not fighting the channel shift; it is participating in it. Whether participation converts into profit is the open item.
VIII. Financial Performance and the "H2 Recovery" Pattern
The most useful way to assess a management team is not to read its guidance but to check its guidance against what subsequently happened. Emami's last two fiscal years provide an unusually clean natural experiment.
FY25: The Good Year
Revenue rose 6.5% to ₹3,809 crore, with domestic up about 7% and international about 4%; profit after tax was ₹803 crore on a consolidated basis.3042 Margins held, returns held, the balance sheet stayed pristine. Nothing about FY25 was spectacular, but it was a solid year for a mature consumer company, and it was the base from which management guided FY26 to double-digit growth.
FY26: Four Quarters, Four Different Stories
Q1 (June 2025): Revenue flat at ₹904.1 crore as the summer portfolio cracked on an early monsoon. Profit still grew 9.1% on margin expansion. Management pointed to a favourable monsoon ahead, stabilising inflation and expected rate cuts, and guided to improvement.25
Q2 (September 2025): Revenue fell 10.3%, domestic fell 15%, profit fell 29.7%, and EBITDA margin contracted 570 basis points to 22.4%.26 The cause was largely genuine and industry-wide: India's GST rate reform led trade and consumers to defer purchases in anticipation of lower prices, while distributors liquidated higher-cost inventory. Emami passed the benefit through in full, cutting prices 7-13% across 293 products and 497 SKUs, and about 93% of its core domestic portfolio ended up in the lowest 5% slab.31 Excluding the GST-impacted categories, the rest of the portfolio grew 10%.31 Vice Chairman Harsha V. Agarwal told the market: "With improving sentiment and a favourable season ahead, we are confident of a strong recovery in the coming quarters."31
Q3 (December 2025): The recovery arrived. Revenue rose 9.8% to ₹1,151.8 crore, profit rose 14.5% to ₹319.5 crore, domestic grew 11% on 9% volume growth, gross margin reached 70.6% and EBITDA margin 33.4%, and international grew 9%.32 Quick commerce doubled to 20% of e-commerce. On the evidence of that single quarter, management's guidance looked vindicated.
Q4 (March 2026): It did not hold. Revenue fell 4% to about ₹925 crore, EBITDA fell 15% to ₹187 crore, and profit fell 11.7% to ₹143.2 crore.5
For the full year, revenue declined about 1% to ₹3,779.5 crore and consolidated profit came in at ₹775.3 crore against ₹802.7 crore.45 Against guidance of roughly 10% growth, that is a miss of approximately eleven percentage points.
What the Pattern Actually Shows
The lazy version of this analysis is that management repeatedly promised recovery and repeatedly failed to deliver. The record does not support that framing, and it is worth being precise.
Management guided to recovery after Q1 and after Q2. The recovery did materialise in Q3 — decisively. It then reversed in Q4. Two of the three stated causes across the year — an early monsoon and a national GST transition — were genuinely exogenous and hit the entire sector, not Emami uniquely. Blaming management for the Indian monsoon is not analysis.
What management is accountable for is the guidance itself. Entering a year with a portfolio this weather-levered and guiding to double-digit growth was an aggressive setting of expectations, not a conservative one. The miss was as much a forecasting failure as an operating one. And the deeper issue the year exposed is structural rather than episodic: a business where a single quarter can swing from minus 10% to plus 10% to minus 4% on weather and tax timing is a business whose underlying growth rate is very hard to observe in real time — which is precisely the condition under which "next half will be better" becomes a reflex rather than a forecast.
Then came Q1 FY27 (June 2026), and the same ambiguity repeated in a new form. Consolidated revenue up 14.9% to ₹1,039.2 crore. EBITDA up only 5.6% to ₹226.2 crore, with margin down 190 basis points to 21.8%. Gross margin down a heavy 360 basis points to 65.8%, as materials rose to 34.2% of revenue from 30.6%. Profit before tax up 4.3% to ₹194.7 crore — but profit after tax down 15.4% to ₹138.9 crore, because the effective tax rate normalised toward the 25-26% management guided for the full year.67 Mohan Goenka broke the input-cost pressure down as roughly 200 basis points from the West Asia conflict and 160 from business mix, and told analysts "the next three quarters should be relatively better than this," with international expected to return to significant growth in Q3 and Q4 FY27.7
That is now the fourth consecutive quarter in which management has guided to a better period ahead. Three of those four guidances rested on causes outside the company's control. The forward-looking test is narrow and checkable: whether FY27 domestic like-for-like growth — not reported growth, which now includes Axiom and IncNut — sustains near the 12% posted in Q1, and whether gross margin recovers from 65.8% back toward the high-sixties as pricing actions flow through.
The Balance Sheet Is Not the Problem
Whatever is wrong with Emami, it is not financial fragility. Overall gearing of 0.03x. Debt to gross cash accruals of 0.10x. Consolidated cash and liquid investments of ₹845 crore at end-September 2025. Negligible working-capital limit utilisation. No term-debt repayment obligations.2 CARE reaffirmed a long-term rating of AA+ with a Stable outlook and a short-term A1+ in December 2025, and withdrew the commercial paper rating simply because no paper had ever been issued.2 Planned inorganic investment of about ₹200 crore is comfortably fundable from internal accruals.2
Dividend payout ran at approximately 53%, producing a yield of about 2.7% at the current price, and the board declared interim dividends of ₹4 and ₹6 per share during FY26.32632
The valuation has adjusted accordingly. A market capitalisation that was near ₹25,000 crore a year ago now sits around ₹16,000 crore, on a trailing P/E of roughly 21, with the stock trading close to its 52-week low of ₹361.15.3 The market has already repriced Emami's growth expectations substantially downward. That is neither a bull nor a bear point in itself — it simply means the debate is no longer about whether growth has slowed. It is about what the business is worth if the slow growth is permanent, and what it is worth if it is not.
IX. Bull Case vs. Bear Case
The Bull Case, Stated at Its Strongest
Emami owns a small number of genuinely defensible positions. Navratna in cool oil, BoroPlus in Ayurvedic antiseptic cream — including outright leadership in Russia, Nepal and Ukraine — Zandu in Ayurvedic pain relief, and a men's grooming franchise that led its category for two decades. These are not commodity businesses; they carry 65-70% gross margins and mid-to-high-20s operating margins, which is only possible when consumers will pay a premium for a specific name.2
The balance sheet is close to ideal for the situation the company is in. Zero meaningful debt, ₹845 crore of liquidity, ROCE near 28% and ROE near 26% mean Emami can fund a multi-year portfolio transition out of operating cash flow while continuing to pay out half its earnings.23 Very few Indian consumer companies attempting a digital pivot can do it without raising capital or cutting the dividend.
The strategic-investments platform is a coherent, funded, already-operating response to the single biggest structural threat to legacy FMCG — and it is showing 61% like-for-like growth off a real base.6 And promoter ownership of nearly 55% with pay of ₹8.5 crore against peers at ₹14-39 crore means the people running the business are paid the way outside shareholders are paid.183
The Bear Case, Stated at Its Strongest
Five-year compounded sales growth of roughly 6%, ten-year compounded profit growth of roughly 6%, and an FY26 in which revenue actually declined.34 In the most recent quarter, the two legacy segments that define the company grew 3% and 2%.6 In real terms, the historic business is not growing at all.
That stagnation sits alongside a set of specific vulnerabilities. A portfolio structurally exposed to weather, demonstrated twice in consecutive quarters. A distribution network smaller than HUL's and roughly level with Marico's, which removes distribution as a source of advantage against the peers that matter most.224 A flagship 2000s brand carrying a live social-licence and legal problem that forced a defensive rebrand.910 An M&A record that is good at the top (Zandu) and demonstrably mixed below it (Kesh King's slow ramp and eventual BCG-led relaunch; a stock at a 52-week low on the Dermicool announcement; The Man Company and Brillare declining in FY25 after full acquisition).215
And a promoter family that has not fully retired the practice of collateralising the listed company's shares for other purposes, with loans against pledged stock barely moving between August 2024 and July 2025 and fresh pledges disclosed through 2026.221
The Activist's Stress Test
What would a skeptical investor push hardest on?
Portfolio complexity versus focus. Emami now holds full ownership of two D2C brands, majority control of a beverages business and of a personalised-beauty group, 47% of a pet-care brand, and a legacy FMCG portfolio spanning skin, hair, health and grooming — while the core is not growing. The bear reading is diworsification: capital and management attention spreading across nine or ten brand stories while the two that actually pay the bills, BoroPlus and Zandu, deliver low single digits. The bull reading is a deliberate mix shift funded by a business that is throwing off cash it cannot reinvest at high returns in its own categories. Both readings fit the same facts; what separates them is whether the acquired brands ever produce EBITDA, which by management's own account they do not yet.7
Brand-level disclosure. Emami discloses segment-level revenue and periodic brand commentary but not consistent brand-level revenue and profitability. For a company whose entire thesis rests on the health of five or six specific brands, that is a real limitation on outside diligence. It is why a rating agency's throwaway line — that Kesh King, Fair and Handsome, The Man Company and Brillare all declined in FY25 — is more informative than most of what the company publishes about itself.2
Related-party and group exposure. The pledge history means Emami Limited's shareholders have an indirect interest in the health of unlisted family ventures they cannot analyse. A careful investor should read each annual report's related-party disclosures and the auditor's CARO annexure directly rather than relying on the absence of headlines.
The tax-rate question. Screener flags that Emami's effective tax rate has historically been low.3 Management has now guided to a normalised 25-26% for FY27, and the Q1 FY27 profit decline was driven substantially by that normalisation rather than by operations.7 Investors modelling forward earnings from historical net income will systematically overstate them.
Porter's Five Forces
Rivalry: high and intensifying. Reckitt, HUL, ITC, Dabur, Marico and Sun Pharma all compete directly in at least one Emami category, and venture-funded D2C brands compete for the same digital shelf. The Iodex precedent shows how quickly a leader can lose a balm category to better execution.
Buyer power: rising. Historically low — millions of small retailers, no concentration. But quick commerce concentrates purchasing into a handful of platforms with their own private-label ambitions and their own economics. Organised channels at 32% of Emami's domestic business is a materially different buyer structure than the general trade Emami was built for.6
Supplier power: moderate and currently biting. Menthol, light liquid paraffin, rice bran oil, sesame oil and crude-linked polymer packaging drive the cost line, and Emami cannot pass increases through immediately in price-sensitive categories.2 Q1 FY27's 360-basis-point gross margin hit is exactly this force in action.6
Substitutes: high in the base categories, low in the specific ones. Anyone can substitute coconut oil for cool oil or a generic cream for BoroPlus. The moat exists at the brand level, not the product level, which is why the advertising spend is non-negotiable.
New entrants: barriers have fallen sharply. Building a brand once required a distributor network and a television budget. Today it requires performance marketing and a quick-commerce listing. This is the single largest structural change to Emami's competitive environment in fifty years, and it is the reason the strategic-investments bet exists.
Seven Powers
Against Hamilton Helmer's framework, Emami holds essentially one power convincingly. Branding is real: consumers pay more for Navratna and Zandu than for chemically similar alternatives, and have for decades. Cornered resource applies in a limited sense — Emami owns category-defining names that competitors cannot use.
The rest are weak or absent. Scale economies favour HUL, not Emami. Network economies do not apply to hair oil. Switching costs are near zero — no consumer is locked into a balm. Counter-positioning is arguably running against Emami: D2C brands are counter-positioned against exactly the mass-market, celebrity-endorsed, general-trade model Emami perfected, and Emami's response has been to buy the challengers rather than to out-innovate them. Process power is not evident in the public record.
One power, continuously purchased with 18% of sales, in categories deliberately too small to attract the largest competitors. That is the accurate description of Emami's moat. It is genuine and it has lasted forty years. It is also not the kind of compounding advantage that gets stronger with scale.
The Honest Synthesis
The "why Emami wins" case rests on narrow but real brand moats, an exceptional balance sheet, and a management team that has structured its recent deals more carefully than its predecessors structured Kesh King. The "why it might not" case rests on the fact that growth has stalled across the entire legacy portfolio at the same moment the company is asking investors to underwrite a fourfold scale-up of a portfolio that currently earns no profit, run by a team whose capital allocation and governance record reads as competent and improving rather than exceptional.
Neither case is dominant on the evidence. What matters is that both are testable, and the tests are the same handful of numbers.
X. Risk Radar
Weather and seasonality. The most underpriced risk in the business, and the one with a demonstrated mechanism rather than a theoretical one: talc and prickly-heat down 17% in a single quarter on an early monsoon, followed by a second consecutive quarter of extended rains hitting the same portfolio, followed by deferred BoroPlus winter loading.25262 Emami has bought more of this exposure through Dermicool. There is no hedge; there is only the discipline of judging the company on multi-year rather than quarterly data.
Competition and channel disruption. The threat is not that Mamaearth will out-sell Navratna. It is that the cost of building a consumer brand in India has collapsed, which permanently devalues the distribution asset Emami spent fifty years constructing, while HUL's acquisition of Minimalist shows the largest incumbent will contest the digital-first space with far greater resources. Emami's counter — buying scale-stage brands — is directionally right and financially affordable, but it is a response to disruption rather than immunity from it.
Regulatory and reputational. Fairness products remain a contested category in India and globally. The ₹15 lakh consumer-court penalty in December 2024 is immaterial financially and material as precedent, given the case ran eleven years.9 The rebrand reduces forward exposure; it does not extinguish historical claims.
Governance. Promoter pledging is the live item. It has fallen from 89.24% of promoter holding at the 2019 peak to a fraction of that today, but loans against pledged shares moved only from ₹776 crore to ₹723 crore across eleven months to July 2025, and fresh encumbrances were created and released repeatedly through 2026.21921 CARE has named it in both directions of its rating sensitivities.2 A second, smaller item: AGM support for family non-executive directors runs several percentage points below support for the executives, suggesting some institutional discomfort with board composition.23
Input costs. Menthol, vegetable oils and crude-linked packaging drive gross margin, and the Q1 FY27 compression to 65.8% shows how fast the P&L responds.62 Management expects to recover it through pricing, productivity and procurement.7 In categories where a price increase can lose shelf velocity, that recovery is a claim to verify, not to assume.
Geopolitical and FX. BoroPlus's leadership in Russia and Ukraine, plus West Asia exposure that produced both a 12% international revenue decline and roughly 200 basis points of input inflation in a single quarter, means a meaningful slice of Emami's economics is determined in places its management cannot influence.67
Execution risk in the transition itself. Emami is simultaneously integrating a beverages business, a personalised-beauty group, two grooming brands and a pet-care associate, while relaunching two legacy brands under new names and new positioning. That is a great deal of change running through one mid-sized management team at a moment when the core is already underperforming. The two oldest members of the acquired portfolio declining in FY25 is the concrete evidence that integration attention is finite.2
What is not a material risk. Refinancing and cost of capital, given no term debt and ₹845 crore of liquidity.2 Technology disruption of the product itself — nobody is disrupting balm with software. Cybersecurity exposure is rising alongside the D2C businesses, which handle consumer data directly, but nothing in the public record suggests it is currently material.
A note on second-layer signals. Two are worth flagging without over-reading them. The first is the credit file: an AA+/Stable reaffirmation with a withdrawn commercial paper line is an unambiguously comfortable position, but the agency chose to make promoter pledging a named sensitivity in both directions for a company with effectively no debt — which is an unusual thing for a rating agency to bother doing.2 The second is disclosure asymmetry: the most useful brand-level fact available about FY25 — that four named brands declined — came from a rating rationale rather than from the company's own reporting.2 Investors relying only on Emami's segment disclosure will systematically know less about brand health than the credit market does.
XI. Durable Lessons and Playbook
Distressed brand-buying works — at distressed prices. The through-line from Himani in 1978 to Zandu in 2008 is that Emami's best acquisitions were made when the seller had a problem. Its most expensive acquisition was made in a competitive process during a bull market, and it took a decade and an outside consulting engagement to sort out. The lesson is not "acquisitions are good" or "acquisitions are bad." It is that the same team, running the same playbook, produced very different outcomes depending entirely on the entry price — which is the most reliable finding in the whole capital-allocation literature and one that Emami's own fifty-year record confirms in both directions.
Categories built on function outlast categories built on insecurity. Cool oil solves heat. Antiseptic cream solves a cut. Balm solves pain. Those categories were profitable in 1990 and remain profitable in 2026. The men's fairness category solved a socially constructed anxiety, and when the society changed its mind, the category's economics and its legal standing changed with it. For an investor evaluating any consumer brand, the question of what physical problem does this solve has a longer half-life than any brand-equity metric.
A twenty-year succession beats a twenty-day one. Harsha Agarwal and Mohan Goenka ran functions inside Emami for two decades before taking the top roles, and the formal transition in April 2022 changed titles more than it changed decision-making.172 That gradualism eliminated the single largest risk in Indian family businesses. What it did not eliminate — and could not — is that governance quality in a company with a 55% promoter block ultimately depends on promoter discipline rather than on board structure. The independent half of a sixteen-member board did not prevent the pledge build-up before 2019, and the market's response to the pledge unwind was more decisive than any governance mechanism.
Owning the mental category is worth more than owning the product. The most transferable lesson from Navratna is that Emami did not win by making a better hair oil. It won by inventing an attribute — cooling — and attaching its name to it before anyone else thought the attribute was worth selling. Forty years later, a competitor entering cool oil still has to explain what cool oil is, which is free advertising for the incumbent. The corollary is the uncomfortable one: this power is bought, not earned once. Emami's 18%-of-sales advertising line is the annual rent on the mental category, and it does not decline with scale the way a manufacturing cost does.
Debt-free balance sheets buy time, not answers. Emami's clean balance sheet is genuinely what makes the strategic-investments bet possible without financial strain — the company can fund a fourfold portfolio scale-up while paying a 53% dividend and never touching the capital markets. But optionality is only valuable if it is exercised well. A pristine balance sheet attached to a stagnant core is a company that can afford to wait; it is not a company that has solved anything. The waiting has to end in something.
Guide to what you control. The most avoidable damage Emami did to its own credibility in FY26 was self-inflicted: entering a year with a portfolio levered to monsoon timing and guiding to double-digit growth, then missing by roughly eleven percentage points on causes it had correctly identified as exogenous.4 A company that knows its revenue depends on the weather has the option of guiding in ranges, guiding on a two-year stack, or not guiding at all. Choosing to guide precisely and then explaining the miss with the monsoon is a pattern that costs management credibility it will need later, when it asks investors to believe an FY30 target for a business that today earns no profit.
XII. Future Outlook & Conclusion
The next two to three years at Emami hinge on two things happening at once, and neither is guaranteed by the other.
The first is the legacy portfolio stabilising once the weather noise and the GST transition wash out. That means BoroPlus, Navratna, Zandu and the relaunched Kesh King Gold and Smart and Handsome collectively growing at something above inflation on a like-for-like basis, sustained across four consecutive quarters rather than one. Q3 FY26 showed the business can do this — 11% domestic growth on 9% volume growth is a genuinely good quarter for a mature Indian FMCG company.32 Q4 FY26 showed it does not yet do it reliably.5
The second is the strategic-investments portfolio actually scaling rather than settling into a collection of small stakes. The FY27 milestone management has set — ₹750-800 crore of revenue from four subsidiaries — is checkable within twelve months.7 The FY30 target of 25% of turnover is checkable only much later, and should be treated as an ambition to track rather than a plan to underwrite.29
The two or three numbers that matter most. First, domestic like-for-like revenue growth excluding acquisitions — the single cleanest read on whether the core has restarted, and the number that reported growth increasingly obscures as Axiom and IncNut consolidate. Second, the strategic-investments portfolio's EBITDA contribution, not its revenue: revenue at breakeven is a cost centre, and the transition from breakeven to positive is the moment the bet starts paying. Third, and specific to this company's governance rather than its operations, the outstanding loan balance against promoter-pledged shares — the one number that tells an outside shareholder whether the family's capital needs are being met from outside the listed company or from it.
There is a version of Emami's future in which none of this resolves cleanly: the core keeps growing at 2-4%, the acquired brands grow fast but never turn profitable enough to matter, and the company becomes what a skeptic already sees — a well-run, cash-generative, fairly-priced collector of royalties on inventions from the 1980s and 1990s, paying out half its earnings because it has run out of things worth building. There is another version in which the D2C portfolio compounds into a genuine second engine and the market's 39% repricing over the last year proves to have been an overreaction to two quarters of weather and one national tax reform.
The question underneath both is the one this story opened with. The skill that built Emami was the ability to see a category nobody else had bothered to name, and to name it first. That skill was exercised in a market with almost no organised competition, where a rickshaw and better packaging constituted a distribution advantage. The market Emami operates in today is crowded with venture-funded challengers who can build a brand from a laptop and legacy giants with nine million outlets chasing the same digitally-native customer. Buying the challengers is a rational response. It is not the same skill.
From ₹20,000 and a hand-pulled rickshaw to a company worth roughly ₹16,000 crore is one of the more complete entrepreneurial arcs in Indian business, and nothing in the recent numbers takes that away. The open question for an investor in 2026 is narrower and harder: whether the people running it now are managing the returns on that achievement, or genuinely building the next one. The evidence available today is genuinely mixed, and the tests that would settle it are close enough to check.
References
-
Emami Journey — Tale of Two Families, Milestones (Emami Ltd.) ↩↩↩↩↩↩↩↩↩
-
CARE Ratings Press Release — Emami Limited, 2025-12-17 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
EMAMILTD: FY26 revenue and profit remained stable; acquisitions and leadership moves support future growth — Quartr via TradingView, 2026-05-21 ↩↩↩↩↩
-
Emami Q4FY26 results: Net profit declines 11.72% to ₹143.17 crore — Business Standard, 2026-05-21 ↩↩↩↩
-
Emami Q1 FY27: Domestic growth stays strong as margins absorb inflation and the portfolio mix shifts — Multibagg, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Emami Ltd (BOM:531162) Q1 2027 Earnings Call Highlights — GuruFocus via Investing.com, 2026-08-04 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
In The Eye Of The Tiger: 50 Years of Spreading Happiness — Marwar India ↩
-
Emami fined ₹15 lakh in decade-old Fair & Handsome misleading-ads case — Business Standard, 2024-12-11 ↩↩↩
-
Emami rebrands products: 'Fair and Handsome' now 'Smart and Handsome' — Business Standard, 2025-01-09 ↩↩↩
-
Emami spends ₹15 crore to rebrand Fair And Handsome to 'Smart And Handsome' — Storyboard18, 2025 ↩
-
Zandu-Emami Deal Dissected — Nishith Desai Associates M&A Lab, 2008-12-03 ↩↩
-
Emami to acquire Kesh King for ₹1,654 crore, stock surges — Goodreturns, 2015-06-03 ↩↩
-
Kesh King pays off for Emami — Business Standard, 2016-11-05 ↩
-
Emami acquires Dermicool brand for ₹432 crore, stock hits 52-week low — Business Standard, 2022-03-28 ↩↩↩
-
Emami to acquire remaining 49.6% stake in The Man Company — Business Standard, 2024-08-31 ↩
-
Emami founders pave way for gen-next to take over control — The Print, 2022 ↩↩
-
Emami's HV Agarwal draws ₹8.5 crore in FY26, still trails Marico, ITC, HUL, Nestlé bosses — Storyboard18 ↩↩↩↩
-
Emami promoters sell 10% stake to pare Group debt, pledged shares — Business Standard, 2019-02-18 ↩↩↩↩
-
Emami to sell cement business to Nirma group arm for ₹5,500 crore — Business Standard, 2020-02-06 ↩
-
Emami promoters pledge shares with Bajaj Finance, HSBC — ScanX ↩↩↩
-
Emami Limited: 43rd Annual General Meeting Minutes — InvestyWise, 2026-08-25 ↩↩↩↩↩
-
HUL vs Marico FMCG Comparison 2026: Gross Margin and Distribution Moat — Business Behind Stocks ↩↩
-
Emami Q1: PAT grows 9% YoY; early monsoon, soft summer impact Talc/PHP portfolio — Upstox, 2025-07-31 ↩↩↩↩
-
Emami Q2 results: PAT falls 29.7% to ₹148 crore on temporary trade disruption — Business Standard, 2025-11-10 ↩↩↩↩
-
Emami says quick commerce sales tripled in FY26; e-commerce contributes 14% of domestic revenue — Storyboard18, 2026 ↩↩↩↩↩
-
Emami acquires 60% stake in Vedix, SkinKraft parent IncNut Digital for ₹321 crore — Storyboard18, 2026-05-07 ↩↩
-
Emami bullish on revenue from strategic investments' portfolio contribution to 25pc turnover by FY30 — The Print ↩↩
-
Emami Q4FY25 net profit rises 8.9%, revenue up 6.5% in FY25 — Business Standard, 2025-05-16 ↩
-
Emami Q2 FY26 revenue down 10% amid GST shift; 90% portfolio now under 5% slab — Adgully, 2025-11-10 ↩↩↩
-
Emami Q3FY26 net profit up 14.5% YoY — Business Standard, 2026-02-04 ↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube