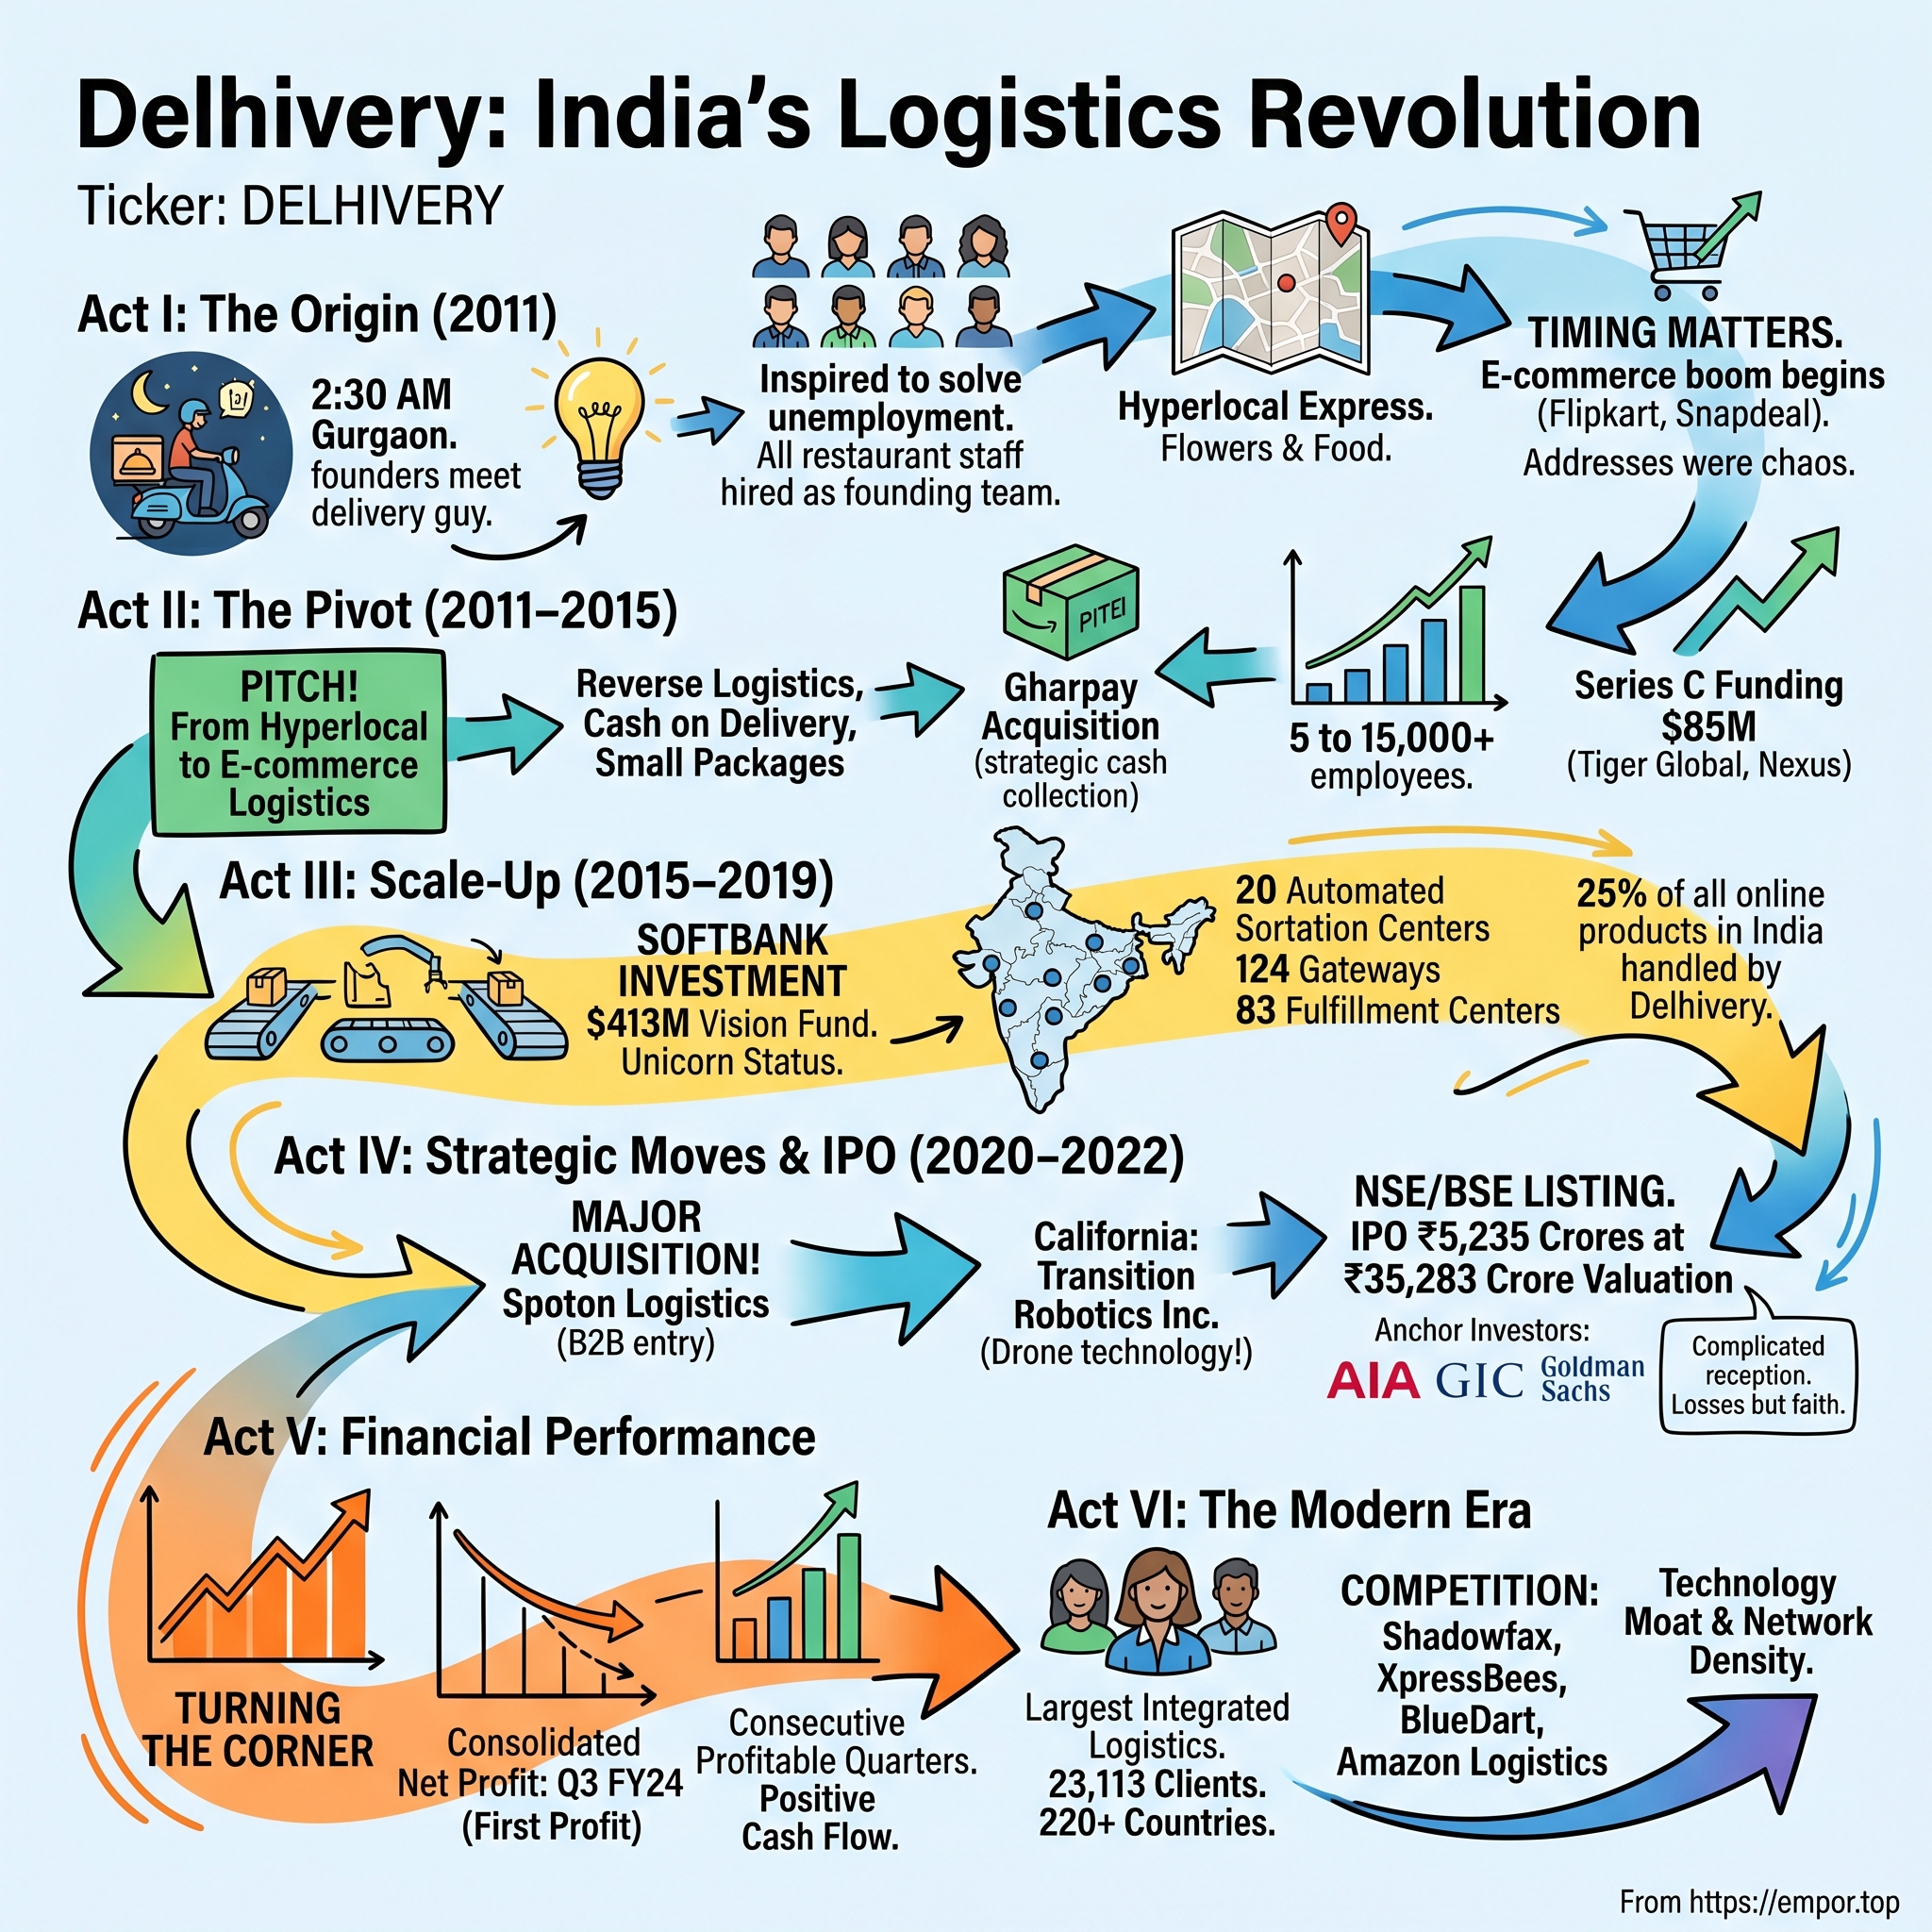
Delhivery: India's Logistics Revolution
I. Introduction & Episode Roadmap
In the winter of 2010, two Bain & Company consultants sat in a Gurgaon parking lot after midnight, talking to delivery workers for a local restaurant. The consultants were not on a client assignment. They were trying to understand why, in a country of over a billion people with abundant low-cost labor, moving a small parcel from one address to another remained extraordinarily difficult.
Sixteen years later, the company spawned by those conversations moved more than a billion parcels in a single financial year.1 Delhivery — its name combining "delivery" with "Delhi" — stands as the largest independent integrated logistics network in India. It is also the only company of its founding cohort to survive intact, list publicly, acquire its two largest competitors, and weather a decade-long debate over whether a technology-heavy logistics provider can achieve durable profitability when competing against informal, motorcycle-based transport.
That debate remains unresolved; its focus has simply shifted.
Three recurring themes define Delhivery's trajectory.
The first is its foundational pivot. Founded in May 2011 as SSN Logistics Private Limited, the company began as a hyperlocal courier for Gurgaon restaurants and florists before abandoning that model within months for a far steeper challenge: constructing physical delivery infrastructure for Indian e-commerce.2 Hyperlocal logistics offered poor unit economics, while e-commerce lacked physical infrastructure. Choosing the latter proved to be the most consequential decision made by the five co-founders — though the company eventually revisited hyperlocal services fifteen years later with mixed results.
The second is its public market performance. Delhivery raised ₹5,235 crore in a May 2022 initial public offering priced at ₹487 per share, valuing the company at roughly ₹35,283 crore during a challenging market window for unprofitable technology listings.3[^4] The offering was 1.63 times subscribed, sustained primarily by institutional buyers as retail participation lagged.4 What followed was a demanding multi-year transition: integration friction from an earlier acquisition, a ₹1,007 crore net loss in FY23, declining yield per parcel, and eventually a return to profitability in FY25, generating ₹162 crore in net profit on ₹8,932 crore of service revenue.56
The third is strategic consolidation. Delhivery acquired Spoton Logistics in August 2021 to enter B2B express freight, incurring significant operational disruption.7 In April 2025, it agreed to acquire Ecom Express — a key competitor focused on smaller towns and rural markets — for up to ₹1,407 crore in cash, receiving approval from the Competition Commission of India in June and closing the transaction in July.89 Management's core premise is that market consolidation turns a fragmented, price-competitive sector into a rational oligopoly. However, recent operational metrics highlight a counter-trend: parcel volumes have expanded while real pricing per unit has compressed.
The narrative unfolds across distinct stages. It begins with the Gurgaon inception and the strategic shift into cash-on-delivery management, where financial settlement systems proved as critical as transportation logistics. It examines the SoftBank-backed expansion of an automated mesh network between 2015 and 2020, along with the operational strain revealed during peak seasonal spikes. It assesses the governance restructuring and the 2021–22 Spoton integration challenges, which offer essential context for evaluating subsequent M&A execution. The narrative then covers the IPO, subsequent yield compression, segment performance, competitive moats, and the 2025 Ecom Express transaction. Finally, it analyzes governance under a professional, promoterless management structure, concluding with the risk matrix, key playbooks, and bull-versus-bear investment cases as of September 2026 — with the stock trading at ₹464 and a market capitalization of roughly ₹34,800 crore, below its May 2022 listing price.10
This valuation gap serves as a central thesis. Operationally, Delhivery has broadly met its key expansion and revenue milestones. Yet public market investors who bought at the IPO have seen flat capital returns over a four-year horizon. Reconciling strong operational scaling with subdued equity returns is the central focus of this analysis.
 Subscribe on LinkedIn
II. The Gurgaon Hyperlocal Origins: From Flower Delivery to E-Commerce Infrastructure
Gurgaon in 2010 was a city of glass towers and unpaved roads, where multinational corporate offices often shared property lines with dusty rural lanes. Sahil Barua and Mohit Tandon worked there as consultants for Bain & Company — Barua an engineer focused on operations and supply chains, and Tandon an associate with similar operational interests. What caught their attention was not a technology deficiency, but an operational coordination gap: local restaurants had cooking capacity and delivery riders were available, but no reliable system matched the two.
In May 2011, they incorporated SSN Logistics Private Limited alongside three co-founders: Bhavesh Manglani, Suraj Saharan, and Kapil Bharati, a technologist who had led engineering teams at Sapient.2 Operating with modest capital and a single delivery vehicle, the startup functioned as a shared logistics provider for local merchants, moving food, flowers, and small packages within thirty-minute to two-hour windows.
The model proved unsustainable quickly.
Hyperlocal delivery in 2011 India presented three structural handicaps. Demand was volatile and unforecastable, leaving riders idle during off-peak hours before overwhelming capacity during short demand spikes. Order values were small, restricting merchant delivery margins to single-digit rupees. Furthermore, merchant acquisition was highly fragmented, requiring individual onboarding and training for every restaurant without generating network density benefits. Rather than constructing a scalable network, the company was essentially operating an inefficient labor agency.
Meanwhile, India's e-commerce sector was reaching an early inflection point nearby. Online marketplaces such as Flipkart, Snapdeal, and Myntra were expanding nationally, discovering that incumbent express logistics carriers were ill-equipped for B2C e-commerce demands. By June 2011, Delhivery signed its first e-commerce customer, and by August, it had pivoted entirely away from hyperlocal delivery.11
Understanding why traditional carriers struggled requires examining the unique characteristics of Indian e-commerce shipments in 2011. Unlike developed markets where prepaid parcels move to standardized, machine-readable addresses, Indian parcels posed distinct operational challenges.
First, most orders were unpaid. Cash on delivery (COD) dominated online retail due to low credit card adoption and consumer hesitation around digital sellers. Couriers had to function as financial collection agencies, with delivery agents collecting cash that needed daily reconciliation across thousands of riders and prompt remittance to hundreds of merchants without loss or dispute. Legacy express carriers like Blue Dart, DTDC, and Gati had spent decades optimizing corporate document and B2B freight networks, lacking last-mile financial treasury systems.
Second, delivery addresses were rarely standardized. Indian addresses frequently relied on descriptive landmarks, repeated house numbers, or broad postal codes covering expansive areas. Automated sortation required resolving free-text addresses into precise geographical delivery nodes. Delhivery devoted early engineering resources to developing natural language parsing tools that mapped unstructured addresses into geolocated delivery beats — a localized data challenge that off-the-shelf logistics software could not solve.
Third, return rates were high. COD orders were frequently refused at destination when customers changed their minds or were unavailable. Reverse logistics, or return to origin (RTO), became a structural feature rather than an edge case. Returned parcels forced carriers to absorb two legs of transport without generating net revenue.
Combined, these factors required a provider to operate simultaneously as a transport network, financial clearinghouse, mapping service, and merchandise custodian. While incumbent carriers excelled at point-to-point B2B freight between major hubs, they lacked the systems to collect ₹1,800 in cash from a recipient in Kanpur, reconcile it within a week, and credit the exact amount to a specific merchant in Delhi.
Delhivery's founders focused on building this middle-tier infrastructure: ledgers, cash reconciliation, address graphs, and exception handling systems. In 2012, while venture capital flowed primarily toward consumer marketplaces and digital payments, building back-end logistics execution was unglamorous but underserved. The company steadily accumulated merchant partnerships, postal code coverage, and location data to refine its proprietary routing engines.
Falsification pass: did the COD focus actually create a moat?
While narrative history often attributes Delhivery's early advantage to a first-mover moat in B2C cash-on-delivery logistics, historical execution data suggests a more nuanced reality.
From an economic standpoint, high RTO rates — often ranging between the high-twenties and mid-thirties percentage range for certain categories and regions during that era — initially resulted in negative contribution margins per parcel. Delhivery had to develop fraud detection models, cash reconciliation workflows, and merchant-level RTO scoring before achieving positive unit economics.
However, operational capabilities did not translate into exclusive market control. Competitors quickly developed comparable infrastructure. Ecom Express, established in 2012 by former Blue Dart executives, built a nationwide COD-capable e-commerce network, while XpressBees and Flipkart's internal logistics arm, Ekart, scaled similar operational capabilities. Cash reconciliation proved to be a solvable engineering and operational task rather than an unassailable moat. Furthermore, the growth of the Unified Payments Interface (UPI) and digital payments gradually reduced COD reliance across Indian e-commerce, steadily diminishing the relative advantage of COD specialization.
Ultimately, the early focus on COD handling and unstructured address parsing provided an essential entry ticket into e-commerce logistics in 2012, securing initial contracts with platforms like Snapdeal and Myntra. It provided Delhivery the time and parcel volume needed to establish scale. However, long-term competitive differentiation depended on subsequent investments in fixed infrastructure, automated sortation, and capital efficiency.
III. Riding the Indian E-Commerce Wave: Building the Automated Mesh Network
Walk into a legacy Indian freight hub in 2015 and the sound was human: shouting, the scrape of handcarts, and the slap of parcels thrown into cloth sacks marked with city names in felt marker. Walk into Delhivery's gateway at Tauru, on the Haryana side of the Delhi border, a few years later, and the sound was mechanical — a low, continuous rumble of belts and the click of a cross-belt sorter diverting parcels into chutes at a rate no human team could match.
That contrast illustrates the physical expression of a core strategic thesis: the operational case for automated logistics over manual sorting.
Hub-and-spoke versus mesh, in plain terms. A classic hub-and-spoke network operates like a commercial airline. All freight from a region flows into a central hub, gets resorted, and flows back out. It is structurally simple — the model FedEx built in Memphis — and works efficiently when volume flows are unpredictable and central hub facilities are inexpensive relative to point-to-point routes. Its weakness is circuitous routing; a parcel traveling between Pune and Nashik, two cities a few hours apart, may travel hundreds of kilometers out of its way to a distant sorting hub and back.
A mesh network instead connects multiple mid-sized sorting nodes directly to one another, dynamically selecting active lanes based on daily volume density. When Pune-to-Nashik volume reaches sufficient scale, a direct linehaul truck runs between them. When volume drops, freight routes through an intermediate node. In theory, this arrangement reduces vehicle kilometers, minimizes parcel handling touches, and improves truck fill rates.
A secondary operational advantage lies in resilience. In a hub-and-spoke system, the central hub represents a single point of failure and congestion where all queues accumulate. In a mesh network, sorting capacity is distributed across nodes, allowing traffic to reroute around localized bottlenecks.
Executing a mesh network requires significant computational infrastructure. The operator must monitor real-time volume on every lane, capacity at every node, vehicle positioning across the fleet, and precise geocodes for delivery addresses. This operational requirement explains why Delhivery positioned itself as a technology company operating physical logistics infrastructure. The dynamic routing engine, address resolution software, and freight operating system made the mesh topology viable, creating a technical barrier that legacy transport operators without software layers could not readily replicate.
The capital that made it physical. Constructing automated network infrastructure requires substantial capital, as reflected in Delhivery's venture history. Early financing rounds were backed by Nexus Venture Partners, Times Internet, Tiger Global, Carlyle, and Multiples. The inflection point occurred in March 2019, when SoftBank Vision Fund led a $413 million Series F round alongside Carlyle and Fosun, valuing the business at over $1.5 billion and making it India's first logistics unicorn.12 In May 2021, a subsequent $277 million funding round raised the company's valuation to approximately $3 billion.13
This capital was deployed into physical assets: mega-gateways at Tauru, Bhiwandi outside Mumbai, and Chakan near Pune, equipped with automated cross-belt sorters, supported by regional sorting centers and last-mile delivery hubs. By the first quarter of FY27, the network encompassed 48 automated sort centers housing 73 automated sorters, 4,266 express delivery centers, and 23.3 million square feet of total operational footprint, supporting an active fleet of more than 20,000 vehicles per day.14
The strategic rationale relies on fixed-cost operating leverage. High-speed automated sorters incur fixed capital expenses regardless of throughput volume. As parcel volume through an automated gateway increases, fixed costs distribute across more units, lowering marginal unit costs. This creates a cost advantage over smaller carriers, while simultaneously rendering the business capital-intensive, sensitive to utilization rates, and vulnerable during volume downturns.
Falsification pass: does the mesh actually deliver linear cost reduction with scale?
Management framing has often suggested that network automation eliminates bottlenecks and yields smooth unit-cost reductions as volume expands. However, Delhivery's operational record demonstrates that cost leverage is lumpier and more conditional than theoretical models suggest.
A clear test of network scalability occurred during the Spoton integration in 2022. On the Q1 FY23 earnings call, Chief Executive Sahil Barua attributed the quarter's margin contraction to network congestion, noting that "higher than forecasted volumes created bottlenecks at automated gateways in Tauru and Bhiwandi," while un-automated regional facilities in Chennai and Pune faced severe operational strain.15 The flagship automated gateways — built to deliver scale economies — became primary points of network congestion. When a major node in a mesh network saturates, overflow queues propagate across connected lanes rather than resolving automatically.
The financial impact reflected this operational fragility. Out of a ₹217 crore adjusted EBITDA loss in Q1 FY23, management attributed approximately ₹150 crore to fixed-capacity underutilization, ₹46 crore to non-recurring integration expenses, and ₹60 crore to lost revenue from service disruptions.15 Capacity underutilization exceeded direct integration fees as the primary cost drag. Operating leverage functions in both directions: fixed-cost structures that expand margins during high-volume periods accelerate margin compression when volumes drop below facility thresholds.
Empirical evidence suggests the scale-economies thesis holds, but within specific operational boundaries. Delhivery maintains a cost advantage from automated sortation and route density, as demonstrated in FY26 when a 40% increase in express parcel volumes accompanied a near-doubling of EBITDA to ₹764 crore.16 However, operating leverage remains contingent on maintaining facility utilization within optimal design thresholds and preventing localized volume spikes from overloading primary sortation gateways. The critical metric for network efficiency is whether service EBITDA margins remain stable during volume surges rather than solely during predictable operational periods.
This structural dynamic set up the moment when management moved to test the network's capacity at scale through aggressive market consolidation.
IV. M&A Capital Deployment & Governance Shocks
By early 2021, Delhivery faced an operational challenge that appeared enviable from the outside. Its express parcel network was functioning reliably and the public market window in India was opening wider than it had in years. What the company lacked was a second growth engine. Business-to-consumer (B2C) parcel delivery is light, high-volume, and directionally imbalanced — creating heavy outbound freight flows from a small number of fulfillment hubs against thin return traffic. That imbalance left linehaul trucks running half-empty on return legs, an enduring inefficiency in long-haul transport.
The logical expansion was B2B freight. Part truckload (PTL) shipping involves moving palletized industrial goods for manufacturers, distributors, and small and medium-sized enterprises. This freight features heavier consignments, more predictable demand, and counter-directional traffic patterns that complement e-commerce flows. By filling backhauls with industrial cargo, the same linehaul vehicle could generate revenue on both legs of a journey.
The governance reset. Before executing that expansion, the founding team restructured executive leadership. In March 2021, two of the five original co-founders, Mohit Tandon and Bhavesh Manglani, stepped back from executive roles ahead of the company's initial public offering filing. Sahil Barua remained managing director and chief executive officer, alongside Kapil Bharati as chief technology officer and Suraj Saharan overseeing people and operations. The company filed its draft red herring prospectus with the Securities and Exchange Board of India (SEBI) in November 2021 for an issue then sized at ₹7,460 crore.17
A more unusual structural decision was choosing to list without an identified promoter group. Under Indian securities regulations, listed companies typically maintain an identified promoter group with residual voting control and explicit accountability. Delhivery classified itself as a professionally managed company with zero promoter shareholding — a structure standard in Western capital markets but rare on Indian exchanges. This choice created a distinct strategic trade-off: a company without a controlling shareholder lacks a cushion of patient promoter capital when market sentiment turns hostile.
The Spoton deal. In August 2021, Delhivery announced the acquisition of Bengaluru-based Spoton Logistics, an established PTL operator, to accelerate its entry into B2B freight.18 While the company did not publicly disclose the purchase price at announcement, contemporary press reports estimated the all-cash transaction in the range of roughly $200–300 million.7 Delhivery framed the deal around clear operational synergies: Spoton brought enterprise B2B relationships, an active PTL network, and freight tonnage that could be layered directly onto Delhivery's linehaul and sortation assets.19
While the strategic logic was sound, operational execution encountered immediate strain.
Falsification pass: the Spoton integration collapse.
The key assertion to test is the common acquisition thesis in network industries — that M&A yields immediate revenue synergies and operating leverage as facilities and software systems combine. Delhivery's performance directly refuted that immediate synergy thesis.
The integration ran through the first quarter of FY23, producing severe financial strain. Consolidated quarterly net losses tripled to ₹399 crore.20 PTL revenue dropped nearly in half sequentially, falling from ₹482 crore in Q4 FY22 to ₹259 crore in Q1 FY23.20 Total freight volume fell to approximately 234,000 tonnes, compared to 279,000 tonnes on a pro-forma combined basis a year earlier — meaning the merged entity moved less freight than the two separate companies had.15 Adjusted EBITDA swung to a loss of ₹217 crore, representing a negative 12.5% margin, down from a positive ₹81 crore in the previous quarter.15
The root cause was operational rather than financial. Spoton's software architecture had been built specifically for B2B freight, incorporating distinct protocols for consignment tracking, documentation, and enterprise client billing. Delhivery's platform was designed for high-velocity B2C mesh parcel routing. Merging the systems required unifying incompatible data definitions of what constituted a shipment. Physical consolidation compounded the problem: combined freight volumes overwhelmed sorting gateways built for single-network throughput. The resulting bottlenecks caused delivery delays and severe shipment damage. Barua acknowledged during an analyst call that operational friction created excess package damage alongside notable losses and transit delays originating at Tauru and Bhiwandi.15 As senior Spoton executives managing key enterprise accounts departed, Delhivery deliberately paused client onboarding, choosing to suspend volumes from select major accounts until "operational parameters were conclusively stabilized."15
Public commentary on that earnings call highlighted the severity of the operational disruption. A CLSA analyst questioned why post-integration freight tonnage dropped below Delhivery's standalone volumes when integration was intended to improve efficiency. Goldman Sachs analyst Pulkit Patni observed that without Spoton, the company could have done similar numbers, if not more.15 Barua did not attribute the performance to macroeconomic factors; he defended the decision to prioritize network stability over immediate volume, setting out a recovery framework rather than disputing the operational shortfall. Multiple equity brokerages downgraded the stock.21
From a 2026 perspective, evaluating this integration yields two contrasting interpretations.
The critical view regards the acquisition as a costly capital allocation error executed shortly before a public listing, disrupting roughly two years of B2B freight momentum. Management's pre-deal synergy projections proved inaccurate in both timeline and scale, establishing a demanding benchmark for evaluating future network consolidations.
The counter-perspective notes that the PTL business eventually recovered and achieved profitability. The segment returned to positive EBITDA in FY25 and crossed 500,000 tonnes in a single quarter for the first time in Q3 FY26, up 23% year on year,22 reaching 2 million tonnes for the full year.16 The strategic capabilities targeted in the Spoton transaction were ultimately realized. The failure stemmed from integration pace and operational sequencing rather than a flawed core thesis.
The ultimate conclusion is that historical execution narrows management's capability claim rather than invalidating it entirely. Delhivery demonstrated it can integrate an acquired freight network, but the process required roughly eight quarters and incurred substantial financial expense. This historical timeline serves as the precise benchmark for assessing the 2025 Ecom Express transaction.
First, however, the company had to navigate its transition into the public equity markets.
V. The ₹5,235 Crore IPO & The Brutal Post-Listing Reality Check
May 2022 presented a difficult backdrop for growth-stage public offerings. Global technology equities were under selling pressure, domestic public market investors were cautious following Paytm's post-listing decline in late 2021, and institutional focus had shifted sharply toward profitability. In this environment, Delhivery opened its public subscription book.
The offering ran from May 11 to May 13 at a price band of ₹462 to ₹487 per share, seeking to raise ₹5,235 crore — comprising ₹4,000 crore in fresh capital and ₹1,235 crore in an offer for sale by early investors including SoftBank, Carlyle, and Times Internet.3 The company had already scaled back its valuation expectations: its November 2021 draft prospectus had targeted a ₹7,460 crore issue.17 The 30% reduction in issue size between filing and launch reflected public market pushback on initial valuation expectations.
The offer closed 1.63 times subscribed, sustained primarily by qualified institutional buyers while retail participation lagged.4 For a high-profile technology issuer emerging from an era of heavy oversubscriptions, the modest demand signalled underlying investor skepticism.
On listing day, May 24, 2022, the stock opened modestly above its issue price at ₹493 on the BSE and ₹495.20 on the NSE.23[^25] Shares traded up in subsequent weeks, briefly placing Delhivery among India's top 100 most valuable listed companies by market capitalization in July 2022.24
However, operational friction from the Spoton integration soon impacted financial results. Within months of listing, service disruptions and declining freight tonnage dragged down quarterly earnings. By October 2022, the stock fell 13% in a single session following a subdued business update.25 Delhivery closed FY23 with a consolidated net loss of about ₹1,008 crore.26
The yield problem. Beyond integration friction lay a deeper structural constraint: an inability to command pricing power.
The mechanics of Indian e-commerce shipping procurement enforce strict price competition. Major marketplaces and aggregators allocate shipment volumes dynamically using automated systems that continuously compare rate cards, transit times, and delivery performance across multiple providers. By distributing volume across three or four logistics partners, e-commerce platforms ensure no single carrier gains leverage. The switching cost of shifting volume between competing carriers is low and immediate. Under this structure, a logistics provider attempting to raise rates risks immediate volume reallocation rather than securing higher margins.
This dynamic directly challenges the thesis that market dominance yields pricing power. Delhivery's average revenue per parcel has declined across successive periods of market share expansion. In the third quarter of FY26, despite handling 295 million shipments — a 43% year-over-year volume increase during the peak festive season — average realization per parcel fell 13.7% year-over-year to approximately ₹62.3.27 For full-year FY26, express parcel revenue reached ₹6,685 crore on over one billion shipments, yielding a lower average price per parcel than in FY25, when ₹5,318 crore in express revenue was spread across a smaller volume base.166
Management and market analysts note that product mix shifts account for part of this decline, pointing out that integrating networks like Ecom Express added lighter, lower-ticket parcels that lower the blended average realization.1427 While valid, this explanation does not establish pricing leverage. Even accounting for parcel mix, Delhivery's four-year track record demonstrates that scale translates into cost efficiency and volume expansion rather than premium pricing. Market leadership in Indian express logistics has allowed Delhivery to handle larger volumes at lower unit costs, but not to command higher unit rates.
This distinction is central to the company's valuation framework. A business that converts scale into pricing power expands its profit margins over time. A business that converts scale into cost efficiency relies on volume expansion and unit cost reductions outpacing price compression. Delhivery operates strictly as the latter. A sustained period of volume expansion accompanied by increasing realization per parcel would challenge this assessment, but that trend has yet to materialize.
Myth versus reality on the IPO itself. A common narrative attributes Delhivery's post-listing share price underperformance to broad market timing and negative sentiment toward unprofitable technology stocks. Operational evidence presents a more nuanced reality.
Public market skepticism proved justified regarding near-term execution. Within a single quarter of listing, net losses tripled as integration challenges disrupted core operations. Retail investors who avoided the IPO at ₹487 per share were validated over the subsequent four years, as the stock continued to trade below its issue price in 2026.10 Attributing the share price trajectory entirely to macro market conditions overlooks management's execution missteps during the Spoton integration.
Concurrently, public markets initially overlooked the company's underlying operational progress. Over the four years following the IPO, Delhivery systematically reduced express delivery costs per unit, expanded its part-truckload freight segment into a ₹2,254 crore annual revenue business, achieved profitability in warehousing, and generated positive free cash flow.16 While initial IPO investors experienced flat equity returns, the underlying operating metrics demonstrated structural business scaling beneath a depressed stock price.
Subsequent financial results reflected this operational turnaround. Delhivery narrowed its net loss to approximately ₹249 crore in FY24,6 before achieving its first full year of net profitability in FY25. Evaluating the business at this stage requires assessing how its operational engine functioned once profitability was established.
VI. Core Business Segment Analysis & Strategic Economic Engine
Delhivery operates less like a single monolithic entity and more like four distinct business lines sharing a transport fleet, a technology stack, and physical sorting facilities. Shared infrastructure is the central operational thesis — each business unit is intended to lower the marginal unit costs of the others — yet the segments feature markedly different economics, client profiles, and competitive dynamics.
In FY25, when Delhivery achieved its first full year of net profitability, total consolidated revenue reached ₹9,372 crore, of which ₹8,932 crore was service revenue, generating ₹376 crore in adjusted EBITDA and ₹162 crore in net profit.56 Performance expanded in FY26, with total consolidated revenue rising to ₹10,486 crore and EBITDA nearly doubling to ₹764 crore at a 7.3% margin, while transport service EBITDA margins reached 15.6% and transport return on invested capital rose to 16.0% from roughly 5% in prior periods.16
Express parcel: the cash engine, and the price-taker. Express parcel delivery represents roughly two-thirds of Delhivery's business, generating ₹5,318 crore in FY25 revenue and expanding to ₹6,685 crore in FY26 as annual volumes crossed one billion parcels.2816 The segment serves direct-to-consumer (D2C) brands, social commerce platforms, and major e-commerce marketplaces across urban and regional markets.
The segment's underlying economics depend on route density. A delivery agent covering a route with fifteen parcel drops operates at a low unit cost, whereas the same route with only four drops incurs heavy unit margin drag. Consequently, volume consolidation within existing postal codes yields higher operational efficiency than expanding thinly into new territories. This dynamic provided the financial rationale for the Ecom Express acquisition, which added overlapping volume within established geographies rather than extending geographic reach, supporting unit cost reductions even amid declining average realizations per parcel.
However, operational density does not automatically yield expanded profit margins. E-commerce marketplaces and merchant aggregators leverage competing carriers to capture density savings through rate reductions. While price compression limits margin expansion, express service EBITDA margins reaching management's target band of 16% to 18% indicates that a portion of operational scale leverage is retained.14
PTL freight: the margin expansion story, with a scar. B2B part-truckload (PTL) freight generated ₹1,889 crore in FY25 revenue — up 25% year-over-year — and grew to ₹2,254 crore in FY26 across 2 million tonnes of freight.2816 Following operational disruptions from the Spoton acquisition, segment EBITDA returned to profitability in FY25.22
The PTL freight business features three structural advantages over express parcel delivery. First, client relationships involve commercial shippers under negotiated contracts rather than automated, algorithmic bidding by e-commerce aggregators. Second, contract pricing is explicitly indexed to fuel costs, insulating the company from diesel price volatility. Third, heavier industrial freight fills linehaul trucks by weight rather than volumetric space, balancing the lighter, high-volume shipments of the express parcel business.
This operational complementarity forms the core premise of Delhivery's dual-engine network strategy — combining B2B freight backhauls with B2C parcel linehaul routes. Management's stated internal objective is to exit FY27 with PTL EBITDA margins of 15% to 15.5%, aiming for a long-term range of 16% to 18% through annual margin improvements of 1.5 to 2 percentage points.14 This quantitative target provides a measurable benchmark for ongoing operational execution.
Supply chain services: small, sticky, and finally profitable. Supply Chain Services (SCS) provides integrated warehousing and fulfillment, managing client inventory, warehouse operations, and omnichannel order routing. Accounting for approximately 7% of total revenue, SCS generated ₹729 crore in FY26.16 After years of operating at a loss, SCS generated ₹79 crore in service EBITDA in FY26 — roughly four times the prior year's level — supported by a commercial deal pipeline in the ₹1,800 crore range and a medium-term EBITDA margin goal of 12%.1628
The strategic value of SCS lies in customer retention rather than revenue scale. Integrating a client's enterprise resource planning (ERP) system with Delhivery's warehouse management platform creates high switching costs, as contract transitions require multi-year commitments and complex technical integrations. This creates a structural contrast within Delhivery's portfolio: high switching costs are concentrated in its smallest business segment, whereas its largest segment, express parcel delivery, features minimal customer lock-in.
The segment also exhibits margin volatility during growth phases. During the Q1 FY27 earnings call, management attributed a sequential decline in SCS margins to onboarding costs associated with two large client contracts, which were expected to stabilize within 45 to 60 days.14 Initial integration expenses routinely suppress short-term margins before new warehousing contracts achieve steady-state profitability.
Truckload and cross-border: fillers with a purpose. The full-truckload (FTL) business operates as an asset-light digital brokerage matching commercial shippers with independent fleet operators, providing low profit margins while helping to optimize fleet utilization across directional lane imbalances. Cross-border express functions as a minor segment dependent on international carrier partnerships. Neither segment drives primary earnings growth, but both contribute incremental revenue by utilizing idle capacity across existing transit routes.
And a new one worth watching sceptically. In January 2025, Delhivery launched Rapid Commerce, a sub-two-hour delivery service for direct-to-consumer brands that began operating in Bengaluru using a network of shared urban fulfillment centers.2930 By the Q1 FY27 call, this hyperlocal initiative — referenced as Delhivery Local — reached an annualized gross merchandise value of roughly ₹150 crore, surpassing internal projections and prompting management to raise its target above ₹250 crore. Management also disclosed that the new service operated at a negative contribution margin of around 50%, with costs exceeding revenues by approximately 1.5 times.14
This unit economics disclosure underscores the capital intensity of the venture. With operating expenses consuming ₹1.50 for every rupee of revenue generated, the initiative remains an unproven operational experiment. The launch reflects a notable strategic shift: after abandoning hyperlocal delivery in 2011 due to unfavorable unit economics, Delhivery re-entered the segment in 2025 facing similar margin challenges. The key analytical question is not whether gross merchandise volume expands, but whether contribution margins can reach breakeven before consuming substantial growth capital.
In aggregate, Delhivery's operational structure consists of four distinct business lines: a dominant, low-margin express parcel core that provides volume density and cost efficiency; a growing B2B freight business with index-linked contractual pricing and expanding margins; a small, high-retention warehousing unit entering profitability; and an unproven hyperlocal delivery venture that remains unit-negative. This segmented reality presents a more grounded operational profile than broad claims of operating a unified logistics operating system for Indian commerce.
Whether market conditions and competitive dynamics will permit these segment economics to improve remains the key question facing the business.
VII. Industry Structure, Moats & Competitive Strategy
Here is the single most important fact about Indian e-commerce logistics, and the one most often left out of bullish presentations: Delhivery's largest competitors are also its largest customers' subsidiaries.
Flipkart's Ekart and Amazon Transportation Services together fulfil roughly half of India's e-commerce volumes internally. That is not a market Delhivery competes for and loses; it is a market that structurally does not exist for third parties. The addressable pool for all independent 3PLs combined is the remainder — plus whatever the captives choose to outsource in peak weeks, which they do precisely when capacity is scarce and pricing should be strongest.
And in 2026 the captives stopped being purely captive. Amazon announced that it would open its supply chain network — freight, warehousing, fulfilment, and last mile — to third-party businesses in India, effectively converting an internal cost centre into a competing 3PL.31 Delhivery's shares fell as much as 3.5% on the news; FedEx and UPS each dropped more than 9% in the United States on the same theme.32 Ekart has moved the same way, taking on external clients across marketplaces, beauty, fashion, and big-box retail, including an IKEA last-mile mandate that launched in Delhi-NCR in March 2025 and expanded to Chennai in April 2026.33
This is the marketplace-insourcing risk from the outline, and it is worth being precise: it did not stay hypothetical. It happened, in the current financial year, and it is the most material competitive development in the story since the Ecom Express deal.
Barua's public response has been characteristically combative. On the Q4 FY26 call he dismissed Amazon's third-party push as an "old product in new wrapper," arguing that captive networks built around a single marketplace's flow patterns do not translate into competitive open-market economics.34 There is a real argument underneath the bravado — a network optimised for one shipper's parcel profile carries structural inefficiency when serving a heterogeneous customer base, and the captives' cost base was never built to be sold at market rates. But the argument cuts less cleanly than he suggests. Amazon and Flipkart do not need to win the open market. They need only to place marginal capacity into it at marginal cost, which is exactly the behaviour that caps industry pricing.
The rest of the field. Among independents, the landscape consolidated sharply in 2025 and 2026. Delhivery absorbed Ecom Express. Shadowfax completed an IPO and listed on 28 January 2026 — at a discount, debuting near ₹112.60 against an issue price of ₹124, having reported FY25 revenue of about ₹2,485 crore with a turn to profitability.3536 Blue Dart remains the premium air-express and B2B incumbent, structurally more profitable and far smaller in e-commerce volume. XpressBees remains private and lossmaking, reporting a net loss of roughly ₹370 crore on ₹2,874 crore of FY25 revenue.37
Barua's assessment of that field, delivered on the Q4 FY26 call in response to an analyst question about further consolidation, was unusually blunt: three listed express players — Delhivery, Blue Dart, and Shadowfax — is a "sensible and appropriate" market structure, and of XpressBees he said he did not see "any structural advantages compared to the three listed companies" and did not "see a reason for them to exist."37 It is a striking thing for a CEO to say aloud about a competitor. It also functions as a statement of intent about where Delhivery believes remaining share will come from.
Quick commerce: substitute or channel? The genuine structural threat is not another parcel carrier. It is a different shape of commerce. Blinkit, Zepto, and Instamart deliver in ten to twenty minutes from dark stores holding local inventory. If an urban consumer buys a phone charger, a lipstick, or a t-shirt from a dark store rather than ordering it from a marketplace warehouse three states away, a Delhivery parcel simply never exists. Because metro deliveries are the densest and therefore cheapest parcels in the network, losing them at the margin is worse than losing an equivalent number of rural parcels.
Delhivery's stated posture is deliberate abstention from the part of quick commerce that would be most obviously adjacent. On the Q1 FY27 call in August 2026, Barua said the company has consciously stayed out of operating dark stores and doing last-mile delivery from them, because "the point-to-point nature of deliveries from dark stores offers limited network efficiencies for third-party logistics providers," and questioned "how the additional cost of very fast delivery will ultimately be absorbed."38 He noted that dark-store specialists had disappeared after an initial burst because the economics did not scale.38 Delhivery's chosen role is upstream: hauling goods into dark stores and fulfilment centres, where consolidation economics still apply.
That is intellectually coherent — and it is in tension with Delhivery Local's negative contribution margins, which is precisely the kind of internal inconsistency worth flagging. The company argues that rapid last-mile has no defensible economics for a 3PL, while simultaneously running a sub-two-hour service at a 50% negative contribution margin. Both can be defended as staged experiments. Neither should be described as strategy.
The 7 Powers audit. Applying Hamilton Helmer's framework honestly:
Scale economies — strong, but conditional. Fixed sortation and line-haul costs spread across a billion-plus parcels create a cost position no sub-scale independent can match. FY26's ROIC improvement to 16% in transport is the best evidence yet that the fixed-cost base is being absorbed.16 The condition, established in Section III, is utilisation.
Network economies — moderate, and often overstated. True network effects mean each additional user makes the service more valuable to other users. In logistics the effect is real but indirect: more volume means more density means lower cost, which is a scale effect operating through geography. The genuine network property is the dual-direction lane balancing between express and PTL, which no pure-play parcel or pure-play freight competitor can replicate. Call it moderate and improving.
Process power — strong, and underrated. A decade of resolved Indian addresses, delivery-beat data, and route history is not something a competitor buys. It is accumulated by operating. This is probably Delhivery's most durable and least visible advantage.
Counter-positioning — effectively gone. In 2013, incumbents could not serve e-commerce without cannibalising their B2B franchise. By 2026, Blue Dart runs surface express, Ekart sells externally, and Amazon sells its own network. Nobody is trapped by their business model anymore.
Switching costs — bimodal and mostly low. Near-zero in express, where APIs reallocate volume daily. Genuinely high in SCS, which is 7% of revenue. The weighted average is low.
Branding and cornered resource — absent. No consumer pays extra for a Delhivery label, and there is no scarce input the company exclusively controls.
Porter, briefly. Buyer power is high and is the defining feature of the industry. Supplier power is moderate — fleet owners and fuel are largely commoditised, but statutory wage floors are not, and labour is where the pressure sits today. New entrant threat is genuinely low at national scale; the capital and the loss-absorption required are prohibitive, which is why the entrants that matter are incumbents from adjacent positions rather than startups. Substitutes are the real question, and quick commerce is the substitute. Rivalry has moderated with consolidation but has not disappeared.
The Ecom Express play. Delhivery announced the acquisition of at least 99.4% of Ecom Express on a fully diluted basis for a consideration not exceeding ₹1,407 crore on 5 April 2025, received CCI approval on 17 June 2025, and completed the deal on 18 July 2025 — in time to run the combined network through the festive season.89[^41]
The price is the first thing to note. Ecom Express had once been valued at multiples of that figure and had filed for its own IPO before withdrawing. Buying a major national competitor for roughly ₹1,400 crore in cash, from a position of financial strength, is a materially better entry point than the Spoton deal represented. Delhivery framed the transaction as lower-risk and profitability-accretive, on the logic that incremental volumes improve utilisation of assets it already owns while overlapping facilities and central overheads get removed.39
The execution, so far, tells a mixed story that maps closely onto the Spoton lesson — with one crucial difference. Management did not try to merge two live networks in a single quarter. Client, technology, and operational processes were integrated within Q2 FY26; redundant network infrastructure and contracts were wound down through Q3 FY26.40 Network rationalisation was completed with only seven facilities totalling about 1.3 million square feet retained for long-term use, and roughly 1.1 million square feet exited; approximately 85% of Ecom Express's corporate and support costs were removed.41 Integration costs, originally guided at around ₹300 crore, came in below that estimate.41
The cost of that discipline showed up in the reported numbers. Q2 FY26 swung to a net loss of about ₹50 crore, reversing a small prior-year profit, on ₹90 crore of integration expense, and the stock fell 8% on the print.4243 Reported profit for FY26 as a whole came in around ₹153 crore — slightly below FY25's ₹162 crore — even though EBITDA doubled, because integration costs, depreciation on acquired assets, and lower other income absorbed the operating improvement.44 Management's presentation of profit "excluding Ecom Express costs" at a substantially higher level is legitimate as an analytical bridge, but the reported line is the one that reaches shareholders.
The verdict on the Spoton lesson, then: it appears to have been learned. This integration was sequenced, disclosed, and delivered under its own cost guidance, and volumes went up through it rather than collapsing — express shipments grew 43% year on year in the festive quarter that ran straight through the integration.22 That is the opposite of 2022 in the metric that matters most. What has not been proven is the second half of the thesis: that removing a price competitor produces better pricing. Realisation fell during exactly the period when a competitor was being removed. Consolidation has demonstrably improved Delhivery's cost position. It has not yet demonstrated any effect on its revenue per parcel.
VIII. Management, Governance & Institutional Capital Allocation
Sahil Barua does not fit the template of a conventional Indian public-company chief executive. Rather than leaning on broad macro optimism, he frequently uses earnings calls to challenge analyst assumptions and offer unvarnished commentary on competitors — asserting that XpressBees lacks structural advantages and framing Amazon’s third-party logistics push as old infrastructure in new packaging.3734 Whether this approach represents refreshing candor or a governance risk depends on an investor's perspective. What remains indisputable is that his blunt framing makes management claims explicitly testable.
The executive leadership team surrounding Barua exhibits notable stability for a growth company. Co-founder Kapil Bharati has directed engineering, sorter integration, software automation, and machine-learning routing engines since inception. Co-founder Suraj Saharan returned to an executive role on the board in May 2025 as a whole-time director overseeing human resources and partner networks. Operations are managed by Ajith Pai, while Sandeep Barasia leads enterprise sales and commercial partnerships.
The credibility record. Evaluating management credibility requires tracking executive commitments against operational delivery over time.
The negative record is well-documented. Management initially framed the Spoton acquisition as immediately accretive before operational bottlenecks created a multi-quarter earnings strain, while public projections in 2022 consistently ran ahead of execution capabilities.
Recent performance shows improved alignment between guidance and execution. Following the Spoton disruption during the first quarter of fiscal 2023, Barua acknowledged internal execution failures directly without attributing losses to macroeconomic headwinds. Subsequent corporate targets have broadly met expectations: annual part-truckload margin expansion of 1.5 to 2 percentage points has tracked target trajectories; express service EBITDA margins reached the guided 16% to 18% band; Ecom Express integration expenses remained below the initial ₹300 crore budget; and positive free cash flow of ₹89 crore in fiscal 2026 arrived ahead of internal schedules.144116
However, the composition of reported net income warrants careful examination. Earnings quality has relied significantly on treasury income generated from the company's substantial cash balances. In the fourth quarter of fiscal 2026, non-operating income accounted for roughly ₹59 crore of the ₹72.3 crore reported net profit.44 In the third quarter of fiscal 2026, non-operating income exceeded profit before tax, indicating that core operational activities were not the primary driver of reported bottom-line profitability.32 While treasury returns on liquid reserves represent legitimate earnings, sustained operational cash flows provide a more reliable indicator of underlying business strength. In this context, fiscal 2026 positive free cash flow offers a clearer benchmark of financial recovery than reported net profit alone.
Governance in a company with no owner. Delhivery operates under a promoterless structure with zero promoter shareholding since its initial public offering. Institutional funds hold the majority of equity. By mid-2026, SoftBank's SVF Doorbell reduced its stake to 7.61% following a gradual exit from 9.67% in September 2024; Nexus Venture Partners' combined vehicles decreased to approximately 3.55% by April 2026; and both Carlyle and CPPIB completed major block transactions in 2023 and 2024, respectively.454647 Executive ownership remains modest, with Barua holding a low single-digit percentage stake.
This ownership structure creates distinct governance trade-offs.
On one hand, the absence of a controlling promoter family eliminates traditional governance risks such as related-party transactions, promoter share pledging, or opaque family-group capital allocation. The board remains directly accountable to institutional shareholders.
On the other hand, the absence of an anchor shareholder creates persistent market friction. Ongoing equity sales by early venture investors maintain continuous supply pressure without an offsetting strategic buyer. Furthermore, limited equity ownership restricts management's ability to signal operational conviction through open-market share purchases, leaving a promoterless structure with modest executive ownership structurally exposed to potential activist campaigns or unsolicited acquisition proposals.
An activist shareholder could assemble a clear list of operational and valuation concerns: equity trading below its May 2022 offering price four years post-listing;10 over ₹4,500 crore in cash reserves earning treasury yields while return on equity lags peer metrics such as Blue Dart;1632 corporate overhead representing roughly 9.3% to 9.4% of revenue, which management acknowledged on the Q1 FY27 call delays operational leverage;14 and a new hyperlocal initiative operating at a negative 50% contribution margin. Regardless of whether these factors stem from transitional investments, they present clear focal points for institutional scrutiny.
Executive turnover. Management experienced key leadership changes in late 2025. Chief Financial Officer Amit Agarwal resigned in November 2025 after a thirteen-year tenure, citing personal reasons. Vivek Pabari, who led financial execution on the public offering and both the Spoton and Ecom Express acquisitions, assumed the chief financial officer role on January 1, 2026.48 Concurrently, independent director Aruna Sundararajan stepped down following a government appointment, prompting new board appointments.49 While CFO transitions during major integration periods carry operational risk, internal succession by an executive involved in primary M&A transactions provided structural continuity without triggering financial restatements or reporting delays.
IX. Playbook: Business & Investing Lessons
Certain businesses are easier to admire operationally than to own as investments. They construct infrastructure a market visibly requires, resolve localized operational friction, and maintain capable leadership, yet generate minimal equity returns for long periods. Delhivery has fit that description since its 2022 public listing. The lessons below emerge from the divergence between operational scaling and flat market valuation, where the core strategic insights reside.
Build for the market you have, not the one in the textbook. Delhivery's foundational insight was operational rather than purely technological: a logistics network built for India had to be designed around specific local constraints. Cash collection at the doorstep, descriptive landmark-based addresses, high return-to-origin rates, and a transport fleet owned by thousands of independent operators required custom software solutions without direct Western analogues. Entrants that imported standardized international logistics templates struggled to adapt. In emerging markets, defensible capabilities are typically built around solving local operational friction rather than deploying global best practices.
Network M&A is an organ transplant, not a plug-in. The Spoton transaction demonstrates the risks of merging active freight networks. Combining live networks requires unified shipping data protocols, adequate gateway capacity for peak volumes, and retention of key account relationships. Disruption across all three areas cost Delhivery roughly two years of growth momentum in part-truckload freight. The approach applied during the 2025 Ecom Express acquisition — unifying client systems before winding down physical infrastructure, establishing clear integration expense guidance, and protecting network stability over short-term earnings — offers a contrasting model. In network industries, deliberate sequencing and parallel operation are prerequisites for successful integration execution.
Two engines fill one truck. Delhivery's core structural advantage relies on combining light, directionally imbalanced B2C parcel flows with heavy, predictable B2B freight on shared linehaul routes. Mitigating empty backhaul capacity directly targets transport linehaul expenses, the largest cost line in the network. This operational synergy provided the strategic rationale for expanding into part-truckload freight, creating a dual-engine network model that pure-play parcel or pure-play freight operators cannot easily replicate without building dual-segment capabilities.
Zero-promoter governance demands relentless proof. Operating without a controlling promoter group or significant founder equity leaves a company without an anchor shareholder base during periods of market volatility. While a promoterless structure eliminates traditional governance risks like related-party transactions or share pledging, it subjects quarterly execution to immediate public market repricing. For investors, professionally managed structures do not inherently underperform, but they elevate the required standard of consistent operational delivery.
Beware the metric that grows while unit pricing falls. Expanding parcel volumes alongside declining revenue per shipment indicates that volume growth is accompanied by price discounting, shifts toward lighter parcel mixes, or both. Cost-advantaged operators can sustain this dynamic if unit cost reductions outpace price compression. However, this structure shifts the investment thesis entirely onto continuous operational cost reduction, requiring rigorous verification of cost-per-parcel trends rather than relying solely on headline volume growth.
Consolidation buys cost efficiency, not necessarily pricing power. Market consolidation is often expected to restore industry pricing power. However, acquiring Ecom Express improved gateway utilization, eliminated roughly 85% of redundant corporate overhead, and lowered unit operating costs, even as realization per parcel continued to decline. Independent carrier consolidation does not alter the behavior of captive logistics networks like Ekart or Amazon Transportation Services, which establish benchmark pricing across the industry. Evaluating M&A impact requires analyzing structural market pricing power rather than assuming market share gains yield pricing leverage.
Watch what a company re-enters, not just what it enters. After exiting hyperlocal delivery in 2011 due to unfavorable economics, Delhivery re-entered the segment in 2025 with a sub-two-hour service operating at a disclosed negative 50% contribution margin. Re-entering a previously abandoned segment leveraging established network scale can be strategically justified, but it demands strict economic scrutiny. Tracking contribution margins and path to unit profitability is far more critical than evaluating top-line gross merchandise value.
Free cash flow provides the baseline metric in capital-intensive logistics. Over the four years following its public listing, Delhivery's reported net income was influenced by non-recurring integration expenses, asset depreciation schedules, and treasury income from IPO cash reserves. While adjusted EBITDA and net profit reflected accounting adjustments and non-operating income, positive free cash flow after capital expenditures — achieved in fiscal 2026 — provided the first clear empirical validation of self-sustaining network economics.
X. Risk Radar & Skeptical Investor Stress Test
Evaluating a company's risk profile requires identifying specific operational mechanisms—the direct sequence of cause and effect through which revenue is eroded or expenses expand. Broad generalizations regarding competitive intensity or macroeconomic headwinds offer limited analytical value. The following analysis focuses strictly on risks where the causal mechanism is identifiable and backed by disclosed financial and operational metrics.
Quick-commerce substitution. The operational mechanism is inventory placement rather than delivery speed alone. Every stock-keeping unit a brand places into an urban dark store represents an item that no longer moves as an express parcel from a regional fulfillment center. The categories most exposed—personal care, small electronic accessories, and apparel—are precisely those driving Delhivery's highest delivery density in metropolitan centers. Because metropolitan parcel routes yield the lowest unit delivery costs, volume substitution degrades network product mix even if aggregate shipment volumes remain steady. Management's assertion that dark-store last-mile delivery lacks viable third-party economics addresses who operates quick-commerce logistics, but it does not mitigate the volume loss when consumers shift away from standard regional parcel fulfillment.
Labor cost and the new codes. India's new labor codes took effect on April 1, 2026, standardizing wage definitions and extending social security obligations to delivery riders and drivers.50 For an organization employing over 75,000 workers alongside more than 82,000 partner agents, this represents a structural cost expansion.14 A critical asymmetry, highlighted by executive leadership during the Q1 FY27 earnings call, is that fuel expenditures feature contractual pass-through provisions while labor expenses do not.14 While diesel inflation is systematically repriced into client contracts—with over 97% to 98% of contracts revised for fuel adjustments by August 2026—statutory wage increases remain absorbed on Delhivery's income statement until contract renegotiation cycles.14 Combined fuel and wage headwinds cost approximately ₹30 crore to ₹35 crore in a single quarter,14 posing an immediate structural risk to medium-term margin expansion.
Marketplace externalization. Captive logistics networks operating at scale present a structural pricing risk. Because their core fixed-cost infrastructure is absorbed by parent marketplace volumes, captive networks can price external third-party capacity at marginal cost. Captive providers do not need to capture dominant market share to impact independent operators; establishing a lower reference price across the industry is sufficient to cap pricing. Monitoring whether realization per parcel continues to compress after the Ecom Express parcel mix effect normalizes will indicate whether captive networks are effectively setting baseline industry rates.
Integration and overhead drag. While execution of the Ecom Express acquisition proceeded with greater discipline than earlier transactions, financial integration costs persist. Cash integration expenses totaled ₹17 crore in Q1 FY27 alongside ₹30 crore in statutory profit and loss impacts, while asset depreciation continues to weigh on reported net income.14 Concurrently, corporate overhead representing between 9.3% and 9.4% of total revenue remains elevated for a business model premised on operating leverage.14
Demand deceleration and the operating-leverage trap. Delhivery's margin expansion thesis relies on parcel volume scaling into a fixed infrastructure base. Operating leverage functions symmetrically in reverse: if Indian e-commerce order growth decelerates from historical low-to-mid twenty percent rates toward mid-teen percentages, the company experiences both slower top-line expansion and diminished facility utilization, raising per-parcel handling costs. Operational bottlenecks during Q1 FY23 demonstrated how fixed-capacity underutilization accelerates margin contraction. Consequently, maintaining express parcel volume growth within management's target band of 20% to 30% remains essential to sustaining network cost efficiency.
Execution concentration in a single management regime. Key operational capabilities—including proprietary address resolution, dynamic routing engines, mesh gateway topology, and dual-engine linehaul integration—have been designed and refined by the core founding technical team. While this continuity supports technical execution, it creates key-person concentration risks. Leadership transitions, such as the chief financial officer succession during a major network integration, underscore the importance of broadening organizational execution depth.
What a short seller would say. The skeptical investment thesis synthesizes several disclosed vulnerabilities: a capital-intensive logistics business operating with limited pricing power, where reported net profitability relies significantly on interest income from liquid treasury reserves rather than core operations; return on equity that trails established express peers; major marketplace clients offering competing third-party freight services; a rapid commerce venture operating at a negative 50% contribution margin; and equity trading below its 2022 initial public offering price while early venture sponsors systematically reduced their holdings. Addressing this skeptical case requires demonstrating sustained operational cash flow generation, realization stability, and disciplined execution across newly integrated networks.
XI. Bear vs. Bull Case & Future Outlook
The bull case, stated at its strongest.
Industry consolidation has largely materialized. Delhivery has absorbed Ecom Express, Shadowfax listed at a discount while remaining sub-scale in part-truckload freight, XpressBees continues to sustain operational losses that challenge its standalone viability, and Blue Dart remains focused on premium air express. Having three primary independent operators in a market of India's scale establishes an industry structure that historically fosters rational pricing behavior.
Operating leverage is now reflected in financial results rather than forward projections. In fiscal 2026, adjusted EBITDA nearly doubled to ₹764 crore on 18% revenue growth, transport return on invested capital rose from roughly 5% to 16%, capital expenditure intensity declined to 4.7% of revenue, and free cash flow turned positive ahead of corporate targets.16 Together, these metrics indicate that the network has transitioned from consuming capital to generating cash—a critical milestone for a fixed-infrastructure logistics platform.
The part-truckload freight segment represents a significant long-term growth driver. The business benefits from contractual pricing indexed to fuel costs and a path toward management's long-term margin target of 16% to 18%, supported by tax enforcement and digital tracking that shift volume from unorganized truckers to national networks.14 Furthermore, expanding B2B freight volumes improves overall network efficiency by filling return-leg haulage capacity for express parcels.
Finally, the balance sheet provides a distinct competitive buffer. Reserve cash balances exceeding ₹4,500 crore allow Delhivery to navigate operational downturns, fund targeted acquisitions, or invest through economic cycles—strategic flexibility that un-capitalized independent peers lack.16
The bear case, stated at its strongest.
Sustained volume expansion without pricing power presents an ongoing margin challenge. In the first quarter of fiscal 2027, express parcel volumes expanded 55% while segment revenue grew 33%, indicating a continued decline in average realization per shipment.14 This follows a 13.7% year-over-year decline in average parcel realization during the third quarter of fiscal 2026.27 While parcel mix shifts account for part of this compression, they do not fully explain a four-year trend. For a fixed-cost logistics carrier lacking pricing power, valuation relies entirely on reducing unit handling costs faster than per-parcel realizations compress, even as labor expenditures rise under new statutory wage codes without contractual pass-through provisions.
Underlying profit quality also warrants scrutiny. Reported net profit for fiscal 2026 declined slightly year-over-year despite a near-doubling of EBITDA, with treasury returns on liquid reserves accounting for a substantial portion of bottom-line earnings.4432 The divergence between expanding EBITDA and flat net income reflects ongoing asset depreciation, M&A integration charges, and normalizing treasury yields—costs inherent to maintaining a capital-intensive automated sortation network.
Customer concentration dynamics remain unfavorable. Delhivery's primary client base consists of major e-commerce platforms using automated multi-sourcing algorithms, with two major marketplace operators actively offering external third-party logistics services in direct competition.3133 This structural dynamic has limited carrier pricing power for over a decade, with few mechanisms available to alter platform procurement behavior.
Finally, consolidated returns on capital remain subdued. While transport return on invested capital reached 16%, consolidated group return on equity remains in low single digits, constrained by large cash balances and developing segments that have not yet achieved target return thresholds.32 For an enterprise deploying substantial fixed capital, demonstrating durable group-level economic returns remains an ongoing requirement.
Weighing the evidence. The historical data supports a more tempered investment thesis than headline market narratives suggest. Delhivery has demonstrated network scale, unit cost efficiency, and improved post-acquisition integration discipline. However, the company has not established structural pricing power, and empirical realization trends argue against it. While the operating model has demonstrated an ability to generate positive free cash flow, generating strong returns on total invested capital—after fully accounting for facility depreciation—remains unproven. Consequently, the cost-leadership thesis is supported by execution evidence, whereas pricing power and group-level return expansion remain open analytical questions.
Key operational metrics to track.
Realization per express parcel. Revenue per shipment serves as the primary indicator for assessing industry pricing dynamics. Once the Ecom Express parcel mix normalizes during the second half of fiscal 2027, stabilizing or increasing realization per parcel would offer initial evidence that market consolidation has generated pricing discipline. Conversely, continued pricing compression would indicate that scale economies in Indian express logistics translate into unit cost reductions rather than pricing power, placing a ceiling on long-term segment margins.
Part-truckload freight tonnage and segment margin. Performance in B2B freight will demonstrate whether post-acquisition operational integration has created a high-margin asset. Management has outlined targets to exit fiscal 2027 with segment EBITDA margins of 15% to 15.5%, aiming for a long-term range of 16% to 18% through annual margin expansion of 1.5 to 2 percentage points.14 This quantitative benchmark provides a clear measure for evaluating execution discipline.
Free cash flow after capital expenditures. Generating ₹89 crore in positive free cash flow in fiscal 2026 provides a foundational benchmark, as free cash flow reflects underlying operational execution without adjustment for treasury yields or non-cash accounting items.16 Sustaining positive cash generation through statutory wage inflation and planned capital expenditures will determine whether the business model can consistently deliver long-term returns on capital.
XII. Epilogue & Future Outlook
What would long-term success look like for Delhivery? On the trajectory management outlines—express parcel volumes compounding at 20% to 30% annually, express service margins reaching 16% to 18%, part-truckload margins expanding toward that same band, supply chain services building toward an ₹1,800 crore commercial pipeline, and capital expenditure intensity remaining below 5% of revenue—the company would move well over 1.5 billion parcels a year within five years, operate India's largest organized B2B freight network alongside it, and consistently generate cash rather than consume it.1416 That represents a coherent, internally consistent operational plan, and it aligns with what management has outlined for several years.
The alternative scenario is equally plausible. Shipment volumes continue to expand, but average realization per parcel keeps falling, statutory wage inflation outpaces contractual price adjustments, and captive logistics networks dictate pricing across major accounts. Under those conditions, the company risks remaining an indispensable piece of national logistics infrastructure that fails to earn economic returns commensurate with the capital it absorbed. Historically, numerous capital-intensive transport and telecommunications networks have occupied that exact position: essential to commerce, yet difficult for equity investors.
Which outcome prevails depends less on India's overall e-commerce expansion rate and more on industry pricing dynamics. That trajectory will manifest first in a single metric: revenue per parcel.
Time horizons provide critical context for this evaluation. By September 2026, Delhivery has operated for fifteen years and spent four as a public company. That timeframe is sufficient to assess operational execution, where the management record includes both initial integration missteps and subsequent operational turnarounds. However, four years post-listing is insufficient to evaluate long-term returns on a capital base that is still expanding. Automated sortation infrastructure depreciates across extended cycles; a network's true cost structure becomes clear only after a full asset replacement cycle is funded from operating cash flow rather than equity offerings. Consequently, viewing recent improvements in transport return on invested capital as a finalized validation reflects an incomplete business cycle.
Furthermore, the most critical strategic variable remains outside management's control. Whether Indian express logistics consolidates into a three-player oligopoly with disciplined pricing, or remains a price-compressed sector capped by captive marketplace networks, depends primarily on decisions made by Amazon and Flipkart. Delhivery can optimize its facility utilization, service mix, and balance sheet reserves, but it cannot dictate market clearing prices. Any investment thesis assuming guaranteed pricing power overlooks the structural dynamics of the industry.
The company has expanded significantly from its origins in a Gurgaon parking lot, where co-founders evaluated local delivery hurdles. What emerged instead is a major physical layer for Indian digital commerce—comprising automated sortation centers, dynamic linehaul routes, geocoded address mapping, and financial reconciliation ledgers that connect regional merchants with nationwide consumers. Building that physical infrastructure represented a complex operational undertaking.
Whether that physical infrastructure ultimately translates into a high-return business remains the core question public markets are evaluating.
References
-
Delhivery delivers 1 billion parcels in FY26, revenue jumps to Rs 10,486 crore — Indian Startup News, 2026-05 ↩
-
Delhivery's Rs 5,235-cr IPO to open on May 11; price band set at Rs 462-487 — Business Standard, 2022-05-05 ↩↩
-
Delhivery IPO ends with 1.63x subscription — Business Standard, 2022-05-16 ↩↩
-
Delhivery reports turnaround Q4 performance — Business Standard, 2025-05-17 ↩↩
-
Delhivery jumps post Q4; achieves first full year of PAT profitability — Business Standard, 2025-05-19 ↩↩↩↩
-
Delhivery to acquire express logistics rival Spoton for $200 million — Indian Transport & Logistics News, 2021 ↩↩
-
Logistics firm Delhivery to acquire Ecom Express in Rs 1,407 crore deal — Business Standard, 2025-04-05 ↩↩
-
Delhivery share rises 2% on CCI nod to acquire Ecom Express for Rs 1,407 cr — Business Standard, 2025-06-18 ↩↩
-
Delhivery (NSE:DELHIVERY) Market Cap & Net Worth — StockAnalysis ↩↩↩
-
Delhivery joins the unicorn club with SoftBank-led $413 million funding — Business Today, 2019-03-25 ↩
-
Logistics firm Delhivery raises $277 million, now valued at $3 billion — Business Standard, 2021-05-31 ↩
-
Delhivery Q1 FY27 slides: volumes surge 55% as margins compress — Investing.com, 2026-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Delhivery Ltd Q1 FY23 Earnings Concall Transcript — AlphaStreet, 2022-08 ↩↩↩↩↩↩↩
-
Delhivery Limited Q4 and FY26 Earnings Report — InvestyWise, 2026-05 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Logistics startup Delhivery files DRHP with Sebi for Rs 7,460 cr issue — Business Standard, 2021-11-02 ↩↩
-
Supply chain firm Delhivery acquires Spoton Logistics — Business Standard, 2021-08-25 ↩
-
Delhivery acquires Spoton to boost B2B capabilities — Delhivery press release, 2021 ↩
-
Delhivery Q1 results: Net loss widens to Rs 399 cr, total income rises 32% — Business Standard, 2022-08-08 ↩↩
-
Analysts bearish on Delhivery as volumes, integration costs weigh on Q1 — Business Standard, 2022-08-10 ↩
-
Delhivery makes listless debut; opens 1% higher against issue price — Business Standard, 2022-05-24 ↩
-
Delhivery enters top 100 most-valued firms' club; m-cap tops Rs 50,000 cr — Business Standard, 2022-07-21 ↩
-
Delhivery plunges 13% post September quarter business update — Business Standard, 2022-10-20 ↩
-
Delhivery 3QFY26 Result Update — Motilal Oswal Financial Services, 2026-01-31 ↩↩↩
-
Delhivery posts its first full-year profit as partial truckload services boom — YourStory, 2025-05 ↩↩↩
-
Delhivery launches rapid commerce with 2-hr delivery service in Bengaluru — Business Standard, 2025-01-16 ↩
-
Delhivery Launches Shared Dark Stores for Rapid Same-Day Deliveries — Logistics Insider ↩
-
Amazon opens its logistics network to third-party businesses — Entrackr, 2026 ↩↩
-
Delhivery Falls as Amazon Expands Logistics Services — Asia Business Outlook, 2026 ↩↩↩↩↩
-
Flipkart, Amazon Flex Logistics Muscles; Will It Bring New Growth Levers? — Inc42 ↩↩
-
Delhivery CEO Sahil Barua calls Amazon's 3PL push "old product in new wrapper", questions XpressBees edge — Entrackr, 2026-05 ↩↩
-
Shadowfax IPO Listing Review: Subdued Debut, Valuation Check & Outlook — Sahi, 2026-01 ↩
-
Shadowfax IPO: From Hyperlocal Challenger to India's Logistics Powerhouse — Qualcomm Ventures, 2026 ↩
-
No reason for XpressBees to exist: Delhivery's Sahil Barua — MediaNama, 2026-05 ↩↩↩
-
Delhivery flags pressure on outsourced quick-commerce logistics — Indian Transport & Logistics News, 2026-08 ↩↩
-
Ecom Express' Acquisition To Boost Profitability, Poses Lower Risks: Delhivery — Inc42, 2025 ↩
-
Delhivery Limited Q4 FY26 earnings call highlights — Yahoo Finance, 2026-05 ↩
-
Delhivery trims Ecom Express integration costs below Rs 300 cr estimate — Indian Transport & Logistics News, 2025-11 ↩↩↩
-
Delhivery posts 17% revenue growth in Q2 FY26 but slips into Rs 50 crore loss amid Ecom Express integration — Indian Startup News, 2025-11 ↩
-
Delhivery slumps 8% even as analysts affirm 'bright outlook' after Q2 loss — Business Standard, 2025-11-06 ↩
-
Delhivery revenue grows 30% in Q4 FY26; profit remains flat — Entrackr, 2026-05 ↩↩↩
-
After Alpha Wave & Nexus, SoftBank Pares Stake In Delhivery To 7.61% — Inc42, 2026 ↩
-
Carlyle Group sells 18.4 million shares of Delhivery for Rs 710 crore — Business Standard, 2023-06-22 ↩
-
CPPIB sells 2.8% stake in Delhivery for Rs 908 crore via open market — Business Standard, 2024-04-24 ↩
-
Delhivery appoints Vivek Pabari as new CFO, Amit Agarwal steps down — Indian Transport & Logistics News, 2025-11 ↩
-
Delhivery Announces CFO Resignation and Board Member Departure — ScanX, 2025-11 ↩
-
Delhivery: Growth Peaks Amid Margin Pressure & Labor Code Risk — Whalesbook, 2026 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube