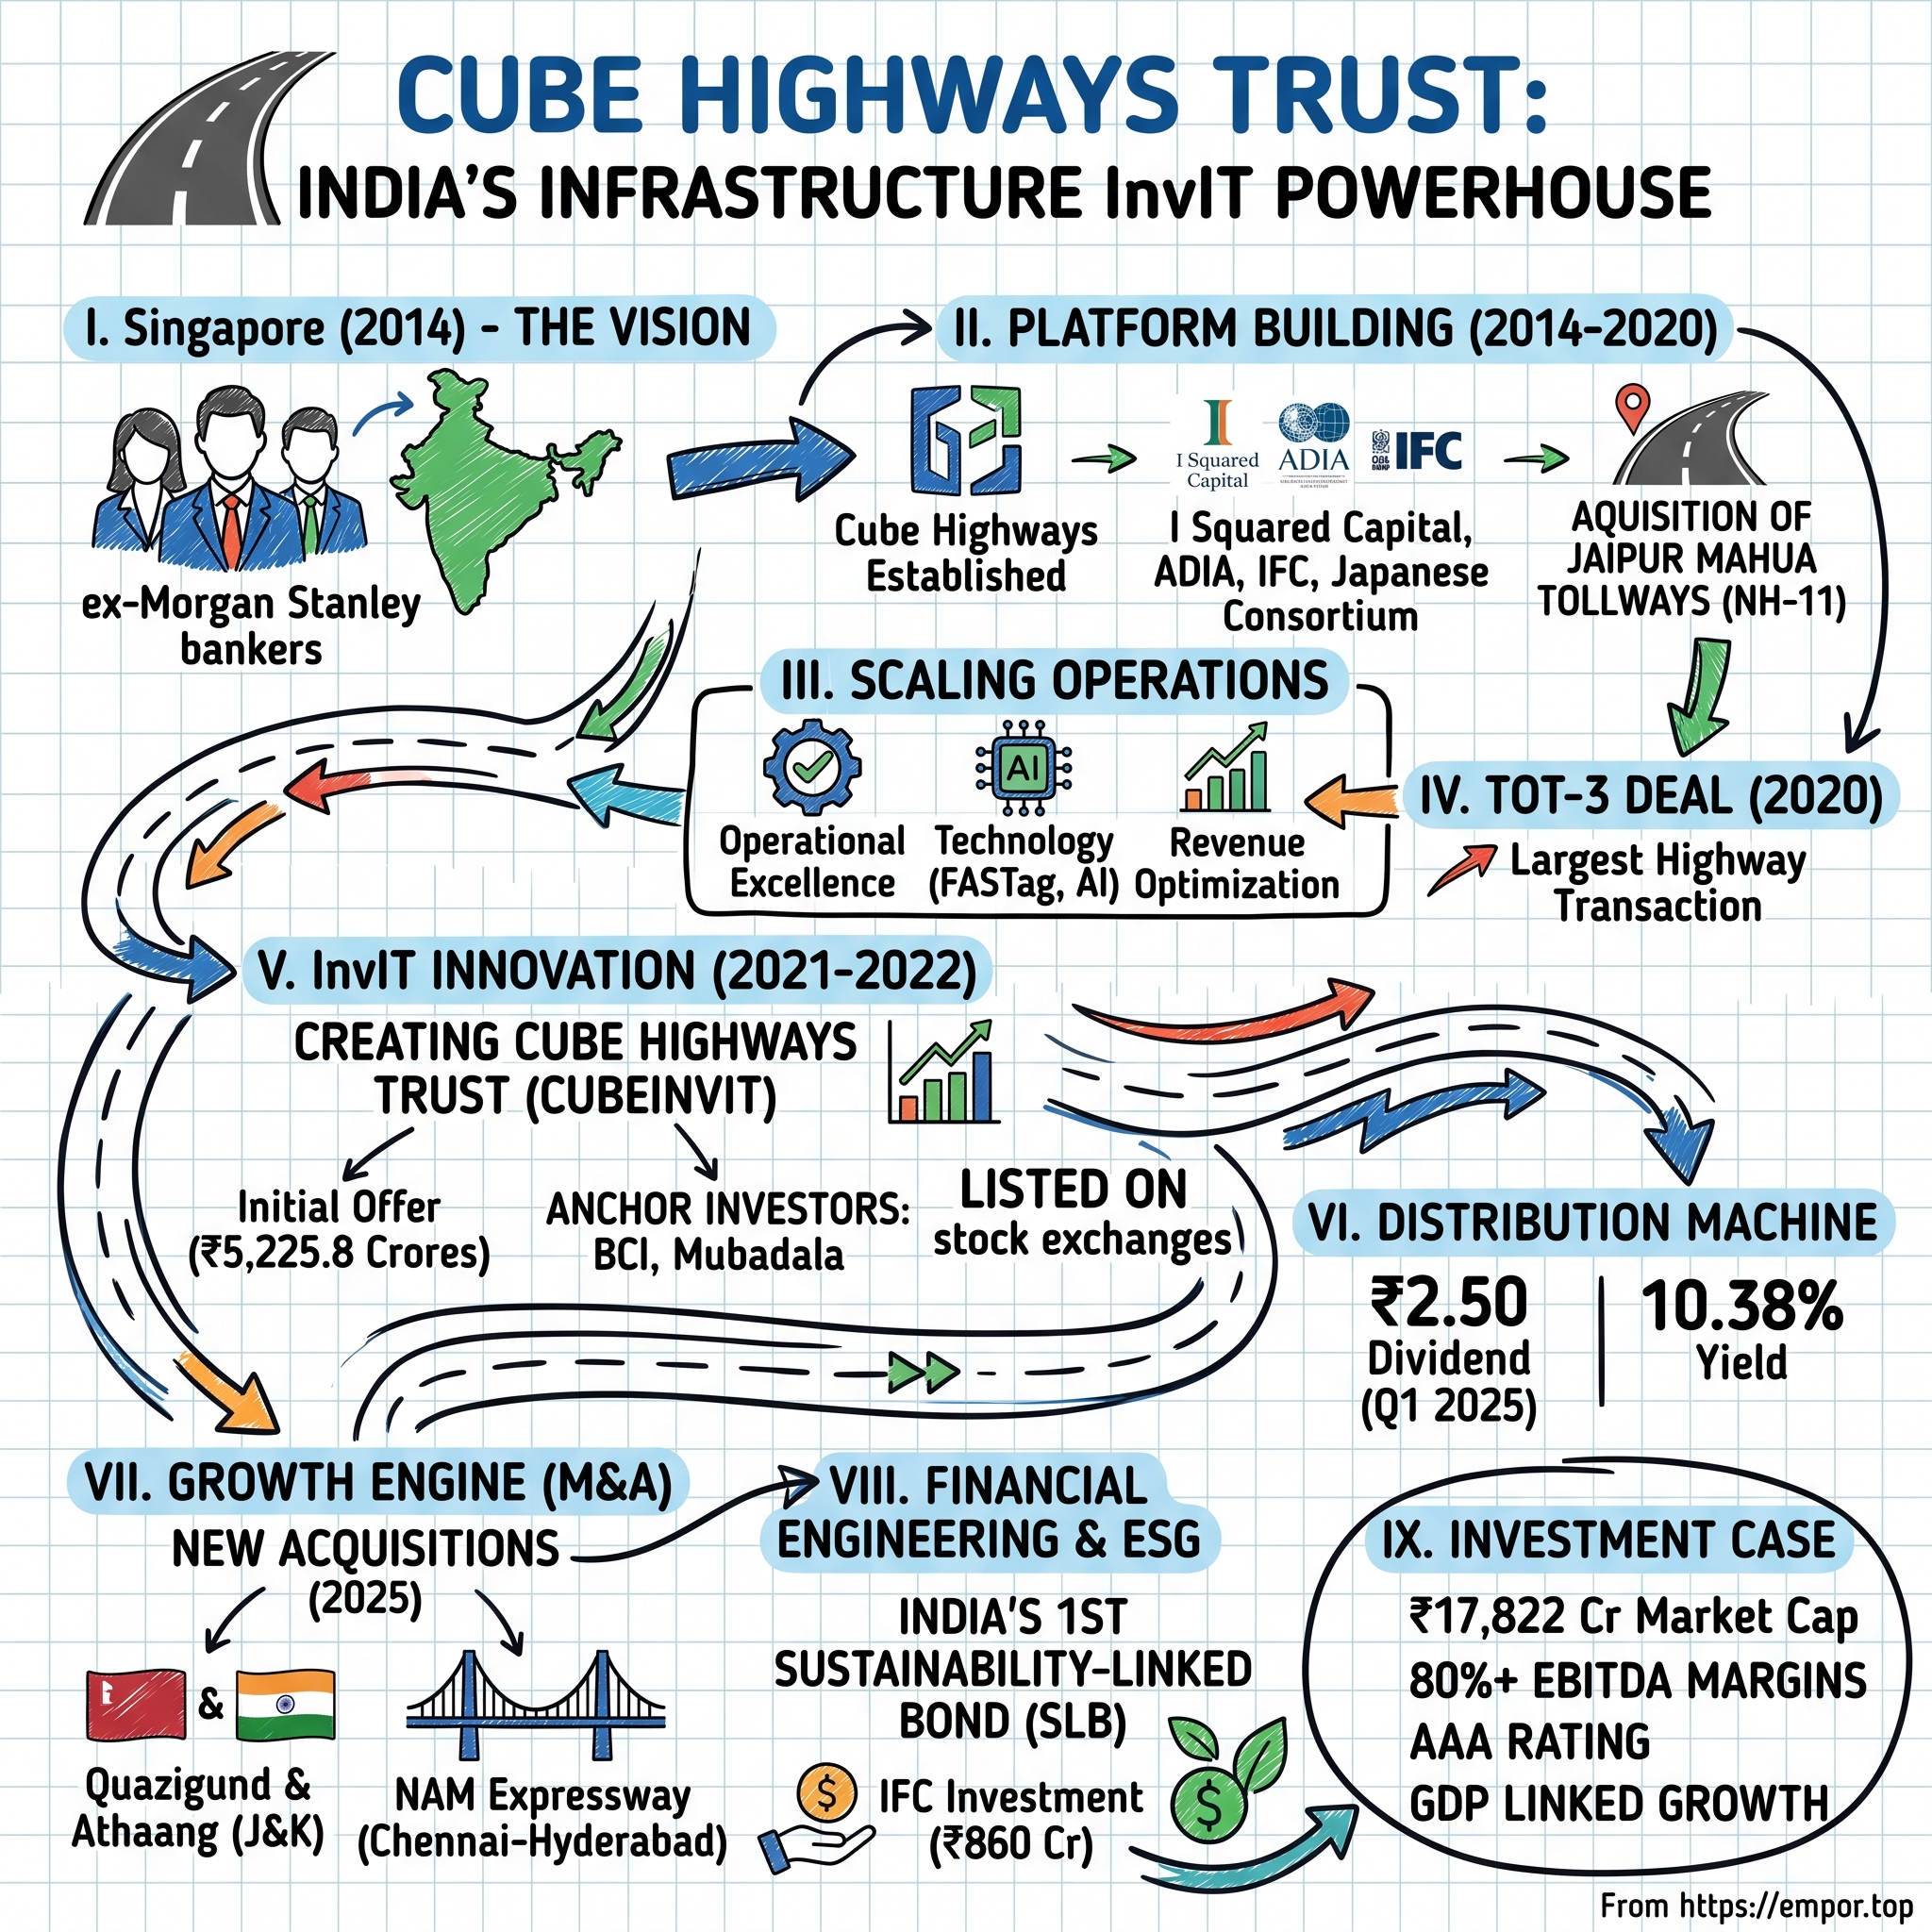
Cube Highways Trust: India's Infrastructure InvIT Powerhouse
I. Introduction & Episode Roadmap
On July 31, 2026, Cube Highways Trust (ticker CUBEINVIT) completed India's first conversion of a privately placed, listed infrastructure investment trust into a fully public entity. While its units had traded on the National Stock Exchange and BSE since April 2023, the transaction altered its legal status through a ₹5,000 crore offer for sale that was subscribed more than nine times over.141516
The units opened at ₹155 and closed at ₹156.88 on the BSE, representing a 2.7% gain over the ₹152 offer price.16 The modest debut reflected the core nature of the vehicle: Cube Highways Trust is built not for trading volatility, but for predictable quarterly cash distributions per unit.
At its core, the trust functions as a consolidated holding vehicle for mature toll roads. Created by Miami-headquartered infrastructure private equity firm I Squared Capital, the Singapore-incorporated platform spent roughly a decade acquiring operating Indian toll roads from over-leveraged domestic contractors and government bodies. The platform wrapped 27 assets—spanning 2,005 kilometres, 8,754 lane kilometres, across 12 states and one union territory—into a trust regulated by the Securities and Exchange Board of India (SEBI), placing units with pension funds, insurers, and public investors.1 As of March 31, 2026, the portfolio carried assets under management of ₹36,842 crore and outstanding borrowings of approximately ₹17,665 crore.117
Contrary to frequent market shorthand, Cube is not India's largest road InvIT. As of September 30, 2025, IRB Infrastructure Trust held an enterprise value of approximately ₹63,574 crore and the NHAI-sponsored National Highways Infra Trust stood at ₹47,968 crore, both exceeding Cube's ₹35,913 crore.2 Cube's accurate distinction is that it is India's largest public road InvIT by asset base—a status established by its July 2026 conversion rather than superior scale relative to private peers.16 Disentangling this scale distinction is critical because competitive advantage in this sector relies heavily on portfolio size.
The trust represents a broader model: the financialization of physical infrastructure in an emerging market. Institutional global capital—including the Abu Dhabi Investment Authority, British Columbia Investment Management, Mubadala, the International Finance Corporation, and a Mitsubishi-led Japanese consortium—sought exposure to operating toll roads rather than development-stage projects. By focusing on operational highways past the phase of land acquisition disputes and construction delays, these investors targeted stable toll cash flows.89[^12] The InvIT framework provided the legal container to aggregate these assets at scale.
This structure aligns with India's infrastructure policy strategy. Under SEBI regulations, an InvIT must distribute at least 90% of its net distributable cash flow to unitholders.2 The mandate transforms a portfolio of long-term road concessions into yield-generating instruments linked to inflation-indexed toll rate revisions. The model allows the government to recycle capital into greenfield projects while institutional unitholders receive income without taking on early-stage construction risk.
The analysis follows a structured path. It begins with the platform's origins—a private equity sponsor founded in 2012 and its initial Indian road acquisition in December 2014 from a Malaysian developer.46 It then examines the growth phase, culminating in the ₹5,011 crore Toll-Operate-Transfer (TOT) Bundle 3 auction.[^9] The discussion details the financial engineering behind the private-to-public conversion, the mechanics of toll revenue generation, competitive dynamics, and operational risk factors—including a September 2025 regulatory action. Finally, the analysis evaluates the capital structure, bull and bear cases, and key operational metrics.
An important analytical consideration governs InvIT evaluation: because the structure acts primarily as a pass-through entity, reported net income rarely reflects operational health. Cube reported net accounting losses in three of its first four years as a listed trust, generating its first full-year accounting profit in FY26.217 Throughout that period, the trust maintained uninterrupted quarterly cash distributions. Evaluating the platform requires focusing on distributable cash flow, leverage metrics, and remaining concession life rather than net profit.
 Subscribe on LinkedIn
II. The Origins: I Squared Capital & The Indian Highway Opportunity (2012–2015)
In the years following the global financial crisis, India constructed an immense network of highways while consuming vast amounts of private equity capital. The two outcomes were closely linked.
Under the Build-Operate-Transfer model, private developers bid for concessions to construct highways and collect toll revenues over two to three decades to recover their investments. While structurally sound on paper, aggressive competition drove down bidding margins. Developers subsequently faced unacquired land, multi-year delays for environmental clearances, and overly optimistic traffic projections. Infrastructure conglomerates such as GVK, Lanco, IVRCL, and Jaypee were left holding non-revenue-generating construction assets alongside mounting debt service obligations. Public sector lenders ultimately absorbed these non-performing loans, creating one of the decade's primary macroeconomic challenges.
Amid this stress in the sector, a newly established private equity firm identified an entry point.
I Squared Capital was founded in 2012 by former leaders of Morgan Stanley's infrastructure group, including Sadek Wahba and Gautam Bhandari.5 The firm focused on middle-market global infrastructure across energy, utilities, transport, and digital assets. While the firm later expanded to roughly $60 billion in assets under management across nine global offices, including New Delhi, in 2013 and 2014 it was seeking its initial platform investments.4
The firm's core thesis addressed a specific market imbalance: India faced a shortage not of highway assets, but of well-capitalized balance sheets structured for long-term asset ownership. Operational national highways under multi-decade concessions presented stable asset profiles. However, contractor-owners required liquidity to fund new construction pipelines, placing them in the position of distressed sellers—a favorable dynamic for institutional buyers.
On December 8, 2014, I Squared signed an agreement through its global infrastructure fund to acquire Jaipur Mahua Tollways, a 109-kilometer operational stretch of National Highway 11 in Rajasthan operating since 2009 under a 25-year concession, from Malaysian conglomerate IJM Corporation. The transaction structure provided 100% ownership, with 74% closing immediately and the final 26% subject to approval from the National Highways Authority of India (NHAI).6 This established regulatory approval as a key component of the platform's acquisition model.
The acquisition closed in May 2015, with the holding entity incorporated in Singapore rather than India.9 Singapore offered a creditor-friendly legal framework, governance standards, and arbitration mechanisms for international institutional co-investors alongside the sponsor. Additionally, Cube Highways was established as an active operating platform rather than a passive holding vehicle, creating an internal project management unit and hiring dedicated highway engineers. The group subsequently built an advisory team of over 300 transportation specialists within a broader organization of more than 600 personnel.9 This operating capability forms the basis of the platform's competitive position examined later in this analysis.
Capital deployment proceeded in distinct phases. The International Finance Corporation (IFC), the private-sector arm of the World Bank Group, joined as an early platform partner, providing institutional diligence standards alongside capital.9 In December 2017, a Japanese consortium led by Mitsubishi Corporation—comprising the Japan Overseas Infrastructure Investment Corporation for Transport and Urban Development, East Nippon Expressway, and Japan Expressway International—acquired a minority stake, introducing operational expertise from Japan's toll road network.9 In 2018, the Abu Dhabi Investment Authority (ADIA) invested to gain exposure to long-term Indian infrastructure growth, subsequently committing additional capital.8
Falsification pass — was the early underwriting actually disciplined?
A central premise of the Cube platform is that asset selection outperformed broader market standards. Examining historical execution reveals a more nuanced record.
The principal constraint on early underwriting stemmed from state-level concessions and local political dynamics. Indian toll roads remain susceptible to regional policy shifts, including vehicle toll exemptions, local public protests closing plazas, and traffic leakage via unmonitored local bypasses. Disclosures highlight this operational challenge: at the Luharli plaza on the Ghaziabad–Aligarh Expressway, traffic diverted around collection points until physical split plazas were installed to enforce tolling.19 This demonstrated that realized toll revenues depend significantly on surrounding road network geometry and local regulatory enforcement.
This operational experience shaped subsequent asset selection. Of Cube's 27 portfolio assets, 26 operate under central NHAI concessions, with only one governed by a state authority.2 By comparison, peer entity Shrem InvIT holds 17 state-level concessions out of 37 portfolio assets.2 Cube's concentration in central concessions reflects an explicit shift toward standardized federal contracts and a single counterparty framework.
Consequently, the platform's performance record reflects strategic adaptation rather than flaw-free initial forecasting. When faced with state-level concession risks, Cube adjusted its portfolio criteria to eliminate state counterparty exposure. However, this strategy concentrated platform operations under a single federal regulatory framework—a structural dependence that created specific vulnerabilities in September 2025.
III. The M&A Machine: Building Scale Through Distress & TOT Bundles (2015–2021)
Picture the deal pipeline of an Indian roads platform in 2016. It did not originate from investment bankers pitching auctions. Instead, it was driven by spreadsheets of distress: listed contractors approaching covenant breaches, lender consortia seeking exits from single-asset special purpose vehicles, and promoters needing immediate cash to fund equity commitments on newly awarded projects.
Cube industrialized that process. Between 2015 and 2021, the platform assembled a portfolio one special purpose vehicle (SPV) at a time, acquiring operating road companies from developers who prioritized immediate liquidity over long-term cash flows. The acquisitions reflected the restructuring of the sector: Madhucon's Agra–Jaipur expressway company, the Farakka–Raiganj highway SPV, KNR Constructions' Walayar tollway—which Cube agreed to acquire in January 2020—and the Ghaziabad–Aligarh Expressway, acquired outright in May 2019.9 By the time CRISIL evaluated the platform in early 2026, it noted that Cube Highways had managed over 34 road assets totaling more than 11,000 lane kilometers in India since FY2015, establishing a transaction throughput matched by few domestic peers.10
Then came the auction that defined the decade.
The TOT Bundle 3 auction.
Toll-Operate-Transfer (TOT) represented the federal government's primary asset monetization mechanism. The National Highways Authority of India (NHAI) bundled completed, revenue-generating national highway stretches, auctioning 30-year operational and toll-collection rights for an upfront payment to fund greenfield construction. The model transferred traffic and maintenance risks to investors while eliminating construction risk, offering institutional capital direct exposure to operational cash flows.
The market, however, proved volatile rather than predictable. In March 2018, Macquarie won the inaugural TOT Bundle 1 with a ₹9,681.5 crore bid against NHAI's benchmark estimate of ₹6,258 crore—a 1.55-to-1 ratio that comfortably topped competing offers from Brookfield (₹7,511 crore) and IRB (₹6,930 crore).7 While the outcome validated institutional demand, it raised questions regarding return compression under aggressive bidding. Subsequent rounds illustrated the market's inconsistency: Bundle 2 was canceled when no bids met the reserve price, Bundles 4, 6, and 8 were scrapped in later cycles, and Bundle 10 was withdrawn despite attracting a record ₹17,100 crore bid from Sekura Roads.2 Rather than an orderly pipeline, the TOT program functioned through sporadic auctions that either cleared at steep premiums or failed to execute.
Bundle 3 comprised 566 kilometers across nine toll plazas in Uttar Pradesh, Jharkhand, Bihar, and Tamil Nadu under a 30-year concession. Cube secured the bundle with a ₹5,011 crore bid against NHAI's base price of ₹4,995.48 crore—a ratio of 1.003, pricing the asset nearly exact to the government's floor price.6 Evaluated against Macquarie's 1.55-to-1 valuation multiple on Bundle 1, Cube's bid appeared disciplined relative to the seller's benchmark.
The competitive dynamics tell a different story. National Investment and Infrastructure Fund (NIIF) submitted the second-highest bid at ₹4,230 crore, while IRB Infrastructure offered ₹3,510 crore.6 Cube paid approximately 18% above the runner-up and 43% above the third-place bidder. Because winner's curse risks are evaluated against competing market demand rather than seller reserve prices, Cube won not by a narrow margin, but by bidding well beyond rival valuations.
The transaction closed with a $684 million transfer, with NHAI confirming full receipt of the ₹5,011 crore upfront consideration in the second half of 2020.[^9] Financing included a ₹3,500 crore term loan from State Bank of India, alongside a commitment from Cube to execute over ₹700 crore in additional capital expenditure across the stretches.6 The equity portion was backed by sovereign wealth and institutional investors, allowing the platform to deploy multi-thousand-crore capital commitments without relying on public equity issuance.
Falsification pass — was Bundle 3 accretive, or was it the winner's curse?
The acquisition closed during severe macroeconomic disruption. Financial settlement occurred in the second half of 2020 as COVID-19 lockdowns restricted traffic across India, followed by regional highway disruptions from farmer protests over the subsequent year. Base-case traffic models formulated in 2019 were rendered inaccurate for at least two fiscal years.
Cube has not published asset-level traffic variance for FY21 and FY22 relative to its Bundle 3 underwriting, leaving the exact scale of the initial revenue shortfall undisclosed. Disclosed operational data, however, indicates a subsequent traffic recovery. The Tamil Nadu cluster emerged among the portfolio's top-performing assets. In FY26, the SPVs designated as NKTPL and MKTPL—the latter covering the Madurai–Kanyakumari corridor—recorded traffic growth of 16% and 15% respectively, supported by state policy changes that converted Tamil Nadu state transport buses from non-tolled to tolled status.1 On the Q3 FY26 earnings call in February 2026, chief executive Vinay C. Sekar highlighted the Madurai–Kanyakumari corridor alongside Ghaziabad–Aligarh as continuing to perform exceptionally well.[^4]
Contractual performance across the broader portfolio has also involved ongoing disputes. At the annuity SPV designated as MHPL, NHAI withheld portions of annuity payments over alleged performance deficiencies, initiating an arbitration process.2 Furthermore, Cube portfolio companies filed claims against NHAI citing delays in land handovers for the Ghaziabad–Aligarh Expressway and the Madhucon asset.2 Concession disputes remain a recurring operational feature in Indian toll road management.
These factors yield a nuanced assessment of Bundle 3. The transaction was neither a flawlessly timed acquisition—given the immediate demand shocks—nor did the wide bid gap over NIIF reflect conservative pricing. However, the 30-year concession structure provided sufficient duration to absorb short-term volume disruptions, while underlying traffic growth subsequently recovered at double-digit rates. Cube's Bundle 3 bid was aggressive relative to competing institutional bidders, but traffic execution has helped offset the initial valuation premium across a long-dated concession lifecycle. Going forward, performance against the valuation model's 4.7% long-term portfolio traffic growth assumption serves as the primary metric for evaluating asset returns.1
The integration layer.
Beyond asset acquisition, Cube established a consolidated operational infrastructure. This included an in-house Toll Management System combining toll collection and financial reconciliation, weigh-in-motion sensors to identify overloaded vehicles, video analytics for automated vehicle classification, and centralized procurement. As part of this procurement framework, the platform extended a bitumen supply memorandum with Indian Oil Corporation for five years in FY26 to secure volume continuity and price stability for its largest maintenance input.12
Management claims regarding operational efficiency remain only partially verified in public filings. Cube asserts that its operational scale keeps cost growth well below long-term industry inflation trends, though it does not publish standardized cost-per-lane-kilometer metrics relative to single-asset peers.[^4] Disclosed technical metrics demonstrate specific operational savings: during the quarter ended June 2026, the platform completed approximately 450,000 square meters of micro-fine pavement milling, reducing material consumption by an estimated 2,250 tonnes of bitumen and 32,000 tonnes of aggregates compared to conventional resurfacing, while deploying machine-learning tools for pothole identification.3 While these engineering initiatives provide documented input savings, the precise magnitude of any structural cost advantage over competitors remains unquantified in public disclosures.
IV. The Financialization Shift: Launching Cube Highways Trust (2021–2023)
By 2021, Cube Highways faced a structural capital mismatch. The platform owned a cash-generative portfolio of Indian toll roads backed by private equity capital with finite fund horizons, while its underlying concessions spanned two to three decades. Private equity funds require capital return, whereas highway concessions demand long-duration ownership. Capital providers resolved this friction through a permanent-capital vehicle.
India's regulatory environment provided the mechanism through the Infrastructure Investment Trust (InvIT) framework. Modeled on American Master Limited Partnerships and Real Estate Investment Trusts, the structure provides tax pass-through status in exchange for mandatory distribution of at least 90% of net distributable cash flow to unitholders at least semi-annually.2 To protect unitholders, regulatory guidelines cap net borrowings at 49% of asset value without explicit unitholder approval, require independent portfolio valuation, and mandate an independent trustee to oversee management.
The corporate structure established Axis Trustee Services as trustee, Cube Highways Fund Advisors Private Limited as investment manager, Ernst & Young Merchant Banking Services as valuer, and S.B. Billimoria & Co. LLP, a Deloitte network firm, as auditor.1 The investment manager operates from New Delhi and Noida.[^4] Public documentation explicitly identifies the management entity as Cube Highways Fund Advisors Private Limited rather than a limited liability partnership.
The April 2023 placement.
In April 2023, the trust raised ₹5,226 crore by issuing 380.3 million new units worth ₹3,802.6 crore and offering 142.3 million secondary units totaling ₹1,423.2 crore. Institutional subscribers included British Columbia Investment Management, Mubadala, and domestic institutional investors. The initial portfolio encompassed 18 road assets covering 1,424 kilometers across 11 states, with trading commencing on April 19, 2023.[^12]
The key feature of the issuance lay in its regulatory format. As a listed, privately placed InvIT, the vehicle provided institutional unitholders with secondary market liquidity while avoiding the extensive retail disclosure requirements of a public offering. This hybrid structure served as Cube's corporate format for three years prior to its July 2026 public conversion.
The refinancing engine.
Beyond traffic volume growth, balance sheet refinancing represents a primary lever for value creation in infrastructure trusts.
Single-asset road companies established by project contractors typically carry high-cost debt structured during construction phases. Consolidating 27 operating special purpose vehicles under an AAA-rated trust entity enables centralized treasury management and significantly lower borrowing costs. Cube secured AAA/Stable ratings from CRISIL, ICRA, and India Ratings.1 In February 2026, CRISIL reaffirmed its CRISIL AAA/Stable rating on ₹13,850 crore of bank facilities and ₹1,600 crore of non-convertible debentures, alongside a CRISIL A1+ rating on ₹1,350 crore of commercial paper.10
This credit profile translated directly into reduced interest expense. The trust's weighted average cost of debt declined from 8.19% as of March 31, 2025, to 7.53% one year later—a 66 basis point reduction—and further to 7.49% by June 30, 2026.13 During FY26, the trust raised ₹1,972 crore in AAA-rated non-convertible debentures to refinance existing bank loans while increasing the fixed-rate portion of its debt.1 Across an outstanding debt book of approximately ₹17,665 crore, a 66 basis point rate reduction yields roughly ₹115 crore in annual interest savings, expanding net distributable cash flow.17
However, balance sheet re-rating offers a finite benefit, as cost-of-capital reductions normalize once initial high-cost project debt is fully refinanced.
Falsification pass — are these really bond-like, inflation-protected cash flows?
The investment case for the trust relies on two core attributes: distribution stability and inflation protection—the latter of which presents specific operational nuances examined in Section V.
Regarding distribution stability, the trust maintains a consistent payout track record. Annual distributions expanded from ₹10.09 per unit in FY24 to ₹11.00 in FY25 and ₹13.77 in FY26, reaching a record annual total of ₹1,850.78 crore.1 Cumulative distributions reached ₹34.86 per unit by March 20261 and ₹38.81 by June 2026.3
However, an analysis of distribution composition reveals varying underlying cash flow quality across fiscal periods. On the February 2026 earnings call, Group Chief Financial Officer Pankaj Vasani detailed the source of distributions: of the ₹1,302 crore distributed in FY24, ₹250 crore was drawn from opening cash reserves rather than organic operational cash flow. In FY25, reserve utilization increased, with ₹385 crore of the ₹1,468 crore distribution funded from opening cash rather than net distributable cash flow (NDCF).[^4] Consequently, approximately 26% of FY25 unitholder distributions reflected balance sheet cash reserves rather than current-period earnings.
This payout dynamic shifted in FY26. Payouts for the first nine months of FY26 totaled ₹1,371 crore and were funded entirely from generated NDCF,[^4] supported by full-period contributions from annuity assets acquired in FY25 and FY26. While operational cash generation now fully covers distributions, historical distribution growth initially relied on pre-existing cash reserves.
Leverage management remains aligned with regulatory and debt covenants. Net debt to assets under management stood at 46.82% in March 2026 and 45.17% in June 2026, remaining below the 49% regulatory threshold and the 60% financing covenant cap.1310 Debt service coverage ratios (DSCR) registered at 1.99x in March 2026 and 2.0x in June 2026, comfortably above the 1.25x covenant threshold that triggers cash lock-up provisions.1310 CRISIL's sensitized stress case projected DSCR at 1.65x for FY26 and 1.8x for FY27.10 To support liquidity, the trust maintains a debt service reserve covering three months of debt obligations, comprising ₹287 crore in cash and a ₹250 crore bank guarantee as of December 2025.10
The primary financial risk stems from interest rate exposure. Only 25% of borrowings were fixed-rate as of March 2026, compared to 11% in FY24 and 28% in FY25.1 CRISIL notes that term facilities carry floating interest rates with three-month reset periods.10 With 75% of a ₹17,665 crore debt book subject to quarterly repricing, cash flows remain sensitive to monetary policy cycles. While the Reserve Bank of India's decision to maintain the repo rate at 5.25% with a neutral stance through the June 2026 quarter provided near-term stability,3 higher benchmark rates would directly increase debt service costs, reducing distributable cash flow while elevating unitholder yield requirements.
V. Business Model & Asset Deep Dive: Revenue Engines & Economics
Strip away the trust structure and the credit ratings, and what is a toll road?
It is a machine that converts two inputs into one output. Input one is the number of vehicles that cross a point on the earth. Input two is the price each one pays. Multiply them, subtract the cost of keeping the asphalt intact, and you have the business. Everything else is financing.
Cube's 27 assets divide into three engines with quite different risk profiles.1
Engine one: toll assets. Eighteen of the 27, representing 85% of AUM and, in the most recent full-year mix, 82% of revenue.12 These are the assets that carry traffic risk. Nine are BOT or DBFOT concessions — roads someone built and Cube bought — and nine are TOT concessions won at auction.1 When the Indian economy grows, these assets grow. When freight slows, they slow. The cash flow is genuinely correlated to the real economy, which is exactly why it commands a higher return than the alternatives.
Engine two: hybrid annuity and annuity assets. Six HAM projects and three pure annuity assets, contributing 15% of AUM and roughly 18% of revenue between them.12 Here the mechanics invert entirely. NHAI pays a fixed sum twice a year regardless of how many trucks use the road. Traffic risk goes to zero; what remains is counterparty risk and, more importantly, timing risk. The economics are lower-return and lower-variance — the trust's own valuation applies a 9.7% weighted average cost of capital to toll assets versus 7.9% to 8.1% for HAM and annuity assets, a spread that quantifies precisely how much less risk the market perceives.1
Engine three: state concessions. Exactly one asset out of 27 sits with a state authority rather than NHAI.2 The outline's framing of this as a distinct ~5% revenue segment overstates it; in practice, Cube has deliberately engineered this exposure close to zero, for the reasons discussed earlier.
The pricing engine, and why it is not what you think.
Here is where the standard narrative needs surgery.
The bull case for toll roads everywhere rests on regulated price escalation. Cube's NHAI concessions escalate tolls annually by a formula of 3% plus 40% of the change in the Wholesale Price Index; a small number of older agreements index directly to WPI in a reference month.3 The elegant implication is that inflation is a tailwind: costs rise, tolls rise faster, margins hold. And in the current environment the arithmetic looks spectacular — Indian WPI ran at 8.36% in April 2026, 9.68% in May and 9.87% in June, against a long-run assumption of 4.1% baked into Cube's valuation model.3
Now the disconfirming evidence, which belongs right here rather than in a distant risk section.
On September 13, 2025, NHAI issued a policy circular reducing the "linking factor" used to convert WPI between base years in the toll fee computation, from approximately 1.641 to approximately 1.561. The effect is to lower the converted WPI applied to fee calculation and therefore to reduce base toll rates — and industry and rating analyses cited in Cube's own offer document conclude the revision would permanently lower base tolls on public-funded and BOT toll projects unless relief is granted. The matter is sub judice; the Delhi High Court has directed that NHAI take no coercive action against concessionaires in the interim, but NHAI may still press for implementation.2
Read that again. The single most-cited structural advantage of Indian toll roads — automatic, contractual, inflation-linked pricing power — was unilaterally trimmed by the counterparty with a circular, and the only thing standing between concessionaires and a permanent revenue reduction is an interim court order. This is not a tail risk. It happened, eleven months before this writing, and it remains unresolved.
The second intervention is subtler and, in its way, more interesting. In August 2025 NHAI launched an Annual Pass: a one-time payment — ₹3,000 at launch, raised to ₹3,075 effective April 1, 2026 — that buys a private car 200 toll crossings a year across roughly 1,150 national highway plazas.23 By April 2026 the scheme had crossed 5.6 million users.3 For a car owner it is a bargain. For a concessionaire it replaces per-trip revenue with a compensation payment from NHAI computed under a formula NHAI itself determined — and which, Cube's own risk disclosure notes, NHAI may review.2
Cube's SPVs executed supplemental agreements to accept the scheme. In FY26 the trust recognised ₹176.9 crore as Annual Pass compensation, of which ₹138.2 crore had actually been received by March 31, and ₹108.1 crore in the June 2026 quarter alone, with average receivable days running at 42.13 Portfolio adoption among private cars went from 2% at launch to about 29% by March 2026 and 32% by June.13
So what does this mean? Two things, pulling in opposite directions. Operationally, the pass has been a demand stimulant — management attributes part of the strong passenger car traffic growth to longer, more frequent trips enabled by prepaid tolling, and higher throughput lowers plaza operating costs.3 Financially, it converts a contractually indexed price into an administratively determined receivable. The company now books a growing slice of "toll revenue" that is, in substance, a government reimbursement whose formula the government controls. That is a material change in the character of the cash flow, and it is not reflected in how the asset class is usually described.
The calibrated conclusion on pricing power: the history narrows the claim substantially. Cube's toll assets do have contractual escalation, and in a 9%+ WPI environment that escalation is worth a great deal. But the escalation is not sovereign-proof. The counterparty has demonstrated, within the last year, both the willingness and the mechanism to reduce it. The forward test is simple and observable: whether the Delhi High Court proceeding on the linking factor concludes in concessionaires' favour, and whether the Annual Pass compensation formula is revised.
Operational reality: how the money actually gets collected.
Electronic toll collection reached 96.9% of collections in the nine months to December 2025, with average daily collection across the portfolio running at ₹9.7 crore.[^4] The transition from cash lanes to FASTag transponders did something more valuable than speed: it made revenue auditable. Cash collection at a remote toll plaza is one of the most leakage-prone activities in commerce. Electronic collection with a central reconciliation system converts it into a data problem.
That said, Cube's own disclosures are candid that this creates a new dependency. Nearly all toll plazas run on electronic systems for collection, reconciliation and administration; a cyber incident or systems failure would disrupt collection, delay reconciliation and impair revenue data.2 The company has traded physical leakage risk for concentrated technology risk. That is almost certainly the right trade. It is still a trade.
Weigh-in-motion sensors sit alongside the tolling stack. Overloaded trucks are a double theft — they pay a lower classification than they should, and they destroy pavement faster than the maintenance budget assumes. Cube introduced precast weigh-in-motion infrastructure in FY27 to cut installation downtime.3 The economics here are real but bounded: better enforcement raises revenue per vehicle and lowers maintenance capex, but it does not create a moat, because every operator can buy the same sensors.
Management and incentives.
Vinay Chandramouli Sekar runs the investment manager. He is a mechanical engineer from IIT Madras with an IIM Ahmedabad management diploma, with over 16 years in infrastructure finance and advisory including stints at IndusInd Bank and IFCI.19 Pankaj Vasani, the group CFO, arrived from an unusual direction — 25-plus years in finance and taxation across telecom, media, FMCG and automotive, with leadership roles at Publicis, Vodafone, Coca-Cola and Subros, and a stack of credentials spanning Indian chartered accountancy, ICAEW and Australian CPA.19 The operating side is run by Bovin Kumar at the project manager, a technologist with a masters from IIT Kanpur and prior experience inside NHAI and the road transport ministry itself, as well as at consultancies Ramboll, CH2M Hill and Halcrow.19
That combination — a finance-first CFO from consumer industries, a CEO from infrastructure credit, and an operating chief who used to sit on the government's side of the concession table — is a reasonable answer to what this business actually requires.
The incentive structure deserves scrutiny, because the outline's characterisation of it as an AUM-linked fee is wrong in a way that matters. The investment management fee is the higher of 0.75% of the revenue of the portfolio assets, or ₹19 crore escalating at 7% per annum from April 1, 2023.2 Separately, each project SPV pays the service provider 0.35% of its standalone operating revenue, plus a discretionary fee of up to 0.2% contingent on hitting KPIs set by the investment manager's board.2 In the nine months to December 2025, management fees and trust expenses totalled ₹126 crore — investment manager roughly ₹32 crore, project manager roughly ₹69 crore, and professional fees including legal, audit, ratings and traffic studies about ₹25 crore — against ₹3,685 crore of NDCF inflows.[^4]
Revenue-linked rather than AUM-linked is a better structure than the alternative, because it does not pay the manager for simply accumulating assets at any price. But it still rewards growth in revenue, which is achieved most quickly by buying assets. And the assets Cube buys are increasingly bought from itself.
VI. Competitive Landscape, Industry Structure & Helmer's 7 Powers
There is a peculiar feature of the toll road business that makes competitive analysis harder than it looks: once an entity owns the road, it has no direct competitors along that route. There is no second toll plaza at kilometre 47.5 of the Ghaziabad–Aligarh Expressway. The asset functions as a spatial monopoly for the duration of its concession.
All competition occurs prior to asset ownership—in the auction room and during bilateral negotiations. In those arenas, the field has grown increasingly crowded.
The peer set, measured properly.
As of the most recent comparable disclosures, IRB Infrastructure Trust was the largest road InvIT in India at roughly ₹63,574 crore in enterprise value across 10,567 lane kilometres, with an EV-weighted residual concession life of 22.53 years—meaningfully longer than Cube's 16.49 years on the same basis.2 The NHAI-sponsored National Highways Infra Trust (NHIT) stood second at ₹47,968 crore across 11,967 lane kilometres, carrying a residual life of 21.09 years.2 Cube ranked third at ₹35,913 crore.2
Two major peers recently rebranded, altering historical commentary. Highways Infrastructure Trust, the KKR-backed platform, now operates as Vertis Infrastructure Trust at ₹25,759 crore across 8,302 lane kilometres—a physical scale comparable to Cube at roughly 70% of the enterprise value, reflecting a shorter residual concession life of 14.36 years.2 IndInfravit, originally sponsored by L&T and later backed by CPPIB and Allianz, operates as Interise Trust at ₹18,690 crore.2 IRB InvIT Fund, the original 2017 listing, remains a smaller vehicle at ₹7,846 crore.2
The state-owned player represents a primary competitive benchmark. NHIT is sponsored directly by NHAI, meaning the primary seller of Toll-Operate-Transfer (TOT) bundles also operates a competing acquiring platform. NHIT's fourth fundraising round closed at an enterprise value of approximately ₹18,380 crore—the largest single monetization transaction in Indian roads to date—raising ₹8,340 crore in unit capital and ₹10,040 crore in debt to acquire eleven highway stretches valued at ₹17,740 crore. Cumulative capital raised across NHIT's four rounds exceeded ₹46,400 crore, encompassing 26 toll roads and 41 toll plazas across 2,345 kilometres.2 When the primary asset seller also competes using sovereign cost of capital, establishing a "cornered resource" advantage becomes challenging.
Running Helmer's 7 Powers honestly.
Scale Economies — real, but smaller than claimed. Spreading fixed overhead across 8,754 lane kilometres reduces per-kilometre administrative costs compared to single-asset project companies through centralized bitumen procurement, unified treasury operations, and consolidated credit rating relationships. The direction of savings is clear, but the exact financial magnitude remains unquantified because Cube does not publish per-lane-kilometre cost breakdowns and peer InvITs do not provide comparable operational disclosures. Furthermore, with Vertis operating 8,302 lane kilometres and NHIT managing 11,967, Cube's physical scale is not unique within the peer group.2 Verdict: present, but not a differentiating moat.
Cornered Resource — historically strong, but evolving. Exclusive access to capital from sovereign and institutional partners—including ADIA, BCI, Mubadala, and IFC—allowed Cube to fund large commitments like the Bundle 3 equity payment without public bookbuilding when domestic bidders backed away.68 This provided a structural advantage over domestic contractors. However, two shifts have altered this position. First, the Ministry of Road Transport and Highways (MoRTH) revised the Build-Operate-Transfer (BOT) framework to permit pension funds, sovereign wealth funds, and private equity firms to bid directly on highway public-private partnerships, expanding capital access beyond operational TOT assets. Cube's disclosures explicitly note that "greater participation from large global funds could increase competition for future highway assets."1 Second, following its July 2026 conversion into a public InvIT, Cube's cost of equity is determined by public market pricing. Verdict: previously strong, but weakening amid regulatory and capital market evolution.
Process Power — plausible, but unproven as a moat. The platform's internal toll management architecture, machine-learning pothole detection tools, automated video classification, and predictive maintenance protocols represent active operational investments.319 Whether these tools constitute true process power—a durable operational advantage competitors cannot replicate—remains debatable, as road operations technology is commercially available. The platform's institutional capability to integrate newly acquired asset companies within a single fiscal year is consistent with operational efficiency,[^4] but whether it yields a permanent margin advantage over established peers is unverified. Verdict: an operating competence, but unlikely a durable barrier.
The remaining four powers under the framework—network economies, counter-positioning, brand power, and switching costs—do not apply to highway concessions. Commercial traffic chooses route geography rather than platform operators.
Porter's five forces, war-gamed.
Bargaining power of buyers — high and actively asserted. The federal government acts simultaneously as asset seller, toll price regulator, annuity counterparty, and planner of competing transport corridors. As demonstrated by recent policy shifts, the government cut the Wholesale Price Index linking factor and implemented an administratively controlled Annual Pass compensation structure.2 Furthermore, government agencies control competing route development: Cube's offer document notes that the under-construction Ganga Expressway and Shamli–Gorakhpur Expressway are projected to divert traffic away from the Ghaziabad–Aligarh Expressway and adjoining stretches.2 Concessionaires possess limited leverage against a regulator capable of commissioning parallel corridors.
Threat of substitutes — moderate. Section VII evaluates this dynamic in detail.
Rivalry — bifurcated. Competition is intense in the acquisition phase—as reflected by Sekura Roads' record ₹17,100 crore bid for TOT Bundle 10—and non-existent post-acquisition.2 Consequently, competitive pressure impacts initial acquisition yields rather than ongoing operating margins.
Threat of new entrants — rising. The updated BOT framework, the government's National Monetisation Pipeline target of ₹4.14 trillion in road asset transfers through FY2030, and the expansion of InvIT sponsors continue to attract new capital to the sector.1 A broader pool of bidders for a finite asset supply pressures prospective returns.
Supplier power — low to moderate. Bitumen represents the primary maintenance input, with market prices fluctuating between roughly ₹68,500 and ₹81,600 per tonne in recent quarters. The platform's long-term supply agreement with Indian Oil Corporation and its deployment of micro-fine pavement milling represent direct measures to manage input price volatility.13
The structural summary: the platform operates high-margin individual assets within a heavily regulated market where asset-level returns are largely determined at the point of acquisition. Managing returns depends primarily on disciplined purchase pricing rather than operating differentiation.
VII. The Historical Falsification Layer: Stress-Testing Thesis Claims
Every infrastructure thesis is a story about the future told with a discount rate. The useful exercise is to find the places where the company's own record contradicts the story.
Falsification Pass 1: Traffic predictability and freight substitution.
The claim: Indian highway freight grows at a durable multiple of GDP, forever, and Cube's corridors participate.
The popular disconfirming story is the Dedicated Freight Corridor — Indian Railways' electrified freight-only lines, which were supposed to strip long-haul containerised cargo off national highways. It is a good story. The evidence in Cube's own filings does not support the dramatic version of it.
What the industry research in the offer document actually shows is a gradual, modest modal shift. Road freight measured in billion tonne-kilometres was forecast to grow 5–7% annually from FY25 to FY30; rail freight 6–8%, aided by DFC commissioning and more competitive tariffs.2 Rail is gaining share, but from a low base and at a pace measured in tens of basis points a year, not the 4–7% collapse in heavy commercial vehicle growth that circulating commentary asserts. Cube has not disclosed asset-level heavy-vehicle traffic on DFC-parallel corridors, and no such disclosure appears in the FY26 or Q1 FY27 materials.13 The specific DFC-diversion figure widely quoted is not, on the available record, verifiable.
The real substitution risk shows up somewhere else entirely, and Cube has disclosed it plainly. Jaipur–Mahua Tollways — the platform's very first asset, the 109-kilometre stretch bought from IJM in 2014 — recorded a 7% traffic decline in FY26. The cause was not rail. It was the commissioning of the Bandikui spur of the Delhi–Vadodara–Mumbai Expressway, which pulled traffic off the parallel older highway, compounded by a high prior-year base from Kumbh Mela travel.1 A second Uttar Pradesh asset, LRTPL, was flat for the same Kumbh base effect.1 Western UP Tollway declined 3.4% in the June 2026 quarter, partly reflecting the expiry of its concession on June 23, 2026.3
There is a certain poetry in the founding asset being the one that gets diverted. There is also a clear lesson. The threat to an Indian toll road is not that freight moves to trains. It is that the government builds a better, newer, parallel road — which is precisely what the ₹4.14 trillion roads pipeline under NMP 2.0 exists to fund.1
Management's handling of this is worth noting for credibility purposes. Cube stated that both the Jaipur–Mahua decline and the LRTPL flatness were "in line with expectations and factored in the valuation case."1 That is either genuine forecasting discipline or convenient retrospective framing, and there is no way to verify which from outside. What can be verified is that the portfolio absorbed both: FY26 traffic still grew 8.1% and toll revenue 10.6%, with toll revenue coming in 3.2% ahead of the projection in the prior year's valuation report.1
Verdict: the claim survives, narrowed. Portfolio traffic growth has been robust and has beaten the company's own underwriting. But the growth is driven by passenger cars, not freight — management identified sustained passenger car growth as the key structural trend, driven by vehicle sales, rising incomes and better connectivity.[^4] An investor who believes they are buying an Indian freight play is buying something else. The forward falsifying KPI is asset-level traffic on corridors where a parallel expressway has been announced, versus the 4.7% long-run traffic assumption in the valuation.1
Falsification Pass 2: Sovereign counterparty and arbitration reality.
The claim: annuity and HAM cash flows from NHAI are effectively risk-free.
This is the claim where the popular bear case is overstated and the disclosed record is reassuring — which is worth saying plainly, because falsification cuts both ways.
Cube publishes every annuity payment delay across its portfolio. Over roughly two and a half years, the worst delay disclosed was 20 days, at the SPV designated SIPL in June 2025. Next worst was 18 days at THPL in November 2024, then 12 days at MSHPL in June 2025. Most were one to four days.2 For FY26, all annuities scheduled were received on time, and all six Q1 FY27 annuities were received.13 The trust's own characterisation is that delays and deductions "have not, in the aggregate, materially and adversely affected our results of operations" over the past three financial years.2
Delays measured in days do not tie up capital for three to five years. The popular version of this bear case is not supported.
What is real is narrower and more specific. the MHPL deduction dispute described earlier remains in arbitration, and the mechanism behind it is what matters: NHAI decides unilaterally whether maintenance standards were met.2 Cube has received notices regarding GST applicability on historical annuity receipts, which if determined adversely would create tax liability, interest and penalties.2 And the aggregate litigation picture is not trivial: across the portfolio assets, 11 civil proceedings involving ₹498.8 crore, 8 regulatory proceedings involving ₹176.1 crore, 12 criminal proceedings with no quantified amount, and 12 material outstanding claims involving ₹1,647.1 crore.2 That last figure is roughly 39% of FY26 revenue from operations — not an existential number, but not a rounding error either.
Verdict: the "risk-free" framing is wrong; the "capital tied up for years" framing is also wrong. The accurate version is that NHAI pays substantially on time, occasionally deducts, and litigates at the margins — with the deduction mechanism being the genuine exposure, because NHAI decides unilaterally whether maintenance standards were met. The forward KPI is the annuity delay table and the material outstanding claims balance, both of which Cube discloses.
Falsification Pass 3: M&A discipline, and the related-party problem.
The claim: Cube acquires assets at attractive returns.
Start with the third-party transaction, which is the cleaner test. In February 2025, Cube agreed to acquire two Jammu & Kashmir annuity assets — Quazigund Expressway and Athaang Jammu Udhampur Highway — from the National Investment and Infrastructure Fund at a transaction value of roughly ₹4,185 crore, completing on June 12, 2025. The assets span about 80 kilometres, include one of India's longest bi-directional tunnels, and carry a residual concession life of just over six years backed by fixed semi-annual NHAI annuities. NIIF's announcement indicated the deal was expected to add approximately ₹2.3 per unit annually to distributable cash over five years, taking annuity revenue to 33% of Cube's total.12
That is a defensible transaction on the disclosed facts — traffic-risk-free cash flow bought competitively from a sophisticated counterparty. It also carries an under-discussed cost: a six-year residual life is very short, which means Cube paid for a rapidly amortising cash stream. That is a capital-recycling decision, not a compounding one. Note too the geography — Cube's own disclosure flags that assets in hilly, geologically sensitive regions such as Jammu & Kashmir face landslide and slope-failure risk, with potential closures and higher restoration costs.2
Now the harder test: the sponsor drop-down.
In February 2026, Cube's board approved acquiring four fully operational assets from sponsor-group entities at an enterprise value exceeding ₹7,200 crore — three toll assets from CH-V and one annuity asset, CNTL, a Jammu & Kashmir tunnel concession, from CH-II. The consideration is an equity swap: approximately 25.95 crore units for the three toll assets and 4.07 crore for the annuity asset, issued at the price determined through the public issue bookbuild. Collectively these assets generated about ₹1,390 crore of revenue in FY25.[^4] Cube priced the transaction at a 5.9% to 7.9% discount to EY's fair market value, which it characterised as roughly ₹3 per unit of immediate value accretion for existing unitholders.[^4] Board, unitholder and Competition Commission approvals were secured and share purchase agreements executed on July 13, 2026, with some conditions precedent still open as of August.3
An activist would ask three questions here.
First: who set the price? EY is the trust's own appointed valuer, engaged by the manager, which is an associate of the sponsor.12 A discount to a related-party-commissioned valuation is a weaker fairness test than an arm's-length auction. Cube's own risk disclosure concedes the general point — there is "no assurance that previous related party transactions could not have been made on more favourable terms with unrelated parties."2
Second: what is being bought? CNTL's statutory auditors issued a qualified opinion for FY2023, FY2024 and FY2025. The qualification is substantive: since FY2019 the company measured receivables under its service concession arrangements in a manner not compliant with applicable accounting standards, with the balance-sheet and profit impact not ascertainable. The auditors further noted that CNTL did not recognise accrued interest, default interest or penal charges on borrowings after October 15, 2018 pursuant to NCLAT orders; that it had statutory non-compliances including delayed deposit of statutory dues and deficiencies in cost records; and that it had defaulted on loan repayments since FY2019. An emphasis-of-matter paragraph disclosed a Serious Fraud Investigation Office investigation into the company's erstwhile shareholders, and the auditors identified a material uncertainty casting significant doubt on going-concern status as at the date of those statements, prior to the sponsor group's acquisition.2
Cube has stated that corrective actions have been assessed by management, and the final FY2026 audit opinion was still pending as of the offer document.2 The asset itself — a major tunnel on the Jammu–Srinagar corridor with NHAI annuity backing — may well be excellent. But an InvIT that markets itself on de-risked, AAA-rated predictability is issuing units to its own sponsor to acquire a company with three consecutive qualified audit opinions and a going-concern flag.
Third: what happens to governance? On the same February call, the trust disclosed that as part of the public conversion it was changing sponsor — CH-V replacing CH-I and CH-III, with the outgoing sponsors having "already transferred all eligible assets into the InvIT" and not expected to make further drop-ins.[^4] Simultaneously, Cube disclosed that the expanded list of "Specified Matters" — governance provisions it had adopted voluntarily, beyond regulatory requirement — was "being rationalised" as part of the conversion, back to the SEBI-mandated structure.[^4] The framing was that all statutory safeguards continue. That is true. It is also true that a trust which had chosen to hold itself to a higher standard chose, at the moment of going public, to hold itself to a lower one.
There is a fourth item, disclosed in the offer document and largely absent from market commentary. The World Bank Group's Integrity Vice Presidency has been conducting an audit of Cube Highways and Infrastructure Pte. Ltd. and Cube Highways and Transportation Asset Advisors, along with CHTAAPL's then-CEO, covering the period 2017 to 2021. It is not a criminal or civil investigation by any government authority. External counsel engaged by the entities has not identified evidence of knowing, wilful or intentional misconduct. But the matter may be resolved by negotiated settlement or through the World Bank Group's adjudication process, with no defined timeline, and possible outcomes include non-monetary sanctions such as debarment from World Bank Group-funded projects.2 Given that IFC — the World Bank Group's private-sector arm — anchored Cube's landmark sustainability-linked bond, this is a live reputational and relationship overhang, however unlikely an adverse outcome may be.
Verdict on M&A discipline: the third-party record supports the claim. The related-party record does not falsify it, but it materially weakens the evidentiary basis, because the acquirer, the valuer's appointer, and the seller all trace to the same sponsor group. The KPI that would confirm or falsify the revised claim is concrete and near-term: whether the four drop-down assets, once consolidated in FY27, deliver revenue and NDCF consistent with the ₹1,390 crore FY25 base and the claimed ₹3 per unit accretion — and whether CNTL's FY2026 audit opinion is issued clean.
VIII. Capital Deployment, Financing & Future Optionality
If Section VII was the prosecution, this section is where the defence gets to present its strongest exhibit — and it is a good one.
The debt playbook.
On February 13, 2025, the International Finance Corporation invested ₹860 crore, roughly $98.35 million, in India's first sustainability-linked bond in the road infrastructure sector. The proceeds funded the acquisition of NAM Expressway, a strategic corridor connecting Chennai and Hyderabad, and supported the trust's sustainability and inclusion objectives.11 IFC's regional director Imad N. Fakhoury framed it as a milestone in sustainable infrastructure; Sekar framed it in returns language, calling it a demonstration of the trust's ability to deploy debt capacity on accretive acquisitions.11 The gap between those two framings is the whole story of blended finance.
A sustainability-linked bond differs from a green bond in a way worth explaining plainly. A green bond restricts what the money is spent on. An SLB does not restrict use of proceeds at all — instead, the coupon moves if the issuer misses pre-agreed sustainability targets. It is a bet on behaviour, not on projects.
Cube's SLB carries three KPIs, and the trust reports against them.1 The first is Scope 1 and 2 greenhouse gas emissions intensity per lane-kilometre, which improved from a 2.67 tonnes CO2-equivalent baseline to 2.23 in calendar 2025, against targets of 1.62 by 2030 and 1.13 by 2035. The second is the proportion of road length treated with sustainable technology during major maintenance: 9.6% achieved so far against a target of at least 34% across FY24–FY30. The third is women's participation in the workforce, at 8.6% in FY26 against a 10.5% FY30 target.1 Two of the three are running behind trajectory. That is a genuine, quantified accountability mechanism, and it is refreshing to see it reported rather than buried.
The broader debt architecture matters more to unitholders than the SLB's headline. Cube's maturity profile is deliberately staggered — no single year between FY2027 and FY2044 accounts for more than 9% of maturing debt, with most years in the 5–7% band.1 This is the structural answer to the biggest way infrastructure trusts blow up: a cliff-edge refinancing that arrives in a bad market. Amortisation matched to concession life means the debt shrinks as the asset's remaining life shrinks. Alongside term loans and NCDs, the trust uses commercial paper, bank guarantees and the SLB across a lender base spanning development finance institutions, mutual funds, insurance companies, NABFID and pension funds.13
The result, as of June 2026: debt to EBITDA of 4.18x, net debt of ₹16,558 crore, and net asset value of ₹149.56 per unit against ₹145.77 three months earlier.13 NAV has grown 45.77% since listing, which — combined with cumulative distributions — is where the total return of ₹74.29 per unit over the trust's first 2.75 years came from.1[^4]
Optionality, sized honestly.
There are three adjacent stories attached to this business. Two are small, and one is speculative. Sizing them correctly is more useful than being excited about them.
Solar and energy optimisation. Cube operationalised grid-connected solar at DATRPL's Karman, Mahuvan and Gadpuri toll plazas with combined capacity of about 395 kilowatt-peak in FY26, expanding to roughly 770 kilowatt-peak across additional assets by June 2026, with five further projects in the pipeline.13 Total renewable generation was 138 megawatt-hours in calendar 2025 against total electricity consumption of 35,452 megawatt-hours — under 0.4%.1 The company also procured 6,000 megawatt-hours of renewable energy certificates, cutting about 4,000 tonnes of CO2-equivalent.1
The honest sizing: this is a cost line item, not a business. It reduces plaza operating expense at the margin and supports the SLB's emissions KPI, which has genuine financing value. It is not, on any published evidence, a revenue stream. The right-of-way solar and EV charging opportunity that gets discussed in sector commentary has not, in Cube's disclosures, converted into disclosed revenue. Treat it as maintenance-cost management with an ESG-financing benefit attached.
FASTag data monetisation. Cube holds high-frequency origin-destination data on freight and passenger movements across 18 tolled corridors. In theory this is valuable to logistics companies, retailers and lenders. In practice, Cube uses it internally for traffic prediction and maintenance planning, and there is no disclosed external data revenue.3 Certification is not commercialisation, and a data asset is not a data business until someone pays for it. This belongs in the "interesting, unproven" column.
Adjacent infrastructure sectors. This one got tested live. On the February 2026 call, an individual investor named Saurabh Dugar asked directly whether the trust would consider acquiring assets outside roads. Sekar's answer was measured and, notably, did not overpromise: the current pipeline within roads was strong and visible, with four acquisitions and three ROFO assets; but the capabilities developed in roads "can be extended to other infrastructure sectors as well," and the trust would be open to evaluating opportunities at an appropriate time, subject to board and investor approvals.[^4]
That is the correct answer, and it is also the answer that precedes every diworsification in corporate history. The InvIT architecture genuinely is sector-agnostic — power transmission and renewable InvITs exist in India. But the operating capability Cube has built is specific to pavement, tolling and traffic. Investors should watch this space not for the opportunity but for the discipline.
The visible pipeline.
The four sponsor drop-downs are only part of it. Cube has right-of-first-offer arrangements over three further sponsor TOT toll assets: Kokhraj–Handia, Malayagiri, and the Delhi–Hapur–Meerut Expressway.[^4] Beyond the sponsor, NHAI has identified 17 operational highway projects covering approximately 1,692.5 kilometres across nine states for FY27 monetisation via TOT and InvIT routes, within a broader FY26–27 target of roughly ₹35,000 crore across 28 assets.13
Cube also benefits from a SEBI amendment notified on May 15, 2026, which expanded the permissible uses of borrowings where net borrowings exceed 49% of asset value — now including capital expenditure to enhance asset performance, major maintenance for road projects, and refinancing of principal.1 A parallel amendment clarified that an SPV retains its status after concession expiry, with the manager required to exit or redeploy it within one year.1 Both changes are technical, and both meaningfully increase the trust's operating flexibility.
IX. Investment Case & Bear vs. Bull Analysis
The bull case.
The pipeline argument remains the most compelling element of the growth thesis, as it is anchored in federal policy rather than corporate projection. India's National Monetisation Pipeline 2.0, announced in February 2026, expanded the country's asset monetization target to ₹16.7 trillion, with roads contributing ₹4.14 trillion—roughly one-quarter of the total. The plan encompasses 21,300 kilometres of National Highways Authority of India assets, with annual monetization targets rising from ₹54,700 crore in FY26 to ₹1.11 trillion in FY30.1 Under the preceding monetization framework, NHAI transferred 3,664 kilometres and raised ₹77,940 crore, achieving approximately half of its ₹1.6 trillion target, with 2,347 kilometres and ₹43,638 crore delivered through the InvIT model.1 The prospective supply of operational highway assets is therefore backed by a published government schedule.
The yield profile offers a clear financial baseline. At the ₹152 offer price and FY26's ₹13.77 per unit distribution, the vehicle provided an implied pre-tax yield of approximately 9.1%.18 Set against an Indian sovereign yield environment where benchmark valuation models assume a 7% risk-free rate, this represents a spread of roughly 200 basis points to compensate investors for volume, maintenance, and regulatory risks on a AAA-rated portfolio.1 Institutional demand at that valuation was demonstrated prior to public bookbuilding, with anchor commitments totaling ₹1,250 crore. Premji Invest's Prazim Trading led the allocation with ₹950 crore for 6.25 crore units, alongside ₹100 crore each from HDFC Life and HDFC Pension, and ₹50 crore each from Axis Max Life and WhiteOak Capital—all placed at the top of the price band with 180-day lock-in periods.13 Concentrated long-term domestic capital acquiring units at the upper valuation limit provided significant institutional backing, even if locked-in anchor allocations differ from unconstrained secondary market demand.
Recent financial results support the operational thesis. Revenue from operations in FY26 increased 28.17% to ₹4,238.9 crore, with total consolidated income reaching ₹4,359 crore, driven by an 8.1% rise in traffic volume and a 10.6% expansion in toll revenue.1 Operating momentum continued into the first quarter of FY27, with revenue rising 19.31% to ₹1,126.6 crore, traffic growing 9.3%, toll revenue expanding 11.5%, and a quarterly distribution of ₹3.95 per unit.3 On an individual asset level, the Ghaziabad–Aligarh corridor recorded a 31% traffic increase in the March 2026 quarter and roughly 23% for the full fiscal year, supported by the opening of two logistics parks and a cement manufacturing facility within its catchment area.1 This volume expansion highlights the corridor's capacity to capture local industrial development rather than relying solely on broader macroeconomic traffic growth.
Management communications also present a notable datapoint for unitholders, though one requiring context. During the February 2026 earnings call, when asked about distribution expectations, chief executive Vinay Sekar stated that "we do not formally provide DPU guidance," adding only that distributions should broadly align with the prior three-year trend.[^4] By August 2026, following the public listing, the trust established formal FY27 distribution guidance and subsequently raised it from ₹14.00 to ₹14.50 per unit based on strong June quarter traffic performance.3 Establishing formal distribution targets aligns with public market standards, and an early upward revision signals operational strength. However, it also represents a shift in communication policy within a six-month period, creating an explicit benchmark against which management's execution will be evaluated.
The bear case.
Regulatory pricing risk represents the primary operational vulnerability. The National Highways Authority of India's decision to lower the Wholesale Price Index linking factor demonstrates how administrative actions can alter contractual revenues, a policy change that remains sub judice.2 More broadly, a vehicle whose toll escalation formulas, Annual Pass compensation rates, and competing corridor approvals are determined by a single federal entity operates with contingent pricing power rather than independent market pricing authority.
Finite concession life exerts a structural drag on long-term cash flows. As of March 2026, the portfolio's weighted average residual concession life stood at 18.0 years,1 trailing peer metrics of 22.53 years for IRB Infrastructure Trust and 21.09 years for National Highways Infra Trust.2 Concession expirations have begun to impact operating results: the Western UP Tollway concession expired on June 23, 2026, reducing its operating days in the June quarter from 91 to 84.3 Similarly, the APEPL annuity corridor in Telangana and Andhra Pradesh retained only 1.00 year of concession life as of September 30, 2025,2 while the recently acquired NIIF portfolio carries just over six years of remaining operational life.12 Because toll assets naturally amortize over time, maintaining distribution levels requires continuous asset replacement, while distribution growth demands ongoing portfolio expansion in a market where updated public-private partnership rules are attracting additional institutional bidders.1
Geographic concentration creates localized exposure. Stretches across Delhi-NCR, Uttar Pradesh, and Tamil Nadu accounted for 54.18% of assets under management as of September 30, 2025, representing 21.03%, 17.68%, and 15.47% respectively.2 Under the offer document's Herfindahl-based diversification index, Cube's score of 29 reflects greater geographic concentration than several public peers, where a lower score signifies broader diversification.2 As a result, regional regulatory changes, urban traffic restrictions in Delhi-NCR, or severe weather disruptions in Tamil Nadu exert a magnified impact on consolidated trust performance.
Floating-rate debt structures create ongoing interest rate sensitivity. Approximately 75% of outstanding debt reprices on a quarterly basis,1 while rating agency downside metrics explicitly identify debt-funded acquisitions that fail to generate proportional revenue growth as a threat to credit standing.10 This establishes an ongoing tension between debt-financed asset acquisition and credit rating preservation.
Governance structures and related-party transactions warrant continued oversight. The sponsor group retained a 33% unitholding as of March 2026,1 while both the investment manager and project manager operate as sponsor affiliates.2 In addition, asset expansion relies significantly on sponsor drop-down transactions, voluntary governance safeguards were streamlined upon public conversion, and sponsor entities remain subject to an ongoing World Bank Group integrity audit.[^4]
The synthesis.
The structural evaluation of competitive dynamics leads to a clear conclusion: Cube Highways Trust holds high-quality operational assets within a challenging broader industry environment. Asset-level characteristics—spatial exclusivity along designated corridors, contractual toll indexation, and low incremental costs per vehicle—provide strong operational cash generation. However, industry structure concentrates bargaining power with a single government counterparty while distributing excess returns to the most aggressive auction bidders.
Consequently, the investment thesis does not rely primarily on competitive moats. Instead, it depends on three operational variables: management's capacity to acquire assets at returns exceeding its cost of capital, the scope of future regulatory interventions relative to past toll formula adjustments, and the remaining capacity for debt cost optimization. The first variable can be monitored through quarterly performance, the second represents an exogenous policy risk, and the third is constrained by prevailing interest rate environments.
X. Essential Investor KPIs & What to Watch
While InvIT dashboards typically track dozens of operational metrics, three primary indicators govern the underlying investment thesis.
One: distribution per unit, and the share of it funded from current-period NDCF.
Distribution per unit (DPU) represents the ultimate output of the vehicle, but its underlying composition distinguishes organic operational yield from a return of capital. Cube discloses this net distributable cash flow (NDCF) bridge across its earnings reports, detailing inflows from toll and annuity assets after accounting for operations and maintenance, management fees, taxes, periodic maintenance, cash reserves, and debt service.1[^4] Evaluating this metric requires monitoring two key dimensions: whether distributions track toward the formal ₹14.50 FY27 guidance, and whether payouts remain fully covered by current-period NDCF rather than supplemented by balance sheet cash reserves—as occurred in FY25, when opening cash funded ₹385 crore of distributions.3[^4] A rising DPU driven by declining coverage indicates capital return rather than underlying operational growth.
Two: portfolio traffic growth in passenger car unit terms, relative to the valuation model's assumption.
Traffic volume represents the primary variable outside management's direct control and balance sheet refinancing capability. The platform's independent valuation model assumes long-term annual traffic growth of 4.7% and a Wholesale Price Index (WPI) inflation rate of 4.1%, implying an annual revenue growth trajectory of approximately 8.8% over remaining concession lifespans.1 Recent performance exceeded these baseline assumptions, with traffic growing 8.1% in FY26 and 9.3% in the first quarter of FY27.13 Disciplined analysis requires treating short-term volume acceleration as potentially cyclical, as sustained traffic growth below the 4.7% baseline would render published net asset values overly optimistic. Unitholders should also note that Cube reports traffic figures using both a simple average across its 18 toll assets and an AUM-weighted average, two metrics that can diverge significantly depending on performance across larger corridors.3
Three: net debt to AUM, alongside the acquisition pipeline.
Net debt to assets under management stood at 45.17% in June 2026, remaining comfortably below SEBI's 49% regulatory threshold for enhanced governance requirements and the platform's 60% debt covenant cap.310 However, balance sheet leverage also serves as the funding engine required to acquire replacement assets as existing concessions approach maturity. The central tension lies between balance sheet headroom and portfolio longevity: deploying debt capacity funds asset acquisition, while failing to acquire new concessions eventually leads to declining distributions as revenue streams expire. Tracking leverage therefore requires evaluating balance sheet capacity against the four committed sponsor drop-down acquisitions and three right-of-first-offer assets.
Beyond continuous operational metrics, a key regulatory proceeding requires ongoing tracking: the pending Delhi High Court litigation regarding NHAI's Wholesale Price Index linking factor circular.2 The outcome directly determines base toll rates across the majority of the portfolio. Concurrently, annual toll adjustment cycles and published inflation figures dictate contractual price increases. While WPI inflation near 10% in mid-2026 provided an exceptionally favorable escalation environment against the 4.1% long-term model assumption, this pricing tailwind underscores the risk that regulatory counterparties may act to modify tariff escalation mechanics during high-inflation periods.23
XI. Earnings Call & Transcript Guide for downstream Writer
Cube's investor communication has improved as it approached public status, establishing disclosure quality above the Indian InvIT industry norm. Three sets of primary disclosures merit detailed analysis.
The Q3 FY26 investor call, held February 6, 2026. This briefing provided critical strategic disclosures, simultaneously detailing the proposed conversion to a public InvIT, the sponsor transition from CH-I and CH-III to CH-V, and the four-asset drop-down valued at over ₹7,200 crore in enterprise value.[^4] Chief Financial Officer Pankaj Vasani provided a breakdown of net distributable cash flow (NDCF), detailing the historical split between current operational cash generation and balance sheet cash reserves. Chief Strategy Officer Saurabh Bansal outlined the right-of-first-offer (ROFO) framework and equity-swap mechanics—including issue-price adjustments and revenue-linked earnouts designed to offer downside protection on the acquisitions—while management detailed the rationalization of voluntary governance provisions, known as "Specified Matters."[^4]
The call's question-and-answer session was brief, consisting of three inquiries—none from sell-side analysts, two from individual investors, and one from a family office.[^4] As a privately listed vehicle prior to July 2026, the trust encountered minimal public interrogation. Gautam Babu of Gland Family Office raised the key analytical question regarding how lower Wholesale Price Index (WPI) inflation would affect the valuation model. Chief Executive Officer Vinay Sekar pointed to offsetting expansion in real gross domestic product and the annual March model review, but did not provide a quantified sensitivity analysis.[^4] Following the public conversion, market scrutiny will test whether institutional Q&A becomes more rigorous.
The Q4 FY26 results and investor presentation, dated May 2026. This document provided comprehensive portfolio disclosures, mapping the FY24-to-FY26 trajectory across assets under management, revenue, asset count, leverage, fixed-rate debt share, net asset value, and distributions. It also set out the valuation assumptions—including weighted average cost of capital build-ups across toll and annuity assets—the sustainability-linked bond scorecard, and asset-level traffic performance, identifying both expanding corridors and declining assets.1
The Q1 FY27 results and call, held August 14 and 17, 2026. Marking the trust's initial reporting period as a public InvIT, this quarter saw management introduce and subsequently raise formal distribution guidance.3 Key operational vectors require ongoing tracking: the status of closing conditions on the four drop-down acquisitions—specifically concessioning-authority approval for BFHL, which adjoins the Farakka–Raiganj corridor, and the purchase of the residual 5% minority stake in Western MP Infrastructure & Toll Roads; the collection period for Annual Pass compensation receivables, which averaged 42 days; and management commentary on the WPI linking factor litigation, an issue omitted from prepared remarks in both the March and June 2026 quarter materials despite being flagged as a material risk in regulatory filings.23
Two regulatory documents provide essential context alongside management calls. The draft offer document filed with SEBI on March 17, 2026, sets out risk factors, litigation summaries, annuity payment delay records, CNTL audit qualifications, and the World Bank integrity audit—disclosures omitted from standard investor presentations.12 In addition, CRISIL's rating rationale from February 10, 2026, offers an independent, sensitized assessment of debt service coverage ratios and specifies rating triggers.10 Where investor presentations and regulatory filings diverge in emphasis, the filing carries legal liability.
XII. Closing Thoughts & Key Takeaways
In December 2014, a two-year-old private equity firm signed an agreement to acquire a single 109-kilometre toll road in Rajasthan from a Malaysian construction company.6 Twelve years later, that asset sits within a publicly traded trust valued at approximately ₹21,000 crore in early September 2026, managing 27 assets and distributing over ₹1,850 crore annually to institutional and individual unitholders.117
Yet that founding asset lost 7% of its traffic in FY26 to a newer expressway constructed by the very government that granted its concession.1
Both sides of that comparison capture the platform's history. Cube Highways completed a difficult operational transition: it took an asset class that had strained the balance sheets of a generation of Indian contractors and restructured it for institutional ownership. It achieved this by unbundling three elements historically combined within developer balance sheets: construction risk, operating capability, and long-term capital. Contractors absorbed construction risk, Cube built centralized operational capabilities, and global sovereign wealth funds provided patient equity. The InvIT framework subsequently provided a liquid, tax-efficient holding vehicle. This structural evolution represented a major financial innovation in emerging market infrastructure, and the July 2026 private-to-public conversion established a precedent for privately listed Indian InvITs.14
The broader insight for institutional private equity is more constrained than platform narratives suggest. In a market where a single government counterparty dictates regulatory terms, durable advantage does not derive from independent pricing power—the government sets toll tariffs and has demonstrated a willingness to modify escalation formulas. Instead, competitive differentiation relies on a lower cost of capital combined with operational credibility: the capacity to underwrite lower target returns through patient equity, manage maintenance expenses efficiently, and maintain execution standing with concessioning authorities. That positioning creates a real edge, though a narrower one than marketing claims imply, particularly as revised public-private partnership rules invite direct participation from competing global funds.1
Evaluating the vehicle requires clear analytical framing. Infrastructure trusts are not compounding equities in the traditional sense; concession assets naturally amortize over time as terminal dates approach, requiring management to acquire replacement yield at rates that enhance unitholder value. Cash distributions represent organic operational payouts that have expanded annually since listing.1 Balance sheet leverage remains within covenant limits, supported by a carefully staggered debt repayment profile.1 Furthermore, regulatory filings provide detailed disclosures regarding operational and structural risks.
However, those same regulatory filings highlight significant ongoing vulnerabilities: asset concentration across three primary regions, a drop-down acquisition pipeline priced by a manager-appointed valuer, an active World Bank Group integrity audit of sponsor-group entities, a target acquisition carrying three consecutive years of qualified audit opinions alongside a going-concern warning, and a counterparty that unilaterally reduced base toll escalation formulas through administrative circulars.2
Cube Highways Trust serves as a clear case study in emerging market infrastructure financialization because it illustrates the underlying economic trade-off. Investors receive predictable cash distributions generated by operational transportation assets in an expanding economy. In exchange, unitholders accept cash flow terms governed by a single entity acting simultaneously as regulator, concession counterparty, market competitor, and primary asset seller. The ultimate investment thesis rests on purchase price discipline and operational execution—the key variables unitholders must evaluate across remaining concession lifespans.
References
-
Investor Presentation Q4 FY26 — Cube Highways Trust, 2026-05-26 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Cube Highways Trust Draft Offer Document (Private to Public) — SEBI, 2026-03-17 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Investor Presentation Q1 FY27 — Cube Highways Trust / BSE, 2026-08-16 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
I Squared 2.0: the mid-market champion enters a new era — Infrastructure Investor ↩
-
Road Asset Monetisation: NHAI Receives Rs 5,011 cr In Upfront Payment From Cube Highways For 3rd Tranche Of TOT Bundle — India Infra Hub, 2020 ↩↩↩↩↩↩↩
-
Macquarie bags first project under toll operate transfer with Rs 9,681.5 crore bid — Business Today, 2018-03-01 ↩
-
Cube Highways — Case Study, Abu Dhabi Investment Authority ↩↩↩
-
Cube Highways Trust — Rating Rationale, CRISIL Ratings, 2026-02-10 ↩↩↩↩↩↩↩↩↩↩
-
IFC and Cube Highways Trust Partner for India's First Sustainability-Linked Bond for Road Infrastructure — International Finance Corporation, 2025-02-13 ↩↩
-
Cube Highways Trust Completes Acquisition of 2 Highway Assets in J&K from NIIF, at a Transaction Value of ₹4,185 Crores — NIIF, 2025-06-12 ↩↩
-
Cube Highways InvIT Fixes ₹151-152 Price Band for ₹5,000-Cr IPO Valued at ₹20,430 Cr — Outlook Business, 2026 ↩
-
Sidley Advises on US$520 Million Public Offering of Cube Highways Trust — India's First Private-to-Public InvIT Conversion — Sidley Austin LLP, 2026-08-04 ↩↩
-
Cube Highways Trust Completes Public Listing with 81.36% Public Float — Whalesbook, 2026 ↩
-
Cube Highways Trust Debuts, Becomes India's Largest Public InvIT — Whalesbook, 2026-07-31 ↩↩↩
-
Cube Highways Trust — Consolidated Financials and Key Insights, Screener.in ↩↩↩↩
-
Cube Highways Trust InvIT IPO: Price, Dates, Portfolio & Yield — JM Financial Services, 2026 ↩
-
Investor Presentation — Cube Highways Trust, 2026-06-08 ↩↩↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube