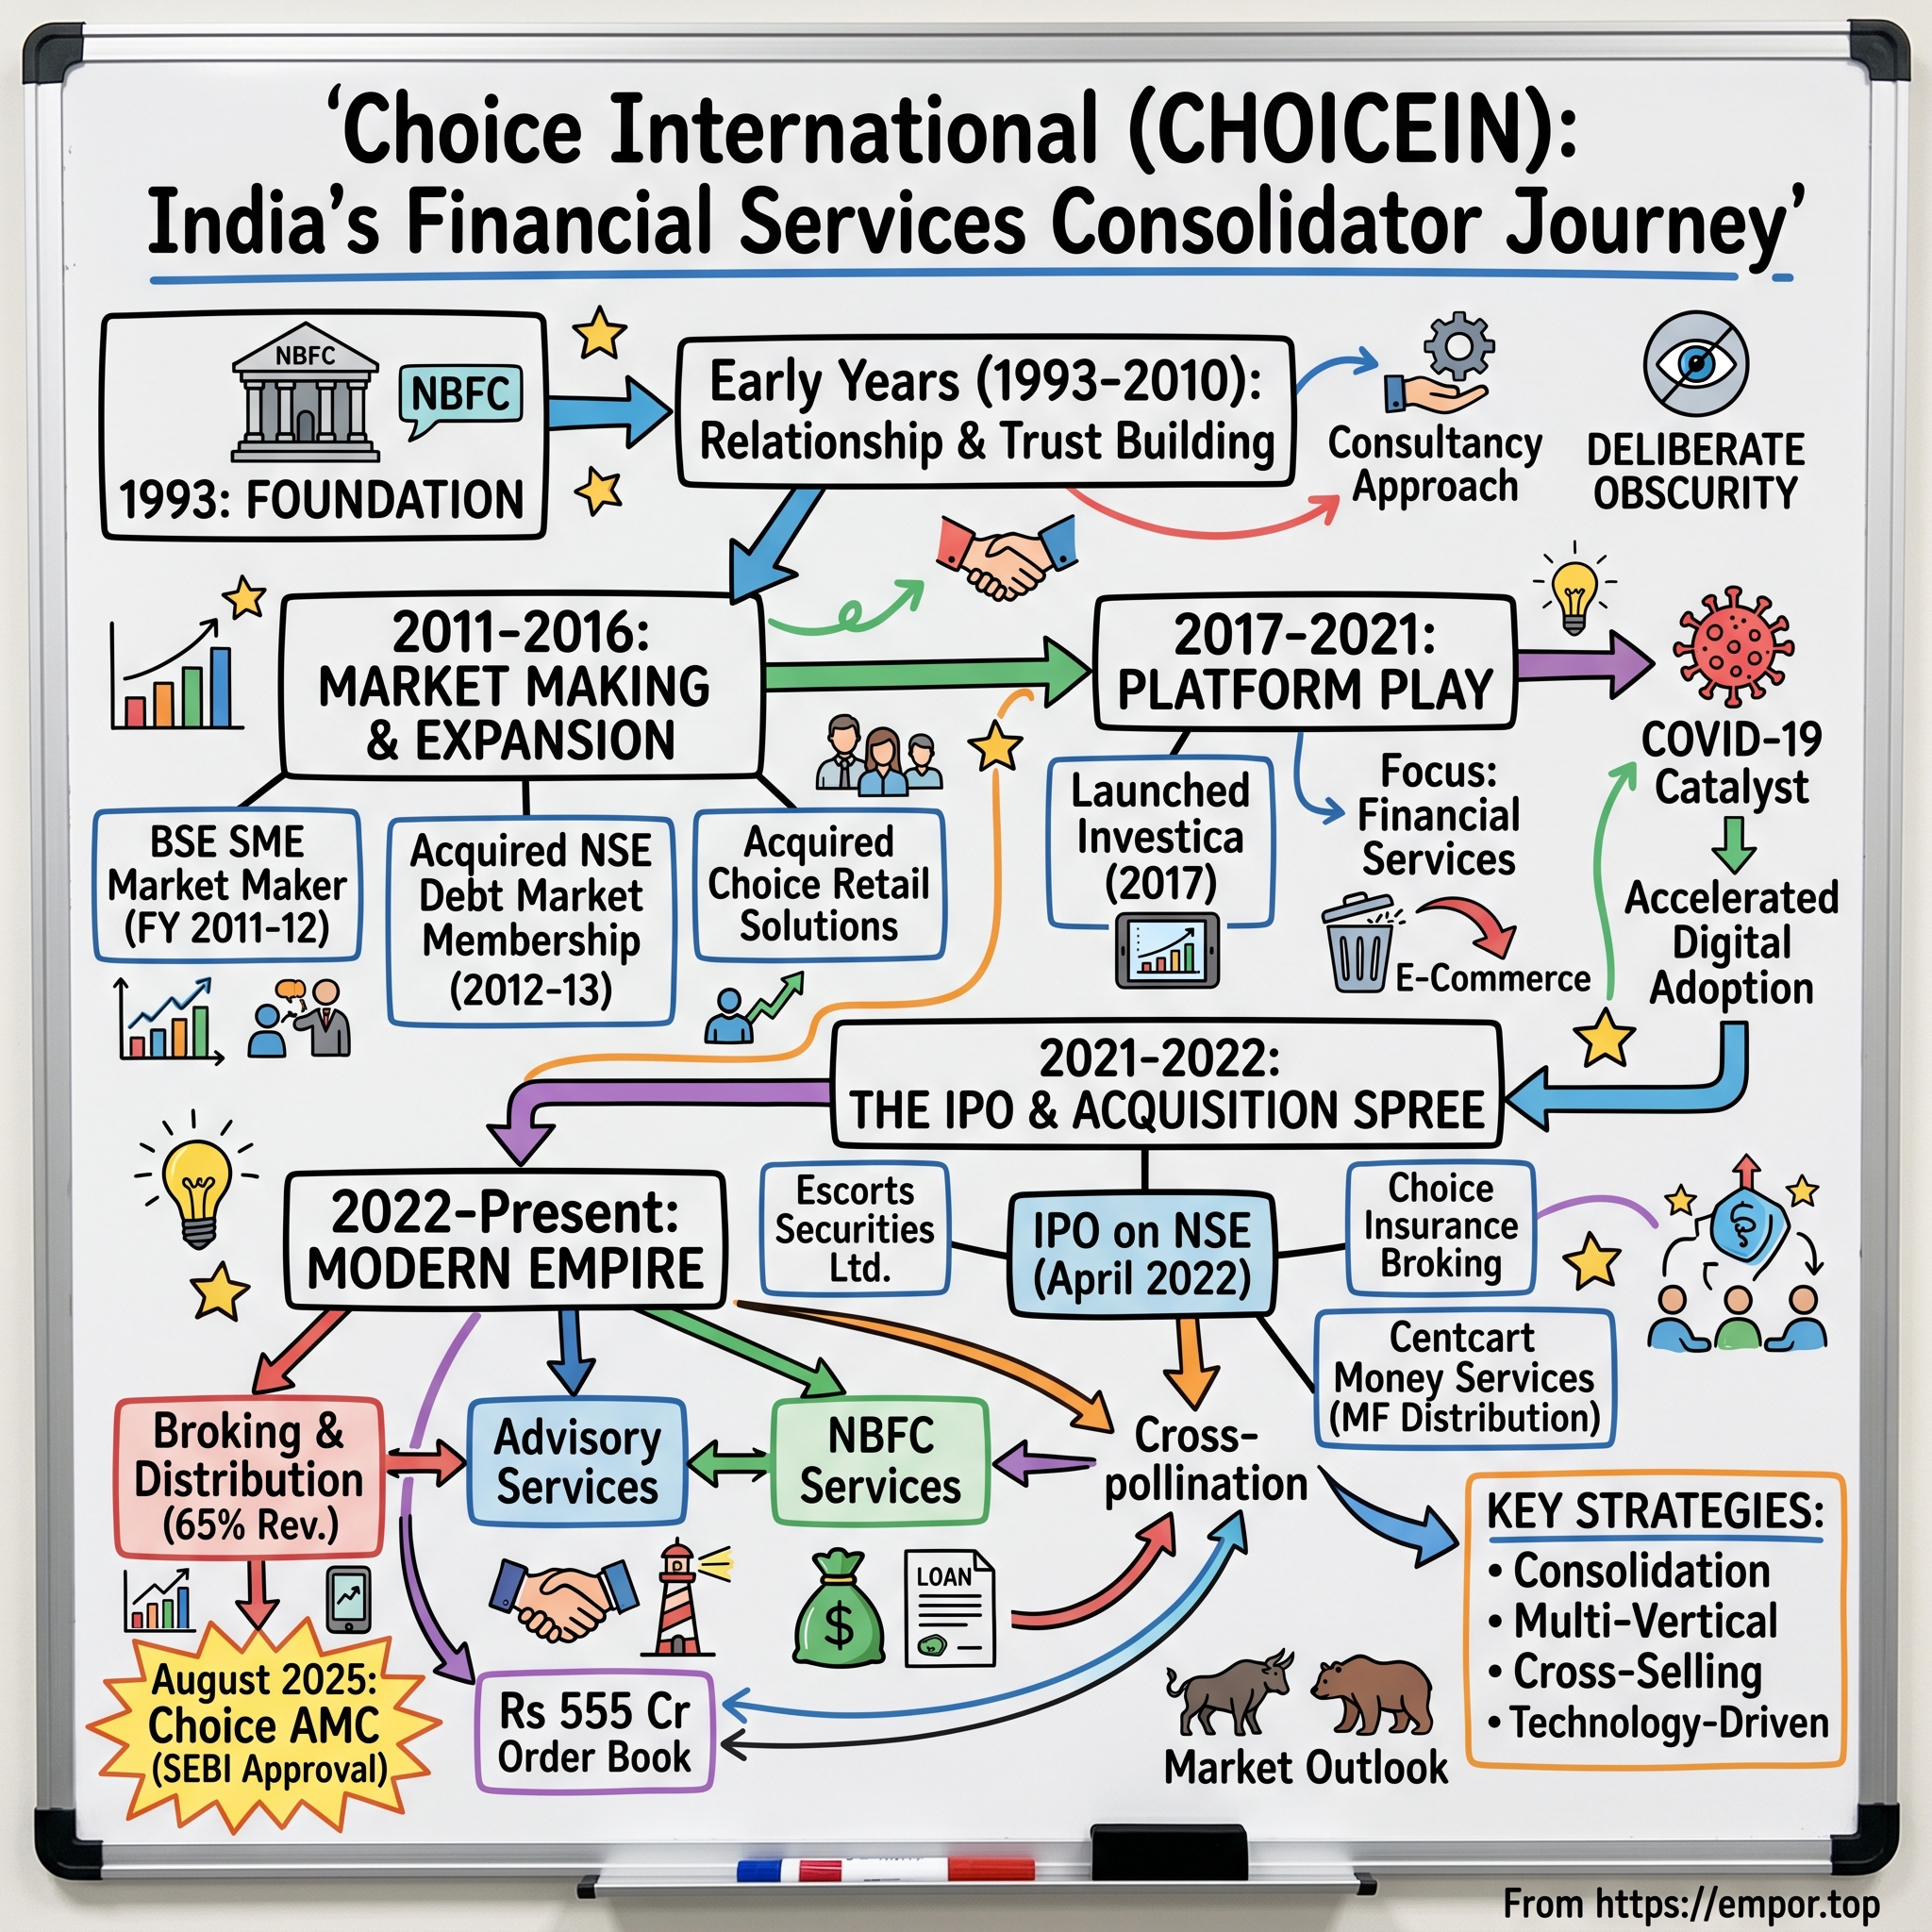
Choice International: The Story of India's Financial Services Consolidator
I. Introduction & Episode Roadmap
On the evening of April 24, 2026, a conference line opened in Mumbai and a familiar ritual began. An Adfactors PR moderator read the forward-looking-statements disclaimer. Arun Poddar, the group chief executive, delivered opening remarks about India's "stable policy environment." Then Ayush Sharma, the head of investor relations, walked through the numbers, and for the next forty minutes he — not the CEO, not the executive director — answered nearly every analyst question on the call.1
The questions themselves were revealing. Analysts asked about dormant demat accounts, artificial intelligence, the insurance mix, and whether the company might demerge its verticals. One asked what return thresholds management applies to new investments. Sharma's answer was flat: "There are no new investments we are making and there are no new segments in which we are expanding as of now."1
Eleven weeks later, on July 9, 2026, Choice International announced that South Korea's NH Investment & Securities (NH투자증권) would invest ₹900 crore into its broking subsidiary through compulsorily convertible preference shares.2 It was the largest single capital event in the company's history, arriving from a direction no analyst on the April call had been advised to monitor.
That gap — between what management tells analysts on Thursday and what the balance sheet does on Monday — forms the analytical spine of this story.
Choice International appears, on the surface, to be one of the more remarkable compounding stories on Indian small-cap screens. Consolidated revenue grew from ₹132 crore in FY2020 to ₹1,119 crore in FY2026, representing a five-year compound annual growth rate of roughly 45%. Net profit rose from ₹12 crore to ₹238 crore over the same window, expanding at a five-year compound annual rate near 67%.3 The company has never paid a dividend. As of September 3, 2026, the stock traded around ₹768, carrying a market capitalisation of roughly ₹17,136 crore, a trailing price-to-earnings multiple near 75 times, and a price-to-book multiple above 10 times.3
Here is the central paradox of the business. Over the five financial years from FY2022 through FY2026, Choice reported cumulative net profit of approximately ₹646 crore. Over those same five years, cumulative cash flow from operating activities was approximately negative ₹628 crore.3 The profits are real in the accounting sense — audited, segment-reported, and expanding. But cash flow, on a net basis, moved in the opposite direction.
There are legitimate reasons why operating cash flows can lag reported earnings at a financial services firm, and this analysis examines each of them alongside less comfortable interpretations. The objective is to evaluate both perspectives rather than resolve the tension by assertion.
The roadmap for this analysis:
- The origins of the Choice franchise in Mumbai's chartered accountancy and corporate consultancy ecosystem, including the distinct founding timelines of the listed vehicle and the operating group.
- The exchange-membership era, when Choice acquired licences before generating the trading volume to fill them.
- The roll-up decade — featuring acquisitions such as Inditrade and Escorts Securities alongside regional broking books — and what customer retention data actually reveals.
- The modern three-engine structure: broking and distribution, government advisory, and micro, small, and medium enterprise (MSME) lending, alongside its expansion into asset management.
- A capital allocation audit, an activist-style stress test, Porter's Five Forces, Helmer's 7 Powers, and valuation mechanics.
The core question: can an acquisition-led roll-up in Indian financial services build a durable, high-return franchise — a kind of Indian Charles Schwab assembled from acquired parts — or does the combination of regulatory tightening, working-capital intensity, and balance-sheet-heavy lending expose the structural limits of inorganic consolidation? Choice's record now spans enough years and transactions to evaluate that question through empirical evidence.
 Subscribe on LinkedIn
II. Foundation & Survival Era (1993–2010): Mumbai's Financial Jungle
In 1993, the most valuable asset in Indian mid-market finance was a filing cabinet and a phone book.
The country was two years past the balance-of-payments crisis that had forced the dismantling of the licence raj, and the consequences were arriving unevenly. Large industrial houses had merchant bankers. Multinationals had law firms. But the vast middle of Indian enterprise — the textile trader, the auto-component maker in Pune, the chemicals promoter in Gujarat — relied on a chartered accountant. That single advisor audited the books, structured term loans, negotiated with bank managers, and explained evolving regulations to businesses accustomed to a forty-year-old framework. The relationship was total, personal, and untransferable.
Choice was built out of that environment rather than a trading floor. Understanding this origin is essential, as nearly every strategic decision the company has made over the subsequent three decades represents an effort to transcend the economic limitations of that advisory model.
The corporate origin story begins with a timeline discrepancy that illustrates how that transition was executed.
Choice International Limited, the listed entity trading on the NSE as CHOICEIN and on the BSE under scrip code 531358, was incorporated in 1993 and is a Reserve Bank of India–registered non-banking financial company.456 However, the Choice Group's milestone timeline dates its founding to 1992 — and records that in 2008 the group acquired a listed NBFC, which became Choice International's public holding vehicle.7
Reading these two facts together clarifies the structure. Choice did not enter public markets through an initial public offering; it reverse-engineered its listing by acquiring a dormant NBFC shell and transferring its operating business into it. This was a conventional path in Indian small-cap finance, and it established an operational template that persisted for eighteen years: when Choice required a new capability, licence, or market presence, its default strategy was to acquire an existing entity rather than build one organically.
The architect of this strategy is Kamal Poddar. A Fellow Member of the Institute of Chartered Accountants of India and Managing Director of Choice International, he remains "involved in all the strategic decisions of the group," according to credit rating agency reports.5 While he does not serve as group CEO — a role held by Arun Poddar — and has stepped back from public earnings calls, the founding generation retains strategic oversight. This division between public representation and strategic control makes governance and management discipline harder to evaluate through transcript analysis alone, a topic examined later in this story.
Governance is shared across two promoter families, though neither family's name appears in the corporate branding. Choice International's board pairs the Poddars with the Patodias: Vinita Patodia serves as Non-Executive Chairperson and Suyash Patodia as Joint Managing Director, alongside Kamal Poddar as Managing Director and Arun Poddar as Executive Director and Group CEO.7 Acuité's credit rating review lists Suyash Patodia and Kamal Poddar together as managing directors of the listed entity.5 Together, the two families hold a 53.66% promoter stake, with second-generation family members occupying key executive positions.3
For an acquisition-led firm, this concentrated family ownership creates distinct operational trade-offs. It enables Choice to negotiate and close regional brokerage acquisitions rapidly without external advisors, competitive auctions, or lengthy board deliberations — speed being an advantage when buying small or distressed assets. Conversely, formal checks on deal terms remain limited. Independent directors hold seven of twelve board seats, exceeding regulatory mandates.5 However, operational leadership across all business lines remains within the two promoter families, and the company does not disclose specific hurdle rates or return-on-capital targets for acquisitions. Consequently, assessing transaction discipline depends primarily on long-term operational execution rather than pre-deal disclosures.
The economic environment of 1990s Mumbai shaped Choice's initial advisory practice. Post-1991 reforms expanded the scope of mid-market corporate finance, leading regional accounting firms across Mumbai and Ahmedabad to move into project finance, capital raising, and regulatory advisory. While lucrative, this traditional consultancy model faced three compounding structural constraints:
- Non-recurring revenue: Fees had to be re-earned with each new transaction or corporate engagement.
- Limited operating leverage: Capacity scaled directly with senior partner hours, creating a ceiling on growth.
- Non-transferable equity: Customer relationships resided with individual partners rather than the firm, limiting enterprise valuation.
Choice's operations prior to 2010 reflected these dynamics, concentrating on corporate advisory, project finance consultancy, and localized MSME lending. The firm lacked the regulatory permissions required to intermediate public capital market transactions. It obtained equity and commodity broking licences in 2010, followed by SEBI registration in 2011.7
The 2008 shell transaction highlights a recurring pattern in the firm's licensing strategy. The listed entity Choice acquired was an RBI-registered NBFC.45 Although Choice possessed a lending licence from 2008 onward, it did not develop a scaled lending operation for over a decade. Choice Finserv Private Limited, the vehicle managing its current MSME loan portfolio, was incorporated in 2016, and its assets under management remained below ₹500 crore as recently as FY24.5
Holding regulatory permissions years in advance of operational execution became a consistent feature of Choice's strategy. While securing licences early provides strategic optionality in India's regulated financial sector, it also indicates that regulatory filings do not automatically signal immediate revenue generation. This multi-year lag between licensing and operational scaling provides important context for evaluating the firm's recent entry into asset management.
This sequence reflects an effort to shift across financial service business models: transitioning from transactional advisory fees to recurring brokerage commissions, balance-sheet interest spreads, and asset management fees. Choice sought to move up this revenue hierarchy primarily through acquisition.
However, each successive tier requires greater capital reserves and faces distinct market dynamics. Brokerage operations face ongoing fee compression, lending returns depend strictly on credit risk management, and asset management requires significant scale to maintain profitability. Choice expanded into these business lines in sequence, with historical returns reflecting the varying competitive pressures of each market segment.
The initial step in this expansion focused on acquiring exchange memberships.
III. The Transformation Arc: Infrastructure & Membership Spree (2011–2016)
An Indian stock exchange membership is sold rather like a taxi medallion. Obtaining it is the easy part. The meter starts running the day it is issued, and it does not stop when the cab is empty.
Between 2011 and 2013, Choice bought several.
Picture the trading floor economics of an Indian broking outfit circa 2012. Membership of an exchange segment is not a piece of paper; it is a standing financial obligation. A clearing member in the futures and options segment has to post collateral, maintain net worth against regulatory minimums, run risk systems, employ compliance officers, and submit to inspection — whether it clears one lakh contracts a day or ten. The cost is largely fixed. The revenue is entirely variable.
Choice went on a licence-buying run anyway. Across FY2011–12 and FY2012–13, the group registered as a market maker on the BSE's SME platform, converted its BSE trading membership into a clearing membership in the futures and options segment, secured cash and derivatives broking permissions on MCX-SX, and added debt market membership on the National Stock Exchange.[^8] It also acquired full ownership of Choice Retail Solutions Private Limited, intended as the chassis for a retail distribution network.[^8]
The strategic logic was coherent on paper: assemble the full stack of permissions first, then fill it with flow. Own the pipe and the water becomes someone else's problem.
It is worth examining what those permissions actually entail, because while the terminology is technical, the underlying economics are straightforward.
A trading member is permitted to place orders on an exchange on behalf of clients. A clearing member goes a decisive step further: it stands behind the settlement of those trades, guaranteeing to the exchange's clearing corporation that the money and the shares will arrive on time. That guarantee must be collateralised in cash and securities, and it must be sized for the worst plausible day rather than the average one. Converting a trading membership into a clearing membership — which Choice did in the futures and options segment — is therefore a decision to lock up capital permanently in order to retain a fee that would otherwise be paid to another firm. It pays handsomely when clearing sufficient volume, but becomes dead weight without it, and the collateral remains tied up while the licence is active.
A market maker on the BSE's SME platform carries a different obligation. Small-company listings are, by nature, barely traded: on many days there is no natural buyer facing a natural seller. The market maker contracts to continuously quote two-way prices in those shares so the listing maintains liquidity, absorbing inventory in an illiquid stock in exchange for the spread. It is capital-consuming work with a real risk of holding shares that lack immediate buyers.
It is also, quietly, how a firm builds relationships with the promoters and merchant bankers behind small-company listings — representing the strongest argument that the licence spree served a broader strategic purpose. Choice's investment banking practice today runs 30 ongoing IPO mandates against a tentative fundraising pipeline of roughly ₹67.6 billion, staffed by a team of more than 150 people.91 The SME market-making seat acquired in the early 2010s provides a plausible initial footprint for that business. While unproven — as the company has not disclosed how much of its current IPO mandate flow originates from relationships formed in that era — it represents the strongest case for the long-term utility of those early seats.
Historical falsification pass — the platform economics test
The thesis embedded in that strategy — and one still advanced regarding Choice — is that aggregating exchange licences creates an immediate, low-cost transaction moat. Testing this claim against the company's own record over the subsequent decade reveals a different picture.
The financial performance of the period that followed demonstrates this tension. Through 2011–2015, Choice's operating margins swung sharply and capacity utilisation across the newly acquired memberships remained low. The company had incurred the fixed overhead of a full-service intermediary years before establishing the client base required to amortise those costs. As late as FY2020 — a full decade after acquiring its first broking licence — consolidated revenue remained at ₹132 crore and net profit stood at ₹12 crore.3 Whatever competitive moat those licences conferred, it did not translate into material earnings growth for nearly ten years.
This mechanism highlights a critical distinction: exchange memberships are necessary enablers, not cornered resources. They are accessible to any entity meeting regulatory net-worth and compliance thresholds. In India, these thresholds are substantial but crossable, as demonstrated by discount brokers like Zerodha, Groww, and Angel One, which met the same standards and subsequently built far larger user bases. A licence prevents exclusion from the market, but it does not deter new entrants. Without substantial distribution volume, an exchange seat functions primarily as a capital drag accompanied by ongoing compliance costs.
The industry timeline underlines this contrast. Choice obtained its equity and commodity broking licence in 2010 and its SEBI registration in 2011.7 Over that same decade, peer firms starting from identical regulatory positions built retail franchises multiple times larger by focusing on two factors Choice did not initially prioritize: lower trade execution costs and seamless digital onboarding. Angel One, an established full-service broker that successfully executed a digital pivot, commanded a market capitalisation of roughly ₹26,165 crore as of September 3, 2026, compared to Choice's ₹17,136 crore, while operating a business far more concentrated in core broking.316 Regulatory permissions were not the primary constraint; customer distribution was the decisive variable, and it was captured by platforms offering superior product economics.
This historical record does not suggest that Choice erred in acquiring these licences — they were indispensable prerequisites for building a distribution business. Rather, it refutes the broader assertion that a licence stack inherently constitutes a protective moat. The evidence indicates that a multi-licence structure represents a replicable entry cost that generates meaningful economic returns only when paired with scale. Going forward, the metric that clarifies this dynamic is whether incremental revenue per licence — measured through revenue per demat account and per business associate — expands as infrastructure is added, or whether Choice must continuously acquire external distribution to cover its fixed operating costs.
That question defined the next phase of the company's growth. From 2017 onward, Choice's approach to expanding distribution shifted decisively from organic development to inorganic acquisition.
IV. The Roll-Up Strategy: M&A, Regional Buying, & Tech Wrappers (2017–2021)
In 2017, Choice launched Investica, a mutual fund distribution application, followed in 2018 by Jiffy, an equity trading application.7 Neither brand remains on the company's active product shelf. Today, retail operations run on Choice FinX for trading and Choice Connect for its business-to-business-to-consumer (B2B2C) agent network, reflecting a cycle of rebuilding, rebranding, and deprecation.
This interface lifecycle highlights a core structural reality of the firm. Choice operates less as a technology-first fintech than as a distribution and licence aggregator that deploys software layers over acquired human networks. Management's comments on the April 2026 earnings call reinforced this distinction. When asked about customer acquisition costs in Tier-2 and Tier-3 cities, investor relations head Ayush Sharma noted that while "the execution is completely digital and tech-driven," client "acquisition is still physical, which is driven by branches, CBAs."1
Physical acquisition paired with digital execution defines the operational model, making the company's merger-and-acquisition record far more central to its trajectory than its application roadmap.
Buying the books
The expansion proceeded through a steady series of transactions. In May 2018, Choice International acquired the broking business of Kochi-based Inditrade Capital for approximately ₹32 crore, establishing an immediate presence in South Indian retail accounts.8 That same year, it absorbed the Pune-based stock and commodity broking operations of the NG Rathi group to expand in western India. In 2020, step-down subsidiary Choice Wealth purchased BankBazaar's mutual fund distribution book. In April 2021, Choice Equity Broking acquired 100% of New Delhi–based Escorts Securities for roughly ₹13 crore, gaining a northern branch network alongside its sub-broker codes.[^10][^11] That year, the company also added Centcart Money Services and secured a 50% stake in an insurance broking venture.
The overarching pattern reveals a consistent deal profile. Each acquisition targeted a legacy full-service regional broker with an active client book, sub-broker networks, and an owner unwilling to commit capital to compete against zero-brokerage discount platforms. Choice systematically acquired assets that traditional capital markets were repricing downward. Identifying distressed regional brokers, evaluating client books, and executing bilateral transactions without investment bankers represents a practical deal-sourcing capability.
However, acquiring client books at low valuations represents only the initial phase of a roll-up strategy; long-term performance depends on post-acquisition integration and customer retention.
Historical falsification pass — M&A integration and customer retention
The core bull thesis asserts that consolidating legacy regional brokers yields high-margin cross-selling synergies once acquired clients transition to Choice's digital platforms.
Operational disclosures offer a benchmark to test this thesis. While Choice expanded its total account count, active trading accounts lagged significantly. In the first quarter of FY2027, the company reported 1.29 million demat accounts—a 13% year-over-year increase—yet active accounts stood at just over 242,000, representing growth of 0.4%.9 Over twelve months, Choice added approximately 150,000 total accounts but netted only about 1,000 additional active traders.
An inactive account generates negligible brokerage revenue, serving primarily as a metric of total scale rather than an active driver of segment earnings. Management acknowledged this engagement challenge on the April 2026 earnings call, where Sharma detailed an internal client segmentation dividing users into "investors, traders and somewhat followers" alongside a digital nudge campaign aimed at activating dormant accounts.1 Despite these initiatives, the active conversion rate has remained stagnant.
This divergence reflects the dynamics of non-metro Indian financial distribution. In Tier-3 markets, retail trading accounts often depend less on application features or fee structures than on local sub-brokers and authorised persons who hold trusted, personal relationships with clients. When a regional broker is acquired, legal client accounts transfer immediately, but local advisor relationships may not. If the acquiring firm fails to retain and align incentives for those agents, advisors frequently migrate to competing brokerages, bringing active traders with them and leaving behind predominantly dormant accounts.
Choice's reported metrics mirror this structural challenge, characterized by steady growth in total registered accounts alongside stagnant active trading volume.
Empirical evidence validates Choice's ability to acquire regional client books cost-effectively across multiple transactions. However, disclosures challenge the premise that acquired accounts automatically yield cross-selling synergies. Inorganic expansion has successfully expanded reach—adding account volume, geographic presence, licences, and assets under custody—far more consistently than it has driven client activity. The active-account ratio, which remains flat at approximately 19% of total demat accounts, serves alongside revenue per active client as the primary metric for evaluating cross-sell efficiency. For the roll-up model to demonstrate operational leverage, active account growth must outpace total account expansion—a trend that has not yet materialized.
This operational reality presents a central question: if acquiring retail client books has not reliably expanded active trading, what mechanism has propelled Choice's revenue growth?
V. NSE Mainboard IPO & The Modern Three-Engine Empire (2022–Present)
The answer is that a substantial portion of growth has not come from retail stockbroking.
Choice International has been listed on the BSE since its 2008 shell acquisition; the NSE listing arrived in 2022, providing a second venue, enhanced liquidity, and access to a broader institutional investor base.710 Institutional participation initially expanded, with foreign institutional holdings reaching 15.44% by September 2023. However, that stake declined to 10.10% by June 2026, with public retail shareholding absorbing the difference — a shift occurring even as reported profits more than doubled over the same period.3 Promoter families held a 53.66% stake as of June 2026, and the company confirmed that no fresh encumbrances were created on promoter shares during FY2026.3
Three engines, three different businesses
By FY2026, the company reported operational results across three distinct business segments, each operating with different capital requirements under a single holding company structure.
Broking & Distribution — 59% of FY26 revenue. This segment encompasses equity broking, mutual fund and wealth distribution, margin trading, and insurance broking, delivered through physical branches and an agent network. As of Q4 FY2026, the segment managed stockbroking client assets of ₹52,482 crore (up 28% year-over-year), wealth assets under management (AUM) of ₹4,268 crore, and a network of 67,000 Choice Business Associates.1 Management has deliberately prioritized the cash delivery segment over higher-velocity derivatives — a decision Group CEO Arun Poddar noted "helped maintain margins and build a more stable clientele base."1 Roughly 70% of segment revenue originates from trades executed via digital channels, with the remainder coming through call-and-trade and dealer terminals.1
Advisory — 28% of FY26 revenue. This division distinguishes Choice from conventional retail brokerages by combining public-sector consulting — including infrastructure programme management, governance reform, and state digital transformation — with mid-market investment banking. In FY2026, the segment generated ₹330 crore in revenue and ₹120 crore in profit before tax, maintaining a pre-tax margin above 36%.1 The division employs approximately 2,000 professionals in government advisory and over 150 in investment banking.1 Its order book stood at ₹698 crore at the end of FY2026 and reached ₹777 crore by Q1 FY2027, providing two to three years of revenue visibility.19
NBFC — 13% of FY26 revenue. Choice Finserv Private Limited, incorporated in 2016 and 80.6%-owned by the parent entity, provides micro, small, and medium enterprise (MSME) and retail loans across Tier-3 and smaller regional markets.5 The loan book reached ₹800 crore by March 2026, operating with a net interest margin of 11.22% and gross non-performing assets of 2.74%.1
Comparing the three segments highlights a clear financial asymmetry. The government and corporate advisory unit generated ₹120 crore in pre-tax profit in FY2026 while requiring minimal balance-sheet capital. In contrast, the NBFC arm earned ₹2 crore in pre-tax profit during the quarter ending March 2026 on revenue of ₹43 crore.1 On a standalone basis in FY2025, Choice Finserv reported a net profit of ₹3.67 crore on equity of ₹355 crore, yielding a return on average net worth of 1.25%.5
This disparity underscores an operational challenge. The lending arm absorbs the largest share of balance-sheet capital, bears the highest regulatory burden, and accounts for much of the group's negative operating cash flow, yet in FY2025 it earned a return on equity below standard risk-free rates. Management presents the NBFC on investor calls as a strategic credit engine designed to cross-sell loans to distribution clients. While that strategy may yield long-term benefits, empirical results show that the lending division remains the firm's least productive asset relative to capital deployed.
The 2024–2026 acquisition acceleration
Inorganic expansion continued through recent financial years. During 2024 and 2025, Choice absorbed the regional operations of Sernet Financial Services, Berkeley Securities, and R K Stock Holdings. In FY2025, it purchased the wealth management division of Arete Capital Services, expanding wealth management AUM from approximately ₹1,090 crore to ₹5,577 crore in a single transaction.11 In Q2 FY2026, it acquired retail lending portfolios from Paisaworth Financial and Paisabuddy Finance via slump sales settled partly through share issuance.11 In November 2025, subsidiary Choice Consultancy Services acquired 100% of Ayoleeza Consultants, an infrastructure advisory firm with live orders exceeding ₹200 crore across railways, metros, roads, bridges, and tunnels — containing a contract base where roughly 69% of projects generate recurring monthly fees.12
The Ayoleeza acquisition targeted the revenue structure of the advisory business by increasing predictable cash flows. Time-and-materials contracts bill monthly, whereas milestone contracts bill upon project completion. Shifting the advisory portfolio toward monthly billing addresses working-capital demands reflected across the group's financial statements.
However, continuous dealmaking has accumulated balance-sheet assets that require monitoring. Goodwill and intangible assets rose from approximately ₹8.25 crore in FY2024 to ₹88.41 crore by Q4 FY2025, marking a more than tenfold expansion.11 While this figure remains modest against a balance sheet of ₹3,566 crore, any underperformance in acquired books would require impairment charges against future earnings.3
The AMC bet — and the difference between a licence and a business
On August 1, 2025, Choice AMC Private Limited received final approval from SEBI to operate as an asset management company for Choice Mutual Fund, with Group CEO Arun Poddar describing the approval as "a significant milestone in expanding our financial services portfolio." The firm adopted a phased launch strategy beginning with passive index funds and ETFs.13
Transitioning from distributor to asset manager carries clear strategic logic. Third-party mutual fund distributors earn a fraction of trail commissions while facing margin pressure from fund houses and direct-plan options. Asset managers earn recurring management fees on proprietary assets, gaining operating leverage and higher-margin economics.
However, regulatory permission does not guarantee immediate commercial scale. By the April 2026 earnings call, Choice had launched a Nifty 50 Index Fund and a Nifty Next 50 Index Fund, setting an AMC AUM target of ₹1,000 crore by the end of FY2027.1 By Q1 FY2027 — a full year after SEBI approval — disclosed holdings showed a Gold ETF with ₹57 crore in assets and index funds with ₹30 crore, totaling approximately ₹87 crore against the ₹1,000 crore target.9 Executive Director Ajay Kejriwal guided that the AMC would achieve break-even within two to three years, though management declined to provide intermediate AUM targets beyond FY2027.914
Passive index funds also represent a highly competitive segment within Indian asset management, where expense ratios have been compressed by established asset managers with superior distribution scale. Choice entered the asset management sector at a low capital cost, but in its least differentiated product category.
The asset management business offers long-term optionality, but initial commercial traction remains modest. The core operational metric to track is quarterly AMC AUM against the ₹1,000 crore FY2027 benchmark, along with whether active equity schemes — which management promised by the end of FY2027 — attract established fund managers.9
The Korean capital, and the guidance that preceded it
This backdrop brings the events of July 9, 2026, into clearer focus. On that date, South Korea's NH Investment & Securities, a unit of NH Financial Group, committed ₹900 crore to Choice Equity Broking Private Limited through compulsorily convertible preference shares (4.2 million CCPS at ₹2,130 per share, converting by July 2027).2 Management outlined plans to allocate the capital toward expanding margin trading facilities, settlement funding, technology infrastructure, customer acquisition, and talent, targeting a fivefold growth in broking and distribution over three years.2 Management framed the partnership as providing strategic value beyond capital, offering access to institutional networks across Asian and US markets alongside institutional risk management expertise.14
This capital infusion carries two distinct implications. On one hand, an international institutional investor completed diligence and priced the broking subsidiary, establishing an external valuation benchmark for Choice's core operating asset, with funds expected in Q2 FY2027 and operational impact anticipated from Q3 FY2027.15
On the other hand, the transaction highlighted a disconnect with prior management communications. During the April 2026 earnings call, an analyst asked about return thresholds for new investments, and investor relations lead Ayush Sharma responded that no new investments or segment expansions were underway.1 In the same call, management stated that "all of our businesses are self-sufficient now, they don't need much of the capital," and affirmed that internal accruals were sufficient to fund future growth.1 Yet eleven weeks later, the broking subsidiary secured ₹900 crore in external capital, with management stating on the August 2026 call that "tremendous growth will be seen after the ₹900 crore capital infusion starts working in the business."14
These two positions present a clear contradiction. If the core operating units were capital-independent, the ₹900 crore investment represents an opportunistic raise; if the business required capital to scale, the April communication understated capital needs. Transaction negotiations of this scale typically require months to structure, indicating discussions were likely in progress during the April call. While confidentiality constraints explain why a private placement cannot be pre-announced, asserting that no investment activity was taking place creates a narrative inconsistency.
For market participants, the relevant takeaway is one of calibration: official guidance on earnings calls has presented a self-funding operational model, whereas actual capital allocation has included major external transactions. Evaluating future management projections requires accounting for this discrepancy.
VI. Management Credibility, Capital Allocation, & The Cash-Flow Audit
Every roll-up story eventually reaches the same room. Someone opens the cash flow statement.
The people, and how they behave
Choice's twelve-member board includes seven independent directors, while executive leadership remains centered on Managing Director Kamal Poddar, Joint Managing Director Suyash Patodia, Non-Executive Chairperson Vinita Patodia, Group CEO Arun Poddar, and Executive Director Ajay Kejriwal, who brings over fifteen years of financial markets experience.57 Promoter families hold a 53.66% stake, supported by warrant conversions and no newly disclosed share encumbrances in fiscal 2026.3 Auditing responsibilities are held by MSKA & Associates, a BDO member firm, which succeeded Deloitte Haskins & Sells LLP.11
On quarterly earnings calls, management demonstrates consistent operational accessibility, directly addressing questions on declining wealth assets under management, provision coverage, product mix, order book concentration, and technology deployment.1 Yet accountability becomes harder to enforce when evaluating specific forward guidance.
Consider the firm's growth targets. Management has stated a consistent goal of maintaining roughly 30% year-over-year growth across both top-line revenue and net profitability.1 For fiscal 2026, Choice reported 24% revenue growth alongside a 46% surge in net profit — exceeding its profit target while missing on revenue.1 However, performance fluctuated significantly within the year. First-half revenue grew by only 15%, which management attributed to delayed revenue recognition in government advisory services.11 While advisory revenue materialized in the second half to meet annual profit targets, the quarterly trajectory proved far more volatile than guidance suggested.
A similar pattern appears in physical network expansion. Choice added 35 new branches in the first half of fiscal 2026 against a full-year target of 100.11 By the first quarter of fiscal 2027, with 214 branch offices and 48 project offices operational, management acknowledged opening only 10 to 20 branches during the quarter and pushed its target to between 300 and 350 offices by March.914
Execution timelines have also shifted for key distribution partnerships. During the April 2026 call, management stated that technical integration with India Post Payments Bank was underway and projected that revenue contributions would begin on July 1.1 By the August 2026 call, customer onboarding had moved to September 1, without updated revenue estimates.1415 While a brief delay in integrating with a state-owned institution is common, it reflects a broader pattern of shifting timeline commitments.
Explanations regarding credit quality in the lending division have also evolved over time. In August 2025, credit rating agency Acuité attributed rising delinquencies to an MSME loan portfolio concentrated among agricultural borrowers in Gujarat.5 By October 2025, management cited stress in the garment sector alongside seasoning across unsecured retail loans.11 By April 2026, leadership offered a third perspective, attributing rising defaults to broader microfinance industry pressures while assuring investors that credit conditions were normalizing.1
These shifting explanations applied to an 800 crore rupee loan book that continued to show stress. Gross non-performing assets rose from 2.74% in March 2026 to 3.78% by June 2026, with net non-performing assets at 2.74% and provision coverage standing at 27.67%.19 The proportion of on-time loan repayments declined steadily from 99.25% in fiscal 2023 to 91.63% in fiscal 2024 and 87.32% in provisional fiscal 2025.5 This downward trajectory signals credit expansion into higher-risk borrower segments, leading rating agencies to highlight asset quality as a key operational risk.5
This pattern reflects an optimistic management team inclined toward favorable interpretations of operational friction. Consequently, forward guidance and project timelines are best evaluated as operational targets rather than firm commitments.
Historical falsification pass — the cash flow and dividend paradox
This operational record intersects directly with capital allocation decisions. Choice has never distributed dividends to shareholders.3 Management justifies retaining all earnings by pointing to high reinvestment returns, with consolidated return on equity averaging roughly 18% over five years and reaching 16% in fiscal 2026.3
However, this reinvestment logic faces disconfirming evidence in the cash flow statement.
Operating cash flows across recent financial years highlight an ongoing divergence: positive 26 crore rupees in FY2020, followed by negative 45 crore in FY2021, negative 52 crore in FY2022, positive 138 crore in FY2023, negative 153 crore in FY2024, negative 294 crore in FY2025, and negative 267 crore in FY2026.3
Over the five-year period from fiscal 2022 through fiscal 2026, Choice reported cumulative net profits of 646 crore rupees, rising annually from 54 crore to 60 crore, 131 crore, 163 crore, and 238 crore rupees.3 Over that same five-year period, cumulative cash flow from operating activities was negative 628 crore rupees, with cash outflows exceeding 260 crore rupees annually in both fiscal 2025 and fiscal 2026.
Two primary structural drivers explain this gap between reported profits and cash generation:
Advisory trade receivables. Government infrastructure and public consultancy contracts operate on extended payment cycles. Budget approvals, milestone certifications, and multi-agency sign-offs extend collection periods to between 90 and 180 days. Trade receivables in the high-margin advisory segment stood at 280.8 crore rupees in the second quarter of fiscal 2026, compared to 274.6 crore rupees in March 2025.11 While receivables have remained stable relative to expanding order volumes, they require ongoing working-capital funding from the group's balance sheet.
NBFC loan book expansion. Under Indian Accounting Standards (Ind AS), loans disbursed by a non-banking financial company are recorded as cash outflows within operating activities. As Choice Finserv expanded its loan book from 481.91 crore rupees in fiscal 2024 to 767.94 crore in fiscal 2025 and 800 crore in fiscal 2026, portfolio growth mechanically registered as a substantial operating cash outflow.51
While these mechanisms explain the operating cash deficit, evaluating capital allocation depends on the returns generated by the capital absorbed.
Here, financial disclosures reveal a structural mismatch. Choice Finserv reported a standalone return on average net worth of 1.25% in provisional fiscal 2025 and 0.68% in fiscal 2024, with return on average assets at 0.50% and 0.33% over the same periods.5 Consolidated group returns on equity — running near 16% — are driven almost entirely by broking and advisory operations. Meanwhile, a significant portion of retained cash has funded the lending division, which generates returns below the cost of capital. This dynamic contrasts with the rationale for retaining 100% of corporate earnings.
While negative operating cash flows stem from identifiable structural sources, the justification for zero dividend payouts requires qualification. Group-level return on equity remains strong, but incremental retained earnings have been directed primarily into the lowest-returning division. Reinvestment justifies full earnings retention in fee-based advisory and broking segments, but current returns in the lending subsidiary do not yet support similar capital absorption. Furthermore, securing 900 crore rupees in external capital for the broking arm — rather than funding expansion through parent company reserves — underscores how retained cash has been distributed across verticals.
Two key metrics will clarify this capital allocation trajectory: (1) the ratio of cumulative operating cash flow to net profit over a rolling three-year period, which should approach parity as loan growth moderates, and (2) Choice Finserv's standalone return on equity, which must improve toward group averages to justify its capital consumption.
During the Q4 and full-year FY2026 earnings call on April 24, 2026, none of the eight participating analysts inquired about operating cash flow, collection cycles, or cash conversion ratios.1 Questions focused instead on artificial intelligence, account activation, and product distribution. This absence of sell-side inquiry highlights a gap in public market scrutiny regarding the firm's cash conversion dynamics.
VII. Industry Structure, Named Competitors, & Strategic Frameworks
Evaluating Choice's competitive position requires recognizing that it operates on terrain its direct peers rarely occupy.
The map
The discount tech giants. Zerodha, Groww, and Angel One dominate metropolitan and high-frequency retail volume through automated onboarding and low cost structures built for digital scale. Angel One alone carries a market capitalisation of roughly ₹26,165 crore against Choice's ₹17,136 crore, while generating a comparable return on equity of 15.6%.316 Choice does not attempt to compete with these platforms on price in metropolitan markets. Management has stated this position explicitly, citing a deliberate strategic focus on cash delivery trades over high-velocity derivatives.1
The full-service and regional consolidators. This peer group includes IIFL Capital Services, Share India Securities, Geojit Financial Services, Monarch Networth Capital, Master Trust, and 5Paisa Capital. Choice competes directly with these firms for both retail clients and regional acquisition targets within a segment facing clear structural pressure. Geojit, an established full-service broker, reported a 48% trailing decline in net profit alongside a return on equity of 7.32%.17 While ongoing industry distress creates Choice's regional deal pipeline, it also highlights the operational vulnerabilities of the legacy assets being acquired.
Choice's actual position. Choice occupies a hybrid niche: human-assisted distribution across Tier-2 to Tier-4 India, where roughly 70% of its client base resides. This network relies on 214 branch offices, 67,000 business associates, and point-of-sale agents cross-selling broking, insurance, credit, and wealth products — coupled with a public-sector advisory practice unmatched in scale by any listed Indian brokerage.1911
This public-sector advisory division represents a central operational distinction. Unlike retail stockbroking, the unit operates as a specialized government consultancy employing 2,000 professionals, holding a ₹777 crore order book, and generating pre-tax profit margins above 36%.19 Valuing Choice solely on a retail brokerage multiple overlooks a division tied to public-sector procurement, while treating the firm strictly as a government consultant ignores its distribution network.
Porter's Five Forces
Bargaining power of regulators (very high). Regulatory oversight represents the dominant force in Indian financial services. The Securities and Exchange Board of India (SEBI) periodically alters unit economics through direct policy mandates, such as the October 2024 derivatives framework. Across the sector, market participants exercise minimal influence over the rules governing transaction pricing and margin requirements.
Threat of substitutes (high). Direct-plan mutual funds disintermediate traditional financial distributors, while discount platforms have compressed equity delivery brokerage toward zero. Choice's expansion from mutual fund distribution into proprietary asset management attempts to counter this structural threat, though commercial traction remains early.
Bargaining power of clients (moderate to high). Digital account transfers in India require minimal friction and no direct cost. However, in non-metropolitan markets, client retention often attaches to local business associates rather than underlying digital platforms, creating localized switching barriers. Yet as operational data demonstrates, this stickiness remains tied to individual agents who can transition between competing firms.
Competitive rivalry (high). The market remains fragmented and undergoing consolidation, characterized by hundreds of regional brokerages alongside nationwide platforms operating at lower per-trade costs.
Threat of new entrants (moderate). Holding regulatory permissions across lending, broking, insurance, asset management, and public-sector advisory establishes a meaningful multi-year entry barrier against full-spectrum replication. Building a digital trading front-end requires modest capital; replicating an advisory practice backed by 2,000 consultants and established government empanelments presents a higher barrier.
Hamilton Helmer's 7 Powers
Counter-positioning: absent. Choice cannot counter-position against discount brokerages, as discount platforms initiated the model that reshaped the industry. Choice operates on the incumbent side of that transition, maintaining a higher-cost human distribution model that discount platforms were designed to bypass.
Cornered resource: moderate and narrowly defined. While regulatory permissions represent a crossable barrier, state-level government advisory empanelments and project track records function as a narrow cornered resource that cannot be replicated through capital allocation alone. This structural barrier makes acquisitions of established infrastructure consultants more strategically significant than additional broking book purchases.
Scale economies: unproven at the segment level. Consolidated EBITDA margins expanded from roughly 22% in the first quarter of fiscal 2023 to 36.5% by the first quarter of fiscal 2026, driven by technology leverage against fixed operating costs.11 However, margins contracted sequentially to 35.75% in the first quarter of fiscal 2027, with EBITDA declining 7% and net profit falling 10.7% quarter-on-quarter.915 While a single quarter does not establish a trend, it indicates that long-term operating leverage remains an unverified thesis.
Process power: moderate. Choice has established a repeatable operational model for sourcing, pricing, and integrating distressed regional brokerages across multiple transactions over eight years. The model's primary constraint lies in customer retention, as acquisition processes reliably transfer client accounts and regulatory seats while less consistently retaining active trading volume.
Switching costs, network economies, and branding: weak. Brokerage accounts offer negligible network effects, the brand commands limited pricing power, and client switching costs depend on advisor relationships rather than platform lock-in.
Evaluating Choice through this framework reveals one moderate power in acquisition integration, a narrow cornered resource in public advisory empanelments, and an unproven scale advantage. While these elements provide operational differentiation, they remain distinct from the structural moats typical of a high-multiple valuation.
VIII. Current Risk Radar & Skeptical Investor Stress Test
Evaluating Choice from a skeptical investor's perspective requires examining several structural vulnerabilities that receive less emphasis in growth narratives.
1. The derivatives regulatory shockwave
On October 1, 2024, SEBI issued a six-part policy package to curb retail speculation in index derivatives. Effective November 21, 2024, index derivative contract values rose from ₹5–10 lakh to ₹15–20 lakh, while the Nifty 50 lot size tripled from 25 to 75. Weekly expiries were restricted to a single benchmark per exchange starting November 20, 2024, removing a substantial share of outstanding contracts. Additional measures included a 2% extreme loss margin on short options on expiry day, the removal of calendar spread margin benefits on expiry day from February 10, 2025, mandatory upfront option premium collection, and intraday position limit monitoring replacing end-of-day checks from April 1, 2025.18 Concurrently, exchange transaction fees shifted from volume-tiered pricing to flat rates, eliminating rebates that had previously subsidized high-volume brokers.
The operational mechanism was direct: larger contract sizes, fewer weekly expiries, and reduced speculative trading. Overall industry futures and options volumes declined materially, with analyst estimates indicating a 20% to 30% contraction, and the removal of weekly contracts alone affecting roughly 35% of industry option premiums.18
Choice's direct exposure to this derivative contraction is lower than that of many peers, as management's focus on cash delivery trading predates and partially insulates the firm from derivative volume shocks.1 This positioning provides a verifiable buffer. However, two underlying constraints remain. First, Choice operates as a clearing member in the futures and options segment, where clearing economics depend on transaction volumes regardless of client origin. Second, the intervention demonstrates regulatory precedent: SEBI can modify per-trade economics across the industry by circular on short notice. Whether future regulatory changes target margin trading facilities, distribution commissions, or intraday leverage, the business model remains exposed to policy shifts. Rating agency Acuité explicitly includes changes in the regulatory environment and potential regulatory actions among its key rating sensitivity triggers.5
2. Government advisory: concentration, credit, and political cycles
Approximately 28% of group revenue depends on securing and executing state government mandates. During the April 2026 earnings call, management was asked directly about geographic and sector concentration—specifically regarding Maharashtra and infrastructure consulting. Executive leadership acknowledged that contributions from these states and sectors are high, but stated that management does not see a major immediate risk from this concentration.1 The company cited its operational footprint across 22 other states with live orders as a key mitigant, though detailed revenue concentration by state or client is not disclosed.1
The advisory order book experienced its first disclosed quarterly contraction in Q4 FY2026. Management attributed this dip to an end-of-year execution push that completed projects within the fiscal year rather than a slowdown in new mandates, pointing to a submission pipeline exceeding ₹400 crore in active bids.1 The advisory order book subsequently expanded to ₹777 crore in Q1 FY2027, validating management's explanation.9 However, when asked to provide the company's tender win rate, leadership stated that the metric depends on various factors and is not a relevant operational figure.1 For a segment where future revenue depends directly on competitive bidding, tender win rates represent a meaningful efficiency metric, and its omission leaves an analytical gap.
Counterparty credit risk further complicates this business line. While state government entities rarely default, payment cycles can extend significantly due to budget reallocations, administrative shifts, or political transitions. This delay directly drives the working-capital intensity and elevated trade receivables balance detailed in Section VI.
3. M&A integration fatigue and goodwill accumulation
Choice has maintained a steady acquisition pace alongside its expanding asset base. Each transaction adds intangible assets that carry no routine depreciation but expose the balance sheet to impairment risk. With the stock trading near ten times price-to-book, a central analytical question is whether inorganic transactions acquire genuinely value-accretive operations or primarily add revenue volume to support growth expectations. Stagnant active-trading account conversion data adds weight to this inquiry.
Capital structure choices reinforce these governance considerations. Management has funded expansion through equity-settled lending book acquisitions, the conversion of ₹173.4 crore in warrants issued in April 2024 at ₹75 per warrant to Plutus Wealth Management LLP and Rupang Properties, and a ₹900 crore compulsorily convertible preference share investment into the broking subsidiary converting to equity by July 2027.219 While each transaction serves an operational purpose, together they describe an enterprise that regularly raises external capital while retaining all earnings. Furthermore, the convertible preference share structure will establish a minority equity interest at the subsidiary level, diluting the parent company's economic claim on its largest profit engine.
4. Credit risk in the MSME and solar book
The trajectory of lending asset quality requires evaluating pricing dynamics alongside credit performance. On the August 2026 earnings call, management disclosed that competitive entry in solar financing had compressed interest rates to approximately 15%.14 Solar lending, initially launched as a higher-yielding niche, experienced yield compression within two years of rollout. Simultaneously, the strategic transition toward secured lending—while prudent for risk management—mechanically compresses net interest margins, as management acknowledged.11 Consequently, the non-banking financial company must simultaneously manage credit risk, absorb lower interest yields, and elevate a return on equity of roughly 1% toward group averages—objectives that operate in operational tension.
Credit covenants specified by Acuité establish clear boundaries for asset quality: gross non-performing assets must not exceed 5% of assets under management, and net non-performing assets must not exceed 4%.5 As of June 2026, gross non-performing assets stood at 3.78% and net non-performing assets at 2.74%, bringing gross asset quality metrics closer to covenant limits than in prior reporting periods.9
5. The disclosure and complexity discount
As of March 31, 2025, Choice's corporate structure encompassed six direct subsidiaries alongside twelve step-down or jointly controlled entities.5 Capital, revenue, and intercompany expenses flow across broking, wealth management, insurance distribution, public consultancy, corporate advisory, NBFC, and AMC divisions. When asked on earnings calls about potential demergers or separate listings for individual business units, management stated that such restructurings would not happen immediately, while acknowledging that unlocking value remains a long-term goal.1 This multi-layered structure creates a basis for holding-company valuation discounts and underscores the need for segment-level disclosures on return on capital employed—data that Choice does not currently publish.
IX. Bear vs. Bull Case & Valuation Conundrum
The bull case, stated at its strongest
The financialisation of non-metropolitan India represents a sustained structural trend, positioning Choice differently from urban-focused discount brokerages. Approximately 70% of the firm's customer base resides in Tier-3 and smaller locations, served through a 67,000-strong network of business associates and a branch footprint that management plans to roughly double.911 Nationwide demat accounts approached 200 million by mid-2025, supported by 2.5 million new accounts opened in June 2025 alone.[^23] Serving households that require human assistance rather than self-directed digital onboarding relies on an extensive physical infrastructure that Choice has systematically assembled.
This multi-engine framework generates potential cross-selling opportunities across business units. The government advisory division establishes institutional relationships with state entities that can yield corporate insurance mandates and alternative investment fund (AIF) assignments. For instance, Choice Capital Advisors was engaged by the Assam state government to assist in establishing the Assam Industrial Green Growth Fund and executing fundraising roadshows.1 Meanwhile, stockbroking captures retail volume, the lending arm provides cross-sold credit products, and the asset management unit offers a path to transition from third-party distribution to proprietary product manufacturing.
The partnership with India Post Payments Bank, despite execution delays, provides access to a distribution network covering more than 650 districts and an estimated client base of 12 crore.19 This channel allows Choice to cross-sell financial products to an established audience, avoiding high direct customer acquisition costs. Management's projected systematic investment plan (SIP) contribution of ₹2,000 to ₹2,500 per customer monthly reflects a modest baseline assumption for retail participation.1
Furthermore, the company's acquisition model has consistently sourced regional brokerage assets from distressed peers at modest valuations—a strategy partially validated by NH Investment & Securities agreeing to invest ₹900 crore for a minority stake in the stockbroking subsidiary.
The bear case, stated at its strongest
The bear case begins with valuation metrics. As of September 3, 2026, Choice traded at approximately 75 times trailing earnings and over 10 times price-to-book value, while paying no dividend.3 By comparison, Angel One—which operated at a larger market capitalisation with a similar return on equity of 15.6%, a 103% dividend payout ratio, and a 1.42% dividend yield—traded at 25.4 times earnings and 4.3 times book.16 Geojit Financial Services, reporting a return on equity of 7.3%, traded at 29.6 times earnings and 1.9 times book.17 Consequently, Choice commands nearly triple the earnings multiple of a larger, dividend-paying peer operating at comparable reported returns on equity.
This premium reflects market expectations for sustained growth, public-sector advisory expansion, and asset management scaling. Maintaining a valuation of 75 times trailing earnings requires multi-year revenue and profit expansion near management's 30% target, uninterrupted by regulatory changes and supported by successful execution across the AMC and India Post initiatives. However, full-year FY2026 revenue growth of 24% alongside flat sequential performance across Q3 FY2026, Q4 FY2026, and Q1 FY2027 presents a slower growth trajectory than the valuation implies.114
A second vulnerability involves cash flow conversion. Across five consecutive fiscal years, expanding reported net profits coincided with cumulative negative operating cash flows, with capital absorption concentrated primarily in the group's lowest-returning lending division.
Underlying operating metrics also indicate structural pressures behind headline growth figures. Total demat accounts expanded 13% year-over-year while active trading accounts grew by 0.4%.9 In insurance distribution, premium volumes rose 5% while policy count increased 73%, reflecting a drop in average ticket size as product mix shifted toward smaller retail policies.914 In wealth management, a five-fold expansion in assets under management stemmed from a single portfolio acquisition rather than organic client inflows.11
In addition, regulatory sensitivity remains substantial. Approximately 59% of revenue relies on capital market activity, a sector subject to policy shifts by SEBI. Credit rating agency Acuité explicitly highlights capital market volatility as a key rating constraint.5
Finally, corporate disclosures present analytical limitations. Choice has distributed no dividends throughout its public history, operates through a complex multi-entity structure, and omits segment-level return on capital employed, advisory win rates, and geographic revenue concentrations. Furthermore, several recent management projections—including the July 1 India Post revenue start date, the 100-branch expansion target, assurances regarding investment freezes, and credit quality normalization timeline estimates—have shifted shortly after being announced.
Weighing it
Evaluating these opposing perspectives requires distinguishing between operational scale and investment valuation.
The underlying business possesses tangible strengths. The advisory division, which generated ₹120 crore in pre-tax profit in FY2026 with minimal capital deployment, represents a high-margin consultancy practice distinct from traditional stockbroking. Similarly, the regional distribution network remains difficult to replicate quickly, and deal sourcing across distressed regional brokerages reflects an established operational process.
However, the investment thesis relies on three operational premises that disclosures have yet to confirm:
- Inorganic expansion generates account breadth rather than active engagement. Account acquisition has expanded total registered users while active trading clients have remained largely flat.
- Retained earnings absorb capital in lower-returning units. Cash reserves have funded lending operations yielding return on equity near 1%, rather than accelerating high-return divisions.
- Asset management scaling remains early. The AMC division has gathered approximately ₹87 crore in assets under management against a ₹1,000 crore FY2027 target, with management projecting break-even within two to three years.914
These operational realities do not negate the company's growth model, but they indicate that current valuation multiples price in execution outcomes that historical disclosures have not yet fully demonstrated.
The KPIs that matter
Three key performance indicators will determine whether operational execution converges with market valuation:
1. Operating cash flow to net profit conversion on a rolling three-year basis. This metric evaluates the working-capital cycle in government advisory, capital absorption in lending, and overall earnings quality. Convergence toward parity as loan book growth moderates would resolve cash conversion concerns; continued divergence would confirm structural capital drag.
2. The active-account ratio and revenue per active client. This indicator measures whether inorganic consolidation generates client activity or simply accumulates dormant accounts. If capital deployment and margin trading expansion accelerate active account growth, operating leverage will improve. If total accounts expand while active trading remains stagnant, dealmaking will yield diminishing economic returns.
3. Choice Finserv's standalone return on equity and gross non-performing assets. This metric tests both credit risk management and the rationale for zero dividend payouts. A recovery in return on equity from near 1% toward group averages alongside stable credit metrics would justify full earnings retention. Conversely, persistent low returns paired with gross non-performing assets approaching the 5% rating covenant would indicate inefficient capital deployment.
X. What Would We Do If We Were Running Choice?
Here is the uncomfortable position a Choice executive actually occupies. The company is performing, by most conventional measures, remarkably well — net profit surged 46% in fiscal 2026, every business segment is expanding, a major foreign strategic partner has validated the broking arm, and a high valuation multiple signals strong market confidence.123 Nothing is on fire. Yet the single most valuable step management could take right now is to operate as though something were.
Four strategic adjustments would meaningfully reshape the investment thesis. Each is evaluated alongside the primary objection management would raise, ensuring every recommendation withstands analytical scrutiny.
Institute a modest, disciplined dividend. Not because shareholders require immediate income — at current growth rates they do not, and a 10% to 15% payout ratio would barely register in total shareholder returns. The primary purpose of a dividend is what a cash payout demonstrates. A firm reporting five consecutive years of predominantly negative operating cash flows while trading near 75 times earnings carries a rational burden of proof regarding earnings quality. That uncertainty cannot be resolved through investor presentations, which rely on the same accounting accruals that generated the doubt. Confidence can only be established by cash physically leaving the balance sheet — cash generated from operations rather than debt or equity capital raises.
The objection: every rupee distributed is a rupee not compounding at a group return on equity of 16%, and investors seeking income would select dedicated dividend stocks. That argument would carry greater weight if incremental retained capital consistently earned 16%. In practice, a substantial portion of retained cash has been allocated to a lending vertical generating returns closer to 1%. Consequently, instituting a dividend functions less as a capital allocation concession than as a signal of financial transparency, providing market reassurance worth more than current marginal reinvestment rates.
Ring-fence and re-underwrite the NBFC before growing it further. The lending subsidiary functions as the group's largest consumer of retained capital while generating its lowest financial returns. Simultaneously, portfolio on-time repayment rates have declined for two consecutive years, pushing gross non-performing assets closer to the 5% covenant ceiling than at any prior point in disclosed reporting.59 The operational sequence should be clear: first stabilize asset quality, second elevate standalone return on equity into double digits, and third expand the loan book. Reversing this sequence — expanding a portfolio earning roughly 1% returns while credit metrics weaken — impairs enterprise value regardless of cross-selling potential, because cross-sell brokerage fees accrue to the distribution division while credit losses remain on the lender's balance sheet.
The objection: the loan book is relatively new, secured lending carries lower yields by design, and returns will normalize as the portfolio seasons and achieves scale. While plausible, management has presented this explanation across multiple reporting periods alongside evolving rationales for credit metric deterioration, without producing measurable return improvements. If double-digit standalone returns cannot be achieved within a defined, publicly stated timeline, the prudent strategy is to cap portfolio expansion and reallocate capital, immediately improving group cash conversion dynamics.
Disclose what the business actually runs on. Three enhanced disclosures would clarify the investment thesis more effectively than any operational initiative on the current roadmap. First, publish segment-level return on capital employed, allowing investors to evaluate the returns generated by each business line against the capital it consumes. Second, disclose advisory receivable collection periods and tender win rates, enabling the ₹777 crore order book to be evaluated as expected cash inflows rather than a headline backlog figure.9 Third, detail state-level and client-level revenue concentration within the advisory division, quantifying management's acknowledgment that concentration in specific regions remains high.1
The objection: tender win rates do not represent a relevant operational metric, as management stated on the April earnings call, because bidding outcomes vary across geographies and project types.1 That explanation conflicts with the segment's underlying economics. When future revenue depends primarily on competitive procurement, historical bid conversion rates provide the clearest indicator of segment demand. Regional variation argues for disaggregated disclosures rather than withholding aggregate figures. None of these disclosures compromise commercial confidentiality, as competitive pricing and project locations are already known to market participants. Providing greater transparency addresses the holding-company valuation discount and aligns with management's stated goal of long-term value creation.
Shift the deal budget from broking books toward the AMC and organic activation. Reallocating acquisition capital represents the highest-value strategic pivot available. Disclosed metrics indicate that acquiring additional client books yields minimal active trading conversion. Conversely, deploying capital into Choice AMC builds a position in proprietary asset management, creating a recurring, annuity-like revenue stream. Redirecting M&A budgets toward seeding proprietary investment strategies, recruiting experienced active fund managers ahead of planned FY2027 product launches, and funding structured re-engagement campaigns for the firm's roughly one million dormant accounts would generate greater long-term economic value than acquiring additional regional brokerages. Choice has already paid to acquire its existing dormant client base; activating those accounts is more cost-effective than purchasing new client rosters that accumulate goodwill on the balance sheet.
The objection: asset management economics require substantial scale, break-even operations remain two to three years away, and acquiring brokerage books provides immediate revenue contributions.14 That trade-off highlights the central strategic choice. Inorganic acquisitions purchase immediate reported revenue without guaranteeing long-term durability, whereas asset management builds long-term earnings durability before producing immediate scale. A business valued at 75 times trailing earnings is priced for structural durability, making investment in high-margin proprietary products more aligned with market expectations than purchasing short-term brokerage volume.
XI. Epilogue & Key Takeaways
Return to that April evening on the conference line, and to what the call did and did not contain.
It contained a company reporting its best year ever: ₹1,145 crore of revenue, ₹425 crore of EBITDA at a 37% margin, ₹238 crore of profit up 46%.1 It contained a management team that answered every question asked of it, in reasonable detail, without deflection. It contained a plan — index funds, government mandates, an India Post partnership, secured lending, more branches.
It did not contain a single question about where the cash went.
That is the story of Choice International in one image, and it generalises well beyond this company. India's small and mid-cap financial services complex is full of businesses reporting spectacular profit growth while their operating cash flow runs the other way — sometimes for excellent structural reasons, sometimes not, and almost always without anyone on the call asking which.
It is worth naming what makes this particular company hard to categorise, because the difficulty is the point. Choice is not a fraud, and nothing in the record suggests it is: the auditors are credible, the segments are disclosed, the rating agency has full consolidated visibility, and a foreign strategic investor conducted its own diligence and wrote a large cheque.2511 Nor is it a straightforward compounder, because a straightforward compounder converts profit into cash and Choice has not. It sits in the uncomfortable middle that Indian markets are least equipped to price — a genuinely growing business whose growth consumes more cash than it produces, run by an owner-operator family that answers questions willingly and discloses selectively.
Markets tend to resolve that ambiguity in one direction during bull phases and violently in the other when sentiment turns. Neither resolution is analysis. The analysis is in the three questions below.
Three takeaways worth carrying beyond this particular ticker.
The roll-up playbook has a specific and knowable limit. Inorganic consolidation reliably transfers assets: licences, client lists, AUM, branch leases, order books. It transfers behaviour only when the acquirer does the harder work of retaining the humans who created that behaviour. Choice's own record — 13% growth in demat accounts against 0.4% growth in active accounts — is as clean a demonstration of that distinction as any Indian listed company currently provides. When you are looking at a roll-up, find the engagement metric. It is usually disclosed, usually adjacent to the headline number, and usually telling a different story.
The phygital thesis is real, and it is a cost structure, not a moat. Pure digital distribution works in metros and stalls in Tier-3 India, where financial products are still sold by a person to a person. Choice's 67,000 associates and 214 branches are a genuine answer to that reality and a genuine competitive differentiator against app-only brokers. But a human distribution network is an operating expense that must be continuously fed, and its loyalty is to the compensation, not the brand. It is a way to reach a market that others cannot reach cheaply. It is not, on the current evidence, a durable barrier to anyone willing to spend the same money.
And earnings must always be audited against cash. Choice's profits are audited, growing, and segment-reported. They are also, over five years, matched by an almost equal and opposite outflow of operating cash — explicable by receivables cycles and loan book growth, both of which are legitimate. The distinction that matters for an investor is not "are these profits real?" but "what return is the retained cash earning, and where did it go?" On the disclosed record, a disproportionate share went into the group's lowest-returning vertical, while the highest-value strategic bet — the asset management company — was funded to approximately ₹87 crore of AUM against its own ₹1,000 crore target.
There is a fourth lesson that applies specifically to companies built this way, and it is the one most likely to be underweighted. A conglomerate assembled from acquisitions is valued as a single security but must be diligenced as a portfolio. Choice's three engines have almost nothing in common economically: one is a capital-light consulting practice selling to state governments at 36%-plus pre-tax margins, one is a distribution business whose unit economics turn on agent incentives, and one is a balance-sheet lender that has so far earned close to nothing on its equity. Blending them produces a group return on equity of 16% that describes none of them accurately. Any investor relying on that single number is, in effect, letting the strongest business subsidise the analytical scrutiny owed to the weakest.
Choice International has assembled something genuinely difficult to replicate: a licence stack, a non-metro distribution network, and a government advisory practice that no listed Indian broker matches at comparable scale. Whether that assembly compounds into a durable high-return franchise or remains a collection of parts that grows by acquisition depends on questions that will be answered in the cash flow statement over the next three years, not in the next quarterly presentation.
The three-year test began, whether management intended it or not, on July 9, 2026, when ₹900 crore of Korean capital arrived at a target of five-times growth in broking and distribution. That target is now on the record, from a partner with money at risk. It is the clearest falsifiable commitment the company has made.
References
-
Choice International Limited Q4 & FY26 Earnings Conference Call Transcript — Choice International Limited, 2026-04-24 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Choice International Partners NH Investment & Securities; ₹900 Crore Infusion for Broking Arm — Whalesbook Corporate News, 2026-07-09 ↩↩↩↩↩↩
-
Choice International Ltd — Consolidated Financials, Ratios and Shareholding — Screener.in ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Choice International Limited — NSE India Stock Quote (CHOICEIN) ↩↩
-
Choice Finserv Private Limited — Rating Assigned and Reaffirmed, ACUITE A- / Stable — Acuité Ratings & Research, 2025-08-06 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Choice International Limited — BSE India Stock Quote & Filings (531358) ↩
-
Choice International Limited — About Us, Company Milestones, Board and Licences ↩↩↩↩↩↩↩
-
Choice International Acquires Inditrade Capital's Broking Business for Rs 32 Crore — Business Standard, 2018-05-15 ↩
-
Choice International: Q1 FY27 Investor Presentation and Results — InvestyWise, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Choice International Ltd (CHOICEIN) — Company Overview and Transcripts — Trendlyne ↩
-
Choice International — Research Note on Segments, Asset Quality, Goodwill and Guidance — Exencial Research Partners ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Choice International Shares Jump 3% as Subsidiary Acquires 100% Stake in Ayoleeza Consultants — Upstox, 2025-11-19 ↩
-
Choice AMC Receives Sebi Nod to Launch Mutual Fund Operations — Business Today, 2025-08-01 ↩
-
Choice International Ltd (BOM:531358) Q1 FY27 Earnings Call Highlights — Yahoo Finance / GuruFocus, 2026-08-11 ↩↩↩↩↩↩↩↩↩↩
-
Choice International Q1 FY27: Growth Holds Up as Broking Scales, Advisory Deepens, NBFC Stays Disciplined — Multibagg, 2026 ↩↩↩
-
Angel One Ltd — Consolidated Financials, Ratios and Shareholding — Screener.in ↩↩↩
-
Geojit Financial Services Ltd — Consolidated Financials and Ratios — Screener.in ↩↩
-
SEBI's New Rules for Index Derivatives: Here's What's Changing — Zerodha Z-Connect, 2024-10-01 ↩↩
-
Choice International Limited Announced INR 1.734 Billion Warrant Funding from Plutus Wealth Management LLP and Rupang Properties — MarketScreener, 2024-04-23 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube