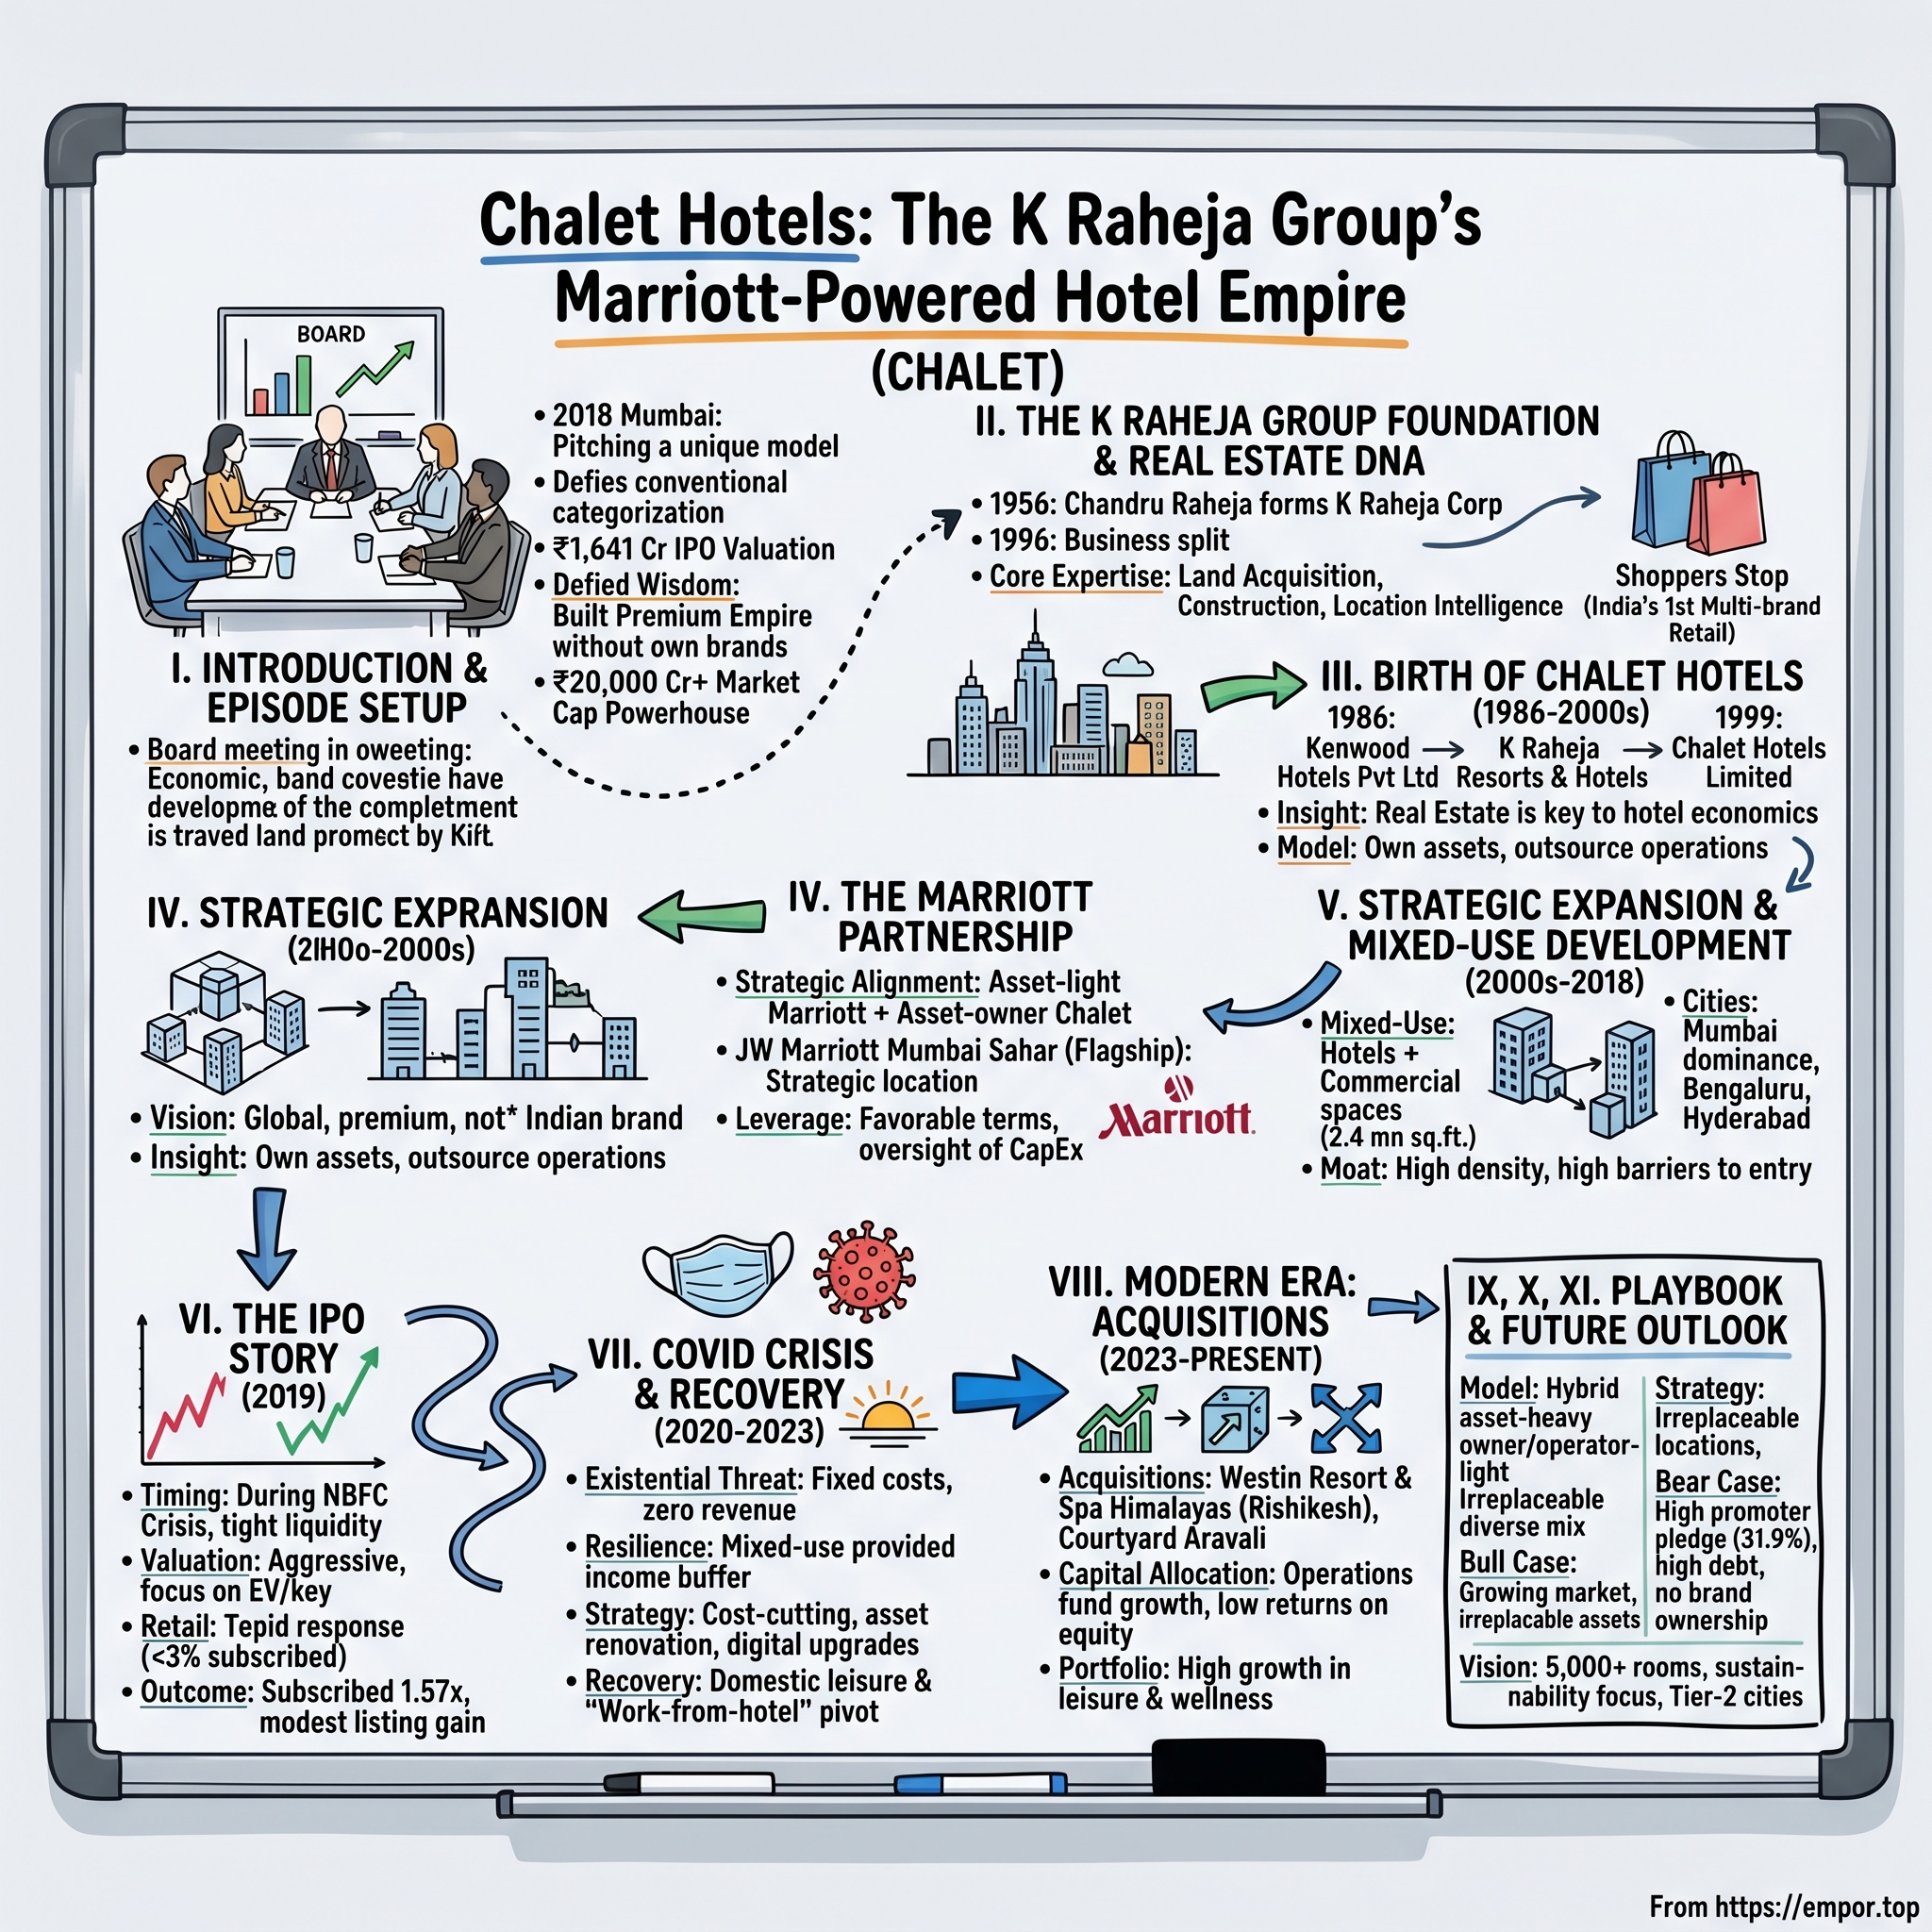
Chalet Hotels: The Landlord Who Learned to Run the Hotel
I. Introduction & Episode Setup
Drive out of Mumbai's Chhatrapati Shivaji Maharaj International Airport on the Sahar elevated road and, before the traffic swallows you, a 588-key hotel rises on the left with the JW Marriott name on it. Almost every business traveller who has flown into India's financial capital has seen it. Very few could tell you who owns it.
The answer is a company most people have never heard of, which is precisely the point. Chalet Hotels Limited owns that building, its land, and its profit-and-loss account. Marriott International puts its name on the door, sends guests through Bonvoy, and takes a fee. The hotel earns money for Chalet. The brand equity accrues to Marriott. For nearly forty years, that division of labour was not a compromise the K Raheja Corp group tolerated — it was the strategy.
Today Chalet operates eleven hotels with roughly 3,390 keys across the Mumbai Metropolitan Region, Hyderabad, Bengaluru, Pune, the National Capital Region and Uttarakhand, alongside about 2.4 million square feet of commercial office and retail space built on the same land parcels.1[^3] In the financial year ended March 2026, consolidated revenue reached roughly ₹2,770 crore and the market capitalisation sat near ₹18,900 crore on 2 September 2026 — a mid-cap by Indian standards, but among the most valuable listed hotel companies in the country.2[^3]
Then, in October 2025, Chalet did something that contradicted its own founding logic. It launched Athiva, its own hotel brand, owned and operated in-house.4
That is the hook of this story. A real estate developer spent four decades deliberately not building a consumer brand, arguing that renting one from Marriott was smarter capital allocation — and then built one anyway. Something changed. This piece is an attempt to work out what, and whether the change deserves credit or scepticism.
Two tensions run underneath everything that follows.
The first is strategic. Chalet's entire earnings history was produced by the partnership model: own the concrete, rent the brand. Athiva reverses that for a bounded slice of the portfolio. Is this a coherent segmentation of a large market, or a company drifting into a capability it has never demonstrated?
The second is arithmetic, and it is the more urgent of the two for anyone reading the headline numbers. Chalet is not only a hotel company. Sitting inside the same consolidated accounts is a residential real-estate project in Bengaluru whose flat sales get recognised in irregular lumps. In FY26 that lump helped push reported profit after tax up 353%.10 One quarter later, in Q1 FY27, reported profit fell 58% — for the mirror-image reason.18 Neither number described what was happening in the hotels.
So the discipline this story imposes on itself is simple: separate the building from the accounting. What follows traces where the land came from, what the Marriott arrangement genuinely bought and genuinely did not, how COVID stress-tested an asset-heavy balance sheet, what the current segment economics actually show once the residential noise is stripped out, whether the Athiva bet is supported by any track record, and what a sceptical investor would attack first.
Start with the land, because in this company the land came before the hotels.
 Subscribe on LinkedIn
II. The K Raheja Corp Foundation — Why a Developer Became a Hotelier
The Raheja name is one of the oldest in Indian real estate, and like most old Indian business names it eventually split. Chandru Raheja's branch became K Raheja Corp, and over six decades the group assembled a portfolio that reads like a map of urban India's commercial expansion: office parks, business districts, malls, and retail.1 By August 2025 the group's disclosed footprint included more than 55 million square feet of leasable office area, seven malls, and 299 retail stores, with three listed entities — Mindspace REIT, Chalet Hotels and Shoppers Stop — carrying a combined market value of about USD 5.8 billion.1
The relevant piece of that history for Chalet is not the size. It is a capital-allocation habit.
An Indian developer who assembles a large urban land parcel faces a fork. Build, sell the floor space, book the profit, redeploy into the next parcel — the merchant model, fast-cycling, capital-light in the sense that nothing stays on the books. Or build, hold, and rent — the annuity model, which locks capital into a single location for decades and only pays if that location keeps appreciating and keeps attracting tenants and guests.
K Raheja Corp repeatedly chose to hold. Hotels, offices and malls became long-duration claims on land the group already controlled. That is the DNA. It explains why Chalet exists at all: not because a family fell in love with hospitality, but because a hotel was one of the highest-yielding things a developer could put on a well-located parcel it had no intention of selling.
The corporate paperwork records the sequence. The entity that became Chalet Hotels Limited was incorporated as Kenwood Hotels Private Limited on 6 January 1986, and was renamed K. Raheja Resorts & Hotels in 1998 before eventually taking the Chalet name.6 For a company that listed in 2019, that is an unusually long private gestation — more than three decades of building hotels without ever asking public markets for money. The company's annual reporting still describes the business in that developer's vocabulary: owner, developer and asset manager, in that order.24
That gestation matters for one reason above all: it meant the portfolio was assembled at land costs that no new entrant can replicate. Sahar, Powai, Hitec City, Whitefield — Chalet was early in each of these micro-markets, before the airport terminal, the IT campuses and the office towers that now surround its hotels made the addresses expensive. When management today talks about "high-value catchment locations" and an "ecosystem approach" to asset ownership, the substance underneath the jargon is that the group bought the ground first and let the ecosystem arrive.1
The honest reading of this is that Chalet's most durable competitive advantage is inherited rather than earned. Land bought in the 1990s and 2000s in what became India's densest commercial corridors is a genuine barrier — it cannot be competed away by a rival with more capital, because the parcels no longer exist to buy. But it is also not a management skill, and it does not renew itself. Every new asset Chalet adds from here is bought at 2020s prices. Whether the company can create value on those terms is a different question from whether it created value on the old ones, and it is the question the rest of this story keeps circling back to.
Which brings us to the second inherited decision — and the more contested one. Having built the buildings, K Raheja chose not to name them.
III. The Marriott/Accor Partnership Model — What It Actually Bought Chalet
Walk the Chalet portfolio and you will not find the word "Chalet" on a single marquee. You will find JW Marriott, Westin, Marriott, Four Points by Sheraton, Marriott Executive Apartments, Courtyard by Marriott, Novotel — eight distinct hospitality brands across the group's assets, operated under agreements with Marriott's India entities and with Accor's AAPC India Hotel Management.1 A Taj-branded hotel is under construction at Delhi International Airport, meaning Chalet will soon be a landlord to IHCL as well.1
Management has explained the logic the same way for two decades. Chalet owns the real estate and consolidates the hotel's revenue and profit. The global operator supplies the brand, the reservation system, the loyalty base and the operating standards, and charges a management fee. The owner takes the property risk and the property upside.
What did that genuinely buy?
Three things, and the evidence for each is different in quality.
The first is distribution, and here the evidence is concrete. Chalet's own FY25 channel data shows that for its business hotels, direct channels accounted for about 51% of bookings, global distribution systems around 25%, online travel agents 14% and the brand website 10%.1 Strip out the brand and a meaningful share of that funnel — GDS access, corporate rate agreements, brand.com traffic, loyalty redemption — has to be rebuilt from scratch. For an owner whose guests are 97% Indian nationals at resorts and 61% at business hotels, the global loyalty engine matters less for inbound tourists than it does for the corporate travel manager who books Bonvoy because their company has a Marriott rate.1
The second is operating standards without operating headcount. Chalet's staff-to-room ratio sat at 0.97 in Q1 FY26 and payroll ran at 14.9% of revenue.1 These are the numbers of a company that does not carry a large central hospitality organisation — because the operator carries it.
The third is the claim that deserves the most scrutiny: that owning multiple hotels inside one operator's system gives Chalet negotiating leverage on management-fee terms that a single-asset owner would not get. This is asserted by management and is intuitively plausible. It is also, on the public record, not verifiable. Chalet has never disclosed like-for-like management-fee terms, and no filing lets an outside investor compare its fee load against a peer's. Treat it as an unproven claim rather than a demonstrated advantage.
Now the other side of the ledger, which the model's defenders tend to skip.
The arrangement bought no brand equity on Chalet's balance sheet. If a Chalet hotel outperforms, the guest's loyalty attaches to Bonvoy, not to Chalet. It bought no independent pricing power: Chalet's rate positioning is bounded by where Marriott positions Westin or Four Points in India. And it bought a permanent claim on the property's cash flow — the operator's fee is paid off revenue and profit regardless of whether the owner's return on capital is adequate. In a downturn, the owner absorbs the operating leverage; the fee shrinks proportionally but does not disappear.
So how do we test whether the trade was good? The obvious test is margin. Chalet's hospitality segment produced EBITDA of ₹760 crore on revenue of ₹1,731 crore in FY26 — a 43.6% segment margin.[^3] That is a strong number in absolute terms and it is achieved while paying management fees to a third party. It is fair evidence that active asset management — budget control, capex discipline, energy and manpower productivity — extracts real value even when someone else runs the hotel.
But it is not decisive evidence, for two reasons. First, the same FY26 margin slipped 81 basis points year-on-year even as revenue grew 13.8%, which is not the signature of widening structural advantage.[^3] Second, the peer set is genuinely split on this question, which is the honest way to frame it. IHCL, EIH and Lemon Tree own their brands and capture the fee themselves. Juniper Hotels runs the same landlord model as Chalet, pure-play with Hyatt. SAMHI Hotels runs a multi-brand version of it. These are two live schools of thought in Indian hospitality, both with listed representatives, and the debate is not settled by anyone's margin in a single strong year.
The most useful conclusion is narrower than either camp's marketing. The partnership model demonstrably works for large, trophy, urban assets where a global brand's corporate distribution is worth more than the fee it costs — that is where Chalet's cash flow actually comes from. It works far less obviously for a 117-key hillside resort in Khandala where no global chain wants to be and the guest is booking a weekend from Mumbai anyway.
Hold that sentence. It is, almost word for word, the argument Chalet would later use to justify building its own brand. But before we get there, we need to see how the portfolio was assembled — because the geography of these assets turns out to be both the company's strongest asset and its most cited risk.
IV. Building the Portfolio: Mumbai Concentration and the Mixed-Use Playbook (1990s–2018)
Look at the roster of assets and a pattern jumps out immediately. Four hotels sit in the Mumbai Metropolitan Region: JW Marriott Mumbai Sahar with 588 keys, The Westin Mumbai Powai Lake with 604, Lakeside Chalet Marriott Executive Apartments with 173, and Four Points by Sheraton Navi Mumbai at Vashi with 152. Together, 1,517 keys — roughly 45% of the operating inventory.1
That is not an accident of history. It is the thesis, executed.
Each of those addresses was chosen for the same reason: proximity to a source of non-discretionary demand that could not move. Sahar is airport-adjacent — the guest is a business traveller with a 6 a.m. flight, and geography, not marketing, decides where they sleep. Powai is a self-contained business district built around a lake, where the hotel is embedded in an office ecosystem. Vashi anchors Navi Mumbai's commercial spine. These are not destination hotels competing on desirability. They are infrastructure hotels competing on adjacency.
The same logic then travelled. The Westin Hyderabad Mindspace (427 keys) and The Westin Hyderabad HITEC City (168 keys) placed Chalet inside Hyderabad's IT corridor, where the demand driver is the global capability centre and its endless rotation of visiting managers.1 The Bengaluru Marriott Hotel Whitefield (512 keys) did the same for Bengaluru's eastern tech belt.1 Novotel Pune Nagar Road (311 keys) took the Pune industrial and IT corridor.1 Read as a portfolio, Chalet is a leveraged bet on Indian corporate travel demand concentrated in four or five specific micro-markets.
Then comes the second move, and this is the genuinely clever piece of the playbook.
Having assembled a large parcel for a hotel, Chalet built offices and retail on the leftover land. The Orb, a 0.5 million square foot retail and office tower, sits at Sahar. CIGNUS Powai Tower I adds 0.9 million square feet at Powai. The CIGNUS Whitefield complex adds another 1.0 million square feet in Bengaluru. That is 2.4 million square feet of commercial real estate as of mid-2025, all of it developed on land the company already controlled.1
Why this matters is worth stating plainly, because the mechanism is easy to miss. The single largest cost in Indian real estate development is land. By building offices on parcels already purchased for hotels, Chalet added a high-margin rental annuity without paying the land cost twice. The commercial segment's EBITDA margin ran at 83.1% in FY26 — the kind of number only a business with almost no marginal operating cost can produce.[^3] Better still, the two businesses feed each other: the office tenants' visiting executives fill the hotel next door, and the hotel's banqueting and F&B serve the office population.
That is a real, mechanical advantage, and it is the most underappreciated part of the Chalet story. It is also, precisely because it depends on legacy land, hard to scale indefinitely.
By the time Chalet prepared to list, the scale was substantial but not enormous. Revenue had grown from ₹516.7 crore in FY2014 to ₹929.5 crore in FY2018, a compound rate in the mid-teens, across a portfolio of hotels and the early commercial assets.67
Two things about that pre-IPO record deserve flagging rather than celebrating. Growth in the mid-teens over four years is good but not extraordinary for an Indian hospitality asset base recovering from the post-2013 downcycle. And the concentration that made the portfolio efficient also made it fragile: a company with 45% of its rooms in one metropolitan region is exposed to anything that stops people flying into that region — a point the rating agencies now make explicitly, and which the following decade tested twice.14
In 2018, with the assets built and the cash flows visible, the family decided to sell part of the story to the public.
V. The IPO and What the Market Paid For (2018–2019)
The draft red herring prospectus went to SEBI on 2 July 2018.7 The offer that eventually came to market was sizeable for an Indian hotel company: roughly ₹1,641 crore in total, structured as ₹950 crore of fresh equity plus an offer for sale by existing shareholders, priced in a band of ₹275–280 per share and managed by JM Financial, Axis Capital and Morgan Stanley India.8
And here is where a small but instructive piece of received wisdom needs correcting.
The Chalet IPO is sometimes remembered as a hot deal. It was not. The issue was subscribed 1.57 times overall. Qualified institutional buyers took it up 4.65 times. Non-institutional investors managed 1.11 times. And retail individual investors — the segment that piles into Indian IPOs it believes in — subscribed just 3% of their allocation.8
That distribution is the story of the listing. Institutions understood what they were buying: a portfolio of well-located, hard-to-replicate hotel real estate with a visible commercial-rental kicker, in a market where new supply takes five to seven years to deliver. Retail investors, offered a capital-intensive hotel owner with heavy debt and no consumer brand, essentially declined.
The shares listed on 7 February 2019, opening at ₹291 on the BSE and ₹294 on the NSE, a premium of roughly 4–5% over the ₹280 issue price, and drifted through a volatile first session that ranged as low as ₹250.15.8 A polite debut, not a celebration.
What were institutions actually paying for? Not current cash yield. At listing the company traded at a high-twenties multiple of enterprise value to trailing EBITDA — a multiple you pay for scarcity and duration, not for the profits in hand. The bet was that India's upper-upscale and luxury supply would stay constrained while demand compounded with GDP, and that whoever already owned the right addresses would capture the resulting rate inflation. It was, in essence, a land bet dressed as a hospitality bet.
That framing sets up a test that only becomes answerable years later, and it is worth planting the marker here.
If the 2019 investor was paying a premium multiple for scarce Indian hotel real estate, then Chalet's own behaviour as a buyer of hotel real estate tells you whether the company shares that view of value or merely benefited from it. In February 2025 Chalet agreed to acquire Mahananda Spa and Resorts, owner of The Westin Resort & Spa, Himalayas at Rishikesh, at an enterprise value of ₹530 crore for a 141-room property.13 Run the arithmetic against the asset's disclosed operating metrics at the time — an average daily rate above ₹26,000 with 45% occupancy in its second year of operation — and the implied multiple lands in the mid-teens on annualised trailing EBITDA.13
In other words: the company that listed at a mid-to-high-twenties multiple has been buying assets at roughly two-thirds of that. That is a point in favour of capital discipline, and it deserves to be counted. It is also a single transaction, in a segment (leisure resorts) structurally cheaper than urban trophy assets, executed in a specific window — not yet a pattern from which to generalise about management's deal-making.
The market's initial verdict on Chalet was, in any case, about to become irrelevant. Thirteen months after listing, India closed its borders.
VI. COVID and the Recovery That Reset the Growth Algorithm (2020–2023)
There is a version of the asset-heavy story that says owning the real estate protects you. The pandemic tested that version, and the honest answer is that it did not hold.
The numbers from Chalet's own five-year disclosures are stark. In FY21, portfolio occupancy fell to 30%. Average daily rate collapsed to ₹4,040. RevPAR — revenue per available room, the industry's summary statistic, calculated as rate multiplied by occupancy — fell to ₹1,214, against ₹6,605 two years later.1 Total income for the year was ₹307.5 crore. EBITDA from continuing operations was ₹29 crore, a 9% margin on a business that normally runs above 40%. The company lost ₹139.1 crore.1 FY22 was better but still loss-making, at ₹81.5 crore of red ink on ₹529.7 crore of income.1
Here is the part that matters for the thesis rather than the history.
The debt did not go anywhere. Net debt, excluding preference capital and promoter loans, was ₹1,871 crore at the end of FY21. It rose to ₹2,234 crore in FY22 and ₹2,437 crore in FY23 — climbing through the crisis, because interest accrued and construction continued while rooms sat empty.1 Net worth simultaneously shrank as losses accumulated, so net debt to equity deteriorated from 1.4x in FY21 to 1.76x in FY22.1 Cash flow from operations, which would exceed ₹950 crore by FY25, was ₹60 crore in FY21 and ₹62 crore in FY22.1
That is what an asset-heavy hospitality balance sheet looks like when demand goes to zero. The land underneath the hotel does not service the loan against it.
This is the single most important disconfirming episode in Chalet's public record, and it should discipline how any investor reads the current, much healthier balance sheet. It does not mean the model is broken — a two-year global shutdown of travel is a genuine tail event, and the company survived it without a restructuring. But it does refute the softer claim, sometimes implied in owner-operator marketing, that real-estate backing makes hospitality cash flows defensive. It does not. It makes them recoverable, which is a different property. The relevant risk is not permanent impairment; it is the speed at which fixed financing costs consume equity when occupancy compresses, and Chalet demonstrated that speed at scale.
The recovery, when it came, arrived through an unusual door: price, not volume.
By FY23, total income had reached ₹1,178 crore with EBITDA of ₹502 crore and a 43% margin, restoring profitability at ₹183.3 crore.1 But look at what drove it. Occupancy in FY23 was 72% — roughly where it had been pre-pandemic. Average daily rate, however, was ₹9,169, well above the pre-COVID level, and it kept climbing: ₹10,718 in FY24, ₹12,094 in FY25.1 The entire Indian upper-upscale and luxury segment repriced upward, as constrained supply met returning corporate travel and a domestic leisure boom.
This is a crucial analytical distinction. Chalet's post-COVID earnings growth has been substantially an industry phenomenon, not a company-specific one. Every listed Indian hotel owner enjoyed the same rate inflation. Rate-led recovery is also a lower-quality growth driver than occupancy-led recovery, because rate is the first thing to soften when demand wobbles and because it eventually collides with what corporate travel budgets will bear.
That reframing sets up the central question for the modern era of this company: once the industry-wide rate tailwind is stripped out, what is Chalet actually doing that its peers are not? The answer lives in the segments — and in an accounting complication that has made those segments unusually hard to read.
VII. The Current Engine: Segment Economics and What Actually Drives the Numbers (2023–Present)
On 14 May 2026, Chalet reported its FY26 results, and the headline was spectacular: consolidated profit after tax up 353% to about ₹645 crore.10 It was the kind of number that gets a company onto television.
It was also, on close inspection, one of the more misleading headline figures a listed Indian company produced that year — and understanding exactly why is the single most valuable thing an investor can take from this story.
Three businesses in one set of accounts
Start with the anatomy. Chalet reports three profit pools.
Hospitality is the core: ₹1,731 crore of FY26 revenue, up 13.8%, generating ₹760 crore of EBITDA at a 43.6% margin.[^3] This is the largest and most stable pool, and it is what most investors think they are buying.
Commercial real estate, which the company calls its annuity business, produced ₹306 crore of revenue in FY26 — up 55.4% — with EBITDA of ₹254 crore at an 83.1% margin, up 490 basis points.[^3] This is the highest-quality earnings stream in the company: contracted, recurring, almost costless at the margin. Occupancy across the leased portfolio reached about 88% by Q4 FY26, against 71% a year earlier, and leased area expanded to roughly 2.1 million square feet.[^3] It is also the most concentrated: management has disclosed that around 63% of commercial rental revenue comes from the top five tenants, which means the loss or renegotiation of one large lease is a materially different event here than it would be in a diversified REIT.
Residential real estate is the Bengaluru project at Koramangala — the segment that broke the income statement in both directions.
The 353% that wasn't
Two separate distortions inflated that headline growth figure, and neither was operational.
The first is the residential recognition itself. Indian real-estate accounting recognises revenue when units are handed over, so a project that hands over ninety-five flats in one quarter and none in the next produces an income statement that looks like a heart monitor. In Q1 FY26 alone, the residential segment contributed ₹439 crore of revenue and ₹163 crore of EBITDA — enough to make consolidated revenue grow 146% and EBITDA 150% in a single quarter.1 Strip it out and the same quarter grew 27% and 37% respectively.1 For the full year, consolidated revenue including residential rose about 61% to ₹2,770 crore; excluding residential, it rose 18% to ₹2,074 crore.[^3]
The second distortion is the one almost nobody mentions, and it is arguably larger. The FY25 base was artificially depressed. Following the withdrawal of indexation benefits under the Finance (No. 2) Act, 2024, Chalet reversed deferred tax assets of ₹2,021.72 million — roughly ₹202 crore — in Q2 FY25, a one-time non-cash charge that pushed the FY25 tax expense to ₹292 crore and crushed reported profit to ₹142.5 crore.1 A 353% increase measured against that base is a statement about tax law, not about hotels. Adjusted for the one-off, FY25 profit was about ₹382 crore and FY26 about ₹646 crore — growth of roughly 69%, still strong, but less than a fifth of the headline.[^3]
Then the mirror image arrived. In Q1 FY27, with no comparable residential handover, reported consolidated profit fell 58% and reported revenue fell 43%.18 The underlying business had done nothing of the sort: core revenue excluding residential grew 10% to ₹514 crore and core EBITDA grew 15% to ₹240 crore, with margins expanding 231 basis points to 46.7%.9
The practical rule this imposes is unavoidable. No headline growth or decline number for Chalet Hotels means anything without the ex-residential figure beside it. Management does disclose the ex-residential line prominently in its own presentations, which is to their credit.1 But keeping a lumpy development business inside consolidated hospitality reporting is a choice, and it is a choice that has already whipsawed the stock in both directions.
It also has a forward-looking consequence that is easy to miss. Sell-side models that build in the residential recognition show FY28 estimated revenue below FY27 estimated revenue — ₹2,698 crore against ₹2,942 crore — and return on equity falling from 19.2% in FY26 to below 14% by FY28, purely because the residential contribution rolls off.[^3] Anyone anchoring on FY26's return metrics as the run rate is anchoring on a distortion.
A capital-allocation record with a blemish in it
The residential segment carries a second, quieter lesson about "real-estate optionality."
Chalet's own disclosure of the Koramangala project's sales history shows historical sales of 83 units at an average realisation of roughly ₹7,700 per square foot, against subsequent sales at approximately ₹18,800 per square foot in FY24, ₹21,200 in FY25 and ₹21,100 in Q1 FY26.1 Those early units were sold years before at a fraction of what the same square footage later commanded — and Chalet has previously taken impairment provisions on flats sold below revised cost per square foot.
The point is not that management was careless. It is that inventory held on a balance sheet for a decade can be marked down as easily as it can be marked up, and that the "optionality" of embedded real estate is a two-sided distribution. When the same company now argues that its land bank represents unrecognised value, that argument should be read against the years in which the same land bank required a provision.
Buying growth, and what the prices say
Against that backdrop, the recent acquisitions look measured.
The Rishikesh resort, discussed earlier, brought 141 keys and a genuine leisure asset with more than 10,000 square feet of event space into a portfolio that was overwhelmingly corporate.13 Then, in a transaction completed in May 2026, Chalet acquired 100% of Seasons Hotels Private Limited, owner of the 144-key Inder Residency Resort and Spa in Udaipur, set on 8.4 acres, for ₹171 crore.[^3] Udaipur is one of India's strongest destination-wedding markets with limited upper-upscale supply; the plan is to refurbish and reposition the property upmarket.[^3] At roughly ₹1.2 crore per key before refurbishment, the entry price is well below what building a comparable resort would cost.
The largest committed bet is different in character. In Hyderabad's Madhapur micro-market, Chalet is developing a 330-key Ritz-Carlton — an ultra-luxury greenfield with an estimated fit-out capex of about ₹561 crore, roughly ₹1.7 crore per room, on a warm-shell lease taken from Mindspace REIT.[^3] Excavation had commenced by mid-2026, with the property targeted for the FY28–29 window.[^3]
Two observations about that project. The favourable one: it sits beside The Westin Hyderabad HITEC City, which has been running at effectively full occupancy under a corporate contract, so demand evidence in the micro-market is unusually direct.[^3] The cautionary one: it is a related-party structure — Chalet is leasing the building from a REIT sponsored by its own promoter group — and ultra-luxury greenfield is the highest-execution-risk format in hospitality, with a long ramp before stabilisation.
What the operating metrics really show
One last piece of the current engine deserves attention, because it complicates the growth story.
FY26 average daily rate rose 13.5% to ₹13,727. RevPAR rose only 5.1% to ₹9,226. The gap is occupancy, which fell 540 basis points to 67.2%.[^3]3 Management attributed the decline to geopolitical instability, adverse weather and the dilution effect of newly added rooms that had not yet stabilised.[^3] In Q4 FY26 the divergence became a genuine deterioration: ADR up 7.7% to ₹15,456, occupancy down 770 basis points to 68.2%, and RevPAR actually falling 3.2% year-on-year to ₹10,544.[^3]
Rising rate with falling occupancy is ambiguous evidence. It can mean deliberate yield management — trading volume for price, which is what a confident operator does. It can equally mean rate has run ahead of what the market will absorb. Chalet's Q4 had specific, identifiable causes: reduced foreign travel amid West Asian conflict, and construction of CIGNUS Powai Tower II physically disrupting the Westin Powai's event business.[^3] Those are temporary. But the pattern is worth watching, because RevPAR — not ADR — is the number that converts into cash.
Which is a fitting note on which to turn to the company's boldest recent decision, because it is fundamentally a bet about rate.
VIII. The Athiva Pivot: From Brand-Agnostic Landlord to Brand Owner
On 16 October 2025, a colonial-era hill resort in Khandala, on the Mumbai–Pune road, changed its name. The Dukes Retreat — a property Chalet had acquired and was expanding in phases — became Athiva Resort and Spa, Khandala.11 Weeks later, the company formally launched the brand: Athiva Hotels and Resorts, from a Sanskrit root meaning abundance, debuting with six hotels and more than 900 keys, positioned as a premium lifestyle brand built around wellness and sustainability and aimed at younger travellers.411
For a company that had spent four decades arguing that it did not need a brand, this was a reversal — and it is worth stating that plainly rather than smoothing it over.
The initial Athiva portfolio was assembled from properties that were already Chalet's or already in its pipeline: Khandala, a hotel in Navi Mumbai, a resort and spa at Aksa Beach in Mumbai, resorts at Varca and Bambolim in Goa, and a resort and convention centre in Thiruvananthapuram.11 By August 2026 the company added two more — 150 keys in Hyderabad and 231 in Pune, 381 in total — taking Chalet's combined operating-plus-pipeline inventory to close to 5,500 keys.17 Management has stated an ambition to roughly double Athiva's key count within three years and has put a revenue target of about ₹550 crore on the brand by FY31.
The rationale, and whether it holds
Management's argument is coherent, and it follows directly from the logic of Section III. Global chains want scale, urban trophies and predictable corporate demand. They are less interested in a 117-key hill resort, a beach property in South Goa, or a convention hotel in Thiruvananthapuram. For assets like those, Chalet was already self-managing several properties under scattered identities — so the choice was not "Marriott versus Athiva," it was "an unbranded property versus a branded one." Consolidating them under a single name captures the management fee that would otherwise leave the building, and creates a repeatable format for the leisure segment where Indian domestic demand has been growing fastest. Management has framed the launch publicly in exactly these terms — as testing its own brand muscle on assets where a global flag adds little, rather than as a repudiation of the partnership model.12
That is a genuinely defensible segmentation. Trophy urban assets continue to go through global brands — Chalet is simultaneously building a Taj at Delhi airport and a Ritz-Carlton in Hyderabad.1[^3] Athiva is being tested on secondary and leisure assets. The two strategies are not in conflict; they are a portfolio split by asset type.
The falsification test
Now apply the test that matters: does Chalet have any demonstrated capability at building a consumer brand?
No. And this is not a close call.
Every rupee of profit in the company's public history was earned under the partnership model. The entire in-house hospitality organisation was built to be an owner and asset manager — to review budgets, control capex, monitor an operator's performance. Brand-building is a different discipline: it requires consumer marketing spend, a distinct service standard enforced across properties, a loyalty proposition that gives a guest a reason to choose Athiva Goa over the branded resort next door, and the patience to underwrite years of sub-scale marketing before recognition arrives. Chalet's own presentation, describing its proven operational capability, at one point referenced a track record spanning two operational self-managed hotels and two more in the pipeline.1 That is a starting point, not a track record.
There is also a structural headwind that the segmentation argument cuts both ways on. The reason global chains do not want these assets is that they are harder to fill. Athiva properties will compete without Bonvoy's corporate rate agreements, without GDS penetration, and without a loyalty base — in leisure markets where the customer is highly price-sensitive and shops on online travel agents. The margin capture is real, but so is the demand cost.
Early evidence is limited and directionally positive. On the Q1 FY27 call, chief executive Shwetank Singh said of the Khandala property, "We are very encouraged by the performance there. We have fantastic customer feedback."9 The company's leisure portfolio as a whole posted 19% RevPAR growth in that quarter.9 That is encouraging, but one refurbished resort in a strong leisure quarter is not proof of brand equity — a rebuilt property with new inventory would be expected to ramp regardless of the name on it.
Where this leaves the thesis
The right calibration is this: the historical record neither confirms nor refutes Athiva. It narrows the claim.
The claim that Chalet can win without owning a brand is not refuted — it remains supported by the cash flows of the urban portfolio, which continue to run through Marriott and Accor. The claim that Chalet can also build a brand is unproven and rests on a capability the company has never demonstrated. Athiva should therefore be valued as optionality with a modest probability weight, not as a second engine.
And the KPI that would settle it is specific: Athiva's realised ADR and RevPAR versus comparable branded properties in the same micro-markets, tracked over two to three years, not keys announced. Announcements of pipeline keys are the least informative metric in hospitality — they cost nothing and prove nothing. Rate realisation against a branded comparable is the only evidence that a guest will pay for the name.
The person who now has to prove it, however, did not choose it. He inherited it.
IX. Leadership Transition: Sanjay Sethi to Shwetank Singh
On an earnings call in late July 2025, Sanjay Sethi told analysts something they were not expecting: he would not seek an extension of his term, which ran to 31 January 2026.523 It was, by the standards of Indian promoter-controlled companies, a remarkably orderly announcement — made in public, six months ahead, with a named successor already identified.
Sethi's career explains a lot about the company he ran. He came to Chalet with more than three decades in Indian hospitality, including fourteen years at the Taj Group across property and regional leadership roles, and later a period as chief operating officer of ITC Hotels.20 In between, he did something unusual for an Indian hotel executive: in 2006 he founded Keys Hotels & Resorts in partnership with Berggruen Holdings of New York, building a mid-market brand from scratch across multiple cities.20 He is a hotel-school graduate — a diploma from IHM Pusa — a Certified Hotel Administrator, and holds a certificate in corporate governance from the Indian Institute of Corporate Affairs.20
That biography contains a quiet irony worth noting. The executive who spent eight years running India's most prominent brand-agnostic hotel owner had, earlier in his career, personally built a consumer hotel brand. Whatever else Athiva is, it did not emerge from a management team with no exposure to the idea.
Sethi's tenure is the record against which his successor will be judged. He arrived in 2018, took the company public in February 2019, absorbed a pandemic that wiped out two years of profitability, and presided over the recovery that took market capitalisation past USD 2 billion by the time he stepped down.20 Rather than exit entirely, he moved to the board as a non-executive director — continuity that helps, though it also means the architect of the current strategy remains in the room while the new chief executive is expected to own it.20
Shwetank Singh took over as managing director and chief executive officer on 1 February 2026.5 He is an internal promotion, but not a lifer: he joined Chalet in August 2023 as chief growth and strategy officer, leading project development and business development, having previously headed the business at Golden Sands LLC in Dubai. He holds a B.Tech from an Indian Institute of Technology and an MBA in finance and marketing from the Faculty of Management Studies, and brings roughly twenty-five years of hospitality experience.23 By August 2025 he was already on the board as executive director.1
The composition of his background is worth pausing on. Sethi was an operator — a hotelier who ran hotels. Singh's Chalet role before promotion was growth and strategy: acquisitions, projects, pipeline. That is a different centre of gravity, and it maps neatly onto what the company is now doing. The Rishikesh and Udaipur acquisitions, the Ritz-Carlton, the Athiva rollout and a ₹3,000 crore capital expenditure programme are all deal-and-development activity.9 An investor should read the succession as the board choosing a builder over an operator at a moment when the company's plan is to build.
That is a defensible choice. It also concentrates a specific risk. A chief executive whose formative expertise is growth is, statistically, less likely to be the one who says no to a marginal project. The check on that is guidance discipline and reporting clarity, and here the early record is genuinely mixed rather than conclusive.
On the positive side, Singh's first full quarters have kept the ex-residential disclosure front and centre and have given specific, checkable operating targets: hospitality inventory growing beyond 5,000 keys with more than 500 keys added annually, commercial rental run rate reaching ₹30–32 crore per month during FY27, and the first 70 rooms of the Delhi airport Taj opening by Q4 FY27 with the remaining 310 in Q1 FY28.9[^3] Those are falsifiable. On the cautionary side, management explicitly declined to give detailed consolidated guidance, citing geopolitical volatility and residential timing — understandable, but it also means the most-quoted headline numbers remain the least guided ones.9
Finally, incentives and control, which in a promoter company are inseparable.
The Raheja family and its entities control Chalet through a web of promoter vehicles — Cape Trading LLP, Anbee Constructions LLP, Casa Maria Properties LLP, Capstan Trading LLP, Raghukool Estate Development LLP, Palm Shelter Estate Development LLP, Touchstone Properties and Hotels, K Raheja Private Limited, K Raheja Corp Private Limited, Ivory Properties and Hotels, Genext Hardware and Parks, and individual holdings by Ravi Chandru Raheja and Neel Chandru Raheja among others.1516 Ravi and Neel Raheja sit on the board as non-executive promoter directors, alongside an independent-majority slate that includes chairman Hetal Gandhi, Arthur De Haast, Joseph Conrad D'Souza, Radhika Piramal and Manish Chokhani.1
A meaningful portion of that promoter stake is encumbered. A SAST Regulation 31 disclosure dated 2 August 2024 shows, as of that date, Cape Trading LLP with 6.01% of total share capital pledged, Anbee Constructions LLP 6.01%, Touchstone Properties and Hotels 6.60%, Raghukool Estate Development LLP 1.56% and Capstan Trading LLP 1.37% — in aggregate more than a fifth of the company's equity encumbered as collateral for bank facilities, with the pledges routed through security trustees for lenders including HDFC Bank and, following a release-and-recreate transaction that week, ICICI Bank.16
In June 2026, the promoters filed the annual confirmation that no encumbrance was created during FY26 "other than those already disclosed."15 That phrasing matters. It confirms no new pledging; it does not mean the existing pledges have gone away. For an outside shareholder, promoter pledges tied to borrowings outside the listed entity are a standing governance watch item, because a stress event at an affiliate can force share sales in a company that is itself performing perfectly well.
None of this is unusual for an Indian promoter group, and none of it is evidence of wrongdoing. It is simply a structural feature that belongs in the risk column rather than being discovered later.
Now zoom out. Chalet is executing this transition inside an industry that has changed more in the last three years than in the preceding fifteen.
X. Competitive Landscape & Industry Structure
For most of the last two decades, Indian hospitality had a simple public-market structure: IHCL was the giant, EIH was the connoisseur's luxury play, Lemon Tree was the mid-market challenger, and everything else was private. That structure has been dismantled at speed.
ITC Hotels was demerged from ITC Limited and listed separately on 1 January 2025, arriving as an instant heavyweight with roughly 140 hotels and 13,000 keys. In May 2025, Schloss Bangalore — the owner of The Leela Palaces, Hotels and Resorts, with thirteen operational hotels and 3,553 keys — raised ₹3,500 crore in what was the largest initial public offering in the history of the Indian hospitality sector, comprising ₹2,500 crore of fresh issue and ₹1,000 crore of offer for sale at a price band of ₹413–435, and closed 4.5 times subscribed.21 Juniper Hotels, the Hyatt-only owner running essentially the same landlord model as Chalet, had listed in February 2024. SAMHI Hotels, a multi-brand acquirer, listed in 2023.
Chalet, which in 2019 was one of a handful of ways to own Indian hotel real estate through the public markets, is now one of many.
Where Chalet sits
By luxury-segment share, Chalet is small. Commonly cited estimates place IHCL around 45% of India's luxury hotel segment, ITC Hotels around 17%, The Leela around 12%, EIH around 7%, with Juniper, Lemon Tree and Chalet each in the low single digits. The broader India luxury hotel market is estimated at roughly USD 4 billion in 2026, growing at a low-double-digit compound rate, and remains only moderately concentrated with no single player above about a quarter of revenues.19
Reconcile that with market capitalisation and you get the essential shape of the company. Chalet is a scale minority player in luxury specifically, but a substantial owner overall — larger by market value than Juniper or Lemon Tree — because its portfolio skews to upper-upscale corporate hotels in expensive cities rather than palace-format luxury. The investment case therefore rests on asset quality and location, not on category leadership. Chalet does not set price in any segment. It benefits when others do.
The five forces, quickly
Entry barriers are high and genuinely so. Assembling a large urban parcel in Mumbai or Bengaluru, obtaining approvals, securing a global brand agreement and completing a five-to-seven-year build is a formidable sequence. This is the industry's real structural feature and it is why supply growth has consistently lagged demand growth in the upper tiers.
Buyer power is fragmented but not negligible. Individual guests have none. Corporate accounts and global capability centres — which drive a large share of Chalet's business-hotel demand — have real leverage, negotiating annual rate agreements at volume. The Westin Hyderabad HITEC City running at effectively full occupancy under a corporate contract is a case in point: excellent utilisation, and a single counterparty setting the price.[^3]
Supplier power is where the model's weakness lives. In this industry, the "supplier" of the brand is a global chain that collects fees off the top line regardless of the owner's return on capital. Marriott's economics improve with every new managed hotel in India; the owner's do not automatically. That asymmetry is permanent under the partnership model and is the strongest structural argument the brand-owning school makes.
Substitutes bite unevenly. At the budget end, aggregators and short-stay rental platforms have genuinely compressed pricing. At upper-upscale and luxury, where a corporate traveller needs meeting rooms, a business centre, a reliable breakfast and an expense-policy-approved invoice, substitution is far weaker. Chalet sits on the defended side of that line, which is a real advantage worth naming.
Rivalry is rising, and this is the change that matters most. Three or more hotel-sector listings since 2023 mean more public capital chasing the same bolt-on acquisition targets. When Chalet bought Rishikesh at a mid-teens multiple in early 2025, it was competing against a shorter list of buyers than it will face in 2027. Deal sourcing is likely to get more competitive and more expensive — which directly threatens the "disciplined acquirer" leg of the growth story.
What this means
The industry structure supports the sector, not any particular participant. Constrained supply and growing demand lift every owner's rate, which is exactly what the last three years demonstrated. What structure does not provide is a reason why Chalet specifically should out-earn Juniper or SAMHI over a cycle. That case has to be made on assets, balance sheet and execution — which is where the numbers come in.
XI. Balance Sheet, Guidance Discipline & the Numbers That Matter
There is a specific moment in the recent financial history where the deleveraging story stops being a narrative and becomes visible.
Between FY22 and FY26, net debt to equity fell from 1.76x to about 0.52x.1 That is a dramatic improvement, and it is worth being precise about how it happened, because "the company deleveraged" is only partly true.
Net debt itself fell from ₹2,234 crore in FY22 to ₹1,991 crore in FY25 and roughly ₹1,900 crore in FY26 — a decline, but a modest one.1 The denominator did most of the work. Net worth rose from ₹1,341 crore in FY22 to ₹1,851 crore in FY24 to ₹3,046 crore in FY25.1 That FY25 jump of nearly ₹1,200 crore came overwhelmingly from a single event: in a qualified institutional placement that opened on 27 March 2024 and closed on 2 April 2024, Chalet issued 1,26,26,263 shares at ₹792 each, raising ₹1,000 crore from a roster of institutions led by Smallcap World Fund, SBI Mutual Fund, ICICI Prudential, Axis Mutual Fund, Aditya Birla Sun Life and Norway's Government Pension Fund Global.25
This is the kind of thing that should be said out loud rather than left in a footnote. The balance sheet did not repair itself purely out of operating cash flow; existing shareholders were diluted by roughly 6% to help fix it. Cash flow from operations did improve enormously — from ₹477 crore in FY23 to ₹950 crore in FY25 — so the operating recovery is real.1 But an investor evaluating whether this management team can fund growth without returning to the market should note that it returned to the market five years after its IPO, and that the current ₹3,000 crore capital expenditure programme for FY27 to FY29 is stated as being largely funded through internal cash flows.9 "Largely" is doing meaningful work in that sentence.
Cost of debt has genuinely improved — from 8.9% in FY24 to 8.4% in FY25 to about 7.5% in FY26 — reflecting both a better rating and a friendlier rate environment.110 The credit view corroborates the equity story: ICRA rates Chalet's long-term instruments AA- with a Stable outlook and short-term A1+, citing healthy performance and prudent funding of capex, while flagging the same concentrations an equity investor should worry about — notably that about 45% of inventory sits in Mumbai, exposing the company to region-specific shocks.14
Reading returns without being fooled
Return on equity readings for Chalet vary wildly by source and period, and now you know why: the residential lumpiness and the FY25 deferred-tax reversal make any single headline figure close to meaningless. The FY26 reported return on equity of about 19.2% is flattered; sell-side models that carry the residential roll-off show it declining to under 14% by FY28.[^3] Return on capital employed — measured by the company as EBITDA over capital employed on operating assets — stood at 18.5% for FY25, which is a cleaner read on the underlying asset base.1
The guidance test
For a new chief executive, the most useful thing an investor can do is write down the specific commitments and check them.
Management has guided to roughly 13% growth in the hotel business in FY27, contingent on the stabilisation of new rooms in Bengaluru and a demand pickup in the second half.[^3] The second-half dependency is explicit and conditional: the case assumes MICE events and the wedding season deliver, and that the disruption at Westin Powai from CIGNUS Tower II construction ends as the tower completes in Q4 FY27.[^3]9
On the Q1 FY27 call, Singh described the Powai disruption in the language of deliberate trade-off — temporary pain for long-term gain — and quantified the ambition, suggesting the completed Powai complex could eventually support ₹900–1,000 crore of annual revenue.9 That is a large number relative to a company doing about ₹2,000 crore of core revenue, and it is precisely the sort of forward claim that should be logged and checked rather than accepted. He also committed to holding the leisure allocation at around 20% of the portfolio despite leisure's strong quarter — a discipline statement that will be easy to verify.9
Valuation, without prescribing anything: against a market capitalisation near ₹18,900 crore and FY26 ex-residential EBITDA of ₹957 crore, the enterprise value sits in the high-teens as a multiple of that core earnings stream.2[^3] Cheaper than the IPO-era multiple, but still a premium rating that prices continued execution rather than a margin of safety.
The two or three numbers that actually matter
Strip everything else away and there are three metrics worth tracking each quarter:
One: RevPAR, not ADR. Rate growth with falling occupancy has already produced one quarter of negative RevPAR in FY26.[^3] RevPAR is the number that turns into cash, and same-store RevPAR — excluding newly added and newly acquired keys — is the honest version of it.
Two: commercial rental monthly run rate, and the top-five tenant concentration behind it. This is the highest-quality earnings pool in the company and the fastest-growing. The stated FY27 target of ₹30–32 crore per month is checkable.9 So is the concentration; if it does not fall as CIGNUS Powai Tower II leases up, the quality of that annuity is lower than the margin suggests.
Three: consolidated results excluding the residential segment. Not a performance metric so much as a reading discipline — but given how badly the headline numbers have misled in both directions within twelve months, it is the most valuable habit an investor in this name can adopt.
With the numbers established, the argument can be put on both sides.
XII. Bull vs. Bear
The bull case
The foundation is an asset base that cannot be recreated. Land at Sahar, Powai, Vashi, HITEC City and Whitefield was assembled before those micro-markets became what they are, and no competitor with unlimited capital can buy the same parcels today because they are built on. In Hamilton Helmer's framework, this is cornered resource — preferential access to a coveted asset on attractive terms. It is the single most defensible thing about the company.
Layered on top is a scale economies argument within the commercial segment, where building offices on already-owned hotel land avoids the largest cost input in Indian real estate and produces an 83% EBITDA margin annuity that is contracted, recurring and growing 55% year-on-year.[^3] That segment is the highest-quality earnings in the company and remains under-appreciated relative to the hotels.
The balance sheet has genuinely improved: leverage down, cost of debt down to about 7.5%, an AA- rating with a stable outlook, and operating cash flow that has roughly doubled since FY23.11014 That combination is what enables continued bolt-on acquisition at sensible multiples — Rishikesh in the mid-teens, Udaipur at roughly ₹1.2 crore per key before refurbishment.[^3]13
And Athiva is a real, if unproven, second vector: margin capture on assets that global brands do not want, in the fastest-growing part of Indian travel demand.
The bear case
The reported numbers do not describe the business, and this is not a technicality. A 353% profit increase driven jointly by lumpy residential recognition and a prior-year one-off deferred tax reversal, followed two quarters later by a 58% decline for the mirror reason, has already whipsawed the stock in both directions.10181 Any investor who does not normalise is trading on noise. Worse, the normalisation cuts the wrong way going forward, as the residential contribution rolls off and pulls reported revenue and returns down with it.[^3]
The Athiva bet is unsupported by track record. The company has never built a consumer brand and is entering the part of the market where it will compete without the distribution advantages that made the rest of its portfolio work.
Concentration is triple-stacked: 45% of inventory in Mumbai, roughly 63% of commercial rental revenue from five tenants, and — in the hospitality mix — a heavy dependence on Indian corporate travel demand in a handful of tech corridors.14
Governance carries a standing asterisk. More than a fifth of the company's equity was encumbered as promoter collateral as of the most detailed disclosure, and the FY26 confirmation attests only that no new encumbrance was created.1615 The Hyderabad Ritz-Carlton is being built on a warm-shell lease from a REIT sponsored by the same promoter group — a structure that may be entirely fair but is, by construction, not arm's length.[^3]
The valuation prices execution. At a high-teens multiple of core EBITDA, there is limited room for a missed opening date, a soft wedding season, or a corporate travel slowdown.
And the chief executive has two quarters on record.
Porter, applied
Running the five forces against Chalet specifically: entry barriers protect the incumbent position strongly; substitution is weak in the defended upper-upscale tier; buyer power is moderate and concentrated in corporate accounts; supplier power is the structural weak point, because the brand owner extracts fees ahead of the owner's return; and rivalry is intensifying as newly listed peers compete for the same acquisitions. The net is an industry that is attractive to be in and a position within it that is good but not commanding.
7 Powers, applied
Cornered resource: yes, strongly — legacy land. Scale economies: partially, in the hotel-plus-office ecosystem and in operator relationships. Counter-positioning: no. Switching costs: essentially none for guests; some for corporate accounts locked into brand agreements, but those accrue to Marriott. Network economies: none for Chalet; Bonvoy's network belongs to Marriott. Branding: none historically — Athiva is an attempt to acquire this power, and it is at year one. Process power: unproven; asset management discipline is claimed and plausible but not independently verifiable against peers.
Two of seven, one of them inherited and non-renewing. That is a fair characterisation, and it argues for a company that is well-positioned rather than structurally advantaged.
The activist stress test
What would a sceptical investor attack first?
Portfolio complexity, immediately. A hotel owner that also books residential flat sales and leases office space produces accounts that require three mental adjustments before a comparison to any peer is possible. The obvious demand would be to ring-fence or exit residential entirely, and to consider whether the commercial portfolio would be better valued inside a REIT structure than buried in a hotel company's consolidated statements.
Second, related-party architecture: a Ritz-Carlton leased from a promoter-sponsored REIT, promoter shares pledged for borrowings outside the listed entity, and a promoter group that is simultaneously the company's controlling shareholder and its counterparty in multiple structures.
Third, capital allocation credibility. Management describes a ₹3,000 crore programme as largely internally funded five years after raising ₹1,000 crore of equity.925 The reasonable challenge is not that the QIP was wrong — it materially improved the balance sheet — but that the promise of self-funding deserves scrutiny rather than assumption.
Fourth, and most pointed: the company's own reporting. Chalet publishes ex-residential figures clearly across its quarterly presentations and investor disclosures, but it also allows headline numbers that it knows will be misread to reach the market unqualified.22 That is a self-inflicted volatility.
XIII. Risks to Watch
Several of these have been developed in place above; what follows is what remains material and forward-looking.
Demand concentration and its geography. With 45% of rooms in Mumbai and most of the rest in tech corridors, Chalet's revenue is a leveraged bet on Indian corporate travel in a handful of postcodes.14 The mechanism to watch is not abstract: FY26 already showed the effect of exogenous shocks, with occupancy pressured by geopolitical disruption to foreign travel and, in Q1 FY26, by flight disruptions during a period of regional conflict.1[^3] Corporate travel is also the first budget line cut in a slowdown, and a meaningful slowdown at India's global capability centres — the demand engine behind Hyderabad and Bengaluru — would show up in occupancy before it showed up in anyone's forecast.
Simultaneous execution risk. Chalet is currently building a 330-key Ritz-Carlton in Hyderabad, a 385–390-room Taj at Delhi airport phased across FY27 and FY28, a 0.9 million square foot office tower at Powai, a resort in South Goa, and doubling Athiva — all inside a ₹3,000 crore capex envelope.1[^3]9 Any one of these is manageable. The combination is a genuine stretch for an organisation that has historically added assets one at a time, and it is being managed by a leadership team in its first year.
Environmental clearance delay is a repeat pattern, not a hypothetical. Chalet's own investor materials disclosed that the planned Hyatt Regency at Airoli was awaiting approvals at the National Green Tribunal stage, noting that changes in NGT regulation had delayed projects across India.1 This is not a one-off: for a developer working on coastal and environmentally sensitive urban parcels in Maharashtra, clearance risk is a structural feature of the project pipeline. Every delay pushes revenue right and carries interest cost in the meantime.
Refinancing and cost of capital. The COVID episode established the mechanism precisely: fixed financing costs against a business whose revenue can compress by 80% in a quarter. Leverage today is far healthier, but the capex programme will consume cash before it generates any, and the rating agency's Stable outlook is explicitly premised on prudent funding of that capex.14 A combination of demand softness and a harder rate environment during the build phase is the specific scenario that would test the balance sheet again.
Related-party and pledge governance. Discussed in Section IX; the standing item is that pledges tied to affiliate borrowings can transmit stress from outside the listed entity into its shareholder register.
Reporting clarity as a self-inflicted risk. Keeping a lumpy residential development inside consolidated hospitality reporting guarantees that headline results will periodically misrepresent the business in both directions. It has already happened twice within twelve months.
What is not on this list, deliberately: technology disruption is not a material near-term threat to upper-upscale hotel ownership, and cybersecurity, while a genuine operational exposure, sits substantially with the global operators who run the reservation systems.
XIV. Durable Lessons for Investors
Four things travel beyond this company.
Owning irreplaceable real estate and renting someone else's brand is a legitimate model — but the "why win" rests on the land, not the management. Chalet's most durable advantage was created by decisions taken in the 1990s and 2000s about which parcels to buy and hold. That advantage is real, defensible and non-replicable. It is also inherited and non-renewing. Every asset added from here is bought at today's prices against a growing field of listed competitors with fresh IPO capital. When evaluating an asset-heavy company, always separate the value of what was accumulated cheaply from the skill of accumulating it — they are frequently different people's achievements, and only one of them predicts the future.
Segment lumpiness can make headline growth numbers actively misleading, and the distortion compounds. Chalet's 353% profit surge combined a lumpy revenue recognition with a prior-year one-off tax reversal — two independent distortions pointing the same way, followed by a 58% decline pointing the other. Neither described the hotels. The general lesson: when a company runs businesses with fundamentally different revenue-recognition rhythms inside one set of accounts, normalise before forming any view, and be alert to the possibility that the distortion reverses and drags reported numbers down in a future period exactly as mechanically as it lifted them.
A strategic reversal of forty years of stated philosophy deserves scrutiny of capability, not credit for ambition. Athiva may work. But the evidentiary bar for "this company can build a brand" is not a launch event, a Sanskrit name, or a pipeline key count. It is rate realisation against branded comparables, sustained over years. The general principle: when a company enters a business it has never been in, the announcement tells you about intent, and only operating metrics tell you about capability. Optionality is worth something; it is rarely worth what the pipeline slide implies.
Leadership transitions in promoter-controlled companies are judged by what changes afterwards, not by the announcement. Chalet's succession was orderly, telegraphed and internal — genuinely good governance by the standards of Indian family-controlled companies. But an orderly process says nothing about the quality of subsequent decisions. What to watch is narrow and concrete: does guidance stay specific and get met; does the ex-residential disclosure remain prominent when the residential contribution is falling rather than rising; does the ₹3,000 crore capex programme stay inside its envelope; and does a chief executive whose background is growth and deal-making demonstrate that he can also decline a deal.
The company that spent forty years being a landlord is now trying to be a hotelier as well. The land was always the moat. Whether the hotelier is any good is a question that the next three years of RevPAR, rental run rate and Athiva rate realisation will answer — and no amount of narrative, from management or anyone else, can answer it sooner.
References
-
Chalet Hotels Limited Q1 FY26 Corporate Presentation, August 2025 (PDF) — Chalet Hotels, 2025-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Chalet Hotels Ltd (CHALET) share price, market capitalisation and valuation metrics — Tickertape, 2026-09-02 ↩↩
-
Chalet Hotels reports consolidated revenue of ₹25 billion for FY26 — Business Upturn ↩
-
Chalet Hotels names Shwetank Singh as new MD and CEO from February 1 — Business Standard, 2025-07-31 ↩↩
-
Chalet Hotels Limited Prospectus (PDF) — Chalet Hotels, 2019-02 ↩↩
-
Chalet Hotels Limited Draft Red Herring Prospectus (PDF) — SEBI, 2018-07-02 ↩↩
-
Chalet Hotels share lists at 5% premium over issue price — Business Today, 2019-02-07 ↩↩↩
-
Earnings call transcript: Chalet Hotels Q1 FY27 results — Investing.com, 2026-07 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Chalet Hotels FY26 PAT surges 353% to ₹6.5 billion on annuity growth — BW Hotelier ↩↩↩↩↩
-
Chalet Hotels Launches Athiva Brand With Six Premium Properties Across India — India Infoline ↩↩↩
-
Chalet Hotels On Testing Its Own Brand Muscle With Athiva — Skift, 2025-11-05 ↩
-
Chalet Hotels to acquire Westin Resort & Spa, Rishikesh for Rs 530 crore — Business Standard, 2025-02-10 ↩↩↩↩
-
ICRA rating rationale for Chalet Hotels Limited (PDF) — ICRA, 2026-03-31 ↩↩↩↩↩↩
-
Chalet Hotels confirms no encumbrance on promoter shares in FY26 — ScanX, 2026-06-23 ↩↩↩
-
Cape Trading LLP — Disclosure under Regulation 31(1) and 31(2) of SEBI (SAST) Regulations, 2011 (PDF) — Chalet Hotels, 2024-08-02 ↩↩↩
-
Chalet Hotels adds two Athiva hotels to pipeline, enters Hyderabad market — Business Standard, 2026-08-06 ↩
-
Chalet Hotels Q1 FY27 profit falls 58%, revenue down 43% — Business Standard, 2026-07-30 ↩↩↩
-
India Luxury Hotel Market Size & Share Analysis — Mordor Intelligence, 2026 ↩
-
Schloss Bangalore (The Leela) IPO ends with 4.50x subscription — Business Standard, 2025-05-29 ↩
-
Chalet Hotels Names Shwetank Singh CEO As Sanjay Sethi Steps Down — Skift, 2025-08-01 ↩↩
-
Chalet Hotels Annual Report FY2025 (PDF) — Chalet Hotels, 2025-07 ↩
-
Chalet Hotels Limited Raises ₹1,000 Crore through QIP — Angel One, 2024-04 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube