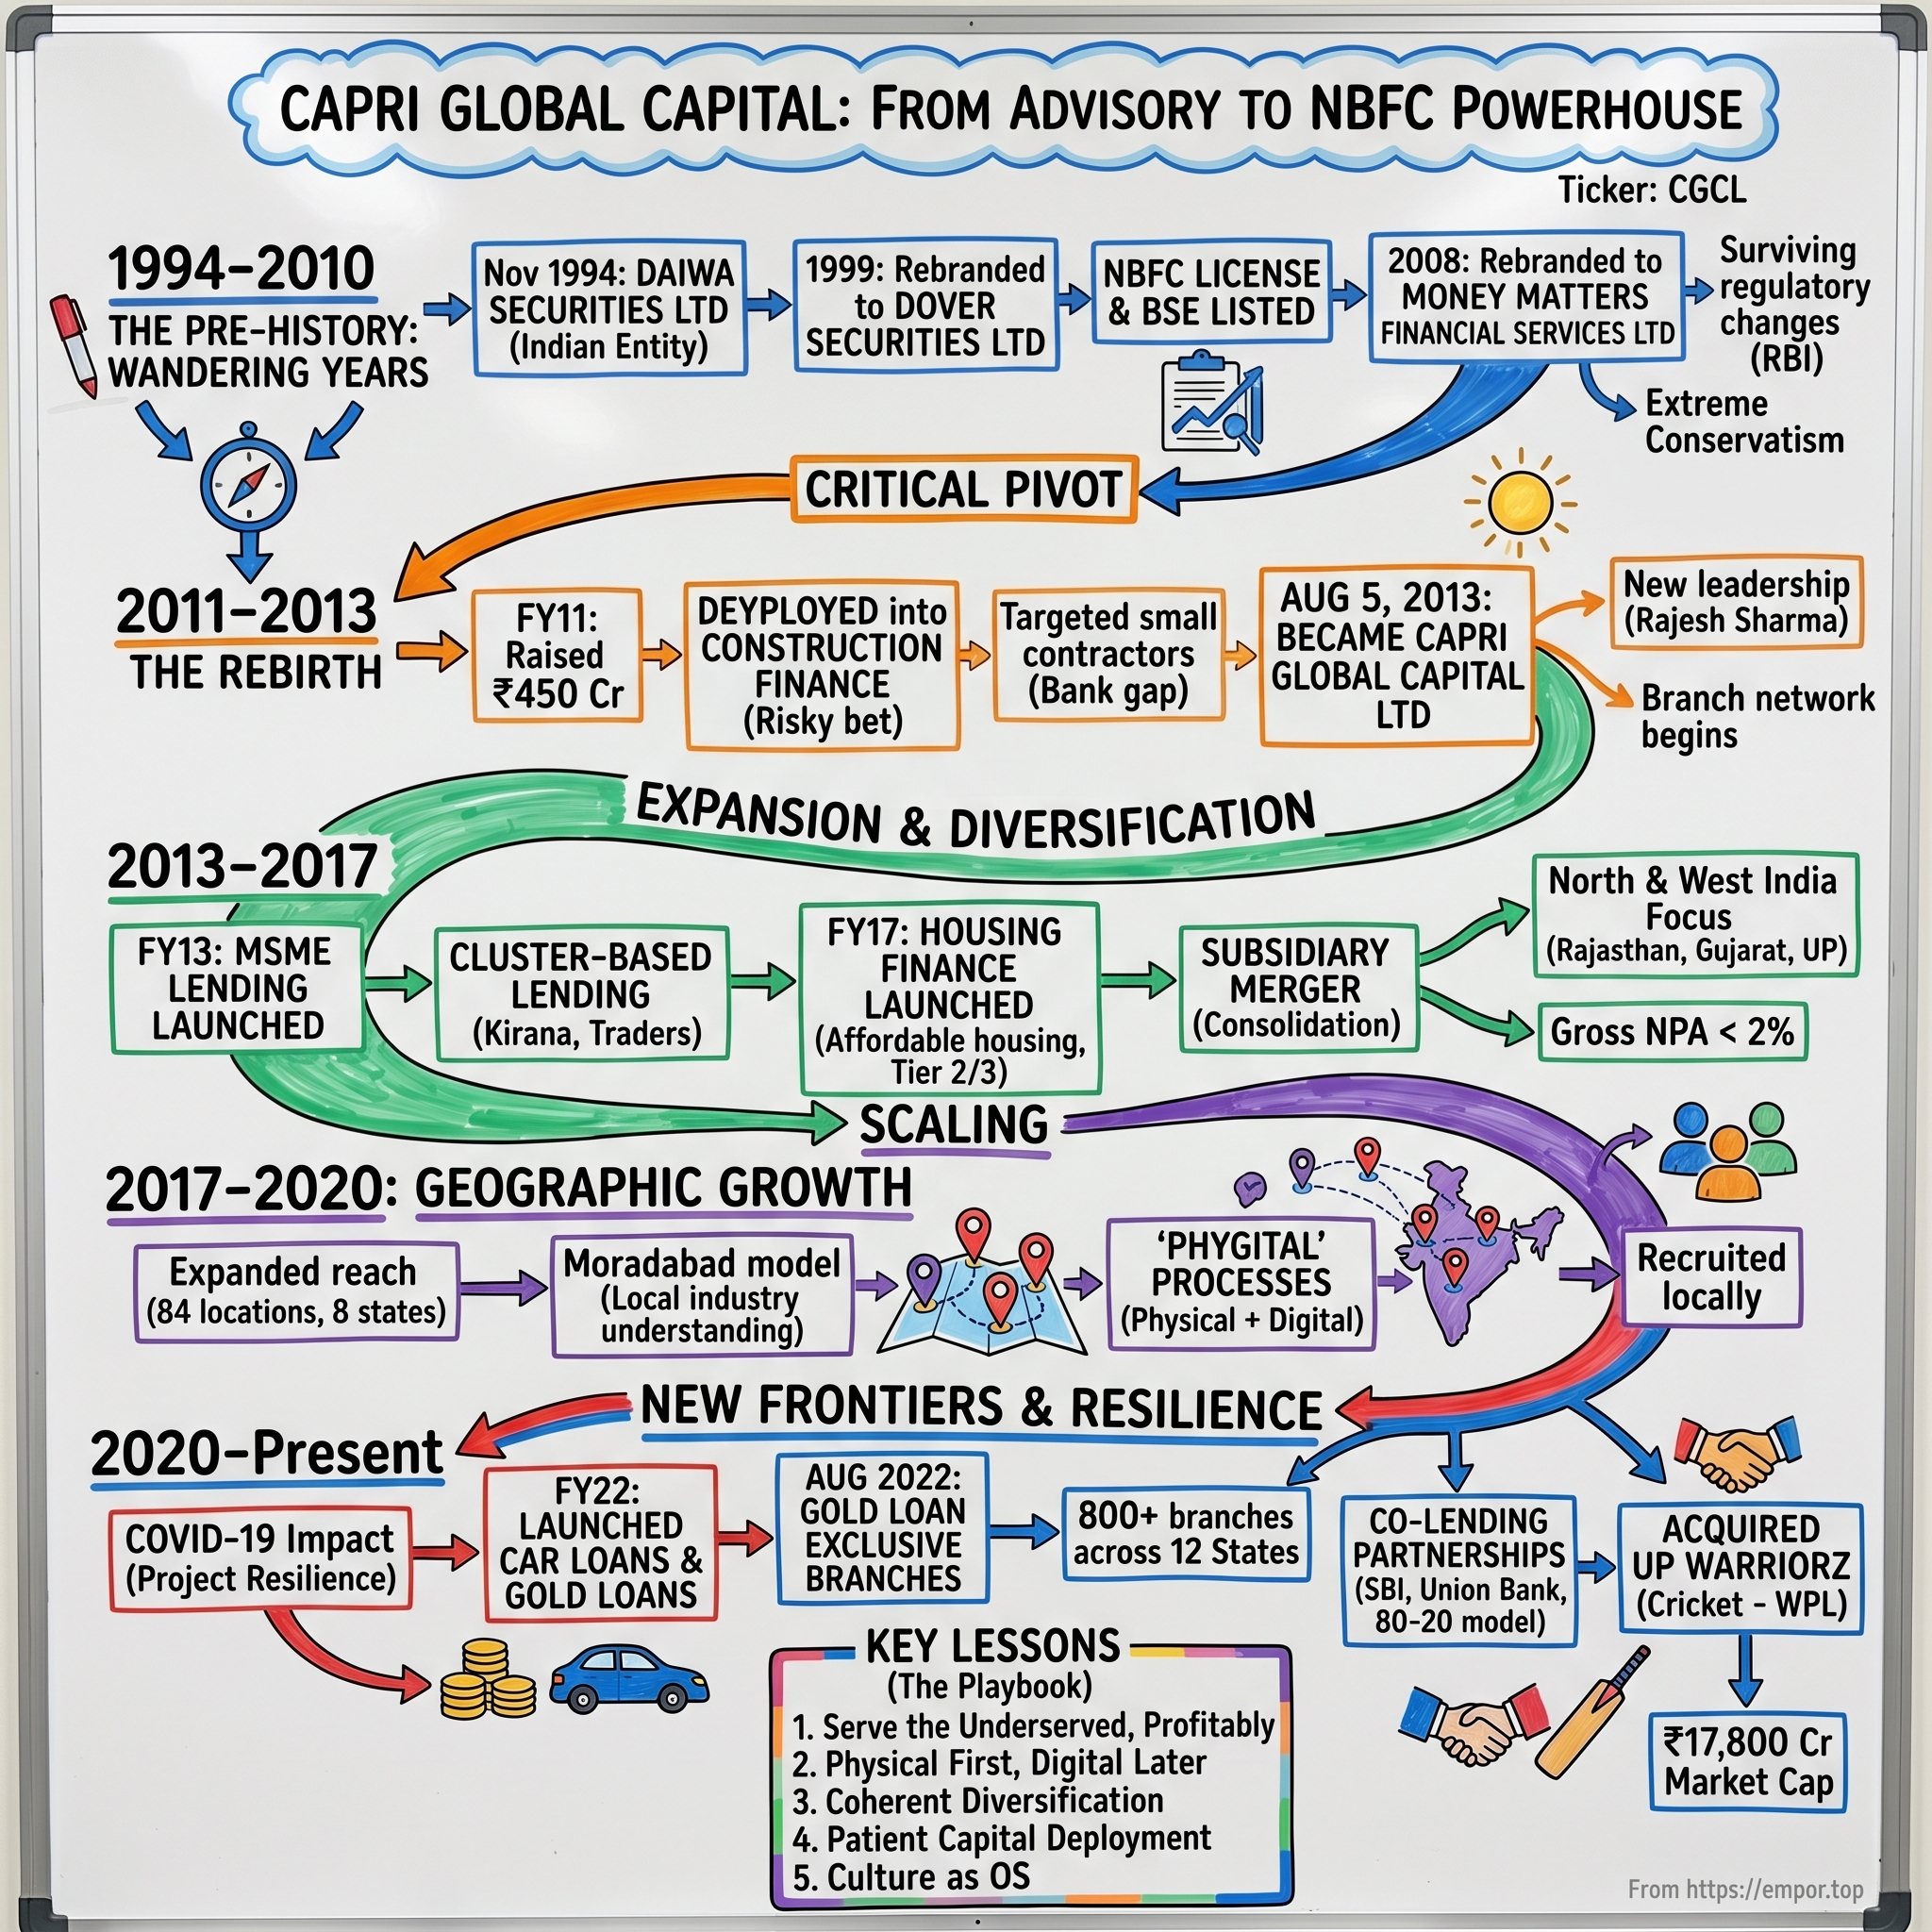
Capri Global Capital: The NBFC Betting Its Next Decade on Gold
I. Introduction & Episode Roadmap
Start with a number that most people who follow Indian financials would guess wrong.
On the morning of the Q1 FY27 earnings call in late July 2026, Capri Global Capital reported that its consolidated assets under management had reached ₹40,112 crore — up 62% from a year earlier and 10% from the previous quarter.1 Two years before that, the same balance sheet was carrying roughly ₹15,600 crore.2 A lender that had spent a decade grinding out a book measured in single-digit thousands of crores had, in eight quarters, more than doubled and then some. Quarterly profit after tax hit ₹353 crore, up 102% year on year.1 Return on average equity, which had been a distinctly unremarkable 13.0% a year earlier, printed 19.1%.1
And yet if you asked a generalist investor outside India — or frankly, many inside it — to name the fastest-compounding mid-cap NBFC balance sheet of the past three years, Capri Global would not be on the list. The market capitalisation sits around ₹24,675 crore, with the stock at ₹257.65 as of August 31, 2026, up roughly 53% over six months and 36.5% over twelve.3 It is a real company with a real re-rating, and it is still, in the mental map of most investors, a footnote.
One piece of housekeeping before the story starts, because it trips people up constantly. If you have heard the words "Capri Global" in the last three years, there is a decent chance you heard them attached to a cricket team. The UP Warriorz franchise in the Women's Premier League was bought by Capri Global Holdings Private Limited — the founder's private vehicle — for ₹757 crore in the January 2023 auction.45 That is not the listed company. No shareholder of Capri Global Capital Limited funded a cricket team. This distinction matters, and this article will keep it clean throughout, because the two entities tell you rather different things: one about a founder's personal ambitions, the other about where public capital is actually being deployed.
Which brings us to the question that makes this company worth five hours of anyone's attention.
How does a corporate shell that has worn three different names since 1994, and whose controlling shareholder was arrested by India's Central Bureau of Investigation in November 2010 in one of the decade's most lurid banking-bribery cases, end up in September 2026 as a lender that international bond investors just handed $300 million to at a 7.55% coupon, oversubscribed 2.3 times?6
That is not a rhetorical flourish. It is a genuine puzzle about how credibility gets rebuilt in financial services — an industry where credibility is, quite literally, the product. Nobody deposits money with, lends money to, or buys the equity of a financial intermediary they don't trust. Capri Global spent sixteen years constructing an answer.
Here is the roadmap.
- Origins and the scandal. Three corporate names, one legal shell, and the 2010 CBI case that arrived right as the founder's advisory business hit its peak.
- The pivot to balance sheet. Construction finance in 2011, MSME lending against property in 2013, and the slow, unglamorous work of building a lending business from an advisory one.
- The branch bet. Housing finance from 2017, and the physical distribution machine that would later be repurposed for something else entirely.
- The gold rush. Launched in 2022 as a rounding error, gold loans are now roughly half of AUM. This is the central strategic bet of the company, and the central analytical question of this article.
- The competitive terrain. Muthoot, Manappuram, IIFL, Bajaj Finance, Five-Star, SBFC, Aptus, Home First — and the RBI rulebook that shapes all of them.
- Management, credibility, and the moat test. A founder who has run this thing through every incarnation, a CEO who lasted three and a half months, and the honest question of whether there is a durable competitive advantage here at all.
Empor publishes stories of top companies, not investor-relations material. Capri Global's management is optimistic. Management is always optimistic. The interesting work is testing whether the record supports them — and naming, specifically, what would prove them wrong.
Let's go back to 1994.
 Subscribe on LinkedIn
II. Origins: Three Names, One Shell (1994-2010)
There is a particular kind of Indian listed company that exists mostly as a legal container: incorporated for one purpose, abandoned, sold, renamed, and eventually filled with an entirely different business by an entirely different person. Capri Global Capital is one of those. Understanding this is not trivia — it explains why the company's stated "founding date" and its actual operating history are two different things.
The shell was incorporated in November 1994 as Daiwa Securities Limited. On May 19, 1999, it became Dover Securities Limited. On September 13, 2008 it became Money Matters Financial Services Limited, and on August 5, 2013 it became Capri Global Capital Limited.7 Four names, one corporate identity number, one continuous listing.
The transformation that matters began in April 2007, when Rajesh Sharma and a promoter-group entity, Money Matters (India) Private Limited, acquired the controlling stake through a share purchase agreement.8 Sharma was a chartered accountant, trained at the Institute of Chartered Accountants of India, who had spent his career in capital markets rather than in lending.9 What he bought was not a business so much as a listed vehicle he could pour a business into.
The business he poured in was debt syndication and corporate financial advisory. In the India of 2008-2010, this was an extremely good place to stand. The country was in the middle of an infrastructure and real-estate credit boom; large corporates needed enormous amounts of debt from public-sector banks and financial institutions; and the process of getting that debt sanctioned was, to put it politely, relationship-intensive. Money Matters positioned itself as the intermediary that could arrange it. Its client roster reportedly included some of the largest names in Indian capital formation — the Adani group, Tata entities, Reliance ADAG, the Jindals, the Jaypee Group.10
The financials followed. Revenue was reported at roughly ₹227 crore in FY10, and the company raised ₹445 crore through a qualified institutional placement that brought in Fidelity and Morgan Stanley Mauritius as shareholders.10 For a mid-cap advisory shop, this was validation of a serious order: global institutional money underwriting the franchise, and a business model that generated fees without consuming balance sheet.
It is worth being precise about what that business actually was, because the distinction becomes load-bearing in the next section. A debt syndicator does not take credit risk. It does not fund loans. It stands between a borrower who wants ₹1,000 crore and a bank that might lend it, structures the paperwork, manages the process, and collects a fee. The economics are wonderful when the pipeline is full — almost no capital employed, high margins — and they are worth nothing when the pipeline stops. More importantly, the entire value of the intermediary rests on its access to the people who say yes at the banks.
That is the fault line. An advisory business whose core asset is access to loan sanctioners is one bad definition away from being something else entirely.
So hold two facts. First, the same legal entity and the same controlling individual that ran a fee-based syndication shop in 2010 run today's ₹40,000 crore lending balance sheet. There is no discontinuity of ownership, no restructuring that severed the past. Second, the business model that made Money Matters successful was precisely the business model that made it vulnerable.
In November 2010, the CBI decided the second thing was true.
III. The Scandal That Named the Company Twice (2010-2013)
On November 24, 2010, India woke up to one of the most spectacular white-collar enforcement actions in its recent financial history. The Central Bureau of Investigation arrested eight people in a single sweep — and the seniority of the names is what made it front-page news for weeks.
Among those taken into custody was Ramachandran Nair, the chief executive of LIC Housing Finance, one of the country's largest mortgage lenders.11 Alongside him were senior officials from Bank of India, Central Bank of India, Punjab National Bank, and LIC itself — general managers and deputy general managers, the people who actually sign off on large corporate credit.12 Shares of LIC Housing Finance fell a record 18% on the day.12 The episode entered the record as the "2010 housing loan scam."
The CBI's allegation, as reported at the time, was that these officials had accepted bribes to fast-track and favourably structure large corporate and real-estate loans, and that they had also passed confidential information about companies and their competitors to interested parties.1211 The borrowers whose facilities were named in press coverage included DB Realty, Lavasa, Suzlon, and Emaar MGF — a roster that tracked exactly the real-estate and infrastructure credit boom described above.
And the channel through which the CBI alleged the money moved was Money Matters Financial Services.
Rajesh Sharma, the company's chairman and managing director, was arrested along with two colleagues, Suresh Sharma and Suresh Gattani.12 The CBI's framing was blunt: it said it had broken up a racket in which Money Matters was "bribing senior officials of public sector banks and financial institutions for facilitating large-scale corporate loans."12 The agency raided the company's premises.10 In the initial bail proceedings, the Bombay High Court characterised Sharma in stark terms as central to the case and declined bail; a special CBI court granted it later on a ₹2 lakh surety.[^13]
Consider what this did to the business. An advisory franchise sells access and trust. Its entire inventory is the willingness of bank officials to take a phone call. The moment the CBI alleged that those phone calls involved envelopes, the inventory was worthless. There was no scenario in which Money Matters continued as a debt syndicator to public-sector banks. The company that had raised ₹445 crore from Fidelity and Morgan Stanley months earlier had, functionally, lost its reason to exist.
What happened next is the part of the story that requires the most analytical care.
In August 2013 — roughly two years and nine months into a pending criminal case — the company changed its name from Money Matters Financial Services Limited to Capri Global Capital Limited.7 No source located in this research states that the rebranding was undertaken as reputational rehabilitation. The company has not said so. But the sequence is a matter of public record: arrest in November 2010, collapse of the advisory model, launch of a balance-sheet lending business, and then the removal of the name that appeared in every CBI headline. Readers can weigh the timing themselves. What should not happen is for an investment narrative to present "Capri Global Capital, founded 2011 as a construction finance company" — which is roughly how the Forbes profile of Sharma renders the history — as the whole story.9 It is the story from the rebrand forward.
On resolution: secondary accounts, including profile coverage of Sharma, indicate that a special CBI court acquitted the accused in December 2018. This research pass did not locate a primary court record or a contemporaneous wire-service report confirming that verdict, and the claim should be treated at that confidence level — reported, not independently verified here.
Now the honest verdict, because this is exactly the kind of fact where investors tend to do one of two lazy things: omit it entirely, or treat it as dispositive.
The claim under test is that the founder is a credible, trustworthy operator of a regulated financial institution. The disconfirming evidence is genuinely serious — not a technical violation, not a disclosure lapse, but a federal criminal allegation of bribing bank officials, going directly to the integrity of credit decisions, against the same individual who is Founder, Managing Director and CEO today. It is documented across independent international and Indian press. It is not a matter of interpretation that it happened.
Against that: it is now nearly sixteen years old. It attached to a business model the company no longer operates. It was, by available accounts, legally resolved. And a targeted search of the record from 2019 through mid-2026 did not surface a comparable enforcement action naming Sharma personally or CGCL as an institution — with one adjacent item worth noting, addressed in Section IX, where SEBI in September 2023 penalised twenty-five individuals a combined ₹1.3 crore for manipulating CGCL's share price, an action against traders rather than against the company or its promoter.13
So the calibrated read: the history does not reject the credibility claim, and it does not confirm it either. It narrows it. What the record supports is a bounded statement — that this is resolved history rather than a live governance problem — and not the broader statement that the founder has an unblemished institutional track record, which is simply not true. The forward marker is specific and easy to watch: any new regulatory or enforcement action naming Sharma personally, or CGCL as an entity, would be a serious reversal of this read and should be treated as such rather than explained away.
With the name changed and the old business dead, the company needed something to actually do. It had already started.
IV. Building a Real Lending Business: Construction Finance & MSME (2011-2017)
Picture the strategic position in early 2011. You control a listed NBFC with a wrecked reputation, a fee business that has stopped generating fees, a criminal case in progress, and — critically — a pile of capital. You have to decide what this company is.
The decision was to stop being an intermediary and start being a principal. In FY11, Capri raised ₹450 crore in fresh equity and launched a construction finance business.2 Instead of arranging someone else's loan for a fee, it would fund the loan itself and earn the spread.
This is a much bigger change than it sounds. An advisory firm has no credit risk, no capital adequacy requirement, no asset-liability mismatch, and no need for collections infrastructure. A lender has all four. It also has a fundamentally different revenue shape: fees are lumpy and disappear in a downturn; a loan book generates interest income every month whether or not new business is being written. The company was trading a high-margin, zero-capital, zero-durability business for a low-margin, capital-hungry, highly durable one.
Construction finance was a logical first step, because it used the only asset the old business had that survived: an understanding of how Indian real-estate developers finance projects. Lending to a developer against a project under construction is not a commodity product. You need to know how to structure disbursement against construction milestones, how to control the escrow of sales receipts, how to value partially built inventory, and — the part that separates survivors from casualties — how to take over and complete a stalled project when the developer fails. It is the highest-risk, highest-yield corner of secured lending in India, and it has bankrupted more NBFCs than any other single product.
Two years later, in FY13, the company launched what would become its identity for the next decade: MSME lending.2 The structure was loan-against-property — secured lending to small manufacturers, traders, and service businesses, collateralised by commercial or residential real estate.
Here is why this matters, explained plainly. A bank underwrites a business loan by reading financial statements: audited accounts, GST filings, bank statements, tax returns. That process works beautifully for a company that keeps proper books. It fails completely for the overwhelming majority of Indian small businesses, which run substantially on cash, keep informal records, and cannot document income in a form a bank's credit model will accept. These are not fraudulent businesses. A fabric trader in Ludhiana or an auto-parts machining shop in Rajkot may be profitable, long-established, and entirely creditworthy — and still be un-underwritable by a bank's centralised process.
The NBFC answer is to substitute judgment for documentation. Send an underwriter to the shop. Count the inventory. Watch the footfall. Talk to suppliers about payment history. Check the electricity bill against claimed production. Then take property as collateral so that if the judgment is wrong, there is a recovery path. It is labour-intensive, it does not scale through a spreadsheet, and it requires physical presence in the market where the borrower operates. That last point becomes the whole story later.
In September 2015, the Bombay High Court approved a scheme merging four promoter-affiliated private entities — Capri Global Distribution, Capri Global Finance, Capri Global Investment Advisors, and Capri Global Research — into the listed company, effective October 2015 with an appointed date of April 2015.2
This deserves a flag rather than a shrug. A related-party consolidation moves assets from entities the promoter controls privately into a company whose shareholders are the public. Whether that transaction created or destroyed value for minority shareholders depends entirely on the swap ratio and the independent valuation — neither of which this research pass located. That is a research gap, not a finding. It is not evidence that public shareholders were treated unfairly, and equally it is not evidence that they were treated fairly. An investor who cares about governance should pull the Scheme of Amalgamation as filed with the stock exchanges and read the valuer's report before forming a view either way. The generic point stands regardless: promoter-to-listco asset transfers are exactly where minority interests get quietly diluted, and "the court approved it" is a procedural fact, not a valuation opinion.
By FY17, the shape of the company was set: a secured lender, funded by equity and wholesale borrowing, underwriting borrowers that banks structurally could not serve, with real property behind every loan. It was small. It was slow. It was, by the standards of what came later, almost boring.
What it needed next was reach.
V. Housing Finance & the Branch Network Bet (2017-2021)
The most consequential decision Capri Global made in this period was not a product launch. It was a decision about physical geography — and it looked, for years, like an expensive one.
In FY17, the company launched housing finance through a subsidiary, Capri Global Housing Finance Limited, targeting affordable home loans in tier-2 and tier-3 towns.2 The product logic was straightforward and, by then, well proven by others: the borrower who cannot document income for a business loan also cannot document income for a mortgage, and the same substitute-judgment underwriting applies. Affordable housing finance in India had already produced several successful franchises on exactly that insight.
The interesting part was the distribution decision. Rather than originate through direct-selling agents and third-party channels — cheaper, faster, asset-light — the company built branches. By FY18-19 it operated from 84 locations across eight states, concentrated in North and West India.14
Branches are expensive. Each one carries rent, a manager, underwriting and collections staff, and a long ramp before it covers its own cost. The financial argument against them is obvious, and for a decade the fashionable view in Indian lending was that digital origination would make them obsolete. The counter-argument is subtler and rests on two things a spreadsheet cannot easily capture.
The first is underwriting. If your entire credit edge is knowing which small businesses in a specific town are actually good, that knowledge lives in a person who has worked that town for years. It does not transmit through an app. The second is collections. Secured lending to informal-income borrowers has a predictable characteristic: a meaningful share of customers fall behind temporarily and cure. The difference between a 3% credit cost and a 6% credit cost is often just whether someone local shows up at the borrower's premises in week two rather than month three. Branch density is, functionally, collections infrastructure disguised as origination infrastructure.
So the company spent years paying for a distribution network whose returns were deferred. It is worth being blunt about how modest the results looked at the time. As of March 2023 — six years after launch — the housing finance subsidiary's AUM was still only around ₹2,665 crore.2 By comparison, Home First Finance, which listed in 2021 and operates in a similar affordable niche, reached ₹12,713 crore of AUM by March 2025.15 Capri's housing arm was not a leading affordable-housing franchise. It was a small book, patiently built, growing at unremarkable rates.
Anyone reading the company in 2021 would have been entitled to a fairly deflating conclusion: here was a mid-sized NBFC with three secured lending products, none of them market-leading, a legacy governance shadow, a branch network absorbing cost, and no obvious path to the kind of scale that changes a company's cost of funds.
What that reading missed is that the branch network was not really a housing-finance asset. It was a general-purpose asset — a distributed physical footprint in exactly the towns where a certain other product happens to work extraordinarily well. Management had built a distribution machine and, for several years, had only underpowered products to run through it.
Then it found one that fit perfectly.
VI. The Gold Rush: Betting the Next Decade (2021-Present)
In February 2022, on an investor call, Capri Global told the market it would enter gold loans in the first half of FY23.16 It was an unremarkable announcement from an unremarkable mid-cap lender entering a product category dominated by two Kerala-based giants who had been doing it for a century between them. There was no reason for anyone to pay attention.
Four and a half years later, gold loans are 47.8% of the company's entire balance sheet.1
That sentence is the single most important fact in this article, and everything that follows in this section exists to interrogate it: how it happened, whether it is defensible, and what it costs.
What a gold loan actually is
Strip away the branding and a gold loan is the most primitive secured credit product in existence. A customer walks into a branch with jewellery. Staff test the purity and weigh it. The lender advances cash against a percentage of the metal's value — the loan-to-value ratio — and locks the jewellery in a vault. If the customer repays, they get the gold back. If they don't, after due notice the lender auctions it.
The elegance is in what the lender does not need to know. There is no income assessment, no credit bureau dependency, no cash-flow analysis, no property title search, no lien registration. The collateral is standardised, liquid, priced continuously on a global market, and physically in the lender's custody. Recovery does not require a court. This is why gold loans in India run credit costs an order of magnitude below almost every other retail product, and why they can be underwritten in twenty minutes by a branch employee with a scale and a testing kit rather than by a credit committee.
The trade-off is equally structural. Because the product is simple, the barrier to entry is low. Anyone with branches, a vault, cash, and a regulatory licence can do it. The competitive question in gold lending has never been "can you underwrite it" — it is "can you get physical distribution close enough to the customer, and fund it cheaply enough to make the spread worth having."
Capri Global already had the branches.
From rounding error to half the book
The business launched in August 2022 with 108 dedicated branches. By the second quarter of FY23 it had 182 branches across seven states, and gold loans accounted for just 1.8% of AUM — but already about 10% of disbursals.17 That gap between stock and flow was the tell. A product that is a tenth of new business and a fiftieth of the existing book is a product that is about to become very large.
The scaling that followed was among the fastest branch roll-outs in recent Indian NBFC history. On May 14, 2026, the company announced that the gold-loan network had crossed 1,000 branches across sixteen states and union territories, carrying more than ₹16,960 crore of AUM.18 By the June 2026 quarter, gold-loan AUM stood at ₹19,179 crore, up 111% year on year and 13% sequentially, out of a total branch footprint of 1,433 — 1,000 dedicated to gold, 433 to everything else.119
This is the point where a fair-minded analyst has to concede something. There is a common failure pattern in Indian mid-caps where a company announces a glamorous new vertical, runs it as a pilot, generates press releases, and quietly lets it stall at 2% of revenue. That is emphatically not what happened here. Gold lending went from launch to largest segment in under four years and now represents nearly half the company's earning assets. Management has stated a long-term intent to take it to around 55% of the mix.19 Whatever else one concludes, this was a real strategic bet that was really executed.
The asset quality has been the cleanest in the company. Gold-loan gross NPA was 0.3% in the June 2026 quarter, improving from 0.7% a year earlier, against a consolidated net NPA of 0.6%.1 Yields ran at about 18.6% in the quarter, which management attributed to a deliberate shift toward smaller ticket sizes — smaller loans carry higher rates — with Rajesh Sharma telling analysts he expected "another 50 to 75 basis further improvement" in yield in the following quarter.19
That last detail is worth dwelling on, because it cuts both ways. Deliberately moving down-ticket to protect yield is a sensible response to competition at the larger end. It is also an admission that competition at the larger end exists and is compressing pricing. When a lender has to work harder for the same spread, the spread is telling you something about the market structure.
Scale in context: the number that governs the debate
Here is the calibration that any bull case has to survive.
Muthoot Finance reported consolidated gold-loan AUM of roughly ₹1.24 lakh crore in the September 2025 quarter, growing 45% year on year, and revised its FY26 gold-loan growth guidance upward to 30-35% from an earlier 21%.20 Capri Global's ₹19,179 crore, as of June 2026, is on the order of one-sixth of that — and Muthoot's book has kept growing in the intervening quarters.
The framing that matters is not "Capri is growing at 111% and Muthoot at 45%, so Capri is winning." Percentage growth off a small base is easy; the incumbent added more absolute rupees of gold AUM in a single year than Capri's entire gold book. Manappuram Finance, the number two, has been compounding its gold AUM in the high teens to 20% range.20 Both incumbents are getting bigger, not smaller, and analyst commentary on the sector has consistently expected consolidation toward the organised leaders as unorganised and smaller lenders exit under regulatory pressure.
So the honest description of Capri Global's position: a fast, credible, well-executed new entrant taking share from the unorganised sector and the long tail, in a market where the top two are simultaneously accelerating. Not a top-three player. Not on a trajectory that obviously makes it one.
The replication problem
The deeper concern is not Muthoot. It is what the low barrier to entry implies.
Bajaj Finance — a AAA-rated lender running roughly ₹4.62 lakh crore of AUM as of September 2025 and targeting ₹5 lakh crore by the end of FY26 — added gold loans to its product suite and scaled the book quickly.21 The precise segment-level disclosure of Bajaj's gold AUM was not located in this research pass, so no specific comparison figure is asserted here. But the structural point does not depend on the number. A lender of that size funds itself at a cost Capri Global cannot approach, already operates a nationwide branch and franchise network, and can enter a product that requires a vault, a weighing scale, and cash — none of which are scarce to it.
This is the crux of the moat argument. Capri Global's genuine differentiated capability — judging the creditworthiness of an undocumented small-business borrower — is not what a gold loan requires. The company built a hard-won underwriting edge over twelve years and is now deploying its balance sheet primarily into the one product where that edge is irrelevant. What transfers is the branch network and the operating discipline, which are real assets but replicable ones for anyone willing to spend the money.
The counter-argument management would make is customer stickiness: the company has cited a repeat-customer rate of roughly 55% in gold loans. That figure appears in company materials and should be treated as indicative rather than independently verified.2 Even taken at face value, repeat behaviour in gold lending is weakly protective. The customer returns because the branch is convenient and the process is fast, not because switching is costly. Open a competing branch two hundred metres away with a fifty-basis-point better rate and a meaningful share of that book is contestable.
The regulatory stress test — and the one competitor who failed it
If you want to know whether a lender's operations are actually sound, the most informative evidence is not a clean quarter. It is what happened when the regulator swept the sector.
On March 4, 2024, the Reserve Bank of India barred IIFL Finance from sanctioning, disbursing, assigning, securitising or selling any gold loans, citing deviations in the assaying and certification of gold purity and net weight both at loan sanction and at auction.22 The ban lasted more than six months; the RBI lifted it on September 19, 2024 after remediation.23 IIFL's gold book contracted sharply during the freeze. For a lender whose product is the vault, being told to stop originating is close to a corporate near-death experience.
That action was the leading edge of a broader tightening. The RBI followed with a September 2024 circular flagging irregular practices across the industry — valuation conducted without the borrower present, weak monitoring of LTV breaches, opaque auction processes — and separately capped cash disbursement of gold loans at ₹20,000. The final framework arrived as the Gold Loan Directions, with compliance required from April 1, 2026, introducing tiered loan-to-value limits: up to 85% for loans up to ₹2.5 lakh, 80% for ₹2.5-5 lakh, and 75% above ₹5 lakh.24
Two observations. First, on the specific question of whether Capri Global was caught in this sweep: a review of RBI enforcement actions and company disclosures over the period from the March 2024 IIFL order through the June 2026 quarter did not surface any origination restriction, business ban, or supervisory action against Capri Global's gold-loan business, and the segment's growth and 0.3% GNPA were sustained across the same window.1 That is a bounded, dated negative finding about a defined period — not a general assertion that the company has a spotless compliance record.
Second, the tiered LTV rules are quietly favourable to the strategy management has already adopted. The most generous LTV — 85% — applies to the smallest loans, which is precisely the down-ticket segment Capri has been pushing into for yield reasons. On the Q1 FY27 call, management described origination at an average 71% LTV, leaving a 29% cushion, and said auction notices are triggered when LTV breaches 85%.19 That is a conservative posture relative to the regulatory ceiling, and it is the right question to ask given what else has changed.
The gold-price problem nobody can hedge away
Here is the risk that sits underneath the entire segment, and it is not a credit risk in the conventional sense.
A gold loan book grows for two reasons that look identical in the AUM number but are completely different in economic substance. It grows because the lender acquires more customers and pledges more jewellery — genuine business growth. And it grows because the price of gold rises, which mechanically increases how much can be lent against the same physical quantity of metal. Indian gold-loan AUM across the sector has been substantially flattered by the second effect during a multi-year bull market in the metal.
That works in reverse. When gold prices fall, existing loans breach their LTV thresholds, requiring top-up margin or auction; new loan sizes shrink against the same collateral; and AUM growth decelerates without any change in customer demand. Notably, management on the Q1 FY27 call framed the quarter's 13% sequential gold growth as achieved "despite the correction in gold prices," attributing it to customer demand and branch productivity.19 That is a defensible framing, and it is also an acknowledgment that the price tailwind is no longer uniformly a tailwind.
When JM Financial initiated coverage in December 2025 with a Buy rating, its thesis was explicitly built on gold loans and fee income as the forward growth and margin engine — and it explicitly named a gold-price correction as the key risk to that thesis.25 The sell-side bull case and the bear case are, in this instance, built on the same variable.
So the segment verdict. The commercialisation claim is confirmed: this was a real bet, really scaled, with genuinely excellent asset quality. The moat claim on this segment is not confirmed and, on the available evidence, is thin. Capri Global has proven it can build a gold-loan business. It has not yet demonstrated anything that would stop a larger, cheaper-funded competitor from building the same one alongside it. The KPI that resolves this is not AUM growth — it is yield and spread. If the company can hold roughly 18.6% gold yields while adding 400 branches into markets the incumbents also want, the distribution argument has substance. If yields grind down as the branch count climbs, then what looked like a moat was just a land grab in an unclaimed field.
Which raises the obvious follow-up: what does the rest of the company look like while gold takes over?
VII. Business Model, Segments & Unit Economics
There is a moment in every diversified lender's story where you have to stop describing it as a portfolio of businesses and start asking which one is actually driving the P&L. For Capri Global, that moment has arrived, and the segment table tells a story management's narrative does not emphasise.
The mix, and how fast it moved
As of the June 2026 quarter, the ₹40,112 crore consolidated book broke down as follows: gold loans ₹19,179 crore or 47.8%; housing finance ₹7,815 crore or 19.5%; MSME ₹6,779 crore or 16.9%; and construction finance ₹6,332 crore or 15.8%.1 Growth rates diverged sharply — gold up 111% year on year, construction finance up 40%, MSME up 24%.1
Compare that to how the company described itself even a year or two earlier, when gold sat in the mid-thirties as a percentage of AUM and MSME was still routinely presented as the core franchise. The mix shift has been fast enough that an investor working from a 2024 mental model of this company is now materially wrong about what they own. This is no longer a diversified secured lender with a gold sideline. It is a gold lender with three legacy secured businesses attached, and the legacy businesses are collectively growing at roughly a third of the pace of the new one.
Where the stress actually is
Now the part that complicates every "diversified moat" framing.
Segment gross NPA as of June 2026: gold loans 0.3%, housing finance 1.2%, construction finance 0.7%, MSME 3.1%.1 The MSME number improved from 4.3% a year earlier, which is genuine progress and should be credited.1 But hold the shape of it in mind: the oldest business, the one built over twelve-plus years, the one that supposedly demonstrates a hard-won underwriting capability, carries roughly ten times the gross NPA of the newest and least differentiated business.
That is not a small analytical inconvenience. It is the central tension in the equity story. The standard bull framing is that Capri Global possesses a rare ability to underwrite borrowers banks cannot touch. The evidence for that ability should show up in the segment where it is applied most intensively over the longest period. Instead, MSME is the weakest segment in the book by a wide margin, and management characterised the segment as subdued through FY25.
There are defensible explanations. LAP-backed MSME lending to informal borrowers simply runs structurally higher NPAs than any collateral-in-vault product; comparing 3.1% to 0.3% is comparing two different risk categories, not two levels of skill. Recoveries on secured MSME loans are high, so gross NPA overstates ultimate loss. And the year-on-year improvement from 4.3% to 3.1% is real. All true. But note what the trend has coincided with: MSME growth decelerated to 24%. On the Q1 FY27 call, analysts pressed on whether that deceleration reflected weak demand or deliberate selectivity, and management attributed it to a conscious choice to allocate capital toward higher-margin gold loans rather than to credit stress.19
Take management at its word and the implication is still awkward. If MSME is the differentiated business and gold is the commoditised one, and capital is being deliberately steered away from the differentiated business, then the company's own capital allocation is a vote against its own moat narrative.
Construction finance deserves its own flag. GNPA there rose to 0.7% from about 0.3%, and analysts on the Q1 FY27 call specifically questioned both that deterioration and an increase in stage-two assets — loans showing significant credit deterioration but not yet non-performing. Sharma's response emphasised collateral strength and the mechanics of recovery, noting that the company keeps "recovering from old account" and that recovery cycles typically run six to nine months.19 That is a reasonable answer. It is also the answer every real-estate lender gives early in a cycle. With roughly 16% of AUM in developer finance, this is the segment where a genuine property downturn would show up first and hardest, and 0.7% is a number to watch rather than a number to dismiss.
The co-lending engine, and why it is the most important thing in the funding story
Here is the mechanism that makes the economics work, explained without jargon.
An NBFC cannot take deposits. A bank can. Deposits are the cheapest funding in the financial system, which means every NBFC competes against banks with a permanent, structural cost disadvantage of several percentage points. No amount of underwriting excellence closes that gap. It is the defining constraint of the entire business model.
Co-lending is the partial workaround. Under RBI's framework, a bank and an NBFC jointly fund a single loan — the NBFC originates it, underwrites it, and services it; the bank funds the majority share at its own cost of funds. The bank gets an asset it could not originate itself, often qualifying for priority-sector lending requirements it is obliged to meet. The NBFC gets to grow its franchise while funding a minority of the exposure, earning origination and servicing fees on the rest. Effectively, the NBFC rents the bank's deposit base.
Capri Global has built this out with State Bank of India, Central Bank of India, Punjab & Sind Bank, and UCO Bank.2 Co-lending AUM grew 74% year on year in the June 2026 quarter — but sequential growth slowed to just 4%, and management explained the slowdown as a transition cost: RBI's new co-lending framework required migration to the CLM1 model, and six partner banks had completed the transition by the time of the call.19
Those new rules matter for the forward economics. The RBI's Co-Lending Arrangements Directions, 2025 came into force on January 1, 2026. They widen co-lending well beyond priority-sector loans to cover all lending activity, require each participating lender to retain a minimum 10% of the loan, and cap default-loss-guarantee structures at 5%, with unified borrower-level asset classification across partners.2627 The widened scope is helpful — more products become eligible. The retention and DLG caps constrain how much risk an NBFC can absorb on the bank's behalf to make the partnership attractive, which is precisely the lever a smaller partner uses to win bank business.
The funding stack and the ratings ladder
As of the June 2026 quarter, total borrowings stood at ₹27,630 crore, funded 55% by banks, 24% by market borrowings such as NCDs and commercial paper, 8% by other financial institutions, and 8% by the National Housing Bank.1 The company has been actively diversifying: it announced plans to raise ₹6,500 crore through bonds and loans in FY26 and launched a ₹400 crore public NCD issue from September 30, 2025.2829
On ratings, the short-term picture is strong — CRISIL and ICRA both at A1+, the top short-term rating.30 Long-term domestic ratings sit in the AA band from Acuité and Infomerics.31 The internationally relevant marks are lower and, for that reason, more informative: Fitch assigned an expected BB- with stable outlook ahead of the dollar bond.32 BB- is squarely sub-investment-grade. That is not an insult; it is the normal territory for a mid-sized Indian NBFC without a deposit franchise, and it prices accordingly.
Which makes the September 2026 dollar bond genuinely notable. The company raised $300 million at a 7.55% coupon on three-year-and-three-month paper with a weighted average life of three years, amortising in equal instalments in June, September and December 2029. The book exceeded $700 million across 64 accounts — a 2.3x oversubscription — and pricing came 20 basis points inside initial guidance, with Barclays, Citi, Deutsche Bank, Emirates NBD and UBS running the deal.63332
The analytical content of that transaction is worth stating plainly, because it is easy to over- or under-read. It does not prove the company is safe; BB- investors are paid to take risk. What it does establish is that a set of international institutional credit investors, with no exposure to Indian retail sentiment and no reason to be polite, examined this credit and were willing to fund it three years out at a spread they found adequate. For a company whose founder's name was in CBI headlines sixteen years earlier, that is a meaningful widening of the funding base — and, more prosaically, it diversifies away from a domestic bank channel that management itself said offers little further room for cost reduction. Asked on the Q1 FY27 call about further funding-cost declines, Sharma was direct: "FY 2027 we don't see much scope in the cost of fund reduction from this level."19
That is a useful piece of guidance discipline, and also a constraint. If cost of funds has bottomed, then future margin expansion has to come from asset yields or from operating leverage, not from the liability side.
What the current numbers say about operating leverage
The June 2026 quarter delivered net interest margin of 9.7% against 8.9% a year earlier, spread on advances of 7.8% against 6.7%, and a cost-to-income ratio of 44.2% improved from the high-forties.119 Return on average assets reached 4.1%, up from 3.2%.1 Capital adequacy remained comfortable at roughly 24.7% at the parent and 27.8% at the housing subsidiary.2
Strip the narrative away and the mechanism behind those numbers is simple: a shift in mix toward a higher-yielding product, combined with a branch network that opened years ago and is now carrying far more assets per rupee of fixed cost. Management cited employee productivity doubling to ₹3.4 crore of AUM per employee.19 That is the mathematical signature of a maturing branch estate — the cost was incurred in the past, the revenue is arriving now.
It is also, importantly, a one-time-ish benefit. Operating leverage on a branch network is a transition, not a perpetual engine. Once branches mature, cost-to-income stops falling from that source, and the company has committed to adding 400 more branches by December 2026, which reintroduces immature-branch drag.19 The high-quality version of this story is that each cohort of branches ramps profitably and the company keeps compounding. The lower-quality version is that reported efficiency gains are partly a function of a maturing vintage mix that reverses when expansion accelerates. Both are consistent with the current data.
Whether any of this is defensible over a decade depends on who else is in the field.
VIII. Competitive Landscape & Industry Structure
Indian non-bank lending is not one market. It is four or five markets that happen to share a regulator, and Capri Global competes in three of them simultaneously against three entirely different sets of opponents. War-gaming this properly means taking each front separately, because the company's position is very different on each.
Front one: secured MSME lending
This is the segment where Capri's claimed edge should be most visible, and it is a crowded field of specialists.
Five-Star Business Finance is the benchmark. It lends small-ticket secured business loans to exactly the informal-income micro-enterprise borrower Capri targets, and it does so with economics that are genuinely exceptional — analyst modelling has projected AUM and profit CAGRs of roughly 31% and 23% over FY24-26 and return on assets and equity in the region of 7.2% and 18.5%.[^35] A 7% RoA in secured lending is extraordinary; it reflects very high yields on very small tickets combined with disciplined credit costs. Five-Star's existence is a standing demonstration that the informal-MSME niche can be underwritten profitably at scale by a focused operator.
SBFC Finance runs a comparable model, listed in August 2023, and has been treated by initiating analysts as a rising franchise in the same secured-MSME space.34 Vistaar Financial Services operates in adjacent territory. And above all of them sits Cholamandalam Investment & Finance, a diversified giant with a cost of funds and distribution reach a mid-cap cannot match.
Capri Global's MSME book, at ₹6,779 crore, is a mid-sized participant in this group — and it carries a 3.1% gross NPA against Five-Star's low-single-digit and generally tighter credit metrics.1[^35] That is the competitive-position problem stated numerically. If the thesis is "we underwrite the informal borrower better than others," the peer comparison does not currently support it. It supports the weaker statement that Capri underwrites the informal borrower adequately while others do it at least as well.
Front two: affordable housing finance
Here Capri's housing subsidiary is a long-tail entrant, and the gap is not close.
Home First Finance reported FY25 AUM of ₹12,713 crore, up 31.1%, with FY25 disbursements of ₹4,805 crore, profit after tax of ₹382 crore, and gross stage-three assets at 1.7%.15 Aptus Value Housing Finance compounded AUM at roughly 28% annually from ₹5,180 crore in March 2022 to ₹10,865 crore by March 2025, with consolidated GNPA of 1.19%.35 Aavas Financiers operates at similar scale. PNB Housing Finance, a far larger institution, has built a dedicated affordable sub-brand that on its own approaches the size of Capri's entire housing book.
Capri Global Housing Finance, at ₹7,815 crore in June 2026, has been growing but is not a top-tier franchise in this space.1 Its GNPA of 1.2% is respectable and comparable to Aptus.135 The honest read is that this is a competent, sub-scale affordable-housing lender in a category where several competitors are both larger and further along the operating-leverage curve. It contributes diversification and priority-sector-eligible assets. It does not, on current evidence, constitute a competitive advantage.
Front three: gold loans
Covered at length in Section VI, so only the structural point is repeated here: this is a market where the top two players are simultaneously large and accelerating, where a damaged third player (IIFL) is rebuilding after a regulatory freeze, and where a very large, very cheaply funded consumer lender has entered from the side. Capri Global is the fastest-growing entrant by percentage and one of the smallest by absolute scale. Sector expectations of continued consolidation toward the organised leaders describe a current that Capri is swimming against, not with.
The regulatory architecture that governs everyone
Two regulatory structures shape the strategic options here, and both are worth understanding because they determine what a mid-sized NBFC can and cannot do.
The first is RBI's Scale-Based Regulation, which sorts NBFCs into layers by size and systemic importance. The Upper Layer contains the fifteen or so largest — Bajaj Finance, Muthoot, Cholamandalam, PNB Housing, Shriram, Tata Capital and peers — subject to bank-like governance, capital and disclosure requirements. Capri Global sits in the Middle Layer. The trade-off is genuine in both directions: lighter compliance burden and more operating flexibility, but also no implicit systemic-importance halo, which matters for how wholesale lenders and rating agencies think about tail risk.
The second is the co-lending regime, which is the single most consequential rule set for a lender in Capri's position. The mechanism was explained in Section VII; what matters competitively is that the 2025 Directions standardise it across the industry from January 2026.2627 Standardisation cuts against the small player. When co-lending was a bespoke, relationship-driven arrangement, an NBFC that had cultivated a bank partnership had something proprietary. When the terms are uniform, the bank's choice of partner reverts to the ordinary criteria — scale, ratings, operational reliability — on which the largest NBFCs win.
Porter, honestly applied
Run the five forces on this business and the picture is not flattering to the moat narrative.
Threat of new entrants is high in gold lending and moderate in MSME and affordable housing. Capital is available, regulatory licences are obtainable, and the branch build-out that took Capri four years is a matter of spending money, not of accumulating a scarce capability. Buyer power — in lending, borrower price sensitivity — is high and rising, particularly in gold where the product is undifferentiated and rate comparison is trivial. Supplier power, meaning the cost and availability of funding, is the structural weakness: an NBFC's supplier is the wholesale market and the banking system, and management has already indicated funding costs have little further room to fall.19 Substitutes are real and growing: fintech lenders such as Lendingkart and FlexiLoans chase the same underserved MSME base with digital origination and no branch cost, banks continue to push down-market, and for the gold customer, an unsecured personal loan from a bank is a direct substitute whenever gold prices are unfavourable. Rivalry is intense on every front.
Now the same exercise through Hamilton Helmer's Seven Powers, which is a stricter test because it asks not "is this business good" but "is there a specific, identifiable barrier that prevents a competitor from replicating it."
Scale economies: Not present at the parent level. Capri is a fraction of the size of the leaders in each of its markets, and in lending, scale translates directly into cost of funds — the one place it matters most. This power currently works against the company.
Network economies: Absent. Lending has no meaningful network effect; a borrower gains nothing from other borrowers using the same lender.
Counter-positioning: Weak. The company's model — branch-led, judgment-based, secured lending — is not something incumbents are structurally unable to copy for fear of cannibalising their own economics. Bajaj Finance's entry into gold lending is the proof: no incumbent has been deterred.
Switching costs: Low. A gold-loan customer can move to the branch across the road at maturity. An MSME borrower faces some friction — re-documenting collateral, re-establishing a relationship — but a refinance offer at a lower rate routinely overcomes it. The 55% gold repeat rate cited by the company reflects convenience, not lock-in.2
Branding: Limited. Capri Global is not a household name and does not command a price premium. It competes on availability and speed, not on brand.
Cornered resource: The plausible candidate is the branch network in specific tier-2/3/4 locations plus the local underwriting teams staffing them. This is the strongest argument available, and it is a real one — being physically first in a small town with trained staff has durable value. But it is a cornered resource only until someone else opens a branch there, and 1,433 branches is not an unassailable footprint in a country with hundreds of thousands of eligible locations.1
Process power: This is where a genuine argument can be made, and where the evidence is mixed. Process power means an organisational capability that competitors cannot copy quickly even knowing exactly what it is — in lending, the combination of underwriting judgment, collections discipline, and operating cadence embedded in thousands of staff. Capri's gold-loan asset quality and its improving cost-to-income ratio are consistent with real process capability. Its MSME asset quality relative to Five-Star is not.
The overall Seven Powers verdict is that Capri Global has, at most, a partial cornered resource and a contested process advantage. It does not have a structural moat in the sense the framework intends. What it has is an operational head start in specific geographies, which is valuable, monetisable, and erodable.
That assessment puts an enormous amount of weight on execution — which means it puts an enormous amount of weight on the people executing.
IX. Current Management: Credibility, Ownership & Capital Allocation (2024-2026)
Rajesh Sharma is 56, a chartered accountant, married with three children, based in Mumbai, and worth roughly $1.5 billion on Forbes' reckoning as of September 2026 — almost entirely through his stake in the company he runs.9 He has been the controlling figure of this corporate entity since 2007, across four names, one criminal case, the death of one business model and the construction of another. Whatever else is true, he is the only constant, and any assessment of this equity is substantially an assessment of him.
The right way to evaluate a founder-operator is not to read their interviews. It is to look at three things: what they promised and what they delivered, how they behave with other people's capital, and who chooses to work for them and for how long.
The churn problem
Start with the most concrete recent yellow flag, because it is the one management is least comfortable discussing.
In August 2025, chief financial officer Partha Chakroborthi resigned, later replaced by Kishore Lodha.36 The head of the insurance business had resigned in January 2025. And in October 2025, the company appointed Monu Ratra — an experienced, externally recruited housing-finance executive — as chief executive officer, in what was presented as a step toward institutionalising the company beyond its founder.37
On January 19, 2026, Ratra resigned. His last working day was January 31.3839 Tenure: roughly three and a half months.
The company's stated explanation was that Ratra's decision was "purely driven by long-term personal aspiration to build and engage in entrepreneurial ventures and is not on account of any disagreement, concern, or difference of opinion with the Board, management, or the affairs of the company."39 Rajesh Sharma resumed direct leadership.
That language is boilerplate, and boilerplate is not evidence of anything. But the pattern is a fact independent of the explanation: three senior departures in roughly twelve months, including a professionally recruited CEO who lasted a single quarter. Executives with established reputations do not typically accept a marquee CEO role at a listed NBFC and discover an entrepreneurial calling fourteen weeks later. The most common real-world explanations for a tenure that short are a mismatch in authority — the founder did not actually cede control — or a disagreement about strategy or standards discovered on arrival. Neither can be established from public disclosure. Both are more probable priors than the stated one.
What makes this analytically material rather than merely gossipy is what it implies about key-person risk. A company adding 400 branches a year, running four lending verticals, migrating co-lending arrangements to a new regulatory model, and issuing debut international debt is an operationally complex institution. If it cannot retain a professional CEO layer, then execution capacity is concentrated in one person who is also 56 years old and who now, by his own account, has no plans to change that.
Asked directly about leadership stability on the Q1 FY27 call, Sharma's answer was unambiguous: "There is no CEO position vacant, and there's no plan to bring any CEO."19 Read that carefully. It is not "we are searching for the right candidate." It is a statement that the experiment in professional management has been closed. Investors should take it at face value — it is clear, honest and internally consistent — and price the founder-dependency accordingly.
Ownership: correcting a misreading
Promoter holding in Capri Global fell from roughly 69.9% in March 2024 to 59.92% as of June 2026, with domestic institutions at 18.42%, public at 13.46%, and foreign institutions at 8.21%.8
A ten-point drop in promoter stake sets off alarms, and in this case the alarm is misplaced. This was not a promoter selling shares. It was mechanical dilution from a qualified institutional placement. Capri Global's board approved exploring a raise of up to ₹2,000 crore in July 2024, and the QIP committee approved pricing and allotment on June 12, 2025 — approximately 136.5 million new equity shares, raising ₹2,000 crore, the company's largest equity raise in a decade.4041 Under SEBI's QIP rules, promoters cannot participate. Issuing that many new shares to institutions arithmetically reduces the promoter's percentage without a single share changing hands from their side.
The buyer list is itself informative. The book included Quant Mutual Fund, 3P Investment Managers, Abakkus Asset Management, BlackRock, Societe Generale, Allspring Global Investments, ICICI Prudential Life, HDFC Life, ICICI Lombard, SBI General, HDFC Ergo, PNB MetLife and a Tata AIF, among other long-only investors.41 That is a serious institutional book for a mid-cap NBFC — a mixture of high-conviction domestic managers and global index-and-active money. Institutional participation is not a validation of the business model, and index-driven or thematic allocations should not be over-read. But a book of that composition does indicate that professional investors conducted diligence on this credit and this governance history and were willing to underwrite it at ₹146.5 a share.
On promoter share pledging — a standard red flag in Indian mid-caps, where promoters borrow against their stake and create forced-selling risk — this research pass did not locate evidence of pledged promoter shares. That is an absence of found evidence over a limited search, not a verified negative. The encumbrance disclosure in the quarterly shareholding pattern filed with the exchanges is the authoritative record, and anyone underwriting this equity should read it directly rather than rely on this article.
One further item belongs in the governance ledger. In September 2023, SEBI penalised twenty-five individuals a combined ₹1.3 crore for manipulating the share price of Capri Global Capital.13 The action was against traders, not against the company or its promoters, and there is no indication in the reporting of company involvement. It is included here because a complete governance picture includes adjacent items rather than only the flattering ones — and because a stock that has attracted manipulation attention is a stock where price action deserves extra scepticism.
Guidance discipline: the strongest positive data point
Here is where management's record is genuinely good, and it deserves to be stated as clearly as the criticism.
The standard failure mode of a fast-growing Indian mid-cap is the guidance ratchet downward: an ambitious target, a quiet revision, a re-based number, an explanation about macro conditions. Capri Global has done the opposite. Management raised its FY27 AUM target from ₹47,000 crore to ₹50,000 crore, lifted the FY28 target to ₹65,000 crore, set an FY31 ambition above ₹1,25,000 crore implying 28-30% CAGR, and raised return targets to 19-21% RoE and 4.2-4.7% RoA.119 Those are upward revisions delivered alongside results that were themselves ahead of the prior trajectory.
This matters more than it might appear. Guidance behaviour is one of the few observable, repeated, falsifiable signals of management honesty available to an outside investor. A team that consistently raises targets while delivering is demonstrating that it sets numbers it believes rather than numbers it wants the market to hear. On this specific dimension, over the FY25-FY27 window, the record is a point in management's favour and cuts directly against a "chronic overpromiser" characterisation.
Two caveats keep it from being an unqualified positive. First, the window is short — three years of raising guidance during a period of favourable gold prices and benign credit conditions is not the same as a decade of discipline through a cycle. This management has not yet been tested on how it communicates a miss, because there has not been a significant one to communicate. Second, raised guidance is now embedded in the price. With the stock up roughly 53% in six months, the market has capitalised the ₹65,000 crore FY28 path.3 Guidance that is both raised and believed leaves no cushion.
Capital allocation, including the parts nobody highlights
Two items warrant mention, sized proportionally.
In FY2021-22, the company divested a subsidiary, Capri Global Resources Private Limited, to Capri Global Holdings Private Limited — the promoter's private vehicle — for a nominal consideration of ₹2.76 lakh. What that entity held and whether it had economic value could not be confirmed in this research. It is flagged as an item for direct diligence in the related-party disclosures of the relevant annual report, not as an assertion of wrongdoing. A ₹2.76 lakh transaction is immaterial to a ₹40,000 crore balance sheet; the reason it appears here at all is that promoter-to-promoter transfers of subsidiaries are precisely the class of transaction where value migrates quietly, and the pattern matters more than the amount.
The second item is the cricket franchise, and it belongs in this section for one narrow reason. Capri Global Holdings Private Limited bought the UP Warriorz WPL franchise for ₹757 crore in 2023.45 The same promoter vehicle bid ₹4,024 crore each, unsuccessfully, for the Ahmedabad and Lucknow IPL franchises in 2021, and was reported as a shortlisted but unsuccessful bidder in the Rajasthan Royals ownership process in 2025-26. None of this sits on the listed balance sheet, and it is not a claim on shareholder capital. What it is, legitimately, is information about where the founder's personal capital and attention are directed — relevant precisely because the company has just told the market it has no plans to appoint a CEO, which makes the founder's bandwidth a real variable rather than an abstract one.
The net management read: a founder with a genuinely impressive operating record over the last four years, a demonstrable and unusual discipline in guidance, a serious and unresolved question about whether the organisation can retain senior professionals, and a governance history that is old but not nothing. That is a mixed scorecard, and it should be carried as a mixed scorecard rather than resolved in either direction.
Which brings us to the question the whole article has been building toward.
X. The Moat Test: Why This Company Wins, Why It May Not
Every investment case in lending eventually reduces to one question: is there a reason this particular lender earns above-average returns that a competitor with equal capital cannot eliminate? Everything else — growth rates, guidance, quarterly beats — is downstream of that.
Capri Global's answer, assembled from its own materials and management commentary, has three parts. Branch density in underserved tier-2, tier-3 and tier-4 markets that competitors have not reached. Underwriting capability for informal-income borrowers that banks structurally avoid. And priority-sector co-lending access that partially closes the funding-cost gap against those same banks. The supporting evidence offered is a network of more than 1,400 branches, a repeat-customer rate around 55% in gold loans, and consistently sub-1% gold-loan asset quality.12
Take each seriously, then test it against the strongest disconfirming evidence in the company's own record.
Testing the underwriting claim
The claim: Capri Global can assess credit risk in borrowers that formal lenders cannot, and this capability is durable and differentiating.
The mechanism that would break it: if the capability were real and durable, the segment where it has been applied longest and most intensively should show the best risk-adjusted outcomes relative to specialists doing the same thing.
The evidence: it does not. The MSME business, launched in FY13 and refined over more than twelve years, carries a 3.1% gross NPA — the highest of any segment in the company and materially above the credit metrics of a focused peer like Five-Star operating in the same customer segment with far higher returns on assets.1[^35] Management itself described the segment as subdued through FY25. And in FY27, capital is being deliberately steered away from it toward gold.19
This is a proper falsification test, and the claim does not survive intact. Nor is it entirely rejected — the improvement from 4.3% to 3.1% is real, the book is secured by property, and the segment remains profitable.1 The calibrated conclusion is that the underwriting-capability claim is narrowed: Capri Global can underwrite informal-income borrowers competently and profitably, but the record does not support a claim of superior or differentiating capability relative to specialist peers. The KPI that would revise this upward is straightforward — MSME gross NPA stabilising below 3% and staying there through a full year, alongside a return to segment growth that is not merely a residual of gold's capital allocation.
Testing the distribution claim
The claim: branch density in underserved geographies is a cornered resource.
The mechanism that would break it: a well-capitalised competitor replicating the footprint on a comparable timeline.
The evidence: Bajaj Finance, running roughly ₹4.62 lakh crore of AUM as of September 2025 and funded at investment-grade domestic cost, entered gold lending and built a book from a standing start during the same window in which Capri was scaling its own.21 Segment-level disclosure for Bajaj was not obtained in this research, so the precise pace of replication is not asserted. But the structural fact is sufficient: the entry happened, it was not deterred by Capri's head start, and nothing in the product's economics prevented it.
The claim survives in a narrowed form. Physical presence in a specific small town, staffed by people who have worked it for years, is genuinely valuable and takes real time and money to replicate. But it is a local advantage that must be re-won town by town, not a system-wide barrier. It is closer to the advantage a well-sited retail chain has than to a network effect. It compounds slowly and can be attacked at any single point.
Testing the co-lending claim
The claim: priority-sector co-lending access partially closes the structural funding disadvantage.
This one holds up best. Co-lending AUM grew 74% year on year, six bank partners have migrated to the new CLM1 model, and the mechanism genuinely does what it claims to do.19
But management's own statements bound it. The RBI's 2025 Directions standardise co-lending across the industry from January 2026 and impose minimum retention and DLG caps that limit how much a smaller partner can differentiate on terms.2627 Sequential co-lending growth slowed to 4% in the June 2026 quarter during the migration, which management explicitly attributed to the regulatory transition.19 And Sharma's own guidance that there is little further scope to reduce funding costs in FY27 is, read plainly, a statement that this lever has been largely pulled.19 An advantage that management says has limited further room to run is not a compounding advantage; it is a level.
The uncomfortable synthesis
Put the three tests together and a specific, awkward shape emerges.
The company's moat, such as it is, is strongest in the businesses where it is deploying the least incremental capital — the legacy secured-lending niches where branch presence and local judgment genuinely matter and where competitors are specialists rather than giants. It is weakest in the business that now constitutes nearly half the balance sheet and virtually all the growth narrative.
That is not a fatal observation. Plenty of excellent companies have earned strong returns for years without a durable moat, simply by executing well in a growing market before it consolidates. The gold-loan opportunity in India is genuinely large, the unorganised sector is genuinely being displaced by regulated lenders, and Capri Global is genuinely capturing some of it. A land grab in an unclaimed field can be highly profitable.
But it should be priced as a land grab, not as a franchise. The distinction matters because they decay differently: a franchise defends its returns as it matures, while a land grab sees returns compress precisely when the growth story is most widely believed.
So the net verdict for anyone carrying this forward: treat the "diversified moat" framing as narrowed, not confirmed. Real, local, and modest in the legacy secured niches. Thin to absent in the fastest-growing, most capital-intensive segment. Three forward indicators would resolve it in either direction — MSME gross NPA trend, gold-loan yield and spread as Muthoot, Manappuram and Bajaj Finance compete harder for the same tier-2/3 customer, and whether construction-finance GNPA stays contained below 1% through an actual property cycle rather than through a benign one.
XI. Bull vs. Bear Case
The bull case
The market Capri Global serves is real and structurally underpenetrated. Tens of millions of Indian small businesses and households cannot document income in a form a bank's credit model accepts; the formal financial system is not going to solve this quickly; and someone will earn attractive returns lending to them against collateral. That is not a story, it is an arithmetic feature of the Indian economy.
Within that market, the execution record over the past three years is difficult to argue with. AUM compounded at roughly 48% over FY23-25 and has accelerated further into FY27, hitting ₹40,112 crore in June 2026.1242 Profitability improved simultaneously — the combination of 62% AUM growth, 102% profit growth, NIM expanding to 9.7%, and cost-to-income falling to 44.2% is the signature of a business getting operating leverage rather than buying growth with margin.1 Return on equity moved from 13.0% to 19.1% in a single year.1 Asset quality held at a 0.6% consolidated net NPA through a period in which a direct competitor was banned from originating.122
Management raised rather than cut its targets, which is rarer than it should be.19 And the external validation is broader than domestic retail enthusiasm: top-tier A1+ short-term ratings from both CRISIL and ICRA, a ₹2,000 crore institutional equity book that included Quant, 3P Investment Managers, Abakkus and BlackRock, and a debut dollar bond that drew a $700 million order book from 64 international accounts and priced 20 basis points inside guidance.3041632 Three separate constituencies — domestic rating agencies, institutional equity investors, and international credit investors — independently examined this company and were willing to fund it.
If gold-loan penetration in India keeps expanding, if the unorganised sector keeps ceding share, and if the branch cohorts added in FY27 mature the way earlier cohorts did, the ₹65,000 crore FY28 target is achievable and the return profile at 19-21% RoE is genuinely attractive for a lender at this scale.
The bear case
Start with governance, because it is the hardest to model and the easiest to underestimate. A professionally recruited CEO lasted three and a half months, the CFO turned over, and a business head departed, all within roughly a year — and the company has now stated it does not intend to appoint a CEO at all.38391936 Whatever the individual explanations, an institution running four lending verticals, 1,433 branches, a 400-branch annual expansion plan, a co-lending migration and an international debt programme is concentrating an extraordinary amount on one person. Key-person risk is not a checklist item here; it is the operating model.
Second, the moat problem detailed above. The longest-tenured proof of the underwriting edge — MSME — shows the weakest asset quality in the book, while the largest and fastest-growing segment shows the thinnest evidence of a durable barrier, competing against a leader roughly six times its scale and a giant with a vastly better cost of funds.12021
Third, gold-price dependency. Roughly half the balance sheet is collateralised by a single commodity whose price has been in a powerful bull market. A sustained correction compresses new loan sizes, triggers LTV breaches on existing loans, increases auction activity, and decelerates AUM growth — all at once, and all without any deterioration in borrower behaviour. The 71% average origination LTV provides a real cushion, and the auction trigger at 85% is disciplined.19 Neither eliminates the exposure. The sell-side bull case explicitly names this as the key risk.25
Fourth, construction finance. Roughly 16% of AUM sits in developer lending, GNPA there has risen from about 0.3% to 0.7%, and stage-two assets drew analyst questions.119 This is the segment that has historically destroyed Indian NBFCs, and it has not yet been through a genuine property downturn under this balance sheet's current size.
Fifth, funding. No NBFC without deposits ever closes the cost gap with banks, co-lending helps only at the margin, the new co-lending rules standardise away relationship advantages from January 2026, and management has said the cost-of-funds lever is largely exhausted for FY27.1926
Sixth, valuation and expectations. The stock rose roughly 53% in six months and 36.5% over a year to ₹257.65 as of August 31, 2026.3 A re-rating of that magnitude embeds continued flawless execution against a backdrop of an unresolved management-stability question, the weakest asset quality sitting in the original business, and a growth engine tied to a commodity price.
And the founder's 2010 CBI case belongs in this list not as a prediction of future behaviour — it predicts nothing, and it was legally resolved — but because any assessment of "the same individual still runs this company" should be made with the full record rather than a curated one.
Where the two cases actually meet
The bull and bear cases here are not describing different companies. They agree on almost every fact. They disagree about one thing: whether an operational head start, executed unusually well by a founder with unusual energy, is worth paying a franchise multiple for.
That is a question about durability, not about quality. Capri Global is, on the current evidence, a well-run lender in a growing market with a real distribution asset and a genuine execution record. It is not, on the current evidence, a company with a structural barrier protecting its returns. Those are two different investments, and the distinction becomes visible only when growth slows.
XII. Lessons, KPIs & What to Watch
Three things in this story generalise well beyond one Indian NBFC.
The first is that a genuine competitive edge can coexist with — and be masked by — deterioration in the very segment that created it. Capri Global's headline AUM growth of 62% is spectacular and entirely real. It is also, overwhelmingly, gold. The business that supposedly demonstrates the company's differentiated capability grew 24% and carries the worst asset quality in the portfolio.1 Aggregate numbers hide composition, and composition is where the thesis lives. The habit worth building is to ask not "how fast did it grow" but "which part grew, and is that the part the investment case depends on."
The second is that management credibility is a scorecard, not a verdict. This management has done something rare and admirable — raised guidance repeatedly while delivering against it — and something genuinely concerning — cycled through three senior executives in a year, including a CEO who lasted a quarter, and then announced that the professional-management experiment is over.1938 These do not cancel. They coexist. An investor who holds only the first is running an incomplete model; one who holds only the second is ignoring the strongest positive evidence available.
The third is about how commoditised growth should be valued. Reaching scale in a product with low entry barriers is an achievement, and it is not the same achievement as building something defensible. The market frequently pays the second multiple for the first result, and the correction arrives not when the business deteriorates but when the growth rate normalises and the absence of a barrier becomes visible in the margin.
The KPIs that matter
Three metrics, tracked over time, will settle most of the open questions in this article. They are deliberately few, and none of them is headline AUM.
One: gold-loan yield and spread. Gold-loan yield ran at approximately 18.6% in the June 2026 quarter, with consolidated spread on advances at 7.8%.119 This is the single most informative number in the company. If Capri can add 400 branches into markets that Muthoot, Manappuram and Bajaj Finance also want while holding that yield, the distribution advantage is real and the moat argument gains substance. If yield grinds lower as branch count climbs, then the growth was a land grab and the returns will normalise toward the cost of capital. Watch yield, not AUM — AUM will keep rising either way.
Two: MSME gross NPA trajectory. Currently 3.1%, improved from 4.3%.1 Sustained movement below 3% would confirm that the legacy underwriting capability is intact and that the improvement is structural rather than a function of a benign credit environment. Movement back above 4% would suggest that the original franchise is genuinely eroding while the company's attention is elsewhere.
Three: senior executive tenure. Not a financial metric, which is exactly why it is easy to ignore. Following the CEO transition and management's statement that no CEO appointment is planned, the relevant observation is whether the CFO and business-head layer stabilises over the next twelve to twenty-four months. Continued churn at that level would substantiate the concern that the organisation cannot institutionalise beyond its founder — which, for a company this operationally complex, is the risk least visible in any quarterly number.
What would most change the assessment in this article? A sustained MSME asset-quality improvement below 3% combined with stable gold yields would meaningfully strengthen the moat case and justify treating the distribution asset as a genuine franchise. Another senior executive departure within twelve months, or a visible compression in gold-loan spreads as the branch count rises, would confirm the narrower reading — a well-executed land grab by a capable founder, priced as something more durable than it is.
XIII. Recent News
As of early September 2026, several threads remain open and will determine how the next twelve months read.
The debut $300 million dollar bond closed at a 7.55% coupon with a 2.3x oversubscribed book, amortising in three equal instalments across 2029.633 How and how quickly those proceeds are deployed — and whether they measurably reduce blended funding cost against the 55% bank-funded base — is the near-term test of whether the international market access is strategically useful or merely symbolic.1 Reporting has also referenced an evaluation of a further raise in the $450-550 million range via private-equity or sovereign-wealth dilution; this research pass did not find confirmation that any such transaction has been executed, and it should be treated as unconfirmed.
Q2 and Q3 FY27 results will be the first real read on whether the ₹50,000 crore FY27 and ₹65,000 crore FY28 AUM targets remain intact, and specifically on whether the 150 branches management guided to add in the September quarter and a further 250 by December arrive on schedule and at the expected productivity.19
On leadership, the company has stated there is no CEO vacancy and no plan to appoint one.19 Any reversal of that position — or any further senior departure — is directly relevant to the third KPI above.
On regulation, the RBI's gold-loan Directions took effect for fresh loans from April 1, 2026, with tiered LTV limits of 85%, 80% and 75% by ticket size.24 Capri's stated 71% average origination LTV and 85% auction trigger suggest a conservative posture, but the first full year of compliance under the new regime — including the industry-wide auction and valuation requirements that triggered the IIFL action — is the period in which operational compliance either holds or does not.1922
Finally, the co-lending migration to the CLM1 model under the Directions effective January 1, 2026 remains partially complete, with six bank partners transitioned as of the June quarter.1926 Whether co-lending growth reaccelerates from the 4% sequential rate once migration finishes will indicate how much of the funding-cost advantage survives standardisation.
References
-
Capri Global Q1 FY27 slides: profit doubles, AUM surges 62% — Investing.com, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Corporate Presentation, May 2025 — Capri Global Capital ↩↩↩↩↩↩↩↩↩↩↩↩
-
Capri Global Capital Ltd share price and performance — Anand Rathi, 2026-08-31 ↩↩↩
-
Capri Global Holdings Private Limited's franchise in inaugural edition of WPL to be called UP Warriorz — India.com, 2023-02-11 ↩↩
-
WPL 2023 — cost of all five teams in the tournament — CricTracker ↩↩
-
Capri Global completes debut dollar debt sale — Business Recorder, 2026-09 ↩↩↩↩
-
Capri Global Capital (NSE:CGCL) Company Profile & Description — StockAnalysis.com ↩↩
-
Capri Global Capital Latest Shareholding Pattern — Trendlyne, June 2026 ↩↩
-
Money Matters Financial raided by Central Bureau of Investigation — Moneylife, 2010 ↩↩↩
-
CBI arrests CEO of LIC Housing Finance and 7 others in Mumbai, unearths housing finance racket — DNA India, 2010 ↩↩
-
Indian police arrest senior bankers over alleged finance scam — ABC News, 2010-11-25 ↩↩↩↩↩
-
SEBI fines Rs 1.3 crore on 25 individuals for share-price manipulation of Capri Global Capital — Zee Business, 2023-09-20 ↩↩
-
Home First Finance Company announces robust Q4 and FY25 results — AUM grows 31.1% y-o-y — PR Newswire, 2025 ↩↩
-
Capri Global Capital to enter gold loan business in first half of FY23 — Business Standard, 2022-02-21 ↩
-
Capri Global Capital Ltd (CGCL) Q2 FY23 Earnings Concall Transcript — AlphaStreet ↩
-
Capri Global Capital's Gold Loan Network Crosses 1,000 Branches Across India — ScanX, 2026-05-14 ↩
-
Capri Global Capital (BOM:531595) Q1 FY27 Earnings Call Transcript — StockAnalysis.com, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Muthoot Finance revises FY26 gold loan growth projection upward — Business Standard, 2025-11-18 ↩↩↩
-
Bajaj Finance Q2 update: AUM surges 24% YoY to Rs 4,62,250 crore — Upstox, 2025 ↩↩↩
-
RBI bars IIFL Finance from sanctioning and disbursing gold loans — Business Standard, 2024-03-04 ↩↩↩
-
RBI lifts restrictions imposed on IIFL Finance's gold loan business — Business Standard, 2024-09-19 ↩
-
RBI Gold Loan Guidelines 2025: Key changes and impact — EY India ↩↩
-
Gold loans, fee income to power Capri Global: JM Financial starts coverage — Business Standard, 2025-12-03 ↩↩
-
RBI revises co-lending norms, mandates 10% loan retention, loss guarantee — Business Standard, 2025-08-06 ↩↩↩↩↩
-
Analysis of RBI Co-Lending Arrangements Directions, 2025 — Cyril Amarchand Mangaldas, 2025-09 ↩↩↩
-
Capri Global Capital to raise Rs 6,500 crore via bonds, loans in FY26 — Business Standard, 2025-09-24 ↩
-
Capri Global Capital to raise Rs 400 crore via NCD issue from Sept 30 — Business Standard, 2025-09-24 ↩
-
CRISIL Rating Rationale — Capri Global Capital Limited, 2025-04-30 ↩↩
-
CARE Ratings Press Release — Capri Global Capital Limited, 2024-07-14 ↩
-
Capri Global taps dollar market with debut debt issue after banks hit pause — Business Recorder, 2026 ↩↩↩
-
Capri Global Capital concludes its maiden USD bond issuance — Business Standard, 2026-09-02 ↩↩
-
SBFC Finance Initiation: The rising star — Ambit Capital, 2025-06-27 ↩
-
Aptus Value Housing Finance India Limited — CARE Ratings press release, 2025-07-14 ↩↩
-
Capri Global Capital says Partha Chakroborthi, CFO, resigns — Reuters via TradingView, 2025 ↩↩
-
Capri Global Capital appoints Monu Ratra as new CEO — Trade Brains, 2025-10 ↩
-
Capri Global Capital says CEO Monu Ratra resigns — Reuters via TradingView, 2026 ↩↩↩
-
Capri Global Capital Limited Announces Resignation of Monu Ratra as Chief Executive Officer, Effective January 19, 2026 — MarketScreener ↩↩↩
-
Board of Capri Global Capital to consider fund raising up to Rs 2,000 cr — Business Standard, 2024-07-31 ↩
-
Capri Global raises Rs 2,000 crore via QIP route — Business Today, 2025-06-16 ↩↩↩
-
Screener.in — Capri Global Capital Ltd consolidated financials ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube