Caplin Point Laboratories: The Twenty-Year Bet on the Markets Everyone Else Ignored
I. Introduction & Episode Roadmap
In August 2026, a team of United States Food and Drug Administration investigators arrived, unannounced, at an industrial estate in Gummidipoondi — a dusty manufacturing belt about an hour north of Chennai, the kind of place where trucks outnumber cars and the skyline is water tanks and stainless steel vent stacks. They stayed nine days. When they left, they handed over a Form 483 listing ten observations.1 For most Indian pharmaceutical companies, that is a Tuesday. For this one, it was the first serious regulatory scuff on a record that had been, until then, conspicuously clean — and it landed at the precise moment the company was pouring the largest share of its capital expenditure into that exact site.
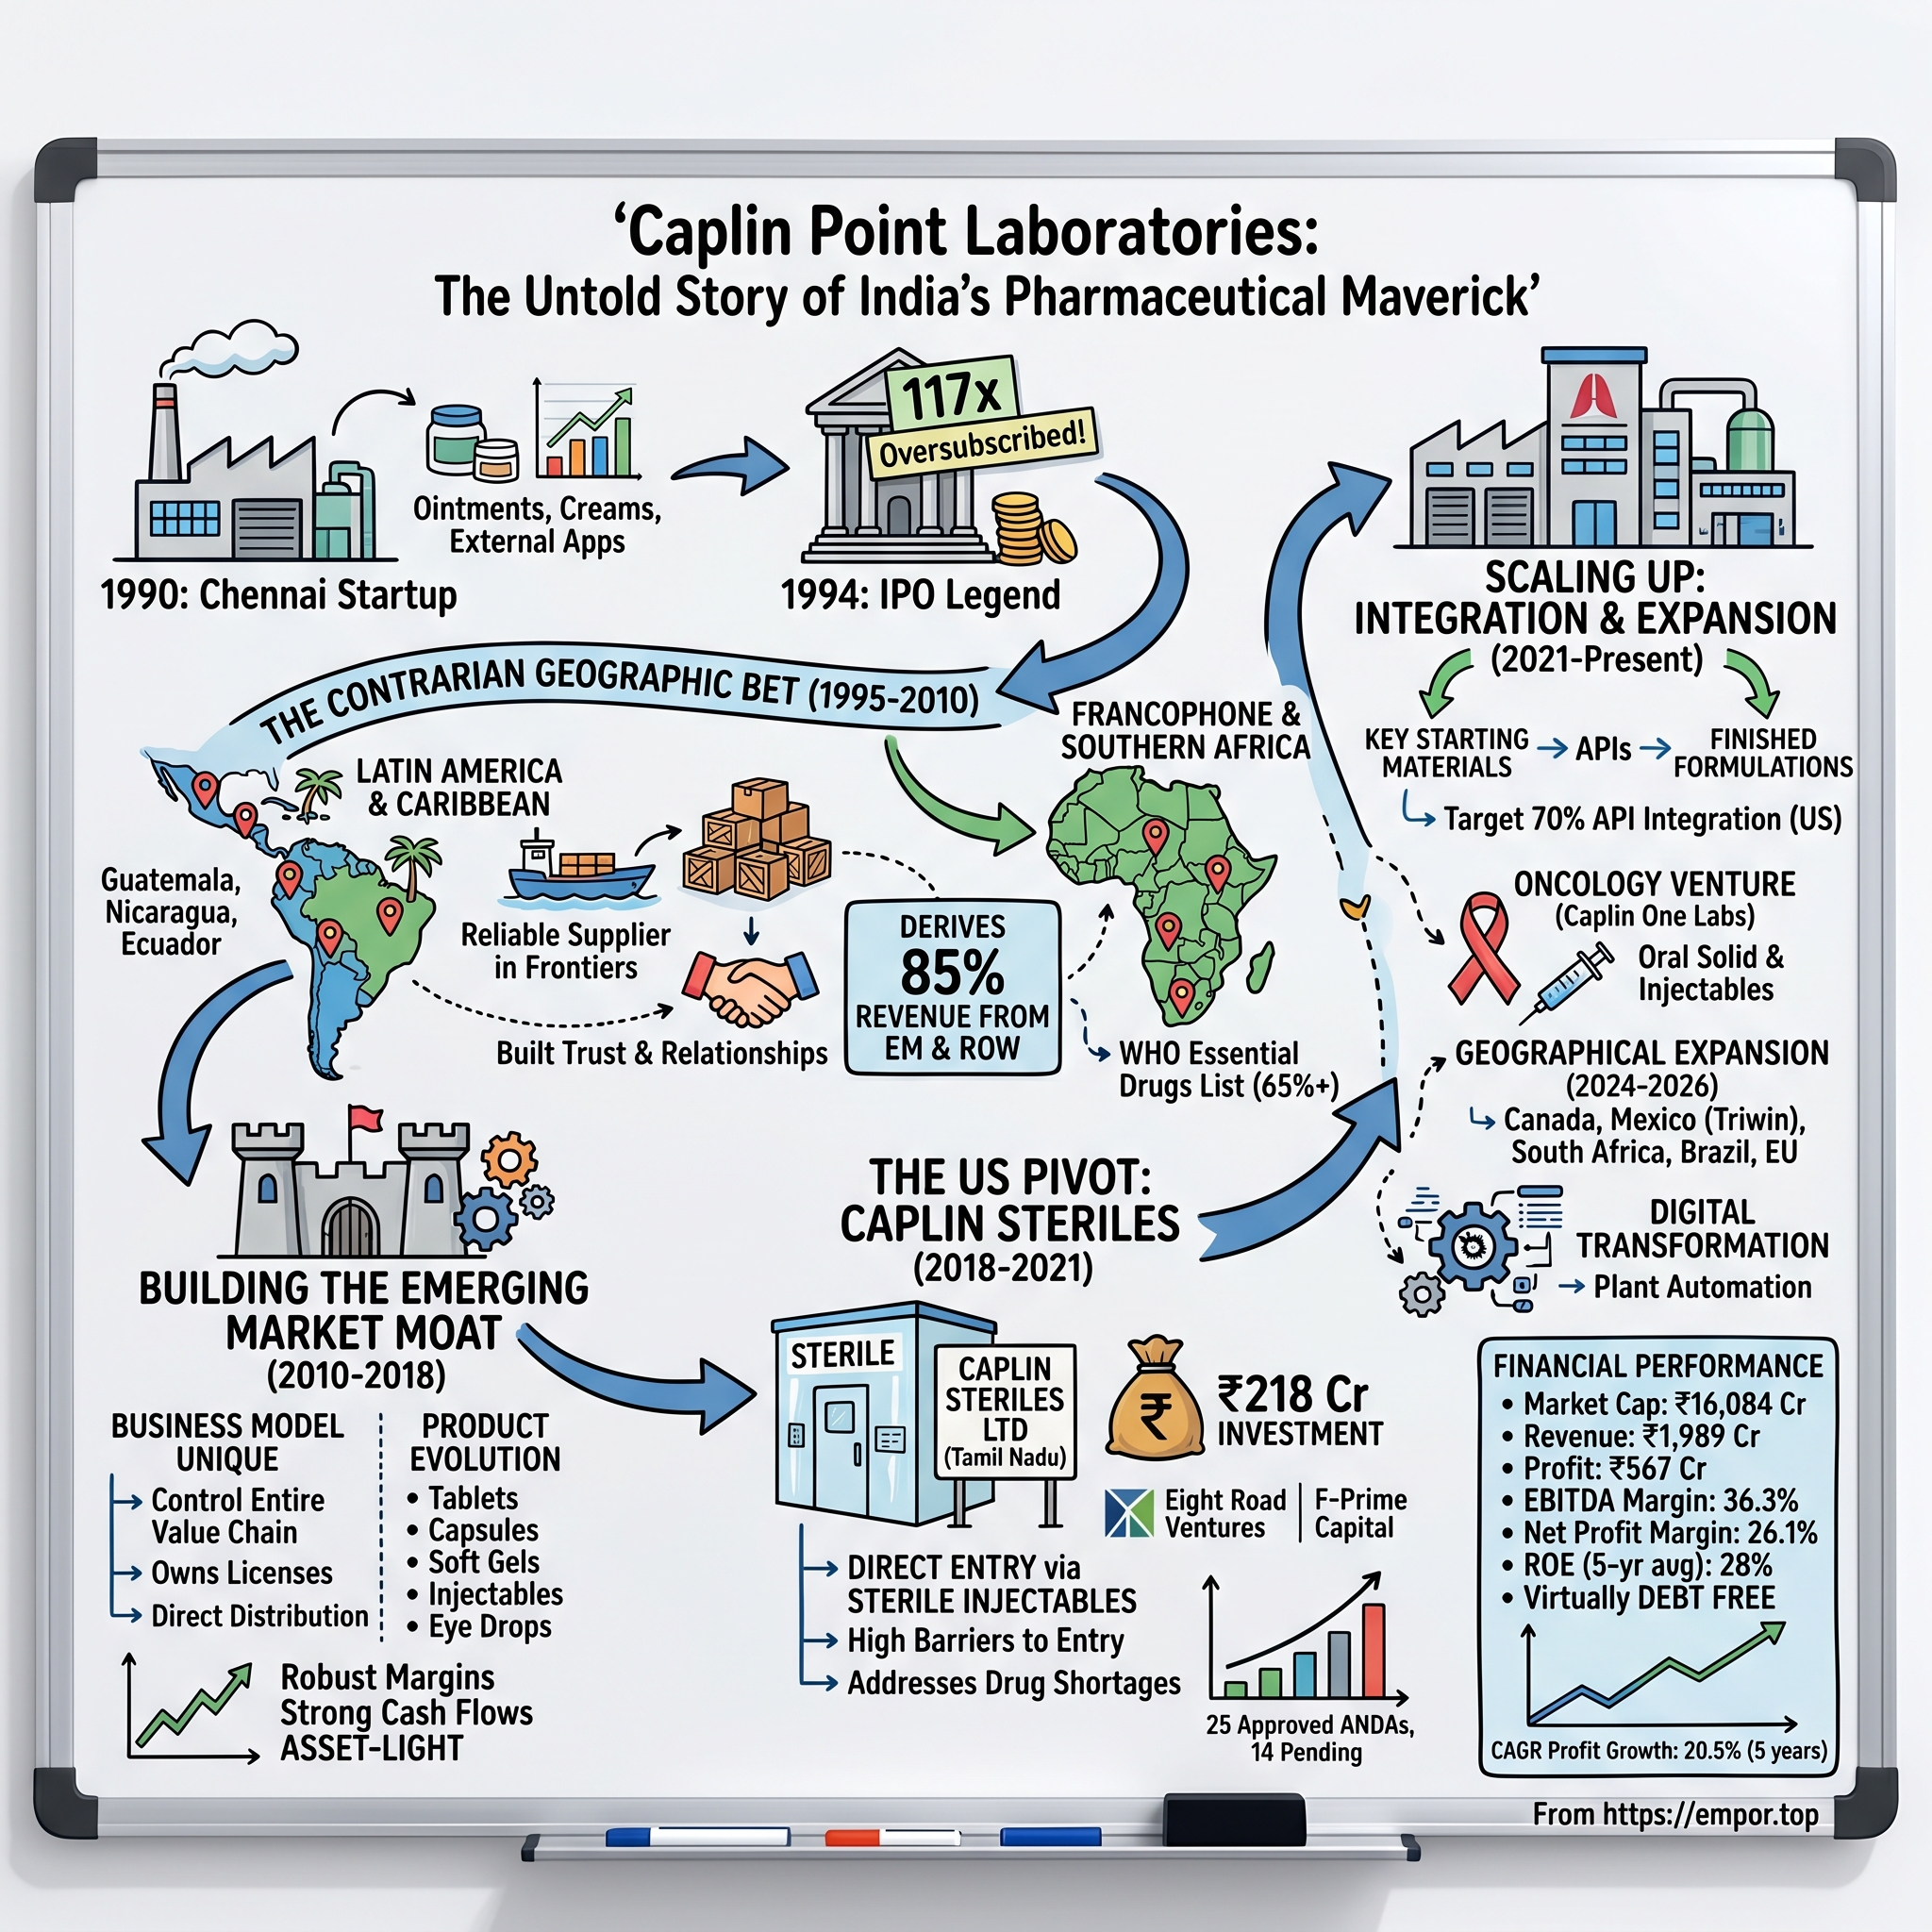
The company is Caplin Point Laboratories. If you have not heard of it, that is by design. It has spent thirty-six years building a business in places that the rest of the Indian pharmaceutical industry treated as rounding errors: Guatemala, Honduras, El Salvador, Nicaragua, the Dominican Republic, Francophone West Africa. It sells branded generics — ointments, tablets, injectables, ophthalmics, suppositories — through distribution networks and product registrations it owns outright rather than licenses to a local partner. Founded in 1990 in Chennai to make creams and external applications,2 it now describes a footprint spanning more than twenty countries across Latin America, the Caribbean and Africa,3 and it ships sterile injectables into the most heavily policed pharmaceutical market on earth. As of early September 2026, the market capitalises it at roughly ₹20,700 crore.4
That combination — frontier-market distribution business plus US-regulated sterile manufacturing — is unusual enough to be worth an episode on its own. But the more interesting question is the one the last eighteen months have forced onto the table.
Caplin Point's entire identity is built on a single instinct: go where the competition will not bother. That instinct produced a genuinely differentiated asset in Central America, one that compounded quietly for two decades while Indian pharma's marquee names fought each other over US oral solids and destroyed a great deal of shareholder capital doing it. The question now is whether that instinct scales. Because the second act — Caplin Steriles, the US injectables subsidiary — is not a road-less-travelled play at all. It is the road most travelled, under the most demanding regulator in the industry, against competitors with vastly larger balance sheets. And the third act, if it happens, involves building actual factories in Mexico and an oncology API plant outside Chennai, which is a very different discipline from registering products and owning shelf space.
There is a second, sharper question underneath. In February 2026, on the Q3 FY26 earnings call, management did something companies almost never do voluntarily: it told investors to expect "low double-digit growth" for the next eighteen to twenty-four months and described the period ahead as a phase of gestation and consolidation.5 That is a company with a fifteen-to-twenty-percent historical growth cadence telling the market, unprompted, that the cadence is breaking. Read one way, it is admirable guidance discipline. Read another, it is the first public acknowledgement that the emerging-market engine has matured faster than the equity story assumed. Both readings deserve to be on the table, and this article will keep them there rather than resolving them prematurely.
Here is the route. First, the founding instinct — brief, because it matters less as history than as a template that gets tested repeatedly. Then the two-decade distribution build in Latin America and Africa, which is where the value actually sits and where the deepest analysis belongs. Then the US pivot and its first real reckoning. Then the smaller, unproven bets: oncology, Mexico, backward integration into active pharmaceutical ingredients. Then management, ownership, and the capital allocation record — including the guidance reset, placed where it belongs, next to the credibility claim it tests. Then the numbers, including the parts of the balance sheet that the marketing language does not describe accurately. Then the playbook lessons, the bull and bear cases, and what to watch.
One framing note before we start. Caplin Point is frequently described — by the company, by brokers, by the retail investing internet — as an asset-light, high-return business. That description is half true, and the half that is false matters. Hold that thought; it will resurface with numbers attached.
 Subscribe on LinkedIn
II. Origins: The Chennai Startup and the Decision to Look Outward (1990–1994)
Picture Indian pharmaceuticals in 1990. The Patents Act of 1970 had, for two decades, allowed Indian firms to reverse-engineer any molecule they liked so long as they invented a new process, and the result was a domestic industry of extraordinary density and ferocity. Hundreds of companies. Thousands of brands. Medical representatives fanning out across every district town in the country, competing on relationships and sample bags. It was a market where the prize was real and the fight for it was brutal.
Into that market, C.C. Paarthipan started a company in Chennai to make ointments, creams and external applications.2 It is hard to overstate how unglamorous a starting position that was. Topicals are the low-margin, low-barrier corner of formulations — easy to make, easy to copy, sold on price. A founder with ambition in 1990 would have been expected to do one of two things: build a domestic branded portfolio and grind out share against incumbents, or set up for the eventual assault on the US generics market that the entire industry could see coming.
Paarthipan did neither. His read, evident in what the company actually built over the following decade, was that the domestic branded market was a knife fight he had no structural reason to win, and that the US was a queue he would be joining at the back. What he wanted instead was somewhere the competition had no incentive to follow — and, critically, somewhere he could own the customer relationship rather than rent it.
That second condition is the one that separates Caplin Point from a hundred other Indian pharmaceutical exporters. The default export model is straightforward: manufacture in India, sell to a local distributor or licensee in the destination country, book the revenue, let the partner handle registration, marketing and collection. It is capital-efficient, low-risk, and produces a business with almost no defensibility — the partner owns the relationship, and can switch suppliers whenever a cheaper Indian or Chinese manufacturer knocks on the door. Caplin's founding instinct was the opposite: go to the market yourself, register the products in your own name, build the distribution, carry the receivable, and accept that this will be slower and more capital-hungry for years before it becomes hard to dislodge.
The first validation came in 1994, when the company went public. The issue was reported as oversubscribed roughly 117 times, and the proceeds funded a manufacturing base at Pondicherry.2 Two things about that IPO matter far more than the multiple. First, it gave the company a manufacturing asset it owned rather than a contract it rented. Second — and this is a fact that will recur throughout this story with real weight — it was the last time Caplin Point raised equity from the public markets. Every subsequent phase of expansion, including the Latin American build-out and the entire US injectables programme, has been funded from internal accruals.6
That is not a rhetorical flourish; it is a constraint that shaped everything downstream. A company that will not dilute must grow at the speed of its own cash generation. That forces patience, and it forces the kind of market selection where a modest capital base can buy a large competitive position — which is exactly what frontier Latin America offered in the late 1990s and exactly what the United States did not.
The founding instinct, then, reduces to two rules: go where competitors will not, and own the distribution rather than licensing it. Everything that follows in this story is either an application of those rules or a test of whether they still hold when the terrain changes.
III. The Contrarian Bet: Building the Latin America & Africa Distribution Machine (1995–2018)
There is no dramatic boardroom scene to open this section with, and that is rather the point. The building of Caplin Point's Latin American franchise was not a bet placed in a single moment. It was twenty years of a small Chennai company sending people to Guatemala City and San Salvador and Santo Domingo, filing product registrations one dossier at a time in one country at a time, hiring local sales staff, building relationships with pharmacy chains and independent pharmacists, extending credit, chasing payment, absorbing currency devaluations, and doing it again the following year. It is the least photogenic form of moat construction there is, and among the more durable.
Why Central America, of all places
The logic was arithmetic before it was strategic. Guatemala, Honduras, El Salvador, Nicaragua and the Dominican Republic are small markets. For a large multinational or a top-tier Indian generics exporter with a US ambition, the addressable revenue in any one of them did not justify the fixed cost of building an in-country organisation, navigating a local regulator, and carrying receivables in a currency with a habit of moving against you. The rational move for a big company was to license to a local distributor and forget about it.
For a company Caplin's size, the same arithmetic pointed the other way. The absolute revenue was small, but so was Caplin. And the competitive intensity was a fraction of what a comparable rupee of Indian domestic revenue cost to defend. Those markets also shared a structural characteristic that turns out to be central to the whole model: pharmaceutical retail is highly fragmented, dominated by independent and small-chain private pharmacies, and prescribing behaviour is heavily influenced by what the pharmacist stocks and recommends. Shelf space, not a molecule patent, is the scarce resource.
If shelf space is the scarce resource, then the company that owns the relationship with the person controlling the shelf owns the economics. That is why the licensing model was unacceptable to Paarthipan — a licensee would have owned that relationship, and Caplin would have been a replaceable input.
What actually got built
The physical output of two decades of this work is a registration portfolio that the company reports in the thousands. Caplin's investor materials have described more than 4,000 registered product licences across its markets and a formulation library running to hundreds of products across dozens of therapeutic areas.7 Those counts have grown over time and readers should treat the precise number as a moving figure rather than a fixed one; what matters analytically is the order of magnitude and what it represents.
A product registration in Guatemala is not intellectual property. It confers no monopoly. Any competitor can, in principle, file the same dossier for the same molecule and receive the same approval. What it represents is elapsed time and accumulated local knowledge — the regulatory dossier, the stability data, the local agent, the translated labelling, the inspection, the queue. Multiply that by four thousand, across twenty-odd regulatory regimes, each with its own idiosyncrasies, and you have something a well-capitalised competitor cannot simply purchase. They can replicate it. It will take them roughly as long as it took Caplin, which is the entire defence.
The second layer of the build was dosage-form complexity. Caplin started where it began in India — oral solids and topicals, the easiest things to make and the easiest to copy. Over time the portfolio migrated toward forms that are meaningfully harder: injectables, ophthalmics, soft gelatin capsules, suppositories.7 Each step up in complexity raises the capital and technical bar for a would-be copycat, and each step also raises the price the product can command in a market where few suppliers can offer it. This is the same instinct as the geographic one, applied to the product shelf: move toward the places where fewer people want to compete.
The parts that did not go smoothly
An honest account of this period has to include the friction, because the friction is where the real cost of the strategy shows up.
Frontier Latin America and Francophone Africa are not benign operating environments for a company carrying its own receivables. Currencies move. Political regimes change, and with them the rules on imports, pricing and foreign exchange availability. Formal banking infrastructure is thinner, which means customers pay slowly and payment terms stretch in ways a company selling to a European wholesaler would find unrecognisable. Caplin absorbed all of it, because absorbing it was the price of owning the distribution rather than renting it.
And this is where the "asset-light" label starts to come apart. The company's business model is genuinely light on fixed assets relative to its Latin American revenue — for most of its history it manufactured in India and sold through a distribution organisation, not a factory network, in the destination markets. But light on fixed assets is not the same as light on capital. Caplin's cash conversion cycle has run in the range of roughly 170 to 215 days across recent years, with days-sales-outstanding regularly north of 110 to 150 days.4 In plain English: a very large fraction of a year's sales is permanently tied up in inventory sitting in warehouses across two continents and in money owed by pharmacies and distributors that has not yet arrived.
That capital is not idle — it is what buys the relationship. A pharmacist in Tegucigalpa who can take stock on generous terms from a supplier who has been reliable for fifteen years has a reason to keep giving that supplier shelf space. The working capital is the moat, at least in part. But it is a moat funded with the shareholder's balance sheet, exposed to currency risk and to the credit quality of thousands of small emerging-market buyers, and it should be described that way rather than as capital efficiency.
So what does the reader take from this period? Two decades of patient, unglamorous, self-funded build produced a distribution asset that is real, that competitors cannot buy quickly, and that generates high reported returns. It also produced a structurally slow-moving balance sheet and a revenue base concentrated in some of the more volatile jurisdictions in the world. Both are true simultaneously, and the second is the price of the first. The question for the rest of this story is what that asset is worth now — how much of the addressable shelf it actually controls, how fast it can still grow, and whether the same instinct works anywhere else.
IV. The Core Franchise Today: Industry Structure, Competition & Unit Economics
Strip away the excitement about US injectables and the oncology facility and the Mexican subsidiary, and here is the plain fact about Caplin Point in FY26: roughly four out of every five rupees of consolidated revenue still came from Latin America and Africa.3 The emerging-market franchise is not the legacy business. It is the business. Everything else is, at present, an option on the future funded by this segment's cash.
That proportion — around 79% of consolidated revenue — is the single most important number for understanding the risk profile of the whole enterprise,3 and it is why this section gets more scrutiny than the more glamorous US story.
How the money is actually made
The mechanics are simpler than the geography suggests. Caplin manufactures formulations, largely in India, ships them into markets where it holds the product registrations in its own name, and sells them through its own distribution organisation into private pharmacies under its own brands. Branded generics, in this context, means an off-patent molecule sold under a Caplin trade name — the value the brand carries is trust and availability at the point of sale, not clinical differentiation.
There is an important qualifier that gets glossed over in the standard telling. This is not a pure private-pharmacy model everywhere. In some markets the company sells into government and institutional tender channels, and its Mexican expansion via Triwin explicitly points at that channel.8 The distinction matters enormously for bargaining power. A fragmented base of thousands of independent pharmacies has almost no individual leverage over its supplier. A government health ministry running an annual tender has all of it — it can dictate price, change specifications, expand its vendor base, or suspend the tender entirely. Any assessment of Caplin's pricing durability has to separate these two channels, and the company's disclosure does not make that separation easy.
Who else is in the room
The competitive set for Caplin's Latin American shelf space includes other Indian exporters pursuing similar strategies and regional Latin American generics houses with home-market advantages. Public reporting and industry commentary point toward Indian names such as Zydus, Alembic and Cipla operating in overlapping geographies, alongside regional players including Brazil's EMS Pharma. That said, a rigorous, sourced market-share breakdown by competitor at the country level is not available in public disclosure, and readers should treat this list as directional rather than precise. Anyone underwriting the durability of Caplin's position seriously would want country-level prescription and sales-audit data, which the company does not publish.
What is checkable, and considerably more useful, is a single operating metric that cuts through the narrative: shelf-space penetration. One independent analysis has estimated Caplin's share of Central American pharmacy shelf space at roughly 41%, against a management-stated internal target closer to 57%.5 Take those figures as approximations rather than audited statistics, but the gap between them is the honest version of the "dominant position" story. Forty-one percent is a genuinely strong position. It is also not saturation — which is simultaneously the bull case (room to grow within existing markets) and the bear case (management's own target implies the dominance is aspirational at the margin, not complete).
The margin story, and what is behind it
The profitability trend has been genuinely good. EBITDA margins that sat in the high-twenties to low-thirties percent range several years ago had moved into the mid-to-high thirties by FY26.49 Readers should reconcile the exact figures against the FY26 annual report, since secondary sources are not fully consistent on the precise percentages.
The more interesting question is why margins expanded, because the answer determines whether the expansion persists. Three mechanisms are plausible and each has different durability. The first is mix — a portfolio migrating from oral solids toward injectables, ophthalmics and other complex forms should carry structurally better pricing, and this effect ought to be durable so long as the mix keeps shifting. The second is backward integration — every API the company makes internally rather than buying removes a supplier's margin, and this too should be durable, though it converts an operating cost into a capital cost, which is a trade-off the return ratios will register. The third is simple operating leverage on a fixed distribution cost base, which is durable only as long as revenue keeps growing — and management has just told the market that revenue growth is downshifting.5 That third mechanism is the one an investor should discount.
The unglossed cost
Return to the working capital point, now with the full weight it deserves. A business running a cash conversion cycle of 170-plus days is one where the balance sheet expands nearly in lockstep with revenue.4 Grow sales 20% and you must fund roughly 20% more inventory and receivables. This is the structural reason why a company with excellent reported margins can still find its return on capital under pressure, and it is the reason the "asset-light" framing is misleading rather than merely imprecise. The asset is not a factory. The asset is a very large pile of goods in transit and money owed by emerging-market customers, and it is exposed to every currency and credit shock that passes through those economies.
Five forces, honestly applied
Entry barriers are real but erodable. Four thousand registrations and twenty years of pharmacist relationships cannot be bought, but neither are they legally protected. A determined competitor with patience faces a long climb, not a wall.
Supplier power is falling, deliberately. The backward-integration programme into APIs is precisely an attack on input-supplier leverage, most of which currently sits with Chinese and Indian API manufacturers.
Buyer power is bifurcated, as discussed — negligible in fragmented private retail, substantial wherever a government tender is the customer. The Mexico strategy increases exposure to the high-power version.
Substitution risk is minimal in the conventional sense. These products are the cheap substitute; there is nothing cheaper to switch to. The relevant substitution risk is supplier substitution — a pharmacist swapping Caplin's brand for a competitor's equivalent molecule — which is a rivalry question, not a substitution one.
Rivalry is moderate and slowly intensifying. As Indian and Chinese exporters exhaust the easy opportunities elsewhere, the same Central American shelf becomes incrementally more interesting to them. Nothing about this is acute today. It is a slow tide.
The power, and its limit
In Hamilton Helmer's framework, Caplin's strongest claim in this segment is a cornered resource: the accumulated country-by-country registration portfolio and the on-the-ground commercial relationships behind it, neither of which a new entrant can acquire with money alone. That is a legitimate power, and it is the correct label — this is not scale economics (Caplin is small), not network effects, and not a brand power in the consumer sense.
But cornered resources have a specific weakness that is directly relevant here. They compound at the speed of the underlying process — in this case, one registration at a time, one relationship at a time — which is a fundamentally linear rate. Capital compounds faster than that, and a share price can re-rate faster still. When a stock has been priced on the assumption that a linear-compounding asset will produce exponential returns, the reconciliation is unpleasant, and it tends to arrive as a growth deceleration rather than a collapse. Which is more or less exactly what management described on the Q3 FY26 call.5
Hold that. It is the pivot for everything in the second half of this story — because the reason management is comfortable guiding to slower growth in the core is that it believes the second engine is about to matter. That engine is a sterile injectables plant in Gummidipoondi, and in August 2026 it had FDA investigators walking its lines.
V. The US Pivot: Caplin Steriles — From Bet to First Real Reckoning (2018–2026)
In January 2019, a Chennai company best known for selling ointments in Guatemala announced that Eight Roads Ventures — the proprietary investment arm of Fidelity International — and F-Prime Capital had committed ₹218 crore to its sterile injectables subsidiary via convertible preference shares.10
Consider what that transaction signalled. Eight Roads and F-Prime are not tourists in healthcare; they are institutional investors with the technical staff to evaluate a sterile manufacturing asset and the mandate to say no. Their willingness to put capital into Caplin Steriles specifically — the subsidiary, not the parent — was an outside underwriting of the one part of the Caplin story that the Indian market found hardest to believe: that a company with no US regulatory history could build an FDA-compliant sterile injectable plant and get products approved. The current status of that investment, including whether and on what terms it has been converted or exited, is not something this article can state from public secondary sources; readers should check the subsidiary notes in the most recent annual report directly.3
Why injectables, and why this was consistent rather than a swerve
On the surface, entering the United States looks like an abandonment of the founding rule. The US generics market is the most crowded, most price-deflationary, most litigated pharmaceutical market in the world, and Indian pharma's collective experience there over the preceding decade had been a study in value destruction — heavy filing costs, brutal channel consolidation among three buying consortia, and repeated FDA compliance failures.
But sterile injectables are a genuinely different sub-market, and the distinction is worth explaining carefully because it is central to the thesis. An oral tablet is, from a manufacturing standpoint, a solved problem: you can build a compliant plant, and dozens of competitors can too, so price collapses toward cost. A sterile injectable is a product that goes directly into a patient's bloodstream, which means every unit must be provably free of microbial contamination and particulate matter. That requirement drives an entirely different plant: aseptic filling lines, cleanroom classification, continuous environmental monitoring, media fill validation, and a compliance regime where a single contamination event can shut the line. The capital cost is higher, the operational discipline required is higher, and consequently the number of credible suppliers per molecule is far lower. Fewer suppliers means prices that erode more slowly, and it means periodic shortages that give a reliable supplier real commercial leverage.
It was also a natural extension of what Caplin had already learned. The company had been moving up the dosage-complexity ladder in Latin America for years. Injectables for the US were the same trajectory pointed at a harder regulator.
The approval machine
By the quarter ended June 2026 — Q1 FY27 — Caplin Steriles reported 60 approved abbreviated new drug applications, with five more under FDA review, 38 products commercially launched, another twelve planned for FY27 and a pipeline running past forty.11 Building that from a standing start in under a decade is a real operational achievement, and it is the strongest available evidence that the company can execute technically outside its home turf.
Management has also claimed a process advantage: an approval turnaround of roughly fourteen to fifteen months against an industry norm nearer twenty.11 That claim is worth flagging as exactly the kind of assertion that should be stress-tested rather than accepted. It is checkable — the filing and approval dates are in the public record — and an investor who cares about it should reconstruct the actual distribution from FDA data rather than rely on the average management quotes. Faster approvals, if genuine, would compound meaningfully: each month saved is a month of exclusivity-window revenue captured in a market where the third and fourth entrants earn a fraction of what the first two do.
Here is where the story gets interesting, and where it stopped being a demand story.
The constraint flipped
On the Q1 FY27 call, management said plainly that the binding constraint was "not depth of orders but lack of capacities."11 The order book was booked through February 2027. The company was operating seven sterile lines and expanding toward seventeen. Product transfers — moving a validated product onto a new line — were running nine to ten months each.11
For a management team, this is close to the best problem you can have. For the market, it was not received that way: the stock fell more than 6% on the disclosure.11
That divergence is instructive and worth sitting with, because it captures the shift in how Caplin is being underwritten. When demand is the constraint, the question is whether the company can sell — a commercial question, and Caplin has a good answer. When capacity is the constraint, the question becomes whether the company can build, validate, transfer and qualify manufacturing lines on schedule — an execution question, and a capital-intensive one with a nine-to-ten month latency between deciding and earning. A fully booked order book that you cannot fill is revenue deferred, not revenue earned, and every month of delay is a month a competitor can use to qualify with the same customer. The market repriced from a growth multiple to an execution multiple in a single session, and on the evidence that was a reasonable thing to do.
The disconfirming event, placed where it belongs
Which brings us back to Gummidipoondi in August 2026.
The FDA conducted an unannounced inspection of the Caplin Steriles facility between August 13 and August 21, 2026, and issued a Form 483 with ten observations. The company disclosed it to the exchanges on August 22.112 Management stated that the observations were procedural in nature, that there were no data-integrity findings and no repeat observations, and no warning letter has followed as of this writing.1
Take the company's characterisation at face value for a moment — procedural, non-repeat, no data integrity — and it is still a materially worse outcome than the alternative, which was no observations at all. A Form 483 is not an enforcement action; it is a list of an investigator's objectionable conditions, and the overwhelming majority are resolved through a written response and a corrective action plan. Most 483s go nowhere. But the escalation path is real: an inadequate response can produce a Warning Letter, and a Warning Letter at a sterile facility can freeze new approvals from that site, which for Caplin would mean the twelve planned FY27 launches and the five pending ANDAs sitting in limbo.
The timing is what makes this analytically significant rather than routine. This is the first serious compliance flag at the flagship US-facing asset, arriving in the same quarter that the company committed to more than doubling that site's line count and told investors that capacity is the thing standing between it and its booked order book. The compliance risk and the capital-deployment risk are now concentrated at the same address.
What does the historical record say about how much weight to put on this? Honestly, not much — and that cuts both ways. Caplin Steriles has no prior FDA enforcement history to extrapolate from, which is why the clean record was part of the bull case in the first place. But one clean decade is a thin base rate, and the industry base rate is not reassuring: several far larger and more experienced Indian manufacturers have taken years and hundreds of crores to resolve sterile-facility compliance issues once they escalated. The correct conclusion is not that the thesis is broken. It is that the "flawless regulatory execution" leg of the bull case has been narrowed from proven to unproven-but-not-yet-contradicted, and there is a specific, dated event that will resolve it: whether the 483 response closes cleanly, with an Establishment Inspection Report and no Warning Letter, on a normal timeline. If it does, this is a footnote. If a Warning Letter arrives, the capacity expansion story and the FY27 launch schedule both have to be rebuilt.
Regulated markets beyond the US, and a timeline that moved
The company has also pursued approvals across Canada, the European Union, Australia, Brazil, Mexico, South Africa, Saudi Arabia and the UAE, reporting 54 products filed and 32 approved in these regulated markets.13 The strategic logic is sound: a sterile line built to FDA standards can serve any of these markets, so the incremental cost of each additional geography is regulatory filing rather than new capital.
But there is a disclosure point here that deserves naming rather than burying. Management now guides that "meaningful revenue" from these regulated markets arrives from FY27 onward.5 Earlier company framing had pointed to European entry contributing by FY26.13 That is guidance that moved — not a risk that might materialise, but a timeline that has already slipped by roughly a year. It is a modest slip in absolute terms. Its analytical value is as a data point on how the company's own forecasts of milestone-to-revenue conversion have performed, which is the right lens to apply to every other optionality claim in this story.
What the US segment actually earns
US revenue was roughly ₹221 crore in the first half of FY26, up about 27% year on year,14 and growth continued at a broadly similar clip into Q1 FY27.11 That is a real business growing at a real rate.
One caution before assuming injectables are automatically the premium-margin part of the company: at least one independent estimate puts the injectables segment's margin below Caplin's blended margin. The company does not publish a clean segment-level margin disclosure that would settle the question. The intuition that complex sterile products must be more profitable than emerging-market branded generics is plausible but not confirmed by disclosure — and if it is wrong, the entire mix-shift argument for future margin expansion needs re-examining. This is precisely the sort of gap an investor should press management on directly, and the sort of gap the company could close with one additional line in its earnings presentation.
The US business, then: real, growing, capacity-constrained rather than demand-constrained, and carrying a live regulatory question at the exact site absorbing the most capital. That is a more interesting profile than either the promotional or the dismissive version. Meanwhile, three smaller bets are being funded alongside it — and they are where the capital allocation discipline gets tested on less proven ground.
VI. The Smaller Bets: Oncology, Mexico, and Backward Integration
Every company that has made one contrarian bet work faces the same temptation: to conclude that the instinct generalises. Caplin Point is currently funding three separate propositions that each assume some version of that. They deserve to be sized as what they are — early, small, and largely unproven — rather than treated as thesis pillars.
Caplin One Labs: oncology
In March 2024, the company's subsidiary Caplin One Labs commenced operations at an oncology facility near Chennai, beginning with oral solid dosage production, with roughly ₹150 crore committed to the venture and stated plans to scale toward fifty-plus oncology products.15
The strategic logic holds together. Oncology generics are complex, require containment infrastructure that most manufacturers do not have, and command better pricing durability than commodity molecules for the same reason sterile injectables do — few qualified suppliers. It extends rather than diverts the capability Caplin has been building.
The record so far requires one honest sentence, and only one. More than two years after commissioning, no separate segment revenue for oncology has been disclosed, and the associated oncology API facility has slipped to a target of the third calendar quarter of 2027 from an earlier date.5 A commissioned facility is a technical milestone, not a commercial one, and the two are separated here by at least a couple of years. The right posture is to treat oncology as not yet material and to watch for the first disclosed revenue contribution, plausibly in FY28 reporting. Anything more confident than that is not supported.
Triwin Pharma: the Mexico question
In June 2025, Caplin Point announced the acquisition of Triwin Pharma S.A. de C.V. in Mexico, executed through a Hong Kong subsidiary.8
The detail that matters most is in the disclosure itself. At acquisition, Triwin had 50,000 equity shares of one-peso face value and zero turnover.8 That is not an operating business being bought; that is a corporate shell — a legal entity, a name, and presumably a set of local registrations or permissions. The purchase price was never publicly disclosed.8
Two consequences follow. First, whatever Caplin acquired, it did not acquire revenue, customers or manufacturing — it acquired a vehicle for building those things itself. Land has since been acquired in Mexico, which suggests a genuine local manufacturing build is underway rather than a paper exercise. Second, and less comfortably, the absence of a disclosed price makes it impossible for an outside investor to assess capital discipline on this specific transaction. A shell company acquisition is usually small, and the probability is that this one was too. But "probably immaterial" is an inference, not a disclosure, and a company that trades substantially on its reputation for capital discipline gives that reputation away cheaply by not stating the number.
The strategic rationale is coherent: Mexico is the largest pharmaceutical market in Latin America, local manufacturing status confers advantages in government tender participation, and Caplin already knows how to sell in the region. It is also a materially different exercise from what the company has done before — building and operating a plant in a foreign jurisdiction, rather than shipping Indian-made product into one. It is too early to call this either a proof point or a misstep. It is an open position.
Sourcing partnerships
The company has been described as pursuing China-sourced biosimilar and ANDA partnerships to accelerate Latin American filings. The logic is the most obviously sensible of the three — it leverages the distribution asset that already exists, which is the highest-return use of that asset. But this is thinly sourced in available public research and should be verified against primary filings before any weight is placed on it.
Backward integration into APIs
The least glamorous of the smaller bets is probably the most consequential. Caplin has reported completing R&D on more than ninety active pharmaceutical ingredients, funded inside a multi-year capital expenditure programme exceeding ₹1,000 crore, of which roughly 38% had been deployed as of Q3 FY26 — entirely from internal accruals, with no equity dilution.5
An API is the actual drug molecule; the formulation is the delivery vehicle around it. Making your own APIs does three things: it removes a supplier's margin from your cost structure, it insulates you from the supply and price volatility of a Chinese API market that has repeatedly demonstrated both, and it gives you control over quality documentation, which matters more than anything else when an FDA investigator is asking where your starting material came from.
It also does a fourth thing that shows up in the return ratios rather than the income statement: it converts a variable cost into a fixed asset. Every rupee of API capacity is a rupee added to the capital employed denominator, earning nothing until the plant runs and the products qualify. That is the mechanical explanation for a good deal of what Section VIII describes, and it is why "margins improved" and "returns on capital compressed" can both be true of the same company in the same year without contradiction.
The self-funding point deserves its full weight and no more than that. Funding a ₹1,000-crore-plus programme, a US expansion and an oncology venture simultaneously without going to the equity markets is a genuine, verifiable capital discipline signal across a company that has not raised public equity since 1994.6 It says nothing about whether the capital is being deployed well — that verdict requires the return on these assets once they operate, which is a FY28-and-beyond question. Discipline in sourcing capital and skill in deploying it are separate competencies, and Caplin has demonstrated the first far more thoroughly than the second.
Which raises the obvious question about the people making these decisions.
VII. Management, Ownership & the Capital Allocation Credibility Test
In February 2026, on the Q3 FY26 earnings call, Caplin Point's management told analysts to expect low double-digit growth for the next eighteen to twenty-four months, and characterised the period as one of gestation and consolidation.5
Companies do not usually do this. The standard playbook when growth decelerates is to reframe — to talk about the long-term opportunity, to blame a base effect, to point at a lumpy quarter, to keep the old growth number in the room for as long as possible and let the disappointment arrive in instalments. Caplin named the number, named the duration, and named the reason.
That statement is the single most useful piece of evidence available about this management team, and it deserves to be examined next to the claims it tests rather than filed away in a risk section.
The people
C.C. Paarthipan remains promoter and Chairman, in a non-executive capacity. Day-to-day operating leadership sits with Managing Director Dr. Sridhar Ganesan, re-appointed for a further two years effective August 2026 subject to shareholder ratification, and with D. Muralidharan, the Chief Financial Officer, who was elevated to Whole-Time Director in August 2026 while retaining the CFO role.163
The structure tells you something. A founder who steps back to non-executive Chairman while retaining a controlling shareholding, and a professional management layer running operations, is a governance arrangement that can work well or badly depending entirely on whether the founder actually delegates. The elevation of a long-serving CFO to the board is generally a constructive signal — it puts financial discipline in the boardroom rather than adjacent to it — though it also concentrates the finance function and its oversight in the same person, which is a structure worth watching rather than applauding uncritically.
Compensation is modest by any comparable standard: managing director pay of roughly ₹57 lakh and CFO pay of roughly ₹54 lakh, set against consolidated net profit of approximately ₹640 crore in FY26.34 Executive pay at well under one-tenth of one percent of net profit is characteristic of a founder-controlled company where the economics accrue through ownership rather than salary. That alignment is real as far as it goes.
What is not visible in available public research is the ESOP and incentive structure — whether long-term incentives exist, what they vest against, and whether operating management has meaningful equity-linked upside. That gap matters more than it might seem. In a promoter-controlled company, the founder's alignment is automatic; the professional managers running the business day to day are the ones whose incentives actually need engineering. Anyone forming a view on this should pull the details directly from the FY26 annual report rather than infer them.3
The ownership base
Promoter and promoter-group shareholding stood at approximately 70.6%, having risen from around 68.9% in mid-2022.17 Rising promoter ownership without a corresponding equity issuance is a straightforward signal: the people with the most information have been buying rather than selling.
Foreign institutional holding moved over the same period from under 1% to roughly 5.8%.17 That is a meaningful shift in the shareholder register — institutional capital does the diligence work that retail capital cannot, and its arrival is at least weak evidence that the diligence came back acceptable.
On promoter pledging: no pledge was found in the searches conducted for this article, but that is a bounded negative result rather than a confirmation, and anyone relying on it should verify against current BSE disclosures directly.18
The capital allocation record
The dividend has grown from ₹0.30 per share in 2012 to a ₹4 per share final dividend for FY26 — 200% of face value — a compound growth rate of roughly 26% over that span.4 There have been no buybacks. There has been no equity raise, qualified institutional placement, or preferential issue at the parent level since the 1994 IPO.6
Taken together, that is a thirty-two-year record of funding growth from operating cash flow while returning a steadily rising cash amount to shareholders. It is rare enough among Indian mid-caps to be worth naming precisely: the entire Latin American build-out, the US injectables entry and the current capital expenditure programme have been paid for by the business itself.
But the record has to be tested through the mechanism that would actually break it, and for capital allocation that mechanism is the fate of prior deployments. Here the available public record is genuinely thin. Caplin's major capital deployments — the Latin American distribution build, Caplin Steriles — have not produced disclosed write-offs or impairments of consequence, which is a point in favour. The problem is that the two most recent and most capital-intensive deployments, the oncology venture and the current ₹1,000-crore-plus API and capacity programme, have not yet produced returns to judge at all. The disciplined-sourcing record is thirty-two years long and verifiable. The skilled-deployment record, on the assets that now dominate the capital base, is roughly two years old and unresolved. Those are not the same claim and should not be granted the same confidence.
The credibility test itself
Now put the guidance reset next to the equity story it revises.
Read generously, February 2026 was guidance discipline of a kind that should earn a management team more credibility, not less. It was specific, dated, volunteered ahead of the deterioration showing up in reported numbers, and framed with a mechanism — a gestation phase while capital converts into capacity. Investors are chronically underserved by managements that keep promising the old growth rate through a visible slowdown, and Caplin did the opposite.
Read skeptically, it is the first public admission that the emerging-market engine has matured faster than the story around it assumed. Growth of 15–22% was the historical cadence; low double digits is a materially different compounding rate, and if it persists past twenty-four months, the entire framing of Caplin as a high-growth compounder needs replacing with something more modest.
Both readings are defensible, and the honest conclusion is that the guidance reset strengthens the case for management's candour while weakening the case for the growth rate. Those are separable, and conflating them is how investors talk themselves into paying a growth multiple for a company that has told them it is not currently a growth company. The specific thing that resolves this: whether FY27 results land inside the low-double-digit band management set, and what management says when the eighteen-to-twenty-four-month window expires around the middle of FY28. A company that hits its own reset guidance and then re-accelerates has earned a great deal. A company that misses its own reset guidance has a much bigger problem than a slow year, because it will have missed a number it chose.
Governance housekeeping
No SEBI enforcement action, insider-trading proceeding or governance controversy involving Caplin Point was surfaced in research conducted for this article, and the statutory auditor, Brahmayya & Co., has been reported in secondary sources as issuing clean opinions.3 Neither of those should be treated as verified. The auditor's report and the CARO annexure are public documents; so are AGM voting results, which reveal institutional dissent that never makes the news. The 35th AGM was scheduled for September 25, 2026,16 and the resolution list — including the ratification of the managing director's re-appointment — is the kind of thing where a low approval percentage from institutional holders would be far more informative than any amount of secondary commentary.
Management's candour is one input. The numbers are another, and they tell a more complicated story than the margin trend alone suggests.
VIII. The Numbers: Growth, Margins, and What the Capex Cycle Is Costing
Here is the shape of Caplin Point's FY26, the financial year ended March 2026: consolidated revenue of roughly ₹2,187 crore and net profit of roughly ₹641 crore.4 Momentum continued into the June 2026 quarter, with Q1 FY27 revenue of approximately ₹610 crore, up around 20% year on year, and net profit of roughly ₹179 crore, up around 19%.11
A twenty-nine percent net margin on a generics business is an unusual number, and it is the first thing a newcomer to this story notices. It is also the thing that most needs explaining, because it is the residue of two decades of the strategy described earlier: branded pricing in markets where Caplin owns the shelf relationship, on products manufactured at Indian cost. That spread is what the whole enterprise was built to capture.
The good part of the story
The margin trend has moved in the right direction for years. EBITDA margins that sat in the high-twenties to low-thirties percent range several years ago had reached the high thirties by FY26 and into Q1 FY27.49 The mechanisms behind that — mix migration into complex dosage forms, incremental backward integration, operating leverage on distribution — were laid out earlier, and the durability of each differs. What matters here is that this is not a one-quarter artefact; it is a multi-year trend, and multi-year margin trends in generics businesses generally reflect something structural rather than something lucky.
The part that is more complicated
Return on capital tells a different story from margins, and the divergence is the most analytically interesting thing on Caplin's financial statements right now.
Return on equity has drifted down from just above 20% in FY21 to the high teens today, and return on capital employed has compressed materially over the same span.4 This is not a sign of the business getting worse. It is arithmetic, and the arithmetic is worth walking through slowly because it is the mechanical signature of the entire strategic shift this article has been describing.
A pure distribution business earns its return on a relatively small capital base — inventory, receivables, a modest manufacturing footprint. Add a US sterile injectables plant, expand it from seven lines toward seventeen, commit ₹150 crore to an oncology facility and more than ₹1,000 crore to a multi-year API and capacity programme, and the denominator of the return calculation expands immediately while the numerator does not. The plants are built before they run; they run before they are qualified; they are qualified before the products transfer, and each product transfer runs nine to ten months.11 Every rupee of that spend sits in capital employed earning nothing for a period measured in years.
So compressing returns on capital, in this specific context, are the price of admission to a different business, not evidence of deterioration in the existing one. That is the generous reading and it is probably the correct one. The disciplined reading adds a condition: this interpretation only holds if the new capital eventually earns a return comparable to the old capital. If the US injectables business turns out to carry structurally lower margins than the Latin American core — which, as noted, is at least a live possibility given the absence of clean segment disclosure — then the return compression is not temporary at all. It is the company migrating toward a permanently lower-return mix while describing it as an investment phase. The evidence to distinguish these two cases will not exist until FY28.
The debt-free claim, precisely
Caplin Point is frequently described as debt-free. As of March 2026 that is accurate — borrowings had been reduced to near zero.4 It is worth stating the correction plainly, though: the company carried roughly ₹222 crore of borrowings as recently as March 2025.4 Debt-free is a description of the present balance sheet, not an unbroken multi-decade condition, and the distinction matters because it means the company has in fact been willing to use leverage when the capital programme demanded it. That is not a criticism — modest, temporary, quickly-repaid borrowing to fund capacity is exactly what a well-run balance sheet is for. It simply means the "never borrowed, never diluted" version of the story is one claim too strong, and the verifiable version is the no-dilution-since-1994 one.6
Against the peer group
Set Caplin against the comparably sized Indian specialty and generics names an investor would realistically consider alongside it — Alembic Pharmaceuticals, Concord Biotech, Granules India, Jubilant Pharmova, Natco Pharma — and its margins and return ratios have generally compared favourably. That comparison is genuinely favourable and it reflects the structural point made earlier: emerging-market branded generics with owned distribution is a better business than contract manufacturing or US commodity generics, and the financial statements show it.
The valuation is where the comparison gets uncomfortable. Price-to-book has been estimated near 4.6x,19 a multiple that embeds an expectation of returning to the historical growth cadence. Management is currently guiding to something slower than that.5 An investor does not need a price target to see the tension: the multiple and the guidance are describing different companies, and one of them will have to move.
What the market has already done about it
The share price ran from roughly ₹1,500 to a fifty-two-week high near ₹2,750, including a stretch in June 2026 when it gained more than 20% in five sessions.20 It then pulled back on the Q1 FY27 capacity commentary and the August Form 483 disclosure — two distinct pieces of news arriving within weeks of each other, both pointing at the same asset.111 Sell-side sentiment moved too, with at least one rating service shifting from Hold to Sell between May and June 2026.19
The pattern is worth reading carefully. This was not a fundamental deterioration — revenue grew about 20% in the most recent reported quarter. It was a repricing of what kind of risk the market thinks it is holding. A company whose constraint is demand is valued on its market opportunity. A company whose constraint is execution at a facility under regulatory scrutiny is valued on its ability to deliver on time. The market spent the summer of 2026 moving Caplin from the first category to the second, and until the Form 483 resolves and the new lines qualify, that reclassification stands on the evidence.
IX. Playbook: Business & Investing Lessons
Strip Caplin Point down to its transferable lessons and you get a set of principles that are genuinely useful well beyond pharmaceuticals — and a couple of warnings about how those principles get misused.
Geographic arbitrage is a real strategy, but the arbitrage is in the difficulty, not the product. Caplin never had a better molecule than anyone else. It had the same off-patent generics available to every manufacturer on earth. What it had was a willingness to operate in places where the operating burden — currency risk, payment risk, regulatory idiosyncrasy, political instability — was high enough to deter better-capitalised competitors. The edge came from tolerating friction that others found not worth tolerating. That is a repeatable idea, and it is also a warning: an edge built on friction disappears the moment the friction does. If Central American payment infrastructure formalises and currencies stabilise, the barrier that kept Zydus and Cipla at arm's length gets lower for everyone.
Owning distribution is slower than owning a factory and harder to replicate. A competitor can build a plant in eighteen months. A competitor cannot build fifteen years of relationships with independent pharmacists in eighteen months, at any price. This is the strongest structural lesson in the story and it generalises to almost any industry where the last mile is fragmented.
Complexity compounds, but slower than capital. Registrations, formulation capability and dosage-form sophistication accumulate over decades and are enormously difficult to leapfrog. They also accumulate linearly. When a market prices a linear-compounding asset as though it compounds exponentially, the correction arrives as a growth reset — which is precisely what happened here.
Self-funded growth is a checkable discipline signal, and it is rarer than it sounds. No equity raised since 1994 is a verifiable fact about a company that has funded two continental expansions and a US manufacturing programme.6 The caveat, stated earlier and worth repeating once here because it is the most commonly missed distinction in this kind of analysis: not diluting proves discipline in raising capital. It proves nothing about the quality of deploying it. Investors routinely conflate the two and give companies credit for a competence they have not demonstrated.
Beware narrative drift. "Asset-light" survived in Caplin's public description long after a 170-plus-day cash conversion cycle and a growing owned-manufacturing base stopped supporting it.4 Labels calcify. They are usually accurate when coined and rarely re-examined afterwards. The discipline for an investor is to re-derive the label from the current financial statements rather than inherit it from the last person who wrote about the company.
A management team that volunteers bad news deserves more credibility, not less — but not more valuation. The February 2026 guidance reset was a genuine act of candour. Candour is an argument for trusting the next number management gives you. It is not an argument for ignoring the number itself. The next several quarters are the actual test of whether "consolidation phase" was accurate self-assessment or the polite opening of something longer.
Which brings us to the two-sided case.
X. Bull vs. Bear Case & the Skeptical Investor's Stress Test
Bull case
The Latin American and African distribution asset is real, it is hard to replicate quickly, and it throws off enough cash to fund everything else the company is doing. Even at a decelerated low-double-digit growth rate, a business with a ~41% shelf-space position in its core Central American markets and an internal target near 57%5 has room to grow inside its existing footprint without needing to win a new geography.
The US injectables business is demand-rich rather than demand-constrained. An order book booked through February 2027 is current, contracted evidence — not a projection, not a pipeline estimate.11 Sixty approved ANDAs and thirty-eight launched products represent a decade of technical execution that has, so far, worked.11
The capital allocation record is verifiable and unusual: no equity dilution since 1994, a dividend compounding at roughly 26% since 2012, and simultaneous funding of a US expansion, an oncology venture and a ₹1,000-crore-plus API programme entirely from internal accruals.465
The ownership signals point the right way. Promoter holding has risen to about 70.6% without dilution, and foreign institutional holding has gone from under 1% to roughly 5.8%.17 Neither group is behaving as though it sees a deteriorating business.
And there are multiple funded optionality vectors — oncology, Mexican manufacturing, backward integration, regulated-market approvals outside the US — that cost relatively little today and could matter by FY28. None is priced as a certainty, which is the correct treatment.
Bear case
Management has already told the market that growth downshifts to low double digits for eighteen to twenty-four months.5 Any bull case must be rebuilt on that base rate, not the historical one, and a valuation near 4.6x book is not obviously consistent with it.19
Return compression is visible now while the payoff is one to two years away.4 The capital is committed; the return is a forecast.
The Form 483 at Gummidipoondi lands at the facility absorbing the most incremental capital, at the moment that capital is being committed.111 This is a live, dated, unresolved regulatory question rather than a hypothetical risk.
Roughly 79% of revenue remains in currency- and politically-exposed Latin American and African markets,3 with a cash conversion cycle that means a large share of a year's sales is sitting as claims on emerging-market counterparties at any given moment.4
The Triwin transaction is opaque — an undisclosed price for a zero-turnover shell.8 The amount is probably small. The disclosure practice is the issue, not the amount.
And the sell-side has already moved: at least one rating service went from Hold to Sell between May and June 2026.19
Porter and Helmer, applied to the whole company
The five-forces read on the Latin American core was set out in Section IV; the US business inverts several of those conclusions and that inversion is the point. In US sterile injectables, buyer power is high — the American generics channel consolidated into a handful of purchasing consortia with enormous leverage. Entry barriers are higher than in Latin America, but they are regulatory and capital barriers that large competitors clear routinely. Rivalry is more intense. Substitution is a live issue in a way it is not in Central America. In short: Caplin is trading a favourable industry structure it dominates for a less favourable one where it is a small participant. The compensating advantage is that the US market is enormous, and a small share of it is worth more than a large share of Guatemala.
On the 7 Powers framework, the cornered-resource power in the core franchise was already discussed. What Caplin does not have anywhere in the business is worth stating explicitly, because the absences define the risk. It has no scale economies — it is a fraction of the size of its US competitors. It has no network effects. It has no switching costs in the technical sense; a pharmacist can stock a different brand tomorrow, and a US purchasing consortium can requalify a competitor. It has no counter-positioning, since its model is not one incumbents are structurally unable to copy — merely one they have declined to. And its process power claim — the fourteen-to-fifteen-month approval turnaround versus an industry twenty11 — is management-asserted and not independently verified. Cornered resource is the one power the evidence supports, it is confined to the emerging-market segment, and it is the segment management has just guided to slower growth. That is the compressed version of the entire investment debate.
The activist stress test
Nothing resembling activist or short-seller pressure exists on Caplin Point today. But the ingredients an activist would assemble are visible, and naming them is more useful than waiting to see whether anyone does.
An accelerating, self-funded capital expenditure programme running straight into declining returns on capital is the canonical activist opening — the argument writes itself: return the capital, or prove the projects clear the hurdle rate. There is a disclosure gap around Triwin's purchase price and around executive incentive structure, both of which are the sort of thing that reads as immaterial until someone chooses to make it material. There is a first FDA compliance flag at the site absorbing the largest share of incremental capital. And there is an "asset-light" narrative resting on a working capital cycle that says otherwise — a mismatch between how a company describes itself and what its balance sheet shows is the single most reliable place a skeptical investor starts.
None of these individually breaks the thesis. Together they describe, quite precisely, what the next four to six quarters need to resolve.
Risk radar
Only the mechanisms specific to this company are worth listing, and each transmits through an identifiable channel rather than a general macro worry.
Currency and political risk in Latin America and Africa transmits through the long receivables cycle: a devaluation does not merely reduce translated revenue, it impairs the value of money already owed and not yet collected, which lands in working capital and in reported margins simultaneously.
An unresolved US compliance issue transmits through approvals: a Warning Letter at Gummidipoondi could freeze new product approvals from the site precisely where the FY27 launch schedule and the capacity expansion both sit.
Capacity execution risk transmits through the nine-to-ten-month product transfer lead time: an order book booked through February 2027 that cannot be filled becomes a competitor's opportunity to qualify with the same customer.11
And capital allocation execution risk sits with Triwin and the oncology API facility, where the payoff is not yet visible in reported numbers and the historical conversion record — a facility commissioned in March 2024 with no disclosed segment revenue two years later15 — argues for patience rather than credit.
The KPIs that actually matter
Three things, tracked over time, will tell an investor most of what they need to know about this company.
First: the Latin America and Africa segment growth rate. This is roughly 79% of revenue,3 and management has bounded it at low double digits for eighteen to twenty-four months.5 Whether it lands inside, above or below that band is the single most consequential number Caplin reports, because it is both the profit engine and the direct test of management's guidance credibility.
Second: Caplin Steriles' regulatory status and line count. Not revenue — regulatory status. Whether the August 2026 Form 483 closes with an Establishment Inspection Report and no Warning Letter, and whether the expansion from seven toward seventeen sterile lines proceeds on the stated schedule.111 These two together determine whether the US business becomes a second profit engine or stays a promising subsidiary.
Third: the cash conversion cycle. At 170-plus days,4 this is where the growth strategy, the emerging-market risk and the return-on-capital question all converge. Improvement would signal that scale is finally producing working-capital leverage. Deterioration would signal that collections in the core markets are getting harder — which is how emerging-market distribution businesses historically break, long before it shows up in the income statement.
XI. Epilogue & What's Next
Thirty-six years after a Chennai company started making ointments, the question in front of Caplin Point Laboratories is whether the instinct that built it still works when the terrain stops rewarding it.
The Latin American playbook — go where nobody wants to go, own the distribution, wait — worked because those markets were structurally unattractive to everyone with a bigger balance sheet. That is not true of the United States, where the company is now a small participant in a market with powerful buyers and unforgiving regulators. It is not obviously true of Mexico either, where a genuine manufacturing build and a government tender channel would put Caplin in front of exactly the kind of concentrated buyer its Central American model was designed to avoid. And it is not yet clear whether Africa can absorb the same playbook at the depth Latin America did.
So the open questions are specific rather than philosophical.
Whether the distribution playbook translates a second time — into real Mexican manufacturing rather than a shell with land attached, into deeper African penetration, and into the regulated markets in Canada, the EU and Brazil where 32 approvals have been secured but meaningful revenue has been pushed to FY27 and beyond.135
Whether Caplin Steriles becomes a genuine second profit engine once the capacity and compliance cycle resolves, or plateaus as a useful but smaller US extension of the core. The order book says the demand exists. The Form 483 and the nine-to-ten-month transfer lead times say the conversion is not automatic.
Whether oncology and the sourcing partnerships turn into anything. Today they are small, unproven, and behind schedule, and the honest position is to revisit them once FY28 disclosure shows whether commissioned capacity became commercial revenue.
The near-term checkpoints are dated and concrete: the annual general meeting on September 25, 2026,16 where voting patterns on the managing director's re-appointment will reveal institutional sentiment more candidly than any commentary; the resolution of the August 2026 Form 483; and the FY27 results, which will either confirm management's own low-double-digit reset or extend it.
There is a version of this story where the reset of February 2026 is remembered as the moment a disciplined management team told the truth about a transition it had already funded, and the capital deployed across Gummidipoondi, Chennai and Mexico starts earning in FY28. There is another version where it is remembered as the moment the emerging-market arbitrage was revealed to have been more finite than the multiple assumed. The evidence available in September 2026 is genuinely consistent with both, and the honest thing to say is that the company built entirely on going where others would not is now being asked to prove that the discipline scales into higher-capital, higher-scrutiny terrain. That answer is not yet written.
XII. Recent News
August 22–24, 2026 — First FDA Form 483 at Caplin Steriles. The company disclosed that the USFDA conducted an unannounced inspection of the Caplin Steriles facility at Gummidipoondi between August 13 and August 21, 2026, issuing a Form 483 with ten observations. Management characterised the observations as procedural, with no data-integrity findings and no repeat observations. No Warning Letter had followed as of this writing.112
August 2026 — Board and leadership changes. Dr. Sridhar Ganesan was re-appointed Managing Director for a further two years effective August 2026, subject to shareholder ratification, and CFO D. Muralidharan was elevated to Whole-Time Director while retaining the CFO role.163
August 2026 — Q1 FY27 results and the capacity disclosure. Revenue of approximately ₹610 crore, up around 20% year on year, with net profit of roughly ₹179 crore. Management stated that the binding constraint in the US business is capacity rather than orders, with the book filled through February 2027 and sterile lines expanding from seven toward seventeen. The shares fell over 6% on the disclosure.11
June 2026 — Share price volatility and a rating downgrade. The stock gained more than 20% over five sessions in early June 202620 before later giving back ground; at least one rating service moved its recommendation from Hold to Sell between May and June 2026.19
June 2025 — Triwin Pharma acquisition. Caplin Point announced the acquisition of Triwin Pharma S.A. de C.V. in Mexico through a Hong Kong subsidiary. The target held 50,000 equity shares of one-peso face value with zero turnover at acquisition; the purchase price was not disclosed.8
Upcoming — Annual General Meeting, September 25, 2026. Shareholder ratification of the managing director's re-appointment and other ordinary business is scheduled for the company's AGM.16
XIII. Links & Resources
- Caplin Point Laboratories — Annual Report Archive
- Caplin Point Laboratories — Corporate Governance disclosures
- FY2025-26 Annual Report (NSE archive filing)
- Q4 FY26 Earnings Presentation (May 2026)
- Q2/H1 FY26 Earnings Call Transcript (November 6, 2025)
- Q1 FY26 Earnings Presentation (August 2025)
- Caplin Point Laboratories — financials, ratios and shareholding, Screener.in
- Caplin Point Laboratories — shareholding pattern trend, Trendlyne
- Caplin Point Laboratories — insider trading disclosures, BSE India
References
-
Caplin Point Laboratories' arm receives Form-483 with 10 observations from USFDA — Business Standard, 2026-08-22 ↩↩↩↩↩↩↩
-
Caplin Point Laboratories FY2025-26 Annual Report — NSE archive filing ↩↩↩↩↩↩↩↩↩↩↩
-
Caplin Point Laboratories — financials, ratios & shareholding pattern — Screener.in ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Caplin Point Laboratories Ltd Q3 2026 Earnings Call Highlights: Navigating Growth and Compliance Amidst Challenges — GuruFocus ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Caplin Point Laboratories — Annual Report Archive, Investor Relations ↩↩↩↩↩↩
-
Caplin Point Laboratories — Investor Presentation, Q4 FY21 (March 2021) ↩↩
-
Caplin Point Laboratories announces acquisition of Triwin Pharma S.A. DE C.V. — Business Standard, 2025-06-04 ↩↩↩↩↩↩
-
Caplin Point Laboratories — Q4 FY26 Earnings Presentation, May 2026 ↩↩
-
Caplin Steriles announces ₹218 crore investment by Eight Roads Ventures and F-Prime Capital — Business Standard, 2019-01-21 ↩
-
Caplin Point Q1 FY27 slides: Revenue up 20%, stock falls on capacity concerns — Investing.com, August 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Caplin Steriles gets 10 USFDA observations at Gummidipoondi facility — Medical Dialogues ↩↩
-
Caplin Point Laboratories — Q1 FY26 Earnings Presentation, August 2025 ↩↩↩
-
Caplin Point Laboratories — Q2/H1 FY26 Earnings Call Transcript, November 6, 2025 ↩
-
Caplin Point arm commences operations at oncology facility in Chennai — Business Standard, 2024-03-27 ↩↩
-
Caplin Point Laboratories — Corporate Governance disclosures ↩↩↩↩↩
-
Caplin Point Laboratories — shareholding pattern trend — Trendlyne ↩↩↩
-
Caplin Point Laboratories — insider trading disclosures — BSE India ↩
-
Caplin Point Laboratories Ltd is rated Sell — MarketsMojo, 2026-06-04 ↩↩↩↩↩
-
Caplin Point Lab jumps over 20% in five days — Business Standard, 2026-06-10 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube