Campus Activewear: Can India's Sneaker Champion Out-Run Its Own Hype?
I. Cold Open & Roadmap
On the morning of May 9, 2022, the trading terminals in Mumbai lit up with a number that seemed to settle an argument India's consumer investors had been having for a decade. Campus Activewear, a Delhi shoemaker that most of the country knew from cricket-sponsorship hoardings and the shelves of small-town multi-brand stores, opened for trading at a premium of roughly 23% to its issue price of ₹292 a share.1 Within days the stock was well clear of ₹370. By September of that year it had run toward ₹640, valuing a company that had earned ₹109 crore in the fiscal year just ended at something on the order of ₹18,000–19,000 crore.2
Put plainly: the market was paying well over a hundred times trailing earnings for a business that sells sneakers to Indians for less than the price of a tank of petrol. The bet embedded in that price was enormous and specific. It said that a family firm from the Delhi footwear trade had solved a problem Nike, Adidas and Puma had all failed to solve — how to make a branded sports shoe, at Indian mass-market prices, at industrial scale, and still earn a fat margin doing it. It said that the shift of India's ₹1,000-to-₹3,000 shoe buyer from unbranded local product to branded product was a decade-long escalator, and that Campus was standing on the fastest step.
Eighteen months later, in the quarter ending September 2023, Campus reported profit after tax of ₹0.30 crore. The year-earlier figure had been ₹14.5 crore. That is a decline of roughly 98%, and it did not come from a fraud, a fire, or a regulatory action. It came from distributors refusing to take stock.3
Today, on September 2, 2026, Campus Activewear trades at about ₹221 a share, a market capitalisation of roughly ₹6,750 crore — still below the ₹292 at which the company's promoters and private-equity backers sold shares to the public more than four years ago, and this despite a genuine, measurable earnings recovery: FY26 revenue of ₹1,774 crore and profit after tax of ₹150 crore, both records.2 An investor who bought the IPO and held has lost about a quarter of their money while the underlying business grew earnings by nearly 40%. That gap between business performance and share performance is the whole story.
So the question this episode has to answer is not "is Campus a good company?" It plainly is a functioning, profitable, cash-generating manufacturer with a real brand. The question is narrower and harder: was 2022's collapse a cyclical air pocket in a durable branded-manufacturing moat, or was the moat always thinner than the multiple implied — a volume-and-utilisation business dressed up in the language of consumer franchises?
It is worth naming, at the outset, the two ways an analyst can get this company wrong. The first is to look at a stock that has halved from its peak, note that earnings have risen every year since FY24, and conclude that the market is simply being slow. The second is to look at the 2023 collapse, note the institutional dissent at the last shareholder meeting, and conclude that the whole thing was a promoter cash-out dressed up as a growth story. Both readings are available from the same public record, which is usually a sign that the truth requires holding two things at once.
We'll get there in stages. First, a compressed origin story, because the positioning decision made in 2005 still explains the P&L in 2026. Then the machine — factories, distributors, an actor, and a private equity firm — that turned a regional brand into a national one. Then the IPO and the unwind, which is where the investment case actually starts. Then the longest section of the episode: what management has changed since 2023, and whether the evidence supports their account of it. Then the competitive war-game, the playbook, the bull and bear cases, and what to watch.
 Subscribe on LinkedIn
II. Origins: From Action Shoes to Campus (1983–2010)
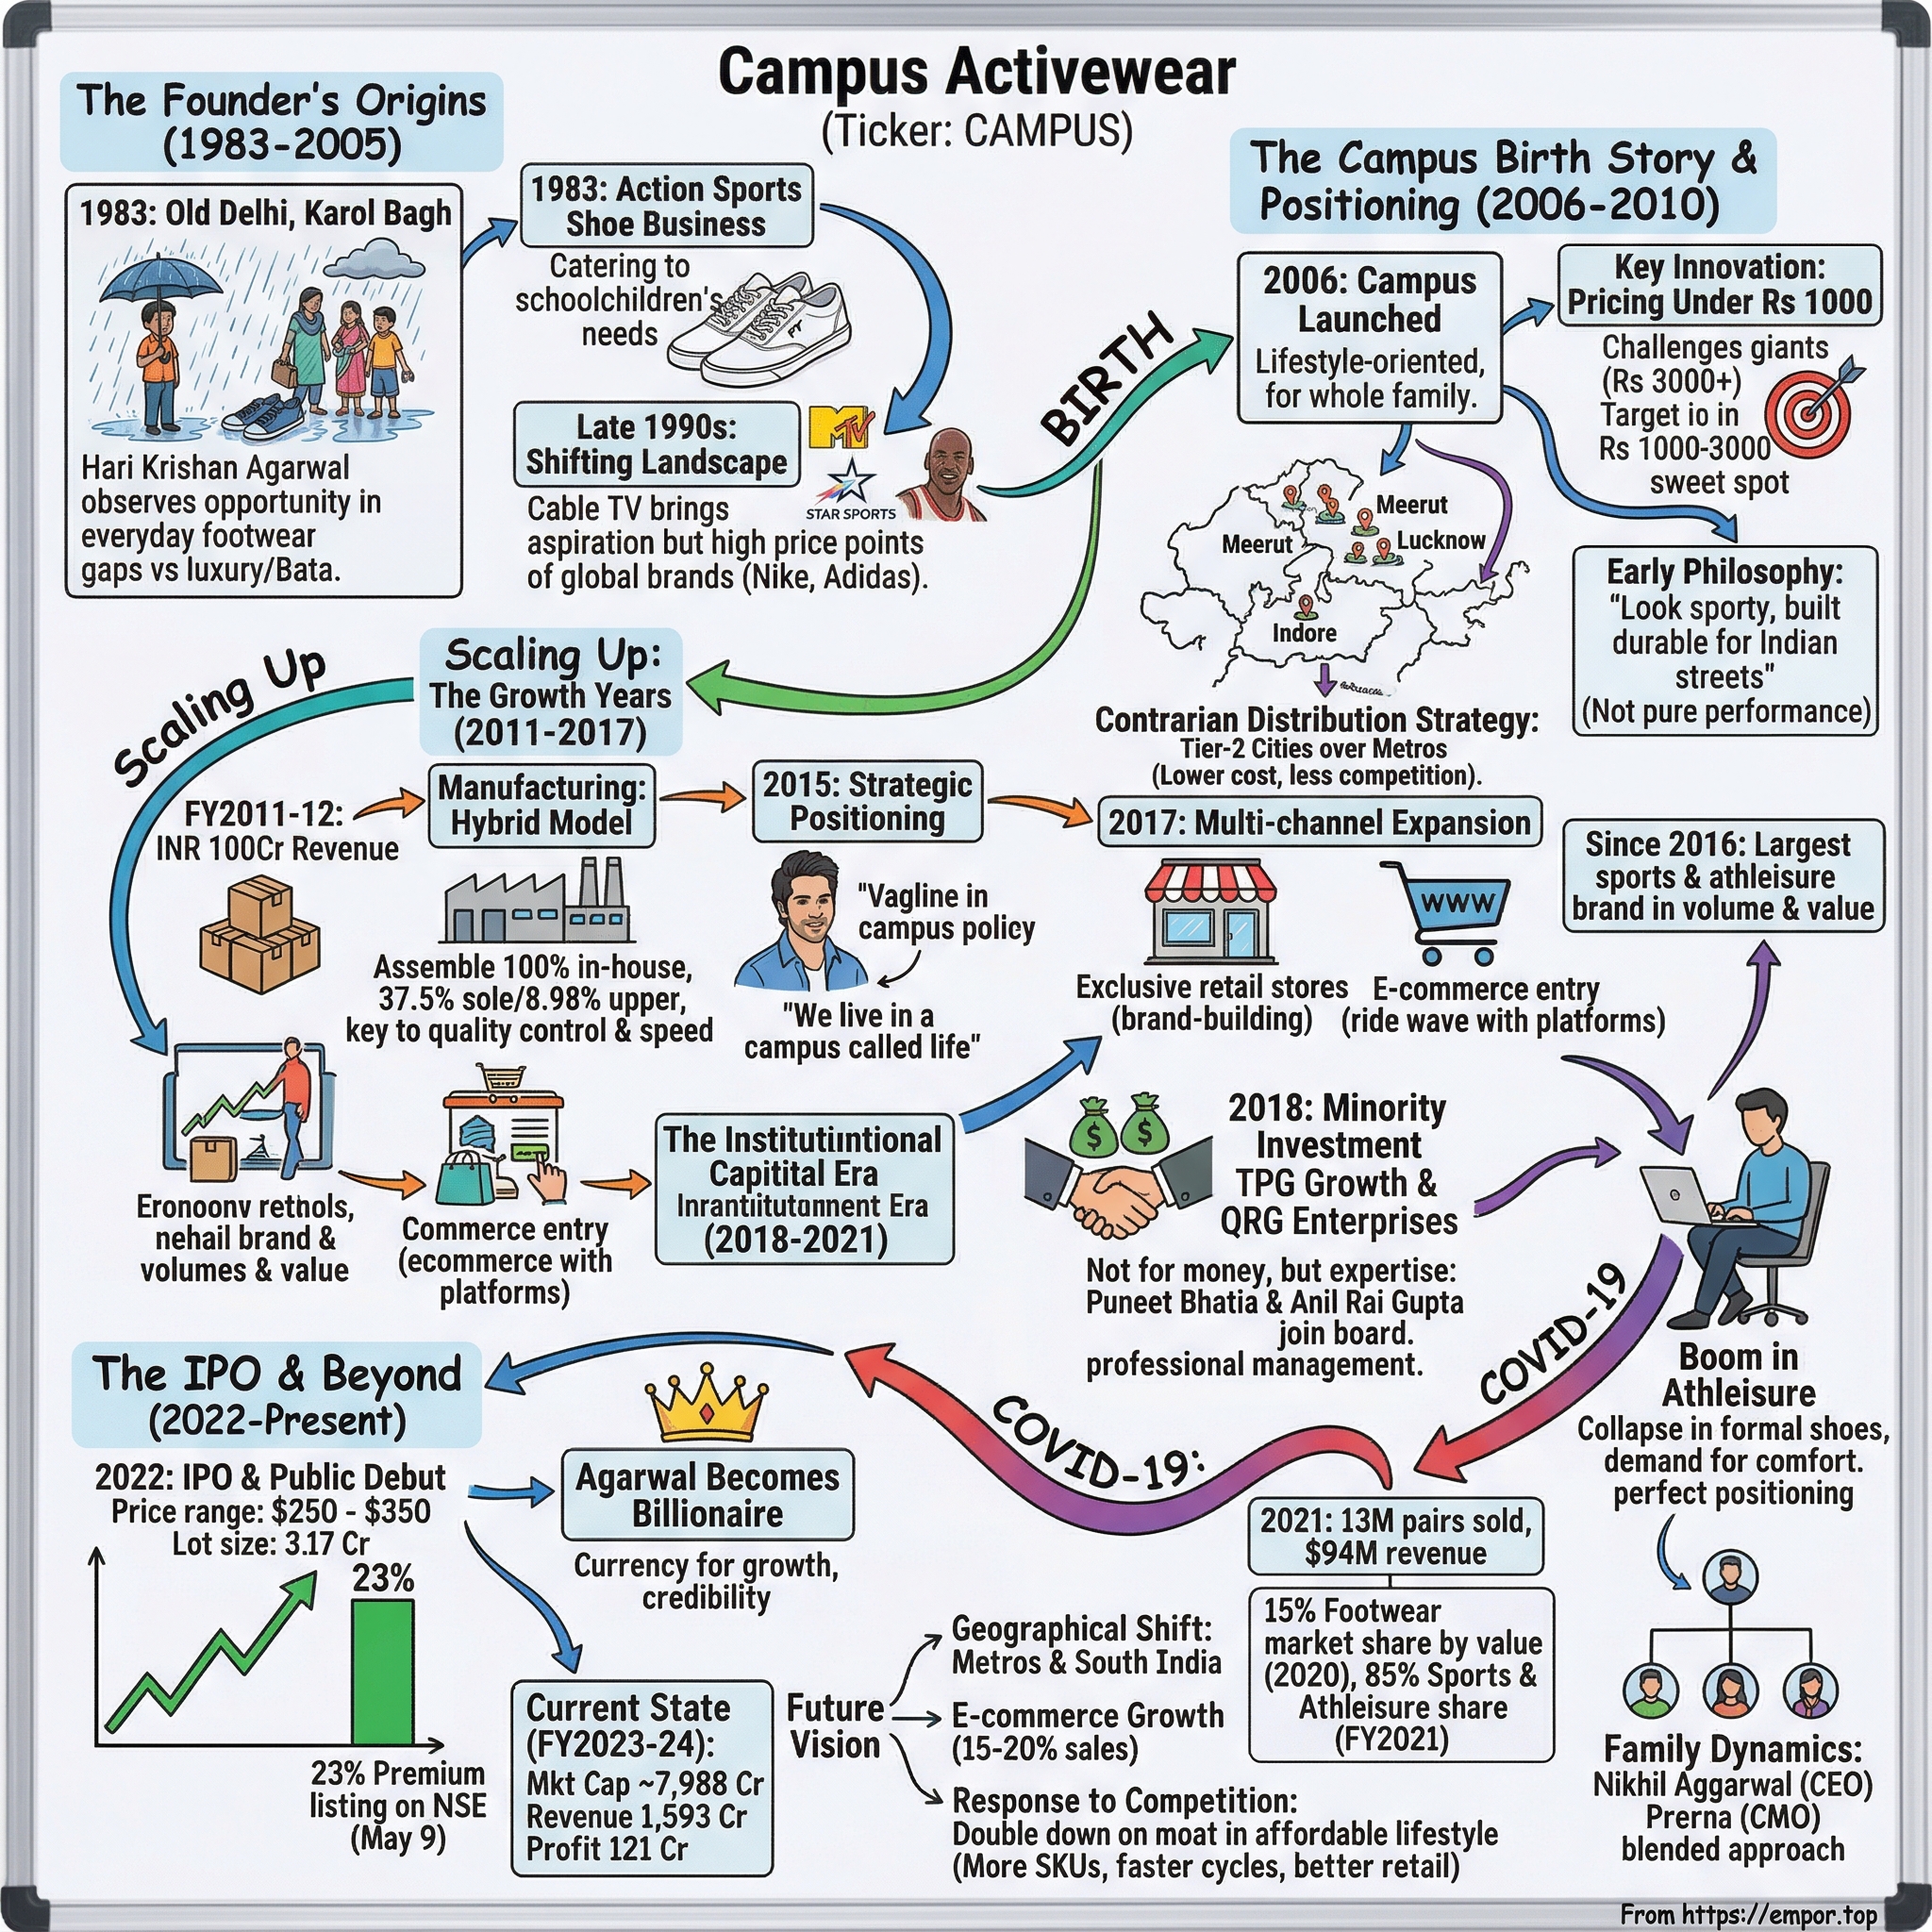
Start in the lanes off Delhi's old wholesale footwear markets in the early 1980s — a trade that ran on cash, on family credit, and on relationships with hundreds of tiny job-work units that could stitch an upper for a few rupees. This was where Hari Krishan Agarwal built his first business. In 1983 he launched the Action footwear brand, and over the following two decades Action became one of the most recognisable names in Indian mass footwear, particularly in school shoes and budget sports shoes.4
To understand what that business actually was, it helps to understand how Indian mass footwear got made in that era. A brand owner rarely owned a factory. It owned a name, a design book, and — crucially — a ledger of distributor relationships. Production was placed with small job-work units, often family-run, often operating on the margins of formal compliance, each of them stitching, moulding and assembling to order at rates negotiated pair by pair. The brand owner's real asset was the ability to get product onto shelves and collect the money afterwards. Credit ran on trust and personal reputation, and a distributor who believed in you would carry your stock through a bad season. Agarwal spent two decades accumulating exactly that kind of capital.
Action was, in the vocabulary of the industry, a trade brand. It sold because distributors pushed it, because it was cheap, and because it was everywhere. It did not sell because a fourteen-year-old in Kanpur wanted to be seen in it. That distinction — push versus pull — is the hinge of everything that follows.
By the early 2000s Agarwal was watching two things happen simultaneously. Global sports brands were entering India in earnest, opening stores in metro malls with shoes priced from roughly ₹3,000 upward. And below them sat a vast, largely unbranded market of local manufacturers selling at ₹300–₹800 with no design language, no warranty, and no aspiration attached. Between those two poles lay a gap: the young Indian who wanted a shoe that looked like the ones in the ads but could spend ₹1,200, not ₹4,500.
The gap was not a secret. Everyone in Indian footwear could see it. What made it hard to occupy was that filling it required doing two contradictory things at once: spending like a brand and costing like a commodity producer. Most companies that tried ended up doing one well and the other badly — either a cheap shoe nobody aspired to, or an aspirational shoe nobody could afford.
Campus was launched into that gap around 2005–2006, positioned deliberately as a sports and athleisure brand rather than as another value shoe line.4 The word "activewear" in the eventual corporate name is not accidental — it signalled a category ambition that the price point did not obviously support. That was the strategic bet: sell at unbranded-adjacent prices, but market like a branded player, and make the arithmetic work by owning the cost structure rather than the pricing power.
This is worth sitting with, because it is the founding trade-off of the company and it has never been renegotiated. A brand that wins on desire can raise prices when input costs rise. A brand that wins on value can only raise prices as fast as its competitors do, and it protects margin by manufacturing more cheaply than they can. Campus chose the second path. Every subsequent decision — the factories, the distribution depth, the utilisation obsession — flows from it, and so does every subsequent vulnerability.
There was also an inheritance in the product mix that persists to this day, and it is worth flagging early because it recurs in the 2026 numbers. Action had been strong in school shoes — the black lace-ups and white canvas that every Indian child needs and every Indian parent replaces annually. School footwear is a wonderful business in one respect: demand is compulsory, seasonal and predictable. It is a difficult business in every other respect: the buyer is a cost-minimising parent, the product is a specification rather than an aspiration, and brand loyalty is close to zero. Campus inherited both the competence and the constraint. When we get to the June 2026 quarter, in which school shoes carried a disproportionate share of volume growth in the same period management was pitching premiumisation, the tension will not be new — it will be forty years old.
The early years were a North India story. Campus grew through the traditional distributor-to-retailer channel across the Hindi belt, where Agarwal's Action-era relationships were an asset that no multinational could replicate quickly. Revenue crossed the ₹100 crore mark in the early 2010s, and the company began the slow, capital-hungry migration from buying finished shoes from third-party units to making them itself.
That migration is the part of the origin story that matters most to a 2026 investor. Outsourcing footwear production in India is easy; there are thousands of units that will take a job order. It is also structurally low-margin, because the job-worker captures a spread and the brand owner has no control over yield, quality consistency, or lead time. Bringing assembly in-house costs capital and management attention, and it converts a variable-cost business into one with fixed costs and operating leverage — which is wonderful when volumes rise and brutal when they fall. Campus made that conversion. Two decades later, both halves of that sentence have been demonstrated in the company's own reported numbers.
The founding-era lesson, then, is not romantic. Campus did not invent a product category or a technology. It identified a price gap, staffed it with distribution muscle inherited from an earlier business, and then spent fifteen years trying to build a cost advantage deep enough to defend a position that anyone could, in principle, attack. Whether that defence holds is the subject of the rest of this story — and the machine that was supposed to provide it got built in the decade after 2010.
III. Building the Machine: Manufacturing, Distribution, and the TPG Era (2011–2021)
There is a moment in the life of most Indian consumer companies when the founder has to decide whether to remain a very good trader or become a manufacturer. The trader's life is asset-light and comfortable. The manufacturer's life involves land, labour law, power tariffs, effluent norms, and the permanent anxiety of a factory running below capacity. Campus chose the factory.
Through the 2010s the company built and scaled owned plants across the northern industrial belt — Haridwar in Uttarakhand and Baddi in Himachal Pradesh among the anchors, both regions long favoured by Indian manufacturers for their tax and logistics profile. The strategic logic was straightforward: if your entire proposition is "a branded shoe at an unbranded price," then your gross margin is manufactured, not marketed. You do not earn it by charging more; you earn it by spending less per pair than the person trying to undercut you.
By FY26 that machine had grown to an annual assembly capacity of about 30.7 million pairs, running at roughly 85% utilisation, plus a separate and deliberately smaller capacity in uppers — the stitched fabric-and-synthetic top half of a shoe, which is the most labour-intensive component and the piece most companies still buy in.5 The gap between those two numbers is the tell. Campus assembles far more pairs than it makes uppers for, which means a meaningful share of its cost base still sits with outside suppliers. The vertical integration is real but partial, and management has been spending money to close that gap — which we'll come to.
It is worth pausing on what "making a shoe" actually involves, because the distinction between the two capacity numbers is the single most important operational fact in this company and it is easy to skate past. A modern sports shoe is essentially two manufactured objects joined together. The sole — the moulded rubber or EVA foam bottom — is a chemistry-and-machinery problem: you buy compound, you heat it, you press it in a die, and the process is capital-intensive but not especially labour-intensive. The upper — the stitched, printed, laminated fabric-and-synthetic shell that wraps the foot — is the opposite. It is dozens of cut pieces joined by human beings at sewing machines, and it is where the labour cost of a shoe concentrates. Assembly is the final step, bonding the two under heat and pressure and finishing the pair.
Most Indian branded players own assembly and buy uppers, because uppers mean managing a large, skilled, unionised workforce with all the labour-law exposure that entails. Campus's decision to build owned upper capacity is therefore the deliberate choice to take on the hardest and least pleasant part of the process — and it is the part where the cost advantage, if it exists, actually gets created. As of the 2025 capacity disclosures, the company operated roughly 8.4 million pairs of upper capacity against 30.7 million pairs of assembly, running at approximately 80% and 75% utilisation respectively.20 The gap between those two figures is, quite literally, the size of the moat still under construction.
The pivot from push to pull
Manufacturing solves cost. It does not solve desire. In 2015 Campus signed the Bollywood actor Varun Dhawan as its face, and the marketing posture shifted from trade-push — persuading a distributor to stock you — toward brand-pull, persuading a consumer to ask for you by name.
The distribution build-out ran alongside it: hundreds of distributors feeding tens of thousands of multi-brand retail counters across small-town India, in districts where a global brand has no store and no reason to build one. This is the least glamorous and possibly the most durable asset Campus owns. A direct-to-consumer challenger can buy Instagram reach in a weekend; it cannot conjure a shoe onto a shelf in a district town in Bihar without either a distributor network or a decade of patience. As of the June 2026 quarter, Campus reported presence across 28 states, more than 850 districts, over 31,000 retail touchpoints, more than 2,350 large-format store counters, and over 260 distributors, supported by an internal sales force of more than 200 people.6
Note that distributor number. It is smaller than the count the company carried around the time of listing, and that is not decay — it is design. As Campus has shifted weight toward its own stores and online marketplaces, it has needed fewer, larger trade partners. But it also means the "distributor moat" is a shrinking asset in relative terms even as the touchpoint count grows.
Enter the private equity firm
In 2017, TPG Growth invested approximately ₹268 crore into the business.4 Later, QRG Enterprises — the investment vehicle associated with the promoter family behind Havells India — also took a position, and both appeared as selling shareholders when the company listed.7
What growth-stage private equity reliably delivers to an Indian family business is process: audited controls, a real CFO function, board discipline, an ESOP structure, MIS that a public-market analyst can interrogate. What it also reliably delivers is a clock. The fund has a life; the investment needs an exit; and the exit is usually an IPO. Those two deliverables — professionalisation and a countdown — arrive as a package, and it is a mistake to credit the first while ignoring the second when interpreting what happened in 2022.
The brand investment is not free, and it recurs. In FY26 Campus spent ₹162.7 crore on advertising and sales promotion — 9.2% of revenue, up 20.2% year on year.5 For a company generating a 17.5% EBITDA margin, that means brand spending consumes more than a third of what would otherwise be operating profit. This is the arithmetic reality of the pull model in a value segment: the brand must be continuously re-purchased with media money, because there is no switching cost holding the customer in place between purchases. It is closer to maintenance expenditure than to investment, and any model that assumes advertising can be dialled back to expand margin is misreading the business.
The COVID accelerant
Then came the pandemic, and with it the single largest demand shock in favour of Campus's exact product. Offices closed, formal footwear collapsed, and hundreds of millions of Indians spent two years in sneakers. Campus's revenue moved from ₹711 crore in FY21 to ₹1,194 crore in FY22 — a 68% jump — while profit after tax went from ₹27 crore to ₹109 crore.2 That is not organic compounding; that is a category reflating violently after a year of suppression, on top of a company that had built the capacity to catch it.
Around this period Campus also began publicising a market-share figure that became central to the IPO narrative: a leading position, on the order of 17%, in India's "scaled" sports and athleisure footwear market. That framing deserves a flag rather than a footnote of admiration. "Scaled" was a qualifier defined within the offer documents' commissioned industry research, not an independently audited category boundary.8 Redraw the boundary to include the unorganised sector, or to include global brands' India volumes, and the share number moves. This is not an accusation of dishonesty — every consumer company defines its addressable market flatteringly — but an investor who anchored on "17% share and rising" was anchoring on a definition, not a measurement.
Finally, the leadership shape that carries into the public era took form. In December 2021 Nikhil Aggarwal, the founder's son, became Chief Executive Officer, with Hari Krishan Agarwal as chairman. A founder-and-heir operating duo, a professionalised back office, a factory base running hot, and a category tailwind that felt structural. It was, in every visible respect, the perfect moment to sell shares. And that is precisely what happened next.
IV. The IPO and the Multiple That Couldn't Hold (2022)
In late April 2022, Campus Activewear opened its initial public offering at a price band topping out at ₹292 per share. Institutional and retail investors piled in; the book was subscribed roughly 51.75 times.9 The issue raised ₹1,399.60 crore.7
Not one rupee of it went to the company.
The offer was structured entirely as an offer for sale. Hari Krishan Agarwal sold 8,000,000 shares for about ₹233.51 crore. Nikhil Aggarwal sold 4,500,000 shares for about ₹131.35 crore. TPG Growth III SF Pte. Ltd. sold 29,100,000 shares for about ₹849.39 crore. QRG Enterprises sold 6,050,000 shares for about ₹176.59 crore.7 No new factory was funded. No debt was retired. No working capital was released into the business. The transaction converted existing shareholders' paper into cash at a price the public market was willing to pay in the spring of 2022.
There is nothing improper about this. Offers for sale are legal, common, and often the only way a private equity holder can exit. But for an investor reading the record afterward, it is a data point with real information content, and it is the first hard evidence we have about how this particular founding family behaves when its own stock is expensive. Both the chairman and the chief executive were direct sellers, not merely passive beneficiaries of a fund's exit. When the people who know the business best convert a portion of their holding to cash at a peak multiple, that is a preference revealed, and it belongs in the credibility file alongside everything they have said since.
The 51.75-times subscription deserves a moment of interpretation rather than admiration. Indian IPO books in 2021–22 were routinely oversubscribed by multiples like this, because the offer sizes were small relative to the pool of institutional and high-net-worth money chasing listing-day gains, and because the leveraged retail bid was effectively a short-term trade rather than an ownership decision. Heavy subscription tells you about the temperature of the primary market. It tells you almost nothing about whether the price was right. Campus is a clean demonstration: a book covered fifty-one times at ₹292 produced a stock that four years later trades below that price.
The listing and the run
The stock listed on May 9, 2022 at a premium of roughly 23% and closed its debut session sharply higher.1 Over the following months it kept climbing, reaching toward ₹640 and a market value in the ₹18,000–19,000 crore range.
Consider what that price was actually asserting. Against FY22 earnings of ₹109 crore, it implied a multiple north of 150 times.2 Multiples that high are not statements about the current year; they are statements about the next decade. They require the buyer to believe that Campus would compound revenue at 20%-plus for many years, expand margin while doing it, and face no serious competitive response. It required, in short, treating a value-segment footwear manufacturer as though it were a consumer-staples franchise with structural pricing power.
It is worth being precise about who was on each side of this trade. The sellers were the people with the deepest possible information about the business: a founder with four decades in the industry, his son running the company, and a growth-equity fund that had sat on the board since 2017. The buyers were institutions and retail investors extrapolating a post-COVID demand surge. That asymmetry is not a scandal — it is the structural condition of every offer for sale — but it is the reason a pure secondary offering should always be read as a price signal from the best-informed participants, not merely as a liquidity event.
The unwind
The market began revising that belief within a year. By August 2, 2023, the shares had fallen below the ₹292 IPO price amid heavy block-deal volume — the mechanical signature of large pre-IPO holders continuing to reduce.10 For anyone who had bought the listing pop, the round trip took fifteen months.
Then came the quarter that defined the company's public life. For the three months ended September 2023, Campus reported revenue of ₹258.7 crore against ₹333.2 crore a year earlier — a decline of over 22%. EBITDA fell 43.6% to ₹24.9 crore, with margin compressing 370 basis points to 9.6% from 13.3%. Profit after tax came in at ₹0.30 crore versus ₹14.5 crore.3 The stock fell about 10% to a new low on the news.3
Credit-rating commentary from the period adds useful texture on how the balance sheet was being read as the demand picture deteriorated: CRISIL's April 2023 rationale on the company was published before the worst of the destocking cycle had landed in the reported numbers, and the agency's subsequent 2024 reaffirmation reflected the working-capital intensity that made the swing so violent.2721 The financial structure was never in question. The earnings structure was.
Management attributed the collapse to weak consumer sentiment and to channel inventory correction — distributors, having over-ordered into the post-COVID boom, simply stopped buying while they worked down what they already held.
That explanation is almost certainly accurate. It is also the most damaging thing that could have been said, because of what it reveals about the business model. Here is the mechanism in plain terms. Campus's factories carry fixed costs — rent, depreciation, a substantial permanent workforce, power. Those costs are absorbed across however many pairs come off the line. When volumes are high, the absorption per pair is small and margins look structural. When distributors pause ordering for a single quarter, production drops, the same fixed costs spread across far fewer pairs, and the margin that looked like a moat evaporates. Ninety-eight percent of a quarter's profit disappeared not because anyone stopped liking Campus shoes, but because of an inventory adjustment two steps removed from the consumer.
That is the difference between a brand with pricing power and a manufacturer with operating leverage. A company with genuine pricing power passes cost through and holds margin in a soft quarter. Campus could not. It absorbed the whole shock in one line of the P&L.
The full-year numbers confirmed it was not a one-quarter aberration: FY24 revenue of ₹1,448 crore was below FY23's ₹1,484 crore, and profit after tax fell from ₹117 crore to ₹89 crore — the first annual decline in the company's public life.2 Two years after listing, the business had gone backwards.
So the question that the rest of this story must answer is a precise one: since 2023, has Campus changed the mechanism that produced that collapse, or has it merely enjoyed a friendlier stretch of the same cycle?
V. Current Strategy & Management: Premiumization as the Second Act (2024–2026)
A. The strategy in management's own words
The fix management arrived at after 2023 has three parts, and they are internally coherent: sell fewer cheap pairs and more expensive ones, sell more of them directly rather than through distributors, and keep building factory capacity so the cost position doesn't erode while doing it.
The premiumisation leg is the most visible. On June 16, 2026 the company launched "Élan by Campus," a neo-casual sub-brand pitched at the space between formal and casual footwear, fronted by the actor Jim Sarbh in a campaign titled "The Most Elegant Man in Town."11 Élan retails between ₹1,899 and ₹2,599 — meaningfully above the company's blended average selling price — and at launch was carried in roughly 100 to 110 Campus-owned stores plus Amazon, Myntra and the company's own website.12 Nikhil Aggarwal framed it as "an important step in our portfolio evolution."11
Alongside it sits a straightforward price action: an approximately 8% increase in maximum retail prices across key categories implemented on April 1, 2026, which the chief executive described on the Q1 call as "a reasonably fair price hike" given input cost pressure.13
The distribution leg has moved further and faster. Direct-to-consumer — company-owned exclusive brand outlets plus online marketplaces and the brand's own site — reached 46.1% of revenue in the June 2026 quarter.6 Over the five years to FY26, the D2C channel compounded at roughly 36.9% annually against 11.4% for the traditional trade channel.5 In the fourth quarter of FY26, D2C touched 48.3% of revenue against 44.8% a year earlier.5
Why does this matter beyond the optics of a modern-sounding channel mix? Two reasons, one good and one uncomfortable. The good one: selling directly captures the distributor's and retailer's margin, and it puts Campus closer to demand signal, which is exactly the information it lacked in 2023 when it was producing into a channel that had stopped selling through. The uncomfortable one: online marketplaces are not a moat. They are a rented shelf on which every competitor also sits, where the consumer sees price comparisons instantly, and where the platform sets the terms. Shifting from a channel you control poorly to a channel someone else controls is a real improvement in working capital and information, but it is not the same as building brand power.
The recovery, and what's actually in it
The headline arc is genuinely good. FY26 revenue rose 11.4% to ₹1,774 crore; EBITDA rose 21.9% to ₹314.7 crore; the EBITDA margin expanded 145 basis points to 17.5%; gross margin improved 120 basis points to 53.5%; and profit after tax rose 23.8% to ₹150.1 crore.5 The fourth quarter was stronger still — revenue up 12.3% to ₹455.6 crore, profit up 25.8% to ₹44.1 crore, EBITDA margin of 19.2%.14 Return on capital employed came in around 22.4% and return on equity around 18.1%.5
But look underneath the revenue line and the composition is the story. Volume for FY26 was 25.97 million pairs, up only 4.2%. Average selling price rose 6.9% to ₹683.5 In other words, roughly 60% of the year's growth came from price and mix, not from selling more shoes. That is exactly what a premiumisation strategy is supposed to look like — and it is also exactly what a business with weak volume momentum looks like. The two are indistinguishable from a single year of data, which is why the volume line deserves as much attention as the ASP line.
There is a harder number still. The company's own investor materials place India's sports-and-athleisure footwear category on a growth path of roughly 21.6% annually, against Campus's 11.4% revenue growth in FY26.5 If both figures are right, the self-described category leader grew at roughly half the rate of its category. A firm gaining share in a growing market grows faster than the market. Campus, on its own numbers, did the opposite. That single comparison does more damage to the "structural share gainer" thesis than any competitor's press release could, and it comes from the company's own presentation.
The June 2026 quarter, discounted honestly
The most recent reported quarter looks like continuation: revenue up 12.2% to ₹385.2 crore, volume up 11.7% to 5.71 million pairs, EBITDA up 13.2% to ₹62.7 crore at a 15.9% margin, and profit after tax up 17.7% to ₹26.1 crore.615
Management, to its credit, volunteered the discounts rather than waiting to be asked. On the earnings call the team identified two distinct one-off effects: an accounting change relating to how sales through Flipkart and Myntra are recognised following Walmart's restructuring of those entities, worth roughly a 2.5% headwind to reported revenue; and the transition of the school-shoe business out of a distributor-invoiced-price model into a direct stock model, worth roughly 2% of ASP dilution.13 Together, four to five percentage points of noise on a twelve-percent growth print.
There was a third item they were equally candid about, and it cuts the other way on quality rather than magnitude. School-shoe sales grew about 50% year on year and contributed roughly 40% of the quarter's volume growth — and management stated plainly that this is seasonal and would normalise from the second quarter.13 School shoes are the least premium, least brand-differentiated, most price-competitive product Campus sells. A quarter whose volume growth is heavily carried by school shoes, in the same period the company is telling investors that premiumisation is the strategy, is a quarter whose composition contradicts its narrative.
The market appeared to reach a similar conclusion: the shares fell about 3.4% on the day, trading near a 52-week low.13
B. Management credibility — testing the claims against the record
Nikhil Aggarwal is a Purdue-educated second-generation operator who took the chief executive role in December 2021, months before the listing, and has therefore run the company through exactly one full cycle: the boom he inherited, the collapse he presided over, and the recovery he has managed. His father remains chairman. Together with family entities they controlled 72.08% of the equity as of June 2026.2 That is a very high level of alignment by ownership, and it argues strongly against the kind of short-horizon extraction that plagues professionally-managed companies with scattered shareholder bases.
It does not, however, argue that the family will always act in the interest of minority shareholders — and the record contains two specific tests worth weighing.
Test one: how they behaved with their own stock. Already covered — both were sellers at ₹292 into a market that would soon pay ₹640. Weighing it fairly: the amounts sold were a modest fraction of holdings, they retained overwhelming control, and every promoter faces legitimate liquidity needs. But the timing was excellent, and no comparable buying at the 2023–2024 lows has been disclosed. The honest reading is that this is a mild negative on the credibility ledger — not disqualifying, but relevant when management asks investors to look through a soft patch that management itself did not look through with its own capital.
Test two: the August 2026 shareholder vote. This one is recent, first-party, and unambiguous. At the 18th Annual General Meeting on August 20, 2026, held over video conferencing with 220 members participating, shareholders considered a special resolution to modify the Campus Activewear Limited Employee Stock Option Plan 2021 – "Vision Pool."16 It passed, with 84.21% of votes cast in favour. But the category breakdown is where the signal lives: promoters voted unanimously in favour, public non-institutional shareholders voted 99.16% in favour — and public institutional investors voted 91.49% against, with only 8.51% in support. Roughly 87.26% of outstanding shares were polled.17
That is not a rounding error or a proxy-adviser quibble. It is nearly the entire professional shareholder base — the mutual funds and institutions that employ full-time analysts to read the fine print of incentive plans — telling the company that it does not accept how management proposes to compensate insiders. The resolution passed anyway, because 72% promoter ownership makes institutional opposition arithmetically irrelevant on ordinary and special resolutions alike.
This is the sharpest illustration available of the double edge of promoter control. High insider ownership aligns incentives on the upside and makes minority dissent unenforceable on governance. Both things are true simultaneously. An investor cannot bank the first and ignore the second. The specific thing to monitor is recurrence: if future incentive or related-party resolutions draw similar institutional opposition and pass on promoter votes alone, the pattern hardens from an event into a governance characteristic.
Test three: guidance discipline under questioning. The Q1 FY27 call is a useful specimen because it shows management being concrete in one register and evasive in another. On costs, the disclosure was granular: a ₹5 crore hit in the quarter from minimum-wage increases, ₹2.5 crore of additional depreciation from the newly commissioned Paonta Sahib and Pantnagar facilities, and an operational admission that LPG supply constraints had disrupted production of open footwear and sandals.13 That is the sound of a management team that knows its own P&L and is willing to name unflattering line items.
On the forward path they reaffirmed a 17–19% EBITDA margin band for the year with, in the chief executive's words, "100% confidence" of delivering it, alongside mid-double-digit revenue growth, high-single-digit volume growth, ASP growth of 6–7% from the second quarter, and 80 to 120 new stores (with 90 to 100 the realistic expectation).13
But two answers were notably thinner. When analysts pressed on why EBITDA grew 13.2% against revenue growth of 12.2% — barely any operating leverage in a quarter with 11.7% volume growth — the explanation leaned on the one-off items rather than on a decomposition of what is structurally absorbing the leverage. And when asked to size Élan's expected contribution to volume or margin, management declined, calling it too early.
The second refusal is more consequential than it sounds. Élan is not a line extension; it is being presented to investors as a strategic pillar of the premiumisation thesis. A company can reasonably decline to forecast a two-month-old product. But it cannot simultaneously ask the market to underwrite premiumisation as the reason the margin structure is now different and decline to quantify the premium product's contribution. Until that number is disclosed, "premiumisation is working" rests on a blended ASP figure that, as the school-shoe quarter demonstrated, moves for reasons that have nothing to do with premium product at all.
To be fair to the company, one disclosure does support the direction: sneakers accounted for 12–13% of volume in the June quarter, with management guiding to roughly 30% growth in that sub-category for the year.13 That is a real, checkable number and it should be tracked.
Narrative consistency, checked across the cycle
One useful discipline when assessing a management team is to line up what they said at different points in the cycle and see whether the story bends to fit the results.
Campus's account has been reasonably stable in its broad strokes — the company has consistently described itself as a value-to-mid-market sports and athleisure brand pursuing premiumisation and direct-to-consumer expansion — but the emphasis has moved in a way that tracks performance rather than strategy. In FY26, with store economics under scrutiny, the flat exclusive-brand-outlet count was presented as deliberate restraint: prioritise profitability over aggressive retail expansion.5 One quarter into FY27, with demand improving, the same management guided to 90–100 new stores and celebrated the highest quarterly opening count in six or seven quarters.13 Both positions are individually defensible. Presented in sequence, they suggest the store-expansion pace is set by conditions and then narrated as philosophy, which is a common and mildly unflattering pattern.
The margin guidance has been more disciplined. CRISIL's 2024 assessment expected EBITDA margins to sustain in a 15–17% band.21 The company delivered 17.5% for FY26 and now guides to 17–19%.513 Delivering at the top of an external expectation and then raising the band is the correct order of operations, and it is the strongest single piece of evidence that the operational rebuild after 2023 was substantive rather than cosmetic. It is also the reason the "100% confidence" language on the most recent call carries some weight — this team has, on this specific metric, done what it said it would do for two consecutive years.
C. Capital allocation — where the money has actually gone
There is no M&A record to evaluate here. Campus has grown organically since inception; it has not bought a brand, a competitor, or a distribution asset of any size. That cuts both ways. The usual failure mode of a cash-generative Indian consumer company — the vanity acquisition, the unrelated diversification, the "strategic" stake that gets written down four years later — has not occurred, and there are no impairments of prior deals to examine. But the absence of acquisitions also means no diversification: there is no second business to carry the company if the core brand stalls. Campus is a single-product, single-geography bet, and management has not hedged it.
What the cash has funded is capacity. On September 2, 2025 — a year ago to the day — the company executed a transfer deed to acquire roughly 47,000 square metres of land and buildings at Sector-05 of the IIE SIIDCUL industrial area in Pantnagar, Uttarakhand, from Nainipanel Industries, for an all-cash consideration of ₹74.75 crore.1819 That purchase forms part of a broader programme of roughly ₹230 crore of capacity investment through FY28, adding an annualised 7.2 million pairs each of uppers and assembly, funded from internal accruals, with the capacity expected to be operational within about two and a half years of the transaction.20
Read strategically, this is the company doubling down on the founding trade-off. It is spending to make more of the shoe in-house — specifically uppers, the labour-intensive piece it currently buys much of. If the plan lands, unit costs fall and gross margin has structural support. If demand disappoints, the company will have added fixed cost and depreciation into a soft market, which is precisely the configuration that produced the 2023 margin collapse. The ₹2.5 crore of incremental depreciation already showing up from the new plants is the first small instalment of that bill.
A related caution on the retail side: in FY26 management deliberately held the exclusive-brand-outlet count flat at around 300 and redirected capital toward the upper-manufacturing plants, framing it as prioritising profitability over aggressive retail expansion.5 Then in the June 2026 quarter it opened 18 stores — the highest in six or seven quarters — and guided to 90–100 for the year.613 That is not a contradiction, but it is a reversal within twelve months, and it is worth noting because the FY26 discipline was presented as a considered strategic choice rather than a response to conditions.
On the balance sheet, and one caveat
The financial risk here is genuinely low, which usefully narrows the debate. In its July 5, 2024 rationale, CRISIL reaffirmed Campus at CRISIL A+/Stable for long-term facilities and CRISIL A1 for short-term facilities, across ₹303 crore of rated facilities, citing net worth above ₹640 crore, gearing below 0.04 times, and interest coverage of 15.7 times.21 Note for the record: that action was a reaffirmation at Stable, not an upgrade to a positive outlook — a distinction worth keeping straight when the recovery narrative gets summarised second-hand.
CRISIL's stated weaknesses are the ones that matter operationally rather than financially: exposure to a price-sensitive segment where Campus competes with Bata, Liberty and a long tail of unorganised players, and working-capital intensity, with gross current assets of 168 days of which inventory alone accounted for 117 days.21 A hundred and seventeen days of inventory is the numerical expression of the 2023 problem — that much stock sitting in the system is what makes a destocking cycle so violent when it comes. To management's credit, FY26 showed real progress here: net working capital fell from ₹363 crore to ₹308 crore and net inventory from ₹423 crore to ₹388 crore, achieved while volumes grew.5 That is one of the more genuinely encouraging operational facts in the recovery, and it gets less attention than the margin line.
One caveat on the frequently repeated "net-debt-free" characterisation: the March 2026 balance sheet showed reported borrowings of roughly ₹236 crore against total assets of ₹1,491 crore.2 Given lease accounting for an expanding owned-store network, a portion of that line is not conventional funded debt — but the clean phrase "net-debt-free" is doing more work than the reported figures strictly support, and it should be read as shorthand rather than as a balance-sheet fact.
D. Segment and channel mix — what actually drives the P&L
A brief but important clarification, because it disciplines the analysis: Campus is a single-segment business. Essentially all revenue is footwear — sports shoes, sneakers, sandals and flip-flops, school shoes, and now neo-casual. There is no meaningful non-footwear operation, no hidden subsidiary, no technology or licensing arm. There is no optionality subplot to be found here, and an investor should be suspicious of any narrative that invents one.
The segmentation that does matter is by channel, because the channels have genuinely different economics. Trade distribution carries lower gross margin, longer receivables, and — as 2023 proved — the risk of phantom demand piling up as channel inventory. Company-owned stores carry higher gross margin but real fixed costs and lease obligations, and their health is measured by same-store growth, which ran around 20% in the June quarter.13 Online marketplaces carry high growth with platform-dictated terms and heavy discounting pressure. The company's own website is the highest-margin channel of all and grew more than 100% year on year in the June quarter — off a small base that the company has not separately sized.13
Concentration is worth one sentence of caution as well: North India represented roughly 42.8% of fourth-quarter FY26 revenue, with the South contributing under 9%.5 The historical distribution advantage is also a geographic dependency, and the southern market — where regional brands are strong and Campus is not — remains largely unpenetrated. That is either the largest untapped growth vector or a demonstration that the brand does not travel. It has not yet been resolved either way.
Which brings us to the people trying to stop them.
VI. Industry Structure & Competitive Set
Walk into a footwear shop in a Tier-2 Indian city and look at the wall. There will be Campus. Next to it, almost certainly, Sparx — Relaxo's sports-shoe brand, at a similar price. Somewhere nearby, Bata's Power line, occupying the same shelf logic with a ninety-year-old name attached. On the counter, a phone showing a Myntra listing where a Puma shoe is on sale for less than the sticker price of the Campus next to it. And in the corner, unbranded product at half the price, made in a unit an hour's drive away.
That wall is the competitive analysis. Let's formalise it.
The five forces, honestly applied
Buyer power: high. The consumer faces essentially zero switching cost. Nobody's second Campus purchase is locked in by the first. There is no ecosystem, no subscription, no data, no habit beyond preference. This is the single most important structural fact about the business and it is not fixable by marketing spend.
Supplier power: low, but volatile. The key inputs — EVA, rubber, synthetic leather, textiles — are commodities, and Campus is a large enough buyer to negotiate. But several are crude-oil derivatives, which means the cost base carries an oil-price beta the company cannot hedge away. The June 2026 quarter added an unusual reminder that supplier risk isn't only about price: LPG supply constraints physically disrupted production of open footwear.13 Minimum-wage revisions, which cost ₹5 crore in a single quarter, are a second non-negotiable input cost in a labour-intensive process.13
Rivalry: intense and structurally so. More below.
Threat of entry: bifurcated. At the low end, barriers are close to nonexistent — a small unit can produce a passable shoe and sell it locally. At Campus's scale, barriers are genuine: 30 million pairs of annual assembly capacity, 31,000 retail touchpoints and hundreds of company stores cannot be assembled quickly or cheaply. The moat, such as it is, lives entirely in that second category — it protects the scale position, not the product.
Substitutes: rising. Digitally-native D2C brands and quick-commerce private labels compete for exactly Campus's buyer with lower fixed costs and faster design cycles. They lack the distribution reach into small-town India, which is why this remains a threat rather than a crisis — but the marketplace channel, where Campus now earns a growing share of revenue, is precisely where that reach advantage counts for nothing.
The competitors, and what the FY26 scoreboard says
Relaxo Footwears is the closest analogue: promoter-controlled at 71.27%, similarly value-positioned, with Sparx directly attacking Campus's category. FY26 revenue was ₹2,702 crore on profit of ₹179 crore, with an operating margin around 14% and return on capital employed of roughly 11%. Its market capitalisation stood at about ₹8,606 crore at a P/E near 46.4 on September 2, 2026.22
The comparison is illuminating in both directions. Relaxo is materially larger by revenue but generates roughly half of Campus's return on capital, and its sales growth has decelerated sharply. Campus earns better returns on a smaller base and trades at a slightly lower multiple — 43.8 times, against a ₹6,752 crore market capitalisation.2 That is a defensible relative position, and it is evidence that Campus's manufacturing and mix are genuinely better than the nearest peer's. It is also evidence that the entire value-footwear category is being priced at mid-40s multiples on high-single-digit growth, which tells you the market is paying for the India consumption story rather than for any one company's execution.
Bata India shows what happens to an incumbent that owns the shelf but not the momentum. FY26 revenue grew 0.79% to ₹3,515 crore, and profit fell to ₹133.56 crore from ₹328.45 crore, largely on voluntary retirement scheme costs and labour-code obligations.23 Bata's Power brand still competes directly with Campus at the value end. The relevant lesson is not that Bata is weak — it is that heritage, store count and brand recognition in Indian footwear have not prevented a decade of stagnation. Whatever Campus's brand is worth, it should be discounted by that observation.
Metro Brands is a different animal — a premium multi-brand retailer rather than a manufacturer, with FY26 revenue up 14% to ₹2,864 crore and profit up 17% to about ₹415.9 crore.24 Metro earns more profit than Campus and Relaxo combined on comparable revenue, because it is a retailer of other people's premium brands, not a maker of its own cheap ones. That contrast is the clearest available statement of where profit pools sit in Indian footwear, and it should temper enthusiasm about premiumisation-by-manufacturing as a route to Metro-like economics.
Below them sit Liberty Shoes, Paragon and a vast unorganised base. Above them, Puma, Skechers, Adidas and Nike, all of which have spent the past several years attacking downward with India-specific price points and aggressive marketplace discounting — often landing in the ₹2,000–₹3,000 band that Élan now occupies.
What rivalry looks like from the shelf
The reason rivalry in this category is structurally intense, rather than merely currently intense, comes down to a design fact: at the ₹1,000–₹3,000 price point, no manufacturer can build a shoe that is meaningfully better than a competitor's. The materials are the same commodities, the moulding technology is available to anyone with capital, and the design language is downstream of whatever the global brands did two seasons ago. What differentiates one wall from another is availability, shelf presence, the retailer's margin, and whichever face happens to be on the poster.
That means competition in this segment resolves into three levers — price, trade margin, and advertising — all three of which are expenditures rather than assets. Every rupee of advantage has to be re-spent annually. It is a very different competitive situation from, say, a spirits brand or a paint company, where the incumbent's position compounds without proportional reinvestment. When investors describe Campus as having a "consumer moat," this is the specific thing the description gets wrong.
Myth vs. reality: the "no worthy competitor" story
The 2022 listing narrative carried an implicit claim that Campus had a category largely to itself. That claim does not survive the record.
Reporting by The Ken in August 2023 documented that both Bata's Power line and Relaxo's Sparx were already targeting the same value-conscious buyer at the time of listing, and traced how the post-IPO period saw smaller regional and unorganised players regain ground in general trade after the January 2022 GST increase on footwear from 5% to 12% raised compliance costs unevenly across the sector.25 The buyer Campus dominates is not a buyer no one else wants. It is the most contested price band in Indian footwear.
There is a second myth worth puncturing, and it is live right now. In September 2025 the GST Council reduced the rate on footwear priced up to ₹2,500 from 12% to 5%, effective September 22, 2025 — a change that dramatically expanded the low-rate band, which had previously applied only below ₹1,000. Footwear stocks rallied up to 10% on the announcement.26
For Campus, whose entire portfolio sits inside that threshold, this is a real and durable demand tailwind: a seven-percentage-point reduction in the tax wedge on every pair it sells, in a segment where the consumer is acutely price-sensitive. It is also, unambiguously, a sector event. Bata, Metro Brands and Liberty rallied alongside Campus, because the cut applies to their sub-₹2,500 product too.26 Any portion of the FY26 and FY27 recovery attributable to GST should be credited to the GST Council, not to management. Investors extrapolating recent quarters need to separate the policy step-change — which is a one-time repricing, not a compounding engine — from underlying execution.
The quick-commerce question
One newer dynamic deserves its own paragraph because it is genuinely structural rather than cyclical. India's quick-commerce platforms — the ten-to-thirty-minute delivery apps — have moved well beyond groceries into general merchandise, and footwear at the value end is an obvious candidate: the product is compact, non-perishable, needs no fitting for a repeat buyer, and is frequently an impulse purchase. Where those platforms introduce private-label footwear, they compete with an advantage no brand can match — they own the demand surface, the customer data, and the placement algorithm simultaneously.
This is the same disintermediation risk that has played out in packaged consumer goods elsewhere, and its relevance here is specific: Campus's principal defensive asset is physical reach into places where getting a shoe onto a shelf is hard. Quick commerce makes that problem easier for everyone. It does not eliminate the 31,000 touchpoints Campus already has, but it steadily reduces what those touchpoints are worth as a barrier to a well-funded challenger. Nothing in the current numbers shows this damaging Campus yet, and it would be wrong to present a forward-looking risk as a present fact. But it is the most plausible mechanism by which the distribution half of the moat erodes over the next five years, and it should be watched in the trade-channel growth rate, which already compounds at roughly a third the pace of the direct channel.5
What the moat actually is, once narrowed
Strip away the rhetoric and there is something real left. Campus does have an owned-manufacturing cost position at a scale its value-segment competitors mostly lack. It does have the largest branded distribution footprint in the sub-₹3,000 sports and athleisure category, reaching districts that D2C-only challengers cannot economically serve. And its return on capital, at roughly double Relaxo's, is objective evidence that the machine works.
But the 2023 collapse and the subsequent margin volatility bound what that moat can do. It confers a cost advantage, which shows up as superior margin at a given level of utilisation. It does not confer pricing power, which would show up as margin resilience when volumes fall. Those are different things, and the company's own history has now tested the distinction and returned a clear answer.
The calibrated conclusion: the moat claim is not rejected, but it must be narrowed. Campus has a defensible cost-and-reach position within the value segment. It does not have a consumer franchise that protects earnings through a demand cycle. The event that would falsify even the narrowed version is a second destocking-driven margin miss inside the current upcycle — which would show the operating-leverage exposure survives untouched despite the channel-mix shift.
VII. Playbook: What This Company Teaches About Investing in Indian Consumer Brands
Every good business story leaves behind a few transferable lessons. Campus's are unusually clean, because the company ran the full experiment in public over four years.
Lesson one: in the value segment, "branded manufacturer" is a manufacturing business wearing a brand's clothes. The tell is what happens to margin when volume falls. If a company's gross margin is generated in the factory rather than at the price tag, the margin is a function of capacity utilisation, and utilisation is a function of channel behaviour, and channel behaviour is a function of the macro. Campus's EBITDA margin has ranged from roughly 9.6% in a single bad quarter to 19.2% in a good one within three years, on a product mix that barely changed.314 Consumer franchises with genuine pricing power do not do that. Anyone valuing an Indian consumer-adjacent manufacturer should look at trough-quarter margin, not average margin, because the trough is the one that tells you what the business is.
Lesson two: a pure offer-for-sale IPO is information, and it should be priced. When 100% of the proceeds go to selling shareholders and none to the company, three things are simultaneously true: the business did not need capital, the existing owners wanted liquidity, and the price was set at a moment those owners found attractive. None of that is wrongdoing. But it removes the alignment that a primary raise creates — where the company's growth plan and the investor's capital are the same money — and it means the post-listing register is dominated by holders who paid a peak price to people who chose that moment to sell. The structural risk of multiple compression in the following eighteen months is higher, and Campus's own chart is a clean illustration.
Lesson three: separate policy from performance before extrapolating. The GST reduction is the live example. It genuinely improves unit economics across the value segment, and it genuinely showed up in the numbers. But it is a step-change in the tax wedge, not a growth algorithm, and it accrues to every competitor. When a couple of strong quarters arrive alongside a favourable policy change, the correct default is to assume the policy did some of the work until the company demonstrates otherwise — and the demonstration is a quarter of strong performance after the policy has annualised.
Lesson four: promoter ownership is necessary evidence of alignment, and nowhere near sufficient. A 72.08% family stake means the controlling shareholders' wealth rises and falls with the share price, which is a powerful anti-extraction mechanism. It did not stop them from selling into the IPO's price. It did not stop an incentive-plan amendment that 91.49% of institutional shareholders rejected from passing anyway. The lesson is that high insider ownership changes the nature of governance risk rather than eliminating it: the risk stops being agency-cost sloppiness and becomes the risk that minority shareholders have views and no votes.
Lesson five, and the most practical: watch the mix disclosure, not the mix narrative. Every consumer company in India is currently telling investors it is premiumising, because that is the story the market pays for. The way to test it is to demand the number — what percentage of revenue comes from the premium tier, and is it growing faster than the base. Where a company launches a premium product as a strategic pillar and then declines to size it, the appropriate response is not disbelief but patience: hold the claim at the confidence its affirmative evidence supports, which today is a sneaker mix of 12–13% of volume and nothing disclosed for Élan.
Lesson six: read the category growth rate the company itself publishes, and check it against the company's own growth. This is the cheapest analytical trick available and almost nobody does it. Consumer companies commission industry research to size their opportunity, and that research goes into the investor deck because it makes the runway look long. But the same deck reports the company's actual growth. When the two are placed side by side and the company is growing at half the category's rate, the deck has quietly published the strongest available argument against its own thesis. It costs nothing to look, and it is more informative than any competitor comparison because both numbers come from the same source with the same definitions.
Which is a reasonable segue into laying out both sides of the argument in full.
VIII. Bull vs. Bear Case
The bull case
The structural argument. India's per-capita footwear consumption remains low by global standards, and the shift from unbranded to branded product is a genuine multi-decade trend with real economic drivers — rising incomes, urbanisation, organised retail penetration, and e-commerce reach into towns that never had a branded store. Campus's own materials put the sports-and-athleisure share of the total footwear market at roughly 21%, up from about 12% in FY15, with the branded share within that category at roughly 60% against 48% over the same span.5 Both of those trends favour organised players, and Campus is one of the two largest domestic ones in the value tier.
The September 2025 GST reduction sharpens this. It is a durable, multi-year improvement in the affordability of every shoe Campus sells, in the exact band where the unbranded-to-branded conversion happens.
The company-specific argument. Owned assembly capacity of over 30 million pairs, combined with distribution into 850-plus districts, is a combination no D2C entrant can replicate and most value competitors have not matched. The proof is in the returns: roughly 21–22% return on capital employed against Relaxo's 11%, on a comparable product and a comparable customer.222 That gap is the most objective evidence available that the manufacturing-plus-distribution machine is a real advantage rather than a slogan.
The premiumisation bet is showing early, measurable traction: FY26 ASP up 6.9%, an 8% MRP increase absorbed in April 2026 without management reporting consumer resistance, and sneakers already at 12–13% of volume.513 Critically, the price increase came alongside volume growth of 11.7% in the following quarter — price hikes that don't destroy volume are the closest thing to evidence of pricing power this company has produced.6
The balance sheet supports the plan. Minimal gearing and interest coverage above 15 times leave room to fund the ₹230 crore capacity programme from internal accruals without approaching the equity market, and the working-capital improvement in FY26 suggests the 2023 lesson was absorbed operationally, not just rhetorically.521
One further point belongs on the bull side because it is frequently overlooked. The trade channel, for all the attention on its 2023 failure, is still slightly more than half the business and it grew in FY26.5 A company that can grow both a traditional distributor network and a direct channel simultaneously is doing something harder than a pure-D2C brand and something harder than a pure-wholesale one, and the working-capital improvement achieved while running both is genuine operational evidence rather than narrative.
In Helmer's terms, the powers Campus can plausibly claim are cornered resource in a weak form — the distribution network and the depth of trade relationships inherited from four decades in the business — and scale economies, which is the real one: at 30 million pairs, fixed costs per pair are lower than any sub-scale entrant can achieve. Process power is arguable, in the sense that running a large owned footwear plant at 85% utilisation with improving working capital is a competence that takes years to build. What is conspicuously absent is branding power in Helmer's strict sense — the ability to charge more for an identical good — and switching costs, and network economies, none of which exist here in any form.
The KPI that would confirm the bull case: the EBITDA margin holding inside the guided 17–19% band across at least two more quarters without a destocking-driven miss, and Élan plus sneakers disclosed as a specific, non-trivial and growing share of revenue. Management has committed to the first and has so far declined the second.
The bear case
The base rate is the warning. The single most important fact in this analysis is that this business lost roughly 98% of a quarter's profit because distributors paused ordering.3 Nothing in the premiumisation strategy removes that mechanism. A richer mix and a higher ASP change the numerator; they do not change the fact that a factory with fixed costs running below capacity destroys margin. Direct-to-consumer at 46% of revenue genuinely reduces the channel-inventory version of the risk — Campus can now see sell-through on nearly half its business — but it does not touch the underlying operating leverage, and it introduces a new dependency on marketplaces whose economics Campus does not control. The exposure has been narrowed, not eliminated, and the capacity being added through FY28 will increase fixed costs before it increases revenue.
The growth-versus-category problem. By the company's own presentation of the category's growth rate, Campus under-grew its market by roughly ten percentage points in FY26.5 A category leader with a structural moat gains share. The most recent full year shows the opposite. Either the category growth figure is overstated, or the leadership claim is — and both readings are unhelpful to a thesis built on share gains.
Competitive intensity is increasing, not decreasing. Sparx, Power, marketplace private labels and quick-commerce entrants all target the same buyer, the GST relief lifts every one of them by the same seven points, and global brands are pricing downward into the exact ₹1,899–₹2,599 band Élan just entered — against consumers who, at that price, may well prefer a Puma on sale.
The governance signal. A 91.49% institutional vote against the ESOP amendment, passed on promoter votes alone at the August 2026 AGM, is recent, first-party evidence of a trust gap between management and professional shareholders under the same management regime the thesis depends upon.17 One instance is an event. The thing to watch is whether it becomes a pattern.
The disclosure gap. The bull case's central pillar — that premiumisation has structurally reset margin — rests on a number management has declined to provide. Meanwhile the most recent quarter's growth was flattered by four to five percentage points of accounting and transition effects, and its volume growth was disproportionately carried by school shoes, which management itself described as seasonal and non-repeating.13 A management team that discloses its own one-offs deserves credit for candour; a thesis that requires those one-offs to be ignored deserves scepticism.
What a short-seller or activist would press on. Three things, none of them exotic. First, valuation versus growth: roughly 44 times earnings for a business guiding to mid-double-digit revenue growth and high-single-digit volume growth, in a category where the nearest peer trades at a similar multiple with half the returns and slower growth — the multiple assumes an acceleration that management is not guiding to. Second, working capital: inventory at 117 days of gross current assets in FY24 is still substantial even after the FY26 improvement, and inventory-heavy fashion-adjacent businesses are where write-downs hide.21 Third, incentive design: after an institutional vote of that magnitude, every future ESOP grant, dilution step and related-party arrangement will be read as a test of whether the board heard anything.
The event that would falsify "premiumisation is working": Élan and sneaker mix eventually disclosed and shown to be immaterial after two or three more quarters, or a single quarter of destocking-driven margin compression inside what is supposed to be an upcycle. Either would collapse the second act back into the first.
The risk radar, restricted to what is actually material
Three exposures matter here and the rest are noise. Input-cost and energy risk is live and mechanical: EVA and synthetic-rubber compounds are crude-linked, LPG availability has already disrupted a production line, and statutory minimum-wage revisions hit a labour-intensive process directly — together these landed real costs in a single recent quarter.13 Demand-cycle risk is the one the company has already failed once, and it is amplified rather than reduced by the capacity being added through FY28, because new plants convert into depreciation and fixed labour before they convert into pairs sold. Execution risk in the premium transition is the third: Élan places Campus, for the first time, in a price band where global brands routinely discount into ₹2,000–₹3,000 on marketplaces, and where the Campus name carries value associations that may work against it.
Two commonly cited risks do not belong on this list, and saying so is part of the analysis. Refinancing and cost-of-capital risk is negligible given the gearing and coverage profile. And technology disruption, in the sense that dominates most 2026 investment discussions, has no obvious transmission mechanism into a business that moulds foam and stitches fabric — the relevant technological threat here is not artificial intelligence but the distribution shift already discussed.
The three KPIs that matter
Everything above compresses into a very short watch list. Track these and you will know what is happening at Campus before the narrative catches up.
-
Volume growth in pairs, reported separately from ASP. This is the honest measure of demand. A company can manufacture revenue growth from price and mix for a year or two; it cannot manufacture pairs. If volume growth persistently runs at or below the high-single-digit guidance while ASP carries the revenue line, the business is optimising a shrinking base rather than growing.
-
EBITDA margin against the guided 17–19% band, quarter by quarter. This is the direct test of whether the operating-leverage vulnerability has actually changed. Management has staked its credibility on this range with unusually absolute language. Holding it through a soft quarter would be the strongest evidence available that 2023 cannot repeat. Missing it would be close to dispositive the other way.
-
Premium mix as a disclosed percentage of revenue — Élan plus sneakers. Currently only the sneaker volume share is available. The moment the company discloses a revenue-level premium mix, the central claim of the second act becomes checkable. Until then, treat the premiumisation thesis as plausible and unproven, which is exactly what the affirmative evidence supports.
IX. Epilogue
There is a particular kind of Indian market story that Campus Activewear now belongs to. A real business, run by people who understand it, gets discovered at the top of a demand cycle. The listing is structured so that the insiders and the fund sell rather than the company raise. The multiple gets set by the marginal buyer's most optimistic assumption. Then the cycle turns, the multiple compresses faster than the earnings recover, and four years later the business is objectively larger and better run while the shareholders who funded the discovery are underwater.
The scorecard, kept honestly, has entries on both sides. Campus is a genuinely good manufacturer — better returns on capital than its closest peer, a distribution position that took forty years to build and cannot be bought, a working-capital discipline that visibly improved after being tested, and a management team that names its own one-off items on earnings calls rather than hiding them in a footnote. Those are not small things, and an investor who dismisses the company as a commodity shoemaker is not reading the numbers.
But the 2022 valuation asserted something more than "good manufacturer." It asserted a structural consumer franchise, and the record since has not supported that. The business proved it could lose almost all of a quarter's profit to an inventory adjustment. It grew, on its own category data, at roughly half the rate of the market it claims to lead. Its most recent good quarter was carried in meaningful part by school shoes and accounting transitions. Its premium second act is two months old and unquantified. And the institutional shareholders who own the float voted overwhelmingly against how management proposed to pay itself, and were outvoted by a family that controls seventy-two percent of the company.
There is a broader observation buried in this round trip, and it applies well beyond one shoemaker. India's public markets since 2021 have repeatedly priced consumer-adjacent manufacturers using the valuation grammar of consumer franchises — the mid-to-high forties multiples that make sense for a business with genuine pricing power, applied to businesses whose margins are produced on a factory floor and are therefore hostage to utilisation. The two are not the same animal, and the market has an expensive habit of discovering the difference one quarter at a time. The tell is almost always visible in advance, and it is always the same: look at what happens to the margin in the worst quarter of the last five years. If it halves, the moat is operational leverage wearing a brand's coat.
The most useful way to hold Campus, analytically, is as a narrowed claim rather than a rejected one. It is a cost-and-reach advantage inside a contested price band, currently enjoying a favourable policy tailwind and a genuine mix improvement, run by owners with enormous skin in the game and an imperfect record of treating minority holders as partners. That is a specific, testable proposition — a good deal more specific than the story sold in 2022.
None of this makes the outcome knowable. It makes it observable, which is a more useful property. The three metrics that decide this story — pairs sold, margin against the guided band, and a disclosed premium mix — are all reported quarterly, in public, by a company that has recently shown a willingness to flag its own one-off items. An investor does not need a view on Indian consumption or a forecast of crude prices to follow this. They need to read four earnings releases and see whether the second act is a strategy or a slogan.
What it is not, yet, is proven. The premiumisation bet has not been sized. The margin band has not been defended through a soft quarter. The GST tailwind has not annualised. Every one of those tests arrives over the next four to six quarters, and each one is observable from the outside without any special access. The second act has a plausible script and a management team that has been more candid since 2023 than it was before. The performance itself has not happened yet.
References
-
Campus Activewear stock makes stellar market debut, lists at 23% premium — Business Today, 2022-05-09 ↩↩
-
Campus Activewear Ltd — financials and shareholding — Screener.in ↩↩↩↩↩↩↩↩↩
-
Campus Activewear tanks 10%, hits new low on weak Q2 results — Business Standard, 2023-11-10 ↩↩↩↩↩
-
Campus Activewear Limited — Red Herring Prospectus (2022) ↩↩↩
-
Campus Activewear FY26 results: profit +24%, revenue +11% — The Daily Datum, 2026-06-17 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Campus Activewear Q1 FY27 investor presentation: 12% revenue growth, Élan launch — Investing.com, 2026 ↩↩↩↩↩
-
Campus Activewear IPO subscribed 51.75 times — Business Standard, 2022-04-28 ↩
-
Campus Activewear tumbles below IPO price amid huge block deals — Business Standard, 2023-08-02 ↩
-
Jim Sarbh fronts Campus Activewear's new Élan campaign — Afaqs, 2026-06-16 ↩↩
-
Campus Activewear Q1 FY27 revenue rises 12.2% YoY to ₹385.2 crore — Apparel Resources, 2026 ↩
-
Earnings call transcript: Campus Activewear Q1 FY2027 — Investing.com, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Campus Activewear Q4 PAT climbs 26% YoY to ₹44 crore — Business Standard, 2026-05-25 ↩↩
-
Campus Activewear 18th AGM proceedings, 20 August 2026 — Tulsian AI ↩
-
Campus Activewear passes all AGM resolutions despite ESOP opposition — ScanX, 2026-08 ↩↩
-
Campus Activewear acquires land and building for capacity expansion — Projects Today ↩
-
Campus Activewear acquires property in Uttarakhand for ₹75 crore to expand manufacturing capacity — Capital Market, 2025-09 ↩
-
Campus Activewear to invest ₹230 crore to expand manufacturing capacity — Moneycontrol via TradingView, 2025-09 ↩↩
-
CRISIL Ratings rationale — Campus Activewear Limited, 2024-07-05 ↩↩↩↩↩↩
-
Relaxo Footwears Ltd — financials and shareholding — Screener.in ↩↩
-
Bata India FY26 revenue up 0.79% to ₹3,515 crore; profit down 59% — Whalesbook, 2026 ↩
-
Metro Brands FY26 PAT rises 17.3% to ₹416 crore — ScanX, 2026 ↩
-
Campus shoes beat Puma and wowed investors. Then came the troubles — The Ken, 2023-08 ↩
-
Footwear stocks Bata, Campus, Metro Brands rally up to 10% on GST cut — Business Standard, 2025-09-04 ↩↩
-
CRISIL Ratings rationale — Campus Activewear Limited, 2023-04-10 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube