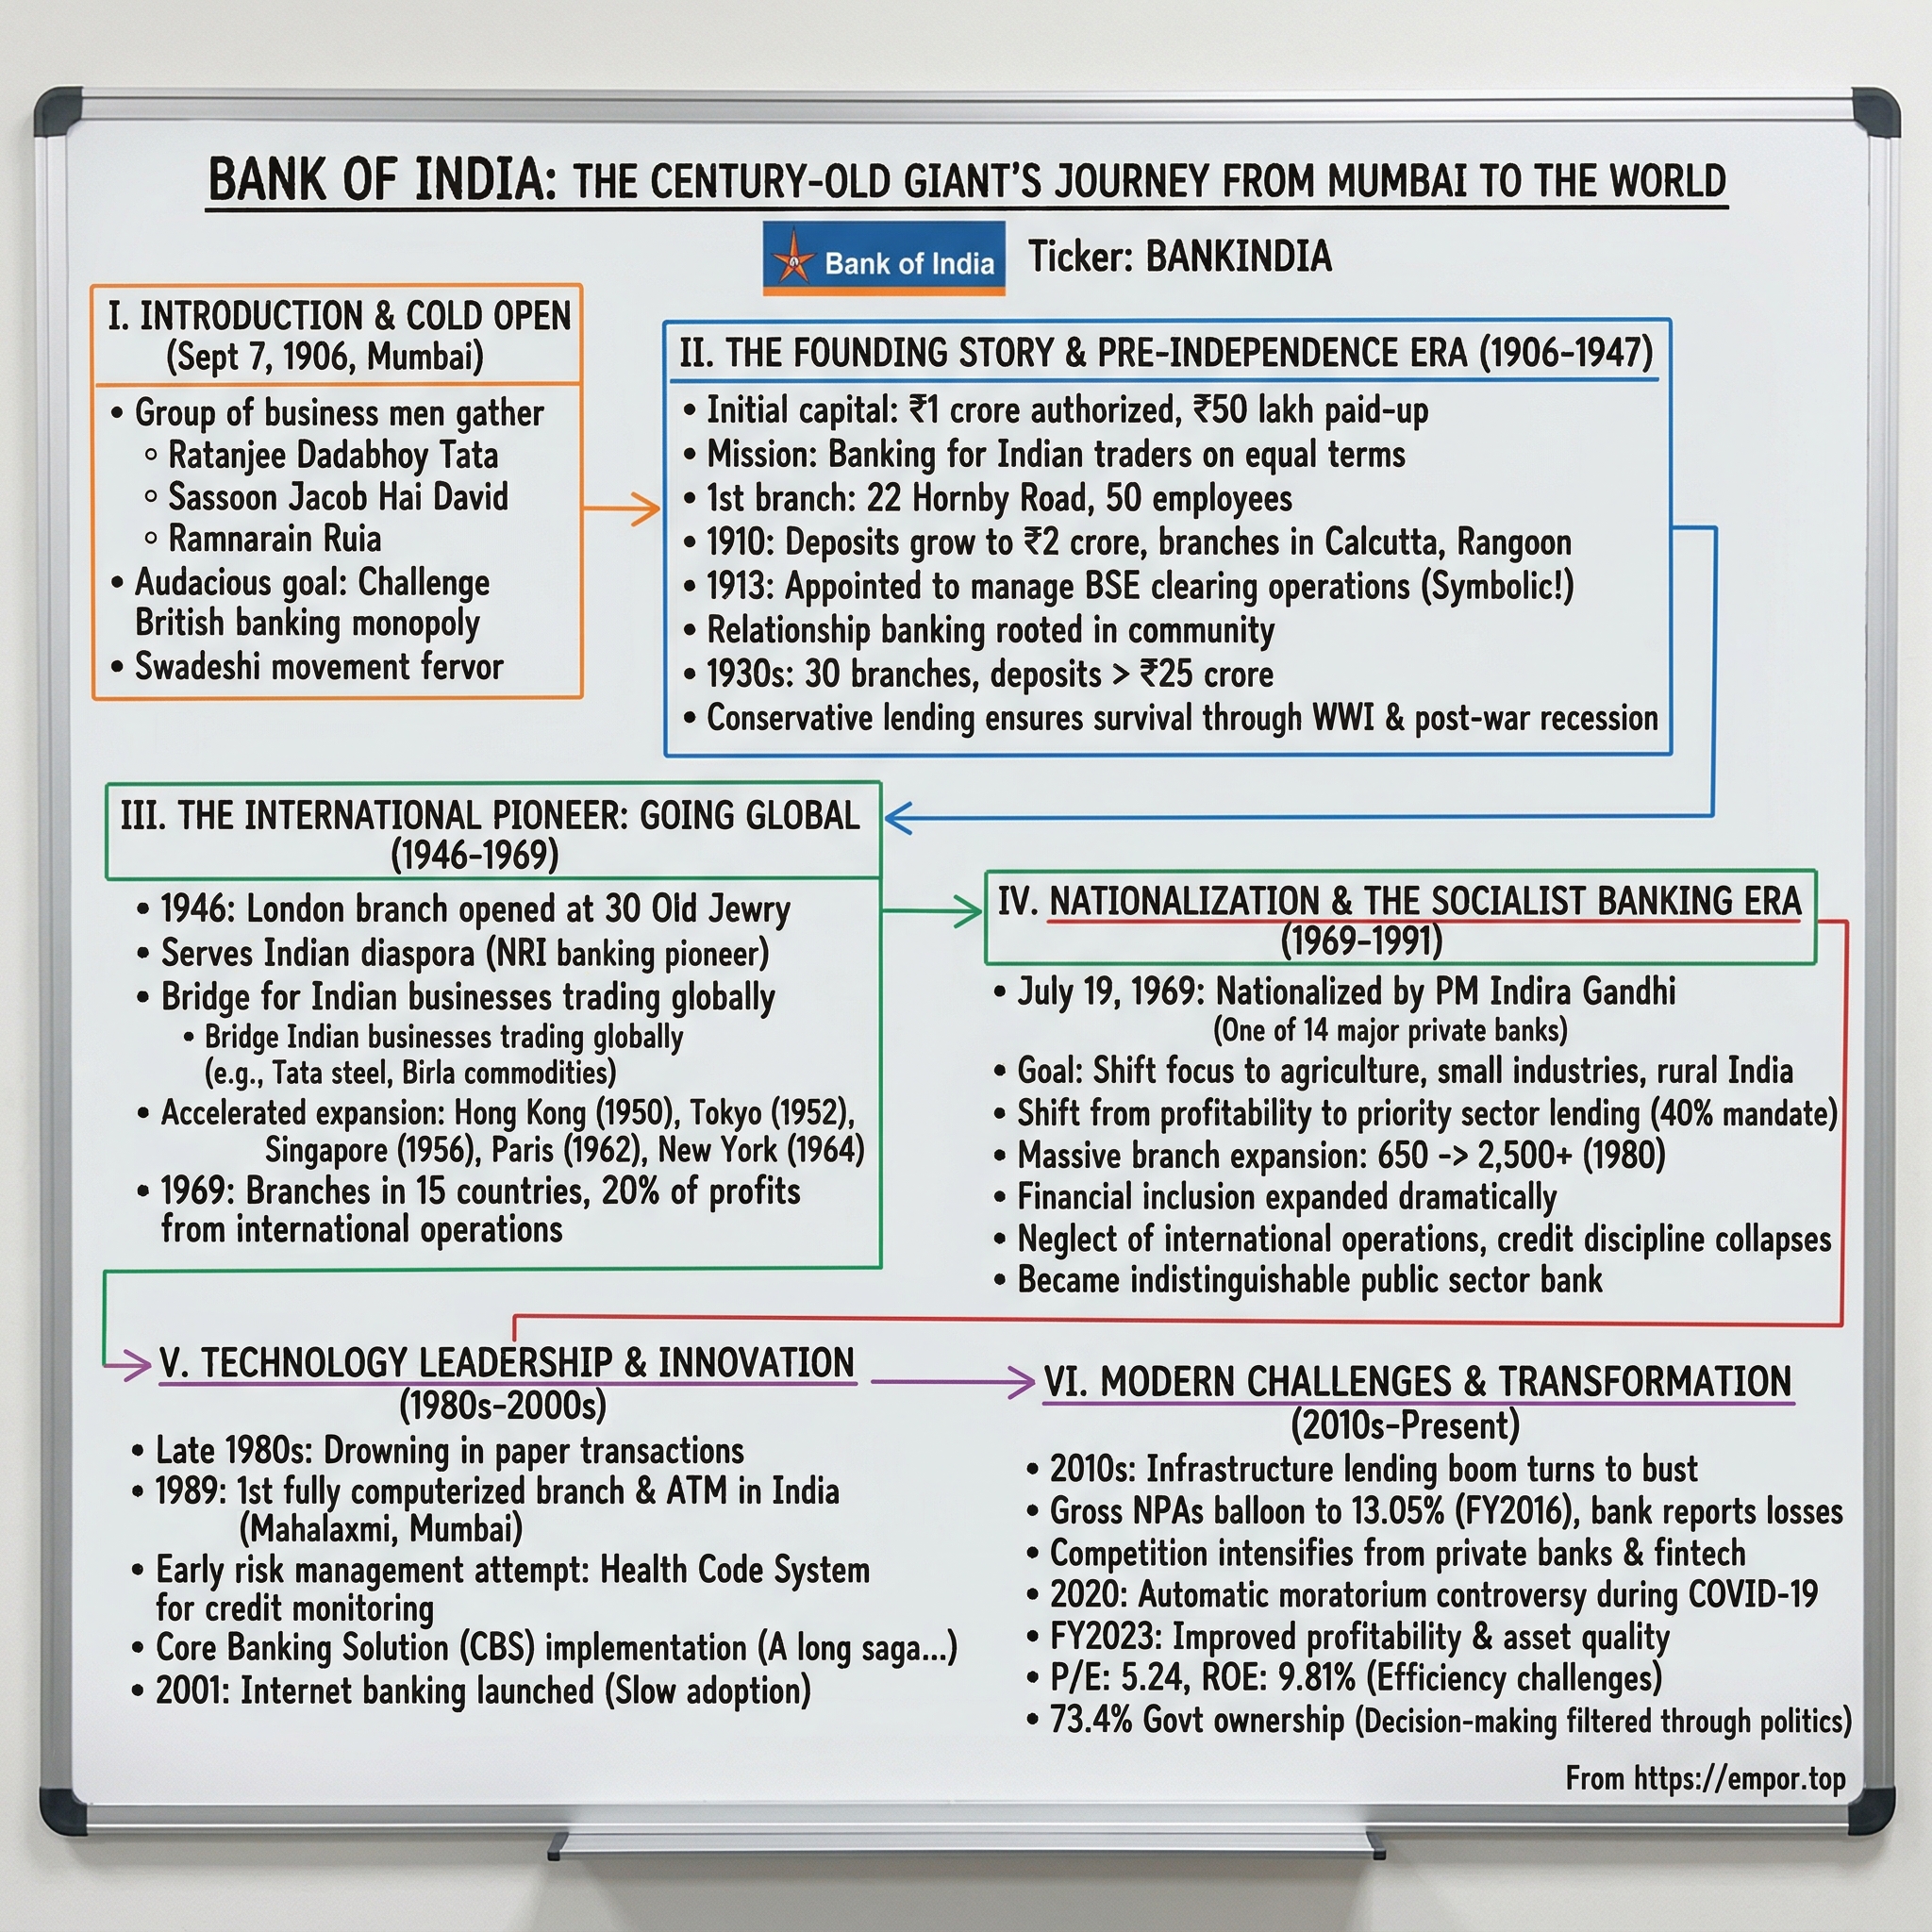
Bank of India: The Century-Old Giant's Journey from Mumbai to the World
I. Introduction & Cold Open
On a December morning in 2017, the senior management of one of India's oldest banks received a letter from the Reserve Bank of India that no bank executive wants to receive. Dated December 19, it placed Bank of India under the Prompt Corrective Action framework — regulatory quarantine — citing high net non-performing assets, insufficient Common Equity Tier 1 capital, and negative return on assets for two consecutive years.[^1] The stock fell roughly five per cent on the news.1 Founded in 1906 as the first Indian bank to establish an overseas footprint and the institution that once ran the Bombay Stock Exchange's clearing house, Bank of India was now on the regulator's watchlist alongside eleven other lenders, forbidden from expanding its riskiest loan portfolio and barred from opening new branches.
Fast-forward to August 2026. The same institution reported a June-quarter net profit of ₹3,068 crore, up thirty-six per cent year on year, with a gross non-performing asset ratio of 1.81 per cent and a provision coverage ratio of 93.83 per cent.2 Its global business crossed ₹17.55 lakh crore. Its capital adequacy stood at 18.69 per cent, backed by a core equity capital ratio of 15.97 per cent — roughly double the regulatory floor.2 For the full financial year ended March 2026, net profit reached ₹10,527 crore, a fourteen per cent increase over the prior year and the first time the bank had crossed the ₹10,000 crore mark in its 120-year history.3
The central question is not whether Bank of India recovered — it plainly did — but what that recovery is worth and whether it is repeatable.
Here lies the primary valuation discrepancy. As of the close on August 31, 2026, the shares traded at ₹142.60, giving the bank a market capitalisation of roughly ₹64,500 crore — about 0.71 times book value and under six times trailing earnings.4 Those valuation multiples suggest the market remains skeptical that the bank has permanently solved its structural problems. Private-sector peers with comparable asset quality trade at two to three times book value. Investors appear to be pricing in a familiar cyclical pattern: Indian public-sector banks clean up balance sheets, generate strong earnings at the bottom of the credit cycle, and then surrender those gains in the subsequent downturn. The burden of proof sits squarely with management.
A second, quieter vulnerability sits within the bank's funding structure. The central proof point of its turnaround — a strong low-cost deposit franchise — has deteriorated. The current and savings account ratio fell from 39.88 per cent in June 2025 to 36.68 per cent in June 2026.25 That represents a loss of more than three percentage points of the bank's cheapest funding source in twelve months. On the latest earnings call, management characterized this shift as deliberate — an explanation that warrants rigorous examination, given how frequently corporate leaders attribute deposit mix shifts to strategy rather than competitive pressure.
The institution's history traces a complete arc: its founding by a syndicate of Bombay merchant princes during the Swadeshi movement; its 1946 decision to open a branch in London before Indian independence; its 1969 nationalisation, which converted a commercial enterprise into an instrument of state development policy; and the subsequent infrastructure lending boom that ended in a bad-loan catastrophe, regulatory quarantine, and a grinding cleanup. Today, under Managing Director and Chief Executive Officer Rajneesh Karnatak, Bank of India has pivoted toward retail, agriculture, and small business lending. Yet the underlying question remains whether a bank whose majority shareholder holds 73.38 per cent of equity and appoints its chief executive to a three-year renewable term can compound capital on par with its private-sector rivals.4
Evaluating the bank requires testing each load-bearing claim against the disconfirming evidence in its own 120-year history — a timeline long enough to challenge most simple recovery narratives. The story begins with five founders, a rented building in Mumbai's Fort district, and a nationalist boycott.
 Subscribe on LinkedIn
II. The Swadeshi Spark & Founders' Blueprint (1906–1946)
Picture Bombay in the autumn of 1906. Lord Curzon's partition of Bengal the previous year had lit a fire under Indian nationalism, and the Swadeshi movement had turned economic self-reliance into a moral cause. Indian merchants who financed the cotton trade found themselves in an absurd position: they generated the trade, but the bills, the foreign exchange, and the credit lines that made it possible were controlled almost entirely by British exchange banks. An Indian trader shipping cotton to Liverpool borrowed from a British bank, insured with a British firm, and settled through a British clearing system. The margin left over was thin, and the humiliation was thick.
On September 7, 1906, a group of Bombay's wealthiest businessmen incorporated Bank of India to change that arithmetic.6 The lead promoter and first chairman was Sir Sassoon Jacob David, scion of the Baghdadi Jewish trading dynasty that had built one of the great commercial fortunes of the Indian Ocean.6 Around him sat Sir Cowasji Jehangir, of the Parsi industrial establishment; Ratanji Dadabhoy Tata, a founding partner of what became the Tata group; and Gordhandas Khatau, of the Gujarati mill-owning families.6 The bank was incorporated under Act VI of 1882 with an authorised capital of ₹1 crore divided into 100,000 shares of ₹100 each; 55,000 shares were placed privately and 45,000 offered to the public in October, and the doors opened for business on November 1, 1906.6 It operated from the Oriental Building on Esplanade Road in Fort — a building that later housed an American Express office — with a paid-up capital of ₹50 lakh and about fifty employees.
What is striking about that founding syndicate is what it was not. It was not a nationalist political project dressed up as a bank. Sassoon David and Cowasji Jehangir were knights of the Empire, deeply enmeshed in the colonial commercial order. What they wanted was not to expel British capital but to capture the fee pool it was earning off Indian trade. The Swadeshi moment gave them customer sentiment and political cover, but commercial logic was the actual engine. That distinction matters because it explains the bank's underwriting culture for its first six decades: conservative, trade-financed, collateralised by goods in transit, and allergic to speculative lending. These were merchants who understood that a bank's liability side is a confidence business.
The most consequential early move came fifteen years in. On February 2, 1921, Bank of India began operating the clearing house for the Bombay Stock Exchange under an agreement with the exchange.7 In modern terms, the bank had become market infrastructure. Every broker settling a trade on India's premier equity market moved money through Bank of India's books. That generated float — low-cost balance-sheet cash — and real-time intelligence on solvency across Bombay. It was the kind of structural position that could compound into an unassailable franchise, though the bank ultimately failed to convert it into a lasting monopoly.
Consider the historical test that this era demands. The comfortable story about Bank of India's early decades is that Swadeshi identity gave it a durable deposit moat — that Indian savers, out of patriotic preference, would fund an Indian bank more cheaply and more loyally than a British one. It is a claim worth testing, because if true, some version of it might still operate today in the bank's regional town franchise.
The historical record does not support it. India's banking system suffered repeated failure waves in the first half of the twentieth century — the crisis of 1913 that took down a string of Swadeshi-era banks, followed by the distress of the 1920s and 1930s. In each episode, depositor behaviour followed solvency, not sentiment. When savers grew anxious, money moved toward the Presidency banks and their successor, the Imperial Bank of India, precisely because they were perceived as safer, British-adjacent, and quasi-official. Patriotism served as a customer-acquisition narrative during expansions but offered little protection in a panic.
The conclusion is that this claim is rejected in its strong form and survives only in a narrower version: the founding merchants' conservatism — high liquid asset ratios, trade-collateralised lending, no maturity mismatches — is what carried the bank through interwar failures, not its brand name. That distinction remains directly relevant to the 2026 investment thesis. Arguments asserting that Bank of India's deposit franchise is naturally protected by historical trust trace back to this same origin. Yet the historical record demonstrates that trust follows perceived solvency, and perceived solvency in an Indian public-sector bank today is primarily a function of sovereign backing — a reality that the nationalisation era would establish far more forcefully than any brand heritage could.
By the mid-1940s, the bank possessed a domestic branch network, a clearing-house franchise, and a trade-finance book. What it did not yet have was the international footprint that would define its identity for the next eighty years. That was about to change in a bombed-out, post-war London.
III. Going Global Before the Nation: London 1946 & Overseas DNA (1946–1969)
In 1946, London was a challenging environment for a new commercial venture. The city remained scarred from the Blitz, Britain faced severe financial distress while negotiating an emergency American loan, and sterling operated under strict exchange controls. Meanwhile, India was in the final, turbulent months leading to independence and partition — a nation not yet fully established as a sovereign state.
That year, Bank of India opened a branch in London, becoming the first Indian bank to establish an operational branch overseas.8 The expansion matched the core commercial logic of a Bombay trade financier. India's export earnings were denominated in sterling and settled in London. To finance an Indian exporter end-to-end — advancing against shipments in Bombay, presenting documents in London, collecting proceeds, and remitting payment — required a presence at both ends of the transaction. Indian banks lacking an overseas location acted as junior partners to British correspondent banks, surrendering the transaction spread.
Subsequent expansion followed established trade routes and diaspora commercial centers. Branches opened in Tokyo and Osaka in 1950 to service expanding India–Japan trade in cotton, textiles, and machinery. A Singapore branch followed in 1951, tapping the Southeast Asian trade corridor. The bank then expanded into Kenya and Uganda in East Africa, where a prominent Indian merchant community required cross-border banking services. By the eve of nationalisation, Bank of India had established a multi-continental trade and foreign exchange franchise as a shareholder-owned, publicly listed institution.
The institution has highlighted this international heritage for eight decades. The bank currently operates a network of overseas branches, subsidiaries, and a joint venture across roughly fifteen countries on five continents, with its international book crossing ₹2.56 lakh crore for the first time in the June 2026 quarter.2
Whether a first-mover advantage in international banking provides a durable competitive edge remains a central question in the modern investment thesis. Evaluating that claim requires examining the actual earning power of the overseas portfolio.
The historical and operational evidence reveals three major structural limitations. First, economics. On the June 2026 earnings call, management disclosed that roughly thirty-two per cent of the international book consisted of trade finance and outlined an explicit strategy to reduce that exposure because of narrow margins, shifting capital toward offshore corporate lending at higher spreads.9 Management's own strategy acknowledges that nearly a third of its legacy international business yields returns below internal targets.
Second, credit quality. During the 2010s, overseas branches of Indian public-sector banks accumulated significant non-performing exposures. These losses stemmed largely from cross-border foreign currency loans to Indian corporations relying on domestic rupee cash flows — a currency and maturity mismatch that collapsed when the rupee depreciated. Rather than diversifying risk, the foreign branch network concentrated corporate credit exposure to the same domestic borrowers.
Third, regulatory and capital overhead. During the late 2010s, under a government-mandated rationalisation program for public-sector banks, Bank of India and its peers closed or downsized several overseas offices. Maintaining branches in strictly regulated foreign jurisdictions imposes high fixed costs for local capital, liquidity reserves, compliance staff, and anti-money-laundering controls. In multiple locations, spread income proved insufficient to cover these ongoing operating expenses.
These factors demonstrate that the international network does not represent an unassailable, high-return moat. However, current management is repositioning the asset. On the June 2026 earnings call, Chief Executive Officer Rajneesh Karnatak outlined a foreign currency mobilisation program targeting $1.2 billion in Foreign Currency Non-Resident (FCNR) deposits by September 2026. More than $200 million had already arrived at interest rates of 6.25 to 6.50 per cent for three-to-five-year tenors, with hedging costs covered under the Reserve Bank of India window to leave roughly a fifty basis point net spread — backed by board approval to leverage that deposit base up to nine times.9 Combined with planned offshore bond, medium-term note, and external commercial borrowing issuances, management guided to as much as $4.3 billion in total foreign currency mobilisation by the end of the financial year.9
This strategy reframes the overseas network from a low-margin lending business into a dollar funding platform designed to raise capital at fixed spreads. While this approach optimizes legacy infrastructure, it remains unproven at scale and introduces new balance-sheet risks: a nine-times-leveraged foreign currency book carries liquidity exposure during periods of global dollar tightness. Key performance indicators will depend on whether international operations expand net interest income without triggering elevated credit slippages.
Regardless of the overseas book's ultimate earning power, the strategic control of the institution shifted fundamentally in the summer of 1969, when Bank of India ceased operating as a private, shareholder-owned bank.
IV. Nationalization, Social Banking & The Socialist Decades (1969–1991)
The announcement came over All India Radio on the evening of July 19, 1969. Prime Minister Indira Gandhi, having stripped the finance portfolio from Morarji Desai days earlier, informed the nation that fourteen major private banks — those holding deposits above ₹50 crore — were being taken into public ownership by executive ordinance. Bank of India was among them. Shareholders who had owned the institution for sixty-three years received compensation in government bonds. By the following morning, a bank founded by Bombay merchant princes belonged to the Republic of India.
Viewed from 2026, nationalisation can appear as a straightforward act of expropriation — and for equity holders, it was. Yet the underlying policy rationale was not frivolous. In 1969, Indian commercial banking served urban industry and trade almost exclusively. Agriculture, which employed most of the population, received a negligible share of institutional credit, while vast rural districts lacked bank branches entirely. The rural credit market relied almost wholly on informal moneylenders charging exorbitant interest. Nationalisation was designed to redirect urban deposits into rural economic development.
What followed transformed Bank of India from a commercial enterprise into an instrument of state development policy. Branch expansion into unbanked areas became mandatory, with locations dictated by regulatory licensing formulas rather than deposit potential. Priority-sector lending quotas mandated that forty per cent of net bank credit go toward agriculture, small enterprises, and weaker economic sections at administered interest rates. Under the Lead Bank Scheme, Bank of India assumed responsibility for coordinating credit planning across designated districts in Maharashtra, Jharkhand, Odisha, and Madhya Pradesh — taking on a role closer to a regional development agency than a commercial lender.
The long-term results proved double-edged. On the deposit side, the expansion built a lasting franchise. Mobilising household savings by pushing branches into underserved areas established a sticky, granular, and geographically dispersed deposit base that remains the foundation of the bank's funding profile today. Modern references to the strength of its retail deposit network in smaller towns describe infrastructure created under a socialist mandate.
On the asset side, the structural damage was substantial. Three factors drove the decay. Administered lending rates compressed net interest margins by removing risk-based pricing. Operating costs per rupee of business escalated as expensive rural branches managed small transaction balances. Most corrosively, credit underwriting atrophied. When loan volumes were governed by top-down targets from New Delhi and periodic political loan waivers, the discipline of credit appraisal dissolved. Real returns on equity throughout the 1970s and 1980s remained depressed, with shortfalls routinely covered by exchequer recapitalisations.
This history illuminates a central thesis of public-sector banking: that state ownership eliminates solvency risk while securing a low-cost deposit moat. With the Indian government holding 73.38 per cent of the equity, this implicit sovereign backing forms the bedrock of the modern bull case.4
Examined against the historical record, that proposition divides cleanly. The deposit-safety premise holds true. Bank of India has never suffered a depositor run, has never been resolved, and has never imposed losses on depositors — surviving asset quality reviews, major losses, and regulatory quarantine intact. The sovereign guarantee ensured the bank could fund itself even after recording a single-year loss of ₹6,089 crore.10
However, the value-creation premise fails. Depositors were protected through repeated equity injections by the government, often at steep dilution to existing shareholders. Sovereign ownership functions not as a shield for equity holders, but as a guarantee for depositors funded at shareholder expense. Conflating depositor safety with shareholder value remains a persistent analytical misstep in evaluating public-sector lenders.
The historical record supports a key distinction: state ownership makes the liability side resilient while subjecting equity to potential dilution. The ongoing test for the bank is whether it can fund growth organically through retained earnings without diluting shareholders further. Supported by a capital adequacy ratio of 18.69 per cent and a core equity ratio of 15.97 per cent as of June 2026, the institution currently meets that benchmark.2
The socialist era concluded not with policy reform, but under the pressure of a balance-of-payments crisis. In 1991, as India faced severe foreign exchange constraints and pledged gold reserves to the Bank of England, the nation initiated broad economic restructuring — fundamentally reshaping the operating environment for Indian banking.
V. Liberation, Early Tech Innovation & Maiden IPO (1991–2008)
The Narasimham Committee report of 1991 was, for Indian bankers, the equivalent of someone switching the lights on in a room they had been working in for twenty years. Its recommendations deregulated interest rates, cut the statutory pre-emption of bank funds through reserve and liquidity ratios, and — most consequentially — imposed prudential norms on income recognition, asset classification, and provisioning.
That last item deserves a plain-English explanation, because it is the hinge on which everything that follows turns. Before these norms, an Indian bank could keep accruing interest income on a loan that had stopped paying. The borrower was in default; the bank's income statement was not. Loans went bad quietly, in the dark, and the balance sheet reflected fiction. The new rules mandated that if a borrower had not paid for ninety days, the bank had to stop booking the income, classify the asset as non-performing, and set aside capital against the expected loss. It converted a discretionary judgment into an arithmetic one. It also meant that for the first time, an outside investor could look at an Indian bank's disclosed asset quality and trust what it said — a precondition for the institution ever being publicly traded again.
Bank of India was, by the standards of its peer group, unusually forward-leaning on technology in this period. In 1989, it became the first nationalised bank to establish a fully computerised branch with an ATM, at its Mahalaxmi branch in Mumbai.7 It was also an early Indian participant in SWIFT, the international messaging network that automates cross-border payments — a natural fit for a bank whose identity was built on trade finance. These were real operational firsts, and management has cited them frequently.
They also offer a useful lesson in what technology firsts are actually worth: very little on their own. Being first to install an ATM in 1989 did not give Bank of India a durable position in retail payments. Being an early SWIFT member did not prevent the international book's margins from compressing to the point where management now seeks to shrink a third of it. Technology adoption in banking is copied within a product cycle; what compounds over time is the customer relationship and the funding cost, not the hardware. This pattern remains relevant when evaluating the bank's current digital transformation narrative, where impressive firsts risk being commoditised just as quickly.
In 1997, the bank entered the public markets with its maiden public issue, diluting the government's holding and listing on the exchanges.7 The significance lay less in the capital raised than in the arrival of an outside constituency. From 1997 onward, Bank of India had minority shareholders, a share price, quarterly results scrutinised by analysts, and formal disclosure obligations. It now answered to two masters: the government that owned a controlling stake and set its social mandate, and a market that priced it on return on equity. The bank has been managing that structural tension ever since, and the 0.71 times book multiple it trades at today is, in part, the market's standing judgment on which master prevails.4
The years that followed were prosperous. India's post-2003 economic expansion lifted credit demand nationwide; the bank raised institutional equity in 2008 and pushed total business past ₹3 lakh crore. Disclosed asset quality appeared pristine, with a gross non-performing asset ratio in the low single digits and respectable returns on assets. On paper, the institution was well run.
Except those figures described a loan book that had not yet been stress-tested. Underwriting quality is observable only in hindsight, because a loan that has not yet defaulted looks identical to one that never will. Bank of India entered the global financial crisis with a clean-looking balance sheet, an expanding corporate franchise, and a majority shareholder that was about to ask it to deploy both in service of state policy.
VI. The Great Infrastructure Debt Bubble & The AQR Debacle (2008–2017)
After Lehman Brothers collapsed in September 2008, most global banking systems retrenched. India took the opposite path. The government responded to the crisis with a fiscal and credit stimulus aimed squarely at infrastructure — power generation, steel, roads, ports, and telecommunications. The primary engine of that stimulus was the public-sector banking system, which was encouraged to fund India's industrial build-out.
The primary vehicle for this effort was consortium lending. A power project or steel plant requiring ₹5,000 crore would be syndicated across eight to ten banks, with State Bank of India or another large peer acting as the lead. Each participant took a slice. The commercial appeal was obvious: rapid volume growth, single-name diversification, the comfort of institutional consensus, and reliance on a lead arranger to conduct due diligence. Bank of India participated heavily.
The structural flaw in this approach took years to surface. In a consortium model, individual participants lacked both the incentive and the leverage to conduct independent credit underwriting. A bank took a ten per cent allocation of a deal structured by another institution, on terms negotiated by third parties, and priced at a spread acceptable to the most aggressive lender in the syndicate. Participant banks could not easily impose strict covenants without risking exclusion from the deal, nor could they reprice a standardized package. In an environment of top-down growth expectations, declining participation was rarely a supported option.
Consequently, Bank of India built a corporate loan book that carried equity-level risk priced at senior-debt spreads. These projects were long-dated, single-asset exposures dependent on regulatory clearances and supply-chain linkages outside the bank's control. When coal allocations failed, environmental approvals stalled, land acquisition dragged, or telecommunications spectrum rules shifted, project cash flows evaporated. A second systemic failure then compounded the first.
Rather than recognizing these credit impairments early, the financial system developed mechanisms to defer them. Programs like Corporate Debt Restructuring, Joint Lenders' Forums, and the 5/25 flexible structuring scheme — which permitted lenders to stretch fifteen-year loans into twenty-five-year tenors on the premise of long asset lives — provided technical rationales for forbearance. In practice, these tools facilitated loan evergreening: advancing new credit to troubled borrowers to cover interest payments and keep accounts classified as standard without requiring provisions. Under the label of "restructured standard assets," balance sheets deferred the underlying credit reality.
The turning point came when the Reserve Bank of India, under Governor Raghuram Rajan, launched the Asset Quality Review. Beginning in late 2015, regulatory inspection teams enforced uniform asset classification rules across the banking system, mandating that accounts performing only on paper be recognized as non-performing. If one lender classified a borrower as substandard, every participating bank had to do the same, removing managerial discretion.
The financial impact on Bank of India was severe and unfolded across multiple fiscal years. For the year ended March 2016, the bank reported a net loss of ₹6,089 crore — the largest annual loss among Indian public-sector banks that year, when the entire public-sector banking system posted a collective loss of ₹17,993 crore.10 The fourth quarter ended March 2016 accounted for ₹3,587 crore of that deficit.11 The following fiscal year registered a smaller annual loss of ₹1,558 crore, with the fourth-quarter loss narrowing to ₹1,045 crore — a trajectory that management and the market initially interpreted as stabilization.12 That assessment proved premature. For the year ended March 2018, the annual net loss widened to ₹6,044 crore, driven by a fourth-quarter loss of ₹3,969 crore.13 By March 31, 2018, the bank's gross non-performing asset ratio rose to 16.58 per cent of gross advances, up from 13.22 per cent a year earlier.13 Provisions doubled again in the December 2018 quarter, resulting in a further quarterly loss of ₹4,738 crore.14
The 16.58 per cent non-performing asset ratio meant that more than one out of every six rupees in the bank's loan book was delinquent. Over three fiscal years, the institution absorbed cumulative net losses exceeding ₹13,000 crore, erasing more than a decade of accumulated shareholder capital.
This era provided a decisive test of whether Bank of India possessed an independent corporate credit franchise with distinct underwriting discipline, pricing power, or informational advantages. The Asset Quality Review demonstrated that it did not. The bank's corporate credit operations accepted syndicate pricing without establishing covenant protections or discriminating between viable and unviable projects, taking equity-scale risks for senior-debt returns over six years.
That historical record remains directly relevant in 2026. Managing Director Rajneesh Karnatak built his career in corporate credit, having previously led large corporate branches, credit monitoring units, and mid-corporate credit divisions.15 Today, Bank of India is expanding its corporate lending through nineteen dedicated emerging corporate credit branches. The initiative targets the ₹25 crore to ₹250 crore middle-market segment to capture higher yields, backed by a corporate loan pipeline exceeding ₹70,000 crore.9 Higher spreads in corporate credit reflect higher risk. As the bank expands its mid-corporate book, monitoring whether enhanced risk controls and updated credit systems can prevent a recurrence of past underwriting failures remains a central analytical priority.
By late 2017, however, the regulator had stopped waiting.
VII. Prompt Corrective Action (PCA) & The Grueling Cleanup (2017–2023)
Prompt Corrective Action is best understood as a regulatory medically induced coma. When a bank's capital, asset quality, or profitability breaches defined thresholds, the Reserve Bank of India curbs its operational freedom — restricting the high-risk activities that caused the distress and, simultaneously, limiting its ability to earn its way out. Bank of India entered this regulatory quarantine following an RBI letter dated December 19, 2017, triggered by three breaches: net non-performing assets above permissible levels, insufficient Common Equity Tier 1 capital, and negative return on assets for two consecutive years.[^1]
The operational restrictions bit hard. Growth in risk-weighted assets was capped, effectively halting expansion in corporate lending. New branch openings stopped, capital expenditure was curtailed, and strict limits were imposed on hiring and management compensation. The bank was left with three primary mandates: recover bad loans, expand low-risk retail lending, and cut costs.
Yet this regulatory restriction provided an unexpected institutional benefit. A public-sector lender facing continuous pressure to meet top-down credit growth targets rarely has an internal mechanism to decline unviable loans. Prompt Corrective Action supplied one. For fourteen months, regulatory prohibition served as an unanswerable shield against high-risk lending proposals. The enforced pivot toward retail, agriculture, and micro, small, and medium enterprise lending — undertaken because it was the only permissible growth path — established the foundation of the retail asset portfolio that drives the bank's net interest margins today.
Two external catalysts drove the balance-sheet recovery. First, the Insolvency and Bankruptcy Code, operational from 2016, rebalanced power between institutional lenders and defaulting corporate promoters. Prior to the code, defaulting borrowers could drag out litigation for years while retaining operational control of assets, turning loan recovery into a war of attrition that banks frequently lost. Admission to the National Company Law Tribunal under the new framework removed promoters from management and imposed strict resolution deadlines, forcing defaulting borrowers to negotiate.
Second, state capital support provided essential balance-sheet repair. The Indian government injected fresh equity into Bank of India as part of a broader public-sector bank recapitalisation program, absorbing accumulated losses with taxpayer funds while diluting existing minority shareholders. On January 31, 2019, fourteen months after imposing restrictions, the RBI removed Bank of India from the framework alongside Bank of Maharashtra and Oriental Bank of Commerce.1617
The capital allocation choices during the turnaround reveal a mixed record. On acquisitions, the bank's single notable transaction occurred in 2021, when it bought out AXA Investment Managers' 49 per cent stake in the BOI AXA asset management joint venture to assume full ownership and rebrand the business as Bank of India Investment Managers.18 Taking full control of an asset manager allowed a bank with 5,500 branches to capture asset management fees directly rather than sharing them with a partner. However, a single small transaction does not establish a broader track record of capital allocation skill.
The equity market transactions present a more demanding record. In August 2021, the bank completed a qualified institutional placement that raised ₹2,550.01 crore by issuing 40,54,71,866 shares at ₹62.89 each — falling short of its ₹3,000 crore board authorization due to weak market demand.19 In December 2023, the institution returned to the market, setting a floor price of ₹105.42 per share and raising ₹4,500 crore.20[^22] Combined with government recapitalisation injections, these equity sales reduced the government's ownership stake to 73.38 per cent.4
The mechanics of these offerings carry clear implications for shareholders. Both institutional placements were executed at prices well below book value per share, diluting existing equity holders to bolster regulatory capital. The bank issued equity not to fund high-return expansion opportunities, but to satisfy capital adequacy requirements following corporate credit losses. The capital raises of 2021 and 2023 were defensive, dilutive, and necessary additions to capital.
This background establishes a testable standard for the bank's current strategy. Supported by a core equity ratio of 15.97 per cent and a return on equity exceeding sixteen per cent in recent quarters, the institution possesses the internal capital generation needed to fund fifteen to sixteen per cent annual loan growth through retained earnings.2 Whether management maintains this self-funding model or executes further dilutive equity sales offers a clear test of whether its structural capital discipline has permanently shifted.
By April 2023, with the balance-sheet cleanup complete, the institution required new leadership to set its long-term direction.
VIII. The Modern Turnaround: Rajneesh Karnatak's Playbook & Current State (2023–Present)
Rajneesh Karnatak took over as managing director and chief executive officer on April 29, 2023, on the standard three-year public-sector bank tenure.15 Holding a Master of Commerce degree and a certification from the Indian Institute of Bankers, his career spans roughly three decades in state banking, focused primarily on credit risk and monitoring rather than retail marketing or digital architecture. He previously served as general manager at Oriental Bank of Commerce overseeing large corporate credit branches, credit monitoring, digital banking, and mid-corporate credit. Following its merger into Punjab National Bank, he headed credit review, monitoring, and corporate credit as chief general manager before being appointed executive director at Union Bank of India in October 2021.15
That credit background is central to evaluating his strategy. Having spent his formative professional years inside the credit monitoring and corporate credit divisions of public-sector banks during the bad-loan crisis of the 2010s, his experience provides both a rational basis for underwriting caution and the technical background to re-enter corporate lending.
On April 23, 2026, the Indian government extended Karnatak's term by three years beyond its initial April 28 expiry under the Banking Companies (Acquisition and Transfer of Undertakings) Act, 1970, extending his leadership through April 2029.21 In public-sector banking, executive tenure directly shapes planning horizons: a multi-year mandate allows leadership to pursue structural investments whose payoffs extend beyond a single reporting cycle.
Yet institutional governance limits executive independence. Karnatak remains a government appointee operating on a standardized public-sector compensation structure without stock options or performance-linked equity incentives. Management performance is evaluated largely against policy targets set by the Department of Financial Services — such as priority-sector quotas, credit expansion targets, and state economic initiatives — rather than long-term total shareholder return. Consequently, executive incentives and minority shareholder interests align only when state policy objectives overlap with commercial return on equity. When government mandates require credit deployment into specific sectors, public-sector banks must execute those directives regardless of risk-adjusted returns — a structural constraint distinct from private-sector peers.
The bank's current operating strategy rests on four primary pillars, supported by balance-sheet metrics through the June 2026 quarter.
The RAM pivot. Retail, agriculture, and micro, small, and medium enterprise (RAM) loans reached 58.30 per cent of gross domestic advances as of June 2026, compared with 58.74 per cent of total gross advances at the end of March.222 For the fiscal year ended March 2026, retail advances expanded by 21.19 per cent, small business lending grew 17.68 per cent, and agricultural credit rose 17.60 per cent, outpacing corporate loan growth of 12.08 per cent.3 The commercial logic rests on yield and risk dispersion. RAM loans carry higher average interest rates, lower regulatory capital weights for retail products, and fulfill state priority-sector quotas. Crucially, portfolio granularity reduces concentration risk: a default on a ₹40 lakh home loan represents an incremental credit loss, whereas a default on a ₹2,000 crore industrial project can impair an entire quarter's profitability.
Within the RAM portfolio, gold loans expanded rapidly. Management reported a gold loan portfolio of ₹57,000 crore, expanding at a twenty-five per cent annual rate and yielding over nine per cent, with non-performing assets below ₹100 crore — describing the segment as a core growth priority within RAM advances.9 Secured gold lending provides attractive risk-adjusted spreads due to short tenors and physical collateral stored in bank vaults that can be liquidated relatively quickly in default scenarios. However, the segment remains exposed to collateral valuation risk: a sharp decline in international gold prices would compress loan-to-value cushions across the entire portfolio simultaneously, introducing systemic collateral risk within a seemingly diversified asset base.
Equally informative are the areas where management exercised restraint. Personal loans grew just three per cent over the year, even as home and vehicle loans expanded rapidly. Management attributed the deceleration to stricter underwriting guardrails, citing elevated credit risks among low-ticket unsecured loans and non-salaried borrowers, which prompted the bank to restrict origination primarily to salaried corporate and government employees maintaining primary salary accounts with Bank of India.9 Curbing high-yield unsecured lending while market peers expanded aggressive consumer credit suggests an emphasis on balance-sheet durability over short-term interest income — a marked contrast to the unconstrained credit expansion of the previous decade.
Asset quality and recovery. The bank's gross non-performing asset ratio of 1.81 per cent and net non-performing asset ratio of 0.51 per cent as of June 2026 represent its lowest delinquency levels in recent decades.2 A provision coverage ratio of 93.83 per cent indicates that ninety-three paise of every rupee of identified bad debt has already been written down or provisioned against. Annualised credit cost fell to 0.15 per cent for the June 2026 quarter, compared with 0.48 per cent for the full 2026 fiscal year.23 Leading indicators of credit stress show similar improvement: special mention accounts above ₹5 crore — loans showing early payment delays — dropped to ₹4,070 crore from approximately ₹7,000 crore a year earlier, while quarterly fresh slippages declined to ₹1,800 crore from ₹2,100 crore.9 External resolution mechanisms supported this trajectory: National Asset Reconstruction Company Limited (NARCL), the government-backed bad bank, recovered ₹4,364 crore for the system in fiscal year 2026 after acquiring ₹1,65,862 crore in bad debt exposure across 33 corporate borrowers through March 2026.23
This asset-quality metric carries an important analytical caveat. An annualised credit cost of fifteen basis points reflects an exceptionally benign phase of the credit cycle, bolstered by provision write-backs and recoveries from legacy bad loans written off in prior years. Because recovery income is inherently non-recurring, current earnings overstate normalized profitability. Normalizing credit costs toward fifty to seventy-five basis points provides a more realistic baseline for valuing sustainable earning power.
Digital infrastructure. Digital platforms accounted for 22 per cent of domestic credit sanctions by volume, while alternate-channel transactions reached 7.6 billion in fiscal year 2026. The bank's Unified Payments Interface (UPI) user base expanded by 5.1 million customers during the year to exceed 27.1 million, and an integrated enterprise data lake linked to its customer relationship management system generated ₹18,000 crore in cross-sold credit and deposit products from existing clients.39 While data-driven cross-selling lowers customer acquisition costs, digital channels in retail banking offer limited proprietary advantage, as peer institutions deploy comparable technology stacks.
Margins and profitability. Maintaining earnings momentum faces stiffer resistance on the funding side — a challenge examined in the next section.
IX. Segment Breakdown & Core Business Economics: RAM vs. Wholesale vs. International
A bank is essentially a spread business wearing a corporate costume. It buys capital from depositors, lends it to borrowers, and generates earnings on the net interest margin minus credit losses and operating expenses. Everything else — branch networks, digital platforms, and business units — simply dictates how efficiently those core transactions occur. Evaluating Bank of India's ₹17.55 lakh crore global business requires examining what each asset class costs to fund and what it yields in return.
The RAM engine. The retail, agriculture, and micro, small, and medium enterprise (RAM) portfolio serves as the bank's primary yield generator. Secured retail products — including housing and vehicle loans, alongside gold lending and selectively targeted personal credit — earn higher yields than corporate loans while carrying lower regulatory capital requirements on mortgage assets. Agricultural and small business loans offer higher yields still, while fulfilling mandatory priority-sector lending targets that would otherwise require purchasing priority-sector lending certificates from peer institutions. Bank of India has converted this regulatory requirement into a net revenue line: the institution earned ₹277 crore selling surplus certificates in the June 2026 quarter, with management noting "some leg room to give some PSL in coming quarters" as RAM expansion continues.9 Monetizing excess priority-sector credits turns a compliance mandate into fee income — a tangible structural benefit of the RAM pivot.
However, the segment carries distinct operational trade-offs. Agricultural and micro-enterprise loans exhibit higher baseline default rates than corporate credit during normal economic conditions and remain exposed to external factors outside management control, including weather patterns, commodity price swings, and state election cycles. Regional political commitments to debt relief can alter borrower repayment discipline, creating an ongoing risk premium within the RAM portfolio.
The wholesale book. Corporate advances, representing roughly forty per cent of domestic credit, provide volume but constrain overall margins. Dispersing ₹6.5 lakh crore of credit solely through small retail loans is impractical, yet top-tier corporate borrowers command substantial pricing power in India. Highly rated conglomerates can source funding across multiple domestic and international debt markets, squeezing lending spreads down to minimal basis points.
To protect margins, management is targeting the mid-market corporate segment. Establishing nineteen specialized emerging corporate credit branches to originate tickets between ₹25 crore and ₹250 crore reflects a strategy to capture higher spreads where competition is less intense.9 While commercially logical, mid-market lending places heavy demands on credit underwriting: these exposures are too large for statistical diversification yet lack the public rating coverage and market scrutiny of blue-chip corporates.
International operations. The overseas network, with total business exceeding ₹2.56 lakh crore, functions as a thin-margin operation, as global trade finance is priced against international benchmark rates in a competitive market.2 Its primary strategic utility lies in providing foreign currency funding rather than generating high-yield offshore loans. Overseas advances expanded 14.25 per cent in fiscal year 2026.3
Treasury operations. The bank maintains a substantial portfolio of government securities to fulfill statutory liquidity requirements. This portfolio creates meaningful earnings sensitivity to domestic interest rate movements. As yields decline, mark-to-market gains enhance non-interest income, whereas rising yields exert downward pressure on earnings. Non-interest income reached ₹2,579 crore in the June 2026 quarter, up 19.07 per cent year-on-year, driven significantly by treasury operations.2 Treasury gains represent the most volatile line item on the income statement; for instance, the 82.5 per cent net profit expansion reported in the fourth quarter of fiscal year 2025 relied heavily on non-interest treasury income, illustrating how rate cycles can temporarily elevate quarterly earnings.24
Funding structure and deposit dynamics. The central analytical debate centers on the bank's liability side. The current and savings account (CASA) ratio dropped to 36.68 per cent in June 2026 from 39.88 per cent a year earlier.25 Low-cost CASA deposits represent a bank's cheapest funding source, paying modest interest rates compared to term deposits. A three-percentage-point shift from low-cost accounts into higher-yielding term deposits compresses net interest margins directly. Consequently, global net interest margin narrowed to 2.52 per cent in the June 2026 quarter from 2.55 per cent in the prior-year period, even as global loan volume grew nearly nineteen per cent.25 Expanding asset volume while net margins compress highlights the funding pressure facing the balance sheet.
Chief Executive Officer Rajneesh Karnatak framed this funding shift around two dynamics. Structurally, Indian household savings are moving away from traditional bank deposits into capital market instruments, mutual funds, and insurance products — a systemic shift affecting all Indian commercial banks. Tactically, management is bidding for medium-sized term deposits in the ₹3 crore to ₹25 crore range at interest rates below large institutional bulk deposit rates, while supplementing domestic liquidity with foreign currency non-resident deposits.9 The bank's overall cost of deposits declined fifteen basis points over the period despite the lower CASA ratio, supporting management's assertion that deposit costs are being managed through tactical funding shifts.
Yet this tactical adjustment alters the underlying investment case. Optimizing liabilities through negotiated term deposits and offshore dollar funding weakens the argument that 5,500 regional branches provide an unassailable, low-cost deposit moat. Negotiated term deposits are accessible to any lender willing to pay market rates, whereas a sticky, low-cost CASA franchise represents a proprietary structural advantage. In managing its funding mix, the bank has substituted a structural liability moat with tactical balance-sheet management — a pragmatic approach, but one that offers less long-term competitive protection.
X. Helmer's 7 Powers & Porter's 5 Forces Competitive Stress Test
Strip away the historical narrative and examine the fundamental question: what, if anything, prevents a competitor from taking Bank of India's market share? Applying Hamilton Helmer's 7 Powers framework provides a clear assessment of whether the institution holds durable competitive advantages.
Scale economies are present but weak. Operating more than 5,500 domestic branches after adding 201 locations in fiscal year 2026 allows the bank to spread technology, treasury operations, and regulatory compliance expenses over a large balance sheet.22 However, branch banking exhibits diminishing scale returns, as opening additional locations in a district incurs costs comparable to initial branch setups. Furthermore, public-sector bank compensation is governed by industry-wide bipartite settlements negotiated between the Indian Banks' Association and employee unions. Consequently, Bank of India cannot lower labor costs to compete with private peers hiring at market rates, nor reduce headcount as automation streamlines operational roles. A cost-to-income ratio of 46.33 per cent for the June 2026 quarter, guided to 48 to 49 per cent for the full fiscal year, reflects operating efficiency that is acceptable but provides little competitive advantage.29
Network effects are absent. Deposit accounts and loan products do not gain value for an individual customer as total user adoption grows. While payment infrastructure exhibits strong network effects in Indian finance, that value resides in the Unified Payments Interface (UPI) — a national public utility that commoditised retail banking layers. Bank of India's 2.71 crore UPI users operate on shared infrastructure that the bank does not control and cannot directly monetize.3
Counter-positioning is absent. Counter-positioning requires adopting a business model that incumbents cannot replicate without damaging their core operations. Bank of India operates a standard public-sector universal banking model, structurally identical to peers such as Punjab National Bank, Canara Bank, and Union Bank of India. The business model presents no structural barriers to competitor imitation.
Switching costs are low to moderate and asymmetric across segments. Retail clients maintaining primary salary accounts, automated bill payments, mortgage facilities, and extensive transaction histories face practical friction when changing institutions — explaining management's strategy of restricting personal loans primarily to existing salary account holders.9 By contrast, corporate and small-to-medium enterprise borrowers routinely refinance credit facilities across institutions for minor interest rate differentials.
Cornered resource dynamics offer limited differentiation. Implicit sovereign backing represents a unique structural feature unavailable to private-sector banks. However, because this sovereign support extends equally to all nationalised lenders, it provides no relative advantage within the public-sector peer group against which Bank of India directly competes.
Process power remains unproven. The underwriting deficiencies highlighted during the Asset Quality Review demonstrate that credit appraisal and recovery capabilities represent ongoing operational remediation rather than proprietary institutional process power.
Brand power is moderate but bounded. The institution retains established brand recognition in secondary and tertiary regional markets, as well as within historical non-resident Indian trade corridors. However, economic brand power manifests in pricing power — a dynamic disproven by the contraction in low-cost CASA deposits as customers seek higher-yielding alternatives.
Evaluating the institution through Michael Porter's Five Forces reveals comparable structural constraints:
- Threat of new entrants: Low. Stringent Reserve Bank of India licensing requirements and substantial capital thresholds protect existing institutions from new banking entrants.
- Bargaining power of depositors: High and rising. The migration of household savings toward capital markets and higher-yielding term deposits elevates funding costs across the sector.
- Bargaining power of borrowers: High among blue-chip corporate clients seeking market pricing, and moderate within retail and small-business segments — reinforcing management's shift toward RAM lending to protect loan yields.
- Threat of substitutes: Moderate to high. Corporate bond markets, commercial paper issuances, non-banking financial companies, and private credit funds disintermediate prime corporate borrowers, exposing traditional lenders to adverse selection risks.
- Intensity of competitive rivalry: High. Eleven state-owned banks execute similar business strategies, while private-sector peers leverage lower funding costs and modern technology stacks.
This competitive analysis indicates that Bank of India lacks strong, proprietary economic moats. The institution operates within an industry characterized by intense rivalry, powerful funding providers, discerning borrowers, and active disintermediation, relying on a banking license that limits new entrants but offers no protection against established incumbents. Consequently, the investment thesis cannot depend on structural moat advantages; it relies on execution discipline, credit cycle positioning, and balance-sheet valuation relative to capital quality.
That dependency places the institution's performance squarely on managerial execution.
XI. Management Credibility, Capital Allocation & Historical Falsification Audit
Assessing a management team requires evaluating their operational guidance against quarterly performance over a multi-year horizon to separate structural execution from favorable credit cycles. On that standard, the leadership team under Managing Director Rajneesh Karnatak presents a brief but consistent operating record.
Guidance discipline. Recent guidance from management has been specific and falsifiable: maintaining a return on assets at or above one per cent, achieving a global net interest margin between 2.55 and 2.60 per cent, containing the cost-to-income ratio between 48 and 49 per cent, and expanding credit by 15 to 16 per cent alongside deposit growth of 13 to 14 per cent for fiscal year 2027.9 These metrics provide clear, measurable benchmarks rather than vague qualitative targets. Recent execution supports these projections: return on assets reached 1.01 per cent in both the March and June 2026 quarters,2 while full-year 2026 credit growth of 15.82 per cent and deposit growth of 13.56 per cent landed within management's guided ranges.3
Where the record is less clean. The net interest margin represents the primary operational vulnerability. Actual global net interest margin stood at 2.52 per cent in the June 2026 quarter, sitting below the guided 2.55 to 2.60 per cent range,2 down from 2.55 per cent in the prior-year period.5 On the earnings call, Chief Executive Officer Rajneesh Karnatak and Executive Director Rajiv Mishra asserted that deposit costs are stabilizing and yield compression should pause as loans reprice toward Marginal Cost of Funds Based Lending Rate (MCLR) benchmarks and mid-corporate originations rebuild margins.9 While this mechanism is economically logical, it remains an unvalidated projection. Expanding net margins from a contracting baseline presents the most immediate risk of a guidance miss in fiscal year 2027.
Willingness to answer hard questions. Management transparency during quarterly calls offers additional operational context. Asked directly about small and medium-enterprise stress from West Asian trade disruptions, Karnatak identified specific watch-list sub-sectors — including chemicals, ceramics, and import-export businesses — and produced detailed Special Mention Account and slippage figures unprompted.9 Addressing the lower low-cost deposit ratio, leadership provided a substantive explanation regarding systemic shifts in household savings rather than dismissing competitive pressures. When asked about persistent market speculation regarding state-bank consolidation, Karnatak remained non-committal, stating that no discussions had taken place.9 Furthermore, when asked whether the bank planned an AS-15 provisioning reversal — an accounting adjustment that would elevate reported earnings by releasing employee-benefit provisions — management stated it had no plans to pursue that option.9 Declining an available, short-term earnings-flattering accounting lever provides a tangible indicator of reporting discipline.
A note on narrative consistency. However, narrative framing has evolved alongside balance-sheet metrics. In earlier reporting periods, a current and savings account ratio near forty per cent was highlighted as a core franchise strength. By June 2026, a reduced ratio of 36.68 per cent was characterized as deliberate balance-sheet optimization.59 While the systemic migration of Indian household deposits into capital market instruments is genuine, investors should note that management reframed the metric precisely as performance deteriorated — a narrative shift requiring continued tracking.
A comprehensive falsification audit tests the four core claims underpinning the modern investment case against the institution's empirical record:
Claim one: the international network is a high-return asset. Narrowed, substantially. A historical record of overseas credit impairments, thin trade-finance spreads, and mandatory branch rationalization disproves the international lending thesis. Management's strategic decision to reduce one-third of its legacy trade-finance book concedes this reality. The surviving thesis relies on using overseas branches as a dollar funding platform — a strategy that remains unproven at scale and introduces foreign-currency leverage risks. A material rise in offshore credit slippages or a failure to convert foreign currency deposits into disclosed net interest income would falsify this claim.
Claim two: the bank possesses corporate underwriting expertise. Rejected. Cumulative net losses exceeding ₹13,000 crore during the late 2010s, a peak gross non-performing asset ratio of 16.58 per cent, and placement under regulatory quarantine represent a definitive historical refutation. While current mid-corporate expansion operates under updated risk controls, underwriting discipline cannot be fully verified during a benign phase of the credit cycle. Higher default rates across corporate and mid-corporate portfolios during the next credit downturn would confirm this structural weakness.
Claim three: sovereign ownership guarantees value. Narrowed to depositor protection. Majority state ownership ensures institutional solvency and protects depositors, but historically subjects equity holders to dilution. Executing two institutional equity placements below book value within thirty months to satisfy regulatory capital minimums demonstrates that sovereign backing prioritizes financial stability over shareholder value. Funding future balance-sheet expansion entirely through retained earnings without further dilutive share issuances serves as the critical test for this claim.
Claim four: digital transformation drives operating leverage. Intact but unproven. Increased digital loan sanctions and enterprise cross-selling demonstrate operational deployment, yet management guides the full-year cost-to-income ratio upward to between 48 and 49 per cent from 46.33 per cent in the June quarter.29 Industry-wide wage settlements periodically reset operating expenses in ways that digital adoption cannot fully offset. A cost-to-income ratio trending structurally below the mid-forties across a complete wage-negotiation cycle would validate this thesis.
In summary, an activist or short-seller analysis highlights specific structural vulnerabilities: a governance structure where the majority shareholder appoints executive leadership on short-term mandates without equity-linked compensation, a history of dilutive equity issuances below book value, profitability currently supported by cyclically low credit costs, a declining low-cost deposit ratio reframed as corporate strategy, and a re-entry into mid-corporate lending — the segment responsible for past capital destruction. None of these factors is inherently fatal to the institution, yet all represent legitimate operational risks that remain reflected in the bank's discounted valuation multiples.
XII. The Investor Spine: Bull vs. Bear Thesis & Key Operating KPIs
The investment debate surrounding Bank of India centers on whether its recent financial performance represents a permanent structural transformation or a temporary cyclical peak.
The bull case rests on valuation arithmetic and balance-sheet repair. Trading at ₹142.60 on August 31, 2026, the shares priced the bank at roughly 0.71 times book value against a book value near ₹200 per share, with a trailing price-to-earnings multiple of about 5.5 and a dividend yield above three per cent.4 For an institution generating quarterly returns on equity above sixteen per cent, a discount to book value implies that current earnings are temporary. Proponents argue that if the shift toward retail, agriculture, and small-business lending holds, alongside a restored credit discipline, the valuation gap should narrow through retained earnings and multiple expansion without requiring aggressive growth.
Second, balance-sheet normalization is providing direct earnings support. With a provision coverage ratio of 93.83 per cent and a net non-performing asset ratio of 0.51 per cent, legacy non-performing assets have been substantially written down or provisioned for.2 Consequently, reductions in credit costs flow directly into net profit.
Third, asset reallocation supports yields, as retail advances expanded twenty-one per cent and gold loans grew twenty-five per cent with minimal default losses.39 Fourth, capital strength protects existing equity holders. Total capital adequacy of 18.69 per cent and a core equity tier-one ratio of 15.97 per cent provide sufficient capacity to fund double-digit balance-sheet growth internally, potentially breaking a decade-long cycle of dilutive equity issuances.2
The bear case focuses on structural earnings constraints and cyclical risks.
First, historical return-on-equity ceilings remain a constraint. Financial data places the bank's last reported annual return on equity at 12.4 per cent and its three-year average at 12 per cent, well below the annualized sixteen per cent reported in recent quarters and below top-tier private-sector peers.4 The gap between quarterly performance and full-year averages indicates that recent profitability has not yet translated into a multi-year trend. Furthermore, mandatory bipartite wage agreements across public-sector banks periodically step up operating costs, creating cost pressures that management cannot unilaterally restructure.
Second, net interest margins are contracting alongside rapid balance-sheet expansion. With the net interest margin missing guidance, the low-cost deposit ratio declining by over three percentage points year-on-year, and net interest income growing 12.61 per cent against an 18.64 per cent expansion in loan advances, asset growth is being driven by volume rather than pricing power.2 Expanding credit volume while loan spreads narrow suggests the bank is taking on balance-sheet growth at reduced yields.
Third, the retail, agriculture, and small-business portfolio remains untested through a full credit downturn. Agricultural and small-enterprise loans benefit from favorable monsoon conditions but face systemic defaults during agricultural downturns and periodic political loan-waiver cycles. Management has already highlighted chemicals, ceramics, and import-export small enterprises as watch-list sub-sectors.9 Additionally, the ₹57,000 crore gold loan portfolio concentrates collateral risk in a single commodity.
Fourth, an annualized credit cost of 0.15 per cent reflects a cyclical low rather than a long-term baseline.2 Valuing earnings at current provision levels risks overstating the institution's normalized, through-cycle profitability.
Evaluating the trade-offs. The disagreement between bulls and bears reflects differing analytical timeframes. The bull case accurately describes current balance-sheet health: capital adequacy, provision coverage, and asset mix are stronger than five years ago, a shift not fully reflected in a sub-book valuation. Conversely, the bear case highlights forward-looking structural risks: balance-sheet repair does not equal a proprietary competitive moat, interest margins face downward pressure, and credit costs will eventually normalize. The valuation discount reflects genuine structural constraints rather than market inefficiency. Whether current entry prices compensate for these risks depends on whether updated underwriting discipline withstands the next credit cycle better than during the 2015 downturn.
Three key performance indicators. Tracking three core metrics will determine which thesis prevails:
One: Net interest margin relative to management guidance. Global net interest margin aggregates deposit costs, asset yields, and pricing power into a single metric. Management has targeted a global margin of 2.55 to 2.60 per cent for fiscal year 2027, compared with an actual 2.52 per cent in the June 2026 quarter.29 Sustaining mid-teen loan growth while expanding margins into the guided range would confirm genuine yield accretion from the asset mix shift. Continued margin compression during loan expansion would indicate that credit growth is being purchased through price discounting.
Two: Fresh slippages and special-mention accounts. Fresh slippages of ₹1,800 crore and special mention accounts above ₹5 crore totaling ₹4,070 crore establish the current baseline.9 Special mention accounts serve as leading indicators for future asset quality. An expansion in early-stage delinquencies, particularly within small-business or agricultural segments, would indicate that loan growth was achieved by lowering underwriting standards, showing up in special mention metrics twelve to eighteen months before impacting headline non-performing asset ratios.
Three: Retained capital self-sufficiency versus equity issuance. With total capital adequacy at 18.69 per cent and core equity at 15.97 per cent, internal earnings generation should fund projected balance-sheet expansion.2 Executing another institutional equity placement below book value would indicate that the institution remains dependent on shareholder dilution for growth rather than compounding capital through operational returns. Sustaining credit growth across the cycle without dilutive capital raises would provide definitive confirmation of structural reform.
XIII. Earnings Call Transcripts & Skeptical Analyst Roadmap
For investors evaluating Bank of India, earnings call transcripts offer a sharp contrast between official narrative and operational reality. The prepared remarks deliver management's curated framing, while the question-and-answer session reveals where analysts probe for vulnerabilities. The bank maintains an archive of these transcripts on its investor relations portal, with the most instructive recent calls being the full-year 2026 results presentation following the May 8, 2026 board meeting and the first-quarter 2027 call in August 2026.2526
The structure of these calls follows a predictable cadence: Chief Executive Officer Rajneesh Karnatak opens with macroeconomic observations — offering a constructive outlook on the domestic economy on the August 2026 call while citing geopolitical risks in West Asia — before outlining headline metrics, handing over to executive directors for divisional updates, and opening the floor to questions.9 Recent prepared presentations have highlighted internal infrastructure initiatives over headline volume: launching a dedicated sales vertical for business outsourcing, opening a Strategic Business Branch in Mumbai for high-value transactions, introducing virtual RuPay debit cards, deploying the BOI Trade Easy supply-chain finance platform, establishing a Testing Centre of Excellence for software quality, and rolling out the Starlight upskilling program for staff.922 Karnatak repeatedly framed management's objective around "sustainable growth, prudent lending, and disciplined execution."9
The question-and-answer sessions provide critical analytical signal, with analyst inquiries consistently focusing on three core operational areas.
First is the compression of net interest margins. Analysts have challenged management on the mechanical mismatch of asset yields falling faster than funding costs. Leadership's response has relied on four key drivers: stabilizing deposit costs, repricing loans toward Marginal Cost of Funds Based Lending Rate (MCLR) benchmarks, expanding higher-yielding mid-corporate originations, and scaling back low-margin overseas trade finance.9 Evaluating this defense requires monitoring reported outcomes: net interest margin will either recover toward the guided range of 2.55 to 2.60 per cent or remain under pressure.
Second is the detailed tracking of asset quality. In response to analyst Ashok Ajmera's inquiry regarding potential small-business stress from West Asian trade disruptions, management disclosed special-mention account metrics, fresh quarterly slippages, and specific watch-list sub-sectors. The exchange also revealed that the bank had sanctioned ₹6,000 crore under the Emergency Credit Line Guarantee Scheme, with ₹4,600 crore disbursed against an overall target of ₹8,000 crore.9 This disclosure underscores a structural reality of public-sector banking: state-guaranteed small-business lending functions as both a development policy tool and a credit product, serving as a reminder that a significant portion of the balance sheet remains aligned with government directives.
Third is capital allocation and foreign currency funding. Questions from analyst Manoj Alimchandani regarding gold loans, GIFT City operations, and foreign-currency deposit leverage produced several of the bank's most strategic disclosures: a board-approved leverage ceiling of nine times, a 50-basis-point net hedged spread, a target of $4.3 billion in total foreign currency mobilisation, and a ₹70,000 crore corporate loan pipeline split between domestic and international borrowers.9 Notably, when an analyst suggested that the $1.2 billion foreign currency non-resident deposit target appeared conservative relative to broader Finance Ministry goals, Karnatak maintained the disclosed target while clarifying the total program scope — demonstrating managerial discipline in adhering to stated targets during a live broadcast.
For analysts evaluating conference call transcripts over time, tracking two specific patterns offers the clearest diagnostic value: observing whether analysts repeatedly ask identical questions across sequential quarters — indicating unresolved underlying issues — and monitoring whether management's narrative explanation shifts when key metrics change direction. On current and savings account deposit ratios, management's narrative evolved as the ratio declined, whereas on asset quality, the explanatory framework has remained consistent.
XIV. Strategic Risk Radar & The 2030 Outlook
Four distinct risks shape Bank of India's forward outlook, each operating through a specific transmission mechanism rather than as vague macroeconomic anxiety.
The deposit competition risk is the most immediate threat. The mechanism is straightforward: Indian households are structurally reallocating savings from traditional bank deposits into mutual funds, equities, and insurance products, forcing commercial banks to bid up term deposit rates to fund credit expansion. For Bank of India, running loan growth near nineteen per cent against deposit growth near fifteen per cent means the funding gap must be closed with higher-cost liabilities.2 The observable consequence is the erosion of its low-cost deposit ratio and the compression of its net interest margin. This is not a temporary cyclical hurdle, but a permanent structural condition.
The MSME and agriculture credit risk represents the primary vulnerability for asset quality. The retail, agriculture, and small-business portfolio has expanded at seventeen to twenty-one per cent across its underlying components during a benign credit cycle.3 Small-enterprise and agricultural loans carry higher sensitivity to macroeconomic decelerations, monsoon failures, and commodity price shocks than corporate credit, while offering far less flexibility in resolution — a lender cannot renegotiate thousands of granular accounts as easily as a single syndicated exposure. Management's watch list covering chemicals, ceramics, and trade-exposed small businesses provides an early signal of potential stress.9
The wage and cost risk functions as a periodic step-up in operating expenses. Industry-wide bipartite settlements between the Indian Banks' Association and employee unions reset compensation across the public-sector banking system in discrete cycles, while accumulated pension and gratuity liabilities demand actuarial provisioning that can absorb a substantial portion of quarterly operating profit. Management guidance expecting the cost-to-income ratio to rise from 46.33 per cent toward 48–49 per cent already incorporates these cost pressures.29 This structural friction explains why the return-on-equity ceiling highlighted in the bear case represents a concrete operational constraint rather than mere skepticism.
The offshore funding risk represents a newly introduced balance-sheet dependency. Mobilising dollar deposits and offshore bonds at a net hedged spread of fifty basis points and leveraging that base up to nine times generates spread income while dollar liquidity remains accessible and hedging costs remain stable.9 Yet during periods of global dollar tightness, hedging spreads can invert and financial leverage magnifies downside risk. While overseas funding remains modest today, scaling the initiative to meet management's $4.3 billion target will convert a tactical funding source into a material risk concentration.
What 2030 would have to look like. While management has not published a formal long-term target, the parameters of a successful 2030 outcome can be inferred from current guidance: compounding total business through sustained mid-teens annual credit growth; maintaining return on assets at or above one per cent across an entire credit cycle rather than solely during benign periods; anchoring the gross non-performing asset ratio below 2.5 per cent through a downturn; and maintaining a cost-to-income ratio capable of absorbing industry-wide wage settlements without eroding profitability.9
Notably absent from those benchmarks is a structural competitive moat. Nothing in the institution's 120-year history indicates it will establish one, nor does the regulatory framework of Indian public-sector banking facilitate such differentiation. The historical record reveals an enterprise capable of executing soundly during steady periods, yet vulnerable to severe capital destruction when credit cycles turn and sovereign policy directives diverge from minority shareholder interests. The turnaround under Rajneesh Karnatak is tangible, measurable, and executed with greater discipline than skeptics anticipated. Whether this recovery represents a structural break from past cycles or merely a familiar phase in a repeating pattern remains the central question for the next downturn — one that the market, pricing the stock at 0.71 times book value, has already answered with cautious skepticism.
References
-
Bank of India falls 5% as RBI puts bank under Prompt Correction Framework — Business Standard, 2017-12-20 ↩
-
Bank of India Q1 FY27 slides: profit surges 36%, NPAs hit new lows — Investing.com, 2026-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Bank of India reports Net Profit for FY26 grew to ₹10,527 crore by 14.19% YoY — Orient Publication, 2026-05-08 ↩↩↩↩↩↩↩↩↩
-
Bank of India share price, key insights and shareholding pattern — Screener.in ↩↩↩↩↩↩↩
-
Bank of India Q1 FY 2025-26 Quarter Results: Detailed Financial Insights & Analysis — Kotak Securities, 2025-07-29 ↩↩↩↩↩
-
Bank of India opened its first overseas branch in Europe at London in 1946 — Bank of India official account, 2024-05-17 ↩
-
Earnings call transcript: Bank of India posts strong Q1 2027 profit growth — Investing.com, 2026-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
PSBs registered net loss of Rs 17,993 cr in FY16: MoS Finance — Business Standard, 2016-12-02 ↩↩
-
BoI March quarter net loss at Rs 3,587 cr as bad loans rise — Business Standard, 2016-05-24 ↩
-
BoI trims Q4 loss to Rs 1,045 cr; checks bad loans — Business Standard, 2017-05-22 ↩
-
Bank of India Q4 net loss widens to Rs 3,969 crore — Business Standard, 2018-05-28 ↩↩
-
Bank of India Q3 net loss widens to Rs 4,738 cr; NPA provisions jump 2-fold — Business Standard, 2019-01-28 ↩
-
Bank of India appoints Rajneesh Karnatak as MD & CEO — HRNxt, 2023-05-01 ↩↩↩
-
RBI lifts Prompt Corrective Action restrictions on Bank of India, Bank of Maharashtra — Business Standard, 2019-01-31 ↩
-
Three banks taken off RBI watchlist: government — Business Standard, 2019-01-31 ↩
-
Bank of India completes acquisition of AXA stake in BOI AXA AMC — Moneycontrol, 2021-02-16 ↩
-
Bank of India announces closure of QIP issue; raises Rs 2,550 cr — Business Standard, 2021-08-31 ↩
-
Bank of India shares in focus as QIP kicks off; floor price set at Rs 105.42 per share — Business Today, 2023-12-06 ↩
-
Rajneesh Karnatak Gets 3-Year Extension as Bank of India MD & CEO — PSU Connect, 2026-04-23 ↩
-
Bank of India Annual Report for Financial Year 2025-26 — InvestyWise, 2026 ↩↩↩
-
NARCL Recovers Rs 4,364 Crore from Stressed Assets — NewKerala, 2026 ↩
-
Bank of India Q4 FY25 results: Net profit jumps 82.5% to ₹2,626 crore — Business Standard, 2025-05-09 ↩
-
Analyst Conference Call Transcripts — Bank of India, Official Portal ↩
-
Board Outcome dated 08 May 2026 — Bank of India, Official Portal ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube