VICI Properties: Who Owns the House?
I. The Casino Landlord That Never Opens a Casino
Walk into Caesars Palace on a Saturday night and everything announces who is in charge. The dealers wear Caesars uniforms. The loyalty cards say Caesars Rewards. The marble statues, the Forum Shops, the sportsbook screens and the comped suites are all part of a brand that has defined Las Vegas excess for more than half a century. And yet the company that owns the land under the craps tables, the hotel towers above them and the convention halls behind them has never dealt a hand of blackjack. It has no pit bosses, no slot technicians, no buffet. At the end of 2025 it had 28 employees.1
That company is VICI Properties, and its business is the quiet half of a casino. Caesars runs the tables; VICI owns the house. Every month the operator sends rent to the landlord, and every year that rent rises by a contractual amount. The landlord does not care whether a whale from Macau has a hot night at baccarat or whether a convention cancels its hotel block. It cares about one thing: that the tenant keeps the doors open and keeps paying.
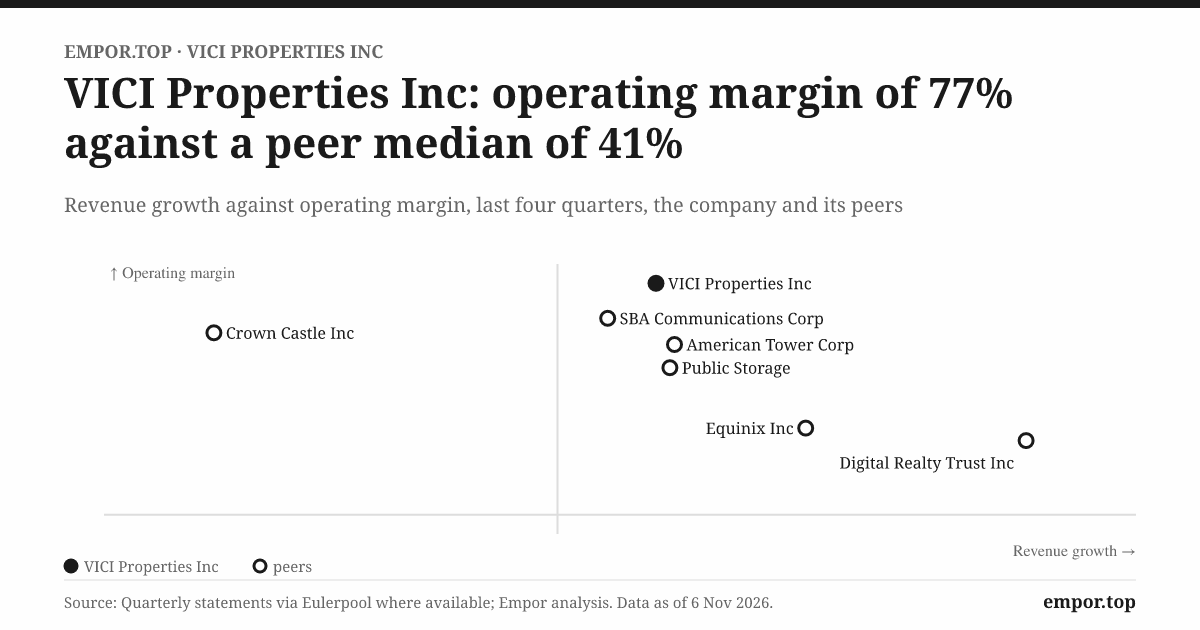
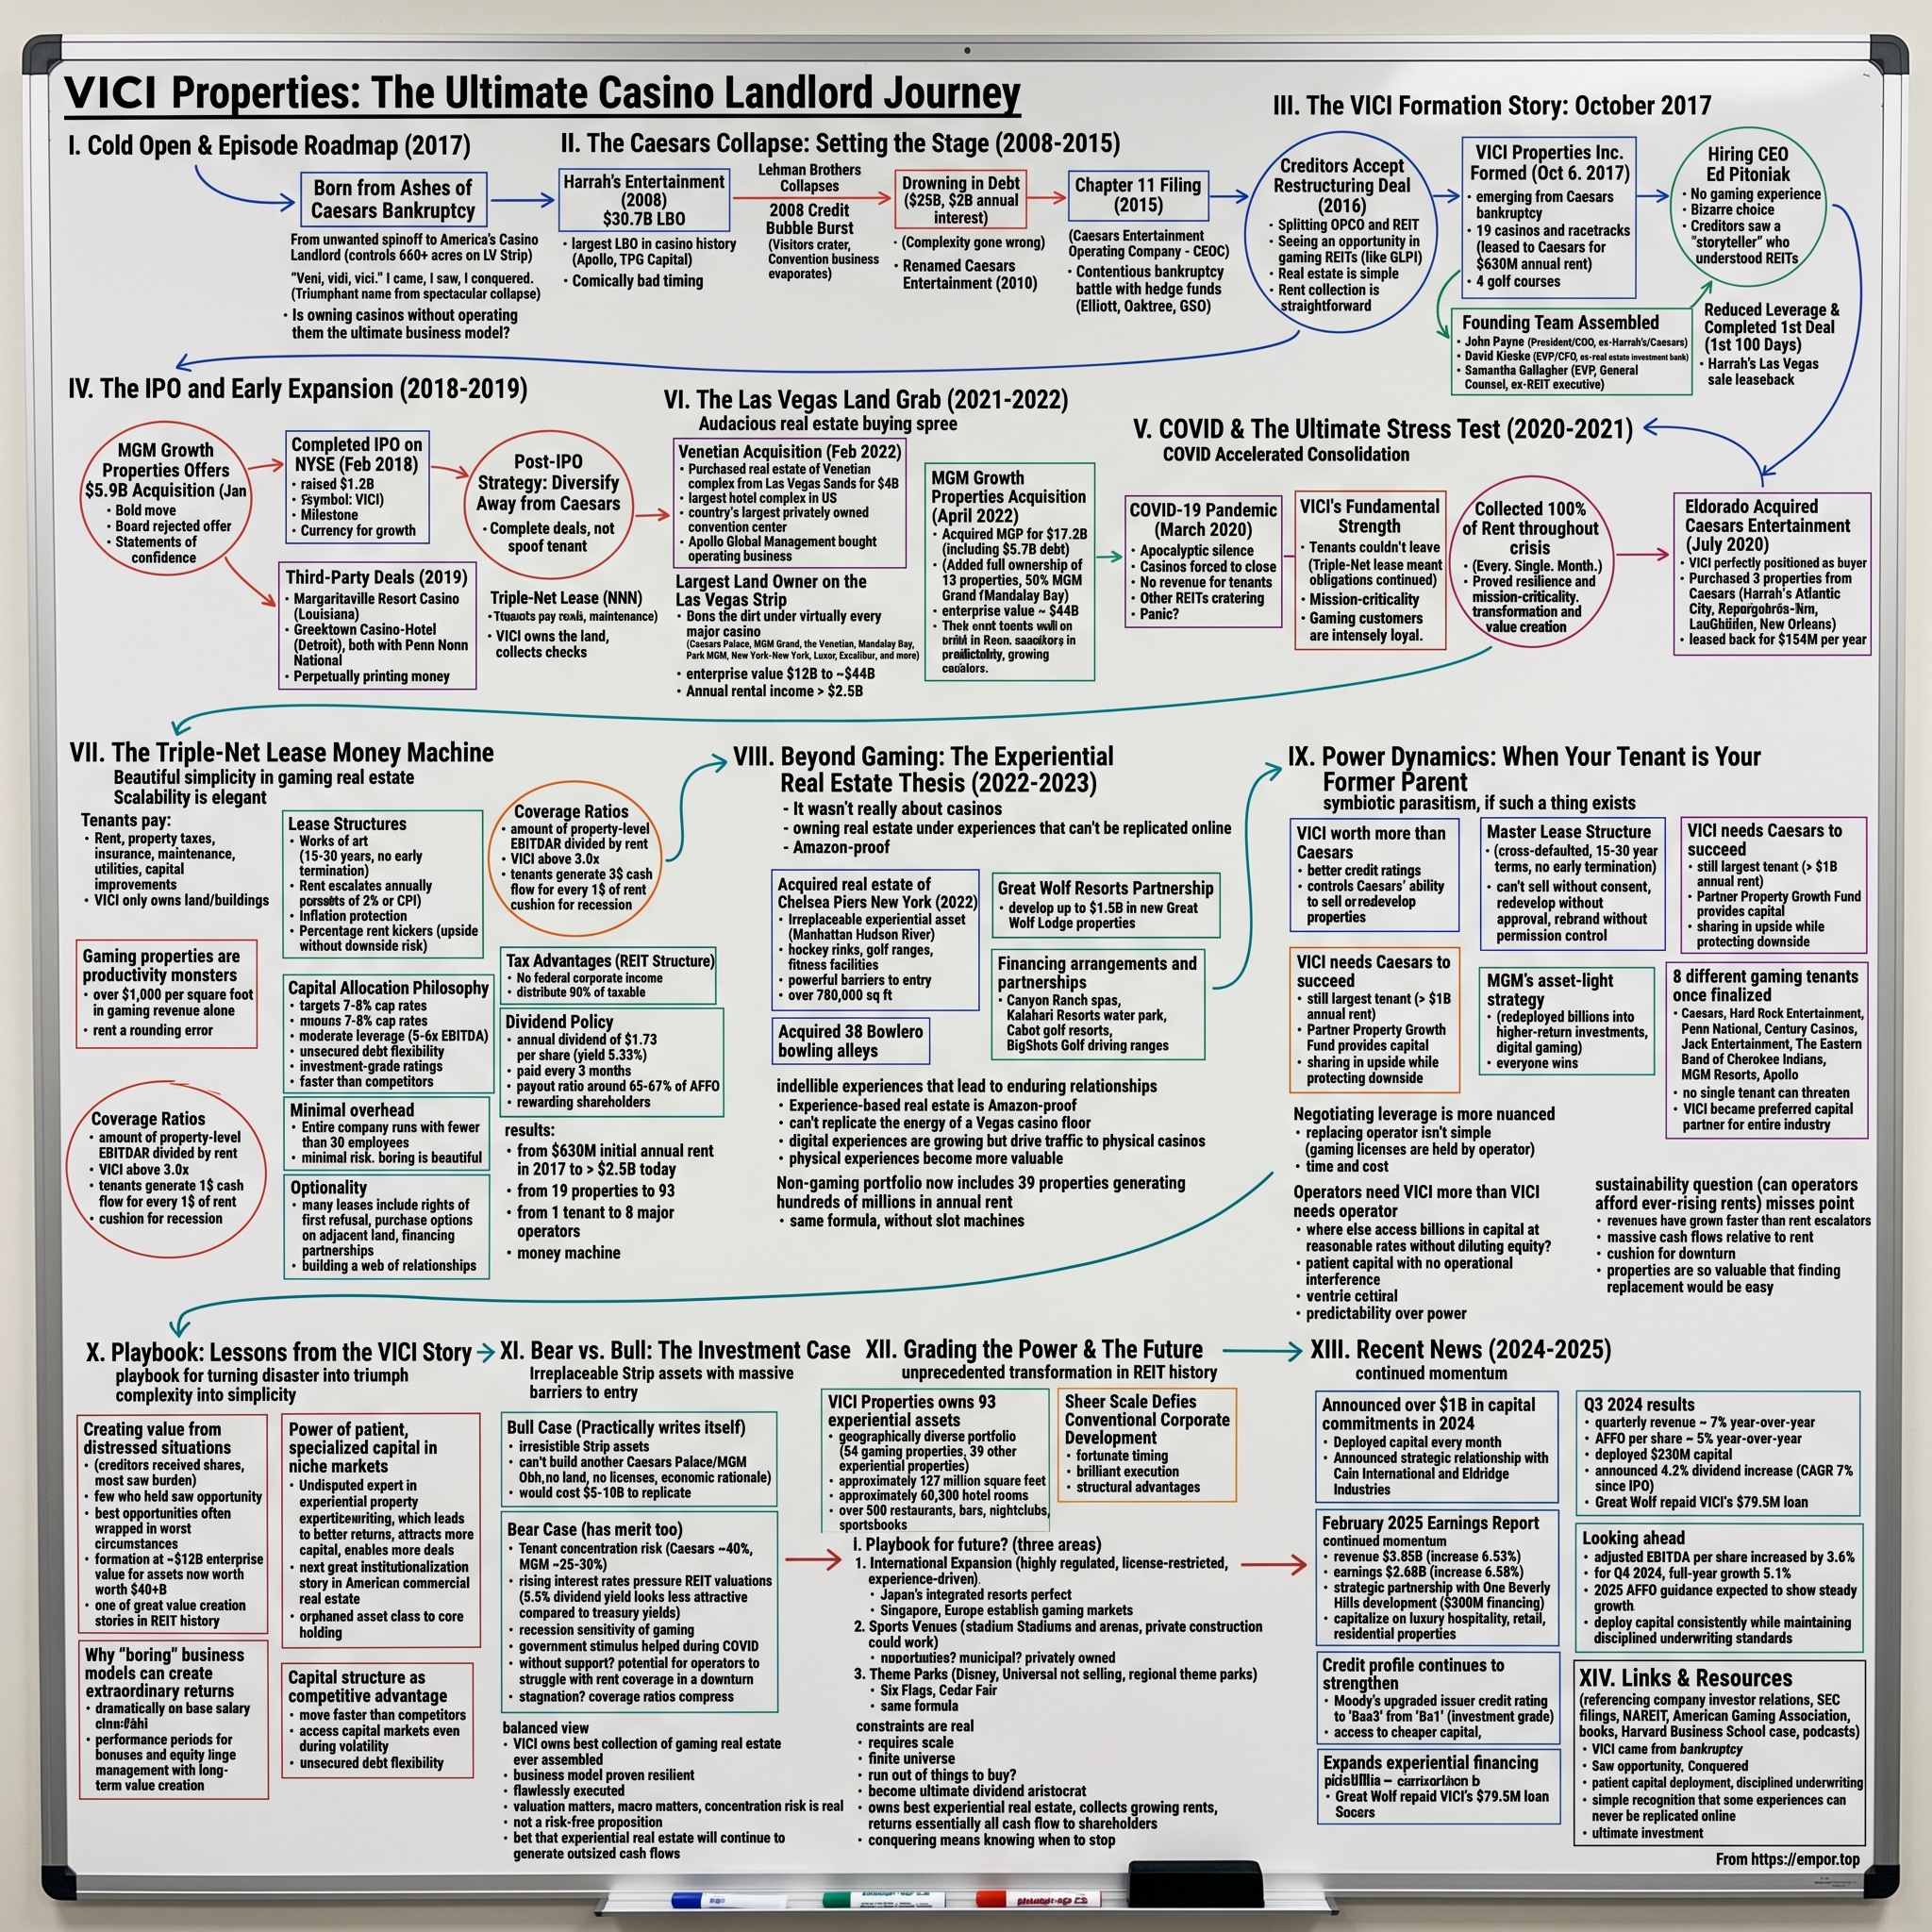
VICI began life in October 2017 with 19 gaming facilities, four championship golf courses and a patch of undeveloped land next to the Strip, all carved out of a bankrupt Caesars subsidiary and leased straight back to it.2 By the end of 2025 it owned 93 experiential assets, 54 of them casinos and 39 others ranging from bowling centers to a Manhattan sports complex, spread across 26 states and Canada.1 Revenue in 2025 came to about $4.0 billion, and its operating margin, the share of revenue left after running costs, was above 90%.1 That margin is the first clue to what kind of business this is. A casino operator spends most of what it takes in on payroll, marketing, food and electricity. A triple-net landlord spends almost none of it, because the tenant pays the property taxes, the insurance and the maintenance.
That arrangement is either the most elegant idea in American gaming or a very long fixed claim on a cyclical industry, depending on who is talking. The bull case says VICI owns irreplaceable ground under some of the most valuable entertainment destinations on earth, leased for decades, with rent that has never once gone uncollected since the company was formed, including the months in 2020 when every casino in the country was ordered shut.1 The bear case points to one number. At the end of 2025, Caesars supplied about 39% of VICI's annualized rent and MGM Resorts about 35%, which meant roughly three dollars of every four came from two tenants.1 A landlord is only as good as its tenants, and VICI's two biggest tenants are casino operators carrying heavy debt.
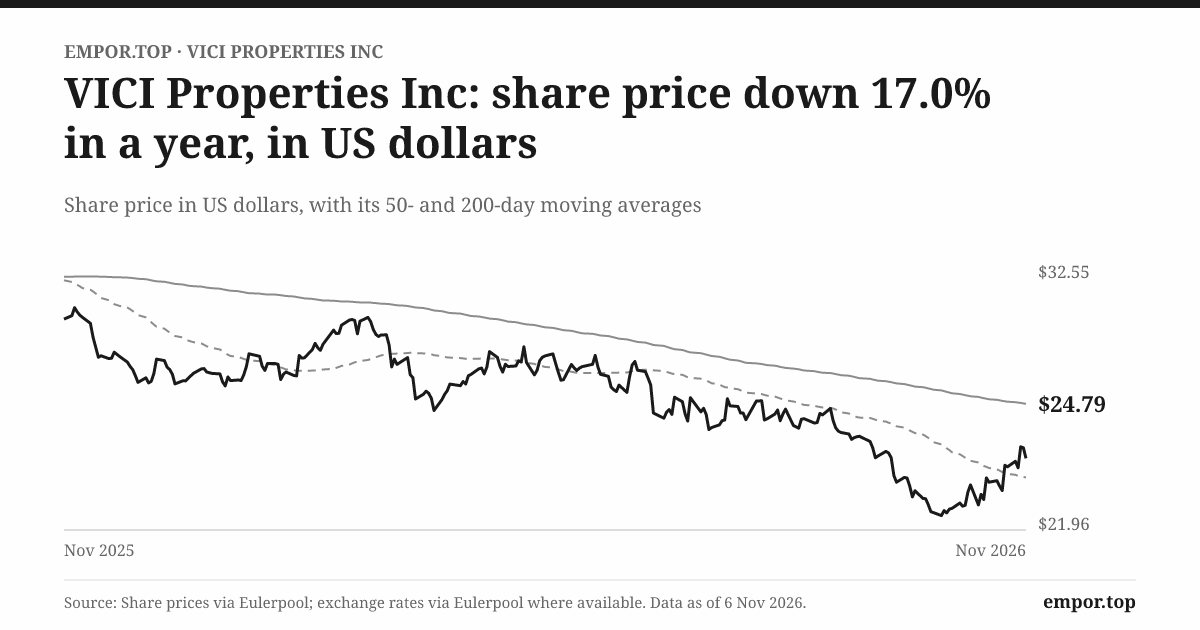
The tension sharpened in 2026. In May, Caesars agreed to be taken private by Tilman Fertitta's Fertitta Entertainment in a deal valued at about $17.6 billion including debt.3 Fitch, which rates VICI's bonds, warned that rent coverage in Caesars' regional lease portfolio was weakening and that the change of ownership could bring rent concessions, asset transfers or lease extensions.4 In the second quarter of 2026, VICI's revenue grew about 6% while its net income fell 39%, because it set aside a further $271 million against the possibility that tenants or borrowers might not pay in full someday.5 On the morning this story was written, the shares traded around $24, near the bottom of their 52-week range and barely above the $20 at which VICI went public in 2018.6
Four questions carry this story. How did creditors of a bankrupt casino company end up owning a landlord? Do VICI's leases protect it from tenant distress, or merely postpone the moment the landlord has to share the pain? Have its giant acquisitions earned enough per share to justify the shares and debt issued to pay for them? And can the newer experiential bets, the bowling alleys, ski resorts and Caribbean beach clubs, ever matter beyond the gaming core?
The answers begin, as the company itself did, in a bankruptcy courtroom in Chicago.
 Subscribe on LinkedIn
II. The Creditor's Casino
On January 15, 2015, Caesars Entertainment Operating Company, the subsidiary that ran most of Caesars' casinos, filed for Chapter 11 in federal bankruptcy court in Chicago.7 It was carrying about $18 billion of debt, much of it a legacy of the roughly $30 billion leveraged buyout of Harrah's Entertainment that Apollo Global Management and TPG Capital had completed in 2008, just as the financial crisis arrived.7 The timing of that buyout became one of the classic cautionary tales of the private-equity boom. Gaming revenue fell with the economy, Atlantic City entered a long decline, and the interest bill on the debt kept arriving regardless.
The bankruptcy itself was a brawl. Junior creditors, led by the hedge fund Appaloosa Management, had already tried to force the operating company into an involuntary bankruptcy in Delaware, where they hoped for a friendlier hearing.7 Their complaint was that valuable assets had been moved out of the operating company and beyond creditors' reach in the years before the filing. The sponsors and the parent company wanted the case kept in Chicago and kept on their terms. For two years the parties fought over who owned what, who had been harmed, and who would pay.
What made the eventual settlement possible was an idea that sounds simple and was not: split the casinos in two. The plan disclosed on the day of filing proposed to cut the operating company's debt from about $18.4 billion to $8.6 billion and to divide it into a company that ran casinos and a real estate investment trust that owned the property beneath them.7 The trust would collect rent. The operator would pay it. Creditors who had lent money to a casino company would end up owning, in large part, a landlord.
There was precedent. In November 2013, Penn National Gaming had spun off the real estate under its casinos into Gaming and Leisure Properties, the first publicly traded REIT focused on gaming, which took ownership of 21 casino facilities and leased most of them back to Penn.8 GLPI showed that investors would pay for casino property separated from casino operations, often at a higher valuation than they would pay for the combined business, because a long lease with a rent escalator looks more like a bond than a slot floor does. A REIT also pays no corporate income tax so long as it distributes most of its taxable income, which is part of why the separated real estate can be worth more on its own.
For Caesars' creditors, the logic was compelling. A claim on casino earnings is volatile; a claim on rent is senior to almost everything the operator spends money on, because if the operator stops paying rent it loses the building. A bankruptcy court confirmed the reorganization plan in January 2017.9 On October 6, 2017, it took effect, and VICI Properties came into existence owning 19 gaming facilities with about 32.5 million square feet of space and about 12,000 hotel rooms, plus the four golf courses and 53 acres of undeveloped land next to the Strip.2 The crown jewel was the real estate of Caesars Palace itself. Every property came with a long-term triple-net lease back to the reorganized Caesars operating company, guaranteed by the Caesars parent.2
The arrangement looked conservative on paper. At formation, VICI calculated that Caesars' earnings covered the rent about 3.5 times over on a pro forma basis.2 That cushion mattered, because it meant the tenant could absorb a sharp drop in casino profits before the rent itself came into question. It was also the founding burden. VICI started life with exactly one tenant, the same company whose bankruptcy had just created it. Its rent roll was a single relationship, its properties were a mix of Las Vegas trophies and regional casinos in markets such as Atlantic City that Caesars itself had struggled with, and it had no public share price, no track record and no obvious way to grow.
Separating the land from the business had produced a landlord. Whether it had produced a real company, one that could raise capital, find new tenants and stand on its own, was a different question entirely.
III. A Landlord With No Public Track Record
In its first weeks, VICI was an odd creature. Its shareholders were the former creditors of a bankrupt casino company, many of them hedge funds and distressed-debt investors who had received stock as part of their recovery and had no particular reason to hold it forever. Its tenant was its former parent. And its chief executive was a man whose career had run through ski magazines, mountain resorts and Canadian hotel trusts rather than casino floors.
Edward Pitoniak had been appointed chief executive on the formation date.10 He had started out at Times Mirror Magazines, spending nine years there and rising to editor-in-chief and associate publisher of Ski Magazine, then spent nearly eight years as a senior vice president at Intrawest, the ski and golf resort developer.10 From 2004 until he retired in 2009, he ran bcIMC Hospitality Group, a hotel owner, and in 2014, he stepped in as managing director and acting chief executive of InnVest, a Canadian hotel REIT that needed a recapitalization, later serving as its chairman until it was sold in 2016.10 He had also served since 2006 as an independent director of Ritchie Bros. Auctioneers, and immediately before VICI was vice chairman of the industrial landlord Realterm.10 The thread that ran through all of it was experiential real estate: places people visit for pleasure, and the economics of owning them.
His operating partner came from the other side of the table. John Payne had spent his career inside Caesars and its predecessor Harrah's, running Harrah's New Orleans, then regional divisions, then serving as chief executive of the operating company that went into Chapter 11.10 Payne knew the casinos VICI owned from the inside, knew what their managers worried about, and knew the operators who might someday want to sell real estate. The finance chief who arrived at the end of 2017, David Kieske, came from the investment-banking side, having spent a decade at Wells Fargo Securities and Eastdil Secured advising real estate and lodging companies.10 Between them, the three men covered the essential skills of the business: picking assets, understanding tenants and raising money. All three are still running the company more than nine years later.11
The first test came before the IPO did. On January 5, 2018, MGM Growth Properties, the REIT that owned MGM Resorts' real estate, sent VICI an unsolicited proposal to buy the whole company for $19.50 a share, paid in MGP stock, valuing VICI at about $5.85 billion.12 When VICI's board said no, MGP made the offer public, hoping to pressure the board through shareholders who had every reason to want liquidity.12 The board held its ground, arguing that VICI's independent prospects, including its options to buy more Caesars properties, were worth more. Two weeks later it went public on its own terms.
The IPO prospectus, dated January 31, 2018, offered 60.5 million shares at $20 each, raising about $1.2 billion before costs, with an option for underwriters to buy roughly 9.1 million more.9 Much of the money went to paying down debt left over from formation, including expensive second-lien notes redeemed at a premium.9 The prospectus also laid out the growth runway the board had pointed to: call rights on Harrah's Atlantic City, Harrah's New Orleans and Harrah's Laughlin, and a right of first refusal on certain other Caesars properties.9 VICI had already used its separation momentum to buy Harrah's Las Vegas from a Caesars affiliate in December 2017 for about $1.14 billion and lease it back.9
Why did going public matter so much? Because a REIT must pay out most of its taxable income as dividends, it cannot grow much by retaining earnings the way an ordinary company can. Almost every acquisition has to be funded with new debt or new shares. That makes access to capital not a supporting function but the business model itself, and it creates a permanent hurdle. Every new share issued dilutes existing owners, so an acquisition only creates value if the rent it brings in, per share, exceeds what the old shares were already earning. Every dollar borrowed has to be repaid or refinanced at whatever rate the market demands years from now.
Pitoniak would later boil the business down to a line he repeated often: the best people plus the lowest cost of capital wins.13 It was a revealing formulation. It admitted that VICI's product, money in exchange for real estate, was not unique. What would distinguish it was the price at which it could raise that money and the judgment with which it deployed it. Rejecting MGP and listing independently had given VICI a currency. The next question was whether it could spend that currency well, and whether anyone besides Caesars wanted to do business with it.
IV. The First Deals Beyond Caesars
Picture a casino owner in Detroit or Cleveland in 2019. The business is solid, but the owner wants capital, perhaps to pay down debt, fund an acquisition or simply cash out some of the value tied up in buildings. A bank will lend against the property, but only at a fraction of its value and only for a few years. VICI offered something different. It would buy the land and buildings outright for cash, then lease them back to the operator for decades. The operator would keep running the casino exactly as before, keep the employees, keep the brand and keep the upside from a good year. It would simply pay rent instead of owning the walls.
This is the sale-leaseback, and it became VICI's core product. Its economics are best understood through one number, the capitalization rate, or cap rate, which is the first year's rent divided by the purchase price. A $100 million property bought at an 8% cap rate generates $8 million a year in starting rent. For the landlord, a higher cap rate means more income per dollar invested. For the seller, a lower cap rate means more cash for each dollar of rent it commits to pay. The cap rate is, in effect, the price of the deal.
In 2019, VICI spent its new public currency outside the Caesars family for the first time. It agreed to buy the real estate of Greektown Casino-Hotel in Detroit for $700 million, leased to Penn National Gaming at about $55.6 million of annual rent, an implied cap rate of about 7.9%.14 It bought Margaritaville Resort Casino in Bossier City, Louisiana, also leased to Penn, for about $261 million at an implied 8.9%.14 It paid about $278 million for two Missouri casinos, Century Casino Cape Girardeau and Caruthersville, leased to Century Casinos at an implied 9.0%.14 And it struck its largest outside deal with JACK Entertainment, the Gilbert family's operator, agreeing to pay about $843 million for JACK Cleveland Casino and the JACK Thistledown racino at an implied 7.8%; that transaction closed in January 2020.14 Across about $4.9 billion of transactions announced in 2019, management put the blended cap rate at about 7.9%.13
Those numbers deserve to be read carefully. A 9.0% cap rate on two small Missouri casinos is not a better deal than a 7.8% cap rate on a Cleveland casino simply because the number is higher. Higher yields compensate for higher risk: smaller markets, weaker tenants, older buildings or thinner rent coverage. A landlord can always buy a higher cap rate by taking more risk, so the cap rate alone proves nothing about whether a deal was attractive. What the 2019 deals did establish was a visible pricing range for regional gaming real estate, roughly 7.7% to 9.0%, against which every later VICI transaction could be measured.
They also did something the Caesars spin-off could not. They brought new tenants onto the rent roll. Penn, JACK and Century each signed long-term triple-net leases. Those leases kept nearly every property-level cost with the tenant, allowing VICI to run a multibillion-dollar portfolio with a staff that would fit in a single conference room.
On the fourth-quarter 2019 call, Pitoniak described VICI's people as relationship builders, not destroyers, and insisted that chasing a bad deal for the sake of growth was "not who we are at VICI, not today, not tomorrow, not ever."13 It was a pointed statement, because the temptation for a REIT whose growth depends on acquisitions is always to keep buying. Full-year 2019 adjusted funds from operations, the cash-earnings measure REITs use in place of net income, came to about $1.48 per diluted share.14 That figure is worth remembering, because it is the yardstick for everything that followed.
Adjusted funds from operations, or AFFO, needs a brief explanation. GAAP net income for a REIT is distorted by large non-cash charges, chiefly depreciation of buildings that often hold or gain value, and in VICI's case by accounting estimates of future credit losses. AFFO adds those back and removes other non-cash items to approximate the recurring cash a REIT generates for its shareholders. It is not a perfect measure, and every REIT calculates it slightly differently, but it is the closest thing to the per-share earning power that pays the dividend.
By early 2020, VICI had shown it could buy from operators other than Caesars and do so at yields that looked reasonable against its borrowing costs. The tenant list was longer, though Caesars still dominated. The question that every triple-net landlord asks privately, and few have to answer publicly, remained untested: what happens to the rent if the entire industry stops operating at once?
V. The Rent Check During the Shutdown
In the middle of March 2020, the lights went out on the Las Vegas Strip. State governors ordered casinos closed across the country as COVID-19 spread, and for weeks the most famous skyline in American leisure stood dark. Slot floors that had not been empty since they were built went silent. Hotel towers emptied. Casino operators furloughed tens of thousands of workers and drew down every credit line they had.
For a landlord whose entire income came from casino operators, this was the test the business model had been built to withstand and never expected to face. A lease is a promise. But a promise from a tenant whose revenue has just gone to zero is only as good as the tenant's cash reserves and willingness to keep paying.
VICI's tenants paid. The company has since said that it has collected 100% of its rent since formation, including through COVID.1 Operating cash flow in 2020 came to about $884 million, higher than the year before.1 Behind that record lay several mechanisms that are worth understanding, because they explain both why it held and why it might not hold in every future downturn. The first was that the leases were master leases, which bundle many properties into a single contract. A tenant cannot stop paying on its weakest casino while keeping its best one, because default on one is default on all. Caesars could not have walked away from a struggling regional property without putting Caesars Palace at risk. The second was the corporate guarantee from Caesars' parent, which made the rent an obligation of the whole enterprise, not just the subsidiaries operating the buildings. The third was simply that casino operators view their real estate as irreplaceable. Losing a gaming license site is not like losing an office lease; the operator may not be able to replace it at any price.
Yet the pandemic record needs to be read precisely. Tenants paid because they had access to liquidity: credit lines, bond markets that reopened quickly, and government support for the broader economy. The shutdown lasted months, not years. It demonstrated that VICI's contractual rent was senior and resilient through an acute shock. It did not demonstrate that every tenant could sustain full rent through a prolonged slump, or through a restructuring of its own balance sheet. Those are different tests, and the second one is the one that has quietly returned in 2026.
While the casinos were closed, the industry's largest merger went ahead. In June 2019, Eldorado Resorts had agreed to buy Caesars Entertainment in a deal that valued Caesars at about $17.3 billion, and VICI had agreed to provide part of the financing by buying real estate and amending its leases.15 When the merger closed in July 2020, VICI paid about $3.2 billion in cash. Roughly $1.8 billion bought the land and buildings of Harrah's New Orleans, Harrah's Atlantic City and Harrah's Laughlin, the properties VICI had held call rights on since its IPO; the rest paid for amendments to the existing Caesars leases that raised the rent.15 Altogether, the transactions added about $253 million of annual rent.15 The three new properties were folded into the old regional lease, which was renamed the Regional Master Lease.15
This was the first public demonstration of a business model that would recur throughout VICI's history. An operator wants to grow by acquisition but does not have enough cash. A landlord buys the operator's real estate, and the proceeds help fund the merger. VICI was not just a passive owner collecting rent; it was a capital partner in the consolidation of an industry. Eldorado's team, led by Tom Reeg, who became Caesars' chief executive, could focus on running casinos while VICI supplied the money tied up in buildings.
The shape of the relationship changed in a way investors would come to feel years later. The new Caesars was a larger company, but it was also more indebted, and VICI's exposure to it had grown rather than shrunk. The Regional Master Lease now included Atlantic City and New Orleans along with the original portfolio, all tied to one tenant's health. As the casinos reopened and the recovery took hold, the record looked unassailable. Over the next five years, operating cash flow would almost triple, to about $2.5 billion in 2025.1 But most of that growth would come not from the rent escalators in the original leases. It would come from a pair of deals in 2022 that changed the company's size, its risk and its shareholder base all at once.
If VICI could collect rent through a nationwide shutdown, how much more could it be worth if it owned the most important buildings on the Las Vegas Strip?
VI. The Strip Changes Hands Twice
The Venetian is one of those Las Vegas buildings that seems too big to belong to anyone. Its replica of the Doge's Palace and canals with singing gondoliers sit atop one of the largest hotel complexes in the world, connected to the Palazzo and to a convention center that hosts trade shows by the hundred. For decades it was the pride of Sheldon Adelson's Las Vegas Sands. But by 2021, Sands had decided its future lay in Macau and Singapore, and it put its Las Vegas holdings up for sale.
The way that sale was structured tells you everything about the logic VICI was built on. Sands did not sell the Venetian to one buyer. It sold it to two. Apollo Global Management, the same firm that had co-led the ill-fated Harrah's buyout more than a decade earlier, bought the operating business for about $2.25 billion. VICI bought the land and real estate for about $4.0 billion in cash, and leased it to Apollo's operating company.16 The deal closed on February 23, 2022.16 The building was worth more as real estate than as a business, at least in the eyes of the people writing the checks, because a long lease from a well-capitalized operator commands a premium that a casino business does not.
VICI paid a 6.25% cap rate, which implies starting annual rent of about $250 million.16 That was well below the 7.7% to 9.0% it had paid for regional casinos in 2019. Does a lower yield mean VICI overpaid? Not necessarily. The Venetian is a trophy Strip asset with one of the largest convention businesses in the city, a type of property that rarely trades and is very hard to replicate. Regional casinos in Missouri or Louisiana face more local competition and more economic sensitivity. A lower cap rate on a better asset can be the right price. But the lower yield also left less room for error, especially as interest rates were about to rise sharply. VICI later committed further money to the property, funding $400 million of capital investment at the Venetian between 2024 and early 2025.1
To pay for the Venetian, VICI settled 119 million shares it had sold under forward equity agreements in 2021, raising about $3.2 billion, and drew $600 million on its revolving credit facility.16 This is where the per-share test first bit. In the first quarter of 2022, total AFFO rose about 20% from a year earlier, but AFFO per diluted share fell about 5%, from $0.47 to $0.44, because the share count had grown faster than the cash flow.16 Management attributed the decline mainly to the higher share count.16 It was the predictable cost of issuing equity before the acquired rent started to arrive in full, but it illustrated the trap that awaits any acquisition-driven REIT. Getting bigger is easy. Getting richer per share is not.
The second deal was far larger. On August 4, 2021, VICI announced that it would acquire MGM Growth Properties, the very REIT that had tried to buy VICI three years earlier, in a transaction valued at about $17.2 billion including roughly $5.7 billion of assumed debt.17 MGP owned the real estate under 15 major MGM Resorts properties across nine regions, including Strip icons such as MGM Grand and Mandalay Bay through a joint venture with Blackstone's REIT, with about 33,000 hotel rooms between them.17 The tables had turned completely. The creditor-owned landlord that had been told it was a takeover target was now swallowing its pursuer.
The price structure was intricate, and the details matter for judging it. MGP's public shareholders received 1.366 VICI shares for each MGP share, which the companies described as an agreed price of $43.00, based on VICI's five-day volume-weighted average price of $31.47.17 That was a premium of about 15.9% to MGP's closing price the day before the announcement.17 MGM Resorts, which owned most of MGP through its operating partnership units, received about $4.4 billion in cash for most of those units and kept roughly 12 million units in a new VICI operating partnership.17 MGM signed a new master lease with VICI carrying initial annual rent of $860 million, a 25-year initial term and escalators of 2% a year for a decade, then the greater of 2% or inflation capped at 3%.17 VICI also kept MGP's 50.1% stake in the Blackstone joint venture that owned MGM Grand and Mandalay Bay.17
A premium of about 16% to MGP's market price is evidence that VICI paid up, but it is not by itself evidence that VICI overpaid. Takeover premiums are normal, and MGP's shareholders were giving up control. The better question is whether the rent VICI acquired, after the cost of the shares and debt used to buy it, raised the cash earnings attributable to each VICI share. Management said at announcement that the deal would be immediately accretive to AFFO per share.17 That was a claim, and it can now be judged by what happened afterward.
The deal closed on April 29, 2022.18 VICI issued about 214.5 million new shares, bringing its total to about 963 million, sold $5.0 billion of new senior unsecured notes and exchanged about $4.1 billion of MGP's bonds for its own.18 Combined attributable rent from the MGM leases came to about $1.01 billion a year.18 The company now owned 43 gaming facilities with more than 122 million square feet of space and about 58,700 hotel rooms.18 On paper, its reported borrowings nearly tripled in a year, from about $5.0 billion at the end of 2021 to about $14.6 billion at the end of 2022.1
One argument VICI made for the MGP deal was diversification. Before it, Caesars accounted for 84% of VICI's rent; after it, management said, the top tenant's share would fall to about 41%.17 That claim was true and also slightly misleading. Concentration in one tenant fell. Concentration in two tenants, each of them a heavily indebted casino operator with a large Strip presence, became the defining feature of VICI's rent roll. Years later, those two still provided about three-quarters of rent.1
So did the Strip deals create durable value? The per-share record gives a partial answer. AFFO per share rose from about $1.48 in 2019 to $2.38 in 2025, a compound gain of roughly 8% a year across a period that included a pandemic, two transformational acquisitions and an interest-rate shock.141 That is real progress for a landlord whose leases escalate by about 2% a year, and it suggests the acquisitions were, on balance, accretive. GAAP earnings per share tell a noisier story, dropping in 2022 before nearly doubling in 2023, but for a REIT those swings mostly reflect non-cash charges rather than economic performance. What the record cannot yet show is whether the price paid will look wise after a full cycle of tenant stress. A landlord's investment returns are not finished until the leases are fully paid.
By 2022, VICI owned Caesars Palace, the Venetian, MGM Grand, Mandalay Bay and much of the rest of the Strip's real estate. It had become, in its own description, the owner of experiential real estate on a scale no one else could match. But scale is not the same as security. The question that follows is what, exactly, makes those buildings and those leases so hard to dislodge, and how much power the tenants who occupy them still hold.
VII. The Lease That Looks Like a Moat
Imagine a contract signed in 2022 that does not fully expire until the 2060s. That is the kind of commitment VICI writes. At the end of 2025, its properties were 100% leased, with a weighted-average remaining lease term of about 39.6 years including tenant renewal options.1 In an economy where software subscriptions run a year and office leases run a decade, that is an extraordinary horizon. A tenant who signs today will pay rent to VICI through several presidential administrations, a few recessions and possibly the careers of everyone who negotiated the deal.
The basic economics are straightforward. VICI collects rent and, increasingly, interest on real estate loans. Rent rises each year under escalators, and about 42% of 2025 rent and 90% of long-term rent features escalation linked to consumer price inflation, subject to caps.1 In 2025, VICI earned about $2.5 billion of AFFO, or $2.38 per share, up about 5% from the year before.1
Why are these buildings hard to replace? Three reasons stand out. The first is location. There are only so many sites on the Las Vegas Strip, and almost all of them are built. The Strip properties accounted for about half of VICI's 2025 revenue.1 The second is regulation. Casino licenses are tightly controlled by state gaming commissions, and in many regional markets a license is effectively tied to a site. An operator cannot simply move its casino across town if the rent feels too high. The third is cost and time. Building a major integrated resort takes years and billions of dollars, and few lenders will finance one on speculation. Together these create real switching costs: a casino operator who stops paying rent loses not just a building but often its right to operate in a market.
Gaming and Leisure Properties is VICI's closest listed peer and its main competitor for new deals. Both REITs compete to buy operators' real estate, and both have leases with Penn and Caesars, among others. VICI is the larger of the two, with roughly twice GLPI's market value, and has far more exposure to the Las Vegas Strip.6 That scale and access to investment-grade bond markets give VICI a lower cost of capital in principle, which is exactly the edge Pitoniak's formula prizes. But neither landlord can assume that every operator will want to sell, and neither can stop an operator from turning to private credit, pension funds or other buyers. Private equity and private credit funds have spent the past decade looking for exactly the kind of long-dated, asset-backed income that casino real estate provides, so VICI's competition for the next deal is not limited to one listed rival.
Now turn the lens around. Buyer power, in Michael Porter's terms, is the ability of customers to dictate prices. For VICI, the customers are the tenants, and two of them dominate. At the end of 2025, Caesars and MGM accounted for about 74% of annualized rent, and VICI expected to receive about $1.3 billion from Caesars and about $1.1 billion from MGM in 2026.1 Fitch has pointed out that most of VICI's tenants carry weaker credit ratings than VICI itself.4 If Caesars or MGM decides its rent burden is too heavy, it cannot walk away without losing irreplaceable properties, but it can renegotiate, restructure, sell individual properties or, in an extreme case, use bankruptcy to try to reject or recharacterize leases. VICI's own annual report warns of the risk that a court could treat certain lease modifications, including the 2020 Caesars rent increases, as a disguised financing rather than a true lease.1
The rent coverage ratio is the clearest single measure of tenant strength. It compares a tenant's property-level earnings before rent with the rent itself; a ratio of 2.0 means the tenant earns twice what it pays. That cushion was substantial at formation.2 VICI does not publish current tenant-level coverage ratios for its master leases, and Fitch has scored its disclosure on that front below that of GLPI.4 What is public is Fitch's warning, repeated in its rationale for VICI's 2026 bonds, of "weakening rent coverage in Caesars' regional master lease portfolio."19 That lease covers 16 properties and carried annualized rent of about $740.5 million as of May 2026, in its ninth lease year, with a variable rent component that resets in lease years 11 and 16.20 Those reset dates matter. They are the moments when the contract itself adjusts rent toward the properties' actual performance, which means that weak regional results can eventually lower what VICI collects even without a default.
Here the moat claim must be narrowed, not rejected. Hamilton Helmer's framework of seven powers identifies two that apply most clearly to VICI. The first is cornered resource: ownership of scarce, licensed real estate that no competitor can duplicate. The second is switching costs: a tenant's inability to relocate a casino without losing its market. Both are real. But they protect the asset, not the rent level. A cornered resource guarantees that someone will want to run a casino at Caesars Palace; it does not guarantee that the operator can pay today's rent plus 2% a year forever. The long lease secures a contractual claim. It does not abolish the operator's balance sheet.
That distinction is the hinge of the entire VICI story. Its collection record remains impressive. But collection and credit loss are not the same thing. Collection describes what has already happened. Credit loss describes what an honest accountant expects might happen. Three measures will tell investors which one dominates over time: AFFO per share, which captures whether acquisitions add value; tenant rent coverage, which captures whether the operators can afford what they owe; and net leverage, which captures whether VICI can absorb a shock without diluting shareholders. The second of those three began flashing amber in VICI's own accounts in 2025, in a line item most investors had learned to ignore.
VIII. When the Rent Stream Became a Credit Allowance
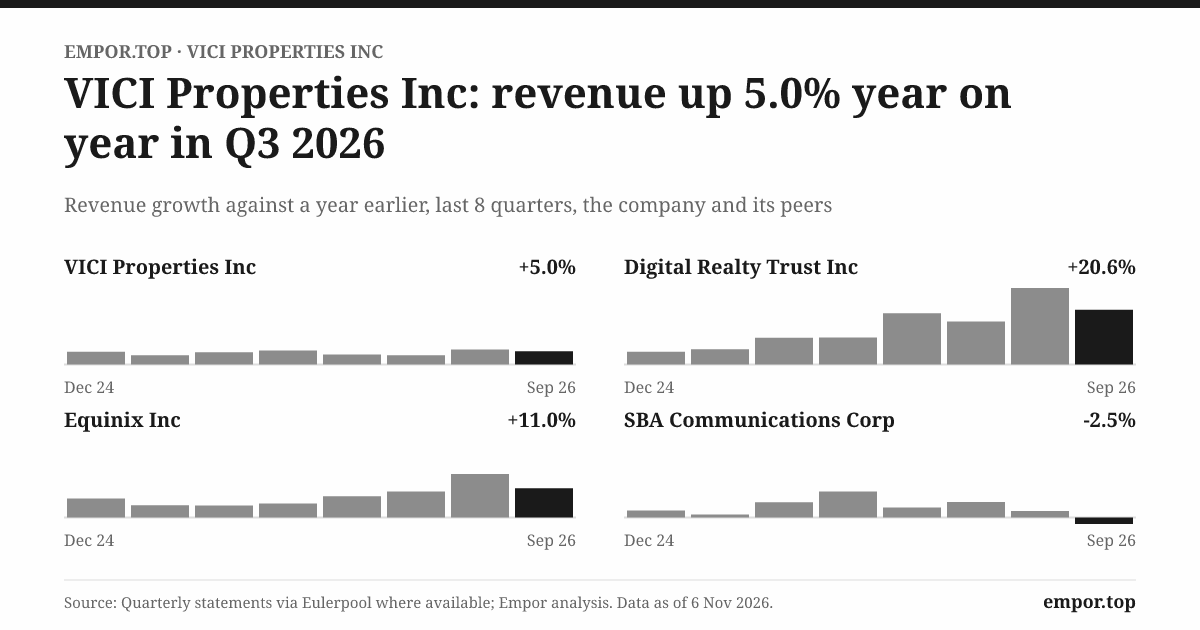
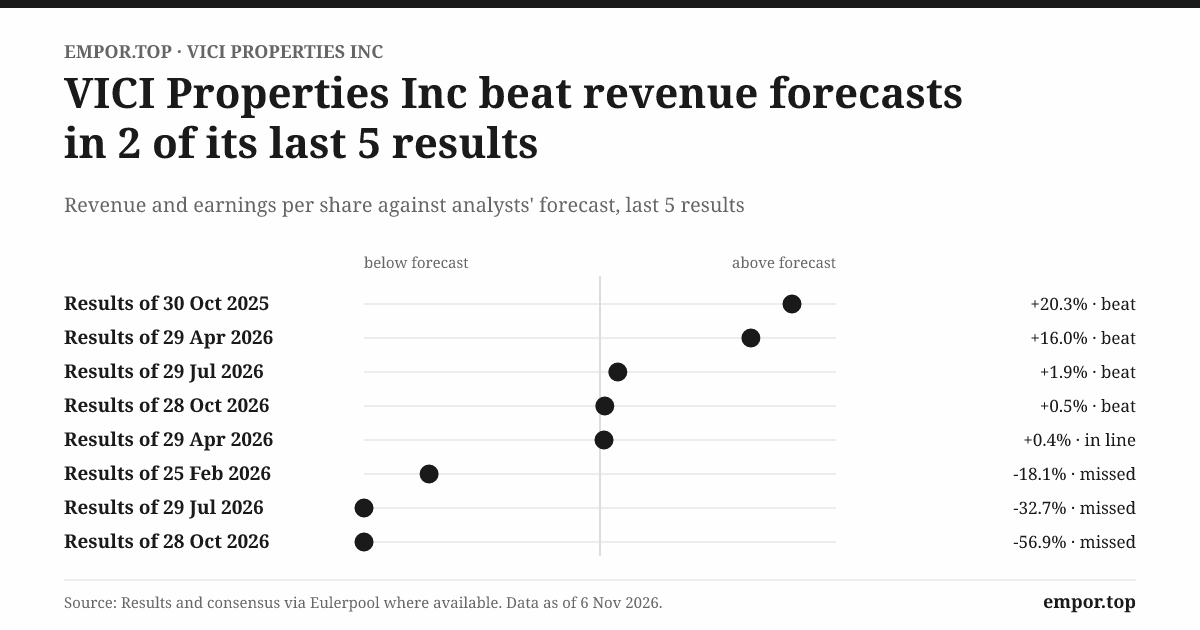
On July 29, 2026, VICI reported its second-quarter results, and the headline looked, at first glance, like a contradiction. Revenue rose about 6% from a year earlier, to roughly $1.06 billion.5 AFFO per share rose about 5%, to $0.62.5 The company raised the bottom of its full-year guidance.5 And net income attributable to shareholders fell about 39%, from $865 million to $527 million.5 A business collecting more rent than ever had somehow earned far less.
The explanation lay in four letters: CECL, short for current expected credit losses, an accounting standard that took effect for most public companies in 2020. Under CECL, a lender or landlord holding certain kinds of financial assets must estimate, every quarter, how much it might lose over the entire life of those assets if borrowers or tenants default, and record that estimate as an allowance. Because many of VICI's leases are accounted for as sales-type leases or financing receivables rather than ordinary operating leases, they fall under the standard. VICI must therefore estimate the probability that Caesars, MGM and its other tenants might default at some point over decades, and how much it would lose if they did. When those estimates change, the allowance changes, and so does reported net income, even though not a single rent check has been missed.
In the second quarter of 2026, VICI increased its allowance by about $271 million. A year earlier, in the second quarter of 2025, it had released about $142 million. The swing between those two quarters, about $413 million, explained the entire decline in net income.5 By June 30, 2026, the allowance against sales-type leases alone stood at about $1.01 billion, up from about $919 million six months earlier.5
It would be easy to dismiss all of this as accounting noise, and the long-run record supports that reading up to a point. Over the company's history through 2025, cumulative net profit and cumulative operating cash flow both came to roughly $12.1 billion, suggesting that reported earnings and real cash have tracked each other closely over the long run.1 VICI's operating cash flow kept rising through 2025, up about $128 million to $2.5 billion, driven by rent escalators, Venetian rent increases and loan income.1 Some of the quarterly allowance volatility also comes from mechanical inputs. The company says its CECL model uses tenants' credit ratings and even the trading prices of their stocks, so a drop in a tenant's share price can lift the allowance without anything changing at the properties.5
But noise is not the whole story, and the trend is the clue. In 2025, the income-statement charge for credit losses rose to about $178 million from about $127 million the year before, which VICI attributed to higher probability-of-default and loss-severity assumptions, a weaker macroeconomic forecast, and initial allowances on new loans.1 Late that year, a fully funded loan of about $83 million to a golf resort was placed on non-accrual, meaning VICI stopped recognizing interest income on it.111 The 2026 increase was larger still.
On the second-quarter call, an analyst from Morgan Stanley asked directly about the allowance jump. VICI's chief investment officer, Gabe Wasserman, explained that for one private tenant, the company had been estimating credit quality using a proxy company's rating. That tenant had since issued debt privately, which produced its own rating, and the updated rating drove the change. "The property's performing well," he said.11 That was a specific, verifiable answer rather than a deflection, and it suggests the second-quarter charge reflected a re-rating of one tenant's credit rather than a sudden collapse in operations. It is also a reminder of how sensitive the allowance is to a single input.
Another exchange on the same call was more revealing. A KeyBanc analyst asked about a roughly $90 million loan that had been modified. Wasserman explained that the loan, secured by a leisure and hospitality asset and representing about 3% of the loan book, had been extended, with the interest rate cut to 2% paid monthly in cash, and amortization added.11 He said it was separate from the golf loan already on non-accrual.11 A rate reduction to 2% on a loan VICI's lending book otherwise prices near 9% is not a sign of a healthy borrower; it is a concession made to protect principal. VICI's loan book is still small relative to its leases, with about $2.6 billion of principal outstanding at the end of 2025 at a weighted average rate of about 9.1%.1 But the lending business is where VICI has been reaching for higher yields, and it is where the first cracks have appeared.
The judgment involved is large enough that VICI's auditor, Deloitte, identified the credit-loss allowance on sales-type leases and lease-financing receivables as a critical audit matter in its 2025 report, the area of the audit requiring the most difficult and subjective judgments.1 That is not a warning of error; Deloitte issued a clean opinion. It is a signal that the number depends heavily on assumptions about default probability and loss severity that no one can verify in advance.
One more distortion deserves mention, because it trips up anyone reading VICI's ratios mechanically. Standard financial screens show VICI's receivables equal to well over a thousand days of revenue, which would be alarming for a manufacturer. For VICI it means nothing about late payment. Its leases accounted as financing receivables sit on the balance sheet as receivables representing decades of future rent, not overdue invoices. Rent has been collected in full.1
So is the earnings volatility accounting noise or a warning? The honest answer is that it is both. Most of the swing in any given quarter is a non-cash estimate driven by models and ratings, and the cash has kept arriving. But the direction of the estimates over the past two years has been unambiguous: the allowance has grown, one loan has stopped paying interest, another has been restructured at a concessionary rate, and the rating agencies have flagged weakening coverage at the largest tenant. Collection is a backward-looking fact. The allowance is a forward-looking opinion. When the opinion keeps worsening while the facts stay perfect, investors should watch the opinion. And that matters most for the one thing VICI cannot stop doing: raising money to buy more.
IX. The Next Deal Has to Beat the Cost of Capital
On April 30, 2026, VICI closed a deal that captured both the promise and the arithmetic of its business model. It bought the land and buildings of seven Nevada casinos from Golden Entertainment for about $1.16 billion, in a transaction that took Golden's operating business private under its chairman and chief executive, Blake Sartini.5 VICI leased the properties to Sartini's new company for an initial 30 years at about $87 million of annual rent, an acquisition cap rate of 7.5%, with 2% escalators starting in the third lease year.5 To complete the transaction, VICI issued about 24.3 million of its own shares to Golden's shareholders and retired about $426 million of Golden's debt.5
Here is where the hurdle becomes concrete. At June 30, 2026, VICI's total debt was about $17.2 billion, at a weighted-average effective interest rate of about 4.45% and an average maturity of about 5.5 years.511 On the surface, a 7.5% yield against a 4.45% cost of debt looks like an easy spread. But that 4.45% is a blend of bonds issued when rates were much lower. The marginal cost is higher. In August 2026, VICI sold $1.75 billion of new senior notes: $900 million at 5.40% due 2031 and $850 million at 5.75% due 2036, to refinance $1.75 billion of notes maturing in 2026 that carried coupons of 4.25% and 4.5%.2119 Each refinancing replaces cheaper debt with more expensive debt, which is a slow, steady drag on per-share cash flow that the escalators must outrun.
Equity is not free either. At about $24 a share and with full-year AFFO guidance of $2.45 to $2.47 per share, VICI's stock trades at roughly ten times AFFO, which implies a cost of equity in the neighborhood of 10% before any growth.65 Paying for a 7.5% asset partly with stock priced at a 10% AFFO yield is dilutive on day one unless the debt portion is cheap enough to compensate. The Golden deal was agreed in 2025, before the latest leg down in VICI's share price, and it brought a new tenant and Nevada locals casinos that are a different exposure from the Strip, but it shows why the share price matters to the business model. When the stock falls, every future acquisition financed with equity becomes harder to justify.
VICI has kept its balance sheet more conservative than its own targets. Net debt stood at about 4.9 times annualized adjusted EBITDA at the end of the second quarter, below its target range of 5.0 to 5.5 times.11 Fitch, which rates VICI at BBB-, the lowest investment-grade rung, has said that leverage sustained above 5.5 times or coverage of unsecured debt by unencumbered assets falling below 2.0 times, from about 2.1 times now, could trigger a downgrade.4 Moody's and S&P rate it at the equivalent level, all with stable outlooks.[^22] That is a balance sheet with some room, but not a great deal. VICI's investment-grade rating is part of its competitive edge, and it sits just one notch above junk.
How has the current management team used its currency? The fairest test is per share, over time, and the record is mixed but positive. The 2026 guidance midpoint implies about 3.4% further growth in AFFO per share.111 That rate, however, is slower than the acquisition-fueled pace of recent years. The slowdown is the natural consequence of size: a $1 billion acquisition moves a $45 billion enterprise much less than it moved a $15 billion one. It also reflects higher financing costs. Organic growth from escalators alone runs around 2% a year, so to grow faster VICI must keep finding deals that clear an ever-higher hurdle.
Pitoniak's own stake and pay give a sense of alignment, without settling the quality question. He held about 1.31 million shares as of the 2026 proxy date, and his reported 2025 compensation was about $14.0 million, most of it in equity awards.22 Shareholders have supported the pay plan strongly, with about 96% approval in 2025 and at least 95% in every year since the IPO.22 The board has an independent chair, and the largest shareholders are index giants Vanguard, BlackRock and State Street, which together held nearly 29% of the stock.22 There is no controlling holder, no family dominance and no related-party fee arrangement. Those facts establish that governance is clean and incentives are equity-linked. They do not by themselves prove that capital has been deployed well; only the per-share numbers can do that.
VICI has tried to widen its opportunity set beyond gaming. Its 39 non-gaming assets at the end of 2025 included 38 Lucky Strike bowling centers and Chelsea Piers in New York, alongside loans and partnerships with Great Wolf Resorts, Canyon Ranch and the developers of Cabot Citrus Farms in Florida and One Beverly Hills in Los Angeles.1 In June 2026 it announced its first Caribbean investment and its first build-to-suit deal, paying about $20 million for the Carambola Beach Resort in St. Croix and committing about $55 million to redevelop it for Club Med, with a targeted opening in late 2027.5 On the call, Pitoniak described VICI's approach to new partners as being "in learning mode," not sales mode.11 These relationships may open future deal channels. But at present they are small. Gaming still accounts for the large majority of rent, and the Strip remains the center of gravity.1
The tenant roster is broadening, but more slowly than the headlines suggest. In the second quarter VICI welcomed its fourteenth, fifteenth and sixteenth tenants: Clairvest, Golden Entertainment and Club Med.5 Look closely at the Clairvest deal, however. When Clairvest took over MGM Northfield Park in Ohio, VICI signed a new lease with it at about $53 million a year, and reduced MGM's master lease rent by the same amount.5 That was a transfer of rent from one tenant to another, not new rent. It did diversify the roll a little, because Clairvest is not MGM, but it added nothing to VICI's income. VICI also expanded its Canadian portfolio in June, paying about C$200.6 million for Gamehost's Alberta casinos and adding them to an existing lease with PURE Canadian Gaming.5 Century Casinos remains on the roll,14 but none of these moves has yet changed the basic fact that Caesars and MGM dominate the rent.20
The second-quarter call offered a revealing contrast between prepared remarks and answers. The prepared remarks emphasized new partnerships, Club Med's ambitions and Las Vegas strength. When analysts pressed, the key issues surfaced. A Goldman Sachs analyst asked how conversations with the two largest tenants had changed now that both were "in the news" as potential buyout targets; Pitoniak said they "haven't fundamentally changed."11 A Jefferies analyst asked whether strong regional gaming results reduced the urgency of the Caesars regional lease conversation. Pitoniak answered: "I wouldn't say it alleviates or eliminates," adding that VICI would "collect every dollar rent in the meantime."11 He declined to give a timetable for the Caesars talks and said the tenant's M&A process could take about a year.11 Asked by Scotiabank about buying back shares at a depressed price, Kieske said that lending at SOFR plus 8.25 percentage points was a more attractive use of capital, calling buybacks "not something that makes a lot of sense" for a net lease REIT.11 That answer is internally consistent, but it means management is choosing higher-yielding, higher-risk loans over its own discounted equity, at the very moment its loan book is producing its first problem credits.
Third-quarter results are scheduled for release on October 28, 2026, the day after this story was written.6 They will be the next checkpoint for guidance, the credit allowance and any progress on the Caesars lease. Until then, the question hanging over the stock is the one investors always ask about VICI, but with more urgency than at any time since the pandemic: is the market price a bargain or a warning?
X. Bull vs. Bear
The same lease can look like two completely different things. To one investor, a 40-year triple-net lease on Caesars Palace with inflation-linked escalators is the closest thing in the equity market to an inflation-protected bond backed by real estate no one can replicate. To another, it is a fixed claim on a leveraged casino operator, payable in an industry whose fortunes rise and fall with consumer spending, and owned by a company that must keep issuing stock and debt to grow. Both descriptions are accurate. The market's verdict, at this moment, leans toward the second.
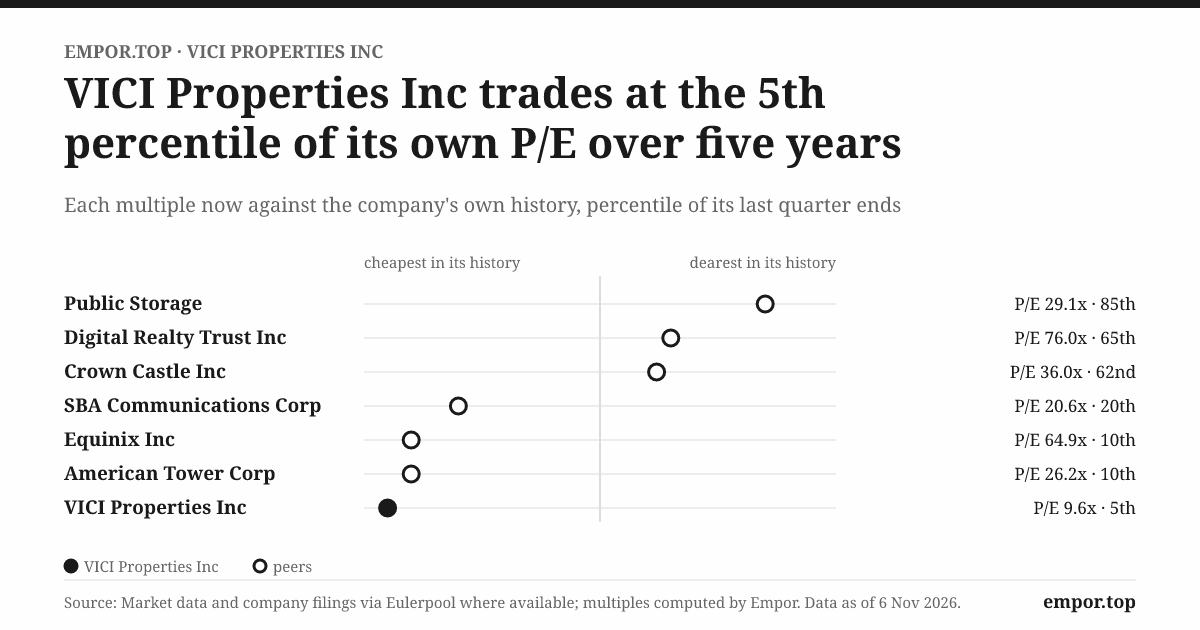
On October 27, 2026, VICI traded at about 9.2 times trailing GAAP earnings,6 compared with its own five-year median of about 12.8 times. The price was near the bottom of its 52-week range, roughly a quarter below the high.6 On the more appropriate REIT measure, it traded at roughly 9.9 times AFFO, and the annualized dividend yielded about 7.7%.6 GLPI, its closest peer, traded at about 11.5 times trailing earnings with a yield of about 8.4%.6 Those numbers say that investors were demanding a high return for owning VICI's rent stream, close to what they demanded from GLPI despite VICI's larger scale and Strip concentration.
GAAP P/E is a poor tool for ranking REITs. Depreciation and, in VICI's case, the swinging CECL allowance distort net income so badly that the ratio can move by a third from one quarter to the next without any change in the business. VICI's 10.1% free-cash-flow yield is closer to the real economics but still misleading for an acquisition-led REIT, because it excludes the capital VICI spends buying new properties. AFFO per share, debt cost, lease coverage and investment spreads are the measures that matter.
Start with the bull case. VICI owns scarce, licensed real estate, and its leases run for decades with some inflation-linked escalators. Rent held through the pandemic shutdown. Its balance sheet carries investment-grade ratings from all three major agencies, leverage below its own target, and mostly fixed-rate debt with no large maturities left in 2026 after the August refinancing.5[^22]21 Its AFFO per share has grown steadily, with only one year of meaningful dilution. At about ten times AFFO, the stock offers a cash yield well above the cost of VICI's own new debt. If the leases simply perform as written, shareholders will collect a high dividend and modest growth for years.
Now the bear case. Caesars and MGM still account for about three-quarters of rent. Caesars is being taken private by Fertitta Entertainment in a deal that adds debt to an already indebted company, and the future of the Caesars regional lease remains unresolved until that transaction is resolved. Fitch has identified possible outcomes: rent concessions, asset transfers or lease extensions, any of which could reduce near-term rent even if they preserve the relationship.4 The CECL allowance has climbed for two years, one loan has stopped paying interest and another has been restructured at a fraction of its original rate. The cost of new debt is now roughly a percentage point above the average cost of existing debt, so every refinancing slightly erodes per-share cash flow. And the stock's discount makes equity-funded acquisitions harder, which slows growth precisely when management needs it.
Porter's five forces help clarify which risks are structural. The threat of new entrants is low for the physical assets, since no one can build a new Caesars Palace next door, but moderate for capital, because private equity, private credit and other REITs can all finance casino real estate. Substitutes for the lease model exist: operators can own their buildings, borrow against them, or sell to other buyers. Supplier power is weak; VICI's main input is capital, which it buys in deep, competitive bond markets. Rivalry among gaming landlords is moderate, essentially a duopoly with GLPI, with each competing on cost of capital and relationships. Buyer power remains the dominant force: two tenants control three-quarters of the rent, and their capacity to renegotiate, restructure or threaten not to renew is the single largest constraint on VICI's pricing power.
Helmer's seven powers point the same way. VICI has some scale advantage in cost of capital, which allows it to bid for large deals such as the Venetian and MGP that smaller buyers could not finance. It has no network effects, no proprietary process power and no brand of its own; the brands on its buildings belong to the operators. Its powers protect the existence of the rent. They are weaker at protecting the level of the rent when a tenant's economics deteriorate.
An activist or short seller would ask why management prefers making high-yield loans to buying back stock at a 10% AFFO yield, press for tenant-level rent coverage disclosure, and challenge whether the newest tenants have diversified rent materially.4
The skeptical-investor test is the clearest way to frame the decision. Suppose management paused acquisitions entirely. Escalators of about 2% a year, plus some inflation-linked upside, would lift rent modestly. Refinancing maturing debt at higher rates would subtract a little. Net, AFFO per share might grow at a low-single-digit rate, and the dividend would remain well covered: VICI paid about 67% of GAAP net income as dividends in 2025, and Fitch puts the AFFO payout typically around 74%.14 In 2022, when GAAP earnings were depressed in the year of the big acquisitions, the dividend exceeded net profit, which shows why the GAAP payout ratio alone is a poor guide.1 At ten times AFFO with a 7.7% dividend yield, such a business does not need fast growth to justify its price, provided the rent keeps arriving. The whole debate therefore narrows to the Caesars lease and the credit trend. If both hold, the current price is pricing in a risk that does not materialize. If either breaks, the discount was warranted.
XI. Playbook: Lessons from VICI's Story
The first lesson is the one written in the gap between VICI's perfect collection record and its growing credit allowance. Both can be true. A good landlord can outlast an operator's bad quarter, but it cannot abolish the operator's bad balance sheet. The pandemic tested collections; the rising allowance and Fitch's warning about Caesars' regional coverage speak to future tenant credit. For investors in any landlord, the record of collection describes the past; the tenant's leverage describes the future.
The second lesson comes from the Venetian and the Golden deal. Buying the ground is only half the deal; the rent has to clear the financing. The Venetian's low cap rate reflected a trophy asset, while the Golden deal shows how higher funding costs can narrow the spread. A net-lease REIT is a spread business. When the spread narrows, the case for growth through acquisition narrows with it.
The third lesson is that scale is not the same as compounding. VICI grew from 19 gaming properties at formation to 93 experiential assets by 2025 and became the largest owner of Strip real estate. But its per-share growth has slowed as the company has grown, and its 2026 guidance points to a slower pace than in its acquisition years. The returns came through the dividend and through per-share growth that slowed as the company grew. The wider lesson for any serial acquirer is to judge each deal by what it adds per share, after financing, and to watch the rate of per-share growth as the company gets bigger.
The fourth lesson belongs to Clairvest. Diversification starts when a new tenant can change the risk math. The Clairvest deal is a reminder that a new name on the check may not reduce VICI's overall exposure. Newer partnerships broaden the roll at the margin. Real diversification will come only when the share of rent from Caesars and MGM falls meaningfully, and that has not happened since the MGP deal closed.
The management verdict should stay measured. VICI's leadership has maintained a consistent strategy and investment-grade ratings through a pandemic and a rate shock, while shareholders have strongly supported its pay. Its early insistence that it would not do a bad deal for the sake of growth has largely held up in the per-share numbers. The next test is harder: whether its leaders can keep acquisitions accretive through higher funding costs, negotiate a Caesars lease outcome that preserves value, and contain the credit problems in the lending book before they spread.
XII. Epilogue
Tonight, VICI sits at an unusual crossroads. The business has never been larger or more profitable on a cash basis. Its leases are full, its debt maturing in 2026 has been refinanced, and its rent has never gone unpaid. Yet its stock trades near its 52-week low, its largest tenant is in the middle of a take-private, and its credit allowance has grown for two consecutive years.
Tomorrow, October 28, VICI will report its third-quarter results.6 The release and the call that follows will answer a few immediate questions. Will management hold or adjust its AFFO guidance? Will the credit allowance rise again, or begin to release as tenant ratings stabilize? Will there be any concrete news on the Caesars regional lease? Each answer will move the story in a different direction. A stable allowance and a reaffirmed guidance range would support the view that 2026's charges were model-driven noise. A further increase, especially tied to a major tenant, would strengthen the bear case that credit quality is weakening.
Beyond the quarter, the defining event is the Caesars transaction. Fertitta agreed to pay $31 a share in cash for Caesars in May 2026, a 49% premium to the undisturbed price, after a contest in which Carl Icahn had also bid.323 The deal can run until November 2027 before either side may walk away, and it requires shareholder and gaming regulatory approval.24 Jefferies analyst David Katz has called the regional master lease "a key overhang on VICI shares."23 As of mid-October, lease terms between Fertitta, Caesars and VICI had not been finalized, and rent was still being paid under the existing agreements.25 The outcomes range widely. A lease extension with a modest rent reset could actually strengthen VICI's position by locking in a larger, better-capitalized tenant for longer. Asset transfers or significant rent concessions would reduce income from VICI's largest rent stream and test whether the long leases are as strong in negotiation as they are on paper. Whatever happens will set the reference point for how much negotiating power a casino landlord truly holds when its biggest tenant changes hands.
Three indicators will tell the story from here. AFFO per share, last guided to about $2.46 at the midpoint for 2026, will show whether growth continues after financing. Rent coverage and collection by major tenant, particularly at Caesars' regional portfolio, will show whether the operators can keep paying what they owe. And net leverage, currently about 4.9 times, together with the spread between new investment yields and funding costs, will show whether VICI can keep growing without diluting shareholders or straining its credit rating.11
The thesis remains credible but conditional. VICI has proven its leases can survive an acute shock. It has not yet proven they can survive a slow squeeze, in which a tenant's earnings erode and its owner seeks to reset the rent rather than default on it. That is the test the next year will bring.
XIII. Outro
Go back to Caesars Palace on that Saturday night. The tables are busy, the hotel is full, and the operator is counting chips. Somewhere far from the casino floor, VICI’s small staff is counting something else: rent, set against a reserve for the day it might not arrive.
That is VICI’s whole wager: the landlord does not need to win at blackjack, only to keep collecting rent. Born from the wreckage of a bankruptcy, it has so far made the case that the ground can outlast the game. Whether it keeps paying depends less on VICI than on the tenants who run the tables above it.
References
-
2025 Form 10-K — VICI Properties Inc. and VICI Properties L.P. via SEC, 2026-02-25 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
VICI Properties Inc. Completes Spin-Off from Caesars Entertainment Operating Company — VICI Properties via SEC, 2017-10-06 ↩↩↩↩↩
-
Caesars Entertainment Enters Into Agreement to Be Acquired by Fertitta Entertainment — Caesars Entertainment, 2026-05-28 ↩↩
-
Fitch Rates VICI Properties' Senior Unsecured Notes 'BBB-' — Fitch Ratings via MarketScreener, 2026 ↩↩↩↩↩↩↩
-
VICI Properties Inc. Reports Second Quarter 2026 Results — VICI Properties via SEC, 2026-07-29 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
VICI Properties and Gaming and Leisure Properties stock quotes and statistics — Stock Analysis, 2026-10-27 ↩↩↩↩↩↩↩↩↩
-
Caesars Entertainment's operating unit files for bankruptcy — CNBC, 2015-01-15 ↩↩↩↩
-
Penn National Gaming Completes Tax-Free Spin-off of Gaming and Leisure Properties — Penn National Gaming via SEC, 2013-11-01 ↩
-
Initial Public Offering Prospectus — VICI Properties Inc. via SEC, 2018-01-31 ↩↩↩↩↩
-
2019 Proxy Statement — VICI Properties Inc. via SEC, 2019-03-18 ↩↩↩↩↩↩
-
VICI Properties Q2 2026 Earnings Call Transcript — Stock Analysis, 2026-07-30 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
MGM Growth Properties Proposal to Acquire VICI Properties — MGM Growth Properties via SEC, 2018-01-16 ↩↩
-
VICI Properties Q4 2019 Earnings Call Transcript — Stock Analysis, 2020-02-20 ↩↩↩
-
Q4 2019 Supplemental Financial and Operating Data — VICI Properties via SEC, 2020-02-20 ↩↩↩↩↩↩↩
-
VICI Properties Completes Transactions Related to Eldorado's Acquisition of Caesars — VICI Properties via SEC, 2020-07-20 ↩↩↩↩
-
VICI Properties Inc. Reports First Quarter 2022 Results — VICI Properties via SEC, 2022-05-04 ↩↩↩↩↩↩
-
VICI Properties Strategic Acquisition of MGM Growth Properties — VICI Properties via SEC, 2021-08-04 ↩↩↩↩↩↩↩↩↩
-
VICI Properties Completes $17.2 Billion Acquisition of MGM Growth Properties — VICI Properties via SEC, 2022-04-29 ↩↩↩↩
-
VICI Properties Prices $1.75B Bond Offering to Refinance 2026 Debt — Casino.org, 2026-08-05 ↩↩
-
Q1 2026 Supplemental Financial and Operating Data — VICI Properties via SEC, 2026 ↩↩
-
Final Term Sheet, Senior Notes due 2031 and 2036 — VICI Properties L.P. via SEC, 2026-08-05 ↩↩
-
2026 Proxy Statement — VICI Properties Inc. via SEC, 2026-03-16 ↩↩↩
-
Fertitta Entertainment to acquire Caesars in $17.6B transaction — CDC Gaming Reports, 2026-05 ↩↩
-
Caesars Entertainment Q2 2026 Form 10-Q — Caesars Entertainment via SEC, 2026 ↩
-
VICI Properties (VICI) Is Waiting On Lease Terms For Its Largest Tenant — Simply Wall St via Yahoo Finance, 2026-10-15 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube