Realty Income: Can the Monthly Dividend Keep Growing?
I. The Rent Check That Arrives Every Month
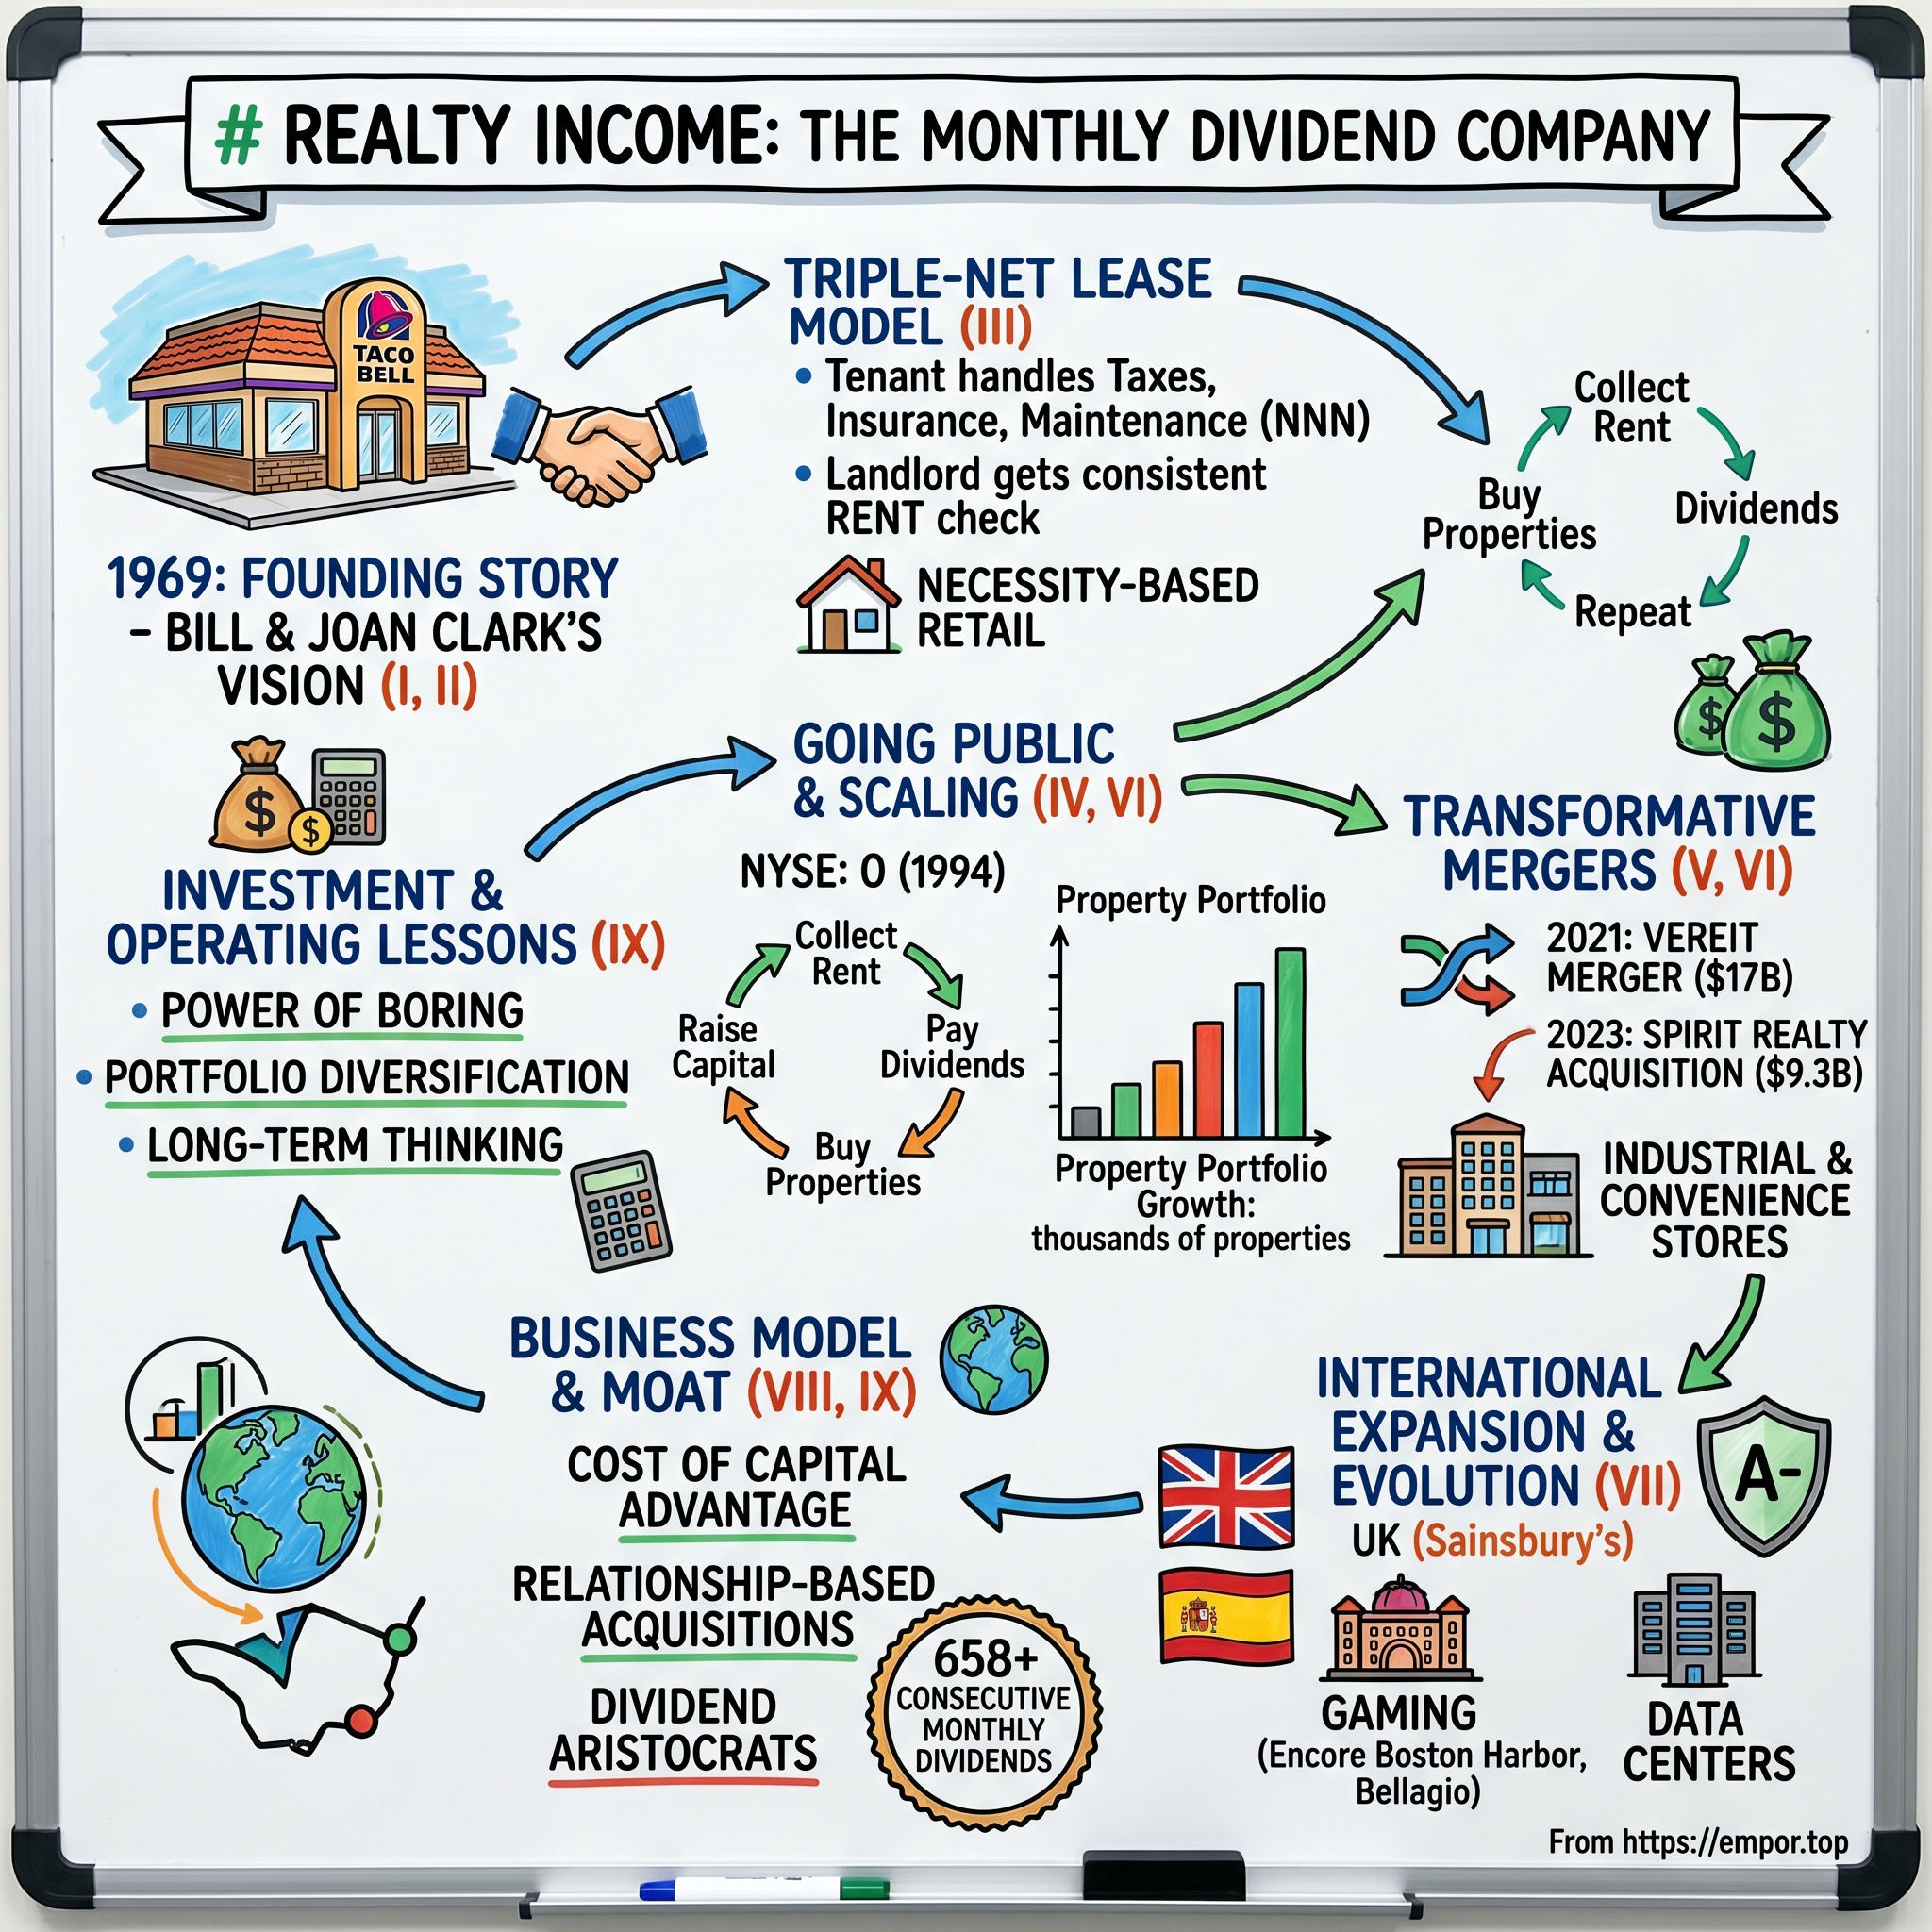
In 1969, in Northridge, a suburb at the northern edge of Los Angeles' San Fernando Valley, Bill and Joan Clark struck a deal that looked almost too simple to be the seed of anything large. They bought a Taco Bell property from Glen Bell, the man who had founded the chain, and leased it straight back to the restaurant.1 Nothing visible changed. The same staff kept frying the same tortillas behind the same counter. The building simply had a new owner, and the restaurant had a new obligation: a rent check.
That small rearrangement contains the whole idea of Realty Income. A restaurant operator, a convenience store chain or a pharmacy wants to run stores, not tie up its money in land and bricks. An investor wants a steady stream of income that does not depend on knowing how to sell tacos. Put the two together and each side gets what it values more. The operator turns a building into cash it can use to open more stores. The landlord gets rent that arrives on schedule as long as the tenant stays in business.
Fifty-seven years later, the Clarks' one property has become 15,588 properties. By June 30, 2026, Realty Income held interests in properties across the United States, the United Kingdom and eight other European countries, making it one of the largest owners of single-tenant commercial real estate anywhere.2 And the company has turned that rhythm of rent into a promise to its own owners. In mid-October 2026, it declared its 676th consecutive monthly dividend, $0.2715 a share, payable in November.3 That is more than half a century of monthly checks, and the company counts 136 increases along the way.4
The monthly dividend is the company's defining feature. It is in the trademark slogan, "The Monthly Dividend Company," it is a large part of why retirees and income funds own the shares, and it is the standard against which every decision Realty Income makes is ultimately judged.4 A conventional landlord tells investors about occupancy and property values. Realty Income tells them, in effect, that the mailbox will never be empty.
That promise is the story's engine, and also its central question. A dividend can be declared by a board. It cannot be manufactured by one. The money has to come from tenants paying rent, minus what it costs to borrow, run the company and replace tenants who fail. And because Realty Income pays out most of its cash flow every year, it cannot grow by quietly reinvesting retained profits the way an industrial company might. To buy more properties, it has to keep raising money: new shares, new bonds, new loans and, lately, money from private partners.
So the real test is not whether Realty Income can get bigger. It plainly can; it went from about $1 billion of revenue in 2015 to roughly $5.7 billion in 2025.5 The test is whether scale turns dependable rent into durable per-share growth, or mostly into more properties, more debt and more shares. A landlord that doubles its rent roll by doubling its share count has made itself larger without making any individual owner richer.
There is a second test hiding inside the first. Every new property Realty Income buys produces an initial return, a yield, and every dollar used to buy it has a cost, whether that is interest on a bond or the dilution of issuing new stock. The company only creates value when the first number exceeds the second by enough to cover everything else. In good years that spread is easy to find. In others, as interest rates have risen and competition for well-leased buildings has stiffened, it is the whole game.
Those two tests frame everything that follows: the founding idea and why it became a public-market brand, the economics of a lease that shifts costs onto tenants without removing the risk of losing them, the patience the company showed when credit markets froze in 2008, the two giant mergers that turned it into a consolidator, the funding machine behind today's ambitions, and the accounting gap that makes the dividend look either alarming or comfortable depending on which number you read.
Underneath it all sits one question worth carrying to the end. The next dividend increase will be declared, almost certainly. What has to go right for it to be earned?
 Subscribe on LinkedIn
II. A Taco Bell Becomes a Public Promise
The Clarks had spotted the appeal of sale-and-leaseback for operators of small, standardised stores.1
The bargain had a particular structure that would matter for decades. Under what came to be called a net lease, the tenant does not just pay rent. It also typically pays the property's taxes, its insurance and its maintenance, so the landlord's income is close to the full rent check rather than what is left after running the building.5 The landlord supplies capital. The tenant supplies rent and takes on the day-to-day costs of the property. For the investor, it is about as close to a bond as real estate gets: a contractual stream of payments from a counterparty, backed by a physical asset.
Repeat that trade enough times and you have a business. The Clarks did repeat it, gathering money from investors to buy more single-tenant properties and lease them to operators.1 It was not glamorous. These were fast-food restaurants, childcare centres, auto-service shops, the low buildings that line suburban arterial roads. But each one came with a lease, and each lease came with a monthly payment.
The real turning point arrived in 1994, when Realty Income listed its shares on the New York Stock Exchange.5 It took the single-letter ticker "O," and it put the monthly dividend at the centre of how it explained itself to the market.1 That decision was more strategic than it looks. A portfolio of hundreds of small properties, each leased to a different operator with its own credit story, is hard for an ordinary investor to evaluate. A dividend paid every month, and raised over time, is easy to understand. The dividend made a complicated pool of leases legible.
It also turned the company's main constituency into income seekers. Most American companies that pay dividends do so quarterly. Realty Income's monthly cadence matched the rhythm of a household budget, the same rhythm in which rent, mortgages and utility bills arrive. For a retiree, it was a paycheck substitute. For the company, it became a brand, and brands create obligations. Once investors buy a stock precisely because it has never missed a monthly payment, cutting that payment would be catastrophic for the shareholder base and for the company's ability to raise money from it.
The record that followed was remarkable.4 Few public companies anywhere can point to such a record. It is the kind of record that becomes self-reinforcing: the longer it runs, the more investors trust it, and the more they trust it, the more cheaply Realty Income can sell them new shares.
But a payment record is evidence about willingness and history, not about coverage today. A company can keep paying a dividend for years while the economics underneath it weaken, especially if it is issuing new shares and borrowing to buy more properties at the same time. The record shows that management has treated the dividend as sacred. It does not, on its own, show that the current portfolio produces enough recurring cash, after costs and after replacing failing tenants, to fund the dividend and still grow it per share.
That tension was baked in from the moment of listing. The dividend became a promise to customers, if one thinks of shareholders as the people buying the product. Meanwhile, the company's growth would depend on returning to capital markets for more money. Realty Income had built a business whose product was a monthly payment and whose raw material was other people's money.
To understand whether that machine creates value, it helps to sit on the other side of the table and ask why a retailer would sell the very store it needs.
III. Why a Retailer Sells the Store It Needs
Picture the chief financial officer of a growing convenience-store chain. The company owns many of its locations outright. Each one is a profitable store, but each one also holds a few million dollars of value in the land and building that earns the chain nothing directly. The CFO wants to open more stores, refit old ones and keep the balance sheet tidy. A bank loan would add debt. Issuing stock would dilute the founders. Then a landlord arrives with a third option: sell the buildings to Realty Income, sign a long lease, and keep operating exactly as before.
That is a sale-leaseback, and it is the cleanest way to see what Realty Income actually sells. The tenant receives cash up front and gives up ownership. Realty Income receives contractual rent, typically paid monthly, and a property whose usefulness depends heavily on the tenant's continued business.5 The rent usually rises over time, either by fixed steps or with inflation, and in a small number of cases includes percentage rent tied to the tenant's sales; that last category was less than 1% of rental revenue in 2025.5
By the end of 2025, this one transaction, repeated thousands of times, had produced a portfolio of 15,511 properties leased to 1,761 clients, with an average of 8.8 years left on the leases and $5.31 billion of annualised base rent.5 That last figure is the cleanest summary of the machine: the rent Realty Income is contractually entitled to over the next twelve months, before any growth.
The net-lease structure is often described as if it made the landlord's life risk-free. It does not. It transfers costs, which is different from transferring risk. That shields Realty Income from routine property costs, but Realty Income still owns the building. If the tenant goes bankrupt, the rent stops, and the landlord inherits an empty, single-purpose box that it must re-lease, sell or redevelop. If the neighbourhood declines, the property's value falls. The net lease moves the operating bills. It leaves default, vacancy, re-leasing and property-value risk squarely with the owner.
Rent growth is where the contract shows both its comfort and its limits. By June 2026, 79.8% of Realty Income's in-place leases had one or more provisions for rent increases.6 That sounds generous until one remembers what those provisions usually are: fixed annual bumps of a percent or two, or inflation links that are often capped. The result is predictable but slow. Same-store rental revenue, the rent from properties owned throughout both periods, grew 1.3% in 2025.5 In the second quarter of 2026, it grew 1.2%.6 In a world of 3% inflation, a portfolio growing rent at 1.3% is shrinking slightly in real terms before any acquisitions.
Credit quality is the other half of the contract. A lease is only as good as the company signing it, and at year-end 2025, investment-grade clients and their subsidiaries or affiliates accounted for 32.2% of annualised base rent.5 Put the other way, about two-thirds of the rent came from tenants without an investment-grade rating. That does not make them weak; many are large private companies or franchise operators that simply do not borrow in public bond markets. But it does mean the portfolio's resilience rests heavily on Realty Income's own underwriting of thousands of smaller credits, rather than on rating agencies doing that work for it.
There is also a reason these particular buildings have aged better than much of the property world. A convenience store, a quick-service restaurant, a grocery store, a gym or a car wash has to exist in physical space, near where people live and drive. That makes these locations less exposed to the pure digital substitution that hollowed out department stores and suburban malls. It is not immunity. Store footprints shrink, chains close weaker branches, and changes in how people shop can make one corner less valuable than another. Artificial intelligence is no direct substitute for a lease, but it can work indirectly, by changing tenants' labour costs, their store formats and the locations they need.
That slow organic growth is not a flaw so much as the nature of the product. Tenants accept long leases in exchange for modest escalators; landlords accept modest escalators in exchange for long leases. But it means that almost all of Realty Income's headline growth must come from buying more rent, not from raising rent on what it already owns.
The scale argument, tested
Scale is the obvious edge. At year-end 2025, Realty Income owned more than 15,500 properties.5 NNN REIT, a long-established peer, owned 3,692.7 Agree Realty, a fast-growing rival focused on investment-grade retailers, owned 2,674.8 Realty Income is roughly four times the size of the next-largest listed specialists. Yet property count is not market share. Net-leased real estate in the United States and Europe is a vast, fragmented market of private investors, family offices, pension funds, private-equity vehicles and other REITs. Realty Income is the biggest fish, not the owner of the pond.
Size helps in three concrete ways. It lets the company finance itself cheaply, because a diversified, investment-grade borrower pays less than a small one. It brings deal flow: when a chain wants to sell hundreds of properties at once, there are few buyers who can write that cheque. And it spreads tenant risk. No client exceeded 10% of revenue in 2023, 2024 or 2025, and at year-end 2025 the top 20 clients together represented 35.8% of annualised base rent.5 The largest single exposures were 7-Eleven at 3.3%, Dollar General at 3.2%, Walgreens at 3.1% and Family Dollar at 2.6%.5 The names are a reminder that diversification does not mean immunity: discount stores and drugstores have been among the most stressed corners of American retail.
The leasing record is the best evidence that the properties themselves hold value. When leases expire, Realty Income has generally re-leased space at or above the previous rent. Its rent recapture rate was above 100% in 2025, and by the second quarter of 2026 the year-to-date figure stood at 103.0%.6 That is a meaningful sign that the company is not overpaying for buildings nobody wants. But there is a nuance: most of those re-leased properties went back to the same client.6 A tenant renewing its own store is a vote of confidence in the location, but it is not proof that Realty Income could easily fill the building with someone else if the tenant walked away.
So what is the moat? The honest answer is that the evidence supports a low-cost, high-volume platform more than a fortress built on pricing power. Realty Income's sourcing network, its underwriting data on thousands of properties and its access to capital may help it win deals. But tenants can choose other landlords, other forms of financing or simply keep owning their stores. Public filings do not show that Realty Income consistently outbids competitors or earns a uniquely high spread on what it buys. The advantage is real, but it is the advantage of being the cheapest, most reliable large-scale buyer, not of being irreplaceable.
That leaves the operating question that will run through the rest of this story. If contractual rent grows by a little over 1% a year, acquisitions must do most of the work. Can they do it without diluting the very shareholders the dividend was built to reward? The best early evidence comes from a year when acquisitions were the last thing anyone wanted to fund.
IV. When the Credit Market Closed, Realty Income Waited
The usual story told about disciplined real-estate investors goes like this: when the crisis hits, they swoop in and buy cheap assets from forced sellers. It is a satisfying story. In 2008, it was not quite what Realty Income did.
The year started normally. In the first quarter, the company invested $181.4 million in new properties.9 Then the financial system began to come apart. Credit spreads widened, banks stopped lending, and the prices of commercial property began to slide while the yields buyers demanded rose. For a company whose growth depended heavily on raising capital to buy rent, this was the equivalent of a factory losing its supply of raw materials.
Realty Income's response was to slow almost to a stop. For all of 2008, it invested $189.6 million in 108 properties, which meant that the remaining three quarters together accounted for only about $8 million.9 Management said it was waiting for property prices to adjust and the economy to stabilise before investing more aggressively.9 The company acquired fewer properties in 2009 as well, preserving liquidity, and only signalled an intention to accelerate in 2010.10
Why does that matter for a dividend company? Because a strong balance sheet is only useful if the company protects enough liquidity to survive the downturn. A REIT that had committed to buying hundreds of millions of dollars of property in 2008, and then found it could not raise equity or debt at sensible prices, would have faced an ugly choice: fund the purchases with expensive short-term money, sell assets at distressed prices, or cut the dividend. Realty Income avoided that trap by refusing to make the commitments in the first place.
There is a less flattering way to read the same record, and it deserves a hearing. Waiting also meant passing on deals as the market repriced. The best buying opportunities of the cycle arguably came in late 2008 and 2009, when yields were highest and competition thinnest, and Realty Income bought relatively little. Its discipline protected the downside. It did not, on the evidence of those filings, capture the upside of buying at the bottom. The record supports selective patience under stress, not a heroic "buy when others can't" narrative.
When investing did resume, it came with a vivid illustration of how far the model could stretch. In June 2010, Realty Income agreed to buy about $269 million of Napa Valley winery and vineyard properties and lease them back to Diageo Chateau & Estate Wines under 20-year, triple-net leases guaranteed by Diageo plc.11 The package included roughly 2,000 acres of vineyards and the Sterling Vineyards and Beaulieu Vineyard winery buildings.11 Diageo would continue to make the wine and own the brands.11 Realty Income owned the land and the buildings.
It was a long way from a Taco Bell in Northridge, but it was the same deal. A business that wanted capital more than it wanted ownership sold its property to a landlord who wanted rent more than it wanted to run a business. The asset was real estate. Wine production was never Realty Income's business. The transaction also made Diageo one of the company's largest tenants overnight, a reminder that a single large sale-leaseback can quickly concentrate a portfolio built on diversification.11
The 2008–2010 sequence showed the company at its most conservative and its most opportunistic within three years. It also showed the limits of one cycle as proof of anything permanent. One well-handled downturn does not demonstrate timing skill; it demonstrates that management, at that moment, prioritised survival of the dividend over growth. That is consistent with the brand promise. Whether it would survive larger ambitions was a question the next decade answered.
The episode also says something about how the company's growth model behaves under stress, which is worth holding onto for later. When the capital markets close, its existing leases keep paying, but growth stalls. In 2008 the portfolio was small enough, and the acquisition budget modest enough, that stopping was easy. A company guiding to $10 billion of annual investment would face a far larger gap between ambition and reality if the same thing happened again, and a far larger set of commitments, from development projects to joint-venture capital calls, that cannot simply be switched off.
Because the next phase was not about buying individual buildings at all. It was about buying entire landlords.
V. Two Mergers Turned Realty Income Into a Consolidator
On April 29, 2021, with the world still emerging from pandemic lockdowns and interest rates near zero, Realty Income announced that it would merge with VEREIT, one of its largest net-lease rivals, in an all-stock transaction.12 VEREIT shareholders would receive 0.705 Realty Income shares for each share they owned.12 Press coverage described it as an $11 billion deal for VEREIT's equity; once VEREIT's debt was included, the combined enterprise was presented as a giant of the sector.13 When the transaction closed, Realty Income recorded preliminary purchase consideration of about $17.3 billion.5
The man behind the deal was Sumit Roy. He had joined Realty Income in 2011 after a career in investment banking, including at UBS, where he had covered real-estate companies including Realty Income itself.14 He became chief operating officer in 2014, president in 2015, and in October 2018 succeeded John Case as chief executive.14 Roy's background matters to the story. He was a banker by training, comfortable with capital structures and large transactions, and he came to the top job with an instinct that scale itself could be a competitive weapon in a fragmented industry.
The VEREIT pitch was explicit about what scale would buy. Management said the merger would add more than 10% to annualised AFFO per share on a leverage-neutral basis, and estimated $45 million to $55 million of annual run-rate cost savings from combining two overlapping corporate platforms.15 AFFO, or adjusted funds from operations, is the company's preferred measure of recurring cash earnings per share; it adds back depreciation and strips out other non-cash items. The promise, in plain language, was that each Realty Income share would earn noticeably more recurring cash after the deal than before.
There was a wrinkle. VEREIT owned a meaningful portfolio of office buildings, an asset class that sat uneasily inside a company built on retail and industrial net leases and that, after the pandemic, looked increasingly risky. The solution was to separate the office properties into a new listed company, Orion Office REIT, and hand its shares to the combined company's stockholders.15 That boundary matters. Orion's subsequent struggles belong to Orion's shareholders, not to Realty Income's portfolio. Realty Income kept the retail and industrial assets and left the offices behind.
Two years later, the environment had changed completely. Interest rates had surged, REIT share prices had fallen, and the cost of capital for every property buyer had jumped. On October 30, 2023, Realty Income agreed to buy Spirit Realty Capital in another all-stock deal valued at about $9.3 billion including debt.16 Spirit shareholders would receive 0.762 Realty Income shares for each Spirit share, which, at Realty Income's closing price on October 27, 2023, implied $37.34 per Spirit share.17 Management presented the deal as more than 2.5% accretive to annualised AFFO per share and highlighted Spirit's complementary retail and industrial properties.18 The merger closed in January 2024.5
The financing structure of both deals deserves a moment, because it is the crux of the per-share question. Paying in stock rather than cash avoided the need to borrow tens of billions of dollars at a time when debt was getting expensive. But stock is not free. Every share issued to VEREIT and Spirit holders gave them an ongoing claim on Realty Income's future rent. Whether existing owners came out ahead depended entirely on whether the acquired cash flows were worth more, per share, than the cash flows the old owners gave up a portion of. The accretion forecasts were management's estimates of exactly that, made at the time the deals were announced.
What the record shows since
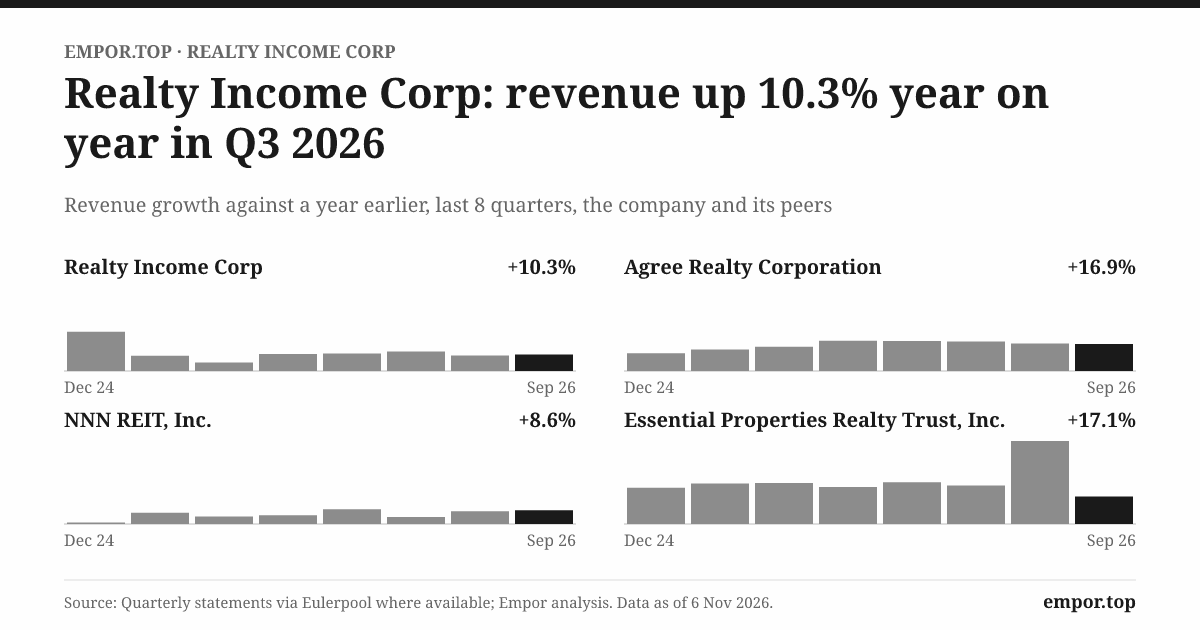
The deals unquestionably made Realty Income bigger. Revenue grew at about 19.8% a year from 2022 to 2025, and the company's balance sheet more than tripled from 2020 to 2025.5 Net profit grew far more slowly, at about 6.8% a year over the same three years.5 Neither figure isolates the mergers, and net profit is a poor measure of a REIT's recurring cash, as the dividend discussion will show. But the gap is a warning against the most common shortcut in coverage of these deals: treating revenue growth as if it were value creation.
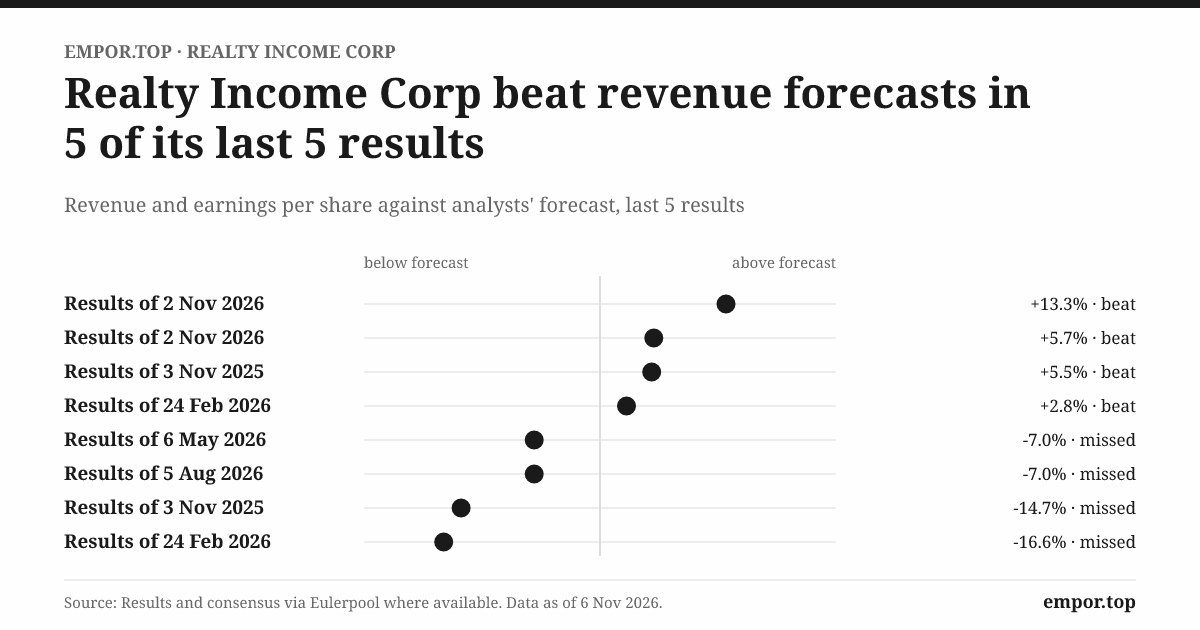
The fairer test is per-share AFFO. Realty Income reported AFFO of $4.28 per share for 2025, and in August 2026 raised its guidance for 2026 to $4.44–$4.45.19 Those are increases, and they occurred after both mergers were absorbed. But they are modest increases, in the low single digits, for a company that issued hundreds of millions of shares to complete the deals. A skeptic could argue that most of the mergers' benefit went into making the platform bigger and more liquid rather than meaningfully richer per share; an optimist could argue that without the deals, per-share growth would have been lower still in a period of rising rates.
Was either deal a bargain? The honest answer is that public filings do not provide a clean set of comparable transaction multiples that would let an outsider conclude either deal was cheap or overpriced. The full comparison would require the initial yield on the acquired portfolios, the cost of the debt assumed, the value of the shares issued at the time, the synergies actually realised, and the subsequent AFFO per share. Management's accretion estimate and a headline enterprise value are not enough. What can be said is that the deals were strategically coherent, that they were financed in a way that limited balance-sheet strain, and that their success is still being measured, share by share, in the AFFO line.
The share count itself tells part of that story. By the end of 2025, Realty Income had about 934 million common shares outstanding.5 Each of those shares has a claim on the same rent roll, which is why the company can grow revenue at close to 20% a year while AFFO per share rises by a few percent. The mergers did not cause all of that issuance; routine equity raising for ordinary acquisitions contributed a great deal. But they accelerated it, and a shareholder judging the deals has to judge them per share, not in aggregate.
That shifts the question from mergers to the everyday mechanics of growth. If acquisitions are the engine, the most important number in the company is the spread between what new properties earn and what it costs to pay for them.
VI. The Seven-Percent Yield Meets the Cost of Capital
On the second-quarter call in August 2026, Roy and his team gave investors a headline that would once have seemed implausible for a landlord: they raised full-year investment-volume guidance to $10 billion.20 In the second quarter alone, Realty Income had put $2.1 billion to work on a pro-rata basis.19 For a company whose total portfolio rent was a little over $5 billion a year, $10 billion of new investment in twelve months is an enormous number. It is also a reminder of what the business has become: less a landlord that occasionally buys buildings, and more a capital-deployment machine that must find billions of dollars of new rent every year to keep growing.
The machine has several moving parts. There are straightforward acquisitions of leased properties, mostly in the United States and Europe. There is development, where Realty Income funds construction of a new building for a tenant who has agreed to lease it. There are what the company calls other investments, including credit-like investments that sit somewhere between owning property and lending against it. And there are sales of properties the company no longer wants, which recycle capital back into the pipeline.6 On the funding side, the money comes from unsecured bonds, bank loans, new shares, and increasingly from joint ventures and private funds in which outside investors put up much of the capital.5
The single most important relationship in this machine is the spread. In 2025, Realty Income's acquisitions and development produced an initial weighted-average cash yield of 7.0%.5 At year-end, its debt cost an average of 3.9%.5 Put those two numbers side by side and the business looks like a money printer: borrow at under 4%, buy rent at 7%, pocket the difference.
That comparison is seductive and incomplete. The 3.9% is a blended average of debt issued over many years, including bonds sold when rates were far lower; new debt raised today costs more. The 7.0% is an initial yield on properties bought now, which will grow only slowly from there. And Realty Income does not fund itself only with debt. Its leverage limits mean that a large share of every acquisition must be paid for with equity, and equity is the most expensive capital of all. A shareholder buying at a 5.8% dividend yield, and expecting that dividend to grow, demands a total return well above that. The true test is whether a new property's yield exceeds the blended cost of the debt and equity used to buy it, after operating costs and the occasional tenant failure.
The yield also varies with the type of investment, and the variation is revealing. In the second quarter of 2026, acquisitions carried a 6.4% initial yield, development 7.6%, and other investments 9.2%, for a combined 7.3%.6 Plain acquisitions, the traditional business, now offer the thinnest margin over funding costs. Development and credit-like investments offer more, but they also carry more risk: construction delays, tenant build-outs, and in the case of credit investments, exposure that looks more like lending than owning. Higher yield is compensation for something.
Scale adds its own penalty. At June 30, 2026, Realty Income's net debt was $30.4 billion, or 5.4 times its annualised pro-forma adjusted EBITDAre, the REIT version of operating cash earnings.6 That ratio is moderate for a net-lease REIT and well within what rating agencies tolerate for an A-rated issuer. In August 2026, Fitch assigned the company an A rating with a stable outlook, adding to existing A3 and A- ratings from Moody's and S&P.21 Strong ratings matter because they lower borrowing costs and keep bond markets open. They do not remove refinancing risk. As cheap legacy bonds mature, they will be replaced with more expensive ones, and the average 3.9% will drift upward unless rates fall.
Europe adds a further layer. By June 2026, about 34.6% of the portfolio's market value sat in currencies other than the dollar, while only 12.0% of pro-rata debt did.6 The company hedges with foreign-currency debt, forwards and cross-currency swaps, but not every hedge is designated as such for accounting purposes, so currency swings flow through reported earnings. Foreign-currency and derivative results swung from a $13.4 million loss in 2023 to a $3.4 million gain in 2024 and a $28.7 million loss in 2025.5 Those amounts are small beside the rent roll, and they do not always match cash moving in the same period. But they explain why a REIT that once owned only American taco stands now reports earnings that wobble with sterling and the euro, and why a sharp, lasting move in the dollar could change what the European portfolio is worth to a dollar-based shareholder.
Liquidity is the cushion that stops these moving parts from becoming a crisis. At the end of June 2026, the company reported about $3.47 billion of liquidity once undrawn credit lines, unsettled forward equity sales and commercial paper were taken into account.6 Forward equity is a quiet but important tool in this machine. In 2025, Realty Income sold about 12.6 million shares through its at-the-market programme on a forward basis, for expected proceeds of roughly $708.5 million.5 A forward sale lets the company lock in today's share price while delaying delivery of the shares until it actually needs the cash for a closing. It is a sensible way to match funding to deals. It is also a reminder that dilution is part of the plumbing, not an occasional event.
A funding mix that is changing
On the same call, management described a striking shift in how growth is being financed. Management said that, year to date, public equity had supplied only 18% of investment volume, against a three-year average of 47%.20 On its face, that is good news for shareholders: fewer new shares means less dilution. But the money has to come from somewhere. The other 82% is coming from debt, retained cash, property sales, and partner capital. In January 2026, for instance, Realty Income sold $862.5 million of 3.5% convertible notes due 2029 and used about $101.9 million of the proceeds to buy back 1.8 million shares at the same time.2 Convertible debt is cheaper than ordinary bonds precisely because buyers receive the option to convert into shares, at an initial conversion price of $69.42.2 Dilution deferred is not always dilution avoided.
The newest funding channel is private capital: funds and joint ventures in which institutional investors put money alongside Realty Income, which earns management fees and a share of returns. It is a well-trodden path for large real-estate managers, and it lets Realty Income expand its buying power without putting all of the capital on its own balance sheet. But it is still small. In the second quarter of 2026, management fees were $3.2 million, against total quarterly revenue of about $1.55 billion.6 That is a rounding error today. Treating it as a new earnings engine would be premature.
Two partnerships illustrate the ambition. In June 2026, Realty Income announced a programmatic joint venture with Cloud Capital to own hyperscale data centres, the vast buildings that house cloud computing and artificial-intelligence workloads. The seed assets were valued at more than $6 billion, and Realty Income's potential investment was up to $1.4 billion for a 45% interest.22 In September 2026, it set up a euro-denominated joint venture with KKR to expand its European platform.23 Both are real-estate optionality. Data centres in particular offer long leases to some of the most creditworthy tenants in the world. But they are also capital-hungry, competitive and technologically fast-moving, and a commitment of up to $1.4 billion is a capital commitment, not recurring earnings. In both cases, the useful question is how much rent and fee income flows to Realty Income's own shareholders, not how large the partner assets are in total.
A skeptical listener to that call would want three answers that guidance alone cannot supply: how the $10 billion would be funded if equity stays expensive, how much of it carries development or credit risk rather than plain ownership risk, and whether the data-centre and private-capital ventures will earn returns that justify the added complexity. Management's stated case rests on access to capital and the breadth of the opportunity set.20 The evidence that would settle the matter, realised AFFO per share through a refinancing cycle, is still accumulating.
All of this leads back to the one number that brought most shareholders to the company in the first place. The dividend is paid in cash. So what cash, exactly, pays it?
VII. The Dividend Is Not the Same Thing as GAAP Profit
Imagine a shareholder opening a standard stock screener and typing in "O." Somewhere on the page sits a number that looks like an alarm bell: a dividend payout ratio of 276%. Realty Income, the screener says, paid out almost three times its 2025 net income as dividends.5 Over the twelve years from 2014 to 2025, the payout never dipped below 191% of reported profit.5 To someone used to industrial companies, where a payout above 100% means the dividend is being funded by borrowing or by running down the balance sheet, that history looks like a company living beyond its means for more than a decade.
The puzzle resolves when one looks at where the profit goes. Real estate, under accounting rules, is depreciated: the cost of each building is written off over decades, as if it were wearing out like a machine. For a company that owns more than 15,000 buildings, that charge is enormous. In 2025, Realty Income's cash-flow statement added back $2.52 billion of depreciation and amortisation against $1.07 billion of net income.5 Depreciation is a real economic concept, since buildings do age, but it is not a cash expense in the year it is recorded, and for well-located land and buildings with tenants paying for upkeep, accounting depreciation often runs well ahead of the actual loss of value.
That is why the gap between profit and cash is so wide. Over 2014 to 2025, Realty Income reported a cumulative $6.4 billion of net profit and $20.5 billion of cash from operations, more than three times as much.5 Dividends paid over the same period totalled about $15.7 billion.5 In 2025 alone, dividends of $2.9 billion compared with $4.0 billion of operating cash flow.5 Measured against the cash the business actually generated, the dividend has been comfortably covered.
The industry's own answer to this distortion is AFFO, the company's preferred measure of recurring cash earnings per share. Realty Income reported AFFO of $4.28 per share for 2025, and in August 2026 raised its 2026 guidance to $4.44–$4.45.19 The monthly dividend declared in October 2026 annualises to about $3.26 a share.3 Against the midpoint of 2026 guidance, that is a payout of roughly 73% of AFFO. That is a far more reassuring number than 276%, and it is the number most REIT investors use. But it carries a caveat worth stating plainly: AFFO is a company-defined measure, not an audited accounting standard, and each REIT adjusts it in its own way.
The trap on the other side
If the GAAP payout ratio makes the dividend look too dangerous, a different shortcut makes it look too safe. Standard free-cash-flow calculations subtract capital expenditure from operating cash flow. For Realty Income, that line captures almost nothing, because the company's real reinvestment is not maintenance on existing buildings but the purchase of new ones. In 2025, recurring capital expenditure on the existing portfolio was a trivial $0.3 million, while the company invested $4.15 billion in acquisitions and $485 million in development.5 Those purchases sit in investing cash flows, so a screener's free-cash-flow figure ignores them entirely. Free cash flow by that definition looks healthy. Free cash flow after the investment the business actually requires to grow is deeply negative, and has been for most of the past decade.
That is not necessarily a problem. Buying income-producing property is what Realty Income exists to do. But it means the dividend and the acquisition programme are competing for the same pool of cash. Every dollar of operating cash flow paid out to shareholders is a dollar that must be replaced with new debt or equity to fund the next acquisition. The dividend is covered by operations; growth is funded by capital markets.
Two other accounting details help separate real problems from apparent ones. The first is receivables. At year-end 2025, Realty Income reported $1.05 billion of accounts receivable, which might suggest a lot of unpaid rent.5 But $880 million of that was straight-line rent, an accounting entry that spreads a lease's scheduled increases evenly over its life, so that rent recognised in early years exceeds cash received.5 It is not overdue money. The client receivables, the money tenants actually owe, were about $173 million.5 The company does not publish an ageing table showing how long those balances have been outstanding.
The second is credit stress, and here the warning is real. Real-estate impairments in 2025 reached $434.5 million, with properties leased to bankrupt or financially distressed clients among the stated causes.5 That charge was large enough to push the fourth quarter of 2025 to an operating loss of about $273 million on a reported basis, the only negative quarter in the recent record.5 Separately, the allowance for credit losses on loans and financing receivables stood at $108.9 million at year-end, after a $40.4 million write-off during the year, with provisions attributed in part to deterioration in certain clients' creditworthiness.5 In the first half of 2026, the company also recorded $41 million of lease termination income, a reminder that tenant exits can flatter a period's results even as they shrink future rent.6
Put together, the evidence says something specific. The dividend is not in danger because GAAP profit is low; GAAP profit is low largely because of depreciation. The dividend is covered by recurring cash, with room to spare on the company's own AFFO measure. But its future growth depends on two things that the cash-flow statement cannot guarantee: tenants continuing to pay, and capital markets continuing to fund acquisitions on terms that add to AFFO per share. The right test is not the GAAP payout ratio or operating cash flow alone. It is AFFO per share and the dividend payout after recurring property costs, watched alongside credit losses.
Cash on hand is not the answer, either. Realty Income ended 2025 with about $435 million of cash and roughly $553 million by the end of June 2026, tiny amounts beside a dividend bill near $3 billion a year.52 That is by design. A REIT that keeps little idle cash is one that relies on predictable inflows and open credit lines. It is efficient in calm markets and leaves little room for error in turbulent ones, which is why the company's undrawn credit facilities and commercial-paper access matter as much as its income statement.
Which raises the question of who is running that test from the inside, and how well they have done it.
VIII. Sumit Roy's Growth Test
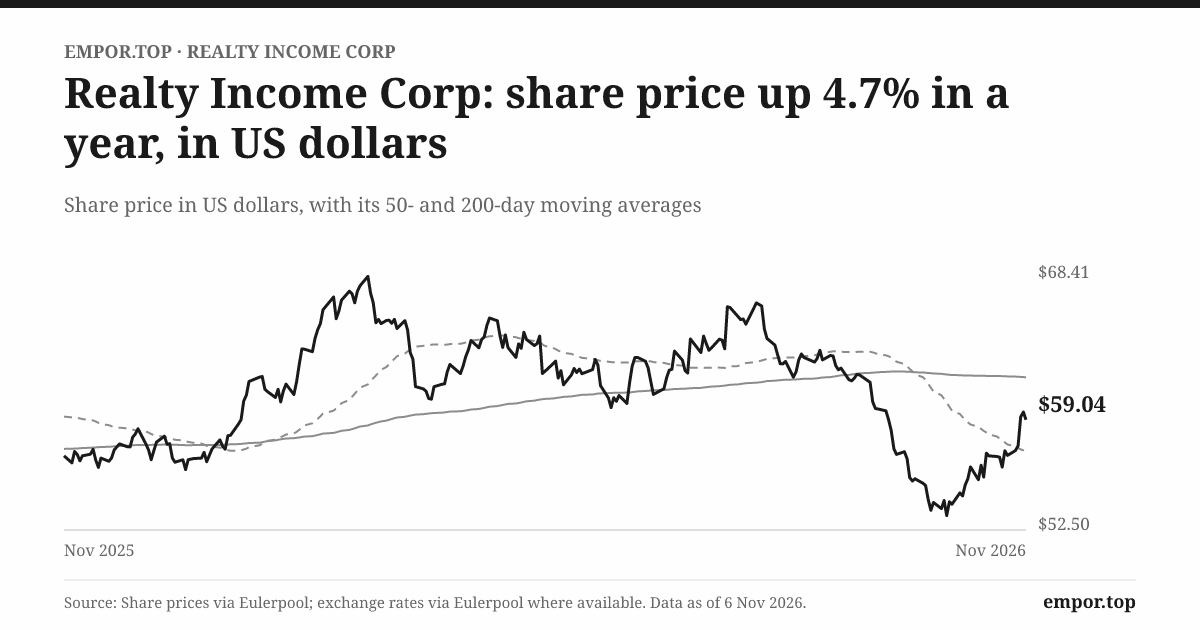
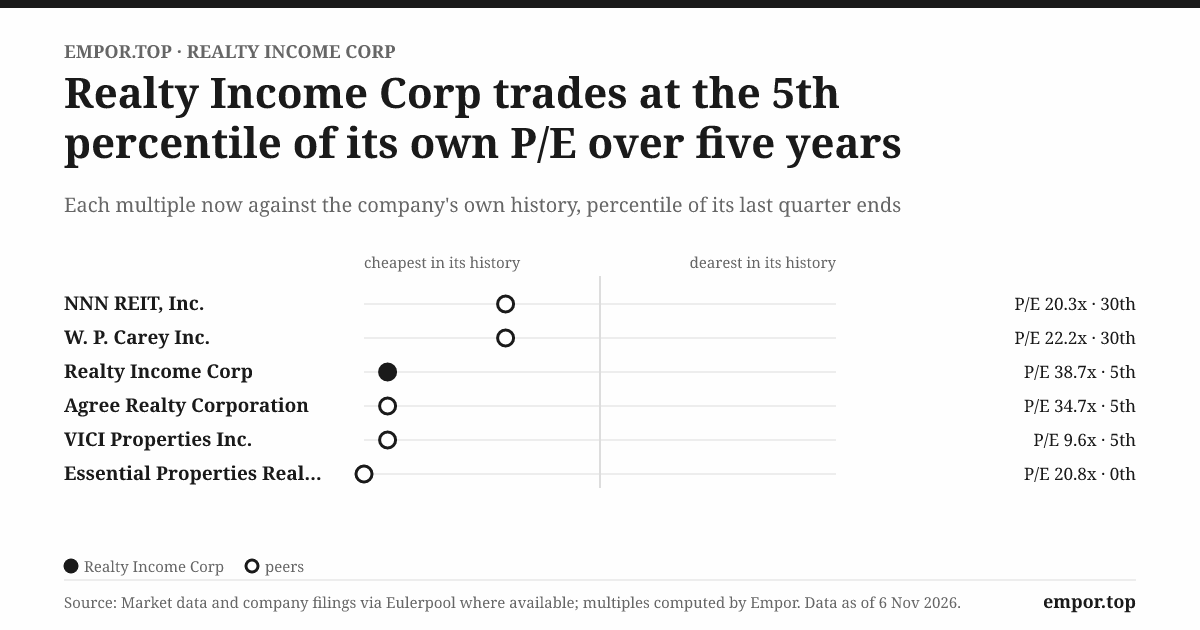
When Sumit Roy walked through the revised 2026 outlook on the August call, the backdrop was an awkward one for a chief executive with an ambitious plan. The company had just raised its AFFO guidance and its investment target.20 Yet its shares, at about $56 by late October, were trading roughly 17% below their 52-week high, and on a price-to-earnings basis the stock sat well below its own five-year median.4 The market was not rejecting the dividend. It was declining to pay up for the growth story.
Roy's tenure has been defined by moves that made the platform bigger and more complex. He became CEO in October 2018, after rising through the company's acquisitions team.14 Under his leadership, Realty Income completed the VEREIT and Spirit mergers, expanded in Europe, added development and credit-like investments, and began building a private-capital business with partners such as Cloud Capital and KKR.2223 Its international reach had grown substantially by June 2026.6
On the headline numbers, the strategy has worked. Revenue compounded at about 18.8% a year from 2015 to 2025.5 Occupancy has stayed near 99%.5 The dividend has risen every year. But the record looks different once it is split between what the company bought and what it already owned. In 2025, same-store rental revenue grew just 1.3%, while newly acquired properties contributed $329.6 million of new rental revenue.5 Recent reported growth is, in other words, overwhelmingly acquisition-led. That is the strategy by design. It also means that the question of whether Roy's team creates value is identical to the question of whether its acquisitions do.
Incentives offer one window into how management thinks about that question. Roy's target direct compensation rose from about $11.1 million in 2024 to $12.5 million in 2025, and 74% of the 2025 target was performance-based.24 "Performance-based" is a description of structure, not proof of good outcomes; it matters which metrics are rewarded and how hard the targets are. Insider ownership tells another part of the story. The 17 directors, nominees and executive officers as a group held about 0.1% of the shares.24 Realty Income has no controlling holder; its largest owners are index giants, with Vanguard at about 12.2%, BlackRock at 9.8% and State Street at 6.5%.24 That is a common pattern for large REITs, and it means that shareholders depend on board oversight and executive pay design, rather than founder-style ownership, to align management with per-share results.
Governance signals are, on the available record, steady rather than dramatic. The 2026 proxy reported no related-party transactions in 2025 and a majority-independent board.24 At the May 2026 annual meeting, shareholders approved the director slate, the auditor and the say-on-pay vote.25 KPMG issued an unqualified opinion on the 2025 financial statements and internal controls.5 The one senior change in 2026 was the departure of chief legal officer Michelle Bushore, effective September 2, 2026.24 It is a notable role, but it is not a change at the top; the chief executive, Roy, and chief financial officer, Jonathan Pong, remain in place.24
The finance chief's pay moved in the same direction. Jonathan Pong's target direct compensation rose from about $2.2 million to $3.1 million between 2024 and 2025.24 Pay increases at a company whose total assets more than tripled in five years are not surprising, and the board can point to a larger, more complex platform as justification. The question an owner would ask is whether the pay plan rewards the size of that platform or the cash each share earns from it, because those two goals can diverge when acquisitions are the main lever.
Guidance behaviour is the other credibility test. The pattern in 2026 has been upward revision: higher investment volume and a higher AFFO-per-share range by mid-year.19 Raising guidance is better than cutting it, but the more useful question is what gets raised. A $10 billion investment target is an input. AFFO per share of $4.44–$4.45 is an output. The ratio between them is the real story. Moving from $4.28 to roughly $4.45 implies AFFO-per-share growth of about 4% for the year, a respectable but not spectacular figure for a company deploying capital at that scale.19
A skeptical investor, or an activist with a long-only fund, would press on exactly that ratio. If headline investment volume is growing much faster than AFFO per share, the extra investment is either earning a thin spread, being funded with expensive capital, or offsetting losses elsewhere in the portfolio, such as the tenant failures behind the 2025 impairments. Each explanation has different implications. The skeptic would want proof that the acquisitions are enriching each share, not merely enlarging the platform, and would point out that the company's growth has never really been tested in a prolonged period of high rates without access to cheap equity.
The defence is just as concrete. Management has not cut the dividend, has kept leverage moderate, has preserved investment-grade ratings through two large mergers and a rate shock, and has grown AFFO per share through all of it. That is not nothing. Many REITs that grew aggressively in the 2010s did not survive the 2022–2023 rate shock with their ratings and dividends intact.
So where does that leave the overall verdict? It requires putting the bull case and the bear case side by side, at today's price.
IX. Analysis & Bear vs. Bull Case
On October 30, 2026, Realty Income's shares closed at $56.23, giving a dividend yield of about 5.8%.4 Lay that number beside the facts already established: same-store rent growth of 1.2% in the second quarter, occupancy of 98.8%, net debt of 5.4 times adjusted EBITDAre, and AFFO guidance implying roughly 4% per-share growth.619 An investor buying today is, in effect, paying for a 5.8% income stream that grows by whatever the company can add through acquisitions, minus whatever leakage comes from tenant failures and rising funding costs.
The bull case starts with the portfolio's durability. Tenants are diversified across thousands of locations and more than 1,700 clients, no single one above a few percent of rent.5 Leases have nearly nine years left on average.5 Occupancy has stayed near 99%, and expiring leases have been renewed or re-let at above previous rent.6 The company's A-level ratings give it some of the cheapest access to debt in the real-estate sector.21 And because the dividend is covered roughly one-and-a-third times by AFFO, there is room to absorb a bad year of tenant failures without threatening the payout. In this view, Realty Income is a slow-growing but exceptionally resilient income machine, whose scale makes it the natural buyer when large portfolios come up for sale.
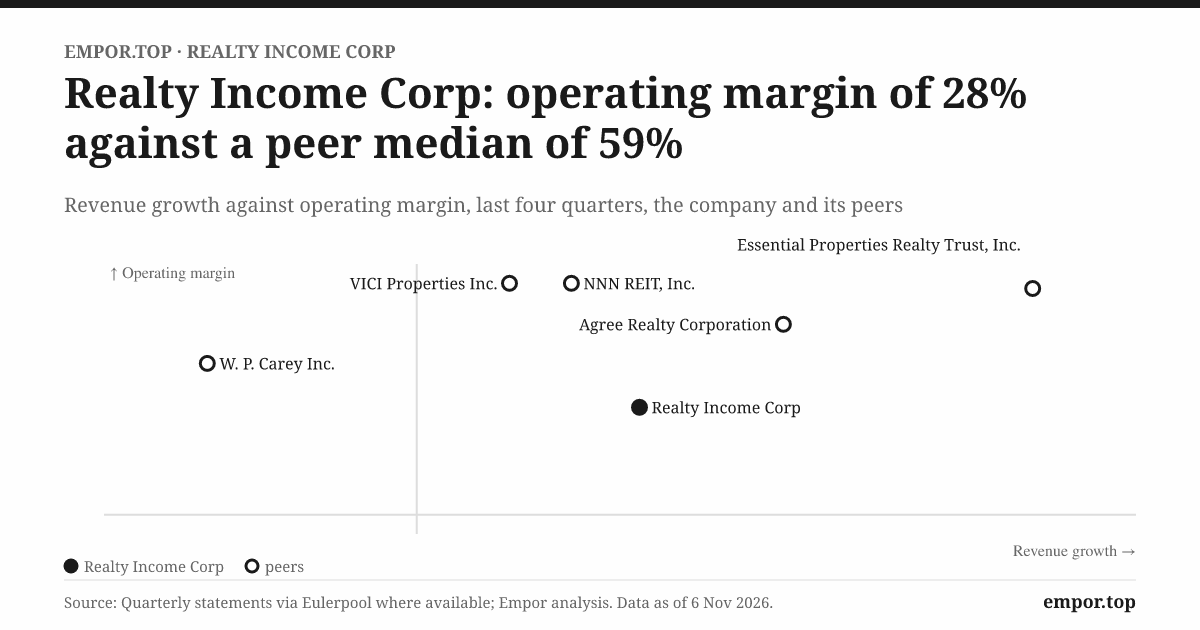
The bear case turns each of those strengths into a limit. Same-store growth of about 1% means the portfolio barely keeps pace with inflation on its own. Tenant distress is not hypothetical; it drove hundreds of millions of dollars of impairments in 2025, and the largest tenants include discount and drugstore chains under well-known pressure.5 Growth depends on capital markets, which means that a prolonged period of expensive equity and higher bond yields could squeeze the acquisition spread just as legacy cheap debt needs refinancing. The shift away from public equity in 2026 lowers dilution but leans more on debt, convertibles and partner capital, each with its own cost.20 And the company's sheer size means that each year it must find more acquisitions just to move the per-share needle by the same amount.
There are smaller items in the bear file, too. At year-end 2025, the company had about $805 million of construction commitments on development projects, plus $43 million of tenant-improvement and building commitments, which is the natural consequence of leaning further into development yields.5 Development creates higher initial returns, but it also creates obligations that must be funded whatever the capital markets are doing when the bills arrive. None of these items is alarming at Realty Income's scale. Together, they show a business taking on slightly more complexity and slightly more risk per dollar invested than the plain sale-leaseback that built it.
The industry structure explains why neither case is a slam dunk. Using Michael Porter's five forces, the most powerful force on Realty Income is the bargaining power of its customers, the tenants. A creditworthy retailer seeking a sale-leaseback can choose among dozens of landlords and private funds, can borrow from banks instead, or can simply keep owning its stores. That competition limits how much rent Realty Income can extract. Rivalry among buyers is intense, especially for the investment-grade tenants that every net-lease REIT prizes, and that competition compresses acquisition yields. Suppliers of capital, the bond and equity markets, hold real power too, because their pricing sets Realty Income's funding cost. The threat of substitutes, such as traditional mortgage financing or unsecured corporate debt, is ever-present. Barriers to entry are low for small players but high for anyone hoping to buy at Realty Income's scale. The result is a fragmented industry in which no single player sets prices.
Hamilton Helmer's 7 Powers framework sharpens the moat question. Realty Income's most credible power is scale economies, in the specific sense that its size lets it spread overhead thinly, borrow cheaply and underwrite large portfolios that smaller competitors cannot. There is a plausible, if unproven, case for a process power in its underwriting data, built from decades of observing how thousands of tenants and locations perform. The company does not show switching costs that lock tenants in beyond the lease itself, network effects, or a cornered resource. Its brand is powerful with investors, which lowers its cost of equity, but has little visible effect on what tenants will pay. The moat, in short, is a cost-of-capital and execution advantage, real but narrower than the stock's long dividend record might suggest.
The irony is that Realty Income's own strategy illustrates the competitive threat. Its move into private funds and joint ventures with partners like KKR is a response to the same reality every net-lease buyer faces: huge pools of institutional money want long, bond-like leases, and they can either compete with Realty Income for deals or invest alongside it.23 By inviting that capital in, the company turns a potential rival into a source of fees and buying power. By the same token, it acknowledges that its balance sheet alone is not enough to dominate the market, and that the spread on any given deal will be set by a crowd of well-funded buyers rather than by Realty Income.
The newer ventures belong in proportion. The data-centre joint venture and private-capital partnerships are strategically relevant and could, over years, add fee income and exposure to faster-growing property types.2223 They are not yet large enough to underwrite the investment case. The current fee line is an option, not a pillar.6
Valuation sends mixed signals. The shares trade at about 36.8 times trailing earnings, below Realty Income's own five-year median of 55.8 times, and at about 1.3 times book value.4 That looks like a discount, but price-to-earnings is a weak tool for a REIT because depreciation suppresses earnings so heavily. A more useful lens is price to AFFO. At $56.23 and guidance of $4.44–$4.45, the shares trade at about 12.6 times this year's expected AFFO. Whether that is cheap or expensive depends on comparable multiples for peers like NNN REIT and Agree Realty on the same date and basis, and on whether one believes AFFO per share can grow faster than the 3–4% range implied by the past few years. What the price appears to assume is a reliable, modestly growing income stream, not a growth company.
For investors who want to watch the case unfold, three measures do most of the work. The first is same-store rent growth, the clearest read on the portfolio's organic health.6 The second is AFFO per share and the dividend's payout of it, measured against current guidance and the annualised dividend.193 The third is net debt to adjusted EBITDAre, read alongside the yields on new investment.6 If same-store growth holds, AFFO per share keeps rising and leverage stays near current levels, the bull case is intact. If any of the three slips, the bear case starts to look like the story.
X. Playbook: Business & Investing Lessons
Go back to the Taco Bell in Northridge, and follow the same lease forward through everything that came after: the pause in 2008, the Napa vineyards, the VEREIT and Spirit mergers, the $10 billion investment target. The contract barely changed. What changed was the scale of the capital behind it, and that is where the lessons live.
The first lesson is that a lease moves costs; it does not make risk disappear. The 2025 impairments showed where that risk remained.5 For anyone building a business on contracts, the lesson is to price the counterparty, not the contract.
The second is that scale is useful only when each share gets more. VEREIT and Spirit made Realty Income vastly larger. The gap between its revenue growth and modest AFFO-per-share growth reflects, in part, the cost of the shares issued to make the deals happen. For founders and acquirers, the lesson is that consolidation is a financing decision as much as a strategic one, and the per-share outcome is the only scoreboard that matters to the people who already own the company.
The third is that a dividend promise needs an investment test. Realty Income's monthly dividend is its brand and its constraint. The spread between new investment yields and funding costs is thinner and more fragile once equity costs and refinancing rates are included.5 A company that promises income forever has to be most disciplined precisely when it is most tempted to grow.
The fourth is that accounting profit is a poor REIT cash proxy, but acquisition cash is still real. The standard payout and free-cash-flow measures mislead in opposite directions.5 The truth sits between the two: the dividend is paid from operations, and growth is paid for by capital markets. Investors who confuse the two will either panic too early or relax too much.
The fifth, and the most surprising given the company's reputation as an acquirer, is that the safest growth plan may be to wait. In 2008, Realty Income paused acquisitions as markets seized up, preserving liquidity but passing on deals.9 Discipline, in that moment, looked like inactivity. The lesson for any business built on a promise to its owners is that sometimes protecting the promise means refusing to grow.
XI. Epilogue
Tonight, as October 2026 closes, Realty Income stands at the most ambitious point in its history. Its 2026 investment and AFFO-per-share outlooks have risen, and it projects same-store rent growth of 1.1% to 1.3% for the year.19 It added Fitch's A rating to its existing investment-grade grades and expanded into data centres and Europe through ventures with Cloud Capital and KKR.212223 The shareholder who bought for the monthly dividend has, almost without noticing, become a part-owner of a global property investor with ambitions in private capital and digital infrastructure.
The next few quarters will start to show whether that ambition is earning its keep. The fourth-quarter results, due early in 2027, will show whether the $10 billion investment target was met and at what yields. If the company hits the target with yields holding near 7%, and if AFFO per share lands at or above the top of guidance, the acquisition engine will have passed another test. If volume is met only by leaning on lower-yielding acquisitions or higher-risk credit investments, the target will look more like a measure of activity than of value.
The portfolio's health will tell its own story. Same-store rent growth, occupancy, lease recapture and credit-loss provisions are the vital signs. A year of renewed tenant bankruptcies among discount retailers or drugstore chains would show up first in impairments and then in rent. A year in which those indicators hold steady would strengthen the case that diversification is doing its job.
Then there is the refinancing calendar. Notes due in 2027 and a £900 million term facility initially due in January 2028 will need to be replaced, probably at higher rates than the bonds they replace.5 As that happens, the 3.9% average cost of debt will creep upward, and the acquisition spread will narrow unless new investment yields rise too. Leverage near 5.4 times gives room, but not unlimited room.
And the new partnerships will face a test of conversion. Capital commitments and seed-asset valuations are not recurring earnings. The data-centre venture and the KKR partnership will prove themselves only when they deliver fees and rent that show up in AFFO per share, in amounts large enough to matter.
The dividend itself will keep sending small signals along the way. Its increases in recent years have come in increments of a fraction of a cent per share per month, as with the move from $0.2710 a share for the August payment to $0.2715 by the autumn.263 Those tiny steps are deliberate. They keep the streak of increases alive while holding the payout comfortably inside AFFO. If AFFO per share accelerates, the steps could grow. If it stalls, the steps will shrink further, and the gap between the brand promise and the underlying growth will become harder to hide.
The tension that remains is the one this story began with. Realty Income can almost certainly keep declaring dividends and keep raising them by small increments. What is not certain is whether external investment can keep lifting AFFO per share fast enough to fund those increases without pushing leverage, dilution or tenant losses beyond what the portfolio can absorb.
XII. Outro
Picture a Taco Bell like the one the Clarks bought in Northridge, its lights coming on before the morning rush. The tenant fires the grills, the staff open the drive-through, and the customers come and go. None of them think about who owns the building.
That quiet rhythm became Realty Income's public-market promise: a monthly dividend declared 676 times in a row.3 The test for the next chapter is not how many properties carry its name, or how many billions it can invest in a year. It is how much durable rent, and how much AFFO, each share earns, one month at a time.
References
-
Q2 2026 Form 10-Q — Realty Income Corporation, SEC, 2026-08-06 ↩↩↩↩
-
Realty Income Announces 676th Consecutive Common Stock Monthly Dividend — PR Newswire via Finviz, 2026-10 ↩↩↩↩↩
-
2025 Form 10-K — Realty Income Corporation, SEC, 2026-02-25 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Q2 2026 Supplemental Operating & Financial Data — Realty Income Corporation, SEC, 2026-08-05 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Realty Income Agrees to Acquire Napa Valley Winery and Vineyard Properties — Realty Income Corporation, SEC Form 8-K, 2010-06 ↩↩↩↩
-
Realty Income to Merge With VEREIT in an All-Stock Transaction — Realty Income Corporation, 2021-04-29 ↩↩
-
Realty Income to Buy VEREIT for About $11 Billion — Reuters via Investing.com, 2021-04-29 ↩
-
Realty Income Announces CEO Succession — Realty Income Corporation, SEC Form 8-K, 2018-10-16 ↩↩↩
-
VEREIT Merger Agreement and Transaction Presentation — Realty Income Corporation, SEC, 2021-04-29 ↩↩
-
Realty Income to Acquire Spirit Realty for $9.3 Billion — The Real Deal, 2023-10-30 ↩
-
Spirit Acquisition Agreement and Exchange-Ratio Details — Realty Income Corporation, SEC, 2023-11-01 ↩
-
Spirit Acquisition Conference Call Transcript — Realty Income Corporation, SEC, 2023-10-30 ↩
-
Q2 2026 Operating Results — Realty Income Corporation, SEC, 2026-08-05 ↩↩↩↩↩↩↩↩
-
Q2 2026 Earnings Call Transcript — The Motley Fool, 2026-08-12 ↩↩↩↩↩
-
Fitch Assigns Realty Income an A Rating — Realty Income Corporation, 2026-08-03 ↩↩↩
-
Cloud Capital Hyperscale Data Center Joint Venture — Realty Income Corporation, 2026-06-30 ↩↩↩↩
-
KKR Euro-Denominated Joint Venture — Realty Income Corporation, 2026-09-14 ↩↩↩↩↩
-
2026 Proxy Statement — Realty Income Corporation, SEC, 2026-03-25 ↩↩↩↩↩↩↩
-
2026 Annual Meeting Results — Realty Income Corporation, SEC, 2026-05-21 ↩
-
Realty Income Announces 673rd Consecutive Common Stock Monthly Dividend — Realty Income Corporation, 2026-07-07 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube