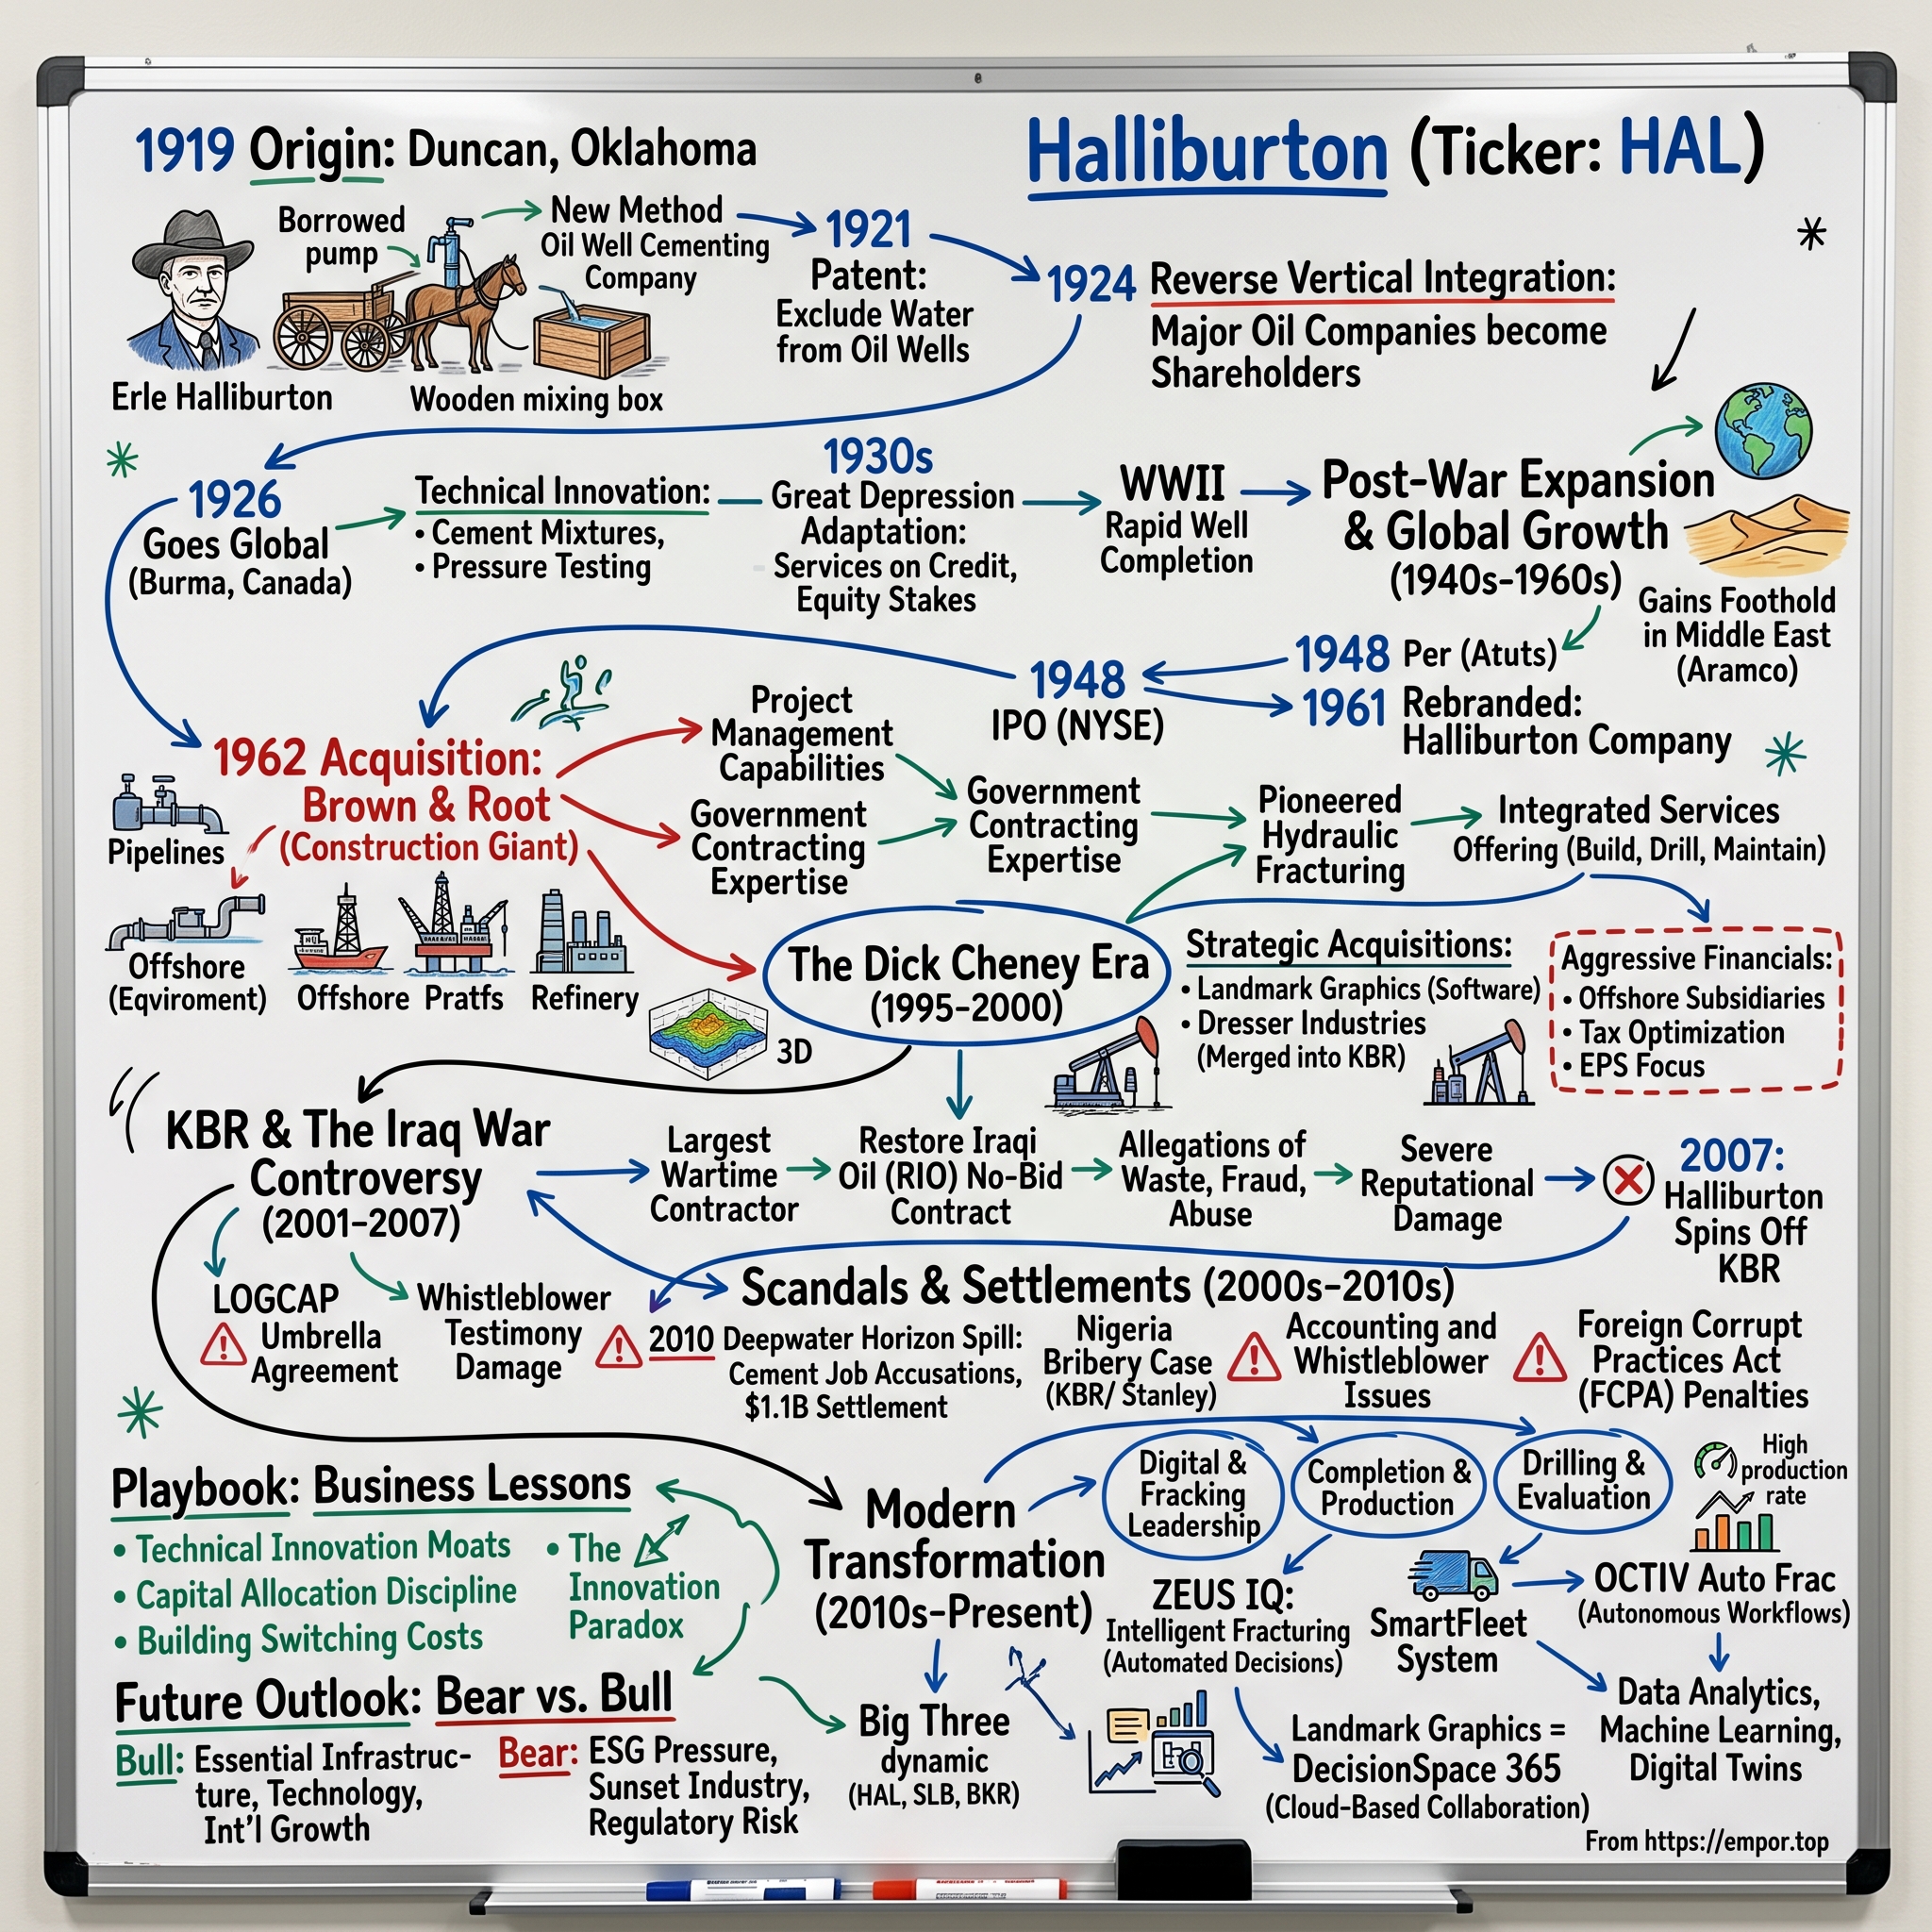
Halliburton: The Frac King, The Geopolitical Lightning Rod, and the Battle for Oilfield Cash
I. Introduction & Episode Roadmap (10–12 min)
The wire transfer
On a Sunday in early May 2016, with crude prices only beginning to recover from a bruising downturn, Halliburton issued a brief statement: the company "will pay Baker Hughes the termination fee of $3.5 billion by Wednesday, May 4, 2016."1 Eighteen months earlier, the same executive team had taken the stage in Houston to pitch the transaction of a generation. Halliburton proposed acquiring its closest domestic rival for $78.62 per share, representing an equity value of $34.6 billion and an enterprise value of $38.0 billion. The combined company would have generated $51.8 billion in 2013 revenue and employed more than 136,000 people worldwide.2 Then-CEO Dave Lesar reassured the market, telling investors, "Our stockholders know our management team and know we live up to our commitments."2
The contractual fine print told a different story. To secure the Baker Hughes board's support, Halliburton had agreed to divest business units generating up to $7.5 billion in revenue if antitrust authorities demanded remedies, and agreed to pay $3.5 billion if the deal died on antitrust grounds.2 The transaction collapsed. The U.S. Department of Justice sued to block the merger in April 2016, with Attorney General Loretta Lynch stating that the combined companies would control as much as 90 percent of U.S. sales in the markets at issue.1 The sheer scale of the $3.5 billion penalty was devastating in the context of Halliburton's 2016 financials: that year, the company held capital expenditures to $798 million, while operating cash flow was negative $1.7 billion.3 Halliburton effectively handed its chief rival more than four times its own annual downturn investment budget and walked away empty-handed.
The paradox
That episode captures the defining tension at the heart of Halliburton. It is an engineering powerhouse of the modern energy era, yet also one of the most politically scrutinized corporate brands in American history. Over successive industry cycles, management repeatedly proved capable of running complex field operations with technical excellence while misjudging legal, political, and balance-sheet risks. Founded in 1919 with a borrowed pump, a wagon, a team of mules, and a wooden mixing box, the company evolved across a tumultuous century. Along the way, it operated as a major defense contractor, navigated crippling asbestos liabilities, became a political lightning rod as the former corporate home of a sitting vice president, served as the primary cementing contractor on the Deepwater Horizon rig, absorbed a record $3.5 billion breakup penalty, and stands today as one of the world's largest oilfield services providers.
The scale today
Halliburton reported $22.2 billion of revenue in 2025, down from $22.9 billion in 2024.4 It employs more than 46,000 people from 146 nationalities in more than 70 countries.5 The business operates through two primary divisions: Completion and Production, which handles hydraulic fracturing, well cementing, and completion tools, generated $12.8 billion in 2025 revenue, while Drilling and Evaluation, which steers drill bits, logs subsurface formations, and sells reservoir modeling software, brought in $9.4 billion.4 Geographic exposure has become equally decisive: North America accounted for $9.1 billion of 2025 revenue, while international operations generated $13.1 billion, meaning roughly three dollars in five now come from outside the United States and Canada.4
Recent results underscore these cross-currents. In the second quarter of 2026, revenue was $5.7 billion and adjusted operating margin was 12%.6 While armed conflict disrupted operations in parts of the Middle East, North American hydraulic fracturing activity showed signs of steadying. Internationally, revenue expanded, with Chief Executive Jeff Miller telling analysts that overseas operations delivered the "highest second quarter revenue in more than a decade."7 Investors now face a defining question: can recent contract wins and pricing gains sustainably compound returns, or does this simply mark another cyclical peak in an inherently boom-and-bust business?
The roadmap
The story runs in eight movements. First come the origins: Erle Halliburton, his pioneering cement patents, and the wildcatters who learned they could not complete wells without him. Next is the conglomerate era, which bolted Brown & Root—a politically entrenched engineering and construction giant—onto an oilfield services firm. Then come the Cheney years and the Dresser merger, which inherited an asbestos liability that ultimately pushed two subsidiaries into Chapter 11 bankruptcy. The narrative then traces the controversial Iraq War logistics contracts, the spinoff of KBR, the 2010 Macondo disaster, and the failed Baker Hughes takeover. The focus then turns to the modern operating engine built under Jeff Miller: electric fracturing fleets, higher-margin international expansion, and a disciplined capital-return framework. From there, the analysis evaluates Halliburton's competitive moat and stress-tests the core bull case against historical performance. Finally, the story examines the management playbook, weighs the bull and bear theses, and highlights the decisive metrics that will determine whether the company can compound cash across the next commodity cycle.
To understand why a company that pumps cement into holes became central to so much American history, start in a Texas boomtown just after the First World War.
 Subscribe on LinkedIn
II. The Erle Halliburton Origin Story: Turning Mud into a Moat (1919–1950s) (25–30 min)
Fired into a fortune
Erle Palmer Halliburton was born on September 22, 1892, near Henning, Tennessee. He joined the U.S. Navy in 1910 and was honorably discharged in 1915.8 Like many young men of his generation, he headed west to the California oilfields, finding employment with Almond A. Perkins at the Perkins Oil Well Cementing Company, an early pioneer of the craft. When Halliburton repeatedly proposed ways to improve the process, Perkins rebuffed the unsolicited ideas and eventually fired him. Halliburton later converted the sting of that dismissal into a favorite quip: "the two best things that ever happened to me were being hired, and fired, by the Perkins Oil Well Cementing Company."8
He and his wife, Vida, relocated to the oil boomtown of Burkburnett, Texas, intent on pitching well cementing to drillers who had never paid for the service. In 1919, Halliburton established the New Method Oil Well Cementing Company, launching operations with a borrowed pump, a wagon and team, and a wooden mixing box.9 Early finances were so precarious that Vida pawned her wedding rings to meet payroll and washed empty cement sacks by hand so they could be resold.8
Why cement is existential
For those unfamiliar with drilling operations, understanding the basic physics of well construction is essential to following the company's trajectory. An oil or gas well is a borehole drilled thousands of feet into the earth, cutting through geological strata that trap water, oil, gas, and extreme subterranean pressure. Drillers line the hole with steel casing, but the metal does not form a seal against the surrounding rock. Without an impermeable barrier in the annular space between the pipe and the formation wall, water from shallow aquifers can migrate down and drown an oil-bearing zone, while high-pressure gas can travel up toward the surface and cause a blowout. Cement provides that barrier. Functionally, it acts like industrial grout: unnoticed and unappreciated when it holds, but catastrophic when it fails.
Halliburton's core breakthrough was engineering that seal to set reliably at an industrial pace. The enterprise was reorganized as the Halliburton Oil Well Cementing Company (HOWCO) on May 7, 1920, and established permanent headquarters in Duncan, Oklahoma, in 1921. On March 1, 1921, Halliburton received a U.S. patent for a "Method and Means for Cementing Oil Wells."10 In 1922, he patented a jet-cement mixer that blended cement and water far faster and more consistently than manual mixing.9 By late 1922, HOWCO was running seventeen trucks across Texas, Oklahoma, Louisiana, and Arkansas under the operational slogan "We will get there, somehow."9 Over his career, Halliburton was granted 38 patents, including early iterations of the float collar and guide shoe, which remain standard components in modern well construction.10
Customers as shareholders
The most strategically consequential early maneuver arrived in 1924, when HOWCO was formally incorporated with seven major oil companies taking equity stakes as significant investors.9 The underlying logic remains instructive. For an oilfield service specialist, the principal structural threat is backward vertical integration—the risk that major exploration and production operators choose to bring specialized services in-house. By turning those prospective competitors into equity owners, Halliburton ensured that his largest customers directly shared in the financial upside of his firm's expansion. It proved to be an early masterclass in mitigating buyer power, a recurring tension that continues to define oilfield services.
Going global and inventing fracking
HOWCO pursued international expansion early. In 1926, the company exported five cementing units to Burma, while family members established an operating foothold in Alberta, Canada. During the 1930s, HOWCO opened its first dedicated research laboratories and performed its first offshore cementing assignment in the Gulf of Mexico's Creole Field. It entered Venezuela in 1940. In 1946, the company expanded into Colombia, Ecuador, Peru, and the Middle East, where it began serving the Arabian-American Oil Company, the forerunner of Saudi Aramco.11 That commercial relationship endures eighty years later, representing both a critical long-term growth engine and a notable geographic concentration risk.
The most consequential technical breakthrough of the era occurred on March 17, 1949. Near Duncan, Halliburton and Stanolind Oil Company completed the first commercial hydraulic fracturing treatment, pumping fluid under pressure to crack open tight rock formations and stimulate oil flow.10 Six decades later, modernized variants of that technique would ignite the American shale revolution, turning Halliburton into what Wall Street routinely calls "the frac company." The company listed its shares on the New York Stock Exchange in 1948 and formally changed its corporate name to Halliburton Company in 1960.9 Erle Halliburton died in Los Angeles on October 13, 1957.8
This formative era explains why Halliburton established such an enduring market position. Its foundational service was safety-critical, operating under asymmetric economics where the catastrophic cost of well failure vastly exceeded the price of the service itself—leaving operators reluctant to switch to unproven providers. Similar economic dynamics continue to govern modern completions. For the next generation of Halliburton leadership, however, specialized cementing seemed too narrow a base, prompting a search for a vastly larger corporate canvas.
III. Conglomeration, Vietnam, & The Brown & Root Megastructure (1960s–1990s) (25–30 min)
Buying a political machine
In 1961, Halliburton relocated its corporate headquarters from Duncan to Dallas. The following year, it acquired Brown & Root, the Houston engineering and construction firm founded by brothers Herman and George Brown.9 Brown & Root was far from a conventional contractor. Its ties to the federal government stretched back to the late 1930s and 1940s, when the Brown brothers secured the contract to construct the Mansfield Dam near Austin with help from a rising young Texas congressman named Lyndon B. Johnson.12 Once Johnson ascended to the presidency, Brown & Root captured massive federal construction awards. By the mid-1960s, syndicated columnists and congressional Republicans openly suggested that the firm's extraordinary run of public works had much to do with its substantial campaign contributions to Johnson.12
On paper, the strategic logic appeared straightforward. Brown & Root possessed the engineering capacity to fabricate offshore platforms, lay subsea pipelines, build refineries, and erect military installations. Paired with Halliburton’s specialized wellsite services, the combination theoretically spanned the entire hydrocarbon value chain from reservoir to refinery. Yet the transaction fundamentally altered Halliburton's corporate identity. Alongside high-margin technical oilfield services, Halliburton now operated a sprawling, lower-margin engineering and construction business heavily reliant on public contracts—introducing acute political and reputational exposure.
The Vietnam template
That exposure became fully visible in Southeast Asia. As American involvement in the Vietnam War deepened, a joint-venture consortium that included Brown & Root secured a $380 million contract to construct airfields, naval bases, radar stations, hospitals, and logistical depots for the U.S. Navy in South Vietnam.12 By 1967, the General Accounting Office had faulted the consortium—dubbed the "Vietnam builders"—for severe accounting deficiencies, inadequate inventory controls, and pervasive material theft. At home, anti-war demonstrators branded Brown & Root the living embodiment of the "military-industrial complex."12 Allegations of contractual overcharging, political favoritism, and wartime profiteering created a playbook of criticism that would reemerge almost verbatim four decades later during the war in Iraq.
Following the oil wherever it went
While Brown & Root anchored its government contracting business, Halliburton pressed ahead with the international oilfield expansion it had begun decades earlier in Burma, moving into frontier basins few Western service companies dared to enter. In 1984, Halliburton supplied completion equipment for China's first offshore multiwell platform. In 1986, it became the first American oilfield services company to operate in mainland China, and in 1991, as the Soviet Union disintegrated, it opened an operating office in Moscow.11 Establishing early technical footholds and embedding crews alongside national oil companies had defined Halliburton's commercial playbook since its 1946 partnership with Aramco. It is the same operating instinct behind the company's recent push into Argentina, Algeria, and Iraq.
The long bust
The conglomerate structure, however, offered little shelter from the underlying boom-and-bust cycle of global energy. During the oil shocks of the late 1970s and early 1980s, Halliburton surged: annual revenue peaked in 1981 at $8.5 billion, while global headcount reached 115,000 employees. But when crude prices collapsed in the mid-1980s, the entire organization contracted sharply. By 1991, following the oil collapse of the mid-1980s, revenue had slid to $7 billion and headcount fell to roughly 73,000.9 More than 40,000 jobs disappeared in less than a decade. The downturn demonstrated a structural pattern that continues to shape oilfield services: providers aggressively add equipment and payroll at the top of the cycle, only to absorb painful restructurings and asset write-downs when drilling slows, leaving equity holders to absorb the volatility.
For investors, the Brown & Root era proved that diversifying into industrial construction did not dampen commodity cyclicality. Instead, it layered fixed-price contractual risk and political vulnerability directly on top of volatile drilling demand. That structural exposure was about to face a far more consequential test: in 1995, Halliburton's board selected a chief executive whose career had been spent not on the drilling floor, but in the upper echelons of Washington politics.
IV. The Dick Cheney Era & The Asbestos Trojan Horse (1995–2000) (30–35 min)
A defense secretary in the oil patch
Richard B. Cheney became Halliburton's chief executive in October 1995 and chairman in January 1996. He had served as U.S. Secretary of Defense from 1989 to 1993 and worked as a senior fellow at the American Enterprise Institute until joining the company.13 Cheney possessed no background running a commercial enterprise. What he brought was unparalleled geopolitical access: to heads of state, to national oil companies, and to defense procurement officials within the Pentagon. Halliburton's veteran operational bench supplied the technical execution, anchored by a finance executive named David Lesar, who would later succeed him at the helm.13
The Landmark bet: buying the subsurface brain
Cheney's first major transaction was an astute strategic move that is often overshadowed by later controversies. In 1996, Halliburton agreed to acquire Landmark Graphics, the leading seismic interpretation and reservoir modeling software provider, exchanging 0.574 of a Halliburton share for each share of Landmark.14 The commercial rationale was compelling: whoever controls the digital tools geoscientists rely on to evaluate where to drill enjoys a decisive advantage in marketing the specialized wellsite services needed to drill and complete the well. The transaction agreement contained a notable provision: Landmark agreed to pay Halliburton an $18 million breakup fee if its shareholders rejected the deal under specified conditions.14 Two decades later, Halliburton would find itself on the losing side of a similar contractual mechanism, only the penalty would be nearly two hundred times larger.
Landmark proved to be an enduring franchise. Three decades later, its DecisionSpace suite and related geoscience software continue to generate lucrative, high-margin year-end license renewals that lifted the Drilling and Evaluation division's operating results in the fourth quarter of 2025.4 In mid-2026, Halliburton continued to expand that digital footprint, acquiring the Norwegian reservoir modeling firm InformatiQ.6
The Dresser merger: scale, and a hidden bill
The second major deal under Cheney fundamentally altered the company's risk profile. On September 29, 1998, Halliburton completed its acquisition of Dresser Industries, a diversified industrial giant manufacturing drilling products, engineering services, and energy equipment.13 It was structured as an all-stock transaction: Dresser shareholders received one Halliburton share for each share they owned, requiring the issuance of roughly 176 million new shares and expanding Halliburton's share count from 263 million to 439 million—a dilution of 67 percent.15 The combined enterprise generated $16.3 billion in 1997 revenue, employed more than 100,000 workers across 130 countries, and stood as the world's largest energy services, engineering, and construction firm.15 Cheney hailed the combination, stating that the merger "significantly broadens the company's offerings."15
It also imported a catastrophic legal exposure. Halliburton's own 1998 annual report disclosed that Dresser and its former operating units had been entangled in asbestos personal-injury litigation since 1976. Approximately 183,000 claims had been filed across two decades, with 29,400 new claims arriving in 1998 alone.13 More critically, the filing flagged an indemnity dispute that should have served as an unmistakable warning to due diligence teams. Global Industrial Technologies, a former Dresser spinoff that had ostensibly assumed liability for claims tied to the Harbison-Walker refractories division, "now disputes that it assumed responsibility" for some of them.13 In short, the contractual shield Halliburton expected to insulate it from liability was actively unraveling before the merger closed.
Chapter 11 by design
As state court dockets swelled with new filings, the asbestos liabilities began to threaten the entire enterprise, eventually prompting Halliburton to pursue a prepackaged Chapter 11 bankruptcy to cap the exposure. On December 16, 2003, DII Industries (Dresser's legal successor), Kellogg Brown & Root, and other affected subsidiaries filed for bankruptcy protection in Pittsburgh.16 Under the reorganization plan, Halliburton funded settlement trusts for current and future asbestos and silica claimants with up to $2.775 billion in cash, 59.5 million newly issued Halliburton shares valued at approximately $1.6 billion, and promissory notes worth about $50 million.17 The arrangement received overwhelming creditor support, with more than 99% of voting silica claimants casting ballots in favor.17 In total, Halliburton surrendered approximately $4.4 billion in cash and equity—substantially diluting its shareholders—simply to extinguish a legacy liability acquired in a deal designed to chase sheer scale.
Cheney's exit
Cheney did not remain to see the legal crisis resolved. He resigned in the summer of 2000 to become George W. Bush's vice-presidential running mate. An analysis of Cheney's federal financial disclosures by PolitiFact determined that his exit compensation from Halliburton totaled approximately $34 million above his ordinary salary and annual bonus, consisting primarily of $21.96 million in stock option income and $7.56 million in restricted stock awards.18 PolitiFact also highlighted his "impeccable" market timing: Halliburton shares traded near their cyclical peak in the low-to-mid $50s when Cheney joined the national ticket, but tumbled to $33 per share by November 30, 2000, as asbestos litigation mounted.18
The Cheney era left Halliburton with two enduring legacies. Landmark provided a durable, high-margin software business that continues to anchor its evaluation offerings. The Dresser acquisition, by contrast, delivered a preventable four-billion-dollar lesson in due diligence: the warning signs had been spelled out directly in the company's public disclosures. For equity investors, the episode established that when an acquisition relies on a contested indemnity to wall off legacy tort liabilities, the litigation invariably returns to the parent balance sheet. Halliburton's political connections would also reemerge shortly thereafter—this time under intense wartime scrutiny.
V. The Iraq War Firestorm, Deepwater Horizon, & The KBR Severance (2001–2010) (30–35 min)
The government's concierge
In a dining hall on an American military base in Iraq in 2004, soldiers lined up for hot meals, soft-serve ice cream, and air conditioning—and every tray was served by a corporate contractor rather than an Army cook. By the middle of the decade, that scene had made "Halliburton" national shorthand, fairly or not, for the privatization of modern warfare.
The legal vehicle behind this deployment was LOGCAP—the U.S. Army's Logistics Civil Augmentation Program—an umbrella contract designed to provide logistical support for overseas military bases. In December 2001, after a competitive bidding process, the Army awarded the LOGCAP III contract to KBR, the Halliburton engineering and construction subsidiary descended from Brown & Root.19 A critical distinction often lost in the political shouting was that while the umbrella agreement itself had been competed, the subsequent follow-on work was not. KBR was not required to compete for individual task orders, which multiplied over the following decade; by July 2011, those task orders totaled more than $37 billion.19 As one critic quoted by the Center for Public Integrity described the arrangement: "You become the government's concierge, and it's like a gigantic monopoly."19
The Restore Iraqi Oil contract and a whistleblower
An even more contentious deal arrived separately. In 2003, at the Pentagon's direction, the U.S. Army Corps of Engineers prepared a sole-source award to KBR known as Restore Iraqi Oil, justifying the non-competitive procedure by citing urgent operational need. The Corps' senior contracting official, Bunnatine Greenhouse, objected. She questioned why KBR was treated as the only qualified vendor and raised serious concerns ranging from absent cost estimates to the lack of justification for extending a sole-source contract beyond a single year.19 A subsequent audit by the Defense Contract Audit Agency found that KBR had overcharged on the contract by $61 million. Greenhouse stated that the Army retaliated against her for speaking out, and she was eventually removed from her senior executive post and lost her security clearance.19
The financial scale of these military assignments was large, but the strategic damage to Halliburton was worse. Government services operated at the modest margins typical of engineering contractors, yet they dragged Halliburton into relentless congressional hearings, contentious audit disputes, and a toxic public relations firestorm. That brand damage hindered campus recruiting and strained relationships with foreign national oil companies. In short, Halliburton's core oilfield services franchise—which generated the vast majority of corporate profits—was paying a steep reputational tax to support a structurally lower-return business.
Cutting the cord
Recognizing this friction, Halliburton announced in January 2005 that it planned to separate KBR. Management executed the divestiture in two steps: it floated a minority stake in KBR through an initial public offering in November 2006, then completed the divorce through an exchange offer that expired on April 2, 2007.20 In that transaction, Halliburton accepted 85.3 million of its own shares in exchange for the 135.6 million KBR shares it still held, an exchange ratio of 1.5905 KBR shares for each Halliburton share surrendered.20 Dave Lesar framed the separation as an operational clarification, stating, "As a pure oilfield services company, Halliburton now can focus on the global growth opportunities in its core energy services business."20
The financial mechanics of the transaction were notably shareholder-friendly. Unlike a conventional spinoff that distributes new subsidiary paper to all existing stockholders, a split-off retires the parent company's own shares, effectively functioning as a tax-efficient equity repurchase that shrank Halliburton's share count. Strategically, the separation created an uncluttered pure-play energy services company that was far easier for public markets to analyze and value. Just as importantly, it closed the chapter on more than four decades of political exposure that had begun with Brown & Root during the Vietnam War.
The bill for Bonny Island
Divesting KBR, however, could not immediately erase legacy liabilities already in motion. On February 11, 2009, the Securities and Exchange Commission announced coordinated settlements with KBR and Halliburton over allegations that KBR predecessor entities had bribed Nigerian government officials over a ten-year span to win engineering and construction awards on the Bonny Island liquefied natural gas complex. A joint-venture consortium that included those entities had secured contracts valued at more than $6 billion.21 Under the agreements, KBR and Halliburton agreed to pay $177 million in disgorgement to the SEC, while Kellogg Brown & Root LLC agreed to pay a $402 million criminal fine to the Department of Justice.21 Regulators noted that the combined $579 million penalty represented the largest settlement under the Foreign Corrupt Practices Act ever paid by U.S. companies up to that time.21 The SEC's complaint highlighted the acquisition trail, noting that Halliburton had absorbed that liability when it acquired Dresser Industries—and with it the M.W. Kellogg lineage—in September 1998.21 More than a decade after the transaction closed, the Dresser merger continued to generate unexpected legal bills.
Macondo
On April 20, 2010, BP's Macondo well blew out beneath the Deepwater Horizon drilling rig in the Gulf of Mexico. Eleven workers died, and millions of barrels of crude flowed into the ocean in what became the largest marine oil spill in U.S. history.22 Halliburton had performed the cementing work on the well. In the litigation that followed, injured victims and BP accused Halliburton of defective cementing work, while Halliburton insisted that the disaster stemmed from well-design choices and operational decisions made by BP, which owned the well.22
The legal disclosures that followed proved far more damaging than the disputed engineering calculations. In July 2013, Halliburton agreed to settle the federal criminal investigation. Its subsidiary Halliburton Energy Services pleaded guilty to one misdemeanor count of destruction of evidence over the deletion of internal computer simulation records created after the blowout, agreeing to pay a $0.2 million fine and accept three years of corporate probation.23 It also recorded a $55 million charge for a contribution to the National Fish and Wildlife Foundation, and in 2013 booked a $1.0 billion pre-tax Macondo loss contingency.23 The criminal fine was small, but the admission was not: an evidence-handling failure was a grave compliance breakdown, separate from the chemistry of the cement slurry.
Civil liabilities crystallized the following year. On September 2, 2014, Halliburton agreed to pay about $1.1 billion, including legal fees, to settle the vast majority of plaintiffs' class claims arising from the disaster. The settlement resolved punitive damages claims as well as claims BP had assigned to its own settlement class, with funds disbursed into a trust in three installments over two years.24 By then, Halliburton had also incurred approximately $294 million in legal fees and expenses, though insurance coverage absorbed much of that cost.22
Taken together, the years from 2001 to 2014 forced Halliburton to commit more than $5 billion to cash settlements, criminal fines, and litigation trusts across asbestos, foreign bribery, and Macondo. The vast majority of that capital drain stemmed not from routine wellsite execution, but from inherited corporate acquisitions and subsidiary conduct. For investors, that fourteen-year stretch reinforced two core realities: legal tail risk is a structural feature of oilfield services, where a single catastrophic failure can swallow a decade of service-line profit, and Halliburton's most destructive losses have historically originated in boardrooms and structural dealmaking, rather than on the drilling floor. The next of those corporate decisions was underway within weeks of the Macondo settlement.
VI. The $3.5B Blunder: The Baker Hughes Takeover Collapse (2014–2016) (35–40 min)
November 2014: the confident moment
When Dave Lesar announced the Baker Hughes acquisition on November 17, 2014, he framed it as the natural culmination of the American shale boom. The transaction offered Baker Hughes investors 1.12 Halliburton shares plus $19.00 in cash for each share they held, leaving Baker Hughes shareholders with approximately 36% of the combined enterprise upon closing.2 Management promised nearly $2 billion in annual cost synergies and asserted that the transaction would add to cash flow by the end of the first full year.2 The commercial ambition was straightforward: combine the second- and third-largest oilfield services providers into a unified force capable of challenging Schlumberger across global product lines while surpassing it in North American completions.
The macroeconomic foundation, however, was already eroding when the agreement was signed. The companies announced the deal as crude dipped below $70 a barrel, and by January 2016 oil had dropped below $30.1 That pricing collapse exposed an inherent contradiction in the deal's premise. The financial synergy case assumed the combined company would wield formidable pricing power in a healthy market, while antitrust authorities challenged the merger precisely because they feared that same concentration of market power.
The clause that decided the outcome
Reverse termination fees exist to reallocate regulatory risk from target to buyer, signaling to target boards that an acquirer is entirely confident the transaction will clear. Halliburton provided that assurance twice over. It agreed to divest product lines and business units generating up to $7.5 billion in revenue if required—an amount management characterized as "significantly" higher than anything regulators were expected to seek. It also committed to paying Baker Hughes a $3.5 billion cash penalty if the deal failed to secure antitrust approval.2 In its transaction announcement, the company stated it was "confident that a combination is achievable from a regulatory standpoint."2
An outsized reverse fee fundamentally reshapes negotiating leverage once regulatory resistance mounts. For the target, a guaranteed multibillion-dollar payout weakens the incentive to accept compromised structural remedies or renegotiate terms, because walking away unencumbered delivers an extraordinary cash cushion. The buyer, meanwhile, faces compounding pressure to offer broader operational concessions to escape the penalty. That dynamic soon materialized. Courthouse News reported that Halliburton had an "enormous incentive to see the deal through," noting that the company vowed in late April 2016 to contest the government's lawsuit in court even while establishing a self-imposed April 30 deadline to secure approval.1
The government says no
On April 6, 2016, the Justice Department filed suit in Delaware federal court to block the merger.251 Assistant Attorney General Bill Baer remarked that Halliburton was proposing the "most complicated array of piecemeal divestitures and entanglements" he had ever seen.1 Across the Atlantic, the European Commission had opened its own in-depth investigation that January.1 Divestitures are designed to preserve competitive market conditions, but that remedy fails if no rival buyer possesses the operational infrastructure and technical capability to run the divested assets as an effective competitor. Regulators concluded that no such buyer existed.
On May 1, 2016, the companies terminated the merger agreement.26 Lesar cited "challenges in obtaining remaining regulatory approvals and general industry conditions that severely damaged deal economics."1 Baker Hughes Chief Executive Martin Craighead called it "an extremely complex, global transaction" for which "a solution could not be found."1 Under the contract, the $3.5 billion fee was due by May 4.1
The damage, in plain numbers
Halliburton's reported financial results captured the severity of the blow. Annual revenue fell from $23.6 billion in 2015 to $15.9 billion in 2016 as drilling activity contracted. Compounding the market downturn, the company posted an operating loss of $6.8 billion and a loss from continuing operations of $5.8 billion for 2016.3 Total debt stood at $15.4 billion at year-end 2015 and remained elevated at $12.4 billion a year later.3 Absorbing the $3.5 billion cash payout drove operating cash flow into negative territory for the year.3
While caution is warranted before declaring this the most destructive M&A decision in energy history—no standardized ranking exists, and much of the 2016 deficit reflected an industry-wide commodity bust rather than the merger penalty alone—the operational misstep within management's control was unmistakable. Leadership accepted an extraordinary, one-sided penalty tied to an antitrust outcome it could not dictate, in a consolidated sector where the combined company's dominant domestic market share was the central issue. The multibillion-dollar fee was the direct consequence of executive overconfidence.
For investors today, the defining question is institutional memory: did the organization internalize the lesson? That inflection point sets up the next chapter of Halliburton's corporate trajectory, as an executive team that took charge in 2017 began arguing that returns on invested capital must matter far more than gross scale.
VII. The Modern Business Engine: Segments, Economics, and Strategy (2017–Present) (40–45 min)
The accountant in charge
Jeff Miller joined Halliburton in 1997 following a career at a major accounting firm, earning credentials as a CPA.27 He held operational posts across several international divisions, joined the board of directors in 2014, and served as president and chief health, safety, and environment officer before being named president and CEO in 2017; he has served as chairman, president, and CEO since 2019.27 Miller is neither a petroleum geologist nor an empire-building dealmaker. A finance-trained operator who served as corporate president during the failed Baker Hughes takeover, he subsequently set out to reposition Halliburton around capital returns rather than gross operational footprint, supported by Chief Financial Officer Eric Carre and Chief Operating Officer Shannon Slocum.27
Management formalized this operating philosophy under the banner of "Maximize Value," focused primarily on North American operations.4 On an April 2026 earnings call, Miller explained the operational mandate: "we are going to focus on returns, not market share, which means our priority is to improve the returns of our existing fleets before we add capacity."28
The executive compensation structure broadly reflects that return-oriented focus. Under the 2026 proxy statement, 70% of long-term incentive award value consists of three-year performance units benchmarked against return on capital employed relative to an industry peer group, modified by relative total shareholder return. Earning a target payout requires ranking at or above the 55th percentile in ROCE, while payouts are capped at target if Halliburton's own three-year average ROCE turns negative.27 At the 2025 annual meeting, shareholders endorsed the executive compensation program with approximately 94% approval on the say-on-pay ballot.27 One governance detail warrants scrutiny: the board's compensation committee revised its performance peer group, noting that the Philadelphia Oil Service Index includes liquefied natural gas and other non-oilfield businesses while omitting direct peers such as Baker Hughes and Liberty Energy.27 While peer-group recalibrations can be operationally sound, they are also among the first items activist investors examine when relative-performance incentives begin generating maximum executive payouts.
From the bottom of the cycle to the peak
That push for capital discipline was forged during a severe industry retrenchment. In 2019, Halliburton recorded $2.5 billion in impairments and other charges, followed by another $3.8 billion in 2020—largely long-lived asset write-downs as North American hydraulic fracturing activity collapsed during the COVID-19 pandemic.29 Consolidated revenue plunged 36% to $14.4 billion in 2020, North American revenue fell 52%, and the company reported a full-year net loss of approximately $2.9 billion.29 Consequently, North America's contribution to total revenue fell from 53% to 40% in a single year.29 That geographic rebalancing was driven far more by the abrupt contraction in domestic completions than by a deliberate strategic pivot overseas.
By 2023, the operating picture had transformed. Revenue recovered to $23.0 billion, with Completion and Production generating $2.8 billion of operating income on $13.7 billion of revenue—an operating margin of roughly 21%—while Drilling and Evaluation delivered $1.5 billion on $9.3 billion of revenue, a margin of about 17%.30 Capital expenditures stood at 6% of revenue, within management's 5% to 6% target envelope, and the company returned $1.4 billion to shareholders.30 Those operating margins, achieved amid an acute post-pandemic shortage of hydraulic fracturing horsepower, remain the primary benchmark cited by bullish investors today.
Segment one: Completion and Production
Completion and Production is where the wellbore is lined and the reservoir opened to commercial flow. Its product lines encompass cementing, stimulation (fracturing), specialty chemicals, intervention, pressure control, artificial lift, and specialized completion tools.5
The division's core technical offering is its electric fracturing fleet. A traditional fracturing spread relies on a dozen or more truck-mounted diesel engines, each powering a high-pressure pump that forces water, chemicals, and sand into the formation rock. Halliburton's Zeus platform replaces those diesel engines with electric motors driven by natural-gas-fueled turbines, often consuming field gas directly from the wellsite. The operational difference resembles replacing a row of rented diesel generators with a dedicated industrial power hookup: fewer operating units, substantially lower fuel expenses, and tighter process control. Its accompanying software platform, Octiv Auto Frac, automates the pumping sequence using real-time wellsite data,31 while the updated Zeus IQ platform integrates downhole subsurface measurements so that, as management phrased it, "better fracture placement means more value for our customers."7
By the end of 2025, half of Halliburton's North American hydraulic fracturing fleet had transitioned to Zeus electric pumping units.5 Management established a strict commercial deployment rule: Zeus fleets are committed only under contracts sufficiently long "to return the cost of capital and the capital during the term of the first contract."28 That hurdle provides the clearest evidence that leadership absorbed the painful lessons of 2019 and 2020, when uncontracted, idle diesel equipment had to be written down.
Segment margins, however, have retreated from their 2023 peak. Completion and Production earned $2.1 billion of operating income on $12.8 billion of revenue in 2025, generating an operating margin of roughly 17%.4 In the second quarter of 2026, its operating margin dropped to 15%, with management guiding toward a sequential improvement of 125 to 175 basis points in the third quarter.7 While electric fleets offer operational efficiencies, management has not claimed that Zeus immunizes margins against wider commodity swings, and reported results demonstrate that technology alone cannot fully shield returns during regional activity pullbacks.
Segment two: Drilling and Evaluation
Drilling and Evaluation provides the subsurface sensing and guidance technologies that determine wellbore trajectory and reservoir quality. The division includes Sperry Drilling services (rotary steerable tools and measurement-while-drilling sensors), Baroid drilling fluids, wireline logging, formation testing, and Landmark geoscience software. The segment earned $1.4 billion in operating income on $9.4 billion of revenue in 2025, delivering an operating margin of approximately 15%.4 Its margin compressed to 13% in the second quarter of 2026 as higher-margin Landmark software sales dropped off seasonally.7
Drilling automation has emerged as the division's central technological focus. On April 1, 2026, Halliburton acquired Sekal, a Norwegian drilling-automation firm, from Sumitomo Corporation, merging Halliburton's LOGIX automated steering platform with Sekal's DrillTronics dynamic modeling software. Sekal's systems had already been deployed across more than 1,300 wells globally; financial terms were not disclosed.32 Earlier in 2026, Halliburton, ExxonMobil Guyana, Sekal, and Noble Corporation executed what the consortium described as the deepwater industry's first fully automated geological well placement integrated with full rig automation offshore Guyana.33 While an impressive operational milestone, converting digital automation achievements into sustained pricing power remains an ongoing test.
Geography: a partial decoupling
Halliburton's investment narrative now leans heavily on international expansion. Non-North American revenue reached $13.1 billion in 2025 against $9.1 billion domestically.4 By contrast, 2023 figures stood at $12.5 billion internationally and $10.5 billion in North America.30 That shift reflects modest international resilience combined with steady domestic contraction: North American revenue fell 6% in 2025, while international revenue declined just 2%.5
Major international contract awards in 2026 highlighted that momentum. In April, Argentina's state-backed operator YPF awarded Halliburton a multibillion-dollar, multi-year completions contract in the Vaca Muerta shale basin following a competitive tender, marking the first commercial deployment of the Zeus platform outside North America.31 The initial electric fleet was scheduled to begin pumping in the fourth quarter of 2026.7 In the second quarter, Saudi Aramco awarded lump-sum turnkey contracts covering roughly 285 planned wells across multiple onshore fields, alongside a multi-year stimulation contract for unconventional gas exploration.6 TotalEnergies selected Halliburton for integrated well construction on the GranMorgu deepwater project offshore Suriname, while Iraq's Basra Oil Company awarded an integrated field-management and EPCM contract for the Bin Umar and Sindbad fields.6 On the July 2026 call, COO Shannon Slocum told analysts that the company was running "ahead of schedule" on its target of adding $2.5 billion to $3 billion in annual international revenue from its strategic growth engines by 2028 and saw "upside on that number."7
Two operational caveats temper that international expansion. First, lump-sum turnkey contracts reallocate downhole risk, transferring liability for drilling delays and cost overruns from the oil company to the service contractor. Second, ongoing Middle Eastern geopolitical turmoil introduces acute operational friction. Management noted that regional hostilities, characterized by call analysts as the Iran conflict, along with transit disruptions through the Strait of Hormuz, curtailed field activity and drove up freight and logistical expenses. Leadership estimated that disruption reduced earnings by 2 to 3 cents per share in the first quarter of 2026, guiding to an impact of 7 to 9 cents in the second quarter.28 Underscoring that headwind, Middle East and Asia revenue fell 13% year over year in the first quarter of 2026.33
Guidance versus delivery
Management credibility is best evaluated by comparing executive forward guidance against subsequent financial performance. The opening half of 2026 offers a clean test of that delivery.
On the April 2026 call, CFO Carre guided second-quarter Completion and Production revenue to expand 4% to 6% sequentially, with operating margins improving 50 to 100 basis points; for Drilling and Evaluation, he guided revenue flat to down 2%, with margins falling 75 to 125 basis points as high-margin software sales rolled off.28 Actual results proved decidedly mixed. Top-line revenue outperformed expectations in both divisions: Completion and Production grew 6%, while Drilling and Evaluation expanded 5% rather than contracting.6 Operating profitability, however, disappointed. Completion and Production operating income rose only marginally faster than revenue, and Drilling and Evaluation operating income fell 4% despite the top-line gain.6 On the July earnings call, Carre acknowledged that both divisions landed "on the lower end of margin," citing elevated maintenance expenses, equipment mobilization, offshore project delays in the Gulf of Mexico, and adverse product mix.7
Carre's candor in identifying internal operational friction rather than deflecting blame to external headwinds reflected healthy corporate transparency. Yet the economic reality remains telling: the equipment mobilization and startup costs he cited stem directly from the large international awards that underpin the bullish investment narrative. When asked by an analyst to quantify the magnitude of those upfront expenses, Carre responded that he could not "quantify it exactly."7 While front-loaded costs that precede commercial cash flow are standard across multi-year field service agreements, they also confirm that the margin expansion promised for late 2026 and 2027 has yet to materialize in reported divisional financials.
Capital spending followed a similar dynamic. Management initially projected 2026 capital expenditures at $1.0 billion before raising guidance to approximately $1.1 billion. Carre explained that the revision was driven by deferred equipment deliveries rolling into the period rather than discretionary new spending, noting that capital intensity remained at the conservative end of the targeted 5% to 6% of revenue.28 It was a modest adjustment, proactively explained to investors.
Capital returns
Halliburton's capital allocation framework is disciplined on paper. The company commits to returning at least 50% of annual free cash flow to shareholders via dividends and share repurchases, while capping annual capital expenditures at 5% to 6% of revenue.5 In 2025, it generated $1.9 billion in free cash flow and returned $1.6 billion to investors—a payout ratio of approximately 85%.274 Diluted weighted-average share count declined from 883 million in 2024 to 853 million in 2025.4 Repurchases slowed to roughly $100 million in the first quarter of 2026, a moderation Carre noted reflected macroeconomic caution, before stepping up to about $200 million in the second quarter.286 Long-term debt closed 2025 at $7.2 billion, roughly half the $15.4 billion peak recorded a decade earlier in 2015.43
Management has also pruned underperforming assets. In the third quarter of 2025, Halliburton took $392 million in restructuring and other charges, including $169 million in severance payments, bringing total 2025 pre-tax charges to $831 million.4 It divested a portion of its Multi-Chem specialty chemicals business, including a chemical manufacturing plant in Jubail, Saudi Arabia, to Sterling Specialty Chemicals, with the transaction closing in the second quarter of 2026.346 Eyeing adjacent commercial markets, a collaboration with VoltaGrid secured manufacturing capacity for 400 megawatts of modular natural-gas generation systems tailored for data centers, slated for delivery in 2028.5 What emerges is an enterprise that distributes more cash than its formal framework requires, pares overhead during cyclical pauses, and places selective growth bets that remain too nascent to evaluate. The decisive question for investors is how effectively this modernized operating engine can defend its returns against peer competition and customer bargaining power.
VIII. Hamilton Helmer's 7 Powers & Porter's 5 Forces Analysis (25–30 min)
The war room
Evaluating Halliburton's strategic moat requires viewing the global oilfield as an operational chessboard. On one side stands Halliburton, backed by approximately $22 billion in revenue, a modern fleet of electric pumps, and more than a century of downhole cementing experience. Surrounding it are SLB, an enterprise that is larger, more international, and more digitally mature; Baker Hughes; specialized U.S. pressure pumpers such as Liberty Energy and Patterson-UTI; and, most decisively, exploration and production customers who have spent the past decade treating oilfield services as commoditized inputs, purchasing hydraulic horsepower much like airlines procure jet fuel.
A direct comparison against SLB highlights the structural gap. SLB reported $35.7 billion of revenue in 2025, roughly 60% more than Halliburton.35 SLB's operating units also generated higher pretax profitability: Well Construction earned about $2.2 billion on $11.9 billion of revenue, an operating margin of roughly 19%, while its Digital division generated $745 million on $2.7 billion, delivering approximately 28%.35 By comparison, Halliburton's two operating divisions together generated an operating margin of about 16% in 2025.4 While segment accounting definitions are not strictly identical, that profitability spread has proved durable across the cycle. Strategic divergence is equally apparent in portfolio construction: SLB acquired ChampionX in 2025 in an all-stock transaction valued at $4.9 billion, absorbing production chemicals and artificial lift just as Halliburton divested a portion of its own specialty chemicals franchise.3534 The two dominant American oilfield services providers are executing diametrically opposed strategies within the same product vertical, and their divergent bets will test capital discipline across the next five years.
Helmer's 7 Powers, one at a time
Scale economies: real but regional. In North American pressure pumping, scale lowers the operating cost per completed stage. Maintaining a massive deployed fleet distributes the overhead of regional maintenance yards, bulk sand logistics, field engineering, and proprietary software across a wider operational base. Halliburton describes itself as the only fully integrated service provider remaining in North America.28 Yet that scale advantage remains strictly local. Footprint in the Permian Basin does not automatically translate into cost leadership in an overseas play like Argentina's Vaca Muerta until dedicated fleets, skilled local crews, and regional supply lines are established on the ground—which explains why management mandates that each Zeus fleet return its capital within its initial contract.28
Network effects: none. A hydraulic fracturing stage gains no intrinsic value when an adjacent exploration and production operator contracts the same pumping crew. While Landmark's geoscience and reservoir modeling software enjoys certain ecosystem and user-habituation advantages among petroleum engineers, those workflows do not generate self-reinforcing, multi-sided network effects.
Counter-positioning: weak. As an established industry incumbent, Halliburton rarely introduces business models that competitors cannot match without damaging their existing operations. Rival service providers can deploy electric fracturing fleets, license drilling automation, or pursue integrated turnkey contracts without cannibalizing their core revenue models or imperiling their balance sheets.
Switching costs: split. Switching costs vary drastically across product lines. For conventional diesel fracturing spreads, switching hurdles are negligible; an operator dissatisfied with pricing or performance can easily replace a crew on the subsequent well pad. Conversely, switching costs are substantially higher for Landmark software deeply embedded into customer subsurface databases, and for multi-year integrated project agreements where Halliburton designs, drills, and completes entire field developments. The Basra field-management award in Iraq and Aramco's lump-sum turnkey contracts create meaningful customer stickiness, even as they transfer operational execution risk back onto Halliburton's balance sheet.6
Branding: mixed. Within petroleum engineering circles, the red Halliburton logo signals technical reliability and downhole execution. Across the broader public sphere, however, the brand remains tethered to decades of scrutiny surrounding Dick Cheney, military logistics in Iraq, and the Macondo blowout. Among national oil companies, technical relationships and field presence established over decades—such as its commercial partnership with Saudi Aramco initiated in 1946—matter far more than public-facing corporate branding.11
Cornered resource: limited. Halliburton reports leading oilfield services peers in active U.S. patents.27 In practice, intellectual property in the energy services sector protects incremental tool designs and proprietary downhole components rather than broad commercial categories. Well-capitalized competitors regularly engineer effective operational workarounds, as demonstrated by Patterson-UTI fielding its own advanced dual-fuel pumping spreads.36
Process power: the most credible advantage. More than a century spent refining cement slurries, standardizing pressure-pumping protocols, and conducting forensic failure analyses represents an operational asset that competitors cannot easily replicate, because that knowledge is embedded in the muscle memory of thousands of field engineers. Ironically, this capability is also inextricably linked to the company's gravest industrial disaster, given that Macondo centered on a cementing job. Rigorous process power lowers downhole failure rates across complex completions, but it cannot entirely eliminate operational risk.
Viewed through Helmer's lens, Halliburton possesses one durable competitive advantage in accumulated process power, alongside a real but geographically confined advantage in North American scale that ultimately hinges on industry-wide equipment discipline. The remaining strategic powers are either neutral or inherently vulnerable to broader commodity cycles.
Porter's 5 Forces
Buyer power is the dominant force. Across North America, wave after wave of upstream operator consolidation has created massive exploration and production companies that procure services through centralized, highly structured master services agreements. On the April 2026 earnings call, management noted that major public operators "typically come later in the cycle," whereas smaller independent producers are usually the first to accept higher service rates.28 Consequently, Halliburton's largest domestic customers are both the slowest to concede pricing gains and the most aggressive negotiators. Internationally, buyer power is wielded by sovereign national oil companies. On January 30, 2024, Aramco disclosed that the Saudi Ministry of Energy directed it to cap its maximum sustainable capacity at 12 million barrels per day rather than proceed with an expansion to 13 million.37 A single decree from a host government abruptly altered multi-year upstream capital budgets across the kingdom. Aramco's subsequent contract awards to Halliburton in 2026 demonstrate the inverse reality of sovereign leverage: while state-directed spending pivots can instantly cancel programs, favored service providers can capture immense multi-year work volumes when ministries greenlight field activity.6
Threat of new entrants: low offshore, moderate onshore. Constructing a viable deepwater service business requires decades of proprietary tool qualification, specialized subsea engineering, and global logistics infrastructure that effectively bar new entrants. U.S. land fracturing presents a far lower barrier to entry. Hydraulic pumping equipment is easily debt-financed, and during prior commodity upcycles speculative private capital routinely funded new pumping spreads that flooded the market and crushed day rates. While management told analysts that the North American market was "within a handful of premium fleets" of being "sold out,"28 that razor-thin supply buffer also illustrates how fragile industry fleet discipline remains if pricing incentives tempt operators to reactivate idle horsepower.
Rivalry: intense, with consolidation. Domestic competition has grown more concentrated as mid-tier providers seek greater operational scale. Patterson-UTI and NexTier completed an all-stock merger in 2023 valued at approximately $5.4 billion in enterprise value, establishing an integrated drilling and completions rival where nearly two-thirds of deployed fracturing fleets were dual-fuel capable.36 Rather than fracturing into smaller players, Halliburton's primary North American competitors are consolidating into well-capitalized operational peers capable of matching fleet efficiency.
Threat of substitutes: efficiency. The primary substitute for oilfield services is not an alternative energy source, but upstream drilling productivity. Extended horizontal laterals, continuous simultaneous fracturing (simul-fracs), and automated steering dramatically reduce the total service hours and pump time required to extract a barrel of oil. While Halliburton monetizes portions of that technological transition through automated software and proprietary downhole tools, the structural effect of steady upstream efficiency gains is a secular reduction in aggregate service demand per well.
Supplier power: moderate. Raw materials such as proppant sand, bulk chemicals, casing steel, and industrial turbine components are distributed across multiple commercial suppliers. However, regional geopolitical crises periodically expose supply-chain vulnerabilities, as demonstrated during the 2026 Middle East conflict when maritime rerouting drove up freight expenses and material procurement costs.28
Taken together, Porter's framework reveals a structurally challenging operating environment: consolidated customers dictate pricing, sophisticated competitors rapidly engineer equivalent technologies, and divisional returns depend entirely on collective equipment discipline across the sector. Halliburton's modern capital-allocation playbook is engineered to survive that reality, not transcend it. The subsequent section tests that strategic positioning against the company's historical financial record.
IX. Historical Falsification Layer: Testing the Thesis Claims (30–35 min)
The skeptic's desk
To evaluate Halliburton's investment thesis, consider the perspective of a long/short analyst reviewing two decades of regulatory filings. Every bullish assertion can be tested against the company's historical operating record, probing the precise structural mechanisms most likely to break it.
Claim 1: "Zeus and Octiv create a durable North American moat."
Mechanism that would break it: Upstream operators dual-sourcing pressure pumping across multiple suppliers, competitors achieving technical parity with lower-emission equipment, and service pricing tracking the broader commodity cycle rather than proprietary technology.
Evidence against it: Operating margins in Completion and Production fell from approximately 21% in 2023 to roughly 17% in 2025 and 15% in the second quarter of 2026, even as the portion of Halliburton's North American fleet converted to Zeus electric spreads expanded to half.30475 If fleet electrification provided genuine pricing power, divisional profitability should have proved more resilient as that electric proportion increased. Meanwhile, peers have closed the efficiency gap: following its merger, Patterson-UTI fielded an integrated fleet dominated by dual-fuel pumping spreads.36 Crucially, executive commentary on domestic market improvement focused on an industry-wide exhaustion of premium equipment that helped with "restoring price to acceptable levels," rather than any unilateral ability by Halliburton to command a standalone pricing premium.28
Evidence for it: The Zeus platform continues to win demanding international tenders against global competitors, highlighted by YPF's competitive contract award in Argentina's Vaca Muerta.31 Management also reported that North American pricing experienced steadying trends.7
Verdict: narrowed. The Zeus platform provides tangible operational and fuel-efficiency advantages that help retain tier-one customers, but the financial record shows it does not insulate Halliburton from the domestic drilling cycle. The decisive test will be whether Completion and Production margins can climb back toward 20% without requiring widespread, industry-wide retirements of rival hydraulic horsepower.
Claim 2: "International growth has decoupled Halliburton from shale volatility."
Mechanism that would break it: Policy shifts by sovereign national oil companies, regional geopolitical conflict disrupting operations, and margin pressure from larger, more established global competitors.
Evidence against it: International revenue slipped 2% in 2025, weighed down by customer budget revisions in Mexico and Saudi Arabia.5 In early 2026, regional armed conflict disrupted operations in Kuwait, Iraq, and Qatar, driving Middle East and Asia revenue down 13% year over year in the first quarter.336 Furthermore, Saudi Aramco's directive to cap maximum sustainable capacity demonstrated how a single host-government decree can abruptly reset regional capital expenditures.37 Across international basins, larger rival SLB continues to generate structurally higher operating margins across its comparable service segments.35
Evidence for it: Geographic diversification provided counterweights elsewhere: Latin American revenue increased 22% year over year in the first quarter of 2026, while Europe and Africa revenue expanded 19% sequentially in the second quarter.336 Despite Middle Eastern logistical headwinds, management reported that international operations delivered their highest second-quarter revenue in more than a decade.7
Verdict: narrowed. Halliburton has rebalanced its geographic exposures rather than escaped energy cyclicality altogether, exchanging domestic shale volatility for a combination of sovereign budget exposure and geopolitical risk. The critical test is whether international revenue excluding the Middle East achieves the "low double digits" annual growth rate management projected for 2026.7
Claim 3: "Halliburton is now a disciplined capital allocator."
Mechanism that would break it: A historical pattern of acquiring unhedged legal liabilities, overcommitting balance-sheet capital to ill-fated mergers, and writing down idle assets during downturns.
Evidence against it: The historical record includes repeated capital-allocation failures: the unhedged Dresser asbestos liabilities, the $3.5 billion cash breakup fee paid to Baker Hughes, and $6.3 billion in asset impairments recorded across 2019 and 2020 on pressure-pumping equipment purchased during prior boom periods.329 Over the six-year stretch from 2015 through 2020, Halliburton posted a cumulative loss from continuing operations of approximately $9.3 billion, recording an annual profit only once.329 Even in 2025, the company took $831 million in pre-tax charges, covering facility write-downs, severance costs, and an upward adjustment to legacy environmental remediation liabilities.5 Peripheral capital commitments have also faltered, including an Argentine third-party loan that required impairment charges in both 2024 and 2025.5
Evidence for it: Under current leadership, capital expenditures have remained strictly within the guided envelope of 5% to 6% of revenue since 2021, long-term debt has been reduced to roughly half of its 2015 peak, and the company distributed approximately 85% of its 2025 free cash flow to shareholders through dividends and buybacks.3043 Furthermore, commercial deployments of Zeus electric fleets remain strictly tied to contract lengths sufficient to return invested capital.28
Verdict: intact for the current regime but unproven through a full cycle. Management's capital discipline emerged in the wake of the 2020 downturn, following severe shareholder dilution and sustained pressure from institutional investors demanding direct cash returns. This playbook has yet to be tested by a prolonged, exuberant commodity upcycle, when competitive pressures to expand capacity or pursue transformational mergers are most intense. The real test is whether capital expenditures remain capped at 5% to 6% of revenue if North American fracturing day rates surge.
Claim 4: "Low-carbon ventures and power generation are meaningful optionality."
Mechanism that would break it: Extended development timelines failing to convert technical milestones and pilot partnerships into material, disclosed commercial revenue.
Evidence: Halliburton Labs supported 38 participant and alumni companies by year-end 2025.5 The enterprise has commercialized specialized technologies, such as subsurface safety valves for carbon-dioxide injection and directional well-spacing workflows for geothermal reservoirs.33 However, Halliburton does not break out low-carbon revenue as a standalone reporting segment, indicating that current financial contributions remain immaterial. While its power-generation venture with VoltaGrid targets 400 megawatts of modular natural-gas generation capacity for data centers by 2028, management confirmed that associated capital outlays are excluded from 2026 capital budgets.528
Verdict: unproven. These initiatives represent genuine commercial call options on industrial power and energy transition spending, but none has yet produced disclosures confirming material top-line scale or operating profit. The practical test will be whether VoltaGrid generation units secure binding commercial contracts with paying data-center customers on disclosed economic terms well ahead of scheduled 2028 equipment deliveries.
Myth vs. reality
Myth: "Halliburton secured all of its Iraq military logistics work through no-bid awards." The contractual reality was far more nuanced. KBR won the overarching LOGCAP III umbrella contract through a competitive procurement process in December 2001; the subsequent follow-on task orders under that framework were issued without separate competition, while the distinct Restore Iraqi Oil contract was awarded on an urgent sole-source basis.19
Myth: "The Dresser asbestos liability was an unforeseen trap." Halliburton's 1998 annual report explicitly disclosed roughly 183,000 pending and settled claims, alongside an active dispute regarding whether a former spinoff remained bound to indemnify the company for those liabilities.13 The catastrophic risk was transparently detailed in public filings; it was simply misjudged during merger due diligence.
Myth: "Halliburton remains predominantly a North American pressure pumper." Non-North American operations accounted for approximately 59% of total corporate revenue in 2025, reflecting a steady structural shift toward international national oil company contracts.4
Myth: "Electric fracturing spreads neutralize the hydraulic fracturing cycle." Completion and Production operating margins compressed from 21% to 15% even as electric Zeus fleets scaled to represent half of the company's active domestic footprint, proving that technological efficiency cannot fully offset cyclical pricing pressure.
Testing these claims against historical performance does not invalidate the investment thesis, but it fundamentally narrows it. Halliburton is an operationally proficient, technologically sophisticated service provider whose equity returns remain tethered to global commodity cycles and whose capital-allocation discipline is still working to redeem a generation of balance-sheet missteps. That historical perspective clarifies the strategic lessons for operators and investors alike.
X. Playbook: Business & Investing Lessons (20–25 min)
1. A reverse breakup fee is a bet on the regulator
In 1996, Halliburton sat on the collecting side of a breakup clause, securing an $18 million fee if Landmark Graphics shareholders walked away from the merger.14 Two decades later, it paid $3.5 billion to Baker Hughes when antitrust opposition torpedoed their planned combination. The lesson is not that reverse termination fees are inherently flawed; in contested corporate auctions, they are often the necessary price of winning a target board's approval. The strategic error lies in accepting an outsized penalty when the acquirer cannot dictate the regulatory outcome. When high market concentration is the very rationale for the transaction—as it was when combining the second- and third-largest domestic oilfield services providers—antitrust authorities hold all the leverage. Under those conditions, a multibillion-dollar reverse fee ceases to be deal insurance and becomes a one-sided wager on regulatory forbearance.
2. Indemnities fail when you need them
Dresser Industries' asbestos liabilities came accompanied by a disputed indemnity that was explicitly disclosed in Halliburton's 1998 annual report.13 When personal-injury claims surged across state court dockets, that contested contractual shield provided no protection. For corporate acquirers evaluating legacy industrial enterprises, paper indemnities rarely survive a wave of mass-tort litigation. When a former subsidiary or spinoff falters, legacy liabilities invariably migrate back to the parent balance sheet regardless of how contracts were drafted.
3. Customer consolidation shifts power toward the buyer
When upstream exploration and production operators consolidate, customer bargaining power expands. Management's observation that large public operators typically move later in the pricing cycle is an understated acknowledgment that consolidated buyers fiercely resist rate increases.28 Halliburton has responded by shifting commercial pitches from commoditized pumping horsepower to quantifiable operational outcomes, arguing that proprietary automation and downhole data deliver superior fracture placement and faster well construction.7 Yet selling value rather than volume has clear boundaries: it succeeds only when customers possess the technical tools to verify those operational gains and the commercial willingness to share the resulting economic surplus.
4. "Value over volume" depends on everyone else
Halliburton cannot unilaterally dictate North American pressure-pumping rates. A "value over volume" discipline holds only as long as peer competitors—including Liberty Energy, Patterson-UTI, and private pumpers—refrain from reactivating idle horsepower or adding new capacity. The moment rival operators deploy extra fleets to capture market share, industry pricing power erodes. In that fragmented environment, Chief Operating Officer Shannon Slocum's declaration that Halliburton has "zero hesitation" about redeploying domestic fleets to international basins is a pragmatic defensive lever.7 However, exporting equipment to overseas contracts is a mechanism for managing domestic oversupply, not a permanent structural barrier against commodity cycles.
5. Separation can create value
Corporate divestitures can unlock shareholder value when conglomerates become unwieldy. The 2007 split-off of KBR accomplished two objectives at once: it eliminated four decades of political scrutiny and lower-margin construction exposure while retiring 85.3 million Halliburton shares through an exchange offer.20 More recently, divesting non-core assets, such as selling a portion of the Multi-Chem specialty chemicals business along with its Saudi manufacturing facility to Sterling Specialty Chemicals, reflects that same impulse to streamline operations.34 For an enterprise whose historical balance-sheet crises have repeatedly stemmed from expansive, debt-funded acquisitions, portfolio pruning and capital simplification represent some of the highest-return decisions management can make.
These strategic lessons establish the foundation for evaluating the competing bull and bear cases that define Halliburton's investment outlook.
XI. The Investment Spine: Bull vs. Bear Case & Key KPIs (20–25 min)
The setup
In September 2026, Halliburton stands between two competing cycle dynamics. North American hydraulic fracturing activity is stabilizing following a sluggish 2025. On the July earnings call, Chief Operating Officer Shannon Slocum noted that operators had added more than 30 rigs across North America and reported that calendar white space in hydraulic fracturing schedules had been filled.7 Meanwhile, field operations in the Middle East, where Halliburton has maintained an operating presence since 1946, remain curtailed by regional conflict and transit friction.117 Management's third-quarter guidance reflects those cross-currents, projecting Completion and Production revenue flat to down 2% with operating margins improving 125 to 175 basis points, alongside Drilling and Evaluation revenue down 3% to 5% with margins rising 25 to 75 basis points.7
The bull case
A tightening structural macro backdrop. On the April earnings call, Chief Executive Jeff Miller argued that cumulative global production losses were "trending towards a billion" barrels and asserted that "energy security is no longer simply a talking point," dynamics he maintained would underpin years of sustained upstream capital investment.28 If that assessment holds, an inflection in international drilling activity would coincide with firming North American pricing, enabling a diversified service provider to capture compounding operating leverage across both arenas.
A expanding multi-year contract backlog. Major international awards—including multi-year contracts with YPF in Argentina, Saudi Aramco, TotalEnergies in Suriname, Sonatrach in Algeria, and Iraq's Basra Oil Company—represent locked-in, long-term commercial relationships rather than transactional spot work.6731 Leadership reported that Halliburton is tracking ahead of its schedule to add $2.5 billion to $3 billion in annual international revenue from strategic growth engines by 2028.7
High-incremental operating leverage. In response to an analyst inquiry positing incremental margins of 30% to 35%, Miller stated that such levels were "not inconsistent at all" with internal expectations for 2027 and 2028.7 With capital expenditures capped at 5% to 6% of revenue, the bulk of that incremental margin would convert directly into free cash flow, supporting ongoing share repurchases that continue to lower diluted share count.54
Premium technology commanding pricing power. High-spec offerings such as Zeus IQ downhole integration, Sekal drilling automation, and Landmark subsurface software continue to win competitive tenders based on technical differentiation, with management anticipating extended opportunities to deploy closed-loop automated drilling systems across offshore rigs worldwide.732
The bear case
Upstream buyer power constrains pricing upside. Consolidated exploration and production operators remain disciplined price negotiators who adjust drilling budgets slowly in response to service market tightness.28 Even within a firmer domestic market, management characterized pricing progress as "a steady march" rather than an abrupt step-change.7
Execution friction and margin dilution in lump-sum contracts. Expanding into lump-sum turnkey agreements, entering frontier geographies, and absorbing upfront mobilization expenses place sustained pressure on near-term margins. Management acknowledged that mobilization costs escalated following recent contract awards but could not quantify the exact financial impact, with both operating divisions landing at the lower end of second-quarter margin guidance.7
Acute geopolitical concentration risk. Middle East and Asia represents Halliburton's largest international operating theater as well as its primary regional disruption.4 Divisional revenue there contracted 13% year over year in the first quarter of 2026, and forward guidance assumes conditions merely stabilize rather than stage a rapid rebound.337
The cyclical temptation to overexpand. Halliburton's historical base rate demonstrates that exuberant commodity upcycles repeatedly induce aggressive balance-sheet bets. Speculatively building uncontracted fracturing fleets, pursuing large-scale corporate M&A, or overextending peripheral power ventures beyond contracted commitments would reprise past cycle mistakes.
Vulnerability to operational and legal tail risks. The company disclosed an August 2024 cybersecurity incident where an unauthorized third party gained access to internal systems and exfiltrated corporate data. Furthermore, Halliburton recorded upward adjustments to legacy environmental remediation reserves in 2025, serving as a reminder alongside the Macondo disaster that catastrophic legal and operational liabilities remain an ongoing industry hazard.523
The current risk radar
Several near-term risks operate through specific commercial and operational channels:
Procurement inflation and freight logistics. Armed conflict in the Middle East drove up purchased-material and shipping expenses after commercial vessels and supply lines were rerouted around regional hotspots.28 Management indicated that it is working to pass those inflationary costs through to customers under existing agreements, but the degree of cost recovery depends on contractual terms that remain undisclosed.
Natural gas price dynamics. Because Zeus electric fleets run on natural gas, low gas prices in West Texas substantially reduce wellsite operating costs compared with conventional diesel spreads. Management framed those fuel economics as "an opportunity" to support commercial pricing, while maintaining that Zeus IQ's primary value proposition lies in optimized subsurface placement rather than fuel savings alone.28 If regional natural gas prices spike, that relative operating cost advantage diminishes.
Automation productivity and digital risks. Rig automation and digital subsurface modeling form core strategic priorities, reinforced by the acquisitions of Sekal and InformatiQ.326 Yet continuous automation also reduces the aggregate crew hours and on-site service days required to drill and complete each well, potentially shrinking total addressable service volume. Separately, the company's formal risk disclosures warn that increasingly sophisticated, AI-driven cyber threats heighten operational vulnerabilities.5
Balance-sheet durability. With long-term debt standing at roughly $7.2 billion against $2.2 billion in cash and equivalents at year-end 2025, and with senior notes maturing in 2025 already retired, Halliburton faces minimal near-term refinancing strain.4 Balance-sheet leverage does not represent the primary vulnerability in the bear thesis.
An activist's checklist
An activist investor evaluating Halliburton would focus on four specific corporate governance and operational issues:
First, the persistent profitability gap between Halliburton's operating divisions and SLB's higher-margin peer segments.35 Second, whether the board compensation committee's decision to revise its executive compensation peer group lowers the hurdle for relative-performance equity awards.27 Third, whether management should accelerate the divestiture of peripheral assets, minority stakes, and non-core commitments, including the VoltaGrid generation venture, the distressed Argentine loan, and various equity holdings.5 Fourth, whether share repurchases running at roughly $200 million per quarter represent a sufficiently aggressive return of capital given current free cash flow generation.6 While none of these points constitutes an immediate crisis, collectively they represent the primary vulnerabilities a demanding institutional shareholder would challenge.
The three KPIs that matter
1. Completion and Production operating margin. This metric remains the single most reliable gauge of North American pricing traction and a direct test of whether electric Zeus spreads can command a durable technology premium over rival horsepower. The benchmark to track is whether divisional margins can rebound toward their 2023 peak of 21% or remain trapped in the mid-teens.
2. International revenue growth excluding the Middle East. This indicator isolates the commercial performance of Halliburton's strategic growth engines and major contract awards from the geopolitical noise of regional conflicts. Management's stated benchmark is achieving low double-digit top-line growth across these international territories in 2026.7
3. Free cash flow conversion and capital return discipline. This figure tests whether management can maintain full-cycle capital discipline, measured by its pledge to return at least 50% of annual free cash flow to shareholders via dividends and repurchases while restricting capital expenditures to 5% to 6% of total revenue.5
XII. Epilogue & Closing Reflections (10–15 min)
From Burkburnett to Vaca Muerta
In 1919, a dismissed Navy veteran and his wife launched a well-cementing business from a borrowed wagon, pawning her wedding rings to meet payroll.8 More than a century later, the enterprise that bears his name is deploying its first international electric fracturing fleet into Argentina's Vaca Muerta shale, scaling dynamic drilling-automation systems developed in Norway, and directing integrated field management in southern Iraq.7326 The foundational physics of the work has scarcely changed: seal the wellbore, stimulate the reservoir, and keep high-pressure subterranean fluids where they belong.
A survivor, with scars
Halliburton survived the severe oil bust of the 1980s, the political firestorms of Vietnam and the Iraq War, the prepackaged Chapter 11 bankruptcy of its asbestos-laden subsidiaries, a record foreign bribery settlement over Bonny Island, a criminal misdemeanor plea in the wake of Macondo, a $3.5 billion cash breakup fee paid to Baker Hughes, and the pandemic demand shock of 2020.91219162123129 Across each crisis, the damage followed a consistent pattern. The downhole operations held up, while the catastrophic losses originated in executive suites—born of aggressive corporate structures, flawed acquisition due diligence, and misjudged balance-sheet leverage.
What investors are actually buying
An investment in Halliburton today is ultimately a wager that this historical pattern has broken. The technical execution in the field is proven. The unresolved question is whether an executive leadership team that embraced capital discipline during a punishing downturn can maintain that restraint through an extended commodity upcycle. The structural guardrails now in place—an executive compensation framework tied to return on capital employed, a strict ceiling on capital expenditures at 5% to 6% of revenue, disciplined contract-duration hurdles for Zeus fleets, and an institutional memory scarred by prior write-downs—offer the most credible case that management has changed. Yet the company's own century-long record remains the most compelling reason for investor vigilance.
Whatever trajectory the global energy landscape follows, the modern economy still depends on wells that are drilled, cased, and stimulated without catastrophic failure—and much of that essential, unforgiving work continues to be executed by the enterprise Erle Halliburton built with a borrowed pump and a wooden mixing box.
References
-
Failed Merger Costs Halliburton $3.5 Billion — Courthouse News Service, 2016-05-02 ↩↩↩↩↩↩↩↩↩↩↩
-
Halliburton and Baker Hughes Reach Agreement to Combine in Stock and Cash Transaction Valued at $34.6 Billion (Form 8-K Exhibit 99.1) — SEC EDGAR, 2014-11-17 ↩↩↩↩↩↩↩
-
Halliburton Form 10-K for Fiscal Year 2019 (Selected Financial Data 2015–2019) — SEC EDGAR, 2020-02-11 ↩↩↩↩↩↩↩↩
-
Halliburton Announces Fourth Quarter 2025 Results (Form 8-K Exhibit 99.1) — SEC EDGAR, 2026-01-21 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Halliburton Form 10-K for Fiscal Year 2025 — SEC EDGAR, 2026-02-06 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Halliburton Announces Second Quarter 2026 Results (Form 8-K Exhibit 99.1) — SEC EDGAR, 2026-07-21 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Halliburton (HAL) Q2 2026 Earnings Call Transcript — The Motley Fool, 2026-07-21 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Halliburton, Erle Palmer — The Encyclopedia of Oklahoma History and Culture, Oklahoma Historical Society ↩↩↩↩↩
-
Halliburton Company — Handbook of Texas Online, Texas State Historical Association ↩↩↩↩↩↩↩↩
-
Halliburton Cements Wells — American Oil & Gas Historical Society ↩↩↩
-
Halliburton History: Innovations in Energy Solutions — Halliburton Company ↩↩↩↩
-
Halliburton Deals Recall Vietnam-Era Controversy — NPR (via LAist), 2003-12-23 ↩↩↩↩↩
-
Halliburton Form 10-K for Fiscal Year 1998 — SEC EDGAR, 1999 ↩↩↩↩↩↩↩
-
Landmark Graphics Corp Form 8-K (Agreement and Plan of Merger with Halliburton) — SEC EDGAR, 1996-07 ↩↩↩
-
Halliburton Form 8-K: Risks Relating to Asbestos and Silica Liability — SEC EDGAR, 2004-02-06 ↩↩
-
Halliburton Form S-4 Registration Statement (Proposed Asbestos and Silica Settlement) — SEC EDGAR, 2004-02 ↩↩
-
Chris Matthews Says Cheney Got $34 Million Payday from Halliburton — PolitiFact, 2010-05-24 ↩↩
-
Windfalls of War: KBR, the Government's Concierge — Center for Public Integrity, 2011-08-30 ↩↩↩↩↩↩↩
-
Halliburton Completes Separation of KBR (Form 8-K Exhibit 99.1) — SEC EDGAR, 2007-04 ↩↩↩↩
-
SEC Charges KBR and Halliburton for FCPA Violations — U.S. Securities and Exchange Commission, 2009-02-11 ↩↩↩↩↩
-
Halliburton Agrees to $1.1 Billion Gulf Oil Claims Settlement — Insurance Journal (Bloomberg), 2014-09-02 ↩↩↩
-
Halliburton Form 10-K for Fiscal Year 2013 — SEC EDGAR, 2014-02 ↩↩↩↩
-
Halliburton Form 8-K: Macondo Litigation Settlement — SEC EDGAR, 2014-09-02 ↩
-
Justice Department Sues to Block Halliburton's Acquisition of Baker Hughes — U.S. Department of Justice, 2016-04-06 ↩
-
Halliburton, Baker Hughes Call Off $34 Billion Merger — Reuters, 2016-05-02 ↩
-
Halliburton 2026 Proxy Statement (DEF 14A) — SEC EDGAR, 2026-03-31 ↩↩↩↩↩↩↩↩↩
-
Halliburton (HAL) Q1 2026 Earnings Transcript — The Motley Fool, 2026-04-21 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Halliburton Form 10-K for Fiscal Year 2020 — SEC EDGAR, 2021-02-05 ↩↩↩↩↩↩
-
Halliburton Form 10-K for Fiscal Year 2023 — SEC EDGAR, 2024-02-06 ↩↩↩↩↩
-
Halliburton Wins Multibillion-Dollar Fracturing Contract with YPF in Vaca Muerta — World Oil, 2026-04-13 ↩↩↩↩
-
Halliburton Acquires Norway's Sekal to Expand Automated Drilling Capabilities — World Oil, 2026-04-01 ↩↩↩↩
-
Halliburton Announces First Quarter 2026 Results (Form 8-K Exhibit 99.1) — SEC EDGAR, 2026-04-21 ↩↩↩↩↩↩
-
Sterling Specialty Chemicals Enters into an Agreement to Acquire a Portion of Halliburton's Multi-Chem Business — Sterling Specialty Chemicals, 2025-11-21 ↩↩↩
-
Patterson-UTI, NexTier Oilfield Solutions Merge to Create $5.4 Billion Drilling, Well Completions Business — World Oil, 2023-06-16 ↩↩↩
-
Saudi Arabia's Aramco Halts Plans to Increase Maximum Crude Production Capacity — CNBC, 2024-01-30 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube