GlobalFoundries: From AMD Spinoff to Specialty Semiconductor Powerhouse
I. Introduction & Episode Roadmap
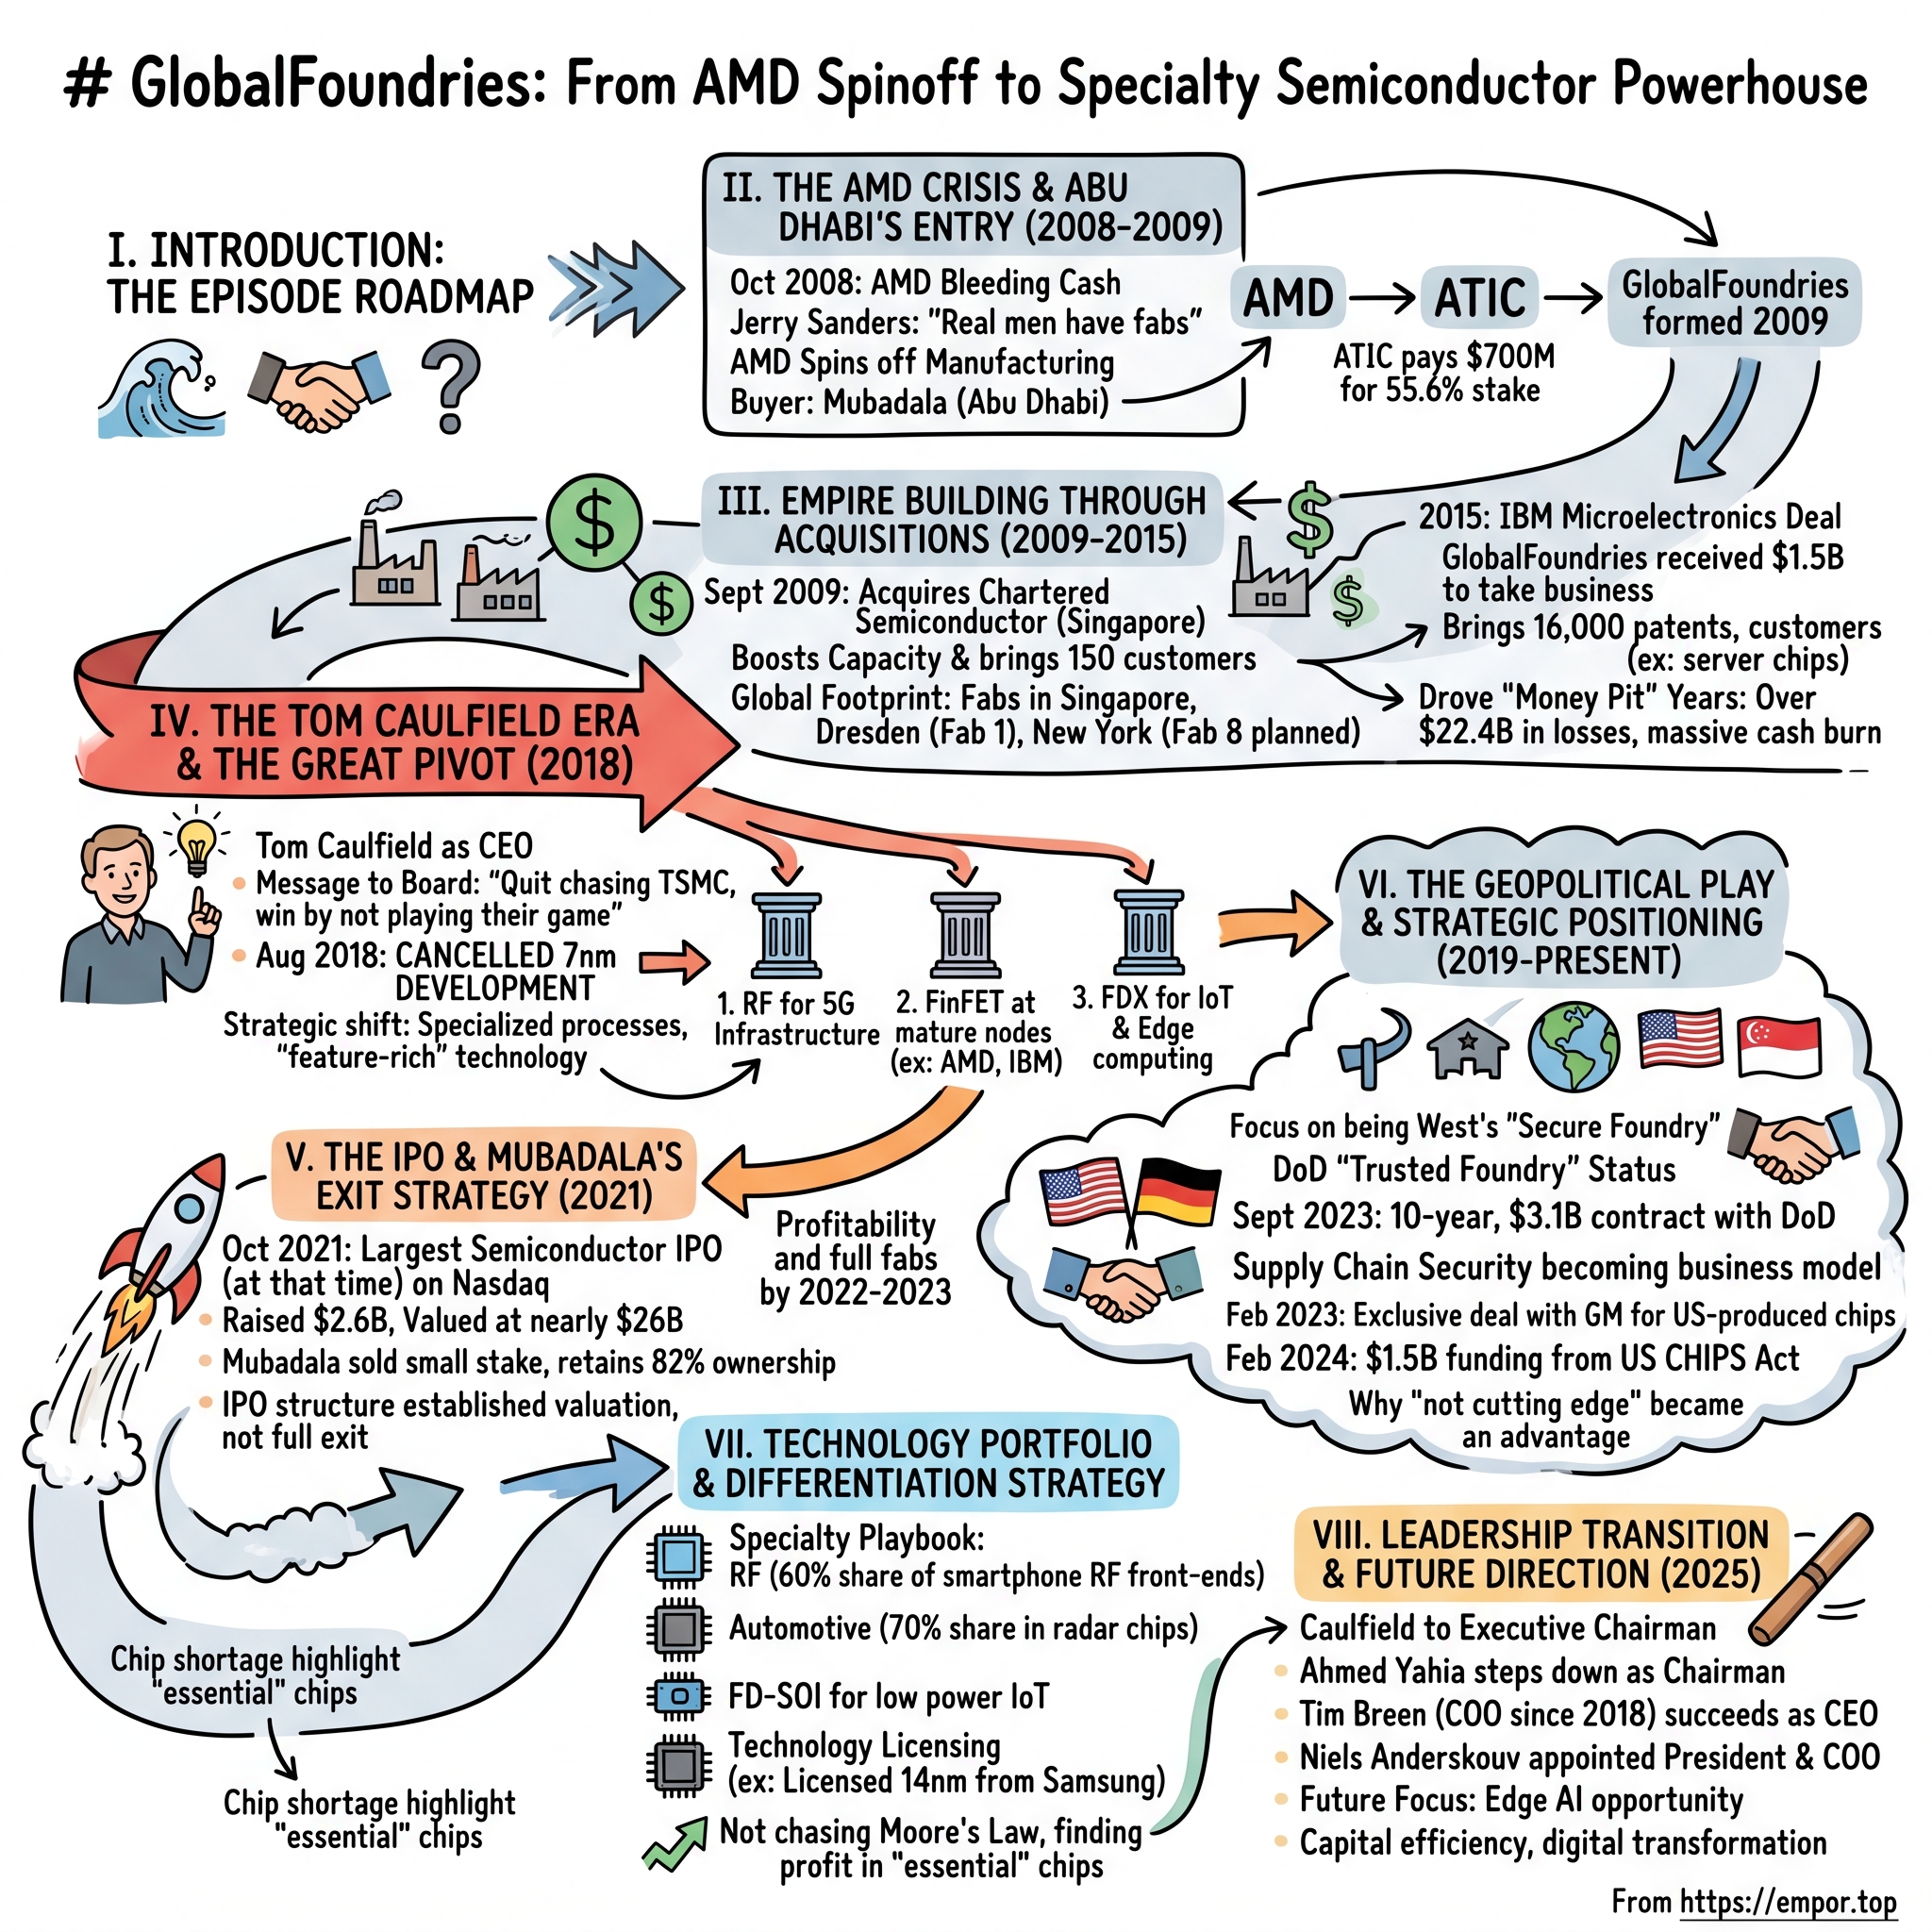
Picture a cleanroom in Malta, New York, on a late-summer day in 2018. The fab is a cathedral of filtered air and yellow light, lined with lithography tools worth more than most of the surrounding town. Engineers there had spent years preparing to manufacture chips at the 7-nanometer frontier, the most prestigious race in industrial technology. Then, on August 27, 2018, its chief executive told the world that GlobalFoundries was stopping. There would be no 7nm, and no 5nm after it. The company was walking off the track.1
That moment sits at the heart of one of the most unusual turnarounds in modern industry. An oil-funded sovereign investor from Abu Dhabi took Advanced Micro Devices' cash-hungry factories, bolted on a Singaporean foundry and IBM's chipmaking division, and absorbed losses that one prominent industry analysis estimated at more than $22 billion.2 Then it quit the race everyone said it had to win. Eight years later, the company is profitable, pays a dividend, and has become a cornerstone of Western industrial policy.
Today GlobalFoundries Inc. trades on the Nasdaq under the ticker GFS. In fiscal 2025, it generated $6.79 billion of revenue, $888 million of net income, and $1.16 billion of non-IFRS adjusted free cash flow.[^3] Its fabs operate in upstate New York, Vermont, Dresden, and Singapore. In the second quarter of 2026, revenue rose 6% year over year to $1.79 billion, while non-IFRS gross margin reached 29.9%.3
The central paradox
Semiconductors have long run on one rule: scale or die. The foundry model that 張忠謀 Morris Chang pioneered at 台灣積體電路製造 TSMC rewarded whoever could shrink transistors fastest, buy the newest ASML scanners first, and spread those immense capital costs over the largest production volumes. Falling behind on Moore's Law was widely assumed to be fatal.
GlobalFoundries stepped off that treadmill on purpose. It ceded leading-edge logic to TSMC and 삼성전자 Samsung Electronics and aimed instead at "specialty" chips: radio-frequency components for smartphones, low-power processors for automotive and industrial applications, power-management circuits, and silicon photonics for data centers. Instead of fading away, it went public in 2021, raised billions in capital, and secured grants from Washington and European governments seeking secure domestic fabrication outside Taiwan.
Whether that turnaround represents a durable competitive position or a temporary windfall from pandemic-era shortages and geopolitical subsidies is the question this analysis tests.
The road ahead
The story moves through six acts. First, AMD's manufacturing crisis and Jerry Sanders' famous boast that "real men have fabs." Second, Mubadala's empire-building era with Chartered Semiconductor and IBM Microelectronics. Third, the mounting losses and the 2018 decision to abandon 7nm. Fourth, the specialty pivot, the 2021 IPO, and long-term customer agreements. Fifth, geopolitics: the CHIPS Act, defense contracts with the Pentagon, and direct supply arrangements with automakers. Sixth, the strategic analysis: evaluating the moat under Hamilton Helmer's 7 Powers and Michael Porter's 5 Forces, assessing management under Tim Breen, and running a historical falsification test against each major bull thesis.
The strategic lesson running through all of it is that a company's best move can be admitting which race it cannot win. That lesson began with a business that refused to admit it for forty years.
 Subscribe on LinkedIn
II. The AMD Crisis & Abu Dhabi's Entry (1969–2009)
Jerry Sanders was the quintessential showman of Silicon Valley's first generation—a former Fairchild salesman in sharp suits who founded Advanced Micro Devices in 1969 and ran it like a scrappy boxer taking on Intel. His operating creed became industry folklore: "Real men have fabs." In Sanders' view, a serious semiconductor company designed and manufactured its own silicon under one roof. The industry called that model the Integrated Device Manufacturer, or IDM.
For decades, the creed held up. AMD's manufacturing complex in Dresden, built in the former East Germany, became a point of corporate pride and provided the manufacturing backbone for its Athlon and Opteron processors, which at times outperformed Intel outright.
The capital treadmill
By the mid-2000s, however, the underlying economics turned decisively against AMD. Each successive manufacturing node cost billions more than the last, and those fixed capital expenses had to be amortized over the total volume of wafers passing through the cleanroom. Intel could spread its multibillion-dollar fab investments across the vast majority of the personal computer processor market. AMD was attempting to match that capital intensity with only a fraction of the unit volume.
The dynamic resembled two competing airlines buying identical fleets of wide-body jets, where one flies with full passenger cabins and the other flies half-empty. The second airline pays the same purchase price per aircraft while generating far less revenue per seat. Moore's Law had evolved into a punishing depreciation treadmill that only the market-share leader could comfortably run on.
AMD compounded the pressure by acquiring graphics chipmaker ATI Technologies in 2006 for $5.4 billion, taking on heavy debt just before the 2008 financial crisis hammered end-market demand. By 2008, the company was hemorrhaging cash, balance-sheet flexibility had vanished, and another costly round of fab tooling loomed that it simply could not afford.4
Enter Abu Dhabi
Relief came from an improbable quarter. Abu Dhabi's sovereign investment vehicle, شركة مبادلة للاستثمار Mubadala, had been deploying state wealth to diversify the emirate's economy beyond hydrocarbons and into high-technology manufacturing. Operating through a dedicated subsidiary, the Advanced Technology Investment Company (ATIC), Abu Dhabi viewed AMD's distressed manufacturing assets as an immediate, ready-made gateway into global semiconductors.
The logic was industrial rather than short-term financial. A sovereign investor operating on a multi-decade horizon could absorb years of substantial operating losses that public equity markets would never tolerate, provided the outcome secured a strategic foothold in global chipmaking. That patient sovereign capital is the sole reason GlobalFoundries exists today. It is also the reason the company's early capital allocation was governed by market-share ambition—an attempt to build a scale foundry capable of directly challenging TSMC—rather than return on invested capital.
The transaction announced on October 7, 2008 was an intricate piece of balance-sheet engineering designed to achieve two objectives simultaneously: de-leveraging AMD while guaranteeing it ongoing access to leading-edge manufacturing capacity. Under the initial framework, ATIC agreed to contribute $700 million to acquire a 55.6% stake in the newly formed manufacturing venture. Mubadala separately agreed to invest $314 million directly into AMD for a 19.3% equity interest, while $1.2 billion of AMD's existing debt was transferred to the manufacturing entity.4 In December 2008, the parties amended the agreement so that ATIC would hold approximately 65.8% of the venture, committing $2.1 billion in total capital, of which $1.4 billion went directly into funding the new manufacturing business.5
On March 4, 2009, the spun-off entity officially commenced operations as GlobalFoundries. AMD's ownership interest steadily diluted, and in March 2012 AMD transferred its remaining equity stake to ATIC. As part of that full separation, AMD agreed to pay GlobalFoundries $425 million in cash and restructured its wafer pricing agreements, absorbing a one-time accounting charge of roughly $703 million.6
The umbilical cord
The defining mechanism of the separation was the Wafer Supply Agreement. AMD committed to purchase guaranteed wafer volumes from its former fabs, providing GlobalFoundries with an indispensable anchor customer while the young foundry attempted to recruit external fabless clients. Yet while the agreement served as a financial lifeline, it also embedded structural vulnerability. The newborn foundry's operational loading was tethered to a single customer whose underlying product roadmaps and commercial fortunes it could not control. The 2012 restructuring, in which AMD paid handsomely to relax its purchasing commitments, established a recurring pattern: the captive anchor customer would repeatedly pay to loosen the commercial knot, until it finally escaped altogether.6
For investors analyzing the company's foundations, the critical takeaway is that GlobalFoundries was not created because the market faced a structural shortage of foundry capacity. It was engineered because AMD could no longer afford its own factories, and Abu Dhabi was willing to write multibillion-dollar checks to enter the semiconductor arena. Abu Dhabi's subsequent moves revealed just how quickly it intended to expand that beachhead.
III. Empire Building & The Capital Sinkhole: Chartered, Fab 8, and the IBM Albatross (2009–2017)
In Singapore, the fabs of Chartered Semiconductor had spent two decades serving as the city-state's national foundry. The company was respected but financially strained, holding a perennial third or fourth place behind TSMC and 聯華電子 UMC and caught in the same punishing scale economics that had broken AMD. In September 2009, ATIC stepped in to acquire it.
Acquisition 1: Chartered Semiconductor
FinanceAsia valued the buyout at $3.9 billion.7 The transaction became effective on December 18, 2009, after Chartered's shareholders approved the scheme of arrangement.8 Over the following year, Chartered was integrated into GlobalFoundries.
Strategically, Chartered delivered what AMD's captive manufacturing base could not: an authentic, diversified foundry customer list. Chartered had spent years fabricating silicon for fabless chip designers across communications and consumer electronics, bringing mature, depreciated 200mm and 300mm capacity in Singapore. Almost overnight, GlobalFoundries transitioned from being AMD's dedicated manufacturing arm into a true multi-customer foundry. That Singapore manufacturing cluster ultimately became the foundation for the company's specialty business, making Chartered arguably the most durable acquisition in the company's history.
The greenfield gamble: Fab 8
Mubadala did not stop at acquisitions; it also built from the ground up. In Malta, a small town in Saratoga County, New York, GlobalFoundries constructed Fab 8, an advanced 300mm logic facility that became one of the largest public-private industrial partnerships in the United States.[^10]
Erecting a leading-edge fabrication facility in upstate New York presented severe operational headwinds. It required recruiting thousands of process engineers far from established talent clusters in Hsinchu or Dresden, navigating an unforgiving yield-learning curve, and absorbing heavy depreciation charges long before commercial production ramped. The executive brought in to lead that manufacturing ramp, a 17-year IBM veteran named Tom Caulfield, would later play a defining role in the company's trajectory.[^10]
The strategic rationale for building in New York blended political incentives with competitive positioning. New York State was eager to anchor a domestic semiconductor manufacturing cluster and contributed significant co-investment. Concurrently, an advanced American fab offered GlobalFoundries a geographic pitch that no Asian foundry could make. In 2010, however, that narrative carried minimal commercial weight; fabless customers allocated orders almost exclusively on unit cost and process maturity, not geographic origin. It would take more than a decade—and a global pandemic—for the broader market to price that distinction.
The 14nm humiliation
The decisive test was node migration, and GlobalFoundries fell behind. Struggling to deliver its proprietary 14-nanometer FinFET process on schedule, the company took an unusual step in April 2014, licensing Samsung's 14nm FinFET process under a multi-year exclusive license to fulfill production commitments for AMD and other key accounts.[^11] While pragmatic, the licensing deal was an operational embarrassment: an entity founded to contest the bleeding edge had to rely on a competitor's process architecture. The Common Platform alliance among IBM, Samsung, and GlobalFoundries had been designed to challenge TSMC collectively, but it never managed to erode TSMC's technological and commercial lead.
Acquisition 2: IBM's reverse dowry
In late 2014 came the most unusual transaction of the consolidation era. On October 20, 2014, IBM announced that it would pay GlobalFoundries $1.5 billion in cash over three years simply to take over its loss-making microelectronics division.9 Through the deal, GlobalFoundries absorbed IBM's fabs in East Fishkill, New York, and Essex Junction, Vermont, along with a massive patent portfolio and world-class packaging and process engineers. In return, GlobalFoundries committed to serve as IBM's exclusive supplier of certain high-performance Power server processors for the following ten years.9 IBM recorded a $4.7 billion pretax charge in connection with the divestiture.10
Securing cash to acquire physical manufacturing assets appeared extraordinarily favorable on paper. In practice, the transaction saddled GlobalFoundries with three structural liabilities: the fabs were older and expensive to maintain; the commercial contract legally bound GlobalFoundries to continue developing leading-edge processes for IBM's enterprise server roadmaps; and the incoming engineering talent was specialized in the exact high-cost, leading-edge R&D the company would eventually need to abandon. That supply commitment created a legal liability that would erupt in litigation seven years later.
The bleed
Throughout this expansion, GlobalFoundries generated staggering operating losses. The prospectus filed ahead of its 2021 initial public offering disclosed annual net losses of $2.70 billion in 2018, $1.37 billion in 2019, and $1.35 billion in 2020.11 SemiAnalysis estimated that Mubadala had absorbed more than $22.4 billion in cumulative losses on the venture by the time the company reached public markets.2
For investors evaluating the business today, this era illustrates the perils of scale-at-all-costs capital allocation. Mubadala pursued global scale and industrial prestige rather than return on invested capital. While Chartered supplied the customer relationships and specialty capabilities that later sustained the business, Fab 8 and the IBM transaction generated years of heavy depreciation and contractual exposure. By early 2018, the burn rate had become unsustainable, and Abu Dhabi required leadership prepared to confront that reality directly.
IV. The Pivot of the Century: Tom Caulfield, Killing 7nm, and the Specialty Thesis (2018–2020)
On March 9, 2018, Sanjay Jha, the former Motorola Mobility chief who had run GlobalFoundries for four years, handed executive leadership to Dr. Thomas Caulfield.[^10] The two men brought contrasting temperaments. Jha was a mobile-industry executive oriented around ambitious technology roadmaps. Caulfield was a shop-floor manufacturing operator, a 17-year IBM veteran who had overseen IBM's 300mm semiconductor operations, departed in 2005 for several industry roles, joined GlobalFoundries in 2014, and directed the construction and 14nm production ramp at Fab 8.[^10] He understood the operating economics of a cleanroom down to the depreciation of individual lithography tools.
The cold arithmetic
Caulfield's initial months became a forensic audit of the 7nm program. The central issue was not technical feasibility—GlobalFoundries could likely yield 7nm chips over time—but return on invested capital. Management estimated that building the 40,000 to 50,000 wafers per month of 7nm capacity required to reach commercial scale would cost $2 billion to $4 billion, with escalating capital commitments required for every node thereafter.1
The customer math was even more unyielding. TSMC had already secured Apple's high-volume mobile processors and was pulling ahead with the remaining tier-one fabless designers. Meanwhile, AMD, GlobalFoundries' historical anchor client, was architecting its Zen 2 processor around a modular chiplet design. The architecture split the processor into high-performance compute dies and a separate input/output (I/O) die. While the compute dies demanded the density of the most advanced node, the I/O die could remain on mature silicon. AMD could route its compute dies to TSMC while leaving GlobalFoundries with the lower-margin legacy silicon. That was precisely what occurred: following the pivot, AMD shifted its 7nm production exclusively to TSMC.12
August 27, 2018
The public announcement on August 27, 2018 was definitive. GlobalFoundries halted all development on its 7LP (Leading Performance) process, refocused R&D on differentiated technologies built on its 14nm and 12nm platforms, eliminated approximately 5% of its workforce, and began renegotiating its wafer supply agreements with AMD and its IP arrangements with IBM. It also planned to spin out its ASIC design business into an independent subsidiary so those clients could source leading-edge fabrication from rival foundries.1 Trade publications characterized the decision as GlobalFoundries halting 7nm work,13 while many industry observers interpreted it as outright capitulation.
Through the lens of Hamilton Helmer's 7 Powers framework, however, the maneuver was closer to Counter-Positioning. TSMC and Samsung could not chase GlobalFoundries into lower-volume, specialized nodes without diluting the massive volume-driven returns underpinning their leading-edge logic investments. Stepping off the Moore's Law treadmill allowed GlobalFoundries to allocate every capital dollar toward silicon platforms that competed on analog physics and material science rather than raw transistor miniaturization.
The specialty menu, explained simply
RF-SOI and silicon-germanium. Every smartphone contains a radio-frequency front-end module: switches that route incoming and outgoing signals between antennas, and power amplifiers that boost weak signals. Fabricating these components on silicon-on-insulator (SOI) wafers—which incorporate a thin insulating layer beneath the transistors—drastically curtails signal leakage, much like thermal insulation traps heat inside a house. Incorporating silicon-germanium adds switching speed and lowers noise for high-frequency communications.
FD-SOI (22FDX). Fully depleted silicon-on-insulator provides a cost-effective route to low-power operation without the complex 3D FinFET architectures used at the leading edge. Its signature feature is "body biasing," which allows software to adjust a transistor's threshold voltage dynamically—effectively switching a chip between high-performance and power-saving modes, analogous to toggling a car between sport and eco settings. That flexibility makes it well-suited for battery-powered sensors, automotive radar, and wearables.
Silicon photonics. Rather than pushing electrical signals through copper wiring, silicon photonics transmits data as pulses of light. This capability becomes indispensable as artificial intelligence clusters and hyperscale data centers struggle to move immense volumes of data between thousands of parallel processors.
BCD and high-voltage. Bipolar-CMOS-DMOS processes integrate analog precision, digital logic, and high-voltage power switching onto a single piece of silicon. They serve as the unglamorous workhorses of battery management systems, power converters, and display drivers.
Pruning the estate
The pivot also demanded pruning the manufacturing footprint. In 2019, GlobalFoundries agreed to sell Fab 3E, an older 200mm facility in Singapore, alongside its MEMS business, to 世界先進 Vanguard International Semiconductor for $236 million, with the transfer completed at the end of 2019.[^17] That same year, it agreed to sell its former IBM fab in East Fishkill, New York, to ON Semiconductor for $430 million, a divestiture completed on December 31, 2022.[^18]
The transaction history underscored the changing value of those assets. IBM had paid GlobalFoundries $1.5 billion in cash to take its microelectronics business; less than five years later, the flagship 300mm fab from that transaction went to ON Semiconductor for $430 million, paid mostly at the end of a multi-year transition.[^18] Physical capacity that once appeared free had rapidly turned into an expensive liability under shifting node economics.
The pivot also overhauled the company's two defining customer relationships. With AMD, GlobalFoundries surrendered its ambition to manufacture AMD's flagship compute processors, renegotiating the wafer supply agreement to reflect a smaller, trailing-edge role.1 With IBM, it had to restructure long-term intellectual property and supply agreements tied to the leading-edge roadmap it had just abandoned.1 One of those renegotiations proceeded smoothly: AMD remained a major customer and later joined as a named partner in the company's US expansion plan.[^19] The other ended up in court, as Section X describes.
For investors, the 2018 pivot stands as the foundational event of the modern company: an exercise in industrial triage that halted an unsustainable cash drain. While early progress showed up in narrowing operating losses, the foundry was still losing more than $1 billion a year through 2020.11 The real proof that the specialty thesis could generate durable profits would arrive with an external shock that nobody in the industry foresaw.
V. The $26B Window: The 2021 IPO, Pandemic Chip Supercycle, and Capital Structure
In early 2021, automakers began parking unfinished vehicles in overflow lots and airfield runways. They were missing a handful of chips each, and none of them were cutting-edge processors. Instead, assembly lines stalled over unglamorous microcontrollers, power-management circuits, and sensor interfaces manufactured on legacy nodes such as 40nm, 55nm, and 90nm. The global economy discovered, painfully and all at once, that mature-node chips were among the hardest to replace.
GlobalFoundries had spent the previous three years preparing for exactly this segment. Almost overnight, mature-node capacity shifted from an overlooked commodity into an acute bottleneck. Customers who had historically haggled over wafer pricing were suddenly desperate to guarantee production capacity years into the future.
The long-term agreement revolution
Caulfield's leadership team converted that industrywide panic into enforceable contracts. Rather than selling wafer output quarter by quarter at prevailing spot prices, GlobalFoundries signed multi-year long-term agreements (LTAs) that paired binding minimum purchase commitments with fixed wafer pricing and substantial upfront customer prepayments to co-fund cleanroom expansions. By the time of its initial public offering prospectus, the company had secured more than 20 of these agreements, representing more than $19.5 billion in aggregate lifetime revenue commitments. That figure included more than $10 billion slated for 2022 and 2023, along with approximately $2.5 billion in advance payments and capacity reservation fees.11
On its fourth-quarter 2021 earnings call, management reported that the portfolio had expanded to 30 LTAs backed by more than $3.2 billion in customer funding, access fees, and prepayments.14 The customer prepayments were structurally significant: by paying upfront for the tools and cleanroom space dedicated to their orders, customers effectively shifted a substantial portion of capacity-expansion risk off GlobalFoundries' balance sheet and onto their own.
Yet the prospectus also illuminated where structural exposure lingered. The company's ten largest customers accounted for approximately 73% of wafer shipment volume in 2020, a roster that featured Qualcomm, MediaTek, NXP Semiconductors, Qorvo, Cirrus Logic, AMD, Skyworks Solutions, Murata, Samsung, and Broadcom.11 That customer base left the foundry heavily tethered to smartphones—historically one of the most volatile, cyclical end markets in consumer technology.
The October 2021 IPO
Mubadala timed the public debut with precision. GlobalFoundries and its sovereign shareholder priced 55 million shares at $47 each, the upper limit of the $42 to $47 marketed range, raising roughly $2.6 billion and valuing the enterprise at approximately $26 billion.[^21] It ranked among the largest US listings of 2021. The shares began trading on the Nasdaq under the ticker GFS, with an underwriting syndicate led by Morgan Stanley, BofA Securities, J.P. Morgan, Citigroup, and Credit Suisse.[^21] Mubadala retained an overwhelming majority stake, maintaining decisive corporate control.
From an investor's perspective, the listing was executed under ideal seller conditions. It arrived at the height of a historic semiconductor shortage, when mature-node pricing and fab utilization were hovering near cyclical peaks and long-term agreements resembled guaranteed revenue. Yet the prospectus also laid bare the recent operating record: three consecutive years of billion-dollar net losses.11 Public equity investors were underwriting a corporate turnaround at its most flattering cyclical inflection. The durability of that transformation would only be tested once the shortage subsided.
The peak and the payoff
The pandemic supercycle propelled GlobalFoundries to its financial high-water mark, with revenue peaking at $8.11 billion in fiscal 2022.15 More fundamentally, the results offered proof-of-concept for the specialty model: with high utilization rates and contracted wafer pricing, the foundry demonstrated that it could generate meaningful operating profits on mature and trailing-edge geometries.
The mechanics of those upfront prepayments also carried important accounting implications for subsequent cash flow analysis. Prepayments enter the cash flow statement as operating cash inflows upon receipt, but they cannot be recognized as revenue immediately. Instead, they sit on the balance sheet as deferred liabilities that are worked down as physical wafers are manufactured and shipped. This dynamic flattered operating cash flow during the capital expenditure build-out, but it also meant that a portion of future reported revenue had already been collected in cash. When assessing GlobalFoundries' cash generation history, investors must distinguish between cash generated by ongoing operations and capital fronted by customers.
The deeper capital structure lesson was twofold. LTAs and customer co-investments provided an effective framework for shifting capital expenditure risk to buyers during a supply squeeze. Yet those same mechanisms introduced latent friction: once supply constraints eased, customers found themselves legally bound to wafer commitments they no longer required. That contractual tension would define the subsequent industry downcycle—arriving just as Western governments concluded that semiconductor manufacturing location had become a matter of national security.
VI. Geopolitical Realignment: The "Western Foundry," CHIPS Act, and National Security Moat (2022–Present)
Consider a map of global semiconductor manufacturing. The vast majority of leading-edge capacity sits on an island roughly 100 miles off mainland China. For decades, that concentration looked like pure economic efficiency. Following pandemic-era supply shocks and intensifying friction across the Taiwan Strait, it began to look like a single point of failure for the global economy.
Against that backdrop, GlobalFoundries' geographically distributed footprint emerged as a strategic asset. The company operates 300mm fabs in Malta, New York; 200mm facilities in Essex Junction, Vermont; its high-volume Fab 1 in Dresden, Germany; and a fabrication complex in Singapore. No other pure-play foundry of comparable scale distributes production across the United States, Europe, and non-Chinese Asia in this manner.
Singapore: the quiet workhorse
On September 12, 2023, GlobalFoundries opened a $4 billion expansion fab in Singapore that added 450,000 300mm wafers annually, lifting its total Singapore capacity to roughly 1.5 million wafers per year.16 The facility created approximately 1,000 jobs.16 While easily overshadowed by debates over Western industrial subsidies, Singapore remains the manufacturing hub where a major share of the company's specialty volume is produced—in an established location insulated from both Taiwan and mainland China.
The CHIPS Act
Washington's industrial policy codified that geographic value proposition. On February 19, 2024, the US Department of Commerce signed a preliminary memorandum of terms with GlobalFoundries, and on November 20, 2024, it finalized an award of up to $1.5 billion in direct funding under the CHIPS Incentives Program.17 The federal capital supports approximately $13 billion in planned investments across New York and Vermont over ten or more years, anchored by capacity expansion in Malta. New York State reinforced that backing with more than $550 million through its Green CHIPS program.17
Building on that foundation, on June 4, 2025, GlobalFoundries unveiled a $16 billion US investment framework, allocating roughly $13 billion to expand its New York and Vermont facilities and $3 billion toward research in advanced packaging and adjacent technologies. The company named Apple, SpaceX, AMD, Qualcomm, NXP, and General Motors as commercial partners committed to sourcing US-manufactured silicon.[^19] Federal backing continued into the following year: in the second quarter of 2026, the company reported a $300 million CHIPS letter of intent targeting silicon photonics and advanced packaging, alongside an expected $375 million grant for quantum technology manufacturing.3
The Pentagon and the automakers
National security and automotive procurement provided parallel commercial validation. On September 21, 2023, the Department of Defense awarded GlobalFoundries a 10-year contract carrying a $3.1 billion ceiling and an initial delivery order of $17.3 million to supply secure, domestically fabricated chips for defense and aerospace applications.18 The company's domestic facilities hold the Pentagon's highest security rating, Trusted Supplier Category 1A, and the agreement marked its third consecutive decade-long engagement with defense authorities.18 For investors evaluating public contracts, however, the disparity between the headline ceiling and the initial outlay requires discipline: a contract ceiling represents spending authorization, not guaranteed revenue.
Commercial manufacturers adopted a related playbook. On February 9, 2023, General Motors and GlobalFoundries announced a long-term agreement establishing a dedicated capacity corridor at the Malta facility exclusively for GM's component pipeline.[^26] The commercial mechanics were nuanced: rather than purchasing bare wafers directly, GM orchestrated the agreement so GlobalFoundries would fabricate silicon for the automaker's tier-one chip suppliers, allowing GM to standardize component designs and sharply reduce the total number of unique chips required across its vehicle platforms.[^26] The arrangement was not a disintermediation of traditional semiconductor suppliers, but rather an automaker deploying its purchasing weight to secure supply through them.
Weighing the geopolitical moat
The central bull thesis holds that geographic diversification has evolved from an overhead burden into a premium product feature. The supporting evidence is tangible: non-dilutive government grants, elite defense accreditation, bespoke automaker pacts, and tier-one corporate commitments behind the $16 billion domestic roadmap. Yet the economic boundaries of that moat are equally sharp. Subsidies lower the cost of building capacity; they do not generate underlying market demand. A federal CHIPS award co-funds cleanroom tooling, but it does not compel commercial buyers to pay a sustained premium for a wafer manufactured in upstate New York over an equivalent component fabricated in Singapore or Taiwan. Furthermore, because industrial policy is subject to shifting legislative priorities, a competitive advantage anchored in statutory subsidies carries political duration risk.
Europe represents a quieter, more ambiguous flank in this strategy. Dresden serves as GlobalFoundries' primary European manufacturing base and the direct institutional heir to AMD's original cleanrooms. Yet recent flagship capital commitments—including the federal CHIPS allocation, the $16 billion expansion roadmap, and targeted grants for photonics and quantum hardware—have been heavily concentrated in the United States.17[^19]3 That regional divergence warrants scrutiny. A multi-continent foundry network is only as durable as the operating margins of its individual clusters, and European clients seeking localized supply chains ultimately depend on Dresden sustaining economic parity with global competitors.
For capital allocators, geopolitical tailwinds have delivered lower-cost financing and privileged positioning across defense and regulated automotive channels. Whether that alignment translates into durable pricing power must be evaluated through the income statement, where the analysis turns next.
VII. The Core Engine: Technology Platforms, End-Market Economics, and Segment Realities
Pick up a flagship smartphone and imagine taking it apart. Deep inside, near the antennas, sit small chips that decide which radio band the phone connects to, amplify faint signals from distant cell towers, and manage power distribution across the circuit board. Few consumers ever notice them, yet the device cannot complete a call without them. Many of these components are the specialized radio-frequency chips around which GlobalFoundries rebuilt its operating model.
How the money breaks down
GlobalFoundries reports as a single operating segment but discloses revenue across five primary end markets. In fiscal 2024, when total revenue contracted to $6.75 billion, the breakdown illustrated the heavy concentration of that portfolio.15
Smart mobile devices: $3.05 billion, roughly 45% of revenue. This represents the company's volume foundation—spanning RF front-end modules, Wi-Fi and Bluetooth combination chips, display drivers, and power management circuits. It is also the most cyclical component of the business, vulnerable to smartphone shipment fluctuations and customer inventory adjustments.
Home and industrial IoT: $1.27 billion, roughly 19% of revenue. A diverse collection of applications including smart meters, factory automation, voice and audio processors, and point-of-sale payment terminals.
Automotive: $1.21 billion, roughly 18% of revenue. Mission-critical silicon for radar units, battery management systems, advanced driver-assistance processors, and in-cabin infotainment.
Communications infrastructure and data center: $577 million, roughly 9% of revenue. Cellular base stations, enterprise networking, satellite communications, and optical transceivers.
Non-wafer and corporate other: $652 million, roughly 10% of revenue. Photomasks, engineering and prototyping services, and related non-wafer billings.
The trajectory of those top-line numbers traced the post-pandemic semiconductor hangover. Revenue retreated from $8.11 billion in 2022 to $7.39 billion in 2023, and fell further to $6.75 billion in 2024 as customers digested excess channel inventory.15 Performance stabilized in 2025, edging up roughly 1% to $6.79 billion, while wafer shipments expanded 10% to approximately 2.35 million 300mm-equivalent wafers.[^3]
The 2026 mix shift
The composition of that revenue began shifting noticeably during 2026. In the second quarter of 2026, communications infrastructure and data center revenue surged 62% year over year to $277 million, expanding to 16% of total revenue compared to 10% in the prior-year period. Over the same span, smart mobile retreated from 40% to 36% of revenue, while automotive eased from 22% to 19%.19 Encouraged by that momentum, management raised its full-year 2026 growth projection for communications and data center to between 50% and 60%, noting that silicon photonics revenue was projected to more than double in 2026 on the back of seven optical networking design wins.19
That acceleration marks the most significant operational reallocation for GlobalFoundries since the 2018 pivot. For the first time, the foundry has established a tangible growth vector tied to artificial intelligence infrastructure rather than consumer handset replacement cycles. Yet two analytical caveats are warranted. First, even annualized at roughly $1.1 billion, data center demand still accounts for a modest minority of total revenue. Second, the declining share of mobile and automotive reflects cyclical softness in those end markets as much as genuine outperformance in networking silicon.
Why specialty nodes are not just old nodes
A natural skeptical objection is whether mature nodes—such as 22-nanometer or 40-nanometer geometries—are simply interchangeable commodities. After all, TSMC, UMC, and an expanding cohort of state-backed Chinese foundries operate substantial capacity at identical dimensions. The distinction lies in the fact that specialty fabrication depends on material physics and process customization rather than sheer lithographic shrinkage: the electrical resistance of the wafer substrate, analog noise floor suppression, breakdown voltage thresholds, and the integration of embedded non-volatile memory directly alongside logic.
An RF switch tailored for GlobalFoundries' proprietary RF-SOI process is tuned to that platform's specific electrical characteristics, much like a racing chassis is calibrated to the contours of a specific circuit. Migrating that design to a rival foundry requires substantial engineering: redesigning the circuit layout, producing new photomasks, and requalifying the component from scratch. In automotive applications, where qualification under stringent AEC-Q100 standards can consume a year or more, those switching costs become formidable. They provide the strongest operational defense in applications where analog precision and RF performance are intimately linked to the underlying silicon recipe.
The strategic limitation of this defense is that GlobalFoundries does not possess a monopoly on specialty recipes. TSMC, UMC, Tower Semiconductor, and Vanguard International Semiconductor all field competitive RF, BCD, and embedded-memory platforms. Furthermore, every generational redesign offers customer procurement teams an opportunity to re-bid production across competing suppliers. Switching costs reliably protect GlobalFoundries during an active product lifecycle—typically lasting three to seven years—but the company must contest and win each subsequent socket anew. The installed base is sticky, but the design pipeline remains intensely contested.
Sizing the optionality bets
To insulate that pipeline, GlobalFoundries has moved to construct a broader technology platform around its specialty fabs. Following its acquisition of MIPS in 2025, the company completed the purchase of Synopsys' ARC processor IP business on June 2, 2026 for $455 million in total consideration, assembling a comprehensive RISC-V processor IP portfolio comprising more than 150 patents and serving over 300 IP licensees.20 That IP expansion followed the November 2025 acquisitions of silicon photonics specialist Advanced Micro Foundry and connectivity developer Infinilink.[^3] Management has branded this unified strategy "Physical AI"—an initiative to bundle proprietary processor cores, specialized wafer fabrication, and advanced packaging for deployment in edge robotics and automotive systems.20
These ancillary initiatives demand sober valuation. Intellectual property licensing operates under an entirely different economic model than wafer fabrication, and pure-play foundries have historically struggled to convert proprietary IP assets into captive manufacturing market share. Moreover, while gallium nitride, quantum computing, and silicon photonics have successfully attracted non-dilutive government development grants, only silicon photonics has translated into rapid, material revenue growth. In the capital-intensive semiconductor sector, research milestones and state subsidies are not commercial revenues—and GlobalFoundries' own history offers a cautionary reminder of the distance between technological ambition and cash returns.
The rapid expansion of data center revenue raises a broader strategic question: is GlobalFoundries gradually transforming into an AI infrastructure supplier, and does its executive leadership possess the appropriate operational background to steer that evolution? That question brings the analysis directly to the executive suite.
VIII. The Leadership Handover & Capital Allocation Under Tim Breen (2025–Present)
On February 5, 2025, GlobalFoundries announced that Tom Caulfield would step aside as chief executive to become executive chairman, handing executive leadership to chief operating officer Tim Breen, effective April 28, 2025.21 Niels Anderskouv, the chief business officer, stepped into the role of president and COO, while Ahmed Yahia, who had chaired the board for more than a decade, stepped down as chairman and left the board.21
Who is Tim Breen?
Breen's résumé does not match that of a conventional foundry chief executive. He did not come up through the cleanrooms or engineering ranks. After graduating from London Business School, he became a partner at McKinsey & Company before joining Mubadala as a senior executive, leading industrial investments across energy, manufacturing, consumer goods, and life sciences. He also chairs the board of NOVA Chemicals.21 Breen joined GlobalFoundries in 2018, the year of the strategic pivot, serving as an adviser and operational partner to Caulfield before formally stepping into the COO role with oversight of manufacturing operations, product quality, supply chain logistics, and IT infrastructure.21
That career trajectory presents two contrasting signals for public investors. On one hand, Breen is an insider steeped in the restructuring that saved the enterprise from insolvency, rather than an external recruit imposing a speculative corporate strategy. On the other hand, he remains an emissary of the controlling shareholder: he spent years inside Mubadala and now directs a public corporation in which that sovereign backer is actively monetizing equity. For minority shareholders, that dual allegiance warrants careful observation.
Anderskouv supplies the complementary operating depth. A 25-year semiconductor industry veteran, he served as a senior vice president and executive officer at Texas Instruments running its analog power division before moving to GlobalFoundries in 2023.21 The resulting executive structure pairs a McKinsey- and Mubadala-trained financial strategist at chief executive with a seasoned Texas Instruments analog operator at president and COO—a balance well tailored to an enterprise whose future depends on specialty process economics rather than bleeding-edge node shrinkage.
Early record
Operating performance throughout Breen's first year at the helm showed steady margin expansion. Non-IFRS gross margin rose from 25.3% in 2024 to 26.1% in 2025, while non-IFRS operating margin widened from 13.6% to 15.7%.[^3] By the second quarter of 2026, non-IFRS gross margin reached 29.9%—up 470 basis points year over year and topping the upper limit of management's guidance—with third-quarter guidance targeting approximately 30.5%.3
Execution against quarterly targets has remained disciplined. In both the fourth quarter of 2025 and the second quarter of 2026, reported financial results landed at or above the upper bound of management's guided ranges.[^3]3 While that track record covers a relatively brief window in a firming market, it demonstrates consistent operational delivery rather than cyclical fortuity.
Capital allocation
Management has established a target capital intensity of 15% to 20% of revenue.19 Recent spending patterns, however, demonstrate how elastic that parameter can be. In 2024, capital expenditures fell to $625 million—under 10% of total revenue—allowing non-IFRS adjusted free cash flow to expand to $1.11 billion.22 Yet across the first half of 2026, capital spending accelerated to $723 million, or roughly 21% of revenue, edging past the high end of the stated corridor. In the second quarter of 2026, adjusted free cash flow dipped to negative $3 million.193
That expenditure profile highlights a critical tension for capital allocators. The $16 billion domestic expansion roadmap, cleanroom capacity for silicon photonics, and intellectual property acquisitions all represent growth initiatives where state subsidies offset only a portion of total project costs. An enterprise whose modern identity was established by abandoning the Moore's Law capital treadmill is once again ramping capital commitments. Surging demand from artificial intelligence data centers may justify that tooling, but the potential for balance-sheet creep requires ongoing evaluation.
Shareholder return initiatives have also commenced. In February 2026, the board authorized a $500 million share repurchase program, and the company distributed its inaugural quarterly dividend of $0.12 per share in July 2026, with the subsequent payout scheduled for October 9, 2026.[^3]3
Promises versus outcomes
Corporate credibility is best evaluated across an entire industry cycle, and the track record presents a nuanced picture. During the 2021 listing, executive leadership emphasized long-term agreements, prepayments, and customer-funded cleanroom capacity as structural shields against cyclical downturns. While that architecture successfully defended average selling prices and cash balances, it failed to protect production volume: revenue contracted for two consecutive years following the 2022 peak.15 Furthermore, the company carried legacy 7nm equipment and idle cleanroom space at Fab 8 on its balance sheet for more than six years after abandoning the node, finally taking a $935 million impairment charge in late 2024 amid the executive leadership transition.22 A charitable interpretation suggests that incoming leadership acted decisively to clean up historical baggage; a more critical reading notes that the write-down lagged the underlying operational reality by more than half a decade.
Management communications have grown noticeably more empirical than during the pandemic-era shortage. Recent quarterly disclosures anchor commercial claims to specific product lines like silicon photonics, verifiable public subsidy milestones, and guidance ranges that were subsequently delivered or exceeded.319 The definitive test for Breen's leadership will be whether that operational transparency persists when artificial intelligence networking demand encounters its first inevitable downshift.
The Mubadala overhang
The execution of the share repurchase authorization has raised governance questions regarding capital allocation. In March 2026, Mubadala offloaded 20 million shares at $42.00 per share in a secondary public offering, accompanied by a 3-million-share underwriter overallotment option; simultaneously, GlobalFoundries deployed $300 million of corporate cash to repurchase shares directly from Mubadala.23 Just two months later, on May 26, 2026, Mubadala sold an additional 22 million shares in a block trade at $89.96 per share, raising nearly $2 billion and trimming its equity ownership to approximately 400 million shares, or roughly 73% of the company.2425
That transaction sequence carries two major implications for public shareholders. First, the stock price more than doubled between March and May 2026, illustrating how rapidly public equity markets re-rated the business around its optical data center and artificial intelligence packaging narrative. Second, using corporate cash to absorb secondary equity from a controlling shareholder warrants rigorous scrutiny. While completed at prevailing market prices, the buyback functioned primarily as an orderly liquidity facility for Mubadala, prompting minority investors to question whether that $300 million outlay would have generated superior long-term returns had it been reinvested in core operations or high-yielding specialty tooling.
Evaluating whether that market re-rating rests on durable competitive advantages or transient cyclical enthusiasm requires testing the company's business model against formal strategic frameworks.
IX. The Strategic Moat: 7 Powers & Porter's 5 Forces Analysis
Picture a procurement review at a major smartphone chip designer. On the table sits an engineering proposal to shift a mature radio-frequency switch from GlobalFoundries to a lower-cost foundry rival. The engineering team points out that migrating the layout demands months of custom redesign. The quality assurance team warns of an extensive requalification cycle. The finance team tallies the balance sheet impact and discovers that projected unit-cost savings fail to offset the switching costs and operational risk. The socket stays put.
That commercial calculation, multiplied across hundreds of active design sockets, forms the company's competitive moat. Testing how deeply that advantage extends requires evaluating the business under formal strategic frameworks.
Hamilton Helmer's 7 Powers
Switching costs (the strongest power). As established in the platform economics, RF, BCD, and automotive semiconductors are calibrated to the idiosyncrasies of specific manufacturing recipes. Relocating an active component requires redesigning circuit masks, fabricating fresh tooling, and restarting customer qualification from scratch. Yet that defensibility remains bifurcated: it firmly protects silicon already in commercial production, but provides virtually no defense during generational design reviews, where procurement teams can evaluate competing foundries on a clean slate. Switching costs secure the installed base; they do not guarantee the next design win.
Cornered resource (moderate). The Pentagon's Trusted Supplier Category 1A accreditation and the accompanying long-term defense relationship represent assets that foreign foundries cannot replicate.18 The company's initial public offering prospectus cited approximately 10,000 patents worldwide.11 Meanwhile, the silicon-on-insulator supply chain is less exclusive than headline partnerships suggest: Soitec supplied 52% of the company's SOI wafers in 2020, indicating that GlobalFoundries dual-sourced the material rather than controlling a proprietary raw-substrate pipeline.11 Subsidized manufacturing sites in New York and Vermont reinforce this geographic moat, though government co-investment represents a capital-cost offset that peer jurisdictions can replicate through their own industrial programs.
Counter-positioning (historical and decisive). Halting development on leading-edge 7nm allowed GlobalFoundries to exit the spiraling capital expenditure cycle that continues to strain competitors at the bleeding edge. As TSMC and other scale foundries expand their own specialty offerings, however, that initial counter-positioning has largely matured from an asymmetric strategic posture into a legacy cost-structure benefit.
Scale economies (moderate to weak). GlobalFoundries operates at a fraction of TSMC's aggregate manufacturing volume. While it commands meaningful niche scale in 300mm RF-SOI and 22nm FD-SOI platforms, it lacks broad volume scale across the wider mature-node landscape.
Process power (moderate). Proprietary process recipes in RF-SOI, silicon photonics, and power management embody years of cumulative cleanroom learning that competitors cannot duplicate overnight.
Network economies: None. Branding: Negligible with end consumers, but carries institutional credibility with procurement authorities in Washington, Berlin, and Singapore.
In aggregate, GlobalFoundries maintains two core powers: switching costs and process power across targeted specialty niches, paired with a geographic footprint that functions as a cornered resource for security-conscious defense and automotive buyers. It lacks the sweeping scale economies that anchor the leading edge.
Porter's Five Forces
Buyer power: high. Customer concentration remains pronounced. Ten tier-one fabless designers absorbed approximately 73% of wafer shipment volume in 2020, creating a client base with significant negotiating leverage.11 Many of those accounts routinely dual-source mature silicon across TSMC, UMC, and other foundries to preserve commercial pricing pressure.
Supplier power: high. Critical cleanroom equipment—spanning lithography, chemical vapor deposition, and etch systems—is controlled by a tight oligopoly of toolmakers, while specialized SOI substrates rely on a narrow cohort of certified wafer suppliers.
Threat of substitutes: moderate. Standard bulk CMOS logic can replace FD-SOI across several end markets, though at the expense of power efficiency and form factor. RF-SOI remains significantly harder to substitute in high-frequency smartphone front ends.
Threat of new entrants: low for greenfield projects, high from state-backed capacity. Constructing a modern 300mm fabrication facility requires billions in upfront capital and years of yield optimization. However, massive state-funded fab construction across mainland China constitutes a formidable wave of new market capacity operating outside standard commercial return thresholds.
Rivalry: high. GlobalFoundries faces direct competition from TSMC's dedicated specialty units, UMC, Vanguard International Semiconductor, Tower Semiconductor, and a crowded cohort of expanding Asian foundries.
The war-game view
Synthesizing both frameworks reveals a foundry positioned around concentrated specialty strongholds but structurally exposed across commoditized product lines. Defensibility peaks where analog physics are most demanding and supply-chain sovereignty is non-negotiable: mobile RF front ends, national defense hardware, and optical networking. It weakens wherever silicon architectures approach generic commodity logic, standard microcontrollers, or routine display drivers.
Formal frameworks map the contours of that moat in steady-state conditions. Determining whether those defenses survive structural industry downturns requires stress-testing the bull thesis against the historical record.
X. Historical Falsification: Testing the Investment Spine & Disconfirming Evidence
Every investment thesis rests on specific operational claims, and every claim contains an identifiable failure mechanism. This section isolates five core assertions underpinning the GlobalFoundries bull case and tests each against the company's historical record.
Claim 1: LTAs provide ironclad revenue visibility through downcycles
The claim. Multi-year long-term agreements (LTAs)—structured with minimum purchase obligations, fixed wafer prices, and non-refundable customer prepayments—transform a volatile, cyclical foundry business into predictable, contracted revenue streams.
How it breaks. When end-market demand collapses, fabless customers cannot absorb silicon they cannot sell. In a severe downturn, enforcing strict take-or-pay penalties risks rupturing vital multi-year commercial partnerships.
The evidence. The 2023–2024 semiconductor inventory correction delivered the first real stress test. Annual revenue contracted roughly 17% over two years, sliding from $8.11 billion in 2022 to $6.75 billion in 2024, despite the existence of dozens of active LTAs.15 While headline disclosures did not itemize how much revenue shortfall was softened by penalty payments or volume deferrals, the structural takeaway was unambiguous: long-term contracts did not prevent a sharp top-line contraction.
Verdict: narrowed. LTAs defended wafer pricing and softened cash flow volatility through advance prepayments, shielding margins far more effectively than pre-pivot spot selling. However, they failed to deliver the volume certainty implied during the 2021 listing. The key metric to monitor in the next cyclical downturn is whether blended wafer prices hold firm as utilization falls.
Claim 2: The IBM deal was a masterstroke that gave GlobalFoundries free capital and world-class IP
The claim. The 2014 takeover of IBM Microelectronics was an unqualified triumph, securing advanced fabs, elite intellectual property, and world-class engineers alongside $1.5 billion in cash dowry.
How it breaks. Depreciating legacy facilities carry structural operating inefficiencies, while long-term supply obligations to leading-edge customers create severe legal and financial liabilities if roadmaps stall.
The evidence. GlobalFoundries eventually divested the East Fishkill fab to ON Semiconductor for $430 million, but the contractual fallout was far more disruptive. On June 8, 2021, IBM sued GlobalFoundries in New York State Supreme Court for fraud and breach of contract, citing failure to deliver advanced server chips envisioned under the 2014 accord and seeking roughly $2.5 billion in damages.26 GlobalFoundries counter-sued in April 2023, alleging IBM had unlawfully disclosed proprietary trade secrets to Japan's ラピダス Rapidus and Intel.27 The parties resolved all claims through a confidential settlement announced on January 2, 2025.[^36]
Balance-sheet legacy issues resurfaced soon after. In the fourth quarter of 2024, GlobalFoundries recognized a $935 million asset impairment on legacy manufacturing capacity in Malta as part of a technology transfer initiative, driving a quarterly net loss of $729 million.22 The charge represented a formal accounting concession that legacy leading-edge tooling was worth significantly less than carried value.
Verdict: rejected. While IBM Microelectronics delivered valuable RF patents, the Essex Junction fab, and crucial engineering talent, the transaction imposed years of heavy operating losses, an asset divestiture at a discount, four years of contentious litigation, and eventual asset write-downs. The 2025 settlement eliminated legal overhang, but the historical economics were net negative.
Claim 3: FD-SOI (22FDX) will disrupt bulk CMOS and FinFET
The claim. Fully depleted silicon-on-insulator (22FDX) would disrupt standard bulk CMOS and FinFET architectures across mainstream digital applications.
How it breaks. A process technology cannot supplant an incumbent architecture on physical efficiency alone; it requires an expansive commercial ecosystem spanning electronic design automation tools, intellectual property libraries, and broad developer adoption.
The evidence. 22FDX achieved commercial traction in automotive radar, low-power IoT, and battery-sensitive applications. However, the broader semiconductor design community largely opted to remain on 28nm and 22nm bulk CMOS or migrate directly to FinFET platforms, leaving FD-SOI confined to specialized niches. Furthermore, dependence on engineered SOI substrates introduces structural input costs: even with diversified procurement, SOI wafers trade at a consistent premium over conventional silicon.11
Verdict: narrowed. 22FDX represents a profitable, highly differentiated specialty platform, but it has not displaced bulk CMOS. The primary indicator of ongoing health is sustained design-win momentum in edge robotics and automotive radar.
Claim 4: Direct OEM deals like GM's insulate GlobalFoundries from auto cycles
The claim. Direct procurement pacts with automotive original equipment manufacturers, such as the General Motors agreement, insulate GlobalFoundries from automotive cyclicality.
How it breaks. Capacity reservations secure manufacturing access for automakers, but they do not dictate end-consumer vehicle demand. Meanwhile, tier-one automotive suppliers continue to control inventory cycles and assembly pacing.
The evidence. Automotive revenue receded from 22% of total sales in the second quarter of 2025 to 19% in the second quarter of 2026, even as the dedicated GM capacity corridor in Malta came online.19 Moreover, the GM framework routes wafer output through tier-one component suppliers rather than establishing direct chip sales between the foundry and the automaker.[^26]
Verdict: unproven. Direct OEM agreements grant GlobalFoundries preferential supplier status and extended planning visibility. They do not neutralize automotive supply-chain corrections. The critical test remains whether automotive revenues can expand through the next downturn in vehicle production.
Claim 5: Silicon photonics becomes a major second engine
The claim. Silicon photonics represents a transformative second growth engine, embedding GlobalFoundries directly into artificial intelligence data center interconnects and doubling optical revenue in 2026.19
How it breaks. Strategic optionality fails if technological differentiation does not convert into durable volume, whether because hyperscalers dual-source optical components, rivals capture next-generation designs, or the industry shifts toward alternative co-packaged optics architectures built on competing foundry platforms.
The evidence. Commercial indicators are tangible: seven major optical networking design wins, a 62% year-over-year surge in communications and data center revenue in the second quarter of 2026, targeted acquisitions of optical and connectivity specialists, and a $300 million federal CHIPS letter of intent.19[^3]3 However, the cautionary analog is 22FDX—a process that demonstrated technical excellence but addressed a smaller commercial market than originally projected. Furthermore, a federal letter of intent remains subject to final contract negotiations.
Verdict: unproven. Silicon photonics has advanced beyond early prototyping into meaningful commercial revenue, but it has yet to be tested across a data center capital expenditure pullback. Continued expansion of data center revenue as a percentage of overall mix will either validate or disconfirm the thesis.
Myth vs. reality
Myth: GlobalFoundries is an exclusively Western foundry immune to Asian competition.
Reality: A major portion of its production capacity is anchored in Singapore and Germany rather than the United States, and its primary customers routinely dual-source mature silicon from TSMC, UMC, and increasingly, mainland Chinese competitors.
Myth: The 2018 pivot was an immediate operational masterstroke.
Reality: Abandoning 7nm was an act of industrial triage compelled by unsustainable cash drain, and the company logged annual net losses exceeding $1 billion in both 2019 and 2020.11 The turnaround only achieved commercial viability when an unprecedented pandemic-era shortage transformed mature capacity into an acute bottleneck.
Myth: Exiting the leading edge rendered GlobalFoundries irrelevant to artificial intelligence.
Reality: Communications and data center revenue expanded 62% year over year in the second quarter of 2026, powered by optical transceiver demand.19 While GlobalFoundries does not fabricate leading-edge accelerator silicon, it manufactures the optical interconnects carrying data between them.
The critical structural variable that the historical record has not yet fully tested is how GlobalFoundries' specialty economics will fare against massive waves of mature-node capacity in mainland China, constructed with state subsidies rather than commercial return thresholds.
XI. The Crucible: Chinese Mature-Node Overcapacity & The Current Risk Radar
Across the industrial corridors outside Shanghai, Hefei, and Wuxi, construction cranes trace the outline of a structural shift in global chipmaking: new fabs rising in rapid succession, many engineered to manufacture the exact mature-node silicon GlobalFoundries produces. Blocked by US and Dutch export controls from acquiring the advanced lithography systems required for leading-edge logic, mainland Chinese foundries redirected their state-backed capital toward the mature trailing-edge nodes that remained accessible.
The legacy flood
TrendForce projected in 2023 that China's share of global mature-process capacity would expand from 29% in 2023 to 33% by 2027, propelled by 中芯国际 SMIC, 华虹半导体 Hua Hong, and Nexchip, with the steepest volume additions concentrated at 28-nanometer and 22-nanometer geometries.28 The economic risk is straightforward. Cleanrooms subsidized by state capital can accept return thresholds that private commercial capital would reject outright. That dynamic threatens to exert structural downward pressure on global wafer pricing for standard mature logic while drawing domestic Chinese chip designers toward local fabricators.
Through mid-2026, cyclical conditions proved more forgiving than that forecast implied. TrendForce reported in June 2026 that mature-node foundry prices rose 5% to 15% across the first half of the year, supported by artificial intelligence peripheral demand, capacity reallocations at TSMC and Samsung, and rising operating costs, with another round of pricing adjustments projected into 2027. Yet the agency also observed that Chinese foundries had reached full utilization on 8-inch lines and were capturing incremental orders as qualified secondary suppliers.29 For now, a firming market has absorbed that capacity. The structural supply wave, however, has not receded.
The defense perimeter
GlobalFoundries' primary line of defense is platform differentiation. Standard digital logic—the segment where Chinese price competition bites hardest—represents a modest fraction of its overall portfolio. By contrast, specialized RF-SOI, silicon photonics, high-voltage BCD, and Pentagon-accredited cleanrooms require proprietary materials science and cleanroom tuning that competitors cannot readily duplicate. Its secondary defense is local adaptation. In 2025, GlobalFoundries established a manufacturing partnership with a Chinese foundry, identified in industry reports as Guangzhou Zen Semiconductor, to fabricate automotive-grade CMOS and BCD technologies inside mainland China for domestic customers, while retaining ownership of its core process recipes.30
That "China for China" arrangement represents a pragmatic compromise: as regulatory mandates push Chinese automakers and device makers to localize silicon sourcing, GlobalFoundries opted to monetize its technology through licensed domestic fabrication rather than surrender the volume entirely. The latent hazard is technological spillover—licensing process know-how to a domestic partner inevitably risks accelerating the closure of the competitive capability gap.
The material risk radar
Customer concentration. The customer base remains structurally top-heavy. Ten tier-one fabless designers accounted for approximately 73% of wafer shipment volume at the time of the public listing, meaning a redesign loss or dual-sourcing shift by a single key handset account can immediately compress cleanroom utilization.11
Western operating costs. Labor, energy, and cleanroom construction expenses across New York, Vermont, and Saxony are structurally higher than in Asian manufacturing hubs. While non-dilutive government subsidies narrow that differential during the initial build-out, sustained cost parity in the United States remains dependent on durable public co-investment.
Capital expenditure creep. After receding to less than 10% of revenue in 2024, capital intensity rebounded to roughly 21% of revenue across the first half of 2026, edging past management's stated 15% to 20% corridor as domestic expansion and advanced optical packaging investments gathered pace.19
Controlling shareholder overhang. Mubadala retains approximately 73% of outstanding equity following its 2026 secondary distributions, ensuring that future equity sales and lockup expirations will remain recurring supply overhangs for public market investors.24
Smartphone cyclicality. Smart mobile devices remain the company's largest single revenue pillar, even as their share of total revenue receded to 36% in the second quarter of 2026.19 Until industrial IoT and data center platforms expand substantially, the top line remains exposed to global handset replacement cycles.
Trusted-status compliance. Privileged positioning across defense and aerospace depends on maintaining the Pentagon's Trusted Supplier Category 1A accreditation.18 Any operational breach or regulatory change to security certification would jeopardize one of the company's few geographically non-replicable commercial advantages.
Policy reversal and execution risk. A foundational share of the long-term expansion thesis relies on federal grants, preliminary terms, and agency letters of intent. Preliminary agreements remain subject to binding negotiation, and public capital commitments running for ten or more years carry exposure to shifting legislative and administrative priorities.[^19]
The practical reality is that the Chinese capacity challenge is formidable but uneven. It poses an immediate threat to undifferentiated, commodity logic at the outer edges of the portfolio, while leaving specialized analog, RF, and defense franchises comparatively insulated. That divergence ensures that product mix—and the blended pricing power it commands—remains the decisive variable governing corporate profitability, bringing the analysis directly to the financial statements.
XII. Financial Anatomy, Valuation & The Investment Ledger
Think of GlobalFoundries' income statement as a machine with one dominant lever: utilization. A fab's costs are mostly fixed: depreciation on tools, the cleanroom, the staff. When a fab runs full, each extra wafer is highly profitable. When it runs half-empty, the same fixed costs are spread over fewer wafers, and margins collapse. Almost every financial swing in the company's history follows that lever.
The financial profile
Revenue went from $8.11 billion at the 2022 peak to $6.75 billion in 2024 and $6.79 billion in 2025.15[^3] Through that trough, non-IFRS gross margin stayed around 25%–26%, and adjusted free cash flow stayed above $1 billion in both 2024 and 2025.22[^3] That is the clearest evidence of structural improvement. Before the pivot, the company lost more than $1 billion a year even in normal conditions.11 After the pivot, it stayed profitable on a non-IFRS basis through a two-year revenue decline.
The 2026 upturn shows the lever working in the other direction. Second-quarter wafer shipments rose 8% to 625,000 300mm-equivalent wafers, and non-IFRS operating margin reached 16.7%.3 Third-quarter guidance points to revenue of about $1.885 billion and non-IFRS gross margin of about 30.5%.3
There is an accounting caveat. The company reports under IFRS, and the gap between IFRS and non-IFRS results is material. In the second quarter of 2026, IFRS net income was $167 million, compared with $256 million on a non-IFRS basis, and IFRS net income fell 27% year over year while non-IFRS net income rose 9%.3 Investors should reconcile the two rather than rely on the adjusted numbers alone.
How the market has re-priced the story
The shares tell their own story about sentiment. Mubadala sold stock at $42.00 in March 2026 and at $89.96 in late May 2026.2324 In little more than two months, the market's valuation of the company roughly doubled. Earnings did not double in that time. What changed was the narrative: GlobalFoundries went from a mature-node foundry recovering from an inventory downturn to a supplier of optical and power components for AI data centers. Some of that re-rating is supported by the data center growth reported in the second quarter.19 Some of it is an expectation that the growth continues. Investors should be clear which part of the valuation rests on reported results and which rests on hope.
The skeptic's stress test
A skeptical long/short investor would press three points.
Returns on capital. Tens of billions of dollars have gone into these fabs over two decades. Net income of $888 million in 2025 is a meaningful turnaround, but it is still a modest return on the capital that built the company.[^3]2 The key question is whether a specialty foundry can reliably earn more than its cost of capital across a full cycle, or only near the top.
The AI gap. The largest pool of profit in semiconductors today is leading-edge AI logic, and GlobalFoundries deliberately left that pool. Its photonics growth is real, but it is participating in the edges of the AI buildout, not the core.
Governance. A controlling sovereign shareholder, a CEO who came from that shareholder, and buybacks that funded that shareholder's exits are all legitimate, but together they limit the influence of minority investors.
The bull case
Geopolitical premium. Customers with security or supply-resilience concerns, including defense agencies, automakers and large US technology companies, have shown they will sign long-term deals for Western and Singaporean capacity.18[^26][^19]
Subsidized reinvestment. Grants from US programs lower the net cost of growth capex.173
Edge and data center specialty demand. Silicon photonics, RF, power management and edge processing are all growing, and the second-quarter 2026 data center numbers suggest GlobalFoundries is gaining real exposure to AI infrastructure.19
The bear case
Chinese commoditization. State-funded capacity could erode pricing in IoT, displays and standard mobile chips once the current tight market eases.28
Sub-scale economics. TSMC's mature and specialty fabs benefit from scale and lower capital costs, and TSMC can bundle specialty processes with leading-edge relationships.
Sovereign overhang. Continued Mubadala sales and limited minority influence could weigh on the shares regardless of operating progress.24
Three KPIs to track
- Blended wafer ASP (revenue per wafer). This is the direct measure of whether specialty mix and pricing power are offsetting mature-node competition.
- Communications infrastructure and data center revenue growth. This is now the test of whether the AI and photonics story becomes a lasting second engine or a single upcycle.
- Free cash flow as a share of revenue. With capex rising, this is the test of whether the 2018 escape from the capital treadmill still holds under Tim Breen.
Numbers describe the company. The broader lessons come from the choices behind them.
XIII. Playbook: Business & Investing Lessons
Inside the Malta cleanroom in August 2018, engineers who had spent years working on 7nm watched their roadmap halted overnight. Some departed; others redirected their efforts toward RF, silicon photonics, and FD-SOI. The enterprise that emerged was far less glamorous than the scale foundry Mubadala had originally set out to build, but it proved vastly more durable. Five business and investing lessons stand out.
1. Know when to quit a race
The hardest strategic choice is often abandoning a race in which an organization has already sunk billions of dollars. Pursuing 7nm and 5nm would have demanded billions in additional capital expenditures with little realistic prospect of earning an attractive return on invested capital. Stepping off the leading-edge treadmill did not immediately produce profits—the pandemic-era supply crunch provided the crucial external catalyst. Yet without that pivot, GlobalFoundries would have entered the shortage saddled with the wrong product portfolio and an unsustainable cost structure. Sound corporate strategy often means choosing to lose a contest you cannot win in order to redeploy capital into one where you can.
2. Be wary of "free" assets
IBM paying $1.5 billion in cash to offload its microelectronics division in 2014 looked on paper like a windfall. In reality, it saddled GlobalFoundries with an aging fabrication facility later divested for $430 million, onerous supply commitments that sparked four years of contentious breach-of-contract litigation, and leading-edge roadmap obligations the company could not fulfill.9[^18][^36] When an asset comes with a cash dowry, the first question for capital allocators is why the seller is willing to pay someone else to take it.
3. Indispensability beats glamour
The 2021 semiconductor crunch proved that an automobile worth tens of thousands of dollars could sit stalled on an assembly line for want of a microcontroller or power-management circuit costing only a few dollars. Establishing a defensible position across specialized niches—such as radio-frequency front ends, power management, or accredited defense hardware—can generate switching costs and pricing durability that rival, and sometimes exceed, the returns available at the capital-intensive bleeding edge.
4. Patient capital has a price
GlobalFoundries could never have absorbed its 2009–2018 operating losses as a standalone public company. Navigating that build-out required sovereign balance-sheet backing willing to absorb cumulative losses measured in the tens of billions of dollars over a decade.2 That sovereign patience preserved the business, but it also came with long-term governance trade-offs. As Mubadala monetizes its equity through secondary offerings, public minority shareholders must navigate the persistent supply overhang and capital-allocation priorities of a controlling owner.
5. Geography can be a product feature
In an era of frictionless globalization, the lowest-cost producer inevitably wins. In a fragmented, security-conscious world, the physical location of fabrication becomes an intrinsic attribute of the product itself. GlobalFoundries' long-term defense arrangements, federal CHIPS awards, and dedicated automotive capacity corridors all monetize that geographic diversification.1817[^26] The critical question for investors is how much of that geographic premium endures if geopolitical tensions moderate or statutory subsidies expire.
These lessons point directly back to where the story began: an industry pioneer who insisted that fabs were the ultimate measure of a semiconductor company.
XIV. Epilogue & Reflections
Jerry Sanders famously insisted that real men have fabs. History gave that creed an ironic conclusion. Spinning off its manufacturing operations saved AMD. Freed from the punishing capital demands of cleanrooms and lithography tools, AMD routed its flagship processors to TSMC and orchestrated one of the great corporate turnarounds in modern technology.12 The factories it left behind, after absorbing more than a decade of heavy losses, emerged as GlobalFoundries: a specialty foundry that is profitable, geopolitically indispensable, and participating in the artificial intelligence buildout.
The business that exists in September 2026 is fundamentally different from the enterprise Mubadala set out to construct in 2009. It does not contest leading-edge transistor density, nor does it intend to. Instead, it fabricates the radio-frequency switches in smartphones, the radar sensors in automobiles, the accredited components in defense platforms, and increasingly, the optical silicon linking artificial intelligence clusters. Its operating margins hover near historical highs, while its data center revenue is expanding at its fastest pace since the 2022 cyclical peak.319
The open questions for investors are equally clear. Can specialty pricing power withstand a rising tide of state-subsidized Chinese mature-node capacity? Can capital spending accelerate for optical and data center demand without unraveling the discipline that rescued the company in 2018? And can public minority shareholders count on equitable capital allocation while a controlling sovereign shareholder steadily monetizes its equity? From Dresden to Malta and Singapore, GlobalFoundries illustrates how patient sovereign capital, a disciplined strategic retreat, and geopolitical realignment can revive a struggling industrial franchise. Whether it can generate durable returns on invested capital on its own operational merits—without the lift of cyclical shortages or state subsidies—remains the test of the coming years.
References
-
GlobalFoundries Stops All 7nm Development: Opts To Focus on Specialized Processes — AnandTech, 2018-08-27 ↩↩↩↩↩
-
GlobalFoundries $GFS IPO – Mubadala Lost Over $22.4B, Now They Are Hoping Public Markets Bail Them Out — SemiAnalysis, 2021-10-06 ↩↩↩↩
-
GlobalFoundries Reports Second Quarter 2026 Financial Results — GlobalFoundries via GlobeNewswire, 2026-08-05 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
After a bad 2008, AMD tries to reinvent itself — InfoWorld ↩↩
-
AMD, the Advanced Technology Investment Company and Mubadala amend transaction agreements — Mubadala, 2008-12 ↩
-
AMD gives up remaining shares in GlobalFoundries, amends wafer supply agreement — TechSpot, 2012-03 ↩↩
-
Abu Dhabi firm attempts $3.9 billion buyout of Chartered Semiconductor — FinanceAsia, 2009-09 ↩
-
Chartered Semiconductor Manufacturing Ltd Form 6-K — U.S. Securities and Exchange Commission, 2009-12 ↩
-
IBM to Pay Globalfoundries $1.5 Billion to Take Chip Unit — Bloomberg, 2014-10-19 ↩↩↩
-
International Business Machines Corp. Form 8-K — U.S. Securities and Exchange Commission, 2014-10-20 ↩
-
Form F-1 Registration Statement — U.S. Securities and Exchange Commission / GLOBALFOUNDRIES Inc., 2021-10-04 ↩↩↩↩↩↩↩↩↩↩↩↩
-
GlobalFoundries ceases all development on 7nm process, AMD to exclusively use TSMC for 7nm — Notebookcheck, 2018-08 ↩↩
-
GlobalFoundries Inc. (GFS) CEO Tom Caulfield on Q4 2021 Results - Earnings Call Transcript — Seeking Alpha, 2022-02 ↩
-
Form 20-F Annual Report for the Fiscal Year Ended December 31, 2024 — U.S. Securities and Exchange Commission / GLOBALFOUNDRIES Inc., 2025 ↩↩↩↩↩↩
-
GlobalFoundries opens $4 billion Singapore expansion fab to meet 'demand for essential semiconductor chips' — CNBC, 2023-09-12 ↩↩
-
Biden-Harris Administration Announces CHIPS Incentives Award with GlobalFoundries to Strengthen Essential Chip Supply for Key U.S. Industries Including Auto and Defense — U.S. Department of Commerce, 2024-11-20 ↩↩↩↩↩
-
U.S. Government Awards GlobalFoundries New $3.1 Billion, 10-Year Contract for Secure Chip Manufacturing — GlobalFoundries, 2023-09-21 ↩↩↩↩↩↩
-
GlobalFoundries Q2 2026 slides: AI pivot, $675M in government support — Investing.com, 2026-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
GlobalFoundries completes acquisition of Synopsys' Processor IP Solutions Business, delivering a holistic technology platform for Physical AI — GlobalFoundries, 2026-06 ↩↩
-
GlobalFoundries Announces Leadership Transition to Drive Next Phase of Growth — GlobalFoundries, 2025-02-05 ↩↩↩↩↩
-
GlobalFoundries Reports Fourth Quarter 2024 and Fiscal Year 2024 Financial Results — GlobalFoundries via GlobeNewswire, 2025-02-11 ↩↩↩↩
-
GlobalFoundries Announces Pricing of Public Secondary Offering and Concurrent Share Repurchase — GlobalFoundries, 2026-03-11 ↩↩
-
Mubadala Announces Sale of 22 Million Shares of GlobalFoundries — National Law Review, 2026-05-27 ↩↩↩↩
-
Mubadala Offers $1.91 Billion GlobalFoundries Share Block — Bloomberg, 2026-05-26 ↩
-
Why IBM Is Suing GlobalFoundries Over Chip Roadmap Failures — The Next Platform, 2021-06-10 ↩
-
GlobalFoundries sues IBM, says trade secrets were unlawfully given to Japan's Rapidus — CNBC, 2023-04-20 ↩
-
China's Share in Mature Process Capacity Predicted to Hit 29% in 2023, Climbing to 33% by 2027, Says TrendForce — TrendForce, 2023-10-18 ↩↩
-
AI Component Capacity Squeeze and Foundry Output Cuts to Extend Mature-Node Price Increases in 2027, Says TrendForce — TrendForce, 2026-06-30 ↩
-
GlobalFoundries Partners with Chinese Foundry for Localized Automotive-Grade CMOS Production — TrendForce, 2025-08-06 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube