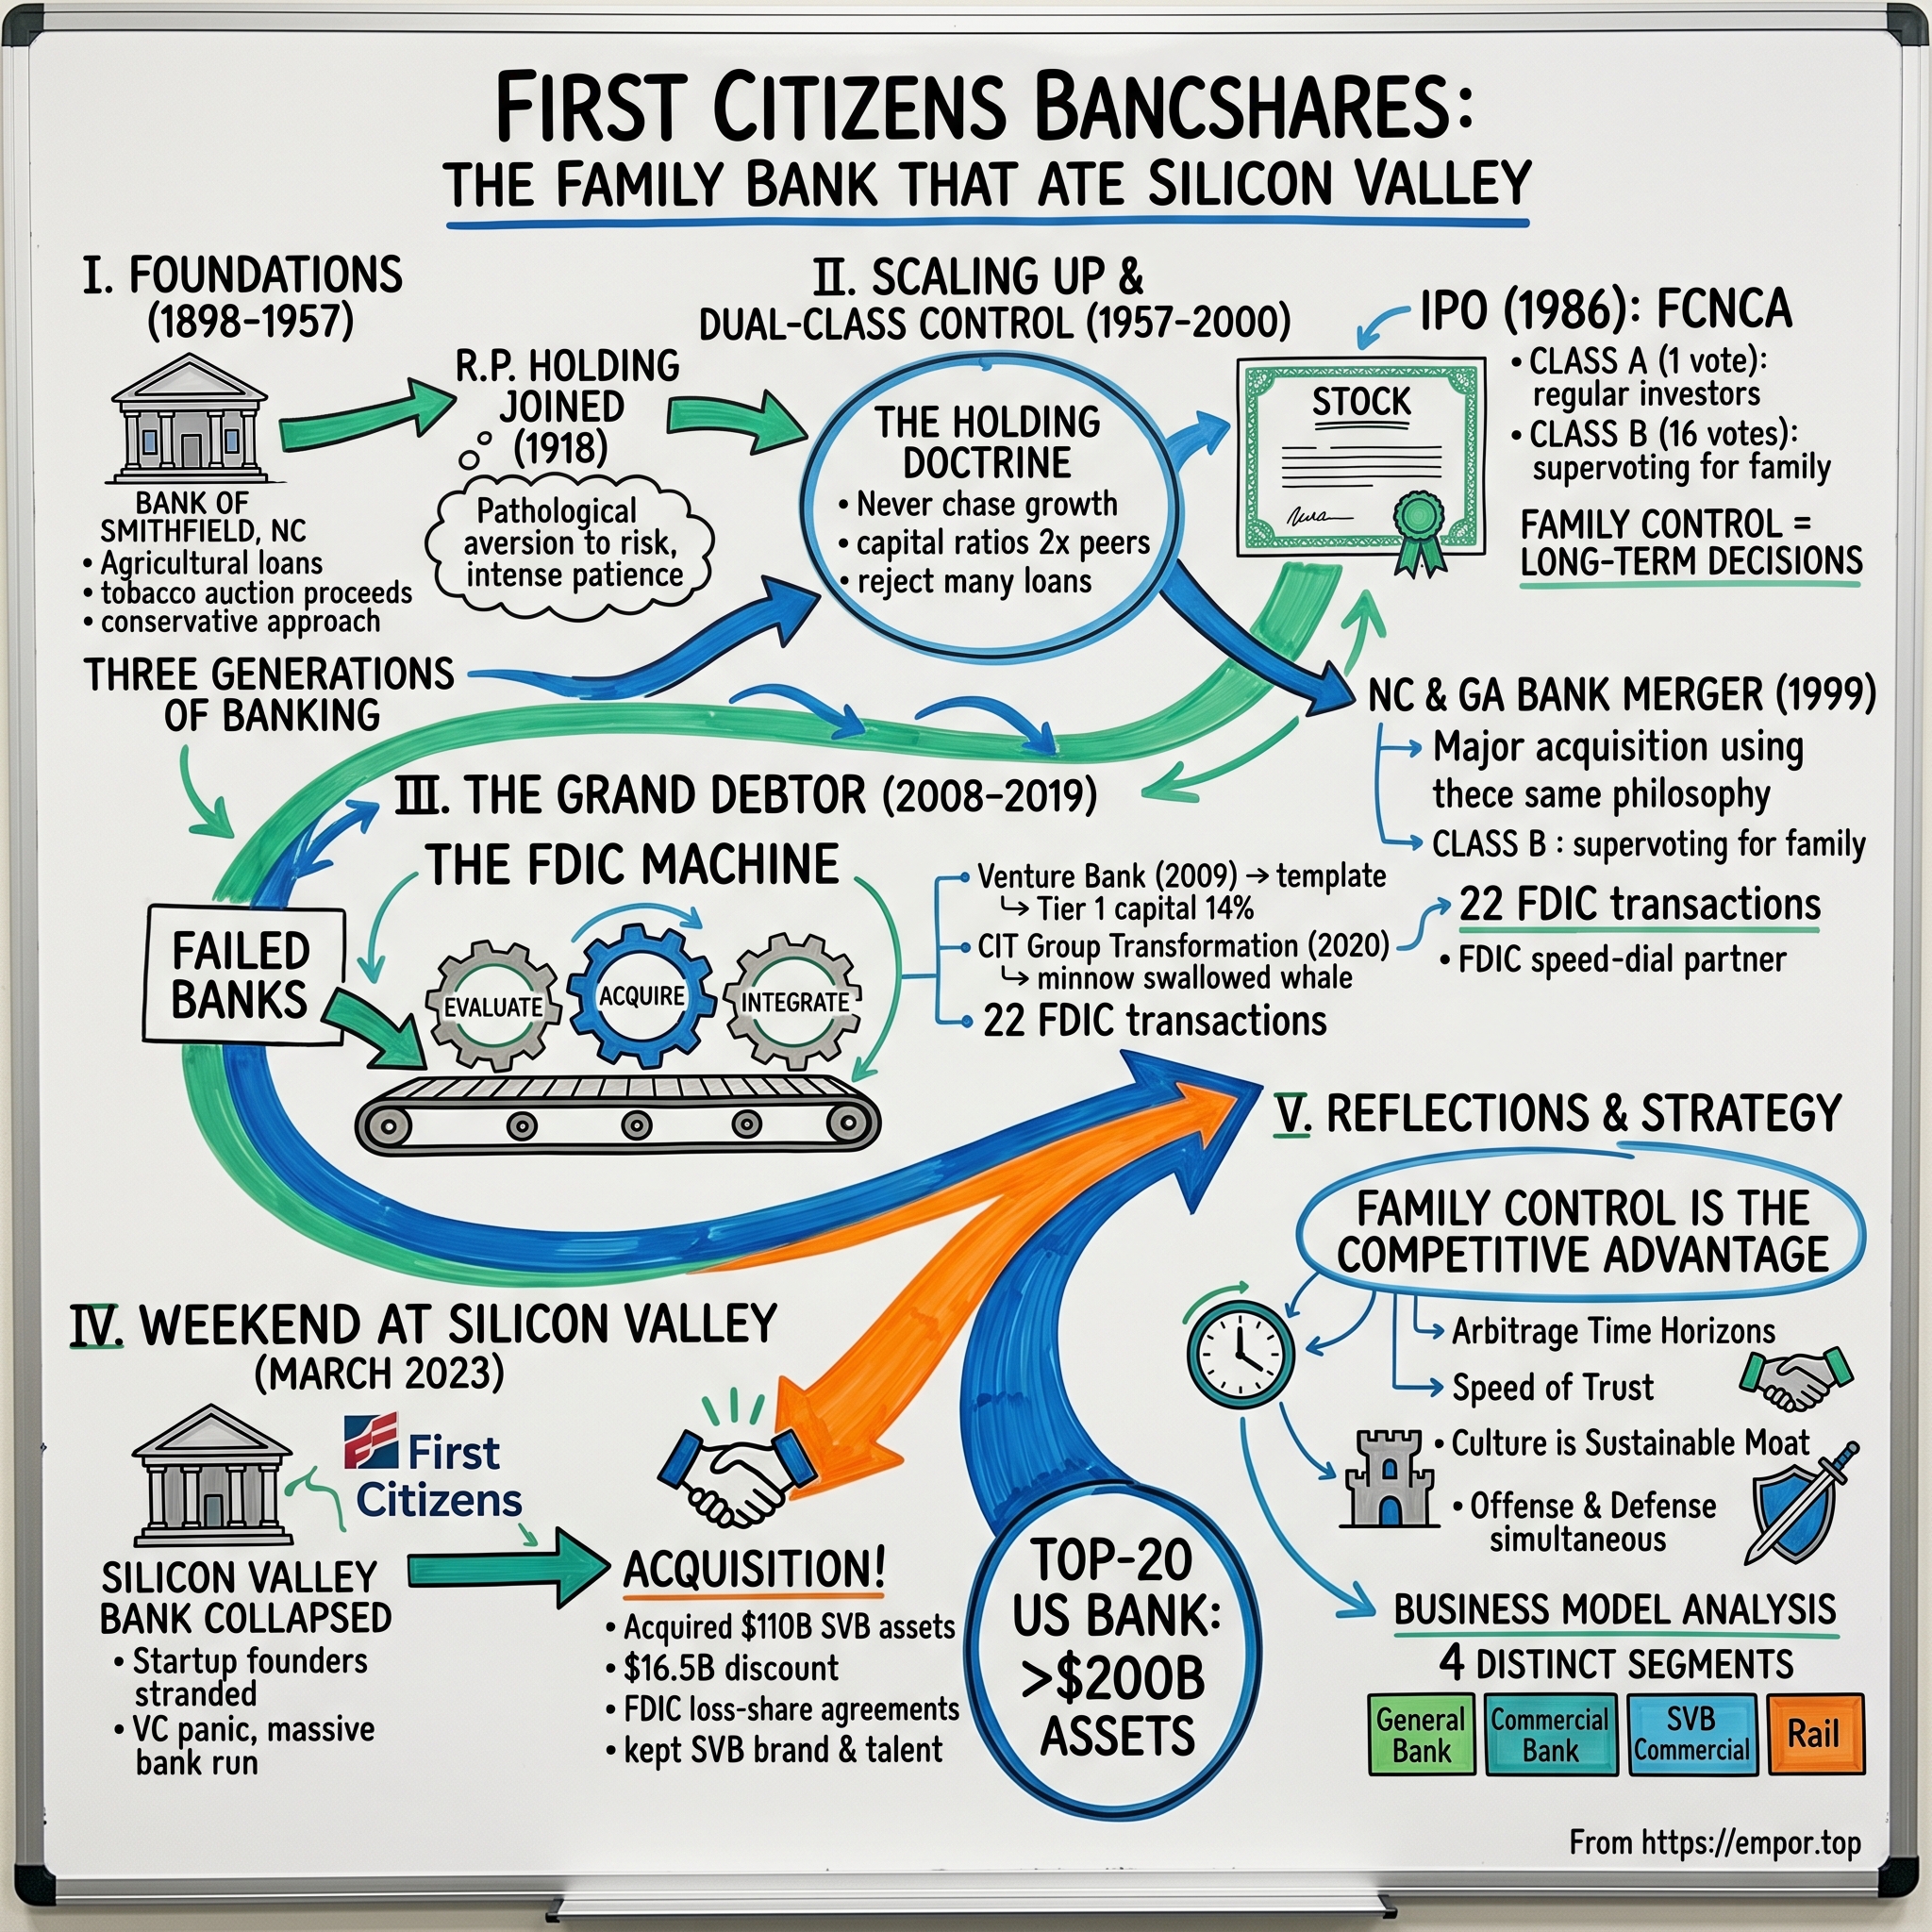
First Citizens BancShares: The Family Bank That Ate Silicon Valley
I. Introduction & Cold Open
On the evening of Sunday, March 26, 2023, the Federal Deposit Insurance Corporation issued a press release that caught Silicon Valley unprepared. After two weeks in which the venture capital ecosystem watched its primary bank collapse — marked by a $42 billion single-day withdrawal attempt, a failed capital raise, a Friday regulatory seizure, and a hastily created bridge bank — the buyer was not JPMorgan Chase, Bank of America, or a consortium of private equity firms backstopped by the Treasury.
It was a 125-year-old bank from Raleigh, North Carolina, whose founding branch had once financed tobacco farmers in Johnston County, and which had been controlled by the same family since the Great Depression.
First-Citizens Bank & Trust Company agreed to assume all of the deposits and acquire substantially all of the loans of Silicon Valley Bridge Bank, N.A. from FDIC receivership.1 In the deal announced that weekend, First Citizens took on approximately $110 billion in assets, including roughly $72 billion of loans purchased at a discount of $16.5 billion, and assumed about $56 billion in deposits along with 17 former SVB branches that reopened Monday morning as First Citizens offices.1 The FDIC retained roughly $90 billion of securities and other assets in receivership, extended a five-year loss-share arrangement covering commercial loans, provided a line of credit for contingent liquidity, and received equity appreciation rights in First Citizens stock worth up to $500 million.1
The acquisition was enabled by seller financing: a $35 billion, five-year purchase money note issued by First Citizens to the FDIC.2 Rather than providing immediate cash funding on Monday morning, First Citizens financed the $110 billion asset purchase primarily through government-backed seller debt.
Under acquisition accounting, when an institution purchases assets below fair value, the difference is recorded on the income statement as a bargain purchase gain. First Citizens recognized a preliminary gain on acquisition of $9.82 billion, net of tax, in the first quarter of 2023 — driving net income available to common stockholders to $9.50 billion, or $653.64 per diluted share, for a bank that had earned $72.28 per share in the entire prior year.3 The figure was later finalized at $9.81 billion following measurement-period adjustments required by purchase accounting.4 Market reaction was swift: shares rose roughly 50% on March 27, 2023, and the Financial Times described the transaction in a headline as "stupendous."56
The central strategic question is how a conservative, family-controlled Southern retail bank — historically subject to a valuation discount due to its control structure — managed to out-position global megabanks for the decade's most significant distressed banking asset.
The short answer points to institutional design rather than chance: dual-class shares that insulated management from quarterly market pressures; a two-decade track record of acquiring failed banks from the FDIC; and a $2.2 billion merger with CIT Group in 2022 that built the national commercial banking infrastructure required to absorb SVB within 72 hours.
The longer answer requires examining post-acquisition execution. Three and a half years after the transaction, First Citizens holds more than $225 billion in assets, a deposit base of $173.43 billion, and a common equity Tier 1 ratio of 10.77%.7 Over that period, the bank has paid down the FDIC note, managed deposit costs that reached 2.07% in the second quarter of 2026 compared to a pre-crisis baseline near zero, worked through legacy commercial office real estate exposures, and defended its market position as competitors sought to hire away teams and client accounts.78 With the initial accounting gain realized, long-term performance depends on the durability of the acquired franchise.
This analysis details the bank's trajectory: the Holding family and its capital structure; the FDIC acquisition framework; the CIT merger integration; the SVB transaction structure; the earnings drivers across operating segments; an evaluation of management's track record; and the key financial metrics shaping future performance.
The story begins in an eastern North Carolina town of 2,000 residents.
 Subscribe on LinkedIn
II. The Holding Dynasty & The Power of Dual-Class Capital (1898–2008)
Smithfield, North Carolina, sits about thirty miles southeast of Raleigh, in a flat agricultural region that in 1898 produced mostly tobacco and cotton. The Bank of Smithfield opened that year as a local depository tied to regional crop cycles, dependent on weather conditions and auction pricing.
The institution's long-term trajectory shifted two decades later when Robert Powell Holding joined the bank in 1918. He assumed leadership during the 1930s amid a nationwide banking crisis that forced thousands of lenders to fail. Experiencing depositor runs during the Great Depression shaped an enduring operating philosophy focused on maintaining higher liquidity buffers and avoiding exotic assets relative to competitors. Three generations later, the bank retained that conservative approach.
Through the mid-twentieth century, the family expanded through dense branch coverage across small and mid-sized Carolina towns, relationship lending to local businesses, and a low-cost deposit franchise built on geographic convenience rather than promotional rate pricing. Deposits gathered in markets with limited local competition proved structurally cheaper and stickier than high-yield deposits, compounding steady growth over several decades.
The 1986 Decision That Defined Everything Since
The defining capital decision occurred when First Citizens BancShares listed on NASDAQ. The company adopted a dual-class capital structure: Class A common stock carrying one vote per share, and Class B common stock carrying 16 votes per share.9 Class A stock trades under the ticker FCNCA, while Class B stock trades less liquidly under FCNCB.
The 16-to-1 voting ratio established permanent family control, enabling a family holding a minority of the economic equity to maintain majority voting control. Chairman and CEO Frank B. Holding, Jr., Vice Chairwoman Hope Holding Bryant, and affiliated family trusts and entities control a majority of the combined voting power of the corporation.9
Evaluating this capital structure requires examining both its strategic advantages and its governance tradeoffs.
The structure insulates management from short-term market pressures that often encourage procyclical risk-taking. Conventional regional banks carrying surplus capital and excess liquidity during credit expansions frequently underperform peers on return on equity, face analyst downgrades and compressed valuation multiples, and encounter activist pressure to leverage their balance sheets. That dynamic often leads institutions to expand aggressively at market peaks and contract during downturns. Dual-class control eliminates proxy contests, hostile bids, and board seats conceded to short-term investors, allowing management to maintain a conservative balance sheet through long economic cycles.
However, dual-class control does not guarantee optimal capital allocation, as evidenced by the company's historical performance.
The Falsification: The Cost of the Discount
For roughly two decades prior to the 2008 financial crisis, First Citizens did not consistently outperform its peers. The bank operated with lower leverage, an elevated efficiency ratio, and modest returns on equity compared to regional peers that expanded aggressively into commercial real estate and consumer credit. Consequently, the stock traded at a persistent discount to peer valuation multiples—a discount market participants attributed directly to the control structure and share illiquidity.
That valuation discount reflected tangible governance constraints. Class A shareholders held economic exposure without corresponding voting influence, leaving them unable to force strategic sales, restructure board composition, alter executive compensation, or dissent effectively. Proxy advisers have flagged structural governance issues at the company—including unequal voting rights, family representation in senior executive and board roles, and related-party considerations—for years.9
Rather than guaranteeing continuous value creation, family control functioned historically as a long-dated option. For extended periods, the structure constrained returns; however, it preserved the flexibility to deploy capital decisively during market disruptions when distressed assets became available and traditional buyers were constrained. Investors who held the stock strictly prior to 2008 realized modest returns, whereas those who maintained positions through subsequent banking crises saw that structural option yield significant value.
Whether that capital allocation advantage persists with a balance sheet exceeding $225 billion, heightened regulatory standards, and a smaller pool of distressed acquisition targets remains a key ongoing question.
The first major test of that structural option occurred during the 2008 financial crisis.
III. The FDIC Playbook: Serial Acquirer in the Great Financial Crisis (2008–2019)
In the United States, failed-bank resolution follows a predictable weekend schedule. The FDIC closes a failing institution after business hours on Friday. Over the weekend, an acquiring bank's integration team assumes operational control over systems, branches, loan files, and deposit records. By Monday morning, branches reopen under new management, ensuring uninterrupted access for depositors.
Executing this transition seamlessly requires experienced institutional machinery. Between 2009 and 2019, First Citizens completed more than 20 FDIC-assisted transactions.
These acquisitions focused primarily on small-to-midsize institutions: Temecula Valley Bank in California in 2009, Venture Bank in Washington, First Regional Bank in Los Angeles in 2010, and Williamsburg First National Bank in South Carolina. The bank absorbed community banks and thrifts across Washington, Georgia, Wisconsin, Colorado, Virginia, and Florida. Most targets held a few hundred million dollars in assets, with occasional multi-billion-dollar portfolios. American Banker later characterized the cumulative effect plainly: this was how First Citizens became the FDIC's go-to acquirer.[^10]
Why First Citizens Could Bid When Others Could Not
The macroeconomic environment of 2009 dictated buyer capacity. Major regional banks were absorbing severe residential mortgage and construction loan losses, issuing dilutive equity, or managing balance sheets constrained by Treasury Troubled Asset Relief Program (TARP) capital and accompanying regulatory restrictions. Their capacity—and regulatory authorization—to assume additional credit risk was virtually nonexistent.
In contrast, First Citizens entered the crisis with an unlevered, highly liquid balance sheet. The conservative capital posture that had historically suppressed its return on equity provided unencumbered capacity to absorb distressed assets at valuations dictated by urgent regulatory sales.
The economics of FDIC-assisted acquisitions established a favorable risk-reward dynamic that would later reappear on a larger scale in 2023. Under its statutory least-cost mandate to the Deposit Insurance Fund, the FDIC evaluates whether liquidating a failed bank and paying out insured depositors is costlier than selling the institution to a healthy acquirer. To facilitate a sale, the FDIC frequently sells the loan portfolio at a steep discount to face value and, in crisis-era deals, enters loss-share agreements to cover a defined percentage of future loan losses over a set term.
For the buyer, this framework creates an asymmetric return profile. The purchase discount is fixed at transaction closing, while downside risk is capped by the loss-share agreement. Any recovery on loans performing above discounted expectations accrues entirely to the acquirer—effectively creating a regulator-backed option on credit recovery.
Building the Machine
The primary advantage First Citizens built during this era was operational rather than financial. While evaluating purchase-and-assumption agreements is straightforward, integrating core banking platforms, re-underwriting loan portfolios, retraining branch staff, repricing high-cost deposit bases, and administering FDIC loss-share claims on a 72-hour turnaround requires specialized execution capability.
A dedicated integration team with a standardized runbook became a core operational asset, refining execution across successive transactions. Alongside failed-bank acquisitions, the company executed structural consolidations. In 2014, First Citizens BancShares merged with First Citizens Bancorporation of South Carolina, a separately listed entity controlled by the Holding family since the 1960s. The transaction integrated a sister bank's branch network into the parent company, increasing Southeastern market density while consolidating family holdings into a single publicly traded vehicle.
So What
The primary strategic takeaway from this decade extends beyond transaction volume. First Citizens built valuable regulatory standing with the FDIC, the Federal Reserve, and the Office of the Comptroller of the Currency by consistently executing acquisitions without operational disruptions or regulatory compliance failures.
Regulatory trust is an intangible competitive advantage that accumulates through consistent execution and cannot be readily acquired or duplicated. When regional bank distress re-emerged in 2023 and the FDIC sought an acquirer for a $110 billion institution over a single weekend, First Citizens' track record positioned it among the few qualified bidders.
However, absorbing a national commercial lender presented operational challenges fundamentally different from integrating a $1 billion community bank. Bridging that gap required a transaction that tested the bank's integration capabilities.
IV. The CIT Group Merger: Doubling Down & Building Scale (2020–2022)
In October 2020, amid a global pandemic that had chilled bank mergers and acquisitions, First Citizens announced an all-stock merger with CIT Group Inc. valued at approximately $2.2 billion. The deal represented the largest transaction in the bank's history by an order of magnitude, creating a combination that traditional regional bank governance might have found difficult to execute.
CIT brought significant historical complexity. Founded in 1908 as a commercial finance firm, it spent decades as a leading lender to American manufacturers and retailers—factoring receivables for apparel makers, financing industrial equipment, and leasing railcars and aircraft. In 2008, CIT converted to a bank holding company to access Federal Reserve liquidity and received $2.3 billion in Troubled Asset Relief Program (TARP) funds, before filing for bankruptcy in November 2009 and wiping out the government's equity stake. After emerging reorganized, the company spent the 2010s divesting non-core assets under new leadership. By 2020, CIT stood as a roughly $61.7 billion commercial lender facing a structural challenge: a lack of low-cost retail deposits.
That imbalance provided the strategic foundation for the merger. First Citizens held roughly $47.9 billion in assets backstopped by one of the lowest-cost retail deposit franchises in US banking, paired with a conservative loan portfolio that underutilized that liquidity. CIT possessed high-yielding commercial originations—including equipment financing, factoring, asset-based lending, and rail leasing—funded expensively through online deposits and wholesale borrowing.
Combining the institutions allowed First Citizens to fund CIT's higher-yielding assets with its low-cost liability base. The transaction roughly doubled First Citizens' balance sheet to approximately $110 billion in assets, transforming a regional retail network into a national commercial lending platform with established origination teams, industry verticals, and credit infrastructure.
The Falsification: Fifteen Months in Regulatory Purgatory
While First Citizens built a reputation as an efficient acquirer during the post-2008 era, the CIT transaction highlighted regulatory and integration friction.
Initially targeted to close in the first half of 2021, the merger did not obtain Federal Reserve approval until December 17, 2021, and officially closed in January 2022—roughly 15 months after its announcement, requiring both boards to extend the merger agreement.10 The regulatory delay reflected detailed oversight. The Federal Reserve's approval order addressed public comments concerning fair lending and Community Reinvestment Act performance, alongside systemic financial stability and managerial resource evaluations required when an institution crosses the $100 billion asset threshold.10
This extended review period created three distinct operational and financial implications.
First, execution costs escalated. A 15-month transition required prolonged retention packages, duplicate systems maintenance, legal expenses, and key personnel attrition ahead of closing. Consequently, original synergy projections modeled on a mid-2021 timeline were eroded.
Second, credit quality shifted. The loan portfolio evaluated during 2020 diligence degraded prior to closing as hybrid work altered commercial real estate demand. Legacy CIT commercial real estate holdings—specifically general office properties—emerged as an ongoing source of credit loss provisions and charge-offs. On its second-quarter 2026 earnings call, management attributed an improved net charge-off ratio of 29 basis points to accelerated resolutions within the general office portfolio, while noting that losses would likely persist over the medium term across office and investor-dependent commercial exposures.8
Third, the approval process demonstrated that regulatory standing remains conditional. Expanding across major asset thresholds triggered heightened supervisory standards regardless of prior failed-bank acquisition performance, underscoring the boundaries of regulatory goodwill.
The Railcars Nobody Expected
The merger also added an unconventional asset for a commercial bank: a major railcar leasing operation. First Citizens acquired CIT Rail, an operating unit that owns and leases railcars and locomotives to shippers and railroads. By the end of 2025, this operating lease fleet totaled approximately 128,400 railcars and locomotives, maintaining a utilization rate—including lease commitments—of 96.2%, down from 97.6% a year earlier.11
Rather than liquidating the fleet as CIT had previously contemplated, management chose to retain and operate the unit.12 The operation provides multi-year lease contracts that generate steady cash flows largely decoupled from broader bank credit cycles, while equipment depreciation offers tax benefits that offset earnings across the wider enterprise.
However, the business presents distinct portfolio considerations. Bank equity investors rarely seek exposure to physical freight assets, which trade at lower valuation multiples than pure-play leasing companies and remain subject to industrial shipping cycles. The modest decline in utilization through 2025 reflected those cyclical pressures in freight demand.
So What
The CIT merger served as a critical operational transition. While the transaction required 15 months of regulatory review, introduced persistent commercial real estate credit headwinds, and added a specialized non-bank leasing unit, it re-engineered First Citizens' fundamental capacity. The deal expanded the bank from a regional retail lender into a national commercial institution exceeding $100 billion in assets, establishing the scale, regulatory clearances, and corporate infrastructure required to execute larger transactions.
When regional banking instability emerged 14 months later, that national scale and operational framework proved essential to absorbing Silicon Valley Bank.
V. Weekend at Silicon Valley: The SVB Deal (March 2023)
The regulatory crisis of March 2023 stemmed directly from the structural contradiction of Silicon Valley Bank: the very qualities that made the institution extraordinary also made it acutely fragile.
SVB operated as the primary financial institution for the venture capital ecosystem, serving startups, venture funds, and technology executives. During the 2020–2021 venture boom, capital raised by portfolio companies flowed directly into SVB accounts as operating deposits—yielding massive, low-cost, non-interest-bearing balances that any commercial lender would covet. Total deposits expanded to roughly $173 billion. SVB invested this liquidity surge into long-duration U.S. Treasuries and agency mortgage-backed securities at prevailing interest rates near zero.
When the Federal Reserve subsequently raised interest rates at the fastest pace in four decades, SVB faced dual pressures. First, its fixed-rate securities portfolio suffered steep unrealized mark-to-market losses. Second, the venture capital funding environment contracted, forcing portfolio companies to draw down operating deposits to fund operations without fresh capital inflows. To meet deposit redemptions, the bank was forced to liquidate underwater securities, realizing severe capital losses.
The underlying catalyst was deposit concentration. SVB’s client base was not a geographically diversified retail network; it was a tightly interconnected ecosystem of founders and venture capitalists who communicated through shared digital channels, held balances well above the $250,000 federal deposit insurance limit, and could transfer funds instantaneously via digital banking platforms. When prominent venture firms began advising portfolio companies to diversify capital, depositors initiated roughly $42 billion in withdrawal requests in a single day—a traditional bank run operating at digital speed. State and federal regulators closed the institution on Friday, March 10, 2023, establishing Silicon Valley Bridge Bank, N.A., to stabilize operations.
Why the Obvious Buyers Did Not Bid
An initial FDIC resolution auction failed to produce a buyer. The largest U.S. financial institutions evaluated the asset but declined to submit bids acceptable to regulators.
Global megabanks faced distinct regulatory and structural hurdles: statutory deposit concentration caps prohibiting institutions holding over 10% of total U.S. insured deposits from expanding via acquisition, capital surcharges for global systemically important banks that raised the cost of balance sheet expansion, and asset growth limits imposed on specific institutions. Beyond regulatory barriers, loan underwriting presented a major obstacle. SVB’s portfolio did not consist of standard middle-market commercial credit; it comprised capital call lines for private equity and venture funds, venture debt to early-stage enterprises, and jumbo mortgages for technology executives. Evaluating and pricing specialized credit assets over a single weekend without prior operational domain expertise represented an unacceptable underwriting risk for most bank credit committees.
That dynamic created a narrow opportunity for an institution with sufficient balance sheet scale to absorb $110 billion in assets, proven operational experience in executing FDIC resolutions, freedom from systemic capital surcharges, and established supervisory standing with banking regulators.
The Structure, and Why Each Piece Mattered
The transaction announced on March 27, 2023, featured a structural risk profile that warrants detailed examination.1
The $16.5 billion discount on roughly $72 billion of acquired loans provided a substantial margin of safety. First Citizens paid approximately $55.5 billion for portfolio assets carried at $72 billion. A discount of this scale allowed the loan book to experience elevated credit degradation while still delivering positive net economics—establishing immediate credit protection at closing rather than relying on future operational recovery.
A five-year loss-share agreement, under which the FDIC agreed to absorb a portion of credit losses and share in recoveries on covered commercial loans, capped tail risk. While the purchase discount absorbed expected credit losses, the loss-share agreement protected against severe downside scenarios.
The $35 billion purchase money note resolved immediate liquidity constraints.2 Rather than liquidating cash buffers or issuing expensive wholesale debt to fund the transaction, First Citizens issued a five-year note directly to the FDIC. This government-provided seller financing carried a fixed interest rate without mandatory principal amortization, converting a prohibitive upfront funding requirement into a manageable liability structure.
In exchange, the FDIC received equity appreciation rights in First Citizens Class A common stock valued at up to $500 million, which regulators subsequently exercised as the equity appreciated—providing taxpayer participation in the transaction's upside.1
The financial impact appeared in the bank's first-quarter 2023 results, which recorded a preliminary gain on acquisition of $9.82 billion net of tax, later finalized at $9.81 billion.34 Under acquisition accounting, this bargain purchase gain—or negative goodwill—reflects the amount by which the fair value of acquired net assets exceeded the purchase price. The accounting gain does not represent immediate cash inflows; rather, it reflects economic value realized over time as loan principal is collected and acquired liabilities are serviced. This cash flow manifests as purchase accounting accretion within net interest income over subsequent periods, prompting First Citizens to report net interest margin metrics both with and without loan accretion adjustments.7
The Falsification: What Was Actually Bought
Popular accounts often frame the acquisition as the purchase of SVB’s low-cost deposit franchise at a steep discount. However, corporate financial disclosures present a more nuanced reality.
SVB held approximately $173 billion in deposits prior to the run, but First Citizens assumed roughly $56 billion in the resolution transaction.1 More than $115 billion in deposits had already fled the institution. The core asset that had defined SVB’s funding advantage—low-cost, non-interest-bearing operating balances from venture-backed companies—had largely eroded before the acquisition closed.
Furthermore, retaining the remaining deposit base required competing directly against national and regional institutions actively soliciting tech-sector accounts. As a result, the bank's funding costs repriced upward over subsequent periods. By the second quarter of 2026, non-interest-bearing deposits declined to 24.5% of total deposits—falling by $1.13 billion during that quarter alone—while the average cost of total deposits reached 2.07%.7 On the second-quarter 2026 earnings call, Chief Financial Officer Craig Nix characterized deposit competition as intense, noting that competitors were offering aggressive rates and reporting marginal funding costs above 4% in the Direct Bank segment against a spot interest rate of 3.71%.8
Consequently, the transaction is more accurately understood as the purchase of SVB’s commercial lending franchise and institutional client relationships at a substantial discount, paired with the acquisition of a depleted deposit base at market interest rates. The primary economic value resided in the discounted loan portfolio and FDIC loss-share protections rather than zero-cost liabilities—a structural distinction that continues to dictate net interest margin trajectory and earnings dynamics.
So What
The SVB acquisition delivered exceptional economic returns, but those returns were derived from specific structural mechanics: a deeply discounted asset purchase, long-term government seller financing, and loss-share credit protection. First Citizens captured these terms because larger competitors were constrained by regulatory limits, capital surcharges, or underwriting friction. The core institutional lesson lies in maintaining balance sheet liquidity, supervisory trust, and unconstrained capacity to act as the primary bidder during market dislocations.
How those acquired assets perform over long economic cycles—and where underlying earnings manifest across operating segments—remains the central test of post-acquisition integration.
VI. Segment Deep-Dive & Financial Engine: Where the Profits Live
Behind the transformational acquisitions of recent years, First Citizens operates as four distinct business segments, each with a different funding profile, customer base, and cyclical driver. Evaluating the bank's earnings durability requires distinguishing between the units that generate yield and the units that supply low-cost capital—because they reside in different parts of the balance sheet.
General Bank: The Engine Room
The General Bank segment represents the institution's core retail engine, encompassing branch networks across the Southeast and California, retail and small business banking, wealth management, and residential mortgage lending.
Its primary strategic function is not generating high asset yields, but gathering durable retail deposits that remain stable across interest rate cycles without requiring competitive price bidding. These low-cost liabilities form the foundational funding layer for the broader commercial lending franchise.
First Citizens has continued expanding this deposit base through targeted acquisitions. On October 16, 2025, the bank agreed to acquire 138 branches from BMO Bank N.A. across the Midwest, Great Plains, and West—a transaction that closed and converted on September 4, 2026, bringing roughly $5 billion in deposits and $650 million in loans into the franchise at a net deposit premium of approximately 5%.1314 Paying a mid-single-digit premium for granular branch deposits, at a time when marginal Direct Bank funding costs exceeded 4%, reflects straightforward liability economics: acquiring durable, low-cost retail deposits is structurally cheaper than relying on price-sensitive digital funding. Management explicitly tied the deal's net liquidity benefit to its ability to accelerate FDIC note repayment in the third quarter of 2026.8
The segment also includes a secondary deposit channel: the Direct Bank, an online, rate-driven platform acquired through the CIT merger. Operating nationally by competing directly on price, the Direct Bank exhibits the opposite characteristics of the physical branch network—rapid deposit gathering paired with higher funding costs and lower customer retention. Management has described running the platform at a roughly neutral net interest income impact,8 positioning it as a flexible liquidity buffer rather than a core competitive moat.
Commercial Bank: The Yield
The Commercial Bank segment combines legacy CIT commercial operations with the acquired SVB commercial lending units, spanning middle-market lending, factoring, asset-based finance, equipment leasing, commercial real estate, and specialized industry verticals in technology, healthcare, and fund banking. As of mid-2026, the Commercial Bank segment represented $86.7 billion of loans, accounting for 57% of the total loan portfolio.15
This segment functions as the primary yield driver—and the principal locus of credit risk. Because a significant portion of the loan book is tied to short-term benchmark interest rates, asset yields expanded rapidly during the Federal Reserve's rate-hiking cycle, but face downward margin pressure as benchmark rates decline. Credit risk remains concentrated in legacy office real estate and investor-dependent commercial lending portfolios, which management has continued to work down while projecting elevated charge-offs over the medium term.8
SVB Commercial: The Franchise in Question
Within the commercial business sits the unit that determines whether the 2023 transaction functions as a short-term asset trade or a durable franchise acquisition.
The centerpiece of this division is Global Fund Banking, which provides subscription lines of credit—capital call facilities—to venture capital and private equity funds. These short-dated credit lines allow fund managers to execute investments quickly before calling capital from limited partners. Credit risk is backed not by early-stage portfolio startups, but by the contractual commitments of institutional fund investors, giving the asset class a historically low loss record. However, subscription facilities remain highly relationship-driven, short in duration, and subject to intense price competition.
Operating alongside fund banking is Tech and Healthcare Banking, which provides financing to technology, life sciences, and healthcare enterprises. In the second quarter of 2026, this unit delivered 3.7% sequential loan growth, which management highlighted as its strongest quarterly expansion since the 2023 acquisition. Over the same period, Global Fund Banking expanded by $2.6 billion through new originations and secondary market activity, supported by an origination pipeline that management described as healthy at approximately $11 billion.8
While recent loan expansion indicates stabilizing client activity, it also represents the first growth quarter following a three-year period of stagnant venture activity. Furthermore, the unit's economic model relies heavily on fee income alongside interest spreads: equity warrants attached to venture loans, treasury management fees, foreign exchange trading, and off-balance-sheet client investment funds. In the second quarter of 2026, off-balance-sheet client investment accounts expanded by $1.1 billion at period-end and averaged $6.1 billion higher during the quarter.8 This growth in off-balance-sheet funds highlights a structural post-2023 shift, as commercial tech clients increasingly maintain cash buffers in yield-bearing money market vehicles rather than uncompensated bank deposits, shifting revenue from net interest margin toward fee streams.
Rail: The Odd One Out
The Rail segment remains the company's smallest and most distinct unit, generating operating lease revenue from a fleet of approximately 128,400 railcars and locomotives.11 Accounting for a mid-single-digit share of consolidated revenue, the business provides modest earnings diversification alongside equipment depreciation tax benefits that offset income across the broader enterprise. Its primary performance metric is fleet utilization, which stood at 96.2% at the end of 2025—a high absolute level, though down from the prior year due to broader industrial shipping demand.11 Analytical evaluations typically treat Rail as a stable, capital-intensive asset unit rather than a primary catalyst for earnings growth.
So What
As of mid-2026, First Citizens reported a consolidated balance sheet exceeding $225 billion in total assets, supported by $173.43 billion in deposits and $151.03 billion in loans. Financial strength and credit metrics remained stable, with a net charge-off ratio of 0.29%, nonaccrual loans at 0.96% of total loans, a Common Equity Tier 1 ratio of 10.77%, and a net interest margin of 3.10%, or 3.01% excluding purchase accounting accretion.7
These results reflect a fundamental transition: the substantial accretion tailwind from 2023 purchase accounting is steadily unwinding, as demonstrated by the narrowing nine-basis-point spread between reported and adjusted net interest margin. As purchase accounting benefits normalize, long-term performance increasingly depends on traditional banking execution—funding commercial loans through low-cost retail branch deposits. While this structural alignment supports stable underlying profitability, it lacks the extraordinary accounting gains that defined the post-acquisition period.
This normalization shifts the central strategic focus to execution: in a banking environment without crisis-era asset discounts, how effectively can First Citizens defend its acquired commercial franchise against aggressive regional and national competitors?
VII. Competitive Landscape, Industry Structure & Helmer's 7 Powers
American commercial banking effectively operates across three distinct arenas fought simultaneously by the same institutions.
The first arena centers on gathering retail deposits across geographic footprints, driven by branch density, brand reputation, and customer inertia. The second focuses on middle-market commercial lending, where institutions compete on balance sheet capacity, industry specialization, and pricing. The third encompasses venture and fund banking, demanding rapid execution, deep ecosystem networks, and underwriting capabilities tailored to non-traditional corporate structures.
First Citizens now operates across all three arenas, maintaining a distinct competitive posture in each.
The Competitive Set
In core regional banking, First Citizens compares directly against institutions in the $150 billion to $250 billion asset class, including Fifth Third, Huntington Bancshares, M&T Bank, KeyCorp, and Regions Financial. These peers operate with similar balance sheet scale and regulatory oversight, and several maintain superior efficiency ratios and traditional single-class governance structures. The core branch network offers limited structural differentiation; profitability relies on geographic density and operational cost discipline rather than proprietary products.
In venture and fund banking, the competitive dynamic is far more aggressive. JPMorgan Chase’s commercial division expanded its dedicated innovation-economy unit, while mid-tier institutions such as Stifel, Western Alliance, HSBC—which acquired Silicon Valley Bank’s UK operations—and Banc of California actively target tech clients. Concurrently, private credit funds have aggressively expanded into capital call facilities and venture debt. Following Silicon Valley Bank's collapse, its talent pool and client relationships instantly became some of the most fiercely contested assets in commercial finance.
Porter's Five Forces, Applied Honestly
Buyer power (depositors) represents the most significant shift since 2022. Within the retail branch network, depositor bargaining power remains modest, as consumer and small-business accounts exhibit low yield sensitivity. Conversely, commercial and technology clients possess elevated, structural buyer power. Corporate treasurers recognize that uninsured balances carry credit risk, prompting systematic cash management behaviors: diversifying deposits across multiple institutions and sweeping excess liquidity into money market instruments and Treasury securities. This structural shift is evident in First Citizens' financial disclosures, which show non-interest-bearing deposits contracting to 24.5% of total deposits alongside expanding off-balance-sheet client investment funds.78 This heightened depositor sensitivity explains why an average deposit cost of 2.07% persists even as underlying net interest margins stabilize.
Supplier power in banking resides primarily with regulatory authorities and, during periods of financial distress, with the FDIC. Regulatory discretion is nearly absolute: the FDIC determines eligible bidders in receivership sales, while the Federal Reserve controls merger approval timelines—a dynamic illustrated by the 15-month regulatory review required for the CIT Group transaction.
Threat of new entrants into traditional banking remains low due to strict chartering requirements, capital minimums, and prudential supervisory standards. However, functional competition from non-bank institutions is accelerating. Private credit providers compete directly for middle-market and asset-based loans within the Commercial Bank segment without incurring bank regulatory capital mandates or deposit maintenance costs. Concurrently, fintech platforms and money market funds compete for client liquidity. The bank charter secures a regulatory license, but it no longer shields core lending and deposit activities from disintermediation.
Competitive rivalry is highly fragmented. Competition is intense in high-margin sectors like fund banking and corporate lending, but moderate in stable, lower-yielding retail deposit markets. Managing this structural dichotomy represents a central strategic challenge for First Citizens.
Helmer's Powers: What Survives Scrutiny
Hamilton Helmer's framework evaluates which structural advantages produce persistent differential returns. Applied to First Citizens, the assessment yields mixed findings across key powers.
Cornered resource — a temporary strategic advantage. The bank's multi-decade track record of seamless FDIC resolutions established a unique position: built regulatory trust that enabled management to acquire a $110 billion institution over a single weekend. That standing generated a preliminary bargain purchase gain of $9.81 billion net of tax in a single quarter.4 However, this advantage yields value only during severe banking dislocations when competing buyers face balance sheet constraints. Consequently, it produces episodic rather than recurring earnings. Furthermore, expanding past $225 billion in total assets subjects First Citizens to enhanced prudential regulation, moving the bank closer to the constrained category of regional peers.
Process power — a verified operational capability. First Citizens has demonstrated repeatable execution across more than twenty FDIC-assisted transactions, the CIT Group integration, and the 138-branch BMO conversion completed in September 2026.14 Standardized integration playbooks lower transaction costs and mitigate operational disruption, representing the company's most durable internal capability.
Scale economies — emerging without market leadership. Expanding the balance sheet beyond $225 billion allows the enterprise to distribute technology, compliance, and administrative overhead across a significantly larger asset base compared to its historical $47.9 billion footprint. However, regional peers operate with comparable scale, and management's target of an adjusted efficiency ratio in the low-60% range for 2026 is aligned with industry averages rather than market-leading.8 Scale eliminates a previous cost disadvantage rather than establishing an unassailable economic moat.
Counter-positioning — a contested structural thesis. Proponents argue that dual-class share ownership allows management to maintain elevated liquidity during economic expansions and acquire distressed assets during downturns. While performance during the 2009 and 2023 banking crises supports this view, lower returns prior to 2008 highlight its historical opportunity cost. Today, the primary operational constraint stems from regulatory requirements rather than shareholder activism: with a Common Equity Tier 1 ratio of 10.77% approaching management's target corridor of 10.0% to 10.5%, the bank has moderated share repurchases to approximately $600 million in the third quarter and $300 million in the fourth quarter of 2026.78 Capital allocation decisions are increasingly governed by regulatory capital targets rather than family discretion.
So What
In summary, First Citizens possesses one specialized operational asset—a regulatory-backed resolution and integration capability—alongside an acquired, highly contested commercial technology franchise and a conventional regional retail bank. While the bank's standing as a preferred FDIC acquirer generated historical gains, its long-term durability relies on conventional execution. With crisis-era asset discounts behind it, future performance depends on executive leadership's ability to defend acquired client relationships while managing a substantially larger balance sheet.
VIII. Management Credibility, Capital Allocation & Governance Stress Test
Frank B. Holding, Jr. represents the third generation of his family to lead First Citizens. Having joined the bank in the early 1980s, he became chief executive officer in 2008—timing that positioned him to navigate the initial wave of FDIC-assisted failed bank acquisitions. Serving as Chairman and CEO through both the CIT Group merger and the Silicon Valley Bank transaction, Holding has maintained a low public profile compared to peers at major financial institutions, rarely granting media interviews. Consequently, evaluating his leadership relies primarily on the bank's execution record.
That operational record presents both strategic achievements and ongoing governance trade-offs.
The Executive Bench
Hope Holding Bryant serves as Vice Chairwoman, representing direct family operational leadership alongside ownership through family trusts.
Craig L. Nix, Chief Financial Officer, acts as the bank's primary public communicator on financial strategy. He oversaw the purchase accounting for the SVB bargain purchase gain, structured the management of the $35 billion FDIC purchase money note, and executed the share repurchase program. During the second-quarter 2026 earnings call, Nix attributed performance to "resilient net interest income, fee-based non-interest income expansion, and disciplined expense management," while offering direct assessments of industry dynamics—describing deposit competition as "very fierce" and characterizing rival interest rate pricing as unprofitable.8
Peter M. Bristow, President, leads the ongoing commercial integration aligning the CIT Group and Silicon Valley Bank operating units.
The Capital Allocation Record, Examined
Three distinct capital allocation decisions illustrate management's approach to balance sheet expansion and capital return.
Acquisitions. The expansion record highlights significant financial returns alongside operational friction. The Silicon Valley Bank transaction generated a $9.81 billion after-tax bargain purchase gain that doubled tangible book value.4 Conversely, the CIT Group merger required a 15-month regulatory approval process and introduced legacy commercial real estate exposures that continued to generate loan charge-offs into 2026.108 Most recently, the acquisition of 138 BMO Bank branches at an approximate 5% deposit premium closed in September 2026, though long-term deposit retention remains to be proven.14 The broader pattern reflects a management team accustomed to purchasing assets during periods of stress, accepting extended integration complexity in exchange for discounted valuations.
Debt repayment. Management has followed a structured timeline to retire the $35 billion FDIC purchase money note. An initial $2.50 billion principal payment in the fourth quarter of 2025—funded primarily through securities sales—was followed by $5.00 billion in prepayments during the first half of 2026 and an additional $1.00 billion in July 2026. These transactions reduced the note balance from $35.85 billion as of September 30, 2025, to $28.42 billion by June 30, 2026, bringing cumulative prepayments to $8.50 billion.716 For the third quarter of 2026, leadership projected $6 billion to $8 billion in further paydowns, supported by liquidity from the BMO branch transaction.17 While retiring below-market fixed-rate financing ahead of schedule suppresses short-term net interest spread, management justified the strategy as establishing an orderly refinancing runway ahead of the note's 2028 maturity, utilizing asset sales, Federal Home Loan Bank borrowing, long-term debt, and brokered deposits to avoid a concentrated refinancing obligation.8
Buybacks. Following the 2023 transaction, First Citizens deployed capital into substantial share repurchases. Cumulative buybacks under the 2024 authorization totaled $6.19 billion through June 30, 2026, including $600 million executed during the second quarter of 2026, leaving $1.31 billion in remaining authorized capacity.7 Management subsequently guided to a moderated repurchase cadence—targeting approximately $600 million in the third quarter and $300 million in the fourth quarter of 2026—as the Common Equity Tier 1 ratio approaches the target corridor of 10.0% to 10.5%.8 Retiring shares below post-acquisition tangible book value enhanced per-share metrics, while the decision to slow repurchases as capital levels normalize aligns with declared capital targets.
The Stress Test a Skeptic Would Run
An institutional investor or analyst evaluating the bank's long-term risk profile faces structural governance limits, shifting earnings drivers, and operational complexity.
The voting structure. Economic ownership and voting control remain decoupled. The 16-to-1 voting preference enjoyed by Class B shares ensures that public Class A equity holders cannot alter board composition, adjust executive compensation, modify dividend policy, or compel strategic transactions.9 Institutional investors possess no formal mechanism to force governance changes.
Key-person and succession risk. Family members occupy key board and executive positions, and core strategic execution has depended on a small group of senior leaders since 2008. The bank lacks a detailed, publicly disclosed executive succession plan typical of top-20 U.S. banking institutions—a notable vulnerability given that regulatory relationships remain tied to key individuals.
Portfolio complexity. Operating an enterprise that encompasses 128,400 railcars, commercial factoring units, a specialized venture capital lending business, and a retail network of over 500 branches complicates financial modeling. Diversified, non-standard business lines often lead institutional markets to apply a conglomerate valuation discount rather than a premium.
Earnings quality. Post-2023 reported earnings have received substantial support from loan purchase accounting accretion, an accounting effect that diminishes as acquired loans mature or refinance. While First Citizens transparently reports both headline and adjusted net interest margins, the nine-basis-point variance in the second quarter of 2026—3.10% reported versus 3.01% adjusted—quantifies the ongoing contribution of temporary accounting tailwinds.7
Normalizing earnings trajectory. Full-year 2025 net income contracted to $2.21 billion, down $571 million from $2.78 billion in 2024, yielding diluted earnings per share of $165.24 compared to $189.41 in the prior year.18 Executive leadership attributed the decrease to declining interest rate benchmarks and reduced purchase accounting accretion.18 These disclosures highlight that extraordinary transaction gains previously amplified reported income, meaning that subsequent performance—including second-quarter 2026 net income of $672 million, or $55.52 per diluted share—must originate from core commercial and retail banking operations.7
So What
Evaluating management performance over multi-year cycles reveals strong operational execution against stated financial commitments: leadership executed FDIC note prepayments on schedule, moderated share buybacks upon approaching target capital ratios, and maintained consistent disclosures regarding persistent credit costs in commercial real estate portfolios.
However, the long-term investment thesis remains constrained by structural factors rather than operational execution. Concentrated family voting control offers no shareholder remedies, executive succession planning remains undisclosed, and earnings continue to adjust downward from temporary crisis-era accounting gains. For institutional investors, these structural characteristics explain why the market continues to apply a valuation discount despite recent asset growth.
The concluding section evaluates the core investment thesis against these operational and structural realities.
IX. Historical Falsification Pass: Testing the Thesis Claims
Every investment case for First Citizens rests on three load-bearing claims. Each deserves to be tested against the strongest disconfirming evidence in the company's own record—not generic risk factors from a filing, but empirical evidence from what actually transpired.
Claim 1: "SVB Commercial provides a durable tech and venture banking franchise."
The mechanism that would break it: client attrition, banker poaching, and a structural shift toward multi-bank treasury arrangements that permanently caps deposit share per client.
The disconfirming evidence: all three occurred. In the weeks following March 2023, competitors—including JPMorgan Chase's commercial bank, Stifel, HSBC, and Western Alliance—recruited aggressively from Silicon Valley Bank's relationship management ranks, targeting a business model where client loyalty often attaches to individual bankers rather than the institution. Simultaneously, venture capital funds adopted strict treasury policies requiring portfolio companies to divide cash reserves across multiple institutions, typically anchoring primary balances with a global systemically important bank. That behavioral change reflects a structural, risk-management shift in response to frozen uninsured deposits rather than a transient cyclical trend.
Corporate disclosures confirm the economic impact: non-interest-bearing deposits fell to 24.5% of total deposits by mid-2026, contracting by $1.13 billion in the second quarter alone as client funds migrated to off-balance-sheet investment vehicles.78 Commercial technology clients are deliberately maintaining liquidity outside uncompensated bank accounts.
Verdict: narrowed, not rejected. The commercial lending apparatus remains functional: 3.7% sequential loan growth in Tech and Healthcare Banking, $2.6 billion in Global Fund Banking expansion, and an $11 billion origination pipeline demonstrate concrete operational momentum following three years of stagnant activity.8 However, the assumption that SVB provided a low-cost, captive deposit funding monopoly did not survive. SVB Commercial operates as a high-quality commercial lending and fee-generating business subject to permanently higher deposit sensitivity. The key performance metric: sustained loan expansion in Global Fund Banking and Tech and Healthcare Banking alongside a stabilization—rather than merely a slower contraction—in non-interest-bearing deposit share.
Claim 2: "First Citizens is a seamless acquirer."
The mechanism that would break it: regulatory friction that delays or conditions transaction approvals, combined with inherited credit portfolios that underperform initial diligence.
The disconfirming evidence: the Federal Reserve required 15 months to approve the CIT Group merger—evaluating public comments regarding fair lending and Community Reinvestment Act performance alongside systemic stability concerns triggered by crossing the $100 billion threshold before granting approval on December 17, 2021.10 Furthermore, inherited commercial real estate portfolios—specifically general office properties—have required extended workout periods, with executive leadership projecting in mid-2026 that credit losses in office and investor-dependent commercial exposures will persist even as the consolidated net charge-off ratio improved to 0.29%.8
Verdict: the absolute claim is rejected, while a qualified version holds. First Citizens is not a frictionless acquirer, but it remains an exceptionally capable one. Operational integration capabilities are evidenced by completing the 138-branch BMO conversion on schedule in September 2026 and absorbing a $110 billion institution without core systems disruption.14 Nevertheless, regulatory approvals represent a dynamic variable that scales with institutional size and balance sheet complexity. The key performance metric: net charge-off ratios and nonaccrual trends across commercial real estate portfolios, evaluated against the 0.96% total nonaccrual ratio reported at mid-2026.7
Claim 3: "The low-cost deposit franchise insulates the bank from rate cycles."
The mechanism that would break it: balance migration from non-interest-bearing accounts into higher-yielding products, combined with aggressive price competition for marginal liquidity.
The disconfirming evidence: average total deposit costs rose to 2.07% in the second quarter of 2026, up significantly from pre-tightening baselines near zero.7 Marginal funding costs proved even higher: Direct Bank deposit rates exceeded 4% against a benchmark spot rate of 3.71%, leading Chief Financial Officer Craig Nix to characterize competitor rate pricing as economically unviable.8 Paying an approximate 5% deposit premium to acquire 138 BMO branches underscored that gathering marginal deposits organically through digital channels had become costlier than purchasing established branch liquidity.1314
Verdict: materially narrowed. The core retail branch network provides genuine deposit stickiness, and a reported net interest margin of 3.10% in an aggressive rate environment demonstrates fundamental liability strength.7 However, describing the overall franchise as insulated overstates balance sheet dynamics. First Citizens maintains a below-average deposit beta across its retail footprint alongside an above-average deposit beta across its commercial and technology client base, causing overall funding costs to reprice as deposit mix shifts. The key performance metric: net interest margin excluding purchase accounting accretion—which held at 3.01% across both the first and second quarters of 2026—offering the clearest measure of core funding defense.7
What the Falsification Pass Leaves Standing
Evaluating these findings together indicates that process and operational integration capabilities represent the company's most defensible structural advantage, supported by consistent transaction execution. Conversely, the assertion of an insulated, ultra-low-cost deposit franchise is contradicted by consecutive quarterly funding disclosures. The SVB commercial franchise occupies an intermediate position: a valuable, highly contested commercial asset displaying its first sustained operational growth since acquisition.
These operational realities do not diminish the scale of the 2023 transaction. They demonstrate that First Citizens' recurring earning power reflects a well-managed regional commercial banking institution operating alongside a specialized tech lending division, rather than an unassailable financial engine.
The progress of that operational transition remains most evident in executive leadership's quarterly performance reporting.
X. Earnings Call & Transcript Analysis: What Management vs Analysts Say
Earnings calls test whether a company's narrative consistency holds under scrutiny. For an institution whose reported financial results were transformed overnight by a massive accounting event, these quarterly discussions reveal how executive leadership framed its sudden windfall and managed post-acquisition expectations.
The Arc of the Calls
The first-quarter 2023 call, held weeks after the transaction, functioned primarily as a structural briefing on deal mechanics: explaining the preliminary after-tax gain of $9.82 billion, the parameters of the FDIC loss-share agreement, the funding terms of the $35 billion purchase money note, and initial assumptions regarding retained SVB deposits.3 Executive leadership maintained a cautious tone regarding deposit retention—a restraint that subsequent capital outflows validated.
The fourth-quarter 2023 call in January 2024 confirmed the finalized $9.81 billion bargain purchase gain and a full-year diluted earnings per share of $784.51, up from $72.28 in the prior year—a spike driven almost entirely by the one-time accounting adjustment.4 Throughout this period, management consistently separated the non-recurring gain from core operating results, ensuring that the subsequent normalization in annual net income remained clear to market participants.
The 2025 calls addressed a period of earnings normalization: full-year net income contracted to $2.21 billion from $2.78 billion in 2024, bringing diluted earnings per share to $165.24 down from $189.41 as benchmark interest rates declined and purchase accounting accretion ran off.18 Executive leadership attributed the decrease directly to accretion runoff and interest rate shifts, maintaining the prospective guidance it had previously outlined.
The second-quarter 2026 call on July 23, 2026 highlighted operational stabilization. Chairman and CEO Frank Holding reported that adjusted earnings expanded by over 20% sequentially, exceeding internal targets and consensus estimates with adjusted net income of $691 million, or $57.09 in adjusted diluted earnings per share.8
Where Management Points, and Where Analysts Push
Management's prepared remarks focused on core operating momentum: sequential earnings expansion, loan and deposit growth, a net charge-off ratio of 0.29% that outperformed prior guidance, robust capital buffers, and the pending closing of the BMO branch acquisition.78 Leadership raised full-year fee income guidance to between $2.14 billion and $2.22 billion, lowered expected non-interest expenses to between $5.34 billion and $5.41 billion, reaffirmed net interest income guidance of $6.60 billion to $6.75 billion, and reiterated a targeted 2026 adjusted efficiency ratio in the low-60% range.8
Analyst questioning focused on three core operational areas, highlighting key areas of market scrutiny.
Margin sustainability. Analysts questioned whether recent net interest margin performance could be sustained. Executive leadership offered a measured response, projecting a flat net interest margin for the third quarter under its baseline scenario rather than extrapolating short-term expansion.8
Deposit competition. CFO Craig Nix characterized market competition for liquidity as exceptionally intense, pointing to marginal deposit costs exceeding 4% in the Direct Bank platform and noting that rival interest rate pricing had reached unsustainable levels.8 This candid assessment acknowledged the broader reality: defending low-cost funding in a competitive rate environment requires ongoing pricing discipline.
Credit. Despite reporting quarterly charge-offs below guidance, management explicitly cautioned that credit losses in general office real estate and investor-dependent commercial portfolios would likely persist over the medium term.8 Acknowledging ongoing portfolio stress alongside favorable quarterly metrics demonstrated a pragmatic risk assessment.
On regulatory capital requirements, leadership declined to offer detailed projections regarding Basel III endgame rules pending final regulatory publication.8 While standard for institutions navigating evolving standards, the regulatory framework remains an unquantified consideration for a bank operating within the enhanced prudential supervision threshold.
Consistency Assessment
From 2023 through 2026, management adhered consistently to its stated capital deployment hierarchy: systematically retiring the FDIC purchase money note, repurchasing shares while capital levels exceeded targets, moderating buybacks as the Common Equity Tier 1 ratio approached the 10.0% to 10.5% target range, and maintaining conservative underwriting standards. The execution sequence—comprising $2.50 billion in note prepayments in the fourth quarter of 2025, $5.00 billion during the first half of 2026, $1.00 billion in July 2026, projected prepayments of $6 billion to $8 billion in the third quarter of 2026, and share repurchases stepping down from $600 million in the second quarter to a guided $300 million in the fourth quarter—aligned directly with executive commitments.716178
This alignment between strategy and execution highlights management's operational discipline. By fulfilling capital deployment commitments and addressing competitive dynamics transparently, executive leadership has established credibility in its forward guidance.
However, consistent execution does not insulate the institution from broader structural challenges and market headwinds.
XI. Bear vs. Bull Case & Core Risk Radar
The Bull Case
A permanently expanded capital base. The $9.81 billion after-tax gain roughly doubled tangible book value, and First Citizens has since built upon that higher baseline—tangible book value per share expanded 11% in 2025 even as reported earnings contracted.418 Book value compounding while purchase accounting accretion unwinds indicates that the underlying bank is actively generating capital rather than merely recognizing accounting adjustments.
A specialty commercial franchise acquired at a discount. The $16.5 billion purchase discount on acquired loans and the five-year FDIC loss-share arrangement lower the credit threshold needed for the transaction to generate positive economics below typical underwriting standards.1 Meanwhile, the commercial technology franchise is demonstrating its first sustained loan growth since the acquisition.8
Proven integration capabilities and active branch expansion. The acquisition of 138 BMO branches converted on schedule in September 2026, securing low-cost retail deposits during a period of elevated marginal funding costs.148 Industry consolidation remains an ongoing secular trend, and First Citizens possesses a repeatable operational playbook to absorb additional networks.
Disciplined capital deployment. The company executed more than $6 billion in share repurchases, established a clear Common Equity Tier 1 capital target corridor of 10.0% to 10.5%, and outlined a transparent step-down in buyback volume rather than running an unconstrained repurchase program.78
Structural flexibility during downturns. Despite governance trade-offs, dual-class share ownership insulates management from short-term market pressures, enabling the bank to maintain liquidity and deploy capital counter-cyclically during systemic disruptions when traditional peers contract.
The Bear Case
Funding advantages face structural pressure. An average total deposit cost of 2.07%, a non-interest-bearing deposit share that contracted to 24.5%, marginal digital funding costs exceeding 4%, and executive assessments describing deposit competition as fierce highlight emerging pressure on the bank's core liability advantage.78
Cyclical vulnerability in venture and technology lending. Demand within Global Fund Banking directly tracks private market deal velocity. Extended downturns in venture capital and private equity fundraising simultaneously constrain capital call facility utilization, venture loan originations, warrant valuations, and fee income streams, as demonstrated by stagnant activity between 2023 and 2025.
Ongoing commercial real estate credit headwinds. Executive guidance projects that credit losses in general office and investor-dependent commercial portfolios will persist over the medium term.8 Nonaccrual loans stood at 0.96% of total loans alongside an allowance for credit losses of 0.98% at mid-2026, indicating adequate coverage for a loan portfolio still navigating structural shifts in office demand.7
Governance constraints limit valuation multiples. The lack of voting recourse for public equity holders, executive positions held by family members without publicly disclosed succession plans, and operational complexity across diverse business lines lead institutional investors to maintain a persistent valuation discount.
Heightened regulatory oversight. With total assets exceeding $225 billion, First Citizens faces enhanced prudential standards, formal stress testing, and elevated liquidity requirements, while pending Basel III endgame rules remain unquantified by executive leadership.78
Earnings normalization remains incomplete. Contraction in 2025 net income and diluted earnings per share was driven primarily by declining purchase accounting accretion, leaving the nine-basis-point spread between reported and adjusted net interest margins as a fading tailwind.187
Risk Radar
Deposit cost inflation represents the highest-impact vulnerability, directly compressing net interest margins as client funding reprices.
Private market deal volume serves as the primary growth variable, dictating whether the acquired venture and technology units expand or stabilize.
Commercial real estate workout speed remains a measured risk, backstopped by visible allowance coverage and explicit executive loss projections.
Evolving regulatory standards introduce unquantified policy uncertainty as final capital rules take shape.
Integration retention on BMO deposits presents a near-term execution test, determining whether retail accounts across Midwest and Western markets remain stable following conversion.
So What
The long-term investment case for First Citizens no longer hinges on the extraordinary terms of the 2023 transaction; those gains are recognized and embedded in tangible book value. The central question is whether a well-capitalized institution with proven integration capabilities can compound book value through a standard economic cycle while defending net interest margins against intensifying funding competition.
The evidence indicates that First Citizens possesses the operational capability to manage an enlarged balance sheet effectively. However, the record does not demonstrate an unassailable economic moat over well-managed regional peers during routine operating conditions. The bank's primary strategic advantage remains episodic: deploying balance sheet capacity and regulatory standing when financial dislocations occur.
XII. Playbook: Lessons for Founders, Investors & Banking Executives
Lesson 1: The capacity to act is a strategic asset, and it must be paid for in advance. First Citizens' ability to buy in 2009 and 2023 was purchased with two decades of accepting lower returns than peers. Optionality is not free and does not arrive on demand. The uncomfortable corollary: most of the time, a balance sheet built for a crisis resembles underperformance, and there is no reliable way to distinguish prudence from timidity until the crisis arrives.
Lesson 2: Regulatory trust is real, slow to build, and has limits. More than twenty clean failed-bank resolutions bought a seat at the table for a $110 billion transaction. But those same regulators took fifteen months to approve a $2.2 billion merger, demonstrating that supervisory standards escalate with asset size.10 Regulatory trust secures consideration; it does not grant waivers.
Lesson 3: Structure the downside, then let the upside take care of itself. Every key term of the SVB transaction was a downside risk control: the $16.5 billion purchase discount, the FDIC loss-share arrangement, and the fixed-rate seller note.12 The $9.81 billion bargain purchase gain was the mathematical residual of those structural protections, not a speculative bet on rapid economic recovery. Transactions requiring optimism to succeed belong to a fundamentally different asset class than transactions structured to perform unless severe unexpected disruptions occur.
Lesson 4: Capability must exist before opportunity arrives. First Citizens could not have absorbed SVB in 2023 without the national commercial banking infrastructure, regulatory clearances, and $100 billion-scale operating platform established through its earlier CIT merger—a transaction that appeared costly and complex at the time. Infrastructure built for one strategic objective renders unplanned opportunities executable.
Lesson 5 — the unadvertised reality: verify what was actually purchased. Popular narratives frame the acquisition as acquiring SVB's low-cost deposit franchise. In reality, First Citizens acquired roughly a third of that deposit base at prevailing market rates, subsequently defending those balances against aggressive nationwide competition. The primary value resided in the discounted loan portfolio and institutional client relationships. Distinguishing the specific assets purchased from popular headline descriptions remains the core discipline of transactional analysis.
XIII. Epilogue & Key KPIs to Watch
In September 2026, First Citizens Bank completed the conversion of 138 branches across Illinois, Kansas, Missouri, Arizona, and neighboring markets—locations where the signage had read BMO the previous week, and Harris or Marshall & Ilsley in earlier eras.14 The transition proceeded without operational disruption, with deposits opening on Monday where they had closed on Friday. It marked more than the twentieth time the institution had executed its integration playbook, albeit with a willing commercial seller rather than a bank receiver.
That narrative arc defines the company's evolution: a bank that originated in an eastern North Carolina agricultural community in 1898, adopted a conservative liquidity culture during the Great Depression, insulated its leadership from short-term market pressures through dual-class control in 1986, spent a decade acquiring failed community institutions, expanded national scale through a 15-month commercial merger, and ultimately executed the largest distressed bank transaction of the decade over a single weekend in March 2023.
The outcome is an institution holding more than $225 billion in total assets: combining a conventional retail network, a specialized commercial technology division facing aggressive competition, an equipment leasing fleet, majority voting control held by a founding family, and roughly $28 billion in seller debt remaining on the FDIC note.7 The initial accounting windfall has been recognized; the central question is whether the expanded balance sheet can compound capital through traditional operating channels.
The Three Metrics That Matter
1. Net interest margin excluding purchase accounting accretion. This metric provides the clearest view of core operational earning power. First Citizens reported a net interest margin of 3.10% for the second quarter of 2026, while the margin excluding purchase accounting accretion stood at 3.01%, unchanged from the previous quarter.7 As the accretion tailwind unwinds toward zero, the stability of the adjusted margin will indicate whether the bank's retail deposit base can continue offsetting broader funding cost pressures.
2. Tangible book value per share growth. In the absence of a substantial dividend payout or shareholder recourse to alter corporate governance, tangible book value growth serves as the primary measure of long-term value creation. Tangible book value per share expanded 11% in 2025 even as reported earnings contracted—demonstrating organic capital accumulation distinct from non-recurring accounting gains.18
3. SVB Commercial loan growth paired with non-interest-bearing deposit share. These metrics must be evaluated in tandem. Expanding loan volumes without stabilizing low-cost deposit balances indicates that commercial growth is being financed through higher-cost liabilities, reducing long-term franchise value. Conversely, stabilizing non-interest-bearing deposit share while maintaining loan expansion across Global Fund Banking and Tech and Healthcare Banking would demonstrate that core client relationships remain intact. As of mid-2026, commercial loan originations were expanding, whereas non-interest-bearing deposit balances continued to contract.78
Secondary factors—including rail fleet utilization, share repurchase volume, and the FDIC note repayment schedule—remain subsidiary to these three core indicators.
The distinguishing feature of First Citizens is not an unexpected windfall, but an institutional capital structure designed for multi-decade patience that enabled a single weekend's decisive expansion. Moving forward, executive leadership must demonstrate that this enlarged enterprise can deliver durable operating performance without relying on crisis-era asset discounts.
References
-
FDIC Enters into Purchase and Assumption Agreement with First Citizens Bank & Trust Company for Silicon Valley Bridge Bank, N.A. — Federal Deposit Insurance Corporation, 2023-03-27 ↩↩↩↩↩↩↩↩
-
First Citizens Agrees to Buy Silicon Valley Bank Deposits and Loans — Reuters, 2023-03-27 ↩↩↩
-
First Citizens BancShares Reports First Quarter 2023 Earnings — PR Newswire / First Citizens BancShares, 2023-04-26 ↩↩↩
-
First Citizens BancShares Reports Fourth Quarter 2023 Earnings — PR Newswire / First Citizens BancShares, 2024-01-26 ↩↩↩↩↩↩
-
First Citizens to Buy Silicon Valley Bank, FDIC Says — The Wall Street Journal, 2023-03-27 ↩
-
First Citizens' Stupendous Silicon Valley Bank Deal — Financial Times, 2023-03-28 ↩
-
First Citizens BancShares Reports Second Quarter 2026 Earnings — First Citizens BancShares Newsroom, 2026-07-23 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Earnings Call Transcript: First Citizens Posts Strong Q2 2026 Profit Beat — Investing.com, 2026-07-23 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
First Citizens BancShares Form DEF 14A Definitive Proxy Statement — SEC EDGAR, 2024-03-18 ↩↩↩↩
-
Federal Reserve Board Approves Merger Application of First Citizens BancShares, Inc. and CIT Group Inc. — Board of Governors of the Federal Reserve System, 2021-12-17 ↩↩↩↩↩
-
First Citizens BancShares Form 10-K Annual Report for FY2025 — SEC EDGAR, 2026 ↩↩↩
-
First Citizens Plans to Keep CIT's Railcar Business Rolling — American Banker ↩
-
First Citizens to Acquire 138 BMO Branches — Banking Dive, 2025-10-16 ↩↩
-
First Citizens Bank Completes Branch Acquisition, Expanding Presence Across the Midwest, Great Plains and West — First Citizens BancShares Newsroom, 2026-09-08 ↩↩↩↩↩↩↩
-
First Citizens BancShares Second Quarter 2026 Investor Presentation — SEC EDGAR, 2026-07-23 ↩
-
First Citizens Says It's Repaid $8.5B Tied to SVB Acquisition — American Banker, 2026 ↩↩
-
First Citizens Projects $6B–$8B FDIC Note Paydown in Q3 2026 Backed by BMO Branch Acquisition — Seeking Alpha, 2026-07-23 ↩↩
-
First Citizens BancShares Reports Fourth Quarter 2025 Earnings — PR Newswire / First Citizens BancShares, 2026-01 ↩↩↩↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube