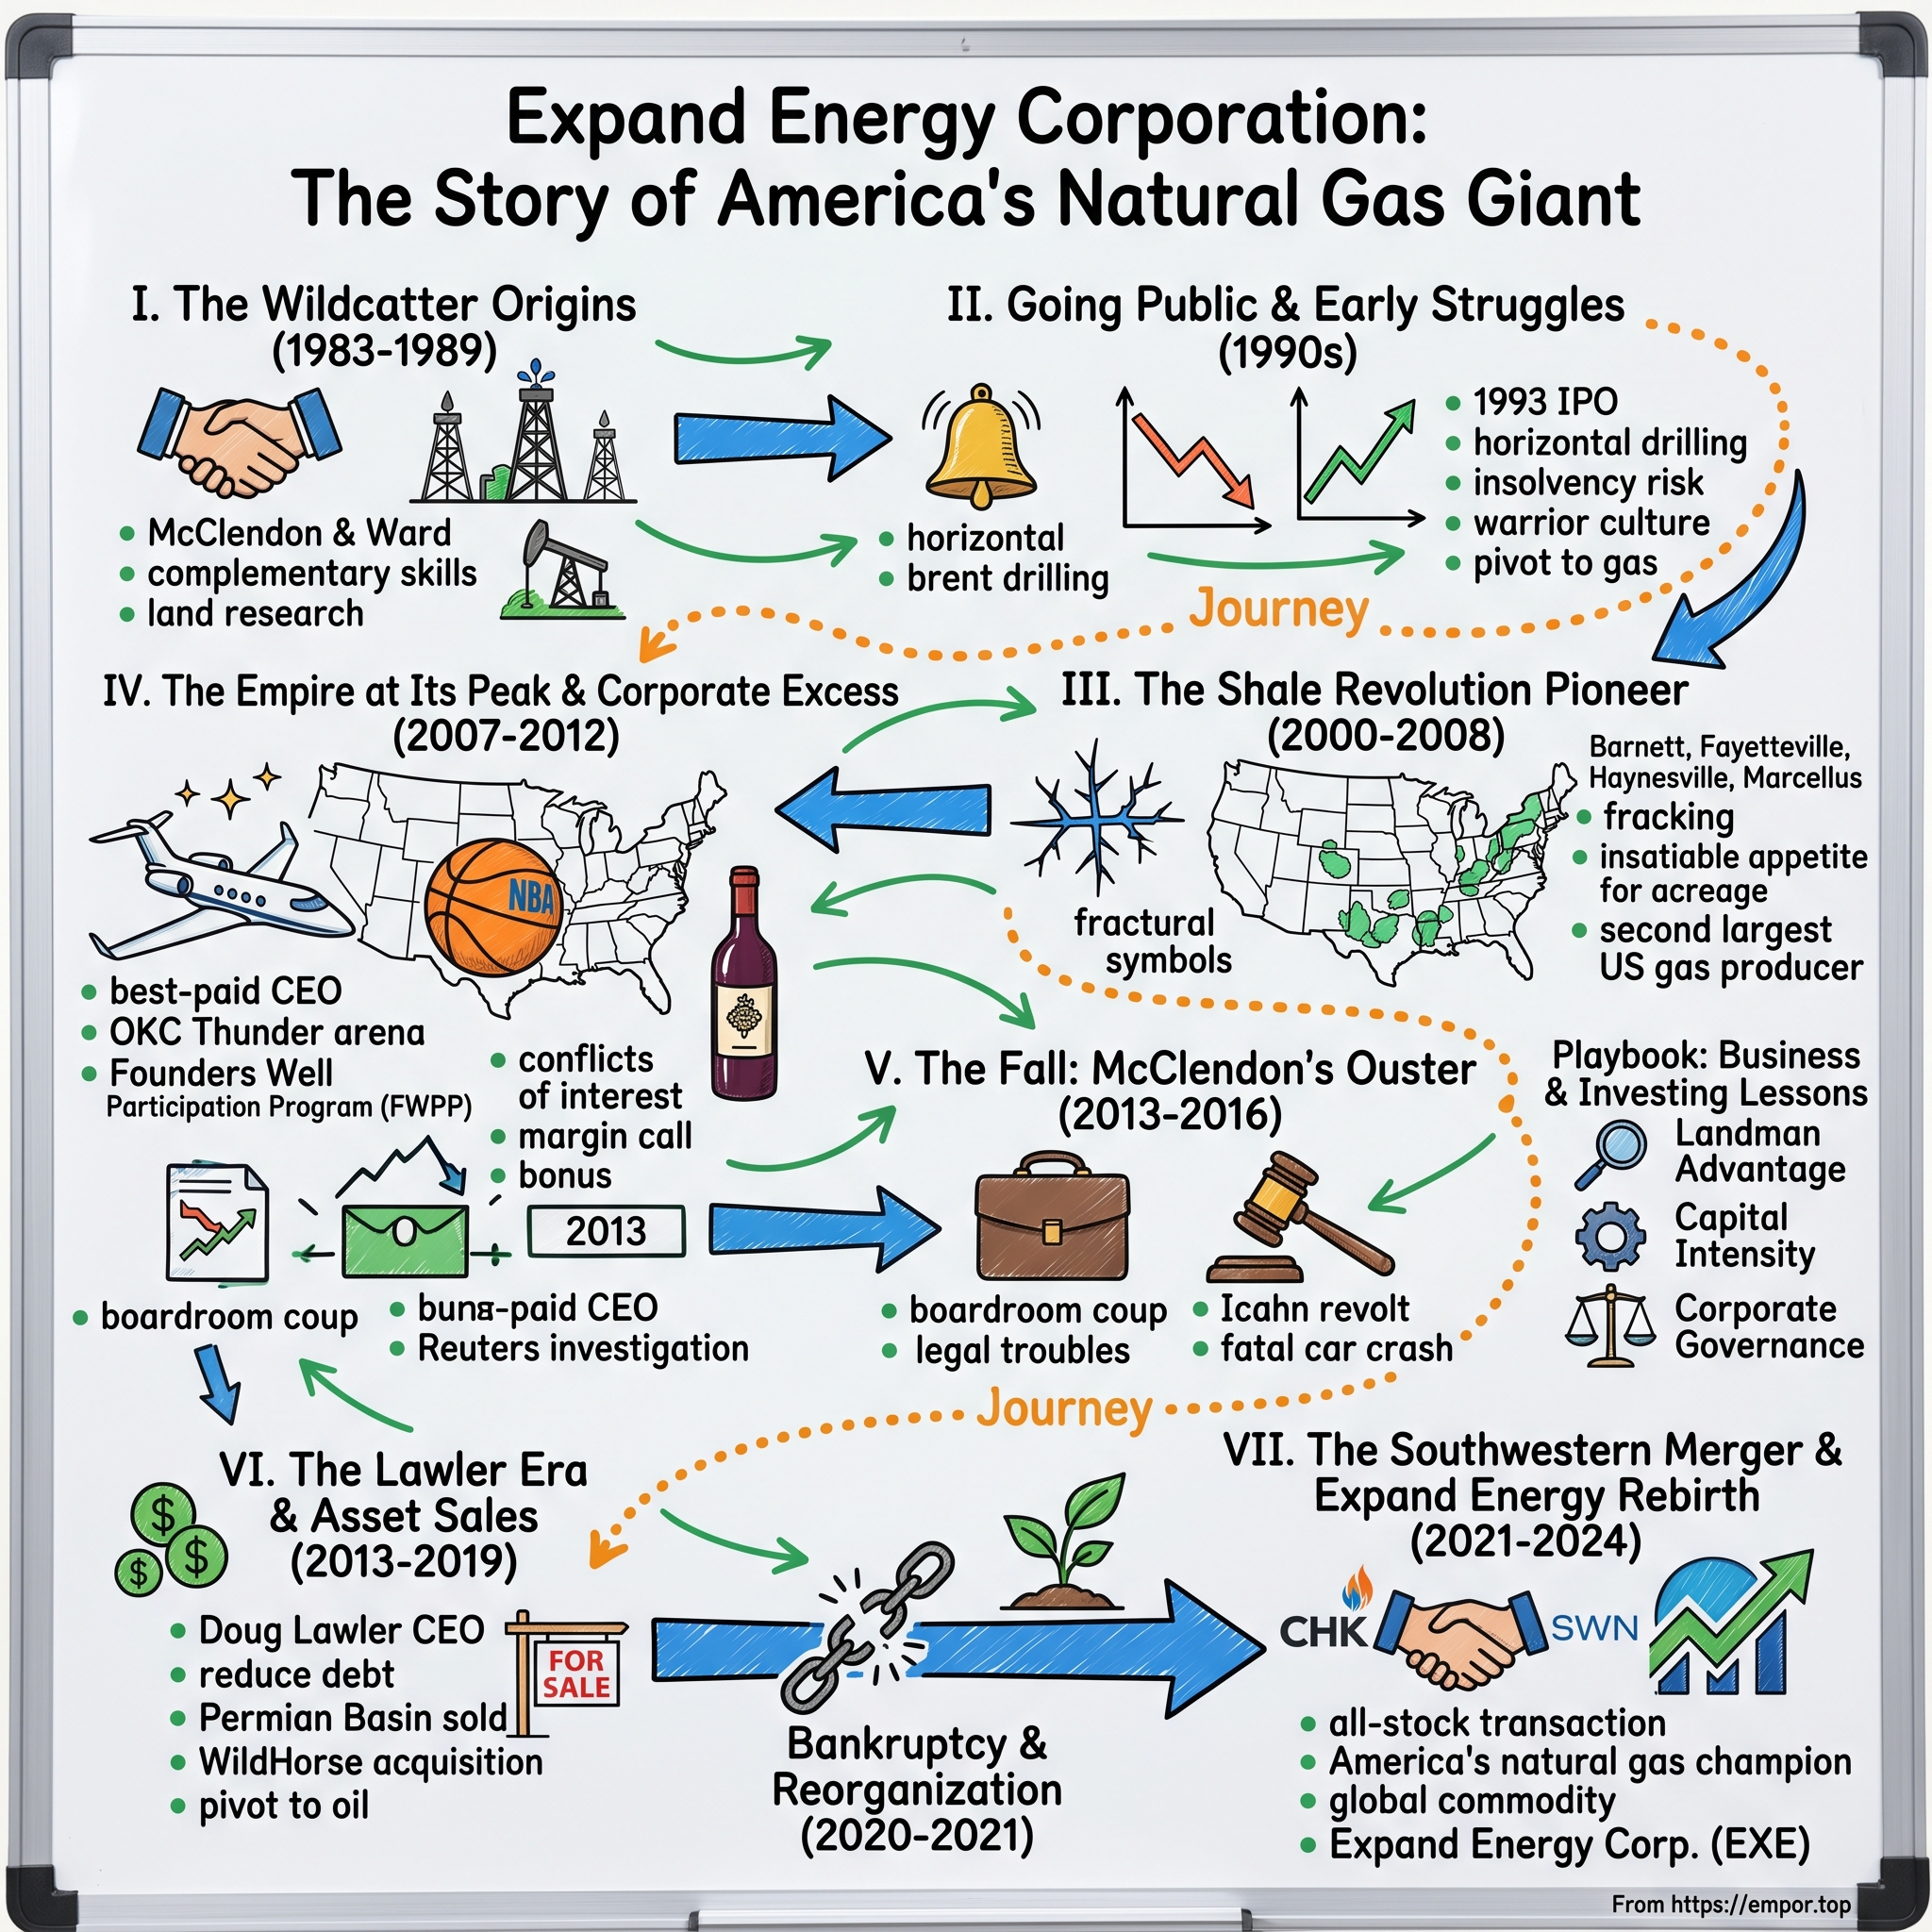
Expand Energy Corporation: The Story of America's Natural Gas Giant
I. Introduction & Episode Roadmap
On the morning of October 1, 2024, the company that spent thirty-five years operating as Chesapeake Energy retired its corporate name and CHK stock ticker. In its place on the NASDAQ, a new symbol began trading: EXE. The renamed company, Expand Energy Corporation, had just closed a roughly $7.4 billion all-stock merger with Southwestern Energy, creating the largest independent natural gas producer in the United States with combined output of approximately seven billion cubic feet per day.[^1]1
Rebrands are often cosmetic, but this name change marked a deliberate attempt to distance the business from a turbulent corporate legacy.
The entity behind the new ticker carried one of the most dramatic boom-and-bust records in American corporate history. Founded in 1989 by two entrepreneurs in their twenties with $50,000 in seed capital, the firm briefly reached a $35 billion market valuation in 2008 as the nation's second-largest natural gas producer. It pioneered the aggressive land-leasing model that unlocked U.S. shale resources, but accumulated overwhelming debt in the process. A decade of financial strain culminated in a June 2020 Chapter 11 filing — the year's largest exploration-and-production bankruptcy — which eliminated more than $7 billion in debt obligations and virtually wiped out equity holders.32
The central question facing the company is not merely how it achieved scale, but whether a business historically defined by aggressive leverage, out-of-cash-flow spending, and founder-driven expansion can credibly operate as a disciplined, low-cost producer focused on free cash flow. If that transformation holds, a secondary question emerges: does this newly combined scale confer a true competitive advantage, or simply size?
This question is particularly relevant in 2026, as natural gas sits at the intersection of two major demand drivers in the industrial economy: the expansion of U.S. Gulf Coast liquefied natural gas export terminals pulling gas toward Louisiana and Texas, and rising power demand from artificial intelligence data centers straining regional electric grids such as PJM and MISO.76 Expand Energy is positioned directly across both trends, holding low-cost dry gas acreage in the Marcellus Shale alongside Haynesville acreage located near Gulf Coast export hubs.
Four central themes define this business analysis.
First is the paradigm shift in exploration and production. From 2005 to 2019, the U.S. shale sector prioritized volume growth over capital discipline, destroying significant investor capital. Surviving operators now compete on inventory depth, unit costs, and capital return to shareholders. Expand Energy represents a clear large-cap test of this model, driven partly by strategic pivot and partly by the restructuring mandates of its bankruptcy.
Second is basin economics. Expand Energy operates a two-basin portfolio with distinct operating dynamics: Appalachian assets offer low extraction costs but face takeaway constraints, while Haynesville acreage carries higher drilling costs but provides direct transport access to Gulf Coast buyers. These geographic trade-offs form the core of the company's valuation thesis.
Third is commercialization — the midstream optimization, marketing, and transportation capacity that management expanded, culminating in the September 2026 acquisition of Twin Eagle.[^16] Management's core thesis assumes that in a commoditized market, controlling physical takeaway and delivery generates durable margin rather than negligible cost adjustments.
Fourth is governance — specifically, whether the capital allocation discipline instituted following the 2021 emergence from bankruptcy represents a permanent structural change or a temporary response to market conditions.
Examining that question requires returning to the company's origins and a $50,000 initial investment in Oklahoma City.
 Subscribe on LinkedIn
II. Wildcatter Origins, The Land Grab & Peak Empire (1983–2012)
Aubrey McClendon measured success in acreage — not barrels of oil, and not cash flow. The great-nephew of an Oklahoma governor and a Duke University graduate, McClendon returned to Oklahoma City in the early 1980s to work as a landman: negotiating with property owners, checking county deed records, and securing mineral rights under farmland. Though among the least technical roles in the energy sector, controlling access to prospective land proved to be one of its most lucrative functions.
When McClendon co-founded Chesapeake Energy in 1989 alongside fellow landman Tom L. Ward, the pair was still in their late twenties. The company went public four years later in 1993 at a valuation of approximately $25 million — a microcap firm drilling early horizontal wells in Oklahoma's Golden Trend, years before horizontal drilling became an established industrial standard.
The company's first financial crisis arrived quickly. By 1997, underperforming wells in the Austin Chalk play forced a write-down exceeding $200 million, bringing the firm to the brink of collapse. That early setback established a recurring pattern: Chesapeake's core vulnerability was rarely an inability to identify productive geology, but rather an inability to finance its aggressive land acquisitions. The company was consistently early to top-tier acreage and consistently over-leveraged when it arrived.
The land grab. The onset of the U.S. shale revolution both rescued and ultimately endangered Chesapeake. By pairing long horizontal wells with multi-stage hydraulic fracturing — drilling downward two miles, steering laterally, and fracturing dense rock along horizontal runs — operators transformed tight source rock into commercially viable reservoirs. For landmen, this created unprecedented land arbitrage: marginal farmland previously valued at $100 per acre soared to thousands of dollars per acre once designated as drillable shale inventory.
Chesapeake outpaced competitors in securing land, leading aggressive leasing campaigns across the Barnett Shale in Texas, the Fayetteville in Arkansas, the Marcellus in Appalachia, and the Haynesville in Louisiana. Management operated a circular funding model: purchase vast acreage with debt, drill initial wells to demonstrate commercial potential, sell partial working interests to major international oil companies at steep markups, and recycle the proceeds into additional land. In a rising commodity market, this strategy functioned like a high-leverage real estate development enterprise.
By mid-2008, the strategy reached its peak. Chesapeake's stock climbed above $65 per share, pushing its market capitalization beyond $35 billion. McClendon ranked among the highest-paid corporate executives in the United States, constructing an expansive corporate campus in Oklahoma City, acquiring an ownership stake in the NBA's Oklahoma City Thunder, and amassing a wine collection later auctioned during subsequent bankruptcy proceedings.
The governance breakdown. Behind the growth, structural governance issues began to surface. Under a unique board arrangement known as the Founders Well Participation Program, McClendon held the right to co-invest personally for a 2.5 percent working interest in every well Chesapeake drilled. To fund his share, McClendon pledged those interests as collateral, eventually borrowing up to $1.1 billion in personal loans secured by the very wells his public company chose to drill.
This structure created a severe misalignment of executive incentives. A chief executive officer borrowing heavily against well participation possessed a direct financial incentive to maximize overall well count and drilling activity, regardless of whether marginal wells earned their cost of capital. McClendon's private financial liabilities diverged from shareholder interests, leaving corporate capital deployment tied to personal leverage.
Corporate financing became equally opaque. Chesapeake relied on volumetric production payments — pre-selling future natural gas production for immediate cash upfront — alongside complex commodity hedges and long-term midstream transport commitments. Because many of these off-balance-sheet arrangements and future drilling commitments were excluded from headline debt metrics, reported leverage underrepresented the company's true total financial obligations.
Underlying this expansion was a fundamental cash flow deficit: between 2008 and 2012, Chesapeake consistently generated negative free cash flow, spending far more on capital expenditures and leasing than it generated from operations. The company closed this capital gap through continuous asset sales and debt issuance. That funding model relied on two assumptions: sustained high natural gas prices and uninterrupted access to capital markets. Rapid shale gas production growth after 2008 depressed commodity prices, and when natural gas prices collapsed below $2 per million British thermal units in 2012, capital market access narrowed rapidly.
The board of directors that had authorized these financing structures soon faced intense shareholder pressure.
III. Governance Breakdown, Empire Collapse & Bankruptcy Reset (2013–2021)
The revolt came from two directions at once. Carl Icahn, who had accumulated a major position in the stock, and Southeastern Asset Management's Mason Hawkins, the company's largest shareholder, applied coordinated pressure through late 2012 as details of the well-participation loans became public. The board stripped McClendon of his chairmanship, and in April 2013 he resigned as chief executive of the company he had founded 24 years earlier.
He did not step away from energy development. McClendon immediately launched American Energy Partners, raising billions of dollars to replicate his high-leverage leasing model. Then, on March 1, 2016, a federal grand jury in Oklahoma indicted him on charges of conspiring to rig bids for oil and gas leases in northwestern Oklahoma between roughly 2007 and 2012, alleging that he had orchestrated an arrangement in which competing companies agreed not to bid against each other at lease auctions.[^6] The following day, McClendon died when his vehicle struck a concrete bridge abutment at high speed. He was 56. The medical examiner did not rule the death a suicide, and the charges were dismissed following his death, leaving the allegations untested.
The Lawler years. McClendon's successor was Doug Lawler, a former Anadarko engineer with a clear directive: stop the financial bleeding. Lawler cut headcount, sold corporate assets, unwound costly midstream commitments, and systematically reduced total leverage over several years. In 2014, he sold a major southern Marcellus and Utica shale position to Southwestern Energy for roughly $5 billion — a transaction carrying notable retrospective irony given the companies' eventual merger.
However, Lawler made a strategic acquisition that proved financially disastrous. In late 2018, Chesapeake agreed to acquire WildHorse Resource Development, an Eagle Ford oil producer in southeast Texas, in a cash-and-stock deal valued at roughly $4 billion including assumed debt.4 The strategic logic reflected the era's industry consensus: with natural gas prices depressed by shale oversupply, expanding into higher-margin crude oil would improve revenue realizations.
While the strategic rationale was defensible, the financial timing was flawed. The transaction failed to deleverage the balance sheet, adding oil exposure atop an already heavy debt load when crude traded near $70 per barrel. Sixteen months later, in early 2020, the COVID-19 pandemic crippled global demand, sending West Texas Intermediate crude futures briefly below zero. Chesapeake reported a first-quarter loss of roughly $8.3 billion, driven overwhelmingly by impairments on the assets it had bought at the market peak.2
Chapter 11. On June 28, 2020, Chesapeake Energy filed for Chapter 11 protection in the Southern District of Texas.3 The company secured $925 million in debtor-in-possession financing as it entered court proceedings burdened by more than $9 billion in total debt.
The restructuring was completed swiftly. Chesapeake emerged from bankruptcy in February 2021 after eliminating more than $7 billion of funded debt, converting creditors into new equity holders and erasing pre-petition equity.2 This financial reset underpins the modern company's cost structure. While management highlights ongoing operational improvements, Expand Energy's low cost baseline stems significantly from shedding historical capital liabilities through court restructuring. Bankruptcy served as a debt-clearing mechanism: court proceedings reduced financial claims on the company's assets without altering the underlying geology.
In September 2021, a reconstituted board chaired by restructuring specialist Michael Wichterich elevated Chief Financial Officer Nick Dell'Osso to chief executive. Dell'Osso was an insider who had served as CFO throughout Chesapeake's decline since 2010. The board reasoned that an executive who had observed the mechanism of financial distress from the finance seat would be uniquely disciplined in avoiding a repeat.
Dell'Osso received a strict mandate: focus exclusively on natural gas, eliminate speculative exploration, and return capital to shareholders rather than reinvesting it. What followed was the systematic divestment of non-core assets to align the enterprise around low-cost natural gas production.
IV. The Post-Bankruptcy Blueprint & Asset Pruning (2021–2023)
Throughout 2023, Chesapeake executed a complete exit from the Eagle Ford, selling its crude oil assets across three separate transactions for approximately $3.5 billion in total proceeds.[^8] Staggering the sales across multiple buyers suggested management prioritized asset pricing over speed, though limited disclosure regarding individual transaction economics made evaluating per-asset value capture difficult.
Strategically, the divestment streamlined Chesapeake from a multi-asset operator into a focused two-basin natural gas producer. Crude oil and natural gas compete for capital on distinct commodity cycles; maintaining oil assets within a gas-focused firm created internal friction over capital deployment. By exiting the Eagle Ford, management eliminated that allocation conflict while recycling capital from an acquisition made near the 2018 crude market peak back into core inventory where the company possessed existing scale.
The full financial accounting of the WildHorse transaction underscores the strategic reset. Having acquired the assets for roughly $4 billion in 2018 before filing for Chapter 11 in 2020, Chesapeake recovered about $3.5 billion through its 2023 divestments alongside interim operational cash flows. While not a complete loss of principal, the transaction proved flawed in market timing, balance-sheet impact, and strategic alignment—providing a critical benchmark for evaluating the company's subsequent consolidation decisions.
Deferred completions. Alongside asset sales, management introduced a flexible operational strategy centered on deferred completions.
In shale operations, drilling and completion are distinct steps. An operator can drill and case a wellbore without performing the hydraulic fracturing and pipeline connection required to initiate production. The industry terms such a well a drilled-but-uncompleted well, or DUC, and refers to bringing it online as a turn-in-line. Historically, producers maintained a continuous drilling-and-completion schedule to avoid paying for idle equipment and contracted crews.
Chesapeake departed from this standard rhythm by deliberately accumulating an inventory of DUCs, holding capacity offline until market prices justified bringing wells online. Management likened this approach to an underground storage facility, framing uncompleted wells as gas preserved in the rock rather than sold into depressed shoulder-season markets around $1.80 per million British thermal units.[^10]5
This operational flexibility involves clear financial trade-offs. Deferring completions leaves roughly 35 to 40 percent of total well capital tied up in the ground generating no immediate cash flow. However, in a market marked by sharp seasonal price swings, retaining the option to time market entry holds tangible value. The practice gained credibility when management actively curtailed production during weak-price periods, accepting lower quarterly output rather than producing into low-margin spot markets to hit short-term volume targets.
Yet curtailment has structural limits. Unilateral supply reductions support broader market prices only if industry-wide volumes adjust. Even as the nation's largest natural gas producer, Expand Energy accounts for well under ten percent of total U.S. dry gas production. As a result, its curtailments cannot set Henry Hub benchmark pricing; they function to optimize the company's own realized margins at the edge rather than dictate market conditions.
Responsibly sourced gas. The third element of the post-bankruptcy strategy centered on environmental certification. Chesapeake obtained independent certification across its Marcellus and Haynesville operations under MiQ and Equitable Origin standards, targeting a methane emissions intensity below approximately 0.02 percent of produced volumes.[^9]
To date, certification serves primarily as a market-access requirement rather than a premium pricing driver. International buyers and liquefied natural gas offtakers increasingly demand verified low-emissions supply, making certification necessary to maintain access to premium export buyers. Because company disclosures show no consistent per-unit price premium for certified gas, environmental standards represent commercial risk mitigation rather than a direct margin enhancer.
By late 2023, the operational reset was complete: Chesapeake was focused on a single commodity across two core basins, backed by a deleveraged balance sheet and a commitment to capital discipline. The remaining strategic question was how management would leverage this rebuilt foundation—an answer that arrived early the following year.
V. The $7.4B Southwestern Mega-Merger: Mechanics & Comps (2024)
On January 11, 2024, Chesapeake and Southwestern Energy announced an all-stock merger valued at approximately $7.4 billion, under which Southwestern shareholders received 0.0867 Chesapeake shares for each share of Southwestern stock.1 The exchange ratio gave Chesapeake shareholders roughly 60 percent ownership of the combined entity, leaving Southwestern investors with the remaining 40 percent.1
The timing of the deal was counterintuitive. Henry Hub spot prices spent the first half of 2024 in the low two-dollar range per million British thermal units—dipping at points below two dollars, among the weakest real natural gas prices in decades.6 Announcing the sector's largest transaction at a cyclical trough reflected either strong conviction in long-term demand recovery or a recognition by both boards that operating scale was their best remaining lever.
The structural logic was straightforward. Chesapeake brought primary scale in the Haynesville along with a major Marcellus position, while Southwestern held primary scale in Appalachia alongside its own Haynesville acreage. Rather than overlapping within a single basin—the typical formula for exploration and production mergers seeking contiguous land—the two portfolios functioned as geographic complements.
The synergy claim. Management targeted approximately $500 million in annual run-rate synergies within two years of closing, divided across three main categories: corporate administrative consolidation, capital efficiency from operating fewer rigs over longer lateral wells, and commercial savings from midstream and marketing optimization.1
Evaluating those synergy targets requires distinguishing between contractual cost cuts and operational estimates. General and administrative savings in a corporate combination are largely mechanical: consolidating corporate headquarters, board seats, legal fees, and enterprise software systems generates predictable reductions. Capital efficiency savings are plausible but harder to measure independently because they rely on counterfactual baseline assumptions. Expanding average lateral lengths—targeting distances above 11,000 feet compared with historical averages closer to 8,000 feet—reduces costs per foot by spreading fixed drilling expenses across a larger volume of producing rock, though the resulting savings represent projections rather than verified accounting totals. Commercial optimization represents the most speculative synergy bucket.
Investor skepticism stems less from the underlying math than from historical precedents. Chesapeake's previous major transaction—the 2018 acquisition of WildHorse Resource Development—was presented as a balance-sheet enhancer but ultimately accelerated its 2020 bankruptcy. Material structural differences distinguish the two deals: WildHorse was a cash-and-stock transaction funded by a heavily levered balance sheet at a cyclical oil peak in an unfamiliar basin, whereas Southwestern was an all-stock transaction executed on a deleveraged balance sheet at a natural gas price trough within familiar basins. While these structural differences significantly reduce balance-sheet risk, a safer transaction structure does not automatically guarantee full synergy capture.
The key test of execution will be whether unit operating metrics—specifically cash administrative expenses and lease operating costs per thousand cubic feet equivalent—show durable declines relative to pre-merger baselines as full run-rate savings are expected by late 2026.[^15] If unit costs fail to meet those targets, the projected $500 million in savings will have proven to be a theoretical modeling exercise.
Valuation context. At closing, the combined enterprise held a total enterprise value in the mid-20 billion dollar range against an equity value of approximately $17 billion, implying forward enterprise value to EBITDAX multiples in the mid-single digits at prevailing strip prices. These valuation metrics aligned closely with peers such as EQT following its acquisitions of Tug Hill and Equitrans, as well as Coterra Energy's blended trading multiple.[^1]1 Independent natural gas producers rarely command high growth multiples; public markets evaluate them primarily on free cash flow yield and inventory duration, pricing the equities as depleting asset bases defined by how long low-cost reserves will last.
The shape of the combined company. Following the transaction's close on October 1, 2024, the combined entity produced roughly seven billion cubic feet of natural gas per day across two distinct geographic hubs.[^1] The Appalachian Basin accounts for the larger share, producing approximately four billion cubic feet per day across more than one million net acres in Pennsylvania and West Virginia, and generating the majority of corporate earnings due to North America's lowest extraction costs. The Gulf Coast region contributes roughly three billion cubic feet per day across several hundred thousand net acres in Louisiana and East Texas, where higher extraction costs are offset by direct proximity to export markets.
This operational asymmetry—low-cost gas subject to regional takeaway constraints alongside higher-cost gas positioned adjacent to Gulf Coast demand centers—defines the company's core asset strategy.
VI. Core Operational Engine & Basin Economics: Marcellus vs. Haynesville
Comparing a well pad in Washington County, Pennsylvania, with one in DeSoto Parish, Louisiana, reveals two distinct operational models producing the exact same commodity.
The Marcellus: the cheapest rock, the worst address. The Marcellus shale sits at depths of roughly 5,000 to 8,000 feet, featuring moderate pressure and a thick, laterally continuous reservoir across an expansive footprint. Operationally, these characteristics make wells relatively inexpensive to drill, gentle on surface equipment, and highly predictable. Operators deploy multi-well "super-spec" pads—drilling six, eight, or twelve horizontal wells from a single surface location to share roads, water infrastructure, and processing equipment—with lateral lengths routinely exceeding 12,000 feet. This structural efficiency yields the lowest full-cycle supply cost of any major natural gas play in North America, generating NYMEX-equivalent breakevens that management and third-party analysis place below roughly $1.50/Mcf.[^9]6
If low extraction costs were the sole variable, Appalachia would represent an unrivaled natural gas business. The governing constraint, however, is transportation.
The benchmark Henry Hub spot price reflects delivery at Erath, Louisiana. Natural gas produced in Pennsylvania is worth Henry Hub pricing minus the transportation cost to reach liquid demand centers—a differential known as basis. When regional pipeline exit capacity is ample, basis roughly equals the transit tariff. When takeaway capacity is constrained, basis widens sharply as regional producers compete for limited pipeline space, leaving captive volumes worth only what local buyers will pay.
Appalachia has operated under takeaway bottlenecks for over a decade. Regional infrastructure projects faced severe headwinds: the Constitution Pipeline was canceled following years of state permitting resistance in New York, while the Mountain Valley Pipeline suffered years of delays before requiring Congressional intervention to complete. Consequently, regional pricing benchmarks like Dominion South and Transco Leidy trade at persistent, sometimes severe discounts to Henry Hub—discounts that widen dramatically during spring and autumn shoulder seasons when local residential heating demand drops and regional pipelines fill.6
This takeaway constraint represents the primary structural qualification on the Marcellus cost advantage. The company's lowest-cost molecules are also its most geographically captive. A sub-$1.50 breakeven realized at a dollar-per-Mcf basis discount yields significantly compressed economic returns. Expand mitigates this regional discount through a portfolio of firm transportation contracts—pre-purchasing pipeline capacity to guarantee a path to premium markets. However, firm transport is a fixed demand charge incurred whether utilized or not, transforming market access risk into an ongoing operational expense.
Consequently, the Marcellus provides Expand with an industry-leading cost floor alongside limited volume growth upside, as incremental production cannot move without new interstate pipelines that regional politics have repeatedly refused to permit. The basin operates essentially as a cash-generative asset enclosed by infrastructure constraints. Quarterly disclosures of realized price as a percentage of NYMEX serve as the primary metric indicating whether those pipeline constraints are tightening or easing.
The Haynesville: harder rock, better address. By contrast, the Haynesville play across Louisiana and East Texas presents far more demanding subsurface conditions. Reserves sit at depths of 10,500 to 13,500 feet, where temperatures exceeding 300°F and extreme reservoir pressures place heavy mechanical strain on equipment. Operating in this environment requires heavier casing, greater hydraulic fracturing horsepower, larger proppant volumes, and specialized downhole electronics capable of enduring high heat. With steep initial production decline rates, finding and development costs run materially higher, raising NYMEX breakevens into the $2.00–$2.25/Mcf range rather than below $1.50.6
What the Haynesville lacks in extraction economics, it regains in commercial geography. The play sits within a few hundred miles of the world's largest concentration of liquefaction capacity—including Sabine Pass, Golden Pass, and Plaquemines—alongside the Gillis Hub trading point that serves as the region's pricing center. The area faces no major interstate pipeline bottlenecks; intrastate networks across Louisiana and Texas are dense, and new capacity is permitted under a fundamentally more accommodating regime than New York's or Pennsylvania's.7
Rather than competing directly for capital, the two basins function as an operational hedge. In a domestic market with weak export demand, Appalachia's cost floor protects base profitability. In an export-driven market with Gulf Coast pricing premiums, the Haynesville delivers unconstrained volume access. Running both plays insulates Expand against shifts in market structure, though it also prevents the company from achieving the highest single-basin unit margins in any given year. Peer strategies reflect this trade-off: EQT focuses purely on Appalachian scale—enhanced by its 2024 acquisition of Equitrans, which made it the sole major producer owning its pipeline network—while Comstock Resources and privately held Aethon Energy focus on the Haynesville. Expand is the only independent producer operating multi-billion-cubic-foot positions in both plays simultaneously.
For investors, this dual-basin footprint converts a directional bet into a structural spread strategy. While this diversification is strategically defensible, it carries higher average operating costs than a single-basin Appalachian model. Consequently, the investment case for Expand cannot rest on rock quality alone; it depends on management's ability to optimize physical takeaway, transportation capacity, and commercial marketing downstream of the wellhead.
VII. The Hidden/Optionality Drivers: Twin Eagle Acquisition, LNG & AI Power
For most of its history, Expand Energy operated as a literal price-taker: producing gas, delivering it to an interconnect, and accepting published index prices minus transport deductions. Decisions regarding where that gas flowed, which pipelines it used, and which end-users ultimately consumed it were handled by third parties that captured the intermediary margin.
On September 16, 2026, the company moved to alter that dynamic by announcing the acquisition of Twin Eagle Holdings—a physical natural gas marketing, transportation, and trading platform—for approximately $1.25 billion in cash funded partly through its credit facility.[^16] Management framed the acquisition as adding more than $200 million in annual EBITDA alongside roughly $150 million in annual commercial synergies phased in through 2028.[^16]
What a marketing platform actually does. Beneath industry terminology, physical gas marketing functions primarily as a logistics business. Marketers manage portfolios of pipeline transport contracts, storage assets, and regional delivery commitments across multiple pricing hubs. Their commercial edge relies on identifying locations where natural gas commands a higher value after accounting for transit costs—and holding the firm pipeline capacity required to move it. Marketers also structure multi-year, fixed-price physical delivery contracts with power plants or industrial buyers, offering supply guarantees that an unintegrated producer cannot easily provide.
Vertically integrating that commercial capability into the nation's largest natural gas producer follows a clear logic: Expand supplies the physical molecules, while Twin Eagle identifies regional supply deficits. In theory, this combination converts regional basis discounts from an operational cost into a trading opportunity.
The case for skepticism. Three primary factors warrant caution and should be evaluated alongside the strategic rationale.
First, marketing and trading earnings command lower valuation multiples than core upstream cash flows. While a dollar of EBITDA from producing wells is backed by proved reserves in the ground, a dollar from physical optimization depends on volatile price spreads that can narrow quickly. Investors will need separate segment reporting to prevent marketing results from obscuring underlying upstream performance.
Second, physical trading operations introduce risks absent from traditional exploration and production, including counterparty credit defaults, margin calls during sudden price spikes, and operational risk. The industry's record with internal trading desks remains mixed; Winter Storm Uri in February 2021 demonstrated how rapidly physical gas exposure can generate unexpected financial liabilities.
Third, the transaction represents Expand's first major cash acquisition since its bankruptcy restructuring, funded through debt facility borrowings rather than equity by an executive team committed to balance-sheet discipline. While the $1.25 billion purchase price is modest relative to Expand's total scale, cash-funded expansion following extended periods of capital restraint mirrors the operational patterns that preceded the company's previous financial crisis. The test of execution will be whether Twin Eagle generates its projected EBITDA contribution by 2028 as a transparently reported segment, while keeping net debt below the target threshold of 1.0 times EBITDAX throughout the integration.[^15]
LNG indexing. Alongside midstream integration, management has shifted away from complete reliance on domestic Henry Hub pricing. Expand has secured long-term supply agreements indexed to international benchmarks—such as the Japan Korea Marker (JKM) for Asian deliveries and Title Transfer Facility (TTF) for European markets—rather than selling output exclusively at domestic hubs.[^9]7 International natural gas has historically traded at substantial premiums to U.S. spot prices, a spread that expanded dramatically during the 2022 European energy crisis.
However, the structural limits of this strategy are significant. Expand is not constructing liquefaction facilities or acquiring equity stakes in export terminals; it is contracting for price exposure without committing the multi-billion-dollar capital required for terminal infrastructure. While this approach avoids massive capital risk, it leaves the company reliant on third-party facilities where project delays, force majeure events, or regulatory pauses can re-expose international volumes to domestic pricing. International index exposure improves realized pricing relative to Henry Hub, but it represents commercial price exposure rather than hard asset ownership.
AI and power demand. The most widely discussed potential catalyst for natural gas is expanding electric power demand. The rapid construction of data centers for artificial intelligence workloads has driven the first sustained growth in U.S. electricity demand in two decades, concentrated within regional grids like PJM and MISO that overlay Appalachian producing fields.6 Because natural gas turbines represent the primary dispatchable generation capacity that can be permitted and constructed on schedules matching data center development, turbine manufacturers face multi-year order backlogs.
While the growth in power demand is real, the assumption that it will drive a structural increase in benchmark gas prices warrants scrutiny. Between 2012 and 2016, a similar thesis held that coal-to-gas switching in power generation would permanently re-rate natural gas prices. Although gas successfully replaced coal as the primary fuel for U.S. power generation—representing a major volume expansion—benchmark Henry Hub prices remained depressed because technological improvements and drilling efficiency enabled producers to expand supply faster than utilities absorbed it.6
That same dynamic threatens the AI demand thesis. In a commodity market characterized by highly elastic, technologically improving supply, incremental demand growth is frequently satisfied without sustained price inflation. Consequently, AI-driven power demand offers volume optionality rather than price optionality—supporting overall production capacity and accelerating the turn-in-line schedule for deferred wells without guaranteeing higher baseline prices. The benchmark for evaluating this catalyst remains public financial disclosures showing direct, long-term supply agreements or power purchase contracts with hyperscale buyers rather than preliminary corporate discussions.
Which raises the question of who, exactly, is making these calls right now.
VIII. Current Management, Governance & Capital Allocation Framework
In February 2026, Nick Dell'Osso stepped down as chief executive of Expand Energy following the board's decision to relocate corporate headquarters from Oklahoma City to the Houston area. Michael Wichterich — board chairman, and the executive who served as Chesapeake's interim chief executive during the post-bankruptcy transition — stepped in as interim president and chief executive while the board initiated a search for a permanent successor.[^14][^9]
The company tied the executive transition directly to the headquarters relocation. Dell'Osso had led the business for roughly four and a half years, guiding it through the Eagle Ford exit, the Southwestern merger, and the corporate rebrand. While public disclosures do not specify whether the relocation caused or merely coincided with his departure, a chief executive transition in the middle of integrating the largest transaction in company history remains a significant governance event.
The relocation carries a clear commercial rationale: Houston is the central hub for natural gas trading, liquefied natural gas commercialization, and midstream counterparties. For a producer reorienting toward commercialization and export markets, establishing a presence there is logically sound. Operationally and symbolically, however, the move is consequential. Oklahoma City served as Chesapeake's home for thirty-five years and was the site of McClendon's corporate campus; leaving it marks the final severance from the founder era. Corporate relocations also risk losing institutional knowledge, as technical personnel who understand field-specific well dynamics may not all relocate.
Wichterich's appointment signals continuity rather than a new strategic direction. Having played a central role on the post-restructuring board, he is a non-operator; an interim chief executive who also serves as chairman represents a caretaker arrangement rather than a long-term strategic mandate. That context makes the September 2026 Twin Eagle acquisition particularly notable: executing a $1.25 billion cash transaction under interim leadership leaves a permanent chief executive to inherit, rather than design, a major commercial integration.
The capital allocation framework. The post-bankruptcy framework rests on three commitments that management has repeated consistently across earnings calls and investor materials.[^10]5[^15]
The first is a reinvestment rate cap holding exploration and production capital expenditures below roughly half of operating cash flow during weak price environments. This directly inverts the 2008–2012 model, when reinvestment routinely exceeded 100 percent of cash flow and debt covered the deficit. Capital discipline is the single most critical commitment because violating it led directly to the predecessor company's bankruptcy.
The second is a leverage target keeping net debt below 1.0 times EBITDAX at a $3.00 per Mcf NYMEX natural gas price. Specifying a conservative price deck gives the constraint real teeth, whereas quoting leverage ratios at peak strip prices during favorable years offers little meaningful risk control.
The third component is a structured shareholder return model: a base dividend designed to remain payable even at $2.00 per Mcf natural gas, supplemented by variable distributions and opportunistic share buybacks funded entirely from free cash flow. This design ensures fixed obligations survive cyclical market troughs while variable returns absorb market spikes. This structure has become standard across the consolidated E&P sector; Expand is following established industry practice rather than setting a new template.
The credibility assessment. Executive compensation is tied to free cash flow per share, return on capital employed, and safety and emissions metrics rather than production volume growth, alongside share ownership guidelines for executives.[^14] Removing volume targets from executive scorecards eliminates the primary incentive that drove Chesapeake's historical overexpansion.
Since 2021, management's operational record has aligned with its strategic claims: the company exited crude oil liquids as planned, curtailed natural gas production during price troughs as promised, executed its mega-merger with equity rather than cash, and avoided re-leveraging the balance sheet. Five years of consistent execution across regulatory filings, earnings calls, and investor presentations offer tangible evidence of an operational shift.
However, this discipline was demonstrated under favorable conditions. Capital discipline has yet to face its ultimate stress test: a sustained high-price environment where aggressive volume growth appears highly lucrative. Operators rarely over-leverage during two-dollar gas environments. The true test of whether this capital discipline represents a permanent structural transformation or a temporary response to market conditions will come if Henry Hub prices sustain at five dollars per Mcf, presenting a new permanent chief executive with an obvious incentive to expand production. Until then, investors should treat the framework as supported but unproven, watching reinvestment rates during the next commodity upcycle as the definitive measure of governance reform.
IX. Strategic Moats & Industry Structure: 7 Powers & Porter's 5 Forces
The uncomfortable starting point for any competitive analysis of a commodity producer is that the underlying product is by definition undifferentiated. A molecule of methane extracted from Expand Energy's Marcellus acreage is identical to one produced by EQT. There is no brand equity, no switching cost, no network effect, and no durable customer relationship that confers pricing power. Whatever advantage exists must be cost-based, resource-based, or structural—and it must be evaluated directly against peers operating in the same geology.
Applying Hamilton Helmer's Seven Powers framework under these constraints reveals distinct structural limits:
Scale economies—real but bounded. Operating at roughly seven billion cubic feet per day, Expand is the largest gas-focused buyer of oilfield services in North America. That volume translates into preferential rig day rates, lower pressure-pumping fees, and priority access to hydraulic fracturing crews and proppant during tight market conditions. These advantages typically reduce service costs by 10 to 15 percent relative to a small independent producer, providing critical operational security when service availability is constrained. However, the relevant peer group is not small independents, but large-scale operators such as EQT, Coterra Energy, and Aethon Energy, which command comparable commercial terms. Against its primary peers, Expand's scale advantage is narrow.
Cornered resource—the strongest power, with key qualifications. Expand controls a decade or more of inventory that breaks even below $2.00 per million British thermal units across North America's two premier natural gas plays. This acreage is cornered in a literal sense: premier geology cannot be replicated, and top-tier acreage in both the Marcellus and Haynesville is almost entirely held by incumbents. This represents the most defensible element of the company's investment case. Nevertheless, important qualifications apply. Inventory depth remains a management estimate dependent on assumed well spacing and recovery rates; definitions of premium inventory are not standardized across the industry, preventing direct comparisons; and a ten-year inventory runway in a depleting asset base represents a finite timeline rather than a perpetual cash engine. The critical metric to monitor is well productivity per thousand lateral feet over time: if productivity declines, the company is exhausting its tier-one inventory faster than headline counts suggest.
Process power—modest. Capabilities such as multi-well pad sequencing, real-time completion analytics, water recycling, and drilling-cycle optimization represent genuine operational proficiencies. However, these techniques are widely shared across the industry. Service contractors transfer innovations between operators, technical personnel move between firms, and operational best practices are published in public filings. In shale operations, proprietary process techniques historically yield a temporary advantage of two to three years rather than a permanent competitive moat.
Counter-positioning, switching costs, branding, and network economies—absent. None of these four powers applies to an upstream gas producer. Instead, external counterparties hold structural counter-power. Liquefied natural gas exporters and interstate pipeline operators control critical logistical chokepoints between Expand's production sites and high-demand end markets, extracting margin accordingly. The acquisition of Twin Eagle represents an attempt to capture a portion of that midstream margin, serving as an operational mitigation rather than a structural reversal.
Applying Porter's Five Forces highlights similar structural dynamics across the industry:
Supplier power is moderate and cyclical. The consolidation of oilfield service providers allows contractors to raise rates quickly during market upturns, compressing producer margins precisely as commodity prices improve.
Buyer power remains high. Benchmark pricing is established at transparent public hubs, while utilities and liquefied natural gas offtakers negotiate against a broad supply curve featuring multiple competing producers. The Twin Eagle marketing platform and international contract indexing mitigate this pressure at the margin, but do not alter the underlying market structure.
Threat of new entrants is low, representing the industry's most improved structural force. Premier North American acreage is fully allocated, and capital markets have remained effectively closed to uncapitalized natural gas exploration and production startups since 2020.
Threat of substitutes is low to moderate over a five-year horizon. Renewable energy expansion displaces natural gas in total energy generation but cannot replace its role in providing firm, dispatchable capacity. Intermittency challenges have reinforced reliance on natural gas generation, though long-term shifts in grid-scale battery cost curves remain a key variable over a decade-long horizon.
Rivalry has diminished noticeably. Consolidation among major natural gas producers has reduced the number of market participants, curbing the historical tendency of operators to expand production into market weakness.
Synthesizing these framework evaluations indicates that Expand's competitive advantage is real but narrow. It possesses a cost and resource advantage over the industry's fragmented long tail rather than its primary peers, in a market where price continues to be set by the marginal producer. Expand is structured to navigate market cycles and outperform broader sector averages, but it does not function as a compounding growth business. The investment case rests on the durability of its free cash flow through commodity cycles and the duration of its low-cost inventory runway—and should be evaluated on those fundamentals rather than on expectations of a structural moat.
X. Historical Falsification Layer: Testing Thesis Claims Against Reality
The advantage of analyzing an enterprise with a history of financial distress is that key counterfactuals are not merely theoretical. Chesapeake Energy already tested these operational dynamics, offering empirical evidence against which current thesis claims can be measured.
Claim 1: This management team can execute large mergers and deliver the promised synergies.
The strongest counter-evidence stems directly from the company's recent history under overlapping leadership. The 2018 acquisition of WildHorse Resource Development was presented as a balance-sheet-enhancing transaction, yet it preceded an $8.3 billion first-quarter impairment and a Chapter 11 bankruptcy within sixteen months, with the assets ultimately sold for less than their purchase price.42[^8]3 Chief executive Nick Dell'Osso served as chief financial officer during that transaction, placing the underlying financial analysis under the direct purview of his leadership team.
Evaluating the comparison: while the corporate entity overlaps, the mechanism of failure differs structurally. WildHorse was a cash-and-stock deal leveraging the balance sheet at a cyclical oil peak in an unfamiliar basin. The Southwestern merger was an all-stock transaction executed on a deleveraged balance sheet at a natural gas price trough within familiar basins. Furthermore, Dell'Osso stepped down in early 2026.
Verdict: historical precedent does not outright invalidate the claim, but it restricts its scope. Expand Energy has demonstrated competence in conservative deal structuring, but has yet to prove equal capability in synergy capture. The critical benchmark remains quantitative: realizing the $500 million annual run-rate synergy target by late 2026, evaluated through reductions in cash administrative expenses and lease operating costs per unit relative to pre-merger baselines.[^15]
Claim 2: Capital allocation discipline is now structural rather than situational.
The historical counter-evidence includes five consecutive years of negative free cash flow between 2008 and 2012, off-balance-sheet financing structures that obscured financial leverage, and an executive compensation model that rewarded drilling volume over capital returns.
That historical record, however, reflects a superseded governance regime. The reconstituted board introduced inverted compensation metrics tied to cash flow per share and return on capital, and capital deployment since the 2021 restructuring has aligned with stated targets across a weak commodity price environment.
Verdict: while post-bankruptcy execution provides tangible evidence of capital restraint, the framework remains untested under peak market conditions. Maintaining capital discipline during price downturns aligns with basic survival; the true test will occur during a sustained commodity rally. The key metrics to monitor are whether the reinvestment rate remains below half of operating cash flow if benchmark prices drop below $2.25 per Mcf, and whether capital discipline holds if prices rise above $4.50 per Mcf under new executive leadership.
Claim 3: The Marcellus low-cost position translates into pricing advantage.
The disconfirming evidence is immediate and ongoing: persistent pipeline takeaway bottlenecks in Appalachia have exposed regional producers to local price benchmarks that trade at substantial discounts to Henry Hub, particularly during spring and autumn shoulder seasons.6 Pipeline capacity constraints represent an active operational limitation rather than a historical artifact.
Verdict: geographical reality narrows this claim. Expand Energy holds the lowest extraction cost baseline in North American natural gas, providing robust downside protection during market troughs. Low extraction costs, however, do not generate premium pricing power or volume growth optionality in Appalachia without new interstate pipeline infrastructure. The asset position reflects a low-cost baseline rather than an advantaged realized price. The primary metric to track is quarterly realized pricing as a percentage of benchmark NYMEX.
Claim 4: AI and data center demand will absorb the gas surplus and support prices.
The primary historical parallel is the coal-to-gas switching cycle of the 2010s: a structural expansion in power-sector gas consumption that drove substantial volume growth without generating a sustained increase in benchmark prices, as supply growth outpaced utility absorption.6 A secondary headwind is associated gas production from the Permian Basin, where oil-directed drilling produces natural gas as a byproduct regardless of gas market pricing, periodically depressing regional hubs such as Waha into negative territory.
Verdict: market precedent confirms potential volume growth but challenges expectations of sustained price increases. Power demand from artificial intelligence infrastructure offers volume optionality for existing production capacity rather than a guarantee of higher baseline benchmark prices. The critical benchmark for verifying this catalyst remains public financial disclosures showing firm, long-term supply agreements or power purchase contracts with hyperscale buyers or utilities, rather than preliminary corporate announcements.
The activist's stress test. A skeptical investor evaluating Expand Energy would focus on three operational vulnerabilities. First is governance: operating under an interim chief executive who also serves as board chairman during a simultaneous headquarters relocation and multi-billion-dollar corporate integration creates a concentration of executive authority. Second is financial disclosure: if physical gas marketing and trading results from Twin Eagle are not transparently segment-reported, evaluating core upstream cash flow quality becomes difficult. Third is capital allocation sequencing: with a deleveraged balance sheet and an equity valuation driven by free cash flow yield, management must justify deploying $1.25 billion in cash for a commercial platform over direct share repurchases.
XI. Playbook: Business & Investing Lessons
Debt is the primary failure mode for an exploration and production company. Chesapeake held tier-one acreage in the Marcellus and Haynesville in 2019—the same underlying geology Expand monetizes today. Subsurface asset quality was never the firm's problem. Rather, carrying debt that equaled multiples of trough cash flow eliminated the flexibility to wait out low-price environments, and operational optionality is a commodity producer's most valuable asset. The broader lesson for cyclical industries is clear: financial leverage does not merely amplify returns; it converts a cyclical business into a high-stakes bet on commodity timing. Tier-one assets burdened by over-leveraged balance sheets ultimately pass to creditors.
Judge acquisitions by per-share free cash flow across a full cycle, not by initial presentation decks. Virtually every transaction is framed as accretive on select metrics. The WildHorse acquisition was presented as balance-sheet-enhancing, yet it accelerated Chesapeake's descent into bankruptcy. The Southwestern merger will not be judged by whether total production expanded—which occurred automatically through scale—but by whether per-share cash generation at a given natural gas price remains higher five years post-closing than it would have been on a standalone basis. That evaluation requires years to observe, but it remains the sole metric of long-term value creation.
In commoditized markets, the last mile provides the primary opportunity for margin differentiation. The rationale behind acquiring Twin Eagle reflects a recognition that while physical methane is undifferentiated, the commercial transactions surrounding its delivery can yield additional value. Upstream production lacking physical marketing capabilities leaves an operator accepting whatever local hub index prices dictate. However, integrating a midstream marketing desk introduces distinct trading risks, and maintaining the operational discipline required to prevent optimization from turning into speculation remains a governance challenge rather than a strategic one.
Governance functions as an operational mechanism rather than administrative overhead. The Founders Well Participation Program was not merely a peripheral governance failure; it served as the core incentive engine of Chesapeake's historical strategy, converting executive personal leverage into a corporate mandate for continuous drilling. Expand Energy's post-bankruptcy framework—tying executive compensation to free cash flow per share and return on capital rather than volume growth—provides the structural counterweight. The broader lesson extends beyond energy: an executive compensation plan functions as a company's true strategy document, revealing what management is financially incentivized to execute rather than what public communications claim.
XII. Analysis & Bear vs. Bull Case
The bull case.
The bull case for Expand Energy rests first on expanding export demand. U.S. liquefied natural gas export capacity is on track to roughly double between 2024 and 2028 as facilities such as Plaquemines and Golden Pass, alongside expansions at Sabine Pass and Corpus Christi, enter service.7 Liquefied natural gas export demand differs structurally from domestic consumption: it is backed by long-term contracts, operates as baseload demand, remains price-inelastic within wide ranges, and is physically concentrated along the U.S. Gulf Coast. Controlling roughly three billion cubic feet per day of Haynesville production near these facilities positions Expand Energy directly in the path of export growth without the pipeline permitting constraints affecting Northeastern production. If export facilities operate near design capacity, this structural call on Gulf Coast supply could alter regional pricing dynamics.
The second pillar of the investment thesis is free cash flow generation. Assuming a baseline benchmark price of $3.00 per million British thermal units at Henry Hub, management projects the combined asset base will generate low billions of dollars in annual free cash flow. That generation supports an equity valuation where natural gas exploration and production companies trade at high single-digit to low double-digit free cash flow yields.[^15]5 With a net leverage target below 1.0 times EBITDAX and a base dividend structured to remain funded at $2.00 per Mcf natural gas, the payout offers downside protection through commodity troughs.
Third, the portfolio incorporates operational optionality that is not fully reflected in base valuations: capturing synergies beyond the $500 million annual target, integrating Twin Eagle's physical marketing desk, expanding international index exposure, and servicing incremental power demand from data centers. The core valuation thesis does not depend on these catalysts materializing simultaneously; rather, each provides upside potential beyond the baseline cash flow model.
The bear case.
The primary counterargument centers on persistent supply expansion rather than demand weakness. Associated natural gas produced alongside crude oil in the Permian Basin arrives as a price-inelastic byproduct, periodically driving local spot pricing at West Texas hubs like Waha into negative territory. So long as crude oil economics incentivize Permian drilling, several billion cubic feet per day of low-cost, price-indifferent natural gas will flow toward the Gulf Coast, competing directly against Haynesville volumes for export capacity.6 Ongoing drilling efficiency gains further flatten the cost curve, mirroring the supply expansion that limited Henry Hub price appreciation during the power sector's earlier transition from coal to gas.
A second vulnerability involves project execution and regulatory risk for export infrastructure. Liquefied natural gas export projects frequently face construction delays, commissioning hurdles, financing constraints, and policy shifts. The 2024 federal pause on non-Free Trade Agreement export authorizations highlighted the potential for regulatory interruptions. If Gulf Coast export expansion experiences prolonged delays, higher-cost Haynesville output could be forced into an already well-supplied domestic market, reducing the regional price premiums that justify its higher extraction expense.
Third, management faces a significant concentration of operational and corporate execution risk. The firm is concurrently integrating its largest corporate merger, absorbing a $1.25 billion physical marketing acquisition, relocating its corporate headquarters from Oklahoma City to Houston, and conducting a search for a permanent chief executive. While each initiative presents manageable operational demands individually, executing them simultaneously increases organizational complexity and risks personnel turnover that could degrade operating performance over time.
A fourth consideration involves financial accounting baselines. Exploration and production reserve valuations rely on pricing assumptions, development schedules, and well-spacing estimates. Expand Energy's balance sheet reflects fresh-start accounting valuations established following its 2021 bankruptcy emergence, alongside asset revaluations from the 2024 Southwestern merger. This structural reset lowers ongoing depletion, depreciation, and amortization expense relative to industry peers carrying legacy capital costs, requiring analysts to adjust for cost-basis differences when comparing operating margins across the sector.2[^15]
The KPIs that matter. Evaluating Expand Energy's operational execution relies primarily on three quantitative metrics:
Realized price as a percentage of benchmark NYMEX Henry Hub. This metric synthesizes regional basis differentials, firm pipeline transportation commitments, international index contracts, and physical gas marketing optimization from Twin Eagle into a single realized price comparison. Sustainable commercial execution will reflect directly in this ratio.
Cash cost per thousand cubic feet equivalent (Mcfe), encompassing lease operating expenses, gathering, processing, transportation, and general and administrative costs. This cost figure provides an empirical test of post-merger synergy capture and unit-cost control, serving as an objective measure of structural cost advantage.
Free cash flow per share evaluated at a normalized benchmark natural gas price. Evaluating cash generation on a per-share basis ensures that capital allocation prioritizes shareholder returns over expansion funded by equity dilution, addressing a key vulnerability of the predecessor company's legacy strategy.
Production volume growth is deliberately excluded from this core evaluation metric set. In an adequately supplied natural gas market, expanding output without realized margin improvements signals capital misallocation rather than operational success.
XIII. Strategic Guidance & Critical Transcripts for Article Writers
For anyone analyzing the company's financial and operational trajectory, four earnings and transaction calls carry disproportionate information value, with Q&A sessions consistently yielding clearer insights than prepared executive remarks.
The merger announcement call of January 11, 2024 serves as the foundational record for the consolidated enterprise. It details the initial synergy targets—spanning general and administrative expense cuts, capital efficiency, and commercial optimization—alongside the rationale for the exchange ratio. Delivered during a natural gas price trough, management's presentation established why scale mattered at that point in the cycle, providing the baseline against which subsequent synergy progress must be measured.1
The Q3 2024 call in late October 2024 marked Expand Energy's first quarterly transcript following the transaction's close.[^10] Its primary value rests in detailing integration mechanics, including combined capital spending guidance, rig count rationalization, and the initial framework for managing deferred completions across a two-basin portfolio. The call also established management's initial leverage targets, serving as a benchmark for subsequent balance-sheet discipline.
The Q4 2024 and full-year call in February 2025 provided the first comprehensive operating guidance for the combined entity, giving analysts their initial opportunity to test whether synergy capture was tracking.5 The key detail lay in how management addressed unit-cost trajectories, where specific per-thousand-cubic-feet-equivalent figures provided a clearer signal than general operational reassurances.
The leadership transition call in early 2026 and the Twin Eagle acquisition call of September 2026 provide the most recent operating context.[^9][^16] The leadership call clarified how the board framed the corporate relocation to Houston alongside the chief executive transition. The Twin Eagle call detailed the economics of the physical marketing platform, its EBITDA contributions, and the crucial question of whether management would commit to separate segment reporting for its trading operations.
Across these transcripts, analyst inquiries consistently focus on three core areas: Appalachian basis differentials and firm transportation commitments; the operational triggers and commodity price thresholds governing deferred completions and turn-in-lines; and Gulf Coast delivery commitments to liquefied natural gas facilities, specifically whether gas volumes are contractually firm or merely positioned adjacent to export hubs.
XIV. Epilogue & "If We Were CEOs"
There is an unmistakable symmetry to this corporate trajectory. Aubrey McClendon built a business on the conviction that securing top-tier rock was paramount. He was right about the quality of the geology, but wrong about the financial assumptions required to make owning it profitable. The company he established assembled premier natural gas acreage across North America, only to surrender it to creditors after borrowing against a sustained high price deck that failed to materialize. Over thirty-five years, the enterprise traversed a trajectory from $50,000 in seed capital to a $35 billion peak market valuation, through bankruptcy, and ultimately into a $20 billion-plus entity—sitting on much of the same rock, but held by new shareholders, governed by strict capital discipline, and operating out of Houston.
The Expand Energy operating in September 2026 represents a fundamental structural departure from the Chesapeake Energy that entered Chapter 11 in June 2020. It is now the largest natural gas producer in the United States, anchored by low-cost inventory across the Marcellus and Haynesville shales, maintaining net leverage below 1.0 times EBITDAX, and aligning executive compensation with per-share cash flow rather than drilling volume. These represent tangible, verifiable operational changes.
What the enterprise lacks, however, is a durable competitive moat in the classic structural sense, or direct control over its realized pricing. It remains a low-cost, long-inventory, cyclically exposed commodity producer backed by credible capital discipline and incremental operational optionality. Evaluated on those realistic parameters, the company presents a coherent investment proposition. Evaluated instead as an unconstrained winner of an artificial intelligence energy supercycle, it risks repeating the overexpansion that defined the sector a decade ago.
For executive leadership, three strategic priorities should govern the next two years.
First, convert geographic proximity into binding contracts. The Haynesville play's location near Gulf Coast liquefaction terminals is valuable only to the extent that firm, long-dated, index-linked agreements secure that access. Physical proximity alone does not constitute a commercial position. Securing a clear majority of Gulf Coast production under firm long-term arrangements—with fully disclosed index pricing formulas—would transform geographic placement into a durable contractual asset, marking the highest-value deployment of management focus.
Second, maintain strict volume restraint during market weakness and establish binding public commitments to enforce it. The shale sector's historical failure stemmed from discipline that remained contingent on peer behavior. Genuine restraint requires establishing a publicly committed commodity price threshold below which turn-in-line completions will not accelerate, and adhering to that policy even when competing operators expand output.
Third, ensure absolute reporting transparency for the Twin Eagle platform. Physical marketing platforms risk value destruction if investors perceive them as opaque trading desks. Management can protect valuation multiples by reporting Twin Eagle as a separate operating segment, detailing risk management limits, and providing clear quarterly metrics to verify its projected $200 million EBITDA contribution. Given the firm's corporate history, investor tolerance for opacity is exceptionally low, and any equity valuation discount applied to unverifiable trading earnings would outweigh the competitive cost of full disclosure.
The permanent chief executive chosen by the board will inherit a business whose primary challenge is no longer subsurface geology or balance-sheet leverage. It is operational temptation. The core inventory is secured, legacy debt has been eliminated, and the primary risk remaining is a return to the capital allocation habits that defined the company's past.
References
-
Chesapeake Energy and Southwestern Energy to Combine in $7.4 Billion All-Stock Transaction — Business Wire, 2024-01-11 ↩↩↩↩↩↩
-
Chesapeake Energy Form 10-K Annual Report for FY 2020 (Bankruptcy & Restructuring Disclosures) — SEC EDGAR, 2021-03-01 ↩↩↩↩↩
-
Chesapeake Energy Corporation Files Chapter 11 Reorganization — Reuters, 2020-06-28 ↩↩↩
-
Chesapeake Energy Agrees to Acquire WildHorse Resource Development — SEC Form 8-K, 2018-10-29 ↩↩
-
Expand Energy Q4 2024 Full Year Earnings Call Transcript — BamSEC, 2025-02-20 ↩↩↩↩
-
U.S. Natural Gas Supply, Consumption and Pipeline Takeaway Data — U.S. Energy Information Administration, 2025 ↩↩↩↩↩↩↩↩↩↩
-
Global LNG Market Outlook & North American Export Capacity — S&P Global Commodity Insights, 2025 ↩↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube