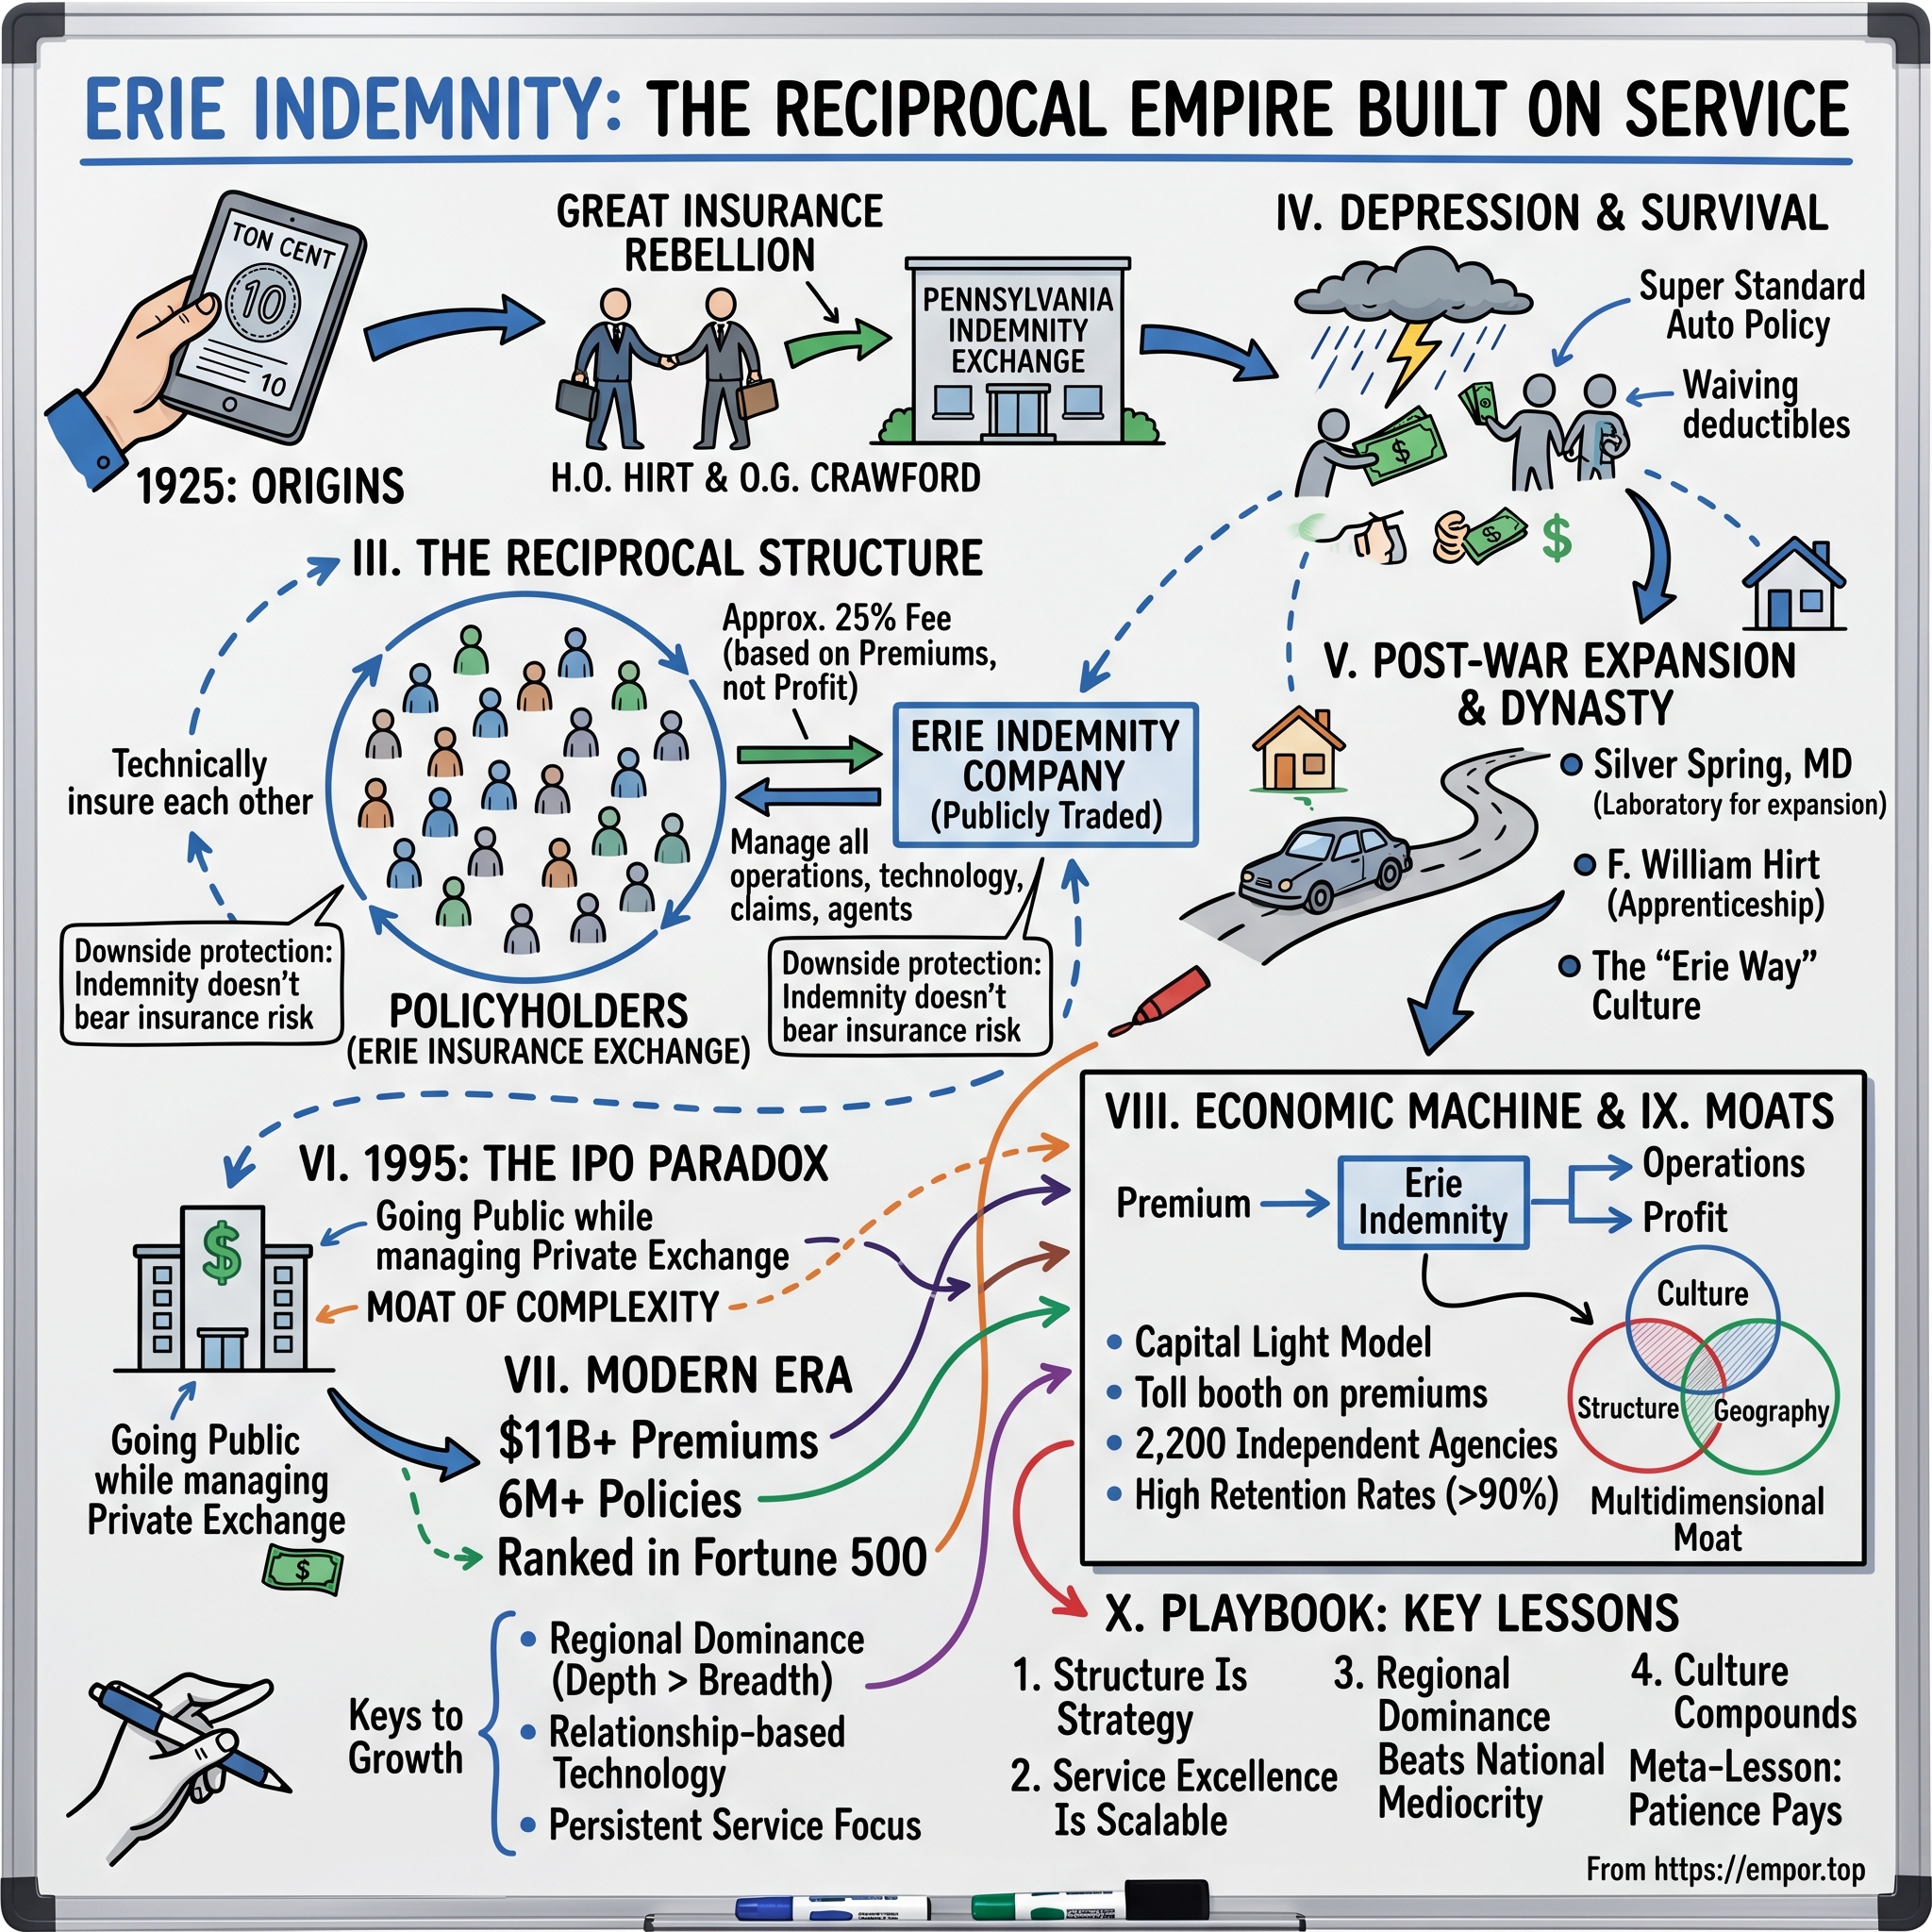
Erie Indemnity: The Reciprocal Empire Built on Service
I. Introduction & Hook: The Tollbooth on a $13B Mutual Machine
In the spring of 1925, two former employees of a Pennsylvania insurance exchange sat in downtown Erie with a pencil and a ten-cent writing tablet. On it, H.O. Hirt sketched a business plan based on a simple premise: that insurance customers were being overcharged and poorly served, and that a differently structured insurer could resolve both issues. It took Hirt and his partner O.G. Crawford three months and twenty days to raise the $31,000 in capital they needed, securing support from roughly 90 local stockholders one conversation at a time.1 One of the first policies issued covered Hirt's own Dodge touring car.
A century later, that initial plan has evolved into an unusual corporate structure in American public markets. Erie Insurance Exchange — the entity the founders established to pool insurance risk — is owned by its policyholders and is not publicly traded. In 2025, the Exchange wrote $13.0 billion of direct and affiliated assumed premium and held $10.1 billion of statutory policyholders' surplus.2 It operates with no internal employees or officers, as Pennsylvania reciprocal insurers are legally prohibited from employing them directly.2
Instead, operational functions — including policy sales, underwriting, issuance, claims handling, and investment management — are performed by a separate, publicly traded entity: Erie Indemnity Company, traded on the NASDAQ under ticker ERIE. Indemnity serves as attorney-in-fact for the subscribers at the Exchange. Under the subscriber agreement, Indemnity receives a management fee calculated as a percentage — capped at 25% — of all direct and affiliated assumed premium written by the Exchange.2
This contract defines both the core investment case and the key risk for Indemnity's shareholders. Indemnity's revenue depends on gross premium volume rather than underwriting profitability. If severe storms cause underwriting losses for the Exchange, the Exchange's policyholders absorb the shortfall. If the Exchange subsequently raises premium rates by 15% to restore its surplus, Indemnity's fee base grows by 15% alongside it. Indemnity carries no insurance reserves and holds no direct underwriting exposure; its revenue reflects volume processed.
The magnitude of this fee structure was clear in 2025, when total operating revenue reached $4.07 billion. Policy issuance and renewal management fees accounted for roughly $3.1 billion of that total, generating operating income of $717.2 million and net income of $559.3 million, or $10.69 per diluted share.23
Three developments highlight why this structure remains relevant in September 2026.
First, the company is undergoing an executive transition. On February 20, 2026, Erie announced that Tim NeCastro will retire as president and CEO on December 31, 2026, concluding a 30-year career at the company, including 10 years in the top role. The board initiated a search for his successor, while NeCastro is slated to become president of the Erie Insurance Foundation.4
Second, the business model recently completed a significant stress test. Post-pandemic repair inflation and frequent severe convective storms drove the Exchange's combined ratio to 110.4% in 2024 and 104.9% in 2025. These figures reflect underwriting losses for the policyholder pool in consecutive years, with catastrophe losses alone accounting for 10.6 percentage points of the 2025 ratio.5 In contrast, Indemnity's earnings expanded across both years, reflecting the fee-based nature of its operations.
Third, corporate governance remains tightly concentrated. Public investors hold non-voting Class A shares, while total voting power resides in 2,542 shares of Class B stock held by eight record holders.2 As a result, public shareholders cannot direct corporate strategy. For example, when Indemnity contributed $100 million to a newly established charitable foundation in 2025 — reducing net income by $80.6 million after tax — Class A shareholders had no governance mechanism to contest the decision.3
The following sections examine how a regional insurer built on customer service reached the Fortune 500 — ranking #323 in 2025 and #308 in 2026 — and why the publicly traded management company attached to it presents a distinct risk and return profile in American financial services.67
 Subscribe on LinkedIn
II. The Reciprocal Architecture: How Erie Indemnity Really Works
Consider a simple thought experiment: two hundred farmers in a valley seeking protection against barn fires. They could purchase policies from a commercial insurance company, which would collect premiums, hold reserves, pay claims, and retain any remaining profit for its outside shareholders. Alternatively, they could pool their resources: each farmer contributes to a shared fund, claims are paid directly from that fund, and any remaining surplus stays with the participants.
The second arrangement describes a reciprocal insurance exchange. The policyholders, known as "subscribers," act simultaneously as insurers and insureds, exchanging contracts of indemnity with one another. It represents genuine mutual risk-sharing rather than risk transfer to a third party.
However, a pool of policyholders cannot easily manage day-to-day operations. Someone must price policies, process claims, invest capital, navigate regulatory filings across state lines, and handle customer service. To solve this, subscribers execute a power of attorney appointing a dedicated manager to oversee operations. That manager serves as the attorney-in-fact.
Erie Indemnity has served as that attorney-in-fact since 1925.2
Three shapes of insurance company
The distinction among insurance structures matters because it dictates where underwriting risk ultimately sits. At a stock insurer — such as Travelers, Allstate, or Progressive — public shareholders supply capital, retain underwriting profits, and absorb underwriting losses. At a mutual insurer — such as State Farm or Liberty Mutual — policyholders own the enterprise, and surplus accumulates for their collective benefit without public equity. A reciprocal insurer splits these roles: the risk-bearing pool is policyholder-owned like a mutual, while the management function is isolated into a separate entity that can be publicly traded.
USAA and PURE operate as reciprocals, but Erie Indemnity is distinct: its management company trades on NASDAQ with a multi-billion-dollar market valuation, creating an unusual hybrid in public financial markets.
Where the money actually comes from
Indemnity's revenue flows through three distinct categories, each carrying different economic weight.
The primary driver is the policy issuance and renewal management fee. In 2025, this fee generated roughly $3.1 billion of the company's $4.07 billion in total operating revenue.2 It is calculated mechanically by multiplying the management fee rate by the direct and affiliated assumed premium written by the Exchange.
The second source is a management fee for administrative services, which compensates Indemnity for handling claims, overseeing the Exchange's investment portfolio, and managing life insurance operations. That fee reached $74.1 million in 2025, representing an 8.3% increase.2
The third category consists of service cost reimbursements, which expand headline figures without altering operating profit. Indemnity is reimbursed by the Exchange for the actual cost of claims handling, investment management, and life management services — totaling $836.6 million in 2025. Because an equivalent amount is recorded as an operating expense, the pass-through has zero net effect on operating income.2 Excluding these pass-through reimbursements reveals an economic revenue base of roughly $3.2 billion against $2.5 billion in policy issuance costs.
Furthermore, roughly half of Indemnity's 6,667 full-time employees work exclusively on claims and life services for the Exchange, with their compensation reimbursed monthly.2 As a result, Indemnity's total headcount overstates the workforce required to run its core fee-generating engine.
The cost structure that makes it work
Indemnity's primary expense line is agent compensation rather than technology or facilities. Agent compensation — comprising scheduled commissions on written premium alongside performance incentives — accounted for approximately 71% of policy issuance and renewal expenses in 2025.2
This structure underpins the company's operating leverage. Because agent commissions vary directly with written premium, the remaining cost base — spanning underwriting, technology, policy administration, and corporate infrastructure — remains relatively fixed. Consequently, when written premium expands through volume or rate increases, a higher proportion of incremental fee revenue flows to operating income. In 2025, policy issuance costs increased 8.7% while fee growth outpaced expenses, lifting operating income from $676.5 million to $717.2 million.2
The compensation model also serves as an operational lever. In the first and second quarters of 2026, commission expenses rose by $28.0 million and $44.7 million, respectively, with management attributing the increases largely to higher agent incentive payouts rather than baseline commission volume.89 These incentive payouts align agent behavior with growth and underwriting targets, placing the associated cost on Indemnity's income statement rather than the Exchange's balance sheet.
The alignment problem, stated plainly
This corporate design creates an inherent structural tension. Indemnity earns fees based on gross premium volume without direct exposure to underwriting losses or claims costs. From 2022 through 2024, the Exchange implemented substantial rate increases to address inflation and restore rate adequacy.2 While these adjustments were necessary to preserve the Exchange's underwriting stability, they also mechanically expanded the revenue base of Indemnity — an entity whose board determines the management fee rate, whose executive incentives tie to premium growth, and whose public equity holders capture the resulting earnings.
Indemnity's annual regulatory filings explicitly note that the rate-setting process evaluates the "relative financial strength and capital position" of both entities, acknowledging that such reviews "could result in a reduction to the management fee rate."2 This places Indemnity's board in the dual role of stewarding shareholder returns while safeguarding the financial position of its sole, policyholder-owned client. State insurance regulators hold authority to intervene in this arrangement, though the historical framework has remained stable.
For investors, this structure defines the core thesis: Erie Indemnity operates a highly predictable, fee-based tollbooth, but its fee rate is governed by a board managing both sides of the relationship, serving a client base without direct board representation. The long-term durability of this arrangement depends on how effectively it navigates periods of sustained underwriting stress.
III. Origins & Founding Ethos: H.O. Hirt and the Anti-Corporate Mandate (1925–1950s)
There is a particular kind of entrepreneur who is less interested in building a company than in proving a point. H.O. Hirt was one of them.
Having previously worked at the Pennsylvania Indemnity Exchange, Hirt and O.G. Crawford concluded that the conventional insurance model was adversarial by design—setting premiums higher than necessary and routinely contesting claims. Their counter-proposal focused not on a novel financial product, but on an operational structure: a reciprocal insurer where the risk pool belonged to policyholders, paired with an aggressive focus on customer service.
Company lore frames this founding mandate as a pledge of near-perfect protection and service at the lowest reasonable cost. The operational record offers more concrete evidence. In 1927, two years after founding, Erie installed a telephone in a claims manager's YMCA room so policyholders could reach a staff member around the clock.1 In 1931, Hirt launched the "Erie App-a-Week Bulletin," a regular publication sharing marketing tips and industry intelligence with sales agents.1 Both initiatives signaled where the company sought competitive advantage: response speed and agent relationships.
Crawford retired in 1933, leaving Hirt to manage the young insurer during the Great Depression.1 For investors analyzing the business model, this period provided the first real-world stress test. Insurance carriers in the 1930s faced twin pressures: policyholders dropping coverage due to financial distress, while remaining policyholders filed more frequent claims. Hundreds of regional insurers failed.
Erie survived due to its structural design. Because a reciprocal's capital consists of policyholder surplus, it lacks public shareholders demanding short-term returns during industry downturns. That structural flexibility helped the Exchange navigate historical downturns, just as it allows the pool to absorb elevated combined ratios during periods of severe storm losses without answering to public equity analysts or activist investors. By contrast, a standard publicly traded insurer experiencing similar underwriting losses faces immediate capital market pressure.
Hirt's operating philosophy shaped Erie's corporate culture for decades. When asked how Erie planned to compete, he reportedly replied that the questioner had it backwards: "We are the competition."1 While bold, the statement reflected a distinct strategic position: Erie aimed to set its own service standards and price policies based on its own loss experience rather than broader market trends.
The motto "Above all in sERvIcE"—with "ERIE" capitalized within the word—remains an enduring piece of company branding. Functionally, it served as an effective internal mechanism, embedding the service mandate directly into the company's identity for employees and agents alike.
Hirt served 37 years in executive leadership and remained associated with the company until his death at age 95 in 1982.1 Governance remained in the family: his son F. William Hirt joined the board in 1965, and his daughter Susan Hirt Hagen was elected to it in 1980.1 The Hirt family maintained both economic ownership and exclusive voting control. This generational continuity sustained the founding operational model, while also establishing the concentrated voting structure that accounts for the governance discount reflected in Indemnity's public shares today.
The founding era established a three-part operating model: a policyholder-owned risk pool, a management company earning fees to service it, and a distribution network of independent agents treated as strategic partners. The subsequent decades centered on expanding this model across new territories.
IV. Scaling the Regional Fortress: Independent Agents & Post-War Expansion (1960s–1994)
For twenty-eight years following its 1925 founding, Erie Insurance operated exclusively in Pennsylvania. While postwar competitors such as State Farm and Allstate built national captive agent networks backed by broad advertising campaigns to spread brand and catastrophe risks across the country, Erie pursued a deliberate strategy of geographic restraint.
In 1953, the company expanded beyond Pennsylvania for the first time, opening a branch office in Silver Spring, Maryland, contiguous with Pennsylvania's southern border.1 Subsequent expansion strictly followed this contiguous pattern, entering neighboring markets including Ohio, Virginia, West Virginia, New York, North Carolina, Tennessee, Indiana, Illinois, Wisconsin, and eventually Kentucky in 2014 — a market entry led by Tim NeCastro prior to his appointment as CEO.4 Today, Erie's footprint spans 12 states and the District of Columbia, supported by 24 field offices.27
Why contiguity was the whole strategy
While market observers often characterized this contiguous growth strategy as conservative, it reflected a focus on local operational economics. In property and casualty insurance, claims adjusting requires physical, localized management — inspecting property damage, negotiating with repair facilities, and evaluating local contractor costs. Geographic density allows an insurer to amortize field office overhead, build relationships with repair networks, and generate deep regional loss experience to refine risk pricing. Regulatory filings highlight this model, noting that it combines localized service with lower operational costs through centralized support.2
Geographic proximity also reinforced distribution efficiency. Independent agencies frequently maintain peer networks across state borders. Expanding outward from its core territory allowed Erie to leverage established brand reputation among regional agencies when entering adjacent states.
The independent agent bet
A second strategic decision centered on distribution. Rather than establishing a captive agent network, Erie distributed policies exclusively through independent agencies — business entities that represent multiple carriers and select insurers on a policy-by-policy basis. By the end of the twentieth century, Erie partnered with roughly 1,500 agencies across nine states.1 Today, the network includes more than 2,200 agencies representing approximately 13,000 licensed agents, with company filings identifying independent agencies as the Exchange's sole distribution channel.27
This reliance on independent distribution introduces structural competition within the sales channel. While captive agents sell a single company's products exclusively, independent agents evaluate competing carriers for every customer. As Erie acknowledges in its regulatory filings, marketing exclusively through independent agents means the Exchange "faces competition within its appointed agencies" based on ease of doing business, product features, pricing, and service quality.2
To navigate this dynamic, Erie seeks to establish itself as the preferred, or "lead," insurer within its appointed agencies.2 In independent agency distribution, agents act as initial underwriters. Securing lead-carrier status gives an insurer first access to preferred policyholder risks, creating favorable selection that can lower loss ratios independently of automated underwriting algorithms.
Maintaining lead agency status requires competitive compensation, reflected in agent commissions and incentive payouts representing roughly 71% of policy issuance expenses. However, because independent agents perform front-line underwriting and administrative service tasks that captive or direct carriers handle internally, higher commission expenditures effectively replace internal operating overhead.2
Conservatism as a capital structure
Throughout its expansion, Erie Indemnity maintained a balance sheet with zero financial leverage, a practice that continues today. Under two generations of Hirt family stewardship, the enterprise prioritized measured growth, pricing based on internal loss experience, and capital preservation over rapid geographic expansion. While this conservative capital strategy shielded the company from aggressive growth risks, it also limited Erie's geographic footprint to a regional scale.
By the early 1990s, however, the Hirt family faced an illiquidity challenge: structuring financial liquidity for the founder's heirs within a corporate model where the underlying insurance operations were policyholder-owned and structurally illiquid.
V. The IPO Paradox & Governance Dilemma (1995–2015)
On October 2, 1995, Erie Indemnity Company's Class A shares began trading on NASDAQ.10
For Wall Street, evaluating the listing required understanding a distinct corporate model. The risk-bearing insurer itself—with its premium pool, reserves, policyholder surplus, and financial strength ratings—was not being offered for sale. It remained owned entirely by its policyholders. Instead, public investors were purchasing equity in the management company: a service provider whose sole primary client was the reciprocal exchange it controlled.
Listing the attorney-in-fact provided a practical mechanism to address the founding family's liquidity needs. A traditional mutual or reciprocal seeking public equity must undergo demutualization, converting policyholders into shareholders—a complex, regulated process that permanently alters corporate ownership. By listing Erie Indemnity instead, the founding family and early investors secured market liquidity for their management operations while preserving policyholders' full ownership rights in the Exchange. However, this arrangement also separated economic participation from corporate control through a dual-class share structure.
2,542 shares that decide everything
The governance framework established absolute voting control for a small group of insiders. Class A common stock trades publicly on NASDAQ but carries no voting rights. Total voting authority rests with Class B common stock. As disclosed in the company's 2025 annual filing, Erie Indemnity had 46,189,068 Class A shares outstanding and 2,542 Class B shares, which were held by eight shareholders of record as of February 17, 2026.2 No established public market exists for the Class B shares. Approximately 471 record holders hold Class A stock, with most public ownership held through institutional custodial accounts.2
The economic distribution between the share classes reflects the concentration of voting power. For 2026, the board set the quarterly dividend at $1.4625 per share for Class A and $219.375 per share for Class B—a 150-to-1 ratio that provides Class B holders with substantial dividend income alongside complete governance authority.11
As a result, traditional shareholder levers do not apply at Erie Indemnity. Public investors cannot initiate proxy contests, submit hostile filings, or execute vote-withhold campaigns against board members. Governance oversight relies entirely on internal board stewardship, family leadership, and the reputation of an enterprise deeply rooted in its home city. Board Chairman Tom Hagen—whose family connection traces to co-founder H.O. Hirt's daughter, Susan Hirt Hagen—led the announcement of the 2026 executive transition.4
This structure presents a clear trade-off for investors. Proponents argue that concentrated family control isolates management from short-term earnings pressure, enabling multi-decade strategic planning and underwriting discipline. Conversely, critics emphasize that public shareholders lack formal remedies or voting leverage if management decisions diverge from investor interests. Both perspectives reflect the structural reality of the company's dual-class design.
Wall Street's valuation problem
The public listing initially created an analytical challenge for market participants. Property and casualty insurance analysts traditionally value carriers based on book value, focusing on loss reserves, statutory surplus, underwriting performance, and investment yields—metrics where an insurer's balance sheet defines its enterprise value.
Erie Indemnity's balance sheet, however, plays a secondary role in its financial results. The company maintains a modest investment portfolio; total investment income reached $84.9 million in 2025 compared with $717.2 million in operating income, representing less than 11% of pre-tax earnings even during a period of elevated interest rates.2 Rather than an underwriting balance sheet, Indemnity's core asset is a contractual fee stream generated from the Exchange's written premium, operating with minimal capital intensity and zero debt. Economically, the business resembles a fee-based asset manager or franchisor more than a traditional property and casualty carrier.
Over time, equity markets increasingly priced Indemnity as a high-margin fee business, awarding the stock a valuation multiple well above conventional property and casualty peers. This premium valuation rests on the assumption that the management fee rate will remain stable near its 25% cap while the Exchange's underlying premium base continues to compound.
The operating decades behind the ticker
The period from 1995 through 2015 was defined by steady operational scaling. Under Stephen A. Milne, who became president and CEO in 1996, Erie executed a major technology modernization program, introducing digital platforms such as DSpro in 1999 to streamline agent quoting and policy administration.1 These infrastructure investments reinforced the company's competitive positioning among independent agencies by reducing administrative friction.
During this era, Erie earned a spot on the Fortune 500, sustaining its position through steady premium growth. By 2015, the enterprise had expanded into a major regional carrier supported by a publicly traded management entity, family voting control, and a service reputation built over nine decades. What remained untested in its modern corporate form was how this fee-reliant model would perform during a period of severe inflationary pressure.
VI. Modern Era & Decennial Inflection: Rate Spikes & The NeCastro Era (2016–2026)
Tim NeCastro is from Erie. He joined the company in 1996, worked his way up through senior roles, led the 2014 expansion into Kentucky, and took over as president and CEO in 2016.4 Chairman Tom Hagen's framing at the retirement announcement — that NeCastro led "with extraordinary kindness and humility" — is the kind of quote that usually signals a caretaker.4 The numbers say otherwise.
Under NeCastro, Exchange written premium roughly doubled, reaching $13.0 billion in 2025, with policies in force passing seven million.24 Erie climbed 53 places on the Fortune 500 in a single year, from #376 to #323, and then to #308 in 2026.67 Indemnity's operating income went from $520.2 million in 2023 to $676.5 million in 2024 to $717.2 million in 2025.2
But a large share of that growth was not a triumph. It was a repair job.
The severity shock
Beginning in 2021, American personal lines insurance ran into a wall. Used vehicle values spiked, replacement parts went scarce, labor rates climbed, and total-loss frequency rose because repair costs blew past vehicle values faster than anyone had modeled. Property claims did the same thing through construction materials and labor. Then the weather cooperated with the worst-case scenario: severe convective storms — the hail, straight-line wind, and tornado events that hammer exactly the Mid-Atlantic and Midwest geography Erie is concentrated in.
The Exchange's own filings name the exposures directly: tropical cyclones, earthquakes, severe convective storms, and severe winter weather, with the added observation that rising insured values and geographic concentration amplify catastrophe severity.2
The damage showed up in the combined ratio — the sum of losses and expenses as a share of earned premium, where anything above 100% means the pool lost money on underwriting before investment returns. The Exchange ran 110.4% in 2024 and 104.9% in 2025, with catastrophes contributing 10.6 points in 2025 against 9.6 in 2024. Management described one first-half 2025 event as the costliest weather event in company history.5
Two years of underwriting losses at a policyholder-owned pool is serious but survivable; surplus is there for exactly this. And surplus held up, rising from $9.3 billion at the end of 2024 to $10.1 billion at the end of 2025 — investment returns and prior-year reserve position doing the work that underwriting could not.2
The counter-cyclical twist
Now watch what happened to the listed entity while its only customer was losing money on every underwriting year.
The Exchange responded to severity the only way an insurer can: rate. Cumulative increases through 2022–2024 drove average premium per policy up 13.4% year-over-year at the end of 2024 and a further 9.6% at the end of 2025.2 Written premium climbed to $11.9 billion in 2024 and $13.0 billion in 2025.2
Indemnity earns 25% of that. So the worse the underwriting got, the larger the fee base became. Net income was $600.3 million ($11.48 per diluted share) in 2024 and $559.3 million ($10.69) in 2025 — and the 2025 decline was entirely self-inflicted, reflecting the $80.6 million after-tax hit from the $100 million foundation contribution. Strip that out and 2025 earnings rose.3
The analytical conclusion is uncomfortable but clear: Indemnity is structurally long insurance inflation. Nothing in the 2021–2025 record contradicts the tollbooth thesis. It confirms it, in the specific scenario most likely to break a traditional insurer's earnings.
What rate increases cost in customers
The confirmation comes with a bill, and it arrived in the policy count.
Renewal premium grew 13.4% to $11.5 billion in 2025 — but that was price, not units. New business went the other way, hard: new business premium fell 17.8% to $1.5 billion, on a 22.8% decline in new business policies written.2 Total policies in force for all lines declined 1.1% in 2025.2 Retention, which Erie has historically treated as a point of pride, slipped from 90.4% at the end of 2024 to 88.4% at the end of 2025 — attributed by the company to competitive market conditions.25
Personal lines premium rose to $9.2 billion from $8.5 billion on a 9.4% increase in average premium per policy, partially offset by a 1.5% decrease in personal lines policies in force. Commercial lines did better on both axes: premium up 10.1% to $3.8 billion on a 7.7% price increase and a 2.2% increase in policy count.2
So the growth of 2024–2025 was price doing nearly all the work while the customer base shrank slightly. That is a normal outcome of a rate-driven cycle. It is also the mechanism by which a fee-on-premium business can look excellent for several years while the underlying franchise quietly loses ground.
2026: the underwriting repair, and the growth bill
By 2026, the rate actions had done their job on the loss side. In Q1 2026, the Exchange's combined ratio came in at 99.4% as catastrophe losses normalized, while direct written premium growth slowed to roughly 3.6%.12 In Q2, the combined ratio was 103.9% — a 13-point improvement year over year, with catastrophes contributing 15 points versus 22 in the prior-year quarter — while premium growth decelerated to 3.3% from 9.2%.13 Policies in force were down about 2% year-over-year and retention had slipped further, to roughly 87.5%.13
Indemnity's own results held up. Q1 2026 net income was $150.5 million ($2.88 per diluted share) against $138.4 million ($2.65) a year earlier, with operating income up about 10%.8 Q2 2026 net income was $180.3 million ($3.45) versus $174.7 million ($3.34), though operating income growth slowed to 2.5% as commissions rose $44.7 million — driven substantially by agent incentive compensation.9 First-half net income reached $330.8 million, or $6.32 per diluted share.9
Read those two quarters together and the model's honest shape appears. The fee revenue line decelerated with premium growth, from mid-single digits toward low-single digits. Expenses — specifically the money spent motivating agents to rebuild the policy count — did not decelerate. Operating income growth compressed from 10% to 2.5% in one quarter.
That is the counter-cyclical trade reversing. The rate cycle that inflated the fee base has passed its peak, and what Indemnity now needs is unit growth: more policies, not more expensive ones. Unit growth is harder, slower, and more expensive to buy than rate. It is the single most important thing to watch for the rest of this decade, and it is the problem NeCastro is handing to his successor.
The handoff
The February 20, 2026 announcement gave the board more than ten months of runway and gave NeCastro a defined landing spot as president of the Erie Insurance Foundation.4 As of mid-September 2026, no successor has been named publicly. The company has also been visibly pushing technology modernization — cloud infrastructure and digital tooling for the agent channel — but the concrete evidence of whether that investment is converting into faster quoting, better conversion, and recovered policy count is not something the disclosures currently let an outsider verify. What can be verified is the direction of the count, and through Q2 2026 it was still negative.
VII. Industry Structure & Competitive Dynamics: David's Agent Network vs. Goliath's DTC Algorithms
Picture a Saturday morning in suburban Pittsburgh. A 24-year-old with a used sedan opens an app, answers nine questions, and obtains a bindable auto quote in four minutes. Two blocks away, a 58-year-old with a house, two cars, a boat, and an umbrella policy calls the agency his family has relied on for decades, knowing the agent has handled three claims for him and understands local repair networks.
Those scenarios illustrate the two distinct models competing for the American personal lines dollar. Erie operates firmly in the second.
The map
Direct-to-consumer carriers, such as Progressive and GEICO, built a fundamentally different cost structure: no agent commissions, national advertising amortized across every state, and pricing algorithms fed by vast datasets. Their massive advertising budgets function as a strategic weapon, transforming customer acquisition into a capital-intensive game that a regional carrier with a $13 billion premium base cannot play at parity.
Captive and hybrid national carriers—State Farm, Allstate, Liberty Mutual—occupy the middle ground, relying on proprietary agent networks and national brand recognition.
Then there is the independent agency channel, where Erie competes directly against carriers like Travelers, Cincinnati Financial, Auto-Owners, and Selective. In its regulatory filings, Indemnity characterizes this environment as a battle inside appointed agencies based on ease of doing business, product features, pricing, and service quality.2
Where Erie is genuinely strong
Erie's core advantage rests neither on aggressive pricing nor proprietary consumer software. It stems from deep agency relationships and a localized claims infrastructure—supported by 24 field offices across 12 states.2 When a severe storm strikes a county, adjusters living in that community can settle claims faster than out-of-state catastrophe teams. Rapid settlements build strong goodwill with agents, who ultimately choose where to place new business.
The structural expression of this advantage is Erie's lead-carrier strategy: positioning itself as the agency's first choice to secure initial access to preferred policyholder risks.2 When successful, this produces an underwriting selection advantage that automated algorithms rarely capture, because high-quality risks often never reach competing quote engines.
A second strength is account bundling. A household placing auto, home, and umbrella coverage through a single independent agent faces high friction when re-shopping, as switching requires unwinding multiple contracts. This dynamic explains why Erie's policy retention historically hovered near 90%.2
Where Erie is genuinely exposed
Operating evidence from 2025 and 2026 highlights three primary vulnerabilities.
First, price sensitivity can overcome relationship loyalty at the margin. As cumulative rate increases reached double digits, policy retention declined from 90.4% at year-end 2024 to 88.4% in 2025, and slipped further toward 87.5% by mid-2026.213 While a drop of roughly three percentage points does not indicate structural failure, across a base of seven million policies it represents a meaningful loss of policyholders, demonstrating that agent relationships modulate churn rather than prevent it.
Second, new business acquisition shows more acute pressure. The 22.8% decline in new business policies written in 2025 is the sharper signal.2 While retention measures whether existing policyholders remain, new business indicates whether the distribution channel can win competitive shopping decisions. When Erie's pricing moved out of line with the market, the independent agent network could not fully insulate it from competitive losses.
Third, demographic shifts pose long-term headwinds. Younger policyholders increasingly favor instant digital quoting, a segment where independent agency distribution operates at a structural speed disadvantage. Furthermore, agency principal demographics create succession risk: as independent agency owners retire, sales to national aggregators can result in policy portfolios being redirected to competing carriers.
The war-game conclusion
Erie is not engaged in direct head-to-head competition with high-frequency direct-to-consumer carriers. It operates within a distinct segment—serving service-sensitive, bundle-heavy, relationship-oriented households where its regional economic model remains viable.
However, that market segment is largely mature. The data from 2025 and 2026 indicates that Erie's operational edge is strong enough to maintain core customer retention during normal market conditions, but insufficient to expand market share during periods of price adjustments. This distinction clarifies the limits of Erie's franchise strength as the enterprise enters its next executive era.
VIII. Management Credibility, Governance & Capital Allocation: The Dual-Class Vault
Every public company has a moment that reveals its actual priorities. Erie Indemnity's arrived in 2025, and it cost $100 million.
How management is paid to behave
Executive compensation reveals corporate priorities more clearly than public relations statements. Indemnity's annual incentive plan relies on corporate performance measures that include reported growth in direct written premium, expansion in policies in force, and the statutory combined ratio of the Exchange and its property and casualty subsidiaries.2 Similarly, its long-term incentive plan tracks direct written premium growth, statutory combined ratio, and the Exchange's return on invested assets over a three-year evaluation window against an industry peer group.2
This compensation framework is better aligned than the tollbooth critique would suggest. If executives were compensated solely on premium volume, the structural conflict highlighted earlier would be severe: the fastest path to a bonus would be raising rates to expand the fee base, irrespective of customer churn. Instead, two of the three annual performance metrics counteract that incentive: tracking policies in force penalizes generating premium through price hikes at the expense of unit volume, while the statutory combined ratio ties executive pay directly to the Exchange's underwriting performance—an exposure that Indemnity's income statement otherwise avoids.
In effect, management performance is evaluated against the financial health of the risk-bearing pool. While this design provides meaningful operational alignment, it does not alter the underlying economics: underwriting losses remain with the Exchange's policyholders, while Indemnity continues to collect management fees on gross written premium.
Capital allocation: simple, and mostly shareholder-friendly
Indemnity operates with a debt-free balance sheet and low capital intensity, as the Exchange owns the primary operating infrastructure and reimburses Indemnity for administrative services. As a result, the majority of Indemnity's earnings converts directly into distributable cash flow.
That cash returns to investors through a steadily compounding dividend. For 2025, the board raised regular quarterly dividends for both Class A and Class B shares by 7.1% over 2024 levels. It repeated that exact 7.1% increase for 2026, raising the quarterly dividend on Class A shares from $1.365 to $1.4625 per share and on Class B shares from $204.75 to $219.375 per share, effective January 1, 2026.211 Authorizing matching 7.1% increases in consecutive years signals a commitment to predictable dividend growth rather than a reaction to short-term earnings fluctuations.
At that same December 9, 2025 meeting, the board set the 2026 management fee rate at 25%—the contractual maximum.11
The stress test an activist would run
This point of capital allocation illustrates where a skeptical investor might push, and where Indemnity's corporate structure prevents external intervention.
The foundation contribution. In 2025, Indemnity contributed $100 million to establish the Erie Insurance Foundation, a tax-exempt private entity designed to support long-term charitable grantmaking. The contribution resulted in an after-tax charge to shareholders of $80.6 million, or $1.54 per diluted share, recognized in the fourth quarter of 2025.3 That discretionary expenditure accounted for the year-over-year decline in net income, dropping reported diluted earnings per share from $11.48 in 2024 to $10.69 in 2025.3
A strategic argument exists for the contribution: Erie Indemnity and its namesake city are deeply interconnected, the majority of its workforce resides locally, and an endowed foundation offers more consistent civic support than discretionary annual line items. However, the governance critique is equally clear: $80.6 million in public after-tax earnings was allocated to a private foundation by a board that non-voting Class A shareholders cannot elect or remove. Furthermore, the decision for outgoing CEO Tim NeCastro to assume the presidency of the foundation upon his retirement represents the type of governance overlap that activist investors routinely challenge.4 While fully compliant with legal standards, the transaction clearly illustrates the practical effect of holding non-voting shares.
The disclosure posture. Erie Indemnity limits its quarterly earnings calls to prepared executive remarks. The transcript for the fourth-quarter 2025 call contained formal management commentary without an analyst question-and-answer session.5 While common among closely held entities, omitting live Q&A removes the primary venue for public investors to question management decisions.
This format prevents Wall Street analysts from probing critical strategic choices: why the board maintained the maximum 25% fee rate while the Exchange posted a 104.9% combined ratio, what surplus threshold might trigger a fee reduction, how future foundation funding will be structured, or how management plans to reverse the 22.8% drop in new business policies. Without voting power or interactive earnings calls, public shareholders must rely almost exclusively on voluntary disclosures. To its credit, management has maintained transparency in its prepared statements, directly disclosing declines in policy retention and unit counts.5 Nevertheless, voluntary disclosure remains fundamentally distinct from answering direct questions under market scrutiny.
Narrative consistency. Across earnings communications from late 2025 through mid-2026, executive commentary has remained consistent. Management's narrative—that rate hikes restored pricing adequacy between 2022 and 2024, rate growth moderated as pricing aligned with loss trends in 2025, and combined ratios improved in 2026—aligns with disclosed financial results.51213 Rather than dismissing policy retention pressures as transient, management acknowledged that competitive market dynamics drove the slowdown. The disclosed record reflects a leadership team that has accurately described its operating cycle, establishing a degree of reporting credibility.
For public shareholders, the governance profile presents a distinct set of trade-offs: executive incentives align more closely with risk-pool health than the fee structure suggests, dividend growth remains steady, and disclosure remains structured around one-way communications. Because Class A shareholders lack voting leverage, evaluating Erie Indemnity ultimately requires weighing predictable fee-based cash flows against a governance structure that offers no shareholder recourse.
IX. Financial Mechanics & Historical Falsification Audit
A century-long operating record provides value only when evaluated against its defining investment assumptions. Three core claims form the bull thesis for Erie Indemnity. Each claim can be tested against potential disconfirming evidence documented in the company's public disclosures.
Thesis Claim 1: "The 25% management fee is an unshakable cash annuity shielded from underwriting risk."
The test: has the fee rate ever moved, and what would move it?
The evidence. The subscriber agreement caps the management fee at 25% rather than fixing it permanently. The rate is set at least annually by Indemnity's board of directors, typically each December for the upcoming calendar year.2 Public filings confirm that the board established the rate at the 25% cap for 2016, 2017, 2019, 2020, 2024, 2025, and 2026.1114152 This record demonstrates consistent board authorization at the contractual ceiling across these reported periods, though it does not guarantee the rate has never varied in prior decades.
The primary counter-evidence appears in the company's risk disclosures rather than its historical rate table. In annual filings, Indemnity explicitly notes that the rate-setting process evaluates the relative financial strength and capital position of both entities, projected revenue and earnings, future capital requirements, and competitive positioning. The filings acknowledge that evaluating these factors "could result in a reduction to the management fee rate," which would materially impair revenues and profitability, while separately noting that regulatory or third-party interventions could force a similar outcome.2
The weighing. Even after the Exchange recorded consecutive annual underwriting losses — including the costliest weather event in company history — the board maintained the 25% maximum rate for 2026.511 While this demonstrates near-term durability during severe storm cycles, it occurred while policyholders' surplus reached $10.1 billion and underwriting ratios were already recovering when the decision was finalized.2 Consequently, the fee structure has not been tested under a scenario of sustained capital depletion at the Exchange.
Conclusion. The historical record narrows the thesis: the management fee functions as a contractual ceiling reset annually by the board, not an absolute annuity. While the fee remained intact through a two-year underwriting strain as Exchange surplus continued to grow, the board retains discretion to lower the rate if financial conditions demand it. What would falsify the narrowed claim: a board decision setting the subsequent year's fee below 25%, or a sustained decline in Exchange statutory surplus below prior-year levels that forces a rate adjustment.
Thesis Claim 2: "The independent agent network is an impregnable local distribution moat."
The test: did the agent relationship hold customers when Erie's price was uncompetitive?
The evidence. The distribution network held existing business more effectively than it captured new accounts. Policy retention fell from 90.4% at year-end 2024 to 88.4% in 2025, reaching approximately 87.5% by mid-2026.213 Total policies in force declined 1.1% in 2025 and fell roughly 2% year-over-year in the second quarter of 2026.213 Although renewal premium expanded by 13.4%, that gain reflected higher rates applied to a shrinking policyholder base.2
The sharper decline occurred in new customer acquisition. New business premium fell 17.8% to $1.5 billion in 2025, driven by a 22.8% drop in new policies written.2 While high retention reflects customer inertia, new policy growth tests competitive positioning. When rate increases pushed Erie's pricing above market peers, the independent agency channel experienced a near-one-quarter drop in new policy volume compared to the prior year.
The weighing. Retention near 88% amidst double-digit price hikes indicates that local agency relationships effectively insulate the existing policy base during broad inflationary cycles. However, the drop in new policy volume reveals a clear boundary: independent agents could not overcome price resistance when competing for new shoppers.
Conclusion. The evidence refutes the notion of an unassailable moat, demonstrating that the agency network acts as a robust retention asset but a weaker acquisition engine during periods of relative price inflation. This distinction is critical for a fee-based management company: as direct written premium growth slowed to 3.3% in the second quarter of 2026, retention alone proved insufficient to expand the revenue base.13 What would confirm or falsify the revised claim: policy growth metrics following rate stabilization. If underwriting gains allow pricing to normalize but new policy acquisition fails to rebound, the distribution bottleneck is structural rather than cyclical.
Thesis Claim 3: "Geographic contiguity prevents scale inefficiencies."
The test: has the regional density model traveled, and what does concentration cost?
The evidence. Erie operates across 12 states and the District of Columbia, supported by 24 field offices.27 However, corporate disclosures highlight that Indemnity's workforce remains heavily concentrated in Erie, Pennsylvania. Annual filings explicitly note that a major localized event affecting personnel in the Erie area could disrupt policy acquisition, underwriting, claims processing, and administrative support.2
Catastrophe exposure poses a broader structural challenge. The Exchange's mid-Atlantic and midwestern footprint exposes the pool to severe convective storms, winter weather, and tropical cyclones. Disclosures caution that a single severe catastrophe or a series of regional weather events could impair the Exchange's financial position.2 In 2025, catastrophe losses added 10.6 percentage points to the combined ratio, driven in part by the costliest single weather event in company history.5
State-level market share and premium concentration details are omitted from public filings, leaving the precise degree of Pennsylvania state concentration unquantified in public disclosures.
The weighing. Geographic contiguity achieves administrative cost efficiency and localized claims density, but it limits risk diversification. While national carriers spread regional weather events across fifty states of earned premium, Erie absorbs storm losses across a twelve-state corridor where convective weather frequently concentrates.
Conclusion. The contiguity model succeeds on cost management but introduces geographic risk concentration. Although underwriting losses are borne by the Exchange rather than Indemnity, severe catastrophe losses that erode policyholder surplus increase pressure on the board to reconsider the 25% management fee cap. The three thesis claims are structurally linked: geographic concentration represents the primary trigger for potential fee reductions. What to watch: Exchange statutory surplus, which serves as the ultimate metric connecting underwriting health to management fee stability.
X. Competitive Moat Analysis: Helmer's 7 Powers & Porter's 5 Forces
Evaluating Erie through established strategic frameworks clarifies which of its business advantages are genuinely structural and which stem from routine operational habits.
Hamilton Helmer's 7 Powers
Counter-Positioning — strong and permanent. This represents Erie's most durable advantage and is purely structural. A conventional stock insurer cannot adopt a reciprocal-plus-attorney-in-fact model without surrendering its own equity claim on underwriting profits. A commercial carrier like Travelers cannot transfer its reserves to policyholders and convert into a fee manager; doing so would dismantle its core business model. Competitors cannot replicate this structure because doing so would be economically self-destructive.
Cornered Resource — strong. Indemnity holds an exclusive, open-ended power of attorney to manage a $13 billion insurer that legally cannot employ staff directly.2 No competitive bidding process exists for this contract. Coupled with the 2,542 Class B shares that control both entities, this management relationship remains virtually unassailable from the outside.2
Process Power — moderate. Decades of localized claims infrastructure and lead-carrier positioning within independent agencies constitute accumulated organizational capabilities that new entrants cannot easily buy. However, the decline in new policy growth in 2025 demonstrates that process efficiency alone cannot overcome uncompetitive pricing.
Switching Costs — moderate. Multi-line policy bundling creates meaningful customer friction, as shown by policy retention remaining near 88% through a sharp rate-increase cycle.2 Nevertheless, the drop from historical retention levels above 90% reveals clear limits to customer inertia when price hikes accumulate.
Scale Economies — weak to moderate. Erie benefits from regional density in claims handling across its core 12-state footprint. However, it lacks national scale in advertising, data processing, and technology spending—the primary cost dimensions where direct-to-consumer leaders like Progressive and GEICO hold structural advantages. Erie's scale advantages are local, while its scale disadvantages are national.
Network Effects — absent. Adding an individual policyholder does not enhance the product's value for existing policyholders. The closest regional equivalent—agency density generating local referral momentum—is a distribution advantage rather than a network effect.
Brand — moderate and asymmetric. Erie commands strong brand equity within its mid-Atlantic and midwestern footprint, but has limited consumer recognition beyond it. Brand strength that ends at regional borders provides real, but inherently bounded, competitive power.
In sum, Erie Indemnity possesses two strong, structural powers, both of which govern the internal relationship between Indemnity and the Exchange rather than the Exchange's position in the broader insurance market. Indemnity's moat against losing its sole client is nearly absolute, whereas the Exchange's moat against losing policyholders remains far more exposed to industry competition.
Porter's Five Forces — applied to the Exchange's market
Threat of new entrants — low. High capital requirements, state-by-state regulatory approvals, complex rate filings, and the multi-year investment needed to cultivate independent agency relationships create substantial barriers to entry. Insurtech entrants have repeatedly shown that distribution access and loss-cost data, rather than software, constitute the main barriers in personal lines insurance.
Bargaining power of buyers — moderate and rising. Individual policyholders possess no leverage over rate filings, but they retain full freedom at renewal and have access to increasingly transparent comparison tools. The pressure on 2025 retention and new policy volume reflects this growing buyer price sensitivity.
Bargaining power of suppliers — high, driven by independent agents. Independent agents represent the primary supplier force in Erie's operating model. Because independent agencies own the customer relationship, represent competing carriers, and can redirect policy portfolios, Erie spends approximately 71% of policy issuance expenses on agent commissions and incentives to maintain channel alignment.2 Escalating agent incentive compensation in both the first quarter8 and second quarter of 20269 illustrates the costs incurred when a carrier relies on its channel to rebuild policy count. Additionally, repair networks and contractors exert secondary supplier power over loss costs, driving much of the 2022–2024 claim severity shock.
Threat of substitutes — high. Direct-to-consumer channels offer the same underlying protection through a different delivery model with lower distribution overhead. This structural cost efficiency makes direct sales a potent substitute for agency-distributed policies.
Competitive rivalry — high. Personal auto and homeowners insurance remain mature, commoditized, price-sensitive markets characterized by transparent filings and intense carrier competition.
Ultimately, Erie Indemnity holds a highly protected management contract over an entity operating in a demanding, competitive industry. While Indemnity's fee revenue is contractually insulated from underwriting losses, it remains tied to underlying market realities: over the long term, the Exchange's ability to defend its policy base determines the gross premium volume that fuels Indemnity's earnings.
XI. Bull vs. Bear Investment Spine & The 3 Critical KPIs
Why this wins from here
The capital-light thesis forms the foundation of the bullish investment case. Indemnity carries no long-term debt, requires minimal capital reinvestment, and converts operating income into distributable cash at a rate traditional carriers cannot replicate because it holds no direct underwriting risk. Operating income grew from $520.2 million in 2023 to $717.2 million in 2025 without requiring capital raises, acquisitions, or balance-sheet leverage.2
Its contractual positioning remains exceptionally rare. Managing a $13.0 billion premium base under a perpetual agreement—where Indemnity's board effectively oversees both sides of the relationship without competitive bidding or contract expiration—creates a revenue stream that functions more like a royalty than a standard operational business.
Furthermore, recent history demonstrated the effectiveness of its inflation pass-through mechanism. During one of the most severe loss environments for personal lines insurance in decades, Indemnity's earnings expanded even as the Exchange suffered underwriting losses.25
This capital model supported two consecutive 7.1% dividend increases in 2025 and 2026, fully funded from operating cash flow while preserving a debt-free balance sheet.211
What breaks the case
Single-customer concentration, which is absolute. The Exchange is not merely Indemnity's primary client; it is its sole customer. Consequently, every fundamental threat facing the Exchange—including catastrophe losses, reserve shortfalls, credit rating downgrades, regulatory scrutiny, and competitive churn—eventually impacts Indemnity's revenue base without a direct operational hedge.
Unit growth has stalled. Total policies in force contracted in 2025 and declined further through the second quarter of 2026, while direct written premium growth decelerated from 8.9% in 2025 to 3.3% in the second quarter of 2026.213 Management fee growth relies on rate adjustments or unit volume. Because recent rate hikes have largely run their course, persistent unit contraction threatens to flatten fee growth, as demonstrated by the slowdown in second-quarter 2026 operating income growth to 2.5%.9
The management fee rate remains discretionary. The 25% fee cap is set annually by Indemnity's board, which explicitly notes in regulatory disclosures that financial stress at the Exchange could prompt a rate reduction—a risk magnified by the pool's geographic concentration.2
Governance structure limits shareholder recourse. Public investors hold non-voting shares, earnings calls omit live analyst questions, and management demonstrated its discretion by committing $100 million of pre-tax earnings to a private foundation in 2025.3 As a result, Class A shareholders must rely entirely on board oversight without mechanisms to challenge corporate decisions.
Distribution channel demographic risks. The independent agency network faces long-term demographic challenges as agency principals retire and policyholders skew older. Meanwhile, Erie's ability to acquire younger, digitally focused policyholders against direct-to-consumer competitors remains unproven in published disclosures.
Climate and geographic exposure. Severe convective storm activity across Erie's mid-Atlantic and midwestern footprint has intensified, with management acknowledging that higher insured property values and regional concentration amplify catastrophe severity.2 Sustained weather losses directly threaten Exchange policyholder surplus, creating downstream risk for Indemnity's fee base.
The three KPIs that matter
Evaluating Erie Indemnity's long-term trajectory depends on monitoring three primary operational metrics.
1. Policies in force — unit volume separated from rate increases. Direct written premium growth combines price adjustments and unit volume, masking customer retention trends during periods of heavy rate hikes. Policy count serves as the direct measure of customer base trajectory, having contracted 1.1% in 2025 and approximately 2% year-over-year in the second quarter of 2026.213 As rate increases moderate, unit volume will dictate long-term management fee expansion.
2. Exchange statutory policyholders' surplus. Statutory surplus functions as the primary indicator of management fee stability. Although surplus expanded from $9.3 billion to $10.1 billion in 2025 despite underwriting losses, a sustained capital decline remains the main scenario that could force the board to reduce the fee rate below 25%—the primary downside risk to Indemnity's earnings power.2
3. Policy retention ratio. Customer retention measures the ongoing effectiveness of the independent agency network, which accounts for roughly 71% of policy issuance expenses. Retention slipped from 90.4% at year-end 2024 to 88.4% in 2025, and reached approximately 87.5% by mid-2026.213 Stabilization would validate the agency distribution advantage, whereas further erosion would indicate structural competitive friction.
Tracking these three metrics provides a clear view of operational momentum, as direct written premium growth, net income, and dividend sustainability will ultimately follow their trajectory.
XII. Epilogue: What Would You Do?
Before December 31, 2026, a new chief executive will step into the executive office at Erie Insurance and inherit a distinct set of operational choices.
In the near term, immediate financial pressures remain low. The Exchange's combined ratio has begun recovering, statutory policyholders' surplus stands at a record high, the management fee rate remains at its 25% contractual ceiling, and dividend coverage remains robust. On the surface, this transition appears to be one of the smoother handoffs in regional financial services.
Underneath that operational stability, three core questions await the incoming leadership team.
The footprint question. Operating across 12 states and the District of Columbia, Erie relies on a claims model that succeeds through regional density, yet remains exposed to severe convective storm risks concentrated in that same footprint. Expanding into non-contiguous territory could diversify catastrophe exposure and enlarge the premium base, but doing so risks diluting the local density that generates Erie's cost advantage, while requiring the carrier to compete against established incumbents in unfamiliar markets. Conversely, doubling down on the core footprint preserves operational efficiency while maintaining geographic risk concentration. Regional carriers seeking to expand beyond their historic territories have repeatedly found that density advantages do not travel easily. The incoming executive team will need to navigate this structural trade-off.
The acquisition question. This issue represents the primary operational challenge. New business policies written fell 22.8% in a single year.2 A portion of that decline may reverse as rate adequacy normalizes and pricing recovers competitiveness. However, another portion could prove structural, as consumers who migrated to digital platforms during rate adjustments may not return to traditional agency channels. Erie's distribution strategy must reconcile two competing demands: preserving independent agents at the center of customer relationships while serving policyholders who expect rapid online quoting. Increasing agent compensation—reflected in the elevated incentive payouts during 2026—buys sales effort, but it does not construct a direct-to-consumer channel. Public disclosures have not yet demonstrated whether recent technology investments are successfully converting into policyholder growth.
The disclosure question. Erie Indemnity remains a Fortune 500 enterprise that omits live analyst question-and-answer sessions from its earnings calls.5 Non-voting Class A shareholders possess neither board representation nor a formal governance forum. Adopting an open Q&A format would cost management little beyond increased scrutiny, while addressing a concrete driver of the governance discount applied by institutional investors. Because such a change remains entirely voluntary, it represents a clear test of corporate transparency rather than regulatory compliance.
A century ago, two founders raised $31,000 from 90 local investors on the premise of a handwritten plan to reform insurance service. Over the subsequent hundred years, that enterprise developed into an unusual dual architecture: a policyholder-owned risk pool isolated from external shareholder demands, coupled with a publicly traded management entity that earns fees regardless of underwriting profitability.
Both sides of that structure will soon pass to a new leader. While the management company's fee tollbooth continues to collect, long-term performance will depend on the volume and health of the policyholder traffic passing through it.
References
-
History of Erie Indemnity Company — FundingUniverse ↩↩↩↩↩↩↩↩↩↩
-
Erie Indemnity Company Form 10-K for Fiscal Year Ended December 31, 2025 — SEC EDGAR, 2026-02-23 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Erie Indemnity Reports Full Year and Fourth Quarter 2025 Results — Form 8-K Exhibit 99.1, SEC EDGAR, 2026-02-24 ↩↩↩↩↩↩
-
Tim NeCastro to retire as president and CEO of Erie Insurance — Form 8-K Exhibit 99.1, SEC EDGAR, 2026-02-20 ↩↩↩↩↩↩↩↩
-
Erie Indemnity (ERIE) Q4 2025 Earnings Call Transcript — The Motley Fool, 2026-02-25 ↩↩↩↩↩↩↩↩↩↩
-
Erie Insurance ranked #323 on the 2025 Fortune 500 list of America's largest corporations — Erie Insurance, 2025 ↩↩
-
Erie Insurance ranked 308th on the 2026 Fortune 500 list — Erie Insurance, 2026 ↩↩↩↩↩
-
Erie Indemnity Reports First Quarter 2026 Results — Form 8-K Exhibit 99.1, SEC EDGAR, 2026-04-23 ↩↩↩
-
Erie Indemnity Reports Second Quarter 2026 Results — Form 8-K Exhibit 99.1, SEC EDGAR, 2026-07-30 ↩↩↩↩↩
-
Erie Indemnity Approves Management Fee Rate and Dividend Increase, Declares Regular Dividends — PR Newswire, 2025-12-11 ↩↩↩↩↩↩
-
Erie Indemnity (ERIE) Q1 2026 Earnings Call Transcript — The Motley Fool, 2026-04-24 ↩↩
-
Erie Indemnity Q2 2026 Earnings Call: Combined Ratio Improves 13 Points as Premium Growth Moderates to 3.3% — BigGo Finance, 2026-07-31 ↩↩↩↩↩↩↩↩↩↩
-
Erie Indemnity Approves Management Fee Rate and Dividend Increase — Form 8-K Exhibit 99.1, SEC EDGAR, 2016-12-07 ↩
-
Erie Indemnity Approves Management Fee Rate and Dividend Increase — Form 8-K Exhibit 99.1, SEC EDGAR, 2019-12-10 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube