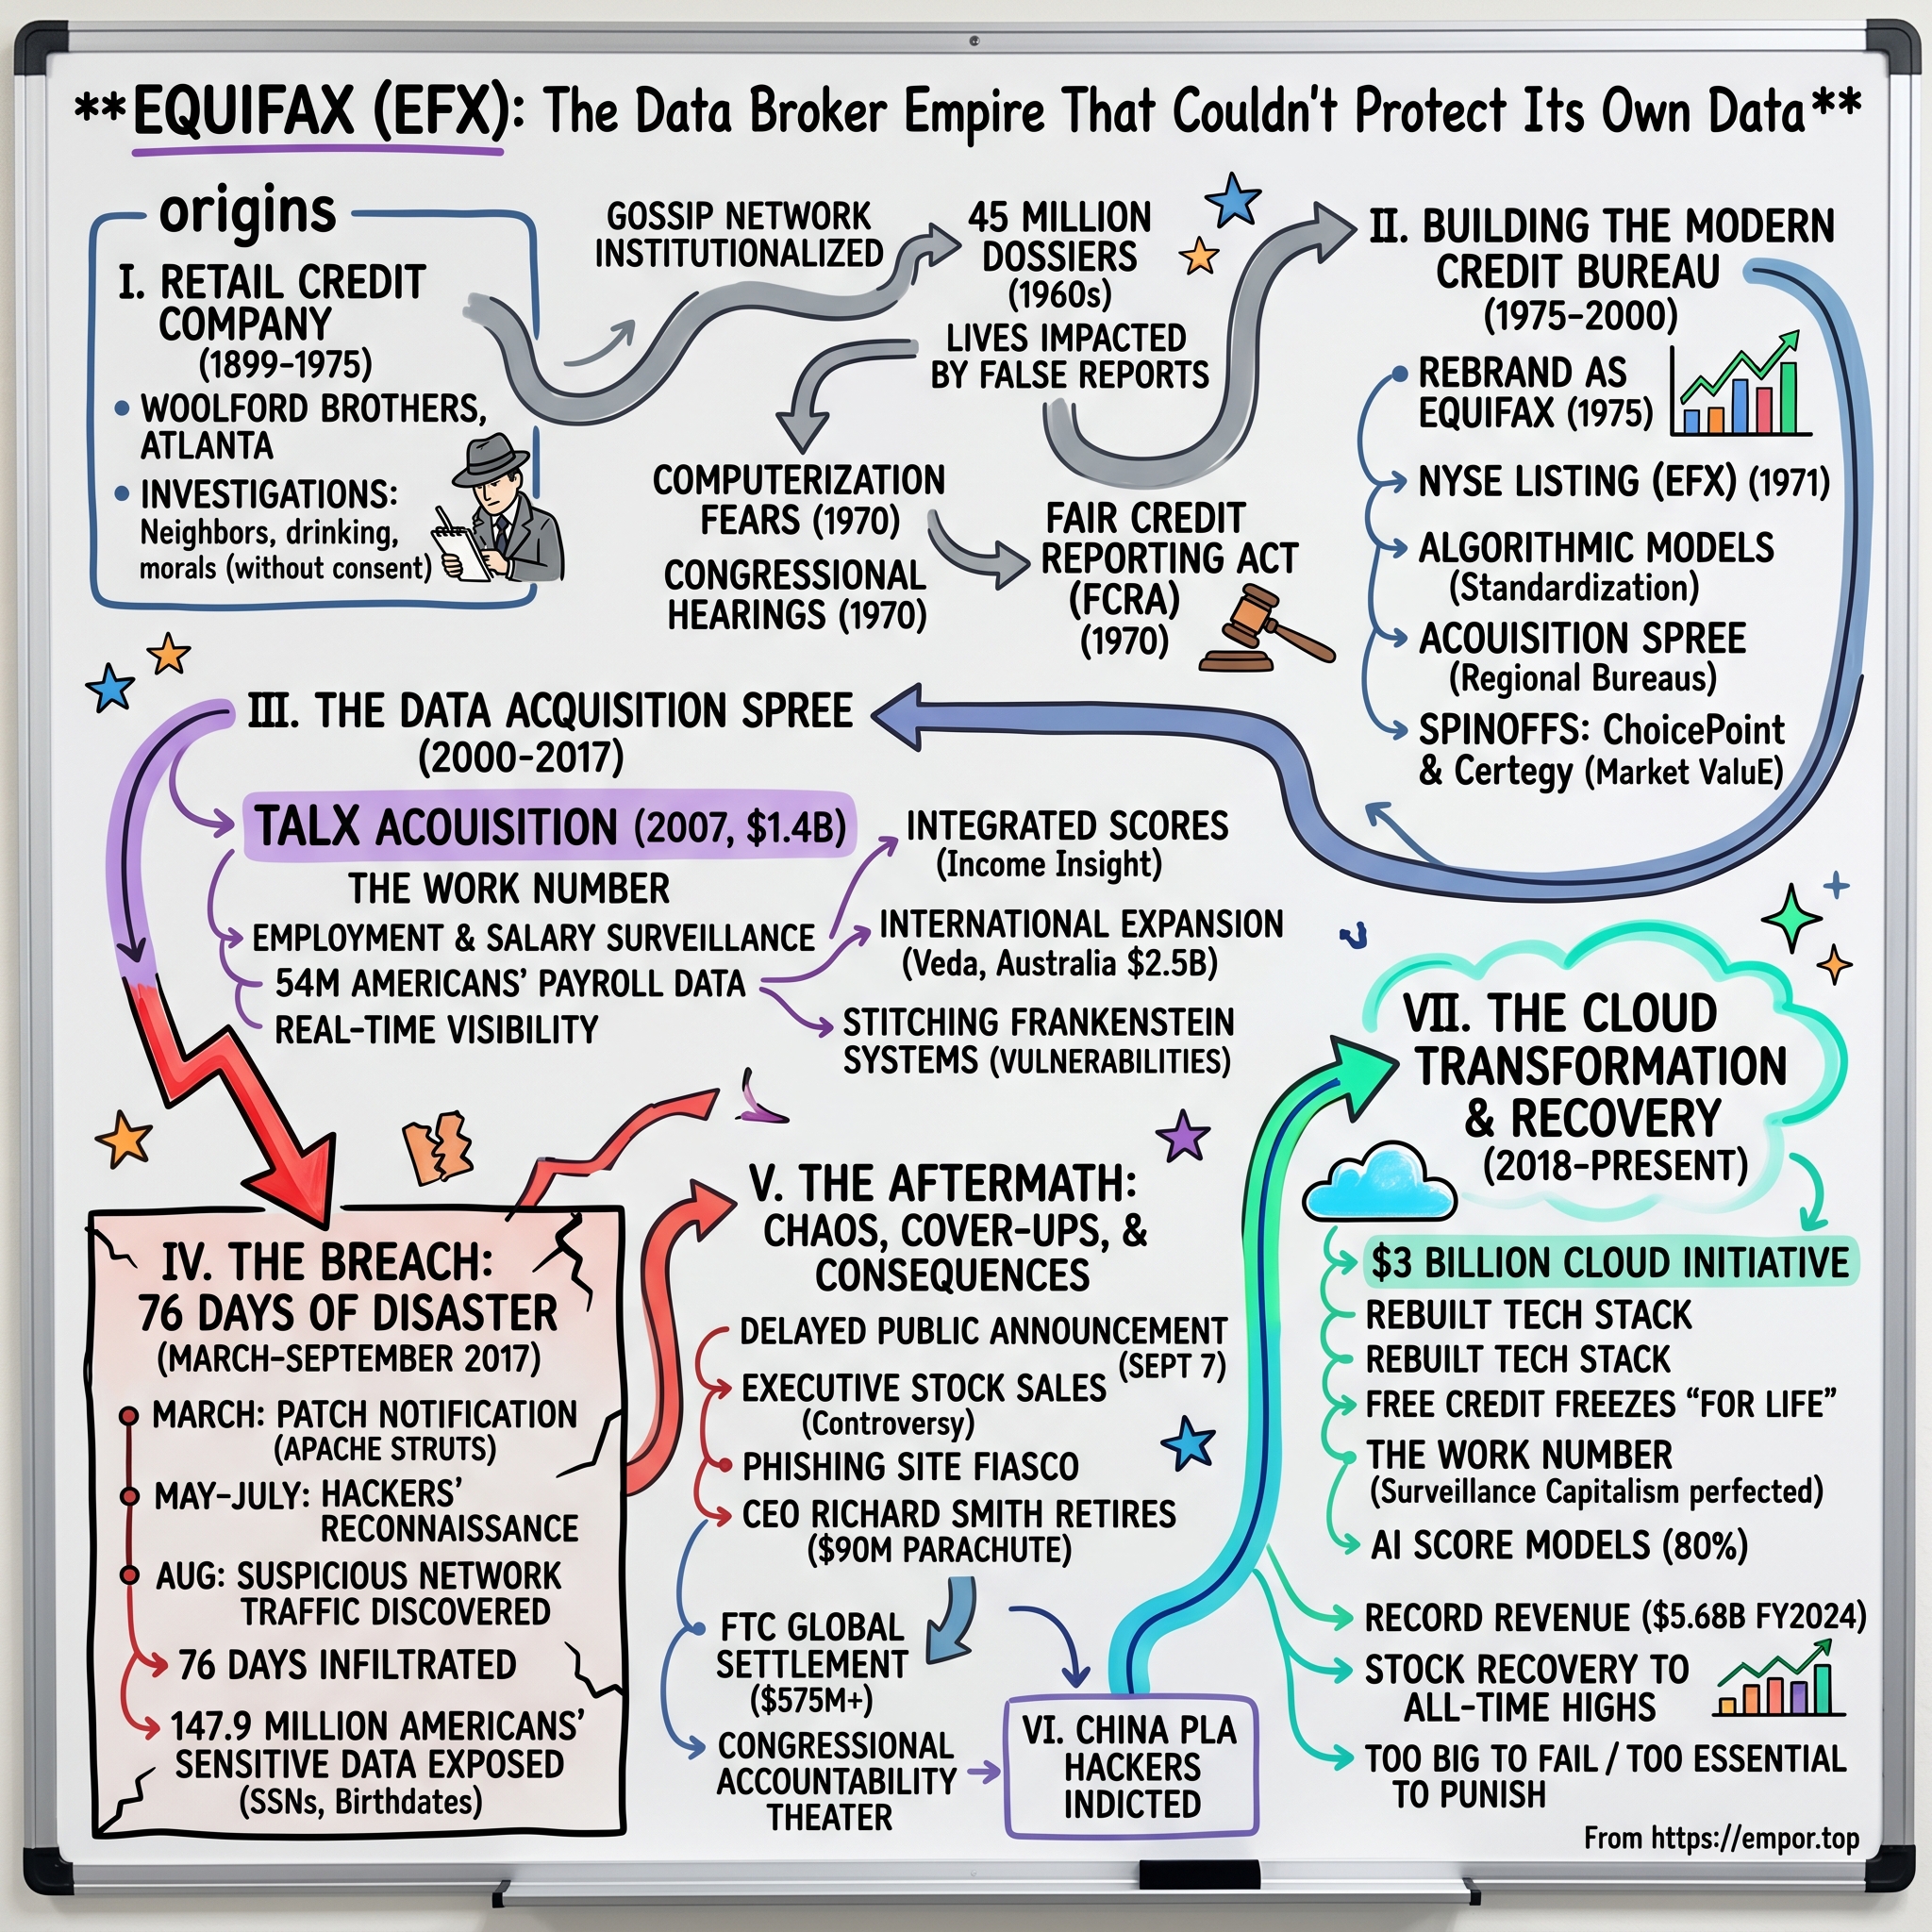
Equifax: The Data Broker Empire, The Verification Monopoly, and The $3B Cloud Turnaround
I. Introduction & Episode Roadmap
On a Thursday morning in July 2026, an analyst from Baird asked Equifax Chief Executive Officer Mark Begor a question that would have been unthinkable a decade earlier. The inquiry was not about credit scores or mortgage inquiries, but about bookings—specifically whether roughly $300 million in state-government contracts signed over four months were holding their pricing.7
Consider the shift. Equifax—widely remembered for its massive 2017 data breach—was being evaluated like an enterprise software vendor on contract retention for income-verification data sold to state Medicaid and SNAP agencies. The focus was not on credit reporting, but on workflow infrastructure.
That distinction explains the company's position in 2026. Equifax Inc. (NYSE: EFX) finished fiscal 2025 with $6.07 billion in revenue, up from $5.68 billion in 2024 and $5.27 billion in 2023.12 The firm embedded itself within major consumer financial transactions across North America, including mortgages, apartment leases, auto loans, employment background checks, and state benefit applications. It operates as shadow infrastructure: essential during routine operations and severe during outages.
The central paradox. In September 2017, Equifax disclosed that attackers had stolen the personal data of approximately 147.9 million Americans—including names, Social Security numbers, birth dates, and driver's license numbers.34 Conventional market logic suggests that a firm exposing sensitive records for nearly half a country would face severe customer attrition or regulatory dismantling. Instead, in the nine years following the disclosure, Equifax's revenue roughly doubled, its operating margins expanded, and its stock price significantly outperformed its pre-breach levels.
The explanation lies in the customer base. Equifax's primary customers are not consumers, who function as the data inventory, but lenders, employers, background screeners, and government agencies with limited alternatives.
The hidden crown jewel. Equifax is no longer principally a credit bureau. Its largest and most profitable segment is Equifax Workforce Solutions (EWS), built around The Work Number—an automated income and employment verification database. In fiscal 2025, Workforce Solutions generated $2.58 billion of Equifax's $6.07 billion in total revenue.1 In the second quarter of 2026, segment EBITDA margins reached 52.1%, compared with 32.8% for U.S. Information Solutions.7 That margin gap illustrates the structural shift: the traditional credit bureau functions as a legacy asset, while the payroll verification database serves as the primary growth engine.
The roadmap. The analysis follows a clear progression: the firm's 1899 origins selling neighborhood gossip to insurers, and the 1970 federal law that inadvertently fortified the credit reporting industry. It examines the 2007 acquisition whose significance escaped initial regulatory scrutiny; the 2017 breach and its operational failure modes; and the subsequent overhaul led by a General Electric veteran alongside a $3 billion-plus cloud migration that exceeded original budgets and timelines. Finally, it analyzes the economics of the verification franchise, potential competitive and regulatory risks, a falsification assessment of four core thesis claims, and the implications of a private firm maintaining a real-time income ledger for most working Americans.
The history begins in Atlanta, with a door-to-door surveyor recording neighborhood gossip for insurance underwriters.
 Subscribe on LinkedIn
II. The Origins & The FCRA Crucible (1899–1975)
Picture Atlanta in 1899. In a city still rebuilding, a grocery merchant named Cator Woolford kept a ledger tracking which customers settled their bills and which did not. He and his brother Guy soon realized the ledger was more valuable than the groceries. Other local merchants were willing to pay for access to it. The brothers began selling subscriptions to a compiled list of local creditworthiness and named the business the Retail Credit Company.
It was a foundational insight—that data about transactions could outlast the transactions themselves—and it remains central to the enterprise today. What unfolded over the next seven decades, however, was far more controversial.
Gossip as a Service
Retail Credit's rapid expansion came not from local grocers but from insurance companies. Life and health underwriters sought detailed intelligence on whether applicants drank heavily, gambled, maintained orderly households, or engaged in behavior deemed high-risk. Retail Credit deployed field investigators to interview neighbors, landlords, employers, and acquaintances, compiling handwritten summaries of personal lives.
The resulting records were dossiers rather than modern credit reports. They documented personal habits, domestic disputes, political affiliations, and sexual orientation. An notation indicating homosexuality could trigger insurance denials, job rejections, and mortgage refusals without notice, explanation, or an avenue for appeal. The same reporting apparatus routinely penalized Black applicants, immigrants, and anyone whose lifestyle diverged from an investigator's personal standards.
No regulatory framework governed these practices because private recordkeeping on individual citizens was virtually unrestricted. Crucially, subjects had no legal right to inspect their own files. That asymmetry formed the core of the product.
The Computerization Collision
During the 1960s, Retail Credit began converting paper dossiers onto magnetic tape. While management framed the transition as an operational upgrade, the shift raised public alarm. A paper filing cabinet in Atlanta was a localized record; a searchable digital database was a national surveillance network. Consumer advocates, journalists, and federal lawmakers quickly recognized the implications.
Congressional hearings in the late 1960s exposed an industry reliant on secret, rumor-based files containing unverified information used to make life-altering financial decisions. In response, Congress passed the Fair Credit Reporting Act of 1970, establishing three structural rules that still define consumer reporting.
First, the FCRA granted consumers the right to inspect their files and dispute errors. Second, it mandated that third parties establish a "permissible purpose" before requesting a report. Third, and most consequential for the industry's economics, it transformed credit reporting into a federally regulated marketplace.
The law was designed to curb the credit bureaus, but its ultimate effect was to insulate them. Operating inside a regulated framework required dedicated compliance systems, dispute-resolution infrastructure, audit logging, legal coverage, and permissible-purpose credentialing. These high fixed costs established significant entry barriers. A new entrant could not easily launch a competing bureau without building a fully compliant, national apparatus from day one. Management still acknowledges this dynamic: on the second-quarter 2026 earnings call, Chief Executive Officer Mark Begor described the FCRA and contractual obligations to data contributors as layers of moat surrounding Equifax's data.7
Far from acting as an operational drag, federal oversight effectively erected a protective wall around the incumbents.
Rebranding to Equifax
By the mid-1970s, the Retail Credit brand had become tied to congressional investigations and media exposés. In 1975, the company renamed itself Equifax—a portmanteau referencing equitable and facts. The rebrand updated the corporate image without altering the underlying business model.
By 1975, the structural principles of the modern franchise were fully established: individuals functioned as data inventory rather than paying clients, regulatory requirements served as barriers to entry, and historical records compounded in value over time.
For the next three decades, the business focused on expanding its traditional credit files. Then, in 2007, Equifax acquired an asset that was not a credit file at all.
III. Building the Oligopoly & The TALX Transformation (1975–2017)
The credit bureau industry of the 1970s was not dominated by three companies. It consisted of hundreds of local credit bureaus, each holding the payment history of an individual city and loosely tied together through national trade associations. What followed was one of the most methodical industry roll-ups in American business history, executed so quietly that public awareness remained minimal.
Equifax, Experian (LSE: EXPN), and TransUnion (NYSE: TRU) each built national coverage through the 1970s, 1980s, and 1990s by absorbing regional credit files one at a time. By the end of this consolidation phase, all three companies held essentially identical assets: a nationwide ledger tracking consumer debt and payment histories. Equifax had listed on the New York Stock Exchange in 1971 under the ticker EFX and has maintained an uninterrupted dividend record for more than a century—a history worth stating precisely, as the dividend has been continuous, though not continuously increasing.
Why Three, and Why Rational
Economists classify the resulting market structure as a natural oligopoly. A credit file is useful to underwriters only if it is comprehensive. Achieving completeness requires lenders to furnish data voluntarily and free of charge, an incentive driven by their desire to access pooled data from other institutions. This dynamic creates a self-reinforcing feedback loop: the bureau with the highest volume of data contributors provides superior coverage, which in turn attracts additional contributors. Once three entities achieve near-complete national coverage, a fourth entrant faces steep structural barriers, offering redundant data to a smaller customer base.
Industry behavior reflects textbook oligopoly dynamics. Three rational operators selling near-identical products into a market with inelastic demand avoid price wars. Instead, prices increase in parallel, competition focuses on analytics and customer service, and data is bought and sold among the incumbents at the margins. Equifax continues to book revenue from "third-party bureau sales" to Experian and TransUnion—a line item disclosed as an operational headwind in the second quarter of 2026, demonstrating that these firms act simultaneously as competitors and commercial partners.7
For decades, credit reporting functioned as a predictable, moderate-growth annuity closely tracking GDP growth. Under Chief Executive Officer Richard Smith, who took leadership in 2005, Equifax sought a higher-growth catalyst.
The 2007 TALX Acquisition: The Inflection Point
In February 2007, Equifax agreed to acquire TALX Corporation for approximately $1.4 billion in cash and stock. At the time, Equifax's annual revenue was under $2 billion. The transaction was not a routine bolt-on acquisition; it committed a substantial portion of the company's capital to a St. Louis-based enterprise unfamiliar to most public investors.
TALX owned The Work Number, an automated income and employment verification service. The strategic mechanics of this asset explain much of Equifax's contemporary profit structure.
Consider the traditional process when a mortgage lender confirms a borrower's income: applicants gathered paper pay stubs and W-2 forms, loan processors telephoned employer Human Resources departments, and records were transmitted via fax. The process routinely consumed three to seven days, incurred high administrative costs, and remained susceptible to document alteration.
The Work Number replaced manual verification with an automated database query. Equifax contracted directly with employers and payroll processors to ingest automated data feeds every pay cycle. When a lender requires verification, an API call returns verified employment and income data within seconds, sourced directly from payroll systems rather than applicant-provided documentation.
The operational economics are highly favorable to the operator. Employers supply payroll data at no direct cash cost to Equifax, frequently in exchange for outsourced services such as unemployment-claims management, W-2 processing, and HR compliance administration. Consequently, Equifax acquires data primarily through service delivery rather than cash outlay. Data ingestion occurs automatically, minimizing collection labor, while the marginal cost of executing additional database queries is negligible.
With zero-cost data inputs, automated ingestion, minimal marginal costs, and a product offering speed unmatched by manual alternatives, the enterprise functions less like a conventional data vendor and more like a financial toll booth.
The Antitrust Oversight
The Federal Trade Commission reviewed the transaction and resolved its inquiry in 2008 through remedies focused on contract exclusivity clauses that bound employer relationships. Within the regulatory framework of the era, the transaction was analyzed as a modest vertical integration within a specialized HR services market.
In retrospect, regulatory scrutiny focused on contractual terms rather than structural market concentration. The core implication was that a single entity was acquiring the sole comprehensive, continuously updated, employer-sourced record of American wages. The value of such a database scales non-linearly with coverage: a verification system covering 40% of the workforce frequently fails to return results, whereas coverage of 75% delivers reliable utility to lenders, creating strong winner-take-most dynamics.
By 2011, the TALX segment generated $404.3 million in revenue.1 By 2016, the renamed Workforce Solutions segment reached $702.2 million, and by 2021, it expanded to $2.04 billion.1 Over that decade, the division grew from approximately one-fifth of Equifax's total revenue to nearly two-fifths, operating at profit margins significantly above those of the legacy credit bureau.
The Rest of the Capital Allocation Record
Assessing management performance requires evaluating the broader capital allocation record alongside the TALX transaction. Between 2000 and 2017, Equifax's acquisition strategy yielded mixed results.
In 2016, Equifax acquired Veda Group for approximately $1.9 billion, securing control of the leading credit bureau across Australia and New Zealand. While the transaction secured established national franchises in stable developed markets, it was executed at a high valuation near a market cycle peak. As a result, the International division has remained the company's slowest-growing and lowest-margin unit, recording a 27.6% EBITDA margin in the second quarter of 2026 compared with 52.1% at Workforce Solutions.7 Whereas Veda expanded geographic footprint, TALX established market concentration in payroll verification.
Smaller acquisitions—including Anakam for multi-factor authentication in 2010 and eThority for analytics in 2011—were integrated into broader segment reporting without materially altering corporate performance.
A balanced assessment indicates that during the Smith tenure, Equifax executed one highly transformative acquisition alongside several routine transactions. The long-term impact of TALX was not fully reflected in initial 2007 strategic disclosures; its profitability expanded as automated underwriting made instantaneous income verification standard across consumer lending.
That transformation leads directly to the next major development of the Smith era, and the events that ultimately defined his tenure.
IV. The 2017 Breach: Anatomy of a Megadisaster
The most damning document in Equifax's history is not the public breach disclosure. It is an internal audit from 2015.
That review, later surfaced during a congressional investigation, revealed that Equifax's patch management process was ineffective. The company had accumulated thousands of unremediated vulnerabilities, lacked a comprehensive software inventory, and operated a flat internal network where an attacker reaching one system could access many others.5 Two years before the breach, Equifax had been informed in writing by its own internal auditors of its systemic vulnerabilities.
For investors, the critical insight extends beyond cybersecurity: the breach was not a single isolated event, but a chronic operational state. The company had existed in a breachable condition for years, making the specific exploited vulnerability almost incidental.
The Timeline
March 7, 2017. The Apache Software Foundation disclosed CVE-2017-5638, a critical vulnerability in Apache Struts, a widely used web application framework. Exploitation was straightforward: an attacker could send a malformed HTTP request to execute arbitrary code on the server. The severity was recognized immediately. The U.S. Department of Homeland Security issued an alert, and Equifax distributed an internal directive instructing teams to patch affected systems.4
The patch was not applied to the U.S. online dispute portal—the consumer-facing web application where individuals contested credit report errors. A subsequent audit scan failed to detect the unpatched system because it searched the wrong directory path.5 Without a complete asset inventory to verify coverage, the oversight went unnoticed.
May 13, 2017. Attackers exploited the unpatched portal. Inside, they found minimal network segmentation, allowing them to access dozens of unrelated databases from the portal and locate unencrypted plaintext credentials to query restricted systems.5
Furthermore, Equifax operated a network inspection appliance designed to decrypt and inspect outbound traffic—the primary control that should have flagged large volumes of exfiltrated data. That device required a valid digital certificate, which had expired ten months earlier.45 As a result, the monitoring system failed to inspect outbound traffic.
For 76 days, attackers executed thousands of queries and exfiltrated encrypted data in small increments without detection.
July 29, 2017. Security personnel updated the expired certificate. Once the monitoring appliance reactivated, it immediately flagged suspicious outbound traffic. Equifax took the portal offline the following day.4
August 1–2, 2017. Prior to public disclosure, Chief Financial Officer John Gamble and two business-unit presidents sold Equifax shares. A Department of Justice review ultimately brought no insider trading charges against those executives, though a lower-level employee was separately convicted for trading on material non-public knowledge of the breach.
September 7, 2017. Equifax publicly disclosed the breach six weeks after its discovery. The incident exposed records of approximately 147.9 million U.S. consumers, 15.2 million British records, and roughly 19,000 Canadian records.34 Exfiltrated data included names, Social Security numbers, birth dates, addresses, and driver's license numbers.
The Response, Which Was Worse
If the technical breach exposed engineering failures, the corporate response demonstrated significant institutional missteps.
Equifax directed consumers to equifaxsecurity2017.com—a newly registered, standalone domain hosted on third-party infrastructure that prompted visitors for the last six digits of their Social Security numbers. Cybersecurity researchers noted that the setup mirrored phishing site characteristics. A parody domain registered at a similar address received hundreds of thousands of visits, while Equifax's official social media accounts mistakenly tweeted links directing consumers to the fake site.
Additionally, the initial terms of service for free credit monitoring included arbitration clauses that appeared to restrict class-action litigation rights. Equifax later clarified that the clause was not intended for breach-related claims and removed it.
Finally, the credit monitoring offer transitioned into a paid subscription after one free year, creating the perception of a commercial upsell attached to a security incident.
The Aftermath
Financial. In July 2019, Equifax reached a global settlement with the Federal Trade Commission, the Consumer Financial Protection Bureau, and 50 U.S. states and territories. The agreement required a minimum of $300 million for consumer restitution—capping at $425 million if claims expanded—along with $175 million to states and $100 million in CFPB civil penalties, totaling between $575 million and $700 million.3
Divided across affected consumers, the FTC restitution fund provided minimal individual compensation, with alternative cash options oversubscribed down to nominal amounts. For Equifax, total settlement costs represented roughly one year of net income, payable over time.
Human. Chief Executive Officer Richard Smith retired in September 2017, alongside the Chief Information Officer and Chief Security Officer. Smith subsequently testified before Congress regarding the company's oversight failures.
Geopolitical. In February 2020, the U.S. Department of Justice indicted four members of the Chinese People's Liberation Army's 54th Research Institute on charges of computer fraud, economic espionage, and wire fraud.6 Prosecutors stated the attackers routed traffic through servers across nearly twenty countries.
The indictment indicated the intrusion functioned as state-sponsored intelligence gathering rather than commercial data theft, as no bulk database appeared on criminal markets. Combined with prior breaches of government security clearance records and commercial travel databases, the stolen data provided target profiles for foreign intelligence.
For equity analysts, the fundamental takeaway was customer retention. Despite severe operational failures and public scrutiny, enterprise clients remained with Equifax due to limited market alternatives. That structural dependence highlights the strength of the firm's market position, while underscoring that regulatory enforcement—rather than customer churn—represents its primary business exposure.
V. The "New Equifax": Management, Strategy, & The Cloud Transformation
In April 2018, Equifax's board handed the company to an executive who had spent 35 years at General Electric.
The choice sent a clear signal. Mark Begor was neither a data executive nor a credit bureau lifer. He had previously led GE Energy Management and GE Capital Retail Finance—businesses anchored in process discipline, operating rhythm, and strict cost benchmarking.[^10] Equifax's central challenge in 2018 was not a lack of strategic ambition, but an absence of operating rigor inside an enterprise managing identity data for half the United States. The board effectively brought in a systems operator to establish discipline.
Reading Begor Through His Own Language
Begor's public communications reflect a distinct, highly structured management style. He consistently relies on explicit operating frameworks: a long-term financial target of 7% to 10% organic revenue growth with 50 basis points of annual margin expansion; a "Vitality Index" measuring revenue generated from products launched within the previous three years; and "diversified markets" as the catch-all category for all non-mortgage business.7 By assigning explicit metrics to operational milestones, his commitments provide clear benchmarks for performance tracking over time.
His commentary also carries an upbeat tone. Executive disclosures during the second quarter of 2026 frequently highlighted "very strong" conditions and an "energized" outlook, while the word "super" was attached to his enthusiasm on two separate occasions.7 Beyond the optimistic framing, however, the core financial metrics demand independent scrutiny.
The central test of credibility is whether management delivers on its targets over time—a track record evaluated in Section IX.
Meanwhile, Chief Financial Officer John Gamble has remained in his role since 2014, spanning the period before the 2017 breach, his equity sales during the discovery window, and current operations today.[^10] Investors view this continuity differently: some see essential institutional memory, while others see limited executive accountability. At minimum, it remains a notable governance fact that the chief financial officer involved in that period was retained, cleared, and continues to sign corporate disclosures nine years later.
Incentives
Equifax ties annual and long-term executive compensation directly to adjusted EBITDA and revenue growth. Compensation metrics specifically emphasize non-mortgage revenue expansion, cloud transformation milestones such as legacy system decommissioning, and cybersecurity maturity as evaluated by independent third-party security ratings.2 Embedding cybersecurity performance into executive scorecards represents an unusual structural mechanism designed to address the vulnerabilities exposed in 2017.
The emphasis on non-mortgage revenue serves a dual purpose. It reduces management's dependence on cyclical housing markets, while simultaneously creating strong incentives to promote the "diversified markets" narrative across public communications—a strategic framing that warrants careful investor examination.
The $3 Billion Cloud Bet
Begor's signature capital decision was an ambitious commitment to migrate Equifax's global technology infrastructure—spanning legacy mainframes and data centers across two dozen countries—onto cloud-native systems, primarily Google Cloud Platform.
The strategic rationale rests on three pillars. First, security: cloud-native architecture featuring automated patching and network segmentation directly mitigates the structural failure modes of 2017. Second, cost efficiency: retiring redundant data centers and mainframe contracts removes a major fixed expense. Third, and most critical, data unification.
Historically, Equifax operated disparate data assets across isolated legacy systems. Credit files, payroll data, and utility payment records existed in separate formats on incompatible platforms, making cross-asset queries complex and labor-intensive. Consolidating these assets into a unified cloud environment with standard data models transformed complex cross-file queries into standard, real-time API calls.
That unified architecture underpins the company's EFX.AI capabilities and powers products such as the TWN Indicator. Instead of delivering a complete income verification report, Equifax can attach a binary flag to standard credit pulls indicating whether payroll records exist for a consumer. Management reported offering the TWN Indicator at no cost across credit card, auto loan, and personal lending channels specifically to differentiate its credit reporting and capture market share from Experian and TransUnion.7 This feature transforms a commodity credit file into a differentiated product—a competitive advantage made possible because credit and payroll datasets reside within the same cloud architecture.
Management initially projected that decommissioning legacy mainframes would yield over $300 million in annual run-rate cost savings. Whether those savings materialized on schedule and within budget represents a primary test of execution analyzed in Section IX. Initial disclosures indicate the transition required significantly more capital and time than originally forecasted.
Capital Allocation Since
Post-breach capital allocation has focused on targeted, programmatic acquisitions in international credit markets and adjacent verification workflows rather than large, transformational deals.
Boa Vista Serviços (2023, approximately $560 million) acquired Brazil's second-largest credit bureau, establishing a substantial presence in Latin America's largest economy.
Círculo de Crédito (announced July 2026, $750 million enterprise value) represents the firm's most recent and instructive transaction. Equifax agreed to acquire the business at 11.7 times estimated 2026 EBITDA, declining to roughly 9.4 times including run-rate cost synergies—a valuation explicitly below Equifax's own trading multiple, which serves as a key test of value creation.7 Círculo is the sole Mexican bureau licensed for both consumer and commercial reporting, maintaining roughly 2 billion trade lines across 80 million validated identities. The business expanded revenue at a 23% compound annual rate from 2023 to 2025 and derives over 40% of its revenue from fintech clients.7
The strategic rationale targets structural market dynamics: Mexico has approximately 33 million informal workers with limited traditional credit histories, making alternative data such as gig transactions and utility records the primary underwriting input.7 The transaction allows Equifax to secure an established alternative-data position in an expanding market rather than paying premium valuations for a mature asset.
Smaller workflow acquisitions—including LawLogix for I-9 employment verification, Efficient Hire, and Midata—follow a consistent blueprint: acquire administrative software adjacent to verification checks so consumer transactions flow directly through Equifax software.
In summary, the valuation discipline and strategic alignment of the Círculo transaction are clear and verifiable. However, the broader international portfolio has yet to demonstrate consistent outperformance. Veda Group has not delivered returns matching its 2016 purchase price, and the International division remains Equifax's lowest-margin segment. Expanding into second-tier bureaus in emerging markets introduces currency, political, and integration risks that U.S.-focused models can overlook. Management's second-quarter 2026 results highlighted economic drag in Canada and the United Kingdom, limiting International revenue growth to 4%.7 While geographic expansion has broadened market reach, it has not yet yielded superior capital returns.
This structural dynamic leads directly into the performance of the verification division that generates the majority of corporate profits.
VI. The Crown Jewel: Workforce Solutions & The Verification Monopoly
The scale of Equifax's payroll verification franchise is unmatched across public or private data registries. As of the second quarter of 2026, The Work Number held 217 million active records—up 10% year over year—of which 124 million were current active records, representing 108 million unique Social Security numbers.7 With roughly 250 million income-producing adults in the United States, Equifax maintains a current, employer-sourced payroll record for nearly half of the nation's working population, refreshed every pay cycle and supported by years of historical depth.
No government agency maintains a comparable real-time dataset. The Internal Revenue Service and the Social Security Administration collect income data annually in arrears. Equifax ingests payroll records biweekly and monetizes instant access for commercial and government buyers.
The Financial Weight
Workforce Solutions generated $2.58 billion in fiscal 2025, accounting for roughly 42% of Equifax's $6.07 billion in total revenue.1 Yet top-line figures understate the division's true economic weight due to a striking margin gap. In the second quarter of 2026, Workforce Solutions generated EBITDA margins of 52.1%, compared with 32.8% for U.S. Information Solutions—or 40.5% when excluding zero-margin FICO royalty pass-throughs—and 27.6% for the International division.7
These margin dynamics mean Workforce Solutions delivers more than half of consolidated operating earnings on two-fifths of revenue. Strategically, Equifax operates as a high-margin payroll verification enterprise that happens to own a legacy credit bureau, rather than a credit bureau with a secondary verification desk.
The Mechanism, Precisely
The competitive moat surrounding the division is not merely the stored data itself, but a specialized, difficult-to-replicate ingestion architecture.
Equifax receives automated payroll feeds directly from major payroll processors and thousands of corporate HR departments. Establishing each data pipeline required an enterprise sales cycle, a technical integration project, a legal data-sharing agreement, and frequently a service exchange in which Equifax assumes administrative burdens that employers prefer to outsource—such as unemployment claims management, W-2 distribution, and I-9 verification.[^7]
Building a competing network presents a classic cold-start barrier. A new entrant would need to negotiate individual integrations across thousands of employers while offering alternative value propositions to match Equifax's suite. Without initial national coverage, a nascent platform fails to return matches on most borrower queries, rendering it unviable for mortgage lenders and starving the venture of the revenue required to expand its sales force.
Management emphasizes a second structural barrier: over 90% of Equifax's total revenue derives from proprietary data sources across more than 100 global data exchanges. Contributors supply non-public data under contracts mandating strict accuracy, currency, and dispute-resolution protocols, governed in the United States by the Fair Credit Reporting Act.7 Because this data is not available for purchase on open markets, access is restricted exclusively to Equifax and its credentialed enterprise customers.
Unit Economics and the Pricing Question
The unit economics of an automated verification query yield exceptionally high incremental margins: data acquisition carries no direct cash cost, compute expenses are negligible, and pricing reflects the value of the manual labor being replaced rather than the cost of fulfillment.
Equifax has leveraged this dynamic to expand unit pricing. Verifications that cost lenders between $10 and $30 a decade ago frequently range from $60 to $90 or more for multi-year employment packages required in mortgage underwriting. This price expansion generated organized pushback from mortgage trade groups and attracted scrutiny from the Consumer Financial Protection Bureau—an issue examined further in Section IX as a central strategic constraint on the business model.
The historical trajectory demonstrates substantial pricing power, while institutional resistance underscores that pricing leverage is not limitless.
The Non-Mortgage Expansion
To reduce vulnerability to mortgage market cycles, management directed the verification franchise into broader verticals less sensitive to prevailing interest rates. Three core sectors drive this expansion:
Government. Public agencies verifying eligibility for Medicaid, Supplemental Nutrition Assistance Program (SNAP), and related social benefit programs require validated income data. Equifax's government vertical approached $800 million in annual run-rate revenue by mid-2026, targeting a management-estimated $5 billion total addressable market.7 Growth is driven primarily by federal legislation enacted in July 2025 that mandated stricter accuracy and higher frequency for income verification, with primary operational impacts expected across late 2026 and 2027.7 Over a four-month period in 2026, Equifax secured approximately $300 million in annual contract value across state agencies, comprising $100 million in new contracts and win-backs alongside $200 million in renewals.7
The win-backs illustrate the specific risks of the government segment. Several state agencies paused Equifax subscriptions in 2024 following changes in federal cost-sharing rules that constrained state administrative funds. Chief Executive Officer Mark Begor noted on an earnings call that certain states "couldn't manage it, and they had to turn our solution off."7 While the subsequent return of these agencies—including one state contract generating nearly $60 million in annual value—confirms that Equifax's automated feeds outperform state wage records and consumer-permissioned tools, it also underscores that government demand remains subject to fiscal appropriations and changing political mandates.
Talent Solutions. Employment background screeners utilize the database to confirm work history during candidate hiring. In the second quarter of 2026, revenue in this vertical expanded at a high double-digit rate, supported by mid-single-digit volume growth despite an underlying contraction in white-collar hiring. Performance was driven by price increases, deeper penetration into education and incarceration datasets, and co-developed screening tools rather than broader hiring expansion.7 This outcome demonstrates effective market share gain and pricing realization, though ongoing expansion remains tied to unit pricing rather than underlying hiring volumes.
Consumer Lending. Originators of auto loans, credit cards, and personal loans use verification queries during underwriting, generating strong double-digit revenue growth in the second quarter of 2026 driven by higher transaction volumes and new product adoption.7
So What
Workforce Solutions represents the most defensible segment within Equifax, backed by structural entry barriers that capital alone cannot overcome. Nevertheless, each non-mortgage growth vector carries distinct cyclical dependencies: government spending relies on legislative mandates and state budgets, talent solutions depends on price realization during softer hiring periods, and consumer lending remains linked to broader credit cycles. Diversifying beyond mortgage originations has not eliminated cyclical exposure; rather, it has replaced a single mortgage cycle with a broader portfolio of macroeconomic sensitivities.
VII. Segment Breakdown & Financial Engine
Strip away the narrative and Equifax is three businesses with distinct economic profiles attached to one balance sheet.
Workforce Solutions serves as the primary growth and profit engine, generating $2.58 billion in 2025 revenue at roughly 52% segment EBITDA margins. In the second quarter of 2026, segment revenue grew 7% year over year, matched by a 7% expansion in its diversified-markets vertical.17
U.S. Information Solutions represents the legacy domestic credit bureau, generating approximately $2.08 billion in 2025.1 The segment reported 17% revenue growth in the second quarter of 2026, though organic expansion was just 6% after excluding pass-through FICO score royalties.7 Parsing that distinction is critical to evaluating the company's operational performance.
The FICO Pass-Through, Explained
When a mortgage lender orders a credit report, Equifax typically bundles the report with a FICO credit score. Equifax collects the total fee from the lender and remits the score component to Fair Isaac Corporation. Because Fair Isaac has instituted aggressive price increases on mortgage scores in recent years, Equifax's top-line revenue expands without generating additional operating profit.
Management explicitly acknowledges the distortion: Equifax earns zero margin on FICO score resales, which account for roughly 50% of U.S. Information Solutions mortgage revenue and nearly 7% of total consolidated revenue.7 Consequently, about 7% of reported top-line revenue functions as a pass-through expense that mechanically dilutes Equifax's consolidated profit margin.
To address this dynamic, management provides parallel disclosures with and without FICO score revenue. In the second quarter of 2026, reported consolidated EBITDA margin stood at 32.5%, flat year over year. Excluding FICO royalties, however, the consolidated margin reached nearly 35%, representing a 120-basis-point expansion.7 Both metrics provide necessary context: the ex-FICO figure captures core operational progress, while the reported figure highlights how much top-line volume carries no underlying margin.
International remains the structural laggard, generating $1.41 billion in 2025.1 The segment posted 4% constant-currency growth in the second quarter of 2026 with a 27.6% EBITDA margin, although segment margins expanded 120 basis points year over year as cloud migration efficiency gains began to materialize.7
The Mortgage Machine
Mortgage origination drives both Equifax's earnings power and its financial volatility. A mortgage application triggers a significantly more valuable transaction chain than a credit card or auto loan pull, requiring multiple credit inquiries across the origination lifecycle, multi-year employment and income verifications, and final pre-closing re-checks. Consequently, revenue per mortgage inquiry represents a substantial multiple of standard non-mortgage queries.
This structural sensitivity exposed the firm during the 2022–2023 interest rate spike. As the Federal Reserve tightened monetary policy, U.S. mortgage origination volumes contracted sharply, with inquiry volumes dropping 40% to 50% from their peak and eliminating hundreds of millions of dollars in high-margin revenue. The financial impact was evident in published results: while total revenue rose slightly from $5.12 billion in 2022 to $5.27 billion in 2023—a 2.8% increase—net income dropped from $696.2 million to $545.3 million, reducing diluted earnings per share from $5.69 to $4.44.1 Operating leverage worked in reverse as high-margin volume vanished while fixed costs, compounded by temporary duplicate infrastructure expenses during the cloud migration, remained intact.
Subsequent recovery has been uneven. In the second quarter of 2026, U.S. mortgage revenue rose 25% overall, but just 7% excluding FICO royalties, while hard mortgage inquiries within U.S. Information Solutions nudged up only 1%.7 The underlying mortgage market remained largely stagnant; growth was driven instead by unit price realization, market share gains, and new product adoption. This performance occurred against a headwind that management described as deteriorating, as 30-year fixed mortgage rates increased roughly 30 basis points during the quarter to approximately 6.6%, prompting full-year guidance to assume a low-single-digit decline in origination volumes.7
Equifax disclosed data illustrating the size of its pent-up refinancing opportunity: more than 16 million U.S. mortgages originated since early 2022 carry interest rates above 5%, including nearly 15 million above 6% and over 9.5 million above 6.5%.7 This borrower pool represents significant embedded refinancing volume, though realizing that potential remains tied to macroeconomic interest rate movements outside management's direct control.
Balance Sheet and Cash
In fiscal 2025, Equifax generated $6.07 billion in revenue, $1.83 billion in EBITDA, and $660.3 million in net income, while incurring $212.3 million in interest expense.1 For full-year 2026, management projected free cash flow exceeding $1 billion—supported by cash conversion above 100%—while maintaining net debt leverage below three times EBITDA and preserving approximately $1.5 billion in available capital capacity.7
Capital allocation in early 2026 favored direct shareholder returns and dividend expansion. During the first half of 2026, Equifax returned $560 million to shareholders, repurchasing 3.1 million shares—representing roughly 2.5% of outstanding stock. That total included a second-quarter repurchase of nearly 1.8 million shares for $300 million, which management characterized as an opportunistic move to take advantage of weakness in Equifax's share price.7 Additionally, the board raised the quarterly dividend by 12% in February 2026.7
This capital deployment strategy involves distinct trade-offs. While management framed accelerating share buybacks during market weakness as disciplined value creation, buybacks can also function as balance-sheet support during periods of heightened market skepticism. Furthermore, repurchasing 2.5% of total shares in six months while committing $750 million to acquire Círculo de Crédito rapidly absorbed capital reserves, prompting management to explicitly signal a reduced repurchase cadence for the second half of the year.7 Financial flexibility remains intact, but near-term capital is largely committed.
So What
Equifax's financial engine effectively operates at two distinct speeds. Evaluated on an ex-FICO basis, the core enterprise compounds at high-single-digit rates with expanding operating margins. On a GAAP reported basis, however, performance appears more volatile, heavily tied to mortgage origination cycles, and less insulated from macroeconomic conditions than corporate diversification messaging suggests. Both perspectives are grounded in financial data, highlighting the contrast between the firm's long-term verification growth driver and its cyclical credit reporting base.
VIII. Business & Strategy Playbook
Evaluating Equifax's strategic durability requires analyzing where a well-capitalized competitor could mount a credible operational threat.
Helmer's 7 Powers, Applied Honestly
Cornered Resource — strong, and the core of the case. The Work Number's employer-sourced payroll feeds cannot be purchased, scraped, or easily replicated by a new entrant, driven by the cold-start and data-integration barriers established in prior sections. This proprietary database remains the core foundation of the company's competitive advantage.
Switching Costs — strong, with an expiry date. Equifax's verification APIs are embedded directly into bank loan origination systems, government benefit portals, and background screening platforms. Replacing these integrations requires institutions to re-engineer underwriting workflows, re-validate compliance, and retrain operations staff. However, these switching costs face long-term erosion as modern API standards and data-aggregating middleware reduce the complexity of integrating alternative data sources over time.
Scale Economies — strong, and improving. Fixed cloud infrastructure costs are distributed across billions of annual API transactions with minimal marginal serving expense. As the technology migration finishes, scale economies should improve further by consolidating multiple legacy systems onto a single fixed cost base.
Counter-Positioning — contested, and frequently overstated. A common bullish thesis holds that consumer-permissioned open banking platforms cannot displace Equifax because lenders require FCRA-compliant, employer-sourced data rather than bank account credentials provided by consumers. Bank transaction records merely infer income, whereas payroll feeds state income directly—a distinction carrying significant compliance weight in government-sponsored enterprise (GSE) mortgage underwriting.
However, this protection stems from regulatory mandates rather than technological barriers. Should consumer-permissioned payroll connectivity attain sufficient coverage and gain explicit supervisory approval, Equifax's competitive advantage would narrow. The firm remains protected primarily by current regulatory standards governing how financial institutions must document applicant income.
Branding, Network Economies, Process Power — not meaningfully present. Equifax possesses no meaningful consumer brand equity or traditional user-to-user network effects. Its consumer reputation remains a liability following the 2017 data breach, while its data contributor flywheel functions as a scale economy rather than a network effect.
Porter's Five Forces
Threat of New Entrants — very low. High entry barriers stem from multi-billion-dollar data acquisition costs, strict regulatory requirements for dispute resolution and permissible-purpose verification, and critical coverage thresholds necessary for commercial utility.
Bargaining Power of Buyers — low to medium, and rising. While individual lenders exercise limited bargaining leverage, buyer groups have increasingly organized to resist price increases. The mortgage industry's extended effort to curb credit-reporting cost inflation led directly to regulatory approval of alternative credit scores, while state government agencies demonstrated their purchasing leverage through contract cancellations during fiscal constraints in 2024.
Bargaining Power of Suppliers — genuinely medium, and the most under-appreciated risk. Major payroll processors represent a material, under-appreciated risk. Rather than operating as passive data providers, major processors recognize the value of their records and retain the capability to negotiate higher revenue splits or develop proprietary verification services. Equifax counters this threat through direct relationships with thousands of individual employers and bundled HR compliance services, though widespread processor defection would strain this defense.
Threat of Substitutes — low. Manual collection of W-2s and pay stubs remains slower, more expensive, and more vulnerable to document falsification, leaving legacy manual processes as an inferior alternative for lenders.
Competitive Rivalry — medium in credit, low in verification. Rivalry reflects predictable three-firm dynamics in legacy credit reporting, contrasted with near-monopoly conditions in automated payroll verification.
The Force Nobody Modeled: Score Competition
A major competitive development occurred in credit scoring rather than payroll verification. In April 2026, the Federal Housing Finance Agency activated VantageScore usage for more than 20 mortgage lenders—the first disruption to Fair Isaac Corporation's long-standing monopoly on mortgage credit scoring following the FHFA's July 2025 decision permitting score choice.7
Equifax's strategic positioning here offers distinct margin benefits. Because Equifax earns zero margin on FICO scores, FICO royalties act as pass-through revenue that mechanically dilutes reported operating margins. VantageScore, by contrast, is jointly owned by the three major credit bureaus. Equifax set VantageScore's price at $1, committed to lock that rate through the end of 2027, and began bundling a free VantageScore alongside every paid FICO score so lenders could test their systems.7
Adoption metrics require careful examination. In the second quarter of 2026, approximately 1,200 mortgage lenders pulled free VantageScore reports alongside paid FICO scores, generating 2.2 million test transactions—nearly tripling the previous quarter's volume. However, only about 100 lenders, primarily smaller home-equity and non-GSE originators, transitioned to VantageScore exclusively, accounting for roughly 10,000 paid transactions during the period.7
While testing volume expanded rapidly, full commercial conversion remains limited. Management characterized the 1,200 testing institutions as lenders preparing for full implementation. In response to analyst inquiries, Chief Executive Officer Mark Begor clarified that these institutions were evaluating workflows while the FHFA continued to limit the number of lenders approved to use VantageScore for agency-backed mortgages.7 Regulatory approval, rather than lender interest, serves as the primary operational bottleneck.
Should widespread adoption occur, the financial impact on Equifax would be structurally favorable despite headline revenue contraction: reported revenue would decline as zero-margin FICO pass-throughs vanish, while operating margins would expand as Equifax retains income from a score it co-owns. Management estimated that transitioning to VantageScore could generate approximately $1 billion in annual cost savings across the mortgage origination industry.7 Consequently, the shift would reduce top-line revenue while simultaneously improving underlying profit margins and unit economics.
This structural dynamic provides the foundation for evaluating the core thesis claims governing Equifax's outlook.
IX. Historical Falsification & Stress Test
Every investment case relies on a set of underlying claims, which are only as credible as their alignment with the company's historical record. Four central claims define the case for Equifax.
Claim 1: "The cloud migration would complete on schedule and deliver $300M+ of savings"
The disconfirming record. Management originally framed the cloud transformation as a roughly $1.2 billion project scheduled for completion around 2022. Actual spending exceeded $3 billion, and final execution stretched into 2024 and 2025—with executive commentary in the second quarter of 2026 still describing "the final stages of our cloud transformation" while referencing technology savings that improved International margins as the migration finished.7 Expenditures ran roughly two-and-a-half times the original budget, and the timeline slipped three to four years past initial expectations.
The overrun occurred during a difficult operational window. Throughout 2022 to 2024, Equifax absorbed duplicate expenses—maintaining legacy mainframe and data center contracts alongside parallel cloud infrastructure—just as the mortgage market contracted and interest rates rose. Capital intensity remained elevated precisely when the cost of capital spiked and high-margin origination volume vanished. Financial disclosures illustrate the impact: net income fell from $696.2 million in 2022 to $545.3 million in 2023 despite higher overall revenue.1
Weighing it. This variance was not a minor accounting adjustment, nor was it inherited from a prior administration. Chief Executive Officer Mark Begor oversaw the program from its inception. The overrun stands as significant evidence against management's initial forecasting discipline and suggests caution when evaluating forward targets.
But operational savings have begun to materialize, albeit delayed. Consolidated ex-FICO EBITDA margins expanded 120 basis points in the second quarter of 2026, while International segment margins rose 120 basis points on technology-driven cost reductions—an outcome consistent with the long-term thesis.7 Furthermore, the unified cloud architecture powers product capabilities not emphasized in initial projections, including the TWN Indicator cross-sell and EFX.AI deployments.
Verdict: narrowed, not rejected. Cost savings are materializing, but initial budget and schedule commitments proved inaccurate by a wide margin. Confirm/falsify KPI: sustained ex-FICO EBITDA margin expansion above the long-term framework of 50 basis points per year through 2027—against full-year 2026 guidance of 75 basis points and 120 basis points realized in the second quarter—alongside capital expenditures declining toward high single digits as a percentage of revenue.7
A similar caution applies to recent operational targets. Management doubled its "AI for EFX" run-rate savings target from $75 million to approximately $150 million across the 2026–2028 period just five months after its initial announcement, citing roughly $2 billion in annual gross labor spend as the target base.7 Upward target revisions shortly after announcement can indicate accelerating operational progress or an initial goal set low enough to ensure an early beat. Given the cloud migration budget history, two additional quarters of margin evidence are warranted before crediting the revised target.
Claim 2: "The Work Number holds unassailable pricing power"
The disconfirming record. Aggressive verification price increases generated structured resistance from institutional clients. Mortgage industry trade groups formally protested credit and verification fee inflation, while the Consumer Financial Protection Bureau actively expanded regulatory oversight of data brokers under the FCRA, issuing guidance targeting consumer report monetization and consent mechanisms.[^8] Additionally, the Federal Housing Finance Agency's decision to permit credit score competition demonstrates that elevated credit-related costs can prompt structural regulatory interventions in market design.
State government contract pauses in 2024 provide additional evidence of demand elasticity. Several state agencies canceled services when federal administrative cost-sharing rules changed. Although Equifax recovered major accounts—including a state contract generating nearly $60 million in annual value—the interruptions established that buyers with tight administrative budgets will suspend automated verification when costs exceed fiscal limits.7
Supplier concentration represents a second structural constraint. Major payroll processors control primary data sources and possess the infrastructure to offer competing services. Equifax does not disclose revenue-sharing percentages paid to payroll partners, creating an analytical blind spot regarding whether data acquisition economics are shifting toward suppliers.
Weighing it. Realized pricing power remains substantial, evidenced by a decade of fee expansion, sustained 52% segment margins in Workforce Solutions, and contract re-wins driven by data coverage. However, regulatory scrutiny, buyer coordination, state budget constraints, and supplier leverage impose verifiable limits on pricing flexibility.
Verdict: narrowed. Pricing power exists but remains bounded by regulatory oversight, client cost sensitivity, public budget cycles, and supplier dynamics. Confirm/falsify KPI: Workforce Solutions segment EBITDA margin remaining above 50%. Because data acquisition costs and net pricing flow directly through segment profitability, sustained margins serve as the primary indicator of Equifax's retention of division economics.
Claim 3: "Post-breach investment made Equifax the operational gold standard"
The disconfirming record. In spring 2022, during legacy technology migration, a software coding error led Equifax to transmit inaccurate credit scores over a three-week period. Lenders rendered underwriting and pricing decisions using faulty data, resulting in loan denials and adverse credit terms for affected consumers.
The incident resulted in ongoing financial commitments. Equifax recorded a $40 million net charge after insurance proceeds in the second quarter of 2026 to resolve legal claims arising from the scoring error.7 The financial settlement landed four years after the operational failure occurred.
Weighing it. The 2022 error resulted from a change-management oversight during infrastructure migration rather than an external security breach. While core cybersecurity architecture has improved significantly since 2017—addressing legacy vulnerabilities like unpatched software, unsegmented networks, and expired certificates—operational execution during software deployments has experienced documented lapses.
Verdict: rejected as an absolute claim. Equifax established stronger cybersecurity protocols post-2017 but has not demonstrated flawless operational reliability. Confirm/falsify KPI: the absence of further disclosed data-accuracy errors or related litigation charges as AI-driven automation expands across dispute processing and core operations.
Claim 4: "Non-mortgage growth insulates Equifax from housing cyclicality"
The disconfirming record. The 2022–2023 mortgage market contraction tested corporate diversification claims. Despite growth in non-mortgage verification lines, consolidated revenue growth slowed to 2.8% in 2023 while earnings per share dropped 22% from 2022 levels.1 Non-mortgage expansion moderated the financial impact but did not offset housing market cyclicality.
Financial results reflect ongoing cyclical sensitivity. In the second quarter of 2026, U.S. mortgage revenue expanded 25% year over year, while organic constant-currency growth in diversified markets stood at approximately 5.5%.7 Mortgage reporting remained the primary top-line catalyst during the period. Full-year 2026 guidance projects U.S. mortgage revenue growth in the low 20% range against high-single-digit expansion in diversified markets.7 Consolidated earnings remain disproportionately tied to mortgage originations.
Weighing it. Revenue diversification into government, talent, and consumer lending verticals has established a higher earnings baseline than existed in 2007. However, elevated baseline performance does not eliminate cyclical exposure. Peak profitability continues to depend on housing market volumes, a dynamic acknowledged in management's financial guidance.
Verdict: narrowed substantially. Expansion into non-mortgage verticals raises the performance floor during housing downturns but does not decouple consolidated results from mortgage cycles. Confirm/falsify KPI: organic constant-currency growth in diversified markets. Segment growth of roughly 5.5% in the second quarter of 2026 trailed management's long-term framework of 7% to 10%, indicating that non-mortgage operations ran below target while mortgage volume carried reported growth.7
An Activist's Angle
An independent evaluation highlights three operational considerations. First, regular reporting of parallel GAAP and ex-FICO results—layered alongside non-GAAP adjustments—reflects genuine pass-through distortions while allowing management latitude in framing quarterly performance. Second, CFO John Gamble's continued tenure following equity sales during the 2017 breach window represents an unusual governance structure for a public enterprise. Third, allocating substantial capital to share repurchases alongside a $750 million international acquisition reduces liquidity reserves if housing weakness persists.
These factors do not invalidate the core enterprise model, but they form essential context for assessing corporate governance and financial strategy.
X. Investment Thesis: Why Win / Why Not & Key KPIs
Why Equifax Wins From Here
The verification database remains the core competitive moat. As established by historical testing, Equifax's payroll database—holding 217 million active records sourced directly from employers and refreshed every pay cycle—cannot be easily replicated by a competitor relying solely on capital, given the steep cold-start barriers.7 Commercial customer retention following the 2017 breach demonstrated high institutional lock-in, while recent state government contract win-backs indicate that buyers departing during fiscal constraints often return for superior coverage.
Operational leverage is beginning to materialize. With the technology migration entering its final stages, duplicate infrastructure expenses are winding down. Excluding FICO royalties, consolidated EBITDA margin expanded 120 basis points in the second quarter of 2026, exceeding management's 75-basis-point full-year guidance and its 50-basis-point long-term annual target.7 Management projected full-year 2026 free cash flow exceeding $1 billion, supported by a cash conversion rate above 100%.7 If sustained, this post-migration cost structure delivers structurally higher earnings power than recent transition years reflected.
Credit score competition presents structural margin upside. Because Equifax earns zero operating margin on pass-through FICO royalties, any client shift toward VantageScore reduces reported top-line revenue while replacing zero-margin volume with high-margin income from a score the credit bureaus jointly own. What appears as a top-line revenue headwind ultimately acts as a profit-margin tailwind.
Why It Might Not
Regulatory and legislative intervention represents the primary operational risk. Increased scrutiny from the Consumer Financial Protection Bureau regarding data broker practices under the Fair Credit Reporting Act, alongside the Federal Housing Finance Agency's restructuring of mortgage credit scoring, demonstrates that regulatory agencies will intervene in market structures when industry costs attract political attention.[^8] Rules capping verification fees, requiring explicit consumer consent for payroll data sharing, or enabling individuals to opt out of The Work Number would directly impair division economics. Furthermore, memory of the 2017 breach exposing records of 147.9 million Americans leaves the firm with limited political goodwill during legislative debates.
Interest rate sensitivity persists alongside softer non-mortgage growth. Sustained high interest rates continue to suppress mortgage refinancing, keeping more than 9.5 million post-2022 mortgages with rates above 6.5% locked out of refinancing activity.7 Concurrently, organic constant-currency revenue growth in diversified markets ran at 5.5% in the second quarter of 2026, trailing management's long-term framework of 7% to 10%. As a result, both cyclical mortgage origination and structural non-mortgage expansion ran below long-term targets during the period.
Supplier margin pressure poses a gradual threat. Major payroll processors seeking higher revenue splits or developing proprietary verification interfaces could compress Workforce Solutions' profit margins without an overt loss of market coverage. Equifax's limited financial disclosures regarding data-acquisition costs make tracking supplier margin compression difficult for outside analysts.
AI deployment introduces operational execution risk. Accelerating automation across dispute processing and core operations at an enterprise built on data accuracy presents operational risks, particularly given the $40 million net settlement charge recorded in the second quarter of 2026 following a 2022 credit scoring software error.7
The Three KPIs That Matter
1. Active payroll records and unique Social Security number coverage. As of the second quarter of 2026, The Work Number maintained 217 million active records covering 108 million unique Social Security numbers against approximately 250 million working Americans.7 Database expansion dictates query match rates and default lender adoption; a marked deceleration in record growth would signal saturation in employer network expansion.
2. Organic constant-currency revenue growth in diversified markets. Stripped of mortgage cyclicality, foreign exchange fluctuations, and acquisition contributions, this metric measures non-mortgage business expansion. The segment grew 5.5% in the second quarter of 2026 against management's 7% to 10% target.7 Persistent performance below target would indicate that non-mortgage diversification is failing to offset housing market volatility.
3. Consolidated ex-FICO EBITDA margin. This metric tracks whether multi-billion-dollar cloud investments and AI productivity initiatives are generating structural cost savings, while confirming whether Workforce Solutions is preserving verification pricing relative to payroll supplier costs. Consolidated margins reached nearly 35% excluding FICO royalties in the second quarter of 2026, led by a 52.1% margin at Workforce Solutions.7
Where to Listen
Four sets of primary corporate disclosures provide essential context for tracking Equifax's ongoing execution. The second-quarter 2026 earnings call establishes the operational baseline, detailing state government contract wins, VantageScore testing progress, the expanded AI cost-savings target, and the Círculo de Crédito acquisition.7 Investor day presentations from 2021 and 2023 provide the long-term organic revenue targets and cloud margin commitments against which performance must be benchmarked. The second-quarter 2022 earnings call documents management's initial response to the credit-scoring technology failure. Finally, Chief Executive Officer Mark Begor's inaugural 2018 call serves as the historical anchor, outlining the post-breach operating framework and original cloud budget prior to implementation.
XI. Epilogue: What This Means for Society
There is a sentence from Equifax's second-quarter 2026 earnings call that warrants examination outside its immediate financial context.
"Only Equifax and our credentialed customers can access our data."7
Management offered the statement as a description of a competitive moat, and from a financial perspective, that assessment is accurate. Yet the statement also highlights the nature of the asset itself: a record, refreshed every two weeks, detailing what roughly 108 million Americans earn—including their employers, length of tenure, wage levels, and job history.7 The dataset is more current than records maintained by the Internal Revenue Service. Crucially, the statement underscores that the individuals whose working lives generate this repository are excluded from accessing it directly.
From Scorekeeper to Gatekeeper
The credit bureau originated as a passive scorekeeper, recording debt repayment histories for lenders to evaluate independently. Over time, it evolved into an active gatekeeper across domains far removed from traditional credit reporting. A Work Number record now shapes whether an apartment application is accepted, a background check clears, a state approves food assistance, Medicaid eligibility is confirmed, or a job offer is finalized.
Federal legislation tightening income verification requirements for Medicaid and SNAP created a subtle but significant institutional shift: it embedded a private enterprise's database directly into public benefits administration.7 When a state agency relies on an Equifax query to determine assistance eligibility, the accuracy of a commercial ledger dictates access to public support. Yet no direct public accountability mechanism governs that database beyond the dispute framework established by the Fair Credit Reporting Act—a process that requires consumers to know the file exists in the first place.
The Consumer Paradox
The structural asymmetry identified by Congress in 1970 has not been resolved; it has been formalized and expanded.
Consumers maintain no direct contractual relationship with Equifax and never opted into the platform. Employers transmit payroll feeds regardless of worker awareness. Individuals cannot withdraw their records from the bureau while remaining able to rent housing, secure loans, or maintain formal employment. When security failures occur, the personal and financial burdens fall on individuals through unchangeable Social Security numbers, years of credit monitoring, and identity theft risks. Equifax's total financial settlement for the 2017 breach was capped at at least $575 million.3 For affected consumers, the exposure remains permanent.
What Comes Next
The 2017 breach involved state-sponsored actors assembling dossiers on American citizens.6 The architecture Equifax built in the years since—a unified cloud infrastructure integrating credit files, real-time payroll records, utility and telecom payment histories, gig-economy alternative data, and predictive analytics—is more comprehensive and centralized than the systems compromised in 2017. Management maintains, with technological backing, that this infrastructure is far better defended.
Both observations are accurate, yet improved security does not eliminate structural risks. The analytical reach of the platform has expanded substantially. By combining income trajectories, borrowing behavior, utility payment consistency, and employment stability, the system can generate predictive profiles that extend beyond any single dataset—and commercialize those insights for entities establishing permissible purpose under a statute enacted in 1970 for an earlier era of credit reporting.
This reporting network did not emerge from a central blueprint. Equifax assembled it transaction by transaction and acquisition by acquisition over 127 years, with each step reflecting standard commercial logic. That incremental construction is precisely what makes the franchise so durable—and why its evolution remains essential to track, whether evaluating the company as an investor or appearing within its ledger as a working citizen.
References
-
Equifax Investor Relations — Financial Information & SEC Filings ↩↩↩↩↩↩↩↩↩↩↩↩
-
Equifax Inc. FY 2024 Form 10-K — U.S. Securities and Exchange Commission, 2025-02-20 ↩↩
-
Equifax to Pay $575 Million as Part of Settlement with FTC, CFPB, and States Related to 2017 Data Breach — Federal Trade Commission, 2019-07-22 ↩↩↩↩
-
GAO-18-559: Data Protection — Actions Taken by Equifax and Federal Agencies in Response to the 2017 Breach — U.S. Government Accountability Office, 2018-08-30 ↩↩↩↩↩
-
House Oversight Committee Majority Staff Report: The Equifax Data Breach — U.S. House of Representatives, 2018-12-10 ↩↩↩↩
-
Chinese Military Personnel Charged with Computer Fraud, Economic Espionage and Wire Fraud for Hacking into Credit Reporting Agency Equifax — U.S. Department of Justice, 2020-02-10 ↩↩
-
Equifax Q2 2026 Earnings Conference Call and Quarterly Results — Equifax Investor Relations, 2026-07-21 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube