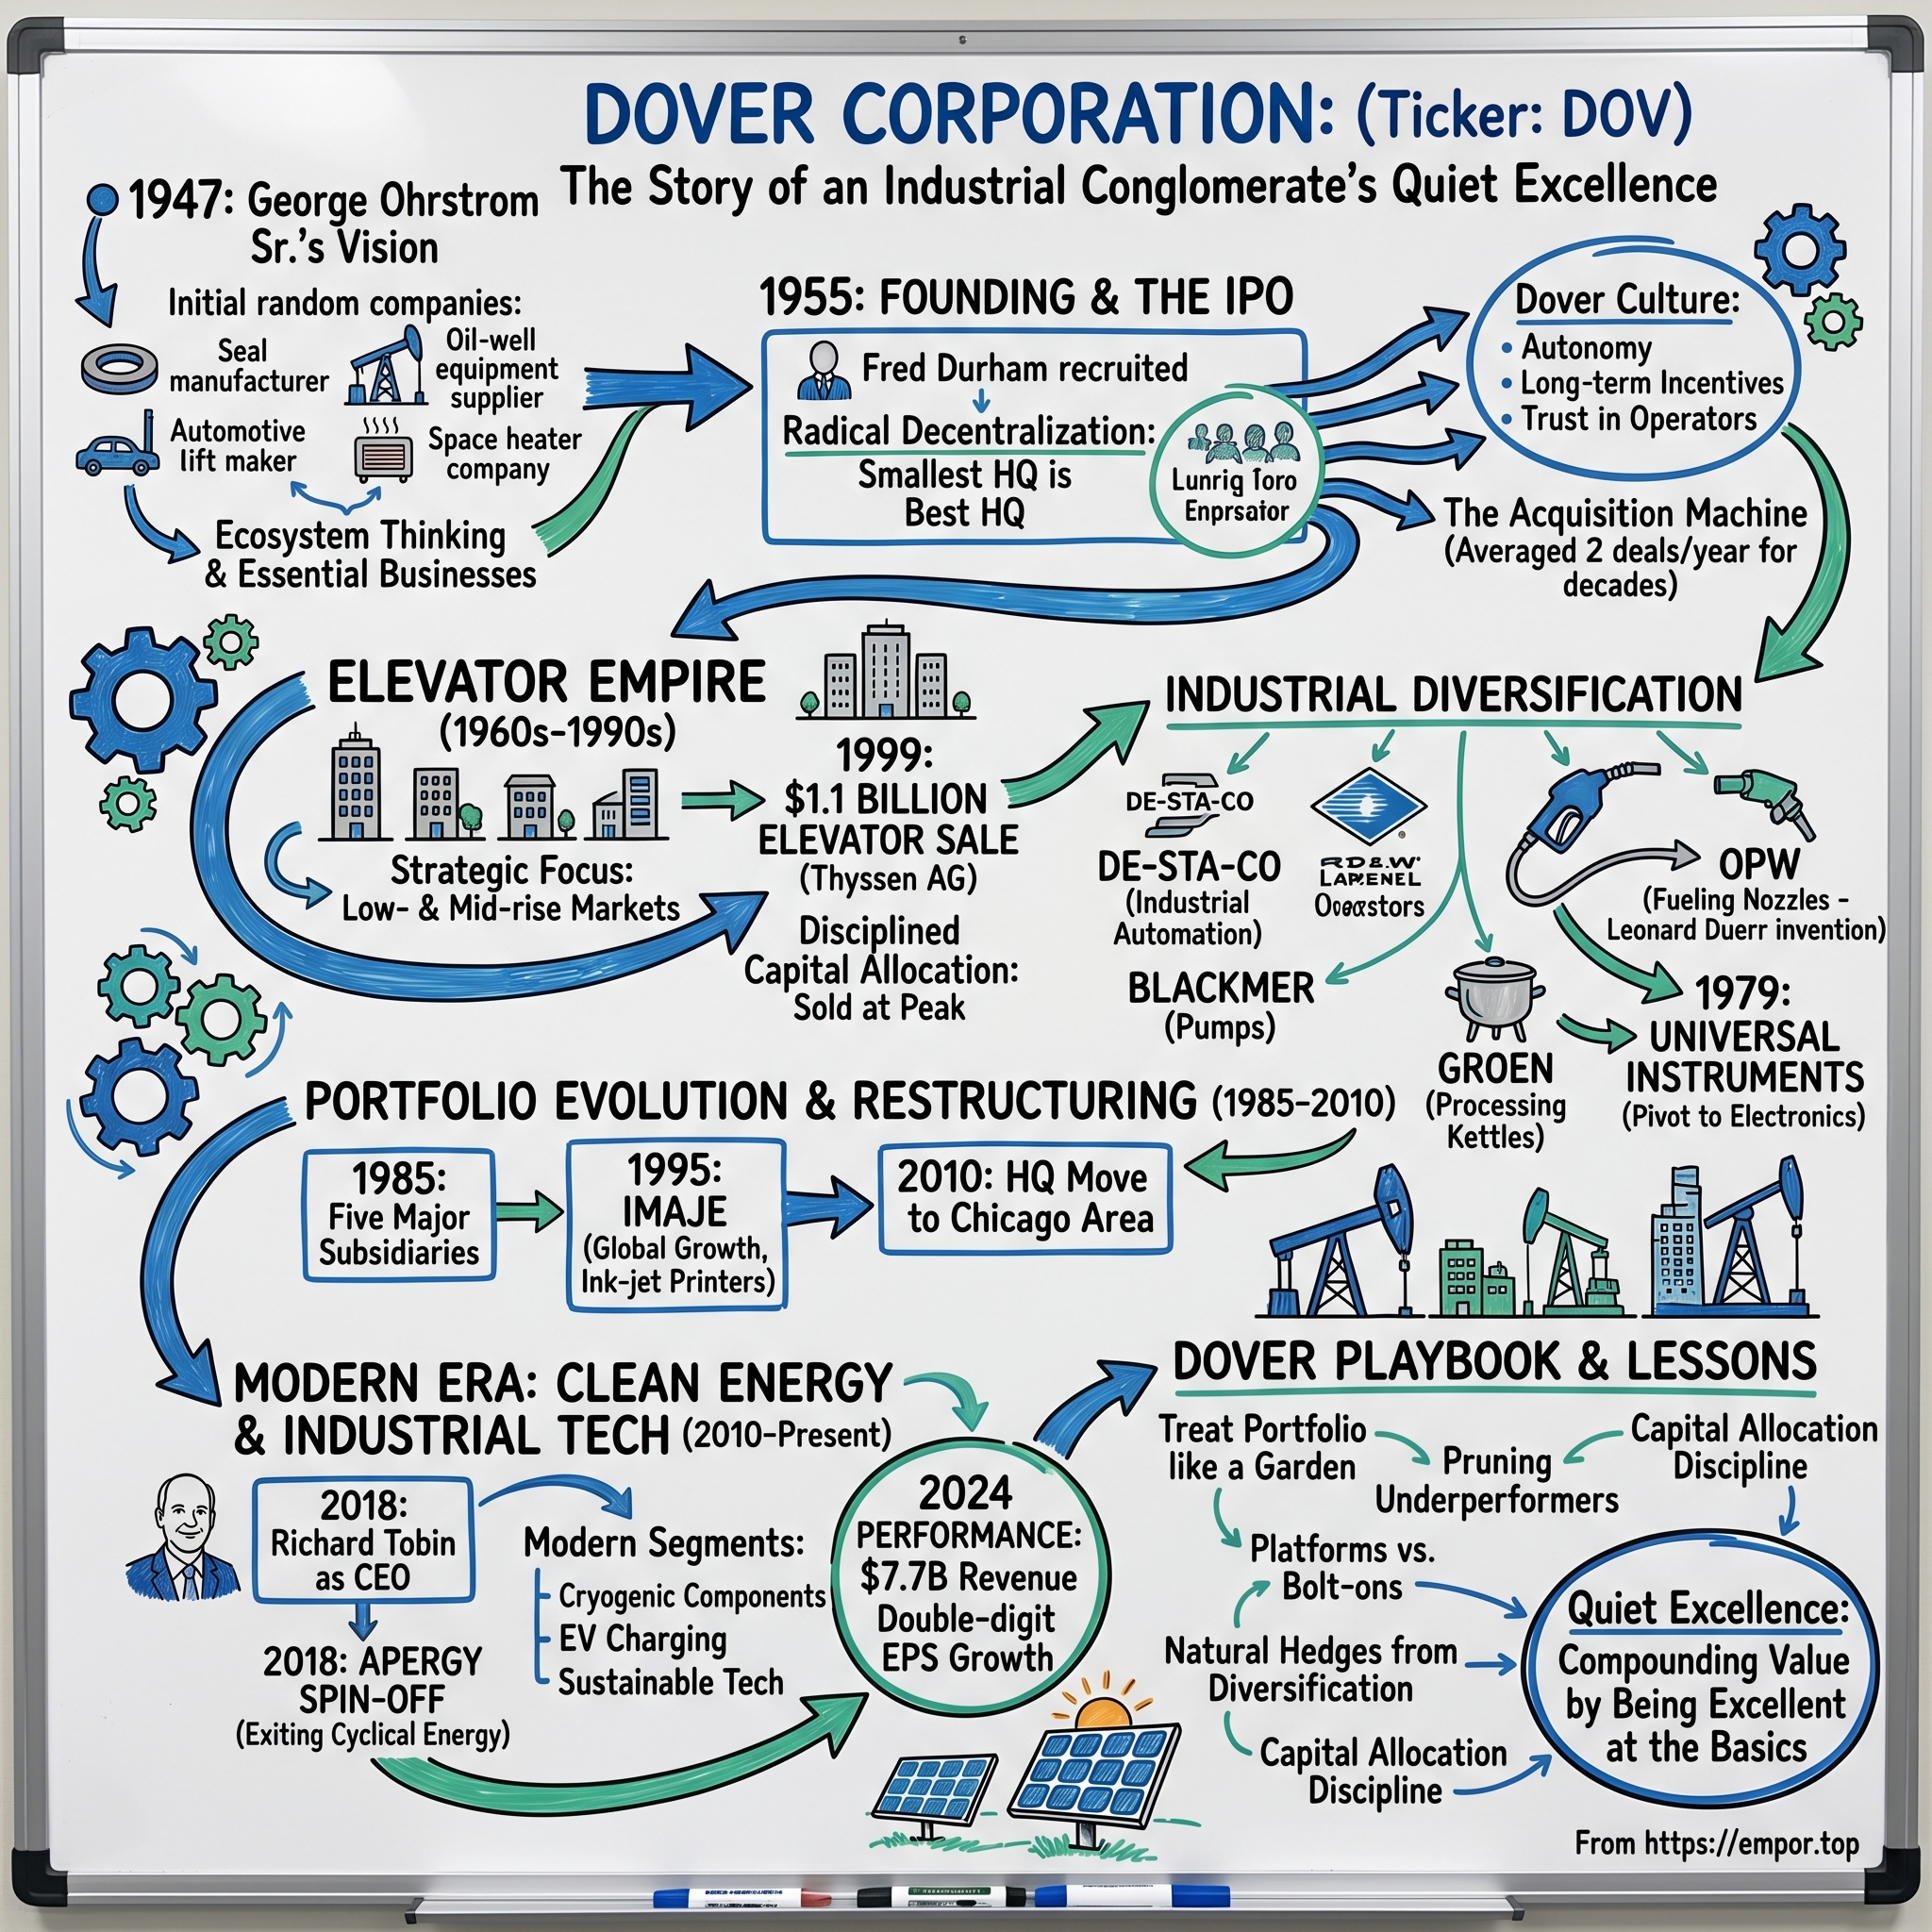
Dover Corporation: The Masterclass in Industrial Portfolio Transformation
I. Introduction & Episode Roadmap
On the morning of July 23, 2026, Richard Tobin, chief executive officer of Dover Corporation, opened an earnings call in an unusual manner. Despite reporting record margins in Dover's pumps segment, Tobin spent the first four minutes of his prepared remarks walking analysts through an operational setback at a refrigeration manufacturing facility.
Dover's refrigeration business was consolidating two plants into one while hiring and training a replacement workforce, but production throughput fell short of target. Unfilled orders accumulated in backlog as shipments stalled. "We frankly did not expect to fall short on our production throughput targets," Tobin said. "That is on me." He estimated the operational misstep cost the corporation between 1.0 and 1.5 percentage points of organic growth in the second quarter.[^1]
Scott Davis of Melius Research, a veteran analyst who has covered multi-industrial conglomerates for two decades, noted on the call that Tobin had not offered such an explicit self-assessment in years.
That exchange offers a clear entry point into Dover Corporation, illustrating both its operational mechanics and its analytical complexity. Dover operates as a portfolio of roughly two dozen businesses across five reporting segments: pumps and flow components, fueling and cryogenic equipment, refrigeration and heat exchangers, vehicle service and aerospace components, and industrial coding printers. In fiscal 2025, the company generated $8.09 billion in revenue—up from $7.75 billion the previous year—and $1.09 billion in GAAP net income.1 None of its subsidiaries are household names. Most produce specialized components costing a few hundred to a few thousand dollars that are installed inside equipment worth millions.
The central question is how a mid-century roll-up of elevator makers, oil-well sucker rod manufacturers, and space heater producers evolved into an enterprise whose primary profit drivers now supply single-use sensors for biopharmaceutical manufacturing and brazed plate heat exchangers for AI data centers. A key issue is whether the portfolio restructuring led by Tobin since 2018 reflects a durable improvement in business quality or simply a favorable demand cycle.
Both perspectives carry supporting evidence, requiring objective evaluation rather than simple assertion.
The story follows three primary phases. The first is its foundational DNA: in the late 1940s, Wall Street broker George Ohrstrom assembled four unrelated manufacturers under a philosophy of extreme decentralization—maintaining a lean headquarters, omitting central engineering, and granting division presidents operational autonomy tied to their unit's returns. That model remained largely intact for nearly six decades.
The second phase is the imperative to prune the portfolio. Dover has periodically divested legacy businesses: its North American elevator operations in 1999, the Knowles acoustics unit in 2014, its upstream energy portfolio in 2018, and both DESTACO and the Environmental Solutions Group in 2024. While several exits proved timely, others—such as Knowles—represented a fast exit from a recent capital allocation error rather than a long-planned strategic divestment.
The third phase is the transition from passive decentralization to active portfolio management under Tobin. Arriving in 2018 from CNH Industrial, Tobin replaced the traditional approach with a centralized productivity program, disciplined M&A hurdle rates, and a willingness to consolidate legacy facilities.
This analysis evaluates multi-industrial economics: how serial acquirers generate returns, where valuation traps emerge, how competitive moats apply to low-cost components in multi-million-dollar production lines, and which operational metrics will validate or challenge the current thesis. The refrigeration plant bottleneck in the second quarter of 2026 highlights both the ambition and the execution risks facing a conglomerate re-engineering its footprint during a strong demand cycle.
 Subscribe on LinkedIn
II. Origins & The Decentralized Genesis: George Ohrstrom & Fred Durham (1947–1970s)
In the immediate aftermath of World War II, the American industrial landscape was populated by thousands of family-owned machine shops and component makers that had expanded during wartime demand. Many founders were nearing retirement without obvious family successors, yet the private equity industry did not yet exist to provide liquidity.
Wall Street stockbroker George Ohrstrom Sr. recognized an opportunity in these cash-generative, niche enterprises. Rather than building a single integrated manufacturing company, Ohrstrom adopted an approach similar to portfolio management: he acquired four unrelated industrial businesses and combined them under a single corporate holding company. The initial portfolio included C. Lee Cook (seals and piston rings), Rotary Lift (hydraulic automotive lifts), W.C. Norris (oil well sucker rods), and Peerless (space heaters). Dover Corporation was incorporated in 1947 and listed on the New York Stock Exchange in 1955.[^3]
The strategic rationale was not corporate synergy, but cash-flow diversification paired with a conviction that autonomous local managers would outperform a centralized executive apparatus.
Fred Durham, Dover's first chief executive officer, codified that philosophy into an operating doctrine. Headquarters remained intentionally small, omitting central engineering, corporate marketing, and shared services of the type later popularized by conglomerates like General Electric or Emerson. Division presidents retained authority over product design, pricing, hiring, and capital requests, with incentive compensation tied directly to their unit's long-term earnings growth and return on investment rather than Dover's consolidated results.
For specialized niche businesses, this architecture offered distinct advantages. A manufacturer of specialized pumps for chemical processing gained little from centralized corporate branding; it benefited instead from local leadership capable of quoting custom configurations quickly and maintaining close customer relationships. Dover's decentralization was fundamentally a strategic bet that operational speed and customer intimacy in fragmented markets outweighed corporate scale.
Historical Falsification Pass — Testing the Early Decentralization Thesis
The central proposition requiring historical examination is the claim Dover presented to investors for decades: that extreme decentralization preserves permanent operational agility while eliminating corporate overhead drag.
The historical record reveals significant structural drawbacks to this approach. Autonomy without centralized capital oversight meant division presidents competed for corporate capital without a unified system to evaluate multi-division opportunities. Operating units purchased goods from overlapping supplier networks without aggregating purchasing power. Manufacturing footprints expanded inefficiently because individual divisions lacked financial incentives to consolidate facilities with sister companies. In addition, technological innovations developed within one unit rarely transferred across the organization.
The model also created financial reporting vulnerabilities. In a conglomerate comprising dozens of small operating entities, underperforming divisions could remain obscured within aggregated results for multiple quarters. During economic downturns, these hidden weaknesses frequently culminated in sudden restructuring charges and asset write-downs rather than early warning signs from management.
The clearest indication that Dover eventually acknowledged these limitations is the operational shift executed by Richard Tobin upon becoming chief executive in 2018. Tobin established the centralized functions that the original model explicitly rejected. Dover's 2025 capital allocation commentary noted that acquisitions are integrated by extracting synergies "through our center-led capabilities" and by leveraging global scale channels and supply chains.[^4] A corporate structure founded on the premise that headquarters adds no operational value would not rely on center-led integration capabilities unless its original thesis had proved incomplete.
The historical evidence suggests a refinement rather than a complete rejection of the founding model. Decentralized operational autonomy remains valuable at Dover in markets where customer responsiveness supersedes scale economies. However, the record disproves the broader assertion that decentralization alone creates a sustainable competitive advantage. Operating autonomy generates durable value only when paired with strict financial hurdles, disciplined capital allocation, and active portfolio pruning. Without those controls, passive decentralization risks accumulating low-margin, capital-intensive laggards.
Dover spent decades navigating those structural tradeoffs, beginning with the business unit that first established its broader corporate visibility.
III. The Elevator Empire: Scaling and Selling at the Peak (1958–1999)
Industrial conglomerates often favor a specific type of business: one anchored by a large installed base. A manufacturer sells equipment once, services it indefinitely, and collects recurring maintenance revenue because the building cannot function without it. Elevators represent the archetype of this model.
Dover entered the market in 1958 by acquiring Shepard Warner Elevator Company and expanded by acquiring smaller regional competitors. Acme Elevator, Elevator Service, and Reddy Elevator were added in the mid-1960s, followed by Hunter-Hayes in 1970. Piece by piece, Dover assembled the third-largest elevator franchise in North America, trailing only Otis and the Westinghouse business that later passed to Schindler.[^3]
For three decades, this division served as Dover's primary cash engine. Each elevator installed in an American office tower, hospital, or apartment building generated a recurring income stream of inspection contracts, modernization projects, and replacement parts. The economics differed sharply from traditional job-shop manufacturing: heavy upfront sales effort yielded years of high-margin recurring revenue, protected by high switching costs defined by the disruption and expense of replacing a building's vertical transportation system.
Why, then, did Dover exit the business?
In December 1998, Dover agreed to sell Dover Elevator International to Thyssen AG in a transaction that closed for approximately $1.1 billion in cash.[^3] At the time, the sale appeared to some observers as a company dismantling its strongest asset.
The strategic logic reflected shifting industry dynamics. The center of gravity in elevators was moving away from mid-rise North American buildings toward high-rise urban developments in Asia and the Middle East. Competing for those capital-intensive projects required global engineering capabilities, international manufacturing scale, and the infrastructure to bid and service installations across four continents. Industry leaders such as Otis, Schindler, Kone, and Thyssen possessed those global capabilities. As a regional third-place operator, Dover faced a choice between committing massive capital over a decade to build global scale or exiting entirely.
Dover's competitive advantage rested on regional service density at a time when the market began rewarding global scale in original equipment manufacturing. Holding an asset whose competitive moat is eroding often leads to a gradual transfer of value to competitors with superior global scale.
The divestment revealed an important aspect of Dover's evolving capital allocation framework. Management sold a high-performing asset when industry consolidation enabled a strategic buyer to pay a premium. Exiting a profitable business at market strength requires greater strategic discipline than divesting an underperforming unit, distinguishing disciplined portfolio managers from traditional corporate empire-builders.
However, successful capital allocation depends as much on redeploying capital as on generating proceeds. While the elevator sale produced substantial liquidity at a favorable valuation, the eventual deployment of those funds yielded far more mixed results in subsequent acquisitions.
IV. The Acquisition Machine & The Dot-Com / Tech Commodity Traps (1970s–2010s)
Through the 1960s, 1970s, and 1980s, Dover expanded its acquisition model across a broad range of industrial niches. In 1962, it acquired DE-STACO, a manufacturer of manual toggle clamps for assembly lines. It subsequently bought Groen in commercial food service equipment, Blackmer in industrial pumps, and OPW—the company that commercialized the automatic shutoff fuel nozzle in 1949, preventing gasoline overflow at service stations across America.[^3]
The operating pattern remained consistent: acquire the category leader in a niche too small to attract large diversified competitors, leave local management in place, and harvest steady cash flow.
That strategy shifted in 1979 when Dover acquired Universal Instruments.
Universal manufactured automated assembly equipment used to place electronic components onto circuit boards—the core surface-mount technology powering the expansion of computing and telecommunications. For two decades, the investment appeared highly successful. Dover Technologies emerged as a high-growth engine within a mature industrial portfolio, recording surging revenues and expanding margins during the late 1990s technology spending boom.
Historical Falsification Pass — The Dot-Com & Electronics Collapse
The claim being tested: acquiring category leaders in high-technology manufacturing equipment creates high-growth industrial technology platforms.
The disconfirming evidence arrived in 2001. When telecom and internet infrastructure capital spending reversed, demand for electronics assembly equipment did not merely contract—it evaporated. Dover's technology business suffered a peak-to-trough revenue decline of roughly 60%, forcing management to spend years restructuring manufacturing capacity built for demand that never returned.
The underlying mechanism is more instructive than the magnitude of the drop. Capital equipment sold to a concentrated customer base subject to rapid technological obsolescence carries three structural vulnerabilities: order books that drop sharply rather than declining gradually, rapid product transitions that strand inventory and development capital, and powerful customers capable of dictating terms. None of these conditions exist when selling low-cost replacement pumps to chemical processing plants. Dover had acquired a business with a fundamentally higher risk profile than its core portfolio, while pricing the transaction as if those risks did not exist.
Historical Falsification Pass — Sound Solutions and the Knowles Exit
If the electronics equipment downturn demonstrated technological cyclicality, the subsequent misstep highlighted buyer power—occurring a decade later, indicating that institutional lessons were not automatically retained.
In 2011, Dover acquired the Sound Solutions business from NXP Semiconductors for $855 million in cash, aiming to merge it with Knowles Electronics—Dover's existing acoustics unit—to create a dominant supplier of speakers and microphones for mobile phones.[^5]
On paper, the strategic logic appeared compelling: smartphone sales were surging, every device required micro-acoustic components, and combining the market's two leading suppliers promised operational scale.
In practice, Dover assumed a highly vulnerable structural position in industrial supply chains: serving as a component vendor to a concentrated group of consumer electronics manufacturers. Industry leaders such as Apple and Samsung held sufficient buyer power to demand annual price concessions as a condition for future design wins, irrespective of underlying input costs. A supplier in that position lacks pricing leverage, facing a recurring negotiation framework that erodes profitability over time. Margins compressed accordingly.
In February 2014, Dover completed the spin-off of Knowles Corporation to shareholders as a separately listed company.2 While corporate messaging emphasized strategic focus, the underlying reality was that Dover had committed nearly $900 million three years prior to expand in a market where it possessed no durable bargaining power. The spin-off offered a clean exit by transferring the capital allocation mistake to public equity markets.
This transaction remains a critical reference point when evaluating Dover's capital allocation history. It occurred recently enough to inform current leadership memory and carried material scale. It serves as a clear counterweight to the narrative that Dover has consistently maintained disciplined underwriting. Capital discipline is an operating policy rather than an inherent organizational trait, and policies can lapse.
The Energy Cycle and the Apergy Spin
The third challenge involved commodity-driven cyclicality. Over several decades, Dover assembled a substantial upstream oilfield equipment portfolio, building on its foundational W.C. Norris sucker rod business by acquiring Harbison-Fischer, Quartzdyne downhole pressure sensors, and wellsite automation providers.
When crude oil prices declined sharply between 2014 and 2016, the energy segment's earnings contracted sharply. The challenge extended beyond short-term operating income: housing a volatile, commodity-sensitive unit within a diversified industrial structure depressed Dover's overall valuation multiple, as public markets frequently price conglomerates according to their most volatile business line.
Dover announced in December 2017 that it would separate the upstream energy businesses,3 completing the spin-off of Apergy Corporation in May 2018.4 Apergy subsequently merged with Ecolab's ChampionX business.
Executing three major corporate separations over fifteen years to exit businesses with structurally inferior economics reveals a consistent strategic pattern. From a critical perspective, these divestments represent necessary corrections of earlier capital allocation choices. While spin-offs provided the financial remedy, the core analytical question is how effectively management institutionalized the operational lessons. That responsibility fell to Richard Tobin, who assumed the chief executive role as the Apergy separation neared completion in 2018.
V. The Tobin Transformation: Strategic Pruning & Portfolio Overhaul (2018–Present)
Richard Tobin arrived at Dover in 2018 with an operating background far removed from the company's tradition of decentralized niche manufacturing.5 Previously chief executive officer of CNH Industrial, Tobin managed agricultural equipment, construction machinery, and commercial vehicles within a complex Italian-Dutch-American corporate structure—an environment of heavy fixed costs where a small shift in capacity utilization determined annual profitability. In that setting, operational success required granular oversight of factory cost structures rather than passive delegation to local plant managers.
That operational orientation is reflected in Tobin's executive communication style. On earnings calls, he speaks candidly, focuses heavily on productivity metrics, and frequently manages analyst expectations downward. Asked during the July 2026 earnings call why order momentum was not converting faster into reported revenue, Tobin resisted encouraging higher sales projections: "If I talk up the revenue, we can explore possibilities of beating the top line... for sure, not going to get in a situation where estimates outrun basically what we are telling you."[^1]
While CEO conservatism is a familiar communication tactic, resisting sell-side attempts to raise forward estimates signals a disciplined approach to managing market expectations.
From Autonomy to Disciplined Execution
The managerial framework under Tobin paired commercial decentralization with centralized cost and capital control.
Dover initiated structural plant consolidations—described as "rooftop" rationalizations in corporate disclosures—while centralizing procurement across business units. Rather than treating operational restructuring as an occasional reaction to industrial downturns, management established an annual productivity program designed to yield structural savings. For 2026, Dover projected approximately $40 million in carryover profit benefits from previously implemented productivity initiatives.[^4]
Executive compensation incentives were aligned with capital efficiency rather than revenue scale. Dover's performance share units evaluate executive payouts based on metrics including adjusted return on invested capital (ROIC) and organic revenue growth, complemented by executive stock ownership requirements.6 The structure aims to ensure that acquiring unprofitable revenue penalizes executive compensation.
However, an evaluation of capital allocation discipline requires examining how ROIC is calculated. A structural gap exists between Dover's adjusted ROIC and its GAAP returns. Goodwill and intangible assets accounted for approximately 54 percent of Dover's total assets at year-end 2025, reducing GAAP-basis return on invested capital to the mid-to-high single digits—substantially below management's adjusted ROIC targets.7 This divergence is common among serial acquirers that accumulate goodwill over decades, including peers such as IDEX and Roper Technologies. Nevertheless, because adjusted ROIC metrics partially exclude past acquisition purchase prices, investors must evaluate raw transaction discipline directly rather than relying solely on adjusted performance figures.
The Divestiture Wave
Two strategic divestments in 2023 and 2024 significantly altered Dover's portfolio composition.
In October 2023, Dover agreed to sell DESTACO, the manual clamping and industrial automation business acquired in 1962, to Stabilus SE for $680 million in a transaction that closed in April 2024.8 DESTACO served automotive assembly markets, exposing its order flow to vehicle model redesign cycles and automotive capital expenditure pauses.
A larger divestment followed in July 2024, when Dover agreed to sell its Environmental Solutions Group (ESG) to Terex Corporation for $2.0 billion in cash, closing the transaction in October 2024.9[^14] ESG manufactured Heil refuse collection vehicle bodies and waste compaction systems. Although the business held strong market share, its operational profile reflected heavy vehicle manufacturing: capital-intensive, steel-dependent, tied to municipal budgets, and subject to vehicle replacement cycles.
These sales aligned with the logic of Dover's earlier elevator divestment: exiting solid operations whose underlying economics lagged portfolio targets, selling to strategic buyers willing to pay full valuation.
The divestments reshaped segment reporting. The Engineered Products segment, which generated approximately $2.0 billion in 2023 revenue prior to selling ESG, generated about $1.09 billion in 2025 and accounted for less than 15 percent of consolidated revenue.10[^4] Despite divesting these units, Dover's total revenue expanded from $7.68 billion in 2023 to $8.09 billion in 2025.1
Gross margins reflected the portfolio mix shift. Dover's consolidated gross margin expanded from 37.3 percent in 2023 to 38.2 percent in 2024 and 39.8 percent in 2025—representing nearly 250 basis points of total expansion.1 This margin expansion stemmed from a combination of divesting lower-margin units, achieving pricing realization during inflationary periods, and realizing cost savings from productivity programs.
Redeploying the Proceeds
The redeployment of approximately $2.7 billion in total exit proceeds provides a direct test of capital allocation strategy.
Over the past five years, Dover directed acquisition capital toward specific growth verticals, including cryogenic components, precision turbine and compressor parts, single-use biopharmaceutical components, natural refrigerant systems, and thermal management. Tobin categorized these businesses as secular growth platforms, which expanded to represent approximately 25 percent of total company revenue by mid-2026, up from roughly 20 percent at the start of the year.[^1]
In 2025, Dover deployed approximately $700 million across four acquisitions—three of which expanded the Pumps & Process Solutions segment—while completing over $500 million in share repurchases, including a $500 million accelerated buyback launched in November 2025. These capital deployments were fully funded through internal cash generation, allowing Dover to execute acquisitions and share repurchases while preserving balance sheet capacity entering 2026.[^4]
Funding acquisitions and capital returns entirely from free cash flow rather than incremental leverage provides structural resilience, insulating the business model from debt market volatility.
What the Calls Reveal
Management's capital deployment commentary across 2026 earnings calls illustrates its decision-making framework.
During the January 2026 earnings call, Tobin noted that Dover favored capital return due to elevated transaction multiples and a limited supply of high-quality acquisition targets. By July 2026, his outlook shifted: "There are more assets coming available and so we would like to keep our powder dry to see whether we are going to choose to participate."[^1][^4] Tobin added that if suitable M&A targets failed to materialize at reasonable valuations, management would pivot back to share repurchases rather than accumulating excess cash reserves.
While management reported that its 2025 acquisitions—specifically Secora—were performing above initial underwriting models,[^4][^1] early post-acquisition performance represents an incomplete test of long-term value creation. Sustained operational execution across economic cycles remains the necessary benchmark for evaluating transaction returns.
VI. Deep Dive: Segment Economics, Moats, & Operating Playbook
To understand why one Dover segment earns 35% margins and another struggles to hold the high teens, it helps to start with a physical object.
A brazed plate heat exchanger is a stack of thin, corrugated stainless steel plates fused together in a vacuum furnace, creating two interleaved sets of channels. Hot fluid runs through one set, cold fluid through the other, and heat moves across the plate walls without the fluids mixing. It looks like a metal brick. It is, functionally, the radiator inside a heat pump, a chiller, or increasingly the cooling loop of an AI server rack.
Making them is harder than it sounds. The brazing process is unforgiving, the plate geometry determines efficiency, and yield problems in the furnace destroy economics. This is why, when an analyst asked Tobin in July 2026 whether doubling capacity was aggressive when liquid cooling peers were quadrupling, his answer inverted the question: "The beauty of the business is that it is very hard to ramp capacity in it. And so there is very few companies that can do it. So the defensive nature of that business is it is hard to ramp capacity."[^1]
That single sentence is the clearest statement of Dover's operating thesis anywhere in the public record. The moat is manufacturing difficulty in a product whose failure is expensive and whose cost is small relative to the system it sits inside.
Let us walk the five segments with that lens.
Pumps & Process Solutions — the profit engine
At roughly $2.15 billion of 2025 revenue, this is now Dover's largest segment and by a wide margin its most profitable.10 It contains Wilden air-operated double-diaphragm pumps, Blackmer, Almatec, Griswold, the Malema flow measurement business acquired in 2022, polymer processing equipment, precision components for turbines and compressors, and thermal connectors used in data center liquid cooling.
In the second quarter of 2026 the segment posted a margin of approximately 35% — a level Tobin himself flagged as a record and noted nobody had been counting on.[^1]
The moat mechanism differs by product but shares a structure. In single-use biopharma, a Coriolis flow sensor measures the mass flow of a fluid by vibrating a tube and detecting the phase shift caused by the moving mass — an elegant bit of physics that produces a reading unaffected by the fluid's density or temperature. In a drug manufacturing process, that sensor becomes part of the validated production method. Changing it means re-qualifying the process with the regulator. The switching cost is not the price of the sensor; it is the regulatory and validation burden of proving the new one works.
Dover's specific position in biopharma is subtler than "supplier to drug companies." As Tobin explained when asked how Dover's trajectory differed from Danaher and Sartorius, Dover is often a component supplier to those companies — Danaher is a customer — and the majority of Dover's revenue stream is consumable rather than new system sales.[^1] That is an important distinction: consumables track production volumes of drugs already approved and in manufacture, not customers' capital budgets. It explains why Dover's biopharma exposure held up better than the bioprocessing capital equipment vendors during the post-pandemic destocking cycle, and it is a genuinely better business than selling the systems.
The caveat is that "less cyclical" is not "acyclical." Management flagged a tough first-quarter 2026 comparison in biopharma caused by heavy restocking in early 2025 — meaning the customer inventory cycle still moves Dover's reported numbers around.[^4]
Clean Energy & Fueling — the transition bet
At roughly $2.13 billion in 2025, this segment is nearly the same size as PPS but earns materially less.10 It contains OPW's retail fueling equipment, dispensers, below-ground fiberglass containment systems, vehicle wash equipment and software, and a cluster of cryogenic businesses — valves, couplers and vacuum-jacketed piping — acquired over recent years.
The segment is in the middle of a margin walk. On the January 2026 call Tobin described a path from the high teens toward a mid-20s target: "You are going to have to walk it up... should get into the low twenties this year. And then walk it up from there."[^4] By the second quarter of 2026 the segment had delivered 170 basis points of expansion on volume leverage and acquisition integration benefits.[^1]
The interesting part of this segment is an accident of the acquisition strategy. Dover bought cryogenic component businesses because it believed in the natural gas and LNG ecosystem. What it got, additionally, was exposure to two markets it had not underwritten: space launch infrastructure, where vacuum-jacketed piping and valves handle cryogenic propellants, and data centers, where the same cooling technology is being specified. Tobin was candid that this was not foresight: "We bought them because of natural gas and LNG, kind of where we live, but we are pivoting now recognizing the opportunity there. So it is relatively new. That is probably why we have not talked about it before."[^1]
Dover expected roughly $50 million of revenue tied to space in 2026 — a small number against $8 billion, and worth keeping in proportion.[^1] The honest framing is optionality, not a thesis.
The more durable piece is retail fueling, where Dover described North America as being in the early innings of a new capital expenditure cycle after years of suppressed spending. Tobin's explanation was commercially specific rather than macro hand-waving: station operators stopped investing when the consensus held that electric vehicles were about to take over, and restarted when fuel retail spreads reached historically high levels, improving project returns.[^4] Dover has also deliberately shrunk its emerging market and EMEA fueling exposure through customer rationalization — a decision that cost top-line growth for several years while improving margins.
Climate & Sustainability Technologies — the operational problem child, and the data center story
At roughly $1.56 billion in 2025, this segment contains SWEP brazed plate heat exchangers, the Hillphoenix commercial refrigeration business, refrigerated door cases and services, and Belvac can-making equipment.10
It is where the best and worst operating news of 2026 both lived. Heat exchange delivered its best quarter ever in the second quarter on liquid cooling demand, with capacity being doubled over twelve months. Refrigeration, in the same quarter, missed its production targets during the plant consolidation described at the opening of this story.[^1]
There is a subtle and important point buried in Tobin's answer to Deane Dray about heat exchanger margins. For roughly two and a half years, SWEP's margins had been depressed precisely because Dover was adding fixed capacity ahead of revenue — visible top-line growth that was not converting to profit. What changed in 2026 was not the margin structure but the timing: demand inflected faster than the capital deployment, so volume began absorbing the fixed cost already in place.[^1]
Investors should hold that mechanism in mind in both directions. Margin expansion driven by absorption of pre-built capacity is real, but it is leverage, and leverage works in reverse.
The CO2 refrigeration business is a cleaner structural story. Commercial refrigeration is moving from synthetic refrigerants toward carbon dioxide, which operates at far higher pressures and requires different system architecture. Dover claims North American market leadership and co-leadership in Europe.[^4] Notably, Tobin argued that adoption is no longer driven primarily by regulation but by total cost of ownership — and, when asked whether a delayed EPA mandate hurt, said the absence of a time-based mandate was better for Dover because the industry could not have met it anyway, turning the opportunity into a multi-year runway.[^1] That is a claim worth testing against future order rates rather than accepting: a company with capacity constraints has an obvious incentive to prefer demand spread over more years.
Engineered Products — the shrunken remainder
Post-divestiture, this segment generated about $1.09 billion in 2025.10 It holds Rotary Lift and the vehicle service group, Warn industrial winches, and an aerospace and defense components business seeing significant demand tied to electronic warfare and signals intelligence.[^4]
The vehicle service business declined by double digits organically in 2025, driven substantially by Europe. Tobin's handling of it is revealing of the broader operating philosophy: rather than chase volume, Dover let the top line shrink. "We are not chasing dilutive sales in vehicle sales group," he told Wolfe Research in July 2026, crediting management with maximizing profitability instead.[^1] Segment margins expanded despite the volume decline.
Imaging & Identification — the annuity
Markem-Imaje makes the printers that put expiry dates, lot codes and serialization marks on bottles, cartons and packages as they move down high-speed lines. At roughly $1.17 billion of 2025 revenue, the segment posted EBITDA margins around 28% in the fourth quarter of 2025.10[^4]
The economics are razor-and-blade. The printer is sold once; ink, fluids, spare parts and increasingly serialization software recur for as long as the line runs. Management explicitly framed an uptick in printer shipments as building the installed base for future recurring attachment.[^4] Switching costs are workflow-based: the printer is integrated into line control software, and a coding failure stops the line and can trigger a recall.
The honest limitation is growth. This is a consumer-goods-exposed, globally distributed business with significant currency noise, and Tobin declined to project a long-term growth rate for it, calling it "such a messy number" while emphasizing its cash flow characteristics.[^4] A high-quality annuity growing at low single digits is a valuable asset, not a growth engine.
Across all five, the common denominator is worth naming once: Dover's best businesses sell components whose cost is trivial relative to the system they protect and whose failure is expensive. That, more than any segment label, is the operating playbook.
VII. Capital Allocation, Governance, & Management Credibility
In November 2025, with its own shares trading at what chief executive officer Richard Tobin would later describe as a cheap multiple, Dover initiated a $500 million accelerated share repurchase.[^4] Two months later, when presenting 2026 guidance, management noted that it favored stock buybacks over acquisitions because private-market transaction multiples remained elevated. Six months after that, management reported that the acquisition pipeline had improved, signaling a desire to keep its powder dry for potential deals.[^1]
That sequence—buying back shares when acquisition targets are expensive and preserving capital when deal valuations moderate—reflects the discipline a capital allocation framework is designed to enforce. Yet because any company can construct an opportunistic narrative after the fact, the underlying framework requires closer examination.
The framework
Dover ranks organic investment as its top priority, operating on the premise that internal projects yield the highest returns. Capital expenditures increased by more than $50 million in 2025, divided between expanding capacity in high-growth platforms and funding productivity and automation initiatives, including plant consolidations. Management projected lower capital spending in 2026—between $190 million and $210 million—as those initial projects neared completion, with work on a new facility in North Carolina extending into 2027.[^4][^1]
At roughly 2.5 percent of revenue, Dover operates as a capital-light manufacturer by multi-industrial standards—a direct result of its portfolio shift. Specialized component businesses requiring high engineering content demand far less heavy manufacturing equipment per dollar of sales than legacy operations like refuse truck body manufacturing.
The company's second priority is bolt-on acquisitions, concentrated in target secular growth verticals and kept at a size that center-led corporate functions can integrate without exposing the firm to systemic operational risk.
Third in the priority order is capital return to shareholders. Dividend growth remains the primary highlight: in August 2026, Dover increased its quarterly dividend to $0.525 per share, marking its 71st consecutive year of dividend increases—one of the longest unbroken records on the New York Stock Exchange.11
That record warrants analytical nuance because dividend longevity is easily misinterpreted. A 71-year payout record demonstrates that Dover has avoided financial crises severe enough to force a dividend cut across eleven recessions—a testament to balance sheet conservatism. It does not, however, prove that historical capital deployment was optimal. Because the dividend consumes only a modest portion of annual cash flow, the commitment acts as a guardrail on managerial excess rather than an engine of compounding returns.
Balance sheet
Dover's net debt to EBITDA ratio stood at approximately 1.1 times at the end of 2025, down from roughly 2.1 times at year-end 2023—a reduction driven by the arrival of $2.7 billion in divestiture proceeds during 2024.7 Free cash flow reached 14 percent of revenue in 2025, representing a year-over-year increase of nearly $200 million, while management guided for free cash flow of 14 percent to 16 percent of revenue in 2026.[^4]
Converting more than 100 percent of net income into free cash flow is a defining characteristic of effective industrial compounders, ensuring that reported earnings can be redeployed rather than remaining tied up in working capital. Dover met that standard in 2025. In the first half of 2026, free cash flow conversion slowed to 8 percent of revenue, reflecting inventory investments to support accelerating growth alongside the company's typical seasonal pattern, where cash generation peaks heavily in the fourth quarter.[^1][^4]
Credibility audit
Evaluating management by historical execution rather than stated strategy reveals a disciplined track record accompanied by notable caveats.
On guidance discipline, the record is consistent. In 2025, Dover set conservative initial targets, raised its adjusted earnings per share outlook through the year, and closed fiscal 2025 at $9.61 per share, representing a 16 percent increase.[^4] For 2026, management initially established an adjusted earnings per share range of $10.45 to $10.65 before raising expectations at mid-year.[^1] Tobin acknowledged that initial guidance incorporated deliberate conservatism, recalling the macroeconomic disruptions that followed the prior year's outlook: "We were here the same time last year, and then the s— hit the fan in February."[^4] While systematically under-promising and over-performing builds market credibility, investors must treat recurring upward revisions as an ongoing communication strategy rather than unexpected fundamental shifts.
Regarding operational missteps, management's handling of the 2026 refrigeration plant bottleneck provides a clear test of transparency. Executive leadership quantified the revenue drag, identified the root cause in facility consolidation, accepted responsibility, and outlined a recovery timeline. Management also acknowledged that delivery delays had occurred while noting it had observed no loss of market share—offering a transparent assessment of customer friction without making unsupported assurances.[^1]
Narrative consistency represents another positive indicator. Management has consistently tracked its secular growth platforms across consecutive earnings calls, disclosing the specific percentage of total revenue these businesses represent each quarter. Because this metric provides a clear basis for tracking progress, any stagnation or shift in definition will be readily apparent to analysts.
A lingering structural question is whether a conglomerate encompassing fuel dispensers, biopharmaceutical sensors, and industrial printing systems should remain under a single corporate umbrella. When questioned about potential divestments or portfolio breakups, Tobin responded pragmatically, affirming that Dover maintains a fiduciary duty to evaluate inbound interest, remains comfortable with its existing operating units, and retains portfolio flexibility as a deleveraging tool if debt is used for acquisitions.[^4] When asked about the prospect of a transformational transaction, Tobin rejected the necessity of large-scale deals, noting that Dover maintains "a very keen eye about execution risk" and is "not required to do anything."[^4]
Management's reluctance to pursue large-scale acquisitions represents a prudent stance given Dover's past experience with Sound Solutions. The enduring question for investors is whether that capital discipline will persist when organic growth decelerates.
VIII. Porter's 5 Forces, Hamilton Helmer's 7 Powers, & Skeptical Investor Stress Test
Strip away the segment structure and Dover is a wager on a single proposition: that in narrow industrial niches, being the incumbent supplier of a critical, low-cost, hard-to-qualify component is a durable economic position.
That proposition can be tested with two standard frameworks and one uncomfortable question.
Helmer's 7 Powers
Switching costs — strong, but unevenly distributed. The strongest case lies in biopharmaceuticals, where a flow sensor written into a validated manufacturing process cannot be swapped without regulatory review, and in Markem-Imaje, where coding printers are integrated into production line controls and any failure halts operations. Both are supported by observable behavior: consumable revenue that tracks customer production volumes rather than capital spending budgets. The weaker case involves general industrial pumps, where switching costs are meaningful but bounded—a chemical plant can qualify a second supplier if it chooses to do so, and many do.
Process power — moderate, and the best-evidenced power Dover has. The brazed plate heat exchanger business is the clearest example: the difficulty of ramping production capacity is itself the barrier, as management directly stated. This power manifests in a verifiable way—if competitors could add capacity quickly, Dover's lead times would not extend, and customers would not be booking orders a year in advance.
Cornered resource — weak to moderate. Dover holds patents and deep OEM integration, but nothing that functions as an exclusive input. Its cryogenic and precision component positions rest on qualification cycles and customer relationships rather than control of a scarce physical asset.
Scale economies — moderate and mostly internal. Dover's scale advantage is largely realized through shared procurement, distribution, and back-office functions across acquired units rather than lower unit manufacturing costs. That is a real but modest power, created primarily by centralization under Richard Tobin.
Counter-positioning — essentially absent. Dover does not execute business models that competitors are structurally disincentivized to copy. It should not be credited with this power.
Branding and network economies — not material in industrial components sold strictly on technical specifications.
Porter's Five Forces
Buyer power — low to moderate, with a critical exception. Across most of the portfolio, the component cost is small relative to the total system value and the cost of failure is high, suppressing buyer price sensitivity. The exception is instructive: in retail fueling, Dover's customers are large convenience store chains with substantial purchasing leverage. Dover responded by exiting relationships with unprofitable customers in Europe, the Middle East, Africa, and emerging markets—accepting several years of top-line drag to protect gross margin.[^4] That is the operational response of a supplier facing genuine buyer power.
The Knowles spin-off remains the clearest historical demonstration that Dover's pricing leverage depends on customer fragmentation. Where customer concentration increases, supplier pricing power diminishes.
Supplier power — moderate and currently rising. Dover relies on raw material inputs, particularly steel and copper, with management explicitly highlighting copper cost pressures in refrigeration and climate solutions. The principal mitigant is price realization: Dover embedded 1.5 to 2.0 percent pricing gains into its 2026 guidance and has historically recovered 1.0 to 1.5 percent annually.[^4] That demonstrates pricing power, but it reflects input-cost pass-through rather than structural margin expansion driven by price increases alone.
Threat of substitutes — low. Fluid handling and thermal management are defined by physical engineering requirements. Software solutions cannot replace mechanical pumps or heat exchangers.
Threat of new entrants — low in core niches, moderate elsewhere. Rigorous customer qualification cycles and manufacturing complexity restrict new entrants in biopharmaceutical sensors and brazed plate heat exchangers. Those barriers are lower in general industrial markets such as standard vehicle lifts.
Rivalry — moderate. Dover competes against IDEX Corporation, Crane Company, Graco, ITT, Xylem, and Veralto across overlapping product categories. This peer group represents a established field of high-quality industrial compounders, which carries two implications: Dover's operating playbook is not unique, and its target acquisition assets attract competing bids from well-capitalized peers. Competition for acquisitions, rather than customer churn, represents the primary structural constraint on Dover's model.
The skeptical stress test
A skeptical thesis on Dover rests on a clear observation: the company is a mid-single-digit organic growth industrial that has generated double-digit earnings growth by divesting lower-margin units, acquiring higher-margin businesses with internal cash flow, rationalizing fixed costs, and repurchasing shares—a combination that cannot be repeated indefinitely.
That perspective highlights structural limits in the model. Management has acknowledged the portfolio's organic growth boundaries. Tobin estimated the through-cycle organic growth entitlement of the current portfolio at "somewhere between three to six, depending on GDP," adding that it "clearly can do five."[^4] That figure represents an executive ceiling that bounds claims that portfolio transformation has fundamentally altered Dover's baseline growth trajectory. While organic growth accelerated in 2026, that performance was driven by cyclical demand across data center cooling, power generation, and space launch infrastructure.
Furthermore, Dover experienced a prolonged slowdown from 2023 through 2025, a period Tobin described as "several years of organic growth below our long-term standard," during which earnings expansion relied on productivity programs and capital deployment.[^4] While supporters view that period as proof of operational resilience during cyclical troughs, skeptics see evidence that earnings growth depended on financial engineering rather than organic volume.
A second operational vulnerability involves acquisition multiples. Dover's compounding model depends on acquiring niche industrial assets at valuations that satisfy internal return hurdles. Tobin acknowledged this pressure in July 2026, noting that while deal flow had increased, transaction prices remained elevated, explicitly leaving open whether value could be created at prevailing multiples: "Can you create value depending on what the prevailing acquisition price is? Remains to be seen."[^1]
That statement acknowledges that a core driver of Dover's model remains sensitive to broader market valuations that management does not control.
A third risk centers on execution. The refrigeration production bottleneck in 2026 was small relative to Dover's $8 billion revenue base. However, the misstep occurred within plant consolidation—the core operational lever of the corporate productivity program—and transpired during a period of strong demand, resulting in permanently lost shipment revenue. Management's plan to restore production throughput in the second half of 2026 provides a direct operational test over subsequent quarters.
Synthesizing these elements: empirical evidence supports the claim that Dover has structurally improved its business mix. The gross margin expansion, the shift toward consumable components, reduced earnings volatility, and self-funded capital allocation represent verified changes. What the evidence disproves is the proposition that Dover has transformed into a high-growth enterprise. Management's guidance establishes clear boundaries on top-line expansion. The defensible conclusion is more measured: Dover has evolved into a higher-margin, highly cash-generative industrial platform growing at a mid-single-digit organic rate, whose long-term compounding depends on disciplined capital deployment at reasonable transaction multiples.
IX. Bear vs. Bull Case & The 3 Critical Forward KPIs
By mid-2026, Dover occupied a rare operational position: every reporting segment was generating organic revenue growth and posting expanding bookings—an alignment Chief Executive Officer Richard Tobin noted occurs infrequently across a portfolio spanning such diverse end markets.[^1] Retiring RBC analyst Deane Dray remarked during an earnings call that he could not recall the last time Dover's segment guidance matrix was entirely positive across every line.[^4]
While broad-based expansion represents an ideal operating environment for a multi-industrial conglomerate, it also complicates forward-looking analysis, as peak-cycle momentum creates a risk of over-extrapolating transient demand.
The bull case
The bullish investment thesis rests on three core pillars: structural portfolio mix improvement, targeted exposure to secular growth markets, and disciplined capital deployment.
The mix argument forms the primary pillar. Dover generates higher gross margins than it did three years prior, reflecting a business mix richer in consumable components and high-switching-cost products, with reduced exposure to heavy vehicle bodies and automotive tooling. In the second quarter of 2026, adjusted EBITDA margin reached 25.9 percent—an 80 basis point expansion—supported by incremental margins of 38 percent.[^1] High incremental margins serve as a critical metric during an industrial recovery, indicating that a substantial portion of each additional dollar of revenue flows directly to operating profit.
Secular growth exposure provides the second pillar, though its durability remains subject to end-market cyclicality. Approximately one-quarter of total revenue is tied to growth verticals with multi-year demand drivers, including liquid cooling, natural gas power generation, carbon dioxide refrigeration, single-use biopharmaceutical components, space launch infrastructure, and semiconductor manufacturing. Trailing twelve-month bookings increased 15 percent as of the second quarter of 2026, maintaining a book-to-bill ratio above 1.0 across all five reporting segments.[^1] While backlog does not guarantee revenue execution, a positive book-to-bill ratio across short-cycle operating units provides a clear near-term indicator of demand momentum.
Capital allocation discipline constitutes the third pillar: a low-leverage balance sheet, cash conversion exceeding net income over full-year periods, and a track record of repurchasing shares when acquisition multiples exceed internal return thresholds.
The bear case
The skeptical thesis highlights five key operational and structural risks.
First, several identified secular growth drivers remain vulnerable to underlying cyclicality. Demand for data center liquid cooling relies on capital expenditure budgets concentrated among a small group of hyperscale technology companies, while orders for natural gas turbine components depend on utility build-out timelines that can be delayed. Tobin urged perspective on earnings calls, clarifying that Dover is "not a data center play" in proportional terms and emphasizing that long-term demand durability remains unproven, even though he noted no signs of a downturn entering 2027.[^1]
Second, capacity expansion introduces two-sided operational leverage. Dover is doubling its heat exchanger manufacturing capacity while constructing a greenfield facility in North Carolina. If order volumes remain robust, fixed-cost absorption will expand operating margins. Conversely, if end-market demand decelerates, fixed overhead will depress segment profitability—mirroring the margin pressure that affected the SWEP unit for several quarters prior to its 2026 demand inflection.
Third, acquisition underwriting faces valuation pressure. With private market multiples elevated, deploying capital effectively grows more challenging, particularly given historical missteps such as the $855 million acquisition of Sound Solutions, which required a subsequent corporate spin-off within three years.
Fourth, persistent weakness in specific regional end markets continues to weigh on performance. European chemical industry softness has restrained polymer processing demand, European vehicle service equipment orders have experienced a multi-year slump, and Belvac's can-making machinery continues to await a capital equipment spending recovery that was not evident in backlog disclosures entering 2026.[^4]
Fifth, cost inflation and trade policy expose Dover to margin timing lags. Management guided for 2026 price realization of 1.5 to 2.0 percent to offset rising raw material costs, particularly in copper, while identifying trade tariffs as an active operational variable.[^4][^1] Although Dover has historically maintained a positive price-cost spread, input cost spikes can create temporary quarterly margin compressions before price adjustments take effect.
The three KPIs
Evaluating Dover's operational execution and portfolio trajectory over upcoming quarters depends primarily on three critical performance indicators.
1. Pumps & Process Solutions organic growth and segment margin. As Dover's largest reporting segment, primary earnings driver, and main recipient of M&A capital, PPS serves as the core barometer of portfolio quality. The segment recorded an operating margin of approximately 35 percent in the second quarter of 2026—a result management characterized as exceeding internal expectations. Consequently, investors must determine whether PPS can convert its biopharmaceutical, thermal connector, and precision component positions into sustainable mid-to-high single-digit organic revenue growth while maintaining margins in the low-to-mid 30 percent range, adjusting for quarter-to-quarter volatility in polymer processing orders.
2. Segment-level bookings and book-to-bill ratios. Because Dover operates primarily as a short-cycle manufacturer, order bookings lead reported revenue by one to two quarters across most business units. The key variable is order breadth. Maintaining a book-to-bill ratio above 1.0 across all five segments represents an exceptional operating state; the first segment to slip below parity will provide an early signal that demand momentum is narrowing. This metric also offers a benchmark for management's guidance discipline, as Tobin declined to raise full-year revenue targets based on order momentum, opting instead to evaluate booking persistence through the third quarter of 2026.
3. Free cash flow conversion as a percentage of revenue. Dover guided for free cash flow of 14 to 16 percent of revenue in 2026, following a 14 percent conversion rate in 2025. This metric synthesizes working capital management, earnings quality, and self-funding capacity into a single figure. An industrial serial acquirer that funds acquisitions, dividend growth, capital expenditures, and share buybacks entirely through organic cash flow maintains structural resilience against credit market cycles—making any erosion in cash conversion an early indicator of operational friction.
X. Playbook: Business & Investing Lessons
Four primary transferable lessons emerge from nearly eight decades of Dover's corporate history, and none of them is simply that "diversification works."
1. Sell good businesses when the axis of competition moves. The elevator sale in 1999 is the template and the Environmental Solutions Group divestment in 2024 is the modern echo. In both cases, Dover exited a business that was performing acceptably because the structural economics were shifting away from Dover's core strengths, selling to strategic buyers for whom the assets were central. The operational challenge is not merely recognizing structural drift; it is executing the exit before deteriorating financial performance forces a distressed sale. Most industrial conglomerates divest underperforming assets last and at depressed valuations.
2. Decentralization is an operating model, not a capital allocation model. Dover maintained an extreme decentralized structure for six decades and accumulated the exact structural inefficiencies the model predicts: duplicated manufacturing footprints, fragmented procurement, and an absence of institutional mechanisms to prune underperforming units. The operational realignment under Richard Tobin preserved commercial autonomy while centralizing procurement, cost discipline, and capital allocation. The broader strategic rule is that operational autonomy should govern decisions where local market knowledge dominates—such as customer relationships, product customization, and field service—while stopping at decisions where portfolio-level oversight provides scale advantages.
3. Never become a component supplier to a concentrated buyer. The acquisition of Sound Solutions and the subsequent spin-off of Knowles cost Dover nearly $900 million in cash and several years of executive focus. The structural vulnerability was predictable: a component vendor serving a concentrated customer base that dictates commercial terms possesses minimal pricing power, regardless of technical merit. Dover's current portfolio is deliberately aligned toward fragmented industrial customer bases. Investors evaluating any component manufacturer should assess customer concentration before evaluating product specifications.
4. The best B2B position is a cheap part that prevents an expensive failure. This principle represents the unifying logic across Dover's highest-margin businesses. Whether it is a single-use flow sensor written into a validated biopharmaceutical manufacturing process, a coding printer integrated into a bottling line, a heat exchanger in a data center cooling loop, or an automatic shutoff nozzle on a fuel dispenser, the component represents a fraction of the customer's total system cost while preventing costly operational failures. That structural asymmetry—rather than corporate scale or brand equity—generates pricing power and suppresses buyer price sensitivity.
A fifth lesson is implicit in Dover's manufacturing footprint: operational complexity can function as a competitive moat. Dover's defensible market position in brazed plate heat exchangers was not created by patent coverage or network effects alone, but by the physical difficulty of ramping precision manufacturing capacity without sacrificing yields. In industrial component markets, manufacturing complexity remains an effective barrier to entry precisely because it is difficult to replicate.
XI. Epilogue & "If We Were CEOs"
In 1947, Wall Street stockbroker George Ohrstrom acquired four unrelated industrial businesses—manufacturing seals, hydraulic lifts, sucker rods, and space heaters—on the premise that autonomous local managers would compound capital. Seventy-nine years later, Dover's primary profit drivers supply sensors for biopharmaceutical manufacturing and heat exchangers for artificial intelligence data centers, while corporate leadership drives plant consolidations in facilities division presidents once operated independently.
The through-line across that evolution is not the specific product lines, but a willingness to divest legacy operations to acquire businesses with superior economics—a process executed sporadically for decades and far more systematically since 2018.
For executive leadership managing Dover from this juncture, three priorities define the strategic agenda.
The first priority is expanding deeper into the consumable and component layers of biopharmaceuticals and hygienic fluid handling, particularly in the Asia-Pacific region, where Dover's footprint remains smaller than its Western presence. The strategic rationale is straightforward: consumable components tied to validated drug manufacturing track production volumes rather than customer capital budgets—generating a more stable revenue stream than equipment sales. While management acknowledges this structural advantage, the segment's global geographic reach remains incomplete.
The second priority is accelerating the software and consumable mix within Markem-Imaje. Serialization software converts initial printer sales into ongoing workflow dependencies, offering the primary source of pricing power within the marking and coding business. However, because this unit operates as a mature global business subject to foreign exchange headwinds, the realistic objective is margin mix improvement rather than top-line growth acceleration.
The third priority is capital discipline: refusing to overpay for acquisitions. Dover's compounding model relies on acquiring niche assets at valuations that satisfy internal return hurdles, even as peer industrial acquirers pursue similar targets. Executive leadership acknowledged this dynamic, observing that value creation at elevated private-market multiples "remains to be seen." In an environment of inflated deal pricing, Dover demonstrated the appropriate strategic response in November 2025 by launching an accelerated share repurchase, choosing to deploy cash into its own shares while waiting for transaction multiples to moderate.
A favorable interpretation of Dover frames the company as a settled compounding engine backed by a 71-year record of dividend increases and a permanently transformed portfolio. That assessment overstates the case. Dover operates as a higher-margin, disciplined industrial manufacturer bounded by a mid-single-digit organic growth ceiling articulated by management, an earnings algorithm dependent on acquiring assets at reasonable multiples, and a demand environment currently benefiting from cyclical tailwinds. While operational improvements and margin expansion are empirically verified, a fundamental shift to higher organic growth remains unproven.
What the evidence since 2018 demonstrates is a narrower, defensible thesis: an executive team that divests businesses before their core economics deteriorate, provides transparent operational assessments when facility consolidations stumble, avoids speculative transformational acquisitions, and funds both growth initiatives and shareholder returns from internal cash flow. In a sector where conglomerates frequently struggle with capital discipline, those managerial practices represent the most durable elements of Dover's operating model.
Whether Dover's specialized components can consistently sustain premium margins near 35 percent remains a question that subsequent quarterly order books will ultimately answer in public view.
References
-
Dover Corporation Annual Financial Statements and SEC Filings (CIK 0000029905) — U.S. Securities and Exchange Commission EDGAR ↩↩↩
-
SEC Form 8-K: Dover Corporation Completion of Knowles Corporation Spin-Off — SEC EDGAR, 2014-02-28 ↩
-
Dover to Spin Off Wellsite Automation and Oilfield Energy Businesses — Reuters, 2017-12-07 ↩
-
SEC Form 8-K: Dover Corporation Completion of Apergy Corporation Spin-Off — SEC EDGAR, 2018-05-09 ↩
-
Dover Names CNH Industrial Chief Richard Tobin as New CEO — Wall Street Journal, 2018-03-20 ↩
-
Dover Corporation 2024 Definitive Proxy Statement Form DEF 14A — SEC EDGAR ↩
-
Dover Corporation Key Financial Metrics and Balance Sheet Data, FY2022–FY2025 — SEC EDGAR filings (CIK 0000029905) ↩↩
-
Stabilus Agrees to Buy Dover Unit DESTACO for $680 Million — Bloomberg, 2023-10-12 ↩
-
Terex to Buy Dover's Environmental Solutions Group for $2 Billion — Reuters, 2024-07-22 ↩
-
Dover Corporation Form 10-K Annual Report for FY 2024 (Filed Feb 13, 2025), Segment Information — SEC EDGAR ↩↩↩↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube