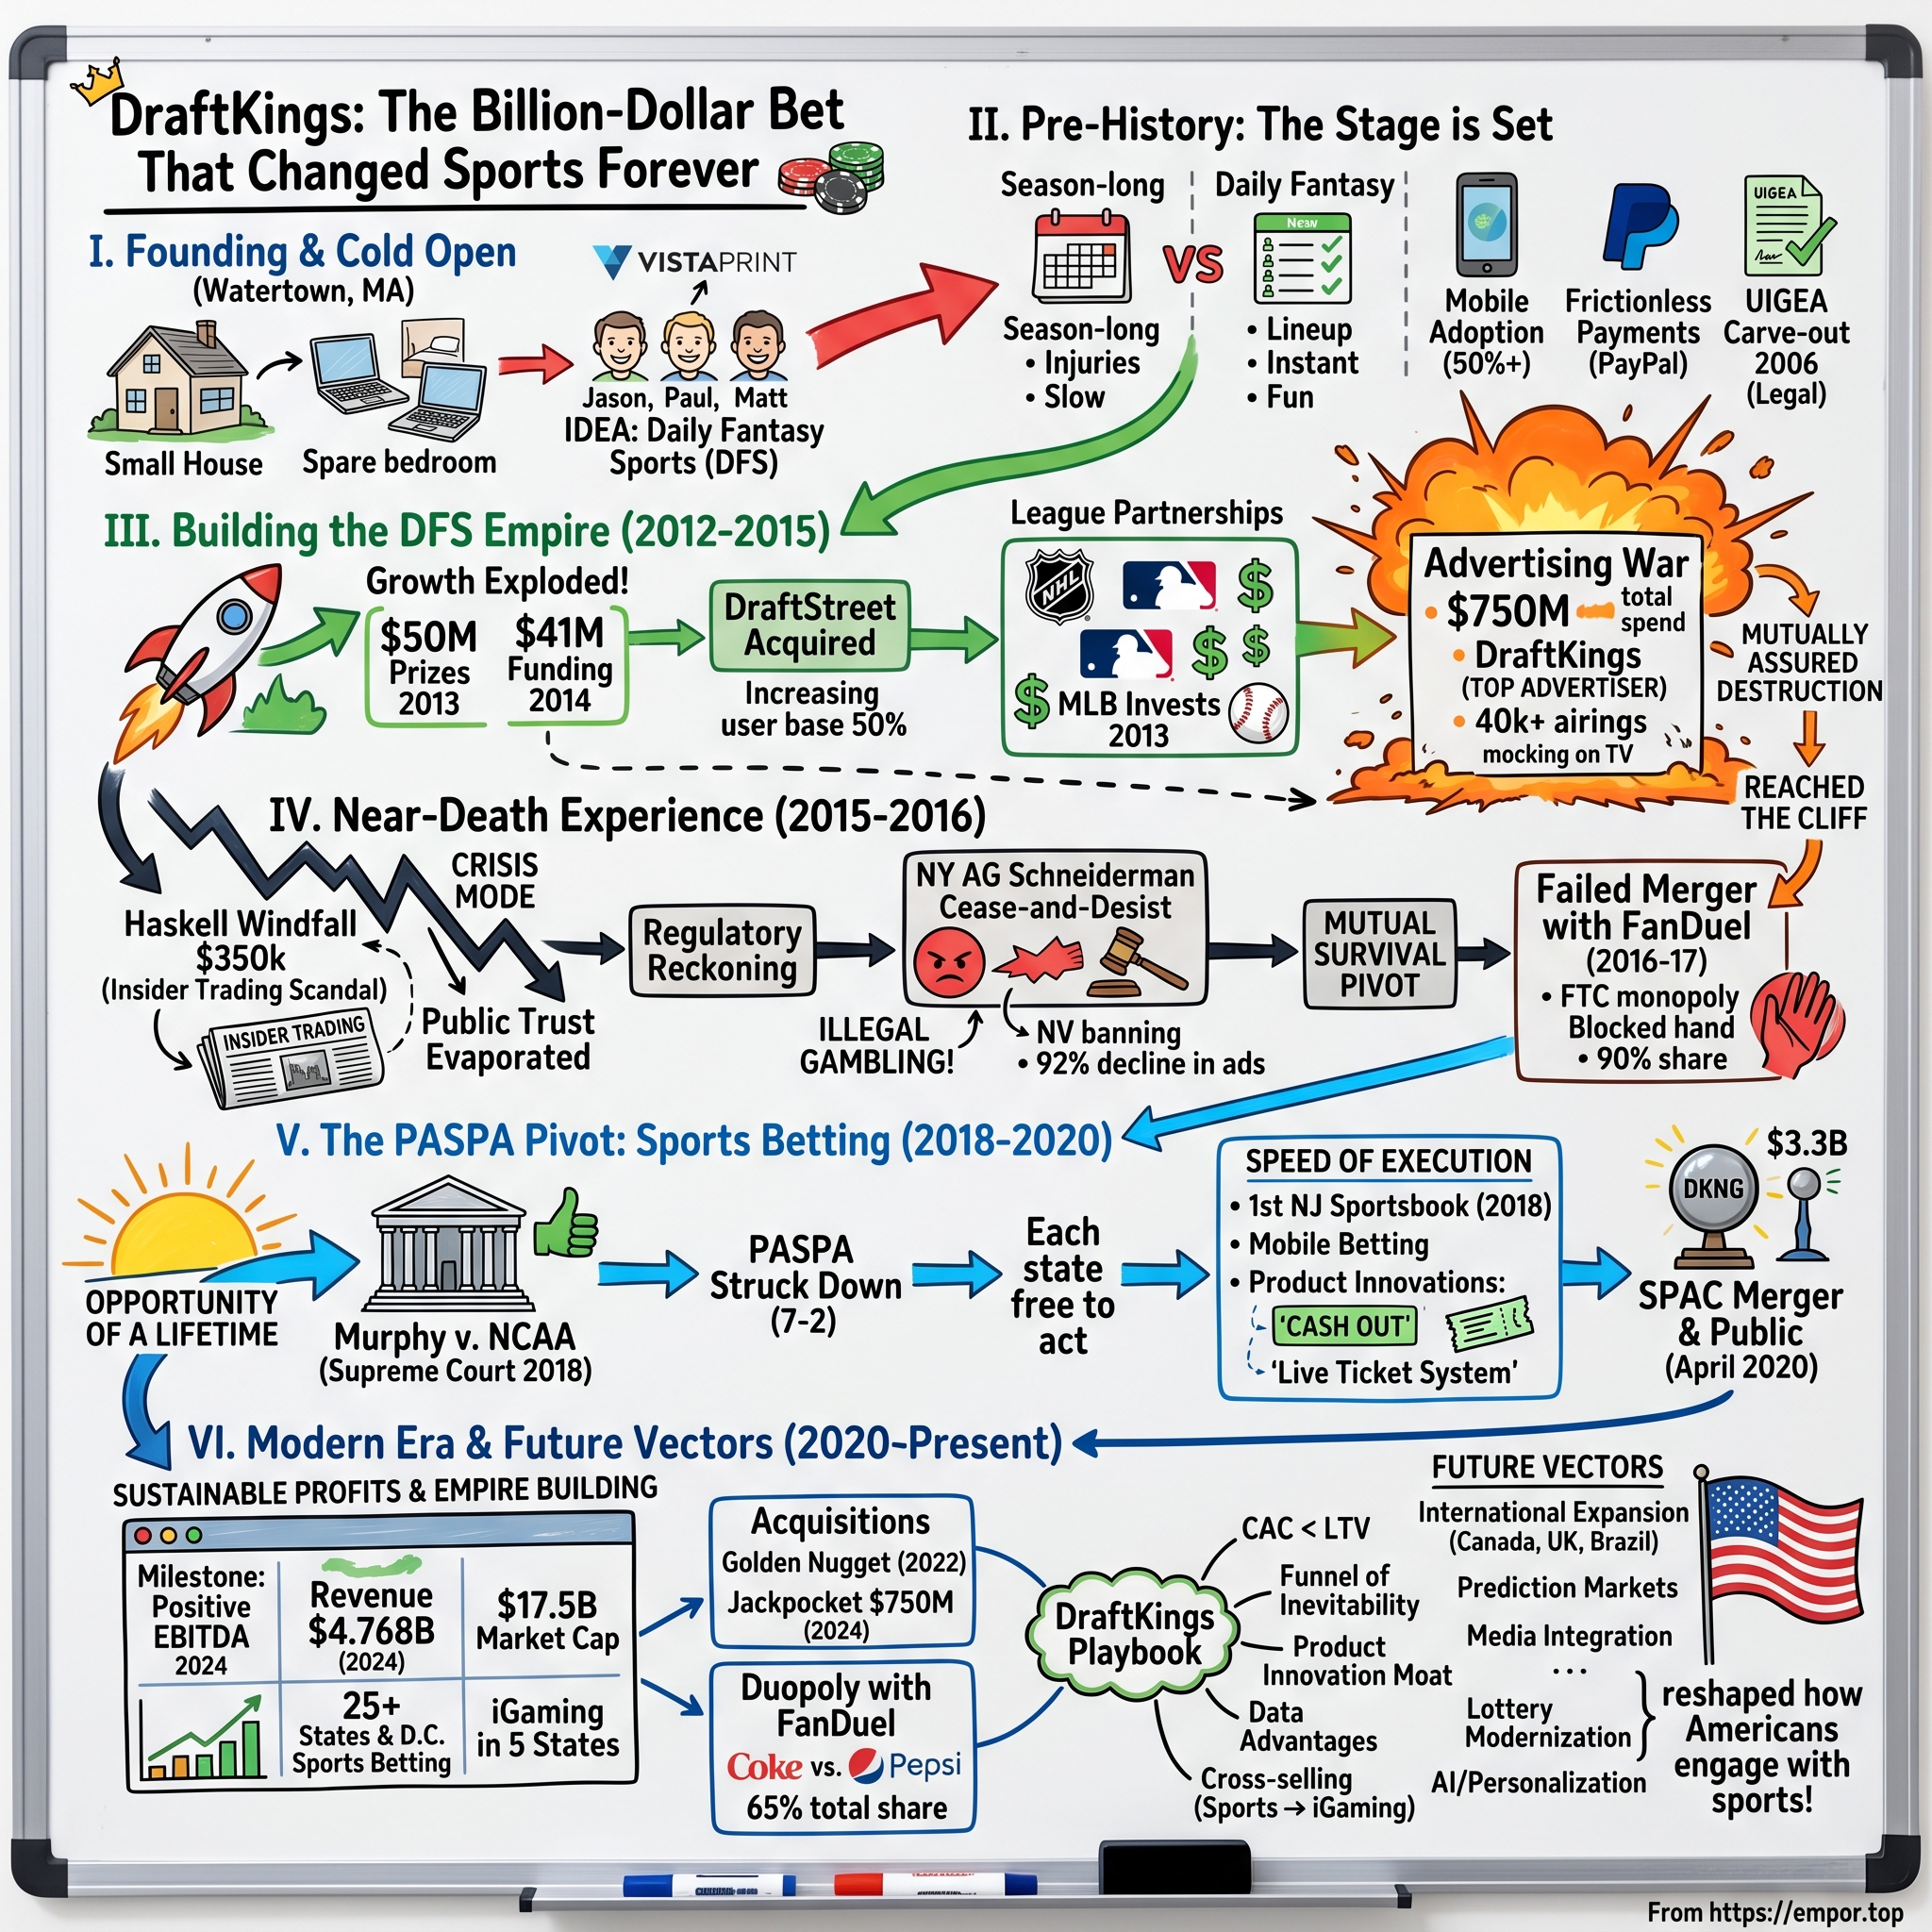
DraftKings: Duopoly Champion, Under New Attack
I. Introduction & Cold Open
On February 13, 2026, DraftKings Inc. did something it had never done in fourteen years of existence. It reported a profitable year.
Not adjusted-profitable. Not EBITDA-profitable. Actually, literally, GAAP profitable. Revenue for fiscal 2025 came in at $6.05 billion, up 27% year over year. Adjusted EBITDA hit $620 million, a record. And at the very bottom of the income statement, after every gaming tax, every promotional credit, every dollar of stock compensation, sat a positive number: net income of $3.7 million.12
It is worth pausing on the size of that number. Three-point-seven million dollars on six billion of revenue is a margin of roughly six one-hundredths of one percent. If DraftKings had held one basis point worse across the NFL season, it would have been a loss. In fact, once you account for the small slice attributable to non-controlling interests, earnings per share for the year still printed at negative one cent.2 This was not a company that had crossed into profitability so much as a company that had, after burning something north of four billion dollars of cumulative losses since 2019, finally touched the waterline.2
The market's reaction told you everything about where the argument had moved. On the day of that release, DraftKings guided fiscal 2026 revenue to $6.5–$6.9 billion and Adjusted EBITDA to $700–$900 million — a range that sat well below where sell-side models had been sitting, and the stock fell.1 By early September 2026, DKNG traded near $24 a share, giving it a market capitalization of roughly $11.8 billion — down from a 52-week high above $46.3 The equity had roughly halved while revenue kept compounding at better than 25%.
Something other than the operating results was driving the price.
The sell side eventually said so out loud. On April 24, 2026, MoffettNathanson cut DraftKings from Buy to Neutral and took its price target from $38 to $27, conceding it was "very late to downgrading" and that a cheap multiple was "no longer enough." The stated reason was not execution, competition from other sportsbooks, or the tax environment. It was that there would be no improvement in the outlook "until there is some regulatory clarity on prediction markets."4 When an analyst downgrades a company on a question that no one at the company can answer, the security has stopped trading on its own fundamentals and started trading on a court docket.
That something is a competitor category that did not meaningfully exist when DraftKings listed. Kalshi and Polymarket are not sportsbooks. They are event-contract exchanges regulated by the Commodity Futures Trading Commission under federal commodities law, and they offer contracts on sports outcomes in all fifty states without a single state gaming license and without paying a single dollar of state gaming tax. Combined monthly volume across the two platforms rose from under $5 billion in September 2025 to roughly $24 billion in April 2026, and sports has accounted for about 80% of everything traded on Kalshi since mid-2024.5 For context, the total amount wagered through every legal U.S. sportsbook combined averaged around $14 billion per month in 2025.5
There is an irony buried in the timing. DraftKings had, by any conventional measure, just won the war it spent a decade fighting. Its most heavily capitalized new challenger had folded its hand, and ESPN — the brand that was supposed to break the duopoly open — ended up piping odds into DraftKings' own products instead.6 The company beat every opponent that showed up to play the game it had mastered. Then the game changed.
That is the whole story, compressed. DraftKings spent a decade and tens of billions of dollars in cumulative marketing and promotional spend building a business whose central protection was that it was very hard and very expensive to get licensed in thirty-odd states. A rival then showed up and argued, with a real chance of winning in federal court, that it does not need those licenses at all.
So the question this episode has to answer is not whether DraftKings is a good operator. On most operating measures it plainly is. The question is narrower and harder: does the playbook that won the daily fantasy war and the first decade of legal sports betting — outspend, out-market, out-scale, get licensed first — still function when the next challenger is playing a different legal game entirely, with a structurally lower cost base?
We will get there. But the path runs from a spare bedroom in Watertown, Massachusetts, through a name-defining regulatory war, through the most expensive growth-at-all-costs experiment in modern consumer internet, to a founder-controlled public company now fighting on two fronts at once — and, in a twist nobody scripted, competing against the new format while also operating in it.
 Subscribe on LinkedIn
II. Origins, Compressed: DFS to a Public Company
Before there was a sportsbook, there was a loophole.
The Unlawful Internet Gambling Enforcement Act of 2006 was written to strangle online poker. In doing so, Congress carved out an exemption for fantasy sports, on the theory that assembling a roster of real athletes over a full season was a game of skill rather than chance. The carve-out was drafted with season-long office leagues in mind. It said nothing about compressing that season into a single day.
Three colleagues at VistaPrint — Jason Robins, Matt Kalish, and Paul Liberman — noticed the gap. They were not gambling people. They were direct-marketing and analytics people, which turns out to matter enormously to everything that followed. In 2012 they quit and started building daily fantasy sports out of the spare bedroom of Liberman's apartment in Watertown, Massachusetts, launching their first product — a head-to-head baseball contest — to coincide with MLB Opening Day.7
It is worth dwelling on what "direct-marketing people" means in practice, because it explains most of what DraftKings did for the next decade. A direct marketer does not think about a customer as a fan; they think about a customer as an acquisition cost, a retention curve, and a lifetime value, and they treat the gap between those three as an engineering problem. That mindset produced a company willing to lose enormous sums up front on customers it had modeled would pay back later — and, critically, a company that measured whether they actually did. Almost every subsequent decision in this story, including the ones that look reckless in hindsight, was the output of a spreadsheet rather than a hunch.
What distinguished DraftKings early was not the product. Rival FanDuel had launched in 2009 and had a head start. What distinguished DraftKings was an almost fanatical willingness to buy customers and a talent for institutional legitimacy. In 2013, Major League Baseball took an equity stake — the first professional league in America to put money into a daily fantasy company, and an enormously useful thing to be able to point at when a state regulator asked whether this was gambling.7 In 2014 DraftKings bought competitor DraftStreet and took its user base up by roughly half in a stroke.7
Then came 2015, and the moment the whole industry nearly ended.
That autumn, DraftKings and FanDuel spent a combined figure widely reported at around $750 million on television advertising in a single season, saturating American sports broadcasts to a degree that became a national irritant. It worked, in the narrow sense that everyone now knew what daily fantasy was. It also worked in a sense nobody at either company wanted: every state attorney general in the country now knew what daily fantasy was too.
In early October 2015, reporting surfaced that a DraftKings employee had released internal data on player-ownership percentages before contests locked, and that the same employee had won a large sum on FanDuel that week.8 Both companies banned employees from playing on rival sites. It did not matter. The story handed regulators a frame — insider trading — that made a skill-game defense sound absurd. On November 10, 2015, New York Attorney General Eric Schneiderman issued cease-and-desist letters to both companies, ordering them to stop accepting wagers in New York State.9 Other states followed.
This is the first and most important pattern in the DraftKings story, and it recurs on almost exactly the same terms in 2026: the company's own growth generated the visibility that invited the regulatory attack. Marketing is not a neutral input in this business. Past a certain volume it is a signal flare aimed at every state house in the country.
The sequel was equally instructive. Having nearly been regulated out of existence separately, DraftKings and FanDuel agreed in late 2016 to merge. On June 19, 2017, the Federal Trade Commission filed an administrative complaint to block it, joined by the attorneys general of California and the District of Columbia, alleging the combined company would control more than 90% of the U.S. market for paid daily fantasy contests.10 The companies abandoned the deal on July 13, 2017, and the FTC dismissed its complaint the next day.10
That episode is worth holding onto. Antitrust authorities have already demonstrated, in this exact industry, with these exact two companies, that they will intervene to preserve competition. Any investor who models the DraftKings–FanDuel duopoly as a stable, permanent, quietly rational two-player equilibrium should remember that the regulatory system has once already refused to let these two combine.
It is easy to skip past what daily fantasy actually left behind, but the asset was specific and it was valuable. Running DFS for six years produced a file of millions of Americans who had voluntarily identified themselves as sports-obsessed, verified their identity and age, linked a payment method, and demonstrated a willingness to risk money on athletic outcomes. In marketing terms, that is not a mailing list; it is a pre-qualified pipeline that had already cleared the two hardest steps in acquiring a betting customer — identity verification and payment friction. When sports betting became legal, DraftKings did not have to find those people. It had to send them a push notification.
Ten months later, on May 14, 2018, the Supreme Court struck down PASPA, and the entire board reset. Every state could now legalize sports betting on its own terms. DraftKings had a national brand, a database of millions of sports-obsessed customers who had already handed over payment credentials, and a marketing organization built for exactly this. It launched in New Jersey within months of the ruling — the first mover in the first meaningful state.
Then came the funding decision that shaped everything after. In April 2020, in the middle of a pandemic that had cancelled live sports, DraftKings combined with the Diamond Eagle Acquisition Corp SPAC and with SBTech, an Israeli sportsbook technology provider, and listed on Nasdaq at a roughly $3.3 billion valuation. The SBTech piece mattered more than the SPAC piece: it gave DraftKings ownership of its own pricing, trading, and risk engine rather than renting one, a point Robins still returns to a decade later as the origin of the company's unit-economics advantage.
But the SPAC piece determined the funding model. DraftKings would not raise a further private round and grind toward profitability in the dark. It would fund a national land grab with public equity — with its own stock as the currency for both acquisitions and employee compensation, in a market that was about to become the most permissive in a generation.
III. The SPAC-Funded Land Grab and Its Bill
Consider what a share of DKNG was worth in March 2021. The stock hit its all-time high that month, closing above $70 a share — roughly three times where it changes hands today.[^11] For a business that would generate $1.3 billion of revenue that year and lose $1.52 billion doing it.11
That is the correct emotional starting point for this section. For roughly eighteen months, DraftKings was not primarily an operating company. It was a call option on the total addressable market of American sports betting, and its stock was the instrument with which it paid for everything.
The mechanics were straightforward. Each time a state legalized mobile wagering, DraftKings arrived at launch with saturation marketing and enormous sign-up promotions, absorbed heavy losses to establish share, and moved to the next state. Selling and marketing expense ran to $981 million in 2021 and $1.19 billion in 2022, against revenue of $1.30 billion and $2.24 billion respectively.11 Free cash flow was negative $518 million in 2021 and negative $729 million in 2022.11 Net losses peaked at $1.52 billion in 2021 and $1.38 billion in 2022 — the two most expensive years in the company's history.11
The unit-level mechanics are worth spelling out, because they explain why the losses were so enormous and why management could argue with a straight face that they were rational. A state launch worked roughly like this: DraftKings bought saturation local advertising in the weeks before go-live, then offered new customers deposit matches and so-called risk-free bets — promotions that hand a customer real betting credit up front. Each of those credits is recognized as a reduction of revenue, so a successful launch mechanically produces a quarter of enormous revenue-adjusted losses in that state. The bet was that the customer stays for years and the promotional cost amortizes across their lifetime. That is a defensible model. It is also completely unfalsifiable in the short run, which is precisely why the era's spending was so hard for outside investors to police.
Some of that was cash. A great deal of it was not. Stock-based compensation was $683 million in 2021 and $579 million in 2022 — figures equal to 53% and 26% of revenue in those years.11 For scale: in 2021, DraftKings paid its employees more in stock than it collected in revenue from its customers. This is the single most important thing to understand about the era. The land grab was substantially financed by diluting shareholders rather than by spending cash, which is why the balance sheet survived it.
The equity market was not the only source of funding. In March 2021, at close to the top of the run, DraftKings issued $1.265 billion of convertible notes due March 2028, struck at a conversion price of roughly $94.85 a share.12 That was, in the moment, close to free money — near-zero coupon debt that management plainly expected would convert into stock rather than ever be repaid in cash. It has not worked out that way. The stock has not been within sight of that conversion price in five years, which turned what was structured as deferred equity into what is now, functionally, a cash maturity. This is the standard afterlife of convertible issuance done at a euphoric multiple, and it is a live item on the balance sheet rather than a historical curiosity.
Nowhere is that clearer than in the compensation event of 2020.
When DraftKings went public, the founders received equity awards tied to the reverse merger with vesting conditions keyed to the company's stock price. The fiscal 2020 summary compensation table records the result: Robins was granted stock awards valued at $231,178,101, for total reported compensation of $236,833,375. Kalish and Liberman each received stock awards valued at $194,210,935, for totals of roughly $197.2 million apiece.13
The fair reading here requires holding two things at once. The hurdles were real, and the stock did clear them during the 2021 mania, so this was performance pay in the technical sense — the awards paid because the metric was hit. But the metric was the share price during the most indiscriminate risk-asset rally in decades, in a year when the underlying business lost $1.2 billion. A grant structure that pays out roughly $625 million across three people for a share-price move driven substantially by a market-wide multiple expansion is not, on any reasonable reading, a tight alignment mechanism. It is a lottery ticket denominated in beta. Investors should weigh it as a data point about how this board has historically calibrated the relationship between founder wealth and shareholder outcomes, because that board composition has not fundamentally changed.
The era's signature acquisition tells a related story. In May 2022, DraftKings closed its all-stock acquisition of Golden Nugget Online Gaming, a deal valued at approximately $1.56 billion when announced.[^15] The strategic logic was reasonable: GNOG brought an established iGaming brand and a customer base skewed toward online casino, the higher-margin and more retention-heavy half of the industry. Management pointed to cross-sell synergies of up to $300 million "at maturity."
Why iGaming, and why pay that much for it? Online casino is a materially better business than sports betting on almost every axis that matters to an investor. There is no meaningful outcome variance — a slot machine's mathematical edge is fixed and realized continuously rather than settled on whether a running back scores. Session frequency is far higher, revenue per customer is higher, and the margin structure is better because there is no trading operation to fund. The strategic logic of buying a casino-first customer base to cross-sell against a sports-first one was sound, and it is the same logic behind everything DraftKings has done since. The question was never whether iGaming was worth owning. It was whether $1.56 billion of stock, issued near a cyclical high, was the right price for this particular version of it.
The deal came attached to a governance problem. GNOG was controlled by Tilman Fertitta. Minority shareholders sued in Nevada and then in the Delaware Court of Chancery, alleging that Fertitta had extracted side consideration for himself at the expense of GNOG's minority holders in steering the company into the DraftKings deal.14 The litigation resolved through a $22 million cash settlement under a stipulation dated March 1, 2024.14
Read that carefully, because it is easy to skim past. The claim was against the seller's controlling stockholder and the seller's former directors. The acquirer wrote the check. Whatever the litigation strategy behind that outcome, an acquirer paying to extinguish claims about how a seller's controller behaved is a governance data point, not a rounding error.
And here is the benchmark test that matters more for forward analysis than either the price or the litigation: GNOG has not been broken out as a reporting segment since integration, and the $300 million synergy figure has never been re-confirmed in subsequent disclosure. There is no line in any filing an outside investor can point to and say: here is what that $1.56 billion purchased.
This is not an accusation that the deal failed. It is a statement that the deal cannot be graded, which is a different and in some ways more useful fact. It means that when DraftKings makes future claims about the economic delivery of an acquisition, the historical record offers no confirmed instance of a large deal whose promised synergies were subsequently demonstrated in public disclosure. That should discipline how much credit management gets in advance for the next one — a point that will matter a great deal when we reach Railbird.
By the end of 2022, the bill for the land grab was fully visible: cumulative losses running into the billions, a share price down roughly 80% from its peak, and an investor base that had stopped asking about total addressable market and started asking a much simpler question. Can this thing ever make money?
IV. The Reckoning: From Cash Burn to Discipline
The answer, it turned out, was a slow and genuinely impressive yes on the operating line — and a much messier story on the question of whether management could be held to its own word.
The 2023–2024 period was the efficiency push. The mechanism was not complicated but it was well executed: stop paying to acquire every customer at any price, start paying to acquire the customers whose modeled lifetime value justifies the cost, and let the analytics organization — the thing these founders actually built their careers on at VistaPrint — grind the numbers. Selling and marketing expense grew only 5% between 2022 and 2024, from $1.19 billion to $1.26 billion, while revenue more than doubled from $2.24 billion to $4.77 billion.112 That is real operating leverage, and it is the single strongest piece of evidence in the entire management-quality case.
The GAAP results, however, stayed ugly. The net loss was $802 million in 2023 and $507 million in 2024.2 Management characterized 2024 as its first year of positive Adjusted EBITDA. Both statements are accurate, and the gap between them is roughly half a billion dollars of stock compensation and depreciation that shareholders were in fact paying for. Adjusted EBITDA is a legitimate operating metric in a business with heavy non-cash comp and amortizing state licenses. It is not a proxy for shareholder value creation, and for these years the distance between the two framings was the whole argument.
Two episodes from this period tell you more about the management team than any margin trend.
Jackpocket, and the rare gift of a falsifiable promise. In February 2024, DraftKings agreed to acquire Jackpocket, a lottery-courier app, for $750 million.15 What made it unusual was not the price or the logic — lottery players are cheap to acquire and cross-sell reasonably well into sportsbook. What made it unusual is that management attached specific numbers to it. DraftKings said the transaction would drive $260–$340 million of incremental revenue and $60–$100 million of incremental Adjusted EBITDA in fiscal 2026, rising to $350–$450 million of revenue and $100–$150 million of EBITDA by fiscal 2028.15
That is an admirable disclosure choice. It is also, in September 2026, a bar the company is on track to miss badly — and the evidence is in its own filings.
Lottery revenue sits inside the "Other" line, alongside daily fantasy and horse racing. In the first quarter of 2026, Other revenue was $89.9 million, down from $103.4 million a year earlier.16 Across the first half of 2026, Other revenue was $179.6 million versus $188.4 million in the first half of 2025 — a decline of about 5%.12 The entire category, of which Jackpocket is only a part, is annualizing at roughly $360 million and shrinking. There is no arithmetic under which Jackpocket alone is delivering $260–340 million of incremental revenue against that backdrop.
The reason is not mysterious, and it is instructive about the fragility of adjacent regulated verticals. Jackpocket suspended operations in Texas — a state where it had operated since 2019 — after the Texas Lottery Commission moved to ban courier services, a decision that followed an $83.5 million winning ticket purchased on the Jackpocket app at a retailer also owned by DraftKings.17 It subsequently exited New Mexico after the state's Department of Justice issued an opinion that its business was unlawful there.18
So the score on Jackpocket is this: management set a public, numeric, two-year target; regulatory action in the largest relevant states removed a material part of the revenue base; and the company has not, on any subsequent call, walked investors back through the original target and explained what happened to it. The acquisition may still prove strategically sound as a customer-acquisition funnel. But the specific promise is not on track, and the silence about it is itself the finding. This is the second consecutive large acquisition — after GNOG — where the stated economic case cannot be verified from disclosure.
The surcharge, and what it revealed about conviction. In August 2024, DraftKings announced it would impose a surcharge on winning bets in states where the tax rate exceeded 20% and multiple operators competed — New York, Illinois, Pennsylvania, and Vermont. The logic was defensible: states were raising taxes, and someone had to absorb it. Roughly two weeks later, after FanDuel declined to follow, DraftKings reversed, saying it had listened to customer feedback.19
Strip away the framing. A company announced a material pricing change, its principal competitor declined to match, and it folded inside a fortnight. Whatever else that was, it was not a decision the company was prepared to defend.
Then, in June 2025, Illinois imposed a new per-wager tax. FanDuel moved first, announcing a $0.50 transaction fee on every Illinois bet.20 DraftKings followed with its own fee.
It would be lazy to treat these as the same event. They are close to opposites. The 2024 episode was a unilateral move made without checking whether the duopoly would hold, abandoned on contact. The 2025 episode was the same economic action taken only once a rival had absorbed the customer-relations damage of going first. The lesson management appears to have drawn was not "don't pass costs to customers." It was "don't go first." That is a more calculated posture, and arguably a more rational one in a two-player market — but investors should be clear-eyed that it also means DraftKings has demonstrated it will not lead on a hard pricing call. In a duopoly, that is a form of dependency on the other player's willingness to act.
By the close of 2024, the shape of the business was settled: sports betting was roughly 61% of revenue, iGaming roughly 32%, and fantasy plus the newly added lottery about 7%.[^23] Sportsbook and iGaming together were, and remain, essentially the entire investment case. Everything else is optionality.
Which sets up the year everything was supposed to come together.
V. The Inflection: 2025 Turns Structurally Profitable — On Paper
Here is the cleanest way to understand fiscal 2025 at DraftKings: it was simultaneously the best year in the company's history and a year in which management's guidance was wrong three separate times, in the same direction.
Both statements are true. Most coverage picked one.
What went right. Fourth-quarter revenue was $1.99 billion, up 43% year over year, with $343 million of Adjusted EBITDA.1 Full-year revenue of $6.05 billion carried $620 million of Adjusted EBITDA and, at last, positive net income.1 Operating cash flow was $663 million and free cash flow $648 million — the first year the business genuinely funded itself.2 Sportsbook handle reached $53.6 billion and the sportsbook net revenue margin — the share of every wagered dollar the house keeps — rose to 7.1% from 6.0%.2 That margin improvement is worth more than the handle growth, because it is the mechanical output of customers shifting toward parlays, which we will unpack in the next section.
The customer file tells you where the growth actually came from, and it is not where most people assume. DraftKings averaged 4.0 million monthly unique payers across 2025, up from 3.7 million, while average revenue per monthly unique payer rose to $125 from $106.2 Put plainly: the paying audience grew by roughly 8% while revenue grew 27%. Fiscal 2025 was overwhelmingly a monetization year, not an audience year — the company got substantially more money out of roughly the same people, which is what a rising hold rate looks like when it reaches the customer file. That is a higher-quality form of growth than buying users, and it is also inherently more finite: there is a ceiling on how much more of each customer's wagered dollar a book can keep before the customer notices the pricing.
A word on the accounting judgment, since so much of this company's narrative runs through a non-GAAP line. DraftKings' Adjusted EBITDA excludes stock-based compensation, depreciation and amortization, and various transaction and restructuring items. In 2025 the stock compensation add-back alone was $339 million against $620 million of Adjusted EBITDA.2 None of that is improper — the reconciliation is disclosed and the treatment is conventional for the sector. But an investor comparing DraftKings' "record profitability" to the GAAP result should understand that more than half the gap between the two is real compensation expense paid to real employees in shares that dilute real owners. The right way to hold both facts is that the cash economics genuinely inflected in 2025, and the accounting profit did not yet meaningfully follow.
The dilution story is real. Stock-based compensation fell to $339 million in 2025, or 5.6% of revenue, from 26% in 2022.211 That is not a promise; it is an audited line item, and it represents a genuine, verifiable change in how much of the enterprise's value is being handed to employees rather than owners. In November 2025 the board doubled the buyback authorization from $1.0 billion to $2.0 billion, and the company repurchased $829 million of stock during 2025.212 After fourteen consecutive years of consuming capital, DraftKings began returning it.
Now the part that gets skipped. On February 13, 2025, DraftKings guided fiscal 2025 to revenue of $6.3–$6.6 billion and Adjusted EBITDA of $900 million to $1.0 billion.22 In May, alongside first-quarter results, it cut both — revenue to $6.2–$6.4 billion and EBITDA to $800–$900 million.22 Robins told investors that "if not for customer-friendly sport outcomes in March, we would be raising our fiscal year 2025 revenue and Adjusted EBITDA guidance."22 In August, the ranges held. Then on November 6, the company cut again, hard: revenue to $5.9–$6.1 billion and Adjusted EBITDA to $450–$550 million, attributing more than $300 million of revenue impact to customer-friendly outcomes in September and October.21
The year finished at $6.05 billion and $620 million. So the celebrated "beat" was a beat against a target that had been reduced by roughly 45% at the EBITDA line over nine months. Measured against what management told investors in February, 2025 Adjusted EBITDA came in about a third below the low end of the original guide.
Both framings are legitimate. The business genuinely improved; the forecast genuinely broke. What an investor needs is a view on which of those tells you more about the next twelve months, and that turns on whether the misses were bad luck or bad forecasting.
On "customer-friendly outcomes." The mechanism is real and worth explaining plainly. A sportsbook does not bet against its customers so much as try to balance the money on both sides of a line and collect a margin on the spread. Over thousands of events that margin is highly predictable. Over a single month it is not — if enough favorites win, or if a heavily backed team runs the table, the book pays out more than its model expected. This is genuine variance, not incompetence, and every sportsbook on earth has it.
But the frequency is the finding. Q1 2024, Q1 2025, Q3 2025, and Q2 2026 all featured bettor-favorable results as a stated driver of a shortfall. In the second quarter of 2026, CFO Alan Ellingson attributed roughly $80 million of revenue headwind to sport outcomes, driven substantially by the Knicks winning a championship in DraftKings' largest state.23 Four instances of the same explanation across roughly ten quarters is not a run of bad luck being disclosed; it is a forecasting process that repeatedly fails to price a known feature of the business into public guidance ranges. Management is describing a real phenomenon. It is also, quarter after quarter, guiding as though the phenomenon will not occur.
The falsifiable version of the bull case here is specific: if parlay mix and in-house risk management are genuinely maturing, the variance around DraftKings' hold should narrow over time, and the frequency of outcome-driven guidance revisions should fall. If instead the explanation keeps recurring at the current cadence through 2027, the honest conclusion is that this management team does not forecast its own revenue line reliably, and guidance ranges should be discounted accordingly regardless of the underlying cause.
The capital structure grew up too. DraftKings built itself on equity and convertible notes — including $1.265 billion of converts issued in March 2021, due March 2028, with a conversion price near $94.85 a share that the stock has not approached in five years.12 In March 2025 the company established its first term loan B, at $600 million.12 Then on August 25, 2026, it closed an upsized $700 million term loan B maturing in August 2033 at SOFR plus 2.00%, alongside a new $750 million revolving facility maturing August 2031, with proceeds earmarked in part for repurchasing the 2028 converts.24
This is prudent housekeeping rather than a dramatic shift. Leverage remains modest against a business generating several hundred million of Adjusted EBITDA. But it is a real structural change: a company that once financed itself entirely from equity markets now has secured lenders with covenants, in a business whose largest input cost is set by fifty state legislatures. That combination deserves monitoring even while the ratios look comfortable.
And it sets up the harder question. All of this — the margin, the discipline, the buyback — rests on a core business whose competitive protection has just been challenged from an unexpected direction.
VI. The Core Business: Industry Structure, Competition, Economics
To understand why DraftKings makes money, you have to understand the parlay. Everything else follows from it.
A straight bet is a coin flip with a small tax. You pick a team, you lay $110 to win $100, and the sportsbook keeps roughly five cents on the dollar over time. It is a commodity product, and in a market with eight apps on every phone, customers will shop it. A parlay is different. You link several outcomes together and every leg must hit. Because each leg carries its own margin and those margins compound multiplicatively, the effective house edge on a four-leg parlay can run several times the edge on a single bet. A same-game parlay — where the legs are correlated outcomes within one contest, like a quarterback's passing yards and his team winning — is harder still to price, which is exactly why it is profitable for whoever prices it best.
Think of it as the difference between selling gasoline and selling a bespoke cocktail. One is a commodity with a posted price; the other is an assembled product where the customer cannot easily compare what they are paying for.
The numbers show the transformation. Parlays have grown from roughly 20% of industry handle four years ago to a record near 39%, and now account for approximately 84% of industry sports betting revenue.6 Industry-wide hold — the percentage of wagered dollars sportsbooks keep — has moved from about 7.2% at its 2020 trough to 10.1% for full-year 2025, the first calendar year above 10%.6 Roughly a third of the industry's revenue growth over that period came from customers changing what they bet, not how much.
The duopoly, honestly cut. As of June 2026, DraftKings led on handle share at 36.7% against FanDuel's 31.8%, having reclaimed the handle crown in May 2025 and widened the gap since. On gross gaming revenue, the order flips: FanDuel led at 36.1% against DraftKings' 33.2%.6
Present both, because they say different things. DraftKings takes in more wagered dollars; FanDuel converts each of them into more revenue. That is a hold-rate gap, and it is the clearest single measure of relative product and pricing quality between the two. DraftKings has been closing it — the GGR gap narrowed from 3.5 points in April to 2.9 points in June 2026 — but as of today the market leader by volume is still the follower by monetization.6
Together the two control 68.5% of regulated wagers, down from peaks near 75%.6 That erosion has gone to a credible middle tier rather than to a single challenger: BetMGM at 9.0% handle, Fanatics at 7.1%, bet365 at 5.4%, Caesars at 4.8%.6 Fanatics is the interesting one — 7.1% of handle but only 3.7% of GGR, a signature of buying volume with aggressive pricing and promotions rather than winning on product.6
The cautionary tale. In 2023, Penn Entertainment paid roughly $2 billion for the right to operate a sportsbook under the ESPN brand, with an out available if share targets were not met.25 ESPN is arguably the most powerful sports media brand in America. It could not move the needle. ESPN Bet stalled in the low single digits of share; Penn exercised its opt-out in November 2025 and relaunched the product as theScore Bet on December 1, 2025, where it now sits near 1.2% share.6 ESPN subsequently partnered with DraftKings for odds integration across its properties.6
This is the most important piece of moat evidence in the entire episode, precisely because it is a negative result. The natural bear argument against DraftKings is that sports betting is an undifferentiated product where brand and marketing dollars determine share. ESPN Bet is the direct test of that hypothesis with the strongest possible brand and two billion dollars behind it, and the hypothesis failed. What ESPN Bet lacked was not awareness — it was a parlay product customers preferred and the liquidity and in-house pricing capability to build one. That is the scale advantage, demonstrated rather than asserted.
But be precise about what it demonstrates. It shows the moat holds against a sub-scale entrant playing by the same rules. It says nothing whatsoever about a competitor playing by different rules — which is exactly the situation now.
Where the moat is thinner than the story. Switching costs in this business are weak and everyone in it knows it. Customers routinely hold four or five apps and shop lines and promotions across them. DraftKings' response was Crown Cash, a unified rewards currency rolled out on August 12, 2026, that works at $1-to-$1 across DraftKings Casino, Sportsbook, daily fantasy, Jackpocket and Golden Nugget Online Gaming, with Predictions to follow, and tiered discounts running from 5% at Bronze to 25% at the top Onyx tier.26
The honest way to characterize Crown Cash is as an admission. A company does not spend engineering and marginal-margin dollars manufacturing a single fungible currency across five products unless the stickiness it wants does not currently exist. This is a bet on building switching costs, not evidence of switching costs already built. The test is straightforward and observable: does retention improve, and does promotional spend per retained customer fall, over the next several quarters. Until then it belongs in the "unproven" column.
Five Forces, applied honestly. Barriers to entry into state-licensed sportsbook are high and always have been — licensing, capital, technology, market access deals. Rivalry between the two leaders is intense but has become more rational; both have shifted from share-at-any-price to modeled-return promotional spending, and Robins told analysts in August 2026 that a competitor's few-hundred-million-dollar promotional increase was "a blip on the radar."23 Supplier power is where states sit, and it is rising: gaming taxes ran $519.6 million in the second quarter of 2026 alone, on $1.44 billion of revenue.12 Read that again — states take a larger cut of DraftKings' revenue than DraftKings spends on sales and marketing. Buyer power is meaningful and rising, because multi-homing is free. Substitutes is the box that used to be empty and no longer is.
In 7 Powers terms, DraftKings holds two defensible positions. Scale economies in marketing are genuine: a national advertising buy amortizes across a customer base no sub-scale operator can match, which is exactly the argument Robins makes for why Predictions costs him little incremental to promote.23 And cornered resource in pricing capability — owning the trading and modeling stack, roughly 95% of sports content priced in-house by management's account — is what produces the parlay depth ESPN Bet could not replicate.23
What DraftKings does not have is counter-positioning against prediction markets. Counter-positioning describes a business model an incumbent cannot copy without damaging itself. That is precisely what a federally regulated exchange with no state gaming tax represents, and DraftKings' answer — operate in that format too — is not counter-positioning. It is matching, which works only if the economics of the new format are as good as the old one.
Which brings us to the fight that is actually setting the stock price.
VII. The Prediction Markets War: The Defining Threat of 2025–2026
In August 2026, the Chairman of the Commodity Futures Trading Commission, Michael Selig, invoked Section 8a(9) of the Commodity Exchange Act — an emergency authority the agency has used roughly seven times in its entire history — to direct Kalshi to keep operating nationwide after the New York Attorney General sued the company seeking damages reported at $36 billion.2728
A federal financial regulator ordered a company to continue doing something a state attorney general had just sued to stop. That is not a normal regulatory disagreement. That is a constitutional turf war being fought in real time over whether sports wagering in America is a state gambling matter or a federal commodities matter — and DraftKings' entire cost structure is the collateral.
The mechanism, in plain terms. A sportsbook takes your bet, holds the risk, and pays a state gaming tax on the revenue. An event-contract exchange does something structurally different: it lists a contract on an outcome, matches a buyer against a seller, and charges a fee for the matching. Because the exchange is not the counterparty, it looks — legally — like a futures market. Kalshi and Polymarket are regulated as such by the CFTC, which means they need no state gaming license and pay no state gaming tax. Same customer, same event, roughly the same experience on a phone, dramatically different cost base.
For DraftKings, whose gaming tax bill runs above a third of revenue, that asymmetry is the whole problem. The moat described in the previous section — state licensing as a barrier to entry — turns out to have a door in it.
The legal fight is genuinely unresolved, and the courts are openly split. In April 2026, the Third Circuit ruled that the Commodity Exchange Act preempts state gambling laws for sports event contracts — a landmark win for the exchanges.27 In July 2026, U.S. District Judge Analisa Torres in the Southern District of New York denied Kalshi's preliminary injunction, holding that New York's gambling laws are not preempted, in direct tension with the Third Circuit.27 Ohio's federal court held that sports contracts do not qualify as swaps; Tennessee's held that they do.27 Minnesota's ban was put on hold; Utah, Michigan, Connecticut and Washington State have all been permitted to press enforcement.27 The CFTC has sued at least nine states — Arizona, Connecticut, Illinois, New York, New Mexico, Minnesota, Rhode Island, Wisconsin and Kentucky — while states have filed criminal counts, cease-and-desist orders and civil actions of their own.27
There is no responsible way to forecast this. A circuit split of this kind typically resolves at the Supreme Court or through federal legislation, and both paths run years. What investors can say is that the range of outcomes is unusually wide and cuts both ways: a clean federal preemption ruling permanently installs a lower-cost competitor beside DraftKings, while a decisive states-win outcome could just as easily sweep up DraftKings' own Predictions product along with everyone else's.
DraftKings' response was to buy its way onto the field. On October 21, 2025, it acquired Railbird Technologies, which had received its CFTC designated contract market license in June 2025 — the federal rails DraftKings needed.29 On December 19, 2025, it launched DraftKings Predictions as a standalone app and web product across 38 states, routing activity initially through CME Group's exchange rather than Railbird's.30 The purchase consideration was modest: $18.3 million cash, $28.7 million in equity, and $37.8 million of contingent consideration, adding $40.2 million of goodwill and a $58.1 million operating-license intangible amortized over four years.1216
The vertical-integration logic Robins laid out on the second-quarter call in August 2026 is coherent and worth taking seriously. There are three layers in this stack: the brokerage that faces the customer, the exchange that matches trades, and the market maker that provides liquidity. DraftKings launched its own exchange, DKeX, in June 2026, obtained approval as a Futures Commission Merchant in July, and runs a market-making operation on three exchanges that Robins says is already profitable — one of the fastest business lines to profitability the company has ever launched.23 By his account, DraftKings is the only operator running all three layers today.23
That is a real, specific, checkable claim, and if it holds it is a genuine unit-economics advantage — the same argument that justified buying SBTech in 2020.
The traction is real; the economics are not yet evidence. From April to July 2026, DraftKings' annualized total volume traded grew from $2.3 billion to $11 billion — roughly fivefold in three months.23 More than 600,000 customers had engaged with Predictions year to date. Combos — the prediction-market analogue of a parlay — reached about 20% of volume within months, a level that took years to achieve in sportsbook.23
There is one number that quantifies the tension better than any narrative. In the second quarter of 2026, monthly unique payers grew 9% year over year — the fastest growth in some time, and largely a Predictions and World Cup story — while average revenue per monthly unique payer fell 13%, to $132.31 More customers, each worth materially less. Some of that is sport outcomes and some is the World Cup cohort, but part of it is structural and management has effectively conceded the point: Robins told analysts that revenue per Predictions customer "will be lower than that of our Sportsbook offering," arguing that a higher-margin profile should deliver comparable gross profit per customer over time.23 That is a coherent thesis and an entirely untested one. Until Predictions margins are disclosed, an investor watching only the headline user count will systematically misread what is happening to the economics underneath it.
Now apply the same skepticism this analysis applied to GNOG and Jackpocket. Volume is not revenue. Revenue is not margin. And the company's own Form 10-Q for the first quarter of 2026 states plainly that prediction markets generated immaterial revenue in the period.16 DraftKings has not disclosed standalone Predictions revenue, contribution margin, or a path to profitability. It is spending $200–$300 million on the vertical in 2026, the vast majority in the back half.3223 Fiscal 2026 Adjusted EBITDA guidance of $700–$900 million reflects that investment against a core business Robins says is tracking to roughly $1 billion of Adjusted EBITDA.23 Read the arithmetic in reverse: the guidance implies Predictions subtracting roughly $100–$300 million from group profit this year.
Note also what the guidance does not include. On the fourth-quarter 2025 call, Robins said flatly of Predictions: "There's nothing in terms of revenue in the guide."33 So the FY2026 revenue range absorbs Predictions' costs but none of its revenue — which makes the top end achievable partly by definition, and makes it impossible for an outsider to score the vertical on the guidance alone.
The bull framing, tested. Cross-selling into an existing base is close to free acquisition compared with Kalshi and Polymarket building users from zero. The evidence partly supports this: Robins says Predictions customer acquisition costs fell more than 80% in April 2026 once the product moved into the flagship app, and that second-quarter Predictions CAC came in about 25% better than planned even while spending 10% more.3223 Those are strong numbers.
The bear framing, tested. If the exchanges are ultimately permitted to operate at scale without state licensing costs, they compete with a structurally cheaper cost base that DraftKings cannot access for its own sportsbook in states where it holds a license. DraftKings would then be running two businesses — a taxed one and an untaxed one — that cannibalize each other at different margins.
Management's rebuttal is that cannibalization is not happening. Robins told analysts there is roughly 1% customer overlap between DraftKings Sportsbook and the largest prediction market operator in sportsbook states, and estimated that 80–90% of prediction-market volume in those states comes from professional betting syndicates and institutional traders — money that "mostly would not have been on Sportsbook to begin with."23 The supporting operating data is not trivial: sportsbook handle grew 11% year over year in the second quarter, and Robins said July handle was up 20% after the World Cup ended.23
Weigh it honestly. The overlap analysis is internal, unaudited, and measured in states where DraftKings already offers a fully featured licensed sportsbook — precisely the states where you would expect the least substitution. It says little about what happens in California, Texas and Florida, where the exchanges are the only game and where the competitive contest is for a customer who has never had a licensed alternative. It also says nothing about the long run, in which a cheaper cost structure eventually shows up in pricing.
The calibrated conclusion: DraftKings' state-licensing moat has been narrowed, not destroyed. It still holds where DraftKings has scale, product depth and an established customer base, and the near-term handle data does not show erosion. But the claim that prediction markets are purely incremental rests on management's internal analysis during the earliest innings of the competition, and the historical record — GNOG's unverifiable synergies, Jackpocket's unmet targets — argues against extending this management team much benefit of the doubt on unverified economic claims.
The KPIs that would settle it are specific: standalone Predictions revenue and contribution margin, disclosed rather than described; and DraftKings' sportsbook handle share in states where prediction markets are most established. Until the first appears in a filing, "annualized volume traded" is a demand signal, not a business.
VIII. Current Management: Incentives, Control, and Capital Allocation Record
Fourteen years after the Watertown spare bedroom, all three founders remain in senior operating roles: Robins as Chairman and CEO, Kalish as President of DraftKings North America, Liberman as President of Operations.34 In a sector that has churned through leadership — Penn, Caesars, and half a dozen smaller operators have all reshuffled — that continuity is genuinely uncommon and deserves credit. The 2026 proxy does note that Kalish agreed to transition out of his executive role by March 31, 2026 while remaining a director, so the founding trio's operating configuration is changing for the first time.34
Robins is worth understanding as an operator, because his temperament is visible in the filings. He is, by background and by disposition, a measurement person — the executive who answers a question about competitive threat by describing a triangulation across internal and third-party datasets rather than by describing a strategy. On the second-quarter 2026 call, pressed on whether prediction markets were cannibalizing his sportsbook, he did not offer reassurance; he offered a customer-overlap statistic and an estimate of what share of rival volume came from professional syndicates.23 That is a genuine strength in a business where the difference between winning and losing is whether your promotional model is better calibrated than the other guy's. It also produces a characteristic failure mode, on display repeatedly through 2025: a management team that trusts its models will keep publishing guidance built on those models even after they have been wrong three times in a row, because each individual miss can be explained by a variable the model treats as random.
Now the governance structure, stated plainly, because there is no soft version of it.
Jason Robins holds 100% of DraftKings' Class B common stock — 393.0 million shares carrying ten votes each — plus approximately 11.5 million Class A shares. Against 495.7 million Class A shares outstanding at the record date, that gives him approximately 88% of total voting power.34 His economic ownership of the Class A float is roughly 2%.35 The proxy states the position without euphemism: the election of the board's nominees "is assured notwithstanding a contrary vote by any or all shareholders other than Mr. Robins."35 DraftKings is a controlled company under Nasdaq rules, though it has voluntarily maintained a majority-independent board and fully independent compensation and nominating committees.34
The 2026 annual meeting on May 12 makes the practical consequence vivid. The non-binding say-on-pay proposal received 4,107,553,941 votes for and 120,320,383 against.36 Robins' Class B alone carries 3.93 billion votes, and he indicated he would vote in favor.36 Strip his block out and the remaining ballots run roughly 178 million for against 120 million opposed — meaning something on the order of 40% of the non-controlling vote was cast against the company's pay practices. A 40% dissent on say-on-pay at a company of this size would, at a normally structured issuer, trigger board engagement, proxy adviser scrutiny, and usually a compensation redesign. Here it triggers nothing, because it cannot.
That is not a scandal. Dual-class structures are common among founder-led technology companies and this one was disclosed at listing. It is simply a fact about the instrument public shareholders own: the only check on capital allocation at DraftKings is financial — do the numbers work — not structural. Shareholders have no mechanism to force a change of course, and a meaningful minority has already registered that it would like to.
Compensation today. All three founders draw $1 base salaries.34 For fiscal 2025, Robins' total reported compensation was $22.6 million, of which $19.2 million was stock awards; Kalish's was $11.8 million and Liberman's $12.0 million.34 Compared with the 2020 outlier this is routine in structure and unremarkable in scale for a company of this size — a real normalization, and one worth acknowledging alongside the criticism of how it started.
The activist stress test. It is worth asking what a skeptical long/short investor would actually attack here, because the list is specific and none of it is hidden. They would start with disclosure: a company with five distinct product lines — sportsbook, iGaming, daily fantasy, lottery courier, and prediction markets — reports revenue in three buckets, one of which is called "Other," and does not break out the vertical absorbing $200–300 million of investment this year.1223 They would move to accountability: an acquisition with published numeric targets that are quietly not being met, and no management commentary reconciling the gap. They would flag the pay-versus-say-on-pay disconnect. They would note that the auditor is BDO USA rather than a Big Four firm — not a red flag in itself for a company this size, but the kind of detail that draws attention when combined with the rest.34 And they would observe that every one of those concerns is unactionable, because the votes are not there. That last point is what makes DraftKings an unusually pure test of whether financial performance alone can substitute for governance accountability.
Grading the capital allocation record. Laid end to end, the arc is: equity-funded expansion at almost any price (2020–2022), a large acquisition with related-party litigation and unverifiable synergies (GNOG, 2022), an acquisition with explicit numeric targets that are currently not on track and have gone unmentioned (Jackpocket, 2024), and finally buybacks and modest secured leverage (2025–2026).
That is genuine evolution. The company is measurably more disciplined than it was — the SBC ratio, the marketing efficiency, and the free cash flow all prove it. But the pattern in the M&A column is consistent and should not be smoothed over: DraftKings has made three significant acquisitions with public strategic rationales, and in none of the three has it subsequently published the disclosure that would let an outsider verify whether the rationale was realized. SBTech's value shows up indirectly in hold rates. GNOG's does not show up at all. Jackpocket's numeric target is quietly slipping away inside a declining revenue line. Railbird is the newest instance of the pattern, and it is being framed with the most ambitious language of any of them.
The forward test is concrete and near. Can management deliver the fiscal 2026 guide without a fourth "customer-friendly outcomes" revision — and will it break out Predictions economics within the next two or three quarters, or continue reporting volume? Those two events, both observable by mid-2027, will tell readers more about whether the discipline story is durable than any amount of strategic narrative.
IX. Bull vs Bear
The bull case.
Start with what is verified. DraftKings leads the largest regulated sports betting market on earth by volume, in an industry structure that has resisted every well-funded challenger for eight years. It has just completed its first self-funding year — $648 million of free cash flow — while growing revenue 27%.2 The dilution that defined the early era has genuinely stopped: stock compensation fell from 26% of revenue to 5.6% in three years, and the company bought back $829 million of stock in 2025 against a $2.0 billion authorization.21121
The moat evidence has a real proof point rather than a slogan. ESPN Bet, backed by the strongest sports media brand in America and roughly $2 billion, could not build parlay share or move past low single digits, and its owner walked away inside three years.625 That is a controlled experiment showing that in this industry, product depth and pricing capability beat brand and marketing money.
Predictions shows genuine demand — a near-fivefold jump in annualized volume traded across three months, 600,000 engaged customers, and combos reaching 20% of volume faster than parlays ever did in sportsbook — acquired into an existing base at costs well below sportsbook CAC.23 If the vertical integration across brokerage, exchange and market maker holds, DraftKings captures a larger share of each customer's economics than Kalshi or Polymarket can.
And there is unusual optionality in the map. Roughly half the U.S. population still lacks legal mobile sports betting, and iGaming — the higher-margin product — is live in only five states plus Ontario, covering about 11% of the population.1 Robins pointed on the first-quarter 2026 call to genuine momentum in Washington D.C., Virginia and Maryland.32 Every new iGaming state is close to pure incremental margin on infrastructure already built.
The bear case.
Now the disconfirming evidence, held against those same claims.
The scale-delivers-profitability thesis depends on margin expansion that state legislatures are actively taxing away. Gaming taxes consumed $519.6 million of $1.44 billion in second-quarter revenue.12 Illinois has already imposed a per-wager tax; other states are following. Every point of tax increase in a major state comes directly out of the margin the bull case is underwriting, and DraftKings has demonstrated it will not lead on passing those costs to customers.
The moat evidence, examined precisely, protects against the wrong threat. ESPN Bet proves DraftKings can beat a sub-scale entrant playing the same game. It proves nothing about an entrant playing a different game with a structurally lower cost base — and that is the entrant that has arrived.
The guidance record is poor, and recently so. Fiscal 2025 Adjusted EBITDA guidance was cut from $900 million–$1.0 billion to $450–$550 million over nine months.2221 Fiscal 2026 revenue came in below Street expectations at the guide. Second-quarter 2026 revenue actually declined 4.6% year over year and Adjusted EBITDA fell 62%, to $115 million from $301 million.1231 First-half Adjusted EBITDA of $283 million against a $700–900 million full-year guide implies an enormous back-half load, and the fourth quarter has to carry most of it.
The capital allocation record cannot be independently verified where it matters most. GNOG's $300 million synergy claim has never been re-confirmed. Jackpocket's $260–$340 million fiscal 2026 revenue target is not tracking, in part because two states shut the product down, and management has not addressed it.1718 These are the two nearest precedents for how to weigh what is being said today about Railbird and Predictions.
Governance offers no remedy. Roughly 40% of the non-controlling vote opposed executive pay in May 2026, and the structure rendered that irrelevant.36
And the regulatory outcome is genuinely binary and outside management's control. The Third Circuit and the Southern District of New York have reached opposite conclusions on the same preemption question within four months of each other.27
Where the evidence lands. The historical record does not reject the core moat claim — the parlay and pricing advantage is real, demonstrated, and has held against a serious challenger. It narrows it. The claim that survives is: DraftKings has a durable product and scale advantage over conventional sportsbooks, of unproven strength against federally regulated exchanges, in a business whose margins are being actively appropriated by its own regulators. That is a meaningfully smaller claim than the one the 2021 valuation was built on, and it is a different claim than the one management makes.
The claim that does not survive intact is the capital-allocation-discipline story as applied to M&A. Operating discipline is proven. Acquisition discipline is asserted and has never once been demonstrated in disclosure.
X. Risk Radar
Regulatory and political risk — the dominant one. The state-versus-CFTC conflict can resolve badly in two opposite directions. Federal preemption permanently installs a competitor that does not pay the tax DraftKings pays. A decisive states-win outcome, or federal legislation drawn broadly, could sweep DraftKings Predictions in alongside Kalshi — leaving the company having spent $200–300 million and an acquisition on a vertical it cannot operate.2723 There is no hedge against this; it is a genuine unquantifiable.
Tax and margin risk. This is the most mechanically certain pressure in the model. State gaming taxes already exceed a third of revenue, and the direction of travel is upward as states face budget gaps and view betting as politically cheap to tax.12 Robins noted on the first-quarter 2026 call that no state raised taxes in the first part of 2026, and credited prediction-market competition for the restraint — an argument that only holds while the competition remains unresolved.32
Execution risk in an unproven vertical. Prediction markets require capabilities sportsbook does not: futures-market compliance, FCM obligations, exchange operations, and market making against professional counterparties rather than recreational bettors. DraftKings launched on CME's exchange rather than its own newly acquired one, and is still migrating volume onto DKeX.23 Robins was candid that the migration will take time and that customer experience takes priority over economics in sequencing it — which is the right call and also means the promised unit-economics benefit arrives later than the narrative implies.23
Financial-strength and refinancing risk. Modest today. Term loan B of $700 million at SOFR plus 200 basis points, a $750 million undrawn revolver, and $1.265 billion of converts due March 2028 whose $94.85 conversion price makes equity settlement improbable at current prices — meaning that maturity is a cash or refinancing event.2412 Against several hundred million of annual free cash flow this is manageable, but it converts what was a wholly equity-financed balance sheet into one with fixed obligations, in a business with genuine quarterly earnings variance.
Demand and discretionary-spend risk. Sports betting is entertainment spending. In a consumer downturn, handle and revenue per customer compress simultaneously — and would do so precisely when state tax pressure is highest, because state budgets deteriorate in the same cycle. The two risks are correlated, not independent.
Cybersecurity and data risk. DraftKings now holds payment credentials and personal data across sportsbook, casino, lottery courier and financial-style event contracts, with more than 5,500 employees across thirteen countries.2 The Predictions business adds obligations of a different regulatory character — an FCM operates under federal financial rules, not gaming rules. The consequence of a breach scales with that surface area.
Concentration risk worth naming. DraftKings is an almost purely U.S.-dollar, U.S.-regulation business. There is no geographic diversification to absorb an adverse domestic regulatory outcome.
XI. Future Vectors & Strategic Options
Predictions is the swing factor, and the disclosure is the tell. For the next twelve to twenty-four months nothing else moves the equity as much. But the thing to watch is not the volume headline. It is whether DraftKings publishes standalone economics. A company that is winning a new vertical discloses its unit economics; a company that is buying volume reports volume. Management has now reported volume for three consecutive quarters.
International is a genuine gap, not a strength. Flutter, FanDuel's parent, diversifies globally through FanDuel, PokerStars, Sisal and others. DraftKings is overwhelmingly domestic, with Ontario as its only meaningful non-U.S. market.1 That concentration amplified the upside during U.S. legalization and amplifies the downside now that U.S. regulation is the primary risk. It should be named as a diversification gap rather than dressed up as focus.
Consolidation optionality exists but should be discounted. Smaller regional operators — Rush Street, Bally's, Boyd's digital arm — remain plausible bolt-ons if DraftKings wants incremental state share. Given the balance sheet and the fragmented tail, this is entirely feasible. Given the GNOG and Jackpocket precedents, any such deal should be assessed on whether management commits in advance to segment-level disclosure that would allow it to be graded. Absent that commitment, the base rate from this company's own history suggests the promised economics will not be verifiable.
AI as an operating lever, not a story. Ellingson said on the first-quarter 2026 call that AI-first execution and streamlined teams had some functions operating at two to three times the prior year's output, and adjusted operating expenses grew only slightly excluding Predictions and the Arkansas launch.32 Applied to promotional optimization and real-time in-play pricing, this is a continuation of the existing analytics playbook rather than a new business. Treat it as a margin input, not a growth vector.
Two things that do not matter. The DraftKings Marketplace NFT platform and the VSiN broadcast network are small and non-core. Robins himself noted the company shut down its Reignmakers NFT product a couple of years ago.32 Neither moves the investment case and neither deserves more than this sentence — though the Reignmakers shutdown is a small point in management's favor: this team has demonstrated it will kill a failed product rather than nurse it.
iGaming is the quiet swing factor nobody discusses. Online casino is live in only a handful of states, and DraftKings has been losing share in it — Robins acknowledged directly on the first-quarter 2026 call that the company "overly focused on the OSB cross-sell and did not focus enough on the iCasino first" player, and that share had been falling for several quarters before stabilizing.32 That is an unusually direct admission of a strategic error, and it cuts both ways: it is a genuine execution failure in the highest-margin product the company sells, and it is also the cheapest available source of upside, because every point of recovered iGaming share arrives on infrastructure already paid for. If the legalization momentum Robins described in Maryland, Virginia and Washington D.C. materializes, iGaming could matter more to 2028 earnings than Predictions does — and it would do so without any of the regulatory ambiguity.
The KPIs that actually matter. Three, and only three. First, sportsbook net revenue margin, or hold — the percentage of every wagered dollar retained, which ran 7.1% for 2025 and reflects the parlay mix that is the core economic engine.2 Second, handle share versus FanDuel in states where prediction markets are most active, which is where substitution would show up first. Third, standalone Predictions revenue and contribution margin, if and when DraftKings discloses it — because until it does, the largest strategic bet in the company's history cannot be evaluated at all.
XII. Playbook: Durable Lessons
Regulatory speed compounds. Being first into New Jersey in 2018 produced share advantages that outlasted the window in which DraftKings was nearly alone there. Customers who deposit first tend to stay first. The company is explicitly trying to run this play again in prediction-market states — Robins drew the New Jersey analogy directly on the second-quarter call, noting that New Jersey ramped far more slowly than later state launches because the playbook and the market awareness did not yet exist.23 It is the right analogy and it is also, quietly, an admission that Predictions adoption has been slower than a mature state launch.
Marketing-led acquisition works, and then it stops working. The 2015 advertising war built the category and nearly destroyed both companies by making them a regulatory target. The 2020–2022 land grab bought share and cost billions. The 2023–2026 period proved the same organization could hold marketing spend roughly flat while more than doubling revenue.2 The lesson is not that marketing does not work — it plainly did — but that its returns are front-loaded and its second-order costs, in regulatory attention and in dilution, arrive later and are rarely modeled.
Product beats brand inside a duopoly. ESPN Bet is the cleanest evidence available anywhere in consumer internet that distribution and brand alone do not win a market where the product has genuine depth. The corollary matters more: DraftKings' advantage is not that people know its name. It is that it prices its own markets and can therefore build parlays competitors cannot match.
Watch what a company does when a rival calls its bluff. The 2024 surcharge reversal and the 2025 Illinois fee are the same economic idea with opposite outcomes, and the variable was who moved first. When a management team announces something bold and unilateral, the useful question is not whether the logic is sound but whether they will still be doing it in three weeks if the other player declines to follow.
A non-GAAP metric becomes the story it was invented to simplify. DraftKings did not do anything unusual in emphasizing Adjusted EBITDA — every operator in the sector does. But the multi-year gap between "first profitable year" as management framed it in 2024 and first profitable year as the income statement recorded it in 2025 is a useful reminder for any investor reading a growth company's shareholder letter. When a company selects the metric on which it declares victory, the useful discipline is not to reject the metric but to ask what it excludes and whether the excluded item is real cash, real dilution, or genuinely non-economic. Here it was real dilution, and it was the largest number in the reconciliation for years.
Founder continuity is an asset; founder control is a separate thing. These are frequently conflated and should not be. Fourteen years of the same operating team in a chaotic industry is a genuine advantage. Eighty-eight percent of the votes on 2% of the economics is a structural fact that removes the market's ability to discipline capital allocation. The first is earned. The second is simply granted, and it means the only accountability mechanism available to a DraftKings shareholder is the income statement.
XIII. Epilogue: Lessons & Reflections
There is a symmetry to this story that is almost too neat.
In 2012, three marketers with no gambling background found a gap in a federal statute written for a different purpose, built a business inside it, and grew fast enough that state regulators eventually came for them. In 2025, a set of exchanges with no gambling background found a gap in a different federal statute written for a different purpose, built a business inside it, and grew fast enough that state regulators came for them too. DraftKings is now on the other side of the argument it once won — and, through Railbird and DKeX, on both sides at once.
There is also a lesson here about what it means for a business to be good at something. DraftKings is genuinely excellent at three things: acquiring customers efficiently, pricing sports markets, and building products people prefer. None of those capabilities were impaired in 2026. All three arguably improved. What changed was the tax and licensing structure of the arena those capabilities compete in, and no amount of operating excellence adjusts for that. Investors who select for quality of execution — a reasonable instinct — should note how completely that variable was overwhelmed here by one they could not observe on any operating dashboard.
What the company's history says about regulated-industry moats is genuinely two-sided, and investors should resist collapsing it to one lesson. These moats can be extraordinarily durable: DraftKings converted a daily fantasy customer base into a sportsbook franchise and then defended it against a two-billion-dollar assault from the ESPN brand without losing meaningful ground. Scale in this business is real, parlay pricing capability is real, and the ESPN Bet failure is the receipt.
And these moats can be routed around, faster than almost anyone modeled, by a competitor that changes the legal category rather than the product. Nothing about DraftKings' operating execution failed in 2026. The stock halved anyway, because the thing that protected the earnings turned out to be contingent on a jurisdictional question that two federal courts have now answered differently.
The through-line from 2015's cease-and-desist letters, to 2017's blocked merger, to the state-versus-CFTC fight now working its way toward a resolution nobody can predict, is that DraftKings has spent its entire public life negotiating the boundary of what regulators will permit a dominant sports-wagering platform to do. It has won more of those negotiations than it lost. It just posted the first profitable year that argument produced.
That negotiation is not over. It may not be close to over. And the company's own record — three large acquisitions whose economics remain unverifiable in disclosure, four guidance revisions attributed to the same cause, and a governance structure that leaves shareholders no lever — suggests that whichever way the legal question resolves, investors will be asked to take a good deal on faith.
XIV. Recent News
Items to track as this story develops through the remainder of 2026 and into 2027:
- Q3 2026 earnings and updated FY2026 guidance, expected in November 2026 — specifically whether the implied back-half Adjusted EBITDA load is met without a fourth outcome-driven revision, and whether the core business holds Robins' stated ~$1 billion trajectory.23
- Resolution or escalation of the prediction-markets turf war — the split between the Third Circuit's preemption ruling and the Southern District of New York's contrary holding, further CFTC emergency actions, and any federal legislative response, each with direct read-through to DraftKings Predictions' own regulatory footing.2728
- Standalone Predictions financial disclosure, if and when the company breaks it out. Volume traded is currently the only metric provided; revenue and contribution margin are the ones that would make the vertical assessable.
- Further state tax legislation in Ohio, Louisiana, North Carolina and others watching the Illinois per-wager model, and whether DraftKings again waits for FanDuel before passing costs through.
- Jackpocket's FY2026 contribution against the original $260–$340 million revenue and $60–$100 million EBITDA targets, and whether management addresses the gap directly on a call.15
- Kalish's transition out of his executive role and the resulting configuration of the founding team.34
XV. Links & Resources
- DraftKings Investor Relations — quarterly results, shareholder letters, earnings presentations and the March 2026 Investor Day materials.3738
- SEC filings — Form 10-K for fiscal 2025, Forms 10-Q for Q1 and Q2 2026, and the 2025 and 2026 DEF 14A proxy statements covering the dual-class structure and executive compensation.216123534
- FTC case file on the blocked 2016–17 DraftKings–FanDuel merger.10
- Golden Nugget Online Gaming shareholder litigation and settlement coverage.14
- State attorney general, federal court and CFTC filings in the prediction-markets dispute; RotoWire maintains a running dated timeline of the litigation.27
- Industry market-share and hold-rate trackers, including the Casino Reports U.S. sports betting statistics database.6
- Earnings call transcripts — Q4 2025, Q1 2026 and Q2 2026 — for management's evolving framing of Predictions, guidance and competition.333223
- Competitor disclosures: Flutter Entertainment/FanDuel, Penn Entertainment/theScore Bet, and public statements from Kalshi and Polymarket.
References
-
DraftKings Reports Fourth Quarter and Full Year 2025 Results — Form 8-K Exhibit 99.1, SEC, 2026-02-13 ↩↩↩↩↩↩
-
DraftKings Inc. — Form 10-K for the fiscal year ended December 31, 2025, SEC, filed 2026-02-13 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
DraftKings (DKNG) Stock Price, Market Capitalization and 52-Week Range — Stock Analysis, retrieved 2026-09-08 ↩
-
MoffettNathanson Downgrades DraftKings: Are Prediction Markets Killing the Sports Betting King? — 24/7 Wall St., 2026-04-24 ↩
-
Trading volume on prediction markets has soared in recent months — Pew Research Center, 2026-05-27 ↩↩
-
U.S. Sports Betting Data: Market Share Stats By Brand, Gross Gaming Revenue, Parlay Handle, Hold — Casino Reports ↩↩↩↩↩↩↩↩↩↩↩↩
-
Insider-trading scandal rocks daily fantasy sports industry — The Washington Post, 2015-10-05 ↩
-
A.G. Schneiderman Issues Cease-And-Desist Letters to FanDuel And DraftKings — New York State Attorney General, 2015-11-10 ↩
-
DraftKings, Inc. / FanDuel Limited, In the Matter of — Federal Trade Commission case file 161-0174 ↩↩↩
-
DraftKings Inc. — Form 10-K for the fiscal year ended December 31, 2022, SEC, filed 2023-02-17 ↩↩↩↩↩↩↩↩
-
DraftKings Inc. — Form 10-Q for the quarter ended June 30, 2026, SEC ↩↩↩↩↩↩↩↩↩↩↩↩
-
DraftKings Inc. 2021 Proxy Statement (DEF 14A) — 2020 Summary Compensation Table, SEC, 2021-03-19 ↩
-
DraftKings Agrees to Pay $22 Million in Golden Nugget Deal Case — Bloomberg Law ↩↩↩
-
DraftKings Reaches Agreement to Acquire Jackpocket for $750 Million — GlobeNewswire, 2024-02-15 ↩↩↩
-
DraftKings Inc. — Form 10-Q for the quarter ended March 31, 2026, SEC ↩↩↩↩
-
Texas Lottery fallout: Jackpocket suspends operations in Texas — FOX 7 Austin ↩↩
-
Jackpocket exits New Mexico as lottery courier scrutiny increases — NEXT.io ↩↩
-
DraftKings Drops Plans to Add Surcharge in High-Tax States — Bloomberg, 2024-08-13 ↩
-
FanDuel adds 50-cent surcharge on Illinois bets to offset state taxes, DraftKings may follow — CNBC, 2025-06-10 ↩
-
DraftKings Reports Third Quarter 2025 Results — GlobeNewswire, 2025-11-06 ↩↩↩↩
-
DraftKings Reports First Quarter Revenue of $1,409 Million — GlobeNewswire, 2025-05-08 ↩↩↩↩
-
DraftKings Inc. (DKNG) Q2 2026 Earnings Call Transcript — Seeking Alpha, 2026-08-07 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
DraftKings Announces Closing of $700 Million Upsized Term Loan B Facility and $750 Million Revolving Credit Facility — Business Wire, 2026-08-25 ↩↩
-
Underperforming ESPN Bet Faces Uncertain Future Following $2B Deal — RG.org ↩↩
-
DraftKings Introduces Crown Cash and Enhanced DraftKings Rewards — DraftKings, 2026-08-12 ↩
-
Prediction Markets Legal Timeline 2026: States, Courts & Federal Regulation — RotoWire ↩↩↩↩↩↩↩↩↩↩
-
CFTC orders Kalshi to continue offering prediction markets in New York after state lawsuit — CoinDesk, 2026-08-11 ↩↩
-
DraftKings acquires predictions platform Railbird — CNBC, 2025-10-21 ↩
-
DraftKings Debuts Predictions App, Entering Prediction Markets — GlobeNewswire, 2025-12-19 ↩
-
DraftKings Reports Second Quarter 2026 Results — Form 8-K Exhibit 99.1, SEC, 2026-08-07 ↩↩
-
DraftKings (DKNG) Q1 2026 Earnings Call Transcript — The Globe and Mail, 2026-05-08 ↩↩↩↩↩↩↩↩
-
DraftKings (DKNG) Q4 2025 Earnings Call Transcript — The Motley Fool, 2026-02-13 ↩↩
-
DraftKings Inc. 2026 Proxy Statement (DEF 14A) — SEC, 2026-03-26 ↩↩↩↩↩↩↩↩↩
-
DraftKings Inc. — Form 8-K reporting 2026 Annual Meeting voting results, 2026-05-12 ↩↩↩
-
DraftKings Investor Day 2026 presentation — DraftKings Investor Relations, 2026-03-02 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube