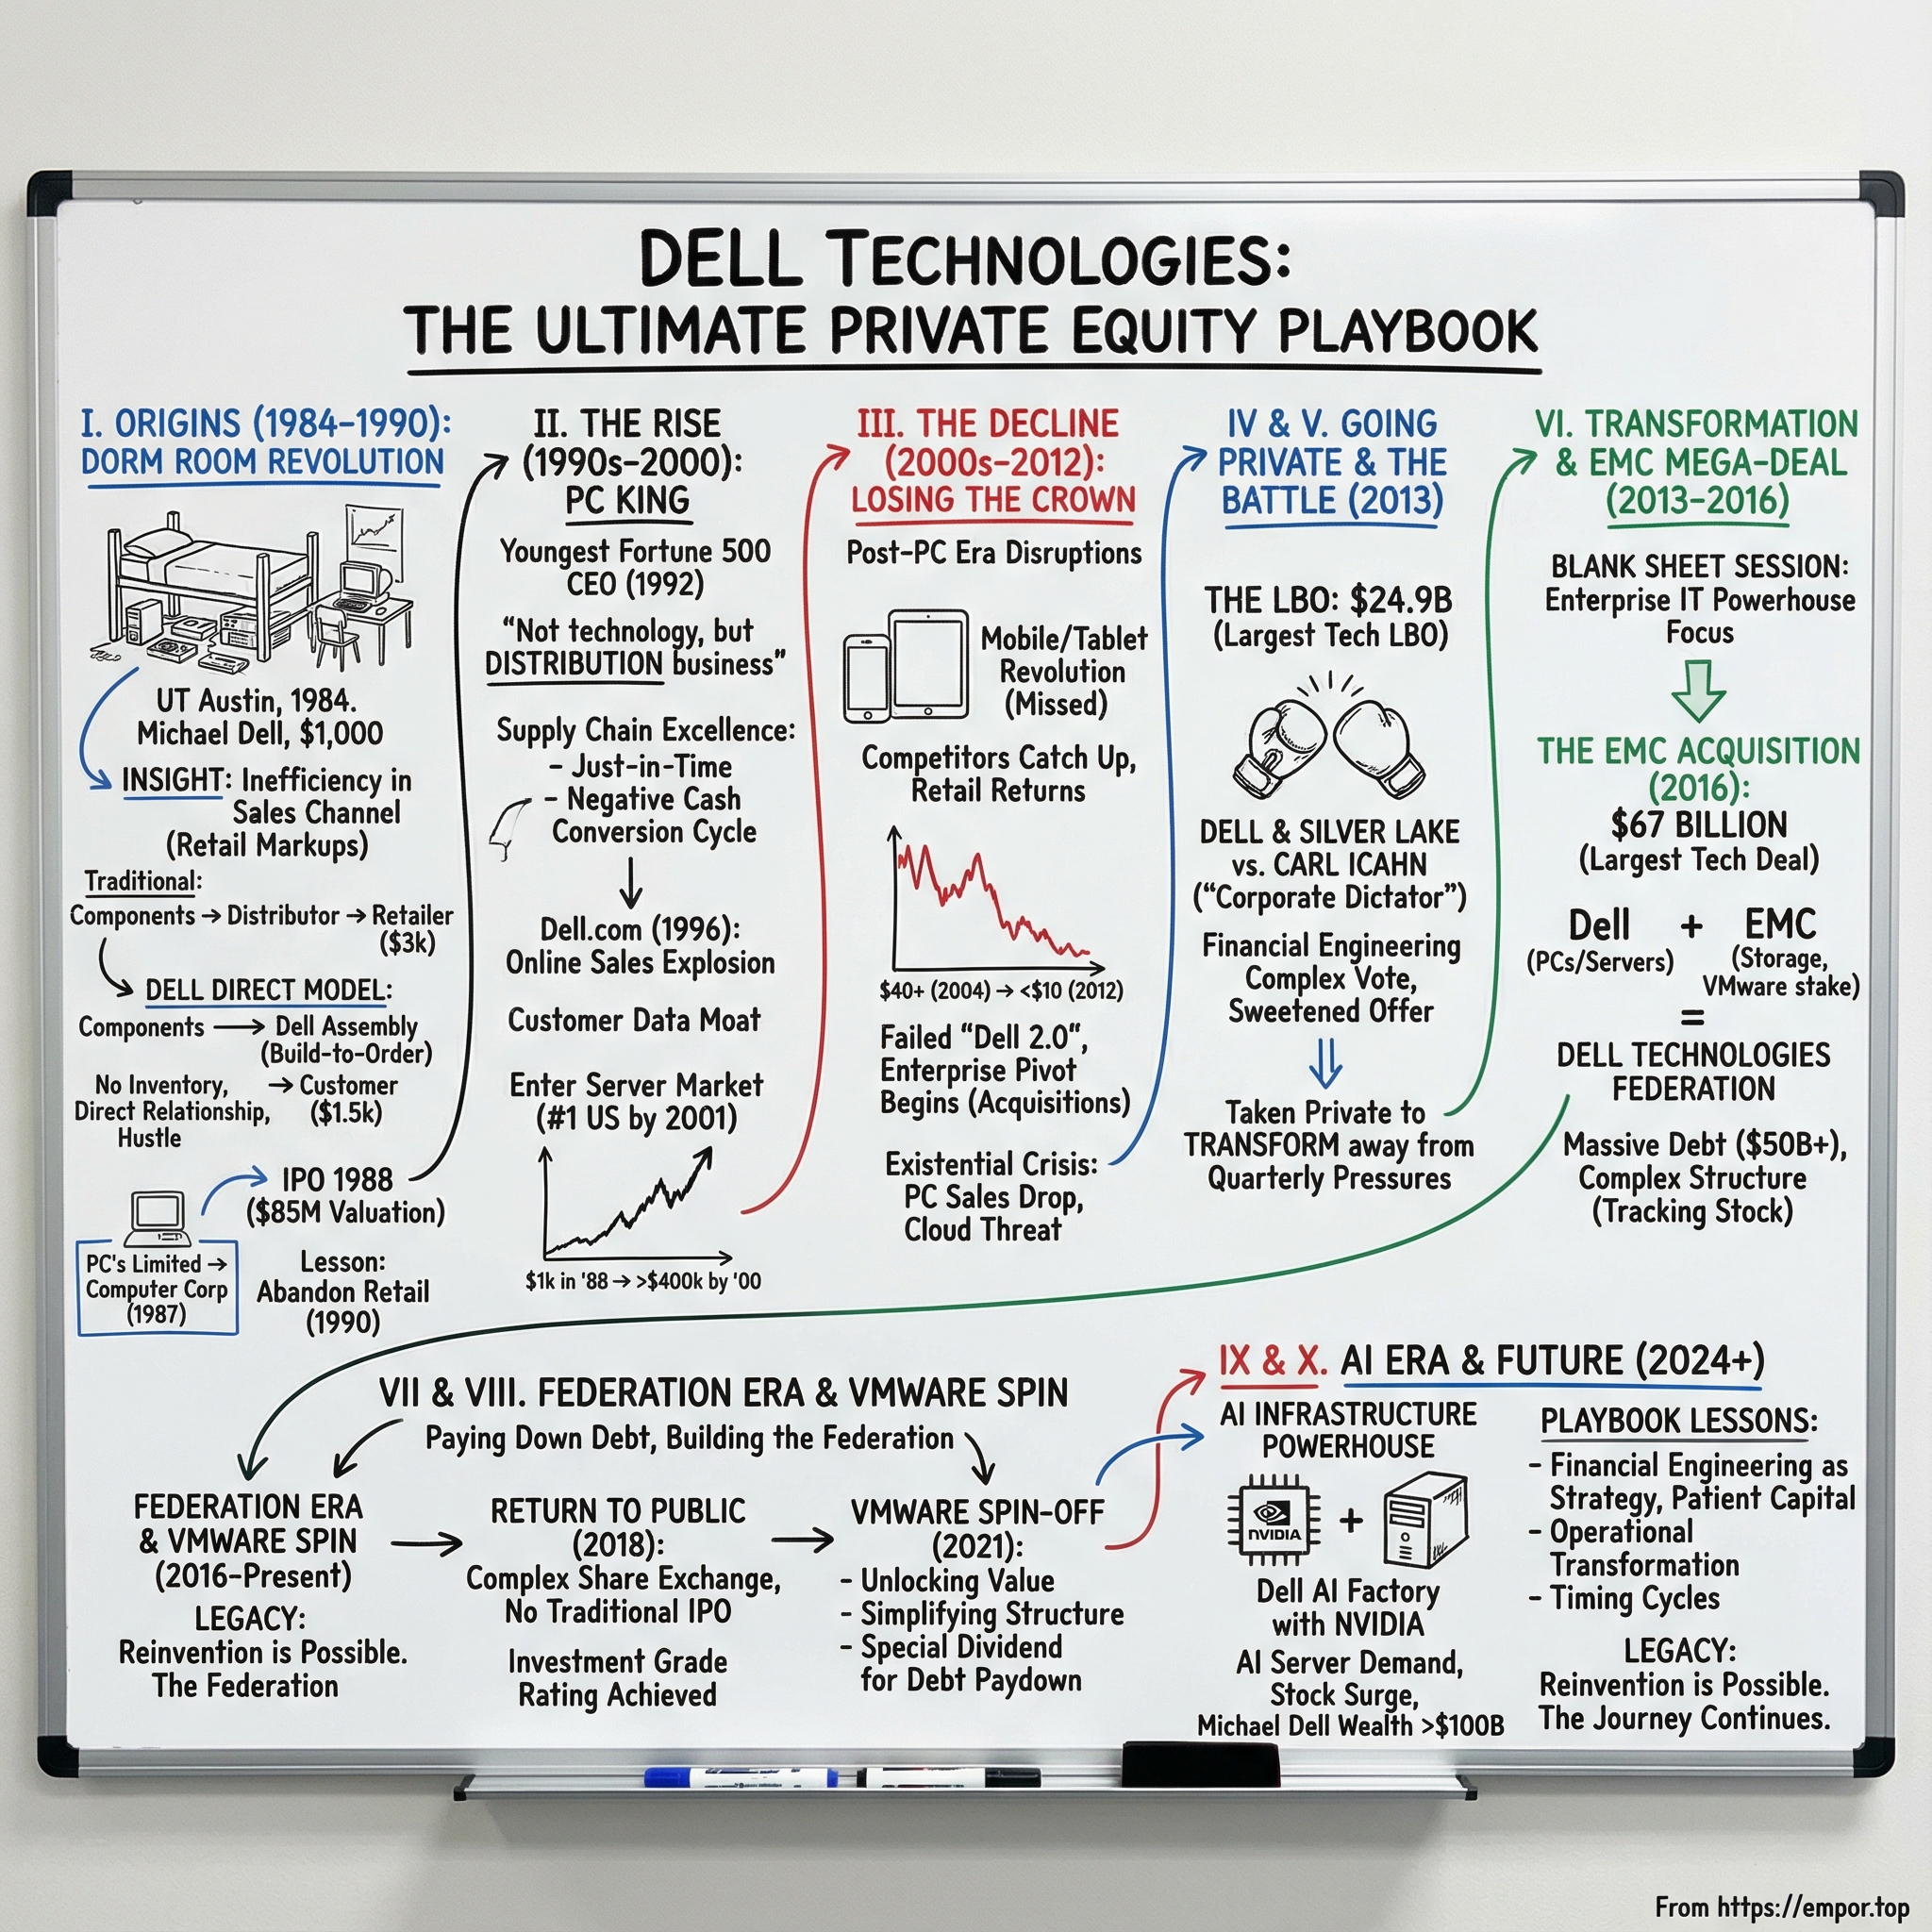
Dell Technologies: From Dorm-Room Direct Model to the AI Factory
I. Introduction & Episode Roadmap
On the evening of September 1, 2026, a small group of executives sat down in Round Rock, Texas, to read out a quarter that would have been literally unimaginable to the same company three years earlier. Revenue of $47.0 billion, up 58% year over year. Diluted GAAP earnings per share of $6.34, up 273%.1 And then the number that stopped the room: $60.9 billion of AI server orders booked in a single ninety-day period, leaving an ending backlog of $95 billion.1
To put that in perspective: Dell's entire consolidated revenue for fiscal 2026 — the year that ended in January 2026 — was $113.5 billion.2 The company had just booked more than half a year's worth of revenue in orders for one product line in one quarter. Shares, which had been trading around $110 a year earlier, closed near record highs, and Michael Dell's personal net worth crossed $100 billion.3
It is a spectacular number. It is also, for a certain kind of investor, an uncomfortable one — because Dell has been here before. This is a company that has ridden a hardware supercycle to euphoric heights, watched the cycle end, and spent a decade digging out. The question this story is really about is not whether the AI backlog is real. It plainly is; the orders are contracted, the customers are named, the racks are shipping. The question is whether Dell has built something durable underneath it, or whether it is executing beautifully as a highly capable pass-through for someone else's silicon.
That question has a long history, and Dell's own record contains most of the evidence you would need to answer it. This company has reinvented its business model three times in forty-two years. It invented direct-to-customer PC manufacturing in 1984 and turned working capital into a weapon. It took itself private in 2013 in what was then the largest technology leveraged buyout ever attempted, then bought EMC for $67 billion in the largest technology acquisition ever attempted, financed with roughly $50 billion of new debt. And now it sits at the center of the largest infrastructure buildout in the history of computing.
The connective tissue across all three acts is not a product. It is control. Michael Dell has never surrendered it — not to the public markets in the 1990s, not to Carl Icahn in 2013, not to Icahn again in 2018, and not today, where a dual-class structure gives him and Silver Lake supervoting shares that make Dell Technologies a "controlled company" under NYSE rules.4 That control is what let Dell make bets the public market would have vetoed. It is also, structurally, what leaves public shareholders holding a minority of the votes on a company where they hold most of the economics.
So this is a governance and capital-allocation story wearing a product story's clothes. Over the next several sections we will work through four questions with real evidence attached. Does Dell have a moat in AI infrastructure, or does it have process power — real, valuable, and perishable? Did the great 2015 diversification thesis work, and what does Dell's own five-year record of unwinding it tell us about how to read the next big acquisition? Is management credible, judged by promises kept rather than promises made? And what actually breaks the case from here?
We start where the DNA was written: a nineteen-year-old in a University of Texas dorm room, discovering that the most interesting thing about selling computers had nothing to do with computers.
 Subscribe on LinkedIn
II. Origins: The Direct Model (1984-2001)
Michael Saul Dell was born in Houston in February 1965, the son of an orthodontist and a stockbroker. The entrepreneurial instinct showed early and commercially: he was buying stocks at thirteen and, as a teenager, made $18,000 selling newspaper subscriptions by working out which households were statistically most likely to want one — newlyweds and people who had just moved.5 That is a small anecdote, but it is the whole company in miniature. The insight was never the product. The insight was the distribution.
He arrived at the University of Texas at Austin as a pre-med freshman and, in May 1984, incorporated a business called PC's Limited with $1,000 in capital.56 The initial trade was almost embarrassingly simple: buy unsold IBM PCs from dealers sitting on excess inventory, upgrade them with memory and disk drives, and resell them ten to fifteen percent below retail.5 He ran it out of a dorm room, then a condominium, while hiding it from his parents.
The reason this became a Fortune 500 company rather than a good local business is what happened when Dell inverted the model. Instead of building machines and pushing them into a retail channel, he took the order first, then built the machine. That single reversal did three things at once. It eliminated the retailer's margin, so Dell could undercut IBM and Compaq on identical hardware. It eliminated finished-goods inventory sitting in warehouses depreciating at the ferocious rate at which PC components lose value. And — the piece that mattered most and that almost nobody outside the company understood at the time — it flipped the direction of cash flow.
Here is the mechanic in plain language. A normal manufacturer buys parts, pays suppliers in thirty days, builds product, ships it to a retailer, and waits sixty or ninety days to get paid. That gap has to be funded with capital. Dell got the customer's credit card number before it bought the components, and then paid its suppliers on ordinary terms afterward. The result was a negative cash conversion cycle: growth generated cash instead of consuming it. Dell could double in size without raising a dollar of outside capital, and every incremental customer was, in effect, an interest-free lender to the business.
That is the reason Dell won the 1990s, and it is worth being precise about the nature of the advantage. It was not a technology moat. Dell's engineers were not building anything IBM's could not build. It was an operating-model moat — a cost position and a capital structure that competitors could only match by dismantling the retail relationships that were their existing distribution. Clayton Christensen would later use Dell as a canonical case. The competitors saw the threat clearly. They could not respond to it cheaply.
The scoreboard followed. Dell Computer went public on NASDAQ in 1988, when its founder was twenty-three, raising roughly $30 million.5 By 1992, Fortune added the company to the Fortune 500 and Michael Dell became the youngest CEO ever to lead one.5 By 2001, Dell was the largest PC vendor in the world, having ground down every incumbent that had once looked unassailable.
Keep two things from this era, because both are load-bearing for what follows. The first is the working-capital discipline, which is not a historical curiosity — it is still the machine that funds Dell today, and in the AI ramp it is under real strain in ways we will get to. The second is a piece of self-knowledge that Dell's own management has never particularly hidden: this was never a technology business in the sense that Intel or Microsoft were technology businesses. It was a logistics and procurement business that happened to ship computers. That framing is generous to Dell in good times and brutally clarifying in bad ones.
The bad ones were coming.
III. The Lost Decade and the Go-Private Playbook (2001-2013)
The trouble with an operating-model moat is that it protects you inside a market. It does nothing for you when the market itself moves.
Through the 2000s, the personal computer stopped being the center of computing. Smartphones and tablets took the consumer, and then the low end of the commercial market. Asian manufacturers — Lenovo above all — matched Dell's cost position without needing Dell's cleverness, because they had structurally lower cost bases. And the direct model's great weapon, cutting out the retailer, mattered less every year as the whole industry moved to build-to-order and online sales became table stakes rather than a differentiator.
Michael Dell had stepped back from the CEO role in 2004, handing it to Kevin Rollins.5 It went badly. Market share bled to Hewlett-Packard, there was a recall of more than four million potentially flammable notebook batteries, and earnings disappointed repeatedly. On January 31, 2007, Rollins resigned as CEO and from the board, effective immediately, and Michael Dell resumed the chief executive role he had left three years earlier while retaining the chairmanship.7
What followed was a strategy that was probably correct and definitely unpopular. Dell began buying its way into enterprise infrastructure — storage, networking, services, software — trying to convert a PC company into a data center company. The logic was sound: enterprise gear carries higher margins, longer replacement cycles, and stickier customer relationships than laptops. The problem was arithmetic. Every quarter, the shrinking PC business was large enough to swamp the growing enterprise business in the reported numbers, and public investors were pricing Dell as a melting ice cube regardless of what was happening underneath.
This is the specific tension that produced the most consequential decision in the company's history. If the market will not pay for a transformation, and the transformation takes five to ten years, and every quarter of the transformation looks worse than the last — you either abandon the strategy or you leave the market.
In February 2013, Michael Dell and Silver Lake Partners offered to take Dell Inc. private at $13.65 per share in cash, valuing the company at approximately $24.4 billion.8 It was the largest technology leveraged buyout since the financial crisis, and it detonated one of the most bitter shareholder fights of the decade.
Carl Icahn, together with Southeastern Asset Management, accumulated roughly 12.8% of the stock and campaigned relentlessly against the deal.9 Their argument was straightforward and, at the level of incentives, hard to dismiss: the person with the most information about Dell's future was buying the company from people with less information, at a price he was setting. Icahn and Southeastern pointed to analysis suggesting Silver Lake could earn an average annualized return of up to 44.7% and Michael Dell up to 50.1% over the following four to five years.9 Icahn's public rhetoric was vintage Icahn — he characterized Michael Dell as running the company like a personal fiefdom and framed the buyout as the ultimate insider transaction.
The deal closed anyway, after a bruising process, a price bump, and a change to the vote-counting rules that treated non-voting shares as abstentions rather than opposition. It is worth being honest about how that looked and about how it turned out, because both are true. The process was structurally conflicted, and the price — with the benefit of thirteen years of hindsight — was very good for the buyers.
What matters for a 2026 investor is that this was not a closed chapter. It was the moment Dell designed the governance architecture it still operates under. When the company returned to public markets in 2018, it did so with a multi-class share structure: Class A and Class B common stock carrying ten votes per share, held by the Michael Dell entities and the Silver Lake entities respectively, alongside a Class C stock carrying one vote that trades on the NYSE.10 Sponsor stockholders agreements govern board nomination rights between the two blocks.4
The practical result, as Dell's own proxy states, is that the company is a "controlled company" under NYSE rules on the basis of Michael Dell's beneficial ownership of shares representing more than 50% of total voting power in director elections, with the Dell and Silver Lake stockholders together holding more than 70%.4 Read that alongside the share counts and the asymmetry becomes stark: as of March 9, 2026, there were 276.7 million Class A shares, 50.6 million Class B shares and 318.4 million Class C shares outstanding.10 The supervoting blocks are under half the shares and the overwhelming majority of the votes.
Every strategic decision from here — EMC, the VMware spinoff, the AI capital allocation — was made possible by that structure. We will come back to what it costs.
IV. The EMC Megadeal and the Federation That Didn't Last (2015-2020)
Free of quarterly earnings and armed with a balance sheet only a private company could contemplate, Michael Dell went shopping. On October 12, 2015, Dell announced it would acquire EMC Corporation for approximately $67 billion — the largest technology acquisition ever announced, nearly twice the size of the next-biggest deal on the board at the time.11[^12] EMC shareholders received $24.05 per share in cash plus a tracking stock linked to EMC's economic interest in VMware.11 The transaction closed on September 7, 2016.12
The financing was audacious. Roughly $50 billion of new debt went onto a company that had been public and conservatively levered three years earlier. The tracking-stock structure — the Class V, or DVMT — was itself a piece of financial engineering designed to avoid raising equity: rather than pay EMC holders in Dell stock or cash Dell did not have, Dell handed them a security whose value tracked VMware, in which EMC held an 81% stake.
The strategic thesis was called the Federation, and it was genuinely ambitious. Dell would own storage leadership through EMC, virtualization through VMware, cloud-native application development through Pivotal, security through RSA and SecureWorks, enterprise cloud managed services through Virtustream, and integration software through Boomi. Seven or eight businesses, sold together, would supposedly form an integrated hybrid-cloud stack that no single-product competitor could match. Dell would become the IBM of the private cloud era: one throat to choke for the entire enterprise IT estate.
Did diversification work? Let the record answer
Here is the test that matters, and it is not a matter of opinion. Ask what Dell subsequently did with the pieces.
RSA Security was sold to a consortium led by Symphony Technology Group for approximately $2.1 billion, announced in February 2020.13 Boomi was sold to Francisco Partners and TPG for approximately $4 billion in 2021.14 Pivotal was folded back into VMware and then left the perimeter entirely when VMware was spun off. SecureWorks — which Dell had partially floated in 2016 and continued to control — was sold to Sophos, backed by Thoma Bravo, for $859 million; the deal was announced in October 2024 and completed on February 3, 2025.1510 Virtustream, which EMC had acquired for $1.2 billion in 2015, no longer appears among Dell's actively sold offerings.16
That is not one venture that did not work out. That is substantially the entire diversification thesis being unwound over five years, at prices that in aggregate recovered a fraction of the enterprise value the Federation narrative implied. RSA and SecureWorks both left for less than what a "security arm of the world's largest infrastructure company" was supposed to be worth. Boomi, arguably the best asset of the group, was sold at $4 billion in 2021 — and integration-platform businesses of that vintage went on to be valued far more richly by private markets in the years after.
So: does the record reject the claim? Not entirely, and the honest version matters. The EMC transaction itself was a good deal — but for two reasons, not seven. First, EMC's storage business plus Dell's server business created a genuine scale position in enterprise infrastructure that is the direct ancestor of the ISG segment now compounding at triple digits. Second, VMware generated enormous cash flow during the deleveraging years and then, when spun off, delivered the cash that repaired the balance sheet. Everything else was decoration.
The right conclusion is a narrower one than either the 2015 pitch or the cynical dismissal. The EMC acquisition worked as a concentration bet on storage and virtualization that was marketed as a diversification bet on a federation. Dell's own capital allocation, over the following half-decade, corrected the marketing to match the reality.
That conclusion has a forward test attached, and investors should hold management to it. If Dell announces a significant acquisition into an adjacent software, security, or services category from here, the appropriate base rate is not the 2015 pitch deck. It is the Federation divestiture record: roughly five of seven acquired or incubated adjacent businesses sold, folded, or discontinued within a decade. The burden of proof sits with management, and the specific evidence that would shift it is retention of the asset through a full cycle with disclosed standalone economics — not a strategic-fit narrative.
There is a second, quieter lesson buried in the Federation era, and it is about what the debt did. Carrying roughly $50 billion of acquisition leverage forced Dell to run the business for cash generation above all else. That discipline is visible in the operating model to this day. It was also, for four years, a genuine constraint on strategic freedom — which is precisely why the next chapter was about getting out from under it.
V. Financial Engineering II: Return to Public Markets, VMware Spinoff, Deleveraging (2018-2021)
By 2018, Dell had a problem of its own creation. The DVMT tracking stock traded at a persistent, embarrassing discount to the VMware shares it was supposed to track — the market's verdict on a security that conveyed economic exposure without control. Dell wanted a real currency, a public listing, and a simpler structure. It did not want an IPO, which would have meant selling equity into a market that had spent five years being skeptical of the strategy.
So Dell bought the tracking stock instead. Announced on July 2, 2018, the transaction offered Class V holders either 1.3665 shares of newly listed Class C common stock or $109 per share in cash, capped at $9 billion in aggregate — a 29% premium to the pre-announcement price, implying a $21.7 billion market capitalization for the Class V holders against a $48.4 billion pre-transaction equity value for the rest of Dell.17 The cash was funded by an $11 billion special dividend from VMware, of which roughly $9 billion flowed to Dell.17
Carl Icahn showed up again, arguing the exchange ratio undervalued DVMT. He lost again, though the terms were sweetened before the vote. On December 28, 2018, Dell Technologies Class C common stock began trading on the NYSE. Dell had returned to public markets without ever holding an IPO — a structure that let Michael Dell and Silver Lake retain the supervoting shares they had held as private owners.
The deleveraging endgame came three years later. On November 1, 2021, Dell completed the spin-off of its 81% equity stake in VMware, distributing the shares to Dell stockholders.18 Alongside it, VMware paid an $11.5 billion special dividend, of which approximately $9.3 billion went to Dell — and Dell used the proceeds plus cash on hand to repay roughly $9.4 billion of principal.18
The result is the single most underappreciated fact about Dell's current position: the EMC leverage is gone. Not managed. Gone. Investment-grade ratings were restored from all three major agencies, and by the second quarter of fiscal 2027 management reported a core leverage ratio of 0.8x and $14.2 billion in cash and investments, alongside what CFO David Kennedy described as positive credit rating actions during the quarter.19
That trajectory is worth tracing because it is a clean promise-versus-outcome test. In August 2025, then-CFO Yvonne McGill described core leverage as sitting "at our target of 1.5x."20 Six months later it was 1.4x.21 Three months after that, 1.2x.22 Three months after that, 0.8x.19 Dell said it would deleverage and then deleveraged past its own stated target — a modest but real data point in a sector where balance-sheet promises are frequently aspirational.
One caveat prevents this from being an unalloyed positive. Deleveraging that fast is partly a function of an earnings explosion that nobody, including Dell, forecast. Net debt has not collapsed in dollar terms so much as EBITDA has quadrupled underneath it. If AI revenue normalizes, the ratio moves back up mechanically without anyone doing anything wrong. The right way to hold this is: the balance sheet is genuinely repaired relative to 2016-2019, and the current ratio flatters that repair.
Which brings us to the business that produced the earnings explosion.
VI. Core Business Today I: Infrastructure Solutions Group (ISG)
There is a moment on the September 2026 earnings call where Jeff Clarke, asked about supply, drops the corporate register entirely: "How I think about supply, as I'm often reminded by our sales force, it's not enough." He then lists the constraints like a man reciting a grudge — "DRAM, DRAM, DRAM, followed by NAND, NAND, NAND" — before adding spotty CPU shortages, disk drives, ABF substrate, T-Glass, optical components, and MOSFETs. "Welcome to the life of a supply chain person at Dell. This is what we do, chasing parts. We love it."19
That is the actual texture of the Infrastructure Solutions Group in 2026: a business where demand is not the problem and has not been the problem for two years.
ISG delivered record revenue of $31.8 billion in the second quarter of fiscal 2027, up 89% year over year, with operating income of $4.8 billion and an operating margin of 15.0%.1 To calibrate how fast the company's center of gravity has moved: as recently as fiscal 2024, the Client Solutions Group was the larger segment at $48.9 billion against ISG's $33.9 billion.23 ISG is now more than double CSG in a single quarter. Dell is no longer a PC company with a data center business attached. That inversion happened in about eight quarters.
Servers: the boring half is not boring
Strip out the AI-optimized servers for a moment and look at what Dell calls traditional servers and networking. That line delivered $10.5 billion of revenue in the quarter, up 122%.1 Over two quarters, Clarke noted, Dell generated almost as much traditional server and networking revenue as in any prior full year in company history.19
This is the part of the story that gets least attention and deserves more, because it is the part where Dell's advantage is most legible. The driver is a data center refresh cycle of unusual size. Clarke put a hard number on the installed base: 1.2 million assets still running Dell's 14th-generation platform or older.19 Those machines have to be replaced — not because Dell wants to sell them, but because consolidation ratios have become extreme. A current-generation 17G server replaces six to eight older servers; the 18G platform, which began shipping in October 2026, replaces twelve to fourteen.19 When you can retire a dozen machines by buying one, the return on refresh stops being an IT preference and becomes a facilities and power-budget necessity.
Layer on a second forcing function: security. Clarke has been explicit that resiliency requirements and coming post-quantum cryptography standards make aged infrastructure untenable for regulated customers.19 And a third: agentic AI workloads, which run on ordinary CPUs and are generating incremental demand for conventional compute rather than cannibalizing it.
Dell says it gained more than ten points of traditional server share over two quarters.19 External data broadly supports the direction. Per IDC's Worldwide Quarterly Server Tracker, Dell led the OEM market in the fourth quarter of 2025 with $12.5 billion of revenue and 10.0% share, with Supermicro second at $11.7 billion and 9.5%, and Hewlett Packard Enterprise fifth at $3.8 billion and 3.1%.24 By the first quarter of calendar 2026, Dell's share had jumped to 16.5% on $20.3 billion of revenue against Supermicro's 7.6%.25
Note what that comparison also reveals. HPE — the company the outline of any Dell episode reflexively names as the primary competitor — is now roughly a fifth of Dell's server revenue, not a third, and IDC attributes its decline to a deliberate repositioning toward edge, hybrid IT, and mission-critical systems rather than head-to-head competition in high-volume x86.24 The competitive frame has changed. Dell's real rivals in volume server revenue are Supermicro and the ODM-direct channel, not the legacy enterprise names.
Storage: the margin engine, finally working
Storage is the least glamorous line in the segment and the most important one for margins. Revenue was $4.9 billion in the quarter, up 26% and up 12% sequentially.1 Dell holds the number one position across external RAID storage, unstructured and scale-out storage, and purpose-built backup appliances, and gained roughly four points of external RAID share in calendar Q1 2026 per IDC.1
The mechanism that matters is the mix shift from what Dell calls partner IP — resold third-party technology — to Dell IP: PowerStore, PowerMax, PowerScale, ObjectScale, PowerFlex, PowerProtect. Dell-designed products carry structurally higher margins. Clarke identified this as the single largest contributor to ISG margin expansion outside of operating leverage.19 PowerStore posted double-digit demand growth for a ninth consecutive quarter; Dell IP storage demand has run above market for six.119
Now the falsification. Exactly one year earlier, this same business was a problem. In the second quarter of fiscal 2026, storage revenue fell 3% and Clarke described the aggregate result in unusually blunt terms: "The challenge we have is we didn't grow. It was unacceptable."20 The cause was specific and named — hyperconverged infrastructure customers rethinking their private-cloud architecture in the wake of industry disruption, pausing purchases while they decided what to buy next.20 Management's stated remedy was equally specific: push the Dell IP portfolio, offer HCI customers an open disaggregated alternative via the Dell Automation Platform, and expand margin within each product line.
Twelve months later, storage is growing 26% with improved profitability.1 The remedy worked, at least so far. That is a genuine promise-versus-outcome win, and it deserves to be recorded as one.
It also comes with a large asterisk that management supplied itself. Asked directly whether storage strength was volume or price, Clarke conceded "there's a notion of inflation inside our growth" and that Dell IP products "cost more because of the cost basis of NAND, in particular."19 Some meaningful portion of a 26% growth rate is component cost inflation passed through to customers, not units. Rising memory and NAND prices are inflating revenue and, for now, margins — and they will not inflate forever. The KPI that separates the two is Dell IP unit demand growth relative to market, which management discloses qualitatively but not in units. Investors should want that disclosure.
Networking, and what the segment economics say
Networking remains the smallest piece of ISG and is best understood as an attach product — sold alongside server and storage deals against Cisco and Arista rather than won on its own merits. Dell does not break it out separately, and nothing in the current disclosure suggests it is a franchise.
Step back and the segment arithmetic tells a clear story. ISG operating margin went from 8.8% in the second quarter of fiscal 2026 to 15.0% in the second quarter of fiscal 2027 — a 620 basis point expansion.201 Kennedy decomposed it on the call: scale and operating leverage contributed just over 400 basis points, with storage mix and pricing discipline supplying the rest.19 He also, to his credit, hedged: "a number of factors came together and went our way this quarter... we would not expect every benefit to continue at this level."19
That hedge is the honest reading. Roughly two-thirds of the margin expansion came from operating leverage on a revenue base that grew 89% — which is to say, it came from the numerator, not from a structural improvement in what Dell charges for a rack. If revenue growth decelerates, the leverage runs in reverse. The durable component is the storage mix shift, which is real, mechanical, and still incomplete.
VII. Core Business Today II: Client Solutions Group (CSG) — The PC Business Is Not Dead, But It Isn't Growing
For a business everyone had written off, the PC group has had a strange couple of years — and the strangeness is instructive.
CSG generated $15.0 billion of revenue in the second quarter of fiscal 2027, up 20%, with operating income of $1.1 billion at a 7.6% margin.1 Commercial revenue grew 22% — the eighth consecutive quarter of revenue growth — and consumer grew 7%.1 Clarke called it the fastest CSG growth rate in five years.19
That deserves a moment of skepticism rather than applause, because a 20% growth rate in a market that is shrinking is a claim that requires explanation. IDC reported worldwide PC shipments fell 4.9% year over year in the second quarter of calendar 2026, to 68.2 million units, with Lenovo leading at 24.4% share, HP second at 19.1%, and Dell third at 13.6% on a 5% shipment decline.26 Units down; revenue up 20%. The reconciliation is price. Memory costs have surged, Dell implemented pricing actions effective January 6, 2026 to pass higher input costs through, and richer configurations have lifted average selling prices.21
So the accurate statement is: Dell's PC revenue is growing because PCs cost more, while Dell's unit position is roughly stable-to-slightly-eroding in a declining market. That is a materially different business than "the PC recovery is here."
The genuine catalyst is time-bound and specific. Microsoft ended support for Windows 10 in October 2025, and as of August 2025 Clarke's read was that "about half of the installed base is now upgraded, which tells you about half of the installed base is not."20 By the first quarter of fiscal 2027 the framing had shifted slightly — roughly one third of the installed base consisting of devices four years or older.22 Management has also observed something counterintuitive and useful: cost-sensitive customers extending upgrade cycles are, in Clarke's words, "increasing the number of older devices in the installed base and expanding the long-term refresh opportunity."19 Deferred demand is not destroyed demand, but it is deferred, and the calendar on the Windows 10 catalyst is finite.
The credibility moment
The most useful thing about CSG for assessing management is not its financials. It is a single exchange from the August 2025 call. Asked about second-half PC prospects, Clarke did not blame macro conditions, tariffs, or the market. He said: "We have every intention to outperform the marketplace and take share. That's our goal. We have not done that consistently enough. That's problematic. I'm not happy with the share performance."20 In the same call, on storage, he used the word "unacceptable."20
This matters more than it might appear. The default corporate behavior when a segment underperforms is to attribute it to the environment. Management that names its own execution failure without an external scapegoat is telling you something about how it runs internal reviews. And in this case there was a follow-through: Dell launched an entry-level commercial notebook to expand its addressable market, leaned into share capture in the fourth quarter at the explicit cost of margin — CSG operating margin fell to 4.7% in Q4 FY26 as a result — and then recovered margin to 8.0% and 7.6% in the following two quarters.21221 Dell said it would trade margin for installed base and then did exactly that, transparently, and reported the cost.
Two cautions keep this from being a clean bull point. First, Dell has guided CSG operating margin back down to roughly 6% for the third quarter, explicitly to balance demand, share and profitability, in a market it expects to be down in units in the second half.19 Second, and more fundamentally: CSG is now a third of revenue and under a fifth of operating profit. Kennedy's own framing on the September call was revealing — he defended CSG not as a growth engine but as "our most capitally efficient business," a source of supply chain scale and cash that helps fund growth elsewhere.19
That is the correct way to size it. CSG is a cash-generative utility attached to a growth company. It matters to the story mostly as a source of funding and a source of evidence about how management behaves when something isn't working.
VIII. The AI Supercycle: Backlog, Margins, and a New Growth Story (2023-2026)
In July 2025, Dell shipped the world's first NVIDIA GB300 NVL72 racks to CoreWeave — a follow-on to having been first in the world with the GB200 NVL72 the year before.20 In September 2026, Dell announced it had again been first to ship rack systems engineered on NVIDIA's Vera Rubin platform.19 Three generations, three firsts. In a market where the constraint is time-to-first-token, that record is the single most concrete piece of evidence Dell has for the claim that it does something competitors cannot.
Now watch what happened to the numbers behind it.
The trajectory
In the second quarter of fiscal 2026 — August 2025 — Dell booked $5.6 billion of AI orders, shipped a record $8.2 billion, and exited with a backlog of $11.7 billion. Management raised full-year AI shipment guidance to $20 billion.20 Six months later, the fourth quarter of fiscal 2026 produced $34.1 billion of orders in a single quarter and a $43 billion ending backlog, with full-year fiscal 2026 orders of $64.1 billion and shipments of $25.2 billion.21 The first quarter of fiscal 2027 added $24.4 billion of orders and $16.1 billion of recognized revenue, with backlog at $51.3 billion.22 And then the second quarter of fiscal 2027: $60.9 billion of orders, $16.4 billion of revenue, $95 billion of ending backlog, and $131.7 billion of orders booked over the trailing twelve months.119
Backlog went from $11.7 billion to $95 billion in four quarters. Dell's customer count for AI infrastructure surpassed 6,500, with 3,300 of those added in the last three quarters — after it took eight quarters to reach the first 3,200.19
The guidance revisions tell the same story from the other side, and they are worth listing because they are a running record of how badly everyone underestimated this. In February 2026, Dell guided fiscal 2027 revenue to $140 billion at the midpoint with EPS of $12.90 and $50 billion of AI server revenue.21 In May 2026, that became $167 billion, EPS of $17.90, and $60 billion of AI revenue.22 In September 2026: $192 billion, EPS of $25.50, and $74 billion of AI revenue.1 A $52 billion increase to a full-year revenue forecast in six months.
There is a second, more awkward guidance record sitting behind those numbers. At its Securities Analyst Meeting on October 7, 2025, Dell raised its long-term financial framework — to 7-9% annual revenue growth and 15%-or-better annual non-GAAP EPS growth, up from 3-4% and 8% previously.27 Eleven months later the company guided to roughly 70% revenue growth and 150% EPS growth for the current year. Blowing through your own long-term framework by a factor of ten is not a mark of forecasting skill; it is evidence that the framework was set with essentially no visibility into what was about to happen. Investors should discount the predictive value of Dell's long-term targets accordingly — in both directions.
The margin question, tested against management's own words
Here is where the analysis gets interesting, because there is a clean falsifiable claim on the record.
In August 2025, Dell's AI business looked economically unimpressive. ISG operating margin had compressed to 8.8%, and Clarke described the AI mix effect in exactly the terms bears wanted to hear: "As we said consistently, that's gross dollar accretive, rate dilutive."20 He attributed the quarter's compression to aggressively priced early Blackwell deals plus one-time supply chain costs to expedite materials, and promised recovery: "We expect those margins to improve through some value engineering, scaling of the business and the expansion of our enterprise customer base."20 Analysts were openly skeptical. Amit Daryanani of Evercore did the arithmetic on the guidance raise live on the call and concluded "it almost looks like AI server margins are in the 2%, 2.5% zone."20
That is a specific, dated, falsifiable promise. What happened?
ISG operating margin recovered to 14.8% by the fourth quarter of fiscal 2026, held at 10.5% in a quarter where AI revenue grew nearly 800% year over year, and reached 15.0% in the second quarter of fiscal 2027.21221 Management has consistently described AI server profitability itself as running at a mid-single-digit operating margin target and reported it in line with that target in each of the last three quarters.2122
So the narrow claim — that AI-server margins would improve from the depressed second quarter of fiscal 2026 and that segment margins would recover — is confirmed. That is real, and it is the strongest single piece of evidence for management credibility in this story.
But be precise about what was confirmed, because the temptation to over-read it is enormous. AI servers are still a mid-single-digit operating margin business by Dell's own repeated description. That is roughly a third of the margin rate Dell earns on Dell IP storage. The segment margin reached 15% not because AI became a high-margin business but because ISG got so much bigger that fixed costs spread across a vastly larger base, and because storage — the genuinely profitable line — grew and mixed richer at the same time. Kennedy quantified it: scale alone was worth just over 400 basis points in the quarter and is worth over 650 basis points for the full year.19
The revised claim that survives the evidence is this: Dell's AI server business is a modestly profitable, enormous-volume business whose principal value to shareholders is the operating leverage it creates across the rest of the P&L and the pull-through it generates in storage, networking, and services. It is not, on current disclosure, a high-margin franchise. Management has never claimed otherwise, and the "mid-single-digit" language has been consistent across four consecutive calls — which is itself a mark of narrative discipline.
The falsification test going forward is specific: if AI revenue keeps tripling and ISG margin fails to hold in the low-to-mid teens, the leverage thesis breaks and the 2025 bear case — that this is a 2-3% pass-through business — was right after all.
What actually differentiates Dell
Clarke's answer to why customers choose Dell is worth taking seriously and then stress-testing. His argument is that AI infrastructure "requires much more than assembling and delivering components," with some engagements requiring "upwards of 50 unique designs" as customers optimize for workload performance, power, cooling, and the specific data center environment.19 Dell's claim is engineering-at-scale plus global deployment plus lifecycle support plus financing through Dell Financial Services — the ability to take a customer from purchase order to first token faster than anyone.
The GB200, GB300 and Vera Rubin firsts are genuine evidence for this. So is the 6,500-customer count, and so is the fact that repeat buyers are growing.19
What it is not is a moat in the structural sense. Dell does not control the GPU. Every rack it sells is gated by NVIDIA allocation, and the differentiation lives entirely in the integration layer around a component Dell buys. That is process power — real, valuable, and copyable by anyone willing to spend enough on engineering and logistics. We will return to this in the competitive section, because it is the crux of the investment case.
The competitive shock
One event in 2026 materially changed the competitive landscape, and it had nothing to do with engineering.
On March 19, 2026, the U.S. Department of Justice unsealed an indictment charging three individuals affiliated with Super Micro Computer with conspiring to illegally export NVIDIA-equipped AI servers to China in violation of export controls — with the Futurum Group citing at least $510 million of servers in the alleged scheme.28 Those charged included a former Super Micro board member and senior vice president of business development, and the general manager of the company's Taiwan office.2829 Super Micro itself was not named as a defendant. Its shares fell roughly 33% in the following week.28
The analytical point is not schadenfreude. It is that in a business where the scarce input is allocated by a single supplier and where the largest buyers are hyperscalers, sovereigns, and regulated enterprises, compliance credibility is a competitive asset. A customer procuring for a sovereign AI program cannot afford a vendor with an active export-control problem. Dell's share moved from 10.0% in Q4 2025 to 16.5% in Q1 2026 while Supermicro's fell from 9.5% to 7.6%.2425
Resist the temptation to over-read this too. Supermicro is not dying. It reported fiscal 2026 revenue of $39.1 billion, up from $22.0 billion, and guided fiscal 2027 revenue to $65-72 billion.30 What it does have is a structurally thinner margin profile — full-year fiscal 2026 gross margin of 10.8%, with management guiding forward quarters to 10-11% after a mix-driven 17.5% spike in the June quarter.30 Against Dell's 21.1% consolidated gross margin, that is a different business model competing for the same racks.1 The competitive question is not whether Supermicro survives. It is whether its willingness to operate at half Dell's gross margin eventually forces Dell's AI economics toward its own.
IX. Current Management: Ownership, Incentives, and the Capital Allocation Record
There is a photograph that circulates of Michael Dell in 1984, nineteen years old, sitting behind a desk with a screwdriver. Forty-two years later he is Chairman and CEO of a company approaching $200 billion of annual revenue, and his personal wealth passed $100 billion in 2026 on the back of the stock's run.3 Almost uniquely among large-cap technology CEOs, he is running the company he founded, in the city where he founded it, with voting control he has never relinquished.
That is the setup. The question for an investor is what it produces.
The control structure, and what it costs
We covered the mechanics in Section III. The economic reality: Dell is a controlled company; Michael Dell alone holds more than 50% of voting power for director elections and, with Silver Lake, more than 70%.4 Mr. CorpGov's analysis of the June 25, 2026 annual meeting calculated affiliated holders at approximately 92.8% of outstanding votes.31
The consequence showed up starkly at that meeting. Say-on-pay passed with 97% support overall — and 46.1% support among unaffiliated shareholders.31 Lead Independent Director Ellen Kullman, who also chairs the nominating and governance committee, received 47.1% unaffiliated support.31 A management proposal to redomesticate the company from Delaware to Texas — approved by the board on May 4, 2026 and effective July 1, 2026 — passed with 97% overall and 45.2% among unaffiliated holders.3132
Read that carefully. On a hypothetical unaffiliated-only basis, the lead independent director, the executive compensation program, and the reincorporation would all have failed to win majority support. Public shareholders holding the majority of the economics registered clear dissent on three separate items and it changed nothing. That is not a scandal — it is exactly what a dual-class structure is designed to do, and every buyer of Class C stock knows it. But it is the honest price of the founder control that made the 2013 and 2015 bets possible, and it should be priced rather than ignored.
Jeff Clarke and the $132 million question
Jeff Clarke is the operational half of this company. Vice Chairman and Chief Operating Officer, a Dell lifer, and the architect of both the supply chain that ships GB300 racks first and the modernization program that took operating expenses to 8.5% of revenue in the second quarter — the lowest level in the company's 42-year history on a full-year guided basis.19
On September 30, 2025, Dell's board approved a special performance-based stock option award allowing Clarke to purchase 2.5 million Class C shares, valued at approximately $132.4 million.33 The options vest on March 15, 2031, contingent on both a market capitalization performance goal and an adjusted free cash flow performance goal, plus continued employment.33 Layered onto his other compensation, it produced total reported compensation of $154.3 million for the fiscal year.33 No other executive received a grant of comparable size or duration.
How should an investor read this? Three ways, and they are in tension.
Positively: the vesting conditions are the right ones. A market-cap hurdle and a free-cash-flow hurdle over five and a half years is a considerably better-designed instrument than time-vesting restricted stock, and free cash flow specifically is the metric most at risk from an AI ramp that consumes working capital. It points the operator's personal wealth at exactly the thing shareholders should care about.
Skeptically: the award was granted on September 30, 2025, when Dell shares traded near $110-125. The subsequent move to record highs means a very large portion of that value was delivered by a supercycle that was already visible in the backlog rather than by five years of future execution. Retention grants sized to catch a wave that has already broken are a familiar governance complaint.
Structurally: the 46.1% unaffiliated say-on-pay support is the market's verdict, and it is the single most concrete piece of evidence that public shareholders object. The dual-class structure ensured the objection was recorded and then overruled.
The CFO transition
On September 8, 2025, Dell announced that Yvonne McGill would step down as Chief Financial Officer effective September 9, after nearly thirty years at the company, describing it as "the right time for me to embark on my next chapter."3435 David Kennedy, a 27-year Dell veteran who had served as SVP and CFO of the Client Solutions Group and COO of Global Sales, took over as interim CFO and was appointed permanently effective November 24, 2025.34 McGill remained in an advisory capacity through the third quarter.34
No disagreement over financial reporting was disclosed, no restatement followed, and the auditor's opinion was unqualified. The succession was internal, fast, and low-drama. Still, it is worth noting plainly what happened: Dell changed CFOs on the eve of the largest and most operationally complex ramp in its history, and the incoming CFO's first four quarters have coincided with the three largest guidance raises the company has ever issued. Kennedy has handled the calls competently and, notably, has been willing to hedge his own good news — the "we would not expect every benefit to continue at this level" caveat on the September call is not what a promotional CFO says.19
Capital allocation
The record here is unusually clean. Since the capital return program began at the start of fiscal 2023, Dell had returned $14.5 billion through buybacks and dividends as of August 2025.20 In fiscal 2026 alone it returned $7.5 billion and repurchased roughly 54 million shares — more than double the prior year.21 Looking into fiscal 2027, the board raised the annual dividend 20% to $2.52 per share and authorized an additional $10 billion of repurchase capacity.21 At the October 2025 analyst meeting Dell committed to growing the quarterly dividend at 10% or more annually through fiscal 2030, extended from a prior commitment through fiscal 2028, alongside a stated target of returning over 80% of adjusted free cash flow to shareholders.27
In the second quarter of fiscal 2027 Dell returned a record $4.3 billion, including $3.9 billion of buybacks — 9.5 million shares at an average price of $401 — which Kennedy noted was "almost 2x any previous spend that we've done in our history."19
That last data point cuts both ways and should be said plainly. Dell repurchased at $401 per share in a quarter when the stock had roughly quadrupled over twelve months. Aggressive buybacks near all-time highs, funded by earnings from a business whose durability is the open question of this entire story, is not obviously value-accretive. It is defensible if the AI franchise proves durable and expensive if it does not. Contrast it with fiscal 2026, when Dell repurchased 54 million shares at prices averaging in the $125 range — that was excellent capital allocation.21 The pattern is buying more as the price rises, which is what most companies do and what few should.
Netting it out: Dell's management scores well on the tests that matter most. It set specific guidance and largely hit it. It named its own misses on storage and PC share without deflecting to macro. It has a five-year record of divesting failed adjacencies rather than defending them. Those are above-average behaviors. The offsets are real too — a long-term framework with essentially no predictive value, a mega-grant that drew majority dissent from unaffiliated holders, and buyback pacing that accelerates into strength.
X. Balance Sheet, Working Capital, and the Shadow of the LBO/EMC Debt
Open Dell's balance sheet for fiscal 2026 and the first thing you notice is that total stockholders' equity is negative $2.47 billion.36 Total liabilities of $103.8 billion sit on total assets of $101.3 billion.
For most companies that would be a flashing red light. For Dell it is an accounting artifact, and it is worth explaining properly rather than either alarming readers or waving it away.
Negative book equity arises here from three compounding causes. The 2013 buyout and the 2016 EMC acquisition were financed with debt, not equity. Years of accumulated losses during the transformation period drove retained earnings deeply negative — as recently as fiscal 2023 the accumulated deficit was $6.7 billion.36 And Dell has repurchased $14.5 billion of treasury stock, which is a direct deduction from equity.36 What book equity emphatically does not measure is the earning power of the assets. Dell generates cash, holds investment-grade ratings from all three agencies, and finished the second quarter of fiscal 2027 with $14.2 billion of cash and investments against a core leverage ratio of 0.8x.19 Retained earnings actually turned positive in fiscal 2026, at $3.3 billion, for the first time in years.36
The genuinely interesting balance sheet story is elsewhere, and it is the oldest theme in this company.
The working capital reversal
Recall Section II: Dell's foundational advantage was a negative cash conversion cycle. Get paid before you pay. Growth generates cash.
The AI server ramp partially inverts that. Building a $95 billion backlog of GB300 and Vera Rubin racks requires Dell to buy enormous quantities of the scarcest components in the world — DRAM, NAND, GPUs — and hold them while systems are assembled, shipped, and installed, often on schedules dictated by customers' data center construction. Inventory rose from $6.7 billion at the end of fiscal 2025 to $10.4 billion at the end of fiscal 2026.36 Net receivables went from $15.6 billion to $26.0 billion over the same period.36
You can see the effect in the cash flow line. In the second quarter of fiscal 2027, Dell earned $4.6 billion of non-GAAP net income and grew revenue 58% — and generated only $2.2 billion of cash flow from operations.119 That is not deterioration. That is a company funding a violently growing order book. Payables also grew sharply, to $33.6 billion, which is the direct model still doing its job on the other side.36
Wamsi Mohan of Bank of America pressed on exactly this in September, asking about the material increase in financing receivables. Kennedy's answer was that the growth "is effectively driven by the growth in the overall business, and it's anchored obviously in the expansion of AI," that Dell's involvement remains "selective" and "primarily focused on short-term financing," and that net income to adjusted free cash flow conversion remains above 1x.19
That answer is reasonable but not fully satisfying, and the reason is worth naming. Dell Financial Services extending credit to customers buying Dell's own AI servers is vendor financing. Modest, short-duration vendor financing to investment-grade enterprises is ordinary. Growing vendor financing to neocloud customers — venture-funded AI infrastructure startups with concentrated, unproven business models — is a different risk. Dell has not disclosed the customer-quality composition of its financing receivables. That is a disclosure gap investors should want closed, and the leading indicator is the trajectory of financing receivables relative to AI revenue.
APEX: the option nobody can size
Dell's as-a-service platform, APEX, appears in strategy discussions as the answer to the recurring-revenue question. Clarke referenced DFS as a differentiator in AI deals on the September call.19
Here is what can be said with confidence: Dell has not broken out APEX revenue or annual recurring revenue as a separate reported line, and it does not appear as a segment or sub-segment in the earnings releases.12 Whatever its strategic merit, its commercial scale is not disclosed. Treat it as unquantified optionality, not a growth pillar, until Dell chooses to disclose it — and note that the "as-a-service transformation" narrative has been in Dell's messaging since roughly 2020 without producing that disclosure.
XI. Competitive Landscape & Industry Structure
War-game this properly. Forget the narrative for a moment and ask where the profits in AI infrastructure actually accrue and why.
Porter, applied honestly
Supplier power is the dominant force, and it is not close. NVIDIA's GPU allocation determines who can grow. Dell's ability to book $60.9 billion of orders in a quarter is meaningful only to the extent NVIDIA supplies the silicon to fill them, and Dell has been supply-constrained for two consecutive years by its own repeated admission.1922 Add the memory makers: Clarke's list of constraints leads with DRAM and NAND, and rising component costs are simultaneously inflating Dell's revenue and squeezing its gross margin rate.19 When your two largest input categories are controlled by a near-monopolist and an oligopoly, your margin structure is substantially determined by someone else's pricing decisions.
Buyer power is high and rising. Hyperscalers, neoclouds, and sovereign programs are sophisticated, concentrated, and openly multi-source. Ben Reitzes framed it plainly on the September call by comparing Dell's growth to NVIDIA's own, treating Dell as one channel among several through which the same silicon reaches the same customers.19 These buyers can and do run competitive processes across Dell, Supermicro, HPE, and direct-from-ODM relationships. Enterprise buyers have less leverage, which is exactly why Dell keeps emphasizing that enterprise customer counts and repeat buyers are growing.19
Rivalry is intense and margin-destructive at the top end. Supermicro operates at roughly half Dell's gross margin and is guiding to near-doubling its revenue.30 A competitor willing to work for 10% gross margin sets the price for the marginal large deal.
Threat of substitutes is moderate but real, and it points in an interesting direction. The substitute for buying a Dell rack is renting capacity in a public cloud. Dell's counter-argument — made repeatedly by Clarke — is that on-premises and edge infrastructure offers "attractive token economics for the right workloads" plus data control.19 That argument has merit for inference workloads at scale and for regulated data. It is genuinely contested for training.
Barriers to entry are moderate, and this is the crux. Assembling servers is not hard. Assembling liquid-cooled 72-GPU racks with fifty custom design variants, deploying them globally in weeks, and keeping them running is hard. But it is an execution barrier, not a structural one — and Supermicro proved it can be cleared by demonstrating speed-to-market advantages against Dell before its 2026 legal troubles.
7 Powers: what Dell actually has
Run Hamilton Helmer's framework and most of the boxes come up empty, which is clarifying.
Dell has no cornered resource — it does not own the GPU, the memory, or any critical patent that competitors cannot design around. It has no network economies; a Dell rack is not more valuable because other customers bought Dell racks. It has no meaningful switching costs at the hardware layer; a customer's next cluster can come from Supermicro without stranding the last one, though services contracts, Dell IP storage, and management software create modest friction. Branding matters at the enterprise margin and not at all to a neocloud buying on price and lead time. Counter-positioning — the power that built the company in 1984 — is long since exhausted; everyone builds to order now.
What Dell does have is scale economies and process power, and both are genuine. Scale economies show up directly in the reported numbers: operating expense fell to 8.5% of revenue in the second quarter, guided to approximately 8% for the full year, the lowest in company history, with Kennedy quantifying scale as worth over 650 basis points of ISG margin for the year.19 That is a hard cost advantage over any smaller competitor, and it compounds. Process power shows up in the GB200, GB300 and Vera Rubin firsts, the 50-design-variant engagements, and the global deployment footprint.
The critical property of process power is that it erodes. It is embedded organizational capability, which means it cannot be bought overnight — but it can be built over three to five years by a determined, well-funded competitor. Supermicro's pre-indictment speed advantage is the proof of concept. Process power is worth paying for; it is not worth paying a structural-moat multiple for.
Naming the field
Dell leads x86 and overall server revenue among OEMs and holds the number one external storage position across all major categories.24251 Supermicro is the closest AI-server pure-play, larger in AI mix and far thinner in margin, now carrying a compliance overhang.3028 HPE has stepped back from volume x86 toward edge and mission-critical systems and is now a fraction of Dell's server revenue.24 Lenovo leads global PC units at 24.4% and is a smaller enterprise player.26 NetApp and Pure Storage compete in storage without the server and PC scale that funds Dell's cost position. Cisco and Arista own the networking layer that Dell attaches to rather than leads.
Where the moat claim is thin
Dell's own history is the best evidence against a durable-moat framing. Every prior hardware category Dell led — PCs, x86 servers, external storage — commoditized once supply caught demand, and Dell's response each time was to compete on cost and operating discipline rather than price. There is no reason inherent to AI servers to expect a different endgame. The current gross margin is a scarcity margin. The question is what remains when NVIDIA's supply constraint resolves, memory pricing normalizes, and Supermicro, HPE, Lenovo, and the ODMs have all had three years to build comparable rack-integration capability.
The honest answer is that nobody knows, and that management has not claimed otherwise. Dell's mid-single-digit AI operating margin target has been consistent across four calls precisely because management is not promising that AI servers become a high-margin business. The bull case does not require it. It requires the volume to persist long enough for the storage, networking, and services attach — the genuinely profitable parts — to compound alongside it.
XII. Governance & the Activist Stress Test
Carl Icahn is not currently in Dell's stock. But it is worth asking what he would say if he were, because the structural conditions that drew him twice have not changed.
The 2013 fight was about a controlling founder buying the company at a price he set. The 2018 fight was about a complex capital structure — the DVMT tracking stock — that Icahn argued undervalued public holders in an exchange Dell controlled. Both grievances shared a root: Michael Dell's ability to determine outcomes over the objection of holders of most of the economics. That root is unchanged in 2026, and the June annual meeting results demonstrate it operating in real time.31
What has changed is the economic grievance. Activists need underperformance to build a campaign around. A stock near record highs with a $95 billion backlog is the least fertile ground imaginable. The activist case against Dell today is not "the strategy is wrong" — it is a governance case, and governance cases without price underperformance do not attract capital.
So run the stress test as a skeptical long/short investor would, on the assumption the cycle turns.
On disclosure. Dell does not disclose AI backlog by customer type, by contracted delivery period, or by cancellation terms. It does not disclose AI server unit volumes, only revenue. It does not break out APEX. It does not disclose the credit composition of a rapidly growing financing receivables book. For a company where a single disclosed number — backlog — is doing most of the work in the equity story, that is a thin information set. A skeptic would argue Dell is asking investors to underwrite $95 billion of future revenue on management's characterization of its quality.
On compensation. The Clarke grant is the obvious target, and unaffiliated shareholders have already voted on it. A campaign would argue that a $132 million retention award granted at the inflection point of a supercycle, in a company where the compensation committee's recommendations pass regardless of unaffiliated sentiment, is precisely what dual-class control produces.3331
On the reincorporation. Dell moved from Delaware to Texas effective July 1, 2026, after board approval on May 4.32 Management framed it as aligning the charter with the company's forty-two-year home and headquarters.32 A skeptic reads it differently: Texas corporate law is generally regarded as offering directors and controlling shareholders more protection from shareholder litigation than Delaware's. Only 45.2% of unaffiliated shareholders supported it.31 Whatever the motive, the effect is to reduce the practical avenues for a minority holder to challenge a controlled company's decisions — which is the precise mechanism through which the 2013 buyout was ultimately fought and partly repriced.
On the balance sheet. Core leverage at 0.8x with an investment-grade rating and a business generating record cash is arguably under-levered.19 An activist would push for more aggressive returns or a large acquisition — which brings us back to the Federation record and why more acquisition would not obviously be an improvement.
The synthesis: Dell's governance is a known, disclosed, priced feature rather than a hidden risk. It has demonstrably produced good outcomes — the 2013 and 2015 bets that public markets would have blocked — and it demonstrably removes shareholders' ability to correct a bad one. The tail risk is not that Michael Dell does something reckless. It is that if strategy or capital allocation ever diverges from public shareholders' interests, the correction mechanism that exists at ordinary companies does not exist here, and the Texas redomestication narrowed it further.
XIII. Bear vs. Bull Case
The bull case
Start with the thing that is simply, verifiably true: Dell has $95 billion of contracted AI server orders and a pipeline management describes as multiples of that even after converting $131.7 billion into orders over twelve months.119 That is not a projection. It is signed business. At the fiscal 2027 guided AI revenue run rate of $74 billion, the backlog alone represents well over a year of AI shipments before a single new order.1
Second, the margin thesis has partially proved out against a specific prior claim. The 8.8% ISG margin of August 2025 became 15.0% by September 2026, and management's stated mechanism — scale, storage mix, elimination of one-time supply chain costs — is the mechanism that in fact delivered it.20119 That is the difference between a thesis that has been tested and one that has only been asserted.
Third, the composition of demand is improving. Enterprise and sovereign buyers grew faster than the neocloud and CSP base, the customer count more than doubled in three quarters, and enterprise buyers attach more storage, networking, and services per deal.1921 Every marginal enterprise dollar is worth more to Dell than a marginal hyperscaler dollar. If that mix shift continues, the blended margin improves without Dell raising a single price.
Fourth, the non-AI half is genuinely strong and less discussed. Traditional servers grew 122% off a refresh cycle with 1.2 million aged units still in the installed base and consolidation ratios of twelve-to-one on the newest platform.19 Storage is growing 26% with a mix shift that is mechanically margin-accretive and still incomplete.1 These are multi-year runways that do not depend on AI at all.
Fifth, alignment. Michael Dell's economic stake and Clarke's free-cash-flow-and-market-cap-linked mega-grant both point management's personal wealth at exactly the outcome shareholders need.33
Sixth, the balance sheet is a weapon rather than a constraint for the first time since 2013 — 0.8x core leverage, investment grade, $14.2 billion of cash, and a multi-year record of returning capital including a 20% dividend increase and $10 billion of incremental buyback authorization.1921
The bear case
Start with the mirror image of the backlog. Contracted orders convert to revenue only when customers can take delivery, and Clarke has been explicit that deliveries depend on "buildings being ready, power being installed, cooling being installed" and that demand comes in "lumpy" and "nonlinear."20 Those are customer-side variables Dell does not control. Neoclouds in particular are venture-funded entities building data centers on aggressive timelines with capital that is not guaranteed. Dell has not disclosed cancellation terms, deposit structures, or the customer-type composition of the $95 billion.
Second, supplier concentration is not a risk factor — it is the business model. Dell's AI economics are downstream of NVIDIA's allocation, roadmap timing, and pricing, and of DRAM and NAND markets in which Dell is a price taker. Rising component costs are currently helping revenue and hurting gross margin rate simultaneously. If memory pricing normalizes, a meaningful slice of the reported growth reverses.
Third, and most fundamentally: the margin evidence supports a narrower claim than the stock price implies. AI servers earn a mid-single-digit operating margin by Dell's own repeated statement. The 15% ISG margin is roughly two-thirds attributable to operating leverage on hypergrowth revenue — Kennedy quantified scale at over 400 basis points in the quarter — which reverses if growth decelerates.19 Dell's own CFO warned that "we would not expect every benefit to continue at this level."19 That warning belongs in the bull case's fine print.
Fourth, the commoditization precedent is Dell's own history. PCs, x86 servers, and external storage all followed the same arc: technical differentiation, scarcity margins, then commodity economics once supply caught up. Management's honest framing of this company as a supply chain and engineering operation rather than a technology franchise is the reason the arc keeps repeating.
Fifth, CSG is growing on price rather than units in a market shrinking 4.9% a year, with Dell's unit share eroding and the Windows 10 catalyst finite.2620
Sixth, governance concentration is a dormant but real tail risk, now with fewer legal avenues for minority holders following the Texas redomestication.3231
Seventh, capital allocation has turned pro-cyclical: record buybacks at $401 per share after the stock quadrupled, versus far better execution a year earlier at $125.1921
The synthesis
The evidence supports a specific, bounded version of the bull case rather than the expansive one. Dell has a real, demonstrated, and currently widening advantage in the execution of AI infrastructure deployment, expressed as scale economies and process power. It does not have a structural moat, does not control its critical inputs, and does not earn high margins on the AI hardware itself. The value accrues from operating leverage and attach, both of which require the volume to persist.
The single most important question is therefore not "how big is the backlog" but "how long does the volume last, and what does the margin structure look like on the other side." That is a question the next four to eight quarters of disclosure will answer, and it is not answerable today.
XIV. Risk Radar
Backlog conversion and customer concentration. The $95 billion backlog is the equity story, and its conversion depends on factors outside Dell's control — customer data center construction, power availability, and cooling installation, all flagged explicitly by management as timing risks rather than boilerplate.20 Dell does not disclose the customer-type or contractual composition of that backlog. Large-scale AI deployments concentrate among a limited number of neocloud, hyperscaler, and sovereign buyers; a pause by a handful would have outsized effect. The mitigating evidence is real — 6,500 AI customers, enterprise growing faster than CSPs — but it is management-characterized rather than disclosed in a quantified breakdown.19
Export controls and compliance. The Super Micro indictment is not a hypothetical. It is a named, dated precedent showing that an AI-server OEM's employees can create a $500 million-plus export-control exposure and a 33% equity drawdown.2829 Dell operates the same product line into the same global markets under the same regulations. This is a genuine, structural risk for every vendor in the category, and the appropriate response is monitoring rather than reassurance.
Component cost and supply. DRAM, NAND, GPUs, CPUs, disk drives, ABF substrate, optical components — Clarke's constraint list runs long.19 Costs are being passed through today because demand exceeds supply. In a normalizing market, cost inflation that once inflated revenue becomes margin compression that cannot be passed on.
Margin-mix reversion. ISG margin at 15% is recent, partly cyclical, and explicitly caveated by the CFO. Reversion toward the "gross-dollar-accretive, rate-dilutive" economics of a year earlier is a plausible near-term scenario, not a tail event, if AI mix keeps rising while operating leverage stops improving.2019
Working capital and free cash flow. Funding inventory and receivables ahead of collection has already decoupled cash generation from accounting profit — $4.6 billion of non-GAAP net income against $2.2 billion of operating cash flow in the second quarter.119 This is mechanically normal for hypergrowth. It becomes a warning if receivables grow faster than revenue for consecutive quarters, or if the financing receivables book shifts toward weaker credits without disclosure.
PC secular demand. The Windows 10 refresh is a known catalyst with a finite calendar. What happens to CSG demand when it passes in 2027 is unresolved, and Dell has already guided CSG margin back toward 6%.19
Leverage optionality. Core leverage at 0.8x is a strength today and a lever management could pull tomorrow — for capacity investment or acquisition. Given the Federation divestiture record, a large adjacent-business acquisition would warrant considerably more scrutiny than a leverage ratio alone suggests.
XV. Durable Business & Investing Lessons
Four things generalize from this story.
The 1984 insight is still the operating system. Dell's founding advantage was never a product; it was funding growth through the balance sheet rather than the capital markets. Forty-two years later, Dell is financing a $95 billion order book largely out of payables and operating cash flow, at 0.8x leverage, while simultaneously returning record capital to shareholders. The mechanism reverses under hypergrowth — inventory and receivables now consume cash where they once released it — but the underlying discipline is what makes the reversal survivable rather than existential. Working-capital design is a durable competitive asset in a way that most product advantages are not.
Founder control is a two-sided instrument, and both sides are visible in the same company. The 2013 buyout and the 2015 EMC bet were made possible by governance that public markets could not veto, and both were, on the evidence, correct. The 46.1% unaffiliated say-on-pay vote and the 45.2% unaffiliated vote on redomestication are the cost of that same structure.31 There is no version of this where you get the upside without the downside. Investors should price control structures as what they are: a bet on one person's judgment, with the correction mechanism removed.
Judge capital allocation by what a company unwinds, not by what it announces. The most informative single fact about Dell's capital discipline is not the EMC acquisition. It is the five-year, roughly five-of-seven retreat from the Federation — RSA, Boomi, Pivotal, SecureWorks, Virtustream — executed without a defensive narrative about strategic fit.131415 Announcements are free. Divestitures are admissions, and a company willing to make them repeatedly is telling you something real about how it evaluates its own decisions.
Process power is worth owning and worth discounting. Being first to ship three consecutive NVIDIA rack generations is a genuine, hard-won capability. It is also the kind of advantage that a determined competitor closes in three to five years, and that a supplier can neutralize with a single allocation decision. The discipline is to distinguish it from a structural moat — to pay for it as a compounding execution advantage rather than as a permanent one, and to watch for the specific evidence of erosion: a competitor shipping a new NVIDIA platform first.
XVI. Epilogue: What to Watch
If you track only a small number of things on this company, track these three.
AI backlog-to-revenue conversion rate. Not the backlog number — the conversion. Each quarter, compare recognized AI server revenue against the prior quarter's backlog and orders. Backlog that grows while conversion stalls means customer-side readiness is binding, and it is the earliest visible signal that the $95 billion is worth less than it looks. Backlog that grows while conversion keeps pace is the thesis working.
ISG operating margin as AI mix rises. The single cleanest test of whether this is a durable franchise or a pass-through. Dell has guided ISG margin up just over a point year over year in the second half even as AI revenue triples.19 If AI grows to 60-70% of ISG revenue and segment margin holds in the low-to-mid teens, the operating leverage and attach thesis is proven. If margin drifts back toward single digits, the 2025 bear case was right and the market has been paying a franchise multiple for a logistics business.
Free cash flow conversion. Kennedy has committed to net income to adjusted free cash flow conversion above 1x.19 In a business consuming working capital to fund growth, with a growing vendor-financing book of undisclosed credit quality, this is the metric that reveals order quality before the income statement does.
Two disclosure improvements would materially change how this business can be analyzed: a breakdown of AI backlog by customer type and contracted delivery period, and any quantification of APEX scale. Neither exists today.
The unresolved question the story leaves is the one it started with. Dell has executed the AI ramp about as well as any company could — first to ship three consecutive platform generations, share gains against a compromised competitor, margin recovery delivered exactly as promised, a balance sheet repaired past its own target. None of that settles whether AI infrastructure is a durable, margin-accretive franchise or a superbly executed commodity pass-through of NVIDIA's cycle. And there is a second-order question underneath it: when that answer arrives, will a board where one person holds most of the votes recognize it faster than an independent board would, or slower? Dell's record contains evidence for both.
XVII. Recent News
The most recent reported period is the second quarter of fiscal 2027, ended July 31, 2026 and reported September 1, 2026: revenue of $47.0 billion, GAAP diluted EPS of $6.34, non-GAAP diluted EPS of $7.04, ISG revenue of $31.8 billion at a 15.0% operating margin, CSG revenue of $15.0 billion, AI server orders of $60.9 billion, AI server revenue of $16.4 billion, and ending AI backlog of $95 billion.1 Full-year fiscal 2027 guidance was raised by $25 billion to $192 billion at the midpoint with non-GAAP diluted EPS of $25.50, and third-quarter guidance was set at $49 billion of revenue with $19 billion of AI server revenue.119
Capital returns reached a record $4.3 billion in the quarter, including 9.5 million shares repurchased at an average price of $401 and a quarterly dividend of approximately $0.63 per share.19 Core leverage stood at 0.8x with $14.2 billion of cash and investments, alongside positive credit rating actions during the quarter.19
Governance developments during the year included the completion of Dell's redomestication from Delaware to Texas, effective July 1, 2026 following approval at the June 25 annual meeting,32 and the disclosure of Jeff Clarke's $132.4 million performance-based option award within total fiscal 2026 compensation of $154.3 million.33 David Kennedy's appointment as permanent Chief Financial Officer took effect November 24, 2025.34
The most significant competitive development was the Department of Justice's March 19, 2026 indictment of three individuals affiliated with Super Micro Computer over alleged illegal exports of NVIDIA-equipped AI servers to China, and the subsequent shift in server revenue share toward Dell.2825
Items still to be updated as they occur: third-quarter fiscal 2027 results and any revision to backlog and full-year guidance; the outcome of any subsequent securities analyst meeting and long-term framework update; further AI infrastructure partnership, capacity, or export-control developments; and any disclosure improvements on backlog composition or APEX scale.
References
-
Dell Technologies Delivers Second Quarter Fiscal 2027 Financial Results — SEC Form 8-K Exhibit 99.1, 2026-09-01 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Dell Technologies Inc. Form 10-K, Fiscal Year 2026 (year ended January 30, 2026) — SEC EDGAR ↩↩
-
Michael Dell's Wealth Surges Past $100B in 2026 as Dell Stock Hits Record Highs — Benzinga, 2026-09-03 ↩↩
-
Dell Technologies Inc. Definitive Proxy Statement (DEF 14A), 2026 — SEC EDGAR ↩↩↩↩
-
Michael Dell Founds "PC's Limited" — History of Information ↩
-
Dell Inc. Form 8-K Exhibit 99.1, Michael Dell named CEO — SEC EDGAR, 2007-01-31 ↩
-
Dell Inc. Form 8-K Exhibit 99.1 — Dell Enters Into Merger Agreement at $13.65 Per Share, SEC EDGAR, 2013-02-05 ↩
-
Icahn and Southeastern Asset Management Form DFAN14A — SEC EDGAR, 2013 ↩↩
-
Dell Technologies Inc. Form 10-K, Fiscal Year 2026 — cover page share counts and subsequent-events disclosure ↩↩↩
-
Michael S. Dell, MSD Partners and Silver Lake Lead Transaction to Combine Dell and EMC — Dell Newsroom, 2015-10-12 ↩↩
-
$67 billion Dell-EMC deal closes today — TechCrunch, 2016-09-07 ↩
-
Dell Technologies sells RSA Security for $2.1B — CIO Dive, 2020 ↩↩
-
Boomi busts out of Dell with $4bn sale to pair of private equiteers — The Register, 2021-05-03 ↩↩
-
Sophos to Acquire Secureworks to Accelerate Cybersecurity Services and Technology for Organizations Worldwide — Sophos, 2024-10-21 ↩↩
-
Dell Technologies Concludes Strategic Review and Reaches Agreement to Exchange Class V Tracking Stock — Silver Lake, 2018-07-02 ↩↩
-
Dell Technologies Announces Completion of VMware Spin-off — Dell Newsroom, 2021-11-01 ↩↩
-
Dell Technologies Inc. Q2 FY2027 Earnings Call Transcript — Dell Investor Relations, 2026-09-01 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Dell Technologies Inc. Q2 FY2026 Earnings Call Transcript — Dell Investor Relations, 2025-08-28 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Dell Technologies Inc. Q4 FY2026 Earnings Call Transcript — Dell Investor Relations, 2026-02-26 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Dell Technologies Inc. Q1 FY2027 Earnings Call Transcript — Dell Investor Relations, 2026-05-28 ↩↩↩↩↩↩↩↩
-
Dell Technologies Inc. Form 10-K, Fiscal Year 2024 (year ended February 2, 2024) — SEC EDGAR ↩
-
IDC: Dell leads server market driven by AI infrastructure needs — Network World ↩↩↩↩↩
-
IDC: AI demand pushes global server market to $122.6 billion in 1Q26 — Back End News ↩↩↩↩
-
Worldwide PC Shipments fell 4.9% YoY in Q2 2026 to 68.2 million units: IDC — The Tech Outlook ↩↩↩
-
Dell Technologies Increases Its Long-Term Financial Framework at Securities Analyst Meeting — Dell Investor Relations, 2025-10-07 ↩↩
-
Will Supermicro's Legal Crisis Shift Server Market Share to New Dell and HPE GPU Platforms? — Futurum Group, 2026-03-27 ↩↩↩↩↩↩
-
US indicts Super Micro co-founder on AI chip exports — The Hill, 2026 ↩↩
-
Supermicro Announces Fourth Quarter and Full Fiscal Year 2026 Financial Results — Super Micro Computer Investor Relations, 2026 ↩↩↩↩
-
Dell Technologies Inc. Form DEFA14A — Board Recommends Redomestication to Texas, SEC EDGAR, 2026-05-04 ↩↩↩↩↩
-
Dell Grants COO Clarke Performance Options Worth $132 Million — Bloomberg, 2026-05-04 ↩↩↩↩↩↩
-
Dell Technologies Announces CFO Transition — Dell Newsroom, 2025-09-08 ↩↩↩↩
-
Dell CFO McGill Stepping Down, Kennedy Named Interim — Bloomberg, 2025-09-08 ↩
-
Dell Technologies Inc. Form 10-K, Fiscal Year 2026 — consolidated balance sheets ↩↩↩↩↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube