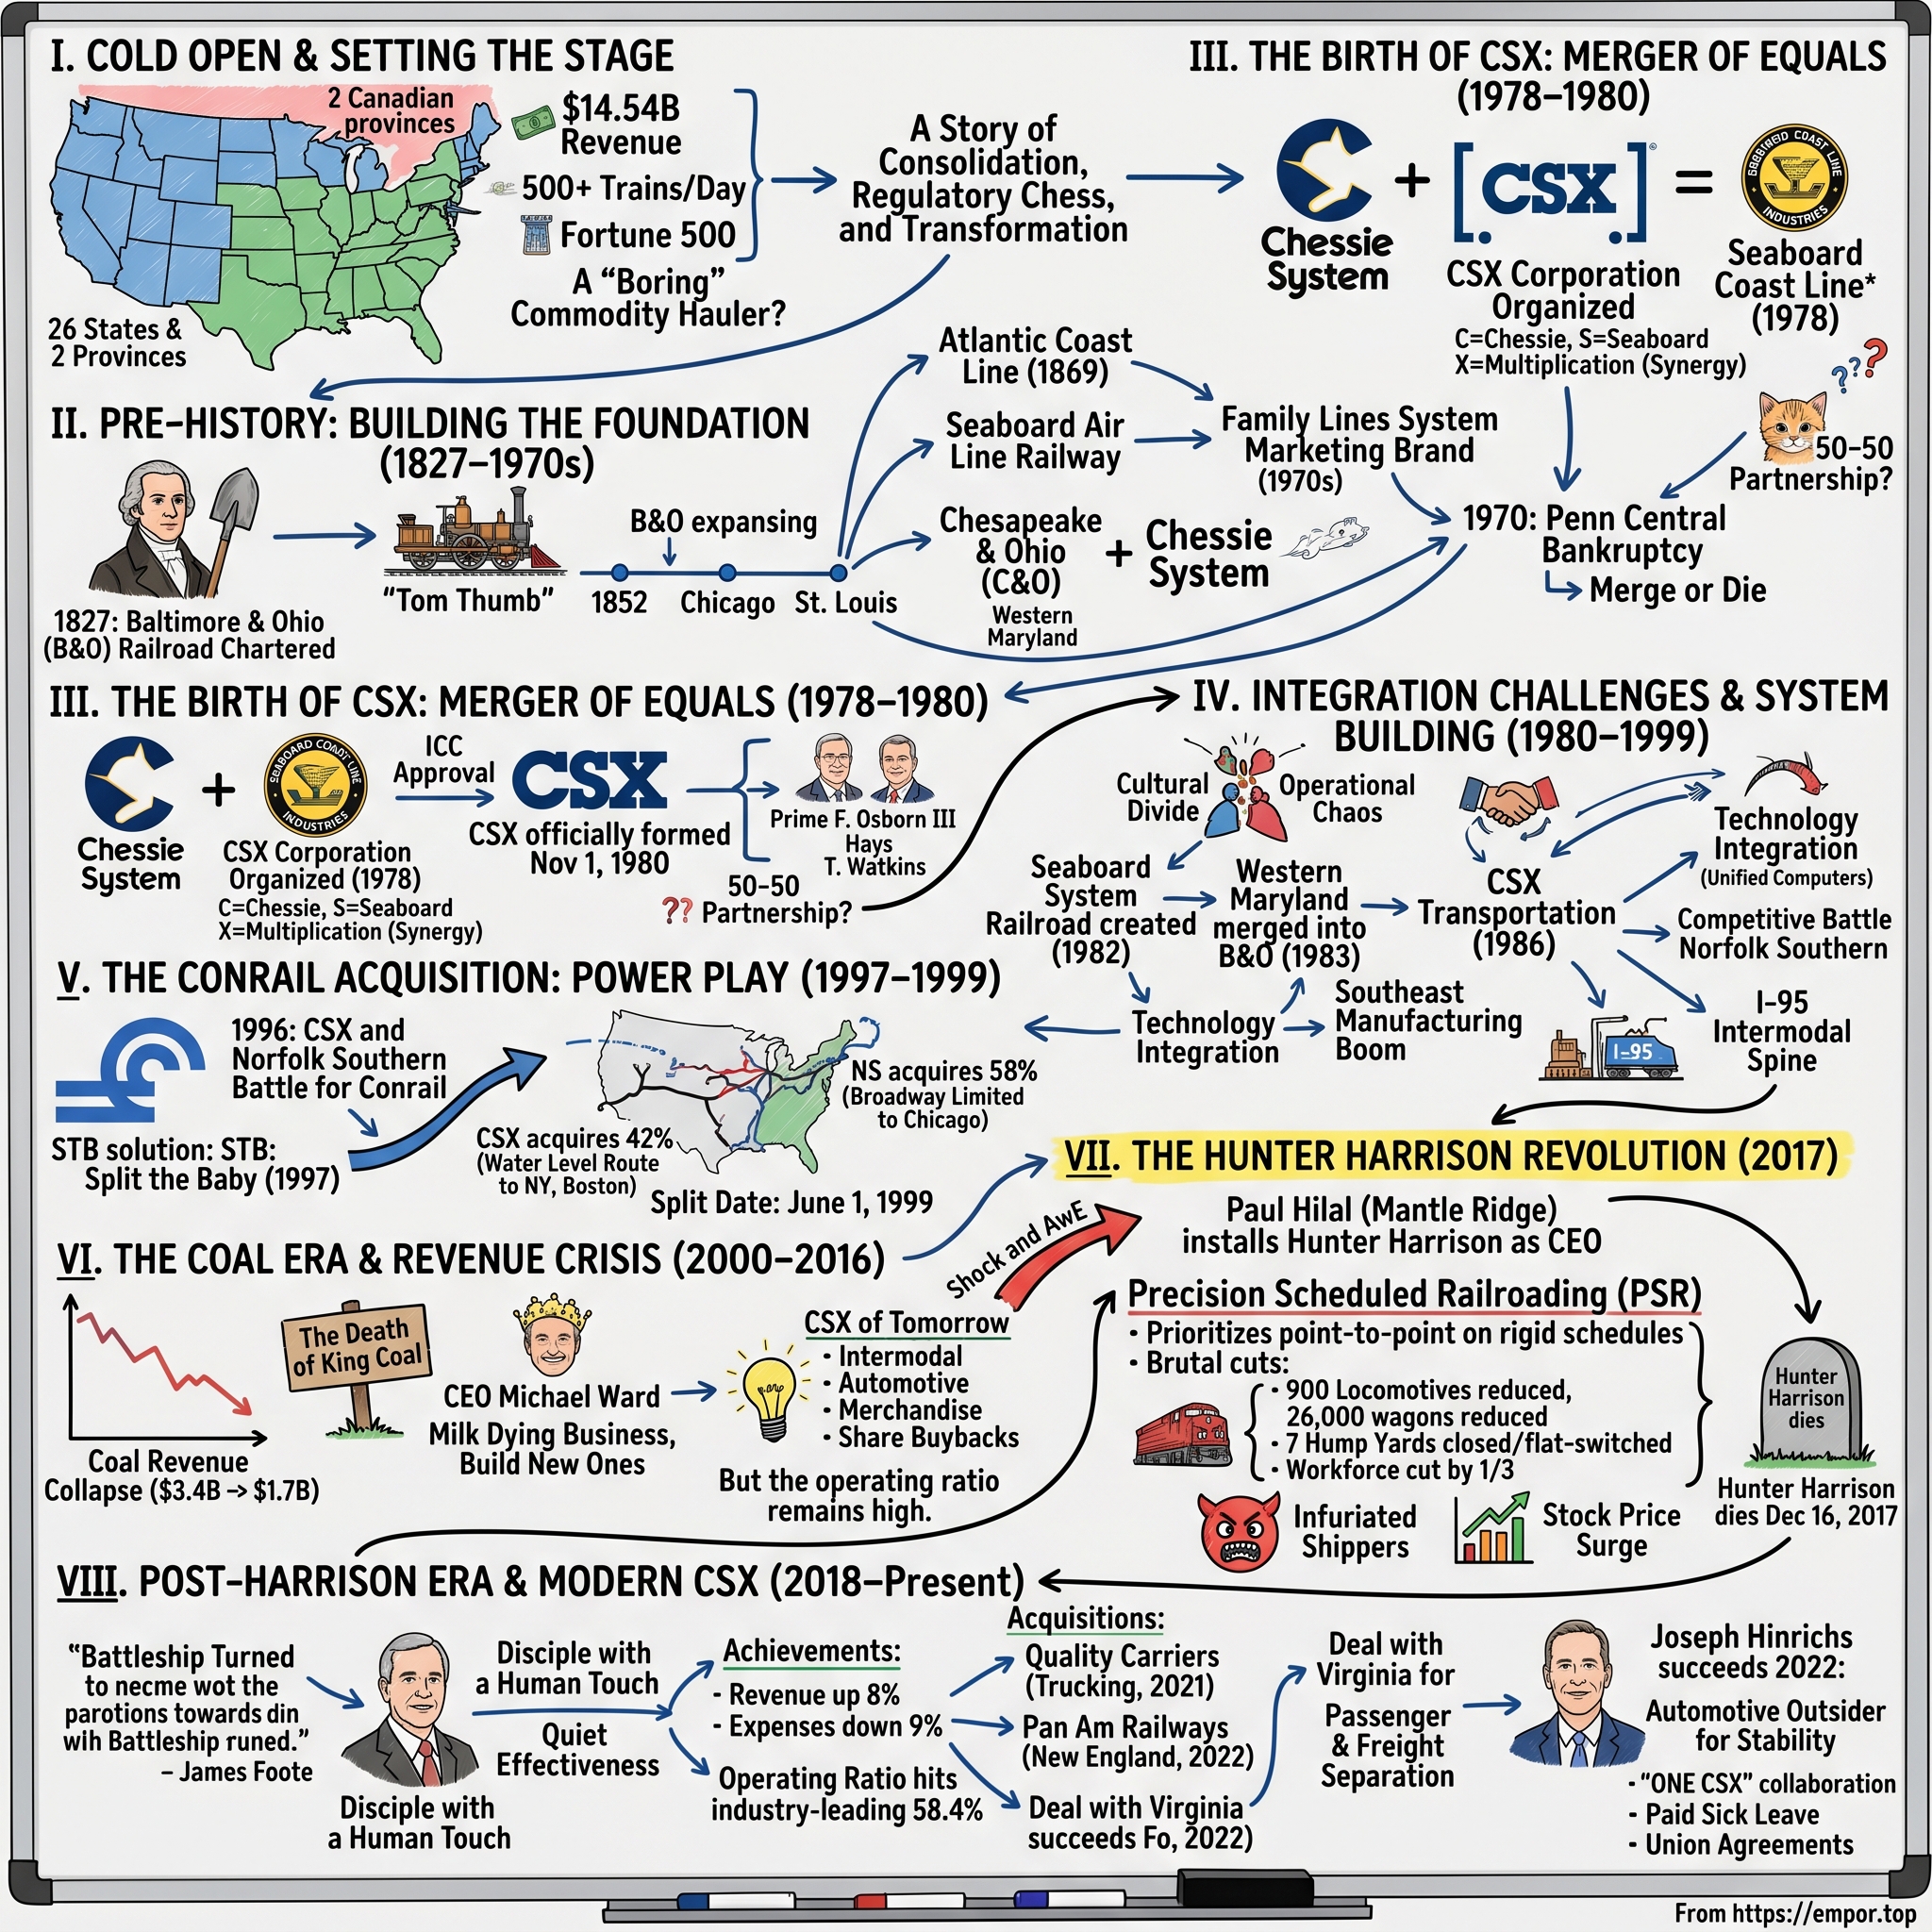
CSX Corporation: The Railroad Oligopoly & The Battle for the Eastern Seaboard
I. Cold Open & Setting the Stage (5–10 min)
On a morning in October 2025, a locomotive moved through the Blue Ridge Mountains of western North Carolina along a stretch of track that had been completely destroyed thirteen months earlier by Hurricane Helene. Floodwaters washed away the roadbed, collapsed bridges, and erased 60 miles of corridor. Rebuilding the line required more than 570,000 worker hours, one million cubic yards of rock, 35,500 linear feet of new track, and two new bridges.1
That physical network underpins CSX Corporation and forms the core of its investment thesis. The company operates roughly 20,000 route miles of railroad — totaling 35,518 track miles including sidings, yards, and turnouts — serving 26 states east of the Mississippi River, the District of Columbia, and the Canadian provinces of Ontario and Quebec.2 Replicating this network is virtually impossible, not only due to modern capital costs, but because assembling rights-of-way through major urban hubs like Baltimore, Cincinnati, Atlanta, and northern New Jersey required two centuries and regulatory conditions that no longer exist.
Despite this formidable moat, financial performance has faltered. In 2025, CSX generated $14.09 billion in revenue and $4.52 billion in operating income, yielding an operating margin of 32.1% — or an operating ratio of 67.9% in the rail industry's standard inverted metric.3 This marked a decline from 2024, when the network produced $14.54 billion in revenue and $5.25 billion in operating income at a 36.1% operating margin.4 Two consecutive years of margin compression on an unreplicable asset base point less to external competitive pressure than to operational execution challenges.
This dynamic highlights a central tension: CSX controls one of the most protected infrastructure franchises in North America, yet its operational execution has frequently lagged. Over the past decade, the company was targeted by an activist investor, overhauled by CEO Hunter Harrison, pivoted toward cultural repair under a former Ford executive, and then, in September 2025, placed under the leadership of an outsider from the industrial gas sector tasked with restoring profitability. Along the way, it fully wrote off the goodwill of a $550 million trucking acquisition held for four years.2
Meanwhile, sector dynamics shifted dramatically. On July 29, 2025, Union Pacific agreed to acquire Norfolk Southern — CSX’s primary eastern competitor — in an $85 billion transaction designed to create the first transcontinental railroad in the United States, spanning over 50,000 route miles across 43 states.5 If approved by regulators, the transaction would dismantle North America’s long-standing four-railroad Class I structure, leaving CSX as the largest US railroad without a transcontinental footprint.
The central question for investors is not whether CSX possesses an economic moat — its physical infrastructure guarantees one. Rather, it is how effectively management can translate that moat into consistent financial returns, and how a regional carrier will fare as the broader industry consolidates. The answer traces back to a charter signed in Baltimore in 1827, moves through one of the costliest rail integration failures in modern history, and culminates in a Jacksonville boardroom concluding in late 2025 that operational culture alone could not drive performance.
 Subscribe on LinkedIn
II. The Pre-History & The Conrail Legacy: Building the Eastern Duopoly (1827–1999) (45–55 min)
The inheritance
The Baltimore & Ohio was chartered in 1827 as America's first common-carrier railroad, and CSX still names it as the foundation of the enterprise in its annual filings.2 That lineage matters less as heritage than as a property claim: the corridors the B&O and its contemporaries surveyed through river valleys and mountain gaps are the corridors CSX runs trains on today, acquired when land was cheap, environmental reviews did not exist, and eminent domain was generous.
What followed was a century and a half of consolidation driven by financial distress rather than expansionary ambition. Trucking competition, the interstate highway system, and capped regulatory rates reduced eastern railroading to a prolonged period of insolvency. The surviving carriers clustered defensively: the B&O, Chesapeake & Ohio, and Western Maryland formed the Chessie System, while the Atlantic Coast Line, Seaboard Air Line, Louisville & Nashville, and Clinchfield merged into Seaboard Coast Line Industries. CSX Corporation was incorporated in Virginia in 1978, and in 1980 it completed the merger of those two holding companies — connecting northern population centers and Appalachian coal fields to the growing Southeast.2 The corporate name reflected that combination: C for Chessie, S for Seaboard, and X to represent the multiplication of the two networks.
That 1980 combination created a major coal railroad operating under a diversified corporate structure — a structural reality that explains much of the company's operational trajectory into the 2010s.
The prize nobody could split
The central asset of the modern network stemmed from a systemic failure. The 1970 bankruptcy of Penn Central — at the time the largest in U.S. history — threatened the entire northeastern rail network. Congress responded by nationalizing the bankrupt properties. Conrail was incorporated in Pennsylvania on February 10, 1976, and began operations that April, combining six insolvent railroads.6 Federal deregulation under the Staggers Rail Act of 1980 restored commercial viability, enabling the government to return Conrail to public ownership in 1987 through a $1.9 billion initial public offering, which was the largest in U.S. history at the time.6
By the mid-1990s, Conrail stood as the final unaligned carrier in the East, controlling essential access to the northeastern industrial market. Both CSX and Norfolk Southern recognized that acquiring Conrail was necessary for regional dominance. The resulting bidding war in 1996 and 1997 pushed valuation past pure standalone financial logic. Recognizing that a sole-winner outcome would leave the victorious bidder overleveraged and the loser structurally disadvantaged, both boards agreed in the spring of 1997 to acquire Conrail jointly for approximately $10.2 billion. Under the division plan, Norfolk Southern acquired 58% of the assets, primarily former Pennsylvania Railroad corridors, while CSX acquired 42%, gaining the former New York Central water-level route along the Hudson River and the Great Lakes.7
The Surface Transportation Board approved the transaction on July 23, 1998, with administrative control transferring that August.6 Mindful of the severe service disruptions that followed Union Pacific's 1996 acquisition of Southern Pacific in the Southwest, regulators instituted five years of operational oversight, capped reciprocal switching fees on former Conrail tracks at $250 per car, and mandated detailed operational reporting.7 Crucial shared industrial nodes that could not be divided — including northern New Jersey, the Philadelphia and southern New Jersey complex, and Detroit — were placed into a jointly owned switching entity covering roughly 1,200 route miles, which remains operational today.6
Falsification: the myth of instant synergy
The merger thesis relied on standard network economics: expanding scale, replacing multi-carrier interline moves with longer single-line hauls to capture freight from trucks, eliminating administrative overlap, and realizing projected cost synergies.
Operational execution diverged sharply from those modeling assumptions. When shared operations split on June 1, 1999, severe integration failures emerged. Information technology systems designed for single-carrier management failed to synchronize across separate operations. Freight cars were misplaced in data systems while sitting in switching yards, crew scheduling broke down, and major sorting terminals jammed under altered traffic flows. The operational paralysis mirrored the earlier Western rail crisis, prompting the Surface Transportation Board to extend its regulatory oversight period.7
The Conrail transaction was not a strategic error; CSX's annual disclosures continue to cite the acquisition as the structural link connecting New England and metropolitan New York with Chicago, the Midwest, and the Southeast.2 However, the operational record demonstrates a key principle of rail consolidation: network benefits accrue gradually over a decade, whereas integration costs and operational friction materialize immediately in year one. Underwriting rail mergers on rapid synergy capture overlooks this structural lag. That historical precedent carries direct relevance in 2026 as regulators evaluate the proposed transcontinental merger between Union Pacific and Norfolk Southern.
CSX secured a highly valuable eastern franchise, but inherited a substantial debt burden from the acquisition cost. For the subsequent decade, strong demand for a single bulk commodity would cushion the financial impact of lingering operational inefficiencies.
III. The Coal Era, Operational Stagnation & The $2B Revenue Collapse (2000–2016) (40–50 min)
The machine that ran itself
Certain businesses can unwittingly insulate management teams from operational rigor by performing too well. For CSX during the 2000s, coal served that exact role.
The economics of unit trains were straightforward. A train of more than one hundred identical hopper cars — loaded at a single mine, delivered directly to a single power plant, and returned empty — bypassed the core operational friction of railroading. It required no complex car classification, no mixed-commodity switching, and no customized service commitments. Appalachian coal moved to eastern utilities and export piers in Baltimore and Hampton Roads, Virginia, in a predictable pattern that functioned almost as an annuity for the rail network.
In 2011, coal generated $3.71 billion of CSX's $11.74 billion in total revenue — representing nearly a third of the top line at margins well above the corporate average.8 Under CEO Michael Ward, whose "CSX of Tomorrow" framework anchored investor communications, the company reported an operating ratio of 70.9% in 2011 and 70.6% in 2012.8 That meant that even during peak volume years for its most profitable commodity, CSX spent roughly 71 cents to generate each dollar of revenue. Rather than driving structural efficiency, the coal annuity masked underlying operational slack.
The floor gives way
Two structural disruptions hit the market simultaneously.
First, hydraulic fracturing sharply lowered the cost of natural gas, making gas-fired power generation cleaner and cheaper than coal across much of the eastern electric grid. Second, stricter federal environmental regulations accelerated the retirement of older coal-fired power plants. Because many of these facilities sat at the terminal end of dedicated CSX rail spurs with no dual-fuel capabilities, their closures caused freight traffic to vanish entirely rather than shift to competitors.
The financial impact was immediate. Coal revenue dropped from $3.71 billion in 2011 to $1.83 billion in 2016 — a reduction of approximately $1.9 billion, effectively cutting the coal franchise in half over five years.89 The quarterly contraction was equally sharp: in the first quarter of 2016, coal revenue stood at $399 million, down 37% from $638 million in the prior-year period as shipment volumes fell 31%.10
This downturn illustrated the severity of negative operating leverage on a high-fixed-cost asset base. Railroad infrastructure costs — maintaining track, signals, bridges, and yards — do not shrink proportionally when freight volumes fall. To protect cash flow, CSX reduced its average workforce from 32,139 employees in 2011 to 26,768 in 2016, eliminating roughly 5,400 positions.89 In 2016 alone, the company realized nearly $430 million in structural cost savings.9 Yet despite those reductions, the first-quarter 2016 operating ratio worsened to 73.1% from 72.2% a year earlier.10 For the full year 2016, the operating ratio settled at 69.4%, remaining virtually unchanged from the start of the decade.9 Five years of aggressive cost-cutting yielded little margin expansion because core coal revenue evaporated faster than expenses could be removed.
Falsification: cyclical, until it wasn't
This collapse challenged a persistent investment thesis: that CSX's regional network franchise provides inherent volume and pricing insulation across economic cycles.
During the initial downturn, management consistently framed the weakness as cyclical, pointing to low commodity prices, a strong U.S. dollar constraining export demand, unseasonably mild winters, and elevated utility stockpiles. In its first-quarter 2016 disclosure, CSX attributed the sharp decline to depressed natural gas prices, broader market oversupply, and reduced export competitiveness, warning investors that these headwinds would persist through the year.10 While those cyclical factors were factually accurate, they obscured a deeper structural shift: a permanent contraction of the coal market left a large rail network carrying fixed overhead for volume that would never recover.
Ultimately, the coal collapse disproved the thesis of absolute network resilience. CSX's high-fixed-cost model possesses limited downside volume elasticity, proving that incremental efficiency measures cannot fully offset the structural loss of a dominant, high-margin commodity block. While the network remains resilient during routine industrial cycles, it stays vulnerable to secular fuel substitution. Consequently, evaluating CSX requires analyzing commodity mix risks rather than relying solely on the presence of an economic moat.
By late 2016, CSX possessed an unreplicable physical franchise, an operating ratio hovering near mid-70s levels during weak quarters, a shrinking core market, and a shareholder base dissatisfied by a decade of stagnant returns. These conditions set the stage for an activist intervention.
IV. The Hunter Harrison Revolution: Precision Scheduled Railroading (2017) (50–60 min)
The man and the mechanism
E. Hunter Harrison began his career oiling journal boxes as a nineteen-year-old carman in a Memphis rail yard and rose to become one of the most influential operating executives in North American railroading. He had previously overhauled Illinois Central, Canadian National, and Canadian Pacific, repeatedly imposing a single operational doctrine despite entrenched internal resistance. By 2016, at age 72 and in declining health, he sought a final rail network to transform.
Paul Hilal, a former Pershing Square partner who had collaborated with Harrison during the Canadian Pacific campaign, formed an investment vehicle called Mantle Ridge specifically to target CSX. Hilal presented the CSX board with a straightforward ultimatum: install Harrison as chief executive, or face a public proxy contest.
CSX agreed to terms on March 6, 2017. Harrison became chief executive immediately, replacing Michael Ward. Mantle Ridge secured five board seats — designated for Harrison, Hilal, Dennis Reilley, Linda Riefler, and John Zillmer — expanding the board to 13 members, with Hilal serving as vice chairman.11 Harrison received options on nine million CSX shares, and the board agreed to submit for shareholder approval an $84 million reimbursement for compensation and benefits he forfeited by departing Canadian Pacific. Harrison stated he would resign if shareholders rejected the package.11 Shareholders ultimately approved the reimbursement.
Harrison's strategy targeted the traditional operating model of North American railroading. For decades, carriers operated on a hub-and-spoke system: freight cars accumulated in massive classification yards — including "hump" yards, where locomotives pushed cars over an artificial hill to let gravity sort them onto destination tracks — until a train was long enough to justify departure. While this approach prioritized asset utilization by ensuring full trains, it introduced severe transit delays. A single railcar could linger in multiple yards awaiting connecting trains, making arrival times unpredictable for freight customers.
Precision Scheduled Railroading (PSR) inverted those priorities. Under PSR, trains run on fixed, published schedules regardless of whether every car slot is filled. Freight is routed to minimize intermediate handlings rather than maximize train length. Hump yards, designed for complex sorting, are converted to simpler flat-switching facilities or closed entirely. Because buffer capacity in locomotives, railcars, and personnel exists primarily to absorb network unpredictability, a disciplined schedule renders that excess capacity redundant — allowing management to remove equipment and reduce headcount.
That cost reduction represented the core financial driver of the model, as well as its primary source of operational friction.
Nine months
Harrison implemented the model at unprecedented speed across the CSX footprint. Hundreds of locomotives were parked in storage lines, railcars were retired in bulk, and hump operations at major classification yards were disabled within days of announcement. The operational contraction directly affected headcount: CSX's average workforce dropped from 27,674 employees in 2016 to 25,230 in 2017 — a reduction of 2,444 positions in a single year — with further workforce reductions following as the operating plan matured.12
The financial results reacted quickly. In 2017, revenue grew 3 percent to $11.41 billion, while operating income rose 8 percent to $3.67 billion. The company's operating ratio improved to 67.9 percent from 69.4 percent in the prior year.12 Over the subsequent two years, the operating ratio dropped below 60 percent — an efficiency level unprecedented in CSX's history — prompting a substantial upward revaluation of its stock.
Harrison died on December 16, 2017, less than ten months after assuming the chief executive role, leaving successor Jim Foote to institutionalize the operational model.
Falsification: the summer the railroad stopped
A central assumption underpins how investors value North American Class I railroads: that Precision Scheduled Railroading delivers a permanently lower cost structure without compromising core commercial capabilities. The summer of 2017 provided an empirical test of that thesis.
During the summer of 2017, the CSX network experienced widespread operational disruption. Terminals backed up, transit delays surged, and industrial shippers — including chemical manufacturers, automotive assembly plants, and grain exporters — were forced to curtail production due to missed railcar deliveries. In response to mounting industry complaints, the Surface Transportation Board opened a formal docket, EP 742, to monitor CSX's service failures and convened a public listening session in Washington on October 11, 2017, where Harrison appeared alongside senior operating leadership.13
The public hearing transcript documented the tension between executive assertions and operational reality. Harrison opened his testimony by contending that "the railroad is back running better than it ever has," while acknowledging in the same breath that there were "some things that I'm not so proud of."14 When asked what he would have done differently during implementation, Harrison pointed not to equipment cuts or yard closures, but to the political pressure surrounding his appointment, observing, "in hindsight I wouldn't have gone from a" — pausing to explain that it was difficult to separate the service disruptions from the contentious proxy battle where each side was publicly arguing the other's candidate was unfit.14 His testimony revealed that the pace of operational restructuring was driven in part by political urgency to demonstrate immediate progress to investors.
Regulatory performance data aligned with shipper testimony rather than executive assurances. By year-end 2017, after the acute service crisis had subsided, average train velocity stood at 15.1 miles per hour compared to 14.9 miles per hour a year earlier, while average terminal dwell time registered 11.3 hours versus 11.4 hours — essentially unchanged.12 The margin expansion achieved in 2017 stemmed almost entirely from resource elimination rather than velocity improvements across the network.
These results clarify the limits of the initial PSR thesis. While PSR generated a genuine, lasting reduction in CSX's structural cost base — evidenced by sub-60 percent operating ratios from 2019 through 2022 — it achieved those gains by stripping out operational buffer capacity, exposing the network to immediate vulnerability. A more precise takeaway is that PSR lowers unit costs by trading away systemic resilience, a trade-off that remains sustainable only if management reinvests a portion of capital savings back into network buffers. The essential test for investors is whether margin expansion and service reliability can advance in tandem or remain inversely linked — an analytical framework that proved central to evaluating CSX's position by 2026.
V. The Post-Harrison Era: From "Cost-Cutting" to "ONE CSX" under Joe Hinrichs (2018–2025) (45–55 min)
Foote's consolidation, and the bill for it
Jim Foote inherited a half-finished operational revolution and an organization shaped by years of aggressive workforce reductions. His contribution was less dramatic but structurally significant: institutionalizing Precision Scheduled Railroading across the network. Through 2018 and 2019, CSX's operating ratio settled below 60 percent. But when the pandemic disrupted global supply chains, cratering freight demand before triggering a rapid rebound, the broader rail sector faced the consequences of its lean staffing. Having reduced crew headcount over the preceding three years, Class I carriers lacked the capacity to handle returning volume. Service deteriorated across the industry, drawing sharp criticism from federal regulators and shippers alike.
By 2021, CSX recorded an operating ratio of 55.3 percent—the most efficient mark in its corporate history. By 2022, however, that ratio retreated to 59.5 percent as inflation pressured fuel, labor, and purchased service costs, while property sale gains normalized.15 That reversal served as an early indicator that peak PSR efficiency was less a permanent plateau than a high-water mark achieved under exceptionally favorable market conditions.
The operational and human costs culminated in late 2022. National rail labor negotiations, governed by the Railway Labor Act framework under which contracts remain active until amended, deadlocked over rigid attendance policies introduced during the PSR rollout—policies that penalized engineers and conductors for taking time off for medical appointments. The dispute neared a nationwide rail strike before Congress intervened to enforce a settlement, exposing severe friction in labor relations that the industry had long characterized to investors as stable.
The Ford man
In September 2022, CSX appointed Joe Hinrichs as president and chief executive officer. Hinrichs was an unconventional choice for a Class I carrier: a veteran automotive executive who had previously served as president of Ford Motor Company's global automotive business, but possessed no prior railroad operating experience. The board's selection reflected a strategic shift—concluding that CSX's primary operational bottleneck was no longer rail operations expertise, but a damaged workforce culture and labor attrition.
Hinrichs launched a cultural initiative branded "ONE CSX," prioritizing frontline engagement over pure headcount reduction. He spent time in yards and locomotive cabs, restructured frontline supervisor workflows, and addressed workforce grievances directly. Most notably, CSX broke from industry peers by becoming the first Class I carrier to reach paid sick leave agreements with its rail unions through 2023, eventually extending coverage to the vast majority of its craft workforce.16 For an organization where employees had spent six years being treated as a cost line, the policy marked a meaningful shift.
The strategy yielded early commercial and operational improvements. Service metrics stabilized, customer satisfaction ratings rebounded, and the network demonstrated operational resilience in 2024. Despite facing major external disruptions—including two severe hurricanes and the temporary closure of the Port of Baltimore following the Key Bridge collapse—CSX maintained total revenue at $14.54 billion while delivering a 36.1 percent operating margin, a result management emphasized on its fourth-quarter call as evidence of network resilience and industry-leading customer satisfaction.4
Falsification: culture is a necessary condition, not a sufficient one
Management's core thesis held that improved workforce morale and higher service reliability would translate directly into market share gains, volume growth, and expanding operating margins.
Financial performance through 2025 disproved that assumption. As operational culture stabilized, underlying financial metrics deteriorated. Operating margin fell from 36.1 percent in 2024 to 32.1 percent in 2025, with reported operating income declining from $5.25 billion to $4.52 billion on revenue that also fell.34 Free cash flow before dividends dropped by $995 million year over year to $1.8 billion.2 Return on invested capital—a metric the incoming leadership would highlight as a primary gauge of capital efficiency—declined as operating income contracted against a flat asset base and rising debt levels.
The financial decline prompted activist intervention. On August 6, 2025, Ancora Holdings issued a public letter to CSX's independent directors, criticizing Hinrichs's leadership and citing an operating ratio that had expanded from roughly 58 percent in 2022 to approximately 67 percent, while arguing that leadership had focused more on social media visibility than operational strategy.17 Ancora's primary demand was structural: urging CSX to explore a potential merger and engage both Canadian Pacific Kansas City and BNSF so as not to negotiate from a position of weakness with a single buyer.17 Although Ancora held a modest stake of roughly $72 million—representing approximately 0.1 percent of outstanding shares—its campaign resonated with broader shareholder dissatisfaction over margin compression.
Seven weeks after Ancora's letter, Hinrichs stepped down. He separated from employment on September 27, 2025, under circumstances that proxy disclosures treated as an involuntary separation, triggering severance benefits that brought his total 2025 compensation to $23.7 million, including an $8.25 million lump-sum severance payment.18
The ultimate evaluation of the cultural initiative reveals clear structural limits. While improving labor relations did not harm performance—and in fact defused acute labor risks while lifting safety and service metrics—it proved insufficient to drive pricing power, structural cost discipline, or top-line volume growth. Workforce satisfaction functioned as a necessary baseline rather than a standalone growth catalyst: its absence caused operational dysfunction, but its presence alone could not deliver margin expansion. Recognizing those limits, the board shifted focus back toward disciplined operational execution.
VI. The 2025 Leadership Reset: Steve Angel & The New Mandate (2025–Present) (35–45 min)
An outsider who wasn't
The CSX board appointed Stephen F. Angel president and chief executive effective September 28, 2025.19 On paper he was an odd fit — a man who had spent two decades in industrial gases, not freight. On his first earnings call three weeks later, he immediately reframed that.
His career, he told analysts, began at General Electric working directly with locomotives and rail operations, and the interest never faded. More usefully, he drew an analogy that does real analytical work. At Linde, he said, the strategy was to build network density in targeted geographies, because that is how a capital-intensive business leverages infrastructure into higher returns on capital. "I think of pipelines and railway track the same way," he said — whoever owns the pipelines, provided they are in the right locations, holds a structural advantage.20
The relevant biography is this. Angel ran Praxair for a decade before merging it with Linde AG, then ran the combined company. Industrial gases is one of the few businesses in the world with an economic structure genuinely similar to railroading: enormous fixed assets, physical delivery networks with local monopolies, customers who are effectively captive once a pipeline or an on-site plant is built, and a business model that lives or dies on price realization and capital discipline rather than on volume growth. Angel spent twenty years running exactly that playbook, and by most industry accounts ran it better than anyone.
He is also, notably, patient. Asked on that first call whether the board had hired him to do a merger, he did not deny the possibility — he redirected it. He had run Praxair for ten years before concluding the Linde combination, he said; the way these things work is that you wait for the right timing and the right conditions, and in the interim you run the company as well as you can, so that "if and when that time comes, you are going into that discussion from a position of strength."20
The first hundred days told you what he cared about
Three moves in his first four months defined the regime.
First, the team. On October 29, 2025, Kevin Boone — who had been chief commercial officer and had previously served as CFO through the pandemic — was moved back into the CFO chair, replacing Sean Pelkey, who departed with no reason disclosed. Maryclare Kenney, a fourteen-year CSX veteran who had been a captain in the U.S. Army before commercial roles at PepsiCo, was promoted to chief commercial officer.21 Mike Cory, a forty-year railroader, stayed as chief operating officer. Note the shape of it: Angel did not import outsiders. He rearranged insiders and put a former investor — Boone spent nearly two decades in the investment industry before joining CSX in 2017 — in charge of the money.
Second, the targets. On the fourth-quarter call in January 2026, Angel withdrew the multi-year 2025–2027 targets that had been issued at the company's 2024 investor day, stating plainly: "I am replacing our 2025-2027 targets with the guidance we've given for 2026 only," on the grounds that the macro environment and industry dynamics had changed materially.22 Investors should read that two ways at once. It is a credibility-preserving move — abandoning targets you will miss is better than defending them — and it is also an admission that the prior regime's framework had detached from reality. Pressed on whether he would offer a long-term algorithm, Angel said nothing was fundamentally broken that would prevent it; he simply wanted to demonstrate execution over several quarters first.22 That is a defensible posture, but it does mean that as of today there is no published multi-year commitment against which management can be held.
Third, the incentives. The 2025 annual plan CSX operated under weighted financial goals at 70% — operating income 30%, operating margin 30%, initiative-based revenue growth 10% — with the remaining 30% split across FRA personal injury rate, train accident rate, trip plan compliance and fuel efficiency; the 2023–2025 long-term plan ran on operating income growth and economic profit, modified by relative total shareholder return, which paid out at a 0.79x modifier.23 Angel has been explicit about where he wants that to go. Asked directly about incentive design, he named operating margin, operating income and safety as the annual metrics that matter, and for the long term he was categorical: "return on capital is the truth serum" for a capital-intensive industry, because it encapsulates every past and present capital decision.20 He repeated the point on the first-quarter 2026 call, adding a specific mechanism — that the way to raise ROIC is to drive the numerator through margin and operating income, while being "more prudent" on the denominator, with every capital project now required to stand on its own and be individually tracked.24
His own pay was structured to match. Angel's package set a $1.5 million base salary with a 175% target bonus and a $10 million sign-on long-term award split evenly between performance units under the 2025–2027 plan and stock options cliff-vesting after three years with a seven-year term; his 2025 reported compensation of $11.7 million was almost entirely equity for roughly three months of service.1823 An investor should note both halves of that: the structure is genuinely weighted to multi-year outcomes, and the absolute quantum for a partial year was large.
What to watch, honestly
The bull framing writes itself: a proven capital allocator inherits an under-earning monopoly asset. The skeptic's version is that CSX has now hired three consecutive chief executives on the theory that the previous one lacked the missing ingredient — operating rigor in 2017, cultural repair in 2022, pricing and capital discipline in 2025 — and that the underlying business has produced a materially lower margin in each of the last two years regardless. Angel's own framework offers the cleanest test available, and it is his: does return on invested capital rise, and does it rise for reasons other than a cyclical upswing in freight? That question cannot be answered from one good year. It can only be answered from the composition of the improvement — which means understanding where CSX's money actually comes from.
VII. The Business Model & Segment Anatomy: Where the Cash Flow Comes From (45–55 min)
The shape of the revenue
Strip away the corporate language and CSX sells one thing: the cheapest way to move heavy objects long distances overland. A train moving a ton of freight burns roughly a quarter of the diesel a truck does over the same distance. That single physical fact is the entire commercial proposition, and everything else — service reliability, terminal density, pricing — determines how much of that efficiency advantage CSX gets to keep versus how much it hands to the customer.
The revenue splits four ways. Merchandise, at roughly $8.8 billion in 2025, is about 64% of the company. Intermodal is roughly $2.1 billion, coal roughly $1.9 billion, and trucking roughly $0.8 billion.25 Understanding why those four behave completely differently is the whole game.
Merchandise is not one business but seven, and its diversity is a feature. In the second quarter of 2026 it comprised chemicals at $774 million, agricultural and food products at $444 million, automotive at $332 million, forest products at $266 million, metals and equipment at $256 million, minerals at $242 million, and fertilizers at $132 million.26 These are the carload movements — plastic pellets from a Gulf Coast producer, rebar to a construction site, salt, cement, finished vehicles, wood pulp. Many of these customers are physically connected to CSX track and to nothing else, which is where the company's genuine pricing power lives. But it is also where the cyclicality lives: automotive volumes track North American light vehicle production, forest products track housing starts, and chemicals track global petrochemical spreads. In the first quarter of 2026, with housing affordability poor and a large auto plant on the network down for extended retooling, merchandise volume was flat year over year while intermodal grew 6%.24
Intermodal is the truck-competitive business: containers and trailers moved on flatcars, handed off to trucks for the first and last miles. Margins per unit are structurally lower than merchandise — the customer always has the option to just drive it — but this is where incremental volume comes from. It is also where CSX has spent its capital. The Howard Street Tunnel in Baltimore, a 1.7-mile bore under the downtown that was too low for double-stacked containers, was reconstructed at a cost of more than $450 million and reopened in 2025.27 The commercial consequence, as Kenney described it, is that it roughly doubles capacity on both the east-west corridor into Baltimore and the I-95 corridor, removes about a day of transit, and — most importantly — makes lanes economic that CSX simply could not serve efficiently before, such as Atlanta into Philadelphia and northern New Jersey.24
Coal is now roughly 14% of revenue and splits into two genuinely different businesses. Domestic utility coal has stabilized and even improved, helped by electricity demand from data centers and by natural gas prices high enough to make coal generation competitive again; several plant retirements on CSX's network have been deferred.24 Export metallurgical coal, sold to steelmakers abroad, is a price-taker on global benchmarks and swings hundreds of millions of dollars a year on those benchmarks alone. Investors should resist reading either as a trend. Coal is now small enough not to determine CSX's fate and volatile enough to obscure the underlying picture in any single quarter.
Trucking is Quality Carriers, the bulk liquid chemicals hauler CSX bought in 2021. It generated $226 million in the second quarter of 2026, up 7%.26 Its economics are ordinary trucking economics, which is to say vastly worse than railroading. CSX does not even disclose it as a separate reportable segment, stating in its 10-K that the trucking segment is not material for separate disclosure.2 More on what it cost shortly.
Reading the 2026 numbers honestly
The first half of 2026 was, on the reported figures, very strong. First-quarter revenue rose 2% to $3.48 billion while operating income rose 20% to $1.25 billion, lifting operating margin to 35.9%.28 The second quarter was better still: record revenue of $3.94 billion, up 10%; operating income up 17% to $1.51 billion; margin up 240 basis points to 38.3%; earnings per share up 23% to $0.54; volume up 6%.2629 Guidance was raised twice — from low single-digit revenue growth and 200–300 basis points of margin expansion in January, to mid-single-digit revenue and the high end of that margin range in April, to mid-to-high single-digit revenue, more than 350 basis points of margin expansion and free cash flow growth above 80% in July.222430
Now the composition, which matters more than the headline. A large share of the revenue increase was fuel surcharge recovery, not underlying price: locomotive fuel prices rose sharply following Middle East conflict, adding $177 million to second-quarter fuel expense, and management was explicit that higher diesel inflates both revenue and cost while pressuring reported margin.2426 Excluding fuel, total revenue per unit actually declined 1% in the second quarter on mix, because intermodal — the lower-yield business — grew at more than double the rate of everything else.30 Merchandise revenue per unit excluding fuel was up only 1%.30 Meanwhile roughly $93 million of first-half operating income came from property gains that management confirmed will not repeat at that scale.2430
And then there is the item nobody wants to lead with. Average employment fell from 23,510 to 22,167 year over year in the second quarter, down about 5.7%.26 Non-fuel expense declined 2% while volume grew 6%.30 That is an impressive productivity outcome — and it came with carload trip plan compliance falling to 71% from 75% and terminal dwell lengthening to 11.0 hours from 10.4, even as train velocity improved to 18.0 mph from 17.5.26 Chief operating officer Mike Cory addressed it directly on the call, attributing the shortfall to demand arriving far above plan while crews were tight during the summer vacation period, insisting "it's not a structural service issue," and committing to a modest increase in train-and-engine headcount plus sequential improvement.30
That is the 2017 test, restated in 2026 language: margin and service moving in opposite directions. The difference this time is scale — a four-point drop in trip plan compliance is not a network meltdown — and the difference is candour, in that management named it rather than being told about it by the regulator. But it is the same trade, and it is the single most important thing to watch over the next three quarters. Which brings us to the harder question about this company: whether the capital it deploys outside the core network has ever earned its keep.
VIII. M&A Strategy & Capital Deployment: Conrail, Quality Carriers & Pan Am (35–45 min)
Three deals, three verdicts
CSX's acquisition record over thirty years is small in count and instructive in outcome.
Conrail remains the defining transaction, though the verdict depends on the timeframe. CSX's roughly 42% share of the $10.2 billion joint purchase was expensive by any contemporaneous metric, driven by a bidding war rather than a strict valuation exercise.7 Integration problems disrupted operations and eroded value for at least two years. Yet a quarter-century later, those acquired corridors provide CSX's primary access to New England and metropolitan New York, and annual disclosures still cite them as foundational.2 The reality is that CSX overpaid for an asset it could not afford to yield to a rival, with the deal ultimately saved by long-term strategic necessity rather than seamless execution. That outcome offers a case study in what happens when strategic necessity intersects with a competitive auction, rather than a repeatable M&A blueprint.
Quality Carriers presents a more troubling record for investors. CSX completed the acquisition on July 1, 2021, for approximately $550 million, purchasing North America's largest bulk liquid chemicals trucking network—comprising roughly 2,500 tractors and 6,400 trailers—from Quality Distribution.31 The strategic rationale appeared sound: chemical shippers require first- and last-mile tank truck transportation, and management posited that owning those assets would enable CSX to convert highway freight onto its rail network.
Instead, the deal served as a clear test of capital allocation logic. A prolonged downturn in the trucking sector compressed operating margins. CSX recorded a $108 million goodwill impairment in its trucking segment in 2024, followed by an additional $164 million impairment in the third quarter of 2025. As stated in the company's 2025 annual report, all goodwill associated with the purchase was fully written off as of September 30, 2025.232 Four years after the acquisition, the entire premium was wiped out, leaving the business too small to qualify for separate segment reporting in financial disclosures.2
That outcome highlights a stark contrast between management narrative and financial accounting. On the third-quarter 2025 earnings call, then-Chief Financial Officer Sean Pelkey asserted that Quality Carriers had "helped drive truck to rail conversions, maintained industry leading share and stable pricing across its end markets," while describing cost-reduction efforts designed to "fully capture the upside when the trucking market recovers."20 While operational conversions may have occurred, that narrative sits uncomfortably alongside a complete goodwill write-off recorded in that same quarter. CSX purchased a cyclical asset at the top of the market, leaving financial returns dictated by broader freight conditions rather than cross-modal synergies. Consequently, any assertion that Quality Carriers serves as a structural growth engine must be weighed against its underlying profitability and return on invested capital—metrics CSX does not separately disclose.
Pan Am Railways presents a far stronger operational outcome. CSX closed its acquisition of Pan Am on June 1, 2022, for approximately $600 million, structured as $422 million in common stock and $178 million in cash, which included a $30 million deposit submitted in late 2020.33 The transaction added about 1,200 route miles across northern New England, granting CSX direct access to regional shippers previously reached only through interline exchanges. Annual filings explicitly highlight this territory as integral to serving every major eastern market.2 Two factors separated Pan Am from Quality Carriers: CSX acquired core rail infrastructure with protected right-of-way rather than an unmooted trucking fleet, and funding a majority of the purchase with equity shared valuation risk with the seller.
The historical pattern is clear. When CSX acquires rail infrastructure, long-term network benefits generally materialize. When it acquires adjacent transportation businesses lacking rail's structural moat, capital has been impaired. That distinction offers an essential framework for evaluating capital allocation as consolidation speculation surrounds the company in 2026.
The capital allocation machine
CSX's broader capital allocation strategy has proven far more consequential over the past decade than its discrete corporate acquisitions.
The company invested $2.90 billion in capital expenditures in 2025, up from $2.53 billion in 2024, driven by major infrastructure commitments including the Blue Ridge corridor restoration and the Howard Street Tunnel clearance expansion.2 Following the completion of those projects, Chief Executive Steve Angel set full-year 2026 capital spending guidance below $2.4 billion, maintaining that ceiling despite two upward revisions to revenue expectations.2230 Whether management preserves that capital discipline as freight traffic expands remains a key test. Chief Operating Officer Mike Cory noted that the core network can absorb additional volume without major structural expansions, while outlining targeted investments in power switches at Cincinnati and Nashville along with siding extensions on southern corridors to relieve localized bottlenecks.24
Capital deployment toward shareholder returns warrants critical examination. In 2025, CSX repurchased $1.4 billion in common stock and distributed $972 million in dividends, returning a total of $2.37 billion to shareholders against free cash flow before dividends of $1.79 billion.2 Management bridged that $580 million shortfall in part by issuing $900 million in new long-term debt, which increased total long-term debt, including current maturities, to $18.87 billion from $18.50 billion.2 Concurrently, the board raised the quarterly dividend to $0.13 per share in March 2025, marking the company's twenty-first consecutive annual dividend increase.2
This capital distribution highlights a dual reality. On one hand, share repurchases have substantially reduced share count over the long term, with diluted shares outstanding falling from approximately 2.84 billion in 2016 to 1.86 billion in 2025—a reduction of nearly one-third. On the other hand, during 2025 CSX returned more capital to shareholders than its operations generated, funding the deficit with incremental leverage during a year when operating income contracted. While leveraging an investment-grade railroad franchise to support capital returns is common industry practice, it increases financial vulnerability if operating margins fail to expand. Steve Angel's focus on return on invested capital as management's primary benchmark directly challenges this practice, as debt-financed buybacks boost earnings per share while diluting overall return on capital.
Ultimately, CSX's capital allocation strategy relies less on transformative M&A than on ongoing network reinvestment and aggressive capital distribution. The business model dedicates roughly 15 to 20 percent of annual revenue toward maintaining its physical franchise, returning the majority of remaining cash flow to investors. The central question for the enterprise is how effectively this capital strategy will perform against a rapidly shifting competitive landscape across the eastern rail corridor.
IX. Industry Structure & Competitive Dynamics: The Eastern Railroad Duopoly (35–45 min)
The map, and what just happened to it
For a quarter-century following the 1999 Conrail division, North American freight rail maintained a stable market structure: two Class I carriers in the East, two larger networks in the West, and two Canadian railroads extending south into the United States. CSX and Norfolk Southern divided eastern territory east of the Mississippi with comparable route miles. Union Pacific and BNSF Railway — a subsidiary of Berkshire Hathaway — controlled the West with networks roughly 50 percent larger. Canadian National and Canadian Pacific Kansas City (CPKC) operated north-south corridors, with CPKC’s 2023 acquisition of Kansas City Southern establishing single-line service connecting Canada, the United States, and Mexico. Coast-to-coast freight required interline transfers between eastern and western carriers, primarily through Chicago, creating long-standing terminal congestion in the Midwest logistics hub.
CSX and Norfolk Southern operate under a mix of rivalry and shared infrastructure. The two carriers jointly own the switching entity carved out of Conrail in dense industrial zones and interchange traffic continuously. Annual filings identify Norfolk Southern as CSX's primary rail competitor while noting that competitive pressure varies by commodity and geography and includes motor carriers, barges, ships, and pipelines.2
That regional framework shifted on July 29, 2025, when Union Pacific agreed to acquire Norfolk Southern for $320 per share — structured as one Union Pacific share plus $88.82 in cash — representing an enterprise value of $85 billion. The proposed transaction would create a single carrier operating over 50,000 route miles across 43 states, with management projecting $2.75 billion in annualized synergies and targeting closure in early 2027.5
The proposed combination poses a direct structural threat to CSX's commercial footprint. Key shippers, particularly in intermodal and automotive freight, would gain access to a unified competitor providing single-line service from West Coast ports directly to Southeastern hubs without an interline handoff in Chicago. CSX's 10-K filing addresses the transaction in its competition disclosures and warns in its risk factors that proposed or future rail industry consolidation could materially alter the regulatory and competitive environment.2
Two responses, and what they reveal
CSX responded to the transaction through both commercial partnerships and regulatory proceedings.
The commercial response materialized rapidly. On August 22, 2025 — three weeks after the merger announcement — CSX and BNSF Railway announced joint intermodal services. The agreement established direct coast-to-coast domestic lanes from Southern California to Charlotte and Jacksonville, a Phoenix-to-Atlanta route targeted at capturing highway truck volume, and international services connecting the Port of New York and New Jersey and the Port of Norfolk to Kansas City, supported by BNSF's investment in two 10,000-foot passing sidings between Phoenix and Flagstaff.34 Because joint marketing agreements do not require Surface Transportation Board approval, the partnership took effect immediately. CSX expanded this strategy through its SMX service with CPKC, connecting the Southeast to Dallas and Mexico; Chief Commercial Officer Maryclare Kenney stated that the partnership added approximately two percentage points to domestic intermodal growth by mid-2026 as management evaluated additional corridors.30
Addressing the shift in inter-railroad coordination, Chief Executive Steve Angel noted on an earnings call that he had not witnessed this level of cross-network cooperation historically, observing that peer executives were regularly meeting at CSX headquarters to focus on capturing freight from highway trucking.20 Whether these voluntary commercial alliances remain durable if the proposed Union Pacific combination is approved or rejected remains an open question for investors.
The regulatory track followed a formal, multi-stage review before the Surface Transportation Board. CSX joined rival carriers in challenging the completeness of Union Pacific’s merger application while launching a public portal for shippers and communities participating in the proceedings. Union Pacific and Norfolk Southern submitted their joint application on December 19, 2025, which the Board rejected as incomplete on January 16, 2026. The applicants filed a revised application on April 30, 2026, which the Board accepted as complete effective May 28, 2026. However, the regulator simultaneously placed the proceeding and environmental review in abeyance, ordering supplemental information across nine areas — including market competition, shipper access, freight diversion, service assurance, gateway access, car supply, market share projections, and downstream merger impacts.35 The applicants submitted their supplemental responses on July 27, 2026, after which the Board announced it would establish a procedural schedule, conduct a full Environmental Impact Statement, and hold at least twelve public hearings.35
The Board’s explicit inquiry into downstream merger effects highlights the broader regulatory stakes for unaligned carriers like CSX and BNSF. This scrutiny leaves three primary regulatory outcomes for the industry: full approval with trackage rights or switching conditions, an outright rejection of the transcontinental combination, or an approval structured in a manner that pressures remaining Class I carriers toward a responsive consolidation.
The competitor that never sleeps
Beyond Class I merger dynamics, long-haul motor carriers represent CSX’s primary day-to-day competitive benchmark. On short-haul routes under a few hundred miles, trucking offers superior dispatch flexibility and transit speed that rail cannot match. On corridors exceeding 500 to 700 miles, rail’s fuel efficiency offsets its transit-time penalty. The economic boundary between rail and highway transport fluctuates with diesel prices and motor carrier capacity. In mid-2026, tightening truck supply — driven in part by stricter regulatory enforcement removing non-compliant carriers — combined with elevated diesel costs to drive highway freight conversions to CSX, particularly in forest products, waste, and metals.30 Chief Commercial Officer Maryclare Kenney noted that yield expansion from highway conversions requires time to materialize, adding that international intermodal volume — dominated by long-term ocean carrier contracts — remains largely unlinked to spot truck market conditions.30
This competitive dynamic underscores CSX's operational footprint: highly defensive where rail network physics and captive geography preserve pricing power, price-sensitive where truck competition is viable, and now exposed to an industry-wide consolidation phase that management cannot directly control. This structural backdrop provides the framework for assessing the durability of CSX's economic moat.
X. 7 Powers & Porter's 5 Forces: Evaluating the CSX Moat (30–40 min)
Where the power actually comes from
Hamilton Helmer's framework asks a specific question: what makes a competitor's attempt to take your customers unprofitable? For CSX, three of the seven powers apply, and only one is genuinely unassailable.
Cornered resource is the primary power. The rights-of-way, terminal footprints, port connections, and tunnel clearances assembled since 1827 cannot be reproduced. The Howard Street Tunnel illustrates the point: rebuilding an existing 1.7-mile bore under downtown Baltimore to fit double-stacked containers required years and more than $450 million while rerouting 16 to 20 trains per day.27 Assembling new land and rights-of-way for a competing corridor in the modern regulatory environment is virtually impossible. Consequently, the threat of new rail entrants in this market is effectively zero.
Scale economies apply, though with an important qualification. A single freight train operated by a two-person crew can move thousands of tons, spreading the fixed costs of track maintenance across total gross ton-miles. CSX's operational metrics demonstrate this efficiency: fuel consumption improved to 0.94 gallons per thousand gross ton-miles in the second quarter of 2026 from 0.98 a year earlier, alongside a sixth consecutive quarter of efficiency gains in gross ton-miles generated per unit of locomotive horsepower.2630 However, CSX's scale advantage exists primarily relative to motor carriers rather than Norfolk Southern, which operates a network of comparable scale across the same eastern footprint. Scale economies differentiate rail transport from highway trucking rather than separating CSX from its primary rail competitor.
Switching costs are tangible but narrower than often assumed. Industrial facilities—such as chemical plants, paper mills, or aggregate quarries—built with a single track spur connected to CSX are physically captive, as routing freight to a rival rail carrier would require building non-existent trackage. However, a significant portion of CSX's freight volume lacks this lock-in. Intermodal shippers can switch traffic to Norfolk Southern or back to highway trucking during annual contract negotiations, while dual-served industrial customers routinely leverage competition. Furthermore, CSX's disclosures reveal that only about half of its contract portfolio can be repriced in any given year, indicating that price realization occurs gradually even where pricing power exists.24
Notably absent from the framework are branding, software-style network effects, counter-positioning, and process power. CSX possesses no meaningful brand pricing power with commercial shippers, who select freight modes primarily on rate and transit reliability. Meanwhile, the core operating doctrine of modern railroading—Precision Scheduled Railroading—has been adopted across the industry, eliminating process power as a durable source of relative advantage.
Porter, applied without flattery
Threat of new entrants is effectively zero due to prohibitive capital requirements, land acquisition barriers, and environmental permitting constraints. This represents the strongest structural barrier protecting the franchise.
Supplier power is high and expanding. Approximately 16,900 of CSX's 23,000 employees are unionized under agreements governed by the Railway Labor Act, where contracts remain active until amended rather than expiring on fixed dates.2 Consequently, labor cost increases occur on an industry-wide timeline rather than an individual corporate schedule. For example, a 3.75 percent union wage increase took effect on July 1, 2026, driving labor cost growth above non-labor inflation as CSX guided toward overall cost inflation between 3 percent and 3.5 percent.2230 Equipment supplier concentration is similarly high, with locomotives and core rail components supplied by a small oligopoly of manufacturers.
Buyer power is mixed across commodity classes. Captive carload shippers possess minimal leverage, serving as the primary source of CSX's price realization. Conversely, intermodal customers exercise substantial leverage; excluding fuel surcharges, intermodal revenue per unit has pressured overall yield growth because intermodal represents the primary segment where top-line volume expansion occurs.30
Substitutes present a persistent threat. Motor carriers compete directly on short- and medium-haul routes, pipelines transport liquid energy commodities, and barges handle bulk freight along river corridors. Over a longer horizon, technological advancements pose additional structural risks: commercial deployment of autonomous or automated trucking could reduce highway freight costs, compressing rail's economic advantage on medium-haul lanes. CSX explicitly identifies this risk in its regulatory filings, noting that advances in alternative transport modes—"such as through the use of automation, autonomy or electrification"—or statutory increases in truck size and weight limits could adversely affect its competitive position.2 While not an immediate operational driver, technological substitution represents a long-term risk to terminal valuation.
Rivalry has historically remained rational, though that stability is now contingent. CSX and Norfolk Southern have traditionally competed on service quality rather than aggressive price discounting. However, Union Pacific's proposed acquisition of Norfolk Southern introduces a major catalyst that could alter established duopoly norms—either by creating a transcontinental competitor with broader routing options or by triggering further Class I consolidation.
In summary, CSX's economic moat is exceptionally durable because its core physical assets cannot be replicated, yet porous because a substantial share of its freight volume remains contestable. The business operates with a high structural floor and a constrained ceiling on pricing power. As a result, long-term financial returns depend far more on disciplined cost control and capital allocation than on widening its competitive moat—validating the core operational focus of current management.
XI. The Activist & Skeptical Investor Stress Test: Thesis Claims vs. Historical Falsification (40–50 min)
Four core claims underpin the CSX investment case. Each requires testing against the strongest disconfirming evidence in the company's operational record, yielding a clear analytical verdict rather than an ambiguous compromise.
Claim one: CSX possesses an unassailable pricing monopoly over industrial freight
The disconfirming evidence is subtle, which makes it all the more persuasive. Through the soft industrial environment of 2023 through 2025, CSX did not translate its captive market position into margin expansion; instead, it delivered two consecutive years of margin contraction as volumes stagnated.34 Corporate disclosures constrain the pricing mechanism in two key ways: only about half of the contract book reprices annually, and international intermodal volume is concentrated among a few customers under long-term agreements largely unlinked to truck spot rates.2430 In the second quarter of 2026, despite a 6 percent volume increase and tightening truck capacity, total revenue per unit excluding fuel fell 1 percent due to segment mix.30 Regulatory scrutiny adds further pressure, as the Surface Transportation Board's focus on reciprocal switching ensures that where a shipper holds a viable alternative route, pricing power remains constrained.
Verdict: narrowed, materially. The pricing monopoly is real for physically captive shippers on long hauls where trucking is uneconomic. It does not hold for intermodal freight, dual-served customers, or short-haul routes — the very segments where top-line volume growth occurs. The falsifying metric to watch is merchandise same-store pricing relative to rail cost inflation. Management publicly committed that same-store pricing in 2026 would exceed 2025 levels, a point Chief Commercial Officer Maryclare Kenney reaffirmed twice under direct questioning while declining to specify figures.2430 If merchandise revenue per unit excluding fuel fails to accelerate through 2027 as contracts reprice into a tighter truck market, the pricing thesis must be discounted further.
Claim two: PSR generates a permanently low operating ratio without service decay
This claim was tested in 2017 and failed. What makes the issue relevant again is that 2026 data are testing it on a smaller scale under new leadership. In the second quarter of 2026, CSX delivered 240 basis points of margin expansion while average headcount fell 5.7 percent — yet carload trip plan compliance dropped from 75 percent to 71 percent as terminal dwell lengthened.26 Management attributed the shortfall to higher-than-expected demand during peak summer crew vacations and outlined a targeted response: modestly increasing train-and-engine headcount, with Chief Operating Officer Mike Cory stating he would not overcorrect and sacrifice earned productivity gains.30
Verdict: rejected in its strong form; the narrow version stands. Precision Scheduled Railroading permanently lowered CSX's structural unit costs — as evidenced by sub-60 percent operating ratios from 2019 through 2022, peaking at a corporate record 55.3 percent in 2021.15 However, the model did not eliminate the trade-off between lean staffing and service reliability; it sharpened it. The falsifying event to watch is trip plan compliance and dwell performance over the next two quarters. If service metrics recover to prior-year levels while margin gains hold, management's productivity thesis will be validated. If margins hold while service quality erodes, CSX will once again be converting operational reliability into short-term earnings, reviving the 2017 cycle of customer frustration, regulatory intervention, and costly operational recovery.
Claim three: multimodal M&A creates high-return cross-selling synergies
Accounting results have already settled this claim. The complete write-off of Quality Carriers' goodwill by September 30, 2025 — consisting of a $108 million impairment in 2024 and an additional $164 million in 2025 against a purchase price of approximately $550 million four years earlier — provides unambiguous evidence regarding capital allocation.23132 Management's contemporaneous commentary highlighted customer retention, stable pricing, and upside potential upon a freight market recovery.20 While those operational benefits may exist, they did not prevent, nor do they offset, the complete impairment of the purchase premium.
Verdict: rejected. Disclosed metrics offer no evidence that acquiring a trucking fleet accelerated rail carload conversions, but substantial evidence that it exposed the enterprise to cyclical motor-carrier economics. The falsifying metric is whether CSX ever separately discloses Quality Carriers' operating margin and returns. As long as the business remains characterized as immaterial for segment reporting, investors should view it as a non-earning asset with option value rather than a strategic platform, evaluating any future cross-modal acquisition proposals against this 2021 precedent.
Claim four: a labor-first culture ensures sustainable operational outperformance
As established in Section V, improved workforce engagement failed to drive financial performance: operational culture stabilized, but margins compressed, prompting board action. What warrants precise framing is the underlying asymmetry. Extending paid sick leave and improving labor relations materially reduced the risk of a 2022-style labor disruption — providing genuine risk mitigation with tangible economic value.16 However, these initiatives did not produce the pricing power or structural cost reductions previously claimed.
Verdict: rejected as a primary driver, retained as a hygiene factor. The falsifying test remains Chief Executive Steve Angel's core benchmark: whether return on invested capital expands over a multi-year period through the numerator — operating margin and income — rather than through balance-sheet engineering. Angel anchored his operating philosophy on return on capital as the ultimate measure for capital-intensive businesses, emphasizing a commitment to building a long-term productivity pipeline for 2027 and 2028 rather than over-harvesting 2026 results.202430
What an activist would still ask
Ancora's 2025 activist campaign focused primarily on potential merger combinations, a possibility Angel kept open by remaining publicly receptive. Yet a skeptical investor in late 2026 faces sharper analytical questions. Why is a carrier experiencing compressed returns on capital returning more cash to shareholders than its operations generate, funding the shortfall with incremental debt?2 Why does an asset whose goodwill was fully written off remain in the operational portfolio? Having withdrawn multi-year financial targets in January 2026, why has management hesitated to replace them following two quarters of strong performance — does this reflect operational conservatism, or does it preserve strategic flexibility while industry consolidation unfolds?22 Finally, how much of the margin expansion in 2026 is repeatable, given that performance benefited from real estate sales and from lapping approximately $150 million in non-recurring prior-year charges identified by management?2224
None of these questions points to a structural failure. However, each represents an empirical test whose answer will become clear in disclosed results over the next four quarters.
XII. Analysis & Investment Case: Why Win / Why Not (30–40 min)
Why CSX wins from here
The strongest version of the bull case does not rest on the economic moat, because that moat is already priced into the stock. Instead, it hinges on the gap between what this asset currently earns and what an equivalently protected franchise should earn, alongside empirical evidence that management is closing that gap for identifiable operational reasons.
That evidence is evident in recent execution. The 2026 cost-reduction program was not a single headcount reduction, but a structured portfolio of more than 100 discrete initiatives organized in the fourth quarter of 2025 and executed ahead of schedule. Management in-sourced maintenance work previously contracted out, reduced third-party operations spend by $23 million in a single quarter, shrank the corporate vehicle fleet by 7 percent, targeted utility and non-locomotive energy consumption, and improved intermodal terminal cost per lift by 12 percent.2430 Chief Financial Officer Kevin Boone noted that the 2027 efficiency pipeline was already half-built by mid-2026, deliberately ahead of historical timelines.30 This represents the playbook of an industrial-gas operator applied to a railroad: replacing one-off cuts with an institutionalized operational cadence.
The commercial side features concrete catalysts rather than optimistic projections. The reconstructed Howard Street Tunnel unlocks high-density container corridors CSX could not previously serve, and Chief Commercial Officer Maryclare Kenney's caution — that new intermodal services typically require two bid cycles to reach full volume — indicates that 2026 gains mark the beginning of realization rather than the peak.24 Meanwhile, joint service arrangements with BNSF Railway and CPKC provide CSX with a coast-to-coast product without the execution risk of a major merger. The industrial development pipeline remains active and diversified, featuring roughly 600 active projects; about 100 are expected to enter service in 2026, projected to contribute 50 percent more volume at full ramp than the 85 facilities brought online in 2025.24 Furthermore, CSX's network covers rapid industrial development across the Eastern Seaboard, where demand from data center construction, power infrastructure, and reshored manufacturing is driving freight volume across metals, minerals, frac sand, and domestic coal.30
Finally, cyclical tailwinds have turned favorable. Management entered 2026 modeling flat industrial production and no macroeconomic assistance, but subsequently raised full-year guidance twice as highway truck capacity tightened and freight conversions accelerated.222430 Demonstrating operating leverage on a network handling 6 percent more volume while trimming non-fuel costs by 2 percent provides the precise financial validation the bull case requires.
Why it may not
The bear case rests on four structural pillars, none of which is speculative.
The demand base is structurally slow. Persistently high mortgage rates and housing affordability constraints suppress forest products. North American light vehicle production was forecast down roughly 2 percent for 2026, exacerbated by extended retooling downtime at a major automotive assembly plant on CSX's network.2430 Domestic coal is benefiting from a temporary reprieve driven by elevated data center power demand and deferred utility plant retirements rather than a structural market recovery. Consequently, CSX's ability to drive volume growth above baseline GDP relies almost entirely on capturing freight from highway trucking — a market whose pricing and capacity dynamics management does not control.
Fuel surcharges cut both ways, artificially inflating near-term top-line results. The top-line revenue expansion that enabled consecutive guidance increases stemmed substantially from fuel surcharge recoveries following Middle East geopolitical conflict.2426 Rapidly rising diesel prices enhance rail's relative cost advantage over trucking while inflating reported revenue; a rapid drop in fuel prices reverses both dynamics. Investors interpreting 10 percent reported revenue growth as expanding freight demand misread the underlying business, given that total volume grew 6 percent while revenue per unit excluding fuel surcharges declined.30
Regulatory and labor costs maintain an escalating floor. Union wage increases take effect on schedule regardless of freight volumes, healthcare inflation continues to outpace historical averages, and the Surface Transportation Board remains actively focused on reciprocal switching, service performance, and industry consolidation.22 Combined with the Board's mandated disclosure requirements on the proposed transcontinental merger and its planned environmental review featuring at least twelve public hearings, the regulatory timeline guarantees prolonged operational and compliance uncertainty.35
The ultimate strategic outcome remains outside management's control. If regulators approve the combination of Union Pacific and Norfolk Southern, CSX will face a single-line transcontinental competitor operating directly within its eastern footprint. If CSX responds by pursuing a merger with BNSF Railway, it enters a multi-year integration process similar to the 1999 Conrail division, which took two years to stop eroding operational value. Chief Executive Steve Angel noted that his experience leading the Praxair-Linde merger required three years to complete, cautioning that a Class I rail transaction would likely face a similar timeline and describing the interim period as "deal purgatory."22 Conversely, if no industry consolidation occurs, CSX will have absorbed significant executive time and advisory expenses — already flagged as an active cost item — on a strategic response that yielded no structural combination.24
Weighing it
The synthesis is that CSX represents an operational self-help initiative operating within broader structural uncertainty, with the two dynamics unfolding on different timelines. The self-help gains are measurable in current disclosures: two quarters of margin expansion driven by verifiable cost reductions, executed by leadership whose capital allocation philosophy aligns with the underlying operational challenges. The structural consolidation questions resolve in 2027 at the earliest under federal regulatory review.
Specific empirical indicators will determine whether the investment thesis trends positive or negative. On the positive side: merchandise pricing acceleration as freight contracts reprice into tighter truck capacity, service metric recovery alongside stable operating margins, and the formal reintroduction of multi-year financial targets anchored by return on invested capital. On the negative side: a recurrence of operational degradation where service reliability is sacrificed for short-term margin gains, a sharp drop in fuel prices exposing weak underlying freight yields, or capital deployment drifting back toward adjacent trucking acquisitions reminiscent of the write-off recorded four years post-purchase.
The defining characteristic of CSX is that each of these variables remains visible in routine quarterly disclosures, keeping the analytical watchlist focused and verifiable.
XIII. The Forward Watchlist & Key Performance Indicators (KPIs) (20–25 min)
Railroad operations generate extensive data, but for CSX, three core metrics contain nearly all essential analytical signal, with remaining data serving primarily as secondary derivatives.
One: operating margin, read alongside its structural composition. CSX now emphasizes operating margin over operating ratio, making its trajectory the clearest gauge of Chief Executive Steve Angel's operational plan: 36.1% in 2024, 32.1% in 2025, followed by 35.9% in the first quarter of 2026 and 38.3% in the second quarter, set against full-year guidance for more than 350 basis points of margin expansion.34262830 However, the headline figure requires quarterly decomposition. Analysts must evaluate how much margin movement stems from fuel surcharge timing, non-recurring real estate sales, and lapping prior-year charges, versus the contribution of a durable productivity pipeline. The first three factors reflect temporary arithmetic, whereas only structural productivity compounds over time.
Two: trip plan compliance and terminal dwell evaluated together. This combined metric serves as the primary test of network resilience — a test where operational performance faltered both during the 2017 restructuring and in the second quarter of 2026. Trip plan compliance measures the percentage of shipments arriving on schedule, reflecting actual customer experience, while terminal dwell measures how long railcars remain in switching yards. In the second quarter of 2026, carload compliance fell to 71% from 75% a year earlier and intermodal compliance declined to 88% from 90%, while terminal dwell lengthened to 11.0 hours from 10.4.26 Average train velocity improved over the same period, illustrating why velocity alone provides an incomplete assessment of network health: a railroad can increase train speed while leaving delayed cars in origin yards. Management committed to sequential service improvements without relinquishing productivity gains.30 Simultaneous progress across both metrics will determine whether the current operational model avoids the service trade-offs of previous cycles.
Three: return on invested capital. Chief Executive Steve Angel cited return on invested capital as the primary metric encapsulating historical capital allocation, aligning long-term incentive design with this benchmark.20 For an enterprise whose operating income declined from roughly $6.0 billion in 2022 to $4.52 billion in 2025 as total debt expanded to $18.87 billion and share repurchases exceeded free cash flow, return on invested capital represents a metric resistant to short-term financial engineering — since debt-financed share buybacks boost earnings per share without improving fundamental capital efficiency.23 Investors must evaluate whether future expansion in return on capital is driven primarily by operating margin and earnings growth.
Two qualitative catalysts also remain on the watchlist. The Surface Transportation Board's procedural schedule for the Union Pacific–Norfolk Southern merger proceeding will clarify the timeline for regional industry consolidation.35 Concurrently, any potential reinstatement of multi-year financial targets — which were withdrawn in January 2026 — would indicate executive confidence in the durability of current productivity initiatives.22
XIV. Earnings Call & Primary Evidence Guide for Downstream Analysis (15–20 min)
For analysts and investors extending this research, the primary evidentiary record is unusually rich, with a handful of core documents carrying disproportionate analytical weight.
Start with the Angel-era earnings calls, in sequence rather than individually. The third-quarter 2025 call on October 16, 2025, served as the initial philosophical statement — setting out the industrial-gas analogy, the framing of rail corridors alongside pipeline networks, the return-on-capital benchmark, and the first public acknowledgement that CSX had received inquiries regarding strategic opportunities.2036 The fourth-quarter 2025 call on January 22, 2026, marked the strategic reset, featuring the withdrawal of the 2024 investor day targets, the initial 2026 guidance, and Chief Executive Steve Angel's perspective on merger review as a multi-year process.22 The first- and second-quarter 2026 calls documented operational execution alongside two successive guidance increases, with the analyst Q&A focusing directly on the sustainability of purchased services savings, pricing acceleration, and the divergence between reported productivity and service compliance metrics.2430
Read the Hinrichs-era disclosures for comparative context. The fourth-quarter 2024 earnings release documented both the operational resilience narrative and the higher margin baseline that subsequently eroded.4 Comparing those figures directly against the 2025 full-year disclosures illustrates the magnitude of margin compression prior to the leadership change.3
For operating history, two regulatory filings remain indispensable. The Surface Transportation Board's public listening session transcript under Docket EP 742, from October 11, 2017, provides the primary record of service disruptions during the initial Precision Scheduled Railroading rollout, including Hunter Harrison's testimony and reflections on implementation.1314 Concurrently, the Board's May 2026 decision accepting the Union Pacific–Norfolk Southern merger application while placing proceedings in abeyance details the nine specific areas of required supplemental information — including downstream competitive effects — establishing the regulatory framework governing CSX's strategic position.35
For financial architecture, the 2025 Form 10-K serves as the foundational reference. It details the physical network footprint, union workforce contract status, debt repayment schedule, dividend history, the complete goodwill write-off for Quality Carriers, and primary risk disclosures covering industry consolidation and automated modal substitution.2 Complementing the 10-K, the 2026 proxy statement outlines the executive compensation structure governing management incentives, providing the formal benchmark for tracking alignment with return-on-capital goals.23
The overarching narrative across these disclosures highlights a persistent structural reality. CSX controls an unreplicable physical asset, yet decades of operational history demonstrate that infrastructure ownership alone does not guarantee financial returns. Over nine years, three consecutive chief executives were appointed to address distinct operational deficits. Current leadership has focused on capital discipline and operational execution, backed by early evidence of margin expansion. However, the ultimate efficacy of this operational strategy remains bound to whether the regional industry map remains intact as regulatory review of transcontinental consolidation unfolds.
References
-
CSX Celebrates Reopening of Blue Ridge Subdivision — CSX Corporation via GlobeNewswire, 2025-10-02 ↩
-
CSX Corporation Form 10-K for the fiscal year ended December 31, 2025 — CSX Corporation, 2026-02-12 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
CSX Corp. Announces Fourth Quarter and Full Year 2025 Results — CSX Corporation, 2026-01-22 ↩↩↩↩↩↩
-
CSX Corp. Announces Fourth Quarter and Full Year 2024 Results — CSX Corporation, Form 8-K exhibit, 2025-01-23 ↩↩↩↩↩↩
-
Union Pacific and Norfolk Southern to Create America's First Transcontinental Railroad — Union Pacific, 2025-07-29 ↩↩
-
FreightWaves Classics: Conrail divided between CSX and Norfolk Southern — FreightWaves ↩↩↩↩
-
CSX Quarterly Financial Report, Fourth Quarter 2012 — CSX Corporation, Form 8-K exhibit, 2013-01-22 ↩↩↩↩
-
CSX Quarterly Financial Report, Fourth Quarter 2016 — CSX Corporation, Form 8-K exhibit, 2017-01-17 ↩↩↩↩
-
CSX Quarterly Financial Report, First Quarter 2016 — CSX Corporation, Form 8-K exhibit, 2016-04-13 ↩↩↩
-
CSX Names E. Hunter Harrison as Chief Executive Officer — CSX Corporation, Form 8-K exhibit 99.1, 2017-03-06 ↩↩
-
CSX Quarterly Financial Report, Fourth Quarter 2017 — CSX Corporation, Form 8-K exhibit, 2018-01-16 ↩↩↩
-
Public Listening Session Regarding CSX Transportation, Inc.'s Rail Service Issues, Docket No. EP 742 — Surface Transportation Board, 2017-10-11 ↩↩
-
Transcript: In Re: Public Listening Session on CSX Transportation, Inc.'s Rail Service Issues — Surface Transportation Board, 2017-10-11 ↩↩↩
-
CSX Quarterly Financial Report, Fourth Quarter 2022 — CSX Corporation, Form 8-K exhibit, 2023-01-24 ↩↩
-
CSX Reaches Agreement with IAM and NCFO on Paid Sick Leave for Railroad Workers — CSX Corporation, 2023 ↩↩
-
Activist investor urges CSX to engage in alternative merger discussions — FreightWaves, 2025-08 ↩↩
-
CEO compensation 2025: Hinrichs was Jacksonville's highest-paid as he left CSX — Jacksonville Daily Record, 2026-05-14 ↩↩
-
CSX Appoints Steve Angel as President and Chief Executive Officer — CSX Corporation, 2025-09-28 ↩
-
Q3 2025 CSX Corporation Earnings Conference Call — CSX Corporation, 2025-10-16 ↩↩↩↩↩↩↩↩↩
-
CSX Announces New Leadership Appointments — CSX Corporation, 2025-10-29 ↩
-
Earnings call transcript: CSX Q4 2025 sees mixed results, stock dips — Investing.com, 2026-01-22 ↩↩↩↩↩↩↩↩↩↩↩↩
-
CSX Corporation Definitive Proxy Statement (Form DEF 14A) — CSX Corporation, 2026-03-26 ↩↩↩
-
Earnings call transcript: CSX beats Q1 2026 EPS estimates, stock steady — Investing.com, 2026-04-22 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
CSX Corporation Investor Relations Portal — CSX Corporation ↩
-
CSX Quarterly Financial Report, Second Quarter 2026 — CSX Corporation, Form 8-K exhibit, 2026-07-22 ↩↩↩↩↩↩↩↩↩↩↩
-
CSX Reopens Expanded Howard Street Tunnel Ahead of Schedule, Strengthening East Coast Freight Growth — CSX Corporation, 2025 ↩↩
-
CSX Corp. Announces First Quarter 2026 Results — CSX Corporation, Form 8-K exhibit, 2026-04-22 ↩↩
-
CSX Corp. Announces Second Quarter 2026 Results — CSX Corporation, Form 8-K exhibit, 2026-07-22 ↩
-
Earnings call transcript: CSX beats Q2 2026 estimates and lifts outlook — Investing.com, 2026-07-22 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
CSX Completes Acquisition of Quality Carriers — CSX Corporation, 2021-07-01 ↩↩
-
CSX Corp. Announces Third Quarter 2025 Results — CSX Corporation, Form 8-K exhibit, 2025-10-16 ↩↩
-
CSX Completes Acquisition of Pan Am Railways — CSX Corporation, 2022-06-01 ↩
-
BNSF, CSX announce new intermodal services, offering seamless coast-to-coast rail solutions — BNSF Railway, 2025-08-22 ↩
-
STB Accepts UP-NS Merger Application for Consideration; Requires Supplemental Information and Holds Proceedings in Abeyance — Surface Transportation Board, 2026-05-28 ↩↩↩↩↩
-
CSX Corp. SEC Filings (Forms 10-K, 10-Q, 8-K) — U.S. Securities and Exchange Commission EDGAR ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube