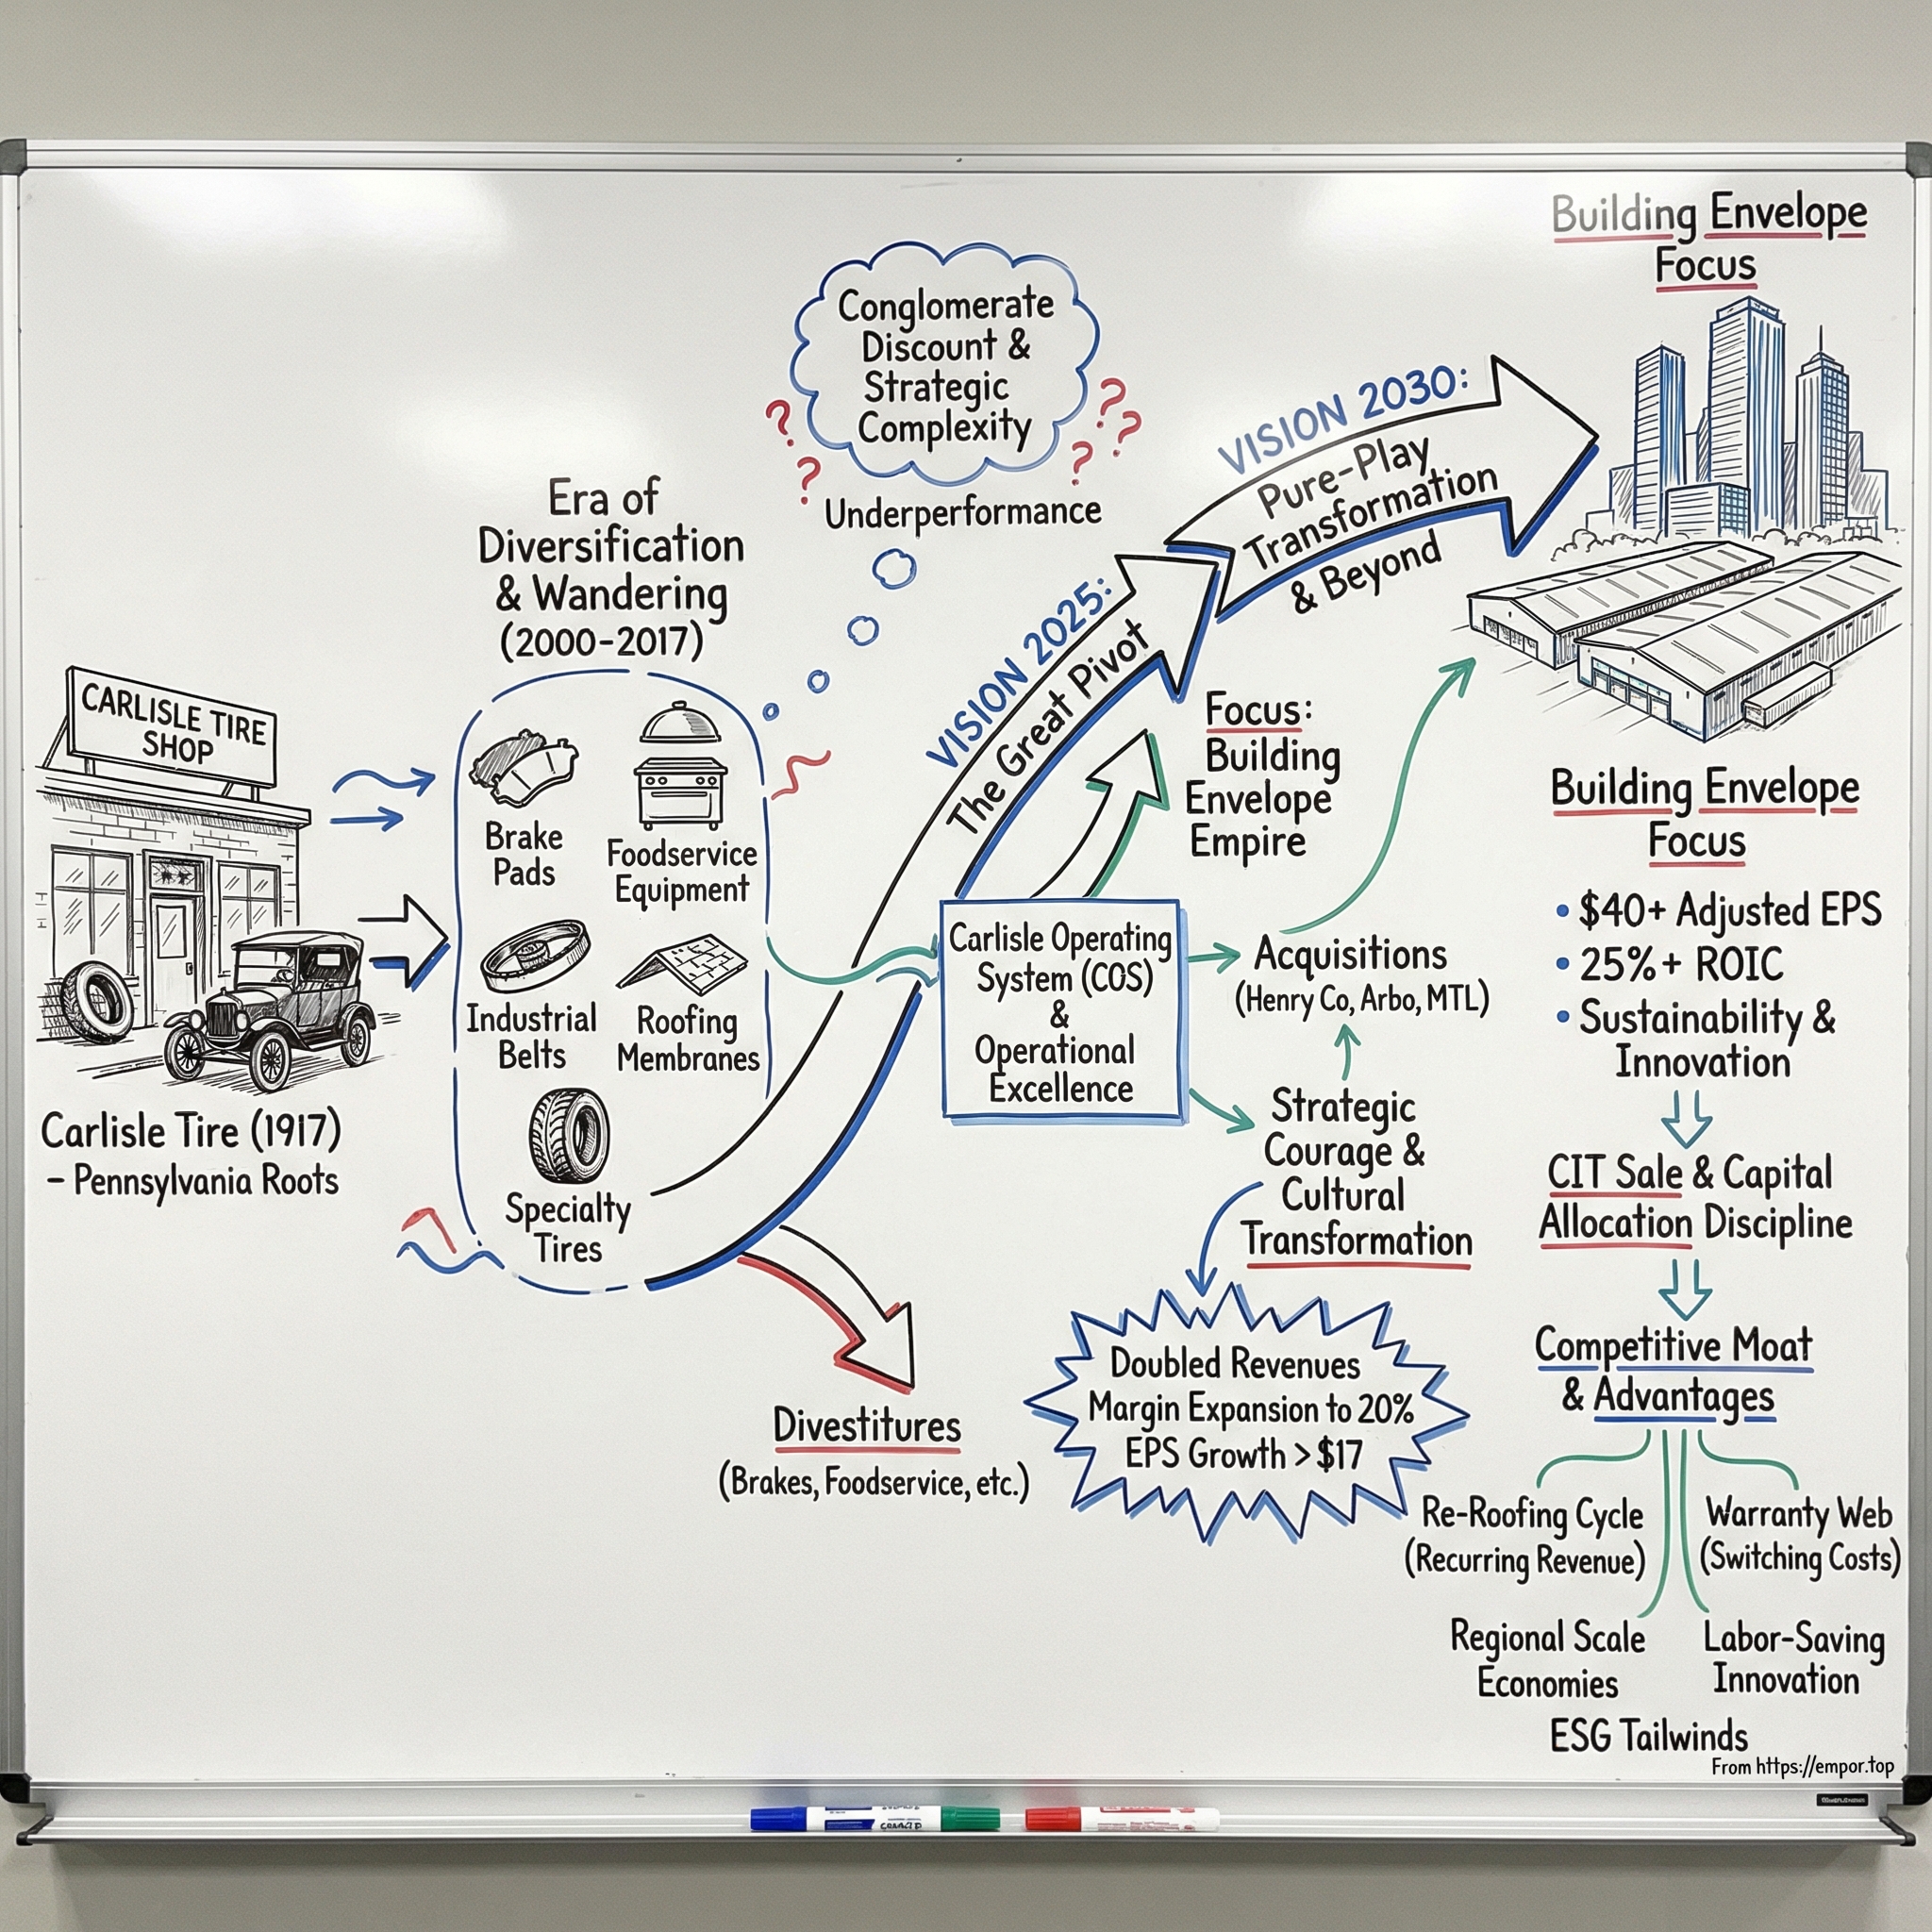
Carlisle Companies: From Pennsylvania Tire Shop to Building Envelope Empire
I. Introduction & The Big Picture
On the afternoon of July 29, 2026, a conference operator handed the line to Chris Koch, and Carlisle's chief executive did something unusual for an executive about to announce record quarterly results: he began with a denial. Before reviewing the financial figures or thanking participants, he addressed the primary question circulating among analysts. "Let me first address the rumors in the market recently regarding a Carlisle effort to acquire Owens Corning," Koch said, before declining further comment, citing Carlisle's policy against commenting on rumors or speculation.3
A month earlier, the Wall Street Journal reported that Carlisle had made multiple unsolicited offers to acquire Owens Corning in a transaction valued well over $10 billion. Owens Corning shares closed up more than 15% on the news at $156.05,20 while Carlisle shares fell roughly 5%.21 That market asymmetry highlighted a key tension for a management team that has long positioned capital allocation as its core competency: investors reacted negatively to its largest proposed capital deployment.
On paper, Carlisle (CSL) presents a striking industrial transformation. Founded 109 years ago as a tire-tube shop in Carlisle, Pennsylvania, the company spent much of the 20th century operating as a diversified holding company before divestment efforts between 2016 and 2024 narrowed its focus strictly to building envelope products. What remains generated $5.02 billion in 2025 revenue across two segments,1 produced $972 million in free cash flow, and returned nearly $1.5 billion to shareholders through $1.3 billion in share repurchases and $181 million in dividends.26 In August 2026, the board raised the quarterly dividend 14% to $1.25 per share, marking its 50th consecutive annual payout increase and placing Carlisle among the few U.S. public companies with a half-century dividend growth record.19
The central investment narrative centers on product function and market demand. While commercial construction materials are frequently classified as cyclical commodities, Carlisle generates higher-than-commodity returns by manufacturing the critical barrier between environmental conditions and commercial interiors. A low-slope roof on a distribution center, data facility, hospital, or school serves a non-discretionary role; when failures occur, operational disruption follows immediately.
Management rests its investment thesis on two primary claims. First, approximately 70% of demand in its core business is driven by re-roofing—the predictable replacement of assets wearing out on a 20-to-30-year physical cycle, largely insulated from interest-rate fluctuations.5 Second, Carlisle's single-source warranties, spanning five to 40 years on installed systems, encourage architects, contractors, and building owners to specify complete Carlisle roof assemblies rather than individual components.1 Management contends this structural positioning yields an annuity-like revenue stream with durable pricing power.
Testing these claims against Carlisle's operating record reveals significant friction points. Concentration risk is notable, as two distributors accounted for 33% of consolidated revenue in 2025.1 Meanwhile, the weatherproofing segment built through $1.575 billion in acquisitions saw its operating margin decline to 7.8%.1 Internal performance targets also fell short: Carlisle's compensation committee reported that 2025 results missed every threshold on the consolidated annual incentive scorecard, resulting in no annual bonus for the CEO.8 Further, in mid-2026, Middle East supply disruptions triggered a price-cost squeeze that compressed segment margins despite record top-line revenue.3 These factors do not disprove the underlying thesis, but they highlight clear boundaries around management's execution.
This analysis examines Carlisle's trajectory across key phases: its 20th-century origins (1917–2000); the conglomerate period (2000–2015); Vision 2025 and the Carlisle Operating System (2016–2022); the M&A-driven building envelope expansion; Vision 2030 and pure-play positioning; single-ply roofing economics and warranty dynamics; corporate governance and execution history; competitive positioning; bull and bear investment cases; and recent quarterly performance.
 Subscribe on LinkedIn
II. The Century-Long Foundation: From Rubber Tires to Industrial Conglomerate (1917–2000)
In 1917, Charles S. Moomy founded Carlisle Tire and Rubber Company in Carlisle, Pennsylvania, using a personal investment of roughly $4,000 to buy machinery and manufacture inner tubes for mail-order giant Montgomery Ward.28 It began as a straightforward industrial operation: a commodity product, a single primary customer, and 30 employees. Little about its origins suggested that the enterprise would endure for more than a century, eventually evolving into a $14 billion public company headquartered in Scottsdale, Arizona.
After growing through the 1920s, the company faced near-collapse during the Great Depression. What enabled its survival—and established a blueprint for its future expansion—was treating rubber compounding as a core capability rather than a single end product. A manufacturer capable of formulating, mixing, calendering, and curing elastomers could adapt its output beyond inner tubes to industrial belting, wire insulation, baby-food container seals, brake linings, and eventually roofing membranes. Over the postwar decades, Carlisle repeatedly applied this underlying chemical and manufacturing expertise to enter new markets, expanding into roofing materials, insulated wire, aeronautical components, and friction products through the 1960s.28
This capability-led approach gradually transformed Carlisle into a diversified holding company rather than an integrated operating business. By the late 20th century, its portfolio included wire and cable assemblies for aerospace (later Carlisle Interconnect Technologies), brake and friction materials for heavy equipment (Carlisle Brake & Friction), fluid-handling equipment (later Carlisle Fluid Technologies), and commercial foodservice products. Each unit operated with its own manufacturing plants, leadership, and customer base, while corporate headquarters functioned primarily as a capital allocator.
The pivotal strategic decision of this era occurred in the early 1960s. At the time, flat commercial roofs relied on built-up layers of asphalt, felt, and gravel—a labor-intensive assembly that was heavy, slow to install, and prone to leaks at seams and penetrations. Leveraging its synthetic rubber expertise, Carlisle introduced the first single-ply EPDM roofing membranes, producing large, flexible sheets of ethylene propylene diene monomer rubber that could be unrolled across a roof deck and sealed with far fewer seams.1
The competitive advantage of entering this market early stemmed from a critical distinction. While a standalone roofing membrane functions as an undifferentiated commodity, a complete roofing assembly—combining the membrane with insulation, adhesives, flashing, and edge details, installed by certified contractors and backed by long-term warranties—creates a defensible system.
Over the following decades, Carlisle developed three structural advantages around this system: a network of regional manufacturing facilities positioned close to demand to minimize heavy freight costs, a certified applicator network, and decades of actuarial claims data to price long-term warranty risks accurately.
Carlisle's primary achievement during its first 80 years was not the performance of its diversification, but its sheer longevity. By maintaining a conservative balance sheet and steady cash flow through the Great Depression, two world wars, and multiple industrial cycles, the company gave its roofing division the runway to compound into a high-return business. By the end of the century, the roofing business had become the crown jewel within a conglomerate that had not yet fully recognized its true core strength—setting up the strategic challenges of the next 15 years.
III. The Conglomerate Trap & The Early Building Products Bet (2000–2015)
Even after several rounds of portfolio pruning, Carlisle's operational disparity remained stark during the conglomerate era. In 2019, Carlisle Construction Materials (CCM) generated approximately 67% of consolidated revenue and approximately 88% of operating income.7 The remaining three segments accounted for a third of sales but only about one-eighth of profits.
A closer look at the 2019 breakdown illustrates the drag on returns. CCM generated $3.23 billion in revenue with a 17.8% operating margin. By contrast, Carlisle Interconnect Technologies achieved a 13.5% margin on $973 million in revenue, while Carlisle Fluid Technologies recorded an 8.6% margin on $278 million, down from 12.7% in 2018. Meanwhile, Carlisle Brake & Friction produced a 6.5% margin on $327 million in revenue—a figure that reflected a rebound from an operating loss of $0.8 million in 2018.7
This imbalance demonstrated the operational mechanics of the conglomerate discount: earnings from the high-return building products business subsidized capital expenditures in lower-return industrial divisions. Every dollar of roofing profit directed toward aerospace cabling or specialty brake tooling was capital unavailable for expanding insulation manufacturing, building regional plants, or repurchasing shares.
At the time, management argued that diversification dampened economic cycles, asserting that aerospace and industrial demand would offset downturns in commercial construction. However, Carlisle's operating history challenged that rationale. The non-roofing divisions operated in distinct, highly cyclical end markets at lower profit margins. Rather than stabilizing earnings, divisions like Brake & Friction introduced additional volatility alongside reduced capital efficiency.
Furthermore, assigning roughly one-third of the asset base to single-digit margin businesses diluted consolidated return on invested capital. During an investor call in the second quarter of 2023, Chris Koch highlighted the scale of the portfolio shift, noting that building products had expanded from about 56% of consolidated revenue in 2016 to roughly 84% on a pro forma basis for 2023.25 When Koch assumed the chief executive role in 2016, nearly half of Carlisle's revenue came from business units generating returns well below those of its core roofing operations.
Despite the structural friction of the conglomerate model, the roofing division captured two major technology shifts between 2000 and 2015 that reinforced its long-term financial performance.
The first was the commercial transition from black EPDM to white thermoplastic polyolefin (TPO). Unlike dark rubber membranes that absorb solar heat, reflective white roofs deflect radiation, lowering building cooling demands. As municipalities adopted stricter energy codes and utilities introduced cool-roof rebate programs, TPO market share expanded rapidly. Having pioneered single-ply rubber membranes, Carlisle established TPO extrusion capacity and leveraged its existing applicator network and system warranties to support the new product line. Today, CCM produces EPDM, TPO, and PVC membranes, catering to varying architect and contractor specifications.1
The second shift delivered even greater financial impact. Building codes progressively raised minimum insulation standards, measured by thermal resistance, or R-value. Polyisocyanurate (polyiso) rigid foam boards provide high R-value per inch of thickness, making them particularly useful when roof heights, parapets, or door thresholds limit insulation depth. As code requirements mandated thicker insulation layers, Carlisle vertically integrated into polyiso manufacturing. This integration increased the average revenue content per square foot of roof deck, expanding sales independent of total square footage installed.
This revenue-per-square-foot expansion became a central driver of Carlisle's growth strategy. Management projects that content growth adds 150 to 200 basis points annually above low-single-digit increases in re-roofing permits, supporting mid-single-digit total re-roofing demand growth.5 This mechanism allows the roofing business to outpace underlying construction volume growth.
By 2015, Carlisle presented a dual narrative. Operationally, the construction materials business was executing effectively by capitalizing on regulatory and technological transitions to increase revenue per installation. Structurally, however, capital allocation across low-margin conglomerate holdings suppressed overall corporate returns, setting the stage for executive leadership to realign the company's corporate structure with its core manufacturing strength.
IV. Vision 2025: The Great Pivot & The Carlisle Operating System (2016–2022)
The executive who ultimately dismantled Carlisle's industrial portfolio had spent his career managing its components.
D. Christian Koch joined Carlisle in February 2008 as President of Carlisle Asia-Pacific. In January 2009, he assumed leadership of Carlisle Brake & Friction—the division he would sell twelve years later. From 2012 to 2014, he served as Group President of Carlisle Diversified Products before becoming President and Chief Operating Officer. He was appointed Chief Executive Officer in January 2016 and added the chairmanship in May 2020.1 Having personally managed these business units, Koch possessed firsthand experience with their operating performance when assessing their fit within the corporate portfolio.
Koch concluded that Carlisle was spread across too many end markets to excel in any single category, misallocating capital away from its high-return core. In 2018, he formalized Vision 2025—a public commitment to reach $8 billion in revenue, a 20% operating margin, a return on invested capital exceeding 15%, and $15 in GAAP diluted earnings per share by 2025.25
Establishing a firm, dated GAAP earnings target created explicit executive accountability, as GAAP metrics leave little room for quiet redefinition during operational downcycles. The target was ambitious: Carlisle had earned diluted earnings per share of $5.71 in 2017, meaning reaching $15 per share required nearly tripling net earnings within eight years.
Underpinning these financial targets was the Carlisle Operating System (COS). Introduced in 2008 and built on lean enterprise and Six Sigma principles, COS serves as the operational framework across Carlisle's plants, supply chain, and administrative offices.15 In practice, the system targets annual cost savings equal to 1% to 2% of sales by eliminating waste, accelerating equipment changeovers, minimizing scrap, improving machine uptime, and standardizing workflows.3
While continuous-improvement programs are standard across manufacturing, Carlisle's operational metrics demonstrate consistent execution. The company maintained adjusted EBITDA margins in Carlisle Construction Materials above 30% through 2026's raw-material cost shock. Furthermore, Carlisle expanded its consolidated adjusted EBITDA margin by 50 basis points in the first quarter of 2026 even as revenue fell 4%.294 Expanding margins on declining volume reflects structural cost control. Koch has also integrated automation and artificial intelligence into the system, deploying robotic equipment across manufacturing plants to raise throughput and cut scrap.35
Following post-pandemic demand acceleration in 2021 and 2022, Carlisle exceeded its plan. The company reported 2022 revenue of $5.45 billion and diluted earnings per share of $17.56, clearing the $15 target three years early.30 Management has consistently cited this early completion as evidence that its Vision 2030 targets are credible.5
Evaluating the Vision 2025 record. Determining whether early target completion proved structural operational improvement requires examining the subsequent two years.
Carlisle's 2023 results challenged a purely structural narrative. Revenue in Carlisle Construction Materials fell from $3.885 billion in 2022 to $3.253 billion in 2023, a decline of roughly 16%. Carlisle Weatherproofing Technologies revenue fell from $1.564 billion to $1.334 billion, down about 15%.27 The decline did not stem from structural flaws, lost customers, or impaired warranties. Instead, distributors and contractors who had accumulated excess inventory during post-pandemic supply shortages halted new orders to draw down existing stock. On the second-quarter 2023 conference call, Chief Financial Officer Kevin Zdimal quantified the impact, reporting roughly $120 million of destocking headwind in that quarter alone—exceeding the initial $100 million expectation—with another $50 million expected in Q3.25
This correction demonstrated that a significant share of the 2022 earnings surge was driven by channel inventory dynamics and historic pricing power rather than permanent structural demand. When channel inventories normalized, roughly one-sixth of the construction materials segment's revenue unwound.
However, the downturn also highlighted pricing discipline. Despite falling volumes, Carlisle avoided price discounting to chase market share. Koch told analysts in July 2023 that product pricing remained flat during the quarter and that he had not seen it.25 Absorbing volume reductions while leveraging COS efficiencies, management guided consolidated margins down only 50 basis points on a double-digit revenue decline.25 Mid-crisis, Zdimal raised the full-year price-cost benefit forecast from an initial range of $40 million to $60 million up to $60 million to $80 million.25
In summary, while Vision 2025's rapid earnings milestone was flattered by transitory pricing and inventory hoarding, the company's margin resilience through the subsequent downturn demonstrated genuine operational durability. Going forward, organic volume growth excluding price remains the essential metric for evaluating Carlisle's underlying expansion.
V. M&A Strategy & The Building Envelope Portfolio Assembly
If a commercial roof functions as an integrated system, expanding beyond the roof deck represents a logical strategic extension. The building envelope—the continuous weather barrier separating a building's conditioned interior from external elements—does not end at the roof edge. It extends down parapets, across wall assemblies, behind cladding, and into the foundation. Because moisture and air infiltration occur at structural junctions, a building owner investing seven figures in a warranted roof remains vulnerable to leakage at the wall-to-roof interface if components are sourced separately.
Carlisle addressed this integration challenge through three major acquisitions, though execution and return profiles have varied significantly across these transactions.
Accella Performance Materials (2017, $670 million). On November 1, 2017, Carlisle acquired Accella Performance Materials, a specialty polyurethane manufacturer, from Arsenal Capital Partners in an all-cash transaction valued at $670 million. The acquisition added roughly $430 million in annual revenue while targeting approximately $30 million in cost synergies.17 Strategic logic centered on polyurethane chemistry—specifically spray polyurethane foam insulation and liquid-applied roofing—with management projecting 10% to 15% annual market growth through 2020.17
Operational integration proved complex. Spray foam insulation is sold to a fragmented contractor base through distribution channels distinct from Carlisle's core commercial roofing network. By mid-2026, Koch acknowledged that polyurethane foam had encountered a difficult market environment characterized by soft pricing.3 Nine years after the transaction, Carlisle adjusted its commercial strategy by transitioning to a direct-to-contractor distribution model using its own delivery fleet, beginning in the Southeast and generating roughly $10 million in 2026 revenue.3 This extended timeline highlights the operational friction of commercializing product lines outside Carlisle's established wholesale distribution infrastructure.
Henry Company (2021, $1.575 billion). On September 1, 2021, Carlisle completed its largest acquisition in this phase, purchasing Henry Company from affiliates of American Securities for $1.575 billion. The purchase price represented 10.5 times Henry's adjusted EBITDA for the twelve months ended May 31, 2021, inclusive of run-rate cost synergies. Over that period, Henry generated $511 million in revenue and $119 million in adjusted EBITDA, implying an unadjusted trailing valuation multiple of approximately 13 times. Carlisle targeted roughly $30 million in pre-tax cost synergies by 2025.13 Henry brought a portfolio of air and vapor barriers, waterproofing membranes, roof coatings, sealants, and residential weatherization products, establishing the foundation for the newly created Carlisle Weatherproofing Technologies (CWT) reporting segment.
The transaction also provided executive continuity: Frank Ready, who had served as Henry's chief executive officer since November 2014, became President of CWT in February 2022 and continues in that role.1
On cost synergies, Carlisle exceeded its initial targets. In July 2026, Koch reported that Henry's EBITDA margins aligned with original deal models and that cost synergies had exceeded initial expectations by 65%, reaching approximately $50 million compared to the $30 million plan.3
However, segment profitability faced severe macroeconomic headwinds. In 2025, CWT generated $1.298 billion in revenue with an operating margin of 7.8%, down from 13.4% in 2024, as operating income fell 41% to $101.9 million. Organic revenue contracted 9.2%, though headline sales were cushioned by a 9.2% contribution from acquisitions.1 Segment adjusted EBITDA margin declined to 17.3% from 20.6%.1 When Carlisle acquired Henry, management outlined a target of mid-20% EBITDA margins with a path to 30%.4 Five years post-acquisition, segment margins remain roughly eight percentage points below that threshold, a shortfall management attributes primarily to weakness in residential and non-residential construction markets.
While CWT's exposure to residential construction cycles explains part of the margin compression and management asserts that acquisitions have performed in line with underlying deal models,4 the financial results underscore the cyclical sensitivity of the asset. Carlisle acquired Henry near the peak of the residential construction cycle, and target capital returns remain unrealized. In April 2026, when asked whether further synergy extraction could offset margin pressures, Koch noted that while incremental operational gains remained achievable, returning to mid-20% margins would require a recovery in market volumes.4 Consequently, achieving target returns remains dependent on an upturn in construction activity.
MTL Holdings (2024, $410 million). On May 1, 2024, Carlisle acquired MTL Holdings from GreyLion Partners for $410 million in cash. The acquisition brought prefabricated edge metal systems under the Metal-Era and Hickman brands, along with non-insulated architectural wall panels under Citadel.12 MTL aligned closely with Carlisle's core roofing operations: perimeter edge metal—including coping, fascia, and gravel stops—represents the primary failure point for wind uplift on commercial roofs, making it a critical component in warranty underwriting. Integrating perimeter metal into Carlisle's single-source warranty allowed the company to capture specification revenue previously directed to third-party manufacturers.
Operational performance following the acquisition met management's targets. In April 2026, Koch characterized MTL's performance as exceptional, citing executive execution around raw material inflation, market share gains, and new product introductions.4 MTL demonstrated the core elements of Carlisle's preferred M&A framework: strong adjacency to the core business, shared distribution channels, direct integration into single-source warranties, and disciplined acquisition pricing.
The falsification pass on M&A. Carlisle's management positions capital allocation as a core organizational competency. However, examining the broader acquisition history reveals notable execution challenges, particularly outside building products within the former medical technology platform.
In 2019, Carlisle acquired MicroConnex for approximately $46.0 million in April and Providien for $332.1 million in November, combining them with redgroup and LHi Technology to build a medical device manufacturing business within Carlisle Interconnect Technologies (CIT).7 Strategic logic focused on offering single-source manufacturing capabilities to global medical OEMs. Providien contributed $11.3 million in revenue and $0.1 million in operating income during its stub period.7 In total, Carlisle allocated roughly $380 million in capital to build a platform in a medical technology market where it possessed no established distribution infrastructure or contractor relationships.
Five years later, Carlisle divested the medical platform as part of the broader sale of CIT, transferring the platform's long-term asset value to Amphenol.
This acquisition record indicates that Carlisle's M&A returns depend heavily on whether target companies utilize the contractor and distributor channels of its core building products business. MTL, distributed through existing channels to the same contractors and integrated into single-source warranties, delivered strong results. Henry achieved cost synergies but experienced return compression due to residential exposure. Accella required nine years to establish an effective direct-to-contractor distribution model. Meanwhile, the medical device platform, operating entirely outside Carlisle's core commercial channels, was ultimately liquidated.
Koch's stated M&A criteria—requiring established organic growth, tangible cost synergies, strong management, and alignment with the Carlisle Operating System—match the profile of MTL while diverging significantly from Providien.3 This contrast underscores the strategic questions surrounding how a proposed acquisition of Owens Corning, valued at well over $10 billion, would have fit into Carlisle's established acquisition framework.
VI. Vision 2030: The Pure-Play Transformation & Financial Engineering (2023–Present)
Selling a business is easy to announce and hard to do. Carlisle did it three times in four years, and the sequence tells you what management actually believed.
Carlisle Brake & Friction went first. On May 25, 2021, Carlisle agreed to sell CBF to CentroMotion of Waukesha, Wisconsin in a structure providing up to $375 million — $250 million cash at closing plus up to $125 million contingent on CBF hitting adjusted EBITDA targets for calendar 2021.14 The deal closed August 2, 2021.15 The earnout structure is telling: Carlisle was willing to take real risk on the back half of the price to get the asset out the door. This was the business Koch himself had run from 2009 to 2012.
Carlisle Fluid Technologies followed. Carlisle agreed in 2023 to sell CFT to Lone Star Funds for $520 million, and the sale completed October 2, 2023.16 CFT had generated $297 million of revenue in 2022. Management explicitly earmarked the proceeds for buybacks rather than reinvestment, taking 2023 repurchases to roughly $900 million.25
Carlisle Interconnect Technologies was the capstone. On January 30, 2024, Carlisle announced the sale of CIT to Amphenol for $2.025 billion in cash — a materially larger number than either prior divestiture, and the transaction that made "pure play" literally true. Koch called it "a significant milestone in our strategic pivot from a diversified industrial portfolio of businesses to a premier pure play building products company," and said proceeds would go to buybacks, building products acquisitions, and other high-returning uses.10 Amphenol closed the acquisition on May 21, 2024.11
What is worth noting about the sequencing is that Carlisle sold into strength. CIT's aerospace end market was recovering hard as aircraft build rates rebounded post-COVID; on the Q2 2023 call, management highlighted CIT EBITDA up 520 basis points year over year with backlog notably above pre-pandemic levels.25 Selling a recovering asset to a strategic buyer who could pay for the recovery is better execution than dumping a broken one. It is also, uncomfortably, an argument that the medical platform inside CIT might have been worth more to Amphenol than to Carlisle — which is a fair reading of why it was worth building and then selling, but not a fair reading of the original growth-platform pitch.
Vision 2030. With the portfolio settled, Carlisle laid out its successor plan on December 7, 2023: adjusted EPS above $40 by 2030 on a mid-teens CAGR from a 2023 base, ROIC above 25%, organic revenue CAGR above 5%, adjusted EBITDA margin above 25%, and free cash flow to sales above 15%.18 Segment-level ambitions were added later: 30%-plus EBITDA margins at CCM and 25%-plus at CWT, with no specific year attached.5
The addressable market framing has moved around, and investors should note the movement rather than the number. The Vision 2030 launch leaned on three mega-trends — energy efficiency, labor savings, and the re-roofing cycle — rather than a headline TAM.18 By the February 2026 call, Koch was describing a broader building envelope addressable market of approximately $70 billion, with Carlisle directly exposed to "just under half" of it.5 TAM expansion is the cheapest thing a management team can do on a slide, and a market definition that grows faster than the business is a claim to treat skeptically. The useful version of the statement is narrower: Carlisle believes there is roughly $35 billion of envelope spend it can already sell into, against $5 billion of revenue — meaning share gain, not category creation, is the realistic growth mechanism.
Where Vision 2030 actually stands. Two and a half years in, the picture is behind plan but not broken. Through the end of 2026, management expects the adjusted EPS CAGR since the plan launched to exceed 11% — against a mid-teens target.3 The gap is almost entirely new construction: both residential and non-residential have been weak for three consecutive years, and the 2026 outlook explicitly assumes no recovery.3 Organic growth above 5% has not happened; 2025 consolidated organic revenue was down 2.9%, with CWT organic down 9.2%.1
Management's framing of this is worth quoting because it is either honest realism or convenient flexibility, depending on your priors. Zdimal told analysts in April 2026 that Vision 2030's levers — organic growth, margin expansion, buybacks, M&A — are "flexible independent levers" and that "our strategy does not depend on all of them contributing significantly in every year," pointing to Vision 2025's own choppy path.4 That is a defensible statement. It is also, mechanically, an argument that if organic growth disappoints, the buyback can carry the EPS target. Which is exactly what has been happening.
The buyback is doing the heavy lifting, and that is a fact, not an insult. Diluted weighted average shares fell from 57.5 million in 2019 to 43.2 million in 2025 — roughly a quarter of the company retired in six years.17 Carlisle repurchased $1.3 billion of stock in 2025, and in July 2026 raised the 2026 target from $1 billion to $1.2 billion, explicitly citing "recent stock price levels versus our internal assessment of the intrinsic value of our shares."326 Cumulative repurchases will exceed $7 billion over ten years.3 The board authorized an additional 7.5 million shares in September 2025.1
Buying back stock when the shares are down and the M&A market is unattractive is textbook capital allocation, and Koch has been explicit that the 2025 M&A environment was one where "sellers expected elevated valuations for quality assets" that had shown "less than premium results in the recent past."5 Declining to overpay is a real decision. But the arithmetic deserves stating plainly: with adjusted EPS at $19.40 in 2025 and a $40 target for 2030, roughly half the required growth can be manufactured by continuing to shrink the share count at the current pace, entirely independent of whether the business grows.526 Investors evaluating Vision 2030 should track adjusted EBITDA dollars, not just adjusted EPS, because the two can diverge for a very long time.
The dividend. In August 2026 Carlisle raised its quarterly dividend 14%, from $1.10 to $1.25 per share, or $5.00 annualized, payable September 1, 2026 to holders of record August 19 — the fiftieth consecutive annual increase, a streak that began in 1976 and puts Carlisle among fewer than sixty U.S. public companies at that milestone.193 Fifty years of increases spans the 1980–82 recessions, 1990–91, the dot-com bust, the financial crisis, COVID, and the current construction downturn. It is genuine evidence of cash generation durability across regimes. It is also, at roughly $200 million a year against nearly $1 billion of free cash flow, a modest claim on capital — the dividend is a signal, and the buyback is the actual policy.
Portfolio mix, then and now. The shape of the company has changed completely. In 2016 building products were roughly 56% of revenue; by 2023 they were about 84% pro forma; today they are 100%.25 Within that, 2025 revenue split $3.72 billion at CCM and $1.30 billion at CWT — 74% and 26%.1 By end market, non-residential construction accounted for $4.03 billion and residential $863 million.1 By geography, the United States generated $4.50 billion of the $5.02 billion total, with Europe at $251 million and the rest of North America at $231 million.1 Koch's claim that over 90% of revenue is generated in North America is accurate and, in a period of tariff volatility and geopolitical supply disruption, is a real structural advantage.4
VII. Deep Dive: Core Business Economics, Industry Structure & The Warranty Moat
Understanding Carlisle's revenue model requires examining a typical commercial roof assembly. On a 200,000-square-foot distribution center, the structure consists of distinct layers built from the deck up: a steel deck, a vapor retarder, several inches of polyisocyanurate insulation board, a cover board, and a single-ply membrane—typically white TPO—heat-welded at the seams. At every penetration sits a pre-molded pipe boot, and along the perimeter, prefabricated edge metal locks over the membrane. In a Carlisle installation, virtually every component originates from Carlisle.
This single-source sourcing is the foundation of Carlisle's business model.
The warranty is the product. Carlisle offers separately priced extended warranty contracts ranging from five to 40 years, the most significant being those on installed single-ply roofing systems in the United States, covering leaks attributable to product defects or installation errors.1 To secure this long-term single-source warranty, building owners must specify a complete Carlisle assembly and hire a Carlisle-authorized contractor.
Evaluating customer and contractor incentives reveals why this model endures. An architect specifying a roofing system faces professional liability if the installation fails; specifying a manufacturer's long-dated system warranty transfers significant operational risk to a producer backed by a century-old balance sheet. Similarly, commercial building owners—such as real estate investment trusts, hospital systems, and school districts—prioritize leak prevention over minor membrane price differences to protect internal assets, preferring a single warrantor over fragmented supplier disputes. Authorized contractors, having invested in Carlisle certification, avoid substituting third-party adhesives or accessories, as doing so voids the warranty and shifts liability directly to the installer.
Roughly half of Carlisle's sales are tied to project specifications where Carlisle is the preferred system of record.5 This specification rate represents the commercial moat in quantifiable terms.
How the warranty economics actually flow. The financial mechanics of these warranties merit close inspection. Carlisle collects cash upfront for separately priced extended warranties and recognizes revenue on a straight-line basis over the contract term. The contract liability balance grew from $294.8 million at the start of 2023 to $372.3 million at the end of 2025, with $52.5 million deferred and only $30.7 million recognized in 2025 alone.1 Consequently, Carlisle collects cash for warranties roughly 70% faster than it recognizes the revenue, generating a growing, interest-free float that enhances cash flow ahead of income statement recognition. Of the $372.3 million in total contract liabilities, $231.3 million is scheduled for recognition after 2030.1
The expense accounting reflects a long-tail commitment. Carlisle expenses current warranty service costs as incurred within cost of goods sold, recording a reserve only if total expected future costs across a product line exceed unamortized deferred revenue. These projected obligations are calculated actuarially using historical claims experience and management judgment.1 Under normal operating conditions, no separate warranty liability appears on the balance sheet. While this treatment aligns with standard accounting for a manufacturer with six decades of claims history, warranty contracts written today cover evolving material formulations that will incur service claims into the 2050s and 2060s. Any material rise in claims would first manifest as gross margin compression in Carlisle Construction Materials before appearing as a discrete charge.
Industry structure. The North American commercial single-ply market operates as a concentrated oligopoly. In its public filings, Carlisle describes the company as "one of four major manufacturers in the single-ply industry," competing on product innovation, long-term warranties, and customer service.1 Its primary competitors are Elevate—formerly Firestone Building Products, which Holcim acquired from Bridgestone in a $3.4 billion transaction closed in April 2021, bringing $1.8 billion in 2020 net sales and $270 million in EBITDA into a global building materials group22; GAF, a subsidiary of privately held Standard Industries; and Johns Manville, a unit of Berkshire Hathaway.
With two key competitors backed by multinational parent companies possessing substantial balance sheets, Carlisle no longer holds a structural cost-of-capital advantage. Holcim, in particular, maintains both the resources and strategic focus to expand its footprint in North American commercial roofing.
The 70/30 demand split. Approximately 70% of Carlisle Construction Materials' commercial roofing volume stems from re-roofing rather than new construction.54 The underlying market drivers remain structural: commercial low-slope roofs require replacement every 20 to 30 years, and more than 70% of the U.S. non-residential building footprint is over 25 years old.53 Combining low-single-digit growth in re-roofing permits with 150 to 200 basis points of annual content growth per square foot yields mid-single-digit demand expansion.
While re-roofing is non-discretionary over full asset lifecycles, timing remains somewhat flexible during economic downturns. A leaking commercial roof can be patched temporarily for a season or two, though complete replacement cannot be deferred indefinitely.
Chief Executive Officer Chris Koch points to two additional operational factors limiting deferrals. First, ongoing labor constraints across roofing contractors mean building owners risk losing scheduled installer slots if projects are postponed.4 Second, corporate facility managers actively track warranty expiration dates, seeking to maintain active coverage on major property assets.4 Operational data supports this dynamics: re-roofing revenue grew approximately 3% in the second quarter of 2026, even as commercial new construction volume contracted in the mid-single digits.3
Distribution, and the uncomfortable number. Carlisle distributes products primarily through specialty wholesale channels, where customer concentration presents an operational vulnerability. In 2025, QXO and Beacon Roofing Supply together accounted for approximately 16.7% of consolidated revenue, while ABC Supply represented 16.3%—concentrating 33% of total revenue within two wholesale counterparties across both CCM and CWT.1
Consolidation among distributor channels has intensified buyer leverage. QXO, led by Brad Jacobs, completed its acquisition of Beacon Roofing Supply in April 2025.241 In 2026, QXO acquired TopBuild for approximately $17 billion and Kodiak Building Partners for $2.25 billion, creating a multi-category distribution platform with combined revenue exceeding $18 billion across roofing, insulation, siding, and lumber.23
Management maintains that distributor consolidation is manageable. Koch acknowledged in 2025 that QXO's operational integration created short-term volume disruption for Carlisle, but noted in early 2026 that integration had progressed and argued that the TopBuild transaction has limited direct relevance because Carlisle does not manufacture residential fiberglass insulation or shingles.45 While the product footprint distinction is accurate, distributor disruption underscores the risk of customer concentration: an operational adjustment at a customer representing one-sixth of revenue directly impacts quarterly results without immediate alternative distribution routes to contractors.
Carlisle's primary counterweight remains contractor specification. When architects write Carlisle products into building plans and contractors hold Carlisle certifications, distributors serve primarily as logistics providers rather than brand decision-makers. This structural positioning enabled Carlisle to implement three broad price increases in 2026 without significant volume resistance outside expanded polystyrene.3 However, maintaining pricing power depends entirely on retaining specification preferences across architectural and contracting networks.
Reflecting management's focus on distribution relationships, Carlisle hired Jason Taylor as President of CCM in November 2025. Taylor previously served four and a half years as President of the West Division at Beacon Building Products before departing in April 2025 during the QXO acquisition.1 Recruiting top operating leadership from its largest distribution partner highlights the strategic priority Carlisle places on managing wholesale channel dynamics.
VIII. Capital Allocation, Governance & Management Credibility Audit
While corporate narratives often claim strict alignment between executive pay and corporate performance, Carlisle’s 2026 proxy statement provides concrete evidence of how its incentive structures operate during an operational downcycle.
For 2025, the compensation committee established four consolidated metrics for Chief Executive Officer Chris Koch and Chief Financial Officer Kevin Zdimal: revenue (weighted at 25%), operating income margin (20%), average working capital as a percentage of sales (15%), and adjusted earnings (40%). Carlisle missed the performance threshold on every single metric. Revenue reached $4.991 billion against a $5.139 billion threshold; operating margin came in at 20.5% against a 22.0% target; working capital rose to 18.6% of sales against a 17.7% ceiling; and adjusted earnings reached $759 million against an $832 million threshold. Consequently, neither the CEO nor the CFO received an annual incentive payout, while Carlisle Weatherproofing Technologies President Frank Ready earned $93,900, representing 19.2% of his target.8
This zero-payout outcome directly impacted realized compensation. Under SEC disclosures, Koch’s total Summary Compensation Table pay for 2025 was recorded at $11.36 million, but "compensation actually paid" calculated under SEC methodology totaled $2.01 million, down from $22.27 million in 2024.8 The reduction reflected shareholder performance: Carlisle's total shareholder return index dropped from $246.48 to $216.26 during 2025 on a 2020 base of $100, while the S&P MidCap 400 index rose to $154.68.1 Over a full five-year period, however, Carlisle outperformed the MidCap 400 index and roughly matched an S&P 500 index value of $196.16 in 2025 terms.18
Despite the stringency of the annual scorecard, the structure of Carlisle’s long-term incentive plan reveals a notable strategic gap. Performance-based restricted stock units are evaluated entirely on Carlisle’s relative total shareholder return against S&P MidCap 400 peers over three-year periods, paying zero below the 25th percentile, 100% at the median, and 200% at or above the 75th percentile.8 The target long-term award is set at 525% of base salary for the CEO.8
While relative total shareholder return measures market performance, it does not explicitly track return on invested capital—the metric Koch cites most frequently in public discussions, describing an "industry leading ROIC of approximately 25%" as an operating philosophy.3 ROIC and adjusted earnings per share represent the two headline financial targets of Vision 2030, yet neither metric appears in the annual incentive scorecard or long-term equity plan. For a company that positions capital allocation discipline as its primary competitive advantage, omitting return metrics from executive compensation structures represents an internal inconsistency between corporate narrative and board policy.
Furthermore, the calculation of Carlisle's reported 25% ROIC relies on a company-defined formula rather than a standard GAAP balance-sheet measure. Carlisle excludes $1.54 billion in goodwill and $1.43 billion in net intangible assets from its invested capital base—assets that represent nearly half of total corporate assets resulting from a decade of acquisitions.1 The company's adjusted metric measures returns on active operational assets, providing relevant context for incremental capital allocation. However, a full balance-sheet calculation incorporating historical acquisition costs yields a substantially lower figure. Investors evaluating corporate performance must distinguish between operational returns on deployed equipment and total returns on acquired assets.
Carlisle's corporate governance framework reflects standard industrial practices with specific shareholder dynamics. Following the April 2026 annual meeting, the board was set at seven directors after Jonathan Collins stepped down pursuant to corporate policy requiring director resignation upon a material change in professional responsibilities.9 At the meeting, the advisory say-on-pay proposal received 30.2 million votes in favor and 4.3 million against, representing roughly 87% approval—passing comfortably, though below the 95% threshold typical of uncontroversial executive compensation plans. Director Sheryl Palmer recorded 3.26 million votes against her re-election.9 Shareholders ratified Deloitte & Touche as independent auditor with minimal opposition.9 Public filings disclosed no related-person transactions in 2025,8 and Carlisle reported no material legal proceedings outside the ordinary course of business in its 2025 Form 10-K or second-quarter 2026 Form 10-Q.61 Institutional ownership remains concentrated among index asset managers, led by Vanguard at 12.3%, BlackRock at 12.0%, and Morgan Stanley at 6.8% of the 40.9 million shares outstanding as of February 28, 2026.8
Evaluating management's public statements across earnings calls indicates overall strategic consistency alongside two operational friction points.
First, margin guidance has shown intra-year downward adjustments. In February 2026, management projected approximately 50 basis points of consolidated adjusted EBITDA margin expansion for the full year,5 an outlook reaffirmed in April.4 By July, management lowered guidance to flat margins, citing raw material price-cost timing caused by Middle East supply chain disruptions.3 CFO Kevin Zdimal noted that the margin adjustment was "100% related to the price cost" dynamics,3 confirming an external origin. Nevertheless, early-year optimism followed by mid-year recalibration represents a recurring execution pattern across demand cycles.
Second, management's narrative regarding Carlisle Weatherproofing Technologies combines claims of structural self-help with reliance on end-market volume. While management highlights operational initiatives—including plant automation, footprint consolidation, and in-sourcing expanded polystyrene production—Koch acknowledged in July 2026 that operational self-help "just does not drive a lot of volume on dollars or EBITDA margins... what we really need is that market turnaround."3 Operational initiatives are projected to generate roughly $20 million in full-year 2026 margin expansion, including $3 million from automation in the second quarter, $1 million from footprint consolidation, and $2 million to $3 million from expanded polystyrene in-sourcing.3 On a $1.3 billion revenue base, these operational gains are insufficient on their own to close CWT's eight-percentage-point margin gap to corporate targets without a broader recovery in construction activity.
Finally, Carlisle's reported interest in acquiring Owens Corning presents a significant test of capital allocation discipline. Management's stated acquisition framework emphasizes bolt-on transactions within the building envelope, offering tangible cost synergies and established integration playbooks.3 Pursuing an unsolicited cash-and-stock transaction valued well over $10 billion for a manufacturer with significant residential and insulation exposure represents a departure from those criteria. A transaction of that scale would roughly double Carlisle's revenue, substantially increase financial leverage above its current 1.7 times net debt-to-EBITDA ratio, and require integrating an operation larger than CWT.321
While Carlisle declined to comment on market reports, equity markets responded with a 5% decline in Carlisle shares against a 15% increase in Owens Corning shares,2021 reflecting investor skepticism regarding transaction rationale and execution risk. The contrast between management's disciplined approach to small bolt-on acquisitions and its reported willingness to pursue a large-scale transaction at a control premium creates an unresolved question regarding Carlisle's long-term capital allocation strategy.
IX. Historical Falsification, Skeptical Stress Test & Risk Radar
Three core claims sit at the heart of Carlisle's investment thesis. Evaluating them against the strongest disconfirming evidence in the company's operating record highlights key operational boundaries.
Claim one: the warranty system creates pricing power that survives cost shocks.
The affirming evidence is substantial. In 2026, facing petroleum-linked raw material and freight inflation triggered by Middle East supply disruptions and supplier force majeure declarations, Carlisle announced three broad-based price increases alongside freight surcharges. The initial two rounds added roughly 5% to 8% price increases on membranes and polyisocyanurate insulation.43 Management reported no material resistance outside expanded polystyrene, where competitive intensity remains higher.3 Chief Executive Officer Chris Koch explained that acceptance was driven by visibility: contractors and distributors track crude oil prices and absorb higher diesel transport costs themselves, making input inflation transparent across the supply chain.4
However, the disconfirming evidence demonstrates that timing lags are material. Price realization takes time to catch up with cost increases. In the second quarter of 2026, net price-versus-cost was negative by approximately $40 million at Carlisle Construction Materials (CCM) and several million dollars more at Carlisle Weatherproofing Technologies (CWT), because Carlisle honors previously quoted project commitments and observes contractual notice periods with distributors.3 Consequently, CCM's adjusted EBITDA margin contracted 90 basis points year over year to 30.7%, while consolidated adjusted EBITDA margin fell 70 basis points to 26.2%.3 Price realization provided low-single-digit gains in the second quarter, with management projecting acceleration to mid-single digits in the third quarter and high-single digits by the fourth.3 Management also highlighted a mechanical dilution effect: recovering cost dollar-for-dollar through price increases expands revenue without adding EBITDA dollars, mathematically compressing margin percentages even after full cost recovery.3
Historical evidence from the 2023 destocking cycle reinforces this limitation. As channel inventories unwound, pricing remained flat rather than rising, allowing Carlisle to preserve pricing structure while CCM revenue declined 16%.2527 Holding prices protected industry structure, but it demonstrated that during a demand contraction, the warranty moat generates price stability rather than pricing power.
Revised conclusion: The claim holds in a narrower form. Carlisle can pass through input inflation with a one-to-two-quarter lag and maintain pricing during demand downturns. However, it cannot prevent margin compression during the lag, nor can it convert warranty coverage into price increases when volume declines. Confirming/falsifying KPI: CCM adjusted EBITDA margin returning above 31% once price realization offsets costs, alongside positive net price-versus-cost realization in the fourth quarter of 2026.34
Claim two: the pure-play building envelope portfolio is a superior use of capital.
The affirming evidence centers on divestiture execution and CCM's standalone returns. In 2025, CCM generated $997.2 million in operating income on $3.72 billion in revenue—a 26.8% operating margin—accounting for roughly 91% of segment operating income on 74% of consolidated revenue.1 None of Carlisle's former industrial divisions approached this return profile.
The disconfirming evidence shows that the pure-play transformation concentrated corporate risk rather than mitigating it. CWT—the building envelope extension built through major acquisitions—generated a 7.8% operating margin in 2025, with organic revenue contracting 9.2%.1 Having previously argued that conglomerate diversification smoothed industrial cycles, Carlisle now derives 80% of revenue from non-residential construction and 90% from the United States.1 Without aerospace or industrial divisions to offset building cycles, Carlisle traded a portfolio of lower-return assets for a concentrated position in a high-return end market. While strategically sound, this model exposes earnings to higher cyclical variance.
The medical technology platform offers additional evidence of portfolio friction. In 2019, Carlisle allocated approximately $380 million to acquire MicroConnex and Providien to build growth optionality outside its core, only to divest those assets five years later within Carlisle Interconnect Technologies.7 This sequence highlights the difficulty of deploying capital outside established contractor and distributor networks.
Revised conclusion: The pure-play thesis is supported on return metrics but unproven on cyclical resilience. Carlisle has structurally increased return on invested capital. However, it has yet to prove that a single-end-market model delivers consistent performance through major downturns, as weak construction activity since the pivot completed has left share repurchases, rather than organic volume expansion, as the primary earnings driver.3 Confirming/falsifying KPI: CWT adjusted EBITDA margin progressing toward its 25% segment target, alongside positive consolidated organic revenue growth without a construction market recovery.
Claim three: management is a superior capital allocator.
The affirming evidence is broad and quantitative: 50 consecutive annual dividend increases; over $7 billion in cumulative share repurchases over a decade; a 25% reduction in total share count over six years; four consecutive years of operating cash flow exceeding $1 billion; a 2025 free cash flow margin of 19.4% against a 15% target; net debt-to-EBITDA maintained at 1.7 times within a 1.0 to 2.0 times target range; and a documented refusal to overpay for acquisitions during full-valuation environments.35261
The disconfirming evidence reflects three structural contradictions. First, acquisition outcomes have depended heavily on channel alignment—delivering strong results within the commercial roofing network (MTL), mixed performance in adjacent markets (Henry, Accella), and divestiture outside core channels (medical). Second, executive compensation benchmarks do not explicitly include return on invested capital, the primary metric management emphasizes to investors. Third, reported interest in acquiring Owens Corning diverges from management's stated focus on small bolt-on acquisitions, a friction reflected in the negative stock market response upon disclosure.2021
Revised conclusion: The claim holds regarding capital return policies, where counter-cyclical share repurchases and dividend growth reflect disciplined execution. It holds conditionally regarding capital deployment, provided target acquisitions align with existing distribution channels. It remains under active test by potential large-scale transactions that would depart from established criteria. Confirming/falsifying KPI: Whether Carlisle pursues a large-scale acquisition, and the resulting transaction price, valuation multiple, and financial leverage.
Risk radar. Four specific operational risks carry direct business mechanisms rather than generic macroeconomic exposure.
Distributor consolidation. Two distributors account for 33% of consolidated revenue, with counterparty concentration intensifying as major distributors consolidate into larger distribution platforms.123 Risk centers on margin transfer through expanded rebate demands, extended payment terms, private-label competition, and short-term operational disruption during integration phases, which Carlisle experienced during distributor integration.5
Petrochemical input volatility. MDI represents Carlisle's largest raw material purchase, recording double-digit price increases in 2026 alongside double-digit increases in TPO resins and high-single-digit increases in polyols.4 Beyond price inflation, Koch highlighted supply availability as the primary operational vulnerability, noting that management prioritizes securing raw material supply over near-term cost pressures.4 By July 2026, MDI supply constraints materialized, with Carlisle securing necessary volume while smaller competitors faced tighter allocations.3 Supply restriction environments favor well-supplied market leaders on margins while constraining industry volume.
Interest rates and new construction. Commercial new construction represents approximately 30% of CCM revenue and a higher share of CWT, having contracted for three consecutive years. Carlisle's 2026 operating plan assumes no near-term market recovery,3 acting as a direct constraint on Vision 2030 organic growth targets.
Competitive capacity additions. Management listed rational capacity expansion as a precondition for industry pricing discipline, noting ongoing commercial capacity additions across the market.5 With major competitors Elevate and Johns Manville backed by parent companies Holcim and Berkshire Hathaway, rival producers possess the financial resources to maintain capacity through market downturns. Persistent weakness in new construction alongside incoming capacity would test oligopoly pricing discipline.
X. 7 Powers, Porter's 5 Forces & Competitive Strategy Playbook
Consider a hypothetical scenario where an investor capitalizes a new entrant to target North American commercial roofing with a billion dollars in capital. A new player can purchase extruders, license polyisocyanurate chemistry, and recruit experienced plant managers. The primary hurdle, however, remains persuading a hospital system's facilities director to buy a 30-year single-source warranty from an unproven counterparty.
That barrier illustrates Carlisle's competitive positioning when mapped onto Hamilton Helmer's 7 Powers framework.
Switching costs represent Carlisle's primary power, operating structurally rather than contractually. While building owners face no legal restriction against purchasing a rival membrane for subsequent projects, replacing a system requires re-specifying components, re-training installation crews, and re-allocating operational risk. Because liability transfer depends on maintaining an integrated assembly, switching costs function through institutional risk aversion rather than contractual penalty fees.
Carlisle's specification rate—where its assemblies serve as the system of record for roughly half of its sales—quantifies this advantage.5 However, because this power applies at the individual project level rather than the overall corporate account level, Carlisle must secure its position on each job. This requirement drives significant ongoing investment in field technical teams and in-house roof designers who collaborate directly with architects during initial drafting.5
Process power provides a real, though modest, operational cushion. The Carlisle Operating System delivers annual savings equal to 1% to 2% of sales, generating between $50 million and $100 million in self-funded cost offsets on a $5 billion revenue base.3 While this cost discipline helps preserve operating margins during downcycles, competing producers such as Holcim, GAF, and Johns Manville maintain their own lean manufacturing programs. Carlisle's process advantage relies more on operational execution than tooling alone; Chief Executive Officer Chris Koch attributed the successful integration of Henry Company to organizational culture, employing a "two-in-a-box" structure that paired acquired executives with Carlisle leaders.3
Scale economies derive from physical freight economics. Rigid polyisocyanurate insulation board consists mostly of trapped gas within a foam matrix, resulting in low-density freight where shipping costs per unit of product value rise sharply over long distances. Consequently, a dense regional manufacturing network creates a cost barrier against smaller regional competitors by locating production close to end demand.
To support regional delivery efficiency and reduce lead times, Carlisle opened a polyisocyanurate facility in Sikeston, Missouri, which began shipping in July 2023.25 Similar freight and cost considerations prompted Carlisle to bring expanded polystyrene resin production in-house, a vertical integration initiative that management estimated contributed $2 million to $3 million in quarterly margin expansion by mid-2026.3
Brand strength remains secondary to warranty coverage, while cornered resources and network economies do not apply. Counter-positioning is similarly absent; Carlisle's pure-play focus reflects a strategic portfolio allocation rather than a structural barrier that competitors like Holcim cannot replicate.
Porter's Five Forces Analysis
-
Threat of new entrants: Low. The primary barrier to entry is operating history rather than capital alone. Underwriting multi-decade system warranties requires extensive actuarial claims data accumulated over decades. Having manufactured single-ply membranes since the 1960s, Carlisle carries $372.3 million in deferred warranty revenue for obligations extending beyond 2030.1 While a competitor can duplicate manufacturing equipment, it cannot immediately offer an established actuarial track record to risk-averse specifiers.
-
Bargaining power of buyers: High and rising. Channel concentration represents the company's primary commercial exposure, with two distributors generating 33% of consolidated sales and ongoing distributor consolidation increasing buyer scale.123 While architect specifications and contractor preferences allowed Carlisle to pass through three price increases in 2026,3 wholesale channel consolidation continues to shift negotiating leverage toward distributors.
-
Threat of substitutes: Low for single-ply membranes; moderate for insulation. While low-slope commercial roofs lack cost-effective alternatives to synthetic single-ply membranes, polyisocyanurate insulation competes with mineral wool, expanded polystyrene (EPS), and spray foam based on thermal efficiency per inch, fire ratings, and building height constraints. Carlisle has mitigated substitution risk by establishing its own EPS manufacturing network through acquisitions, including Plasti-Fab, ThermaFoam, and Bonded Logic.51 However, entering the EPS market exposes Carlisle to higher competitive intensity, where executive Mehul Patel acknowledged that pricing power is weaker than in core roofing lines.3
-
Bargaining power of suppliers: Moderate. Key petrochemical inputs—including MDI, polyols, and specialty polymers—are sourced from a concentrated supplier base subject to geopolitical and supply chain volatility. Carlisle mitigates single-source failure by requiring at least two vendor options for primary raw materials or ensuring single-source suppliers maintain multiple processing sites.1 This sourcing strategy helped Carlisle secure raw material allocations during 2026 supply disruptions,3 though dual-sourcing cannot insulate margins from broader market price inflation.
-
Competitive rivalry: Moderate and historically disciplined. The four major producers have historically maintained pricing discipline, as demonstrated during the 2023 destocking cycle when Carlisle sustained price levels despite a 16% decline in volume.2527 Management identifies four structural conditions required to sustain pricing power: ongoing re-roofing demand, persistent labor shortages, disciplined industry capacity expansion, and positive commercial construction growth.5 While re-roofing demand, labor constraints, and capacity discipline remain in place, prolonged weakness in new commercial construction tests the limits of industry pricing discipline.
In summary, Carlisle's competitive moat remains robust at the architectural specification and contractor level, where switching costs and system warranties drive customer retention. Conversely, its positioning faces pressure at the wholesale distribution level, where customer concentration and channel consolidation present ongoing strategic challenges.
XI. Bull vs. Bear Case Analysis & Investor KPIs
Evaluating Carlisle requires viewing the business as two distinct components: a high-return commercial roofing franchise and an aggressive capital allocation policy. While these drivers can move independently, their current trajectories diverge.
The bull case.
The replacement cycle provides steady demand. Commercial construction expansions from the early 2000s and the logistics buildout of the late 2010s created a massive installed base now approaching replacement. With more than 70% of the U.S. non-residential building footprint older than 25 years, physical wear drives replacement schedules largely independent of economic sentiment.3 Demonstrating this resilience, re-roofing volume expanded in mid-2026 despite contractions in new construction, prompting management to raise its full-year revenue outlook without assuming a macro recovery.3
Content growth expands revenue per installation. Expanding revenue does not require building new square footage. Stricter building energy codes require thicker insulation, while labor-saving products command premium pricing. For example, ThermaThin R-7 polyisocyanurate insulation—which began shipping in June 2026—delivers roughly 23% higher thermal resistance per inch than standard polyiso, reducing board volume, freight requirements, crane lifts, and labor hours required for code compliance.3 Chief Executive Officer Chris Koch noted that Carlisle structures product pricing to capture higher margins while sharing labor and freight savings with contractors and distributors.3 Management targets 150 to 200 basis points of annual content growth, aiming for products launched within the preceding five years to generate 25% of revenue by 2030 as research and development spending approaches 3% of sales.53
Disciplined capital returns support earnings. Carlisle has directed cash flow toward share repurchases during valuation pullbacks and periods of elevated M&A asset prices. Retiring a quarter of outstanding shares over six years while maintaining a 50-year dividend growth streak provides empirical backing for management's capital return model.
Data center demand creates a product mix opportunity. Polyvinyl chloride (PVC) membranes historically served as the standard specification for data center roofs. However, with PVC supply constrained in 2026, Koch reported that architects began accepting premium thermoplastic polyolefin (TPO)—Carlisle's primary product line—as a specification substitute.3 While market-driven supply tightness in a competing chemistry represents a temporary tailwind rather than a deliberate strategy, it broadens TPO's adoption across high-growth digital infrastructure.
The bear case.
Organic growth trails long-term targets. Consolidated organic revenue contracted 2.9% in 2025,1 falling short of the greater-than-5% organic growth target outlined in Vision 2030. Reaching that trajectory would require either an unexpected recovery in commercial new construction—which management explicitly excludes from its near-term guidance—or market share gains sufficient to offset persistent market weakness.
Carlisle Weatherproofing Technologies compresses overall margins. Generating roughly one-quarter of consolidated revenue, the Weatherproofing segment's 7.8% operating margin in 2025 represents the primary obstacle to achieving Vision 2030 financial targets.1 While operational self-help initiatives—such as plant automation and footprint consolidation—are underway, Koch acknowledged that operational gains alone cannot close the margin gap without a recovery in underlying residential construction activity.3 Consequently, CWT's margin recovery remains tied to cyclical housing trends outside management's direct control.
Distributor consolidation threatens supplier pricing power. Wholesale channel concentration represents a key structural risk. As major distributors merge into multi-category distribution platforms generating upwards of $18 billion in combined revenue, consolidated buyers gain increased leverage to negotiate larger volume rebates, demand extended payment terms, or introduce private-label alternatives.23
Share repurchases obscure underlying operational progress. Reaching the Vision 2030 target of $40 in adjusted earnings per share does not require matching growth in operating earnings. If total adjusted EBITDA remains stagnant, continuing share buybacks at the recent pace can push earnings per share toward management's target. While repurchasing undervalued shares represents disciplined capital allocation, investors evaluating core business expansion must track total adjusted EBITDA growth alongside per-share metrics.
Raw material volatility creates margin lags. Operating results in 2026 demonstrated that Middle East geopolitical disruptions and petroleum-linked cost spikes can reduce full-year margin guidance by 50 basis points due to contractual price-cost realization lags, regardless of underlying competitive strength.3
The KPIs that matter.
Investors monitoring Carlisle's trajectory should evaluate three key metrics:
1. CCM organic volume growth, excluding price effects. The central bull thesis depends on whether re-roofing permitting and content expansion drive genuine unit demand rather than inflation pass-through. Carlisle reports volume and price separately, and the two reflect different dynamics: Chief Financial Officer Kevin Zdimal noted that the company's 2026 revenue guidance increase to mid-single digits was driven entirely by price increases.4 Key indicators include whether re-roofing volume maintains its low-to-mid single-digit growth and whether re-roofing continues to represent approximately 70% of segment revenue.
2. CWT adjusted EBITDA margin. Segment profitability serves as the primary test of whether the building envelope acquisition expansion earns its capital cost. Management projected at least 100 basis points of margin improvement in 2026—including year-over-year expansion of roughly 250 basis points in both the third and fourth quarters—toward its 25% segment target.3 Consistent margin progress validates the portfolio strategy, whereas flat margins would indicate that acquisitions expanded revenue without enhancing return profiles.
3. Combined revenue concentration of the two largest wholesale distributors. Representing 33% of consolidated sales in 2025, customer concentration measures how much pricing power Carlisle retains relative to its distribution partners.1 A rising concentration ratio indicates expanding distributor leverage. Conversely, successful channel diversification—such as transitioning spray foam insulation to a direct-to-contractor delivery model or expanding distribution for coatings and linings—strengthens Carlisle's commercial control.3
Notably absent from this list is reported return on invested capital. Management's cited 25% figure is a company-defined metric that excludes goodwill and intangibles, preventing direct comparison with standard balance-sheet calculations, and it is not tied to executive compensation. Consequently, while useful as an internal operational gauge, reported ROIC remains an inconsistent comparative benchmark for external investors.
XII. Synthesis & Strategic Lessons for Builders & Investors
Strip away the segment labels and Carlisle's past decade reflects a single, repeatable strategy: identify which business units earn their cost of capital, and stop subsidizing the rest.
Portfolio simplification is a returns decision, not an identity decision. Carlisle did not divest brake friction, fluid handling, and aerospace interconnect because they were failing operations. It sold them because their market value to external buyers exceeded their internal return on capital, which remained lower than what Carlisle could generate in roofing production or share repurchases. The discipline behind this strategy involved selling into market strength rather than distress, allowing strategic buyers to fund operational recoveries.
The main caveat, illustrated by the medical technology expansion, is that executive leadership built the platform it eventually had to divest—a reminder that portfolio focus requires continuous discipline rather than a single permanent realignment.
Selling risk transfer yields higher returns than selling materials. The core insight of Carlisle's business model is that the physical membrane is only part of the commercial value proposition. The primary product is risk mitigation: giving building owners operational reliability, allowing architects to transfer liability off their professional insurance policies, and providing contractors with certified system warranties. Manufacturers that bundle physical products with long-dated performance guarantees capture profit margins that standalone materials cannot sustain—an advantage that strengthens as the company's operating history grows.
The accompanying risk for investors is that this warranty-driven model concentrates decades of long-tail liability within actuarial estimates that will not be fully tested for a generation.
Operating systems deliver value through cultural integration, not mere procedure. The validity of the Carlisle Operating System rests on runtime execution rather than corporate branding. Carlisle expanded consolidated margins despite declining revenue in early 2026, preserved profitability during the 2023 inventory drawdown, and applied the framework to integrate an acquired workforce following years under private equity ownership.4253 Continuous-improvement programs that function only during market expansions represent operating leverage rather than structural operational discipline.
The core strategic constraint. Combining portfolio focus, high returns on capital, and consistent share reduction creates a powerful compounding mechanism, all three of which Carlisle has executed. However, this strategy relies on an underlying requirement: the core market must eventually expand. While share repurchases can support earnings-per-share growth during prolonged industry downturns, they cannot replace expanding net income indefinitely. The ultimate test of Carlisle's restructuring is not whether its portfolio became streamlined—which is now complete—but whether its specialized building products platform can generate organic revenue growth when end-market demand recovers.
XIII. Recent News & Current Earnings Nuances
Carlisle's second-quarter 2026 performance captured its operational tension in a single reporting period, delivering record top- and bottom-line figures even as profit margins contracted.
Carlisle generated a record $1.6 billion in second-quarter revenue, up 8% year over year, while adjusted earnings per share reached a record $7.03, up 12%.23 Carlisle Construction Materials (CCM) contributed $1.2 billion, matching the company's overall 8% revenue growth; within the segment, predictable re-roofing activity expanded roughly 3%, offsetting a mid-single-digit contraction in commercial new construction. Meanwhile, Carlisle Weatherproofing Technologies (CWT) revenue grew 10% to $389 million, driven by market share gains despite softness across its underlying end markets.3 Through the first six months of 2026, CCM accounted for $1.94 billion and CWT generated $683 million of Carlisle's $2.62 billion consolidated total.6
Two factors qualify that headline 8% growth rate. First, management noted that several percentage points reflected customer pre-buying ahead of announced price increases—pulling existing demand forward rather than creating new organic volume.3 Second, top-line expansion was driven primarily by higher prices rather than unit volume gains, reinforcing the need to track organic volume closely.
The margin compression followed a clear price-cost mechanism. Although management raised its full-year revenue guidance to mid-single-digit growth, it reduced its full-year adjusted EBITDA margin outlook by 50 basis points to flat year over year, a revision Chief Financial Officer Kevin Zdimal attributed entirely to price-cost timing lags.3 Executive leadership outlined a quarterly recovery trajectory: achieving price-cost neutrality in the third quarter and turning slightly positive by the fourth, with CCM adjusted EBITDA margins targeted at approximately 29% in the third quarter, 28% in the fourth quarter, and roughly 29% for the full year.3 That explicit mechanism and timeline give investors clear quantitative benchmarks to evaluate execution.
The balance sheet remains unremarkable in the good sense. As of June 30, 2026, Carlisle held $665 million in cash alongside $1 billion in available revolving credit facilities, offset by $2.89 billion in senior notes carrying interest rates between 2.20% and 5.55% with maturities spanning 2027 to 2040.36 Net debt stood at 1.7 times adjusted EBITDA, comfortably within management's target range of 1.0 to 2.0 times.3 Second-quarter free cash flow reached $203 million on $244 million of operating cash flow, with capital expenditures of $42 million reflecting typical working capital expansion during the peak summer construction season.3 Goodwill remained steady at $1.54 billion with no impairment indicators, while SEC filings confirmed no new material legal proceedings.6
Capital returns accelerated. During the second quarter, Carlisle repurchased $250 million of its common stock, bringing first-half buybacks to $500 million alongside $90 million in dividend payments.3 Management subsequently raised its full-year share repurchase target from $1.0 billion to $1.2 billion, explicitly citing a disconnect between the prevailing stock price and internal intrinsic value estimates.3 With shares trading around $352—within a 52-week range of approximately $293 to $433—management continued its pattern of expanding buybacks during market pullbacks, allocating capital aggressively even as equity markets discounted the record quarterly results.
Innovation is converting, slowly. New product launches demonstrated modest initial commercial traction. ThermaThin R-7 secured its first commercial order for an installation requiring higher thermal resistance within height-restricted roof profiles.3 The insulation board is one of roughly twelve products scheduled for 2026 release—with six already introduced by mid-year, including a temperature-sensing adhesive applicator and a 16-foot seam shield.3 In retail channels, Henry's UltraTouch denim insulation achieved distribution across nearly half of Home Depot locations nationwide.3
Chief Executive Officer Chris Koch acknowledged that these offerings will require time to scale before generating material revenue in 2027.3 Meanwhile, CWT quantified its early market share initiatives: advanced waterproofing sales expanded over 50%, projected to add approximately $15 million in 2026 revenue; direct-to-contractor spray foam is expected to contribute roughly $10 million; and UltraTouch insulation is targeted at $4 million to $5 million.3 On a $5 billion revenue base, these specialized product lines represent incremental growth drivers rather than immediate earnings catalysts.
MTL, two years in. The acquisition of MTL Holdings has proven to be an effective strategic fit, prompting Carlisle to expand its perimeter metal focus. Koch noted that the company is moving "a little bit heavier into the metal panel business," targeting incremental growth through bolt-on acquisitions.3 Operational oversight also evolved: Stephen Schwar, who joined Carlisle in 1984 and managed CCM through the Henry and MTL integrations, transitioned to Vice Chair of CCM in November 2025 to focus on the expanded metal platform, while former Beacon executive Jason Taylor assumed leadership of the core CCM segment.1
The unresolved item. Carlisle's reported acquisition approach toward Owens Corning remains unconfirmed by executive leadership and unconsummated on the public record, with Carlisle maintaining its policy against commenting on market rumors and Owens Corning declining substantial engagement.2021 For investors, the significance lies less in the outcome of this specific offer than in what the pursuit reveals about management's strategic positioning: holding $665 million in cash on an under-leveraged balance sheet, facing a Vision 2030 earnings per share trajectory that trails initial targets due to market softness, and navigating a bolt-on M&A market where quality targets carry elevated valuations.
Historically, such structural conditions increase the likelihood that corporate leaders consider large-scale, transformative acquisitions outside their established parameters. Whether Carlisle ultimately pursues a major transaction—and on what valuation terms—remains the single most critical capital allocation question facing the company, carrying far greater long-term implications than short-term price-cost margin fluctuations.
References
-
Carlisle Companies Incorporated Annual Report on Form 10-K for fiscal year 2025 — SEC EDGAR, 2026-02-13 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Carlisle Companies Reports Second Quarter 2026 Results (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2026-07-29 ↩
-
Carlisle (CSL) Q2 2026 Earnings Call Transcript — The Motley Fool, 2026-07-29 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Carlisle (CSL) Q1 2026 Earnings Call Transcript — The Motley Fool, 2026-04-23 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Carlisle (CSL) Q4 2025 Earnings Call Transcript — The Motley Fool, 2026-02-03 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Carlisle Companies Incorporated Quarterly Report on Form 10-Q for the period ended June 30, 2026 — SEC EDGAR, 2026-07-29 ↩↩↩↩
-
Carlisle Companies Incorporated Annual Report on Form 10-K for fiscal year 2019 — SEC EDGAR, 2020-02-10 ↩↩↩↩↩↩
-
Carlisle Companies Incorporated Definitive Proxy Statement (Schedule 14A) — SEC EDGAR, 2026-03-17 ↩↩↩↩↩↩↩↩
-
Carlisle Companies Incorporated Form 8-K reporting 2026 Annual Meeting voting results and board changes — SEC EDGAR, 2026-04-30 ↩↩↩
-
Carlisle Companies to Sell Carlisle Interconnect Technologies to Amphenol for $2.025 Billion (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2024-01-30 ↩
-
Amphenol Corporation Completes Acquisition of Carlisle Interconnect Technologies (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2024-05-21 ↩
-
Carlisle Companies to Acquire MTL Holdings, a Leader in Edge Metal and Non-Insulated Architectural Wall Systems (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2024-03-18 ↩
-
Carlisle Companies Completes Purchase of Henry Company (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2021-09-01 ↩
-
Carlisle Companies to Sell Carlisle Brake & Friction (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2021-05-25 ↩
-
Carlisle Companies Completes Sale of Carlisle Brake & Friction (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2021-08-02 ↩
-
Carlisle Companies Completes Sale of Carlisle Fluid Technologies (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2023-10-02 ↩
-
Carlisle Companies Incorporated Completes Purchase of Accella Performance Materials (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2017-11-01 ↩↩
-
Carlisle Companies Releases Vision 2030 Strategy and Financial Targets — Carlisle Companies Incorporated, 2023-12-07 ↩↩
-
Carlisle Companies Increases Dividend for 50th Consecutive Year — Business Wire, 2026-08-06 ↩↩
-
Owens Corning shares jump on Carlisle bid report — Investing.com, 2026-06-29 ↩↩↩↩
-
Why Carlisle Companies targets Owens Corning for an M&A combo — HousingWire, 2026-06-29 ↩↩↩↩↩
-
LafargeHolcim to acquire Firestone Building Products from Bridgestone Americas — PR Newswire, 2020-11-30 ↩
-
QXO Closes TopBuild Acquisition, Expands Roofing Reach — Roofing Contractor, 2026 ↩↩↩↩
-
QXO Completes Acquisition of Beacon Roofing Supply — Business Wire, 2025-04-29 ↩
-
Carlisle Companies, Inc. (CSL) Q2 2023 Earnings Call Transcript — Seeking Alpha, 2023-07-26 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Carlisle Companies Reports Fourth Quarter Results (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2026-02-03 ↩↩↩↩
-
Carlisle Companies Incorporated Annual Report on Form 10-K for fiscal year 2023 — SEC EDGAR, 2024-02-16 ↩↩↩
-
Tire and Rubber plant started in Carlisle a century ago — The Sentinel (Cumberland Link) ↩↩
-
Carlisle Companies Reports First Quarter 2026 Results (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2026-04-23 ↩
-
Carlisle Companies Incorporated Annual Report on Form 10-K for fiscal year 2022 — SEC EDGAR, 2023-02-16 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube